Tellurian — Magellan Petroleum — Shareholder Meeting (June 2009)
20 slides from Tellurian's shareholder meeting presentation, Jun 2, 2009
Slide 1: Presentation to the Annual General Meeting May 2009
PRESENTATION TO THE ANNUAL GENERAL MEETING May 2009
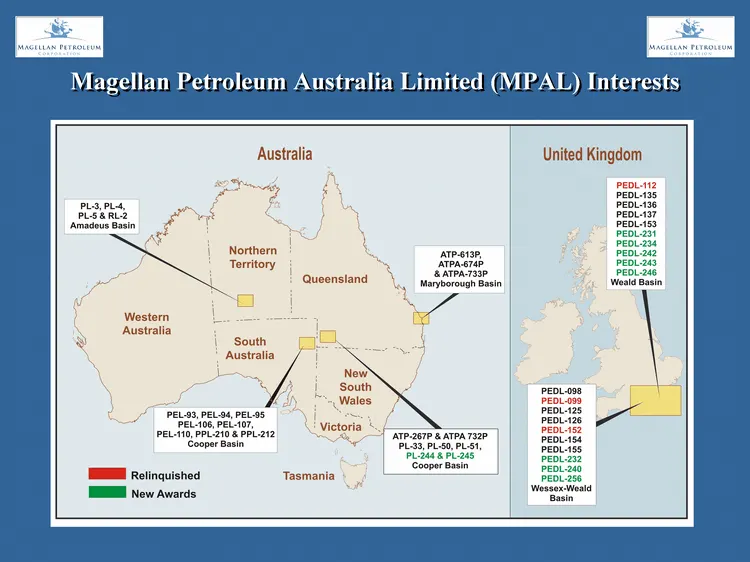
Slide 2: Magellan Petroleum Australia Limited (MPAL) Interests
Magellan Petroleum Australia Limited (MPAL) Interests Magellan Petroleum Australia Limited (MPAL) Interests
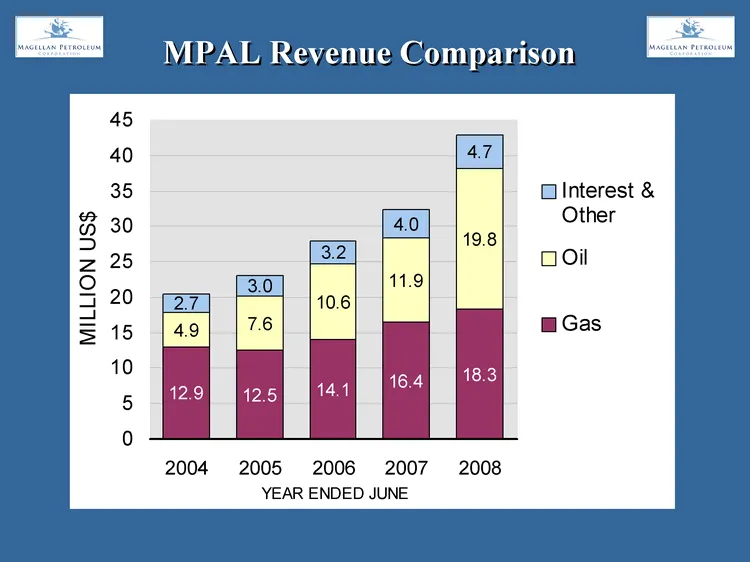
Slide 3: MPAL Revenue Comparison
MPAL Revenue Comparison 45 40 4.7 35 Interest & S $ 30 4.0 Other U 19.8 25 3.2 Oil 3.0 11.9 LION 20 2.7 10.6 MIL 15 4.9 7.6 Gas 10 18.3 16.4 12.9 12.5 14.1 5 0 2004 2005 2006 2007 2008 YEAR ENDED JUNE
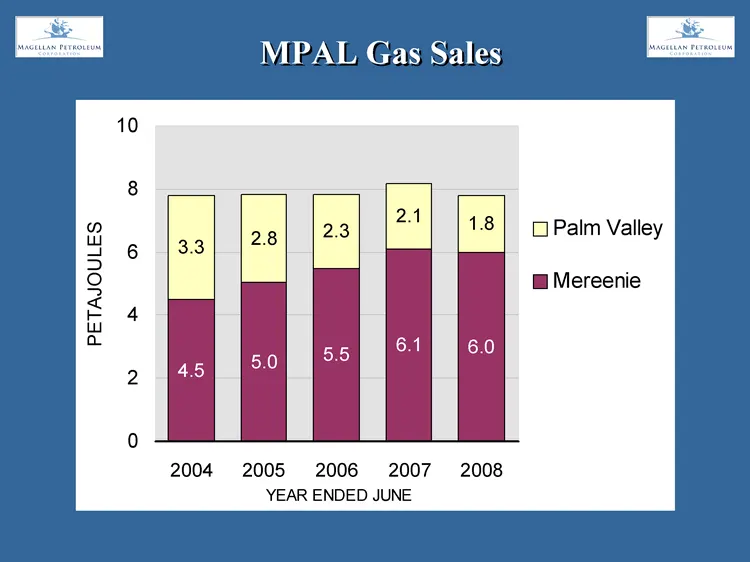
Slide 4: MPAL Gas Sales
MPAL Gas Sales 10 8 2.1 1.8 2.3 Palm Valley ES 3.3 2.8 6 AJOUL Mereenie PET 4 6.1 6.0 5.0 5.5 2 4.5 0 2004 2005 2006 2007 2008 YEAR ENDED JUNE
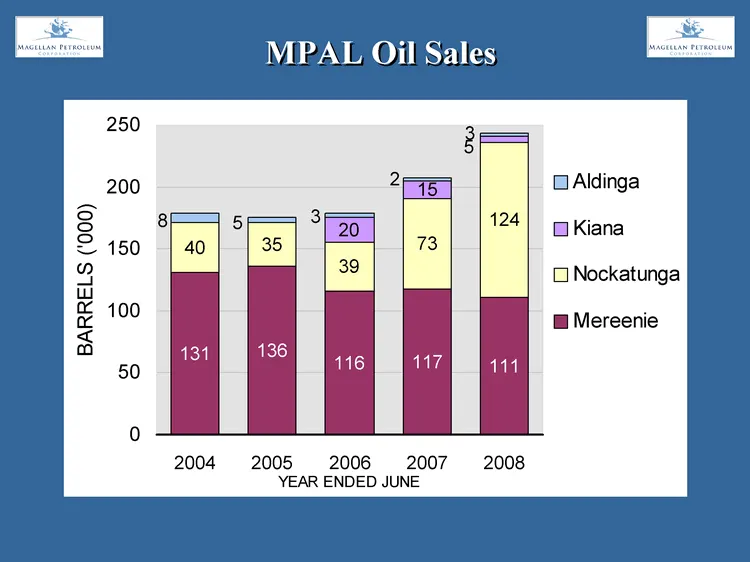
Slide 5: MPAL Oil Sales
MPAL Oil Sales 250 3 5 200 2 Aldinga 15 8 5 3 124 '000) 20 Kiana 150 40 35 73 ( 39 ELS Nockatunga 100 BARR Mereenie 131 136 116 117 111 50 0 2004 2005 2006 2007 2008 YEAR ENDED JUNE
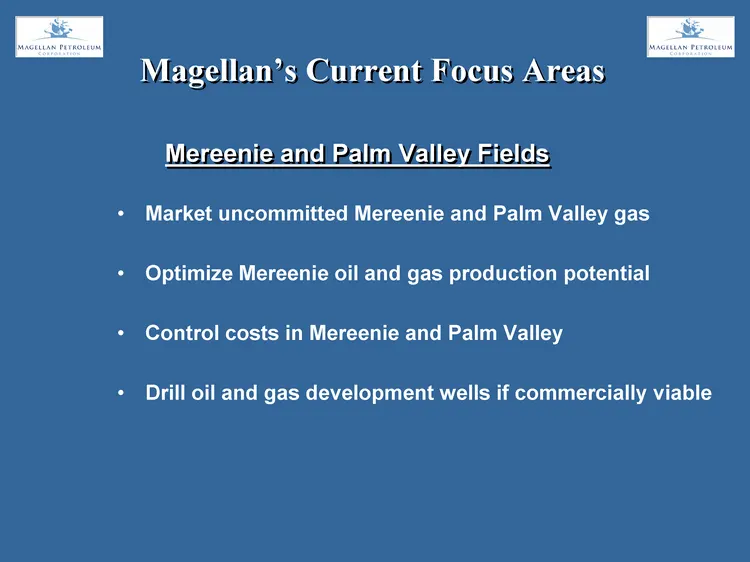
Slide 6: Mereenie and Palm Valley Fields: Magellan's Current Focus Areas
Market uncommitted Mereenie and Palm Valley gas Optimize Mereenie oil and gas production potential Control costs in Mereenie and Palm Valley Drill oil and gas development wells if commercially viable Mereenie and Palm Valley Fields Magellan's Current Focus Areas
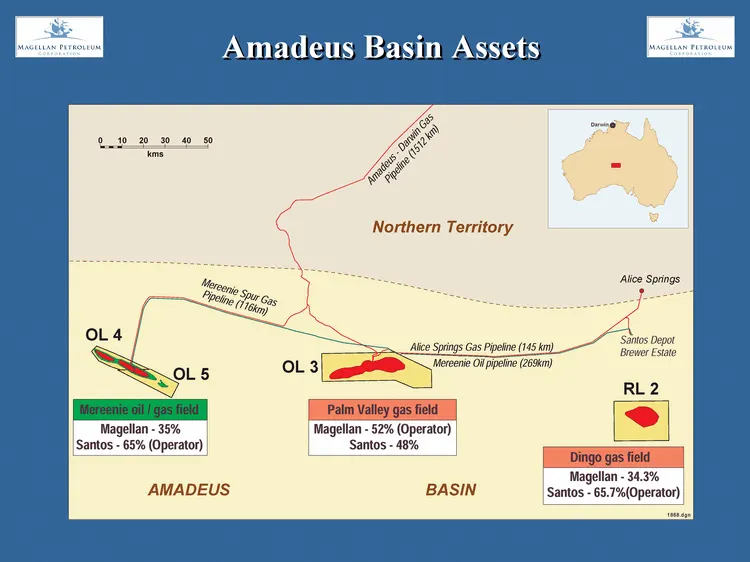
Slide 7: Amadeus Basin Assets
Amadeus Basin Assets Amadeus Basin Assets
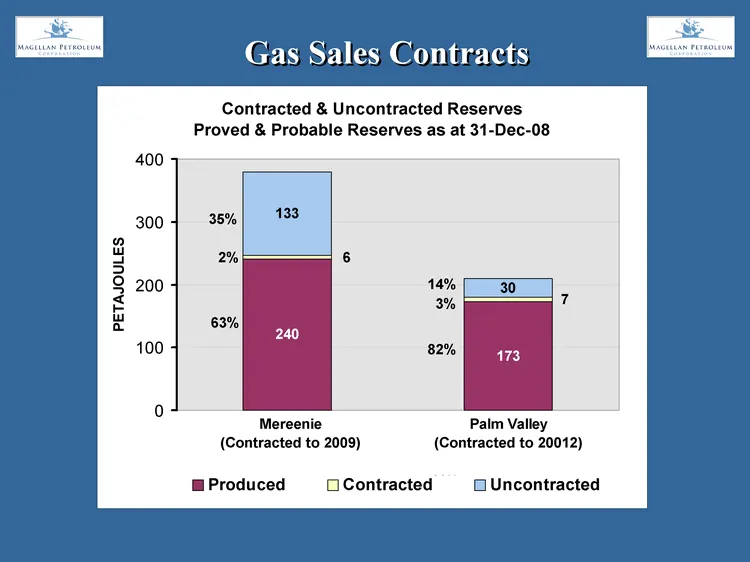
Slide 8: Gas Sales Contracts, Contracted & Uncontracted Reserves
Gas Sales Contracts Contracted & Uncontracted Reserves Proved & Probable Reserves as at 31-Dec-08 400 35% 133 300 S 2% 6 200 14% 30 AJOULE 3% 7 PET 63% 100 240 82% 173 0 Mereenie Palm Valley (Contracted to 2009) (Contracted to 20012) Produced Contracted 29% Uncontracted
Slide 9: Cooper Basin: Magellan's Current Focus Areas
Cooper Basin Maxwell-5 in the Nockatunga assets came on production at an initial rate of 66 BOPD with a higher reservoir pressures than expected Success in Maxwell-5 resulted in acquisition of 3D survey over Maxwell Field and adjacent areas in 2009 Decision on additional development/appraisal/explor
Slide 10: Cooper-Eromanga Basins
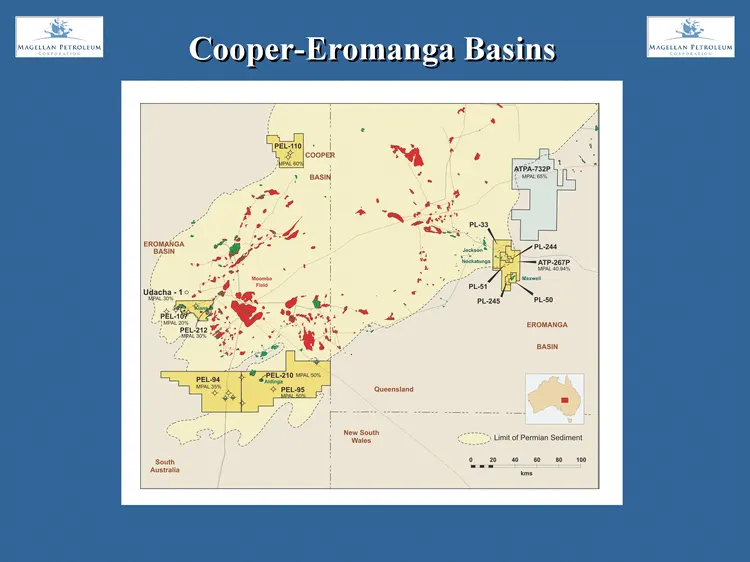
Cooper-Eromanga Basins Cooper-Eromanga Basins
Slide 11: Nockatunga Area S-W Queensland
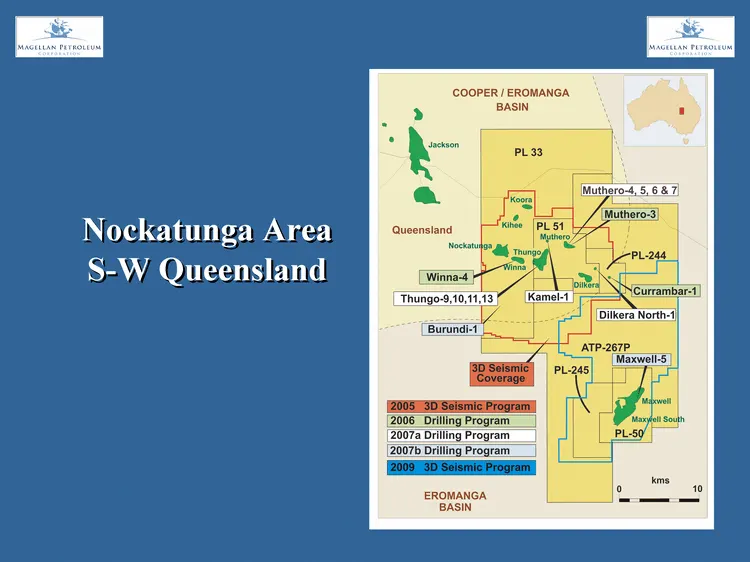
Nockatunga Area S-W Queensland
Slide 12: Maryborough Basin
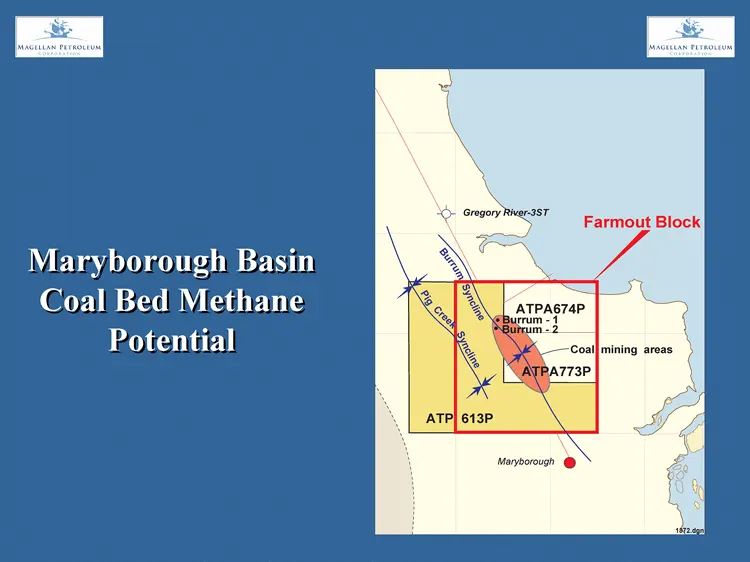
Maryborough Basin In ATP 613P, ATP Application 674P and ATP Application 733P evaluation of coal seam gas potential of Burrum Coal Measures is ongoing. Magellan has farmed out the area to Blue Energy who completed stage one of the farmin obligations by drilling two exploration wells in ATP 613P. Unde
Slide 13: Maryborough Basin Coal Bed Methane Potential
Maryborough Basin Coal Bed Methane Potential Potential Potential Potential
Slide 14: Onshore UK: Magellan's Current Focus Areas
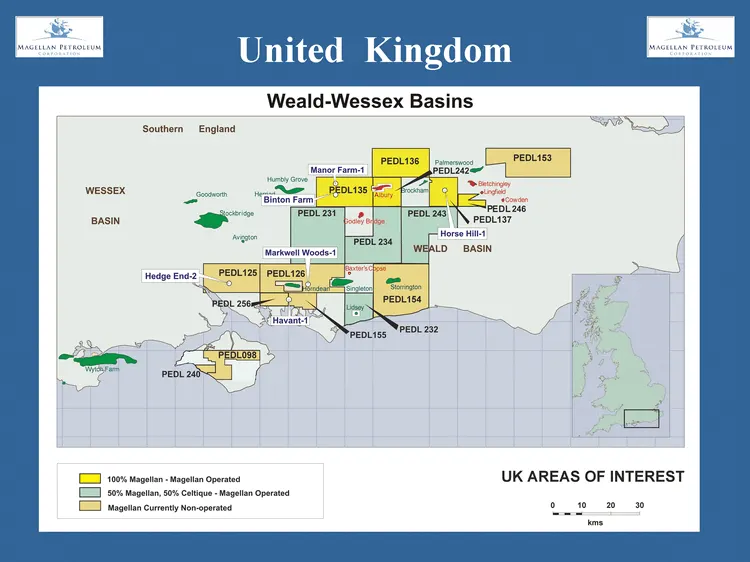
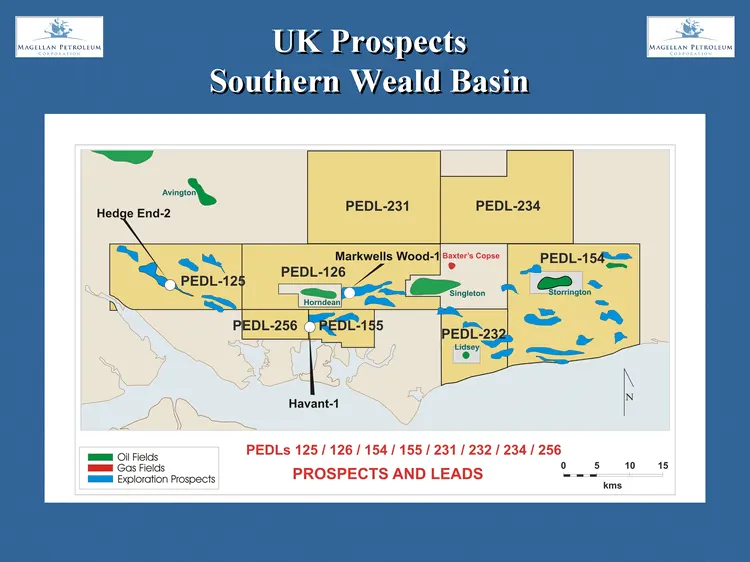
Onshore UK Planning permission for Markwells Wood-1 and Havant-1 received. Site preparation for Markwells Wood-1 is well advanced and once completed negotiations will commence on a rig contract. Site preparation for Havant-1 to commence 3Q 2009. Farmout of Magellan 100% wells Manor Farm-1 and Horse
Slide 15: United Kingdom
United Kingdom United Kingdom
Slide 16: UK Prospects Southern Weald Basin
UK Prospects Southern Weald Basin
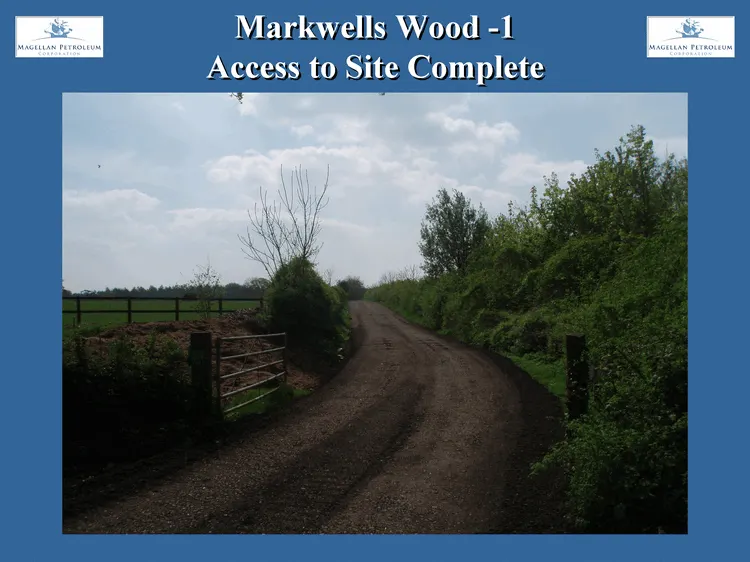
Slide 17: Markwells Wood-1 Access to Site Complete
Markwells Wood -1 Access to Site Complete Access to Site Complete Access to Site Complete
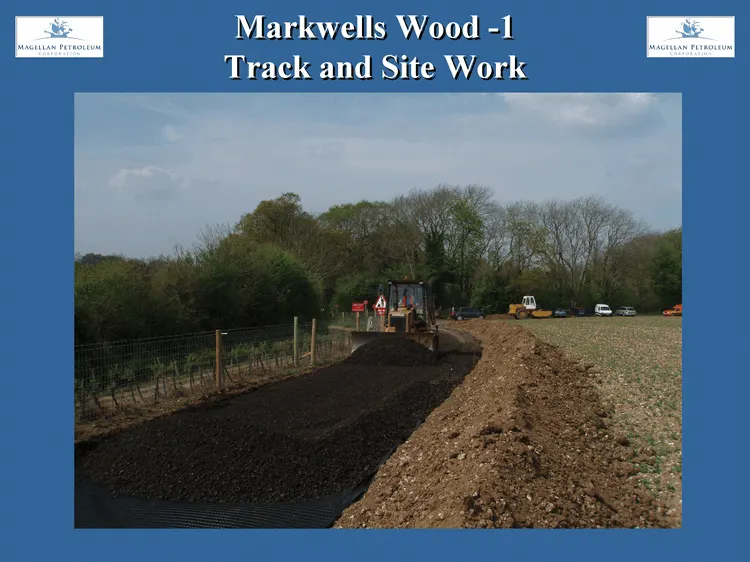
Slide 18: Markwells Wood-1 Track and Site Work
Markwells Wood -1 Track and Site Work Track and Site Work Track and Site Work
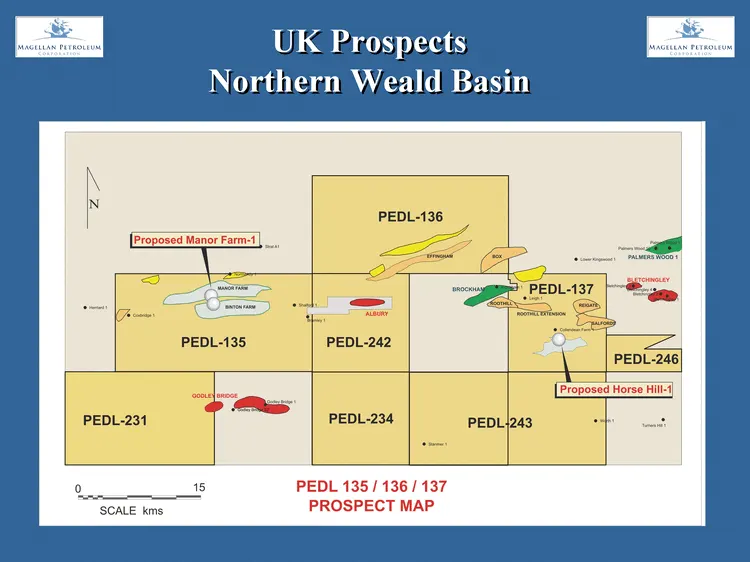
Slide 19: UK Prospects Northern Weald Basin
UK Prospects Northern Weald Basin Northern Weald Basin Northern Weald Basin
Slide 20: Thank You
Thank You
Source: SEC EDGAR · 8-K filed Jun 2, 2009
More decks from Tellurian Inc
 Merger or Acquisition (July 2024)27 slides · Jul 22, 2024
 Investor Presentation (March 2024)16 slides · Mar 4, 2024
 Investor Presentation (August 2023)20 slides · Aug 7, 2023
 Investor Presentation (May 2023)20 slides · May 3, 2023
 Investor Presentation (February 2023)21 slides · Feb 22, 2023
 Investor Presentation (November 2022)19 slides · Nov 2, 2022