Massey Energy — Corporate Update (September 2005)
23 slides from Massey Energy's corporate update, Sep 29, 2005
Slide 1: Utility Sales
Utility Sales John Parker Senior Vice President – Massey Utility Sales September 27, 2005
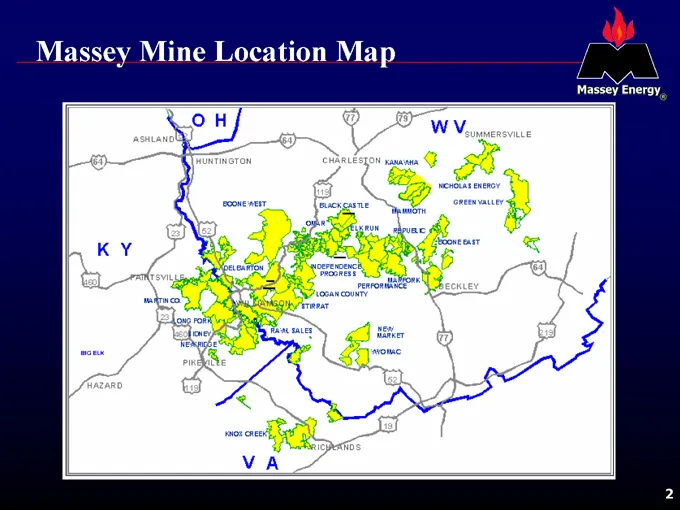
Slide 2: Massey Mine Location Map
Massey Mine Location Map / \ Massey Energy,
Slide 3: Shipping Flexibility
Shipping Flexibility NS – Seven (7) Rail-Loading Facilities Daily rail shipping capacity – 100,000 tons CSX – Twelve (12) Rail-Loading Facilities Daily rail shipping capacity – 160,000 tons Total Rail-Loading Facilities – Nineteen (19) Total daily rail shipping capacity – 260,000 tons
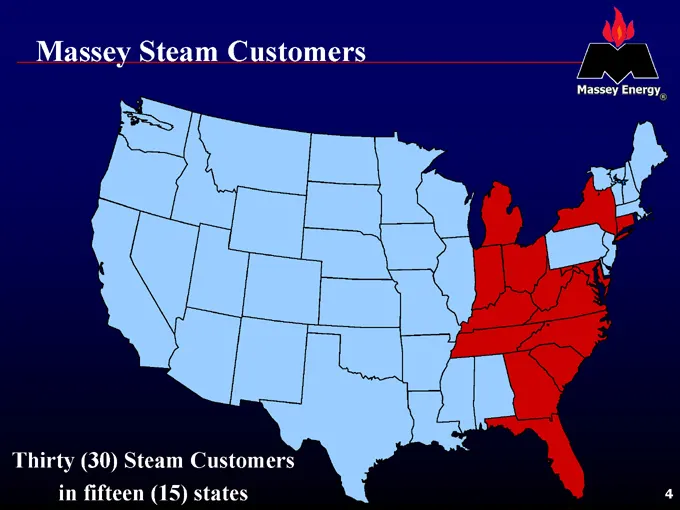
Slide 4: Massey Steam Customers
Massey Steam Customers Thirty (30) Steam Customers in fifteen (15) states
Slide 5: Massey Customers
Massey Customers Steam Customers Metallurgical Customers Industrial Customers Total Massey Customers Location of customers: Thirty (30) Twenty-nine (29) Thirty-seven (37) Ninety-six (96) Twenty-two (22) states; Fourteen (14) countries
Slide 6: Massey Steam Sales Top Five Customers
Massey Steam Sales Top Five Customers 1. American Electric Power Service – Columbus, OH 2. Detroit Edison Company – Detroit, MI 3. Duke Energy – Charlotte, NC 4. Constellation Power Source – Baltimore, MD 5. Progress Energy Corporation/ Progress – Carolinas, Raleigh, NC
Slide 7: American Electric Power Service
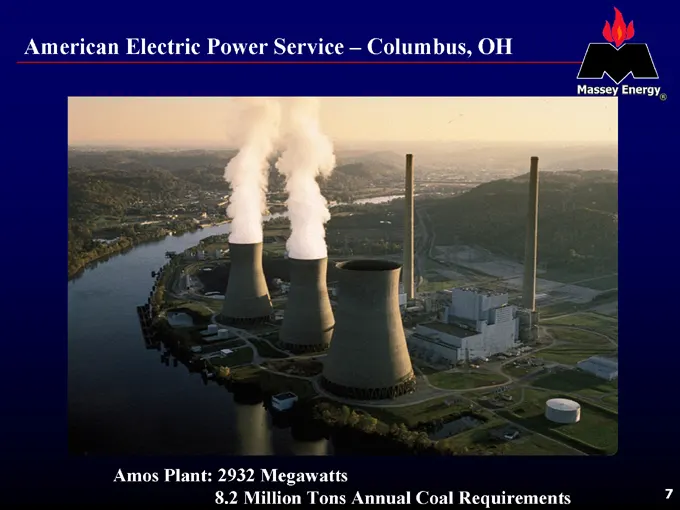
American Electric Power Service – Columbus, OH Amos Plant: 2932 Megawatts 8.2 Million Tons Annual Coal Requirements
Slide 8: Detroit Edison
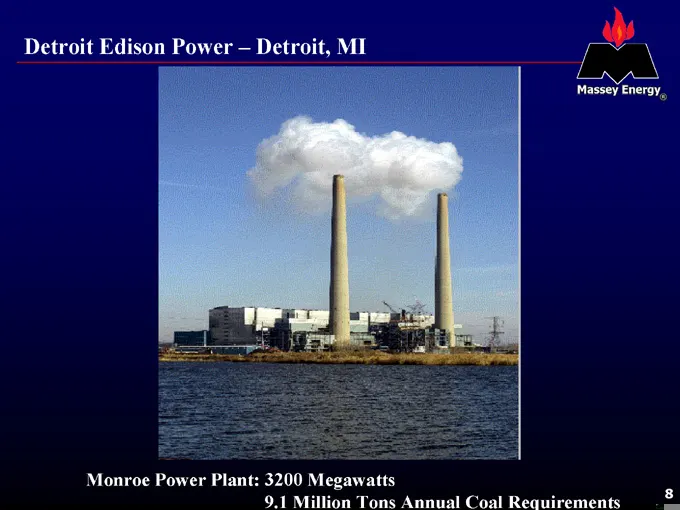
Detroit Edison Power – Detroit, MI Monroe Power Plant: 3200 Megawatts 9.1 Million Tons Annual Coal Requirements
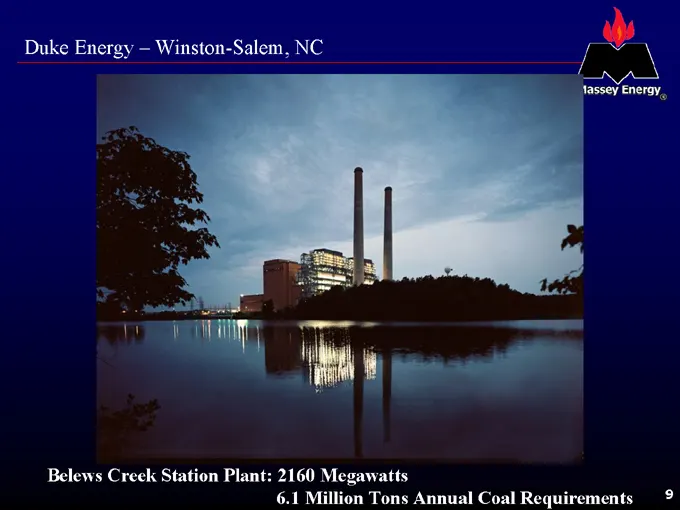
Slide 9: Duke Energy
Duke Energy – Winston-Salem, NC Belews Creek Station Plant: 2160 Megawatts 6.1 Million Tons Annual Coal Requirements
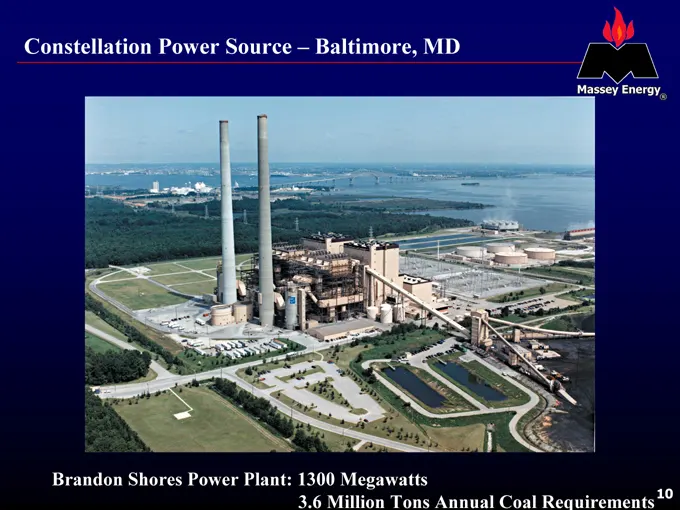
Slide 10: Constellation Power Source
Constellation Power Source – Baltimore, MD Brandon Shores Power Plant: 1300 Megawatts 3.6 Million Tons Annual Coal Requirements
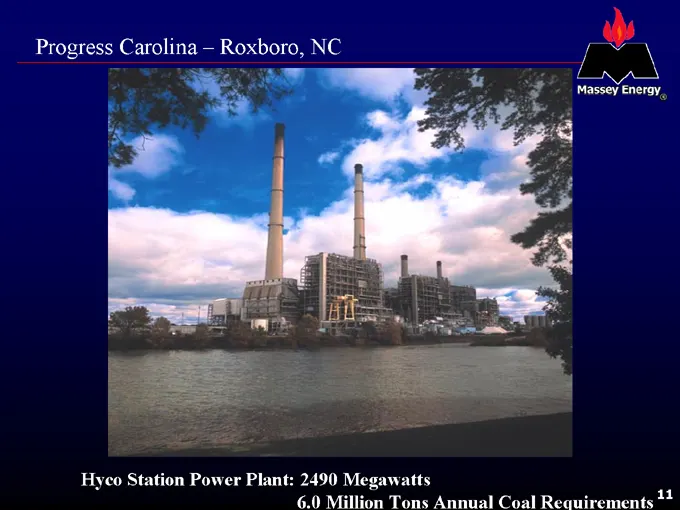
Slide 11: Progress Carolina
Progress Carolina – Roxboro, NC Hyco Station Power Plant: 2490 Megawatts 6.0 Million Tons Annual Coal Requirements
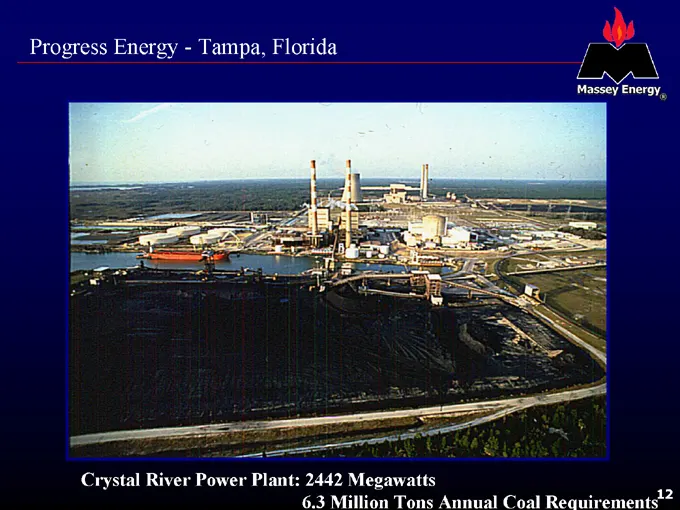
Slide 12: Progress Energy - Tampa, Florida
Progress Energy—Tampa, Florida Crystal River Power Plant: 2442 Megawatts 6.3 Million Tons Annual Coal Requirements
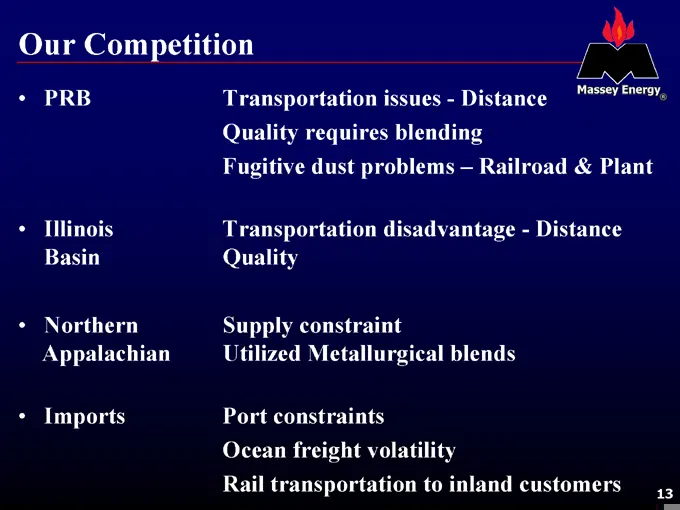
Slide 13: Our Competition
Our Competition PRB Illinois Basin Northern Appalachian Imports Transportation issues—Distance Quality requires blending Fugitive dust problems – Railroad & Plant Transportation disadvantage—Distance Quality Supply constraint Utilized Metallurgical blends Port constraints Ocean freight volatility Ra
Slide 14: New Scrubbers
New Scrubbers Most of our customers will stay with Central Appalachia coal Many Northeastern and Southeastern utilities have concerns with Illinois Basin coal quality.
Slide 15: The Steam Market
The Steam Market Markets firm as supply worries continue & inventory levels remain low.
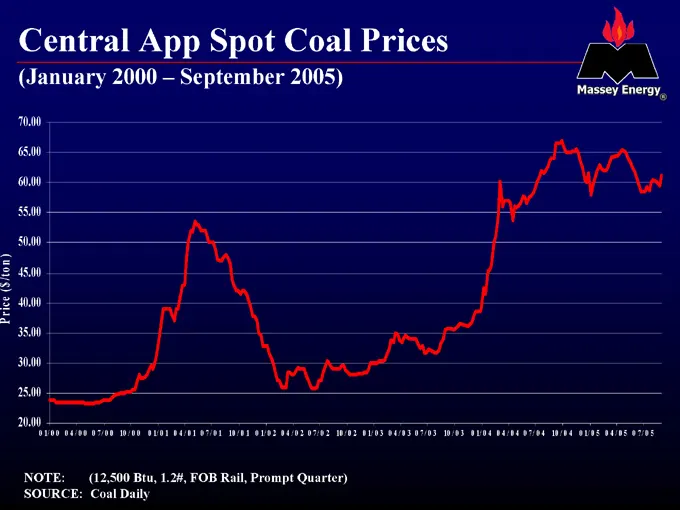
Slide 16: Central App Spot Coal Prices
Central App Spot Coal Prices (January 2000 – September 2005) Price ($/ton) 70.00 65.00 60.00 55.00 50.00 45.00 40.00 35.00 30.00 25.00 20.00 0 1/ 0 0 0 4 / 0 0 0 7/ 0 0 10 / 0 0 0 1/ 0 1 0 4 / 0 1 0 7/ 0 1 10 / 0 1 0 1/ 0 2 0 4 / 0 2 0 7/ 0 2 10 / 0 2 0 1/ 0 3 0 4 / 0 3 0 7/ 0 3 10 / 0 3 0 1/ 0 4 0
Slide 17: Central App Spot Coal Prices
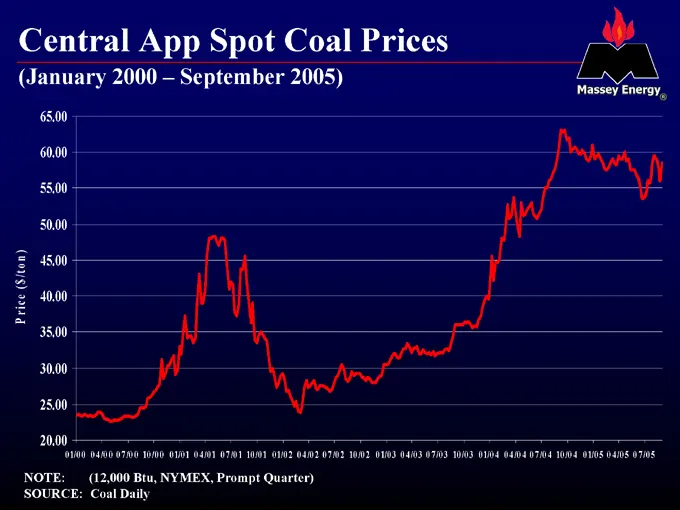
Central App Spot Coal Prices (January 2000 – September 2005) Price ($/ton ) 65.00 60.00 55.00 50.00 45.00 40.00 35.00 30.00 25.00 20.00 0 1/0 0 0 4 /0 0 0 7 /0 0 10 /0 0 0 1/0 1 0 4 /0 1 0 7 /0 1 10 /0 1 0 1/0 2 0 4 /0 2 0 7 /0 2 10 /0 2 0 1/0 3 0 4 /0 3 0 7 /0 3 10 /0 3 0 1/0 4 0 4 /0 4 0 7 /0 4 10
Slide 18: Forward Market
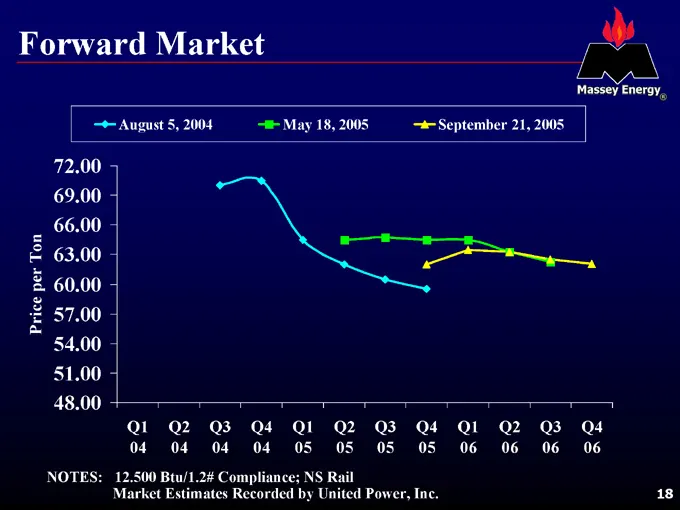
Forward Market August 5, 2004 May 18, 2005 September 21, 2005 Price per Ton 72.00 69.00 66.00 63.00 60.00 57.00 54.00 51.00 48.00 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 04 04 04 04 05 05 05 05 06 06 06 06 NOTES: 12.500 Btu/1.2# Compliance; NS Rail Market Estimates Recorded by United Power, Inc.
Slide 19: The Steam Market
The Steam Market Central Appalachia production continues to decrease Labor, equipment and permits are the major production constraints
Slide 20: Central App. vs. Industry Production
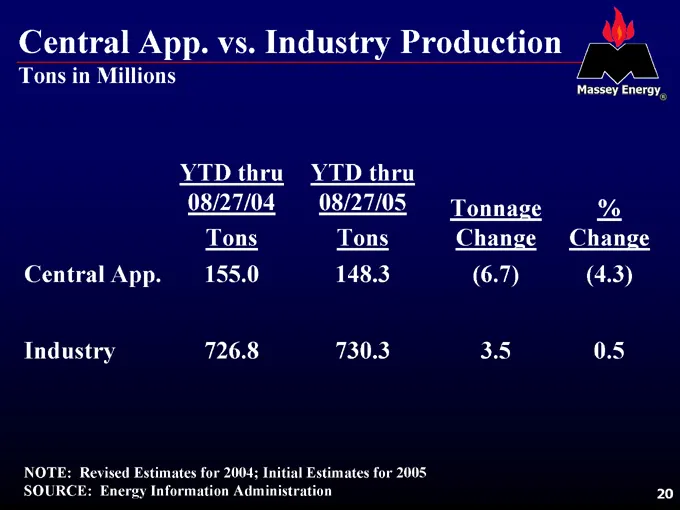
Central App. vs. Industry Production Tons in Millions YTD thru 08/27/04 Tons YTD thru 08/27/05 Tons Tonnage Change % Change Central App. 155.0 148.3 (6.7) (4.3) Industry 726.8 730.3 3.5 0.5 NOTE: Revised Estimates for 2004; Initial Estimates for 2005 SOURCE: Energy Information Administration
Slide 21: Utilities Buying Practices
Utilities Buying Practices Prior to 2002, many utilities had 75 – 80% of their annual burn under long-term agreements (plus 3 years). In today’s market, most utilities are more inclined to secure 90% of their supply with 1 – 3 year agreements. Some utilities elect to utilize lower quality coals in o
Slide 22: Summary
Summary In summary: Massey has a commanding presence in Central Appalachia Extensive coal reserves Multiple shipping sources Diverse customers – Utility/ Metallurgical/ Industrial The Central Appalachian coal region produces coals that can serve any market in the world.
Slide 23: Doing the Right Thing. with Energy
Doing the Right Thing. with Energy
Source: SEC EDGAR · 8-K/A filed Sep 29, 2005
More decks from Massey Energy Co
 Merger or Acquisition (March 2011)18 slides · Mar 9, 2011
 BMO Capital Markets 2011 Global Metals & Mining Conference27 slides · Mar 1, 2011
 Credit Suisse Energy Summit 201126 slides · Feb 10, 2011
 Merger or Acquisition (January 2011)19 slides · Jan 31, 2011
 Proxy Contest (May 2010)32 slides · May 5, 2010
 Proxy Contest (April 2010)26 slides · Apr 30, 2010