Santander Consumer USA Holdings Inc
Santander Consumer USA — Investor Day (November 2014)
58 slides from Santander Consumer USA's investor day presentation, Nov 18, 2014
Slide 1: Analyst and Investor Day Presentation
SANTANDER CONSUMER USA HOLDINGS INC. Analyst and Investor Day Presentation November 18, 2014
Slide 2: Important Information
IMPORTANT INFORMATION Forward-Looking Statements This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Any statements about our expectations, beliefs, plans, predictions, forecasts, objectives, assumptions, or future events
Slide 3: Agenda
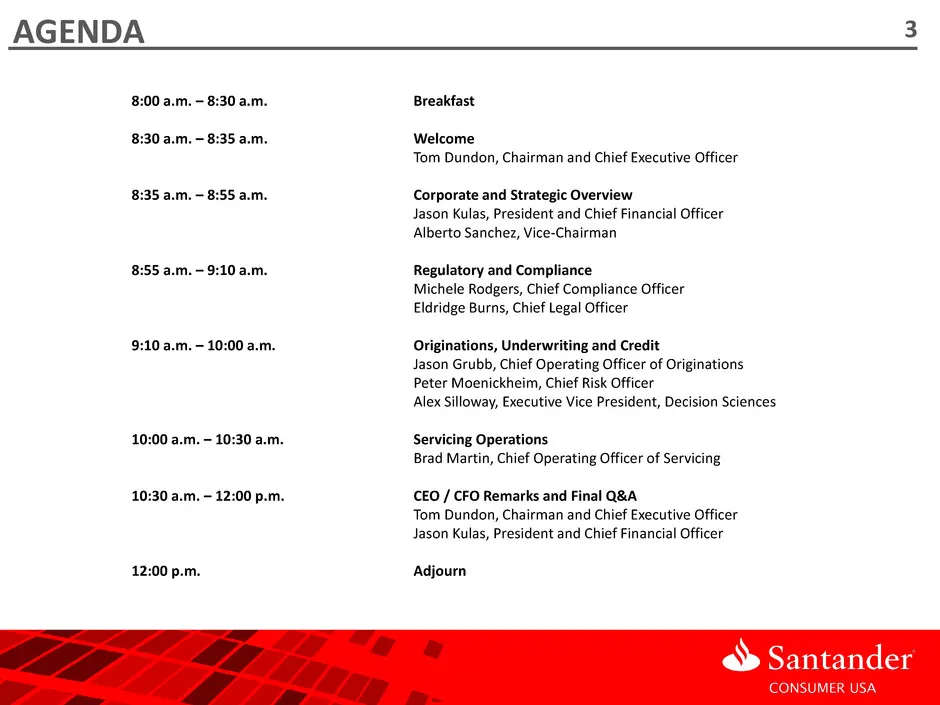
AGENDA 8:00 a.m. – 8:30 a.m. Breakfast 8:30 a.m. – 8:35 a.m. Welcome Tom Dundon, Chairman and Chief Executive Officer 8:35 a.m. – 8:55 a.m. Corporate and Strategic Overview Jason Kulas, President and Chief Financial Officer Alberto Sanchez, Vice-Chairman 8:55 a.m. – 9:10 a.m. Regulatory and Complian
Slide 4: Management Presenters
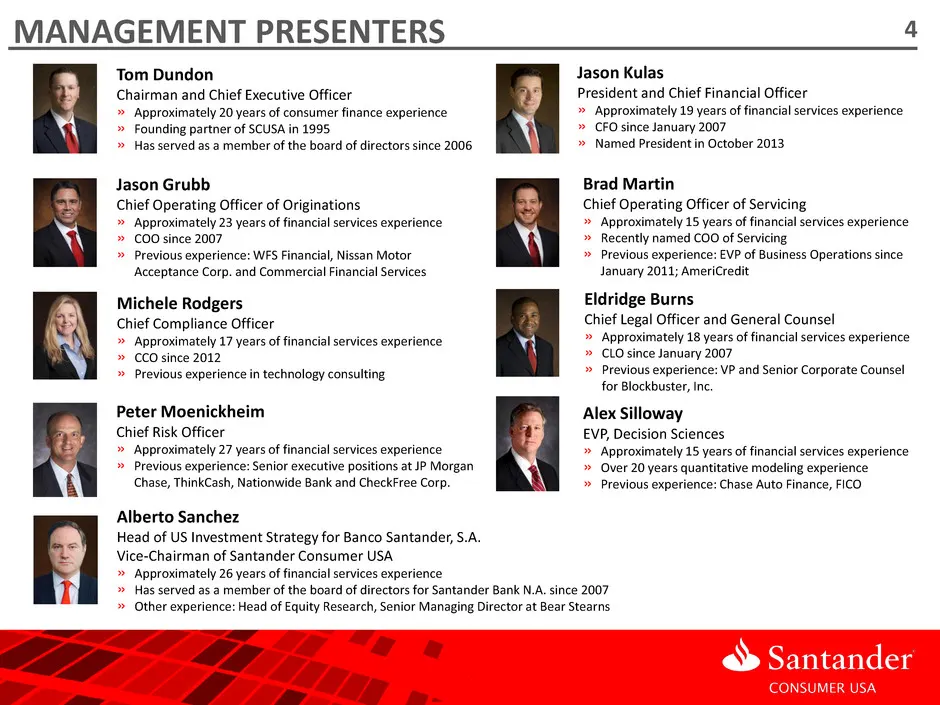
MANAGEMENT PRESENTERS Tom Dundon Chairman and Chief Executive Officer » Approximately 20 years of consumer finance experience » Founding partner of SCUSA in 1995 » Has served as a member of the board of directors since 2006 Jason Kulas President and Chief Financial Officer » Approximately 19 years o
Slide 5: Corporate and Strategic Overview
CORPORATE AND STRATEGIC OVERVIEW Jason Kulas President and Chief Financial Officer Alberto Sanchez Vice-Chairman
Slide 6: Investment Rationale
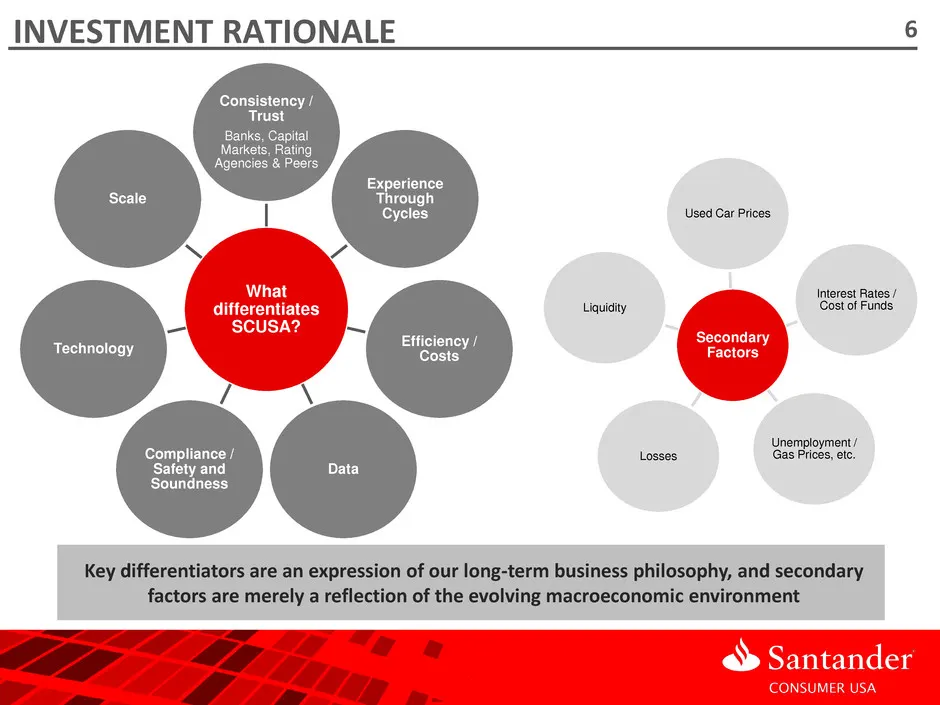
INVESTMENT RATIONALE What differentiates SCUSA? Consistency / Trust Banks, Capital Markets, Rating Agencies & Peers Experience Through Cycles Efficiency / Costs Data Compliance / Safety and Soundness Technology Scale Secondary Factors Used Car Prices Interest Rates / Cost of Funds Unemployment / Gas
Slide 7: SCUSA Overview
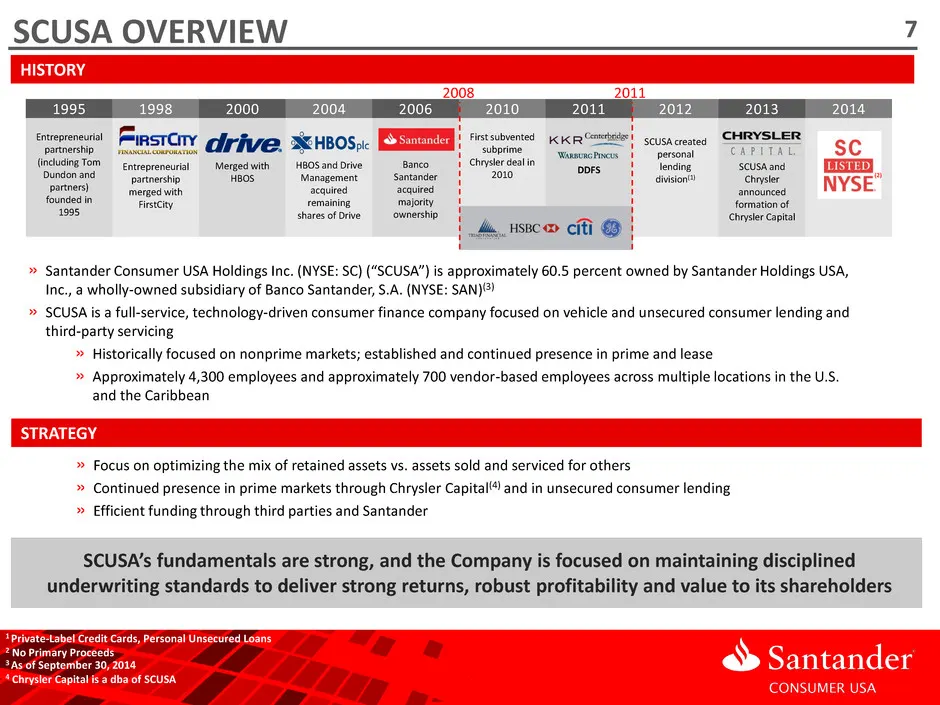
7 Net Income Net Income % of Portfolio 1995 1998 2000 2004 2006 2010 2011 2012 2013 2014 Entrepreneurial partnership (including Tom Dundon and partners) founded in 1995 Entrepreneurial partnership merged with FirstCity Merged with HBOS HBOS and Drive Management acquired remaining shares of Drive Ban
Slide 8: SCUSA Today
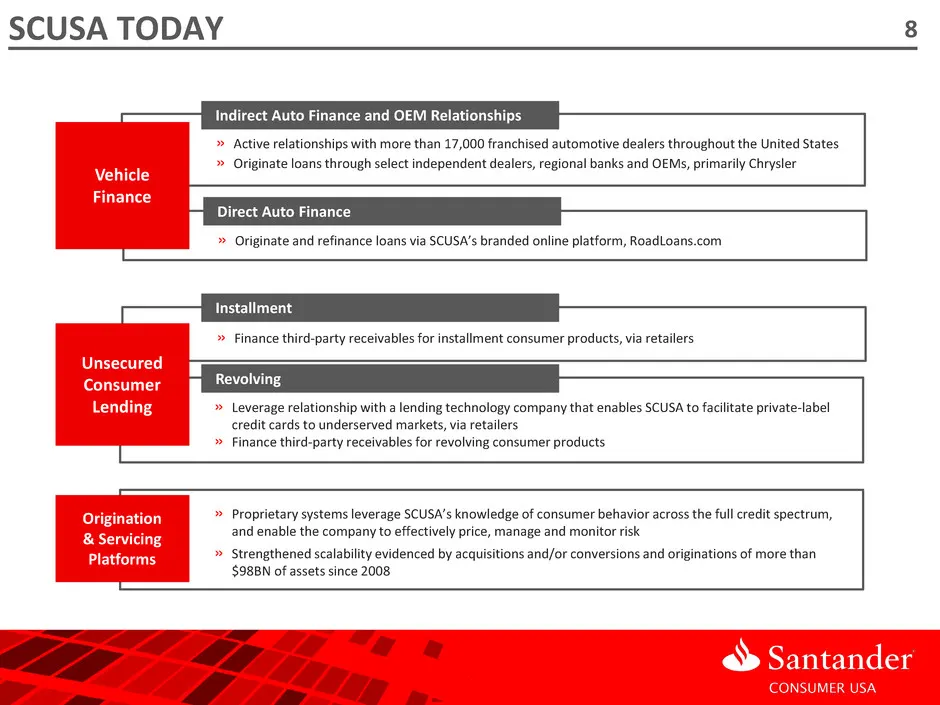
SCUSA TODAY » Originate and refinance loans via SCUSA’s branded online platform, RoadLoans.com » Active relationships with more than 17,000 franchised automotive dealers throughout the United States » Originate loans through select independent dealers, regional banks and OEMs, primarily Chrysler Dir
Slide 9: Chrysler Capital
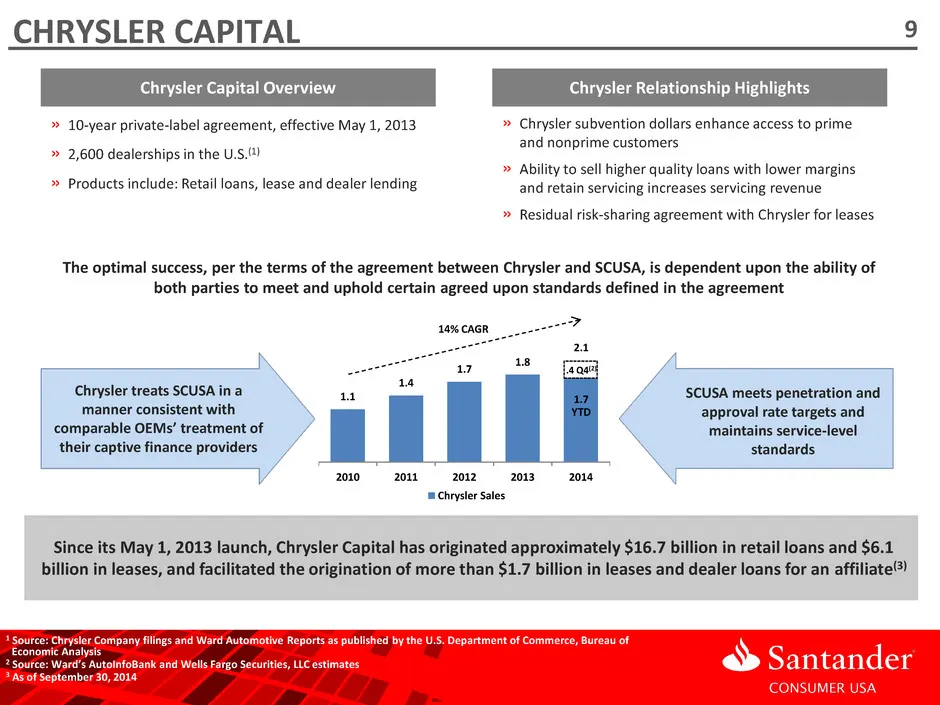
CHRYSLER CAPITAL Chrysler Capital Overview Chrysler Relationship Highlights » 10-year private-label agreement, effective May 1, 2013 » 2,600 dealerships in the U.S.(1) » Products include: Retail loans, lease and dealer lending » Chrysler subvention dollars enhance access to prime and nonprime custom
Slide 10: Continued Unsecured Presence
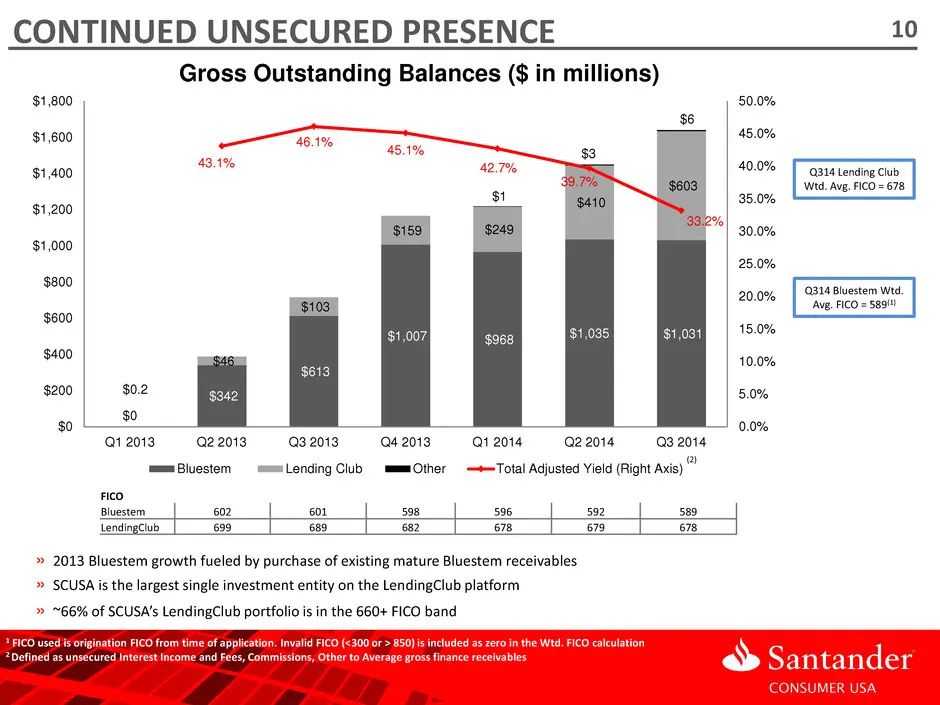
$0 $342 $613 $1,007 $968 $1,035 $1,031 $0.2 $46 $103 $159 $249 $410 $603 $1 $3 $6 0.0% 5.0% 10.0% 15.0% 20.0% 25.0% 30.0% 35.0% 40.0% 45.0% 50.0% $0 $200 $400 $600 $800 $1,000 $1,200 $1,400 $1,600 $1,800 Q1 2013 Q2 2013 Q3 2013 Q4 2013 Q1 2014 Q2 2014 Q3 2014 Gross Outstanding Balances ($ in million
Slide 11: Operating Efficiency
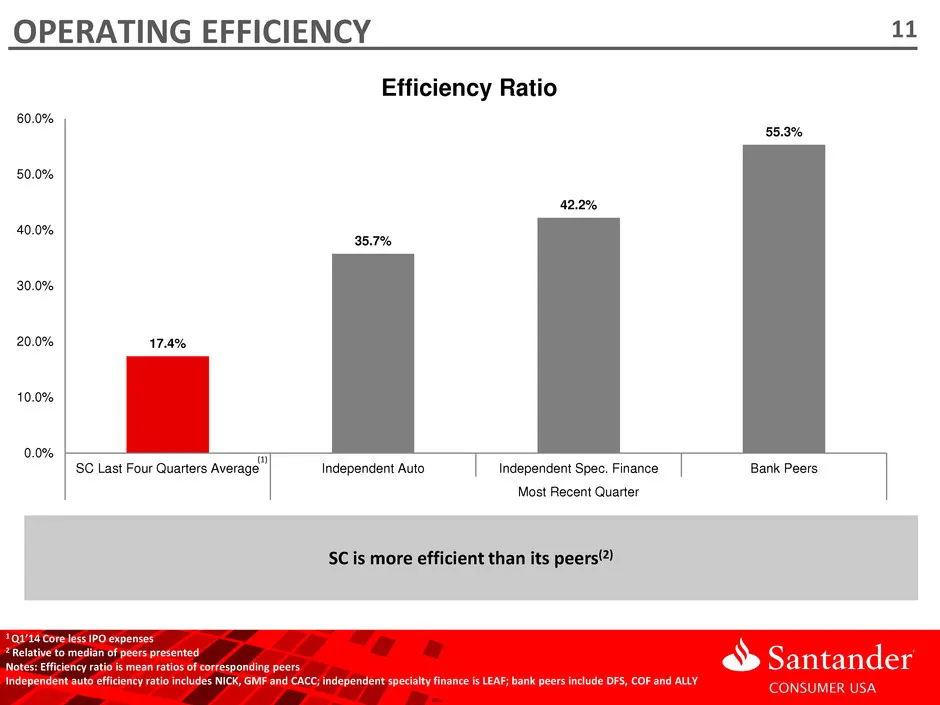
17.4% 35.7% 42.2% 55.3% 0.0% 10.0% 20.0% 30.0% 40.0% 50.0% 60.0% SC Last Four Quarters Average Independent Auto Independent Spec. Finance Bank Peers Most Recent Quarter Efficiency Ratio 1 Q1’14 Core less IPO expenses 2 Relative to median of peers presented Notes: Efficiency ratio is mean ratios of c
Slide 12: Funding Efficiency and Liquidity
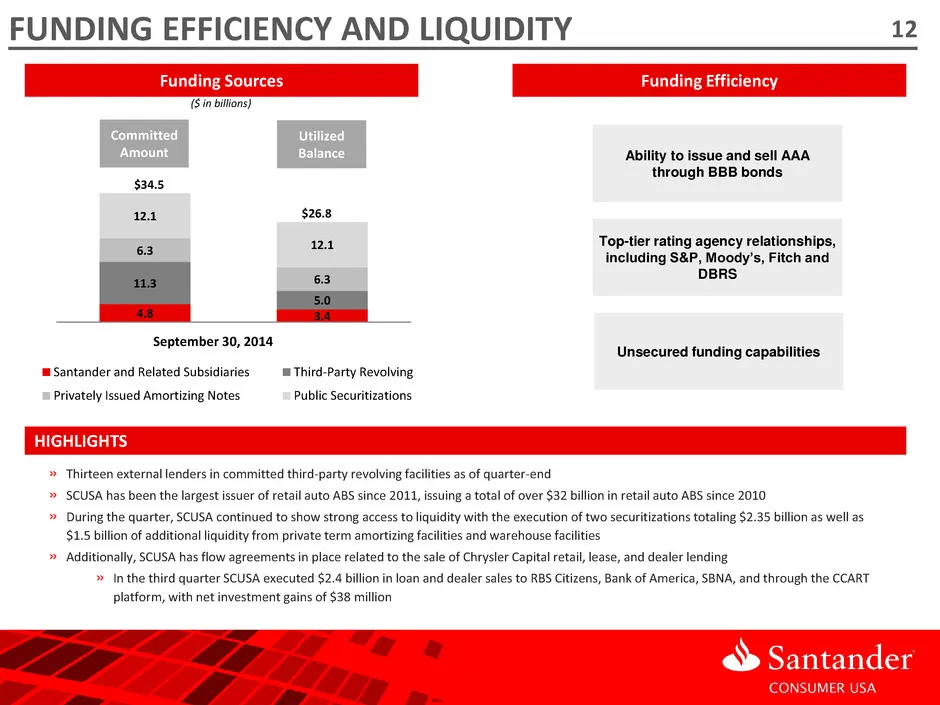
4.8 3.4 11.3 5.0 6.3 6.3 12.1 12.1 Santander and Related Subsidiaries Third-Party Revolving Privately Issued Amortizing Notes Public Securitizations FUNDING EFFICIENCY AND LIQUIDITY Funding Sources » Thirteen external lenders in committed third-party revolving facilities as of quarter-end » SCUSA ha
Slide 13: Provision and Loss Drivers
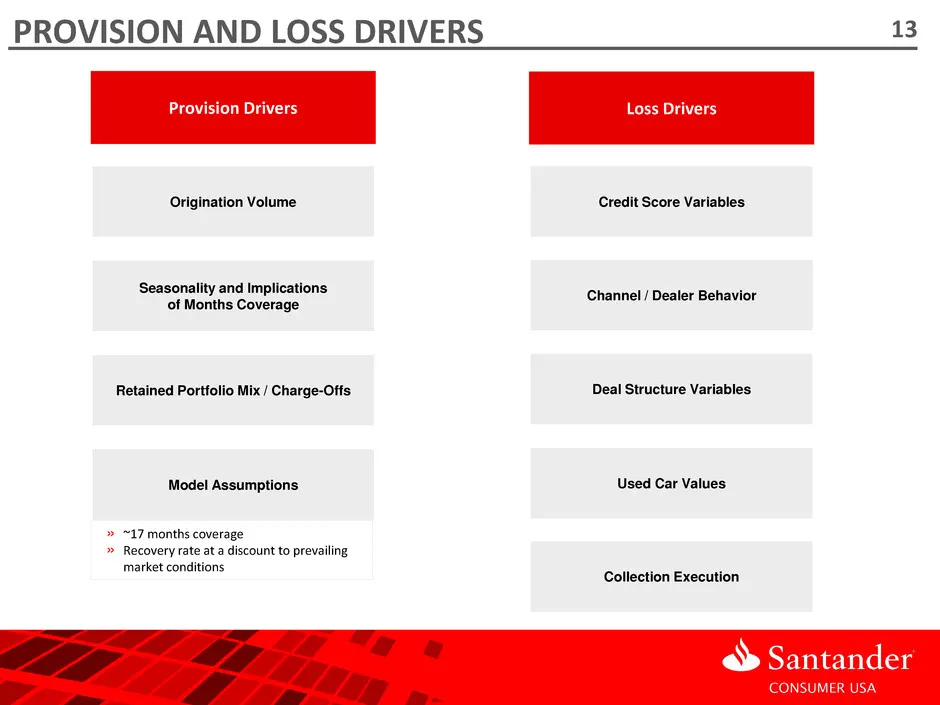
» ~17 months coverage » Recovery rate at a discount to prevailing market conditions PROVISION AND LOSS DRIVERS Provision Drivers Loss Drivers Origination Volume Seasonality and Implications of Months Coverage Retained Portfolio Mix / Charge-Offs Model Assumptions Channel / Dealer Behavior Credit Sco
Slide 14: Industry Trends
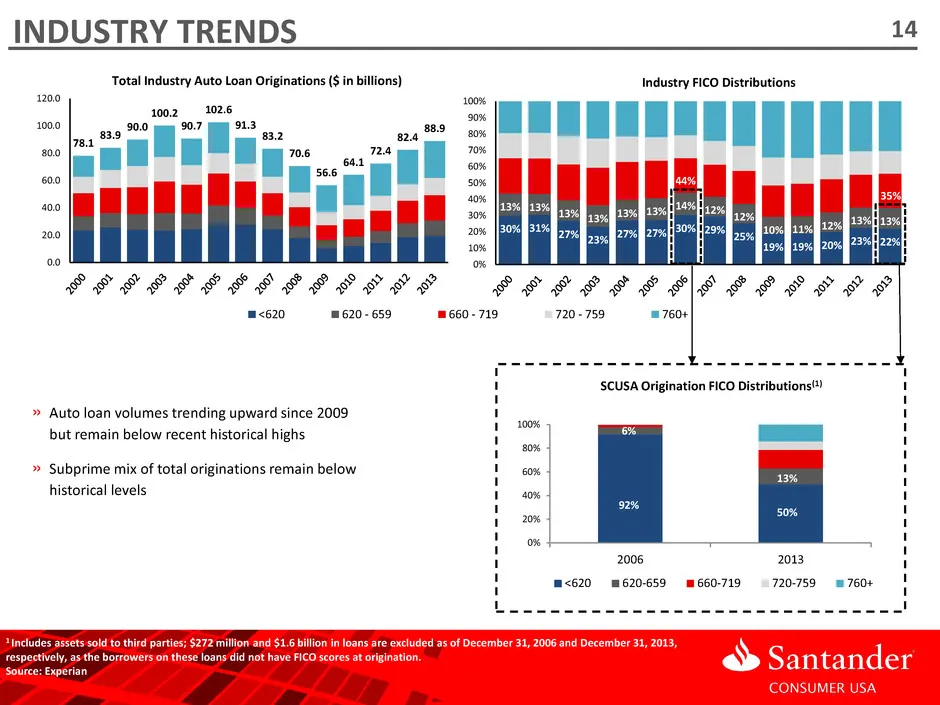
30% 31% 27% 23% 27% 27% 30% 29% 25% 19% 19% 20% 23% 22% 13% 13% 13% 13% 13% 13% 14% 12% 12% 10% 11% 12% 13% 13% 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% Industry FICO Distributions 44% 35% 0% 20% 40% 60% 80% 100% 2006 2013 SCUSA Origination FICO Distributions(1) <620 620-659 660-719 720-759 760+
Slide 15: Regulatory and Compliance Overview
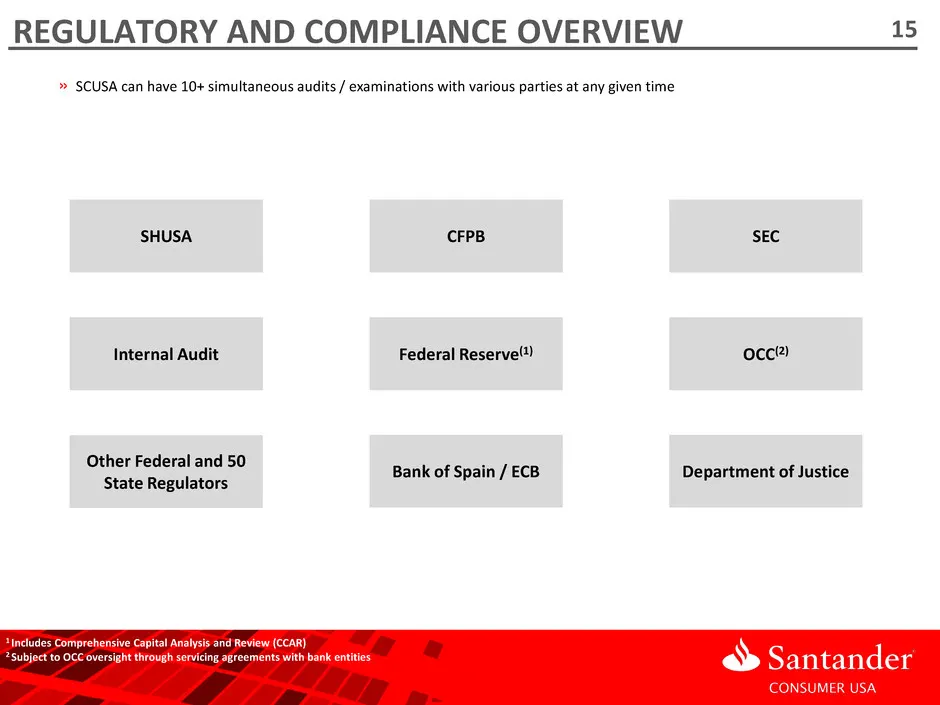
REGULATORY AND COMPLIANCE OVERVIEW Department of Justice Federal Reserve(1) Bank of Spain / ECB CFPB SEC OCC(2) Other Federal and 50 State Regulators SHUSA Internal Audit 1 Includes Comprehensive Capital Analysis and Review (CCAR) 2 Subject to OCC oversight through servicing agreements with bank ent
Slide 16: Strictly Private & Confidential
Strictly Private & Confidential
Slide 17: Regulatory and Compliance
REGULATORY AND COMPLIANCE Michele Rodgers Chief Compliance Officer Eldridge Burns Chief Legal Officer
Slide 18: Compliance Mission and Objective
Mission To define, establish and manage a process that identifies, measures, mitigates, and reports Compliance and Reputational Risks across U.S. operations and all risk domains. Objective » Harmonize each business unit’s Compliance program » Create a centralized compliance risk management and testi
Slide 19: Compliance Management Program
Why? » Responsibility of assuring day-to-day compliance with applicable laws and regulations rests with SCUSA’s individual business departments, their officers and employees » All officers and employees need to fully understand the related laws and regulations applicable to their department, product
Slide 20: Key Compliance Program Elements
» CEO tone from the top » Bank-affiliated for 14 years » Three lines of defense » Compliance involved at all levels Compliance Culture » Monthly executive U.S. Compliance Committee » Working groups formed on compliance topics with LOB participation » Frequent reports to Board and Management committe
Slide 21: Key Compliance Program Elements
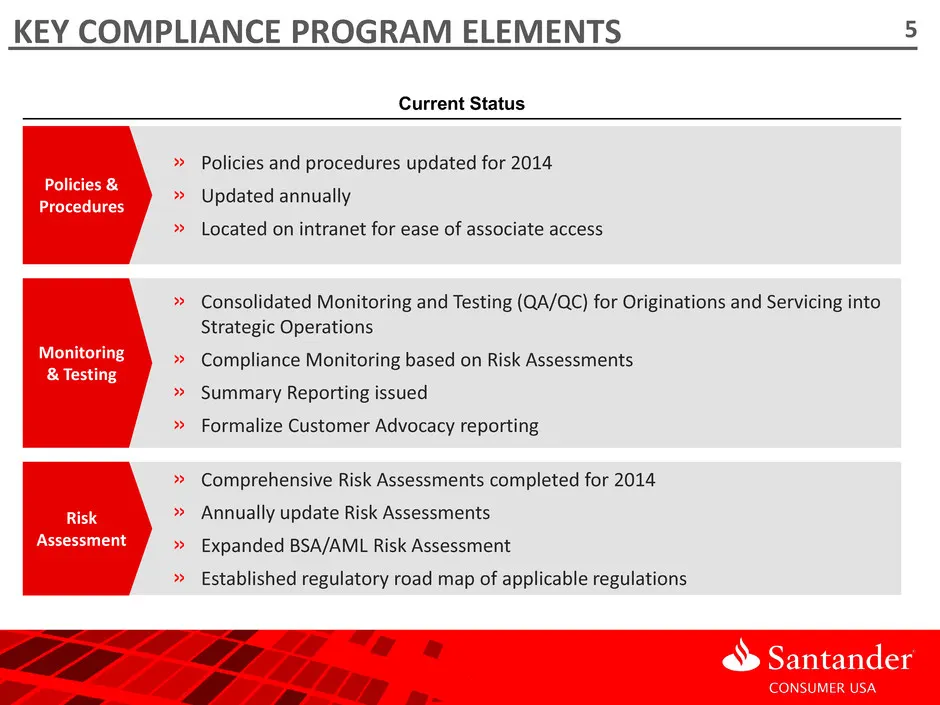
» Policies and procedures updated for 2014 » Updated annually » Located on intranet for ease of associate access Policies & Procedures » Consolidated Monitoring and Testing (QA/QC) for Originations and Servicing into Strategic Operations » Compliance Monitoring based on Risk Assessments » Summary Re
Slide 22: Key Compliance Program Elements
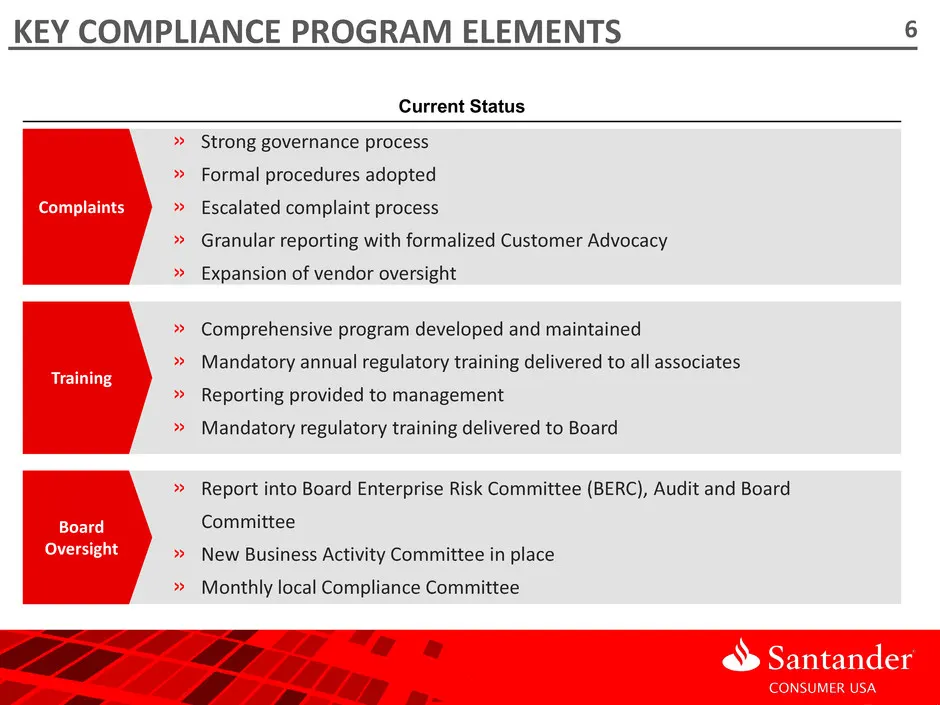
» Strong governance process » Formal procedures adopted » Escalated complaint process » Granular reporting with formalized Customer Advocacy » Expansion of vendor oversight Complaints » Comprehensive program developed and maintained » Mandatory annual regulatory training delivered to all associates
Slide 23: Strictly Private & Confidential
Strictly Private & Confidential
Slide 24: Originations, Underwriting and Credit
ORIGINATIONS, UNDERWRITING AND CREDIT Jason Grubb Chief Operating Officer of Originations Peter Moenickheim Chief Risk Officer Alex Silloway EVP, Decision Sciences
Slide 25: Centralized Originations Staffing
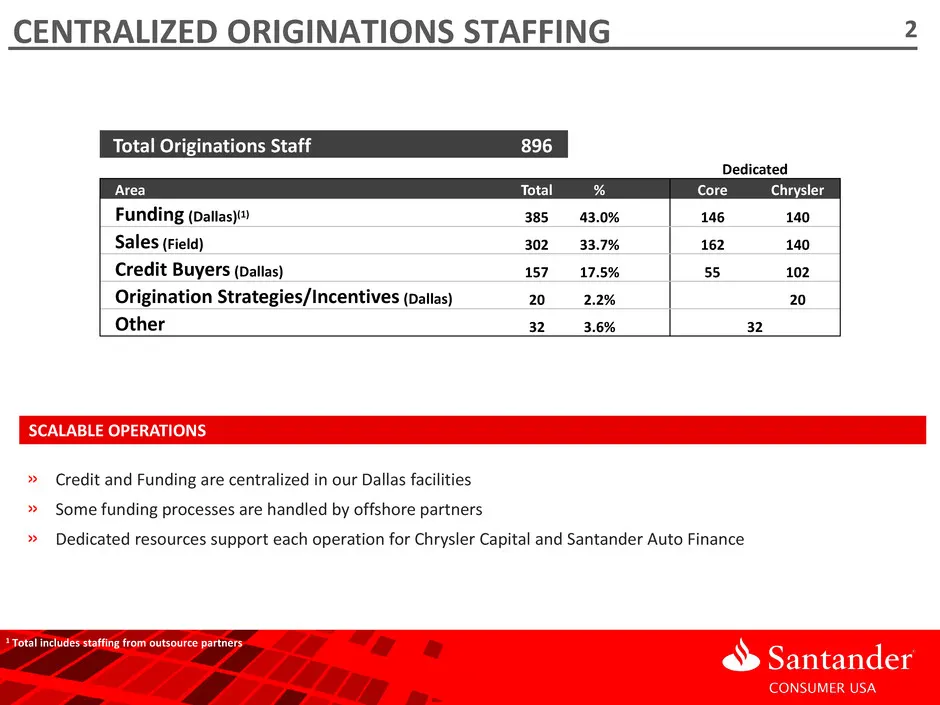
CENTRALIZED ORIGINATIONS STAFFING » Credit and Funding are centralized in our Dallas facilities » Some funding processes are handled by offshore partners » Dedicated resources support each operation for Chrysler Capital and Santander Auto Finance Total Originations Staff 896 Dedicated Area Total % C
Slide 26: Life of a Loan – Credit Process
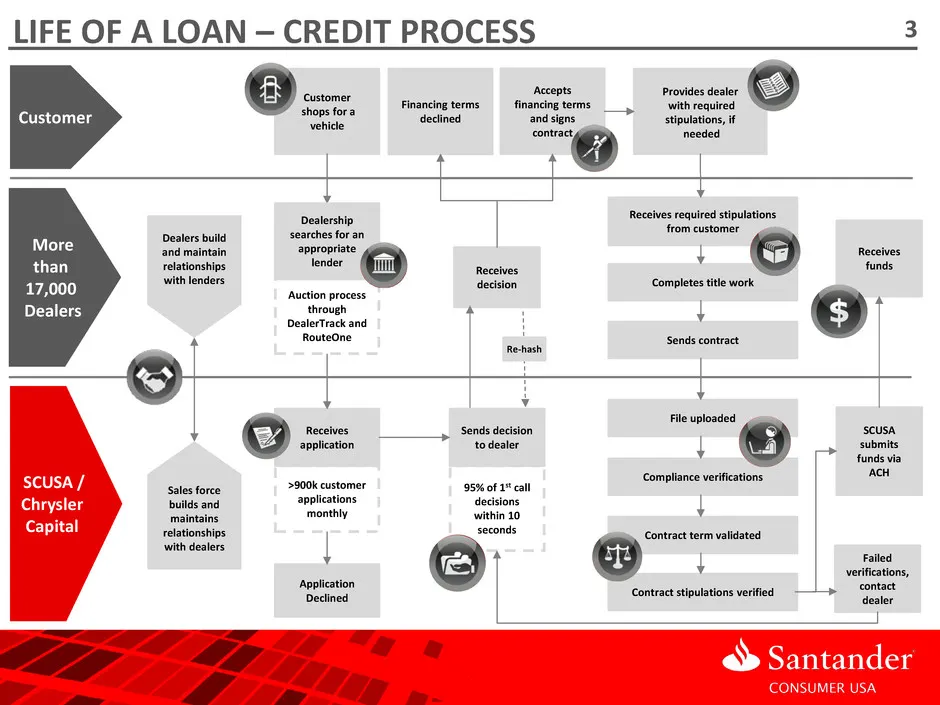
LIFE OF A LOAN – CREDIT PROCESS Customer More than 17,000 Dealers SCUSA / Chrysler Capital Customer shops for a vehicle Receives application Application Declined >900k customer applications monthly Sends decision to dealer 95% of 1st call decisions within 10 seconds Receives decision Accepts financi
Slide 27: Credit Process
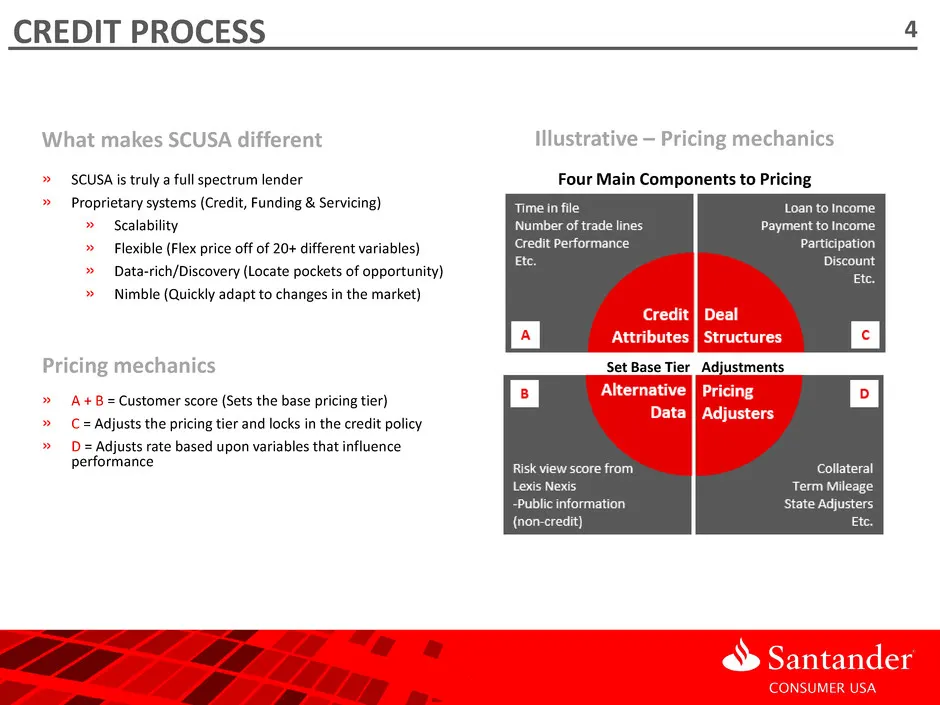
CREDIT PROCESS What makes SCUSA different » SCUSA is truly a full spectrum lender » Proprietary systems (Credit, Funding & Servicing) » Scalability » Flexible (Flex price off of 20+ different variables) » Data-rich/Discovery (Locate pockets of opportunity) » Nimble (Quickly adapt to changes in the m
Slide 28: Originations and Underwriting Framework
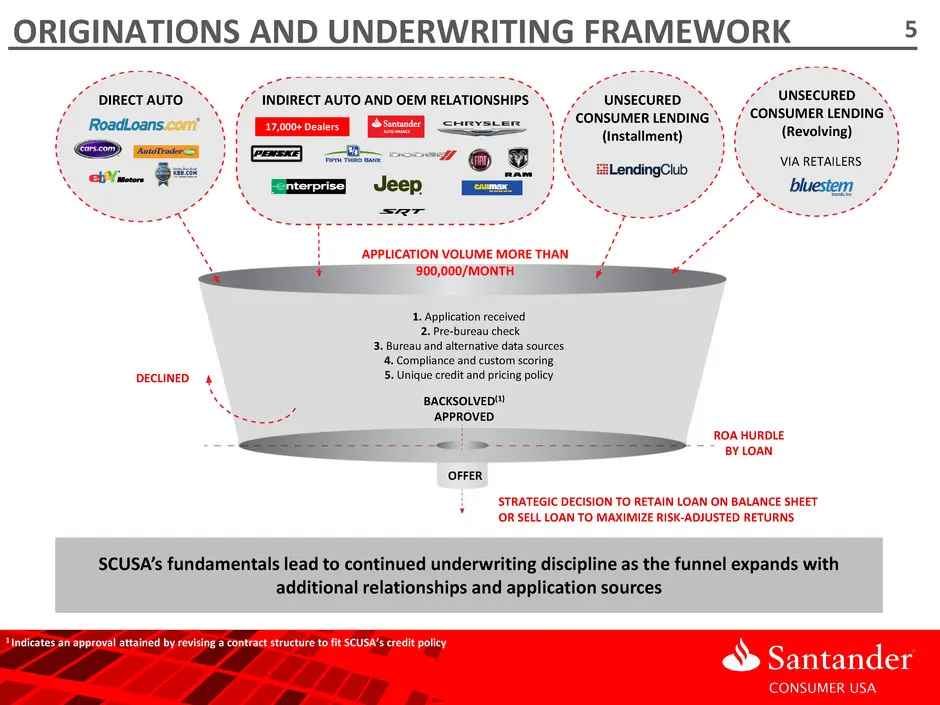
1. Application received 2. Pre-bureau check 3. Bureau and alternative data sources 4. Compliance and custom scoring 5. Unique credit and pricing policy BACKSOLVED(1) APPROVED INDIRECT AUTO AND OEM RELATIONSHIPS ORIGINATIONS AND UNDERWRITING FRAMEWORK STRATEGIC DECISION TO RETAIN LOAN ON BALANCE SHEE
Slide 29: Dealer Performance Monitoring
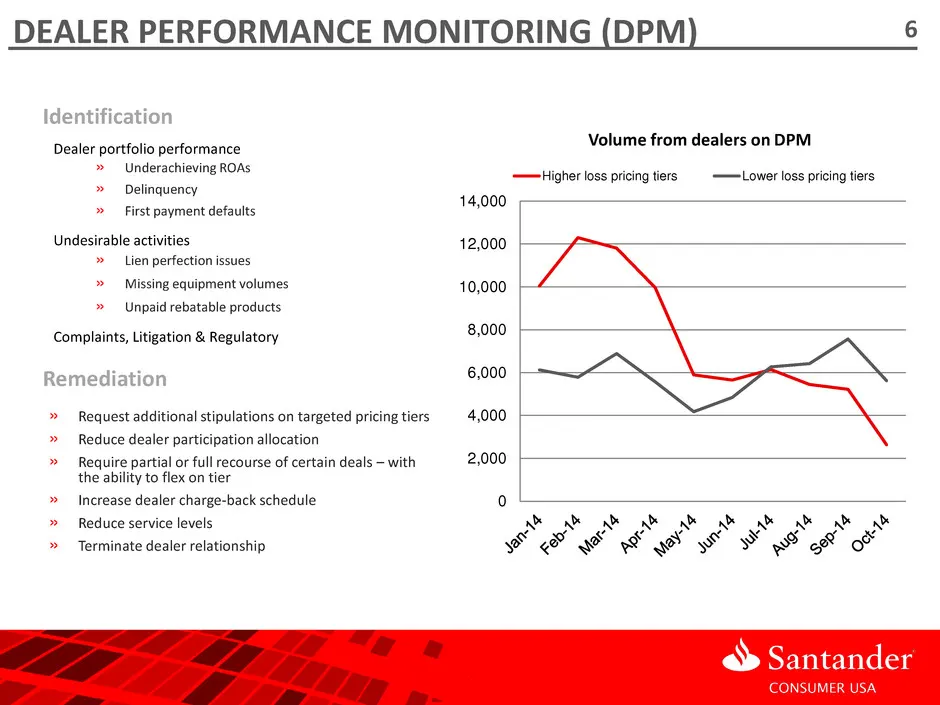
DEALER PERFORMANCE MONITORING (DPM) Identification •Dealer portfolio performance » Underachieving ROAs » Delinquency » First payment defaults •Undesirable activities » Lien perfection issues » Missing equipment volumes » Unpaid rebatable products •Complaints, Litigation & Regulatory Remediation » Re
Slide 30: Risk Management (Second Line of Defense)
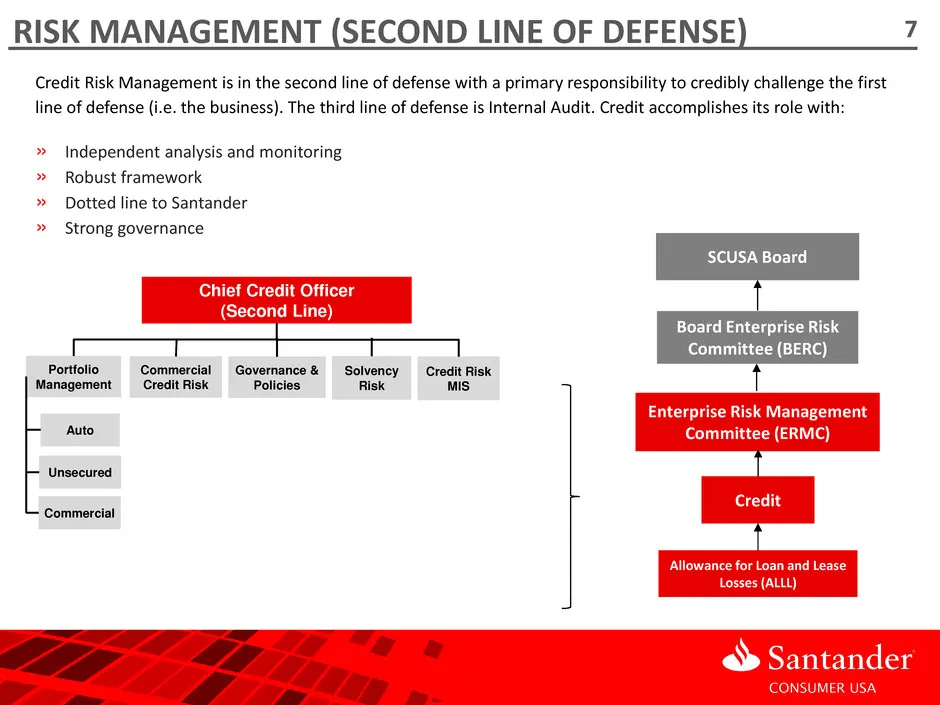
RISK MANAGEMENT (SECOND LINE OF DEFENSE) Credit Risk Management is in the second line of defense with a primary responsibility to credibly challenge the first line of defense (i.e. the business). The third line of defense is Internal Audit. Credit accomplishes its role with: » Independent analysis a
Slide 31: Model Development and Scorecards
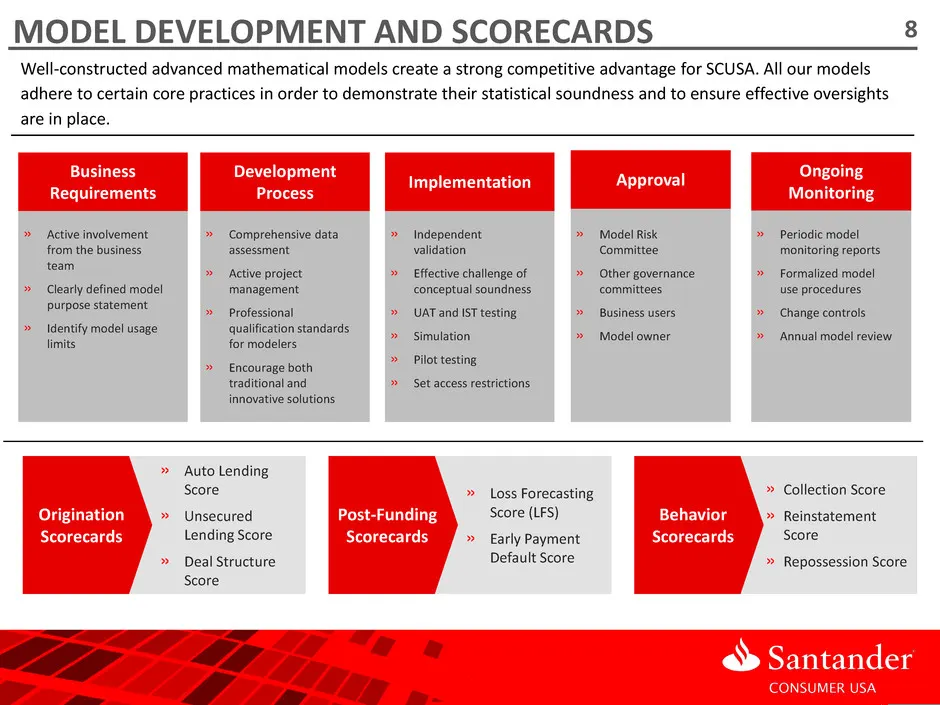
MODEL DEVELOPMENT AND SCORECARDS Well‐constructed advanced mathematical models create a strong competitive advantage for SCUSA. All our models adhere to certain core practices in order to demonstrate their statistical soundness and to ensure effective oversights are in place. » Active involvement fr
Slide 32: Strictly Private & Confidential
Strictly Private & Confidential
Slide 33: Servicing Operations
SERVICING OPERATIONS Brad Martin Chief Operating Officer of Servicing
Slide 34: Life of a Loan – Servicing Operations
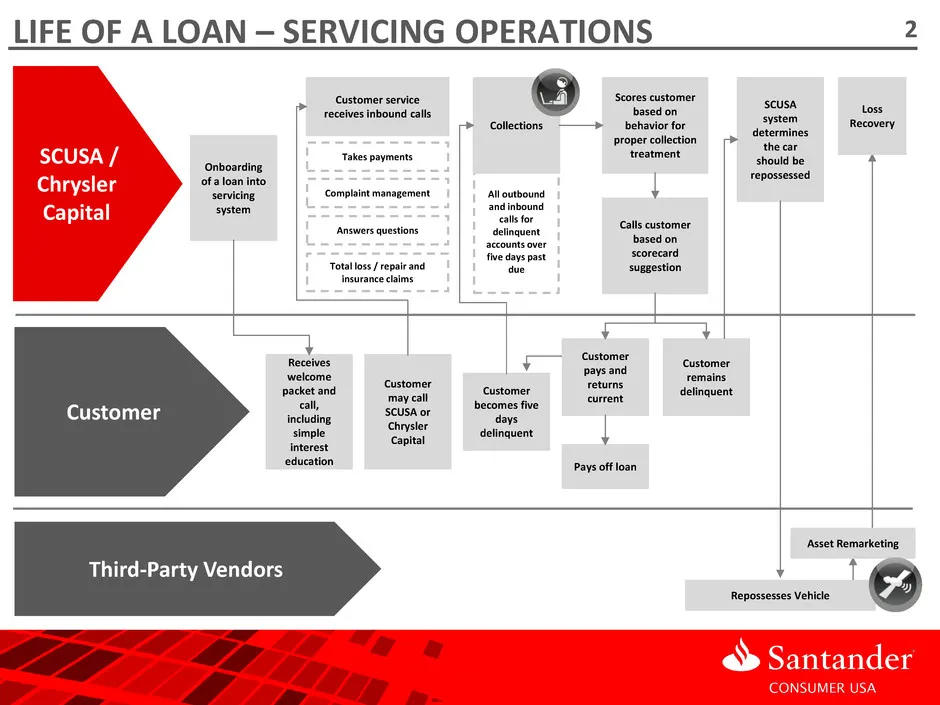
All outbound and inbound calls for delinquent accounts over five days past due LIFE OF A LOAN – SERVICING OPERATIONS Customer SCUSA / Chrysler Capital Third-Party Vendors Onboarding of a loan into servicing system Customer may call SCUSA or Chrysler Capital Customer service receives inbound calls Ta
Slide 35: Scalable Serviced Portfolio
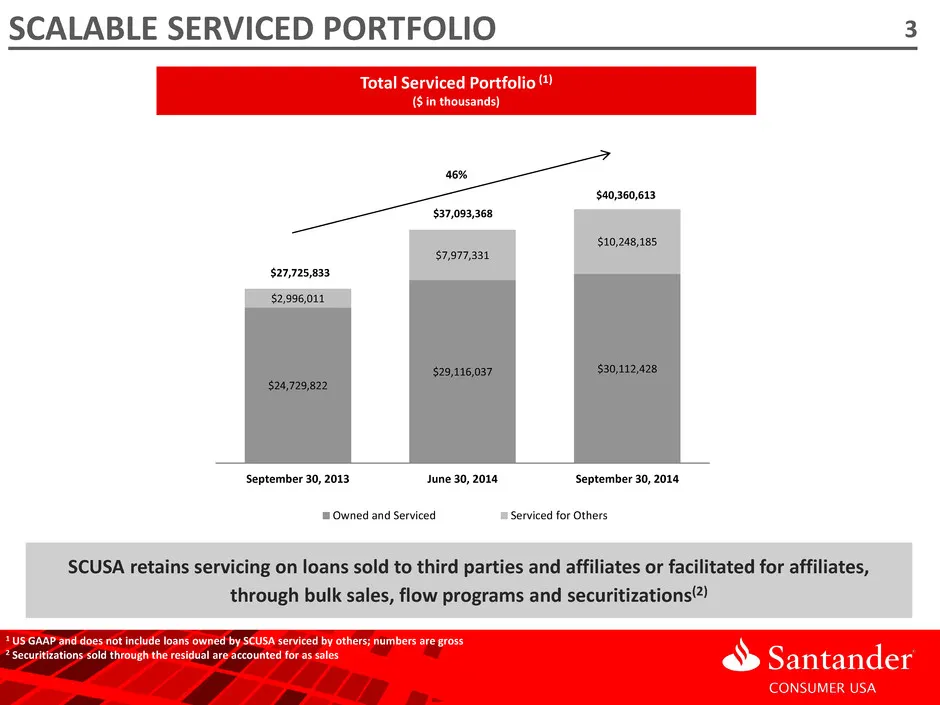
$24,729,822 $29,116,037 $30,112,428 $2,996,011 $7,977,331 $10,248,185 September 30, 2013 June 30, 2014 September 30, 2014 Owned and Serviced Serviced for Others Total Serviced Portfolio (1) ($ in thousands) SCALABLE SERVICED PORTFOLIO SCUSA retains servicing on loans sold to third parties and affili
Slide 36: Loan Servicing Overview
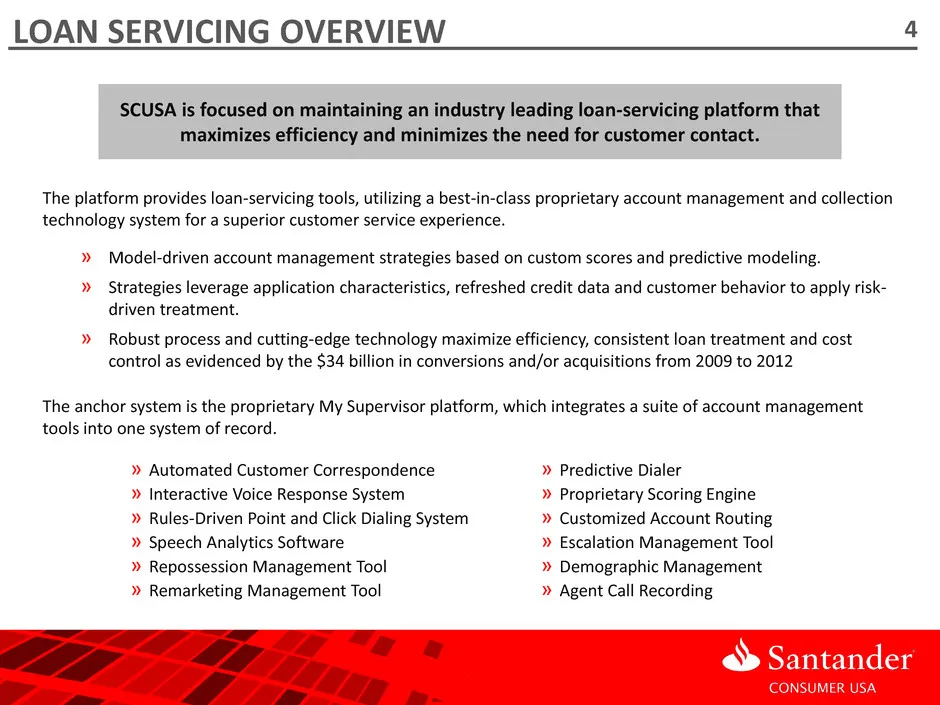
LOAN SERVICING OVERVIEW 42 » Automated Customer Correspondence » Interactive Voice Response System » Rules-Driven Point and Click Dialing System » Speech Analytics Software » Repossession Management Tool » Remarketing Management Tool » Predictive Dialer » Proprietary Scoring Engine » Customized Acco
Slide 37: Systemically Controlled Loan Servicing Platform
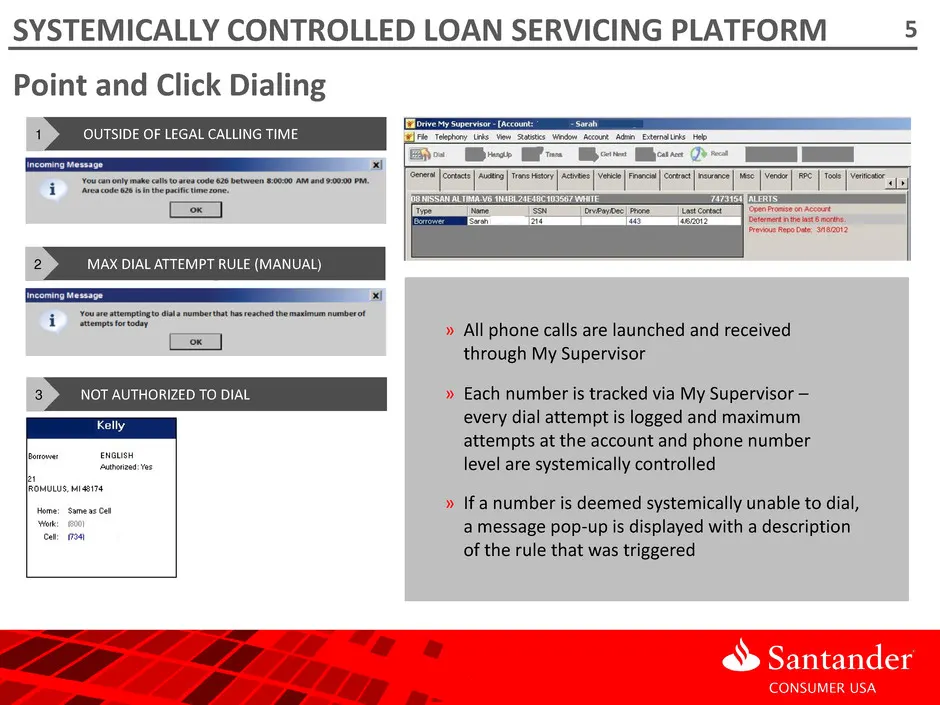
37 SYSTEMICALLY CONTROLLED LOAN SERVICING PLATFORM Point and Click Dialing OUTSIDE OF LEGAL CALLING TIME 1 MAX DIAL ATTEMPT RULE (MANUAL) 2 NOT AUTHORIZED TO DIAL 3 » All phone calls are launched and received through My Supervisor » Each number is tracked via My Supervisor – every dial attempt is lo
Slide 38: Loan Treatment Review
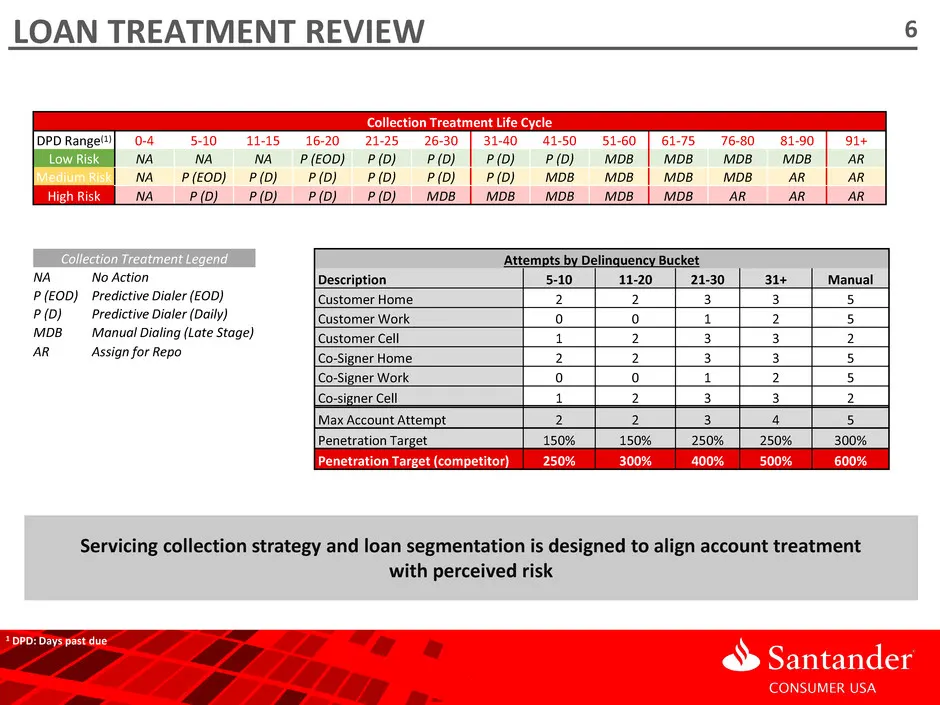
LOAN TREATMENT REVIEW Collection Treatment Life Cycle DPD Range(1) 0-4 5-10 11-15 16-20 21-25 26-30 31-40 41-50 51-60 61-75 76-80 81-90 91+ Low Risk NA NA NA P (EOD) P (D) P (D) P (D) P (D) MDB MDB MDB MDB AR Medium Risk NA P (EOD) P (D) P (D) P (D) P (D) P (D) MDB MDB MDB MDB AR AR High Risk NA P (
Slide 39: Multiple Approaches to Call Quality Assurance
MULTIPLE APPROACHES TO CALL QUALITY ASSURANCE » Real-time alerts allow us to take action during a call to remedy situations before they are escalated » Events that trigger alerts are calibrated on a monthly basis Real-time Speech Analytics Post-call Mining » Targeted Quality Assurance » Can monitor
Slide 40: Quality Assurance
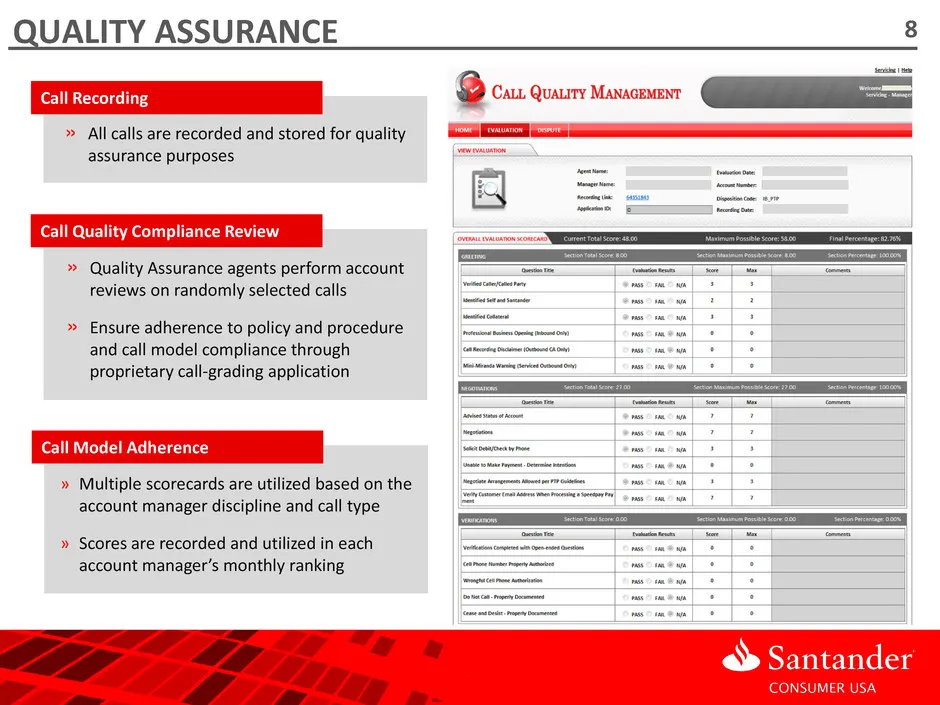
QUALITY ASSURANCE » All calls are recorded and stored for quality assurance purposes Call Recording » Quality Assurance agents perform account reviews on randomly selected calls » Ensure adherence to policy and procedure and call model compliance through proprietary call-grading application Call Qua
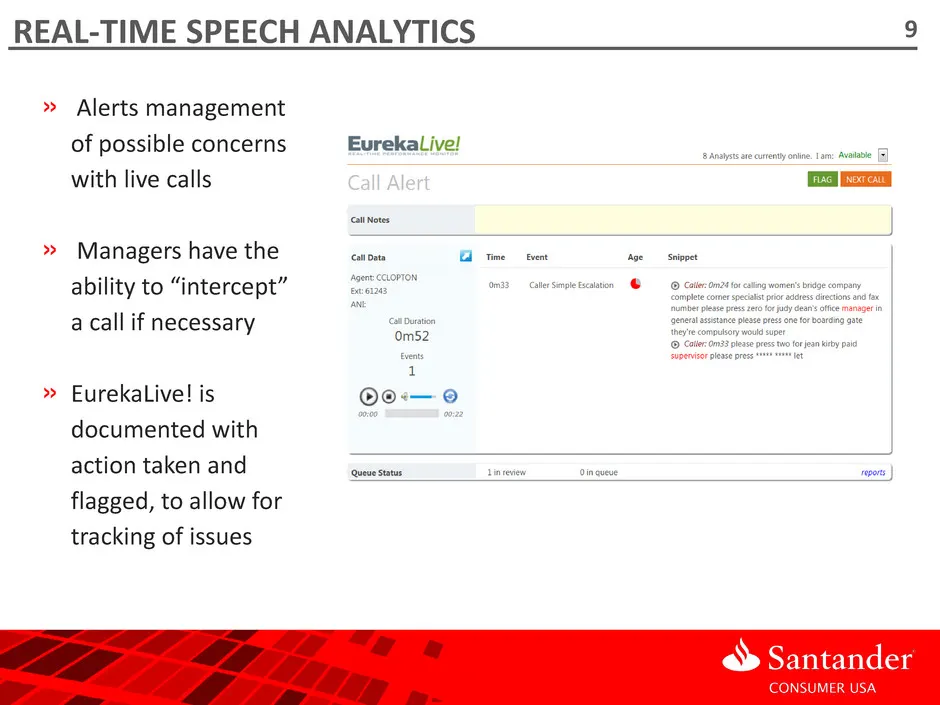
Slide 41: Real-Time Speech Analytics
REAL-TIME SPEECH ANALYTICS » Alerts management of possible concerns with live calls » Managers have the ability to “intercept” a call if necessary » EurekaLive! is documented with action taken and flagged, to allow for tracking of issues 9
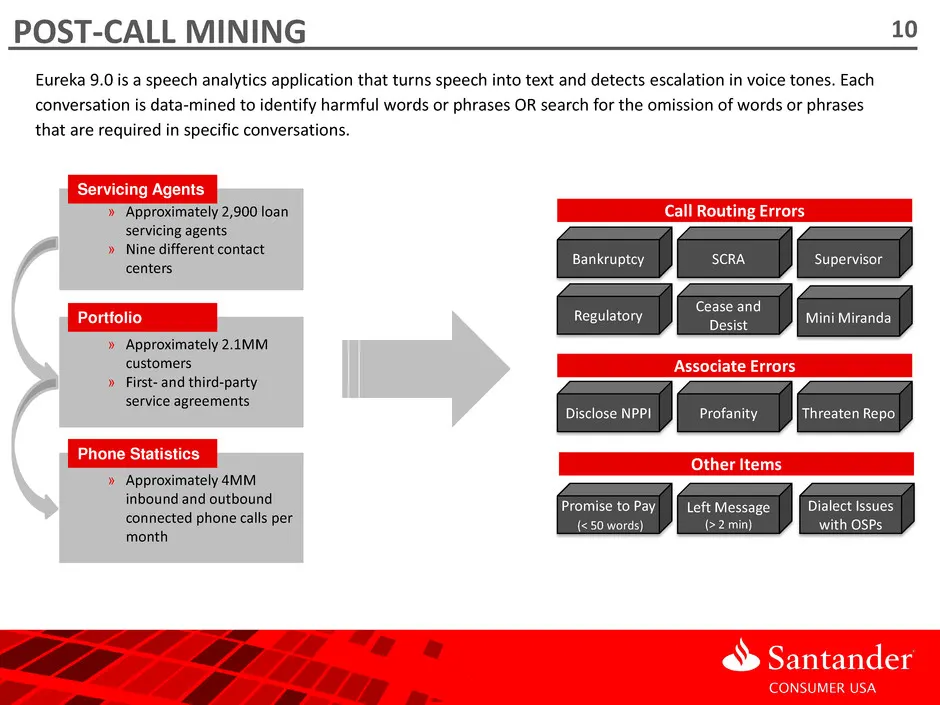
Slide 42: Post-Call Mining
POST-CALL MINING Eureka 9.0 is a speech analytics application that turns speech into text and detects escalation in voice tones. Each conversation is data-mined to identify harmful words or phrases OR search for the omission of words or phrases that are required in specific conversations. Bankruptcy
Slide 43: Strictly Private & Confidential
Strictly Private & Confidential
Slide 44: CEO / CFO Remarks
CEO / CFO REMARKS Tom Dundon Chairman and Chief Executive Officer Jason Kulas President and Chief Financial Officer
Slide 45: Consistent Vintage Profitability
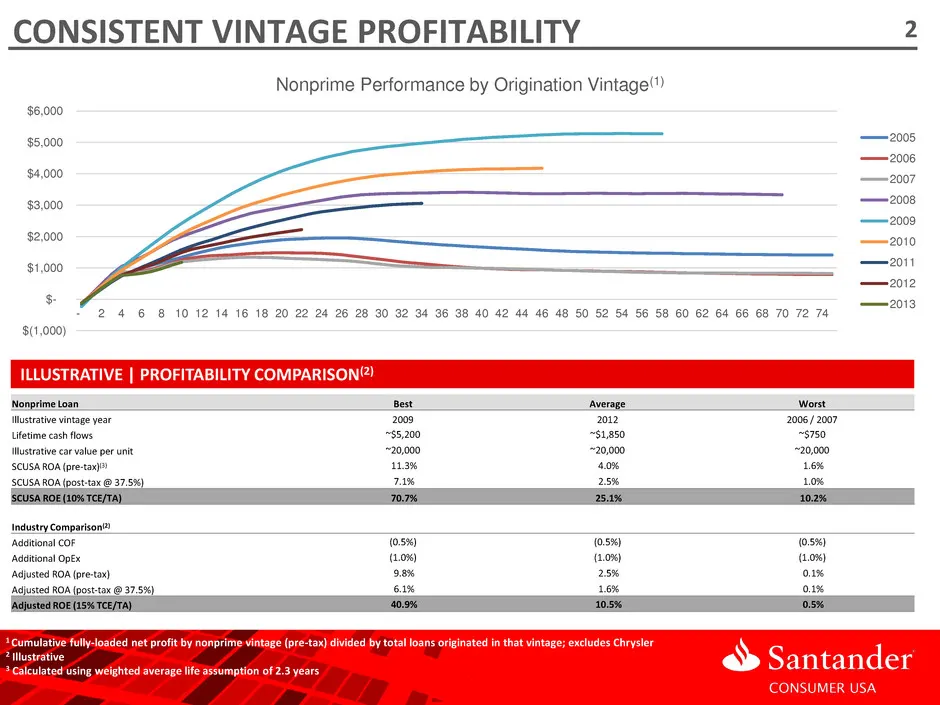
CONSISTENT VINTAGE PROFITABILITY 1 Cumulative fully-loaded net profit by nonprime vintage (pre-tax) divided by total loans originated in that vintage; excludes Chrysler 2 Illustrative 3 Calculated using weighted average life assumption of 2.3 years Nonprime Loan Best Average Worst Illustrative vinta
Slide 46: The Cyclical Nature of Our Business Explained
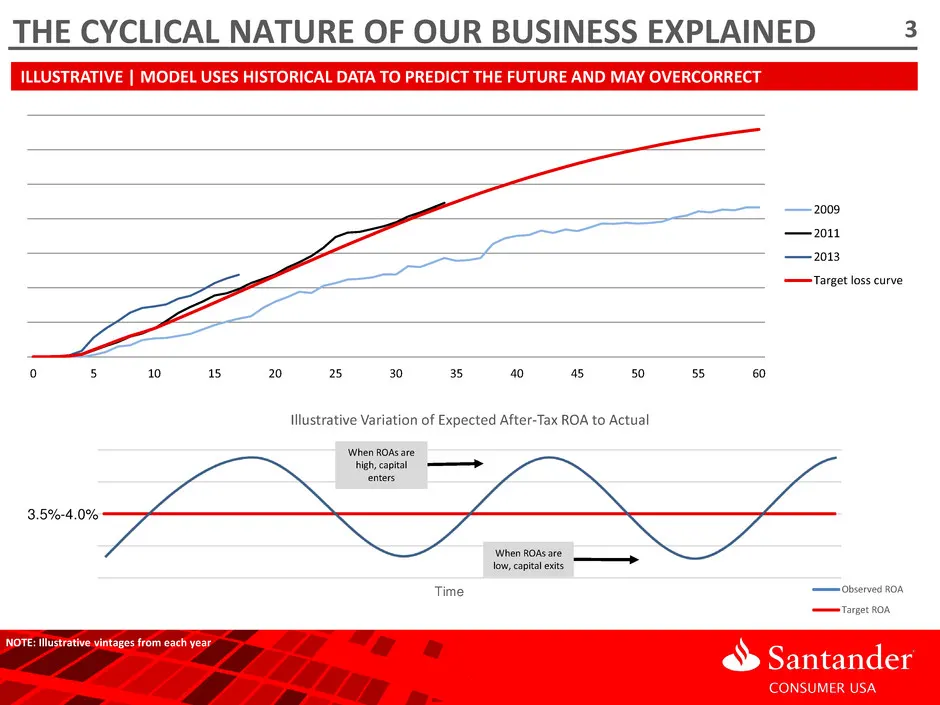
Time Illustrative Variation of Expected After-Tax ROA to Actual Observed ROA Target ROA When ROAs are low, capital exits When ROAs are high, capital enters 3.5%-4.0% 0 5 10 15 20 25 30 35 40 45 50 55 60 2009 2011 2013 Target loss curve NOTE: Illustrative vintages from each year THE CYCLICAL NATURE O
Slide 47: 12-Month Aging Provides Increased Certainty
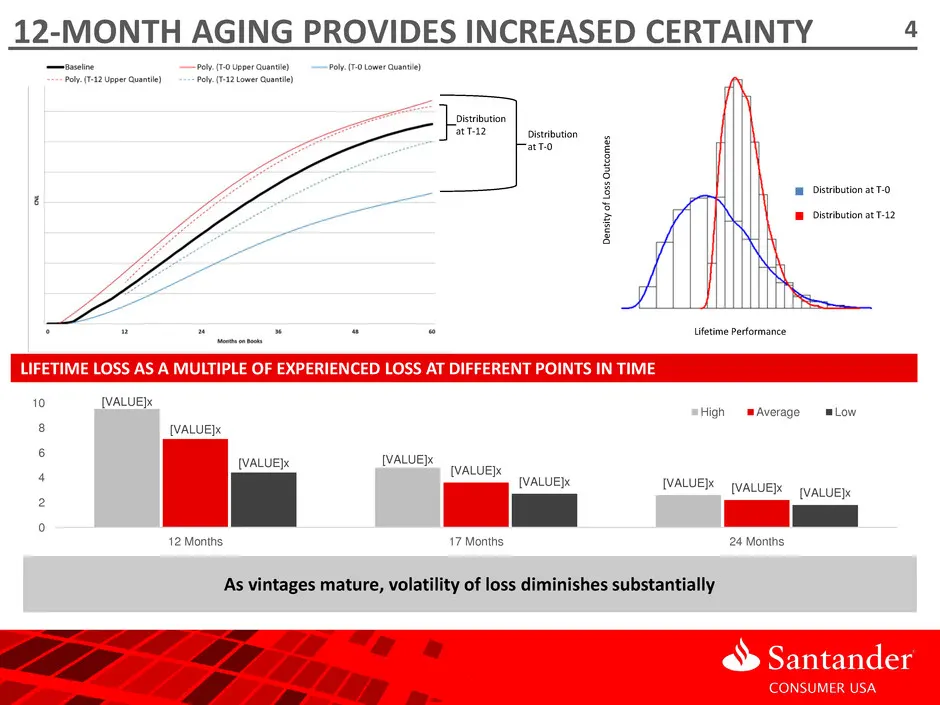
12-MONTH AGING PROVIDES INCREASED CERTAINTY As vintages mature, volatility of loss diminishes substantially LIFETIME LOSS AS A MULTIPLE OF EXPERIENCED LOSS AT DIFFERENT POINTS IN TIME Distribution at T-0 Distribution at T-12 Lifetime Performance D en si ty o f Lo ss O u tc o m es Distribution at T-0
Slide 48: Investment Rationale
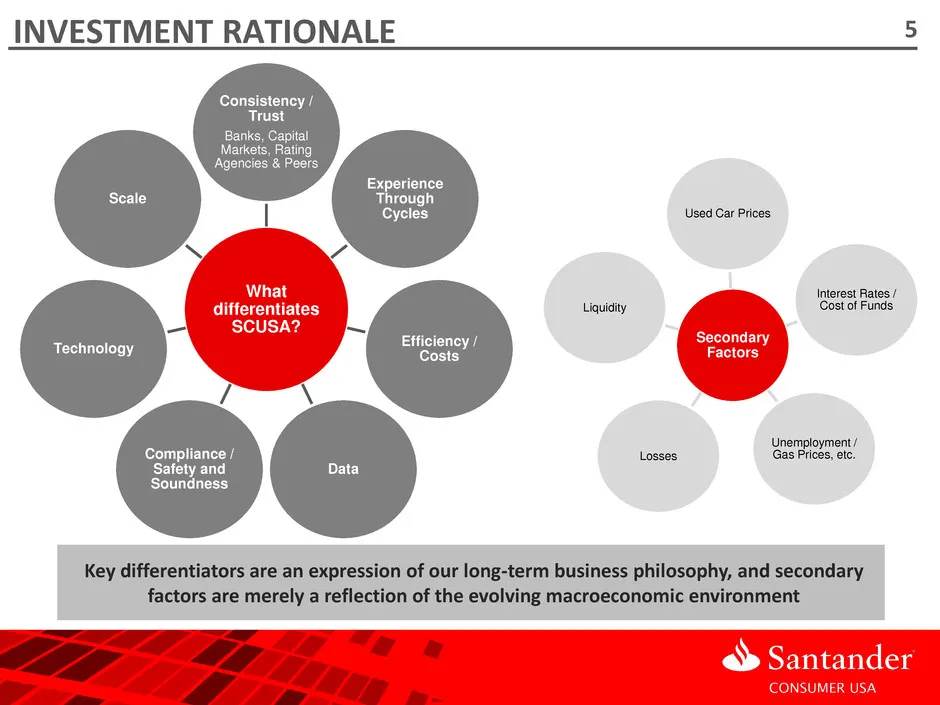
INVESTMENT RATIONALE What differentiates SCUSA? Consistency / Trust Banks, Capital Markets, Rating Agencies & Peers Experience Through Cycles Efficiency / Costs Data Compliance / Safety and Soundness Technology Scale Secondary Factors Used Car Prices Interest Rates / Cost of Funds Unemployment / Gas
Slide 49: Appendix
APPENDIX @® Santander CONSUMER USA
Slide 50: Company Organization
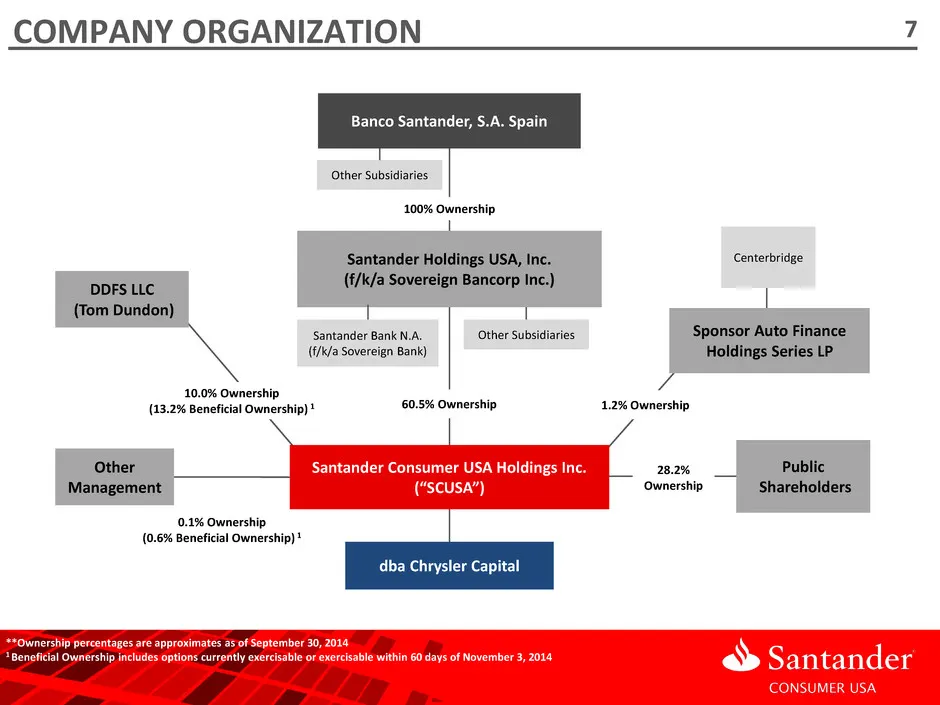
COMPANY ORGANIZATION **Ownership percentages are approximates as of September 30, 2014 1 Beneficial Ownership includes options currently exercisable or exercisable within 60 days of November 3, 2014 Banco Santander, S.A. Spain dba Chrysler Capital Other Subsidiaries Centerbridge Other Subsidiaries S
Slide 51: Seasonality Effects
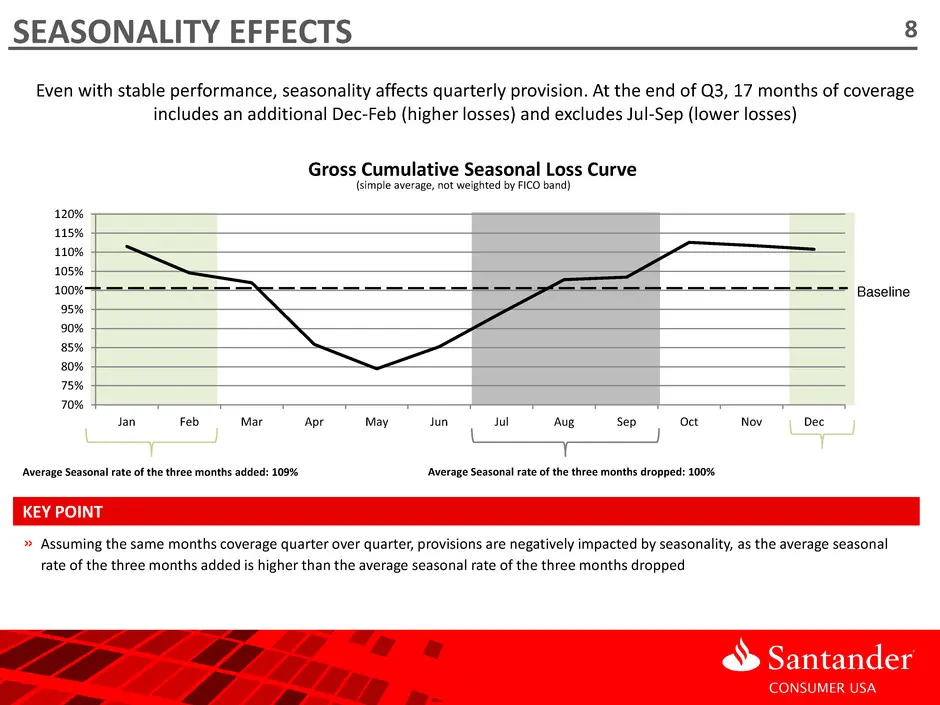
SEASONALITY EFFECTS 70% 75% 80% 85% 90% 95% 100% 105% 110% 115% 120% Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec Gross Cumulative Seasonal Loss Curve » Assuming the same months coverage quarter over quarter, provisions are negatively impacted by seasonality, as the average seasonal rate of the t
Slide 52: Q3 Loan Loss Allowance Walk
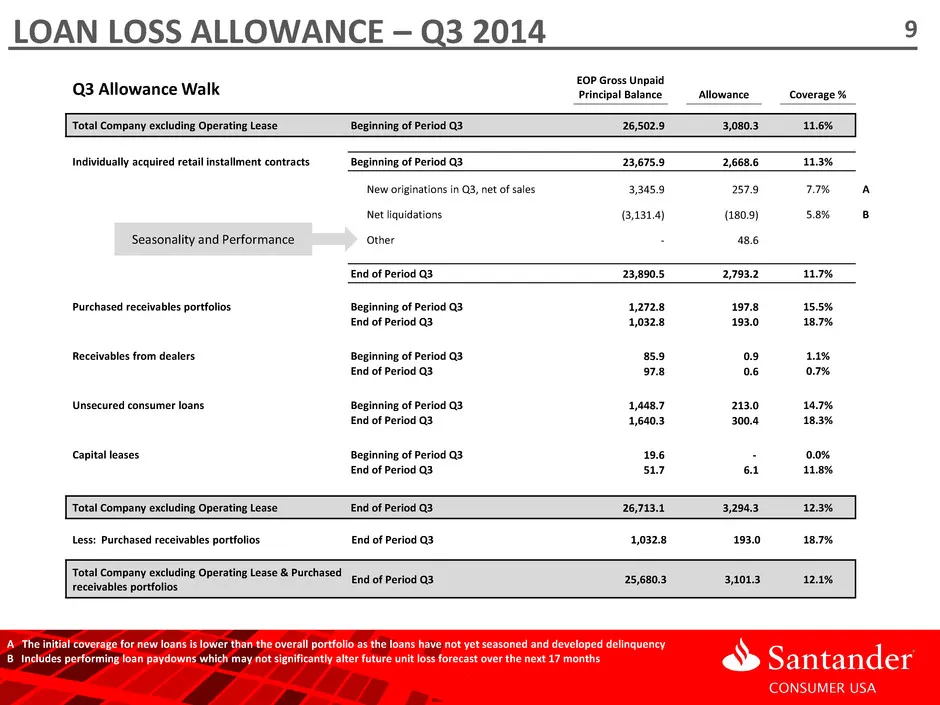
Q3 Allowance Walk EOP Gross Unpaid Principal Balance Allowance Coverage % Total Company excluding Operating Lease Beginning of Period Q3 26,502.9 3,080.3 11.6% Individually acquired retail installment contracts Beginning of Period Q3 23,675.9 2,668.6 11.3% New originations in Q3, net of sales 3,345.
Slide 53: Loan Loss Allowance – Q2 2014
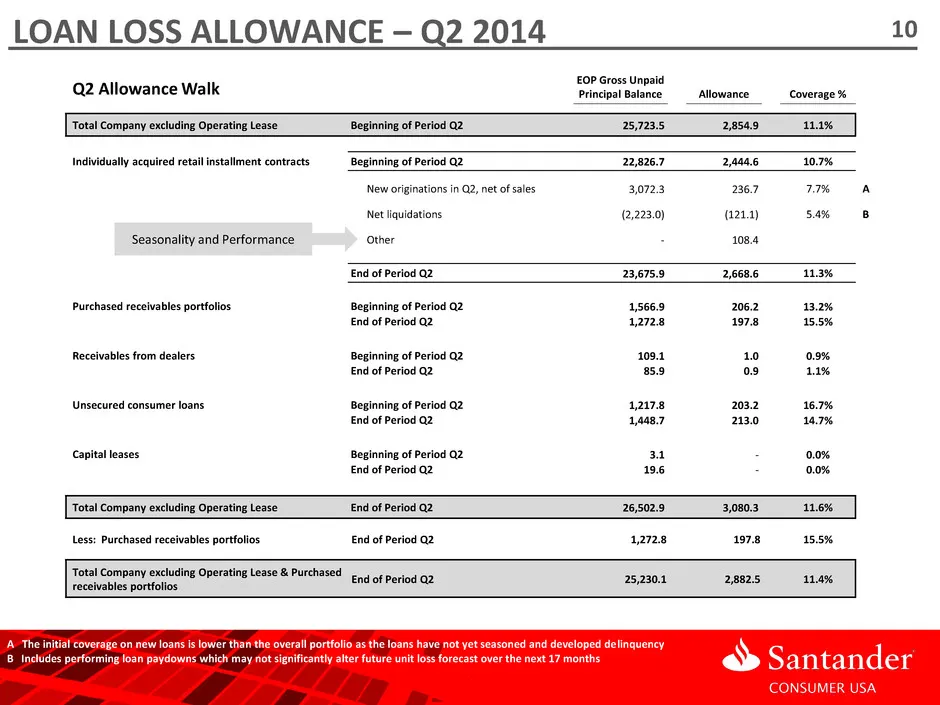
LOAN LOSS ALLOWANCE – Q2 2014 Q2 Allowance Walk EOP Gross Unpaid Principal Balance Allowance Coverage % Total Company excluding Operating Lease Beginning of Period Q2 25,723.5 2,854.9 11.1% Individually acquired retail installment contracts Beginning of Period Q2 22,826.7 2,444.6 10.7% New originati
Slide 54: Consolidated Balance Sheet
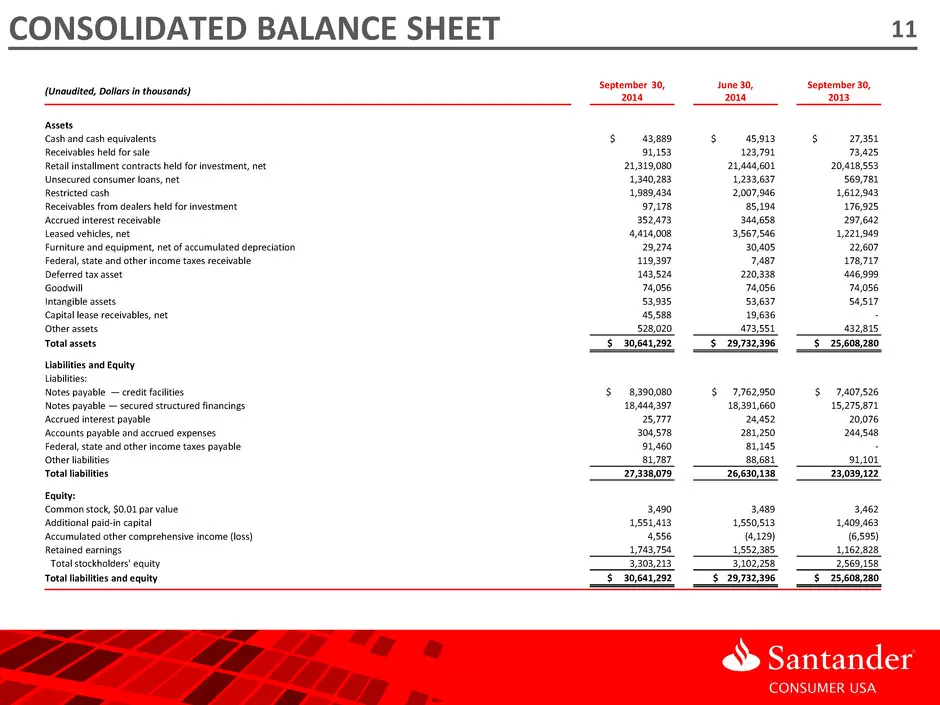
CONSOLIDATED BALANCE SHEET (Unaudited, Dollars in thousands) September 30, 2014 June 30, 2014 September 30, 2013 Assets Cash and cash equivalents $ 43,889 $ 45,913 $ 27,351 Receivables held for sale 91,153 123,791 73,425 Retail installment contracts held for investment, net 21,319,080 21,444,601 20,
Slide 55: Consolidated Income Statement
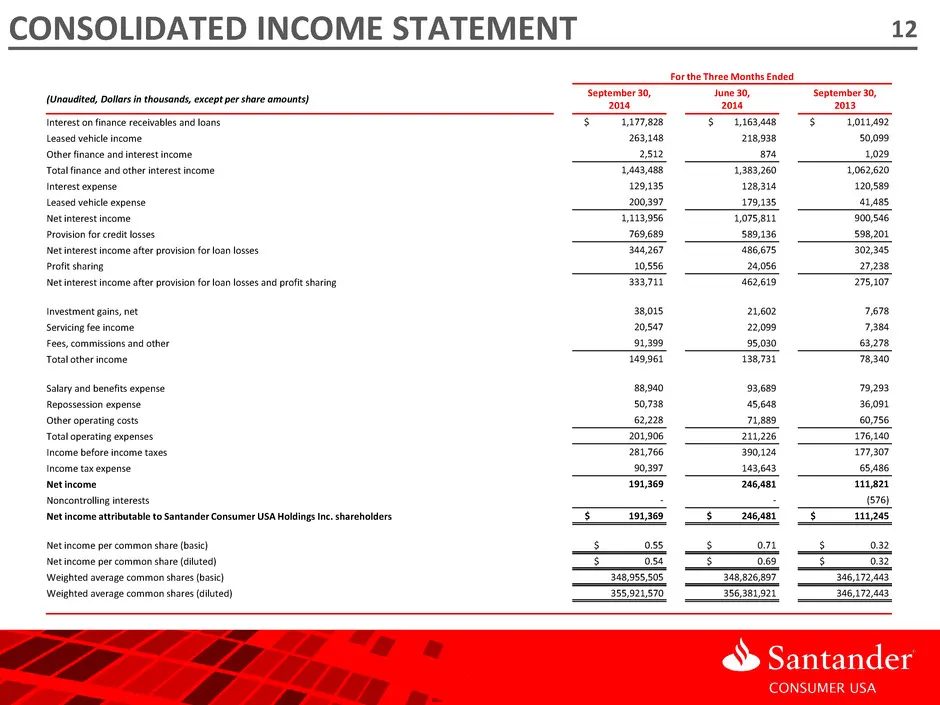
CONSOLIDATED INCOME STATEMENT For the Three Months Ended (Unaudited, Dollars in thousands, except per share amounts) September 30, 2014 June 30, 2014 September 30, 2013 Interest on finance receivables and loans $ 1,177,828 $ 1,163,448 $ 1,011,492 Leased vehicle income 263,148 218,938 50,099 Other fi
Slide 56: 3Q14: Performance
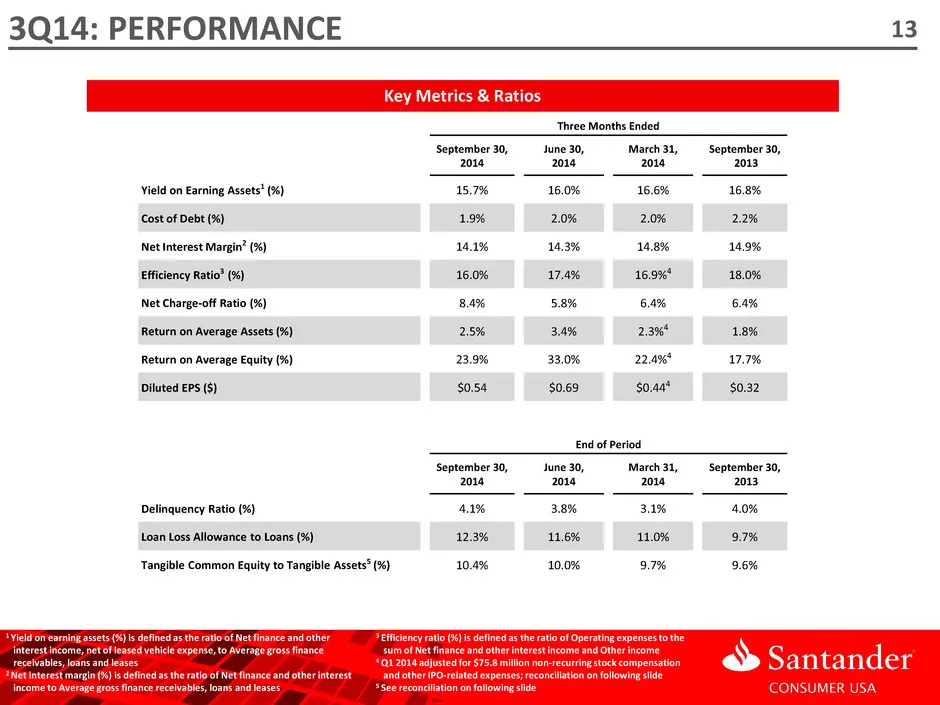
3Q14: PERFORMANCE 1 Yield on earning assets (%) is defined as the ratio of Net finance and other interest income, net of leased vehicle expense, to Average gross finance receivables, loans and leases 2 Net interest margin (%) is defined as the ratio of Net finance and other interest income to Averag
Slide 57: Reconciliation of Non-GAAP Measures
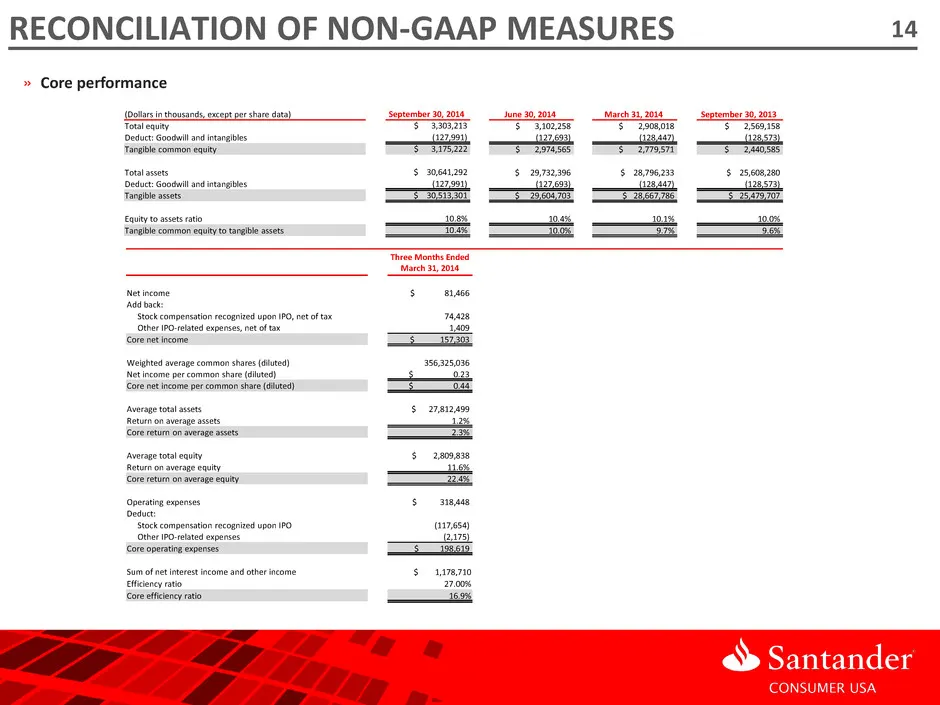
RECONCILIATION OF NON-GAAP MEASURES » Core performance (Dollars in thousands, except per share data) September 30, 2014 June 30, 2014 March 31, 2014 September 30, 2013 June 30, 2013 Total equity $ 3,303,213 $ 3,102,258 $ 2,908,018 $ 2,569,158 $ 2,470,063 Deduct: Goodwill and intangibles (127,991) (1
Slide 58: Strictly Private & Confidential
Strictly Private & Confidential
Source: SEC EDGAR · 8-K filed Nov 18, 2014
More decks from Santander Consumer USA Holdings Inc
 Q3 2021 Earnings Presentation24 slides · Oct 27, 2021
 Q2 2021 Earnings Presentation24 slides · Jul 28, 2021
 Q1 2021 Earnings Presentation24 slides · Apr 28, 2021
 FY2020 Earnings Presentation28 slides · Feb 3, 2021
 Q3 2020 Earnings Presentation25 slides · Oct 28, 2020
 Q2 2020 Earnings Presentation26 slides · Jul 29, 2020