Copano Energy L.L.C — Investor Presentation (August 2010)
47 slides from Copano Energy L.L.C's investor presentation, Aug 31, 2010
Slide 1: September 2010 Investor Presentation
September 2010 Investor Presentation NASDAQ: CPNO
Slide 2: Disclaimer
Disclaimer This presentation includes “forward-looking statements,” as defined in the federal securities laws. Statements that address activities, or events that Copano believes will or may occur in the future are forward-looking statements. These statements include, but are not limited to, statemen
Slide 3: Introduction to Copano
Introduction to Copano Independent midstream company founded in 1992 ■ Best in class service to customers ■ Entrepreneurial approach ■ Focus on long-term accretive growth Provides midstream services in multiple producing areas through three operating segments ■ South and north Texas ● Conventional,
Slide 4: Key Metrics
Key Metrics Service throughput volumes approximate 1.8 Bcf/d of natural gas (1) Over 6,700 miles of active pipelines 8 natural gas processing plants with over 1.1 Bcf/d of combined processing capacity One NGL fractionation facility with total capacity of 22,000 Bbls/d Equity market cap: $1.8 billion
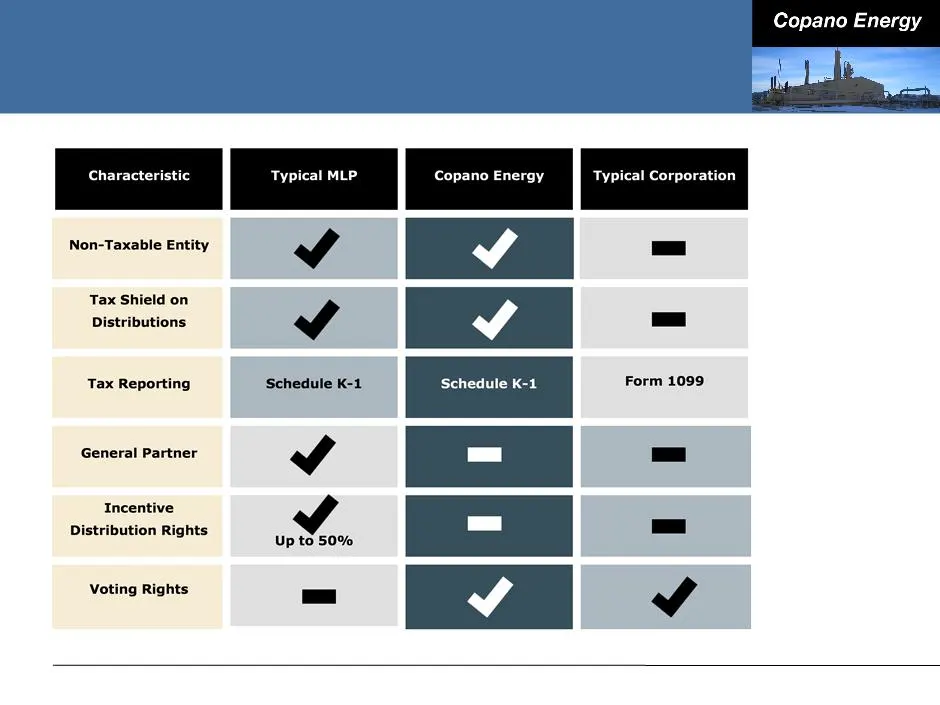
Slide 5: Characteristic comparison: Typical MLP vs Copano Energy
Characteristic Non-Taxable Entity Tax Reporting General Partner Incentive Distribution Rights Voting Rights Typical MLP ‘Schedule K-1 Form 1099 v Copano Energy
Slide 6: Growth Strategy
Growth Strategy Goal: to become a diversified midstream company with scale and stability of cash flows, above-average returns on invested capital and “investment-grade quality distributions” Key tenets of growth strategy: ■ Execute on organic growth opportunities around existing assets ■ Explore opp
Slide 7: Agenda
Agenda 2010 Outlook Commodity Prices and Margin Sensitivities Financing and Commodity Risk Management Conclusions
Slide 8: 2010 Outlook
2010 Outlook Texas ■ Significant drilling and development activity in the Barnett Shale Combo play ■ Ramp up of Eagle Ford Shale directed drilling Oklahoma ■ Moderate drilling activity behind the Hunton De-Watering play ■ Strong drilling activity in the Woodford Shale play Rocky Mountains ■ Minimal
Slide 9: Texas Outlook
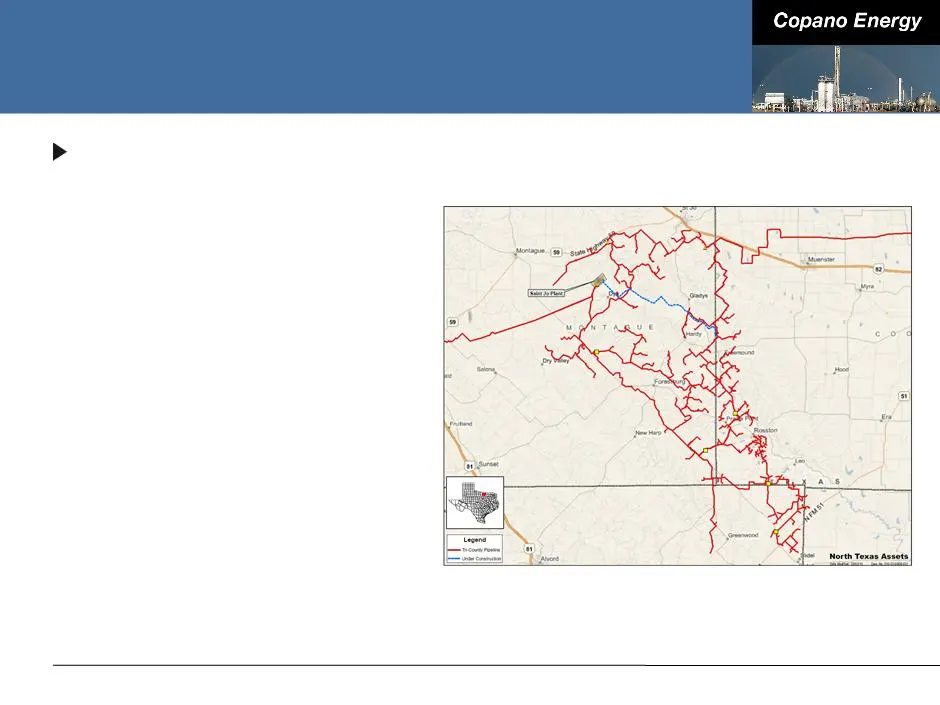
Texas Outlook Saint Jo gathering system ■ 15 rigs running in the area with as many as 2 more anticipated later this year ● Leasing activity continues ■ Crude oil play with associated gas requiring a full slate of midstream services ■ Based on producer drilling schedule, expect steady increase in pla
Slide 10: Texas Outlook
Texas Outlook Eagle Ford Shale play ■ Copano’s current asset base strategically positioned ● Houston Central complex located within 50 miles of the rich gas core of the play ■ 22,000 BPD fractionator placed in service April 2010 ■ 9 Eagle Ford Shale wells connected to date and expect to connect 8 -
Slide 11: Texas Recent Developments
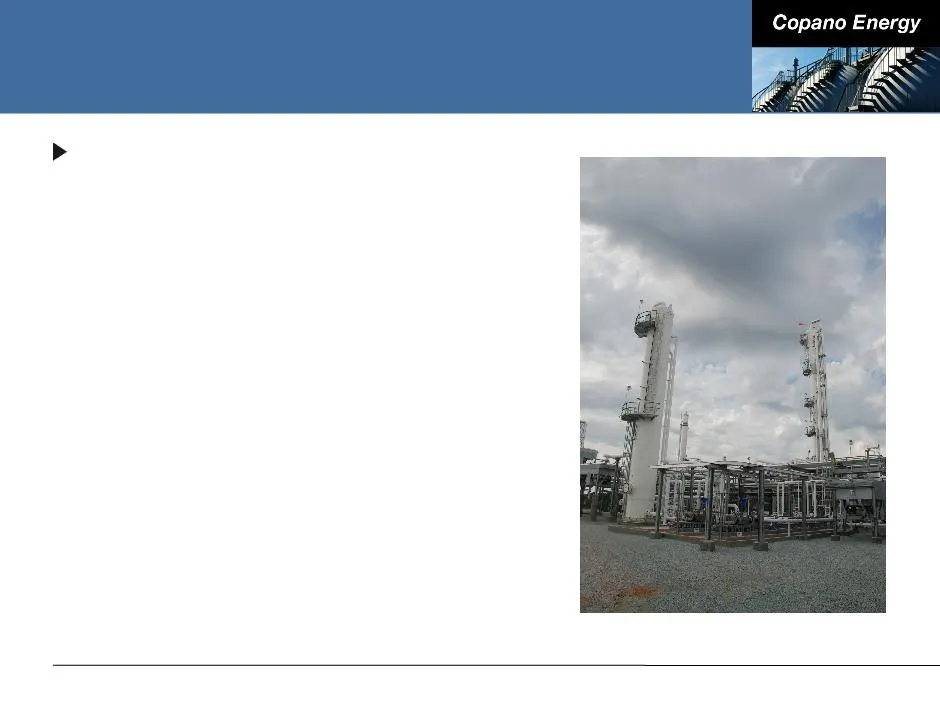
Texas Recent Developments Saint Jo plant ■ Earlier this year, executed key producer contract with highly rated producer ● Long-term gathering, treating and processing agreement ● Fee-for-service contract ■ Additional 50 MMcf/d of compression expected to be in service early 4Q 2010, bringing total pl
Slide 12: DeWitt-Karnes Header
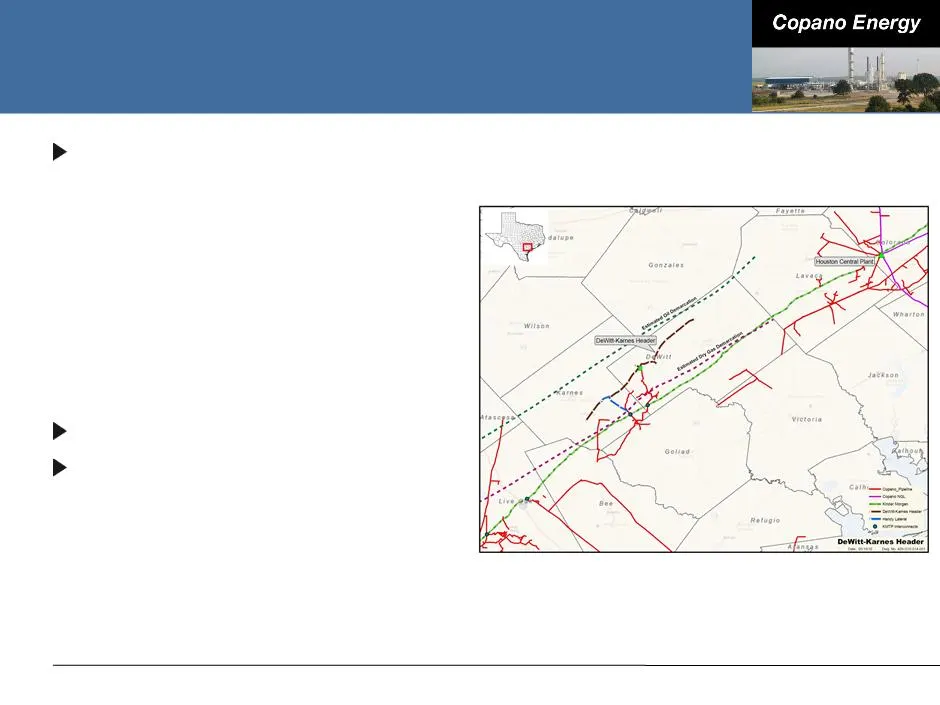
DeWitt-Karnes Header Nearing completion of previously announced DeWitt- Karnes header ■ 38 miles of 24” pipe ■ Initially 185 MMcf/d of capacity with ability to expand to 275 MMcf/d ■ Active producers in the vicinity include: Pioneer, ConocoPhillips, Petrohawk, GeoSouthern and Enduring Resources 11 r
Slide 13: Eagle Ford Gathering Joint Venture
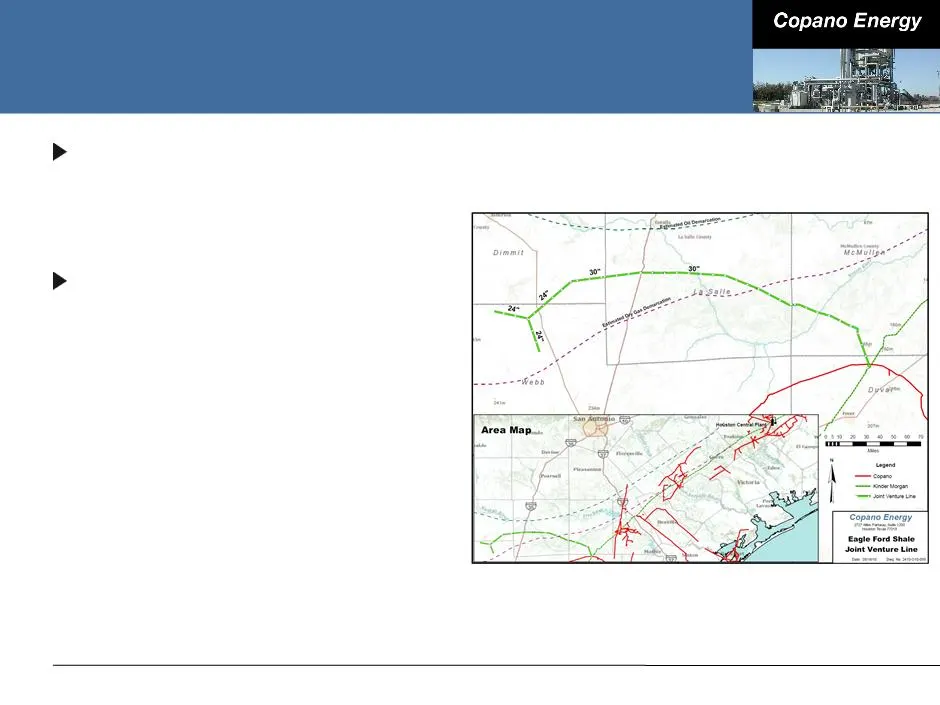
Eagle Ford Gathering Joint Venture Executed joint venture agreements with Kinder Morgan in May 2010 Gas services agreement between Copano/Kinder Morgan joint venture and SM Energy signed in July 2010 ■ Kicked off pipeline construction - expected to be completed summer 2011 ■ Approximately 85 miles o
Slide 14: Texas Fractionation Facility
Texas Fractionation Facility Responding to NGL transportation and fractionation constraints along the Texas Gulf Coast, Copano started its fractionator at Houston Central complex and began to deliver purity products to market in April 2010 ■ Total capacity of 22,000 Bbls/d ■ Approximate cost of $17
Slide 15: Oklahoma Outlook
Oklahoma Outlook Rich gas (primarily Hunton De-Watering play) ■ Drilling activity increased so far in 3Q 2010 ■ 2 rigs currently running in the Hunton and 15 rigs in other rich gas areas ■ Attractive processing upgrade and low geologic risk ■ 3Q 2010 volumes expected to be slightly up vs. 2Q 2010 Le
Slide 16: Woodford Shale Activity
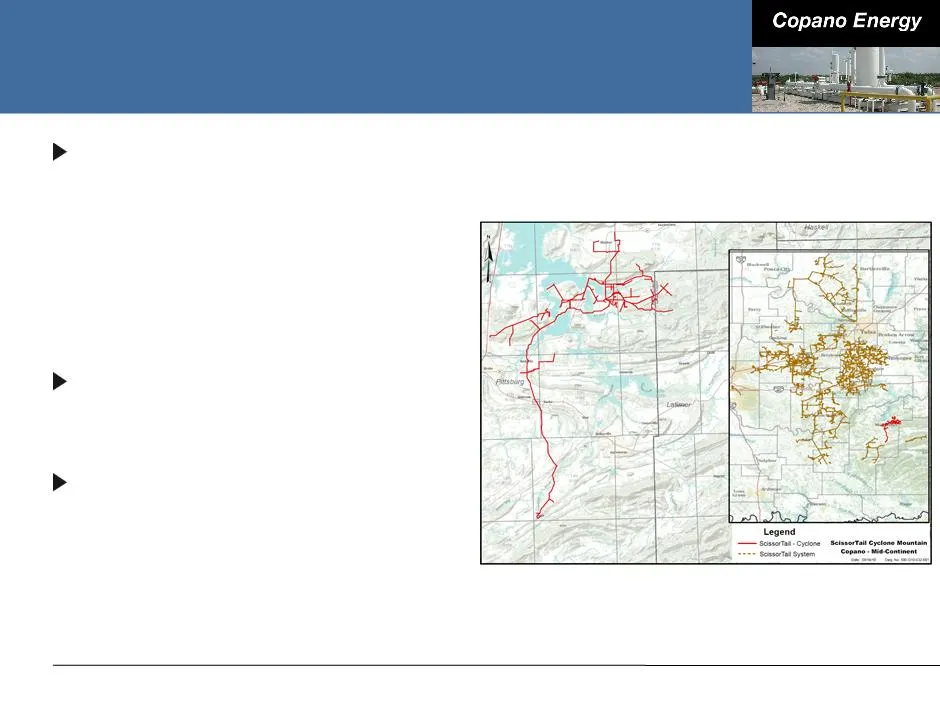
Woodford Shale Activity Significant drilling activity in the Woodford Shale around Copano’s Cyclone Mountain system ■ 2Q 2010 average volumes of approximately 58,000 MMbtu/d vs. 53,000 MMbtu/d in 1Q 2010 Primarily lean gas that requires compression and CO 2 treating Current system capacity approxima
Slide 17: Rocky Mountains Outlook
Rocky Mountains Outlook Drilling and dewatering will be driven by commodity prices and producer economics 3Q 2010 volumes for Bighorn expected to be slightly lower to flat vs. 2Q 2010 3Q 2010 volumes for Fort Union expected to be slightly higher vs. 2Q 2010 Adjusted EBITDA expected to be essentially
Slide 18: Commodity Prices and Margin Sensitivities
Commodity Prices and Margin Sensitivities 2010 Outlook Commodity Prices and Margin Sensitivities Financing and Commodity Risk Management Conclusions
Slide 19: Historical Commodity Prices
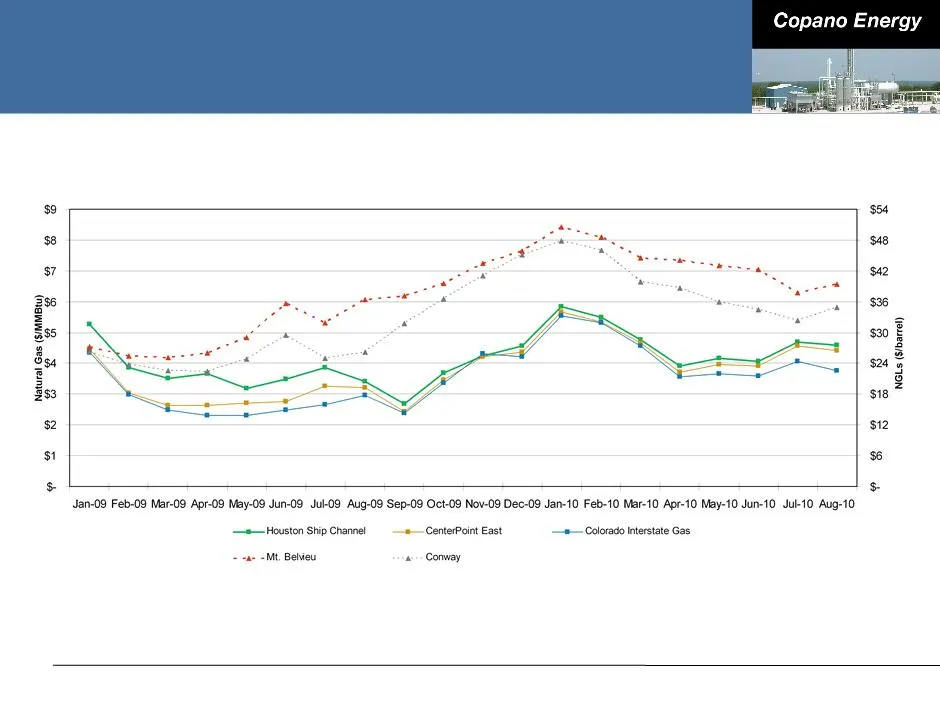
Historical Commodity Prices (1) Aug-10 NGL prices are month-to-date through Aug 20, 2010. (2) NGL prices for Jan-09 through Jun-10 are calculated based on the weighted-average product mix for the period indicated. NGL prices for Jul-10 through Aug-10 are calculated based on the second quarter 2010 p
Slide 20: Forward Commodity Prices
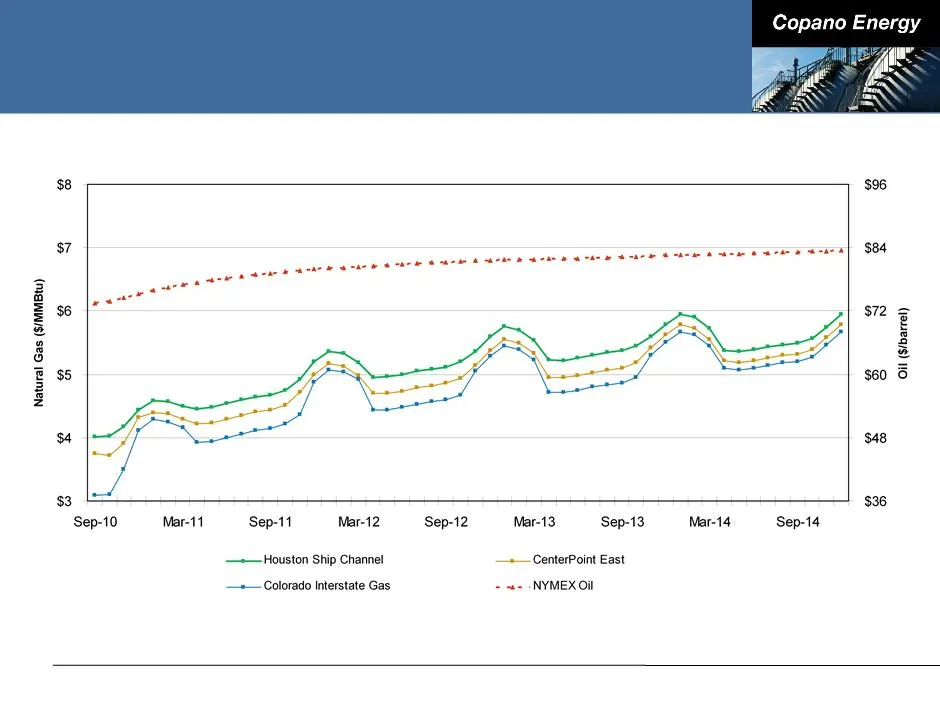
Forward Commodity Prices Note: Forward prices as of August 20, 2010
Slide 21: Combined Commodity-Sensitive Segment Margins and Hedging Settlements
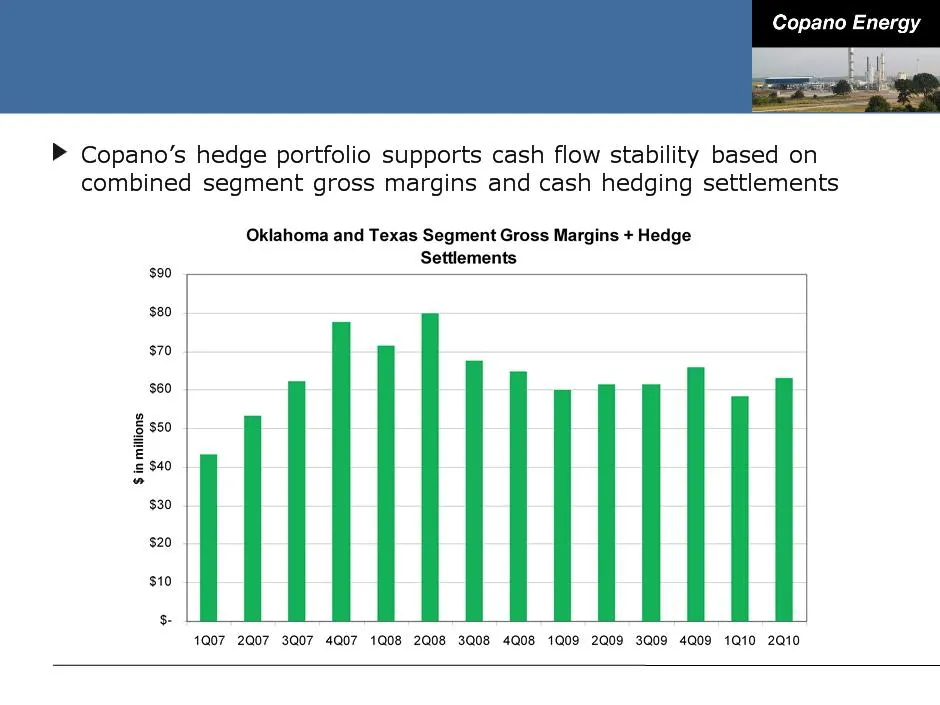
Combined Commodity-Sensitive Segment Margins and Hedging Settlements
Slide 22: Financing and Commodity Risk Management
Financing and Commodity Risk Management 2010 Outlook Commodity Prices and Margin Sensitivities Financing and Commodity Risk Management Conclusions
Slide 23: 2010 Expansion Capex
2010 Expansion Capex 2010 capital expansion budget increased from $130 million (1) in January to $172 million (1) today Major areas of focus include: ■ Eagle Ford Shale and Houston Central complex in south Texas ● DeWitt-Karnes pipeline ● Copano/Kinder Morgan joint venture ■ Saint Jo processing plan
Slide 24: Recent Preferred Equity Offering
Recent Preferred Equity Offering In July 2010 Copano issued $300 million of convertible preferred equity to affiliate of TPG Capital ■ Priced at $29.05 per unit - 10% premium to the 30-day volume weighted average price as of July 19, 2010 ■ Distributions paid in-kind for the first three years ($0.72
Slide 25: Hedging Strategy
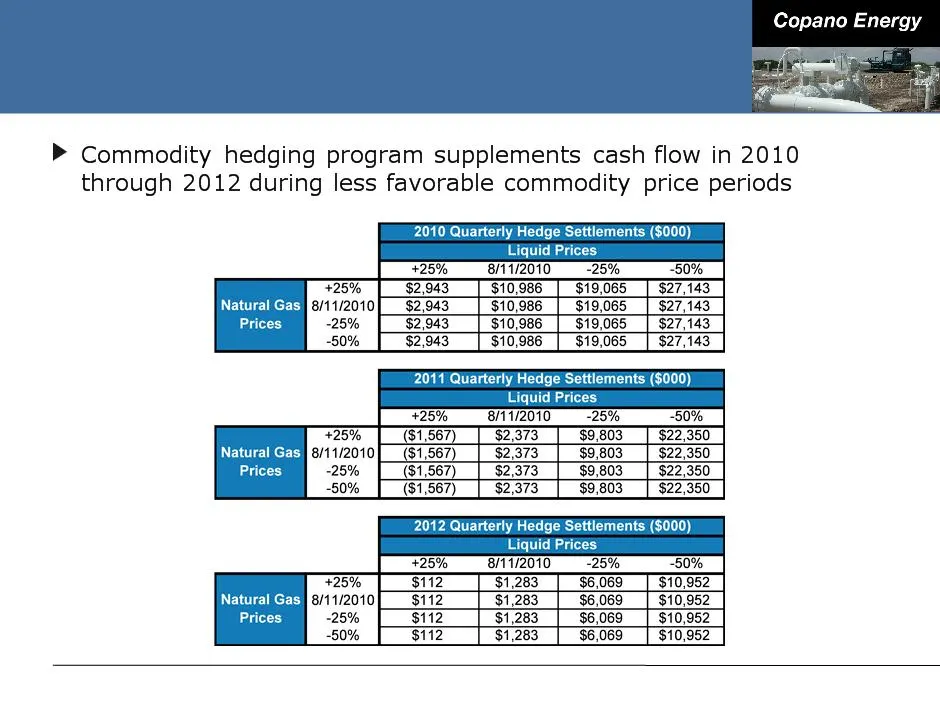
Hedging Strategy Option-based, product-specific 2010 price exposed volumes are well hedged ■ Between 70% and 80% of propane, butane, natural gasoline and condensate price exposure is hedged ■ Approximately 40% of ethane price exposure is hedged ■ Expect $32 - $34 million of non-cash amortization exp
Slide 26: Conclusions
Conclusions 2010 Outlook Commodity Prices and Margin Sensitivities Financing and Commodity Risk Management Conclusions
Slide 27: Conclusions
Conclusions Growth projects recently completed are expected to contribute to Total DCF as volumes come online ■ Volumes at Saint Jo plant increasing ■ Start-up of fractionator at Houston Central complex ■ Burbank plant in service ■ Portions of DeWitt-Karnes header in service Significant future growt
Slide 28: Copano Energy
Copano Energy
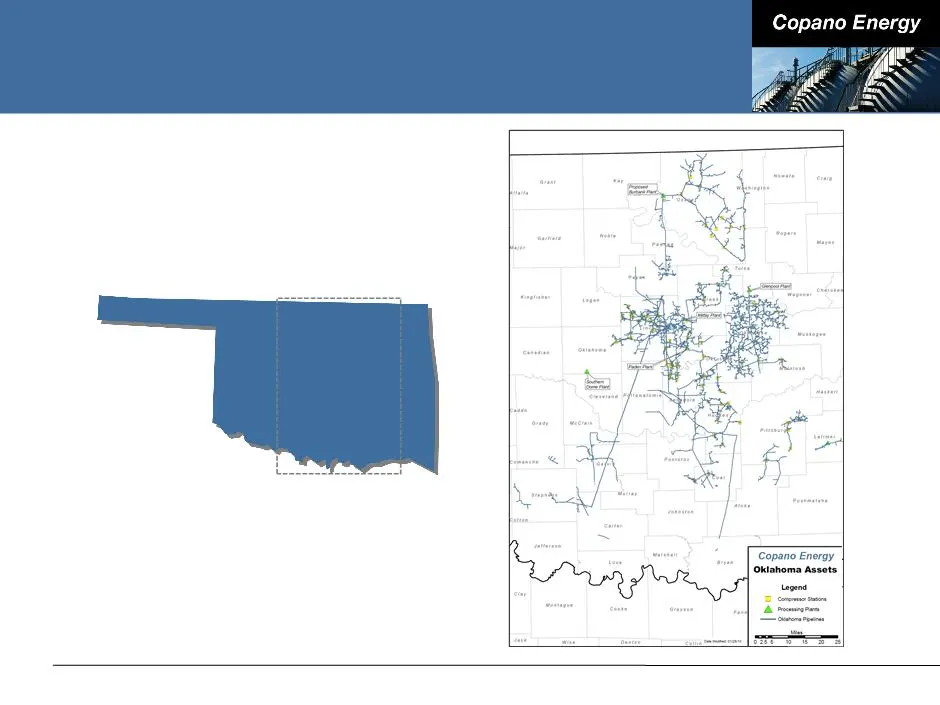
Slide 29: Oklahoma Assets
Oklahoma Assets OKLAHOMA
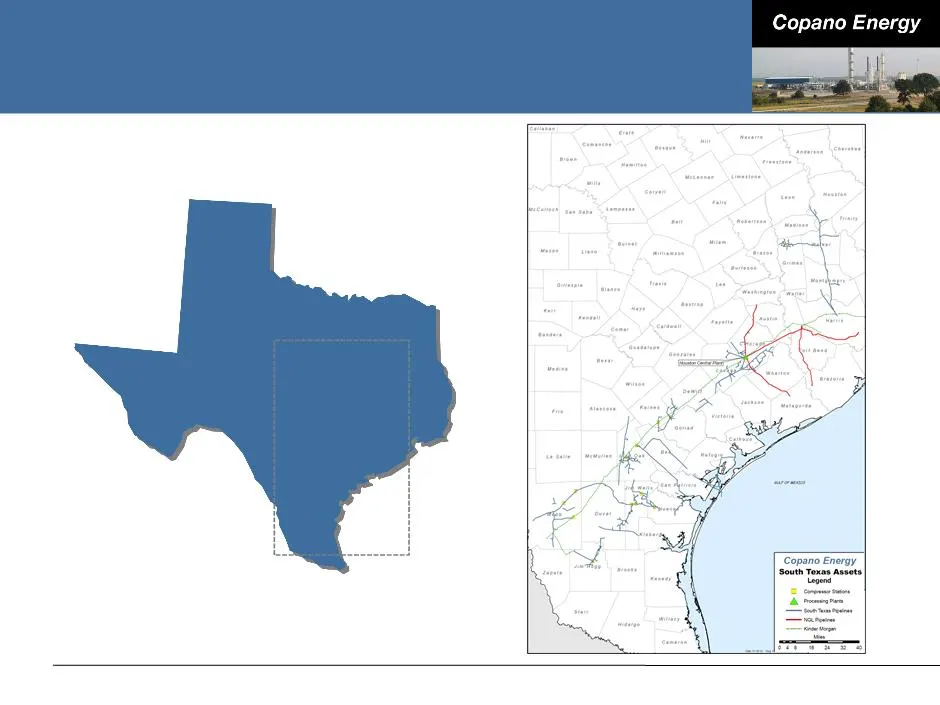
Slide 30: South Texas Assets
South Texas Assets TEXAS
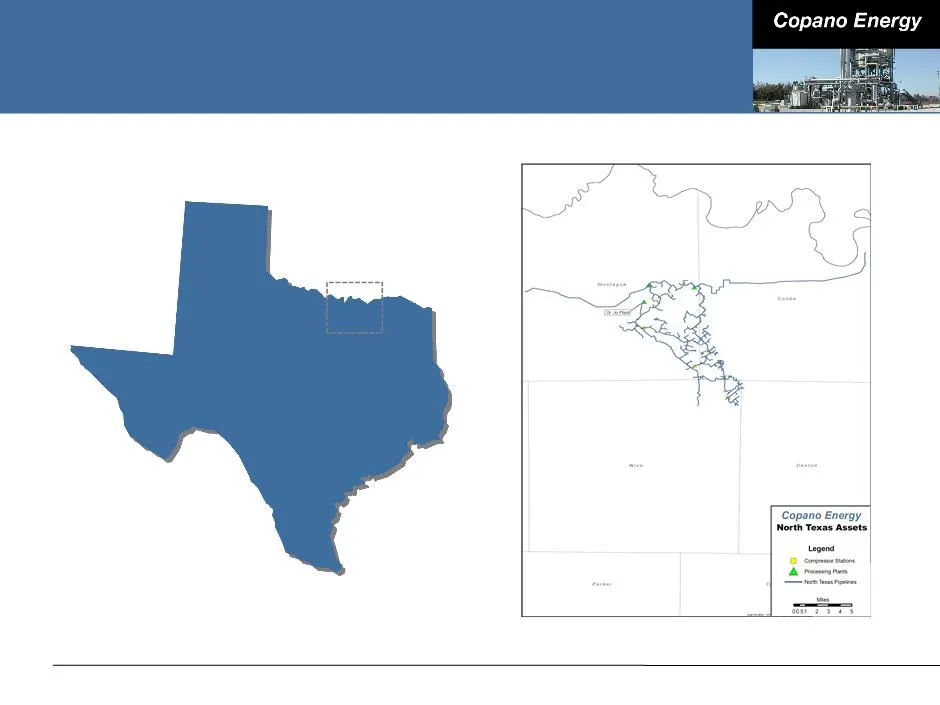
Slide 31: North Texas Assets
Copano Energy f ‘Copano Energy North Texas Assets
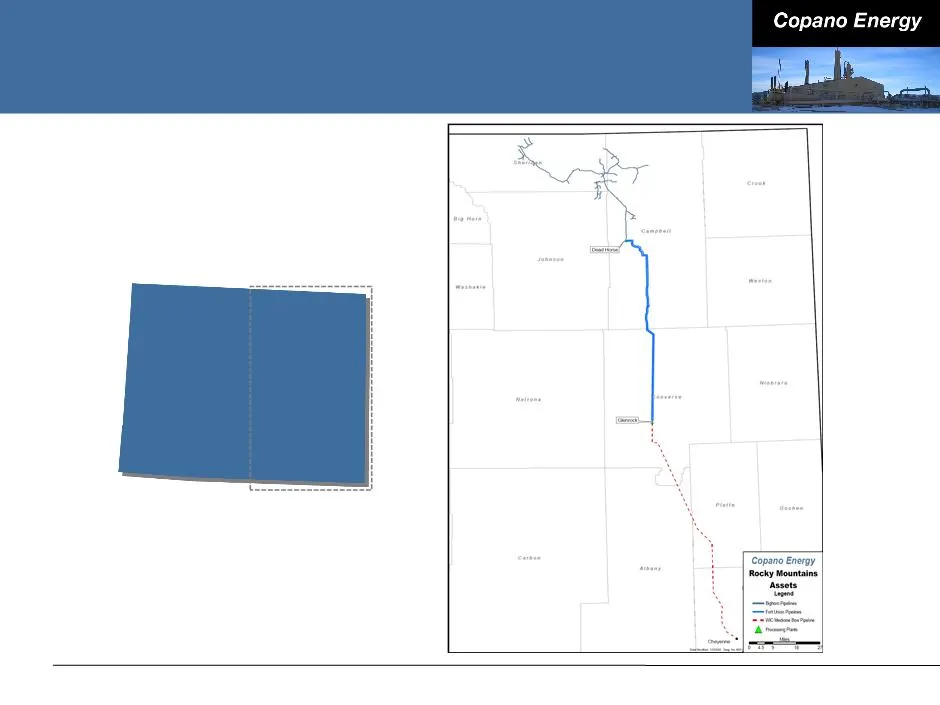
Slide 32: Rocky Mountains Assets
Rocky Mountains Assets WYOMING
Slide 33: Processing Modes
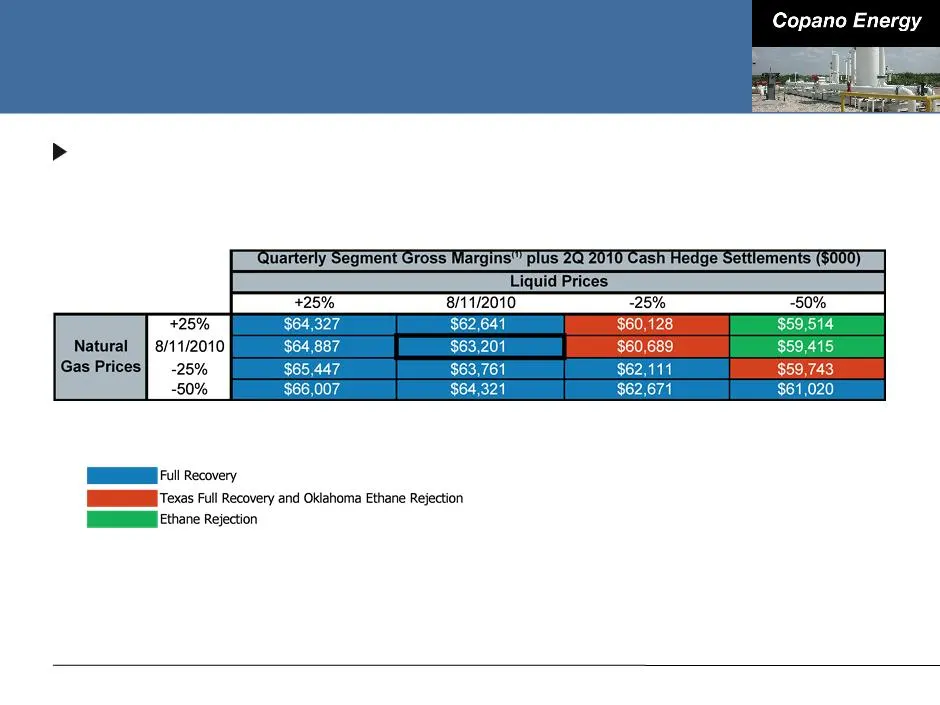
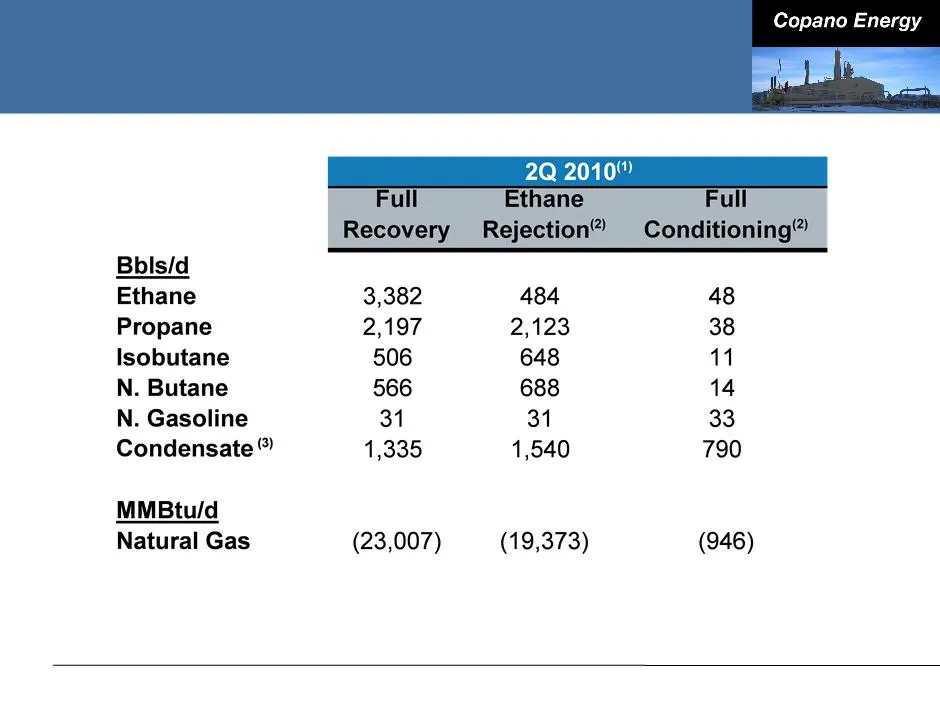
Processing Modes Full Recovery Texas and Oklahoma - If the value of recovered NGLs exceeds the fuel and gas shrinkage costs of recovering NGLs Ethane Rejection Texas and Oklahoma - If the value of ethane is less than the fuel and shrinkage costs to recover ethane (in Oklahoma, ethane rejection at Pa
Slide 34: Commodity-Related Margin Sensitivities
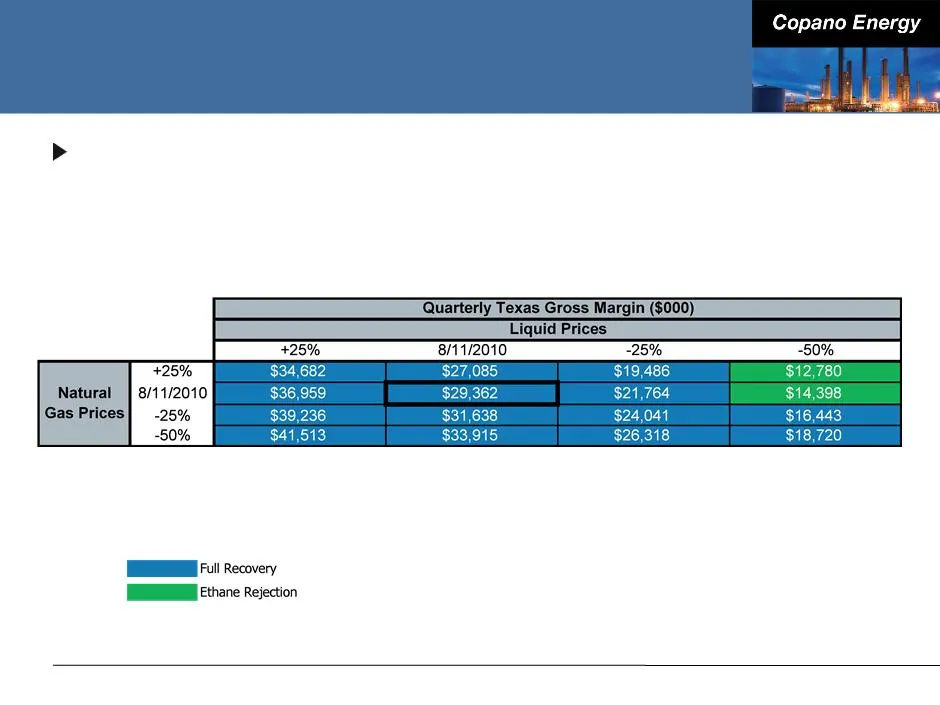
Commodity-Related Margin Sensitivities Matrix reflects 2Q 2010 wellhead and plant inlet volumes, adjusted using Copano’s 2010 planning model Note: Please see this Appendix for definitions of processing modes and additional details. (1) Consists of Texas and Oklahoma Segment gross margins.
Slide 35: Combined Commodity-Sensitive Segment Margins and Hedging Settlements
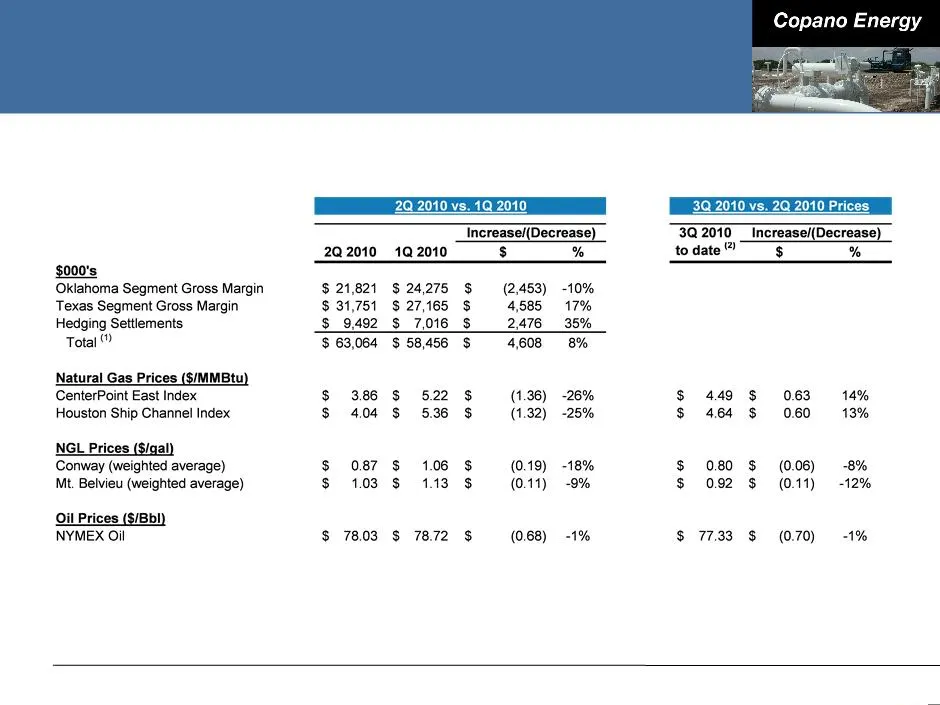
Combined Commodity-Sensitive Segment Margins and Hedging Settlements Note: Weighted average NGL prices are based on Copano product mix for period indicated. (1) Does not include non-cash expenses included in Corporate and Other for purposes of calculating Total Segment Gross Margin. See Appendix for
Slide 36: Oklahoma Contract Mix
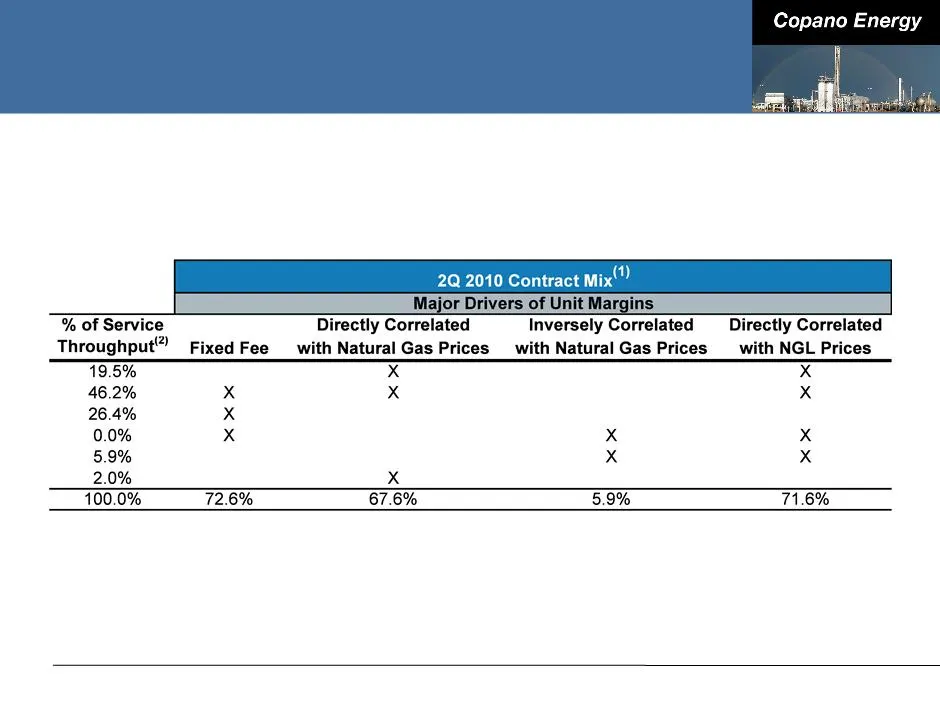
Oklahoma Contract Mix (1) Source: Copano Energy internal financial planning models for consolidated subsidiaries. (2) Excludes 12,689 MMBtu/d service throughput for Southern Dome, a majority-owned affiliate.
Slide 37: Oklahoma Net Commodity Exposure
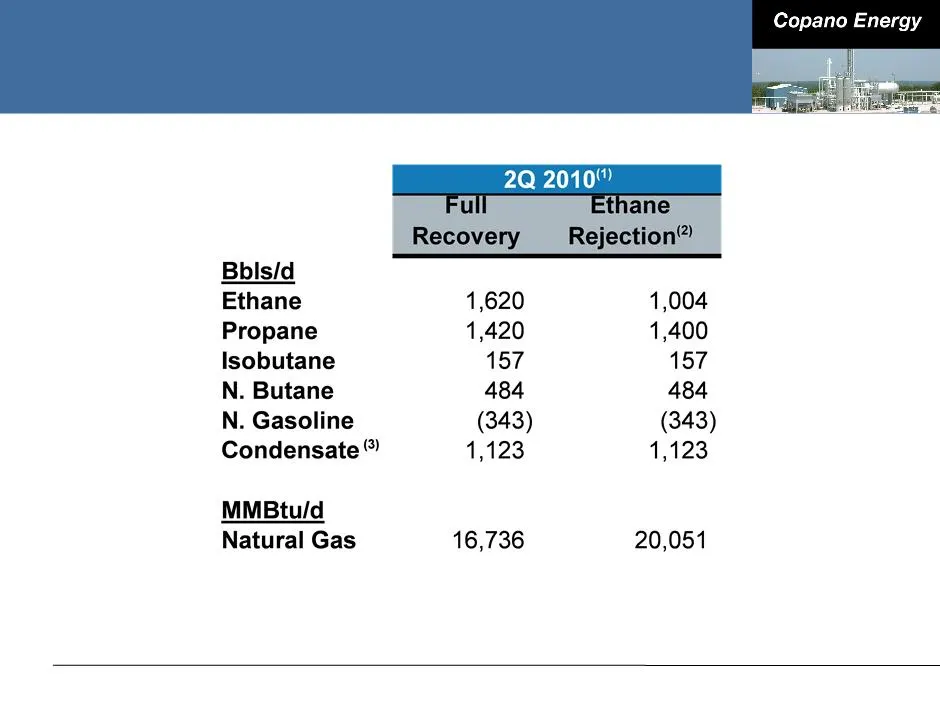
Oklahoma Net Commodity Exposure Note: See explanation of processing modes in this Appendix. Values reflect rounding. (1) Source: Copano Energy internal financial planning models for consolidated subsidiaries. (2) Ethane rejection at Paden plant is limited by nitrogen rejection facilities. (3) Reflec
Slide 38: Oklahoma Commodity Price Sensitivities
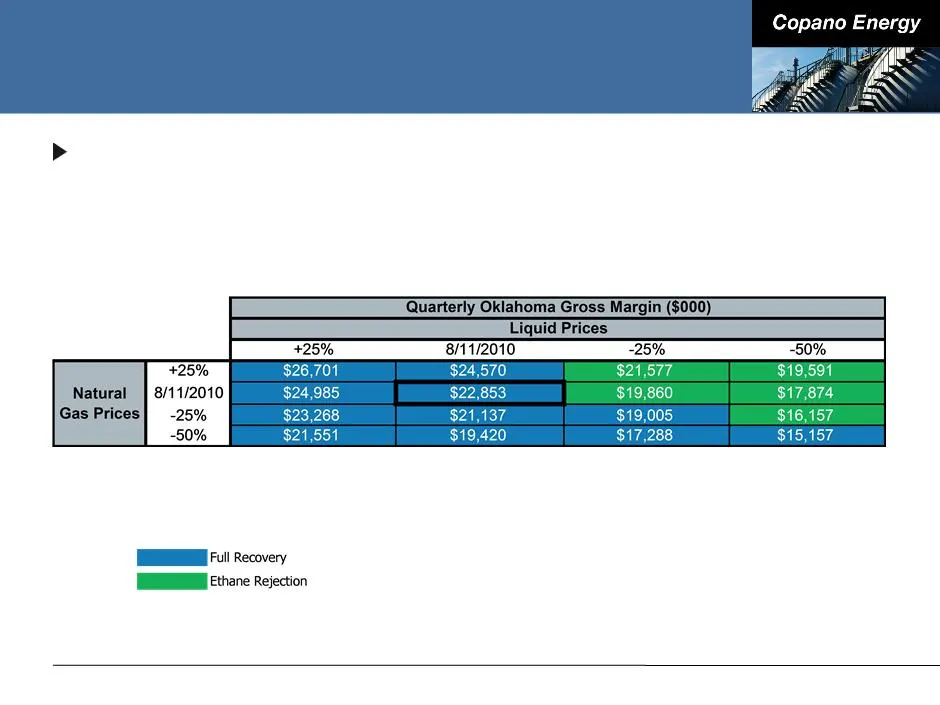
Oklahoma Commodity Price Sensitivities Oklahoma segment gross margins excluding hedge settlements ■ Matrix reflects 2Q 2010 volumes, adjusted using Copano’s 2010 planning model Note: Please see this Appendix for definitions of processing modes and additional details.
Slide 39: Oklahoma Rich Gas vs. Lean Gas
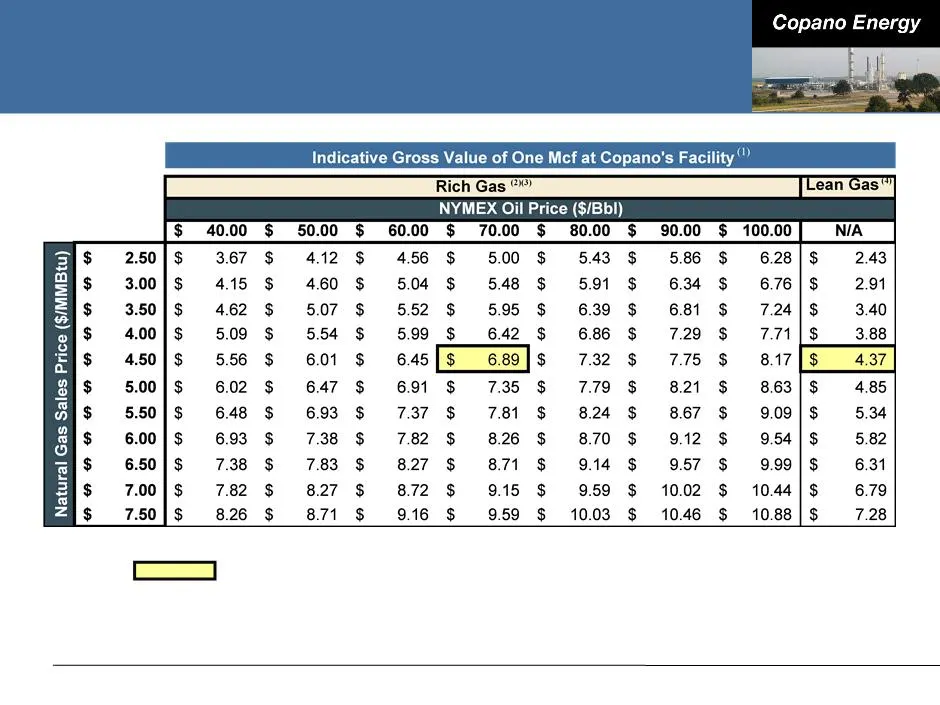
Oklahoma Rich Gas vs. Lean Gas Prices as of 8/19/10 (1) Full value prior to deduction of Copano’s margin. Excludes value of condensate and crude oil recovered by the producer at the wellhead. (2) Implied NGL prices are based on a six-year historical regression analysis. (3) Assumes 9 GPM gas with a
Slide 40: Texas Contract Mix
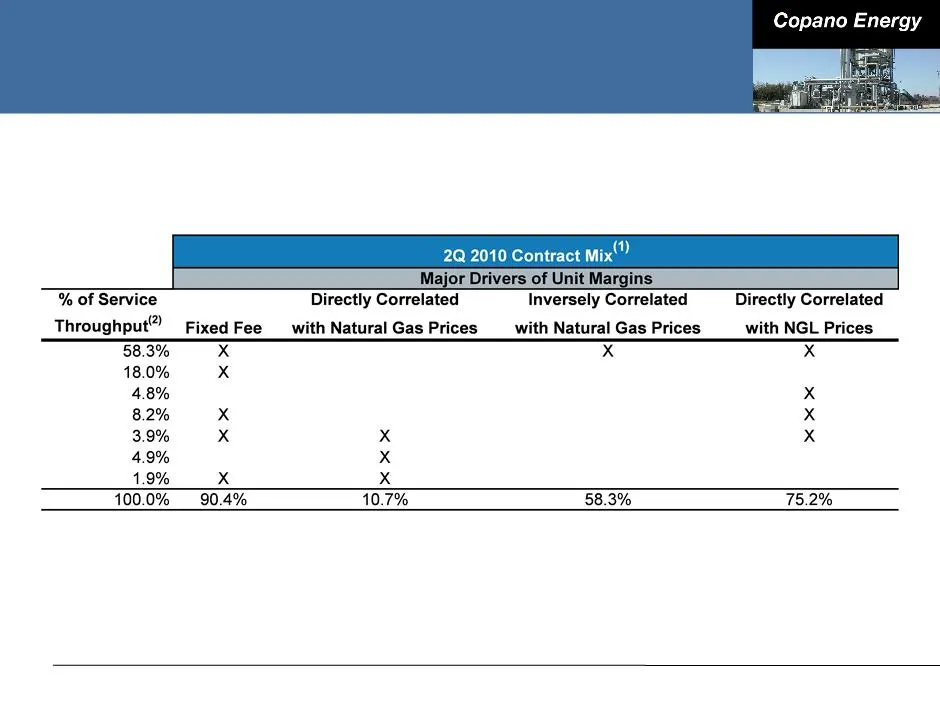
Texas Contract Mix (1) Source: Copano Energy internal financial planning models for consolidated subsidiaries. (2) Excludes 54,747 MMBtu/d service throughput for Webb Duval, a majority-owned affiliate.
Slide 41: Texas Net Commodity Exposure
Texas Net Commodity Exposure Note: See explanation of processing modes in this Appendix. (1) Source: Copano Energy internal financial planning models for consolidated subsidiaries. Based on 2Q 2010 daily wellhead/plant inlet volumes. (2) Fractionation at Houston Central processing plant permits sign
Slide 42: Texas Commodity Price Sensitivities
Texas Commodity Price Sensitivities Texas segment gross margins excluding hedge settlements ■ Matrix reflects 2Q 2010 volumes and operating conditions, adjusted using Copano’s 2010 planning model Note: Please see this Appendix for definitions of processing modes and additional details.
Slide 43: Rocky Mountains Sensitivities
Rocky Mountains Sensitivities 2Q 2010 Adjusted EBITDA volume sensitivity (positive or negative impact) ■ Bighorn: 10,000 MMBtu/d = $245,000 (1) ■ Fort Union: 10,000 MMBtu/d = $70,000 (1) Note: See this Appendix for reconciliation of Adjusted EBITDA. Values reflect rounding. (1) Impact on Adjusted EB
Slide 44: Hedging Impact of Commodity Price Sensitivities
Hedging Impact of Commodity Price Sensitivities
Slide 45: Reconciliation of Non-GAAP Financial Measures
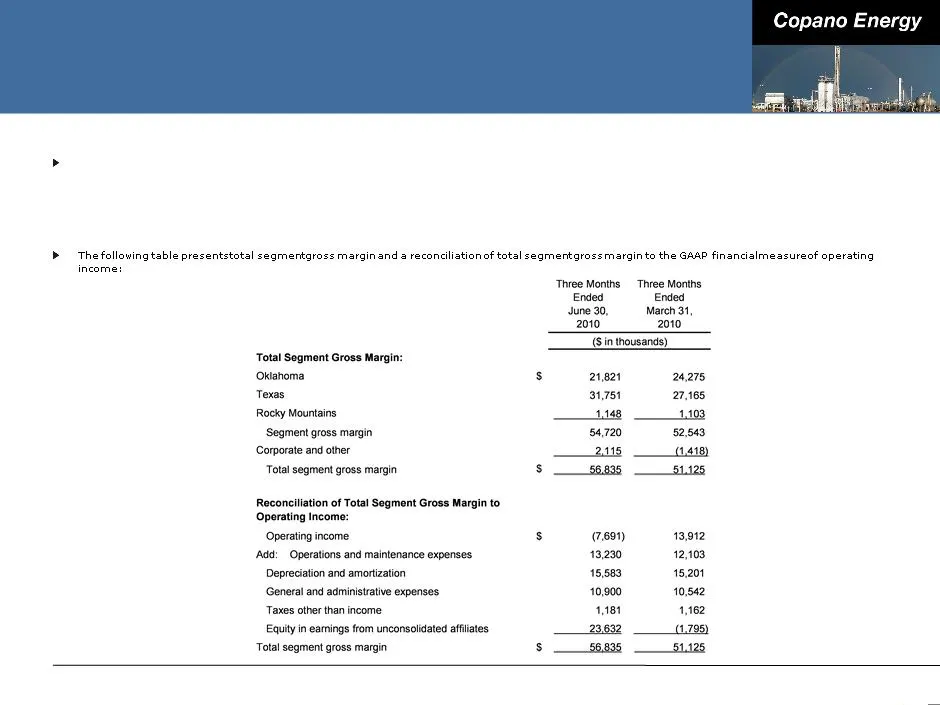
Reconciliation of Non-GAAP Financial Measures Segment Gross Margin and Total Segment Gross Margin We define segment gross margin, with respect to a Copano operating segment, as segment revenue less cost of sales. Cost of sales includes the following: cost of natural gas and NGLs purchased from third
Slide 46: Reconciliation of Non-GAAP Financial Measures
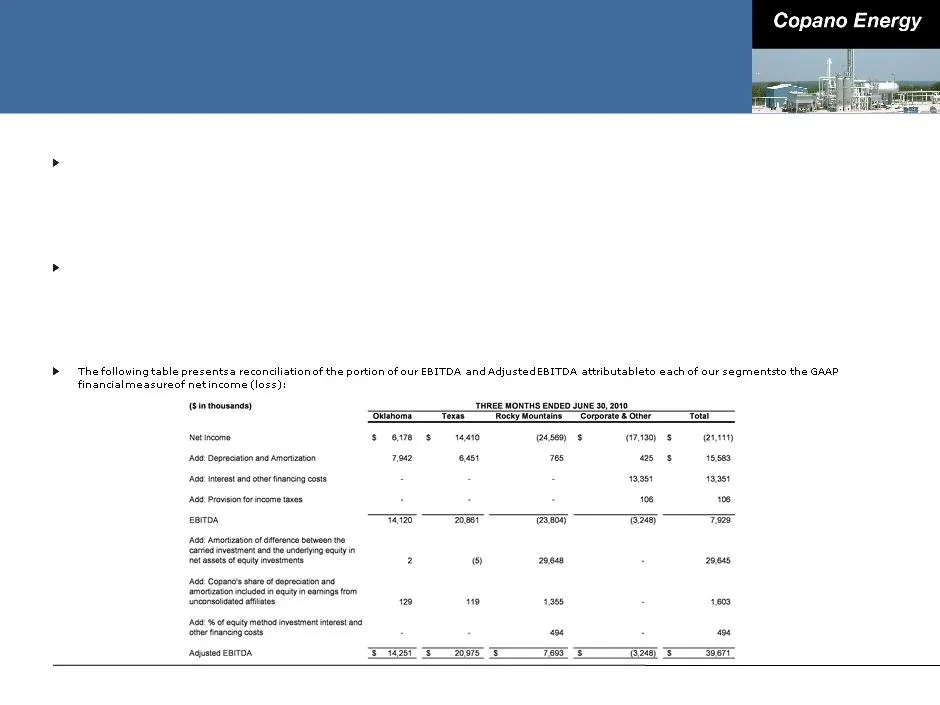
Reconciliation of Non-GAAP Financial Measures Adjusted EBITDA We define EBITDA as net income (loss) plus interest expense, provision for income taxes and depreciation and amortization expense. Because a portion of our net income (loss) is attributable to equity in earnings (loss) from our equity inv
Slide 47: Definitions of Non-GAAP Financial Measures
Definitions of Non-GAAP Financial Measures Total Distributable Cash Flow We define total distributable cash flow as net income plus: (i) depreciation, amortization and impairment expense (including amortization expense relating to the option component of our risk management portfolio); (ii) cash dis
Source: SEC EDGAR · 8-K filed Aug 31, 2010
More decks from Copano Energy L.L.C.
 2012 RBC Capital Markets MLP Conference35 slides · Nov 15, 2012
 2012 Citi One-on-One MLP/Midstream Infrastructure Conference35 slides · Aug 21, 2012
 Investor Presentation (June 2012)34 slides · Jun 18, 2012
 NAPTP 2012 MLP Investor Conference34 slides · May 22, 2012
 Morgan Stanley MLP and Diversified Natural Gas Corporate Access Day 201245 slides · Mar 7, 2012
 2011 RBC Capital Markets MLP Conference42 slides · Nov 17, 2011