1st Century Bancshares — Investor Presentation (December 2010)
27 slides from 1st Century Bancshares's investor presentation, Dec 1, 2010
Slide 1: 1st Century Bancshares, Inc.
1st Century Bancshares, Inc. Alan. Rothenberg Chairman and Chief Executive Officer 4 Century Baneshares, Inc Jason P. DiNapoli President and Chief Operating Officer 4 Century Baneshares, Inc
Slide 2: Safe Harbor Statement
Safe Harbor Statement Certainmatters discussed in this presentationmay constitute fonvard-looking statements within hemeaning of the “safe harbor” provisions ofthe Private Secunties/tigationRefom Act of 1995. You can find many (but not all of these statements by looking forwords such as “approximate
Slide 3: 1st Century Bank
1st Century Bank Founded by business people for business people in 2004, 1st Century Bank meets the specific needs of entrepreneurs, professionals, high net worth individuals and small businesses. Our success has been achieved by providing an extraordinary level of personal service and serving as ad
Slide 4: Bank Profile
1st Century Bank Profile « Attractive Market = Headquartered in Century City - West Los Angeles franchise. = Primary markets include: Bel Air, Beverly Hills, Brentwood, Century City, Los Angeles, Pacific Palisades, Santa Monica, West Los Angeles, Westwood. = Strong demographics; $24 billion in total
Slide 5: Bank Profile (cont.)
1st Century Bank Profile (cont.) = Building Relationships = 1% Century Bank is committed to building long-term relationships by acting as trusted advisors and client advocates. = Big, Small Bank = 1% Century Bank offers its customers big money center banking technologies and services with traditiona
Slide 6: Bank Strategy
1st Century Bank Strategy = Capital = Maintain peer leading Capital Ratios = Twice the regulatory amount that is required = Entirely common equity - no TARP, Trust Preferred, convertible or other forms of capital = Liquidity = Continue to improve loan to deposit ratio = Securities portfolio remains
Slide 7: Bank Strategy
1st Century Bank Strategy = Earnings Continued focus on development of long-term customer relationships Successful growth attributed to increasing core deposit franchise by offering safe and sound “home” Aggressive attitude toward credit resolution and charge-offs = Regulatory Relations Strong relat
Slide 8: 2010 Highlights
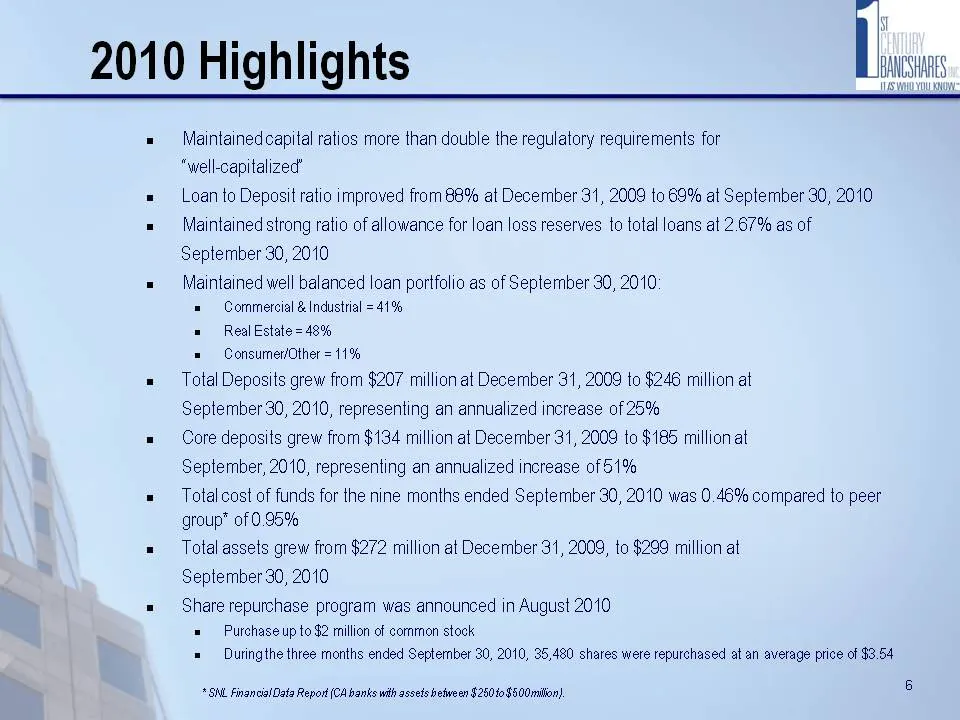
2010 Highlights Maintained capital ratios more than double the regulatory requirements for “well-capitalized’ Loan to Deposit ratio improved from 88% at December 31, 2009 to 69% at September 30, 2010 Maintained strong ratio of allowance for loan loss reserves to total loans at 2.67% as of September
Slide 9: 2010 Highlights (cont.)
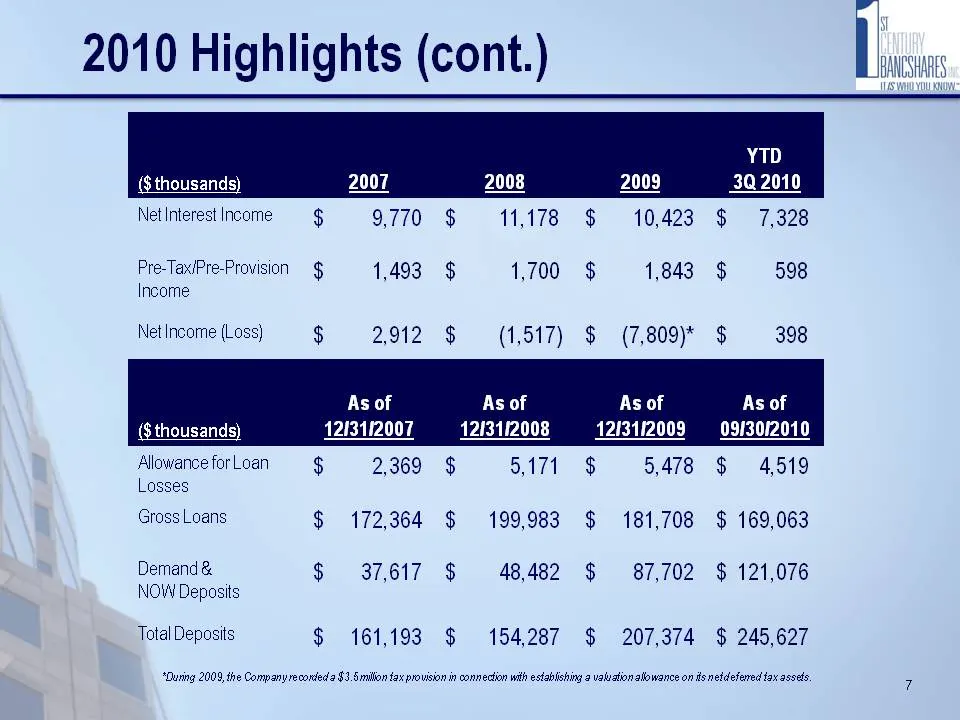
2010 Highlights (cont.) YTD ($ thousands) 2007 2008 2009 3Q 2010 NetInterestIncome 9,770 $ 11,178 $ 10,423 $ 7,328 Pre-Tax/Pre-Provision $ 1,493 $ 1,700 $ 1,843 $ 598 Income Netincome (Loss) $= «2.912 $ (1,517) $ (7,809)* $ 398 As of As of As of As of ($ thousands) 1213112007 1213112008 1213112009 0
Slide 10: Bank Outlook
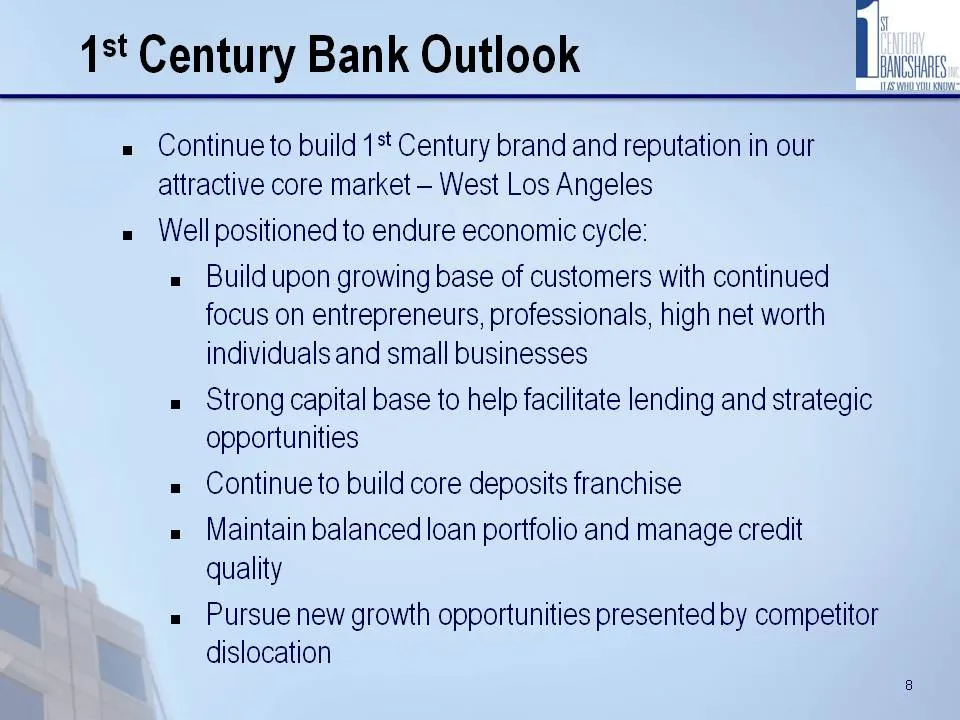
1st Century Bank Outlook » Continue to build 1% Century brand and reputation in our attractive core market - West Los Angeles « Well positioned to endure economic cycle: Build upon growing base of customers with continued focus on entrepreneurs, professionals, high net worth individuals and small bu
Slide 11: Financial Overview
l. SINSHRES Tus yng UO: Financial Overview
Slide 12: Well Capitalized
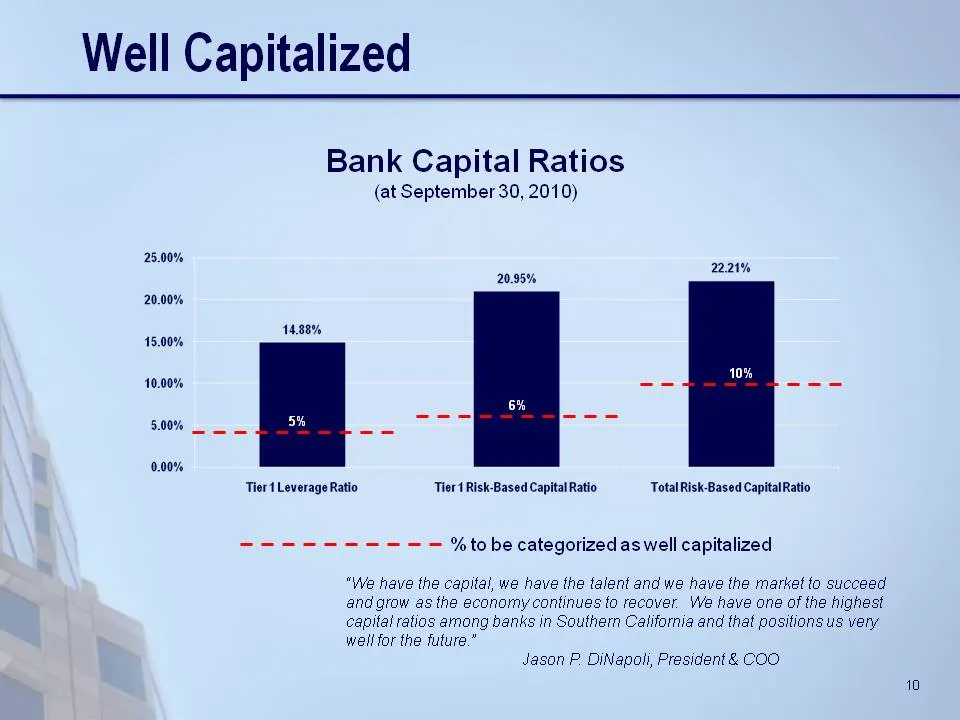
Well Capitalized Bank Capital Ratios (at September 30, 2010) 25.00% 22.21% 20.95% 20.00% 14.88% 15.00% 10.00% a ee 5.00% =e SS = 0.00% Tier Leverage Ratio Tier 1 Risk-Based Capital Ratio. Total Risk-Based CapitalRatio weer ------ ‘to be categorized as well capitalized “We have the capital, we have t
Slide 13: Well Capitalized (cont.)
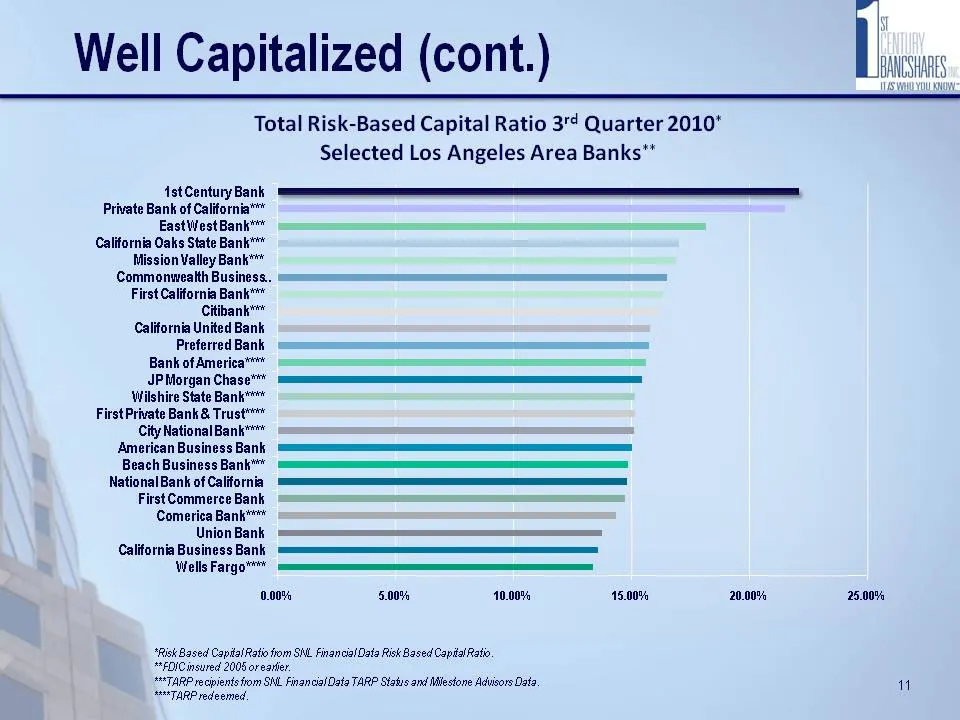
NI Well Capitalized (cont.) EMCSHRES syn OUON Total Risk-Based Capital Ratio 3'¢ Quarter 2010" Selected Los Angeles Area Banks” Ast Century Bank Private Bank of California*™* EastWestBank'** California Oaks State Bank*** Mission Valley Bank"™ Commonwealth Business. axe mm == First California Bank'**
Slide 14: Deposits — Expanding Core Deposit Base
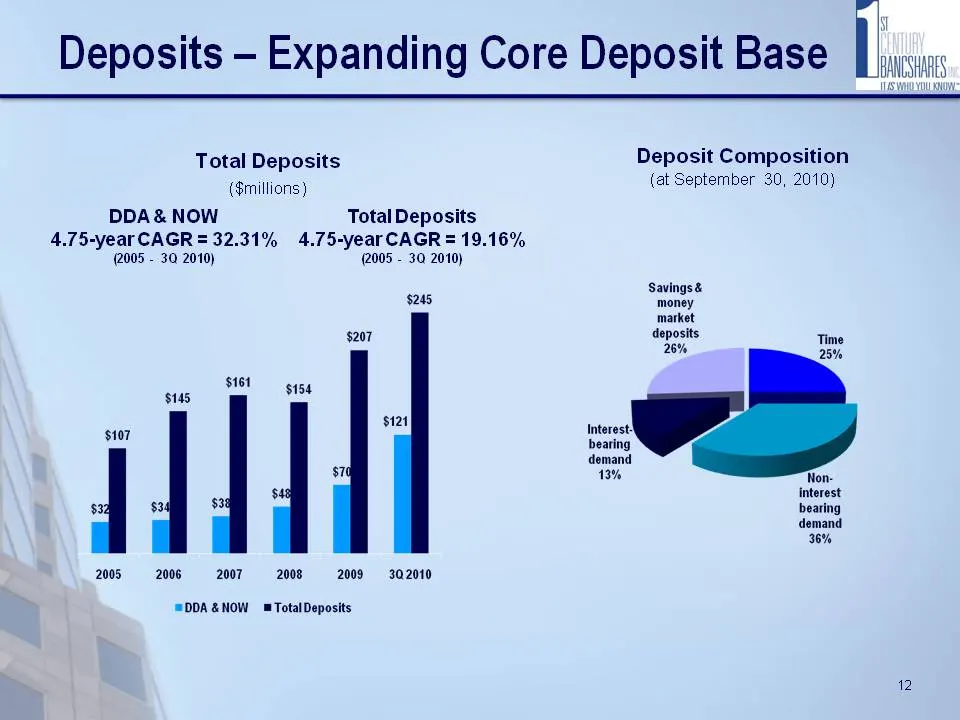
4.75-year CAGR = 32.31% Deposits — Expanding Core Deposit Base Total Deposits ($millions) DDA& NOW Total Deposits (2005 - 30 2010) (2005 - 30 2010) $245 $207 a $21 $107 sm $ $3 $3: $3 2005 = 2006 «= 2007-2008 «2009 302010 =DDA&NOW mTotalDeposits 4.75-year CAGR = 19.16% Deposit Composition (at Septem
Slide 15: Deposit Trends — Expanding Granularity
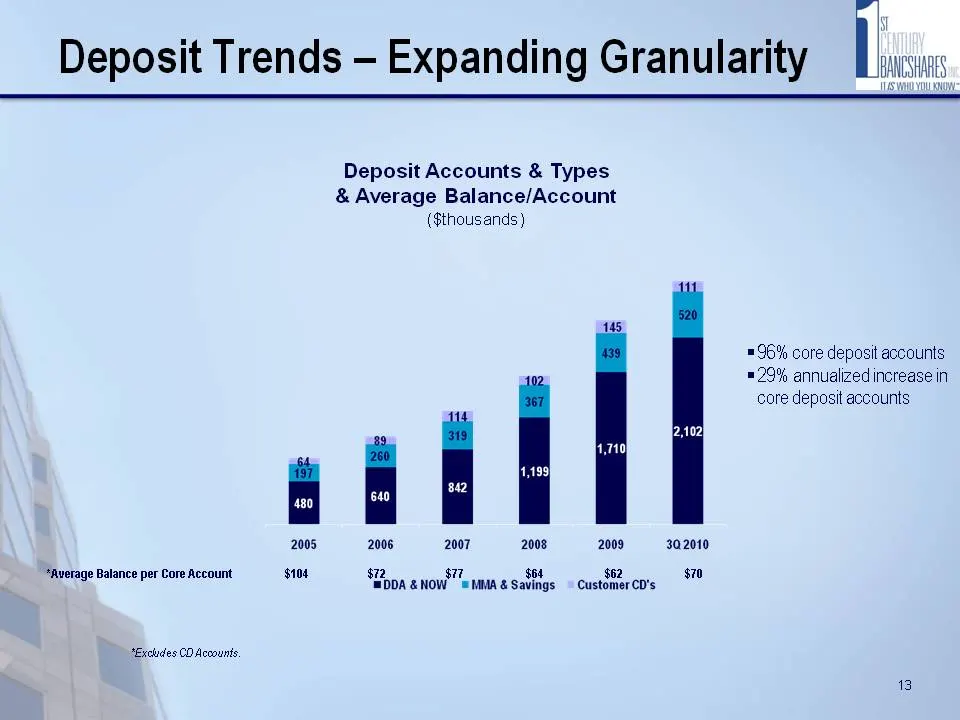
Deposit Trends — Expanding Granularity li *average Balance per Core Account *Excludes CD Accounts. Deposit Accounts & Types & Average Balance/Account ($thousands) 145 = 96% core deposit accounts = 20% annualized increase in core deposit accounts E E 2005 2006 207 2008 2009 302010 $104 § $62 $70 72 $
Slide 16: Deposit Growth
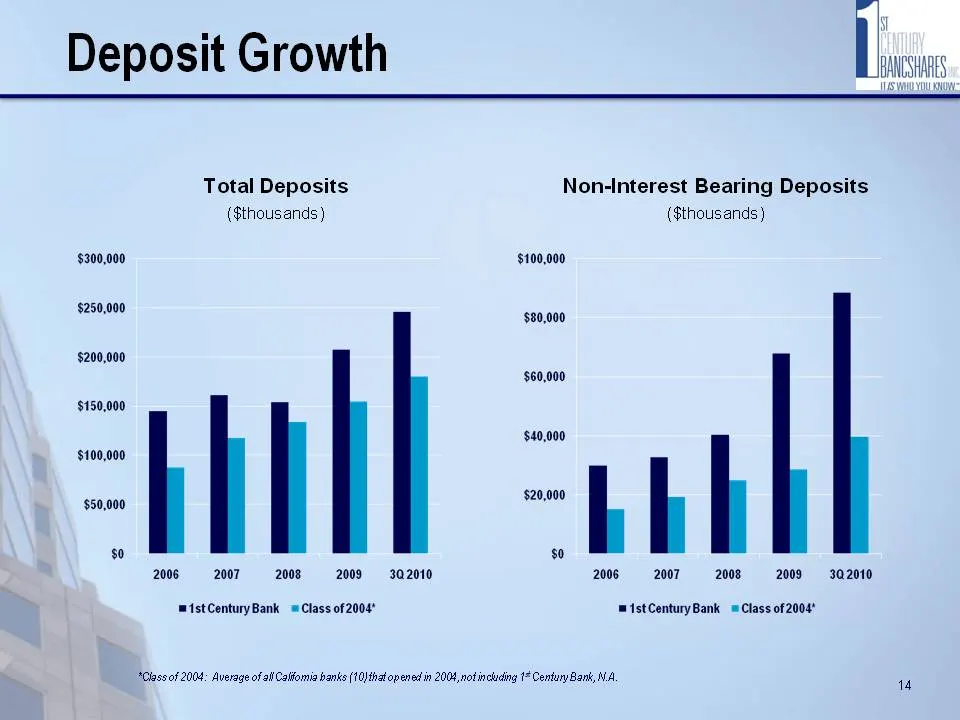
Deposit Growth Total Deposits Non-Interest Bearing Deposits ($thousands) ($thousands) $300,000 $100,000 $250,000 $80,000 $200,000 $60,000 $150,000 $40,000 $100,000 $50,000 snare [ | $0 $0 2006 2007 2008 2009 302010 2006 2007 2008 2009 302010 mstCenturyBank = Class of 200° m= 1stCenturyBank ™ Class o
Slide 17: Deposit Growth (cont.)
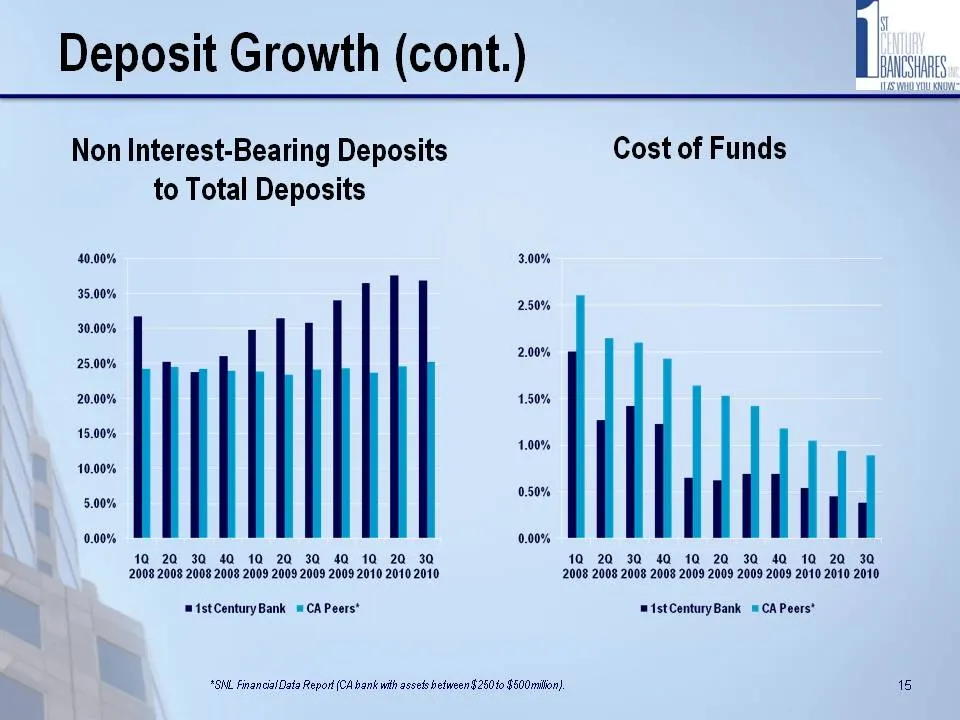
Deposit Growth (cont.) Non Interest-Bearing Deposits Cost of Funds to Total Deposits 40.00% 3.00% 35.00% 2.50% 30.00% 2.00% 25.00% 20.00% 1.50% 15.00% 1.00% 10.00% 0.50% 5.00% 0.00% 0.00% 10 20 30 40 10 20 30 40 ta 20 30 10 20 30 40 10 20 30 40 10 20 30 2008 2008 2008 2008 2009 2009 2009 2009 2010 2
Slide 18: Deposit Growth (cont.)
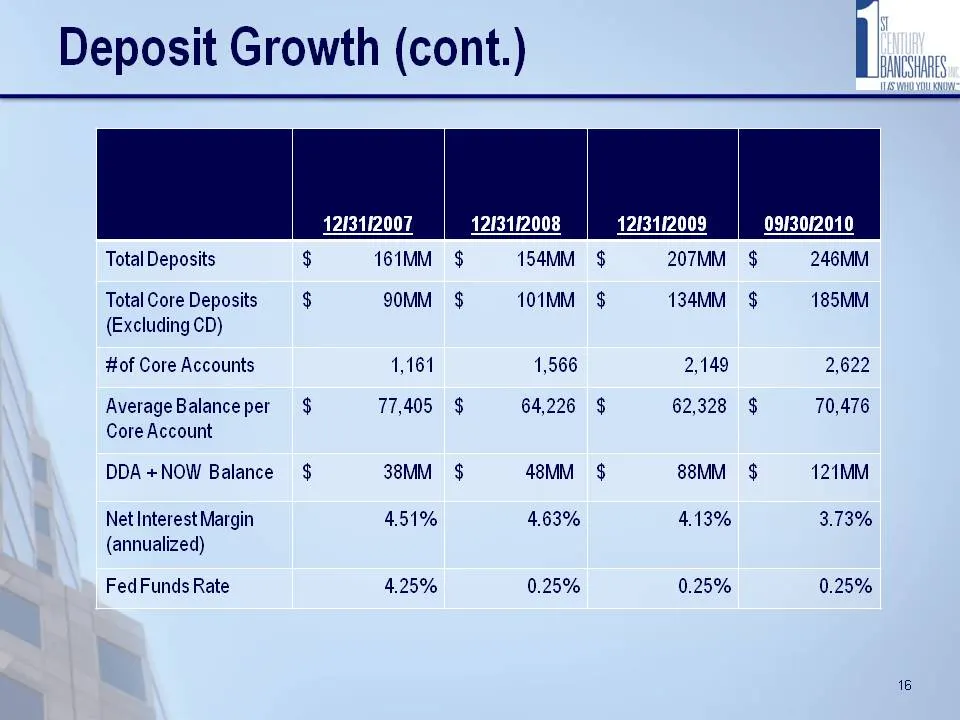
Deposit Growth (cont.) bol 12131172007 | 1213112008 “cas 9130/2010 Total Deposits 161MM 154MM Total Core Deposits $ 90MM $ 101MM (Excluding CD) #of Core Accounts 1,161 1,566 AverageBalanceper $ 77,405 $ 64,226 Core Account DDA+NOW Balance $ 38MM $ 48MM Net Interest Margin 451% 4.63% (annualized) Fed
Slide 19: Liquidity
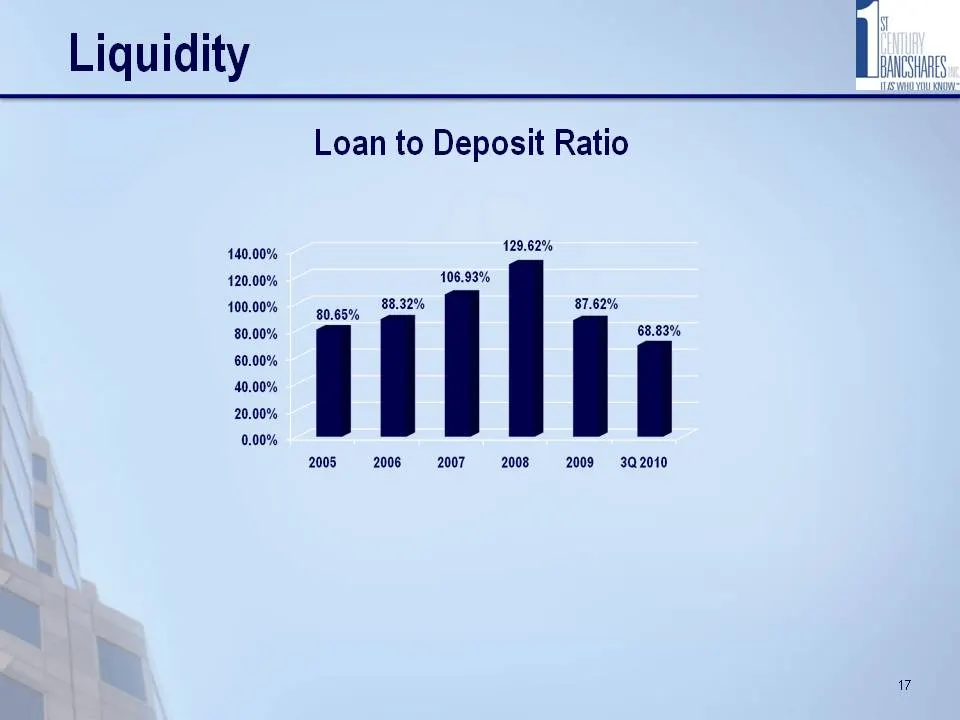
Liquidity BASS Loan to Deposit Ratio 440.00% 128.62% 120.00% 108.93% 100.00% ay ggy, 88.32% 87.62% 80.00% 68.83% 60.00% 40.00% 20.00% 0.00% 2005 = 2006-«S 2007S 2008. «2009 30.2010
Slide 20: Liquidity (cont.)
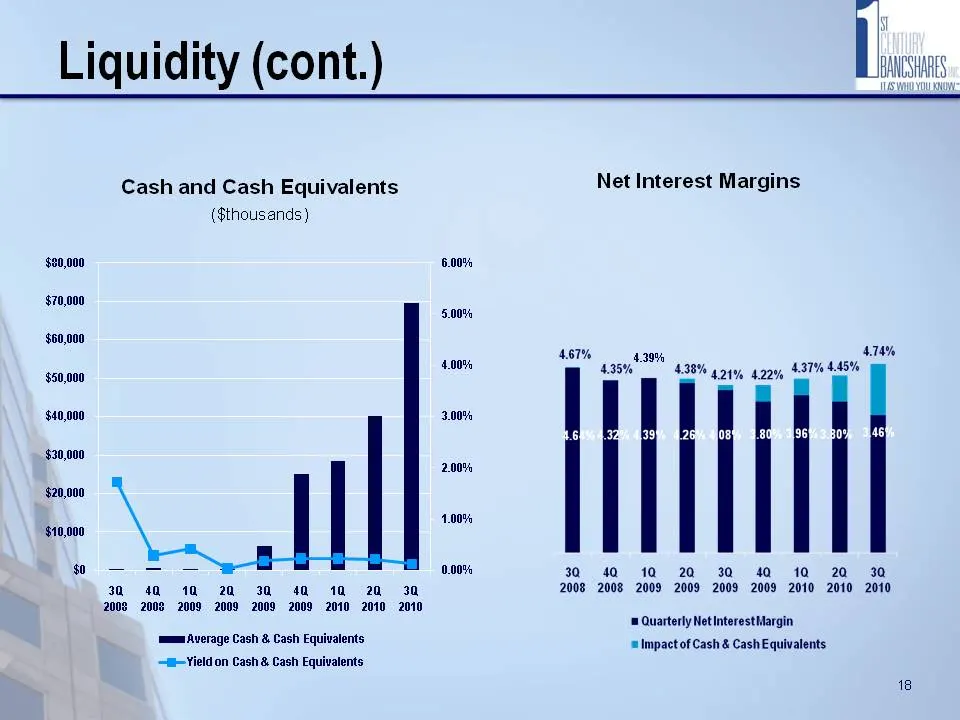
Liquidity (cont.) Cash and Cash Equivalents Net Interest Margins ($thousands) $80,000 6.00% $70,000 5.00% $60,000 467% ATM $50,000 nal 43510 4.39% goin 4p0 43% AMM $40,000 3.00% $30,000 2.00% $20,000 4.00% $10,000 a 0.00% 30 410s 3 1020 8 ao 49 mm 22 4 an ta 2m a0 2008 2008 2009 2009 2009 2009 2010
Slide 21: Asset Base
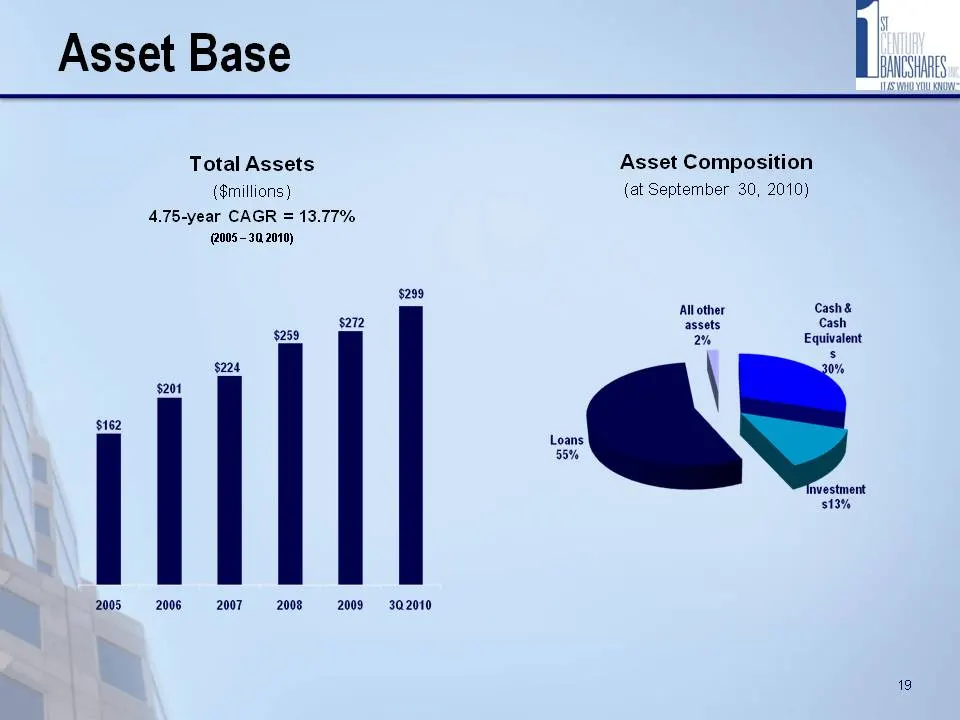
Asset Base Total Assets Asset Composition ($millions) (at September 30, 2010) 4.75-year CAGR = 13.77% (2005-30 2010) $299 a All other Cash& assets Cash $259 2% Equivalent s $224 30% $201 $162 Loans 55% Investment 13% 2005 = 2006 «= 2007-2008» 2009 302010 19
Slide 22: Balanced Loan Portfolio
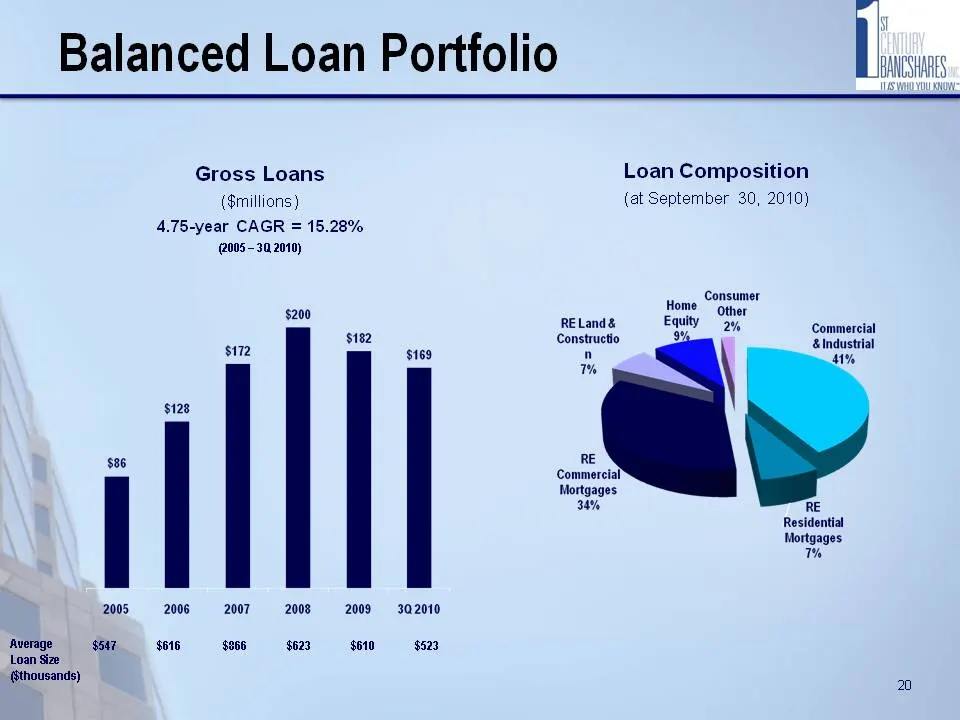
Balanced Loan Portfolio $36 2005 Average $547 Loan Size thousands) Gross Loans ($millions) 4.75-year CAGR = 15.28% (2005-30 2010) $200 $182 $172 $128 2006 = 2007«= «2008-2009 $616 $866 $623 $610 $169 30.2010 $523 Loan Composition {at September 30, 2010) Consumer tome other RELand& quity 2% Commercia
Slide 23: Allowance for Loan Loss to Total Loans
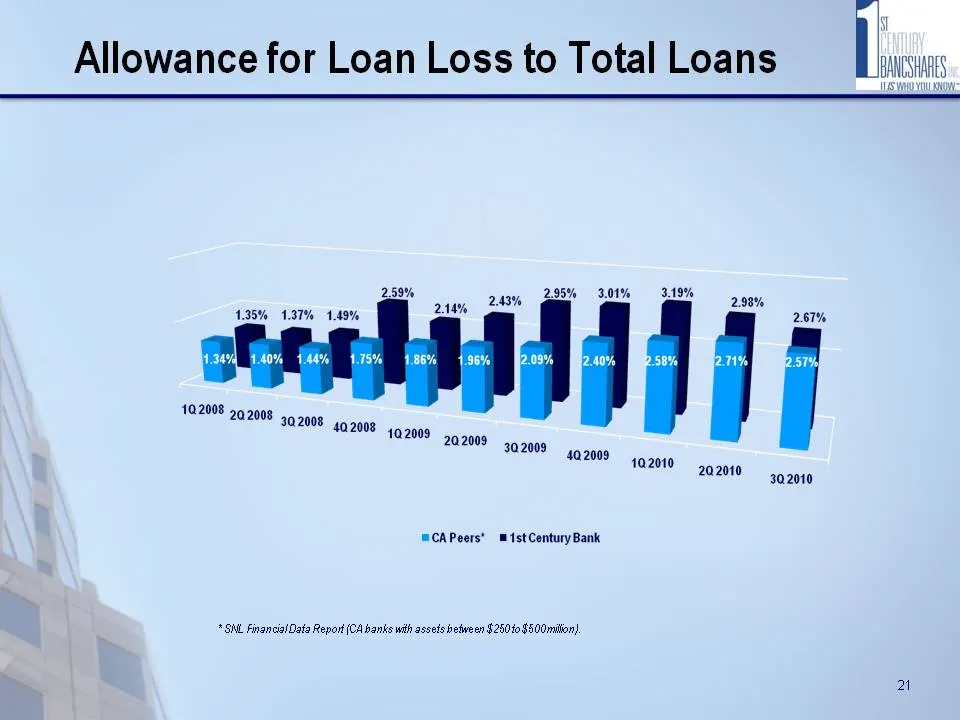
Allowance for Loan Loss to Total Loans 2.59% 2.95% 3.01% 3.19% 2.43% 2.98% aa ] Hy : 302009 49 9099 1.35% 137% 1.49% 102010 202010 52010 |CAPeers' 1st Century Bank * SNL Financial Date Report {CA banks wil assets between $2500 8500milion) 24
Slide 24: Bank Earnings
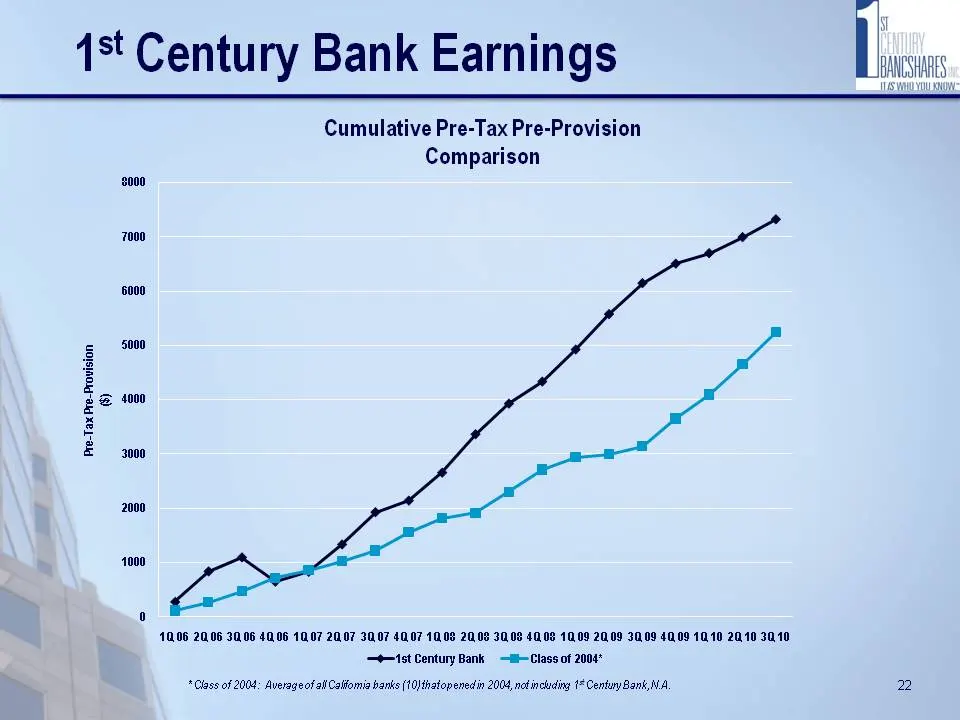
1st Century Bank Earnings Cumulative Pre-Tax Pre-Provision Comparison 2000 7000 6000 000 4000 3000 2000 1000 1006 20.06 3006 40.06 10.07 2007 3007 4007 10.08 2008 30.03 40.08 10.09 20.09 3009 4.09 10,10 20.10 3010, —e1t Century Bank = —B~Class of 2004" * Class of 2004: AverageofallCalfomia banks (10
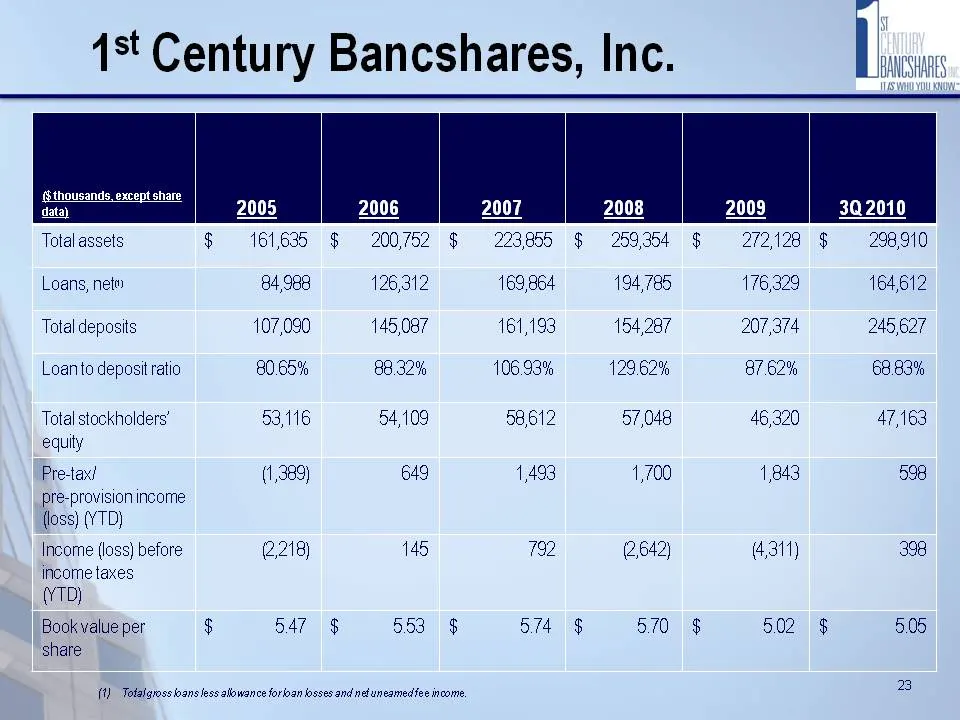
Slide 25: Selected Financial Data
1st Century Bancshares, Inc. ‘Sthousands, except share data) 2007 2008 Total assets $ 161,635 $ 200,752 § 223,855 § 259,354 272128 $ 298,910 Loans, net 84,988 126,312 169,864 194,785 176,329 164,612 Total deposits 107,090 145,087 161,193 154,287 207,374 245,627 Loan to deposit ratio 80.65% 88.32% 10
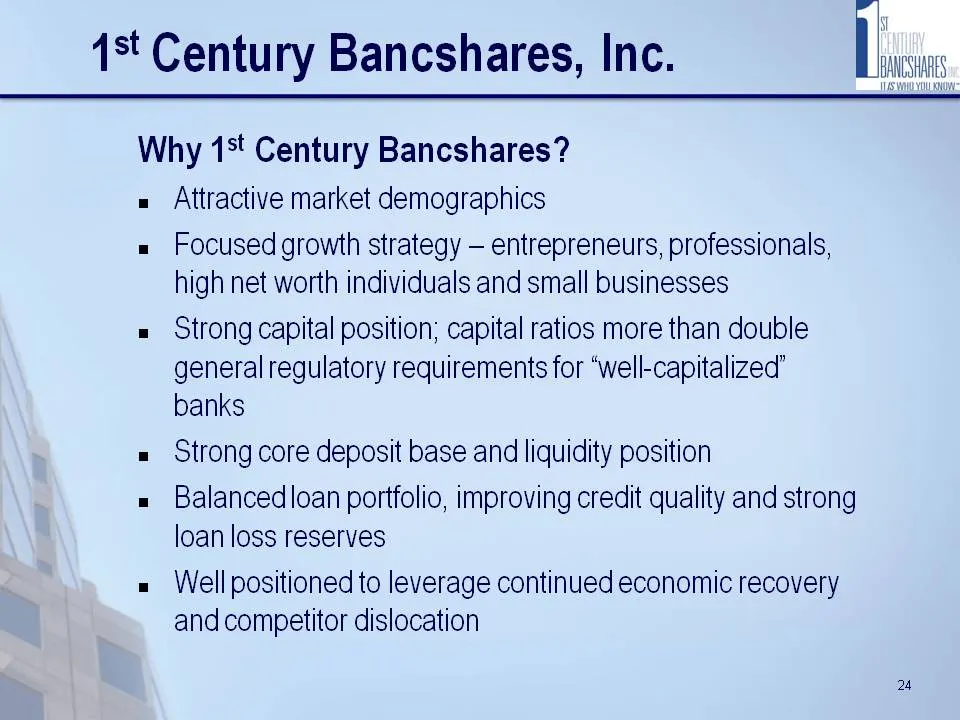
Slide 26: Why 1st Century Bancshares?
1st Century Bancshares, Inc. Why 1st Century Bancshares? Attractive market demographics Focused growth strategy — entrepreneurs, professionals, high net worth individuals and small businesses Strong capital position; capital ratios more than double general regulatory requirements for “well-capitaliz
Slide 27: Contact Us
1st Century Bancshares, Inc. Contact Us Alan |. Rothenberg Chairman & CEO arothenberg@1stcenturybank.com 310.270.9501 Jason DiNapoli President & COO jdinapoli@1stcenturybank.com 310.270.9505 25
Source: SEC EDGAR · 8-K filed Dec 1, 2010
More decks from 1st Century Bancshares Inc
 Shareholder Meeting (May 2015)23 slides · May 7, 2015
 Investor Presentation (May 2014)26 slides · May 8, 2014
 Investor Presentation (May 2013)26 slides · May 8, 2013
 Investor Presentation (May 2012)24 slides · May 21, 2012
 Shareholder Meeting (May 2011)25 slides · May 26, 2011
 Investor Presentation (September 2010)27 slides · Sep 14, 2010