Coventry Group Limited · ASX:CYG
Coventry — Investor Presentation (July 2010)
18 slides from Coventry's investor presentation, Jul 19, 2010
Slide 1: PAT Guidance $7M + Final Dividend Announcement 8¢ + Contextual Presentation
4\) Coventry Group Ltd ABN 37 008 670 102 525 Great Eastern Highway Redcliffe WA 6104 Tel : (08) 9276 0222 Fax : (08) 9436 5406 ASX Release 19 July 2010 PAT GUIDANCE $7M + FINAL DIVIDEND ANNOUNCEMENT 8¢ + CONTEXTUAL PRESENTATION Coventry Group is pleased to confirm to the market that for the year en
Slide 2: Market Update July 2010
4\ Coventry Group Ltd ABN 37 008 670 102 MARKET UPDATE JULY 2010 Roger Flynn Tony Hockley Executive Chairman Chief Financial Officer
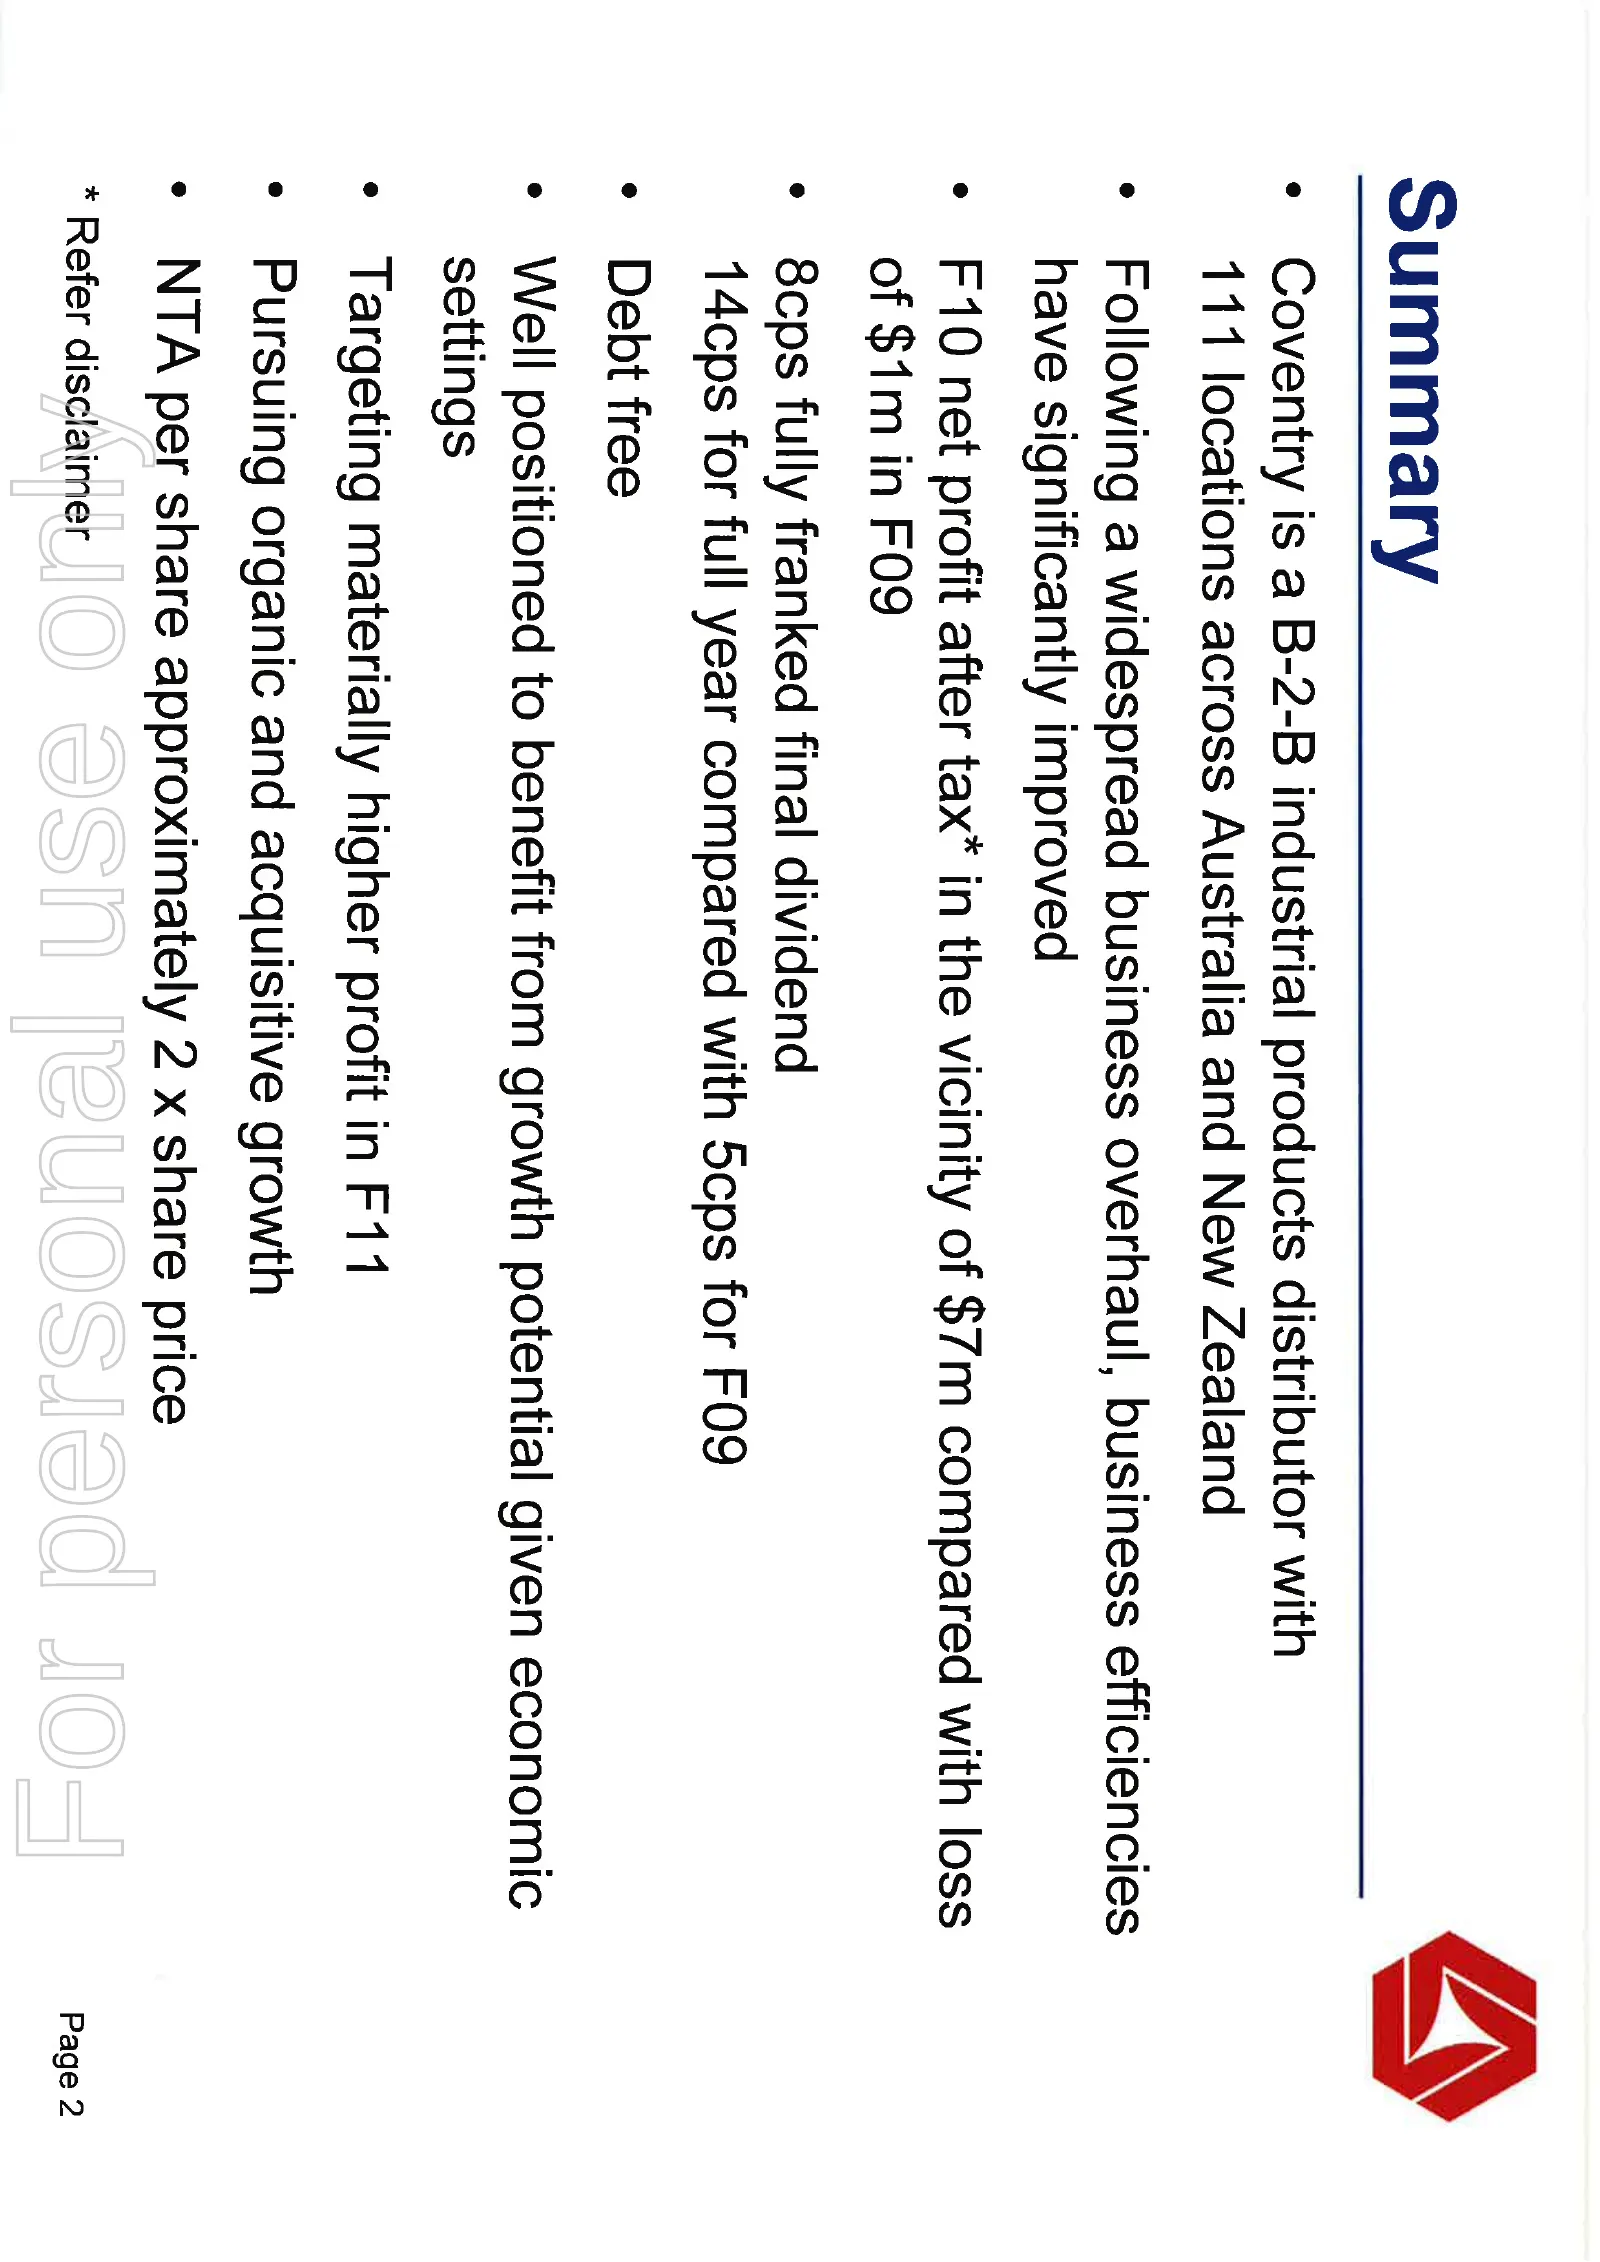
Slide 3: Summary
Summary 4 ¢ Coventry is a B-2-B industrial products distributor with 111 locations across Australia and New Zealand ¢ Following a widespread business overhaul, business efficiencies have significantly improved ¢ F10 net profit after tax* in the vicinity of $7m compared with loss of $1m in FO9 ¢ 8cps
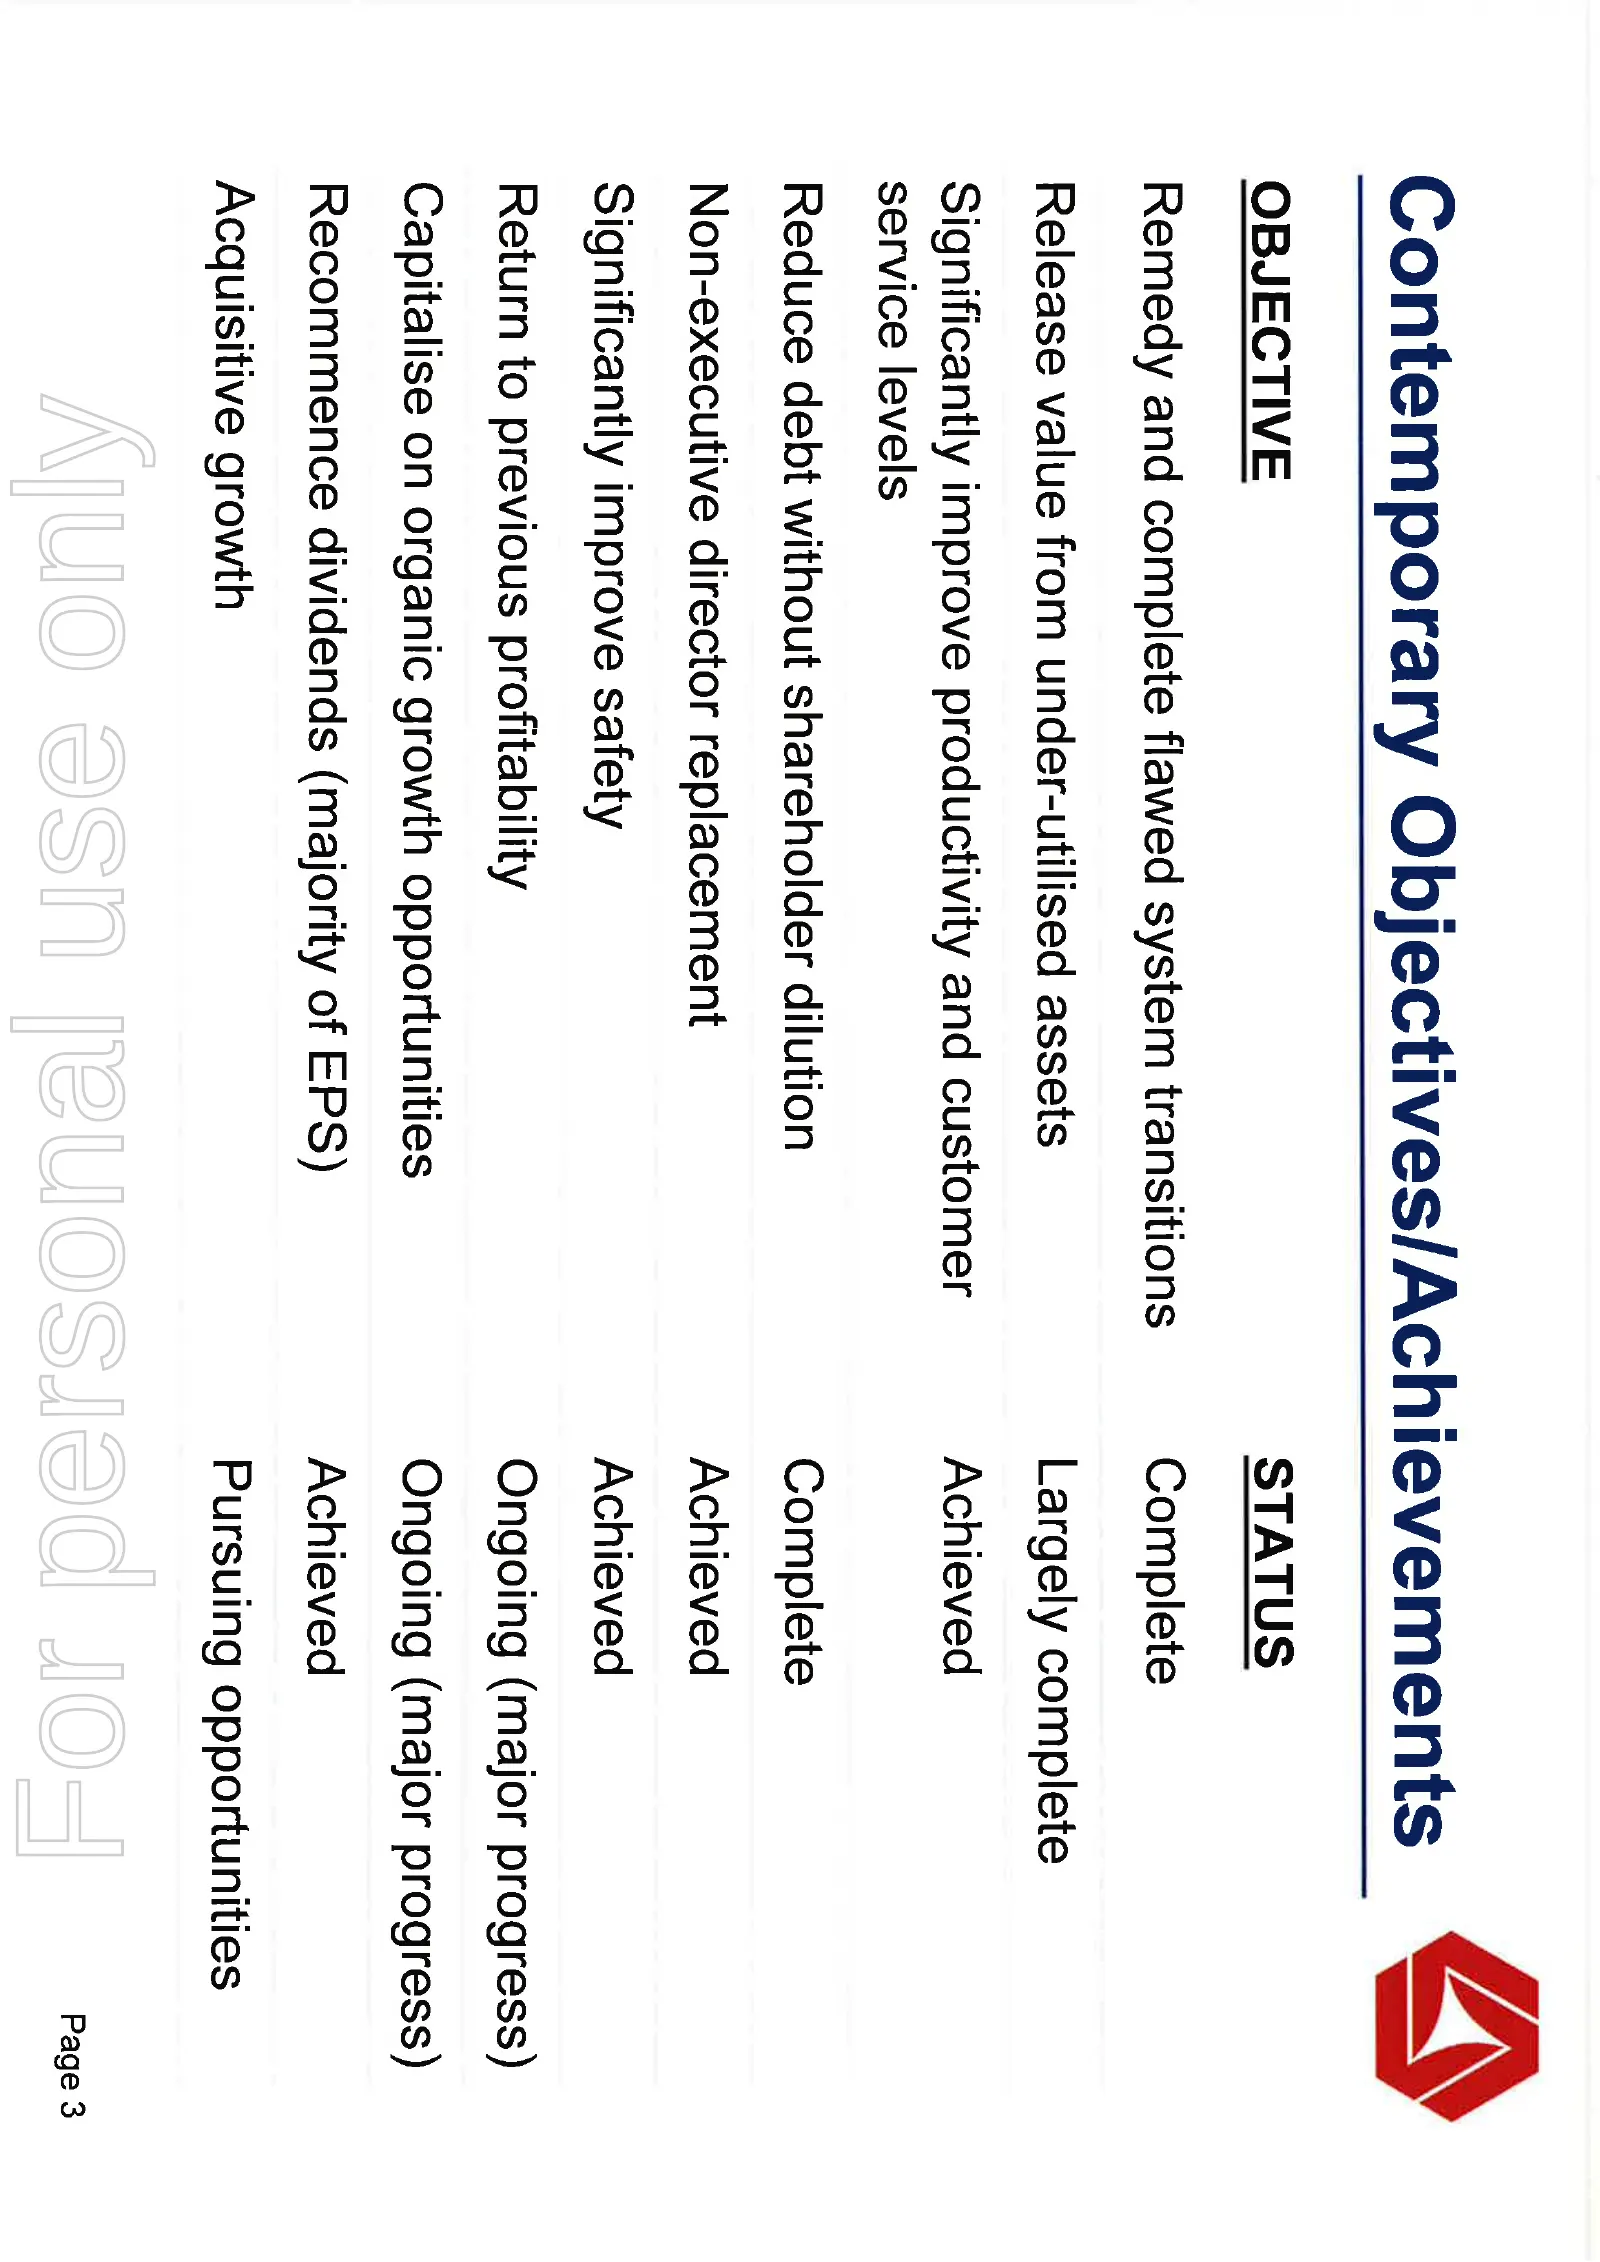
Slide 4: Contemporary Objectives/Achievements
Contemporary Objectives/Achievements 4 OBJECTIVE STATUS Remedy and complete flawed system transitions Complete Release value from under-utilised assets Largely complete Significantly improve productivity and customer Achieved service levels Reduce debt without shareholder dilution Complete Non-execu
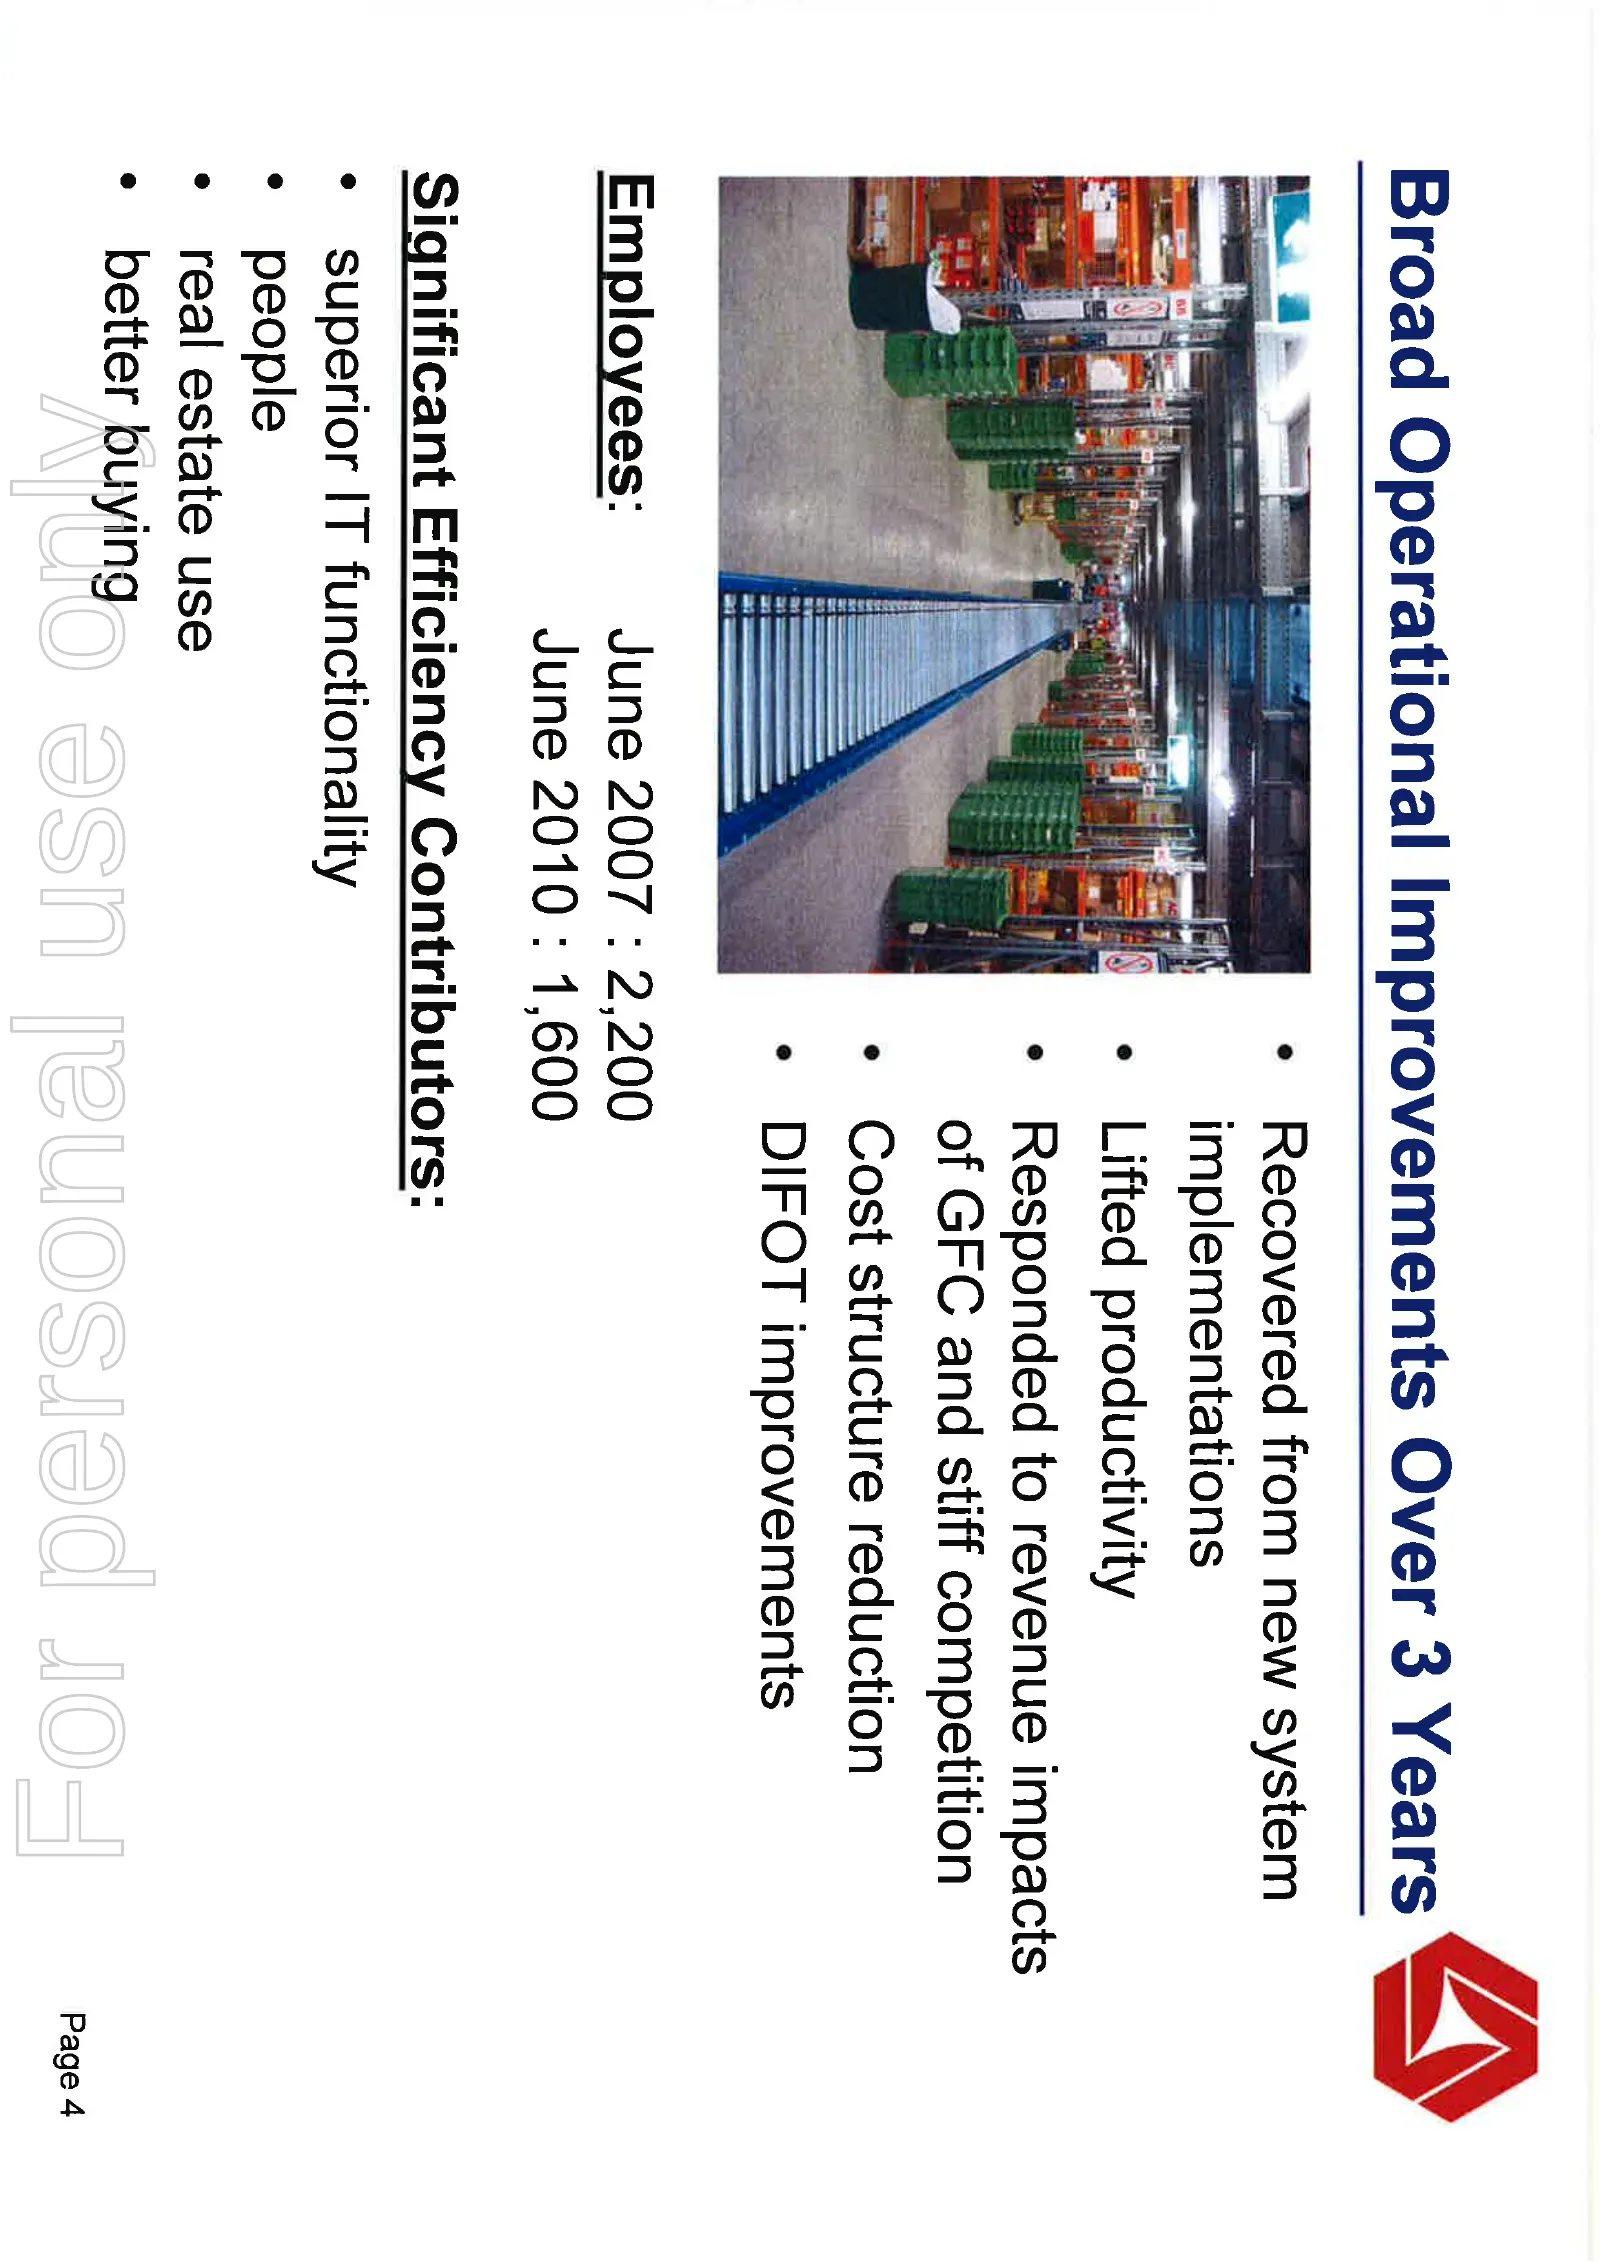
Slide 5: Broad Operational Improvements Over Years
Broad Operational Improvements Over 3 Years gy ¢ Recovered from new system implementations ¢ Lifted productivity ¢ Responded to revenue impacts of GFC and stiff competition ¢ Cost structure reduction ¢ DIFOT improvements Employees: June 2007 : 2,200 June 2010 : 1,600 Significant Efficiency Contribut
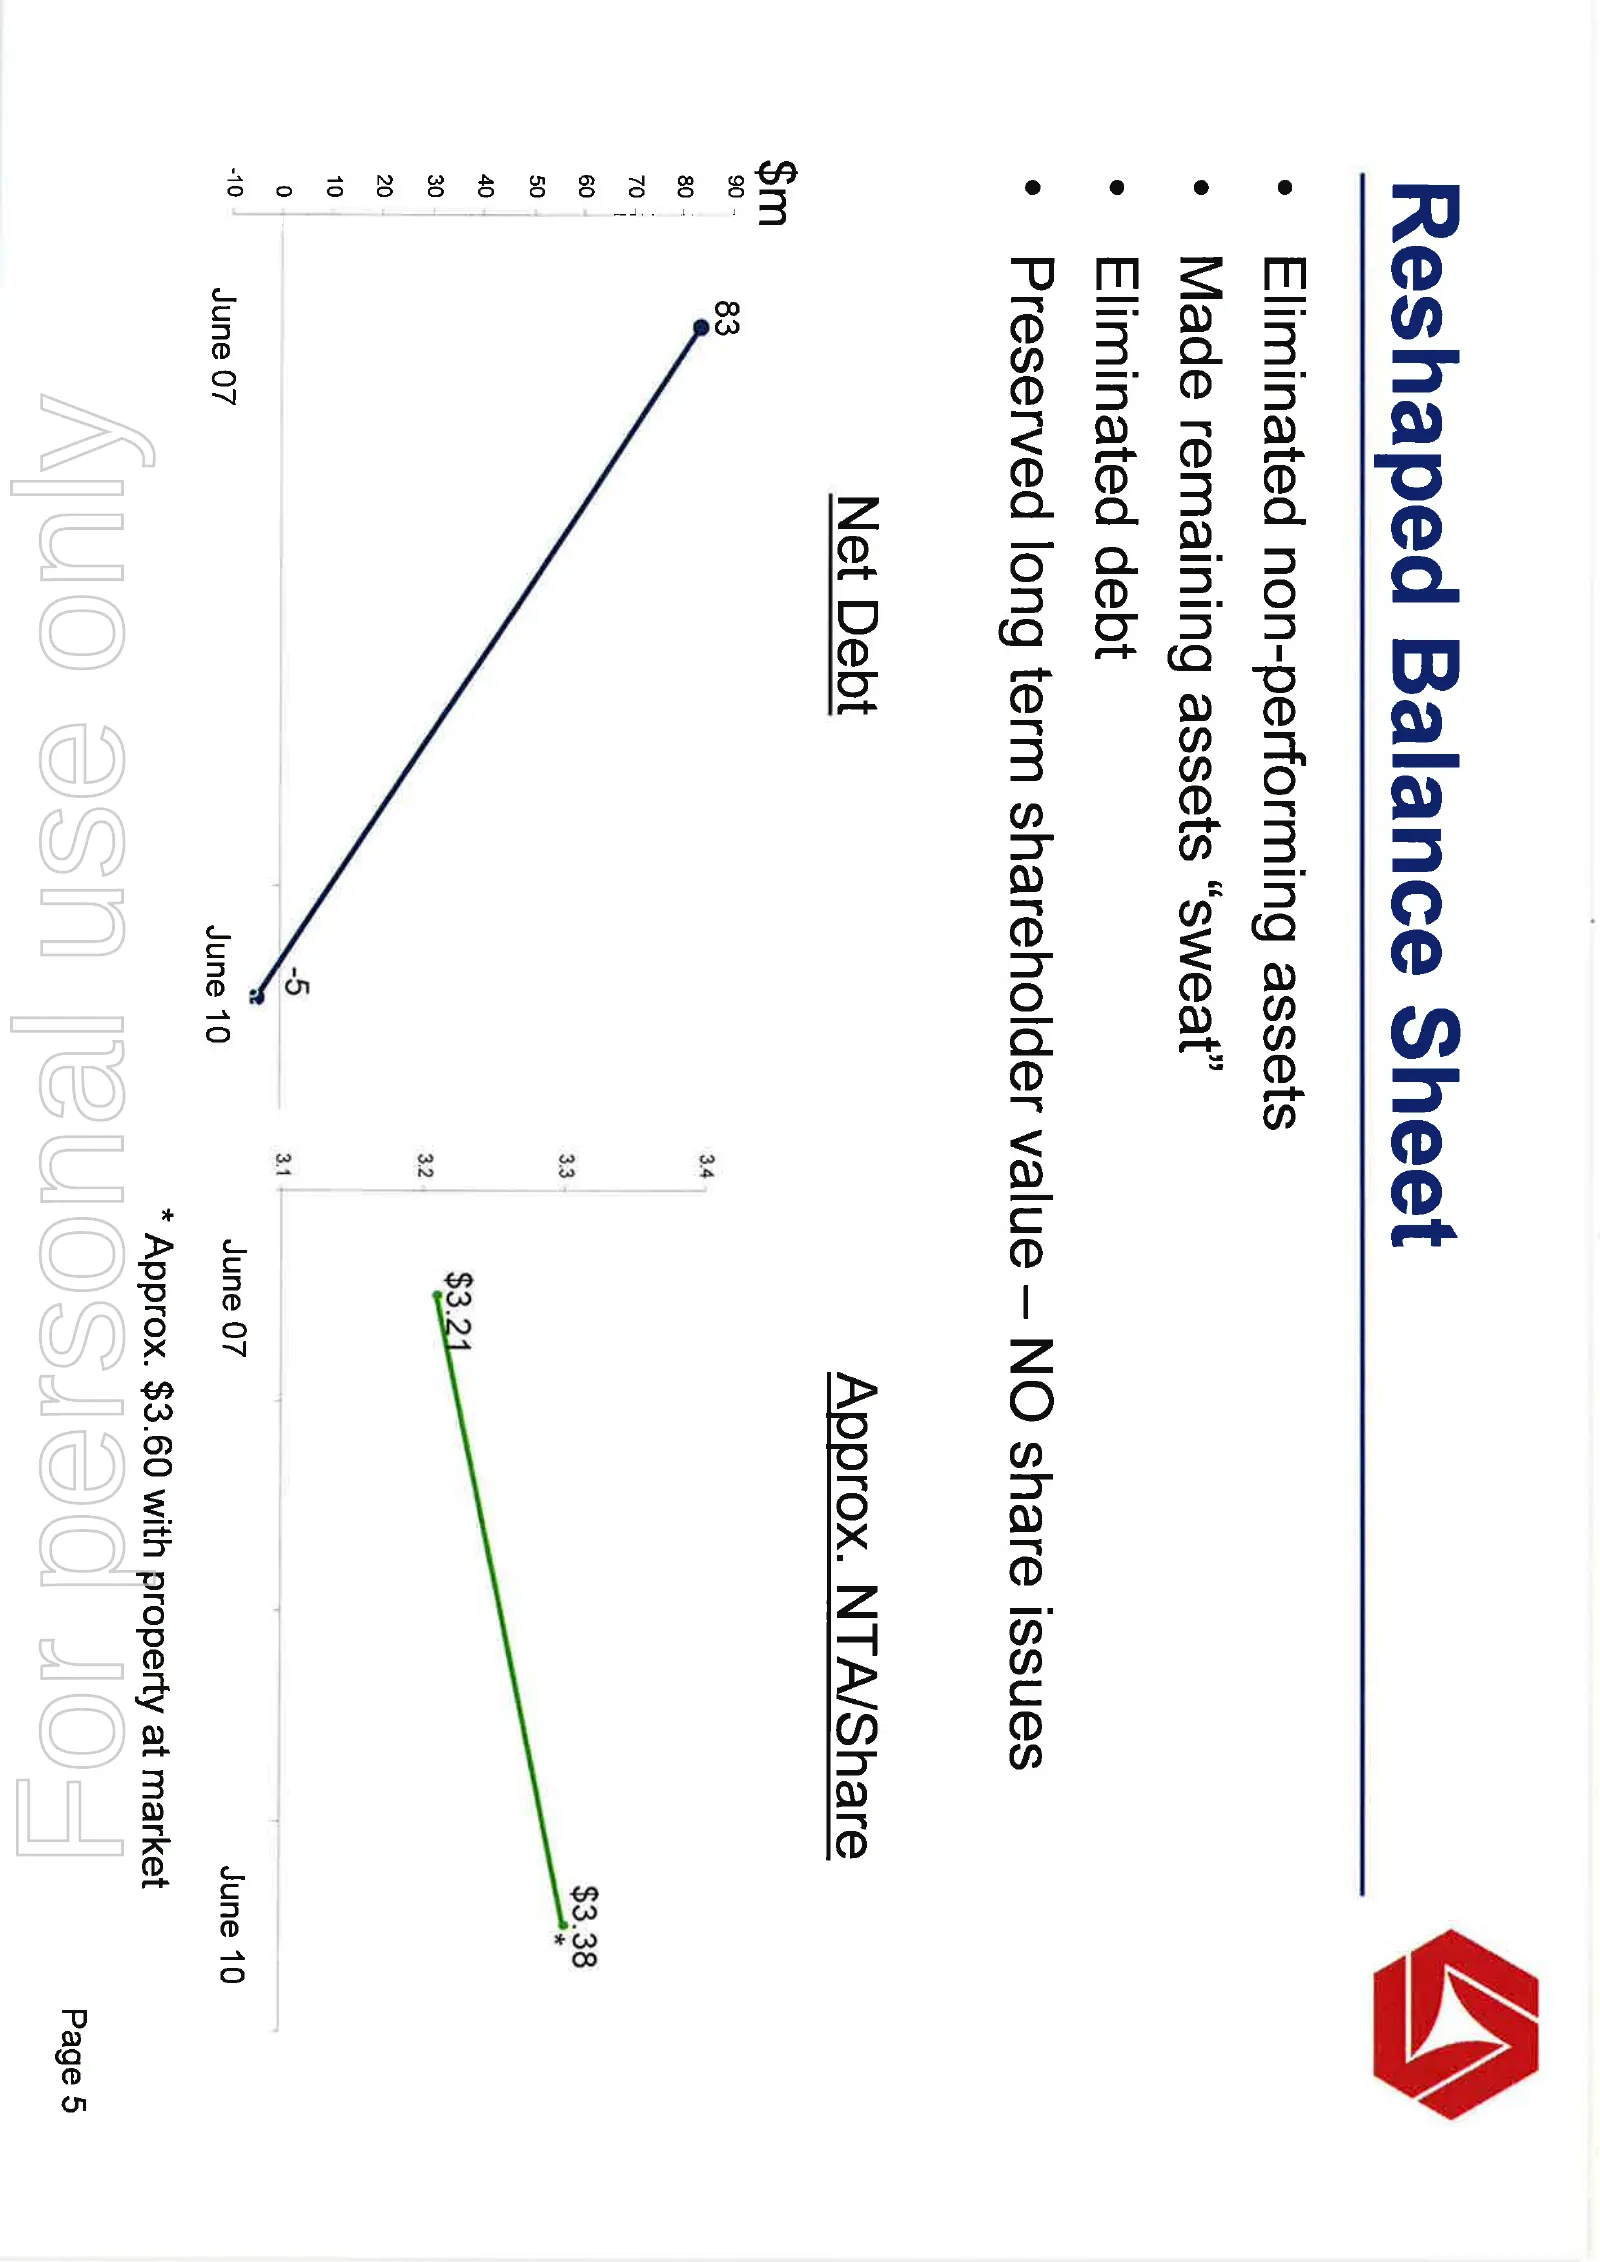
Slide 6: Reshaped Balance Sheet
Reshaped Balance Sheet & Eliminated non-performing assets Made remaining assets “sweat” Eliminated debt Preserved long term shareholder value — NO share issues Net Debt Approx. NTA/Share 83 34 $3.3 33 * 32 <5 31 June 07 June 10 June 07 June 10 * Approx. $3.60 with property at market Page 5
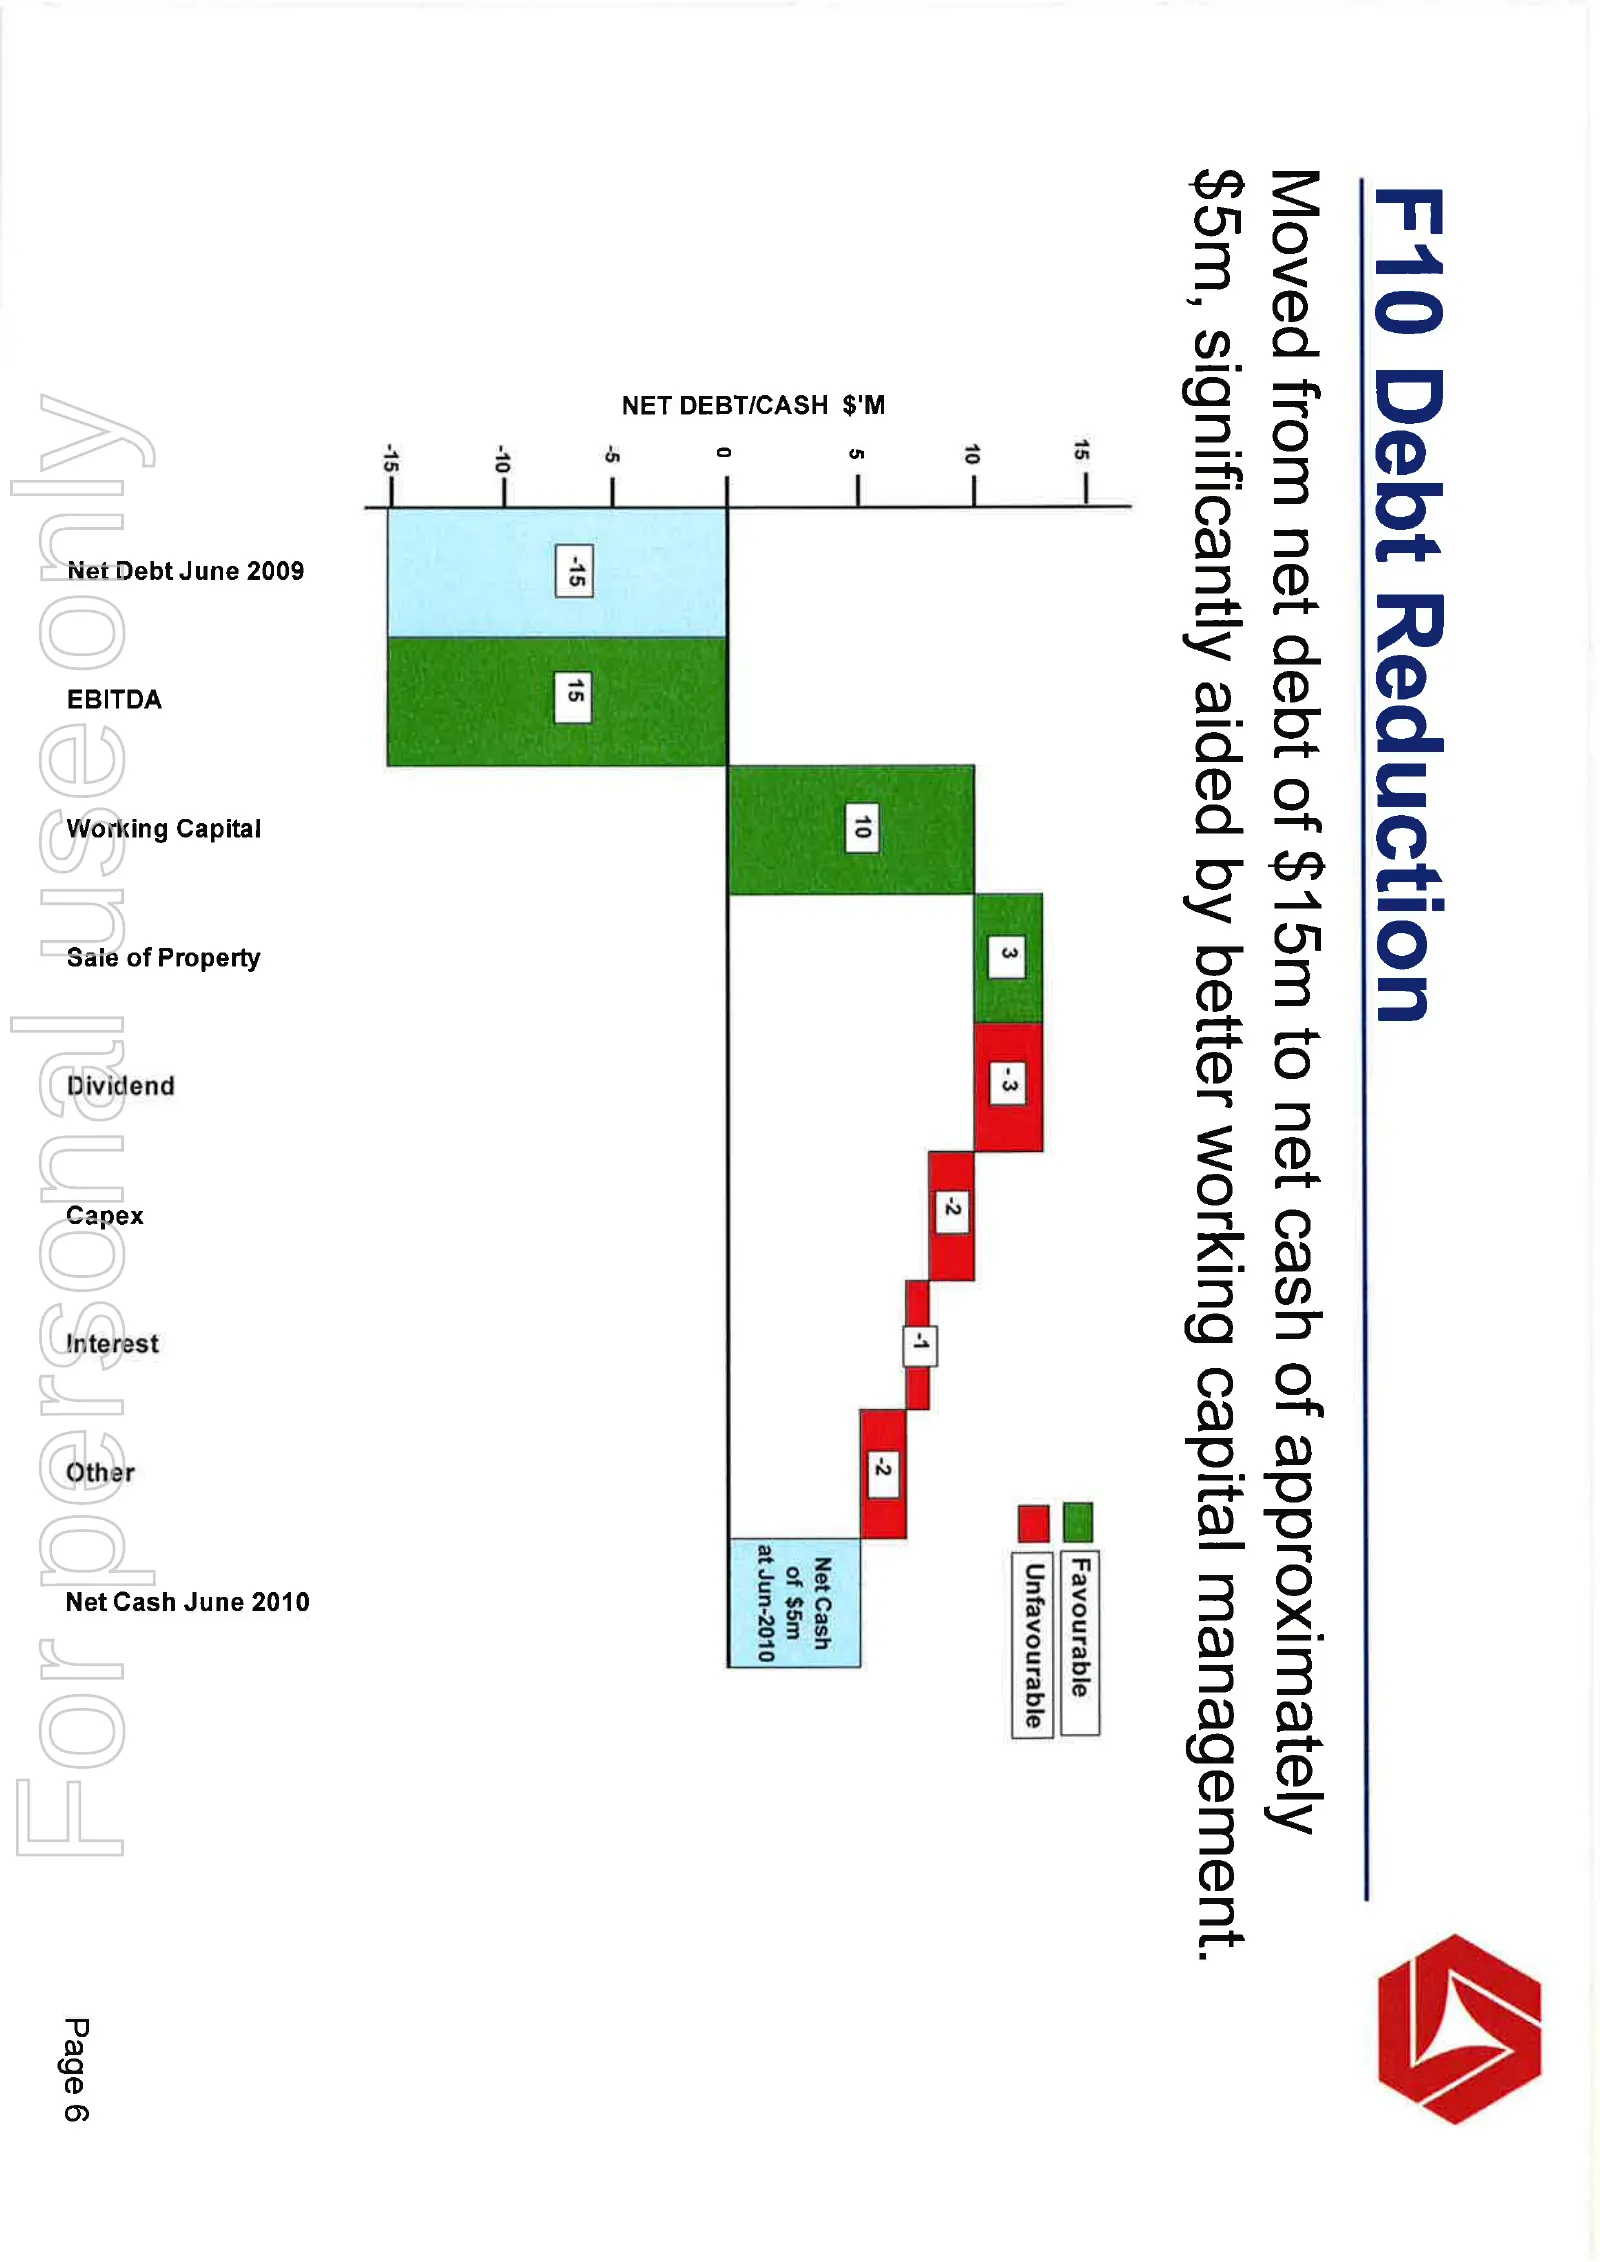
Slide 7: F10 Debt Reduction
F10 Debt Reduction & Moved from net debt of $15m to net cash of approximately $5m, significantly aided by better working capital management. 6 a [Favourabie | [| unfavourable 3 -3 0— ‘ nN Net Cash of $5m at Jun-2010 NET DEBT/CASH $'M [15] 15 -10— 1456— Net Debt June 2009 Working Capital Saie of Prop
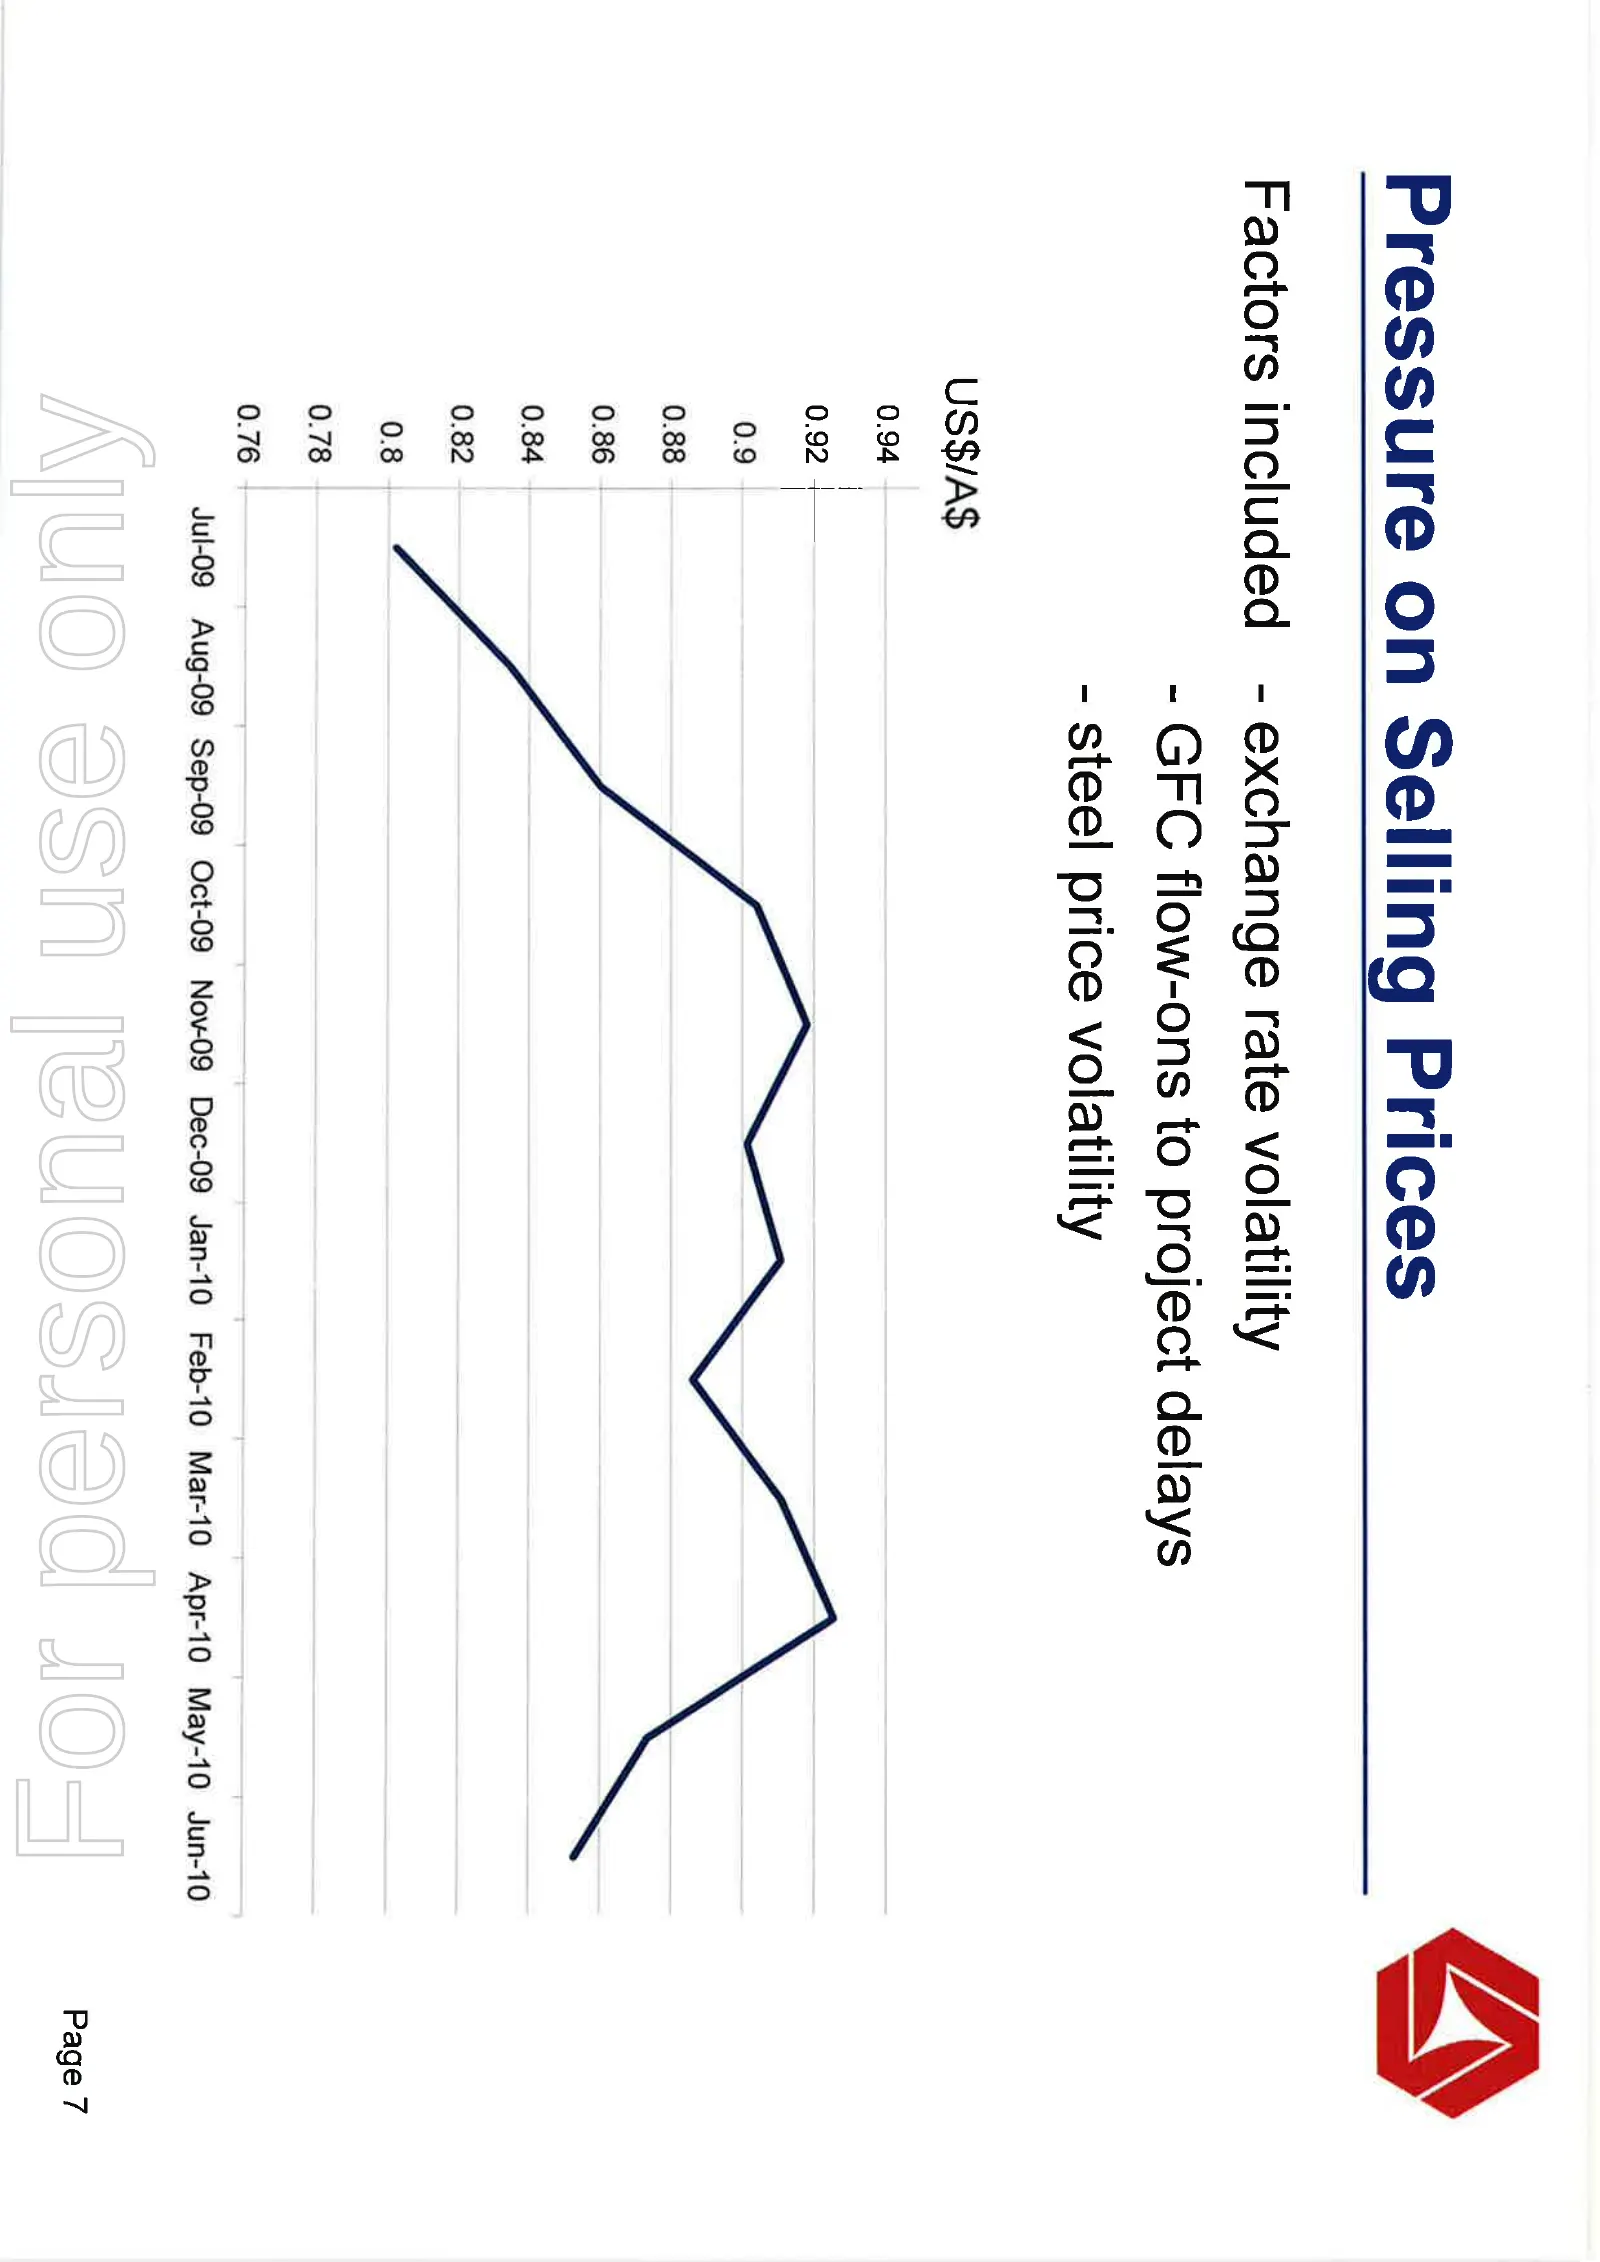
Slide 8: Pressure on Selling Prices
Pressure on Selling Prices & Factors included - exchange rate volatility - GFC flow-ons to project delays - steel price volatility Jul-O9 Aug-09 Sep-09 Oct-09 Nov-09 Dec-09 Jan-10 Feb-10 Mar-10 Apr-10 May-10 Jun-10 Page 7
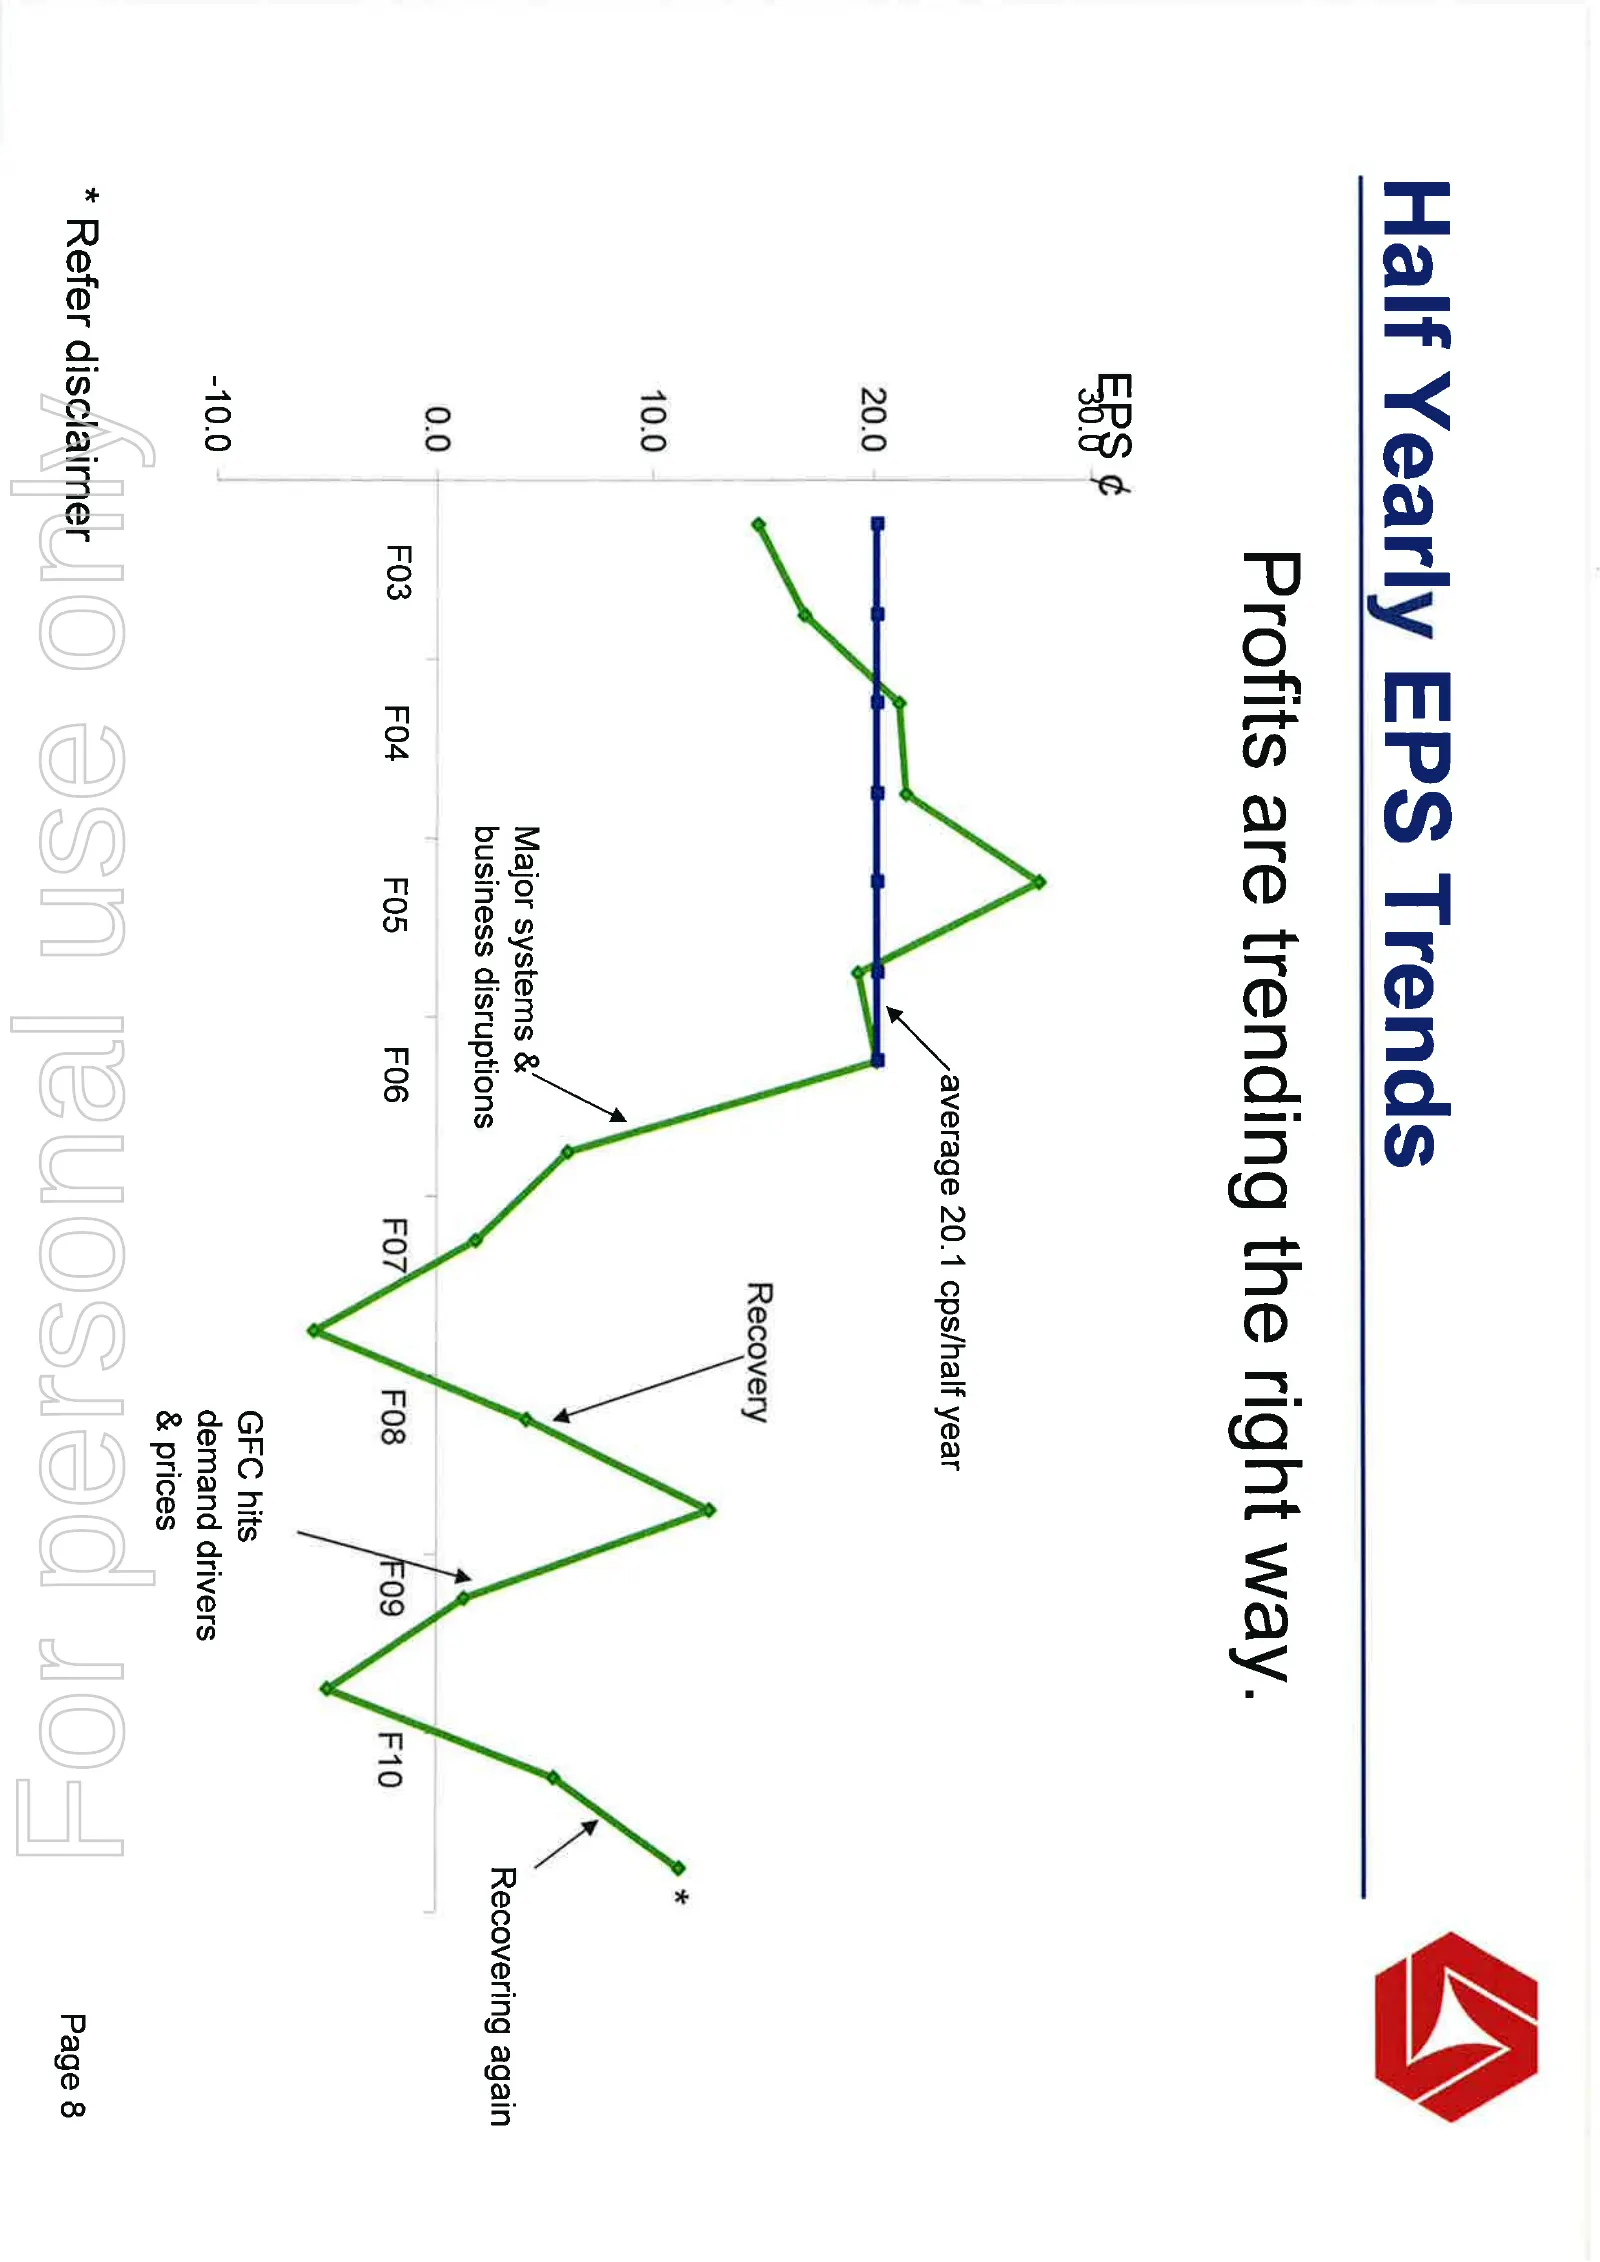
Slide 9: Half Yearly EPS Trends
Half Yearly EPS Trends & Profits are trending the right way. Ebe ¢ aa 20.1 cps/half year 20.0 ® Recovery 10.0 Major systems / \ . . business disruptions Recovering again 0.0 FO3 F04 FO5 FO6 GFC hits ws demand drivers & prices * Refer disclairner Page 8
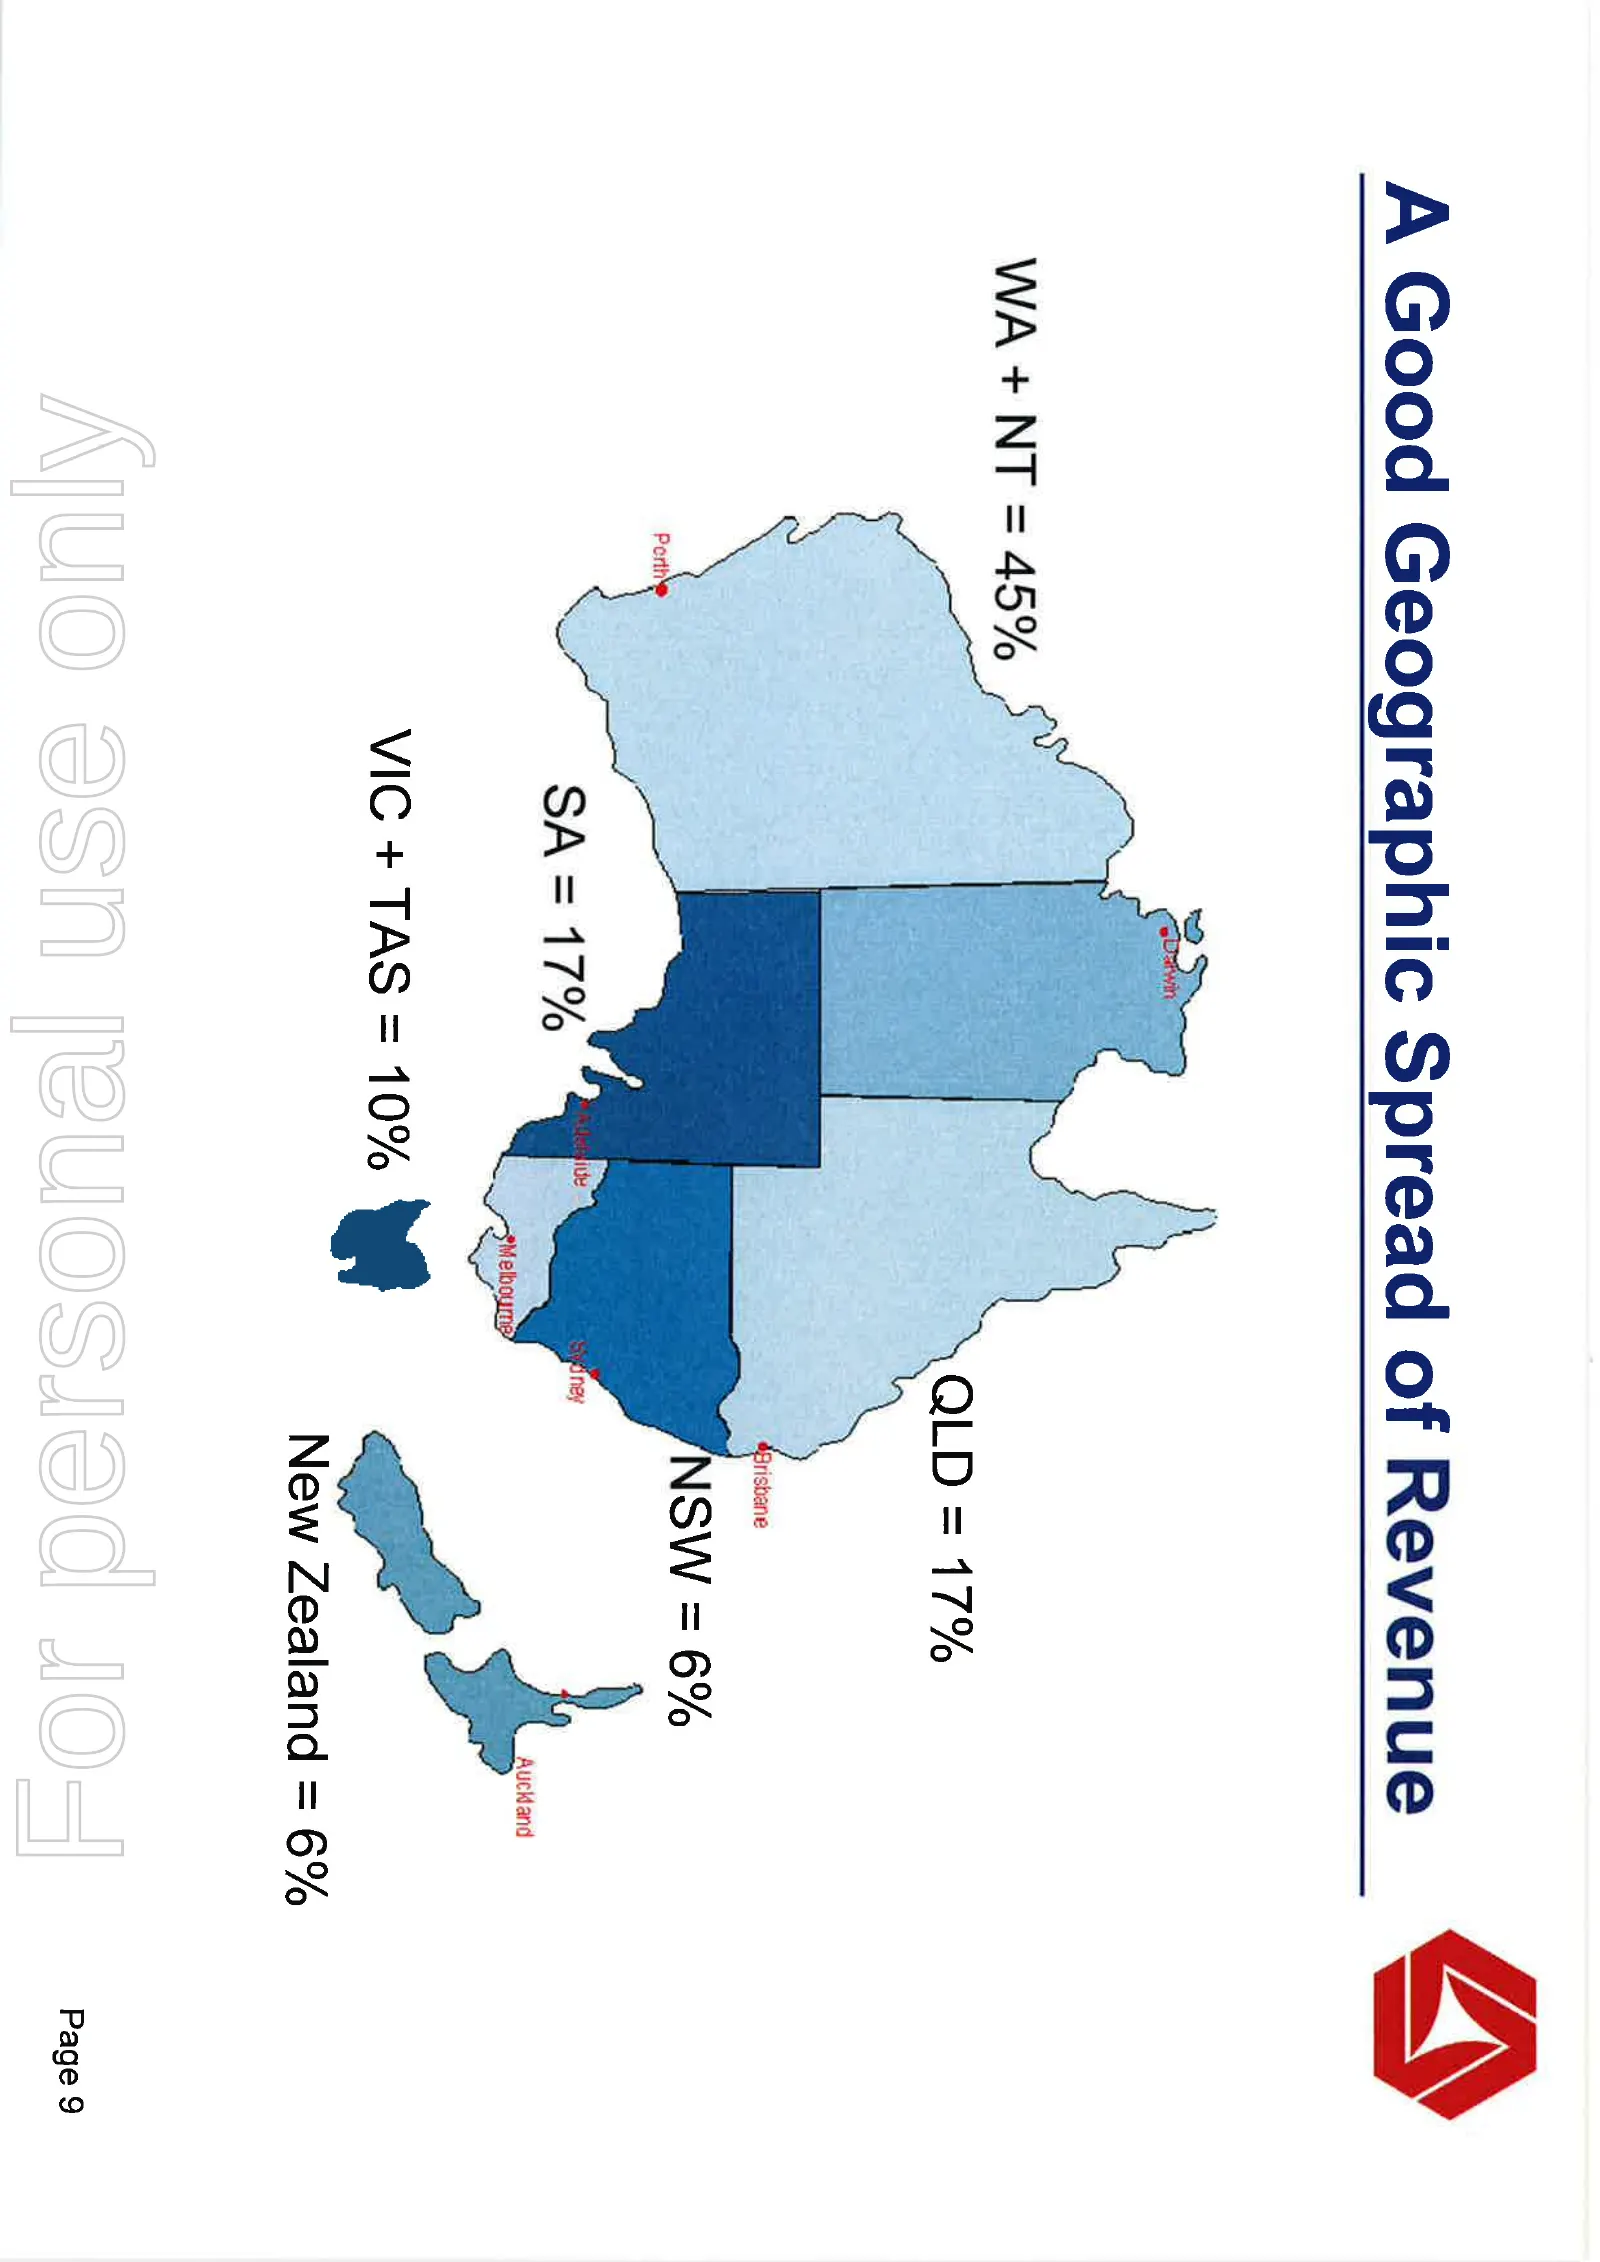
Slide 10: A Good Geographic Spread of Revenue
A Good Geographic Spread of Revenue 4\) of | J 4 WA + NT = 45% a7 ~— 17% NSW = 6% h AucKand New Zealand = 6% Perth / sa= 17% "a VIC + TAS = 10% wa Page 9
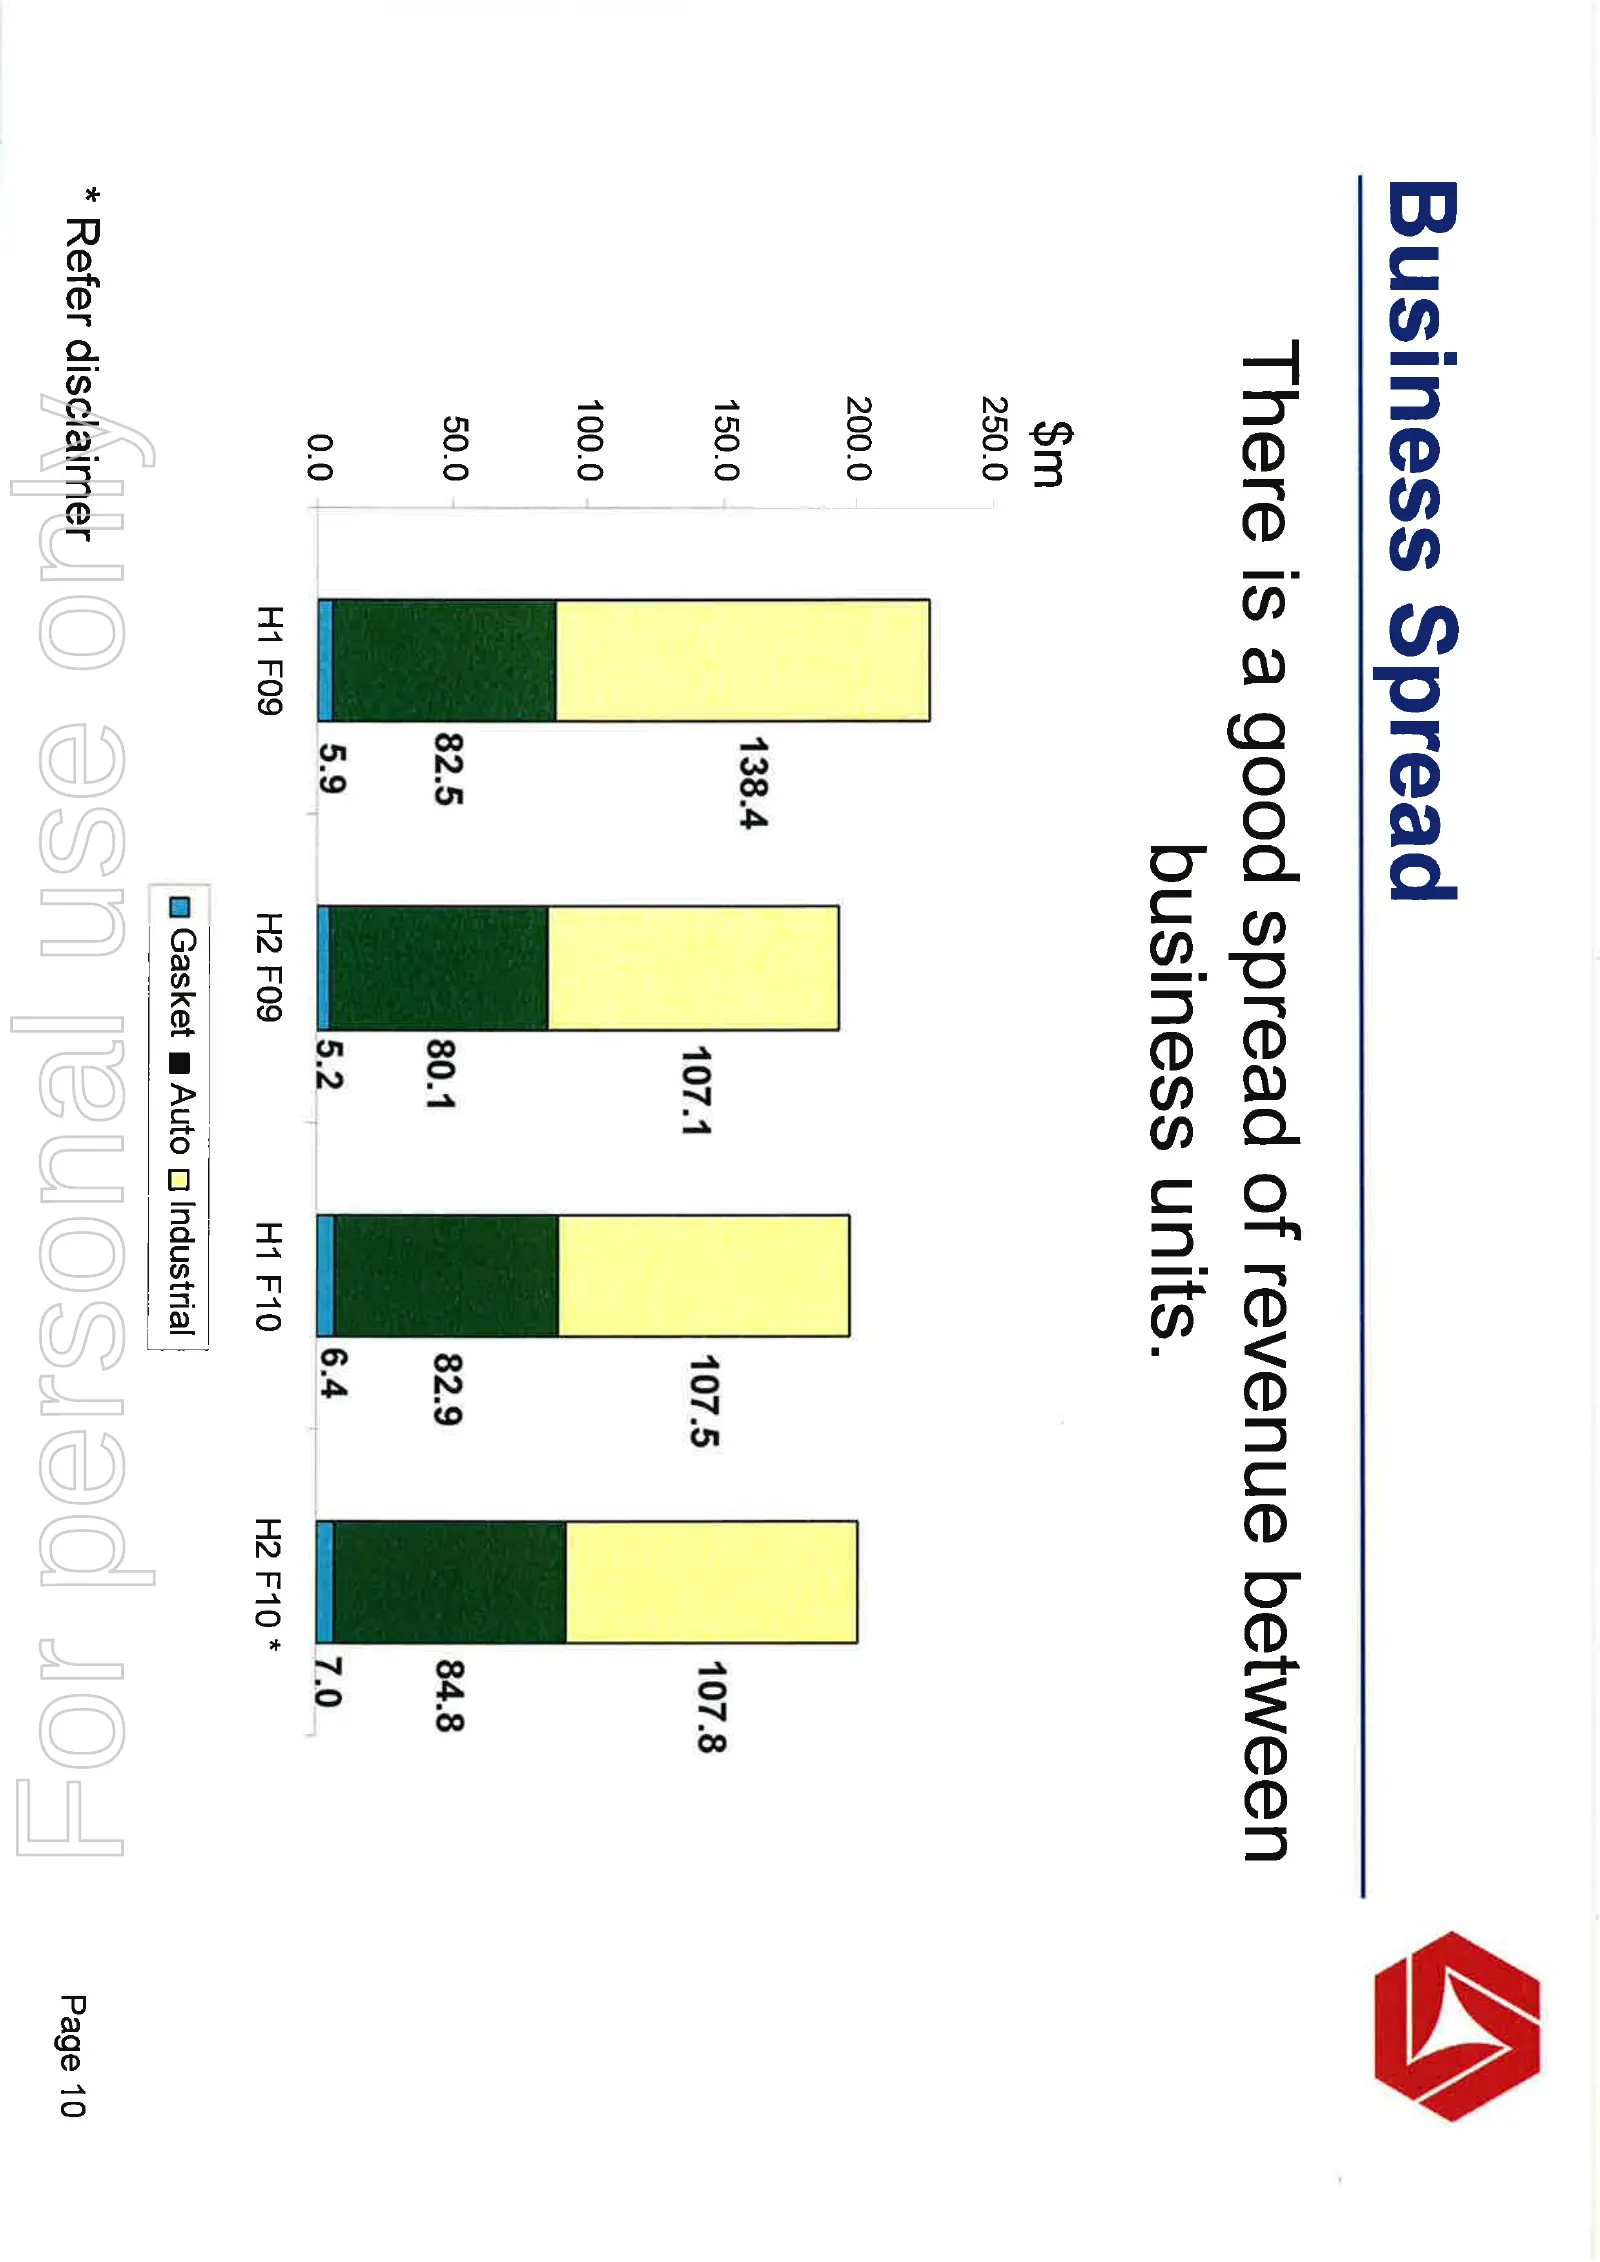
Slide 11: Business Spread
Business Spread 4\) There is a good spread of revenue between business units. $m 250.0 200.0 138.4 150.0 100.0 50.0 82.5 5.9 H1 FO9 H2 FO9 H1 F10 H2 F10* 0.0 @ Gasket m Auto gc Industrial * Refer disclairner Page 10
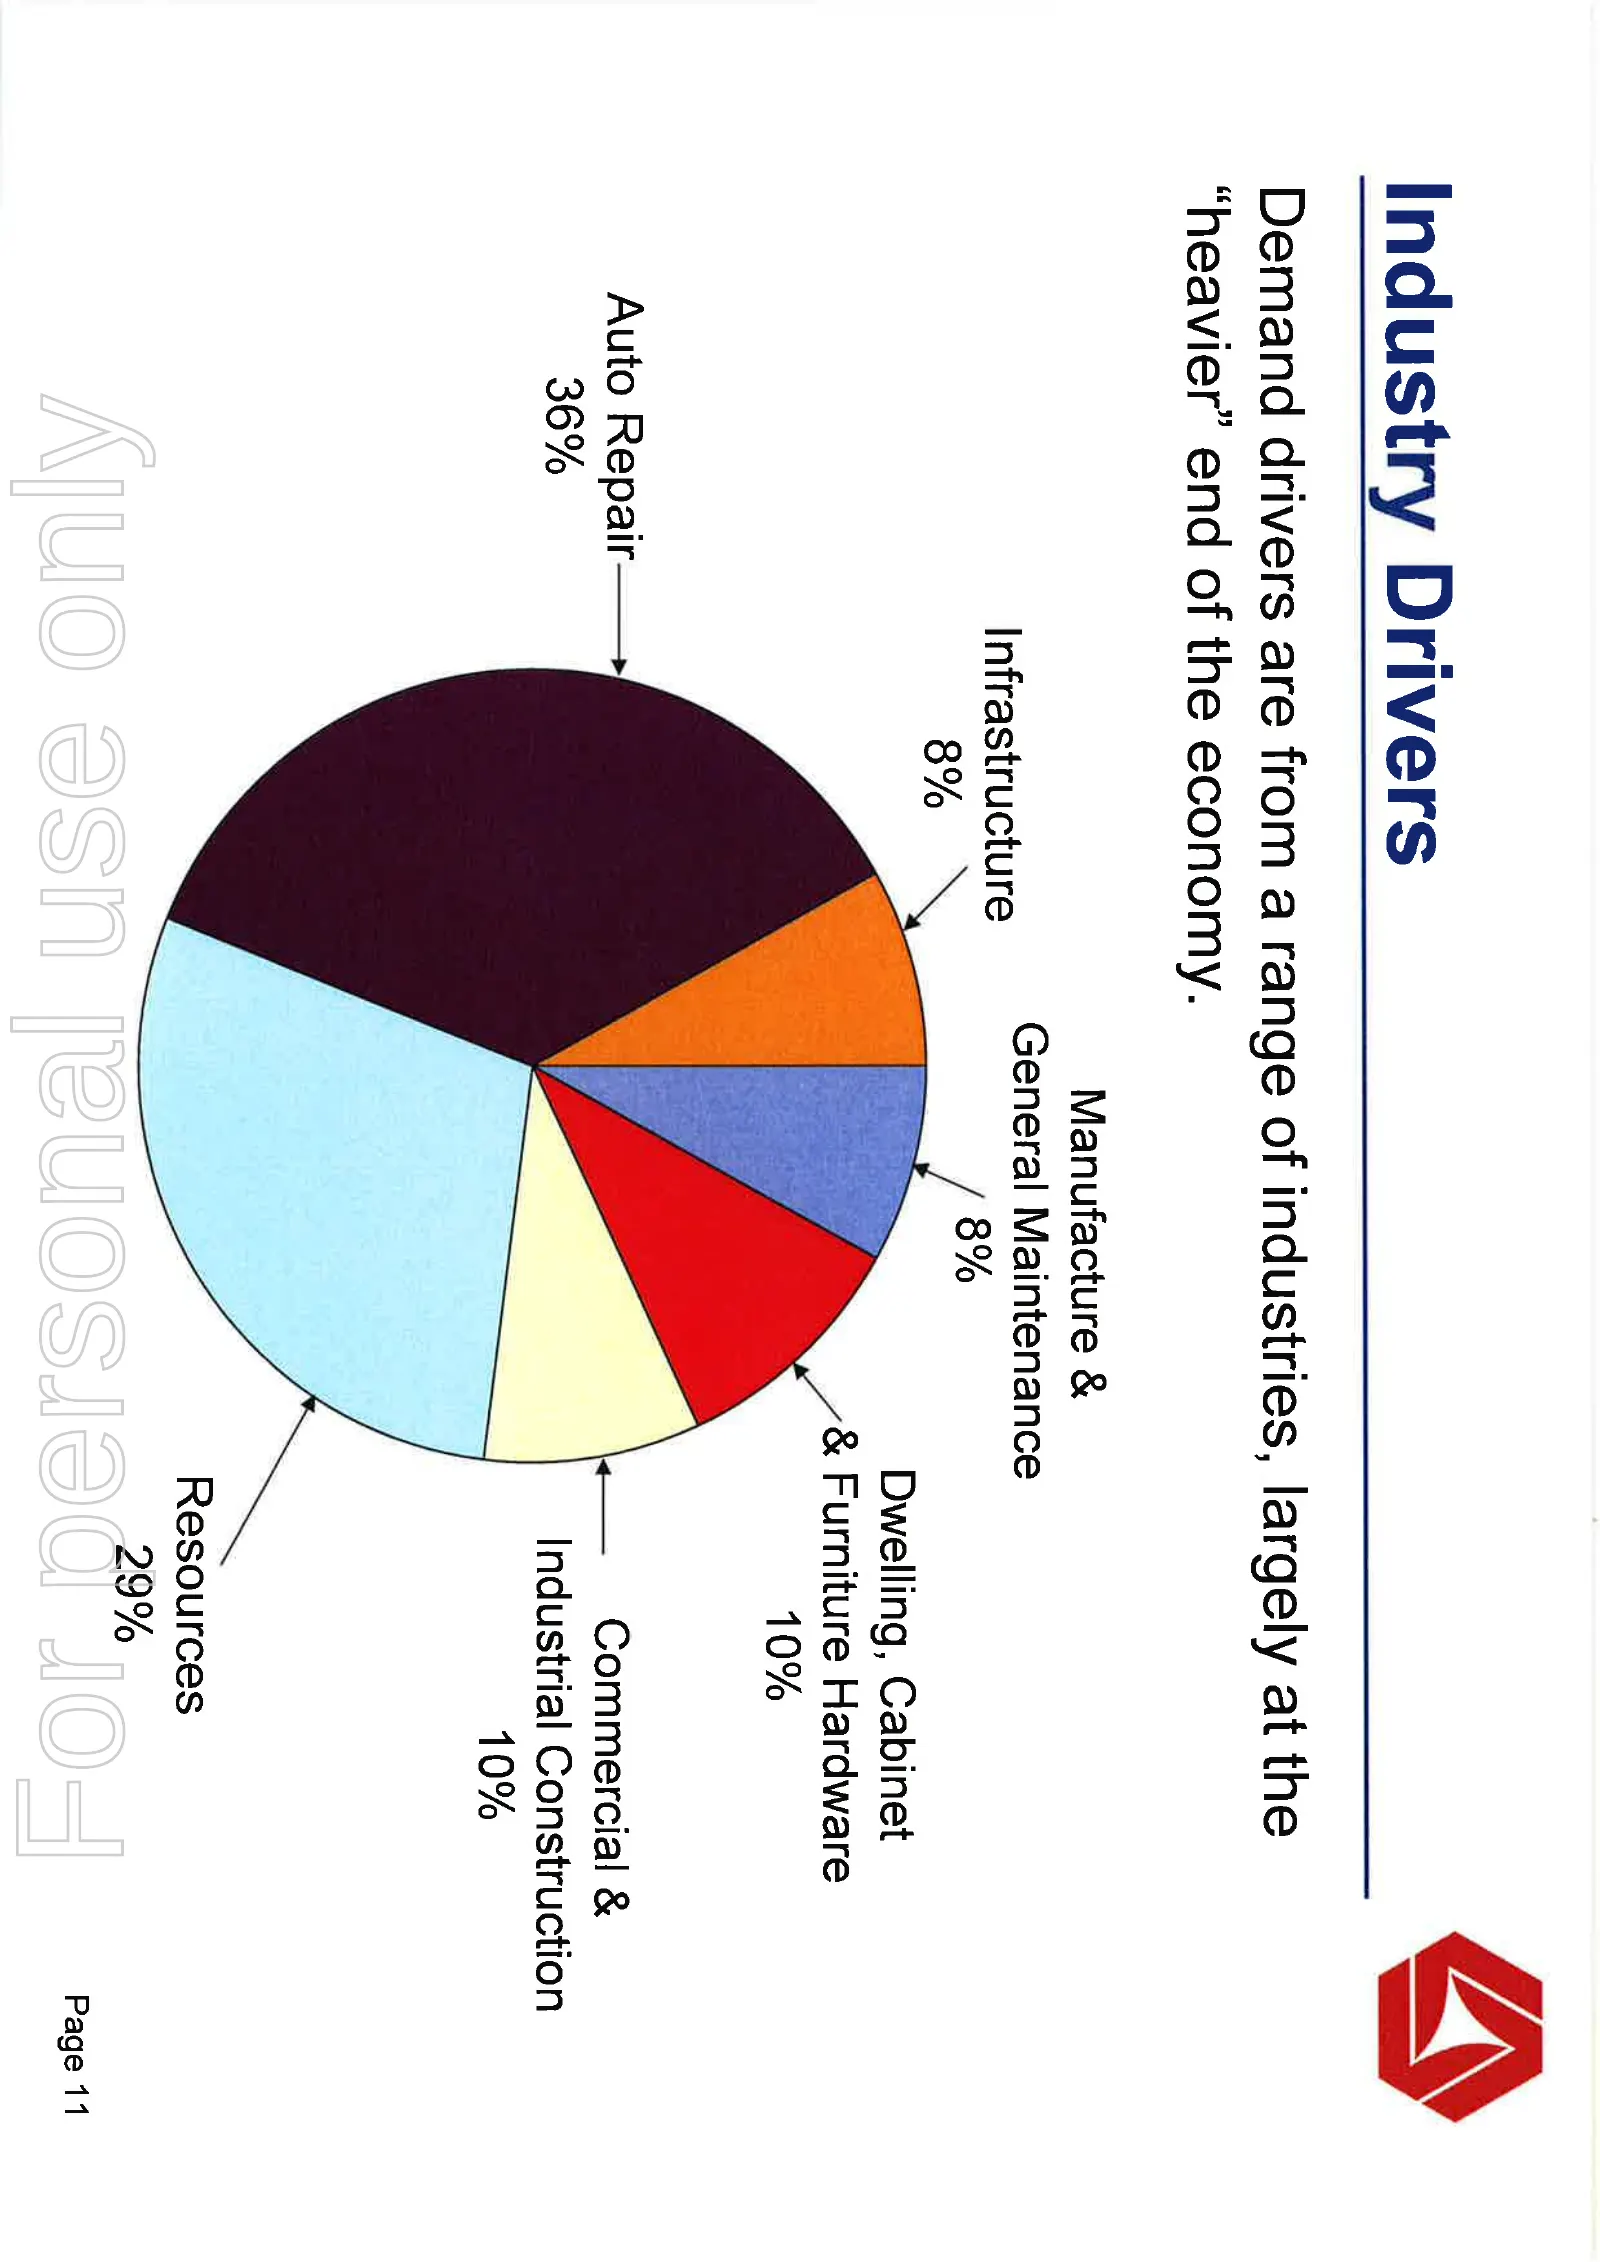
Slide 12: Industry Drivers
Industry Drivers A\) Demand drivers are from a range of industries, largely at the “heavier” end of the economy. Manufacture & General Maintenance Infrastructure 8% 8% Dwelling, Cabinet & Furniture Hardware 10% Auto Repair——, <— Commercial & 36% Industrial Construction 10% Resources 29% Page 11
Slide 13: Key Success Determinants in Our Markets
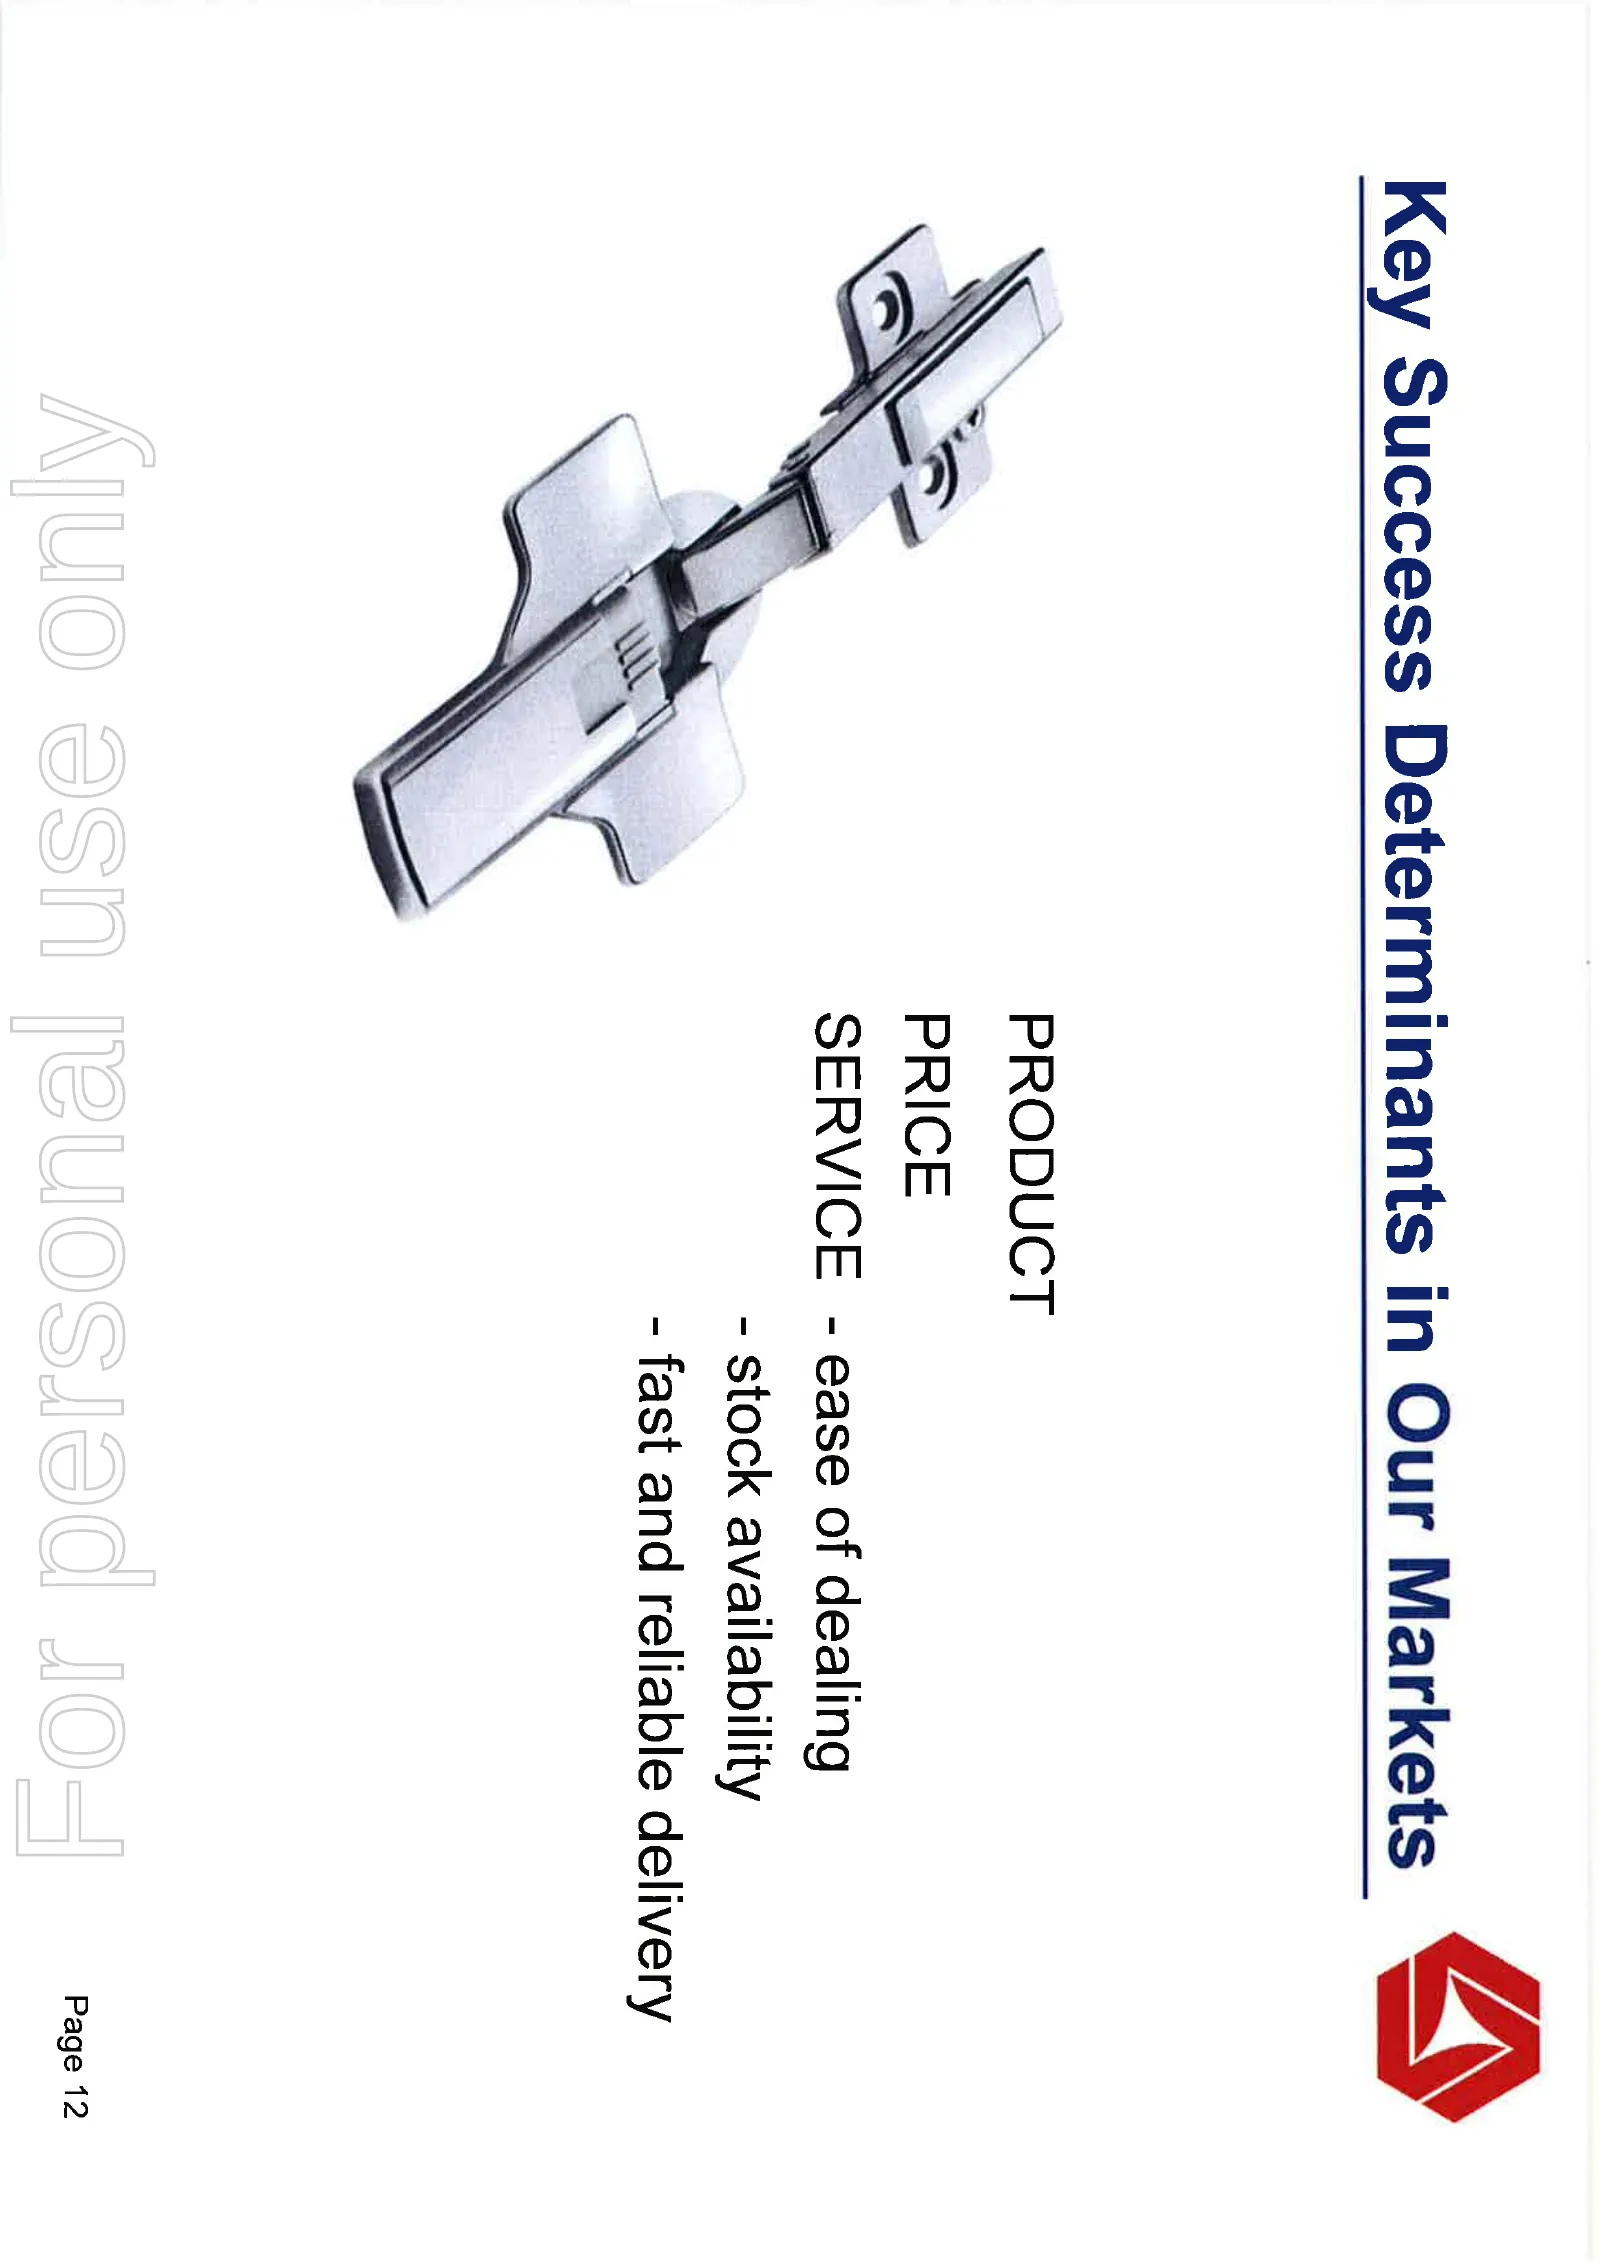
Key Success Determinants in Our Markets & PRODUCT PRICE SERVICE - ease of dealing - stock availability - fast and reliable delivery Page 12
Slide 14: Market Dynamics
Market Dynamics A\) Keen competition in most segments Smaller competitors struggling — some closures Regaining share in auto Weakest demand sector is east coast construction Page 13
Slide 15: Forward Trading Expectations
Forward Trading Expectations Continued gradual demand improvement Dependent on Australia/World economies > volumes Further cost improvements including: — freight — banking transaction costs — product costs — warehousing efficiencies Materially higher profits Likely EBIT: Sales Auto 5% F11-12 Industr
Slide 16: Corporate Moves
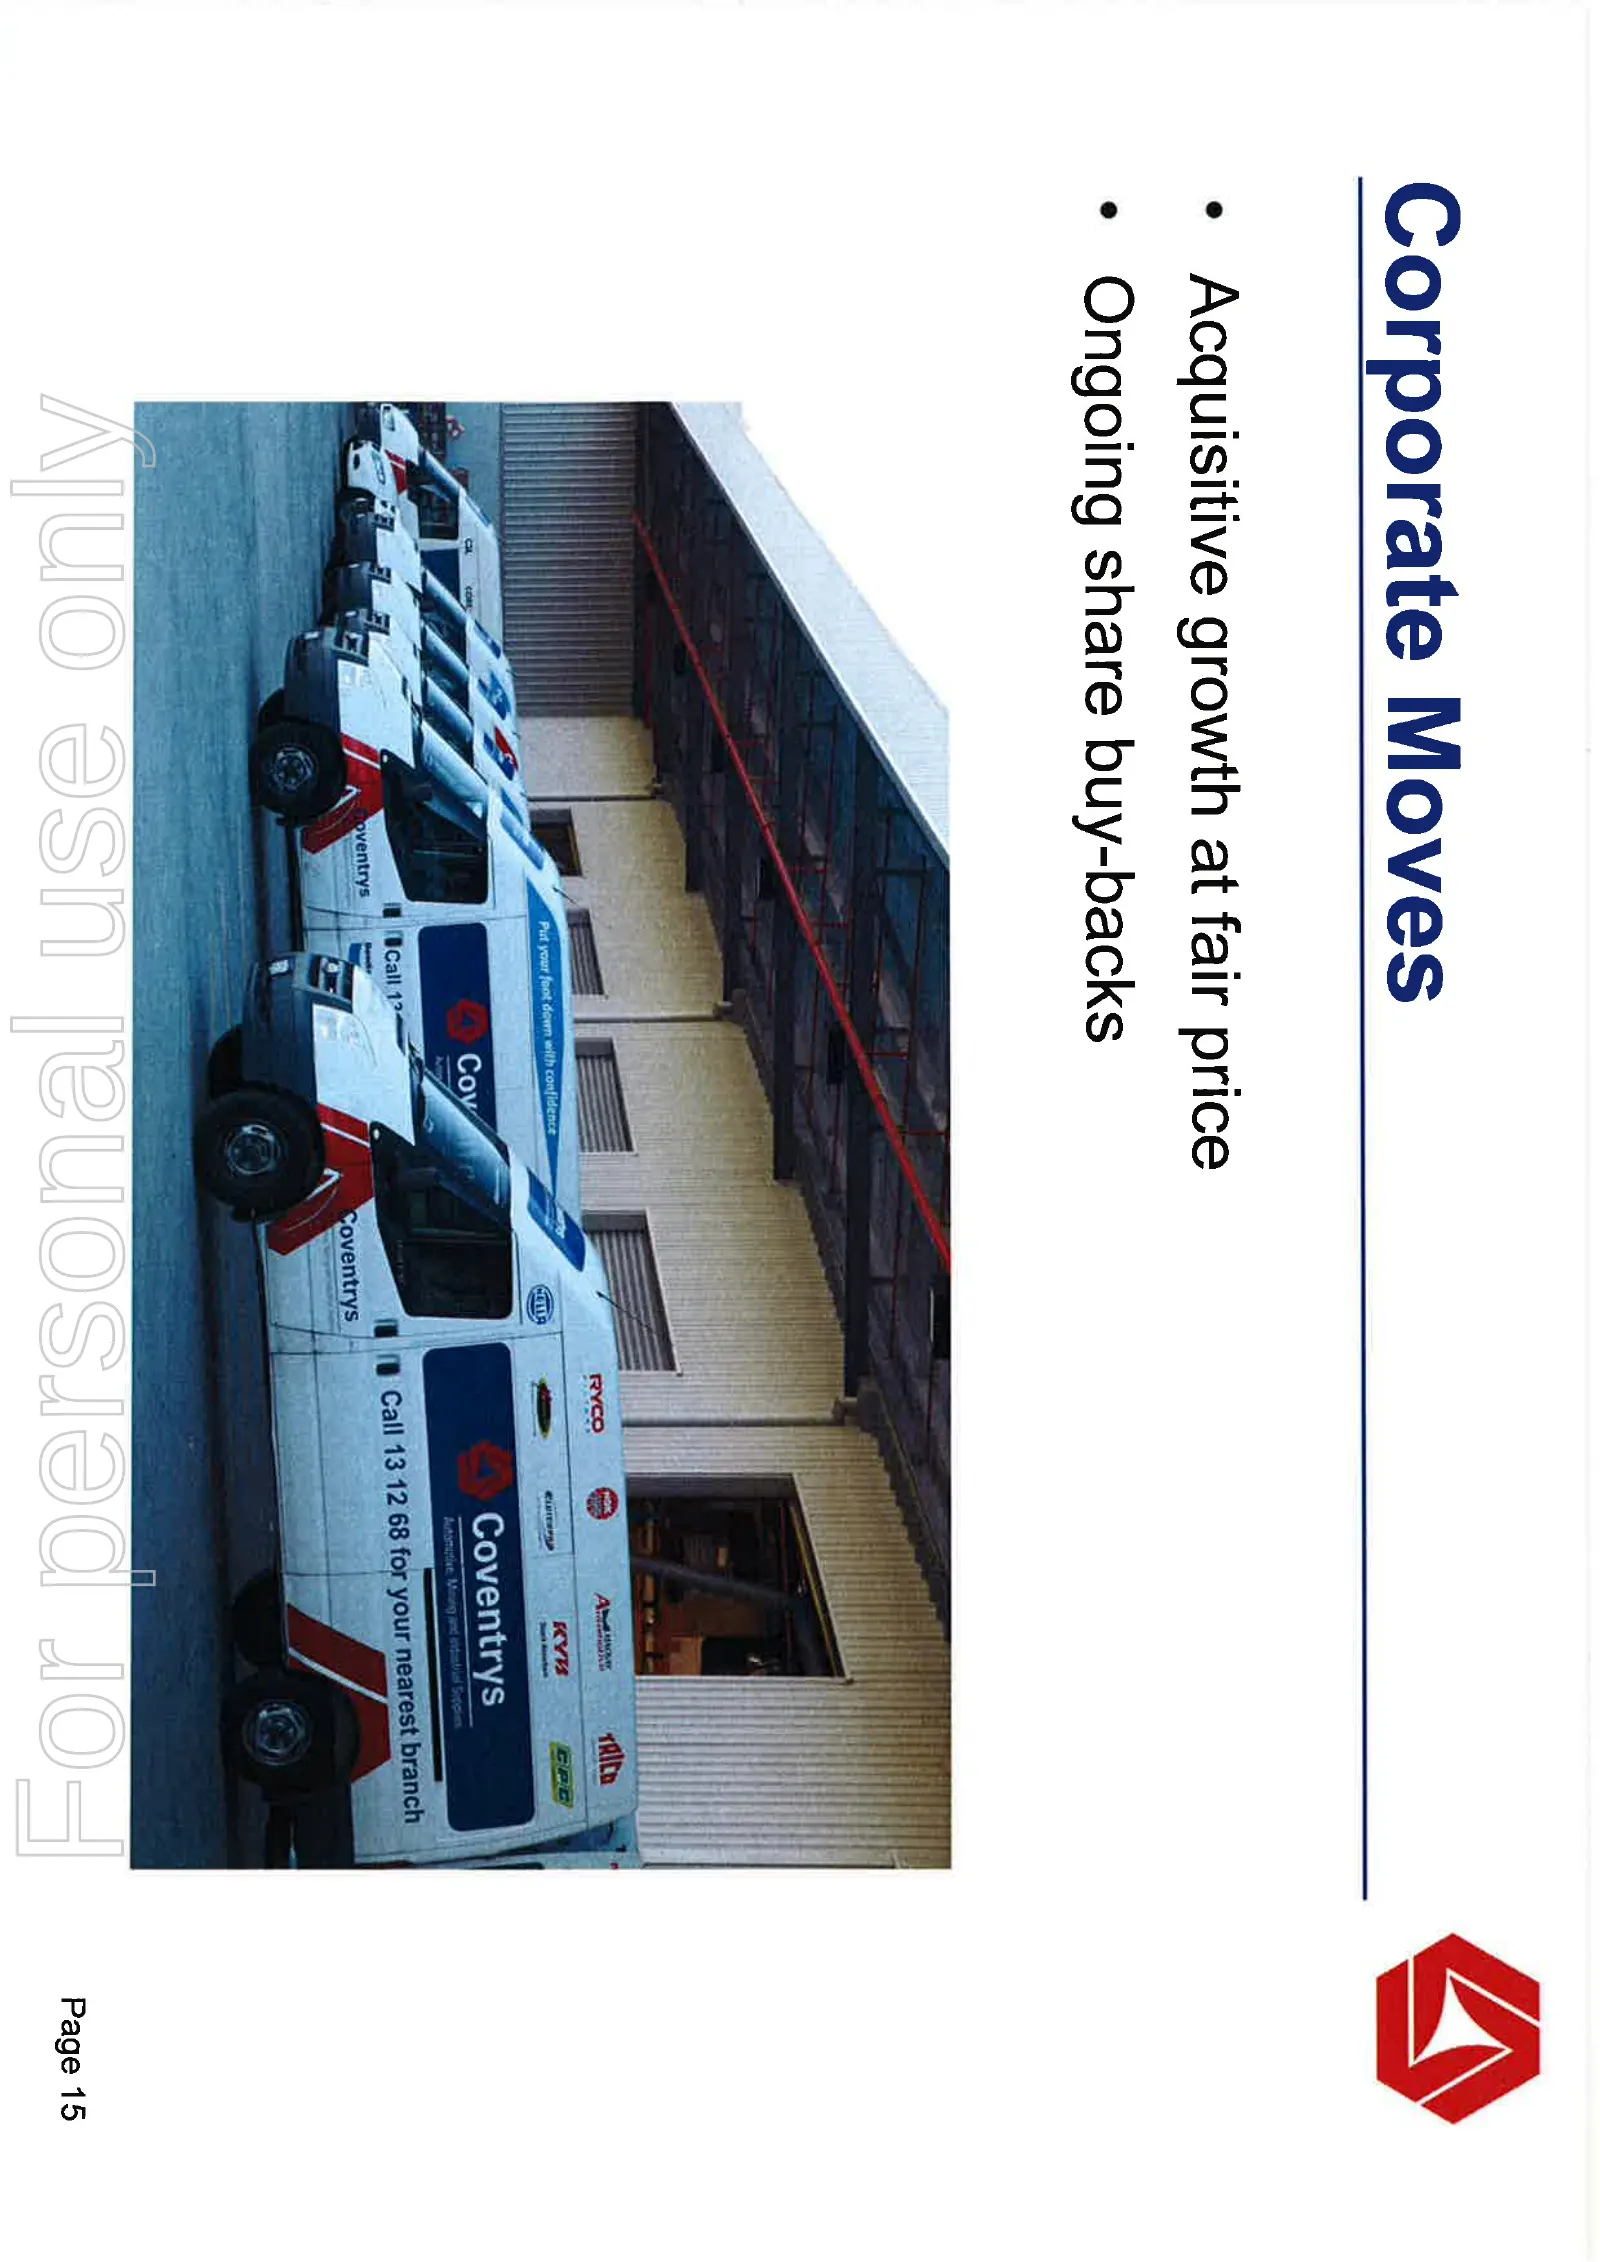
Corporate Moves ¢ Acquisitive growth at fair price ¢ Ongoing share buy-backs © caver” pventrys /°) 1 (® Call 13 12.68 for your nearest branch 1 os : Page 15
Slide 17: Macro Opportunities and Threats
Macro Opportunities and Threats 4) Resurgence of major capital activity — construction — infrastructure — housing * Better acquisition opportunities from more willing sellers ¢ The dreaded “double dip” ¢ A breakout of interest rates * Commodity price falls ¢ A§ fall ?? Page 16
Slide 18: Disclaimer
Disclaimer Statements contained in this presentation, particularly those regarding possible or assumed future performance, estimated company earnings, potential growth of the company, industry growth or other trend projections are or may be forward looking statements. Such statements relate to futur
Source: ASX announcement, Jul 19, 2010
More decks from Coventry Group Limited
 Shareholder Meeting (November 2026)11 slides · Nov 20, 2026
 FY2026 Earnings Presentation31 slides · Aug 31, 2026
 Investor Presentation (February 2026)14 slides · Feb 27, 2026
 Shareholder Meeting (November 2025)19 slides · Nov 21, 2025
 Investor Presentation (September 2025)16 slides · Sep 15, 2025
 FY2025 Earnings Presentation19 slides · September 2025