Pinnacle Foods — Barclays Global Consumer Staples Conference 2015
47 slides from Pinnacle Foods's conference presentation, Sep 9, 2015
Slide 1: Barclays Global Consumer Staples Conference
Barclays Global Consumer Staples Conference September 9, 2015
Slide 2: Forward-Looking Statements & Non-GAAP Financial Measures
2 This presentation contains “forward-looking statements” within the meaning of U.S. federal securities laws. Forward-looking statements are not historical facts, and are based upon management’s current expectations, beliefs, projections and targets, many of which, by their nature, are inherently un
Slide 3: Agenda
3 Agenda Overview Executing Our Strategy Financial Update Outlook
Slide 4: Pinnacle Value Creation Model
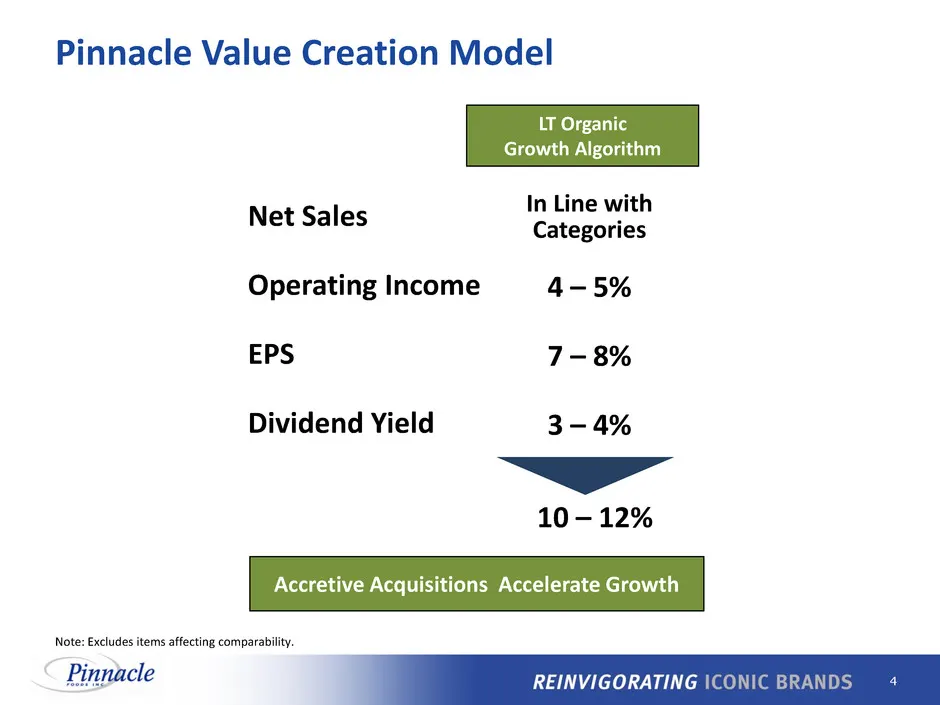
4 Pinnacle Value Creation Model Net Sales Operating Income EPS Dividend Yield In Line with Categories 10 – 12% 4 – 5% 7 – 8% 3 – 4% LT Organic Growth Algorithm Accretive Acquisitions Accelerate Growth Note: Excludes items affecting comparability.
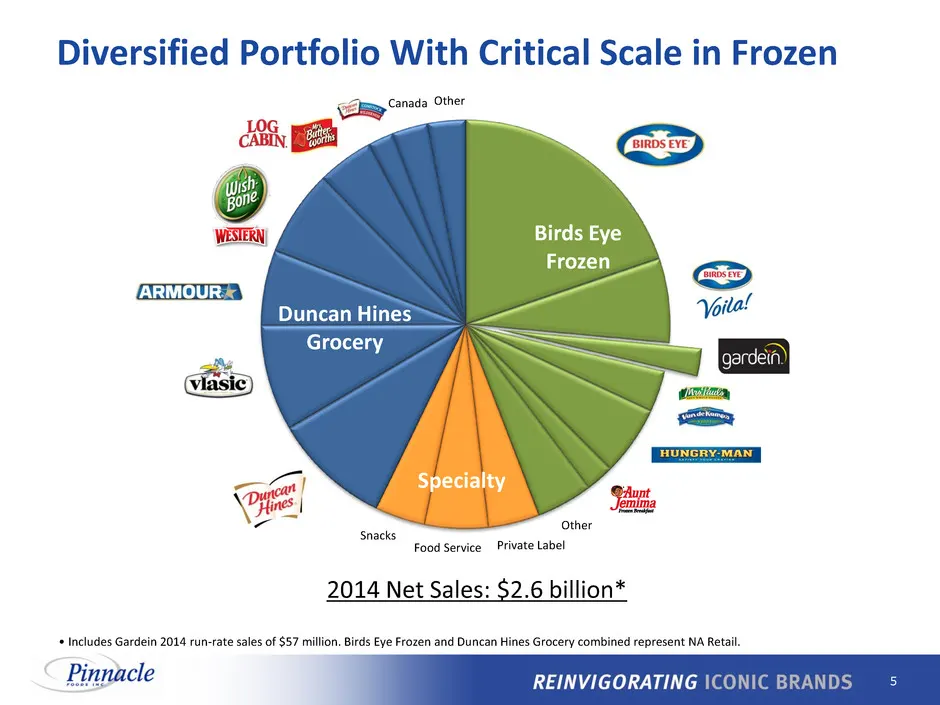
Slide 5: Diversified Portfolio With Critical Scale in Frozen
5 Birds Eye Frozen Specialty Duncan Hines Grocery Other 2014 Net Sales: $2.6 billion* Diversified Portfolio With Critical Scale in Frozen • Includes Gardein 2014 run-rate sales of $57 million. Birds Eye Frozen and Duncan Hines Grocery combined represent NA Retail. Canada Snacks Food Service Private
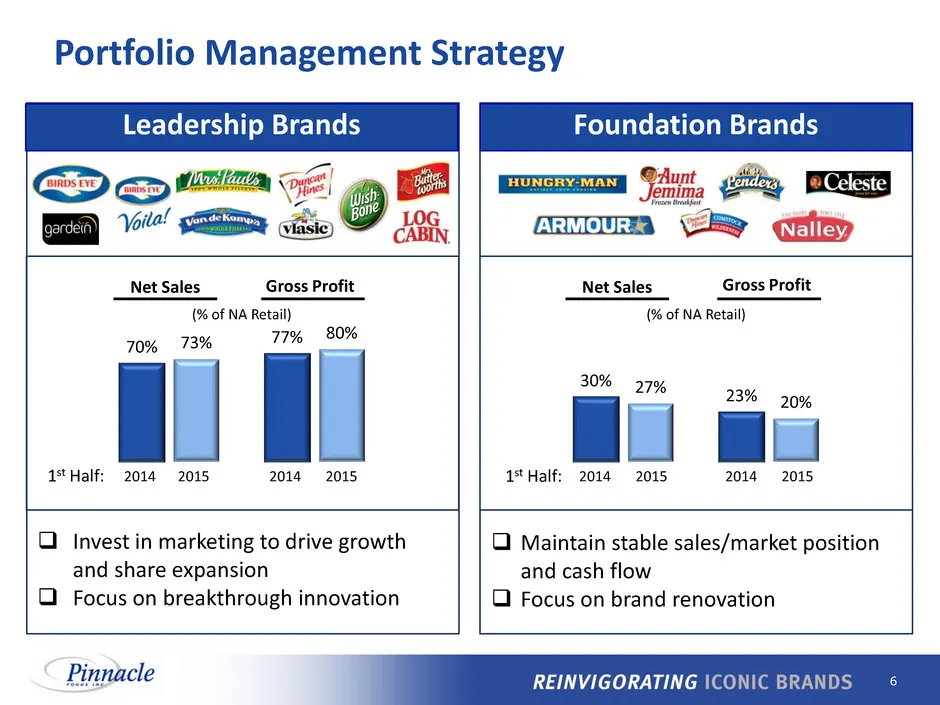
Slide 6: Portfolio Management Strategy
6 70% 77% 73% 80% Net Sales 2014 2015 2014 2015 30% 23% 27% 20% 2014 2015 2014 2015 Invest in marketing to drive growth and share expansion Focus on breakthrough innovation Gross Profit Net Sales Gross Profit Maintain stable sales/market position and cash flow Focus on brand renovation Leade
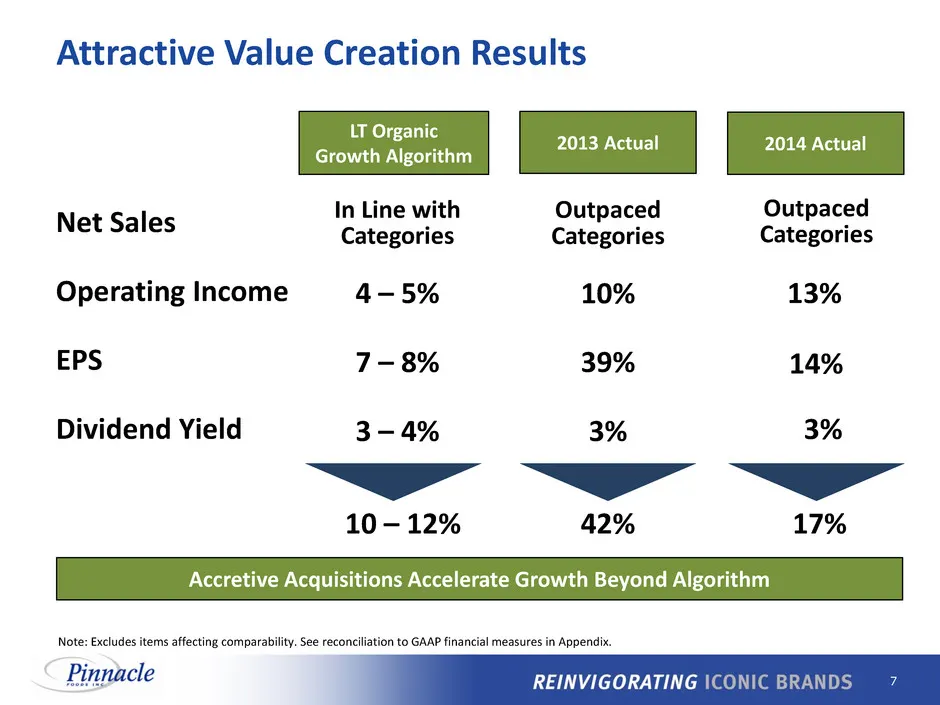
Slide 7: Attractive Value Creation Results
7 Net Sales Operating Income EPS Dividend Yield In Line with Categories 10 – 12% 4 – 5% 7 – 8% 3 – 4% LT Organic Growth Algorithm 10% 39% 3% Outpaced Categories 42% 2013 Actual Accretive Acquisitions Accelerate Growth Beyond Algorithm Note: Excludes items affecting comparability. See reconciliation
Slide 8: Agenda
8 Agenda Overview Executing Our Strategy Financial Update Outlook
Slide 9: Executing Our Strategy
9 3. Generate exceptional cash flow to provide value creation optionality 1. Drive Leadership Brands through innovation and marketing 2. Deliver industry-leading efficiency Productivity SG&A overheads Executing Our Strategy
Slide 10: Leadership Brands
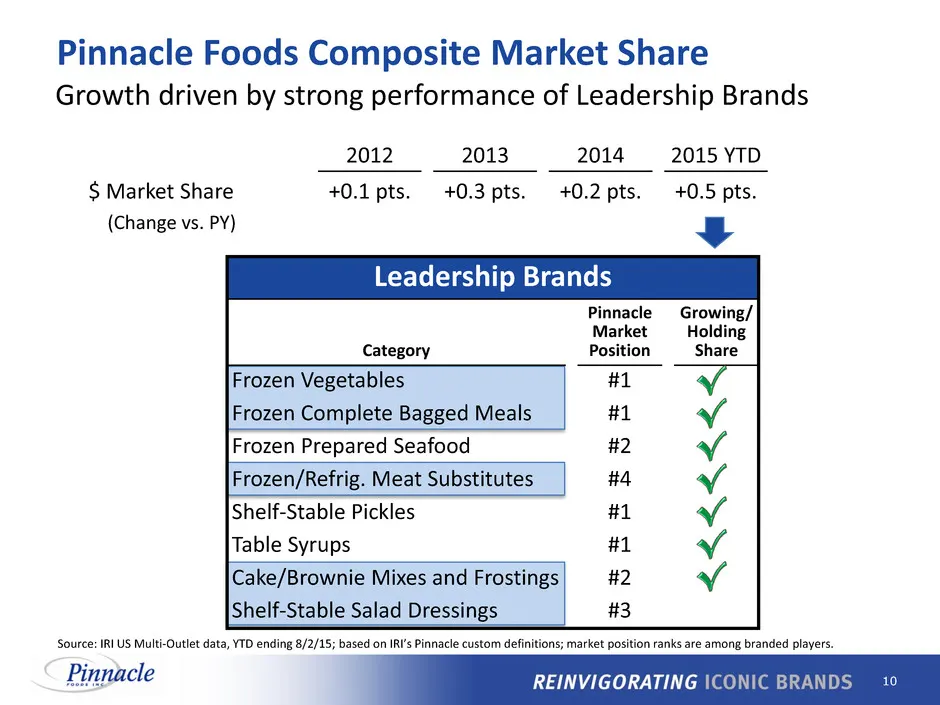
10 Leadership Brands Category Pinnacle Market Position Growing/ Holding Share Frozen Vegetables #1 Frozen Complete Bagged Meals #1 Frozen Prepared Seafood #2 Frozen/Refrig. Meat Substitutes #4 Shelf-Stable Pickles #1 Table Syrups #1 Cake/Brownie Mixes and Frostings #2 Shelf-Stable Salad Dressings #3
Slide 11: Birds Eye - $1 Billion Health & Wellness Brand
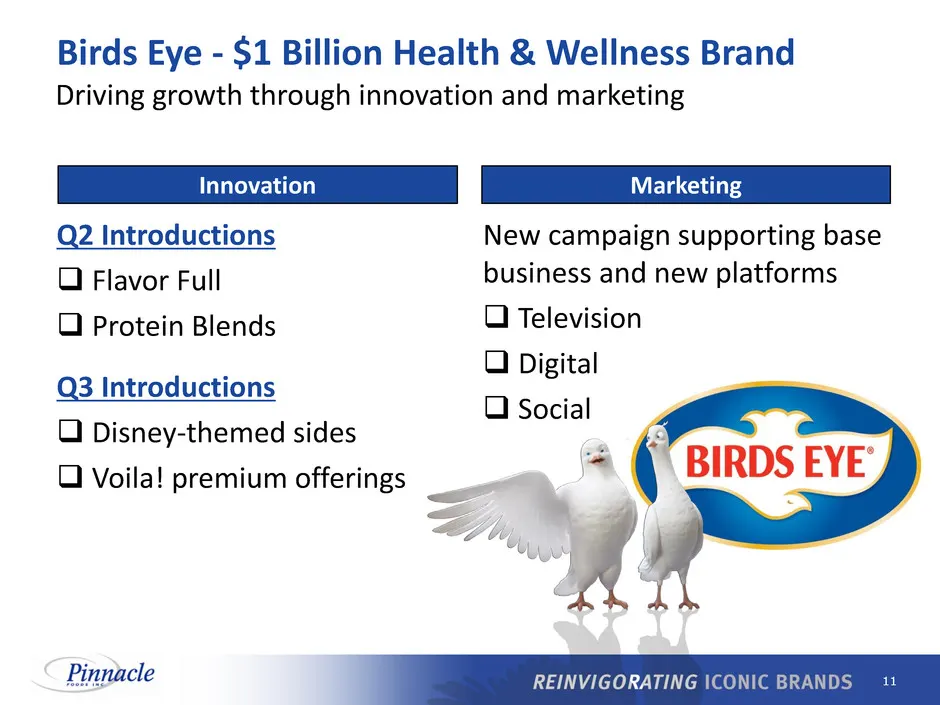
11 Innovation Q2 Introductions Flavor Full Protein Blends Q3 Introductions Disney-themed sides Voila! premium offerings Marketing New campaign supporting base business and new platforms Television Digital Social Birds Eye - $1 Billion Health & Wellness Brand Driving growth through inno
Slide 12: Birds Eye Flavor Full
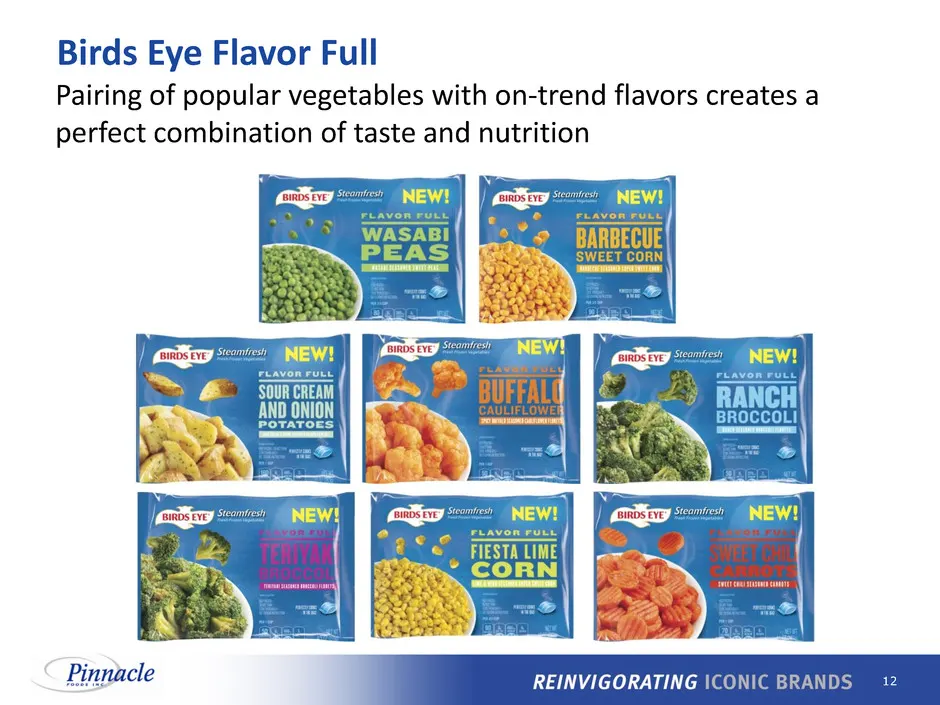
12 Birds Eye Flavor Full Pairing of popular vegetables with on-trend flavors creates a perfect combination of taste and nutrition
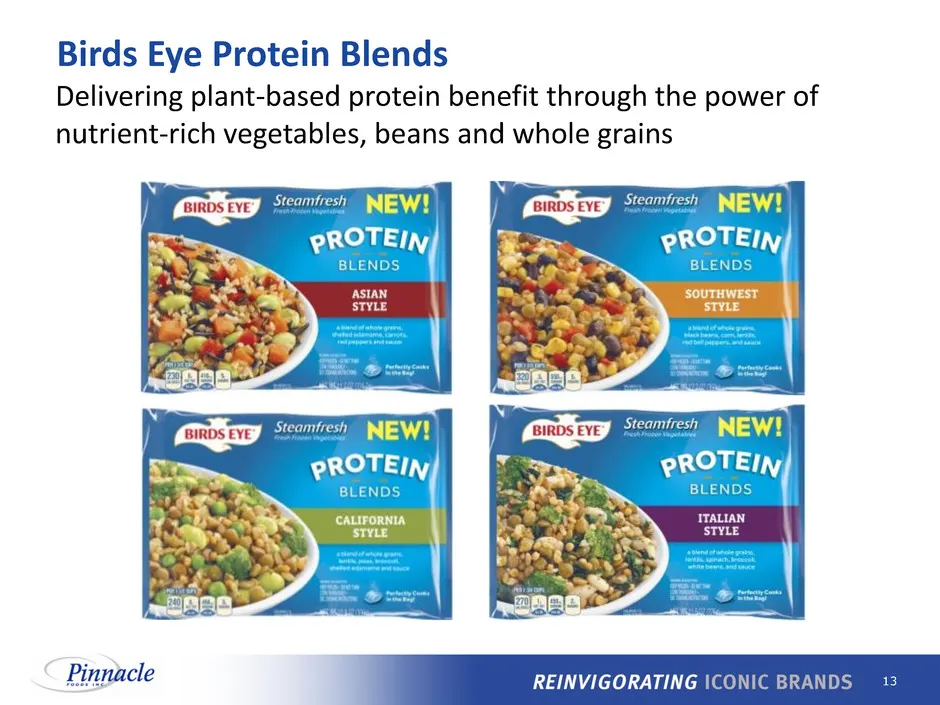
Slide 13: Birds Eye Protein Blends
13 Birds Eye Protein Blends Delivering plant-based protein benefit through the power of nutrient-rich vegetables, beans and whole grains
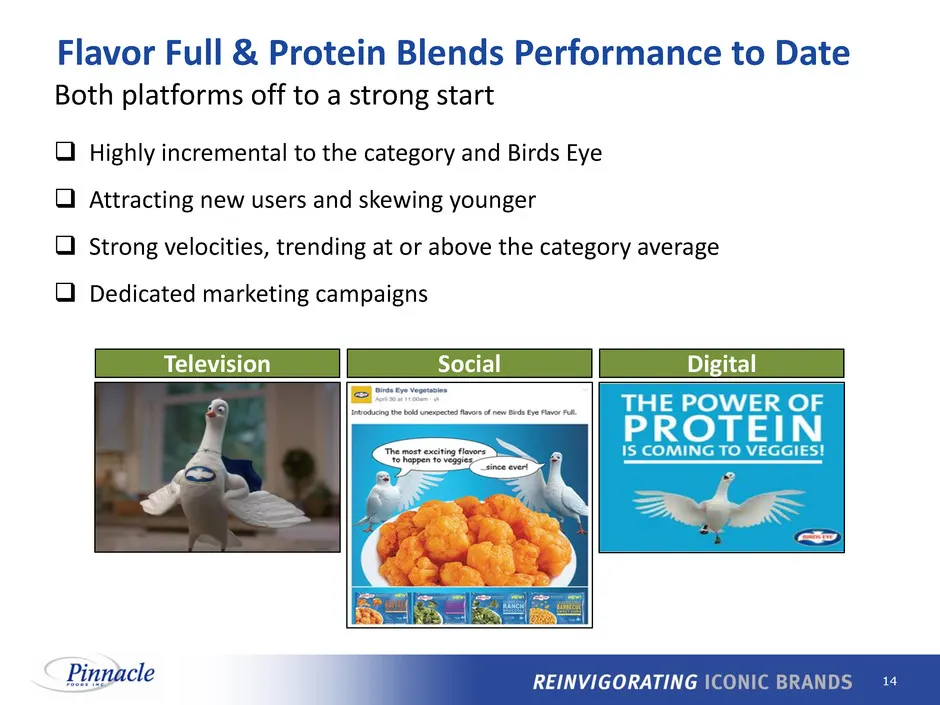
Slide 14: Flavor Full & Protein Blends Performance to Date
14 Both platforms off to a strong start Highly incremental to the category and Birds Eye Attracting new users and skewing younger Strong velocities, trending at or above the category average Dedicated marketing campaigns Flavor Full & Protein Blends Performance to Date Digital Television Soc
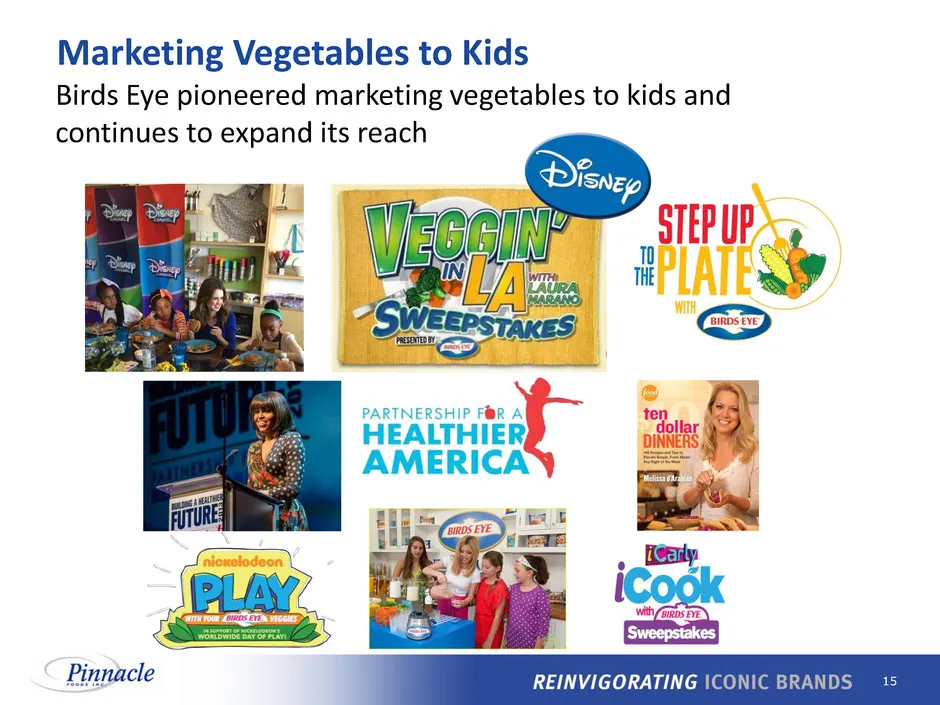
Slide 15: Marketing Vegetables to Kids
15 Marketing Vegetables to Kids Birds Eye pioneered marketing vegetables to kids and continues to expand its reach
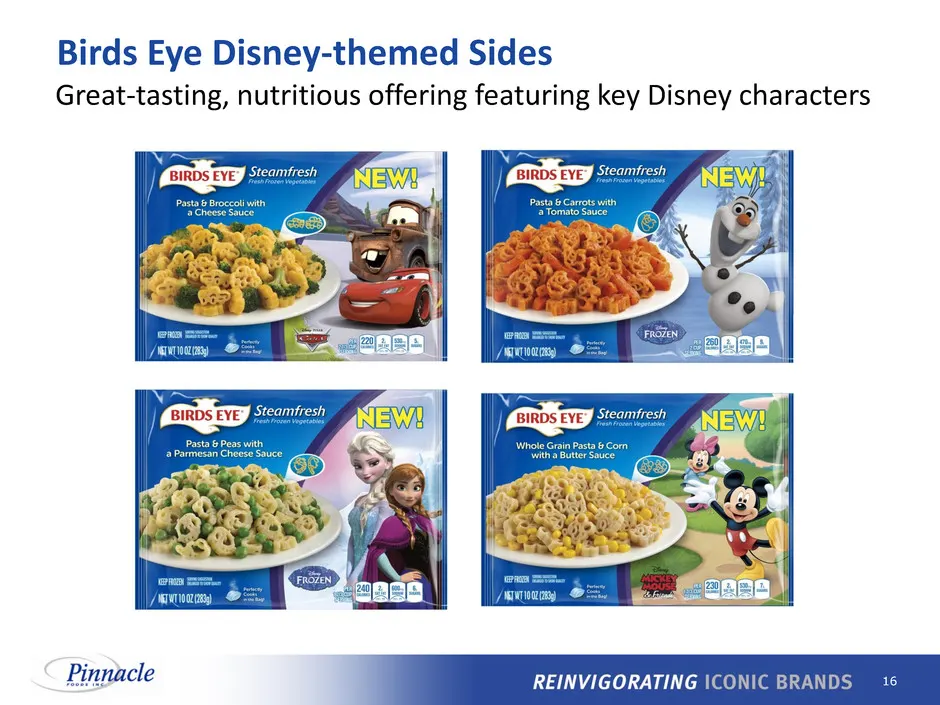
Slide 16: Birds Eye Disney-themed Sides
16 Birds Eye Disney-themed Sides Great-tasting, nutritious offering featuring key Disney characters
Slide 17: Birds Eye Voila!
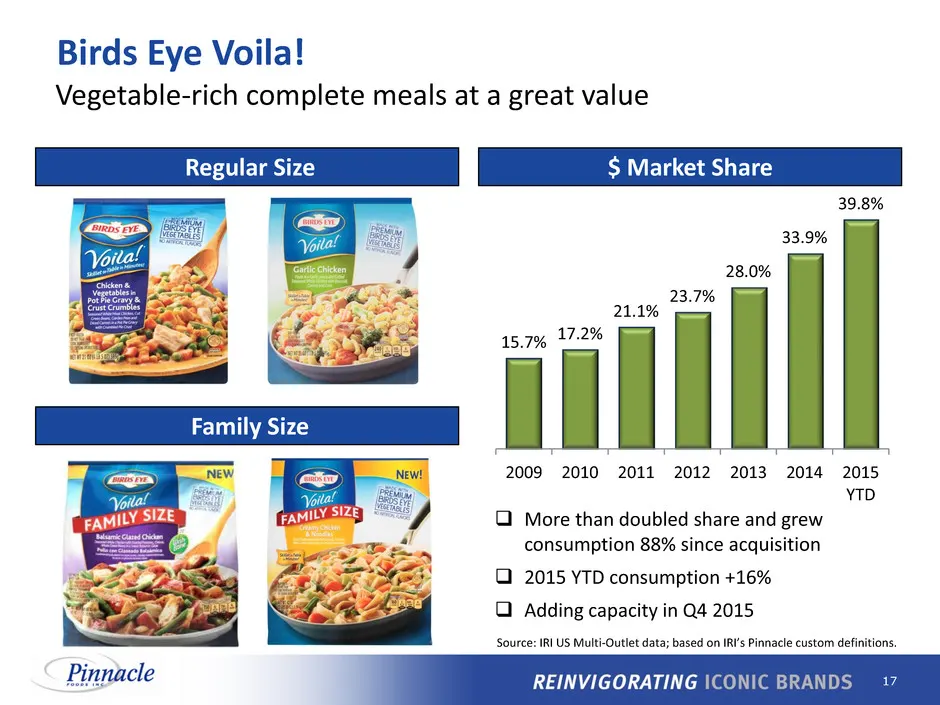
17 Regular Size Family Size 15.7% 17.2% 21.1% 23.7% 28.0% 33.9% 39.8% 2009 2010 2011 2012 2013 2014 2015 YTD $ Market Share Source: IRI US Multi-Outlet data; based on IRI’s Pinnacle custom definitions. More than doubled share and grew consumption 88% since acquisition 2015 YTD consumption +16%
Slide 18: Birds Eye Voila! Innovation
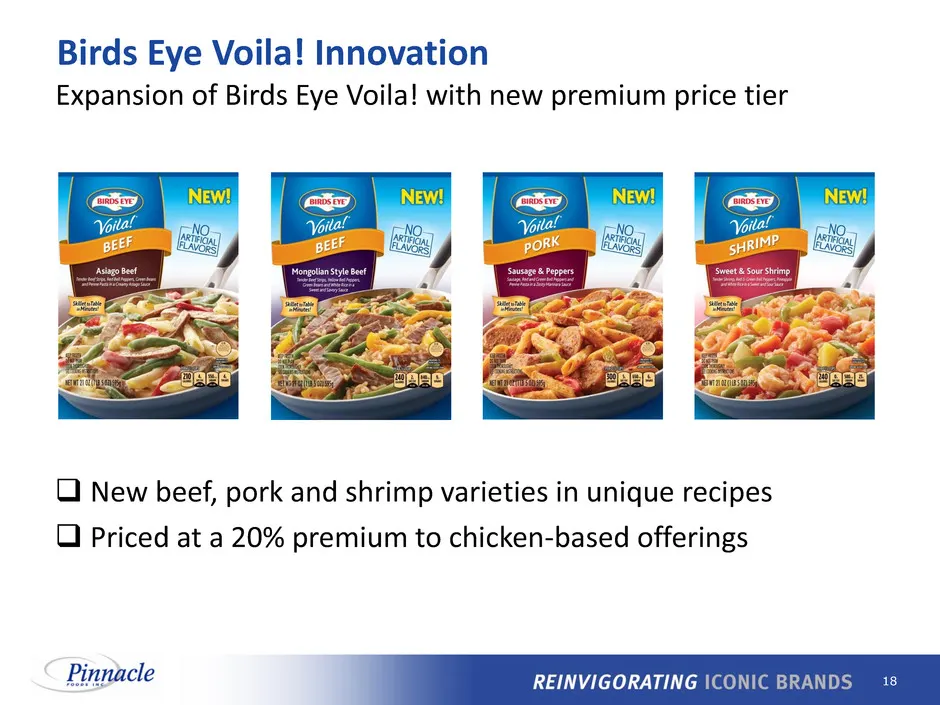
18 New beef, pork and shrimp varieties in unique recipes Priced at a 20% premium to chicken-based offerings Birds Eye Voila! Innovation Expansion of Birds Eye Voila! with new premium price tier
Slide 19: Birds Eye Advertising
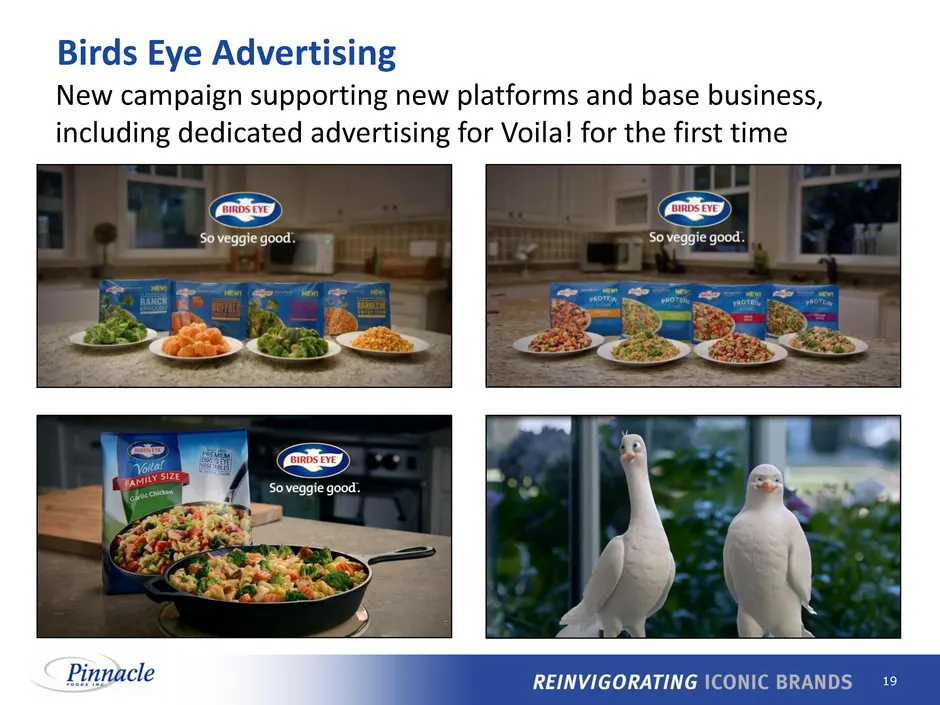
19 Birds Eye Advertising New campaign supporting new platforms and base business, including dedicated advertising for Voila! for the first time
Slide 20: Baking Category
Baking Category REINVIGORATING
Slide 21: Baking Category
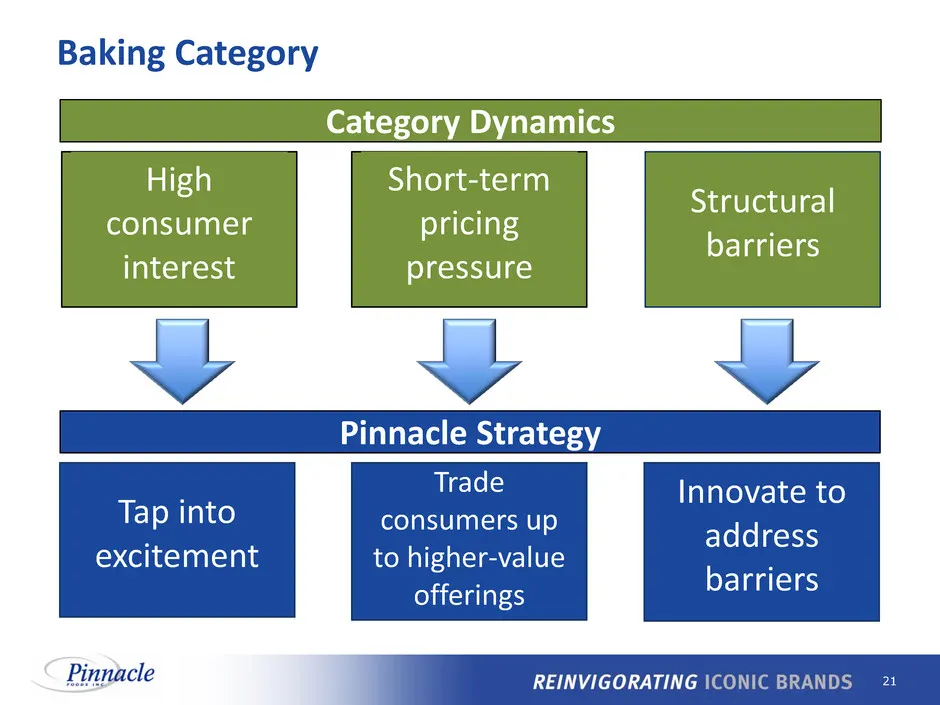
21 High consumer interest Structural barriers Short-term pricing pressure Category Dynamics Tap into excitement Innovate to address barriers Trade consumers up to higher-value offerings Pinnacle Strategy Baking Category
Slide 22: Tapping into the Excitement of Baking
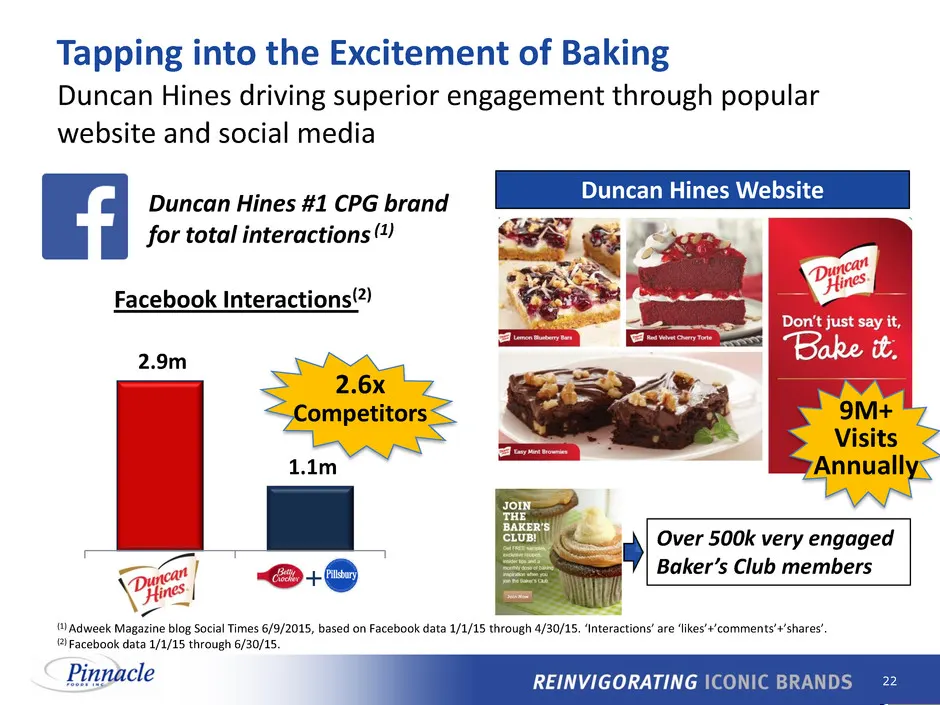
22 Tapping into the Excitement of Baking Duncan Hines driving superior engagement through popular website and social media Duncan Hines Website (1) Adweek Magazine blog Social Times 6/9/2015, based on Facebook data 1/1/15 through 4/30/15. ‘Interactions’ are ‘likes’+’comments’+’shares’. (2) Facebook
Slide 23: Trading Consumers Up to Higher-Value Offerings
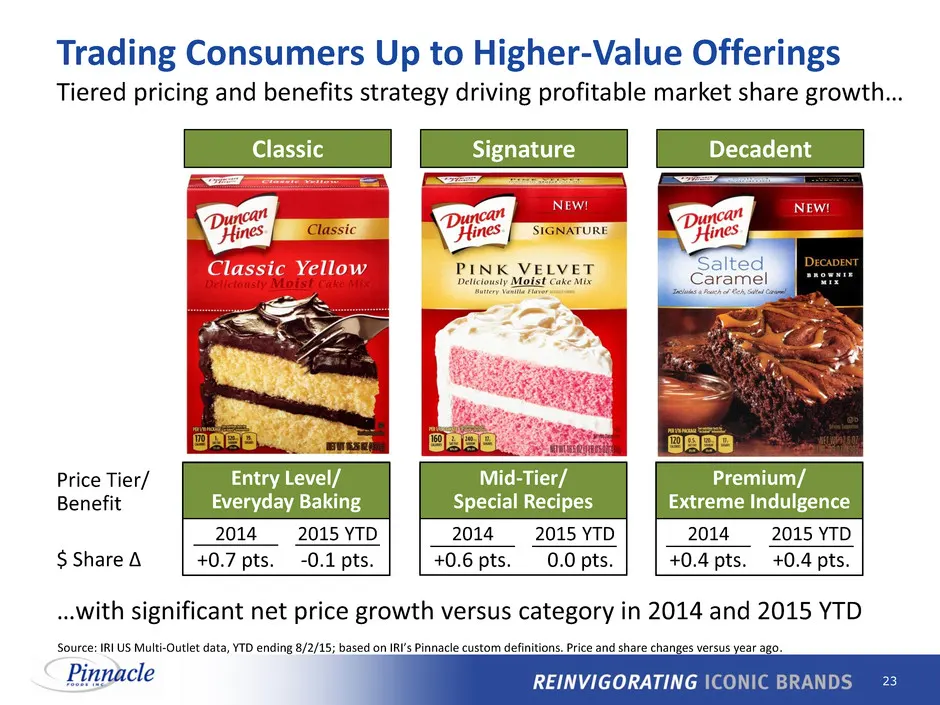
23 Price Tier/ Benefit Decadent Classic Signature Tiered pricing and benefits strategy driving profitable market share growth… Trading Consumers Up to Higher-Value Offerings Source: IRI US Multi-Outlet data, YTD ending 8/2/15; based on IRI’s Pinnacle custom definitions. Price and share changes versu
Slide 24: Innovating to Address Structural Barriers
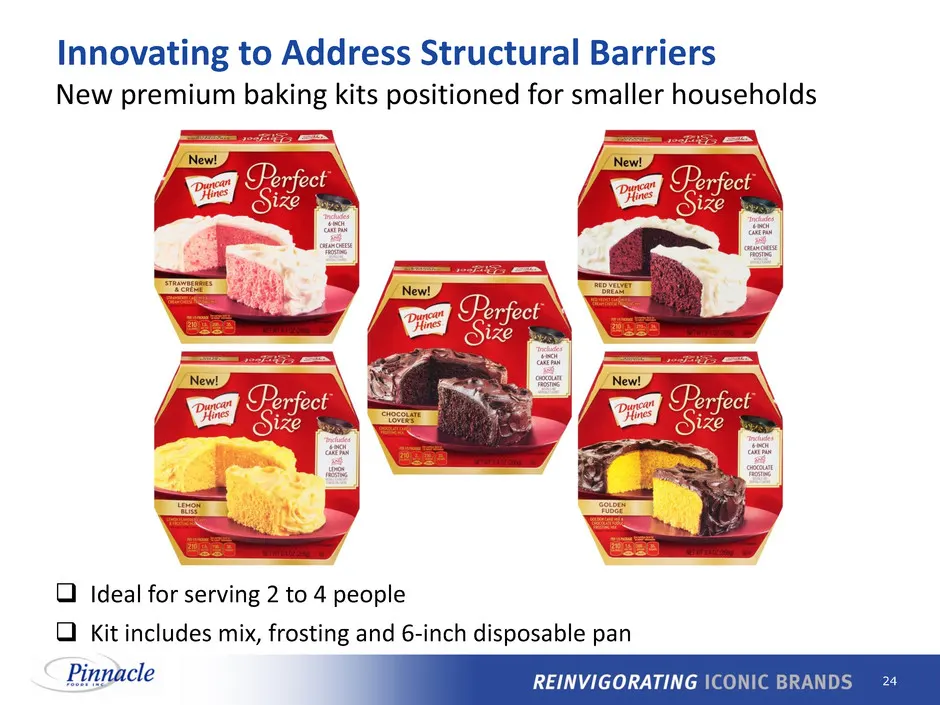
24 Ideal for serving 2 to 4 people Kit includes mix, frosting and 6-inch disposable pan New premium baking kits positioned for smaller households Innovating to Address Structural Barriers
Slide 25: Significant Consumer Excitement for Perfect Size
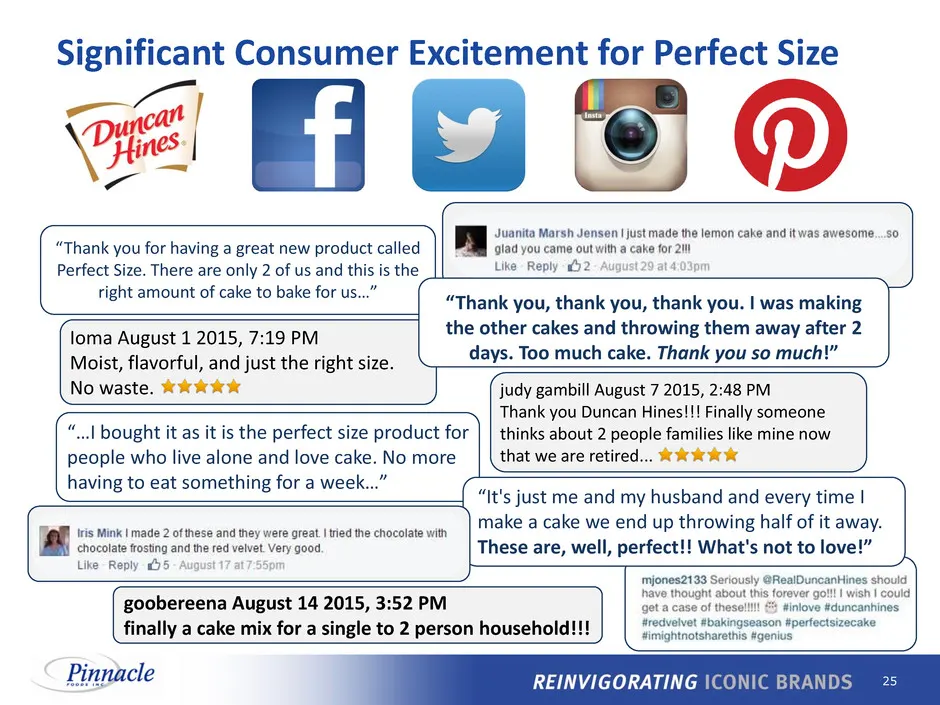
25 Significant Consumer Excitement for Perfect Size goobereena August 14 2015, 3:52 PM finally a cake mix for a single to 2 person household!!! “Thank you for having a great new product called Perfect Size. There are only 2 of us and this is the right amount of cake to bake for us…” “…I bought it as
Slide 26: A Disciplined Approach to M&A
26 A Disciplined Approach to M&A North America focus Existing or adjacent categories Market leadership or line of sight to leadership Synergy-rich transactions Speed of integration
Slide 27: Wish-Bone Update
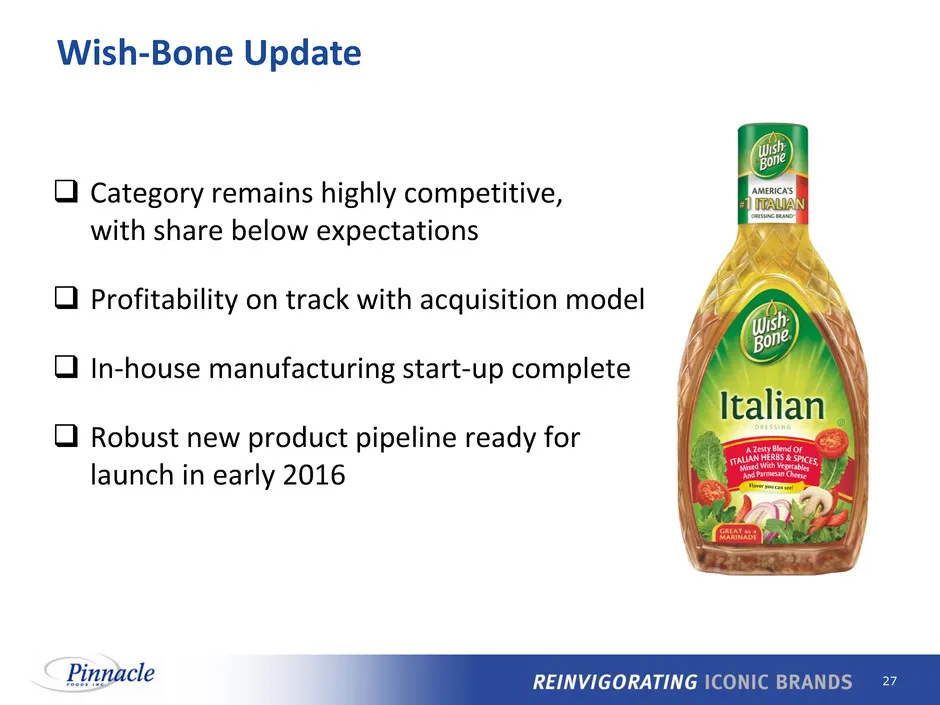
27 Category remains highly competitive, with share below expectations Profitability on track with acquisition model In-house manufacturing start-up complete Robust new product pipeline ready for launch in early 2016 Wish-Bone Update
Slide 28: Gardein Update
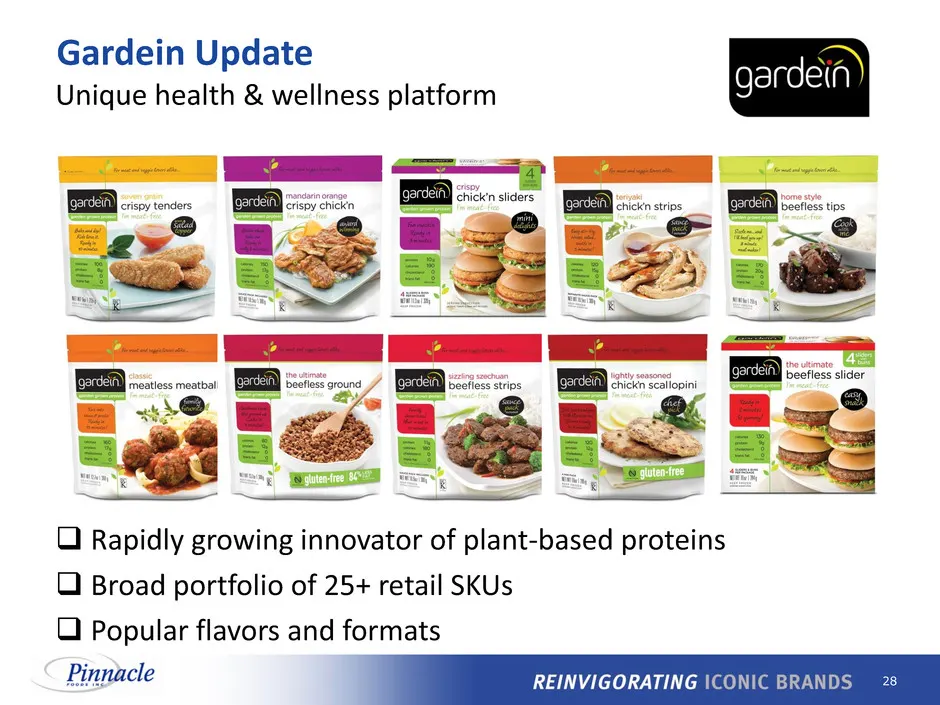
28 Rapidly growing innovator of plant-based proteins Broad portfolio of 25+ retail SKUs Popular flavors and formats Gardein Update Unique health & wellness platform
Slide 29: Gardein Platform Opportunity
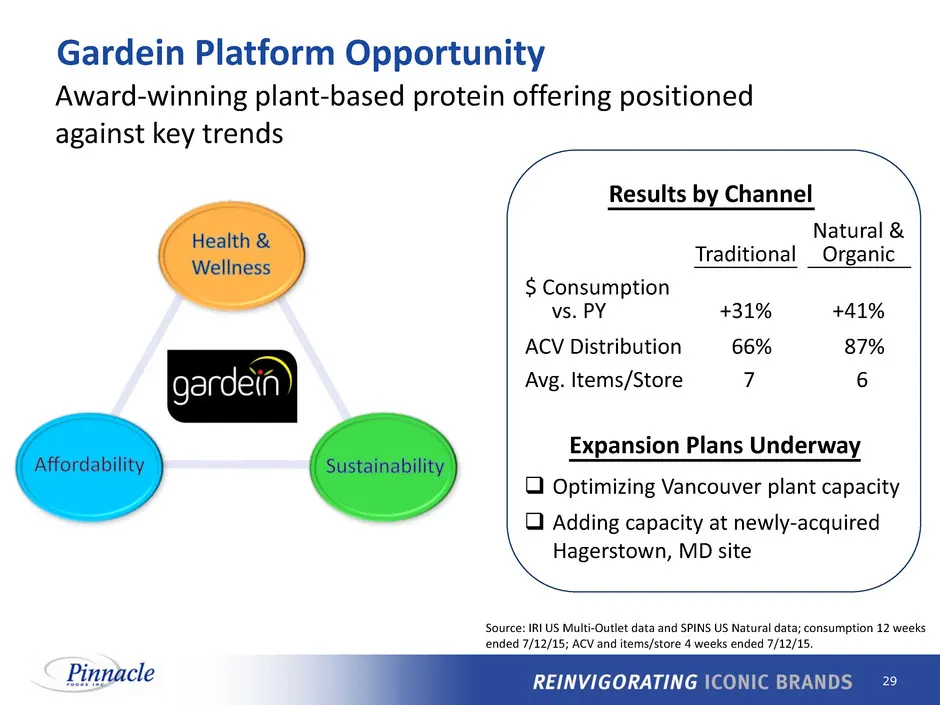
29 Results by Channel Optimizing Vancouver plant capacity Adding capacity at newly-acquired Hagerstown, MD site Expansion Plans Underway Award-winning plant-based protein offering positioned against key trends Gardein Platform Opportunity Traditional Natural & Organic $ Consumption vs. PY +31% +
Slide 30: 2015 New Products
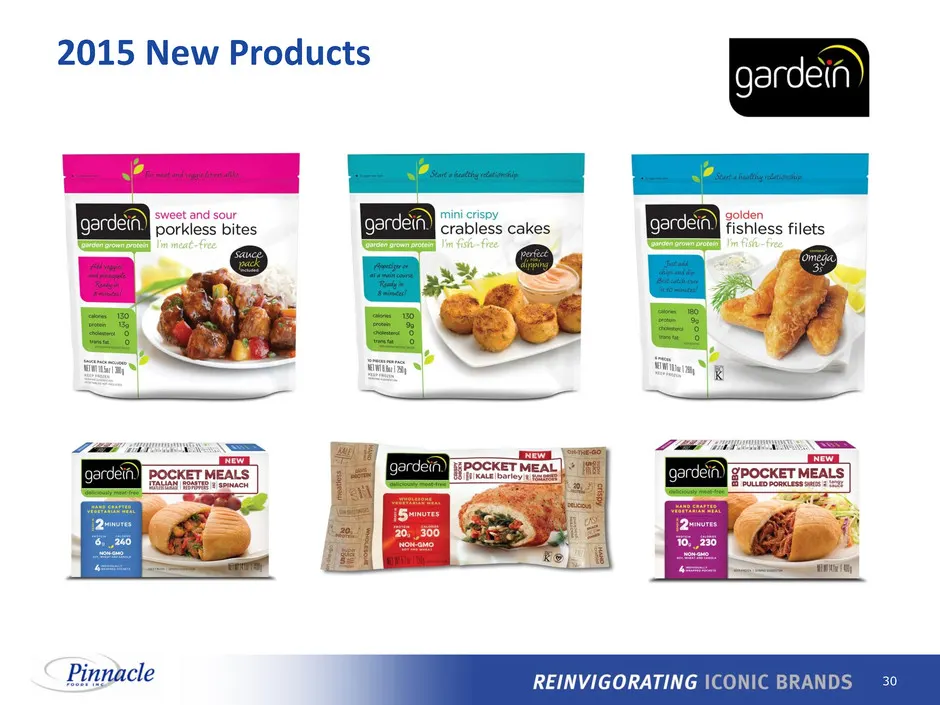
2015 New Products mini crispy crabless cakes
Slide 31: Agenda
31 Agenda Overview Executing Our Strategy Financial Update Outlook
Slide 32: 2015 First-half Financial Results
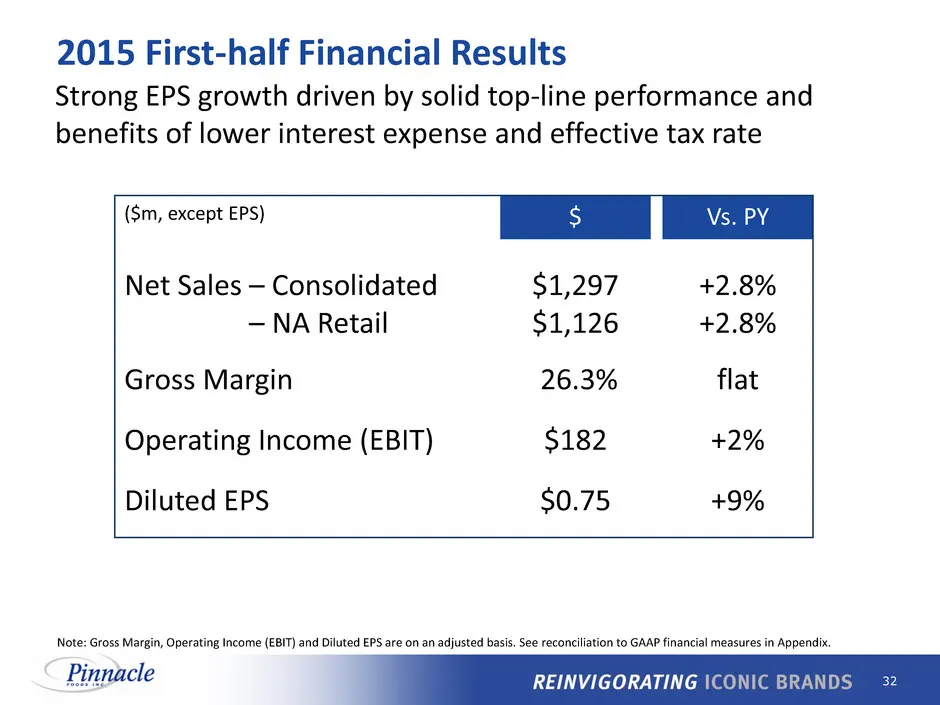
32 ($m, except EPS) $ Vs. PY Net Sales – Consolidated Net Sales – NA Retail $1,297 $1,126 +2.8% +2.8% Gross Margin 26.3% flat Operating Income (EBIT) $182 +2% Diluted EPS $0.75 +9% Note: Gross Margin, Operating Income (EBIT) and Diluted EPS are on an adjusted basis. See reconciliation to GAAP financ
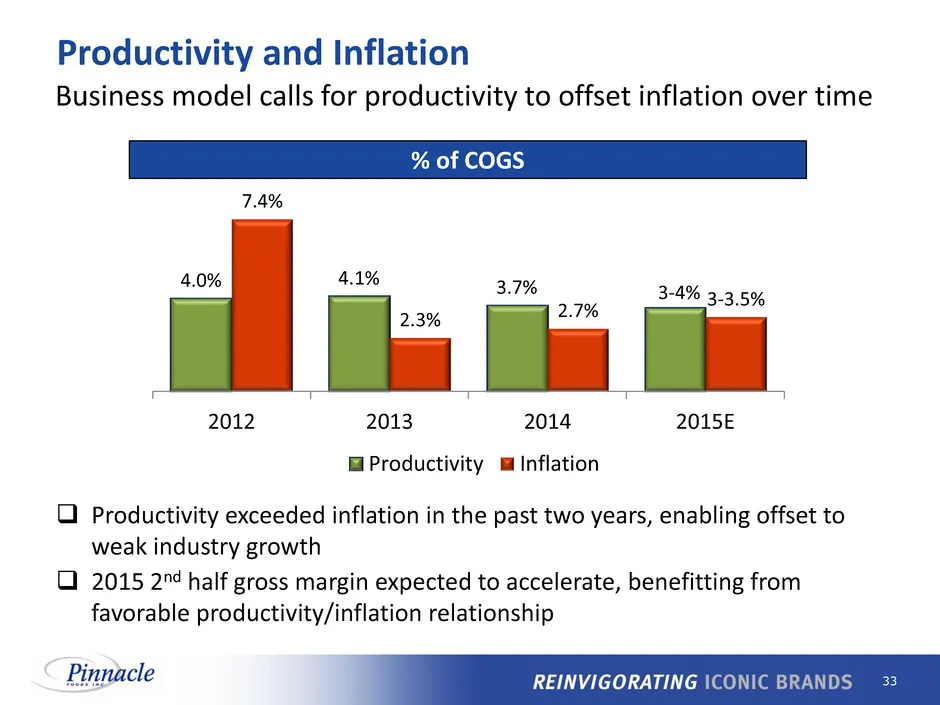
Slide 33: Productivity and Inflation
33 4.0% 4.1% 3.7% 3-4% 7.4% 2.3% 2.7% 3-3.5% 2012 2013 2014 2015E Productivity Inflation % of COGS Productivity exceeded inflation in the past two years, enabling offset to weak industry growth 2015 2nd half gross margin expected to accelerate, benefitting from favorable productivity/inflation r
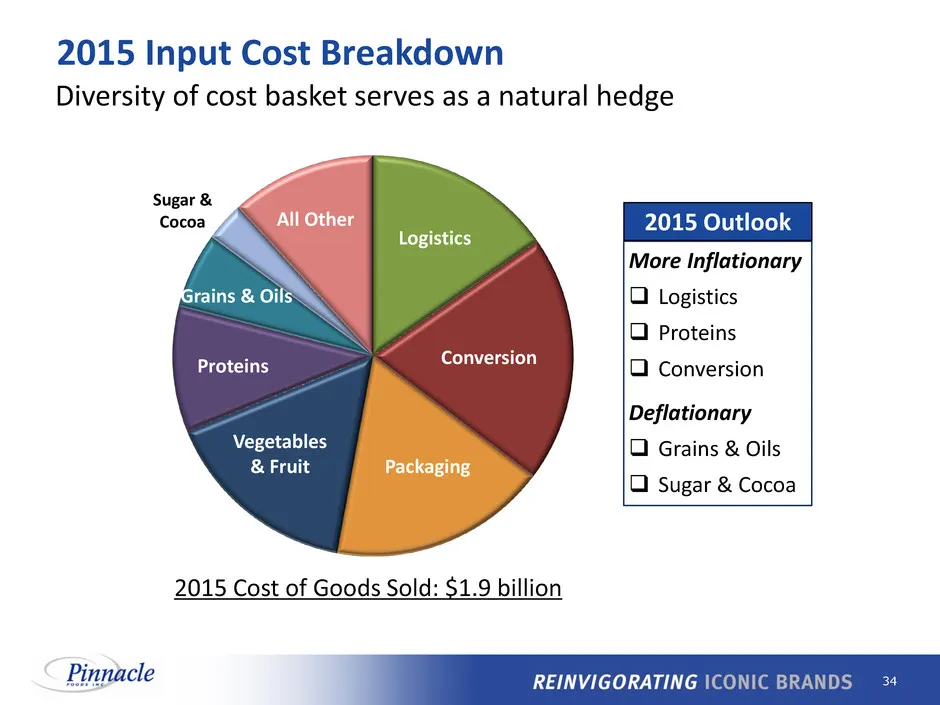
Slide 34: 2015 Input Cost Breakdown
34 Conversion Logistics Proteins Grains & Oils Packaging Vegetables & Fruit All Other Sugar & Cocoa 2015 Cost of Goods Sold: $1.9 billion More Inflationary Logistics Proteins Conversion Deflationary Grains & Oils Sugar & Cocoa 2015 Outlook Diversity of cost basket serves as a natural hedge
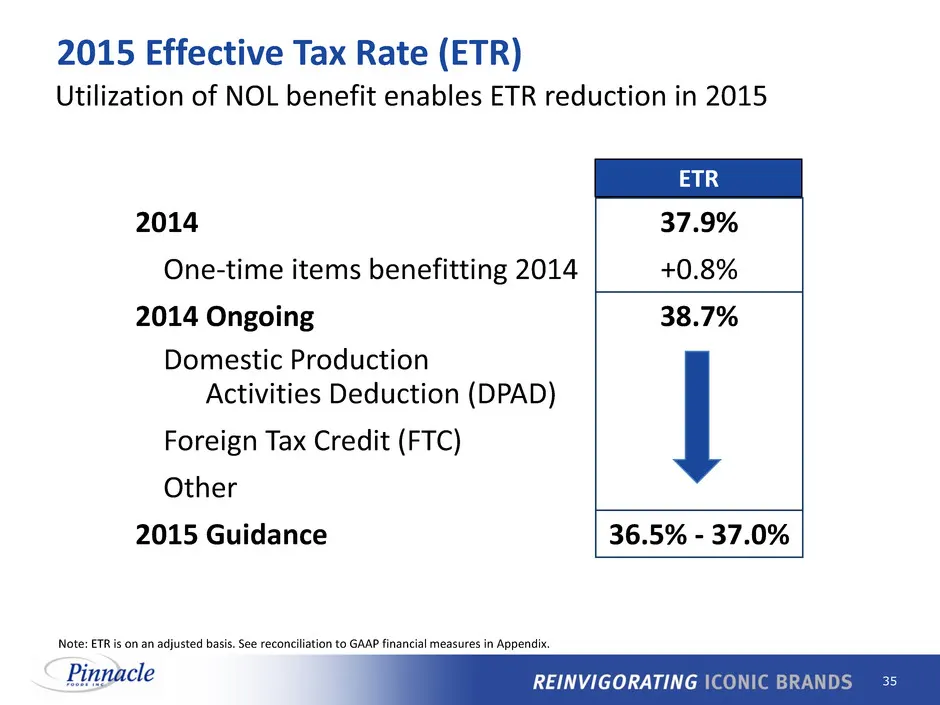
Slide 35: 2015 Effective Tax Rate
35 2014 37.9% One-time items benefitting 2014 +0.8% 2014 Ongoing 38.7% Domestic Production Activities Deduction (DPAD) Foreign Tax Credit (FTC) Other 2015 Guidance 36.5% - 37.0% ETR Utilization of NOL benefit enables ETR reduction in 2015 2015 Effective Tax Rate (ETR) Note: ETR is on an adjusted bas
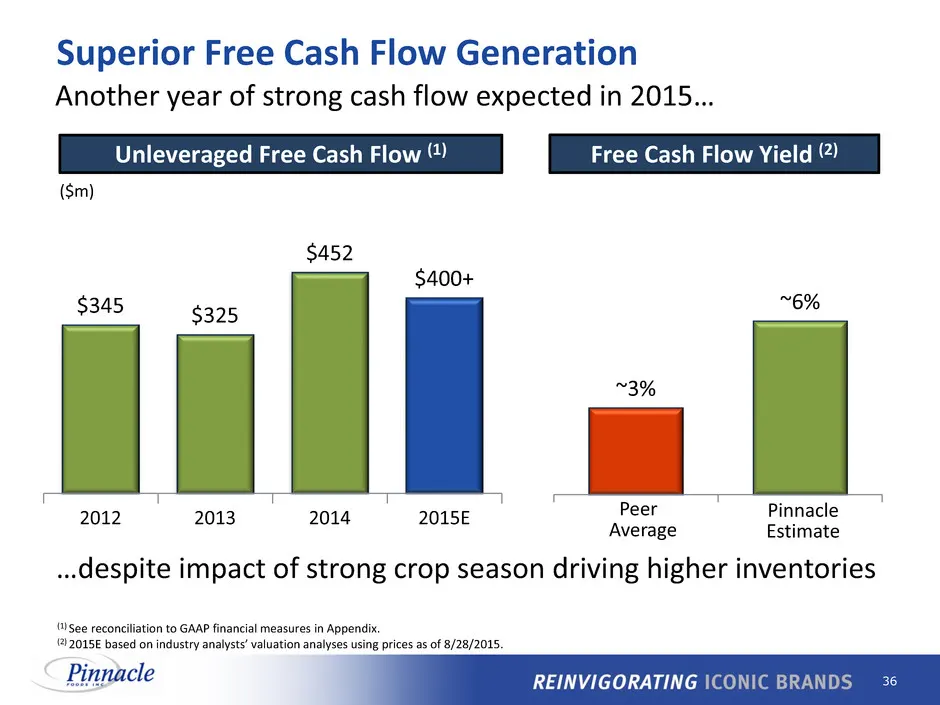
Slide 36: Superior Free Cash Flow Generation
36 $345 $325 $452 $400+ $0 $100 $200 $300 $400 $500 $600 $700 2012 2013 2014 2015E Unleveraged Free Cash Flow (1) ~3% ~6% Peer Average Pinnacle Estimate Free Cash Flow Yield (2) ($m) (1) See reconciliation to GAAP financial measures in Appendix. (2) 2015E based on industry analysts’ valuation analys
Slide 37: Key Drivers of Free Cash Flow
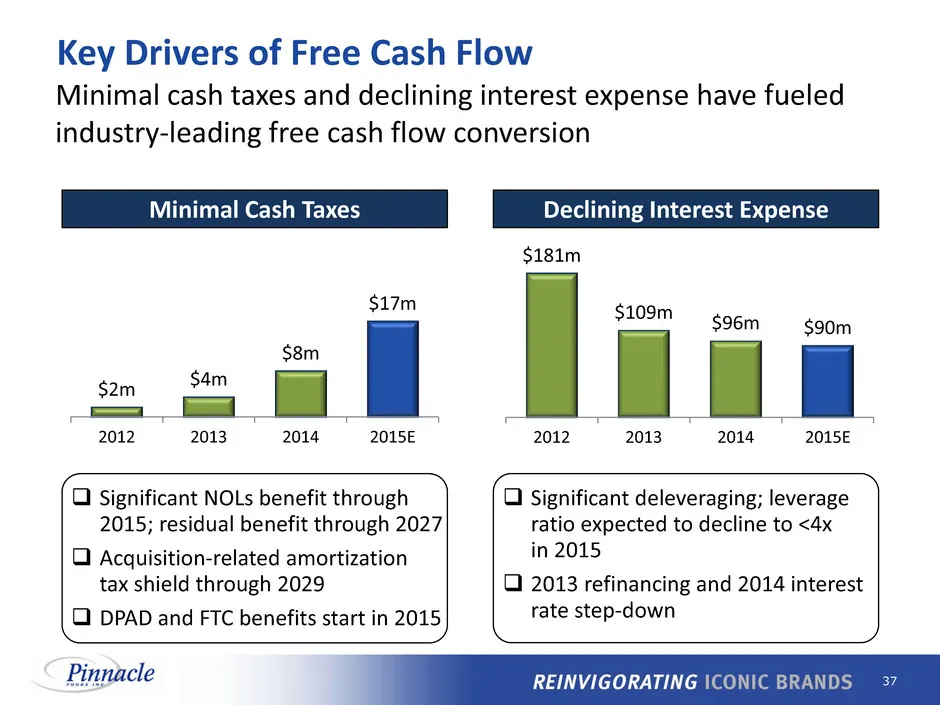
37 Key Drivers of Free Cash Flow $2m $4m $8m $17m 2012 2013 2014 2015E $181m $109m $96m $90m 2012 2013 2014 2015E Minimal cash taxes and declining interest expense have fueled industry-leading free cash flow conversion Minimal Cash Taxes Significant NOLs benefit through 2015; residual benefit thro
Slide 38: Capital Expenditures
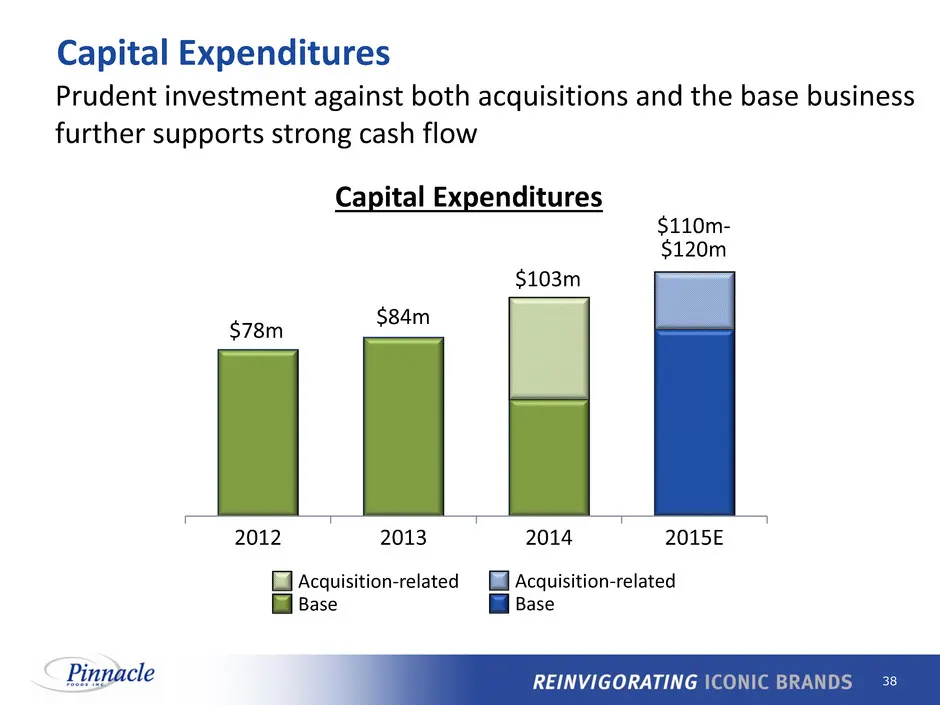
38 2012 2013 2014 2015E Capital Expenditures Capital Expenditures Prudent investment against both acquisitions and the base business further supports strong cash flow $78m $84m $103m $110m- $120m Base Acquisition-related Base Acquisition-related
Slide 39: Capital Allocation Strategy
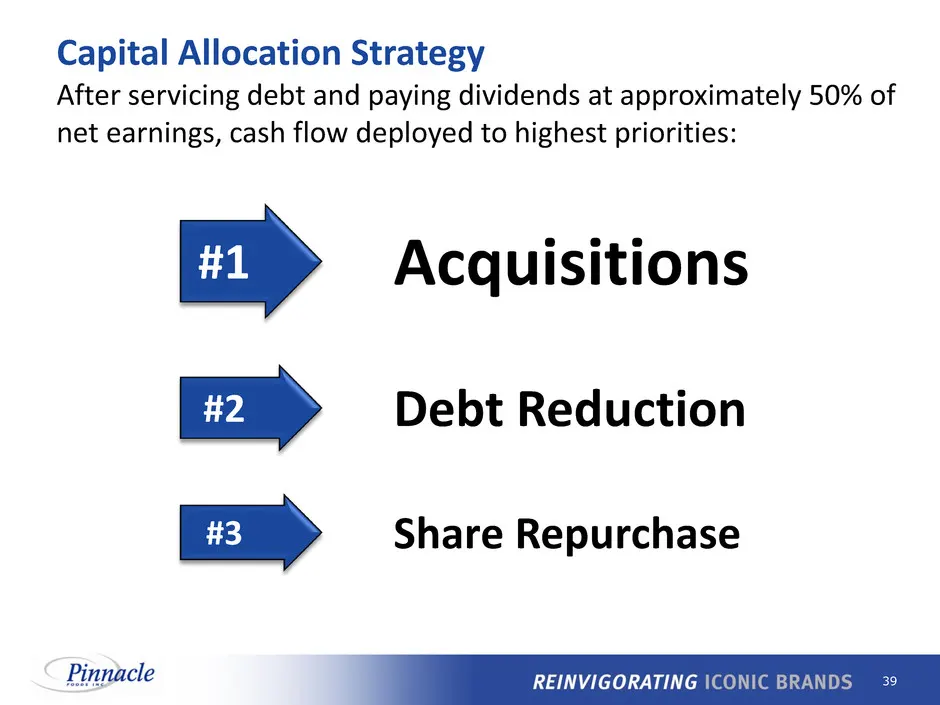
39 After servicing debt and paying dividends at approximately 50% of net earnings, cash flow deployed to highest priorities: Capital Allocation Strategy Acquisitions #1 Debt Reduction #2 Share Repurchase #3
Slide 40: Agenda
40 Agenda Overview Executing Our Strategy Financial Update Outlook
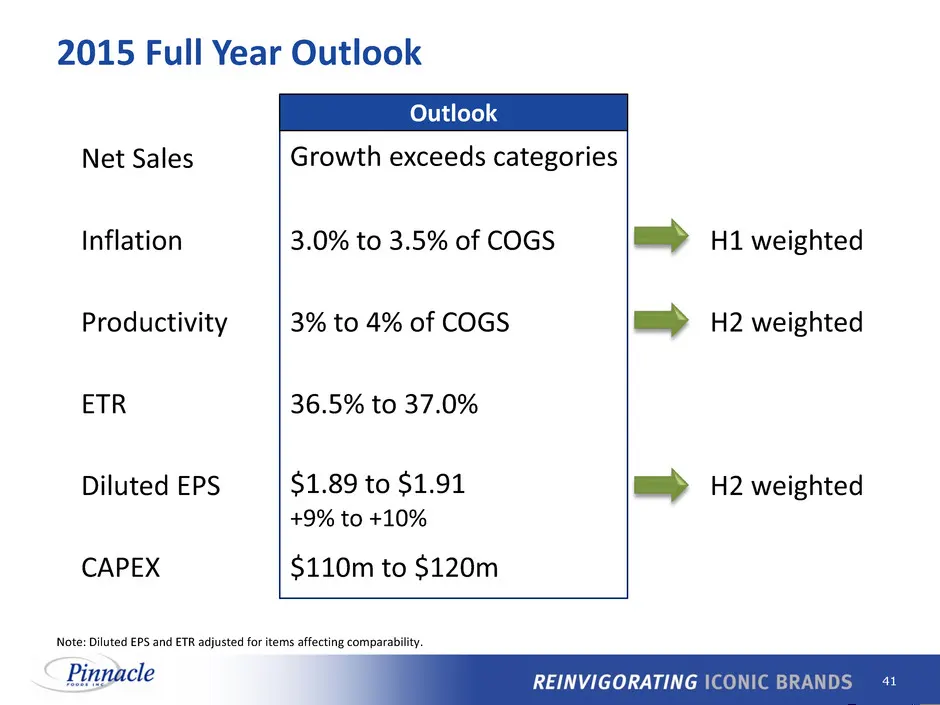
Slide 41: 2015 Full Year Outlook
41 Net Sales Growth exceeds categories Inflation 3.0% to 3.5% of COGS Nm Productivity 3% to 4% of COGS Nm ETR 36.5% to 37.0% Diluted EPS $1.89 to $1.91 +9% to +10% CAPEX $110m to $120m Note: Diluted EPS and ETR adjusted for items affecting comparability. Outlook H1 weighted H2 weighted H2 weighted 2
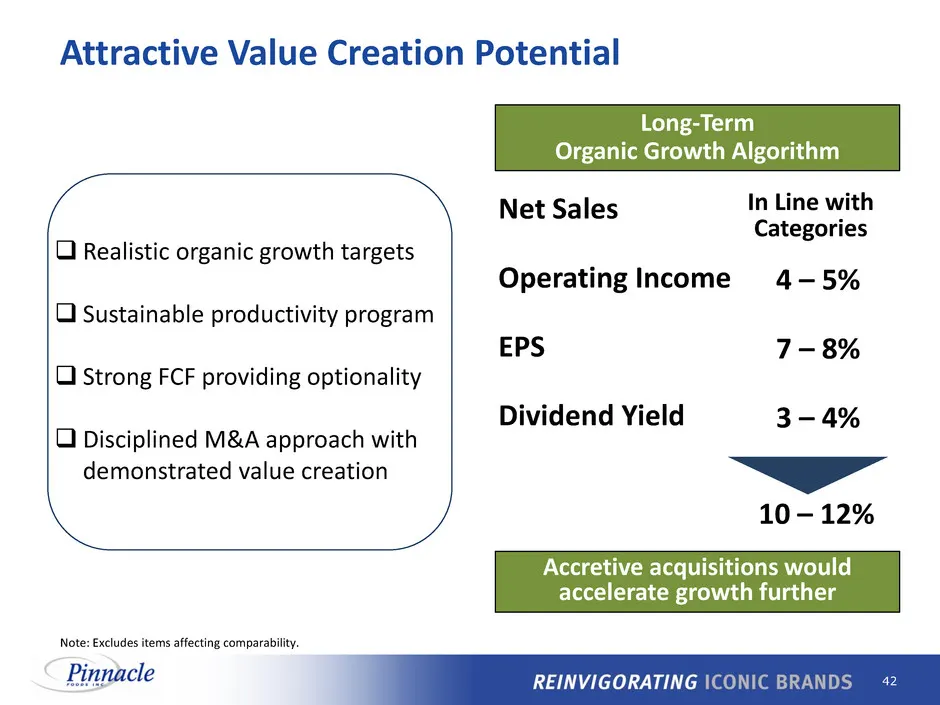
Slide 42: Attractive Value Creation Potential
42 Attractive Value Creation Potential Long-Term Organic Growth Algorithm Net Sales Operating Income EPS Dividend Yield Note: Excludes items affecting comparability. In Line with Categories 10 – 12% 4 – 5% 7 – 8% 3 – 4% Accretive acquisitions would accelerate growth further Realistic organic growt
Slide 43: Appendix
Pinnacle REINVIGORATING Appendix
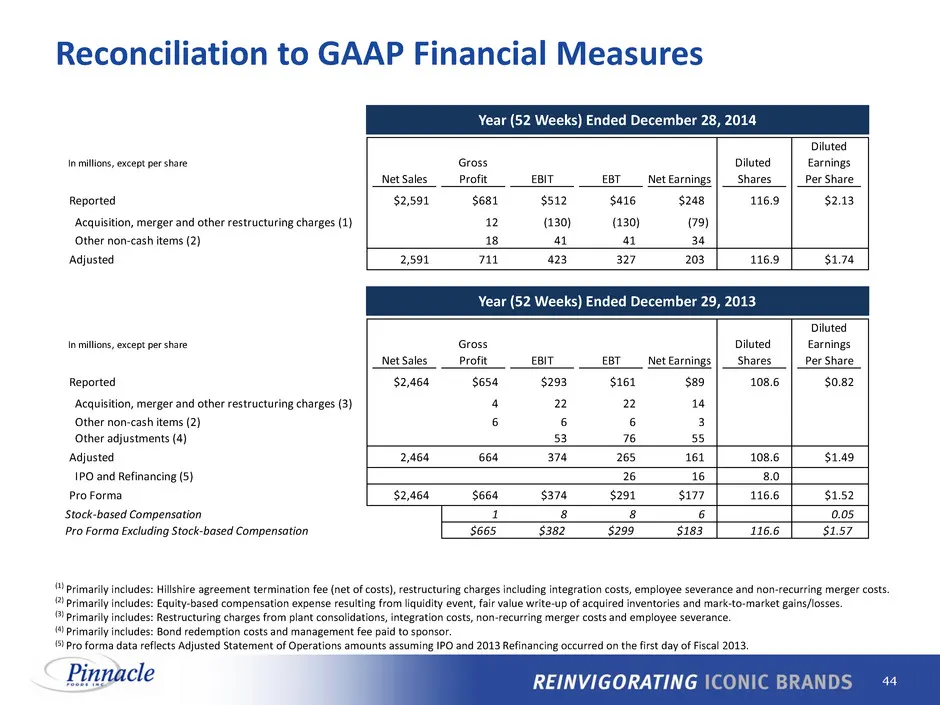
Slide 44: Reconciliation to GAAP Financial Measures
44 Reconciliation to GAAP Financial Measures (1) Primarily includes: Hillshire agreement termination fee (net of costs), restructuring charges including integration costs, employee severance and non-recurring merger costs. (2) Primarily includes: Equity-based compensation expense resulting from liqu
Slide 45: Reconciliation to GAAP Financial Measures
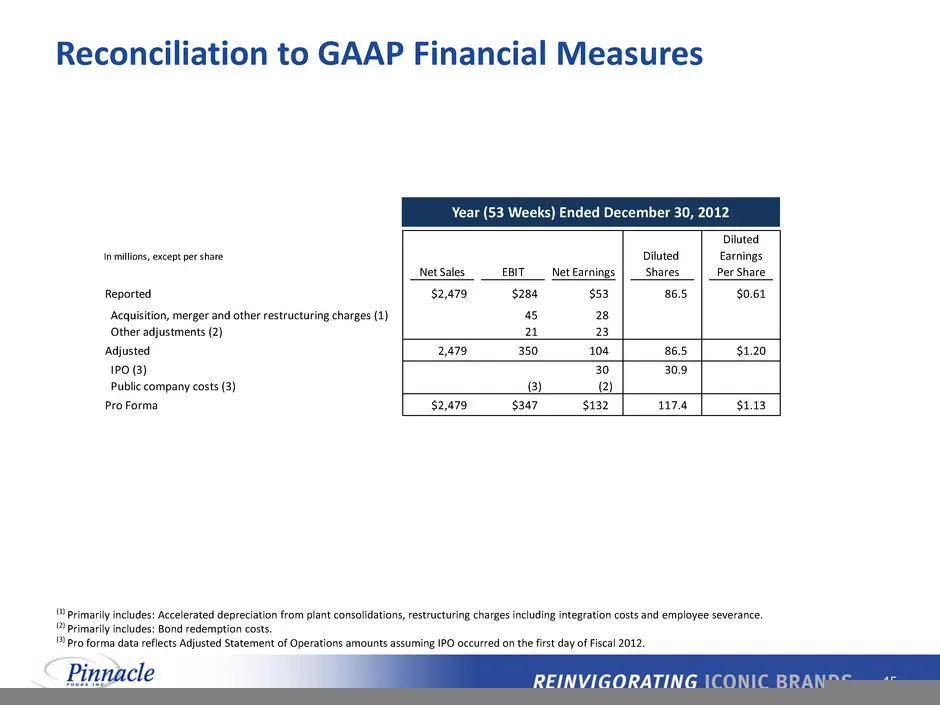
45 (1) Primarily includes: Accelerated depreciation from plant consolidations, restructuring charges including integration costs and employee severance. (2) Primarily includes: Bond redemption costs. (3) Pro forma data reflects Adjusted Statement of Operations amounts assuming IPO occurred on the fi
Slide 46: Reconciliation to GAAP Financial Measures
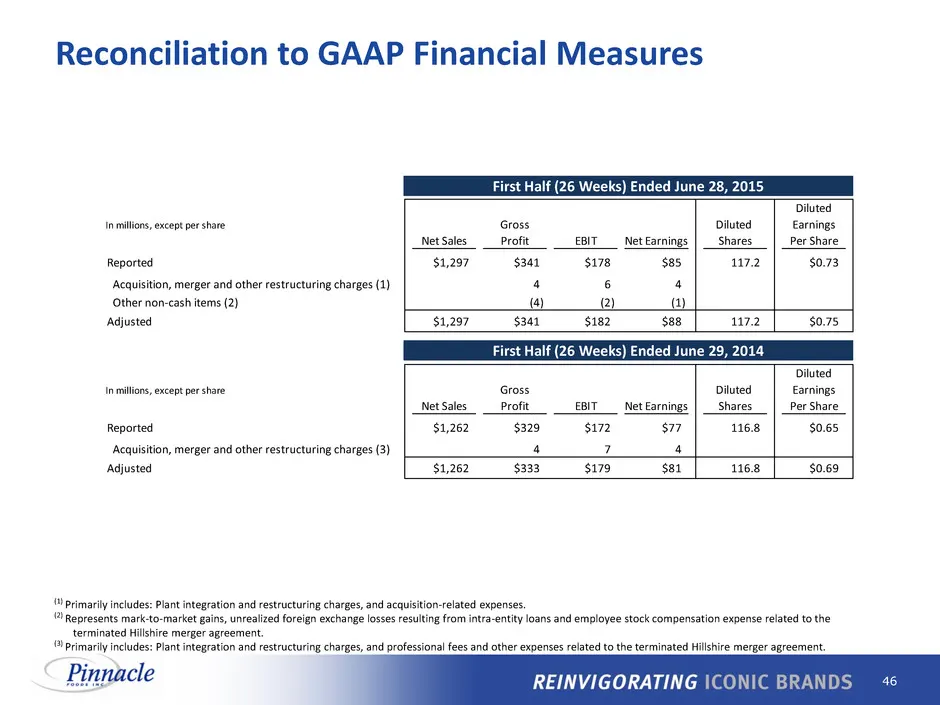
46 (1) Primarily includes: Plant integration and restructuring charges, and acquisition-related expenses. (2) Represents mark-to-market gains, unrealized foreign exchange losses resulting from intra-entity loans and employee stock compensation expense related to the terminated Hillshire merger agree
Slide 47: Reconciliation of Unleveraged Free Cash Flow
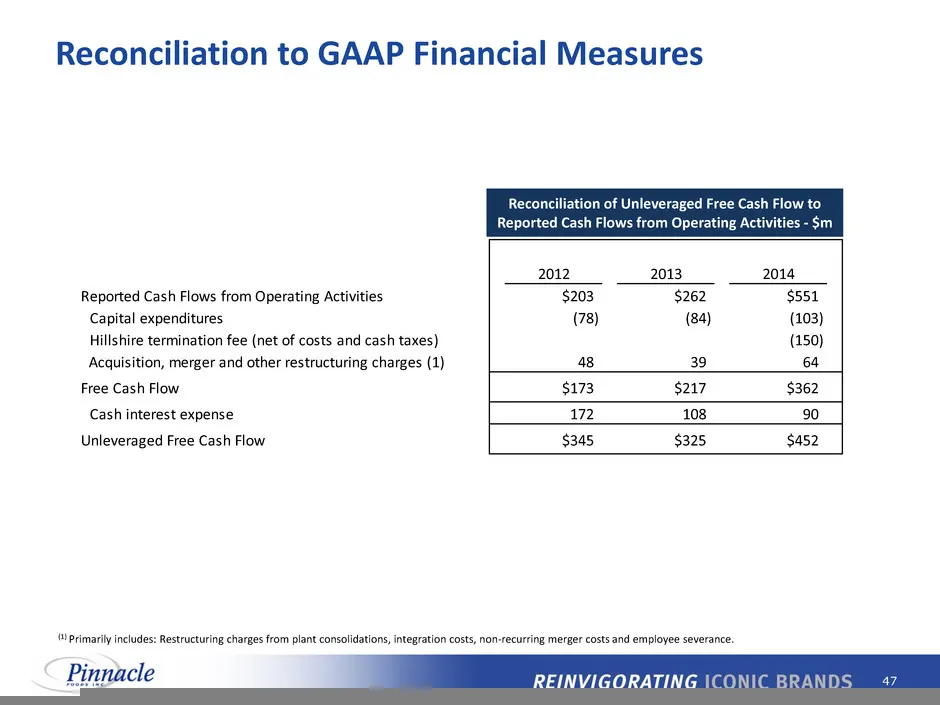
47 (1) Primarily includes: Restructuring charges from plant consolidations, integration costs, non-recurring merger costs and employee severance. 2012 2013 2014 Reported Cash Flows from Operating Activities $203 $262 $551 Capital expenditures (78) (84) (103) Hillshire termination fee (net of costs a
Source: SEC EDGAR · 8-K filed Sep 9, 2015
More decks from Pinnacle Foods Inc
 Q1 FY2019 Earnings Presentation44 slides · Sep 27, 2018
 Q4 FY2018 Earnings Presentation59 slides · Jun 27, 2018
 Barclays Global Consumer Staples Conference 201767 slides · Sep 6, 2017
 Debt Investor Presentation (January 2017)55 slides · Jan 23, 2017
 Investor Day (December 2016)55 slides · Dec 15, 2016
 Barclays Global Consumer Staples Conference 201651 slides · Sep 6, 2016