Pinnacle Foods — Barclays Global Consumer Staples Conference 2017
67 slides from Pinnacle Foods's conference presentation, Sep 6, 2017
Slide 1: Barclays Global Consumer Staples Conference September 6, 2017
BARCLAY’S GLOBAL CONSUMER STAPLES CONFERENCE SEPTEMBER 6, 2017
Slide 2: Pinnacle Management
Mark Clouse Chief Executive Officer Craig Steeneck EVP & CFO Maria Sceppaguercio SVP Investor Relations Tyson Seely Manager Investor Relations Mark Schiller EVP & Chief Commercial Officer 2 Pinnacle Management
Slide 3: Forward-Looking Statements & Non-GAAP Financial Measures
Forward-Looking Statements & Non-GAAP Financial Measures This presentation contains “forward-looking statements” within the meaning of U.S. federal securities laws. Forward-looking statements are not historical facts, and are based upon management’s current expectations, beliefs, projections and tar
Slide 4: The Foundation; Unleashing Brand Potential; Financial Performance; Outlook
• The Foundation • Unleashing Brand Potential • Financial Performance • Outlook 4
Slide 5: Diversified Portfolio
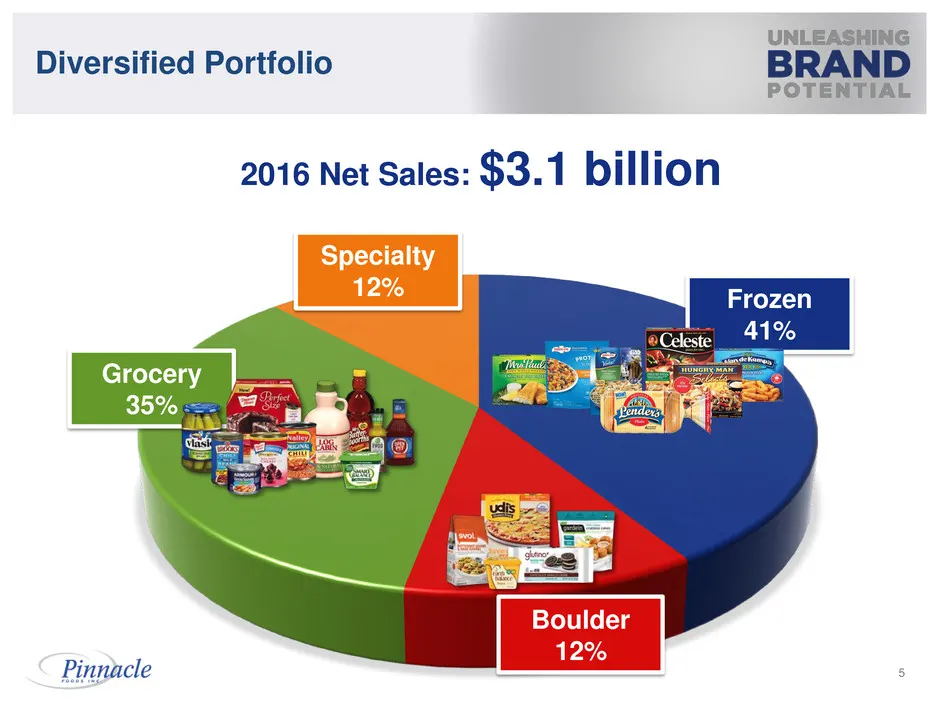
5 Diversified Portfolio 2016 Net Sales: $3.1 billion Grocery 35% Specialty 12% Boulder 12% Frozen 41%
Slide 6: Strengthened Health & Wellness Presence
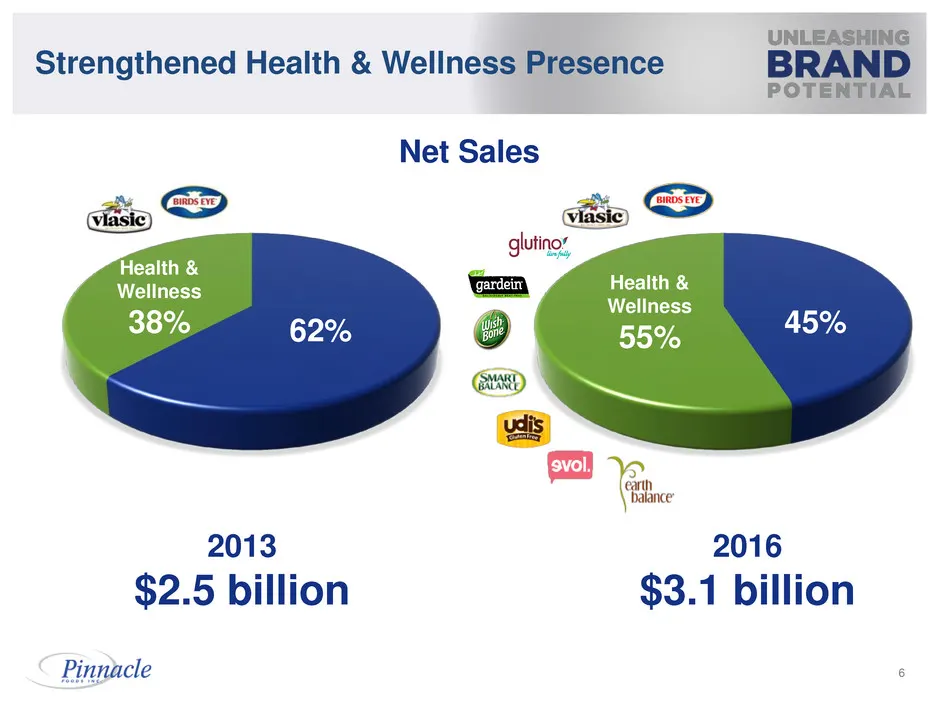
Strengthened Health & Wellness Presence 6 45% Health & Wellness 55% 2016 $3.1 billion 2013 $2.5 billion Health & Wellness 38% 62% Net Sales
Slide 7: Significant Scale in Frozen
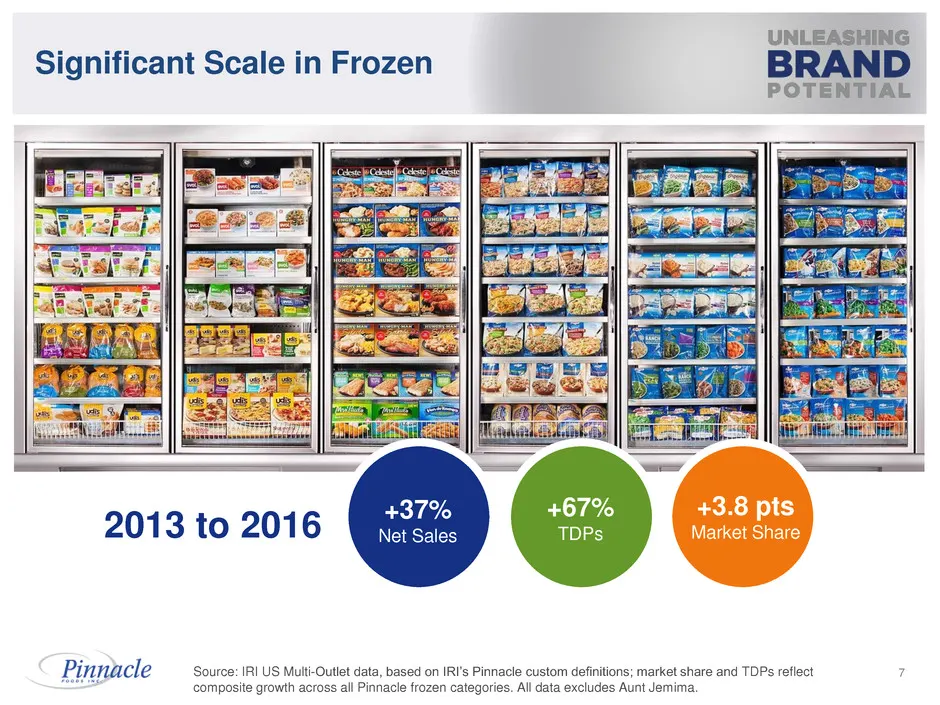
7 Significant Scale in Frozen 2013 to 2016 +3.8 pts Market Share +37% Net Sales +67% TDPs Source: IRI US Multi-Outlet data, based on IRI’s Pinnacle custom definitions; market share and TDPs reflect composite growth across all Pinnacle frozen categories. All data excludes Aunt Jemima.
Slide 8: Enhanced Scale and Capabilities
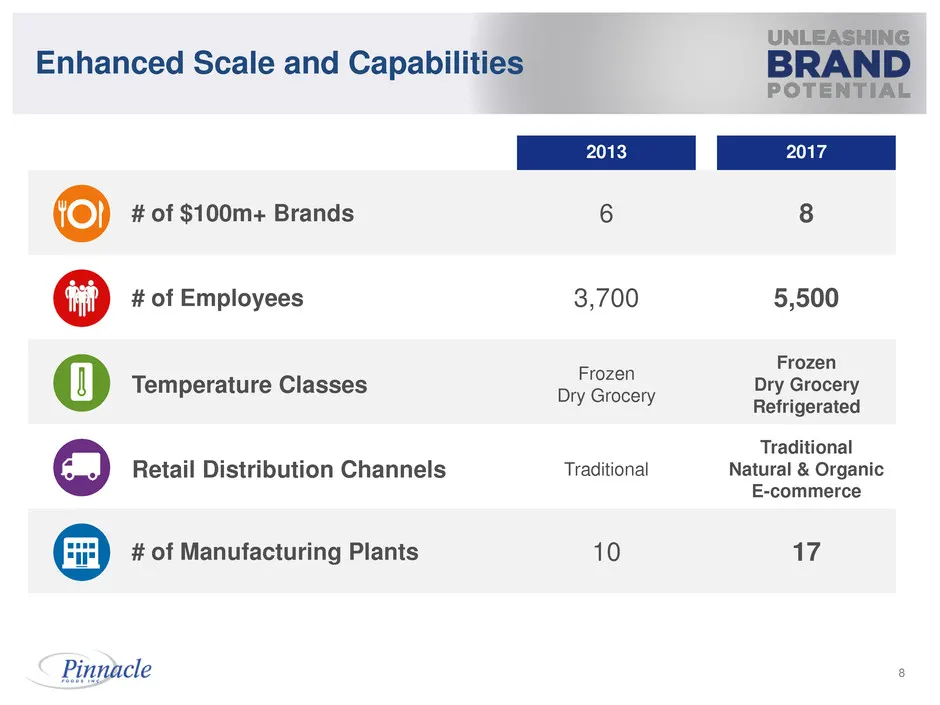
8 Enhanced Scale and Capabilities 2013 2017 # of $100m+ Brands 6 8 # of Employees 3,700 5,500 Temperature Classes Frozen Dry Grocery Frozen Dry Grocery Refrigerated Retail Distribution Channels Traditional Traditional Natural & Organic E-commerce # of Manufacturing Plants 10 17
Slide 9: Macro Trends are Pressuring CPG's
9 Macro Trends are Pressuring CPG’s Consumer Trends Industry Trends
Slide 10: H&W Reshaping Consumer Purchasing Habits
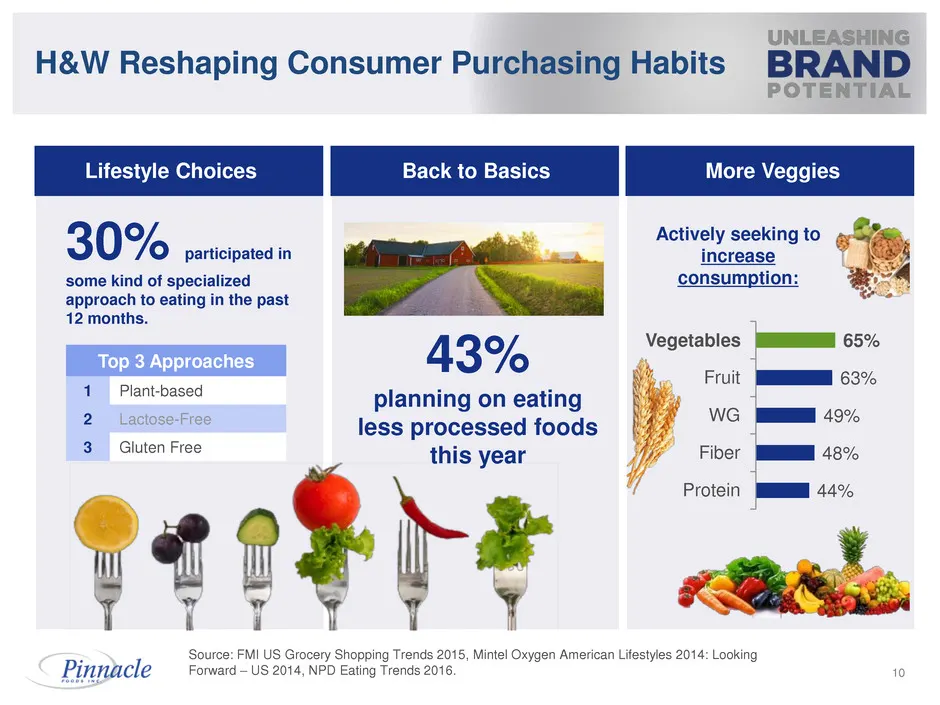
10 H&W Reshaping Consumer Purchasing Habits Source: FMI US Grocery Shopping Trends 2015, Mintel Oxygen American Lifestyles 2014: Looking Forward – US 2014, NPD Eating Trends 2016. More Veggies Actively seeking to increase consumption: 44% 48% 49% 63% 65% Protein Fiber WG Fruit VegetablesVegetabl Lif
Slide 11: Demographic Shifts Present Challenges & Opportunities
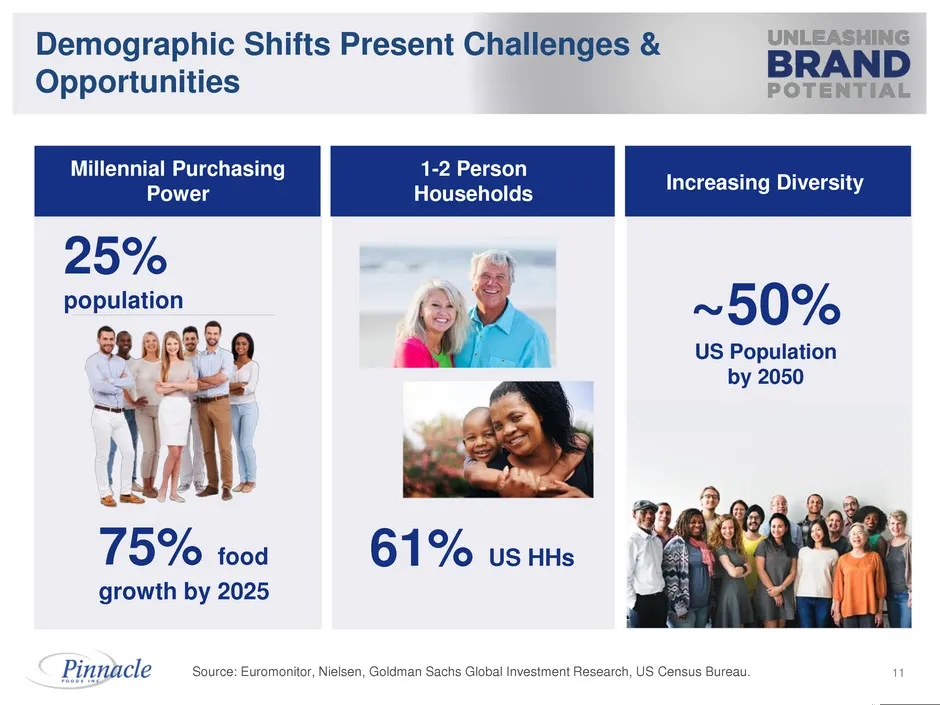
11 Demographic Shifts Present Challenges & Opportunities Source: Euromonitor, Nielsen, Goldman Sachs Global Investment Research, US Census Bureau. 1-2 Person Households 61% US HHs Increasing Diversity ~50% US Population by 2050 Millennial Purchasing Power 75% food growth by 2025 25% population
Slide 12: Food Industry Environment Also Evolving
Consumer Trends Industry Trends 12 Food Industry Environment Also Evolving
Slide 13: Center-of-Store Losing Share
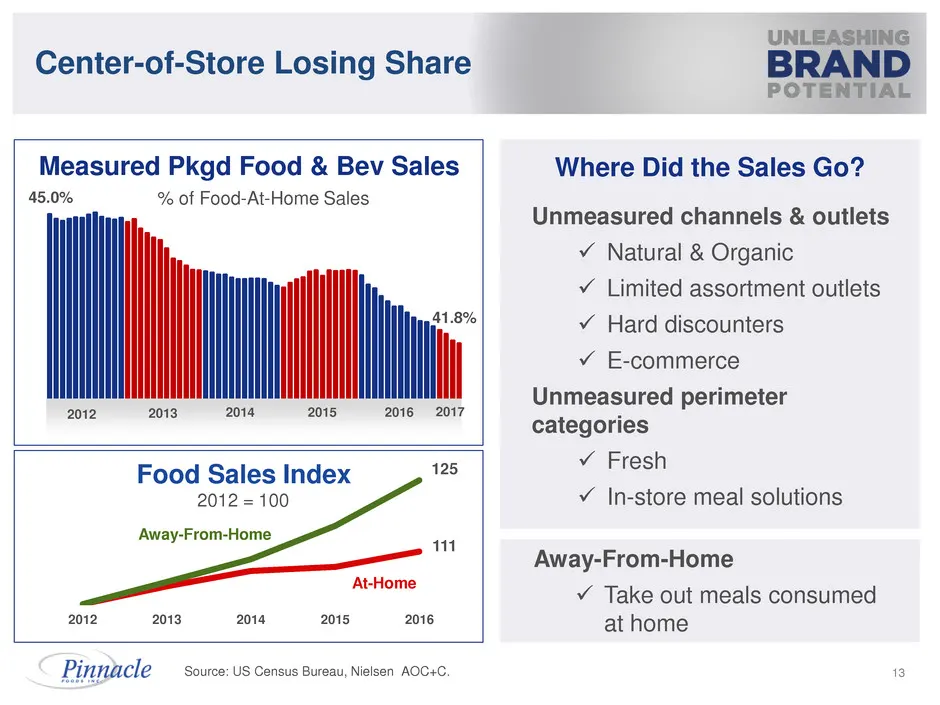
13 Center-of-Store Losing Share Measured Pkgd Food & Bev Sales Unmeasured channels & outlets Natural & Organic Limited assortment outlets Hard discounters E-commerce Unmeasured perimeter categories Fresh In-store meal solutions Where Did the Sales Go? Away-From-Home Take out meals cons
Slide 14: Alternate Channels Growth – Particularly Online
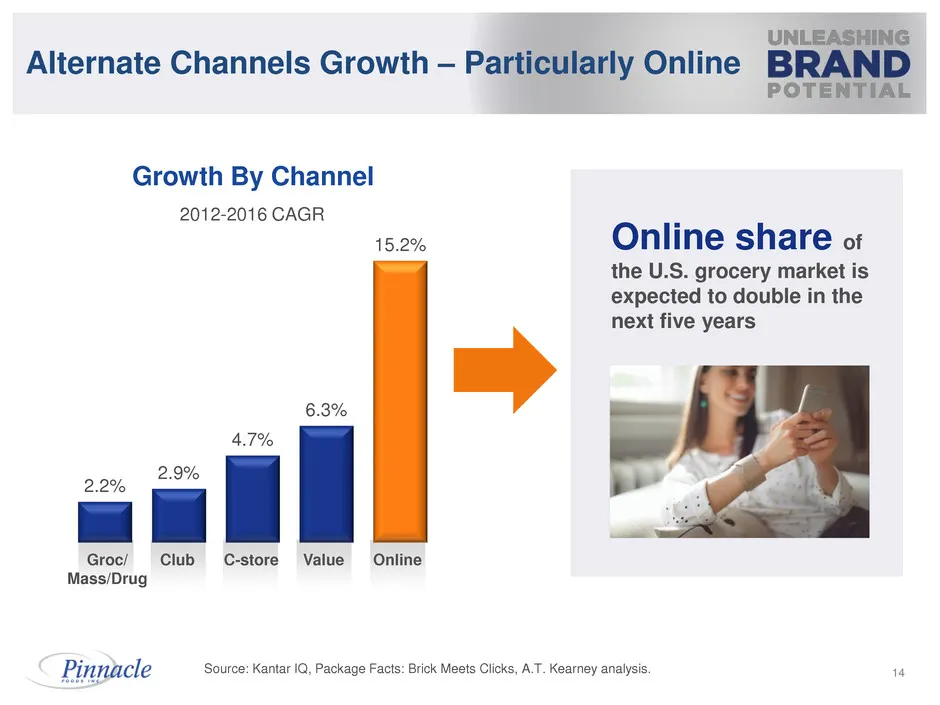
14 Alternate Channels Growth – Particularly Online 2.2% 2.9% 4.7% 6.3% 15.2% Online Club C-store Groc/ Mass/Drug Value Growth By Channel 2012-2016 CAGR Source: Kantar IQ, Package Facts: Brick Meets Clicks, A.T. Kearney analysis. Online share of the U.S. grocery market is expected to double in the ne
Slide 15: Private Label Re-emerging as a Challenge
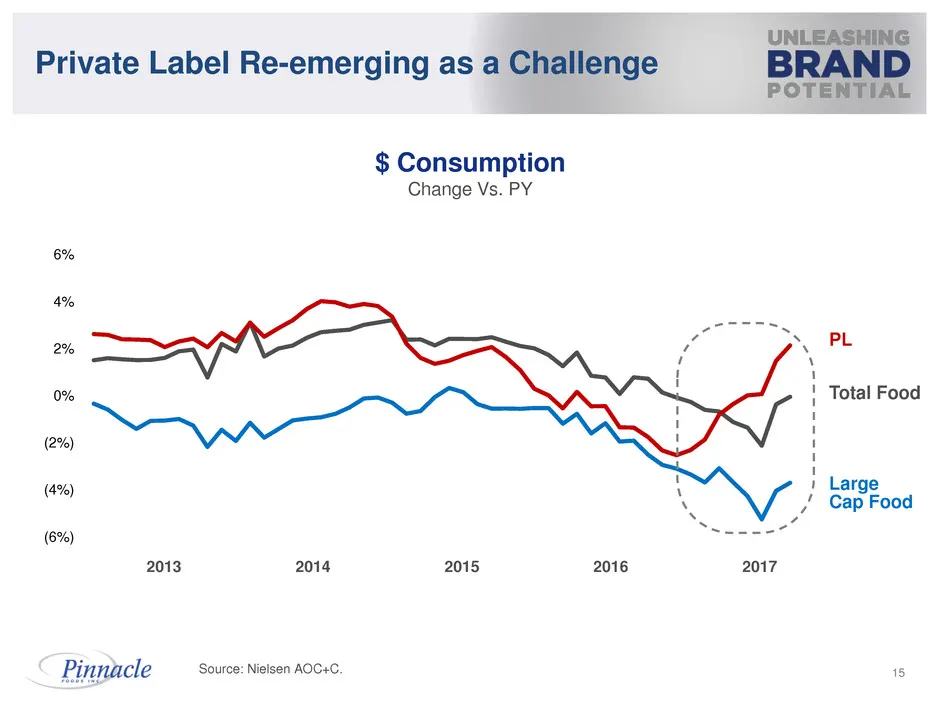
15 Private Label Re-emerging as a Challenge Source: Nielsen AOC+C. $ Consumption Change Vs. PY (6%) (4%) (2%) 0% 2% 4% 6% PL Large Cap Food Total Food 2017 2013 2014 2015 2016
Slide 16: Pinnacle is Outperforming in a Tough Industry
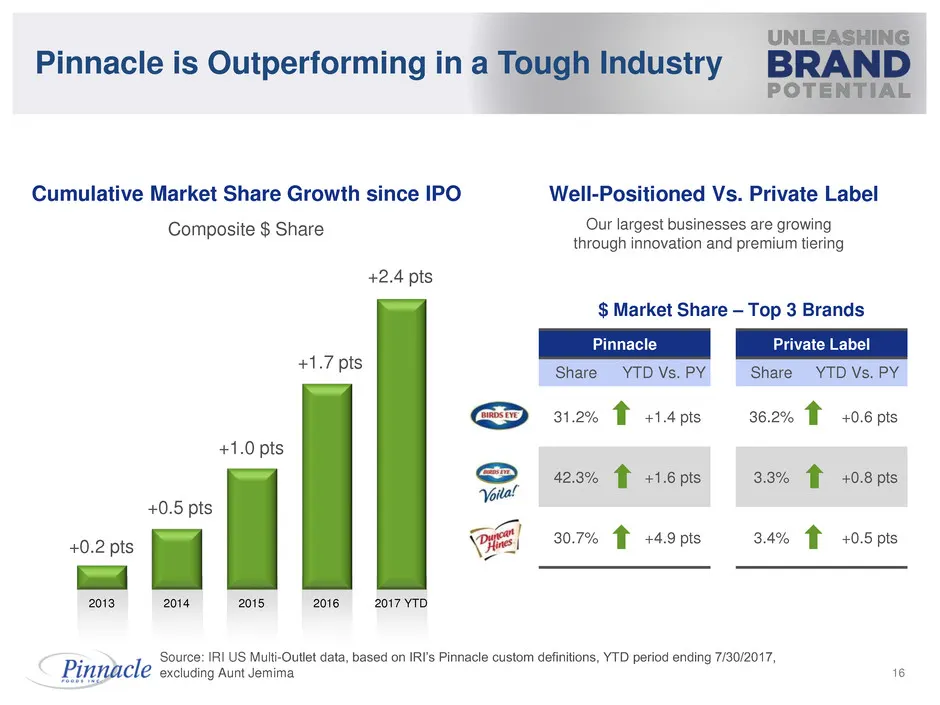
16 Pinnacle is Outperforming in a Tough Industry Cumulative Market Share Growth since IPO Composite $ Share 2013 2014 2015 2016 2017 YTD +1.7 pts +1.0 pts +0.5 pts +0.2 pts +2.4 pts Pinnacle Private Label Share YTD Vs. PY Share YTD Vs. PY 31.2% +1.4 pts 36.2% +0.6 pts 42.3% +1.6 pts 3.3% +0.8 pts 30
Slide 17: Strong Gross Margin Expansion
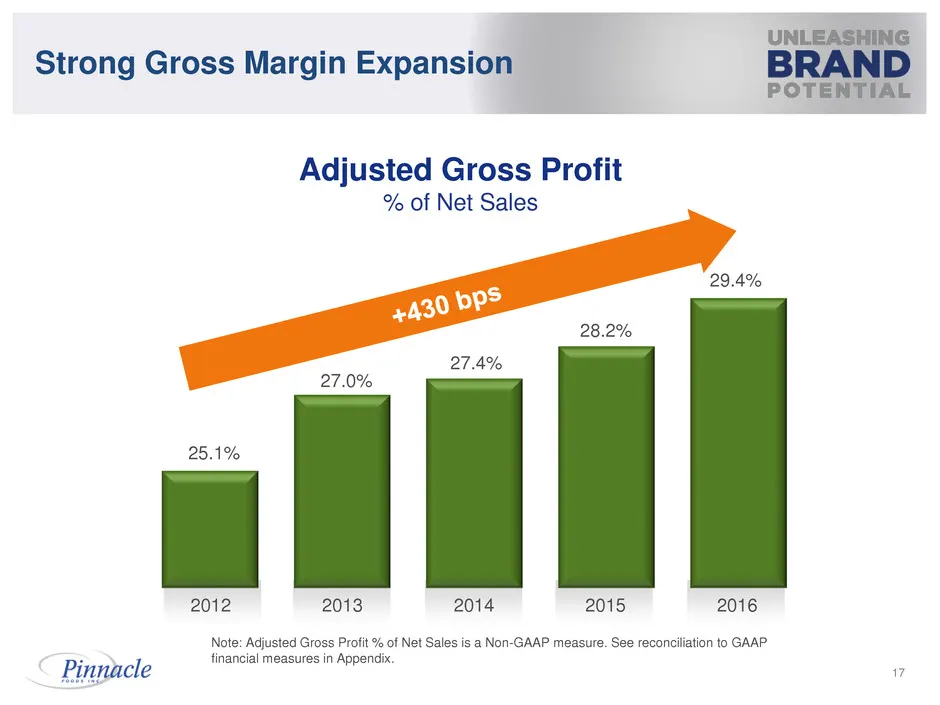
17 Strong Gross Margin Expansion Note: Adjusted Gross Profit % of Net Sales is a Non-GAAP measure. See reconciliation to GAAP financial measures in Appendix. Adjusted Gross Profit % of Net Sales 25.1% 27.0% 27.4% 28.2% 29.4% 2012 2013 2016 2015 2014
Slide 18: Attractive Value Creation Since IPO
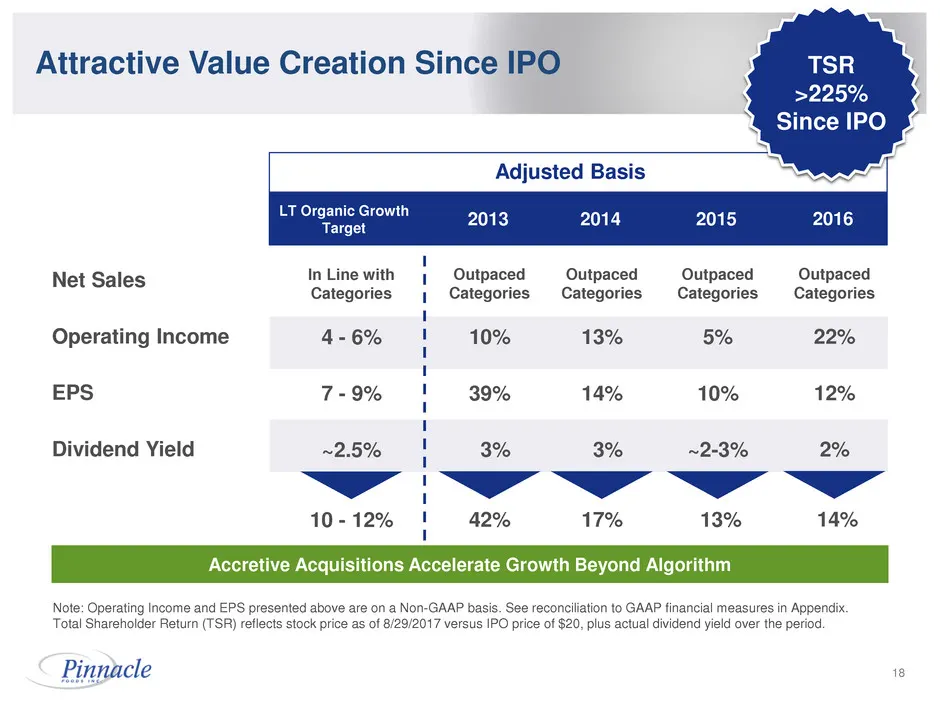
18 Attractive Value Creation Since IPO Net Sales Operating Income EPS Dividend Yield 13% 14% 3% Outpaced Categories 17% 2013 13% Outpaced Categories 10% 39% 3% Outpaced Categories 42% 2014 2015 5% 10% ~2-3% LT Organic Growth Target 4 - 6% 7 - 9% ~2.5% In Line with Categories 10 - 12% Adjusted Basis
Slide 19: Unleashing Brand Potential
UNLEASHING BRAND POTENTIAL
Slide 20: The Foundation; Unleashing Brand Potential; Financial Performance; Outlook
• The Foundation • Unleashing Brand Potential • Financial Performance • Outlook 20
Slide 21: Playbook Remains the Focus
21 Playbook Remains the Focus Increase M&A Potential Strengthen Capabilities; Maintain Costs Expand Margins & Cash Flow Accelerate Profitable Top-Line Growth
Slide 22: Gross Margin Plans Remain on Track
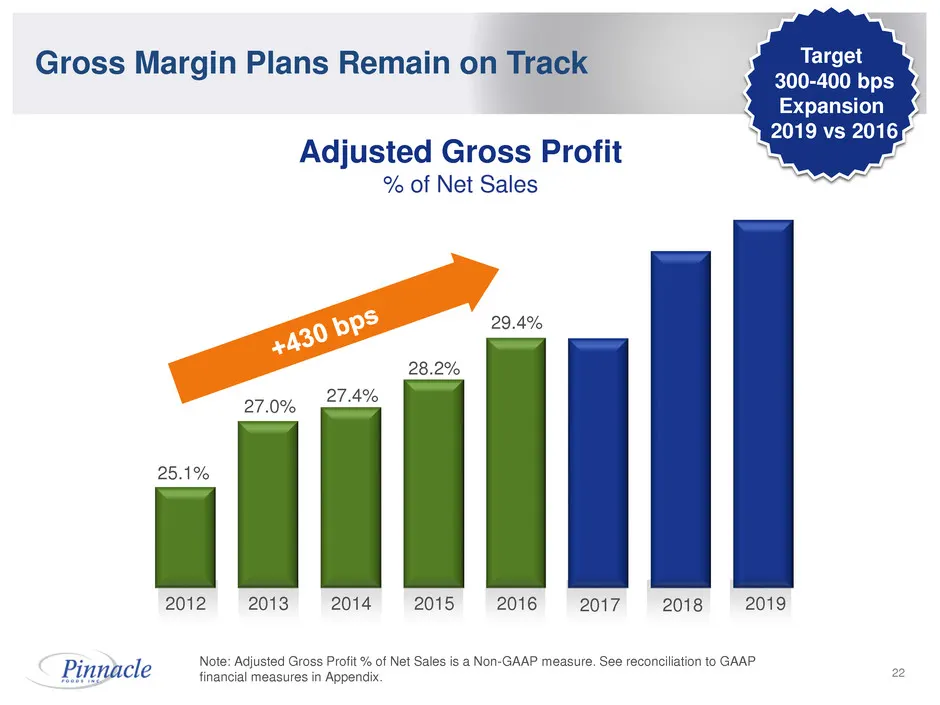
22 Gross Margin Plans Remain on Track Note: Adjusted Gross Profit % of Net Sales is a Non-GAAP measure. See reconciliation to GAAP financial measures in Appendix. Adjusted Gross Profit % of Net Sales 25.1% 27.0% 27.4% 28.2% 29.4% 2012 2013 2016 2015 2014 2019 2017 2018 Target 300-400 bps Expansion 2
Slide 23: Gross Margin Building Blocks
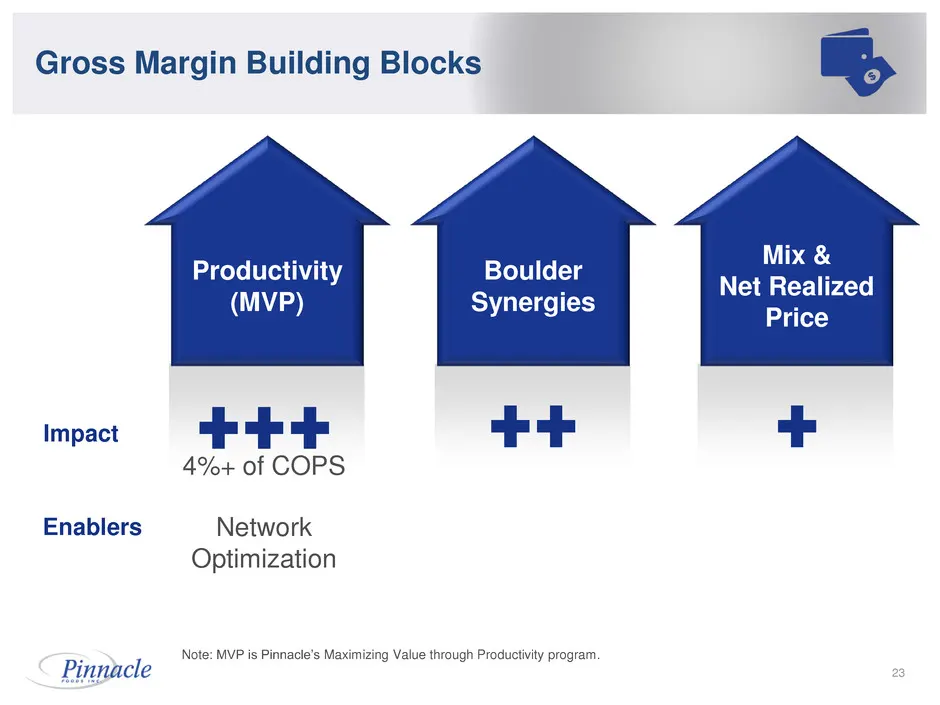
Mix & Net Realized Price Boulder Synergies Productivity (MVP) 23 Gross Margin Building Blocks Note: MVP is Pinnacle’s Maximizing Value through Productivity program. Network Optimization Enablers Impact 4%+ of COPS
Slide 24: Network Optimization Goals
24 Network Optimization Goals • Fuel margin expansion • Support profitable growth • Strengthen quality and capabilities • Pay-As-You-Go program GOALS
Slide 25: Network Optimization Pillars
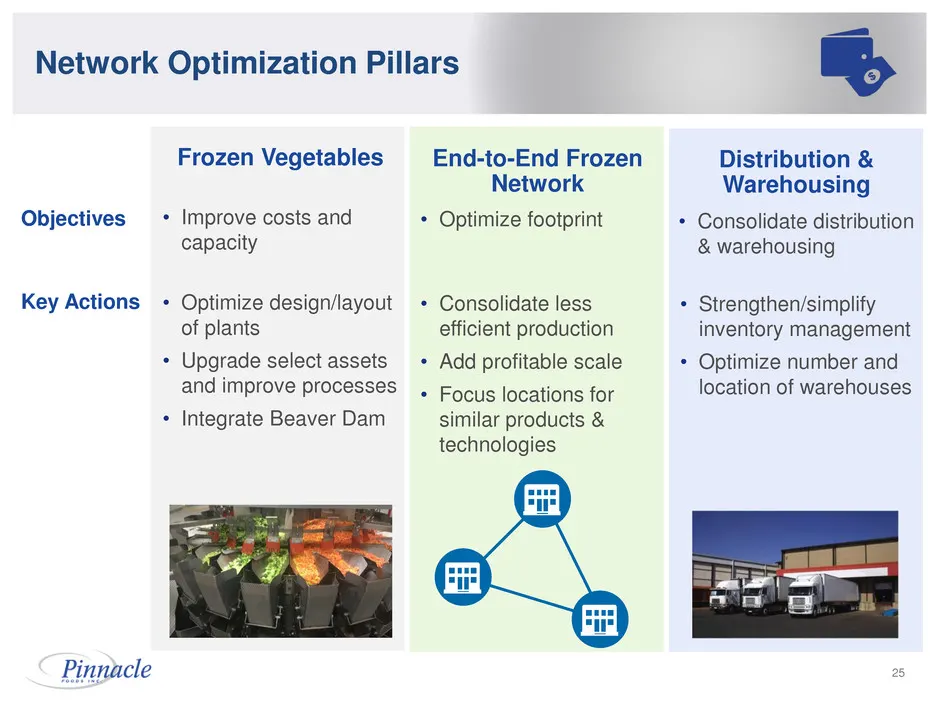
25 Network Optimization Pillars End-to-End Frozen Network Distribution & Warehousing Frozen Vegetables Objectives Key Actions • Improve costs and capacity • Optimize design/layout of plants • Upgrade select assets and improve processes • Integrate Beaver Dam • Consolidate distribution & warehousing
Slide 26: Beaver Dam
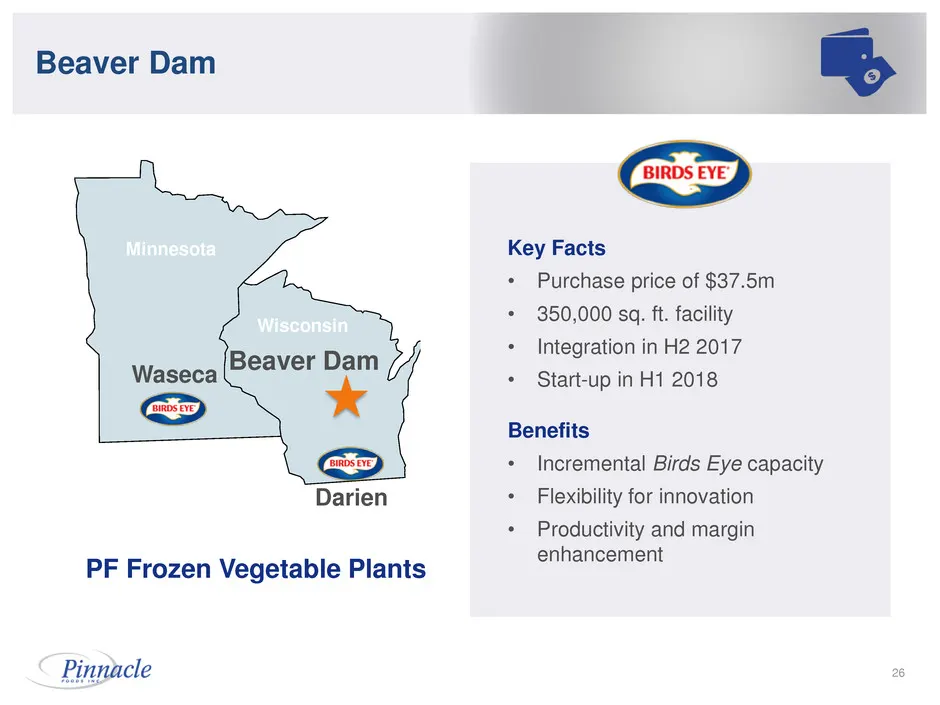
Beaver Dam 26 Key Facts • Purchase price of $37.5m • 350,000 sq. ft. facility • Integration in H2 2017 • Start-up in H1 2018 Benefits • Incremental Birds Eye capacity • Flexibility for innovation • Productivity and margin enhancement PF Frozen Vegetable Plants Minnesota Wisconsin Waseca Darien Beave
Slide 27: Network Optimization 3-Year Roadmap
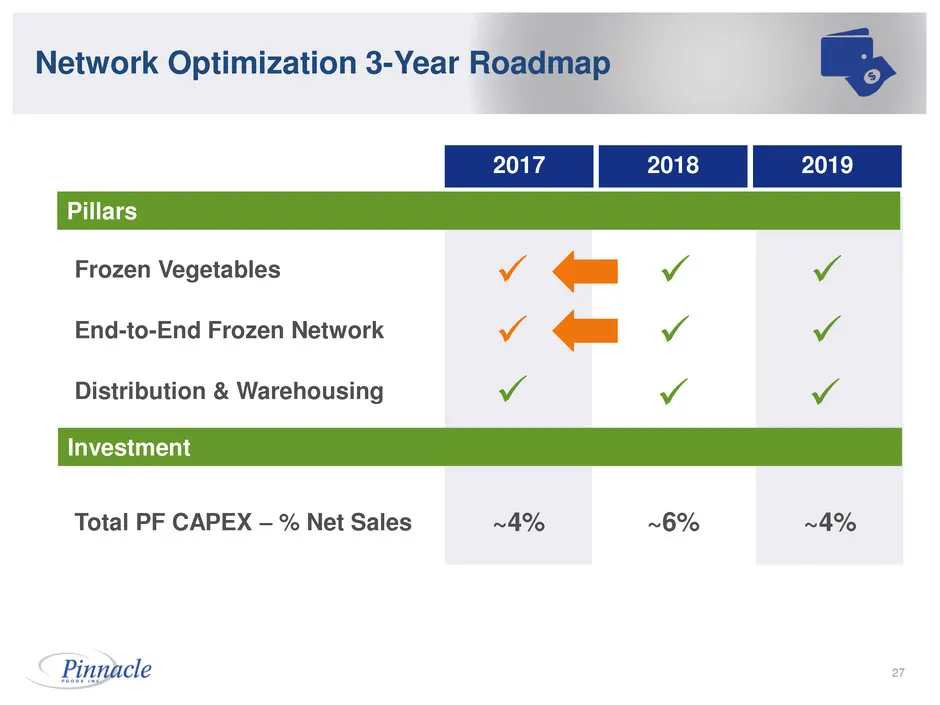
27 Network Optimization 3-Year Roadmap 2017 2018 2019 ~4% ~6% ~4% End-to-End Frozen Network Distribution & Warehousing Frozen Vegetables Total PF CAPEX – % Net Sales Pillars Investment
Slide 28: Gross Margin Building Blocks
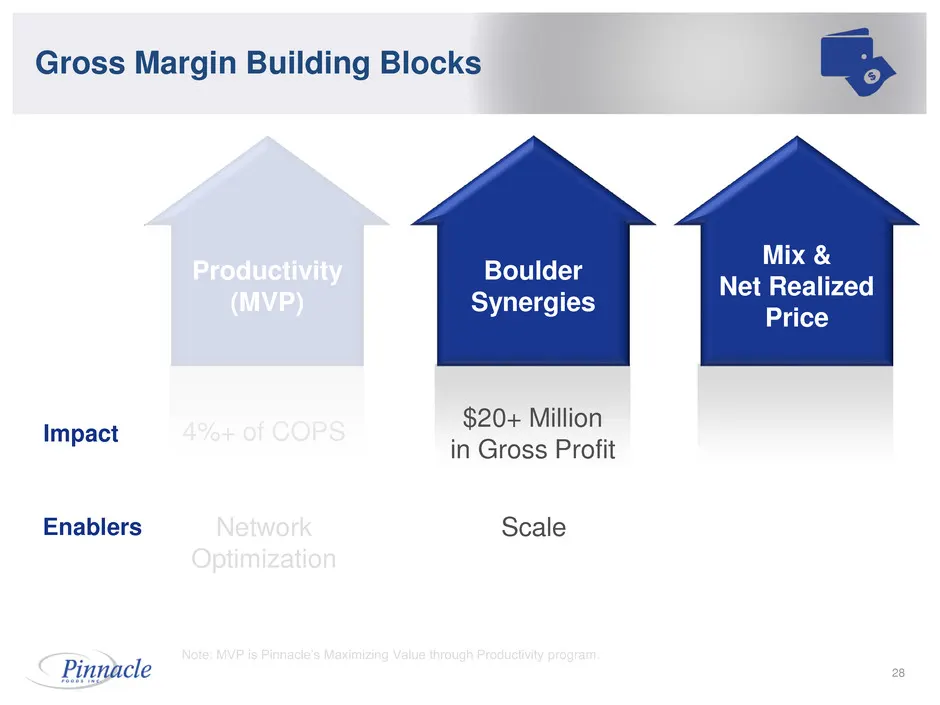
4%+ of COPS Mix & Net Realized Price Boulder Synergies Productivity (MVP) 28 Gross Margin Building Blocks Note: MVP is Pinnacle’s Maximizing Value through Productivity program. Network Optimization Scale Enablers Impact $20+ Million in Gross Profit
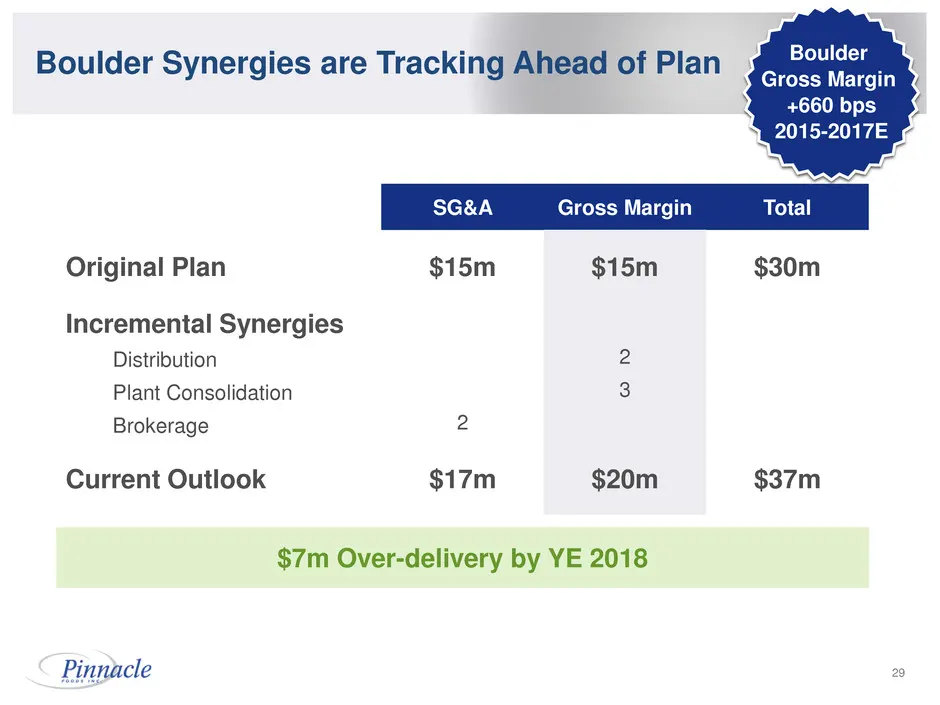
Slide 29: Boulder Synergies are Tracking Ahead of Plan
SG&A Gross Margin Total Original Plan $15m $15m $30m Incremental Synergies Distribution Plant Consolidation Brokerage 2 2 3 Current Outlook $17m $20m $37m 29 Boulder Synergies are Tracking Ahead of Plan Boulder Gross Margin +660 bps 2015-2017E $7m Over-delivery by YE 2018
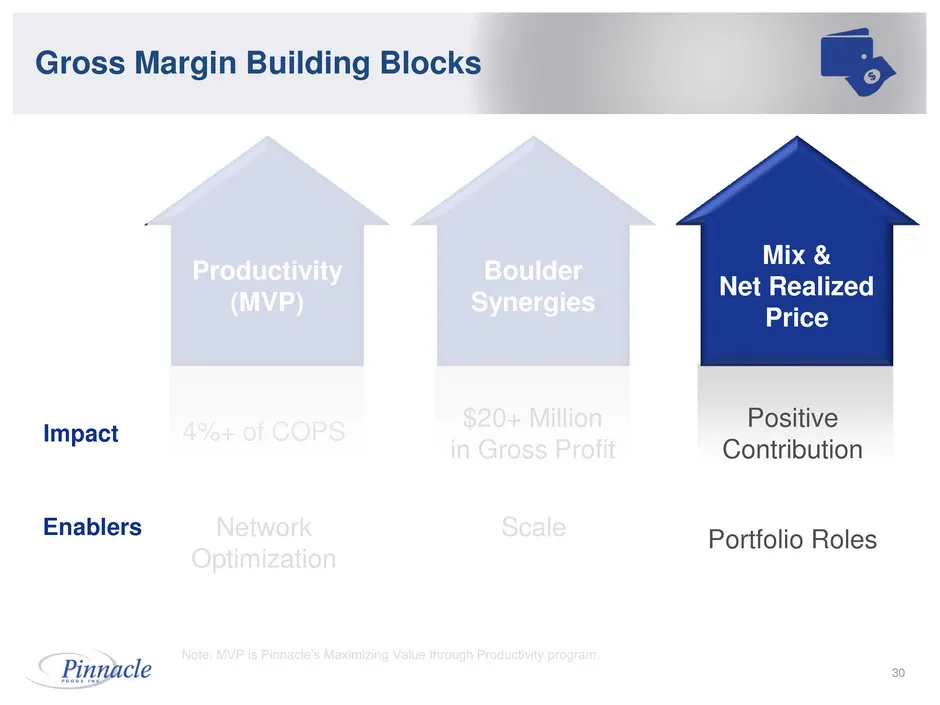
Slide 30: Gross Margin Building Blocks
4%+ of COPS Mix & Net Realized Price Boulder Synergies Productivity (MVP) 30 Gross Margin Building Blocks Note: MVP is Pinnacle’s Maximizing Value through Productivity program. Network Optimization Scale Portfolio Roles Enablers Impact $20+ Million in Gross Profit Positive Contribution
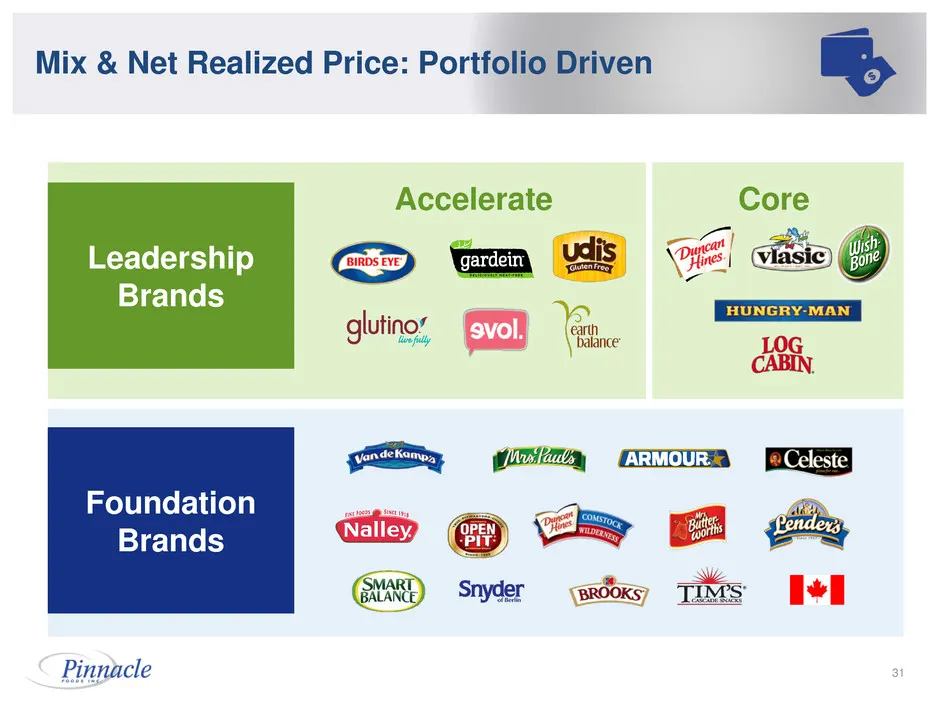
Slide 31: Mix & Net Realized Price: Portfolio Driven
Leadership Brands 31 Mix & Net Realized Price: Portfolio Driven Foundation Brands Accelerate Core
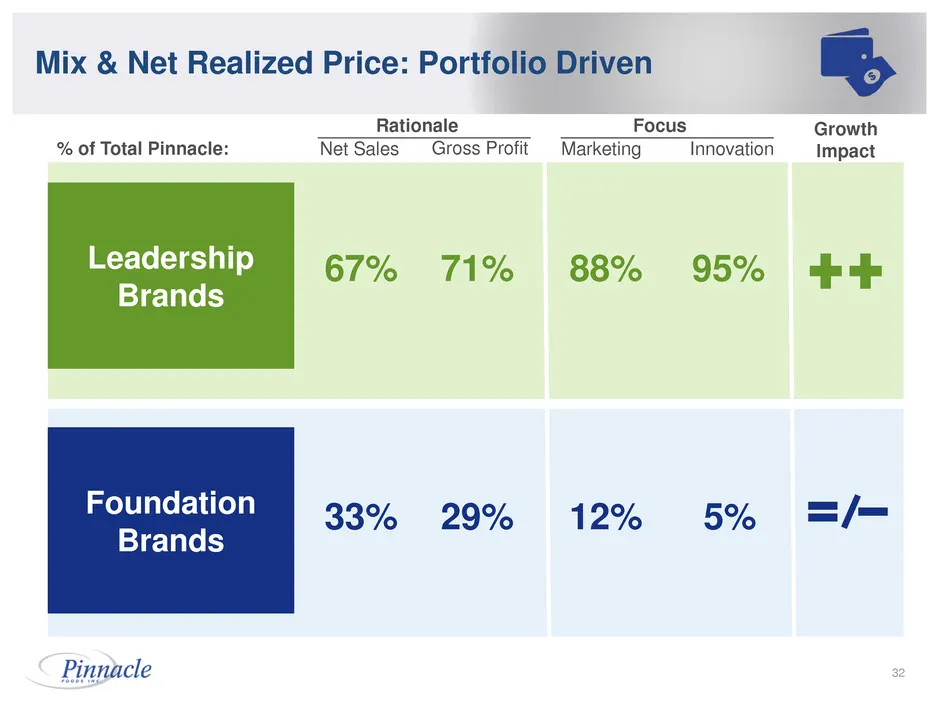
Slide 32: Mix & Net Realized Price: Portfolio Driven
Leadership Brands Foundation Brands Mix & Net Realized Price: Portfolio Driven % of Total Pinnacle: 67% 71% 33% 29% Net Sales Gross Profit Rationale Growth Impact 88% 95% 12% 5% Innovation Marketing Focus 32
Slide 33: Playbook Remains the Focus
33 Playbook Remains the Focus Increase M&A Potential Strengthen Capabilities; Maintain Costs Accelerate Profitable Top-Line Growth Expand Margins & Cash Flow
Slide 34: Accelerate Profitable Topline Growth Building Blocks
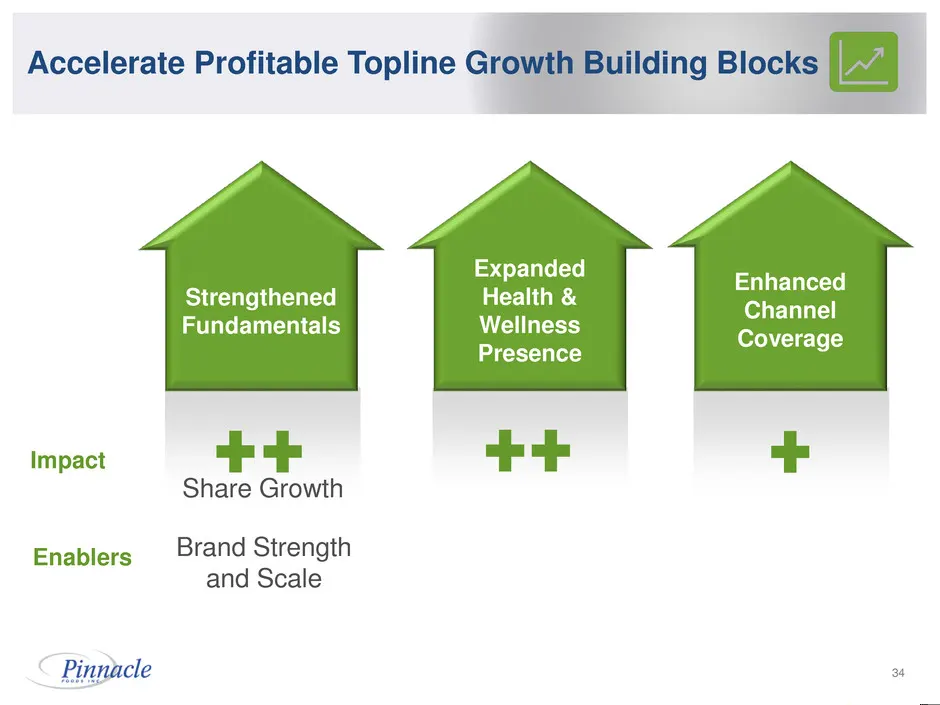
34 Accelerate Profitable Topline Growth Building Blocks Strengthened Fundamentals Expanded Health & Wellness Presence Enhanced Channel Coverage Impact Brand Strength and Scale Enablers Share Growth
Slide 35: Duncan Hines Brand Strength
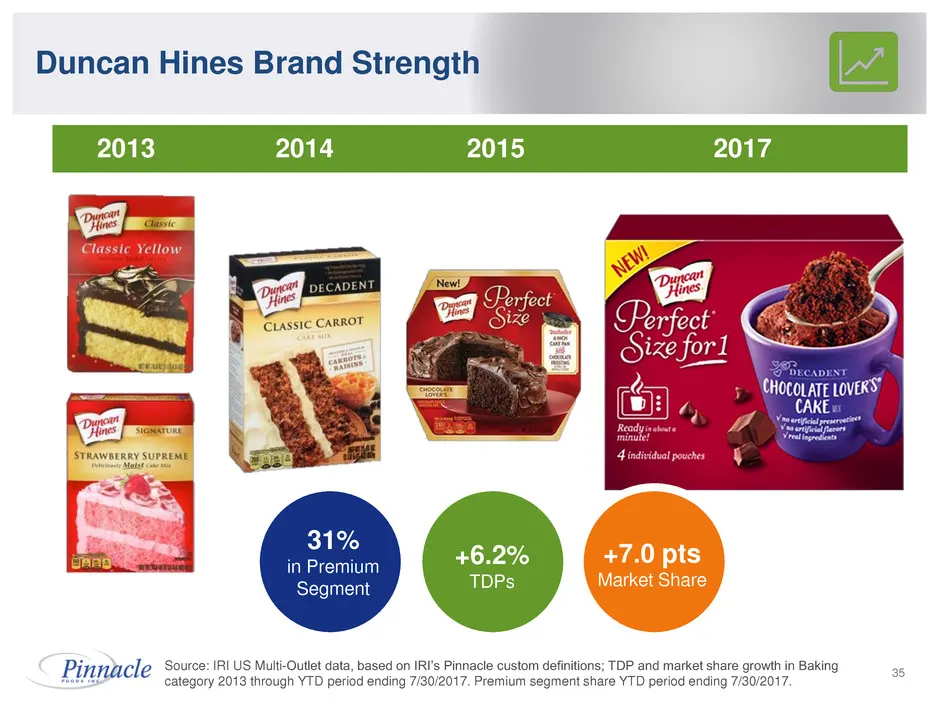
35 Duncan Hines Brand Strength 31% in Premium Segment +6.2% TDPs Source: IRI US Multi-Outlet data, based on IRI’s Pinnacle custom definitions; TDP and market share growth in Baking category 2013 through YTD period ending 7/30/2017. Premium segment share YTD period ending 7/30/2017. 2013 2014 2015 20
Slide 36: Scale – Leveraging the Power of the Portfolio
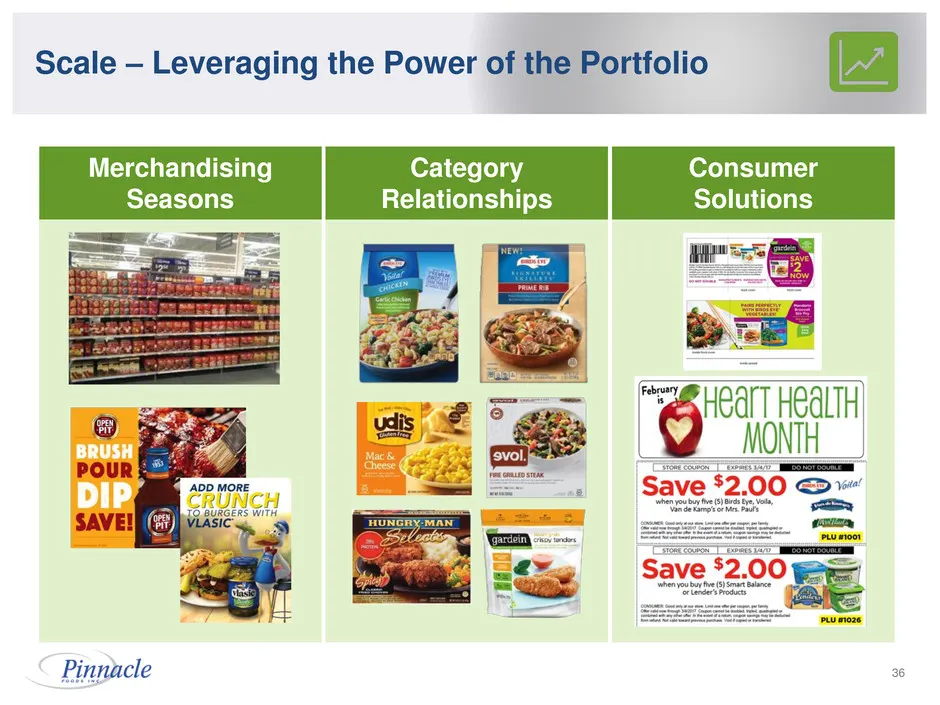
36 Scale – Leveraging the Power of the Portfolio Merchandising Seasons Category Relationships Consumer Solutions
Slide 37: Brand Strength and Scale Accelerate Profitable Topline Growth
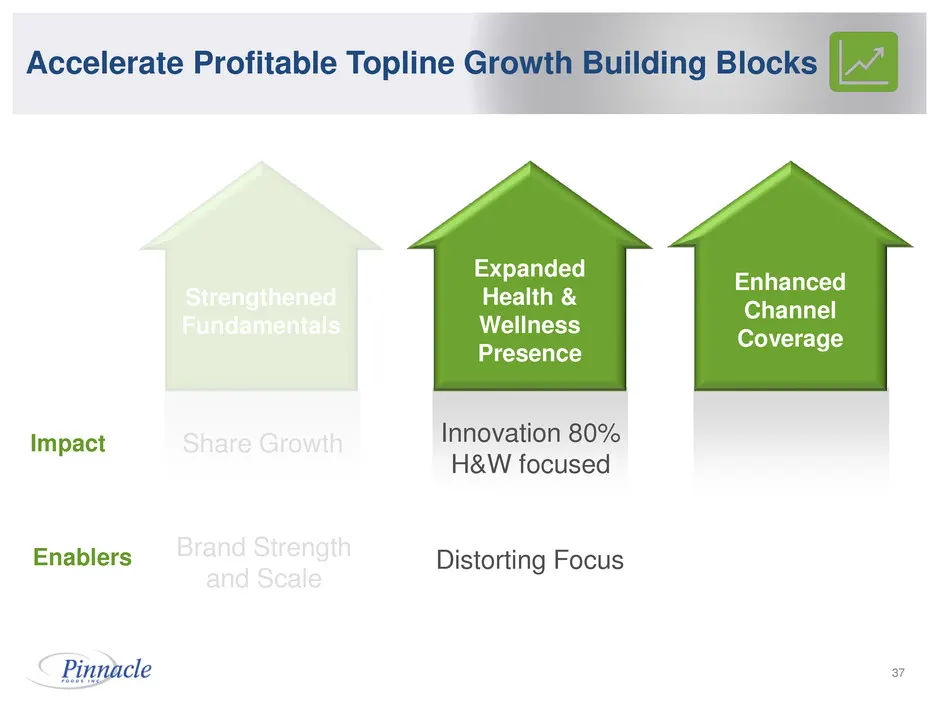
Brand Strength and Scale 37 Accelerate Profitable Topline Growth Building Blocks Strengthened Fundamentals Expanded Health & Wellness Presence Enhanced Channel Coverage Impact Distorting Focus Share Growth Innovation 80% H&W focused Enablers
Slide 38: Expand H&W Presence
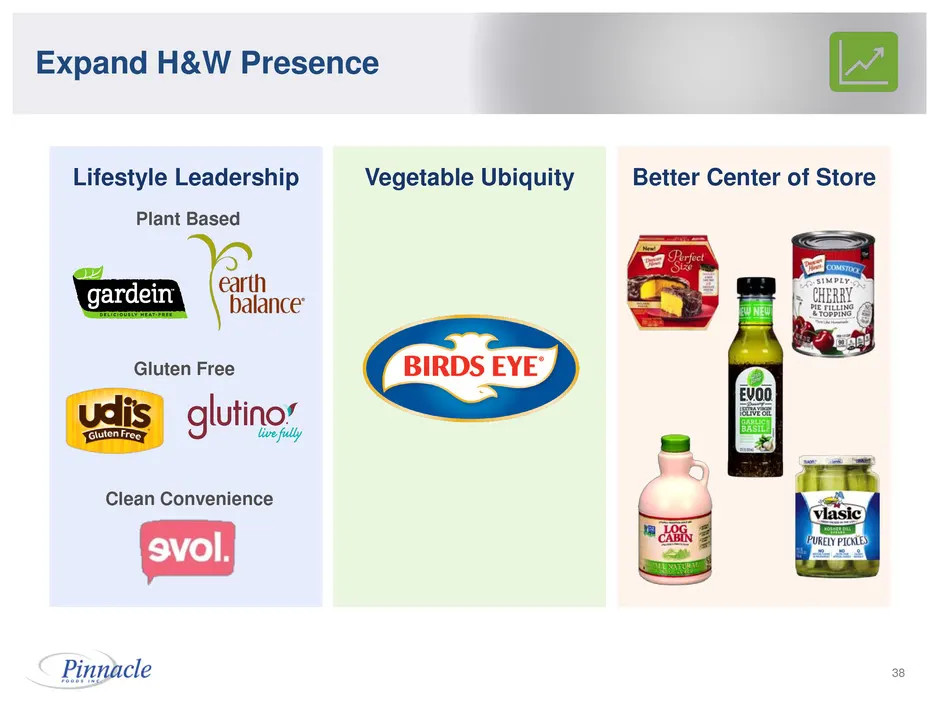
38 Expand H&W Presence Vegetable Ubiquity Lifestyle Leadership Plant Based Clean Convenience Gluten Free Better Center of Store
Slide 39: Lifestyle Leadership Should Mean No Compromise
39 Lifestyle Leadership Should Mean No Compromise Taste Broader Benefits Value • Flavor at parity or better than benchmark • Recipes and offerings that are relevant to consumers • Healthy profile • Convenience • Size and price • Quality No Compromise
Slide 40: Udi's Gluten Free Bread
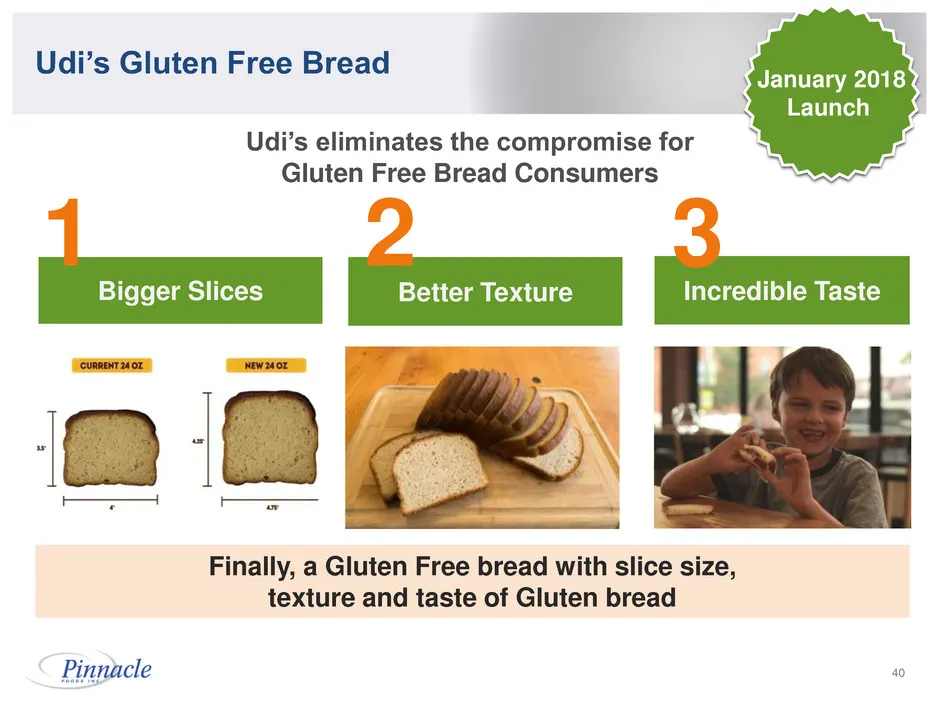
40 Udi’s Gluten Free Bread Finally, a Gluten Free bread with slice size, texture and taste of Gluten bread Udi’s eliminates the compromise for Gluten Free Bread Consumers Bigger Slices 1 Incredible Taste 3 Better Texture 2 January 2018 Launch
Slide 41: Vegetable Ubiquity: Birds Eye Innovation
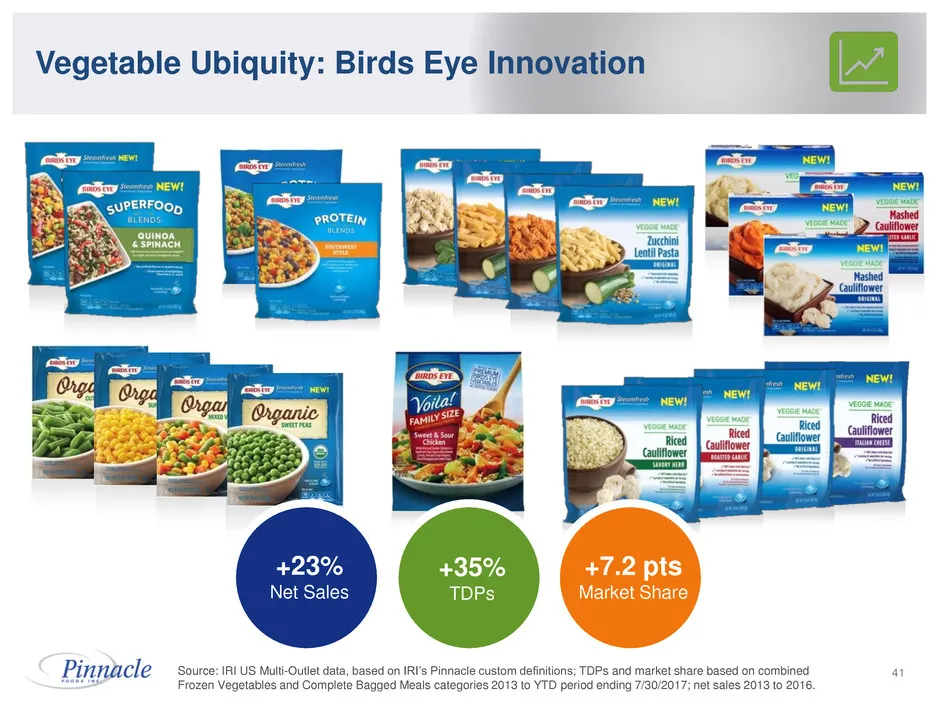
41 Vegetable Ubiquity: Birds Eye Innovation Source: IRI US Multi-Outlet data, based on IRI’s Pinnacle custom definitions; TDPs and market share based on combined Frozen Vegetables and Complete Bagged Meals categories 2013 to YTD period ending 7/30/2017; net sales 2013 to 2016. +7.2 pts Market Share
Slide 42: Transforming Frozen...
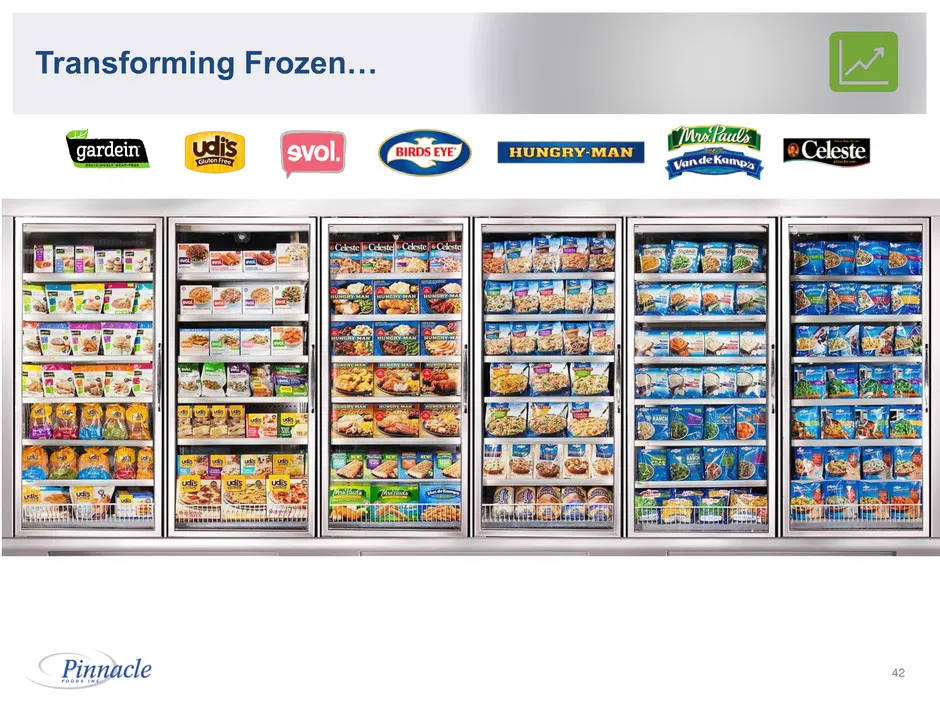
Transforming Frozen... mus @> mom fe ma Pinnacle 42
Slide 43: ...with Room to Grow
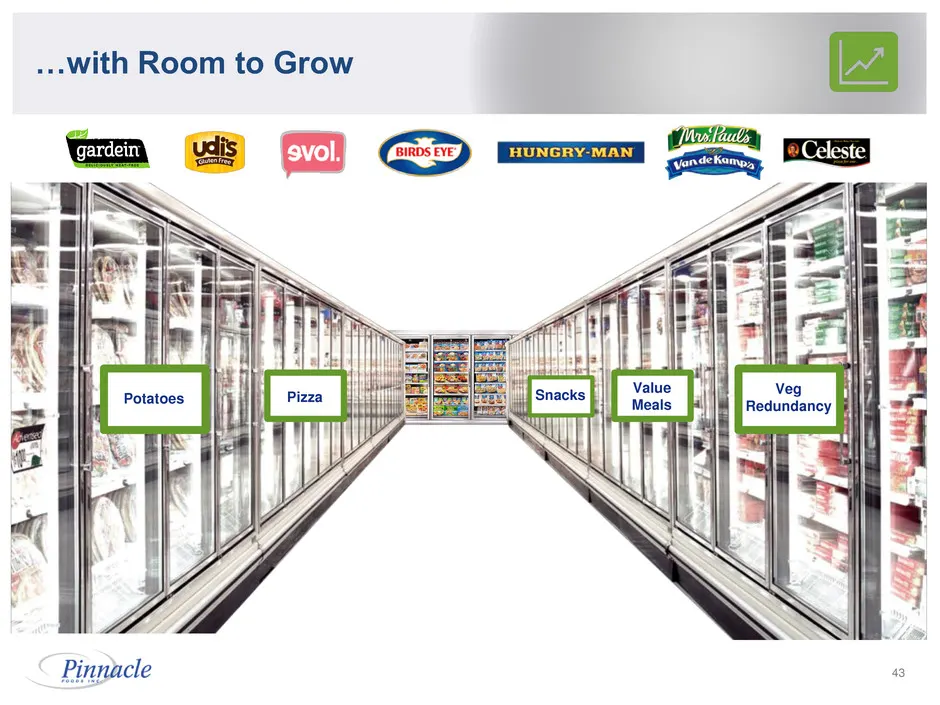
Veg Redundancy Value Meals Snacks Potatoes Pizza …with Room to Grow 43
Slide 44: Better Center of Store
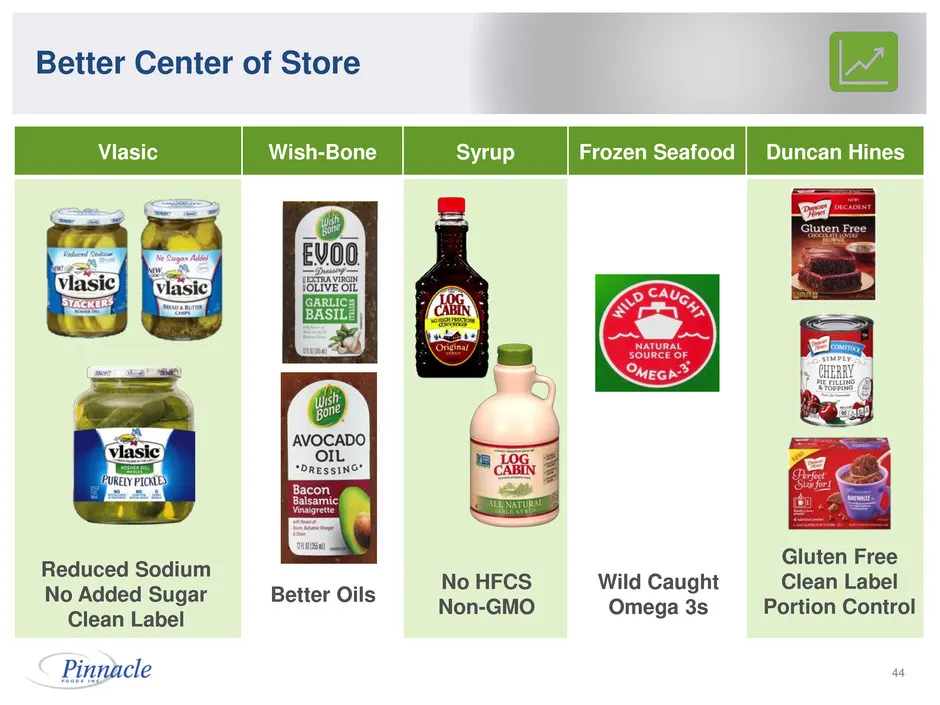
44 Better Center of Store Vlasic Wish-Bone Syrup Frozen Seafood Duncan Hines Reduced Sodium No Added Sugar Clean Label Better Oils No HFCS Non-GMO Wild Caught Omega 3s Gluten Free Clean Label Portion Control
Slide 45: Brand Strength and Scale: E-commerce
Brand Strength and Scale Distorting Focus 45 Accelerate Profitable Topline Growth Building Blocks Strengthened Fundamentals Expanded Health & Wellness Presence Enhanced Channel Coverage Impact E-commerce Share Growth Innovation 80% H&W focused Sales 2X by 2020 Enablers
Slide 46: E-commerce Sustainable Business Model
46 E-commerce Sustainable Business Model Supply Chain Products Marketing & Communications Talent
Slide 47: Early e-commerce Success
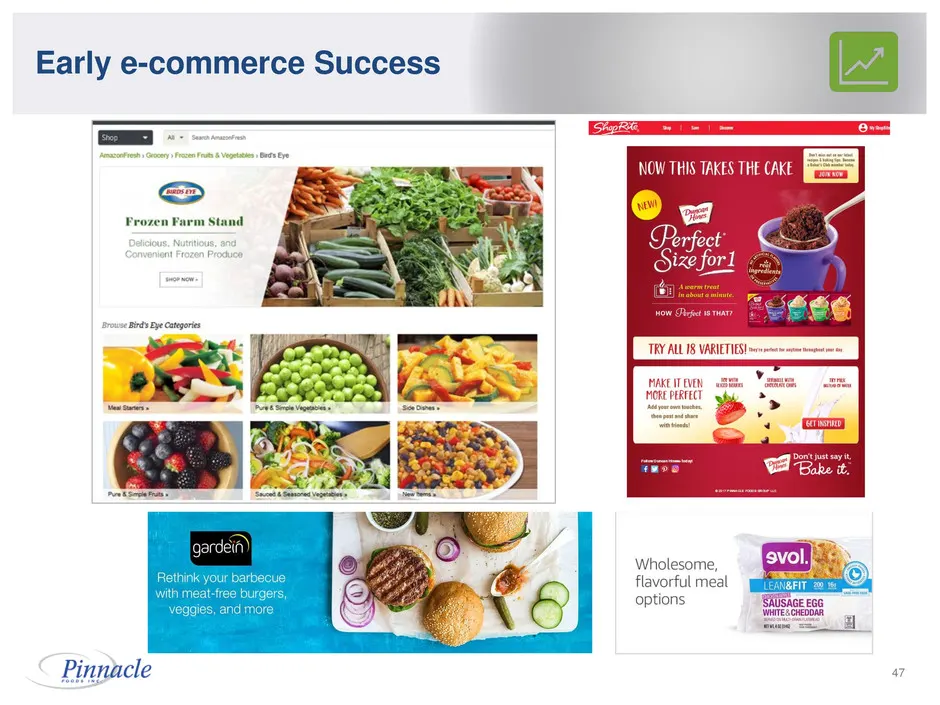
Early e-commerce Success Pinnnele PAKEITEVEN MORE PERFECT » Wholesome, flavorful meal options
Slide 48: Playbook Remains the Focus
48 Playbook Remains the Focus Increase M&A Potential Strengthen Capabilities; Maintain Costs Expand Margins & Cash Flow Accelerate Profitable Top-Line Growth
Slide 49: Strengthen Capabilities / Maintain Costs
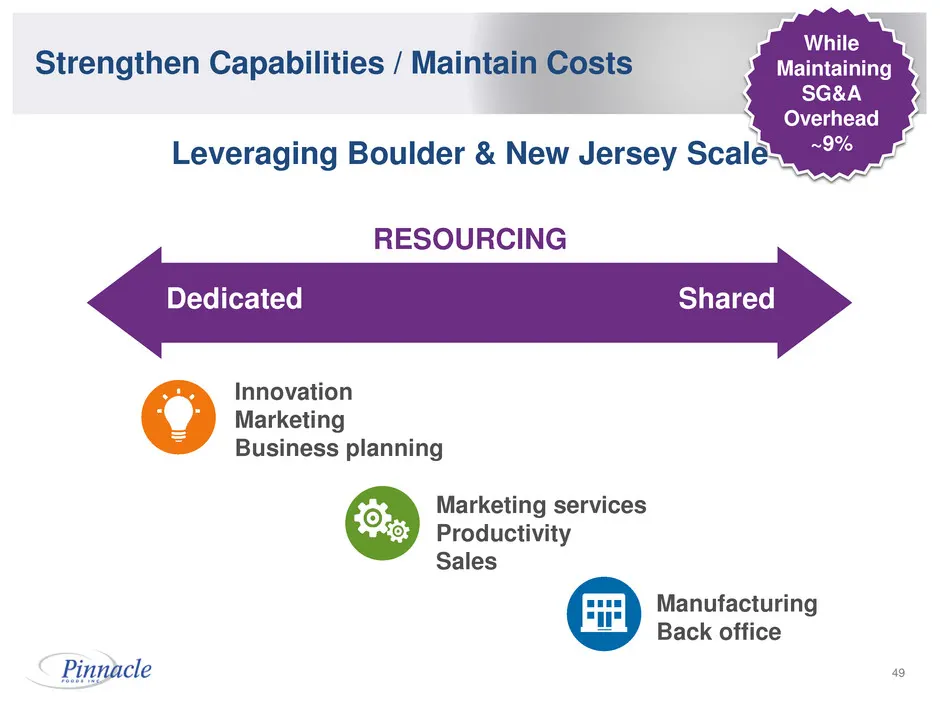
49 Strengthen Capabilities / Maintain Costs Leveraging Boulder & New Jersey Scale While Maintaining SG&A Overhead ~9% Marketing services Productivity Sales Manufacturing Back office Innovation Marketing Business planning RESOURCING Dedicated Shared
Slide 50: Increased M&A Potential
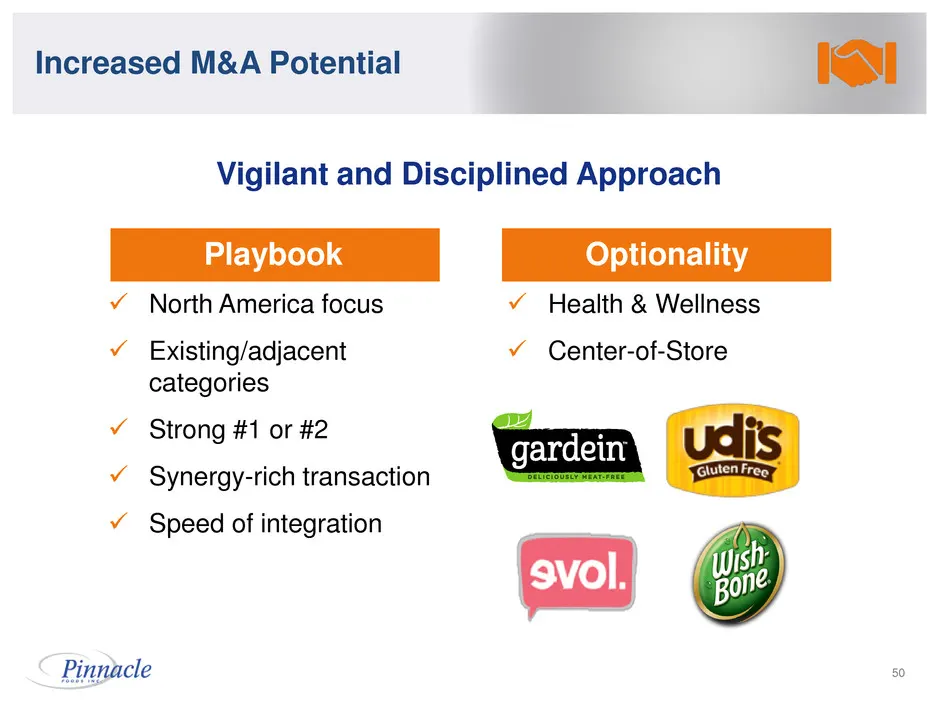
50 Increased M&A Potential Vigilant and Disciplined Approach Playbook North America focus Existing/adjacent categories Strong #1 or #2 Synergy-rich transaction Speed of integration Optionality Health & Wellness Center-of-Store
Slide 51: The Foundation; Unleashing Brand Potential; Financial Performance; Outlook
51 • The Foundation • Unleashing Brand Potential • Financial Performance • Outlook
Slide 52: Strong Underlying H1 2017 Results
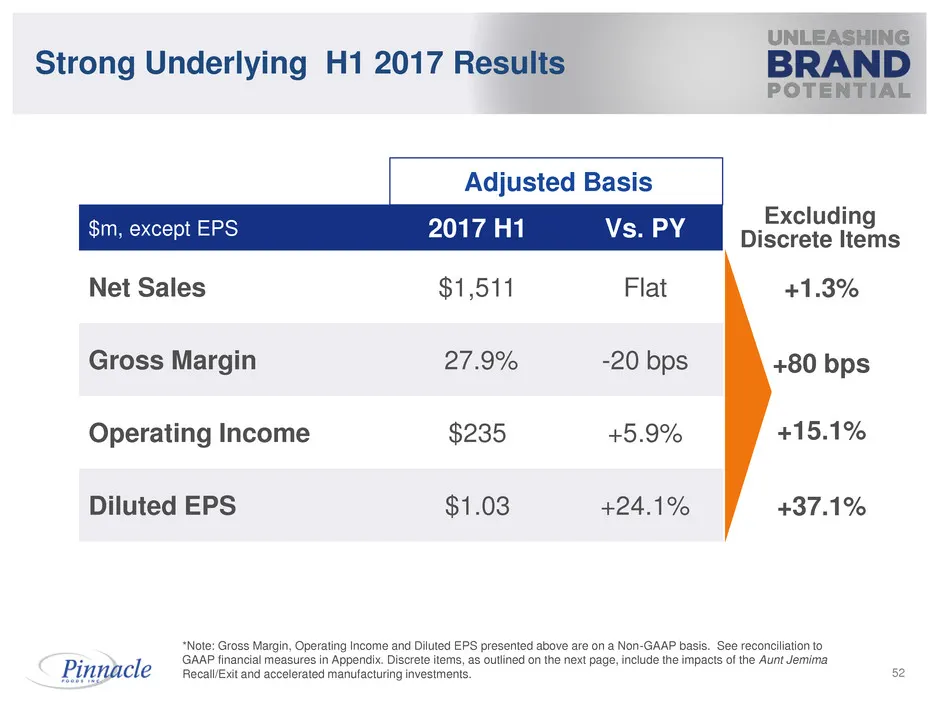
$m, except EPS 2017 H1 Vs. PY Net Sales $1,511 Flat Gross Margin 27.9% -20 bps Operating Income $235 +5.9% Diluted EPS $1.03 +24.1% 52 Strong Underlying H1 2017 Results Adjusted Basis +1.3% +80 bps +15.1% +37.1% Excluding Discrete Items *Note: Gross Margin, Operating Income and Diluted EPS presented
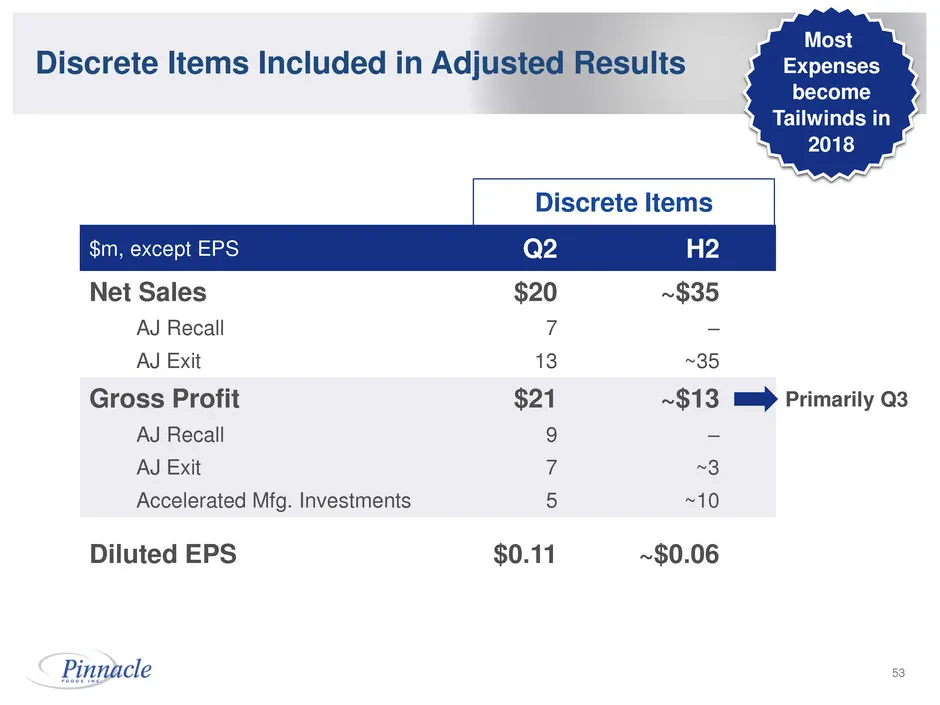
Slide 53: Discrete Items Included in Adjusted Results
$m, except EPS Q2 H2 Net Sales AJ Recall AJ Exit $20 7 13 ~$35 – ~35 Gross Profit AJ Recall AJ Exit Accelerated Mfg. Investments $21 9 7 5 ~$13 – ~3 ~10 Diluted EPS $0.11 ~$0.06 53 Discrete Items Included in Adjusted Results Discrete Items Most Expenses become Tailwinds in 2018 Primarily Q3
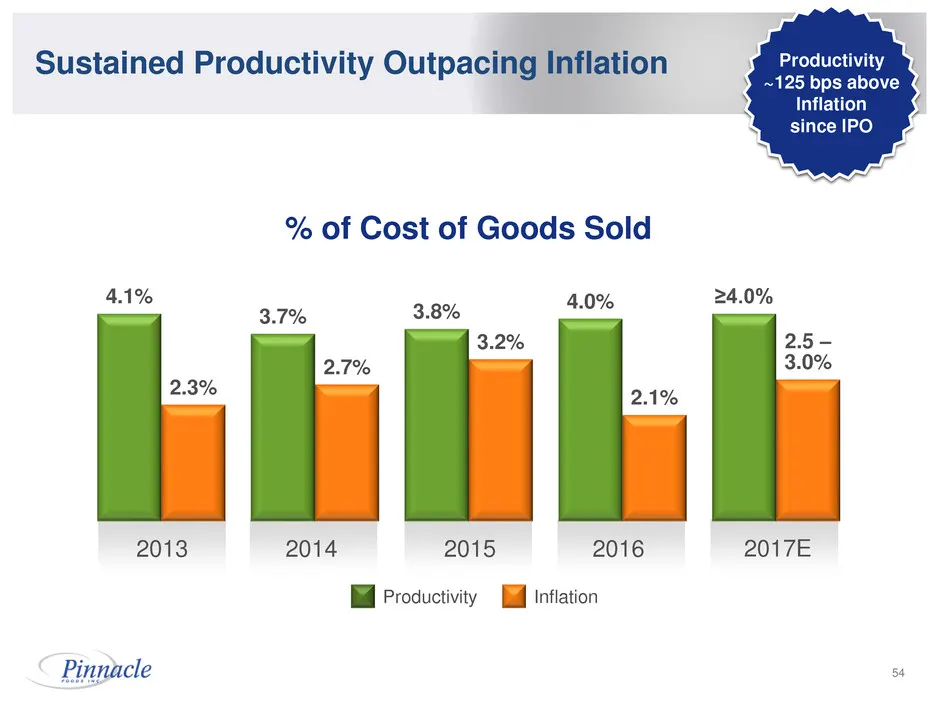
Slide 54: Sustained Productivity Outpacing Inflation
54 Sustained Productivity Outpacing Inflation Inflation Productivity 4.1% 3.7% 3.8% 4.0% ≥4.0% 2.3% 2.7% 3.2% 2.1% 2.5 – 3.0% 2016 2015 2014 2013 % of Cost of Goods Sold 2017E Productivity ~125 bps above Inflation since IPO
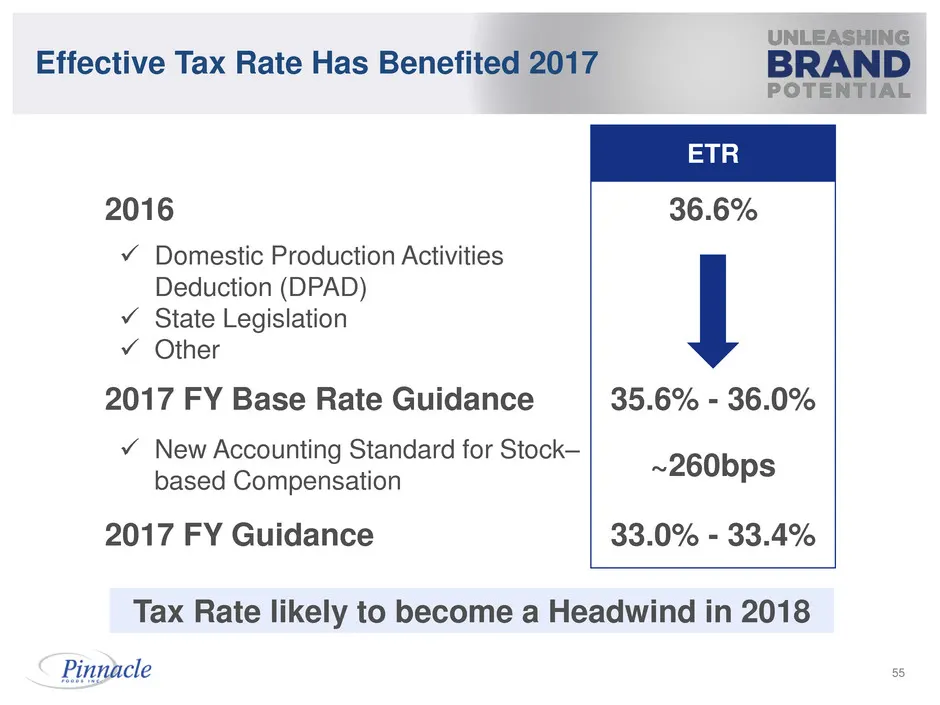
Slide 55: Effective Tax Rate Has Benefited
55 Effective Tax Rate Has Benefited 2017 2016 Domestic Production Activities Deduction (DPAD) State Legislation Other 2017 FY Base Rate Guidance New Accounting Standard for Stock– based Compensation 2017 FY Guidance ETR 36.6% 35.6% - 36.0% 33.0% - 33.4% ~260bps Tax Rate likely to become a He
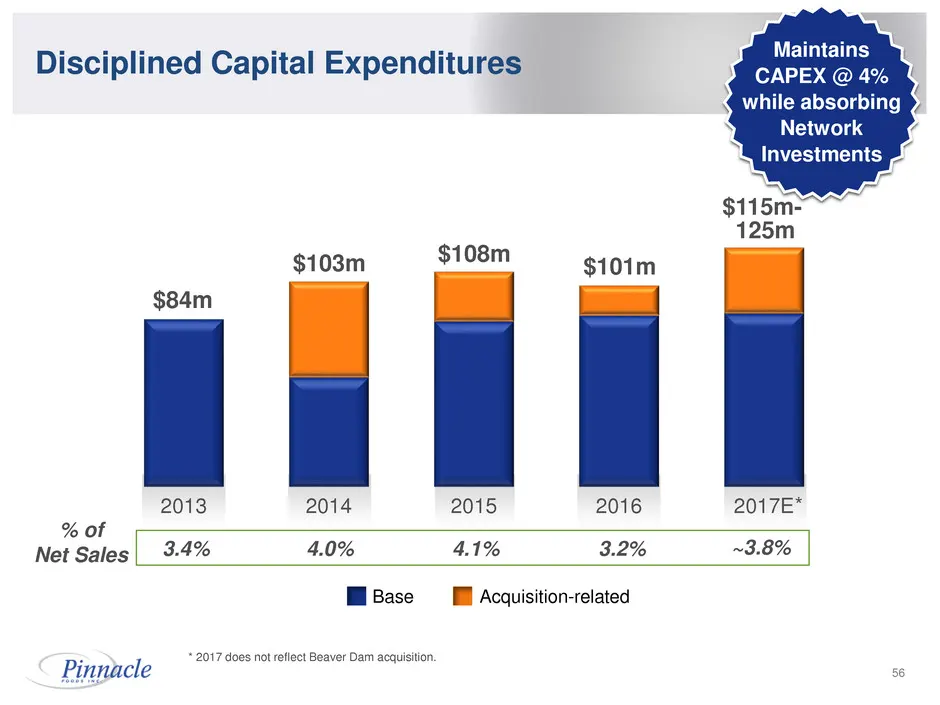
Slide 56: Disciplined Capital Expenditures
56 Disciplined Capital Expenditures * 2017 does not reflect Beaver Dam acquisition. 2013 2014 2015 2016 2017E $84m $108m $101m $103m $115m- $125m % of Net Sales 3.4% 4.0% 4.1% 3.2% ~3.8% Base Acquisition-related Maintains CAPEX @ 4% while absorbing Network Investments *
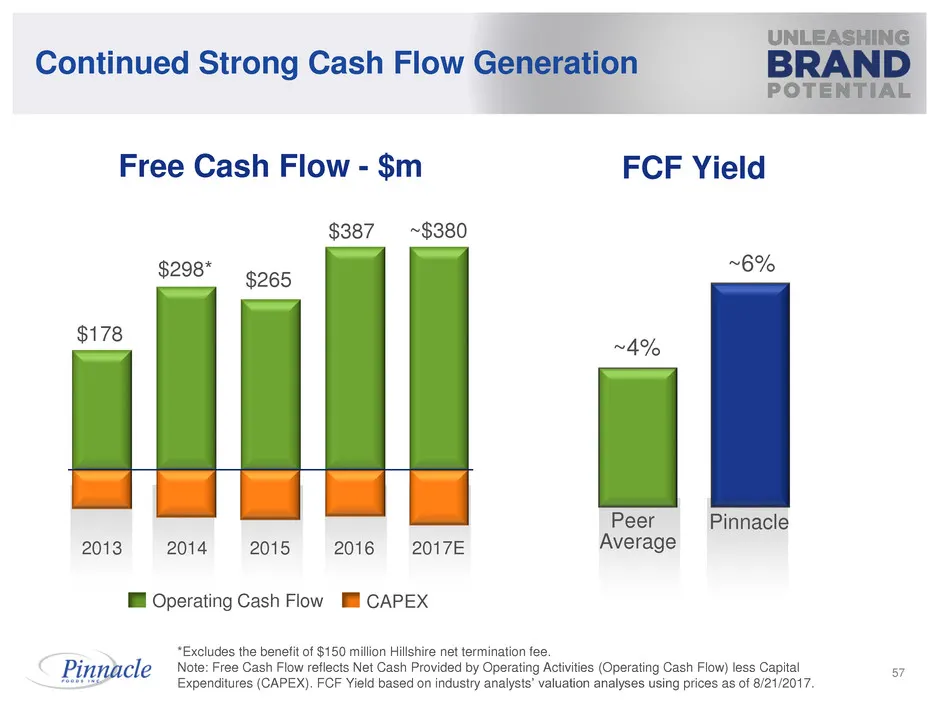
Slide 57: Continued Strong Cash Flow Generation
Peer Average Pinnacle FCF Yield ~4% ~6% *Excludes the benefit of $150 million Hillshire net termination fee. Note: Free Cash Flow reflects Net Cash Provided by Operating Activities (Operating Cash Flow) less Capital Expenditures (CAPEX). FCF Yield based on industry analysts’ valuation analyses using
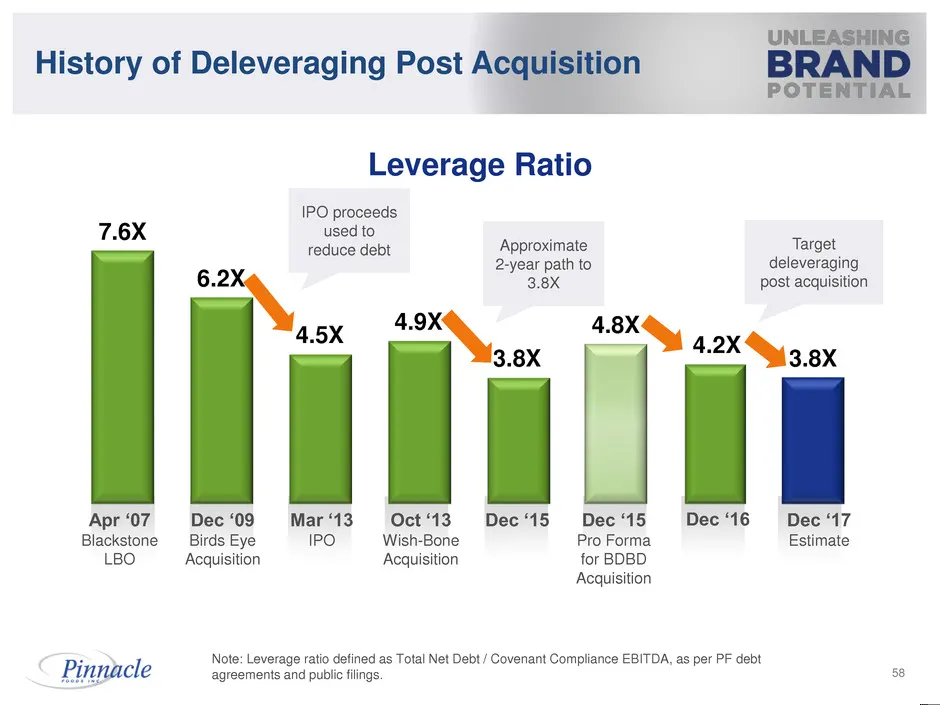
Slide 58: History of Deleveraging Post Acquisition
Leverage Ratio 58 History of Deleveraging Post Acquisition Note: Leverage ratio defined as Total Net Debt / Covenant Compliance EBITDA, as per PF debt agreements and public filings. 7.6X 6.2X 4.5X 4.9X 3.8X 4.8X 4.2X 3.8X Apr ‘07 Blackstone LBO Dec ‘09 Birds Eye Acquisition Mar ‘13 IPO Oct ‘13 Wish-
Slide 59: The Foundation; Unleashing Brand Potential; Financial Performance; Outlook
59 • The Foundation • Unleashing Brand Potential • Financial Performance • Outlook
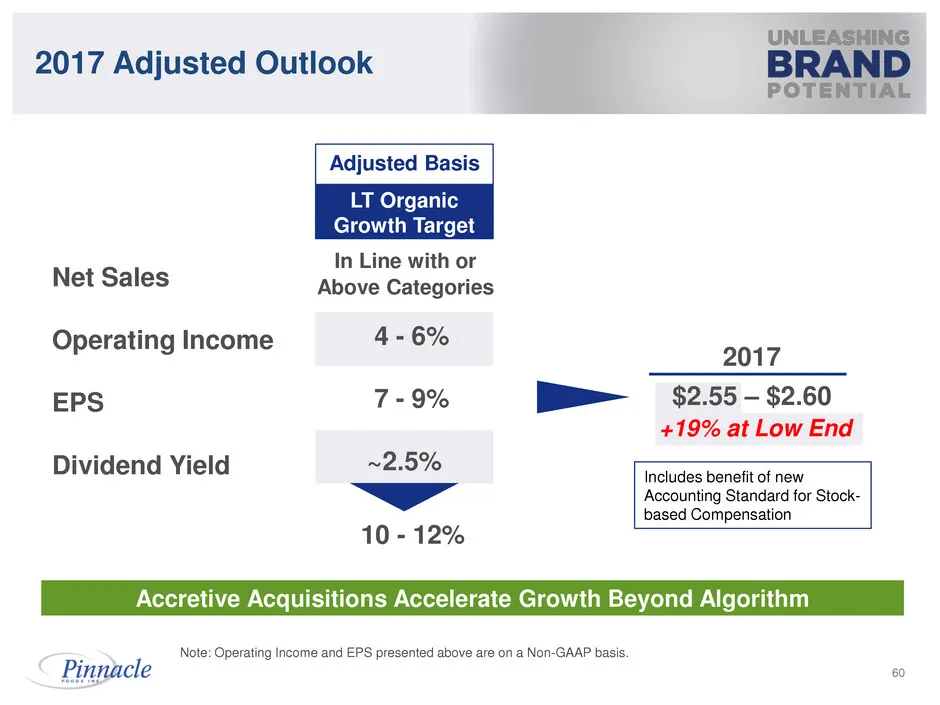
Slide 60: 2017 Adjusted Outlook
Adjusted Basis Net Sales Operating Income EPS Dividend Yield LT Organic Growth Target 4 - 6% 7 - 9% ~2.5% In Line with or Above Categories 10 - 12% Note: Operating Income and EPS presented above are on a Non-GAAP basis. Accretive Acquisitions Accelerate Growth Beyond Algorithm Adjusted Basis Net Sal
Slide 61: Assumptions Included in 2017 FY Adjusted Outlook
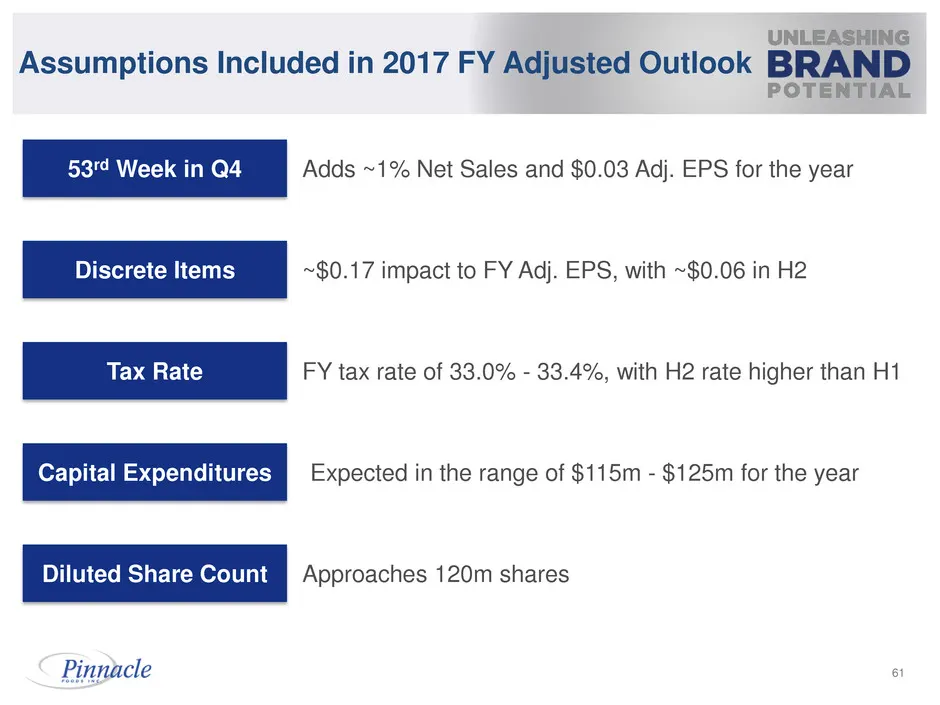
61 Assumptions Included in 2017 FY Adjusted Outlook 53rd Week in Q4 Discrete Items Tax Rate Diluted Share Count Adds ~1% Net Sales and $0.03 Adj. EPS for the year ~$0.17 impact to FY Adj. EPS, with ~$0.06 in H2 FY tax rate of 33.0% - 33.4%, with H2 rate higher than H1 Approaches 120m shares Capital
Slide 62: Margin & Cash; M&A; Capabilities; Growth
62 Margin & Cash M&A Capabilities Growth
Slide 63: Appendix
Pinnacle ‘POTENTIAL =a APPENDIX
Slide 64: (1) Represents charges related to the Aunt Jemima and other frozen breakfast products exit,
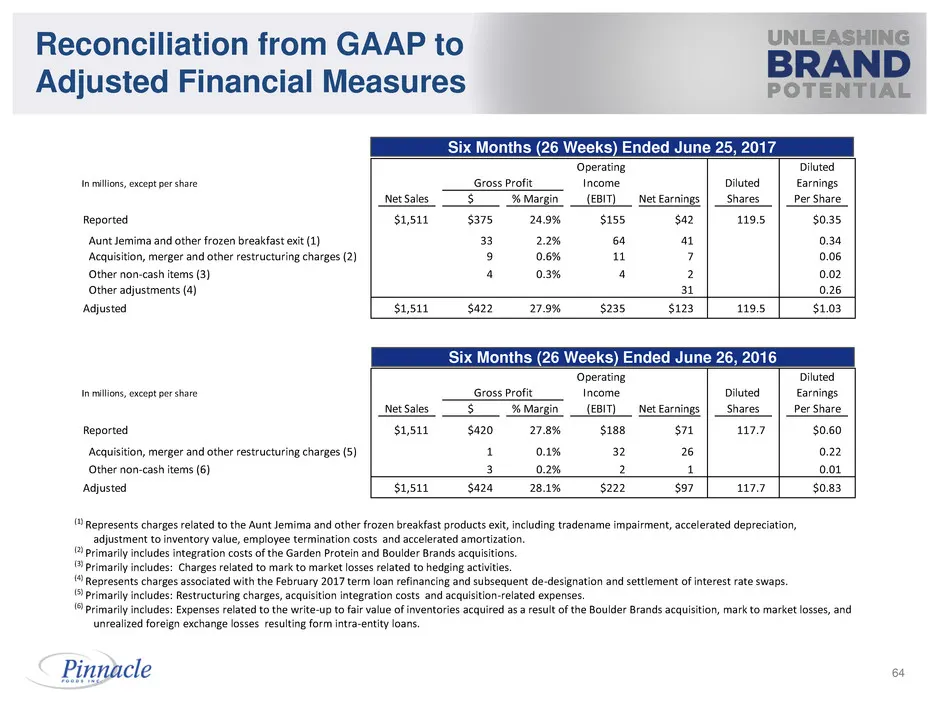
(1) Represents charges related to the Aunt Jemima and other frozen breakfast products exit, including tradename impairment, accelerated depreciation, adjustment to inventory value, employee termination costs and accelerated amortization. (2) Primarily includes integration costs of the Garden Protein
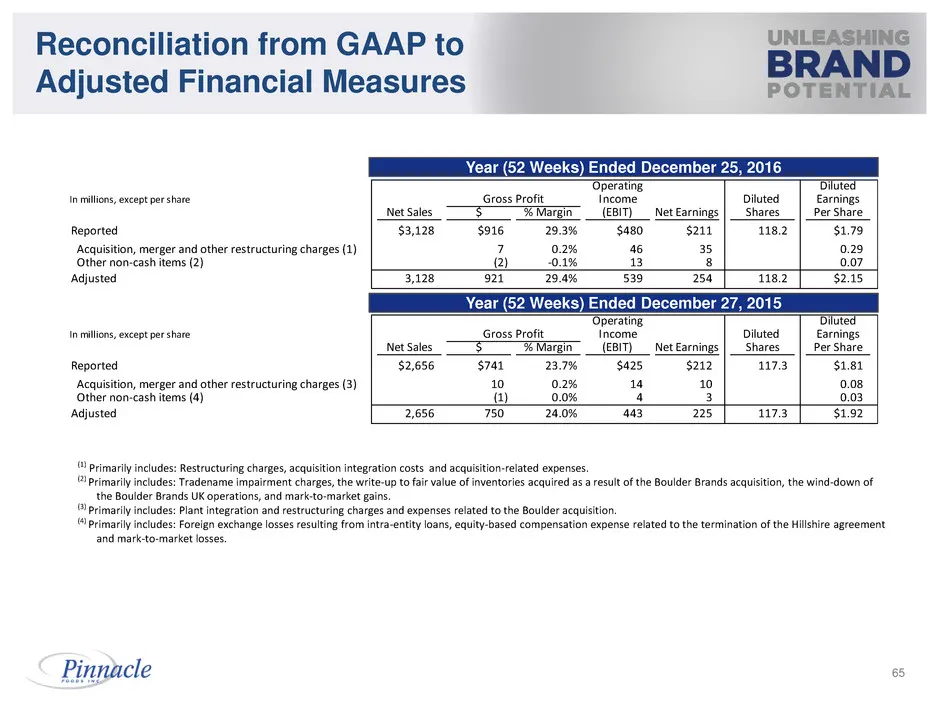
Slide 65: Reconciliation from GAAP to Adjusted Financial Measures
Operating Diluted In millions, except per share Income Diluted Earnings Net Sales $ % Margin (EBIT) Net Earnings Shares Per Share Reported $3,128 $916 29.3% $480 $211 118.2 $1.79 Acquisition, merger and other restructuring charges (1) 7 0.2% 46 35 0.29 Other non-cash items (2) (2) -0.1% 13 8 0.07 Ad
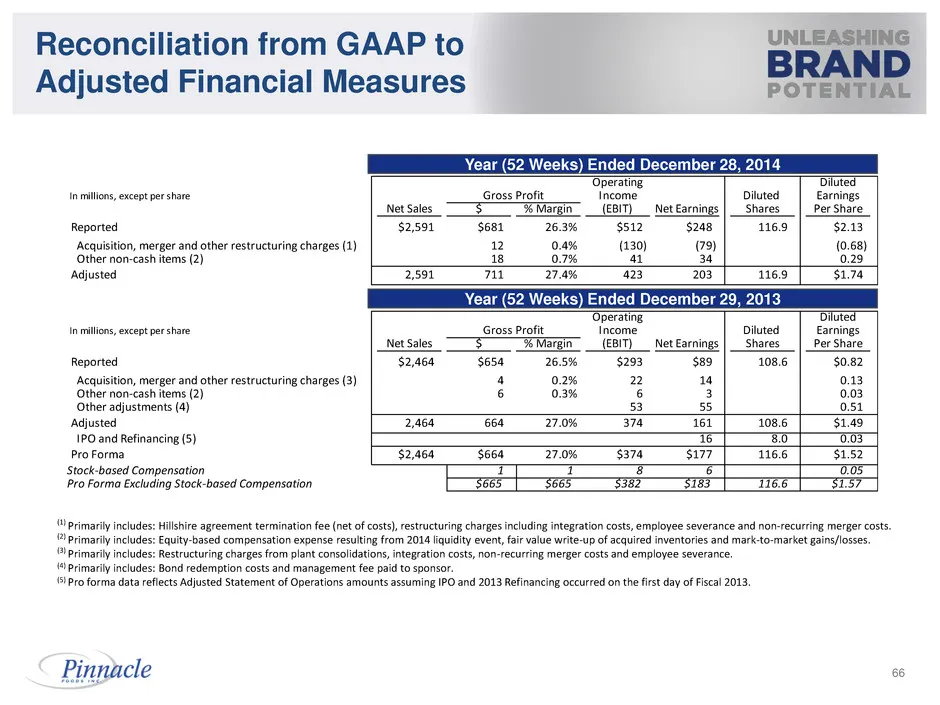
Slide 66: Reconciliation from GAAP to Adjusted Financial Measures
Operating Diluted In millions, except per share Income Diluted Earnings Net Sales $ % Margin (EBIT) Net Earnings Shares Per Share Reported $2,591 $681 26.3% $512 $248 116.9 $2.13 Acquisition, merger and other restructuring charges (1) 12 0.4% (130) (79) (0.68) Other non-cash items (2) 18 0.7% 41 34
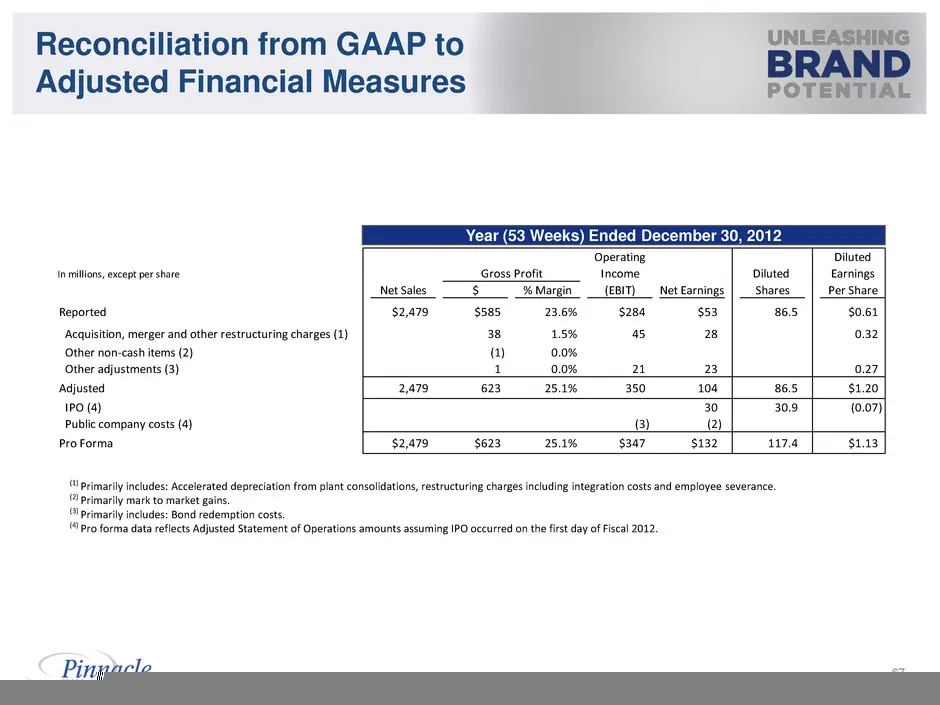
Slide 67: Reconciliation from GAAP to Adjusted Financial Measures
(1) Primarily includes: Accelerated depreciation from plant consolidations, restructuring charges including integration costs and employee severance. (2) Primarily mark to market gains. (3) Primarily includes: Bond redemption costs. (4) Pro forma data reflects Adjusted Statement of Operations amount
Source: SEC EDGAR · 8-K filed Sep 6, 2017
More decks from Pinnacle Foods Inc
 Q1 FY2019 Earnings Presentation44 slides · Sep 27, 2018
 Q4 FY2018 Earnings Presentation59 slides · Jun 27, 2018
 Debt Investor Presentation (January 2017)55 slides · Jan 23, 2017
 Investor Day (December 2016)55 slides · Dec 15, 2016
 Barclays Global Consumer Staples Conference 201651 slides · Sep 6, 2016
 CAGNY 201655 slides · Mar 24, 2016