CenterState Bank — CenterState Banks — Raymond James 2012 Bank Conference
26 slides from CenterState Bank's conference presentation, Aug 13, 2012
Slide 1: Raymond James 2012 Bank Conference
Exhibit 99.1 Raymond James 2012 Bank Conference August 14, 2012, Presented by Ernie Pinner, Jim Antal & John Corbett
Slide 2: Forward Looking Statement
Forward Looking Statement This presentation contains forward-looking statements, as defined by Federal Securities Laws, relating to present or future trends or factors affecting the operations, markets and products of CenterState Banks, Inc. (CSFL). These statements are provided to assist in the und
Slide 3: Corporate Overview
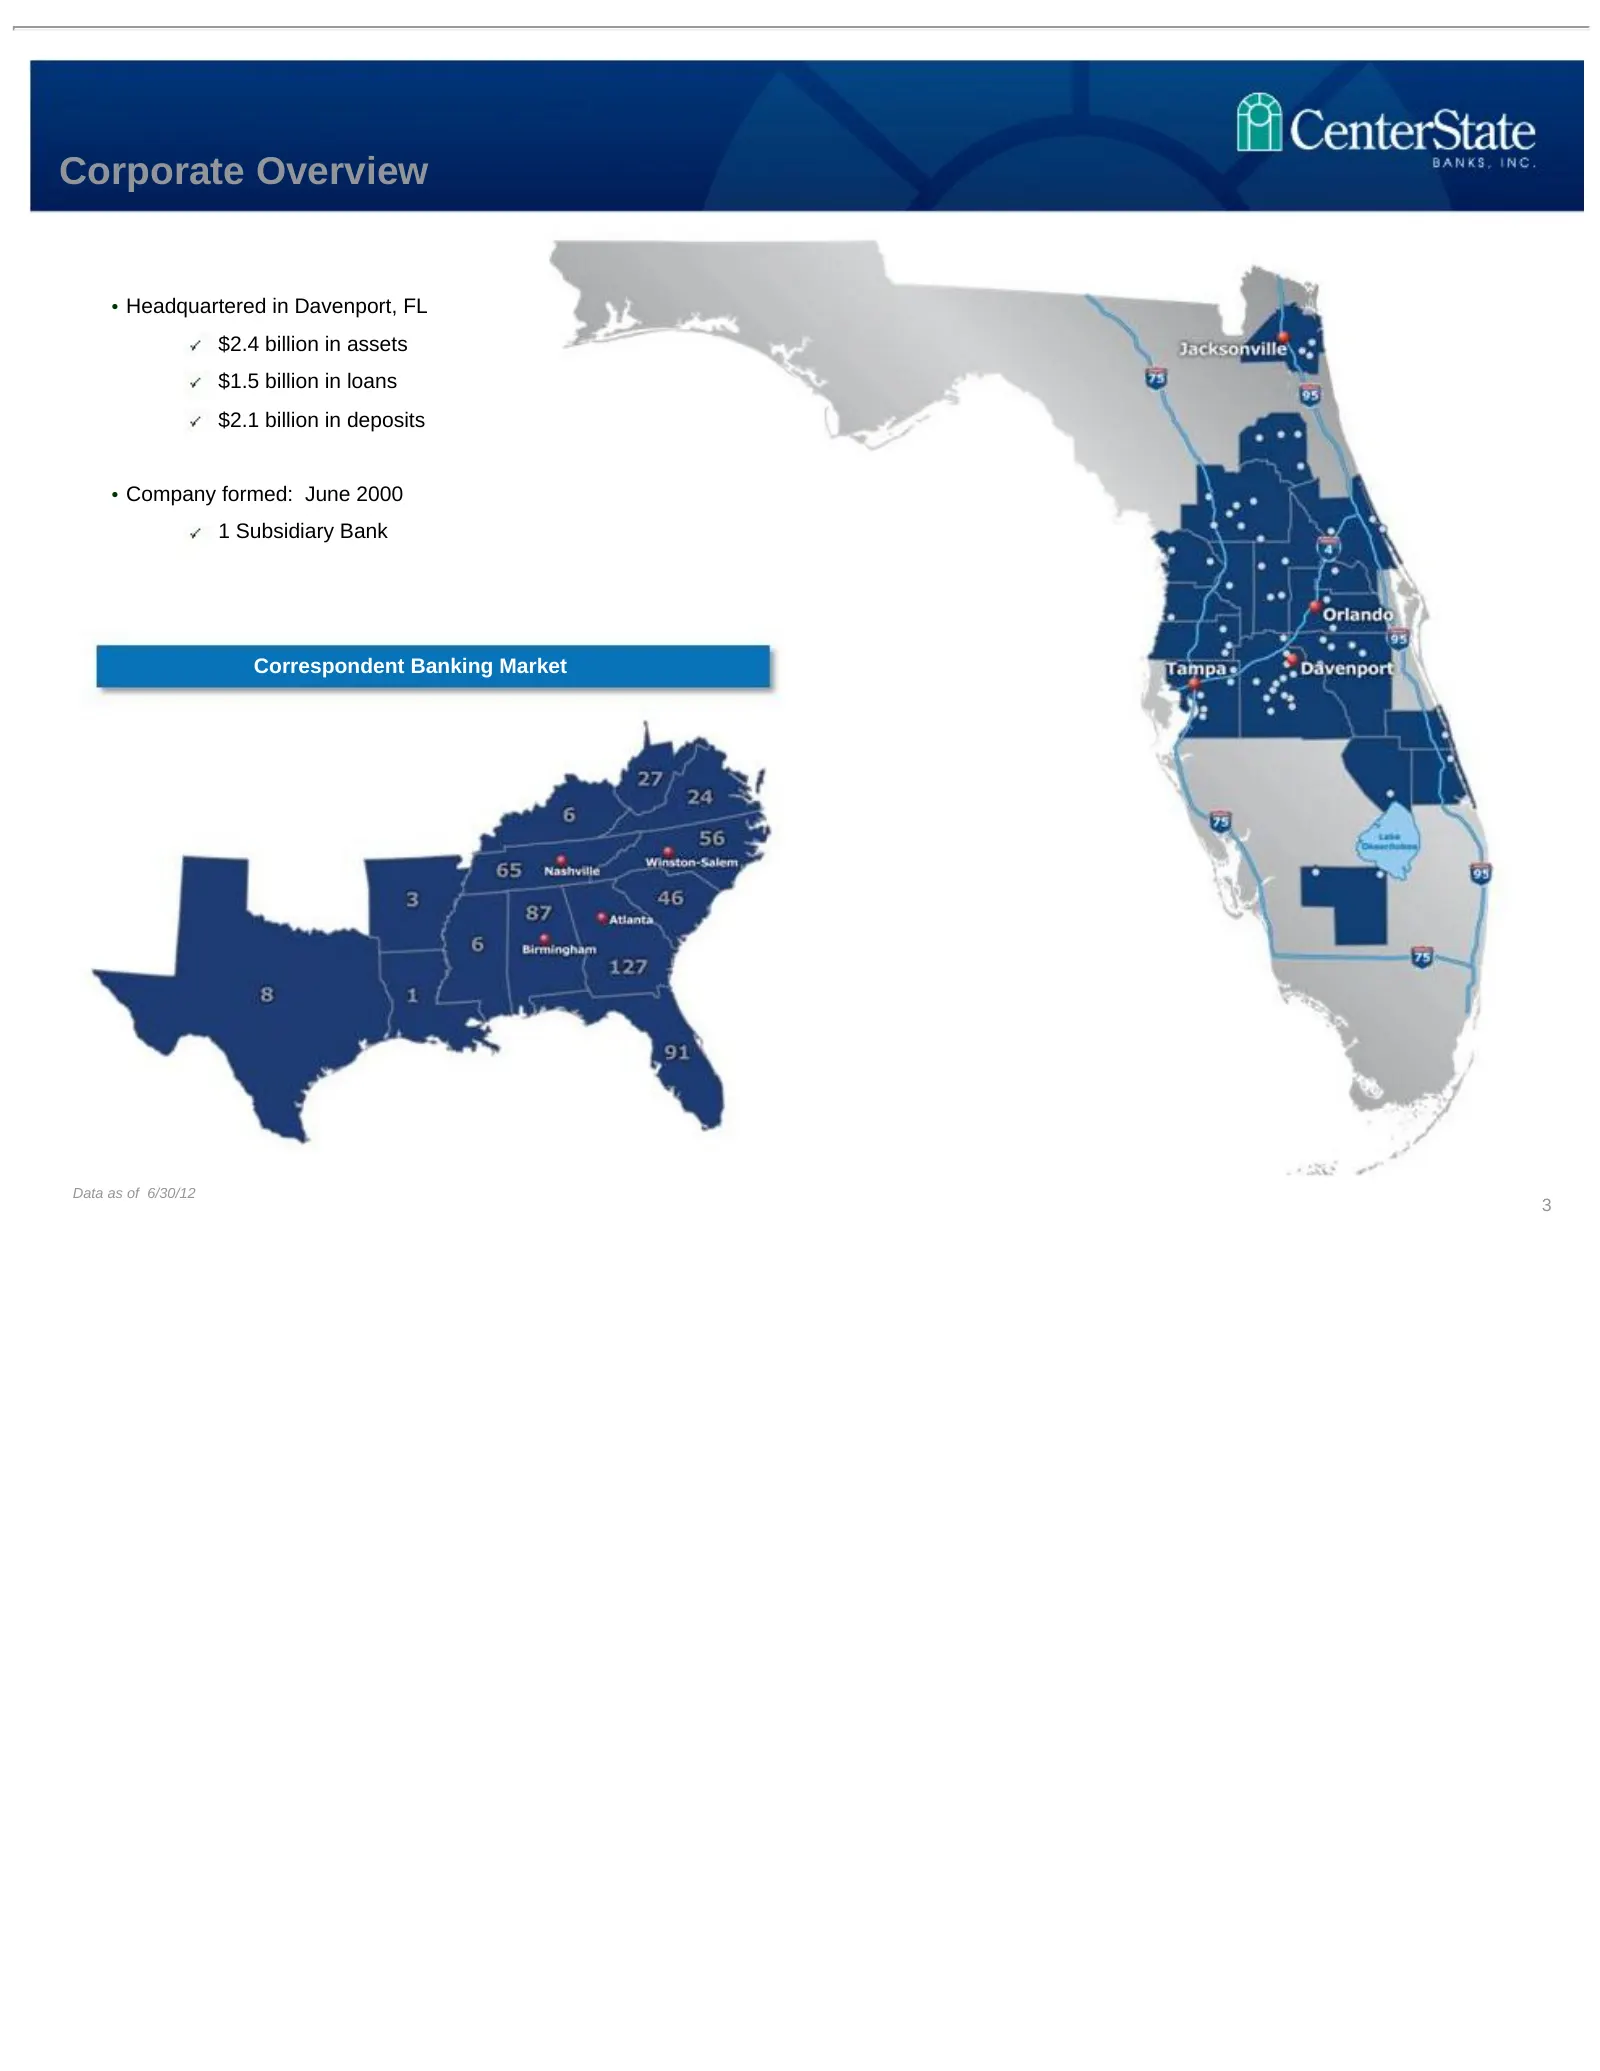
Corporate Overview • Headquartered in Davenport, FL $2.4 billion in assets $1.5 billion in loans $2.1 billion in deposits • Company formed: June 2000 1 Subsidiary Bank Correspondent Banking Market Data as of 6/30/12 3
Slide 4: Conservative Balance Sheet
Conservative Balance Sheet • CAPITAL - Total Risk-Based Capital Ratio – 17.8% • LIQUIDITY - Loans / Assets - 60% • LOANS WITH THIRD PARTY PROTECTION – 38% 23% of loans are covered by loss sharing agreements with the FDIC 15% are subject to “Put Back” agreements with TD Bank or The Hartford Insurance
Slide 5: Opportunistic through the Crisis
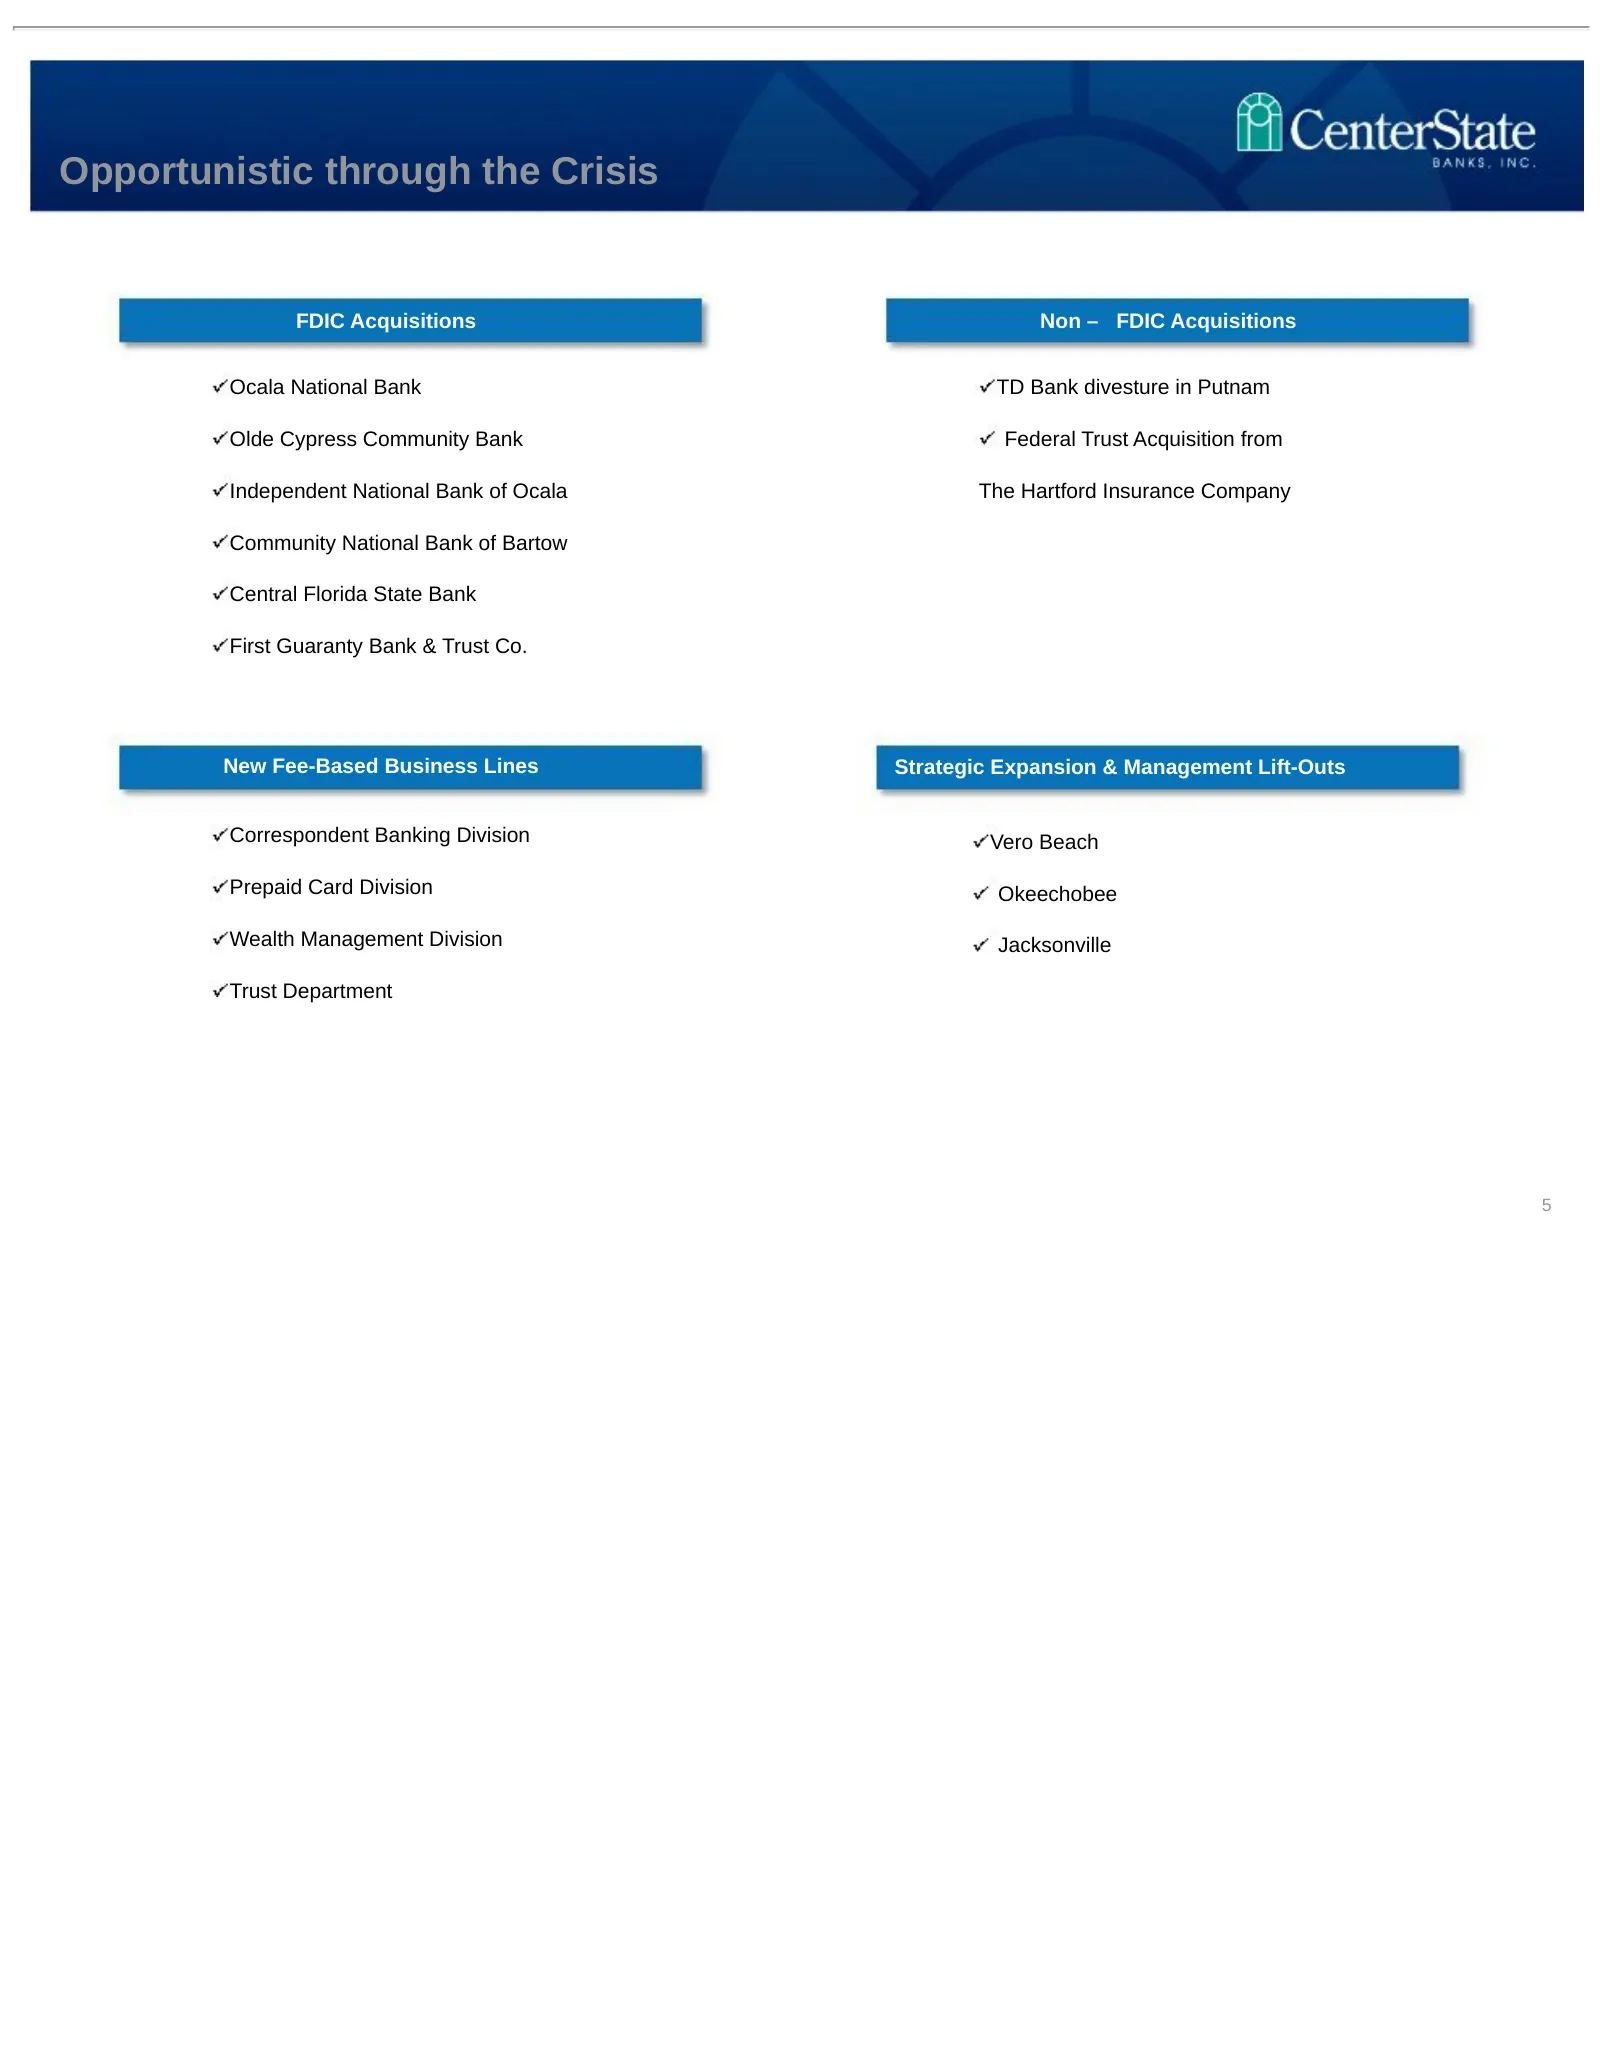
Opportunistic through the Crisis FDIC Acquisitions Non – FDIC Acquisitions Ocala National Bank TD Bank divesture in Putnam Olde Cypress Community Bank Federal Trust Acquisition from Independent National Bank of Ocala The Hartford Insurance Company Community National Bank of Bartow Central Florida St
Slide 6: Profitability Metrics
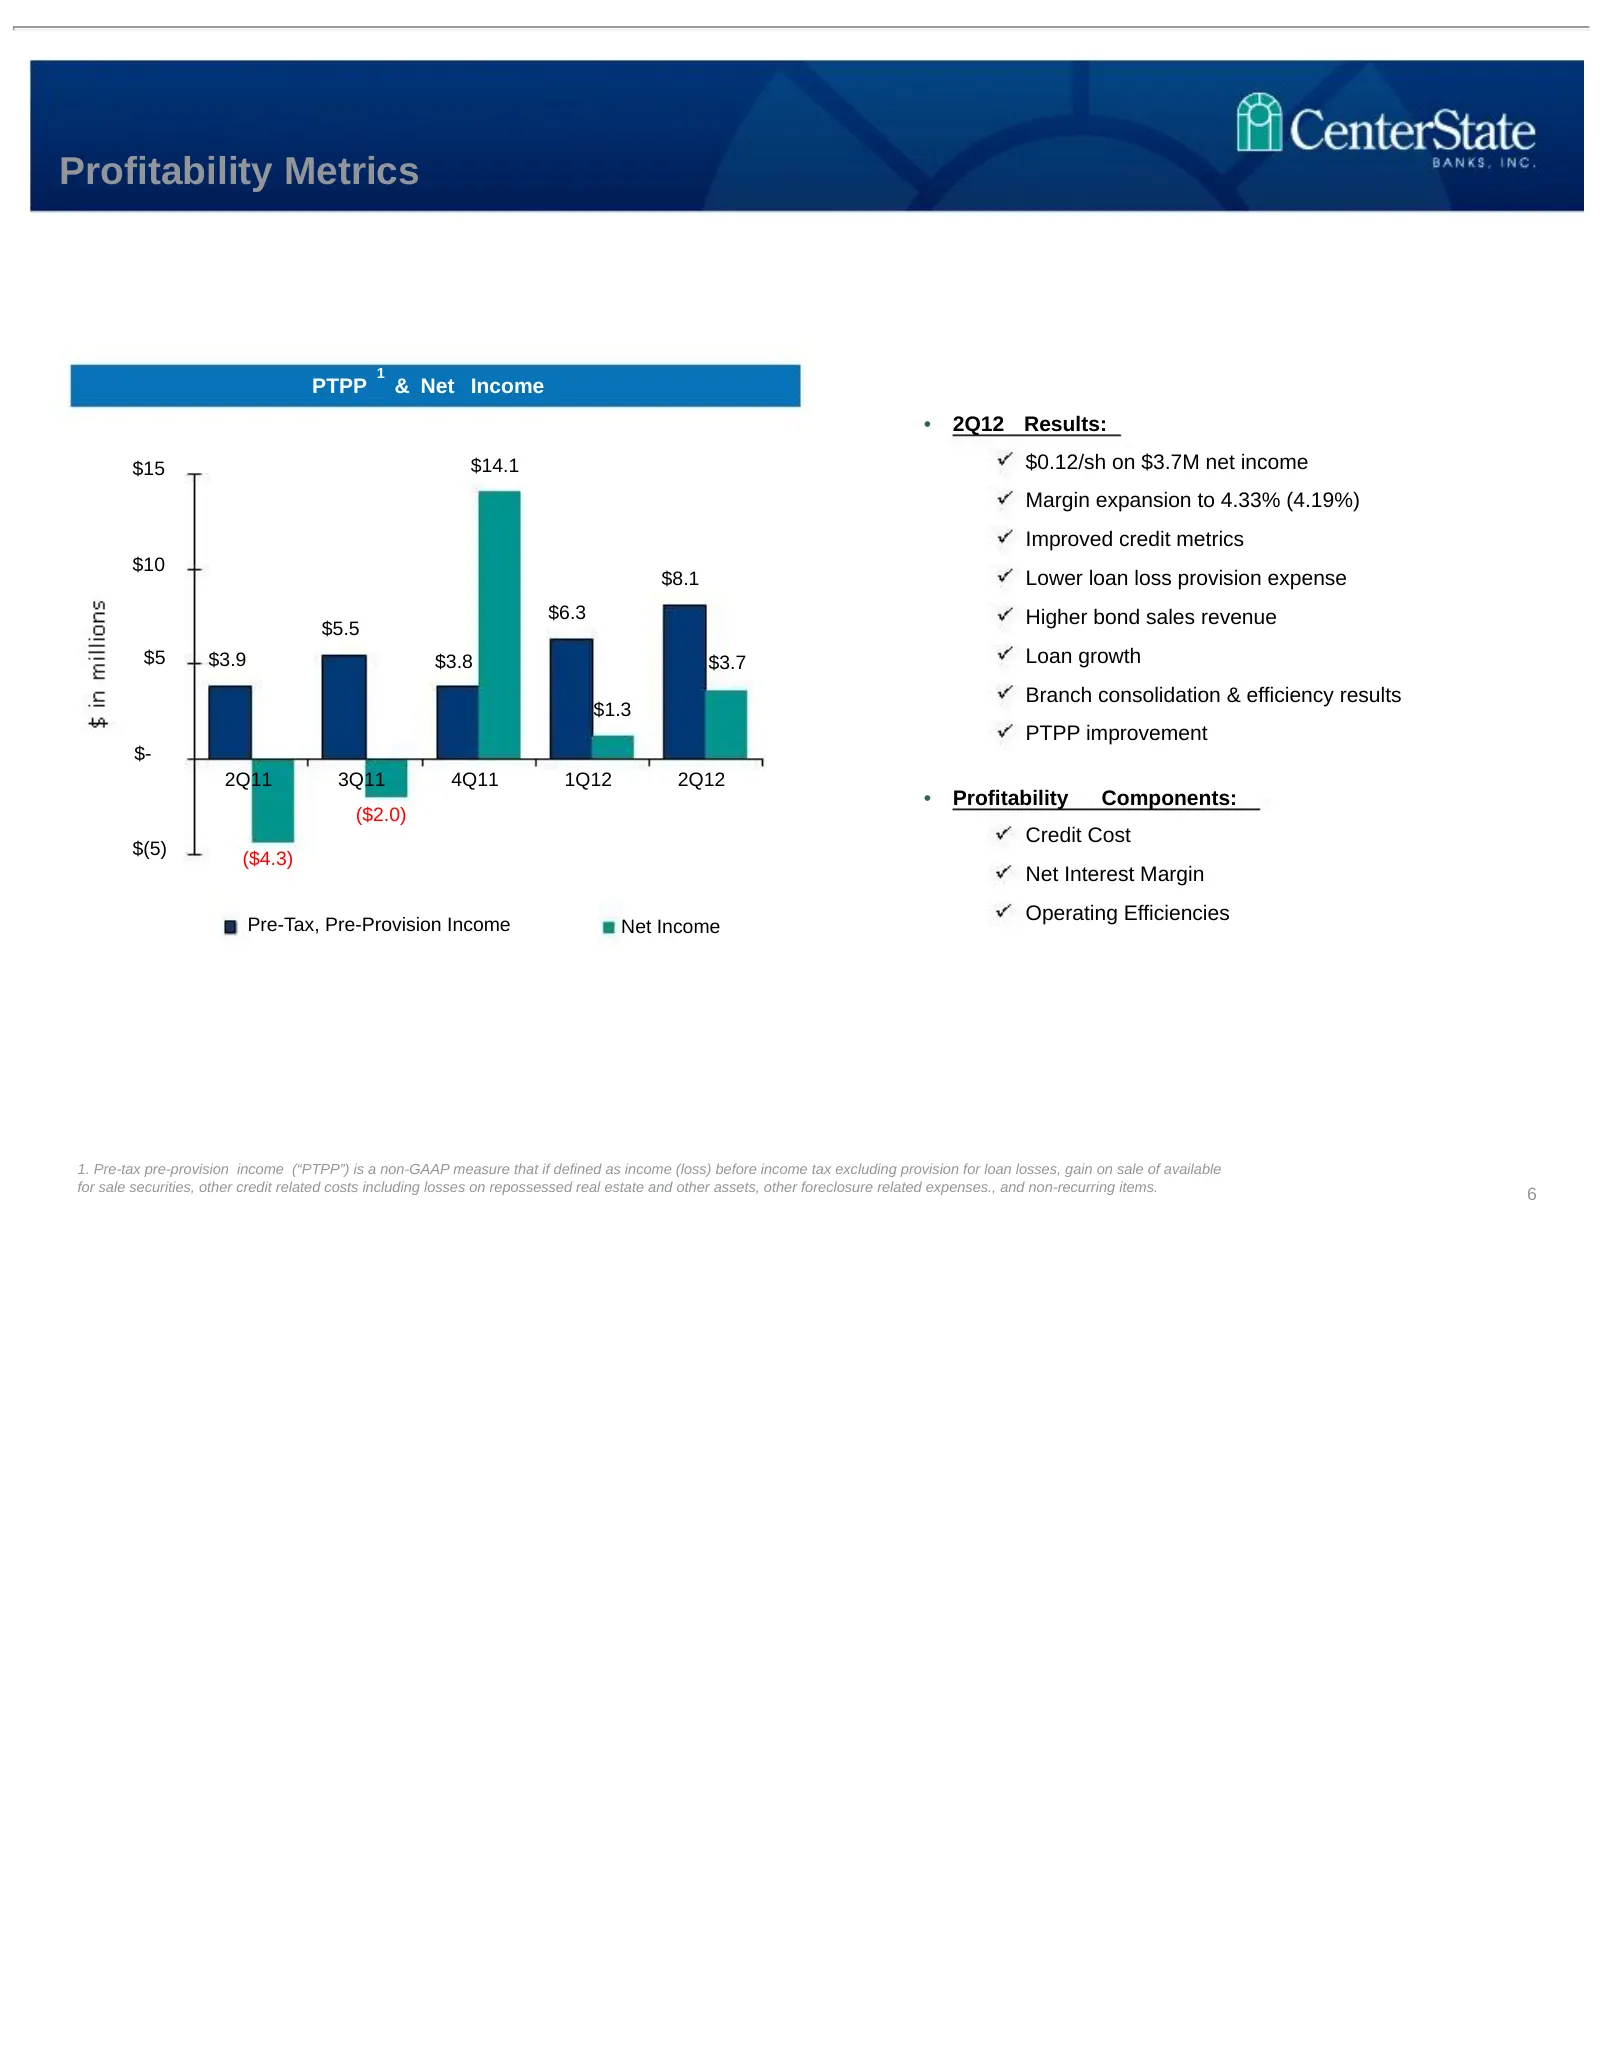
Profitability Metrics 1 PTPP & Net Income • 2Q12 Results: $15 $14.1 $0.12/sh on $3.7M net income Margin expansion to 4.33% (4.19%) Improved credit metrics $10 $8.1 Lower loan loss provision expense $6.3 Higher bond sales revenue $5.5 $5 $3.9 $3.8 $3.7 Loan growth Branch consolidation & efficiency re
Slide 7: Credit Cost
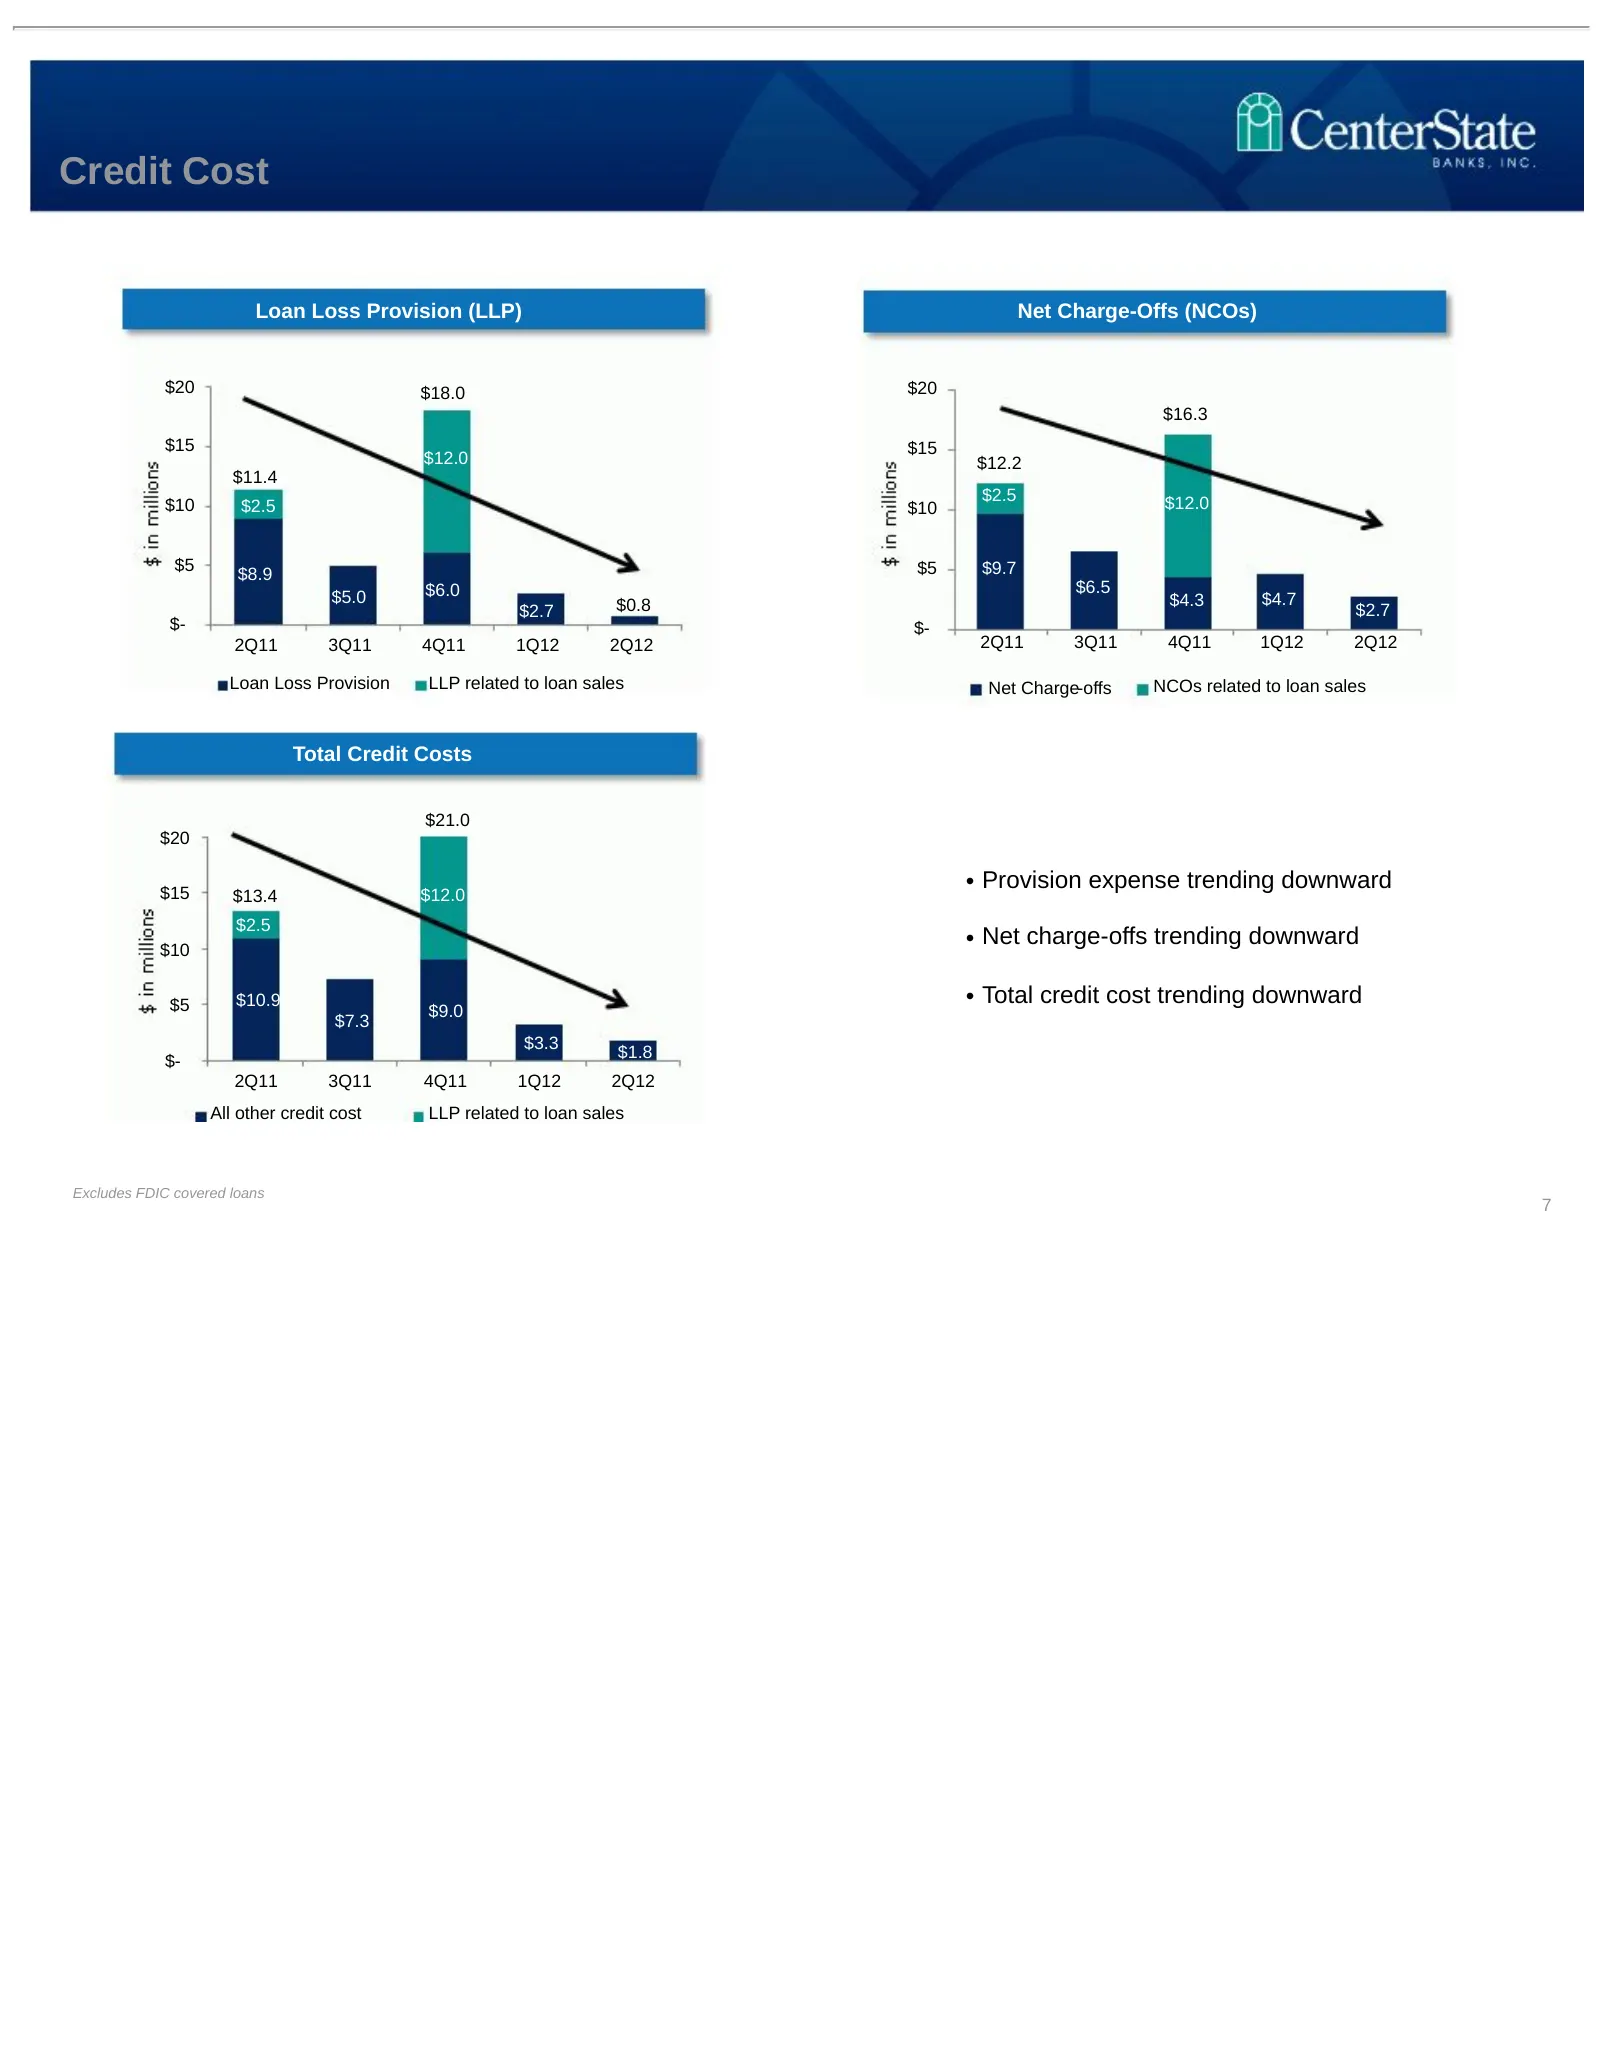
Credit Cost Loan Loss Provision (LLP) Net Charge-Offs (NCOs) $20 $18.0 $20 $16.3 $15 $15 $12.0 $12.2 $11.4 $2.5 $12.0 $10 $2.5 $10 $5 $5 $9.7 $8.9 $6.0 $6.5 $5.0 $0.8 $4.3 $4.7 $2.7 $2.7 $- $- 2Q11 3Q11 4Q11 1Q12 2Q12 2Q11 3Q11 4Q11 1Q12 2Q12 Loan Loss Provision LLP related to loan sales Net Charge-
Slide 8: Loans – Yields and Averages
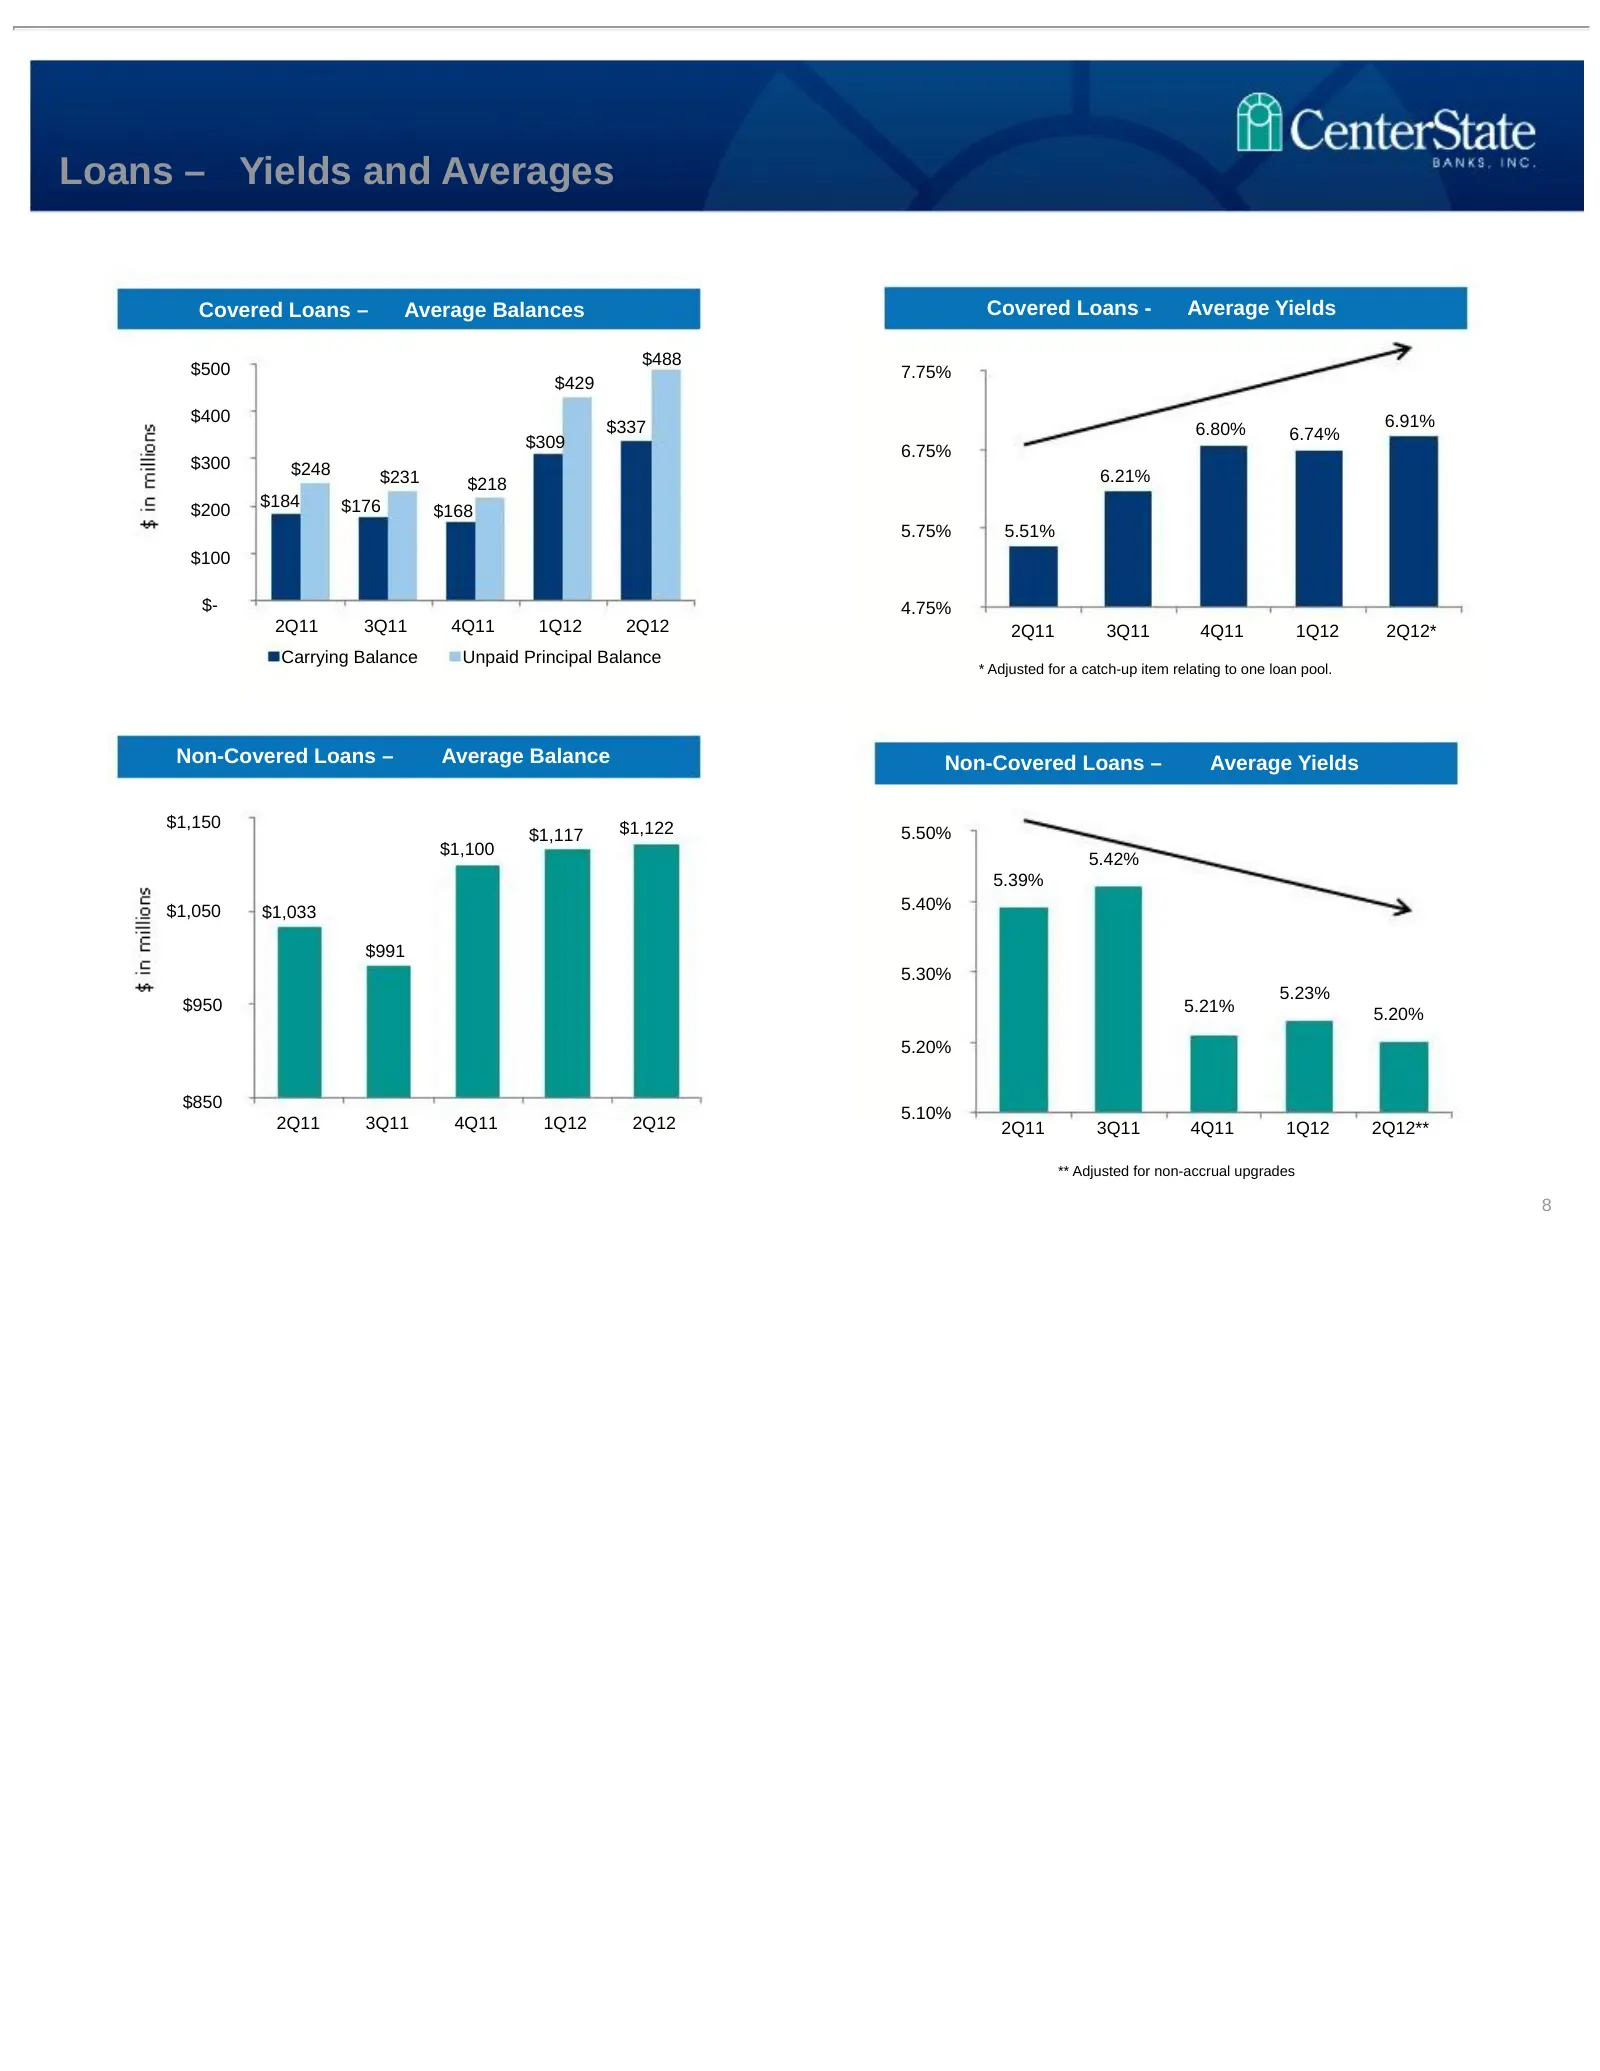
Loans – Yields and Averages Covered Loans – Average Balances Covered Loans - Average Yields $488 $500 7.75% $429 $400 6.91% $337 6.80% 6.74% $309 6.75% $300 $248 $231 $218 6.21% $200 $184 $176 $168 5.75% 5.51% $100 $- 4.75% 2Q11 3Q11 4Q11 1Q12 2Q12 2Q11 3Q11 4Q11 1Q12 2Q12* Carrying Balance Unpaid P
Slide 9: Net Interest Margin
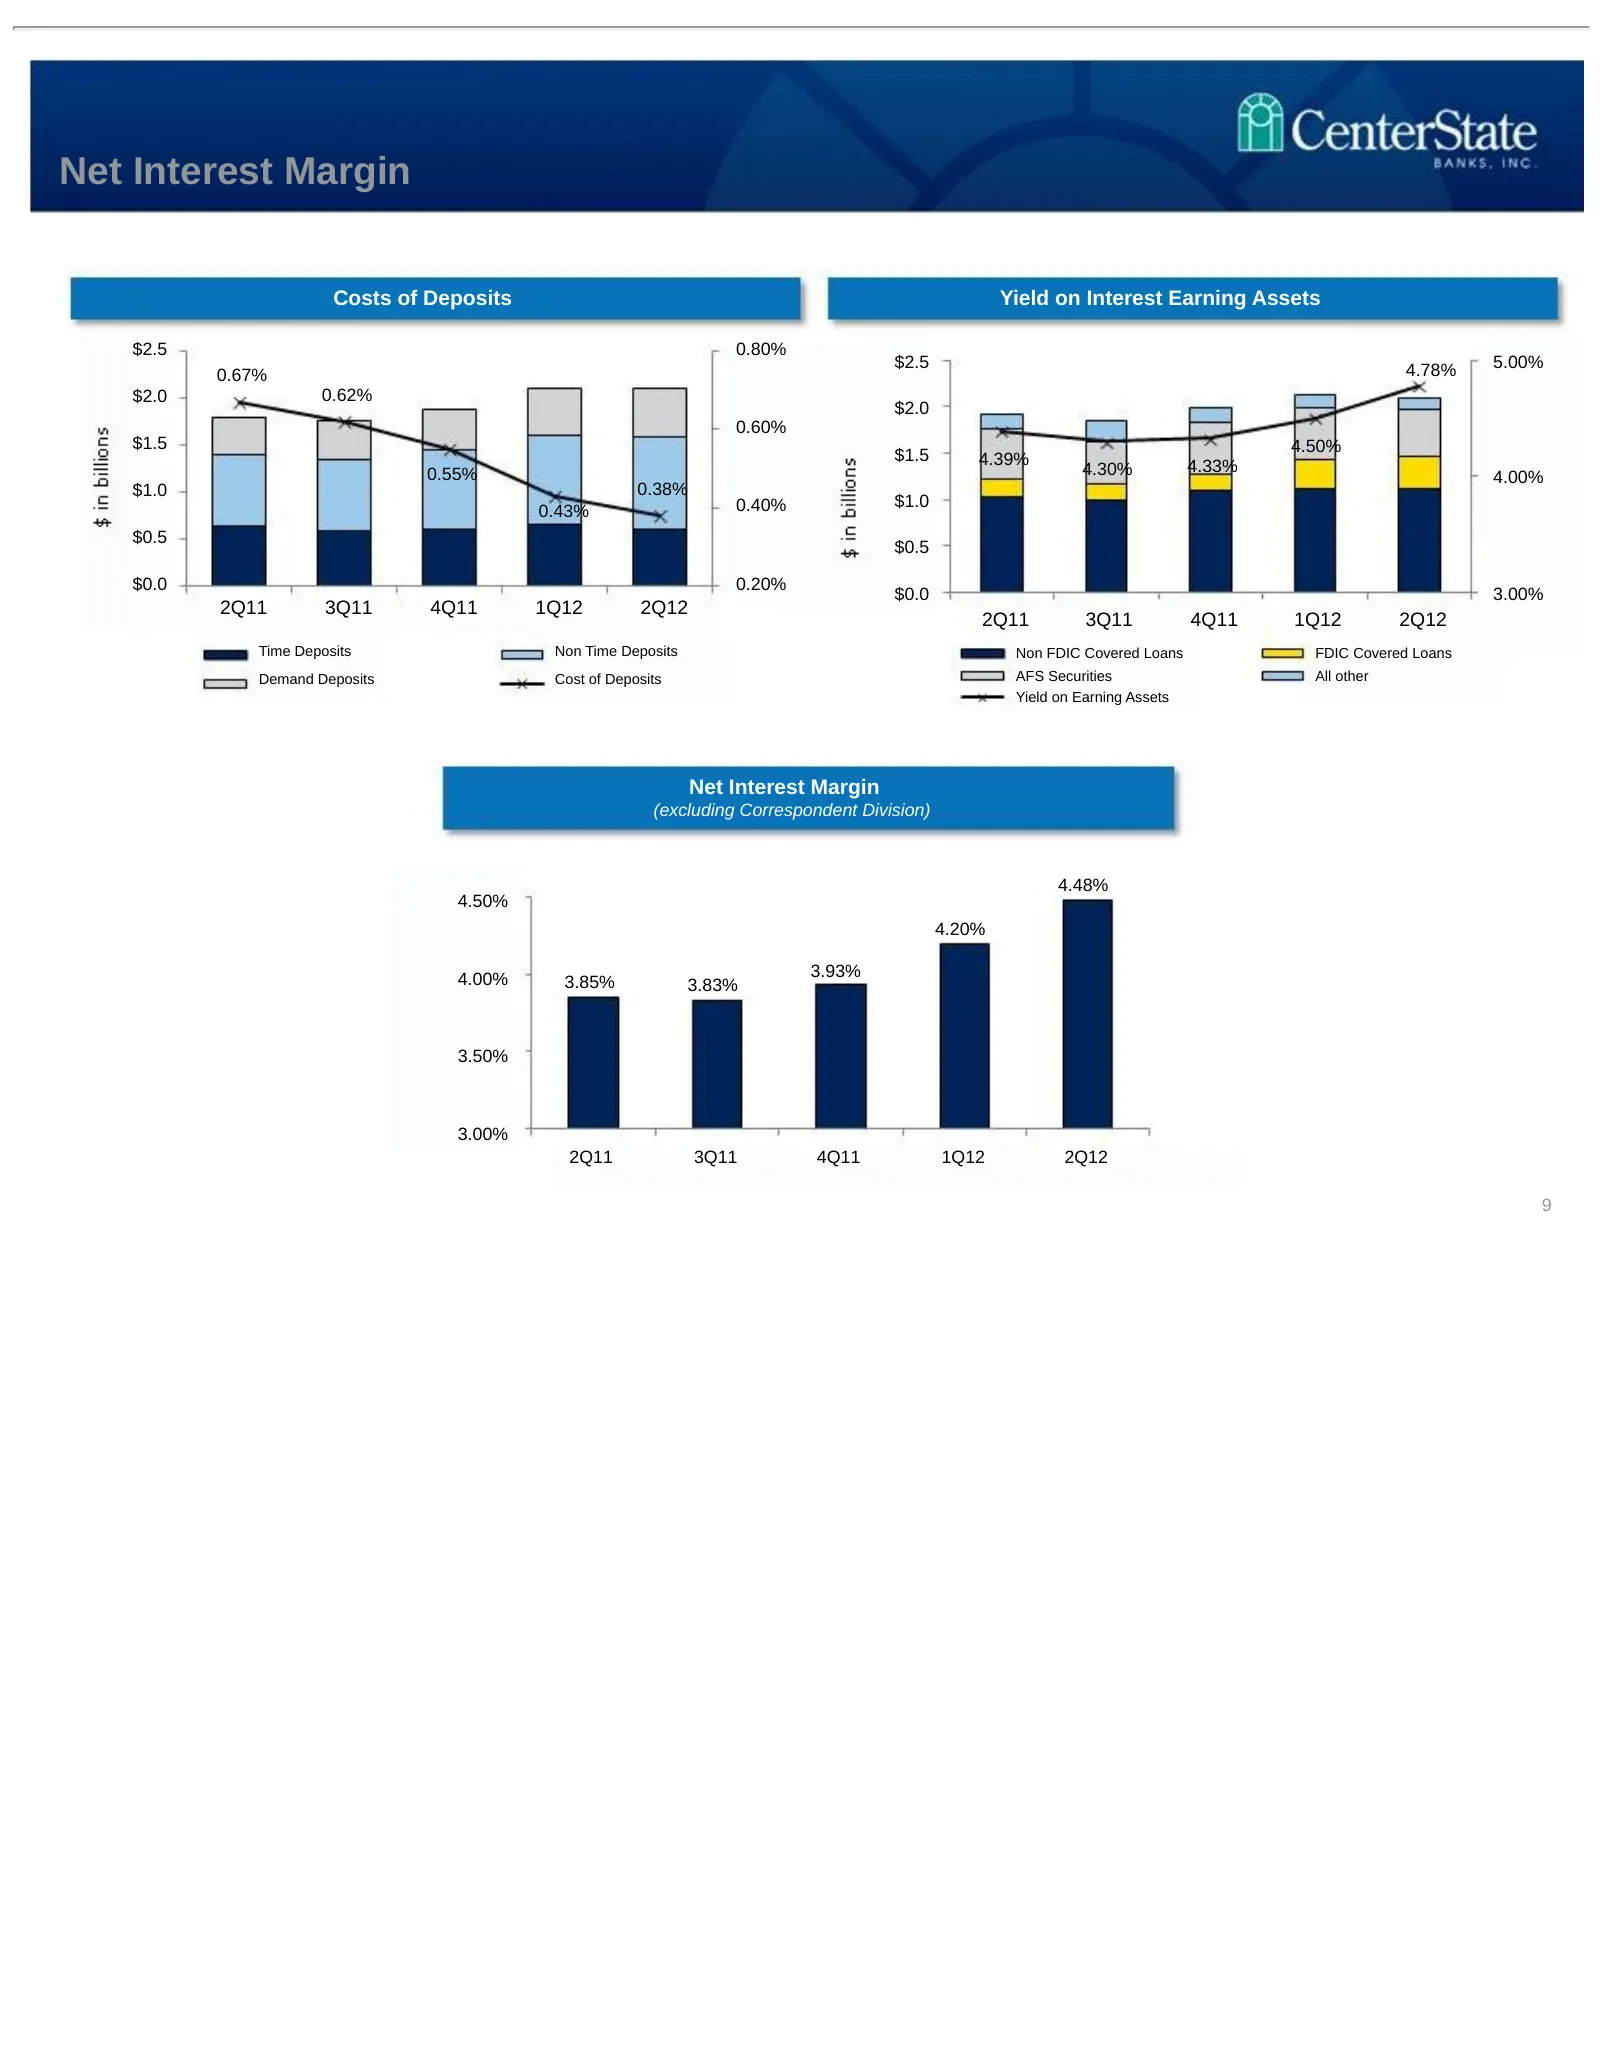
Net Interest Margin Costs of Deposits Yield on Interest Earning Assets $2.5 0.80% $2.5 4.78% 5.00% 0.67% $2.0 0.62% $2.0 0.60% $1.5 4.50% $1.5 4.39% 0.55% 4.30% 4.33% 4.00% $1.0 0.38% 0.40% $1.0 0.43% $0.5 $0.5 $0.0 0.20% $0.0 3.00% 2Q11 3Q11 4Q11 1Q12 2Q12 2Q11 3Q11 4Q11 1Q12 2Q12 Time Deposits Non
Slide 10: Building Franchise Value with Core Deposits
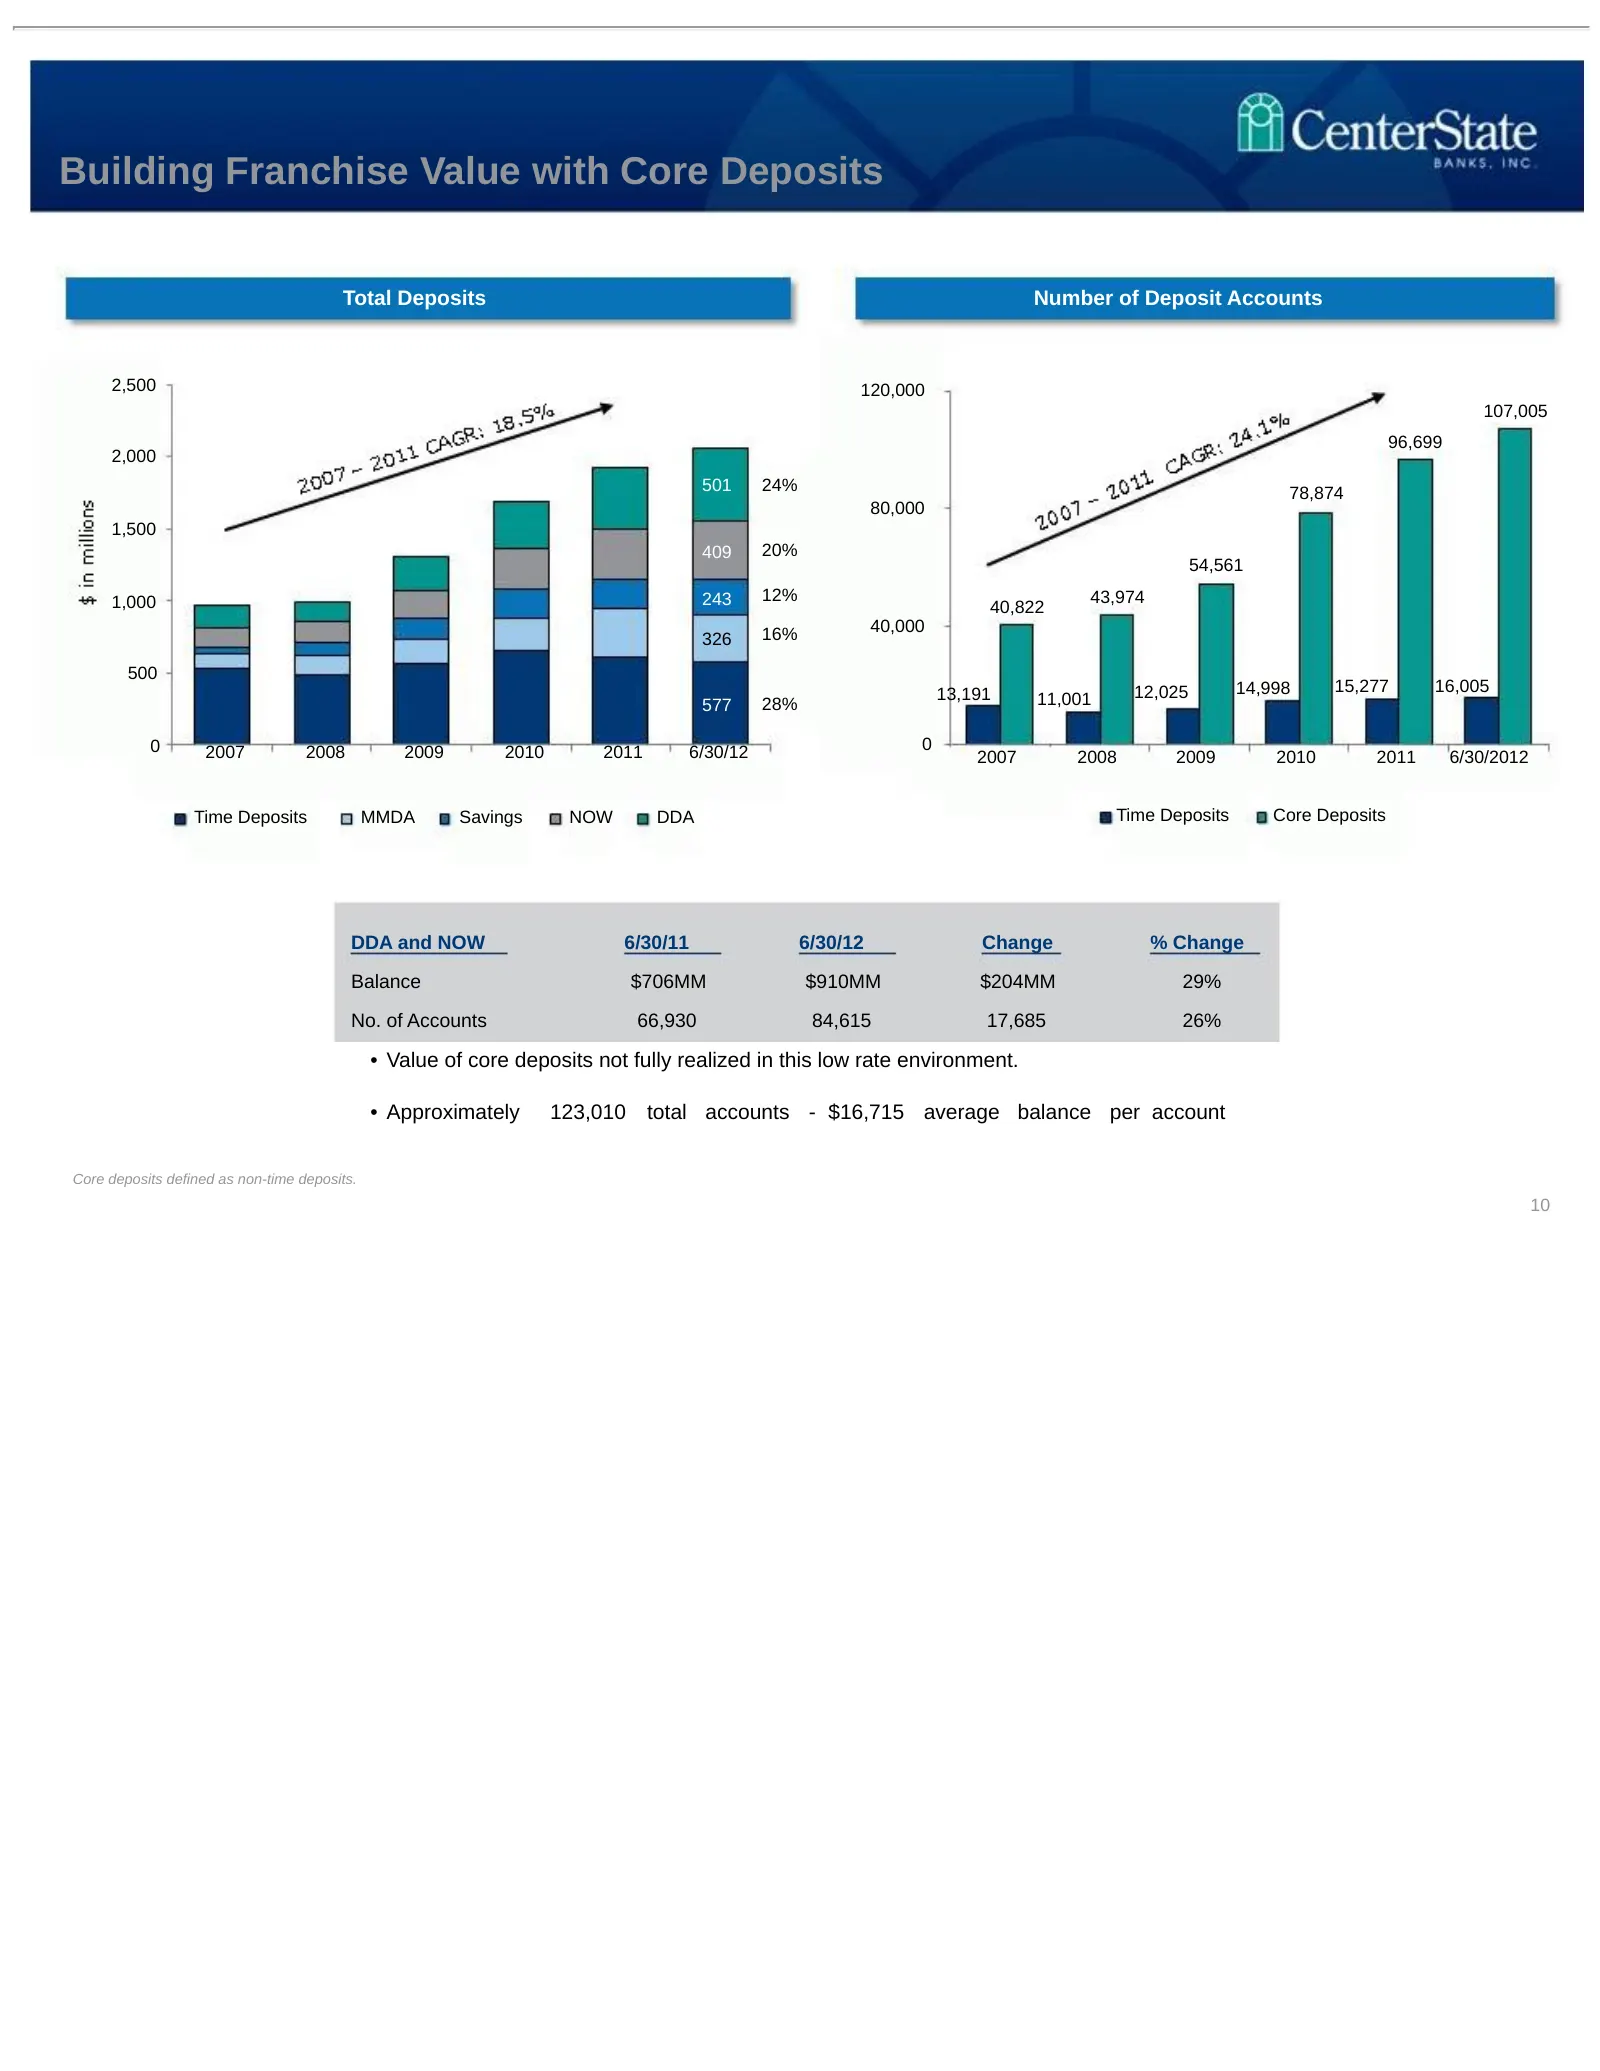
Building Franchise Value with Core Deposits Total Deposits Number of Deposit Accounts 2,500 120,000 107,005 96,699 2,000 501 24% 78,874 80,000 1,500 409 20% 54,561 1,000 243 12% 43,974 40,822 16% 40,000 326 500 13,191 12,025 14,998 15,277 16,005 577 28% 11,001 0 2007 2008 2009 2010 2011 6/30/12 0 20
Slide 11: Operating Efficiencies
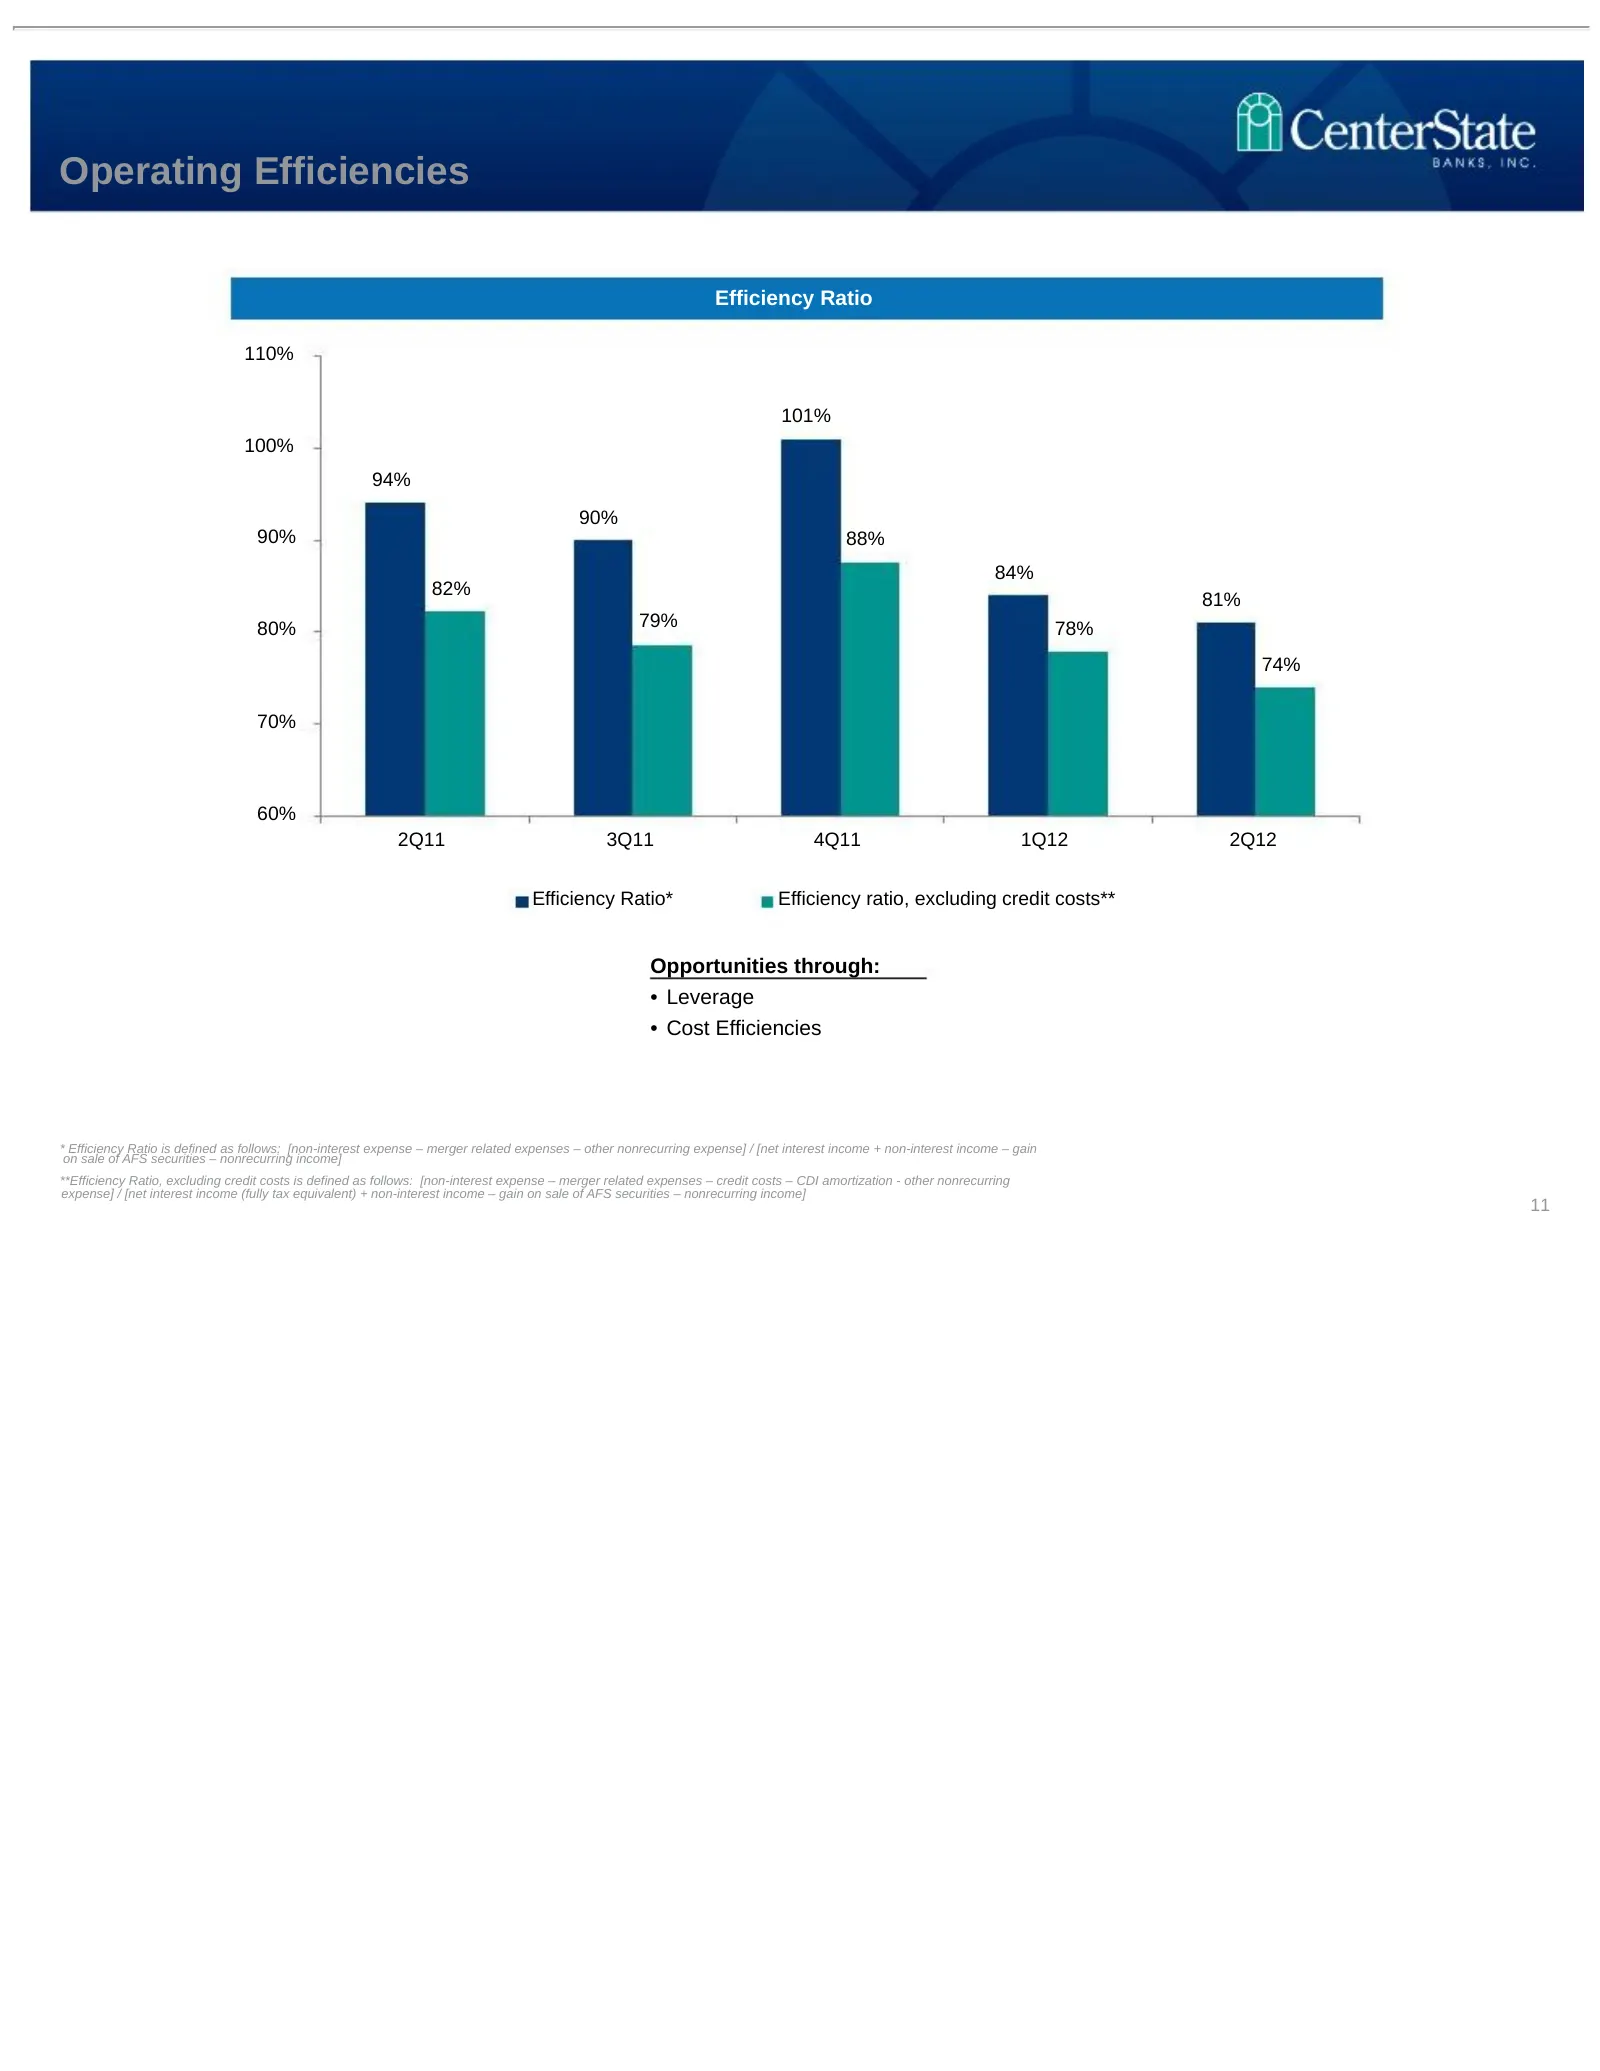
Operating Efficiencies Efficiency Ratio 110% 101% 100% 94% 90% 90% 88% 84% 82% 81% 80% 79% 78% 74% 70% 60% 2Q11 3Q11 4Q11 1Q12 2Q12 Efficiency Ratio* Efficiency ratio, excluding credit costs** Opportunities through: • Leverage • Cost Efficiencies * Efficiency Ratio is defined as follows: [non-intere
Slide 12: Focus on Efficiency and Core Earnings
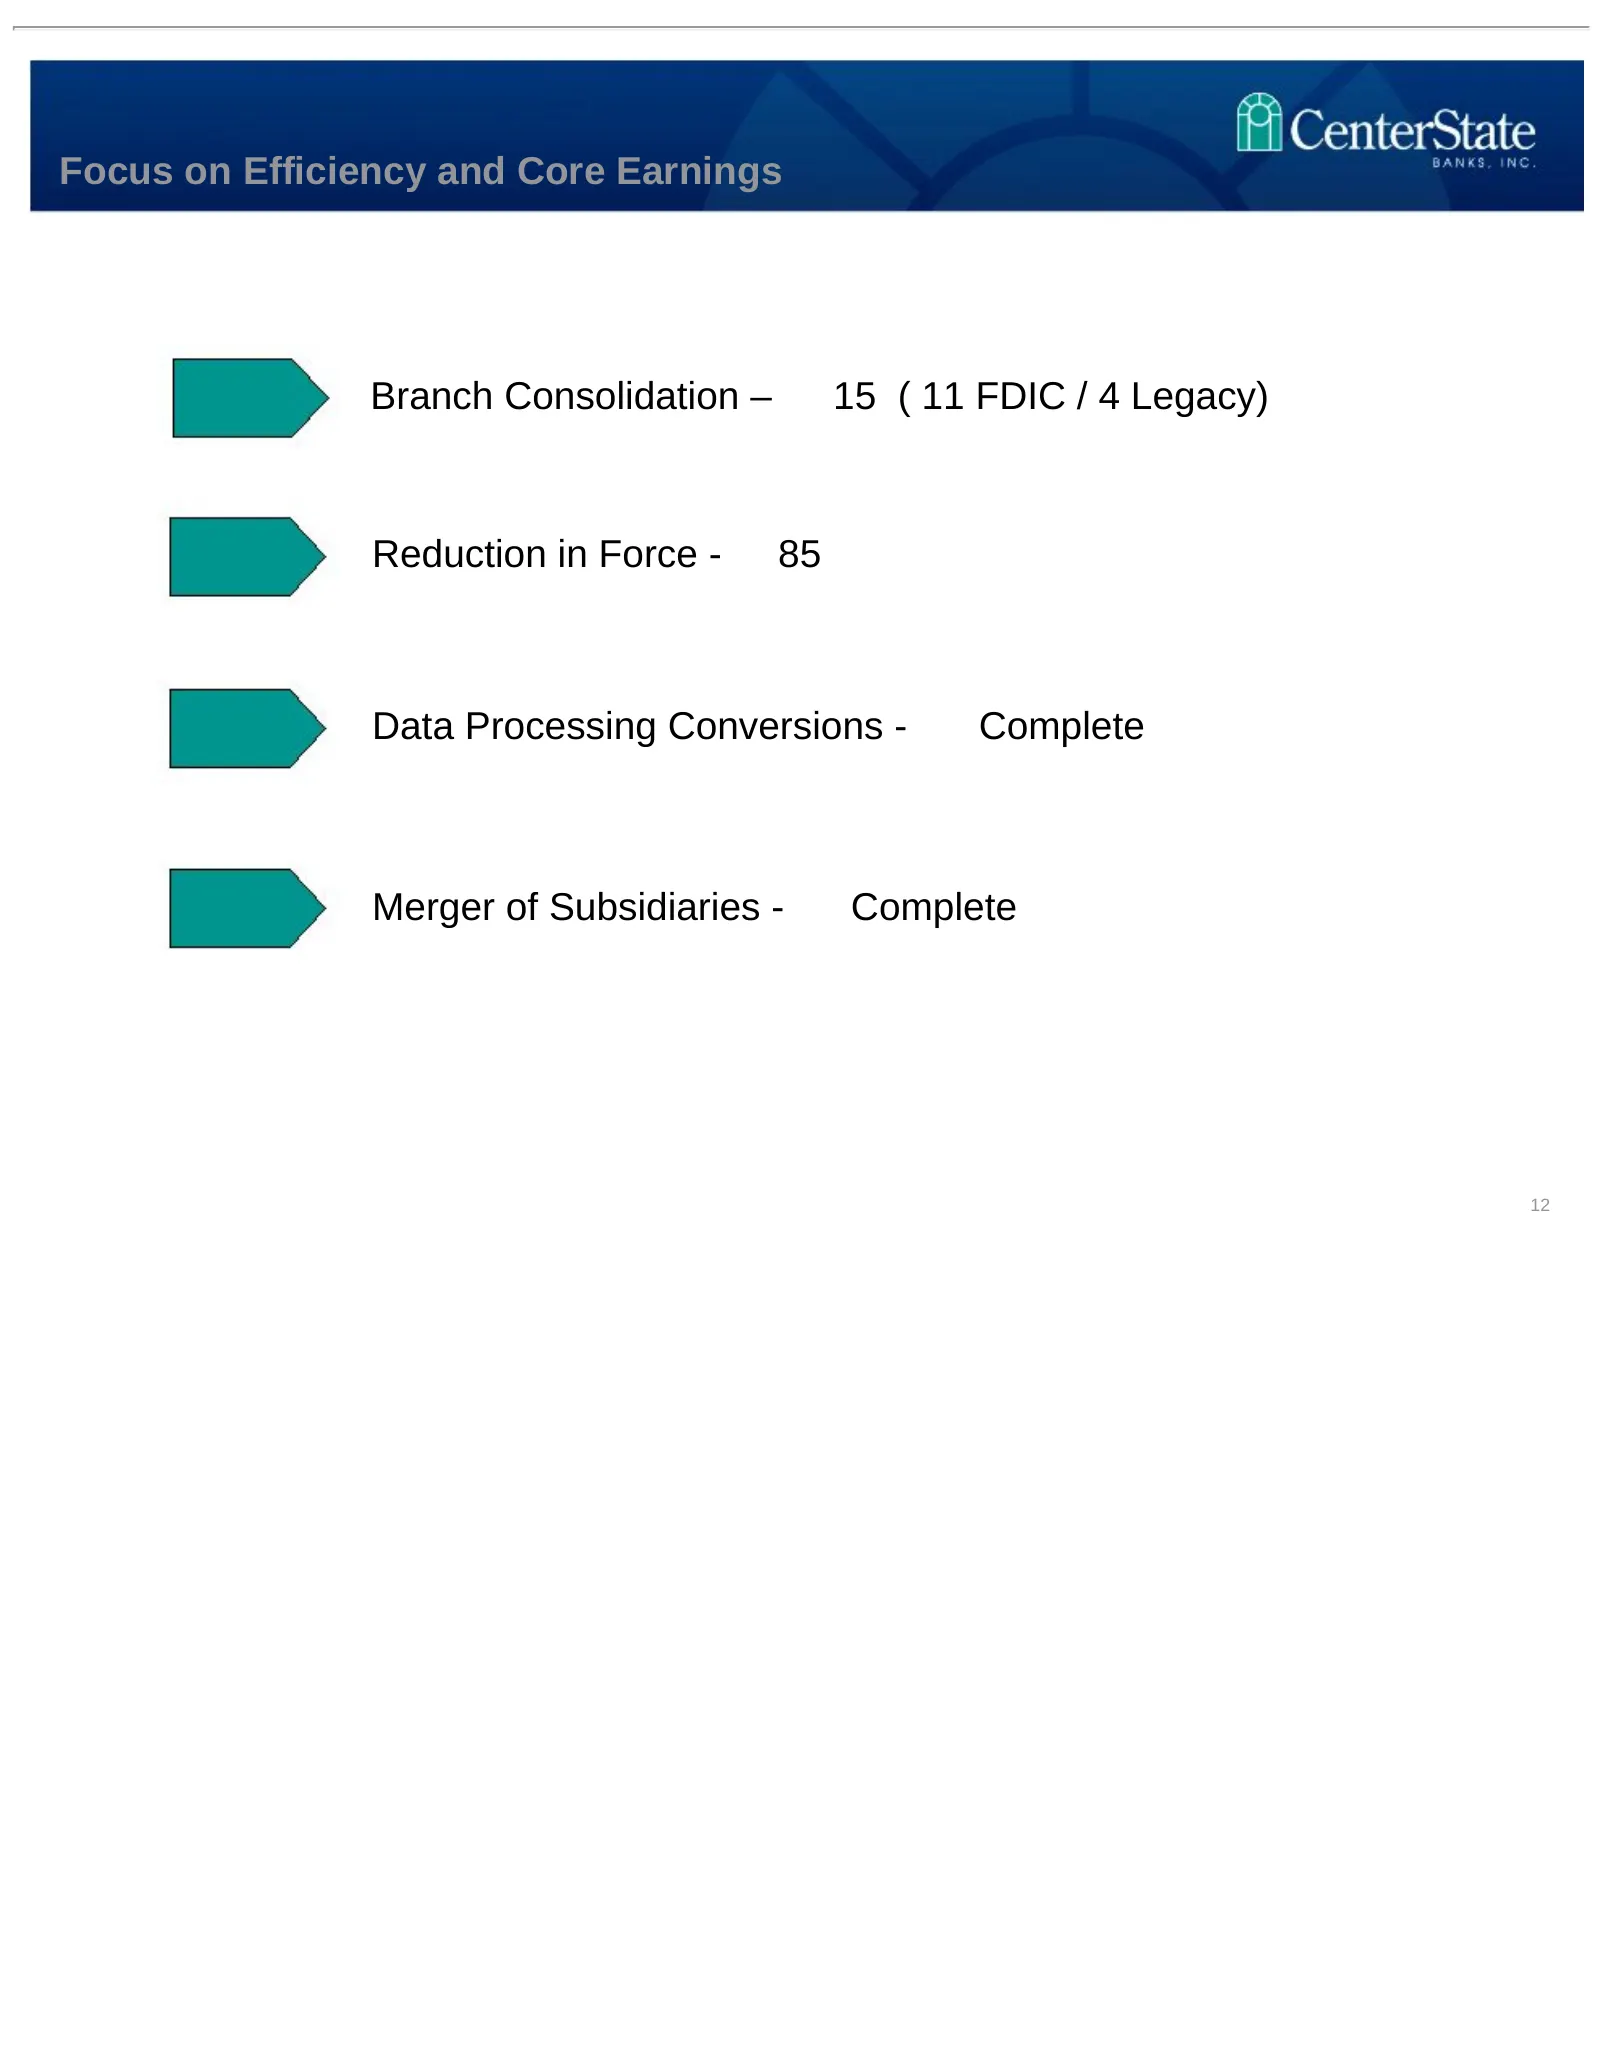
Focus on Efficiency and Core Earnings Branch Consolidation – 15 ( 11 FDIC / 4 Legacy) Reduction in Force - 85 Data Processing Conversions - Complete Merger of Subsidiaries - Complete Events since 1-1-12 11 12
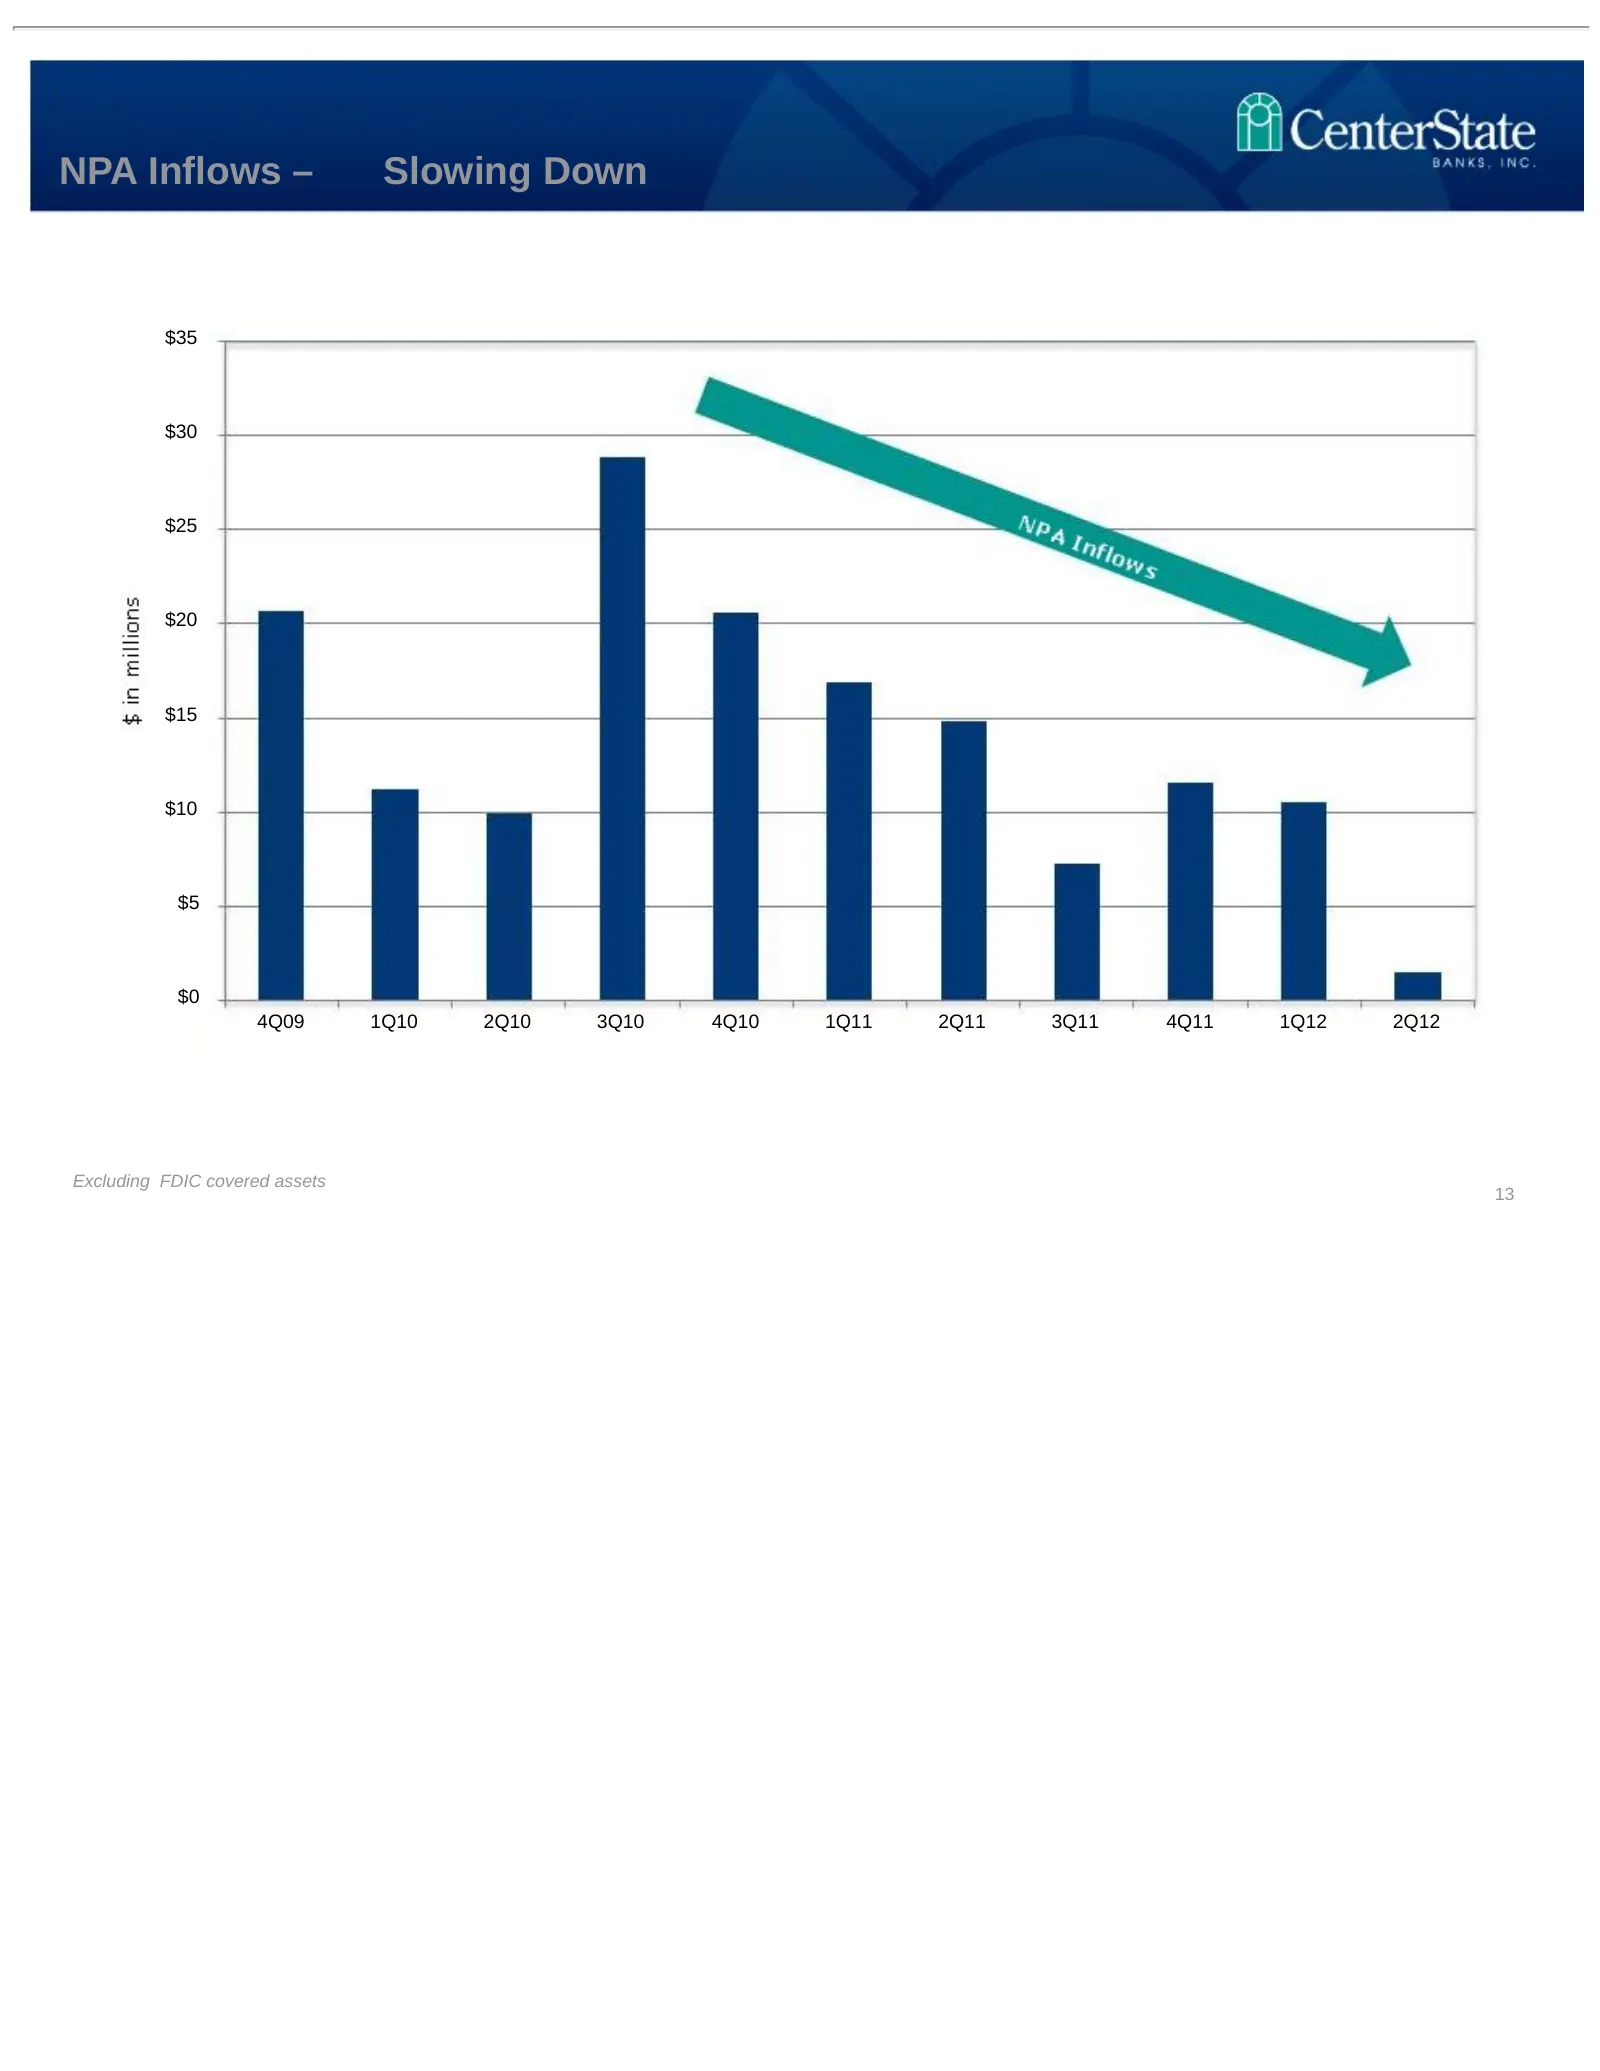
Slide 13: NPA Inflows – Slowing Down
NPA Inflows – Slowing Down $35 $30 $25 $20 $15 $10 $5 $0 4Q09 1Q10 2Q10 3Q10 4Q10 1Q11 2Q11 3Q11 4Q11 1Q12 2Q12 Excluding FDIC covered assets 13
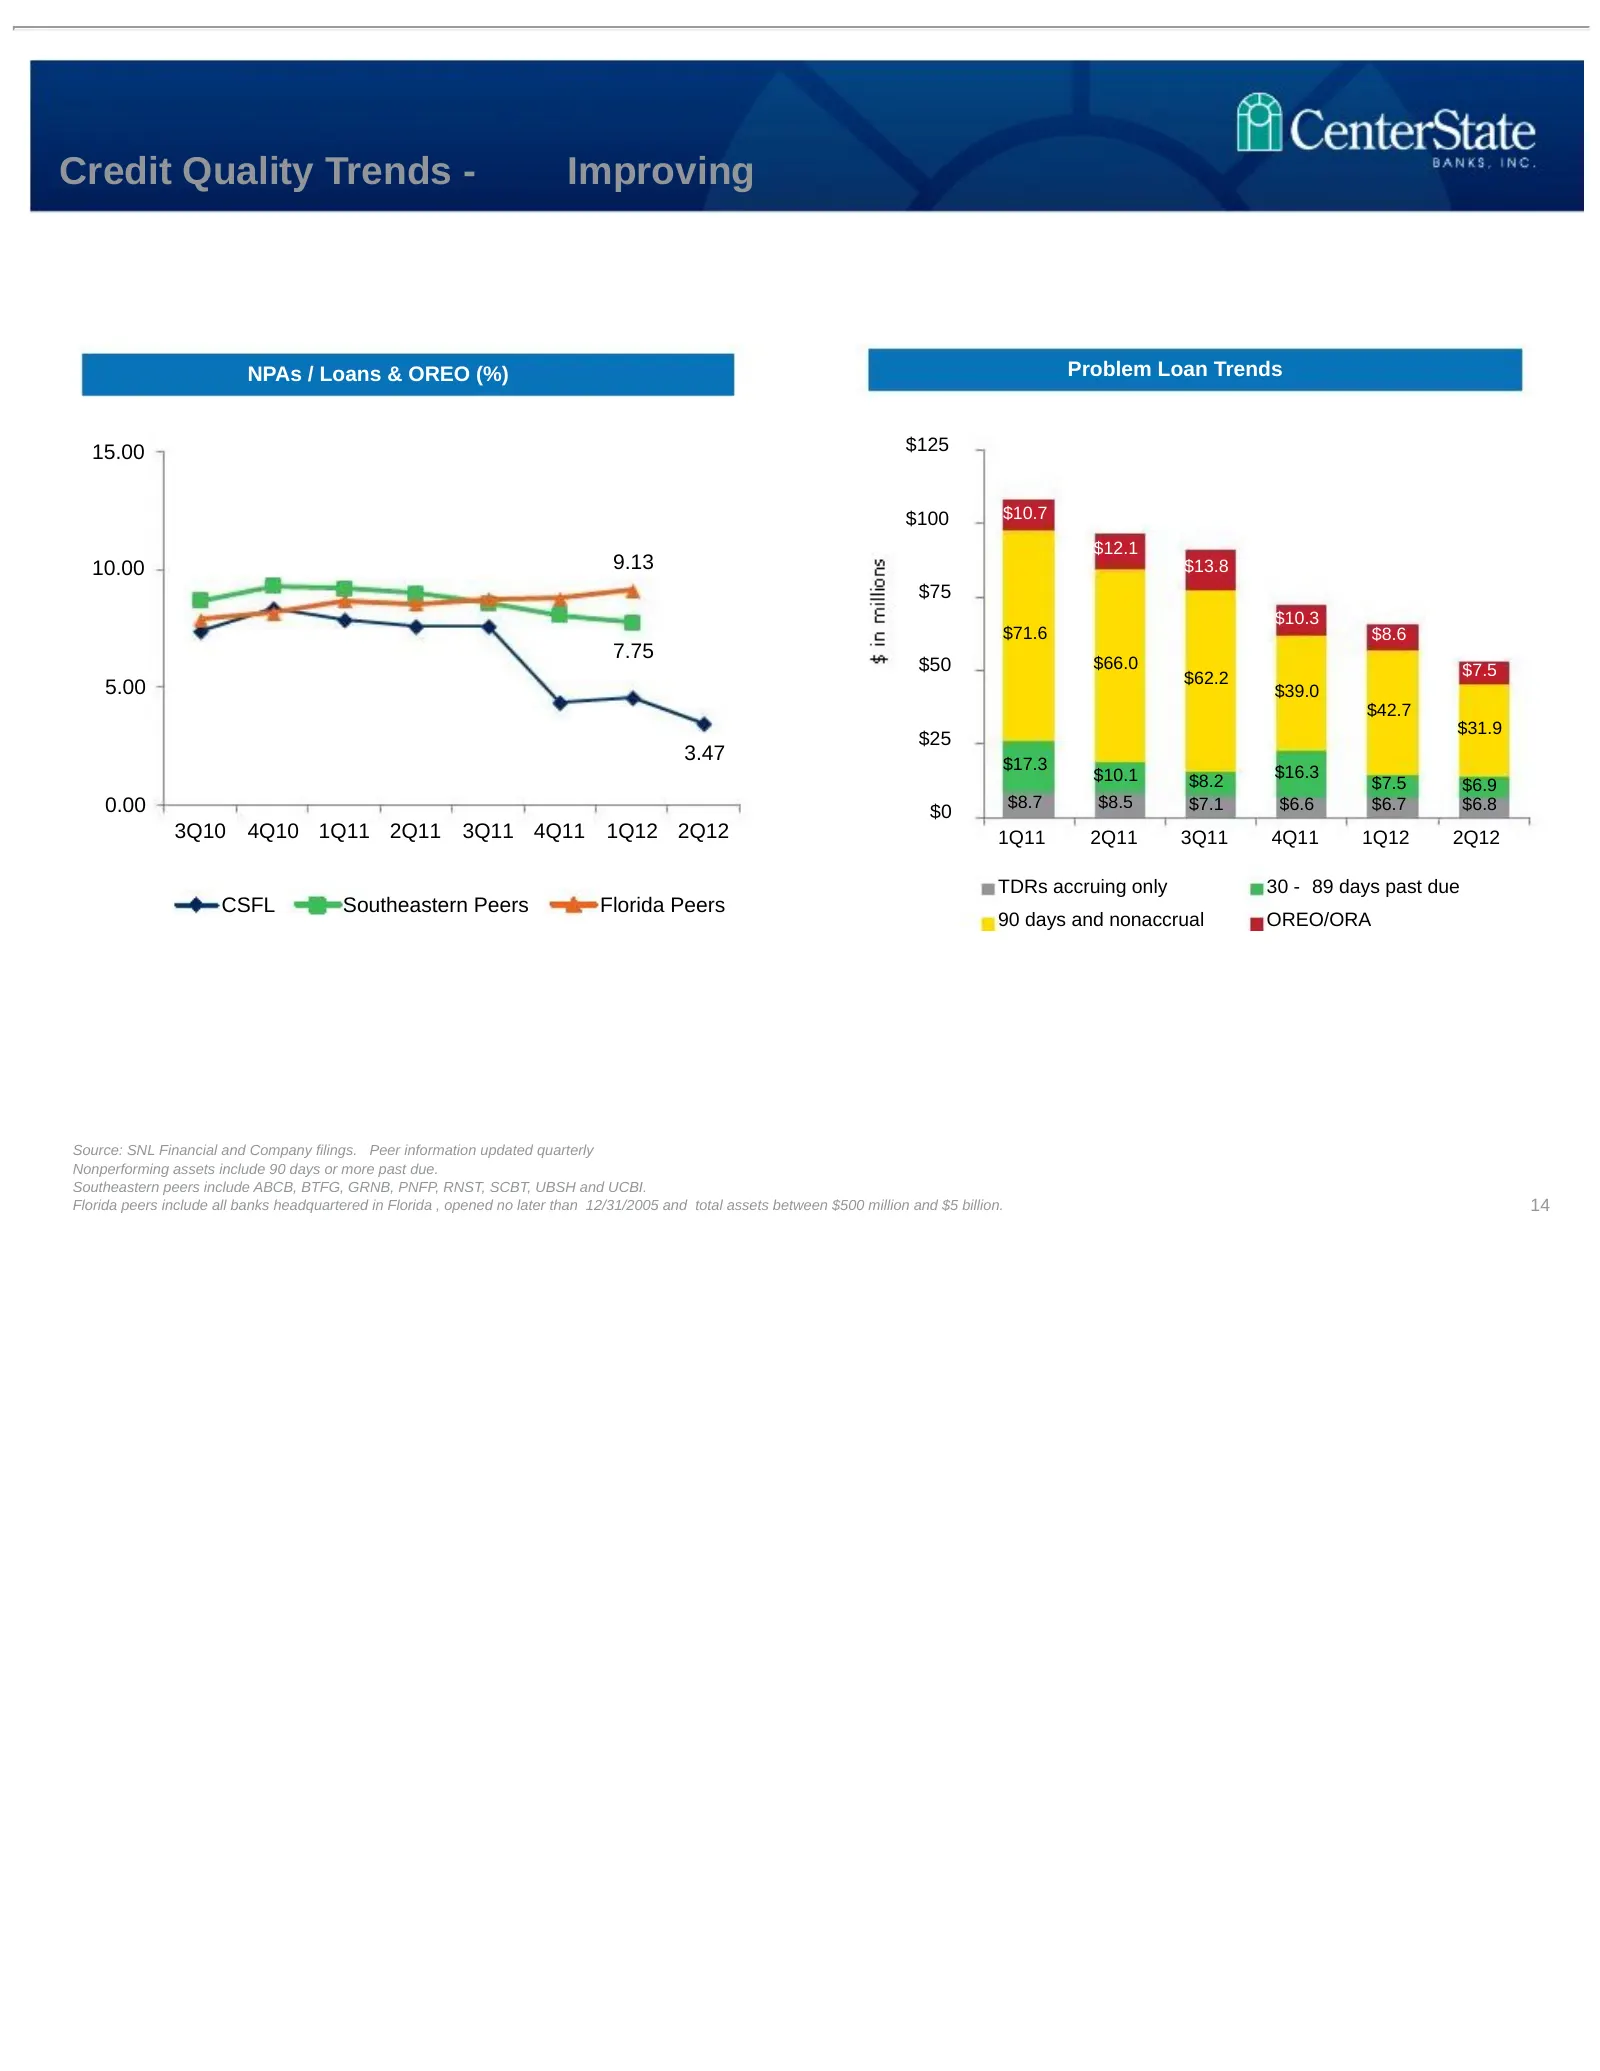
Slide 14: Credit Quality Trends - Improving
Credit Quality Trends - Improving NPAs / Loans & OREO (%) Problem Loan Trends 15.00 $125 $100 $10.7 $12.1 10.00 9.13 $13.8 $75 $10.3 $71.6 $8.6 7.75 $50 $66.0 $7.5 $62.2 5.00 $39.0 $42.7 $31.9 $25 3.47 $17.3 $10.1 $16.3 $8.2 $7.5 $6.9 0.00 $8.7 $8.5 $7.1 $6.6 $6.7 $6.8 $0 3Q10 4Q10 1Q11 2Q11 3Q11 4Q
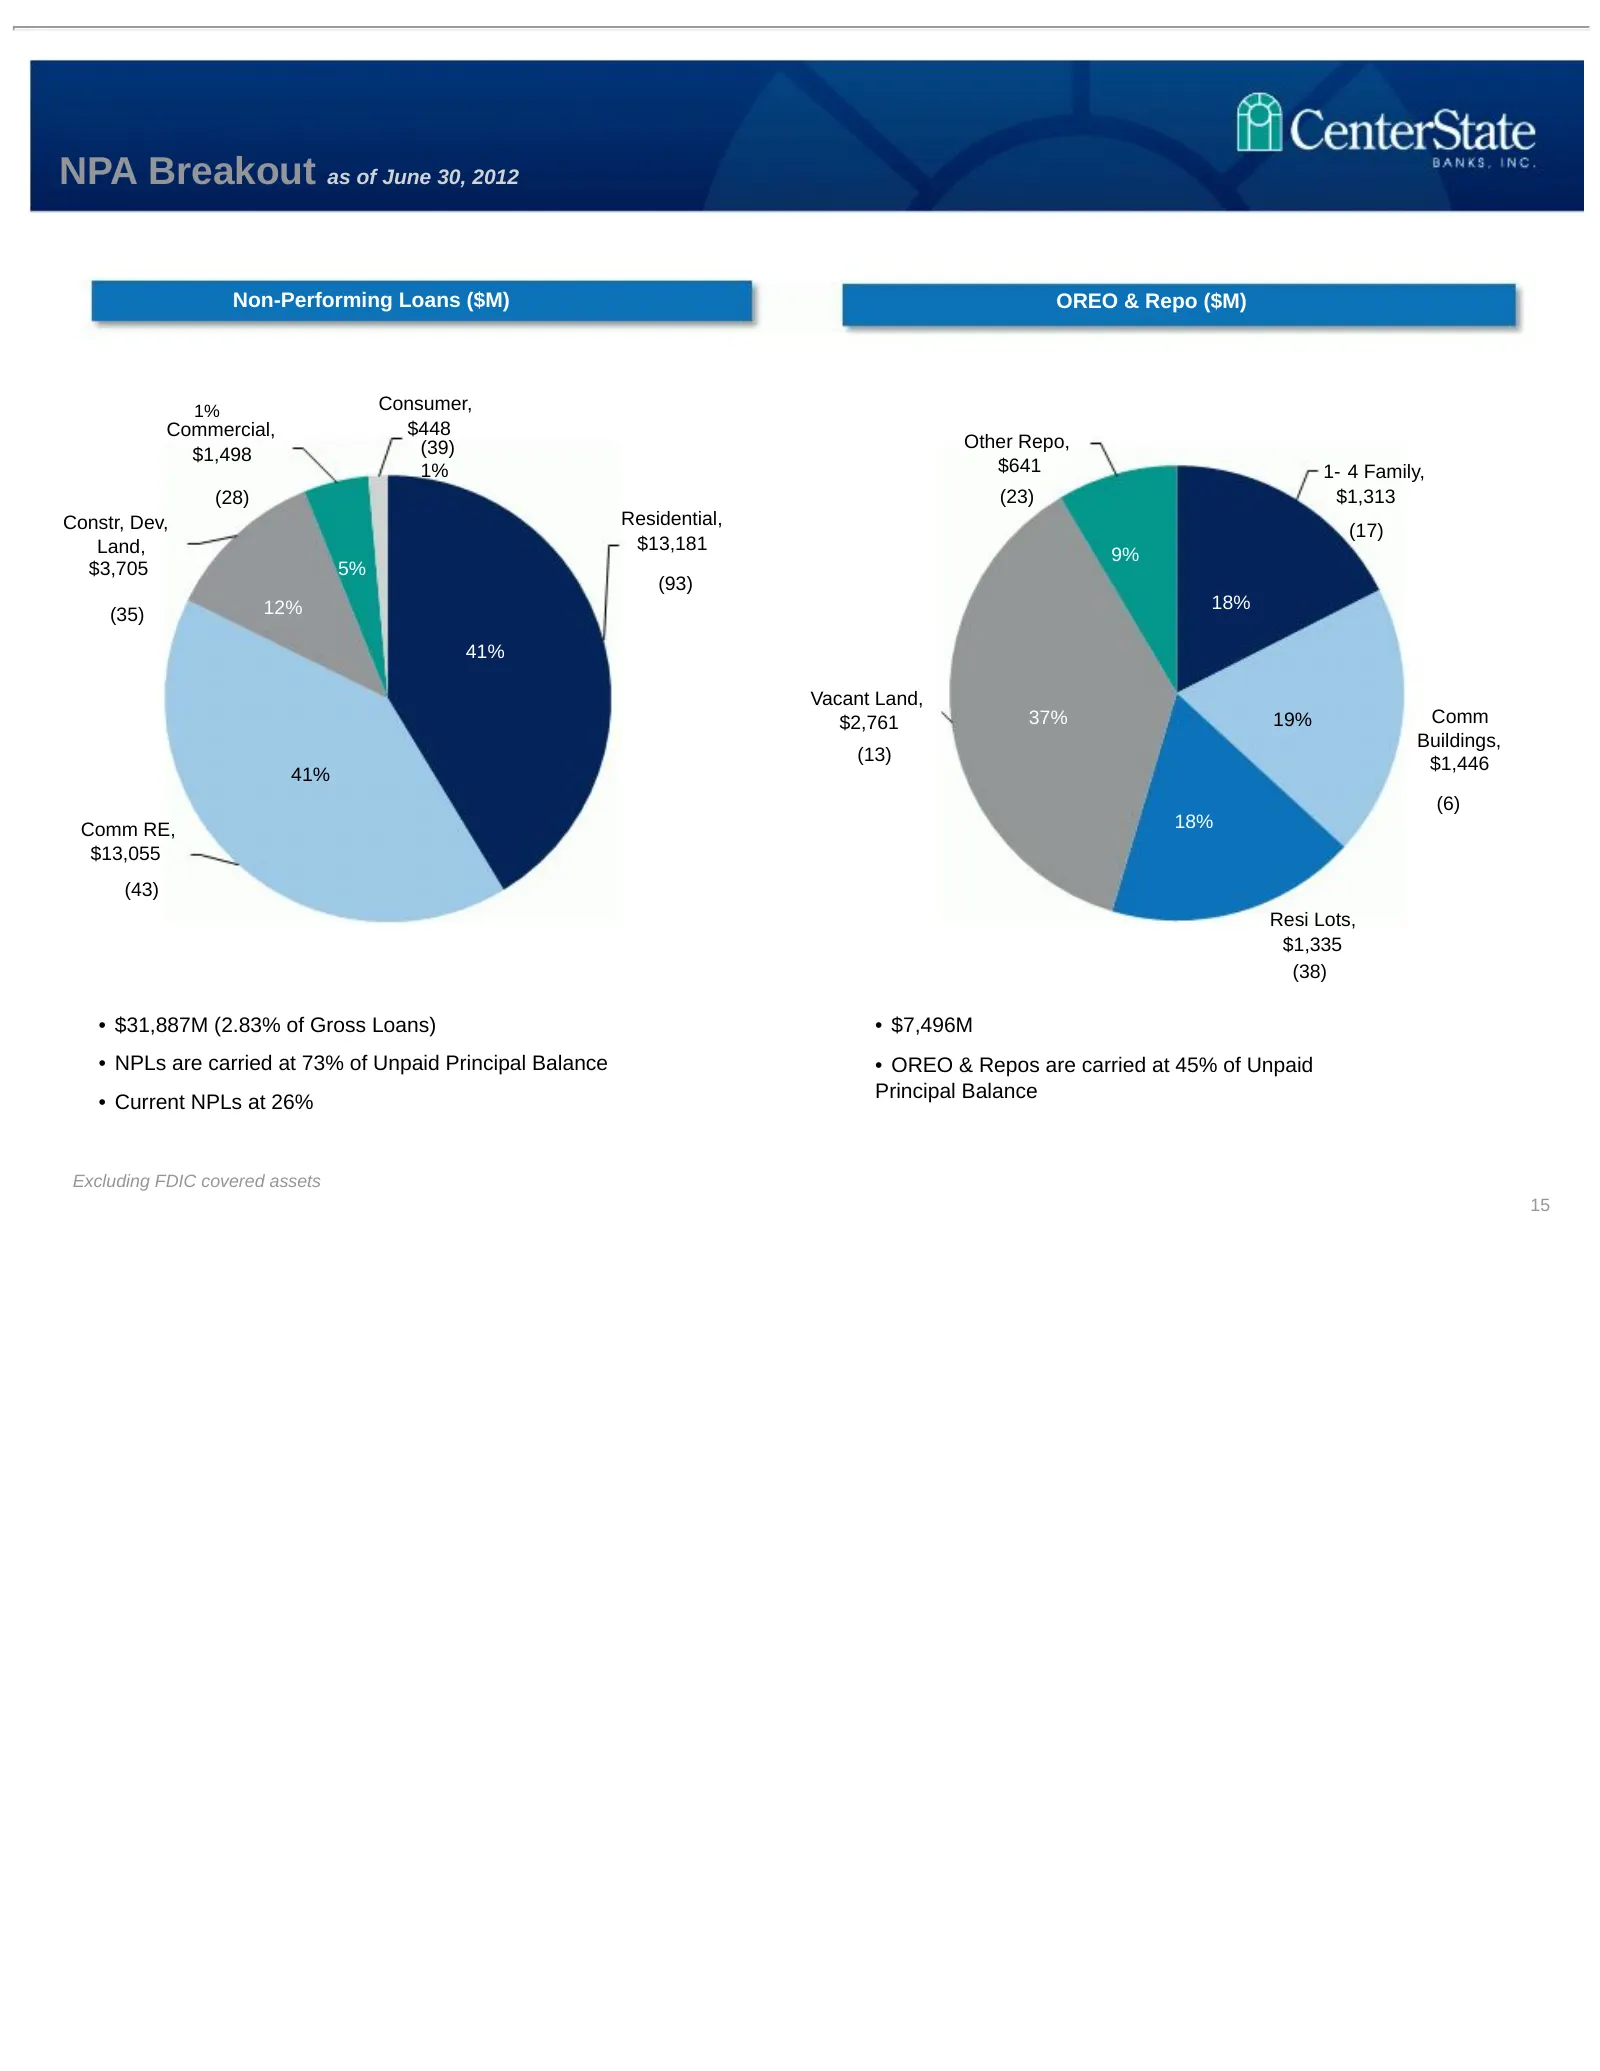
Slide 15: NPA Breakout as of June 30, 2012
NPA Breakout as of June 30, 2012 Non-Performing Loans ($M) OREO & Repo ($M) 1% Consumer, Commercial, $448 (39) Other Repo, $1,498 1% $641 1- 4 Family, (28) (23) $1,313 Constr, Dev, Residential, (17) Land, $13,181 9% $3,705 5% (93) 12% 18% (35) 41% Vacant Land, $2,761 37% 19% Comm Buildings, (13) $1,
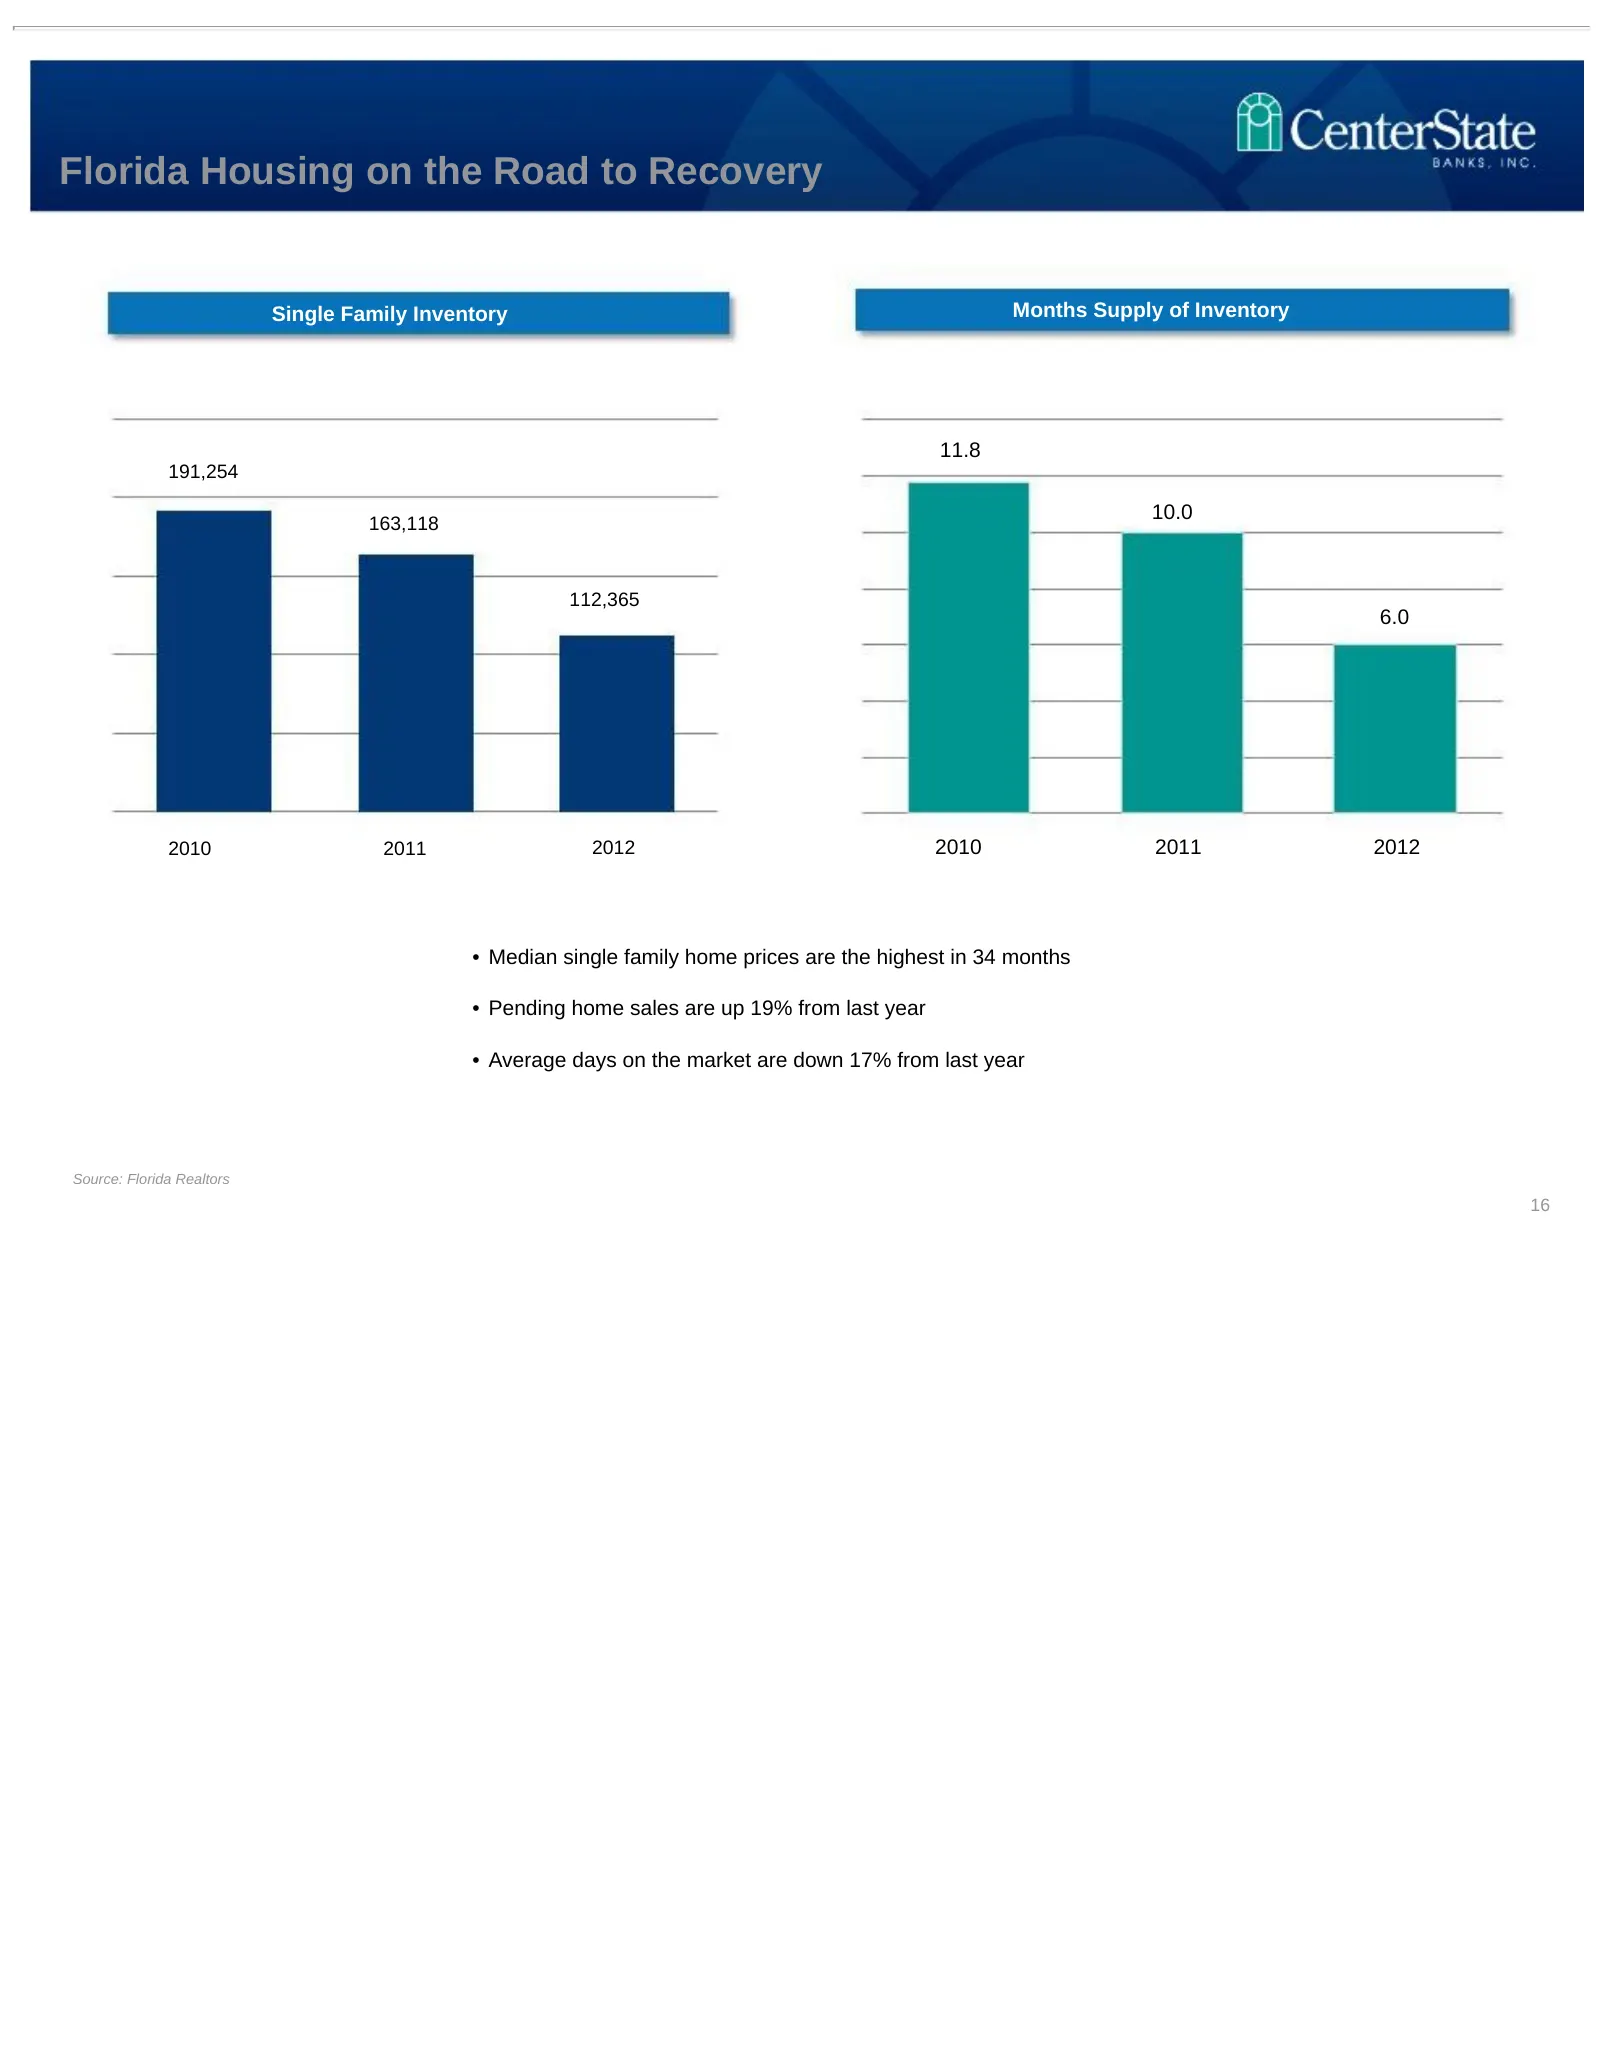
Slide 16: Florida Housing on the Road to Recovery
Florida Housing on the Road to Recovery Single Family Inventory Months Supply of Inventory 11.8 191,254 10.0 163,118 112,365 6.0 2010 2011 2012 2010 2011 2012 • Median single family home prices are the highest in 34 months • Pending home sales are up 19% from last year • Average days on the market a
Slide 17: Loan Trends as of June 30, 2012
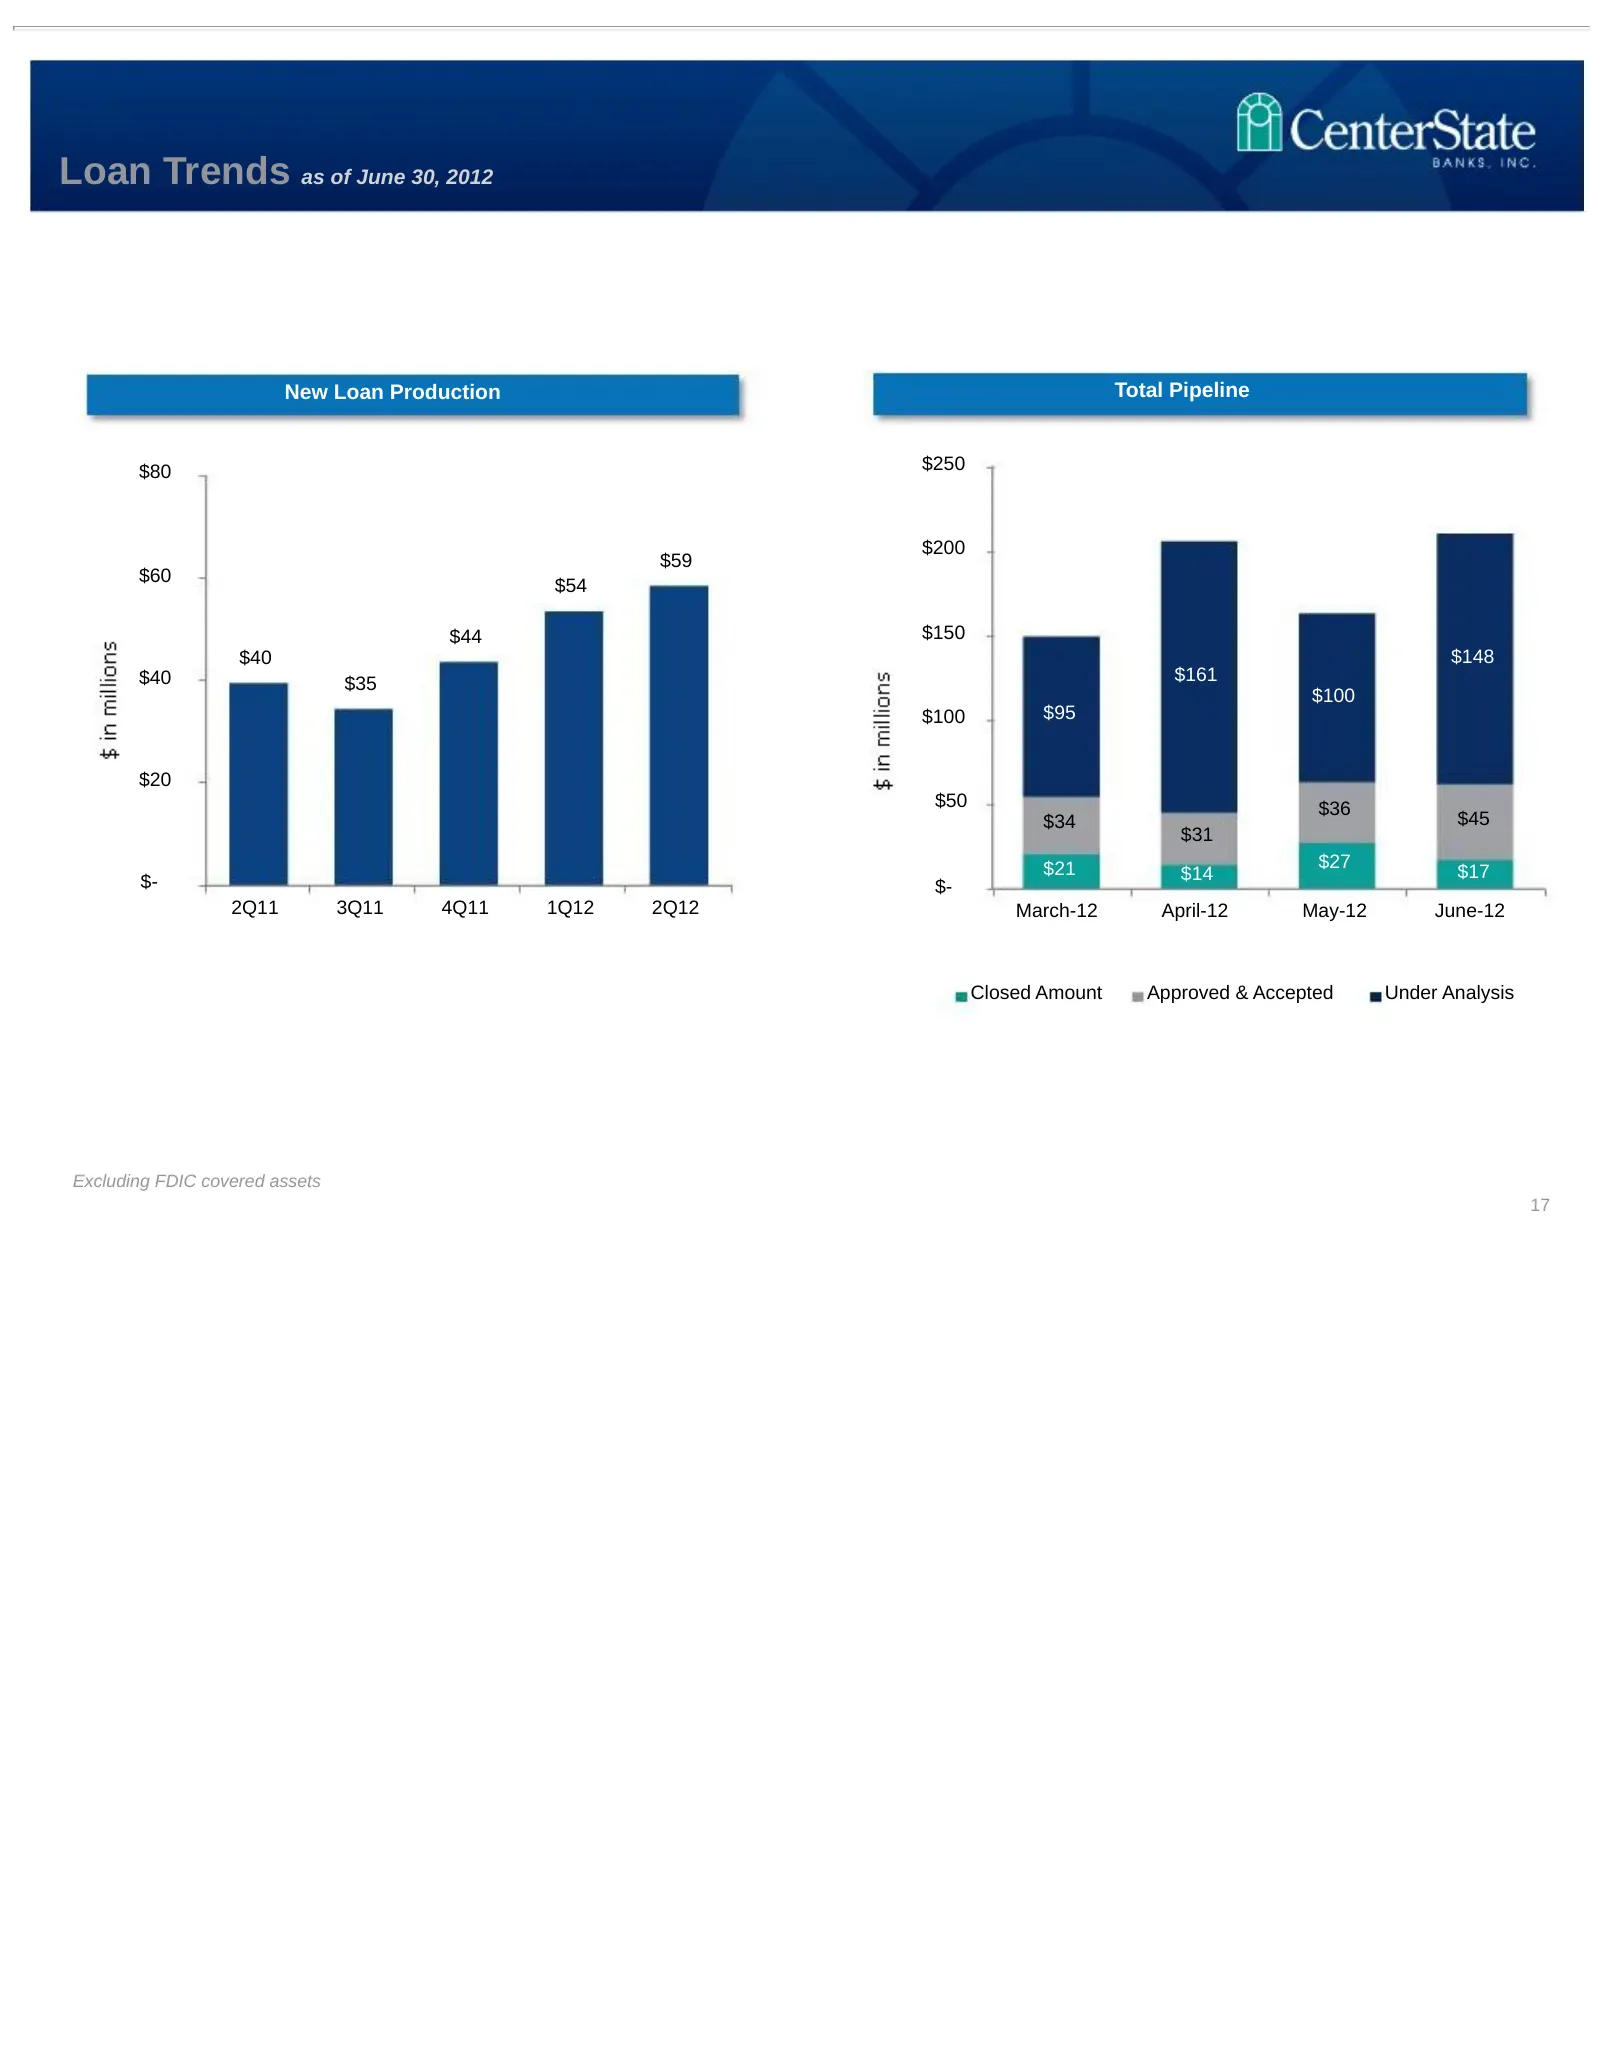
Loan Trends as of June 30, 2012 New Loan Production Total Pipeline $80 $250 $200 $59 $60 $54 $44 $150 $40 $148 $40 $35 $161 $100 $100 $95 $20 $50 $36 $34 $45 $31 $21 $27 $17 $- $14 $- 2Q11 3Q11 4Q11 1Q12 2Q12 March-12 April-12 May-12 June-12 Closed Amount Approved & Accepted Under Analysis Excluding
Slide 18: Banks with Texas Ratio over 200%
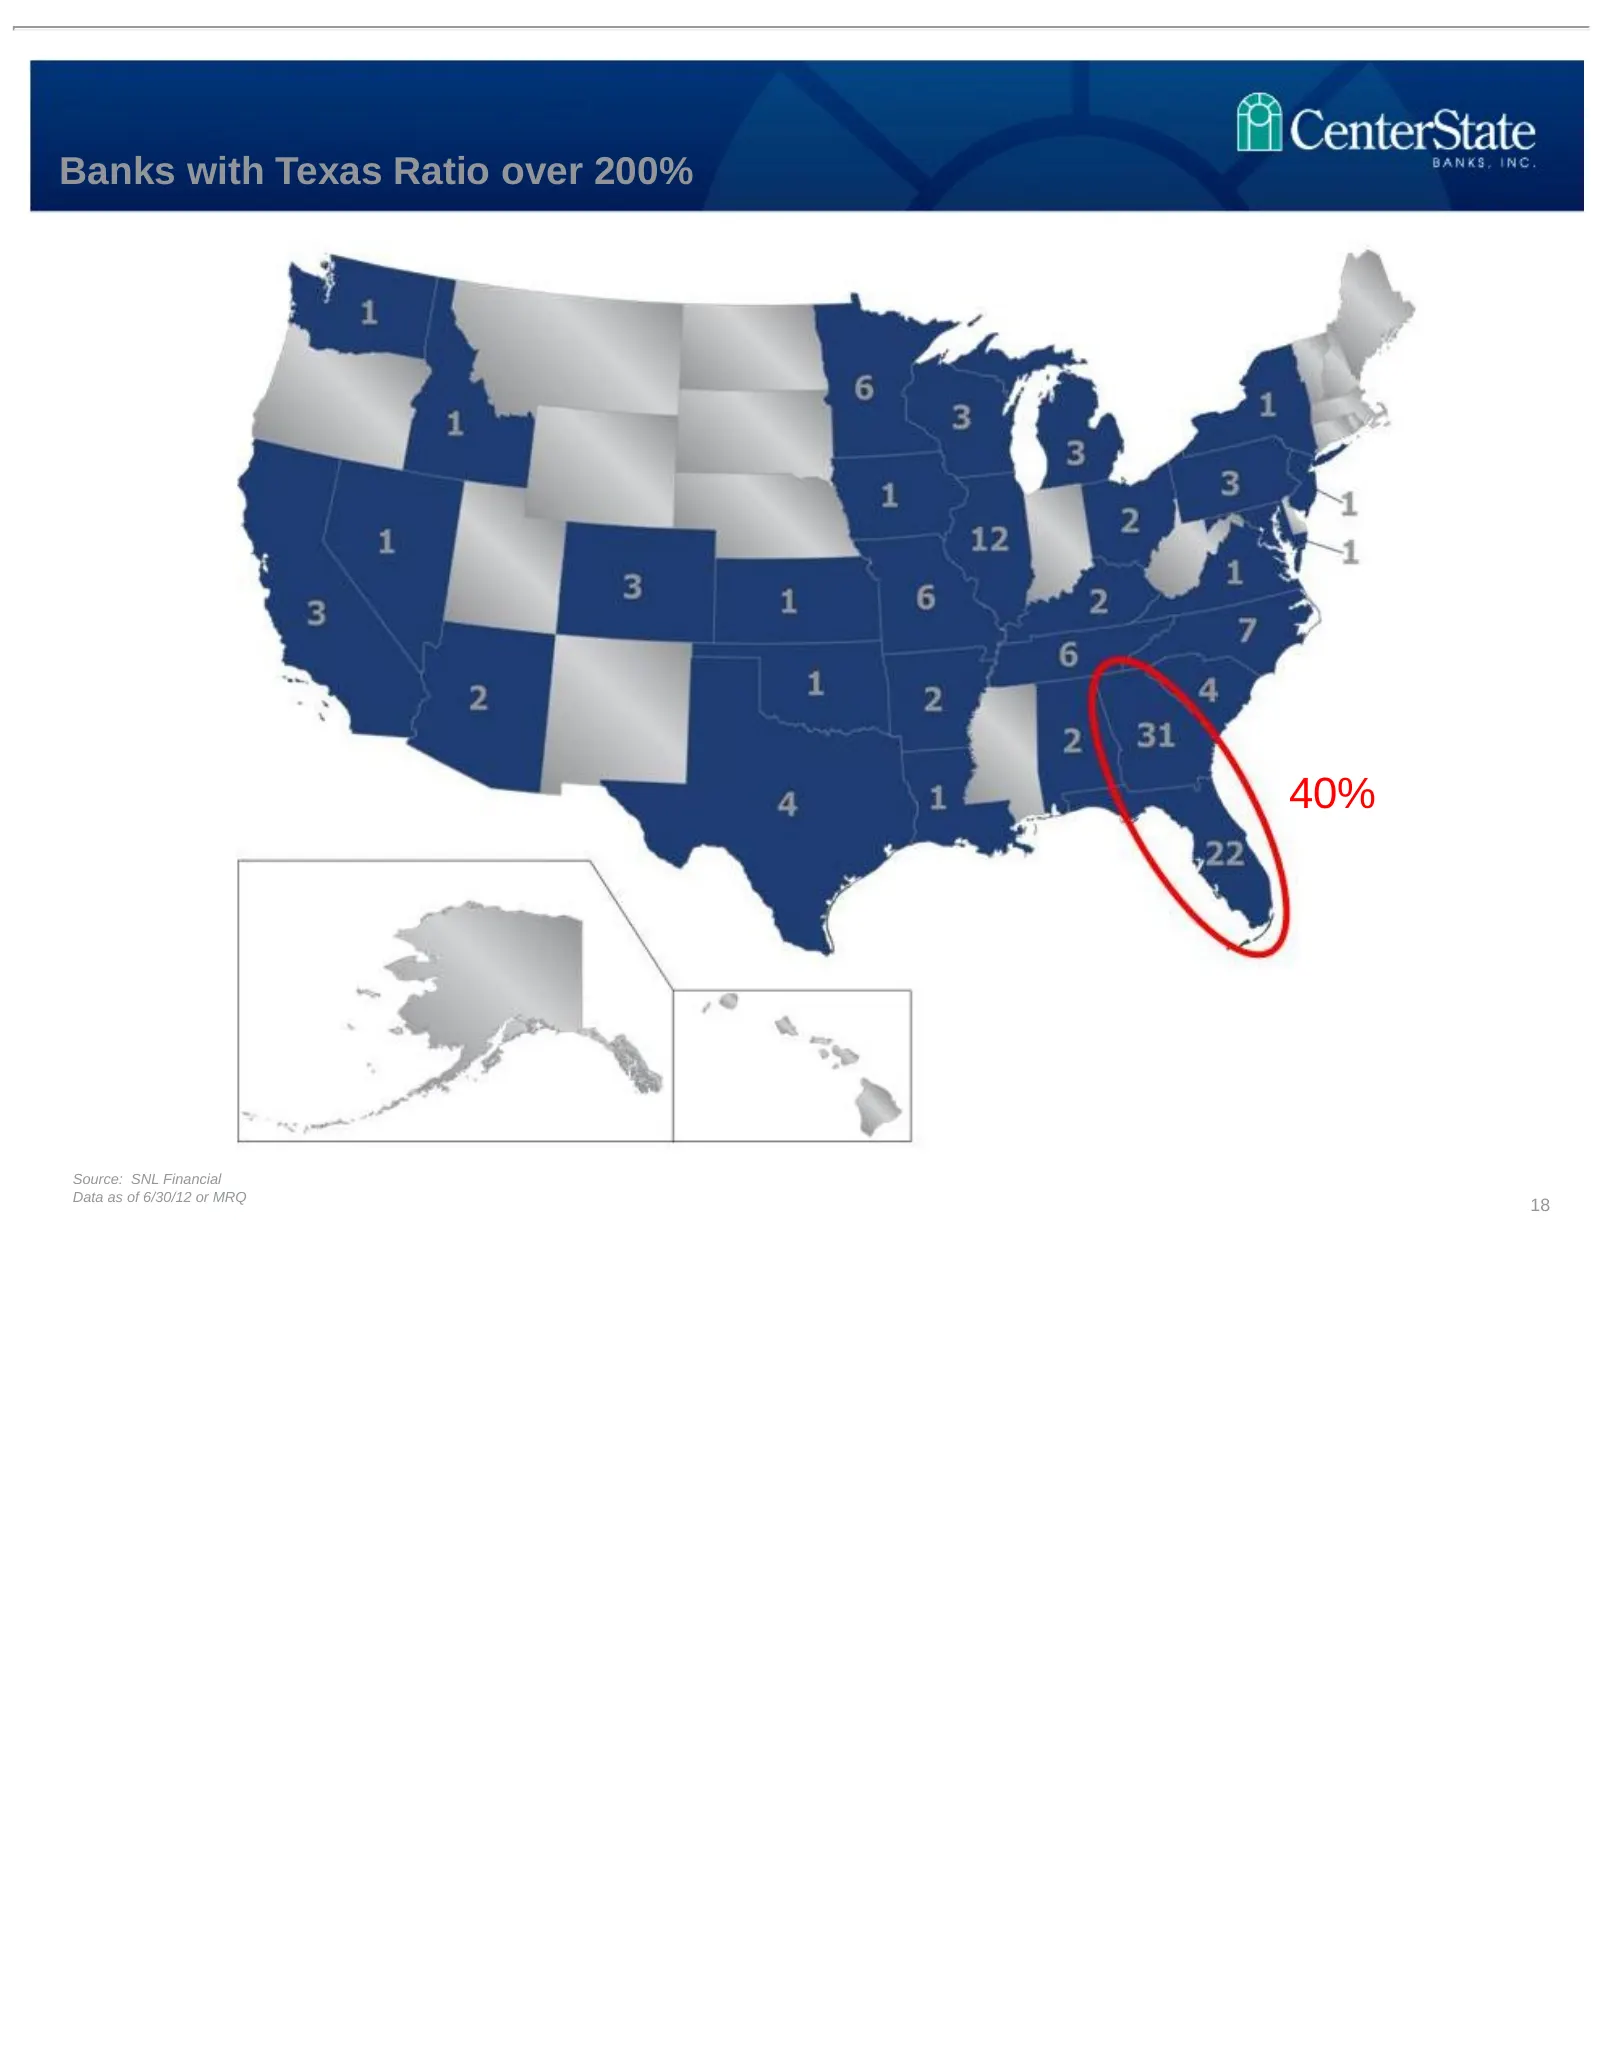
Banks with Texas Ratio over 200% 40% Source: SNL Financial Data as of 6/30/12 or MRQ 17 18
Slide 19: CSFL – Best Positioned Florida Consolidator
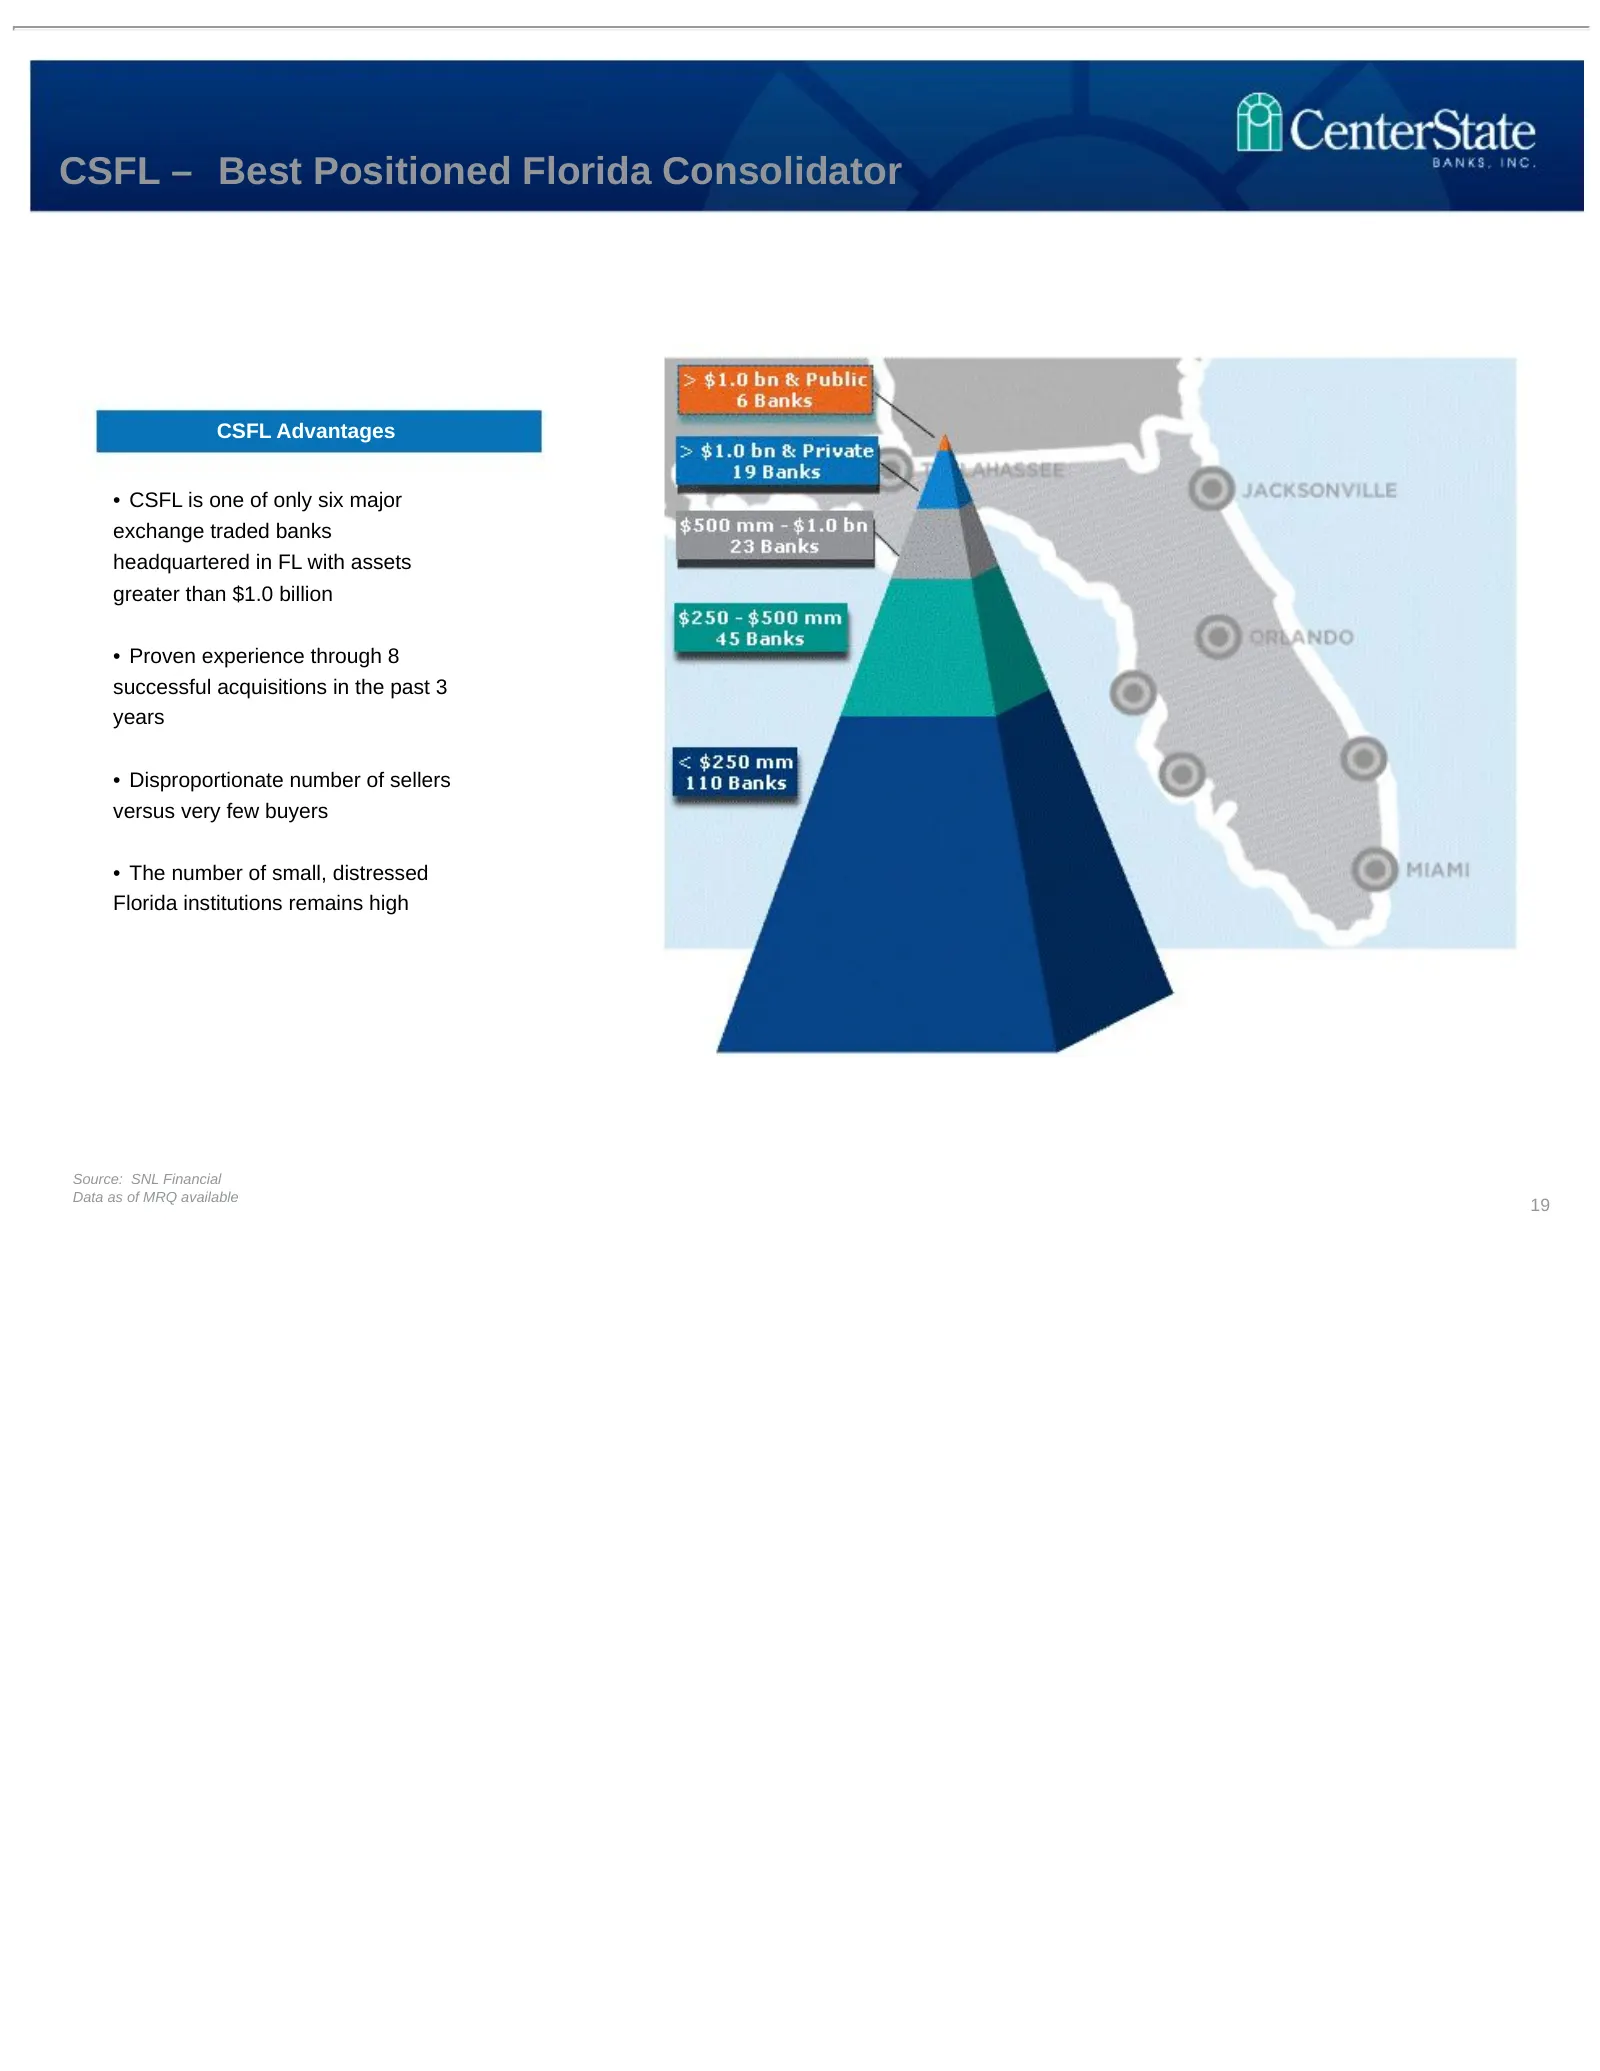
CSFL – Best Positioned Florida Consolidator CSFL Advantages • CSFL is one of only six major exchange traded banks headquartered in FL with assets greater than $1.0 billion • Proven experience through 8 successful acquisitions in the past 3 years • Disproportionate number of sellers versus very few b
Slide 20: Summary
Summary • Florida economy improving • CSFL metrics improving with better performance anticipated • Vision still includes bank consolidations • Expect better efficiencies in the near term • Lifetime local bankers with common lineage 20 20
Slide 21: Appendix
Appendix
Slide 22: Recent M&A Transactions
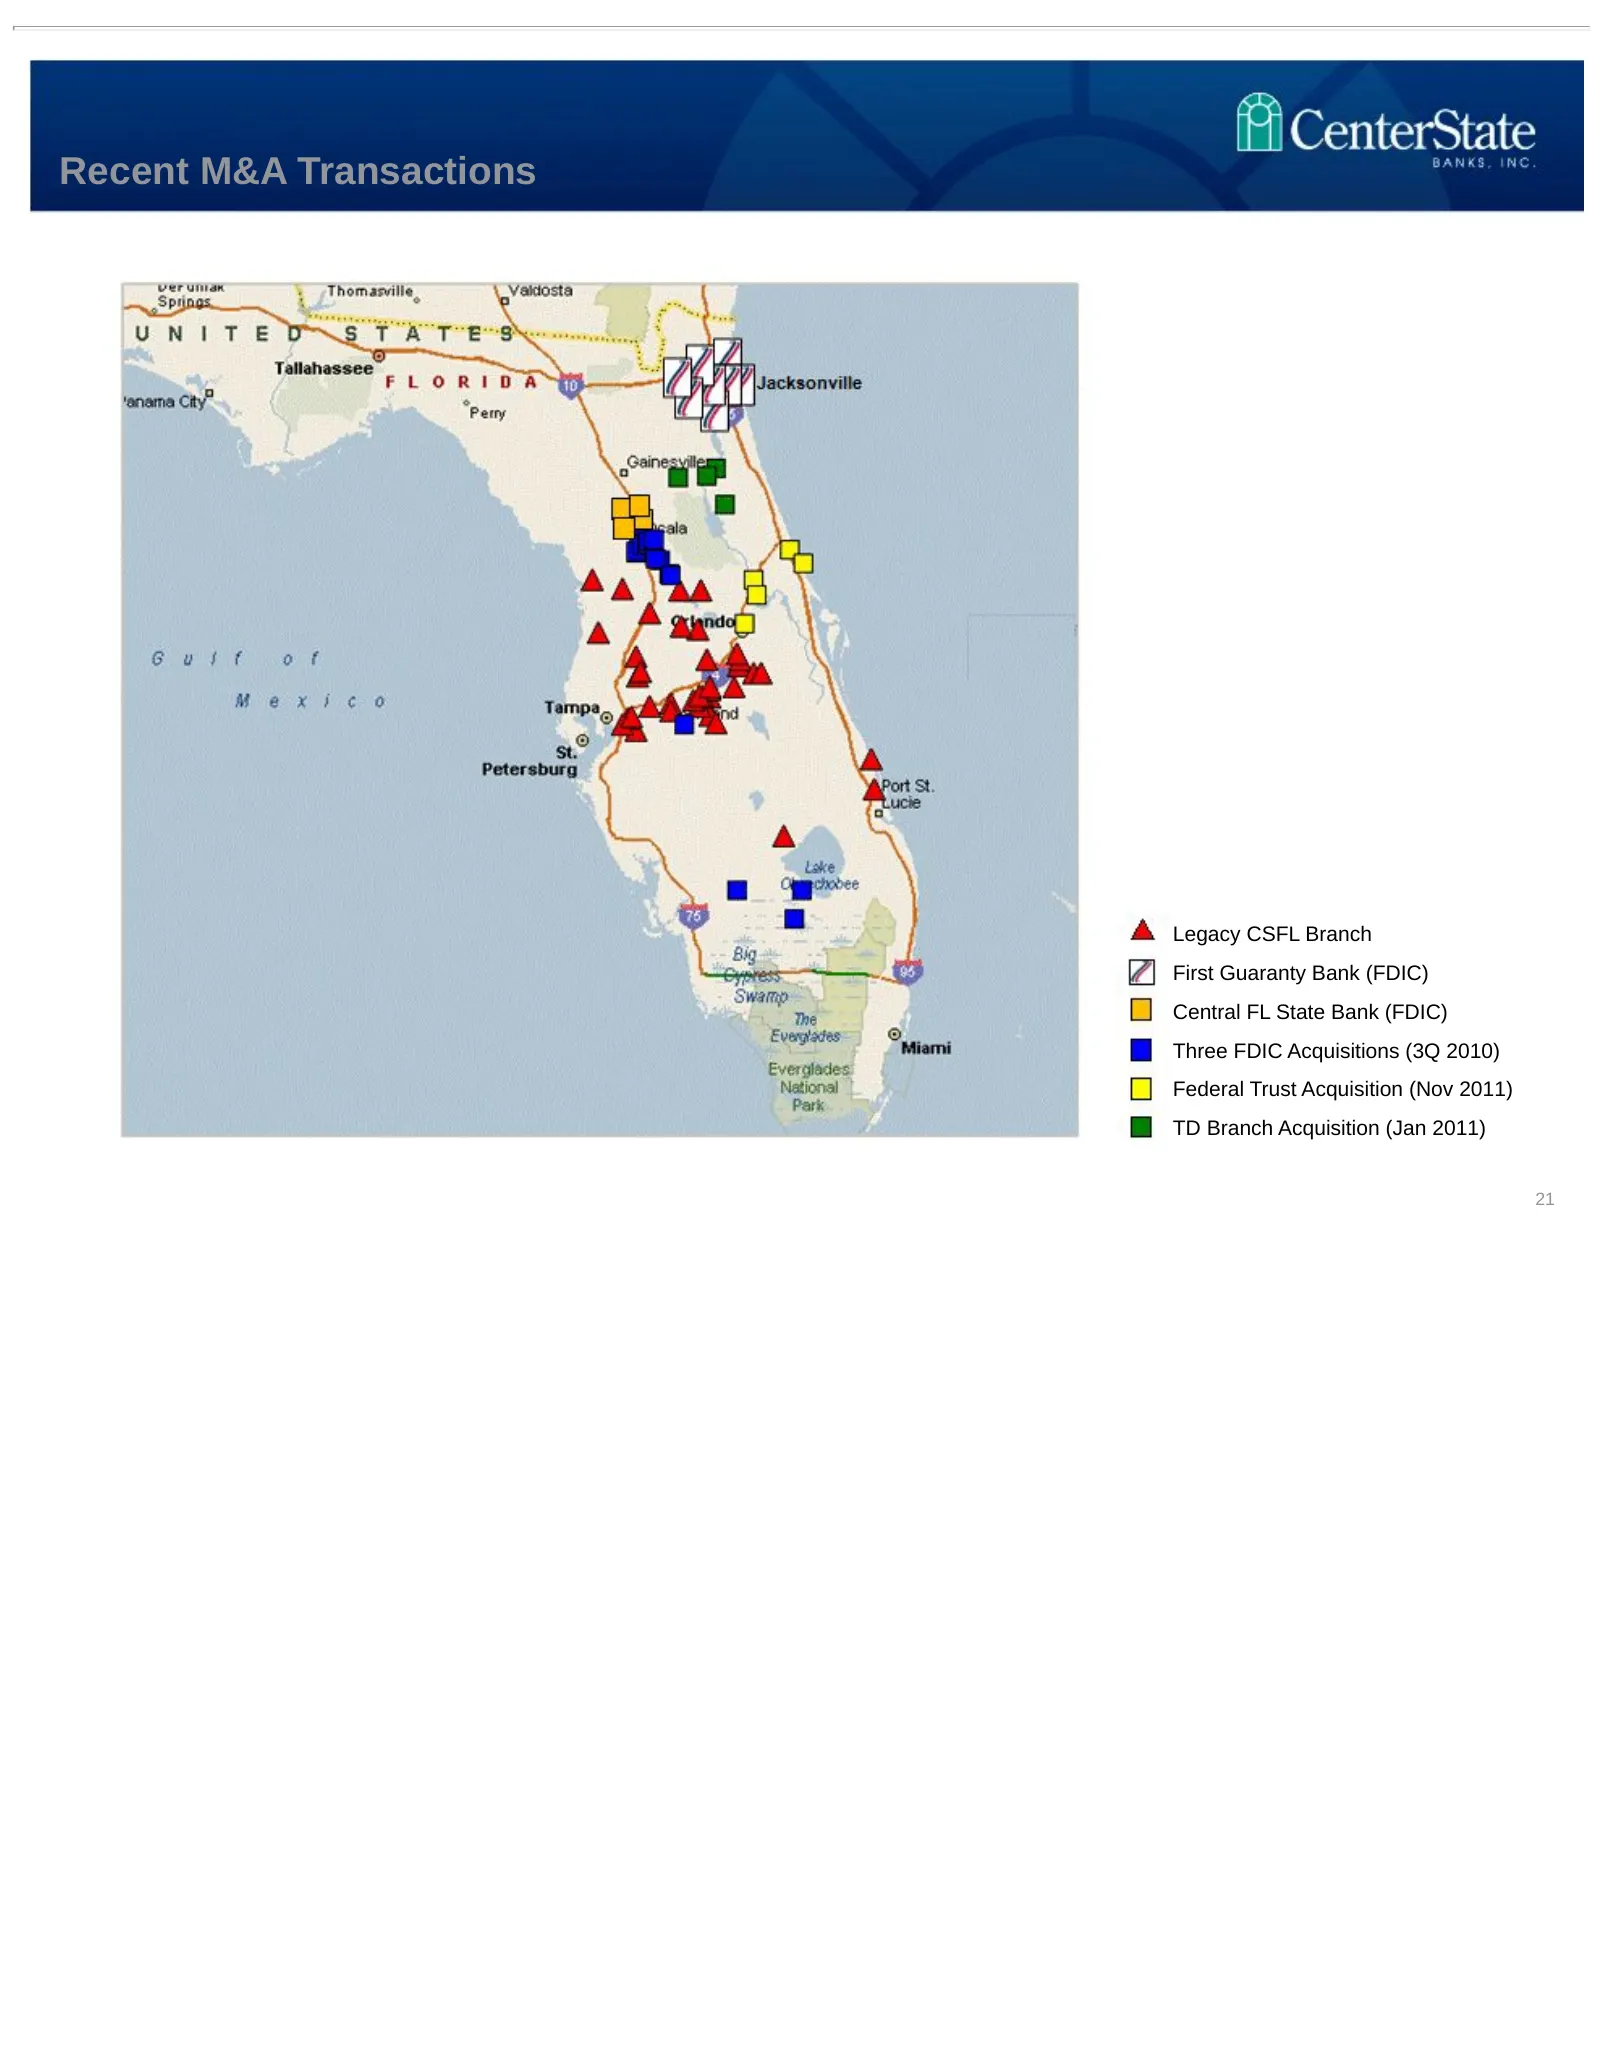
Recent M&A Transactions Legacy CSFL Branch First Guaranty Bank (FDIC) Central FL State Bank (FDIC) Three FDIC Acquisitions (3Q 2010) Federal Trust Acquisition (Nov 2011) TD Branch Acquisition (Jan 2011) Source: SNL Financial 21 21
Slide 23: Capital
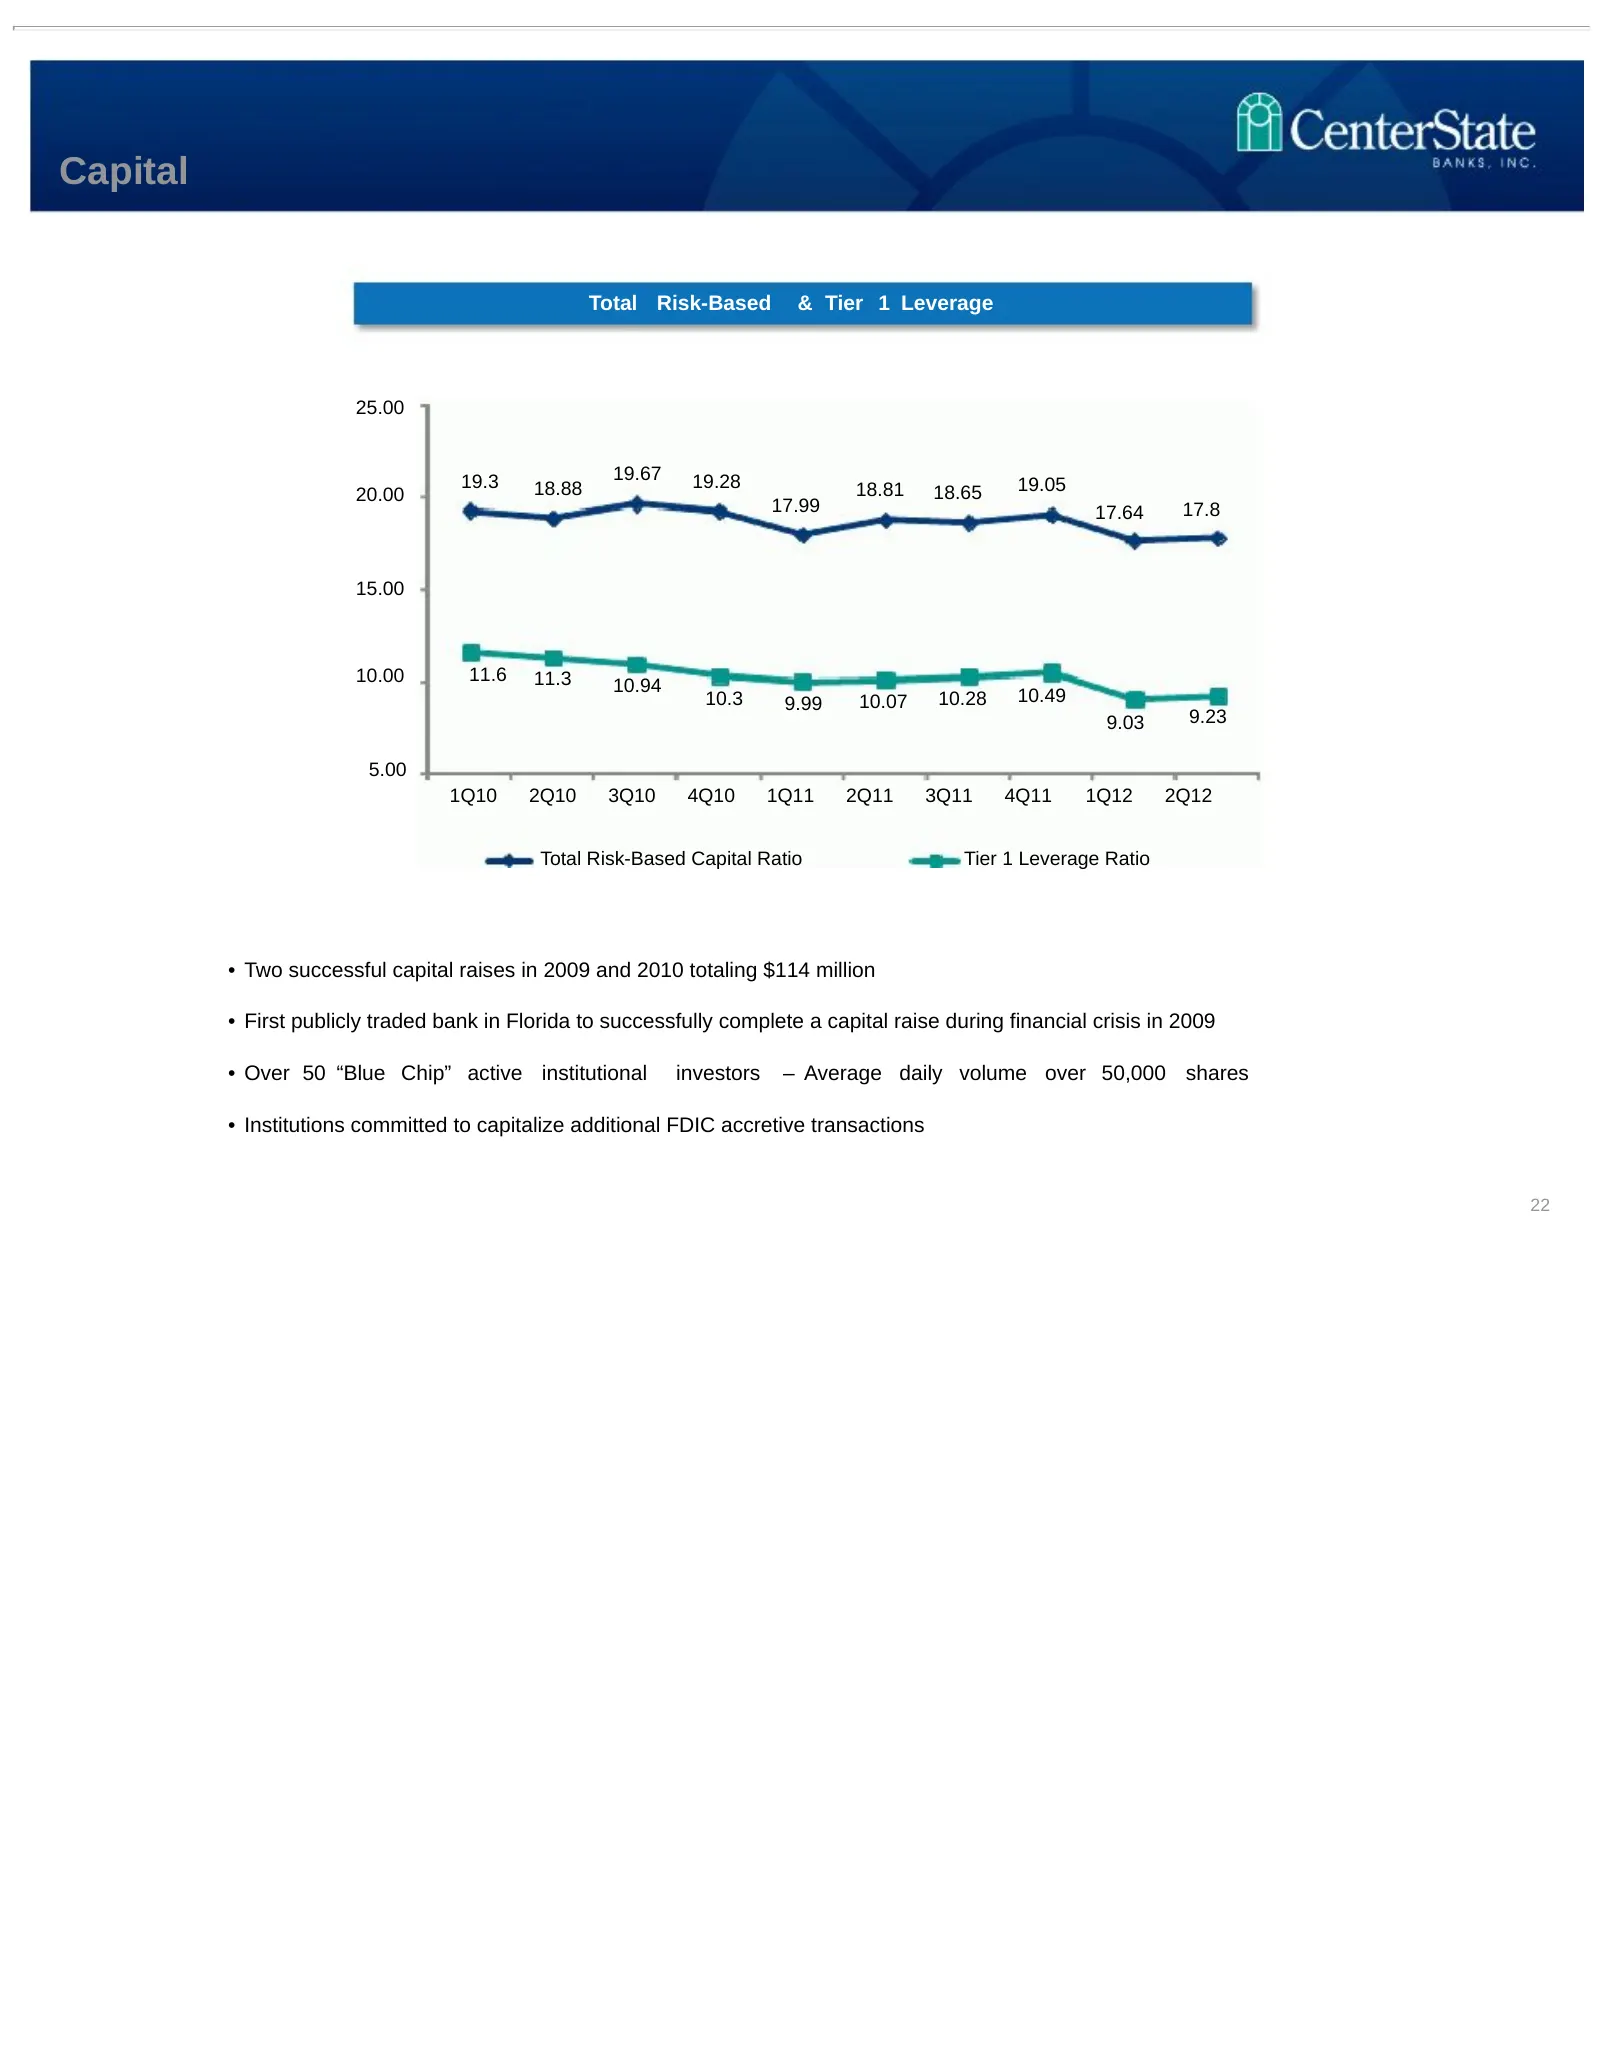
Capital Total Risk-Based & Tier 1 Leverage 25.00 19.3 19.67 19.28 20.00 18.88 18.81 18.65 19.05 17.99 17.64 17.8 15.00 10.00 11.6 11.3 10.94 10.3 9.99 10.07 10.28 10.49 9.03 9.23 5.00 1Q10 2Q10 3Q10 4Q10 1Q11 2Q11 3Q11 4Q11 1Q12 2Q12 Total Risk-Based Capital Ratio Tier 1 Leverage Ratio • Two success
Slide 24: Total Deposit Portfolio as of June 30, 2012
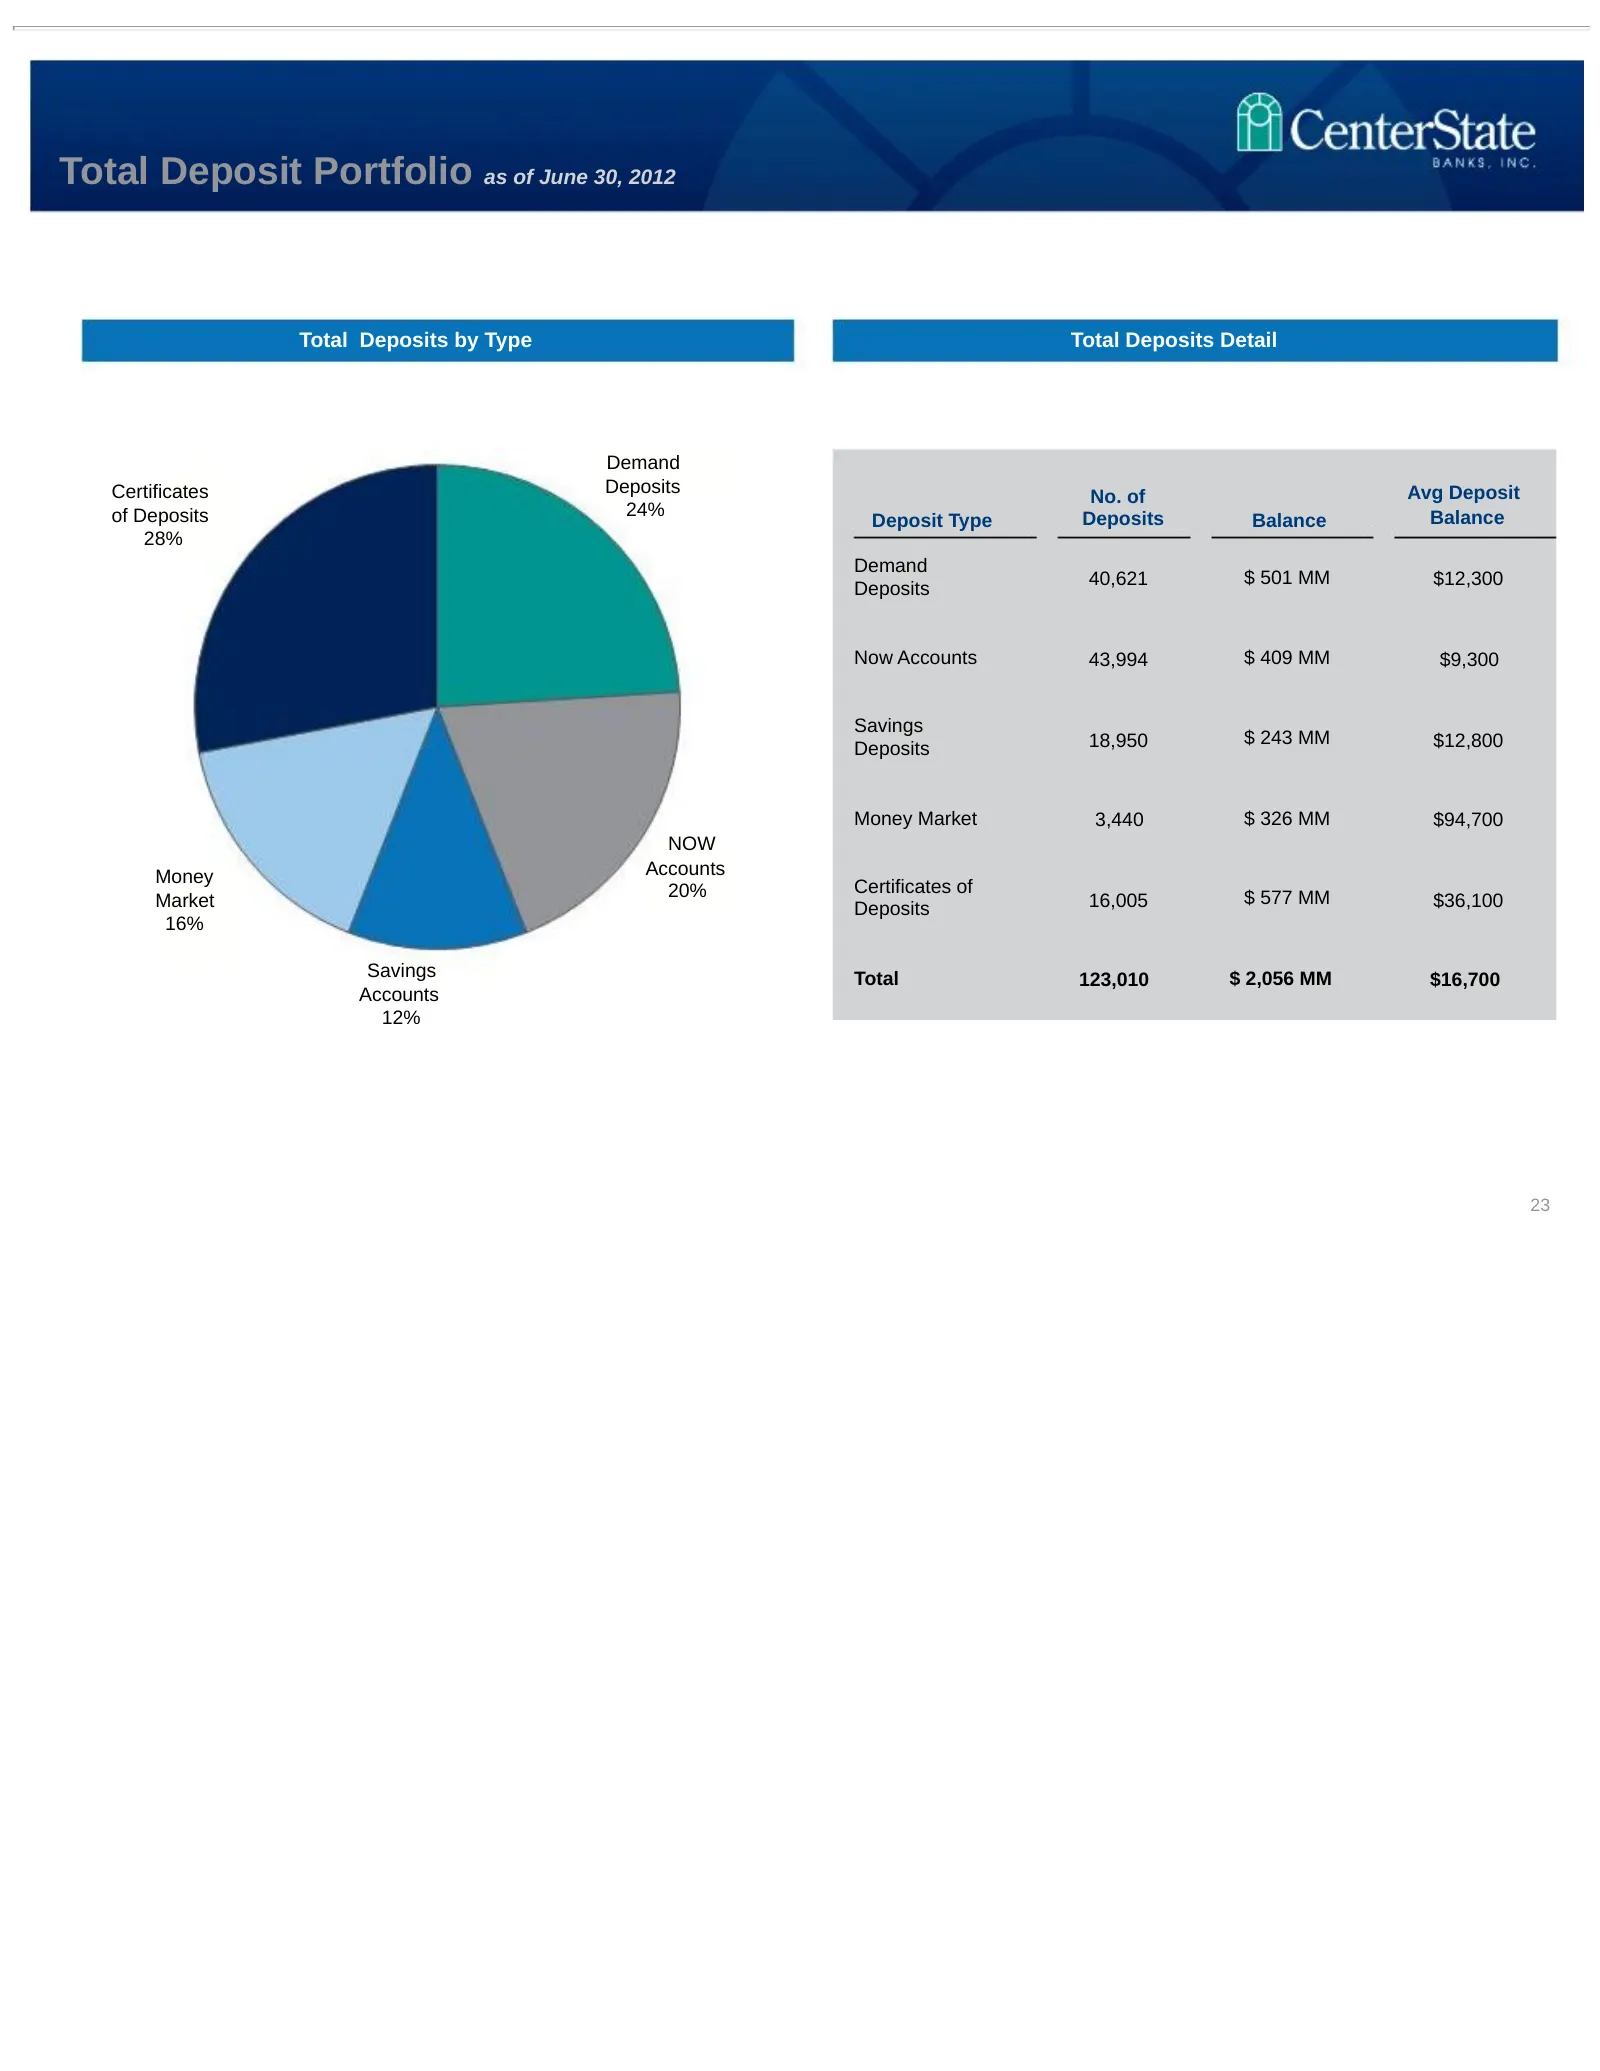
Total Deposit Portfolio as of June 30, 2012 Total Deposits by Type Total Deposits Detail Demand Certificates Deposits No. of Avg Deposit of Deposits 24% Balance Deposit Type Deposits Balance 28% Demand 40,621 $ 501 MM $12,300 Deposits Now Accounts 43,994 $ 409 MM $9,300 Savings 18,950 $ 243 MM $12,8
Slide 25: Total Loan Portfolio as of June 30, 2012
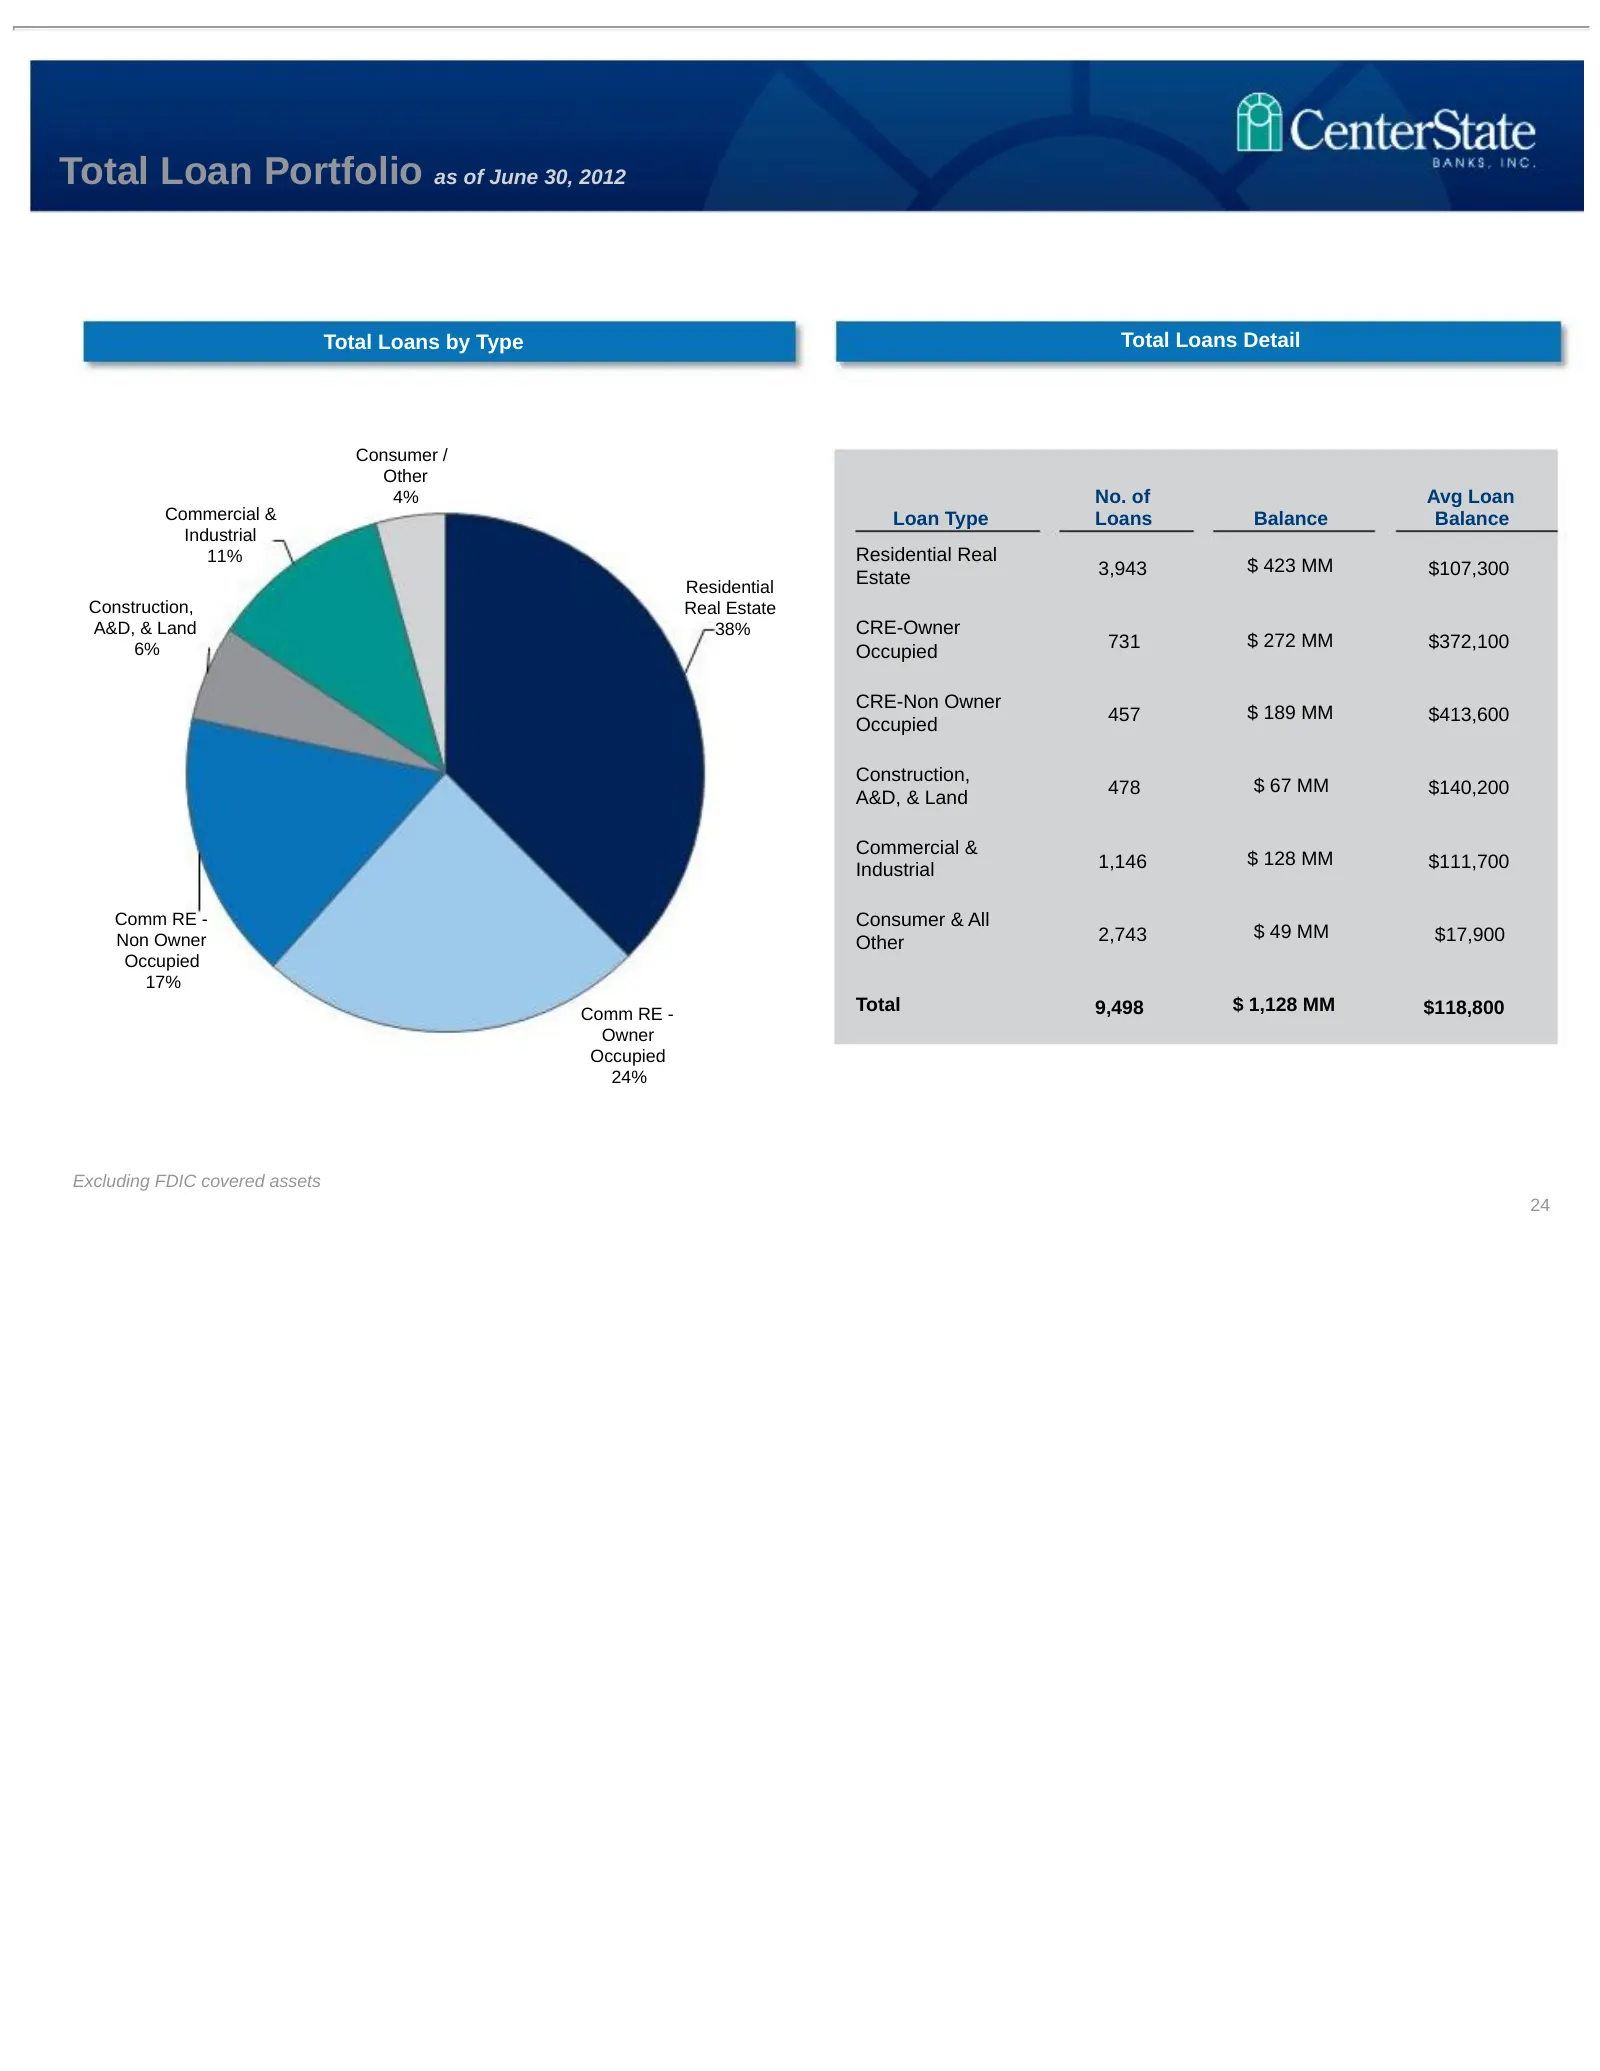
Total Loan Portfolio as of June 30, 2012 Total Loans by Type Total Loans Detail Consumer / Other 4% No. of Avg Loan Commercial & Loan Type Loans Balance Balance Industrial 11% Residential Real 3,943 $ 423 MM $107,300 Residential Estate Construction, Real Estate A&D, & Land 38% CRE-Owner 6% 731 $ 272
Slide 26: CRE Concentrations as of June 30, 2012
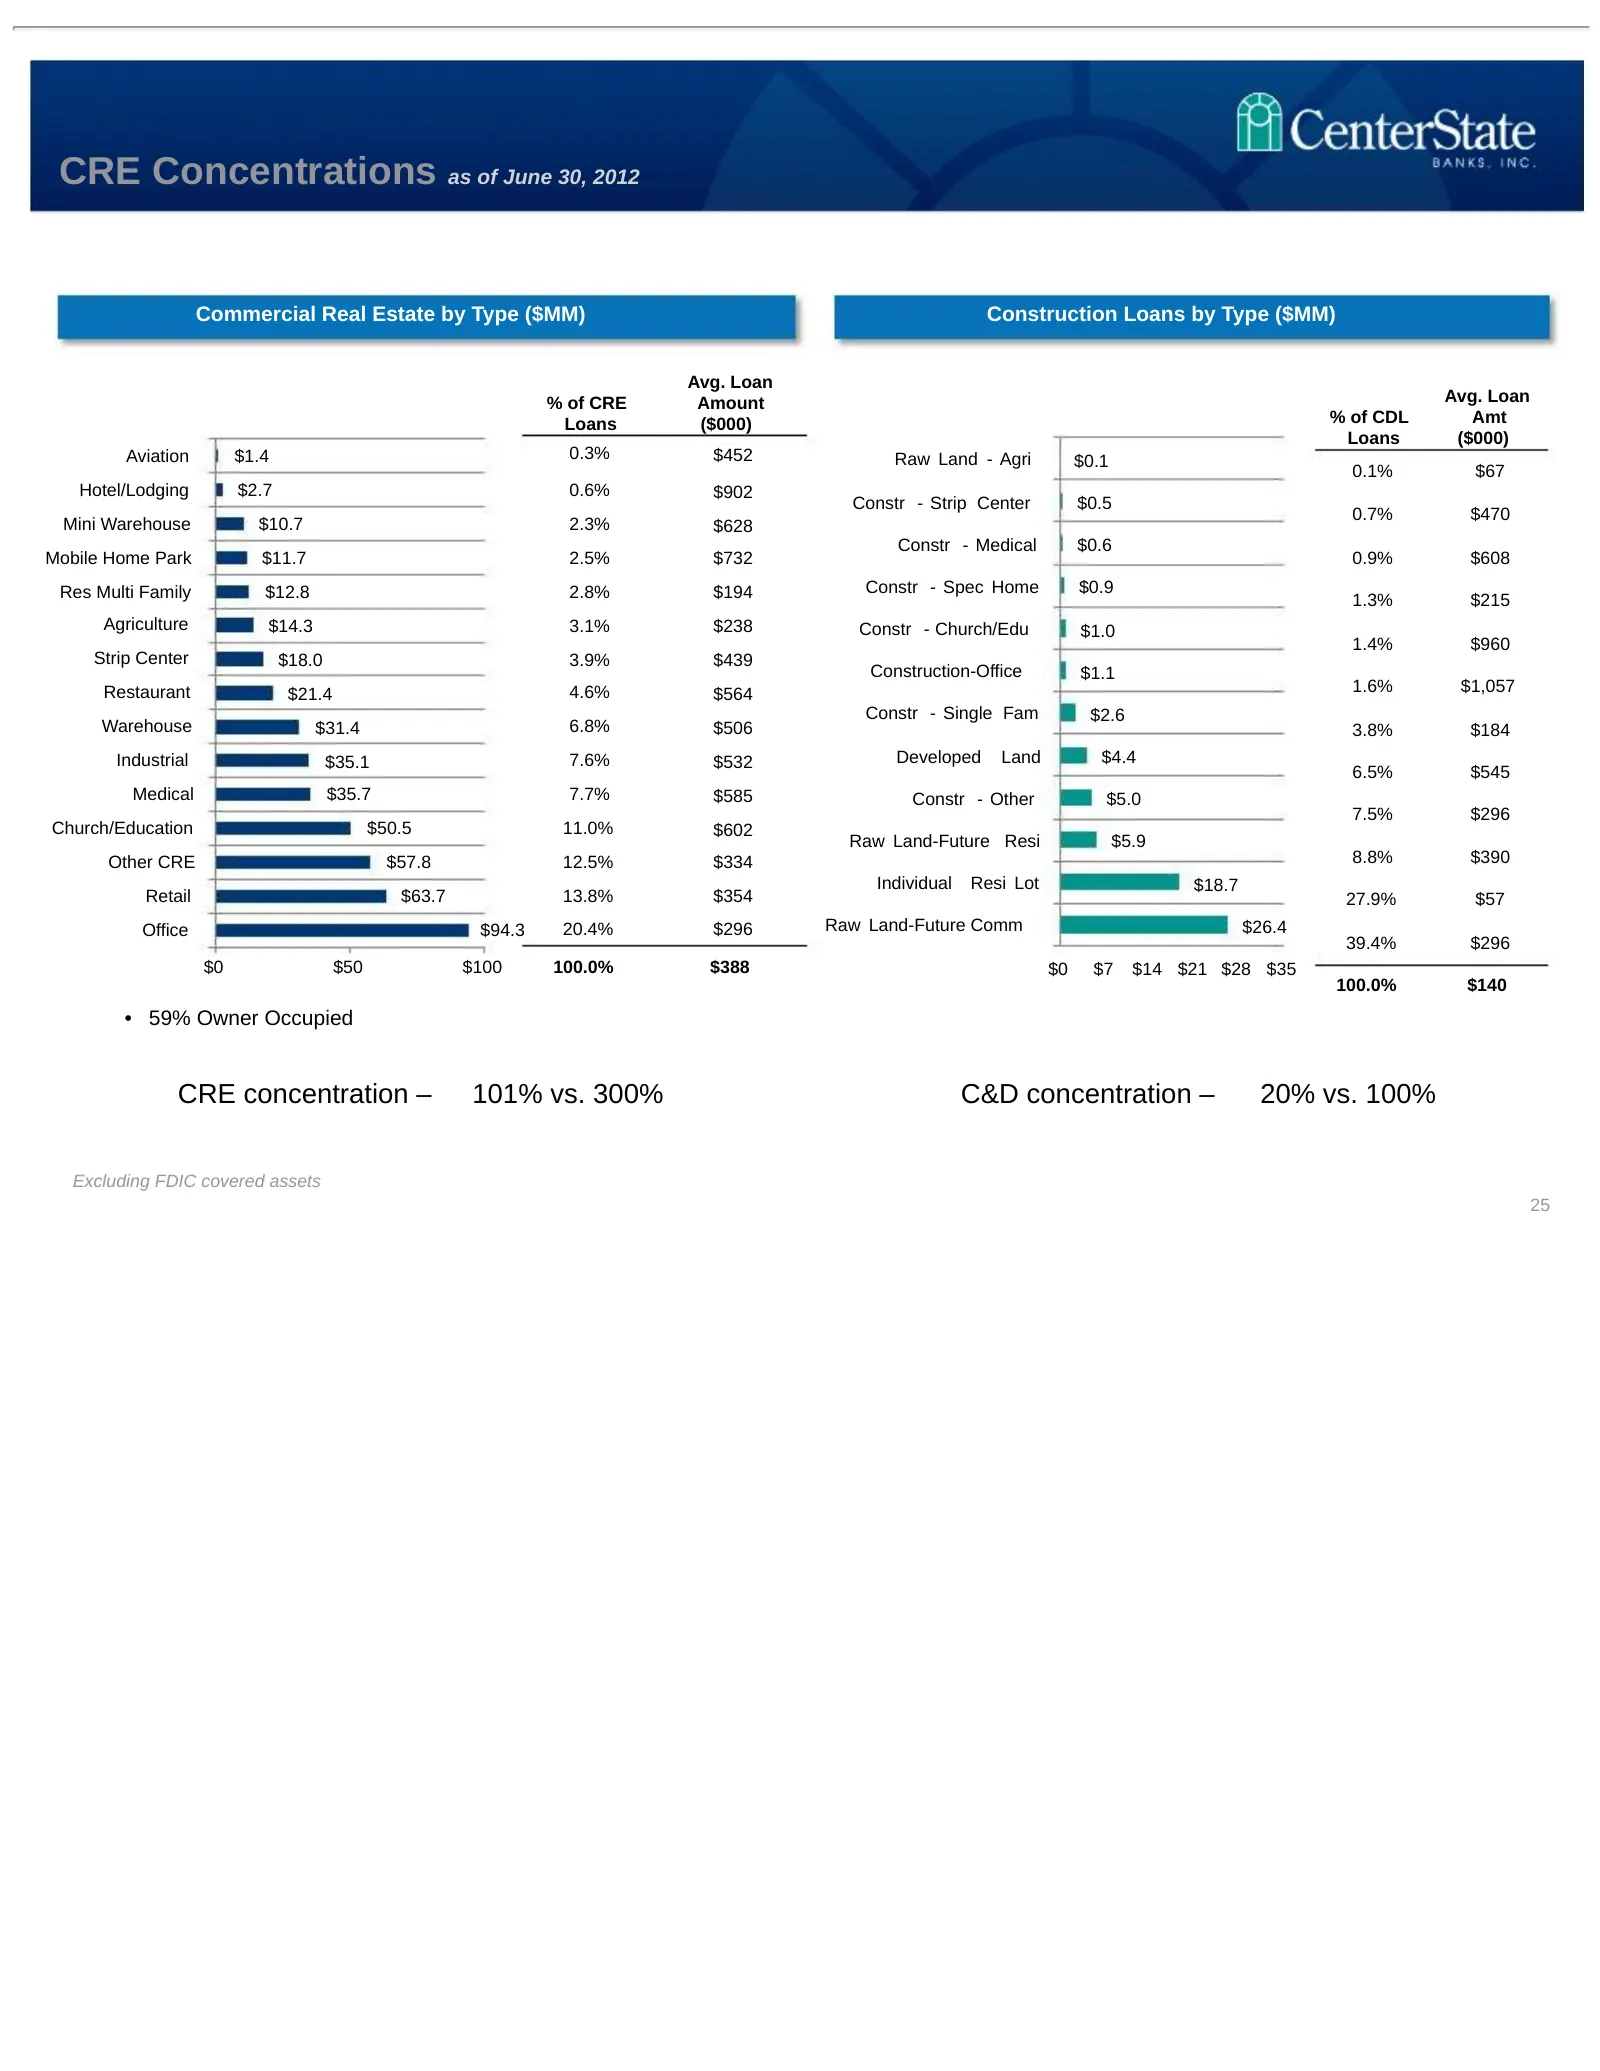
CRE Concentrations as of June 30, 2012 Commercial Real Estate by Type ($MM) Construction Loans by Type ($MM) Avg. Loan % of CRE Amount Avg. Loan Loans ($000) % of CDL Amt Loans ($000) Aviation $1.4 0.3% $452 Raw Land - Agri $0.1 0.1% $67 Hotel/Lodging $2.7 0.6% $902 Constr - Strip Center $0.5 0.7% $
Source: SEC EDGAR · 8-K filed Aug 13, 2012
More decks from CenterState Bank Corporation
 IPO Roadshow (May 2020)42 slides · May 21, 2020
 D.A. Davidson 22nd Annual Financial Institution Virtual Conference (May 2020)25 slides · May 6, 2020
 Q1 2020 Earnings Presentation25 slides · Apr 23, 2020
 Merger or Acquisition (January 2020)24 slides · Jan 27, 2020
 Q3 2019 Earnings Presentation28 slides · Nov 4, 2019
 Investor Presentation (July 2019)28 slides · Jul 30, 2019