QVC Group, Inc. · NASDAQ:QVCG
QVC — Liberty Media — Investor Day (September 2008)
144 slides from QVC's investor day presentation, Sep 26, 2008
Slide 1: Liberty Media Investor Meeting 9.26.2008
Liberty Media Investor Meeting 9.26.2008
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation includes certain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995, including statements about financial guidance, business strategies, market potential, future financial performance, new service and pro
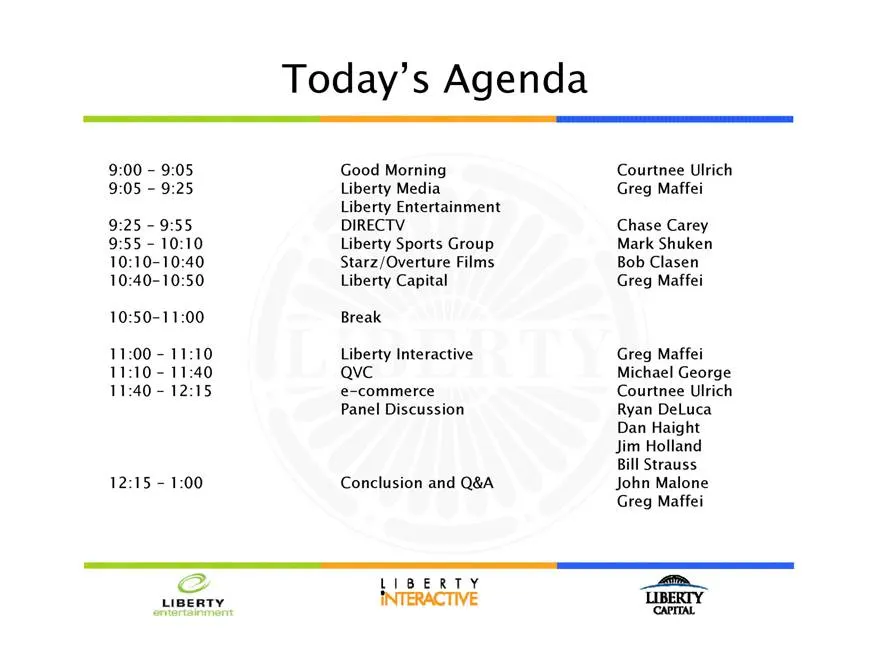
Slide 3: Today's Agenda
Today’s Agenda 9:00 - 9:05 Good Morning Courtnee Ulrich 9:05 - 9:25 Liberty Media Greg Maffei Liberty Entertainment 9:25 – 9:55 DIRECTV Chase Carey 9:55 – 10:10 Liberty Sports Group Mark Shuken 10:10-10:40 Starz/Overture Films Bob Clasen 10:40-10:50 Liberty Capital Greg Maffei 10:50-11:00 Break 11:0
Slide 4: Innovate, Execute, Grow
Innovate, Execute, Grow Gregory B. Maffei President and CEO
Slide 5: Since we met last September…
Since we met last September… Completed swap: NWS for DTV and RSNs · Bought 7% more of DTV Introduced Liberty Entertainment tracking stock Announced split-off of Liberty Entertainment Repurchased 14% of LCAPA in response to market conditions Completed three attractive e-commerce acquisitions at Liber
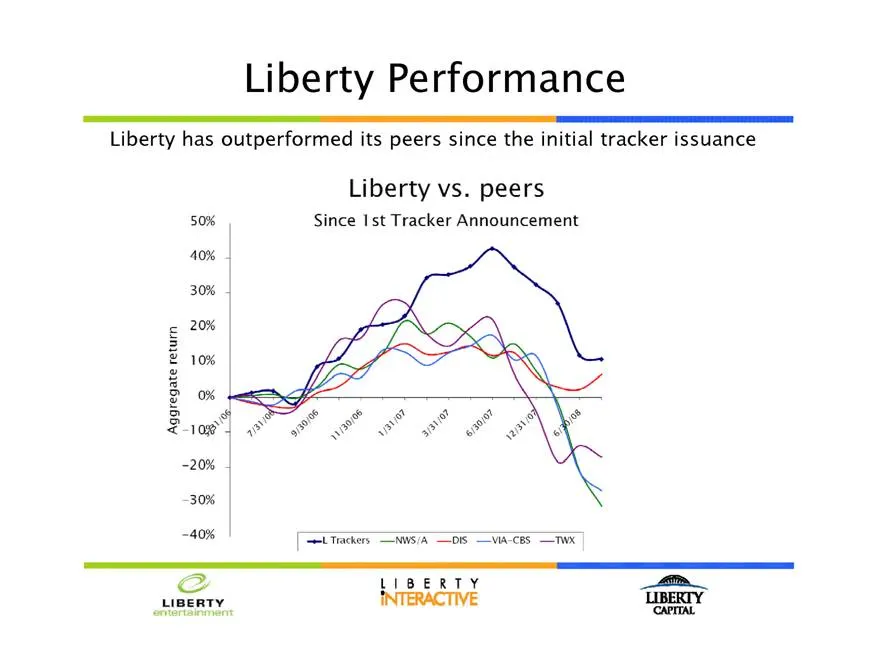
Slide 6: Liberty Performance
Liberty Performance Liberty has outperformed its peers since the initial tracker issuance
Slide 7: What We Do Well
What We Do Well 1. Innovate, especially financially 2. Manage our portfolio of businesses 3. Empower operating managers
Slide 8: Financial Innovation
Financial Innovation Liberty Entertainment · NWS swap – value accretion and increased asset basis · DTV collar and 78.3m share purchase · Encouraged DTV buyback and completed voting standstill Liberty Capital · Share buybacks - reduced outstanding shares by 14% · Tax-efficient transactions, e.g., §3
Slide 9: Swap / Transaction History
Swap / Transaction History News Corp – up $6.5b since deal announcement · NWS down >42%, DTV+3.5% Time Warner - swapped 68.5m TWX shares at ~$21 vs. current $13.96 · Up ~$800m on trade and tax benefits CBS - swapped 7.6m CBS shares tax-free at $30.82 v. current $14.72 OnCommand - sold OnCommand for
Slide 10: Be Safe
Be Safe Protect our downside · Financial innovation limits our equity and other exposure Ensure liquidity · For operations, debt maturities, and opportunities Manage exposure · Counterparty exposure limited to high quality names Corporate cash in AAA and Treasury funds · Not perfect: some risk in mo
Slide 11: Manage Our Portfolio
Manage Our Portfolio Allocate capital · Invest in attractive opportunities · Divest unattractive and non-core businesses and assets tax-efficiently Encourage efficiencies and synergy · Consolidate overlapping costs, especially overhead · Incent managers to work together Create options · Preserve str
Slide 12: Empower Our Managers
Empower Our Managers Part of Liberty’s appeal is (relative) autonomy Encourage CEOs and management teams to work together · Financial incentives · CEO council · Marketing summit, marketing wiki · Strategic purchasing initiative Offer platforms for learning that require Liberty’s scale · NetLeaders F
Slide 13: Objectives and Strategy
Objectives and Strategy Liberty Entertainment · Complete split-off, reduce discount to SOP · Explore DTV options · Consider content and distribution investments Liberty Capital · Rationalize assets tax-efficiently · Deploy cash derived from tax shield · Repurchase stock opportunistically with excess
Slide 14: Chase Carey
Chase Carey President & CEO _ DIRECTV’ LIBERTY
Slide 15: The DIRECTV Group Cautionary Statement
The DIRECTV Group Cautionary Statement This presentation includes certain statements that may be considered to be, “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 (“PSLRA”). These forward-looking statements generally can be identified by words
Slide 16: Goal: Deliver The Best TV Experience
Goal: Deliver The Best TV Experience Through Leadership In: Content Technology Service
Slide 17: Financial Objectives
Financial Objectives Solid Top Line Growth Increasing Margins Strong Cash Flow Growth
Slide 18: Strong First Half Results
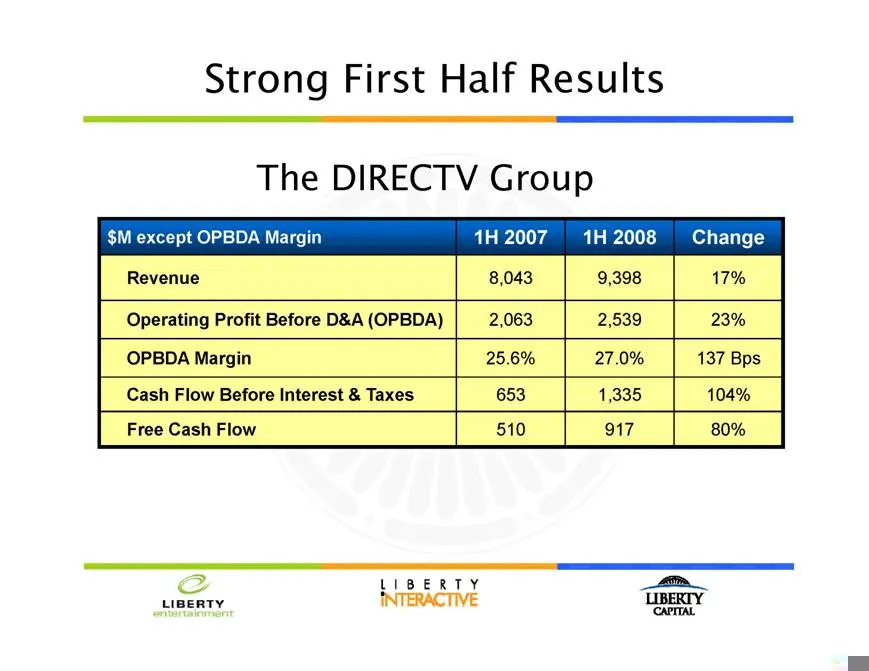
Strong First Half Results The DIRECTV Group $M except OPBDA Margin 1H 2007 1H 2008 Change Revenue 8,043 9,398 17% Operating Profit Before D&A (OPBDA) 2,063 2,539 23% OPBDA Margin 25.6% 27.0% 137 Bps Cash Flow Before Interest & Taxes 653 1,335 104% Free Cash Flow 510 917 80%
Slide 19: High Quality Subscriber Growth
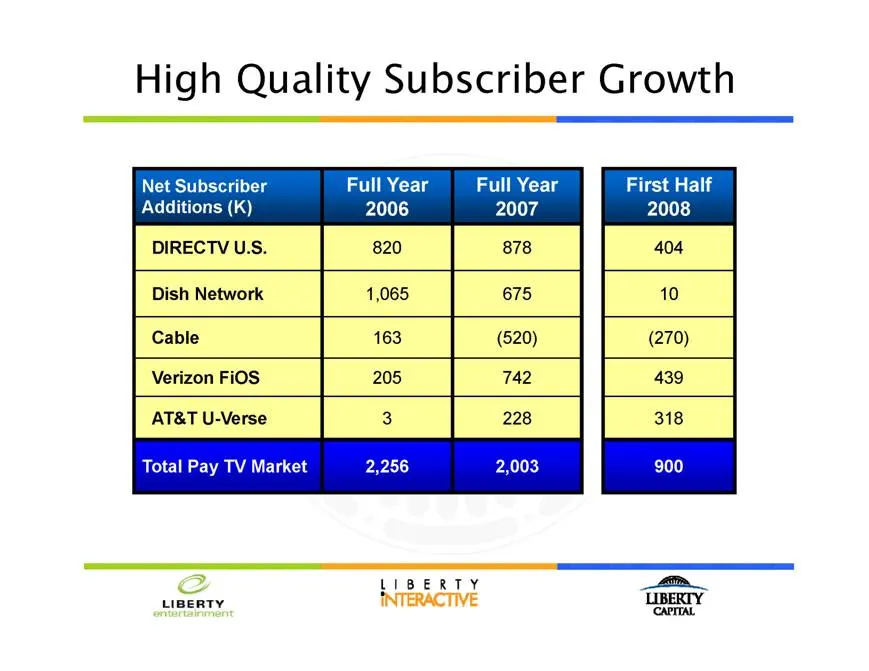
High Quality Subscriber Growth Net Subscriber Full Year Full Year First Half Additions (K) 2006 2007 2008 DIRECTV U.S. 820 878 404 Dish Network 1,065 675 10 Cable 163 (520) (270) Verizon FiOS 205 742 439 AT&T U-Verse 3 228 318 Total Pay TV Market 2,256 2,003 900
Slide 20: Unique Marketing Strengths
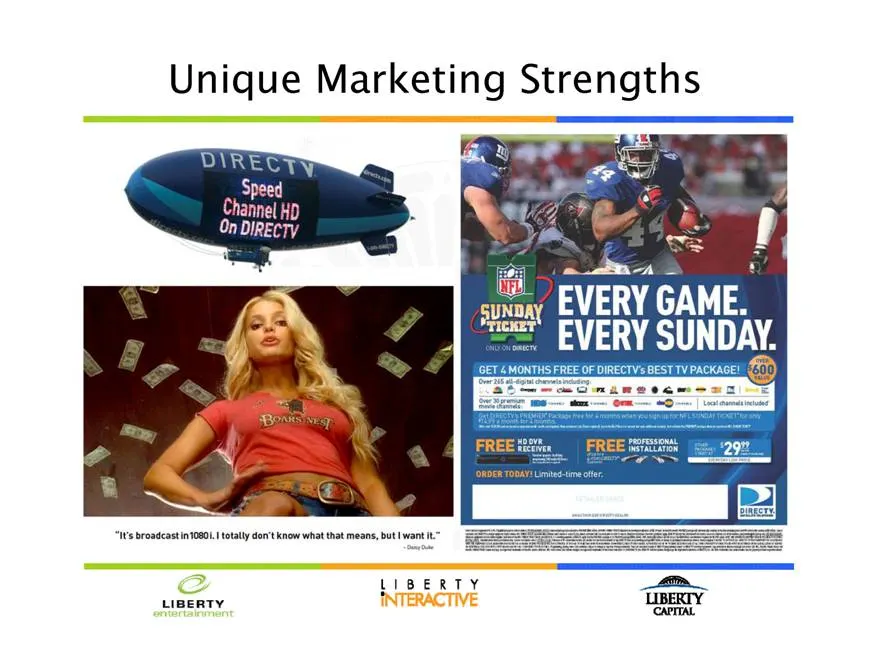
Unique Marketing Strengths -sunaay EVERY GAME. ==. EVERY oN “W's broadcastint0s0.| totally don't know what that means, but want It Cc LIBERTY _ LIBERTY LIBERTY
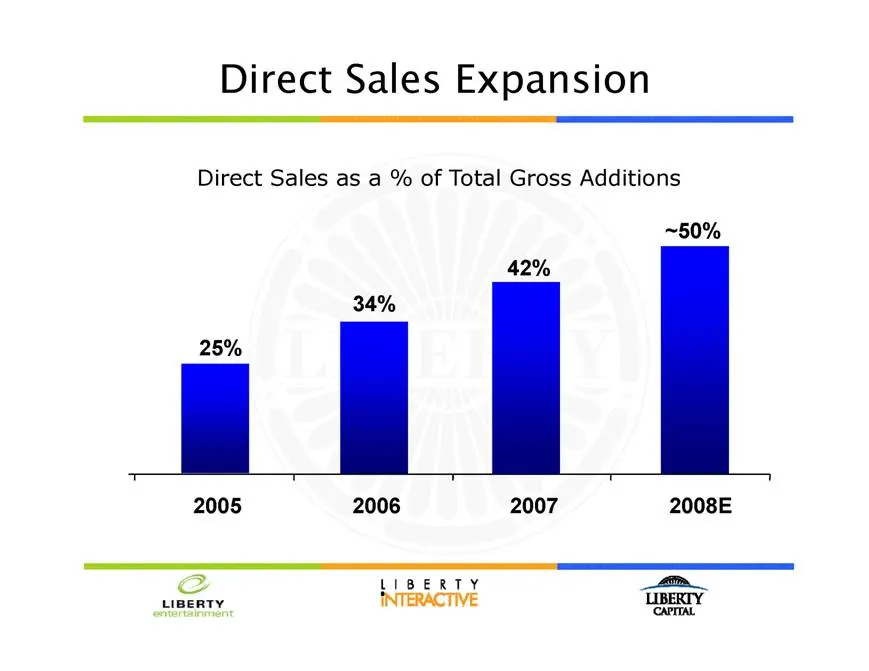
Slide 21: Direct Sales Expansion
Direct Sales Expansion Direct Sales as a % of Total Gross Additions ~50% 42% 34% 25% 2005 2006 2007 2008E
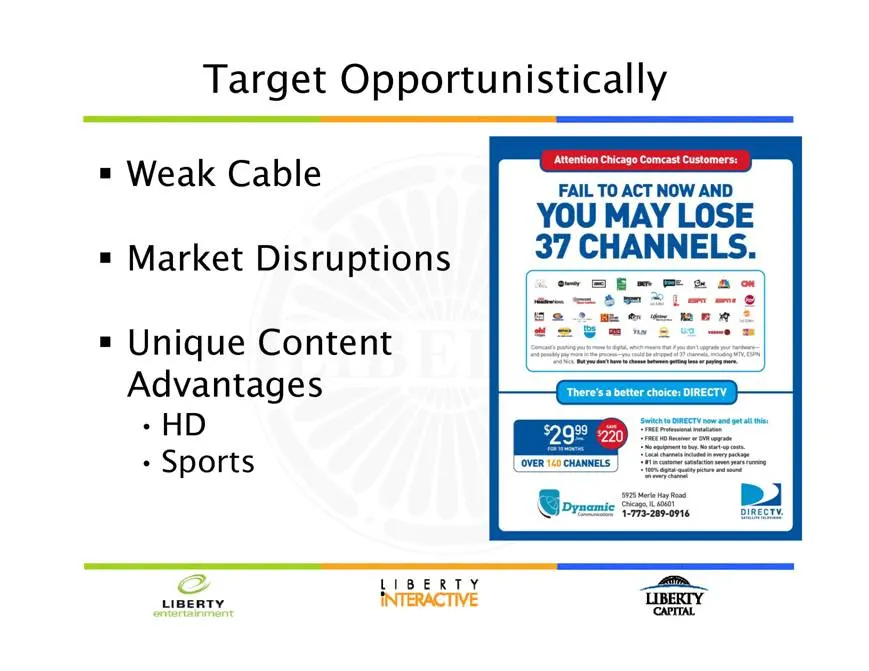
Slide 22: Target Opportunistically
Target Opportunistically Weak Cable Market Disruptions Unique Content Advantages · HD · Sports
Slide 23: Build Key Niches
Build Key Niches Commercial MDU Ethnic Rural
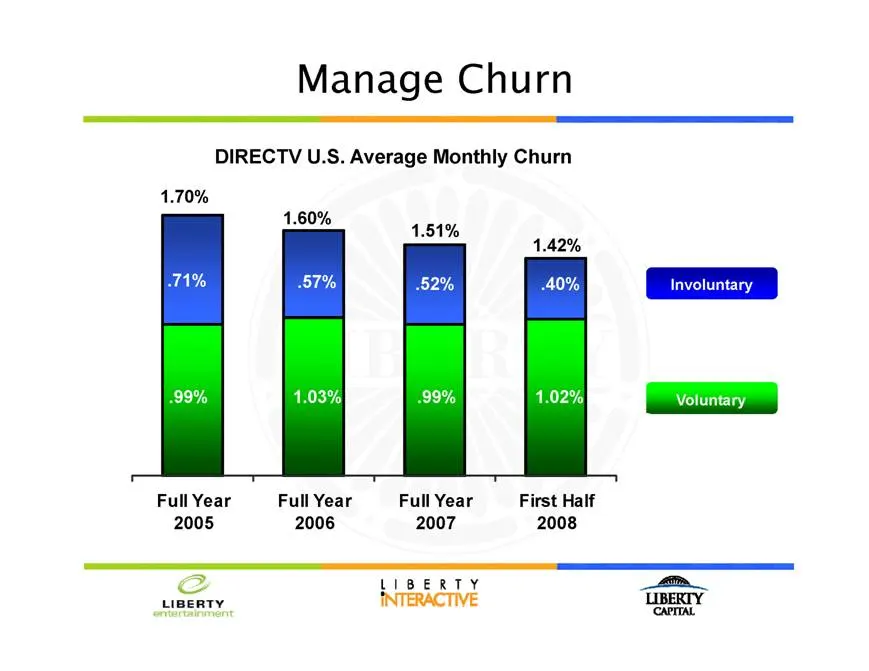
Slide 24: Manage Churn
Manage Churn DIRECTV U.S. Average Monthly Churn 1.70% 1.60% 1.51% 1.42% .71% .57% .52% .40% .99% 1.03% .99% 1.02% Full Year Full Year Full Year First Half 2005 2006 2007 2008 Involuntary Voluntary
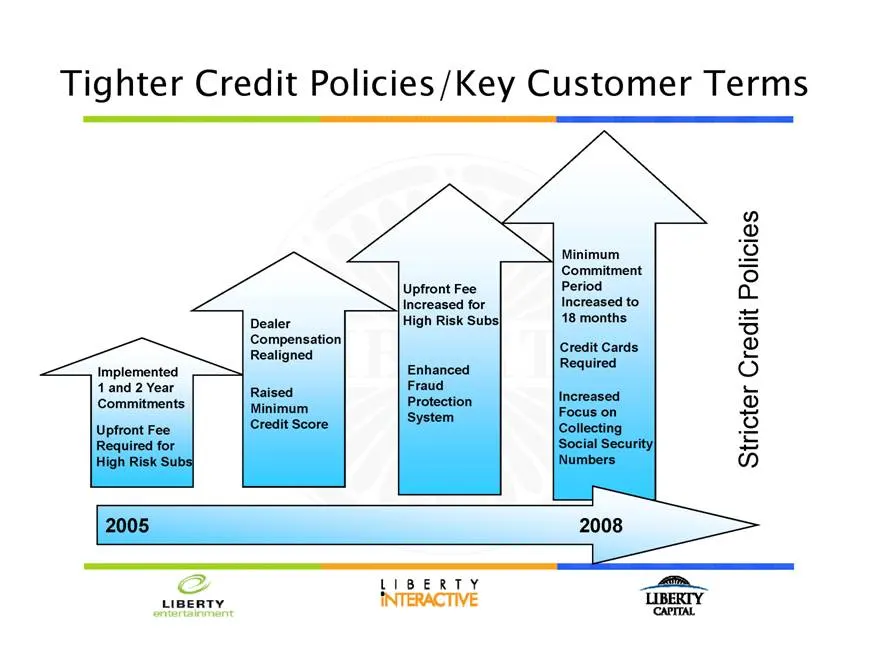
Slide 25: Tighter Credit Policies/Key Customer Terms
Tighter Credit Policies/Key Customer Terms Dealer Compensation Implemented Realigned 1 and 2 Year Raised Commitments Minimum Upfront Fee Credit Score Required for High Risk Subs 2005 Upfront Fee Increased for High Risk Subs Enhanced Fraud Protection System Minimum Commitment Period Increased to 18 m
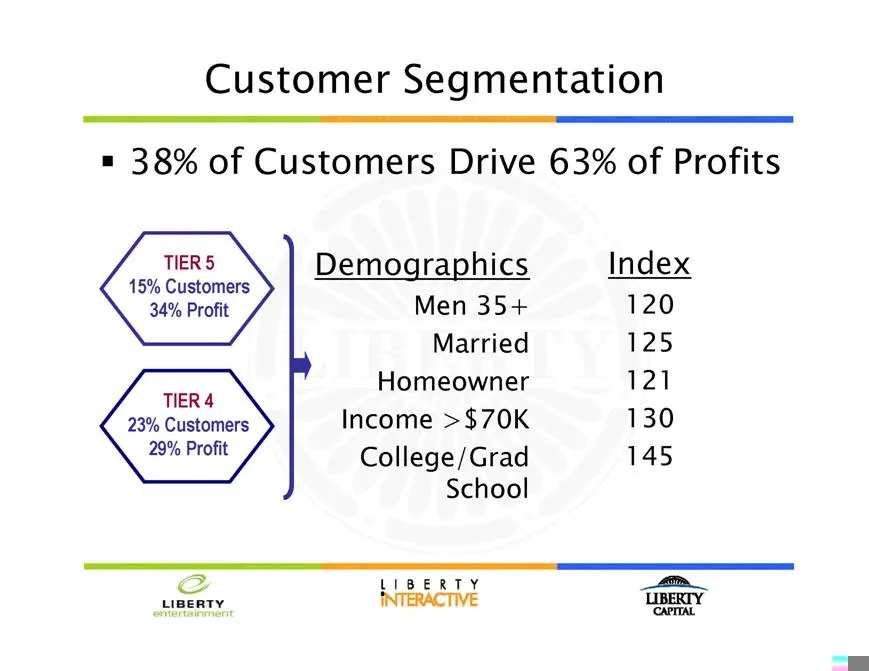
Slide 26: Customer Segmentation
Customer Segmentation 38% of Customers Drive 63% of Profits TIER 5 15% Customers 34% Profit TIER 4 23% Customers 29% Profit Demographics Index 120 Men 35+ 125 Married 121 Homeowner Income >$70K 130 145 College/Grad School
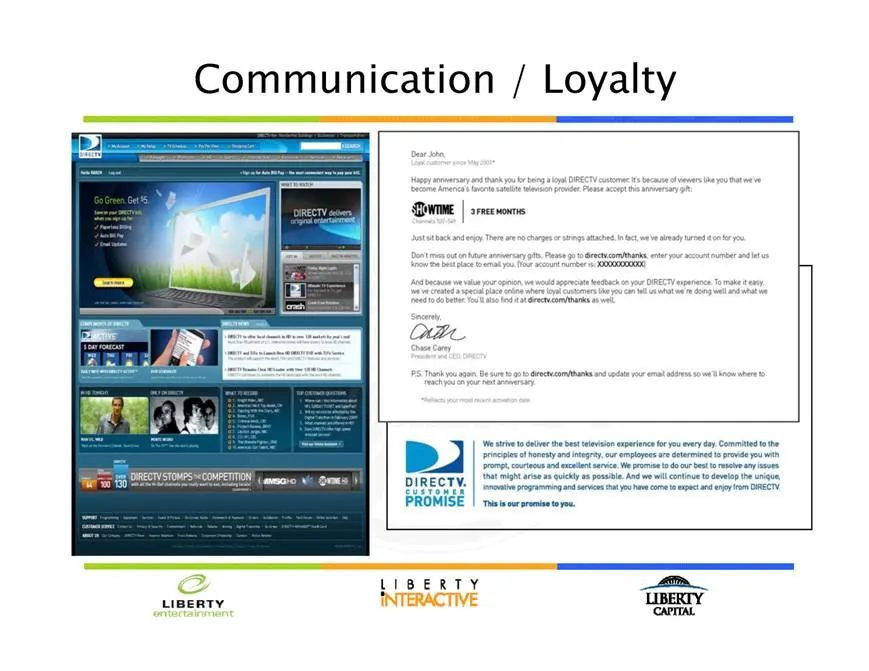
Slide 27: Communication / Loyalty
Communication / Loyalty LIBERTY
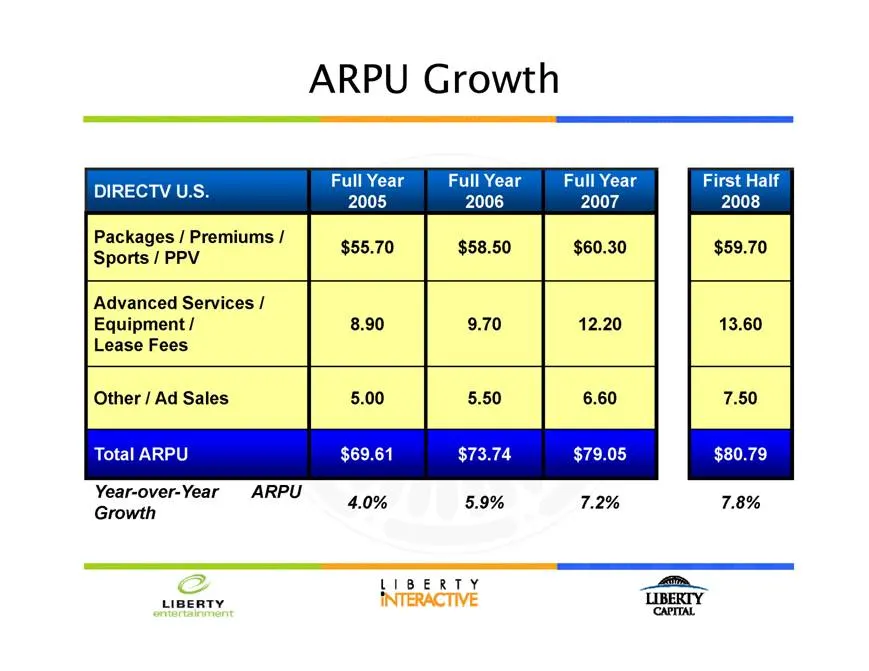
Slide 28: ARPU Growth
ARPU Growth DIRECTV U.S. Full Year Full Year Full Year First Half 2005 2006 2007 2008 Packages / Premiums / $55.70 $58.50 $60.30 $59.70 Sports / PPV Advanced Services / Equipment / 8.90 9.70 12.20 13.60 Lease Fees Other / Ad Sales 5.00 5.50 6.60 7.50 Total ARPU $69.61 $73.74 $79.05 $80.79 Year-over-
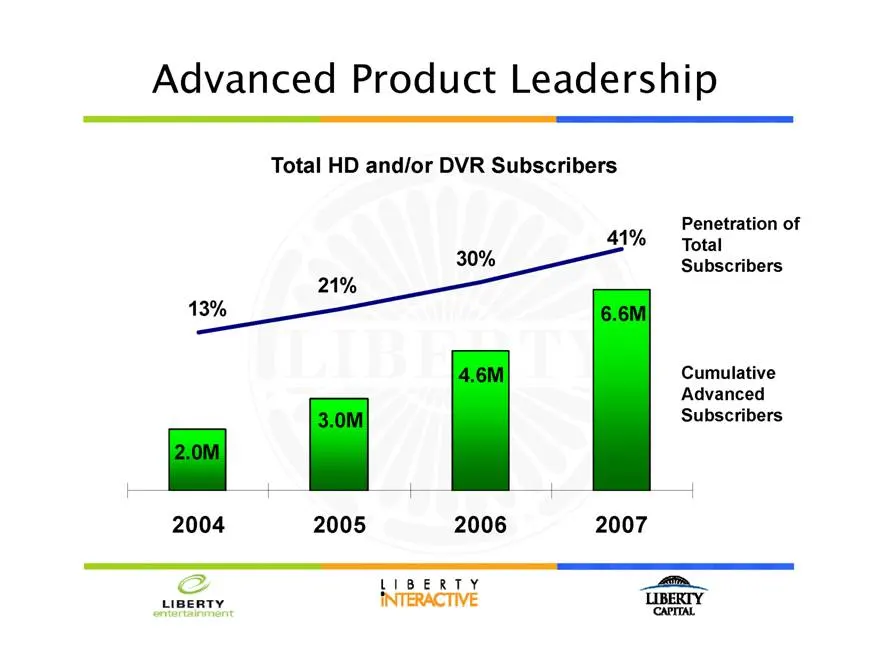
Slide 29: Advanced Product Leadership
Advanced Product Leadership Total HD and/or DVR Subscribers 41% 30% 21% 13% 6.6M 4.6M 3.0M 2.0M Penetration of Total Subscribers Cumulative Advanced Subscribers 2004 2005 2006 2007
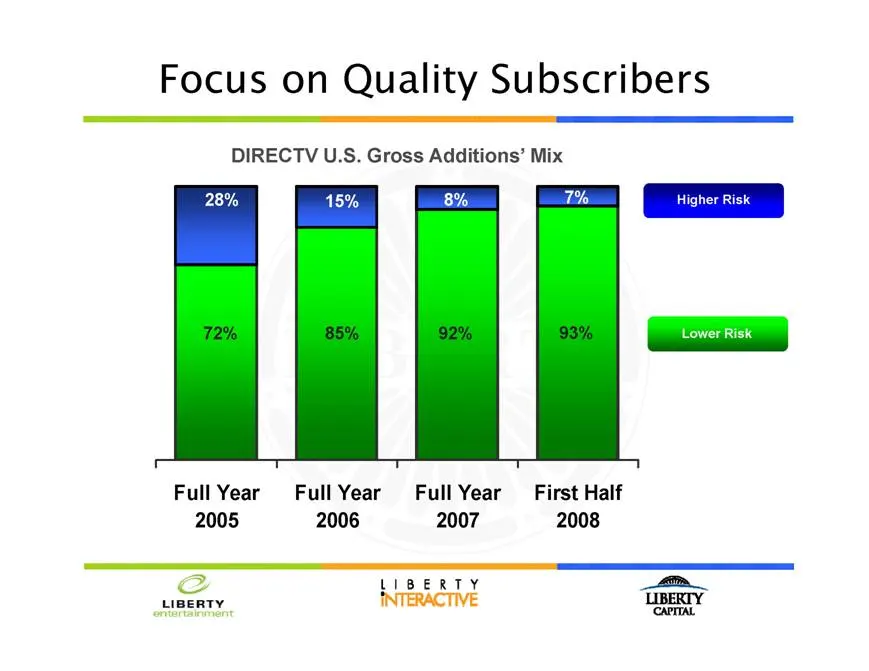
Slide 30: Focus on Quality Subscribers
Focus on Quality Subscribers DIRECTV U.S. Gross Additions’ Mix 28% 15% 8% 7% Higher Risk 72% 85% 92% 93% Lower Risk Full Year Full Year Full Year First Half 2005 2006 2007 2008
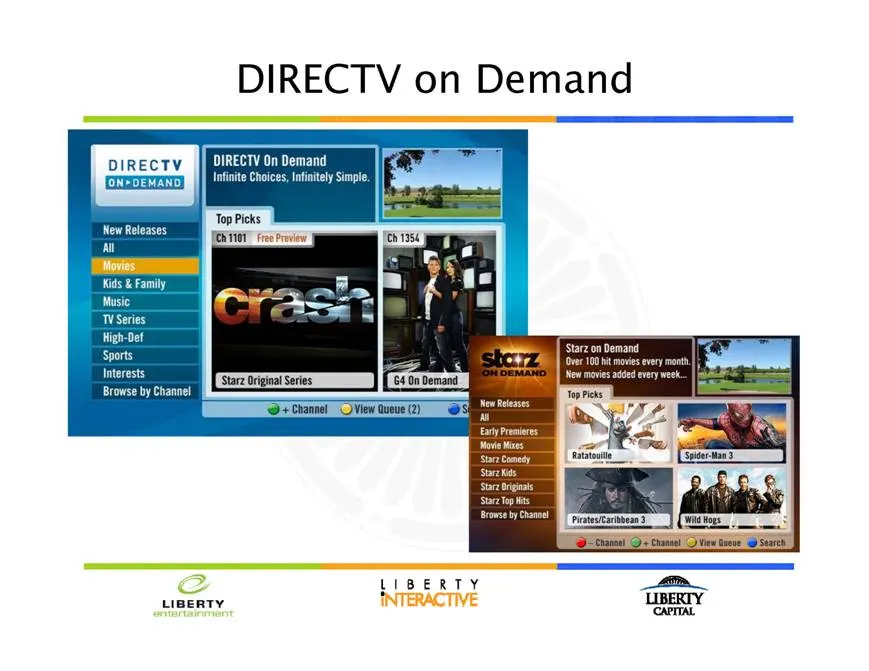
Slide 31: DIRECTV on Demand
DIRECTV on Demand pirecty |e FoNeD MANDI | |nfnite Choices, Infinitely Simple, Top Picks New Releases Cc LIBERTY = JiSEETy, INTERACTIVE TIBERTY
Slide 32: Advertising Opportunities
Advertising Opportunities Interactive Telescoping Local Advertising DVR Insertion Audience Measurement
Slide 33: Content Leadership
Content Leadership all wm ne PT00 BP @® Avo dag EsrnHD QWHD fen’ S&NBC HD ——_ © J me S x HD# Ce nares =SrnzwS VERSUSHD Dovmyg iid WBtis <5 n> By CE 3. Tos con NO ee ee FUR) LIBERTY aa INTERACTIVE LIBERTY
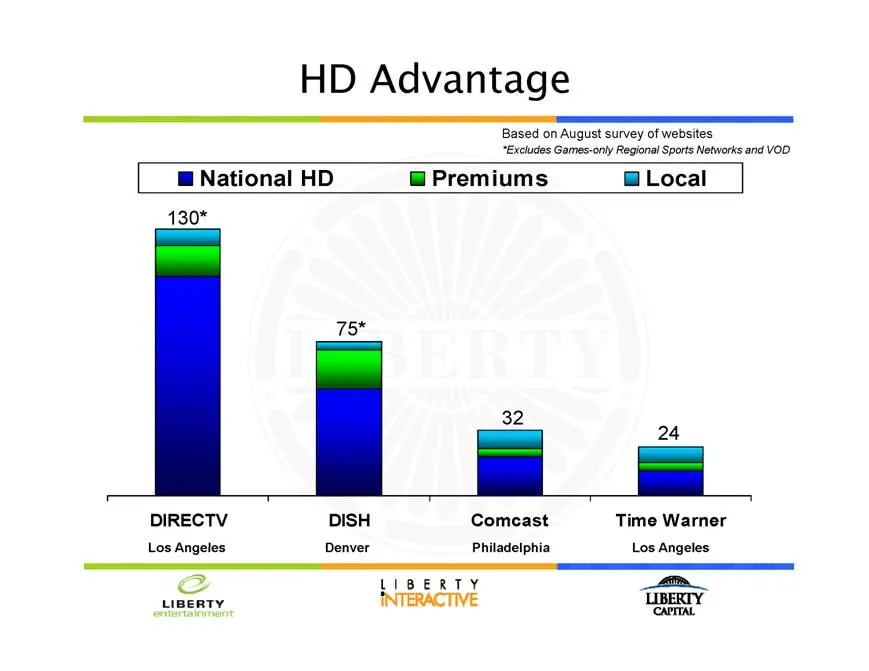
Slide 34: HD Advantage
HD Advantage Based on August survey of websites *Excludes Games-only Regional Sports Networks and VOD National HD Premiums Local 130* 75* 32 24 DIRECTV DISH Comcast Time Warn Los Angeles Denver Philadelphia Los Angeles
Slide 35: Sports Leadership
Sports Leadership ~ Red DIRECTV = ONLY ON DIRECTV. STRIKE zone} a Masters m6 & ae. Coie? CS a fe min Tey “CAPITAL
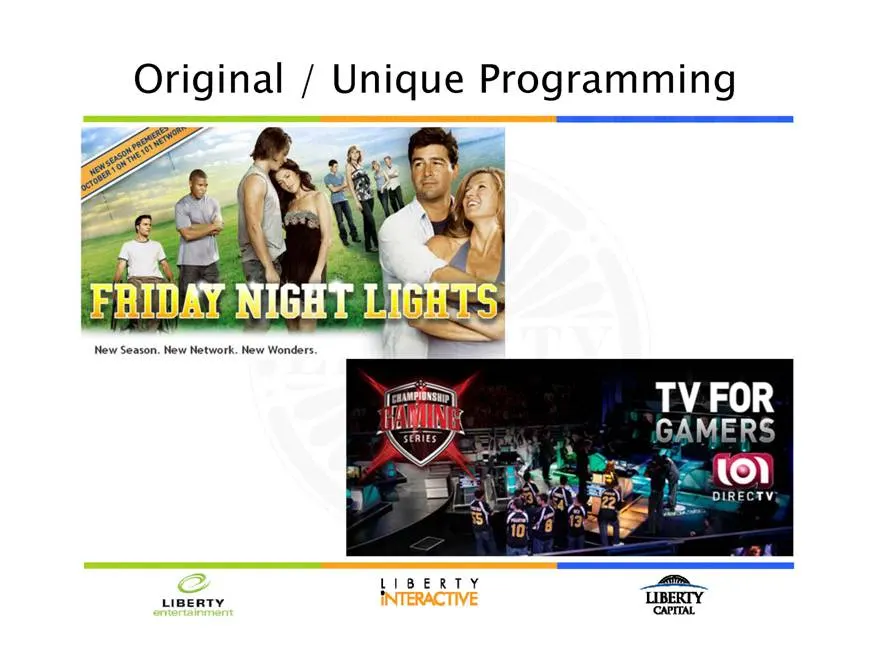
Slide 36: Original / Unique Programming
Original / Unique Programming
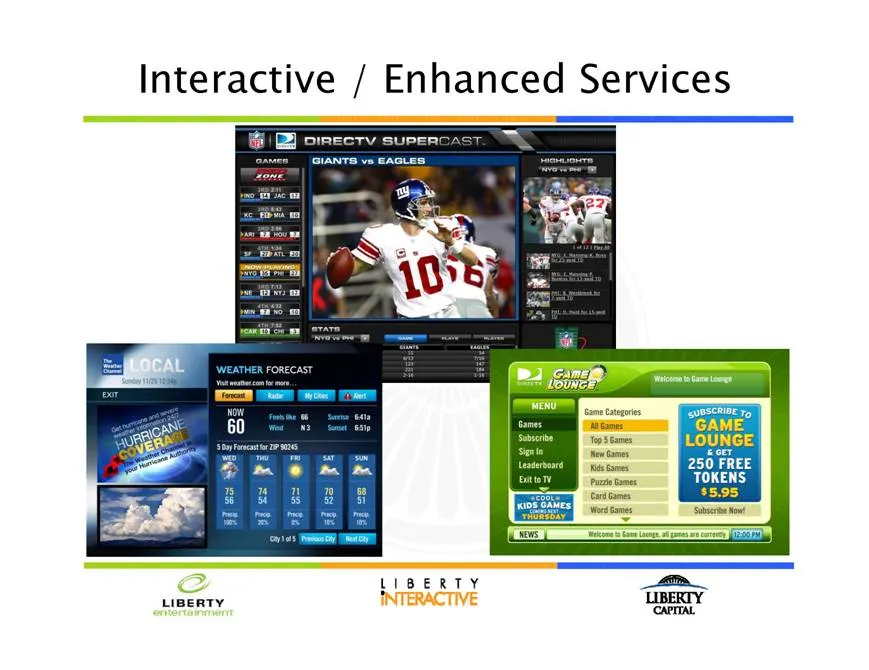
Slide 37: Interactive / Enhanced Services
Interactive / Enhanced Services
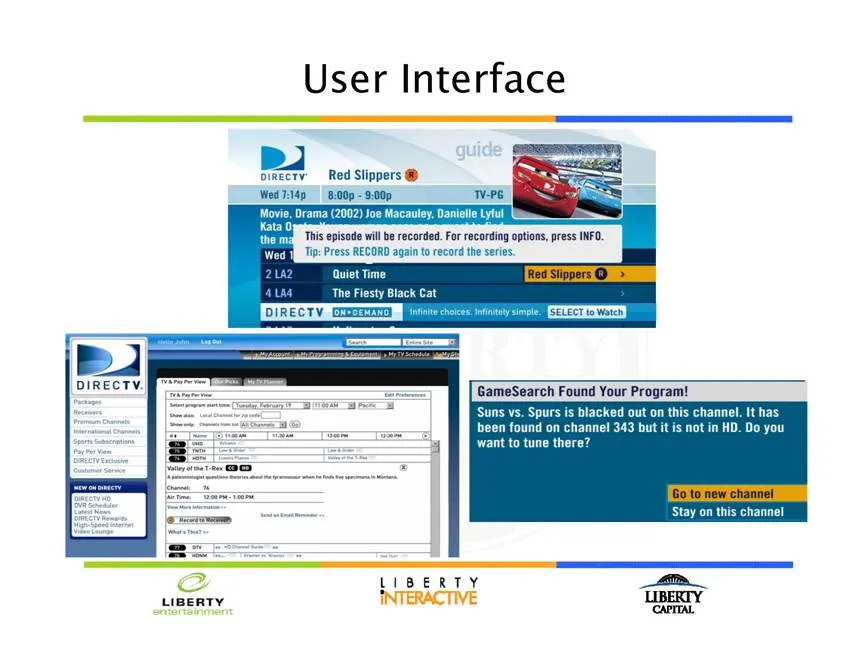
Slide 38: User Interface
User Interface oirecry’ Red Slippers @® Quiet Time l The Fiesty Black Cat DIRECTY mmm By DIRECTV. GameSearch Found Your Program! Suns vs. Spurs is blacked out on this channel. It has been found on channel 343 but it is not in HD. Do you want to tune there? Stay on this channel LIBERTY LIBERTY INTERA
Slide 39: Technology and Engineering
Technology and Engineering Improve Reliability Upgradeable Add Functionality Next Gen/Whole Home Experience
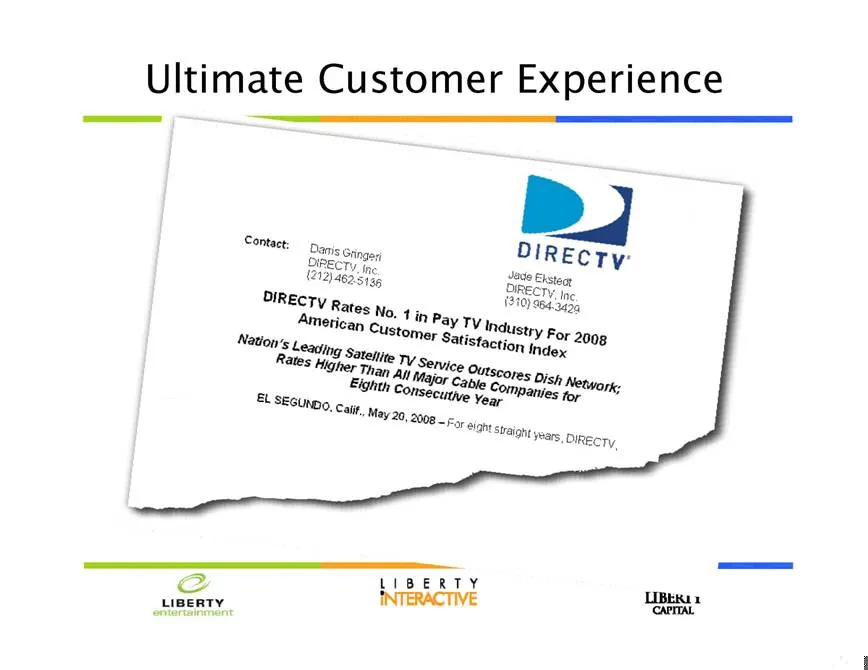
Slide 40: Ultimate Customer Experience
Ultimate Customer Experience
Slide 41: Optimize Quality and Efficiencies
Optimize Quality and Efficiencies Simplify and Standardize Technology Advancements · Home Installation · Wireless Handheld · New Diagnostic Tools Increased Self-Care · Web · IVR
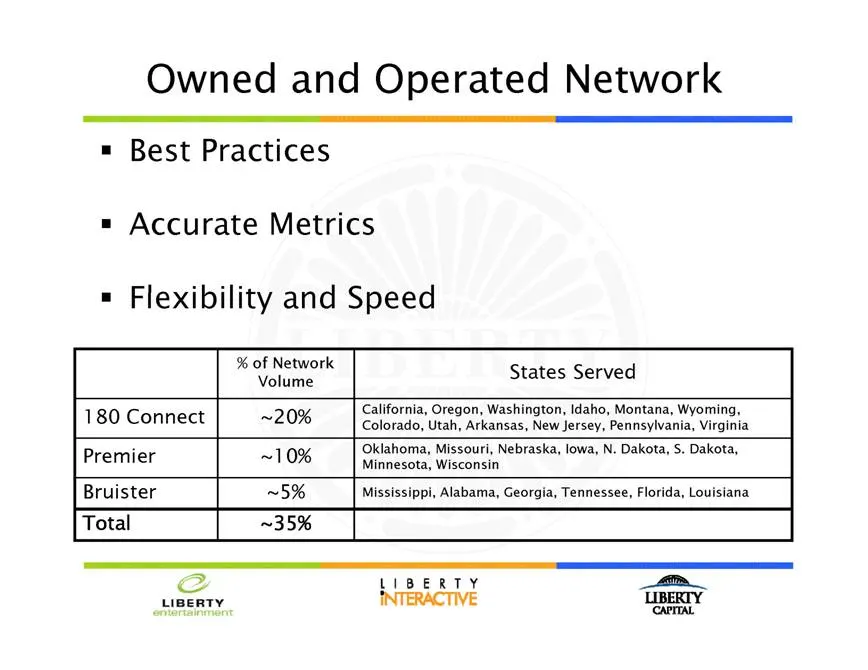
Slide 42: Owned and Operated Network
Owned and Operated Network Best Practices Accurate Metrics Flexibility and Speed % of Network States Served Volume 180 Connect ~20% California, Oregon, Washington, Idaho, Montana, Wyoming, Colorado, Utah, Arkansas, New Jersey, Pennsylvania, Virginia Premier ~10% Oklahoma, Missouri, Nebraska, Iowa, N
Slide 43: Subscriber Acquisition and Retention Costs
Subscriber Acquisition and Retention Costs Upward Pressure · Demand for Advanced Products · New Technologies (e.g. Connecting the Home) · Targeting High Quality Subscribers · Equipment Upgrade Flexibility Offsets: · Lower Box Costs · Use of Refurbished Boxes · Installation and Marketing Efficiencies
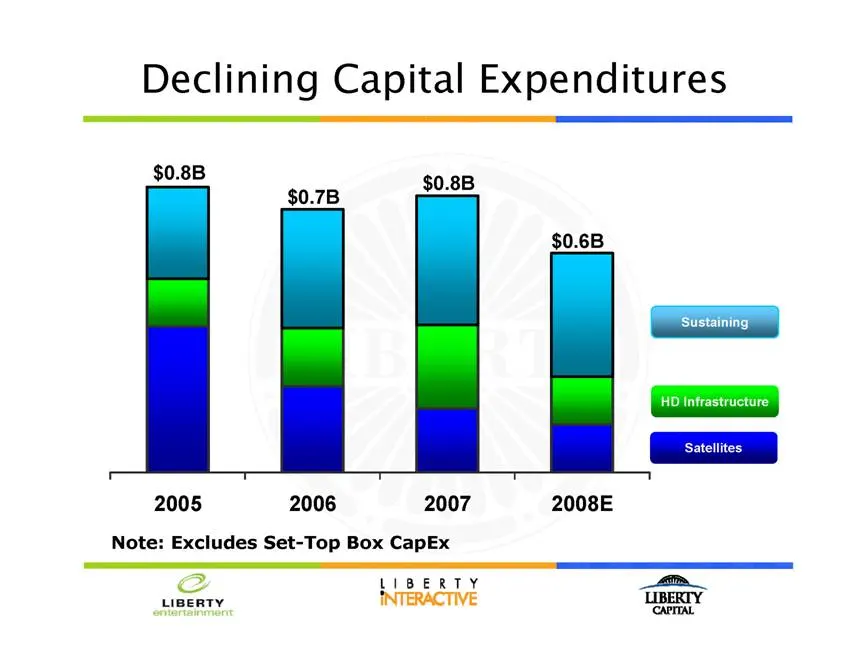
Slide 44: Declining Capital Expenditures
Declining Capital Expenditures $0.8B $0.7B $0.8B $0.6B Sustaining HD Infrastructure Satellites 2005 2006 2007 2008E Note: Excludes Set-Top Box CapEx
Slide 45: DIRECTV U.S. Outlook
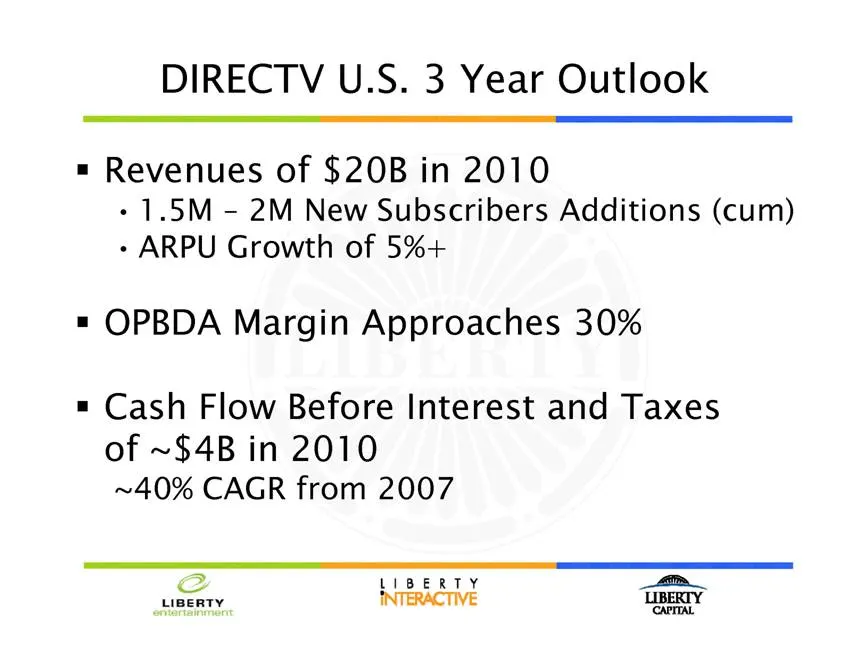
DIRECTV U.S. 3 Year Outlook Revenues of $20B in 2010 · 1.5M – 2M New Subscribers Additions (cum) · ARPU Growth of 5%+ OPBDA Margin Approaches 30% Cash Flow Before Interest and Taxes of ~$4B in 2010 ~40% CAGR from 2007
Slide 46: DIRECTV Latin America
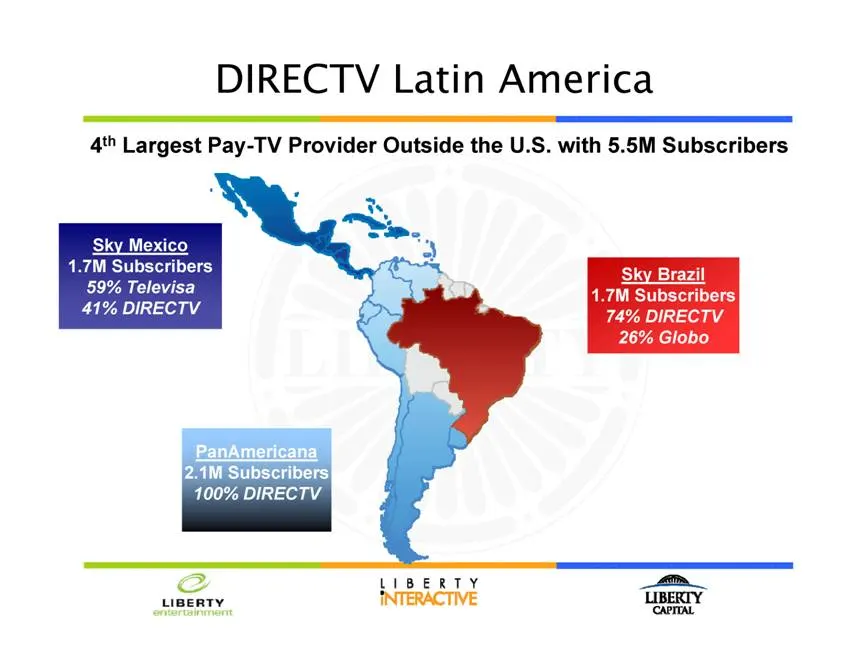
DIRECTV Latin America 4th Largest Pay-TV Provider Outside the U.S. with 5.5M Sub scribers Sky Mexico 1.7M Subscribers 59% Televisa 41% DIRECTV PanAmericana 2.1M Subscribers 100% DIRECTV Sky Brazil 1.7M Subscribers 74% DIRECTV 26% Globo
Slide 47: Latin America Market Overview
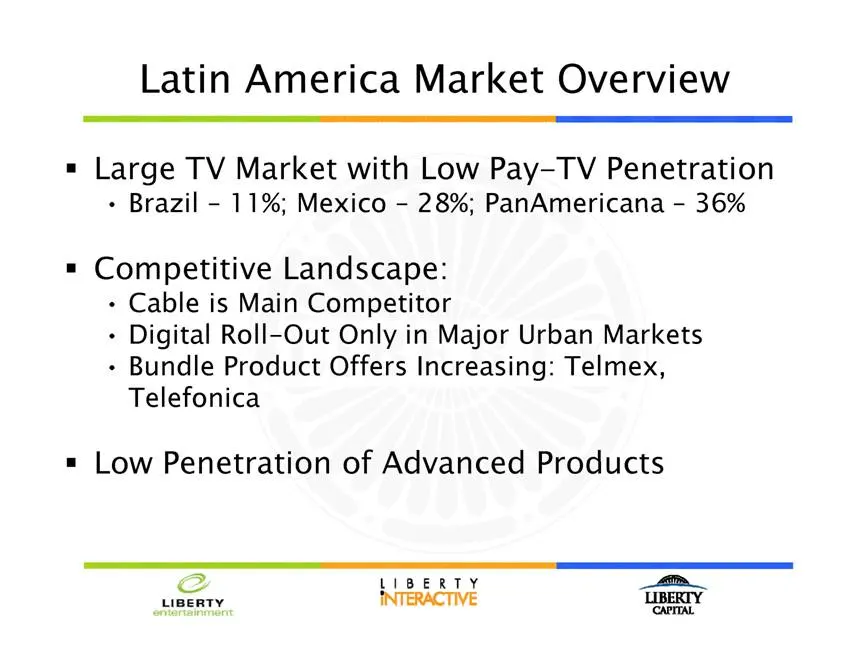
Latin America Market Overview Large TV Market with Low Pay-TV Penetration · Brazil – 11%; Mexico – 28%; PanAmericana – 36% Competitive Landscape: · Cable is Main Competitor · Digital Roll-Out Only in Major Urban Markets · Bundle Product Offers Increasing: Telmex, Telefonica Low Penetration of Advanc
Slide 48: DIRECTV Latin American Strategy
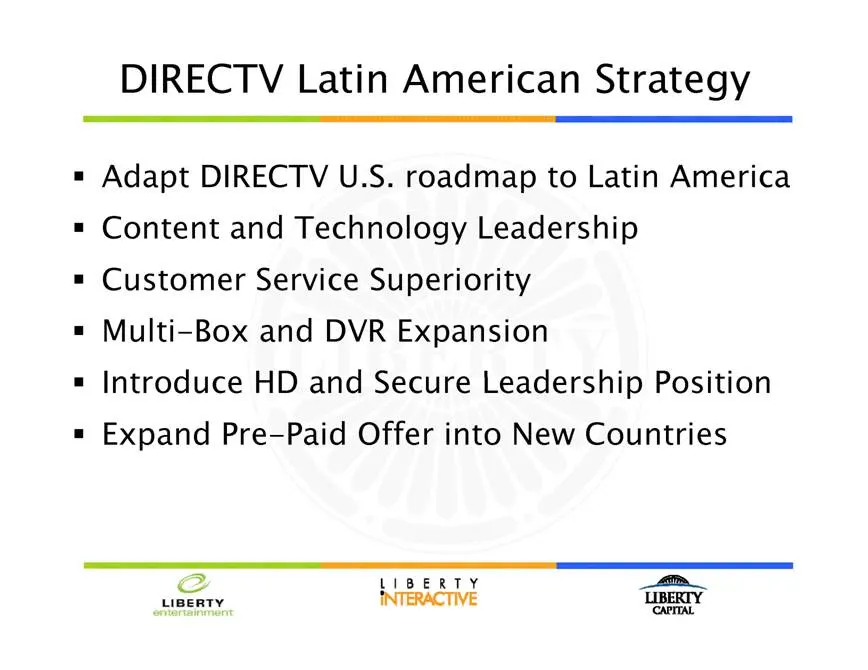
DIRECTV Latin American Strategy Adapt DIRECTV U.S. roadmap to Latin America Content and Technology Leadership Customer Service Superiority Multi-Box and DVR Expansion Introduce HD and Secure Leadership Position Expand Pre-Paid Offer into New Countries
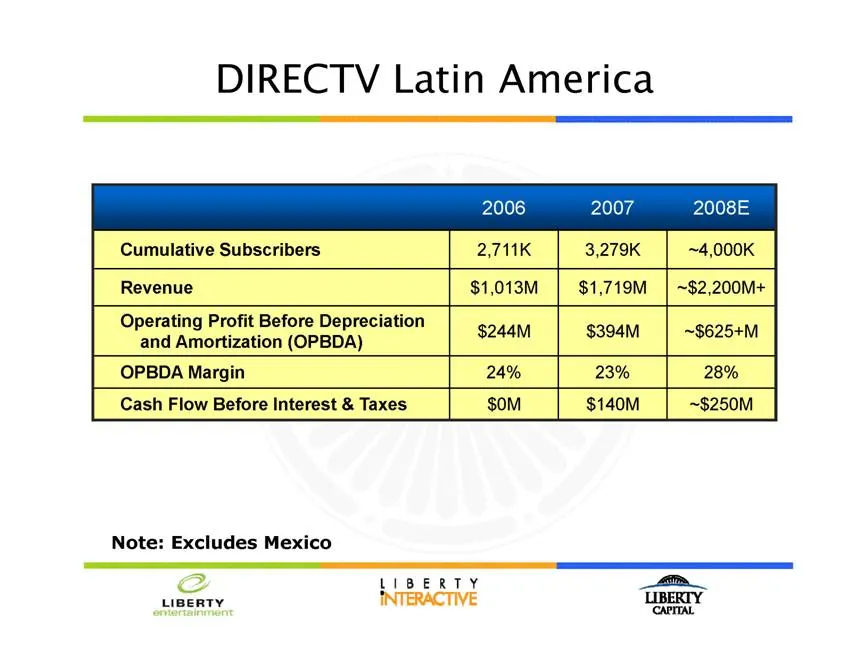
Slide 49: DIRECTV Latin America
DIRECTV Latin America 2006 2007 2008E Cumulative Subscribers 2,711K 3,279K ~4,000K Revenue $1,013M $1,719M ~$2,200M+ Operating Profit Before Depreciation $244M $394M ~$625+M and Amortization (OPBDA) OPBDA Margin 24% 23% 28% Cash Flow Before Interest & Taxes $0M $140M ~$250M Note: Excludes Mexico
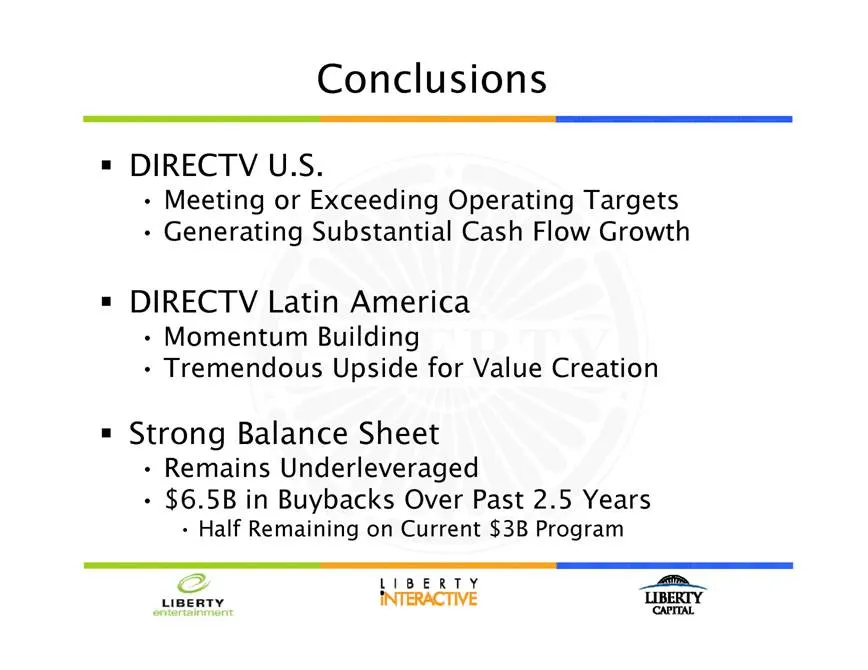
Slide 50: Conclusions
Conclusions DIRECTV U.S. • Meeting or Exceeding Operating Targets • Generating Substantial Cash Flow Growth DIRECTV Latin America • Momentum Building • Tremendous Upside for Value Creation Strong Balance Sheet • Remains Underleveraged • $6.5B in Buybacks Over Past 2.5 Years • Half Remaining on Curre
Slide 51: GOODTV. BETTERTV.
GOODTV. BETTERTV. (D]iiseua’Z LIBERTY INTERACTIVE
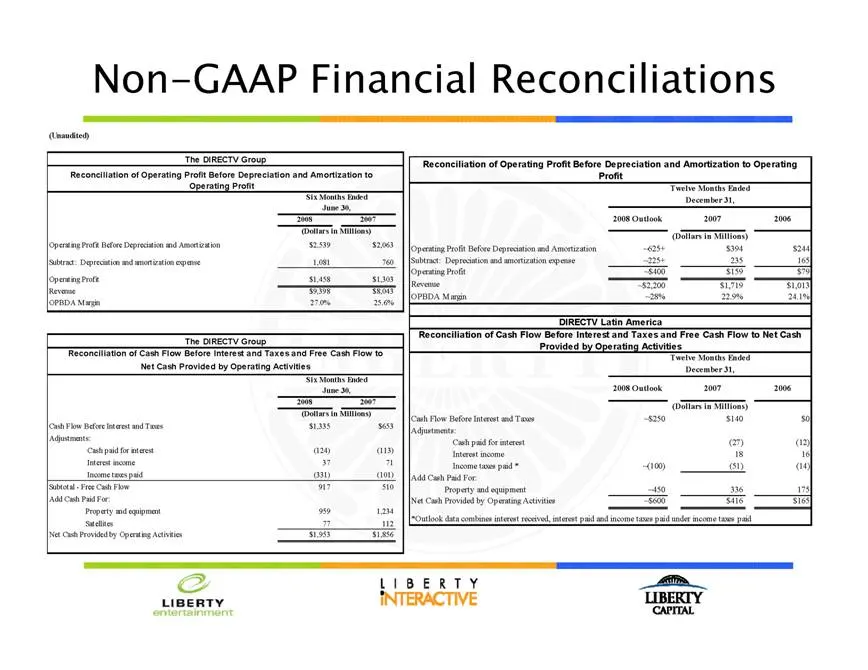
Slide 52: Non-GAAP Financial Reconciliations (Unaudited)
Non-GAAP Financial Reconciliations (Unaudited) The DIRECTV Group Reconciliation of Operating Profit Before Depreciation and Amortization to Operating Profit Six Months Ended June 30, 2008 2007 (Dollars in Millions) Operating Profit Before Depreciation and Amortization $2,539 $2,063 Subtract: Depreci
Slide 53: Mark Shuken
Mark Shuken President & CEO LIBERTY SPORTS GROUP NORTHWEST. PITTSBURGH. ROCKY MOUNTAIN. (e/ LIBERTY An INTERACTIVE CAPITAL
Slide 54: LSG Overview
LSG Overview 3 Regional Sports Networks (RSNs) · FSN Northwest · FSN Rocky Mountain · FSN Pittsburgh Acquired from News Corp (Feb. 28, 2008) Keys: · Exclusive media rights · Affiliate distribution & fees · LMC synergies and growth strategies
Slide 55: Exclusive Relationships
Exclusive Relationships MLB (Mariners, Rockies, Pirates) NBA (Jazz) NFL (Seahawks, Broncos, Steelers) NHL (Penguins) College (Washington, Washington State, Oregon State, Colorado, Pitt, Gonzaga) Conferences (PAC-10, Big 12, ACC, SEC)
Slide 56: Programming & Distribution
Programming & Distribution 900 live events per year 500 in HD (full-time HD started Feb 08) 8M satellite & cable subscribers 17-State footprint Major Affiliates: Comcast, DIRECTV, Dish Network, Time Warner
Slide 57: Business Model Advantages
Business Model Advantages Proprietary, top-tier content Long-term strategic, revenue and cost certainty Multimedia rights and interactive future Advertising and sponsorship: core vs. DVR Operational agility, innovation and flexibility Accretive value in acquisitions
Slide 58: Financial Metrics
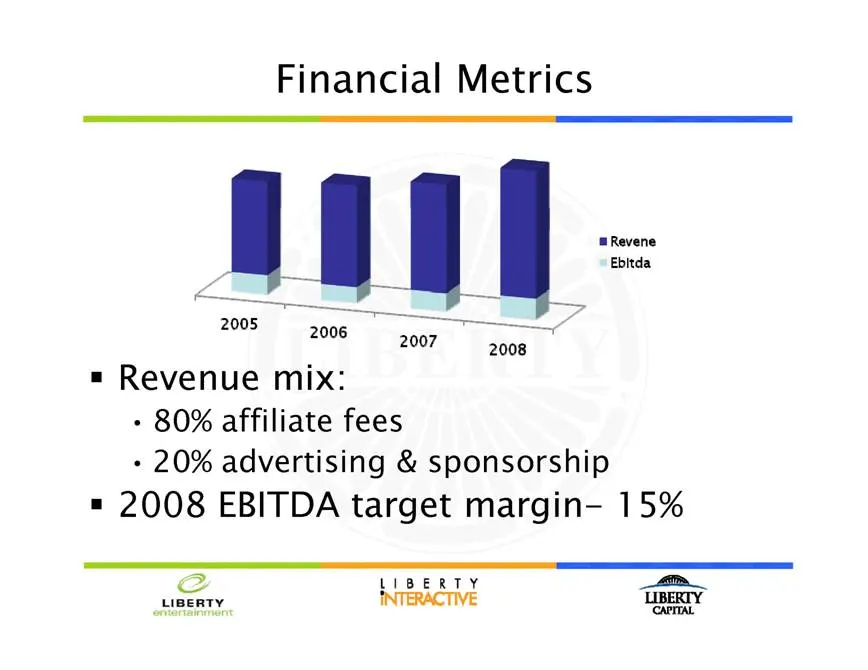
Financial Metrics Revenue mix: · 80% affiliate fees · 20% advertising & sponsorship 2008 EBITDA target margin- 15%
Slide 59: Growth Opportunities
Growth Opportunities Core: increase earnings & asset value Expand portfolio vertically & horizontally Integrate LMC levers for mutual benefit Enhance DIRECTV brand, content & value Multimedia, interactive, digital strategies RSN synergies and best practices
Slide 60: Benefits from Liberty
Benefits from Liberty Aggressive, growth-oriented mandates Creative acquisition/deal structures DIRECTV: sports as driver Liberty Entertainment relationship Team, league, international relationships Financial expertise and partnerships
Slide 61: Bob Clasen
Bob Clasen CEO 2007: The New Starz, Controlling our Own Destiny 2008: Executing on the Plan
Slide 62: Starz, LLC
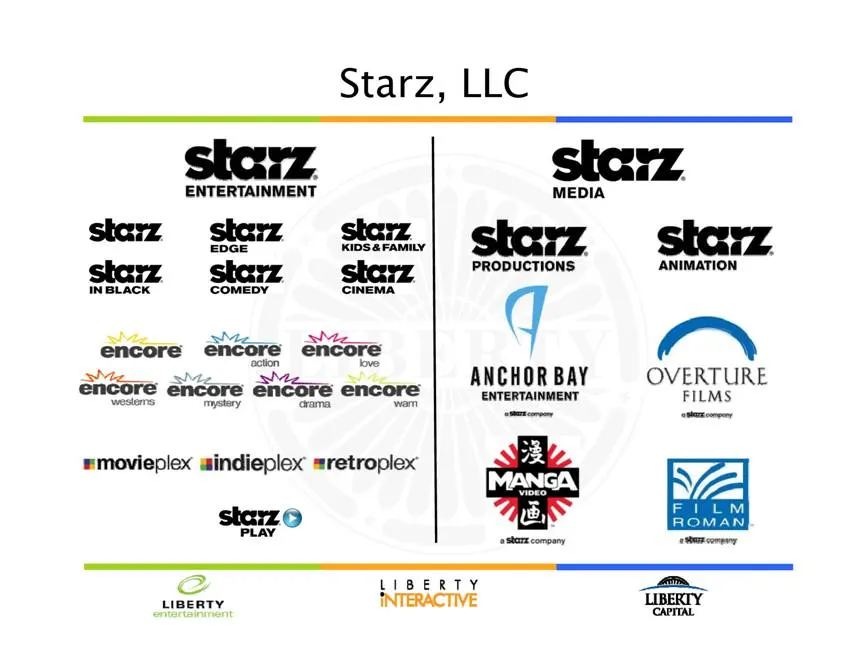
Starz, LLC Coty f ENTERTAINMENT EDGE Ripsaraminy starz starz starz INBLACK comeDy SINEMA ate wie _ wht encore Sore encore wie SMe sh encore encore encore encore comers ONC cana eh mmovieplex windieplex #retroplex starz MEDIA starz starz PRODUCTIONS ANIMATION ANCHOR BAY OVERTURE ENTERTAINMENT FILMS.
Slide 63: Starz Entertainment
starz ENTERTAINMENT > ¢ LIBERTY LIBERTY q
Slide 64: Suite of Video Subscription Services
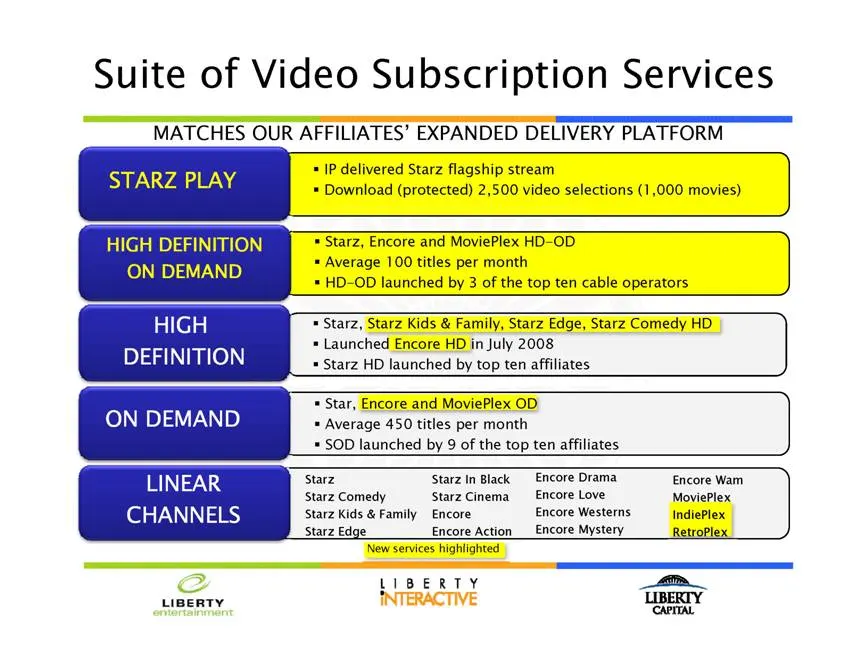
Suite of Video Subscription Services MATCHES OUR AFFILIATES’ EXPANDED DELIVERY PLATFORM STARZ PLAY HIGH DEFINITION ON DEMAND HIGH DEFINITION IP delivered Starz flagship stream Download (protected) 2,500 video selections (1,000 movies) Starz, Encore and MoviePlex HD-OD Average 100 titles per month HD
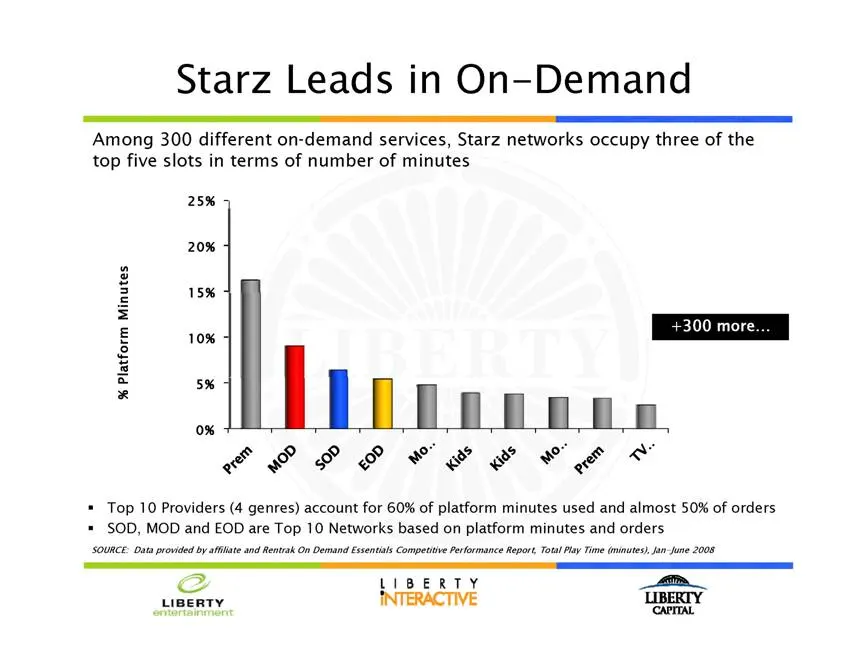
Slide 65: Starz Leads in On-Demand
Starz Leads in On-Demand Among 300 different on-demand services, Starz networks occupy three of the top five slots in terms of number of minutes % Platform Minutes 25% 20% 15% 10% 5% 0% +300 more… Top 10 Providers (4 genres) account for 60% of platform minutes used and almost 50% of orders SOD, MOD
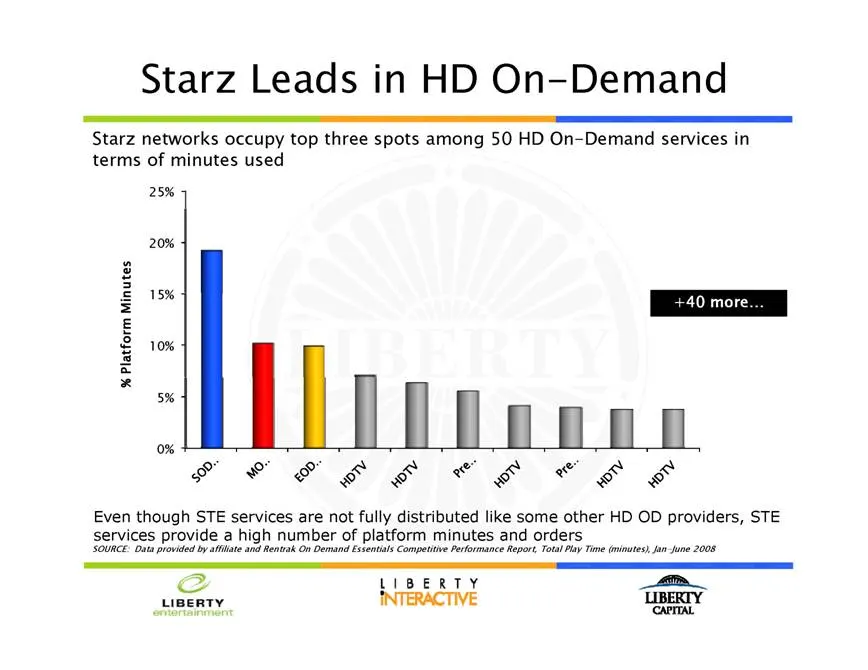
Slide 66: Starz Leads in HD On-Demand
Starz Leads in HD On-Demand Starz networks occupy top three spots among 50 HD On-Demand services in terms of minutes used % Platform Minutes 25% 20% 15 10% 5% +40 more… 0% Even though STE services are not fully distributed like some other HD OD providers, STE services provide a high number of platfo
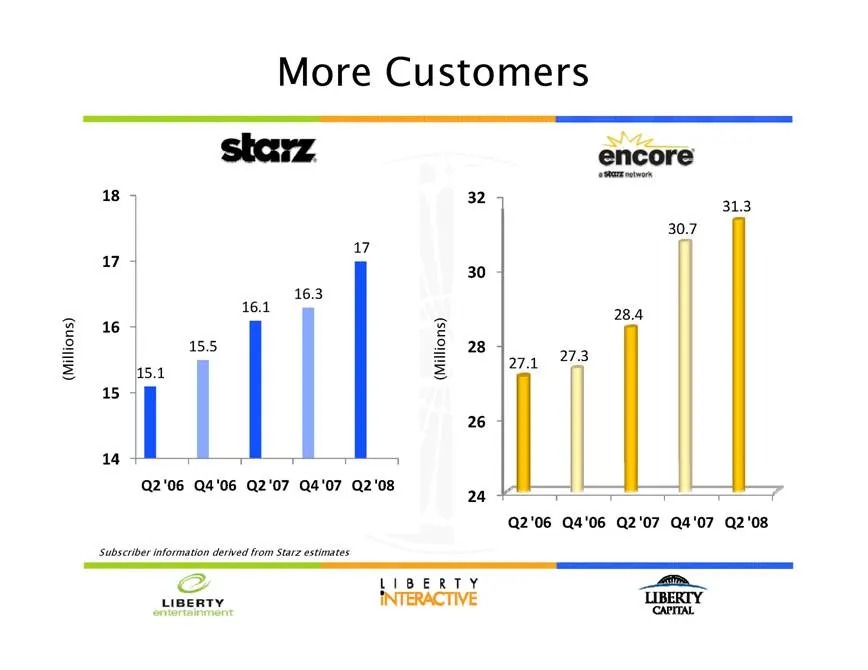
Slide 67: More Customers
More Customers 18 17 32 31.3 30.7 (Millions) 17 16.3 16.1 16 15.5 15.1 15 14 Q2 '06 Q4 '06 Q2 '07 Q4 '07 Q2 '08 (Millions) 30 28 27.3 27.1 26 24 28.4 Q2 '06 Q4 '06 Q2 '07 Q4 '07 Q2 '08 Subscriber information derived from Starz estimates
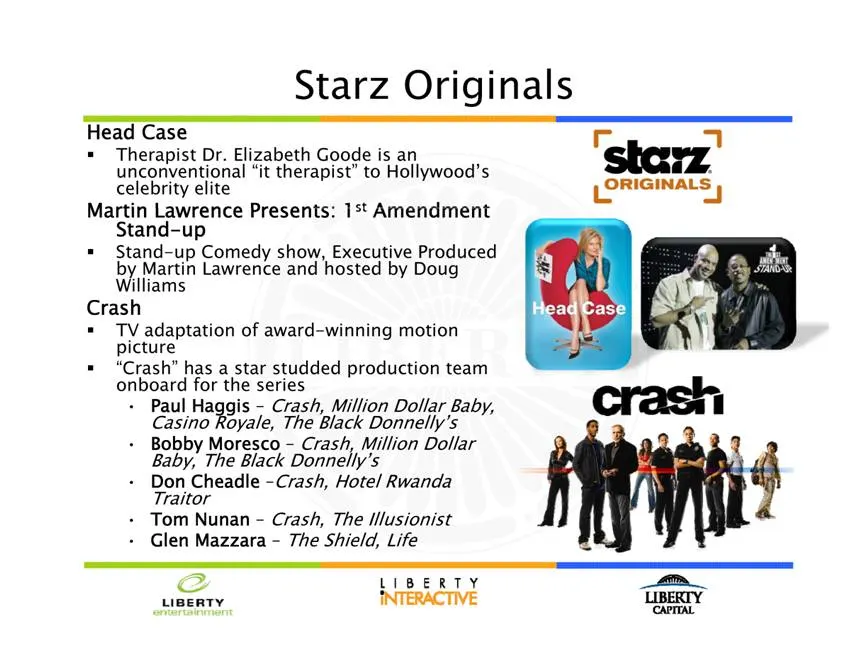
Slide 68: Starz Originals
Starz Originals Head Case Therapist Dr. Elizabeth Goode is an unconventional “it therapist” to Hollywood’s celebrity elite Martin Lawrence Presents: 1st Amendment Stand-up Stand-up Comedy show, Executive Produced by Martin Lawrence and hosted by Doug Williams Crash TV adaptation of award-winning mot
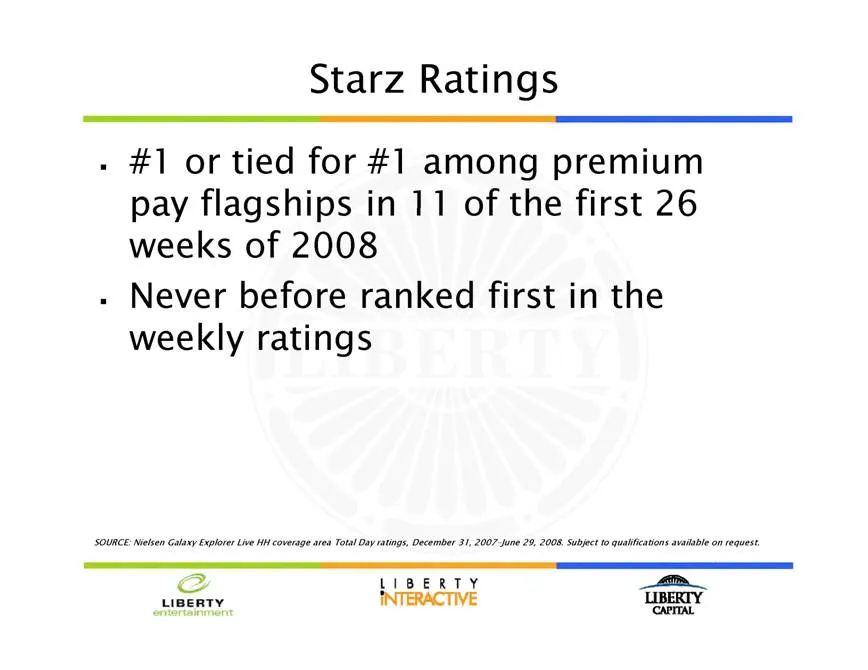
Slide 69: Starz Ratings
Starz Ratings #1 or tied for#1 among premium pay flagships in 11 of the first 26 weeks of 2008 Never before ranked first in the weekly ratings SOURCE: Nielsen Galaxy Explorer Live HH coverage area Total Day ratings, December 31, 2007-June 29, 2008. Subject to qualifications available on request.
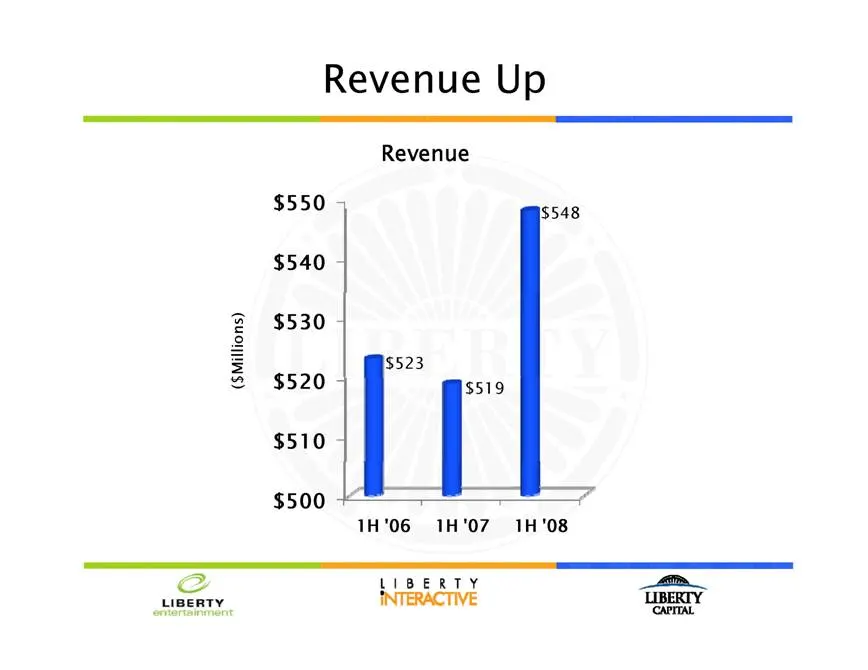
Slide 70: Revenue Up
Revenue Up Revenue ($Millions) $550 $540 $530 $548 $523 $520 $519 $510 $500 1H '06 1H '07 1H '08
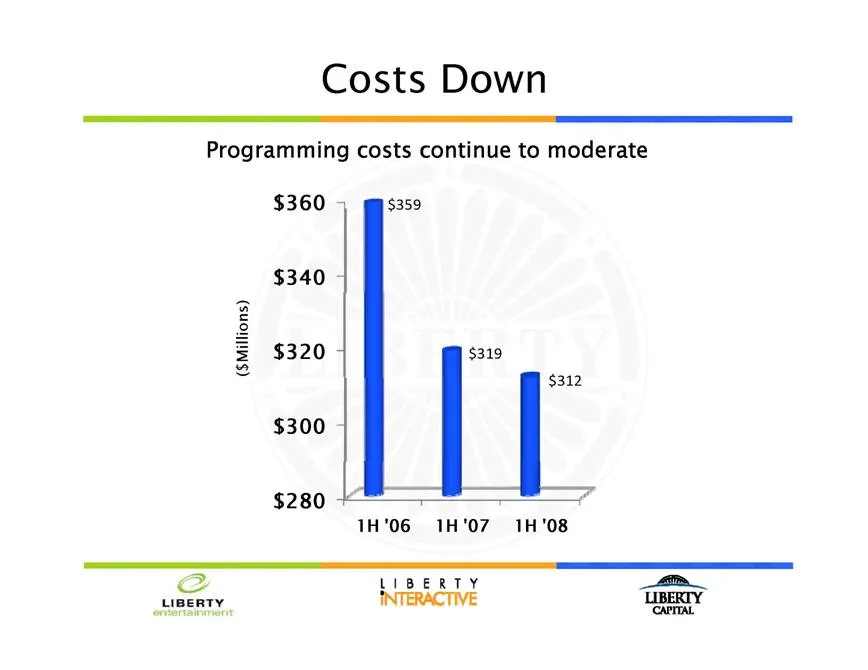
Slide 71: Costs Down
Costs Down Programming costs continue to moderate $360 $359 $340 ($Millions) $320 $319 $312 $300 $280 1H '06 1H '07 1H '08
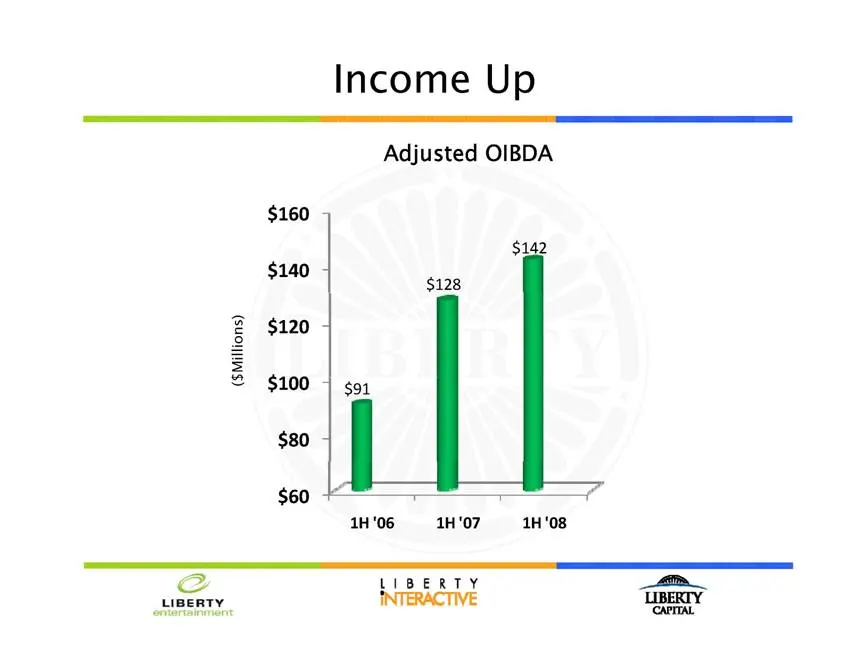
Slide 72: Income Up
Income Up Adjusted OIBDA ($ $Millions) $160 $140 $120 $142 $128 $100 $91 $80 $60 1H '06 1H '07 1H '08
Slide 73: Starz Media
a. MEDIA ey LIBERTY a INTERACTIVE ‘LIBERTY LIBERTY JBERD
Slide 74: Overture Films
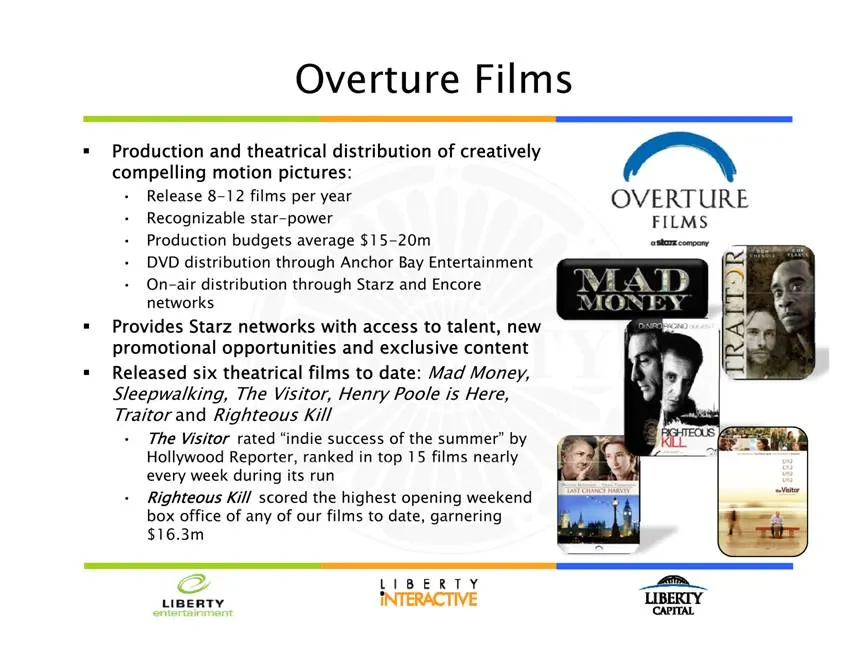
Overture Films Production and theatrical distribution of creatively compelling motion pictures: · Release 8-12 films per year · Recognizable star-power · Production budgets average $15-20m · DVD distribution through Anchor Bay Entertainment · On-air distribution through Starz and Encore networks Pro
Slide 75: Anchor Bay Entertainment
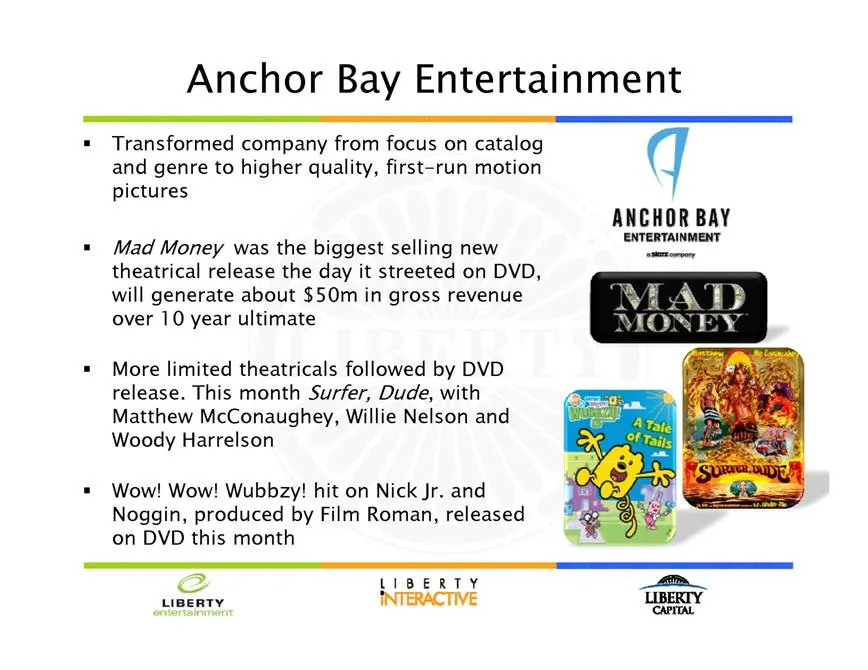
Anchor Bay Entertainment Transformed company from focus on catalog and genre to higher quality, first-run motion pictures Mad Money was the biggest selling new theatrical release the day it streeted on DVD, will generate about $50m in gross revenue over 10 year ultimate More limited theatricals foll
Slide 76: Suite of Digital Services
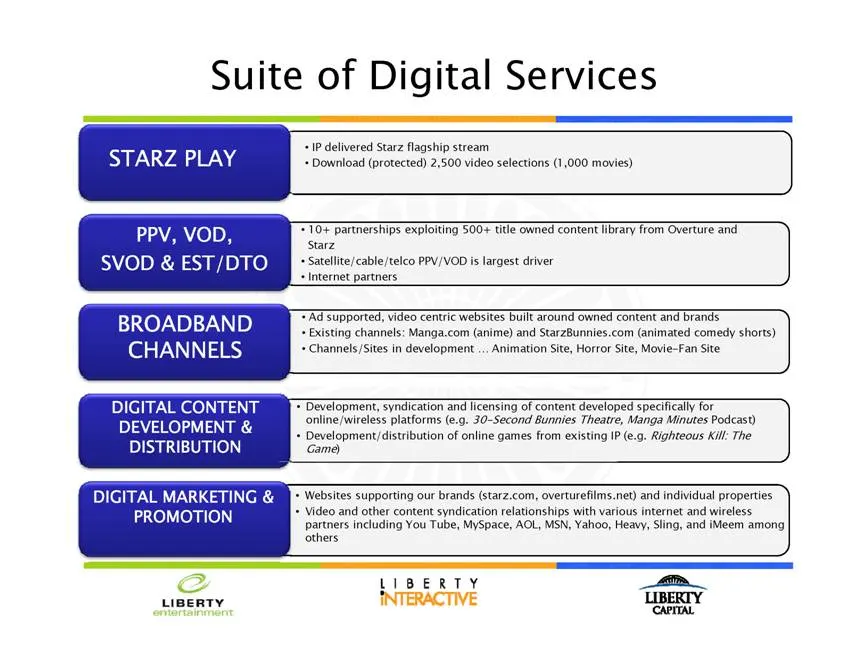
Suite of Digital Services STARZ PLAY PPV, VOD, SVOD & EST/DTO BROADBAND CHANNELS DIGITAL CONTENT DEVELOPMENT & DISTRIBUTION DIGITAL MARKETING & PROMOTION · IP delivered Starz flagship stream · Download (protected) 2,500 video selections (1,000 movies) · 10+ partnerships exploiting 500+ title owned c
Slide 77: Starz Animation
Starz Animation Space Chimps, co-produced with Vanguard and released by Fox, generated about $30m at box office Film Roman: 20th season of The Simpsons, 13th of King of the Hill. The Goode Family for ABC, Deadspace prequel to EA game: and three Marvel projects Toronto Studio: Three CGI films in prod
Slide 78: Consolidated Operations
Consolidated Operations Managed in three divisions – television, theatrical animation Centralized acquisitions - building a library of content with all rights Coordinated marketing & promotion Unified TV production for Starz Entertainment, Anchor Bay & third parties Coordinated support functions - H
Slide 79: Audience Aggregation Example: Mad Money
Audience Aggregation Example: Mad Money Cost: $6m domestic rights acquisition plus $27m P&A $22m box office gross $50m home video gross Pay-Per-View/VOD – Starz Entertainment affiliates Pay TV fees from Starz channels Sold to basic cable by Starz TV syndication team Digital distribution via Starz Pl
Slide 80: Building a Brand in a Fragmented World
Building a Brand in a Fragmented World
Slide 81: Innovate, Execute, Grow
Innovate, Execute, Grow Gregory B. Maffei President and CEO
Slide 82: Making Progress…
Making Progress… Equity shrink of 14% Strong liquidity Continue to seek tax efficient restructurings …but discount persists
Slide 83: Liberty Capital
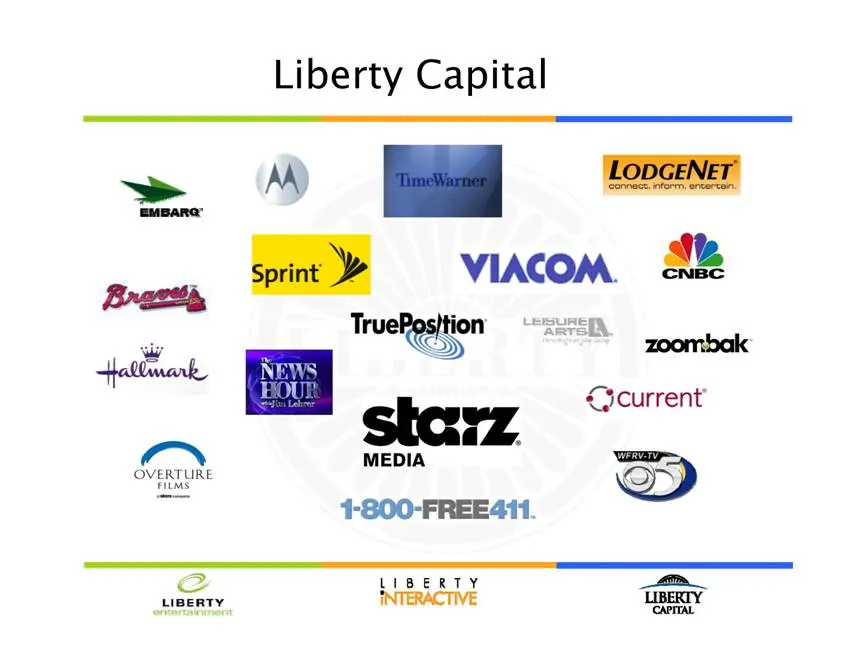
OVERTURE > (e7 LIBERTY Liberty Capital 1-800-FREE411 LIBERTY INTERACTIVE zoombak current’ -—, cop) a LIBERTY fe
Slide 84: Missing LCAPA Value
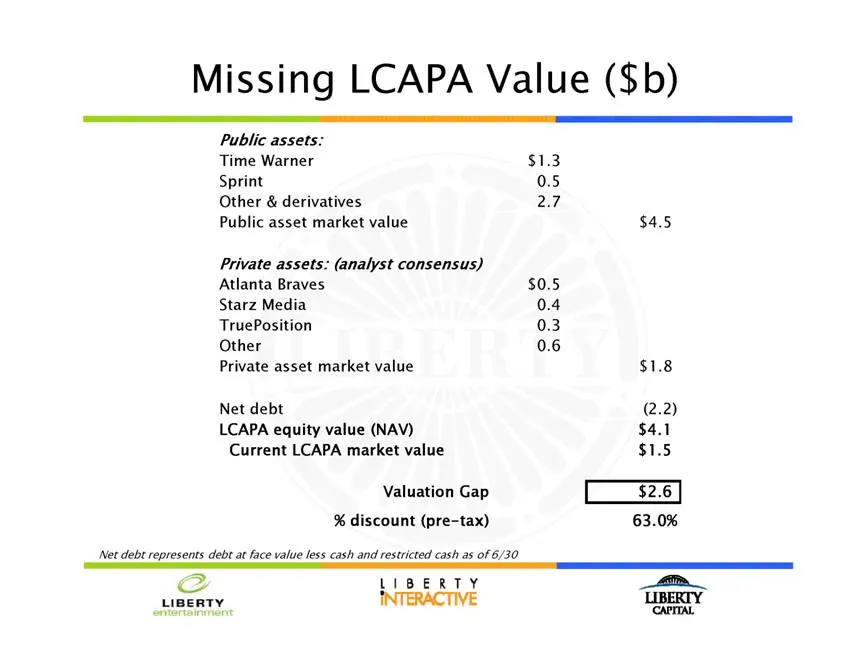
Missing LCAPA Value ($b) Public assets: Time Warner $1.3 Sprint 0.5 Other & derivatives 2.7 Public asset market value $4.5 Private assets: (analyst consensus) Atlanta Braves $0.5 Starz Media 0.4 TruePosition 0.3 Other 0.6 Private asset market value $1.8 Net debt (2.2) LCAPA equity value (NAV) $4.1 C
Slide 85: Liberty Capital Action Plan
Liberty Capital Action Plan Rationalize non-core assets tax efficiently •Convert to cash and attractive assets Reinvest in businesses • growth Reduce discount C h hh h •Capture through share repurchase
Slide 86: Innovate, Execute, Grow
Innovate, Execute, Grow Gregory B. Maffei President and CEO
Slide 87: Continued Expansion
Continued Expansion Strategic acquisitions · Bodybuilding.com · Red Envelope · Celebrate Express · QVC brand acquisitions Growth strategies · Differentiate product and service offerings · Build brand awareness · Enhance QVC.com, e.g., online community · Expand internationally · Leverage best practic
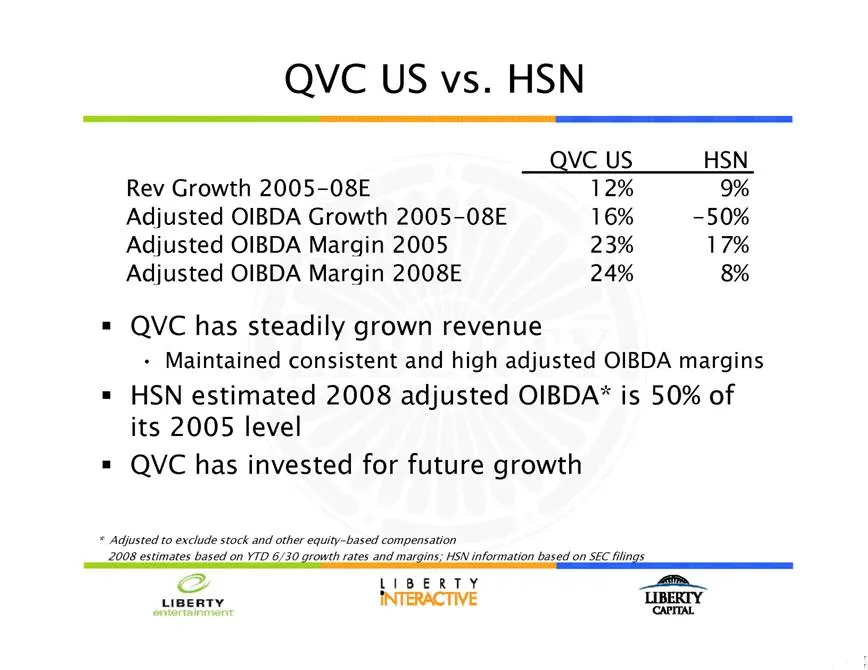
Slide 88: QVC US vs. HSN
QVC US vs. HSN Rev Growth 2005-08E QVC US HSN 12% 9% Adjusted OIBDA Growth 2005-08E 16% -50% Adjusted OIBDA Margin 2005 23% 17% Adjusted OIBDA Margin 2008E 24% 8% QVC has steadily grown revenue · Maintained consistent and high adjusted OIBDA margins HSN estimated 2008 adjusted OIBDA* is 50% of its 2
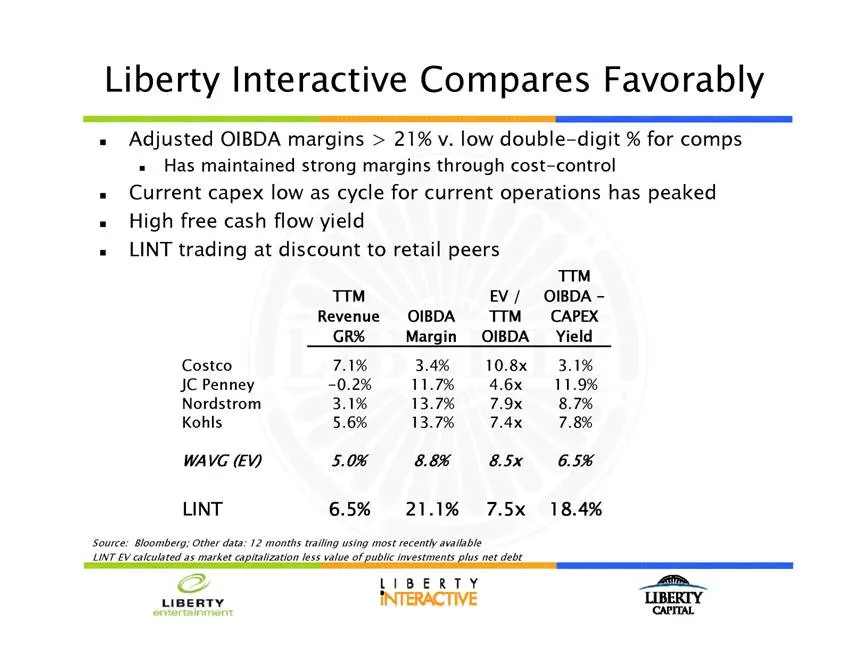
Slide 89: Liberty Interactive Compares Favorably
Liberty Interactive Compares Favorably Adjusted OIBDA margins > 21% v. low double-digit % for comps Has maintained strong margins through cost-control Current capex low as cycle for current operations has peaked High free cash flow yield LINT trading at discount to retail peers TTM TTM EV / OIBDA -
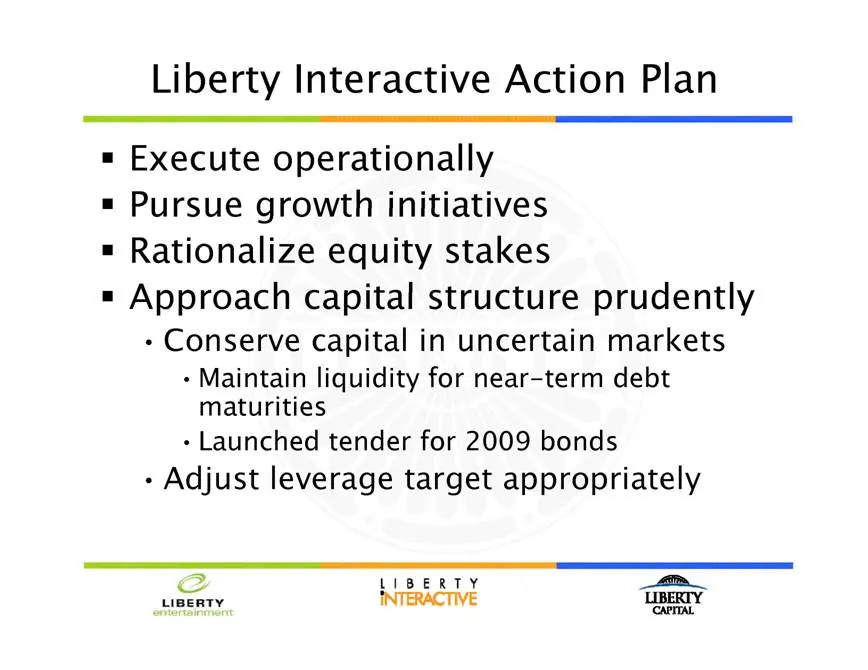
Slide 90: Liberty Interactive Action Plan
Liberty Interactive Action Plan Execute operationally Pursue growth initiatives Rationalize equity stakes Approach capital structure prudently · Conserve capital in uncertain markets · Maintain liquidity for near-term debt maturities · Launched tender for 2009 bonds · Adjust leverage target appropri
Slide 91: Mike George
Mike George President & CEO ave re? LIBERTY “uigerty INTERACTIVE
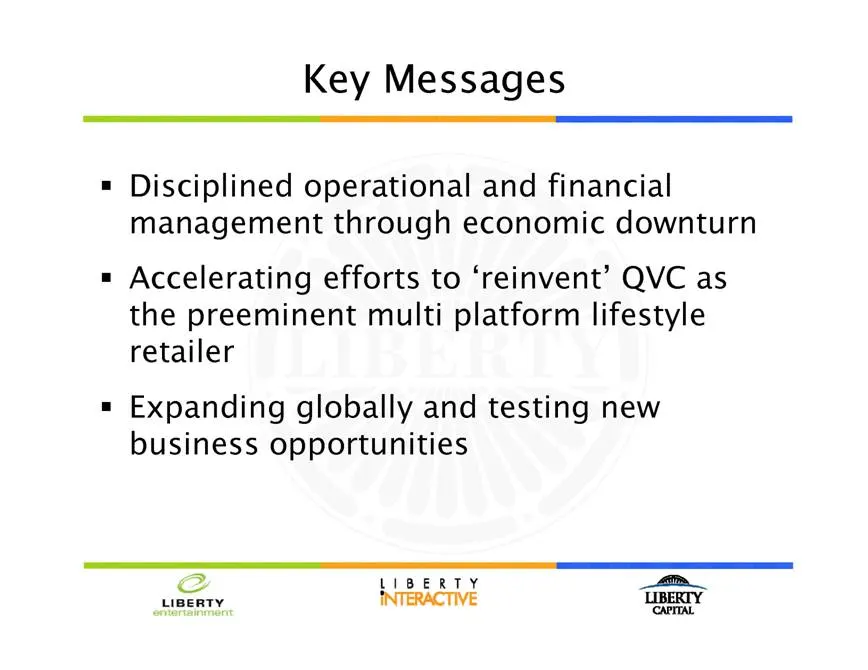
Slide 92: Key Messages
Key Messages Disciplined operational and financial management through economic downturn Accelerating efforts to ‘reinvent’ QVC as the preeminent multi platform lifestyle retailer Expanding globally and testing new business opportunities
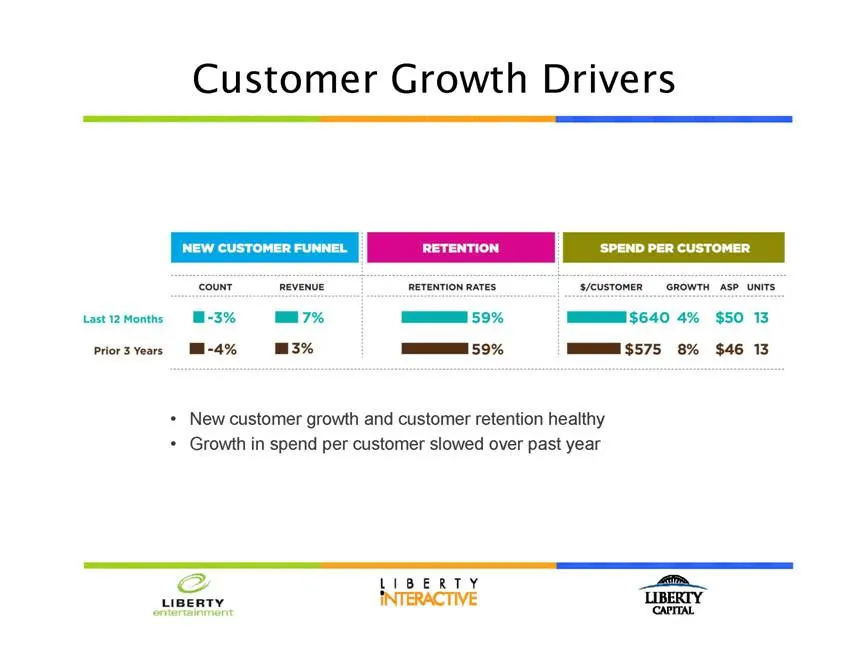
Slide 93: Customer Growth
Customer Growth Drivers · New customer growth and customer retention healthy · Growth in spend per customer slowed over past year
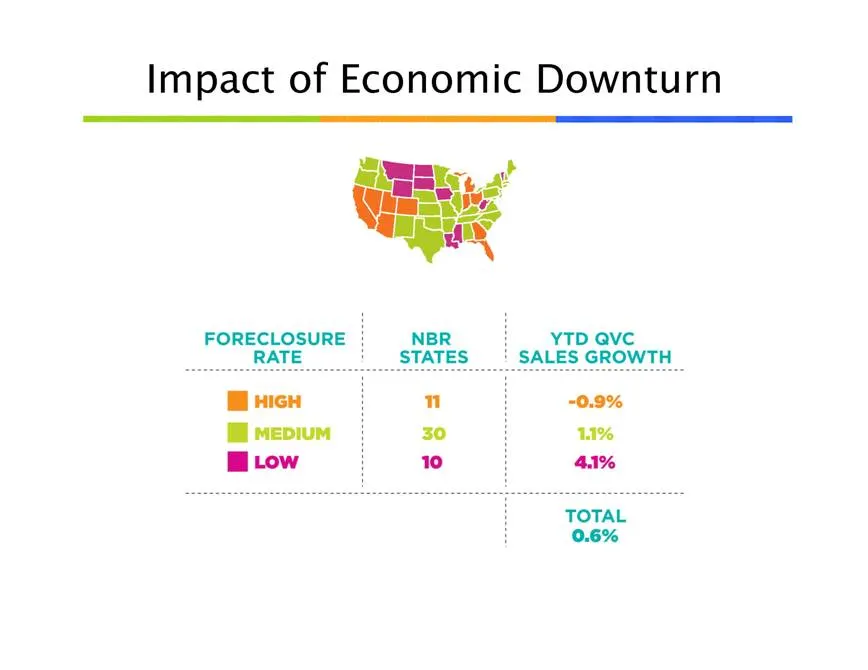
Slide 94: Impact of Economic Downturn
Impact of Economic Downturn FORECLOSURE RATE NBR STATES YTD QVC SALES GROWTH HIGH 11 -0.9% MEDIUM 30 1.1% LOW 10 4.1% TOTAL 0.6%
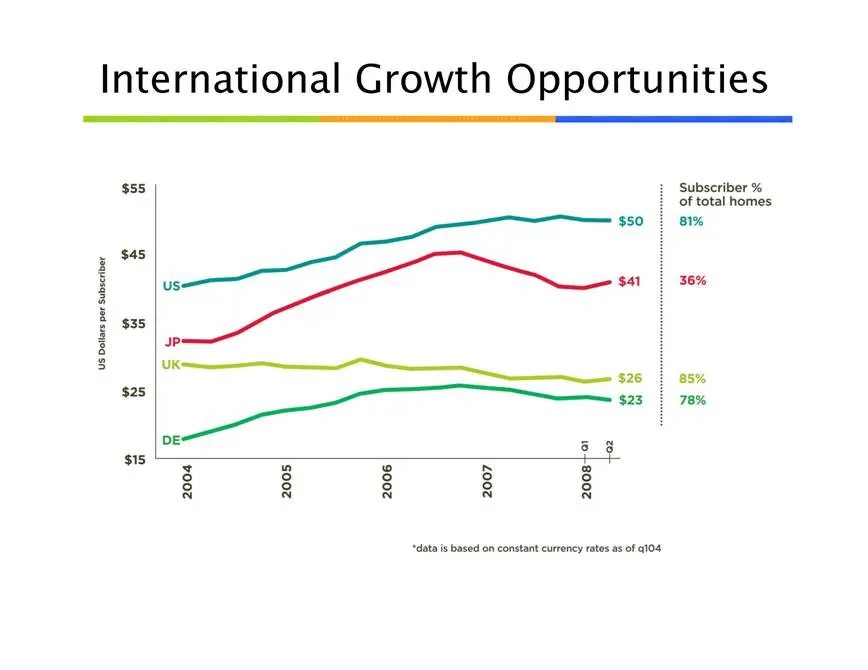
Slide 95: International Growth Opportunities
International Growth Opportunities [GRAPH]
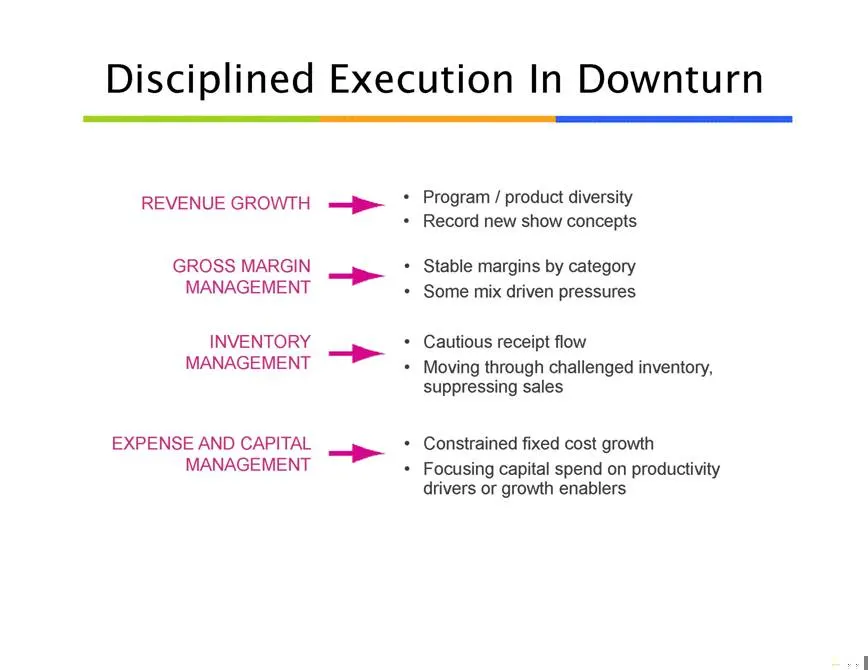
Slide 96: Disciplined Execution In Downturn
Disciplined Execution In Downturn REVENUE GROWTH GROSS MARGIN MANAGEMENT INVENTORY MANAGEMENT EXPENSE AND CAPITAL MANAGEMENT · Program / product diversity · Record new show concepts · Stable margins by category · Some mix driven pressures · Cautious receipt flow · Moving through challenged inventory
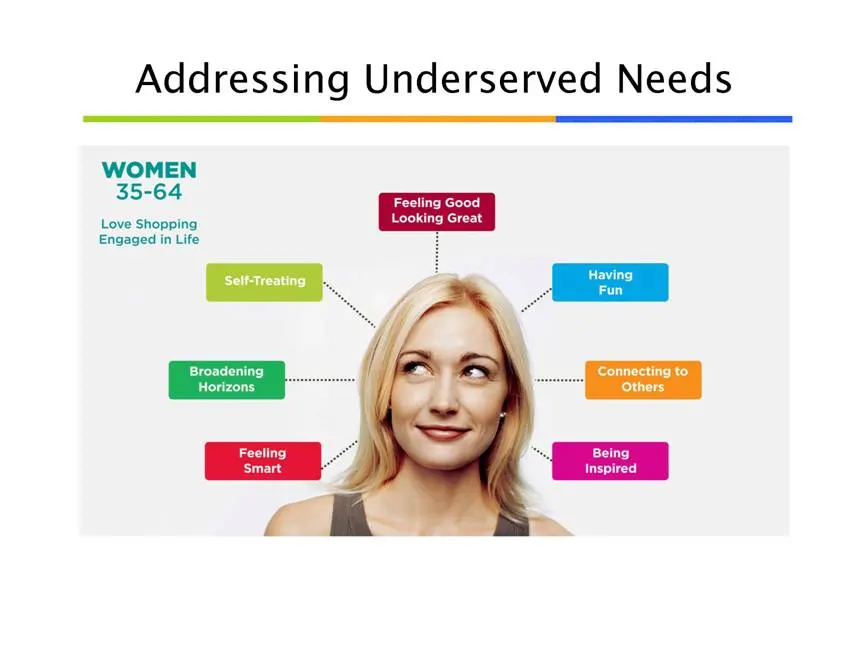
Slide 97: Addressing Underserved Needs
Addressing Underserved Needs [GRAPH]
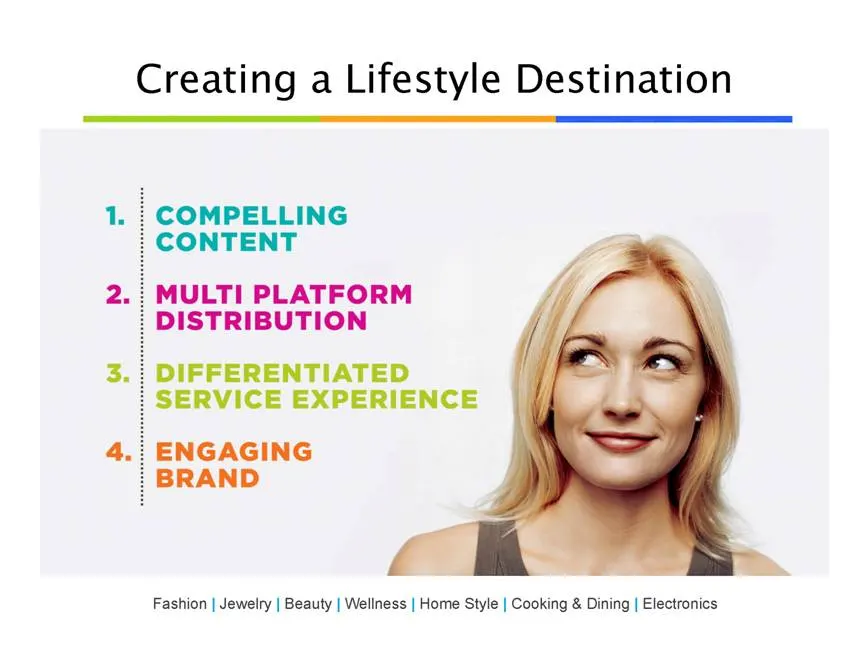
Slide 98: Creating a Lifestyle Destination
Creating a Lifestyle Destination Fashion | Jewelry | Beauty | Wellness | Home Style | Cooking & Dining | Electronics
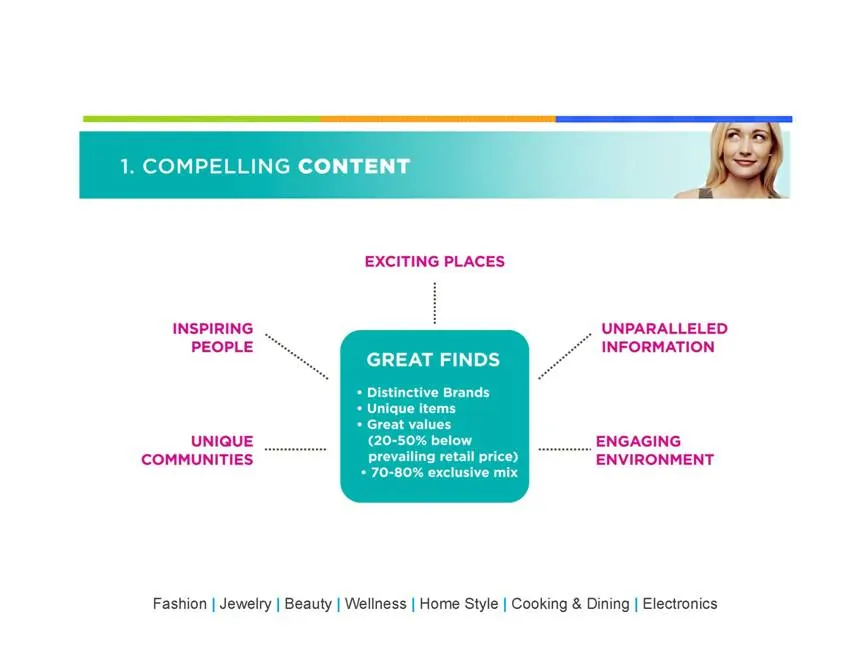
Slide 99: Compelling Content
1. COMPELLING CONTENT Fashion | Jewelry | Beauty | Wellness | Home Style | Cooking & Dining | Electronics
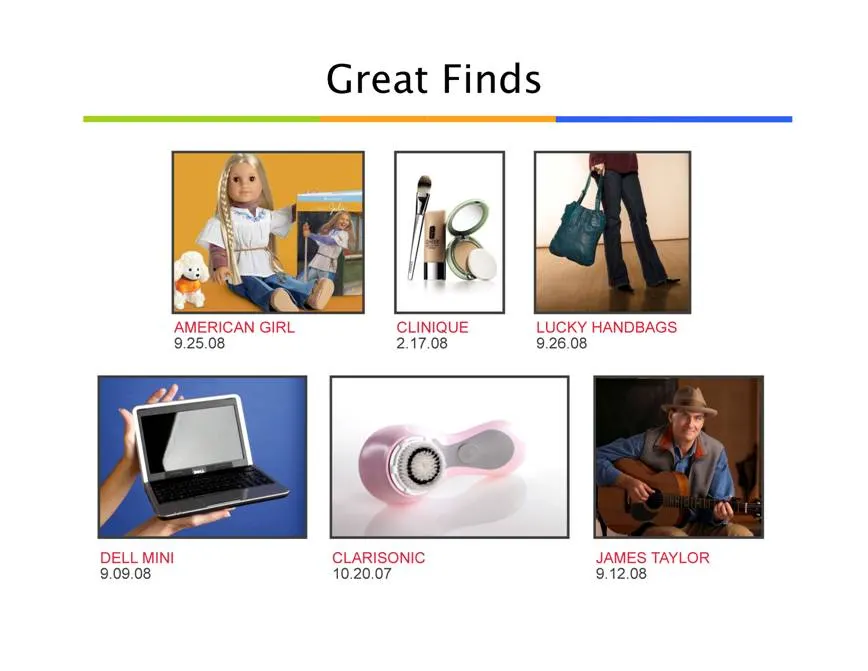
Slide 100: Great Finds
Great Finds AMERICAN GIRL CLINIQUE LUCKY HANDBAGS 9.25.08 2.17.08 9.26.08 DELL MINI CLARISONIC JAMES TAYLOR 9.09.08 10.20.07 9.12.08
Slide 101: Interesting People & Programming
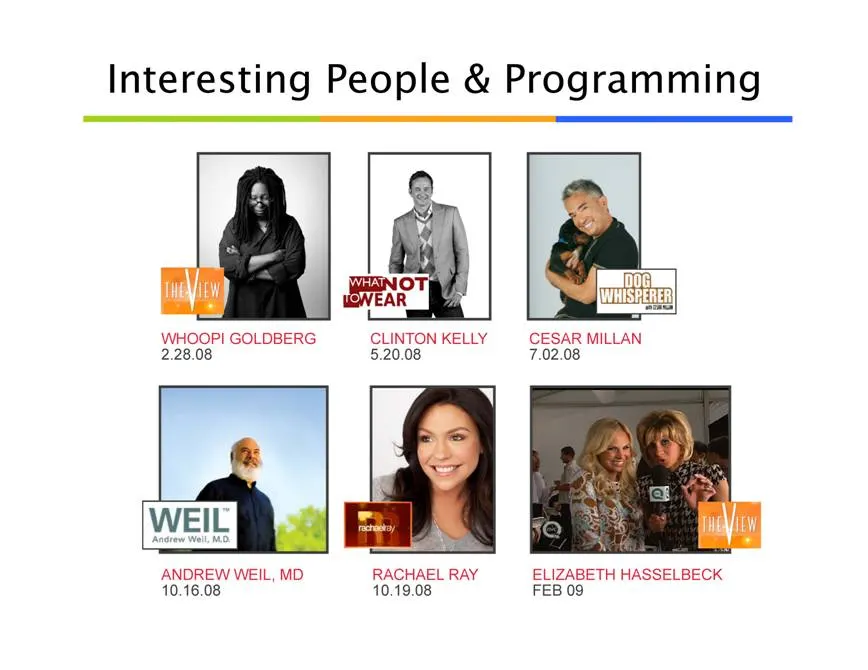
Interesting People & Programming WHOOPI GOLDBERG CLINTON KELLY CESAR MILLAN 2.28.08 5.20.08 7.02.08 ANDREW WEIL, MD RACHAEL RAY ELIZABETH HASSELBECK 10.16.08 10.19.08 FEB 09
Slide 102: Exciting Places
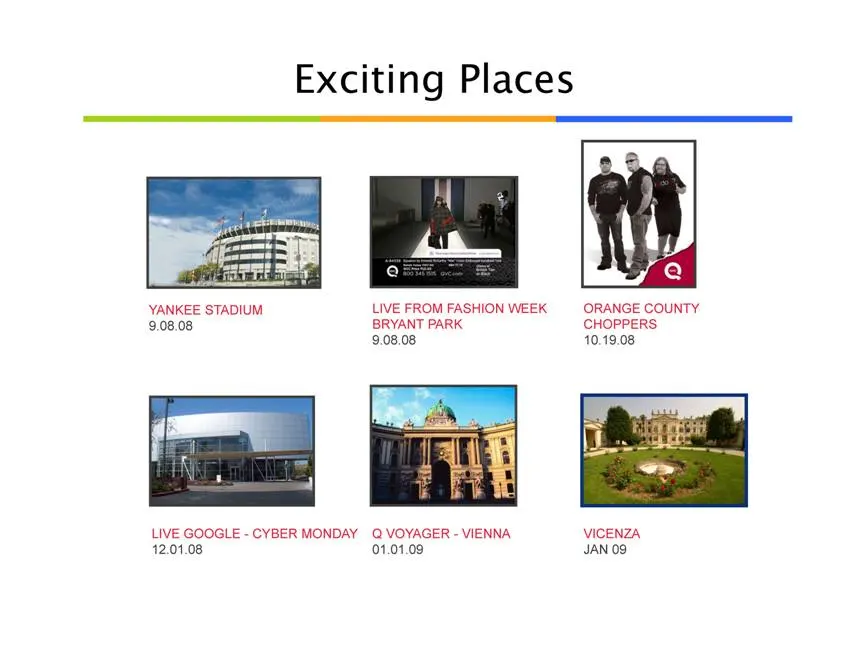
Exciting Places YANKEE STADIUM LIVE FROM FASHION WEEK ORANGE COUNTY BRYANT PARK CHOPPERS 9.08.08 9.08.08 10.19.08 LIVE GOOGLE - CYBER MONDAY Q VOYAGER - VIENNA VICENZA 12.01.08 01.01.09 JAN 09
Slide 103: Engaging Environment
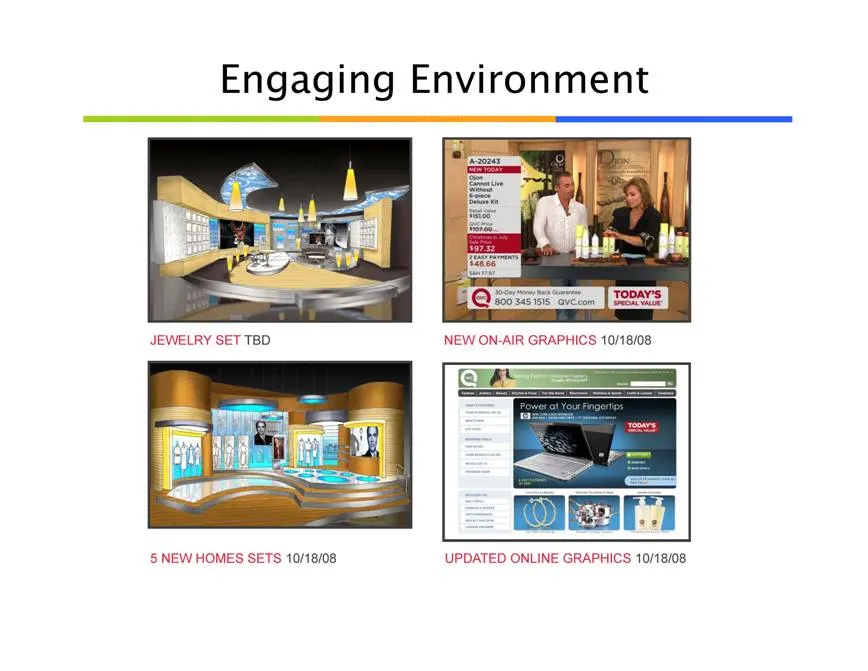
Engaging Environment JEWELRY SET TBD NEW ON-AIR GRAPHICS 10/18/08 5 NEW HOMES SETS 10/18/08 UPDATED ONLINE GRAPHICS 10/18/08
Slide 104: The Big Events
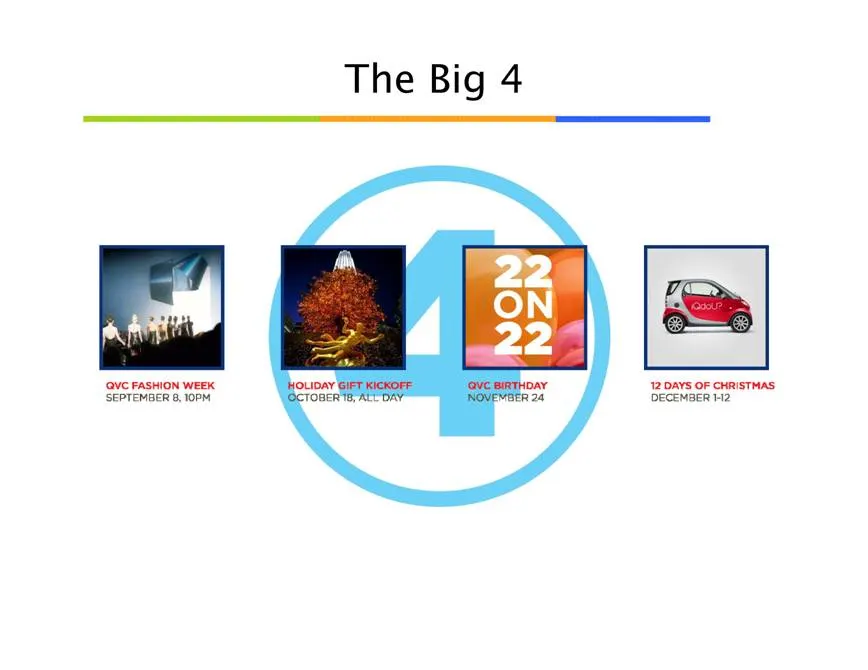
The Big 4 QVC FASHION WEEK SEPTEMBER 8, 10PM 12 DAYS OF CHRISTMAS DECEMBER 1-12
Slide 105: Multiplatform Distribution
2. MULTIPLATFORM DISTRIBUTION Goals: · Increase customer convenience and control · Better target customer sub segments · Increase revenue through off air products/services · Expand presence outside QVC Fashion | Jewelry | Beauty | Wellness | Home Style | Cooking & Dining | Electronics
Slide 106: HDTV: Reaching More Eyeballs
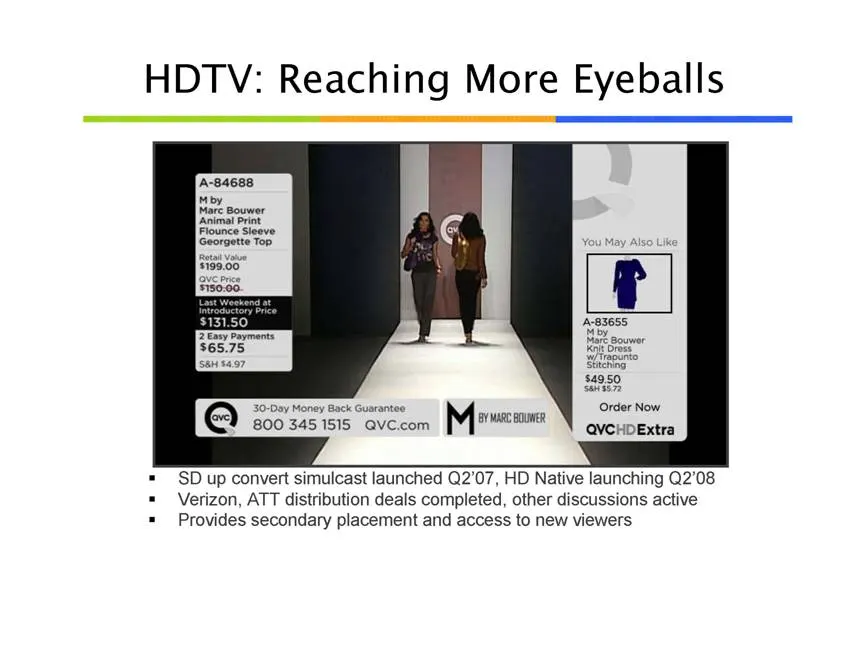
HDTV: Reaching More Eyeballs SD up convert simulcast launched Q2’07, HD Native launching Q2’08 Verizon, ATT distribution deals completed, other discussions active Provides secondary placement and access to new viewers
Slide 107: QVC.com: The Power of Live
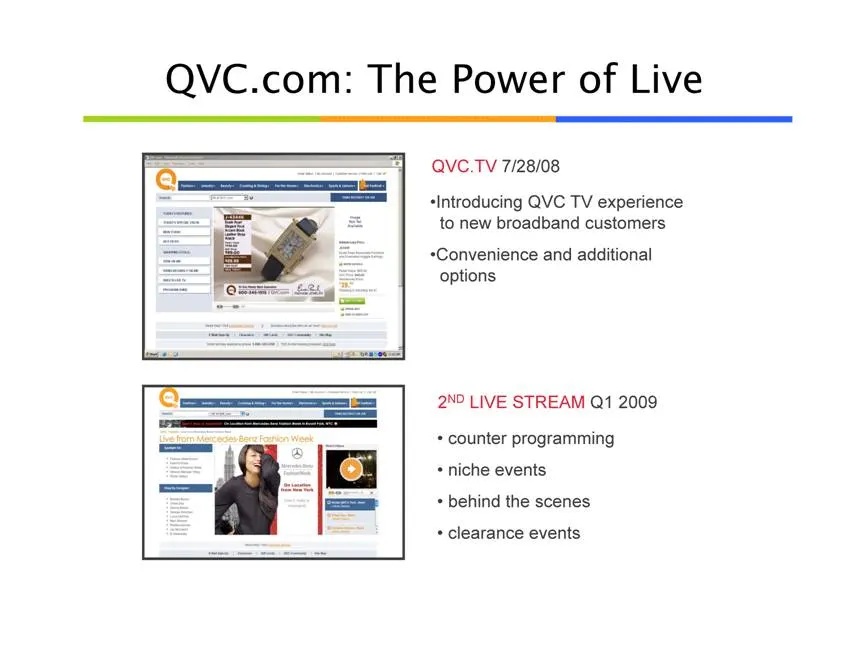
QVC.com: The Power of Live QVC.TV 7/28/08 · Introducing QVC TV experience to new broadband customers · Convenience and additional options 2ND LIVE STREAM Q1 2009 · counter programming · niche events · behind the scenes · clearance events
Slide 108: QVC.com: The Power of Video
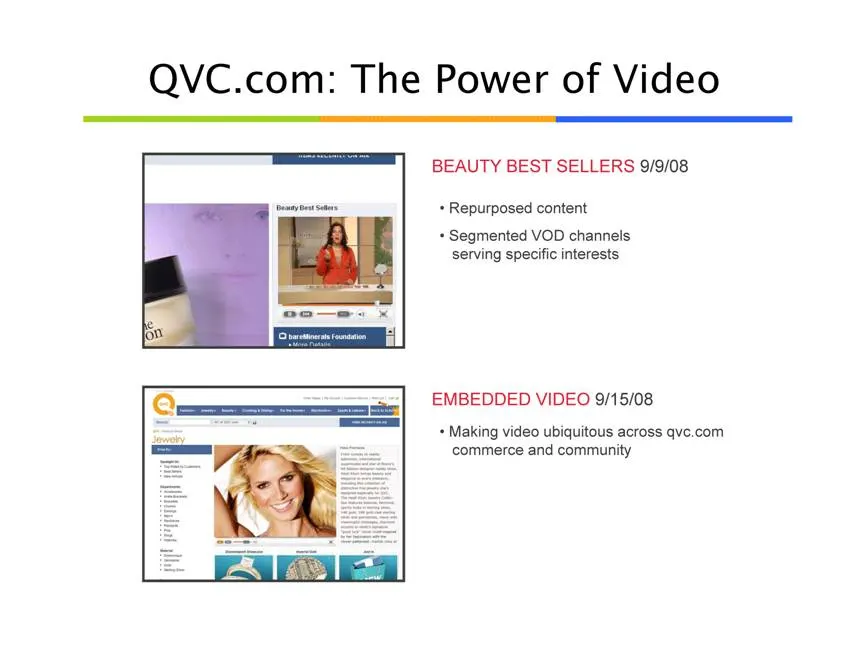
QVC.com: The Power of Video BEAUTY BEST SELLERS 9/9/08 · Repurposed content · Segmented VOD channels serving specific interests EMBEDDED VIDEO 9/15/08 · Making video ubiquitous across qvc.com commerce and community
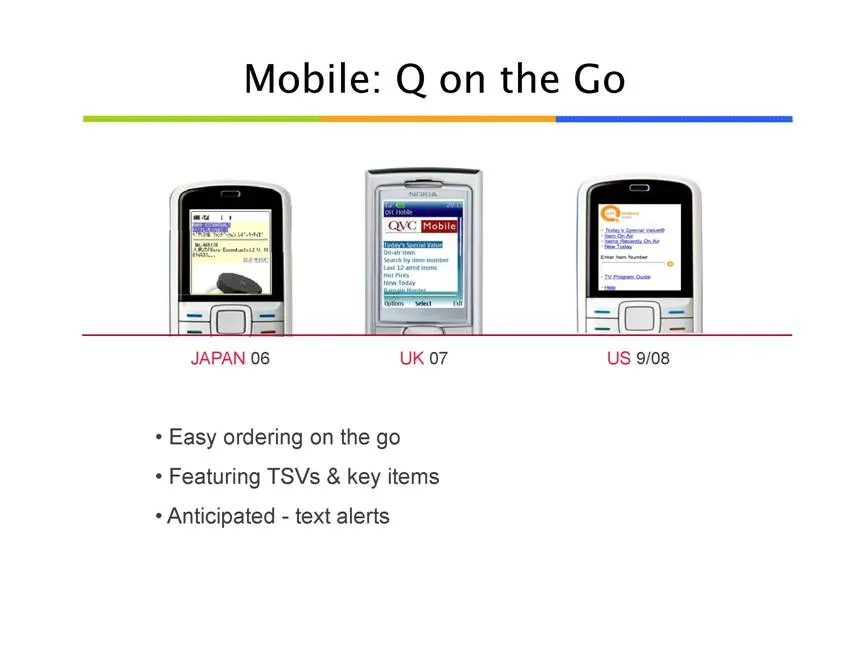
Slide 109: Mobile: Q on the Go
Mobile: Q on the Go JAPAN 06 UK 07 US 9/08 · Easy ordering on the go · Featuring TSVs & key items · Anticipated - text alerts
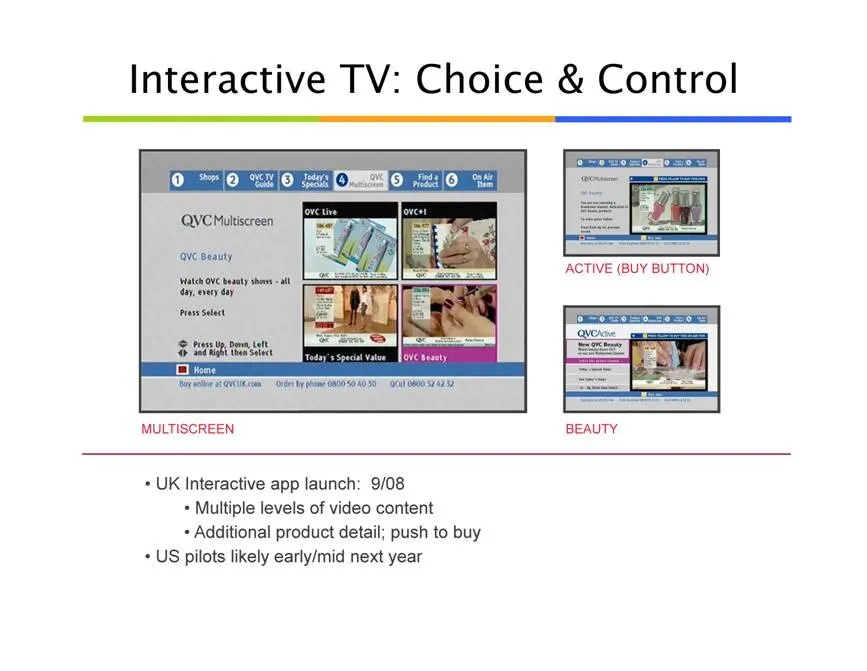
Slide 110: Interactive TV: Choice & Control
Interactive TV: Choice & Control ACTIVE (BUY BUTTON) MULTISCREEN BEAUTY · UK Interactive app launch: 9/08 · Multiple levels of video content · Additional product detail; push to buy · US pilots likely early/mid next year
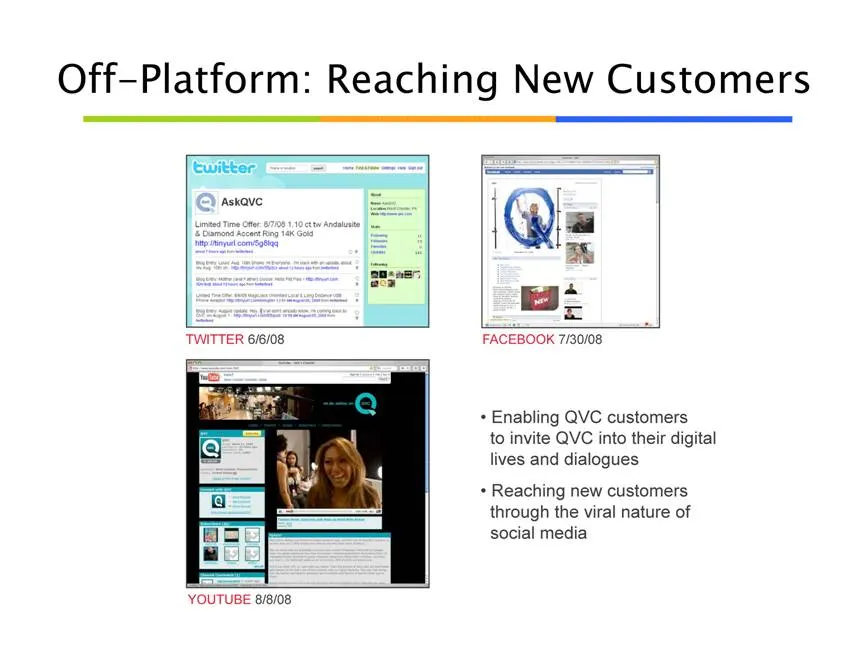
Slide 111: Off-Platform: Reaching New Customers
Off-Platform: Reaching New Customers TWITTER 6/6/08 FACEBOOK 7/30/08 · Enabling QVC customers to invite QVC into their digital lives and dialogues · Reaching new customers through the viral nature of social media
Slide 112: Top Rated Customer Satisfaction
TOP RATED 94% TOP BOX CUSTOMER SATISFACTION 97% CORE CUSTOMER RETENTION · More personalized sales / service · Online/offline personalization · Self service · Improved delivery · Expanded multi line shipping to reduce customer costs · Faster deliveries through regional hubs · More delivery options ·
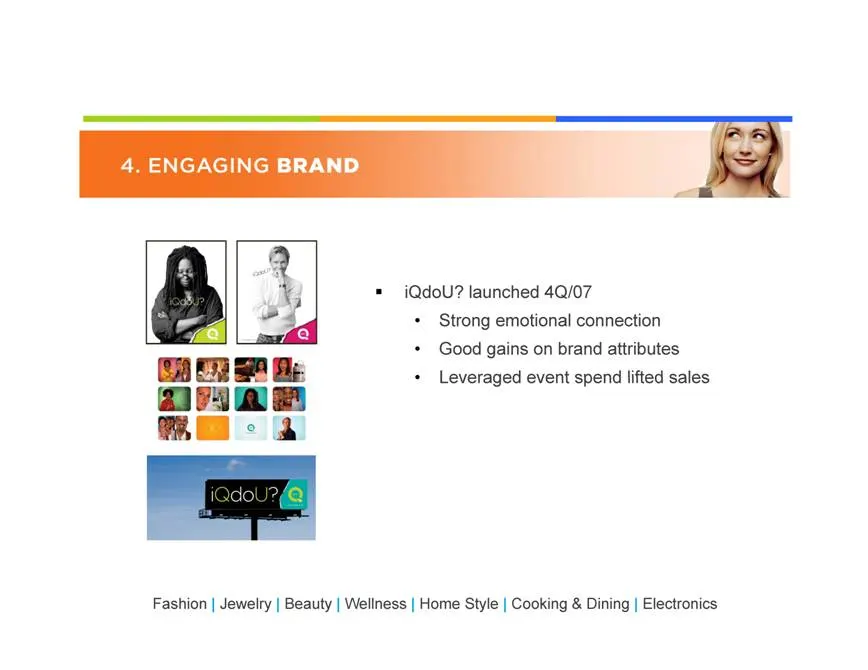
Slide 113: iQdoU? Brand Campaign
iQdoU? launched 4Q/07 · Strong emotional connection · Good gains on brand attributes · Leveraged event spend lifted sales Fashion | Jewelry | Beauty | Wellness | Home Style | Cooking & Dining | Electronics
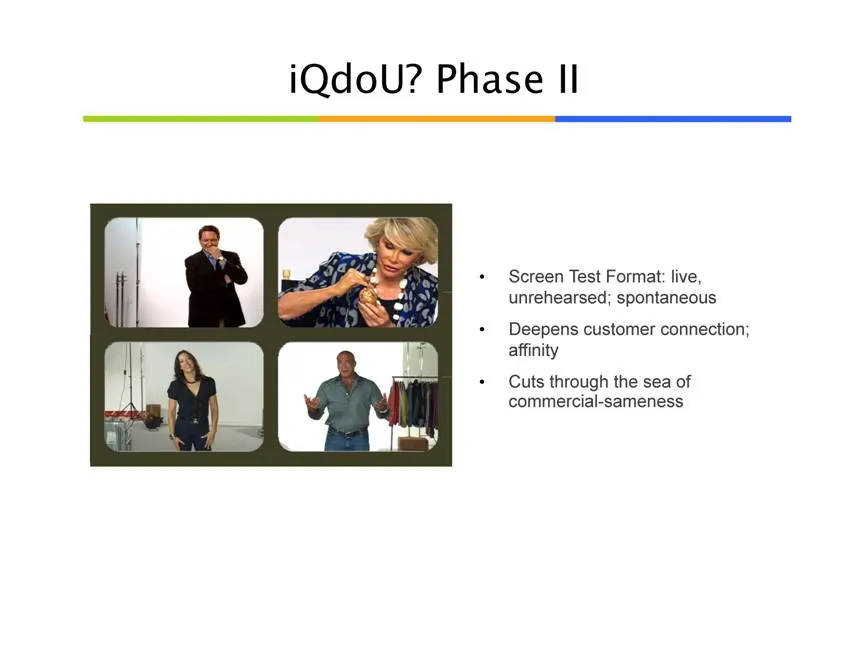
Slide 114: iQdoU? Phase II
iQdoU? Phase II · Screen Test Format: live, unrehearsed; spontaneous · Deepens customer connection; affinity · Cuts through the sea of commercial-sameness
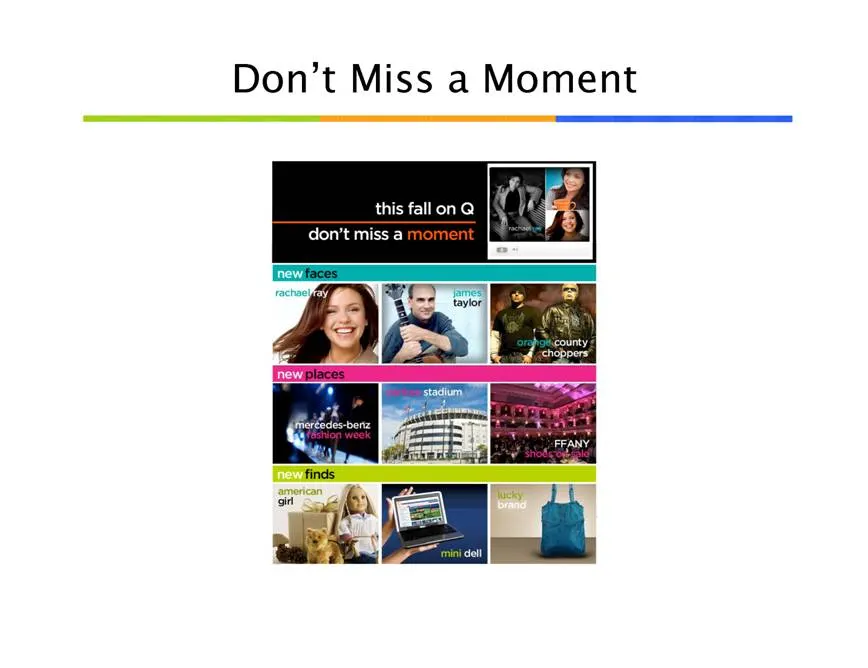
Slide 115: Don't Miss a Moment
Don’t Miss a Moment this fall on @ "t miss a
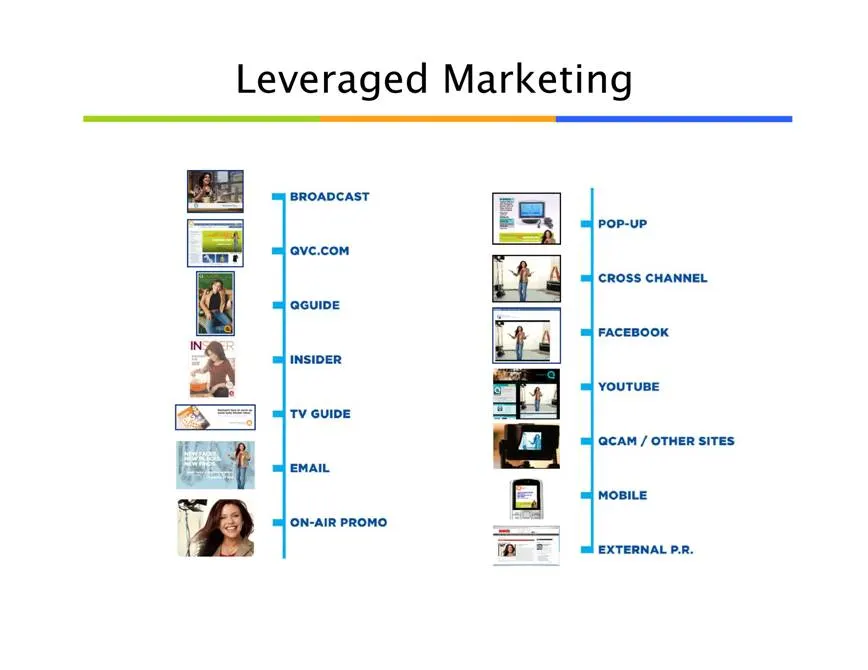
Slide 116: Leveraged Marketing
Leveraged Marketing
Slide 117: Fashion Week
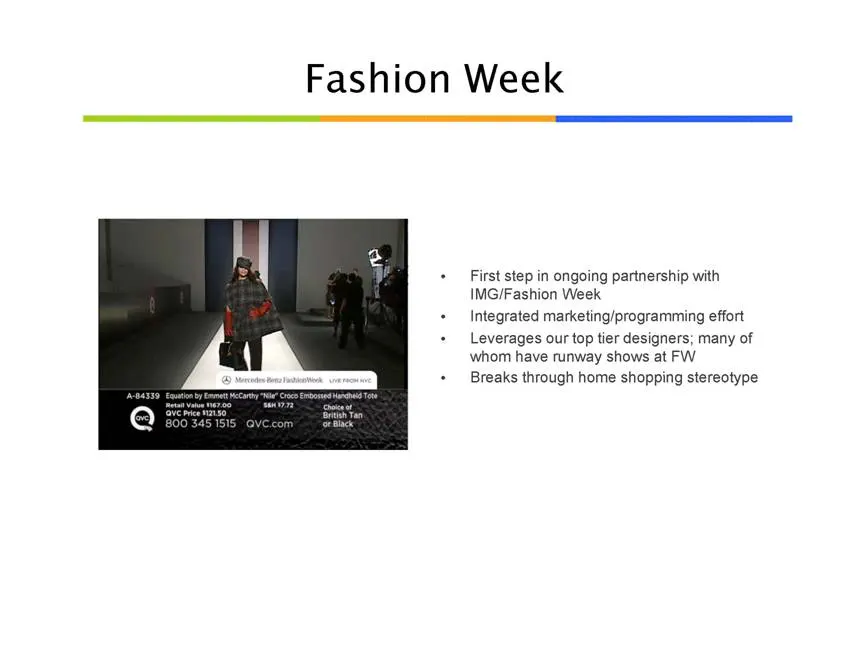
Fashion Week · First step in ongoing partnership with IMG/Fashion Week · Integrated marketing/programming effort · Leverages our top tier designers; many of whom have runway shows at FW · Breaks through home shopping stereotype
Slide 118: Fashion Week Results
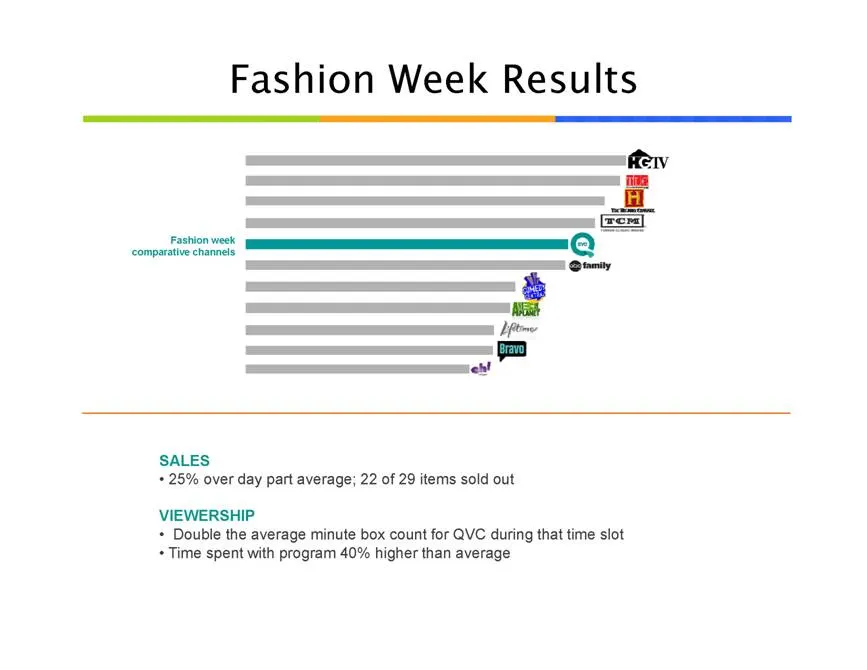
Fashion Week Results Fashion week comparative channels SALES · 25% over day part average; 22 of 29 items sold out VIEWERSHIP · Double the average minute box count for QVC during that time slot · Time spent with program 40% higher than average
Slide 119: Global Expansion
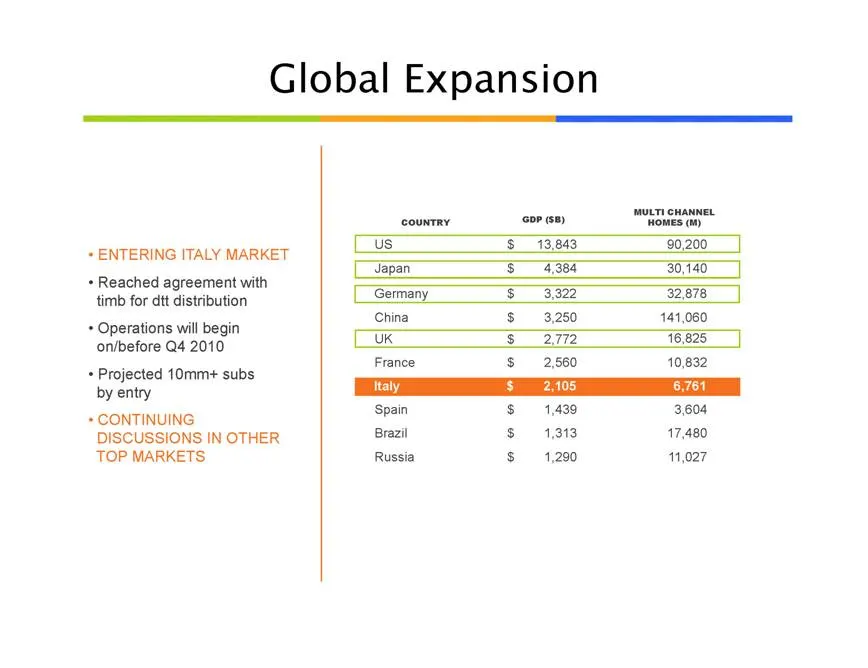
Global Expansion GDP ($B) MULTI CHANNEL COUNTRY HOMES (M) · ENTERING ITALY MARKET US $ 13,843 90,200 Japan $ 4,384 30,140 · Reached agreement with Germany $ 3,322 32,878 timb for dtt distribution China $ 3,250 141,060 · Operations will begin UK $ 2,772 16,825 on/before Q4 2010 France $ 2,560 10,832
Slide 120: International Start Up Experience
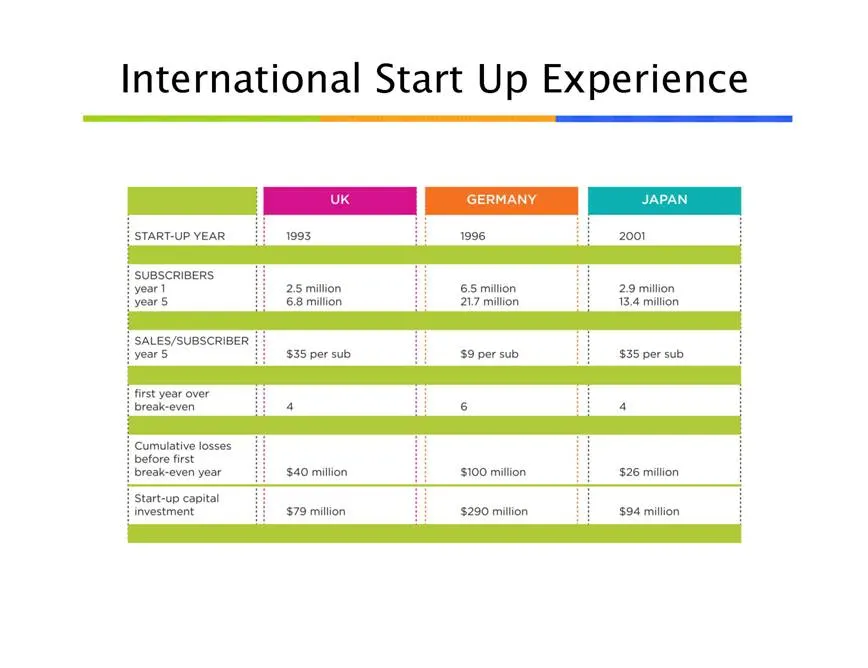
International Start Up Experience
Slide 121: New Business Models
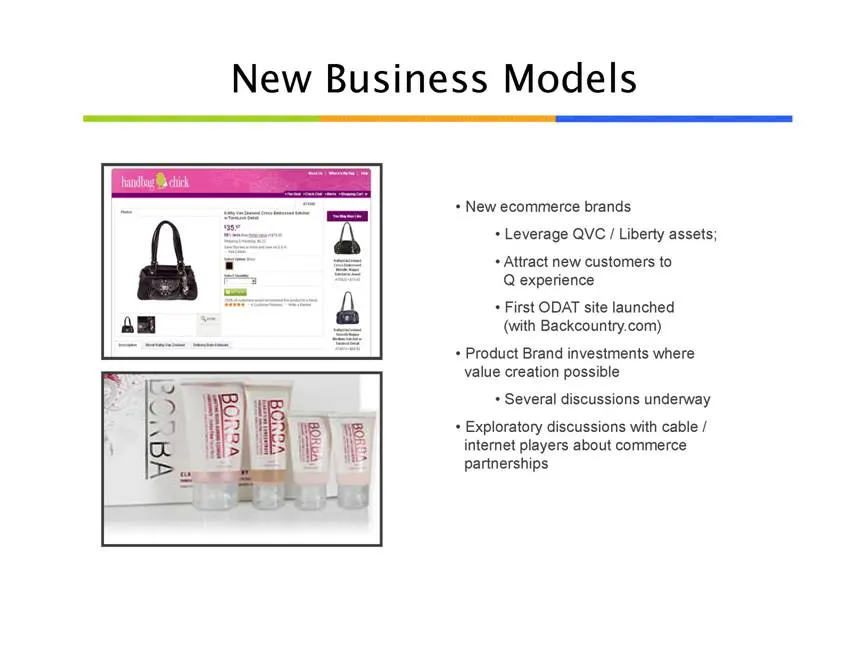
New Business Models · New ecommerce brands · Leverage QVC / Liberty assets; · Attract new customers to Q experience · First ODAT site launched (with Backcountry.com) · Product Brand investments where value creation possible · Several discussions underway · Exploratory discussions with cable / intern
Slide 122: Closing
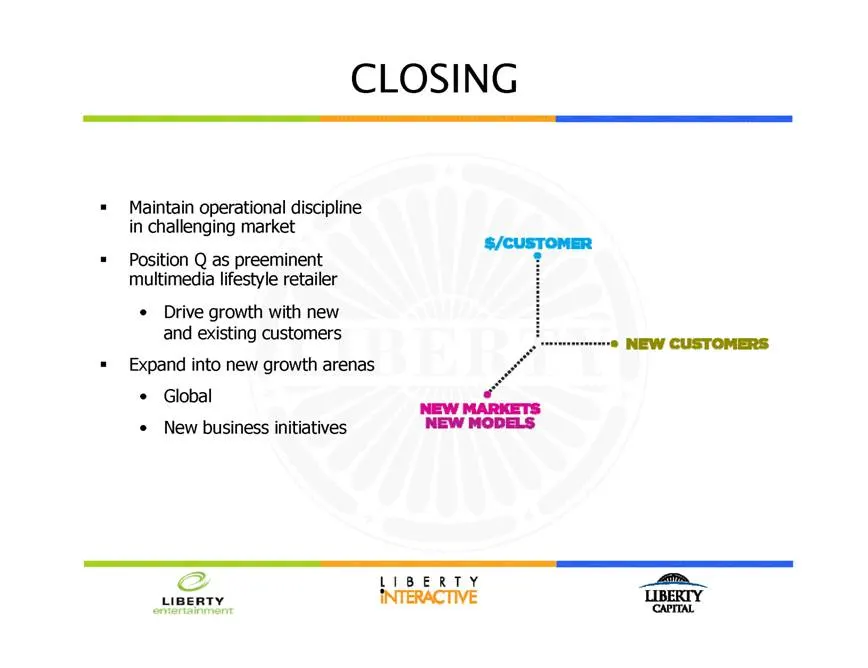
CLOSING Maintain operational discipline in challenging market Position Q as preeminent multimedia lifestyle retailer · Drive growth with new and existing customers Expand into new growth arenas · Global · New business initiatives
Slide 123: e-commerce Discussion
e-commerce Discussion Ryan DeLuca CEO Bodybuilding.com Dan Haight COO BUYSEASONS Jim Holland CEO Backcountry.com Bill Strauss CEO Provide Commerce
Slide 124: Why e-commerce Acquisitions
Why e-commerce Acquisitions Generate strong IRRs Invest in high growth businesses Diversify revenue stream Exploit synergies across portfolio · Video and e-commerce
Slide 125: What We Want
What We Want High growth, strong cash flow Low multiple relative to growth Niche markets Strong management teams Unique value propositions Differentiated business model/practices Synergistic with existing portfolio
Slide 126: Acquisition History
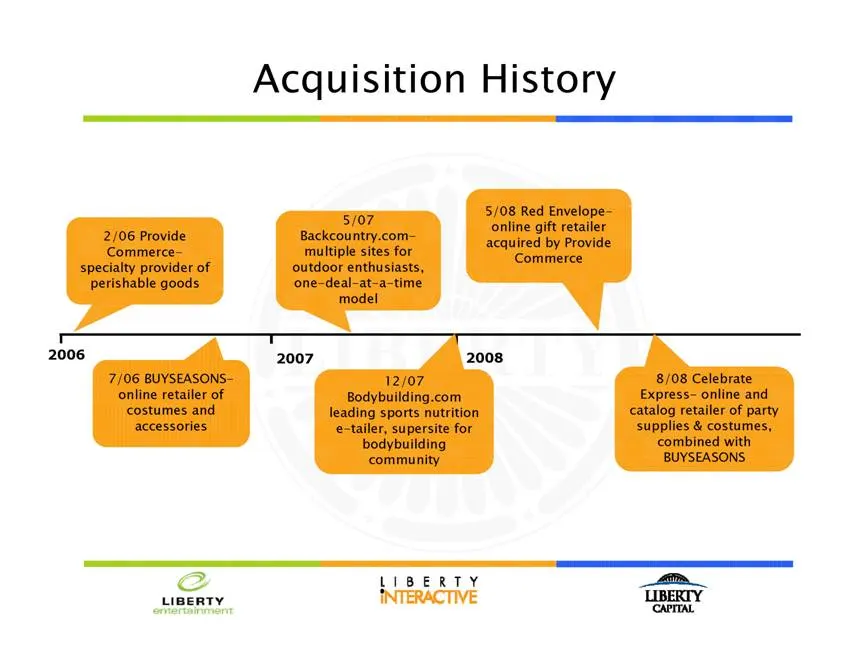
Acquisition History 5/07 5/08 Red Envelope- online gift retailer 2/06 Provide Backcountry.com- acquired by Provide Commerce- multiple sites for Commerce specialty provider of outdoor enthusiasts, perishable goods one-deal-at-a-time model 2006 2007 - 12/07 Express- online and online retailer of Bodyb
Slide 127: Value and Growth
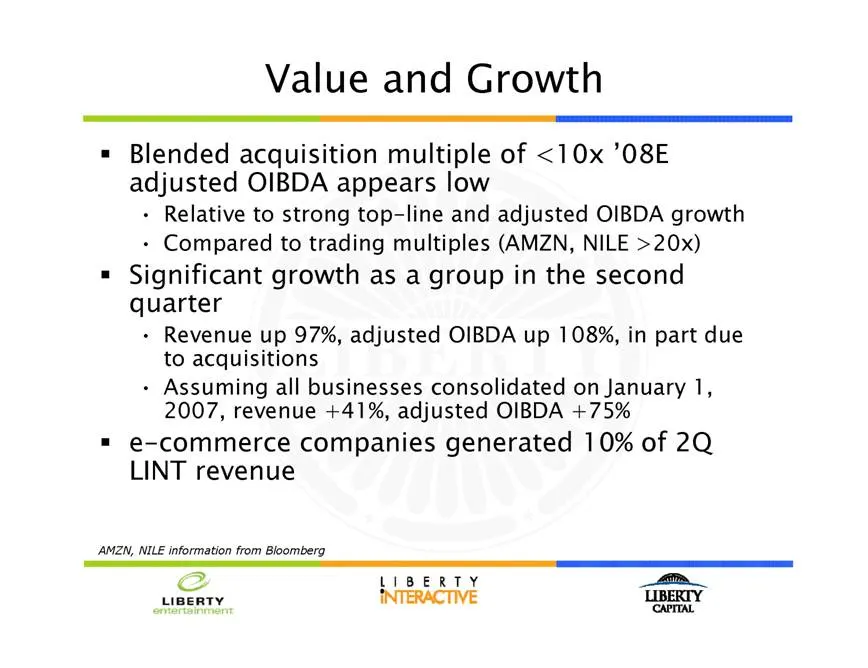
Value and Growth Blended acquisition multiple of <10x ’08E adjusted OIBDA appears low · Relative to strong top-line and adjusted OIBDA growth · Compared to trading multiples (AMZN, NILE >20x) Significant growth as a group in the second quarter · Revenue up 97%, adjusted OIBDA up 108%, in part due to
Slide 128: Appendix
Appendix (ez LIBERTY _Liperty INTERACTIVE
Slide 129: Non-GAAP Financial Measures
Non-GAAP Financial Measures This presentation includes a presentation of adjusted OIBDA, which is a non-GAAP financial measure, for Starz Entertainment, the US operations of QVC, Liberty Interactive (which is not an entity, but rather a group of assets tracked by the Liberty Interactive tracking sto
Slide 130: Reconciling Schedules: Starz Entertainment
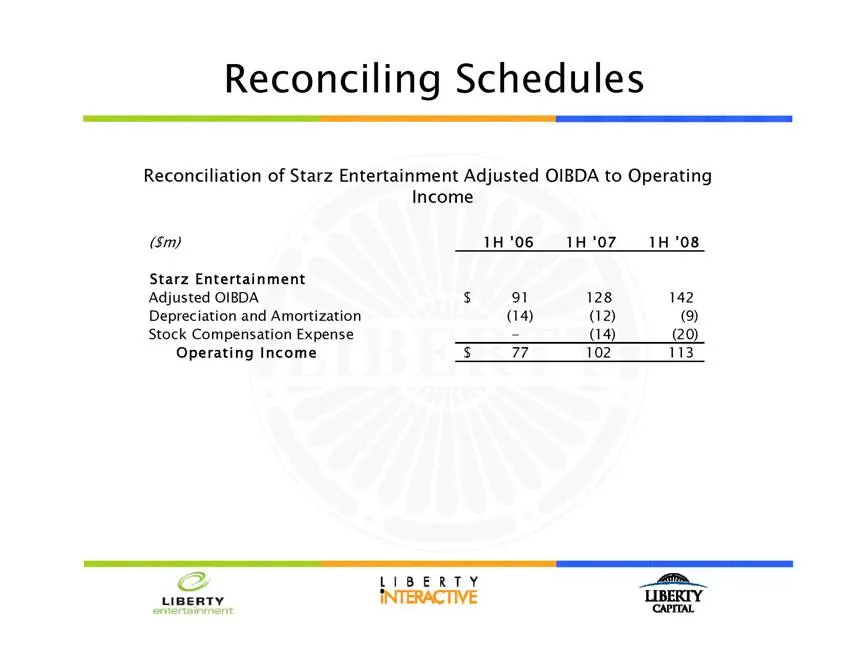
Reconciling Schedules Reconciliation of Starz Entertainment Adjusted OIBDA to Operating Income ($m) 1H '06 1H '07 1H '08 Starz Entertainment Adjusted OIBDA $ 91 128 142 Depreciation and Amortization (14) (12) (9) Stock Compensation Expense - (14) (20) Operating Income $ 77 102 113
Slide 131: Reconciling Schedules: e-commerce
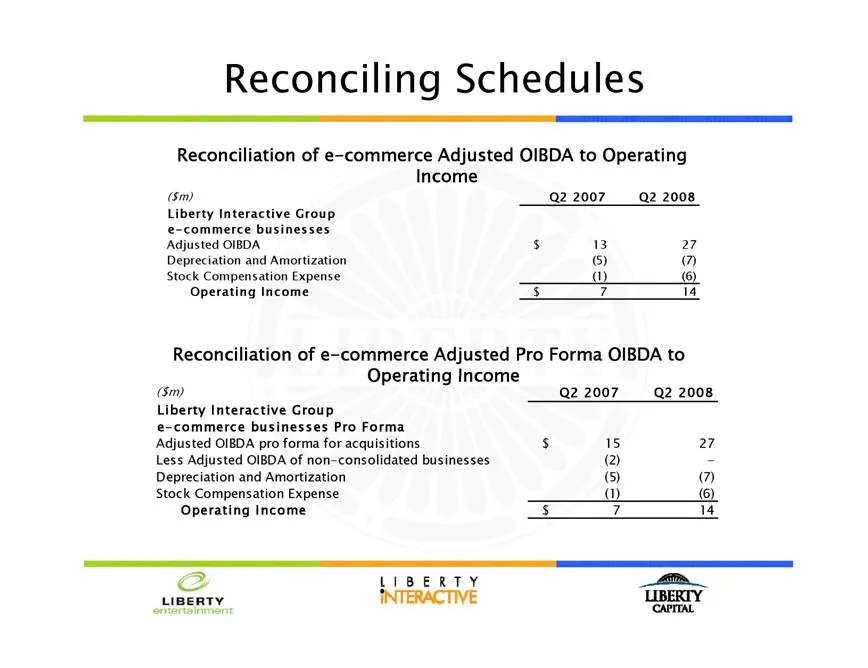
Reconciling Schedules Reconciliation of e-commerce Adjusted OIBDA to Operating Income ($m) Q2 2007 Q2 2008 Liberty Interactive Group e-commerce businesses Adjusted OIBDA $ 13 27 Depreciation and Amortization (5) (7) Stock Compensation Expense (1) (6) Operating Income $ 7 14 Reconciliation of e-comme
Slide 132: Reconciling Schedules: Liberty Interactive
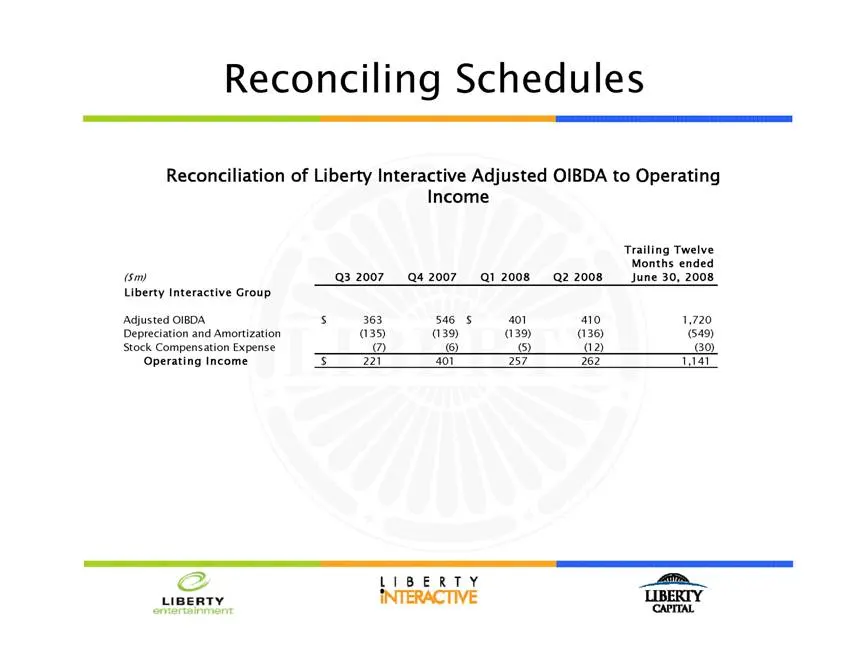
Reconciling Schedules Reconciliation of Liberty Interactive Adjusted OIBDA to Operating Income Trailing Twelve Q3 2007 Q4 2007 Q1 2008 Q2 2008 Months ended ($m) June 30, 2008 Liberty Interactive Group Adjusted OIBDA $ 363 546 $ 401 410 1,720 Depreciation and Amortization (135) (139) (139) (136) (549
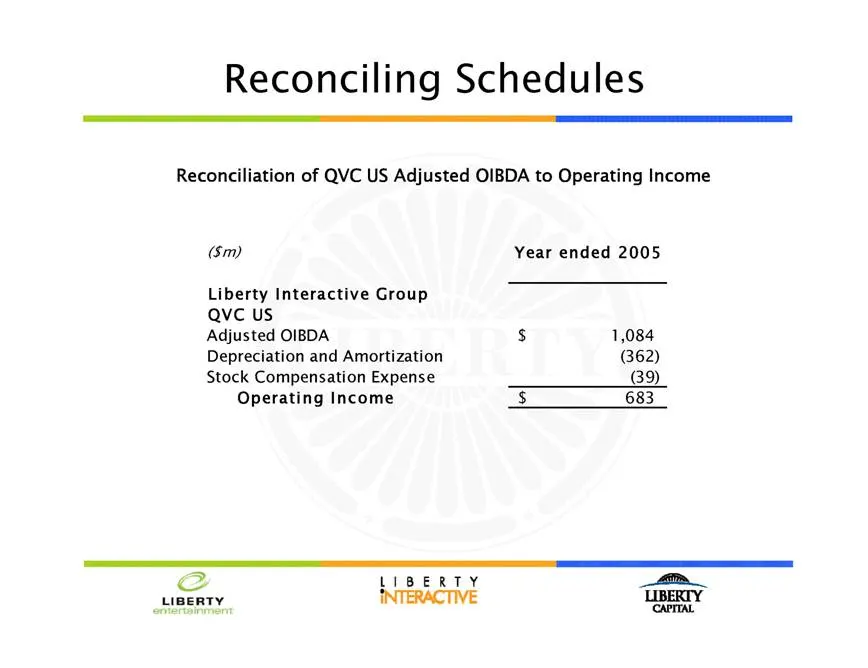
Slide 133: Reconciling Schedules: QVC US
Reconciling Schedules Reconciliation of QVC US Adjusted OIBDA to Operating Income ($m) Year ended 2005 Liberty Interactive Group QVC US Adjusted OIBDA $ 1,084 Depreciation and Amortization (362) Stock Compensation Expense (39) Operating Income $ 683
Slide 134: Bill Strauss
Bill Strauss CEO provide-commerce.
Slide 135: Provide Commerce overview
Collection of branded websites each offering high quality products shipped direct from the supplier to the consumer Designed specifically around the way consumers shop Our proprietary technology allows us to eliminate multiple intermediaries from the legacy supply chain, thereby realizing significan
Slide 136: The Floral Market and Growth Trends
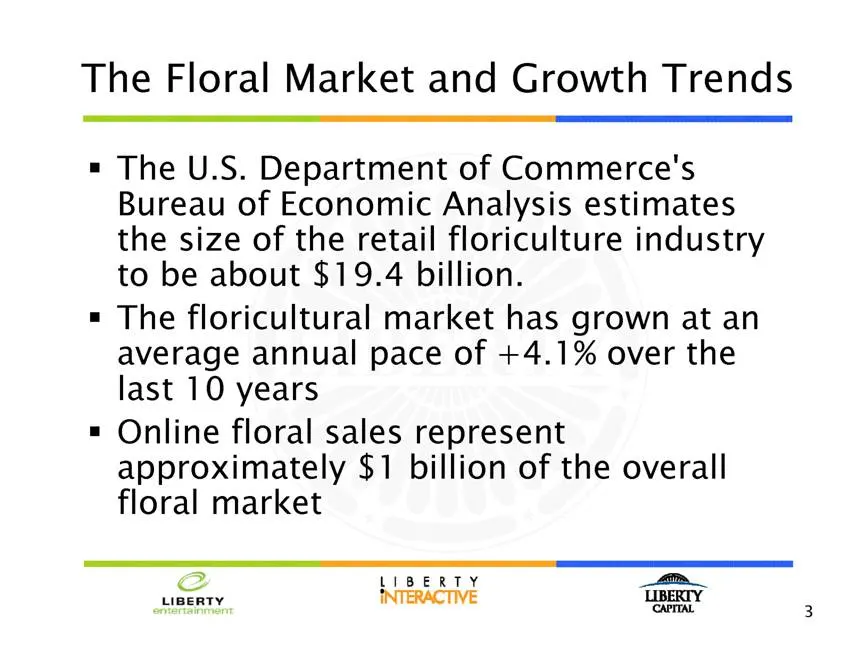
The Floral Market and Growth Trends The U.S. Department of Commerce's Bureau of Economic Analysis estimates the size of the retail floriculture industry to be about $19.4 billion. The floricultural market has grown at an average annual pace of+4.1% over the last 10 years Online floral sales represen
Slide 137: Business Model Advantages
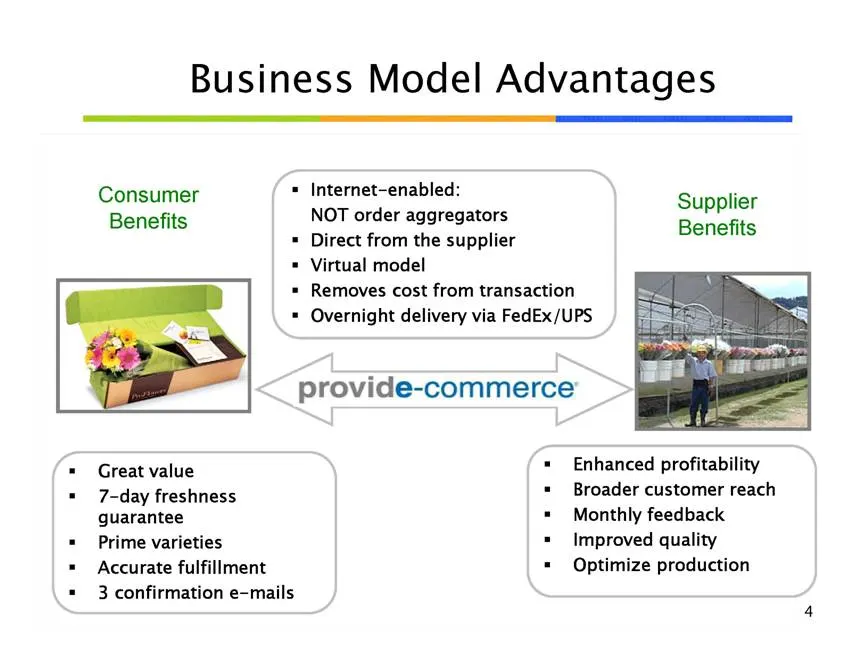
Business Model Advantages Consumer Internet-enabled: Supplier NOT order aggregators Benefits Benefits Direct from the supplier Virtual model Removes cost from transaction Overnight delivery via FedEx/UPS Great value 7-day freshness guarantee Prime varieties Accurate fulfillment 3 confirmation e-mail
Slide 138: Business Strategy Highlights
Business Strategy Highlights Focus on the customer · Ongoing website improvements · Continued investment in quality Optimize the core business · Increase AOV and conversion · Product development and portfolio optimization
Slide 139: It's Also About Our Newest Brand
It’s Also About Our Newest Brand Assumed ownership of RedEnvelope on June 23, 2008 Offers an array of hard goods merchandise targeting “acquaintances, colleagues, and friends” Well-known brand name with high unaided recall Solid customer base Adding our strengths in management, marketing, planning,
Slide 140: Growth Opportunities
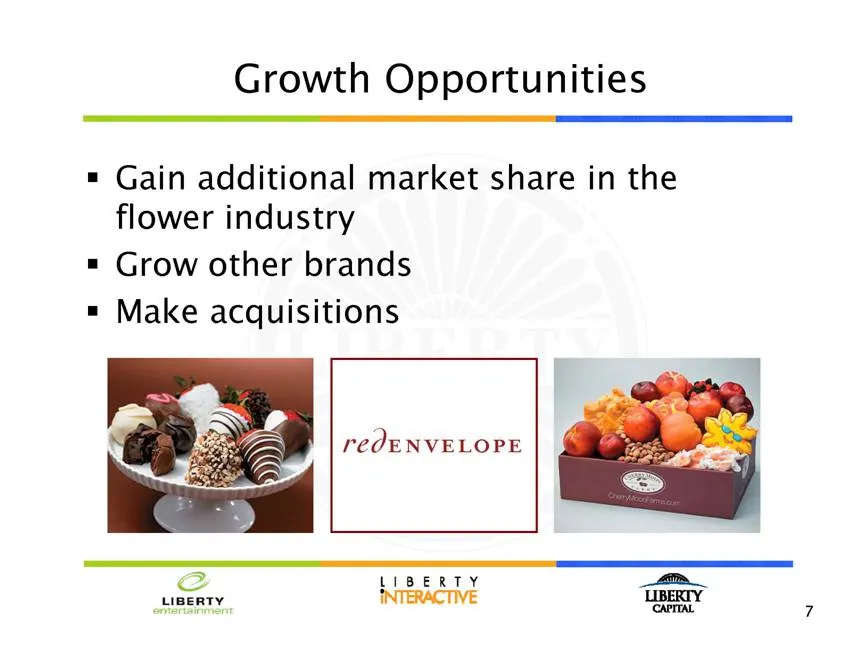
Growth Opportunities Gain additional market share in the flower industry Grow other brands Make acquisitions
Slide 141: Jim Holland
Jim Holland CEO backcountry.com CAPITAL
Slide 142: Backcountry.com
Backcountry.com Founded in 1996, acquired by Liberty June 2007 Located in Salt Lake City and Park City, Utah, 700 employees We run seven category-leading online stores that focus on high-end outdoor gear, snowboarding, skiing and closeout gear The largest and fastest growing outdoor gear and action
Slide 143: Some Brands We Sell
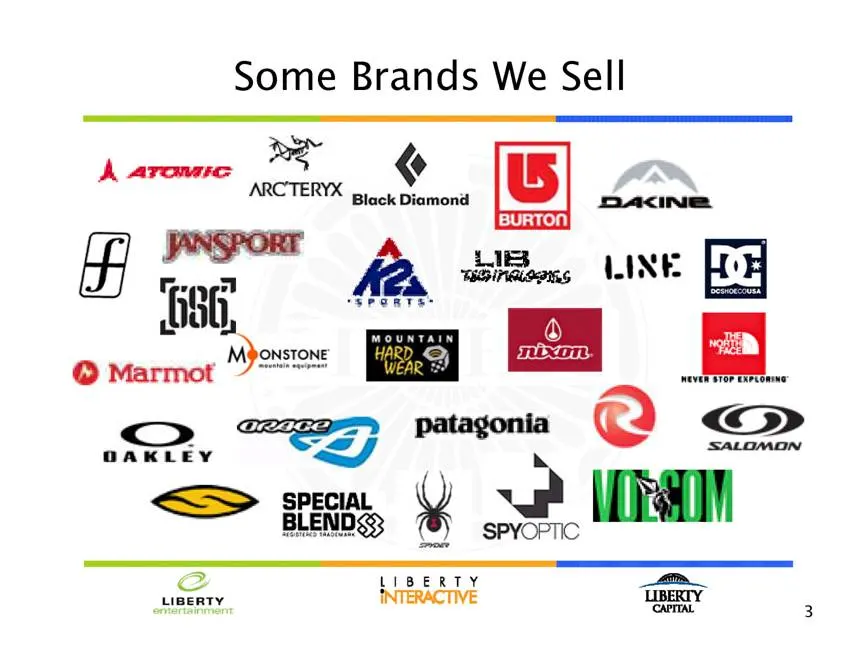
Some Brands We Sell LIBERTY _—_a_ upenty INTERACTIVE TOBERTY Cc
Slide 144: Opportunities / Competitive Edge
Opportunities / Competitive Edge Closeout business does well in a recession; five of our seven sites focus in this area Expanding into cycling · Strengthening our summer business smoothes out our overhead and makes us more profitable Leveraging customer generated content – a snowball effect
Source: SEC EDGAR · 425 filed Sep 26, 2008
More decks from QVC Group, Inc.
 Q3 2026 Earnings Presentation16 slides · Nov 13, 2026
 Presentation (April 2026)103 slides · Apr 17, 2026
 Q3 2025 Earnings Presentation13 slides · Nov 5, 2025
 Q2 2025 Earnings Presentation13 slides · Aug 7, 2025
 Q1 2025 Earnings Presentation13 slides · May 7, 2025
 Q4 2024 Earnings Presentation13 slides · Feb 27, 2025