Coventry Health Care — First Health Group — Merger or Acquisition (October 2004)
18 slides from Coventry Health Care's merger presentation, Oct 14, 2004
Slide 1: Coventry Health Care
&c OVENTRY Health Care October 14, 2004
Slide 2: Safe Harbor & Other Legal Statements
Safe Harbor & Other Legal Statements Certain statements in this presentation will be forward- looking statements. Certain risks and uncertainties, including those in the Company's filings with the SEC, including its annual reports on Form 10-K, may materially impact those statements and could cause
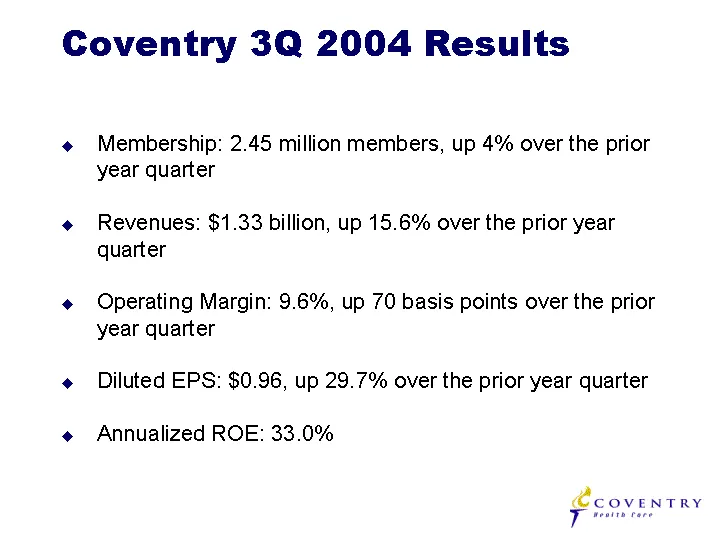
Slide 3: Coventry 3Q 2004 Results
Coventry 3Q 2004 Results Membership: 2.45 million members, up 4% over the prior year quarter Revenues: $1.33 billion, up 15.6% over the prior year quarter Operating Margin: 9.6%, up 70 basis points over the prior year quarter Diluted EPS: $0.96, up 29.7% over the prior year quarter Annualized ROE: 3
Slide 4: Planning for Stability
Planning for Stability Coventry recently announced the retirement of President & CEO, Allen F. Wise, effective January 1, 2005 Allen F. Wise to assume position of Chairman of the Board Current Chairman John A. Austin to remain as member of the Board Concurrently announced implementation of successio
Slide 5: Acquisition Rationale
Acquisition Rationale Strong platform for growth and meaningful synergies and savings from best practices National presence combined with local network strength Broad product portfolio and diversified client base Diversified revenues and cash flow streams Risk / non-risk National accounts / large gr
Slide 6: Acquisition & Integration Experience
Acquisition & Integration Experience Management team experience at creating value through acquisitions Successful integration of 14 acquisitions since 1999 Experience with transformational transactions - Principal Health Care, Inc. Experience with the MetLife / Travelers merger in 1995 Allen Wise Da
Slide 7: Transaction Summary
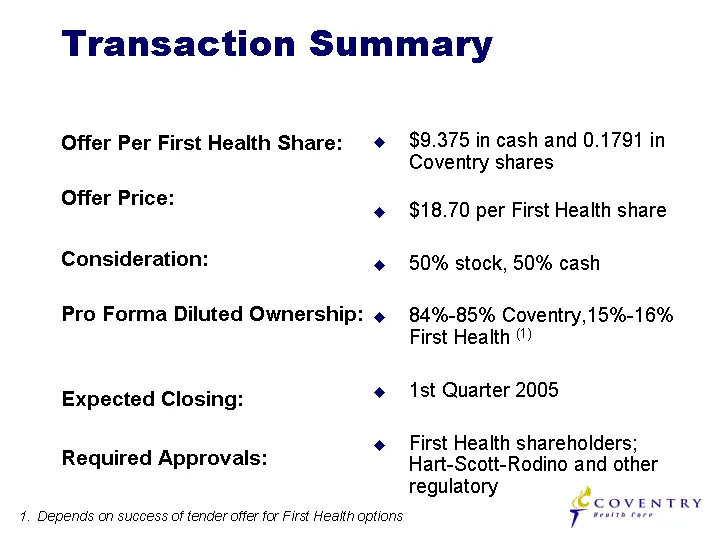
Transaction Summary Offer Per First Health Share: Offer Price: Consideration: Pro Forma Diluted Ownership: Expected Closing: Required Approvals: $9.375 in cash and 0.1791 in Coventry shares $18.70 per First Health share 50% stock, 50% cash 84%-85% Coventry,15%-16% First Health (1) 1st Quarter 2005 F
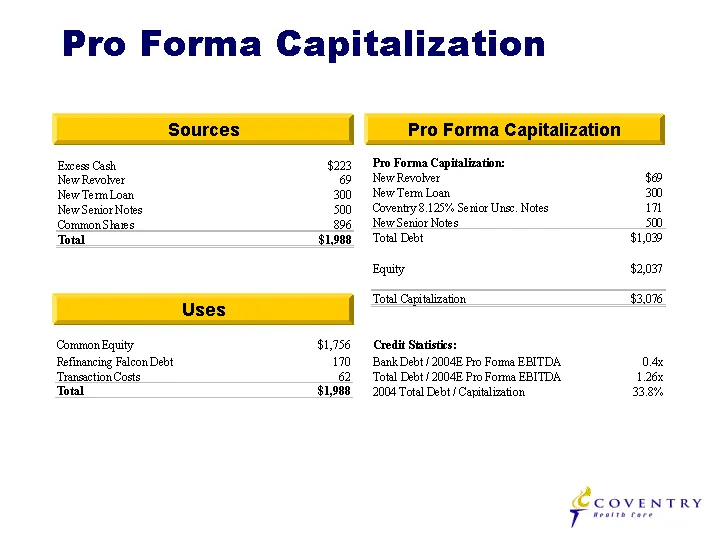
Slide 8: Pro Forma Capitalization Sources and Uses
Pro Forma Capitalization Sources Pro Forma Capitalization Uses
Slide 9: First Health Overview
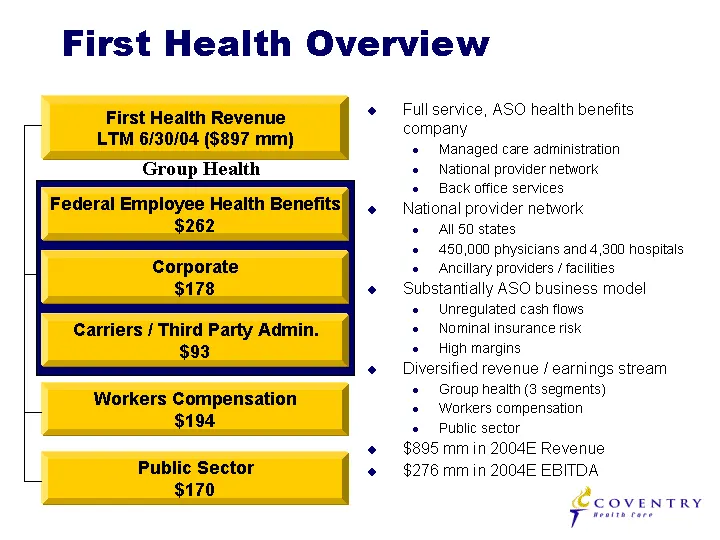
First Health Overview Full service, ASO health benefits company Managed care administration National provider network Back office services National provider network All 50 states 450,000 physicians and 4,300 hospitals Ancillary providers / facilities Substantially ASO business model Unregulated cash
Slide 10: National Presence with Local Network Strength
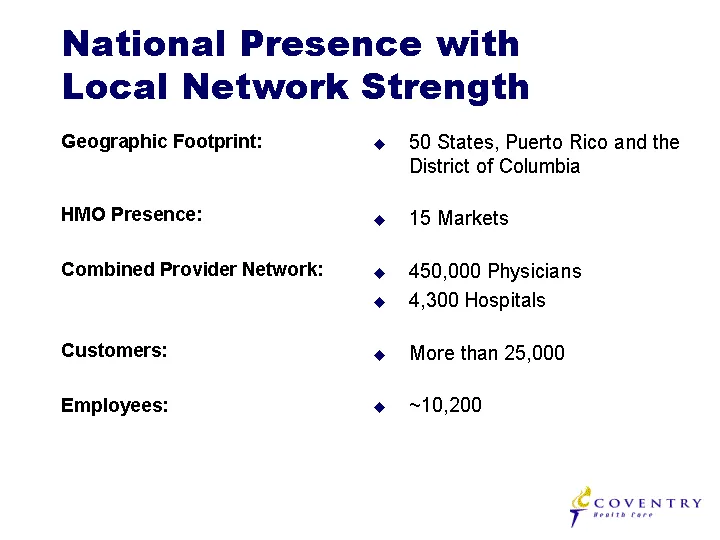
National Presence with Local Network Strength Geographic Footprint: HMO Presence: Combined Provider Network: Customers: Employees: 50 States, Puerto Rico and the District of Columbia 15 Markets 450,000 Physicians 4,300 Hospitals More than 25,000 ~10,200
Slide 11: Broad Product Portfolio and Diversified Client Base
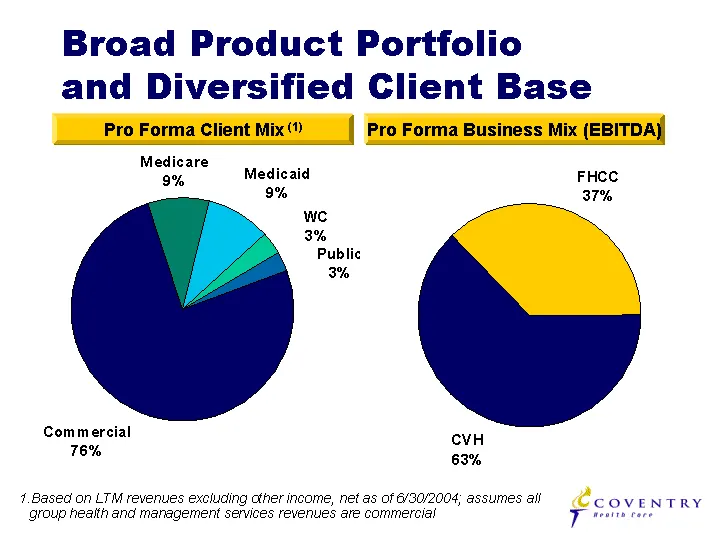
Broad Product Portfolio and Diversified Client Base Commercial Medicare Medicaid WC Public 4435.3 519.2 549.8 194.21 170.18 CVH FHCC East 499.1 295 Based on LTM revenues excluding other income, net as of 6/30/2004; assumes all group health and management services revenues are commercial Pro Forma Cl
Slide 12: Achievable Synergies
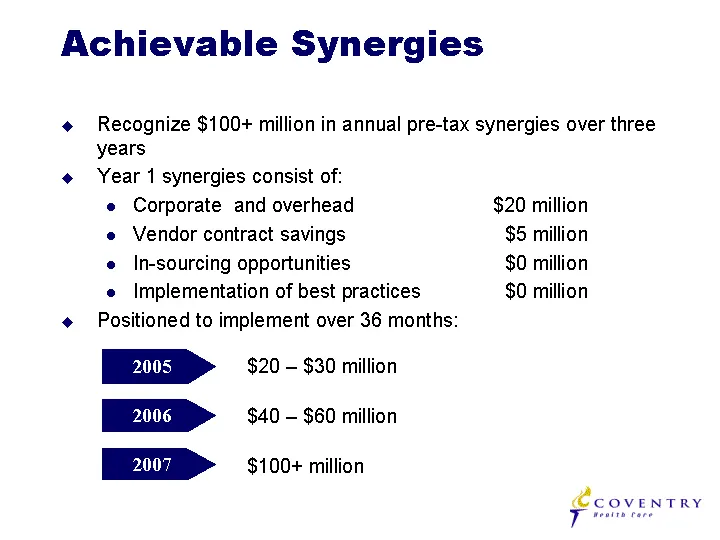
Achievable Synergies Recognize $100+ million in annual pre-tax synergies over three years Year 1 synergies consist of: Corporate and overhead $20 million Vendor contract savings $5 million In-sourcing opportunities $0 million Implementation of best practices $0 million Positioned to implement over 3
Slide 13: Coventry 2005 Guidance
Coventry 2005 Guidance Risk Revenues: $5.90B - $6.00B Management Svcs: $100.0M - $105.0M MLR: 80.5% - 81.5% SG&A: $660.0M - $670.0M D&A: $20.0M - $21.0M Investment Income: $43.0M - $45.0M Interest Expense: $14.5M - $14.8M Tax Rate: 35.8% - 36.2% Diluted Share Count: 90.5M - 91.5M Diluted EPS: $4.13
Slide 14: First Health Discloses Revised 2004 Guidance
First Health Discloses Revised 2004 Guidance Diluted EPS: $1.25 - $1.28
Slide 15: Pro Forma Effect of Transaction
Pro Forma Effect of Transaction Blended cost of new borrowing approximately 6% $20-$30 million pre-tax synergies expected to be realized in 2005 16.4 million new basic shares expected to be issued in the transaction Transaction expected to be 7%-9% accretive to Coventry's 2005 EPS guidance
Slide 16: Summary
Summary Health plan business right on track Opportunity to acquire related businesses we understand Resources to manage exist within Significantly accretive immediately Financially prudent transaction structure Relatively low risk transaction - Companies stronger together than separately in tomorrow
Slide 17: Additional Information
Additional Information This communication is not a solicitation of a proxy from any security holder of First Health. Coventry and First Health intend to file a registration statement on Form S-4 with the SEC in connection with the Merger. The Form S-4 will contain a prospectus, a proxy statement and
Slide 18: Coventry Health Care
&c OVENTRY Health Care
Source: SEC EDGAR · 425 filed Oct 14, 2004
More decks from Coventry Health Care Inc
 Credit Suisse 2012 Healthcare Conference16 slides · Nov 14, 2012
 Merger or Acquisition (August 2012)12 slides · Aug 20, 2012
 Merger or Acquisition (August 2012)29 slides · Aug 20, 2012
 Investor Presentation (March 2008)16 slides · Mar 17, 2008
 Q3 2005 Earnings Presentation21 slides · Nov 7, 2005
 Shareholder Meeting (May 2005)18 slides · May 19, 2005