Rockwool A/S Class A · OMXCOP:ROCK_A
Rockwool A/S Class A — Rockwool International — Basic materials seminar, Exane BNP Paribas, London 2008
52 slides from Rockwool A/S Class A's conference presentation, Mar 19, 2008
Slide 1: Basic materials seminar, Exane BNP Paribas, London 19 March 2008
Basic materials seminar Exane BNP Paribas London 19 March 2008 CFO, Gilles Maria Vice President, Thorkild Diness Jensen 1
Slide 2: Forward-looking statement
Forward-looking statement The statements on the future in this presentation, including expected sales and earnings, are associated with risks and uncertainties and may be affected by factors influencing the activities of the group, e.g. the global economic environment, including interest and exchang
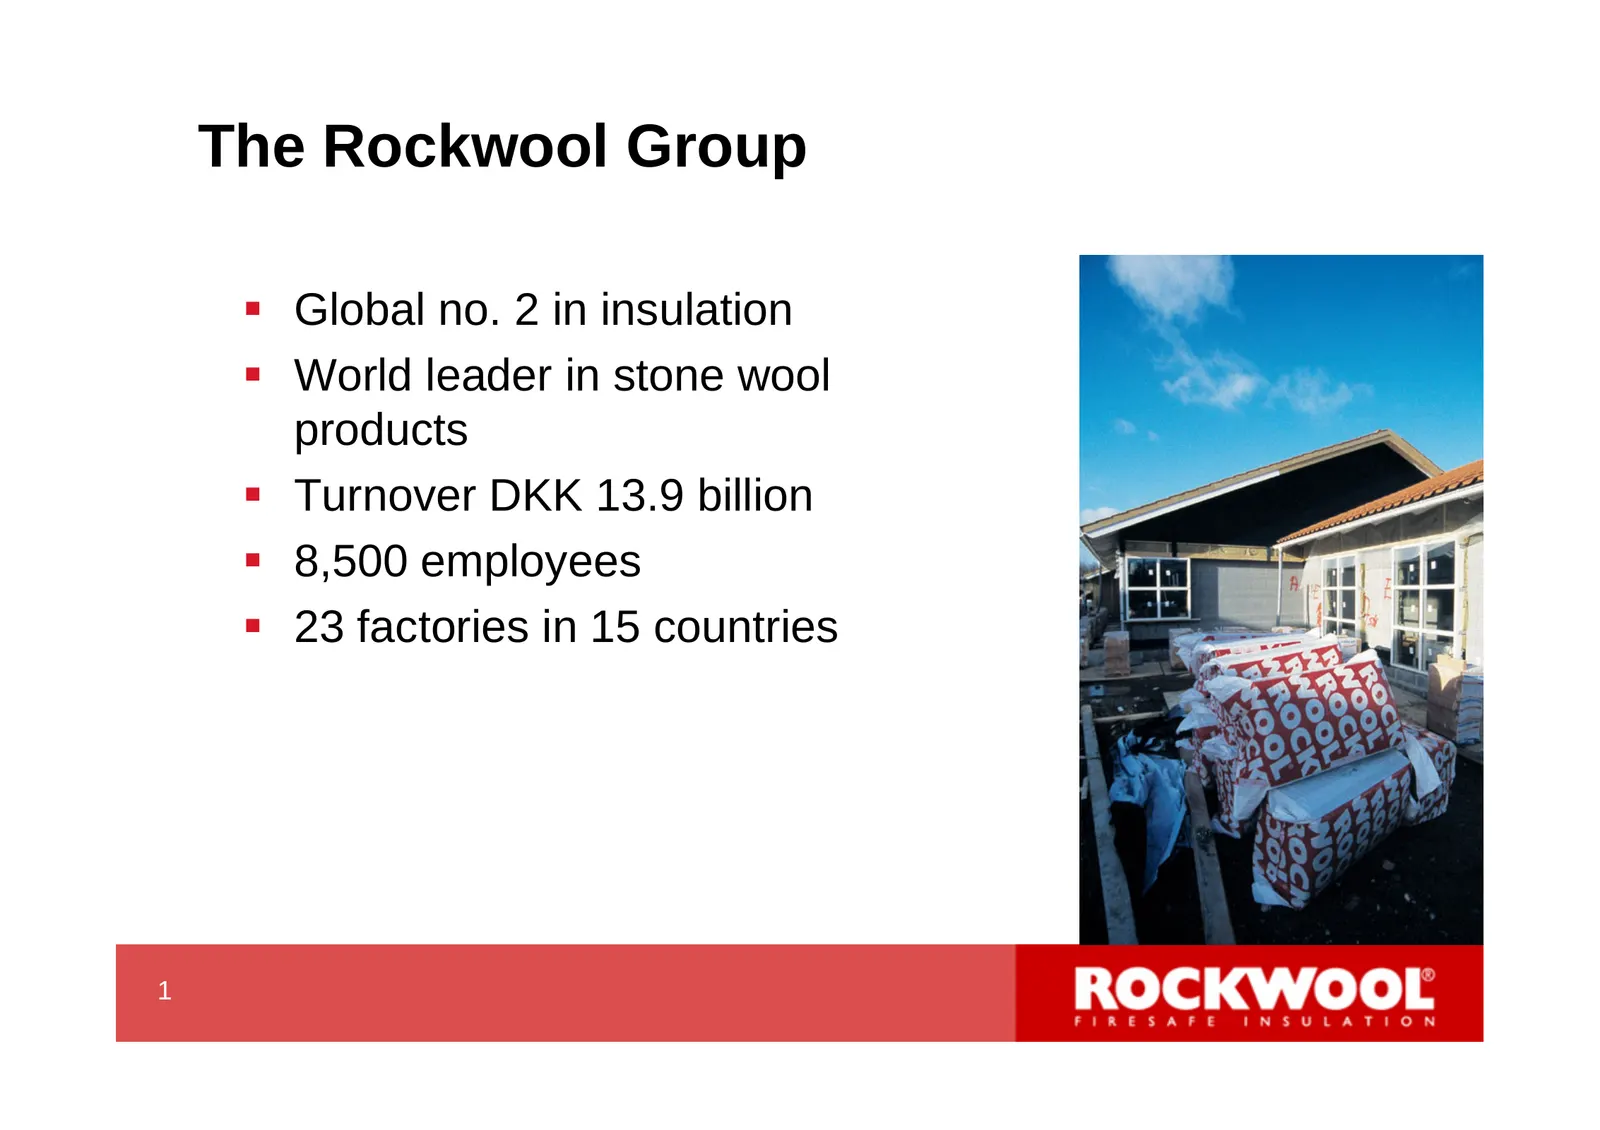
Slide 3: The Rockwool Group
The Rockwool Group Global no. 2 in insulation World leader in stone wool products Turnover DKK 13.9 billion 8,500 employees 23 factories in 15 countries 1 3
Slide 4: The Group's Mission
The Group’s Mission The Rockwool Group must be the preferred supplier of products, systems and solutions for improved energy efficiency, acoustic performance and fire safety in buildings 2 4
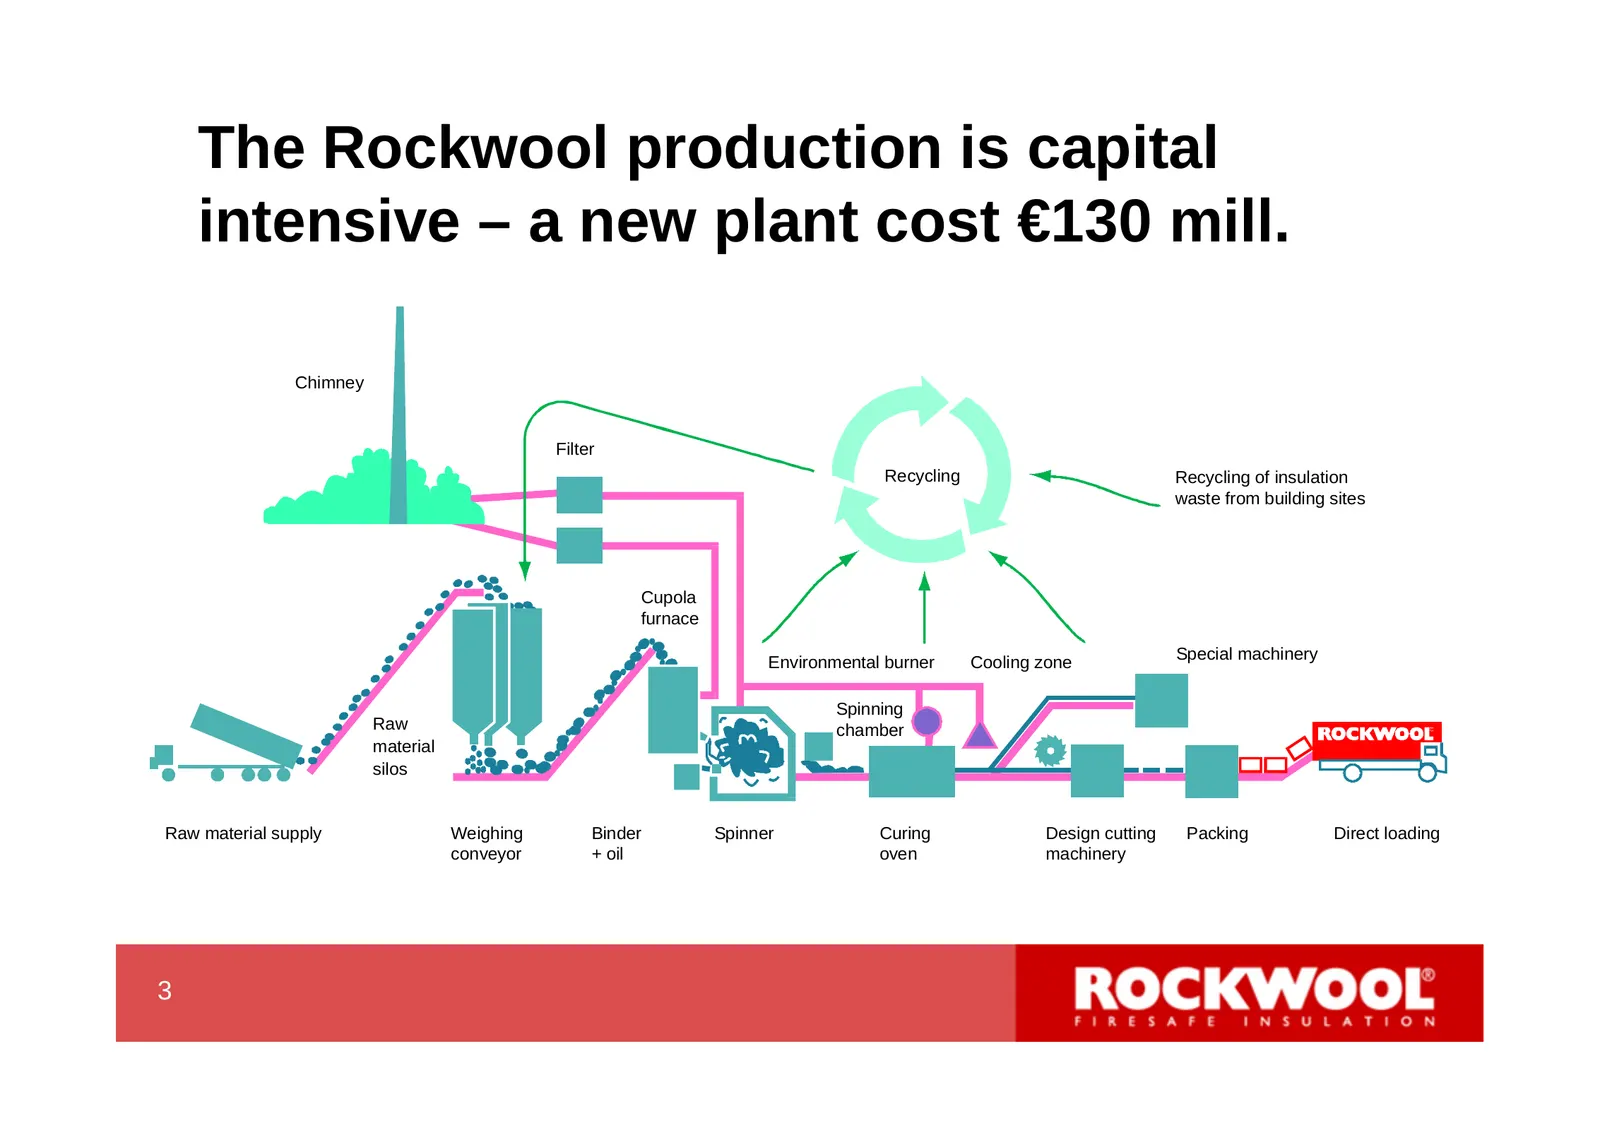
Slide 5: The Rockwool production is capital intensive – a new plant cost €130 mill.
The Rockwool production is capital intensive – a new plant cost €130 mill. Chimney Filter Recycling Recycling of insulation waste from building sites Cupola furnace Environmental burner Cooling zone Special machinery Spinning Raw chamber material silos Raw material supply Weighing Binder Spinner Cur
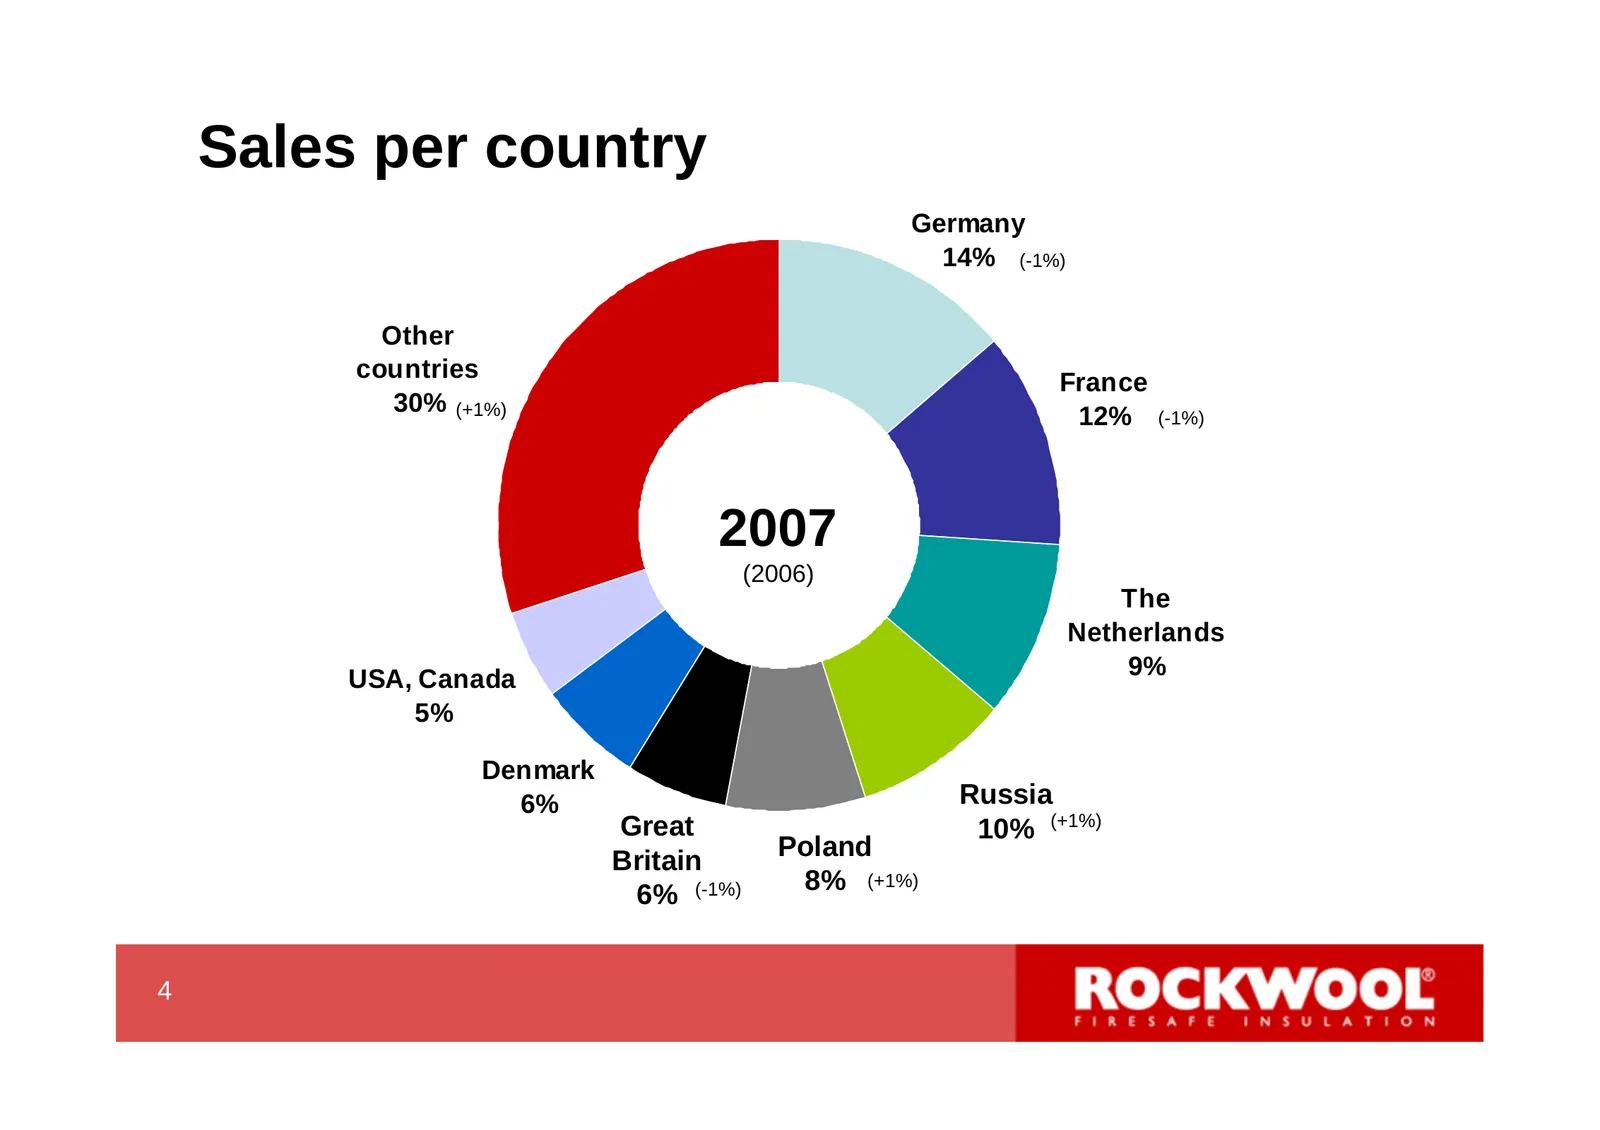
Slide 6: Sales per country
Sales per country Germany 14% (-1%) Other countries France 30% (+1%) 12% (-1%) 2007 (2006) The Netherlands USA, Canada 9% 5% Denmark 6% Russia Great 10% (+1%) Poland Britain 8% (+1%) 6% (-1%) 4 6
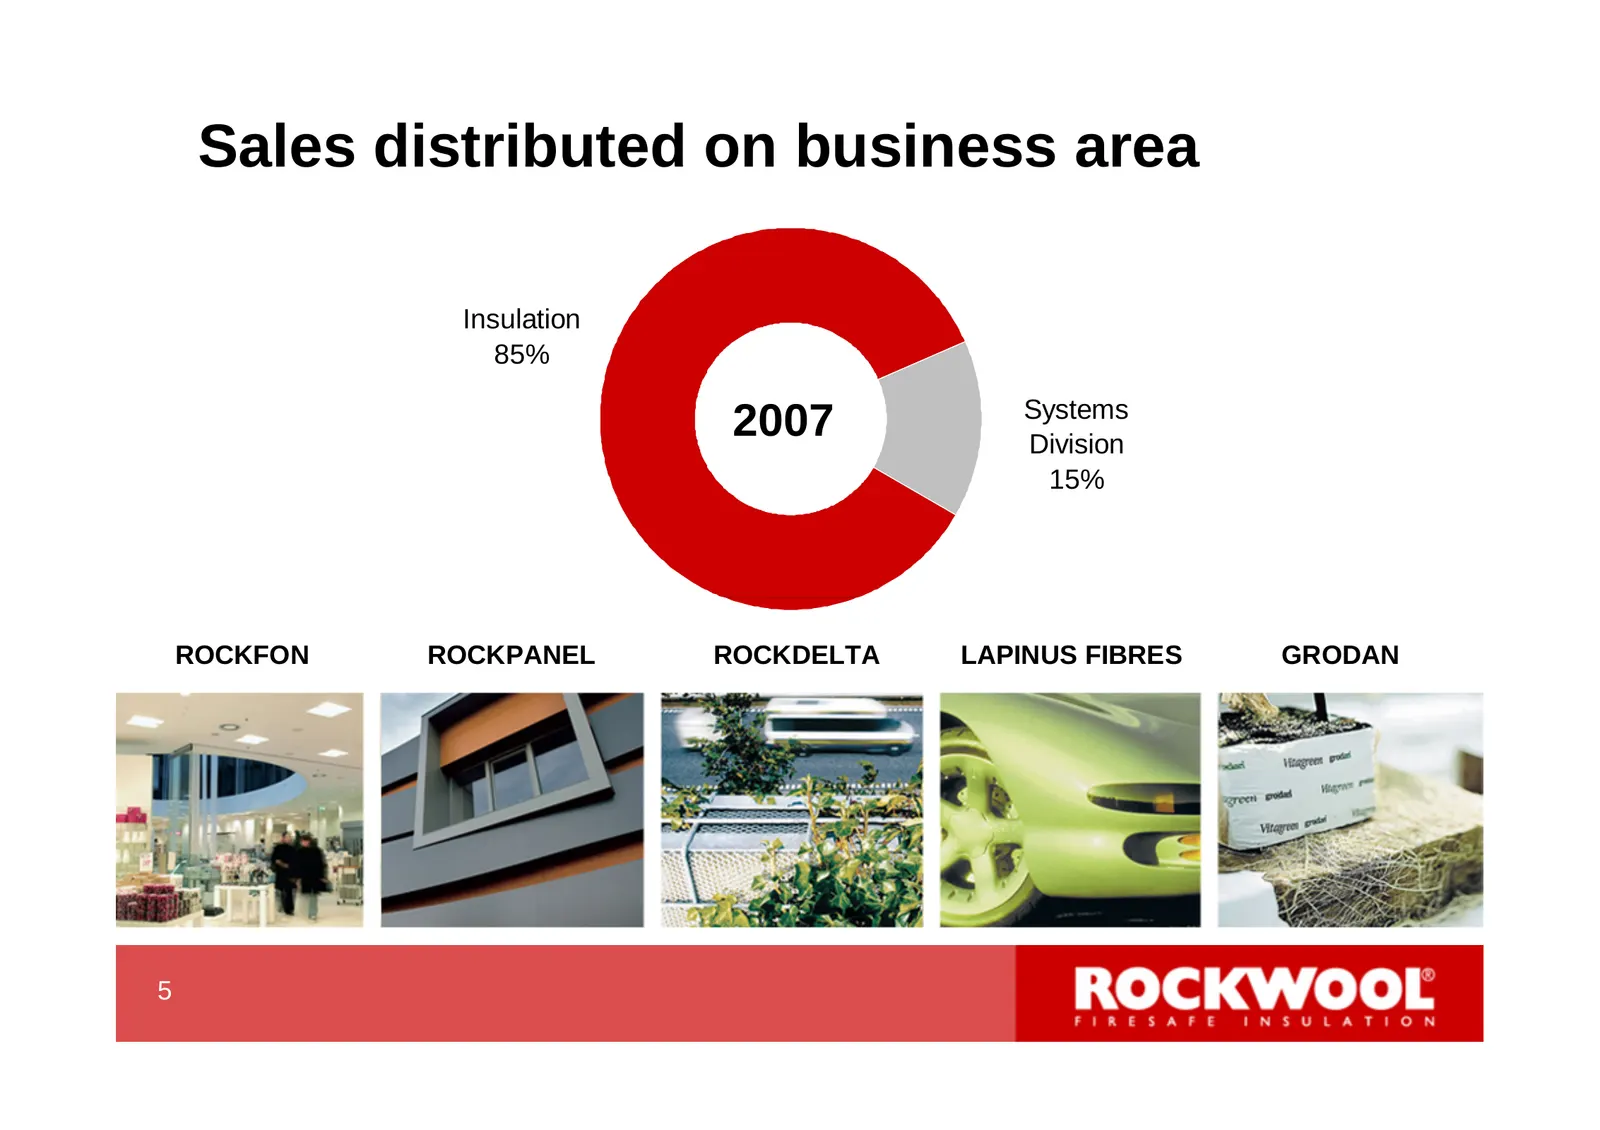
Slide 7: Sales distributed on business area
Sales distributed on business area Insulation 85% Systems 2007 Division 15% ROCKFON ROCKPANEL ROCKDELTA LAPINUS FIBRES GRODAN 5 7
Slide 8: BuildDesk
BuildDesk The Rockwool Group’s consultancy business - focusing on creating an energy efficient and sustainable building environment The BuildDesk division employs more than 100 employees and is market active in Austria, Germany, Holland, Denmark and the UK In 2007, CEA, a leading consultancy b
Slide 9: Main results from 2007
Main results from 2007 7 9
Slide 10: Sales increased by 21% in 2007
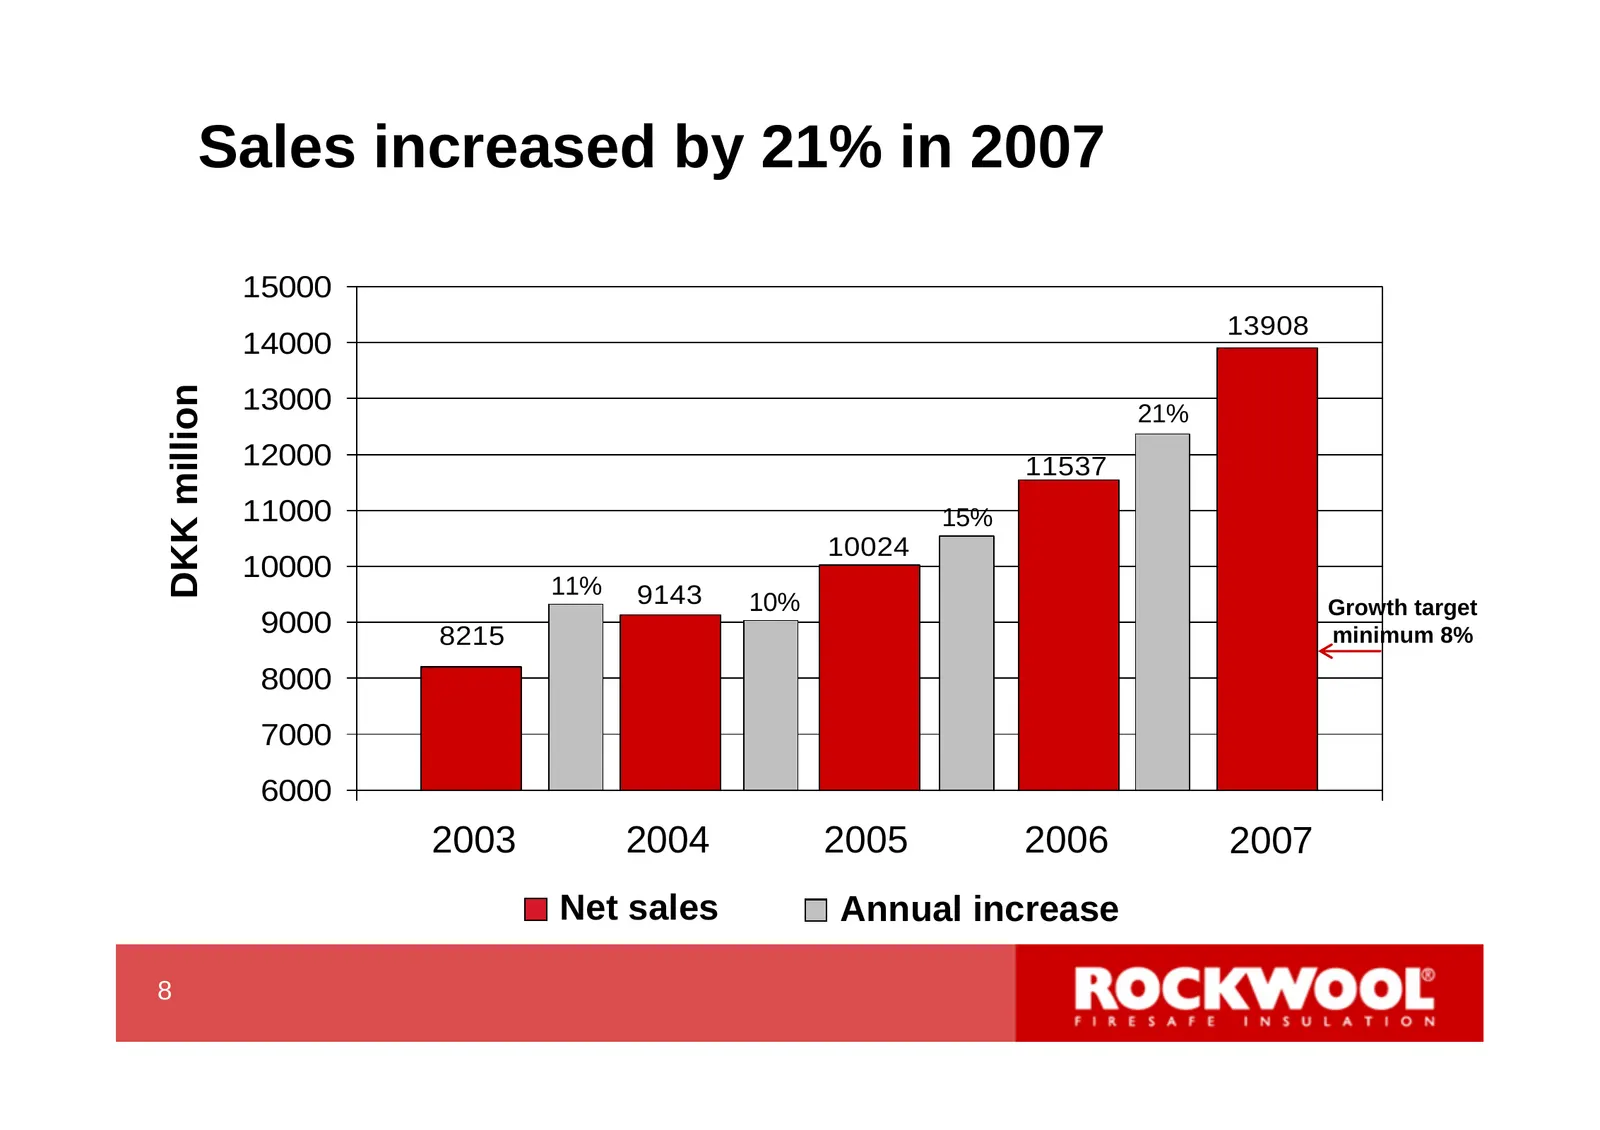
Sales increased by 21% in 2007 15000 13908 14000 DKK million 13000 21% 12000 11537 11000 15% 10024 10000 11% 9143 10% Growth target 9000 8215 minimum 8% 8000 7000 6000 2003 2004 2005 2006 2007 Net sales Annual increase 8 10
Slide 11: Long term sales development
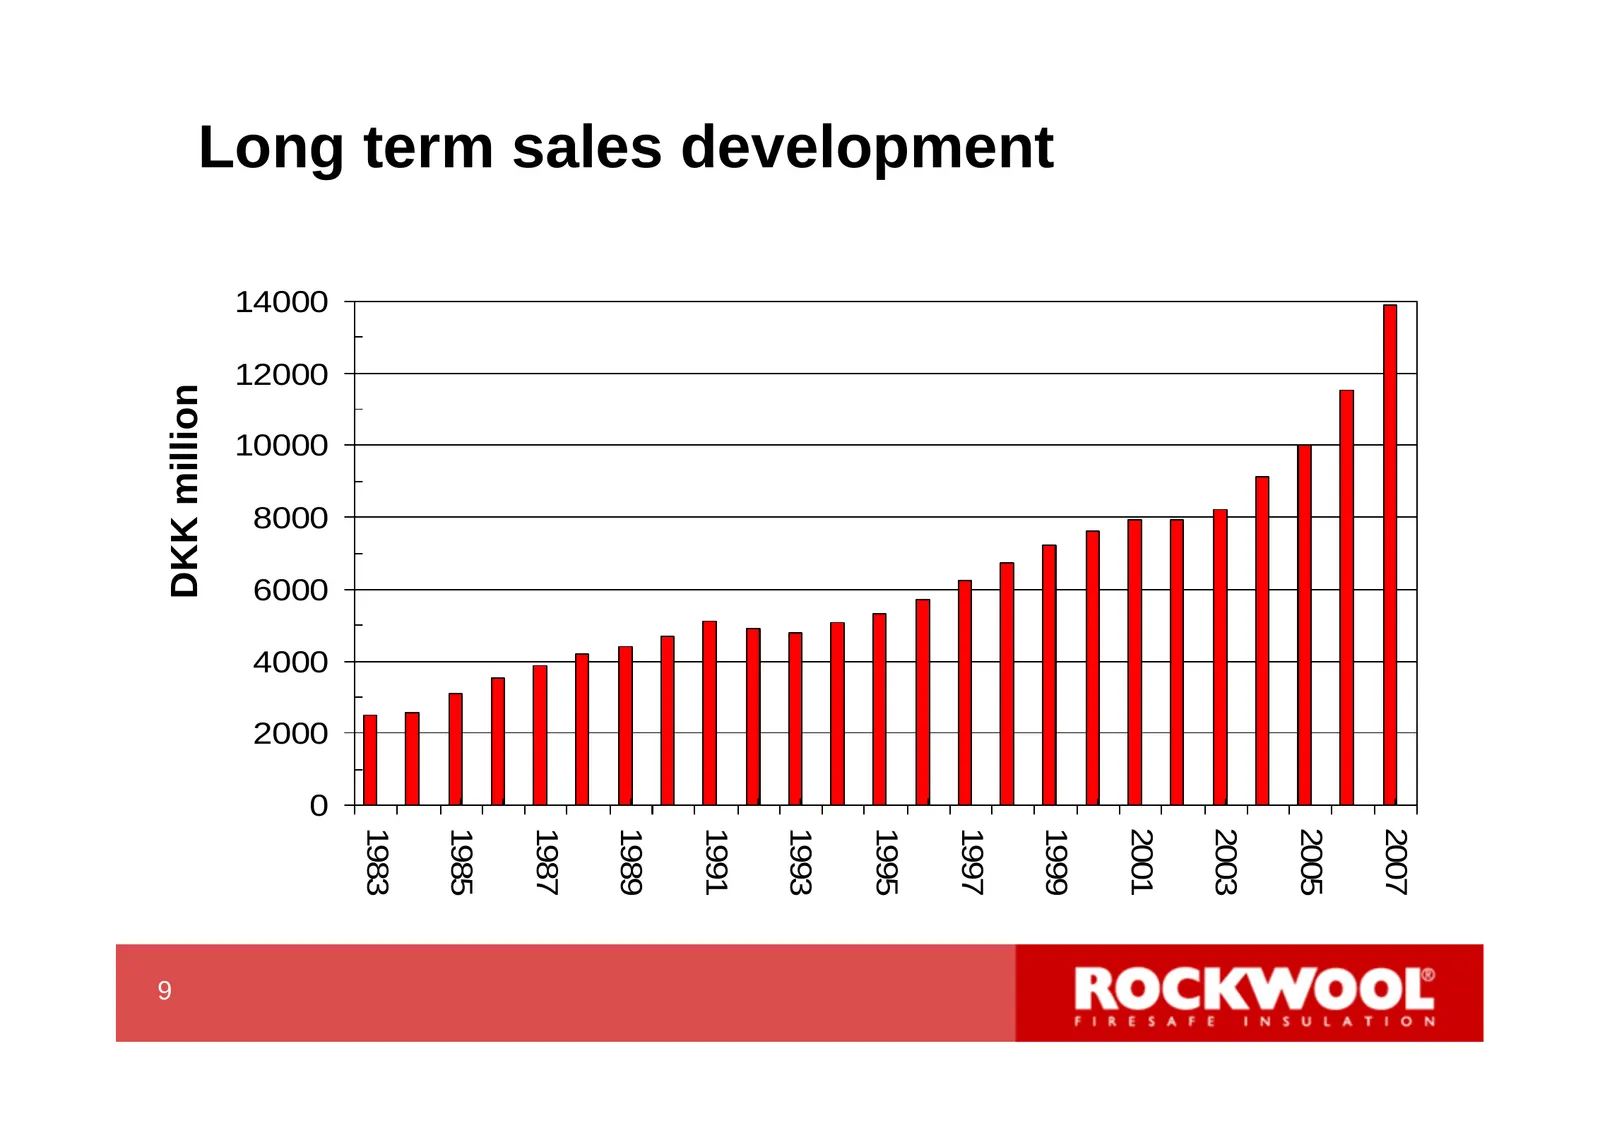
Long term sales development 14000 12000 DKK million 10000 8000 6000 4000 2000 0 1983 1985 1987 1989 1991 1993 1995 1997 1999 2001 2003 2005 2007 9 11
Slide 12: EBIT increased by 93% in 2007
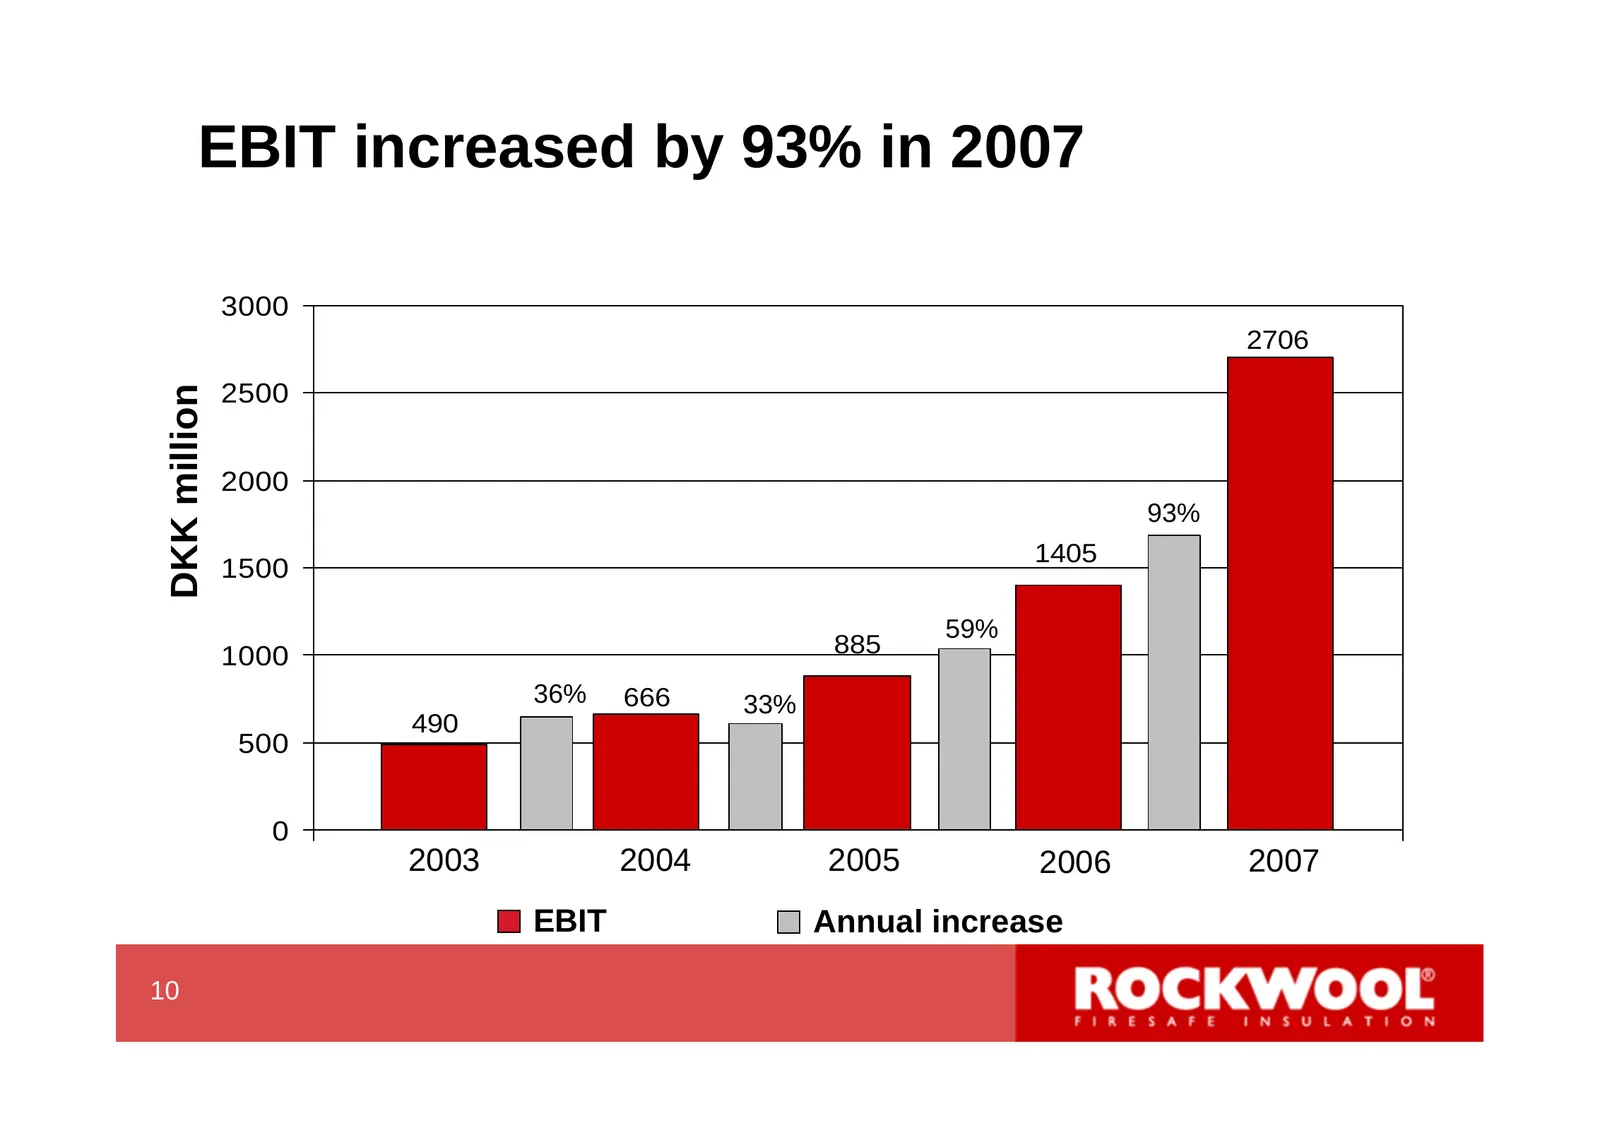
EBIT increased by 93% in 2007 3000 2706 2500 DKK million 2000 93% 1405 1500 59% 1000 885 36% 666 33% 490 500 0 2003 2004 2005 2006 2007 EBIT Annual increase 10 12
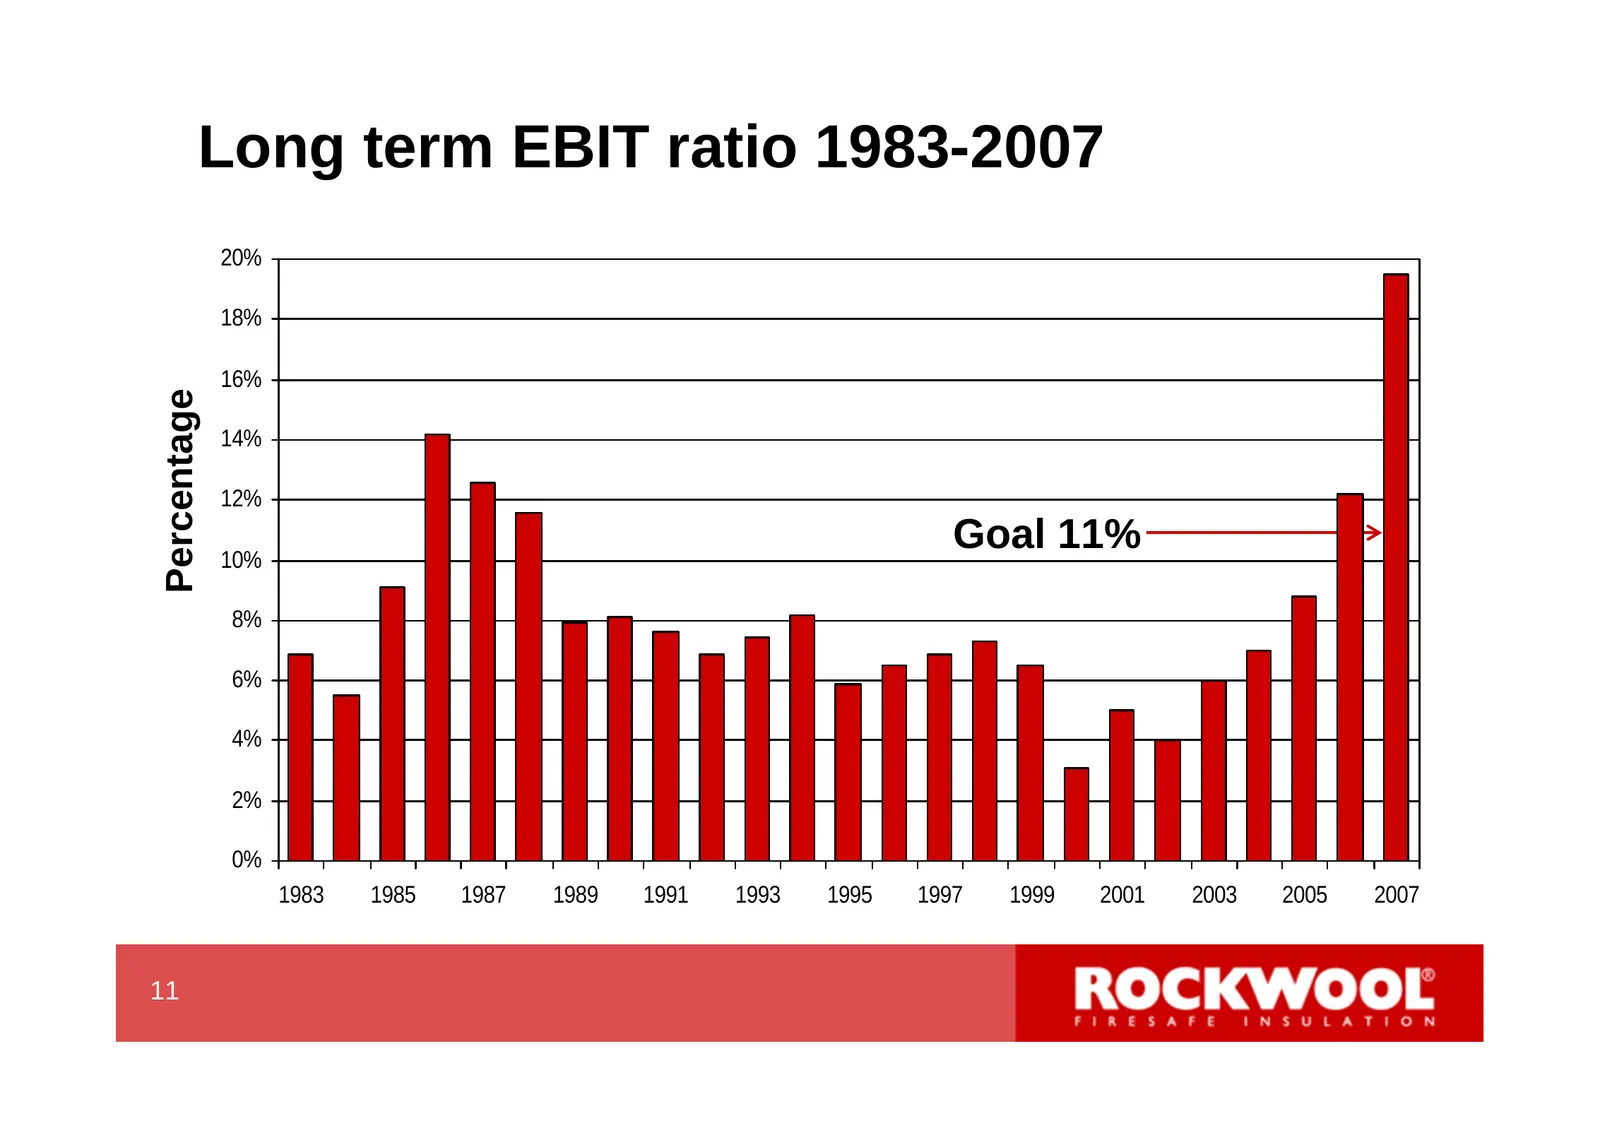
Slide 13: Long term EBIT ratio 1983-2007
Long term EBIT ratio 1983-2007 20% 18% 16% Percentage 14% 12% 10% Goal 11% 8% 6% 4% 2% 0% 1983 1985 1987 1989 1991 1993 1995 1997 1999 2001 2003 2005 2007 11 13
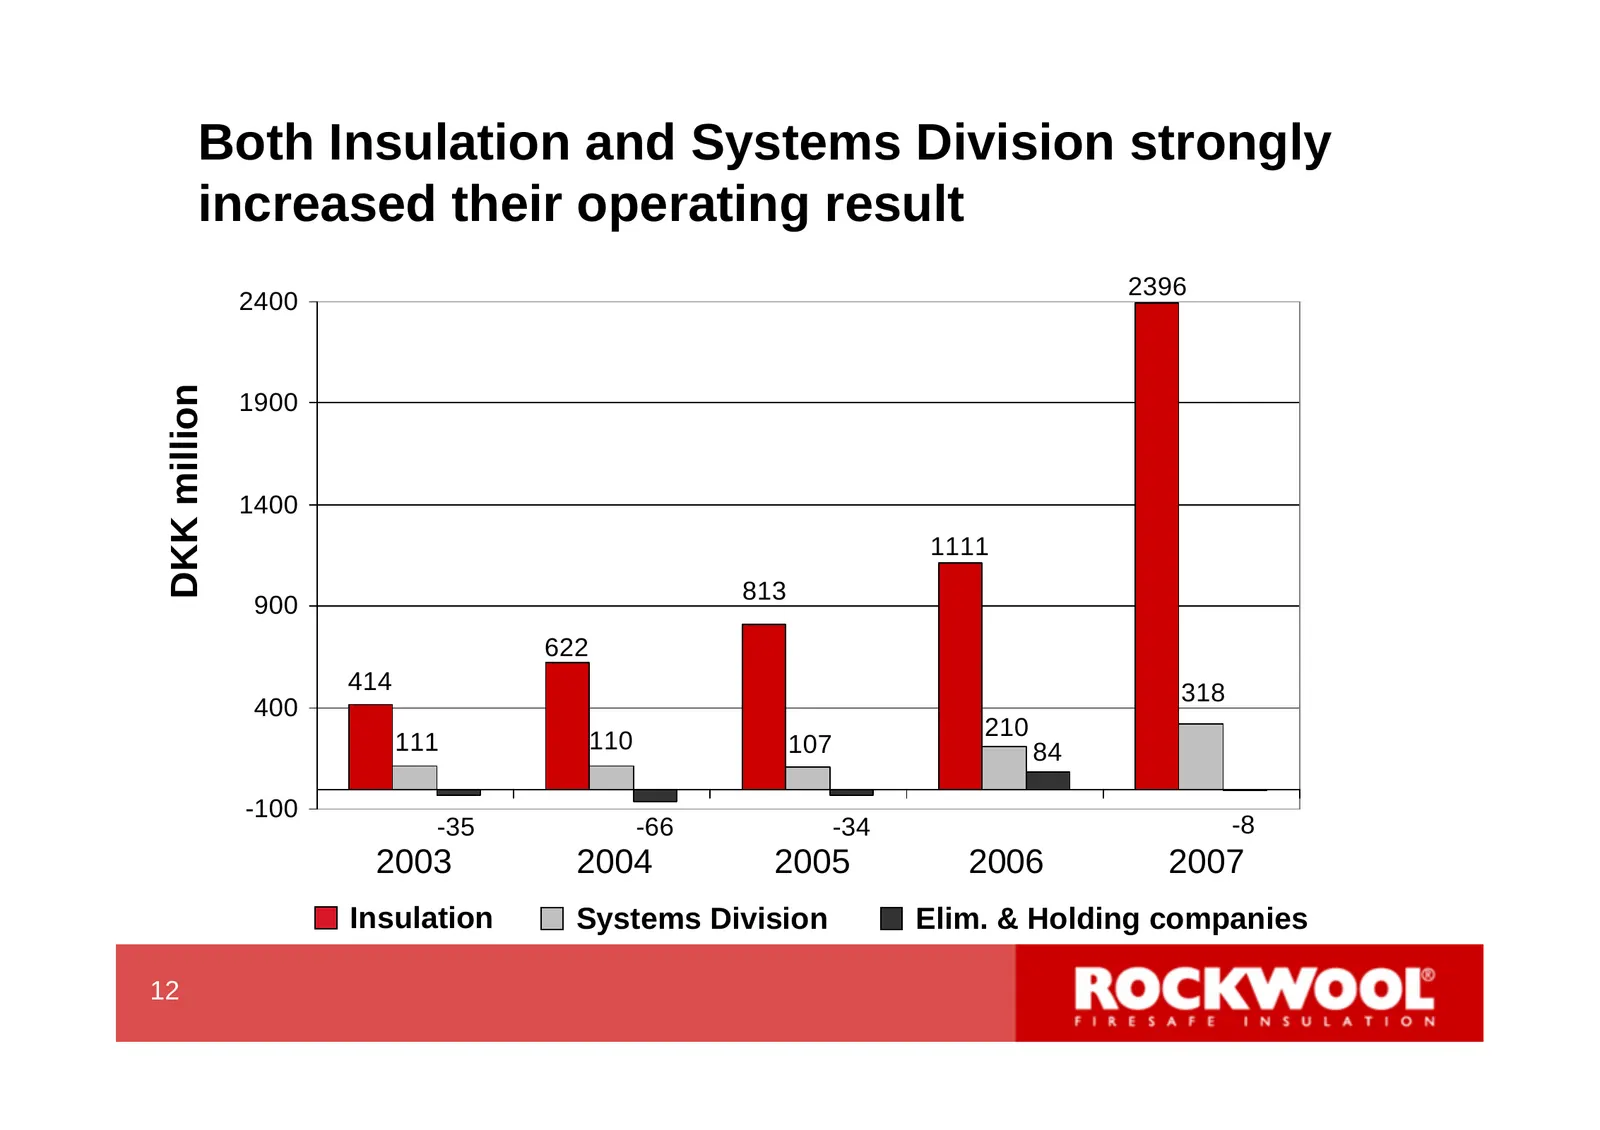
Slide 14: Insulation and Systems Division strongly increased operating result
Both Insulation and Systems Division strongly increased their operating result 2396 2400 DKK million 1900 1400 1111 813 900 622 414 318 400 210 111 110 107 84 -100 -35 -66 -34 -8 2003 2004 2005 2006 2007 Insulation Systems Division Elim. & Holding companies 12 14
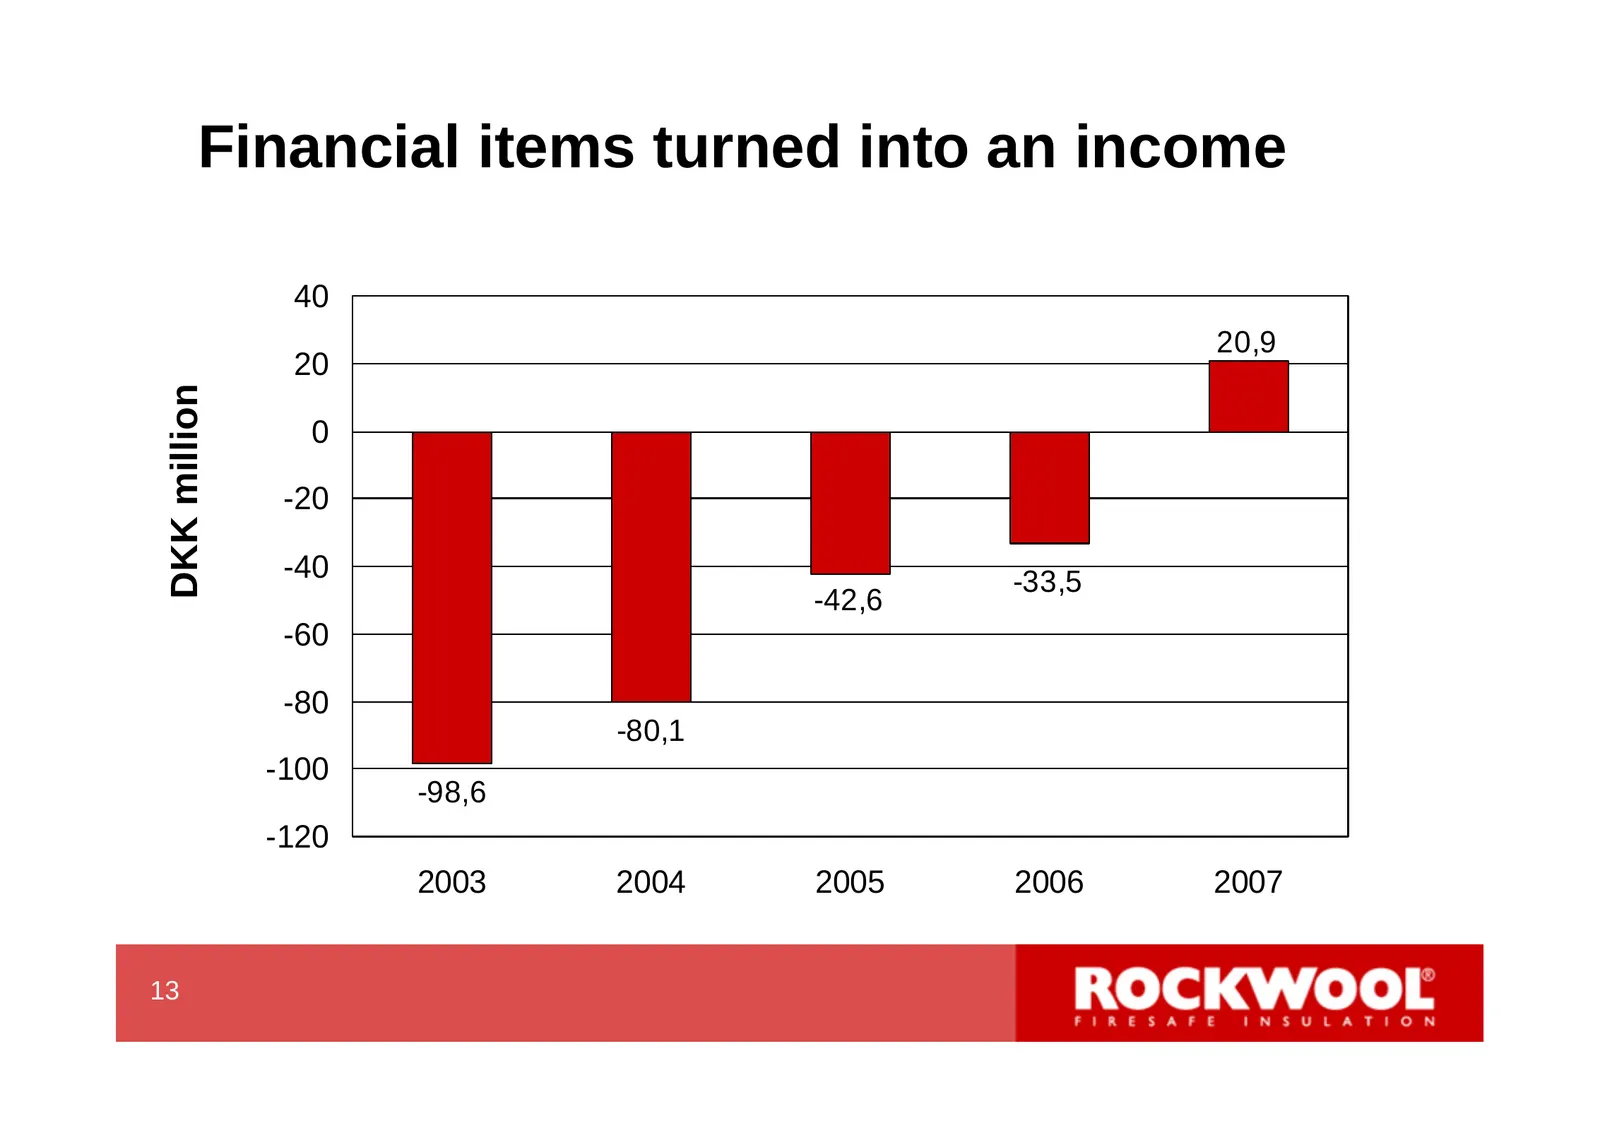
Slide 15: Financial items turned into an income
Financial items turned into an income 40 20,9 20 DKK million 0 -20 -40 -33,5 -42,6 -60 -80 -80,1 -100 -98,6 -120 2003 2004 2005 2006 2007 13 15
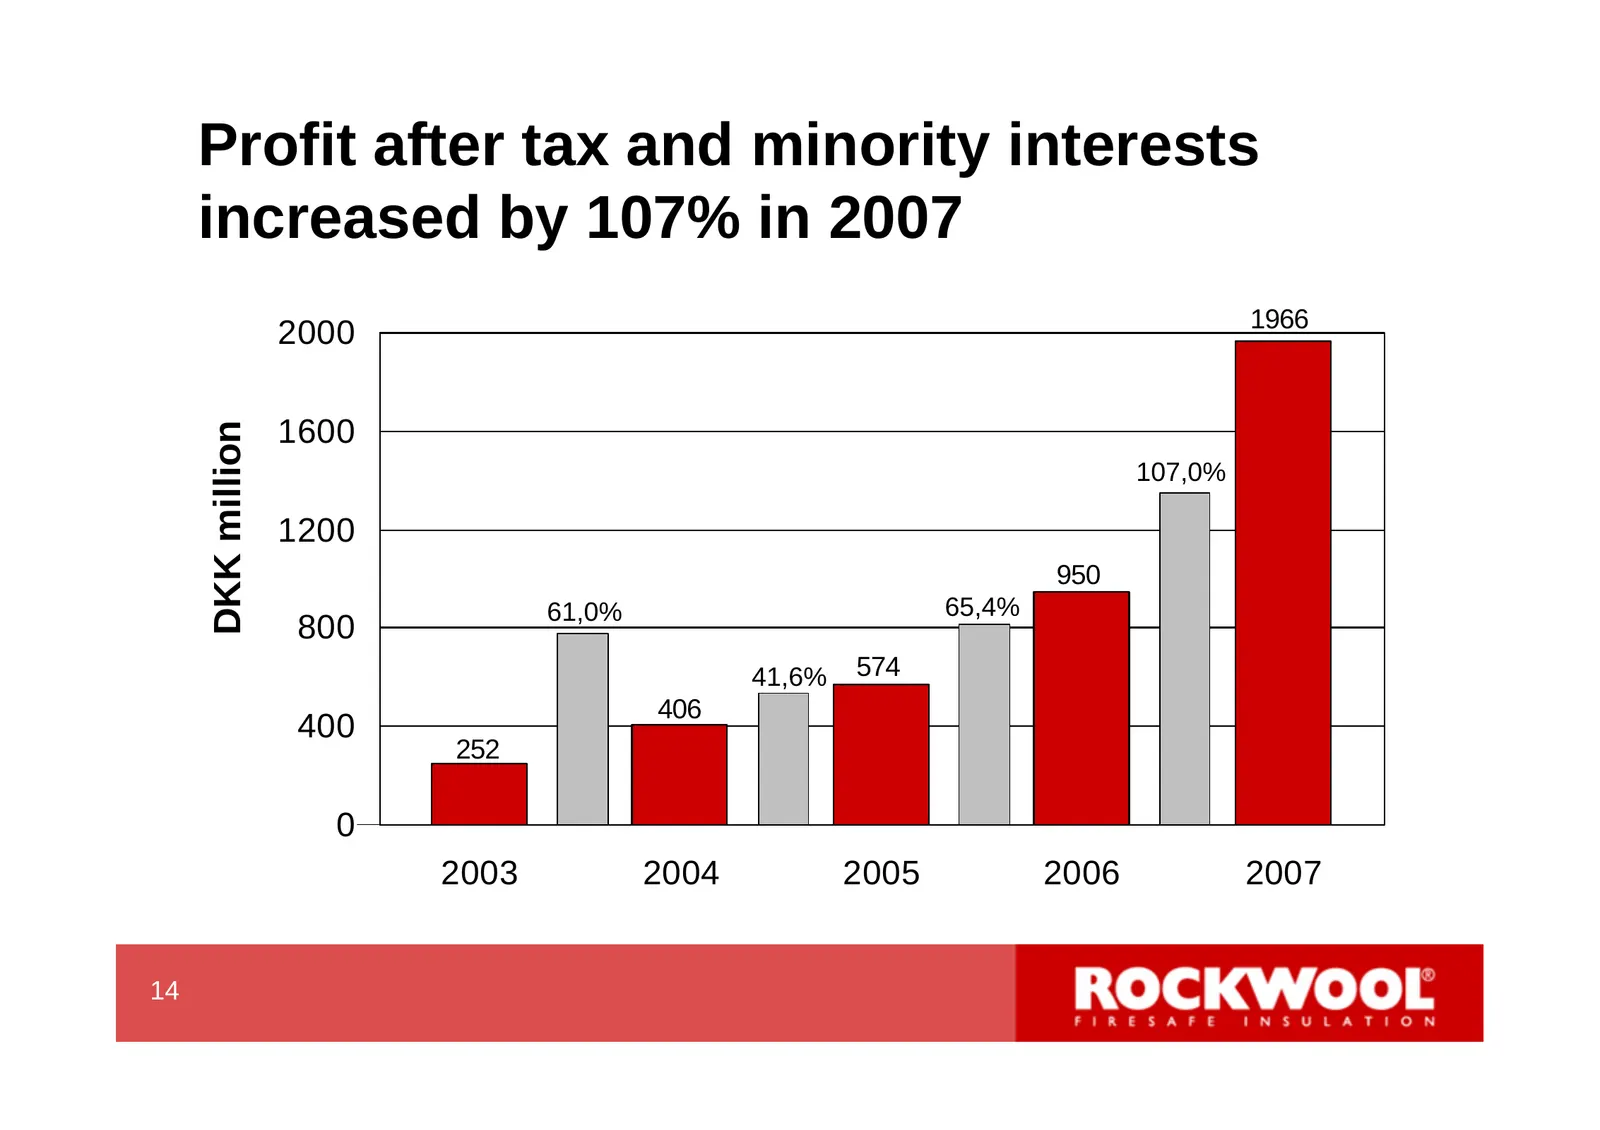
Slide 16: Profit after tax and minority interests increased by 107% in 2007
Profit after tax and minority interests increased by 107% in 2007 1966 2000 1600 DKK million 107,0% 1200 950 61,0% 65,4% 800 41,6% 574 406 400 252 0 2003 2004 2005 2006 2007 14 16
Slide 17: Investments and acquisitions
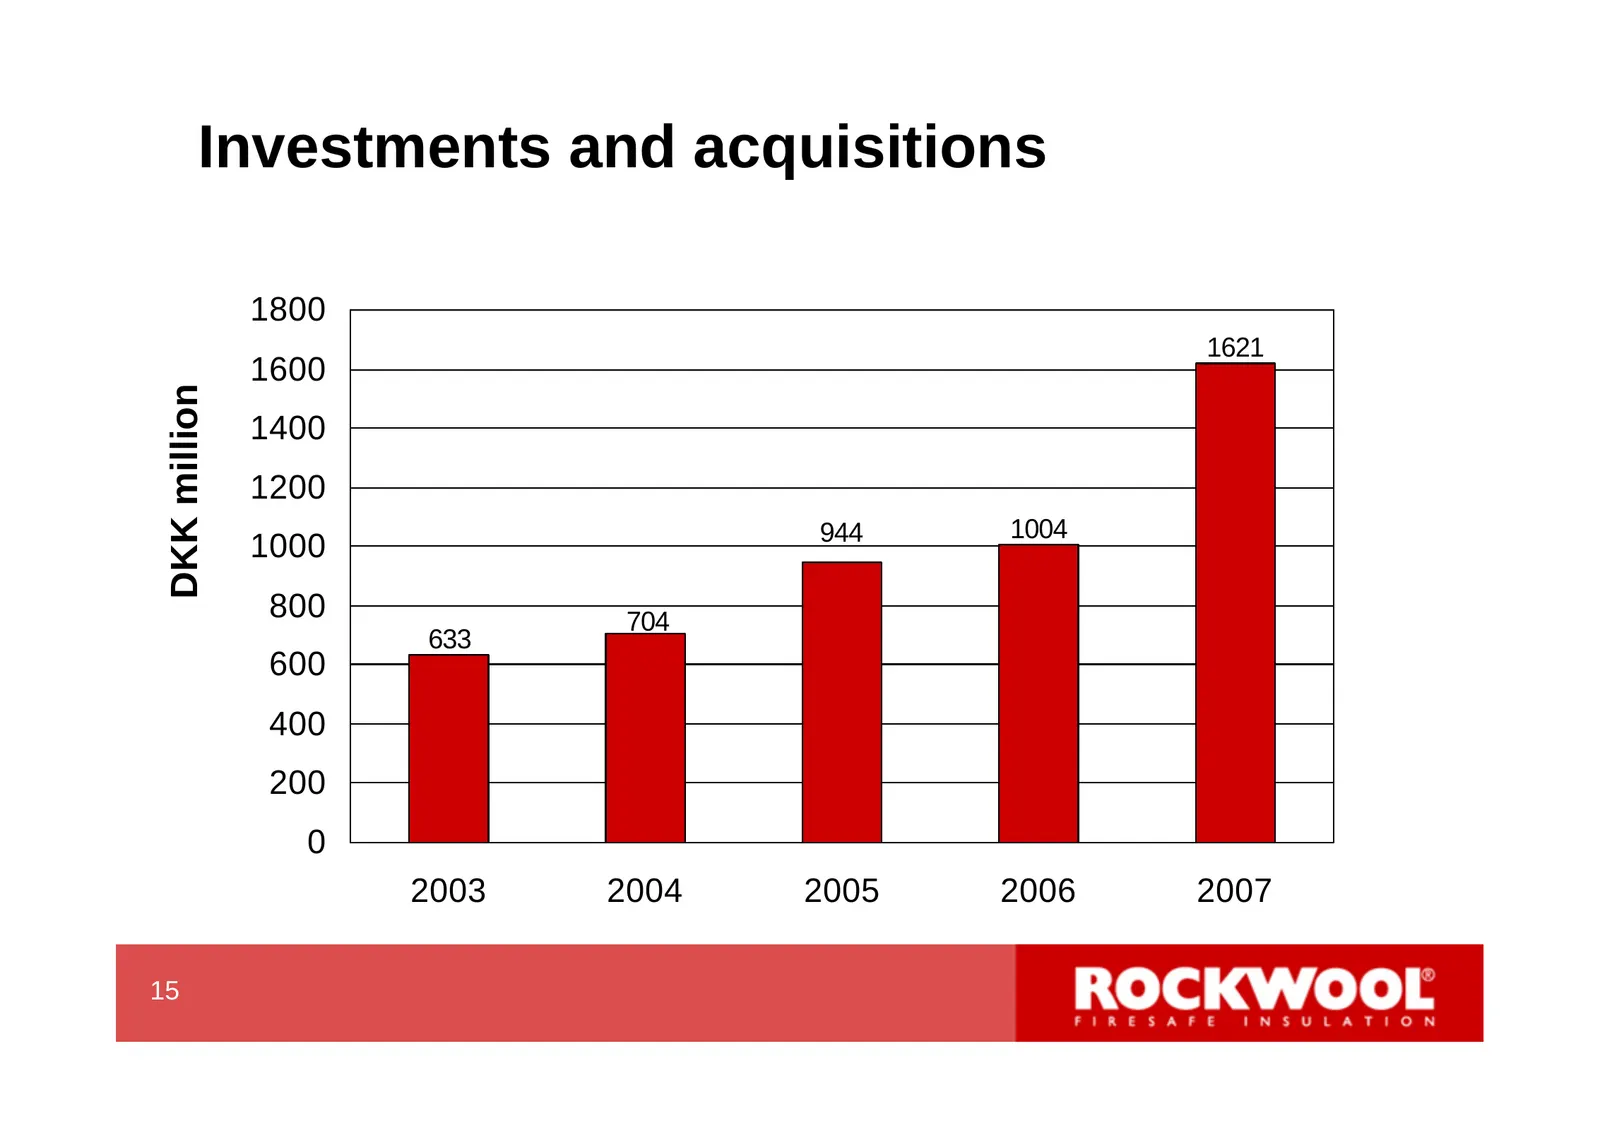
Investments and acquisitions 1800 1621 1600 DKK million 1400 1200 944 1004 1000 800 704 633 600 400 200 0 2003 2004 2005 2006 2007 15 17
Slide 18: Cash flow from operating activities
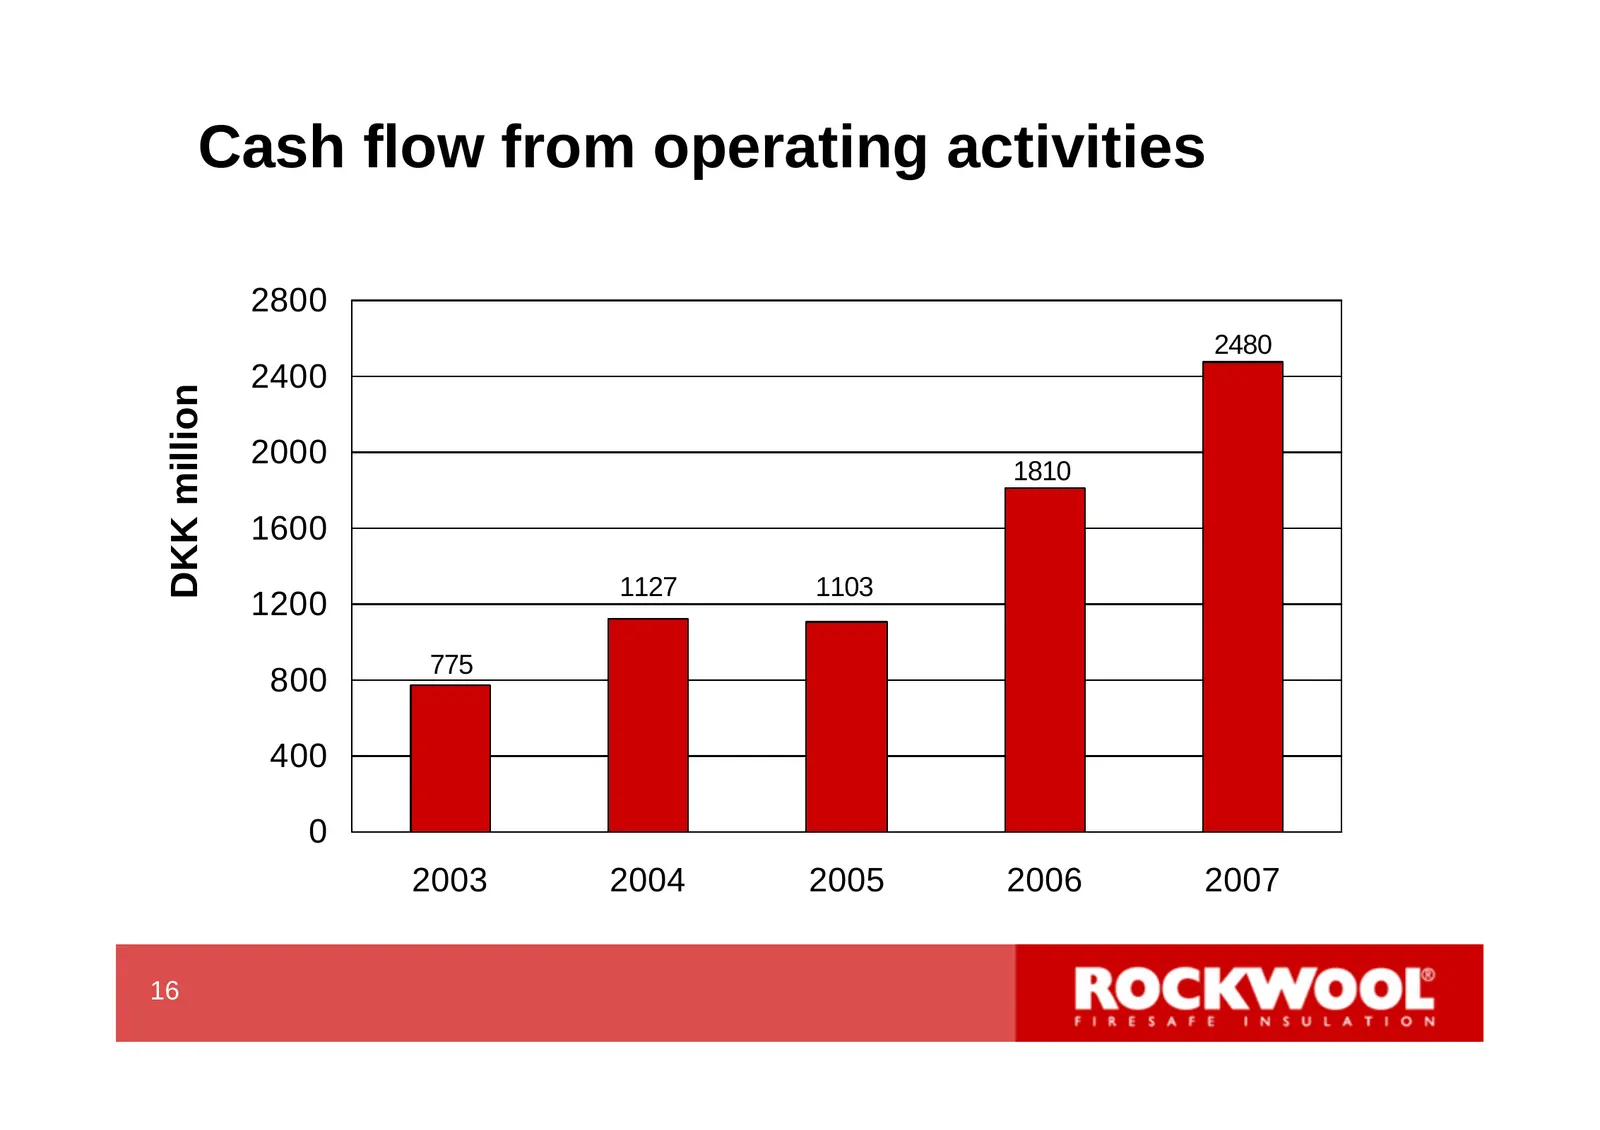
Cash flow from operating activities 2800 2480 2400 DKK million 2000 1810 1600 1127 1103 1200 775 800 400 0 2003 2004 2005 2006 2007 16 18
Slide 19: Financial goals
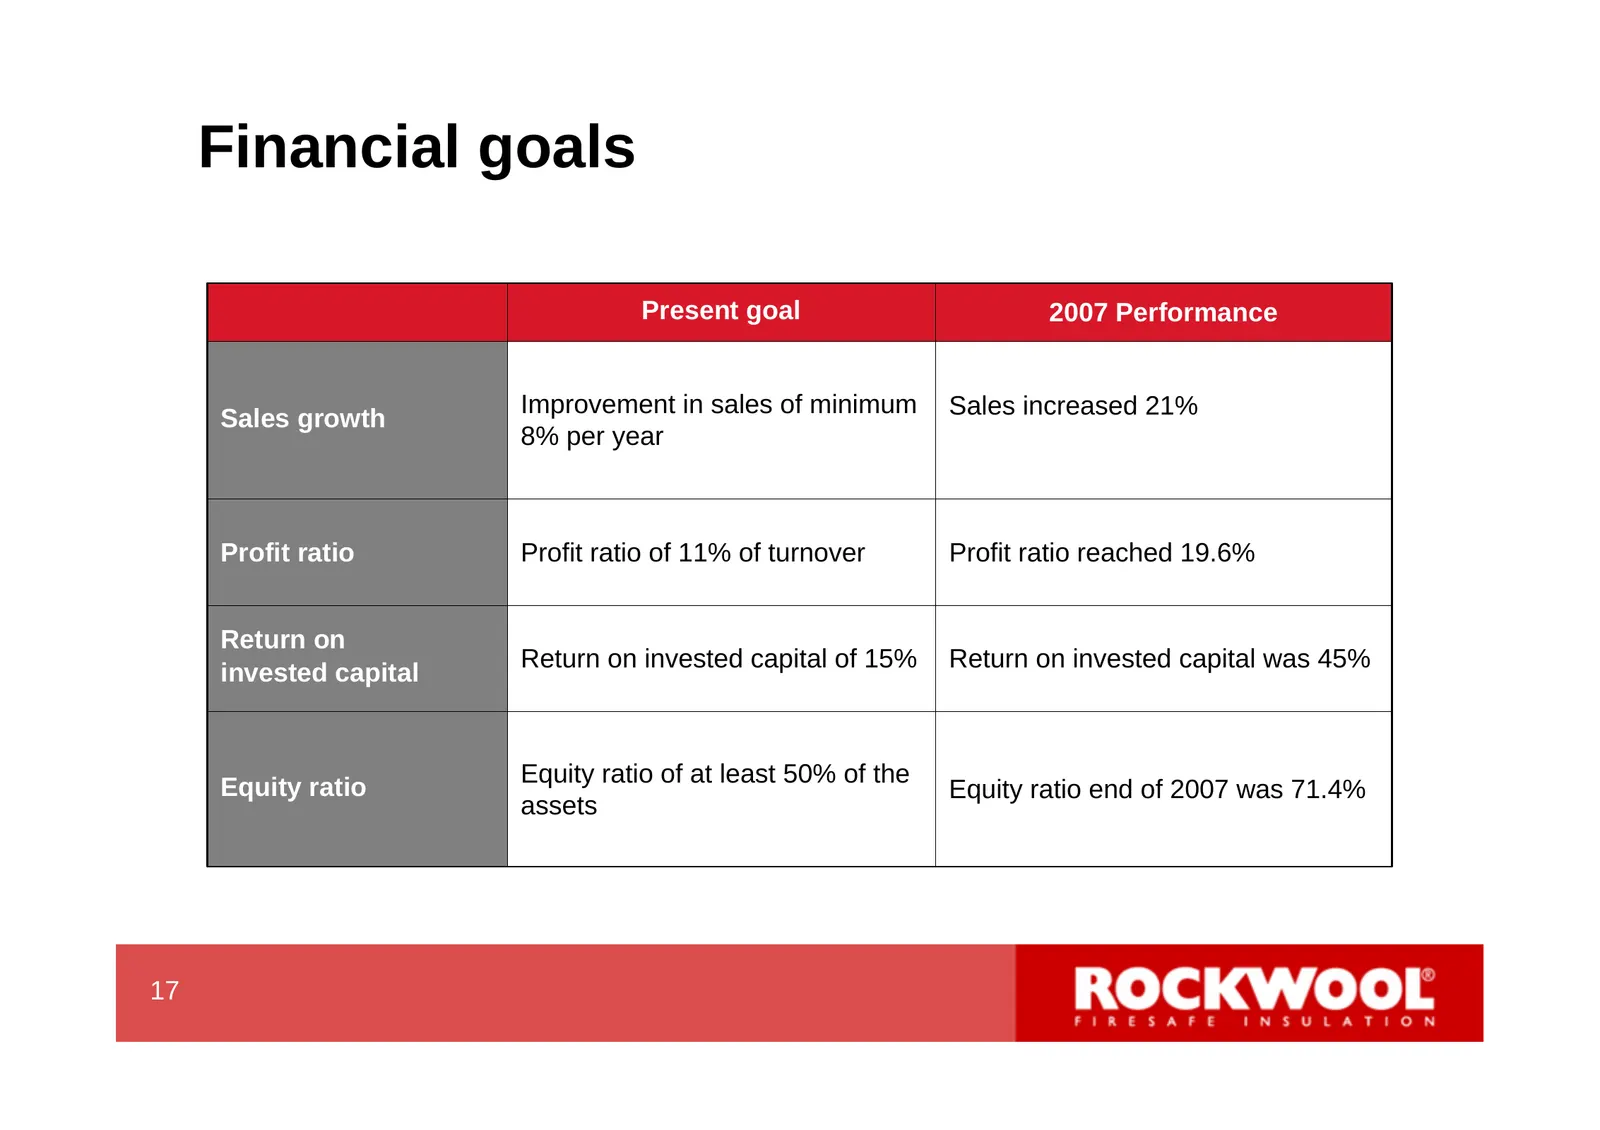
Financial goals Present goal 2007 Performance Improvement in sales of minimum Sales increased 21% Sales growth 8% per year Profit ratio Profit ratio of 11% of turnover Profit ratio reached 19.6% Return on Return on invested capital of 15% Return on invested capital was 45% invested capital Equity ra
Slide 20: Expectations for 2008
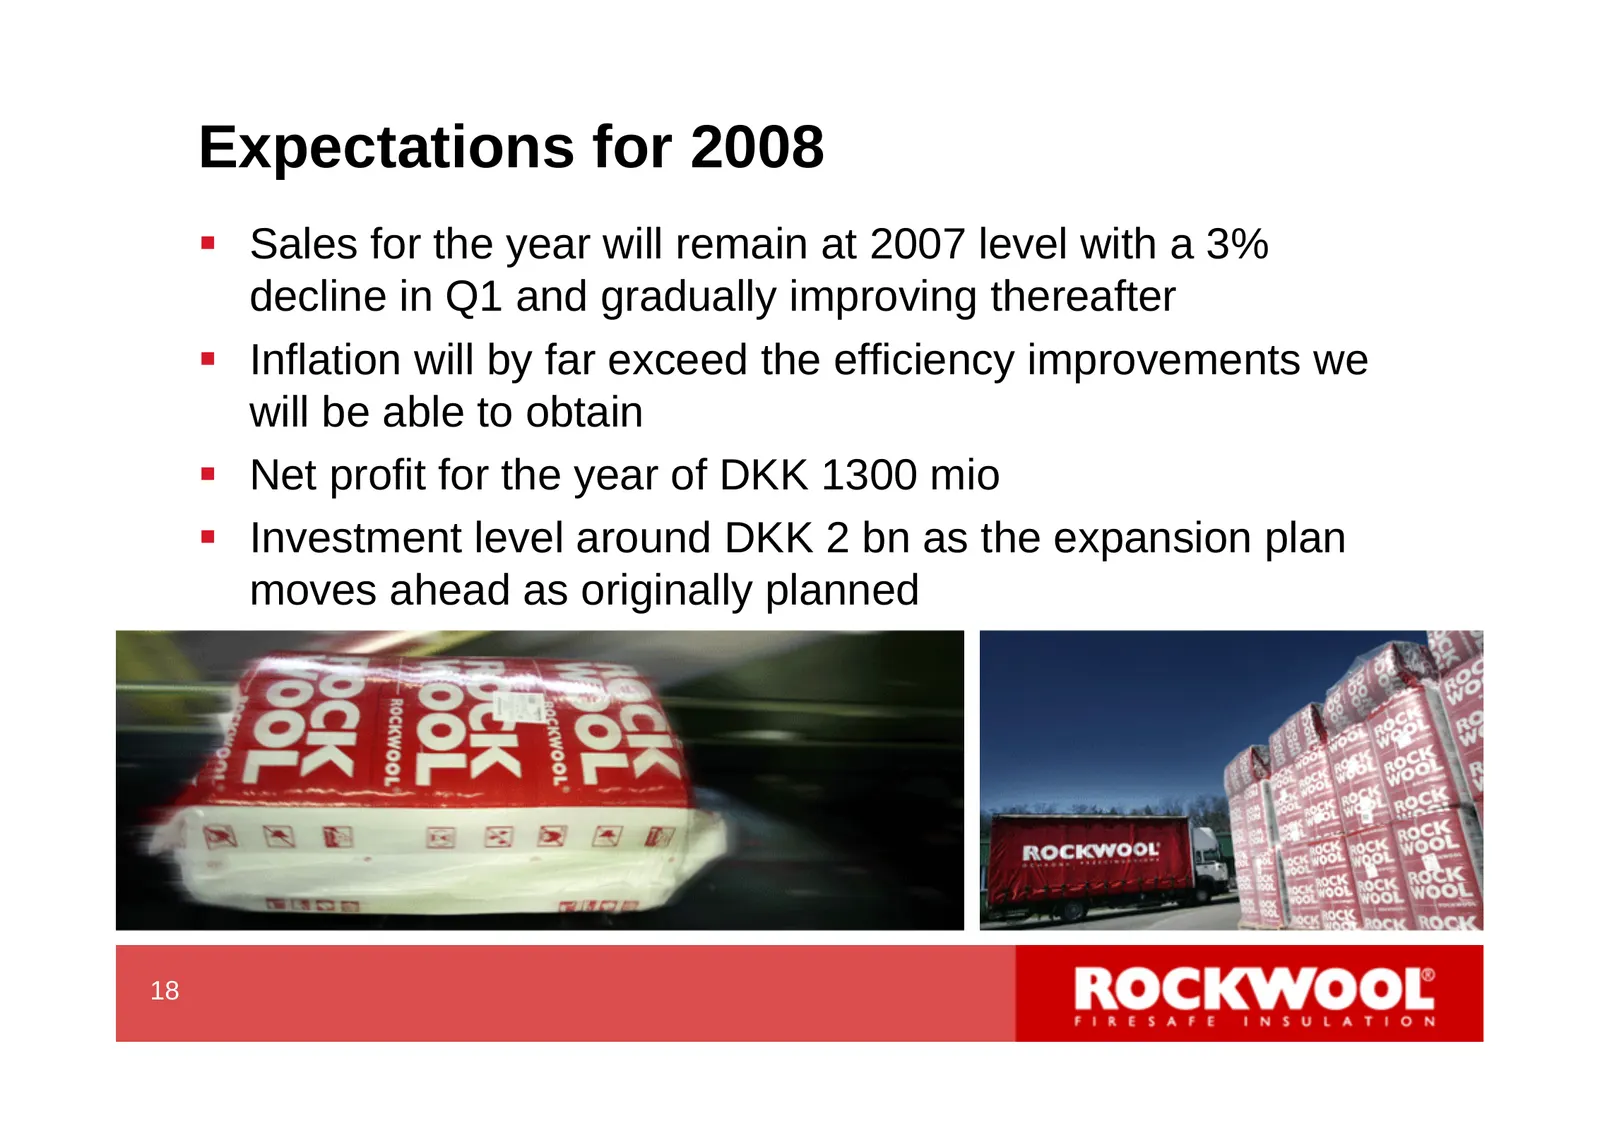
Expectations for 2008 Sales for the year will remain at 2007 level with a 3% decline in Q1 and gradually improving thereafter Inflation will by far exceed the efficiency improvements we will be able to obtain Net profit for the year of DKK 1300 mio Investment level around DKK 2 bn as the exp
Slide 21: Market
Market 19 21
Slide 22: Growth in European construction markets in 2007
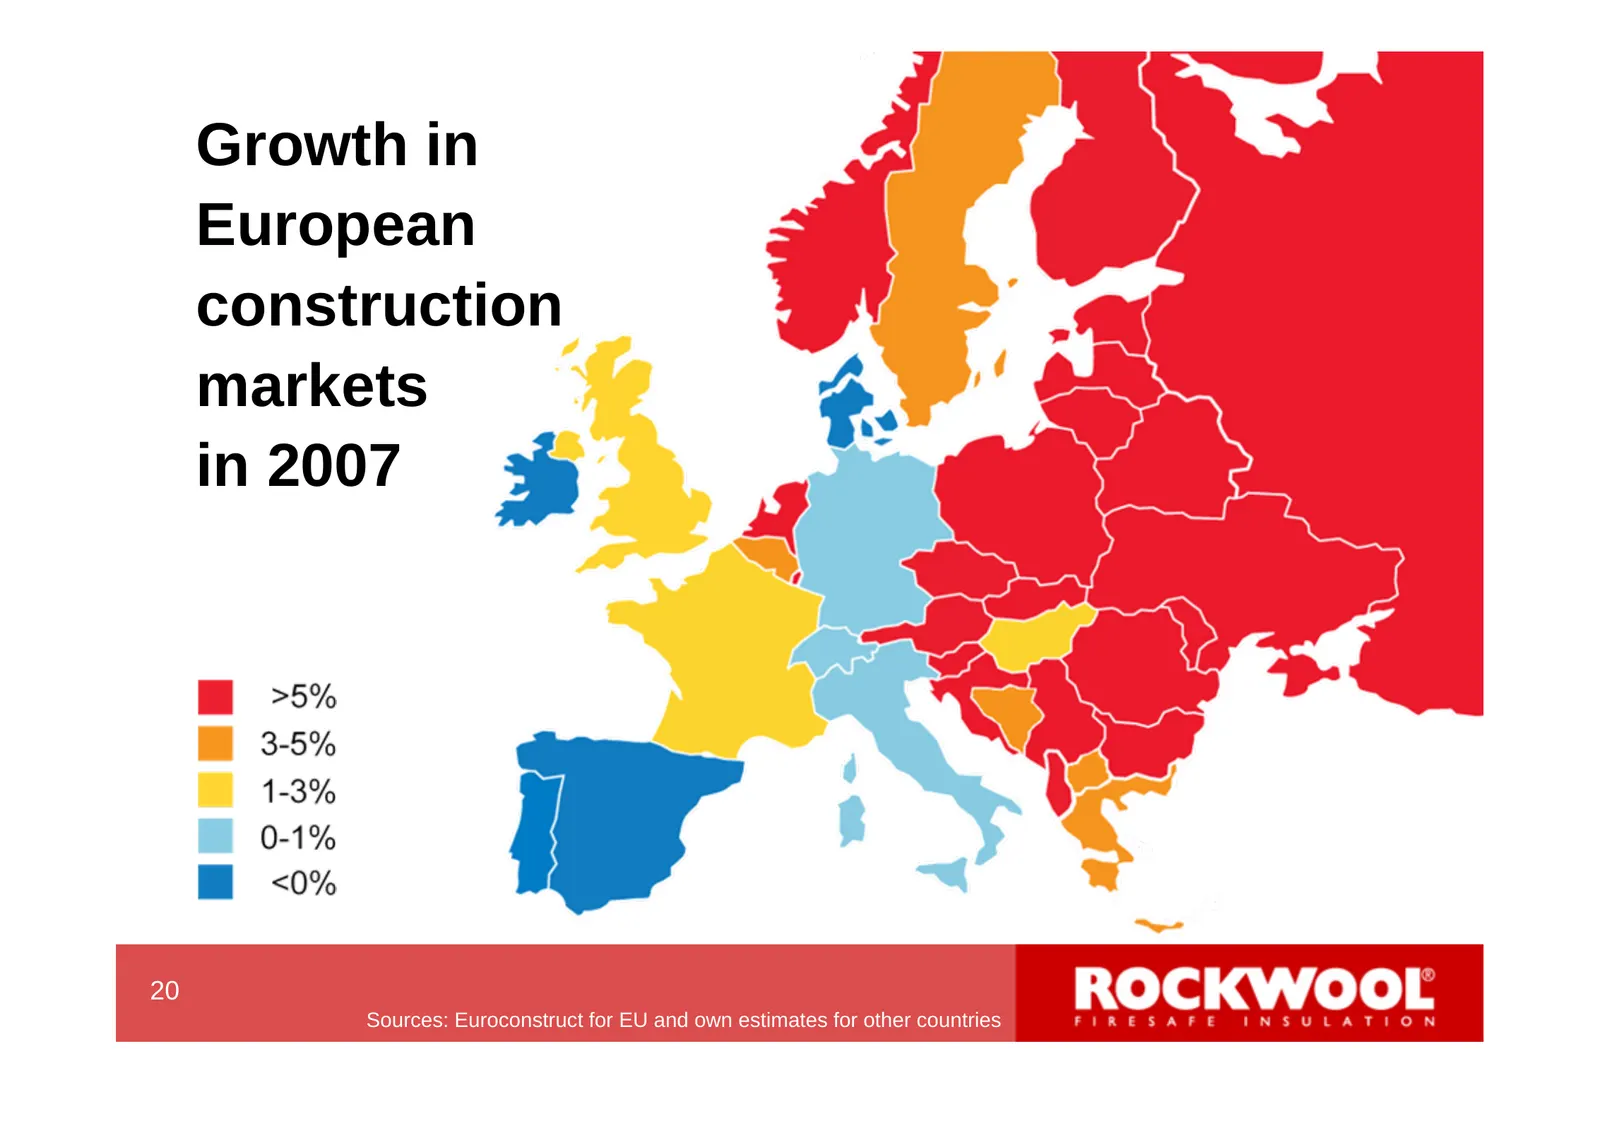
Growth in European construction markets in 2007 20 Sources: Euroconstruct for EU and own estimates for other countries 22
Slide 23: European insulation market 2007
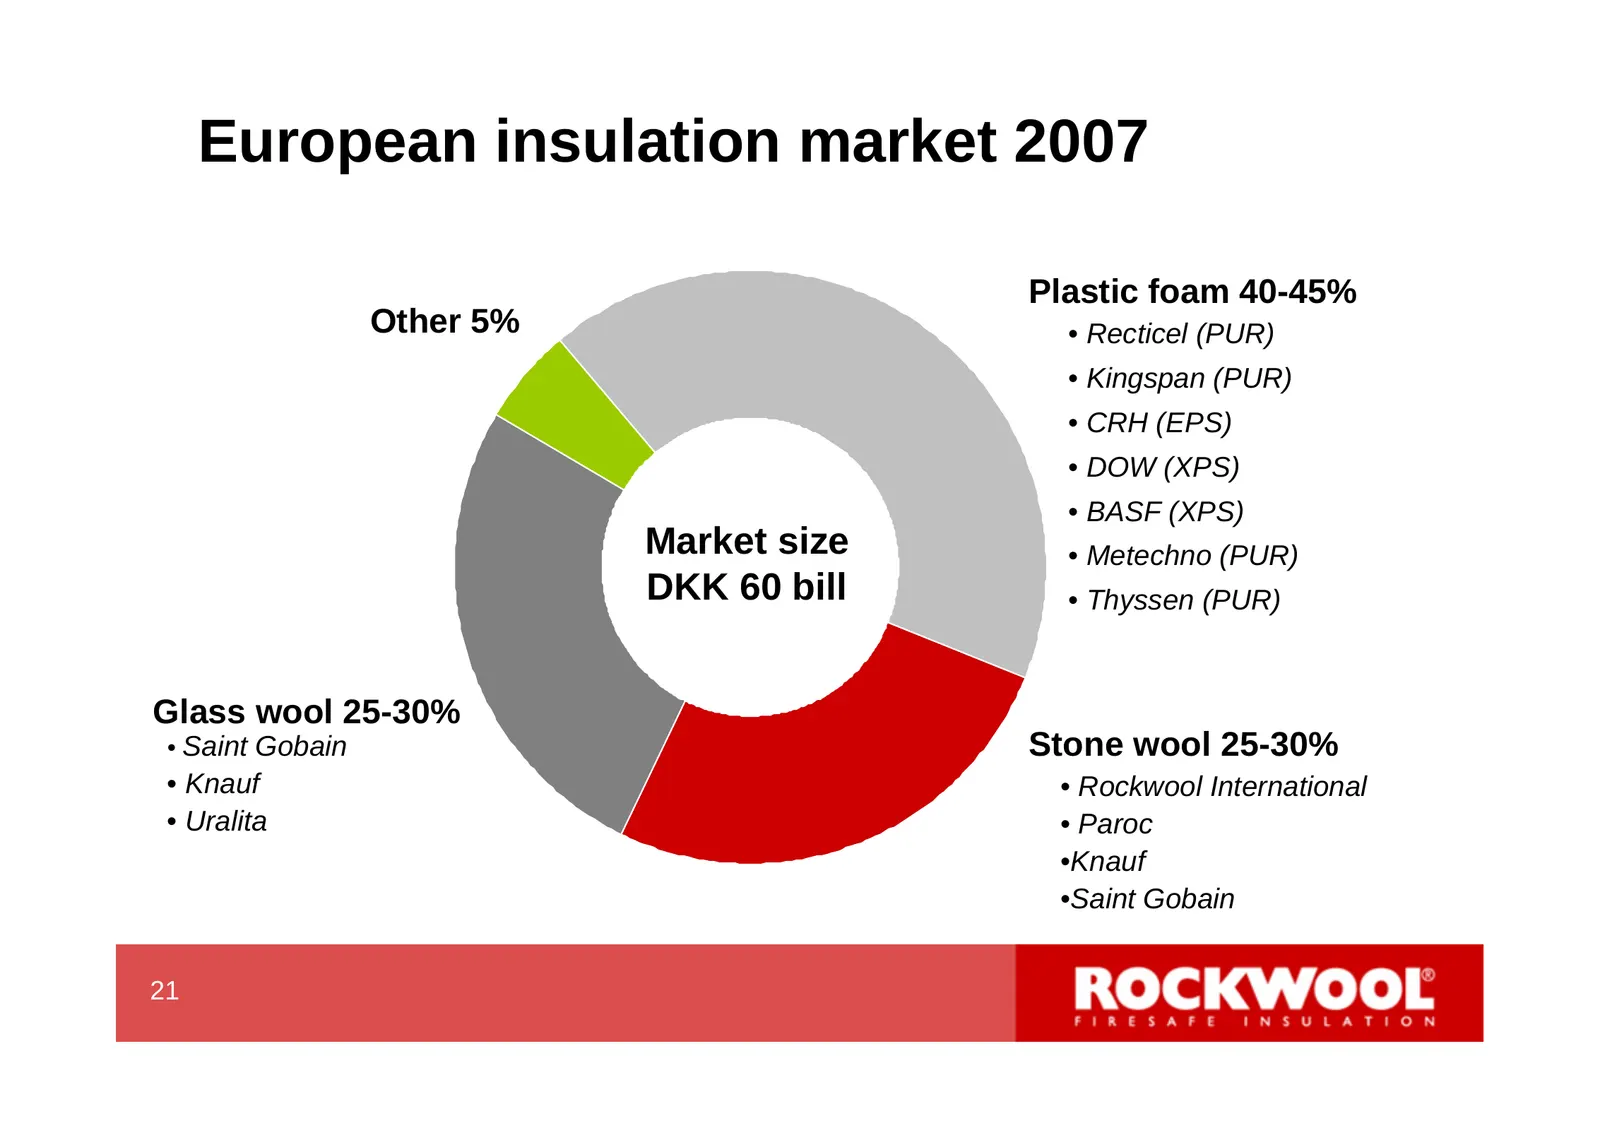
European insulation market 2007 Plastic foam 40-45% Other 5% • Recticel (PUR) • Kingspan (PUR) • CRH (EPS) • DOW (XPS) • BASF (XPS) Market size • Metechno (PUR) DKK 60 bill • Thyssen (PUR) Glass wool 25-30% • Saint Gobain Stone wool 25-30% • Knauf • Rockwool International • Uralita • Paroc •Knauf •S
Slide 24: North American insulation market 2007
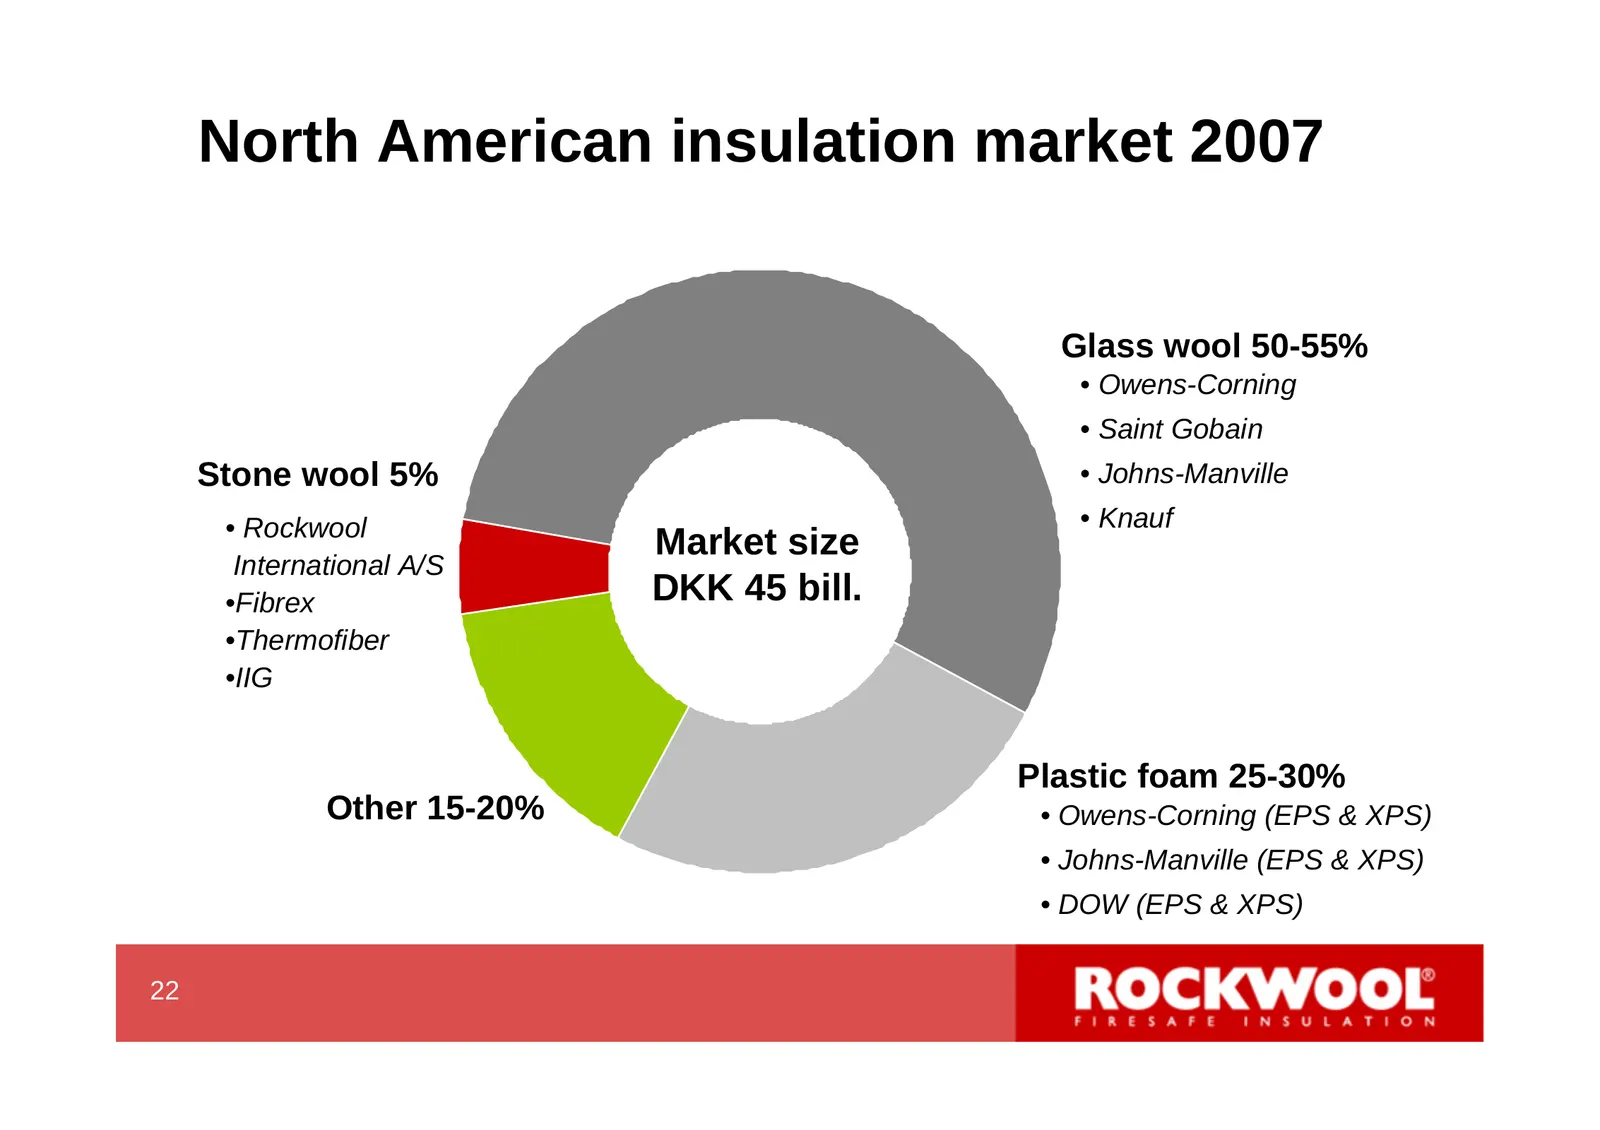
North American insulation market 2007 Glass wool 50-55% • Owens-Corning • Saint Gobain Stone wool 5% • Johns-Manville • Rockwool • Knauf Market size International A/S •Fibrex DKK 45 bill. •Thermofiber •IIG Plastic foam 25-30% Other 15-20% • Owens-Corning (EPS & XPS) • Johns-Manville (EPS & XPS) • DO
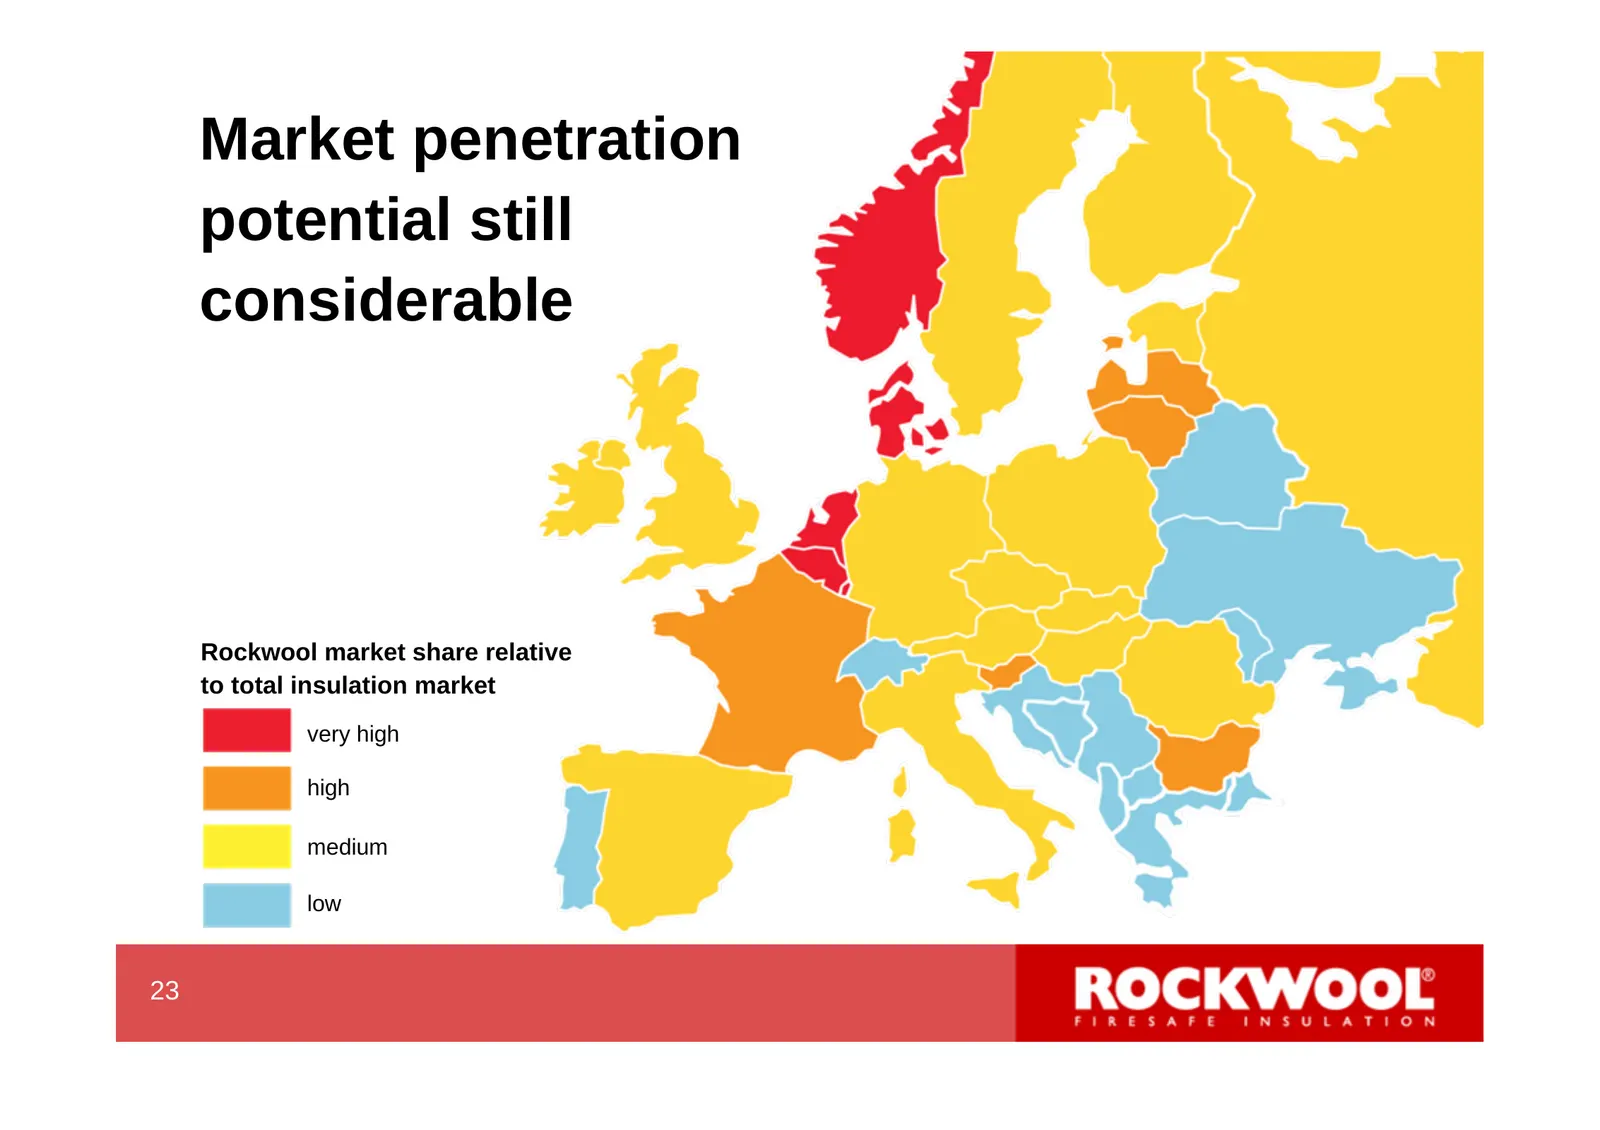
Slide 25: Market penetration potential still considerable
Market penetration potential still considerable Rockwool market share relative to total insulation market very high high medium low 23 25
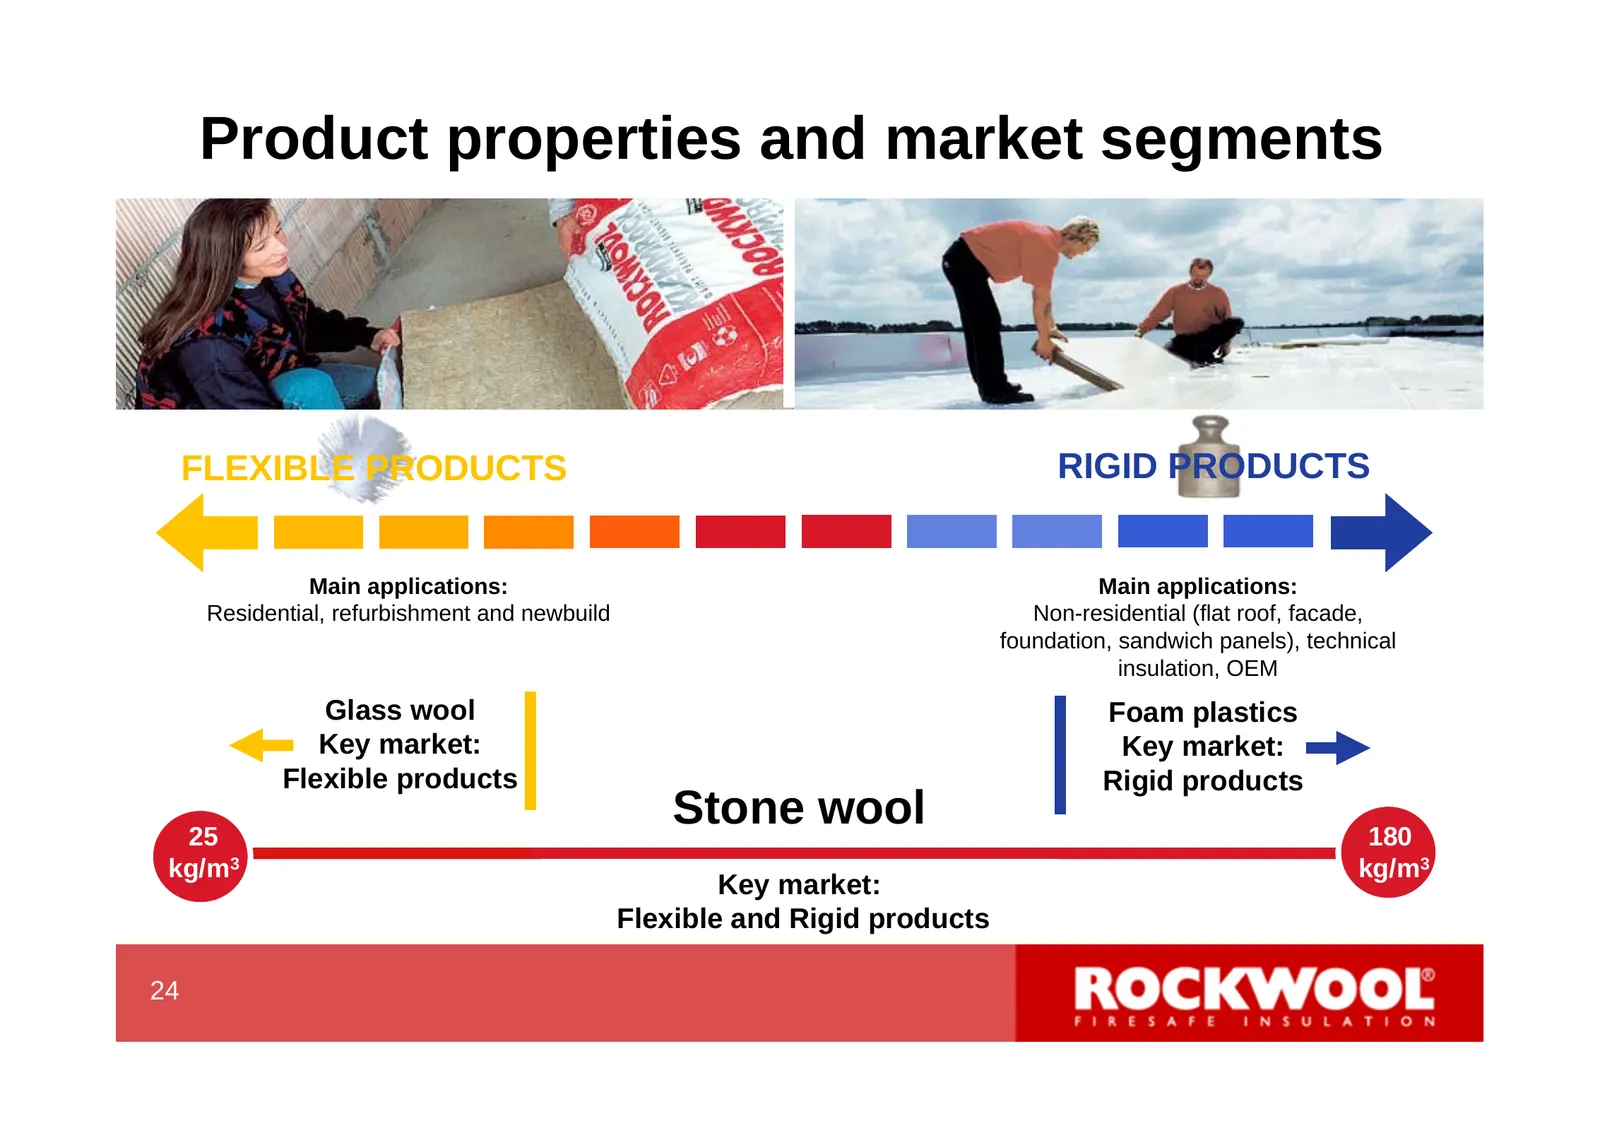
Slide 26: Product properties and market segments
Product properties and market segments FLEXIBLE PRODUCTS RIGID PRODUCTS Main applications: Main applications: Residential, refurbishment and newbuild Non-residential (flat roof, facade, foundation, sandwich panels), technical insulation, OEM Glass wool Foam plastics Key market: Key market: Flexible
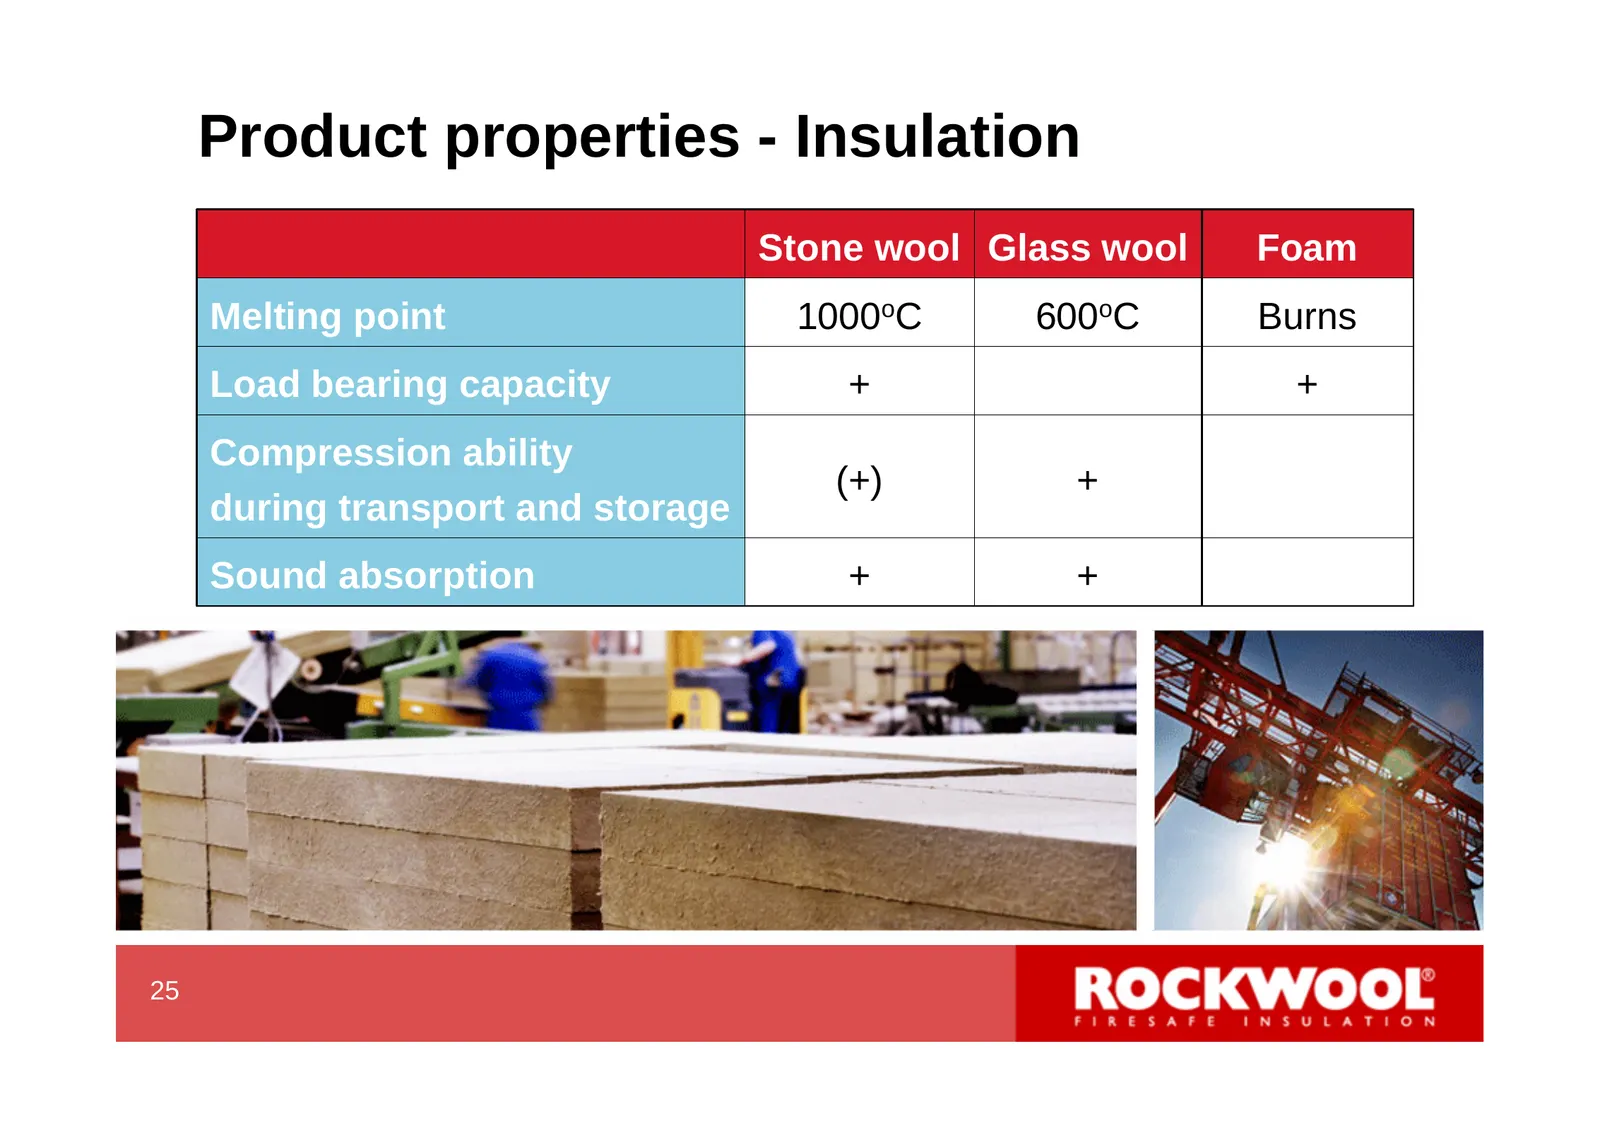
Slide 27: Product properties - Insulation
Product properties - Insulation Stone wool Glass wool Foam Melting point 1000oC 600oC Burns Load bearing capacity + + Compression ability (+) + during transport and storage Sound absorption + + 25 27
Slide 28: European insulation market
European insulation market The construction activity in Western Europe has slowed considerably under the impact of the general macro-economic uncertainty which creates a more cautious business environment. The downturn is most notably in residential but spreading more and more to the non-residenti
Slide 29: European insulation market
European insulation market The slowdown has spread to Central and Eastern Europe where the market situation is becoming more challenging Poland, Czech Republic and Hungary show the poorest performance whereas Russia remains positive We expect the market to improve gradually later in the year
Slide 30: Overseas insulation markets
Overseas insulation markets North America remains an attractive market for the Group. Limited effect on our core stone wool segments from the downturn in US construction Asian operations positive but still on bridgehead level. Shanghai office established 28 30
Slide 31: Systems Division markets
Systems Division markets Strong development in the Rockfon acoustic ceilings business Grodan focus on profitability and organisation showing good results. Horticultural greenhouse market negatively impacted by high energy prices Rockpanel: solid performance in core markets 29 31
Slide 32: Major growth drivers - Energy efficiency in buildings
Major growth drivers - Energy efficiency in buildings 30 32
Slide 33: Energy efficiency of buildings - status
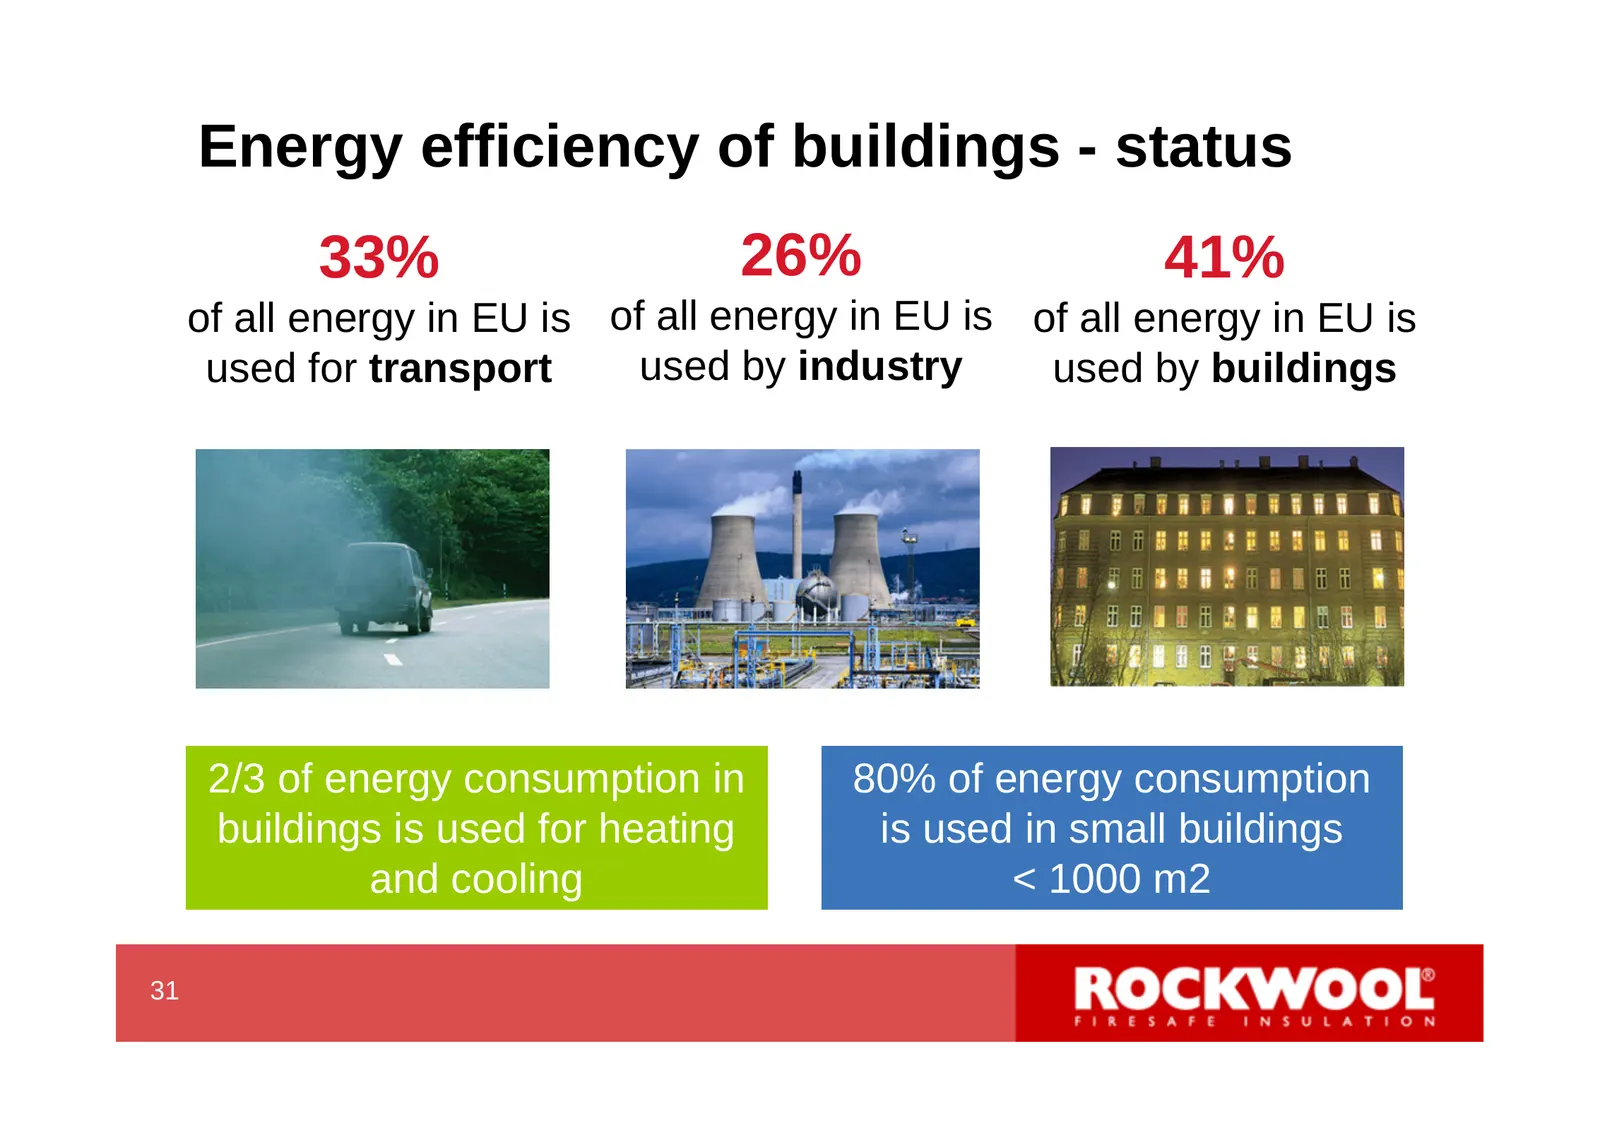
Energy efficiency of buildings - status 33% 26% 41% of all energy in EU is of all energy in EU is of all energy in EU is used for transport used by industry used by buildings 2/3 of energy consumption in 80% of energy consumption buildings is used for heating is used in small buildings and cooling <
Slide 34: The potential - energy used for heating of buildings in DK
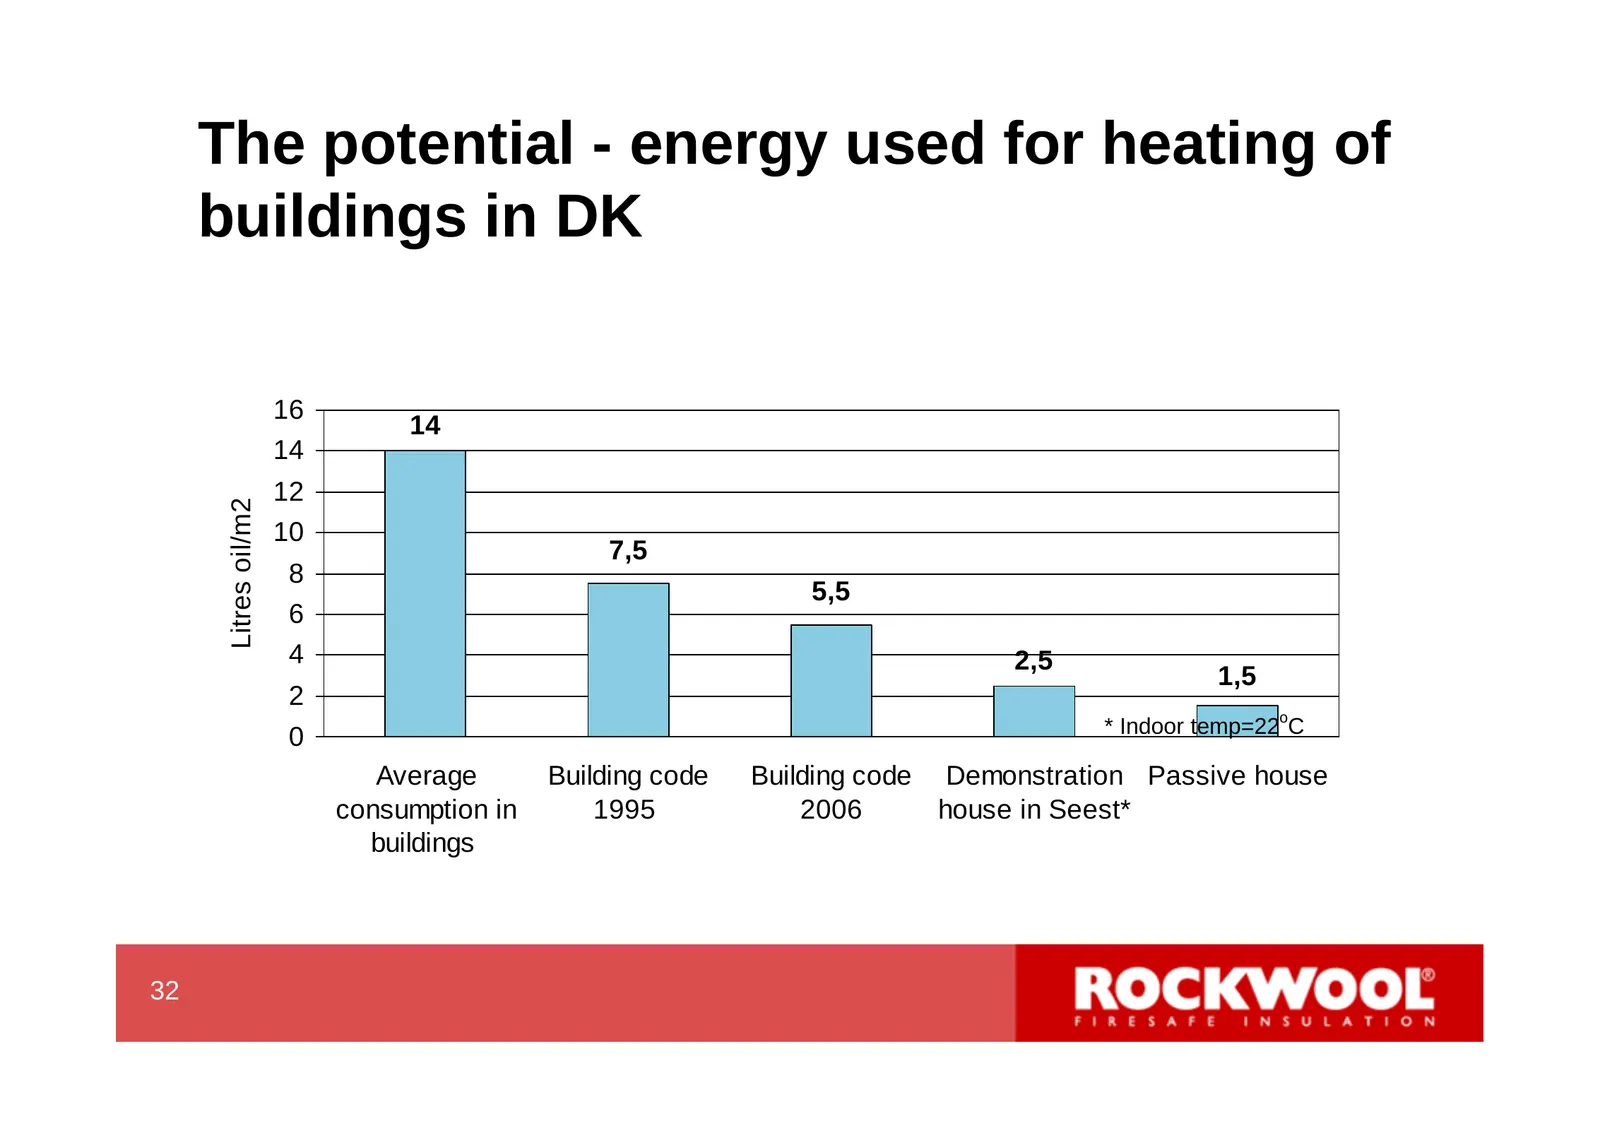
The potential - energy used for heating of buildings in DK 16 14 14 12 Litres oil/m2 10 7,5 8 5,5 6 4 2,5 1,5 2 * Indoor temp=22oC 0 Average Building code Building code Demonstration Passive house consumption in 1995 2006 house in Seest* buildings 32 34
Slide 35: Political pressure for CO2 reductions keeps increasing
Political pressure for CO2 reductions keeps increasing The EU plan of January 2008 now setting national CO2-reduction targets to be achieved by the non-ETS sectors (buildings, agriculture, transport. This will speed up national actions We know that for the non-ETS sectors, buildings and in parti
Slide 36: National saving targets
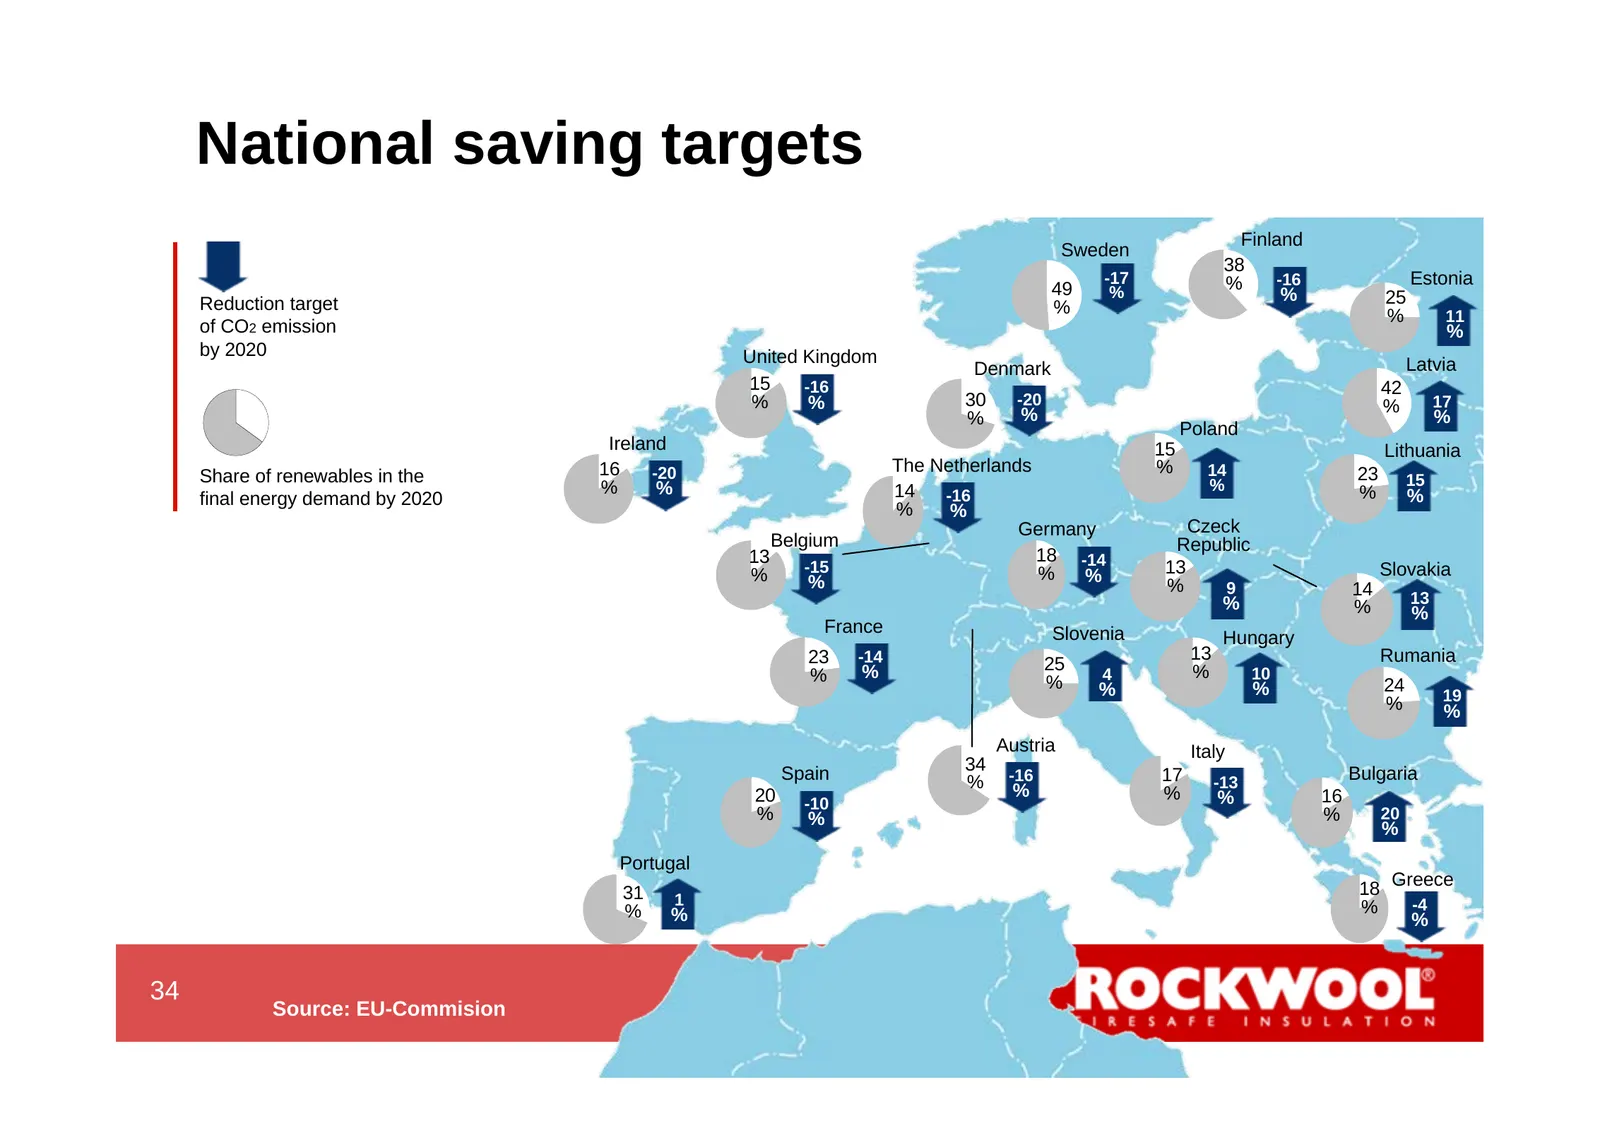
National saving targets Finland Sweden 38 -17 % -16 Estonia 49 % % 25 Reduction target % % 11 of CO2 emission % by 2020 United Kingdom Denmark Latvia 15 -16 42 % % 30 -20 % 17 % % % Poland Ireland 15 Lithuania 16 -20 The Netherlands % 14 23 Share of renewables in the % 15 % % 14 -16 % % final energy
Slide 37: Renovation of existing buildings: plans move ahead on national level
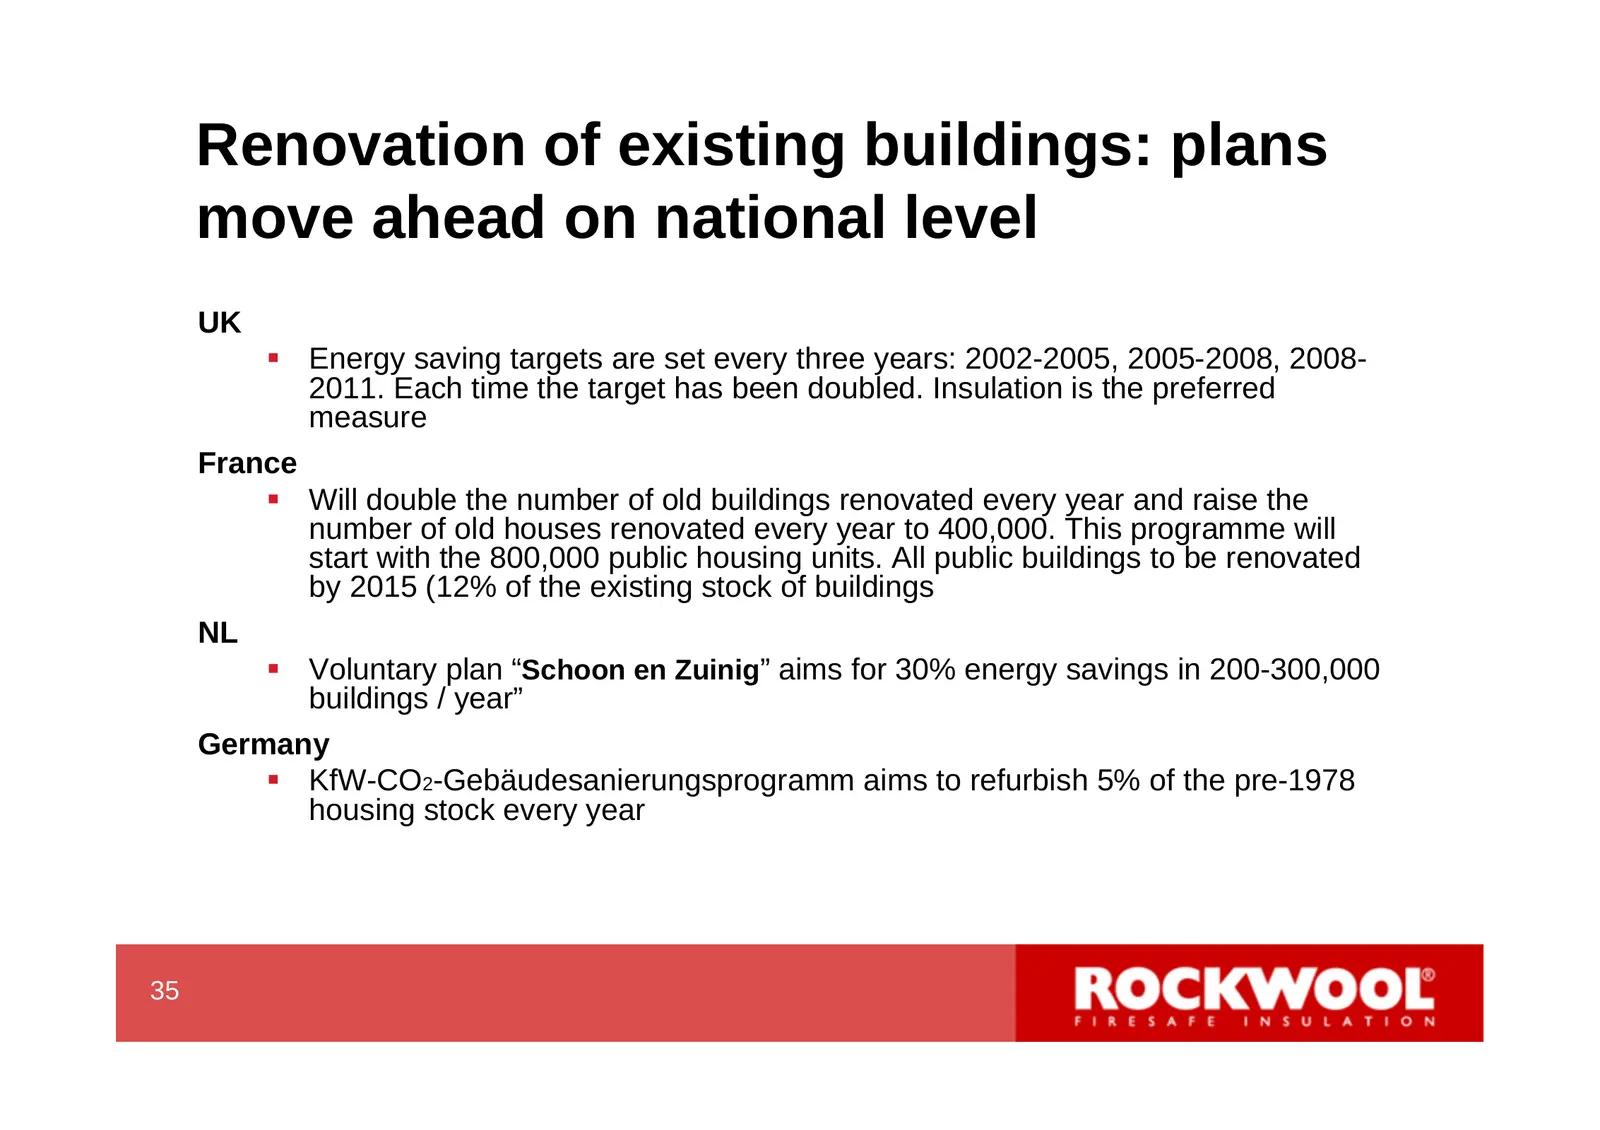
Renovation of existing buildings: plans move ahead on national level UK Energy saving targets are set every three years: 2002-2005, 2005-2008, 2008- 2011. Each time the target has been doubled. Insulation is the preferred measure France Will double the number of old buildings renovated every yea
Slide 38: EPBD - strengthening of building codes
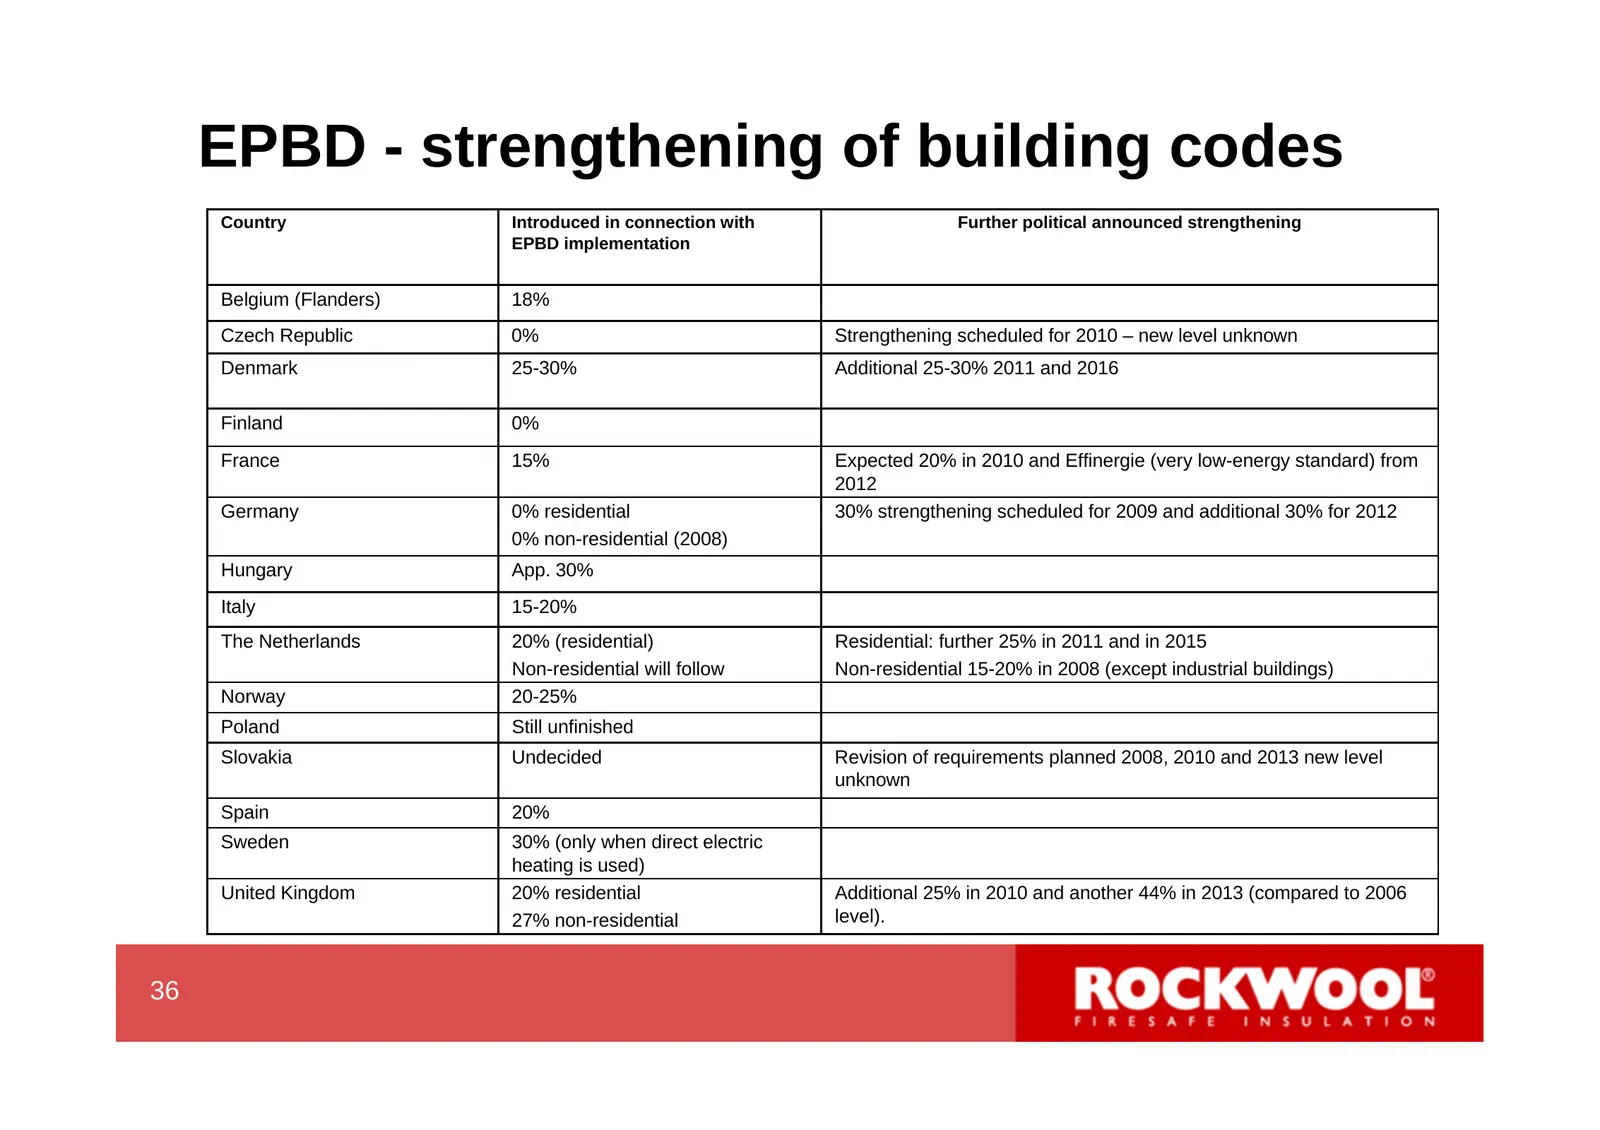
EPBD - strengthening of building codes Country Introduced in connection with Further political announced strengthening EPBD implementation Belgium (Flanders) 18% Czech Republic 0% Strengthening scheduled for 2010 – new level unknown Denmark 25-30% Additional 25-30% 2011 and 2016 Finland 0% France 15
Slide 39: New buildings: Waiting for the EPBD effect in the market
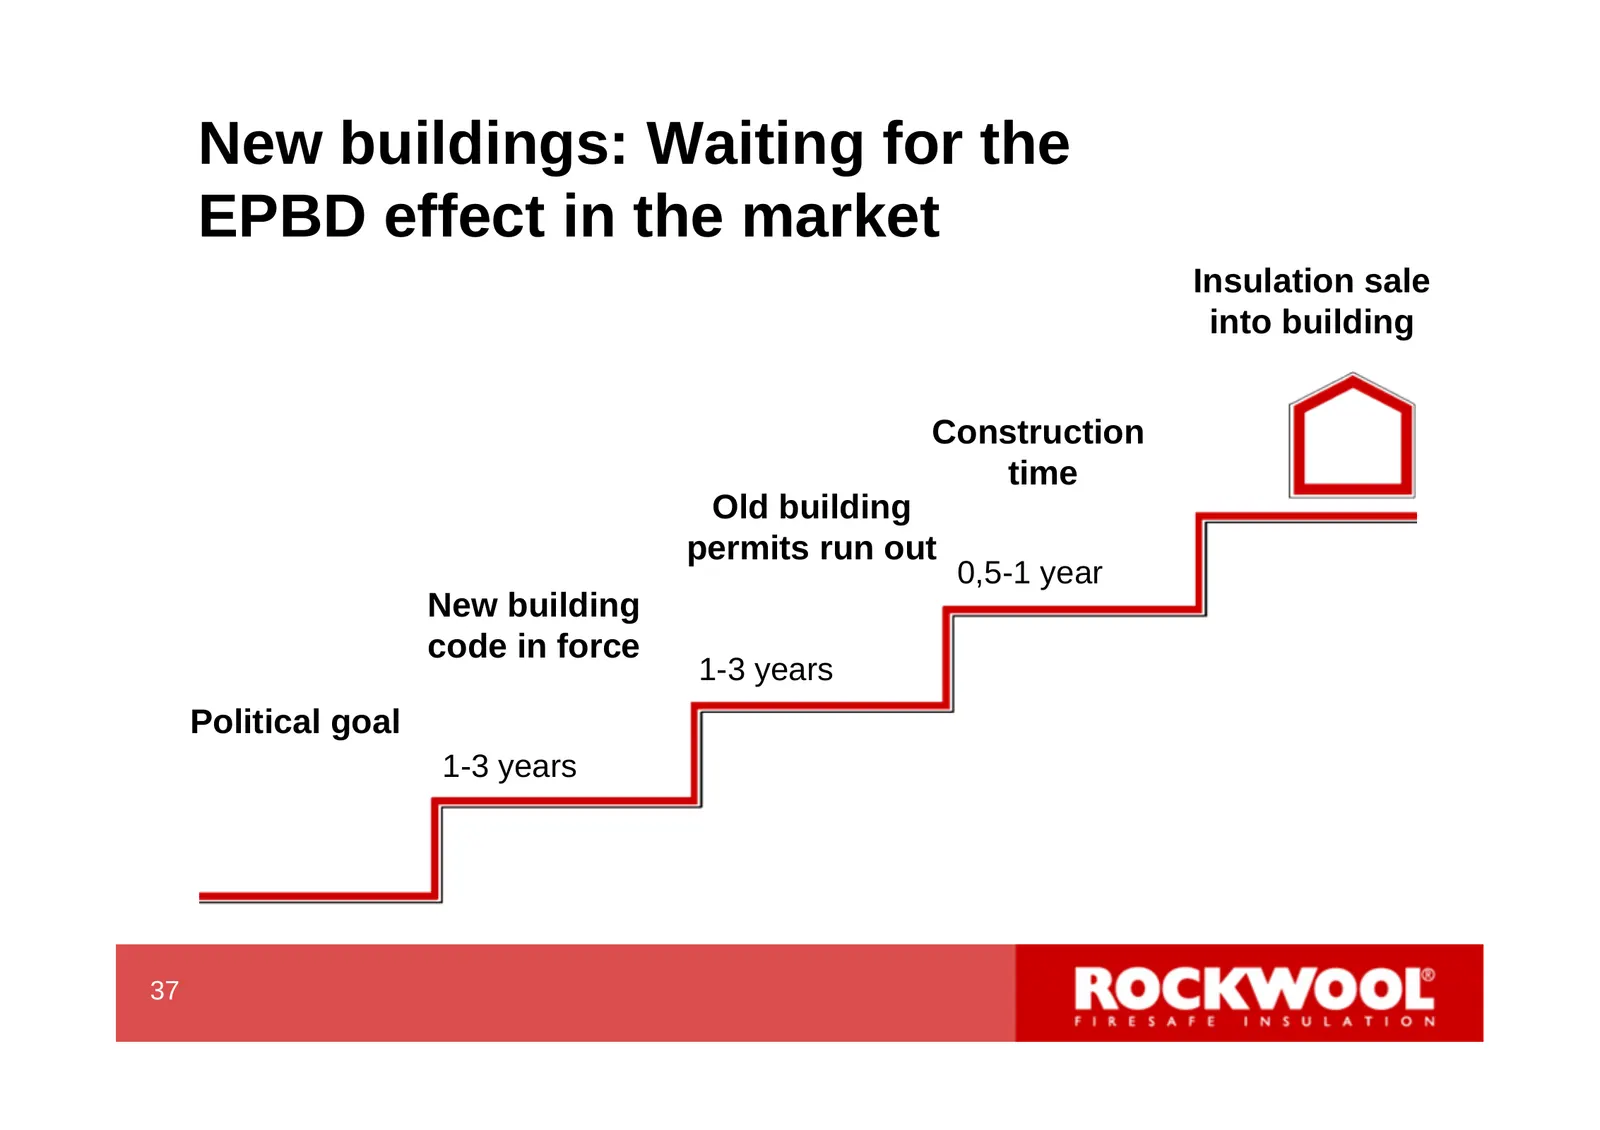
New buildings: Waiting for the EPBD effect in the market Insulation sale into building Construction time Old building permits run out 0,5-1 year New building code in force 1-3 years Political goal 1-3 years 37 39
Slide 40: New buildings: EU Energy action plan
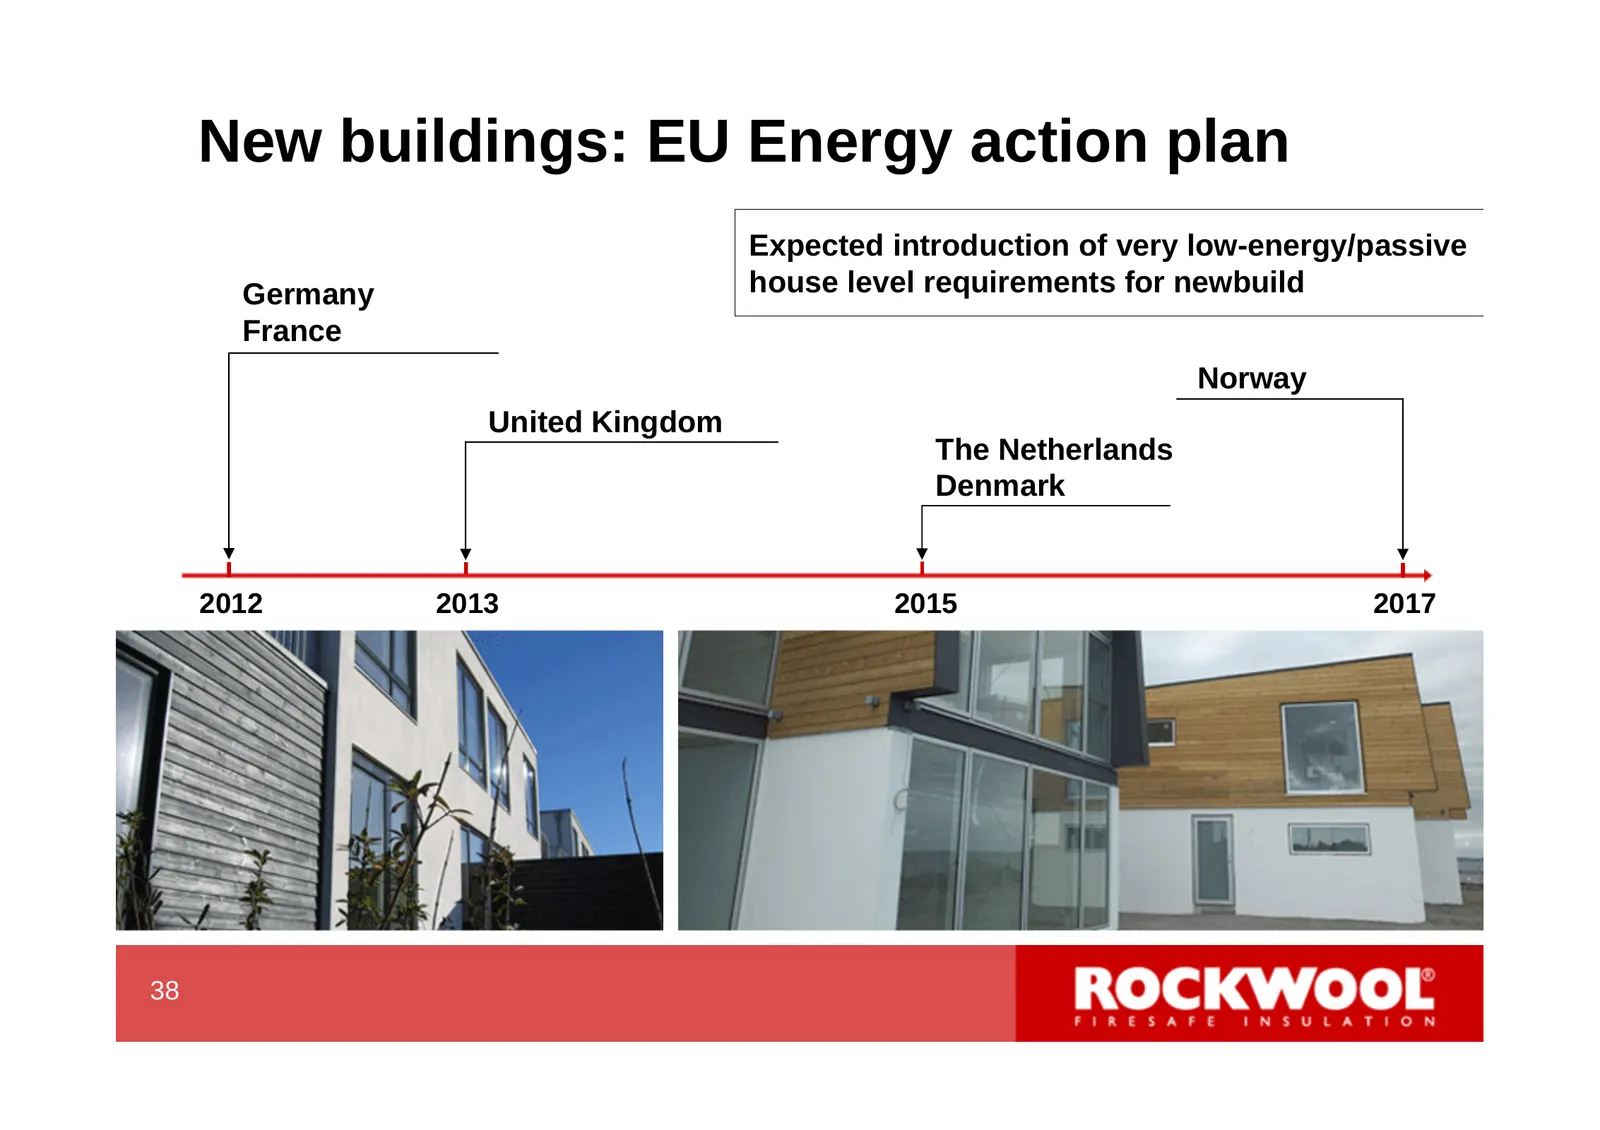
New buildings: EU Energy action plan Expected introduction of very low-energy/passive Germany house level requirements for newbuild France Norway United Kingdom The Netherlands Denmark 2012 2013 2015 2017 38 40
Slide 41: Increased insulation volume required going to passive house
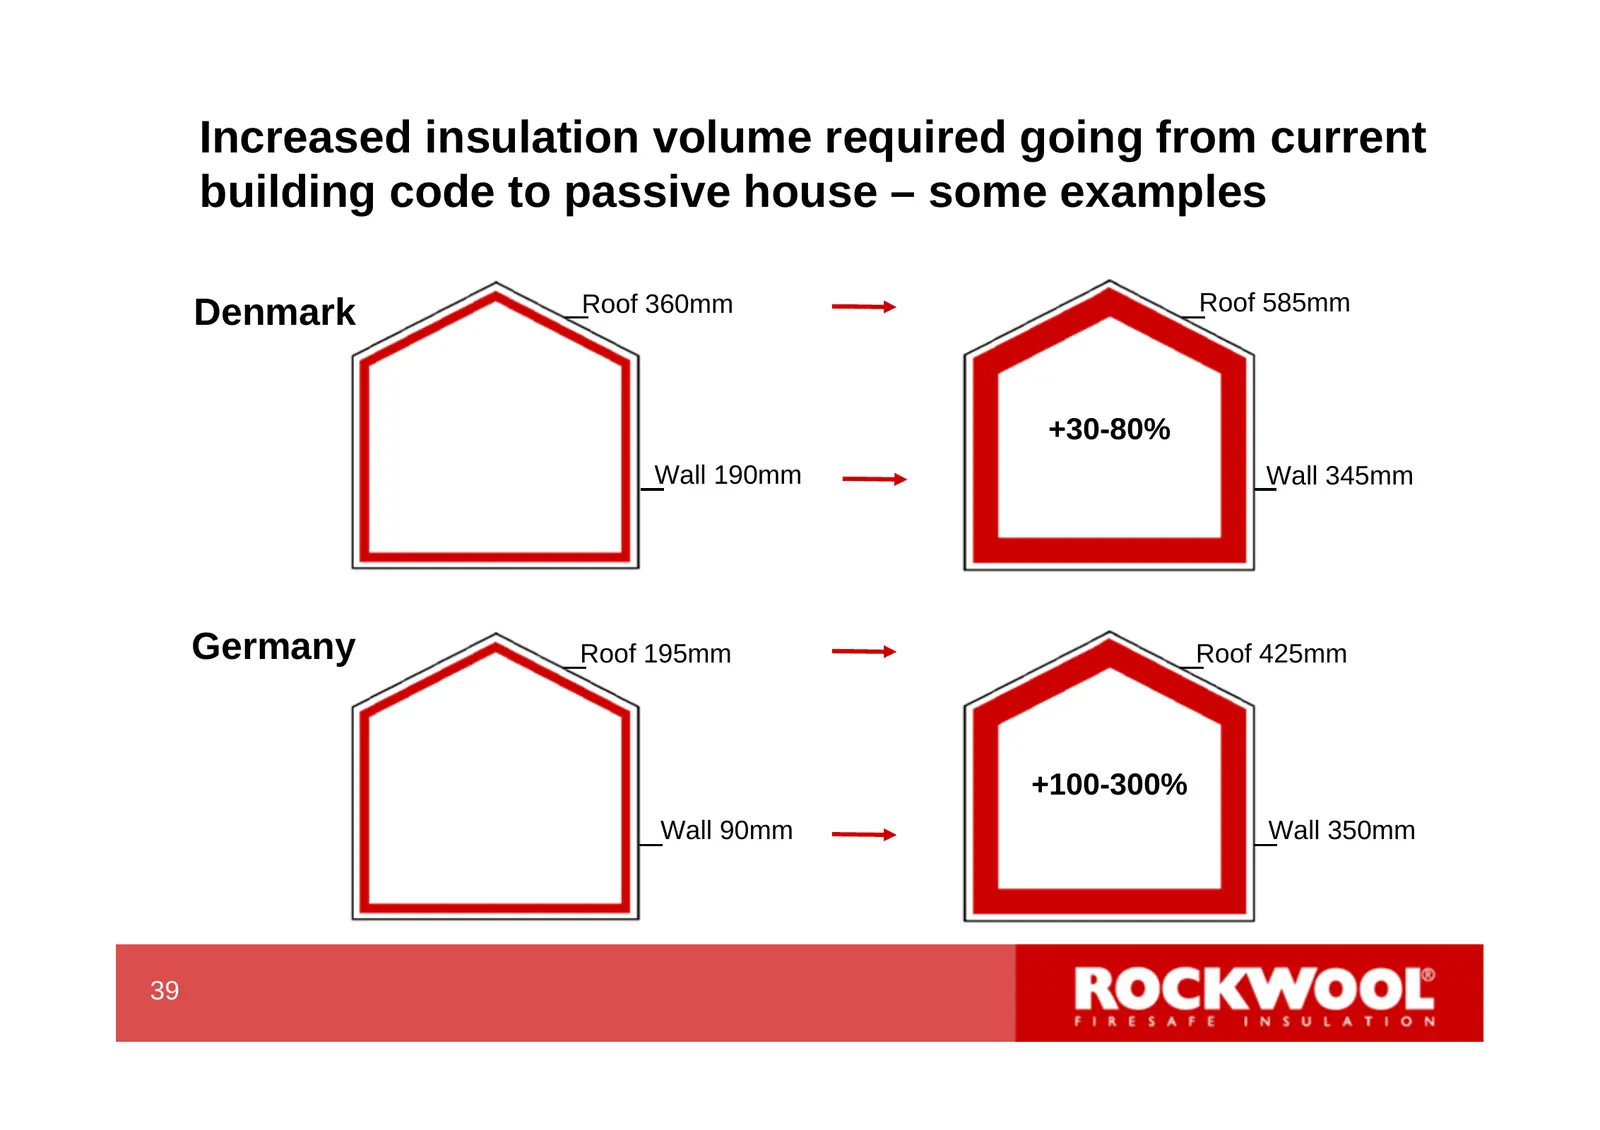
Increased insulation volume required going from current building code to passive house – some examples Roof 360mm Roof 585mm Denmark +30-80% Wall 190mm Wall 345mm Germany Roof 195mm Roof 425mm +100-300% Wall 90mm Wall 350mm 39 41
Slide 42: Major growth drivers - Central & Eastern Europe exposure
Major growth drivers - Central & Eastern Europe exposure 40 42
Slide 43: CEE insulation market still small compared to West but growing fast
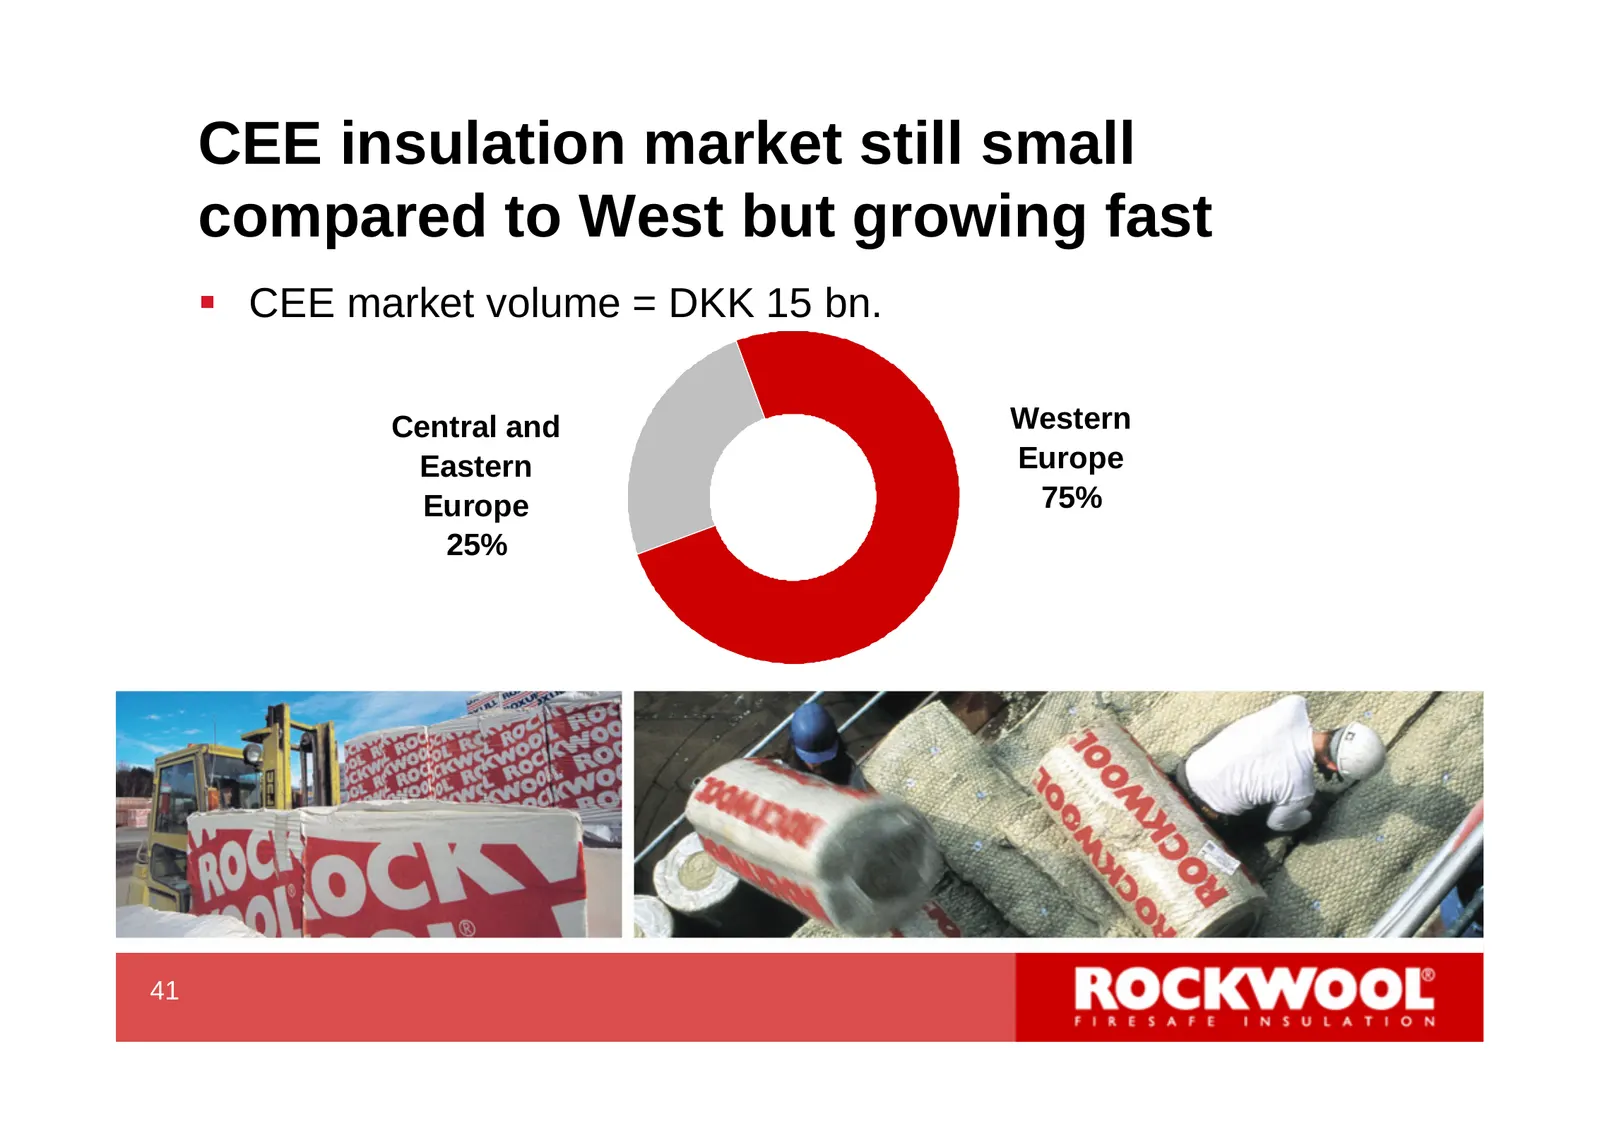
CEE insulation market still small compared to West but growing fast CEE market volume = DKK 15 bn. Central and Western Eastern Europe Europe 75% 25% 41 43
Slide 44: Market attraction – cool climate
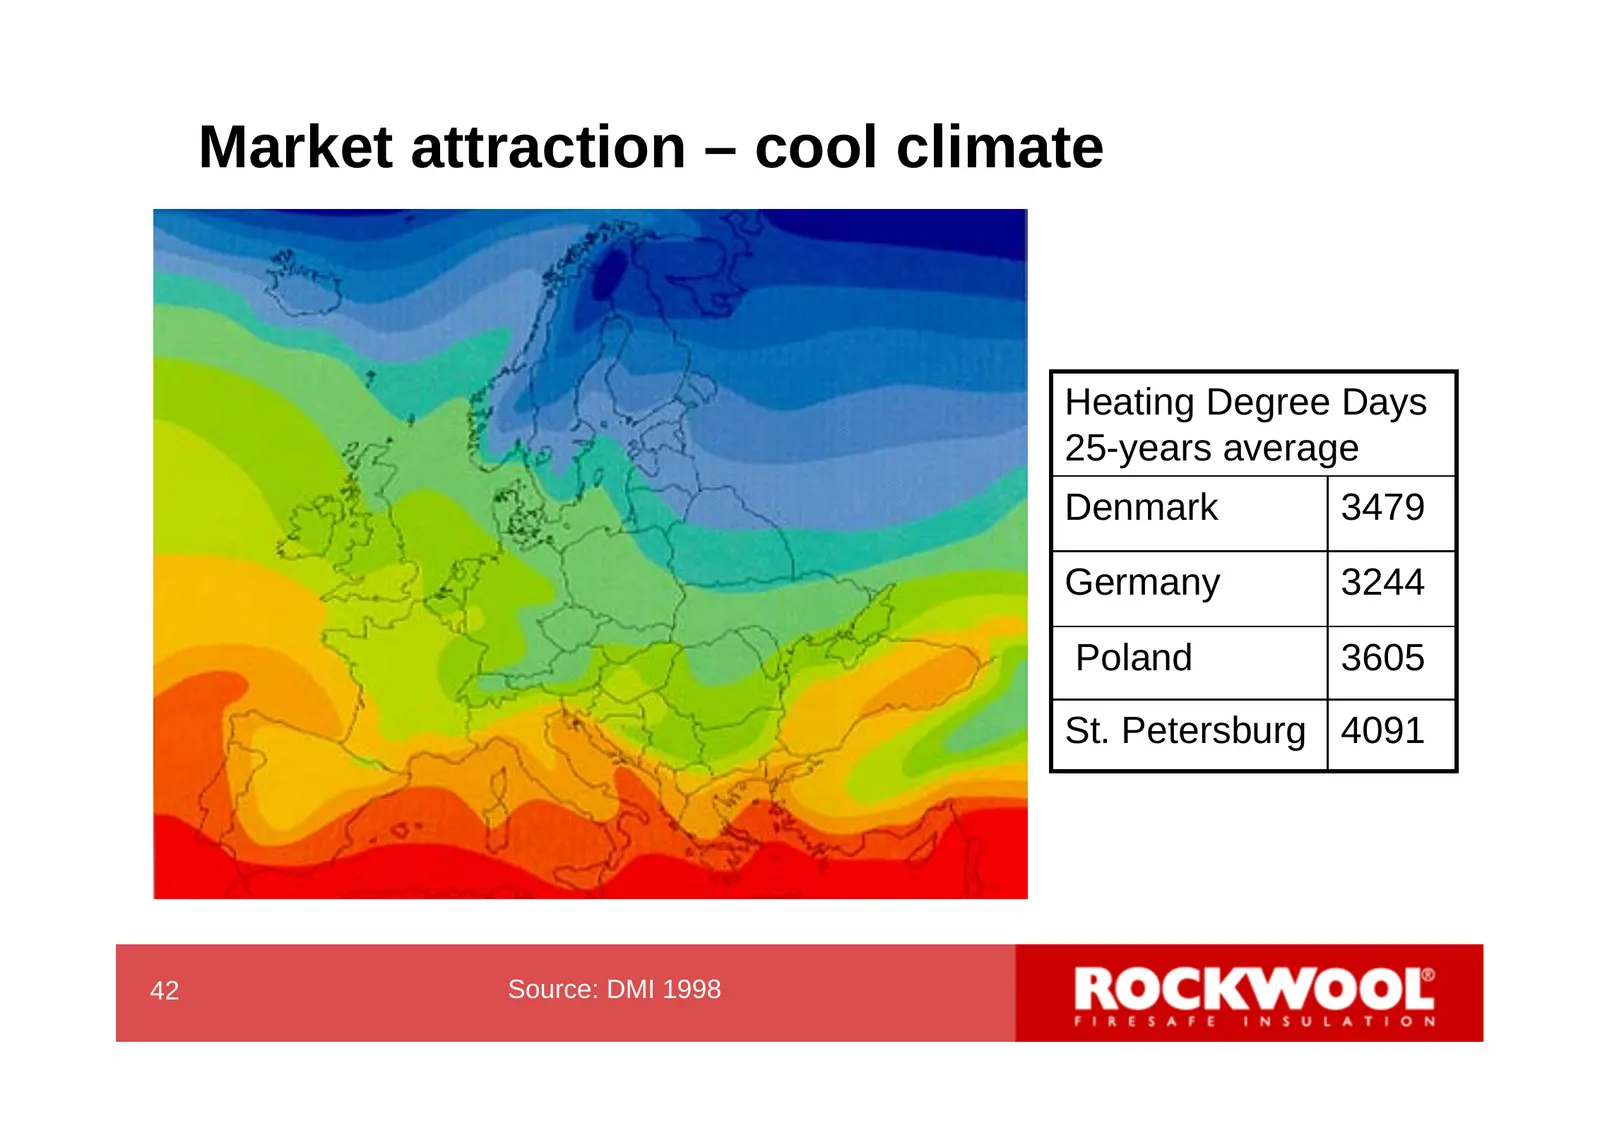
Market attraction – cool climate Heating Degree Days 25-years average Denmark 3479 Germany 3244 Poland 3605 St. Petersburg 4091 42 Source: DMI 1998 44
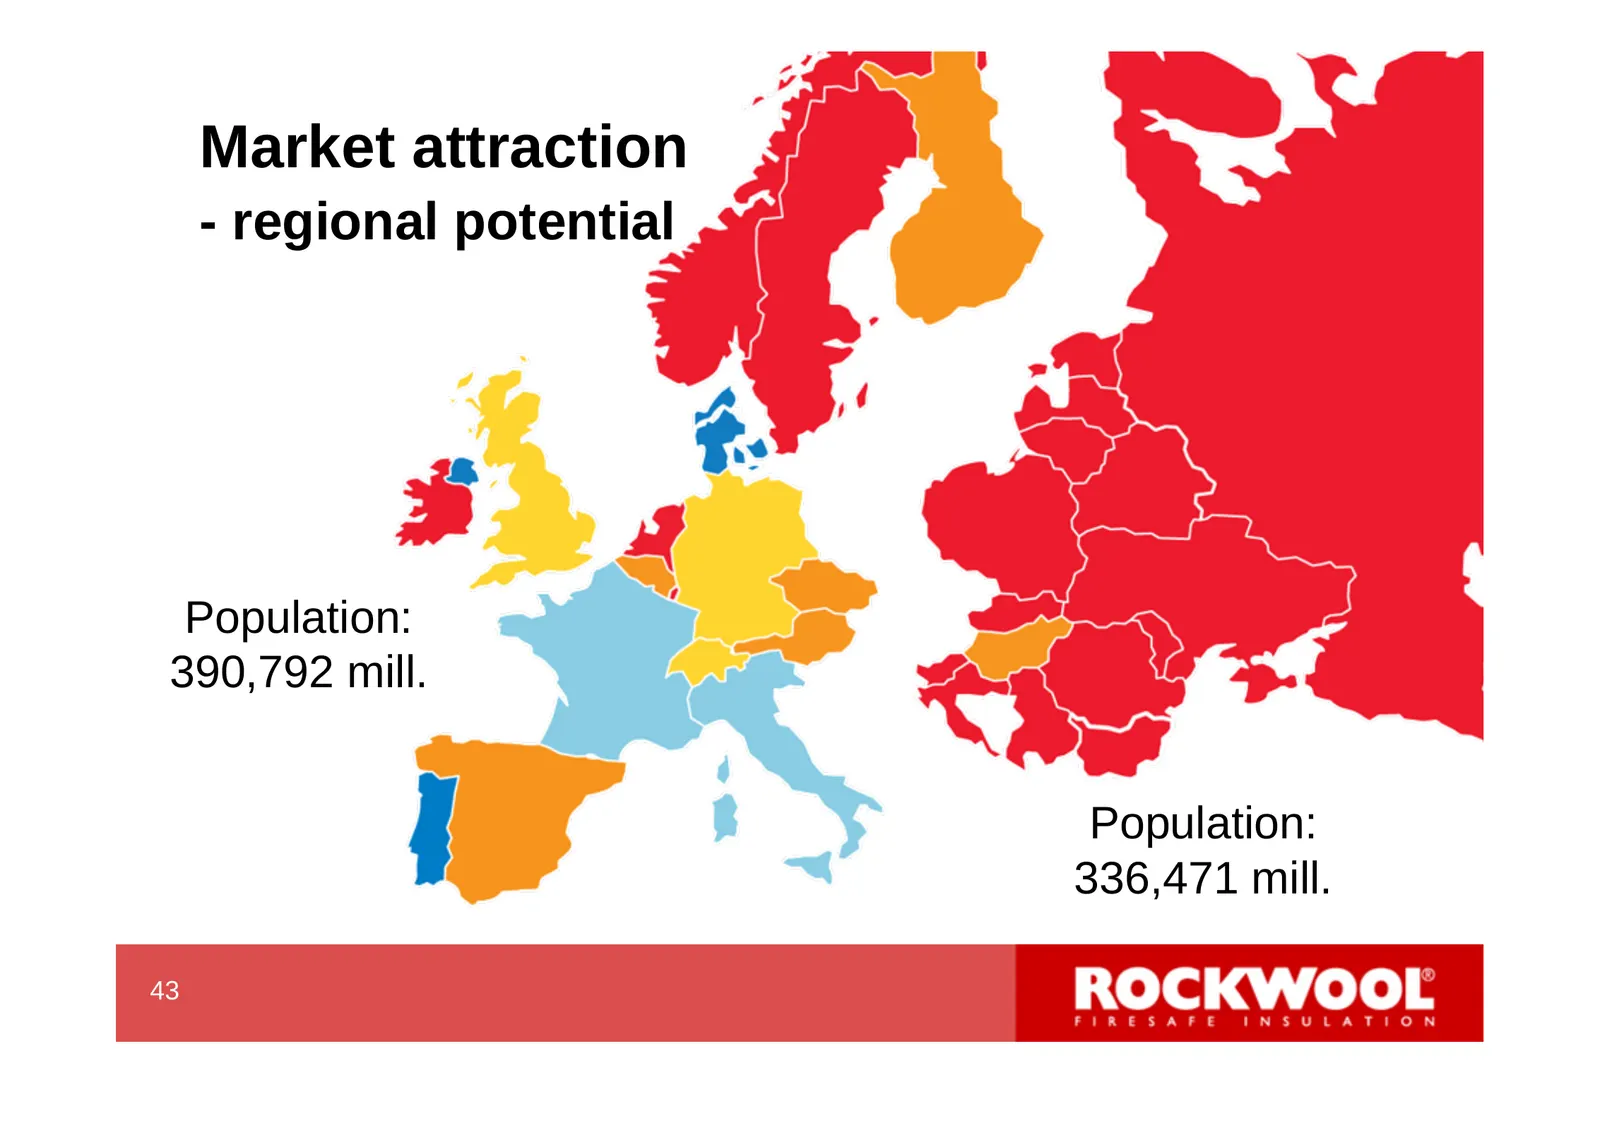
Slide 45: Market attraction - regional potential
Market attraction - regional potential Population: 390,792 mill. Population: 336,471 mill. 43 45
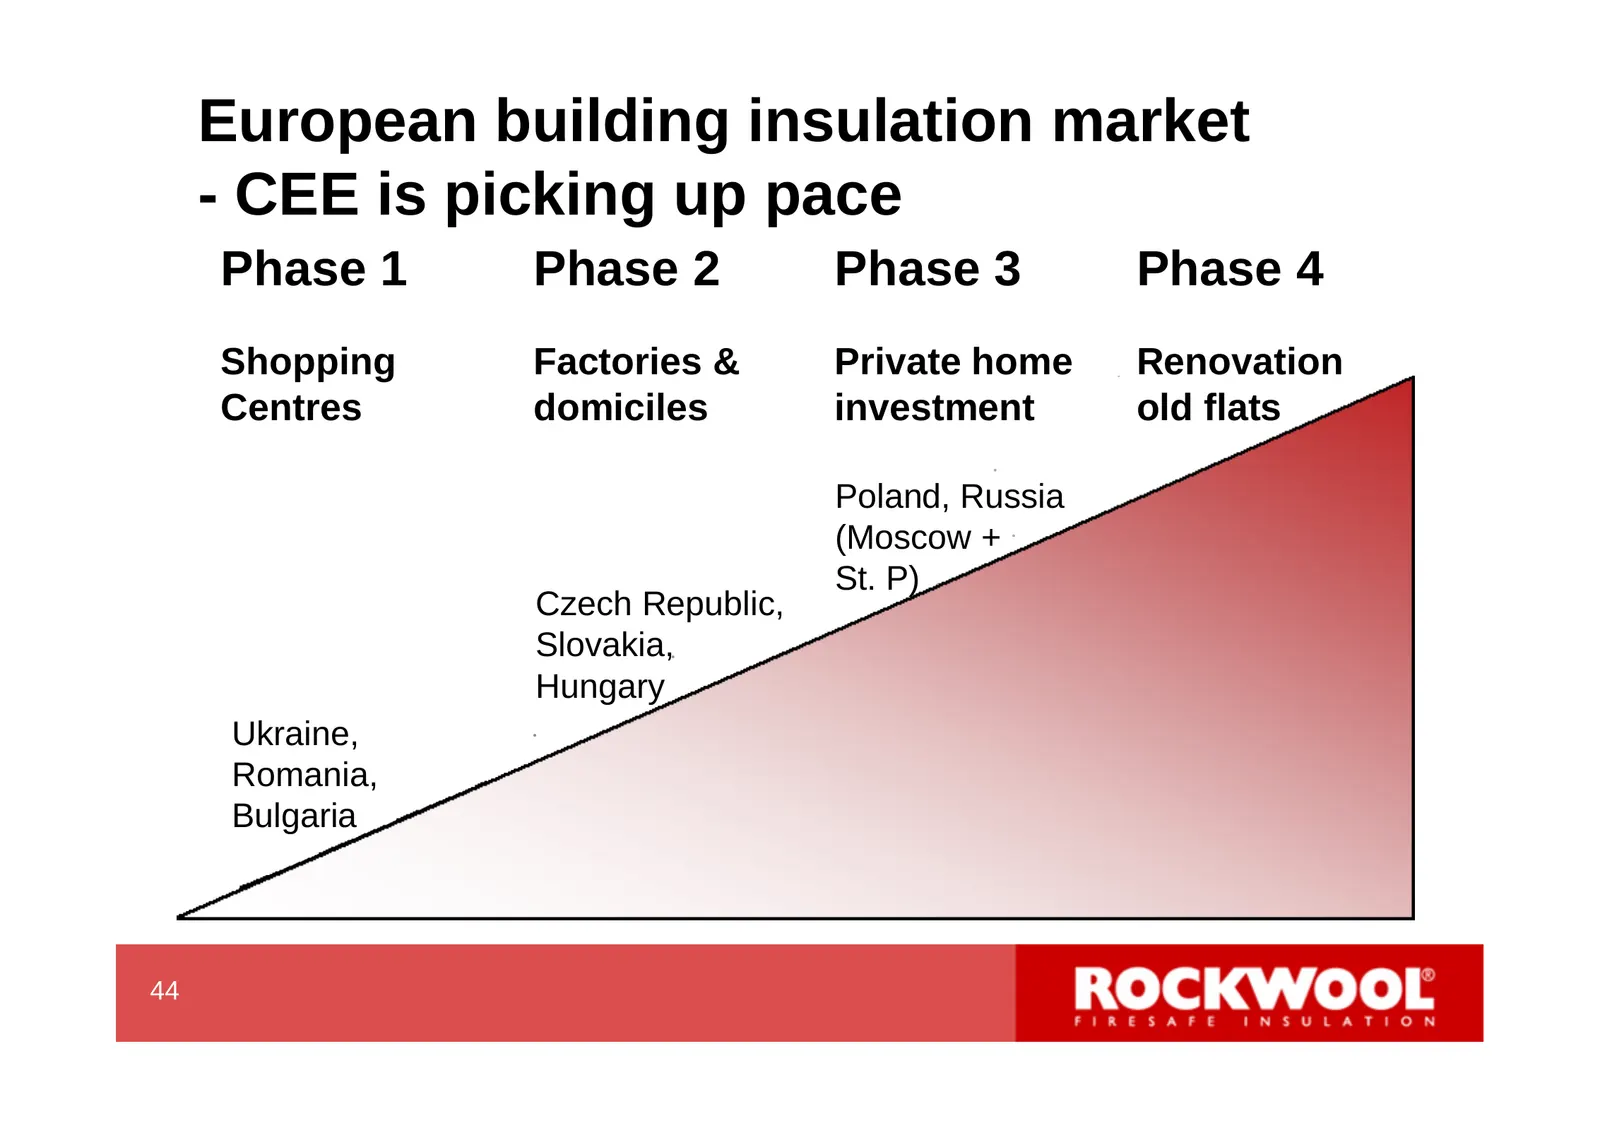
Slide 46: European building insulation market - CEE is picking up pace
European building insulation market - CEE is picking up pace Phase 1 Phase 2 Phase 3 Phase 4 Shopping Factories & Private home Renovation Centres domiciles investment old flats Poland, Russia (Moscow + St. P) Czech Republic, Slovakia, Hungary Ukraine, Romania, Bulgaria 44 46
Slide 47: How to cope with the growth?
How to cope with the growth? 45 47
Slide 48: Building capacity
Building capacity In order to meet the expected increase in demand, the Rockwool Group is presently establishing new capacity in selected places In November 2006 a major capacity expansion plan was announced consisting of possibly 5 new factories/lines. All 5 have now been announced In additio
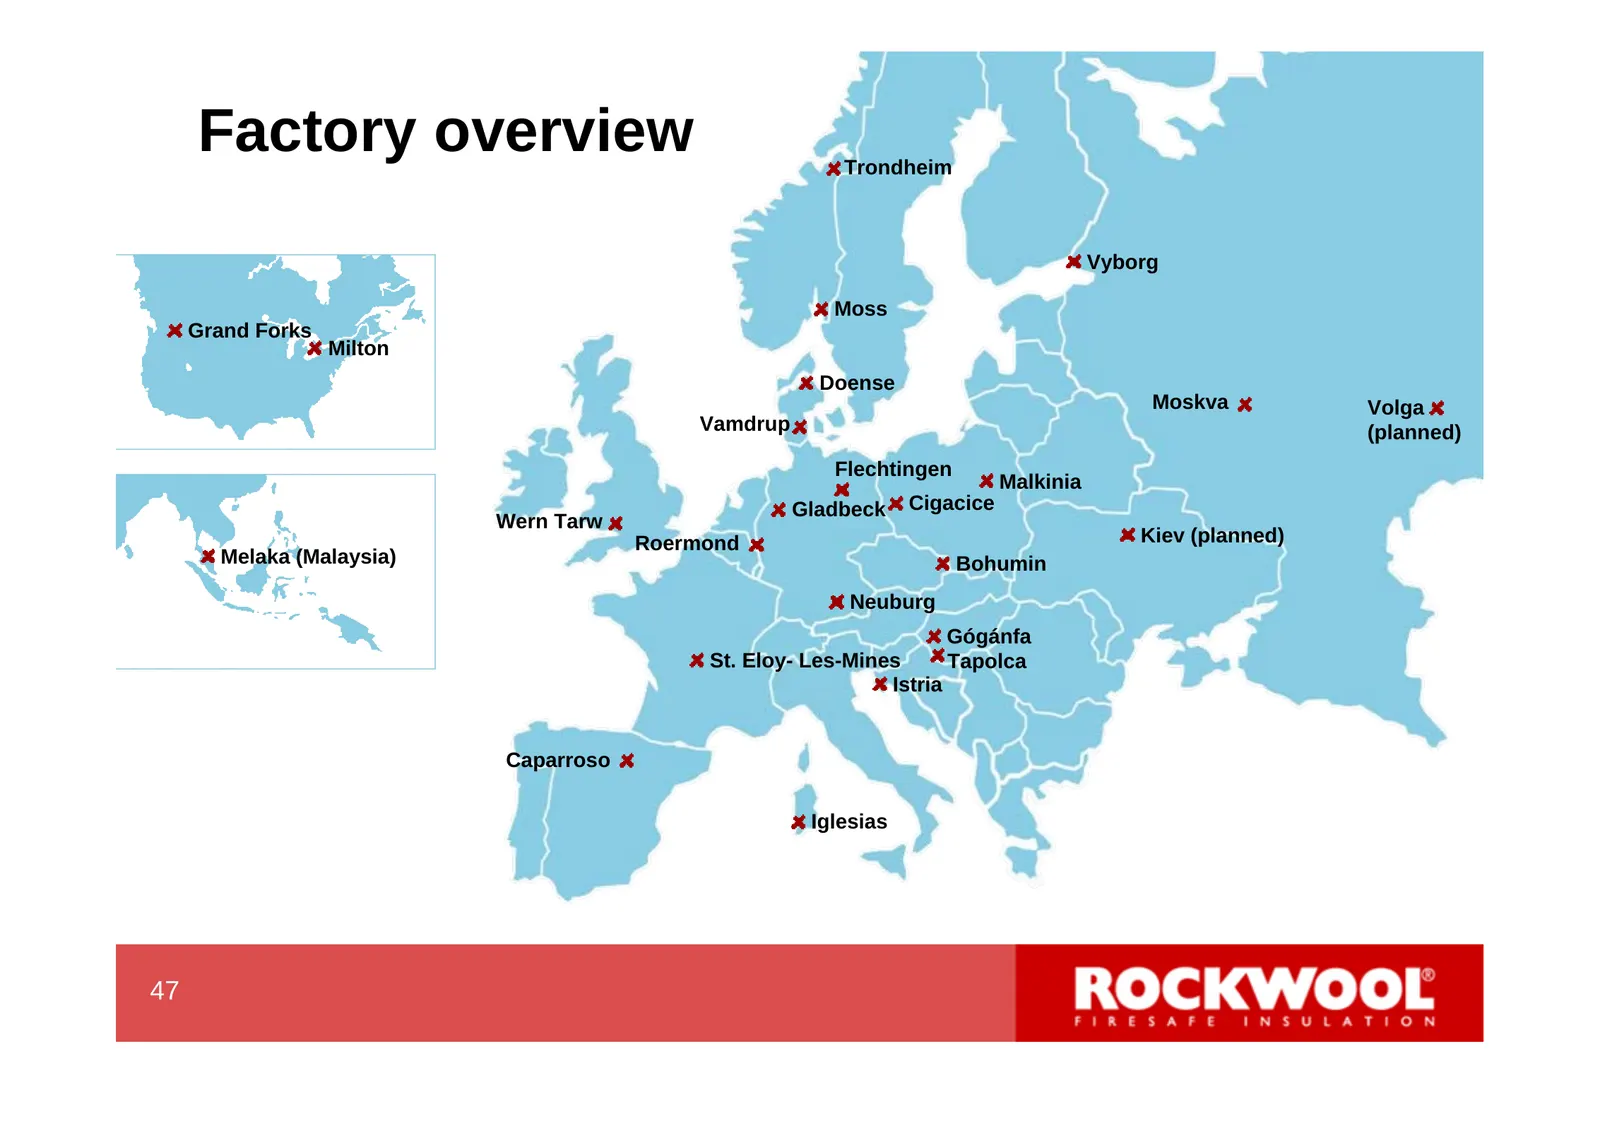
Slide 49: Factory overview
Factory overview Trondheim Vyborg Moss Grand Forks Milton Doense Moskva Volga Vamdrup (planned) Flechtingen Malkinia Gladbeck Cigacice Wern Tarw Roermond Kiev (planned) Melaka (Malaysia) Bohumin Neuburg Gógánfa St. Eloy- Les-Mines Tapolca Istria Caparroso Iglesias 47 49
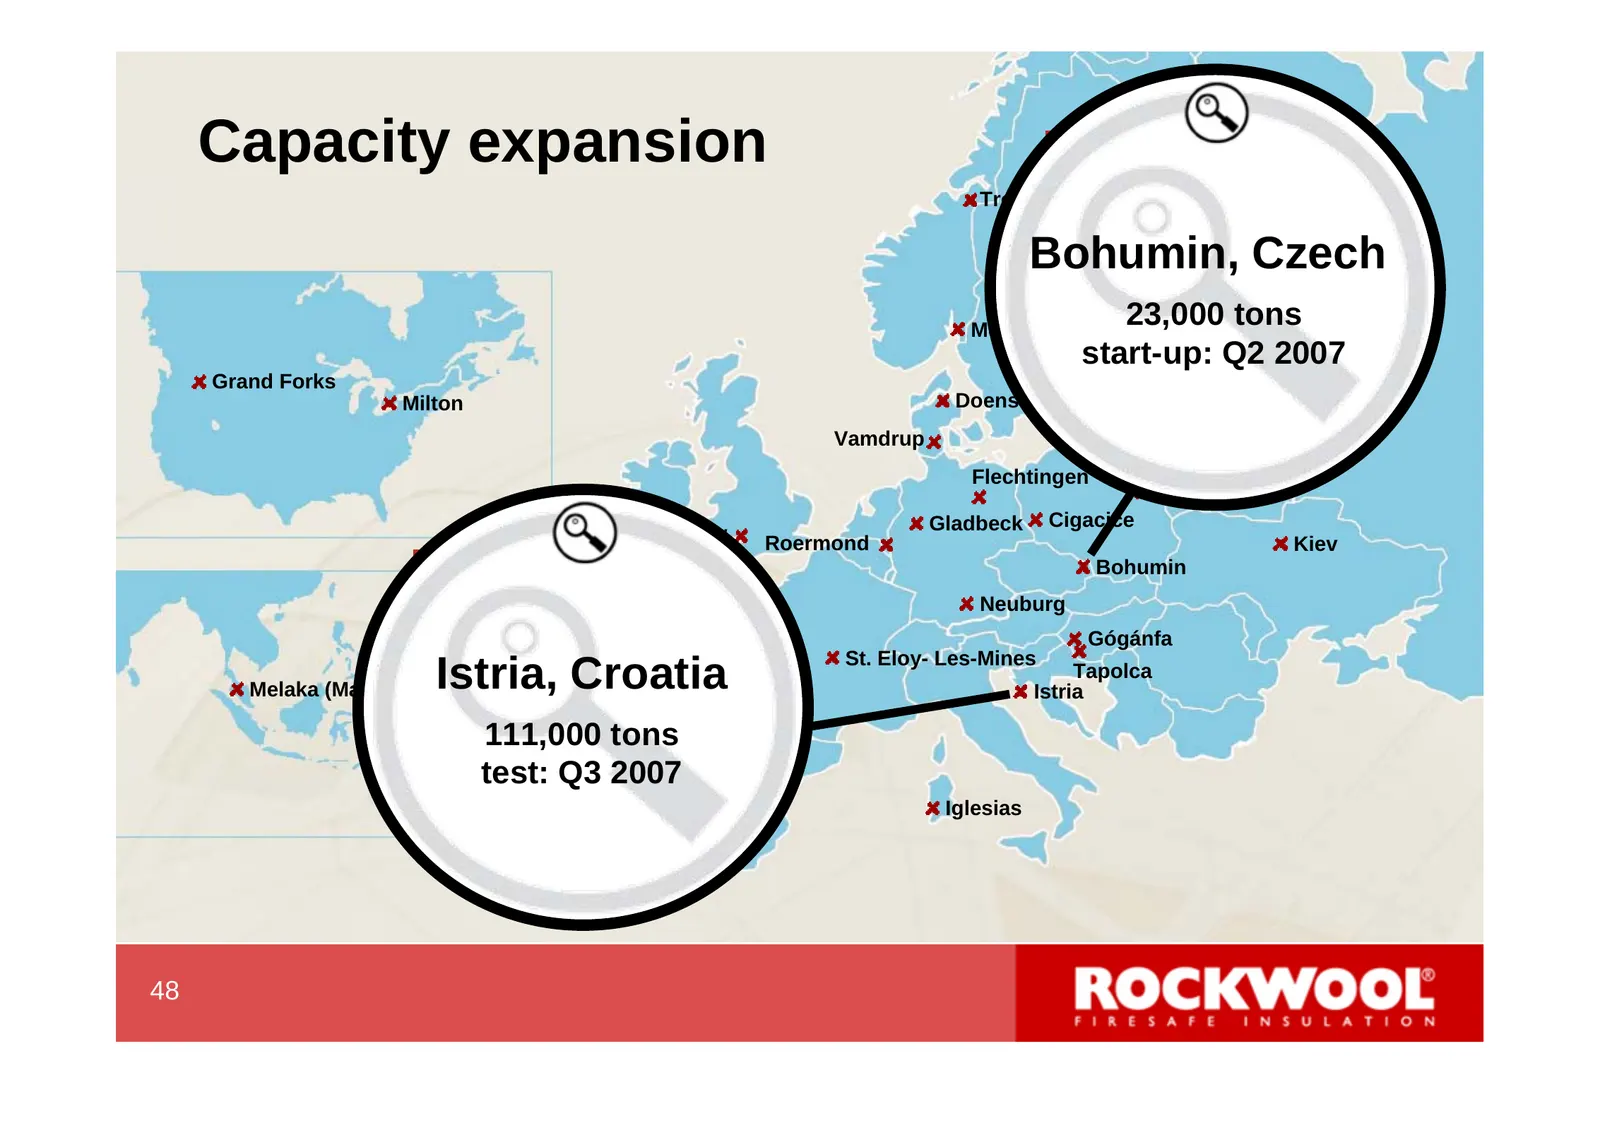
Slide 50: Capacity expansion
Capacity expansion >5% Trondheim 3-5 % 1-3 % Czech Bohumin, Vyborg 0-1 % 23,000 tons Moss < 0 % Q2 2007 start-up: Grand Forks Milton Doense Moskva Vamdrup Flechtingen Malkinia Gladbeck Cigacice Wern Tarw Roermond Kiev >5% Bohumin Neuburg 3-5 % Gógánfa St. Eloy- Les-Mines 1-3 % Melaka (Malaysia) Istr
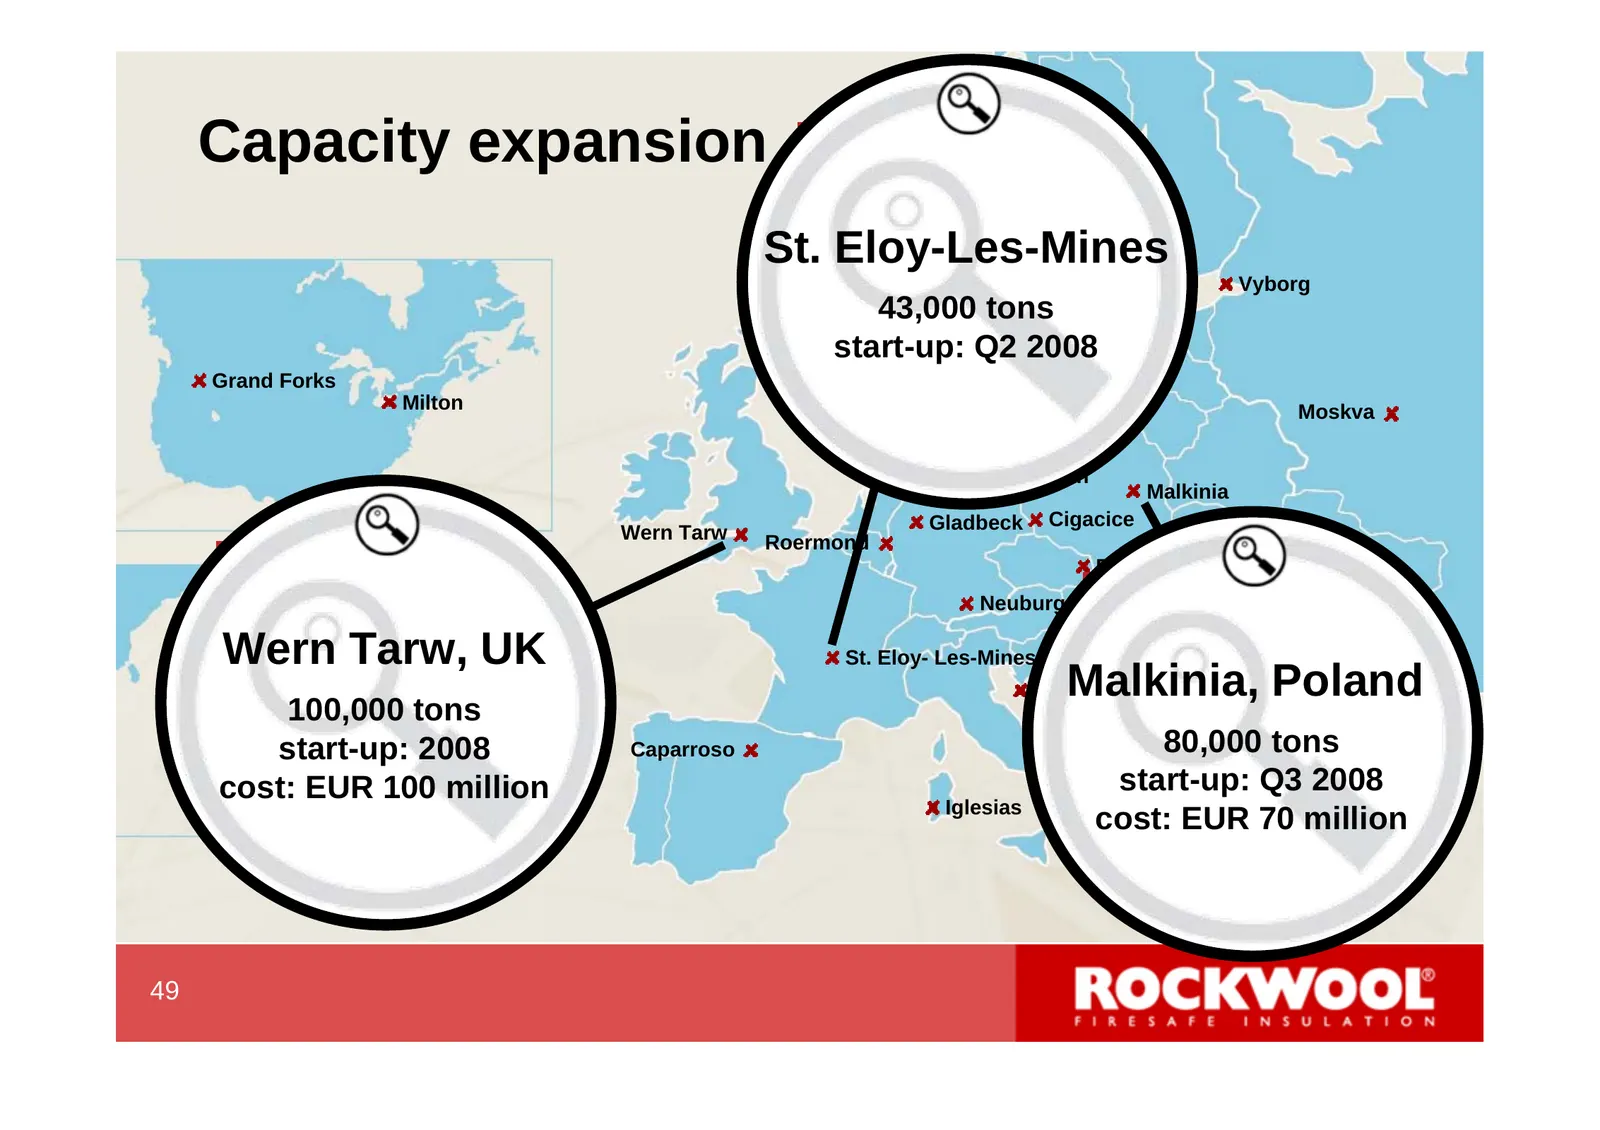
Slide 51: Capacity expansion
Capacity expansion >5% 3-5 % Trondheim 1-3 % St. Eloy-Les-Mines 0-1 % 43,000 tons Vyborg < 0 % Moss start-up: Q2 2008 Grand Forks Milton Doense Moskva Vamdrup Flechtingen Malkinia Gladbeck Cigacice Wern Tarw Roermond Kiev >5% Bohumin Neuburg >5% 3-5 % Wern 1-3 % Tarw, UK St. Eloy- Les-Mines 3-5 % Gó
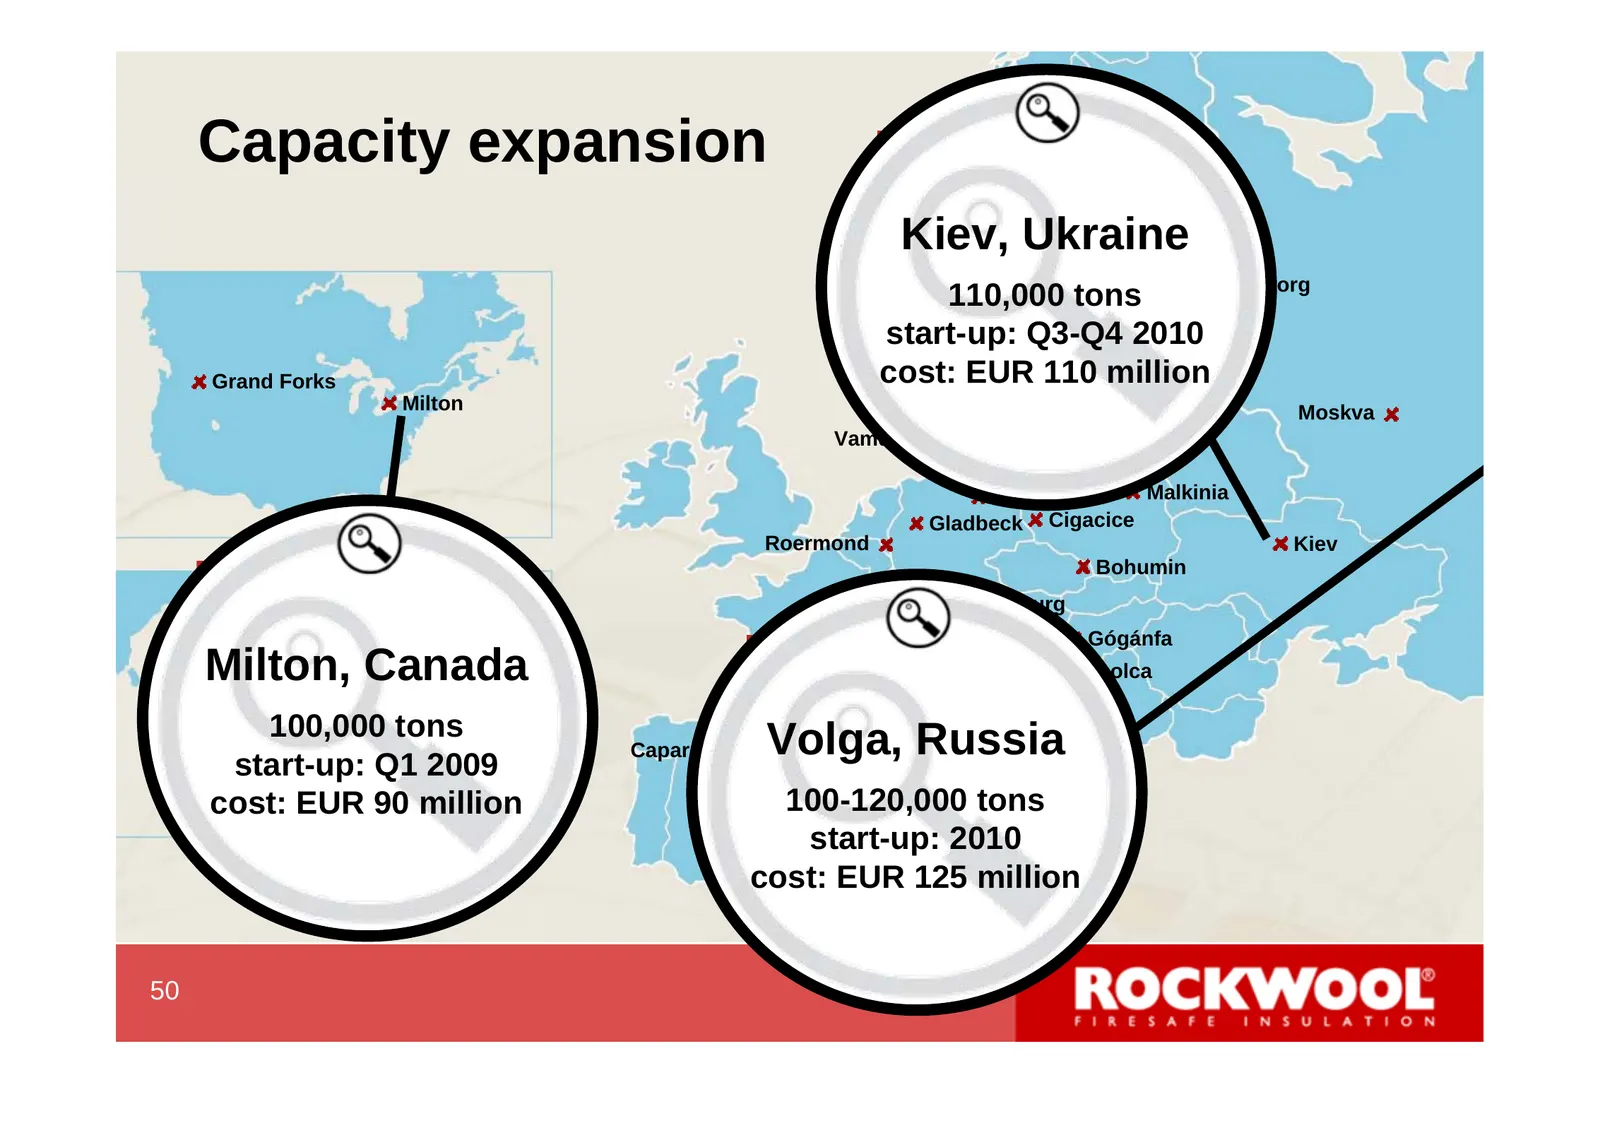
Slide 52: Capacity expansion
Capacity expansion >5% 3-5Trondheim % Kiev, 1-3 %Ukraine Vyborg 0-1 % tons 110,000 start-up: %Q3-Q4 2010 < 0Moss Grand Forks cost: EUR 110 million Milton Doense Moskva Vamdrup Flechtingen Malkinia Gladbeck Cigacice Roermond Kiev Bohumin >5% Neuburg 3-5 % Gógánfa Milton, Canada > 5St.% Eloy- Les-Mine
Source: Internet Archive copy of rockwool.com
More decks from Rockwool A/S Class A
 Q2 2026 Earnings Presentation19 slides · Aug 20, 2026
 Q1 2026 Earnings Presentation15 slides · May 20, 2026
 Shareholder Meeting (2026)10 slides · Apr 15, 2026
 Shareholder Meeting (April 2026)46 slides · Apr 15, 2026
 Q4 2025 Earnings Presentation19 slides · Feb 5, 2026
 Q2 2025 Earnings Presentation17 slides · Aug 21, 2025