Community Banks — Super-Community Bank Conference Mid-Atlantic 2002
38 slides from Community Banks's conference presentation, Oct 30, 2002
Slide 1: Super-Community Bank Conference Mid-Atlantic 2002
CommunityBanks LOCAL PEOPLE » LOCAL DECISIONS Super-Community BANK CONFERENCE Mid-Atlantic 2002 October 29 and 30, 2002
Slide 2: CommunityBanks
CommunityBanks
Slide 3: Agenda
CommunityBanks @ Who We Are @ Building a Competitive Advantage @ Management @ Momentum @ Markets @ Where We’re Going “Vision, without execution, is hallucination.” —Anonymous
Slide 4: Who We Are
Who We Are CommunityBanks @ One-bank financial services holding company headquartered in Harrisburg, Pennsylvania @ Operate 41 banking offices throughout Central Pennsylvania from Poconos to Maryland border @ Network of nearly 100 ATM sites @ Five regional markets served by Regional Presidents @ $1.
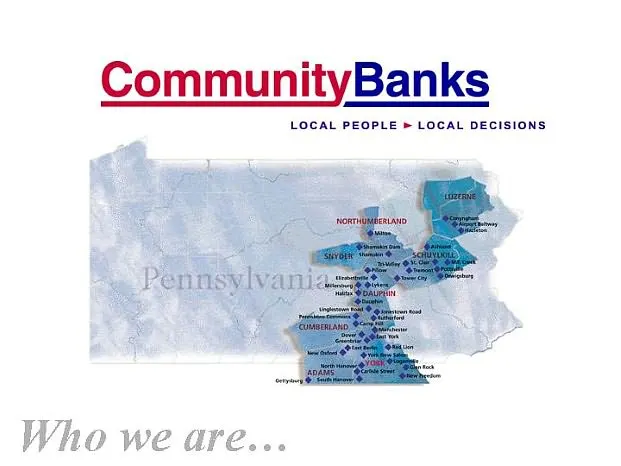
Slide 5: Who we are...
CommunityBanks LOCAL PEOPLE » LOCAL DECISIONS Who we are...
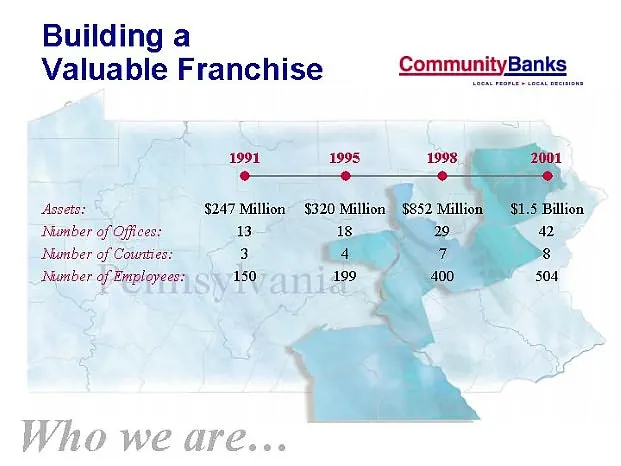
Slide 6: Building a Valuable Franchise
Building a Valuable Franchise CommunityBanks Assets: ‘$247 Million $320 Million $8 Nunber of Offices: Bo 1s Number of Counties? 3 4 Agee PERTTI S Wa Val Let Who we are...
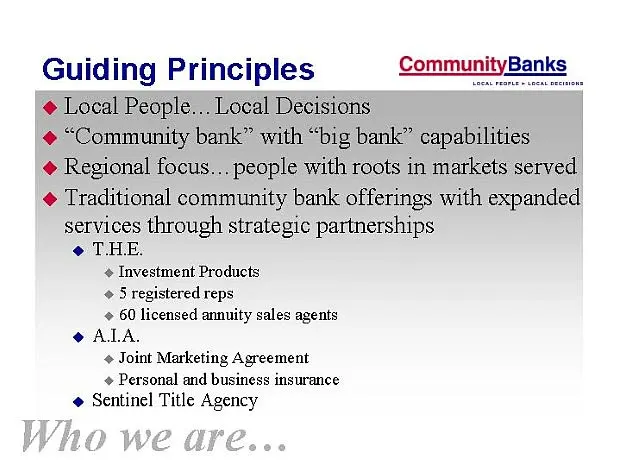
Slide 7: Guiding Principles
Guiding Principles CommunityBanks @ Local People... Local Decisions “Community bank” with “big bank” capabilities @ Regional focus... people with roots in markets served @ Traditional community bank offerings with expanded services through strategic partnerships @ THE. ¢ Investment Products ‘@ 5 reg
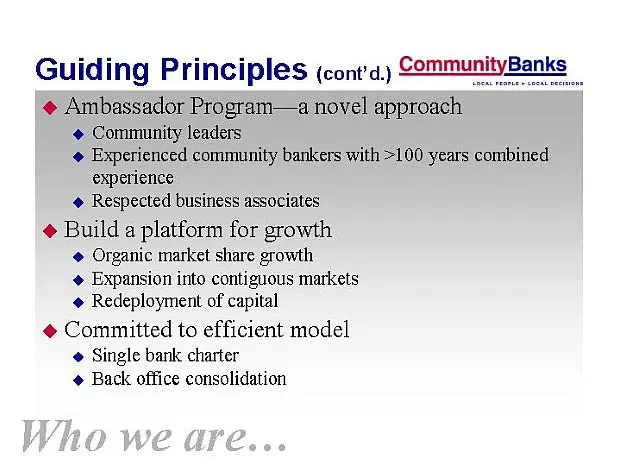
Slide 8: Guiding Principles (cont'd)
Guiding Principles (conta) CommunityBanks — @ Ambassador Program—a novel approach Community leaders Experienced community bankers with >100 years combined experience Respected business associates @ Build a platform for growth ‘@ Organic market share growth Expansion into contiguous markets @ Redeplo
Slide 9: Building a Competitive Advantage
Building a Competitive Advantage Management Momentum Markets
Slide 10: Local People...
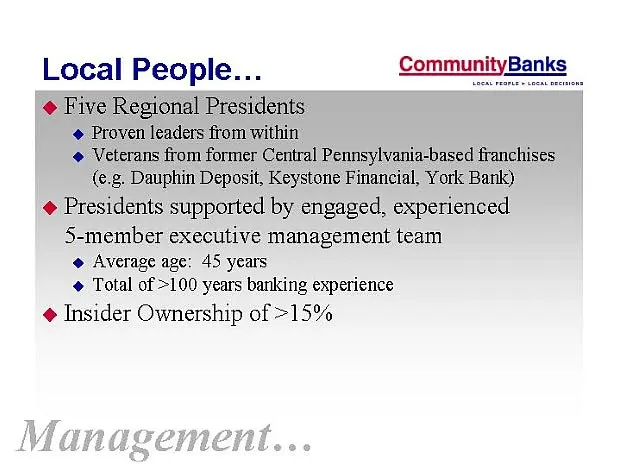
Local People... CommunityBanks — @ Five Regional Presidents Proven leaders from within Veterans from former Central Pennsylvania-based franchises (e.g. Dauphin Deposit, Keystone Financial, York Bank) @ Presidents supported by engaged, experienced S-member executive management team @ Average age: 45
Slide 11: Community Banks Locations
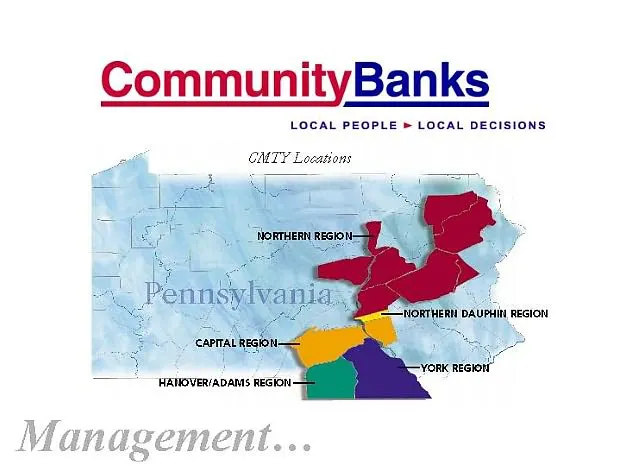
CommunityBanks LOCAL PEOPLE » LOCAL DECISIONS OMTY Locations
Slide 12: Building a Competitive Advantage
Building a Competitive Advantage Management Momentum Markets
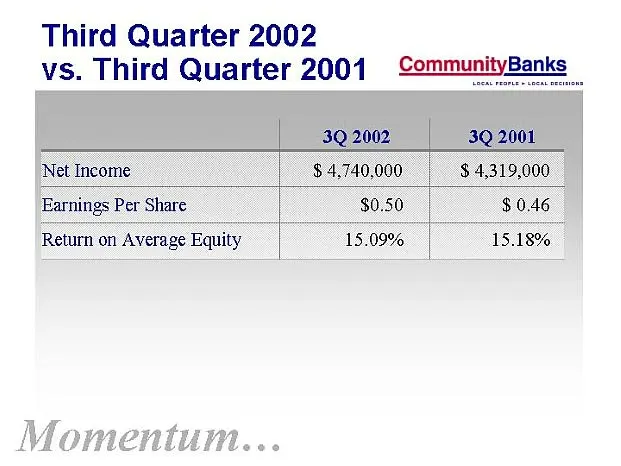
Slide 13: Third Quarter 2002 vs. Third Quarter 2001
Third Quarter 2002 vs. Third Quarter 2001 CommunityBanks Return on Average Equity — Momentum...
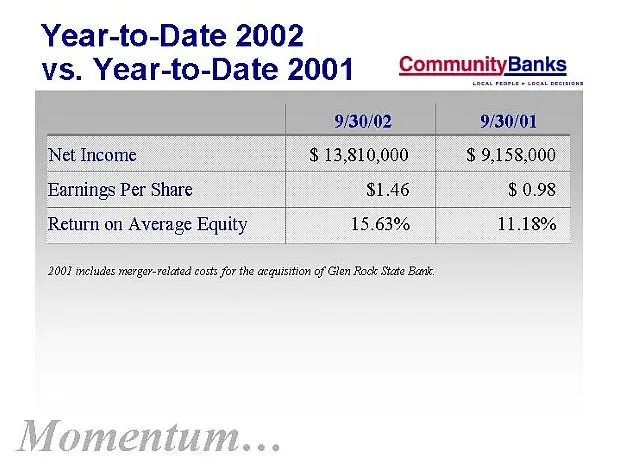
Slide 14: Year-to-Date 2002 vs. Year-to-Date 2001
Year-to-Date 2002 vs. Year-to-Date 2001 CommunityBanks 2002 includes mergor-related costs forthe aequstion of Glon Rack Ste Ban Momentum...
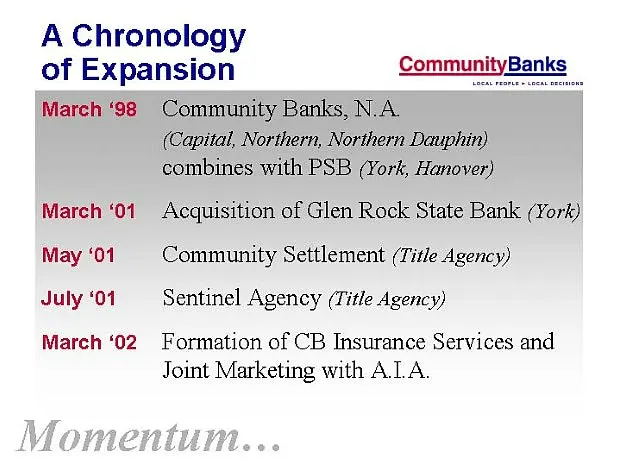
Slide 15: A Chronology of Expansion
A Chronology of Expansion CommunityBanks — March ‘98 Community Banks, N.A. (Capital, Northern, Northern Dauphin) combines with PSB (York, Hanover) March ‘01 Acquisition of Glen Rock State Bank (York) May ‘01 Community Settlement (Title Agency) July ‘01 Sentinel Agency (Title Agency) March ‘02 Format
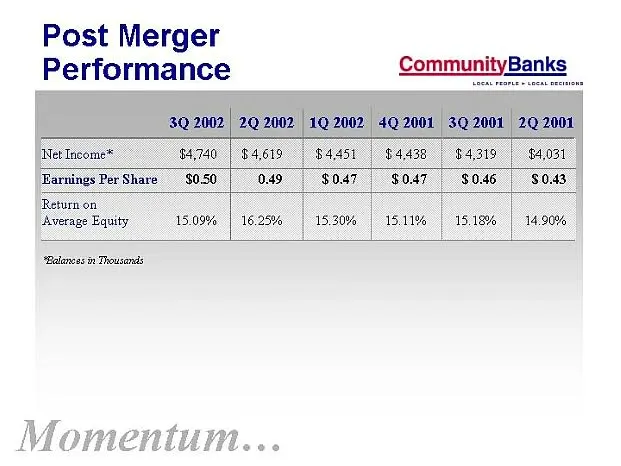
Slide 16: Post Merger Performance
Post Merger Performance CommunityBanks "Balances x Thousands Momentum...
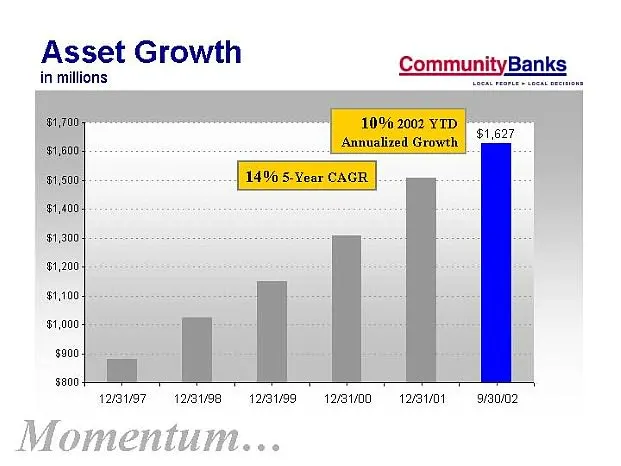
Slide 17: Asset Growth
Asset Growth in millions CommunityBanks i2eves 12/81/99 saan 1281/01 g/S0ID2
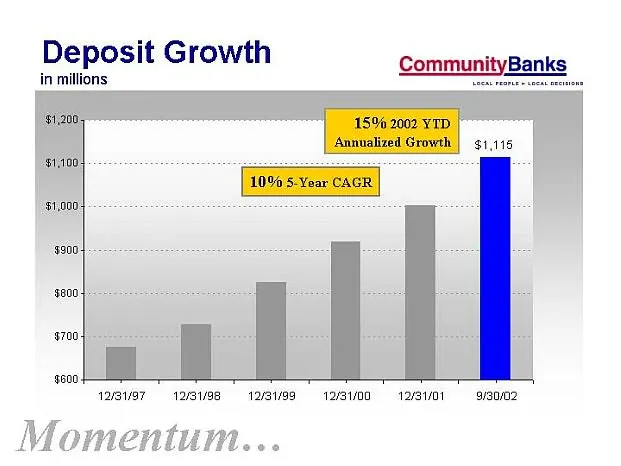
Slide 18: Deposit Growth
Deposit Growth CommunityBanks $1,115 “at a weve? 128198 128/99 «12BVND = 12AVOI —g/s0/02 Atty
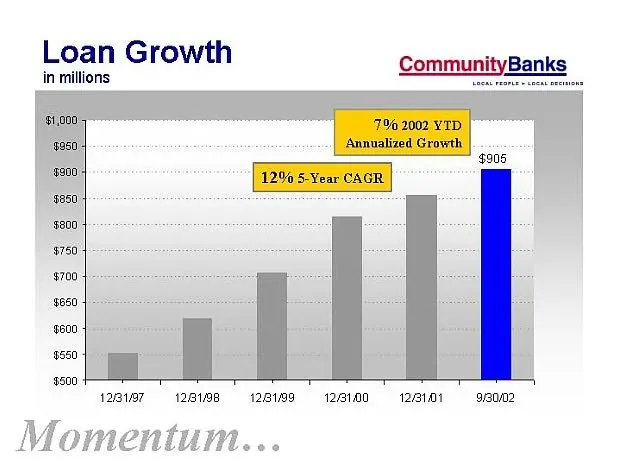
Slide 19: Loan Growth
Loan Growth in millions CommunityBanks 000 “5950, Lata 900 oe io a 1B «1281NB «| 12B1IN9 AMO = AT = gBOMD
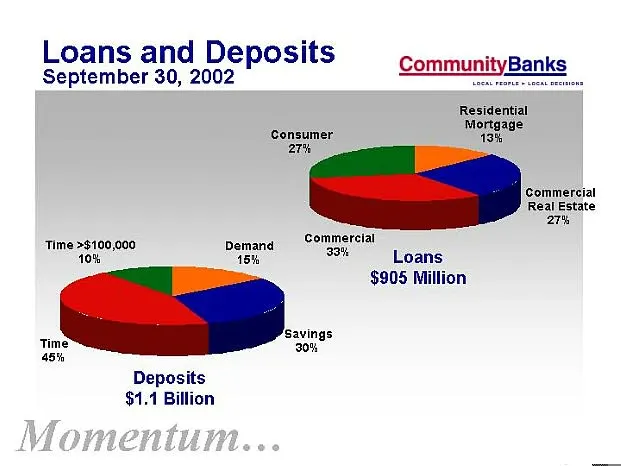
Slide 20: Loans and Deposits
Loans and Deposits , September 30, 2002 P CommunityBanks Residential Mortgage Consumer 13% 27 commercial Real Estate Commercial ‘Time >$100,000 Demand 15% 98 Loans $905 Million savings Time 20% 45% Deposits $1.1 Billion
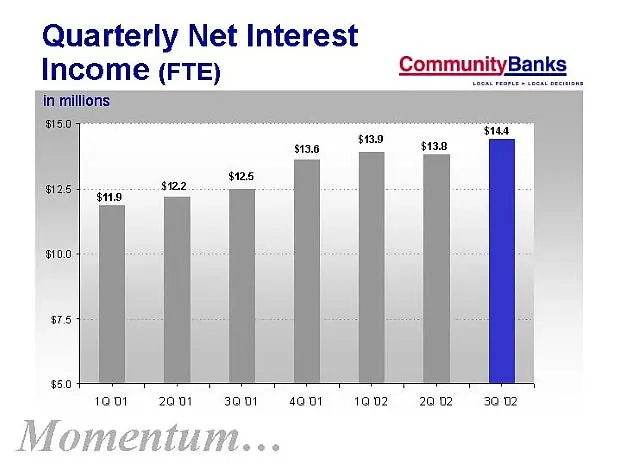
Slide 21: Quarterly Net Interest Income (FTE)
Quarterly Net Interest Income (FTE) CommunityBanks 50 ee 1on1 2001 = 3001 Momentum... 4001 1002 2002 3002
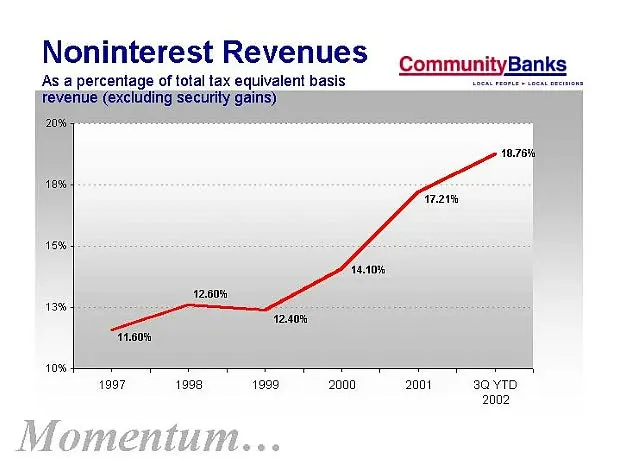
Slide 22: Noninterest Revenues
Noninterest Revenues As a percentage of total tax equivalent basis revenue (excluding security gains) 20% CommunityBanks 10.75% 10% 15% 13% 71.50% 10% 1997 1998 1999 2000 2001 30 YTD 2002
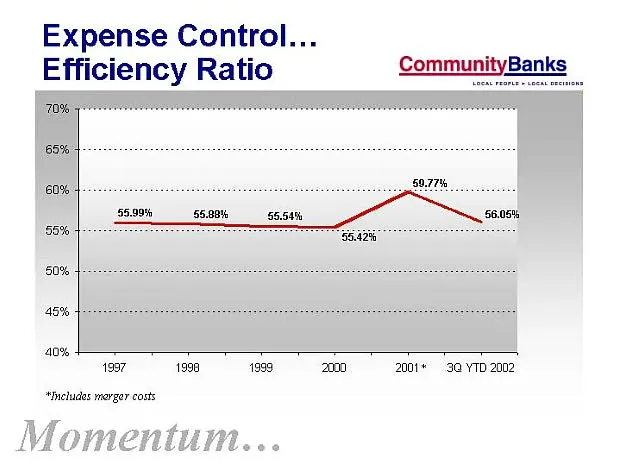
Slide 23: Expense Control...
Expense Control... Efficiency Ratio 7 ppc Ai 50.77% 55.99% 55.98% 55.58% Sey Z 56.4%, 1997 1998 1999 2000 2ont* —3@ YTD 2002 “hucludes merger costs
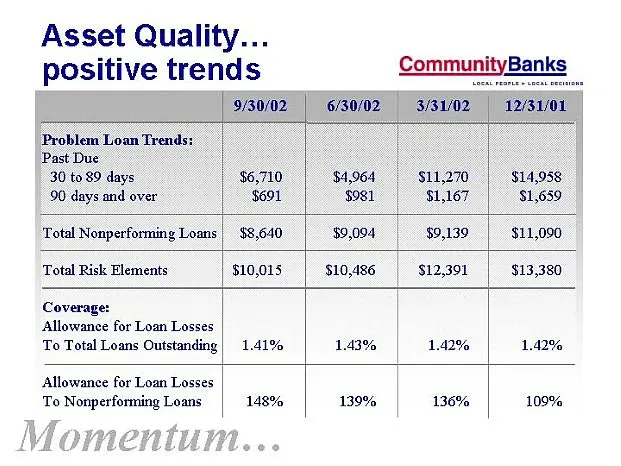
Slide 24: Asset Quality
Asset Quality. positive trends CommunityBanks 9/30/02 | 6/30/02 3/31/02 | 12/31/01 30 to 89 days S670 $4,964 $11,270 | $14,958 90 days and over $691 $981 $1,167 $1,659 Total Nonperforming Loans| $8,640 $9,094 $9,139 $11,090 Total Risk Elements $10,015 $10,486 $12,391 $13,380 Coverage: Allowance for
Slide 25: Financial Goals
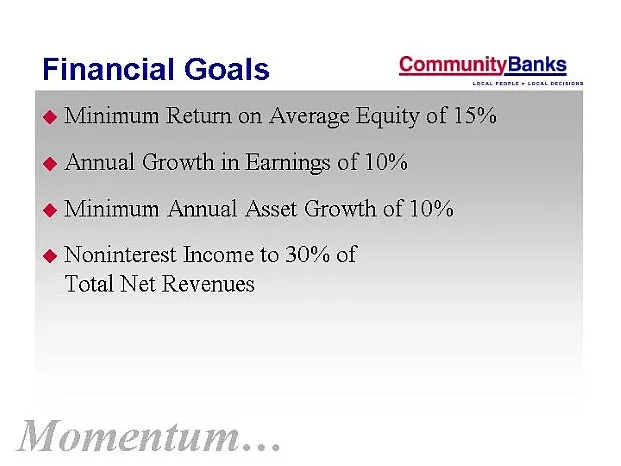
Financial Goals CommunityBanks @ Minimum Return on Average Equity of 15% @ Annual Growth in Earnings of 10% @ Minimum Annual Asset Growth of 10% @ Noninterest Income to 30% of Total Net Revenues
Slide 26: Financial Goals Performance
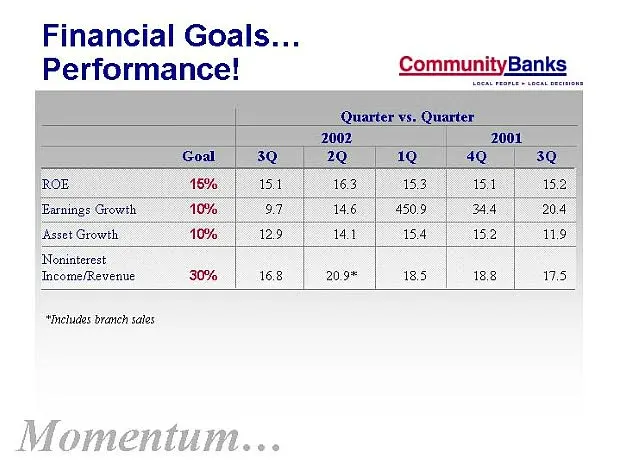
Financial Goals Performance! CommunityBanks ‘Noninterest Tncome/Revenue “Includes branch sates Momentum...
Slide 27: Central PA's Fastest Growing Bank
Central PA's Fastest Growing Bank satis == CommunityBanks So a Member FDIC Visit Us Today and Find Out Why! Momentum...
Slide 28: Cash Dividends & Stock Price Performance
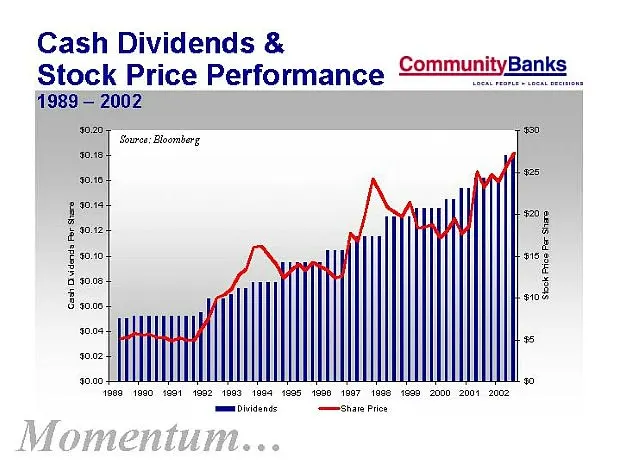
Cash Dividends & Stock Price Performance Som™uniyBanks | 1989 — 2002 |
Slide 29: Historical Share Price Performance
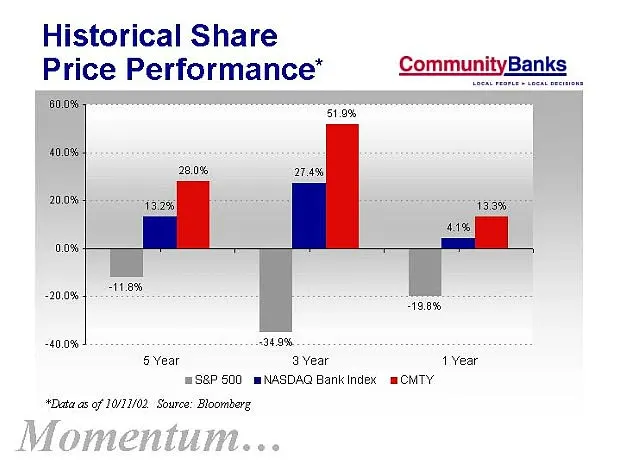
Historical Share i * Community! Price Performance’ CommunityBanks 60.0%. | nts ne 13.2% i 133% ae oa: svea avem vem = SEP 600 mNASDAQ Bank index mCMTY "Data as of 10/11/02 Source: Bloomberg
Slide 30: Building a Competitive Advantage
Building a Competitive Advantage Management Momentum Markets
Slide 31: Market Demographics
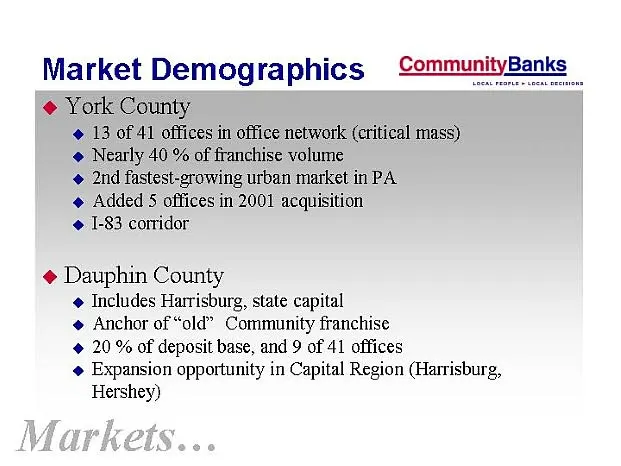
Market Demographics CommunityBanks @ York County 13 of 41 offices in office network (critical mass) Nearly 40 % of franchise volume 2nd fastest-growing urban market in PA @ Added 5 offices in 2001 acquisition @ 1-83 corridor @ Dauphin County Includes Harrisburg, state capital Anchor of “old” Communi
Slide 32: Market Demographics
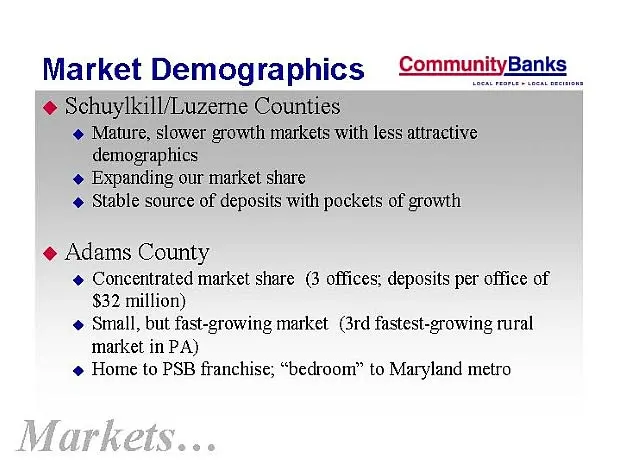
Market Demographics CommunityBanks — @ Schuylkill/Luzeme Counties Mature, slower growth markets with less attractive demographics Expanding our market share Stable source of deposits with pockets of growth @ Adams County Concentrated market share (3 offices; deposits per office of $32 million) Small
Slide 33: Market Opportunities
Market Opportunities | CommunityBanks @ PNC @ Dauphin/Keystone/AllFirstAM&T @ Wachovia/First Union Disruption of larger players @ Emergence of mid-size and smaller performers Community Banks, Inc. ¢ Sterling Financial Susquehanna National Penn
Slide 34: Where We're Going
Where We’re Going CommunityBanks @ Internal Expansion @ Industry Consolidation @ The Role of Community Banks
Slide 35: Internal Expansion
Internal Expansion CommunityBanks — @ Offices in Carroll County, Maryland 2002, Manchester 2003, Westminster @ Solidifying Existing Markets @ York (city) @ Hanover Ops Center/Banking Facility @ Continued Expansion of ATM Network (100 units) @ Convenience store — 50 sites, among largest in Central Pe
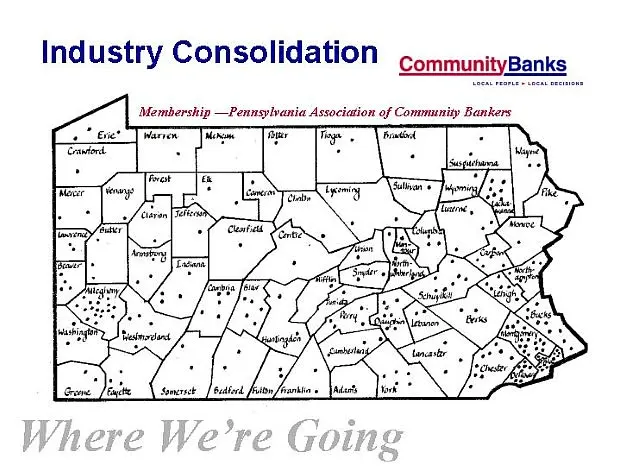
Slide 36: Industry Consolidation
Industry Consolidation CommunityBanks @ Partner of Choice? Large acquirers have consummated market entry Many “potential partners” fall below radar of large acquirers Soft issues to potential partners: * Performance culture ¢ Strategic relevance within new franchise Consolidation goals » Accretive w
Slide 37: Industry Consolidation
Industry Consolidation communityBanks Tot aay sahta, : <E a> Boa head mie Le ED i roo
Slide 38: Summary
Summary CommunityBanks @ Who We Are — An Impressive Past @ Building a Competitive Advantage Management—Engaged, Experienced Momentum—Pattern of Sustained Growth @ Markets— ¢ Vibrant markets with proven potential ® Proximity to growing contiguous markets @ Where We’re Going—A Bright Future
Source: SEC EDGAR · 8-K filed Oct 30, 2002
More decks from Community Banks Inc
 Community Banks — Merger or Acquisition (June 2007)23 slides · Jun 20, 2007
 Community Banks — Merger or Acquisition (May 2007)31 slides · May 1, 2007
 Ferris, Baker Watts Mid-Atlantic Bank Conference 200620 slides · Jul 27, 2006
 Shareholder Meeting (May 2006)45 slides · May 9, 2006
 Emerald Groundhog Day Investment Forum (February 2006)40 slides · Feb 2, 2006
 Mid-Atlantic SuperCommunity Bank Conference 200528 slides · Nov 8, 2005