Vertex Energy — World Waste Technologies — Investor Conference, San Francisco, May 2007
23 slides from Vertex Energy's conference presentation, Jun 5, 2007
Slide 1: World Waste Technologies Corporate Presentation
WORLD WASTE TECHNOLOGIES, INC. Corporate Presentation Investor Conference San Francisco, California May 2007
Slide 2: Forward-Looking Statements and Disclaimer
Forward-Looking Statements and Disclaimer Our presentation contains forward-looking statements including statements regarding (i) expectations or estimates of future financial and operating results or events, (ii) industry and market trends and (iii) other market opportunities for World Waste Techno
Slide 3: Investment Highlights
Investment Highlights Investment Drivers 1. Large supply of residual MSW with increasing costs for handling and disposal + Niche focus on residual waste streams as feedstock (partner with waste hauler) + Feedstock is a revenue, nota cast 2. Increasing demand for altemative energy sources + Rising aw
Slide 4: Market Overview
Market Overview Technology Platforms Strategy Competitive Advantages
Slide 5: Market Overview
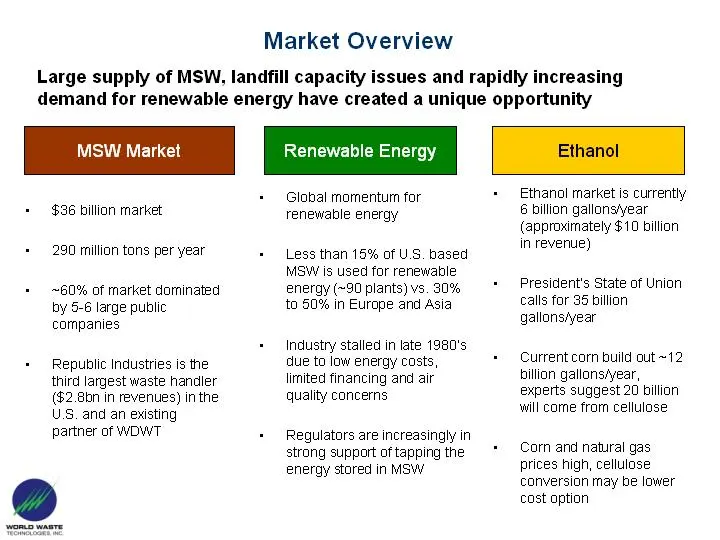
Market Overview Large supply of MSW, landfill capacity issues and rapidly increasing demand for renewable energy have created a unique opportunity + $36 billion market + 230 million tons per year + ~60% of market dominated hy 5-6 large public companies + Republic Industries is the third largest wast
Slide 6: Rising Demand for MSW Conversion
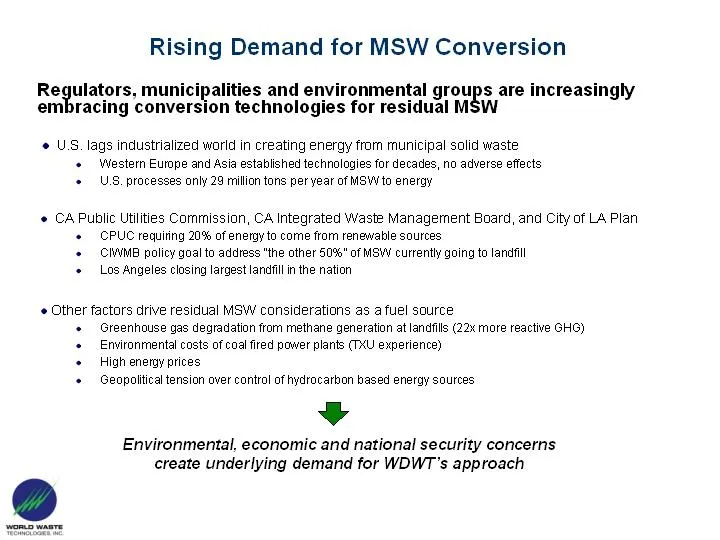
Rising Demand for MSW Conversion Regulators, municipalities and environmental groups are increasingly embracing conversion technologies for residual MSW © U.S. lags industrialized world in creating energy from municipal solid waste + Wester Europe and Asta established technologies for decades, no ad
Slide 7: Ethanol Production
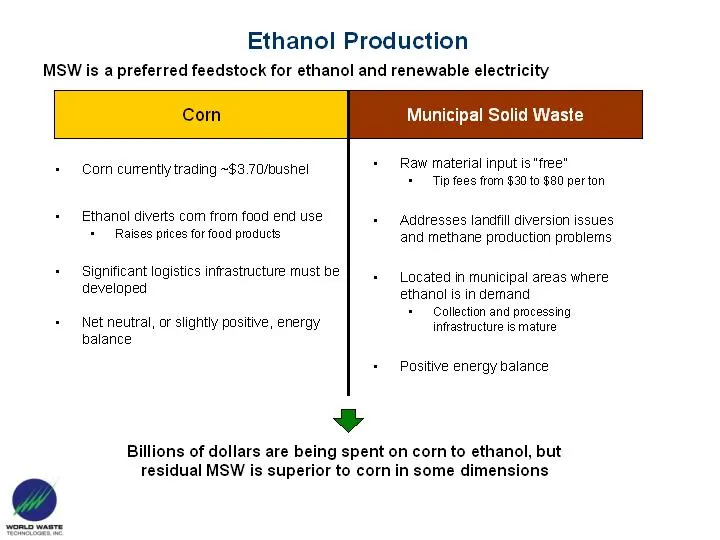
Ethanol Production MSW is a preferred feedstock for ethanol and renewable electricity Municipal Solid Waste + Corn curently trading ~$3.70/tushel * Raw material input is "free" + Tip fees from $30 to $80 per ton + Ethanol diverts com from food end use + Addresses landfill diversion issues + Raises p
Slide 8: Technology Platforms
Market Overview Technology Platforms Strategy Competitive Advantages
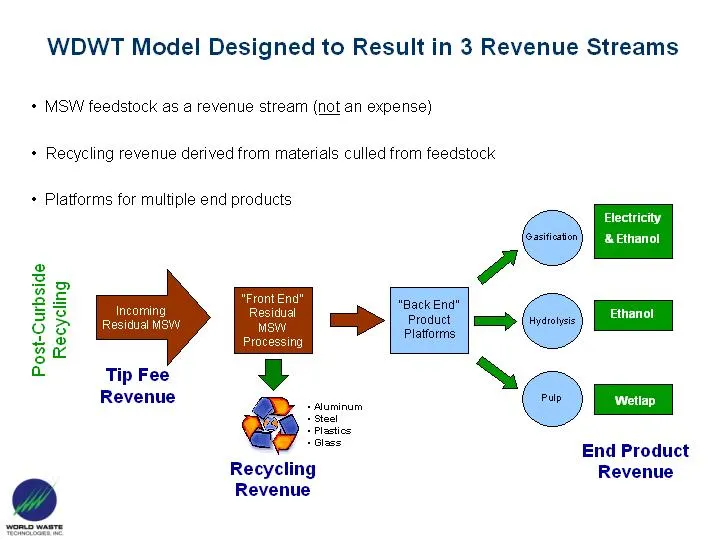
Slide 9: WDWT Model Designed to Result in Revenue Streams
WDWT Model Designed to Result in 3 Revenue Streams + MSW feedstock as a revenue stream (not an expense) + Recycling revenue derived from materials culled from feedstock + Platforms for multiple end products font End” Incoming Residual Ri Post-Curbside Recycling Tip Fee Revenue + Aluminum {steal 1 Pl
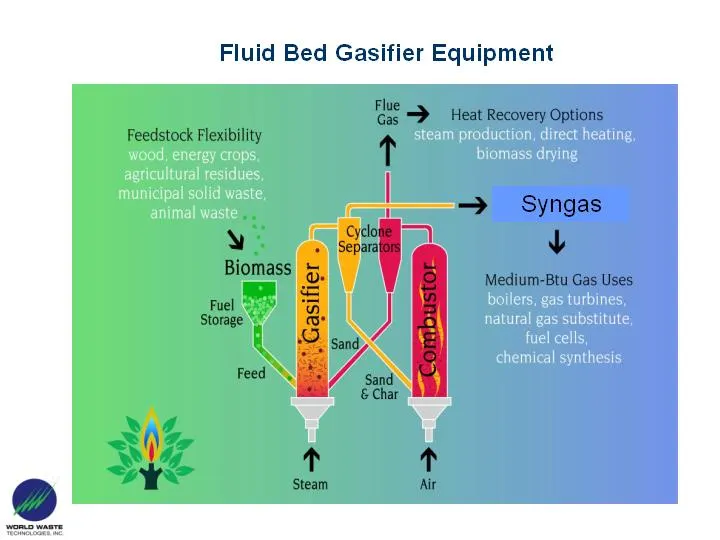
Slide 10: Fluid Bed Gasifier Equipment
mur Fluid Bed Gasifier Equipment animal waste | ro) & steam production, direct heating, biom boilers, gas turbines, natural gas substitute, fuel cells hemical synthesis
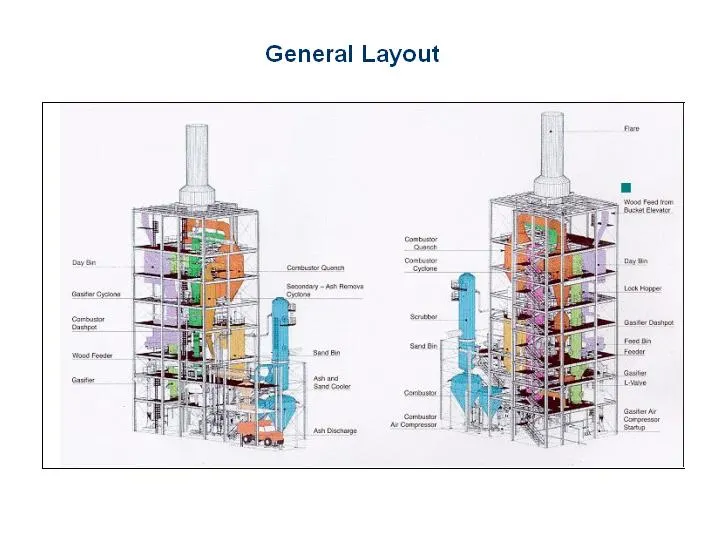
Slide 11: General Layout
General Layout
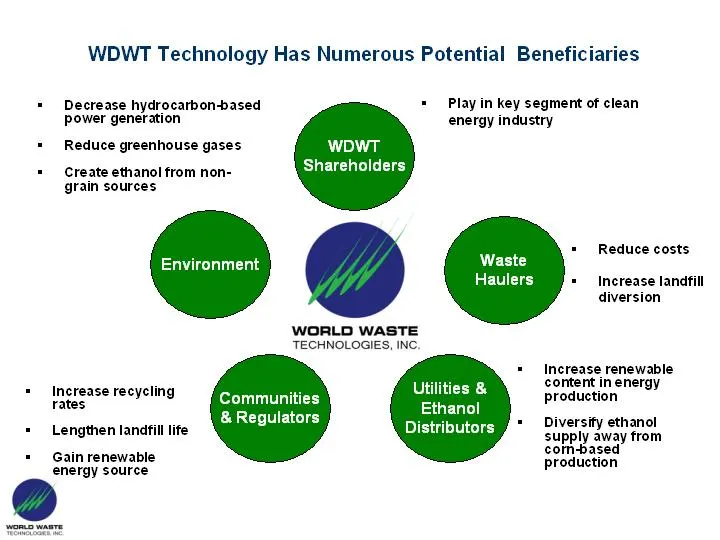
Slide 12: WDWT Technology Has Numerous Potential Beneficiaries
WDWT Technology Has Numerous Potential Beneficiaries + Playin key segment of clean energy industry Decrease hydrocarbon-based power generation Reduce greenhouse gases WDWT Shareholders Create ethanol from non- grain sources = Reduce costs = Increase landfill diversion WORLD WASTE TECHNOLOGIES, INC.
Slide 13: Strategy
Market Overview Technology Platforms Strategy Competitive Advantages
Slide 14: WDWT's Projected Three Phase Plan
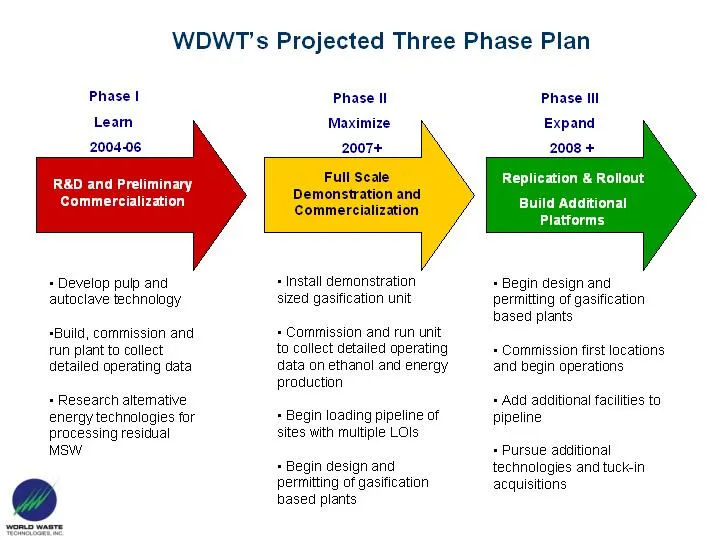
WDWT's Projected Three Phase Plan Phase | Leam 2004-06 R&D and Preliminary Commercialization + Develop pulp and autoclave technology -Bulld, commission and run plant to collect detailed operating data + Research altemative energy technologies for processing residual MSW Phase Il Maximize 2007+ + Ins
Slide 15: Utilize Public Company to Accelerate Strategy
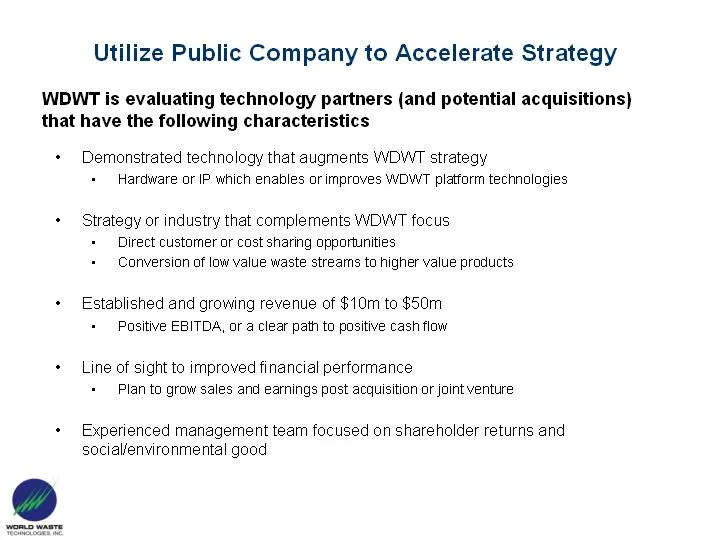
Utilize Public Company to Accelerate Strategy WDWT is evaluating technology partners (and potential acquisitions) that have the following characteristics + Demonstrated technology that augments WDWT strategy Hardware or IP which enables or improves WOWT platform technologies + Strategy or industry t
Slide 16: Competitive Advantages
Market Overview Technology Platforms Strategy Competitive Advantages
Slide 17: WDWT Competitive Advantages
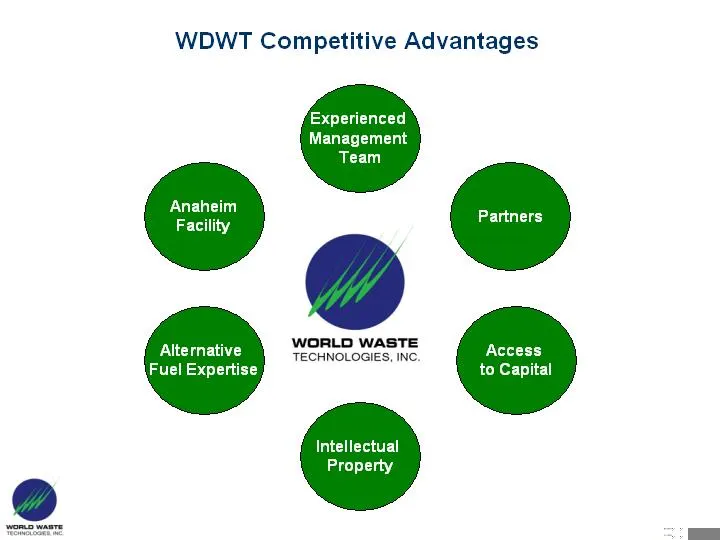
WDWT Competitive Advantages Experienced Management Team Anaheim Facility WORLD WASTE TECHNOLOGIES, INC. Access Alternative Fuel Expertise to Capital Intellectual Property
Slide 18: World Waste Management Team
World Waste Management Team Management team has the requisite experience and expertise necessary to succeed dobn Pimentel, Chief Executive OfficenChairman: Mr. Pimentel was a co-ounder and former board member of Pacife Ethanol (PEDC NASDAG), He maintains an aftlation with Cagan MoAfee Capital Parnes
Slide 19: World Waste Management Team
World Waste Management Team Management team has the requisite experience and expertise necessary to succeed Lee Torrens, Senior Development Advisor; Member of WOWT Technical Advisory Board! Mr. Torrens haz signifeant projedt ‘development and engineering exparice inuding experiance as the Exeuutive V
Slide 20: World Waste Board of Directors
World Waste Board of Directors Non-Employee Members of the Board of Directors also bring significant relevant experience to the company Ross Patten, Mr. Patten was Chaiman and CEO of Synagio (NASDAG: SYGR), a§325mm revenue company engaged in recycling bic: Solids and water wastewaler residuals. Mr.
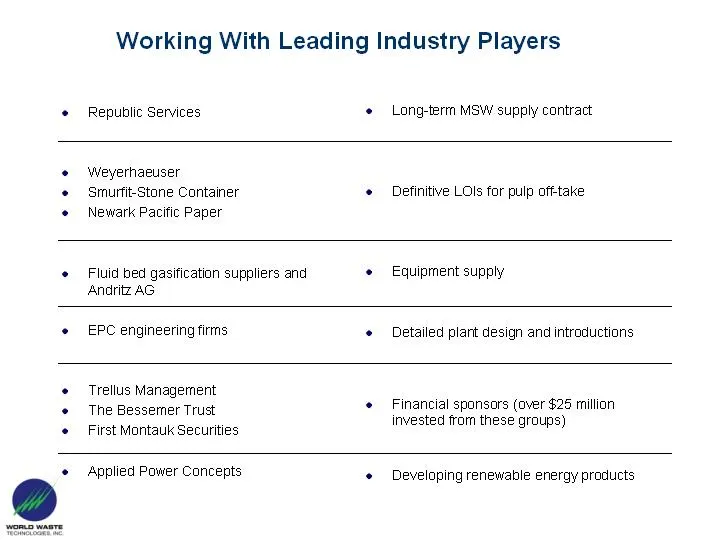
Slide 21: Working With Leading Industry Players
Working With Leading Industry Players Republic Services Long-term MSW supply contract Weyerhaeuser Smurfit-Stone Container Newark Pacific Paper Definitive LOIs far pulp of-take Fluid bed gasification suppliers and Andritz AG Equipment supply EPC engineering firms Detailed plant design and introducti
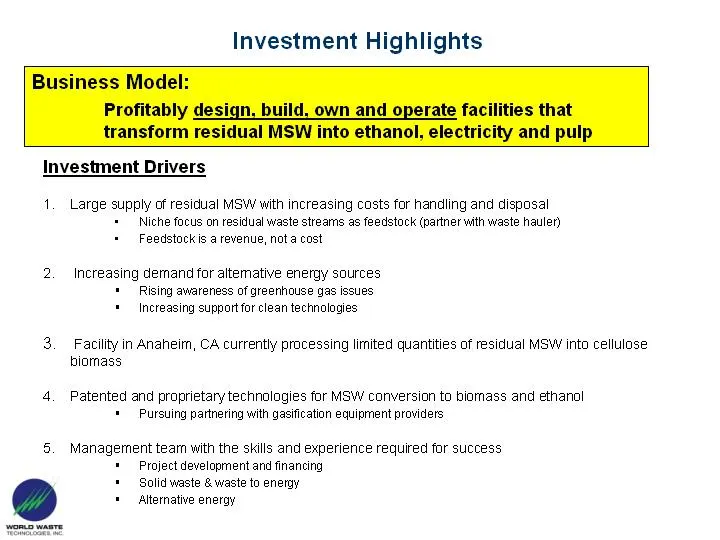
Slide 22: Investment Highlights
Investment Highlights Investment Drivers 1. Large supply of residual MSW with increasing costs for handling and disposal + Niche focus on residual waste streams as feedstock (partner with waste hauler) + Feedstock is a revenue, nota cast 2. Increasing demand for altemative energy sources + Rising aw
Slide 23: World Waste Technologies Contact
WORLD WASTE TECHNOLOGIES, INC. For additional information contact: John Pimentel David Rane Mobile:650-269-8933 Office: 858-391-3453 jpimentel@worldwasteintl.com drane@worldwasteintl.com
Source: SEC EDGAR · 8-K filed Jun 5, 2007
More decks from Vertex Energy Inc
 Q2 2024 Earnings Presentation21 slides · Aug 8, 2024
 Q1 2024 Earnings Presentation20 slides · May 9, 2024
 Q4 2023 Earnings Presentation29 slides · Feb 28, 2024
 Q3 2023 Earnings Presentation27 slides · Nov 7, 2023
 Q2 2023 Earnings Presentation26 slides · Aug 9, 2023
 Q1 2023 Earnings Presentation26 slides · May 9, 2023