ALTERRA CAPITAL — Investor Presentation (February 2011)
27 slides from ALTERRA CAPITAL's investor presentation, Feb 14, 2011
Slide 1: Investor Presentation
Exhibit 99.1 Investor Presentation Year Ended December 31, 2010
Slide 2: Cautionary Note Regarding Forward-Looking Statements
Cautionary Note Regarding Forward-Looking Statements Alterra was formed on May 12, 2010 by the merger of Max Capital Group Ltd. (“Max Capital”) and Harbor Point Limited (“Harbor Point”). This presentation may include forward-looking statements that reflect Alterra’s current views with respect to fut
Slide 3: Alterra's Franchise is Well Positioned For Success
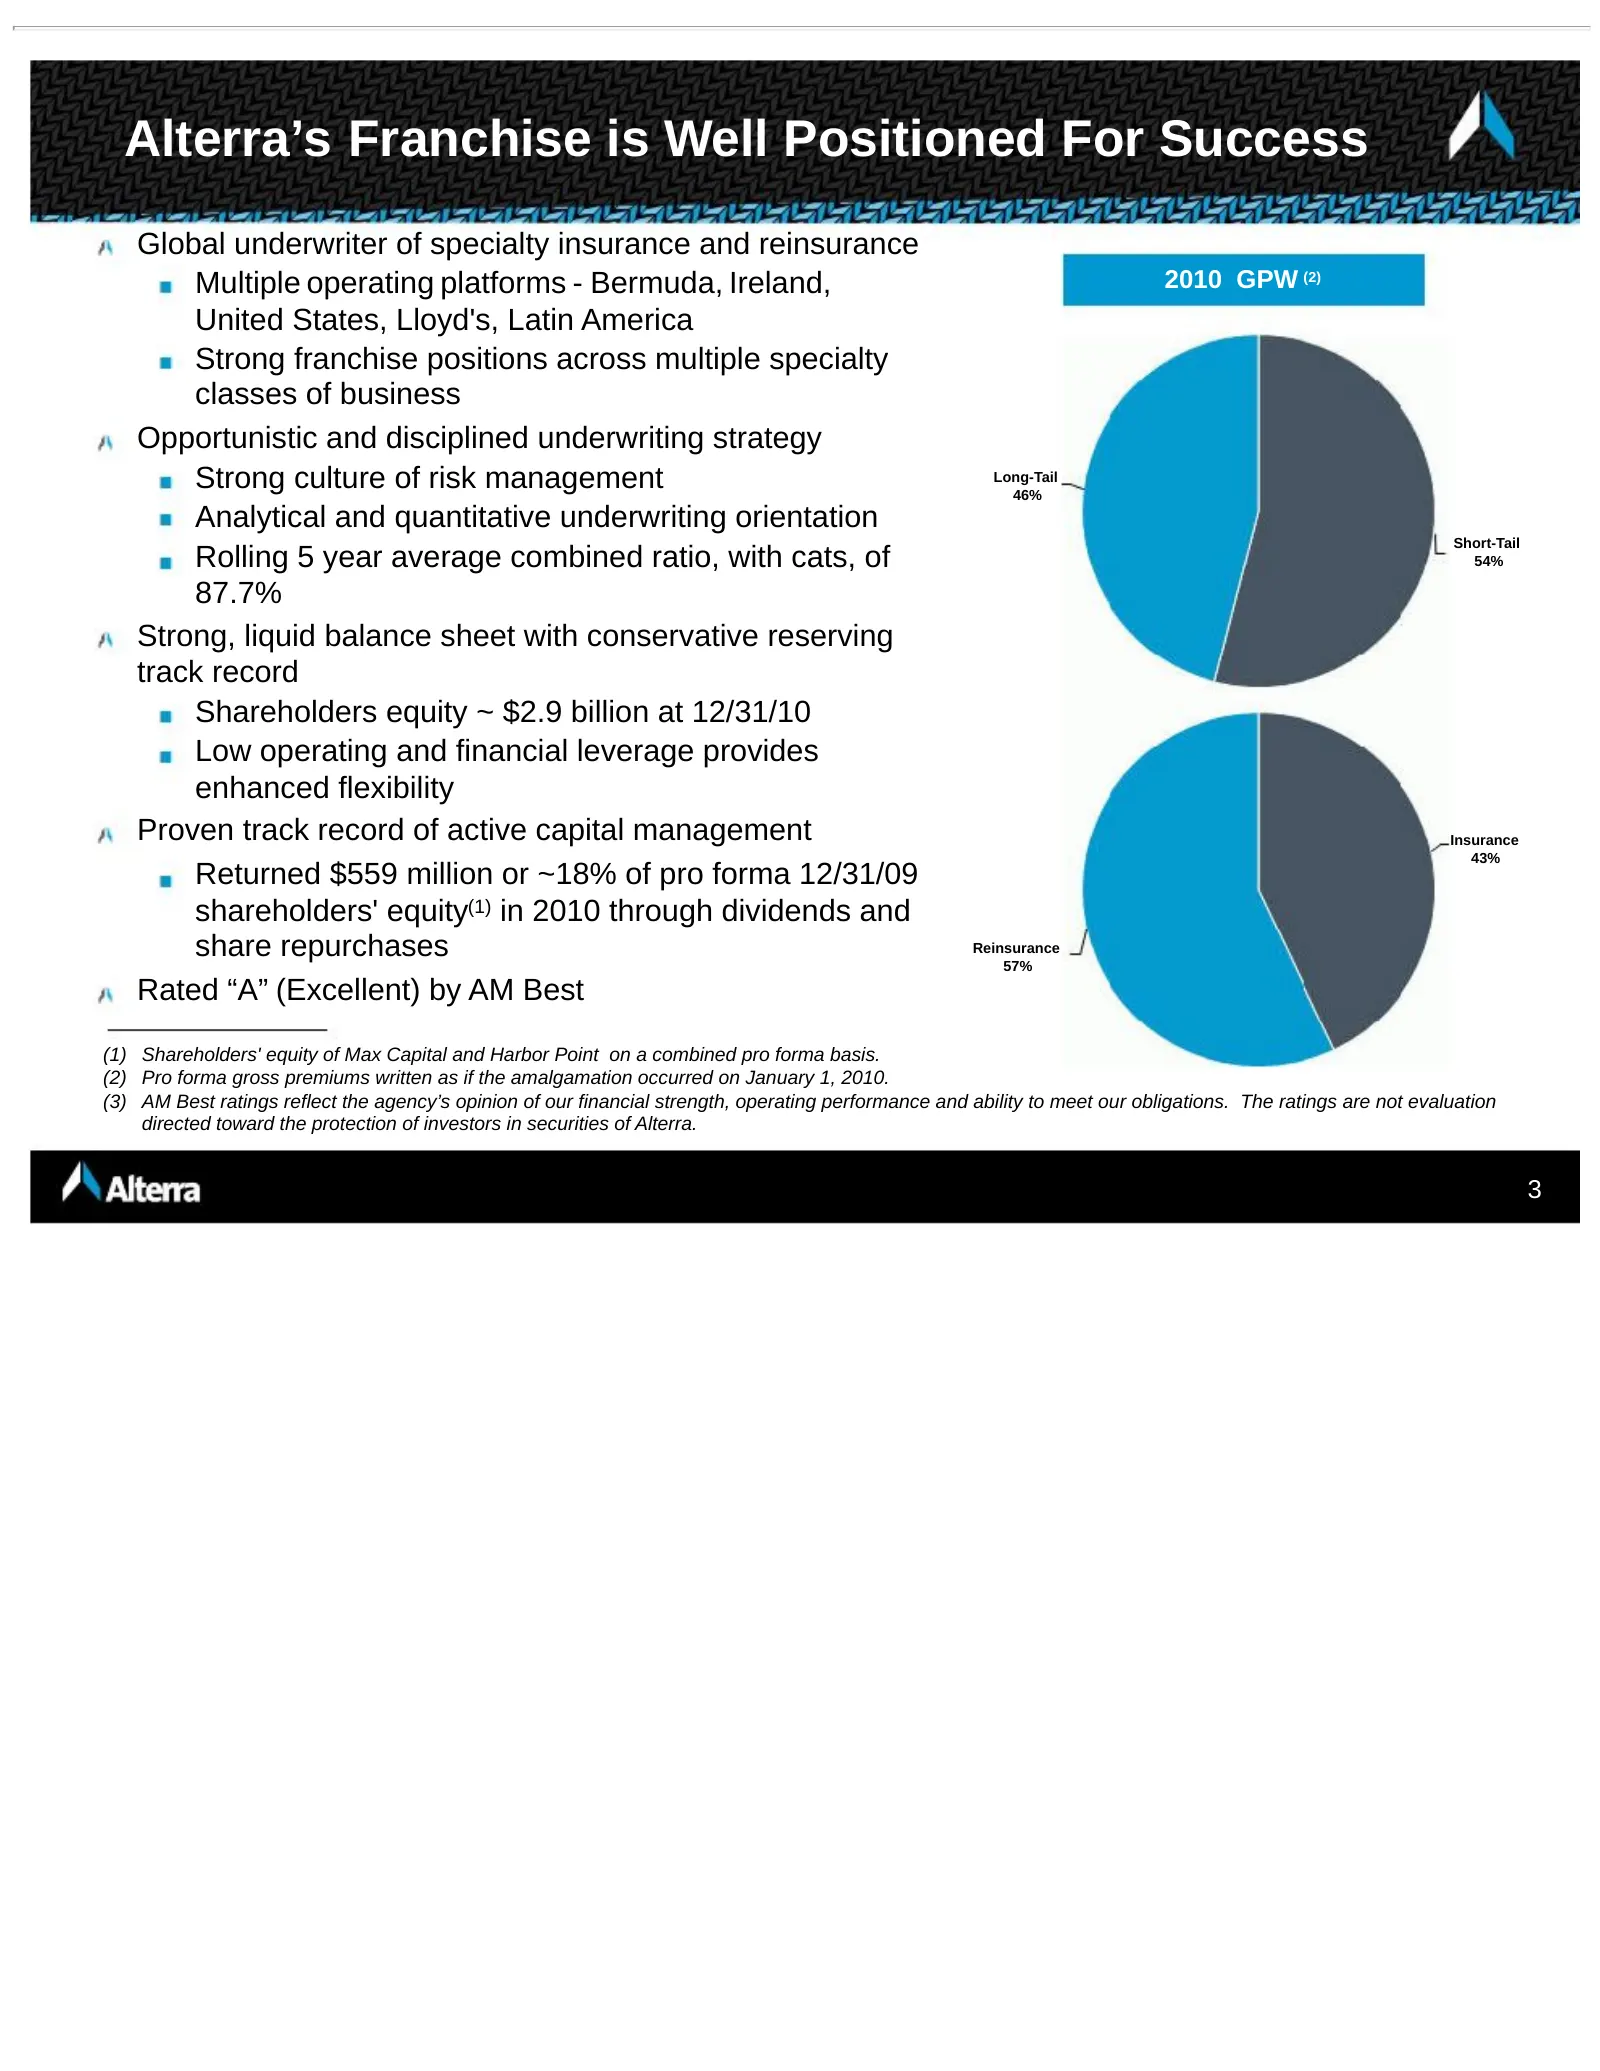
Alterra’s Franchise is Well Positioned For Success Global underwriter of specialty insurance and reinsurance Multiple operating platforms - Bermuda, Ireland, 2010 GPW (2) United States, Lloyd's, Latin America Strong franchise positions across multiple specialty classes of business Opportunistic and
Slide 4: Solid Fourth Quarter Results
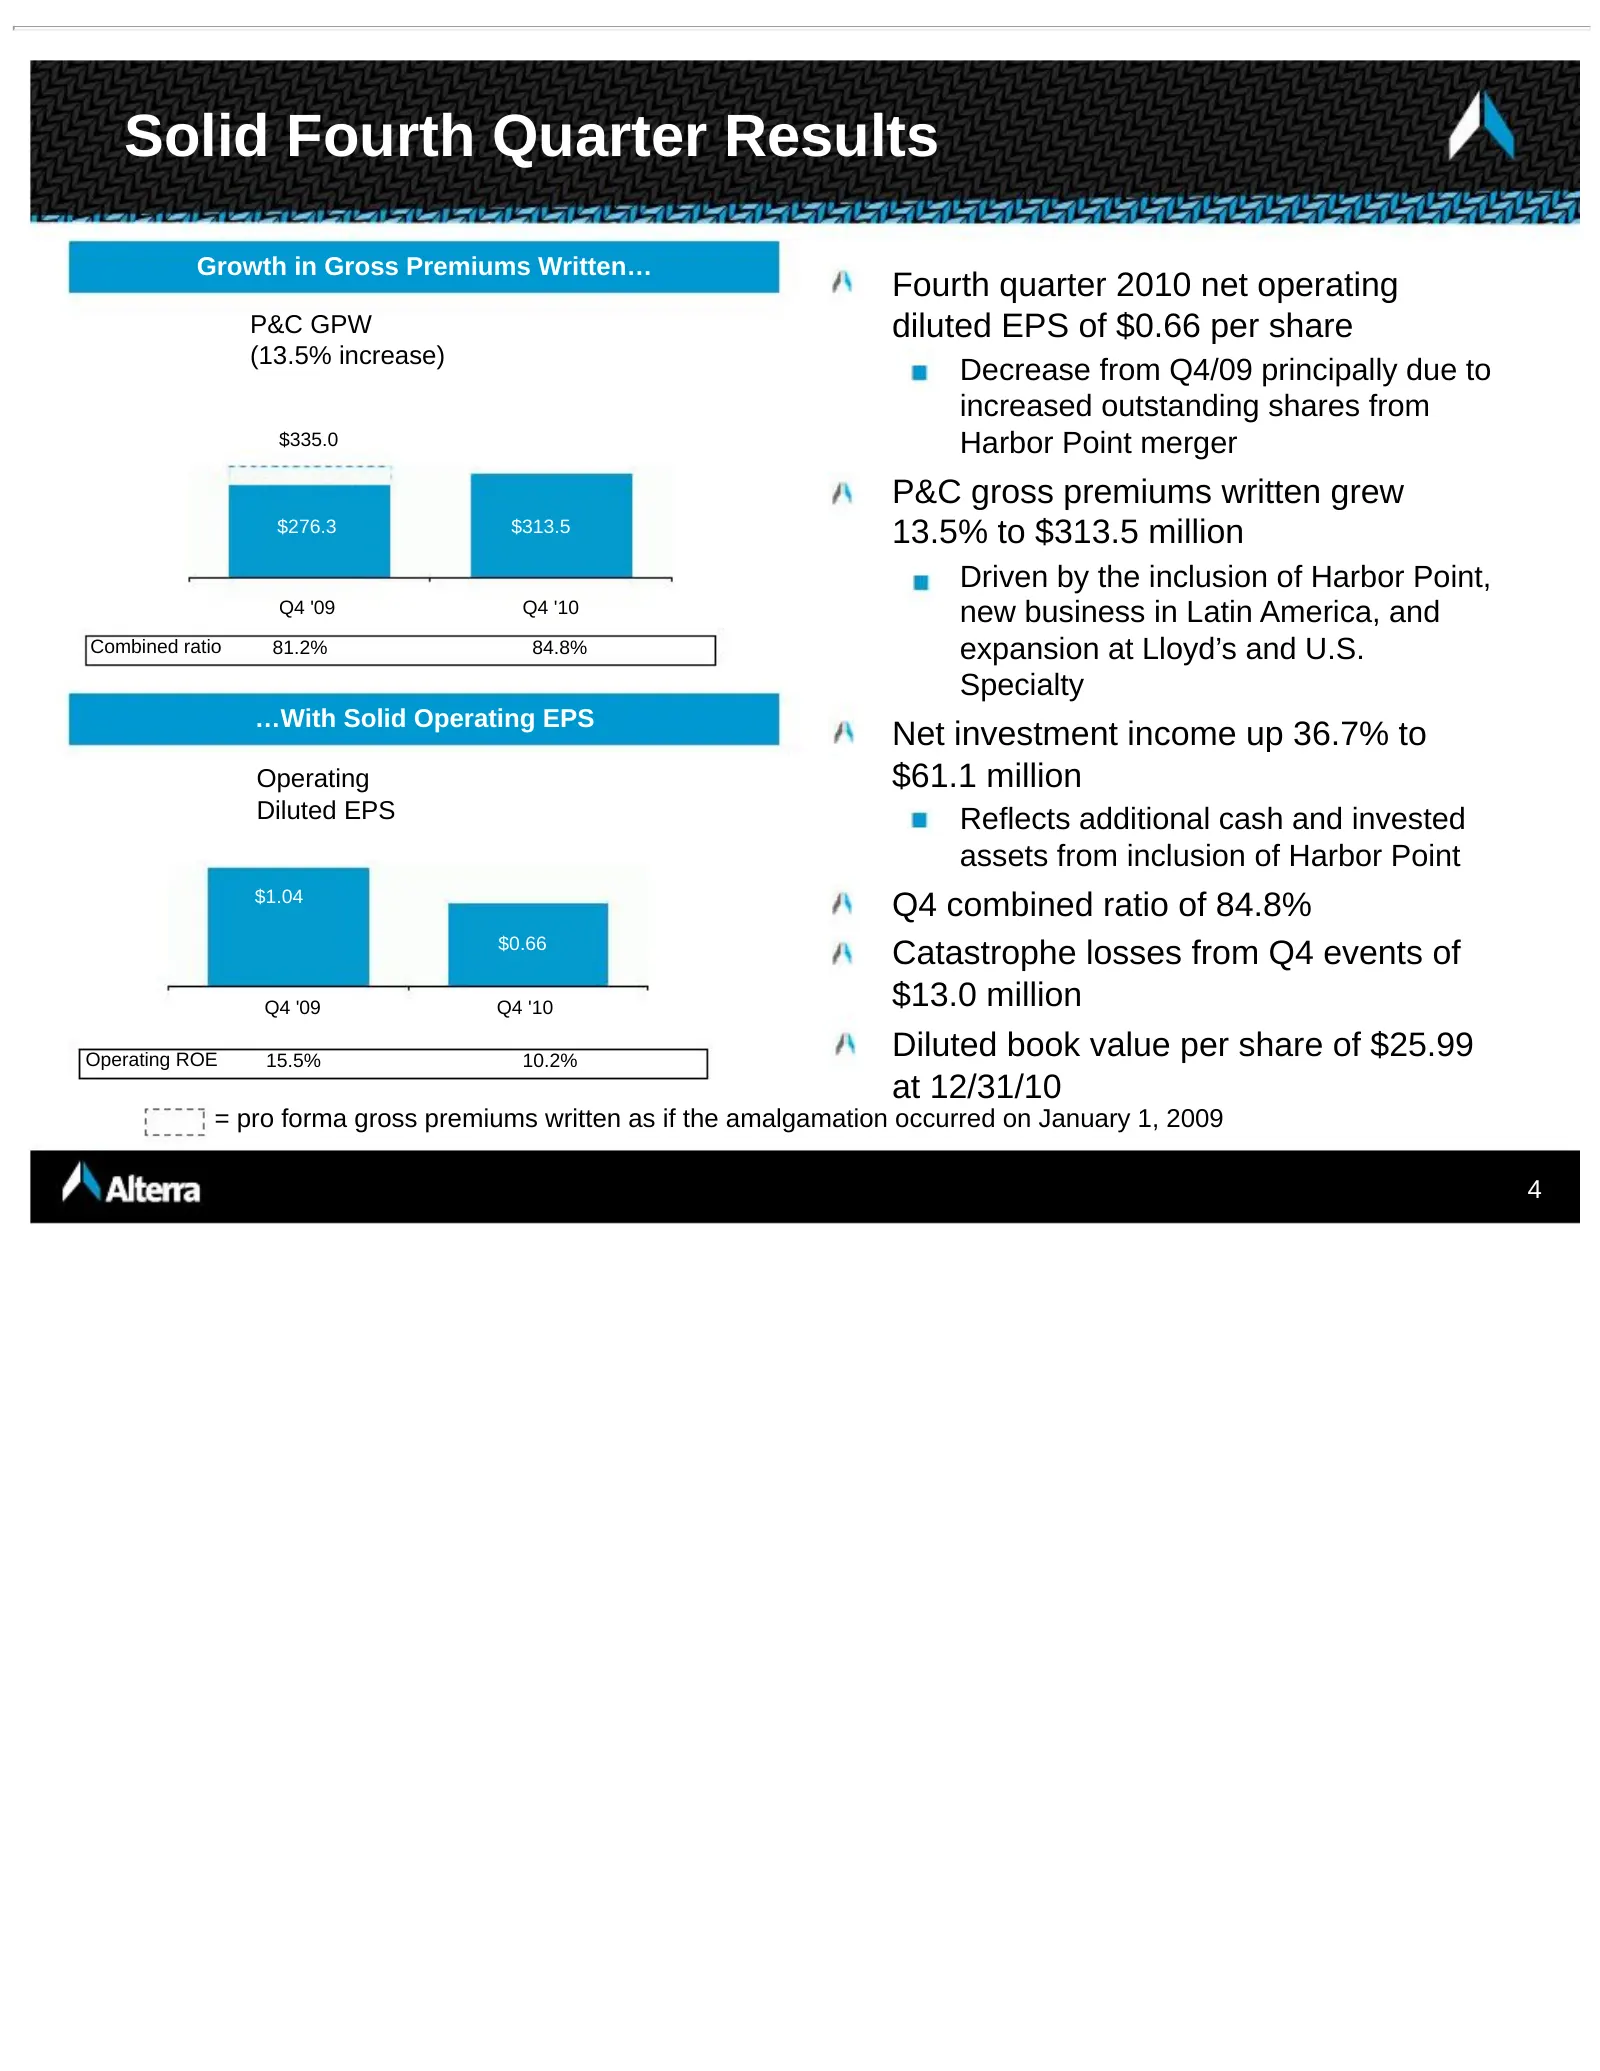
Solid Fourth Quarter Results Growth in Gross Premiums Written… Fourth quarter 2010 net operating P&C GPW diluted EPS of $0.66 per share (13.5% increase) Decrease from Q4/09 principally due to increased outstanding shares from $335.0 Harbor Point merger P&C gross premiums written grew $276.3 $313.5 1
Slide 5: Solid 2010 Year Results
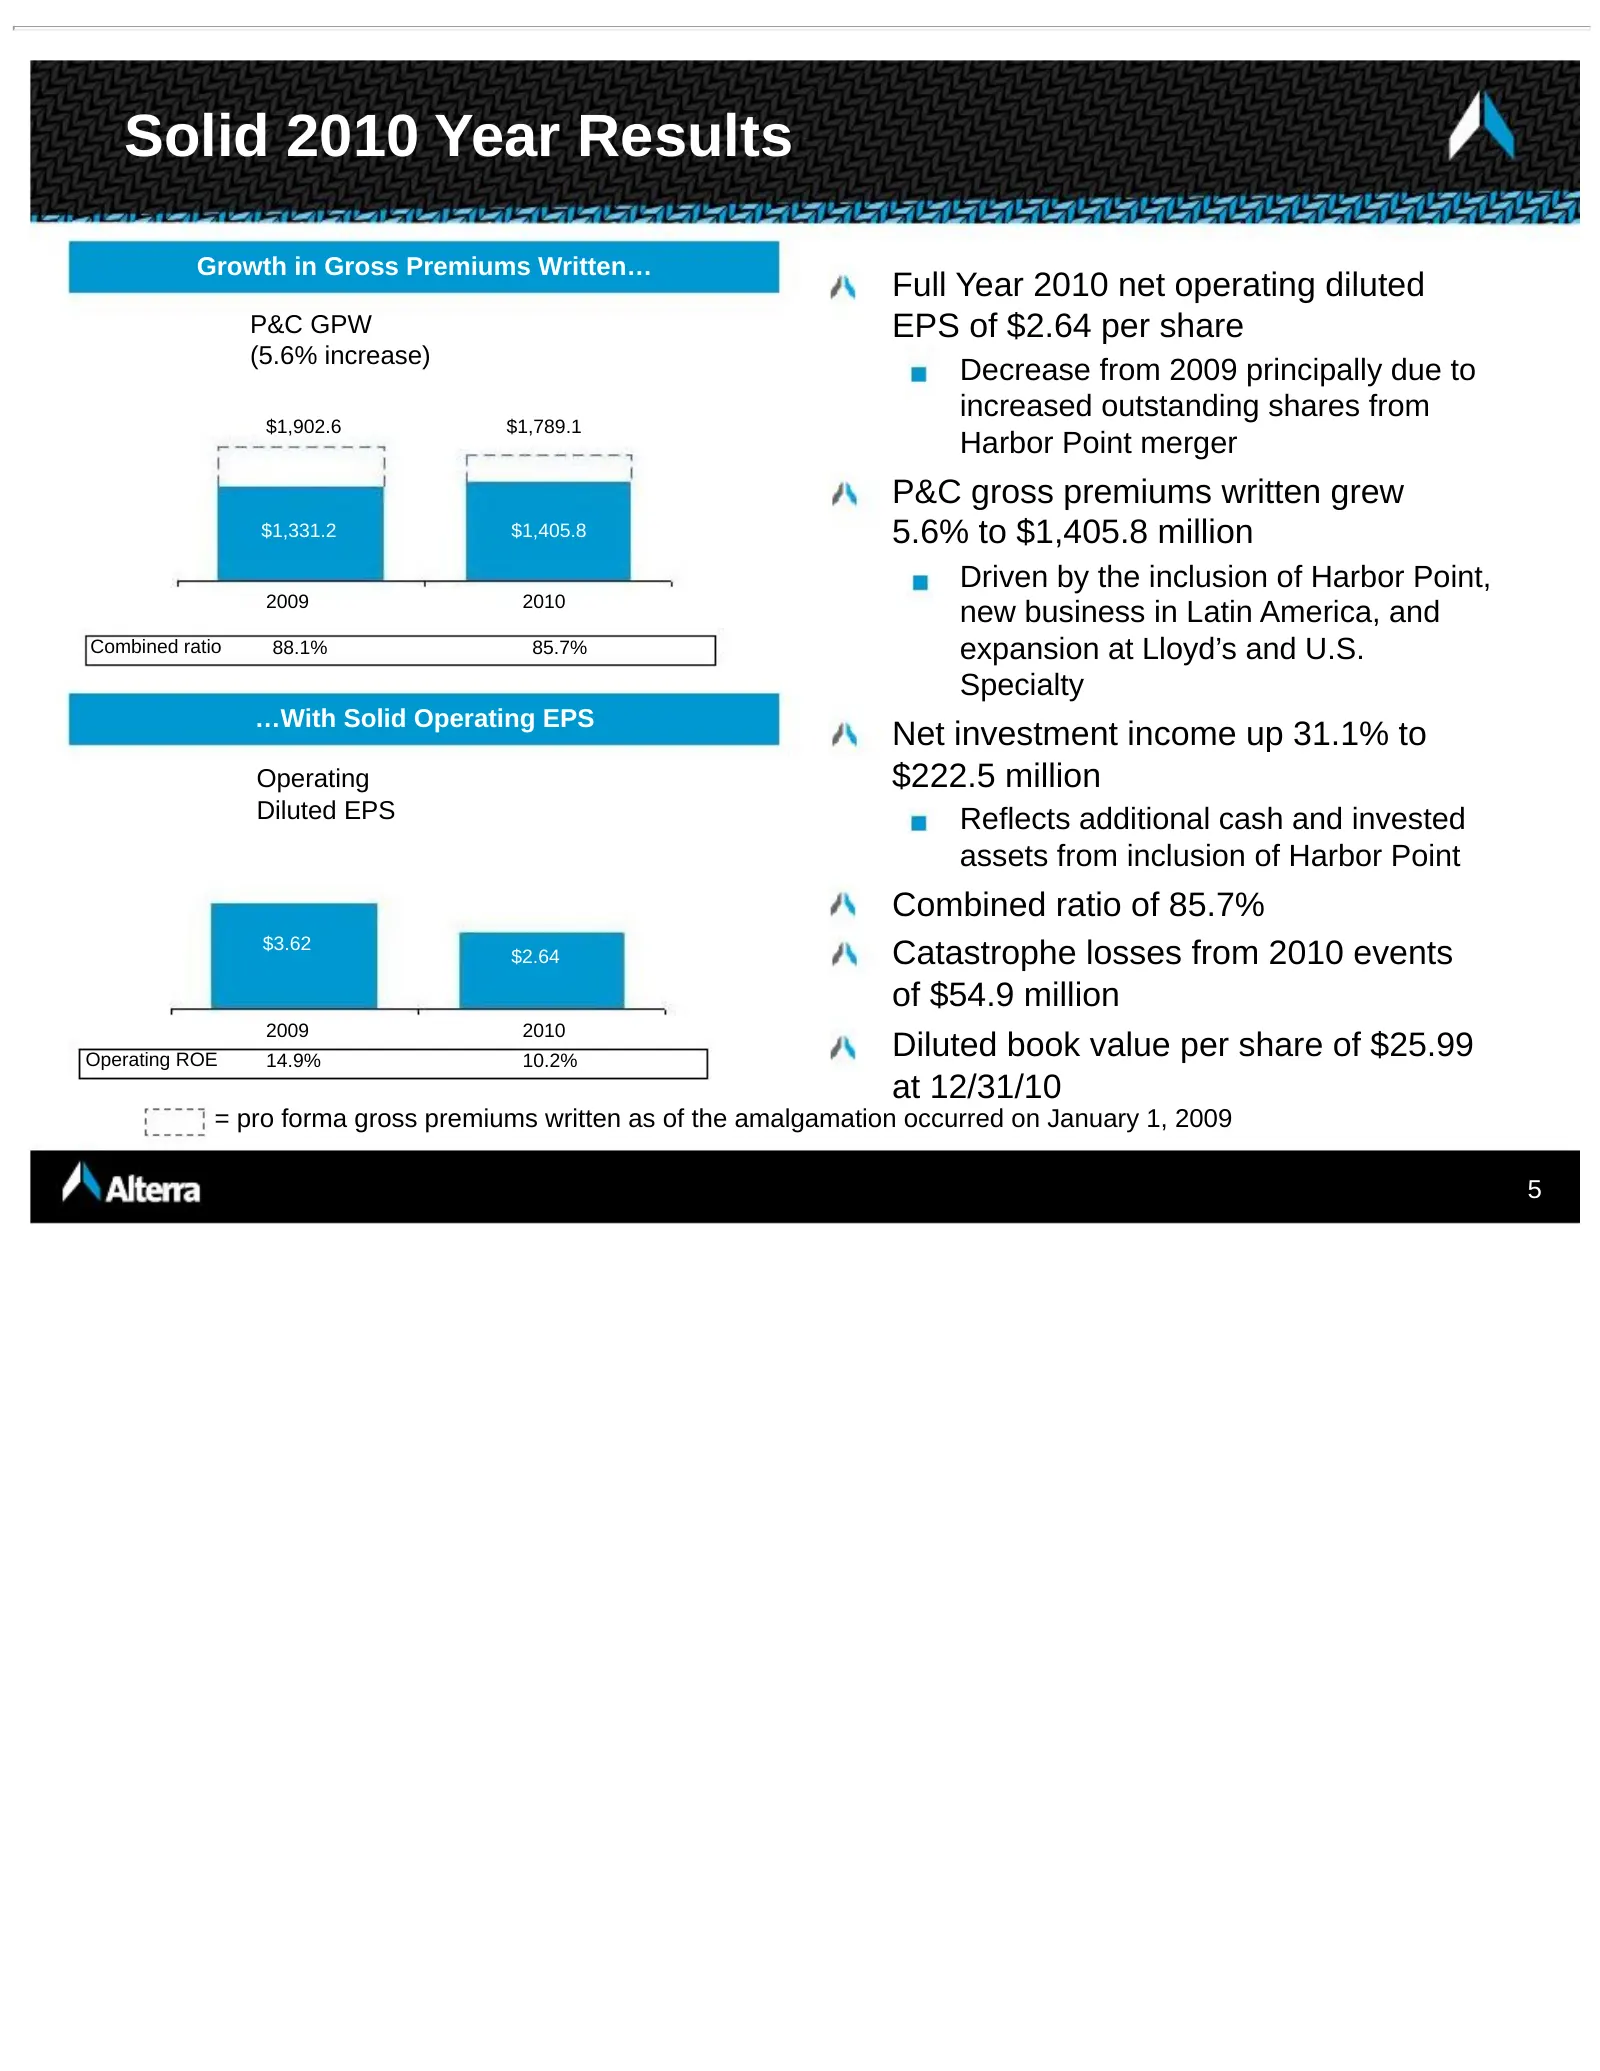
Solid 2010 Year Results Growth in Gross Premiums Written… Full Year 2010 net operating diluted P&C GPW EPS of $2.64 per share (5.6% increase) Decrease from 2009 principally due to increased outstanding shares from $1,902.6 $1,789.1 Harbor Point merger P&C gross premiums written grew $1,331.2 $1,405.
Slide 6: Challenging Times for P&C Insurers
Challenging Times for P&C Insurers Profitable growth opportunities are scarce Market is stressed by historic low returns on invested assets Cash flow levels are deteriorating 2010 Industry loss events have generated high catastrophe losses Reserve redundancies at many companies are diminishing Self-
Slide 7: Pricing Pressure Across Most Platforms
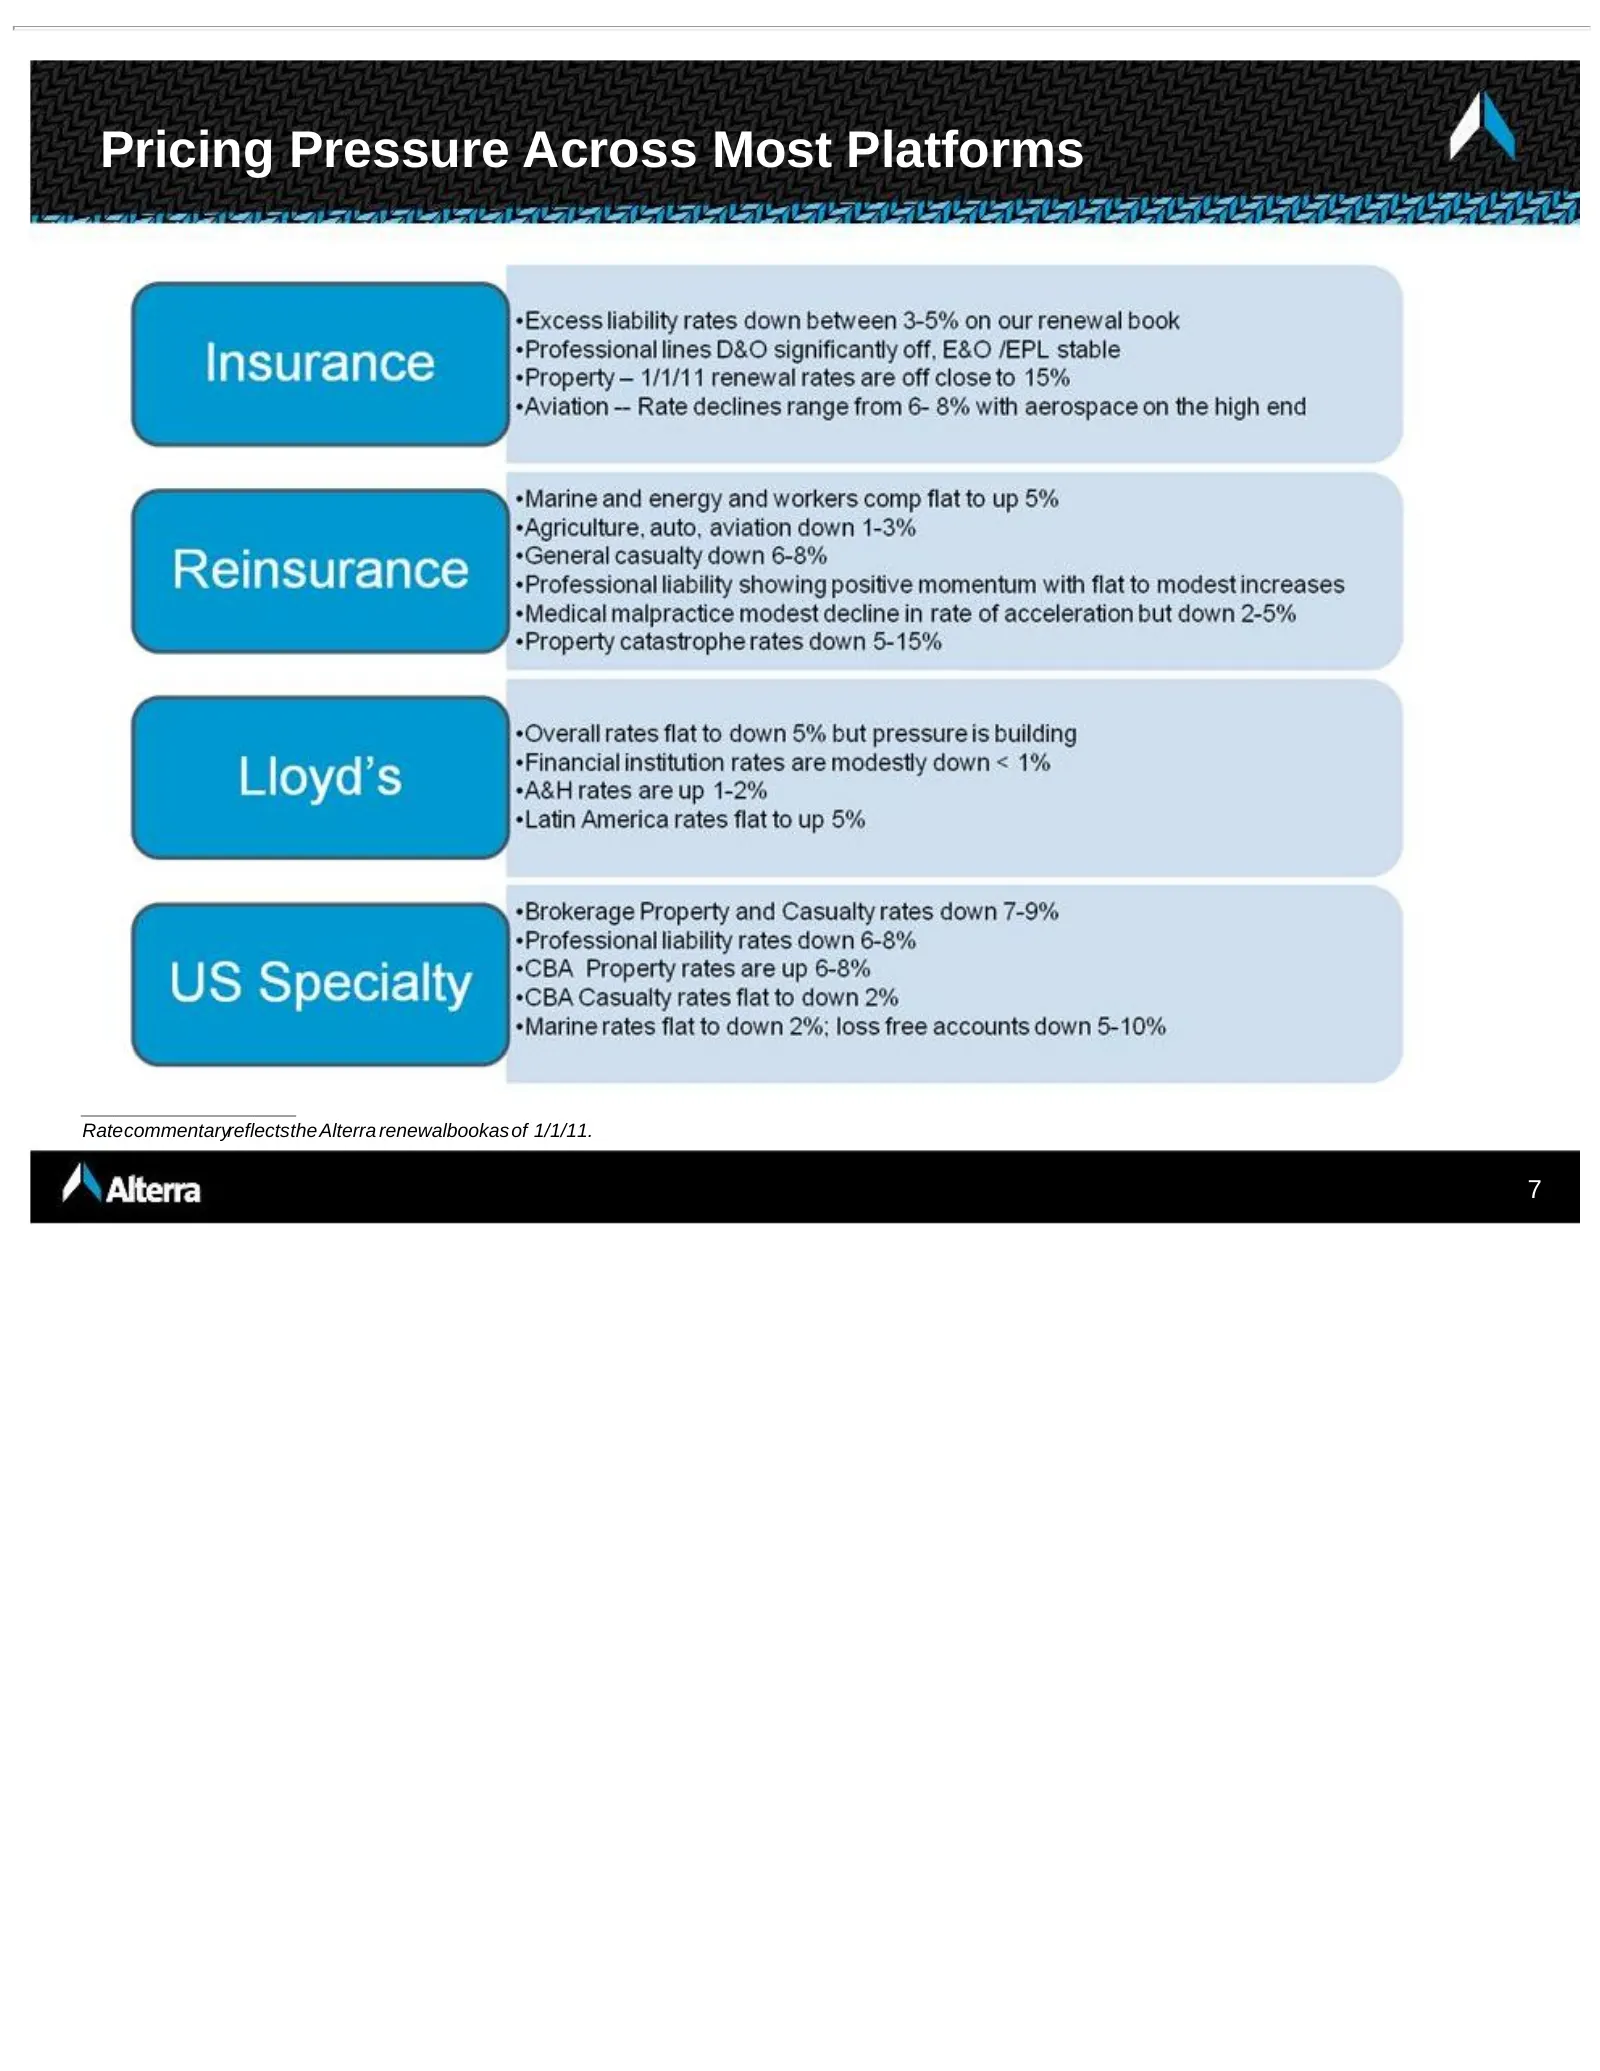
Pricing Pressure Across Most Platforms ____________________ Ratecommentaryreflectsthe Alterra renewalbookas of 1/1/11. 7
Slide 8: Soft Market "Playbook"
Soft Market “Playbook” Stringent underwriting and risk management practices Reward for ROE, not premium growth Avoid mistakes – protect the balance sheet Position for inflection point in pricing Expense management Strong controls across the organization Invest in the future Latin America, Lloyd’s, A
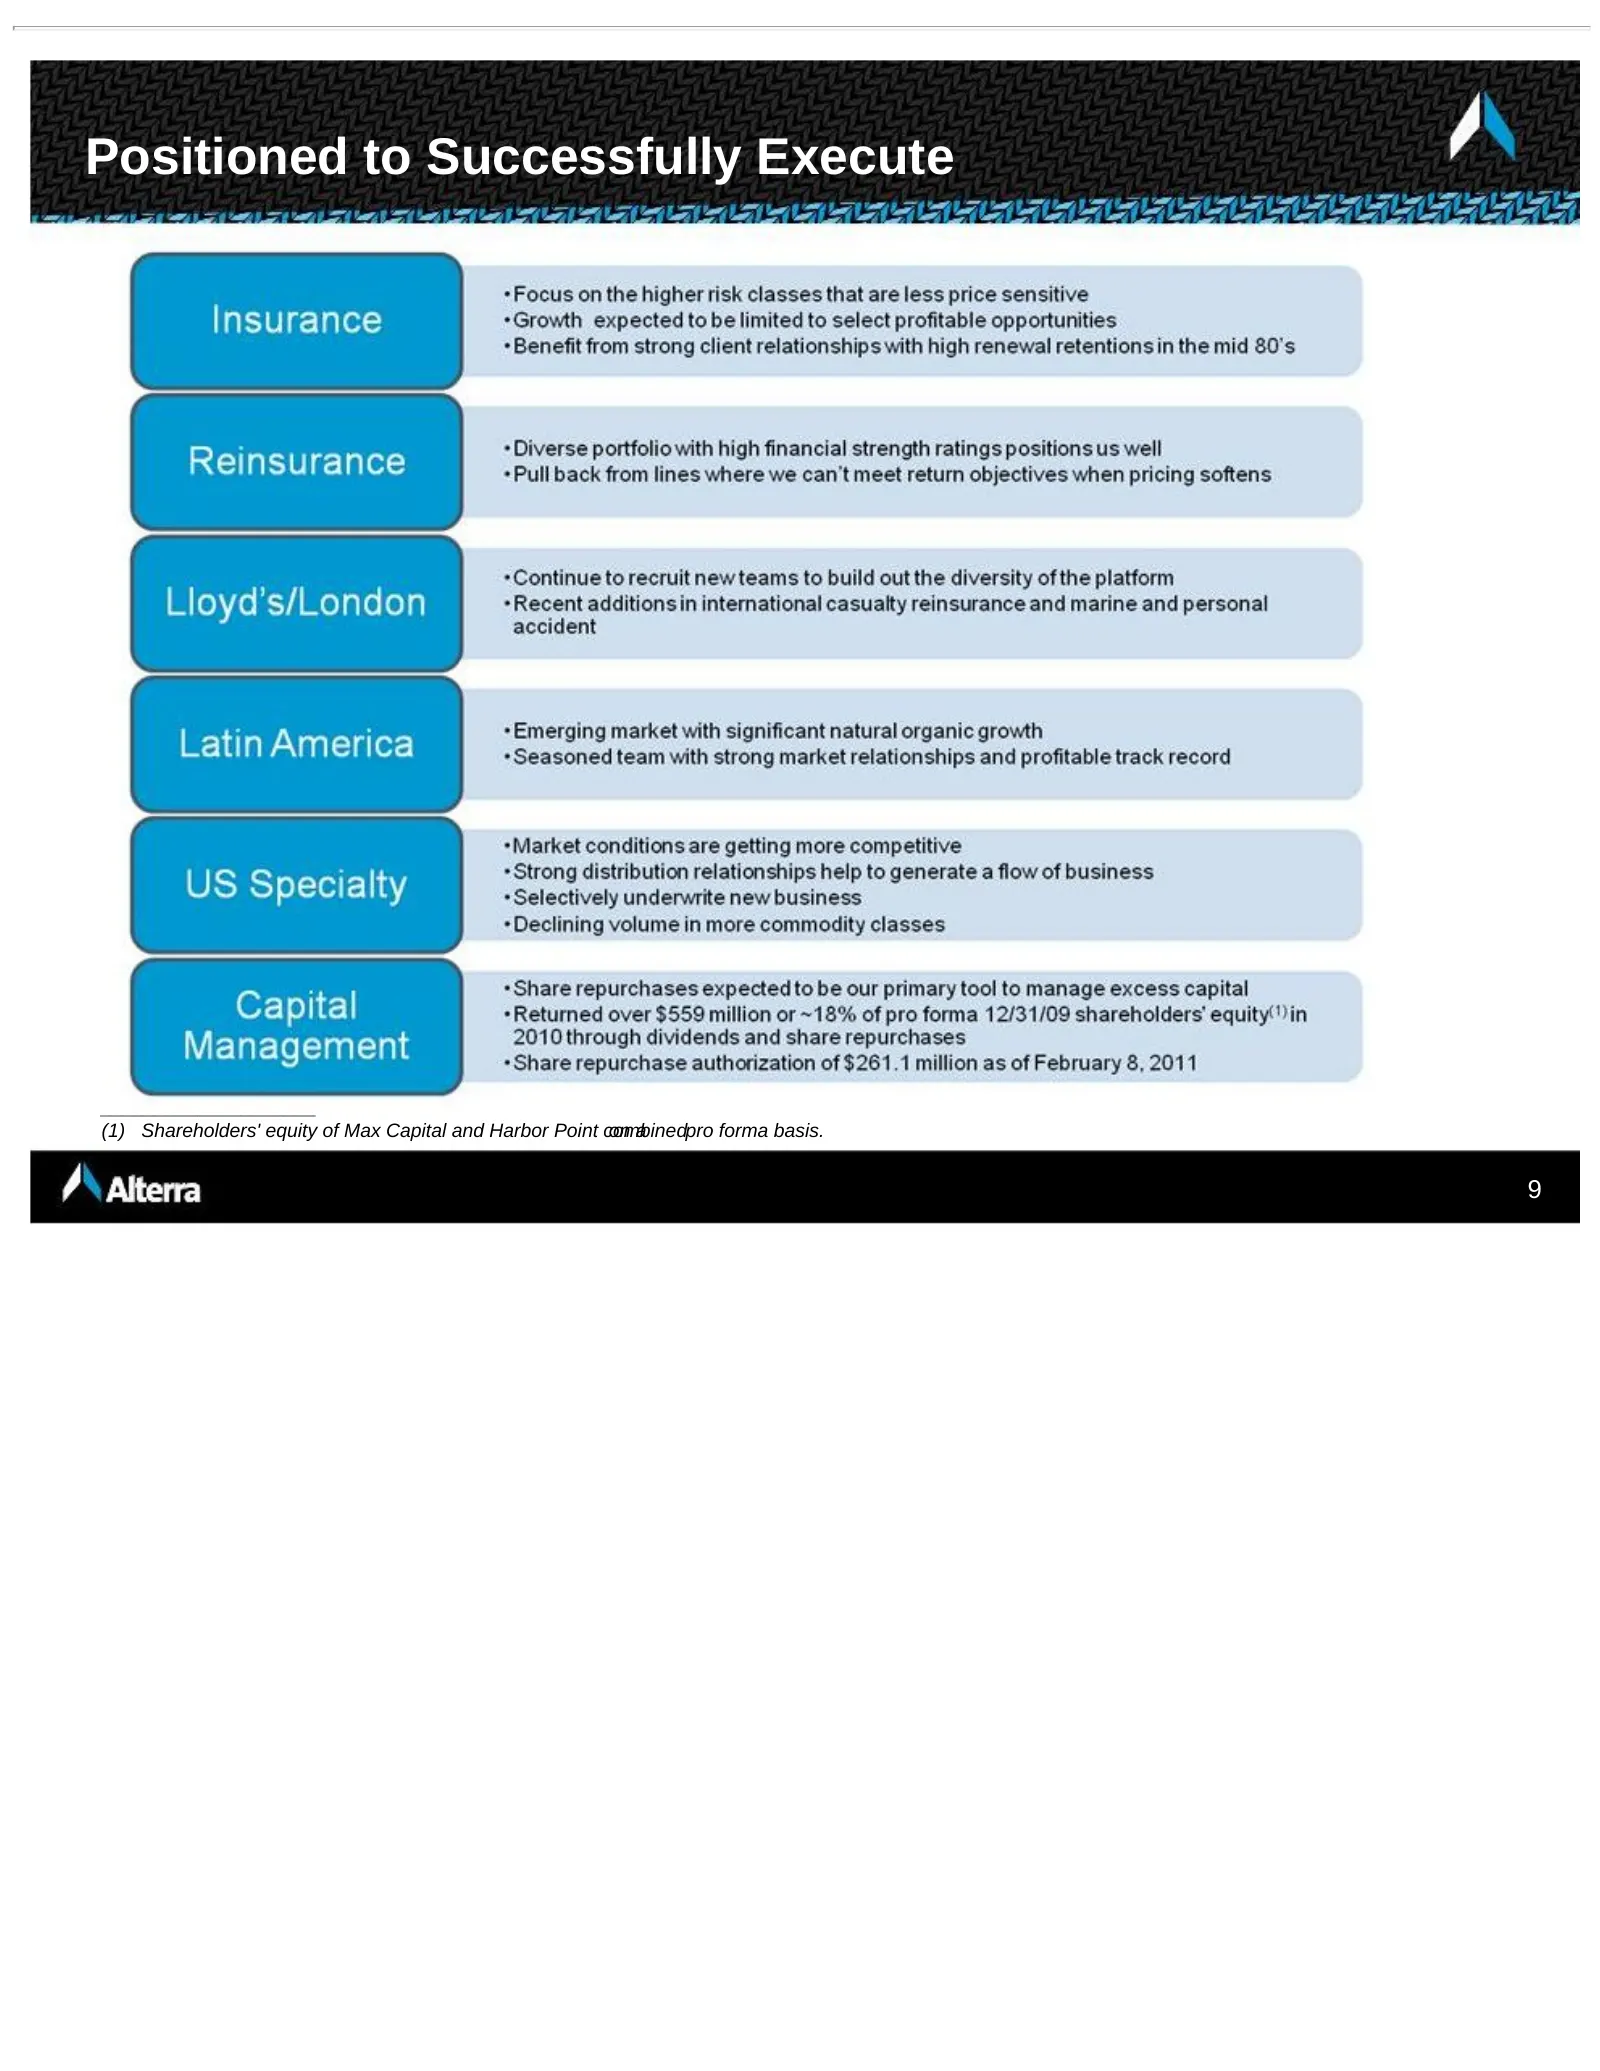
Slide 9: Positioned to Successfully Execute
Positioned to Successfully Execute ____________________ (1) Shareholders' equity of Max Capital and Harbor Point combinedpro on a forma basis. 9
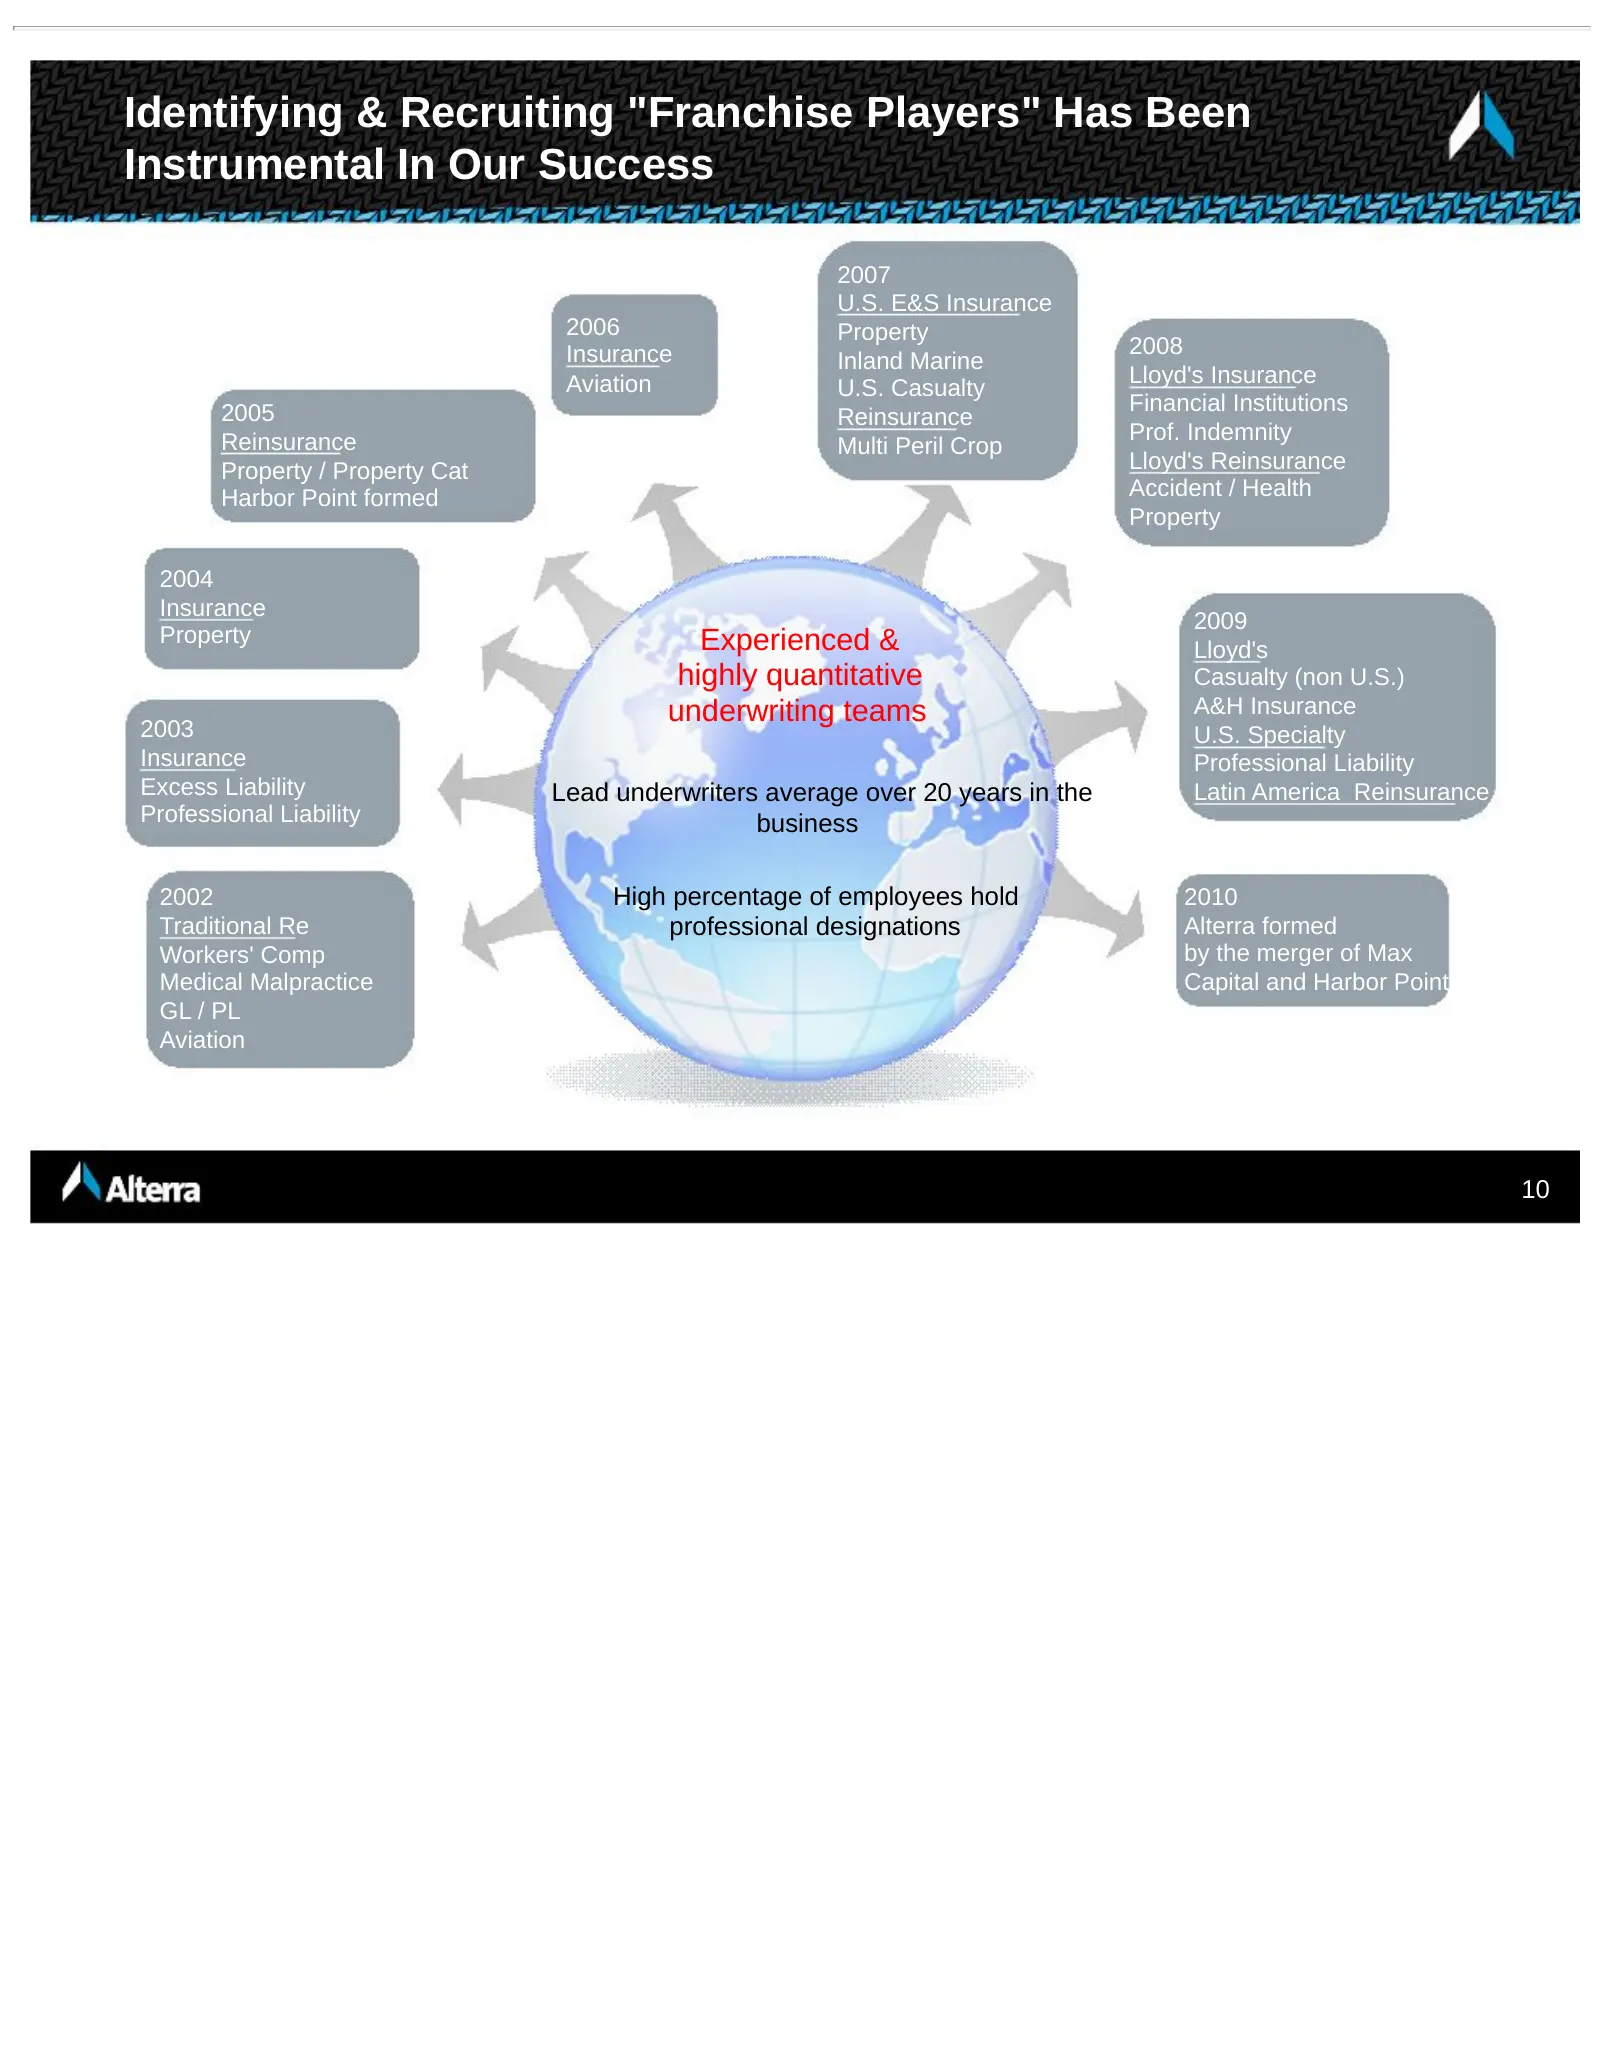
Slide 10: Identifying & Recruiting "Franchise Players" Has Been Instrumental In Our Success
Identifying & Recruiting "Franchise Players" Has Been Instrumental In Our Success 2007 U.S. E&S Insurance 2006 Property Insurance 2008 Inland Marine Aviation Lloyd's Insurance U.S. Casualty 2005 Financial Institutions Reinsurance Reinsurance Prof. Indemnity Multi Peril Crop Property / Property Cat L
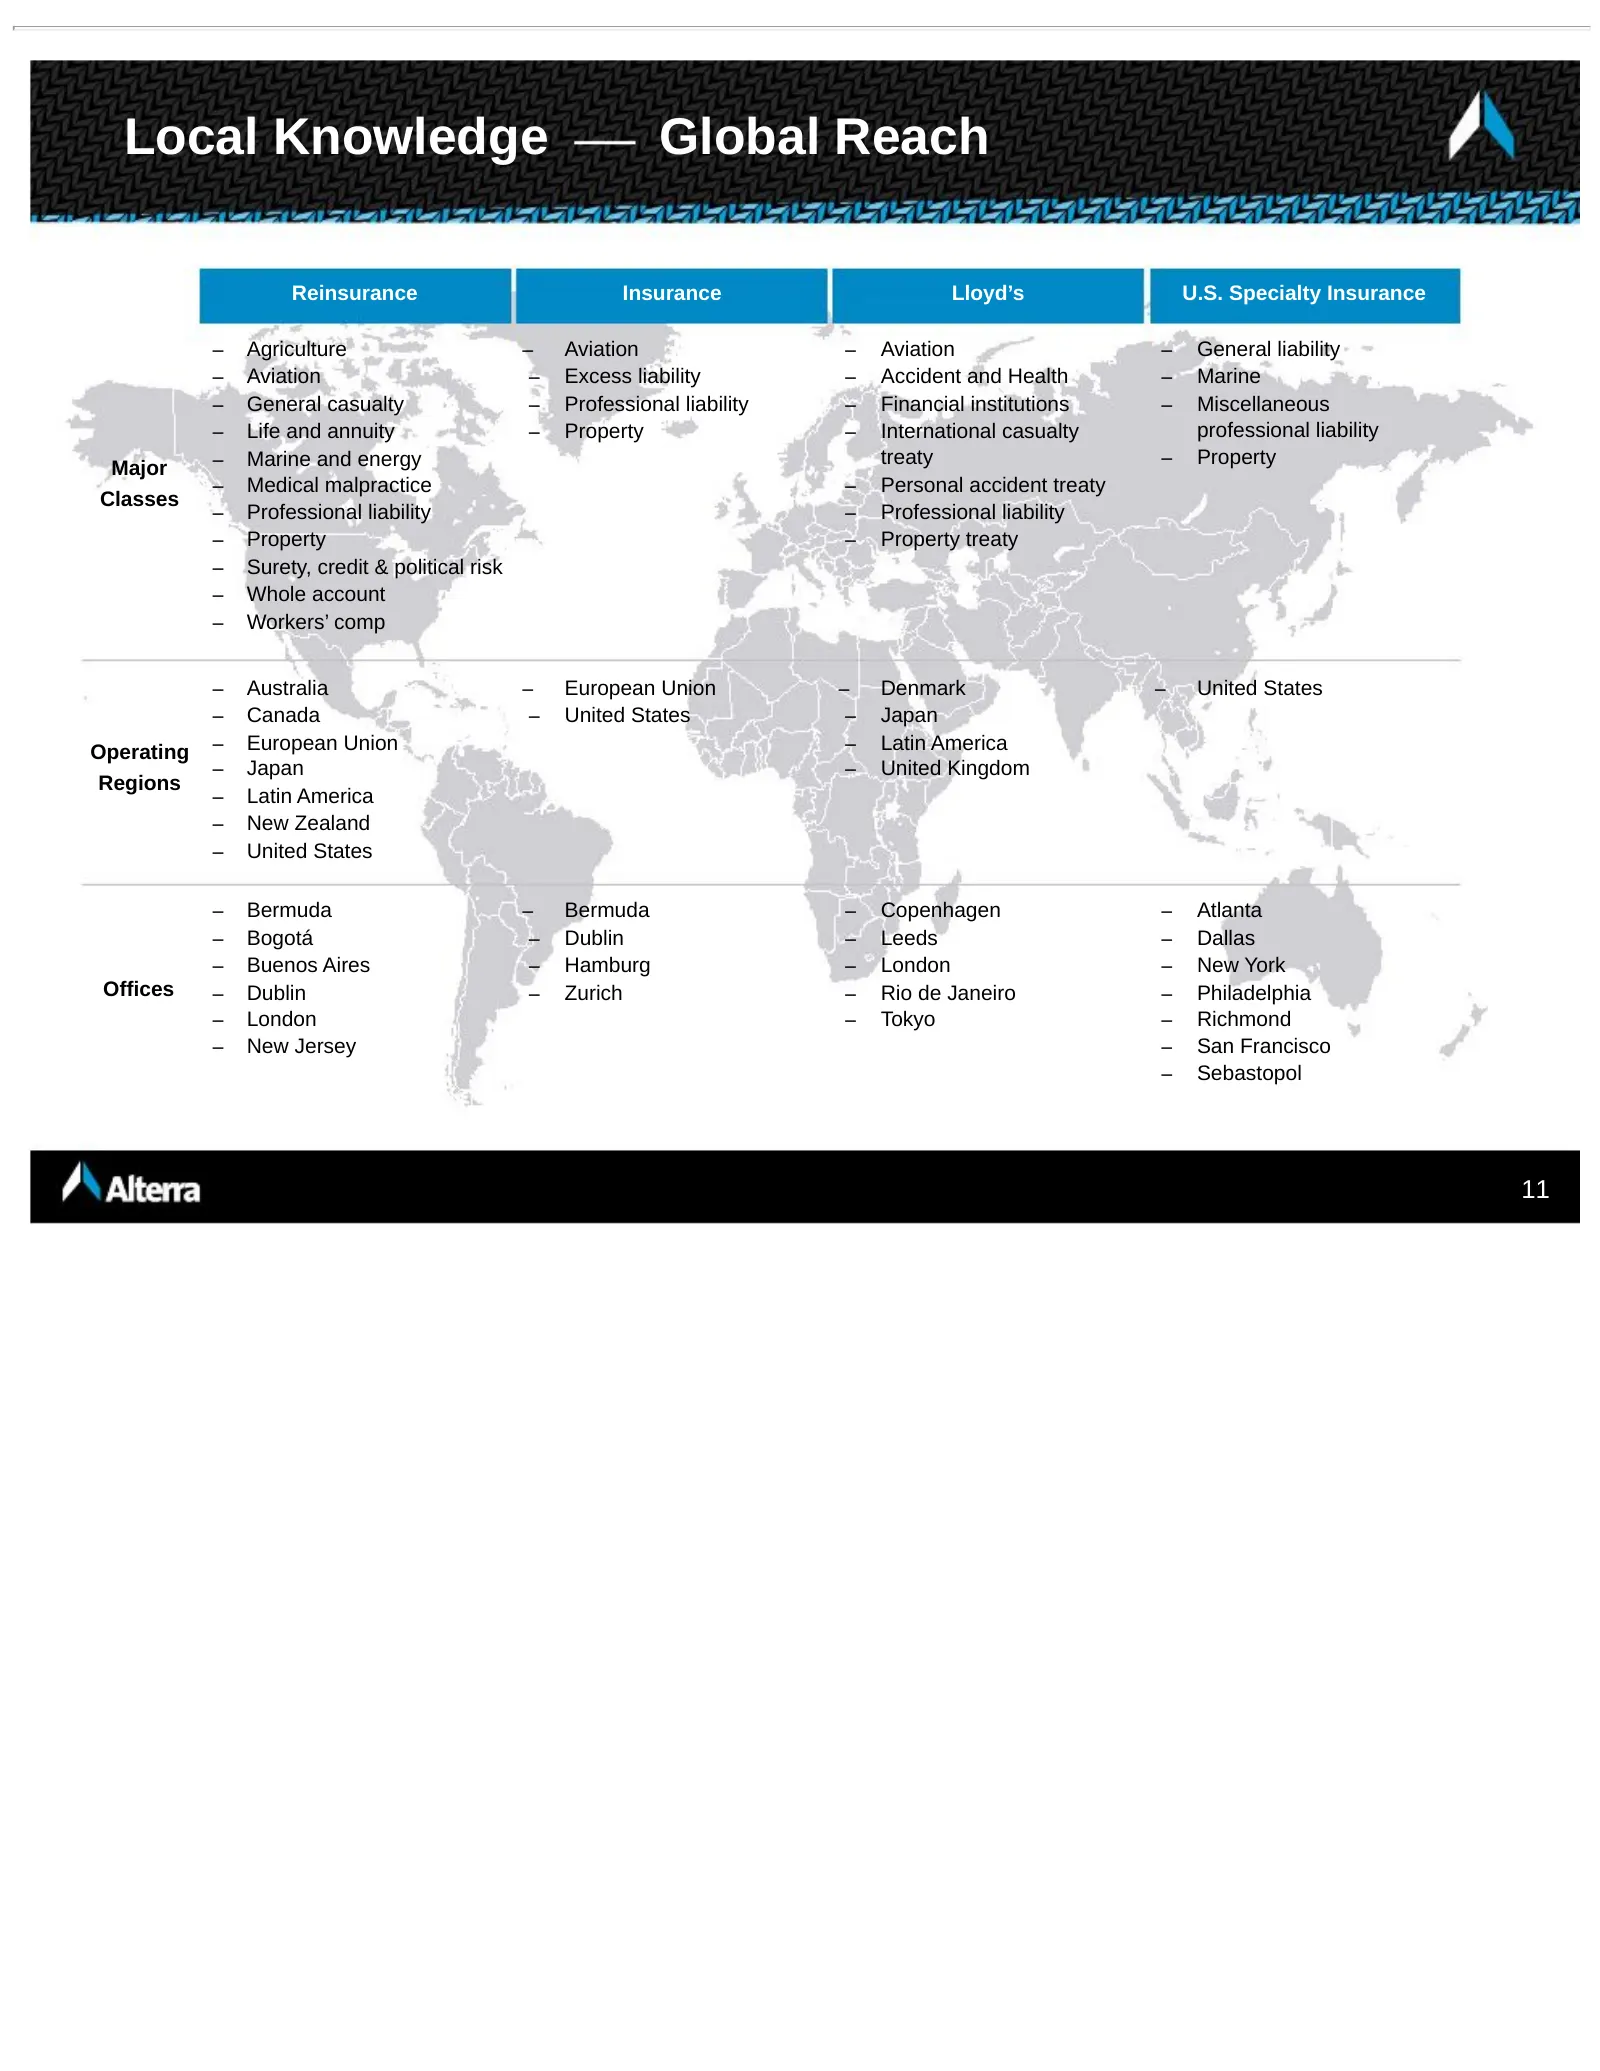
Slide 11: Local Knowledge Global Reach
Local Knowledge Global Reach Reinsurance Insurance Lloyd’s U.S. Specialty Insurance – Agriculture – Aviation – Aviation – General liability – Aviation – Excess liability – Accident and Health – Marine – General casualty – Professional liability – Financial institutions – Miscellaneous – Life and ann
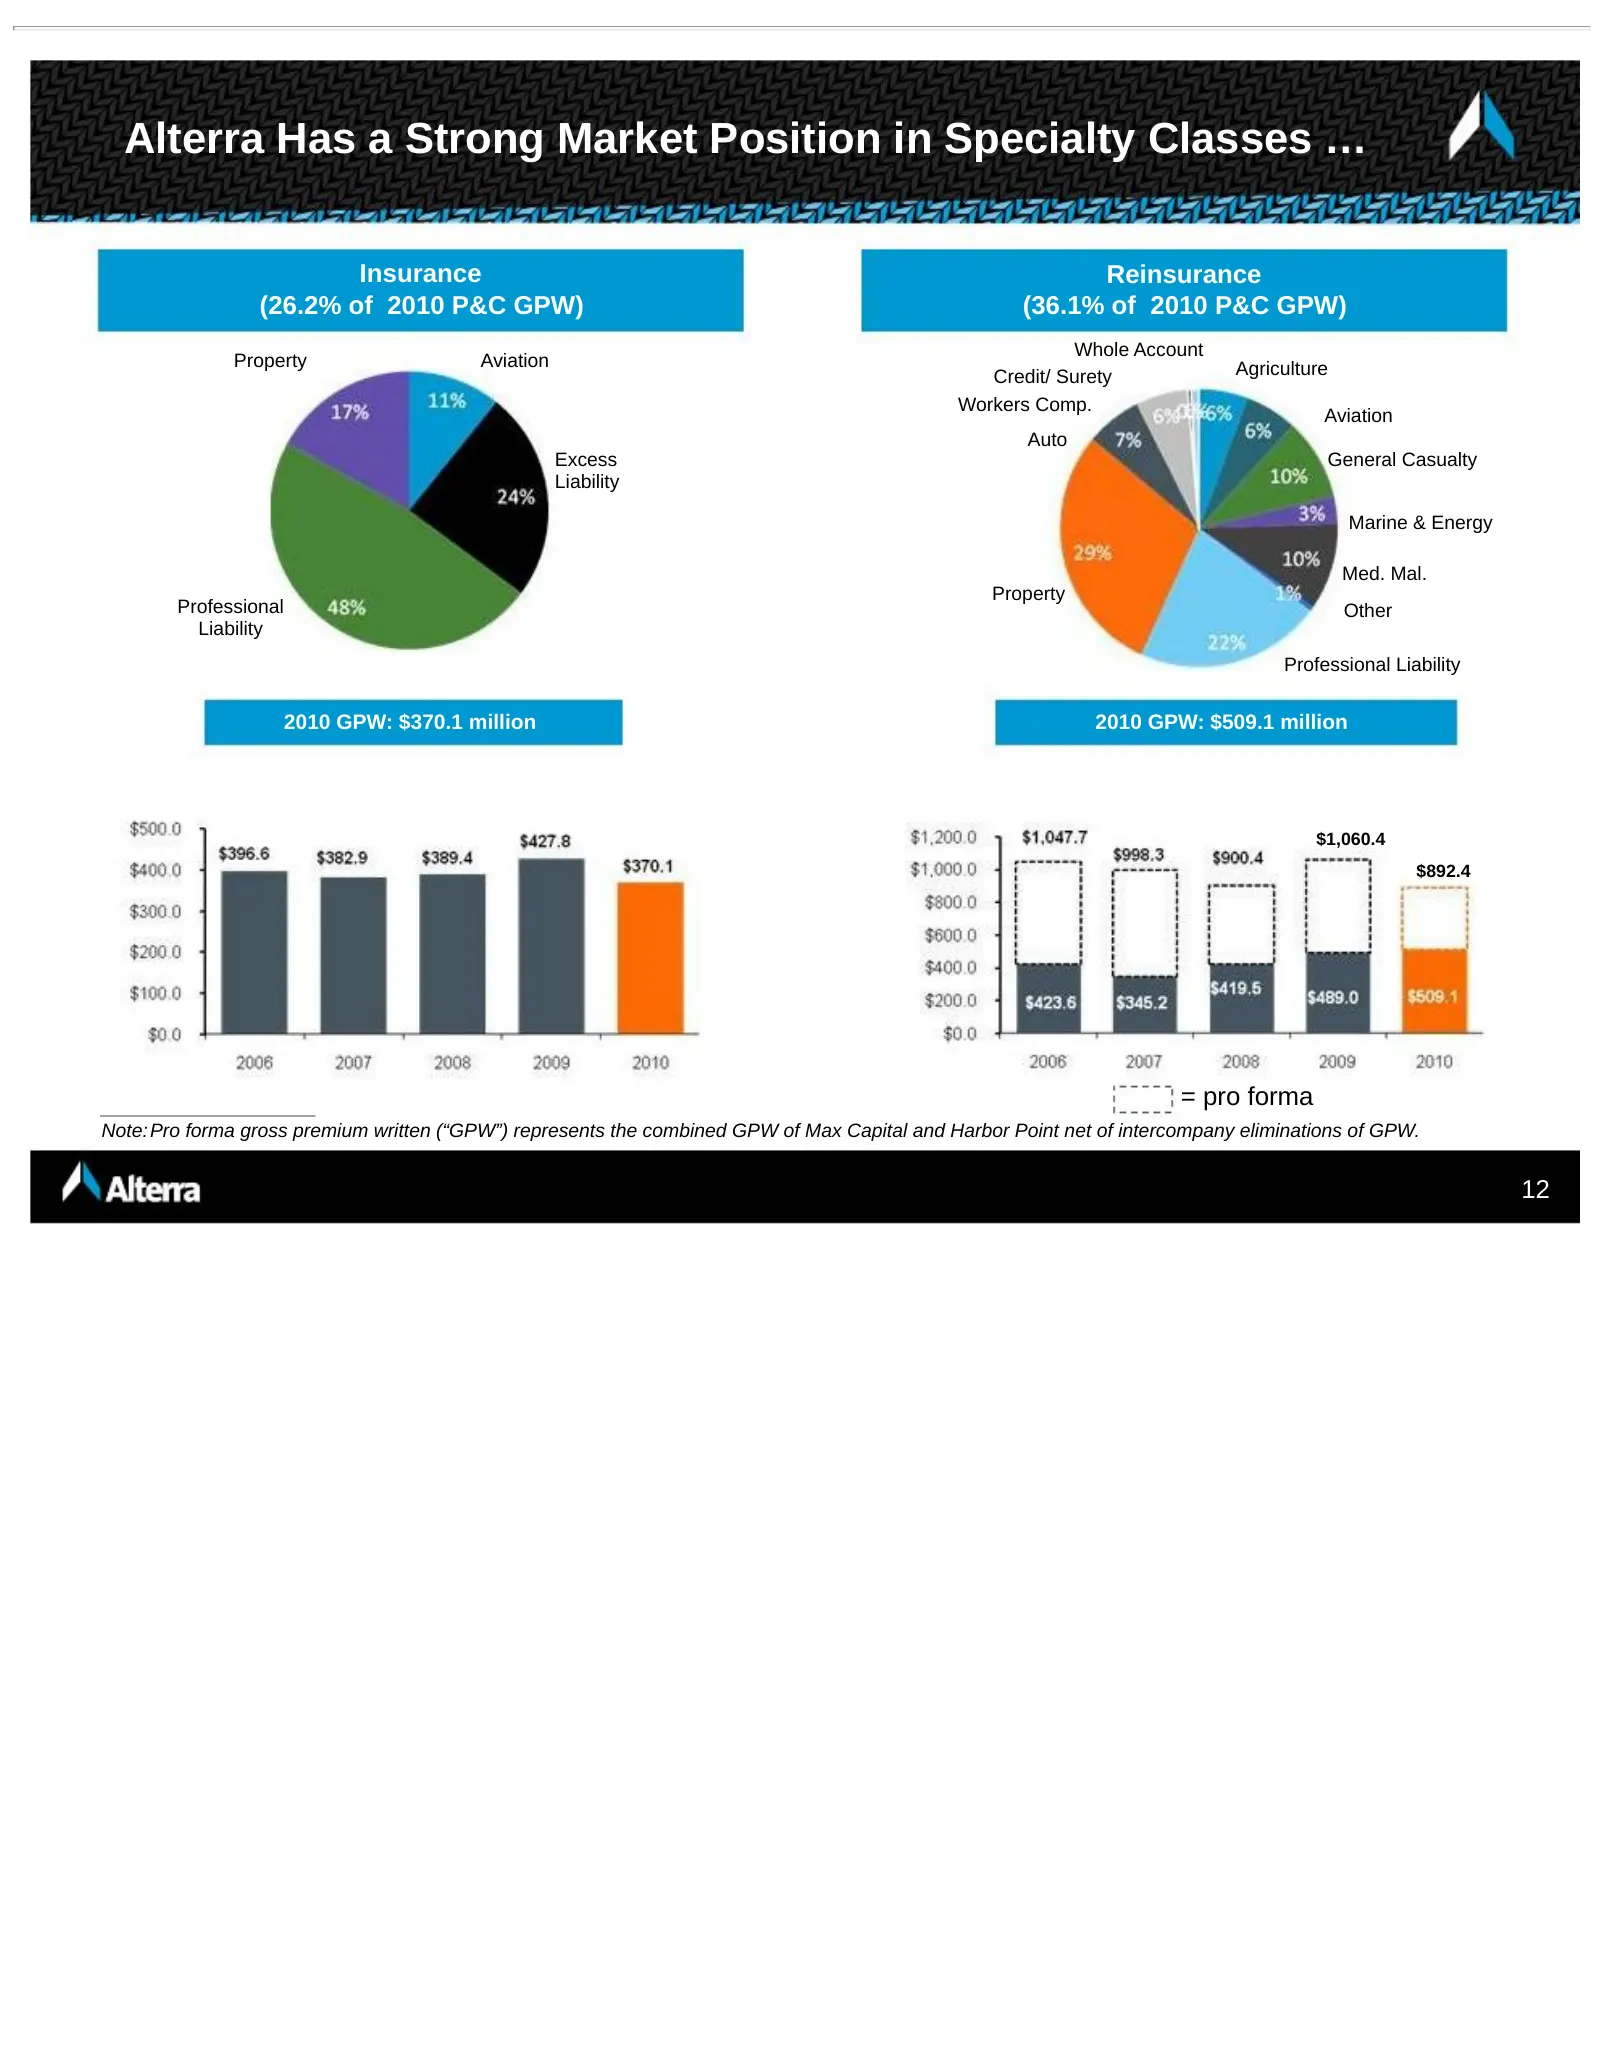
Slide 12: Alterra Has a Strong Market Position in Specialty Classes
Alterra Has a Strong Market Position in Specialty Classes … Insurance Reinsurance (26.2% of 2010 P&C GPW) (36.1% of 2010 P&C GPW) Whole Account Property Aviation Agriculture Credit/ Surety Workers Comp. Aviation Auto Excess General Casualty Liability Marine & Energy Med. Mal. Property Professional O
Slide 13: With an Attractive Position in the U.S. Market and Lloyd's
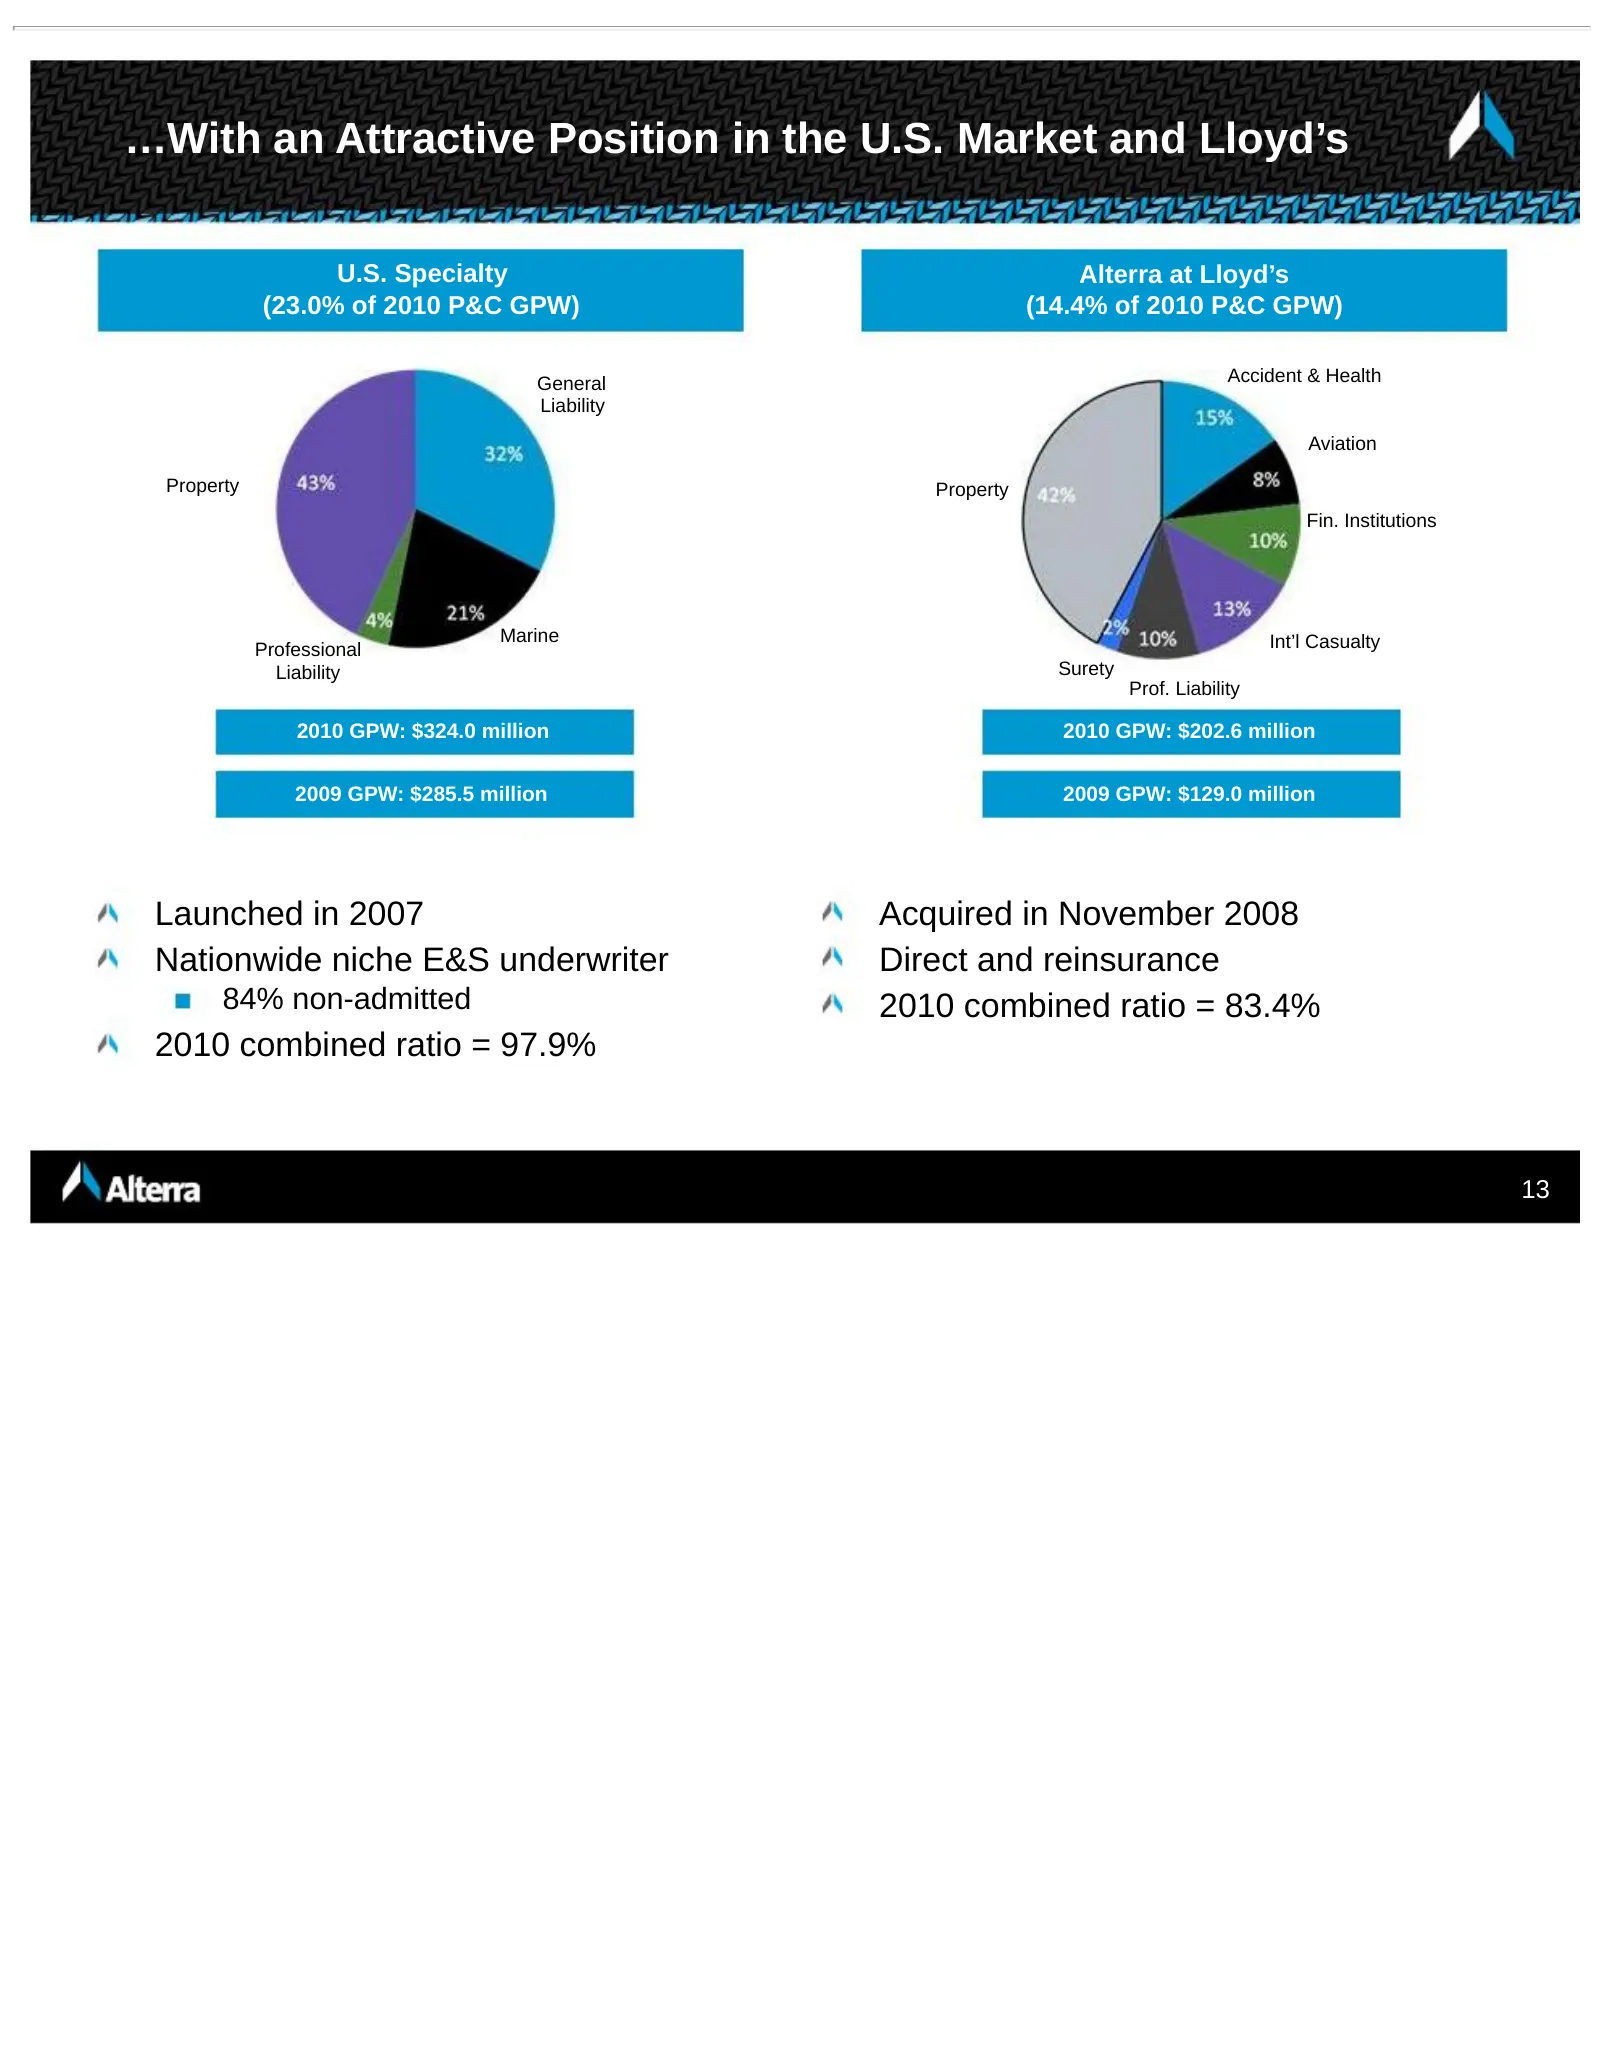
…With an Attractive Position in the U.S. Market and Lloyd’s U.S. Specialty Alterra at Lloyd’s (23.0% of 2010 P&C GPW) (14.4% of 2010 P&C GPW) General Accident & Health Liability Aviation Property Property Fin. Institutions Marine Int’l Casualty Professional Liability Surety Prof. Liability 2010 GPW:
Slide 14: Diversified and Balanced Business Mix
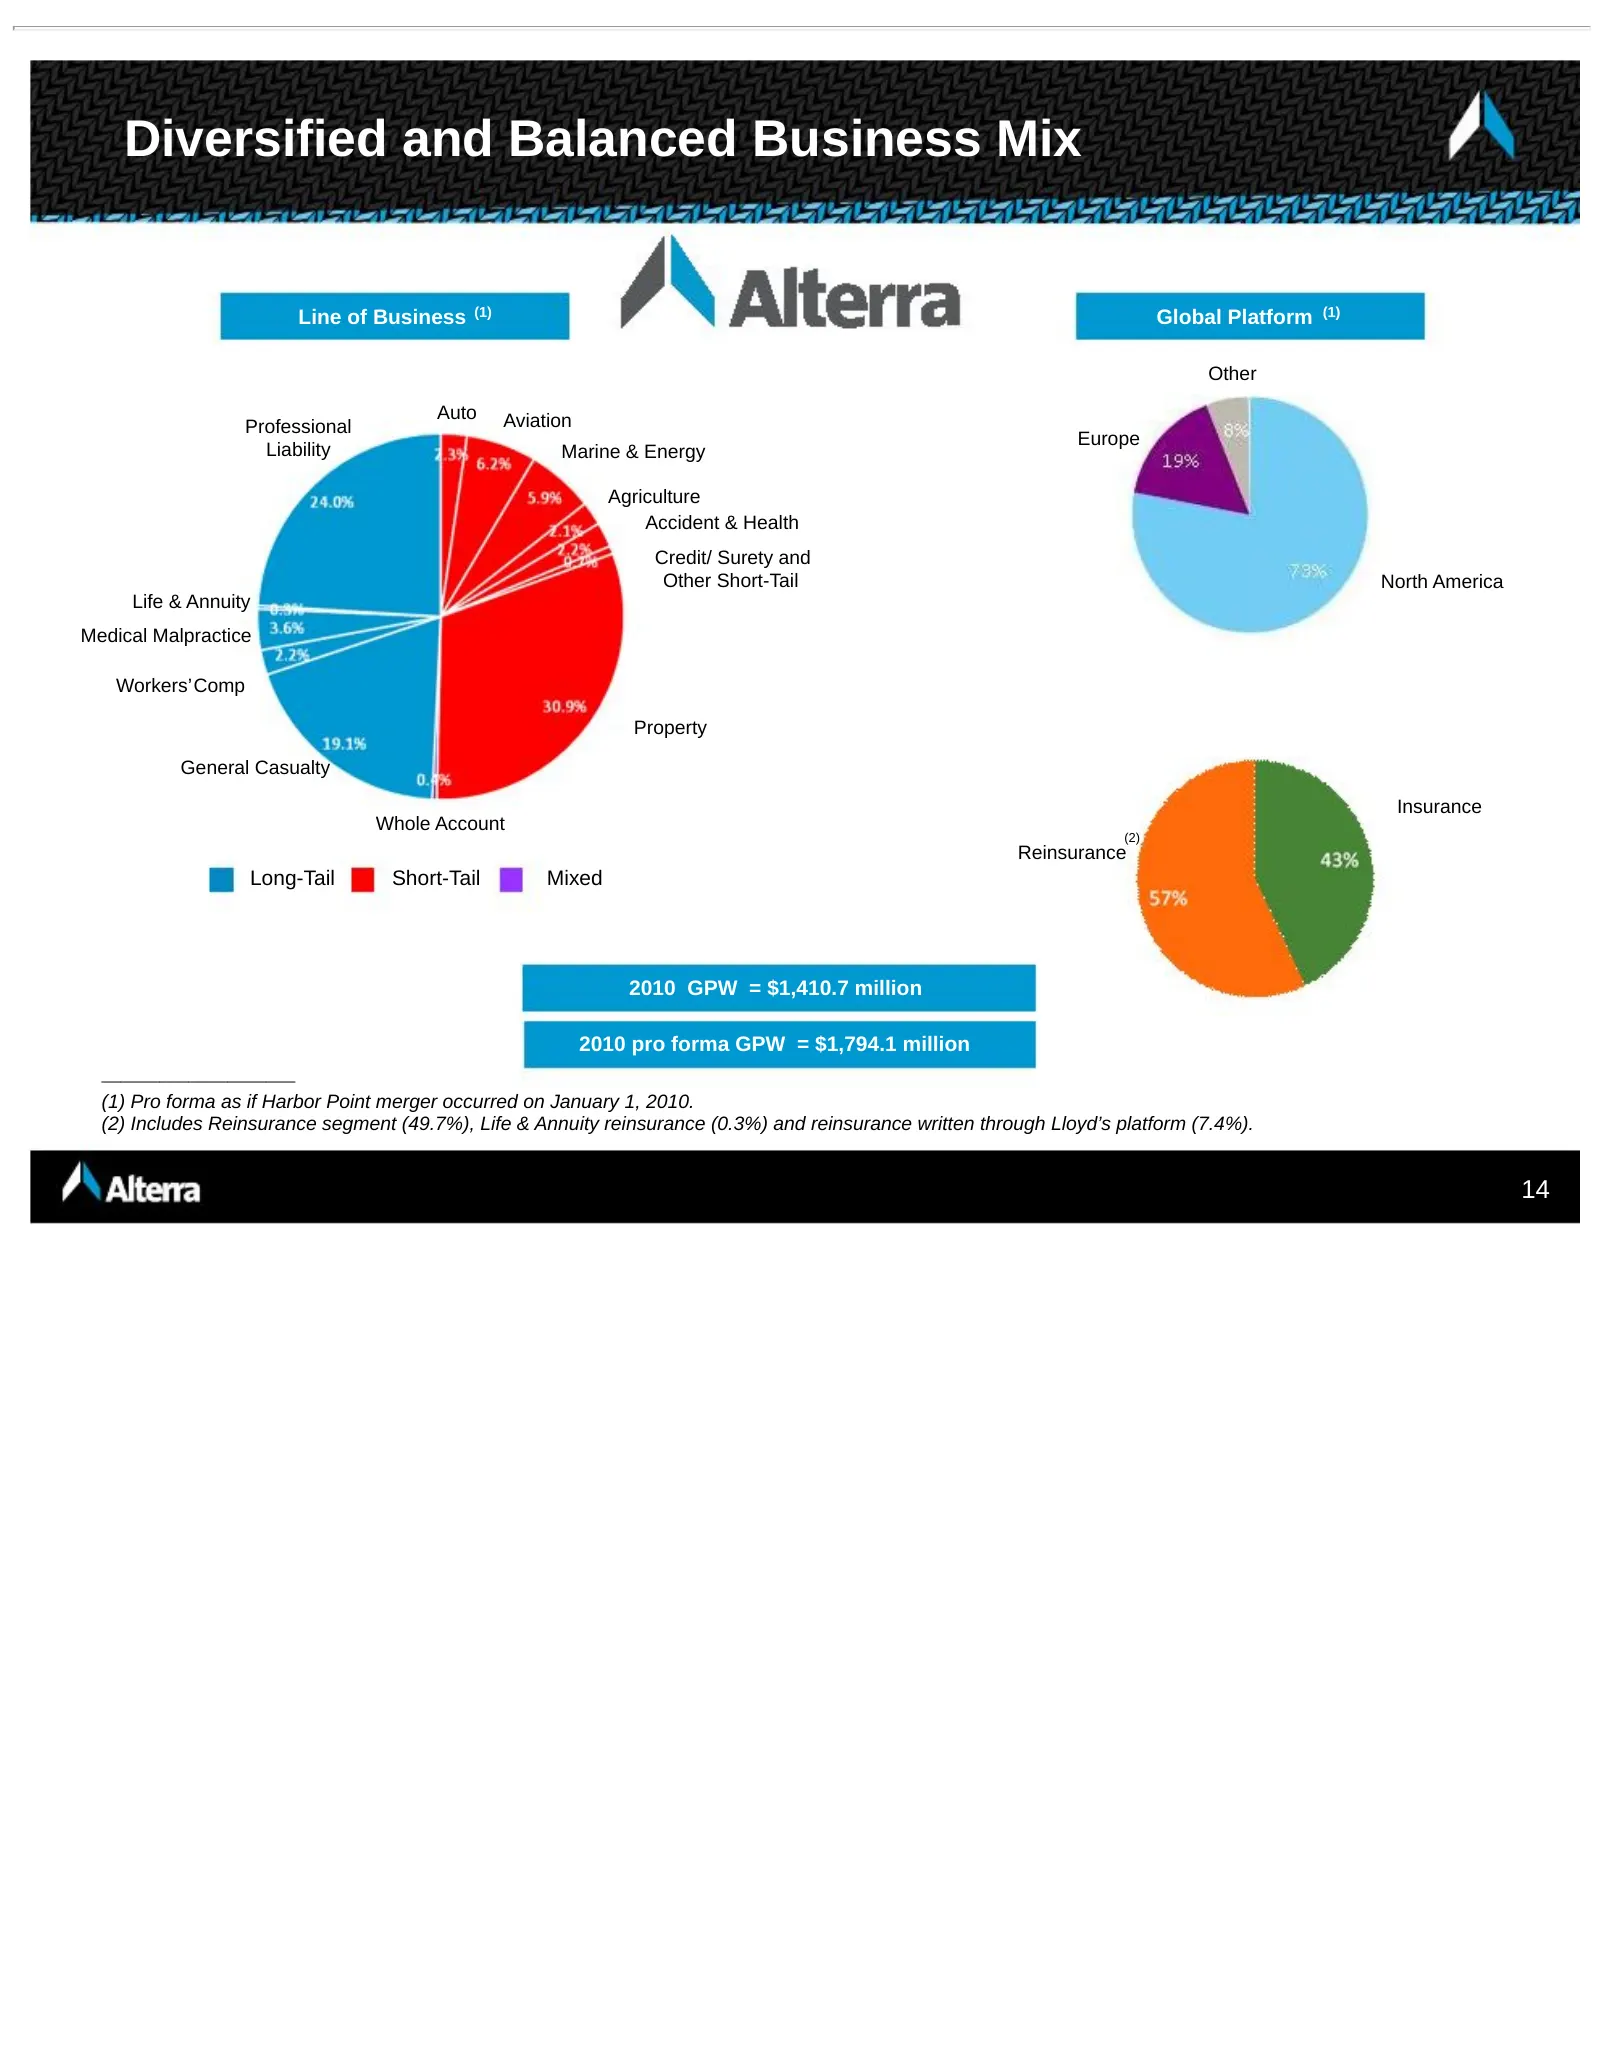
Diversified and Balanced Business Mix Line of Business (1) Global Platform (1) Other Auto Aviation Professional Europe Liability Marine & Energy Agriculture Accident & Health Credit/ Surety and Other Short-Tail North America Life & Annuity Medical Malpractice Workers’Comp Property General Casualty I
Slide 15: Superior Risk Management Skills
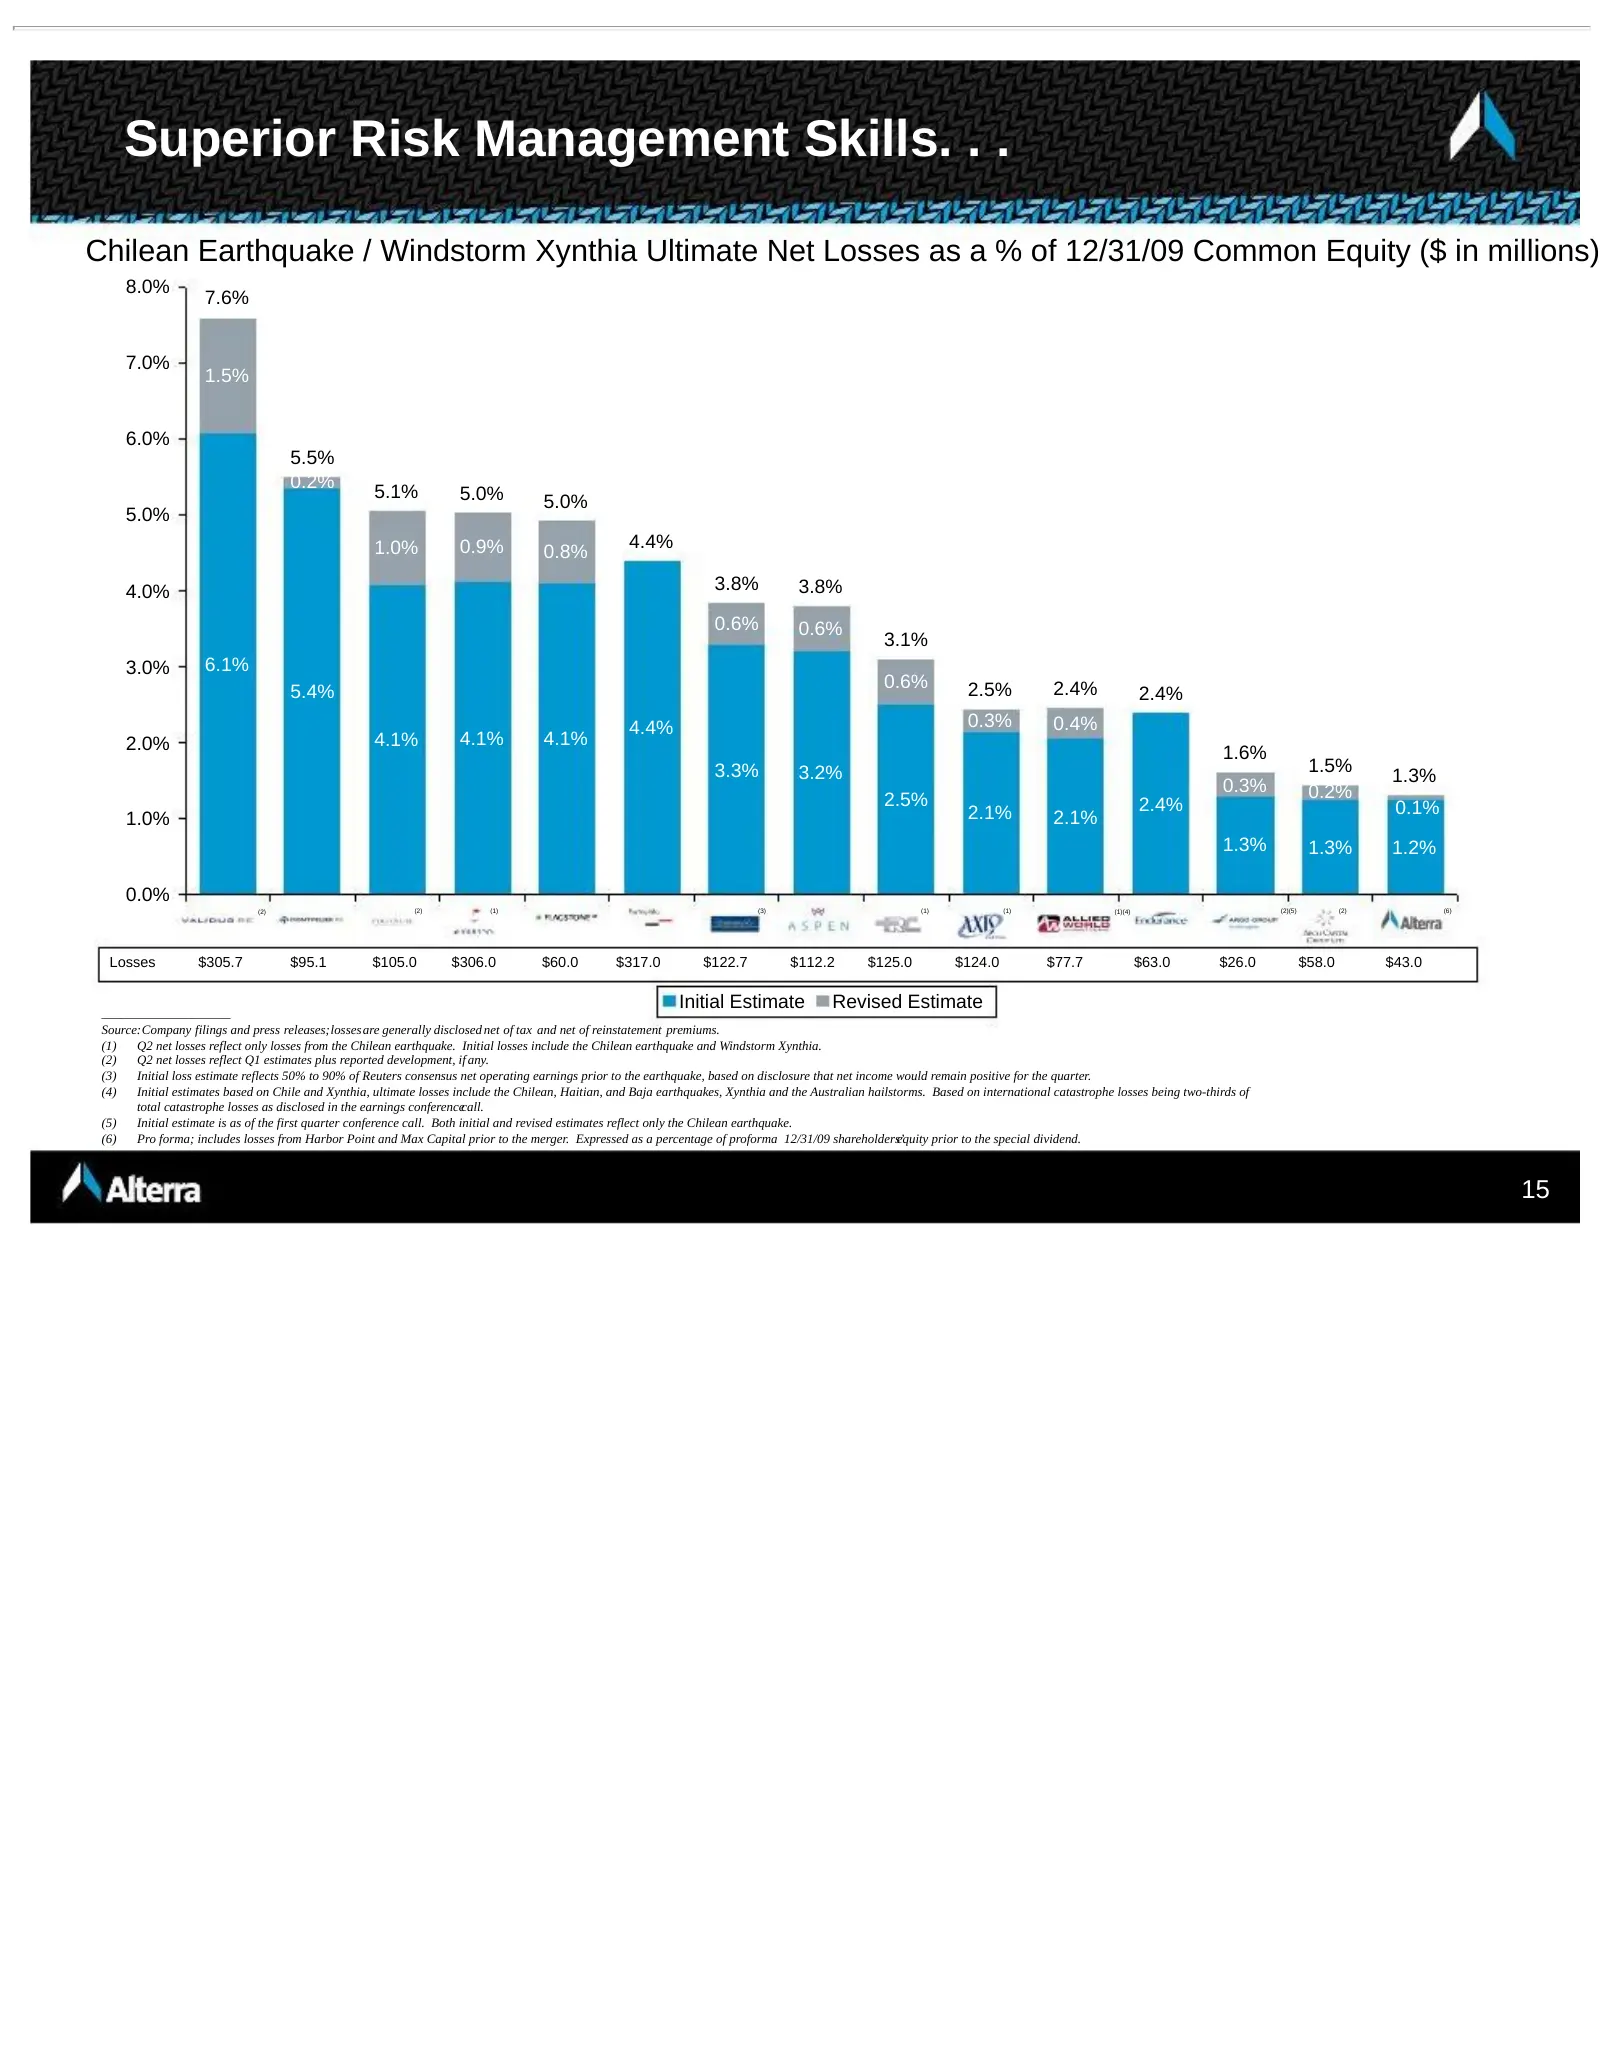
Superior Risk Management Skills. . . Chilean Earthquake / Windstorm Xynthia Ultimate Net Losses as a % of 12/31/09 Common Equity ($ in millions) 8.0% 7.6% 7.0% 1.5% 6.0% 5.5% 0.2% 5.1% 5.0% 5.0% 5.0% 1.0% 0.9% 0.8% 4.4% 4.0% 3.8% 3.8% 0.6% 0.6% 3.1% 3.0% 6.1% 5.4% 0.6% 2.5% 2.4% 2.4% 4.4% 0.3% 0.4%
Slide 16: Less Exposed to Swings in the Cat Market
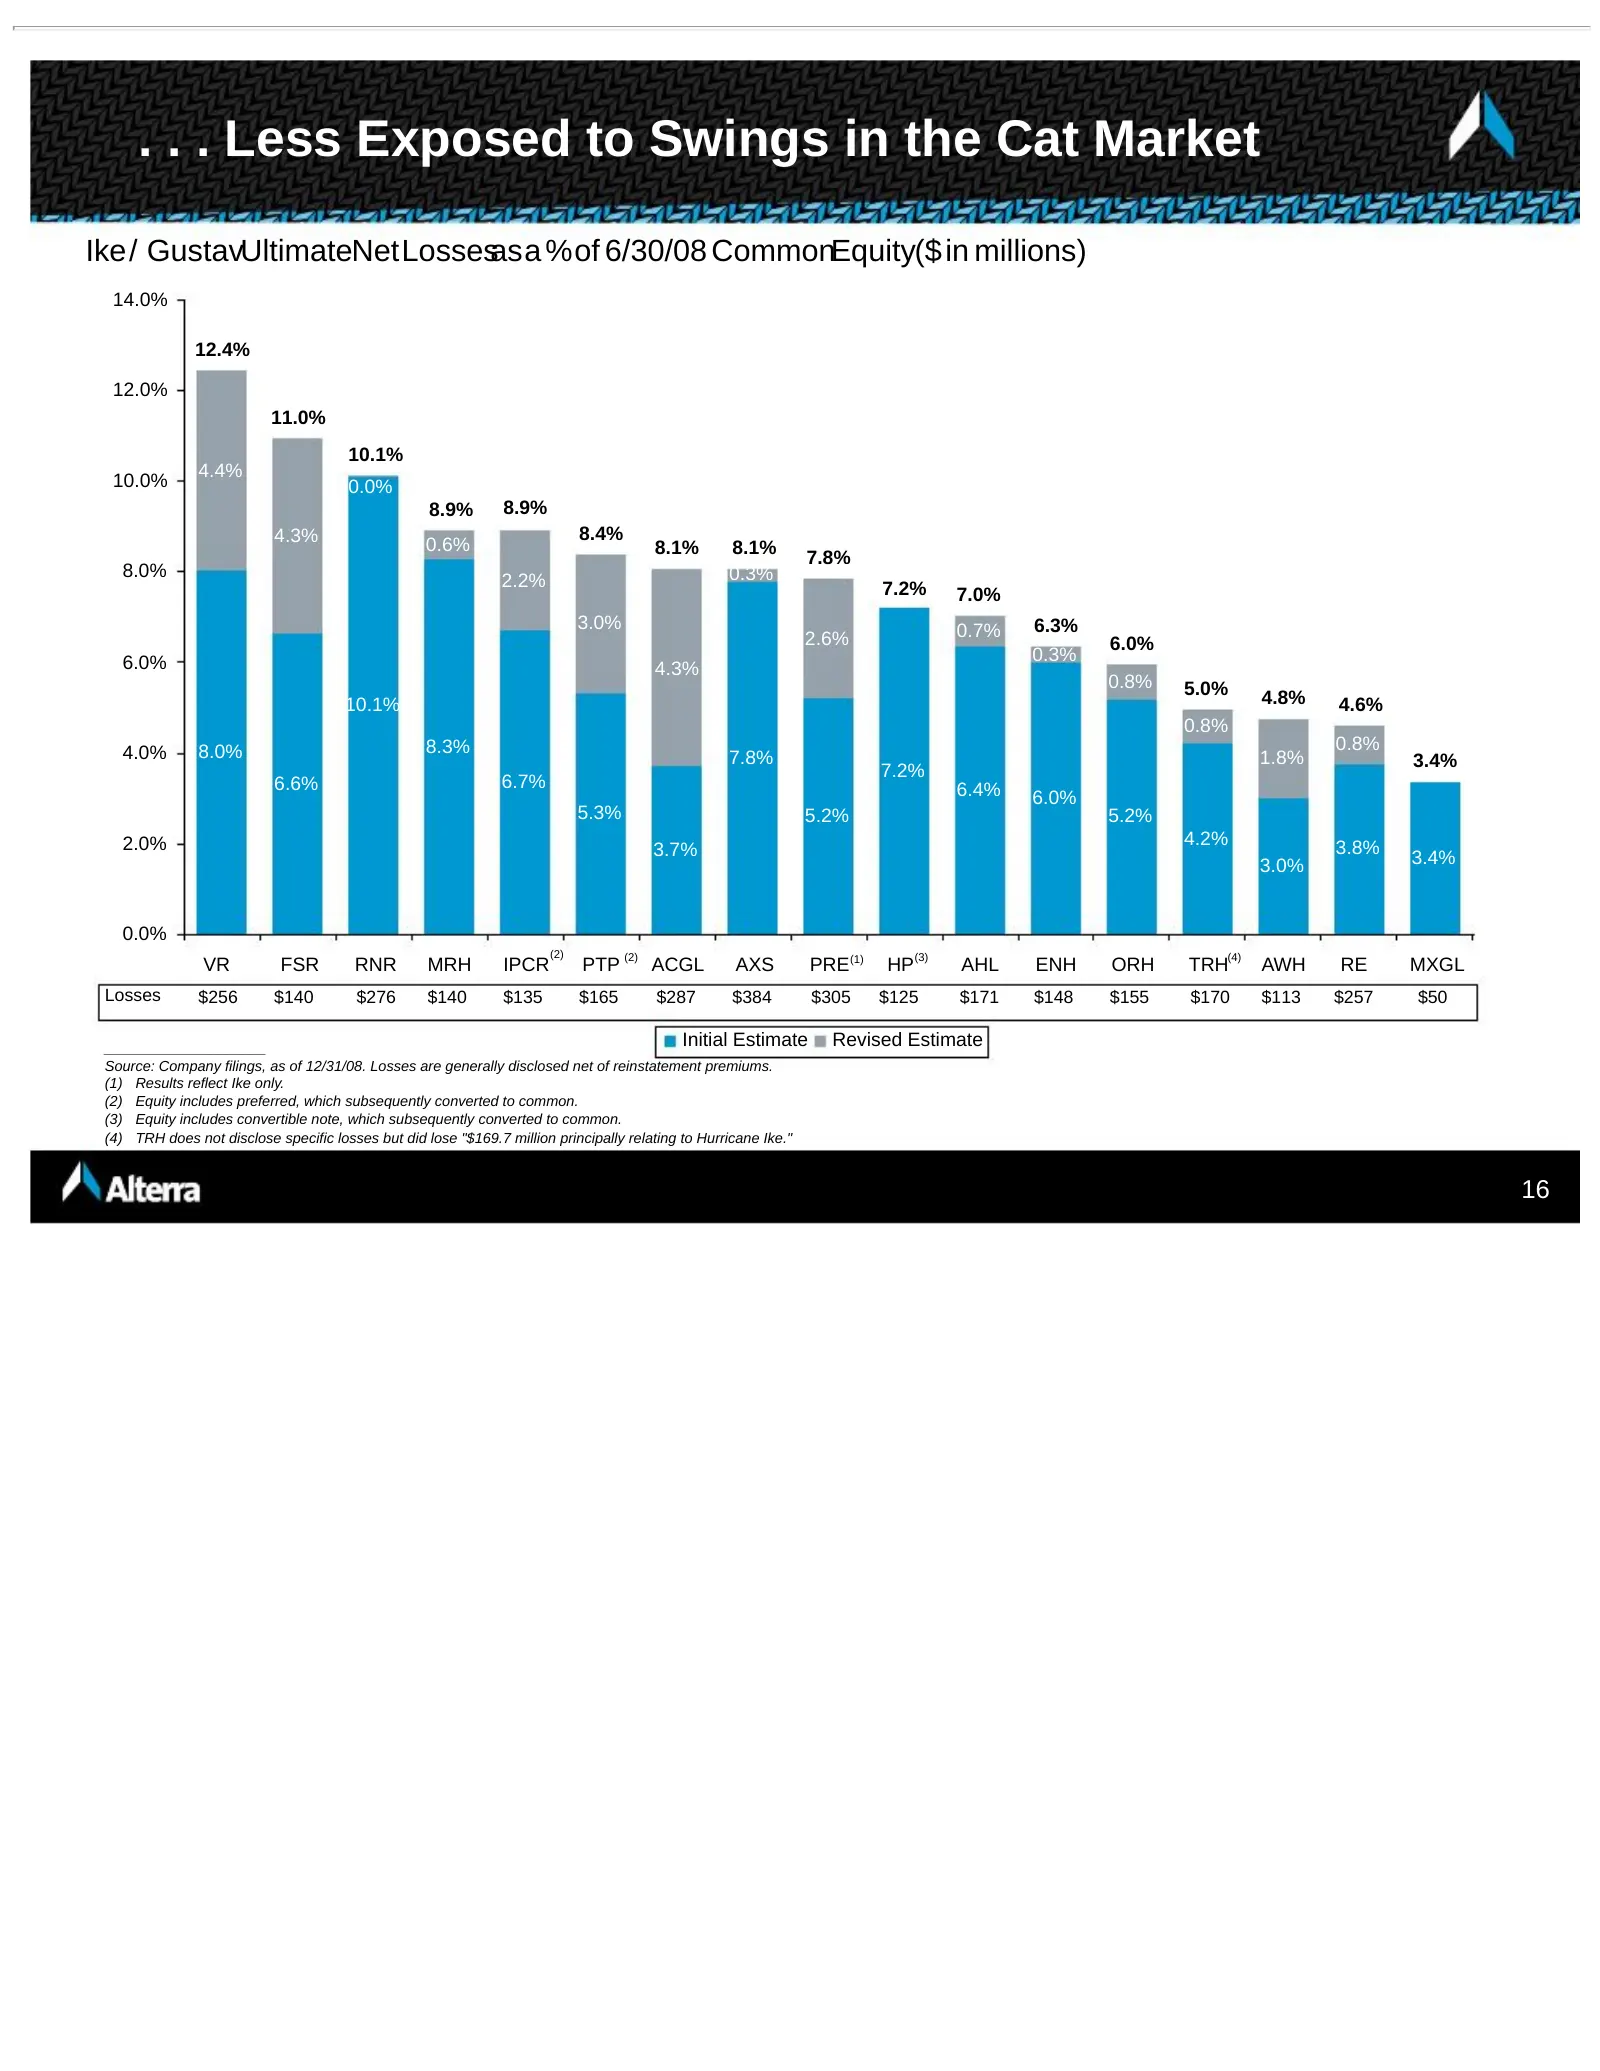
. . . Less Exposed to Swings in the Cat Market Ike/ GustavUltimateNetLossesasa %of 6/30/08 CommonEquity($ in millions) 14.0% 12.4% 12.0% 11.0% 10.1% 4.4% 10.0% 0.0% 8.9% 8.9% 4.3% 8.4% 0.6% 8.1% 8.1% 7.8% 8.0% 2.2% 0.3% 7.2% 7.0% 3.0% 0.7% 6.3% 2.6% 6.0% 6.0% 0.3% 4.3% 0.8% 5.0% 10.1% 4.8% 4.6% 0.8%
Slide 17: PML's In-force as of January 1, 2011
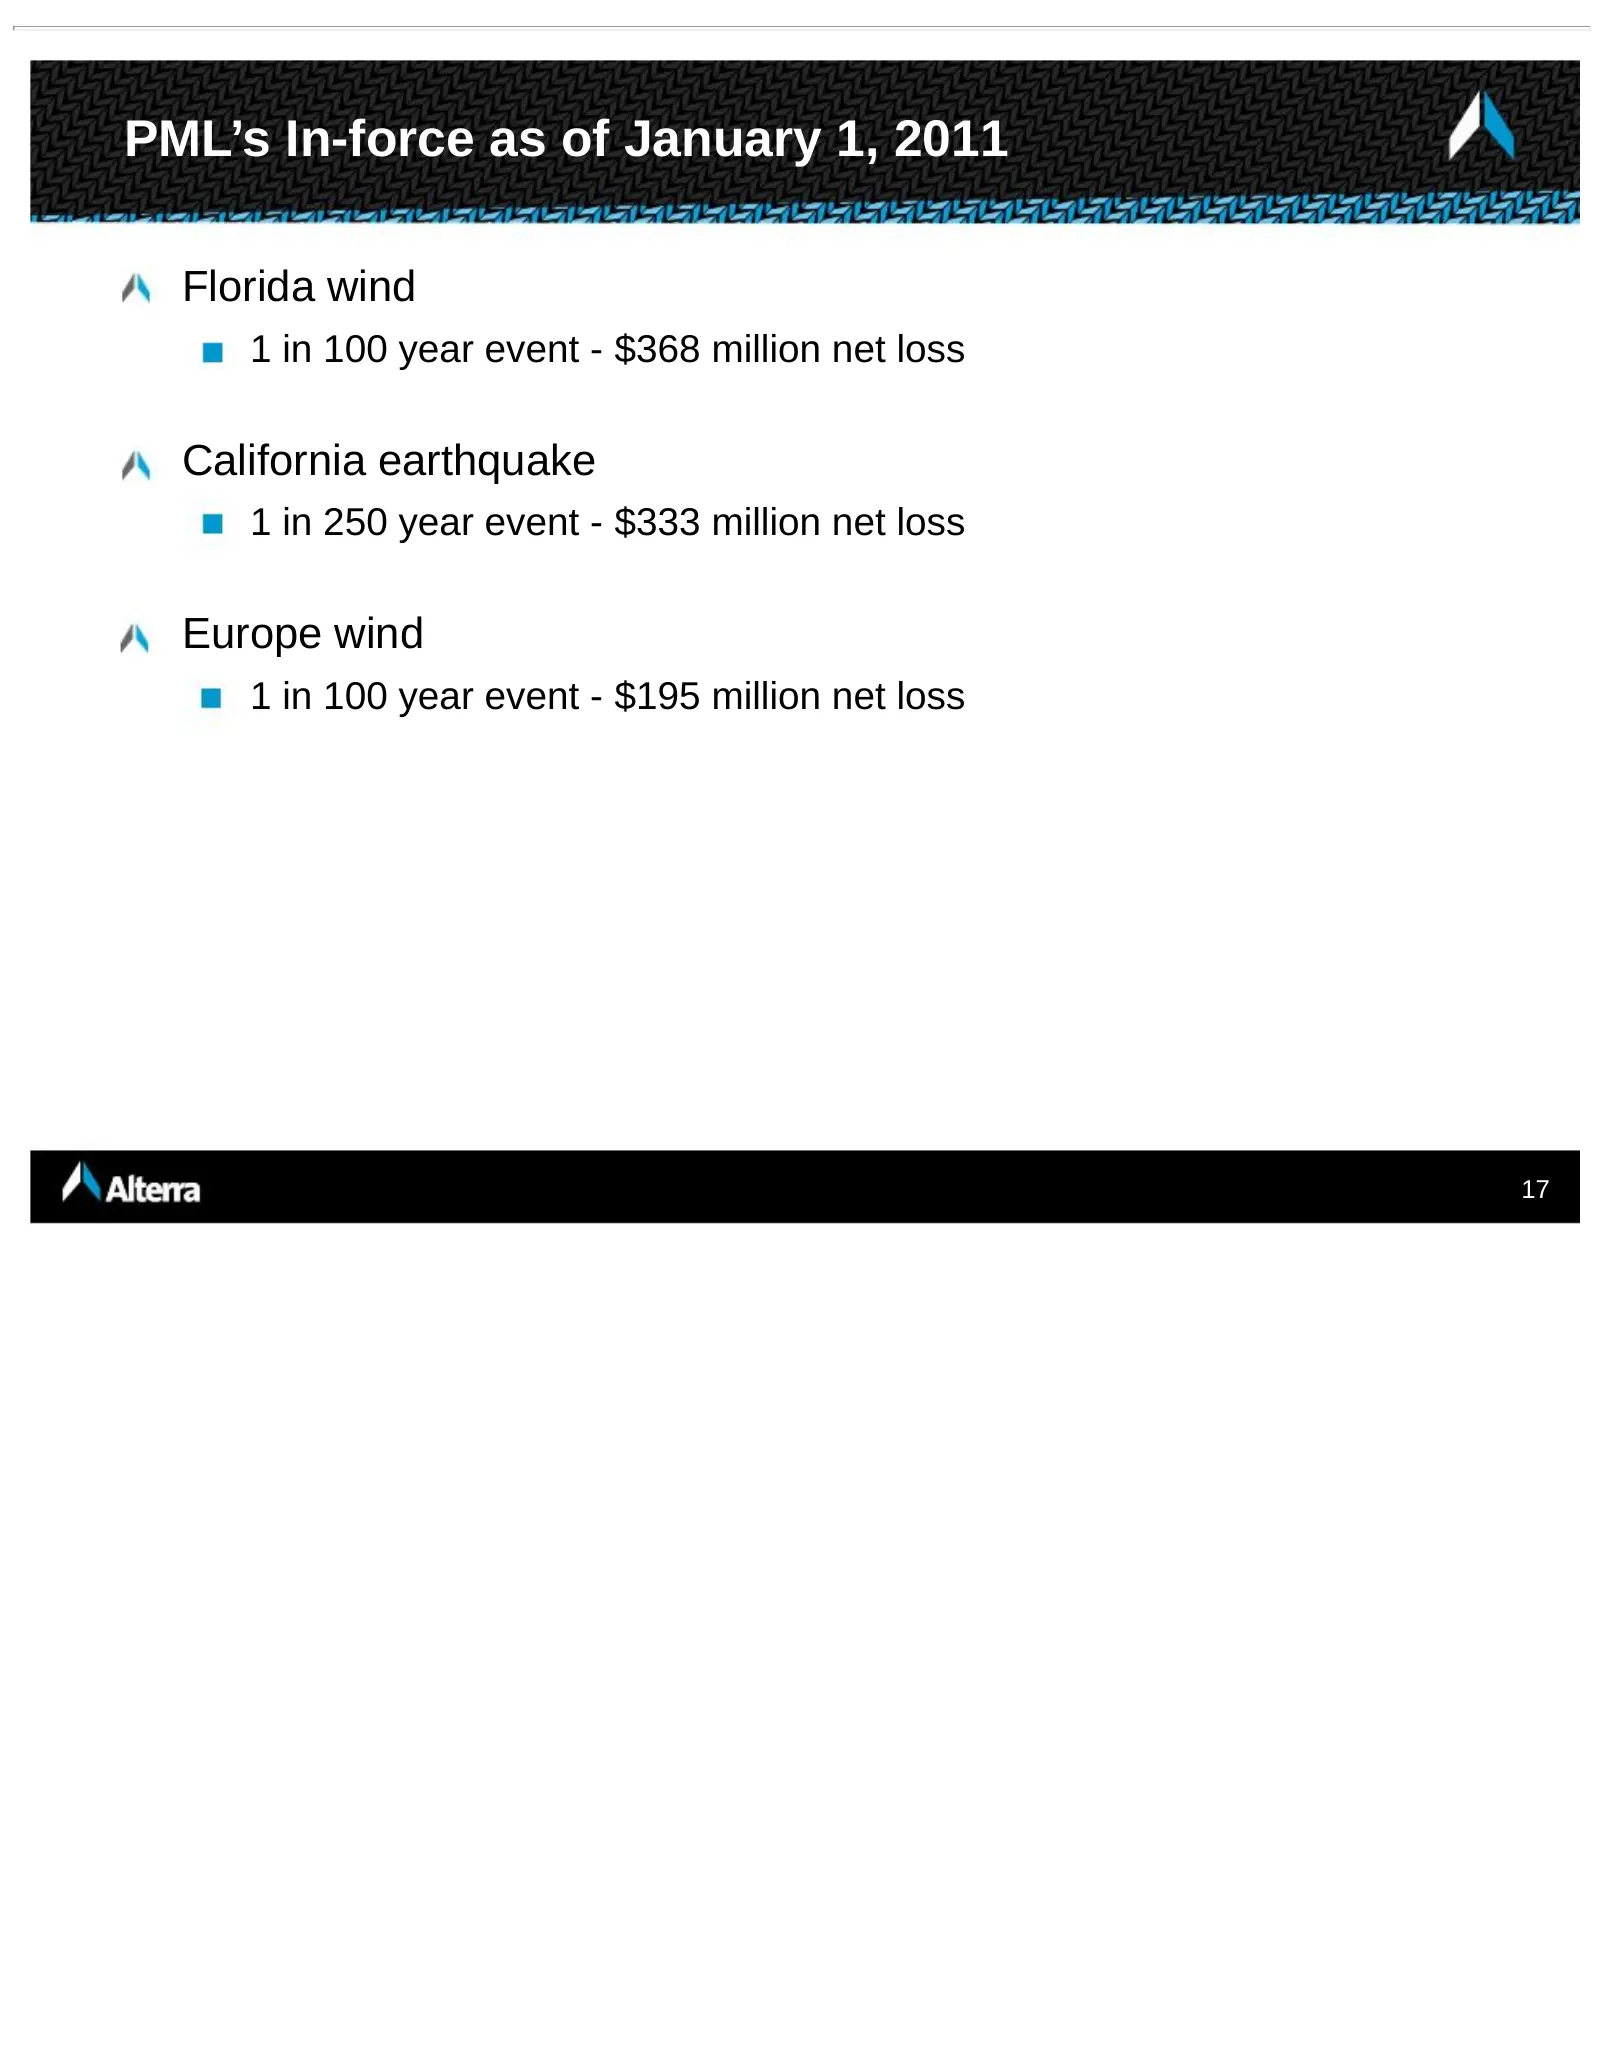
PML’s In-force as of January 1, 2011 Florida wind 1 in 100 year event - $368 million net loss California earthquake 1 in 250 year event - $333 million net loss Europe wind 1 in 100 year event - $195 million net loss 17
Slide 18: Strong Cycle Management Discipline
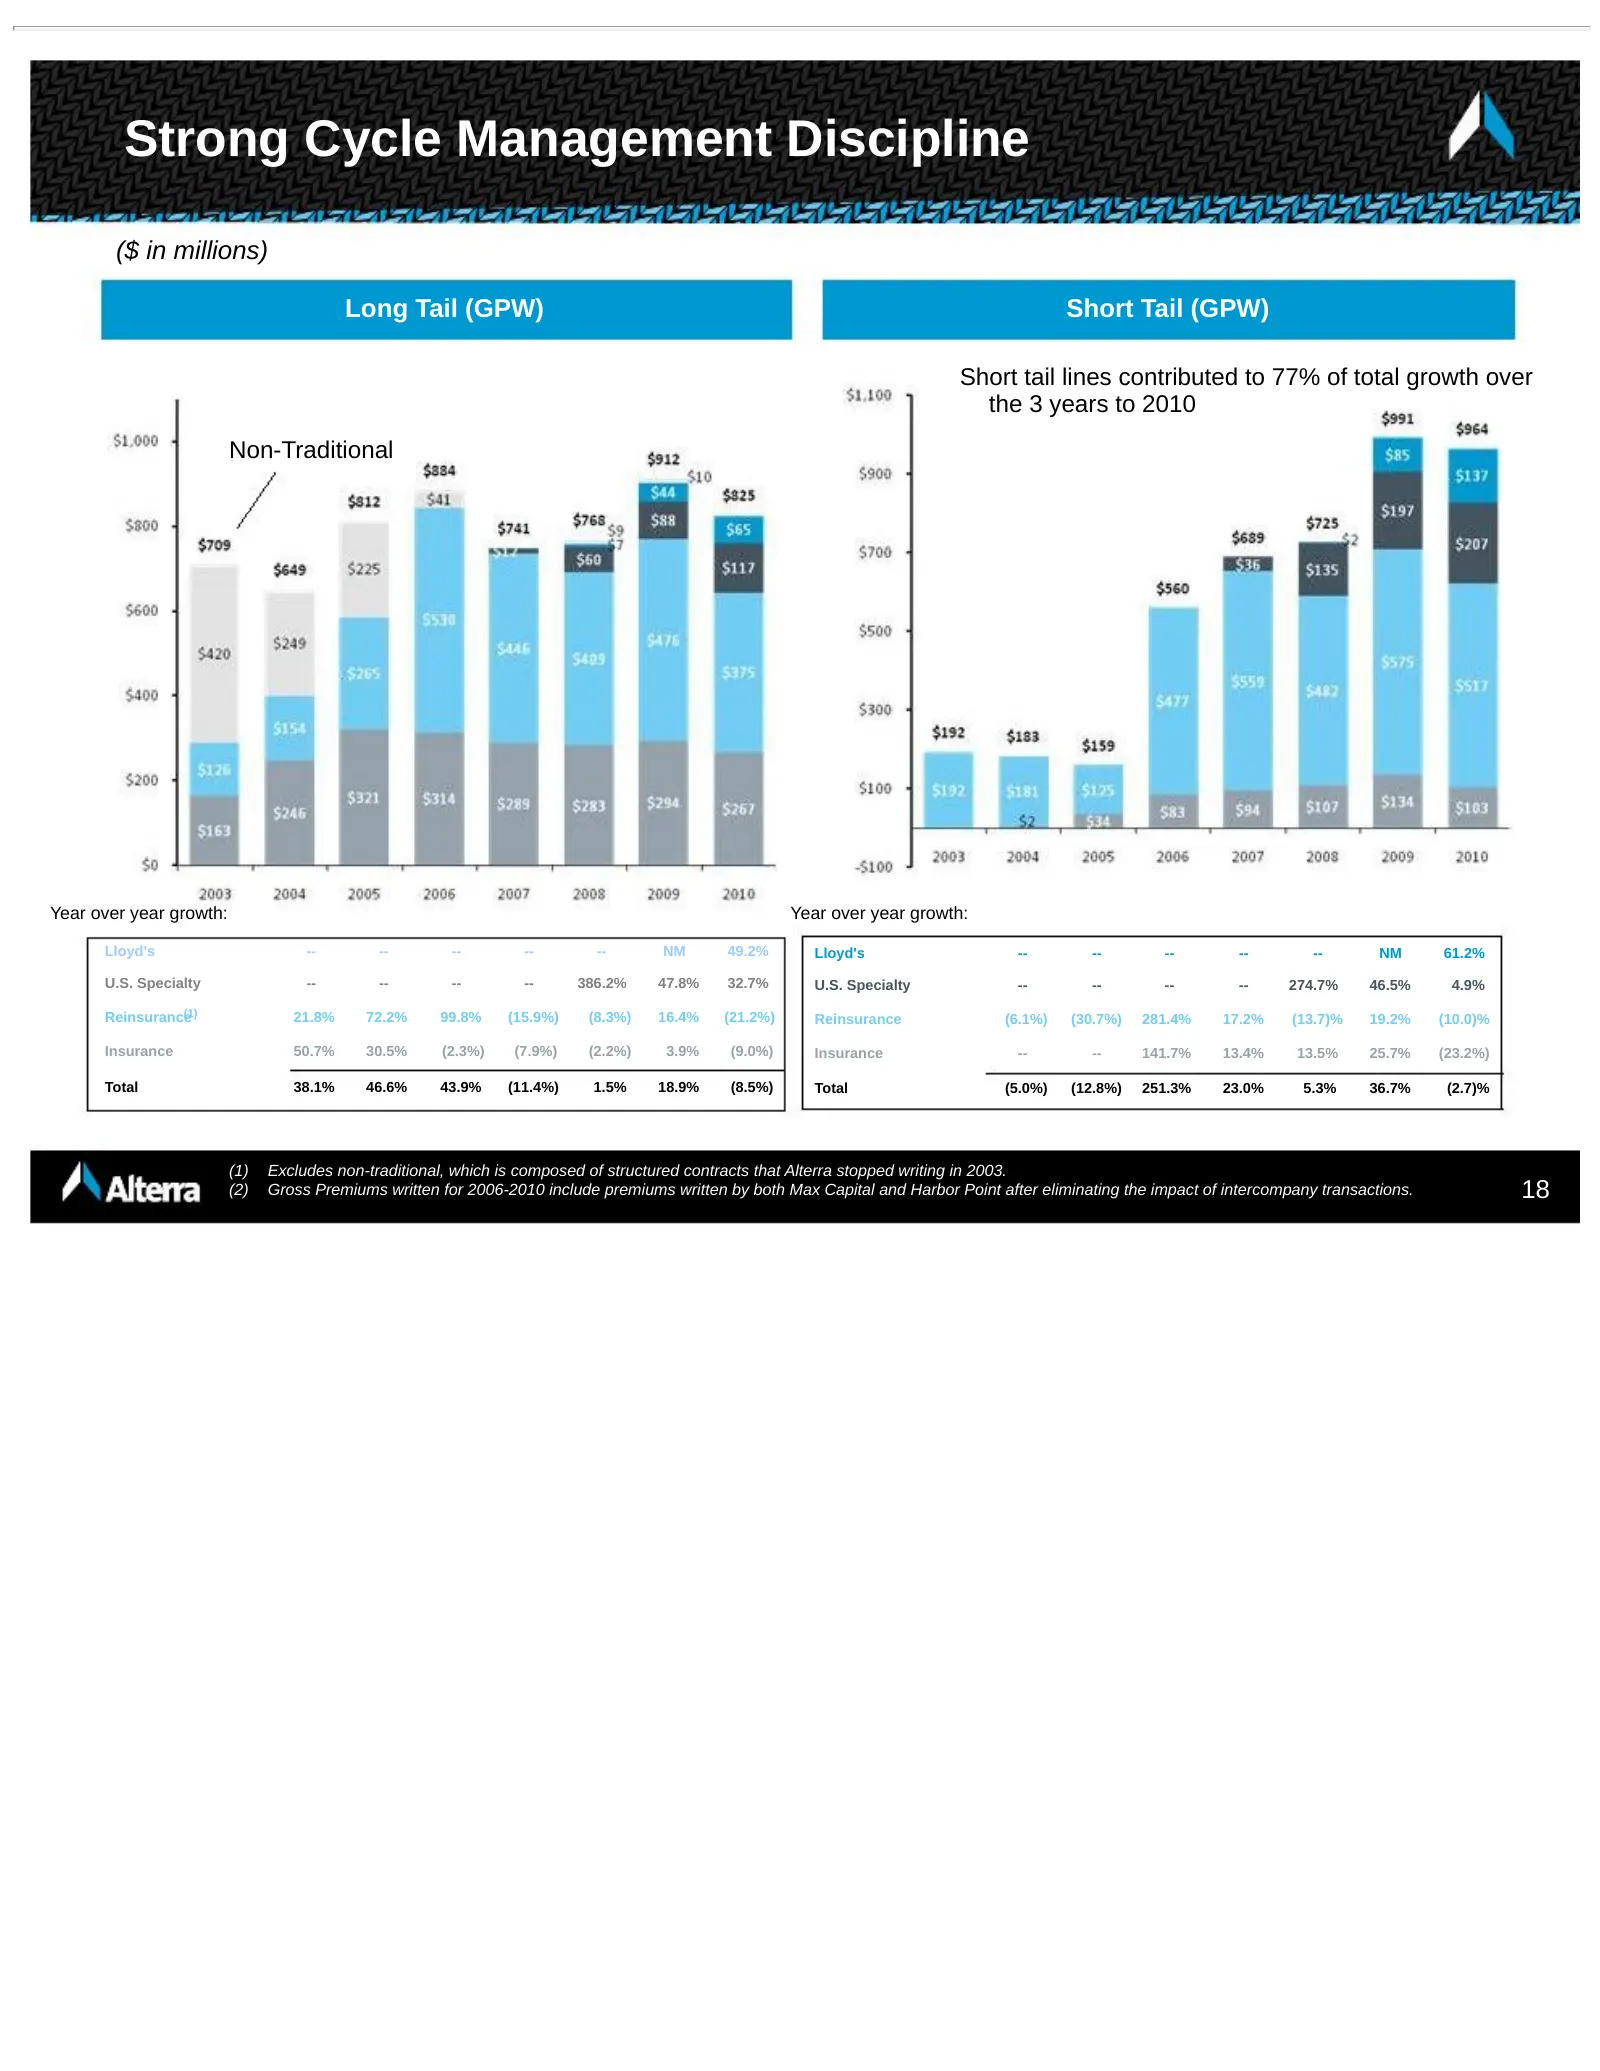
Strong Cycle Management Discipline ($ in millions) Long Tail (GPW) Short Tail (GPW) Short tail lines contributed to 77% of total growth over the 3 years to 2010 Non-Traditional Year over year growth: Year over year growth: Lloyd's -- -- -- -- -- NM 49.2% Lloyd's -- -- -- -- -- NM 61.2% U.S. Specialt
Slide 19: Conservative Reserve Position with High % of IBNR
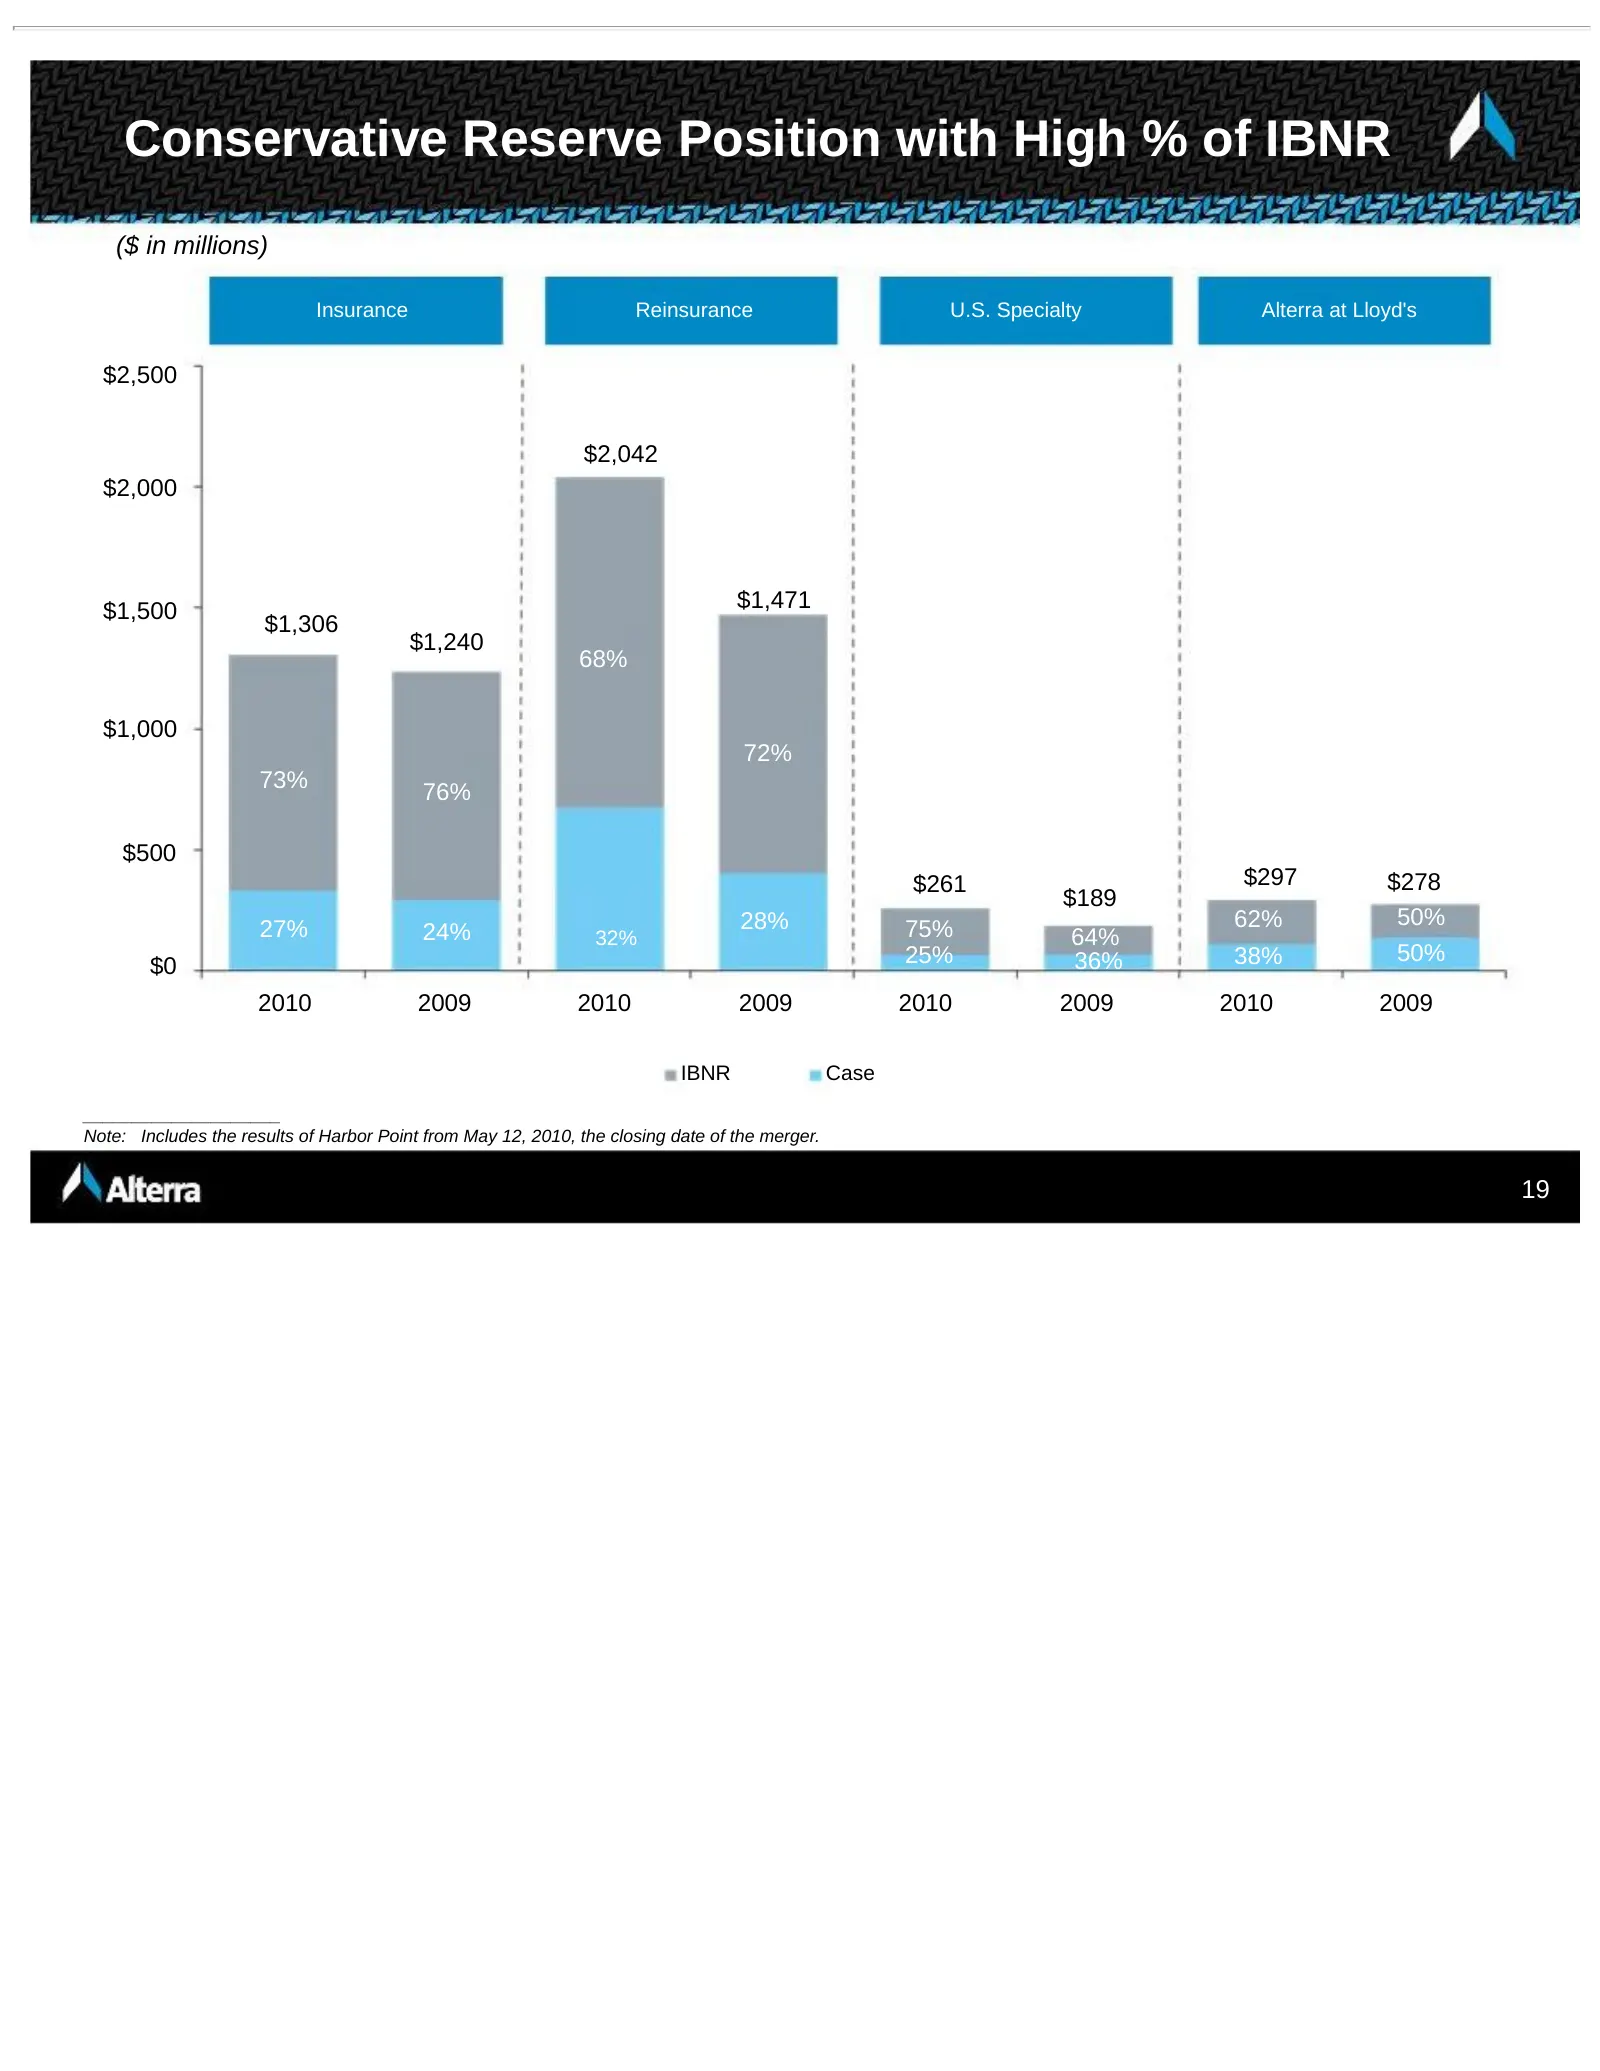
Conservative Reserve Position with High % of IBNR ($ in millions) Insurance Reinsurance U.S. Specialty Alterra at Lloyd's $2,500 $2,042 $2,000 $1,500 $1,471 $1,306 $1,240 68% $1,000 72% 73% 76% $500 $261 $297 $278 $189 27% 28% 75% 62% 50% 24% 32% 64% 25% 36% 38% 50% $0 2010 2009 2010 2009 2010 2009
Slide 20: Consistent Favorable Reserve Development
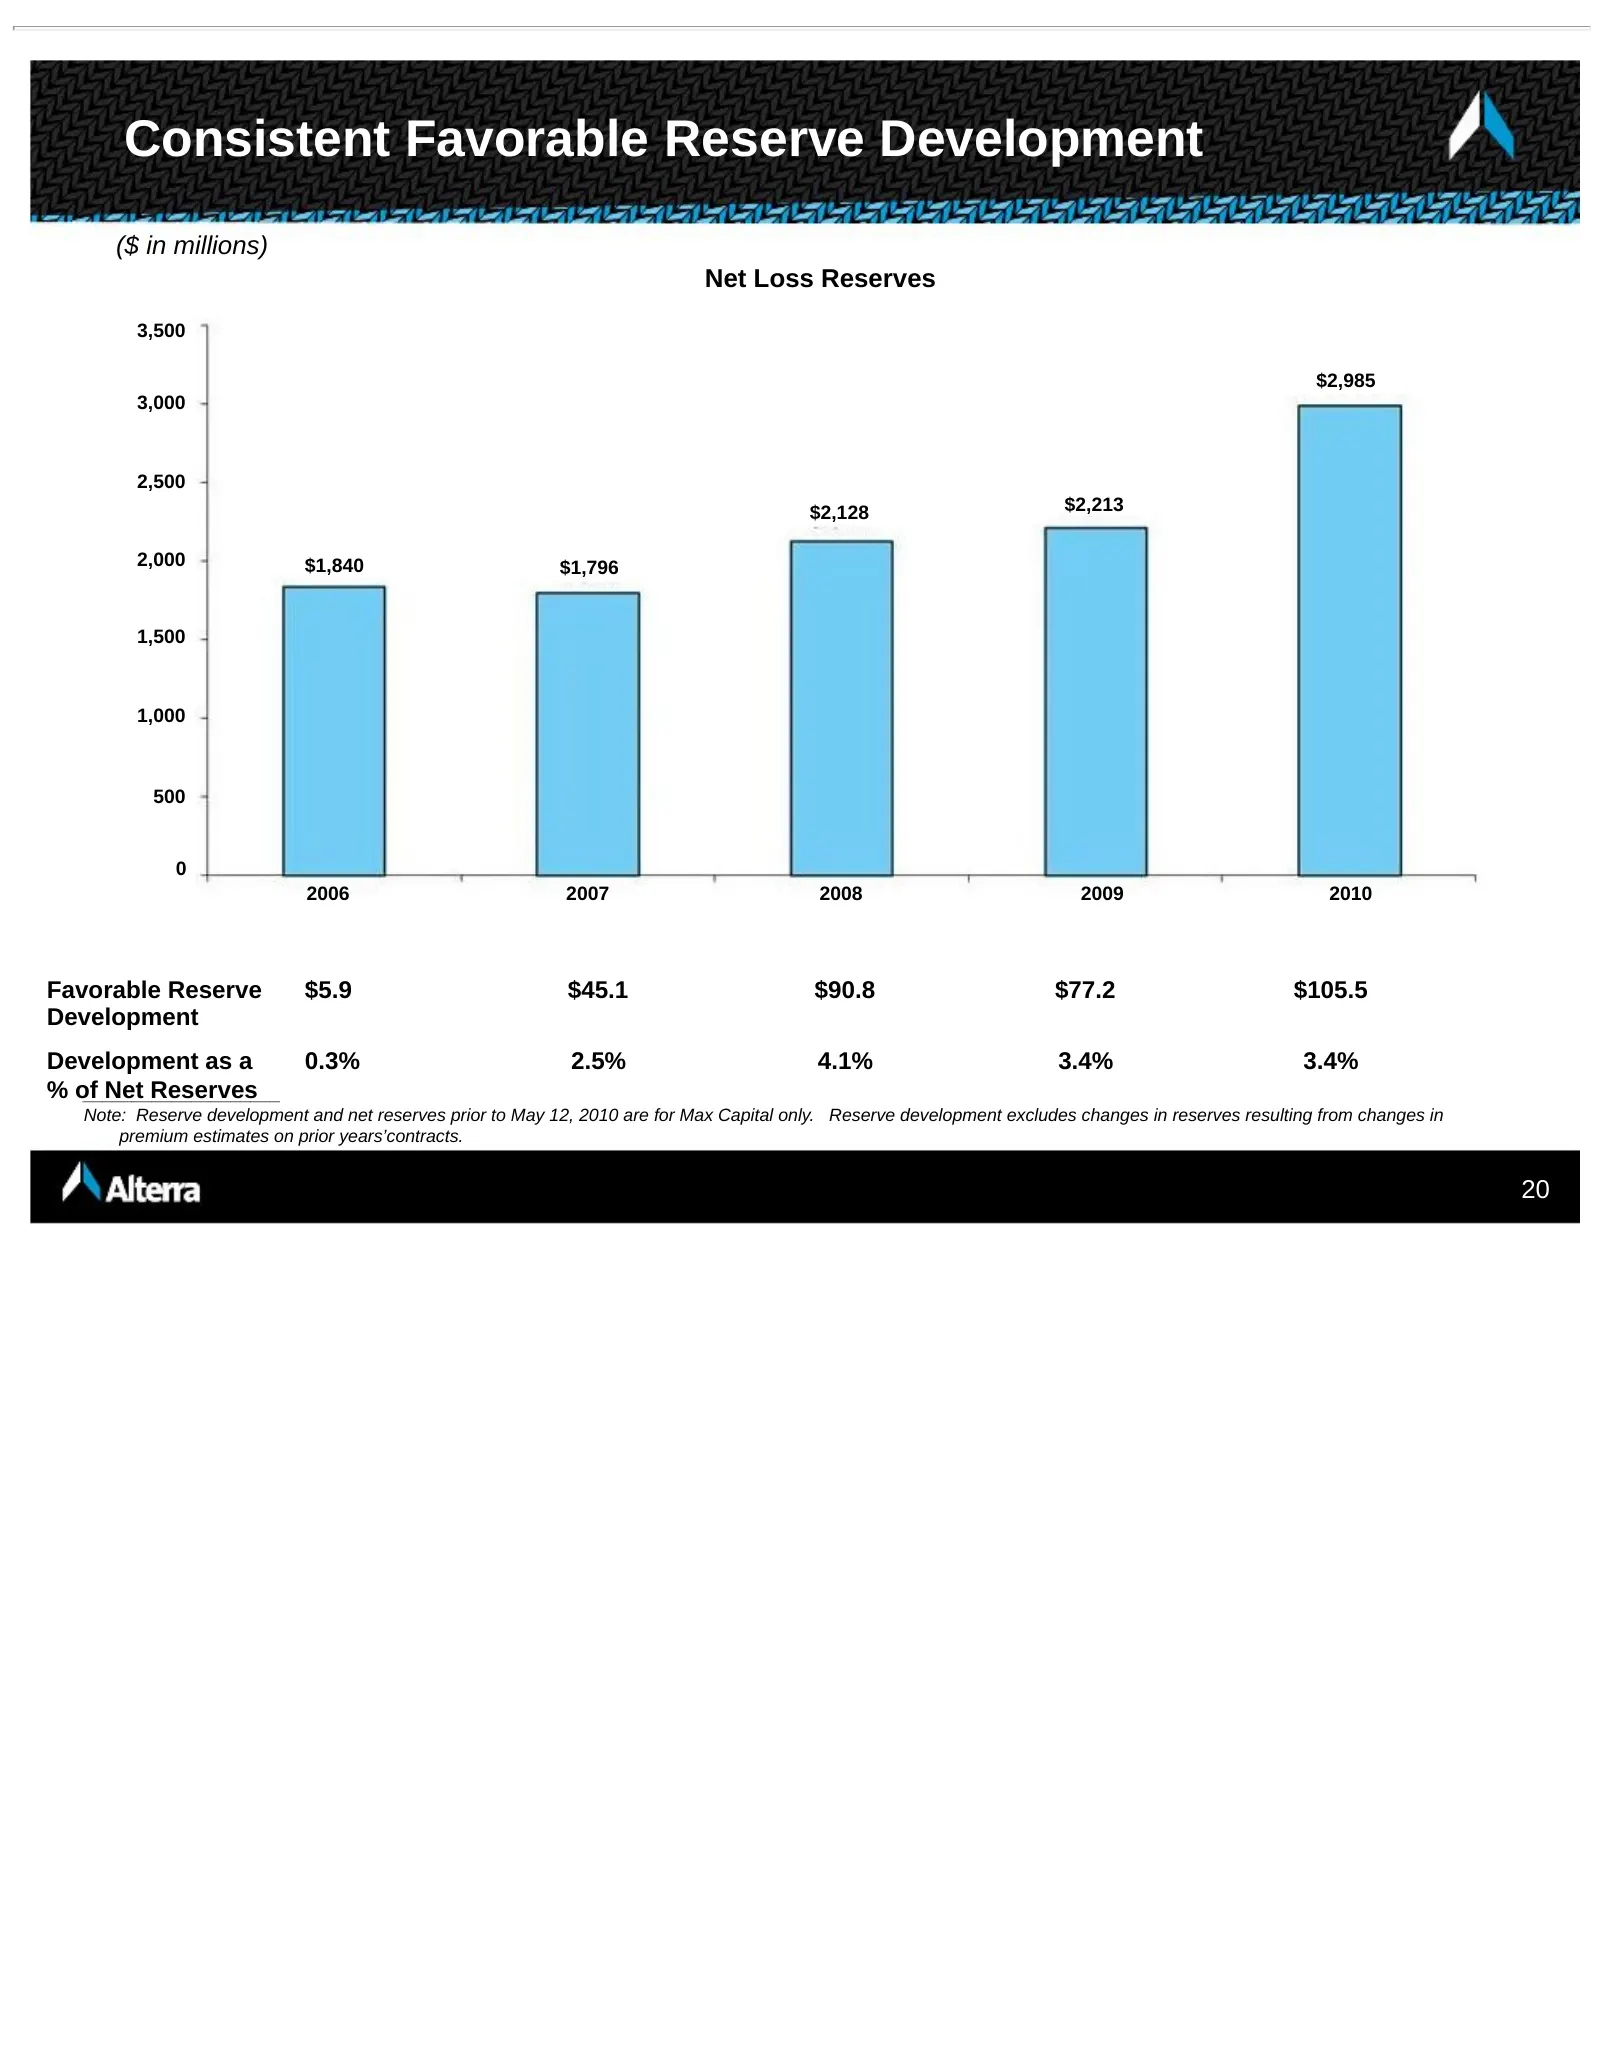
Consistent Favorable Reserve Development ($ in millions) Net Loss Reserves 3,500 $2,985 3,000 2,500 $2,128 $2,213 2,000 $1,840 $1,796 1,500 1,000 500 0 2006 2007 2008 2009 2010 Favorable Reserve $5.9 $45.1 $90.8 $77.2 $105.5 Development Development as a 0.3% 2.5% 4.1% 3.4% 3.4% % of Net Reserves ___
Slide 21: High Quality, Liquid Investment Portfolio
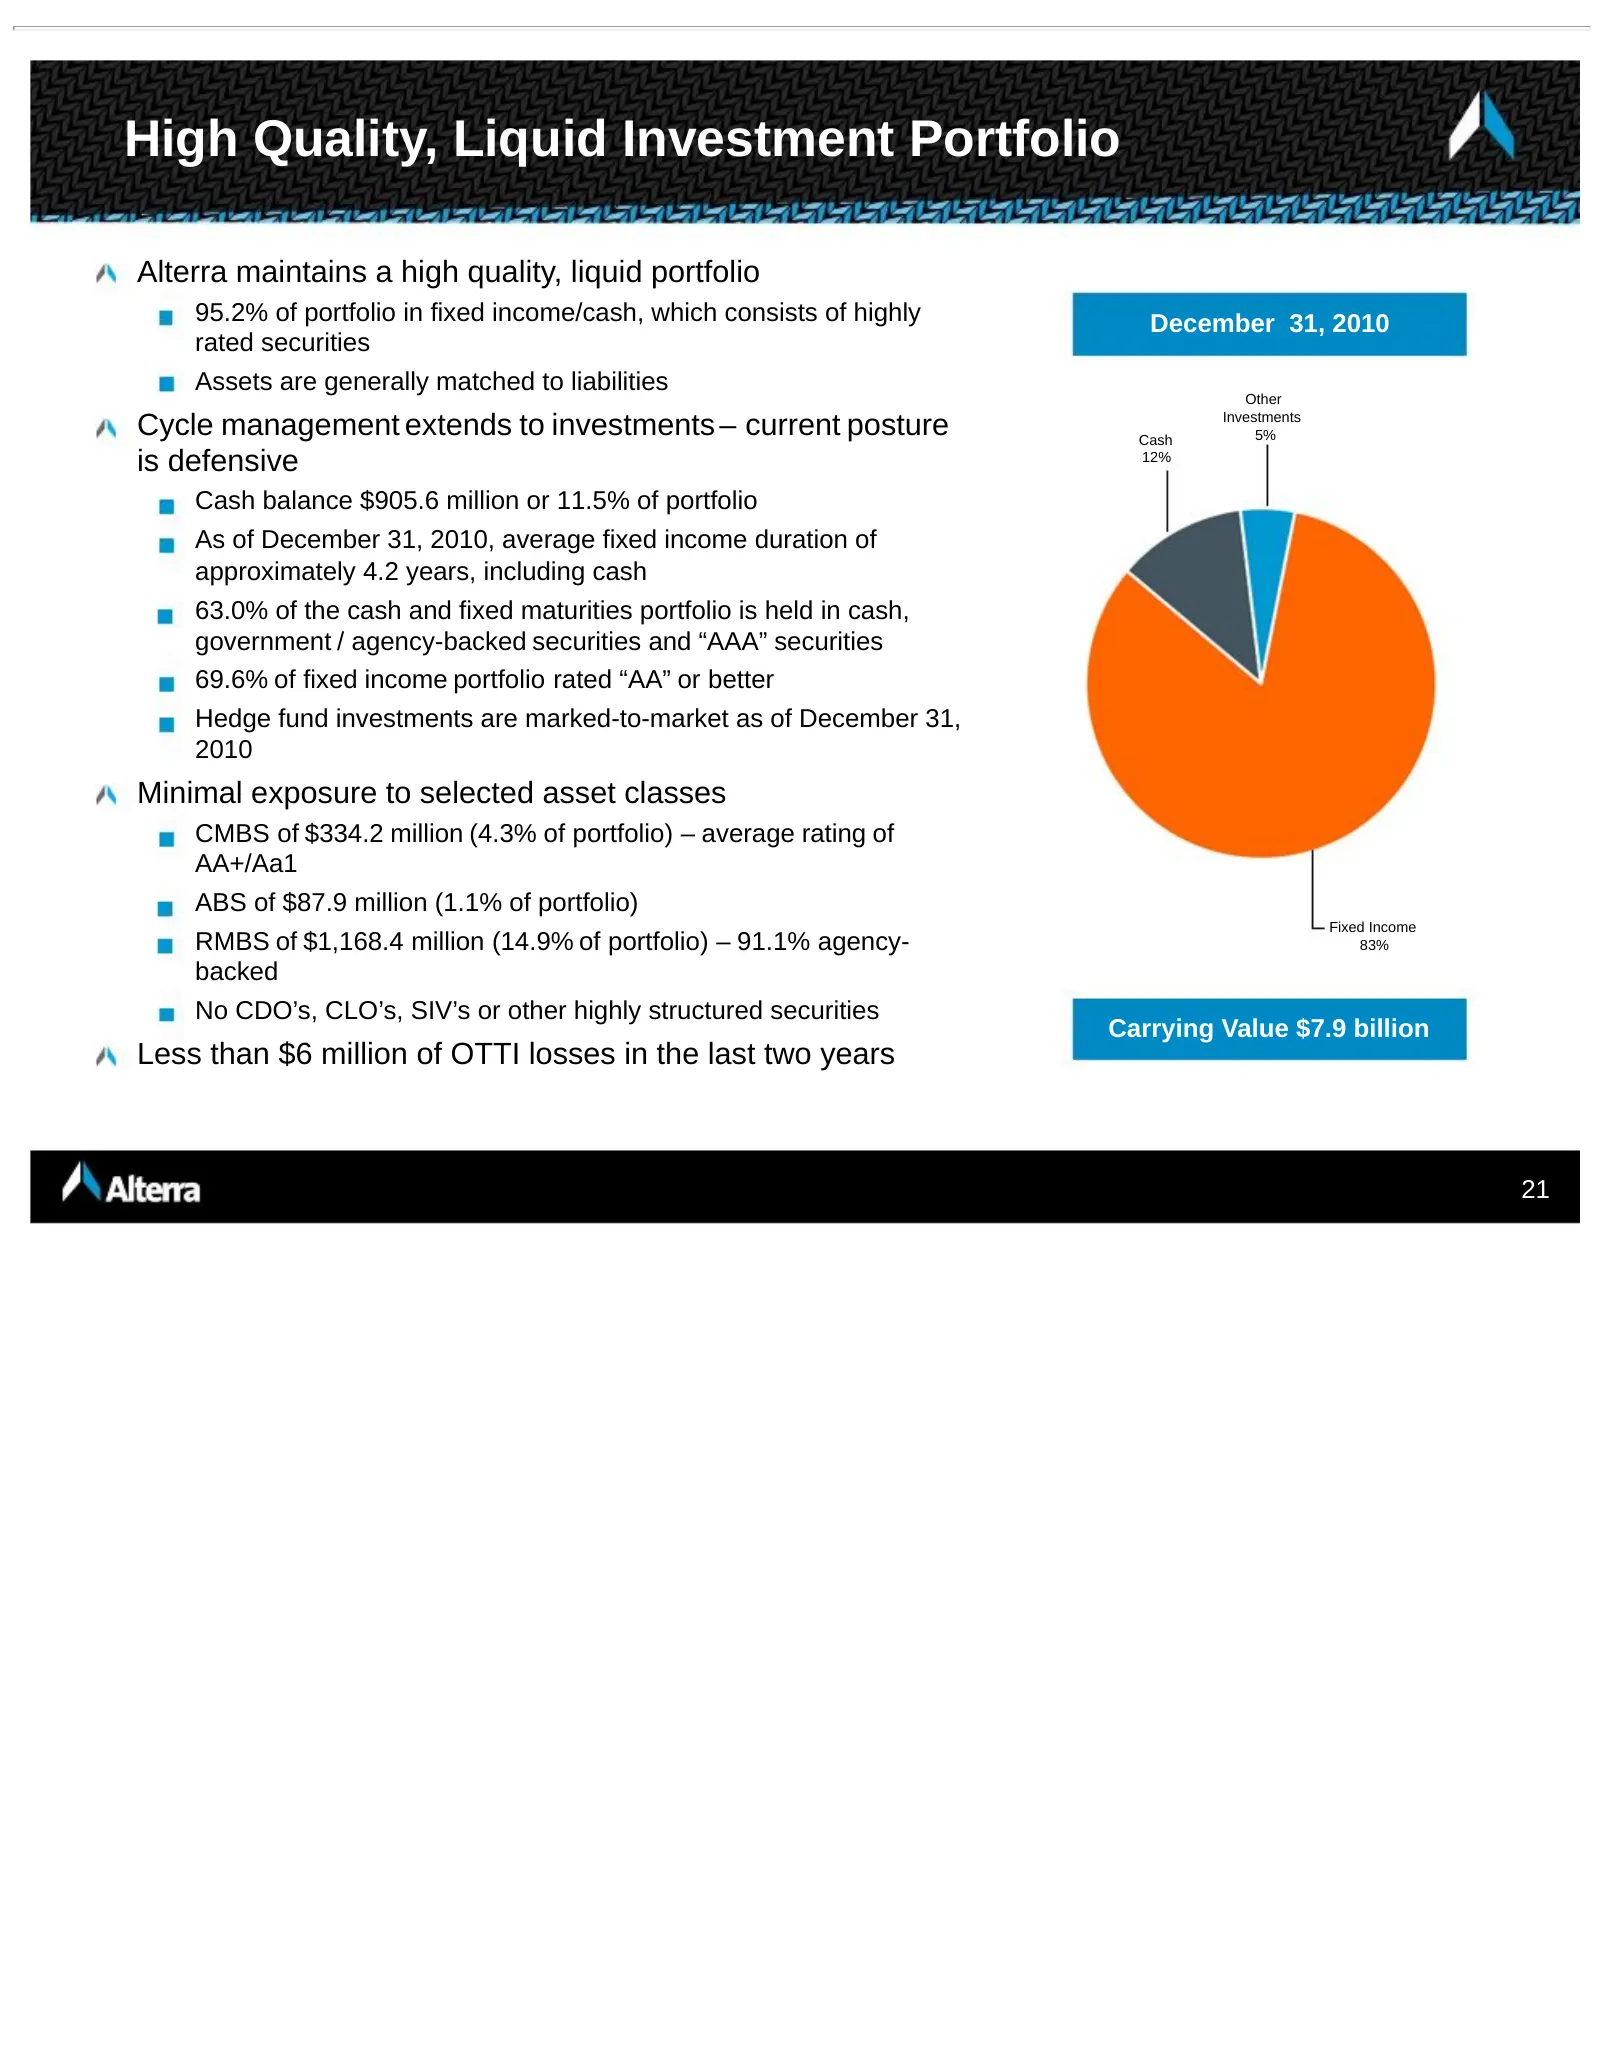
High Quality, Liquid Investment Portfolio Alterra maintains a high quality, liquid portfolio 95.2% of portfolio in fixed income/cash, which consists of highly December 31, 2010 rated securities Assets are generally matched to liabilities Other Cycle management extends to investments – current postur
Slide 22: 2011 Plan
2011 Plan Focus on growing book value per share Opportunistically allocate capital across segments Emphasize shorter-tail lines more than longer-tail New initiatives will be weighted more towards specialty lines Capital management through share repurchases and regular dividends Protect our strong, c
Slide 23: Strongly Positioned to Build Shareholder Value
Strongly Positioned to Build Shareholder Value Franchise positions in attractive specialty markets Well established operating platforms provide global access to business Diversified business portfolio across casualty and property lines Opportunistic approach – nimble and responsive to market trends
Slide 24: Appendices
Appendices A\ Alterra
Slide 25: Strong Balance Sheet
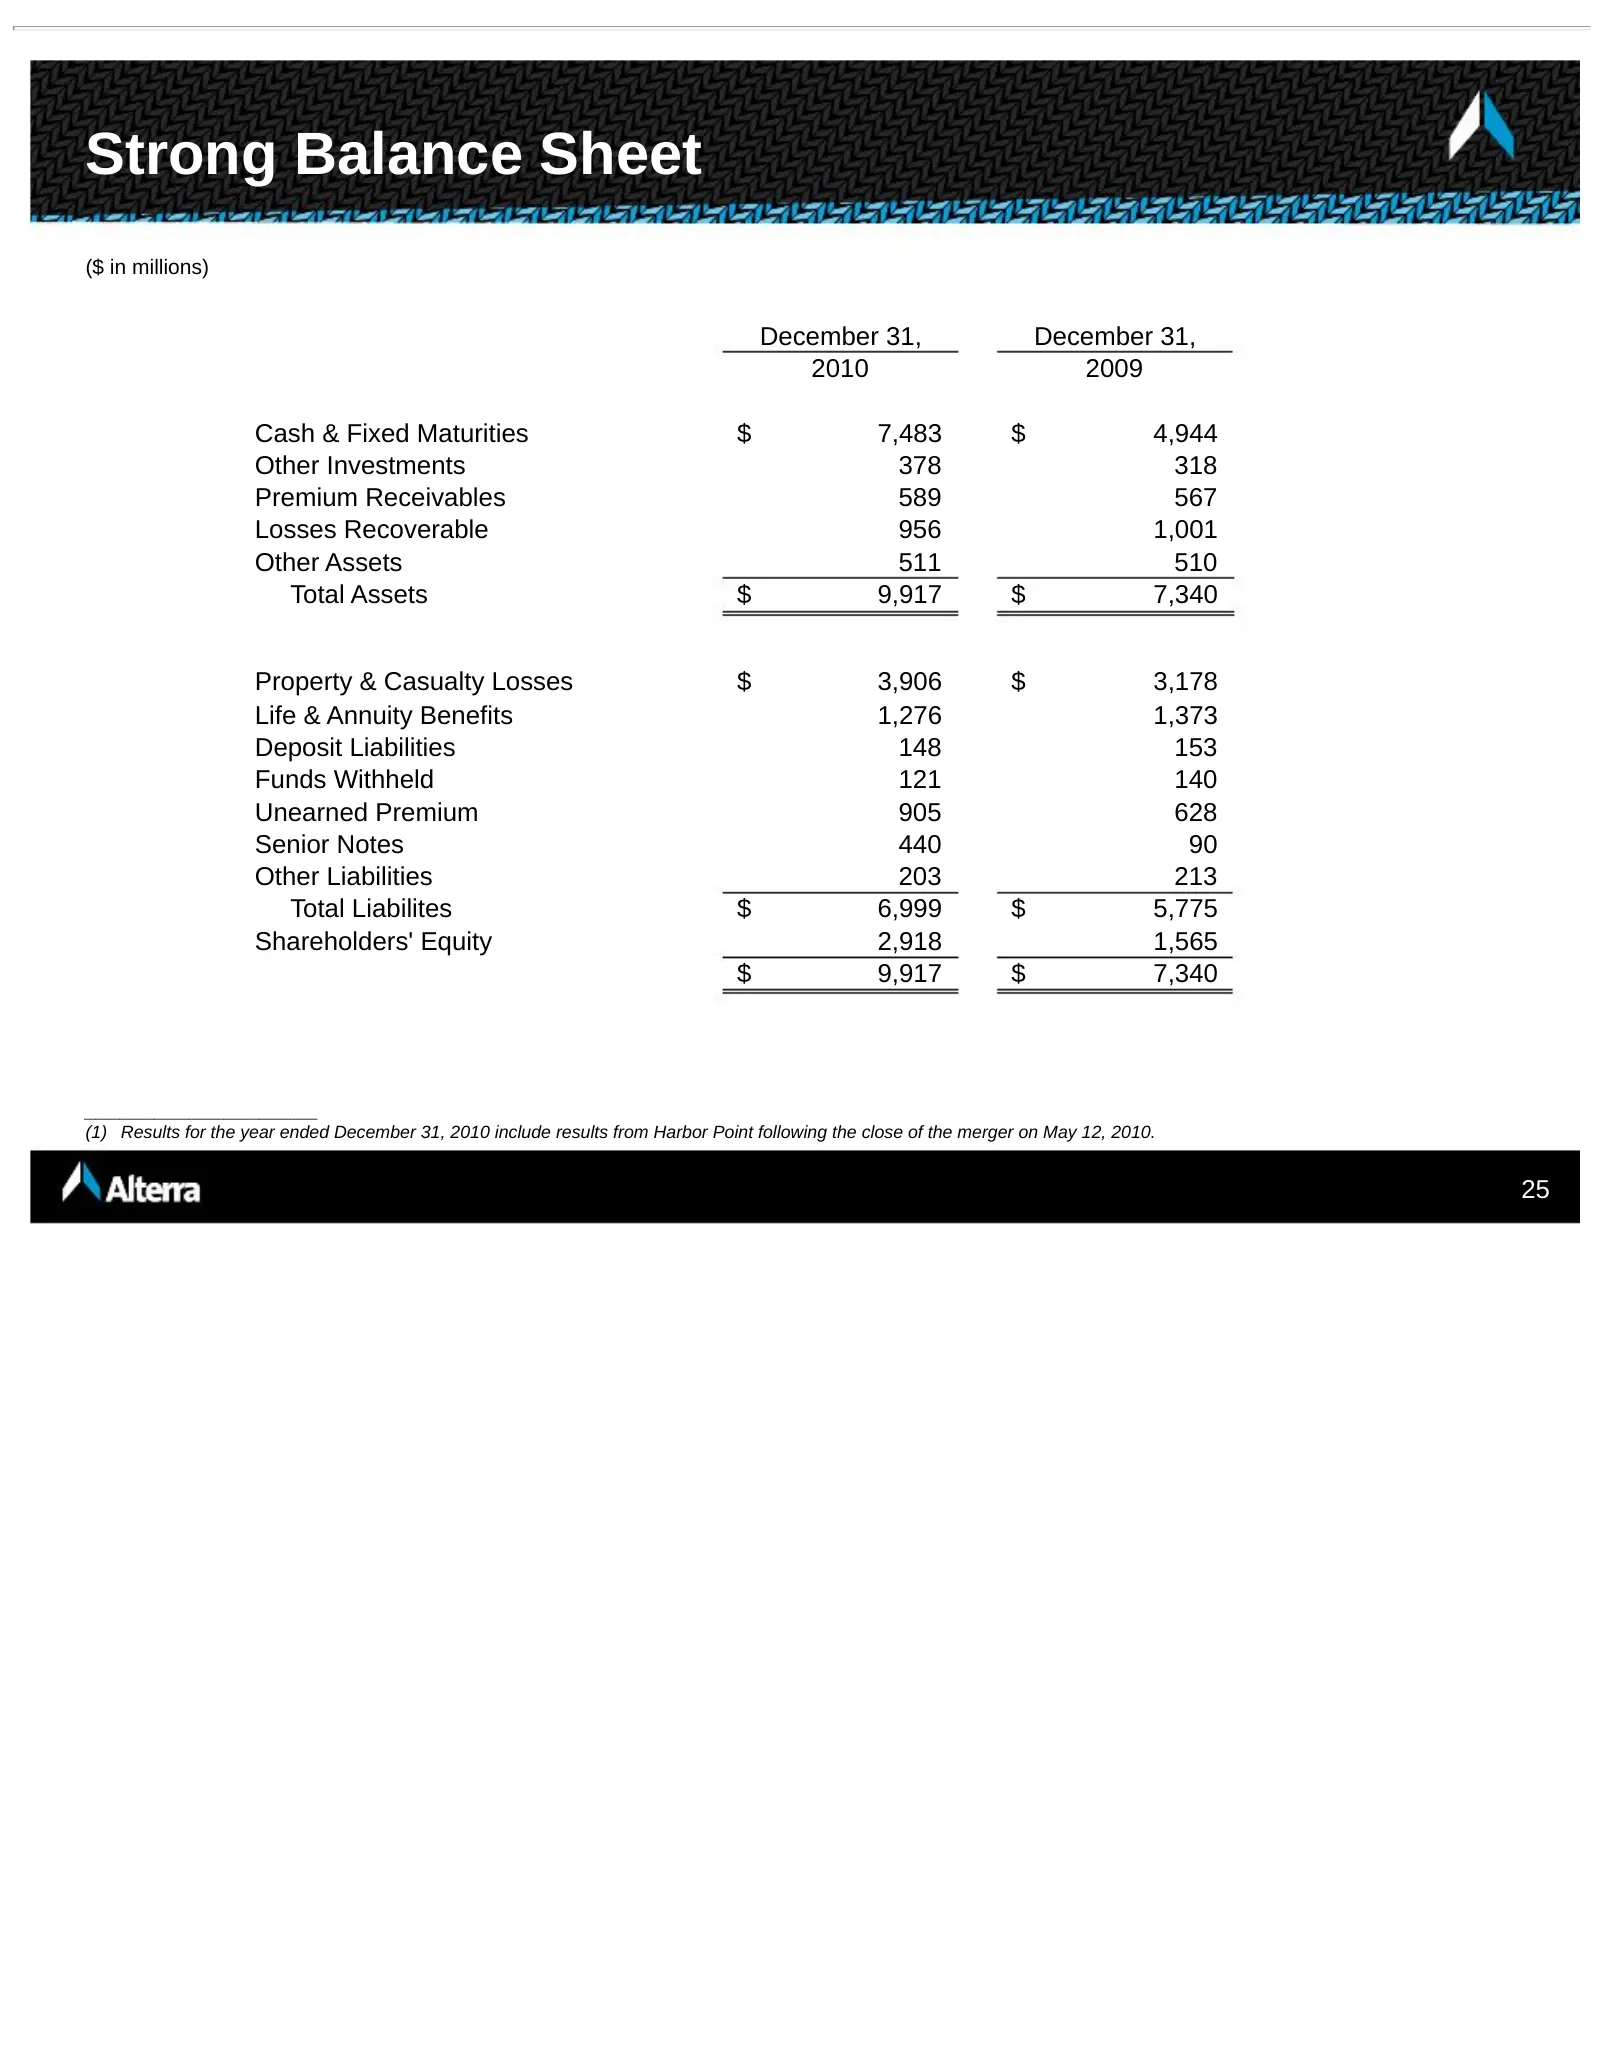
Strong Balance Sheet ($ in millions) December 31, December 31, 2010 2009 Cash & Fixed Maturities $ 7,483 $ 4,944 Other Investments 378 318 Premium Receivables 589 567 Losses Recoverable 956 1,001 Other Assets 511 510 Total Assets $ 9,917 $ 7,340 Property & Casualty Losses $ 3,906 $ 3,178 Life & Annu
Slide 26: YTD Results Comparison
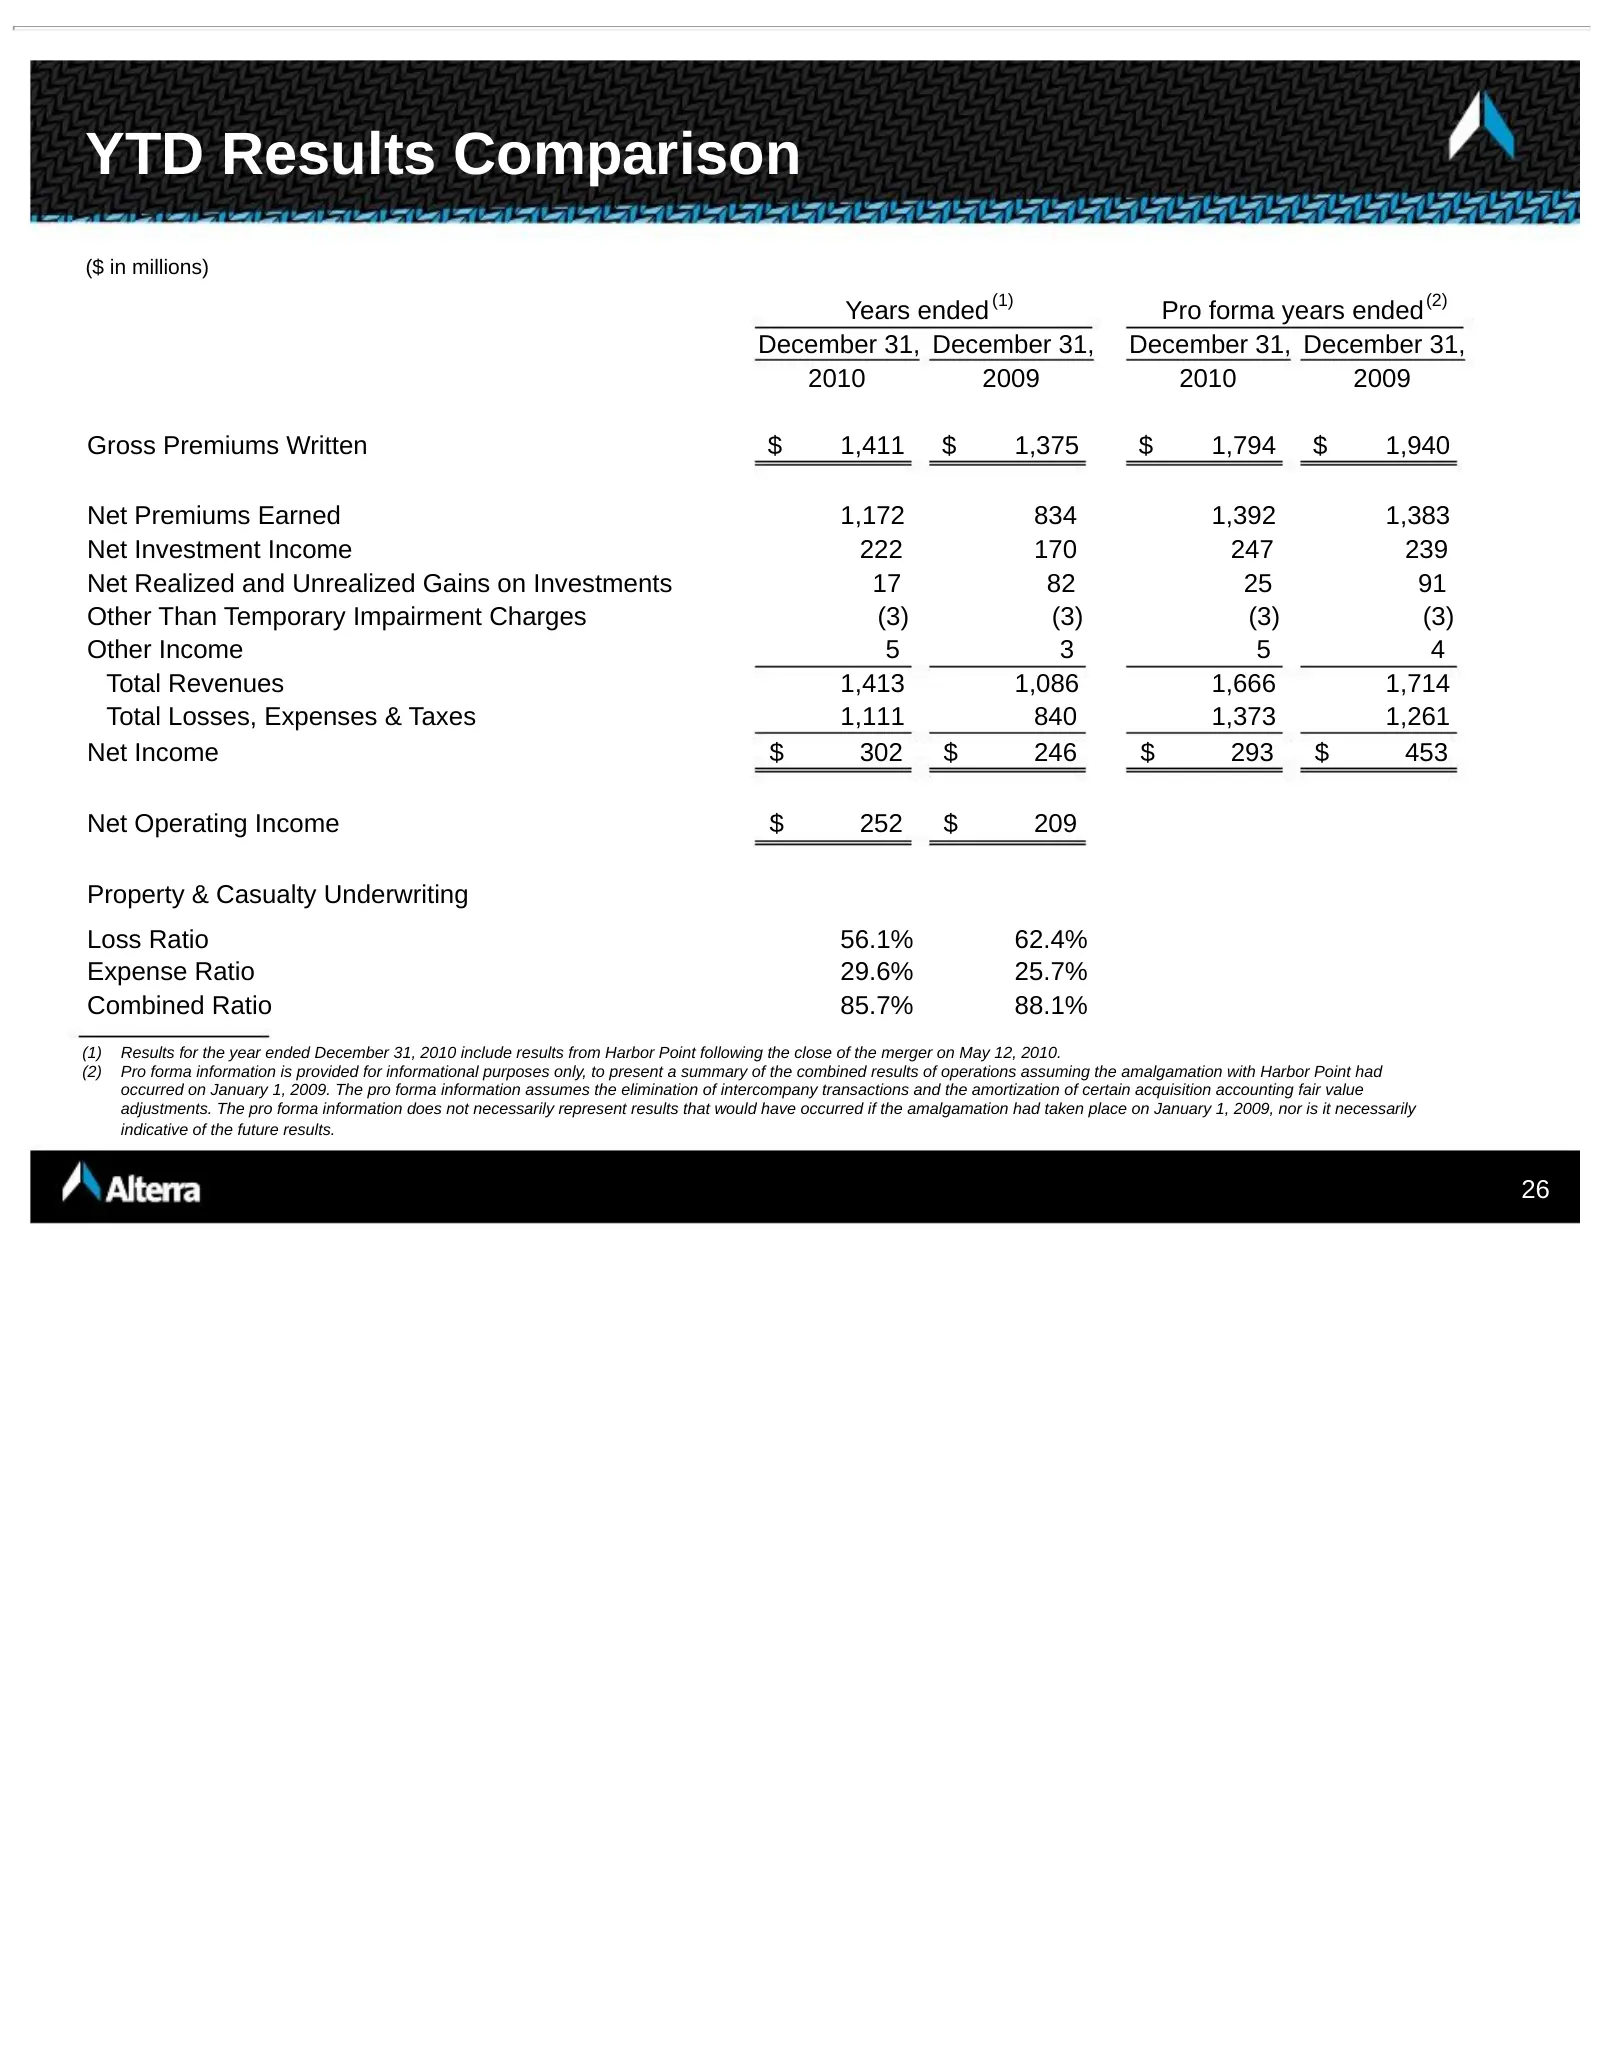
YTD Results Comparison ($ in millions) Years ended (1) Pro forma years ended (2) December 31, December 31, December 31, December 31, 2010 2009 2010 2009 Gross Premiums Written $ 1,411 $ 1,375 $ 1,794 $ 1,940 Net Premiums Earned 1,172 834 1,392 1,383 Net Investment Income 222 170 247 239 Net Realized
Slide 27: Diversified Operating Platform
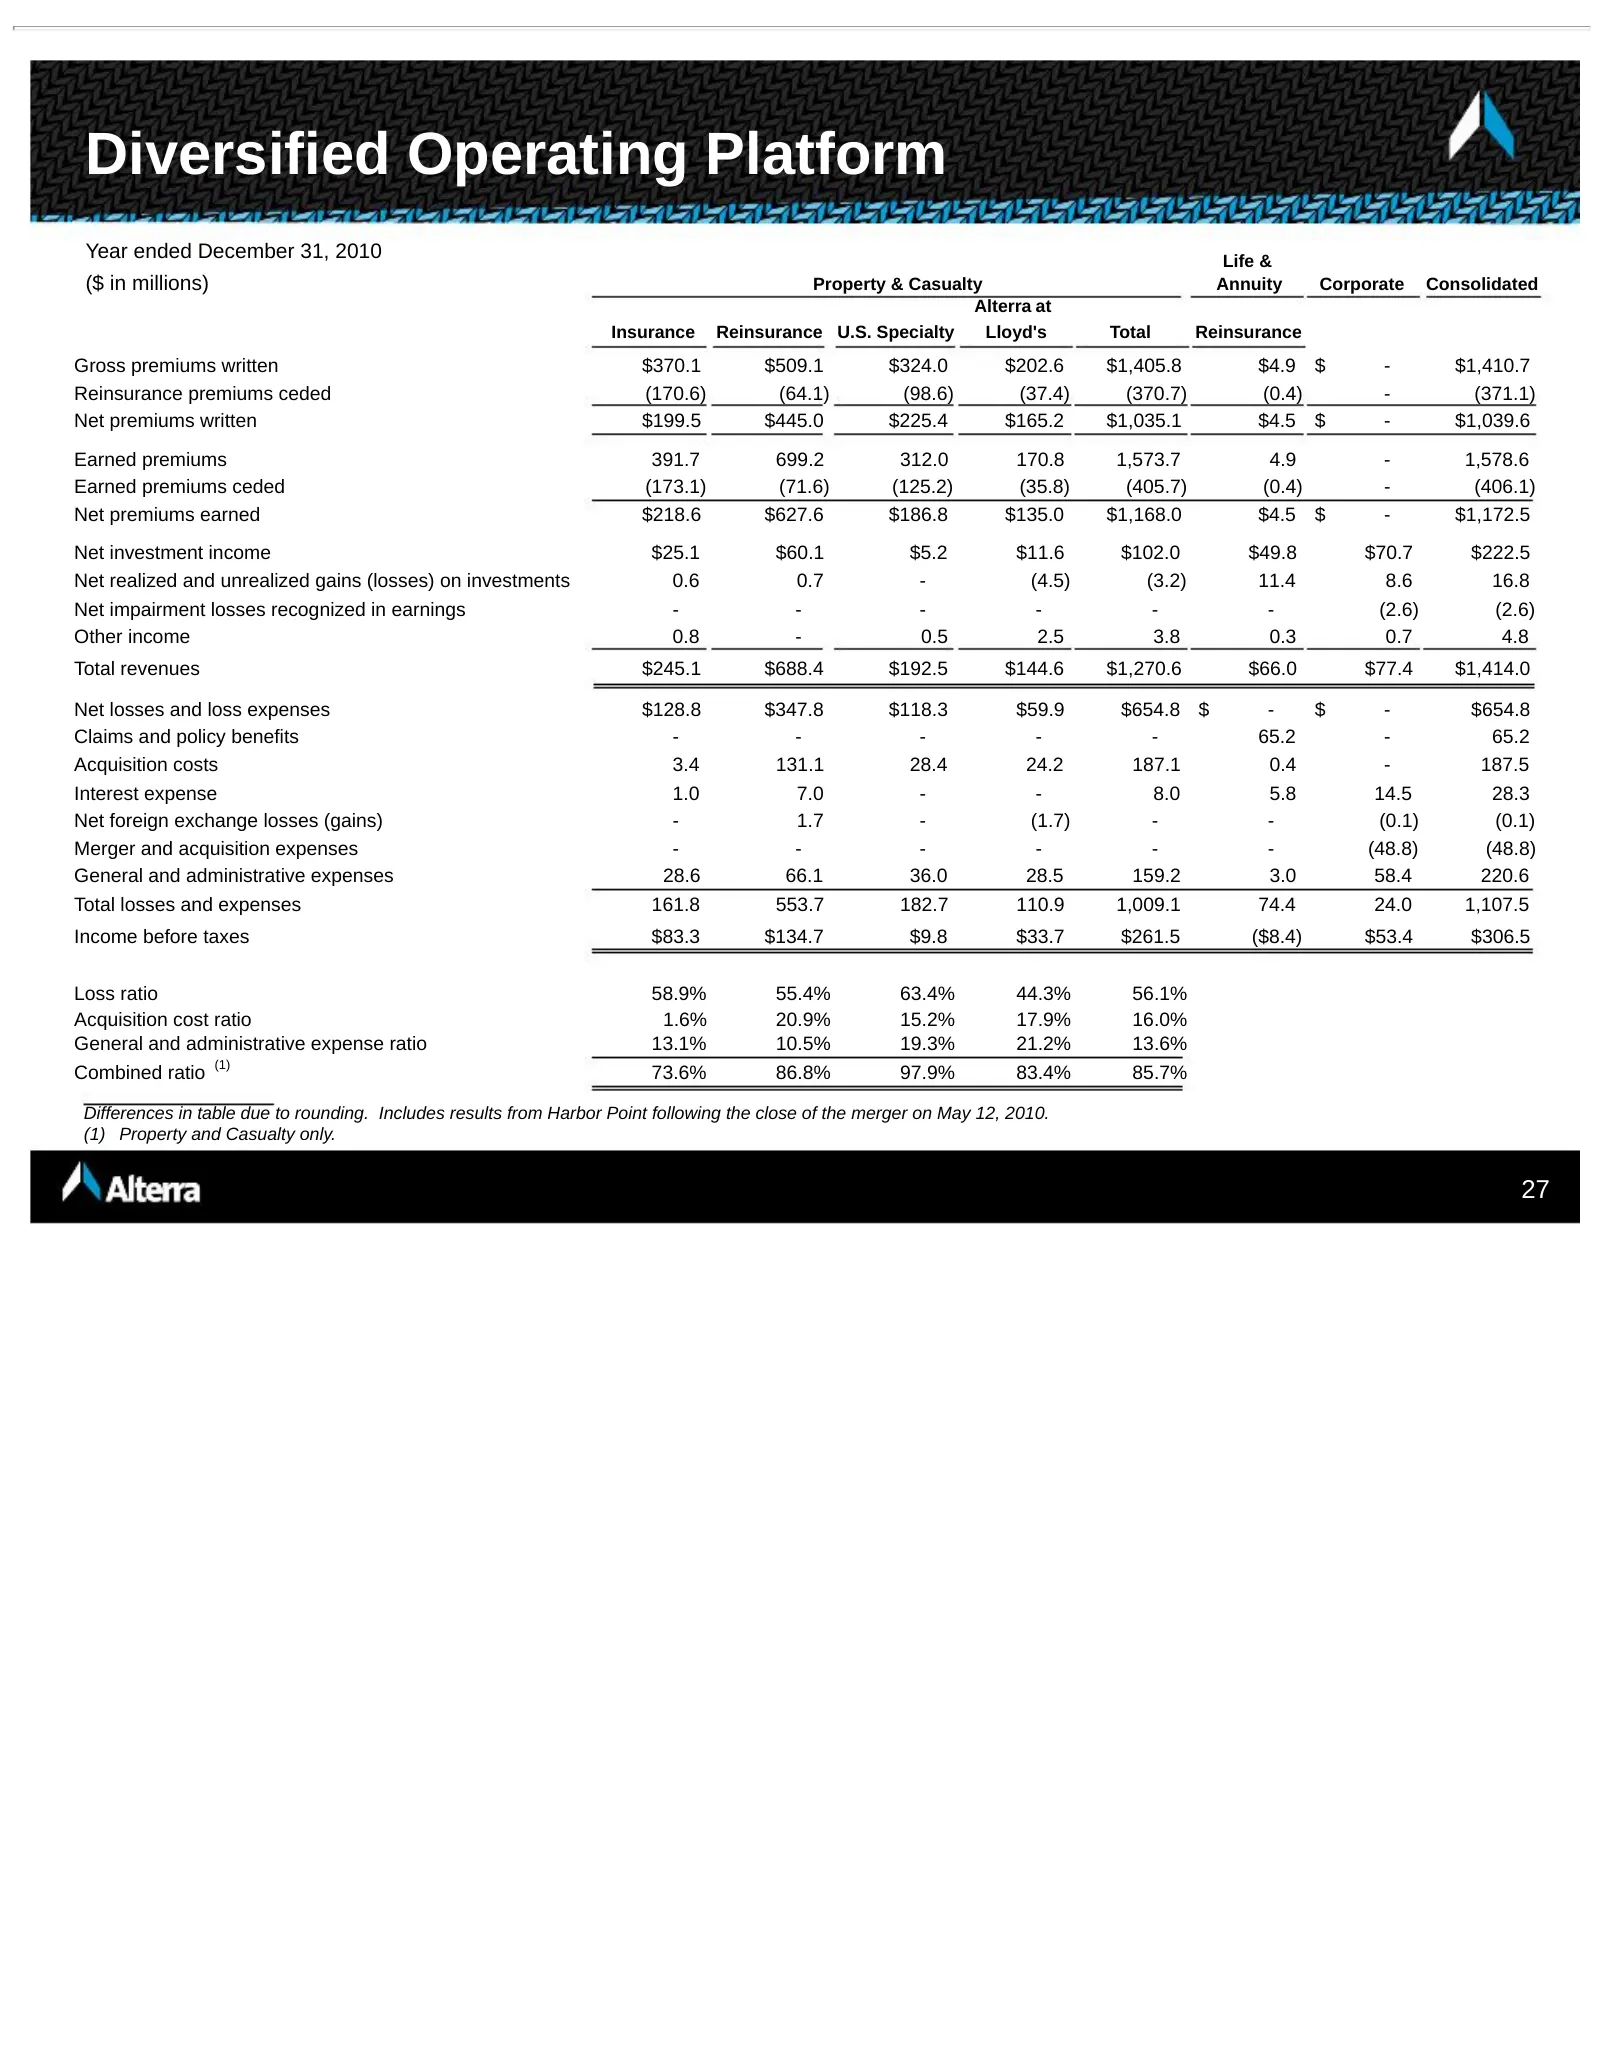
Diversified Operating Platform Year ended December 31, 2010 Life & ($ in millions) Property & Casualty Annuity Corporate Consolidated Alterra at Insurance Reinsurance U.S. Specialty Lloyd's Total Reinsurance Gross premiums written $370.1 $509.1 $324.0 $202.6 $1,405.8 $4.9 $ - $1,410.7 Reinsurance pr
Source: SEC EDGAR · 8-K filed Feb 14, 2011
More decks from ALTERRA CAPITAL HOLDINGS Ltd
 Merger or Acquisition (December 2012)16 slides · Dec 19, 2012
 Investor Presentation (November 2012)32 slides · Nov 29, 2012
 Investor Presentation (September 2012)12 slides · Sep 12, 2012
 Investor Presentation (August 2012)33 slides · Aug 29, 2012
 Q1 2012 Earnings Presentation32 slides · May 25, 2012
 Q1 2012 Earnings Presentation28 slides · May 11, 2012