TD Banknorth Inc.
TD Banknorth — Investor Day (June 2007)
36 slides from TD Banknorth's investor day presentation, Jun 28, 2007
Slide 1: Investor Day
Investor Day June 28, 2007 Investor Day Tim Thompson Vice President, Investor Relations, TD Bank Financial Group 1
Slide 2: Forward-Looking Statements
Forward-Looking Statements From time to time, the Bank makes written and oral forward-looking statements, including in this presentation, in filings with Canadian regulators or the U.S. Securities and Exchange Commission (SEC), and in other communications. All such statements are made pursuant to th
Slide 3: Key Takeaways: Making it Happen at TD Banknorth
Key Takeaways 1. We are taking action now 2. A strong team of operators 3. Confident - we will deliver 5 Making it Happen at TD Banknorth Bharat Masrani President and CEO 3
Slide 4: Key Takeaways and Issues on Investors' Minds
Key Takeaways 1. Re-oriented focus to organic growth 2. Experienced and committed team 3. Goal: grow earnings by 7 – 10% 4. Confident of success: making good progress 7 Issues on Investor’s Minds 1. What are the current and planned initiatives to successfully transform TD Banknorth from a M&A machin
Slide 5: Building a Better Bank
Building a Better Bank Reoriented TD Banknorth’s focus from M&A to organic growth Identified significant opportunities to grow market share over the next 5 years Building Taken decisive steps to reduce operating a expenses. Reinvesting savings in Better revenue-generating initiatives Bank Us
Slide 6: Adapting to U.S. Banking Environment
Adapting to U.S. Banking Environment Despite challenging banking environment, significant growth opportunities exist Competition for loans and deposits remains intense Yield curve expected to stay flat Experienced some weakness in asset quality, particularly for sale real estate. Monitoring
Slide 7: Today's Presenters
Today’s Presenters Tom Dyck Head of Marketing and Product Management Suzanne Poole Head of Retail Distribution John Fridlington Head of Commercial Banking Wendy Suehrstedt Head of Business Banking Solutions Steve Boyle Chief Financial Officer 13 Key Takeaways 1. Re-oriented focus to organic growth 2
Slide 8: Retail Distribution and Product Management
Retail Distribution and Product Management Tom Dyck EVP, Marketing and Retail Product Management Suzanne Poole EVP, Retail Distribution Key Takeaways 1. Orient the bank around the customer 2. Address process and pricing challenges 3. Build a performance culture 4. Optimize our network 16 8
Slide 9: A $6B Opportunity – Achieving our Natural Market Share
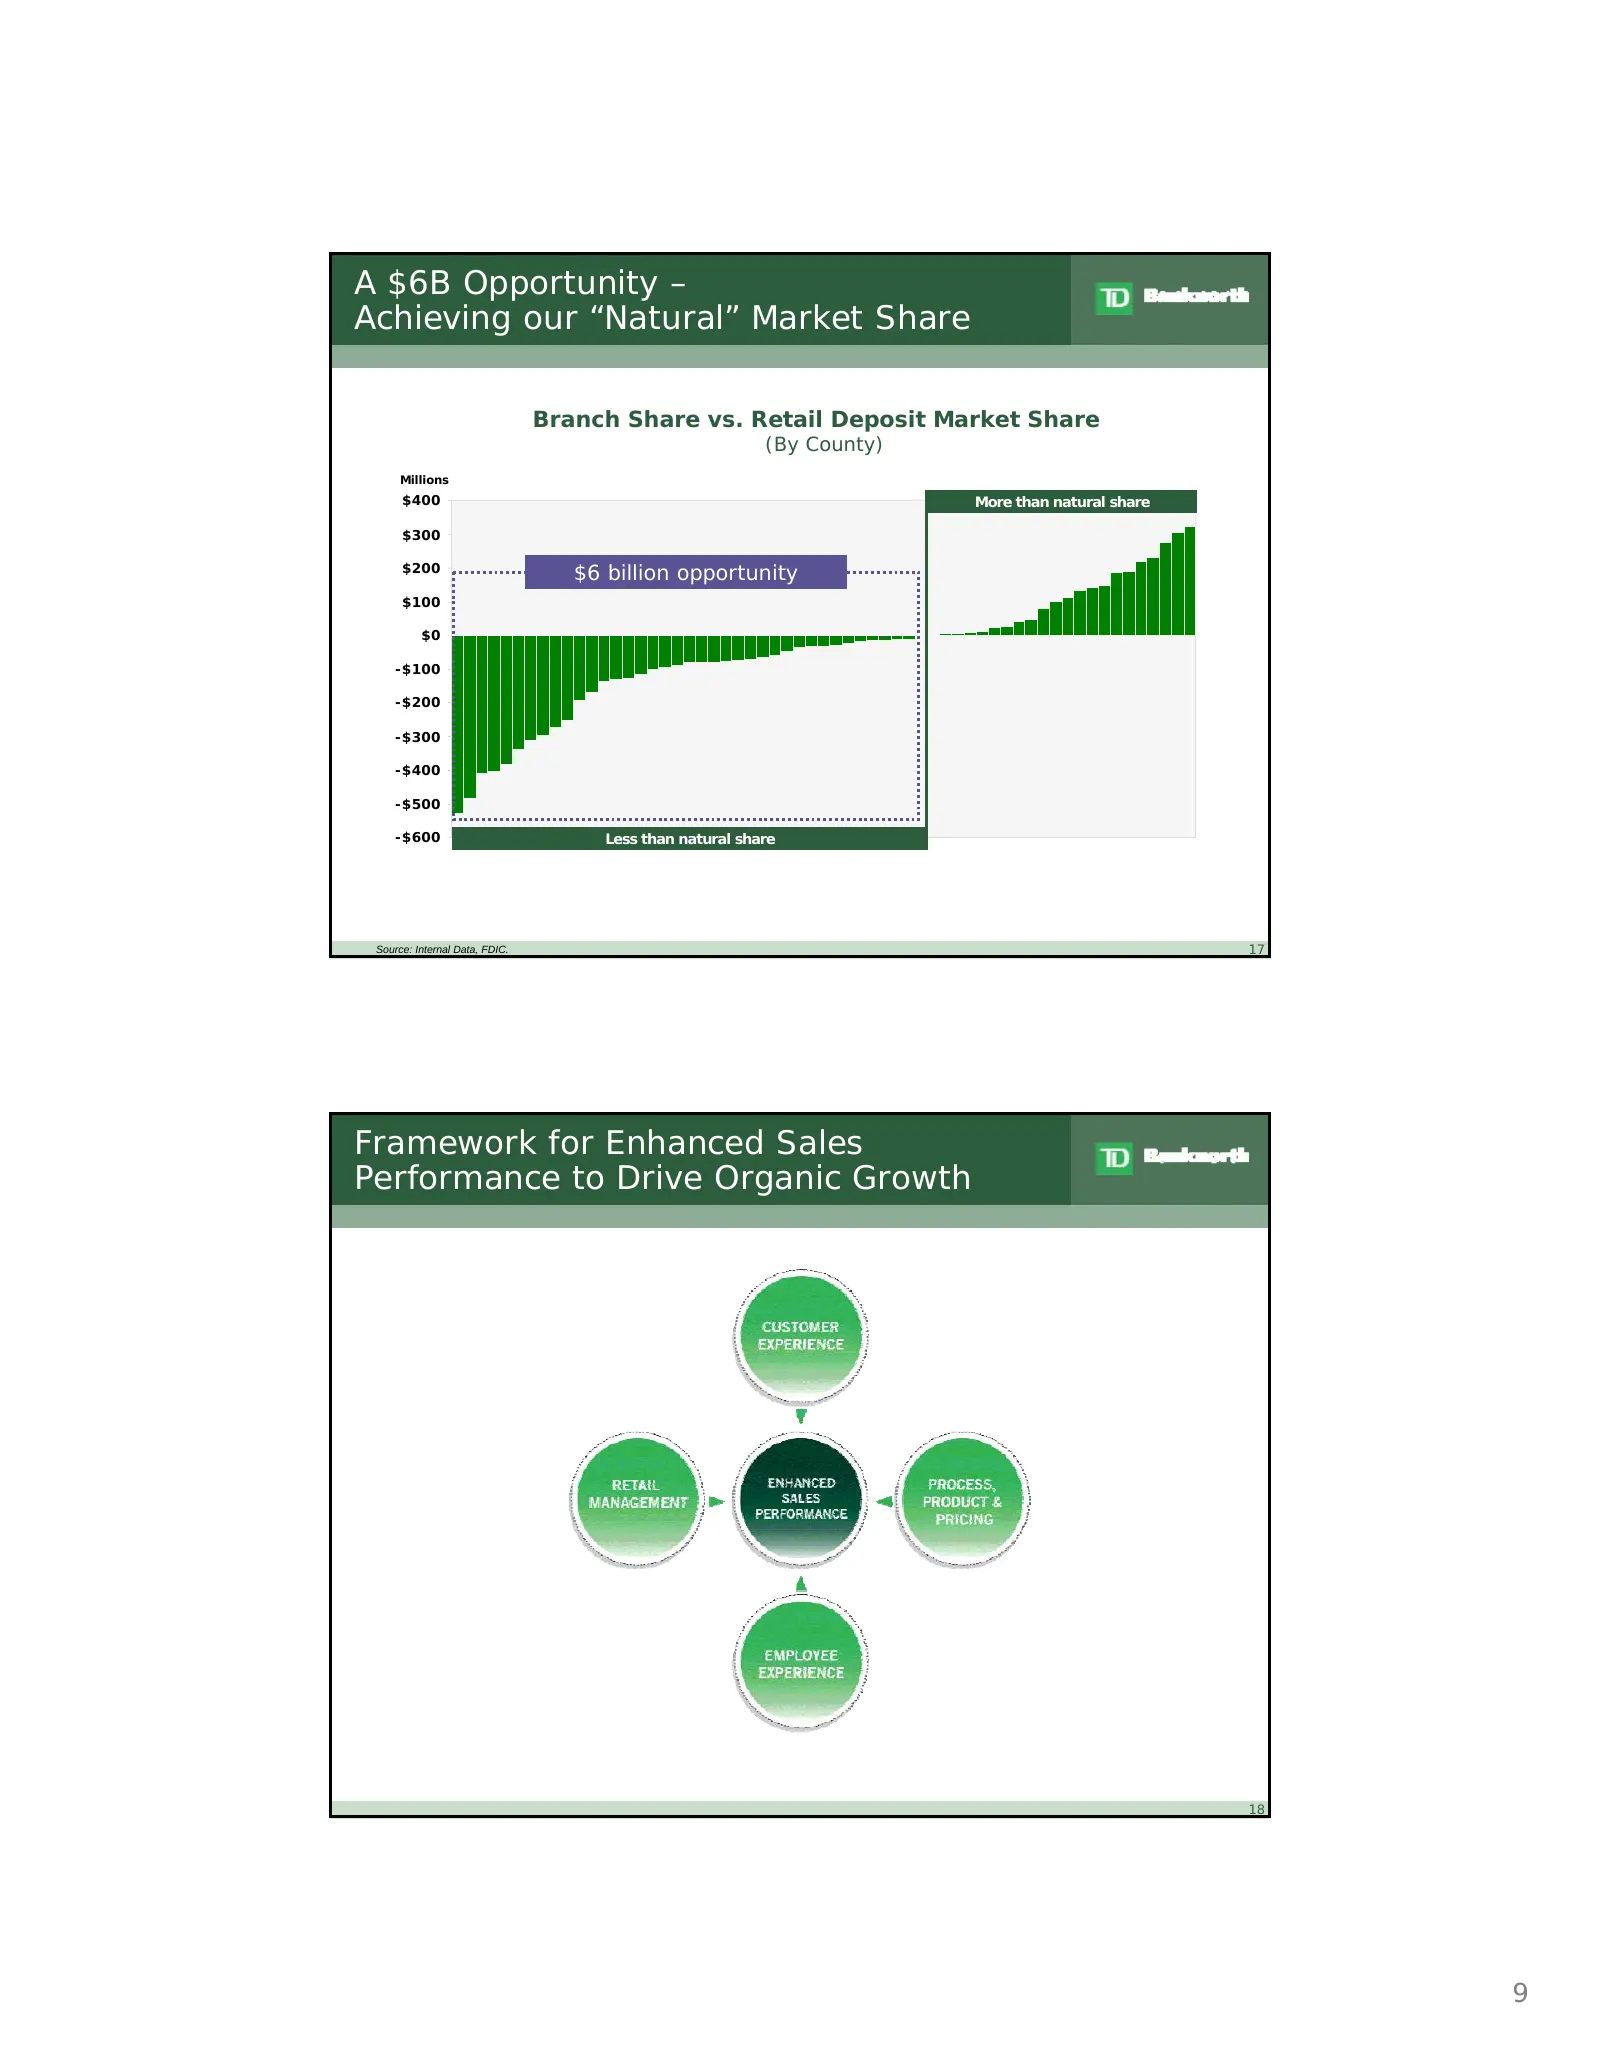
A $6B Opportunity – Achieving our “Natural” Market Share Branch Share vs. Retail Deposit Market Share (By County) Millions $400 More than natural share $300 $200 $6 billion opportunity $100 $0 -$100 -$200 -$300 -$400 -$500 -$600 Less than natural share Source: Internal Data, FDIC. 17 Framework for E
Slide 10: Our Brand Promise and Customer-Centric Focus
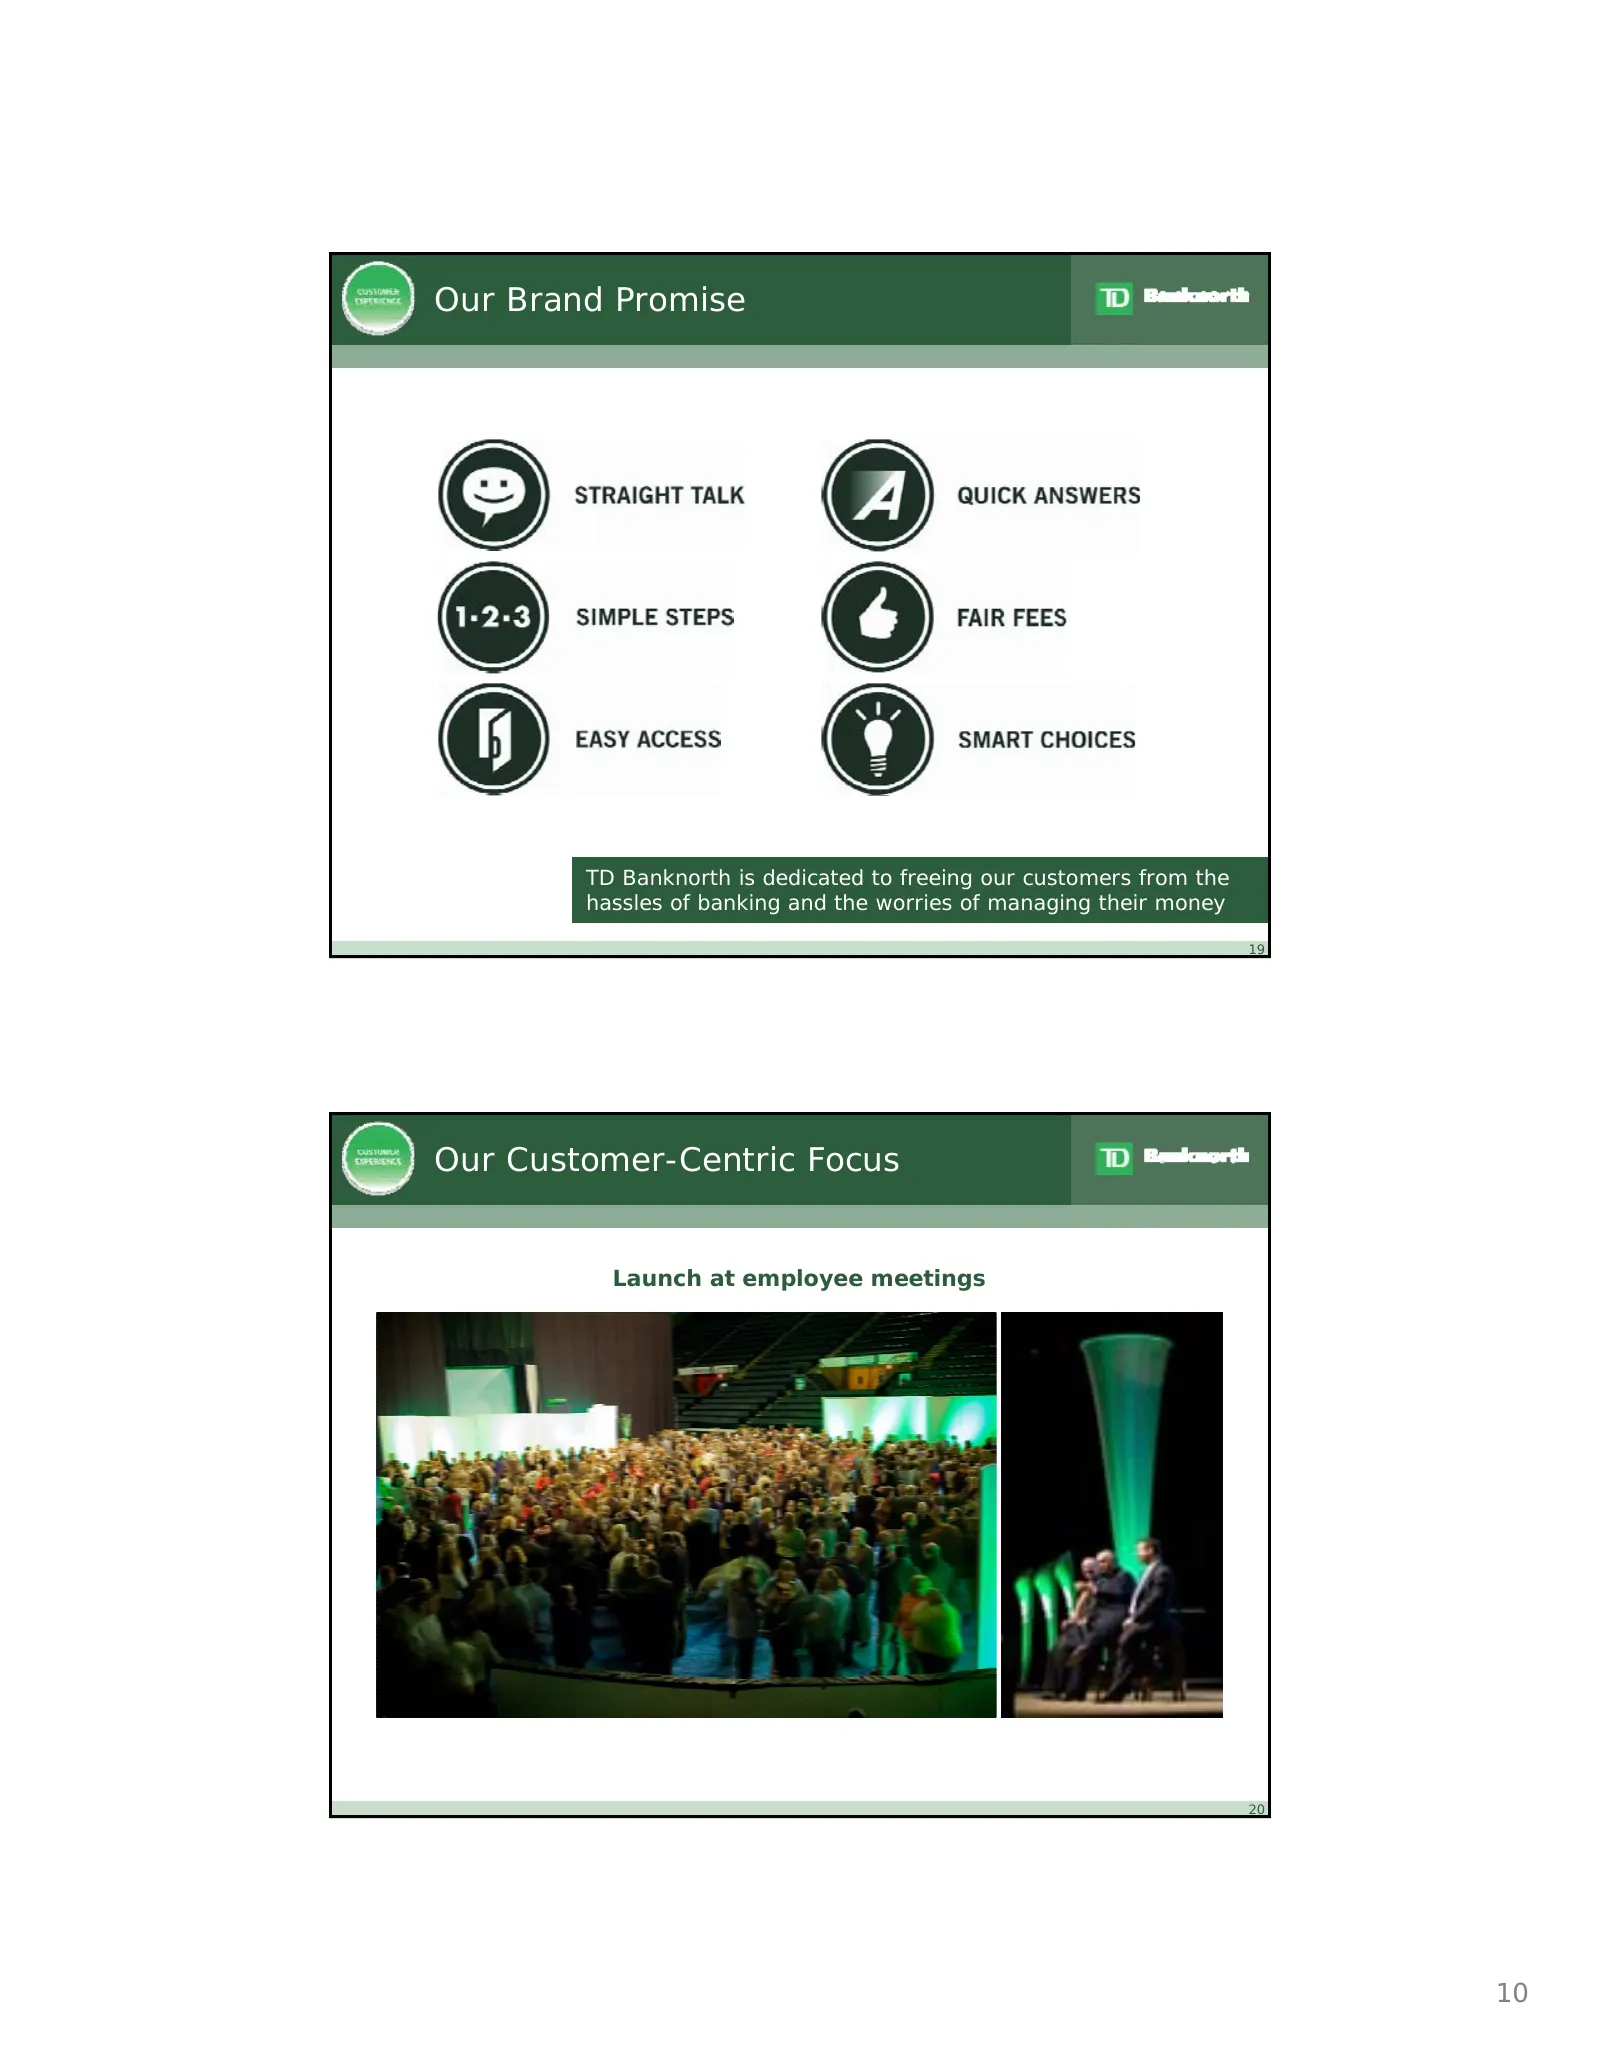
Our Brand Promise TD Banknorth is dedicated to freeing our customers from the hassles of banking and the worries of managing their money 19 Our Customer-Centric Focus Launch at employee meetings 20 10
Slide 11: Bringing Our Brand to Life
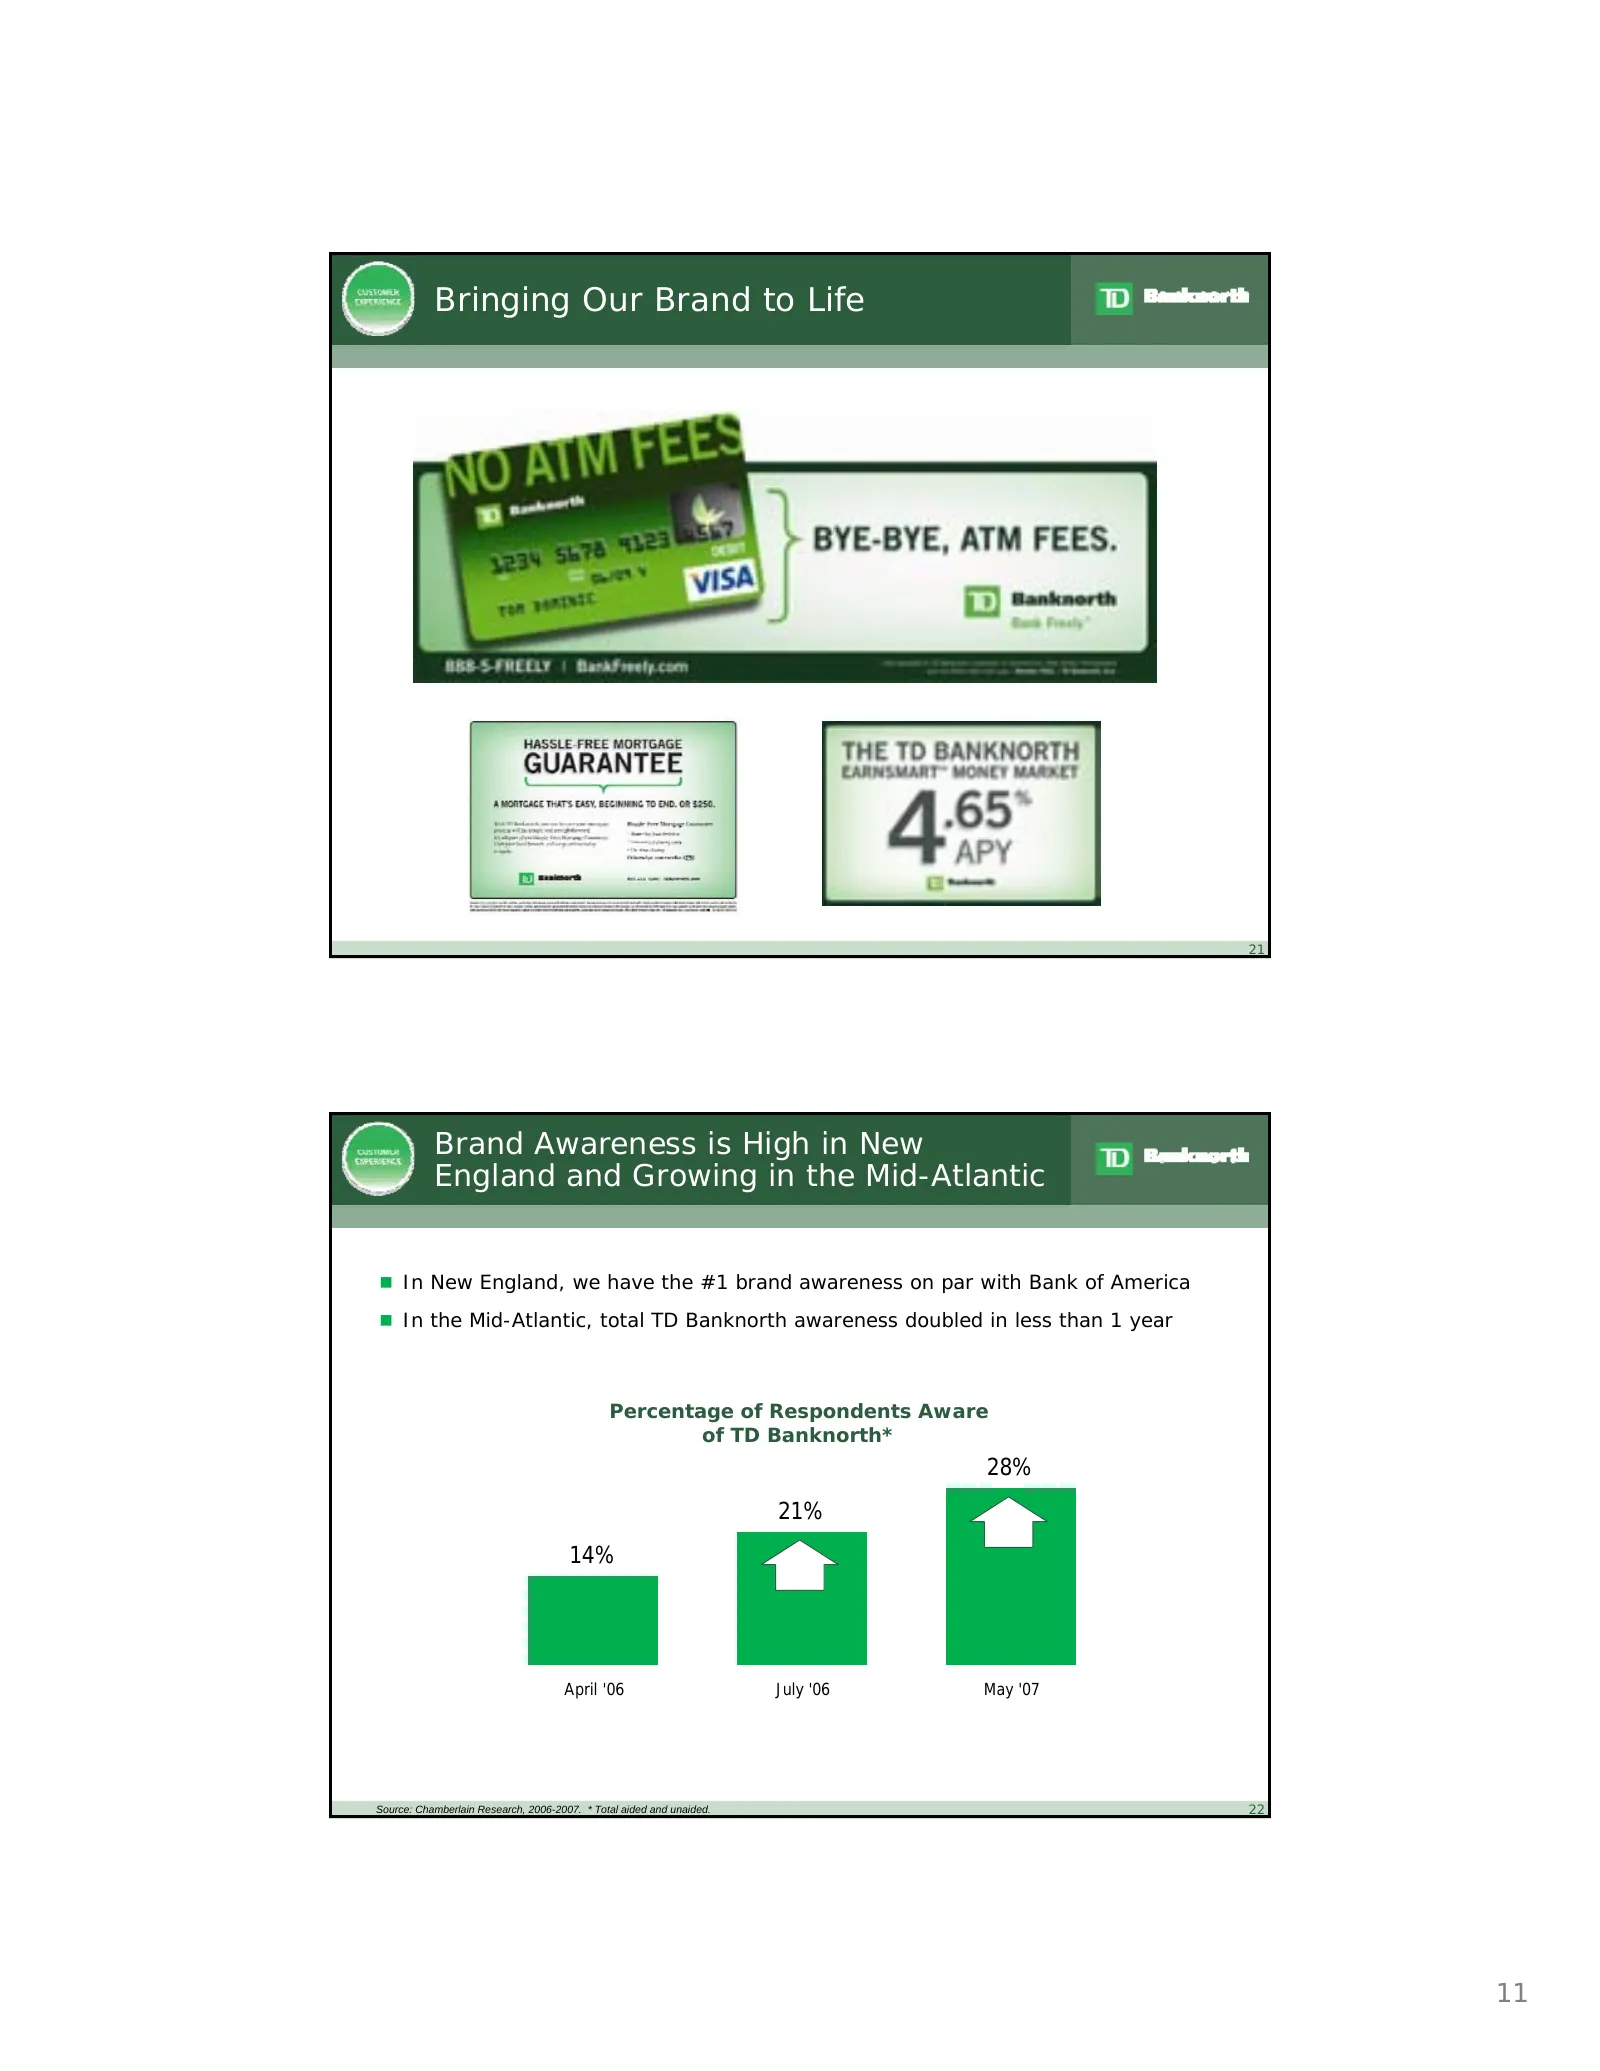
Bringing Our Brand to Life 21 Brand Awareness is High in New England and Growing in the Mid-Atlantic In New England, we have the #1 brand awareness on par with Bank of America In the Mid-Atlantic, total TD Banknorth awareness doubled in less than 1 year Percentage of Respondents Aware of TD Bank
Slide 12: Gains are Being Made on Service and Advocacy
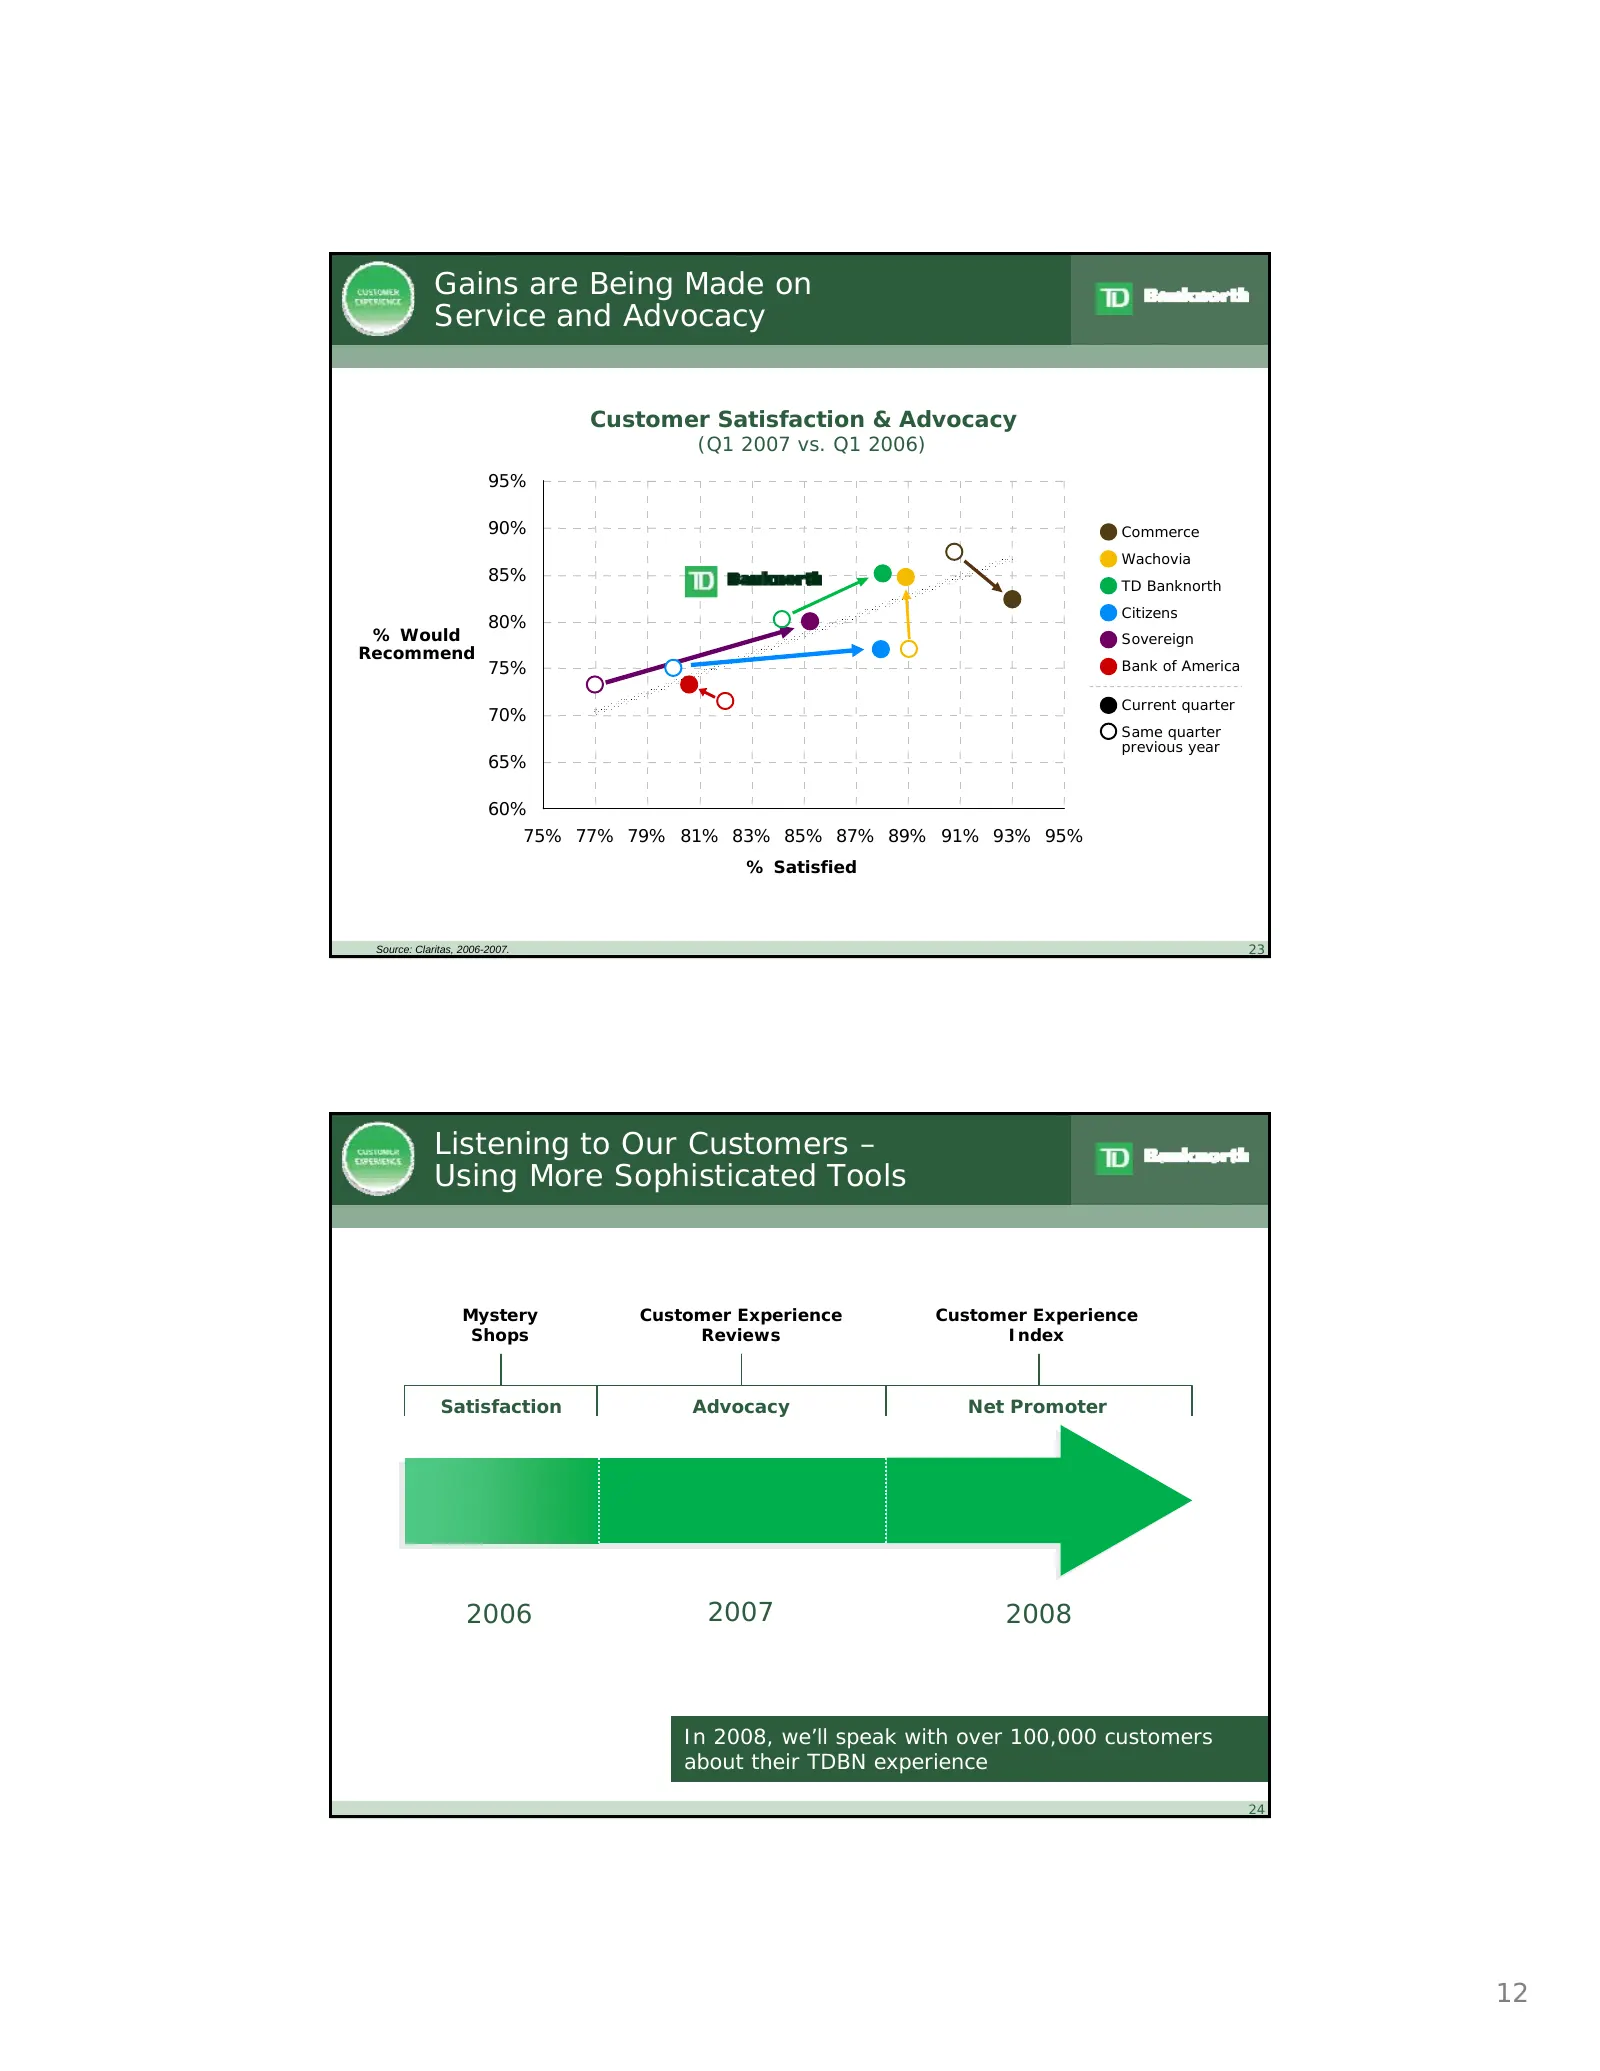
Gains are Being Made on Service and Advocacy Customer Satisfaction & Advocacy (Q1 2007 vs. Q1 2006) 95% 90% Commerce Wachovia 85% TD Banknorth Citizens 80% % Would Sovereign Recommend 75% Bank of America Current quarter 70% Same quarter previous year 65% 60% 75% 77% 79% 81% 83% 85% 87% 89% 91% 93% 9
Slide 13: Improving Pricing, Process and Products
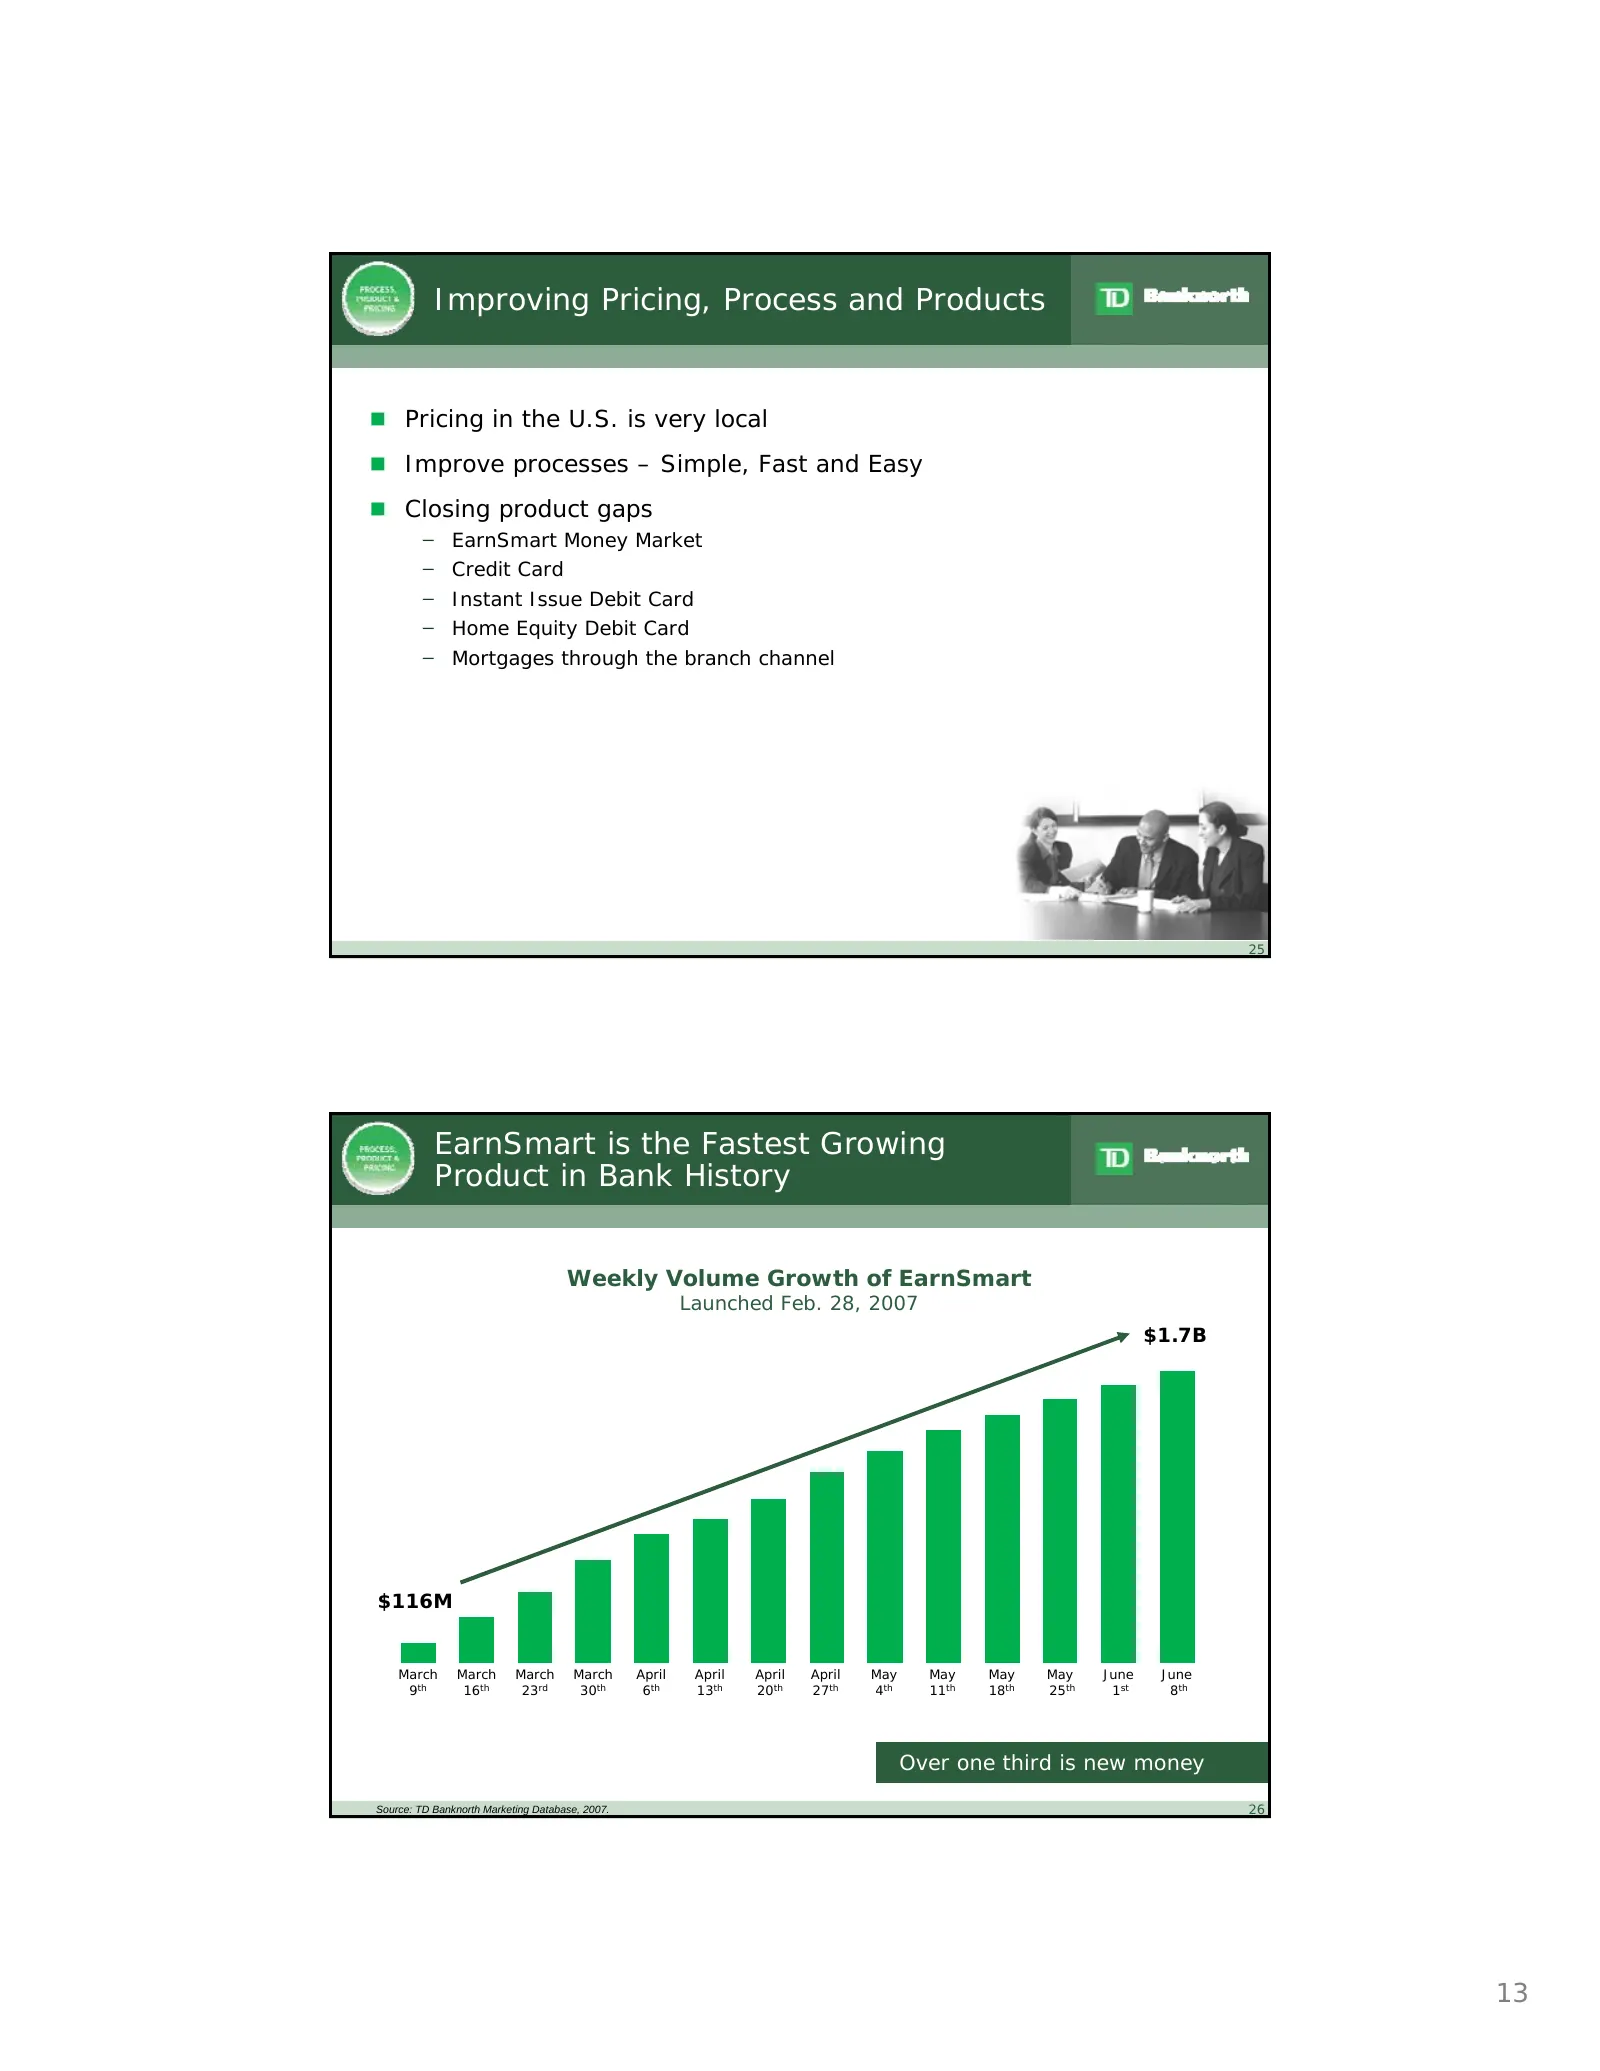
Improving Pricing, Process and Products Pricing in the U.S. is very local Improve processes – Simple, Fast and Easy Closing product gaps ̶ EarnSmart Money Market ̶ Credit Card ̶ Instant Issue Debit Card ̶ Home Equity Debit Card ̶ Mortgages through the branch channel 25 EarnSmart is the Fastest
Slide 14: Captured Nearly Half of Our Fee Opportunity
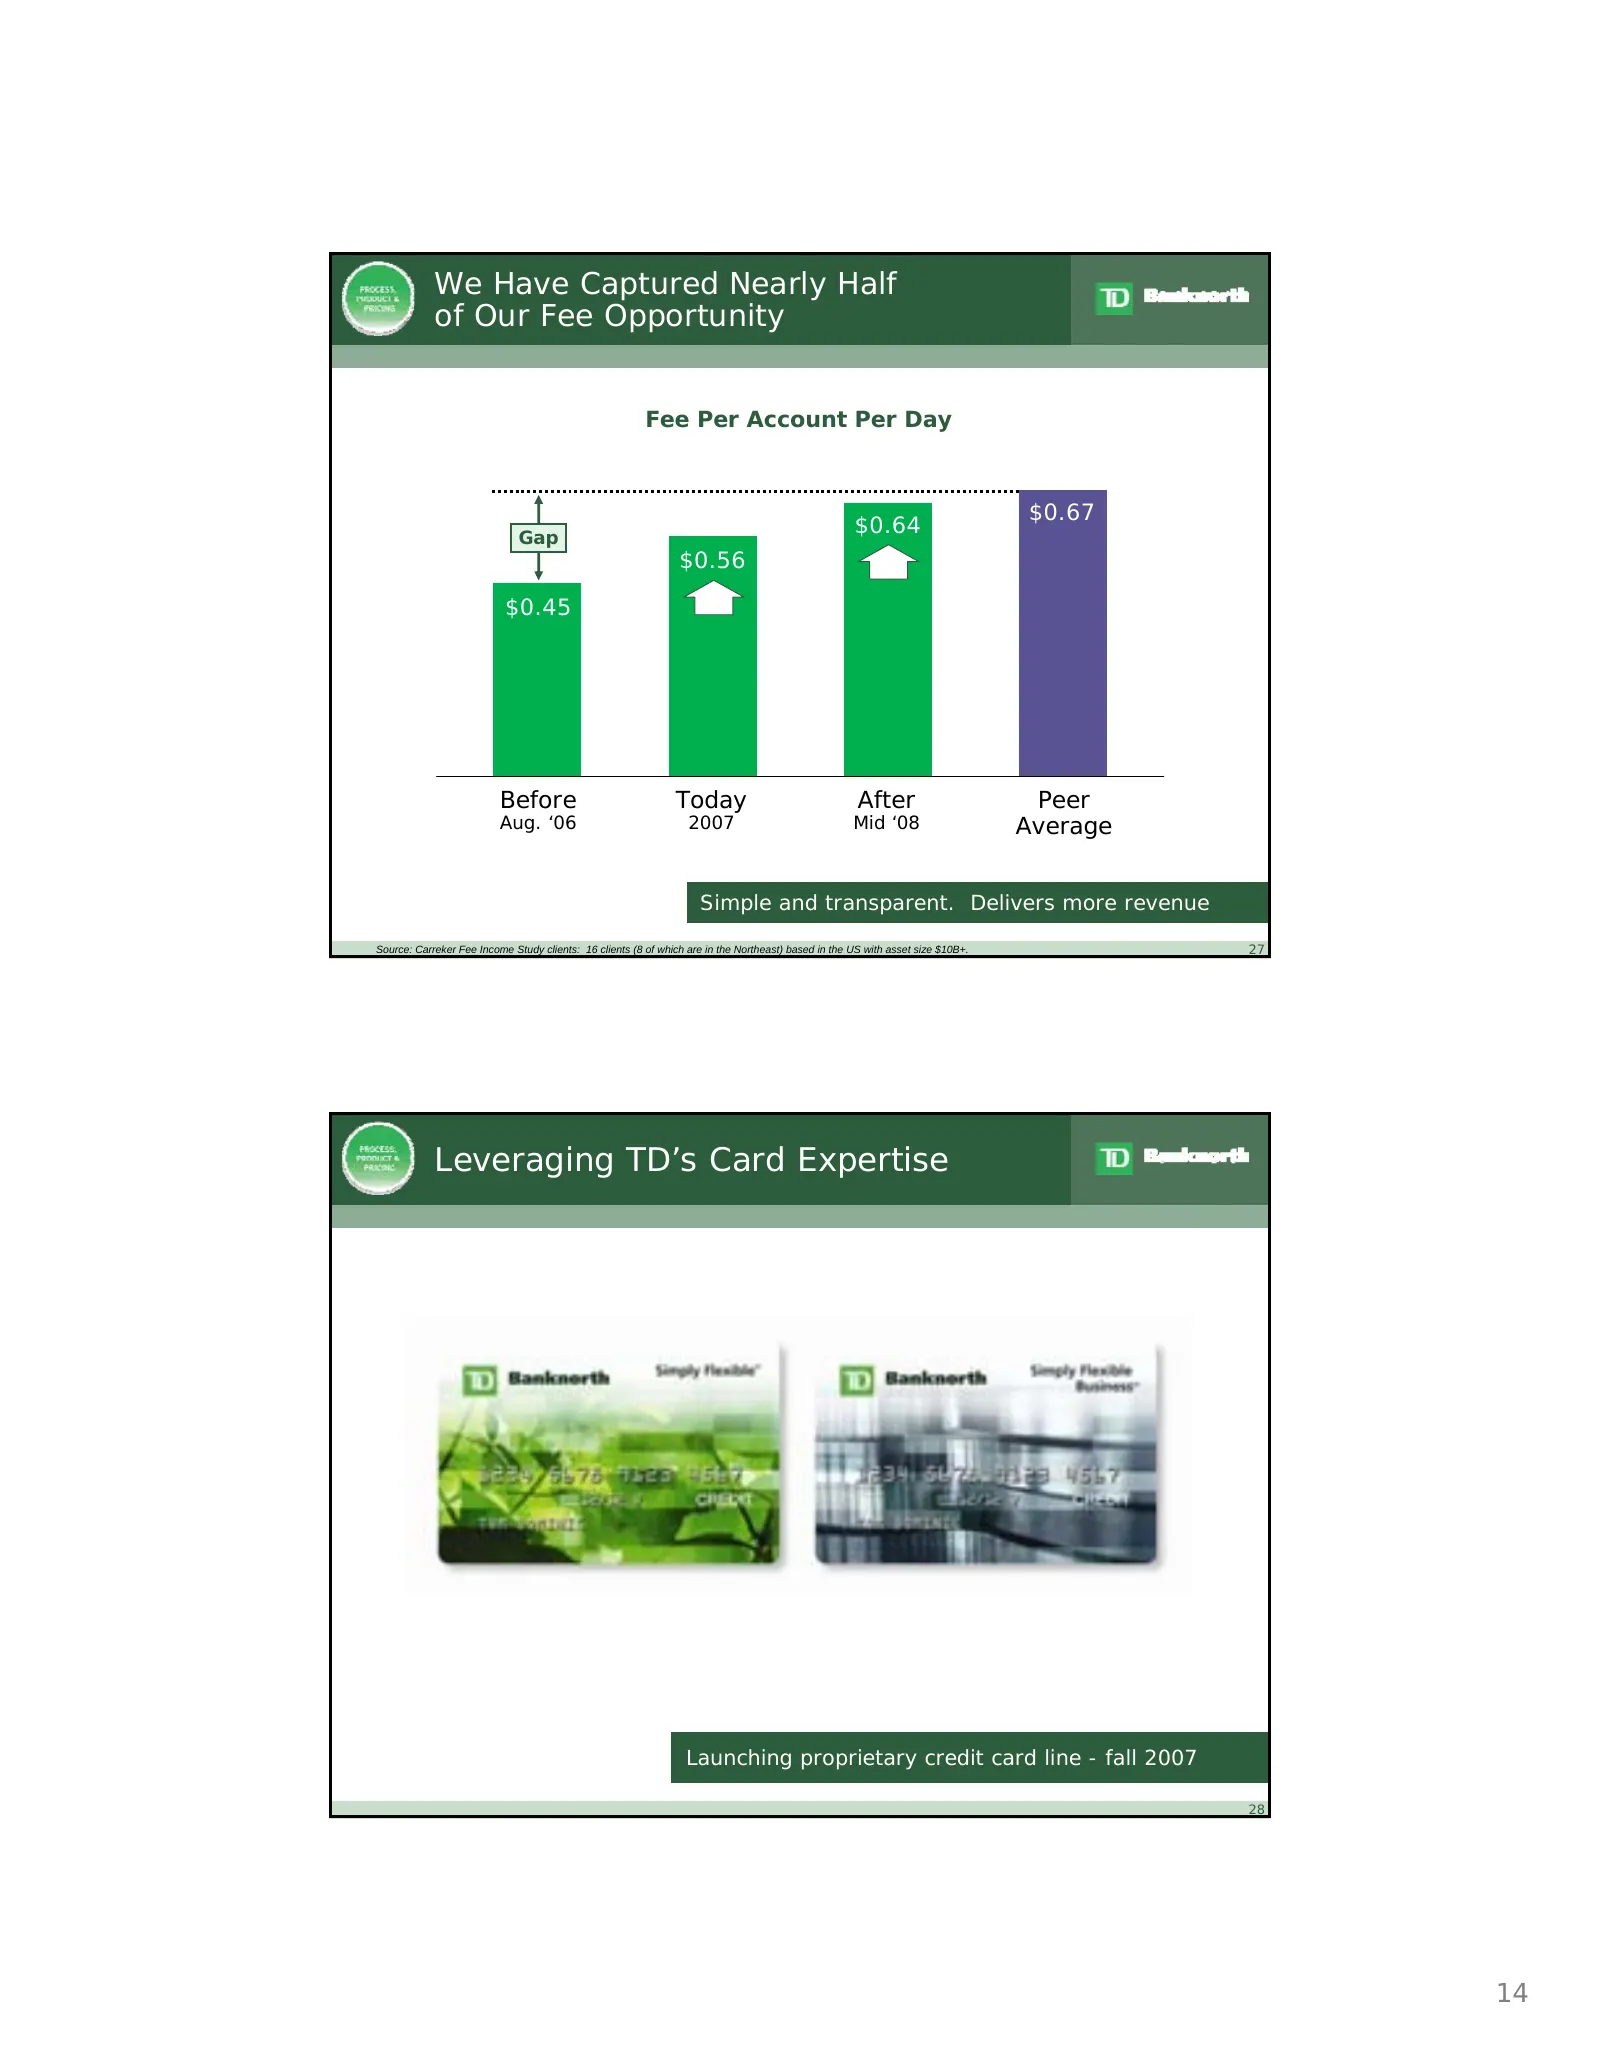
We Have Captured Nearly Half of Our Fee Opportunity Fee Per Account Per Day $0.67 $0.64 Gap $0.56 $0.45 Before Today After Peer Aug. ‘06 2007 Mid ‘08 Average Simple and transparent. Delivers more revenue Source: Carreker Fee Income Study clients: 16 clients (8 of which are in the Northeast) based in
Slide 15: Employee Experience and Retail Management
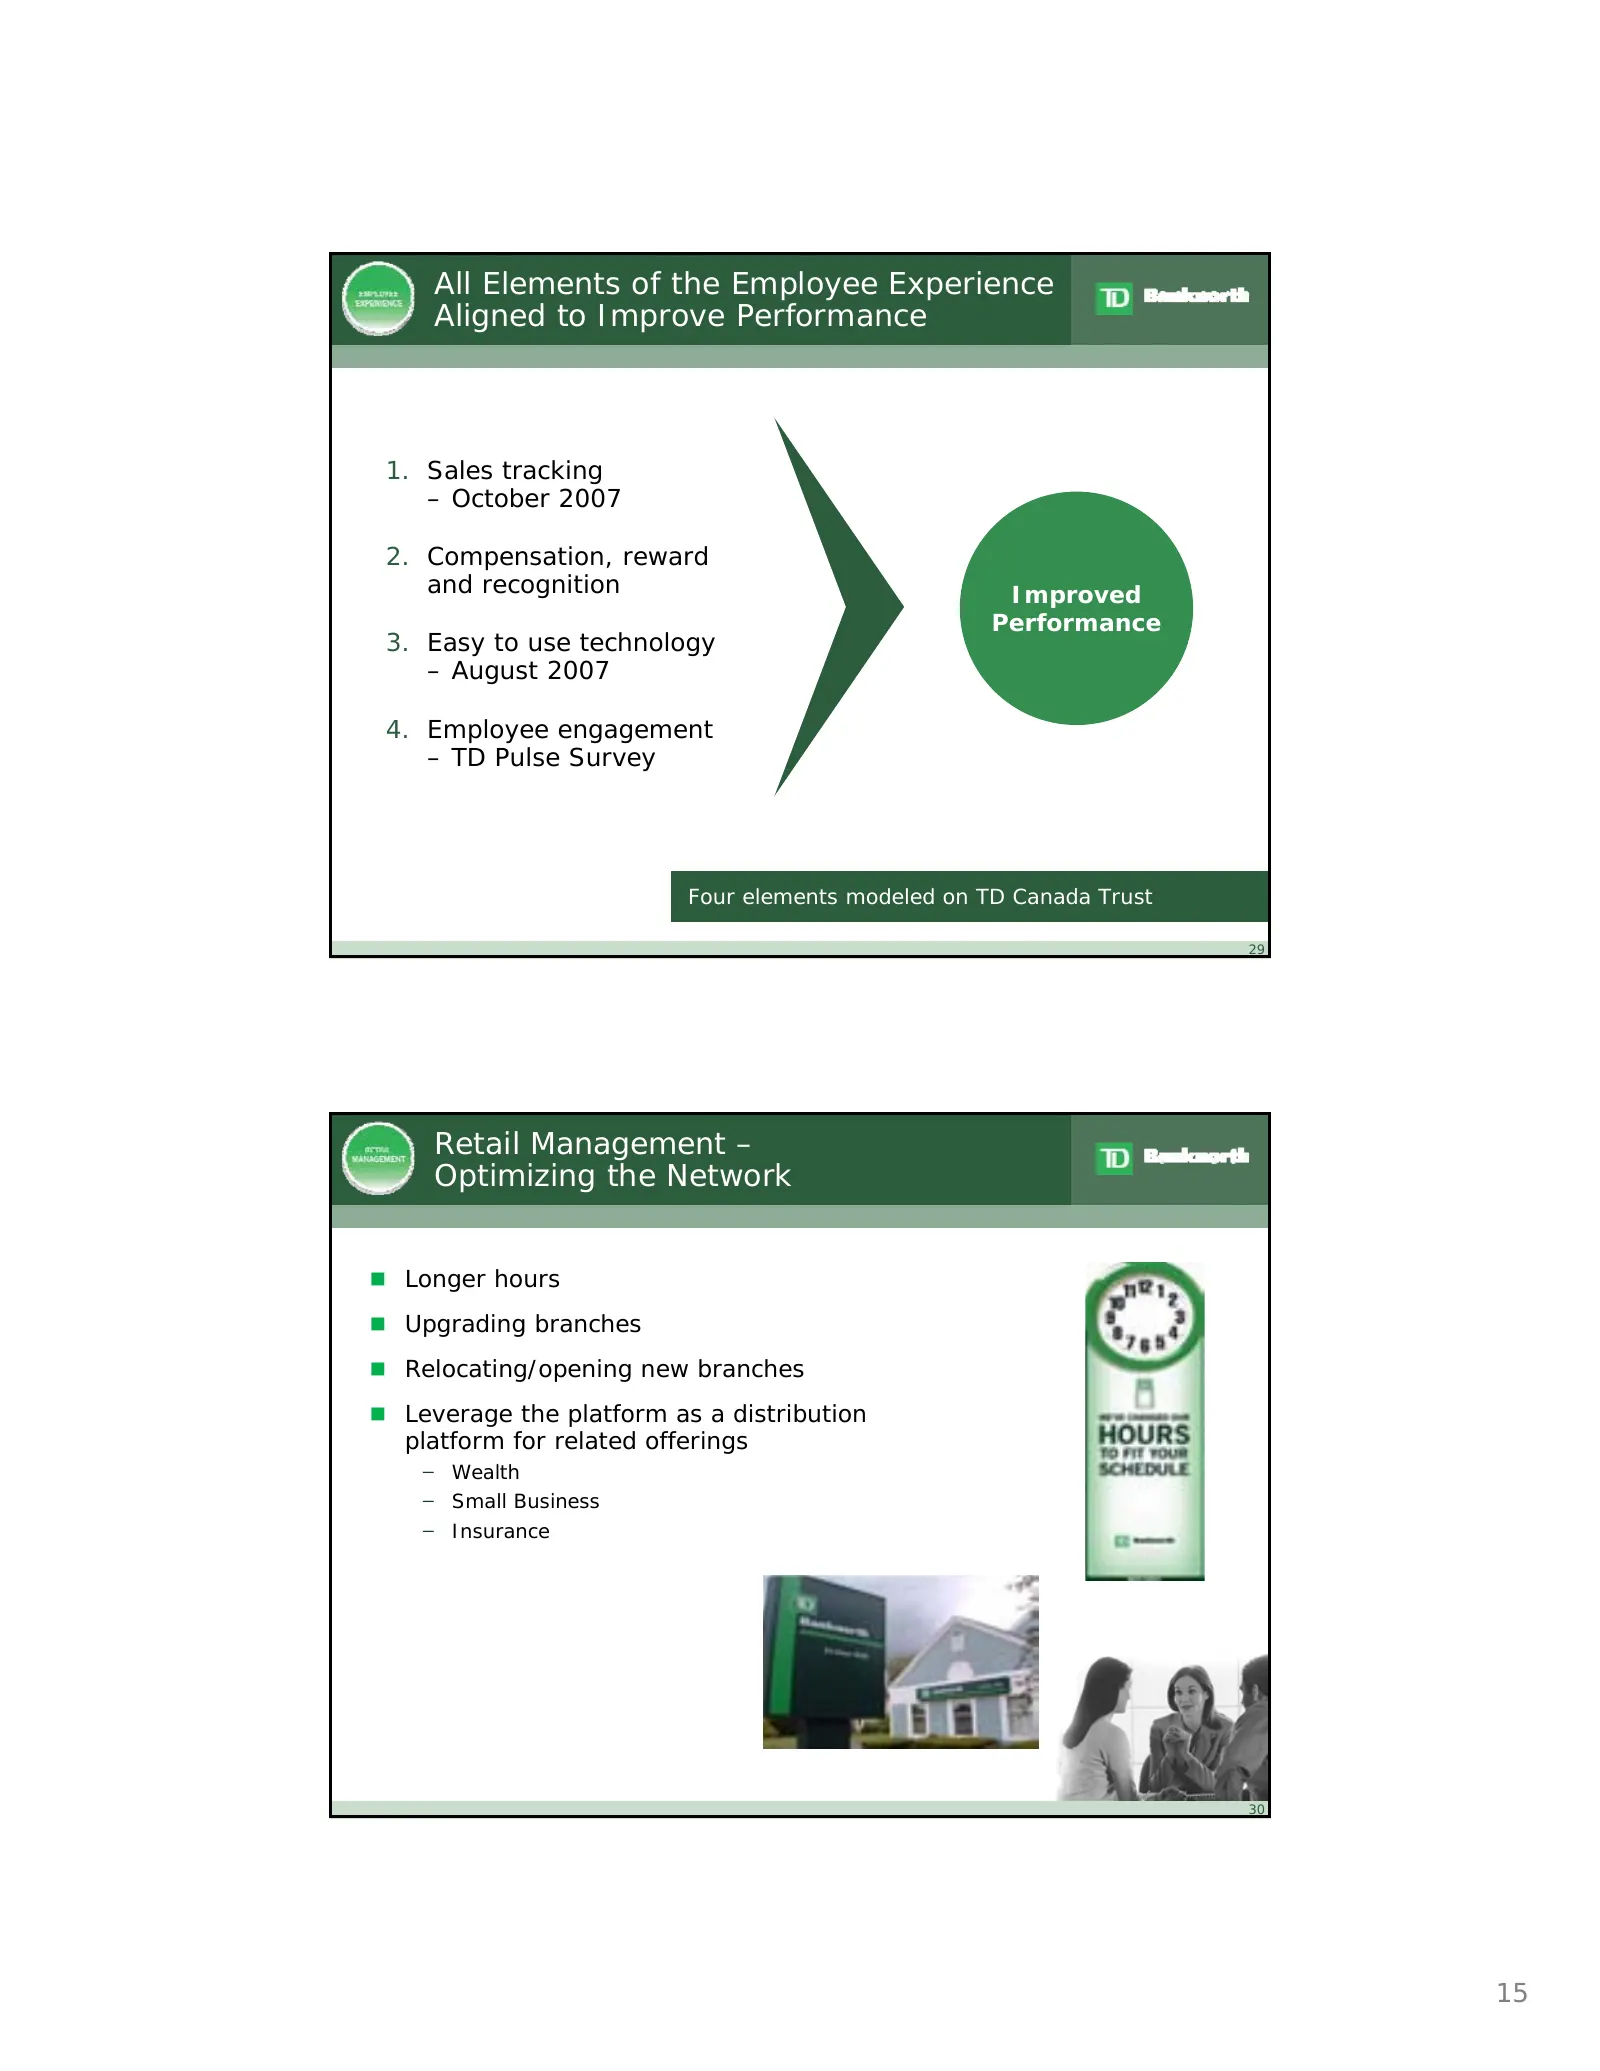
All Elements of the Employee Experience Aligned to Improve Performance 1. Sales tracking – October 2007 2. Compensation, reward and recognition Improved Performance 3. Easy to use technology – August 2007 4. Employee engagement – TD Pulse Survey Four elements modeled on TD Canada Trust 29 Retail Man
Slide 16: Piloting Extended Hours; Improving Our Network
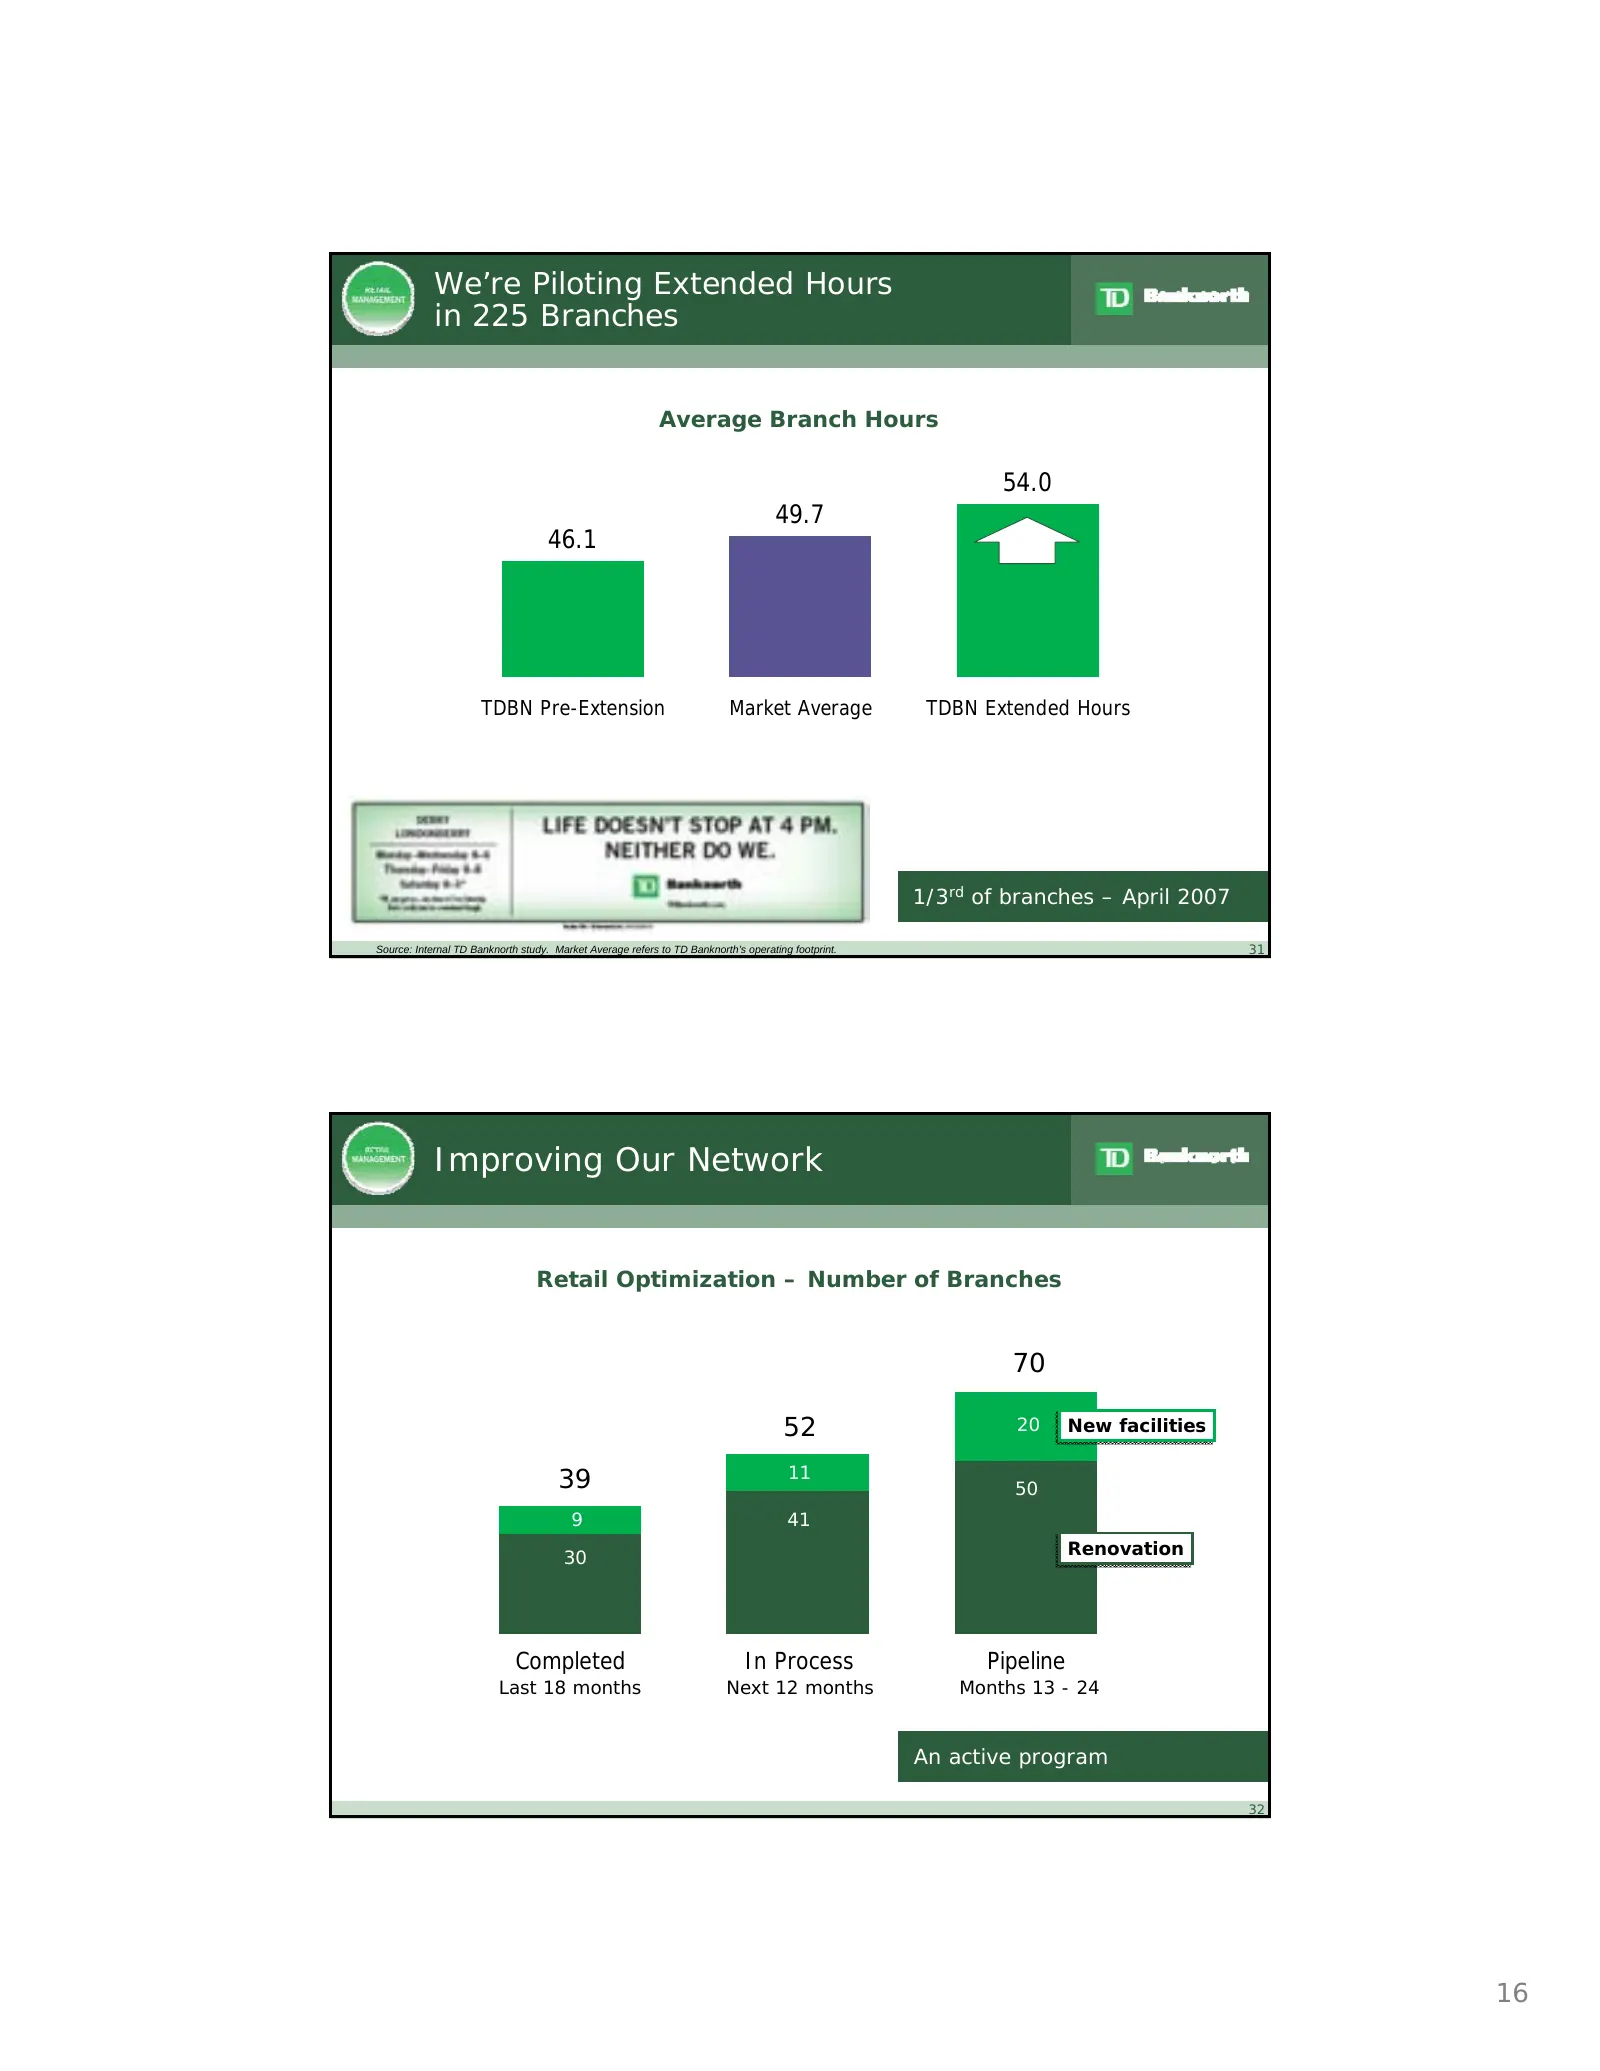
We’re Piloting Extended Hours in 225 Branches Average Branch Hours 54.0 49.7 46.1 TDBN Pre-Extension Market Average TDBN Extended Hours 1/3rd of branches – April 2007 Source: Internal TD Banknorth study. Market Average refers to TD Banknorth’s operating footprint. 31 Improving Our Network Retail Opt
Slide 17: Improving Visual Identity; Leveraging Distribution Channel
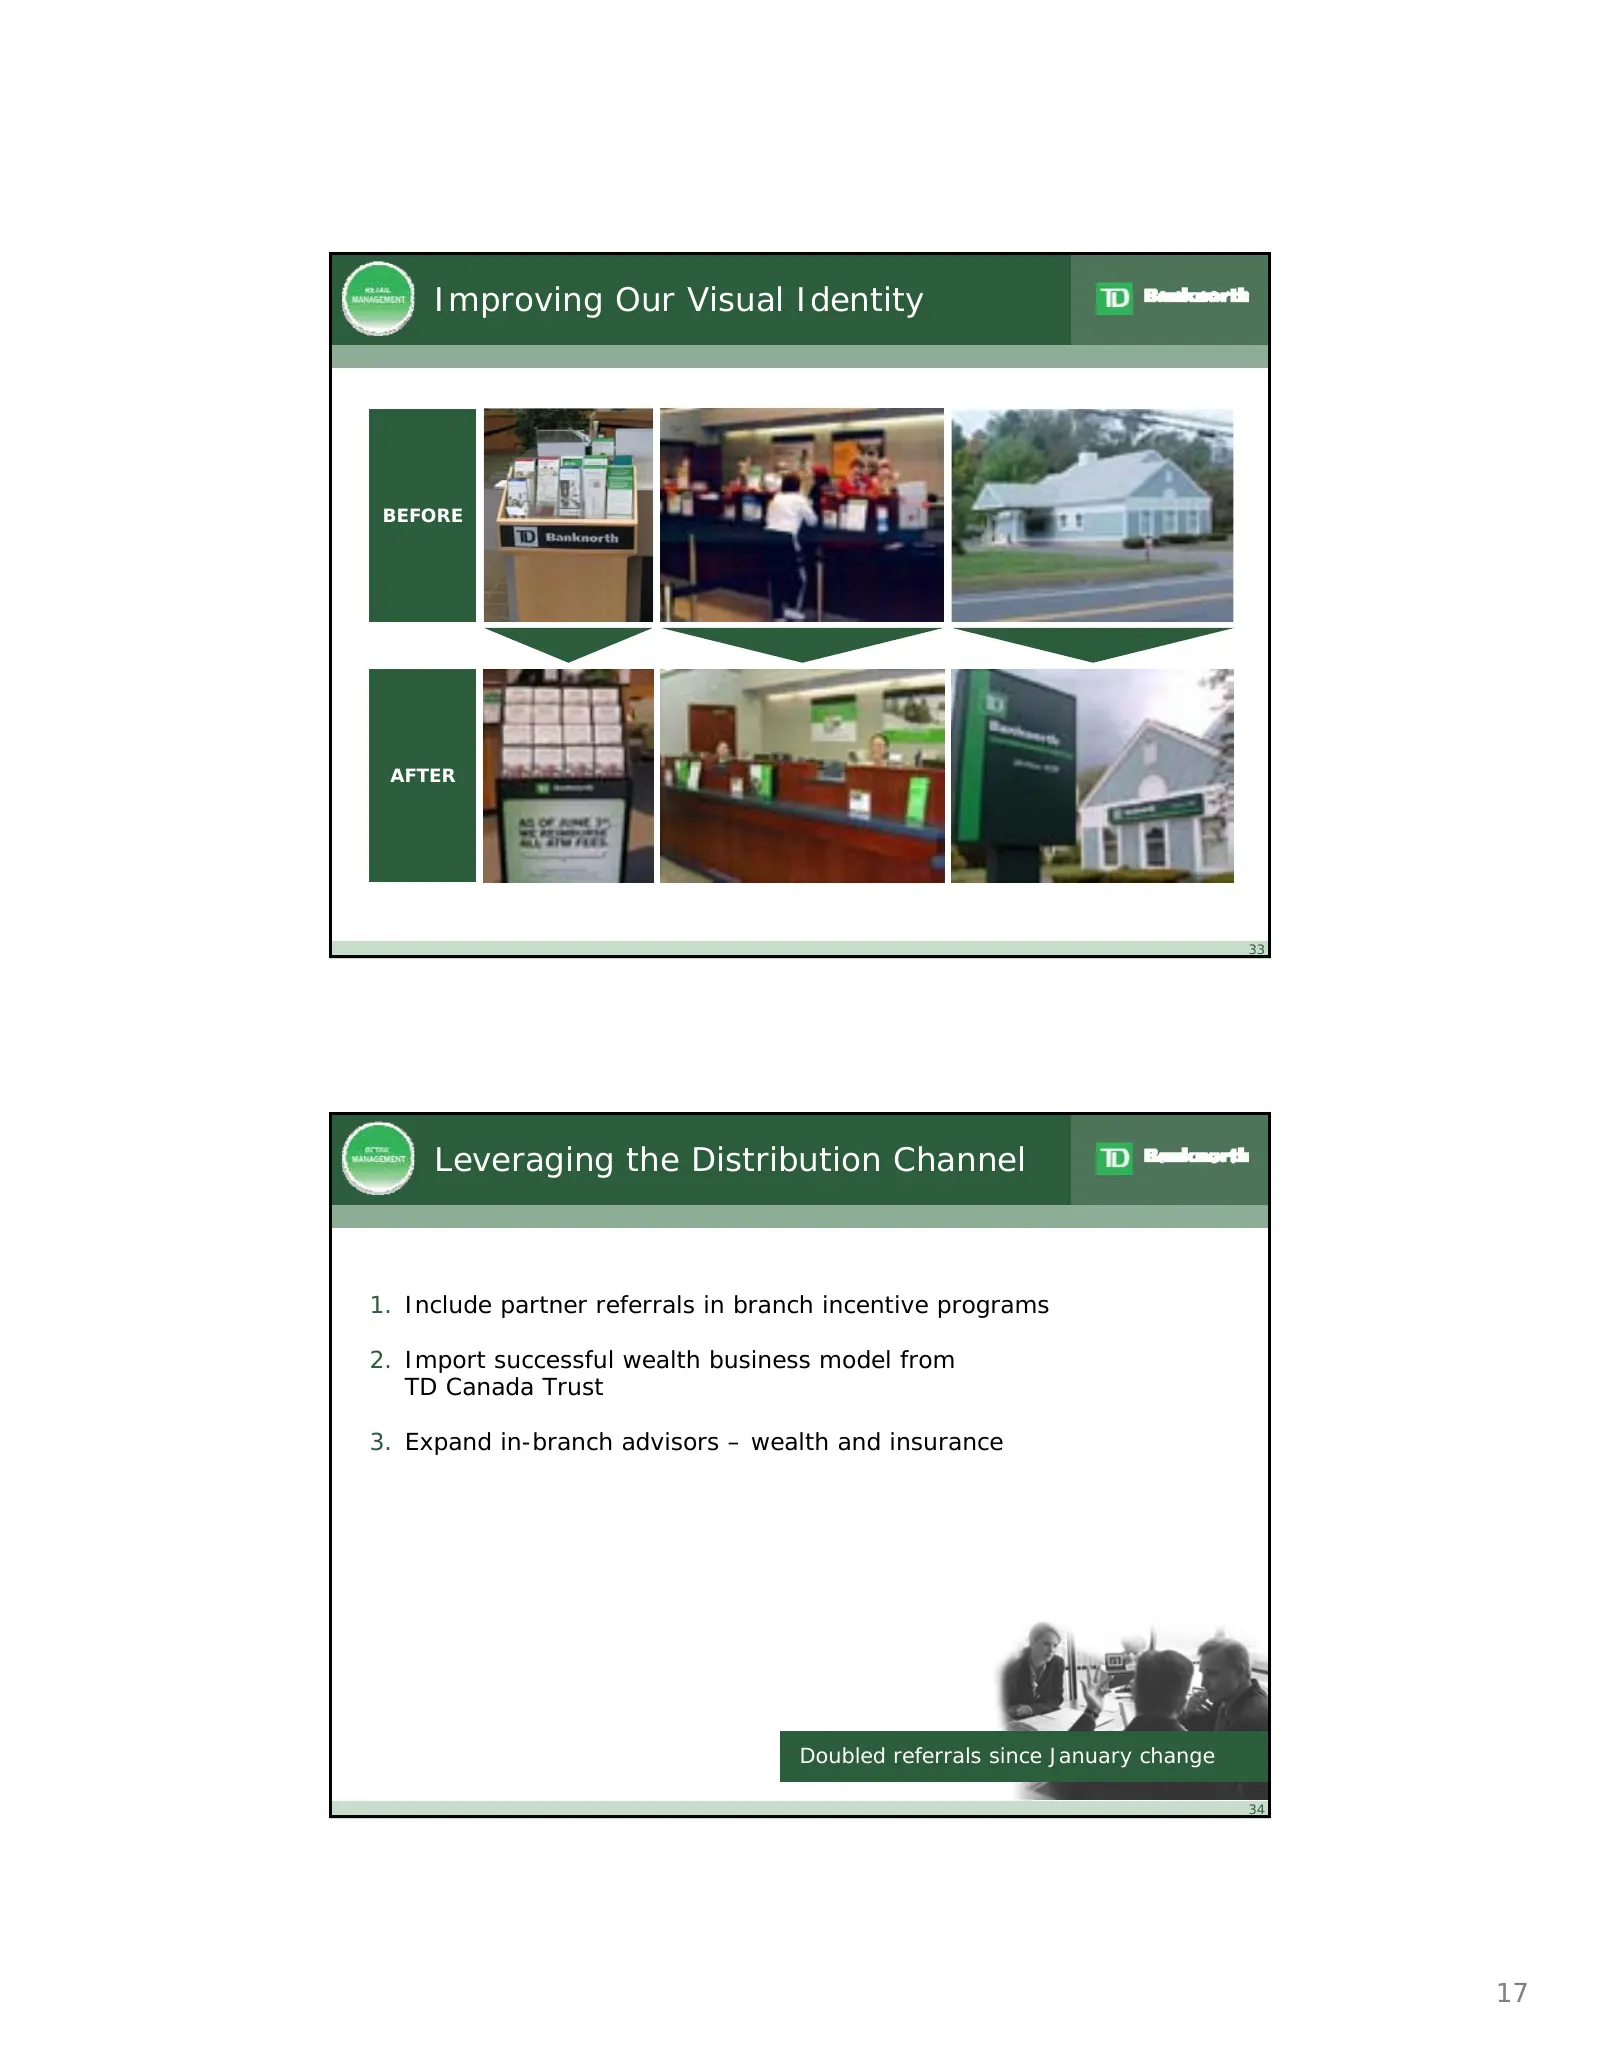
Improving Our Visual Identity BEFORE AFTER 33 Leveraging the Distribution Channel 1. Include partner referrals in branch incentive programs 2. Import successful wealth business model from TD Canada Trust 3. Expand in-branch advisors – wealth and insurance Doubled referrals since January change 34 17
Slide 18: Putting It All Together: Realizing $6B Opportunity
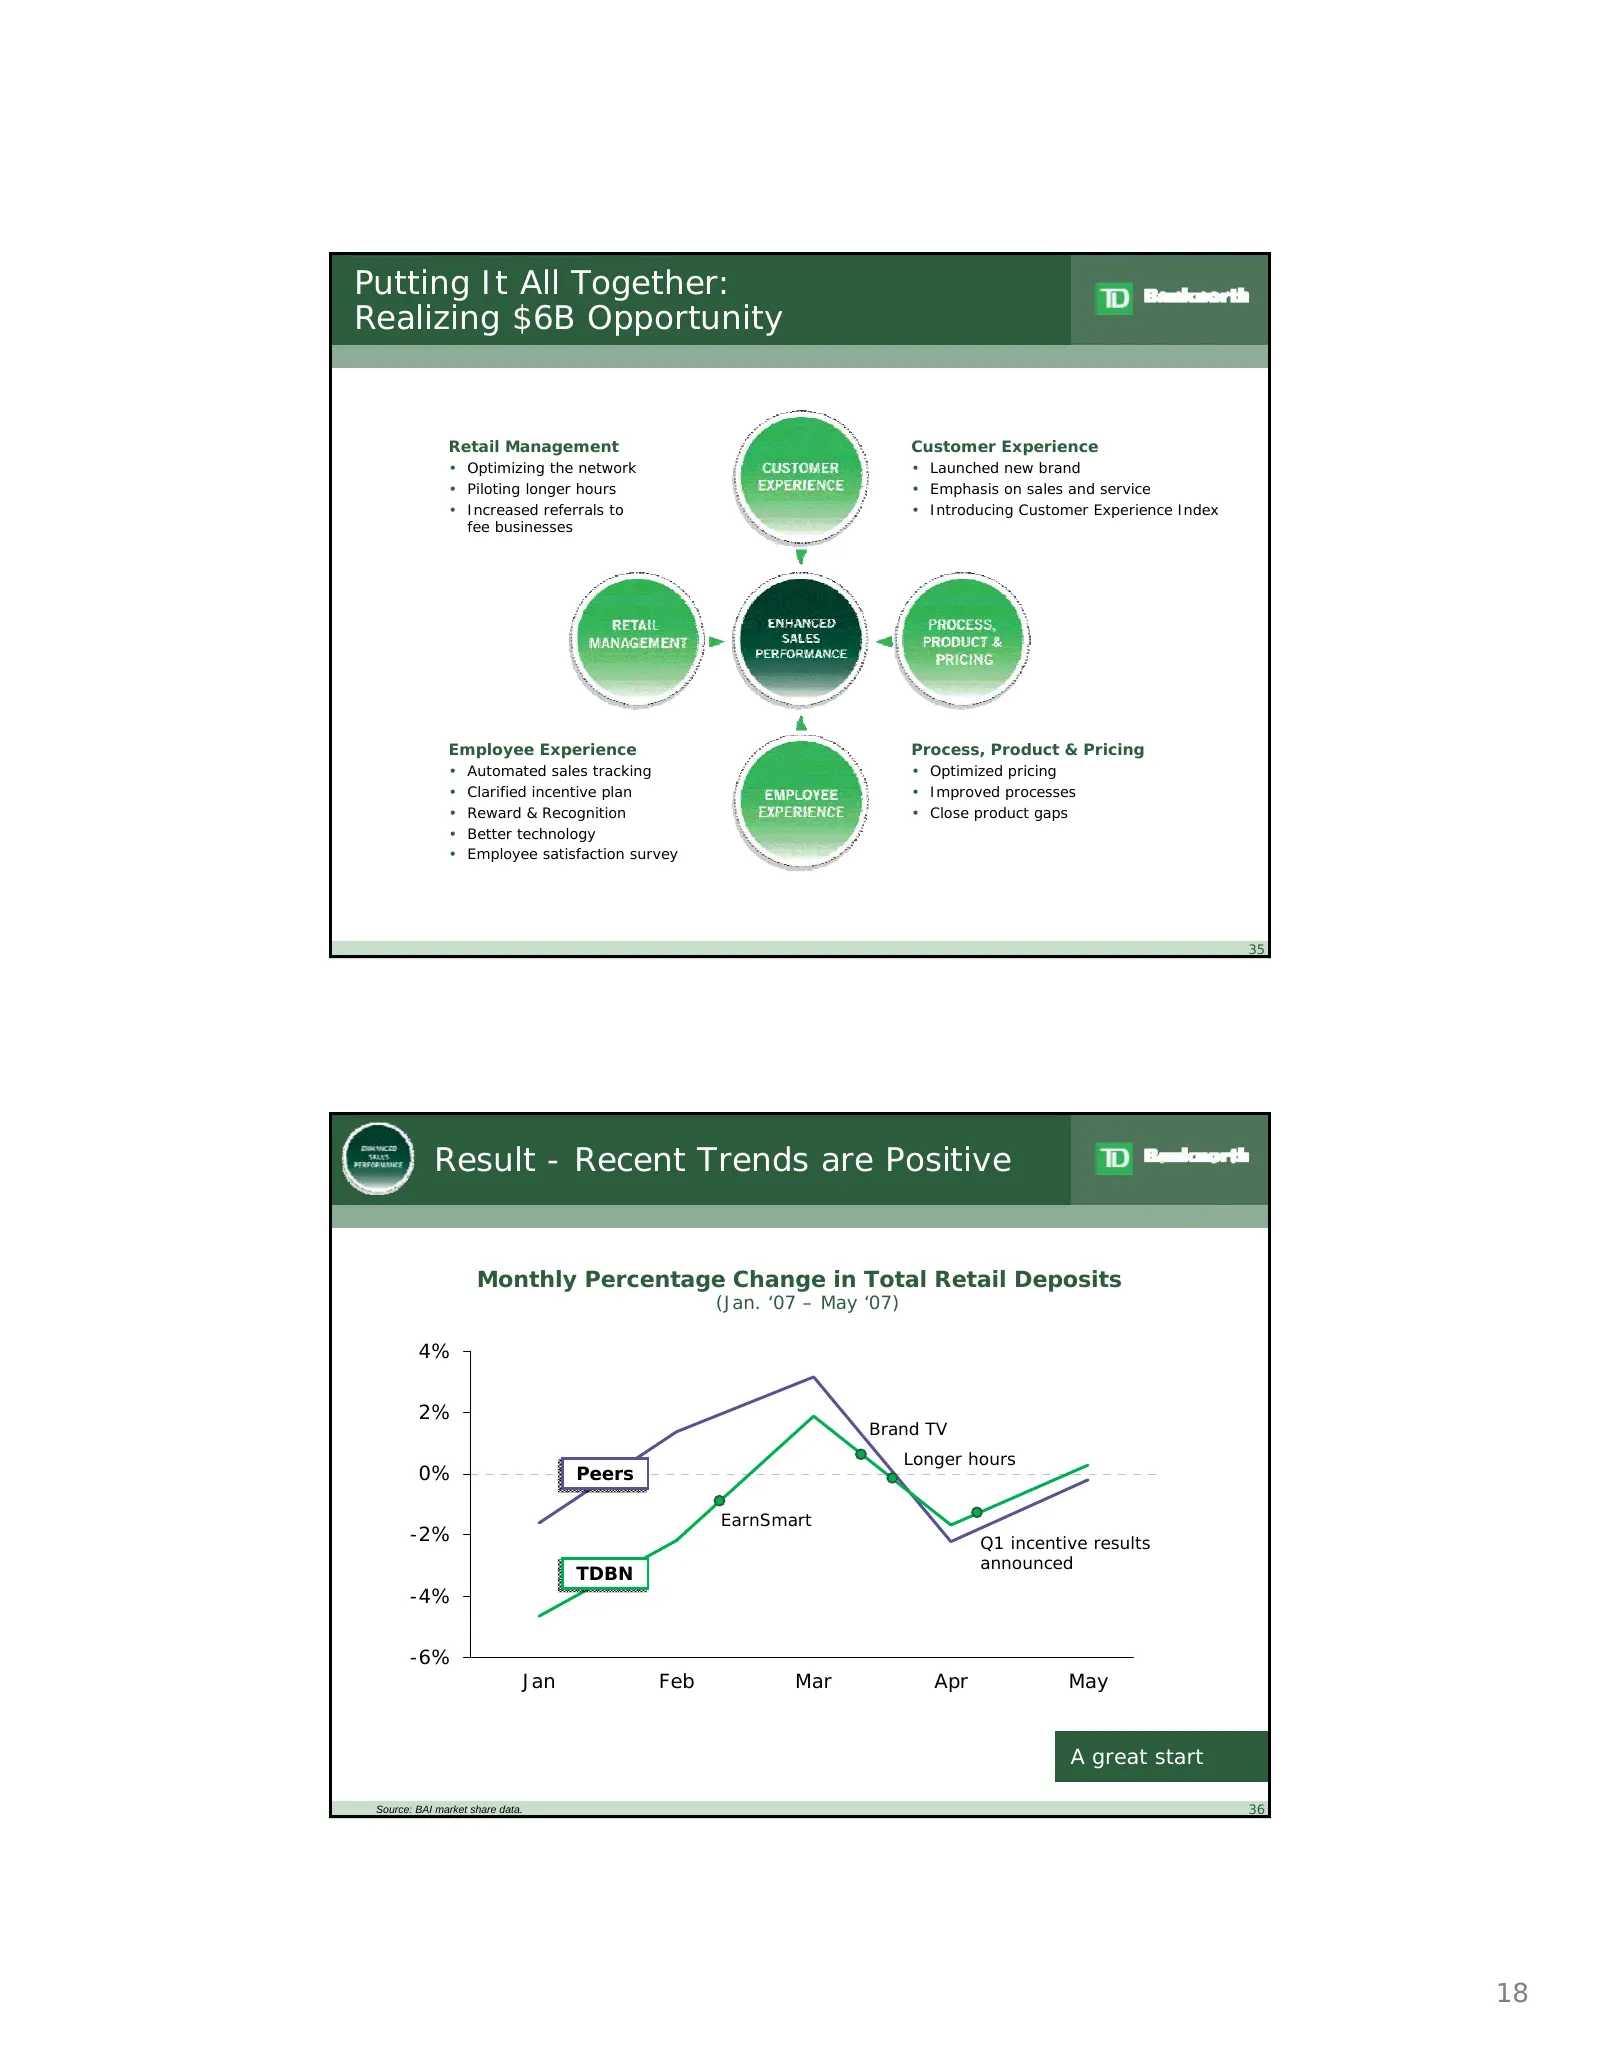
Putting It All Together: Realizing $6B Opportunity Retail Management Customer Experience • Optimizing the network • Launched new brand • Piloting longer hours • Emphasis on sales and service • Increased referrals to • Introducing Customer Experience Index fee businesses Employee Experience Process,
Slide 19: Key Takeaways; Commercial Banking
Key Takeaways 1. Orient the bank around the customer 2. Address process and pricing challenges 3. Build a performance culture 4. Optimize our network 37 Commercial Banking John Fridlington Chief Lending Officer, Sr. EVP, Commercial 19
Slide 20: Commercial Banking Overview
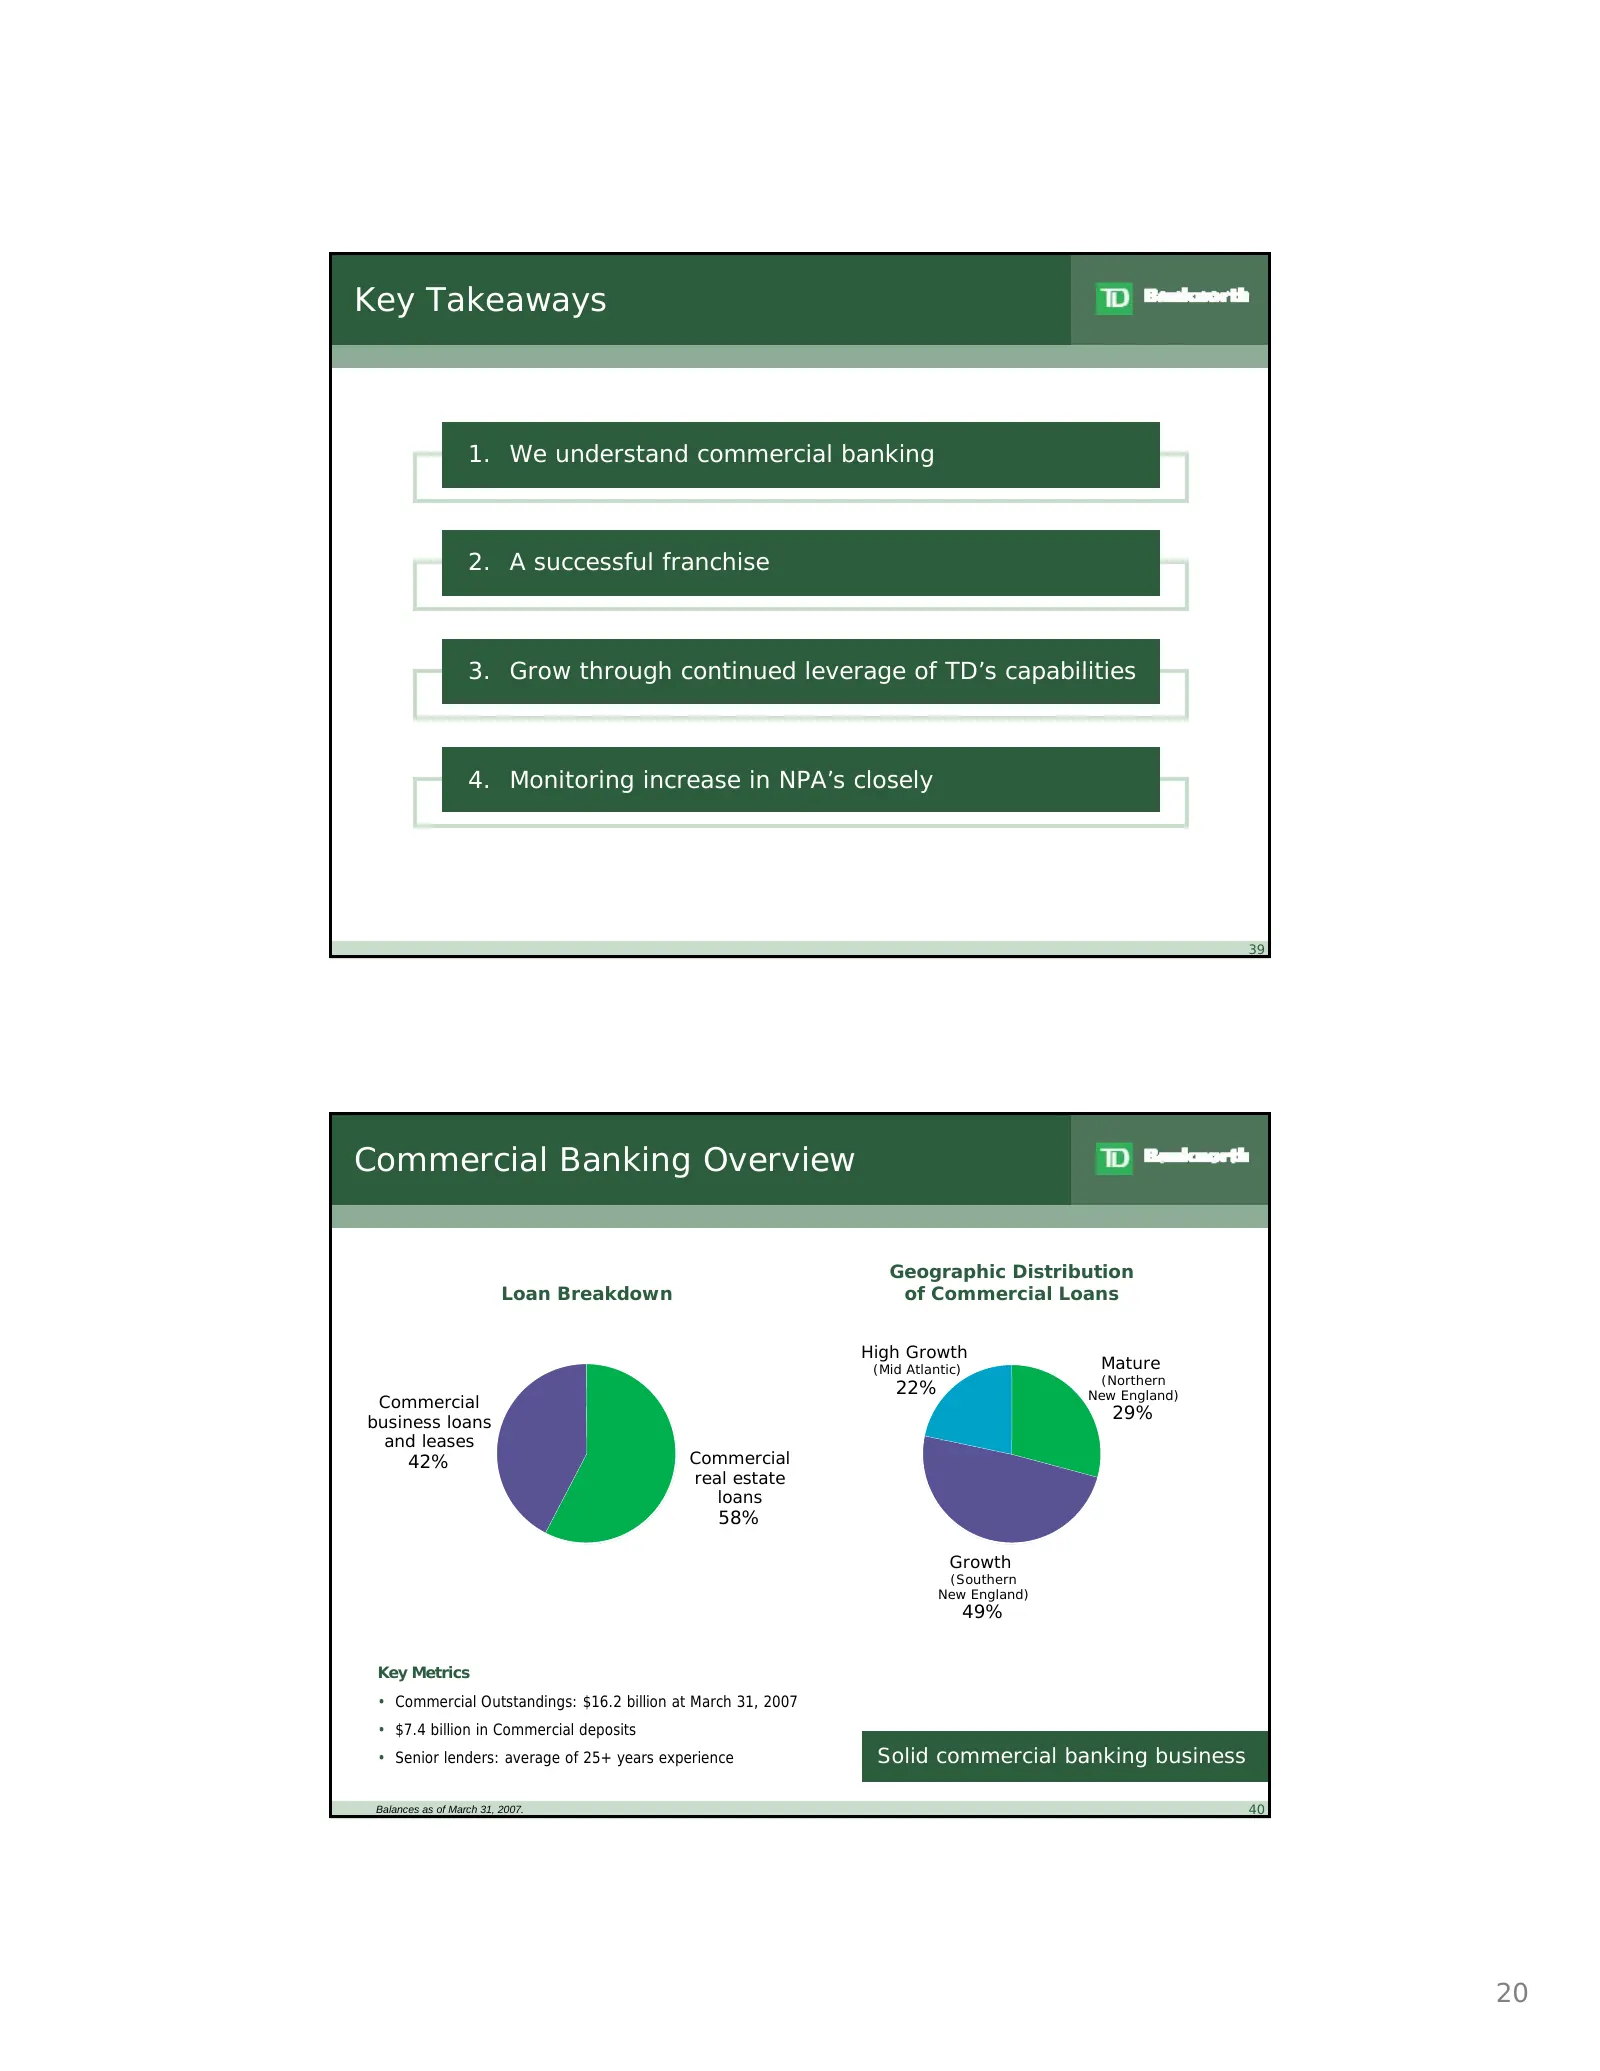
Key Takeaways 1. We understand commercial banking 2. A successful franchise 3. Grow through continued leverage of TD’s capabilities 4. Monitoring increase in NPA’s closely 39 Commercial Banking Overview Geographic Distribution Loan Breakdown of Commercial Loans High Growth (Mid Atlantic) Mature (Nor
Slide 21: Commercial Banking Competitive Landscape
Commercial Banking Competitive Landscape Varied competition ̶ Large banks in all markets: Bank of America, Citizens (RBS), JP Morgan Chase, Sovereign, Wachovia ̶ Hundreds of small banks, unique to each market Our strengths: ̶ Knowledge of local markets ̶ Local decision making Diverse, intense co
Slide 22: Leverage TD Capabilities; Asset Quality Update
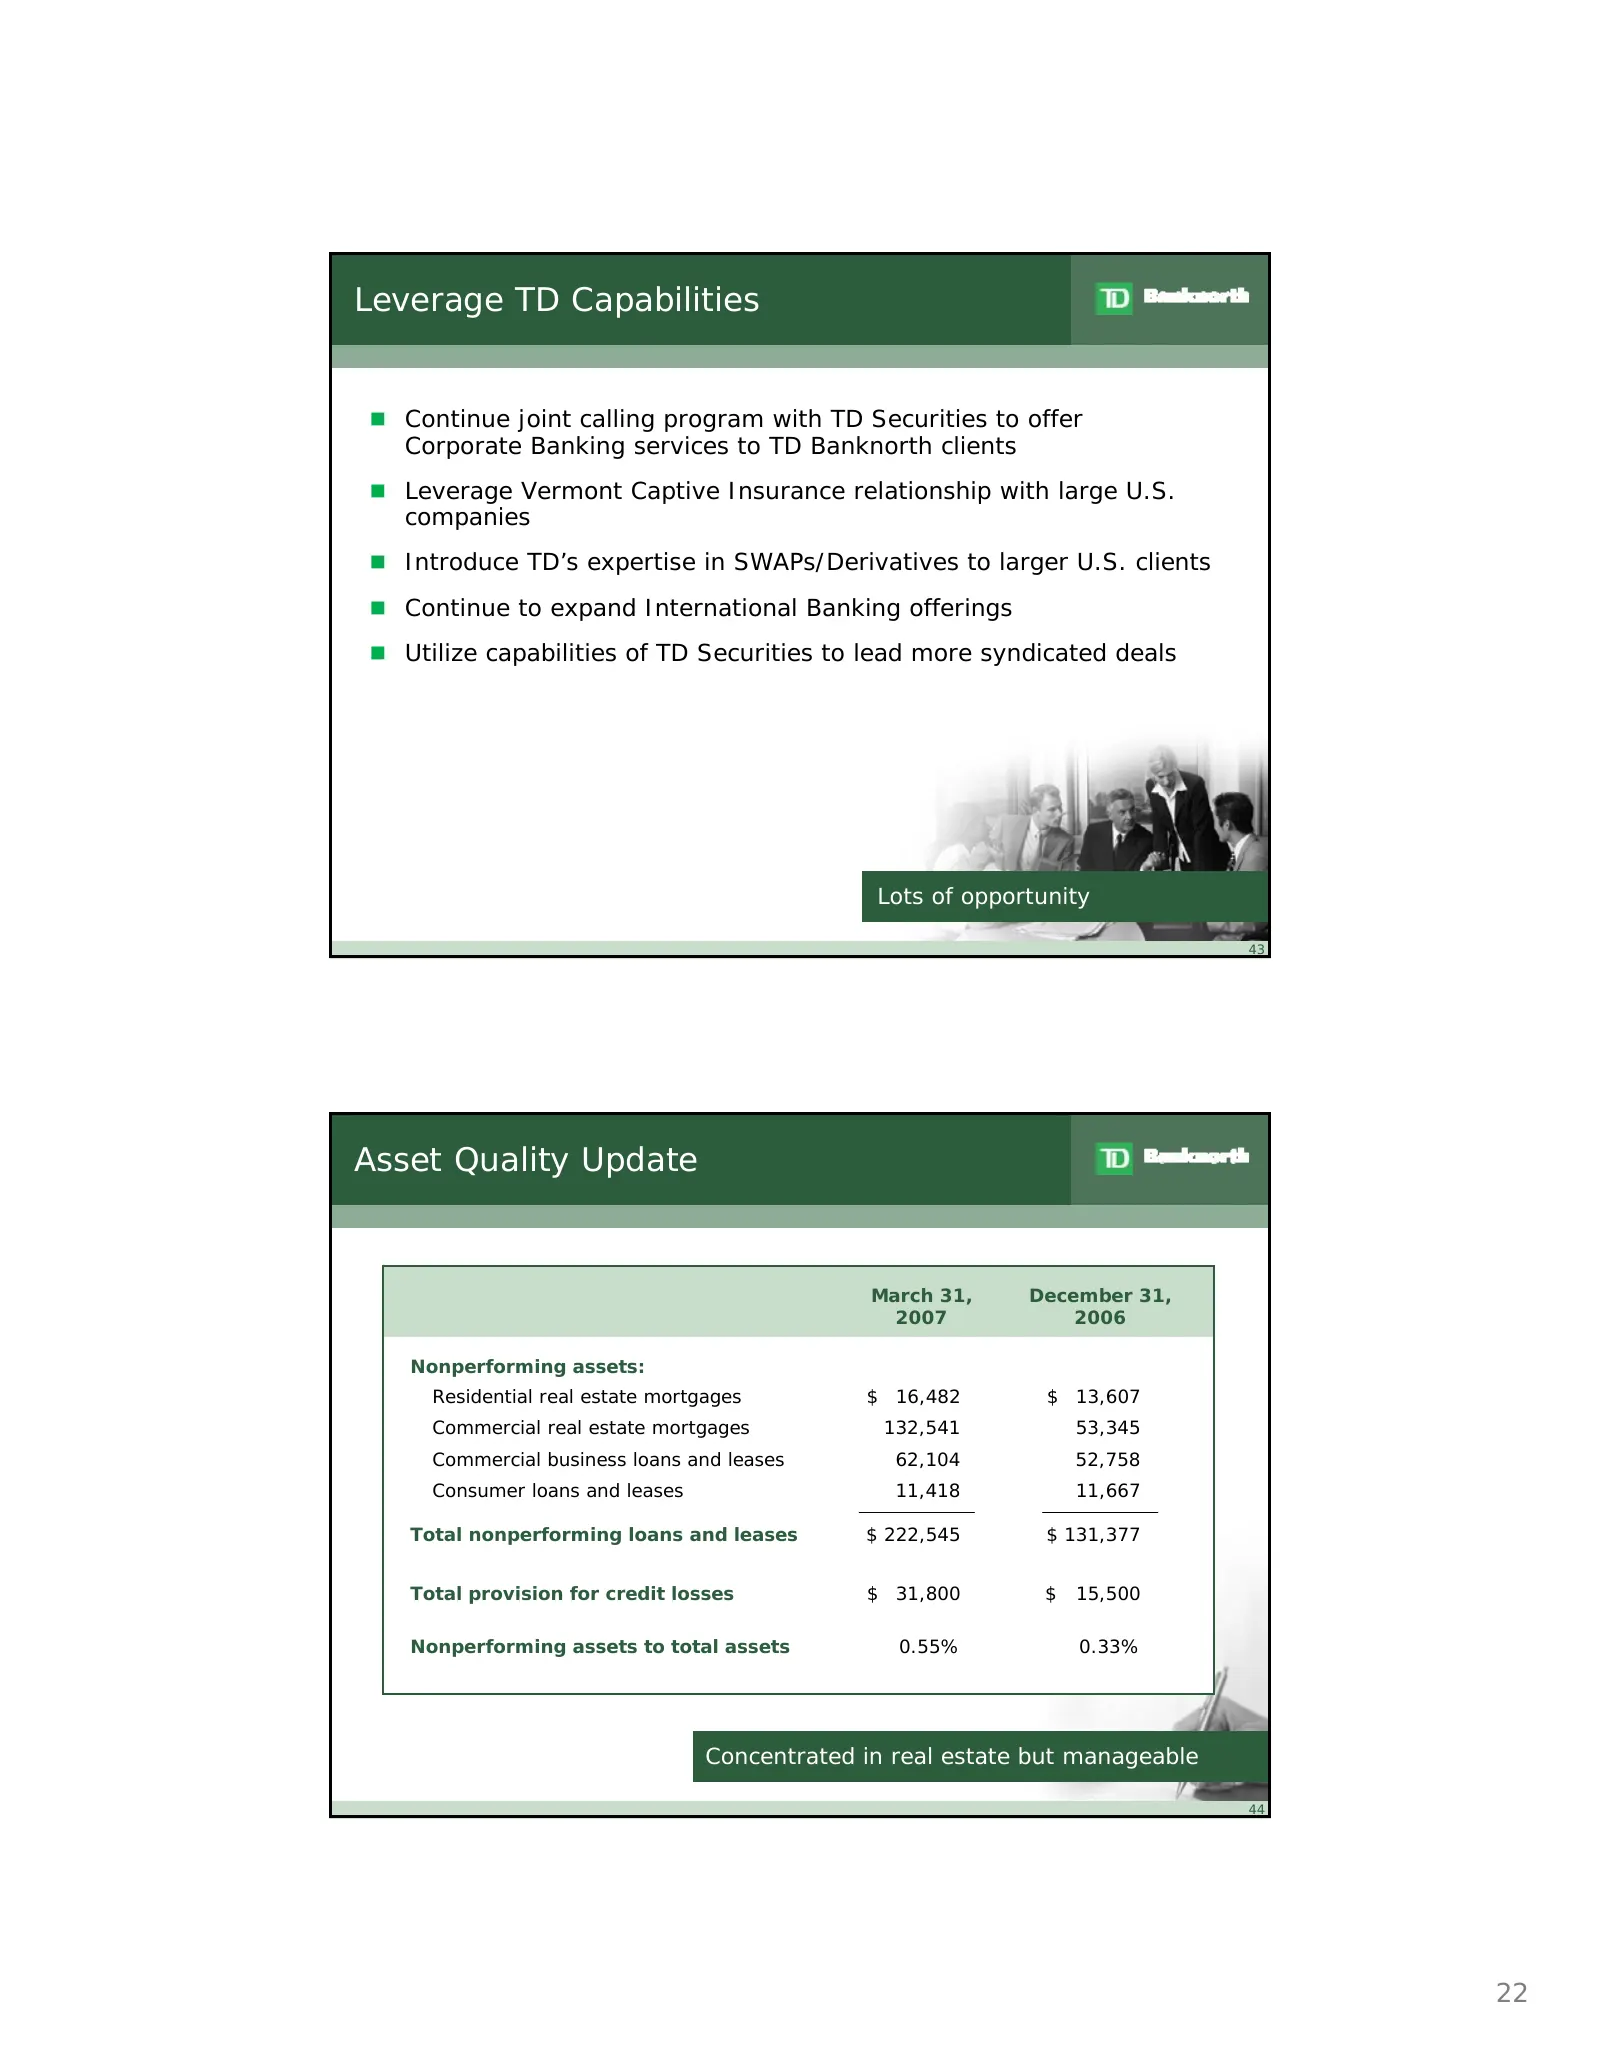
Leverage TD Capabilities Continue joint calling program with TD Securities to offer Corporate Banking services to TD Banknorth clients Leverage Vermont Captive Insurance relationship with large U.S. companies Introduce TD’s expertise in SWAPs/Derivatives to larger U.S. clients Continue to ex
Slide 23: Diversified Commercial Lending Portfolio
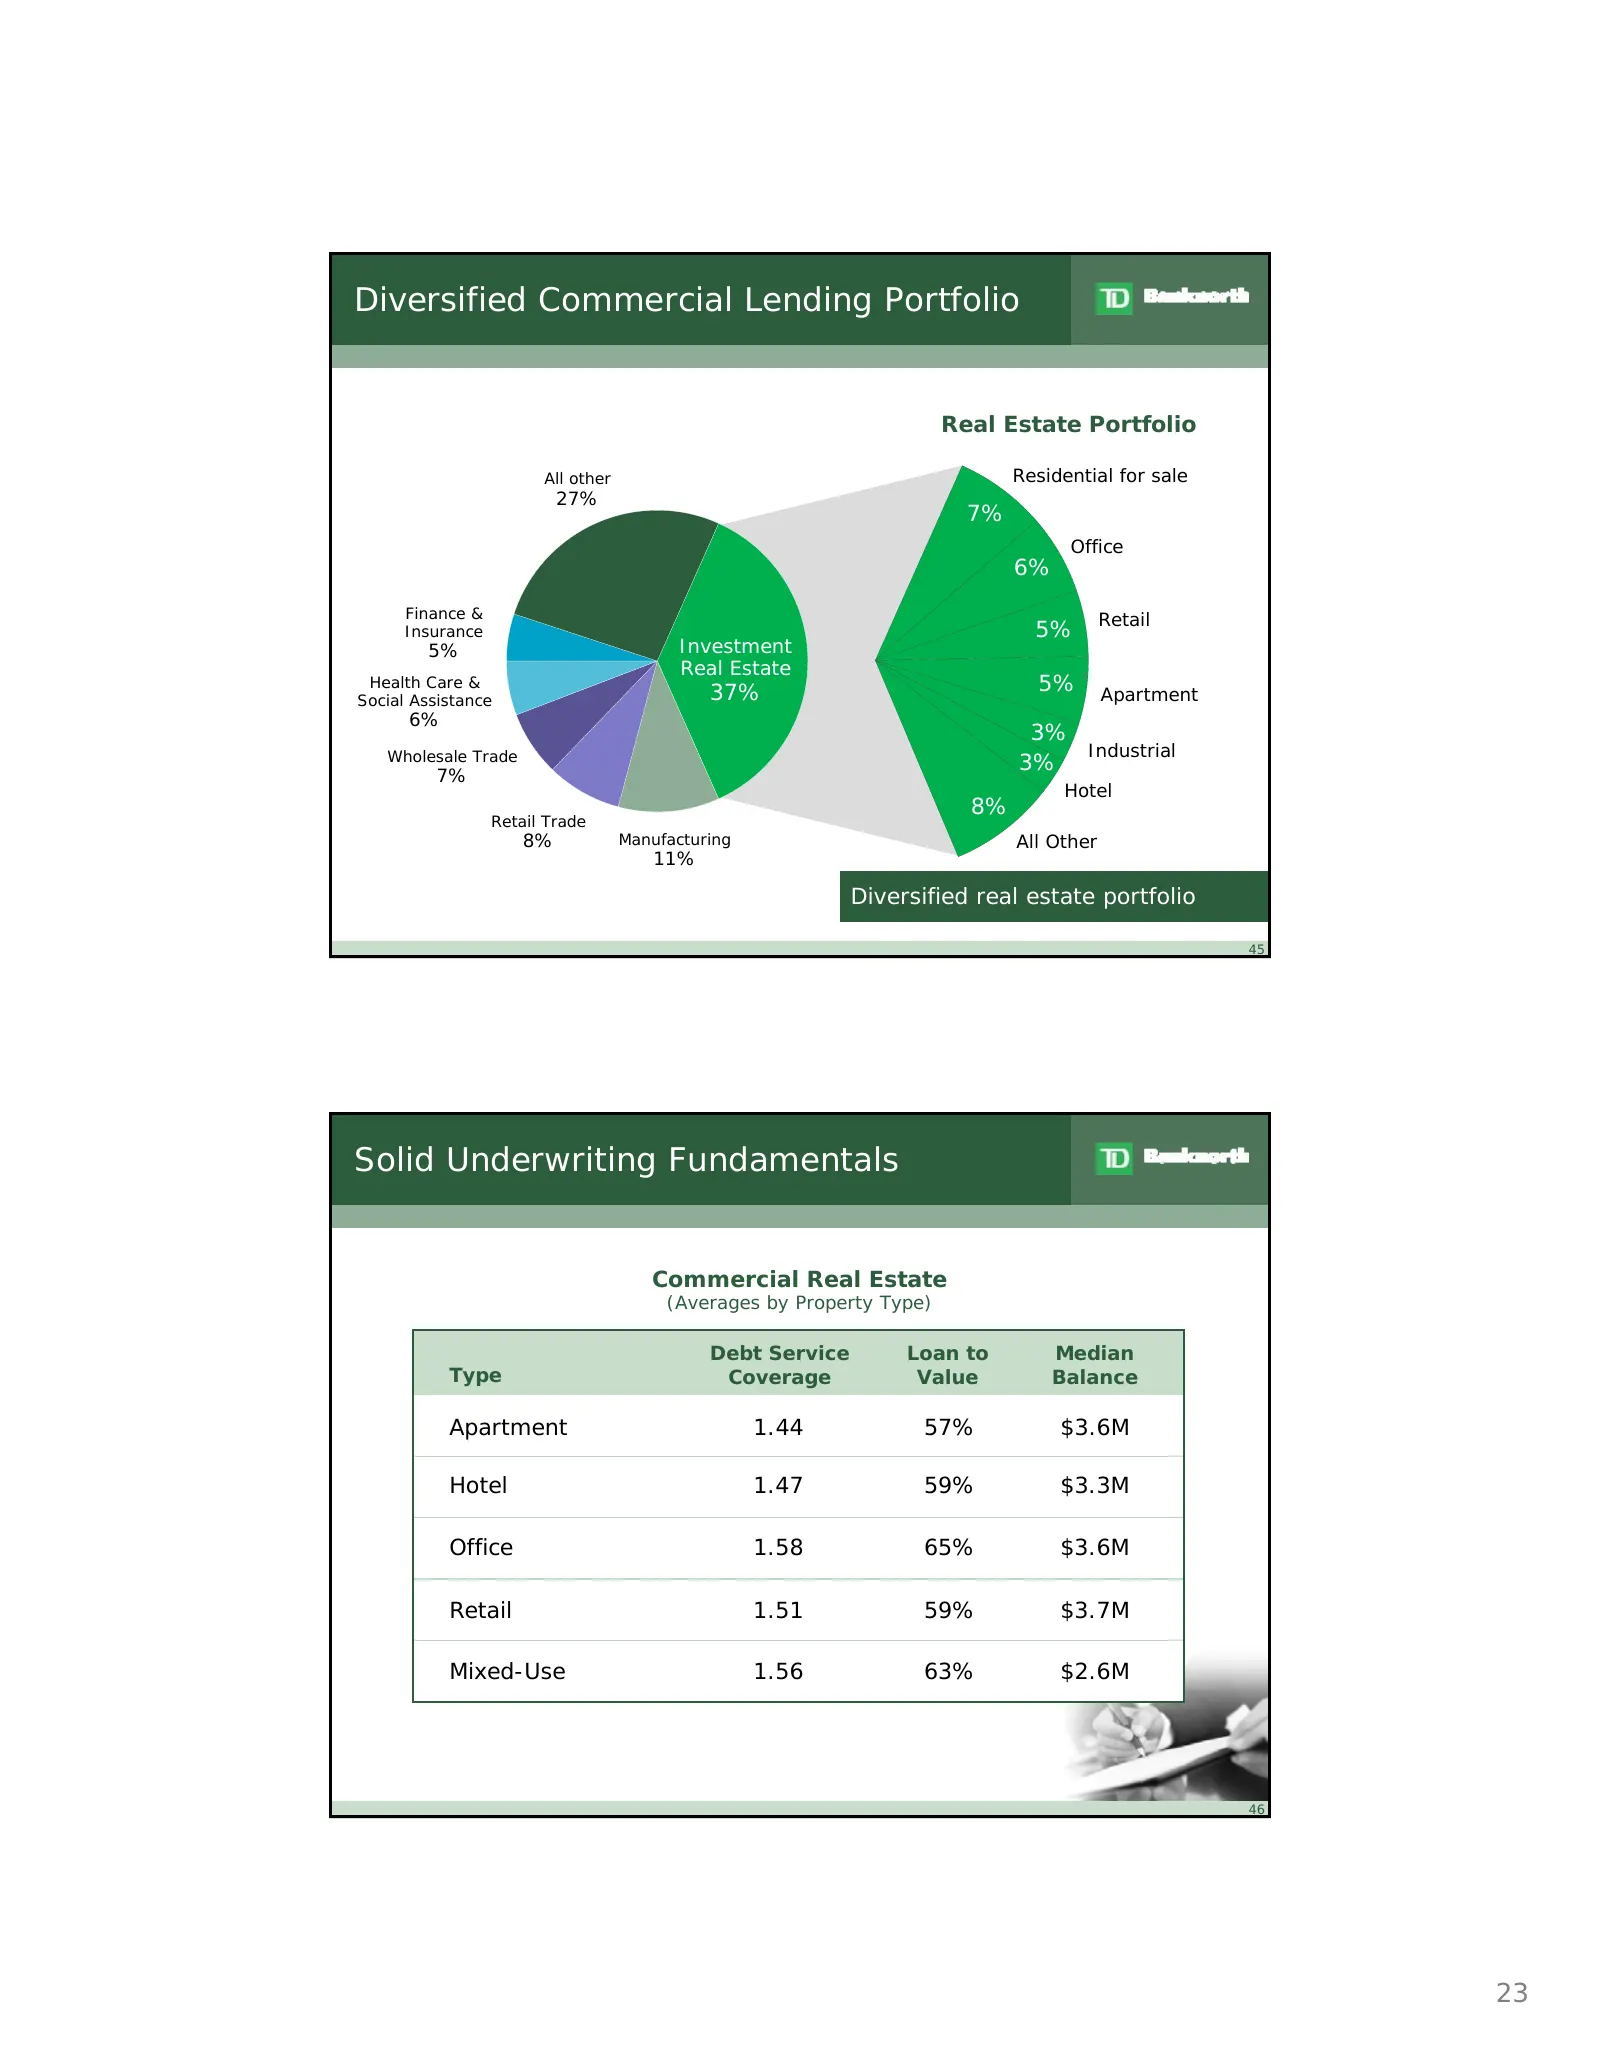
Diversified Commercial Lending Portfolio Real Estate Portfolio All other Residential for sale 27% 7% Office 6% Finance & Retail Insurance 5% 5% Investment Real Estate Health Care & 37% 5% Apartment Social Assistance 6% 3% Wholesale Trade Industrial 3% 7% Hotel 8% Retail Trade 8% Manufacturing All Ot
Slide 24: Key Takeaways; Small Business and Commercial Deposits
Key Takeaways 1. We understand commercial banking 2. A successful franchise 3. Grow through continued leverage of TD’s capabilities 4. Monitoring increase in NPA’s closely 47 Small Business and Commercial Deposits Wendy Suehrstedt Sr. EVP, Business Banking Solutions 24
Slide 25: Why Focus on Small Business?
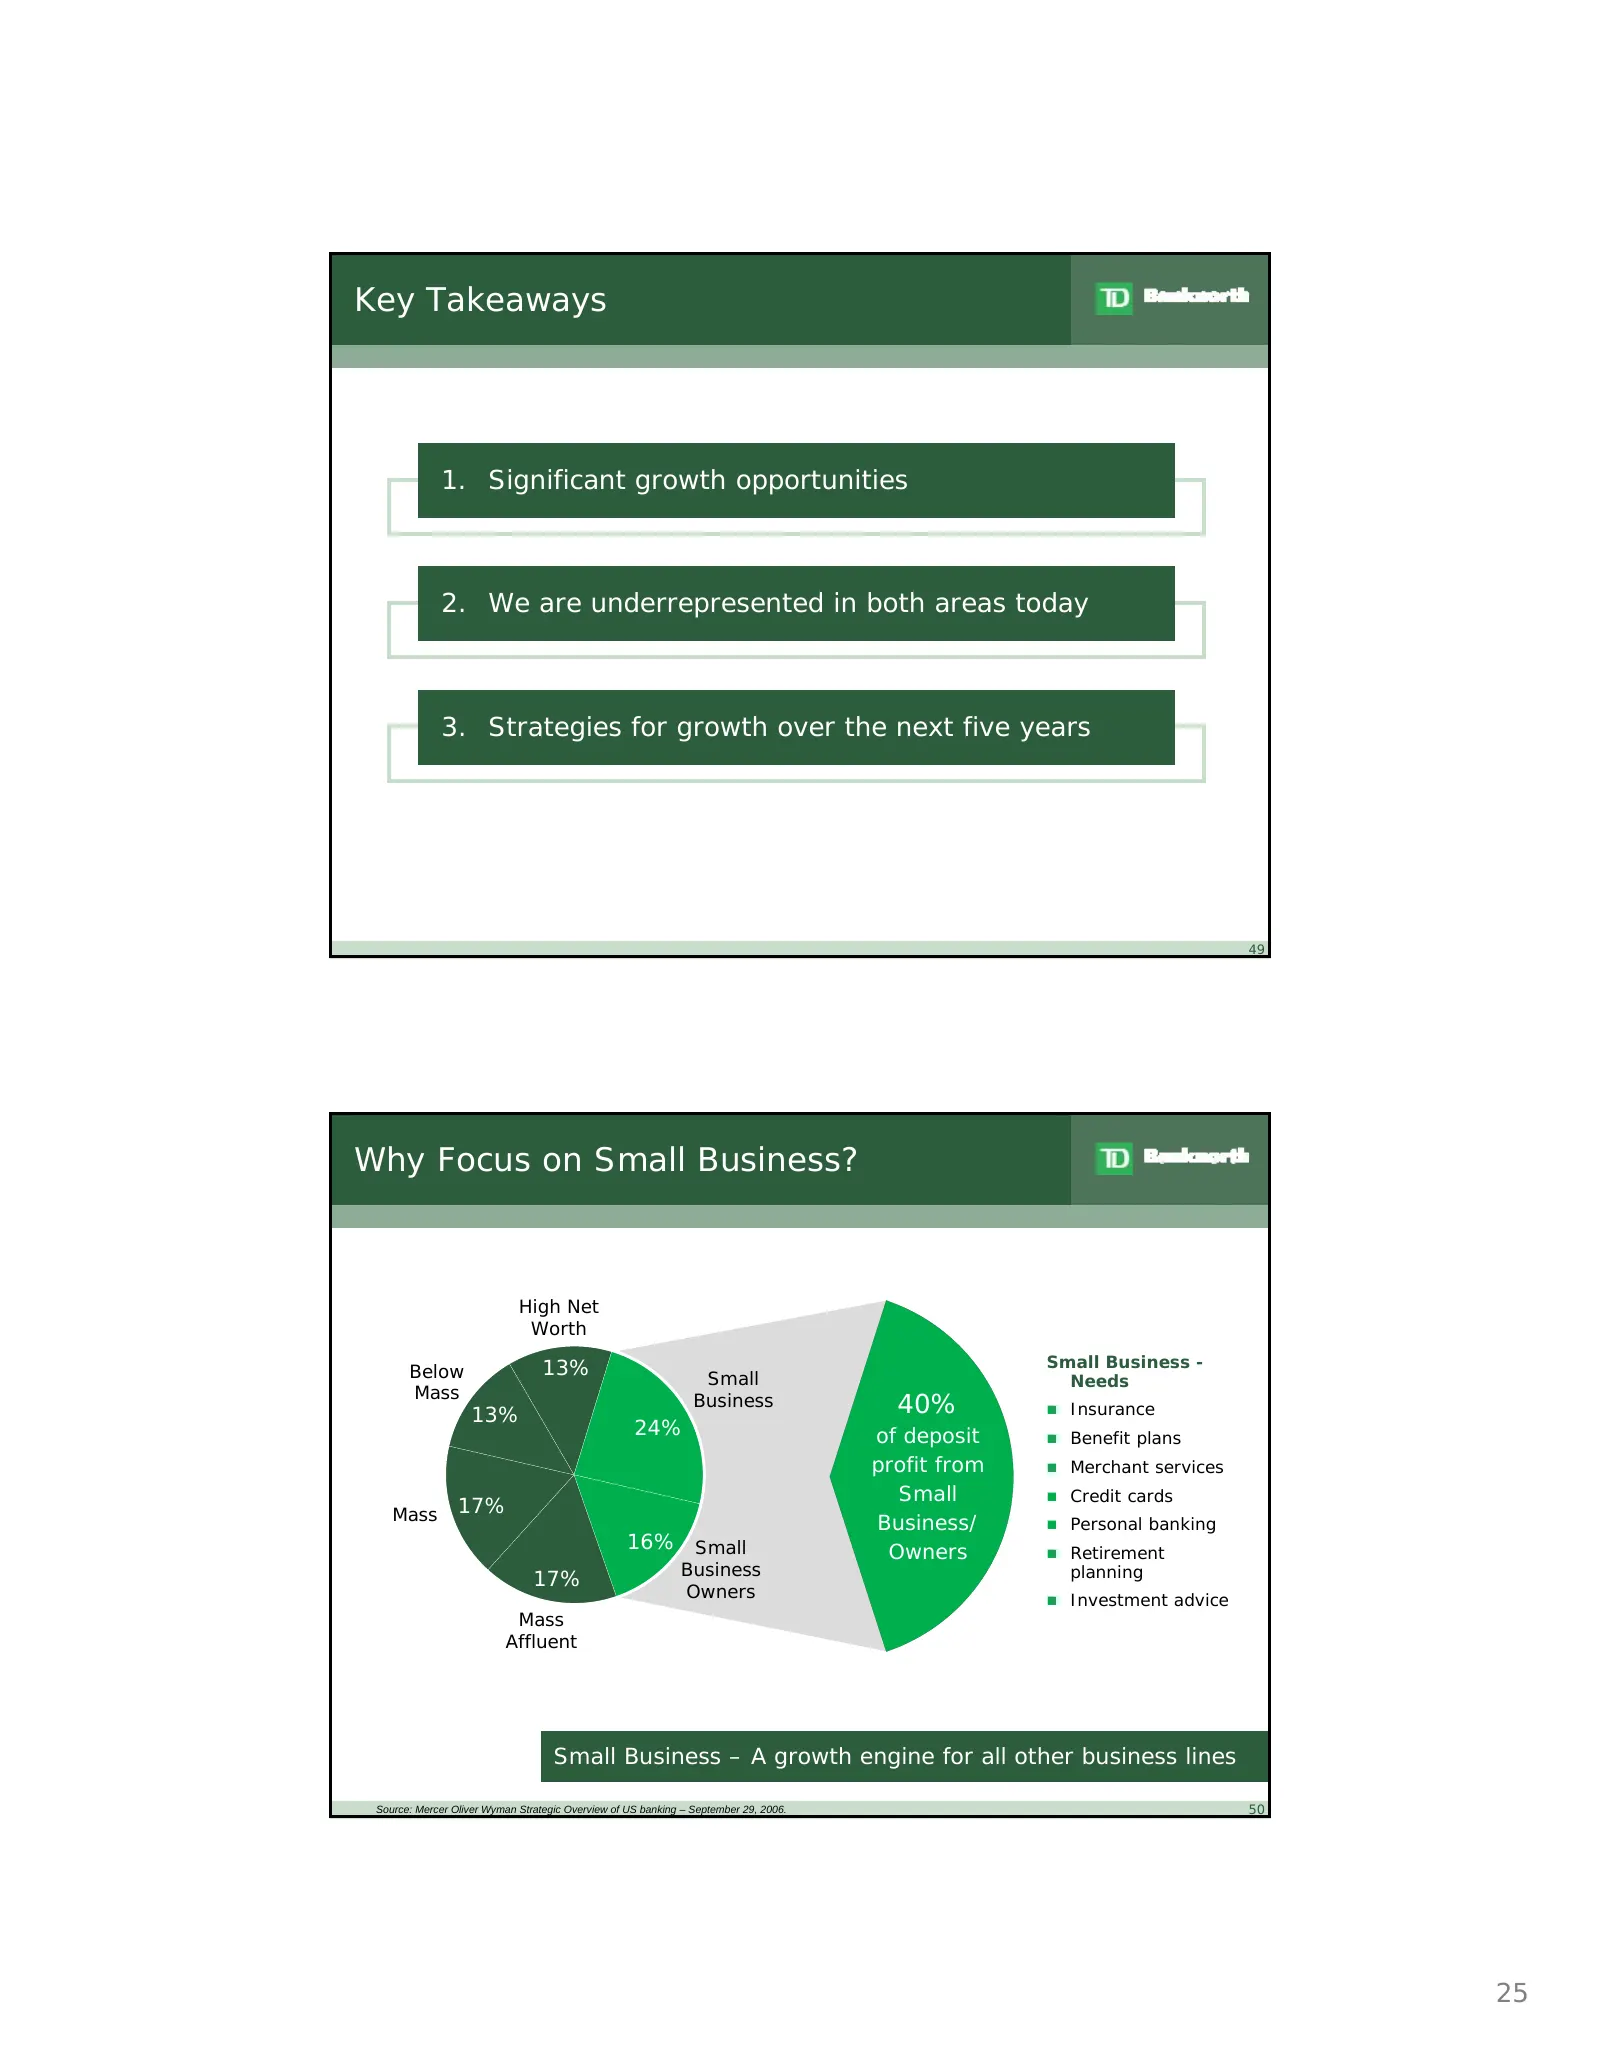
Key Takeaways 1. Significant growth opportunities 2. We are underrepresented in both areas today 3. Strategies for growth over the next five years 49 Why Focus on Small Business? High Net Worth 13% Small Business - Below Small Needs Mass 13% Business 40% Insurance 24% of deposit Benefit plans pr
Slide 26: Small Business: Solid Foundation for Growth
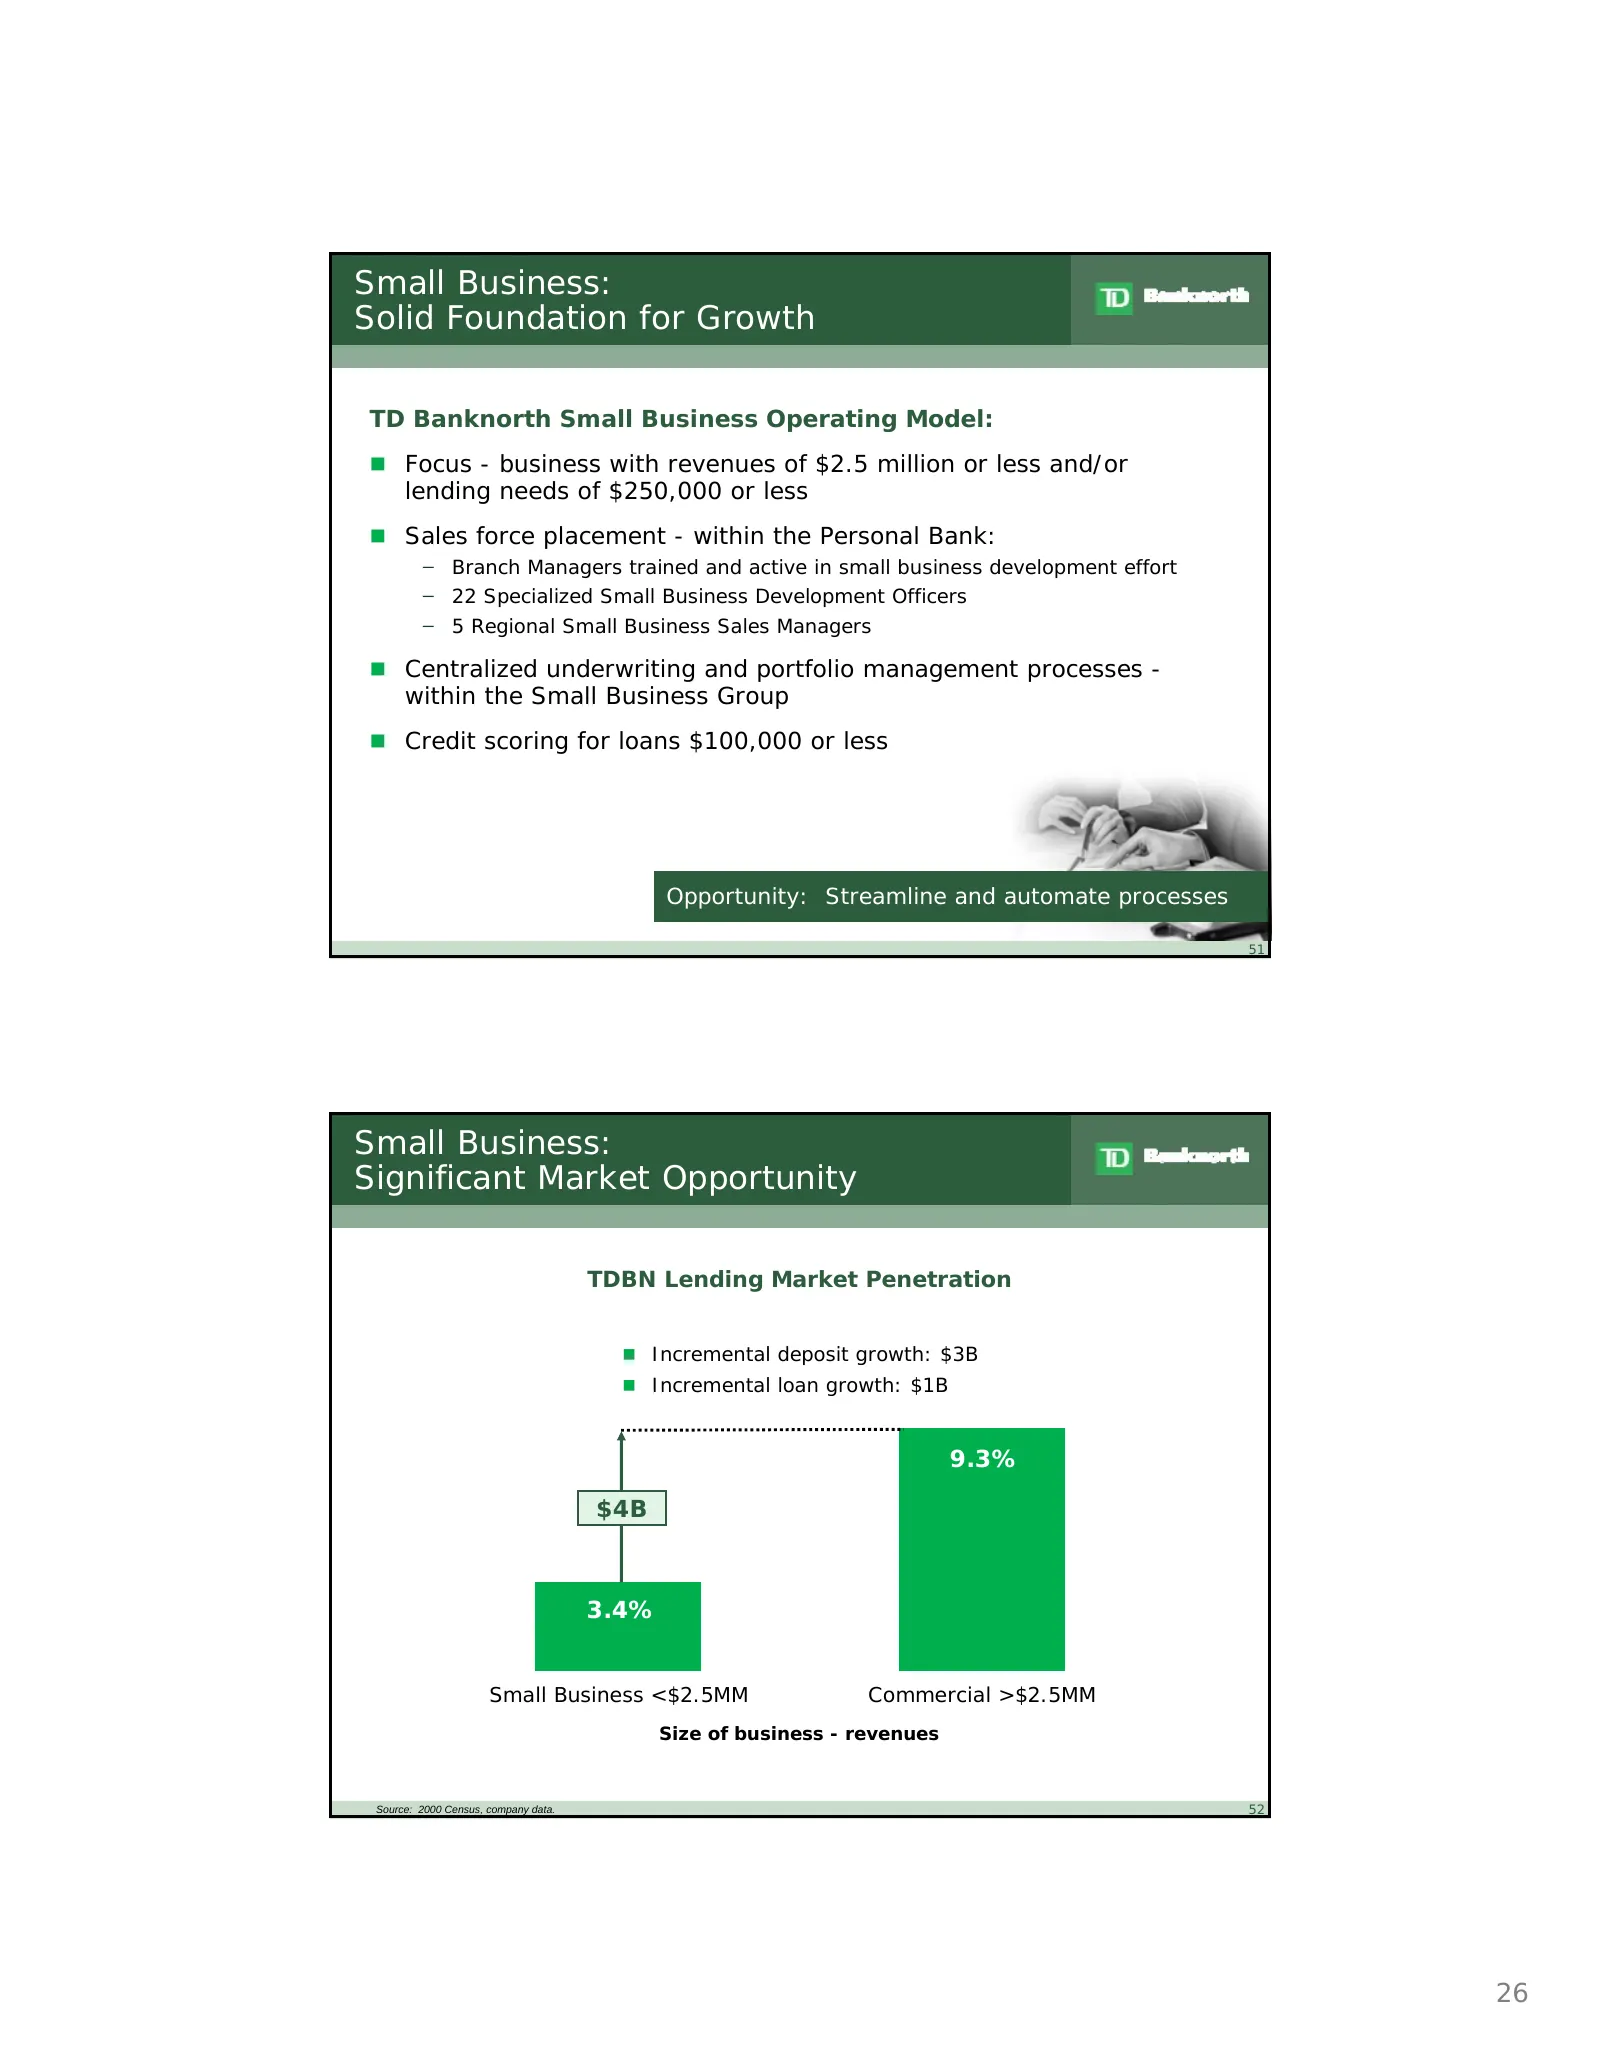
Small Business: Solid Foundation for Growth TD Banknorth Small Business Operating Model: Focus - business with revenues of $2.5 million or less and/or lending needs of $250,000 or less Sales force placement - within the Personal Bank: ̶ Branch Managers trained and active in small business develo
Slide 27: Small Business: Opportunity Within Existing Portfolio
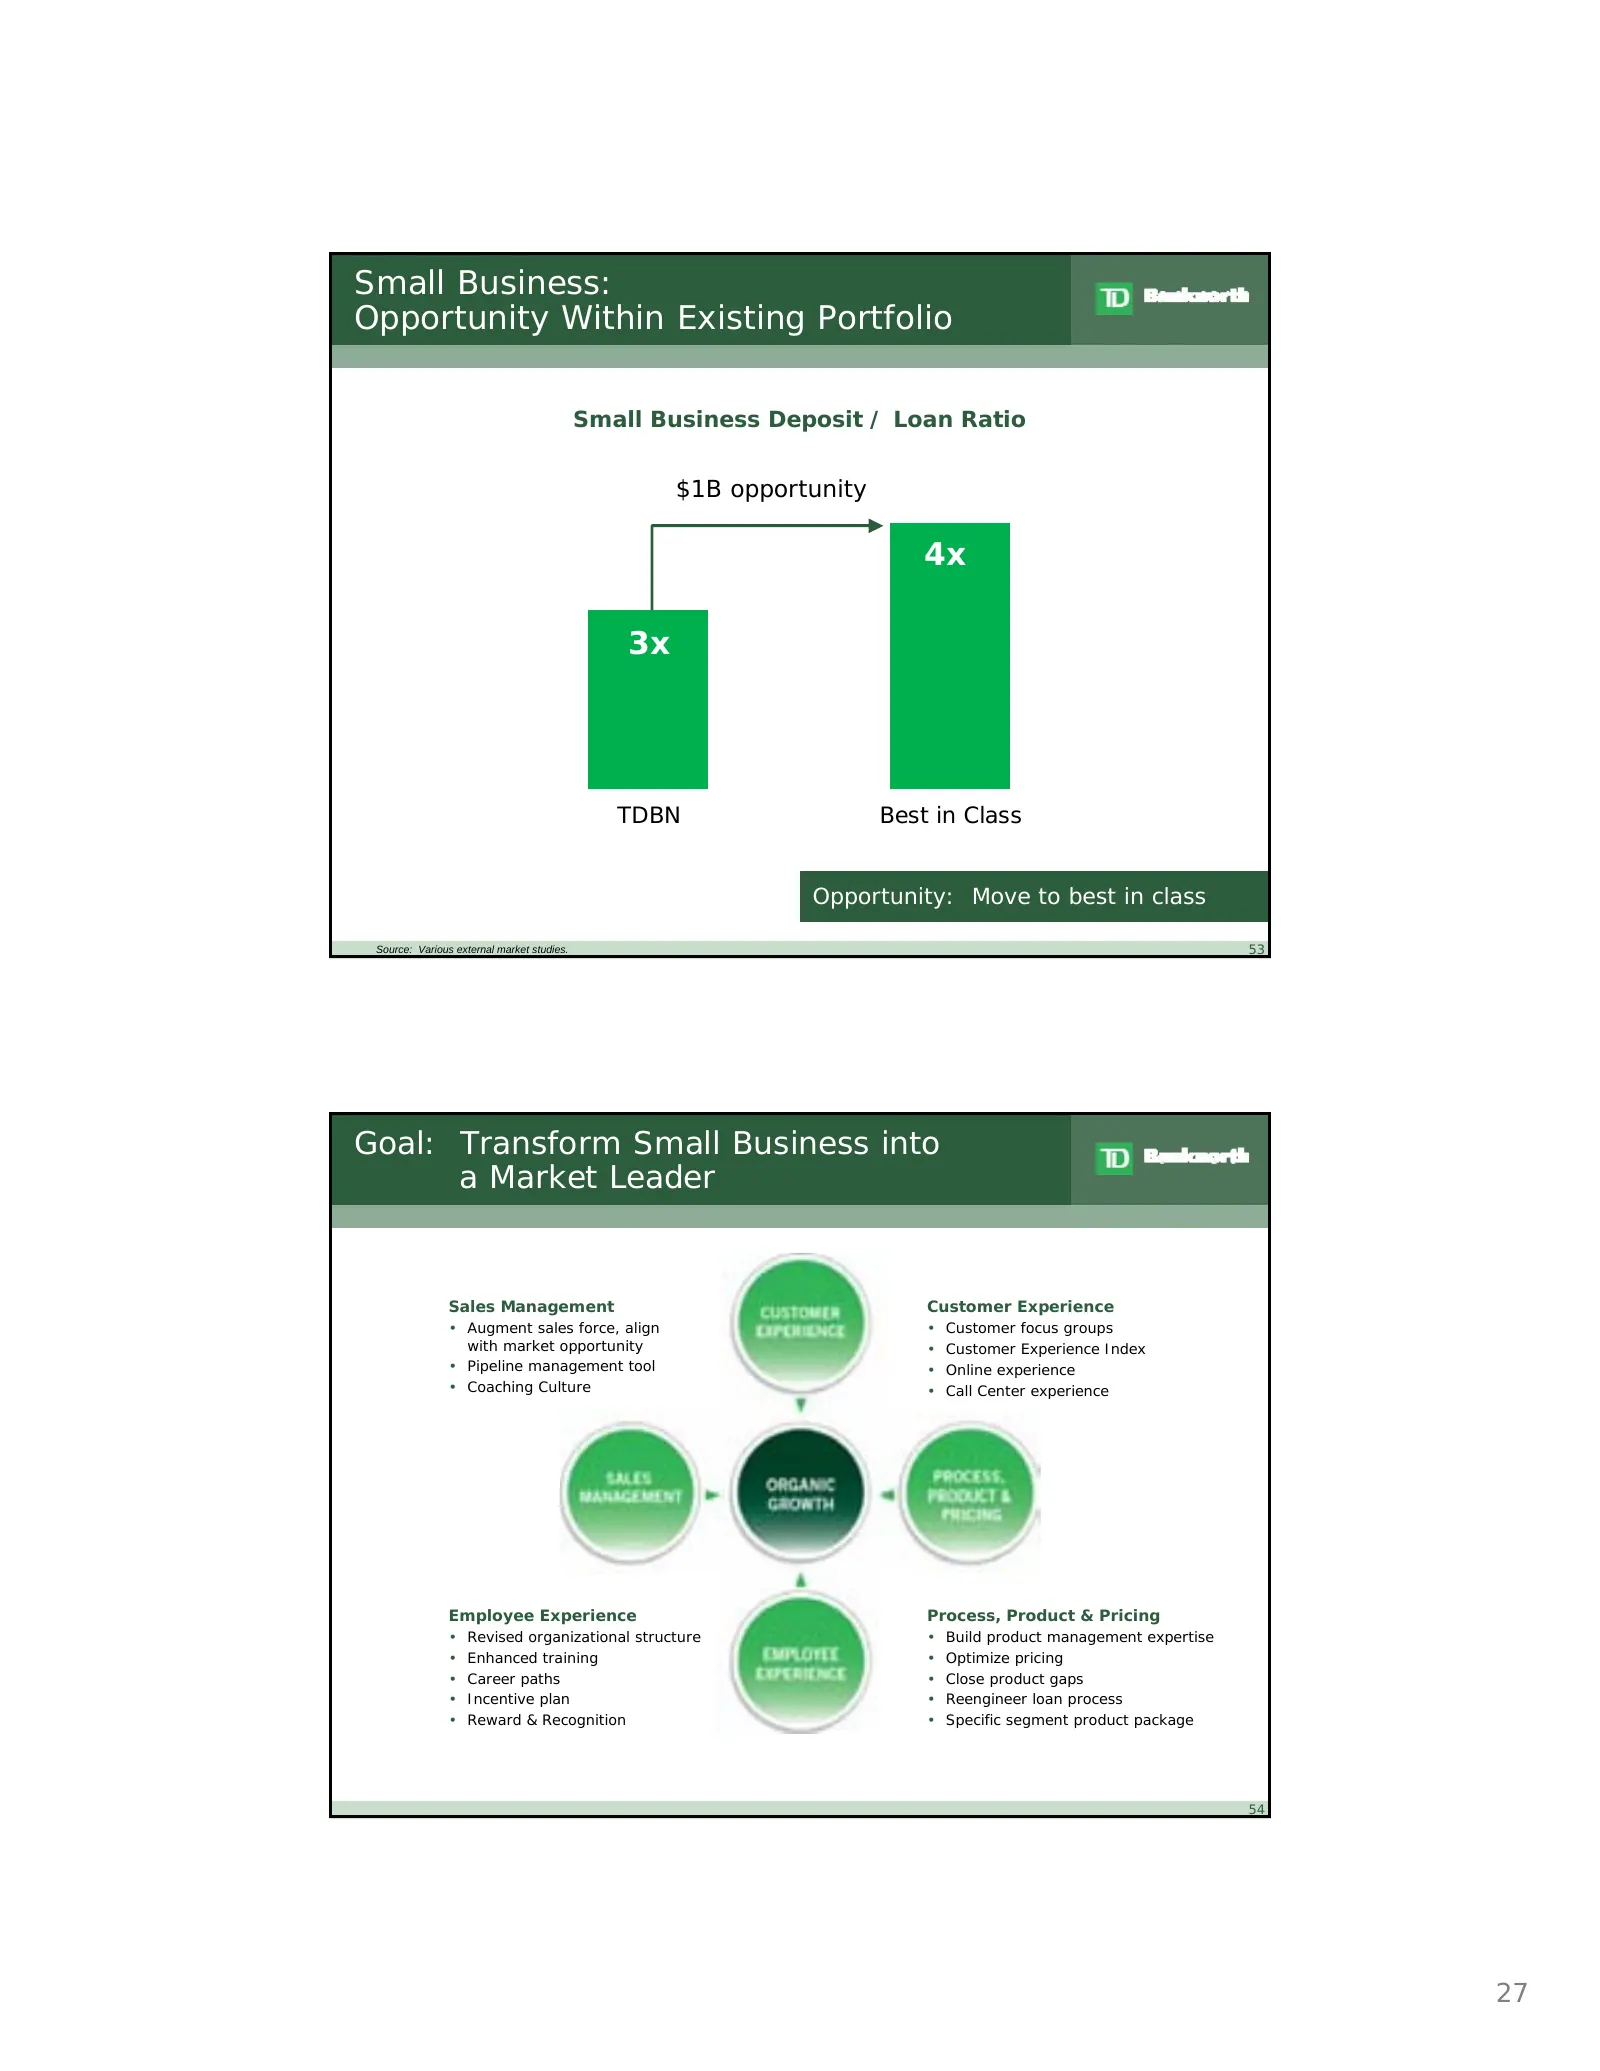
Small Business: Opportunity Within Existing Portfolio Small Business Deposit / Loan Ratio $1B opportunity 4x 3x TDBN Best in Class Opportunity: Move to best in class Source: Various external market studies. 53 Goal: Transform Small Business into a Market Leader Sales Management Customer Experience •
Slide 28: Commercial Deposits/Cash Management Changes
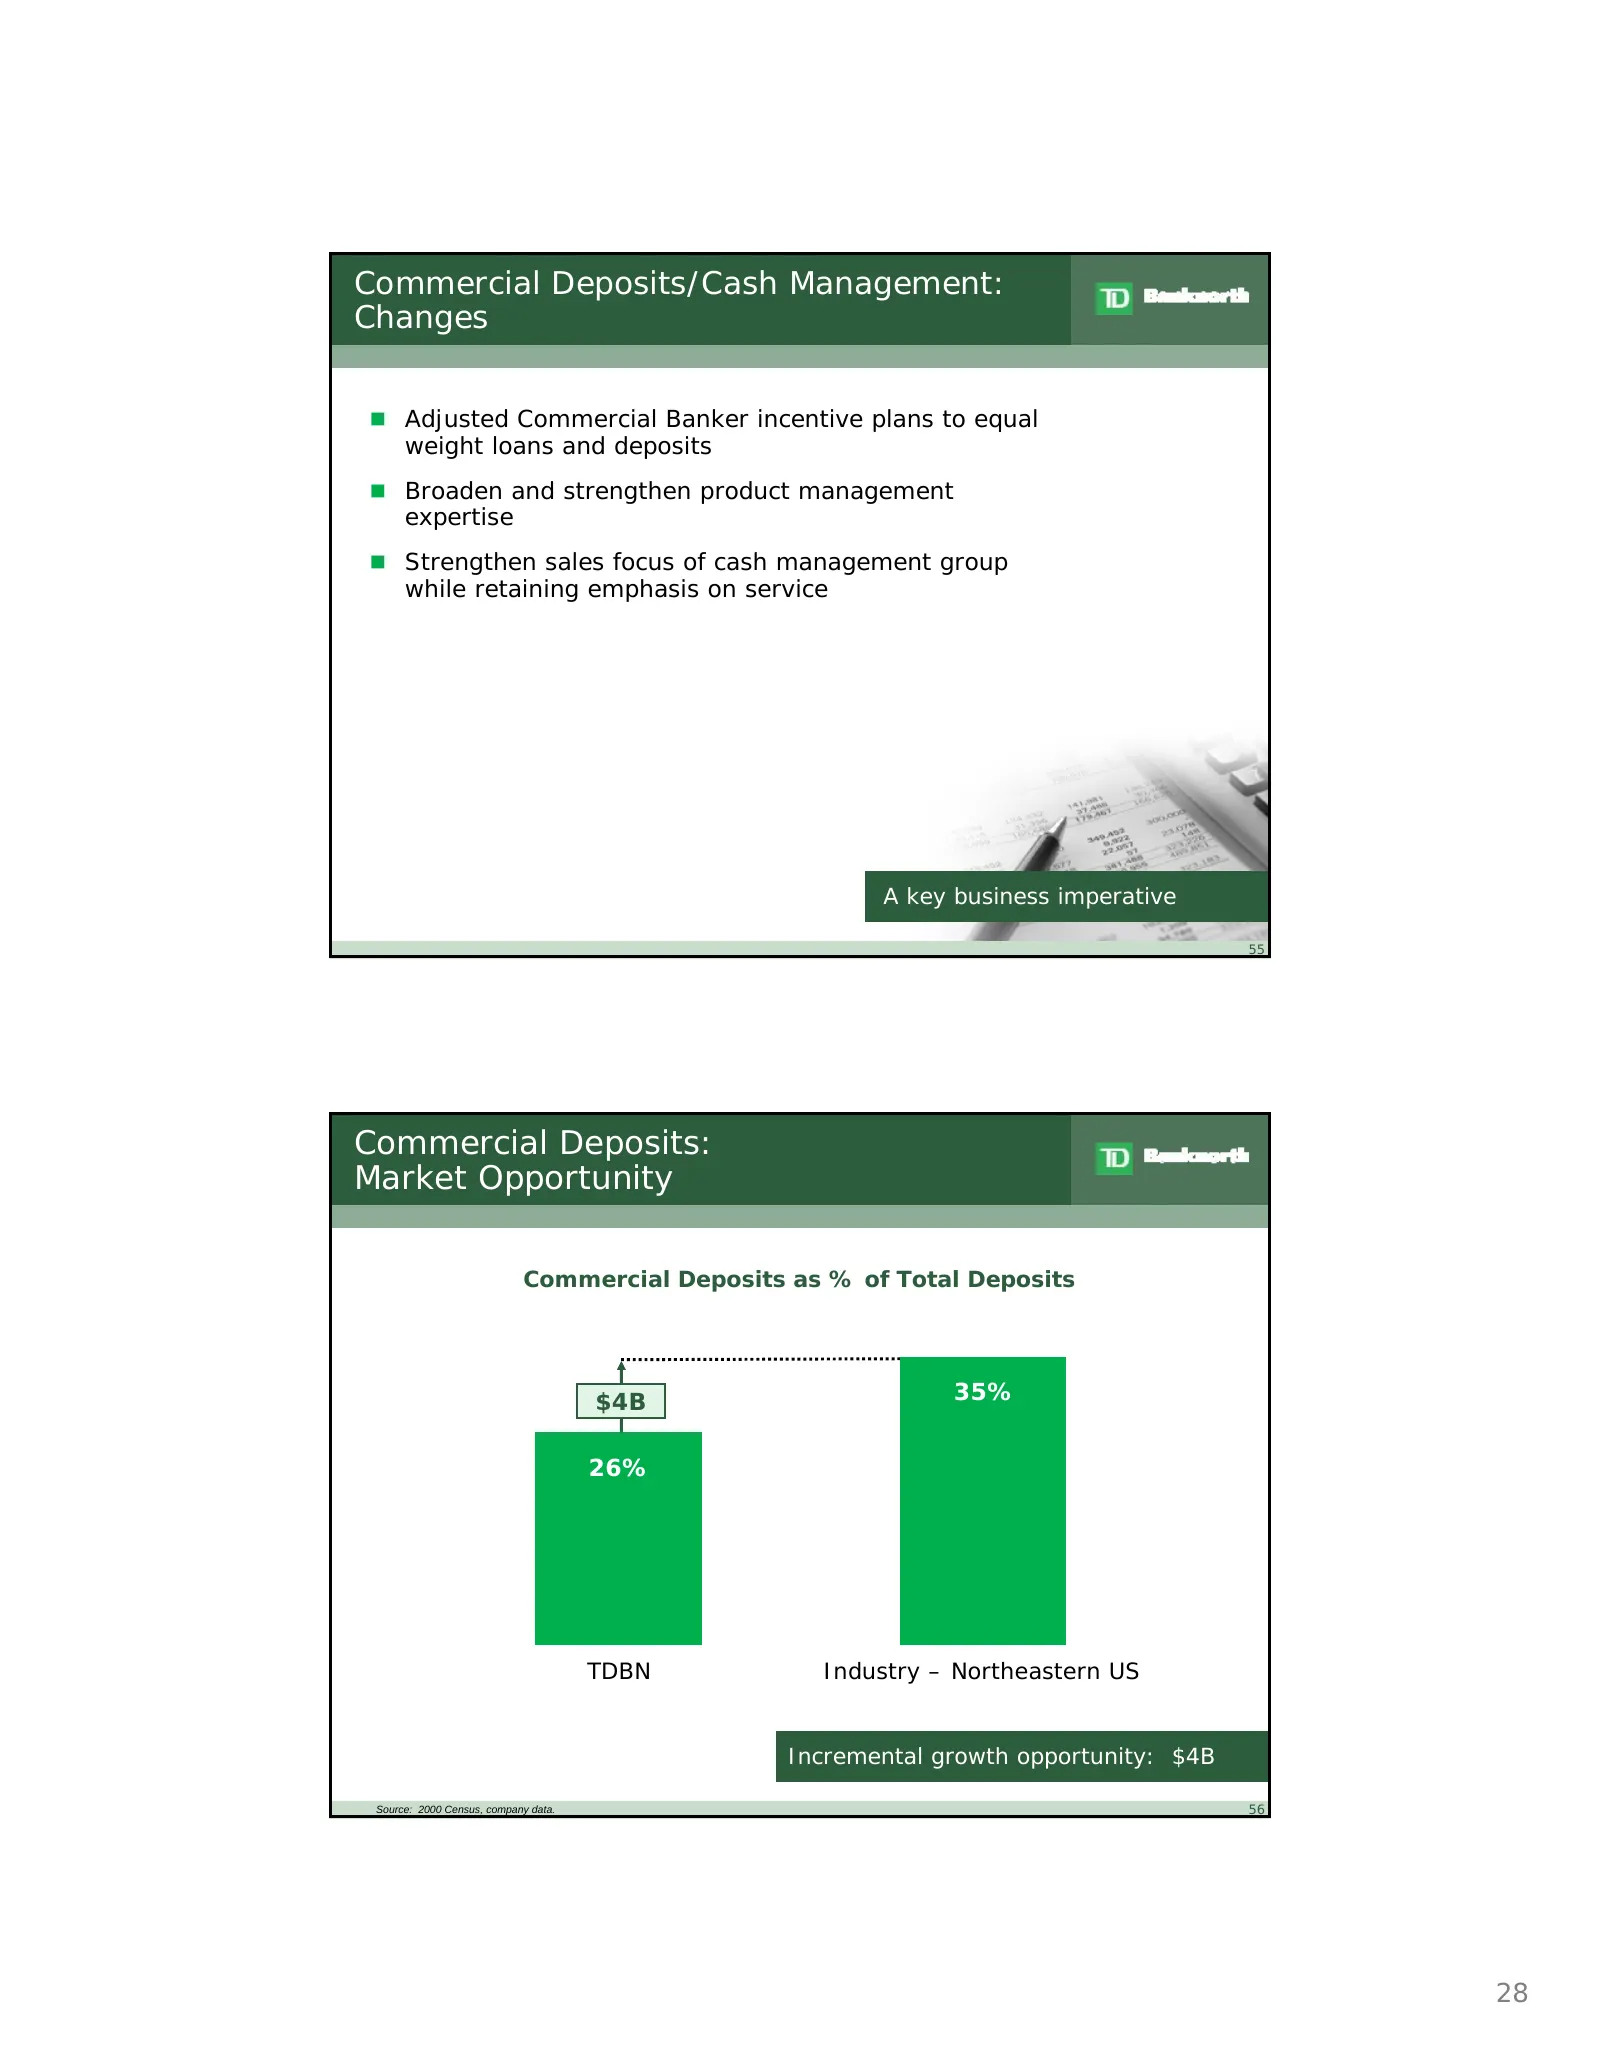
Commercial Deposits/Cash Management: Changes Adjusted Commercial Banker incentive plans to equal weight loans and deposits Broaden and strengthen product management expertise Strengthen sales focus of cash management group while retaining emphasis on service A key business imperative 55 Commer
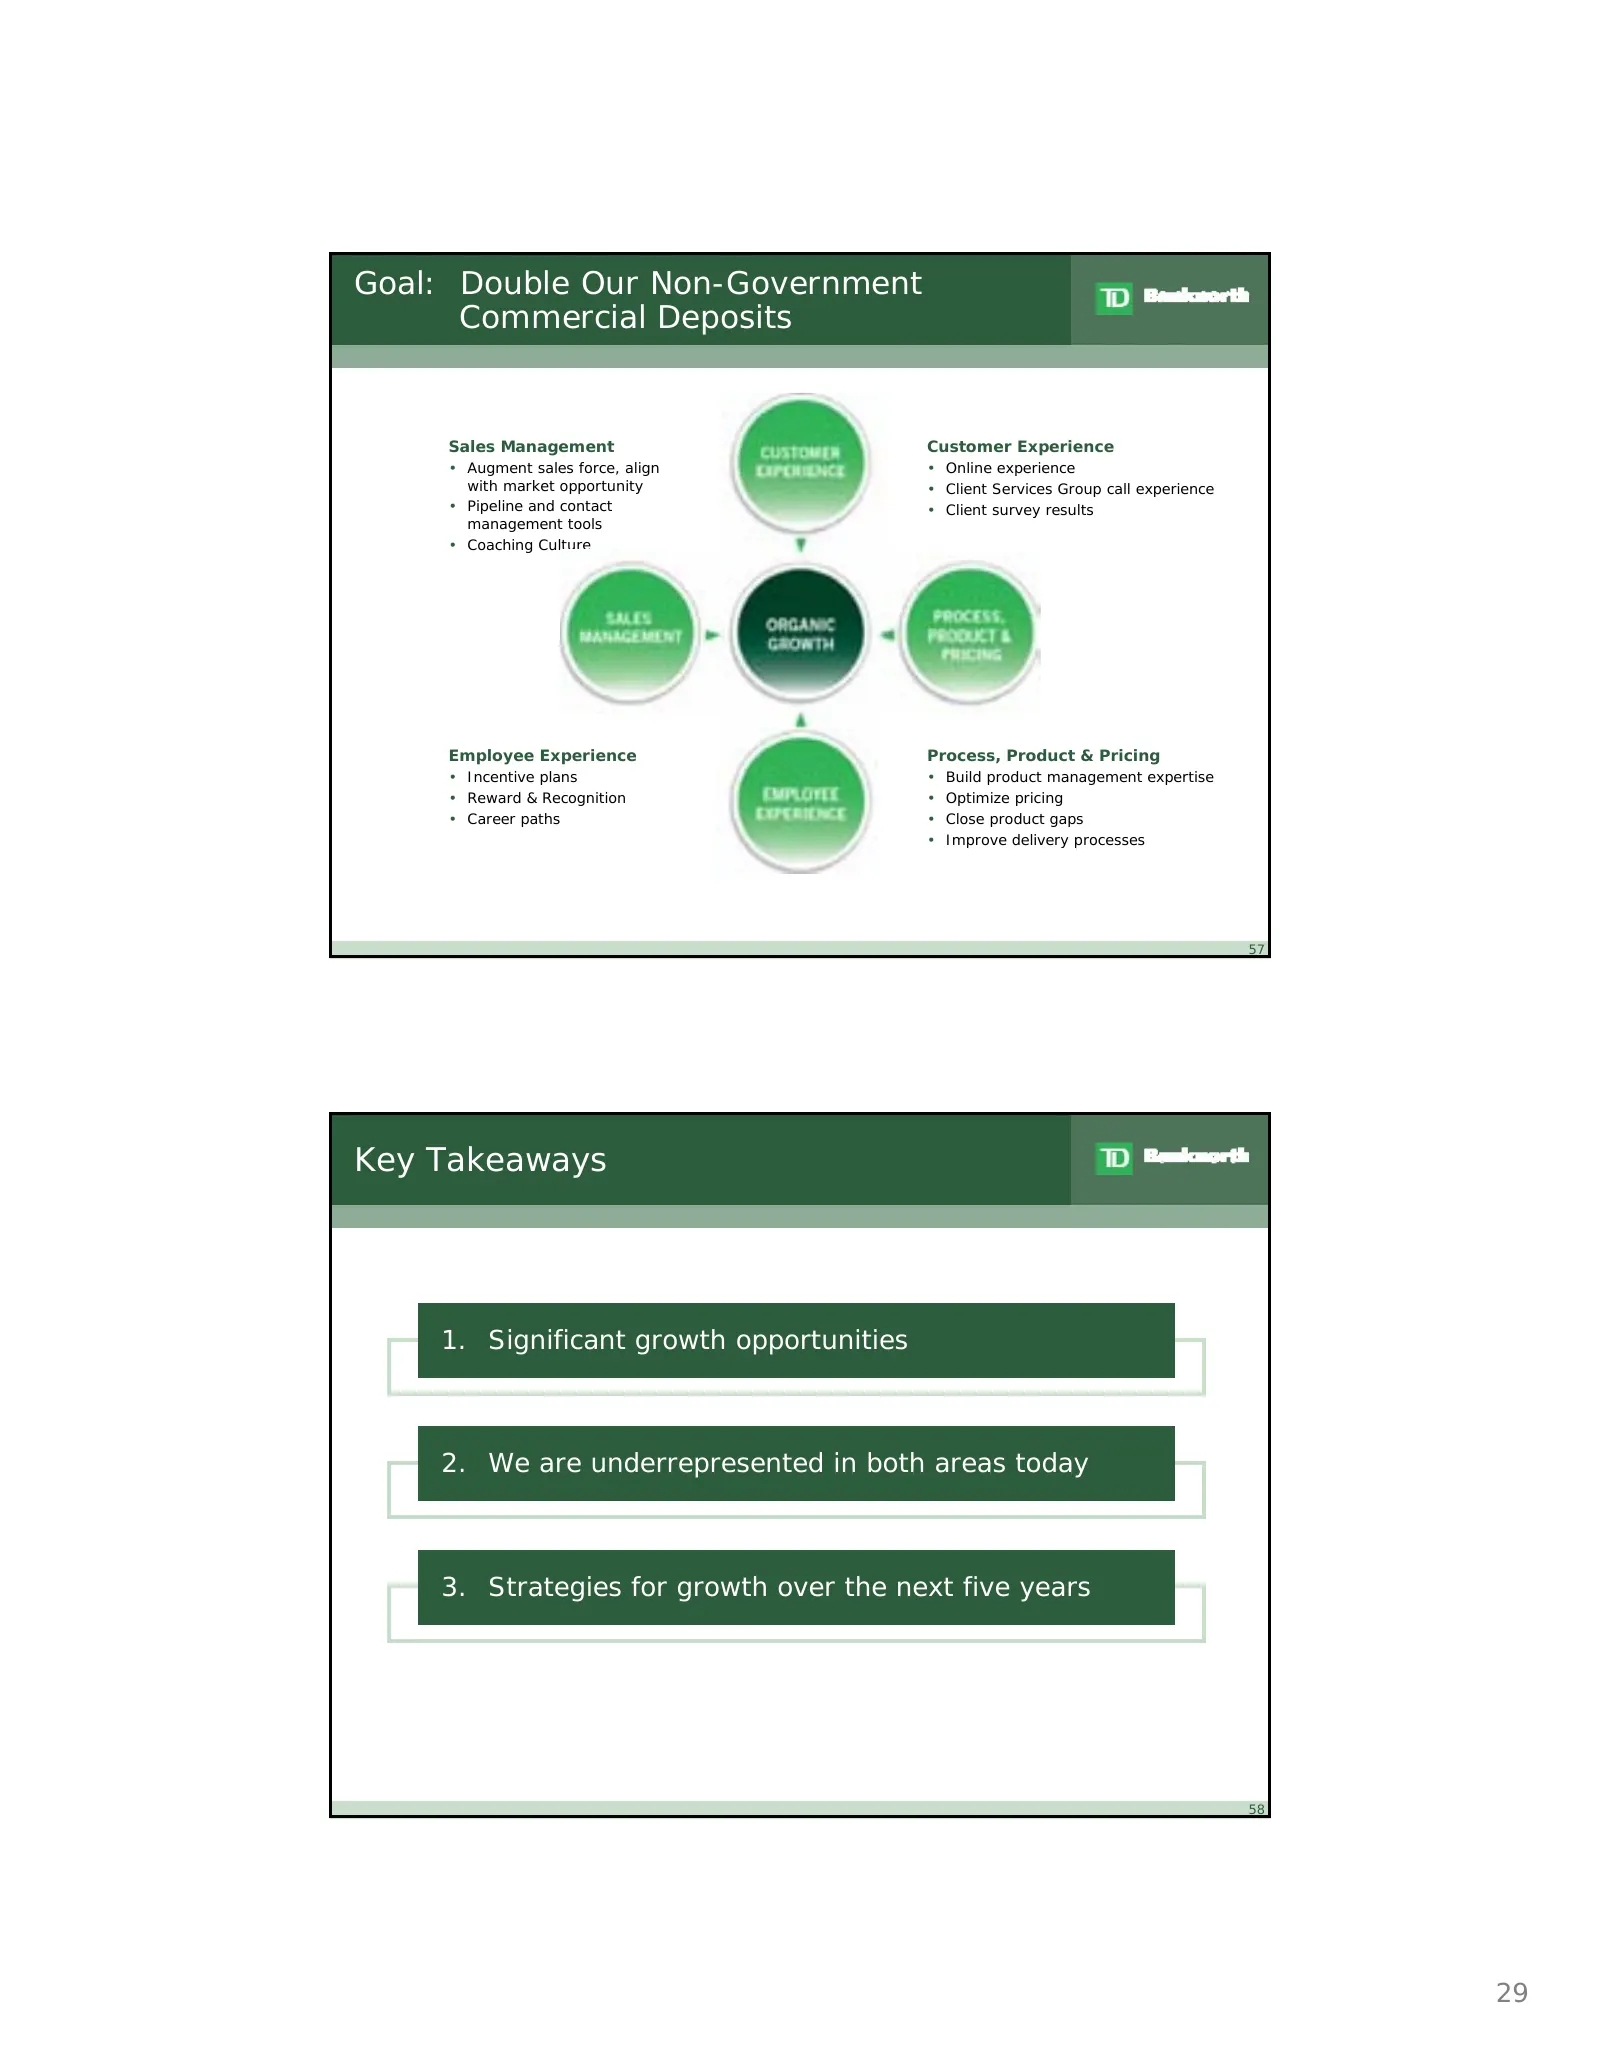
Slide 29: Goal: Double Non-Government Commercial Deposits
Goal: Double Our Non-Government Commercial Deposits Sales Management Customer Experience • Augment sales force, align • Online experience with market opportunity • Client Services Group call experience • Pipeline and contact • Client survey results management tools • Coaching Culture Employee Experi
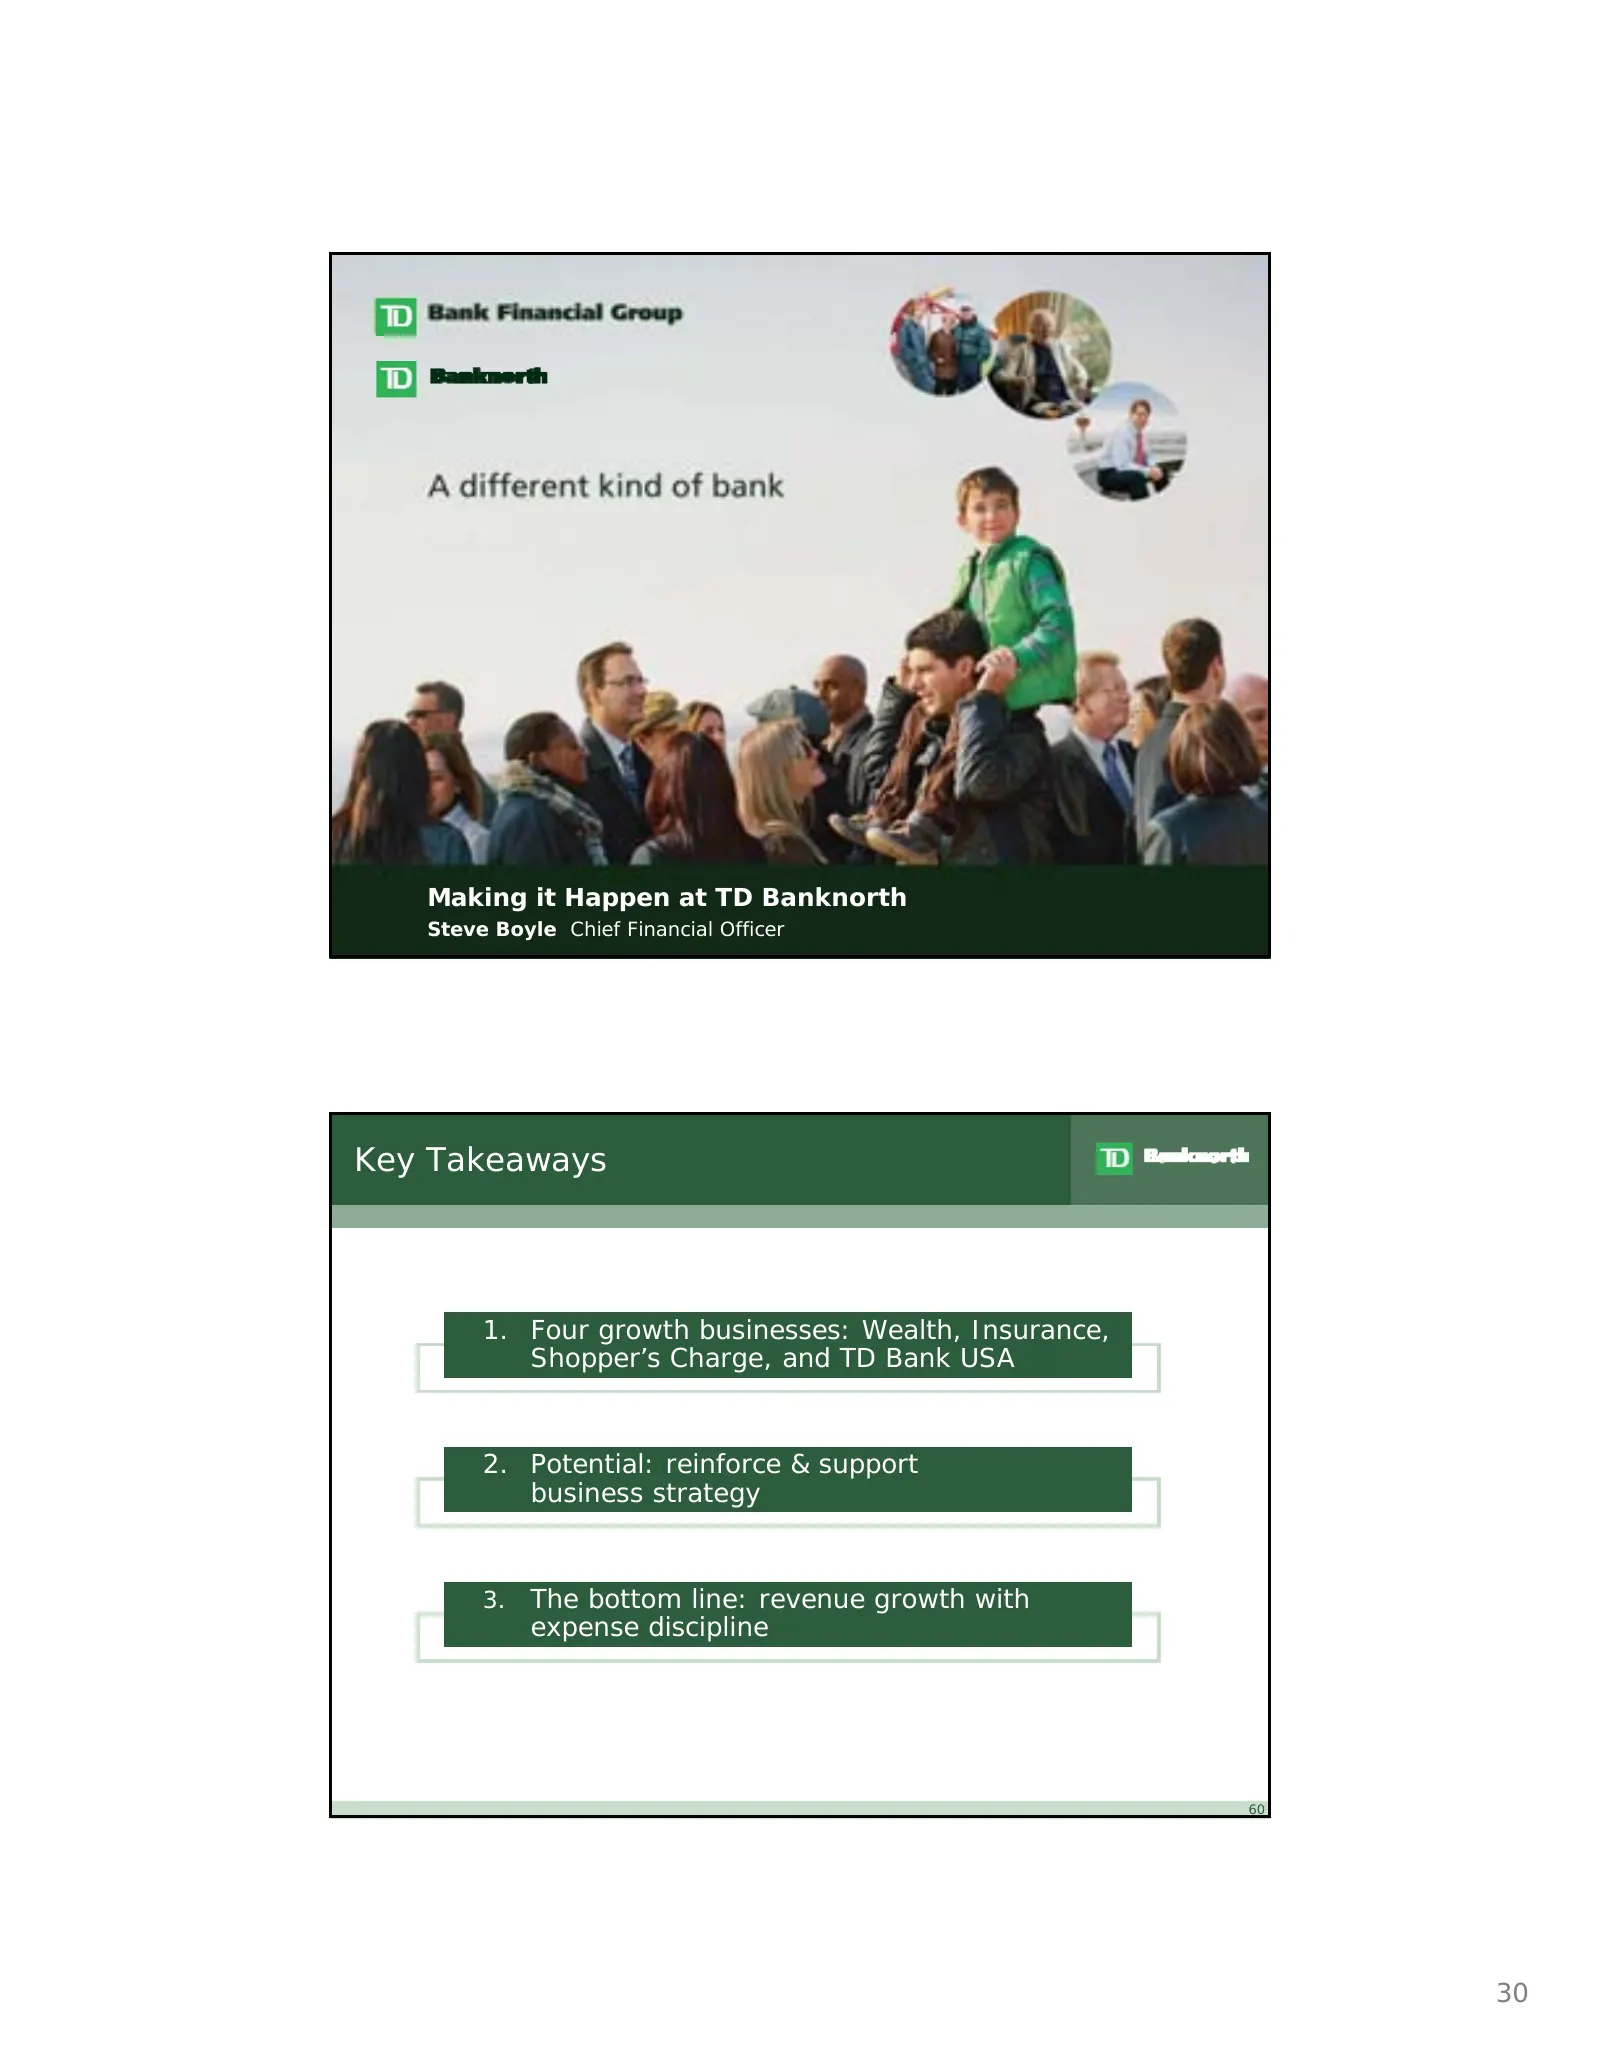
Slide 30: Key Takeaways; Making it Happen at TD Banknorth
Making it Happen at TD Banknorth Steve Boyle Chief Financial Officer Key Takeaways 1. Four growth businesses: Wealth, Insurance, Shopper’s Charge, and TD Bank USA 2. Potential: reinforce & support business strategy 3. The bottom line: revenue growth with expense discipline 60 30
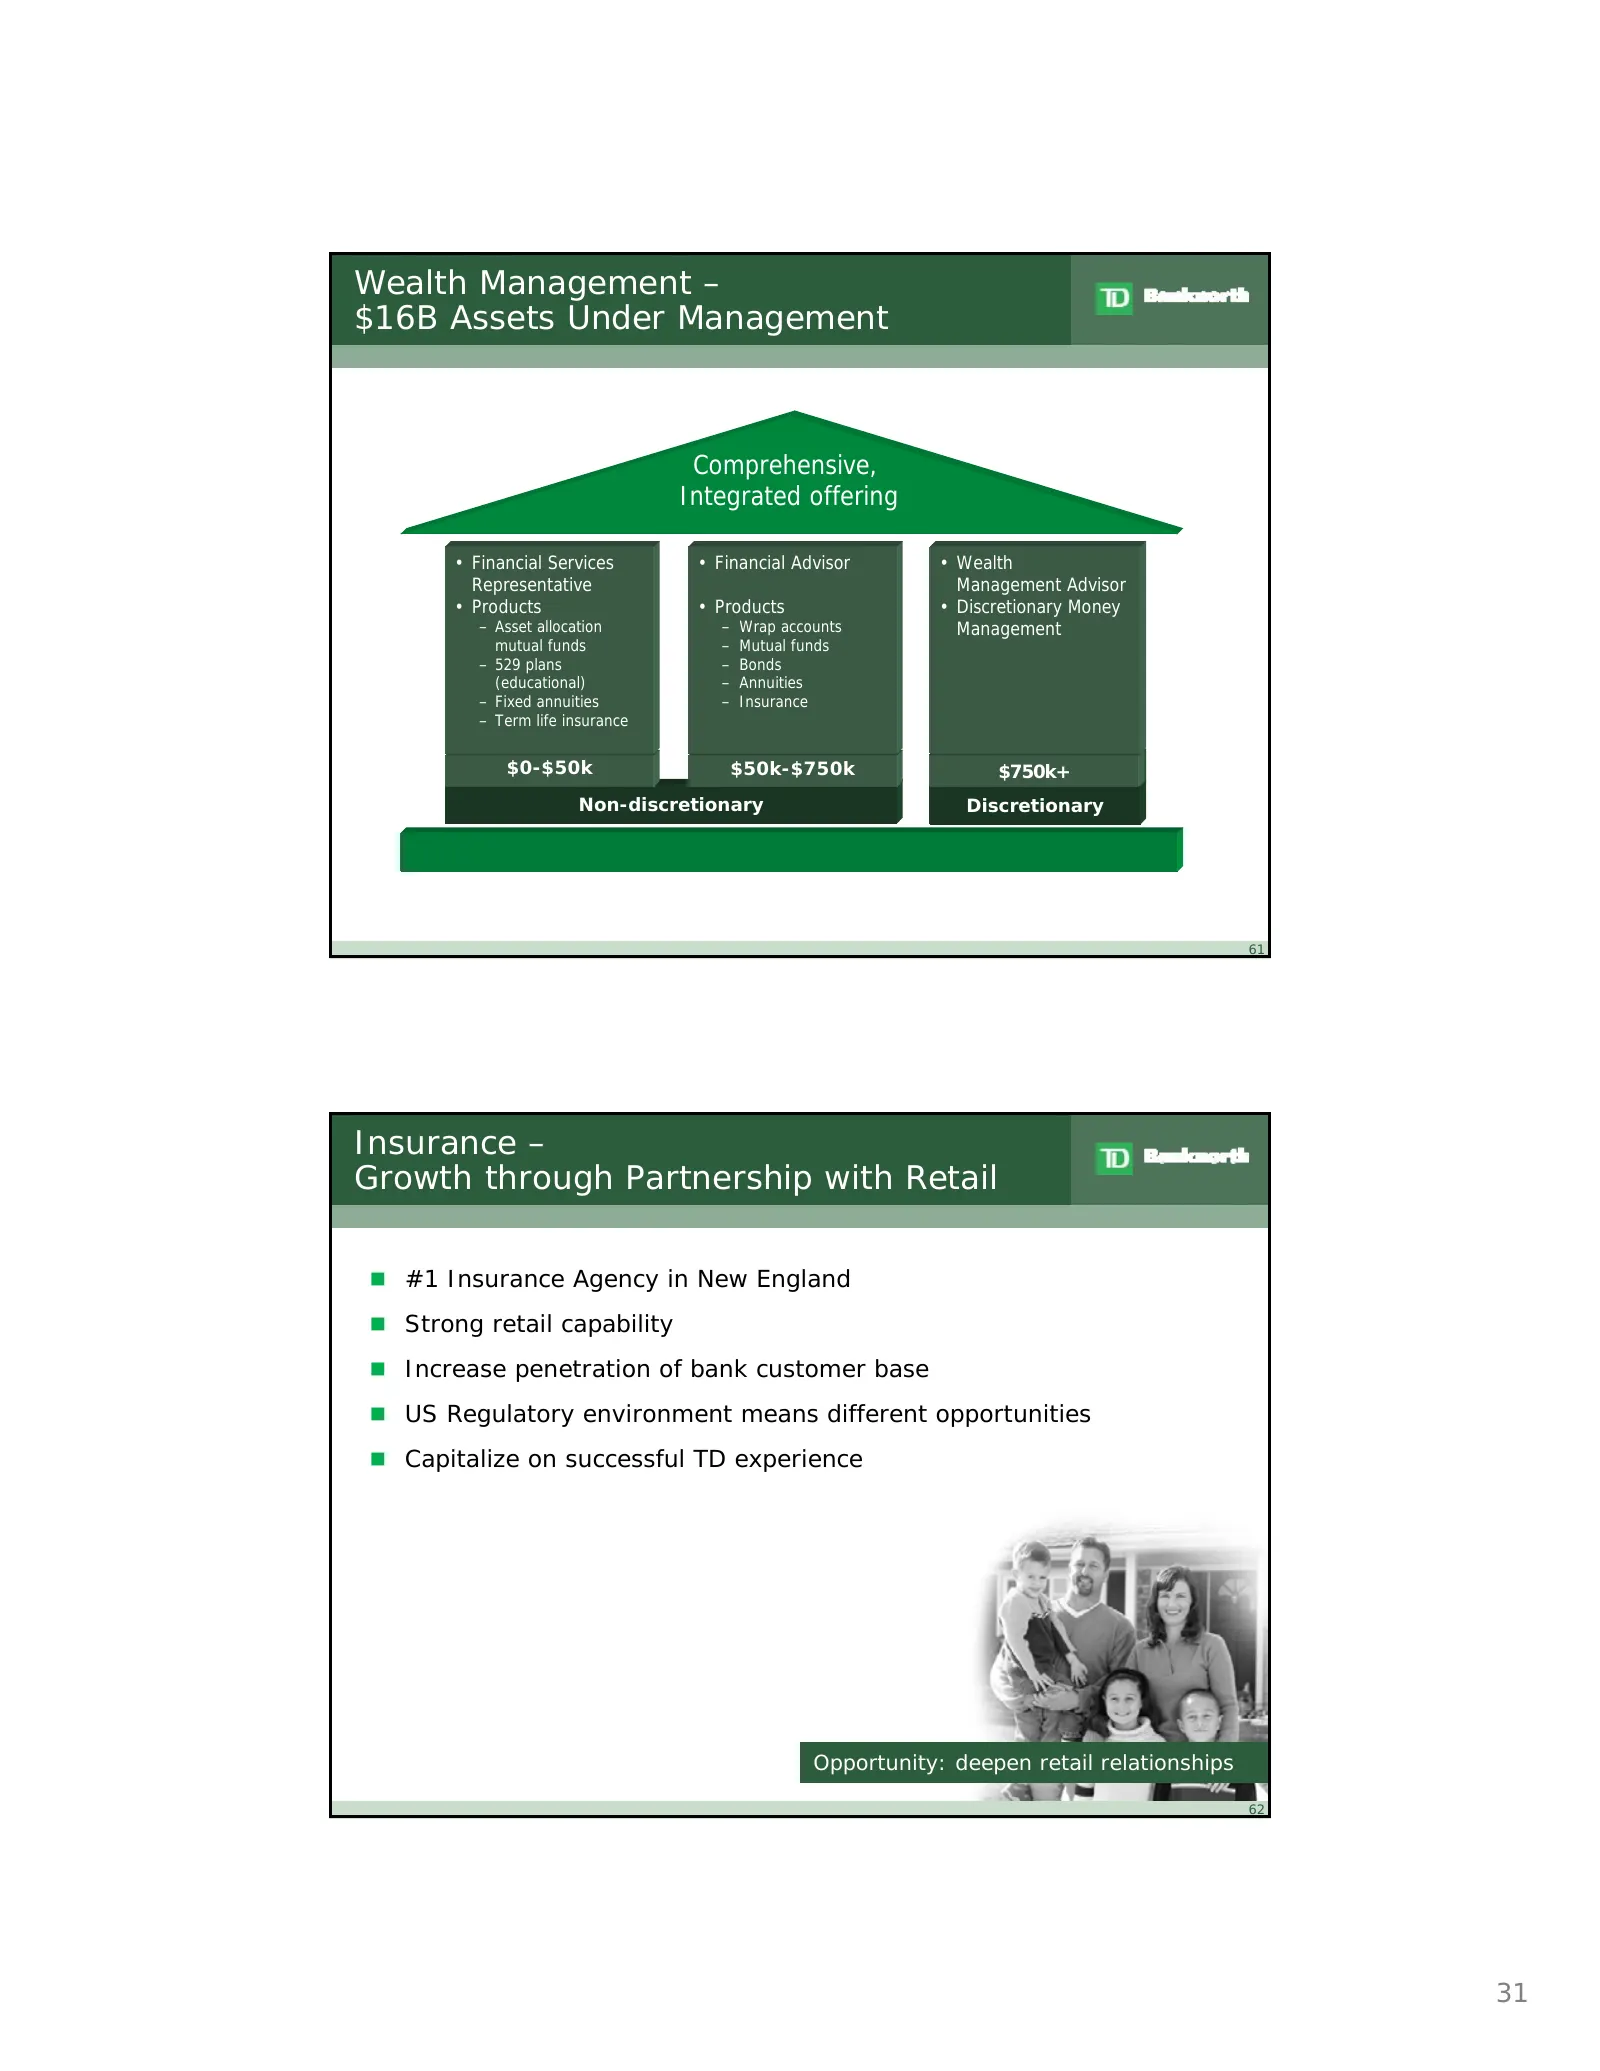
Slide 31: Wealth Management and Insurance
Wealth Management – $16B Assets Under Management Comprehensive, Integrated offering • Financial Services • Financial Advisor • Wealth Representative Management Advisor • Products • Products • Discretionary Money – Asset allocation – Wrap accounts Management mutual funds – Mutual funds – 529 plans –
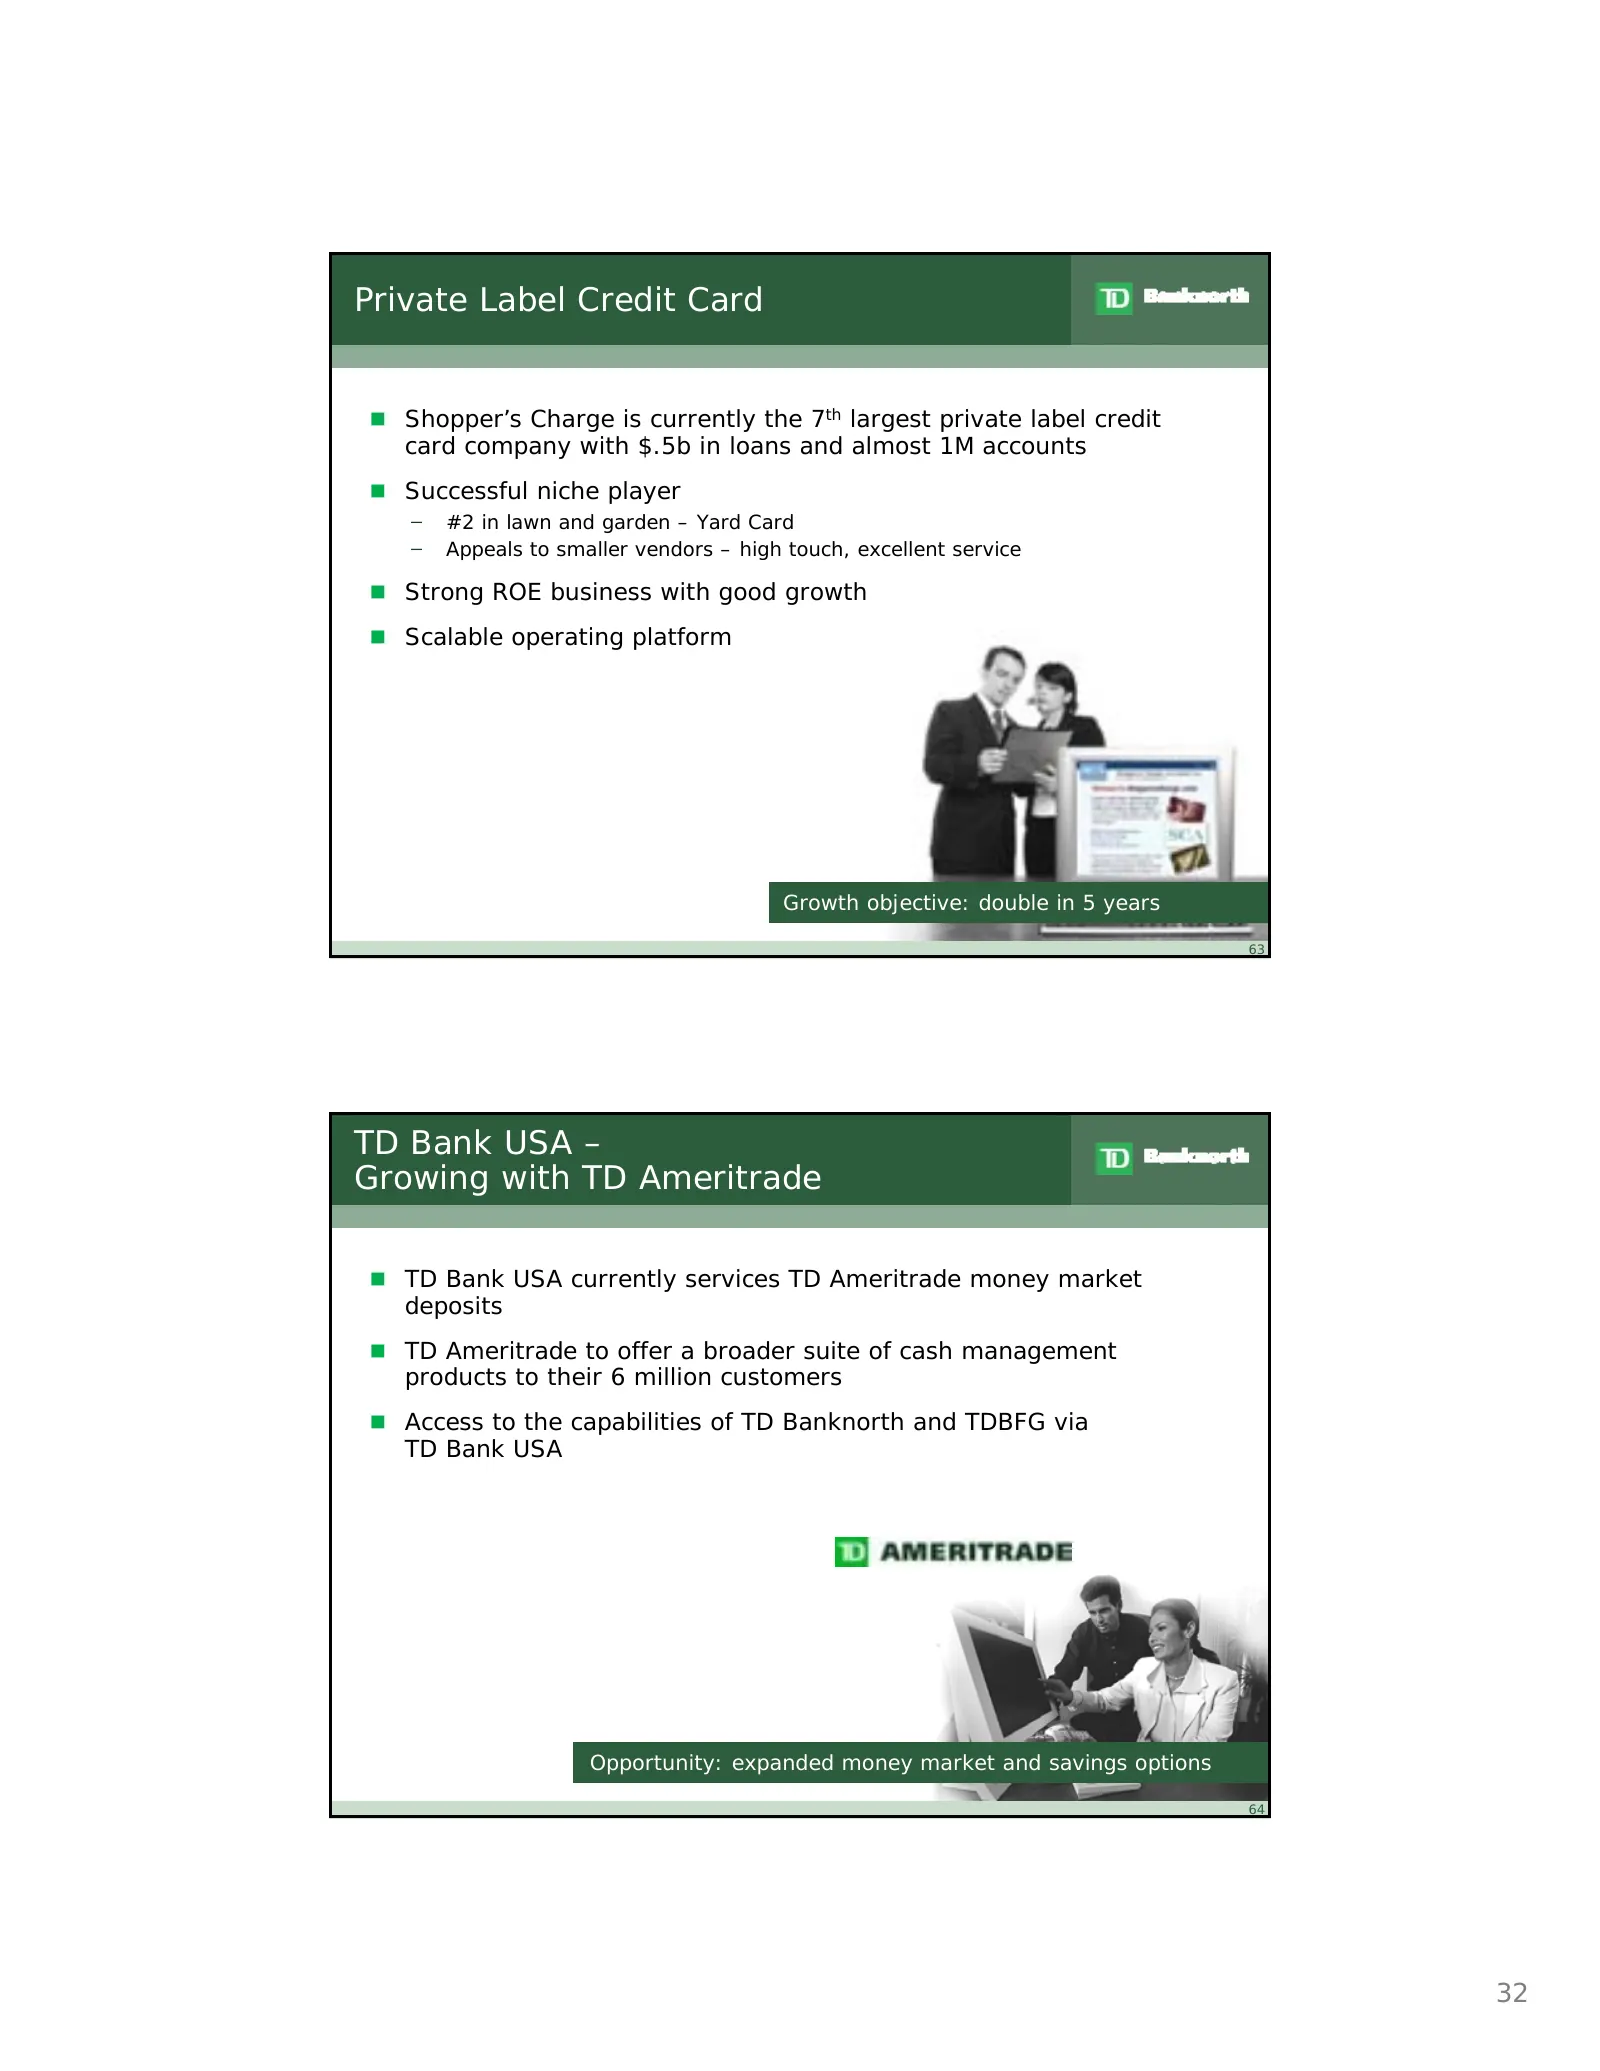
Slide 32: Private Label Credit Card; TD Bank USA
Private Label Credit Card Shopper’s Charge is currently the 7th largest private label credit card company with $.5b in loans and almost 1M accounts Successful niche player ̶ #2 in lawn and garden – Yard Card ̶ Appeals to smaller vendors – high touch, excellent service Strong ROE business with
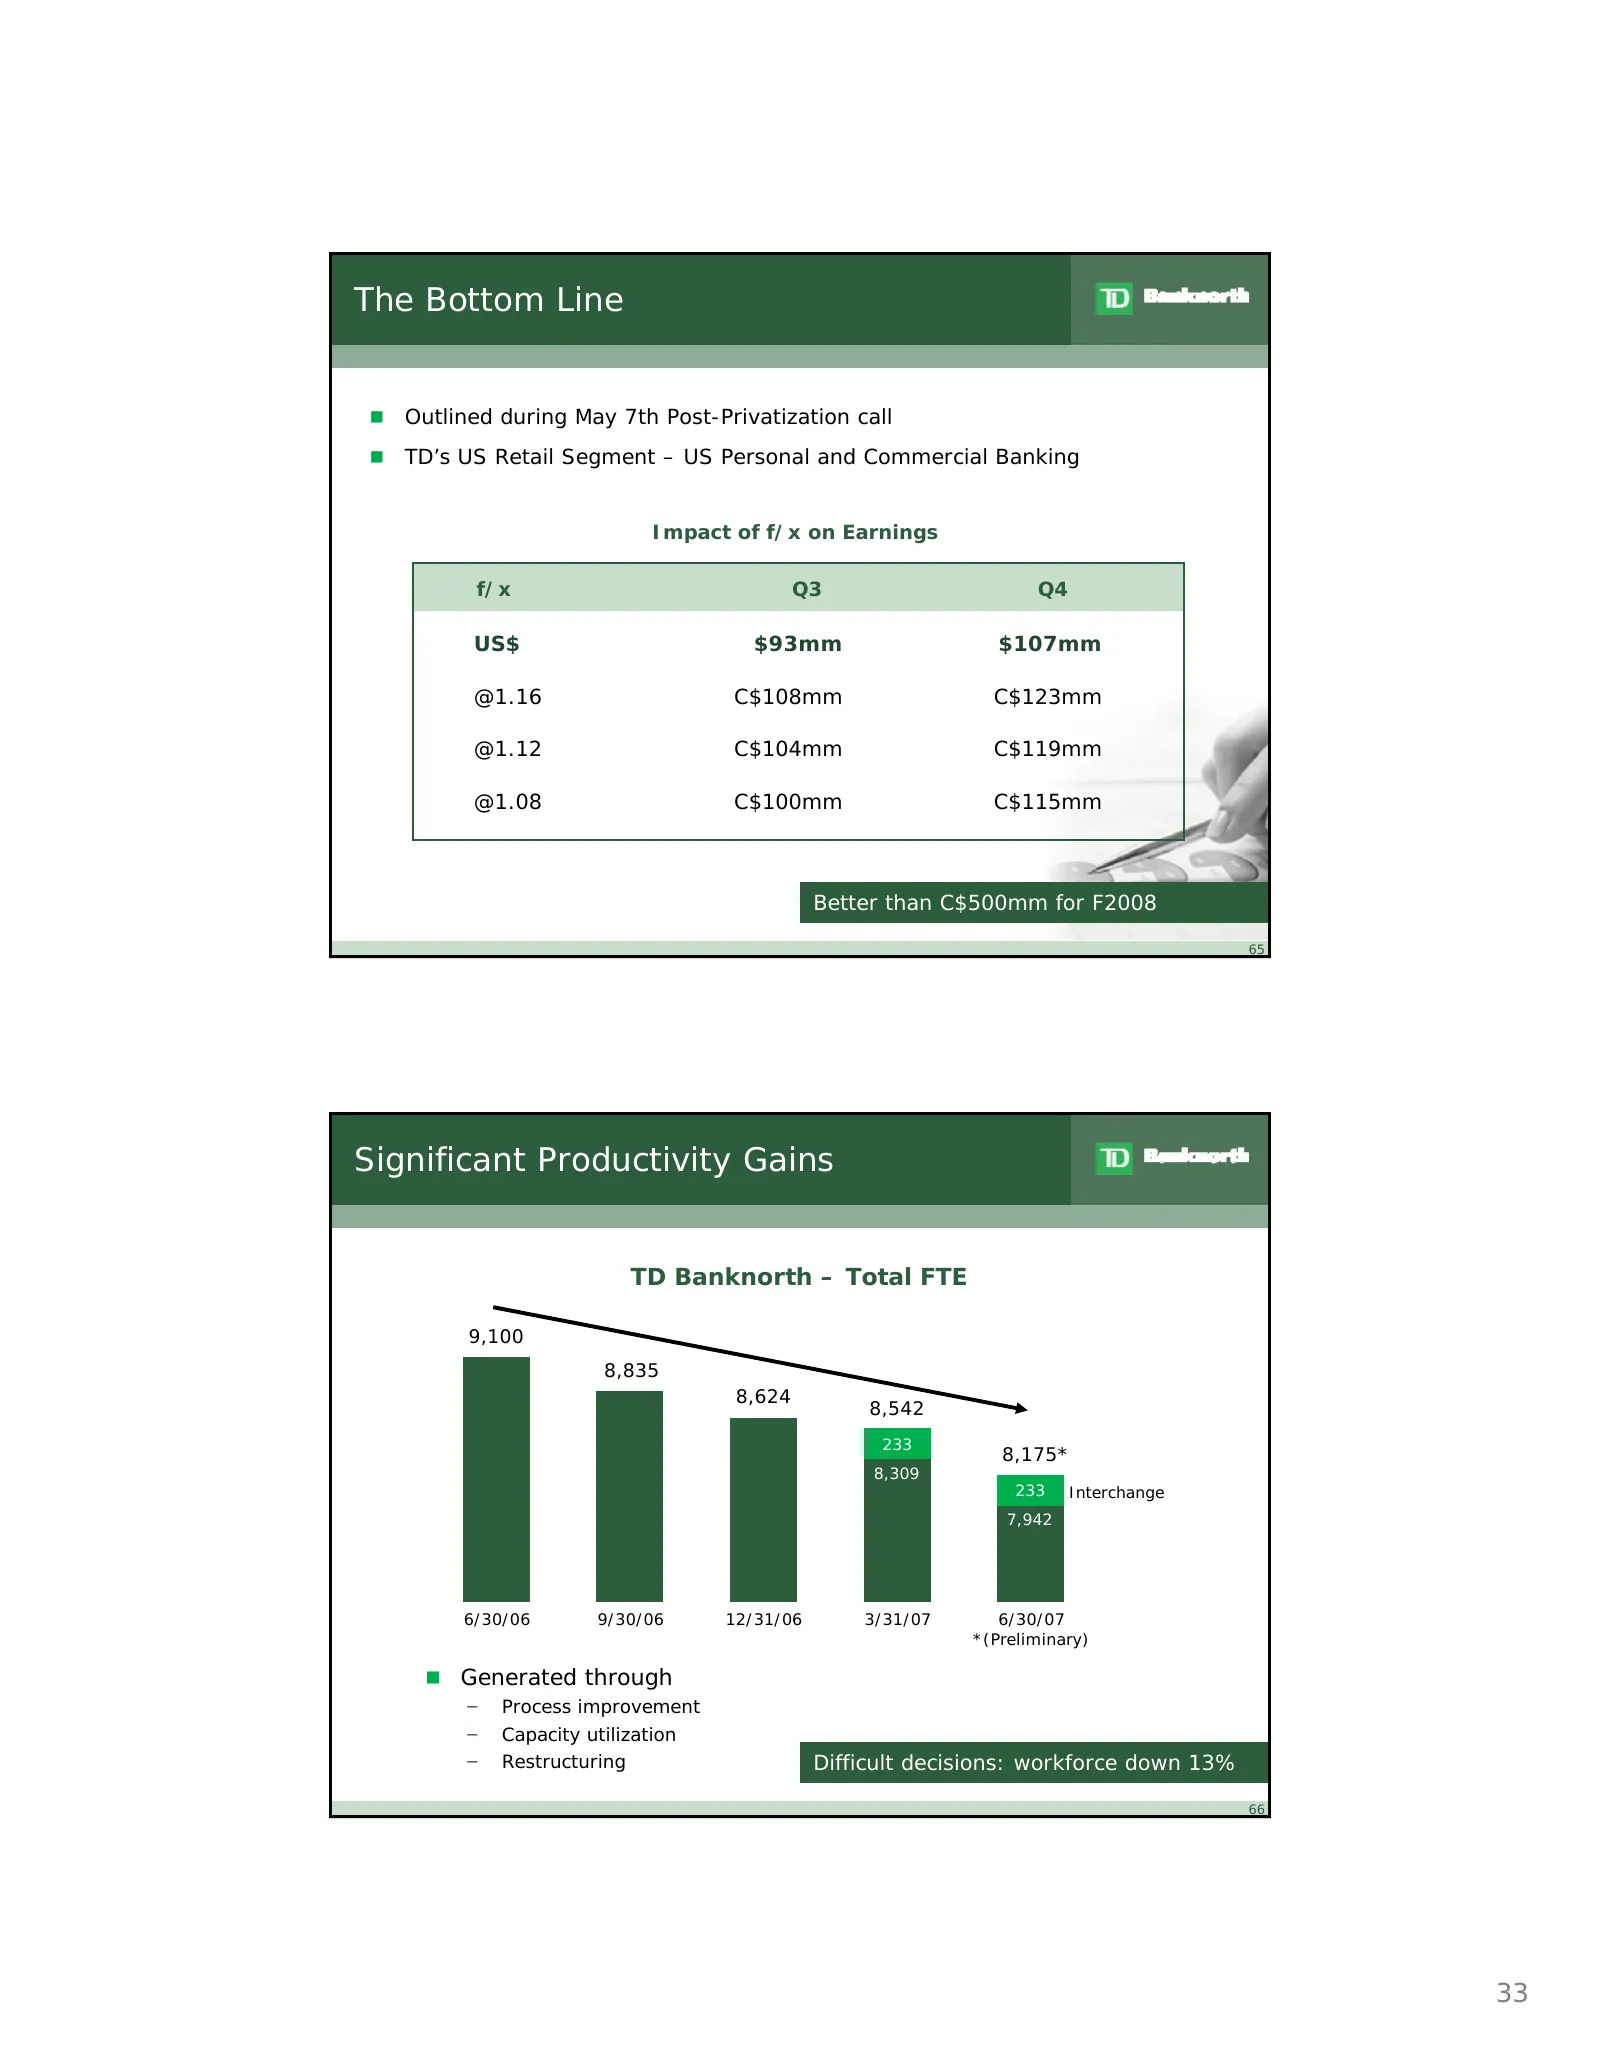
Slide 33: The Bottom Line; Significant Productivity Gains
The Bottom Line Outlined during May 7th Post-Privatization call TD’s US Retail Segment – US Personal and Commercial Banking Impact of f/x on Earnings f/x Q3 Q4 US$ $93mm $107mm @1.16 C$108mm C$123mm @1.12 C$104mm C$119mm @1.08 C$100mm C$115mm Better than C$500mm for F2008 65 Significant Producti
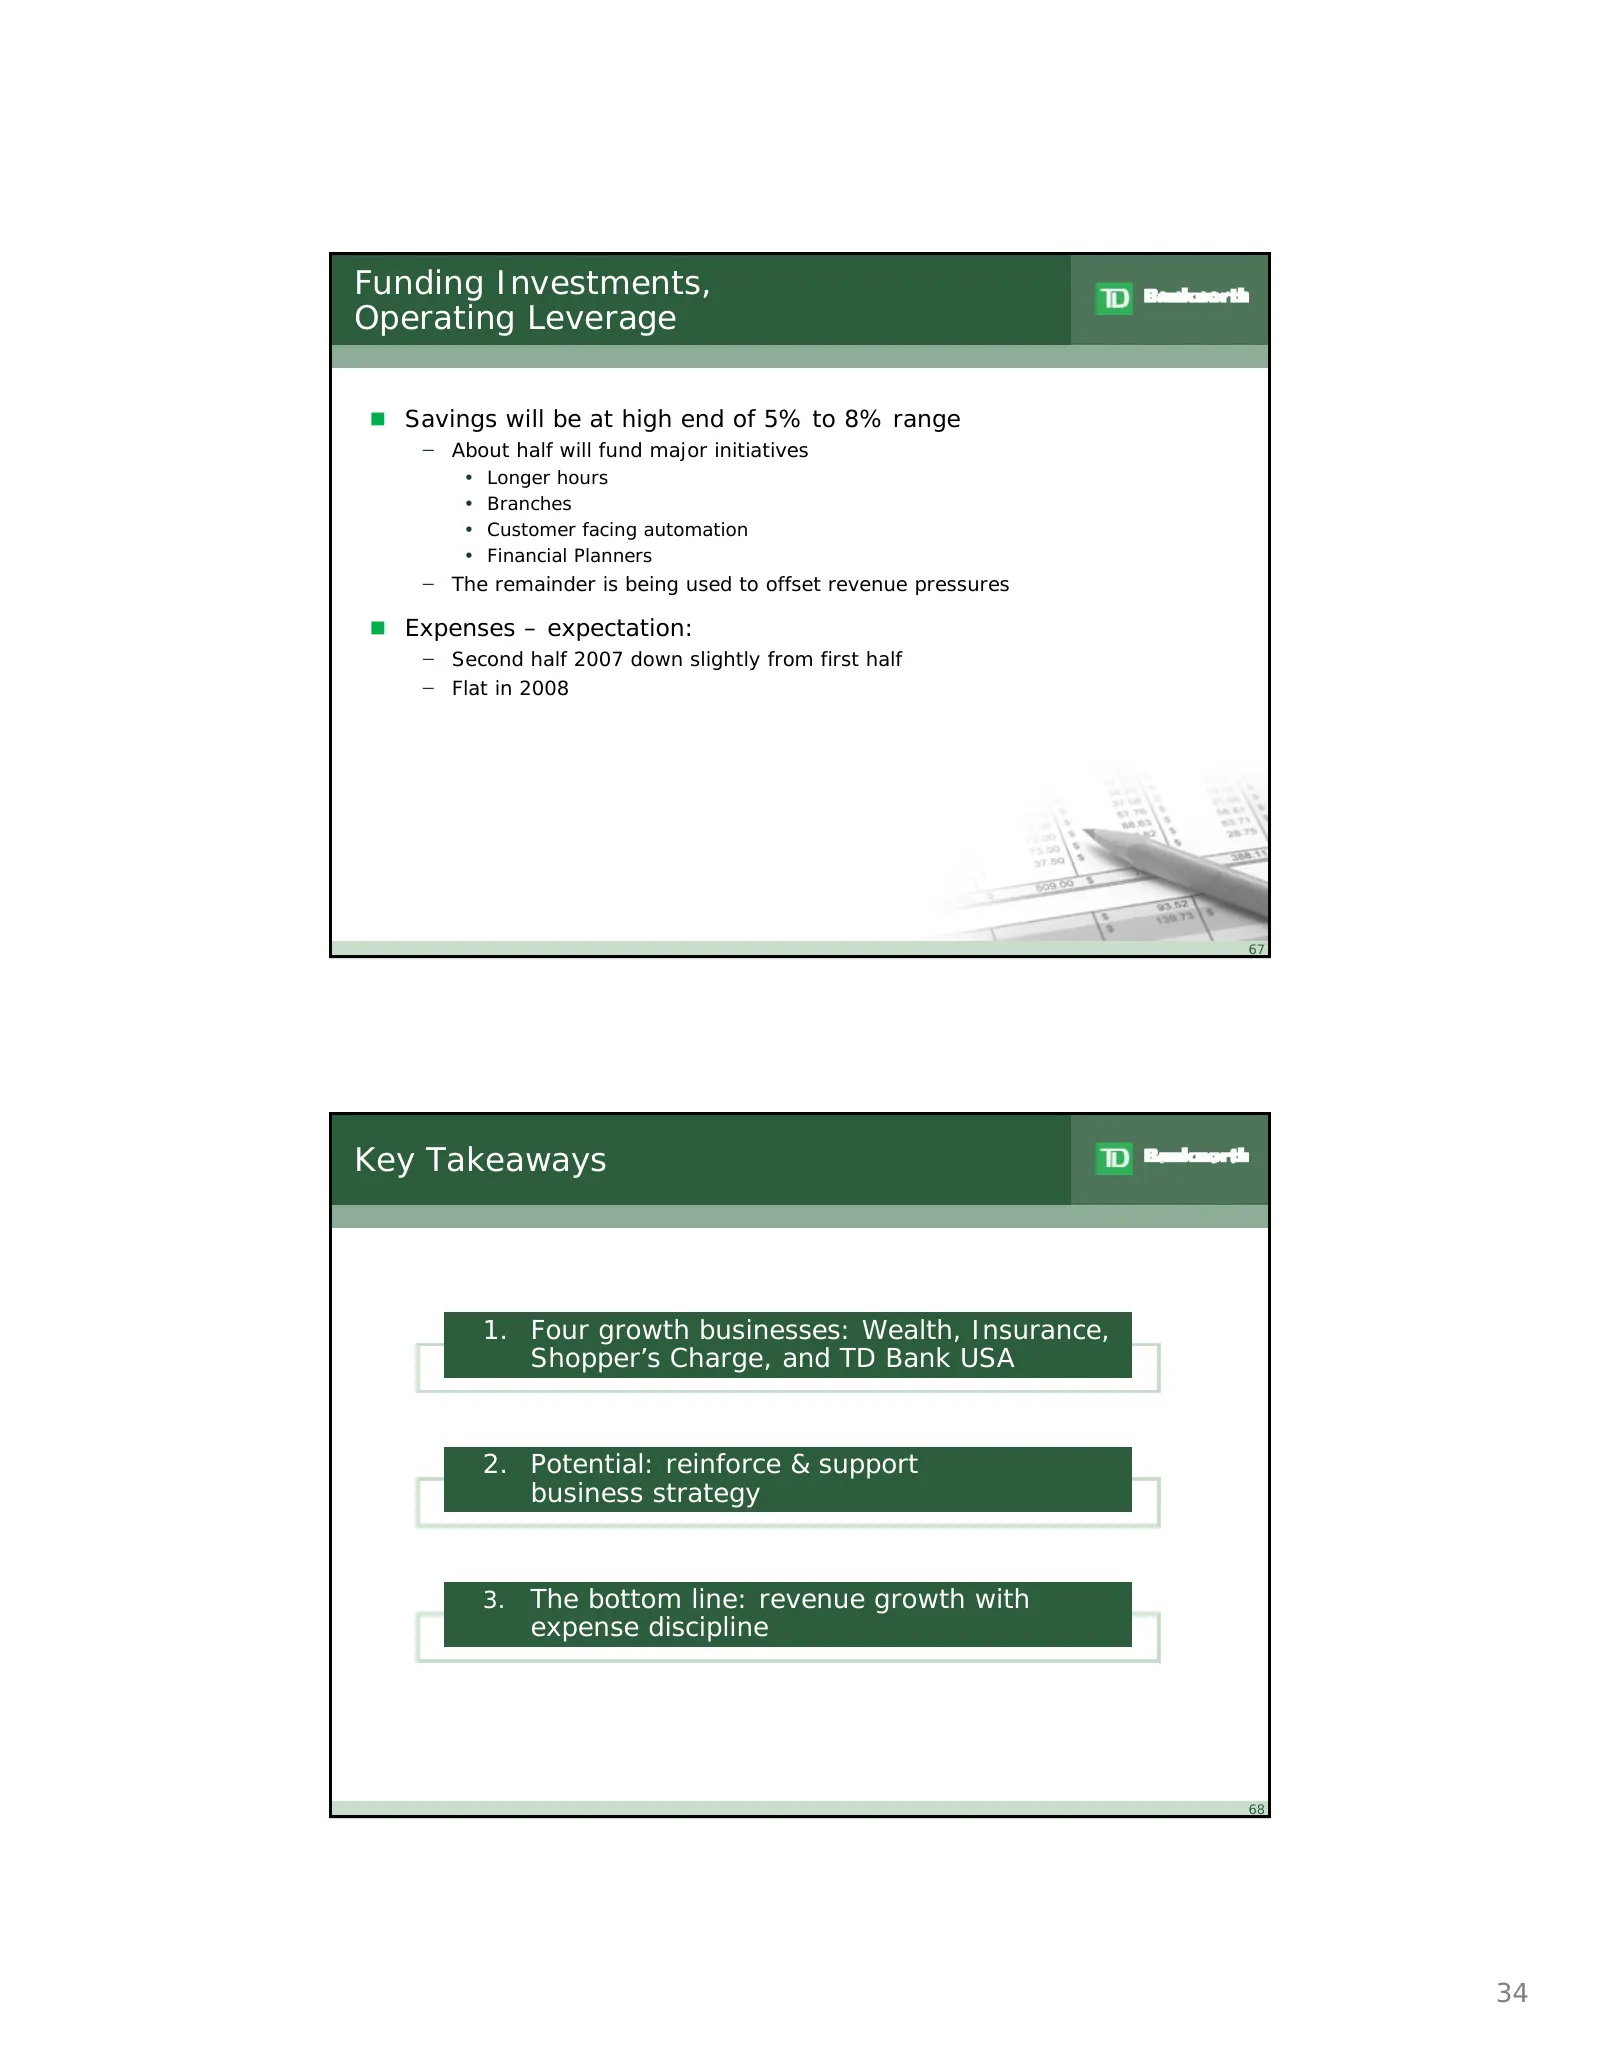
Slide 34: Funding Investments, Operating Leverage
Funding Investments, Operating Leverage Savings will be at high end of 5% to 8% range ̶ About half will fund major initiatives • Longer hours • Branches • Customer facing automation • Financial Planners ̶ The remainder is being used to offset revenue pressures Expenses – expectation: ̶ Second ha
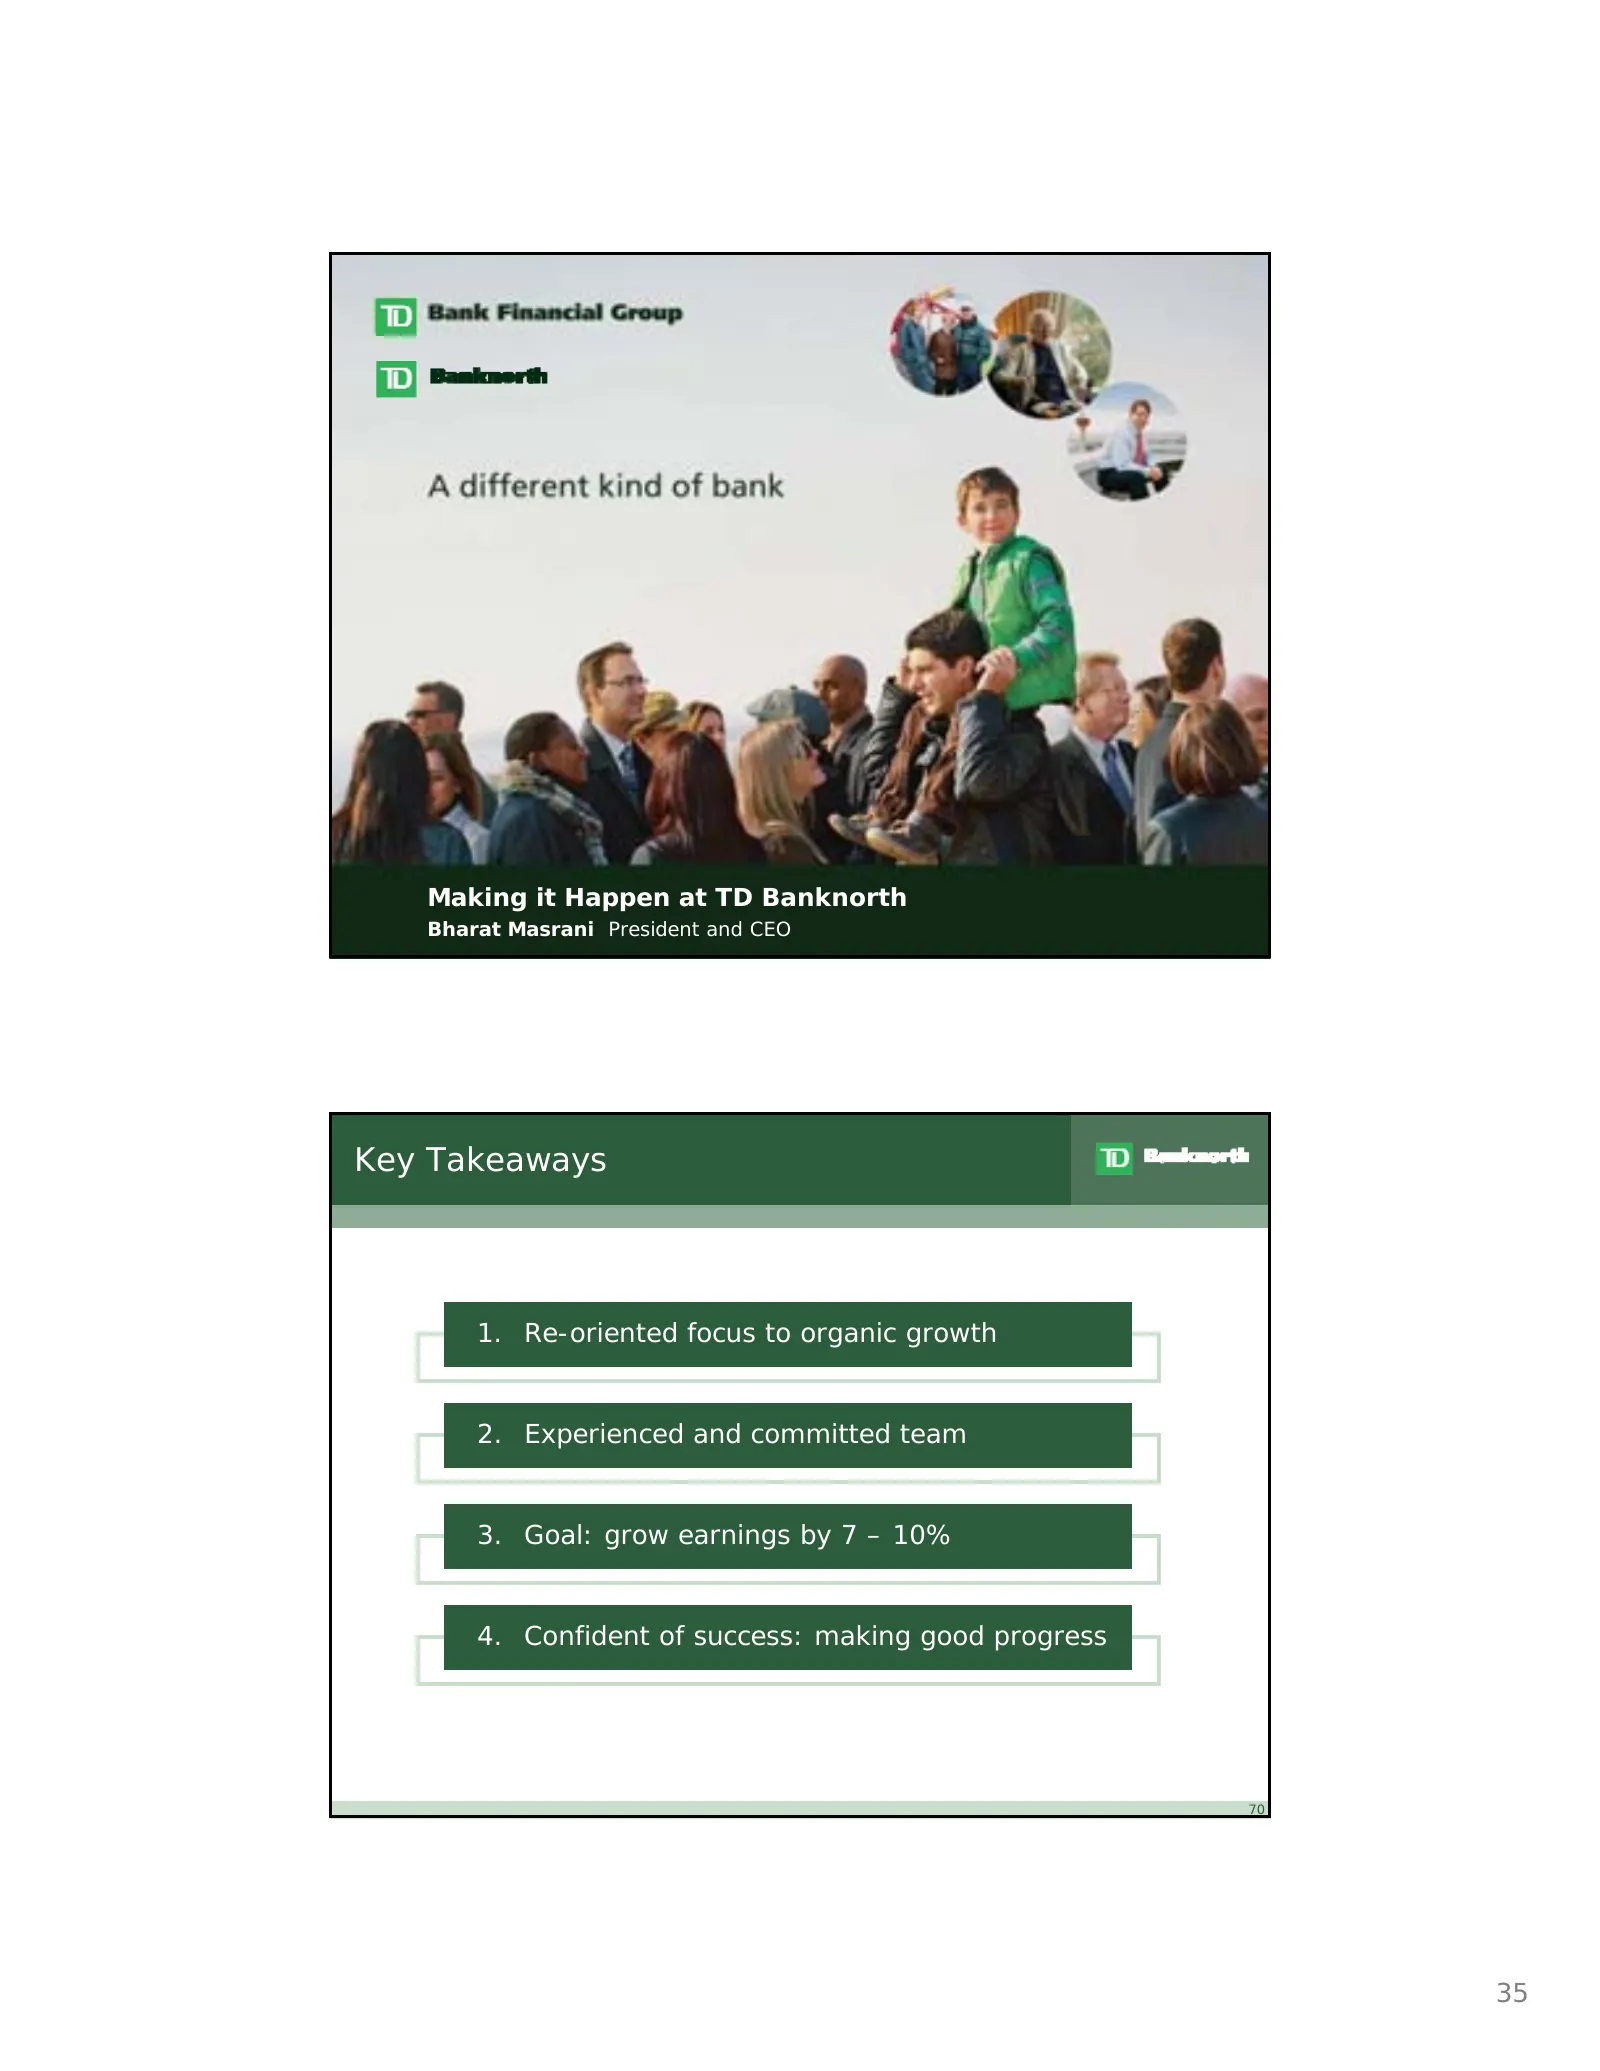
Slide 35: Key Takeaways
Making it Happen at TD Banknorth Bharat Masrani President and CEO Key Takeaways 1. Re-oriented focus to organic growth 2. Experienced and committed team 3. Goal: grow earnings by 7 – 10% 4. Confident of success: making good progress 70 35
Slide 36: Investor Day
{[2) Bank Financial Group A different kind of bank yy Investor Day June 28, 2007 36
Source: company website
More decks from TD Banknorth Inc.
 Merger or Acquisition (April 2007)5 slides · Apr 18, 2007
 Merger or Acquisition (November 2006)8 slides · Nov 20, 2006
 Scotia Capital Financials Summit 200622 slides · Sep 12, 2006
 Investor Day (July 2006)81 slides · Jul 28, 2006
 Merger or Acquisition (April 2006)21 slides · Apr 17, 2006
 Cohen Bros. & Company Annual Investors Conference (March 2006)19 slides · Mar 14, 2006