TD Banknorth Inc.
TD Banknorth — Investor Day (July 2006)
81 slides from TD Banknorth's investor day presentation, Jul 28, 2006
Slide 1: Note on Forward-Looking Information
Note on Forward-Looking Information This presentation contains certain forward-looking statements with respect to the financial condition, results of operations and business of TD Banknorth. Words such as "expect", "feel", "believe", "will", "may", "anticipate", "plan", "estimate", "intend", "should
Slide 2: Agenda
Agenda Overview Mid-Atlantic Division Update Marketing Strategy Commercial Lending Shoppers Charge Account Co. Break Risk Management Update Q&A
Slide 3: Who is TD Banknorth?
Who is TD Banknorth? Headquartered in Portland, Maine Approximately 56% owned by TD Bank Financial Group (TD) Nearly 600 branches and over 750 ATMs located in 8 Northeastern states 9,000 + employees Over $40 billion in assets as of 6/30/06 up from $2 billion in 1991 More than 1.5 million households
Slide 4: A Quick History
A Quick History Went public in 1986; Completed 26 bank acquisitions since 1987; Grown from $2 billion in assets in 1991 to over $40 billion today: Entered MA in 1996; Entered CT in 1999; Entered VT and upstate NY in 2000; Significantly increased CT presence in 2003; Moved into the mid-Atlantic regio
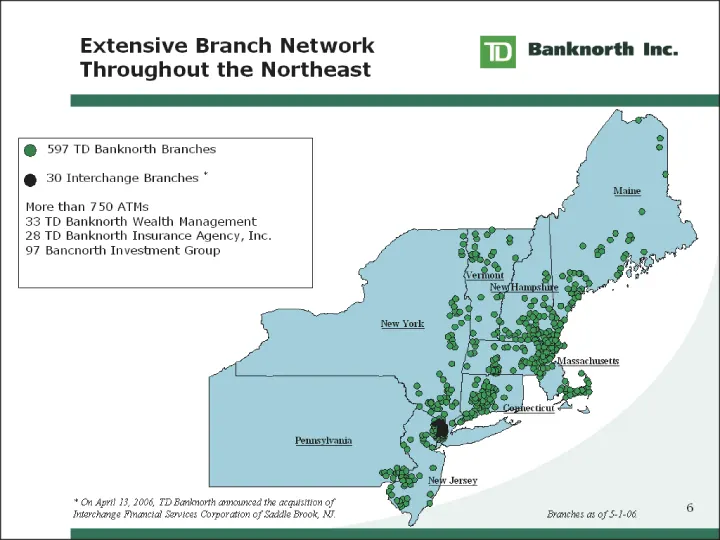
Slide 5: Extensive Branch Network Throughout the Northeast
New Jersey Maine Pennsylvania Connecticut Massachusetts New Hampshire Vermont New York Extensive Branch Network Throughout the Northeast * On April 13, 2006, TD Banknorth announced the acquisition of Interchange Financial Services Corporation of Saddle Brook, NJ. 597 TD Banknorth Branches 30 Interch
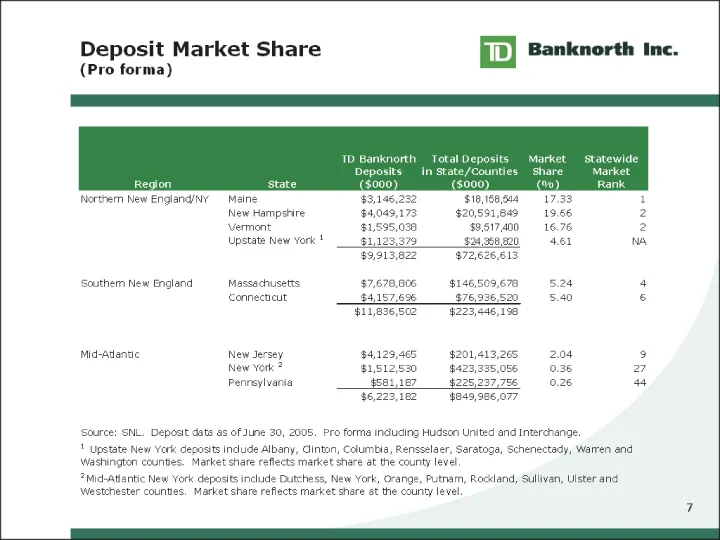
Slide 6: Deposit Market Share
Deposit Market Share (Pro forma) (Pro forma) (Pro forma)
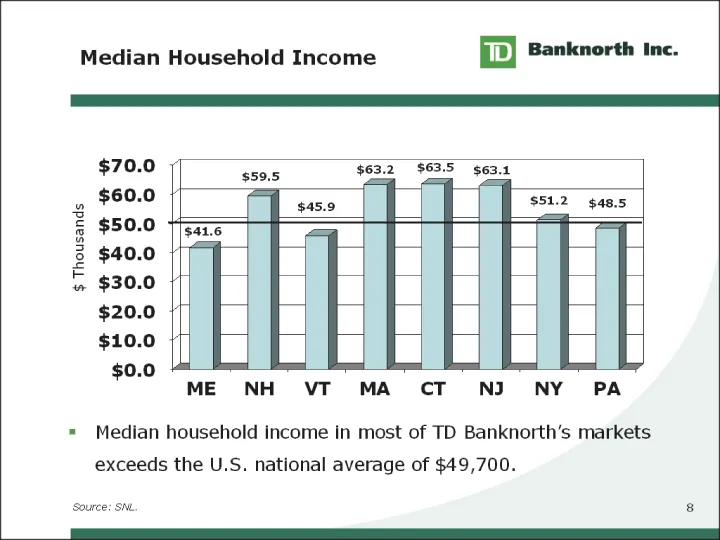
Slide 7: Median Household Income
Median Household Income ME NH VT MA CT NJ NY PA HH Median Income 41.6 59.5 45.9 63.2 63.5 63.1 51.2 48.5 Median household income in most of TD Banknorth's markets exceeds the U.S. national average of $49,700. Source: SNL. $ Thousands
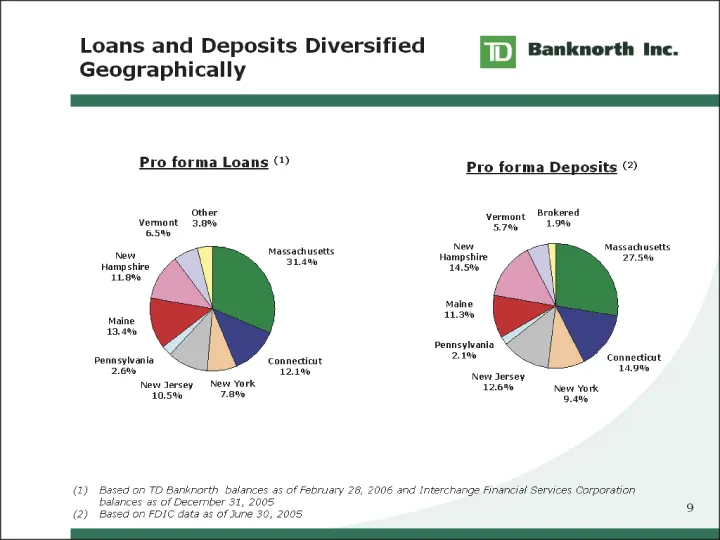
Slide 8: Loans and Deposits Diversified Geographically
Loans and Deposits Diversified Geographically Pro forma Loans (1) Pro forma Deposits (2) Assets Massachusetts 0.275 Connecticut 0.149 New York 0.094 New Jersey 0.126 Pennsylvania 0.021 Maine 0.113 New Hampshire 0.145 Vermont 0.057 Brokered 0.019 Net Loans Massachusetts 0.314 Connecticut 0.121 New Yo
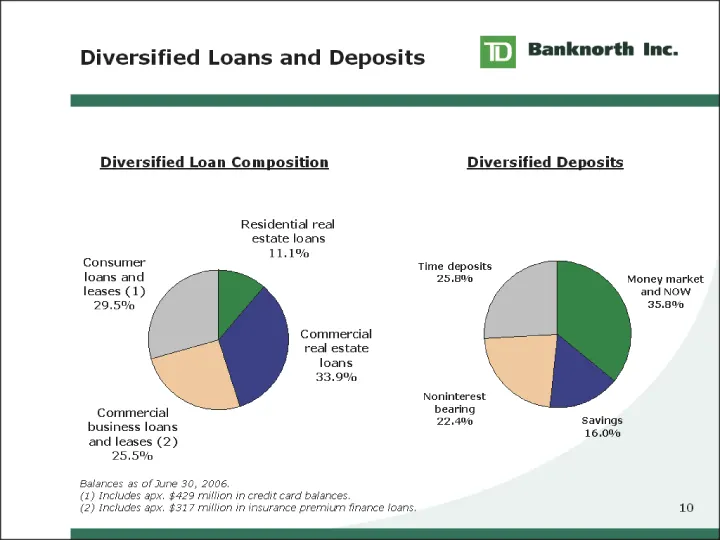
Slide 9: Diversified Loans and Deposits
Diversified Loans and Deposits Diversified Loan Composition Diversified Deposits Assets Money market and NOW 9508171 Savings 4261150 Noninterest bearing 5960781 Time deposits 6849176 Net Loans Residential real estate loans 2862331 Commercial real estate loans 8752137 Commercial business loans and le
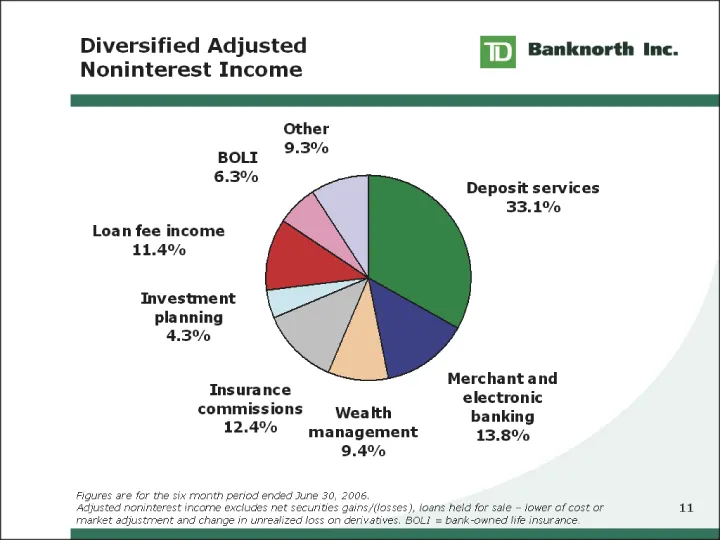
Slide 10: Diversified Adjusted Noninterest Income
Diversified Adjusted Noninterest Income Noninterest Income Deposit services 81105 Merchant and electronic banking 33792 Wealth management 23083 Insurance commissions 30390 Investment planning 10501 Loan fee income 27917 BOLI 15391 Other 22739 Figures are for the six month period ended June 30, 2006.
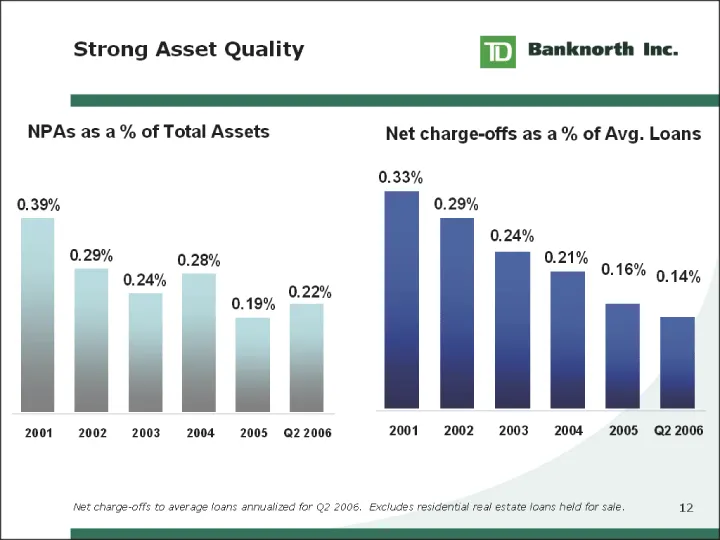
Slide 11: Strong Asset Quality
Strong Asset Quality Total Assets 2001 0.0039 2002 0.0029 2003 0.0024 2004 0.0028 2005 0.0019 Q2 2006 0.0022 NPAs as a % of Total Assets Average Loans 2001 0.0033 2002 0.0029 2003 0.0024 2004 0.0021 2005 0.0016 Q2 2006 0.0014 Net charge-offs as a % of Avg. Loans Net charge-offs to average loans annu
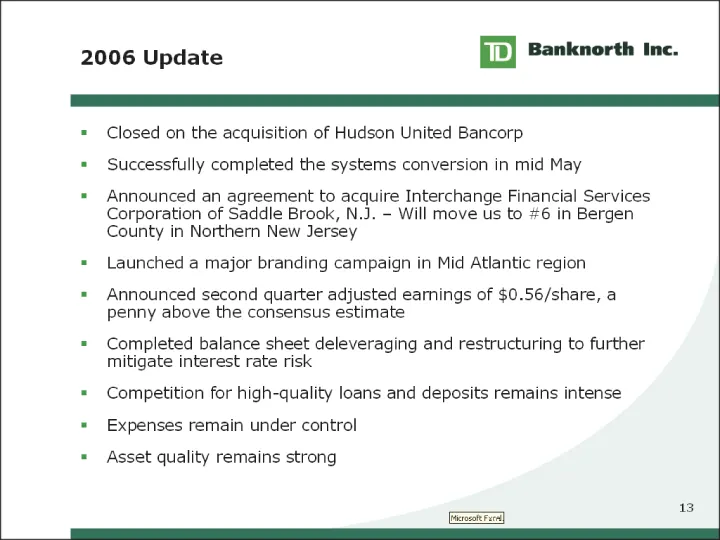
Slide 12: 2006 Update
2006 Update Closed on the acquisition of Hudson United Bancorp Successfully completed the systems conversion in mid May Announced an agreement to acquire Interchange Financial Services Corporation of Saddle Brook, N.J. - Will move us to #6 in Bergen County in Northern New Jersey Launched a major bra
Slide 13: Questions?
Questions? 7D] Banknorth Inc.
Slide 14: Non-GAAP financial information note
This presentation contains financial information determined by methods other than in accordance with accounting principles generally accepted in the United States of America ("GAAP"). The Company's management uses these non-GAAP measures in its analysis of the Company's performance. The Company arri
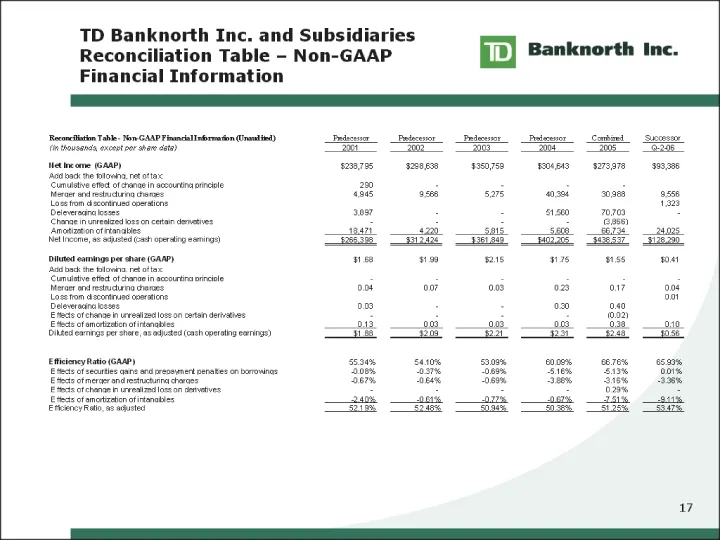
Slide 15: Reconciliation Table - Non-GAAP Financial Information
TD Banknorth Inc. and Subsidiaries Reconciliation Table - Non-GAAP Financial Information
Slide 16: Analyst Day Mid-Atlantic Division Update
Analyst Day Mid-Atlantic Division Update Wendy Suehrstedt President & CEO, Mid-Atlantic Division July 28, 2006
Slide 17: Note on Forward-Looking Information
Note on Forward-Looking Information This presentation contains certain forward-looking statements with respect to the financial condition, results of operations and business of TD Banknorth. Words such as "expect", "feel", "believe", "will", "may", "anticipate", "plan", "estimate", "intend", "should
Slide 18: Agenda
Agenda Conversion/Integration Strengths Challenges Other Improvements Results to Date Focus for the Future
Slide 19: Conversion/Integration Update
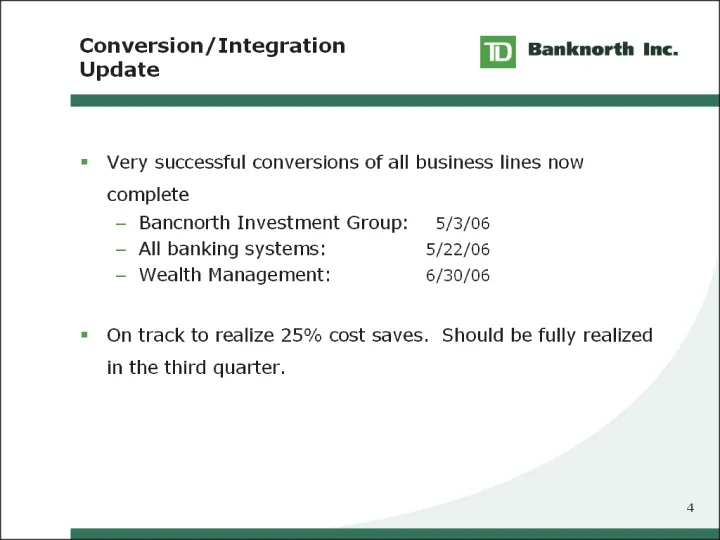
Conversion/Integration Update Very successful conversions of all business lines now complete Bancnorth Investment Group: All banking systems: Wealth Management: On track to realize 25% cost saves. Should be fully realized in the third quarter. 5/3/06 5/22/06 6/30/06
Slide 20: Conversion/Integration Update: Management Team in place
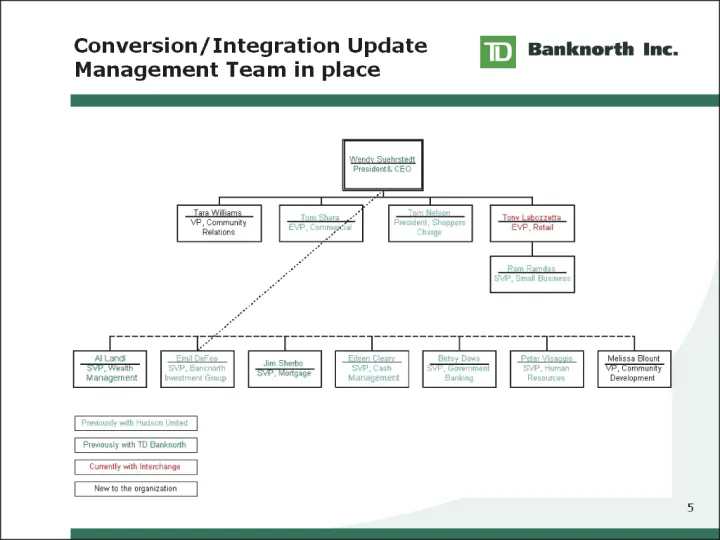
Conversion/Integration Update Management Team in place Management Team in place Management Team in place
Slide 21: Strengths
Strengths Commercial Lending Cash Management International Government Banking Flatiron Shoppers Charge Accounts Co.
Slide 22: Challenges: Build Strong Brand and Name Awareness
Challenges Build Strong Brand and Name Awareness Largest advertising campaign in TD Banknorth history launched June 7 Television Newspaper Magazines Online Outdoor Free Agents Free Agents Free Agents Free Agents Free Agents Free Agents Free Agents Free Agents Free Agents Free Agents Free Agents Free
Slide 23: Challenges: Stabilize & Strengthen Retail Team
Challenges (con't) Stabilize & Strengthen Retail Team Full management team in place 106 openings 12/05 reduced to 31 openings 7/1/06 Retail turnover 42% in 2005 reduced to 25% June, 2006 Incentive plan launched February 1, 2006 Significant training now underway Sales Sales management Service Systems
Slide 24: Challenges: Improve Distribution Network
Challenges (con't) Improve Distribution Network All branch facilities comprehensively reviewed and prioritized 93 need work - 3 year plan Renovate Relocate 5 relocations underway 20 renovations underway Anticipate 38 renovations to be completed by year end Branch hours extended July 1
Slide 25: Other Improvements
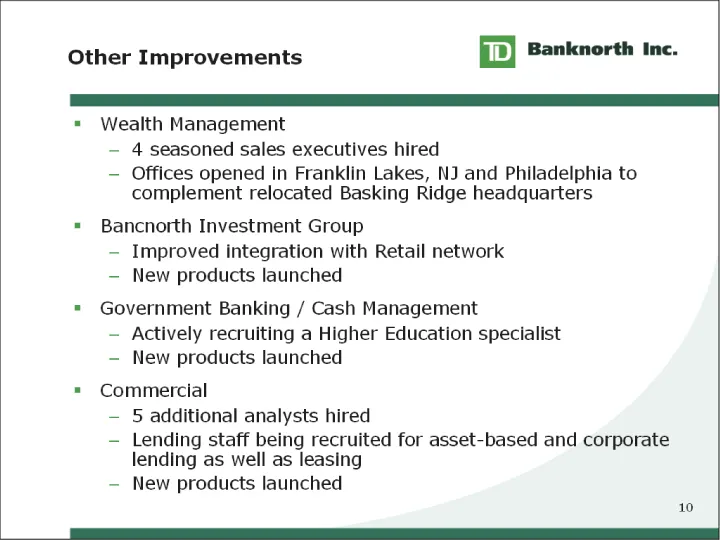
Other Improvements Wealth Management 4 seasoned sales executives hired Offices opened in Franklin Lakes, NJ and Philadelphia to complement relocated Basking Ridge headquarters Bancnorth Investment Group Improved integration with Retail network New products launched Government Banking / Cash Manageme
Slide 26: Other Improvements (con't.)
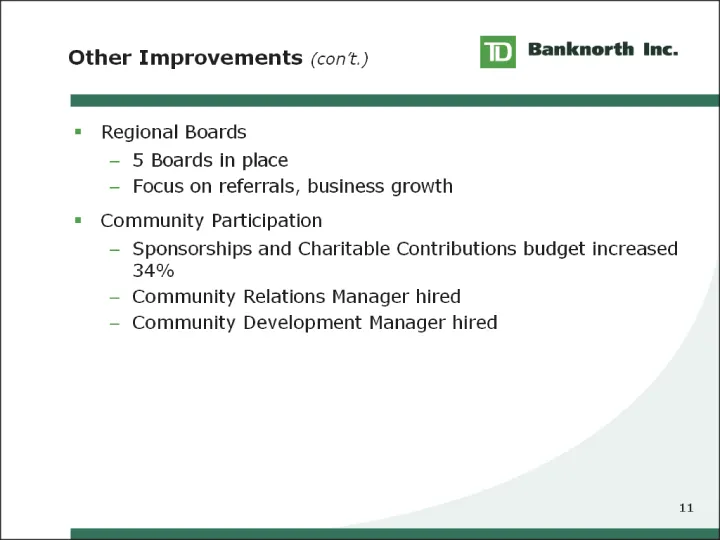
Other Improvements (con't.) Regional Boards 5 Boards in place Focus on referrals, business growth Community Participation Sponsorships and Charitable Contributions budget increased 34% Community Relations Manager hired Community Development Manager hired
Slide 27: Results to Date
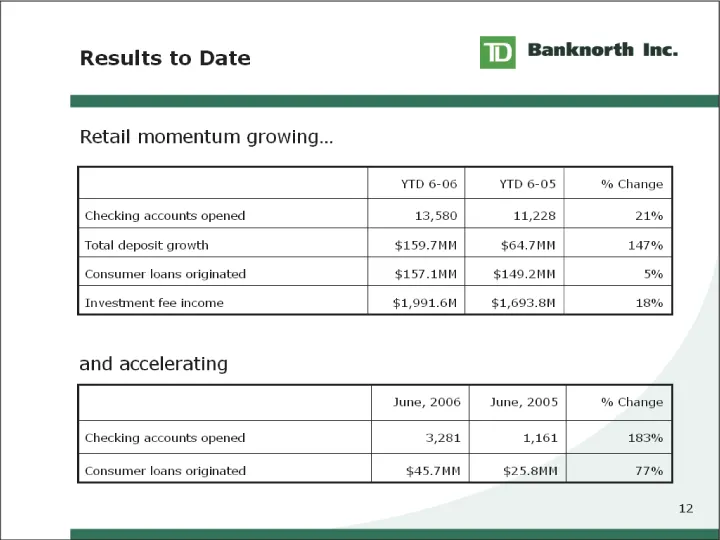
Results to Date YTD 6-06 YTD 6-05 % Change Checking accounts opened 13,580 11,228 21% Total deposit growth $159.7MM $64.7MM 147% Consumer loans originated $157.1MM $149.2MM 5% Investment fee income $1,991.6M $1,693.8M 18% June, 2006 June, 2005 % Change Checking accounts opened 3,281 1,161 183% Consu
Slide 28: Focus for the Future
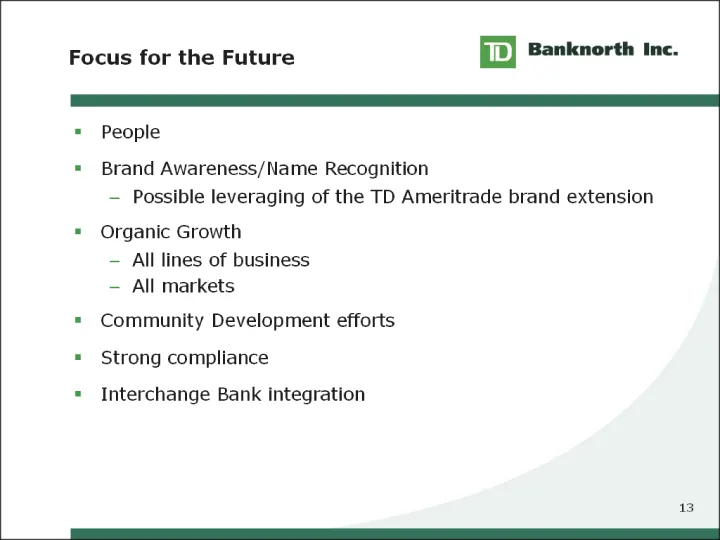
Focus for the Future People Brand Awareness/Name Recognition Possible leveraging of the TD Ameritrade brand extension Organic Growth All lines of business All markets Community Development efforts Strong compliance Interchange Bank integration
Slide 29: Questions?
Questions? BD Banknorth Inc.
Slide 30: Bank Freely Update
Bank Freely Update Tom Dyck EVP, Director of Marketing July 28, 2006
Slide 31: Note on Forward-Looking Information
Note on Forward-Looking Information This presentation contains certain forward-looking statements with respect to the financial condition, results of operations and business of TD Banknorth. Words such as "expect", "feel", "believe", "will", "may", "anticipate", "plan", "estimate", "intend", "should
Slide 32: Decision / Key Consideration
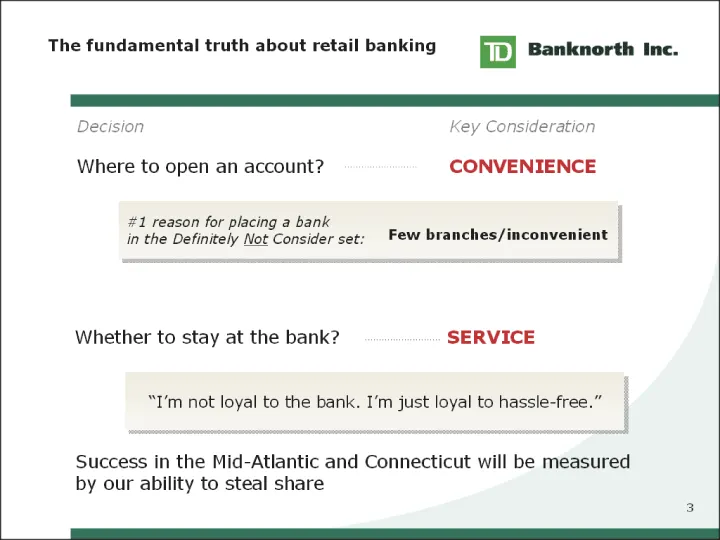
Decision Key Consideration Where to open an account? CONVENIENCE #1 reason for placing a bank in the Definitely Not Consider set: Few branches/inconvenient Whether to stay at the bank? SERVICE "I'm not loyal to the bank. I'm just loyal to hassle-free." The fundamental truth about retail banking Succ
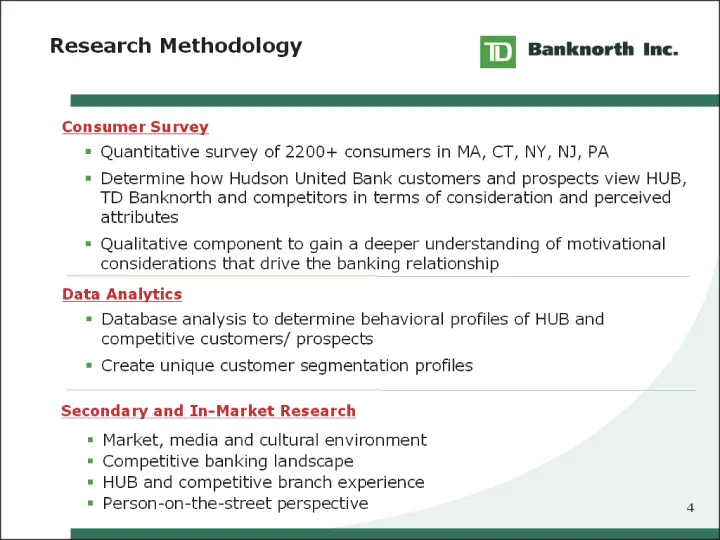
Slide 33: Consumer Survey and Research Methodology
Consumer Survey Quantitative survey of 2200+ consumers in MA, CT, NY, NJ, PA Determine how Hudson United Bank customers and prospects view HUB, TD Banknorth and competitors in terms of consideration and perceived attributes Qualitative component to gain a deeper understanding of motivational conside
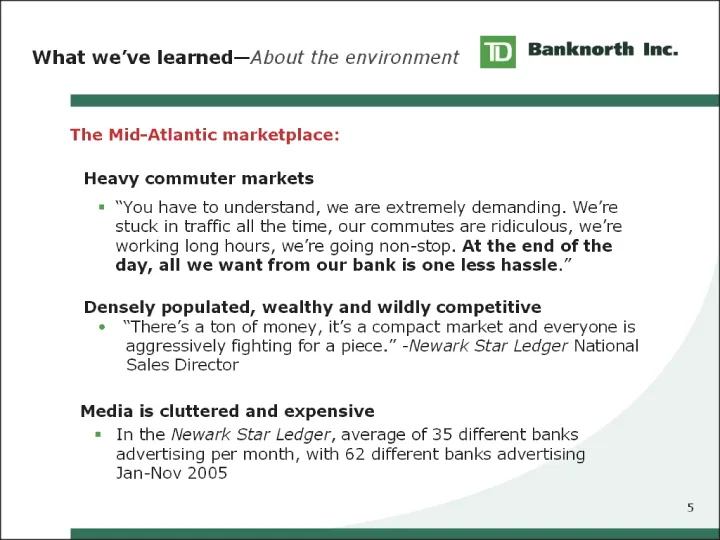
Slide 34: What we've learned - About the environment
What we've learned-About the environment The Mid-Atlantic marketplace: Media is cluttered and expensive In the Newark Star Ledger, average of 35 different banks advertising per month, with 62 different banks advertising Jan-Nov 2005 Heavy commuter markets "You have to understand, we are extremely de
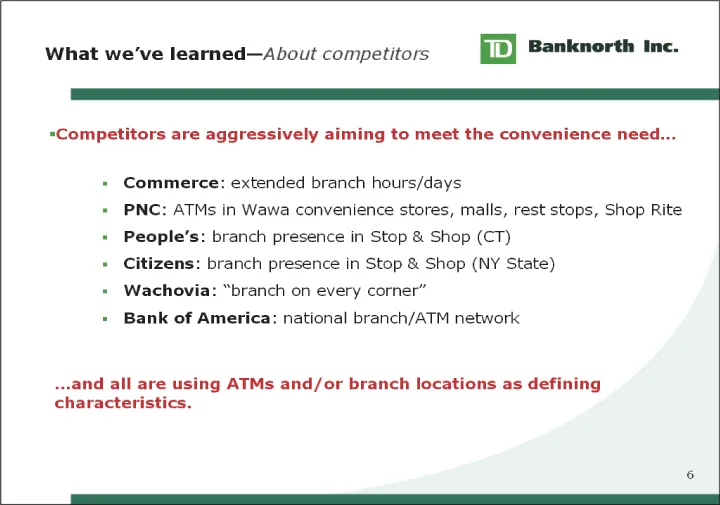
Slide 35: What we've learned - About competitors
Competitors are aggressively aiming to meet the convenience need... ....and all are using ATMs and/or branch locations as defining characteristics. What we've learned-About competitors Commerce: extended branch hours/days PNC: ATMs in Wawa convenience stores, malls, rest stops, Shop Rite People's: b
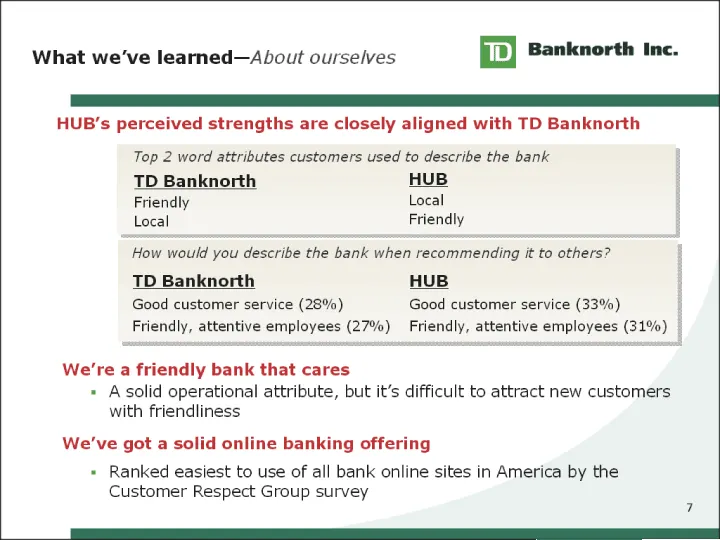
Slide 36: What we've learned - About ourselves
What we've learned-About ourselves HUB's perceived strengths are closely aligned with TD Banknorth Top 2 word attributes customers used to describe the bank HUB Local Friendly TD Banknorth Friendly Local How would you describe the bank when recommending it to others? HUB Good customer service (33%)
Slide 37: Research Recap
Research Recap Competition focusing on retail convenience (hours, locations, etc.) Dissatisfaction with big, institutional banks that are perceived to be impersonal #1 attribute in ideal bank is 'customer focused', defined as "do what's good for the customer, not just what's good for the bank." The
Slide 38: Bank Freely
Bank Freely TD Banknorth is dedicated to freeing our customers from the hassles of banking and the worries of managing their money.
Slide 39: How we deliver on the Bank Freely promise
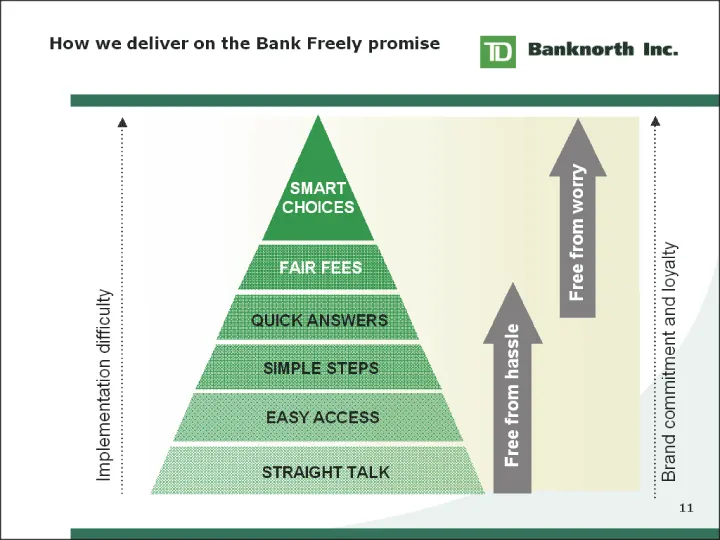
How we deliver on the Bank Freely promise STRAIGHT TALK EASY ACCESS SIMPLE STEPS QUICK ANSWERS FAIR FEES SMART CHOICES Brand commitment and loyalty Implementation difficulty Free from hassle Free from worry
Slide 40: When launching Bank Freely, we wanted to
When launching Bank Freely, we wanted to: Use our competitors' strengths to fix our biggest weakness Solve our distribution challenges overnight Win praise from consumers (and their business) for alleviating their biggest pain point Build instant awareness and credibility One-up the competition by o
Slide 41: No ATM Fees. Any Bank. Anywhere.
No ATM Fees. Any Bank. Anywhere. Bank Freely
Slide 42: Bank Freely
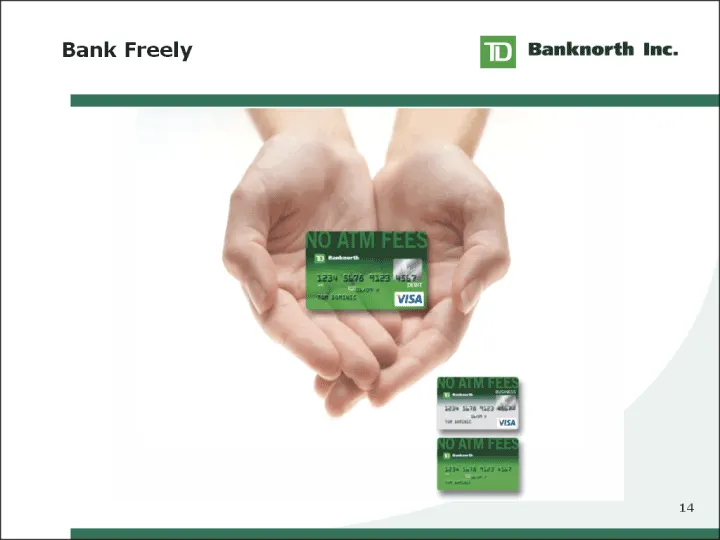
Bank Freely Banknorth Inc.
Slide 43: Launch Overview
Launch Overview Goal: Dramatically increase our rate of customer acquisition Strategies: Build marketing communications plan focusing on the branch outwards Leverage Claritas data to target ideal segments for acquisition Use media vehicles that build reach quickly in order to meet aggressive goals U
Slide 44: Launch Advertising
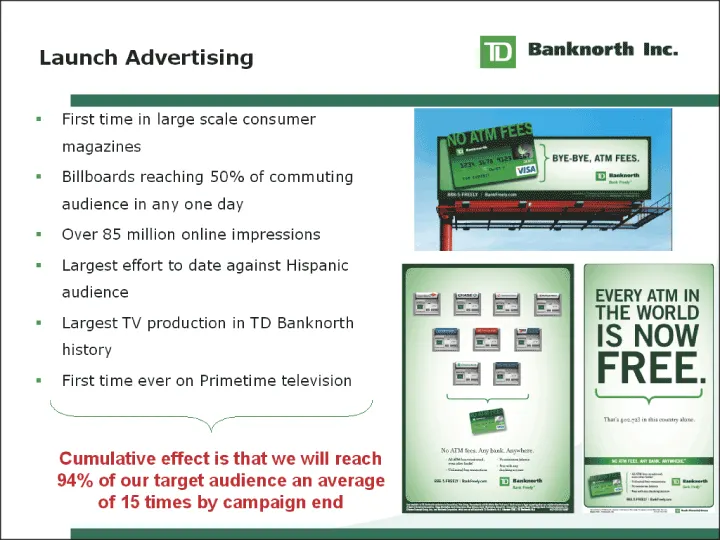
Launch Advertising First time in large scale consumer magazines Billboards reaching 50% of commuting audience in any one day Over 85 million online impressions Largest effort to date against Hispanic audience Largest TV production in TD Banknorth history First time ever on Primetime television Cumul
Slide 45: Guerilla Marketing
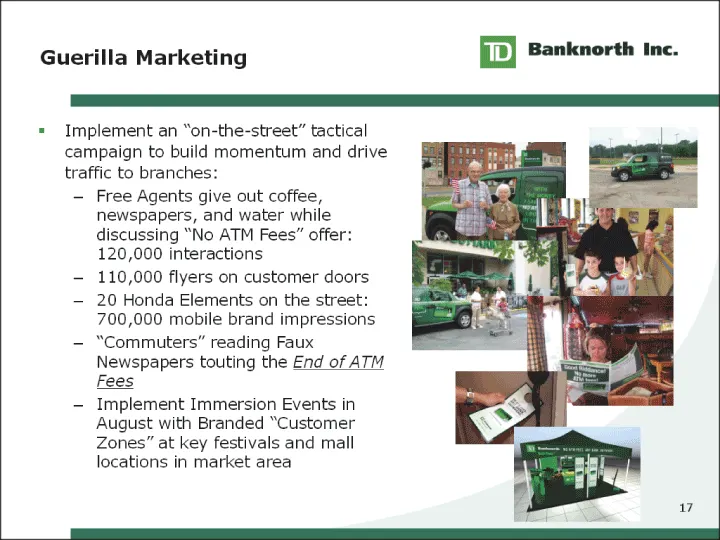
Guerilla Marketing Implement an "on-the-street" tactical campaign to build momentum and drive traffic to branches: Free Agents give out coffee, newspapers, and water while discussing "No ATM Fees" offer: 120,000 interactions 110,000 flyers on customer doors 20 Honda Elements on the street: 700,000 m
Slide 46: Internal Communications
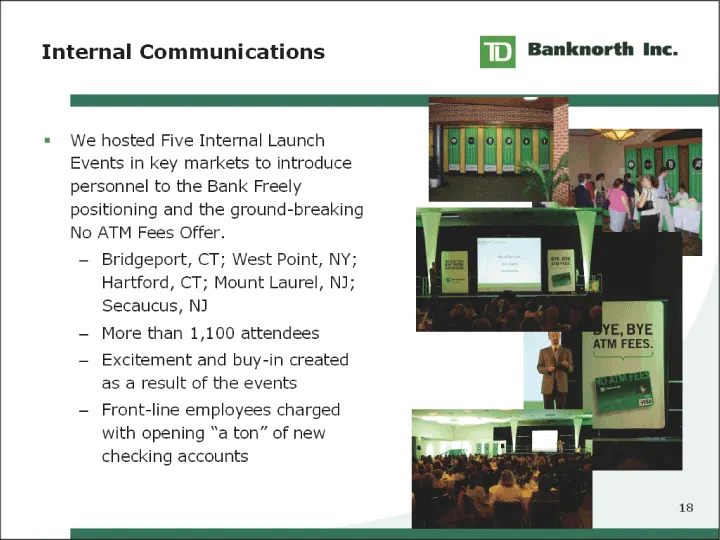
Internal Communications We hosted Five Internal Launch Events in key markets to introduce personnel to the Bank Freely positioning and the ground-breaking No ATM Fees Offer. Bridgeport, CT; West Point, NY; Hartford, CT; Mount Laurel, NJ; Secaucus, NJ More than 1,100 attendees Excitement and buy-in c
Slide 47: Television Commercials
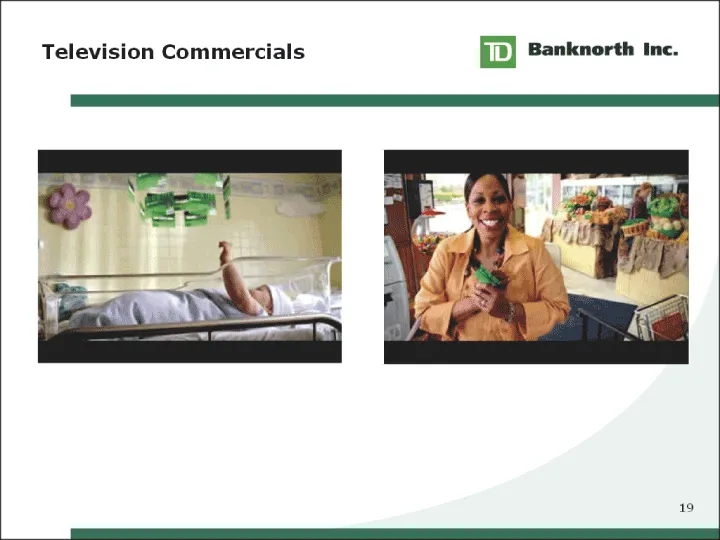
Television Commercials BD Banknorth Inc.
Slide 48: More than a marketing campaign
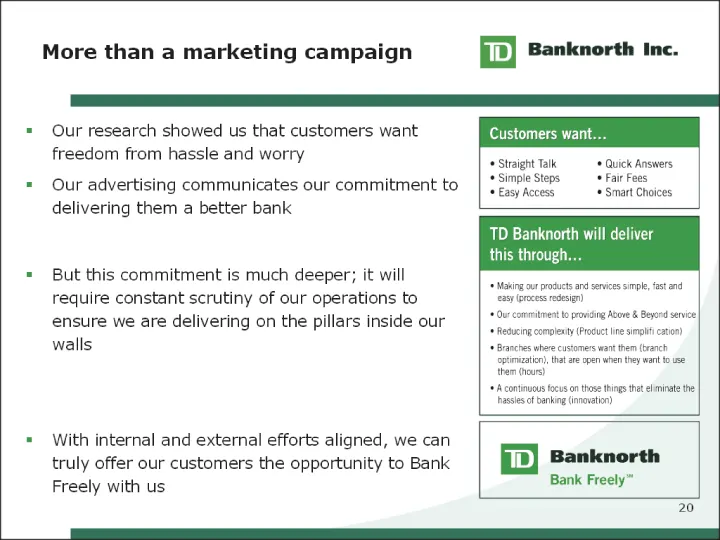
More than a marketing campaign Our research showed us that customers want freedom from hassle and worry Our advertising communicates our commitment to delivering them a better bank But this commitment is much deeper; it will require constant scrutiny of our operations to ensure we are delivering on
Slide 49: Questions?
Questions? Banknorth Inc. 24
Slide 50: Mid-Atlantic Division Commercial Lending
Mid-Atlantic Division Commercial Lending Thomas J. Shara EVP, Senior Commercial Banking Officer July 28, 2006
Slide 51: Note on Forward-Looking Information
Note on Forward-Looking Information This presentation contains certain forward-looking statements with respect to the financial condition, results of operations and business of TD Banknorth. Words such as "expect", "feel", "believe", "will", "may", "anticipate", "plan", "estimate", "intend", "should
Slide 52: Mid-Atlantic Division Commercial Lending
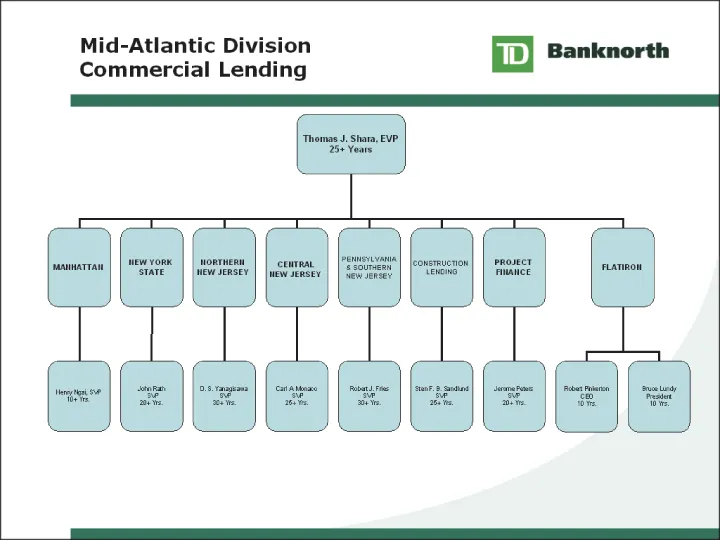
Mid-Atlantic Division Commercial Lending Commercial Lending Commercial Lending
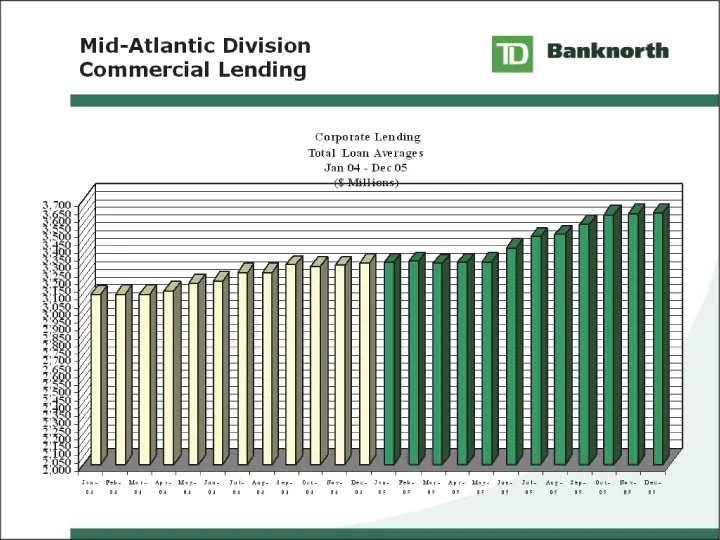
Slide 53: Mid-Atlantic Division Commercial Lending
Mid-Atlantic Division Commercial Lending
Slide 54: Customer Profile
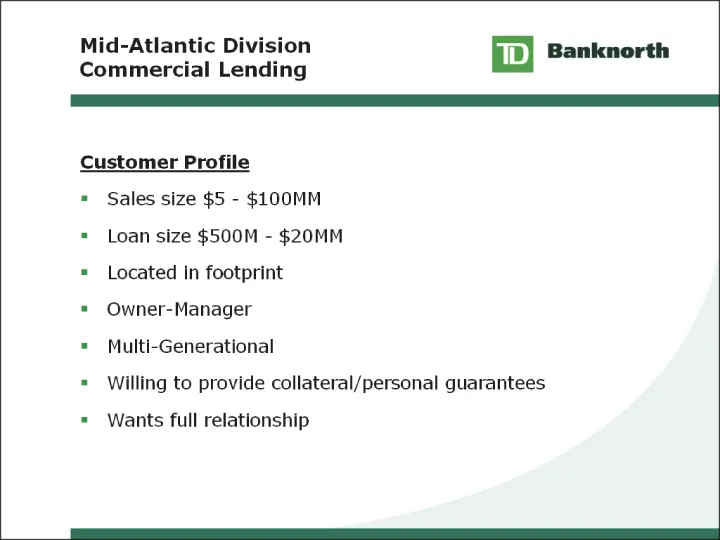
Mid-Atlantic Division Commercial Lending Customer Profile Sales size $5 - $100MM Loan size $500M - $20MM Located in footprint Owner-Manager Multi-Generational Willing to provide collateral/personal guarantees Wants full relationship
Slide 55: Flatiron Credit Company, Inc.
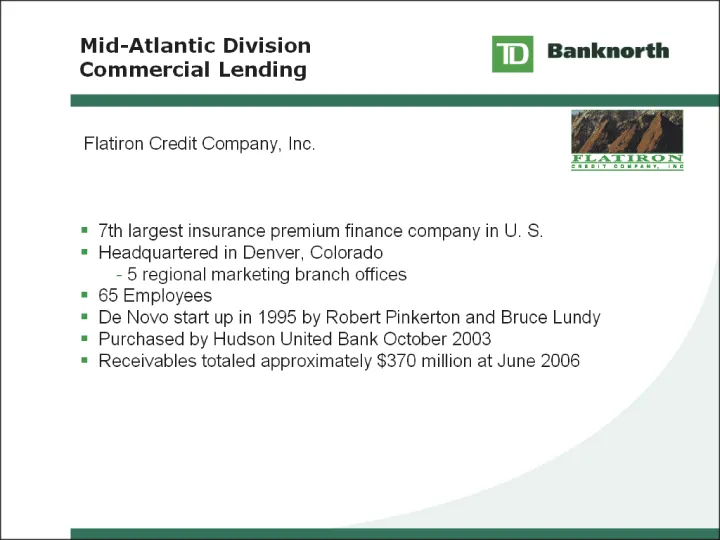
Mid-Atlantic Division Commercial Lending Flatiron Credit Company, Inc. 7th largest insurance premium finance company in U. S. Headquartered in Denver, Colorado 5 regional marketing branch offices 65 Employees De Novo start up in 1995 by Robert Pinkerton and Bruce Lundy Purchased by Hudson United Ban
Slide 56: Geographic Scope
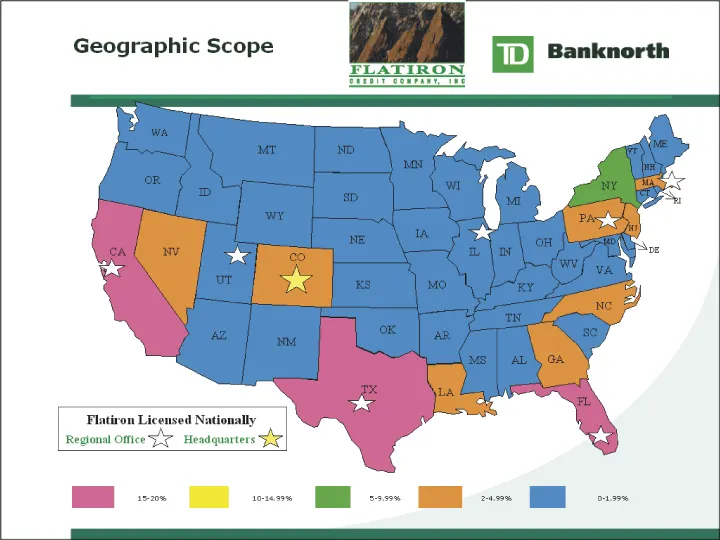
Geographic Scope Flatiron Licensed Nationally Regional Office Headquarters WA OR CA NV CO UT AZ NM TX ID MT WY ND SD NE KS OK MN IA MO AR LA MS AL GA FL SC NC TN KY IL IN WI MI OH PA NY VT NH ME RI VA MD NJ WV MA CT DE 15-20% 10-14.99% 5-9.99% 2-4.99% 0-1.99%
Slide 57: Flatiron Portfolio Growth
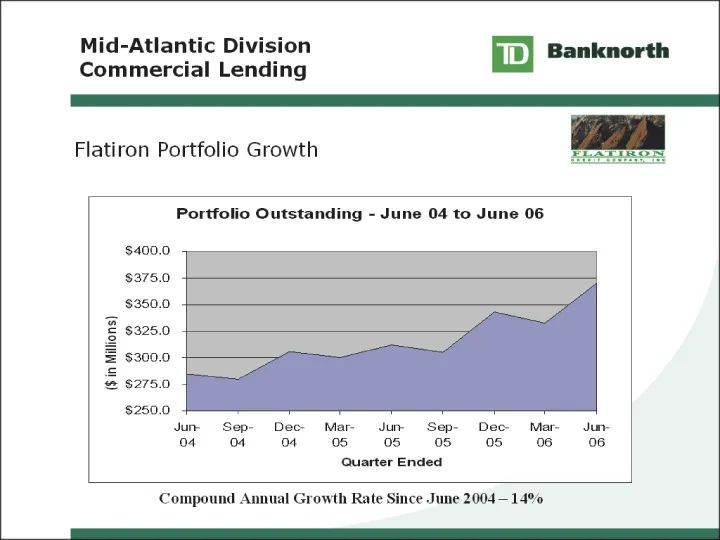
Mid-Atlantic Division Commercial Lending Commercial Lending Commercial Lending Compound Annual Growth Rate Since June 2004 - 14% Flatiron Portfolio Growth
Slide 58: Synergies
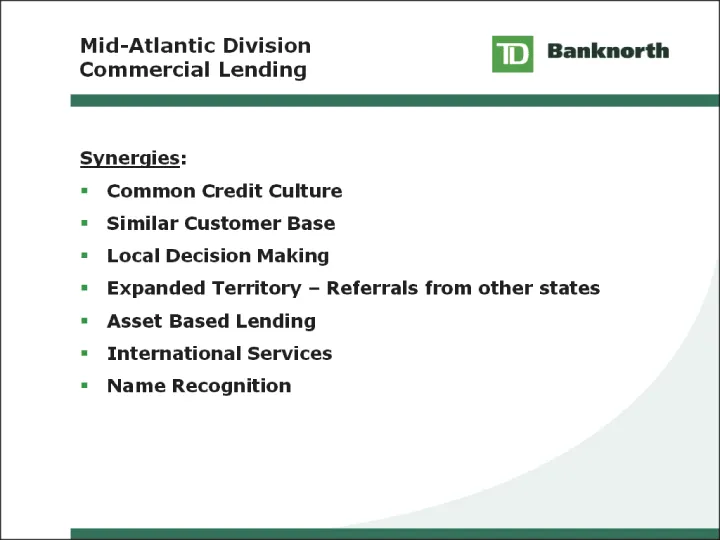
Mid-Atlantic Division Commercial Lending Synergies: Common Credit Culture Similar Customer Base Local Decision Making Expanded Territory - Referrals from other states Asset Based Lending International Services Name Recognition
Slide 59: Questions?
1D} Banknorth Questions?
Slide 60: Shoppers Charge Account Co.
Shoppers Charge Account Co. Thomas R. Nelson President, Shoppers Charge Accounts Co. July 28, 2006
Slide 61: Note on Forward-Looking Information
Note on Forward-Looking Information This presentation contains certain forward-looking statements with respect to the financial condition, results of operations and business of TD Banknorth. Words such as "expect", "feel", "believe", "will", "may", "anticipate", "plan", "estimate", "intend", "should
Slide 62: National private label credit card programs
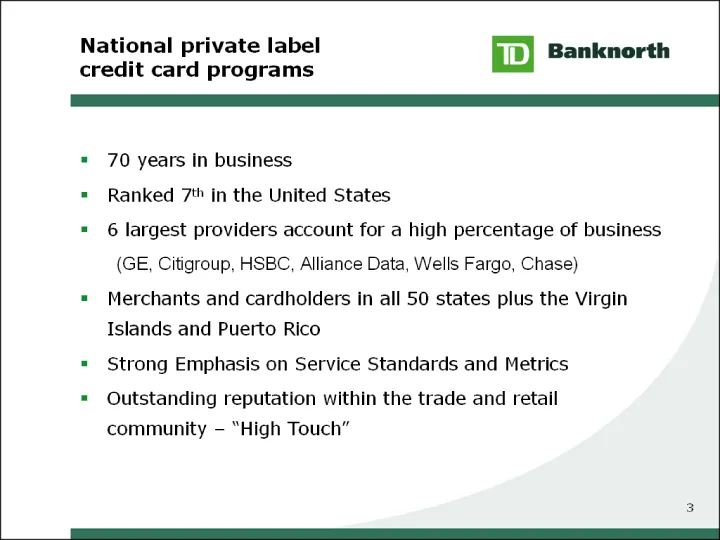
National private label credit card programs 70 years in business Ranked 7th in the United States 6 largest providers account for a high percentage of business (GE, Citigroup, HSBC, Alliance Data, Wells Fargo, Chase) Merchants and cardholders in all 50 states plus the Virgin Islands and Puerto Rico S
Slide 63: Our Industry Experienced Executive Team Remains In Place
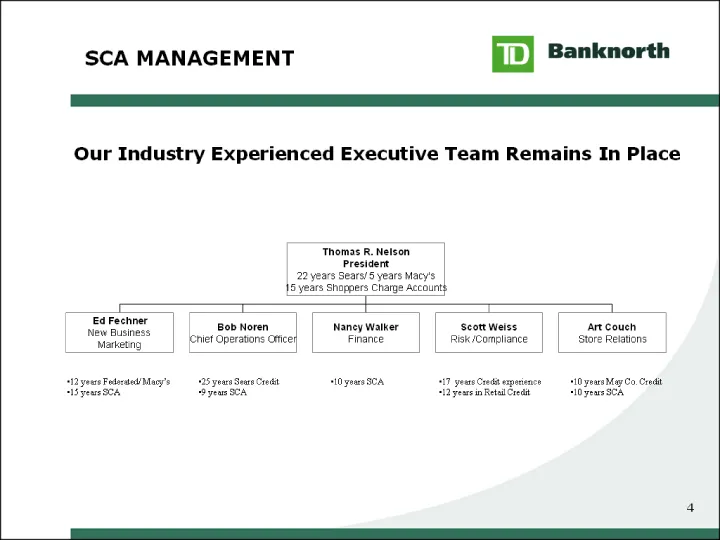
Our Industry Experienced Executive Team Remains In Place Our Industry Experienced Executive Team Remains In Place 12 years Federated/ Macy's 15 years SCA 25 years Sears Credit 9 years SCA 10 years SCA 17 years Credit experience 12 years in Retail Credit 10 years May Co. Credit 10 years SCA SCA MANAG
Slide 64: Merchant Relationships - Last Year
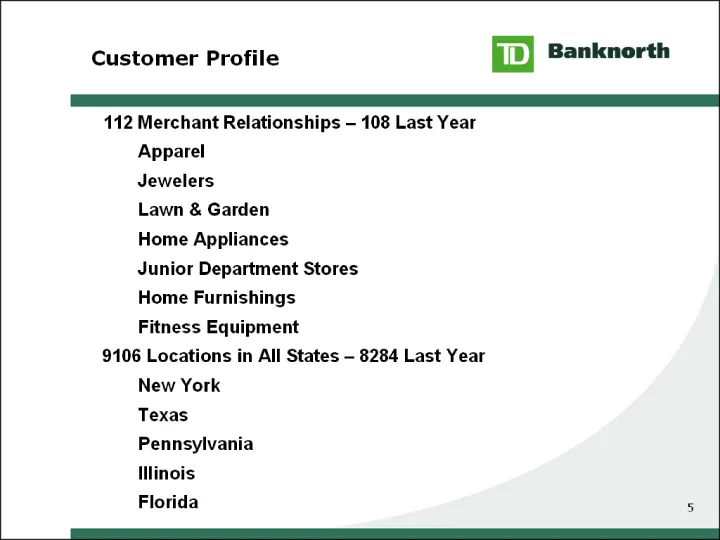
112 Merchant Relationships - 108 Last Year Apparel Jewelers Lawn & Garden Home Appliances Junior Department Stores Home Furnishings Fitness Equipment 9106 Locations in All States - 8284 Last Year New York Texas Pennsylvania Illinois Florida Customer Profile
Slide 65: Our New Business Targets
Start - Ups Established retailers with no existing program Total annual sales volume greater than $5,000,000 Buy - Outs Existing programs administered in-house or by other provider Total receivable to be purchased greater than $250,000 Collect - Outs Purchase portfolio from entity that has gone or i
Slide 66: Our Programs
Standard Revolving Consumer Credit 30 day revolving programs Same As Cash programs for higher ticket purchases Customized rewards programs Unsecured Line of Credit Operates identically to credit card programs except credit cards are replaced by checks Small Business Revolving Fixed monthly payments
Slide 67: What Shoppers Brings to TD Banknorth
What Shoppers Brings to TD Banknorth National Credit Card Company Prime Plus Loans High Yielding Portfolio Significant Non Interest Income - Discount, Late Fees and Other Cross Sell Opportunities For: Merchant Trust Commercial Lending
Slide 68: What TD Banknorth Brings to Shoppers
What TD Banknorth Brings to Shoppers Balance Sheet Strength - Involvement in Larger Deals Improved Bank Name Recognition - Greater Credibility Cross Sell Leads from Merchant Department and Cross Sell Leads from Commercial Lending Increased Marketing Funding Private Label Program Opportunities in Can
Slide 69: Current Opportunities
Current Opportunities Strong pipeline - start ups (16) and acquisitions (6) Significant number of untapped start-up opportunities U.S. Payment Industry Revenues of $18.0 billion Continue to expand Lawn and Garden Industry Acquire portfolios presently owned/serviced by competitors
Slide 70: Questions?
Questions? 1D Banknorth a
Slide 71: Commercial Lending & Risk Management
Commercial Lending & Risk Management Edward P. Schreiber EVP, Credit Risk Officer & Regulatory Liaison July 28, 2006
Slide 72: Note on Forward-Looking Information
Note on Forward-Looking Information This presentation contains certain forward-looking statements with respect to the financial condition, results of operations and business of TD Banknorth. Words such as "expect", "feel", "believe", "will", "may", "anticipate", "plan", "estimate", "intend", "should
Slide 73: Commercial Loan Portfolio Information
Commercial Loan Portfolio Information Average Size Loan Relationship is apx. $650 thousand Number of Borrowers: Apx. 34,000 Geographic Distribution Massachusetts and Connecticut markets (represents apx. 50% of outstandings)
Slide 74: Top Relationships
Top Relationships Twenty Largest Relationships Asset Range from $97 million to $40 million Non-Performing Top 15 range from $9 million to $858 thousand Top Industries Investment Real Estate Manufacturing - Durable & Non Durable Retail Trade Health Care & Social Assistance Wholesale Trade
Slide 75: TD Banknorth Portfolio Concentrations
TD Banknorth Portfolio Concentrations C & I = 46% of Outstanding & Unfunded Commitments CRE Owner = 18% of Outstanding & Unfunded Commitments CRE Investment = 34% of Outstanding & Unfunded Commitments
Slide 76: Investment Real Estate Lending Executive Summary
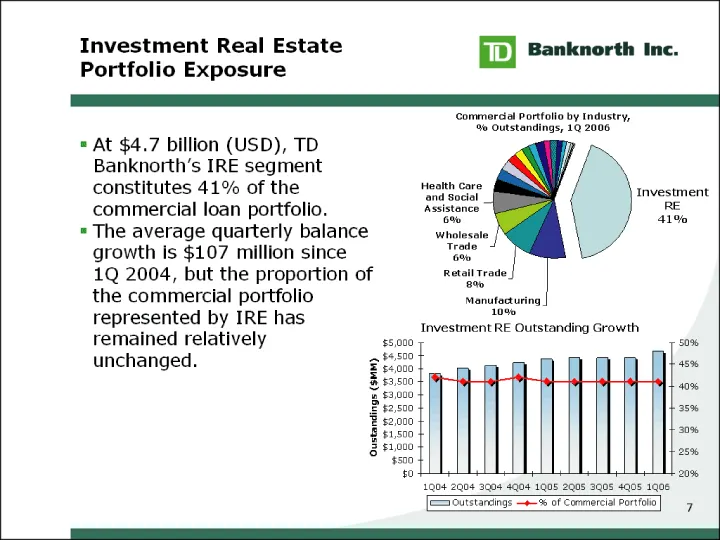
Investment Real Estate Lending Executive Summary Investment Real Estate: Investment Real Estate (IRE) has long been the dominant sector in TD Banknorth's commercial lending portfolio. Asset Quality: Remains very strong with some fundamentals in the market improving. Diversification: The segment is w
Slide 77: Investment Real Estate Portfolio Exposure
Investment Real Estate Portfolio Exposure NAICS INDUSTRY Outstanding Investment RE 4664623774 Manufacturing 1085655300 Retail Trade 947813254 Wholesale Trade 696125088 Health Care and Social Assistance 665959556 Finance and Insurance 401067269 Construction Trade 332416636 Other Services (except Publ
Slide 78: Investment Real Estate Underwriting Standards
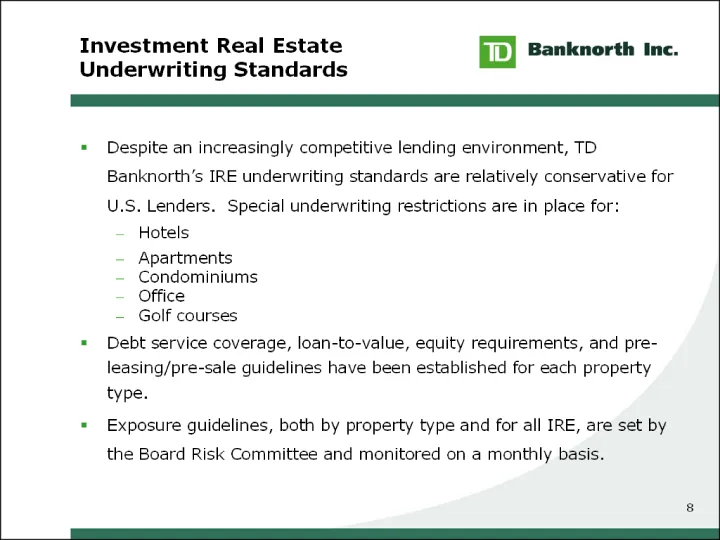
Investment Real Estate Underwriting Standards Despite an increasingly competitive lending environment, TD Banknorth's IRE underwriting standards are relatively conservative for U.S. Lenders. Special underwriting restrictions are in place for: Hotels Apartments Condominiums Office Golf courses Debt s
Slide 79: Investment Real Estate Underwriting Standards (continued)
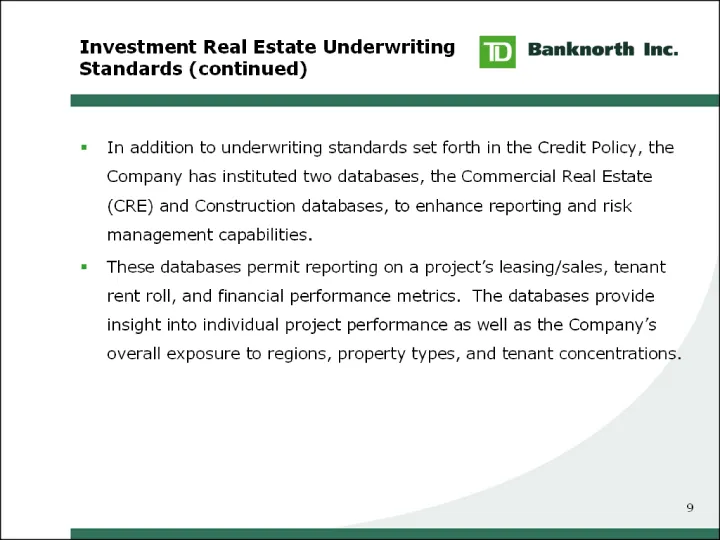
Investment Real Estate Underwriting Standards (continued) In addition to underwriting standards set forth in the Credit Policy, the Company has instituted two databases, the Commercial Real Estate (CRE) and Construction databases, to enhance reporting and risk management capabilities. These database
Slide 80: CRE and Construction Databases
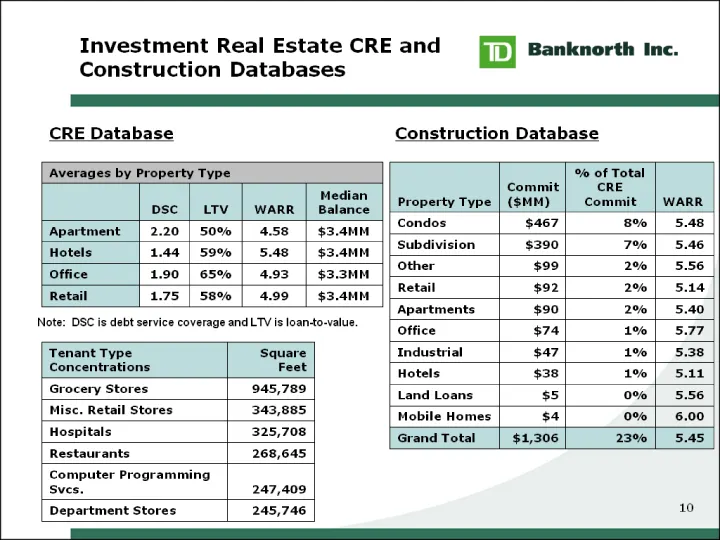
Investment Real Estate CRE and Construction Databases CRE Database Averages by Property Type Averages by Property Type Averages by Property Type Averages by Property Type Averages by Property Type DSC LTV WARR Median Balance Apartment 2.20 50% 4.58 $3.4MM Hotels 1.44 59% 5.48 $3.4MM Office 1.90 65%
Slide 81: Questions?
Questions? 7D] Banknorth Inc. un
Source: SEC EDGAR · 8-K filed Jul 28, 2006
More decks from TD Banknorth Inc.
 Investor Day (June 2007)36 slides · Jun 28, 2007
 Merger or Acquisition (April 2007)5 slides · Apr 18, 2007
 Merger or Acquisition (November 2006)8 slides · Nov 20, 2006
 Scotia Capital Financials Summit 200622 slides · Sep 12, 2006
 Merger or Acquisition (April 2006)21 slides · Apr 17, 2006
 Cohen Bros. & Company Annual Investors Conference (March 2006)19 slides · Mar 14, 2006