Duke Realty — 2011 Citigroup Investor Meeting
79 slides from Duke Realty's conference presentation, Jun 28, 2011
Slide 1: 2011 Citigroup Investor Meeting
RELIABLE. ANSWERS. 2011 Citigroup Investor Meeting June 28, 2011 Exhibit 99.1
Slide 2: Presenters
RELIABLE. ANSWERS . Denny Oklak Chairman & CEO Christie Kelly Executive VP & CFO Jim Bremner President, Healthcare Jim Connor Senior Regional EVP Sam O’Briant Regional EVP Jeff Turner Regional EVP
Slide 3: Agenda
Opening Market outlook Strategy & performance Regional overviews Medical Office Closing comments AGENDA
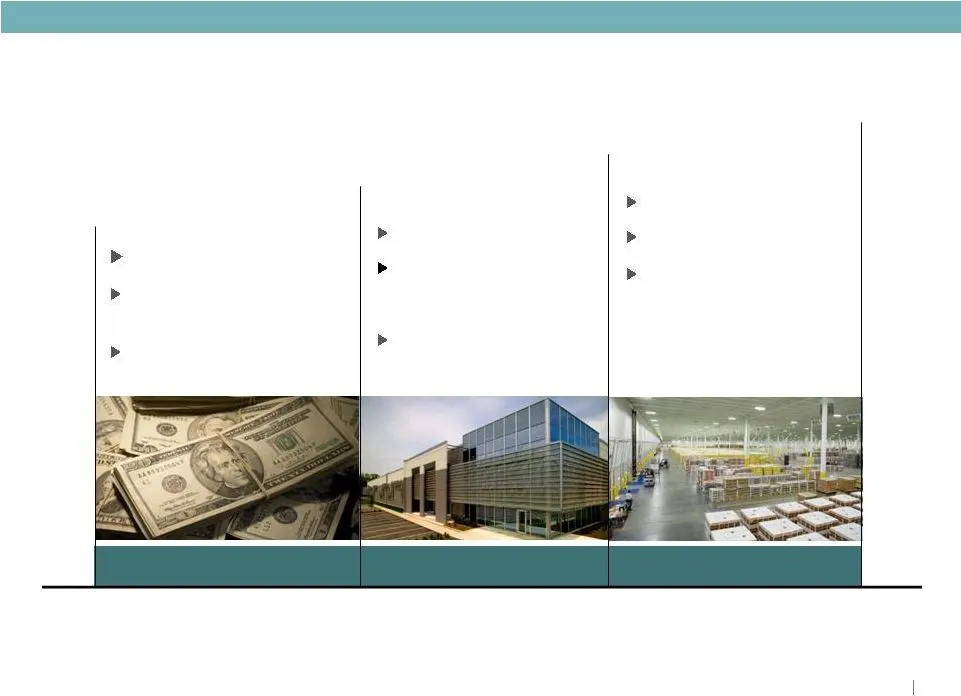
Slide 4: 2009, 2010 and 2011 and beyond
RELIABLE. ANSWERS . 2009 2010 2011 and beyond FOCUS: Liquidity More than $1.5 billion capital raised Strategy refined FOCUS: Strategy execution Operating fundamentals Balance sheet strength FOCUS: Asset quality Cash flow growth Shareholder return Where we’ve been and where we’re going…
Slide 5: Market Outlook
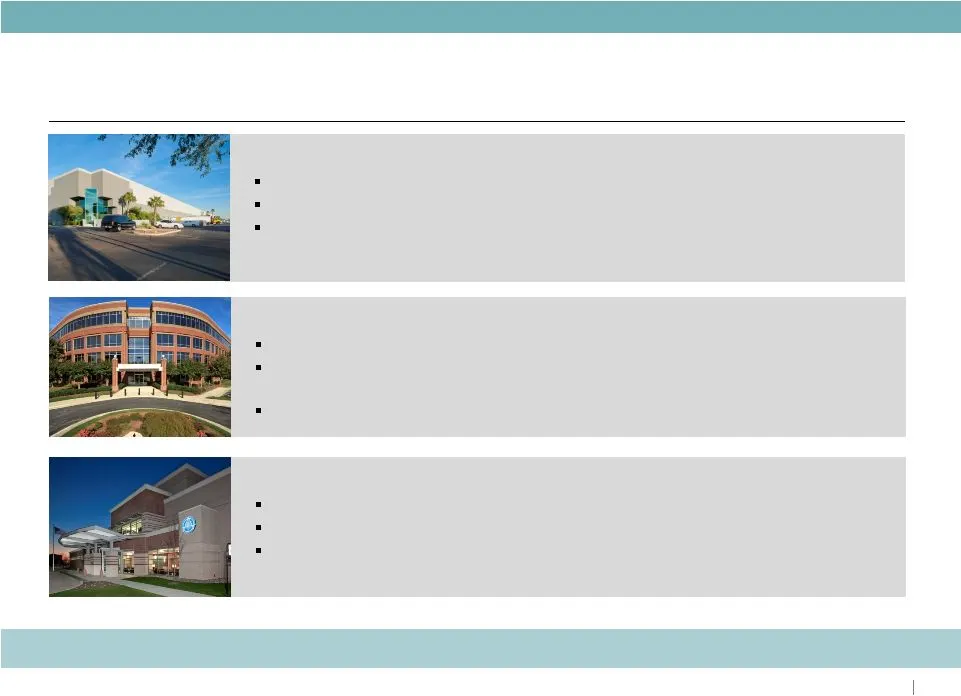
RELIABLE. ANSWERS . Suburban Office Market Still Challenging Economic uncertainty limiting business investment and expansion decisions Continued improvements in consumer spending, corporate profits and job outlook will be catalyst Recovery will be at slower pace Medical Office Regaining Traction Ope
Slide 6: Strategy for Success
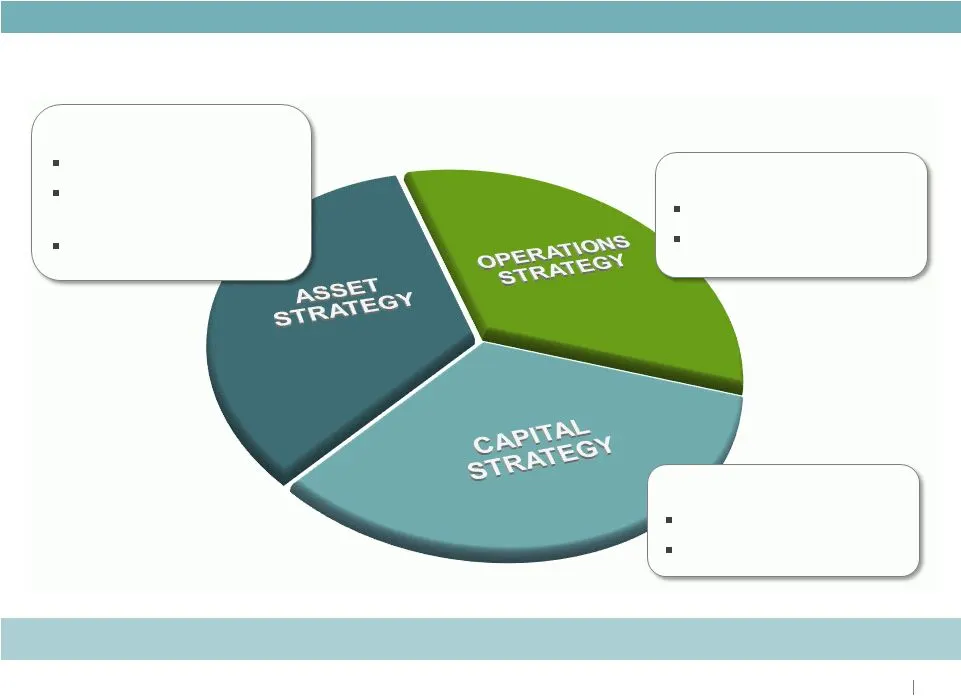
RELIABLE. ANSWERS . Focus on: Increasing cash flow Maximizing return on assets Strategy for Success Focus on: Improving coverage ratios Improving ratings Focus on: Portfolio repositioning Strategic acquisitions & dispositions Development opportunities Delivering on what we say we will do
Slide 7: 2011 Goals and Objectives, Q1 2011 Update
RELIABLE. ANSWERS . 2011 Goals and Objectives Q1 2011 Update Strategic Focus • Lease-up portfolio, manage cap ex; reach positive same property income growth • Balance execution with capital strategy relative to level and quality of cash flow and same property NOI; Debt to EBITDA <7.0x • Development
Slide 8: Asset Strategy
ASSET STRATEGY
Slide 9: Asset Strategy: Proven Performance
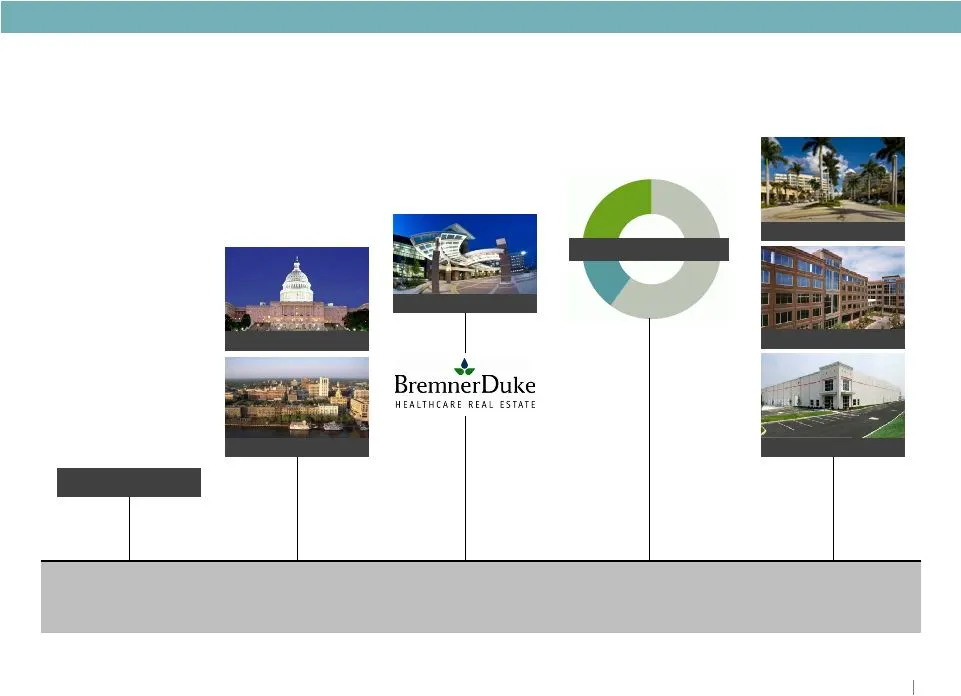
ASSET STRATEGY Flex disposition Savannah Washington DC Healthcare Asset Strategy Dugan CBRERT Premier Depth & experience of team = Consistent execution Proven Performance $1 Billion
Slide 10: Portfolio Strategy by Product and Geography
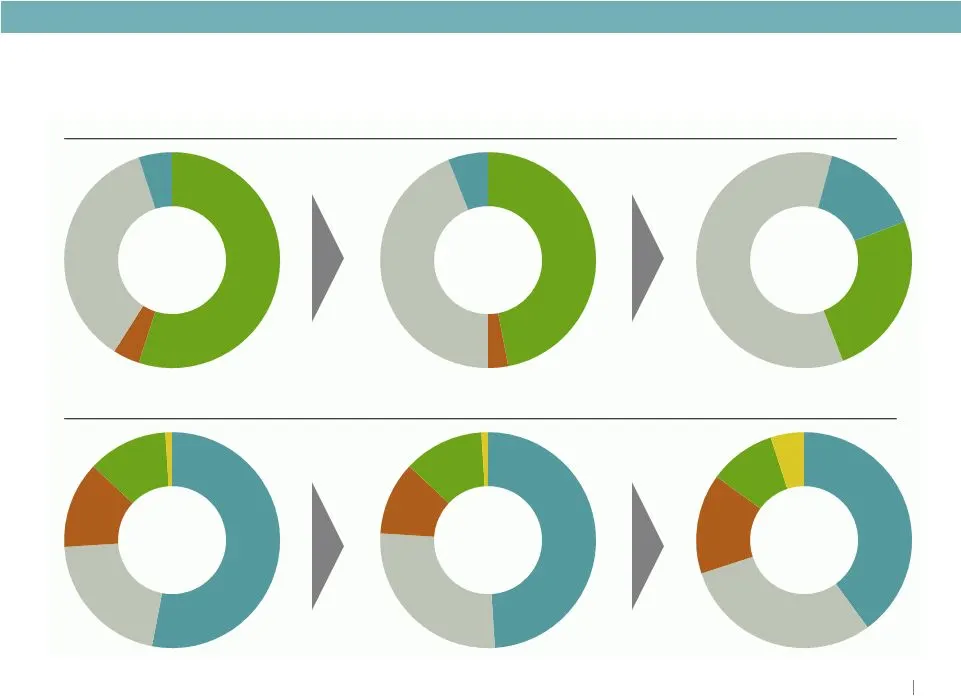
ASSET STRATEGY Portfolio Strategy BY PRODUCT BY GEOGRAPHY Q1 2011 Q1 2011 Southeast 21% Southeast 27% Southeast 30% Industrial 36% Industrial 45% Industrial 60% Medical Office 5% Medical Office 6% Medical Office 15% Office 25% Office 46% Office 55% Retail 4% Retail 3% East 13% South 12% West 1% Midw
Slide 11: Asset Strategy: Road Map
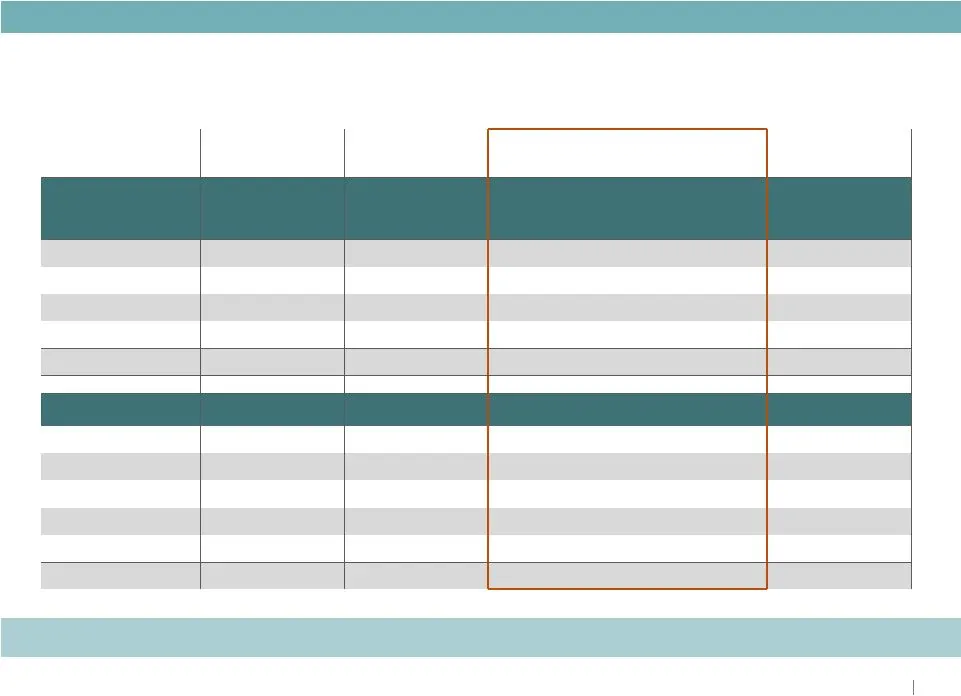
PRODUCT TYPE Amount % Amount % Proceeds from Targeted Dispositions Acquisitions/ Developments/ Repositioning Amount % REGION ASSET STRATEGY Asset Strategy: Road Map ($ in millions) Investment 9/30/09 Investment 3/31/11 ACTION PLAN Investment Industrial $2,930 36% $3,650 45% ($55) $1,250 $4,920 60% O
Slide 12: Asset Strategy: Progress To Date
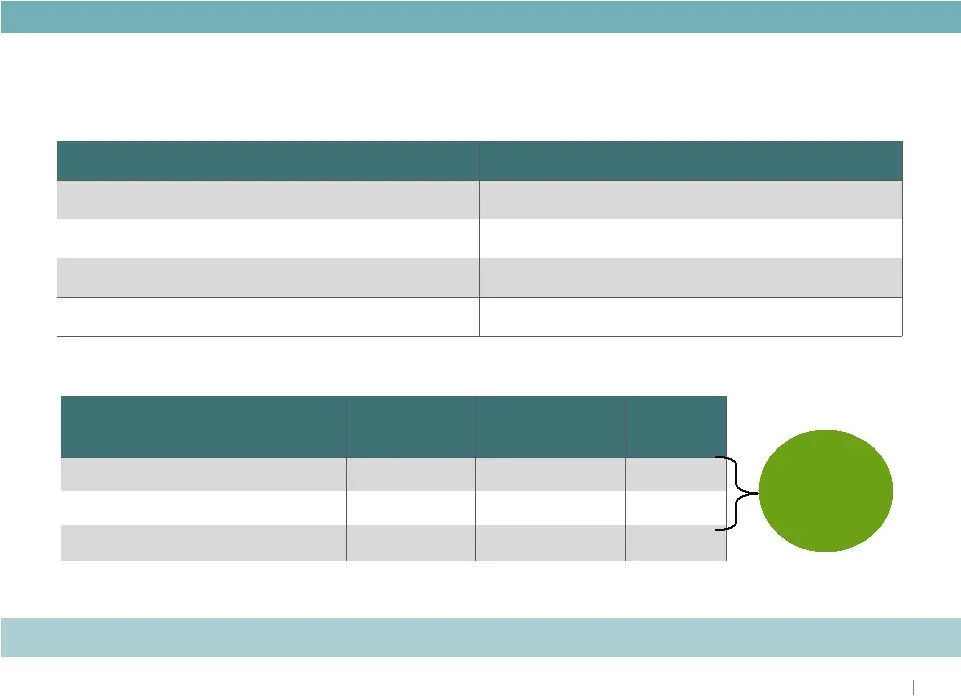
ASSET STRATEGY BUILDING ACQUISITIONS BUILDING DISPOSITIONS PRO FORMA PROGRESS TO DATE TOTAL VALUE ASSUMED DEBT NET Asset Strategy: Progress To Date Q4 2009 $15 Q4 2009 $144 – Remaining Premier – Remaining CBRERT Proforma Total $1,073 Proforma Total $1,099 Dispositions $1,099 ($0) $1,099 Acquisitions
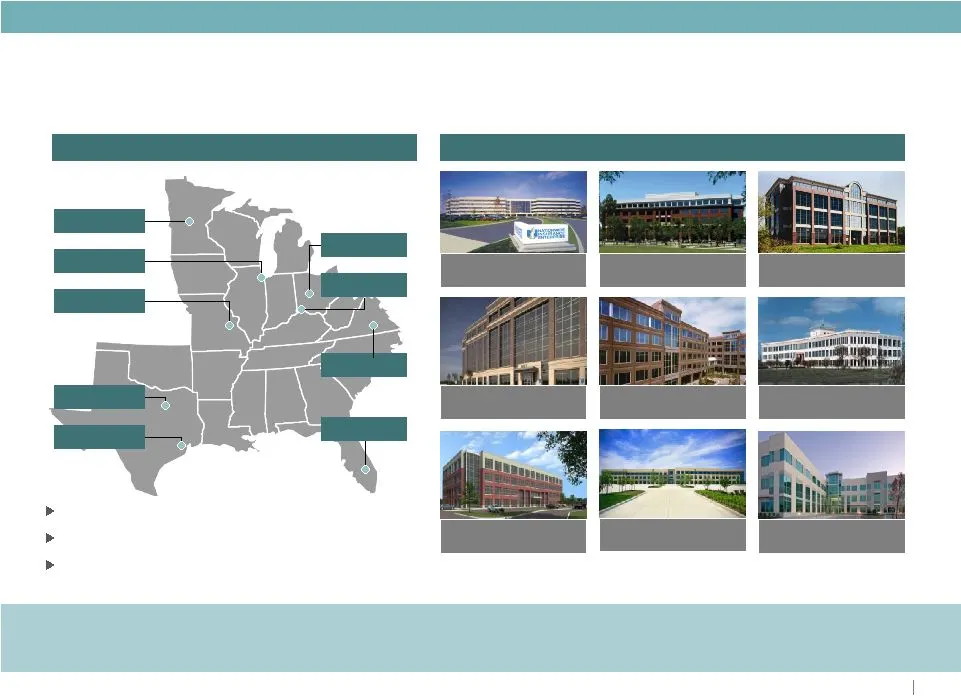
Slide 13: CBRERT: Suburban Office Joint Venture
Columbus (22%) Geographic Footprint Asset Snapshots ASSET STRATEGY Norman Pointe I and II Minneapolis Sam Houston Crossing Houston One and Two Easton Oval Columbus Regency Creek I Raleigh One Conway Park Chicago Nationwide Columbus 533 and 555 Maryville Center St. Louis Landings Building I and II Ci
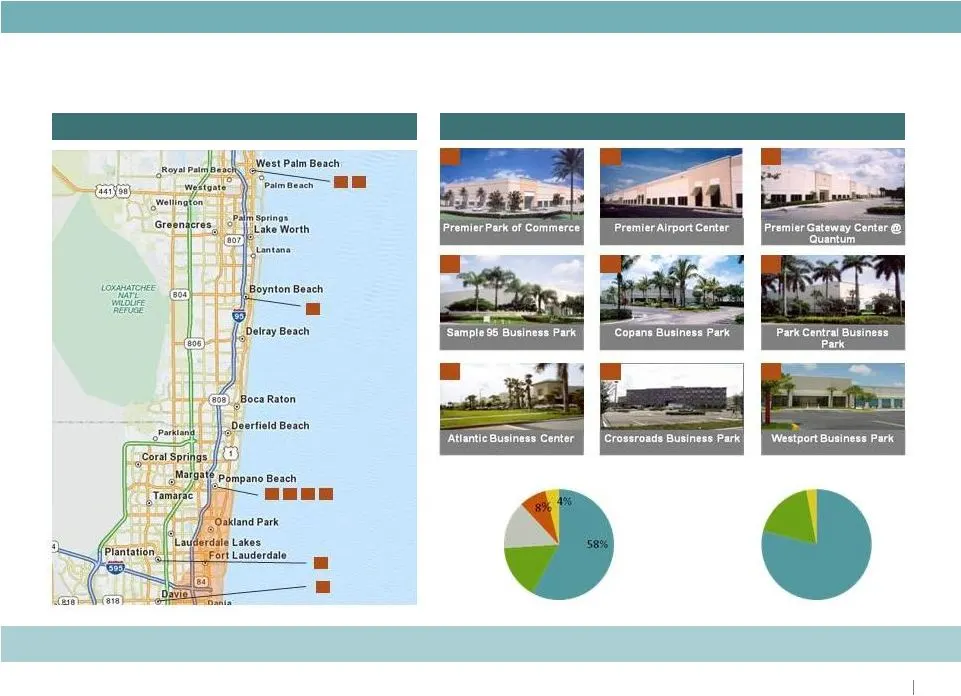
Slide 14: Premier Acquisition Portfolio Overview
Geographic Footprint Asset Snapshots ASSET STRATEGY A B C D E F G H I B A C D E F G H I Premier Acquisition Portfolio Overview Acquired $450 million primarily industrial portfolio in high barrier growth market * Based on dollars invested Pompano Beach Plantation (office) Boyton Beach Palm Beach Cent
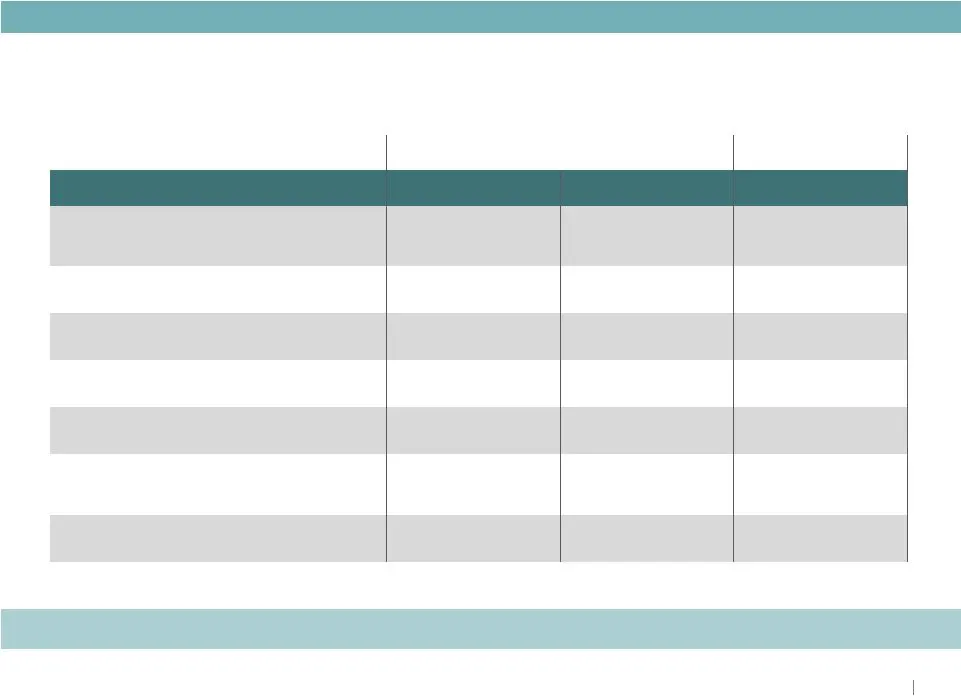
Slide 15: Asset Repositioning Analysis
Dugan Realty Premier Portfolio CBRERT ASSET STRATEGY Asset Repositioning Analysis Making significant progress ACQUISITIONS DISPOSITIONS Location Midwest/ Southeast South Florida Multi Location/ Midwest Product Type Industrial Industrial & Office Suburban Office Square feet 20.8M 4.9M 3.1M Occupancy
Slide 16: Asset Strategy: 2010 Performance and 2011 Goals
2010 PERFORMANCE $533.2 million of dispositions $919.1 million of acquisitions $130 million of development starts 2011 GOALS Strong backlog of dispositions & acquisitions $200 million of new development starts; $75 - $125 million medical office Continue to make significant progress on strategic plan
Slide 17: Operations Strategy
OPERATIONS STRATEGY RELIABLE. ANSWERS .
Slide 18: Focus on Fundamentals
OPERATIONS STRATEGY Focus on Fundamentals LEASING OF PORTFOLIO STRATEGIC NEW DEVELOPMENT AND LAND DISPOSITION AFFO PAYOUT Maximize return on assets
Slide 19: New, High Quality Portfolio with Long-term Leases
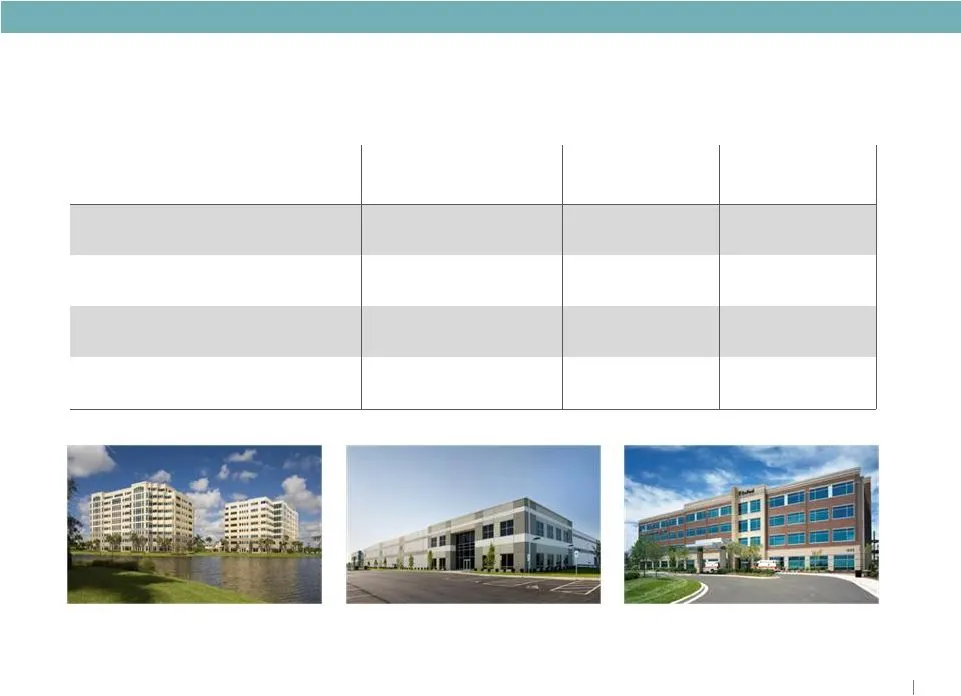
OPERATIONS STRATEGY New, High Quality Portfolio with Long-term Leases Bulk Industrial Suburban Office Medical Office Property age 10.1 years 11.7 years 2.0 years Property size 212,000 SF 118,000 SF 97,000 SF Lease term 7.0 years 7.2 years 11.7 years Tenant size 70,000 SF 12,000 SF 11,000 SF
Slide 20: Consistent Operating Performance
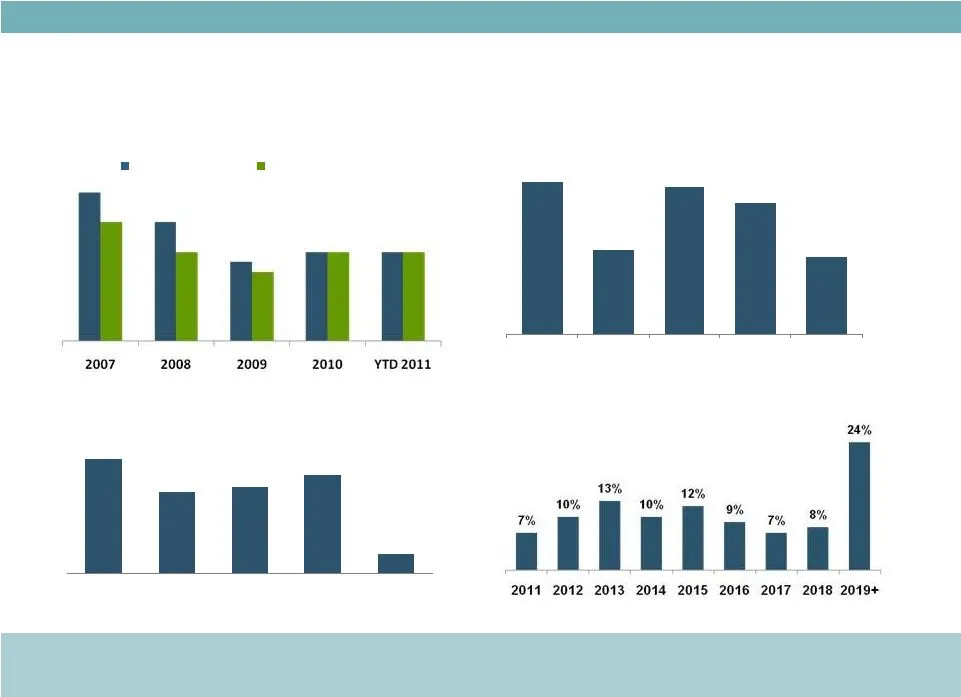
OPERATIONS STRATEGY Operations Strategy: Consistent Operating Performance Stabilized Occupancy (%) Strong historical stabilized occupancy – fundamentals improving Lease Renewals (%) Strong lease renewal percentages Stabilized occupancy In-service occupancy 80% 72% 79% 77% YTD 2011 70% 29.9 21.4 22.7
Slide 21: Land and Development Capabilities
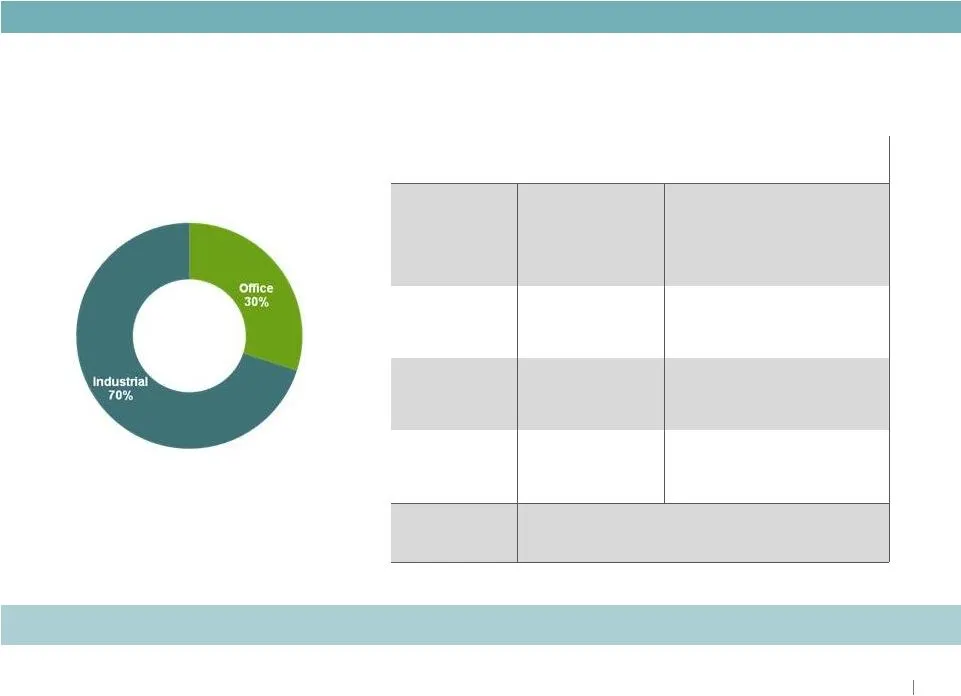
OPERATIONS STRATEGY Land and Development Capabilities $495 million HELD FOR DEVELOPMENT Industrial Development - SF Midwest 26.3 million SF Indianapolis, Chicago, Columbus and St. Louis major positions East 3.1 million SF New Jersey, Baltimore and Washington D.C. Southeast 8.5 million SF Atlanta, Ce
Slide 22: Historical Focus on Occupancy
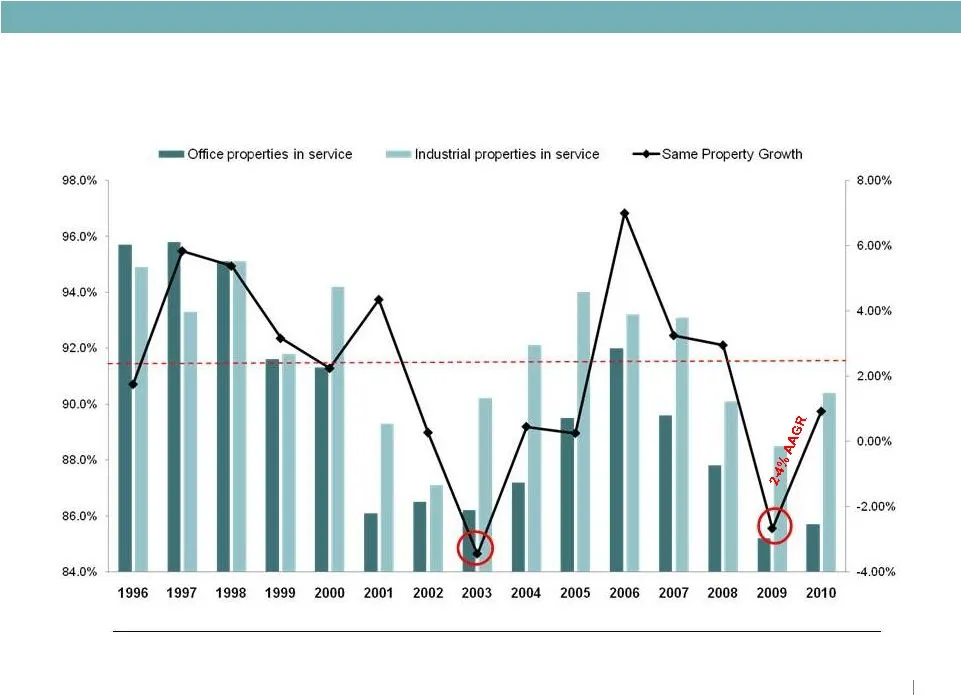
OPERATIONS STRATEGY December 31 Historical Focus on Occupancy 2.3% Avg Technology Bust Market Downturn
Slide 23: Consistent NOI Growth Outperformance
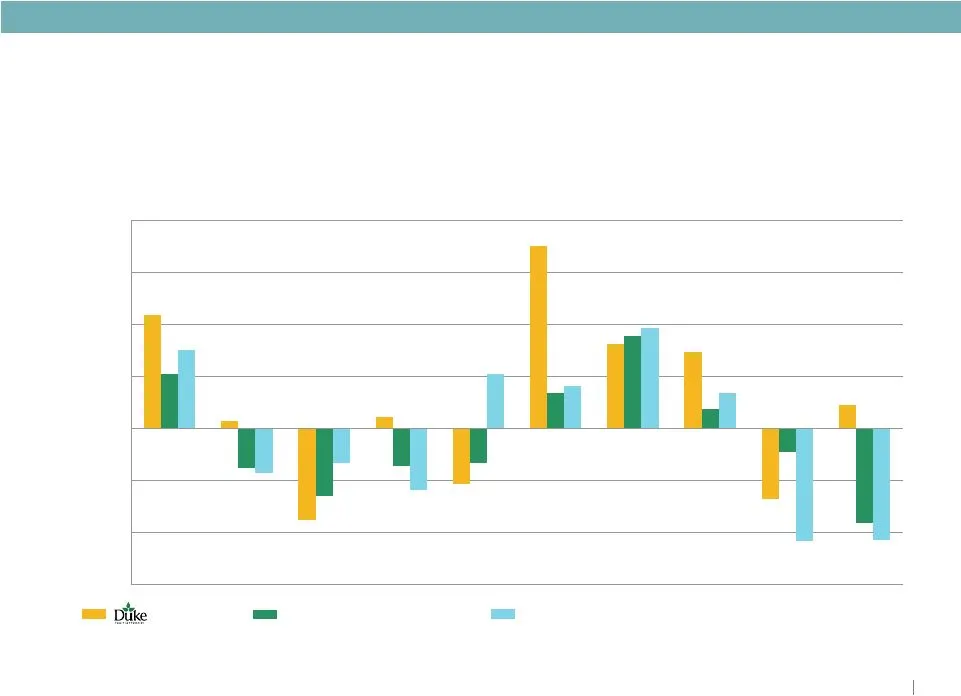
OPERATIONS STRATEGY (2) (3) Consistent NOI Growth Outperformance 3.3% 3.0% (2.7%) 0.9% 2.1% (1.5%) (2.6%) (1.5%) (1.3%) 1.4% 3.6% 0.8% (0.9%) (3.6%) 3.0% (2.4%) 2.1% 3.9% 1.4% (4.3%) (4.3%) 7.0% (2.1%) 0.5% (3.5%) 0.3% 4.4% 1.6% (1.3%) (1.7%) (6.0%) (4.0%) (2.0%) 0% 2% 4% 6% 8% Low Barrier Office Pe
Slide 24: Consistent NOI Growth Outperformance (cont'd)
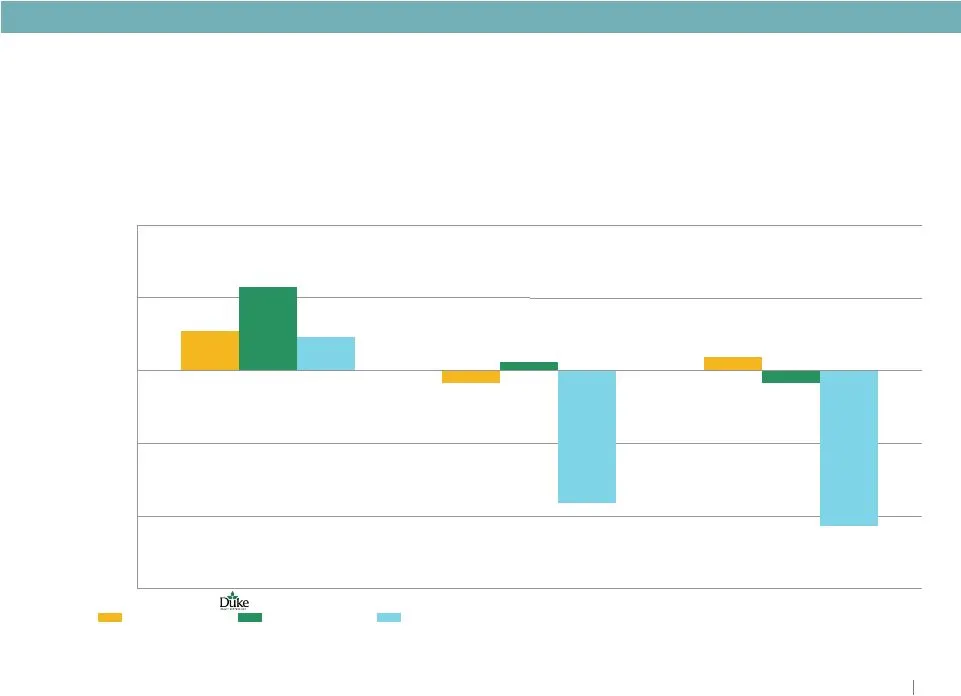
OPERATIONS STRATEGY Consistent NOI Growth Outperformance (cont’d) Relative Performance vs. Peers Notes 1. Based on straight-line average of year-over-year annual same-property NOI growth 2. Low barrier office (“LBO”) includes BDN, CLI, HIW, LRY and PKY; weighted by historical market cap 3. Industria
Slide 25: Operations Strategy: 2010 Performance and 2011 Goals
2010 PERFORMANCE Total portfolio occupancy of 89.1% Industrial at 90.5% occupancy Nearly 26 million SF leases – highest volume since 2007 2011 GOALS Leasing of portfolio Manage capital expenditures and maximize cash flow AFFO guidance 85% - 100% OPERATIONS STRATEGY Quality, well-positioned assets to
Slide 26: Midwest Overview
MIDWEST OVERVIEW
Slide 27: Midwest Overview: Transactions and Market Points
MIDWEST OVERVIEW RECENT TRANSACTIONS Midwest Renewal Industrial Hebron I - Cincinnati 646,000 SF 100% leased New Lease Office Atrium II - Columbus 121,000 SF Tenant: Alcatel - Lucent MARKET OVERVIEW & KEY POINTS Strong distribution base: Over 30% of U.S. population within one day’s drive 74 Fortune
Slide 28: Midwest Overview
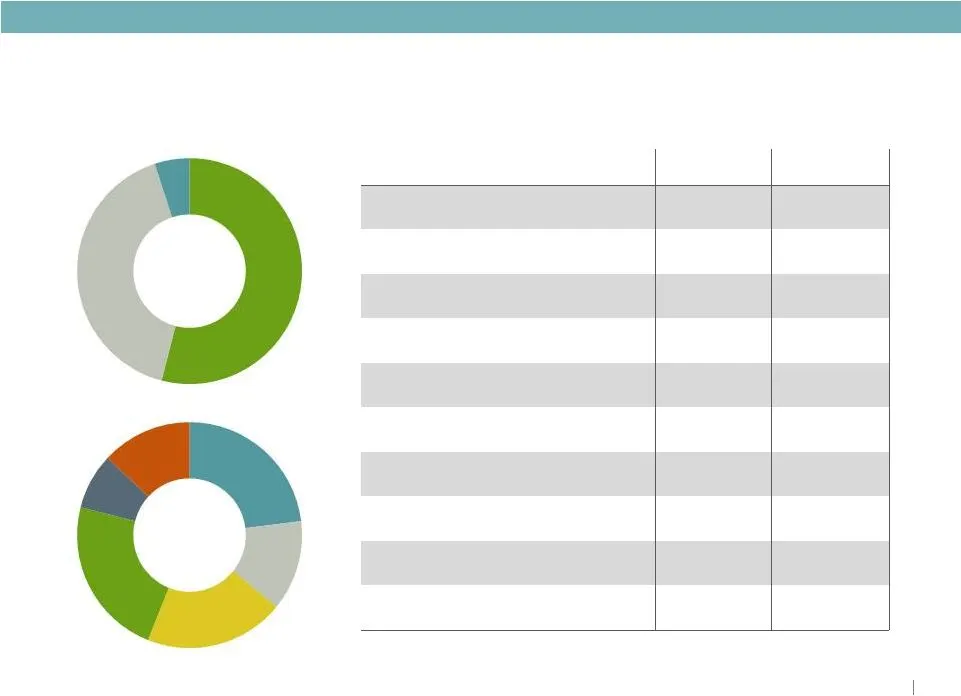
MIDWEST OVERVIEW Midwest Overview Location Product Type Industrial Office Average Age 11.6 years 16.3 years Average Building Size 236,000 SF 130,000 SF Total Square Footage 51.5 million 16.4 million Current Occupancy 93.0% 84.4% Indianapolis 96.7% 86.5% Chicago 96.1% 88.6% Cincinnati 86.4% 82.5% St.
Slide 29: Indianapolis
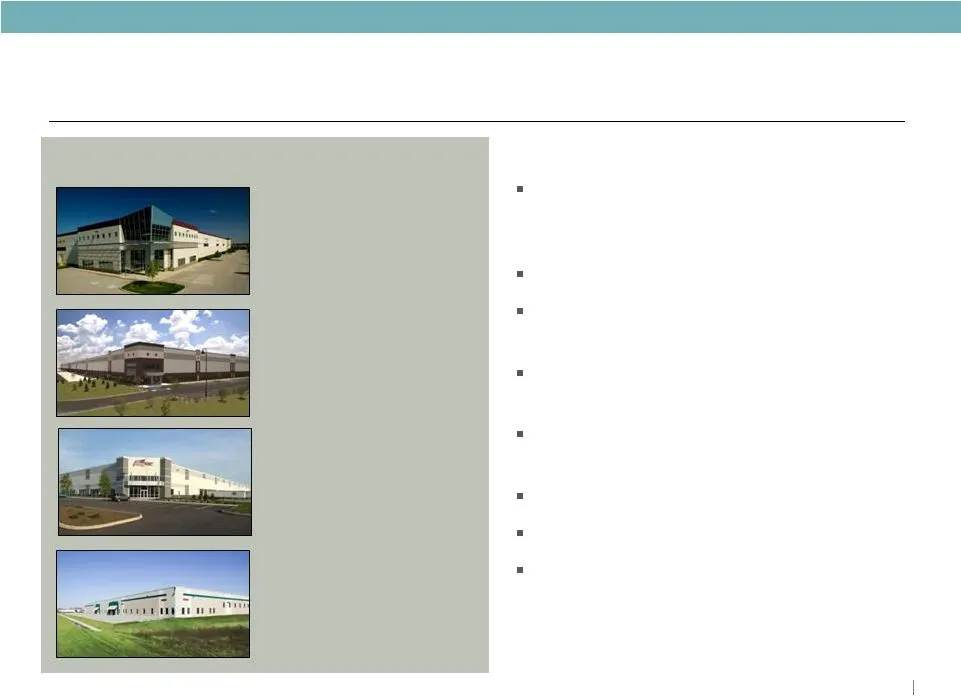
MIDWEST OVERVIEW TRANSACTION EXAMPLES Indianapolis New Lease - Industrial Park 100 – Bldg 87 144, 000 SF – 10 year term Tenant: Hat World New Lease - Industrial Plainfield Building V 426,000 SF – year term Tenant: Genco I, Inc. New Lease - Industrial AllPoints at Anson - 406,000 SF – year term Tenan
Slide 30: Cincinnati
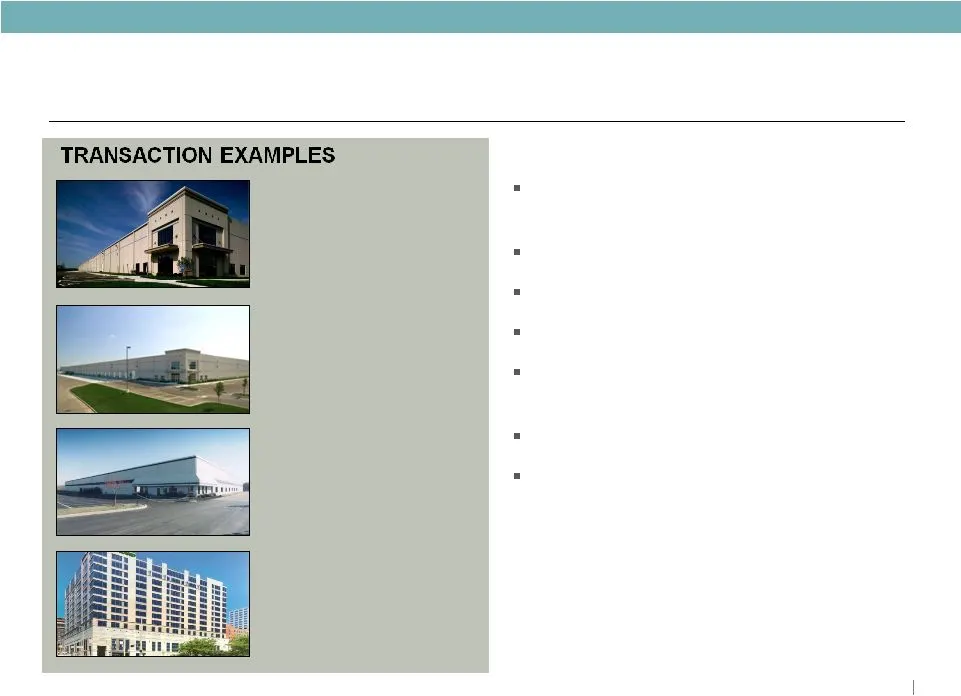
MIDWEST OVERVIEW Cincinnati Disposition – Office (CBD) 312 Plum & 312 Elm 609,000 SF New Lease - Industrial Hebron 2 598,000 SF – 5.5 year term Tenant: HK Systems New Lease - Industrial Union Centre Park 2 118,000 SF – year term Tenant: Bunzl Distribution New Lease - Industrial Southpark Building 4
Slide 31: Chicago
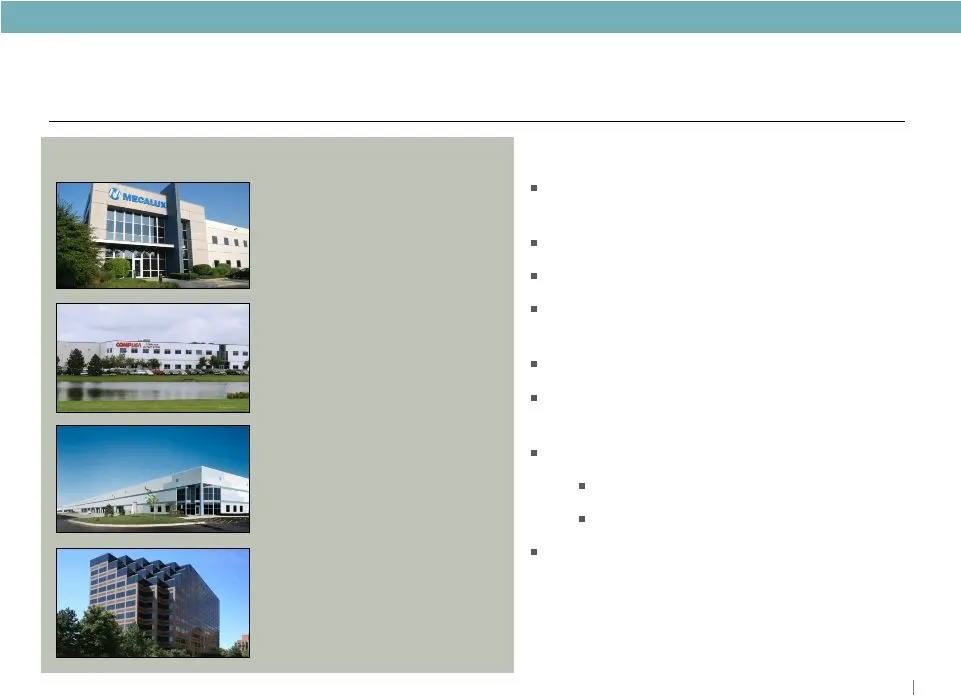
MIDWEST OVERVIEW Chicago Acquisition – Industrial Melrose Business Center 459,000 SF 100% Leased Expansion - Office Riverway East 38,000 SF – 9 year term US Food Service, Inc. Acquisition - Industrial 175 Ambassador Drive 331,000 SF 100% leased MARKET OVERVIEW AND KEY POINTS 1.3 billion SF Industria
Slide 32: Columbus
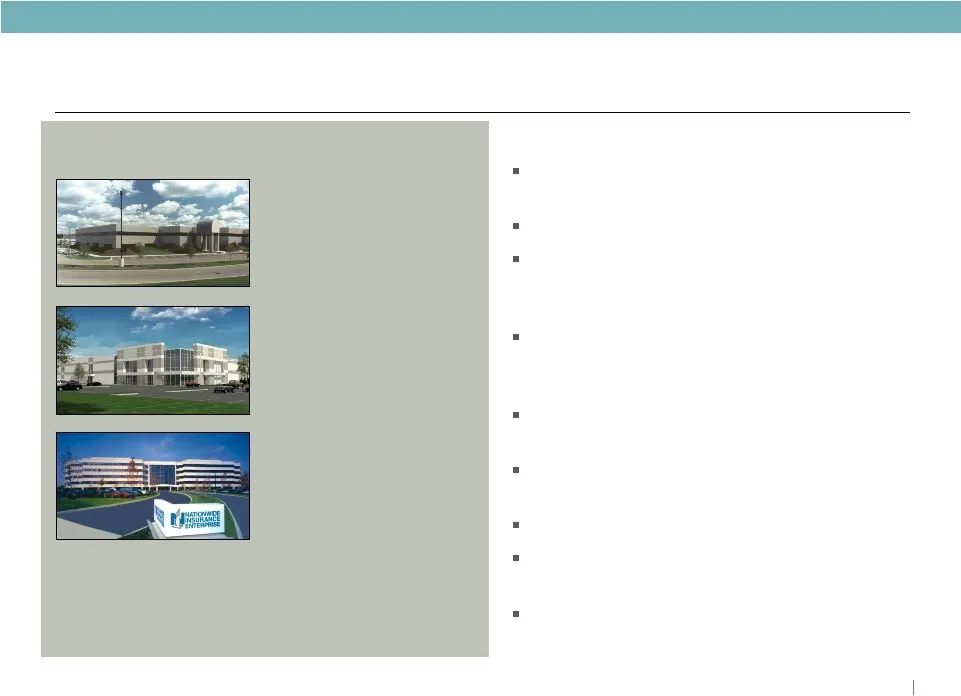
MIDWEST OVERVIEW Columbus Extension - Industrial 6600 Port Road 906,000 SF – 8.5 year term AS America Renewal - Office Nationwide Building 315,000 SF – 7 year term Nationwide Mutual Insurance (Building sold to CBRERT JV) New Development – Industrial Build to Suit West Jefferson Industrial Park 1.3 m
Slide 33: St. Louis
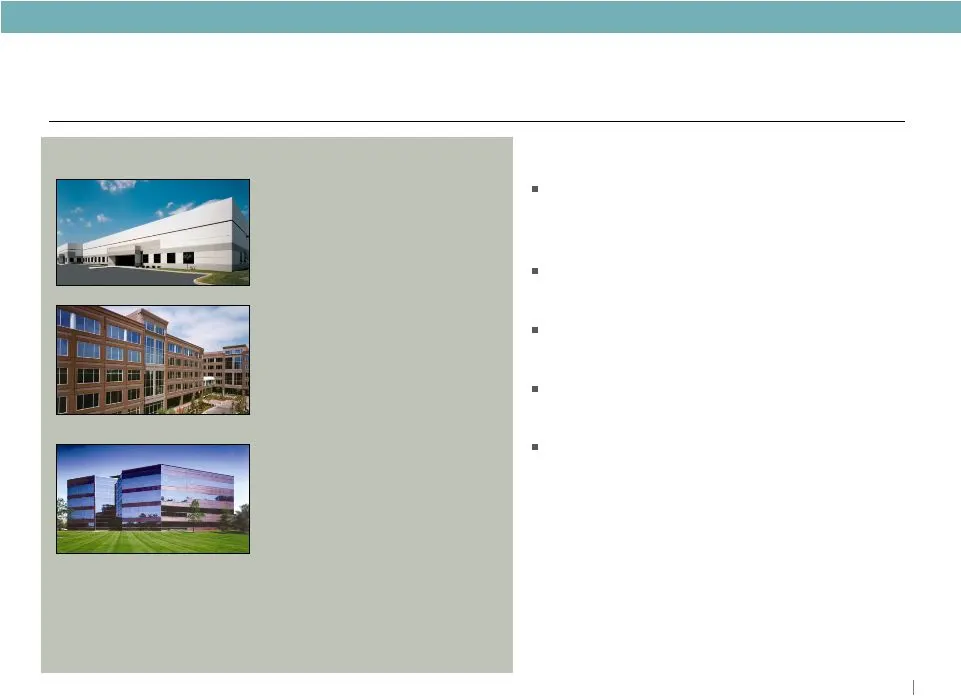
MIDWEST OVERVIEW St. Louis New Lease - Industrial Dukeport I, II, & VI 589,000 SF – 10.5 year term Tenant: Centric Group, LLC New Lease - Office Rider Trail 56,000 SF – 10 year term Tenant: Spectrum Brands Renewal - Office Maryville Centre 533 and 555 168,000 SF – 10 year term Tenant: Eveready Batte
Slide 34: Minneapolis
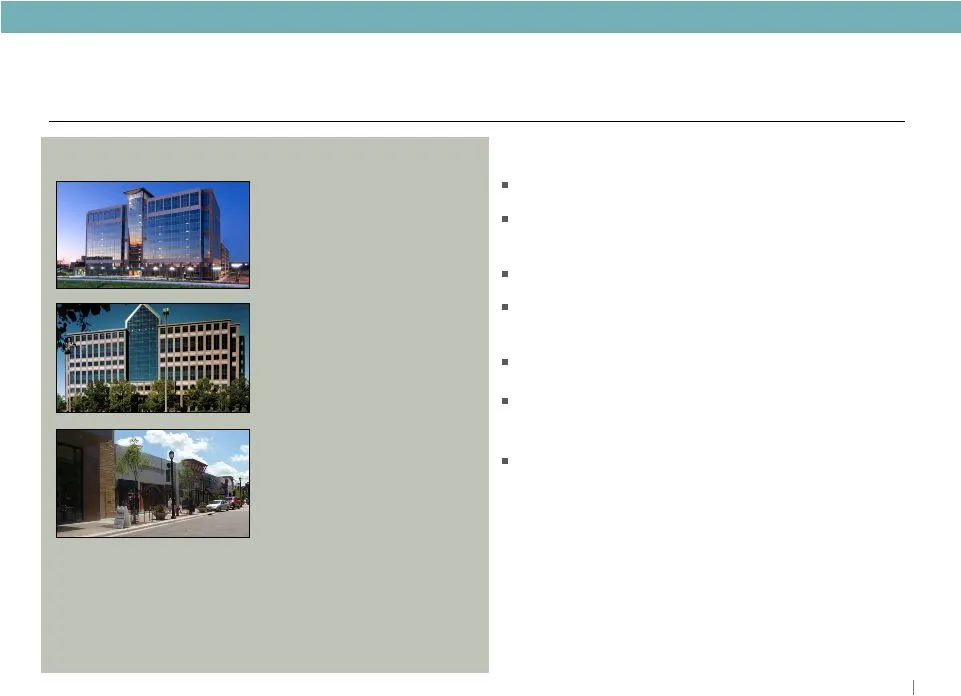
MIDWEST OVERVIEW TRANSACTION EXAMPLES Minneapolis New Lease - Office Norman Pointe II 245,000 SF – 5 year term Tenant: GSA New Lease/Renewal Office 1600 Tower 90,000 SF Multiple Leases Multiple Tenants New Leases - Retail The Shops at West End 30,000 SF Multiple Leases Multiple Tenants MARKET OVERVI
Slide 35: Midwest Focus
MIDWEST OVERVIEW Midwest Focus DOMINANT POSITION BULK INDUSTRIAL REDUCE OFFICE CONCENTRATION Enhancing dominant industrial position in Midwest
Slide 36: Midwest Team
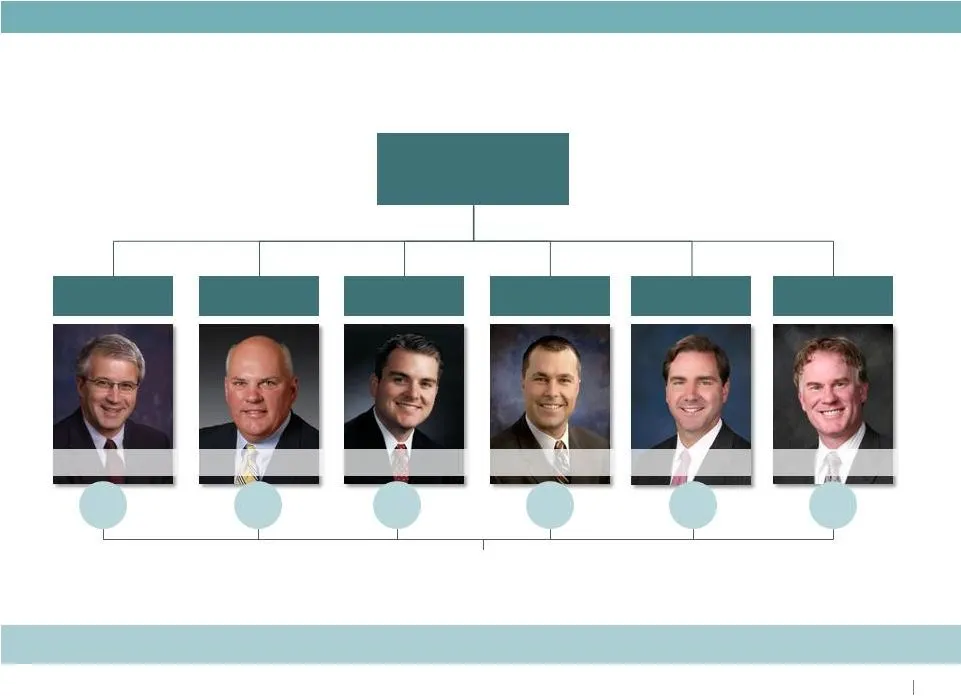
Jim Connor Regional EVP Indianapolis Cincinnati Columbus Chicago St. Louis Minneapolis MIDWEST OVERVIEW Midwest Team Charlie Podell Jon Burger Jim Clark Steve Schnur Toby Martin Pat Mascia Midwest leaders average 10 years with Duke Realty Years with Duke Realty
Slide 37: Southwest Overview
SOUTHWEST OVERVIEW
Slide 38: Southwest Overview: Transactions and Market Points
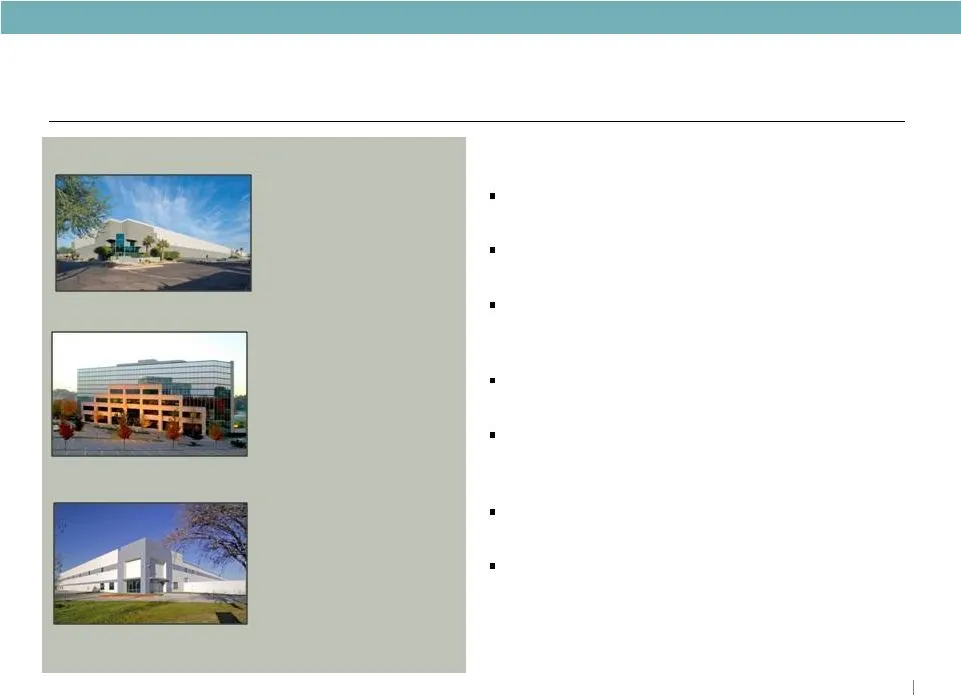
SOUTHWEST OVERVIEW RECENT TRANSACTIONS Southwest Acquisition - Industrial Estrella Buckeye – Phoenix 250,000 SF 100% Leased Disposition Office Lakeview office assets- Nashville 379,000 SF Duke Realty presence since 1999 (Weeks merger) 52 Fortune 500 headquarters Demographic drivers: modern transport
Slide 39: Southwest Overview
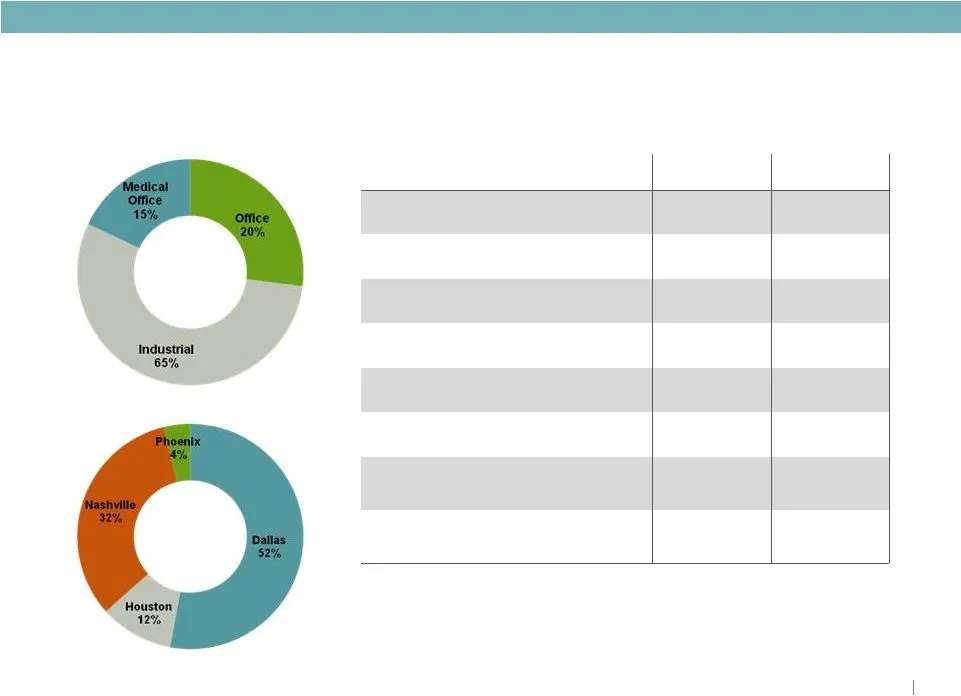
SOUTHWEST OVERVIEW Southwest Overview Industrial Office Average Age 8.6 years 6.5 years Average Building Size 256,500 SF 108,600 SF Total Square Footage 20.0 million 2.1 million Current Occupancy 85.6% 91.9% Dallas 83.8% 83.3% Nashville 80.9% 95.0% Houston 98.0% 100% Phoenix 97.1% N/A Note: All info
Slide 40: Dallas
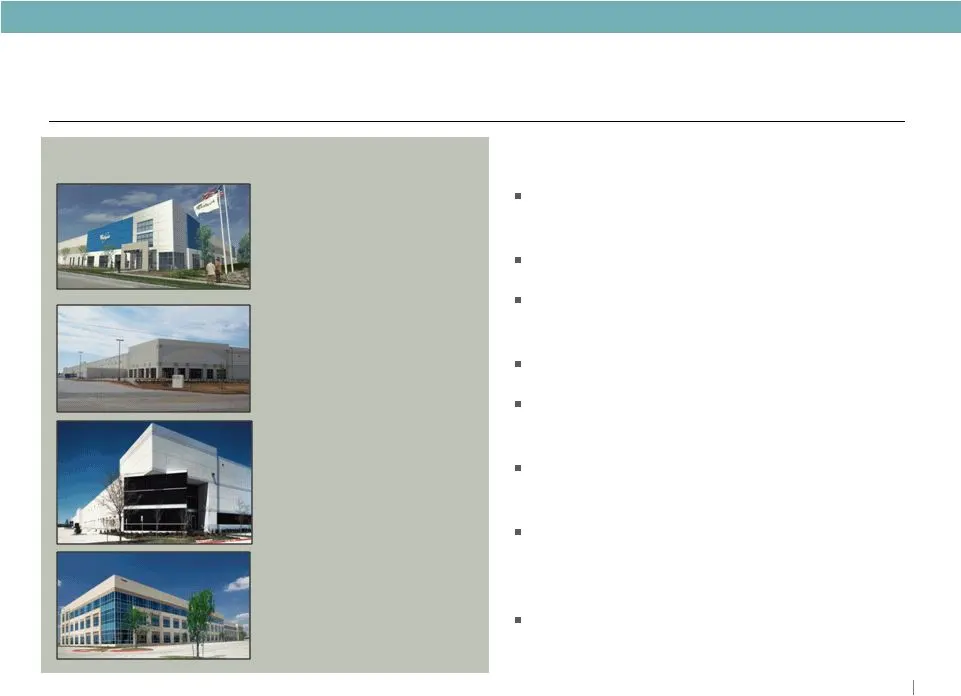
SOUTHWEST OVERVIEW TRANSACTION EXAMPLES Dallas New Development Third Party Build to Suit 1.02 million SF Whirlpool Expansion- Industrial Kingsley Distribution Ctr. 250,000 SF– 9.25 year term Plastipak Packaging Renewal Lease - Industrial Freeport III 116,000 SF- 3.5 year term Round2 Inc. New Lease -
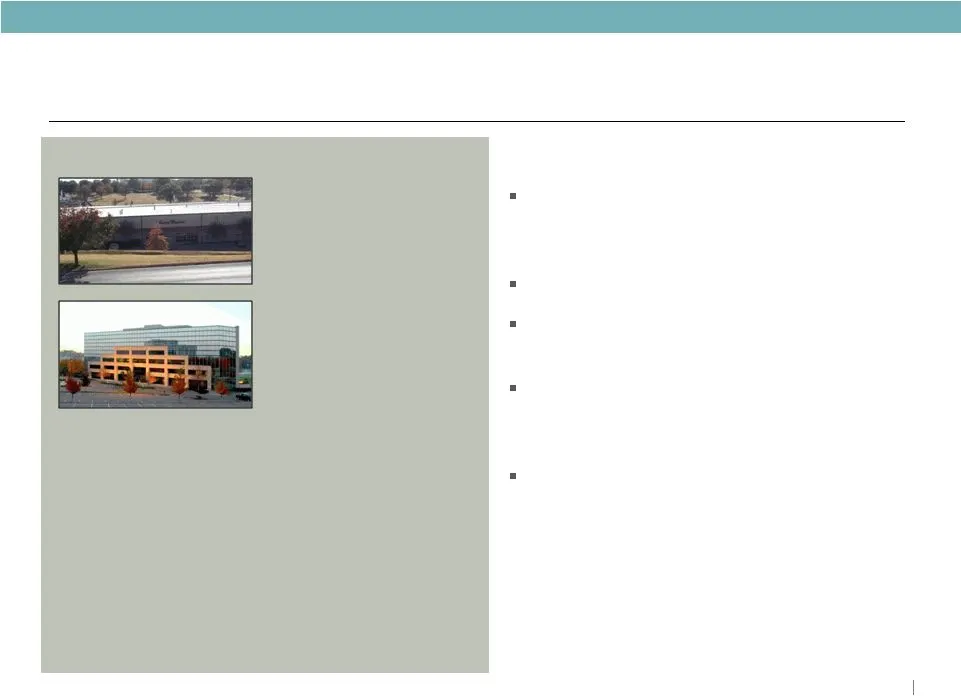
Slide 41: Nashville
SOUTHWEST OVERVIEW TRANSACTION EXAMPLES Nashville Acquisition - Industrial Four Forty Business Center II 133,000 SF 100% leased Disposition - Office Lakeview Office assets 379,000 SF MARKET OVERVIEW & KEY POINTS Long-standing business relationships and 25+ year presence have built Duke Realty brand
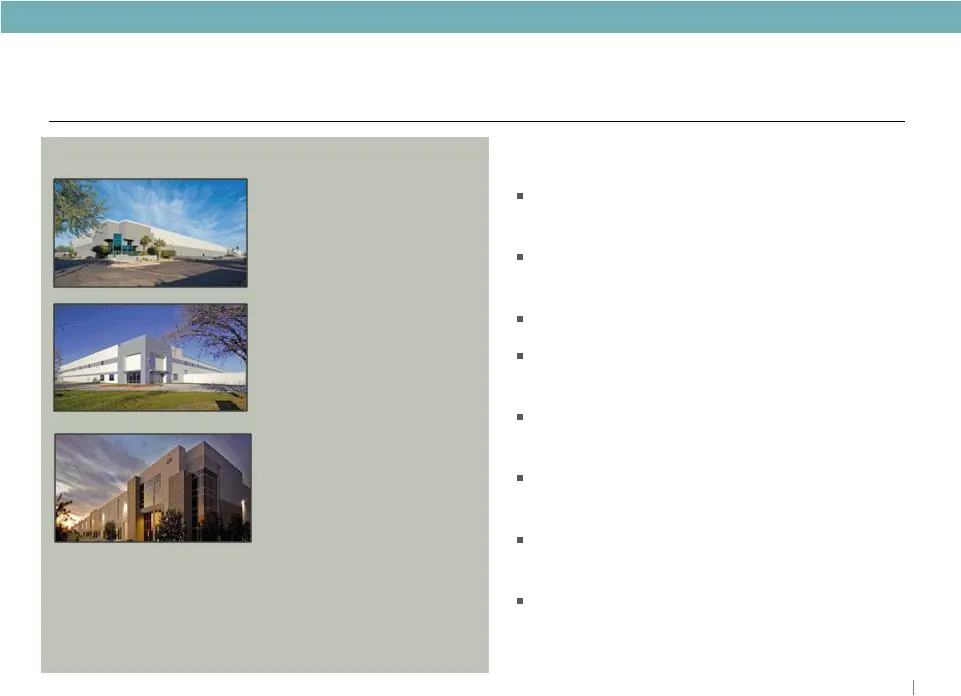
Slide 42: Phoenix
SOUTHWEST OVERVIEW TRANSACTION EXAMPLES Phoenix Acquisition - Industrial Estrella Buckeye 250,000 SF 100% leased New Lease - Industrial Goodyear 1 118,000 SF– 10 year term Sun-Tech MARKET OVERVIEW & KEY POINTS Industrial portfolio comprised of 1.9 million square feet that is 97% leased In 2010, posi
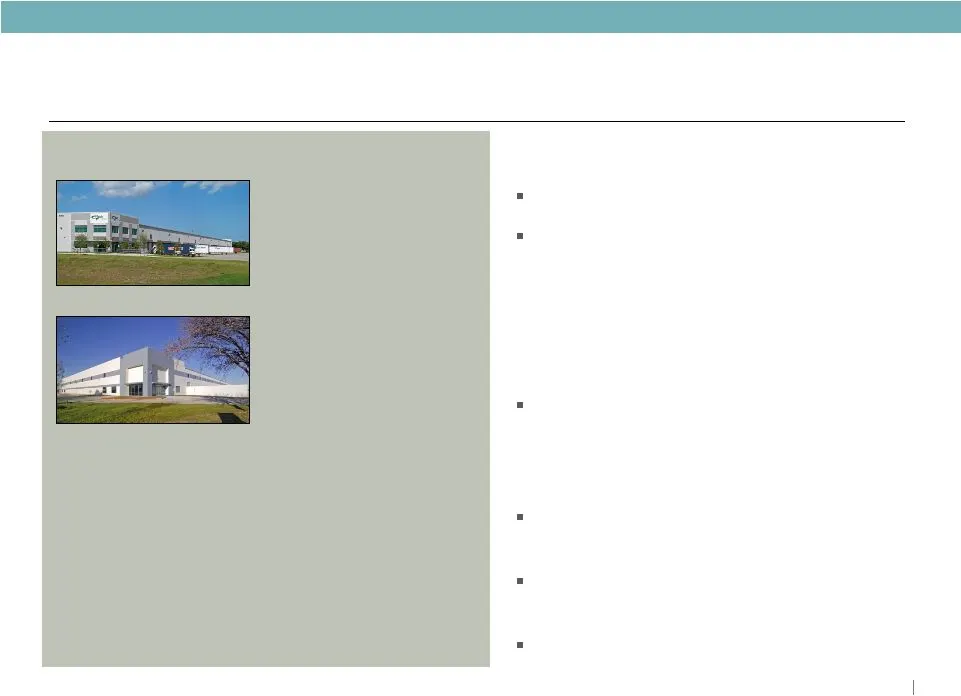
Slide 43: Houston
SOUTHWEST OVERVIEW TRANSACTION EXAMPLES Houston Acquisition - Industrial Granite Portfolio/ Port of Houston 582,840 SF 100% leased New Development Industrial Westland II 300,000 SF 73% pre-leased MARKET OVERVIEW & KEY POINTS 23 Fortune 500 headquarters Port of Houston: • Ranked st in U.S. imports •
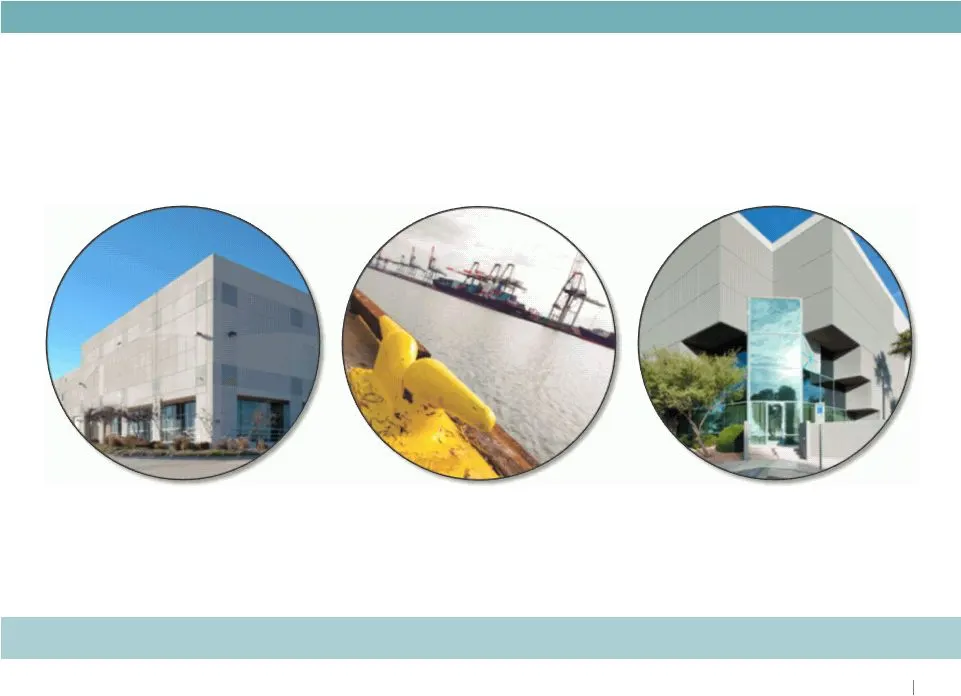
Slide 44: Southwest Focus
SOUTHWEST OVERVIEW Southwest Focus DALLAS LEASE-UP HOUSTON INDUSTRIAL PORT DALLAS INLAND PORT SOUTHERN CALIFORNIA EXPANSION Grow
Slide 45: Southwest Team
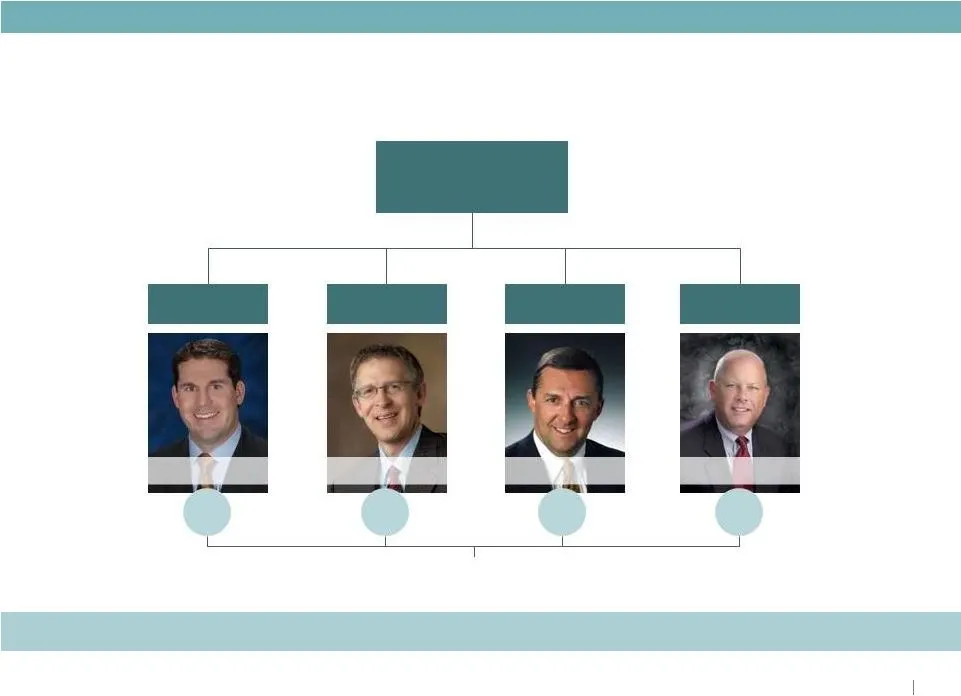
Jeff Turner Regional EVP Dallas Houston Phoenix Nashville SOUTHWEST OVERVIEW Southwest Team Jeff Thornton David Hudson Kevin Rogus Jeff Palmquist Southwest leaders average more than 13 years with Duke Realty Years with Duke Realty
Slide 46: East & Southeast Overview
EAST & SOUTHEAST OVERVIEW
Slide 47: East & Southeast Overview
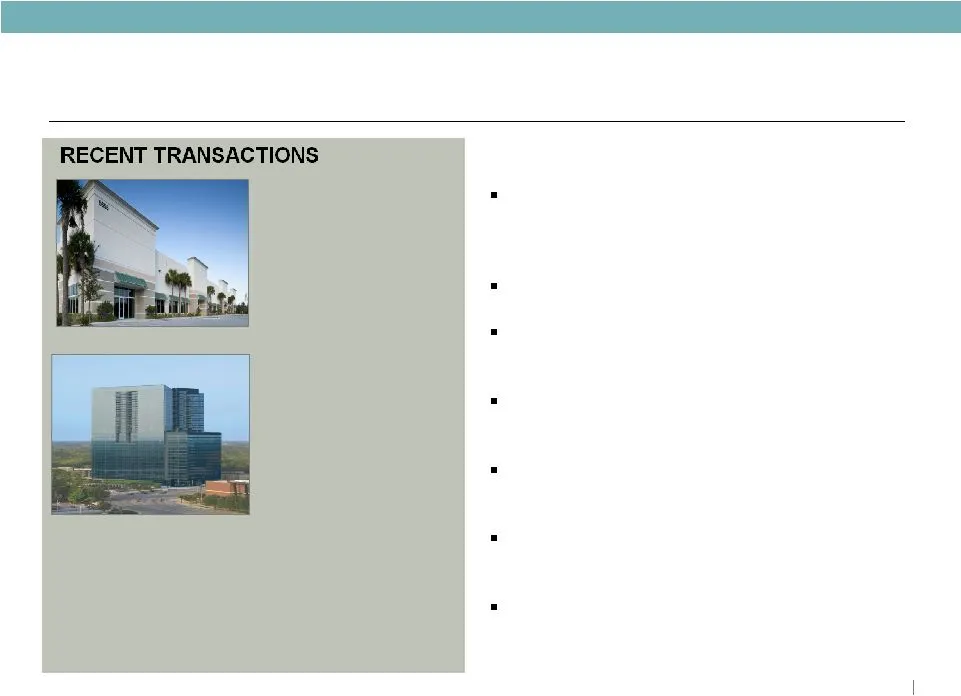
EAST & SOUTHEAST OVERVIEW East & Southeast Overview Acquisition – Office/Industrial Premier Portfolio - South Fl 4.9 million SF MARKET OVERVIEW & KEY POINTS Strong presence: entered Southeast in 1999 (Weeks merger) and East in 2006 (acquisition of Winkler portfolio) 15 Fortune 500 headquarters East
Slide 48: East and Southeast Overview
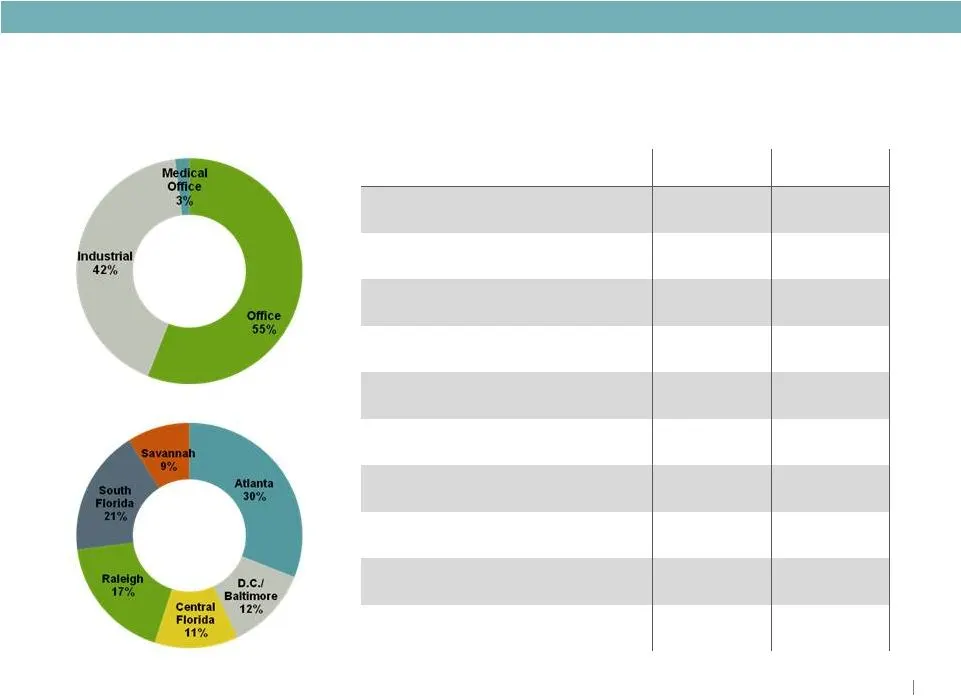
EAST & SOUTHEAST OVERVIEW East and Southeast Overview Industrial Office Average Age 8.8 years 9.7 years Average Building Size 225,000 SF 110,000 SF Total Square Footage 26.9 million 13.7 million Current Occupancy 89.0% 88.5% Atlanta 85.2% 87.3% South Florida 80.5% 89.2% Raleigh 98.1% 89.5% Washingto
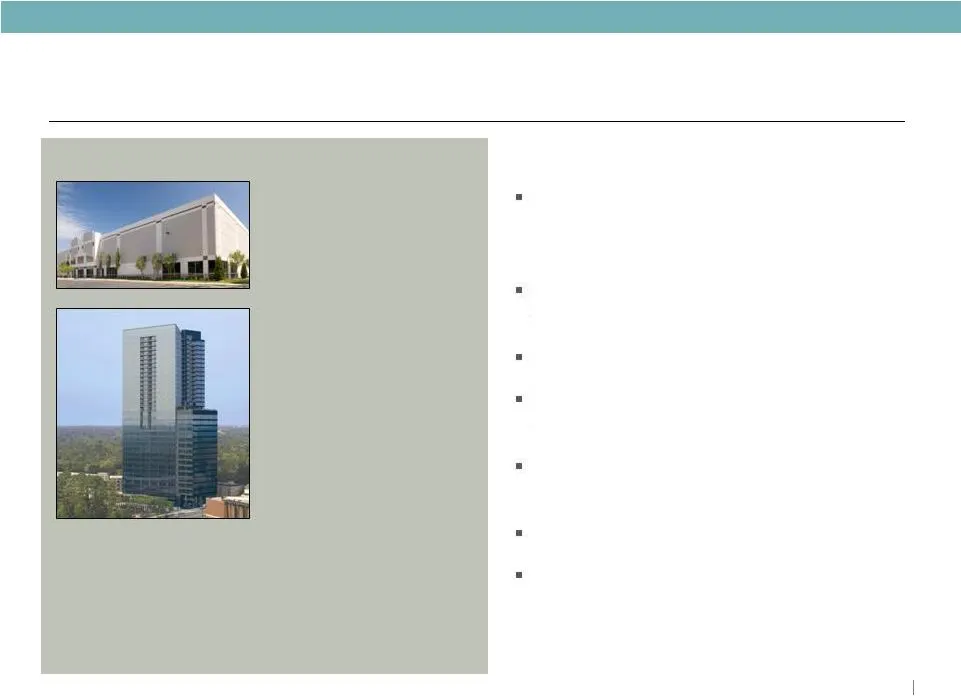
Slide 49: Atlanta
EAST & SOUTHEAST OVERVIEW TRANSACTION EXAMPLES Atlanta New Lease- Industrial Camp Creek 155,000 SF– 5.3 year term National Powersport Auctions New Leases - Office 3630 Peachtree 66,000 SF Multiple tenants 44% leased MARKET OVERVIEW & KEY POINTS Duke Realty a top 5 owner city-wide in office and indus
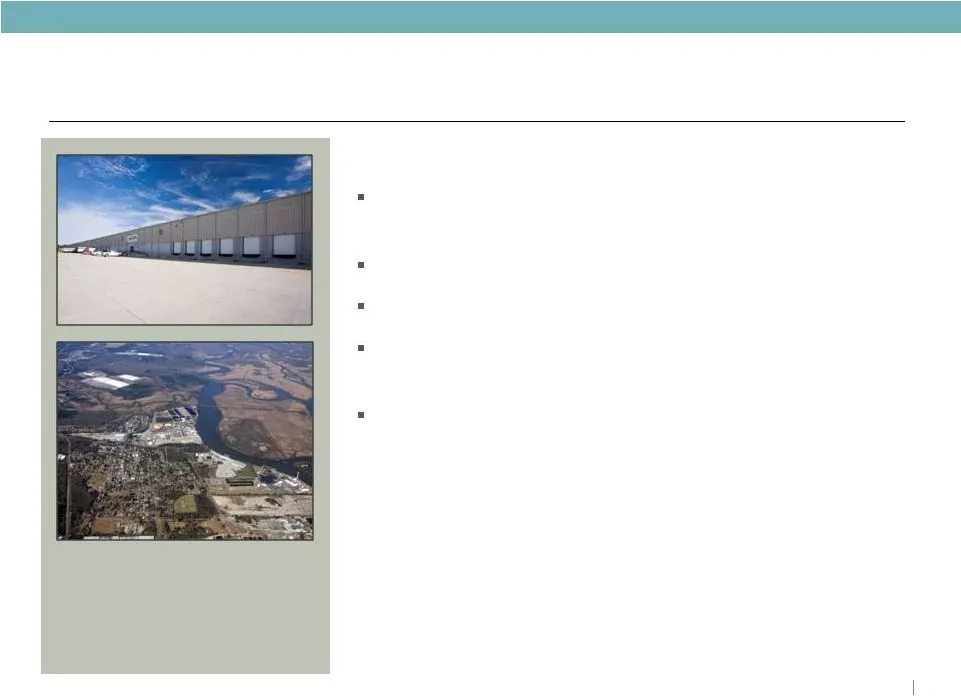
Slide 50: Savannah
EAST & SOUTHEAST OVERVIEW Savannah MARKET OVERVIEW & KEY POINTS Duke Realty dominant position estimated at 35% market share Majority of portfolio within three miles of port Port activity improving – record TEU volume in 2010 Two primary types of tenants: logistics firms and national retailers Duke R
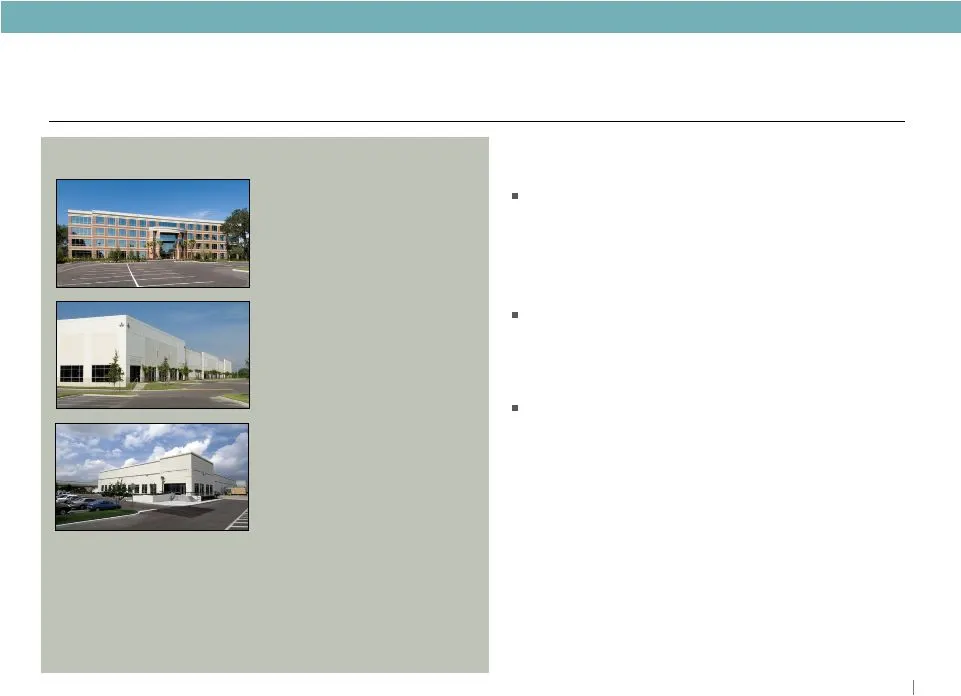
Slide 51: Central Florida (Orlando/Tampa)
EAST & SOUTHEAST OVERVIEW Central Florida (Orlando/Tampa) New Leases - Office Highland Oaks IV 44,000 SF Multiple tenants New Lease - Industrial Eagle Creek Business Ctr. 29,000 SF - 10.5 year term Mike’s Pies MARKET OVERVIEW & KEY POINTS Excellent quality of life and improving affordability. Educat
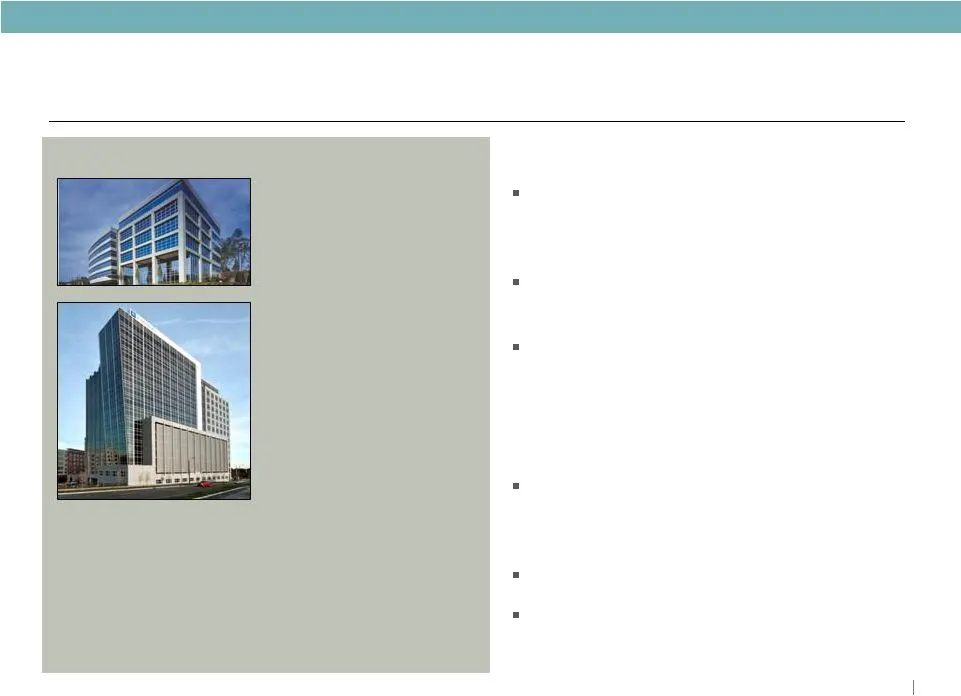
Slide 52: Raleigh
EAST & SOUTHEAST OVERVIEW TRANSACTION EXAMPLES Raleigh New Lease – Office Crabtree Overlook 45,000 SF– 6 year term Nationwide Mutual Insurance Co. New Leases- Office Captrust Tower 65,700 SF Multiple tenants 64% leased MARKET OVERVIEW & KEY POINTS Diversified economy (R&D, education, healthcare and
Slide 53: South Florida
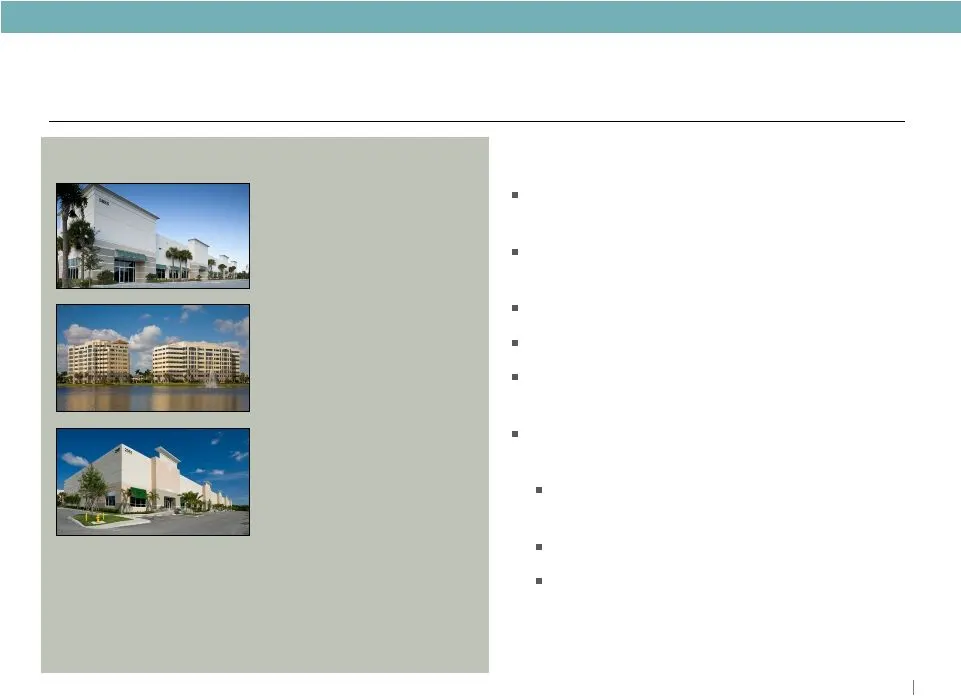
EAST & SOUTHEAST OVERVIEW TRANSACTION EXAMPLES South Florida Acquisition- Office Royal Palm I and II 465,500 SF New Lease - Industrial Pompano Commerce Ctr. 111,000 SF– 15 year term GSA MARKET OVERVIEW & KEY POINTS Duke Realty dominant industrial and suburban office positions in Broward County High
Slide 54: Washington D.C./Baltimore
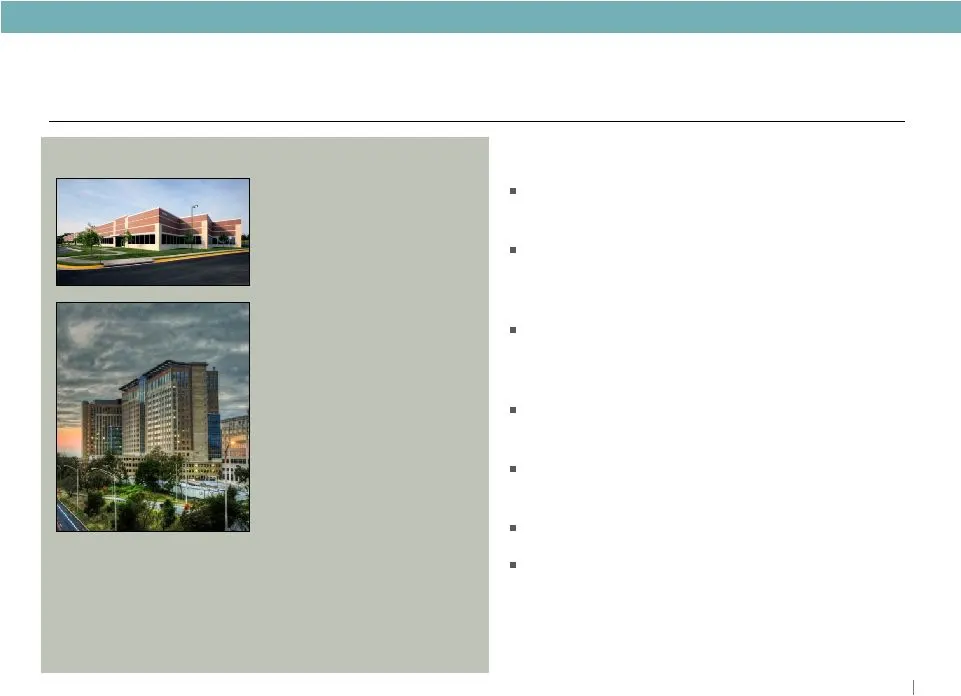
EAST & SOUTHEAST OVERVIEW TRANSACTION EXAMPLES Washington D.C./Baltimore New Lease - Office 15006 Northridge Dr. 32,000 SF– 8 year term TASC BRAC 1.7 million SF office towers On schedule to complete in Q3 2011 MARKET OVERVIEW & KEY POINTS Washington DC will lead east coast cities in population growt
Slide 55: East/Southeast Focus
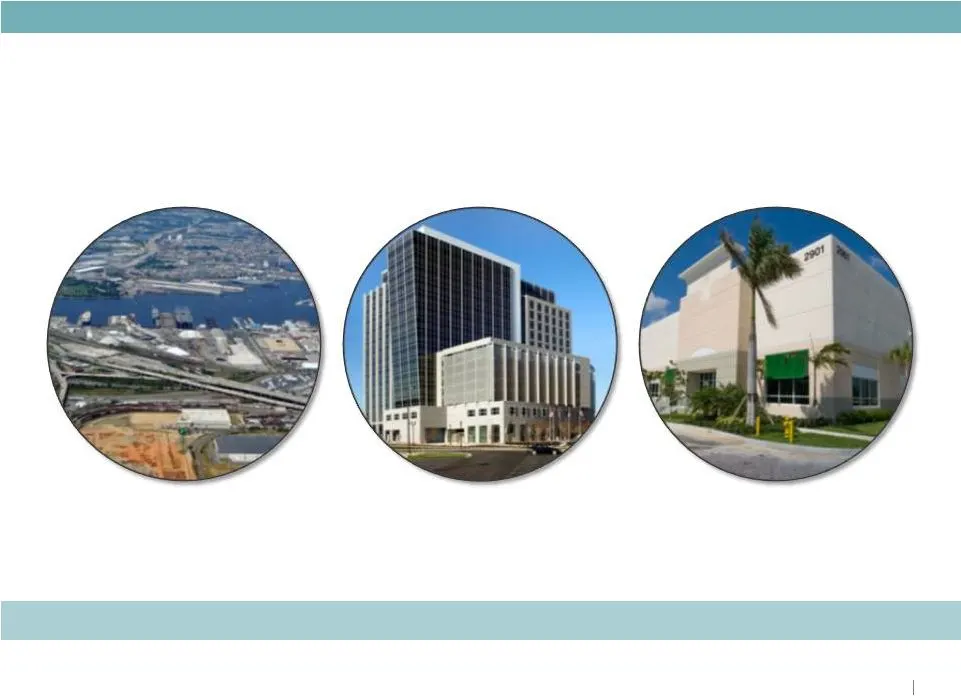
EAST & SOUTHEAST OVERVIEW East/Southeast Focus BULK INDUSTRIAL/PORTS LEASE UP AND RENT GROWTH ACQUISITIONS & DEVELOPMENT Maximize assets and market position
Slide 56: East & Southeast Team
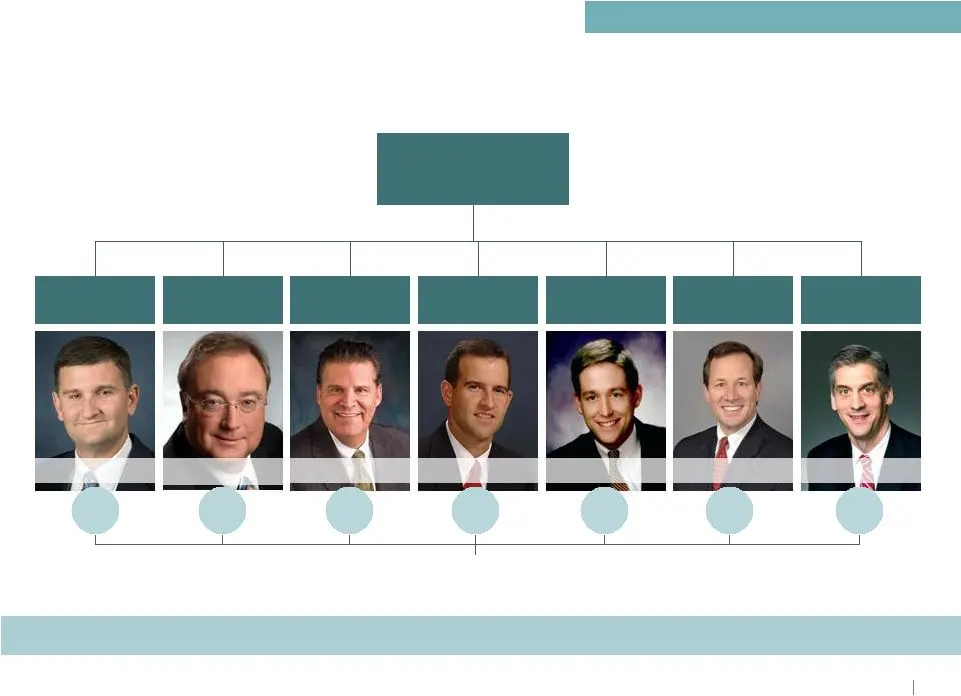
Sam O’Briant Regional EVP Atlanta/ Savannah 3630 Peachtree South Florida Raleigh Baltimore Washington D.C. Orlando/ Tampa EAST & SOUTHEAST OVERVIEW East & Southeast Team Kerry Armstrong Ed Mitchell Jeff Sheehan John Macsherry Peter Scholz East & Southeast leaders average more than 10 years with Duke
Slide 57: Medical Office Overview
MEDICAL OFFICE OVERVIEW
Slide 58: Medical Office Portfolio Strategy
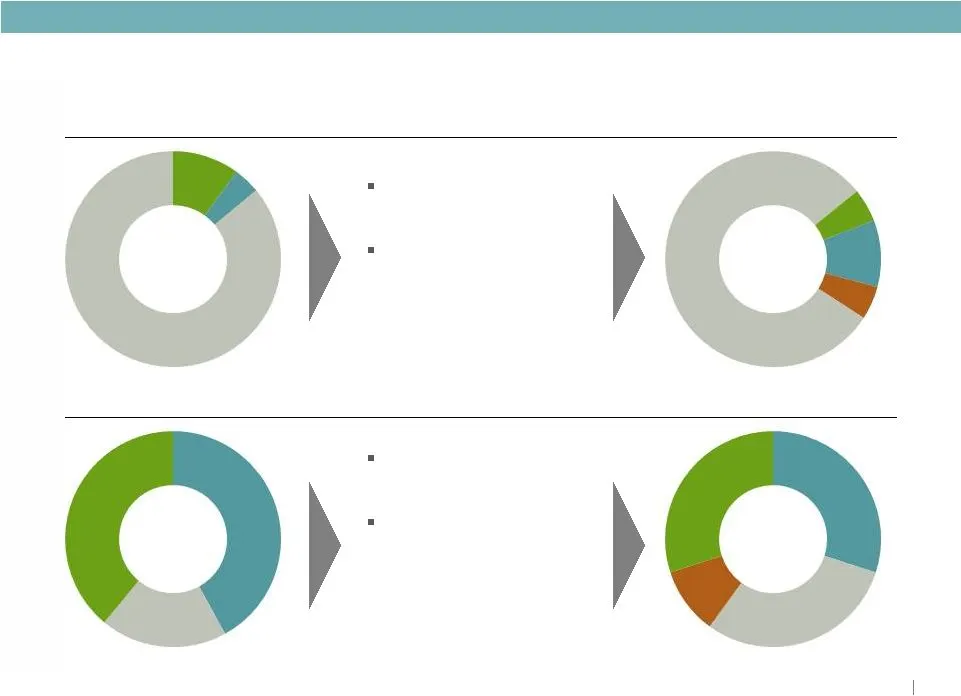
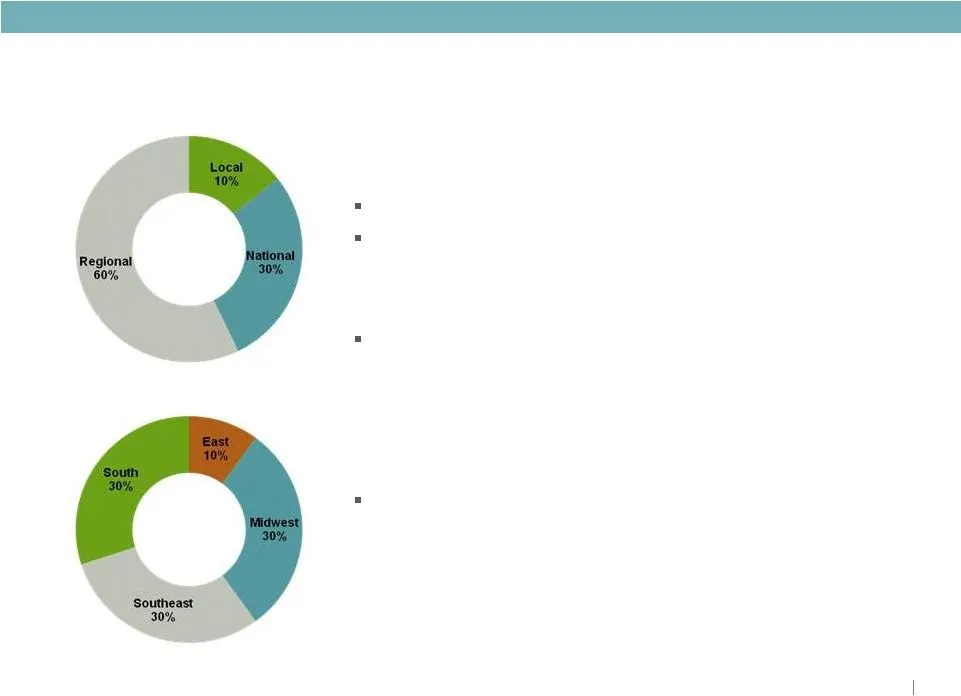
MEDICAL OFFICE OVERVIEW Portfolio Strategy BY PRODUCT BY GEOGRAPHY Focus on “core” assets (on-campus) Focus on national and regional Hospital system relationships Focus on Duke Realty office locations Focus on demographic healthcare growth cities MOB Off Campus 4% Specialty Hospital 10% MOB On Campu
Slide 59: Duke Realty Markets: Demographic Focus
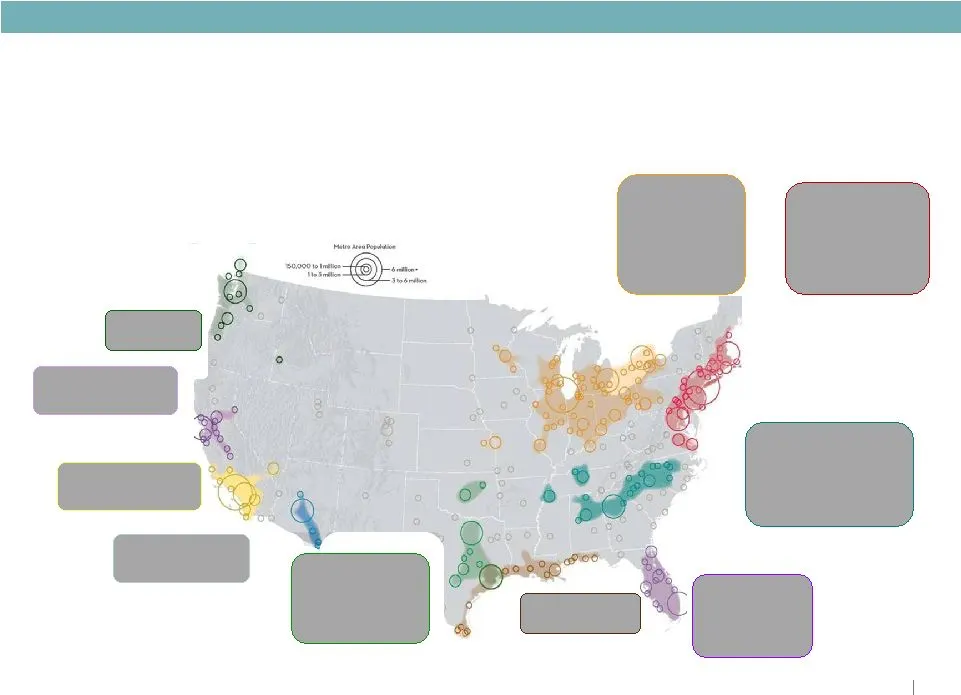
MEDICAL OFFICE OVERVIEW PIEDMONT ATLANTIC Atlanta * Birmingham Charlotte Nashville * Raleigh * NORTHEAST Baltimore * Boston Philadelphia Richmond Washington, D.C. * GREAT LAKES Chicago * Columbus * Indianapolis * Louisville Minneapolis * St. Louis* FLORIDA Jacksonville Miami Orlando * Tampa * GULF C
Slide 60: Healthcare Data Points
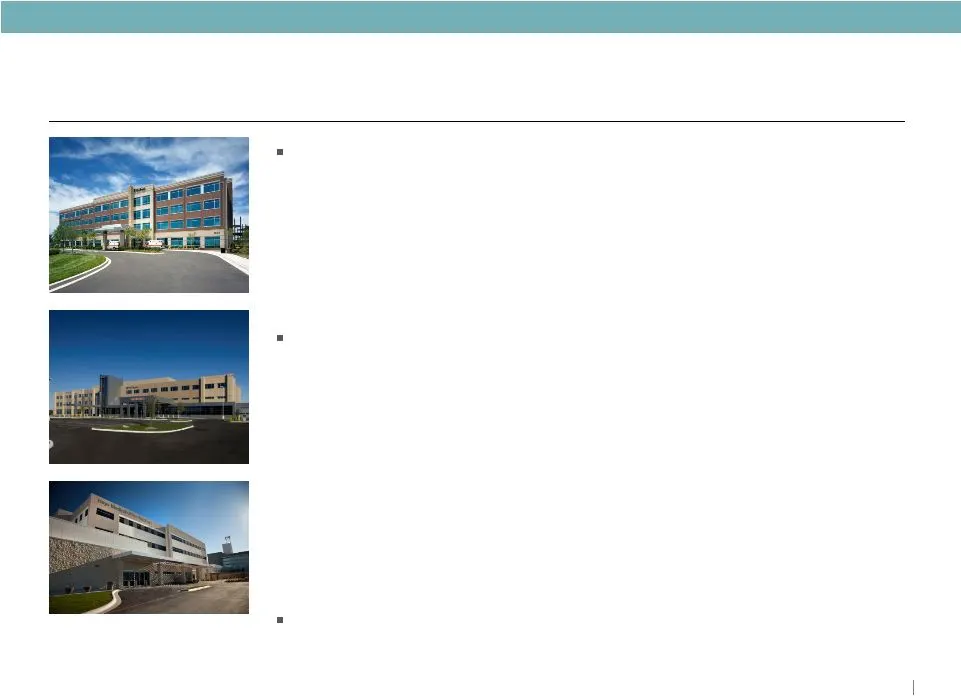
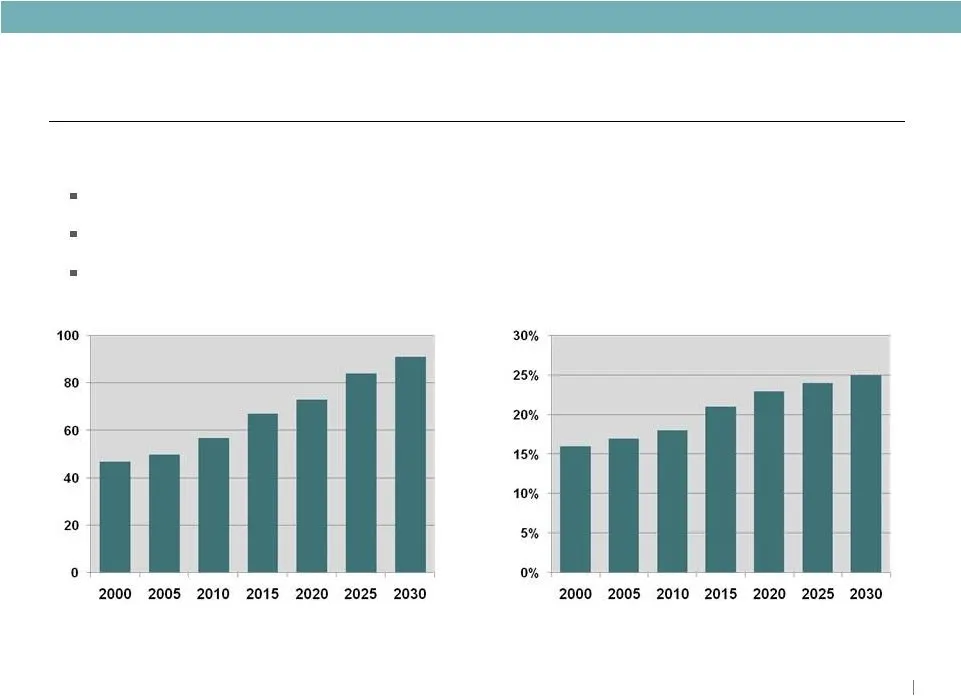
MEDICAL OFFICE OVERVIEW Healthcare Data Points The nation’s largest industry • Represents more than 17% of GDP, predicted to exceed 23% by 2020 • Americans spend more than 5% of pre-tax income on healthcare. Lower income brackets pay 15% or more ($7,800 per capita health expenditures in 2008/2009) R
Slide 61: Demand Driver: The Aging of America
MEDICAL OFFICE OVERVIEW Demand Driver 60+ age group continues to grow at greater than 3% annually through 2030 Fact: Baby Boomers (60 + years old) seek more medical treatments than all others Growth of 60+ age group is creating demand for healthcare services through Number of Americans 60+ % of Amer
Slide 62: Demand Driver: The Outmigration of Care
MEDICAL OFFICE OVERVIEW Demand Driver THE OUTMIGRATION OF CARE Demand for outpatient services is projected to increase by 22% by 2019 while demand for inpatient services will remain flat Ambulatory surgery center (ASC) and diagnostic imaging center (DIC) visits increasing at a rate of 8.4 percent an
Slide 63: Development Focus
MEDICAL OFFICE OVERVIEW Development Focus ACTION PLAN National brand awareness Be “Experts” – Speak at national conferences (ASHE, BOMA) – Third party references National system relationships – Ascension – Tenet – HCA – Adventist Regional system relationships – Baylor Health – Rex Healthcare – Carol
Slide 64: Example: Baylor Relationship
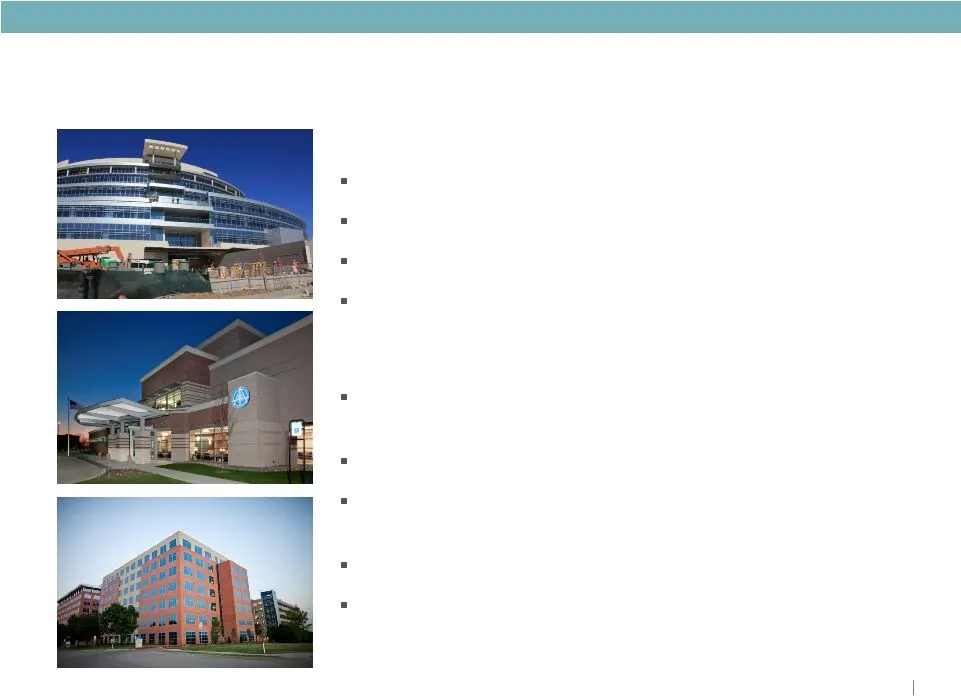
MEDICAL OFFICE OVERVIEW Example: Baylor Relationship BAYLOR CANCER CENTER 10-story outpatient cancer center 250 space underground parking facility 94% preleased with Baylor and McKesson (US Oncology) 460,000 sf OTHER BAYLOR PROJECTS Baylor Administrative Office Building - Dallas, TX (100% leased) Ba
Slide 65: Current Development Pipeline
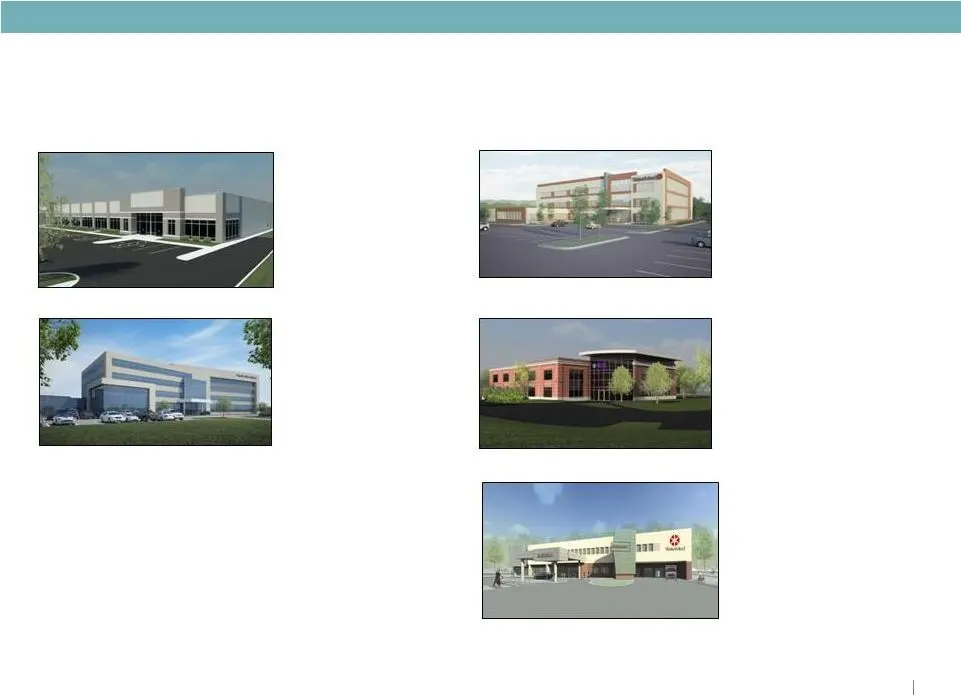
MEDICAL OFFICE OVERVIEW Current Development Pipeline Baylor McKinney MOB McKinney, TX 113,000 SF Baylor 66% pre-leased WakeMed MOB - Sunnybrook Raleigh, NC 86,000 SF Wake Med Health and Hospital 58% pre-leased REX Holly Springs MOB Raleigh, NC 30,000 SF Rex Hospital 100% pre-leased Western Ridge MOB
Slide 66: Healthcare Team
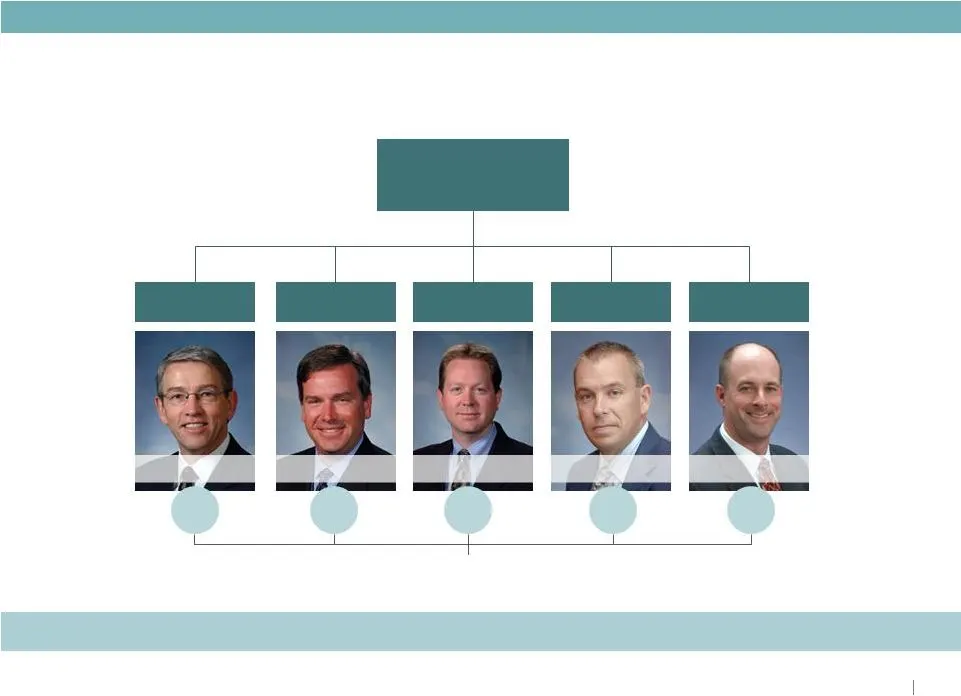
Jim Bremner President, Healthcare South/ Southeast East/ Midwest Development Midwest Southeast MEDICAL OFFICE OVERVIEW RELIABLE. ANSWERS. Healthcare Team Deeni Taylor Don Dunbar Glenn Hoge Keith Konkoli Healthcare leaders average more than 13 years with Duke Realty Jason Hinkel Years with Duke Realt
Slide 67: Capital Strategy and 2011 Guidance
CAPITAL STRATEGY AND 2011 GUIDANCE
Slide 68: Capital Strategy: Key Metrics & Goals
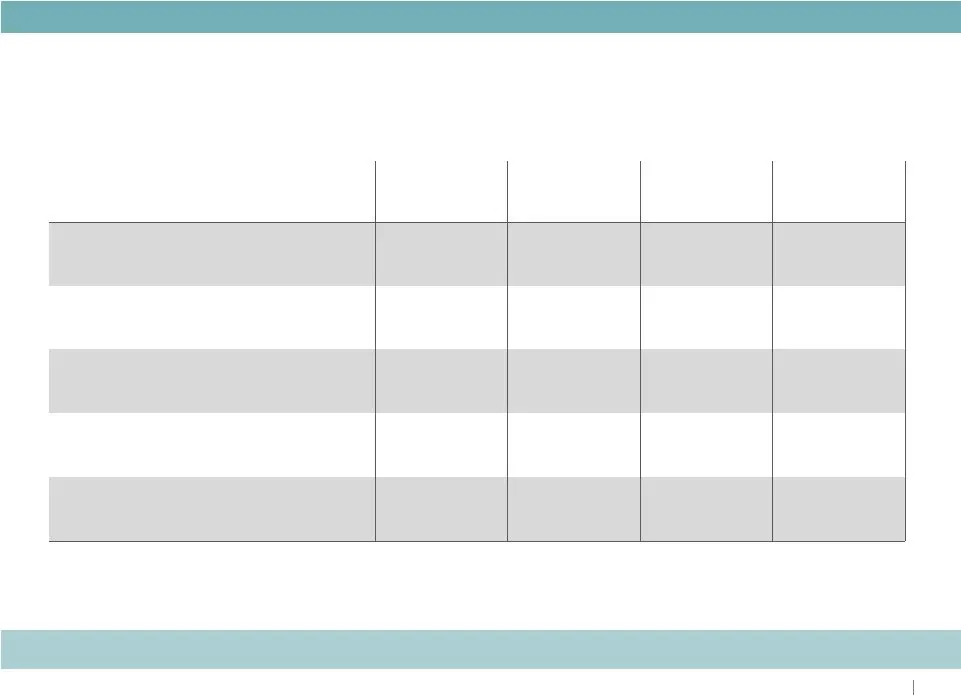
CAPITAL STRATEGY Key Metrics & Goals Actual Actual Q1 2011 Actual Goal Debt to Gross Assets 44.5% 46.3% 46.1% 45.0% Debt + Preferred to Gross Assets 54.9% 55.5% 55.3% 50.0% Fixed Charge Coverage Ratio 1.79 : 1 1.79 : 1 1.81 : 1 2.00 : 1 Debt/EBITDA 6.65 7.31 6.66 < 6.00 Debt + Preferred/EBITDA 8.47
Slide 69: Current Liquidity Position
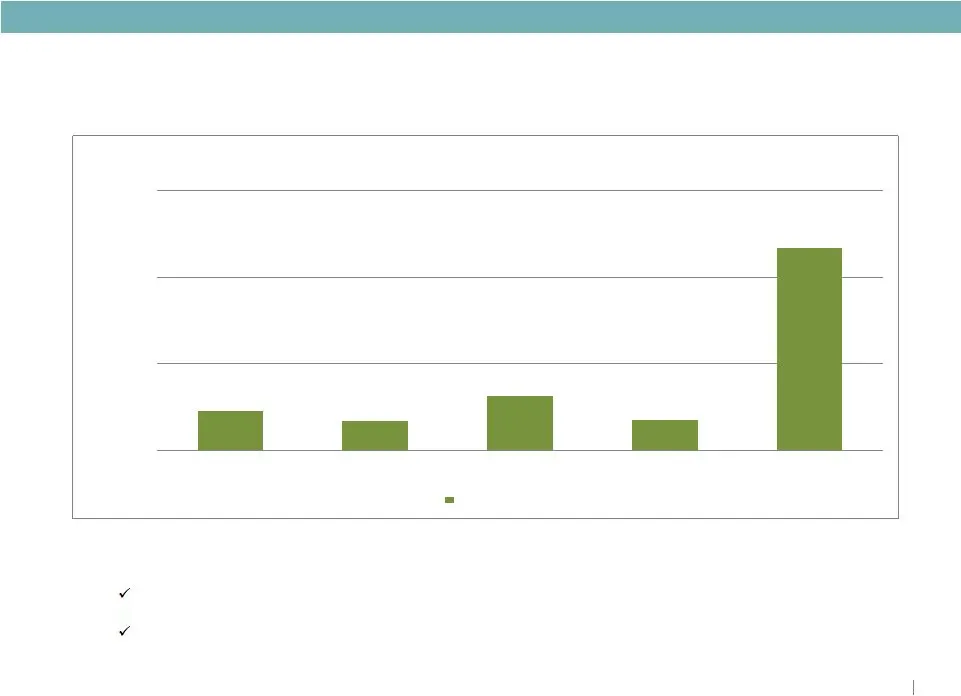
CAPITAL STRATEGY Current Liquidity Position $460 $332 $632 $351 $2,335 $0 $1,000 $2,000 $3,000 Thereafter Debt Maturity and Amortization Schedule 3/31/2011 • Provide for $290 Million 2011 Unsecured Bond Maturities $122 million due 8/15/11 $168 million due 12/1/11 ($ in millions)
Slide 70: Continue to Execute on Capital Strategy Objectives
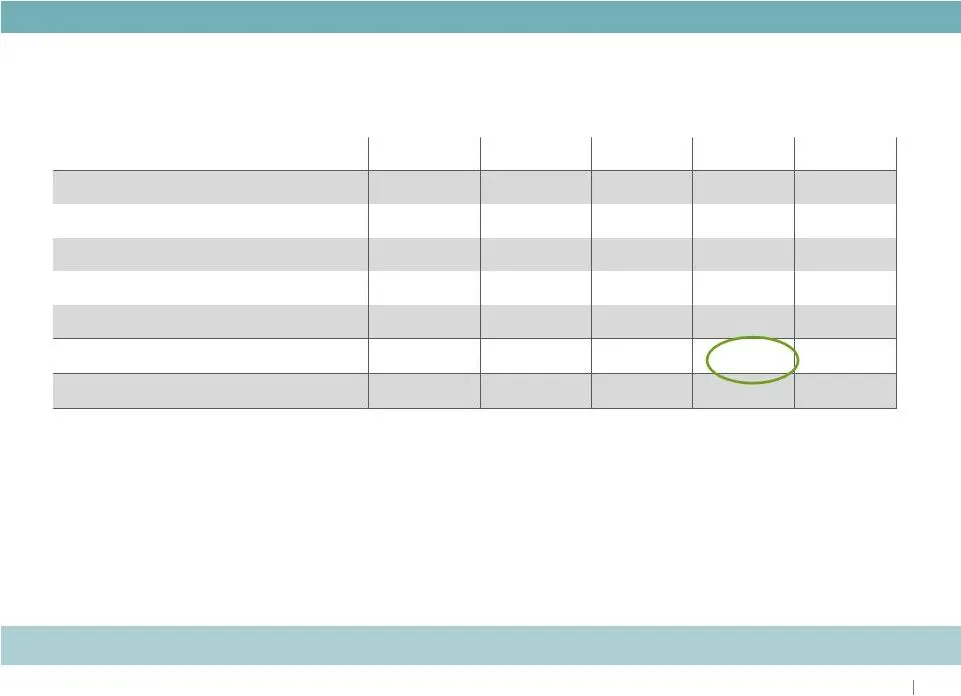
CAPITAL STRATEGY Continue to execute on capital strategy objectives CAPITAL SOURCE TOTALS Common Stock $230 - $575 $311 $1,116 Preferred Stock - $300 - - $300 Unsecured Debt $300 $325 $500 $250 $1,375 Secured Debt - - $270 - $270 Asset Dispositions $614 $426 $121 $533 $1,694 $1,144 $1,051 $1,466 $1,
Slide 71: Maintain Available Options to Advance Capital Strategy
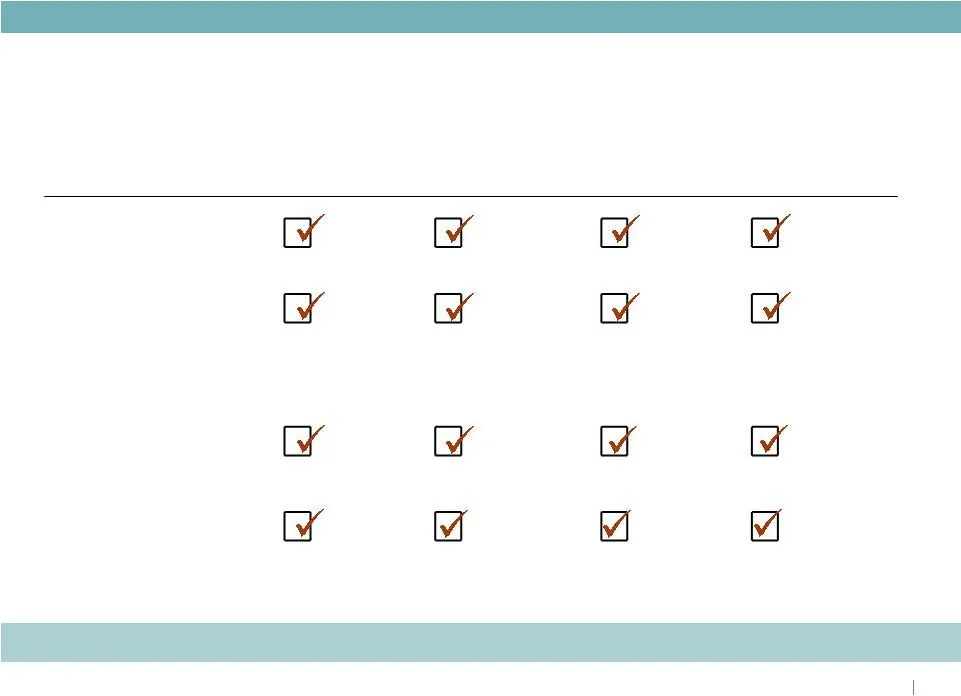
CAPITAL STRATEGY Maintain available options to advance capital strategy and growth 1 st QTR 2 nd QTR 3 rd QTR 4TH rd QTR A) Common equity Set up ATM $311MM equity issuance to fund Dugan N/A N/A B) Tender for debt... Additional unsecured to extend maturities Evaluated Market $212.2MM of bonds repurch
Slide 72: 2011 Range of Estimates
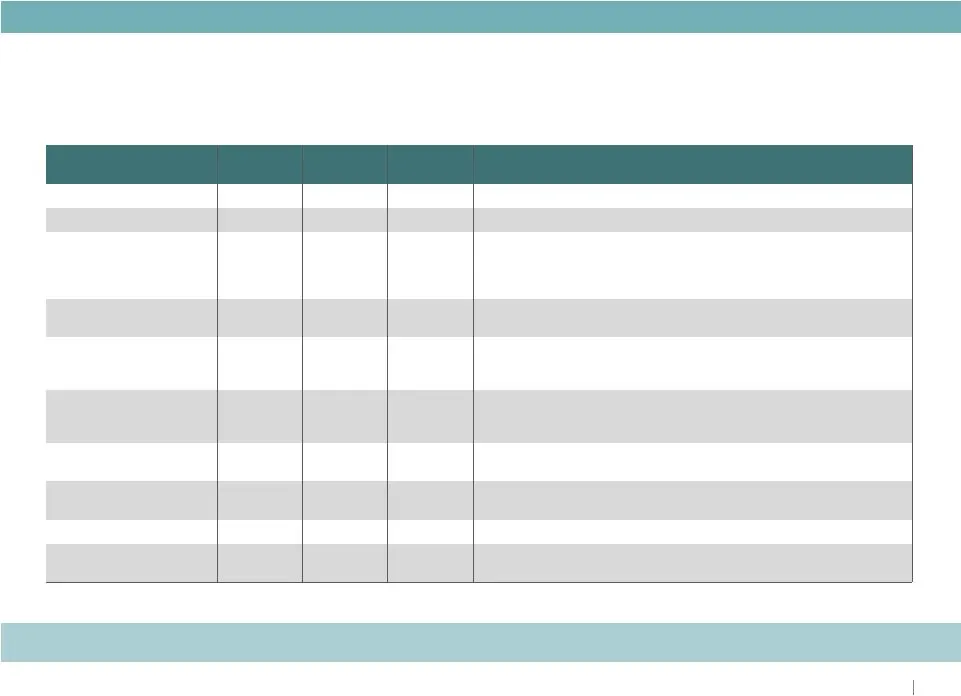
CAPITAL STRATEGY Metrics 2010 Actual Pessimistic Optimistic Key Assumptions 2011 Range of Estimates 2011 RANGE Core FFO Per Share $1.15 $1.06 $1.18 AFFO Payout Ratio 89% 100% 85% • Annual dividend maintained at $0.68 per share Average Occupancy 88.2% 87.5% 90.5% • First half expirations cause dip in
Slide 73: Capital Strategy: 2010 Performance and 2011 Goals
2010 PERFORMANCE $560 million of capital raised Retired $100 million of unsecured bonds Fixed charge ratio of 1.79x and debt to EBITDA of 7.31x Repurchased ~ $280 million par value of bonds and more than $112 million face amount of Series O preferred stock 2011 GOALS Opportunistically access capital
Slide 74: Closing Remarks
CLOSING REMARKS
Slide 75: 2010 Accomplishments and 2011 Opportunities
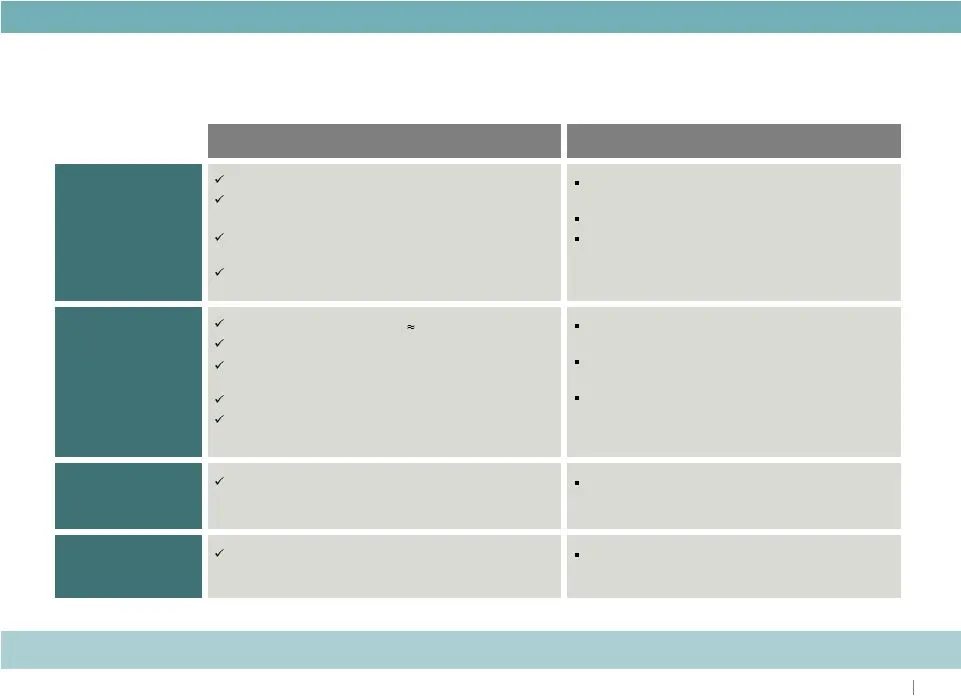
2010 2011 Capital Strategy Operating Strategy Development Expertise Asset Strategy RELIABLE. ANSWERS . 2010 Accomplishments and 2011 Opportunities Drive Shareholder Return Raised nearly $1.1 billion of capital Executed Capital Strategy in alignment with operating and asset strategy Operating with mi
Slide 76: Portfolio Strategy
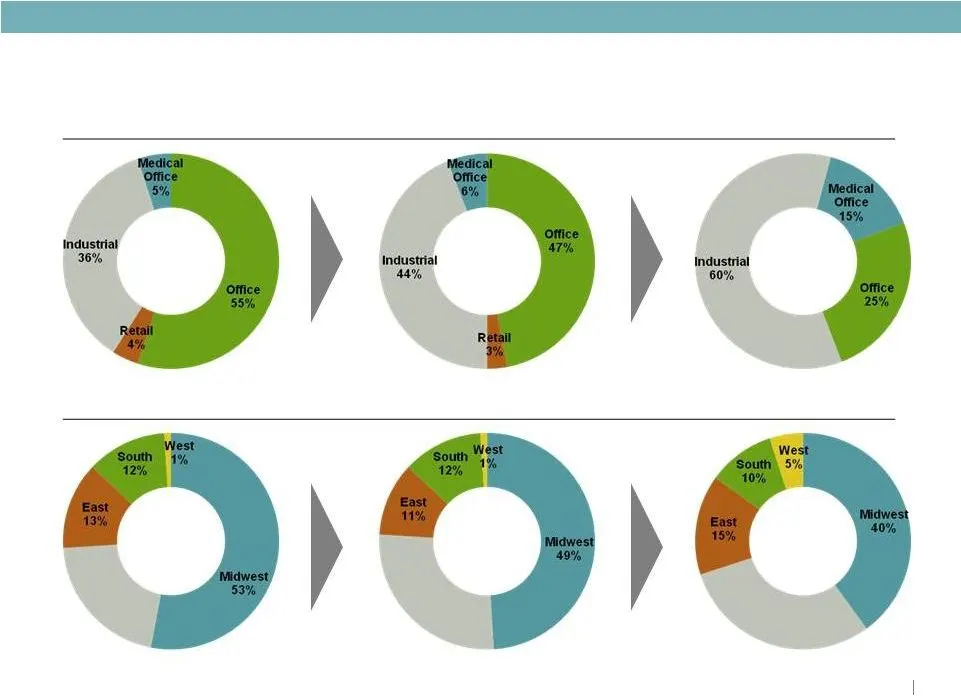
RELIABLE. ANSWERS . Portfolio Strategy BY PRODUCT BY GEOGRAPHY 1. Includes proforma effects of remaining CBRERT and Premier assets Southeast 21% Southeast 27% Southeast 30%
Slide 77: Positioned for NAV Growth
RELIABLE. ANSWERS . Lease up existing vacancy Increased management/ service fees Accretive future development Upside from land holdings Positioned for NAV Growth KEY NAV GROWTH DRIVERS Portfolio occupancy of 89%; 300-400 bps below historical levels Strong leasing pipeline Demonstrated track record o
Slide 78: Why Duke Realty?
RELIABLE. ANSWERS . WHY DUKE REALTY? Quality portfolio improving with asset strategy Solid balance sheet improving with capital strategy Unmatched ability to execute on daily operations Development capabilities in place with existing land bank Talent and leadership depth to execute
Slide 79: Forward-Looking Statement
RELIABLE. ANSWERS . Forward-Looking Statement This slide presentation contains statements that constitute “forward-looking statements” within the meaning of the Securities Act of 1933 and the Securities Exchange Act of 1934 as amended by the Private Securities Litigation Reform Act of 1995. These fo
Source: SEC EDGAR · 8-K filed Jun 28, 2011
More decks from Duke Realty Corporation
 Merger or Acquisition (June 2022)14 slides · Jun 13, 2022
 Investor Presentation (June 2021)58 slides · Jun 7, 2021
 Investor Presentation (May 2021)44 slides · May 10, 2021
 Investor Presentation (February 2021)58 slides · Feb 22, 2021
 NAREIT REITworld Virtual Investor Conference 202056 slides · Nov 16, 2020
 B of A Securities 2020 Global Real Estate Conference56 slides · Sep 15, 2020