USA Compression Partners, LP · NYSE:USAC
USA Compression Partners, LP — 2021 UBS Winter Infrastructure & Energy Virtual Conference
29 slides from USA Compression Partners, LP's conference presentation, Jan 12, 2022
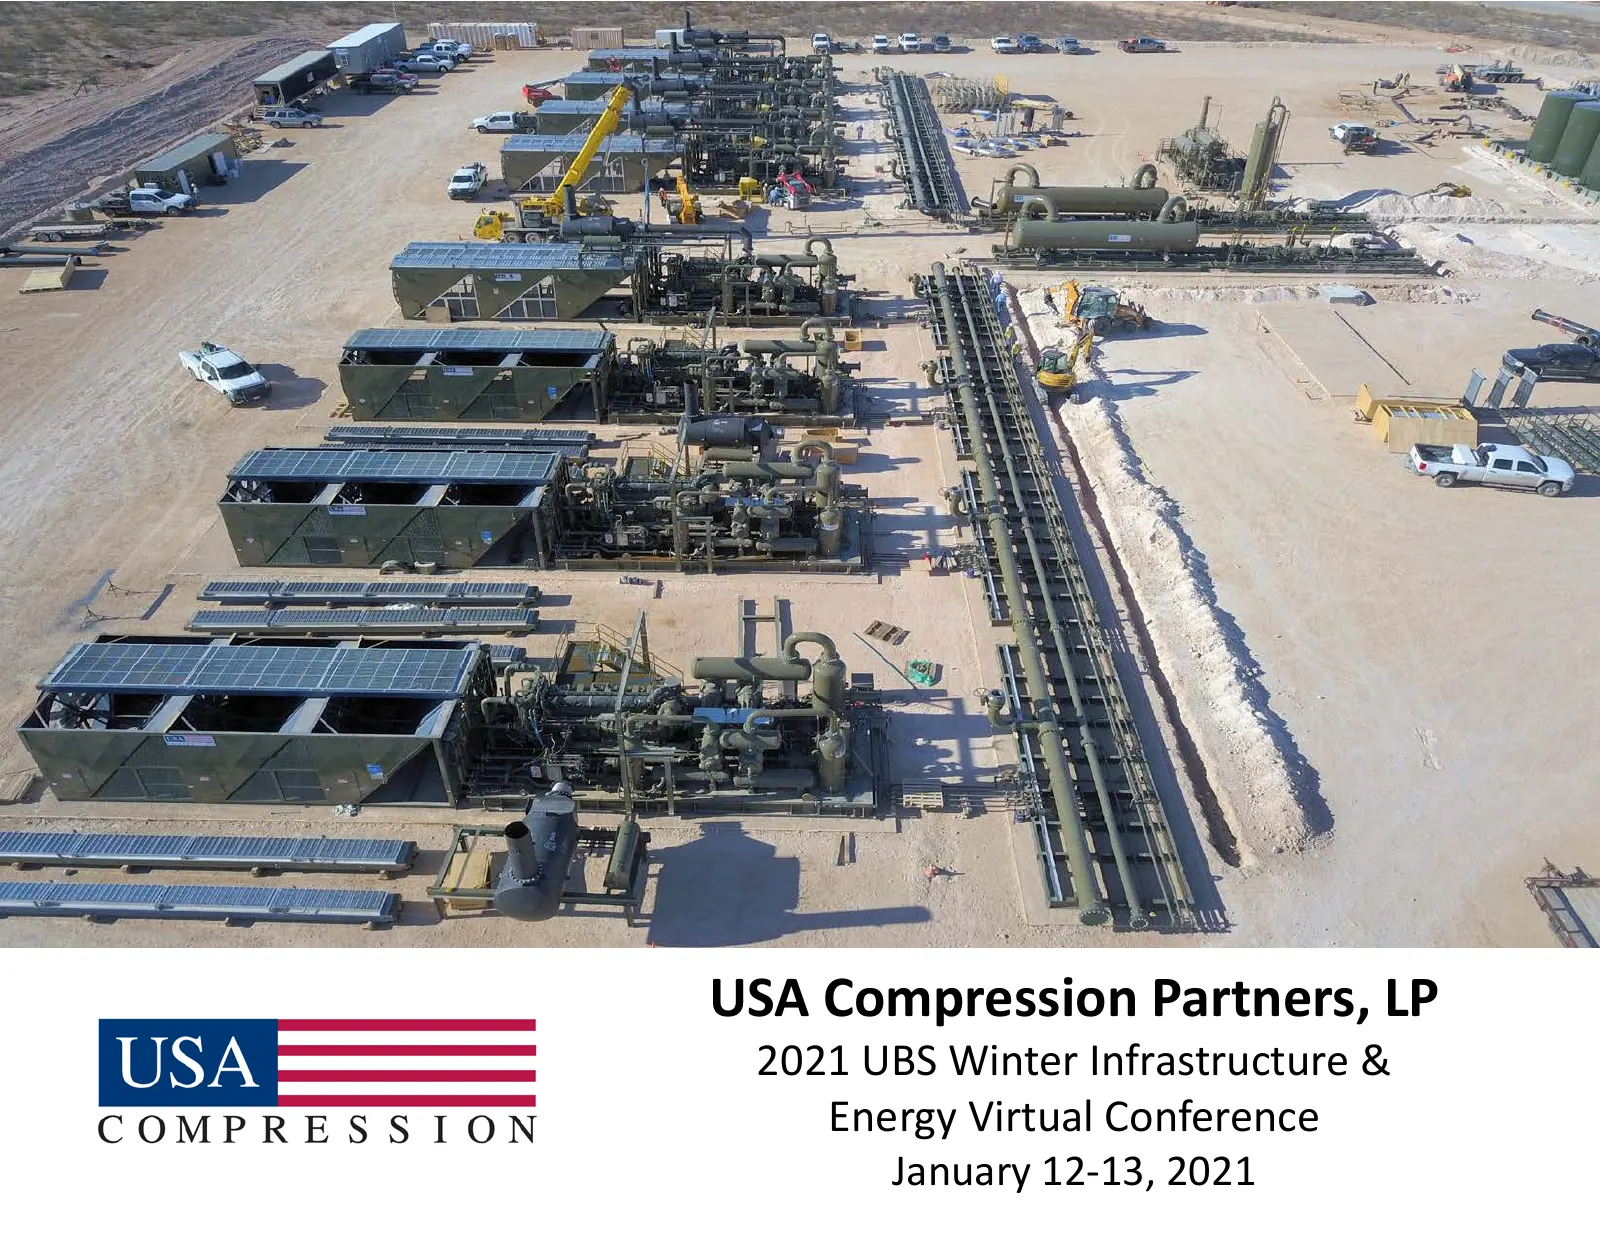
Slide 1: USA Compression Partners, LP – 2021 UBS Winter Infrastructure & Energy Virtual Conference
USA Compression Partners, LP 2021 UBS Winter Infrastructure & Energy Virtual Conference January 12-13, 2021
Slide 2: Disclaimer
Disclaimer This presentation contains forward-looking statements relating to the operations of USA Compression Partners, LP (the “Partnership”) that are based on management’s current expectations, estimates and projections about its operations. You can identify many of these forward-looking statemen
Slide 3: Important Note Regarding Non-Predecessor Information
Important Note Regarding Non-Predecessor Information On April 2, 2018, the Partnership consummated the acquisition of CDM Resource Management LLC and CDM Environmental & Technical Services LLC, which together represent the CDM Compression Business (the “USA Compression Predecessor”), from Energy Tra
Slide 4: USAC Overview
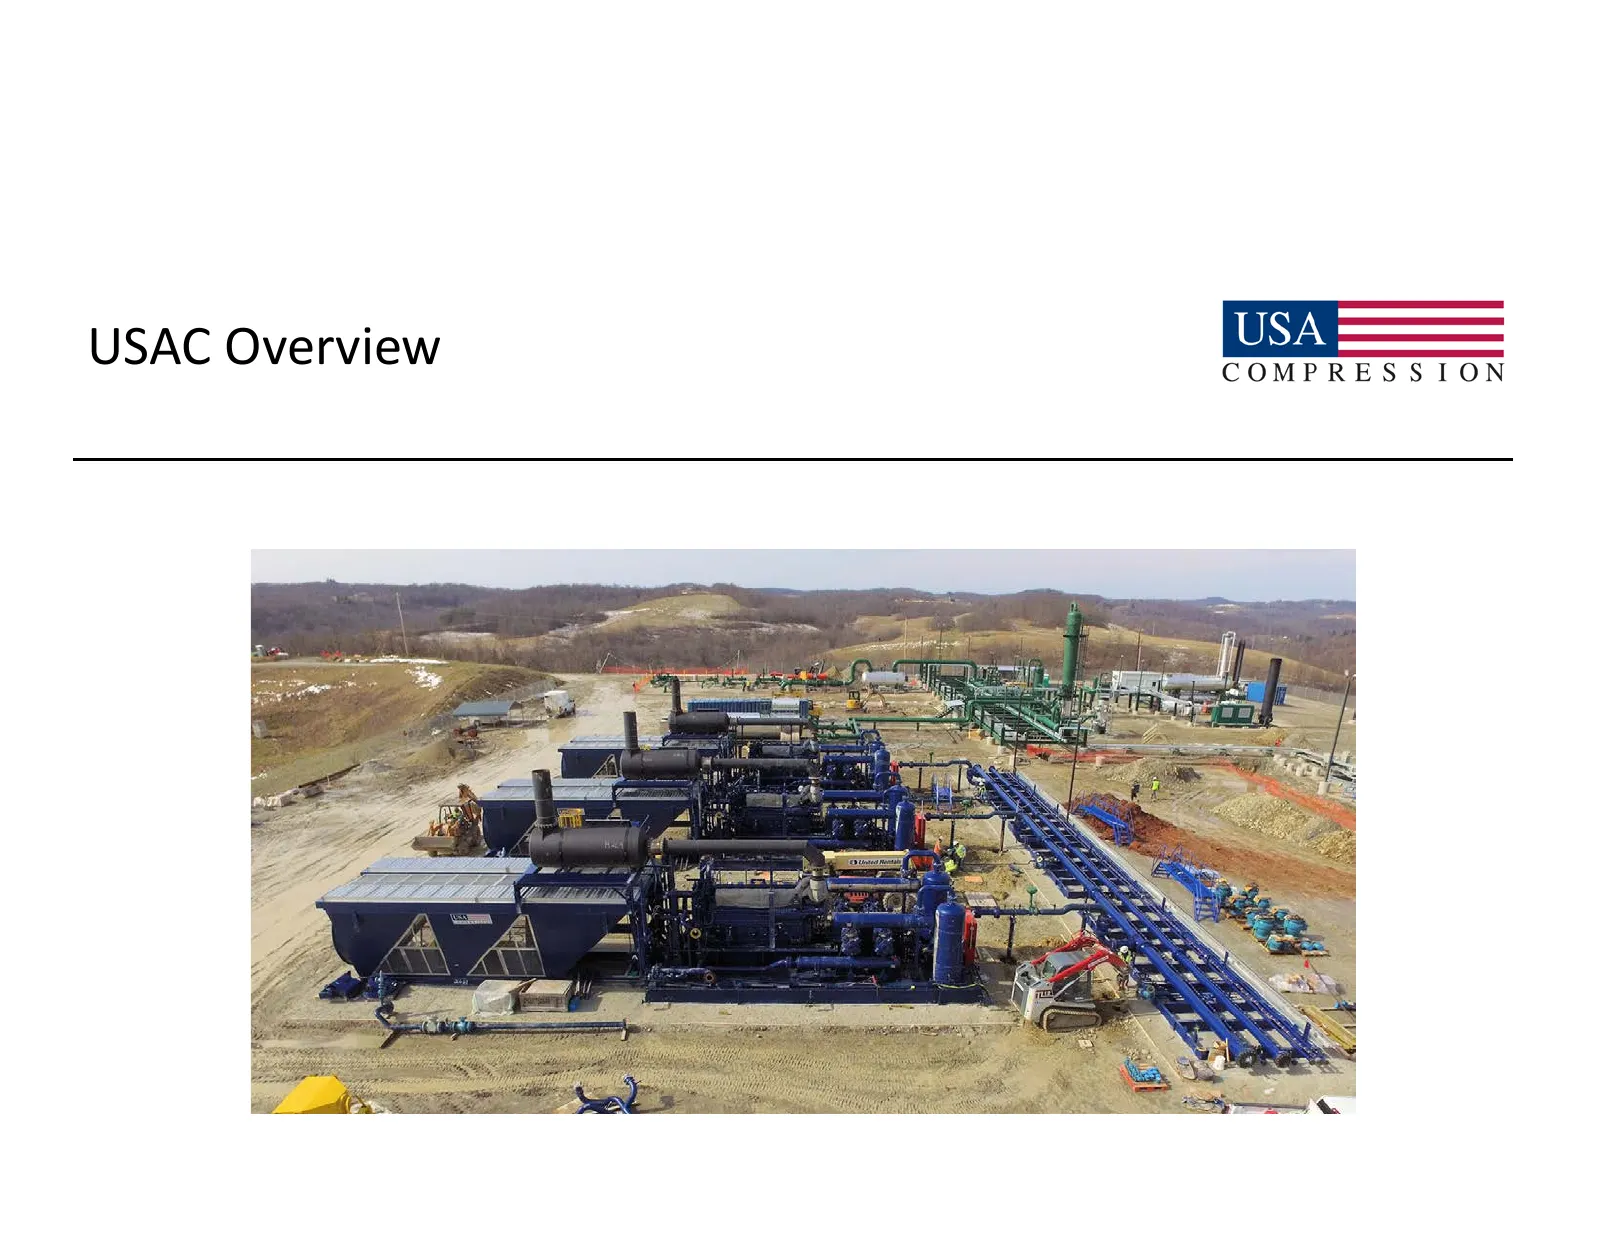
USAC Overview USA COMPRESSION
Slide 5: USAC Overview
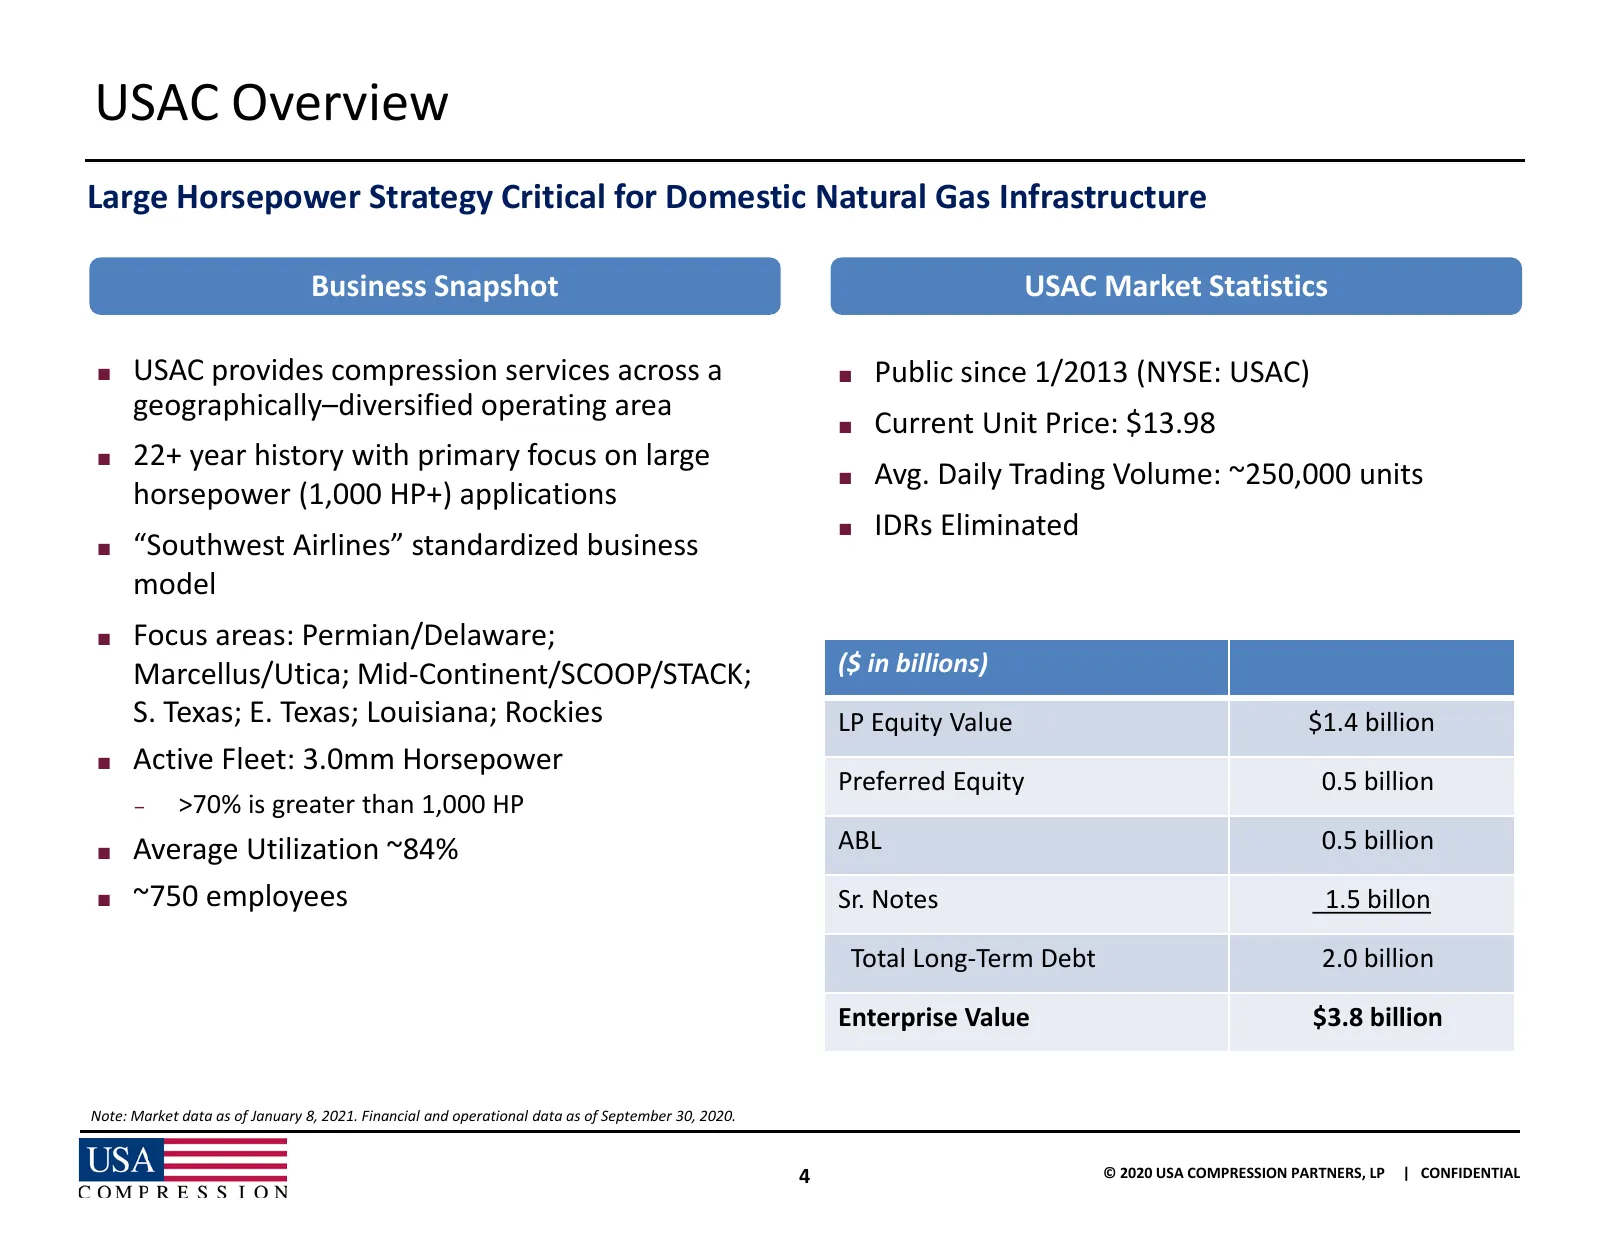
USAC Overview Large Horsepower Strategy Critical for Domestic Natural Gas Infrastructure Business Snapshot USAC Market Statistics ■ USAC provides compression services across a ■ Public since 1/2013 (NYSE: USAC) geographically–diversified operating area ■ Current Unit Price: $13.98 ■ 22+ year history
Slide 6: Q3 2020 Recap
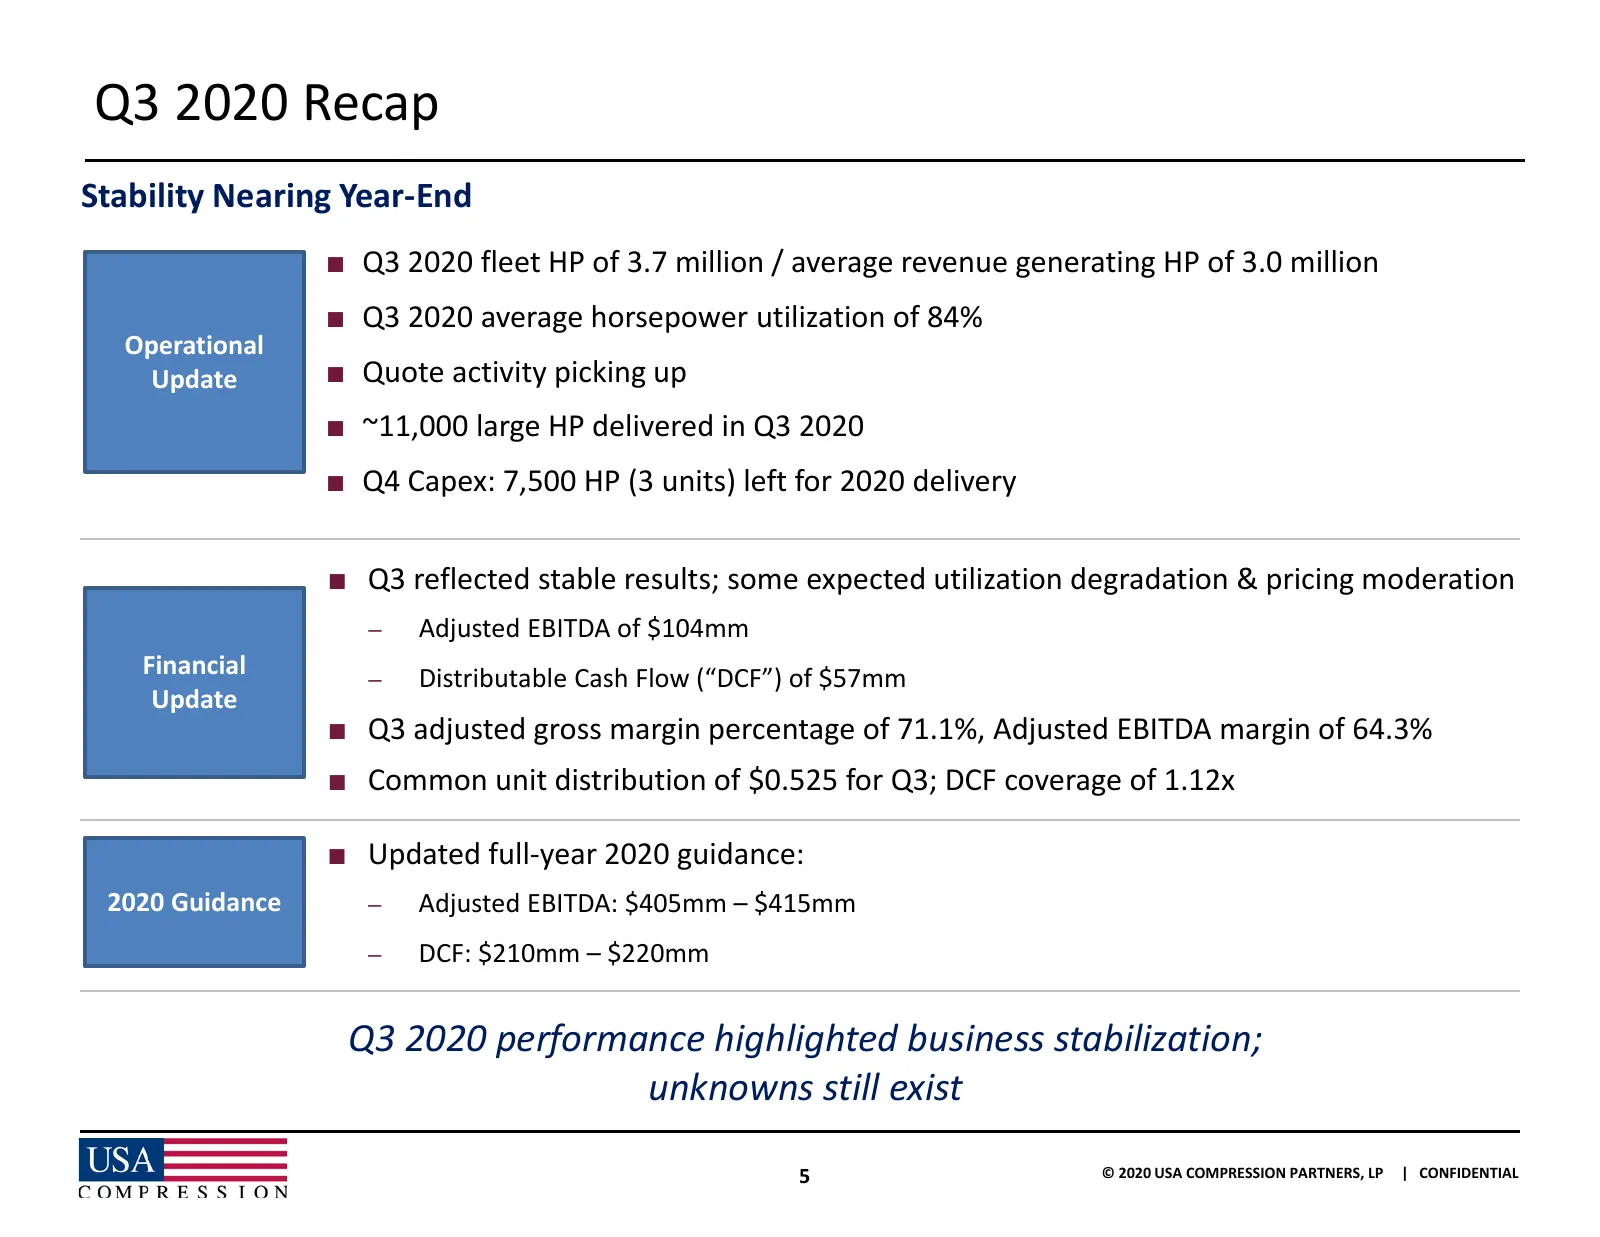
Q3 2020 Recap Stability Nearing Year-End ■ Q3 2020 fleet HP of 3.7 million / average revenue generating HP of 3.0 million ■ Q3 2020 average horsepower utilization of 84% Operational Update ■ Quote activity picking up ■ ~11,000 large HP delivered in Q3 2020 ■ Q4 Capex: 7,500 HP (3 units) left for 202
Slide 7: USAC Offers a Stable Infrastructure Opportunity
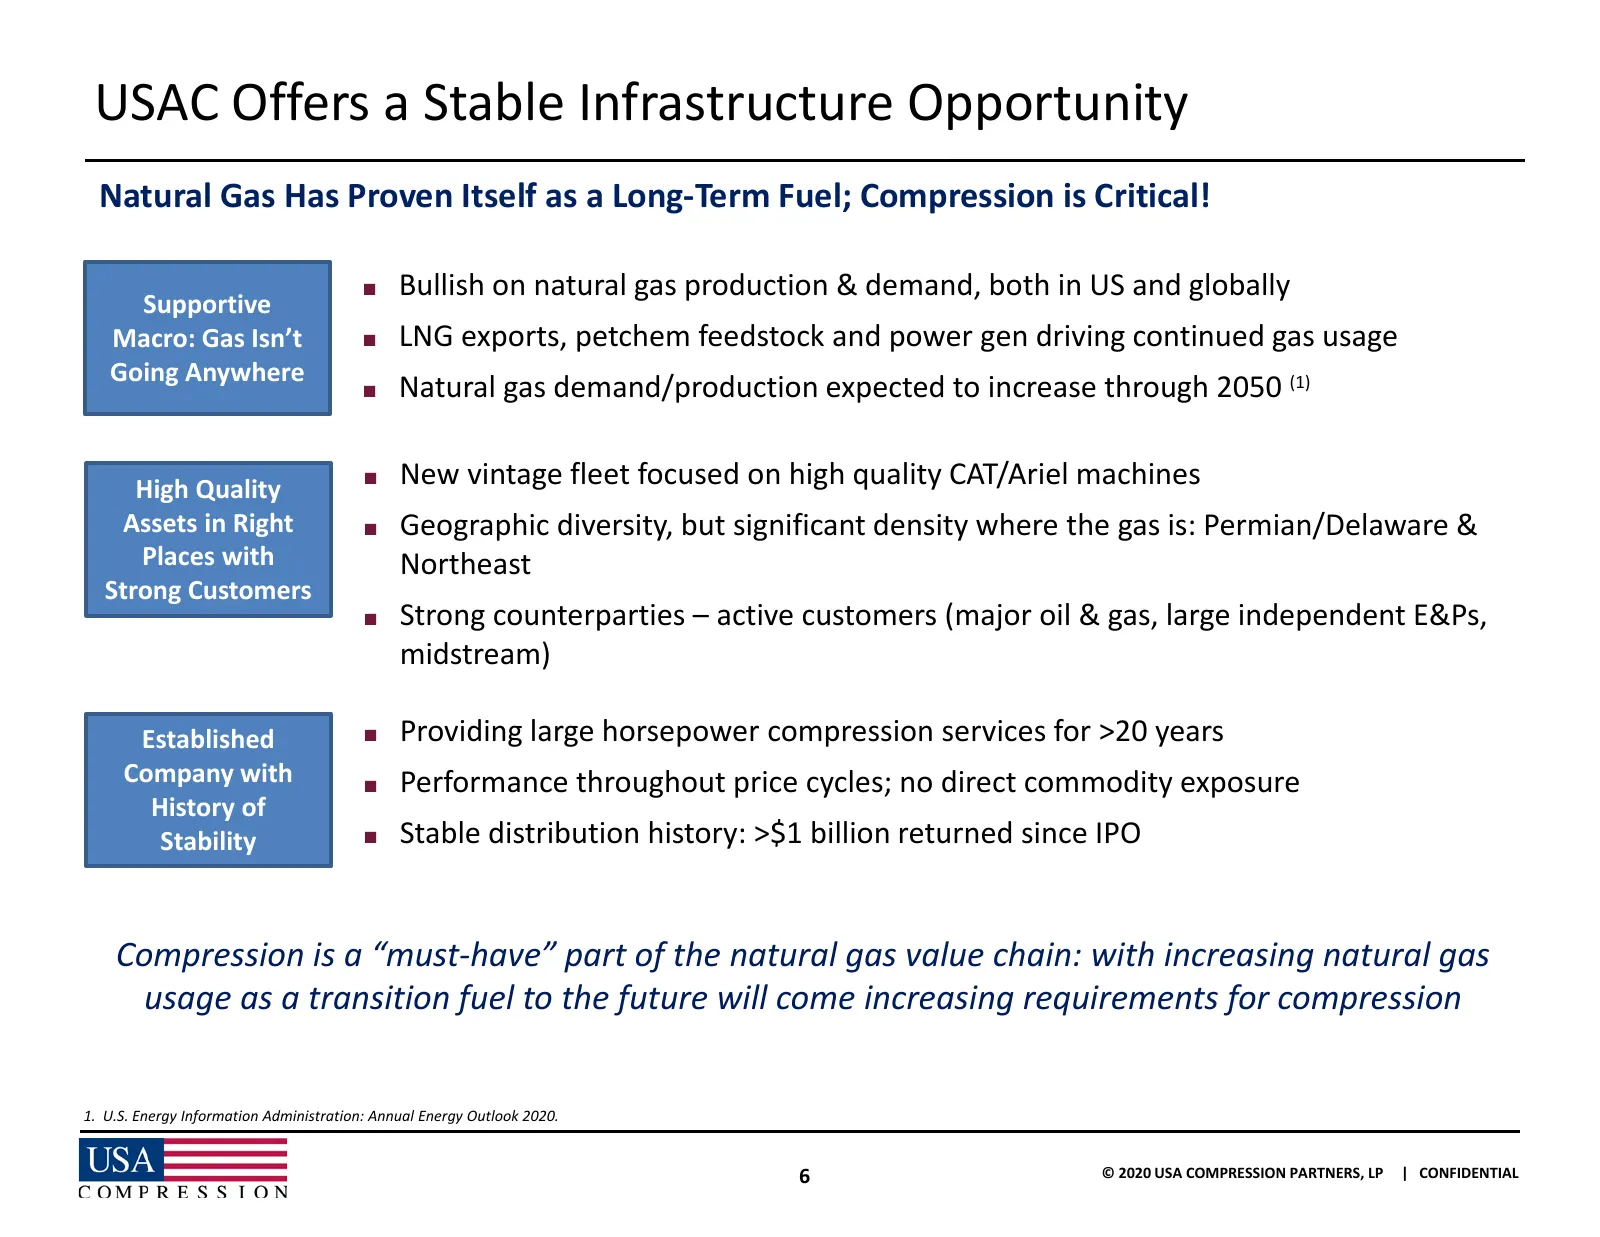
USAC Offers a Stable Infrastructure Opportunity Natural Gas Has Proven Itself as a Long-Term Fuel; Compression is Critical! ■ Bullish on natural gas production & demand, both in US and globally Supportive Macro: Gas Isn’t ■ LNG exports, petchem feedstock and power gen driving continued gas usage Goi
Slide 8: Why Focus on Midstream Compression?
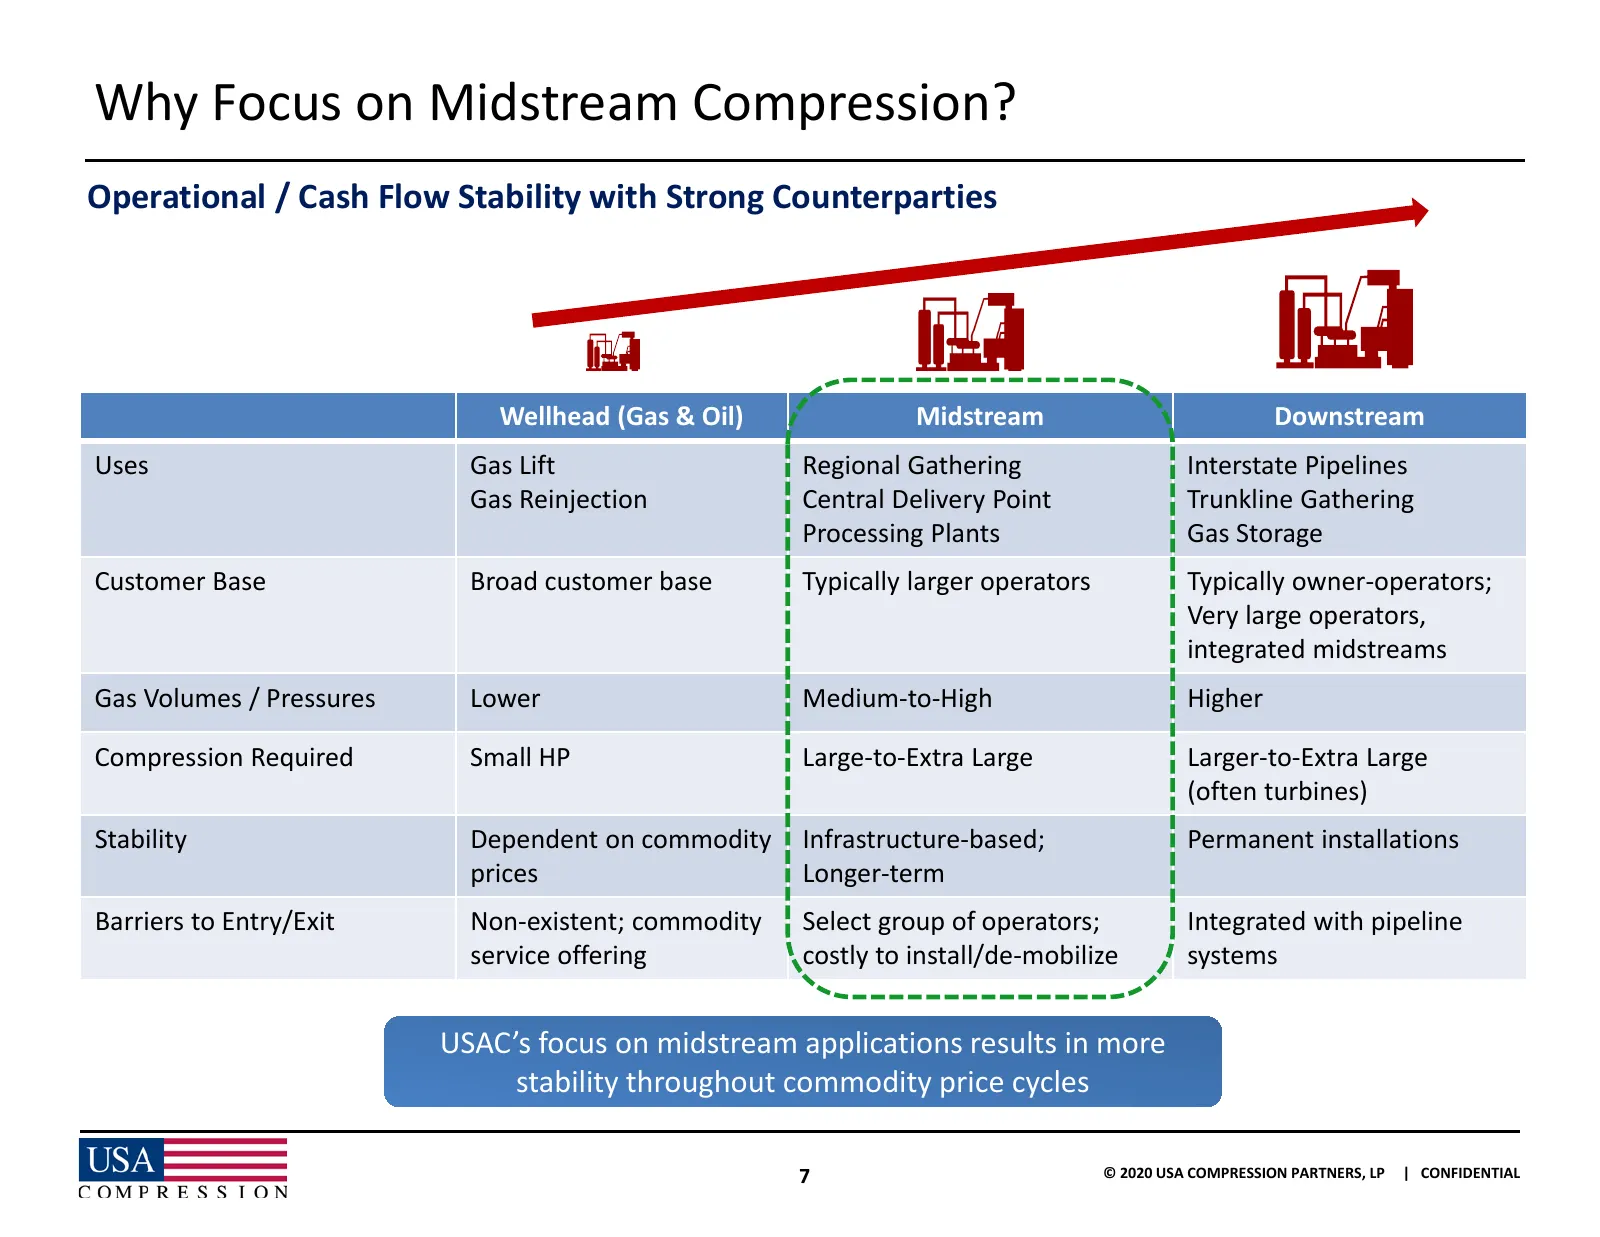
Why Focus on Midstream Compression? Operational / Cash Flow Stability with Strong Counterparties Wellhead (Gas & Oil) Midstream Downstream Uses Gas Lift Regional Gathering Interstate Pipelines Gas Reinjection Central Delivery Point Trunkline Gathering Processing Plants Gas Storage Customer Base Broa
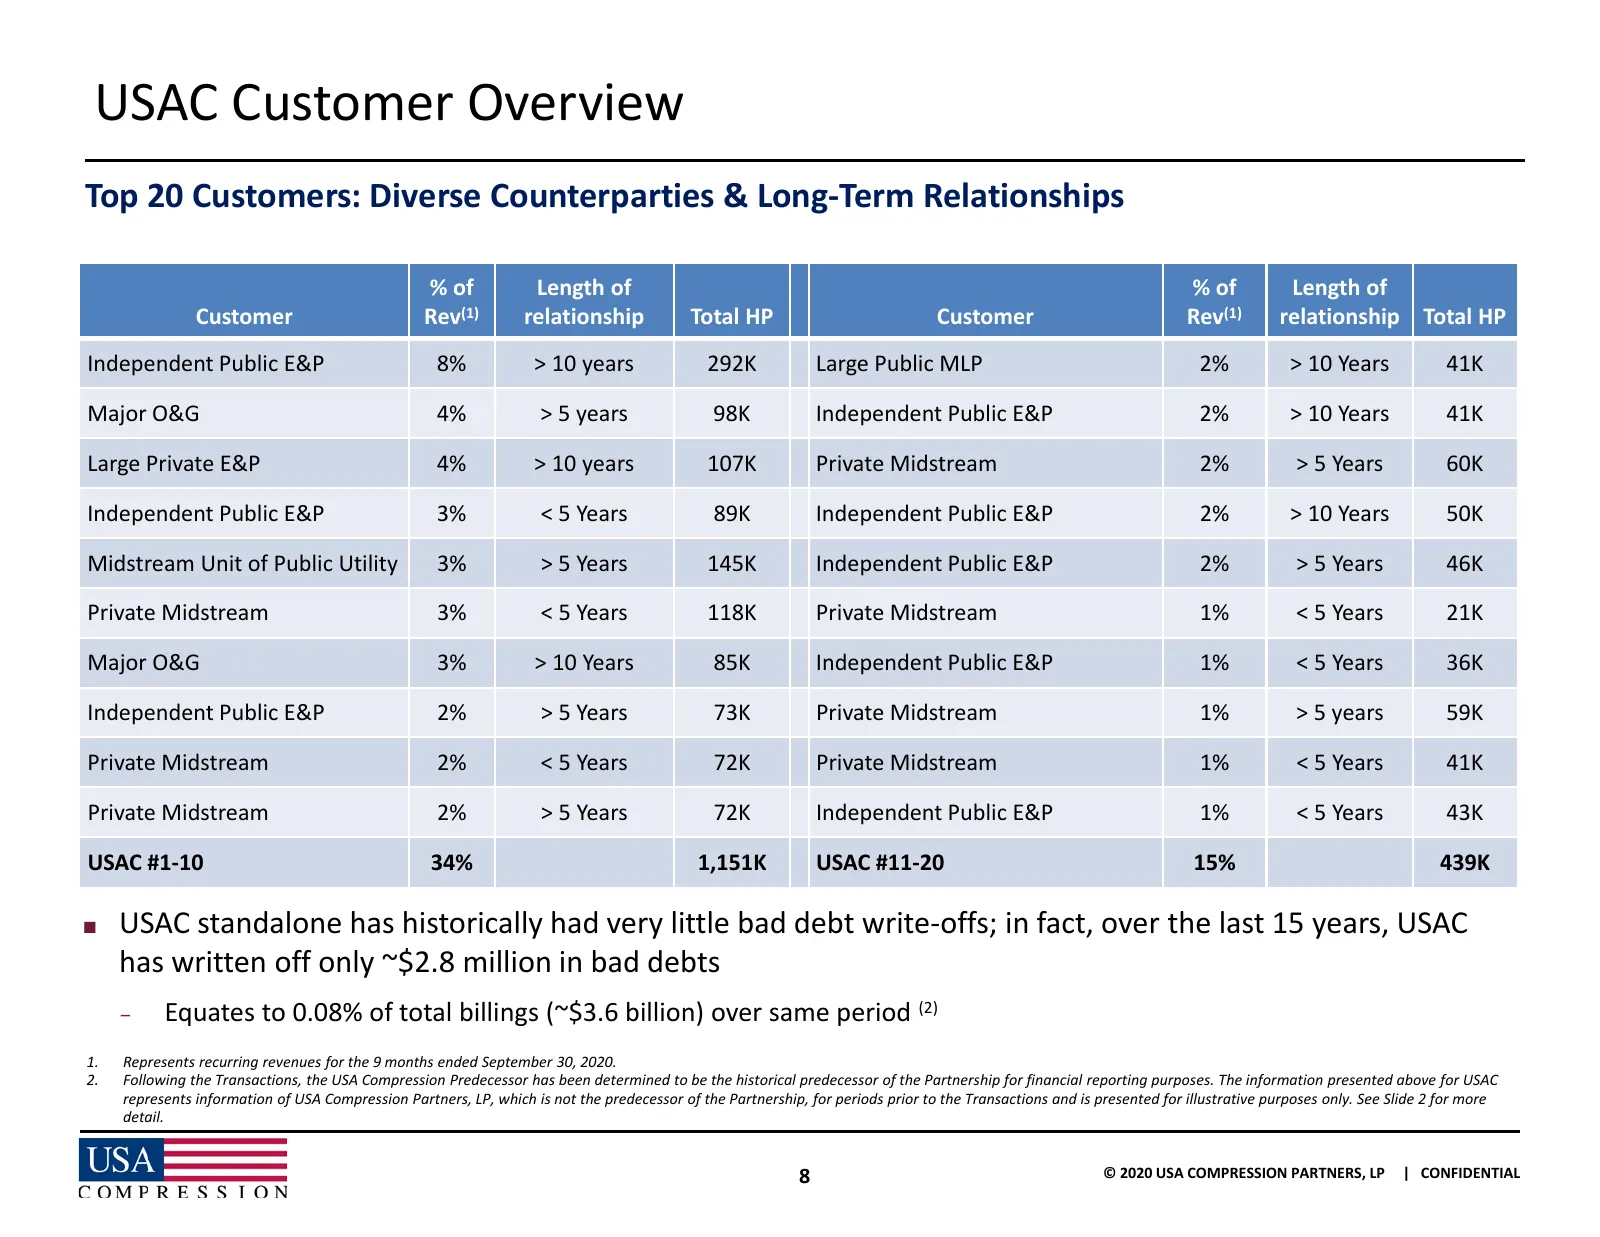
Slide 9: USAC Customer Overview
USAC Customer Overview Top 20 Customers: Diverse Counterparties & Long-Term Relationships % of Length of % of Length of Customer Rev(1) relationship Total HP Customer Rev(1) relationship Total HP Independent Public E&P 8% > 10 years 292K Large Public MLP 2% > 10 Years 41K Major O&G 4% > 5 years 98K
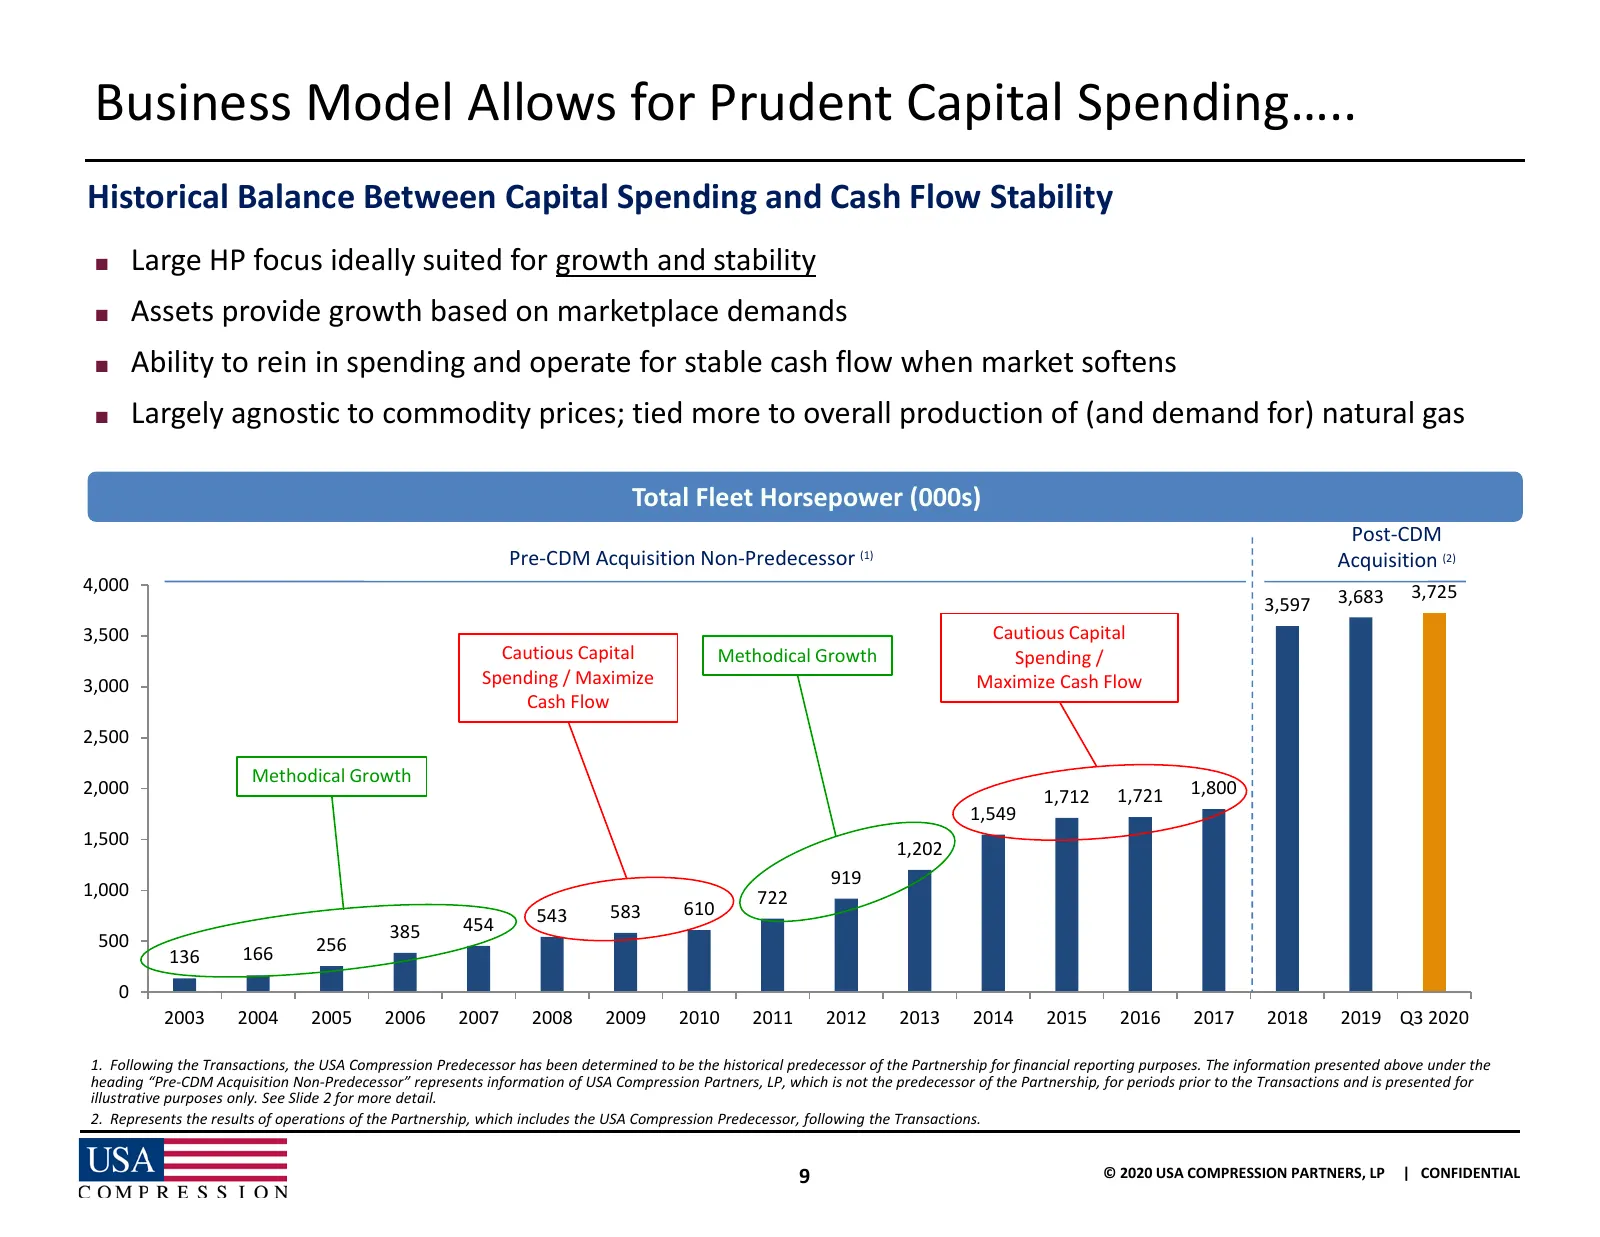
Slide 10: Business Model Allows for Prudent Capital Spending
Business Model Allows for Prudent Capital Spending….. Historical Balance Between Capital Spending and Cash Flow Stability ■ Large HP focus ideally suited for growth and stability ■ Assets provide growth based on marketplace demands ■ Ability to rein in spending and operate for stable cash flow when
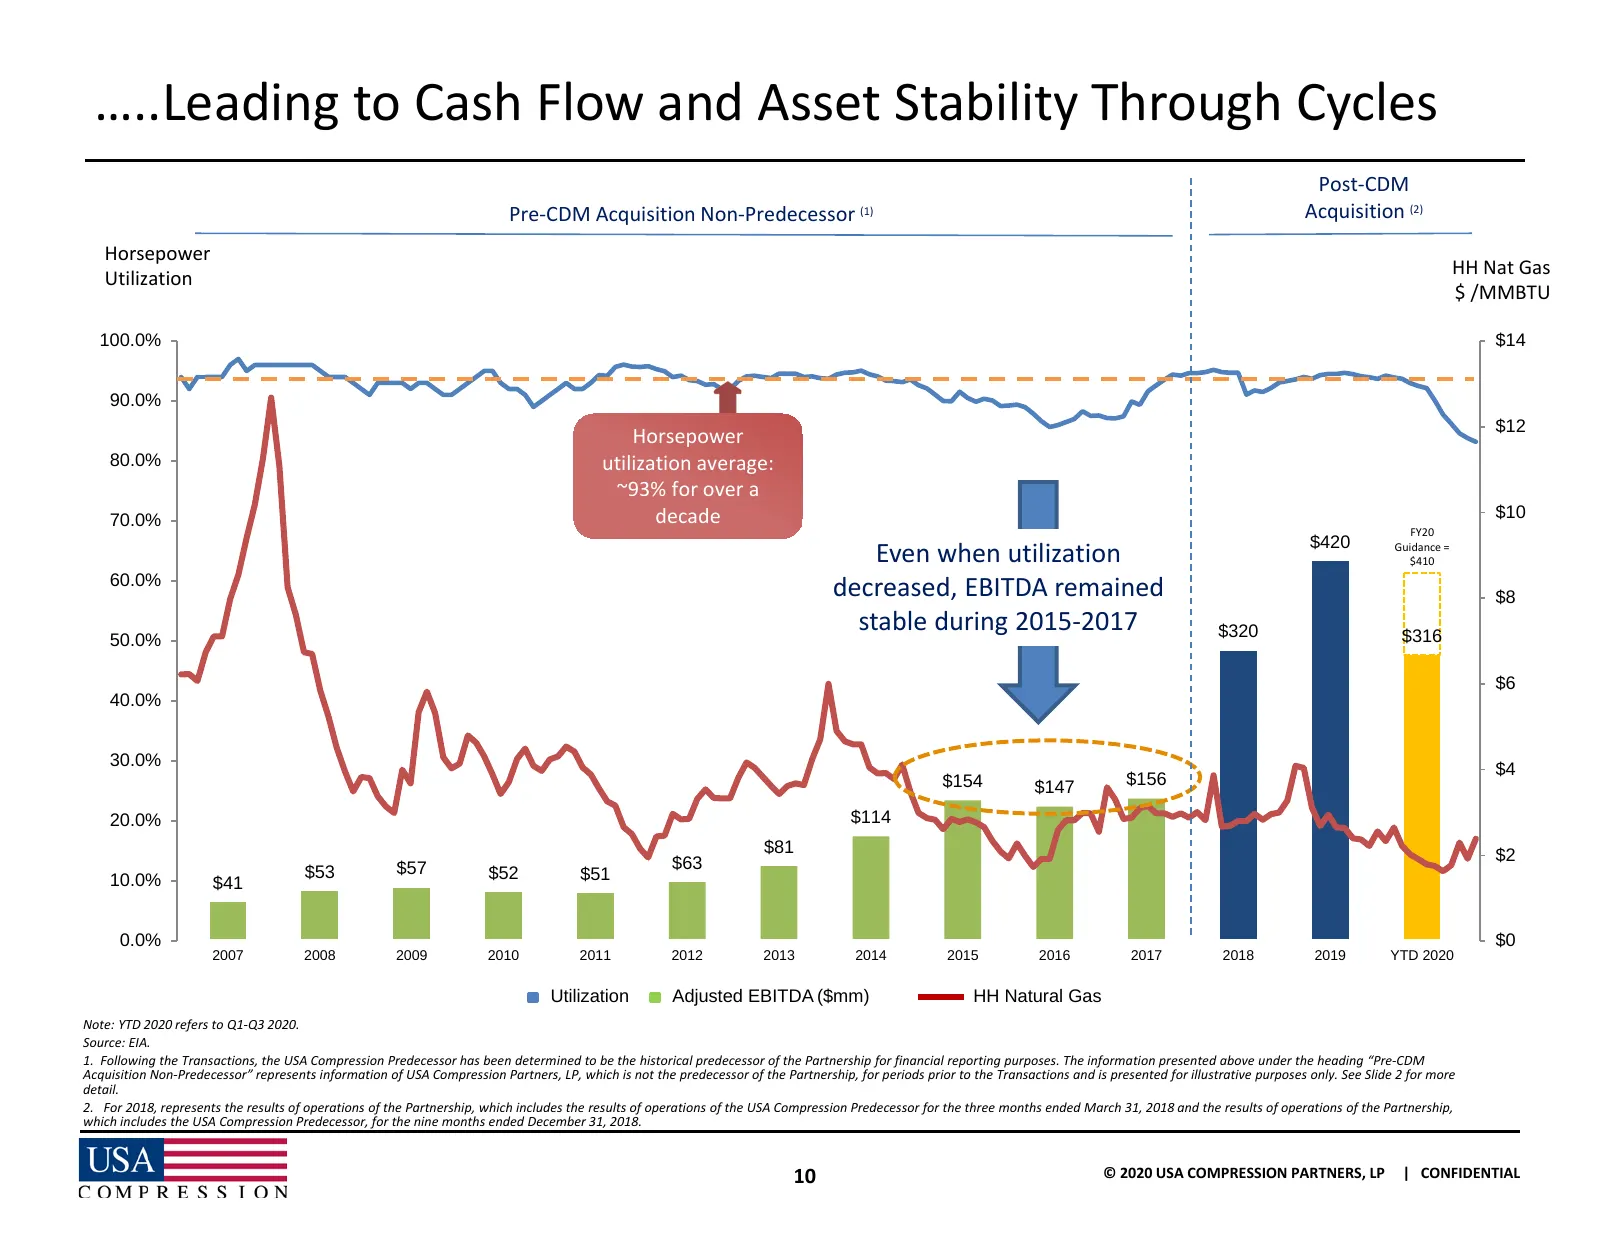
Slide 11: Leading to Cash Flow and Asset Stability Through Cycles
…..Leading to Cash Flow and Asset Stability Through Cycles Post-CDM Pre-CDM Acquisition Non-Predecessor (1) Acquisition (2) Horsepower HH Nat Gas Utilization $ /MMBTU 100.0% $14 90.0% $12 Horsepower 80.0% utilization average: ~93% for over a 70.0% decade $10 FY20 Even when utilization $420 Guidance
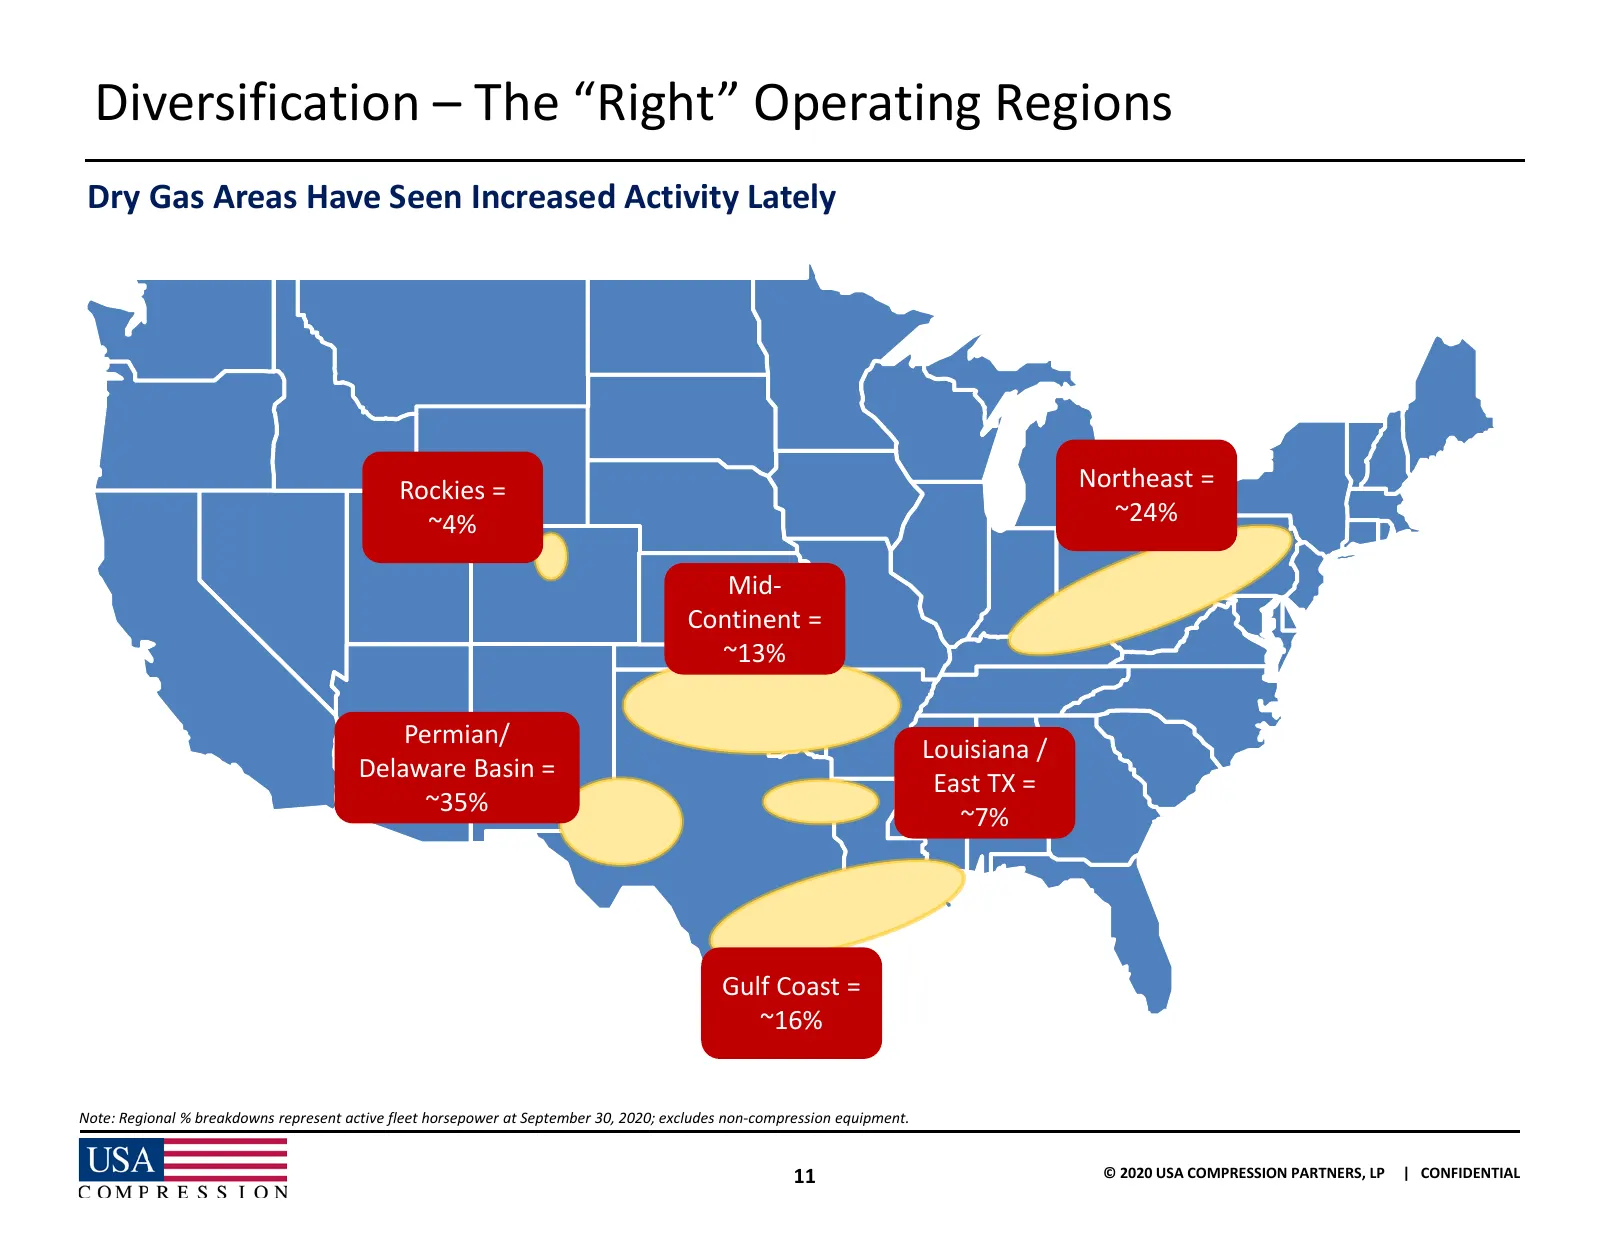
Slide 12: Diversification – The "Right" Operating Regions
Diversification – The “Right” Operating Regions Dry Gas Areas Have Seen Increased Activity Lately Rockies = Northeast = ~4% ~24% Mid- Continent = ~13% Permian/ Louisiana / Delaware Basin = East TX = ~35% ~7% Gulf Coast = ~16% Note: Regional % breakdowns represent active fleet horsepower at September
Slide 13: Natural Gas: Not Going Away!
Natural Gas: Not Going Away! USA = COMPRESSION
Slide 14: Moderating Rig Count Should Cause Near-Term Production Decreases
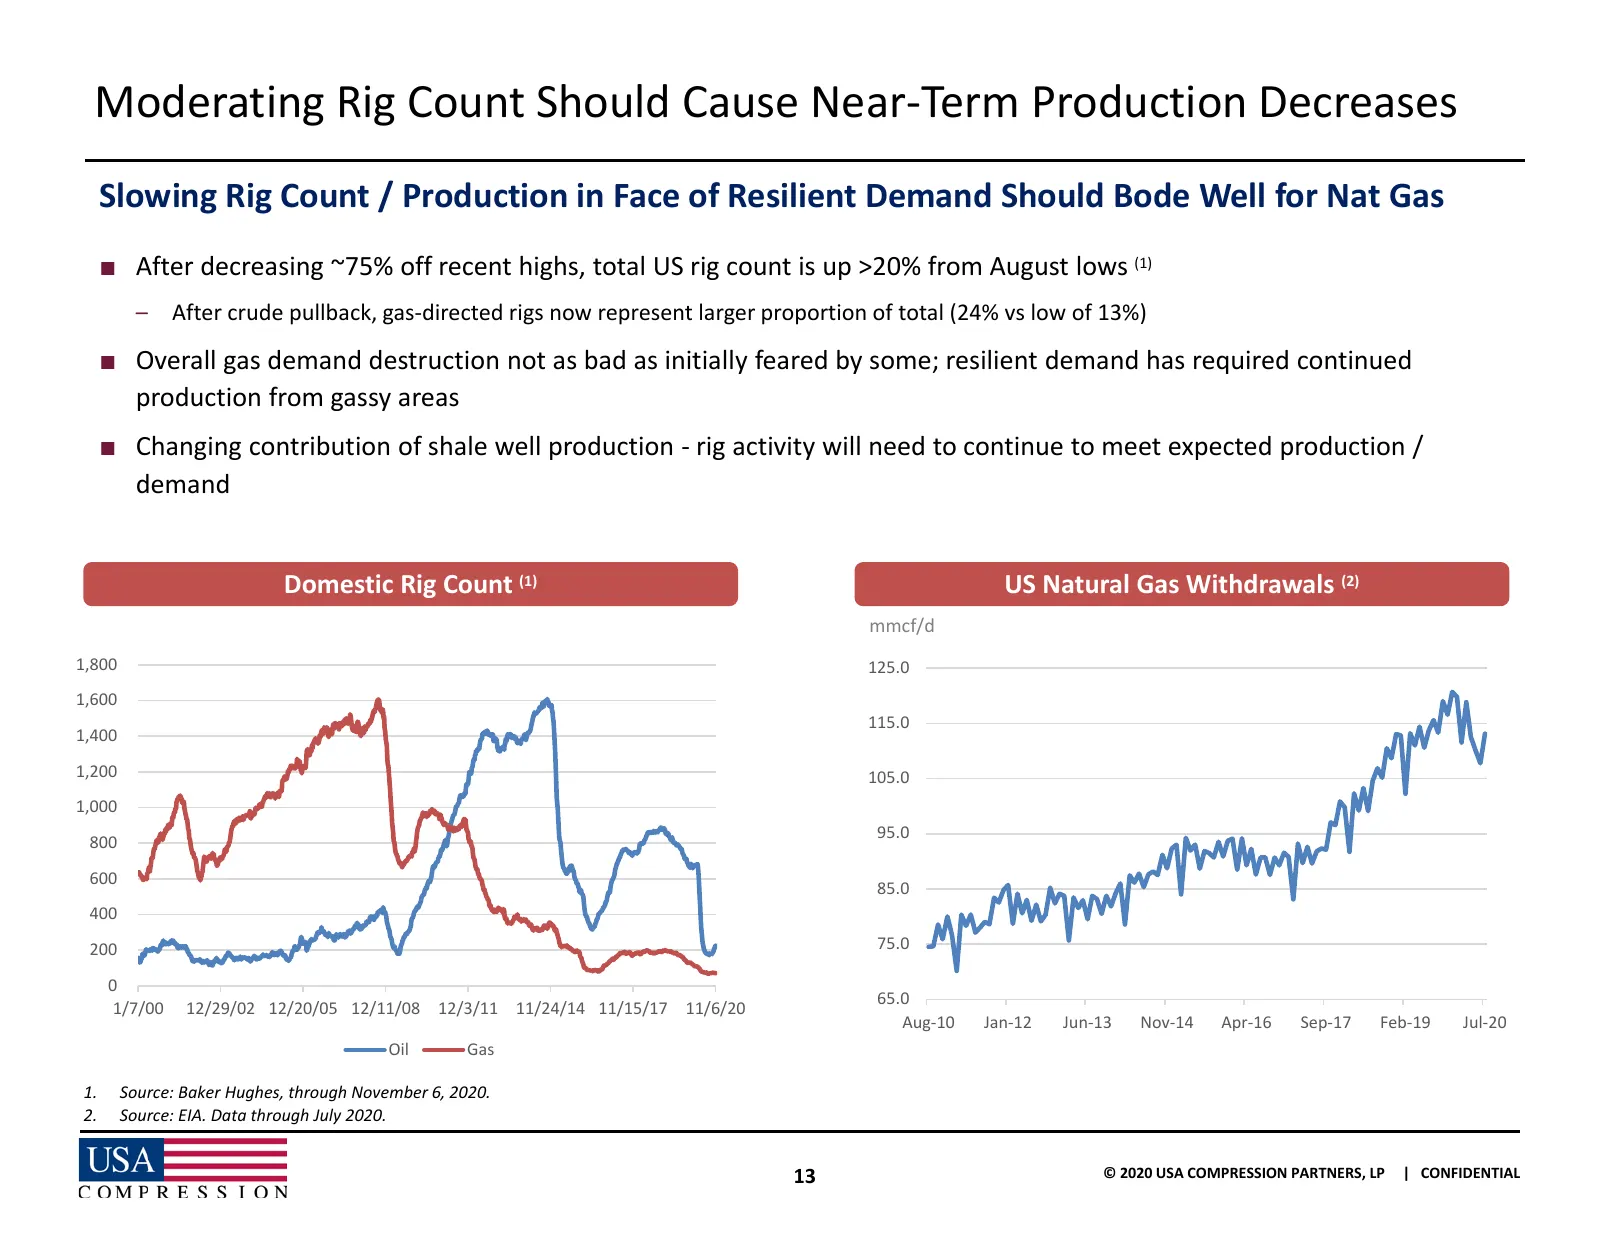
Moderating Rig Count Should Cause Near-Term Production Decreases Slowing Rig Count / Production in Face of Resilient Demand Should Bode Well for Nat Gas ■ After decreasing ~75% off recent highs, total US rig count is up >20% from August lows (1) – After crude pullback, gas-directed rigs now represen
Slide 15: Global Natural Gas Demand
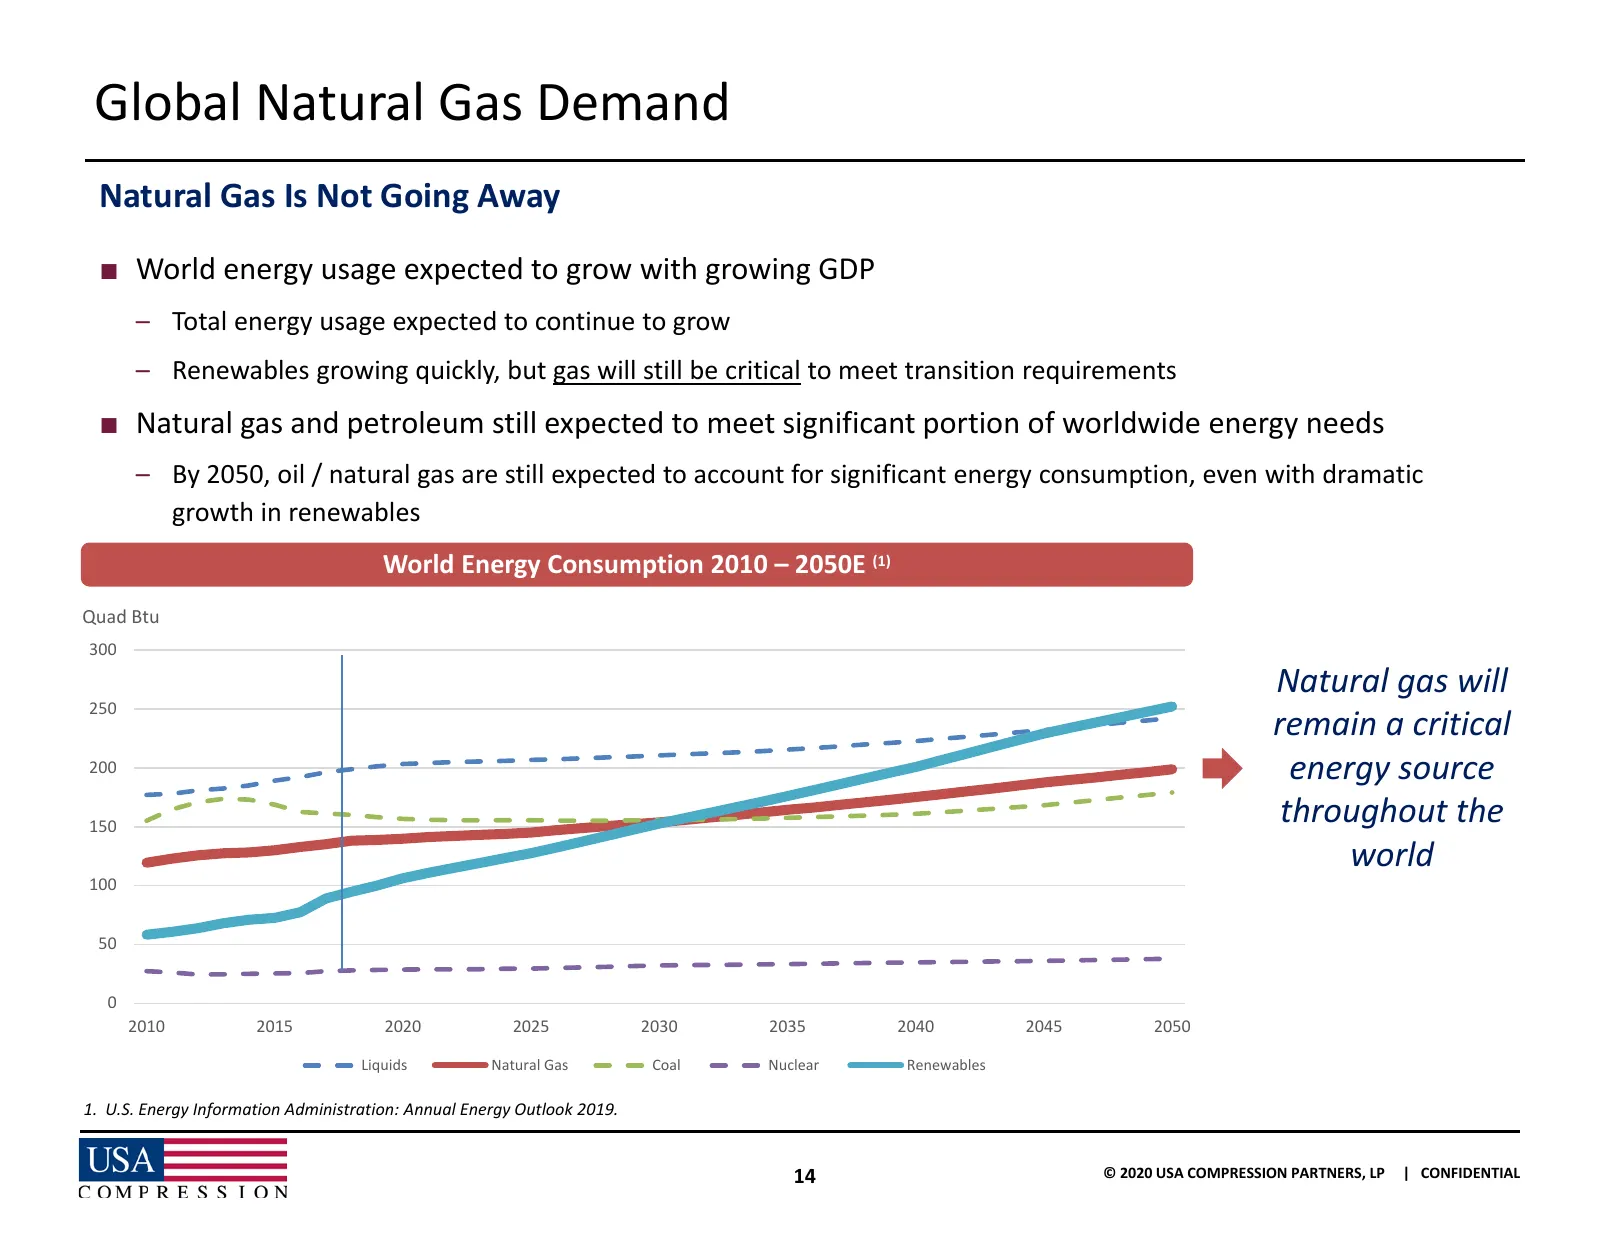
Global Natural Gas Demand Natural Gas Is Not Going Away ■ World energy usage expected to grow with growing GDP – Total energy usage expected to continue to grow – Renewables growing quickly, but gas will still be critical to meet transition requirements ■ Natural gas and petroleum still expected to
Slide 16: Domestic Natural Gas Demand
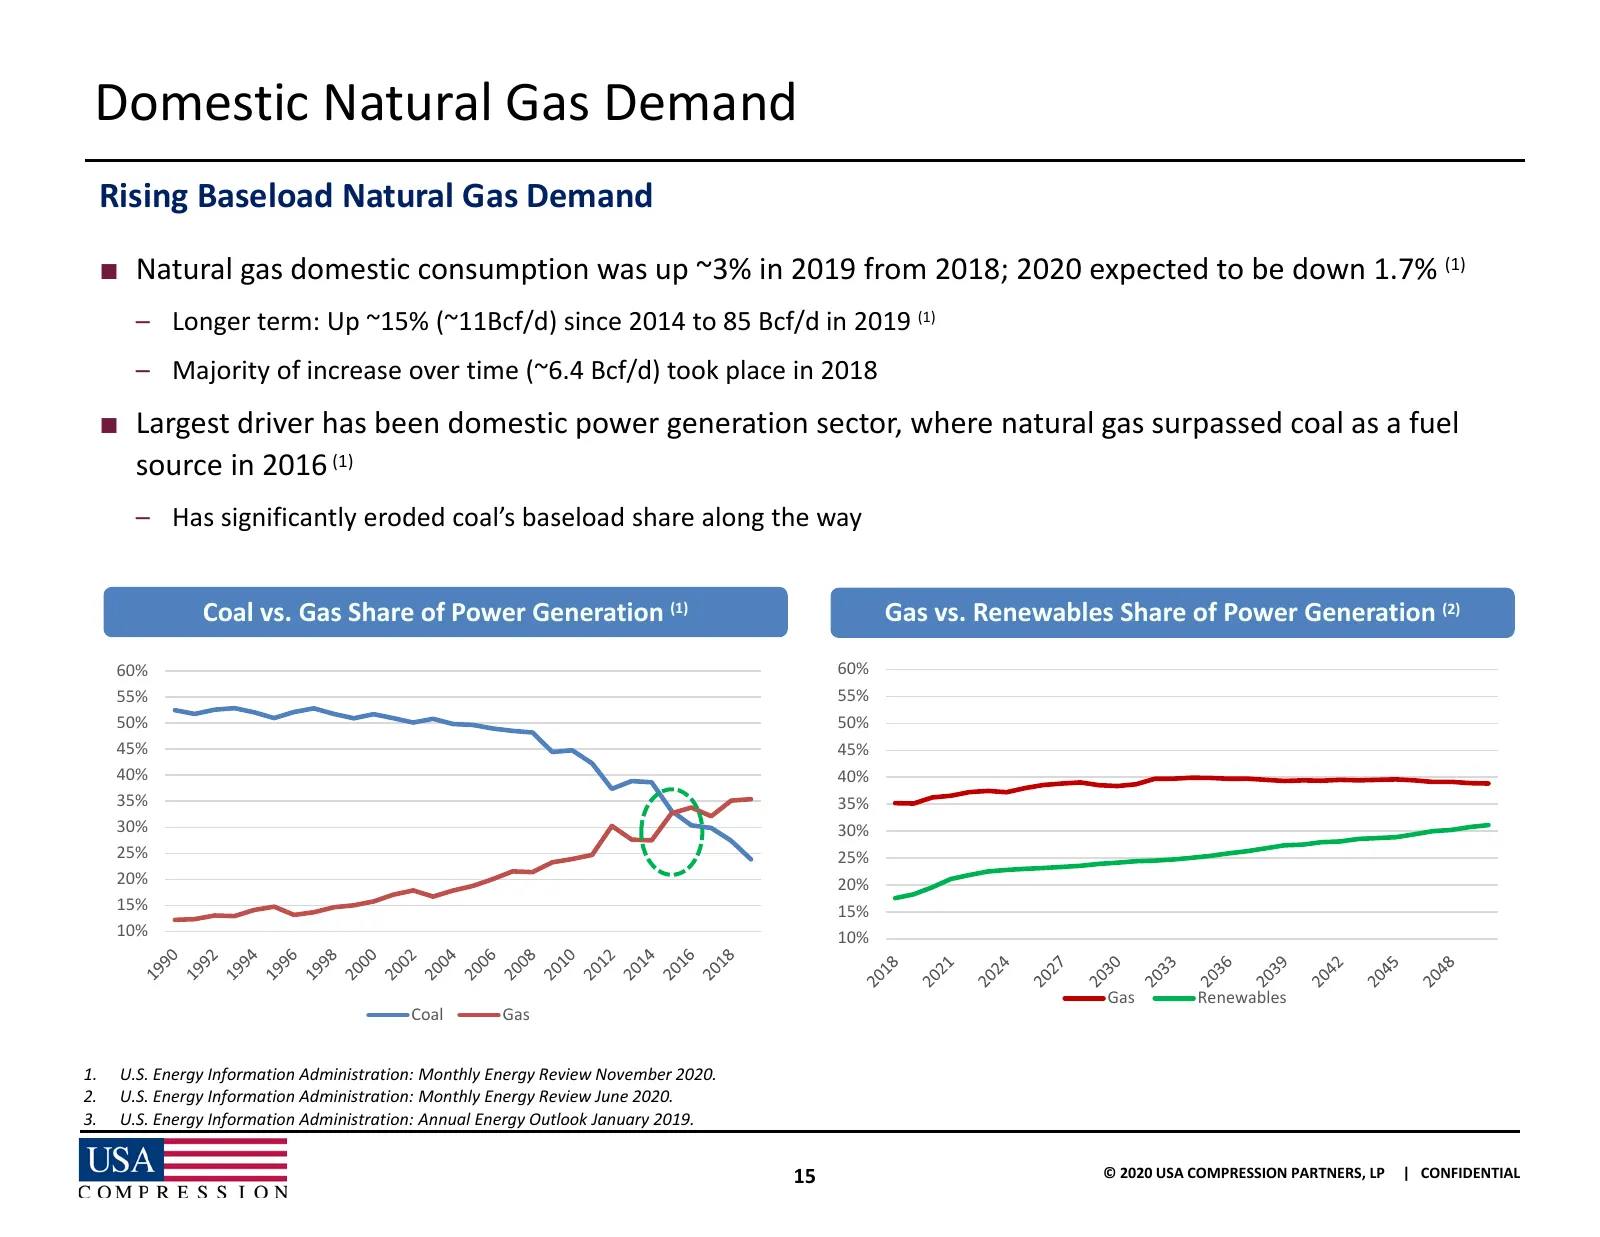
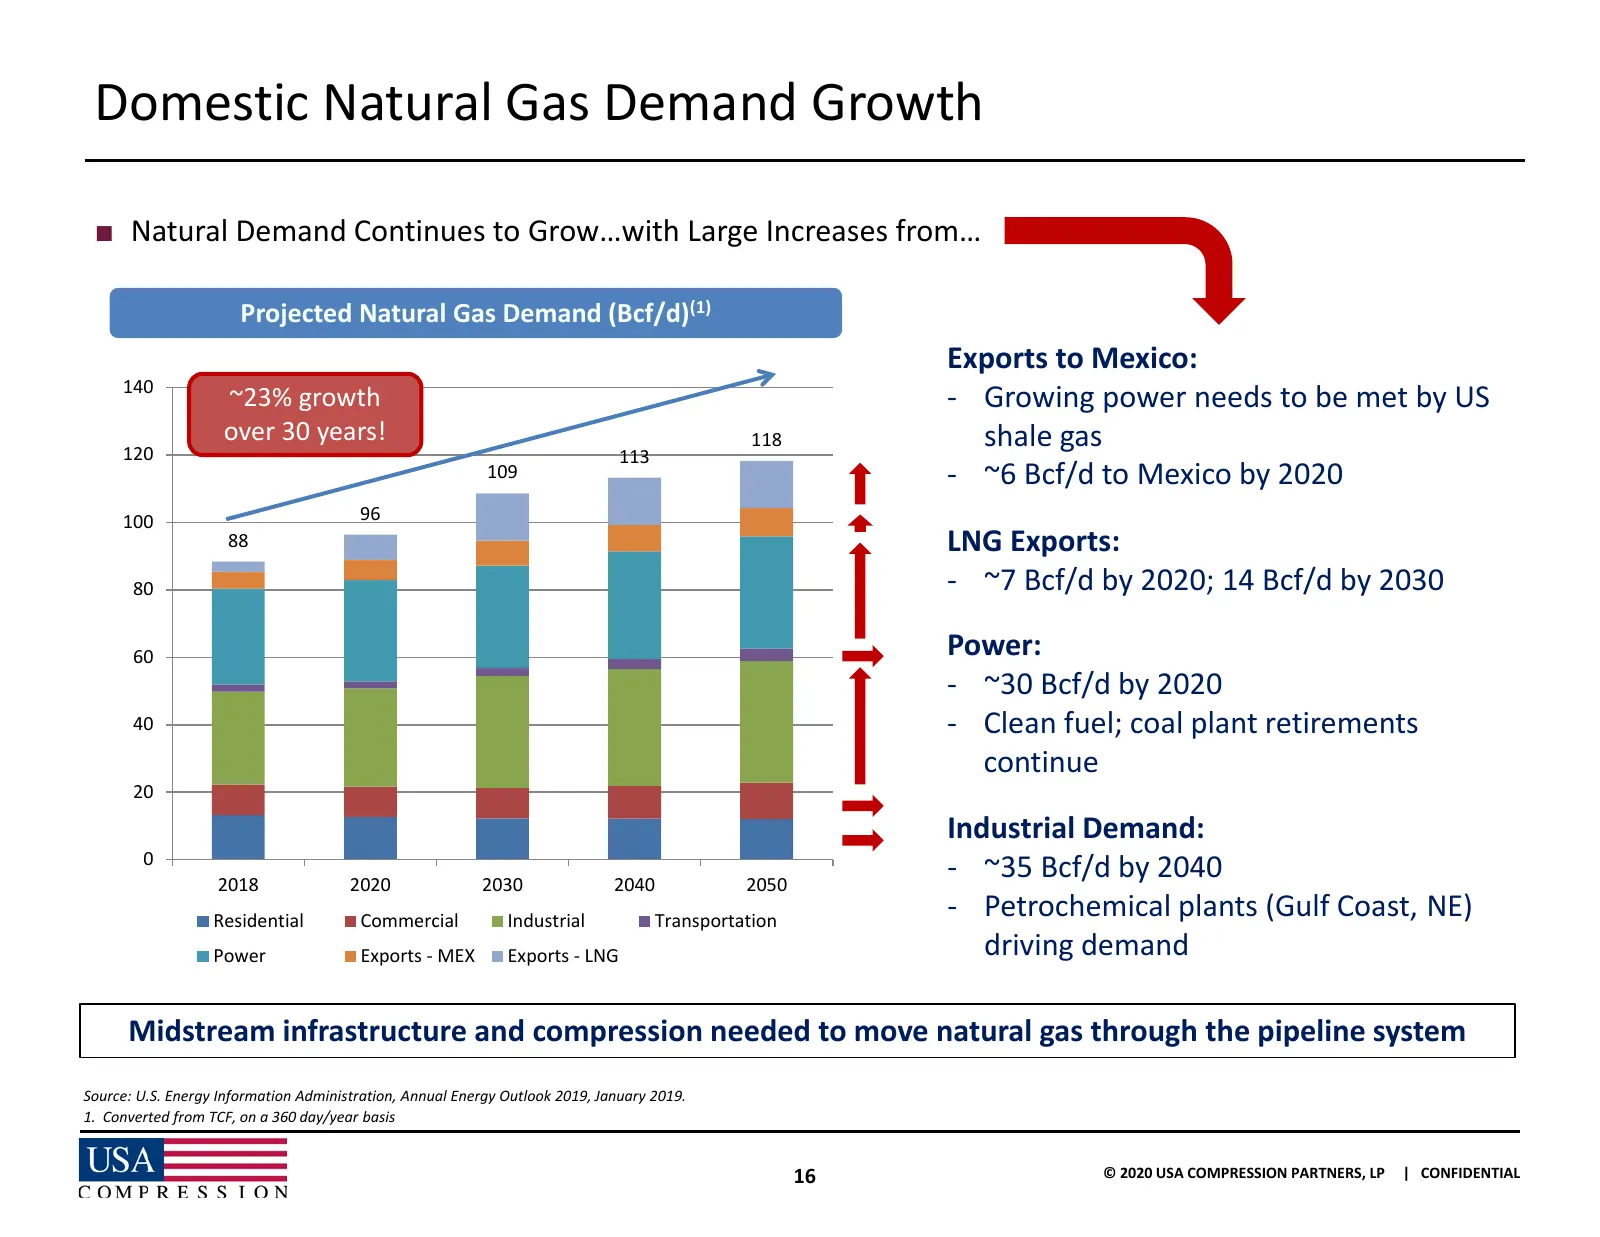
Domestic Natural Gas Demand Rising Baseload Natural Gas Demand ■ Natural gas domestic consumption was up ~3% in 2019 from 2018; 2020 expected to be down 1.7% (1) – Longer term: Up ~15% (~11Bcf/d) since 2014 to 85 Bcf/d in 2019 (1) – Majority of increase over time (~6.4 Bcf/d) took place in 2018 ■ La
Slide 17: Domestic Natural Gas Demand Growth
Domestic Natural Gas Demand Growth ■ Natural Demand Continues to Grow…with Large Increases from… Projected Natural Gas Demand (Bcf/d)(1) Exports to Mexico: 140 ~23% growth - Growing power needs to be met by US over 30 years! 118 shale gas 120 113 109 - ~6 Bcf/d to Mexico by 2020 100 96 88 LNG Export
Slide 18: Appendix
Appendix hy—— COMPRESSION
Slide 19: Organizational Chart
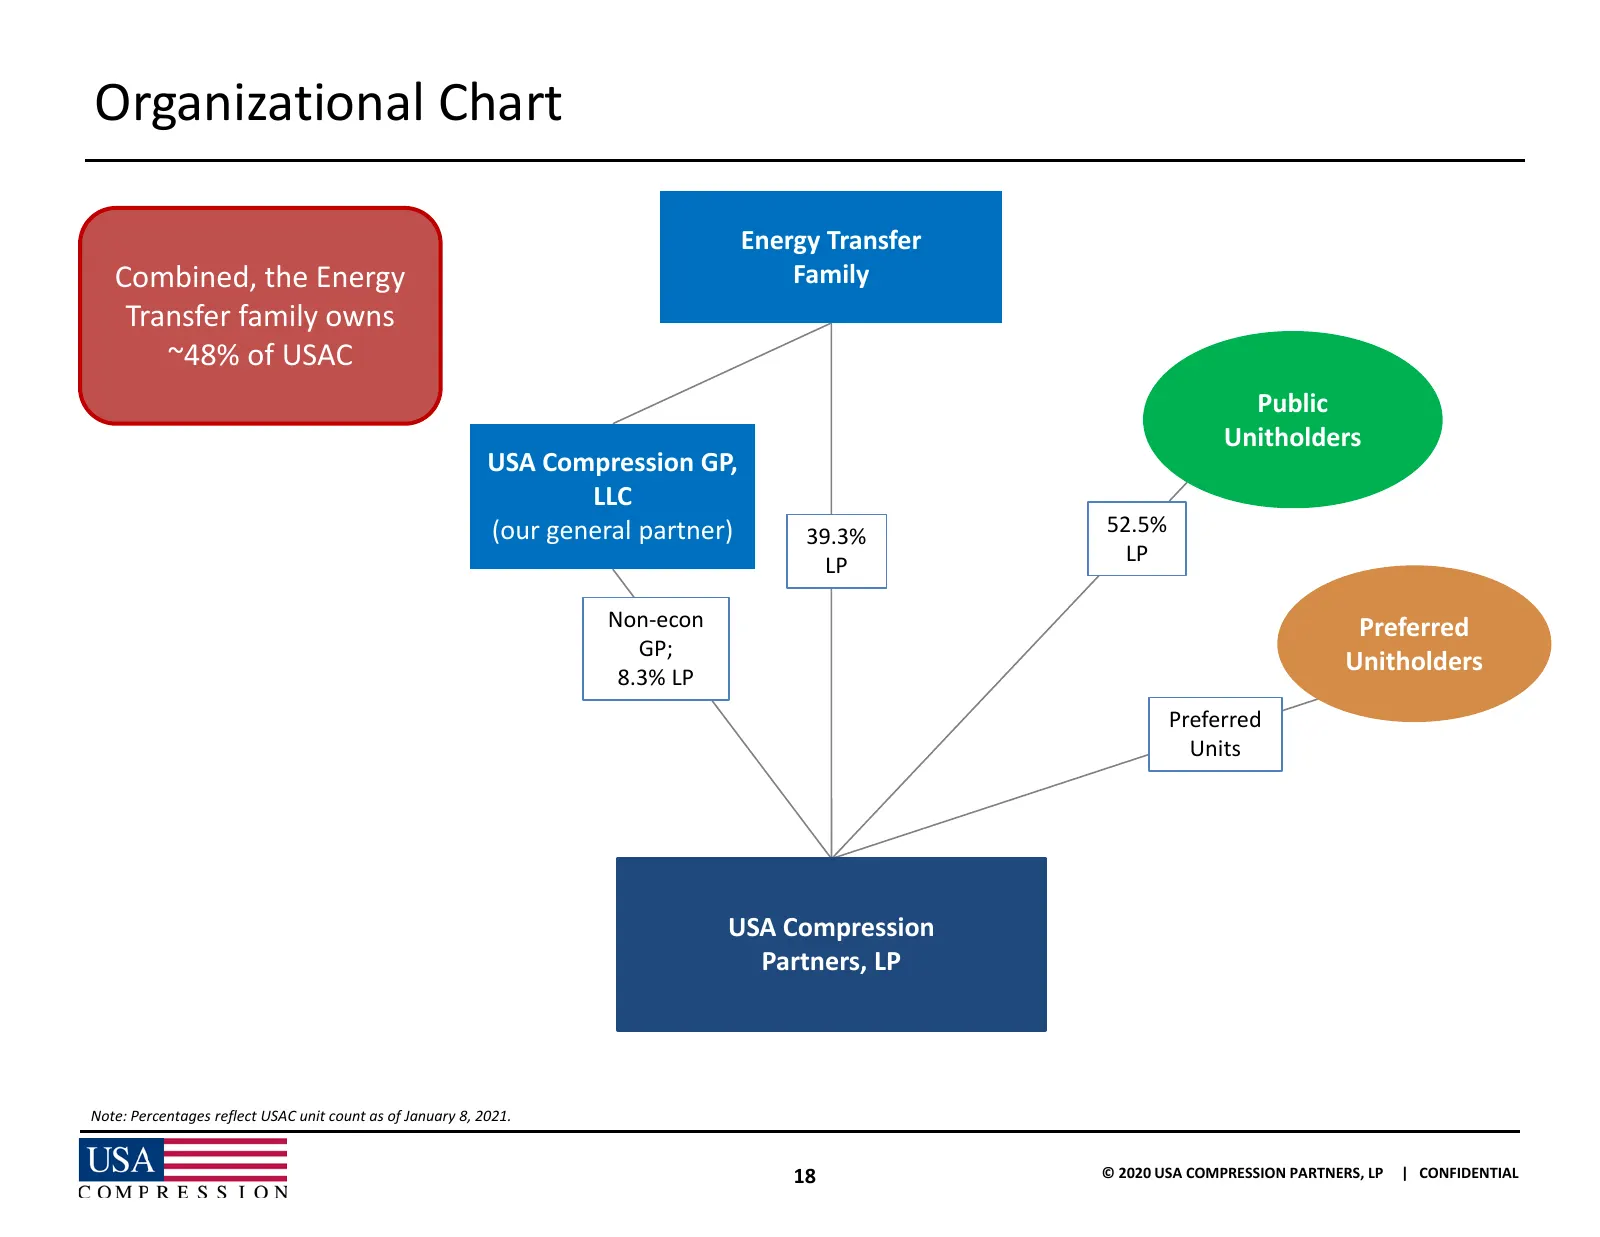
Organizational Chart Energy Transfer Combined, the Energy Family Transfer family owns ~48% of USAC Public Unitholders USA Compression GP, LLC (our general partner) 52.5% 39.3% LP LP Non-econ Preferred GP; Unitholders 8.3% LP Preferred Units USA Compression Partners, LP Note: Percentages reflect USAC
Slide 20: Large Horsepower Gas Applications Drive Stability
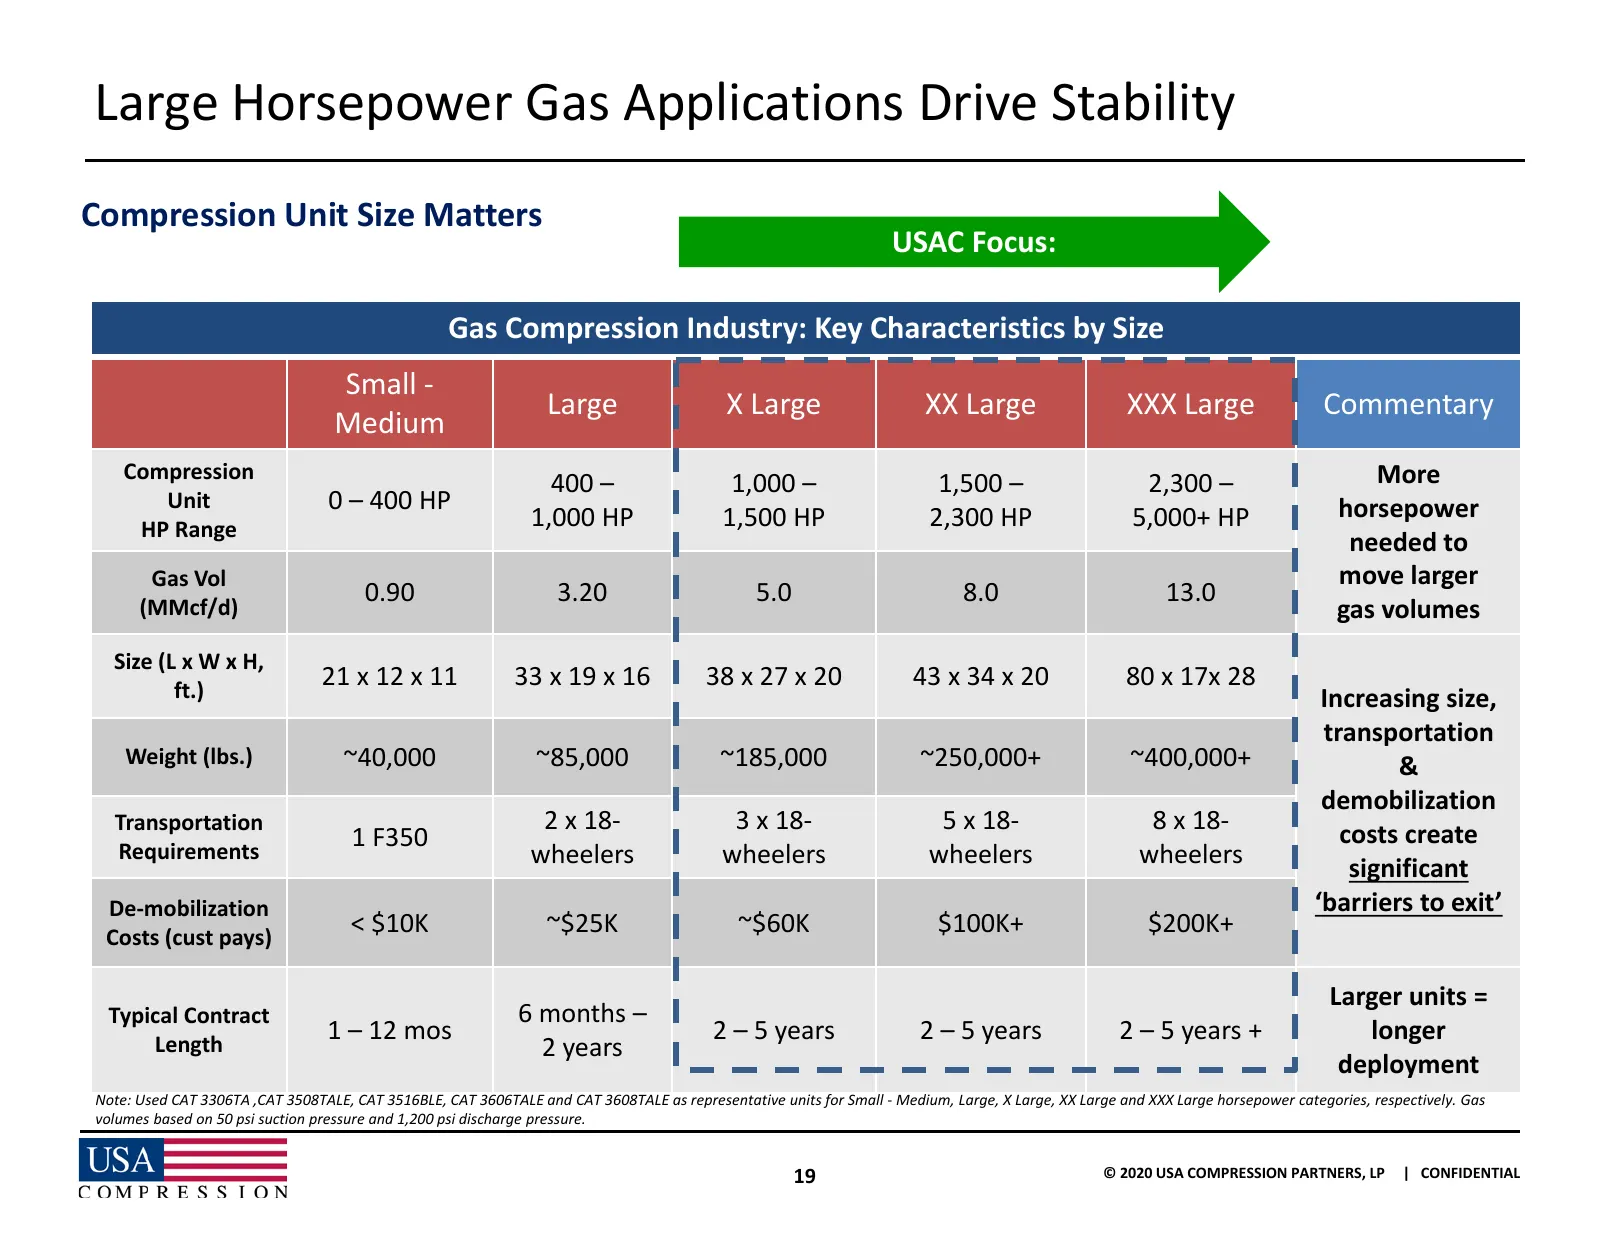
Large Horsepower Gas Applications Drive Stability Compression Unit Size Matters USAC Focus: Gas Compression Industry: Key Characteristics by Size Small - Large X Large XX Large XXX Large Commentary Medium Compression 400 – 1,000 – 1,500 – 2,300 – More Unit 0 – 400 HP horsepower HP Range 1,000 HP 1,5
Slide 21: Balancing Distribution Stability and Leverage
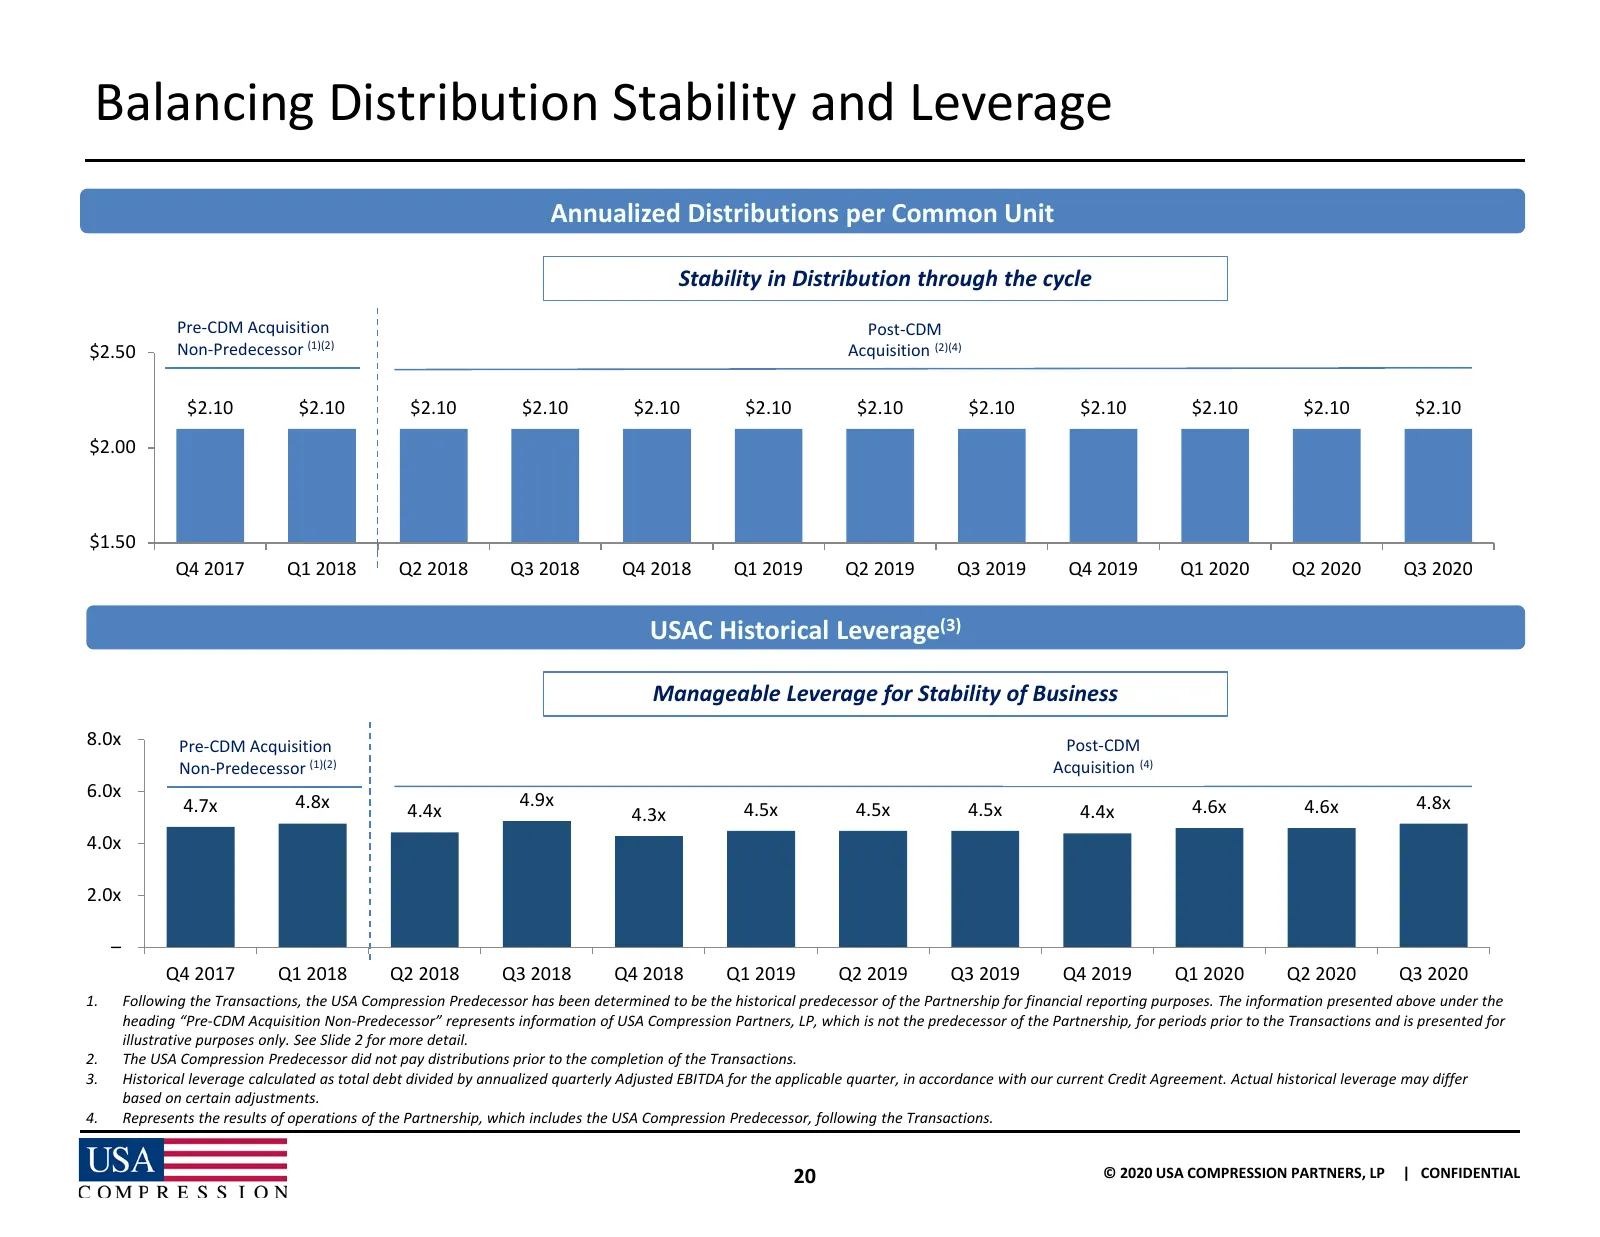
Balancing Distribution Stability and Leverage Annualized Distributions per Common Unit Stability in Distribution through the cycle Pre-CDM Acquisition Post-CDM $2.50 Non-Predecessor (1)(2) Acquisition (2)(4) $2.10 $2.10 $2.10 $2.10 $2.10 $2.10 $2.10 $2.10 $2.10 $2.10 $2.10 $2.10 $2.00 $1.50 Q4 2017
Slide 22: Operational and Financial Performance
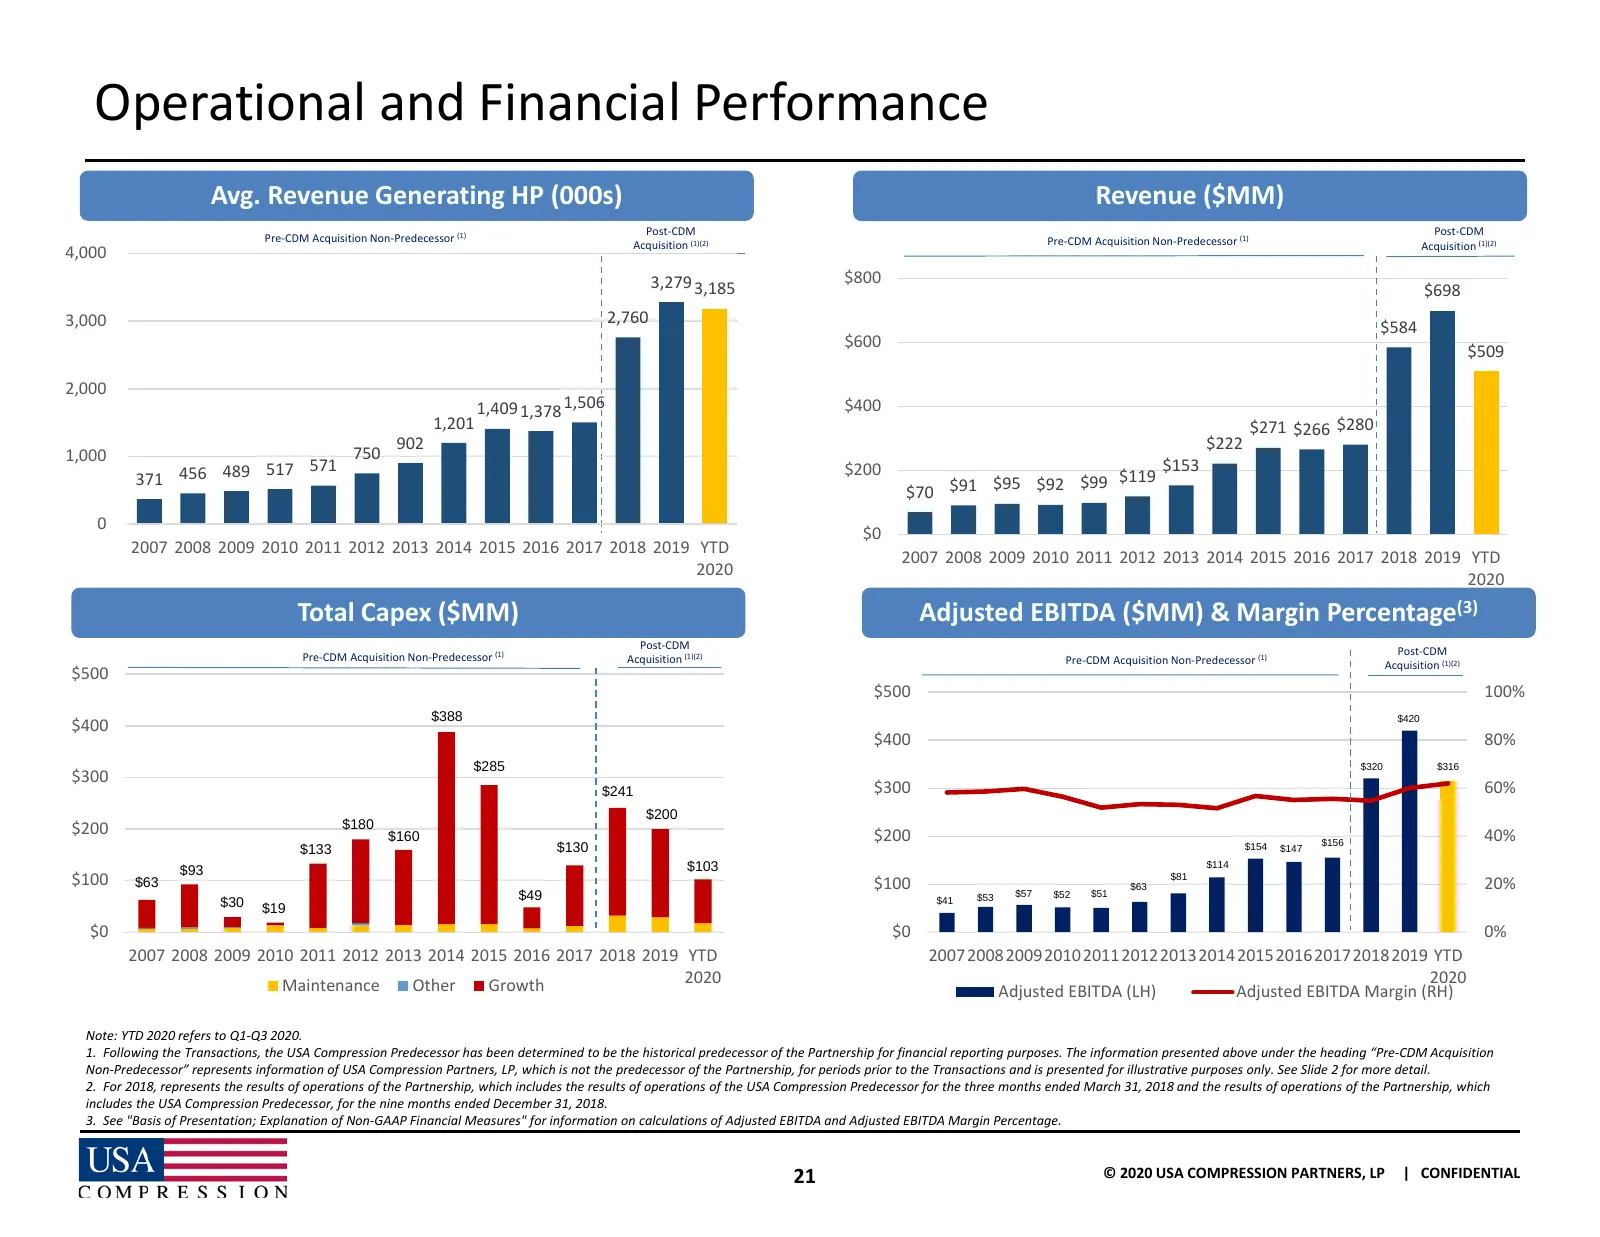
Operational and Financial Performance Avg. Revenue Generating HP (000s) Revenue ($MM) Post-CDM Post-CDM Pre-CDM Acquisition Non-Predecessor (1) Pre-CDM Acquisition Non-Predecessor (1) Acquisition (1)(2) Acquisition (1)(2) 4,000 3,279 3,185 $800 $698 3,000 2,760 $584 $600 $509 2,000 1,409 1,378 1,506
Slide 23: Macro Thesis: The "Shift to Shale"
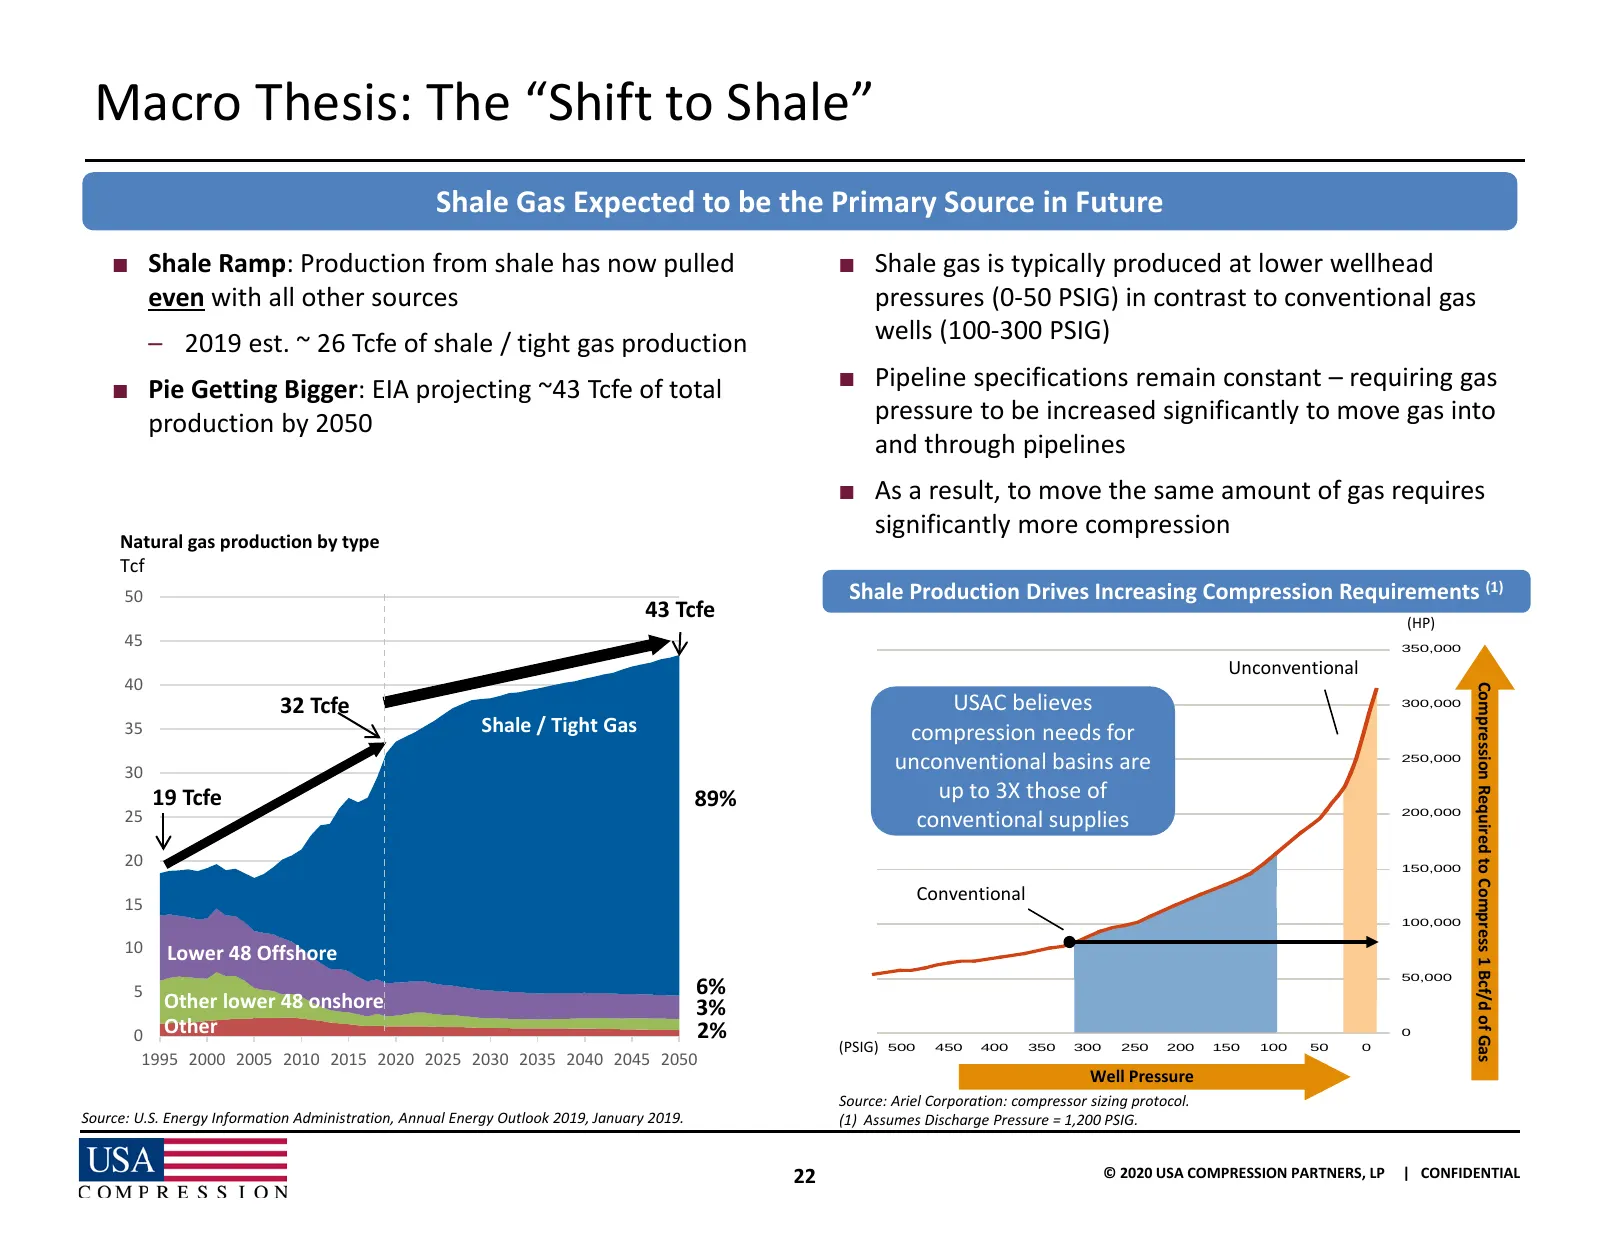
Macro Thesis: The “Shift to Shale” Shale Gas Expected to be the Primary Source in Future ■ Shale Ramp: Production from shale has now pulled ■ Shale gas is typically produced at lower wellhead even with all other sources pressures (0-50 PSIG) in contrast to conventional gas – 2019 est. ~ 26 Tcfe of s
Slide 24: Compression Throughout the Value Chain
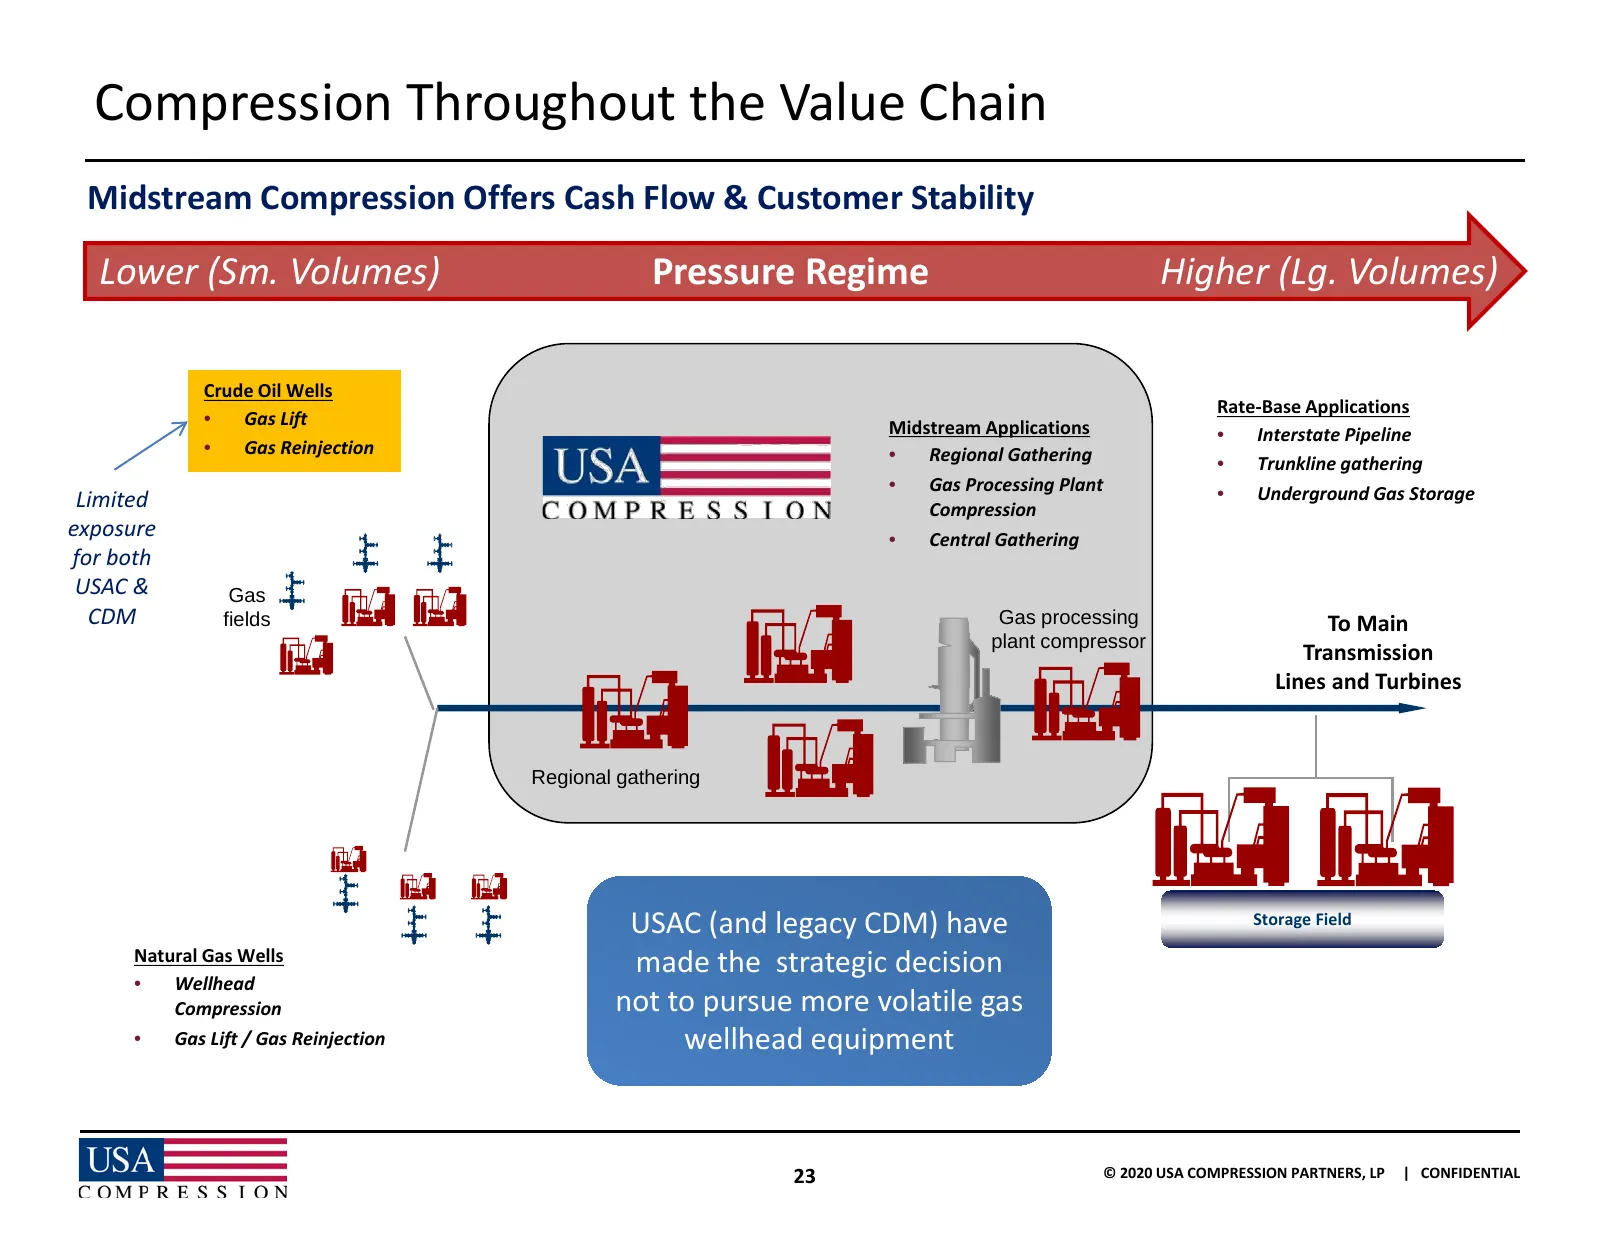
Compression Throughout the Value Chain Midstream Compression Offers Cash Flow & Customer Stability Lower (Sm. Volumes) Pressure Regime Higher (Lg. Volumes) Crude Oil Wells Rate-Base Applications • Gas Lift Midstream Applications • Interstate Pipeline • Gas Reinjection • Regional Gathering • Trunklin
Slide 25: Non-GAAP Reconciliations
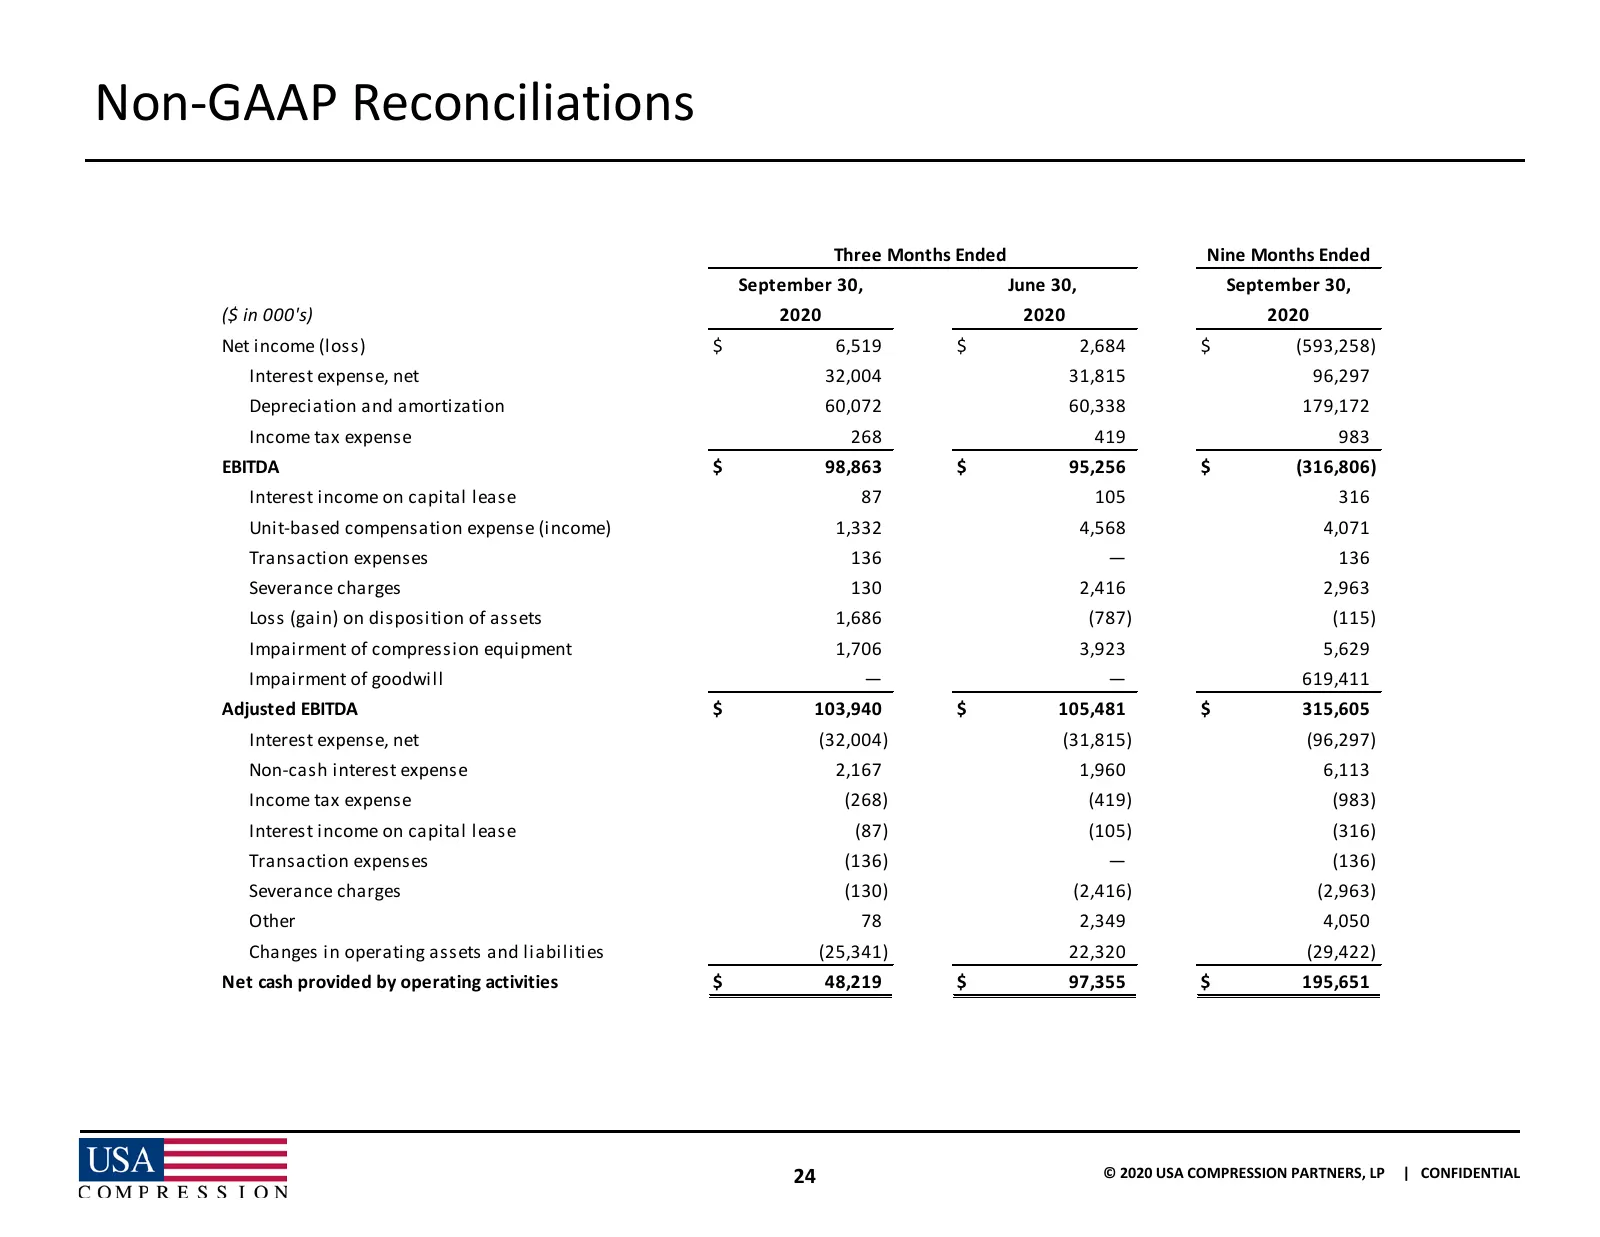
Non-GAAP Reconciliations Three Months Ended Nine Months Ended September 30, June 30, September 30, ($ in 000's) 2020 2020 2020 Net income (loss) $ 6,519 $ 2,684 $ (593,258) Interest expense, net 32,004 31,815 96,297 Depreciation and amortization 60,072 60,338 179,172 Income tax expense 268 419 983 E
Slide 26: Non-GAAP Reconciliations, cont'd.
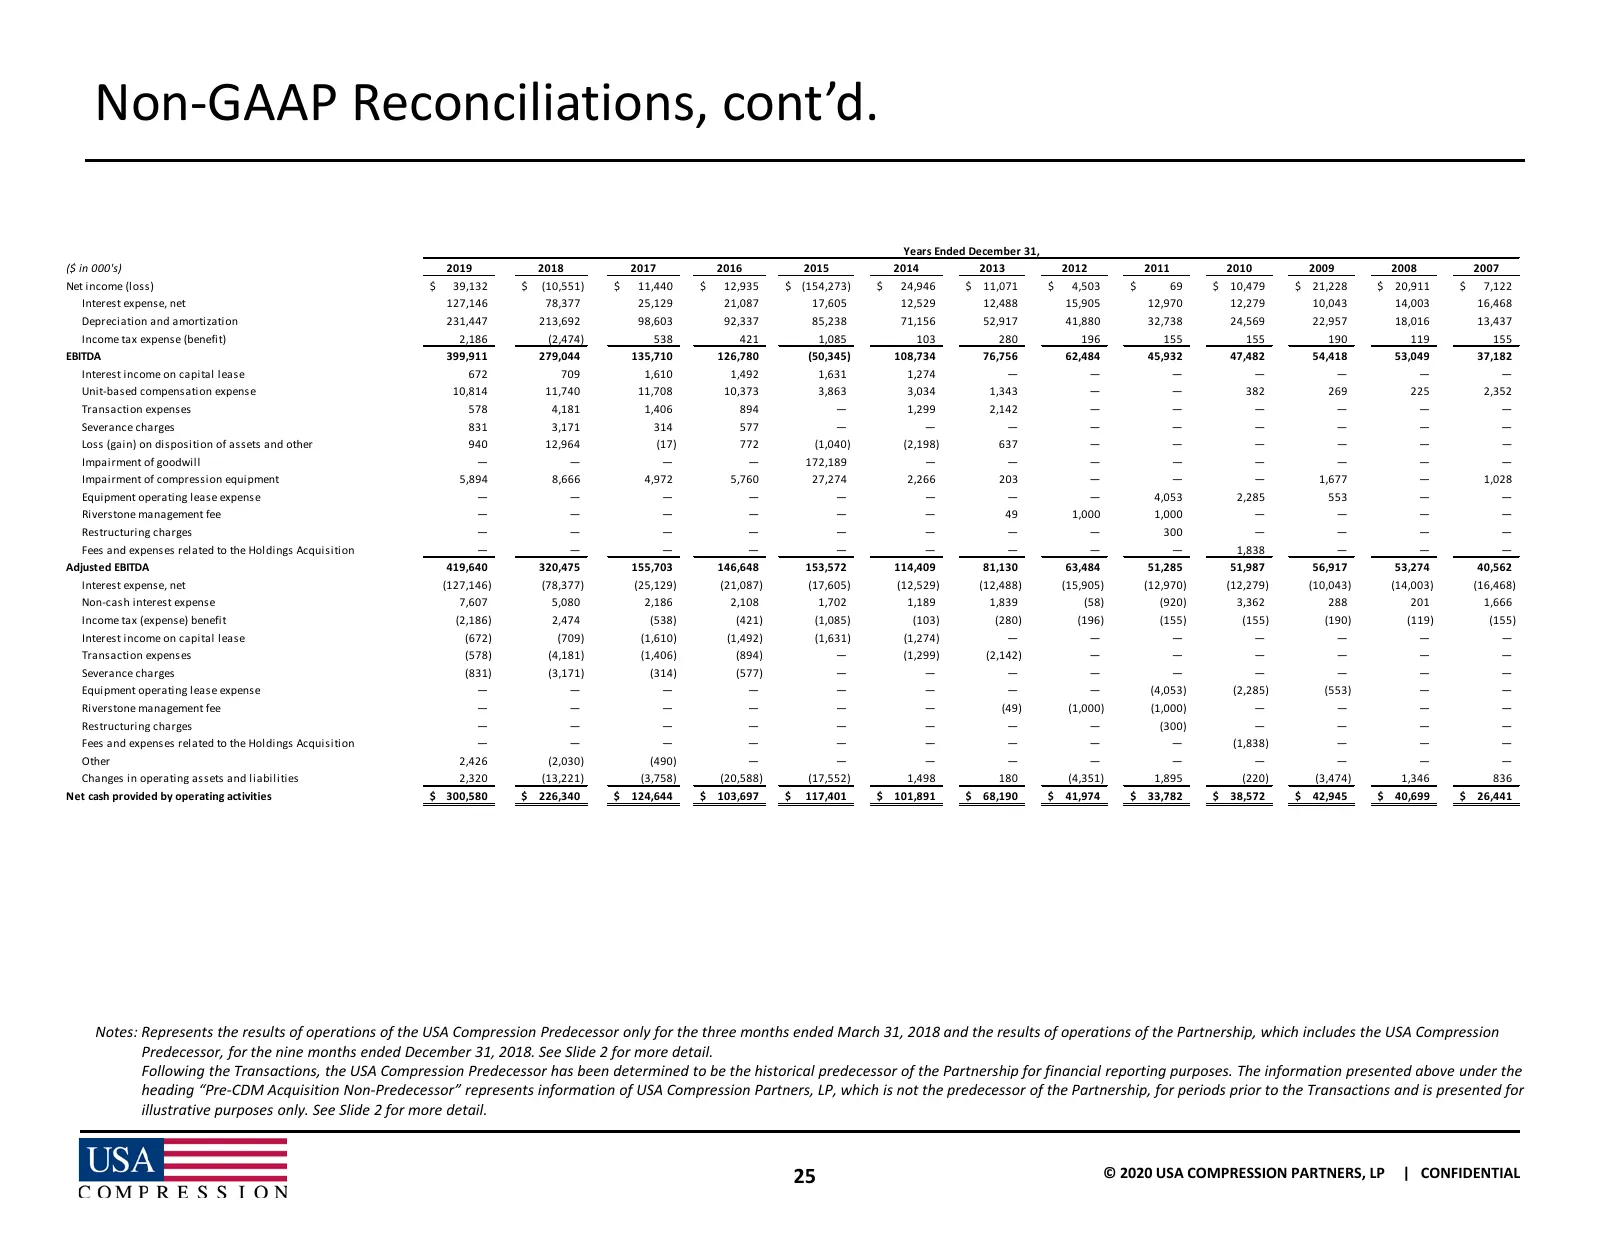
Non-GAAP Reconciliations, cont’d. Years Ended December 31, ($ in 000's) 2019 2018 2017 2016 2015 2014 2013 2012 2011 2010 2009 2008 2007 Net income (loss) $ 39,132 $ (10,551) $ 11,440 $ 12,935 $ (154,273) $ 24,946 $ 11,071 $ 4,503 $ 69 $ 10,479 $ 21,228 $ 20,911 $ 7,122 Interest expense, net 127,146
Slide 27: Non-GAAP Reconciliations, cont'd.
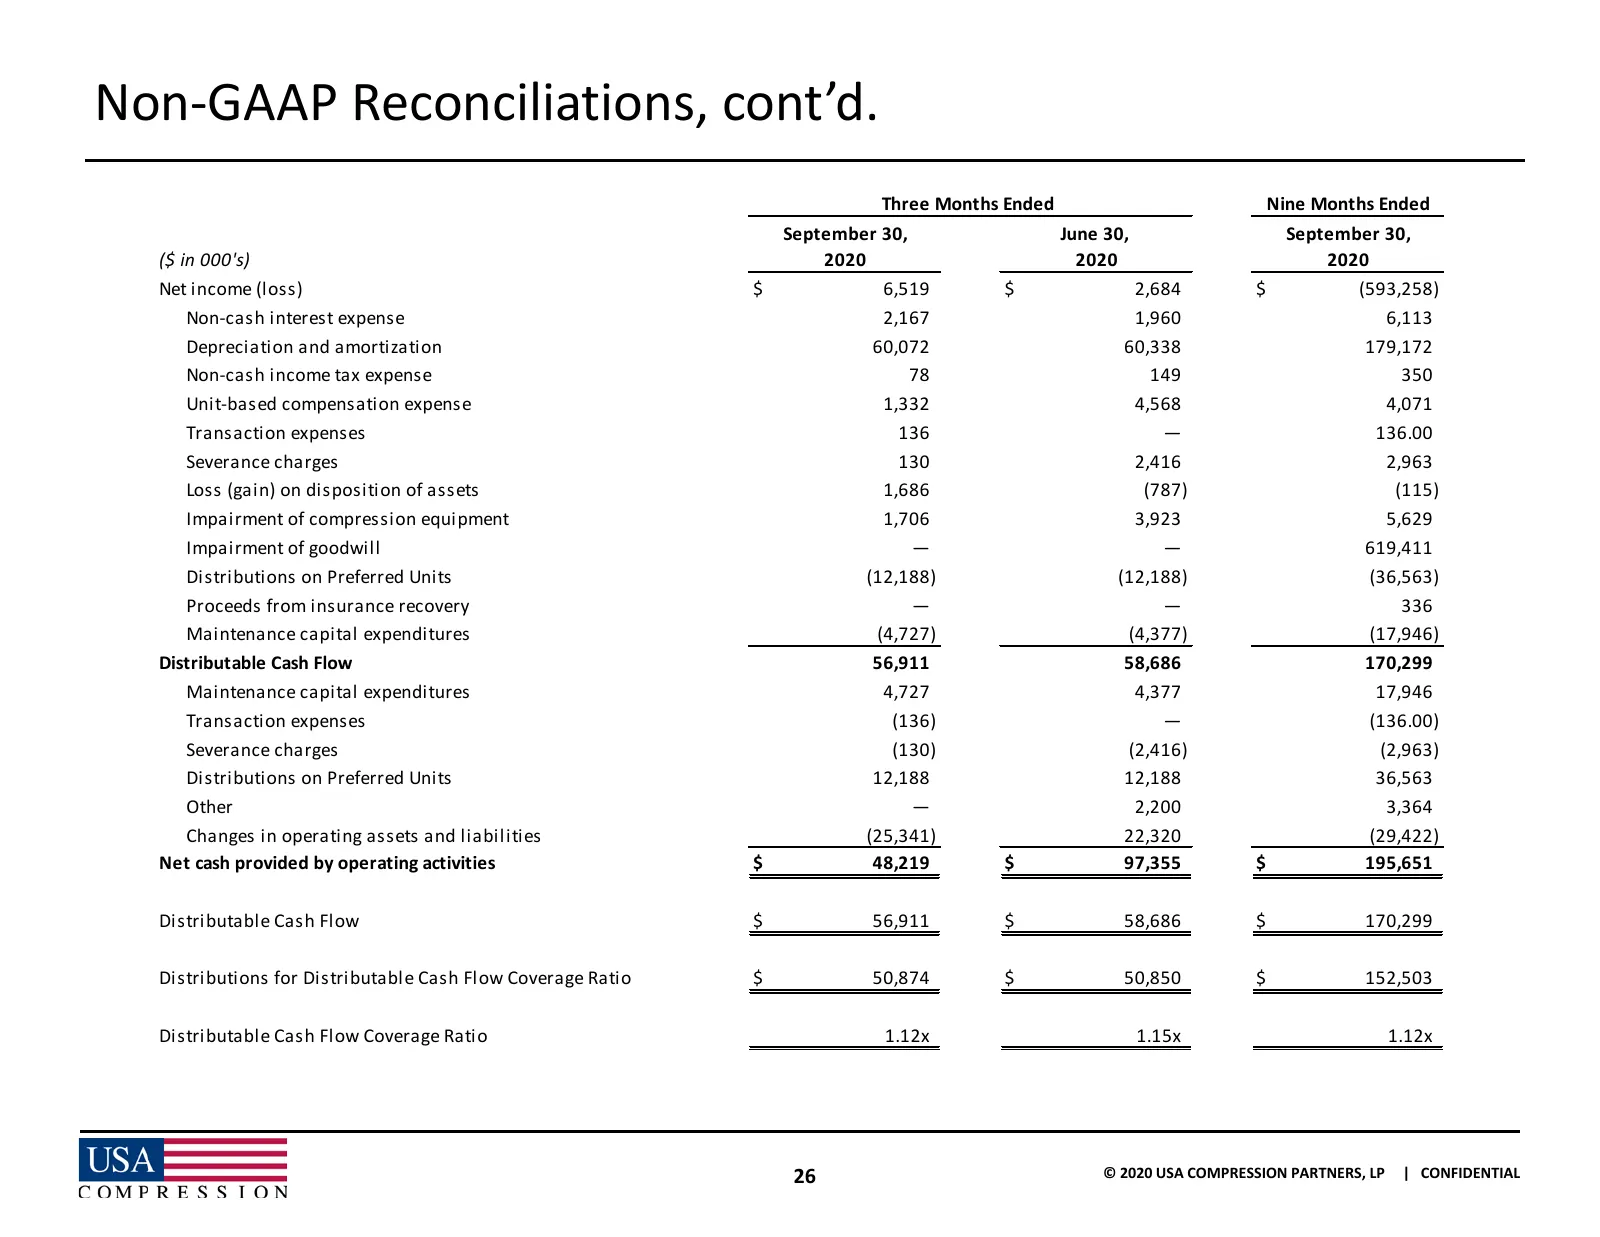
Non-GAAP Reconciliations, cont’d. Three Months Ended Nine Months Ended September 30, June 30, September 30, ($ in 000's) 2020 2020 2020 Net income (loss) $ 6,519 $ 2,684 $ (593,258) Non-cash interest expense 2,167 1,960 6,113 Depreciation and amortization 60,072 60,338 179,172 Non-cash income tax ex
Slide 28: Non-GAAP Reconciliations, cont'd. – 2020 Guidance
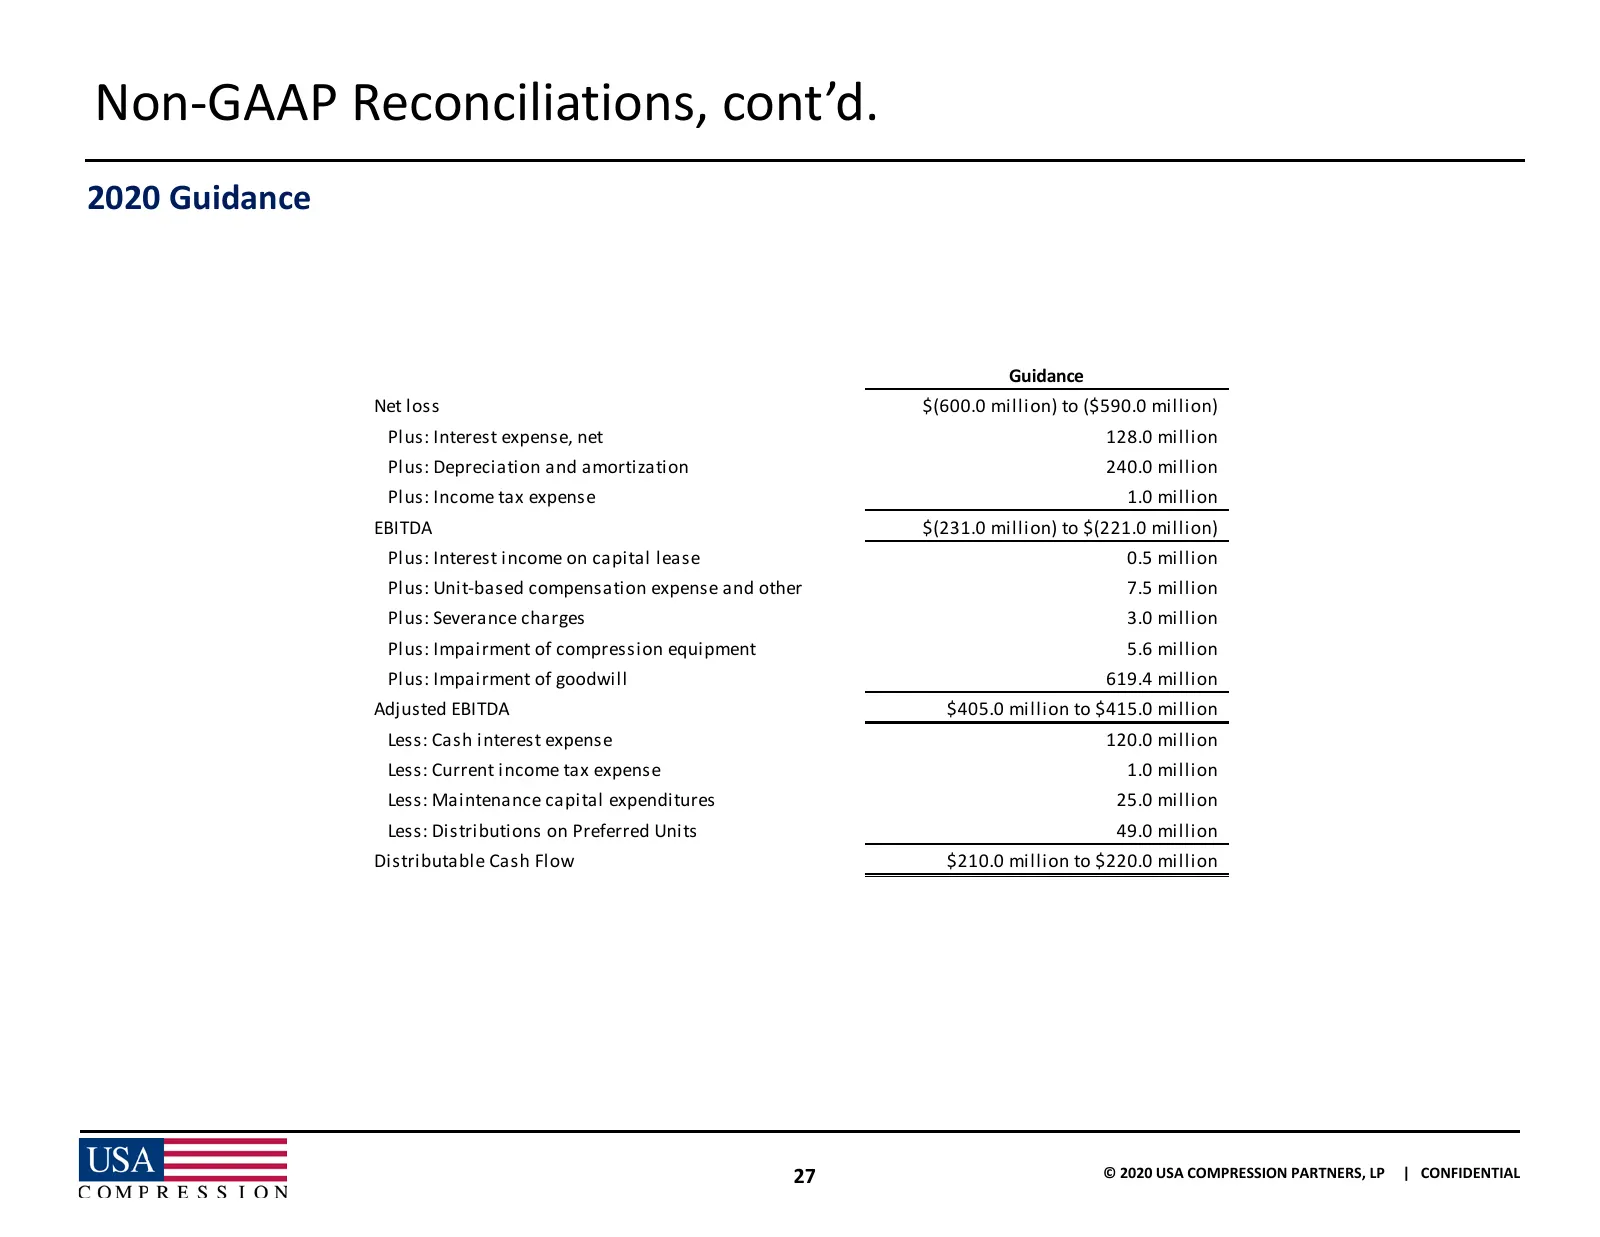
Non-GAAP Reconciliations, cont’d. 2020 Guidance Guidance Net loss $(600.0 million) to ($590.0 million) Plus: Interest expense, net 128.0 million Plus: Depreciation and amortization 240.0 million Plus: Income tax expense 1.0 million EBITDA $(231.0 million) to $(221.0 million) Plus: Interest income on
Slide 29: Basis of Presentation; Explanation of Non-GAAP Financial Measures
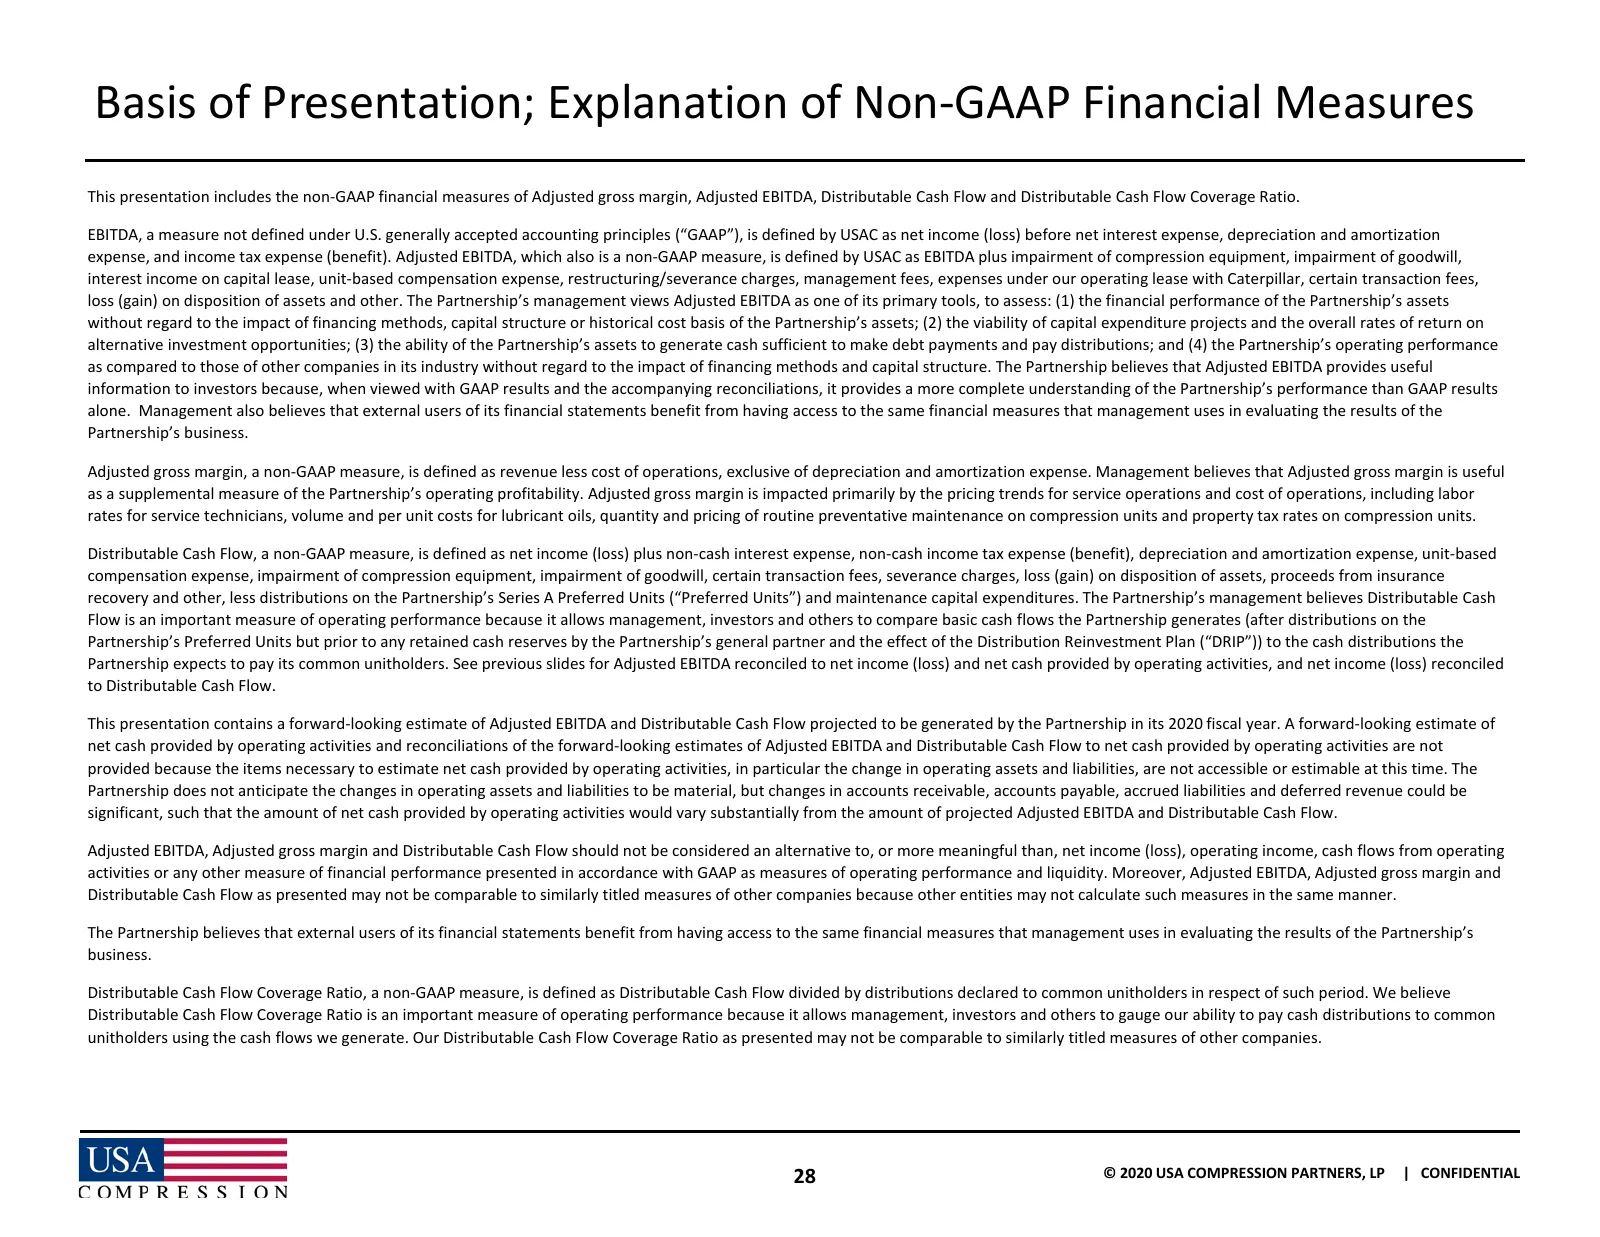
Basis of Presentation; Explanation of Non-GAAP Financial Measures This presentation includes the non-GAAP financial measures of Adjusted gross margin, Adjusted EBITDA, Distributable Cash Flow and Distributable Cash Flow Coverage Ratio. EBITDA, a measure not defined under U.S. generally accepted acco
Source: company website
More decks from USA Compression Partners, LP
 Q3 2026 Earnings Presentation11 slides · Nov 3, 2026
 Q2 2026 Earnings Presentation11 slides · Aug 4, 2026
 Citi 2026 Natural Resources Conference20 slides · August 2026
 RBC Global Energy, Power and Infrastructure Conference 202620 slides · June 2026
 Q1 2026 Earnings Presentation11 slides · May 5, 2026
 J.P. Morgan Global Leveraged Finance Conference 202619 slides · Mar 2, 2026