Mega First Corp. Bhd. · MYX:MFCB
Mega First Corp. Bhd — Q1 2023 Earnings Presentation
26 slides from Mega First Corp. Bhd's earnings presentation, May 25, 2023
Slide 1: 1Q2023 Results Briefing
1Q2023 RESULTS BRIEFING 25 May 2023
Slide 2: Agenda
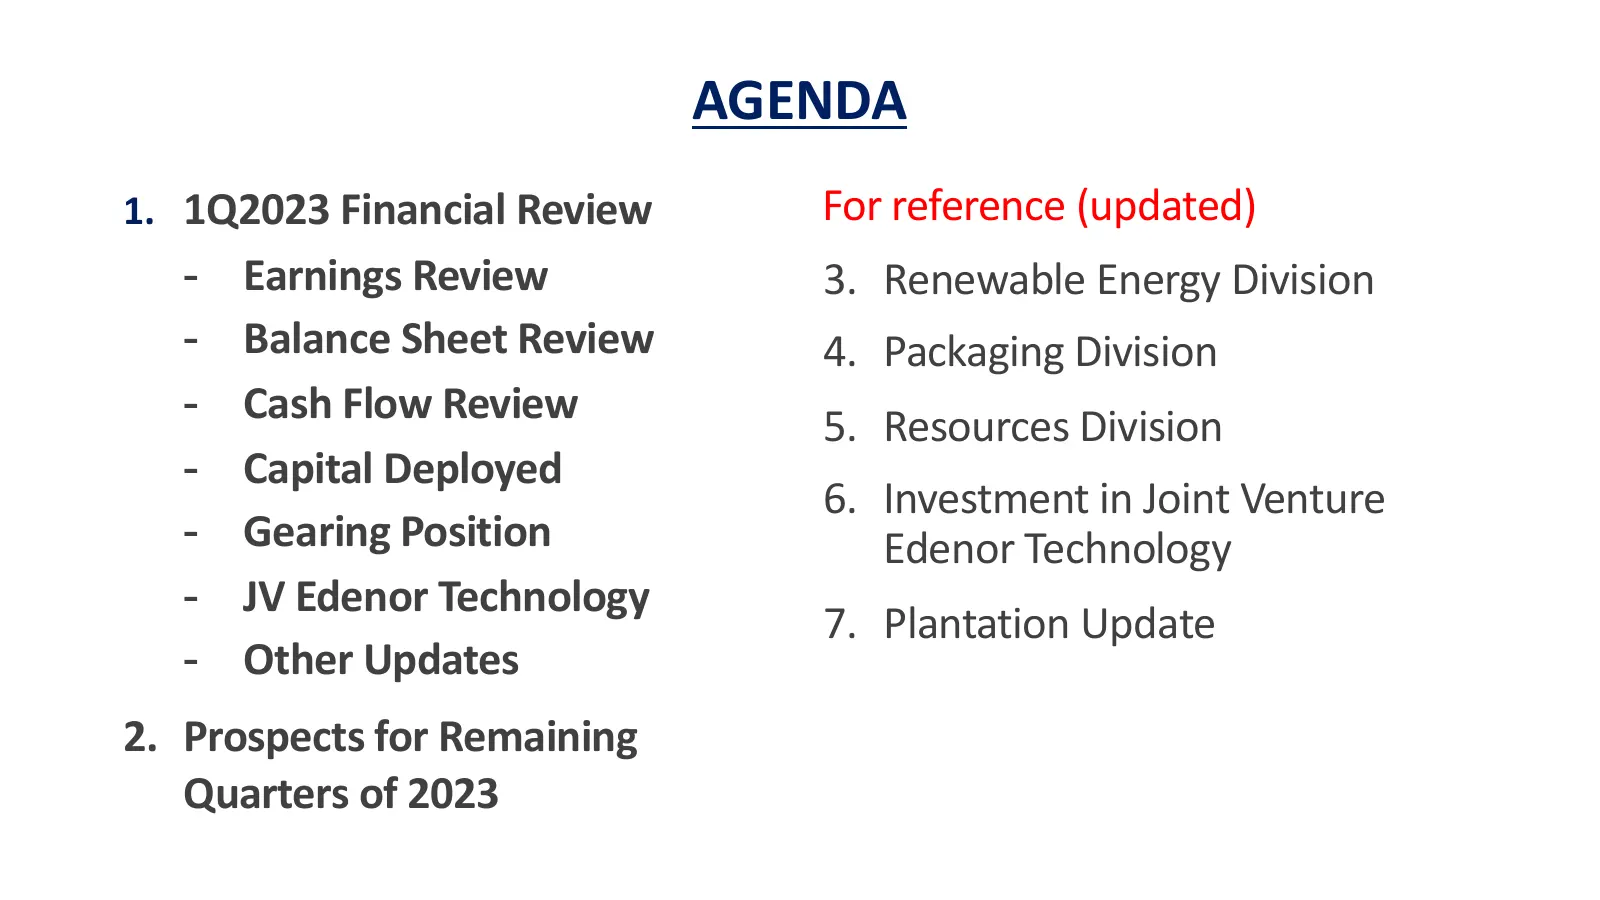
AGENDA 1. 1Q2023 Financial Review For reference (updated) - Earnings Review 3. Renewable Energy Division - Balance Sheet Review 4. Packaging Division - Cash Flow Review 5. Resources Division - Capital Deployed 6. Investment in Joint Venture - Gearing Position Edenor Technology - JV Edenor Technology
Slide 3: 1Q2023 Earnings Review
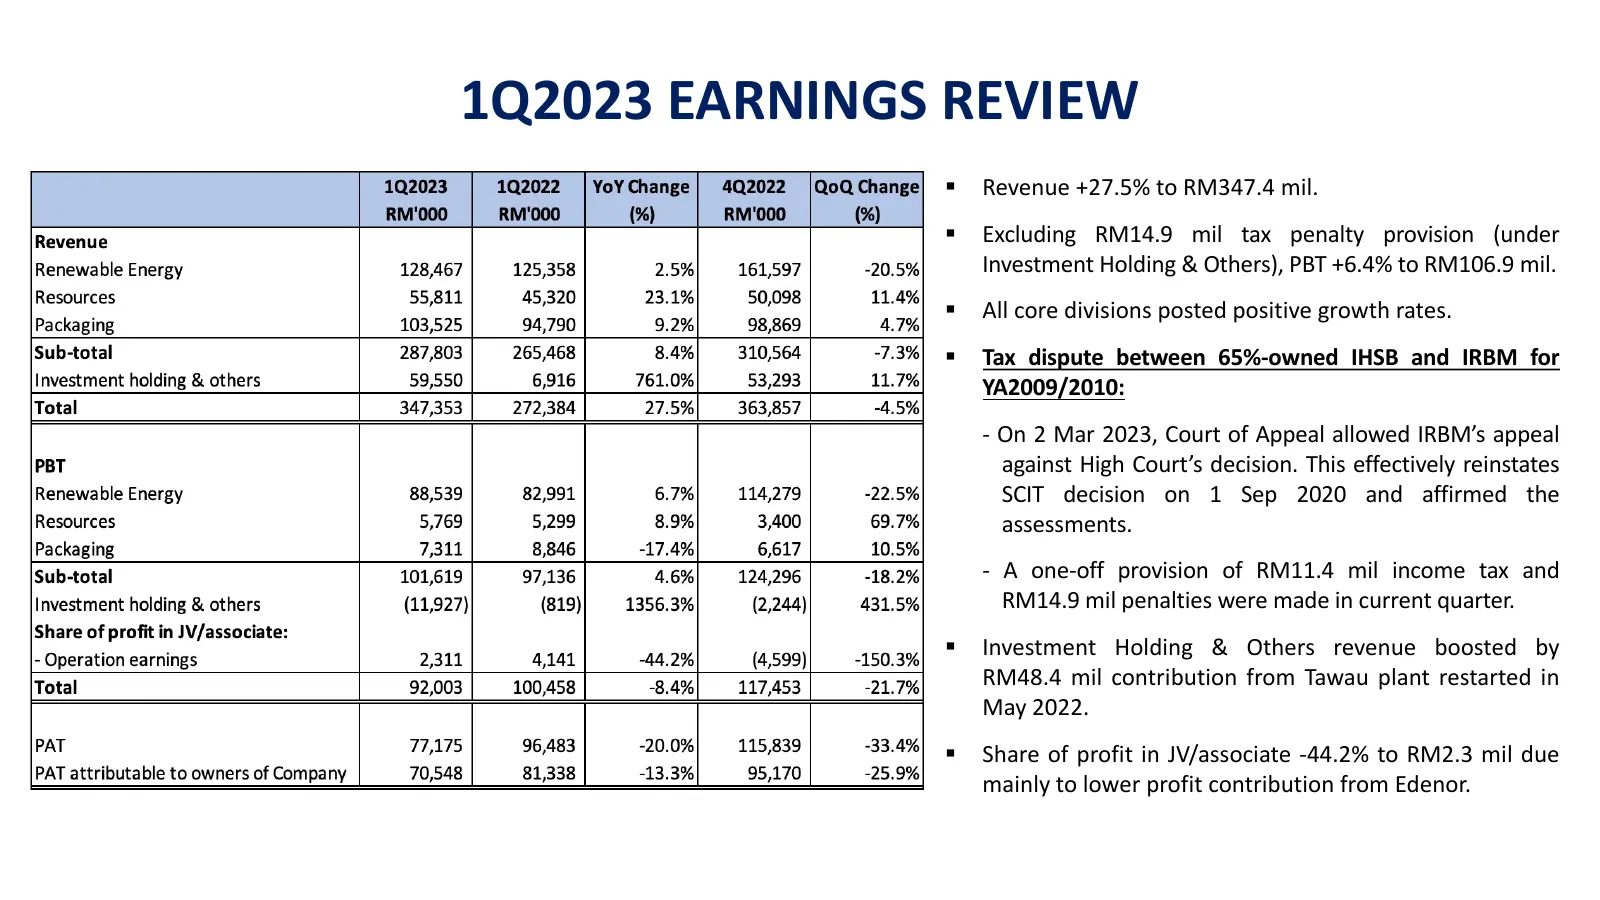
1Q2023 EARNINGS REVIEW § Revenue +27.5% to RM347.4 mil. § Excluding RM14.9 mil tax penalty provision (under Investment Holding & Others), PBT +6.4% to RM106.9 mil. § All core divisions posted positive growth rates. § Tax dispute between 65%-owned IHSB and IRBM for YA2009/2010: - On 2 Mar 2023, Court
Slide 4: Renewable Energy Division
RENEWABLE ENERGY DIVISION
Slide 5: Earnings Review - Renewable Energy Division
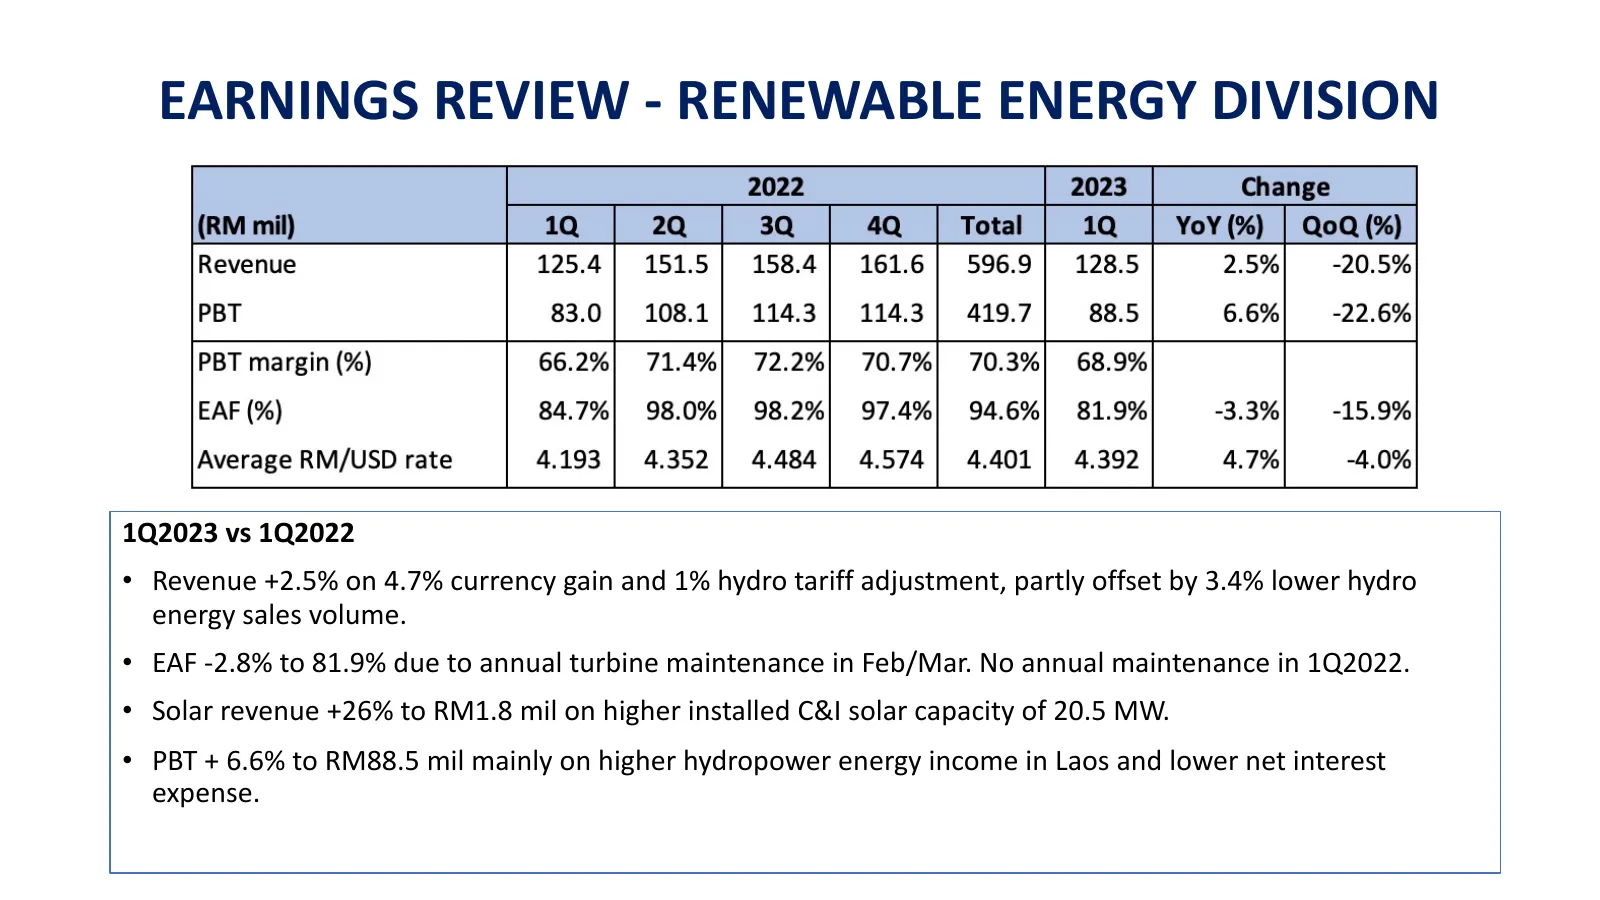
EARNINGS REVIEW - RENEWABLE ENERGY DIVISION 1Q2023 vs 1Q2022 • Revenue +2.5% on 4.7% currency gain and 1% hydro tariff adjustment, partly offset by 3.4% lower hydro energy sales volume. • EAF -2.8% to 81.9% due to annual turbine maintenance in Feb/Mar. No annual maintenance in 1Q2022. • Solar revenu
Slide 6: Renewable Energy Division - Don Sahong
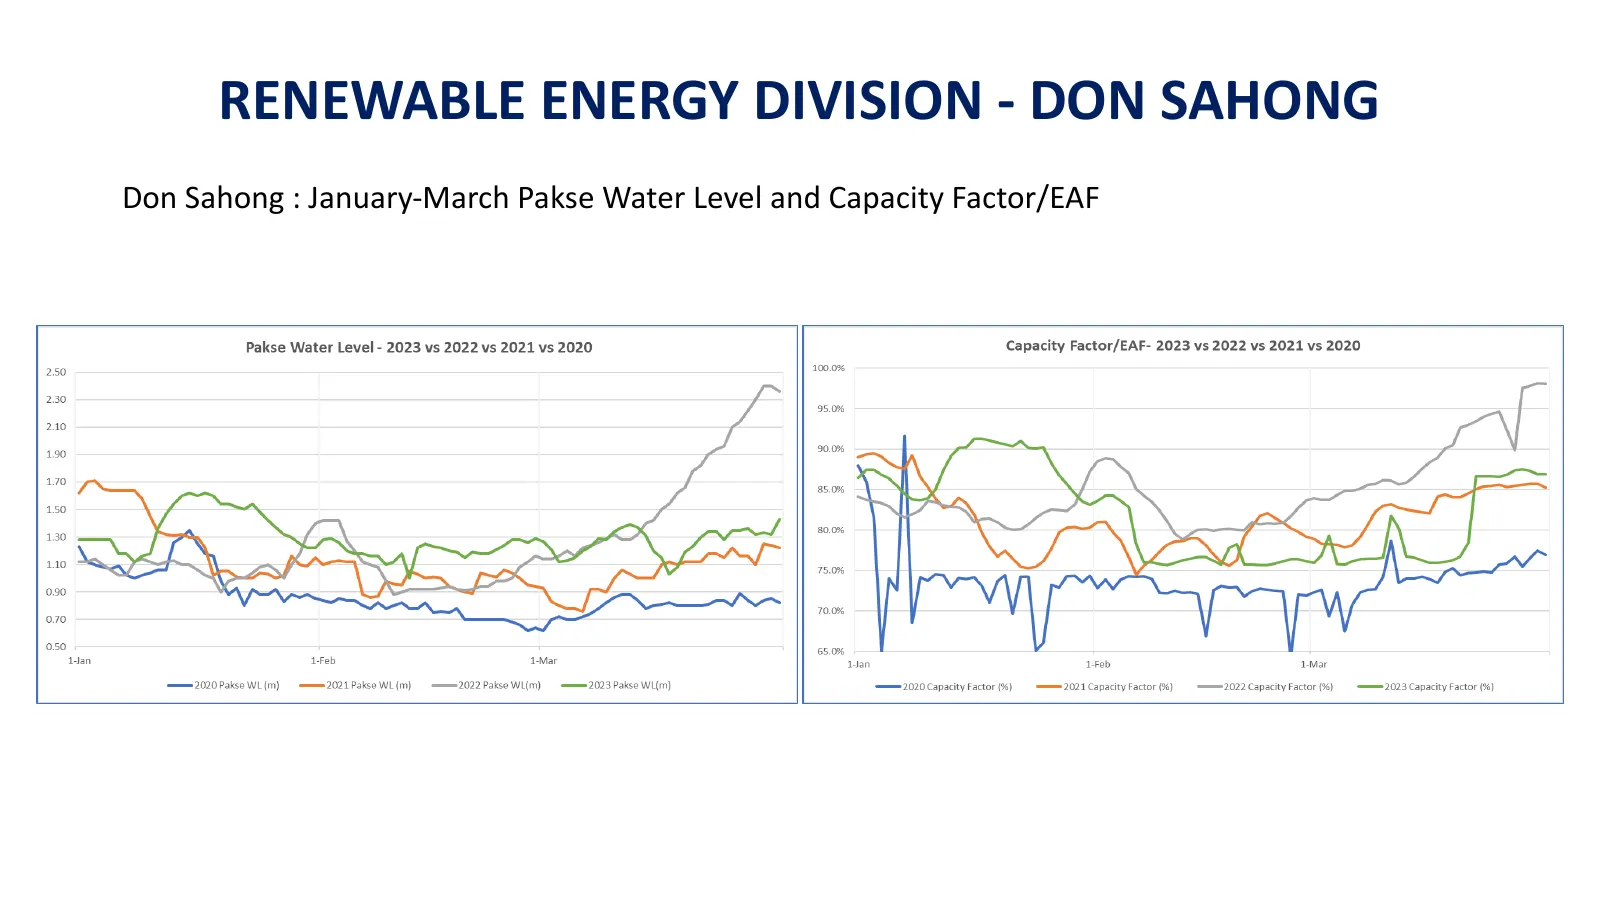
RENEWABLE ENERGY DIVISION - DON SAHONG Don Sahong : January-March Pakse Water Level and Capacity Factor/EAF
Slide 7: Resources Division
RESOURCES DIVISION
Slide 8: Earnings Review - Resources Division
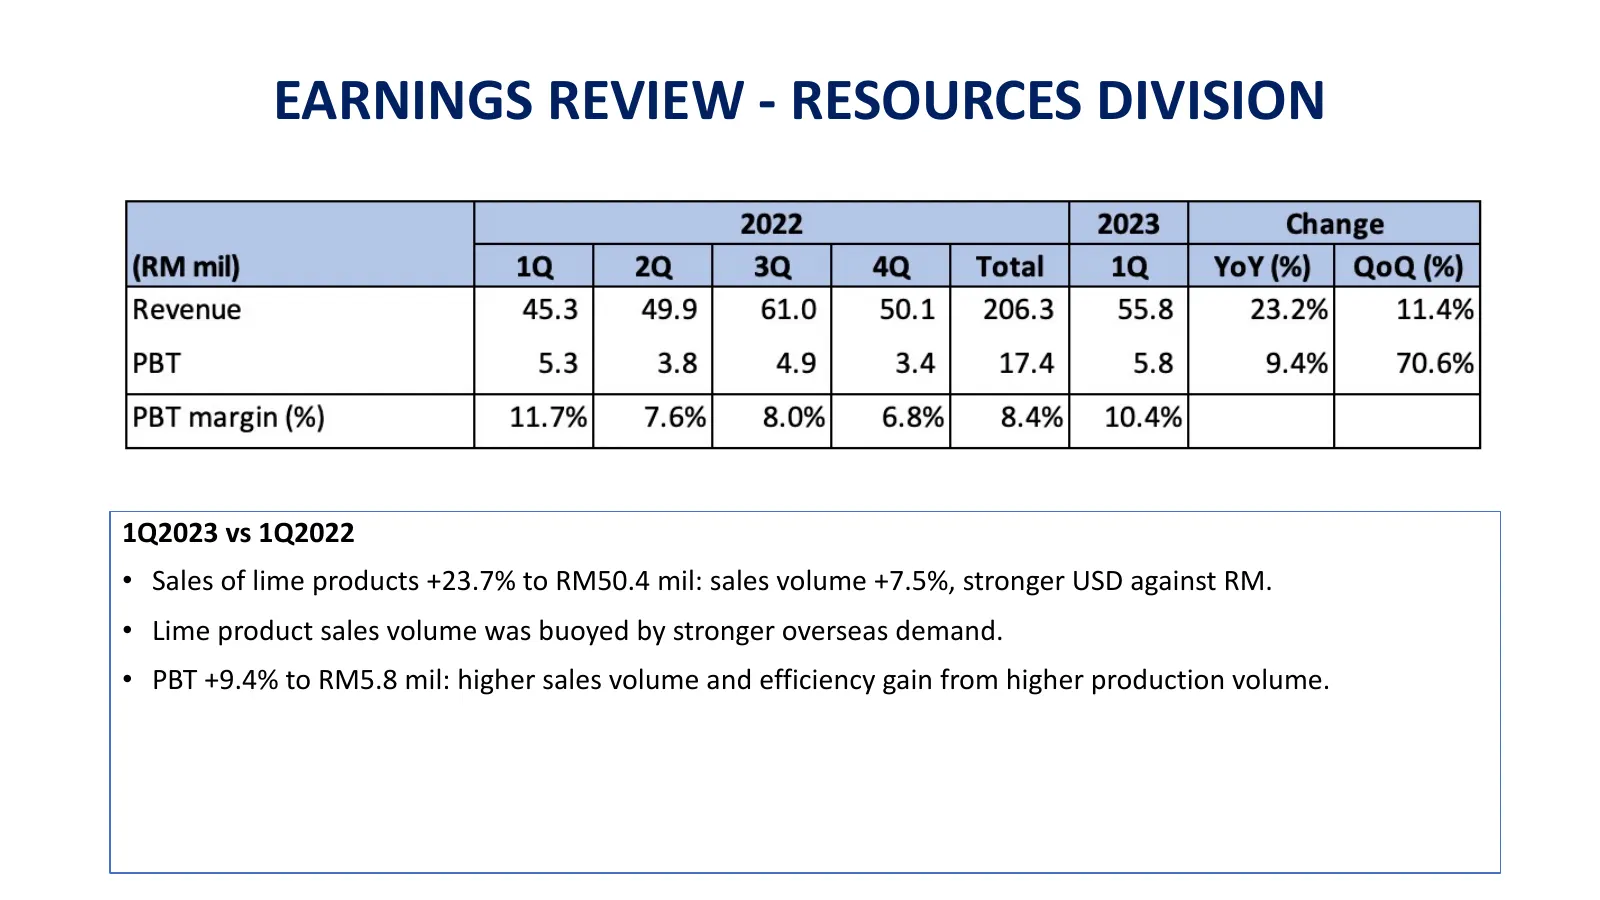
EARNINGS REVIEW - RESOURCES DIVISION 1Q2023 vs 1Q2022 • Sales of lime products +23.7% to RM50.4 mil: sales volume +7.5%, stronger USD against RM. • Lime product sales volume was buoyed by stronger overseas demand. • PBT +9.4% to RM5.8 mil: higher sales volume and efficiency gain from higher producti
Slide 9: Packaging Division
PACKAGING DIVISION
Slide 10: Earnings Review - Packaging Division
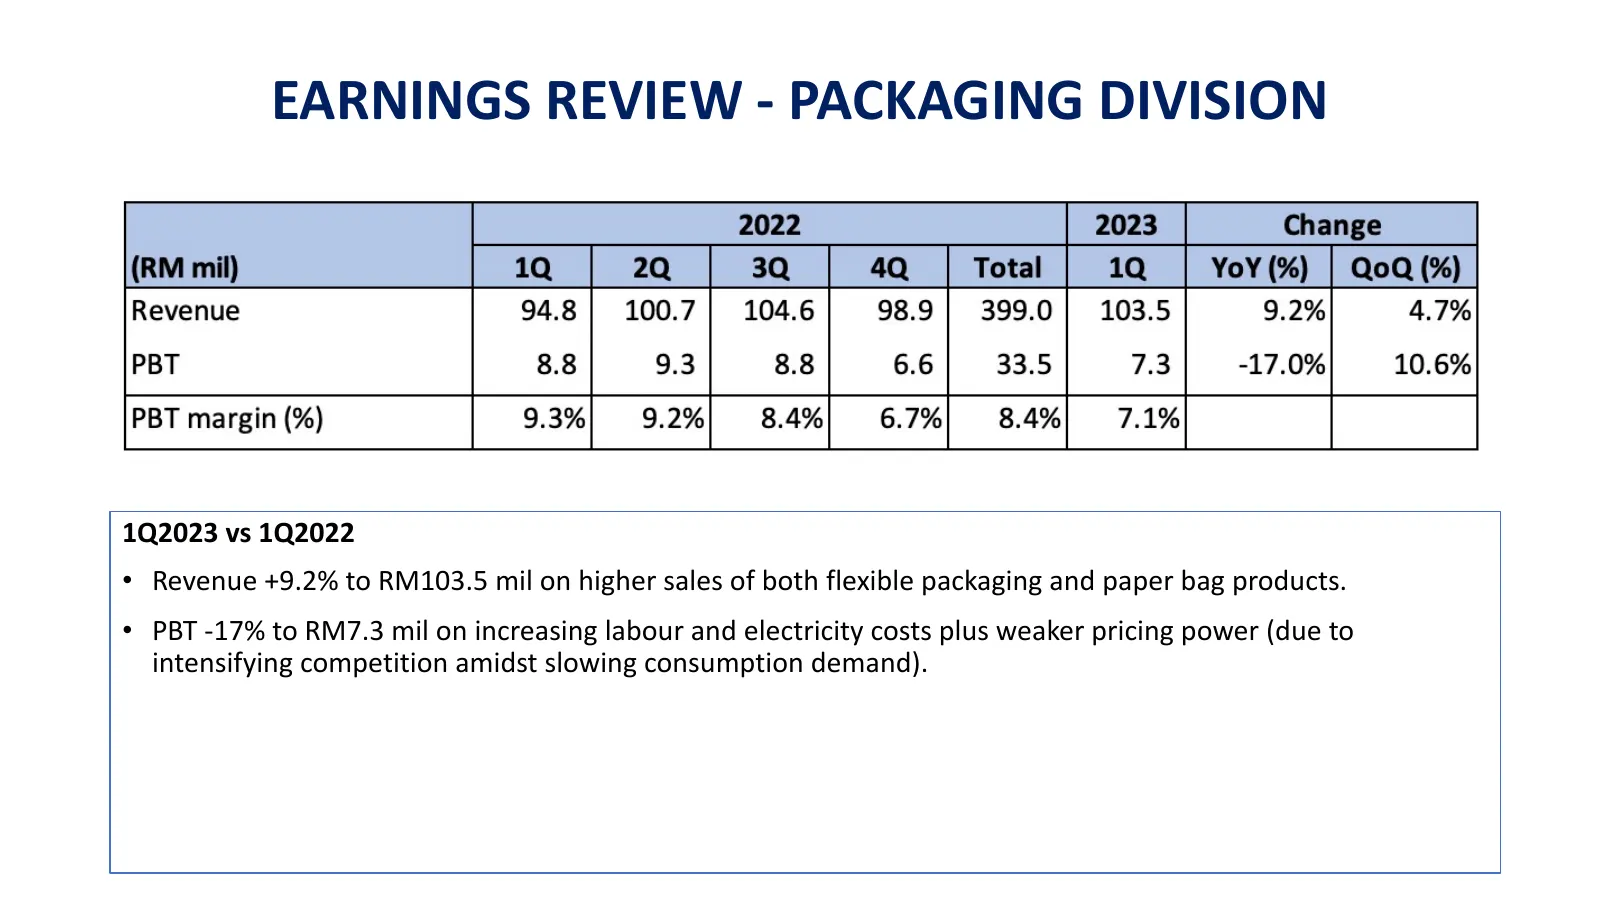
EARNINGS REVIEW - PACKAGING DIVISION 1Q2023 vs 1Q2022 • Revenue +9.2% to RM103.5 mil on higher sales of both flexible packaging and paper bag products. • PBT -17% to RM7.3 mil on increasing labour and electricity costs plus weaker pricing power (due to intensifying competition amidst slowing consump
Slide 11: Balance Sheet Review
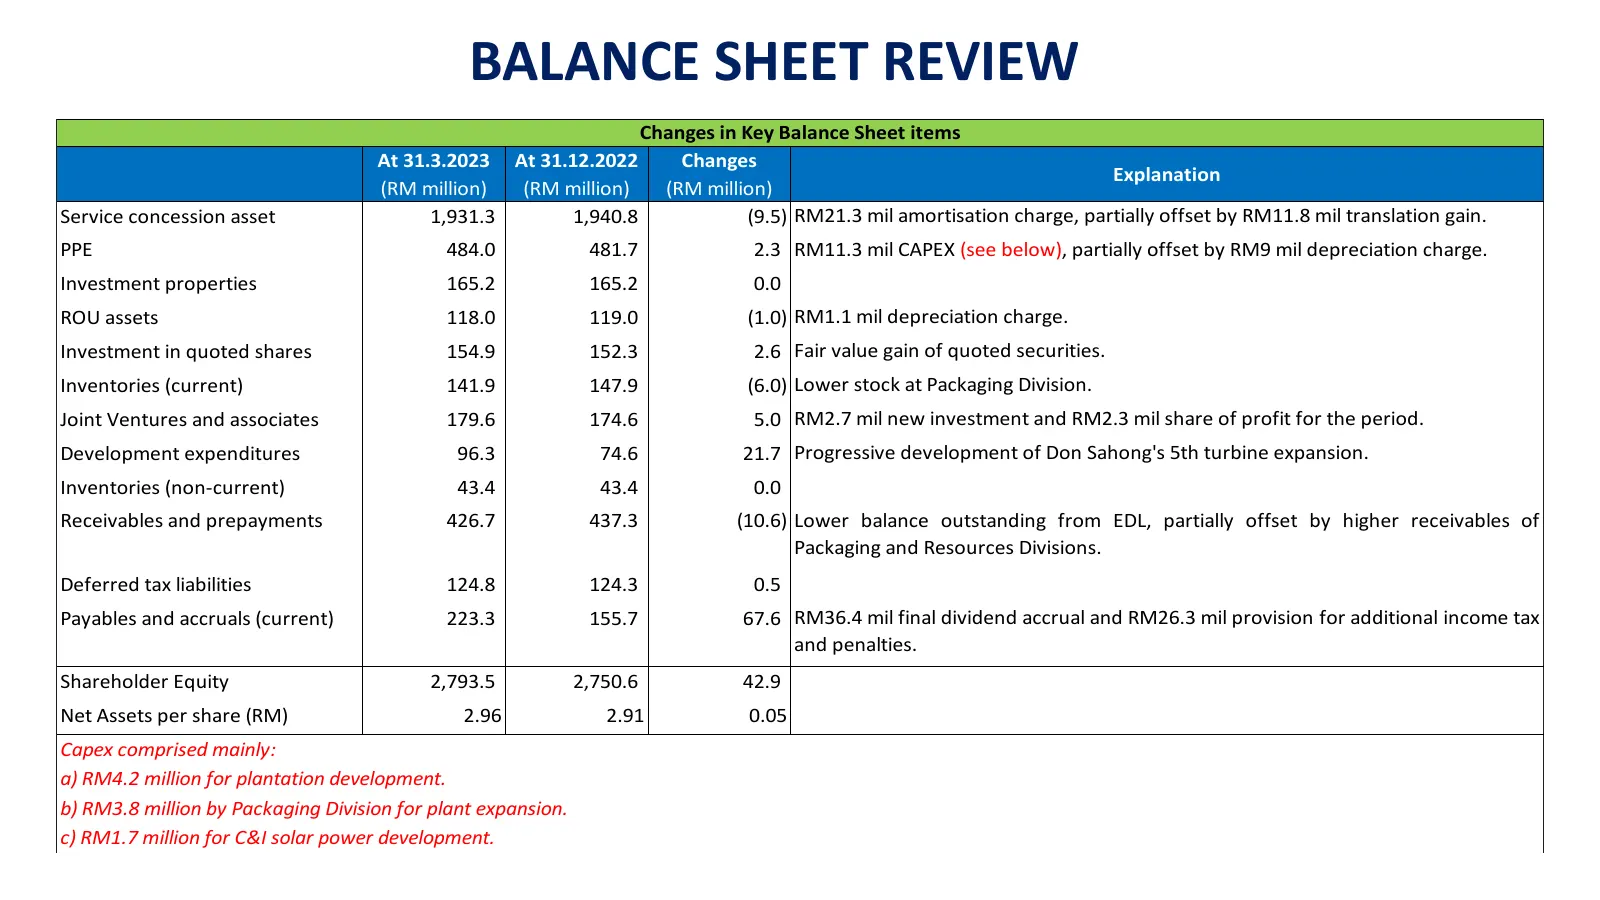
BALANCE SHEET REVIEW Changes in Key Balance Sheet items At 31.3.2023 At 31.12.2022 Changes Explanation (RM million) (RM million) (RM million) Service concession asset 1,931.3 1,940.8 (9.5) RM21.3 mil amortisation charge, partially offset by RM11.8 mil translation gain. PPE 484.0 481.7 2.3 RM11.3 mil
Slide 12: Cash Flow Review
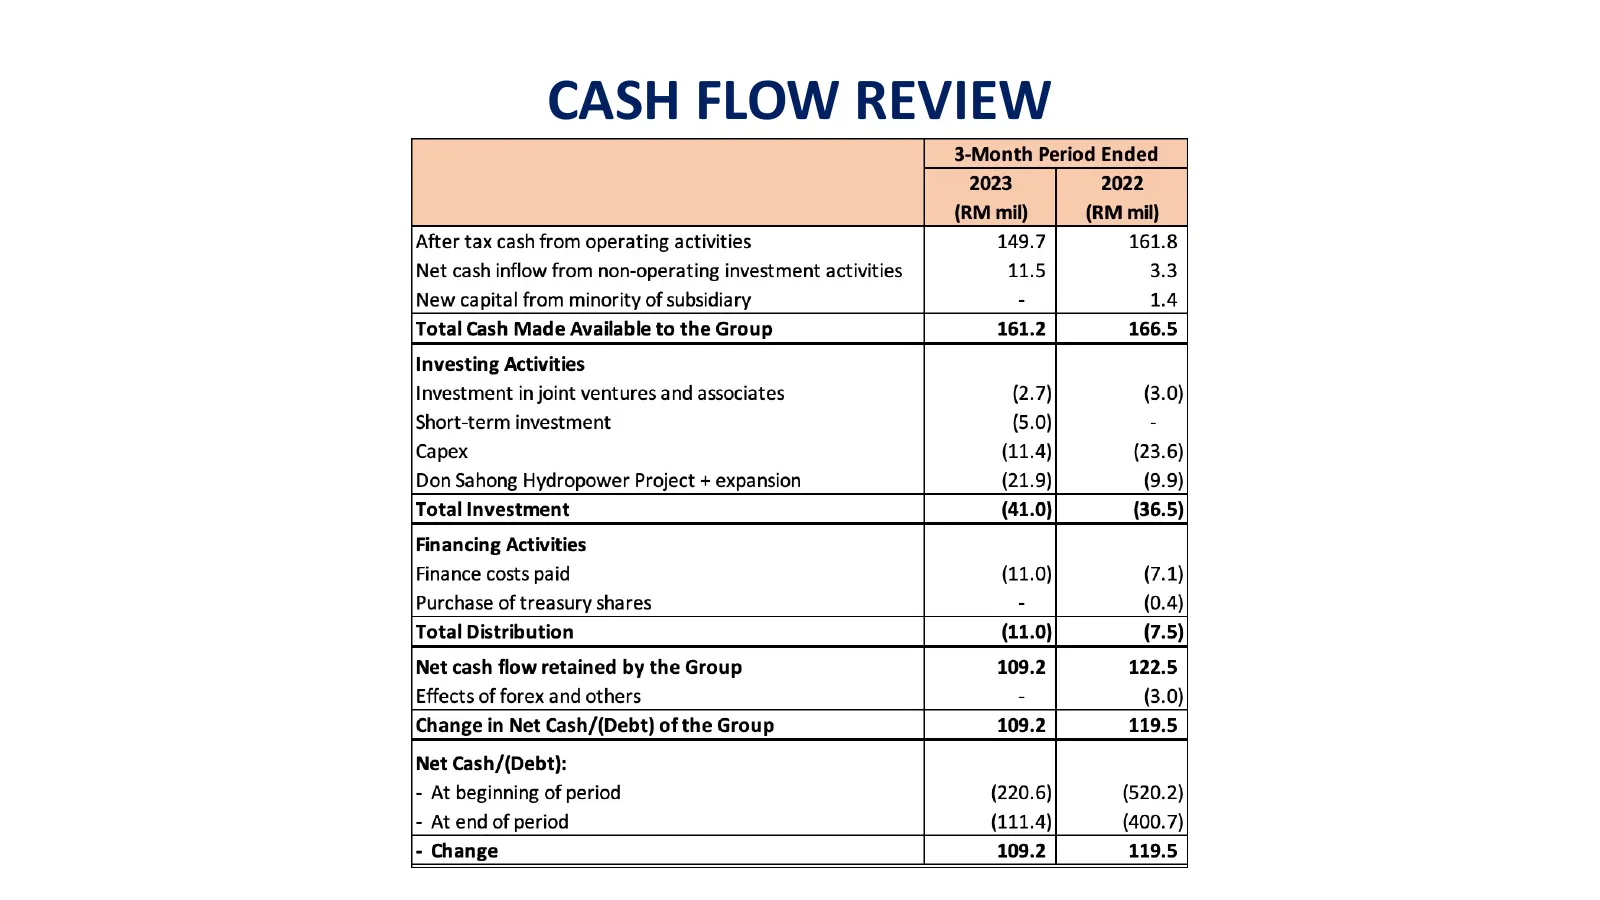
CASH FLOW REVIEW 3-Month Period Ended 2023 2022 (RM mil) (RM mil) After tax cash from operating activities 149.7 161.8 Net cash inflow from non-operating investment activities 11.5 3.3 New capital from minority of subsidiary - 1.4 Total Cash Made Available to the Group 161.2 166.5 Investing Activiti
Slide 13: Expansionary Investment Capital Deployed
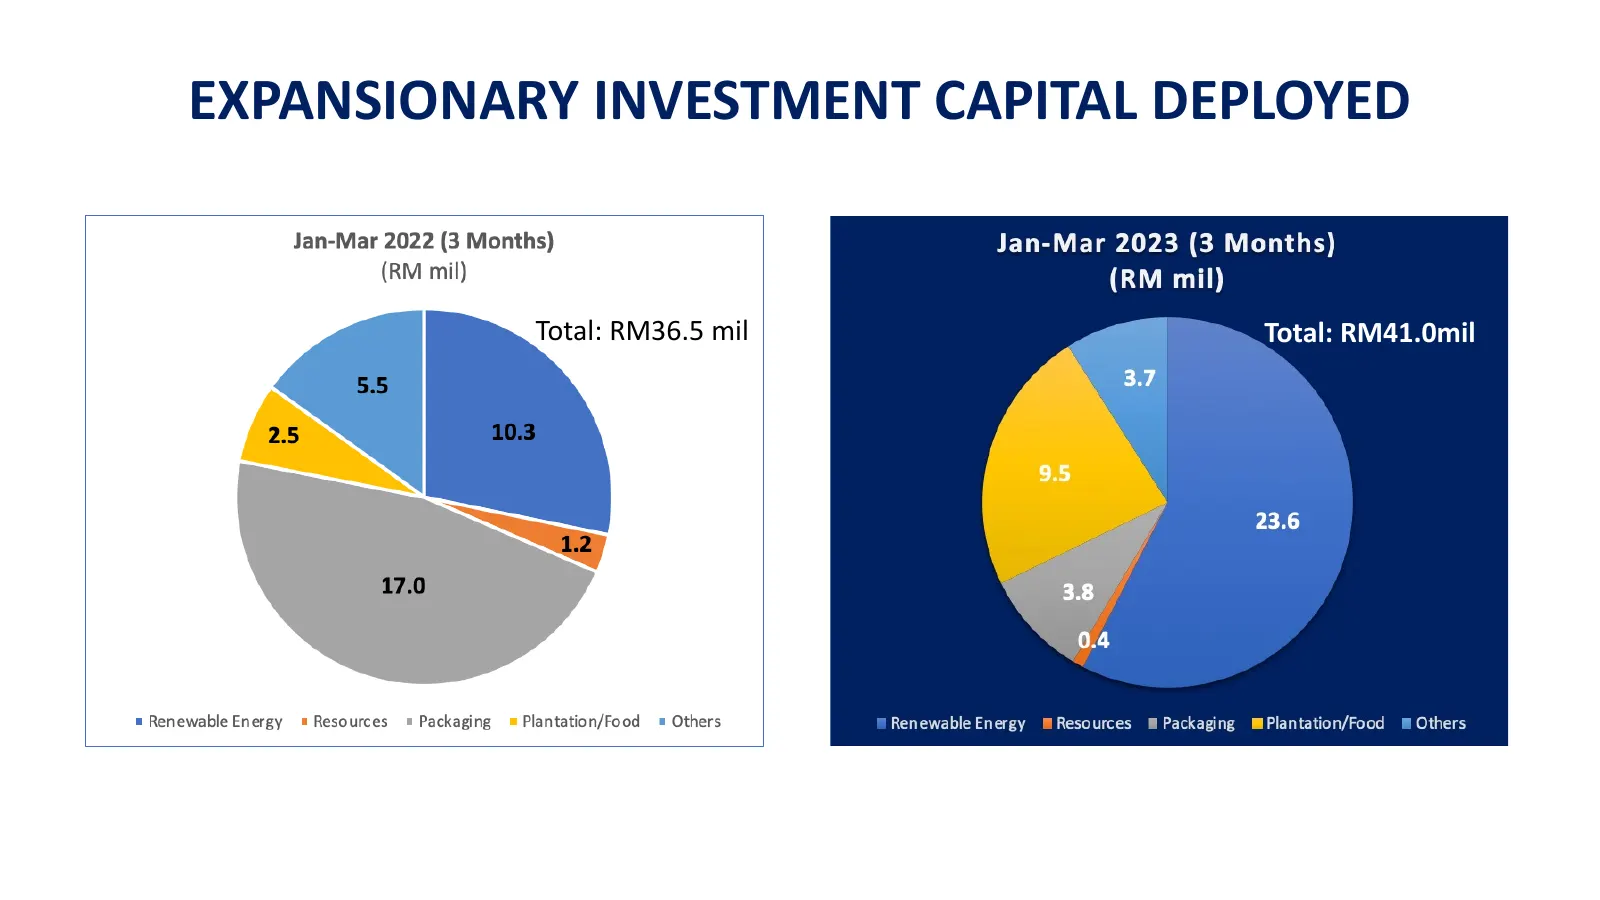
EXPANSIONARY INVESTMENT CAPITAL DEPLOYED Total: RM36.5 mil Total: RM41.0mil
Slide 14: Gearing Position
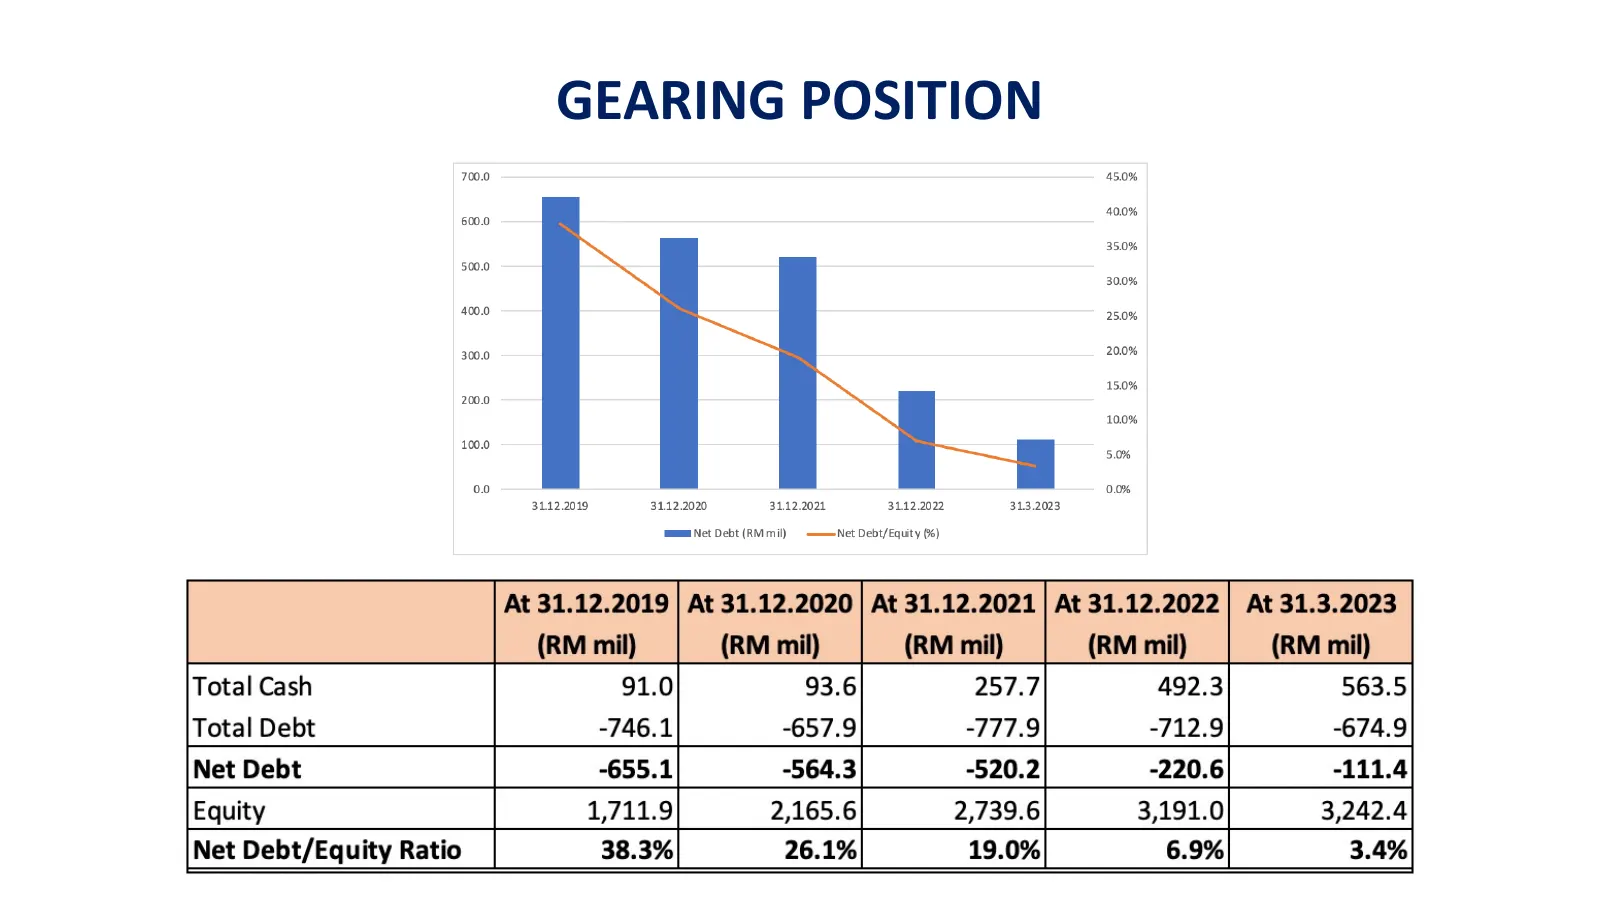
700.0 600.0 500.0 400.0 300.0 200.0 100.0 oo GEARING POSITION 3112.2019 312.2020 31.12.2021 3112.2022 313.2023 mmm Net Debt (RM mil) ——Net Debt/Equity 66) At 31.12.2019 | At 31.12.2020 | At 31.12.2021 | At 31.12.2022] At 31.3.2023 (RM mil) (RM mil) (RM mil) (RM mil) (RM mil) Total Cash 91.0 93.6 257
Slide 15: JV Edenor Technology
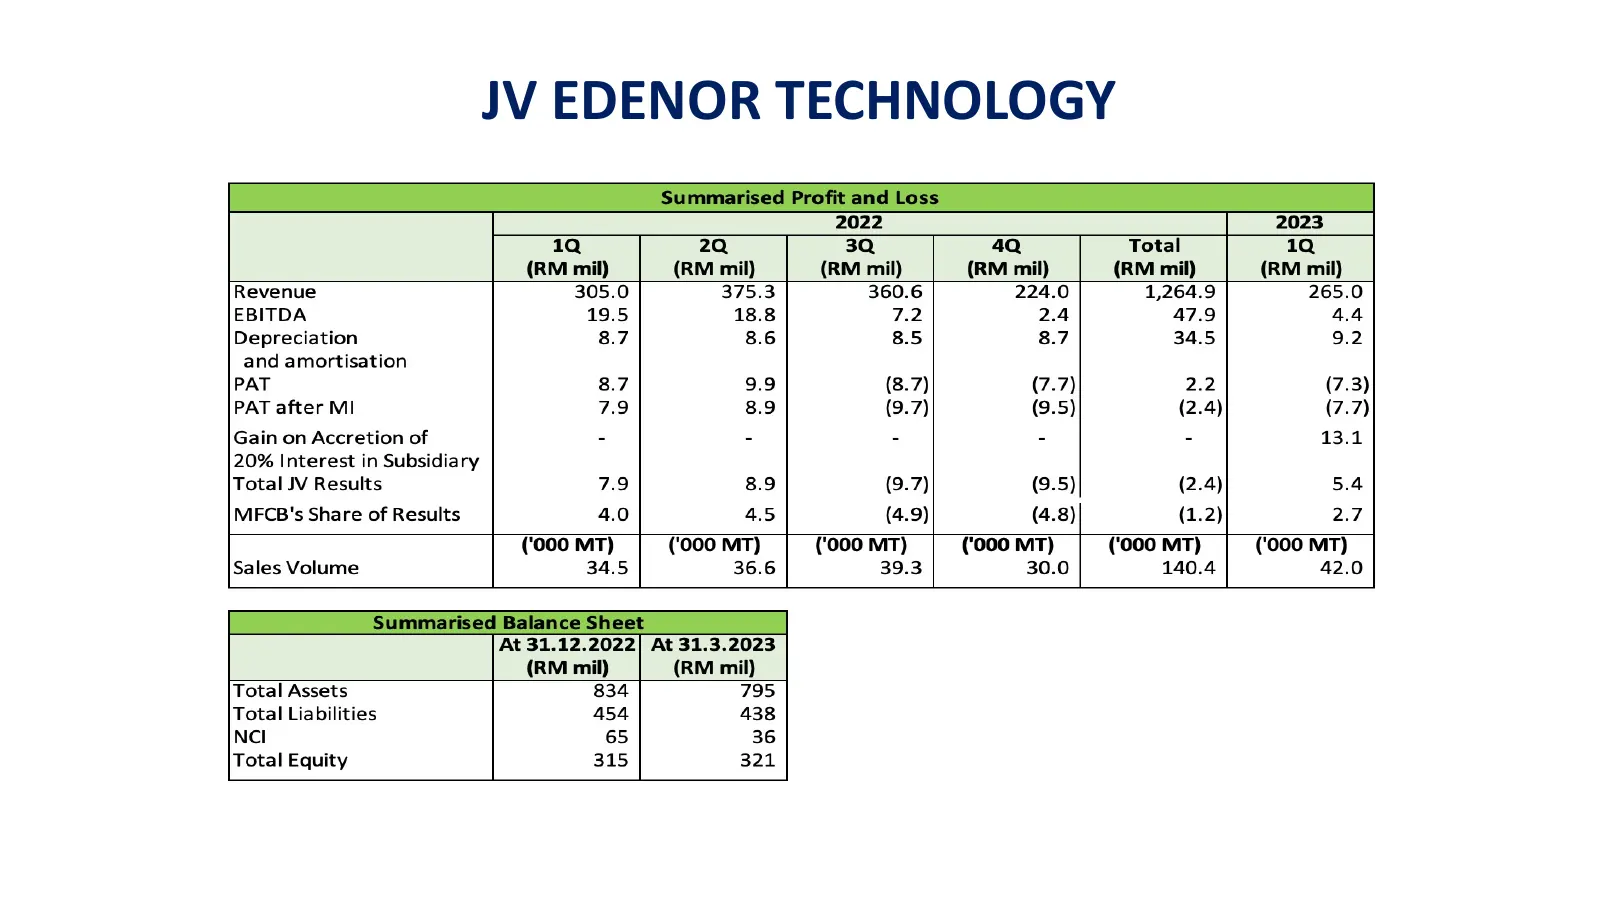
JV EDENOR TECHNOLOGY 2022 2023 1Q 2Q 3Q 4Q Total 1Q (RM mil) (RM mil) (RM mil) (RM mil) (RM mil) (RM mil) Revenue 305.0 375.3 360.6 224.0 1,264.9 265.0 EBITDA 19.5 18.8 T2 2.4 47.9 4.4 Depreciation 8.7 8.6 8.5 8.7 34.5 9.2 and amortisation PAT 8.7 9.9 (8.7) (7.7) 2.2 (7.3) PAT after MI 79 8.9 (9.7)
Slide 16: Other Updates
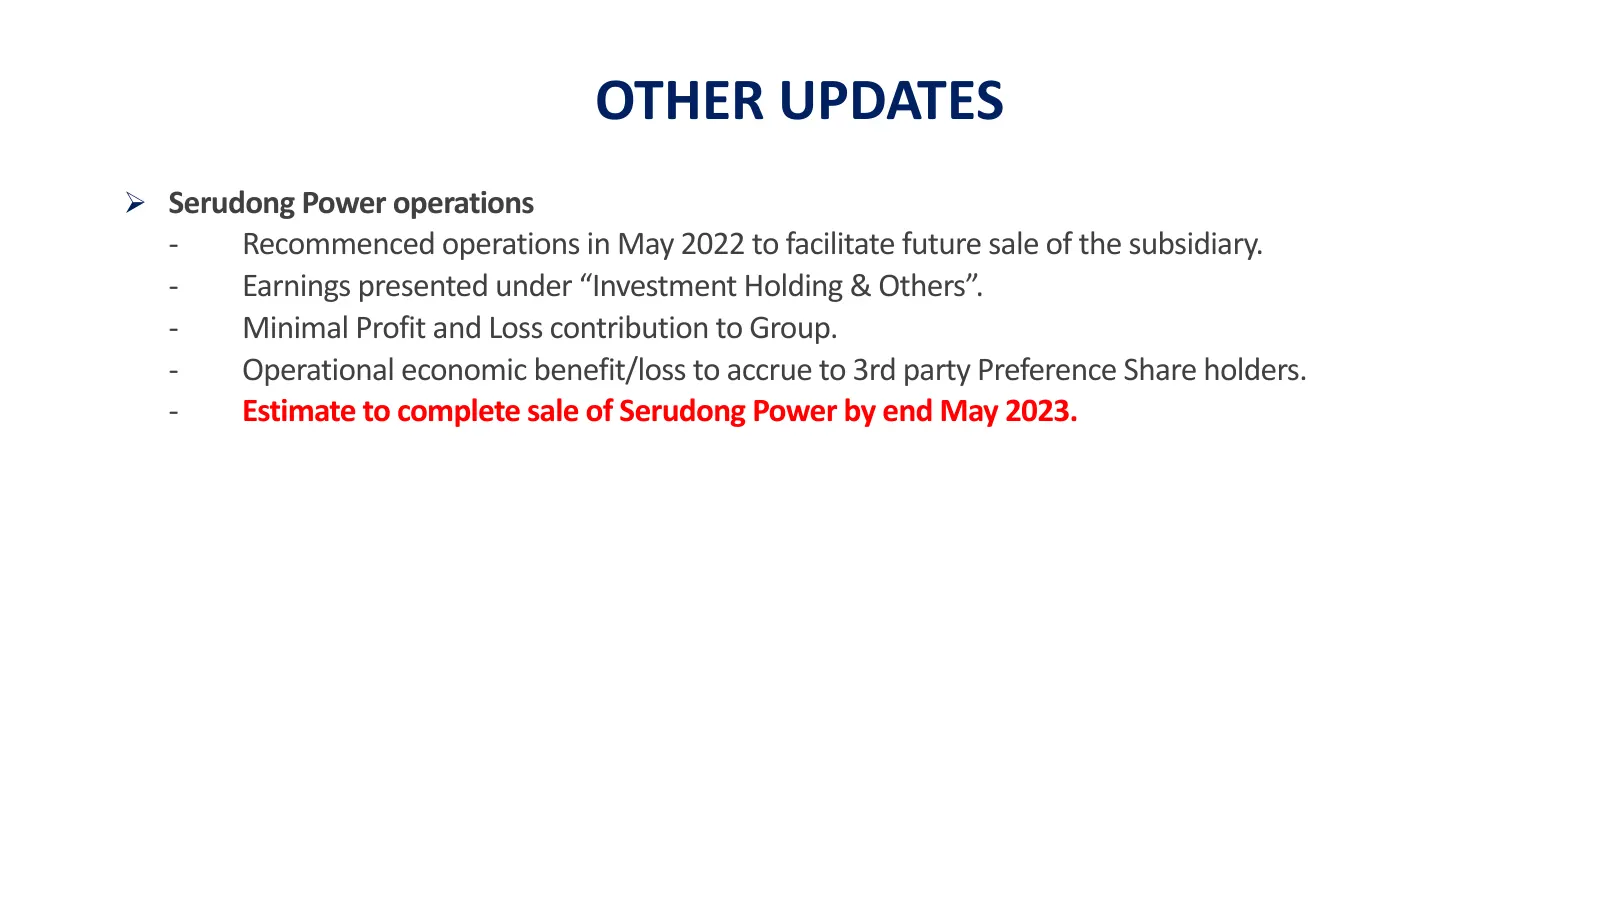
OTHER UPDATES Ø Serudong Power operations - Recommenced operations in May 2022 to facilitate future sale of the subsidiary. - Earnings presented under “Investment Holding & Others”. - Minimal Profit and Loss contribution to Group. - Operational economic benefit/loss to accrue to 3rd party Preference
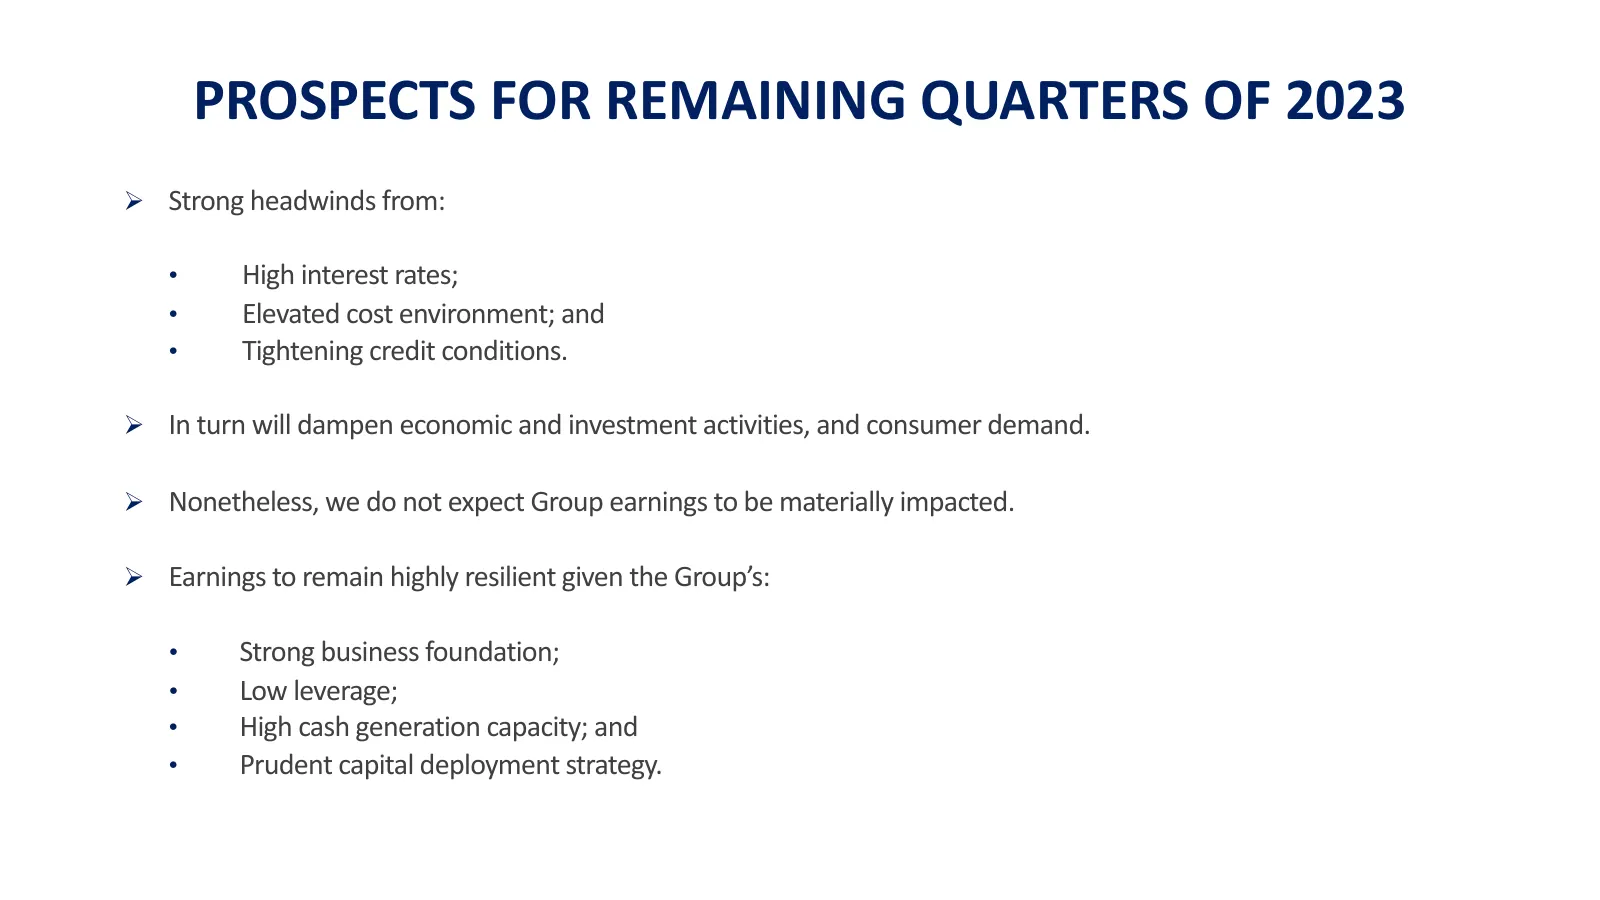
Slide 17: Prospects for Remaining Quarters of 2023
PROSPECTS FOR REMAINING QUARTERS OF 2023 Ø Strong headwinds from: • High interest rates; • Elevated cost environment; and • Tightening credit conditions. Ø In turn will dampen economic and investment activities, and consumer demand. Ø Nonetheless, we do not expect Group earnings to be materially imp
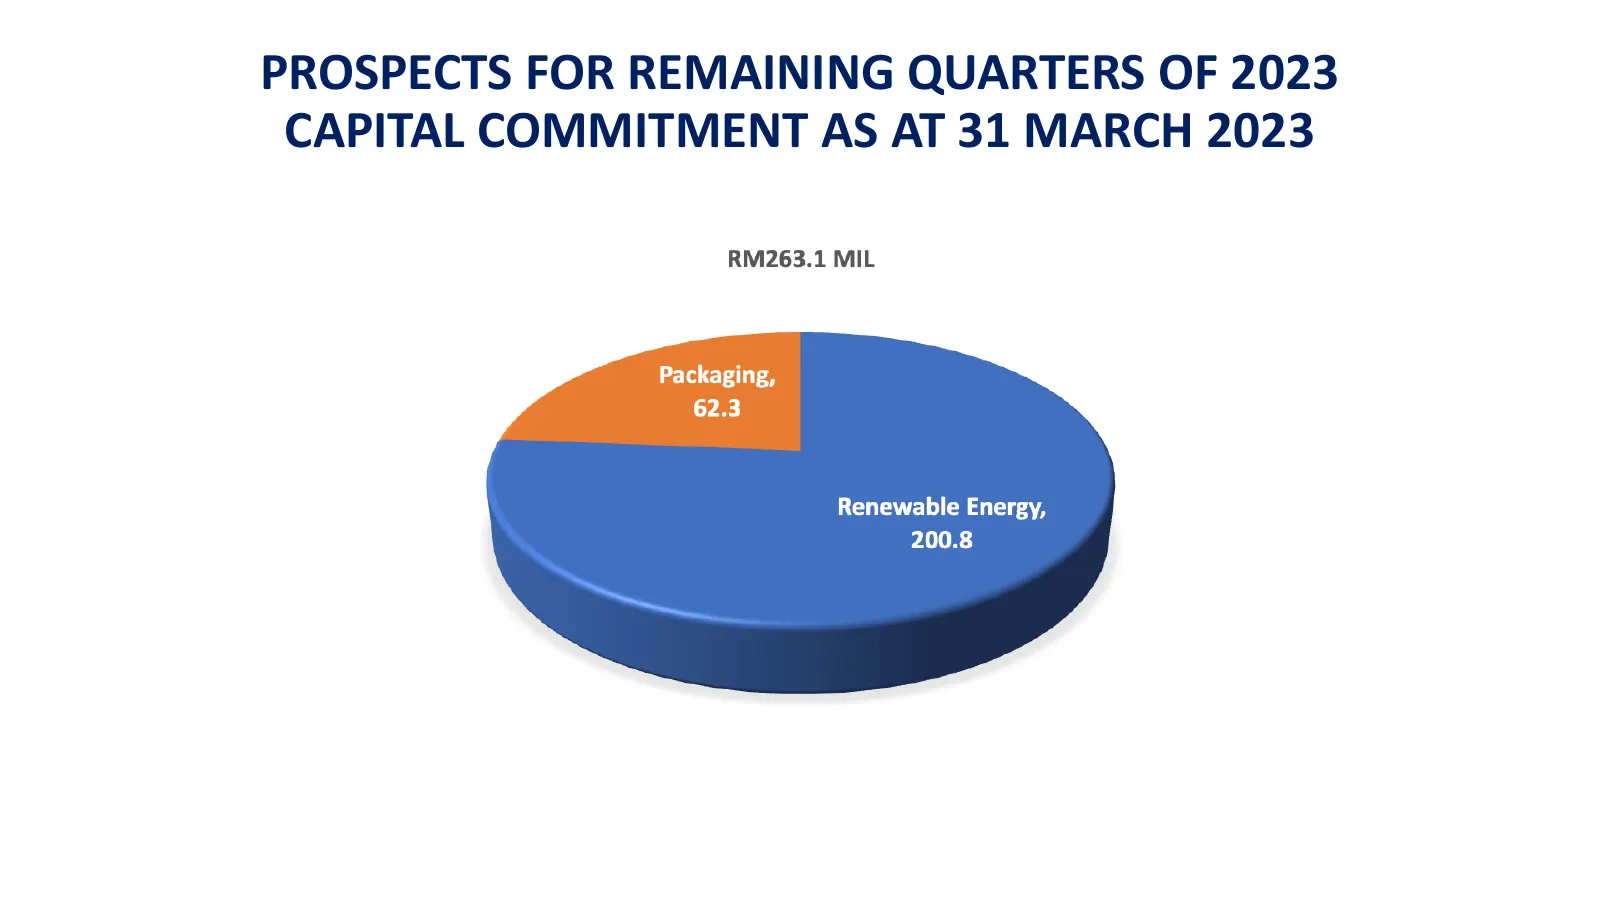
Slide 18: Capital Commitment as at 31 March 2023
PROSPECTS FOR REMAINING QUARTERS OF 2023 CAPITAL COMMITMENT AS AT 31 MARCH 2023
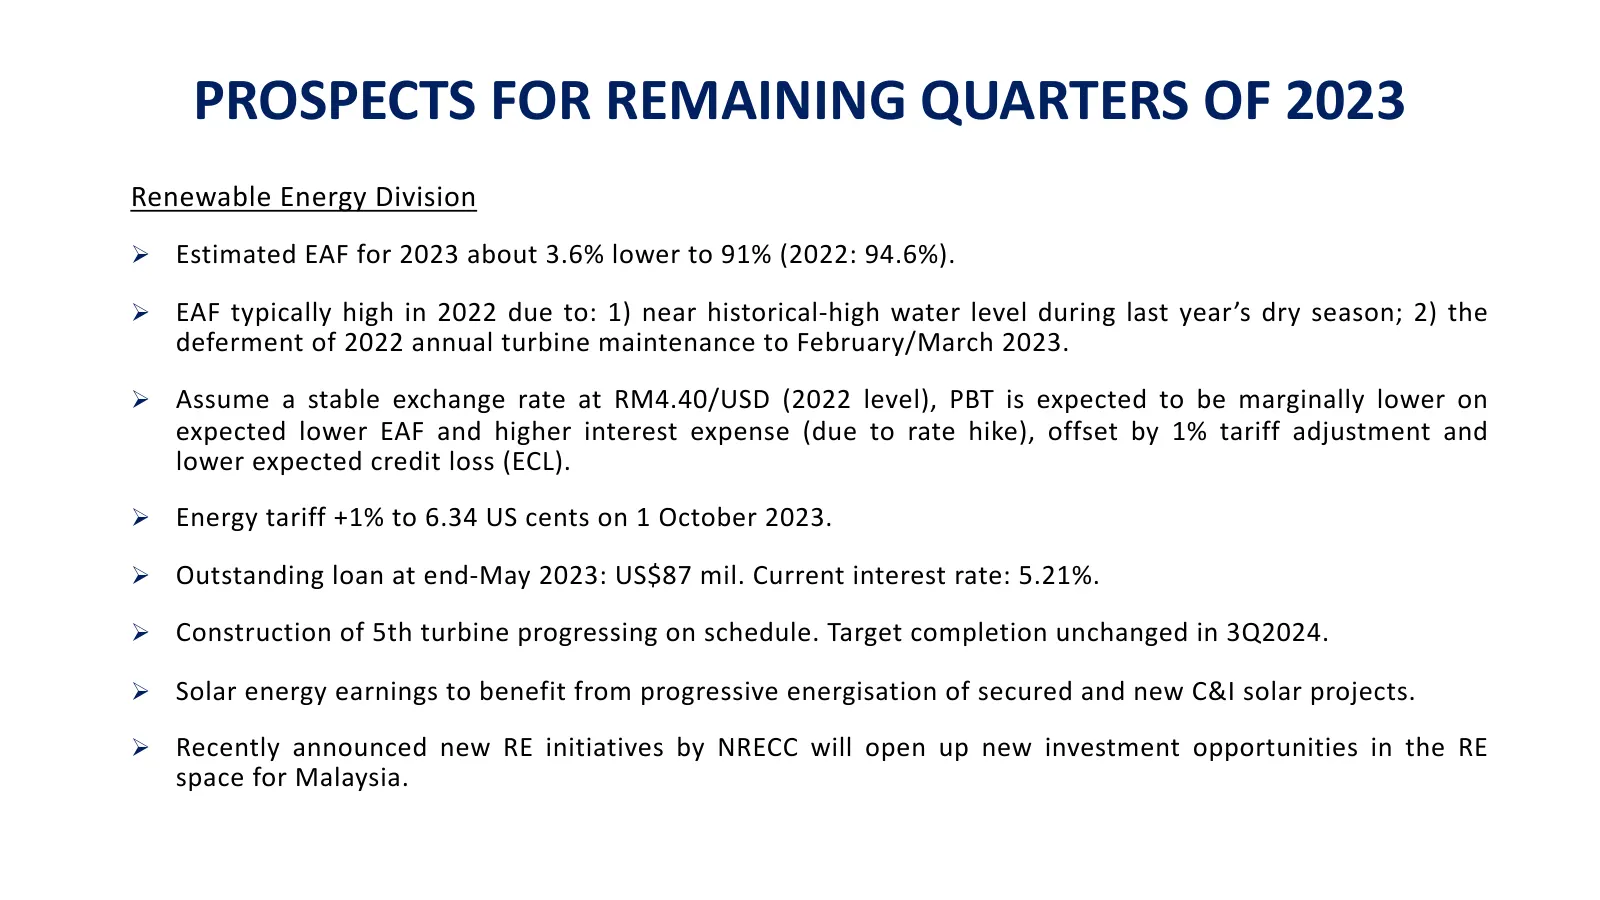
Slide 19: Prospects: Renewable Energy Division
PROSPECTS FOR REMAINING QUARTERS OF 2023 Renewable Energy Division Ø Estimated EAF for 2023 about 3.6% lower to 91% (2022: 94.6%). Ø EAF typically high in 2022 due to: 1) near historical-high water level during last year’s dry season; 2) the deferment of 2022 annual turbine maintenance to February/M
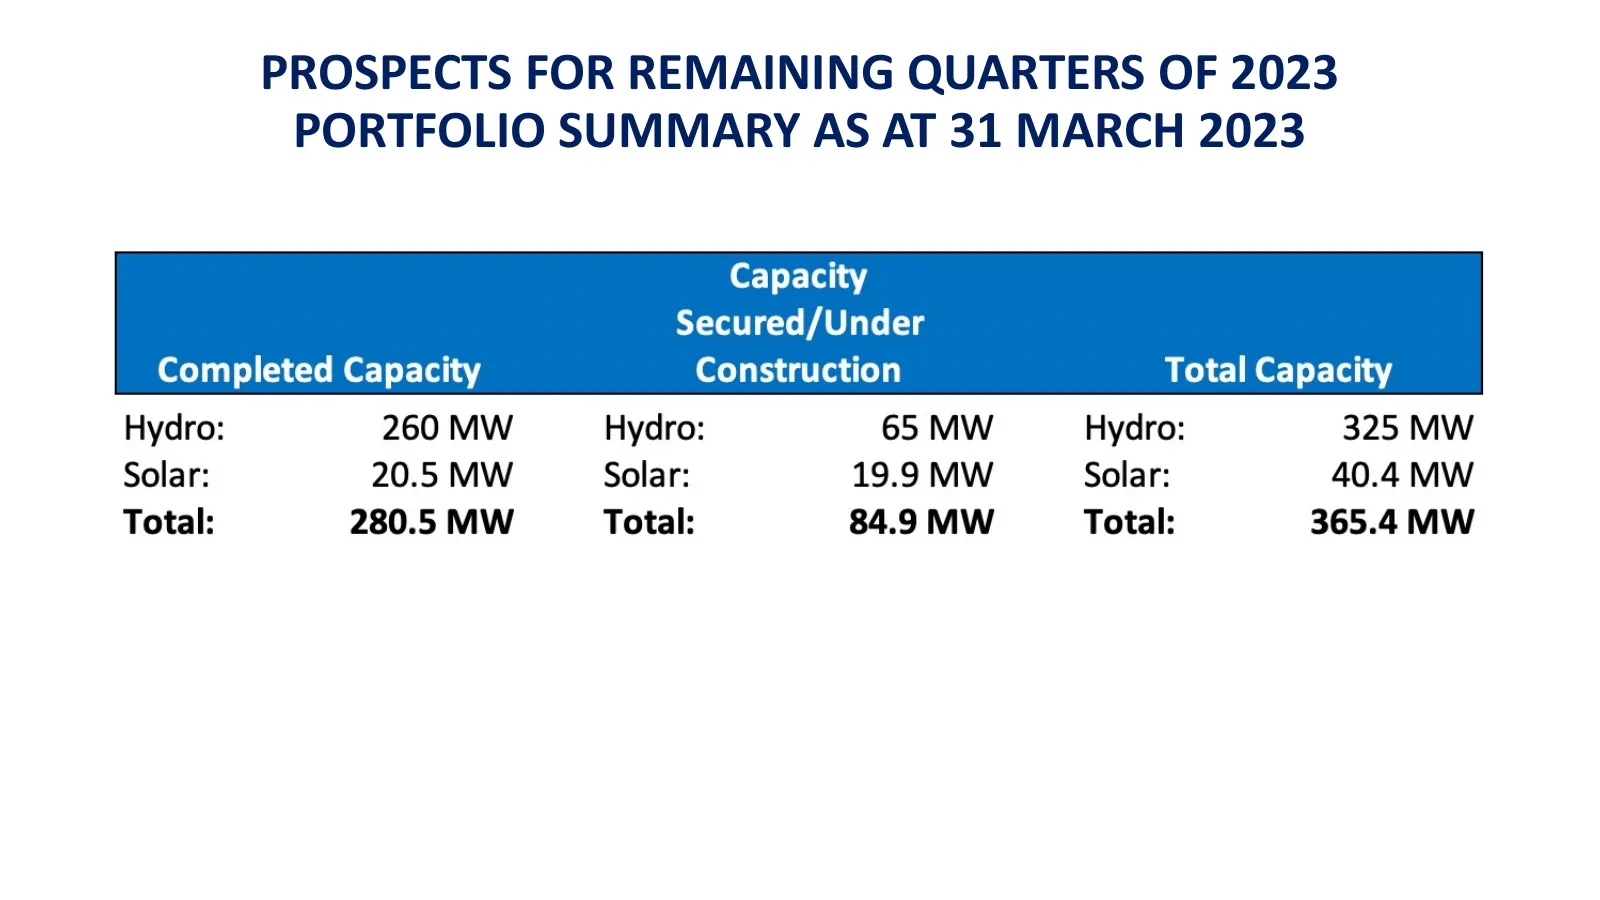
Slide 20: Portfolio Summary as at 31 March 2023
PROSPECTS FOR REMAINING QUARTERS OF 2023 PORTFOLIO SUMMARY AS AT 31 MARCH 2023
Slide 21: Renewable Energy Division - Expansion
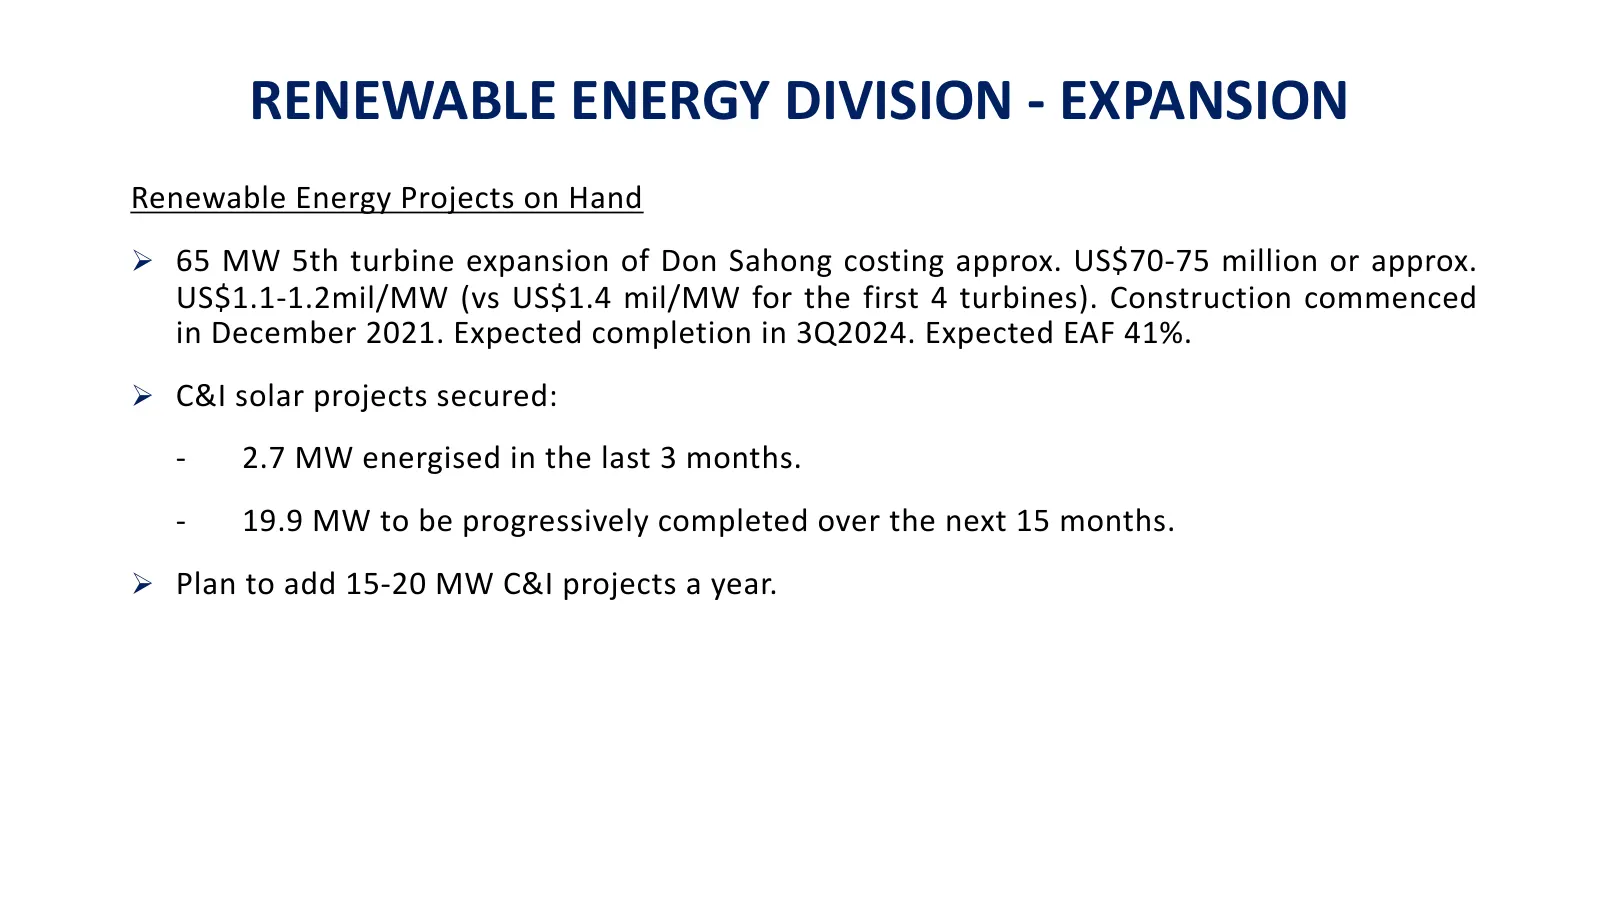
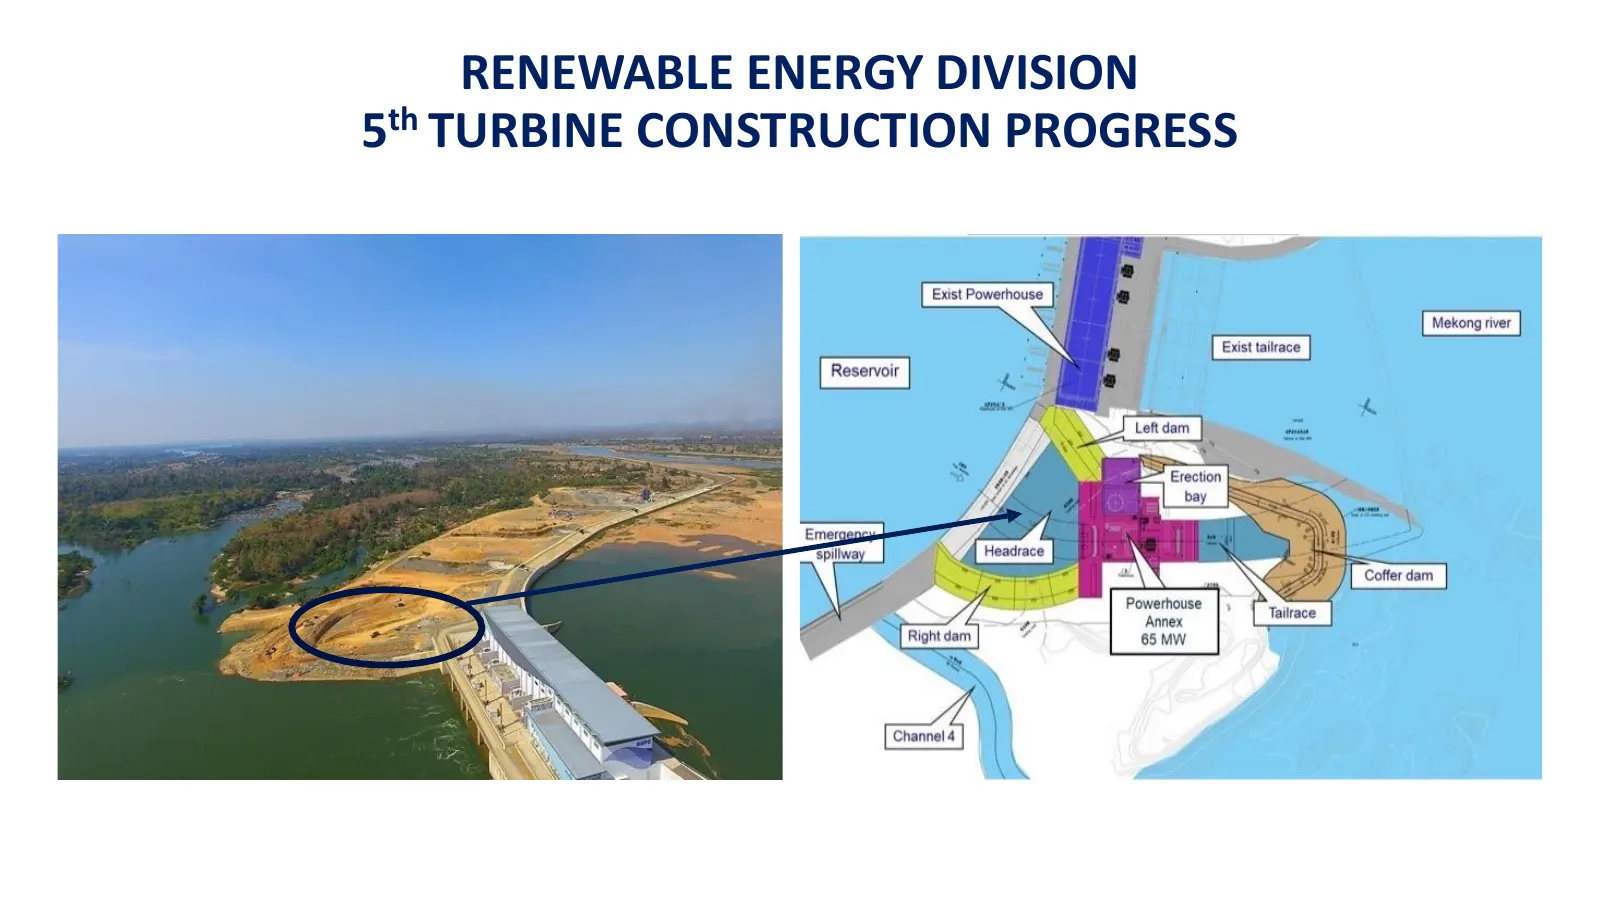
RENEWABLE ENERGY DIVISION - EXPANSION Renewable Energy Projects on Hand Ø 65 MW 5th turbine expansion of Don Sahong costing approx. US$70-75 million or approx. US$1.1-1.2mil/MW (vs US$1.4 mil/MW for the first 4 turbines). Construction commenced in December 2021. Expected completion in 3Q2024. Expect
Slide 22: 5th Turbine Construction Progress
RENEWABLE ENERGY DIVISION 5th TURBINE CONSTRUCTION PROGRESS
Slide 23: 5th Turbine Construction Progress
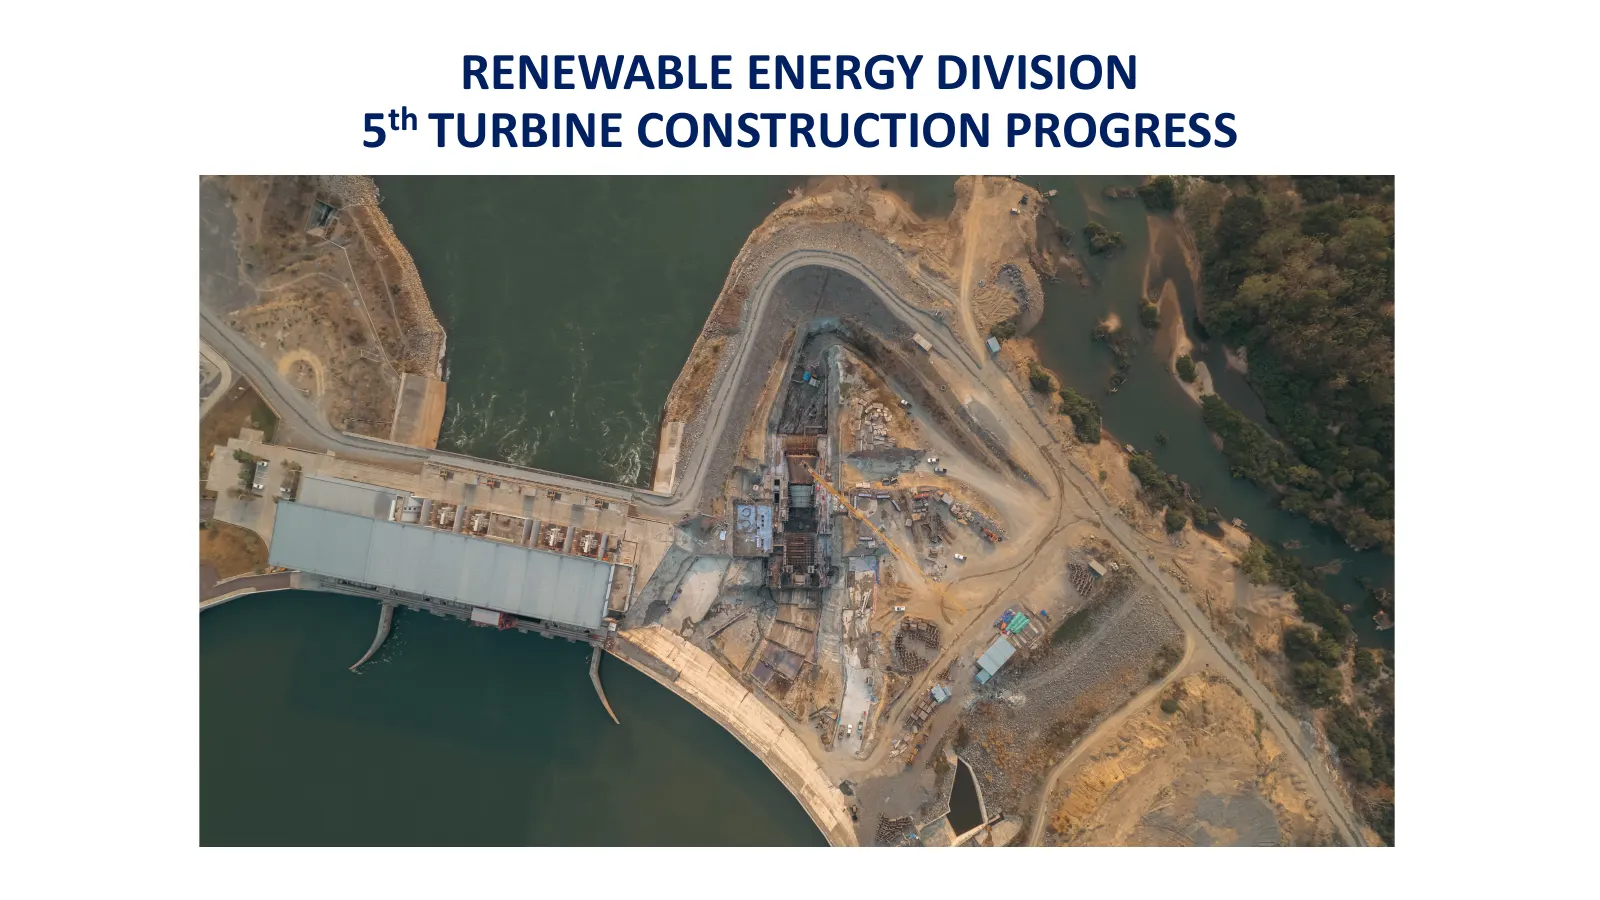
RENEWABLE ENERGY DIVISION 5th TURBINE CONSTRUCTION PROGRESS
Slide 24: 5th Turbine Construction Progress
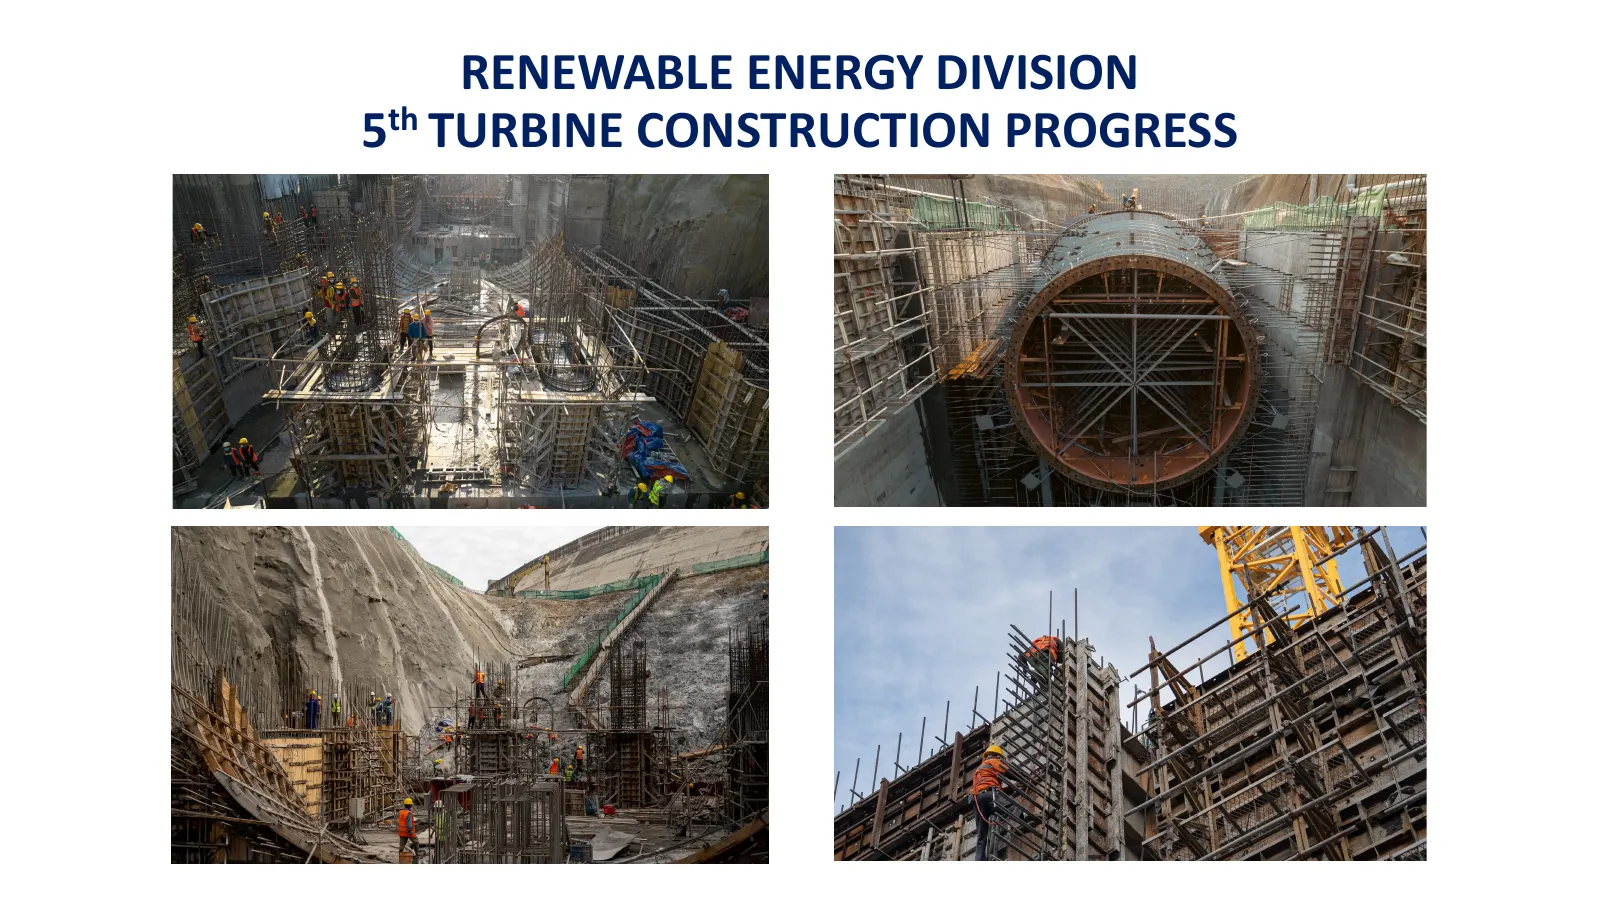
RENEWABLE ENERGY DIVISION 5th TURBINE CONSTRUCTION PROGRESS
Slide 25: Prospects: Resources Division
PROSPECTS FOR REMAINING QUARTERS OF 2023 Resources Division Ø Despite the global recession risk and ongoing geopolitical conflict, the underlying regional demand for lime products is expected to remain robust. Ø Fuel cost has stabilised, but overall production cost is expected to remain elevated due
Slide 26: Prospects: Packaging Division and Edenor Technology
PROSPECTS FOR REMAINING QUARTERS OF 2023 Packaging Division Ø Expected to face strong headwinds from high supply chain inventory, slowing consumer demand and intensifying price competition. Ø Management will strive to expand its customer base, raise production efficiency and reduce wastage. Ø Barrin
Source: company website
More decks from Mega First Corp. Bhd.
 2Q2026 Earnings Presentation55 slides · Aug 20, 2026
 Q1 2026 Earnings Presentation56 slides · May 25, 2026
 Q4 2025 Earnings Presentation62 slides · Mar 3, 2026
 Q3 2025 Earnings Presentation86 slides · Nov 26, 2025
 Q2 2025 Earnings Presentation89 slides · Aug 27, 2025
 Q1 2025 Earnings Presentation90 slides · May 22, 2025