Rockwool A/S Class A · OMXCOP:ROCK_A
Rockwool A/S Class A — The Rockwool Group — Non-Deal Roadshow (June 2011)
54 slides from Rockwool A/S Class A's roadshow presentation, Jun 10, 2011
Slide 1: SRI roadshow Paris 10 June 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 SRI roadshow Paris 10 June 2011 CFO Gilles Maria and VP Thorkild Diness Jensen The Rockwool Group 1
Slide 2: Forward-looking statement
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Forward-looking statement The statements on the future in this presentation, including expected sales and earnings, are associated with risks and uncertainties and may be affected by factors influencing the activities of the group, e.
Slide 3: The Rockwool Group
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 The Rockwool Group World leading supplier of innovative products and systems based on stone wool The world’s second biggest insulation producer Turnover 2010 DKK 11,732 million of which 80% insulation and 20% other stone wool products
Slide 4: Sales distributed on business area
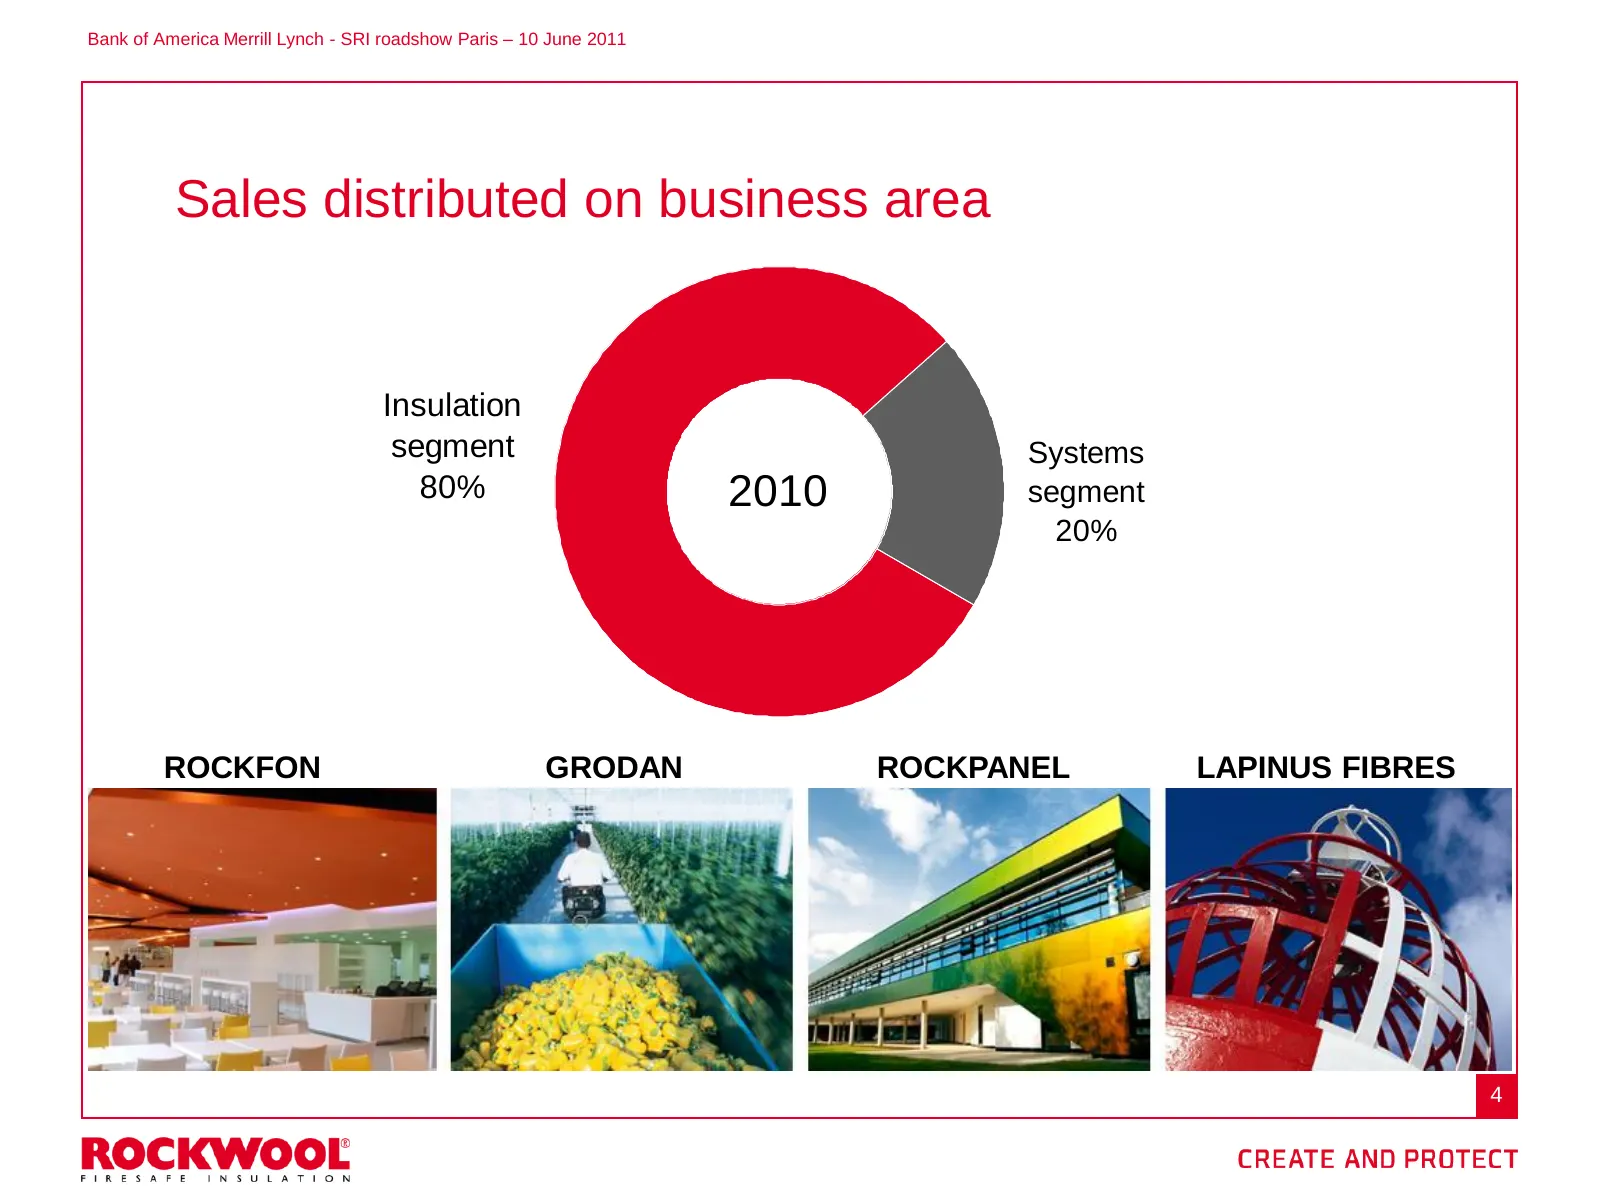
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Sales distributed on business area Insulation segment Systems 80% 2010 segment 20% ROCKFON GRODAN ROCKPANEL LAPINUS FIBRES 4
Slide 5: Sales distributed on countries
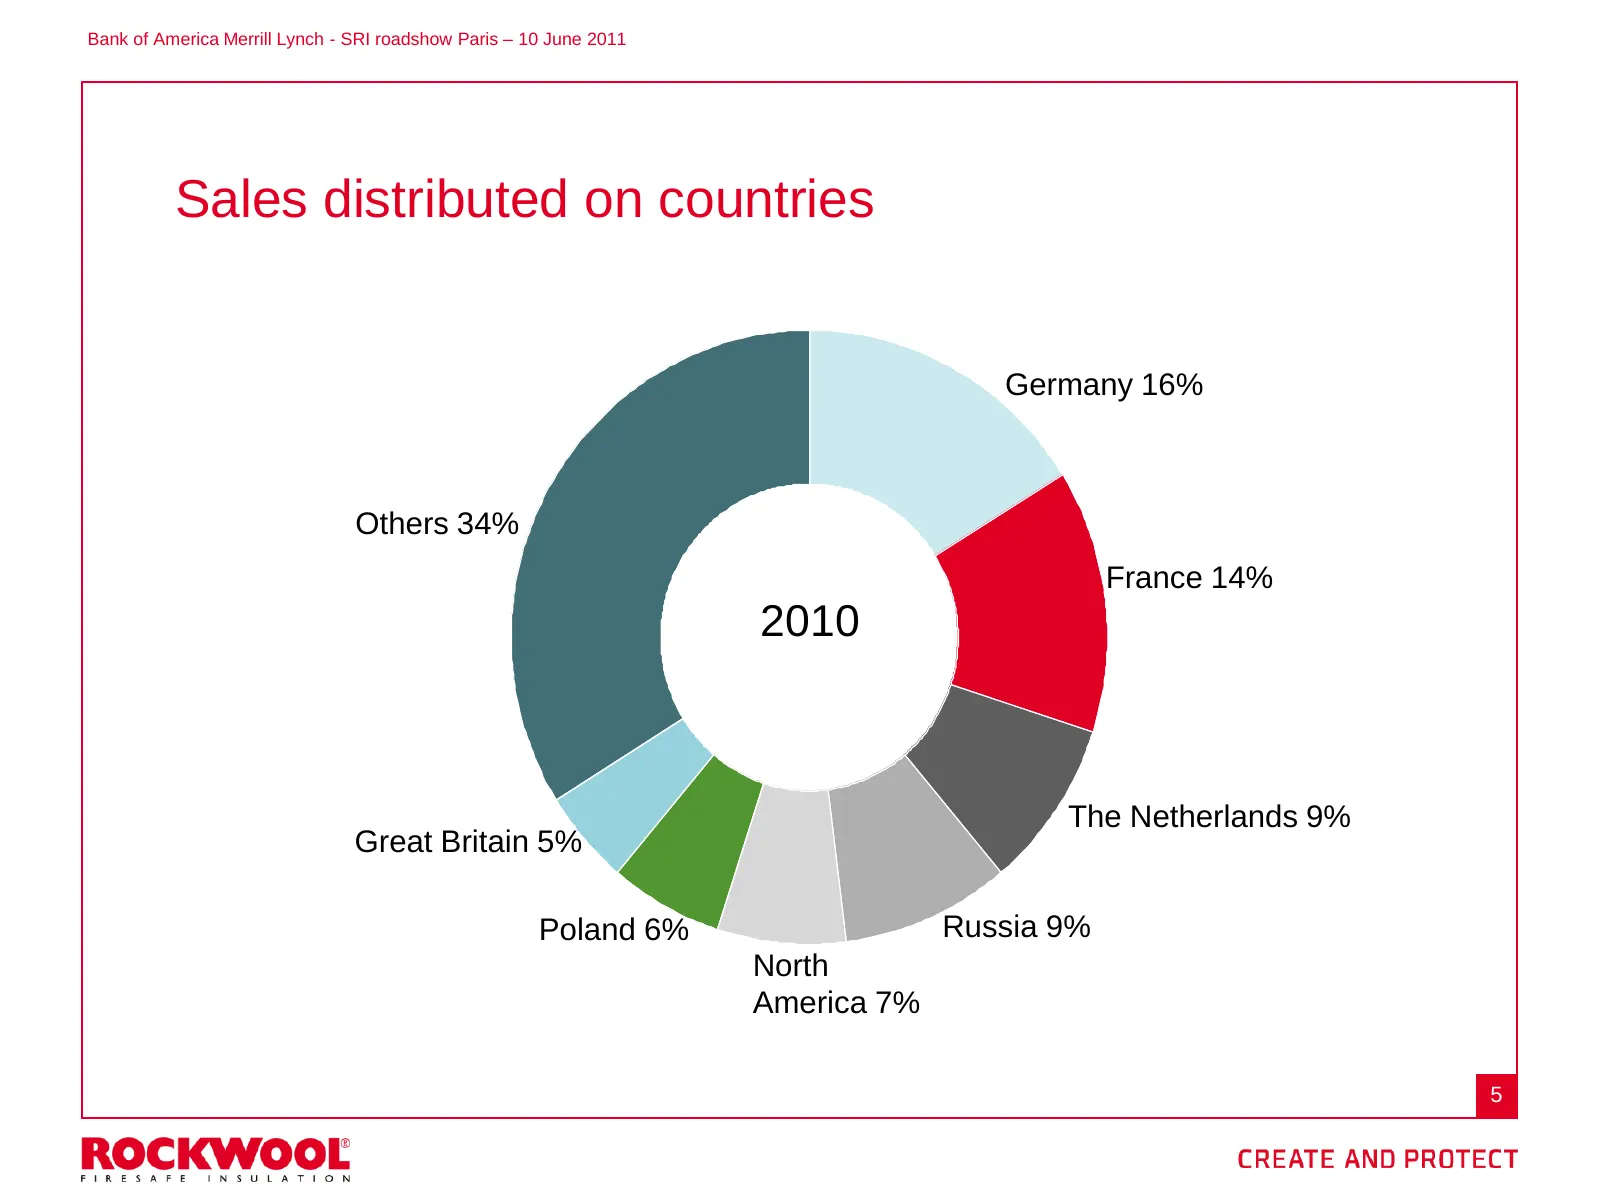
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Sales distributed on countries Germany 16% Others 34% France 14% 2010 The Netherlands 9% Great Britain 5% Poland 6% Russia 9% North America 7% 5
Slide 6: Rockwool locations
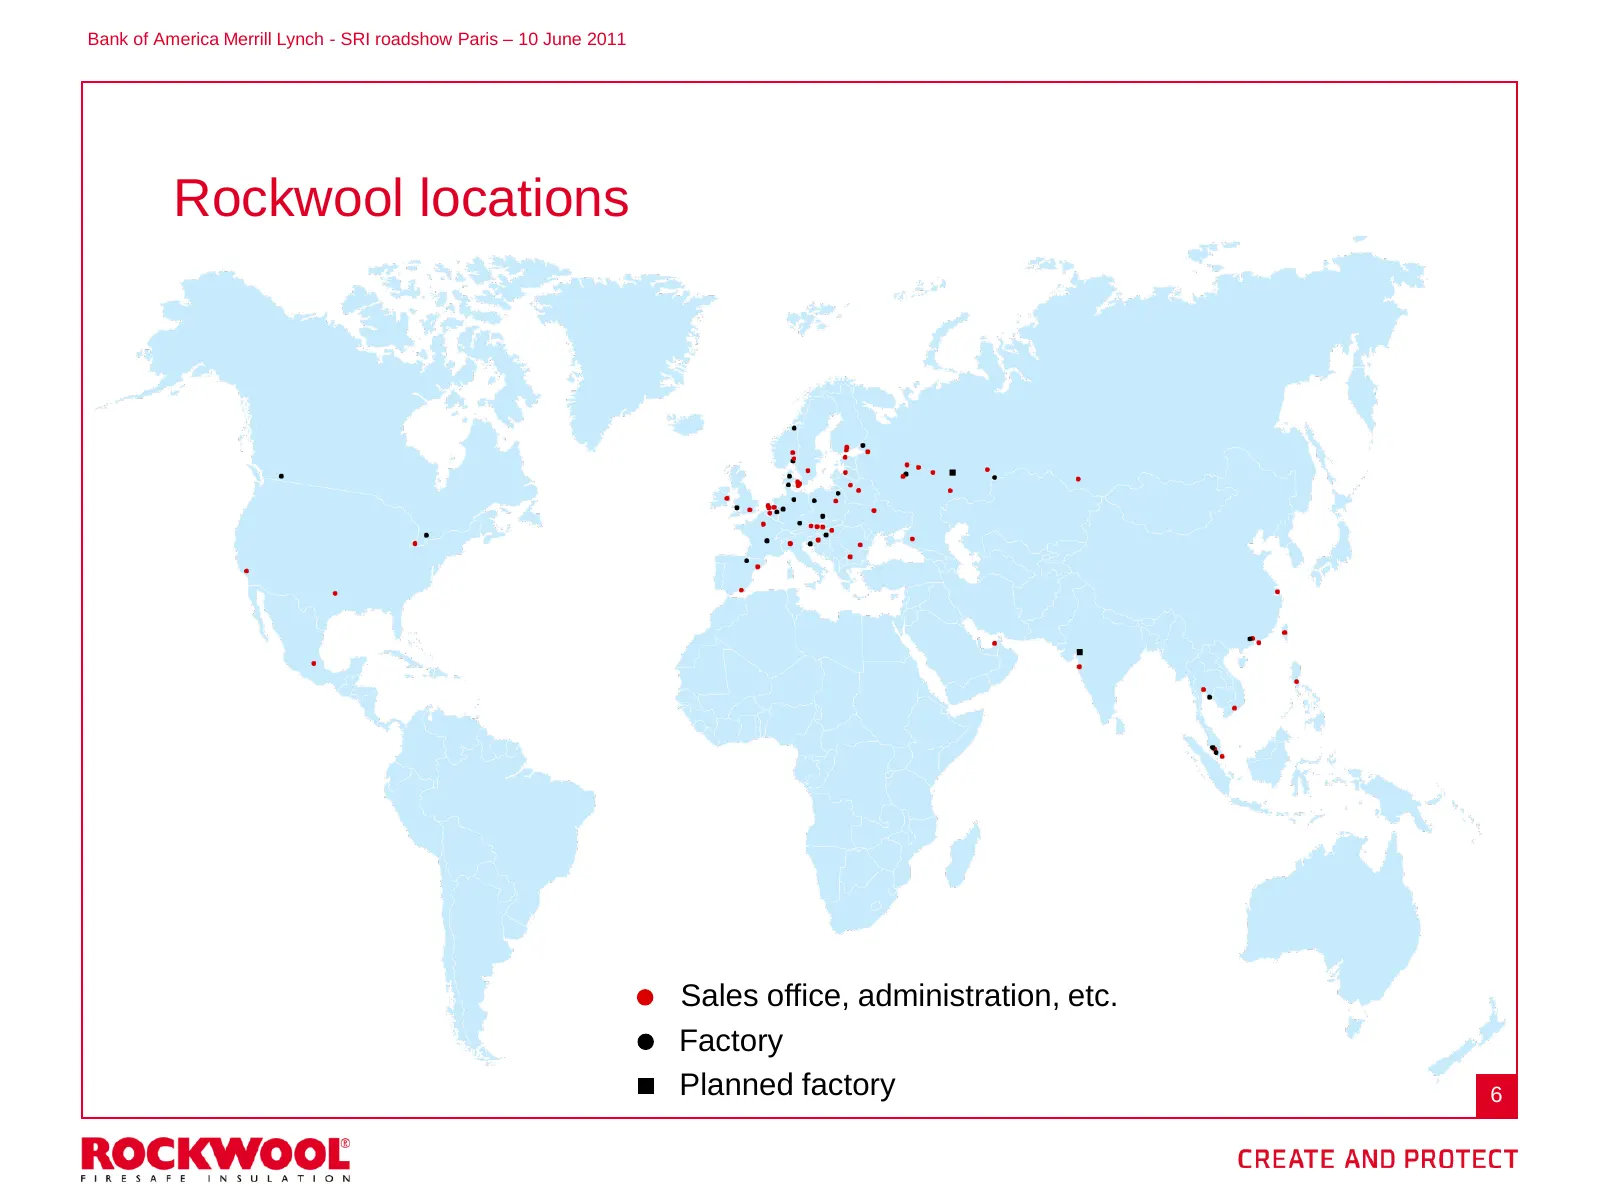
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Rockwool locations Sales office, administration, etc. Factory Planned factory 6
Slide 7: The Rockwool production is capital intensive
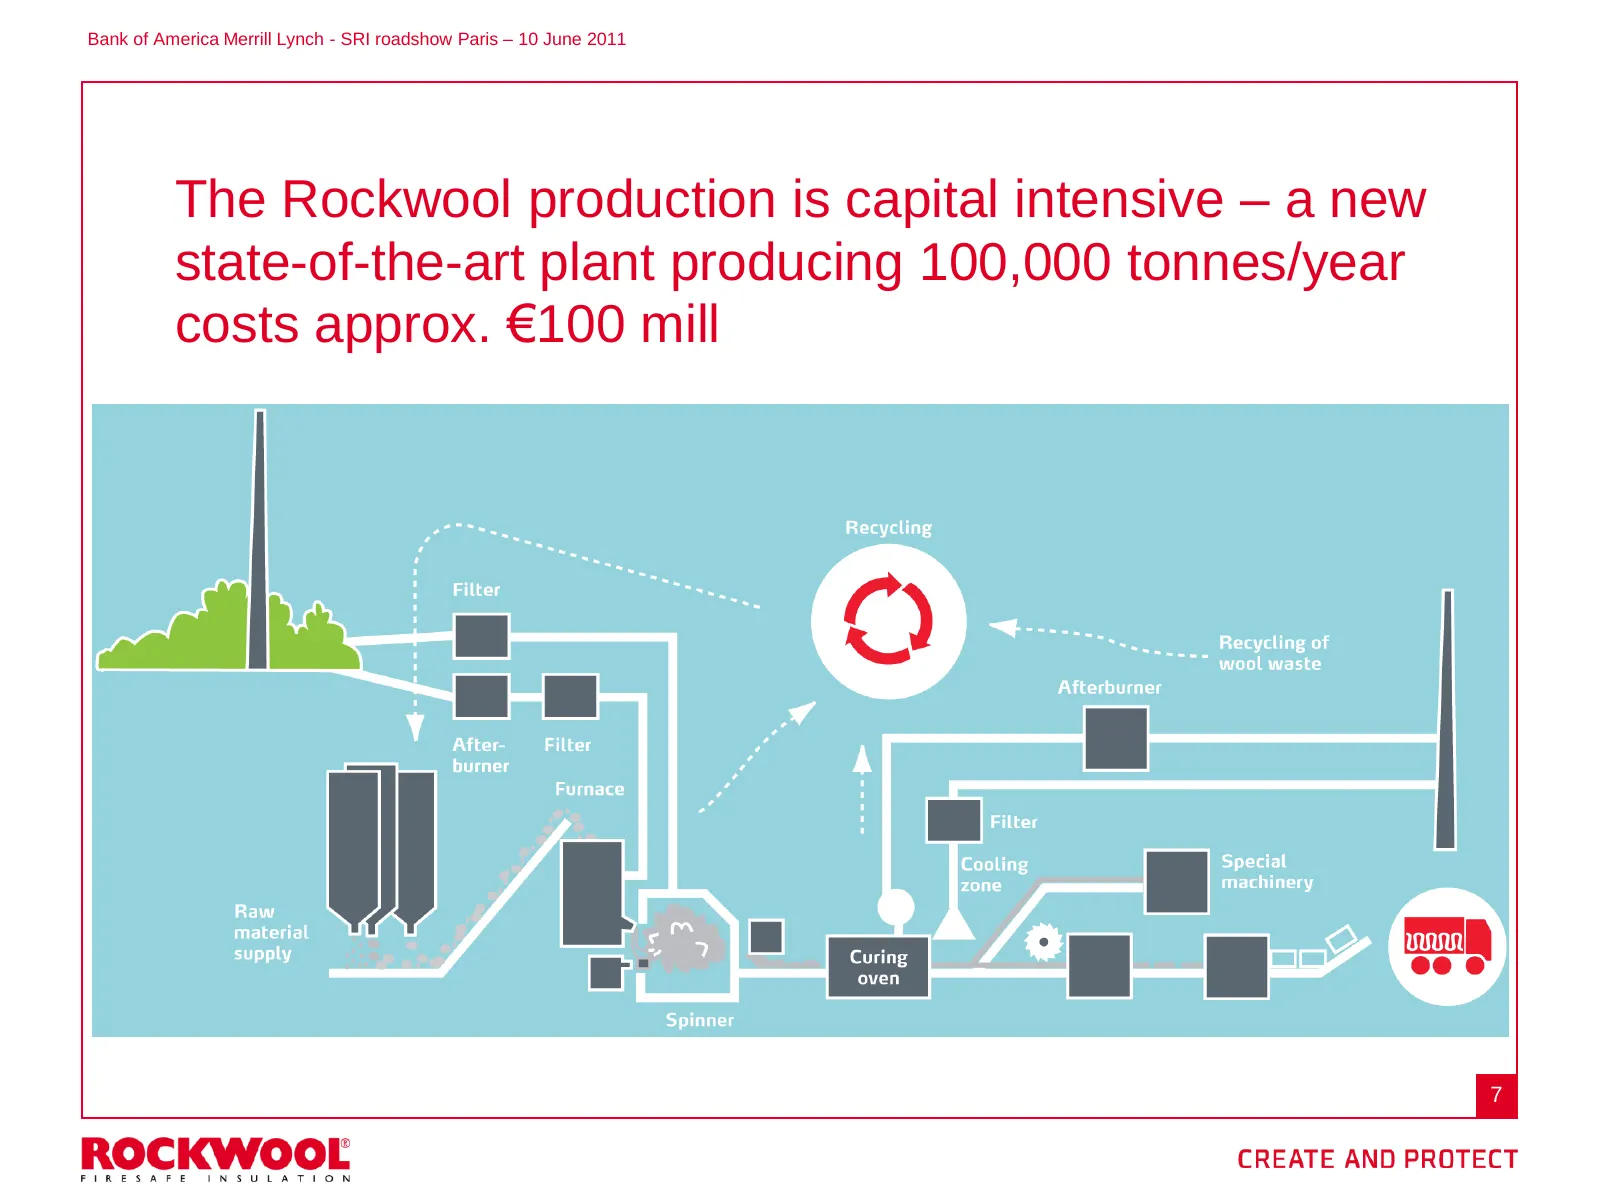
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 The Rockwool production is capital intensive – a new state-of-the-art plant producing 100,000 tonnes/year costs approx. €100 mill 7
Slide 8: Energy and climate as growth drivers
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Energy and climate as growth drivers 8
Slide 9: Sustainable housing key to solve the energy challenge
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Sustainable housing key to solve the energy challenge 50% of world population live in urban areas. This will grow to 70% by 2030 Aircon will triple before 2030 (McKinsey/Vattenfall) CO2 emissions from buildings will grow by 50+% by 20
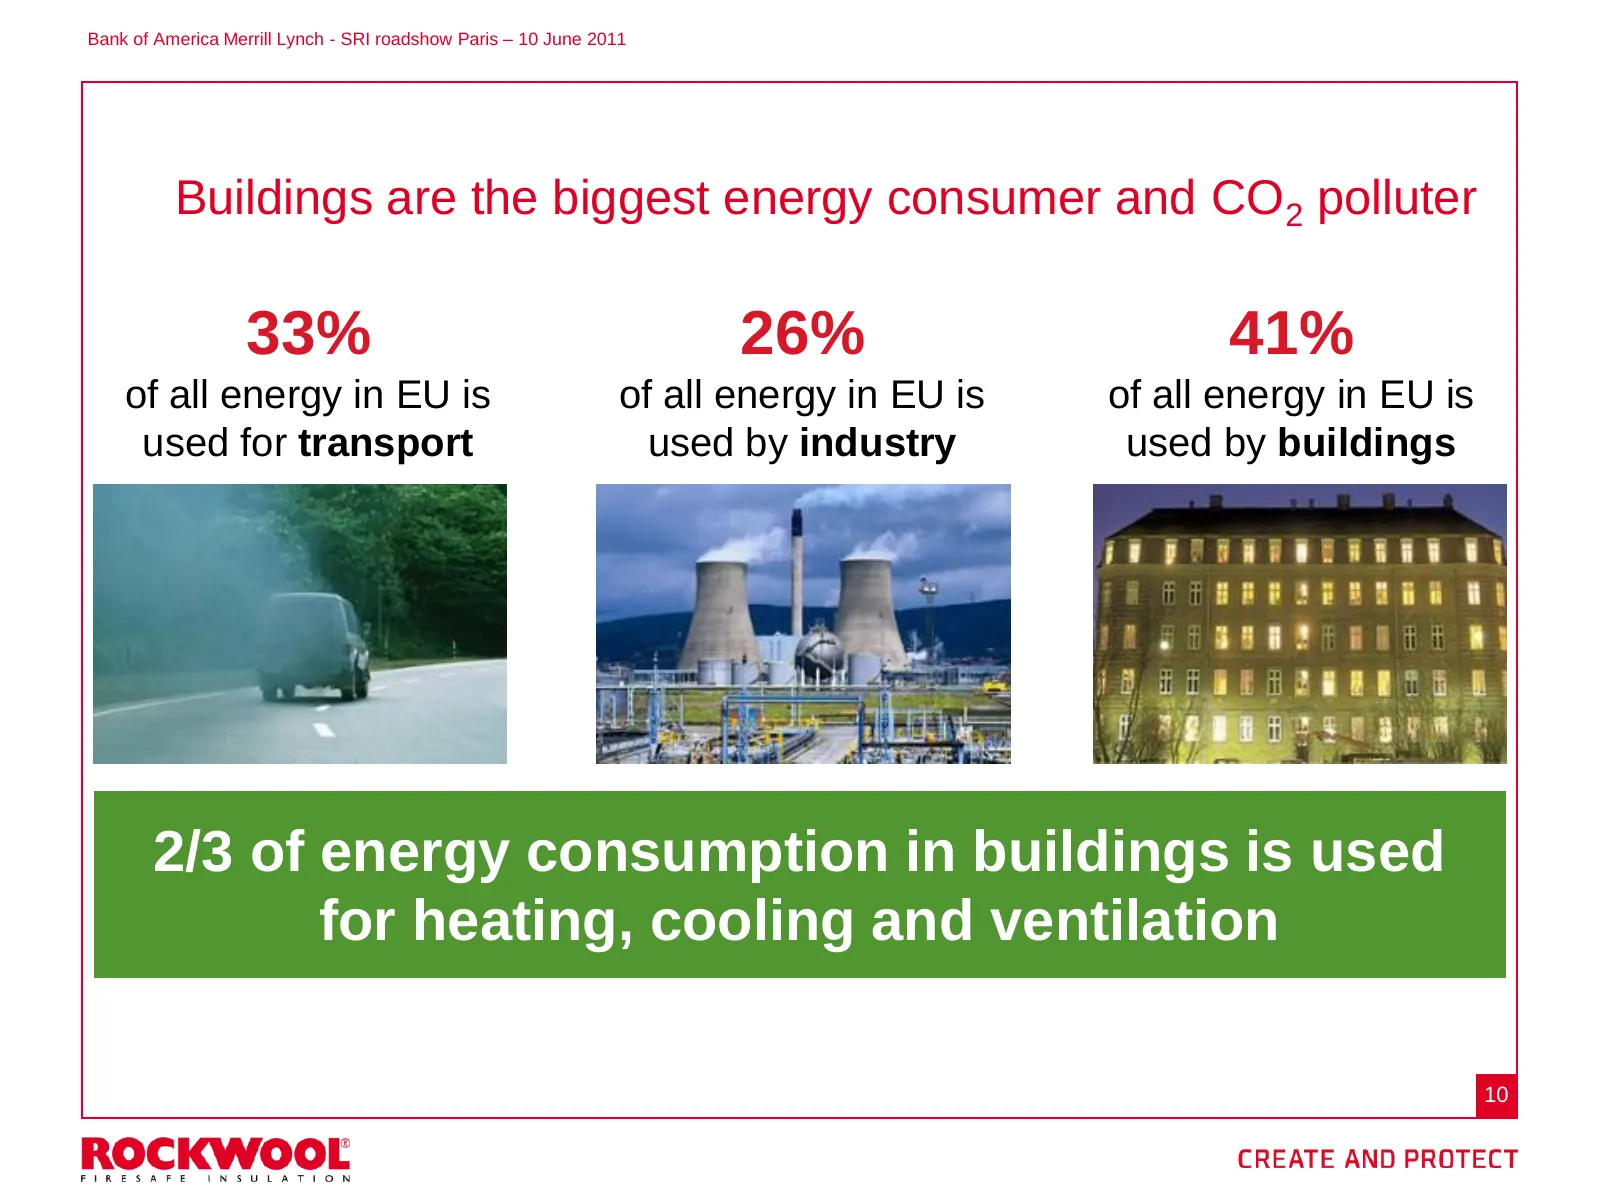
Slide 10: Buildings are the biggest energy consumer and CO2 polluter
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Buildings are the biggest energy consumer and CO2 polluter 33% 26% 41% of all energy in EU is of all energy in EU is of all energy in EU is used for transport used by industry used by buildings 2/3 of energy consumption in buildings i
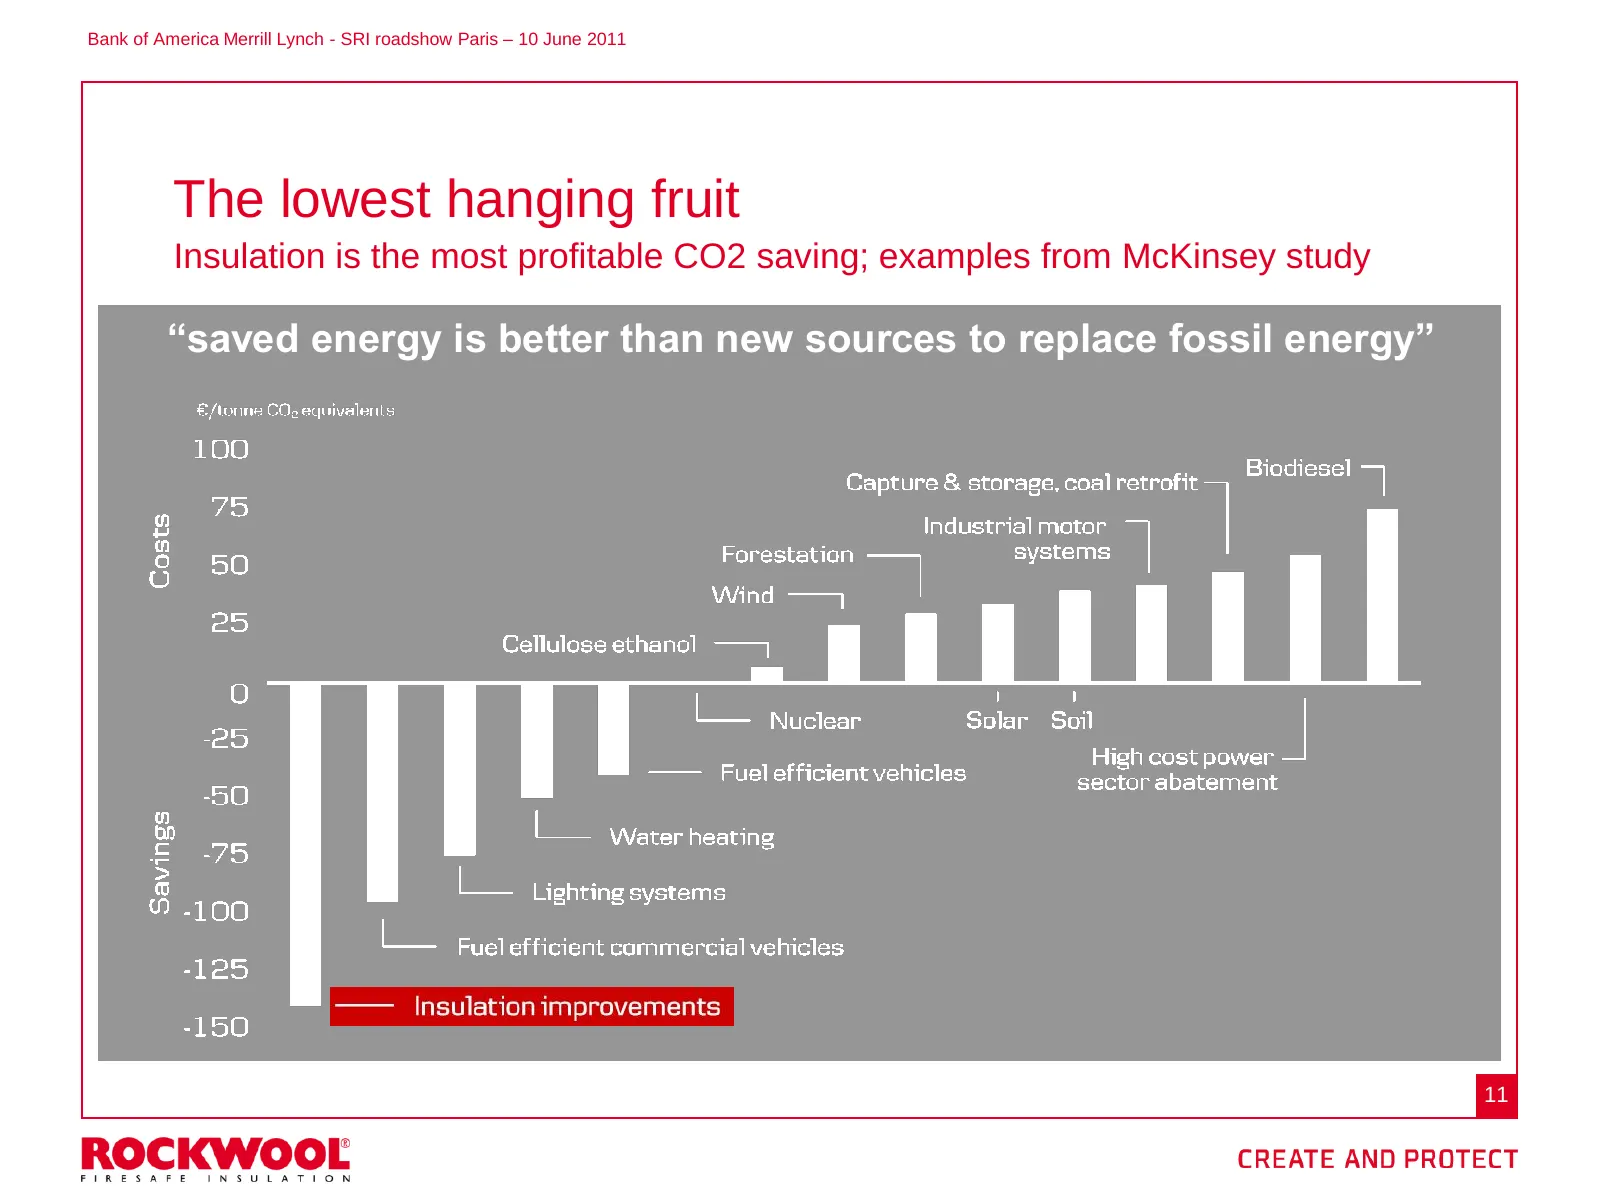
Slide 11: The lowest hanging fruit
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 The lowest hanging fruit Insulation is the most profitable CO2 saving; examples from McKinsey study “saved energy is better than new sources to replace fossil energy” 11
Slide 12: Insulation – Green by nature
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Insulation – Green by nature Insulation is one of few products which saves more energy during lifetime than used for its production The McKinsey study found that insulation was amongst the most cost- effective CO2-abatement measures A
Slide 13: Key drivers for the insulation market
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Key drivers for the insulation market New build rates Long-term legislation towards energy efficient new build Stimulus packages to support energy renovation Energy price level 13
Slide 14: New build rates
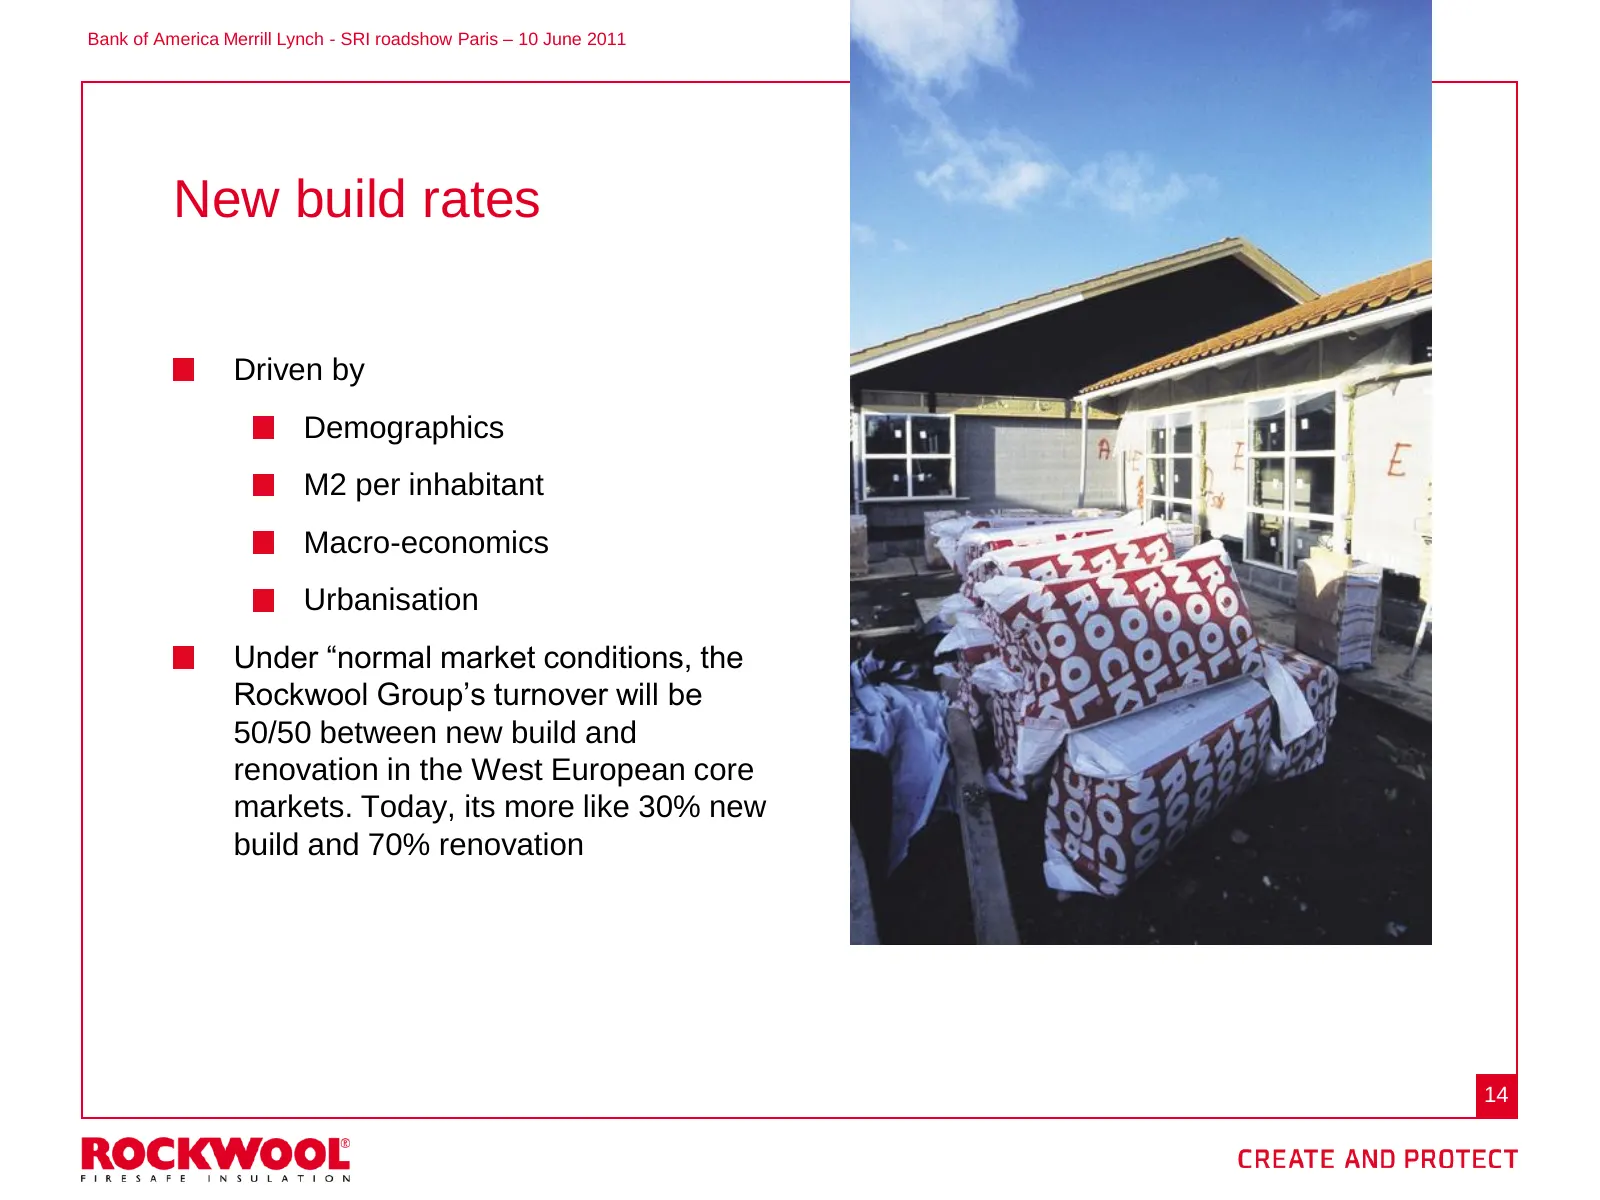
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 New build rates Driven by Demographics M2 per inhabitant Macro-economics Urbanisation Under “normal market conditions, the Rockwool Group’s turnover will be 50/50 between new build and renovation in the West European core markets. Tod
Slide 15: Energy efficiency of buildings: solid trend creates superior growth
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Energy efficiency of buildings: Solid trend creates superior growth Short-term stimulus packages for energy refurbishment Long term legal framework for energy renovation of buildings in EU Energy requirements for major renovations now
Slide 16: EU leads the way in tightening of new build codes
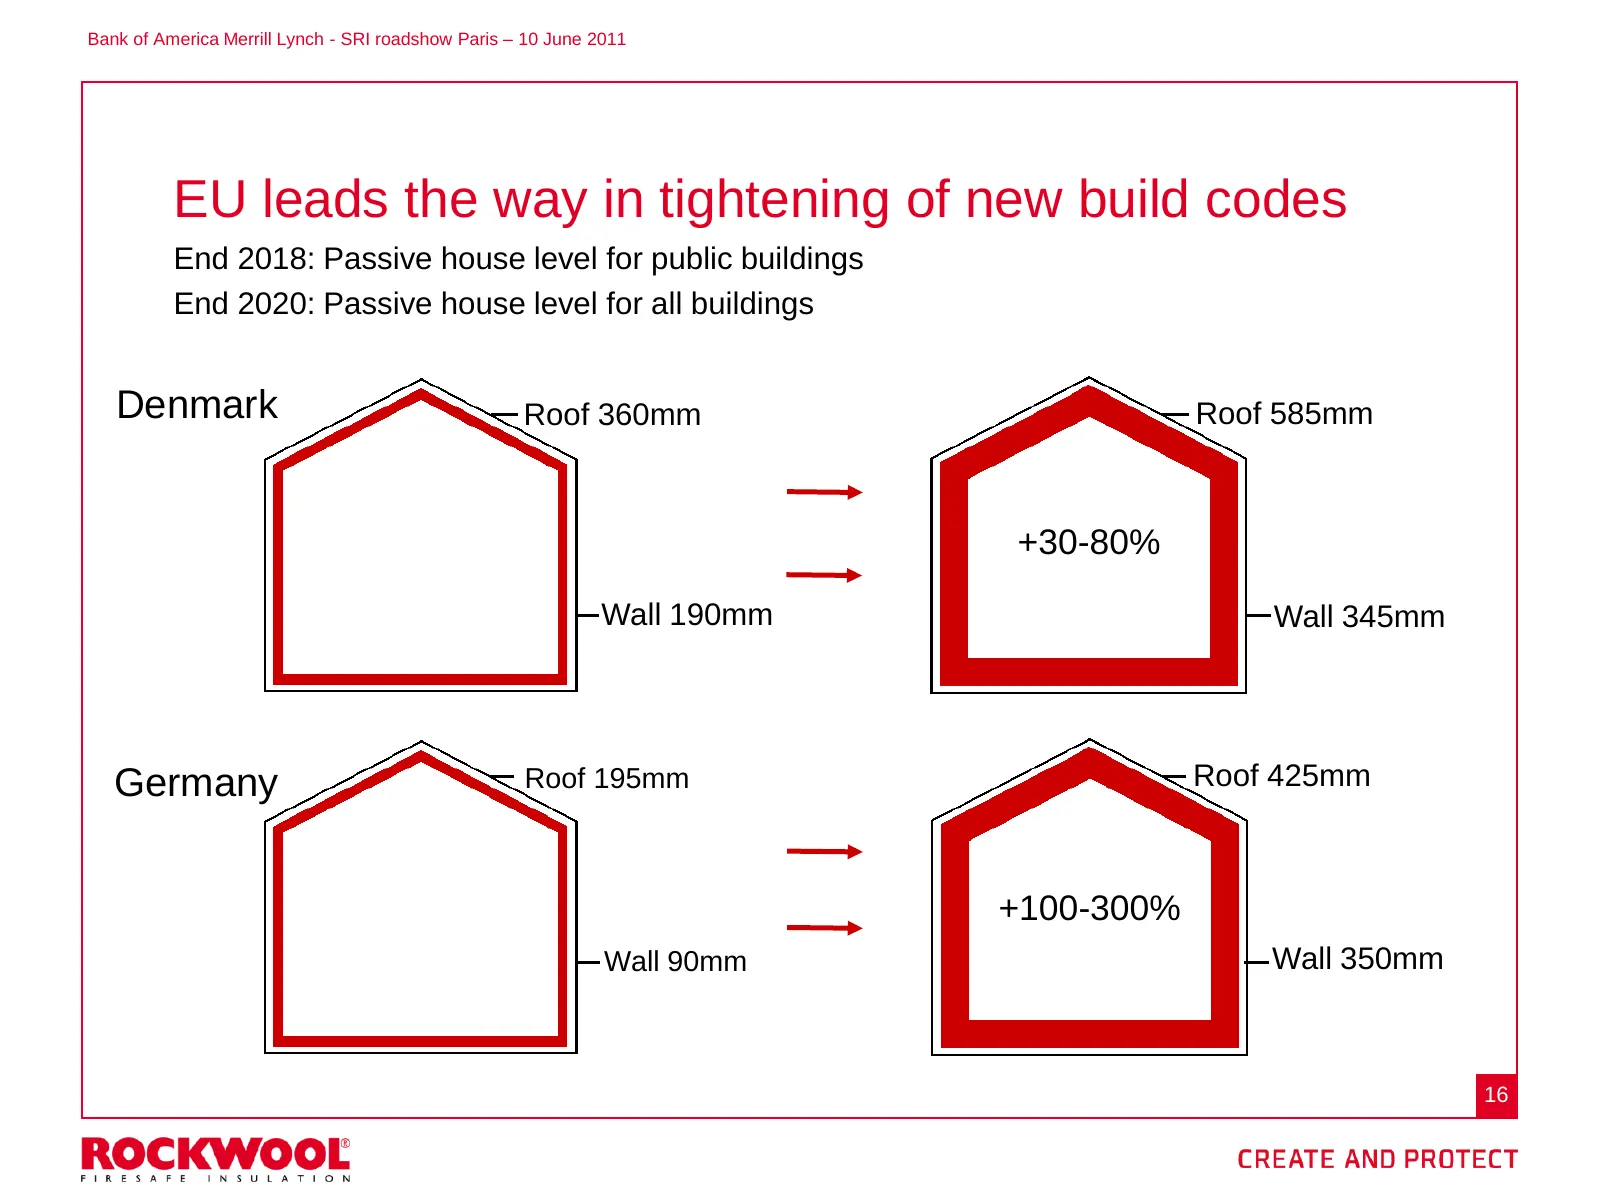
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 EU leads the way in tightening of new build codes End 2018: Passive house level for public buildings End 2020: Passive house level for all buildings Denmark Roof 360mm Roof 585mm +30-80% Wall 190mm Wall 345mm Germany Roof 195mm Roof 4
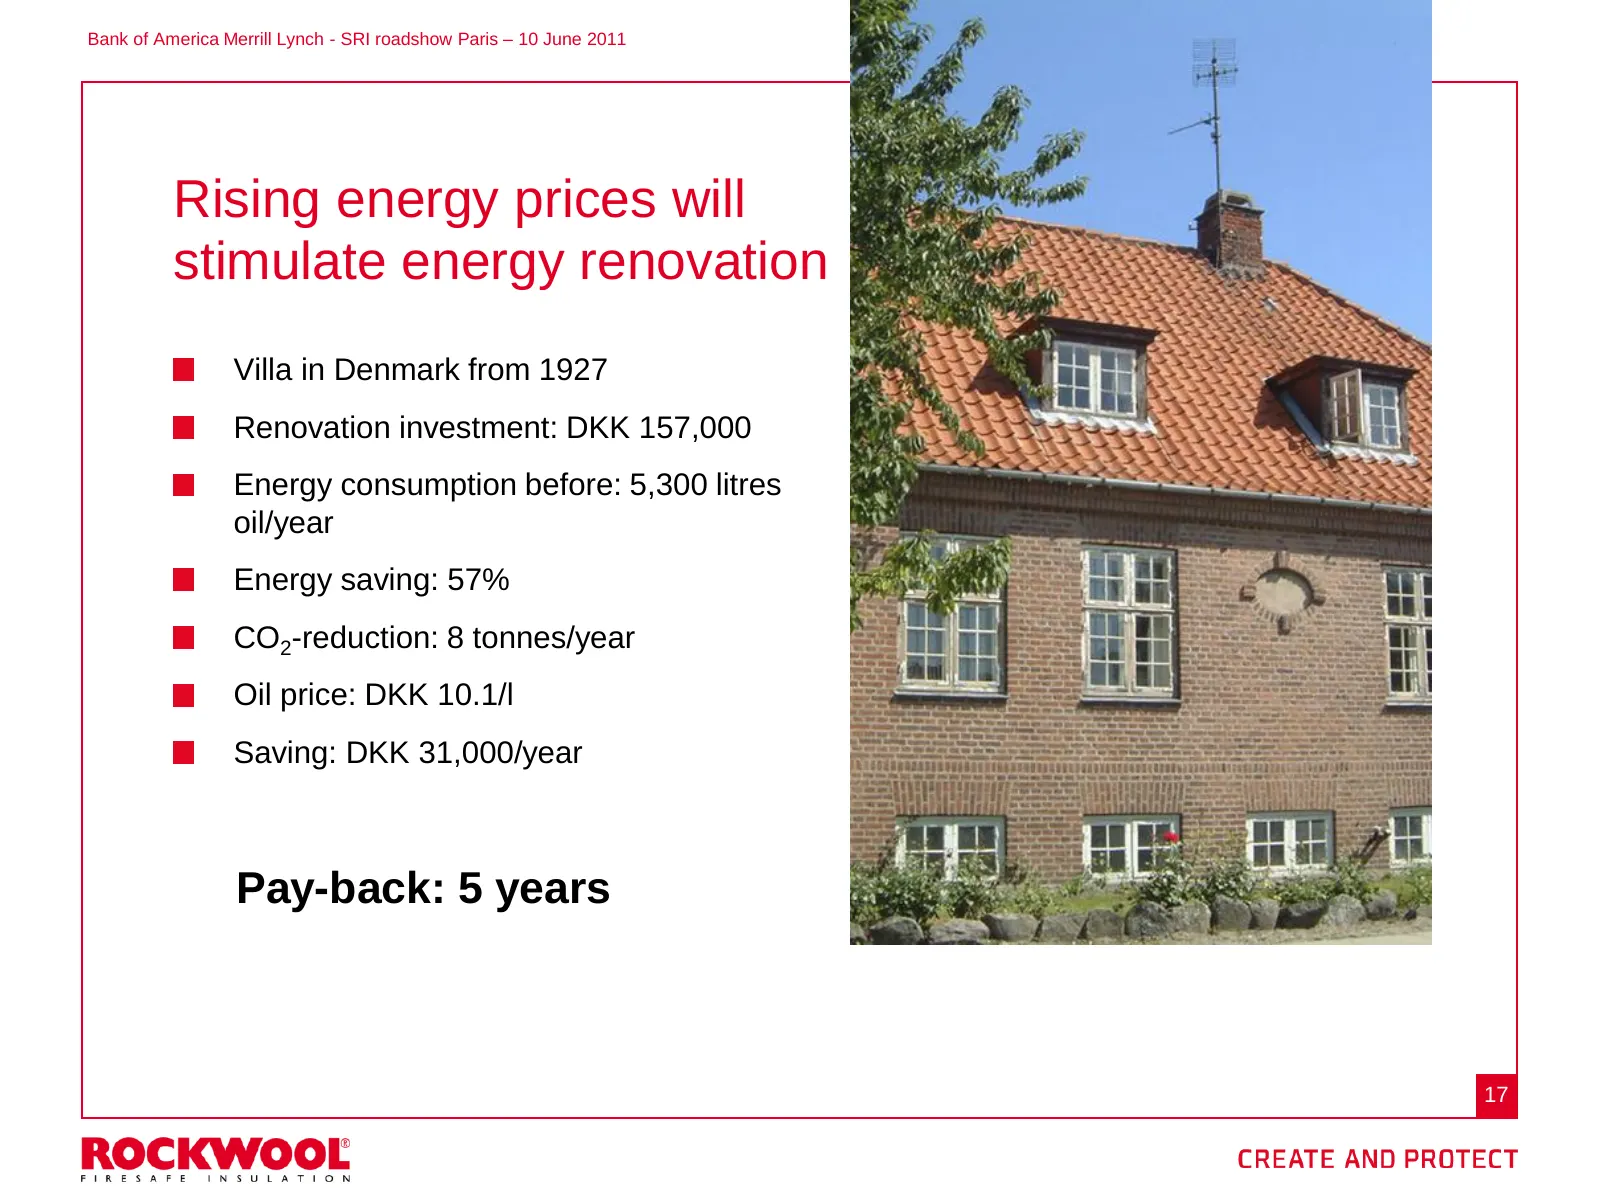
Slide 17: Rising energy prices will stimulate energy renovation
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Rising energy prices will stimulate energy renovation Villa in Denmark from 1927 Renovation investment: DKK 157,000 Energy consumption before: 5,300 litres oil/year Energy saving: 57% CO2-reduction: 8 tonnes/year Oil price: DKK 10.1/l
Slide 18: Segments and product properties
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Segments and product properties 18
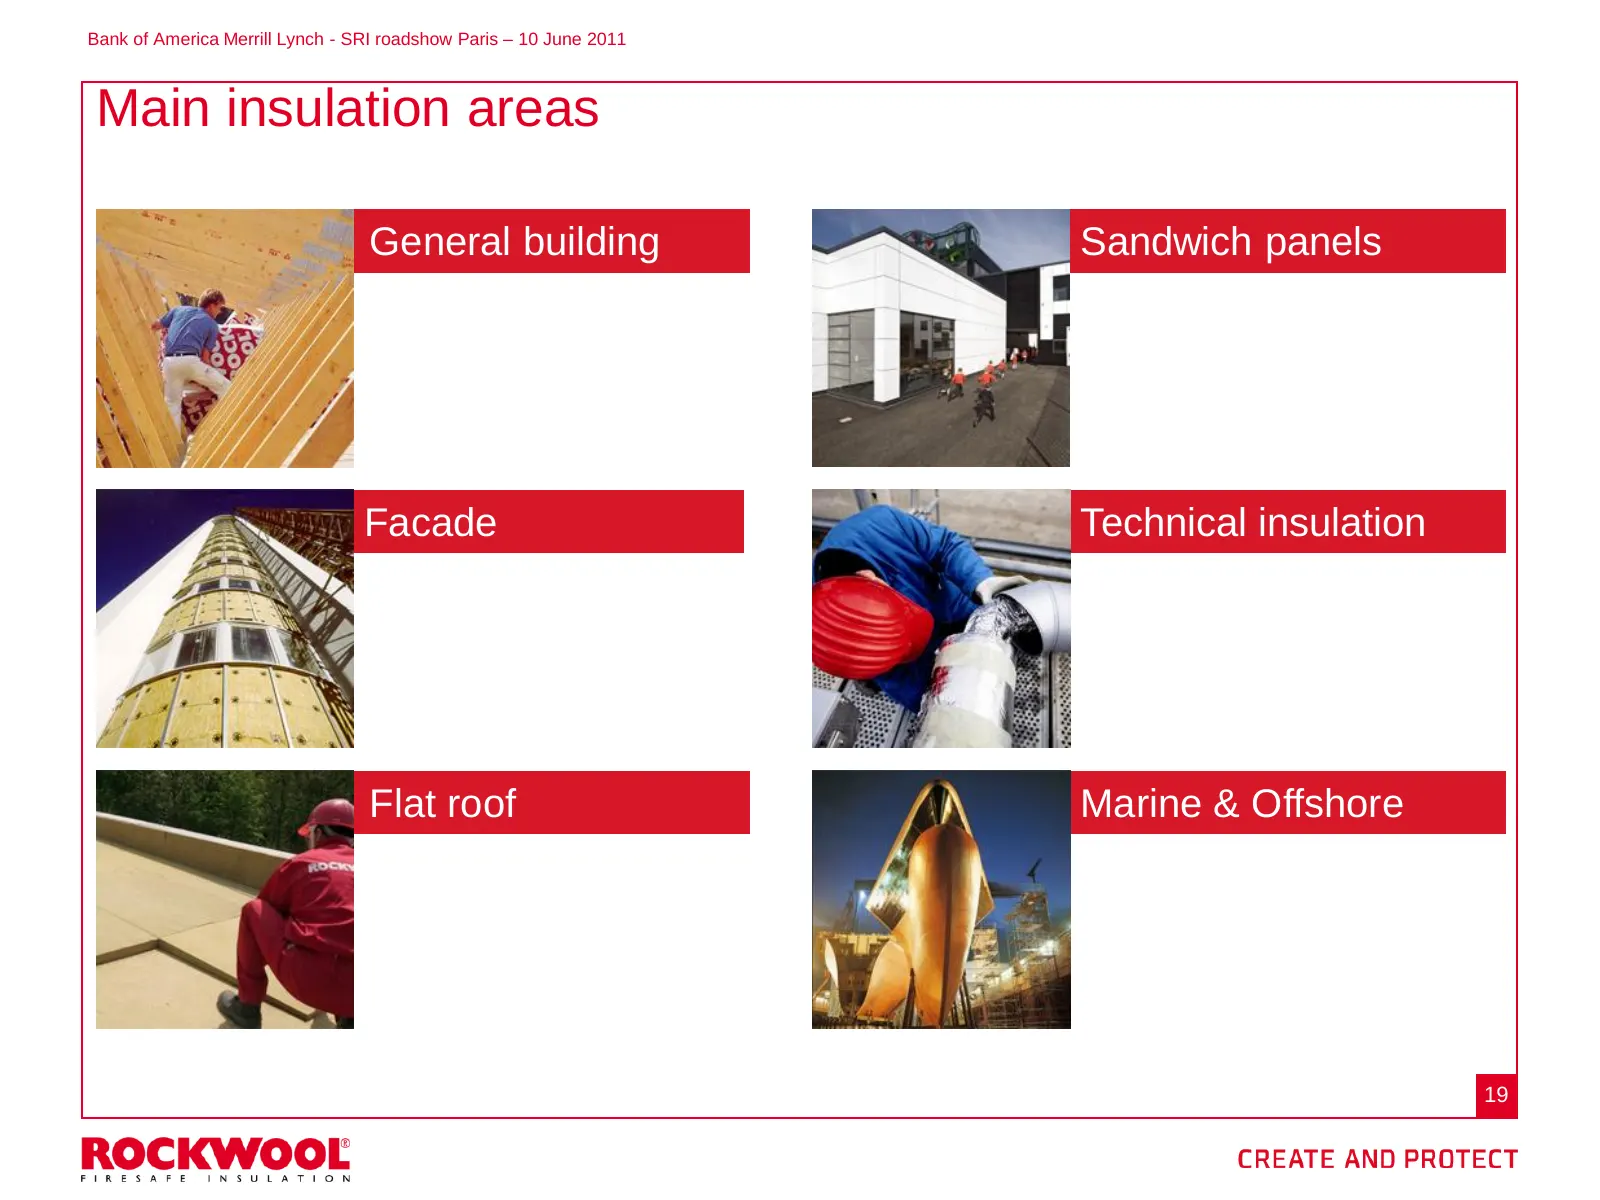
Slide 19: Main insulation areas
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Main insulation areas General building Sandwich panels Facade Technical insulation Flat roof Marine & Offshore 19
Slide 20: Full performance insulation
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Full performance insulation Acoustic Thermal Sustainable Durable solutions Firesafe 20
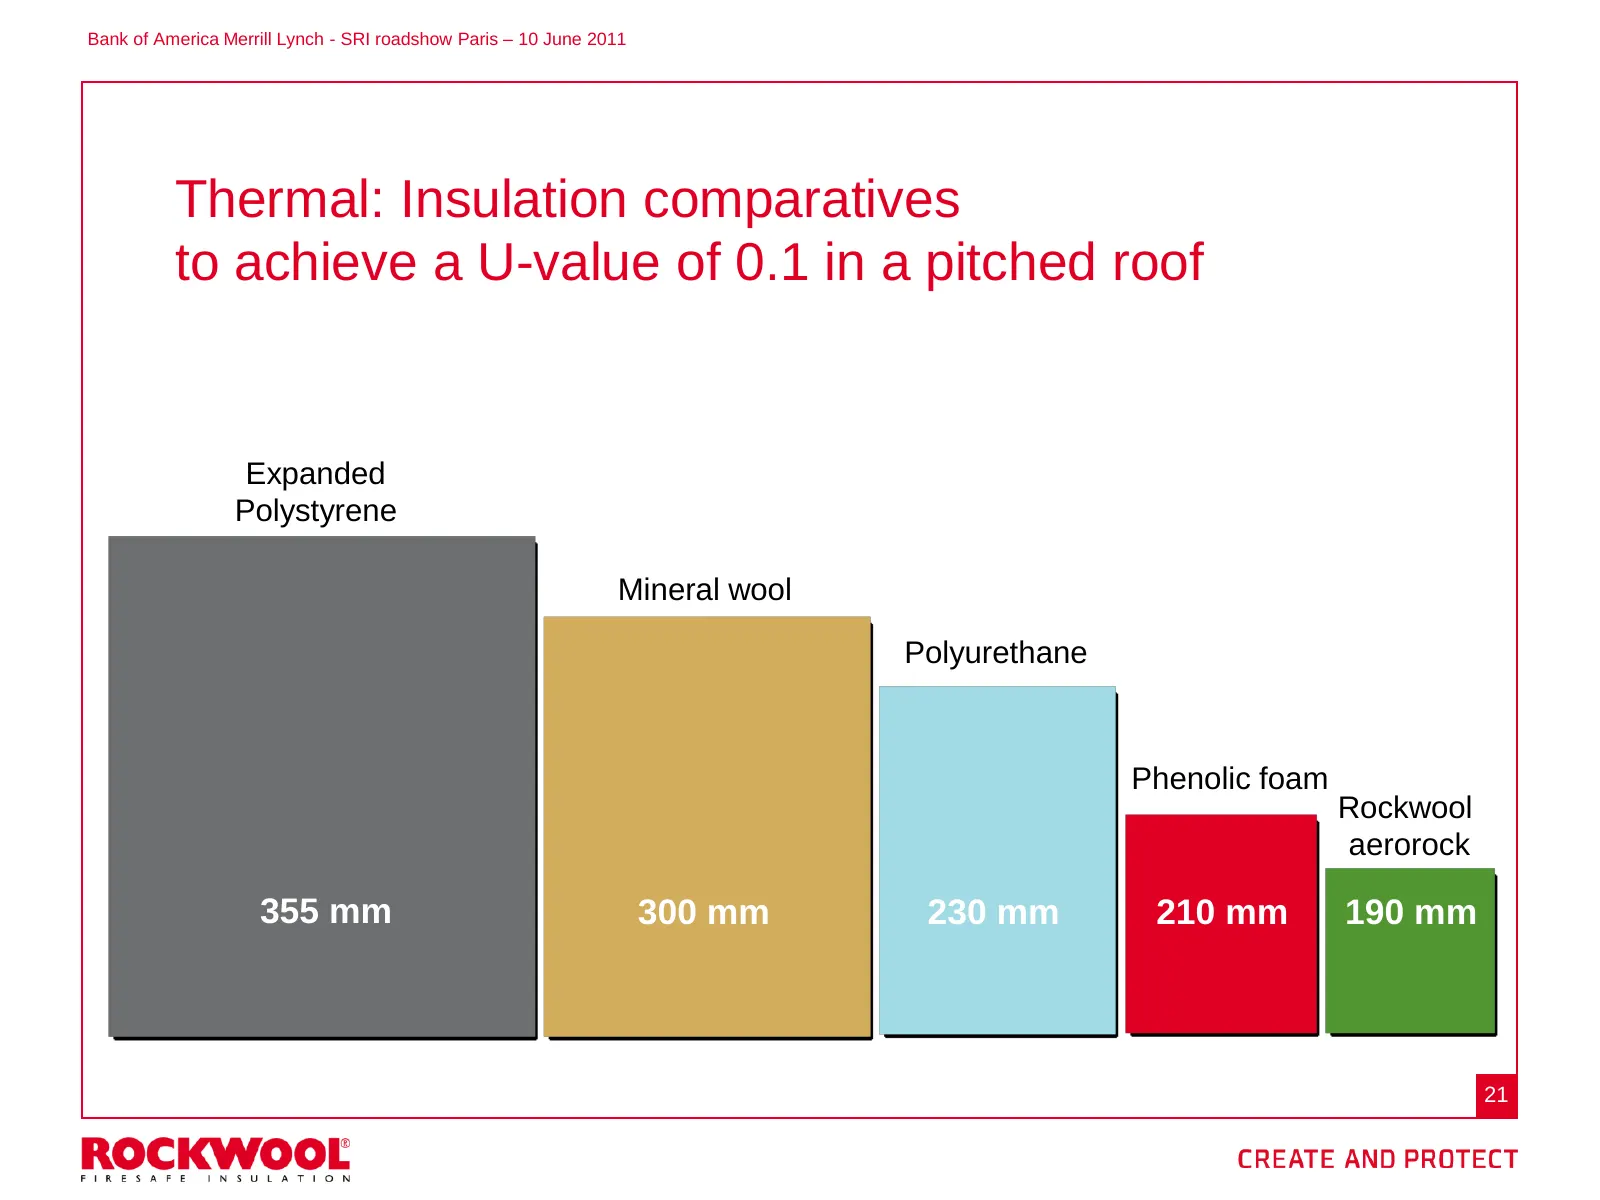
Slide 21: Thermal: insulation comparatives for U-value 0.1
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Thermal: Insulation comparatives to achieve a U-value of 0.1 in a pitched roof Expanded Polystyrene Mineral wool Polyurethane Phenolic foam Rockwool aerorock 355 mm 300 mm 230 mm 210 mm 190 mm 21
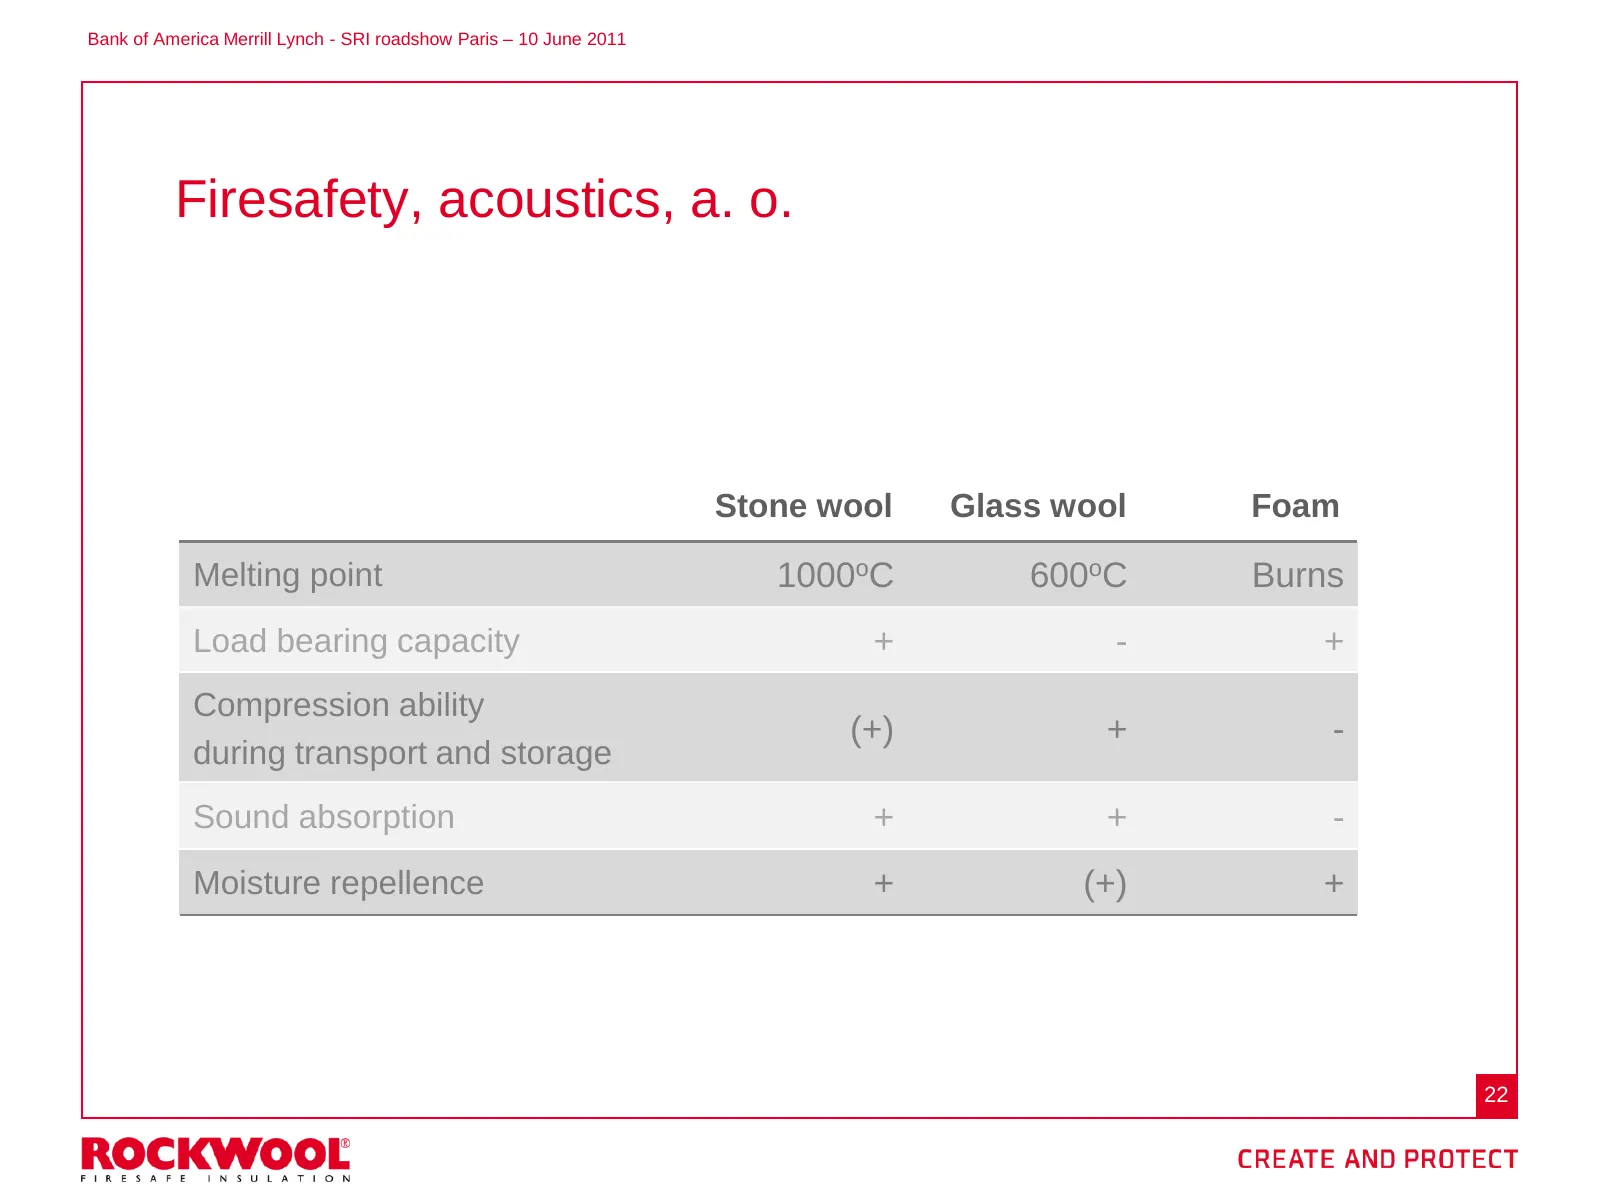
Slide 22: Firesafety, acoustics, a. o.
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Firesafety, acoustics, a. o. Stone wool Glass wool Foam Melting point 1000oC 600oC Burns Load bearing capacity + - + Compression ability (+) + - during transport and storage Sound absorption + + - Moisture repellence + (+) + 22
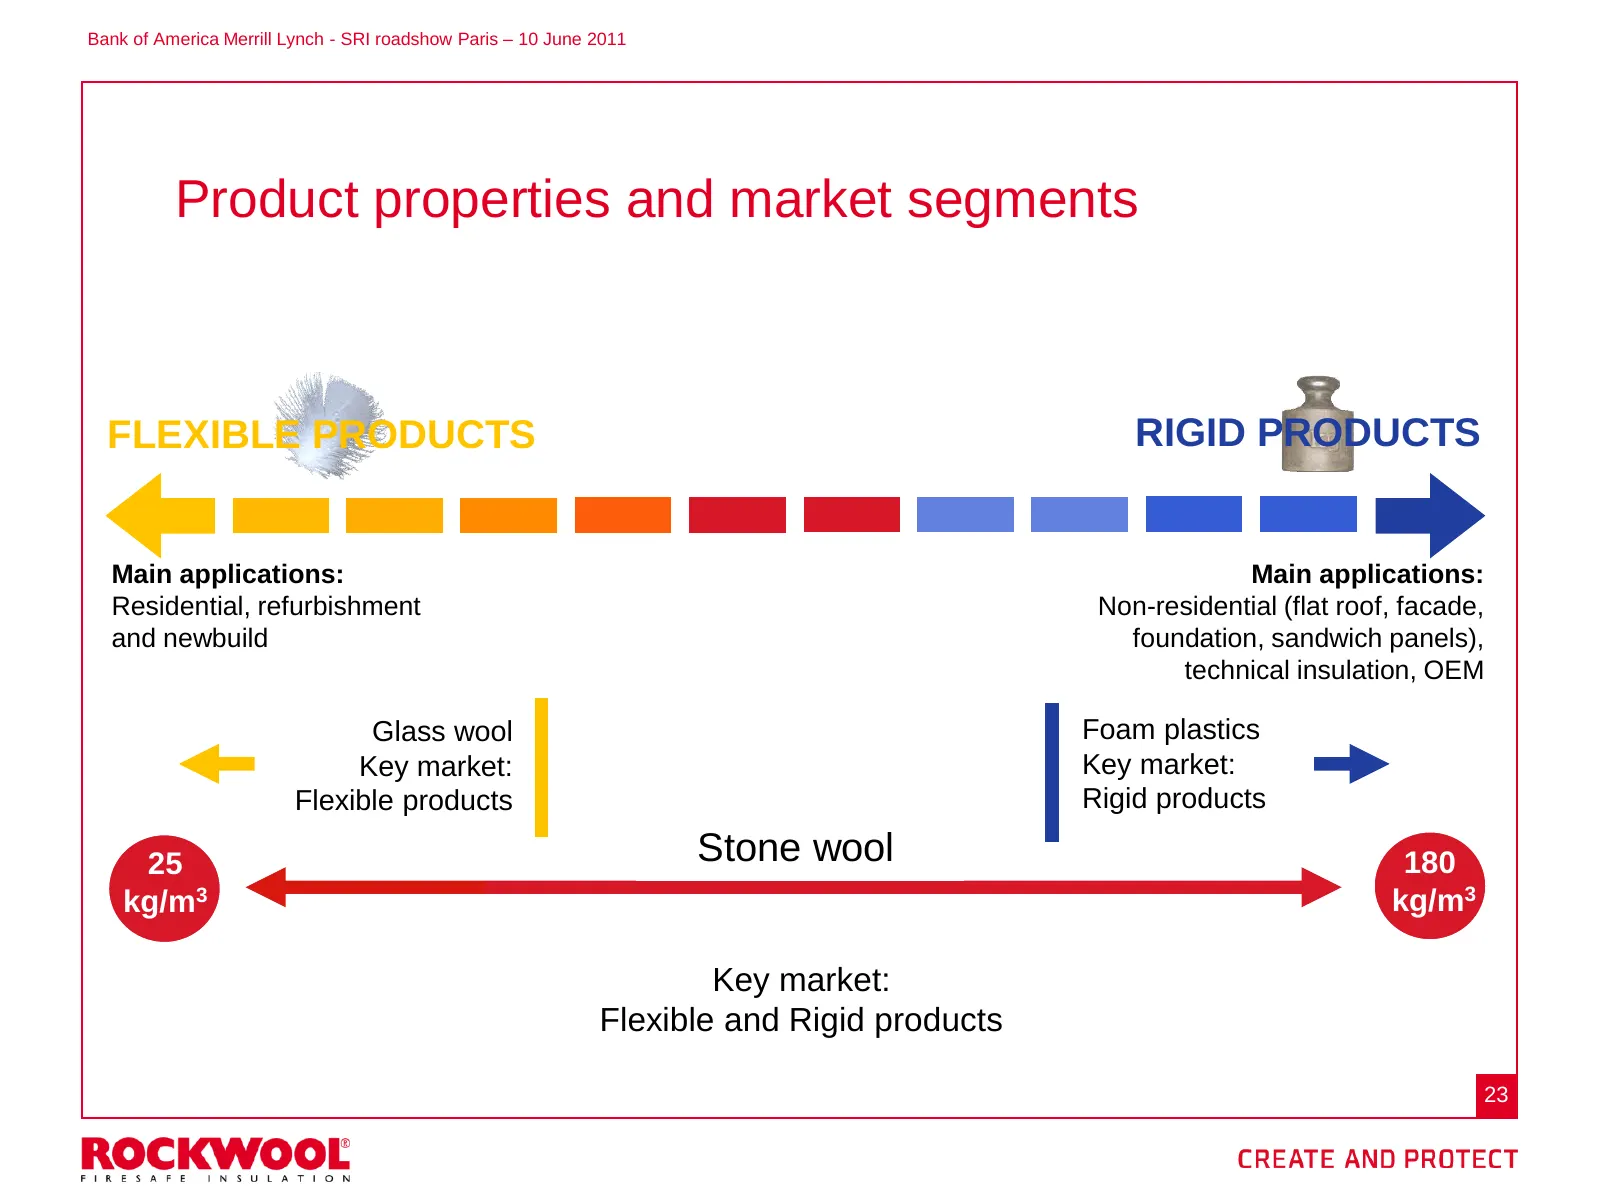
Slide 23: Product properties and market segments
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Product properties and market segments FLEXIBLE PRODUCTS RIGID PRODUCTS Main applications: Main applications: Residential, refurbishment Non-residential (flat roof, facade, and newbuild foundation, sandwich panels), technical insulati
Slide 24: Markets & regions
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Markets & regions 24
Slide 25: Highlights
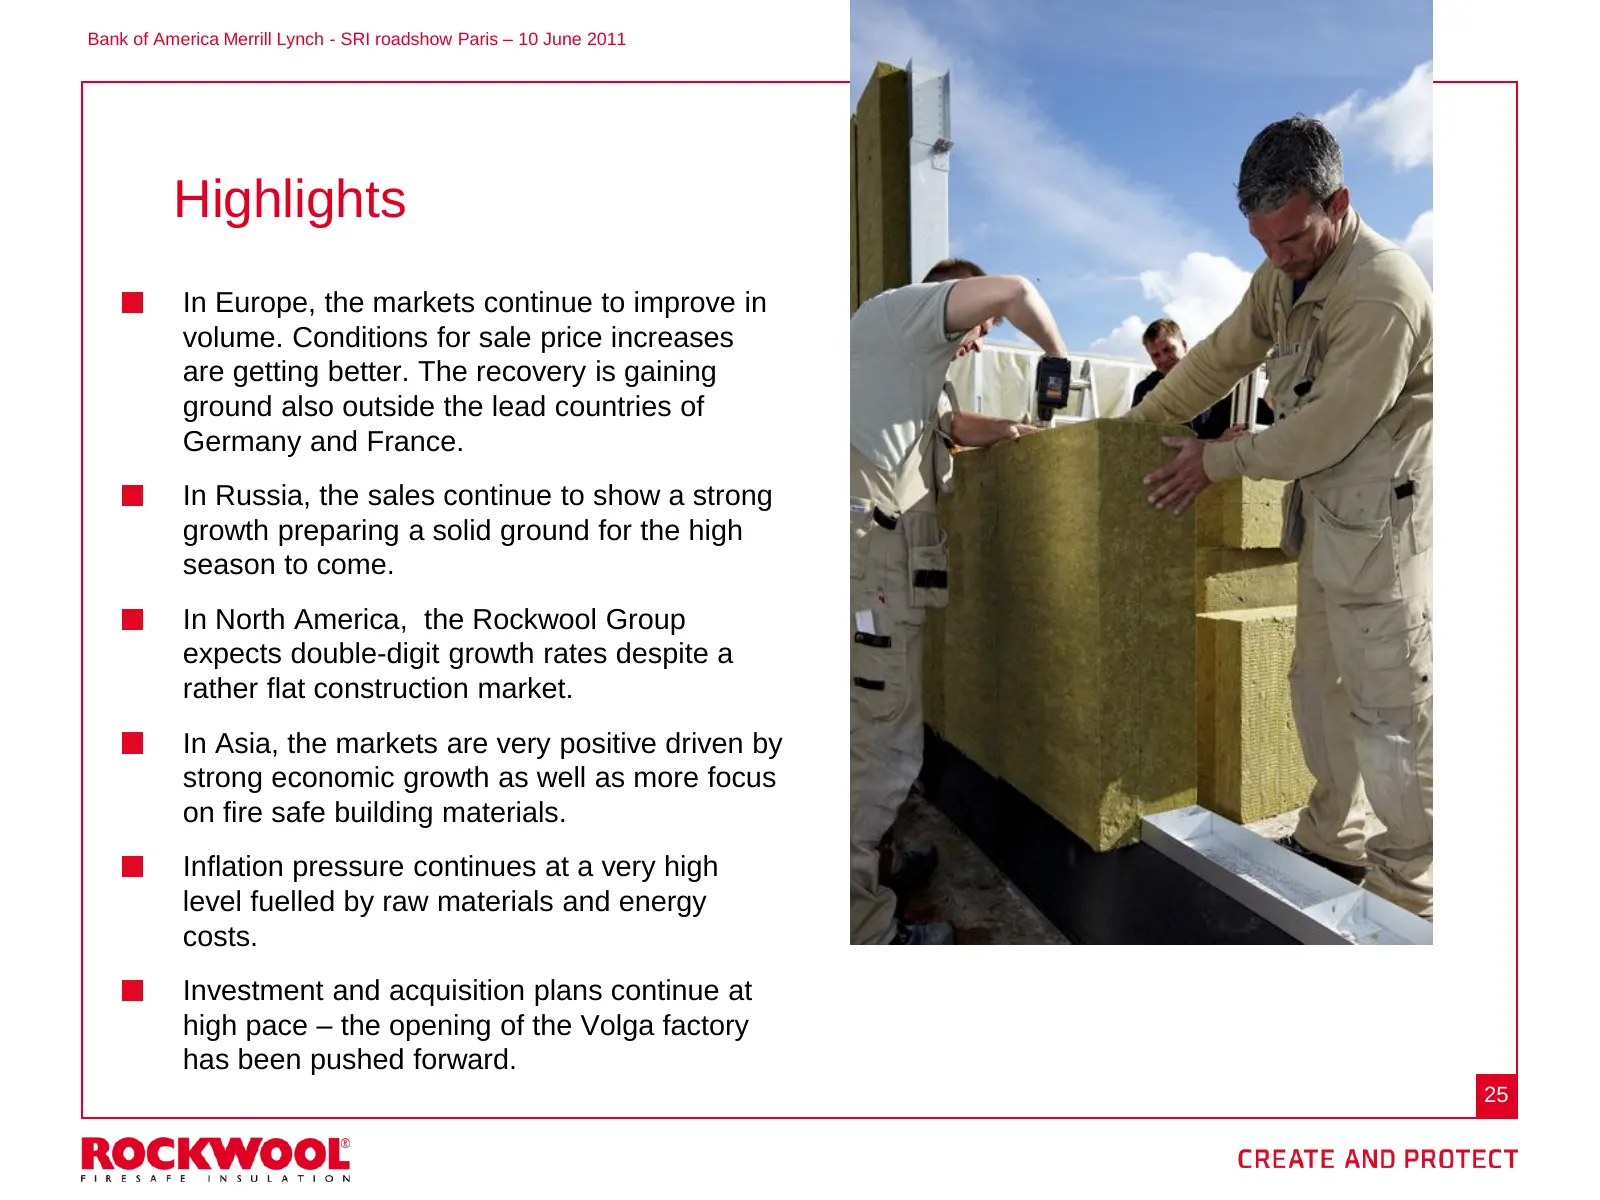
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Highlights In Europe, the markets continue to improve in volume. Conditions for sale price increases are getting better. The recovery is gaining ground also outside the lead countries of Germany and France. In Russia, the sales contin
Slide 26: European insulation market 2010
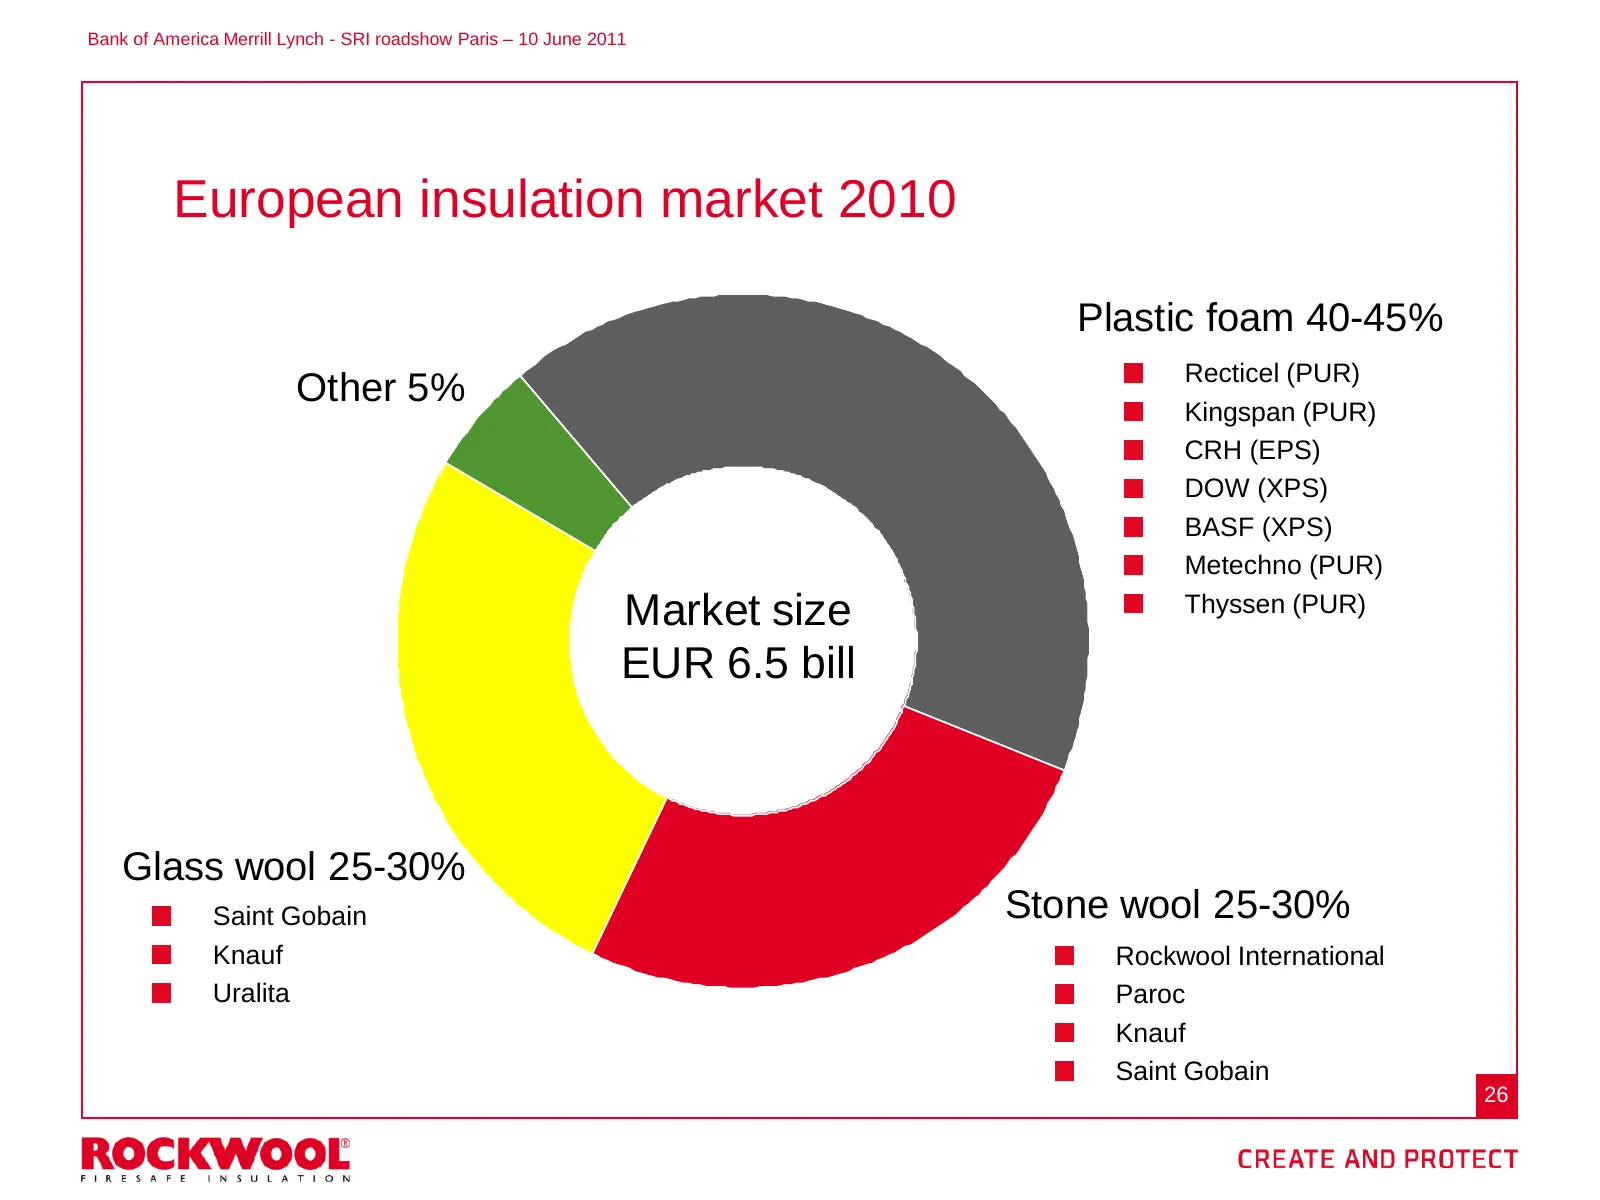
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 European insulation market 2010 Plastic foam 40-45% Recticel (PUR) Other 5% Kingspan (PUR) CRH (EPS) DOW (XPS) BASF (XPS) Metechno (PUR) Market size Thyssen (PUR) EUR 6.5 bill Glass wool 25-30% Saint Gobain Stone wool 25-30% Knauf Roc
Slide 27: Western Europe
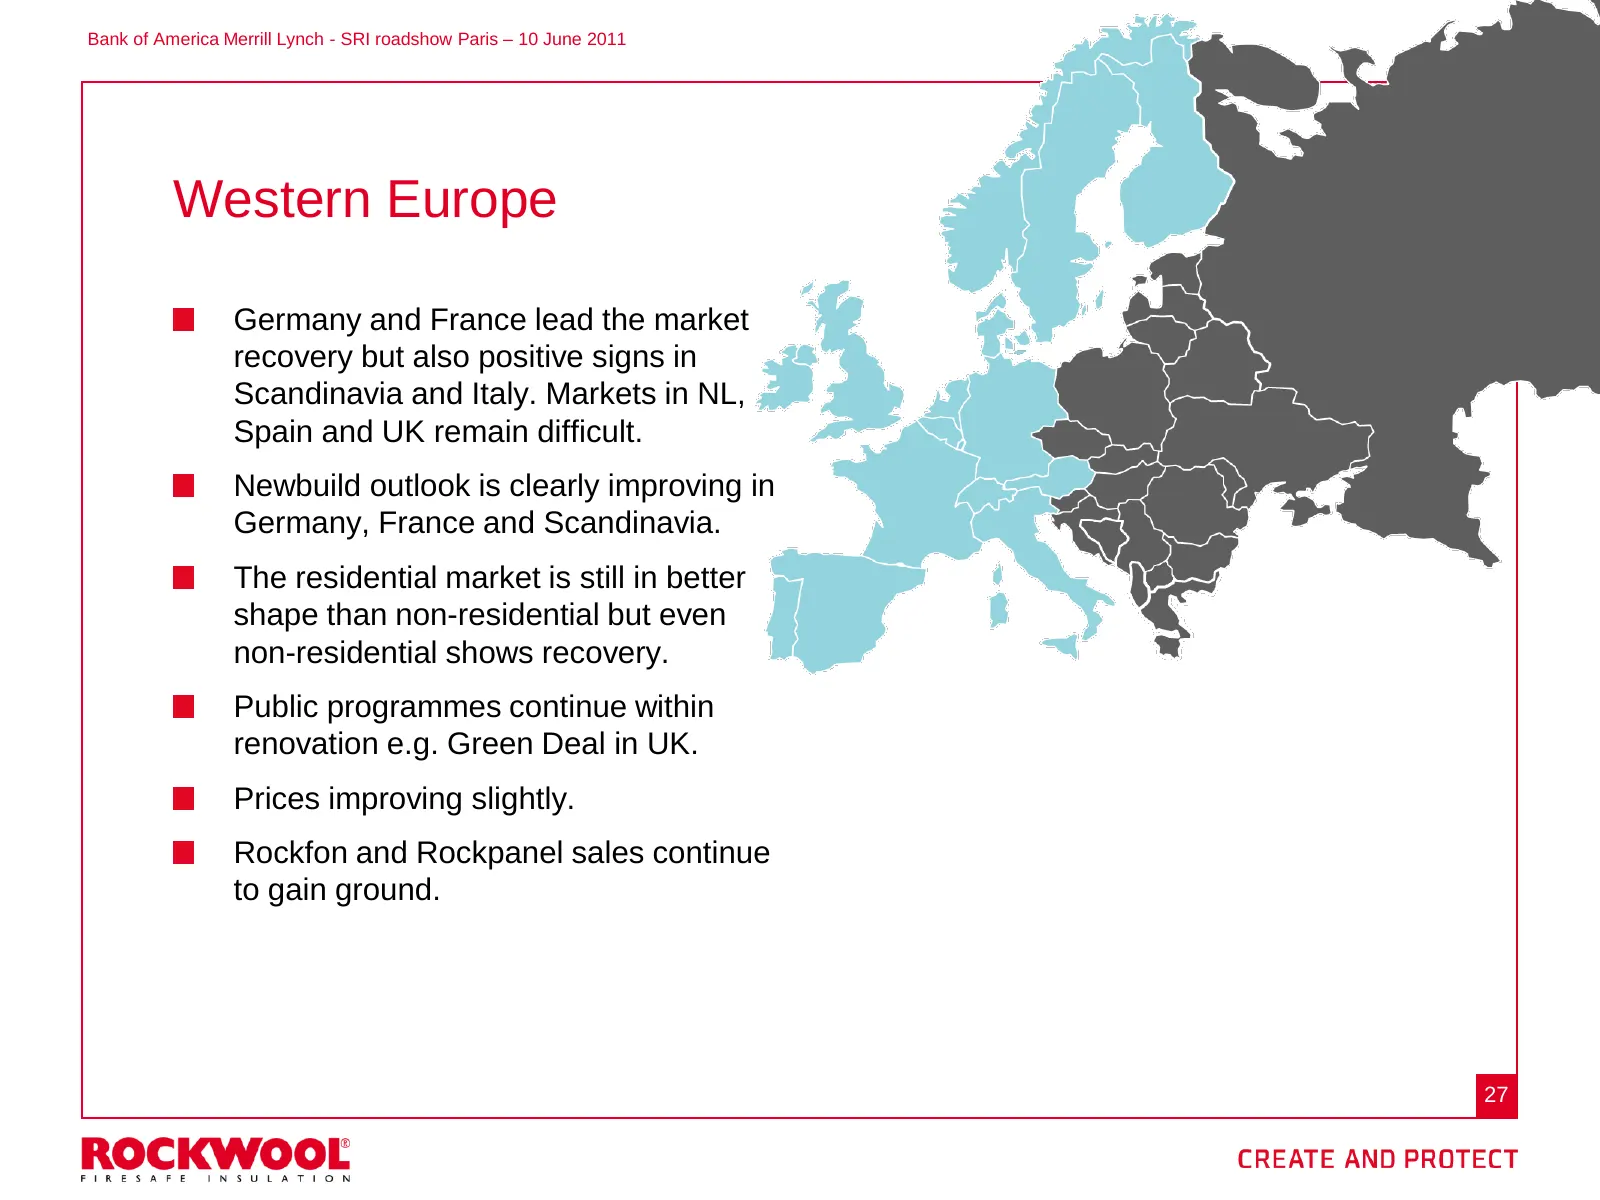
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Western Europe Germany and France lead the market recovery but also positive signs in Scandinavia and Italy. Markets in NL, Spain and UK remain difficult. Newbuild outlook is clearly improving in Germany, France and Scandinavia. The r
Slide 28: Central / Eastern Europe
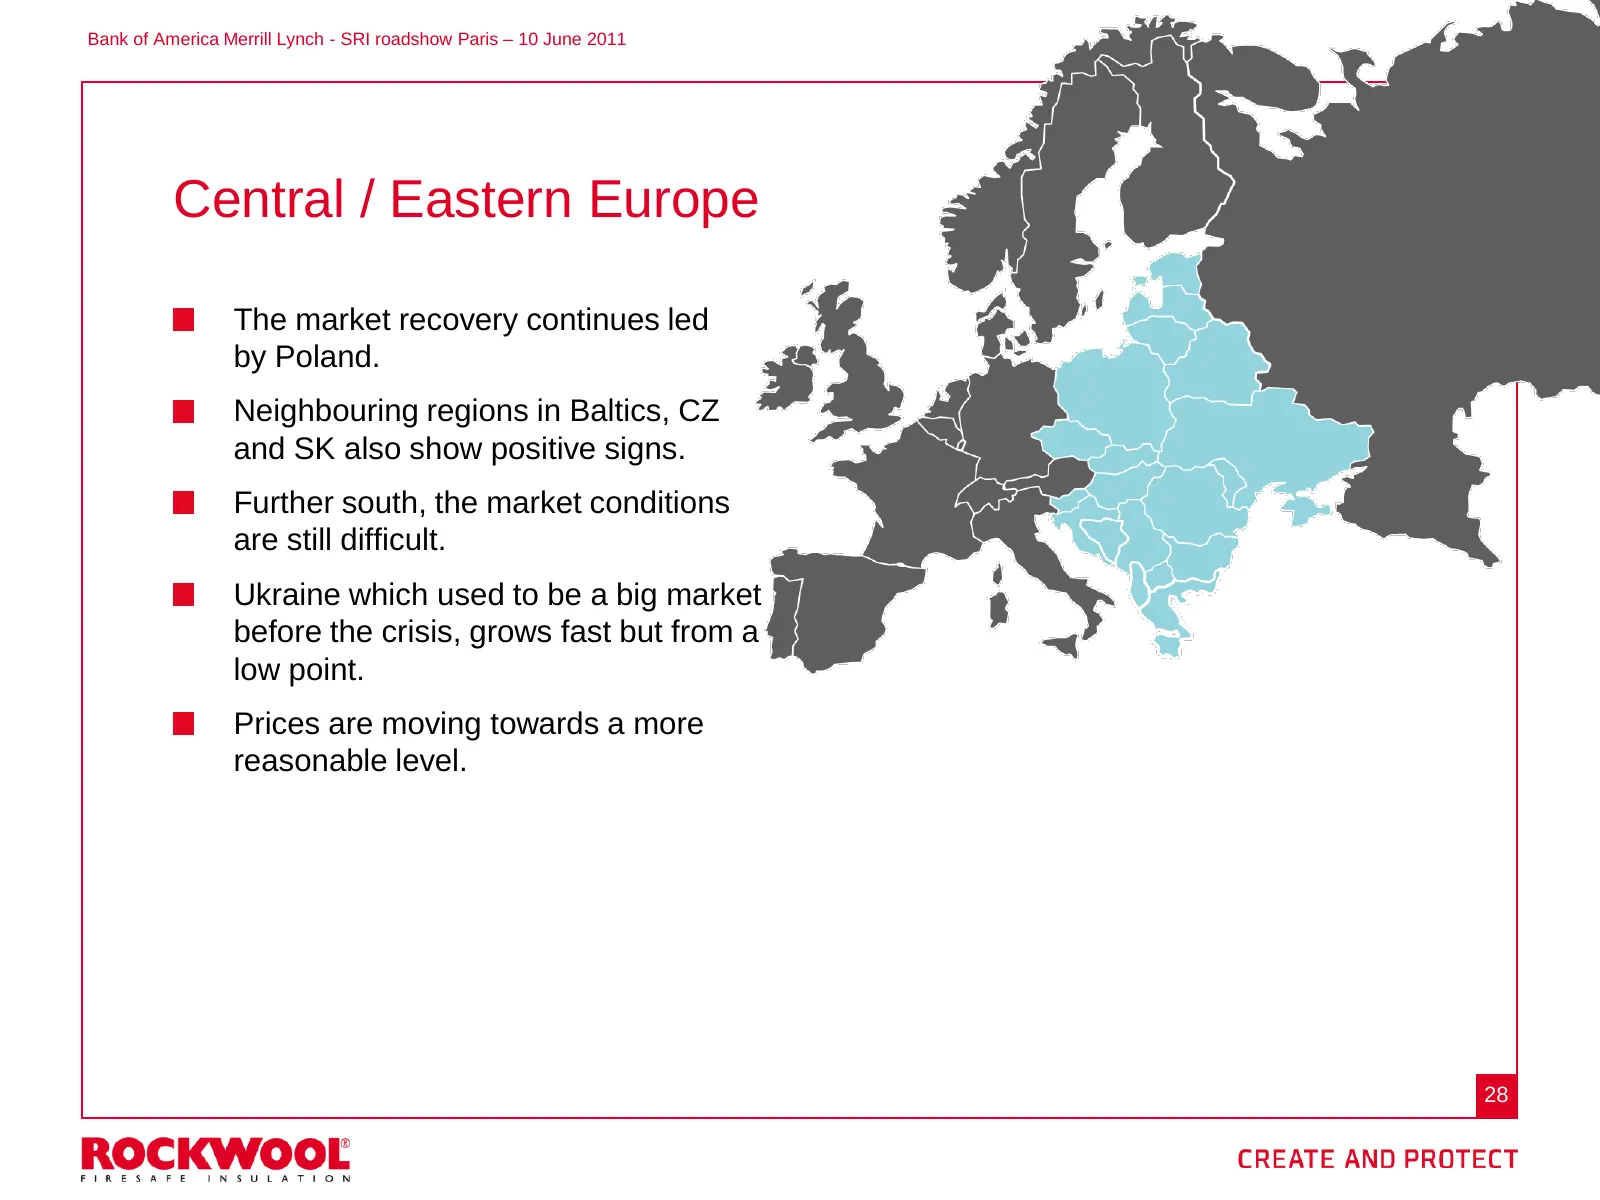
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Central / Eastern Europe The market recovery continues led by Poland. Neighbouring regions in Baltics, CZ and SK also show positive signs. Further south, the market conditions are still difficult. Ukraine which used to be a big market
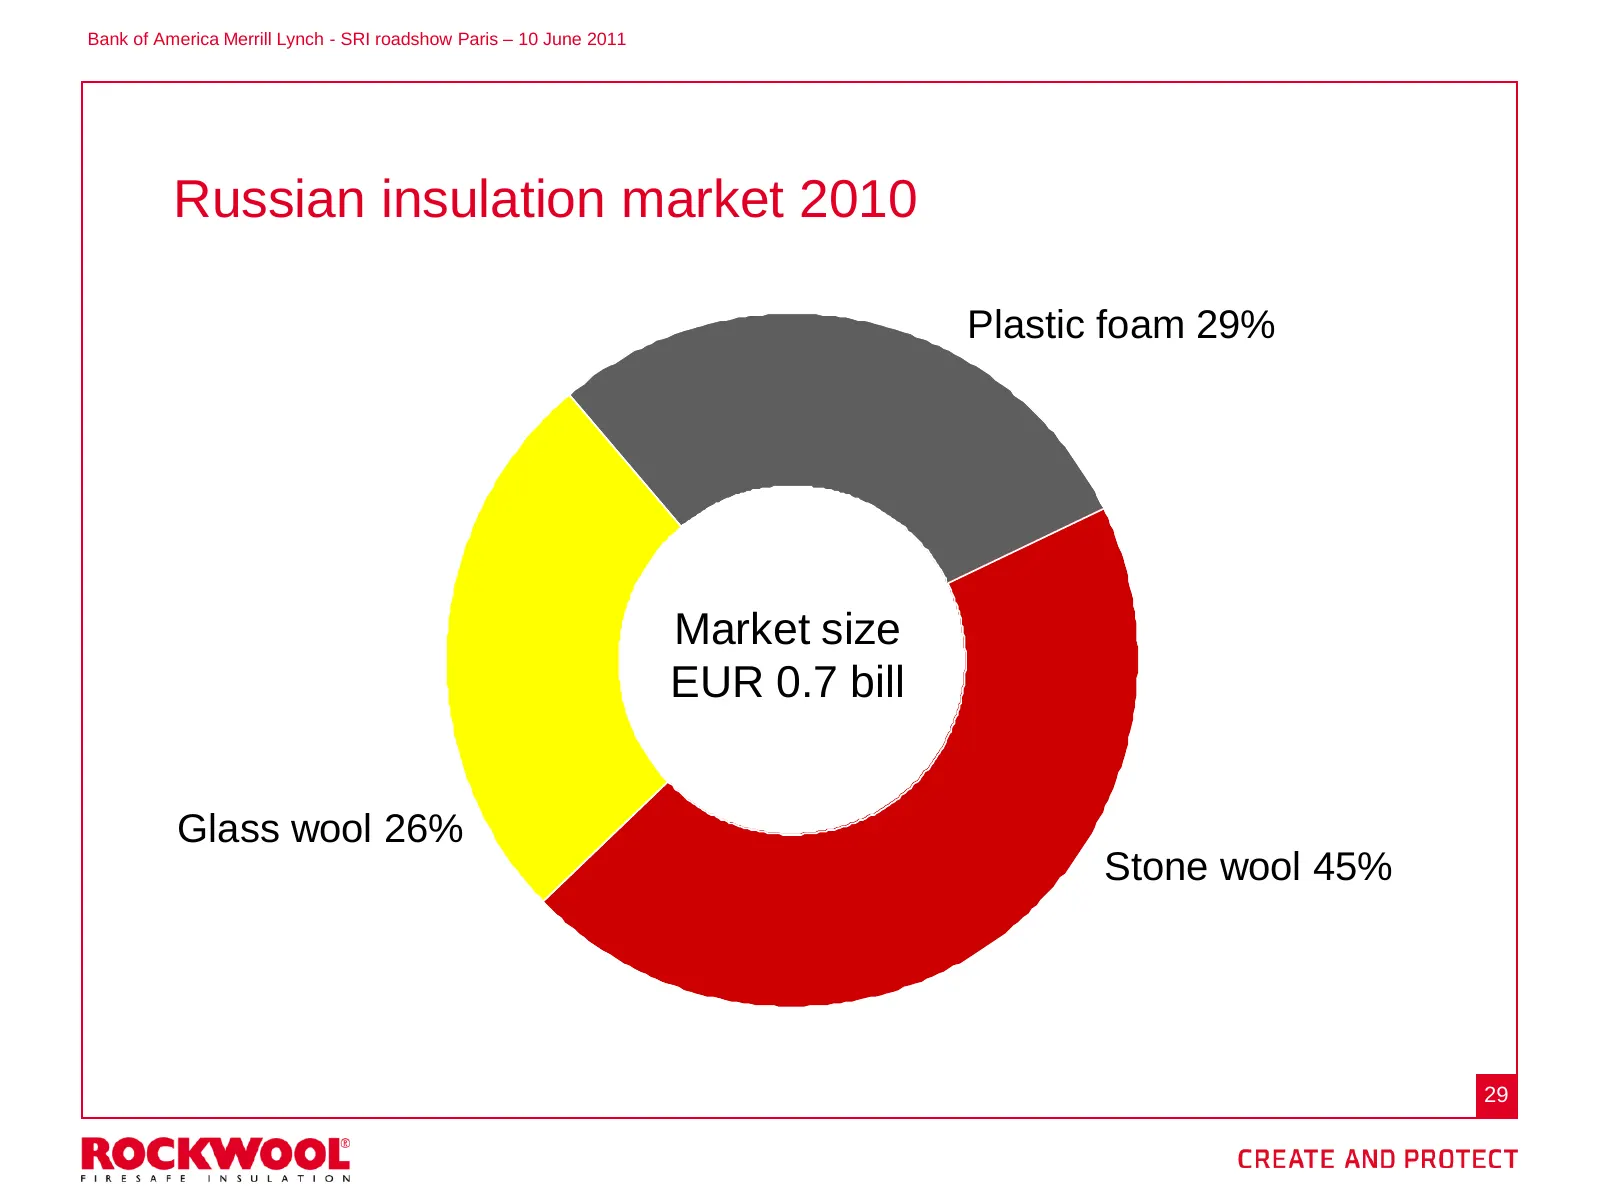
Slide 29: Russian insulation market 2010
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Russian insulation market 2010 Plastic foam 29% Market size EUR 0.7 bill Glass wool 26% Stone wool 45% 29
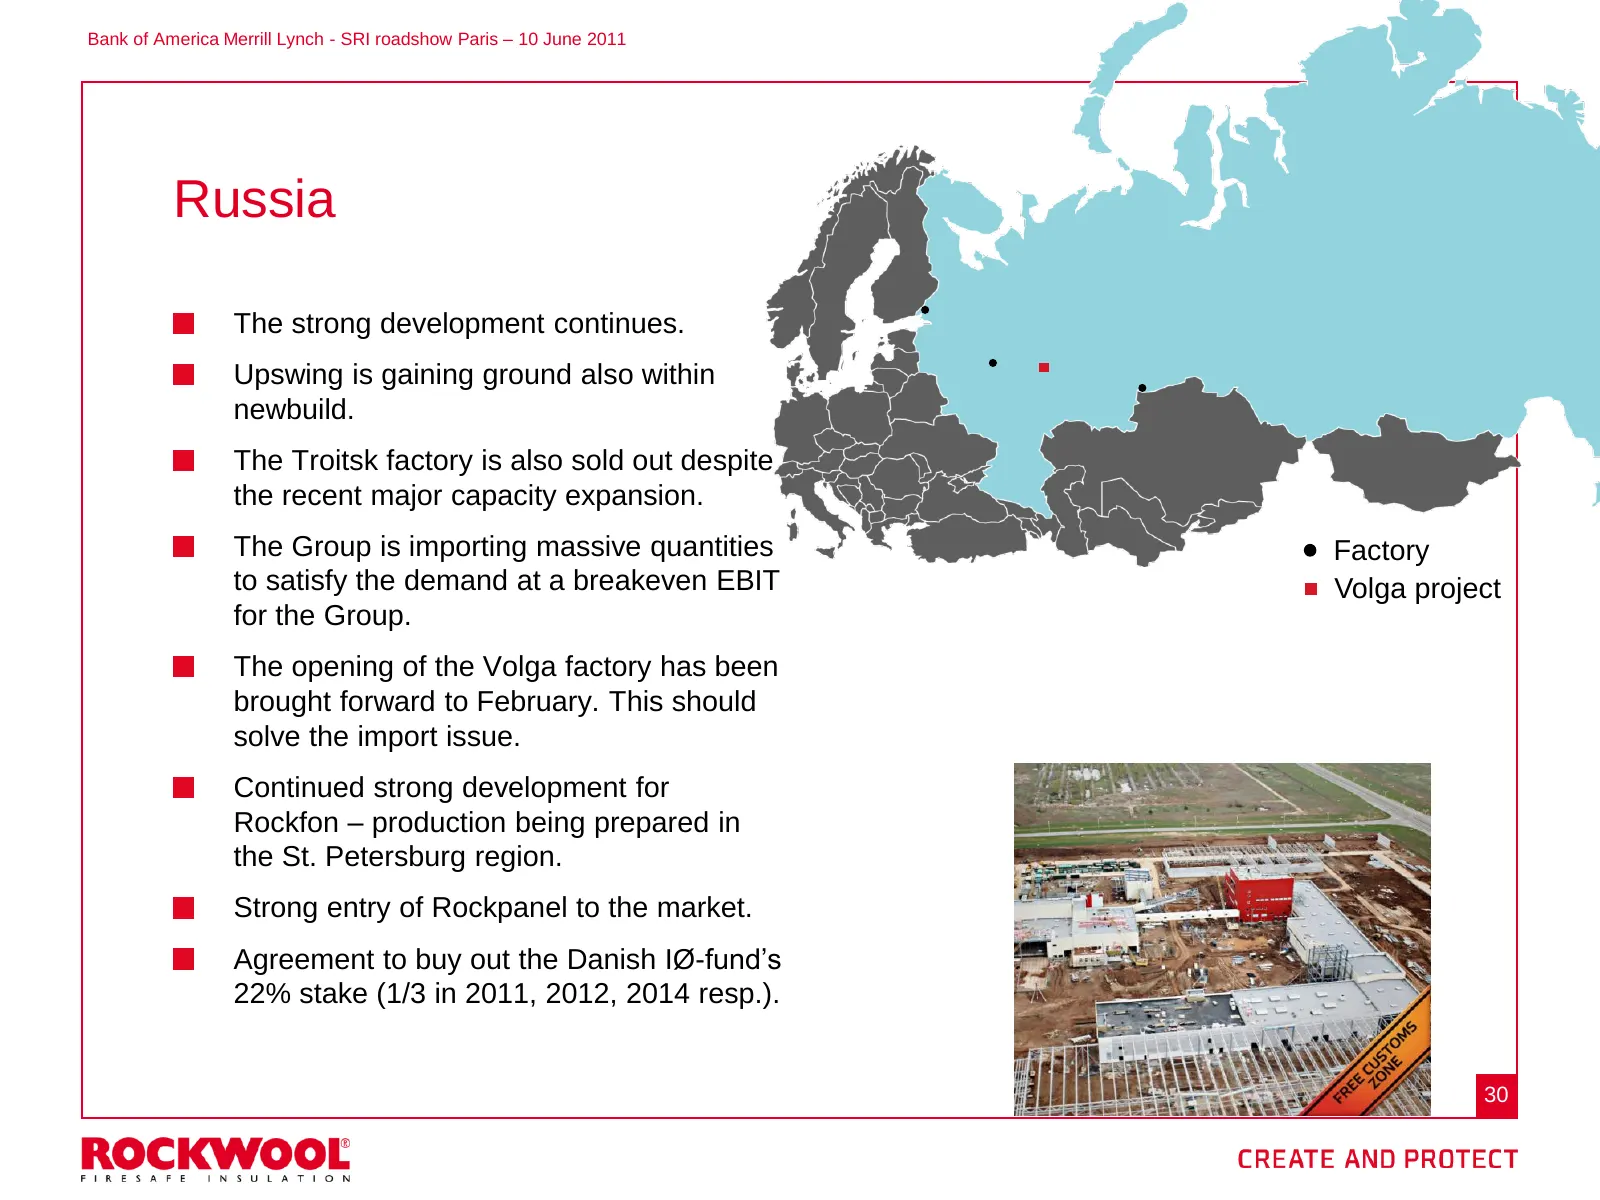
Slide 30: Russia
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Russia The strong development continues. Upswing is gaining ground also within newbuild. The Troitsk factory is also sold out despite the recent major capacity expansion. The Group is importing massive quantities Factory to satisfy th
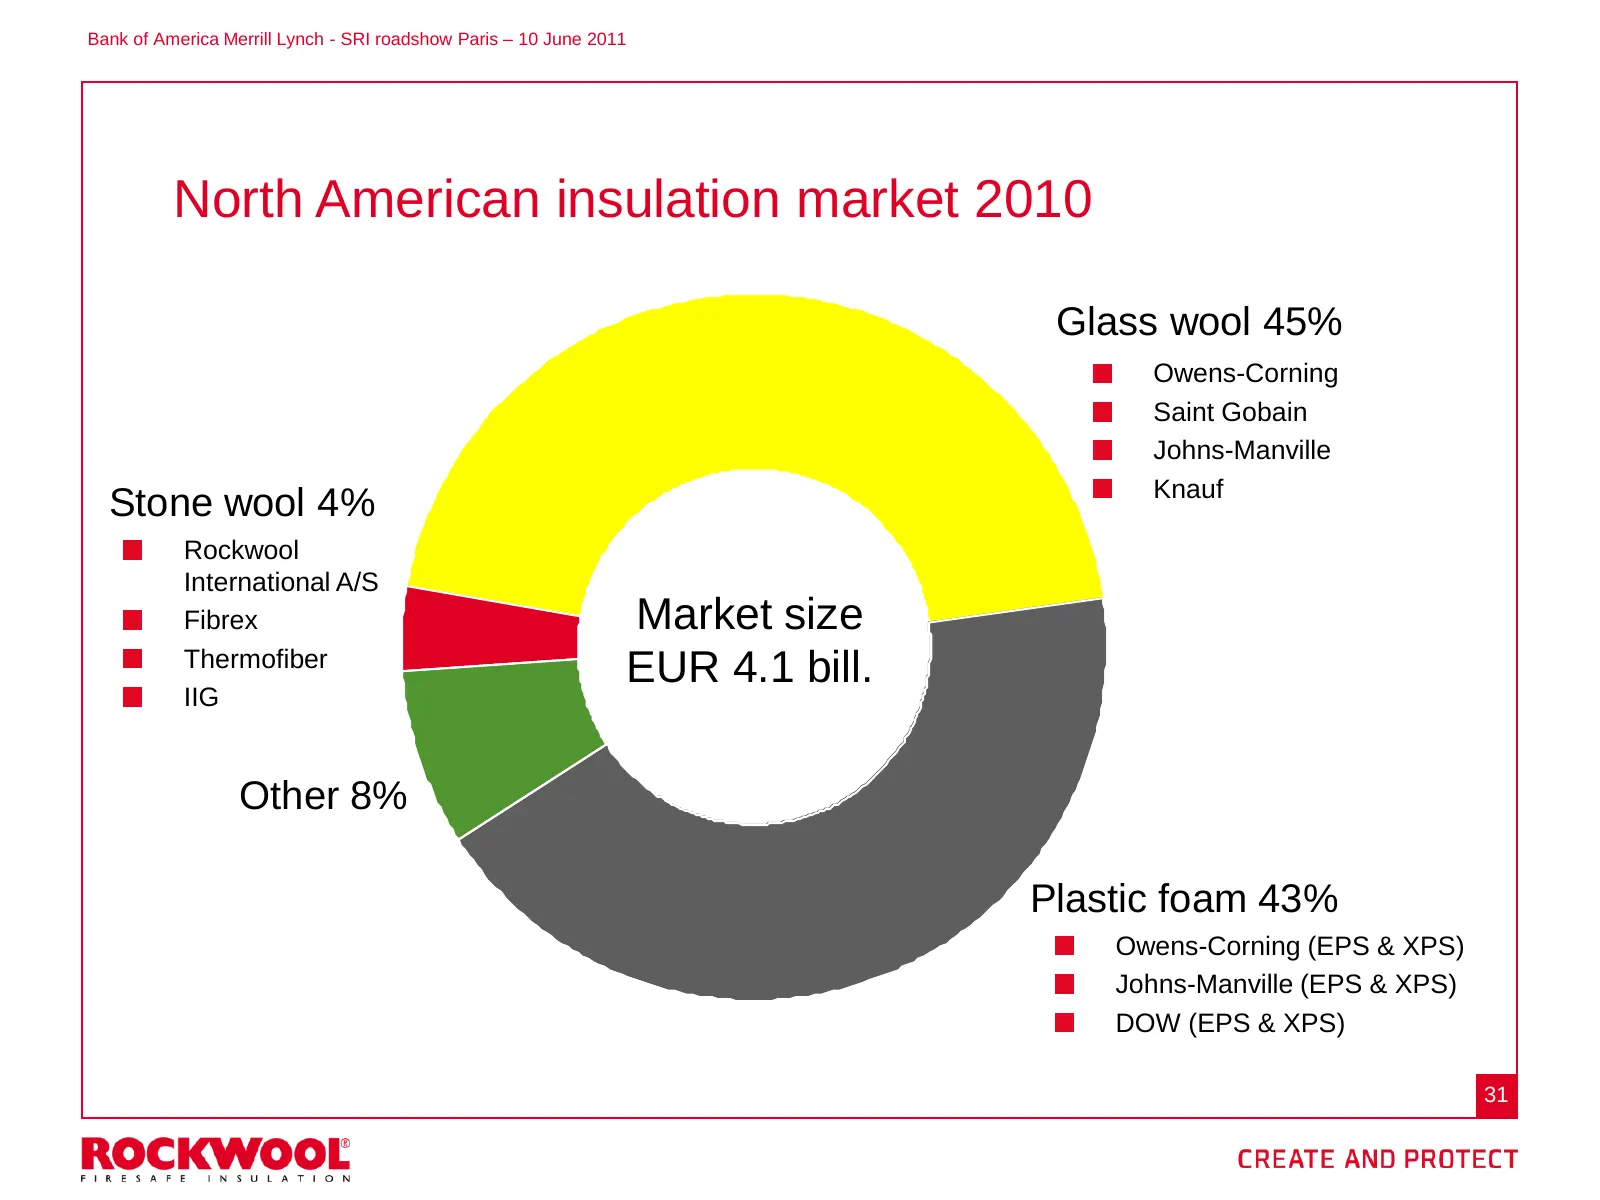
Slide 31: North American insulation market 2010
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 North American insulation market 2010 Glass wool 45% Owens-Corning Saint Gobain Johns-Manville Knauf Stone wool 4% Rockwool International A/S Fibrex Market size Thermofiber EUR 4.1 bill. IIG Other 8% Plastic foam 43% Owens-Corning (EP
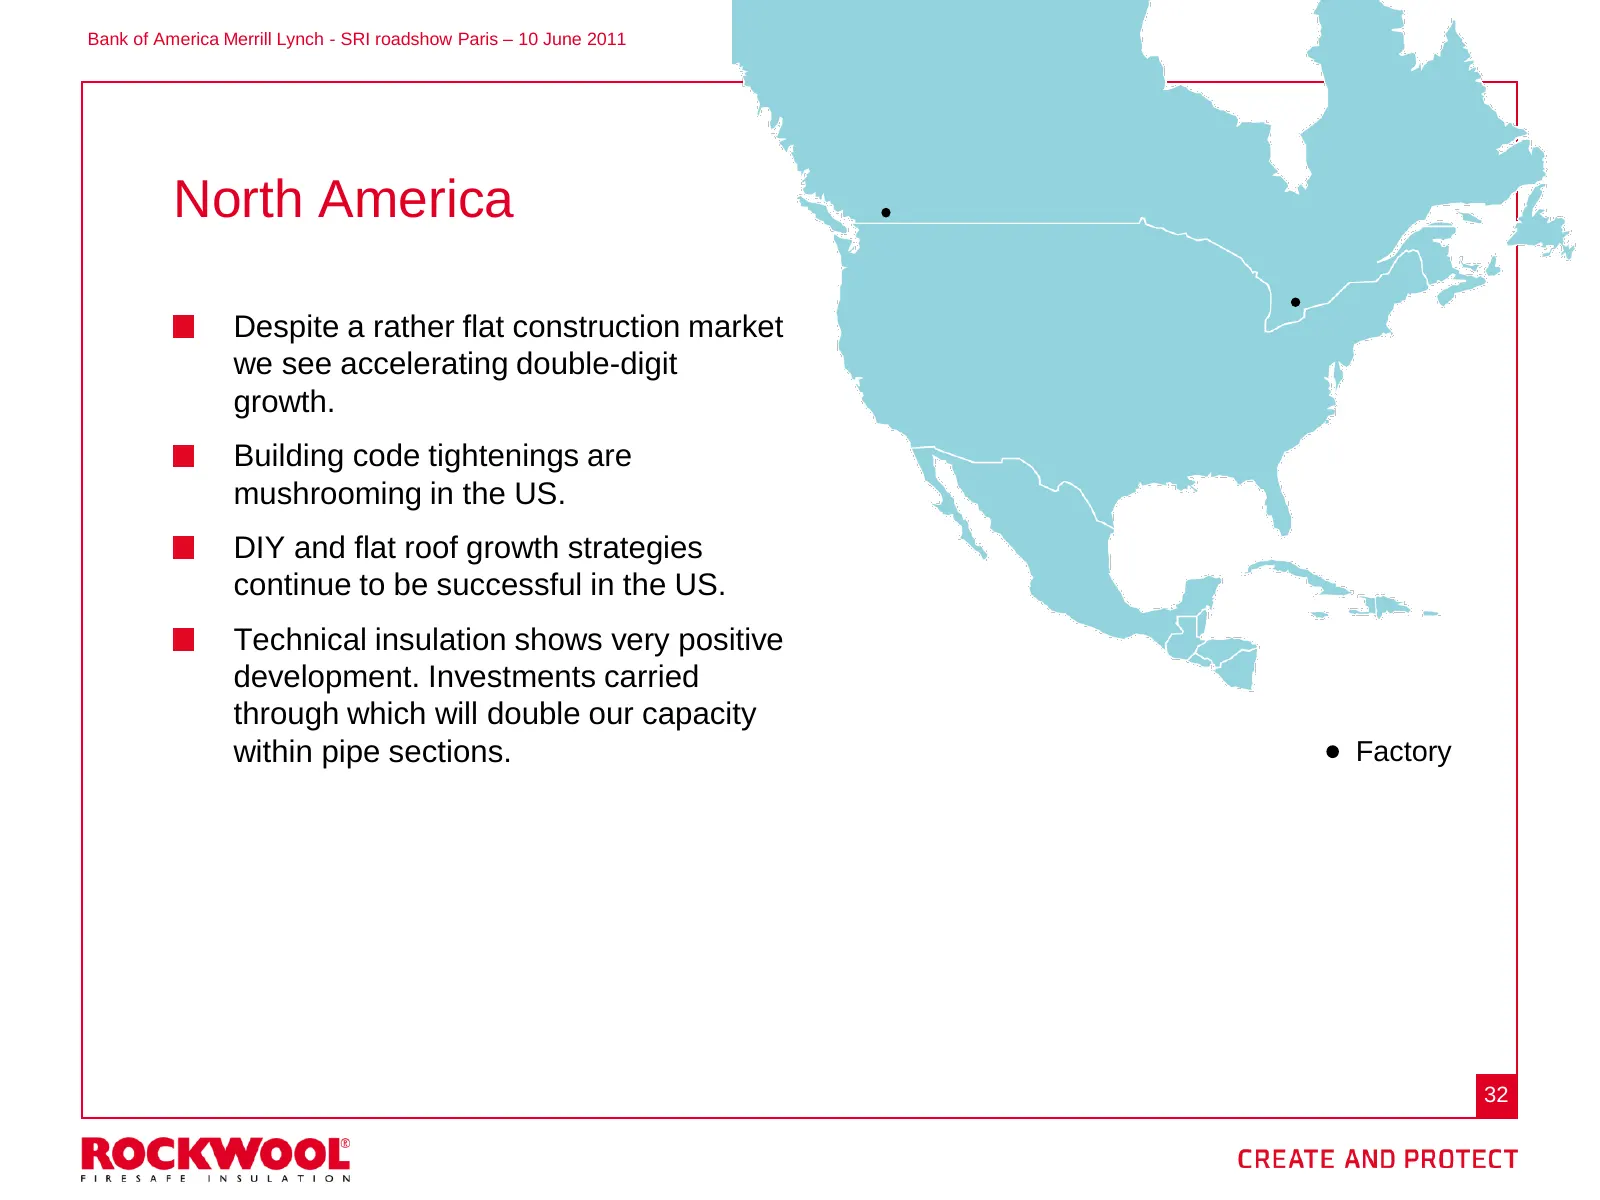
Slide 32: North America
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 North America Despite a rather flat construction market we see accelerating double-digit growth. Building code tightenings are mushrooming in the US. DIY and flat roof growth strategies continue to be successful in the US. Technical i
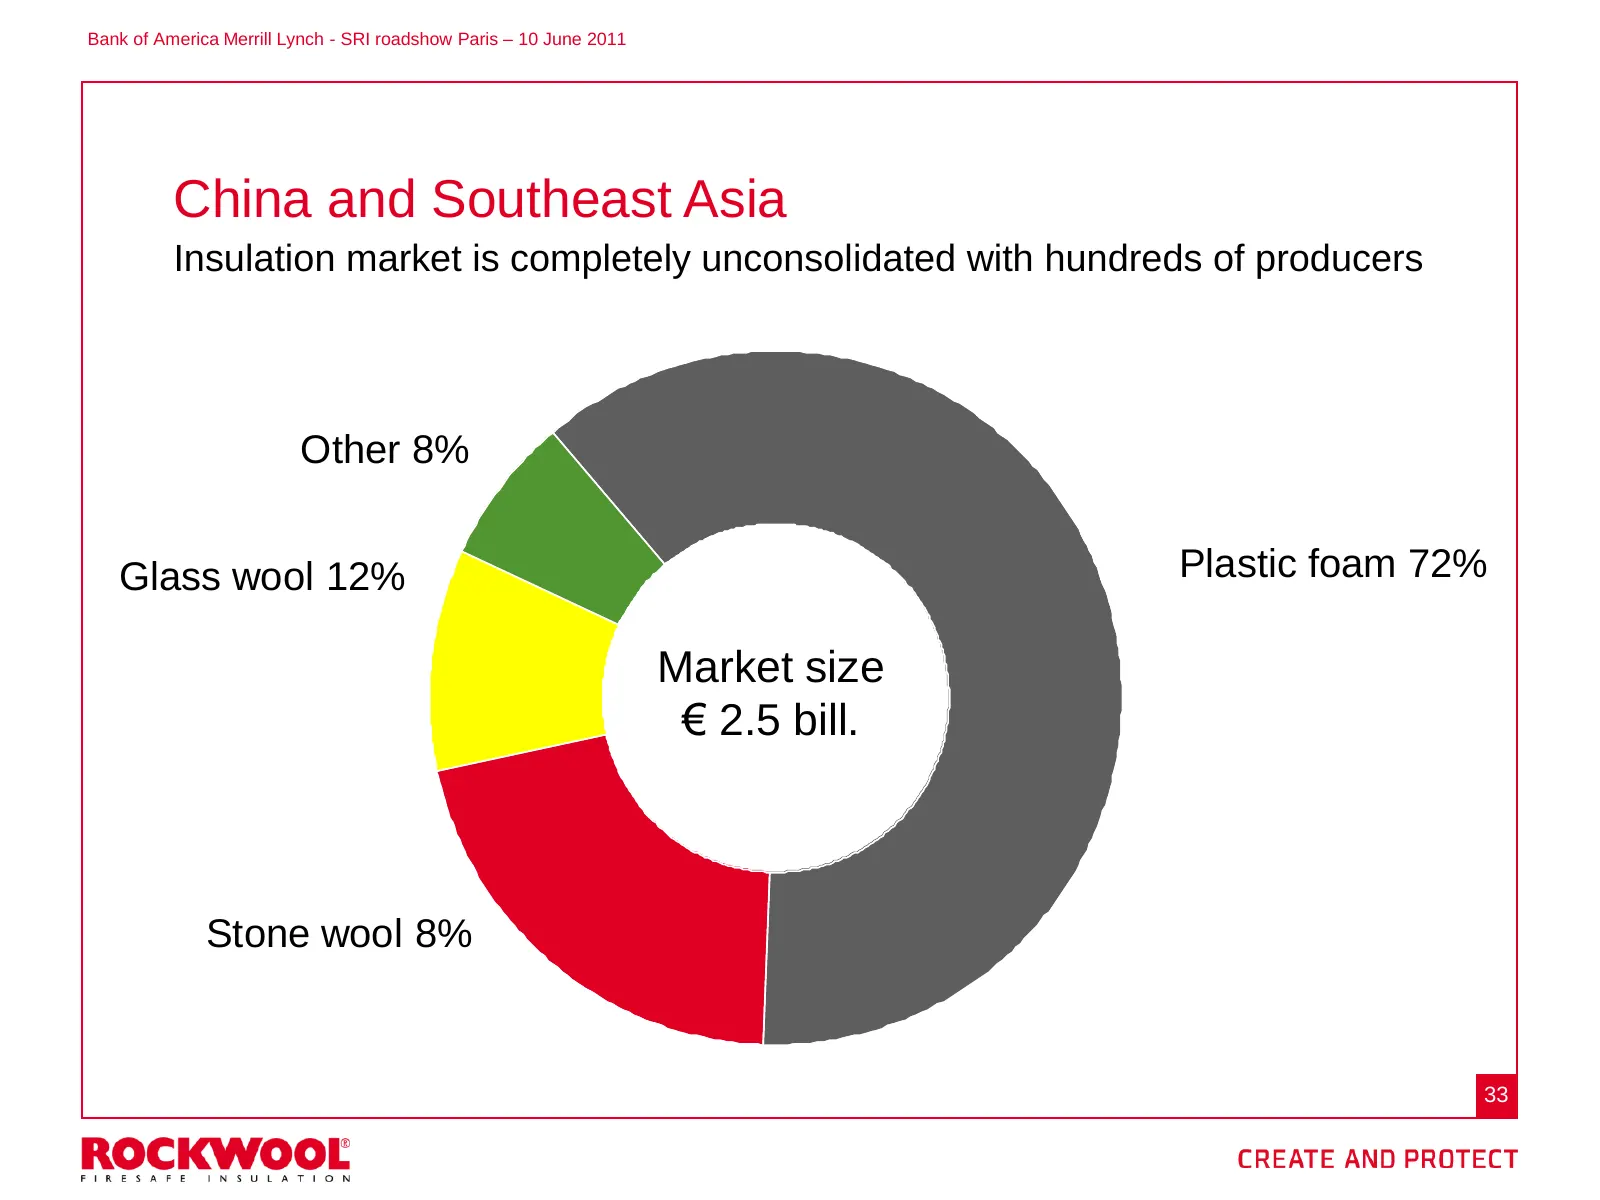
Slide 33: China and Southeast Asia
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 China and Southeast Asia Insulation market is completely unconsolidated with hundreds of producers Other 8% Glass wool 12% Plastic foam 72% Market size € 2.5 bill. Stone wool 8% 33
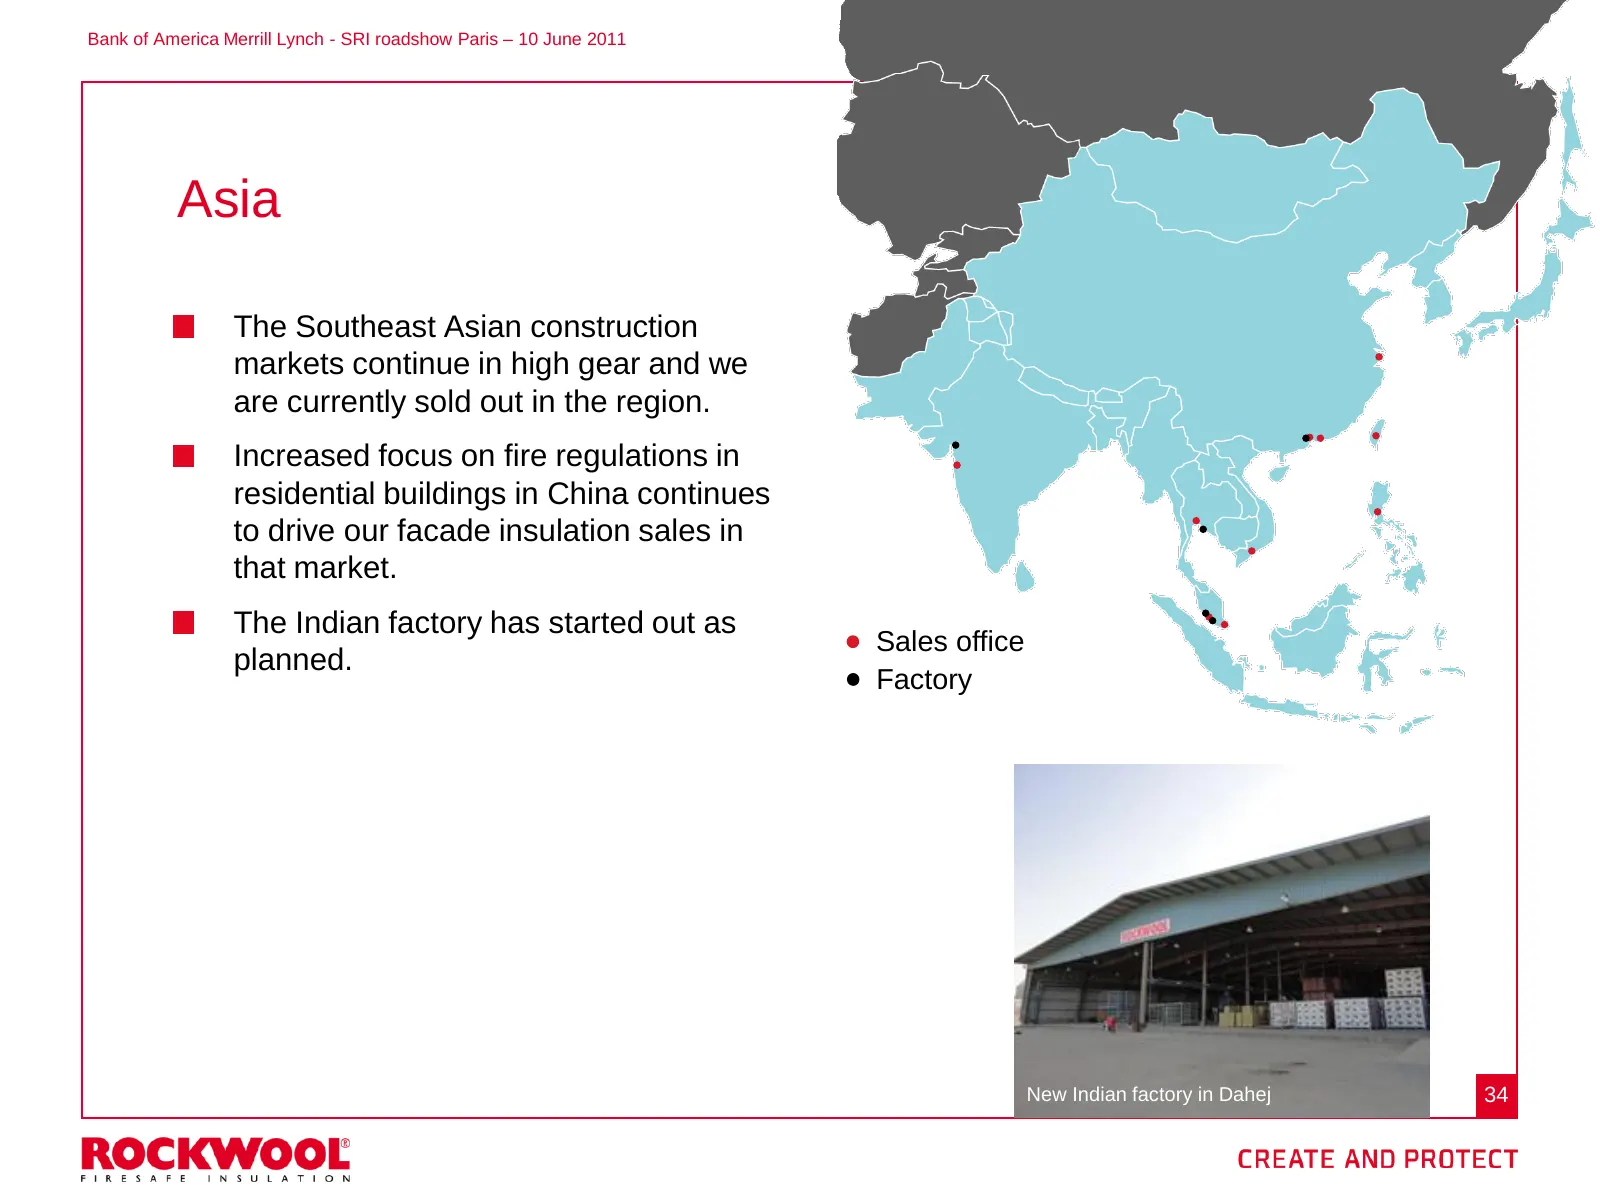
Slide 34: Asia
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Asia The Southeast Asian construction markets continue in high gear and we are currently sold out in the region. Increased focus on fire regulations in residential buildings in China continues to drive our facade insulation sales in t
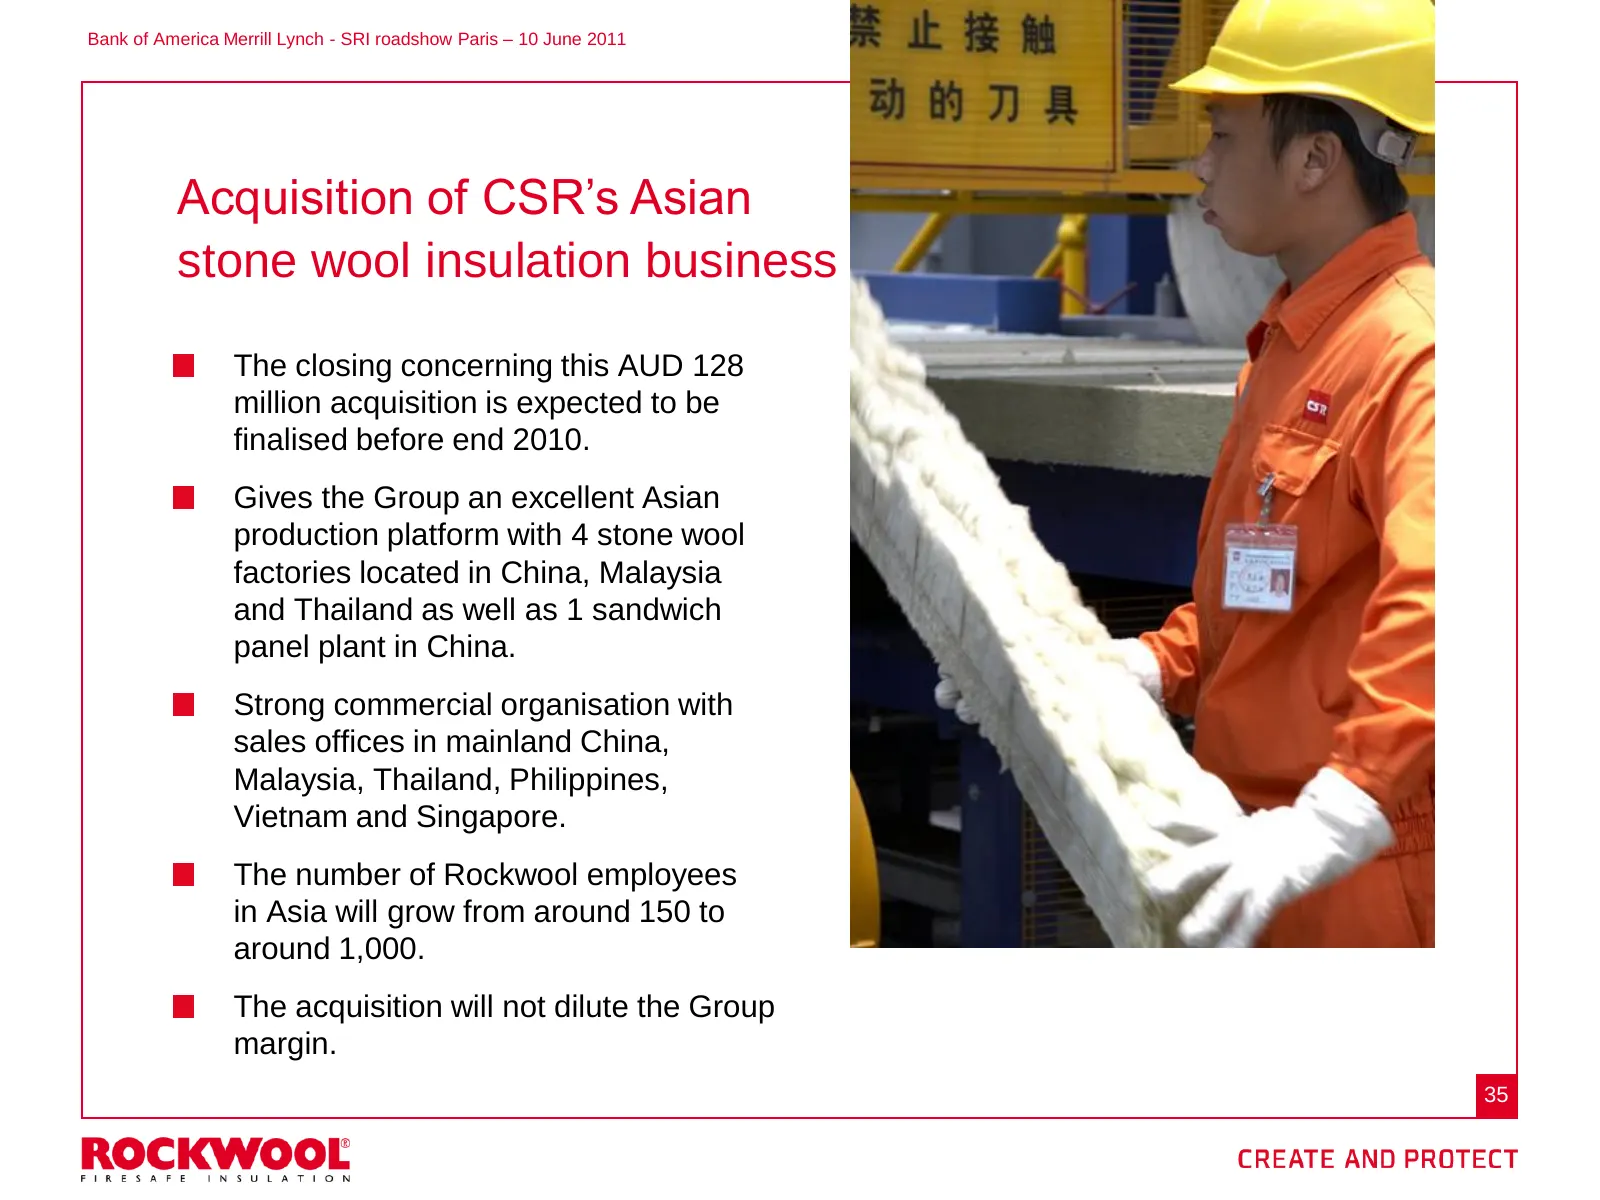
Slide 35: Acquisition of CSR's Asian stone wool insulation business
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Acquisition of CSR’s Asian stone wool insulation business The closing concerning this AUD 128 million acquisition is expected to be finalised before end 2010. Gives the Group an excellent Asian production platform with 4 stone wool fa
Slide 36: Financials
BankRockwool The of America presentation – -May Merrill Lynch SRI roadshow 2011 Paris – 10 June 2011 Financials 36
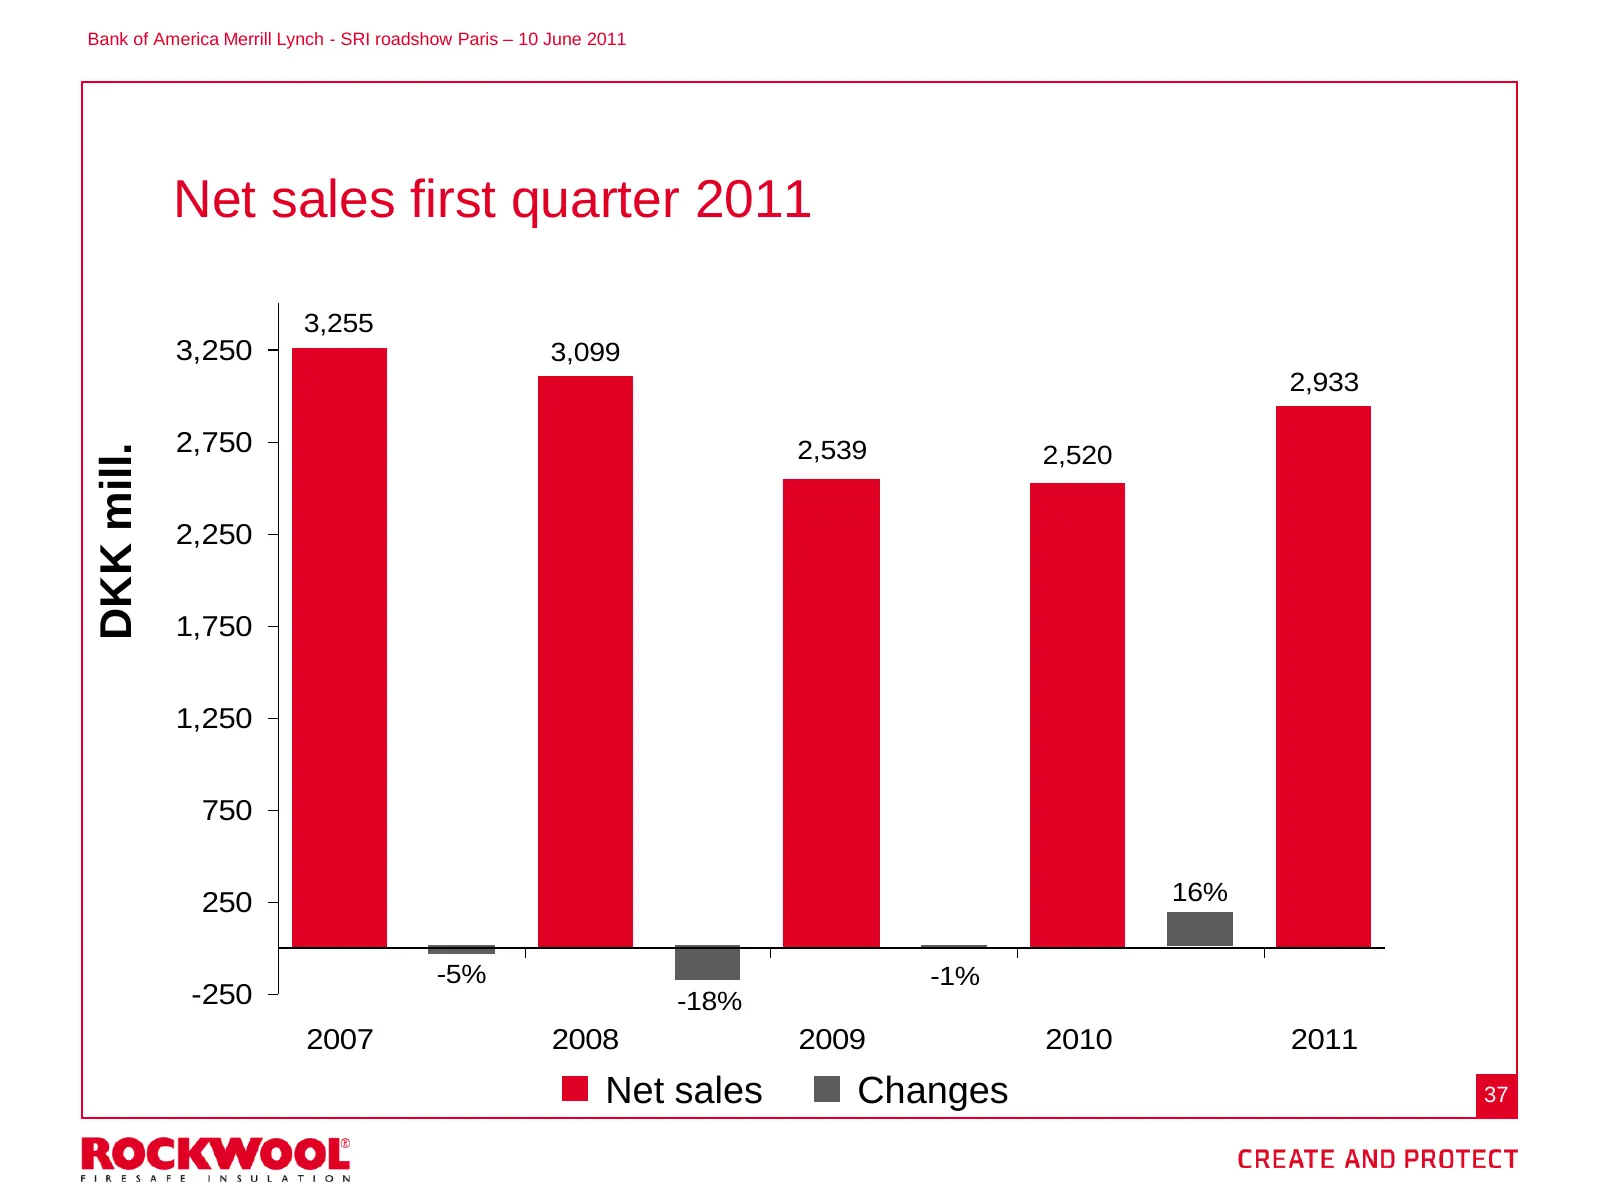
Slide 37: Net sales first quarter 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Net sales first quarter 2011 325% 3,255 3,250 3,099 2,933 275% 2,750 2,539 DKK mill. 2,520 225% 2,250 175% 1,750 125% 1,250 75% 750 250 16% 25% -5% -1% -250 -18% -25% 2007 2008 2009 2010 2011 Net sales Changes 37
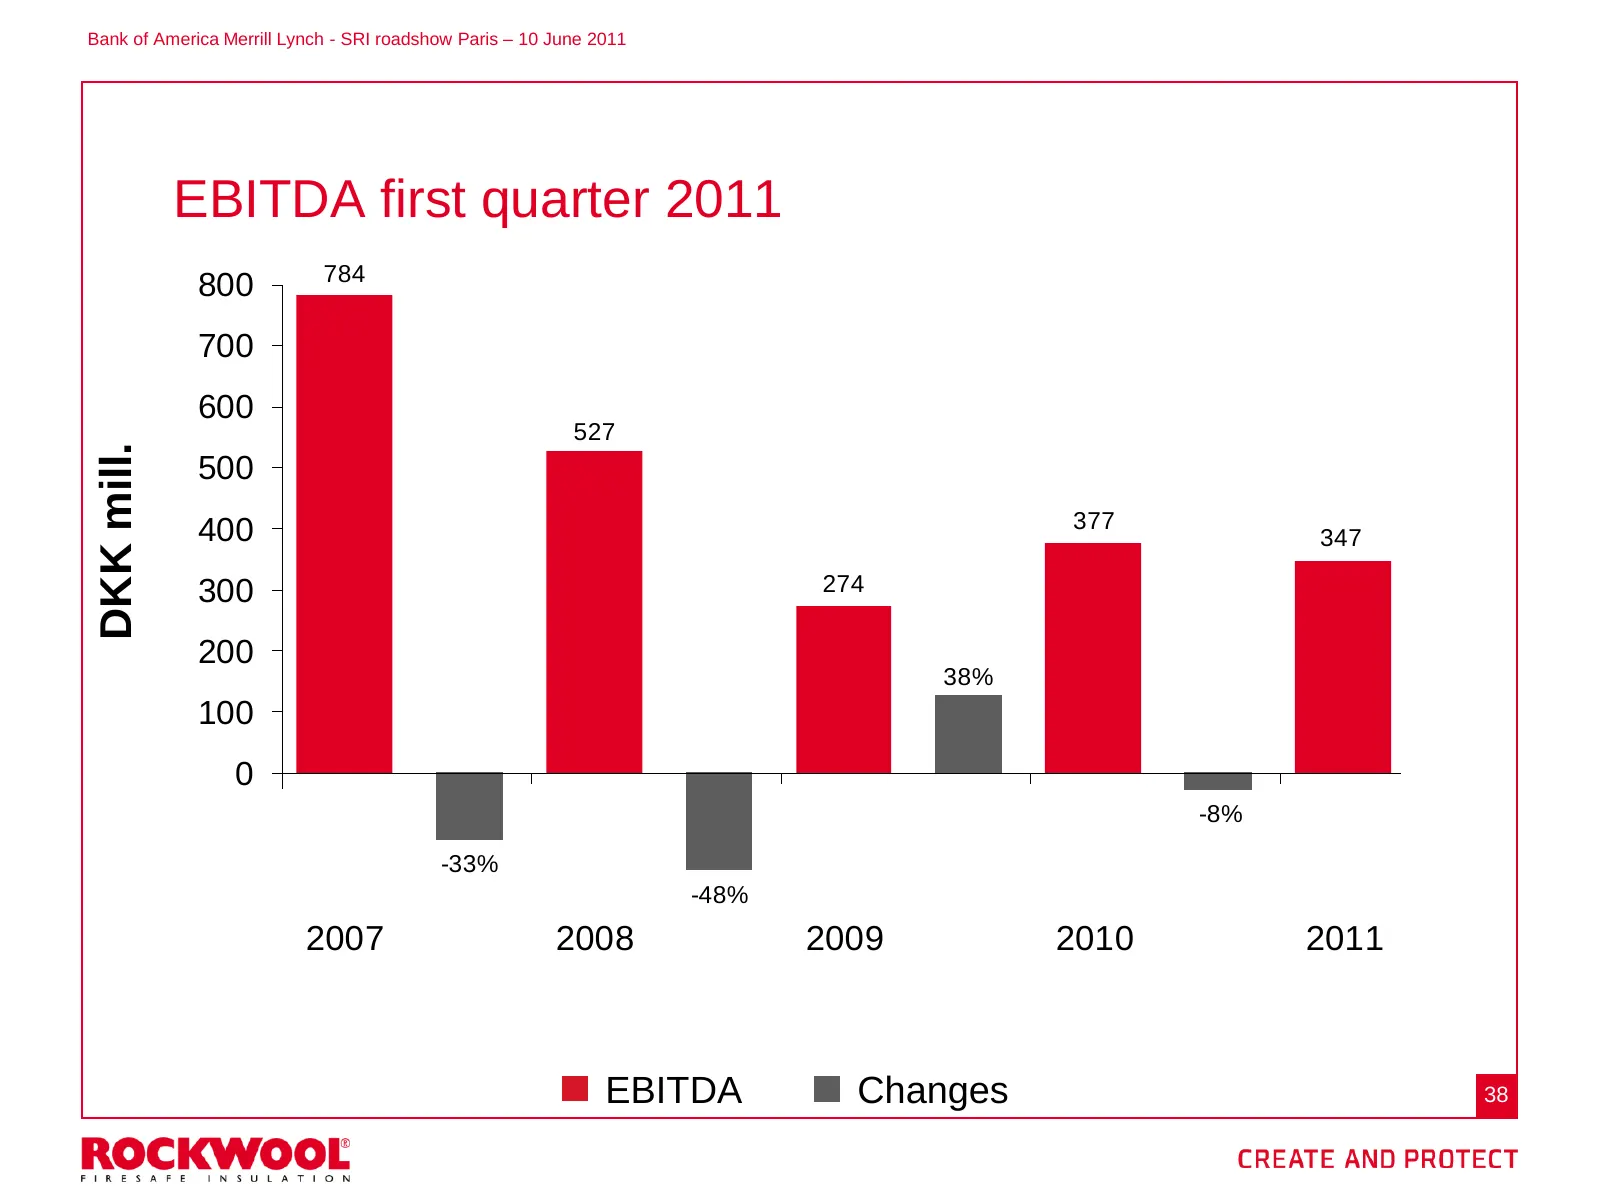
Slide 38: EBITDA first quarter 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 EBITDA first quarter 2011 784 800 240% 700 190% 600 527 DKK mill. 500 140% 400 377 347 300 274 90% 200 38% 40% 100 0 -10% -8% -100 -33% -200 -48% -60% 2007 2008 2009 2010 2011 EBITDA Changes 38
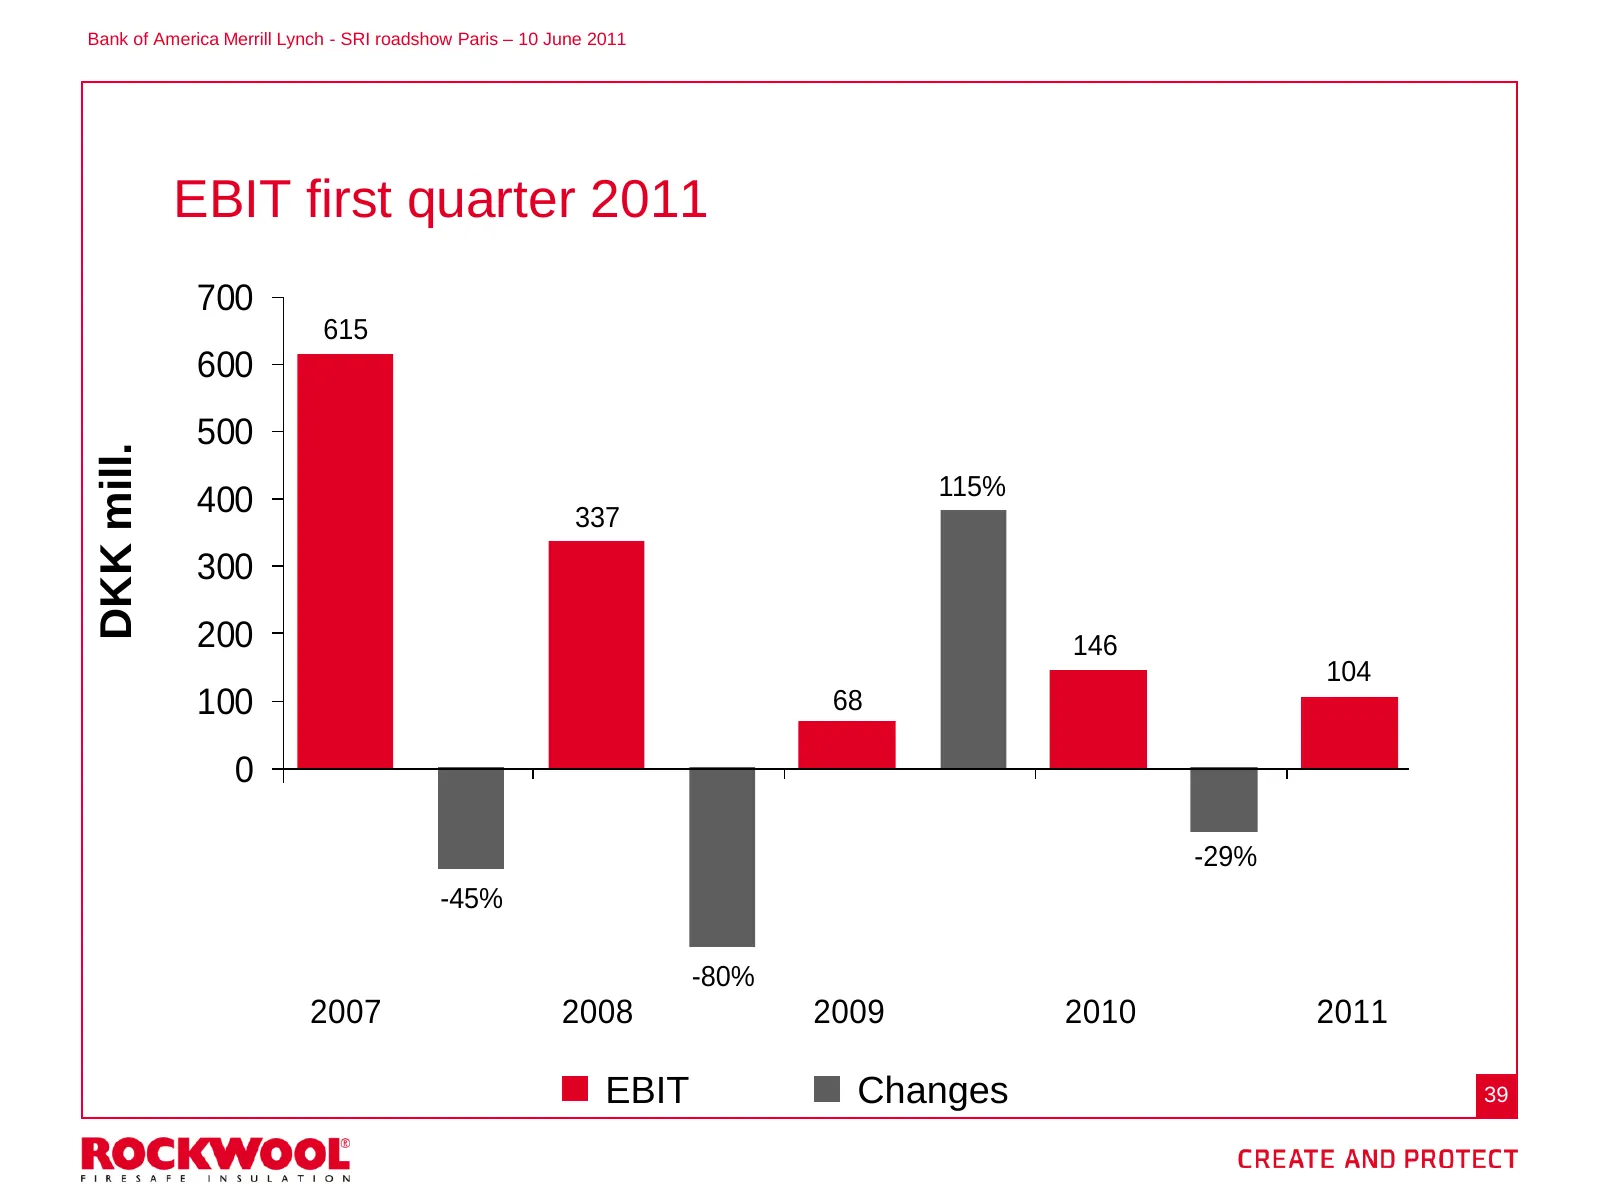
Slide 39: EBIT first quarter 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 EBIT first quarter 2011 700 210% 615 600 160% 500 DKK mill. 115% 400 337 110% 300 200 146 60% 104 100 68 10% 0 -100 -29% -40% -200 -45% -300 -80% -90% 2007 2008 2009 2010 2011 EBIT Changes 39
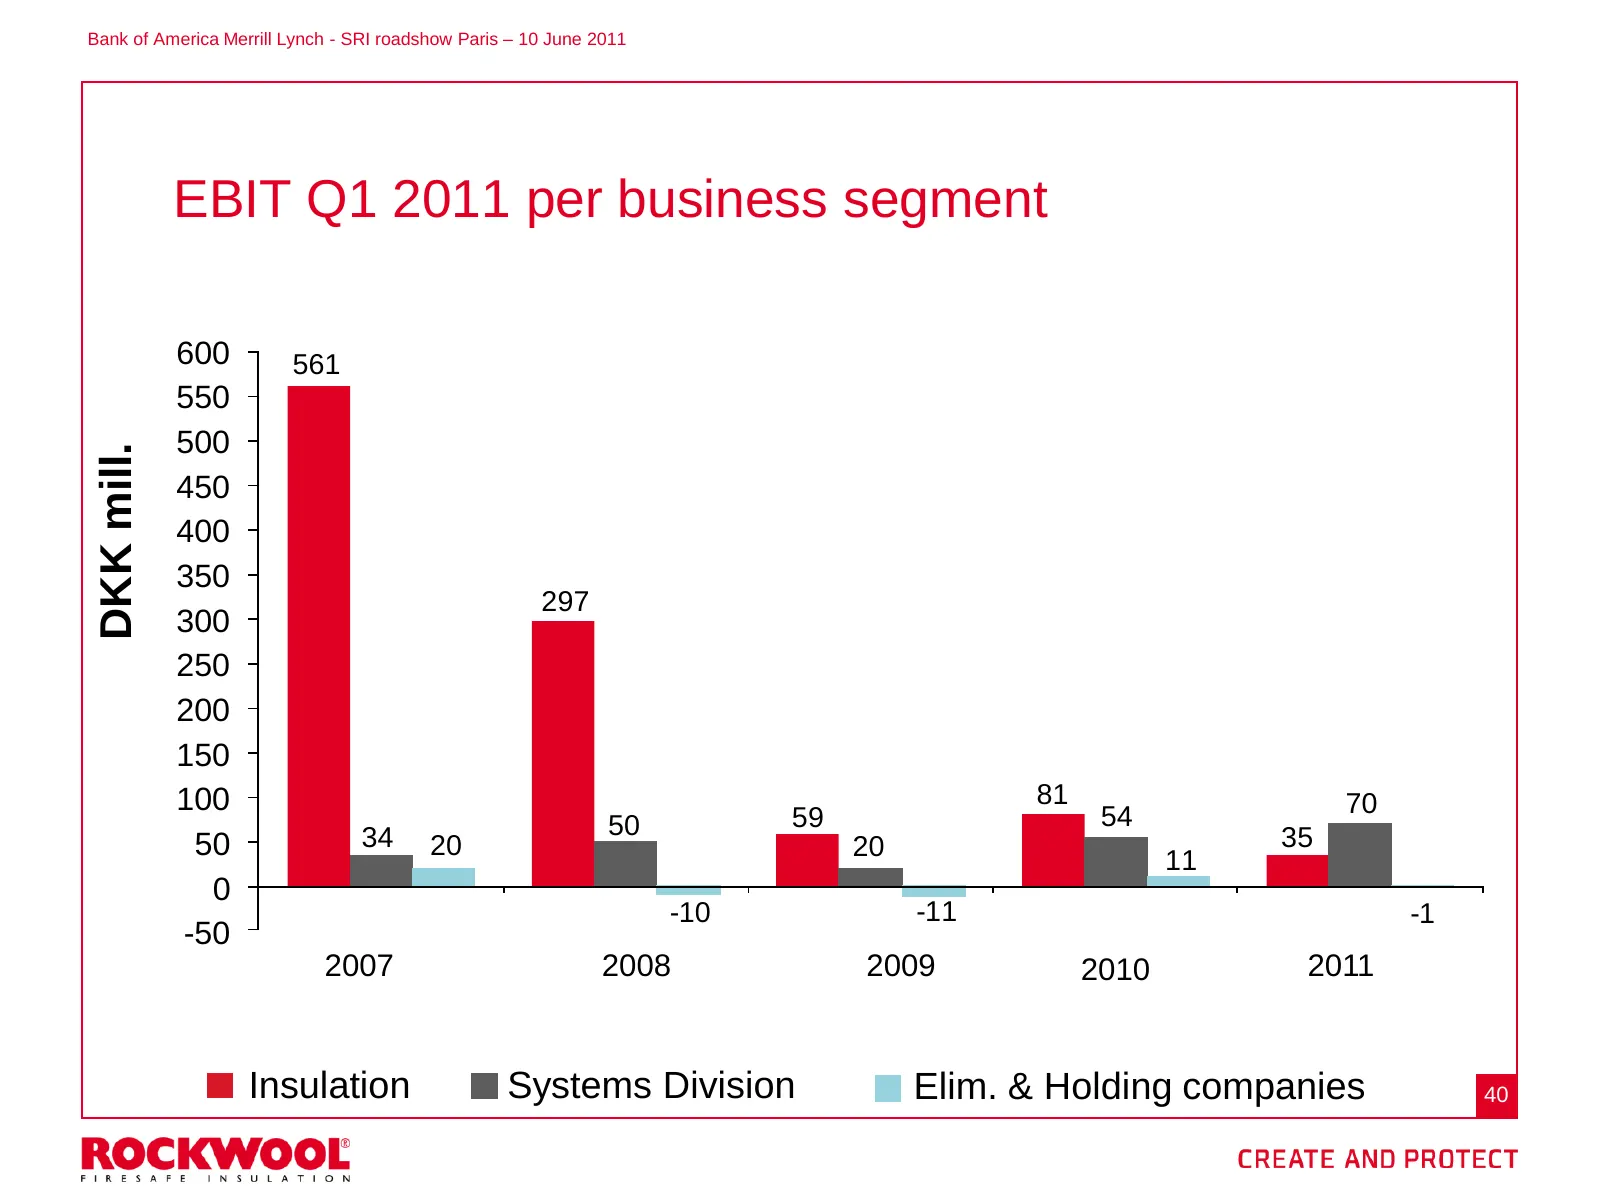
Slide 40: EBIT Q1 2011 per business segment
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 EBIT Q1 2011 per business segment 600 561 550 500 DKK mill. 450 400 350 297 300 250 200 150 100 81 70 50 59 54 50 34 20 20 35 11 0 -10 -11 -1 -50 2007 2008 2009 2010 2011 Insulation Systems Division Elim. & Holding companies 40
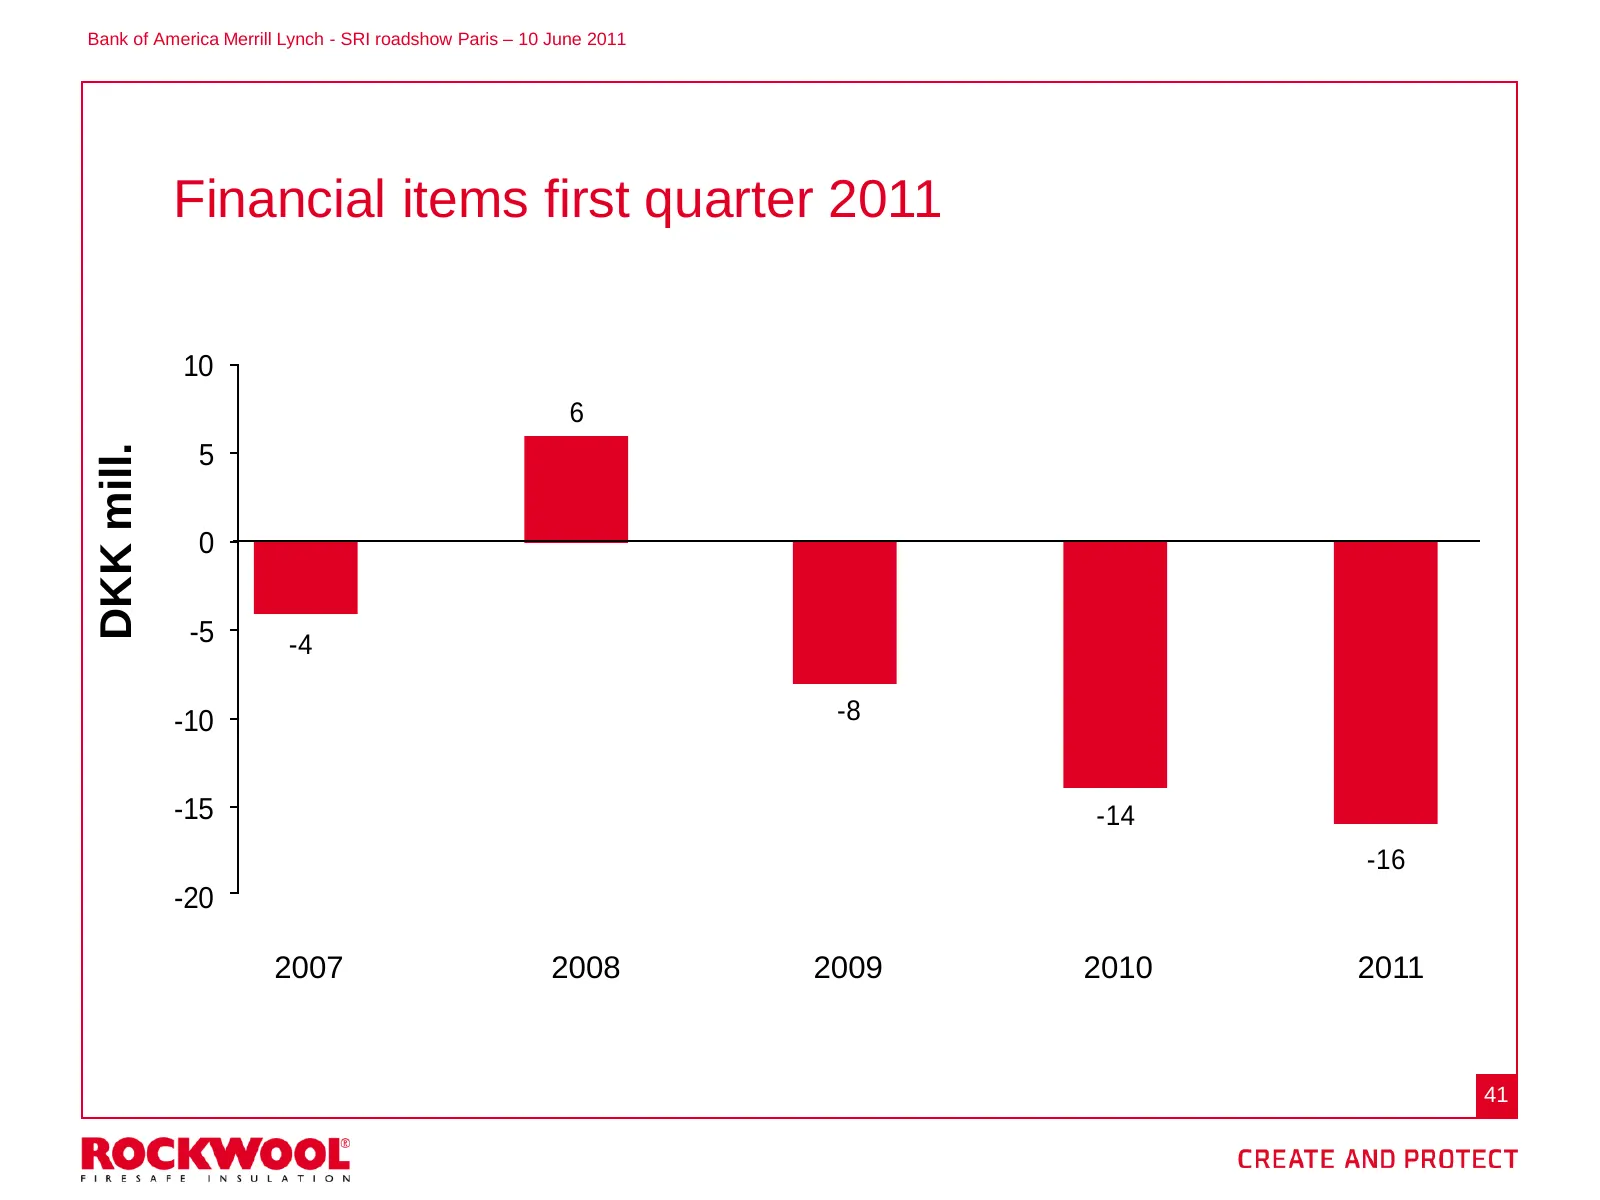
Slide 41: Financial items first quarter 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Financial items first quarter 2011 10 6 DKK mill. 5 0 -5 -4 -10 -8 -15 -14 -16 -20 2007 2008 2009 2010 2011 41
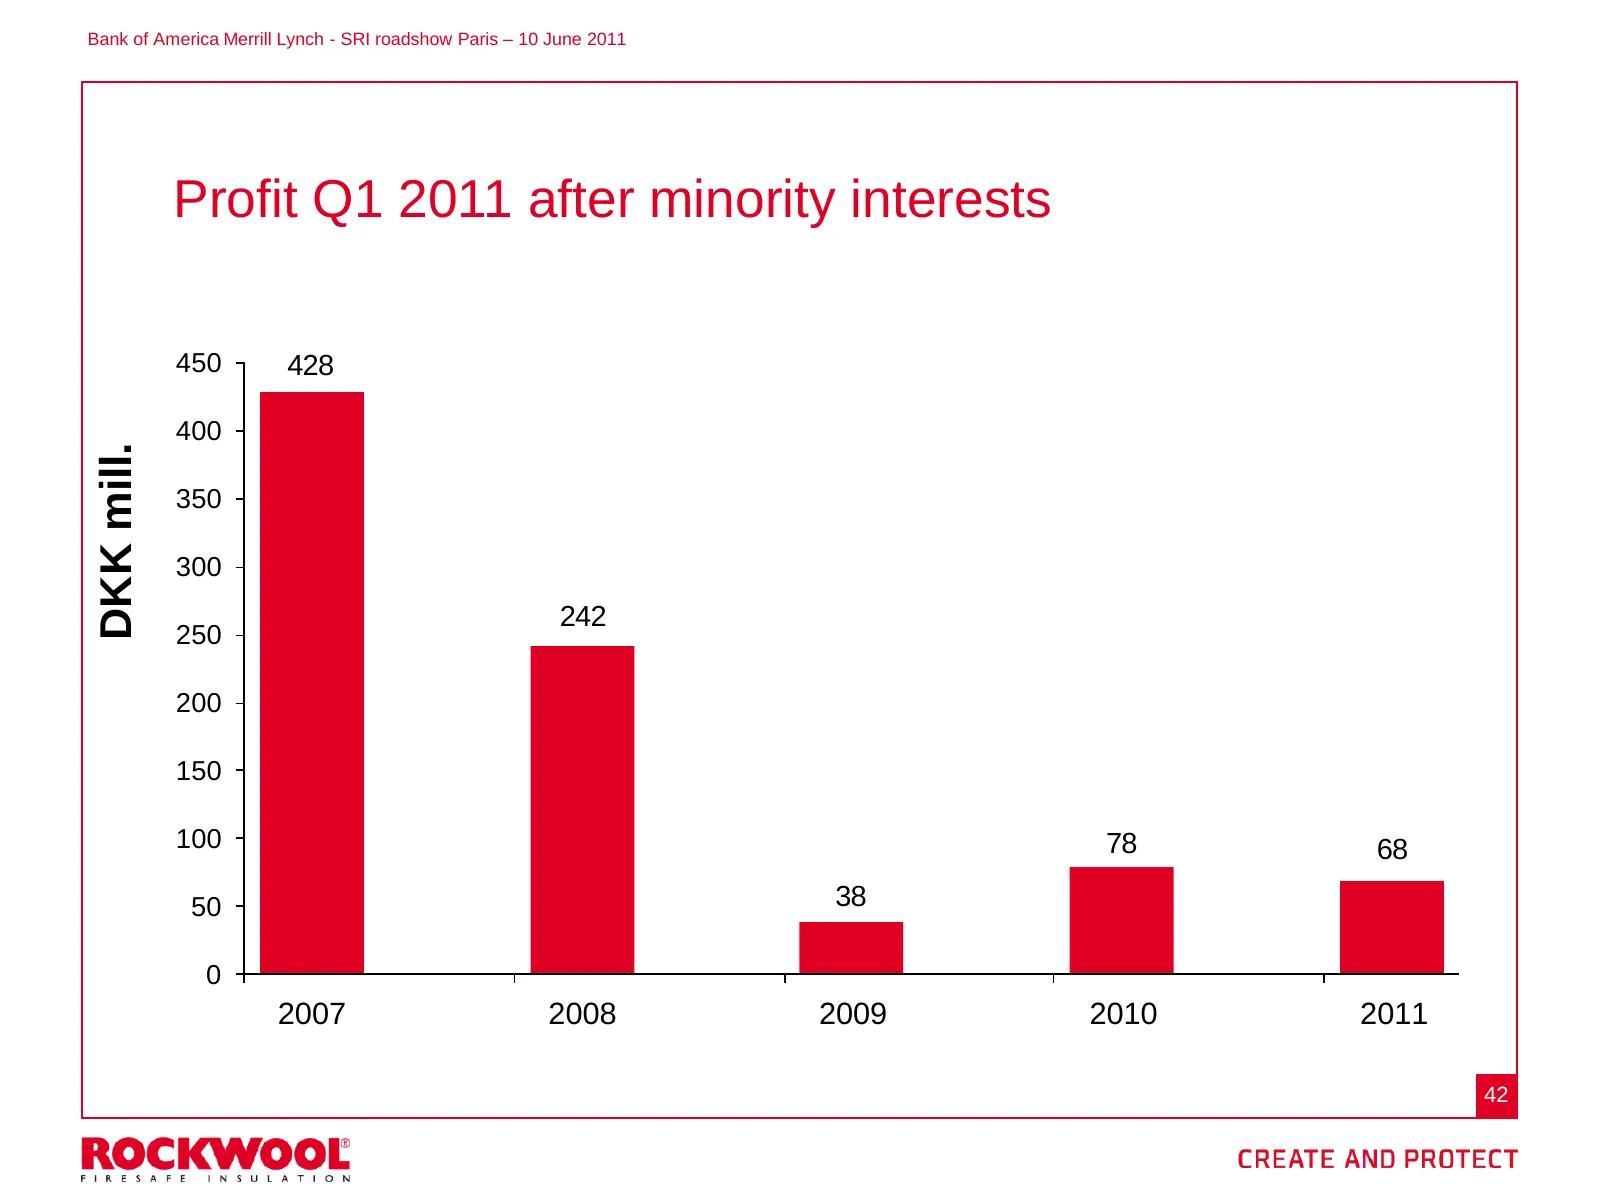
Slide 42: Profit Q1 2011 after minority interests
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Profit Q1 2011 after minority interests 450 428 400 DKK mill. 350 300 242 250 200 150 100 78 68 50 38 0 2007 2008 2009 2010 2011 42
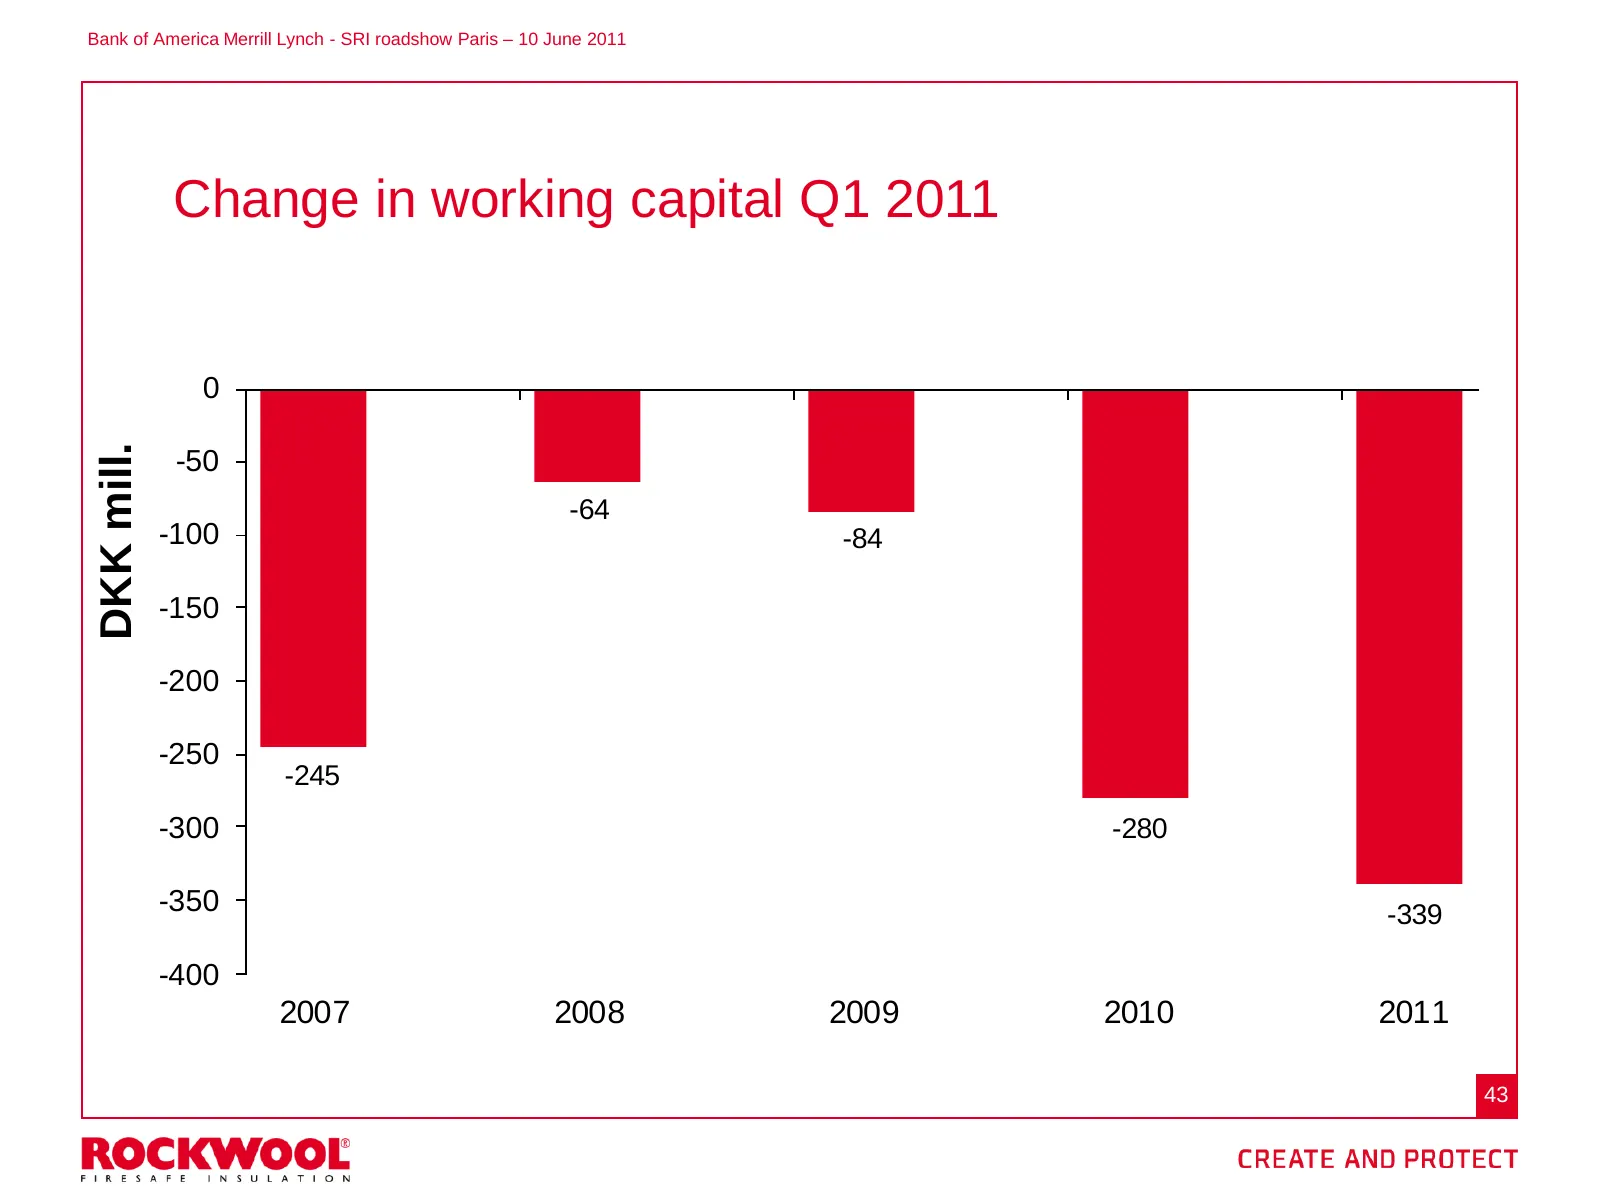
Slide 43: Change in working capital Q1 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Change in working capital Q1 2011 0 DKK mill. -50 -64 -100 -84 -150 -200 -250 -245 -300 -280 -350 -339 -400 2007 2008 2009 2010 2011 43
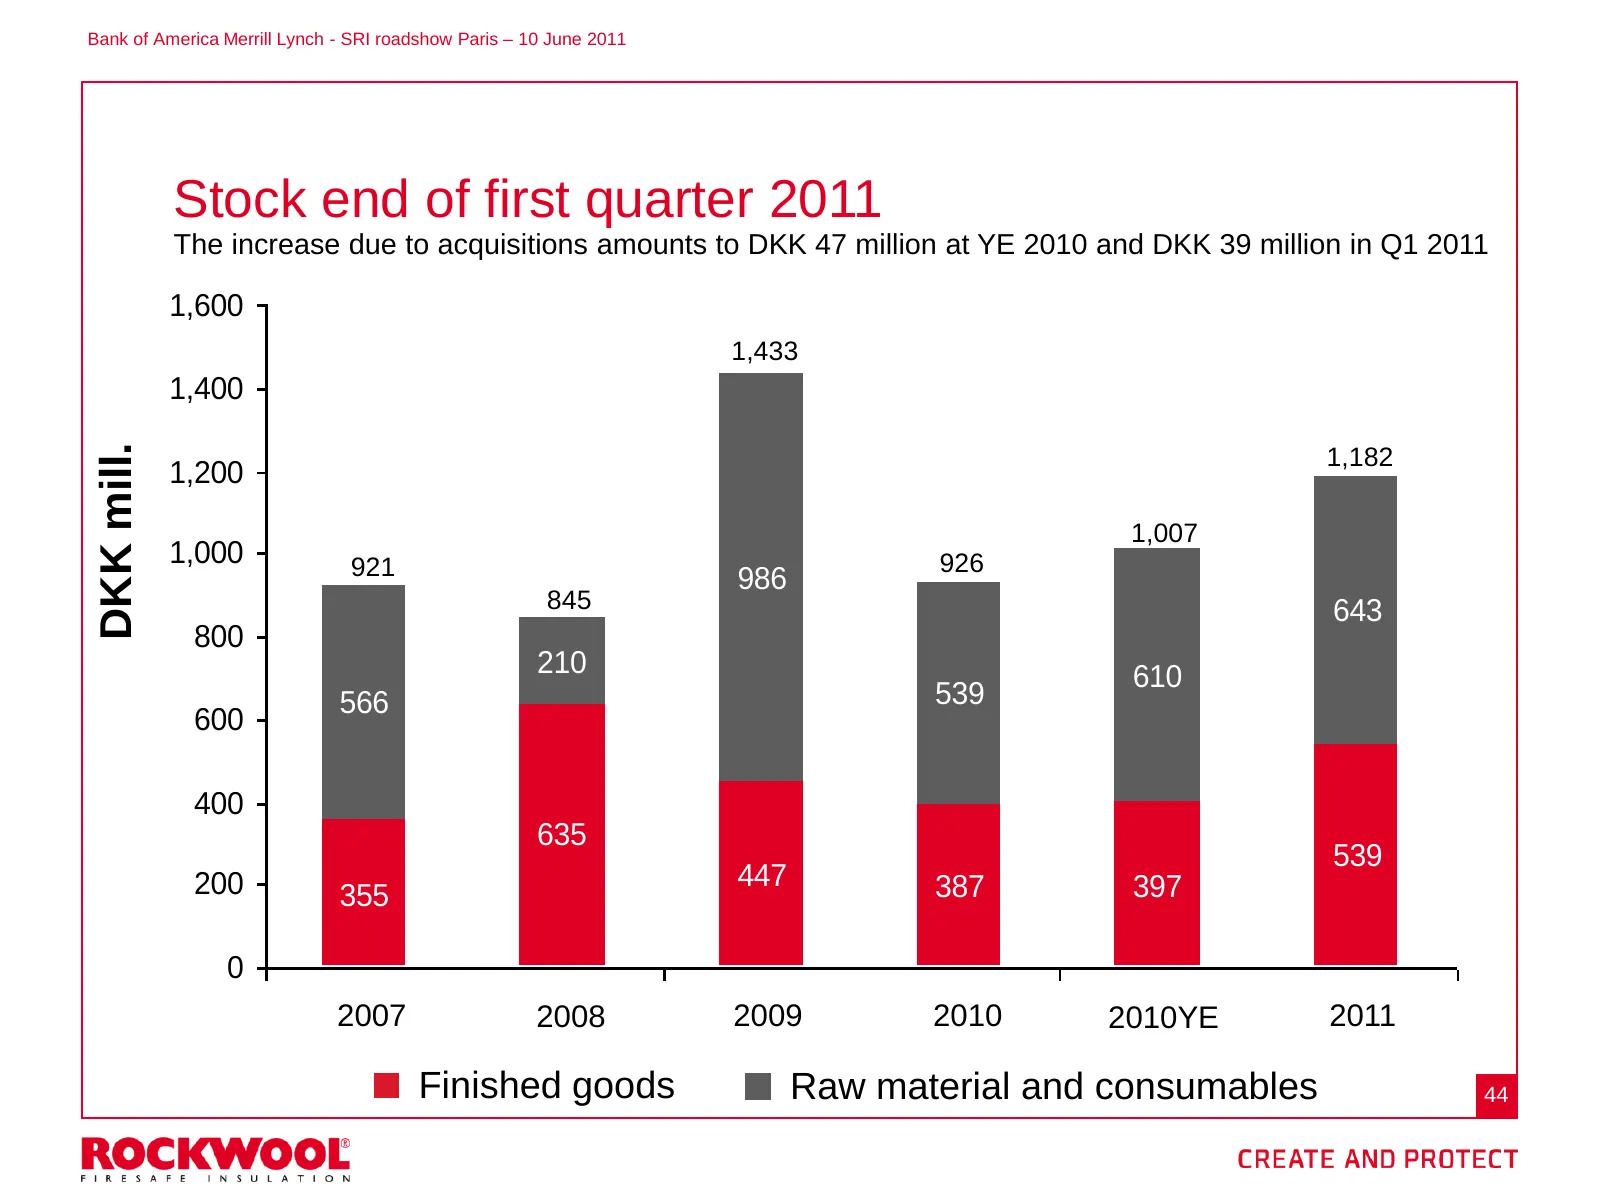
Slide 44: Stock end of first quarter 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Stock end of first quarter 2011 The increase due to acquisitions amounts to DKK 47 million at YE 2010 and DKK 39 million in Q1 2011 1,600 1,433 1,400 DKK mill. 1,182 1,200 1,007 1,000 921 926 986 845 643 800 210 610 566 539 600 400 63
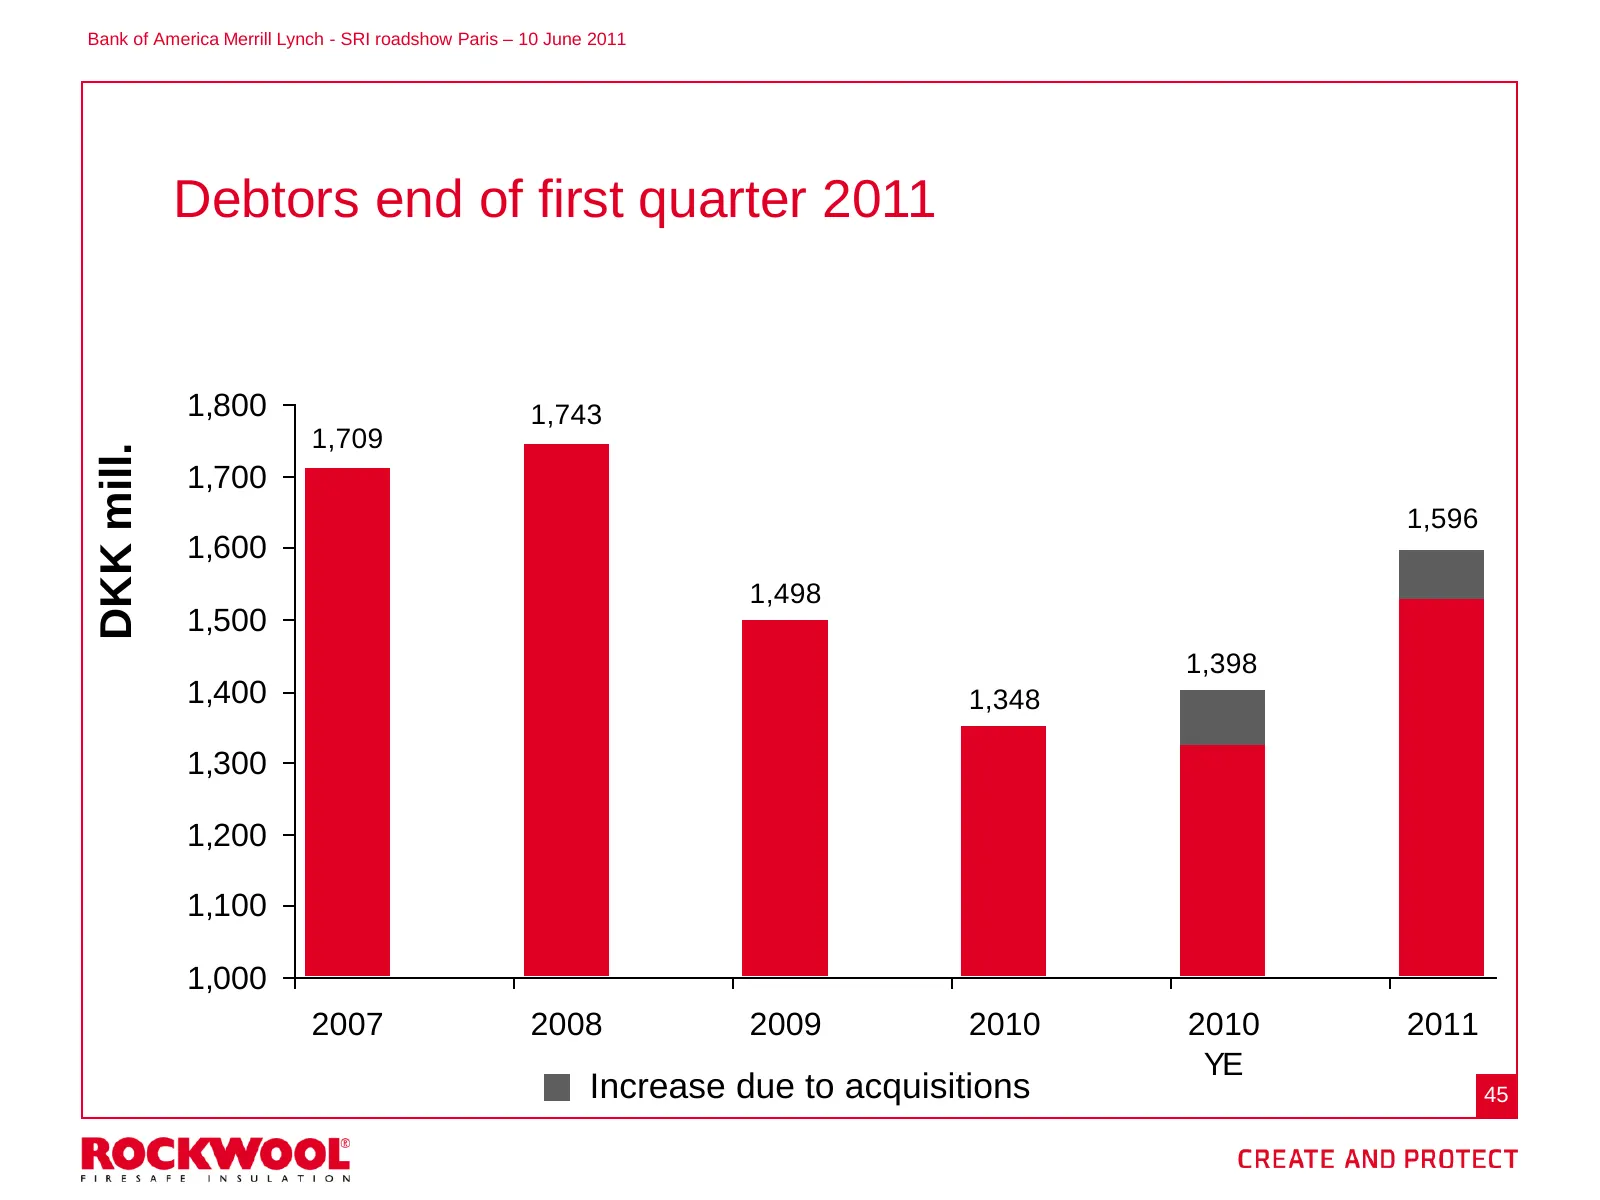
Slide 45: Debtors end of first quarter 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Debtors end of first quarter 2011 1,800 1,743 1,709 DKK mill. 1,700 1,596 1,600 1,498 1,500 1,398 1,400 1,348 1,300 1,200 1,100 1,000 2007 2008 2009 2010 2010 2011 YE Increase due to acquisitions 45
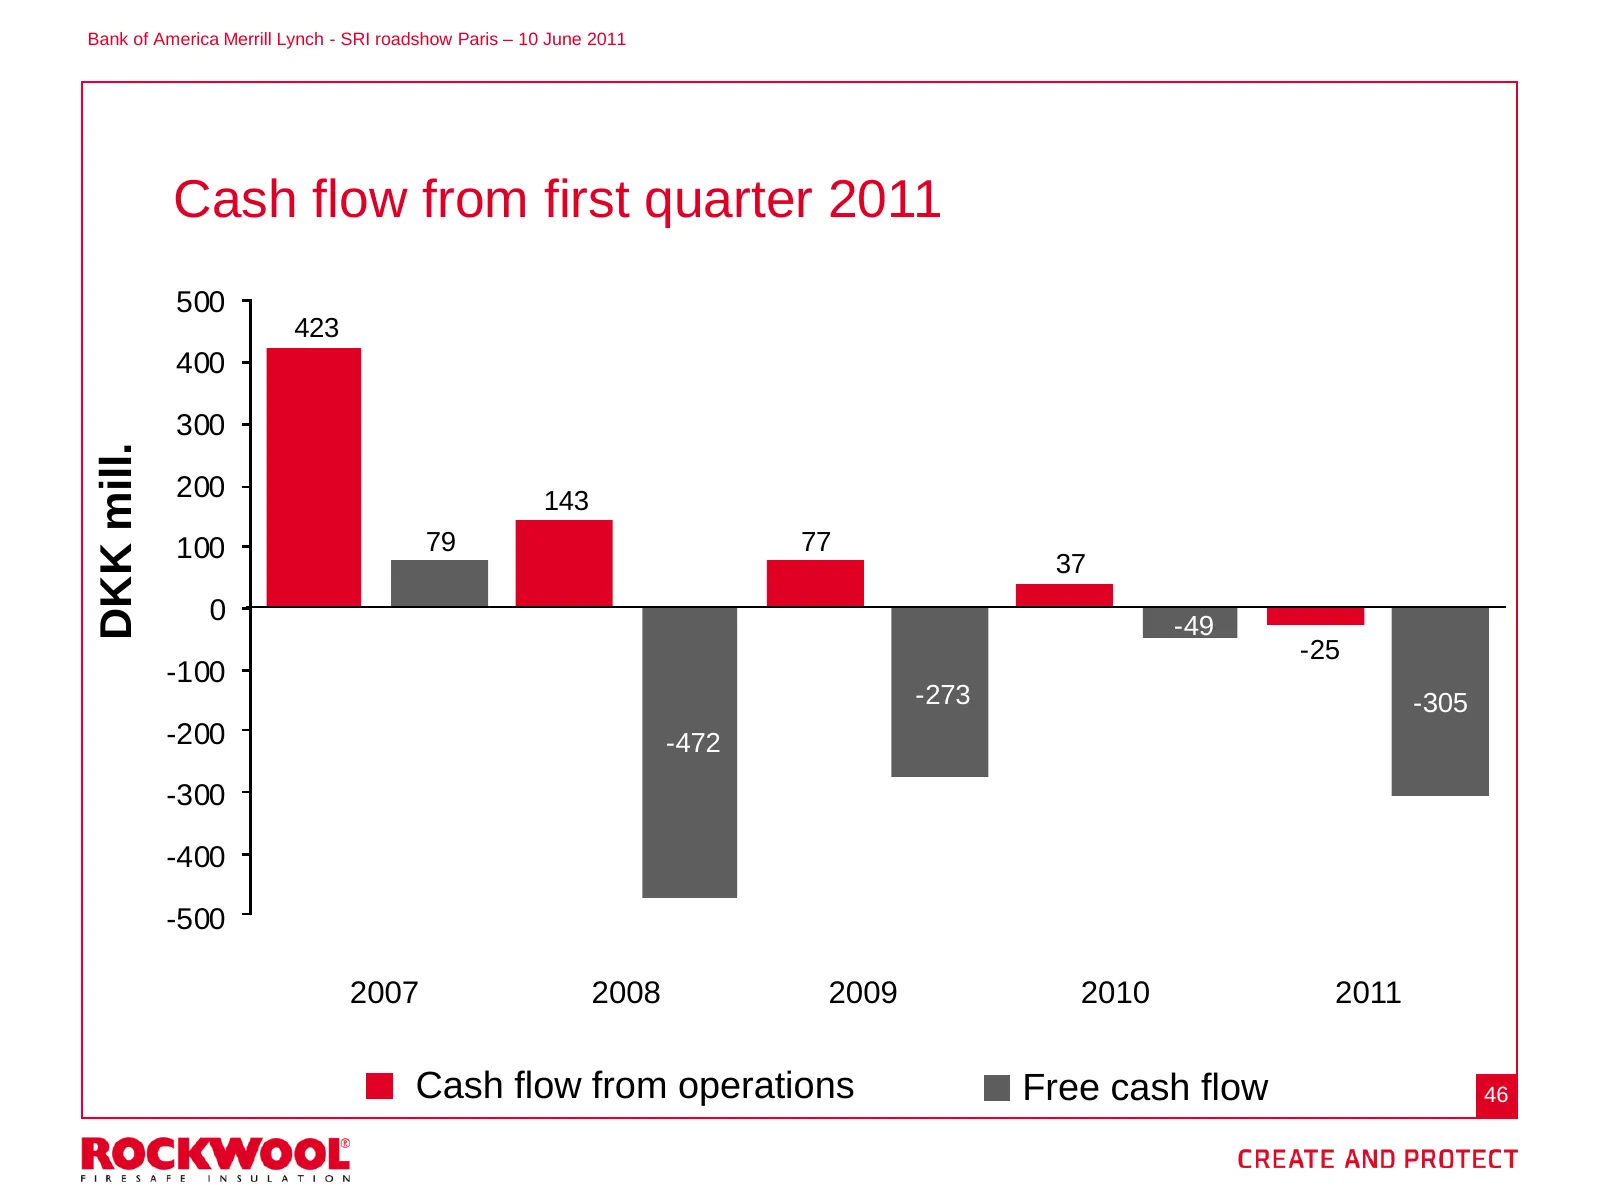
Slide 46: Cash flow from first quarter 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Cash flow from first quarter 2011 500 423 400 300 DKK mill. 200 143 100 79 77 37 0 -49 -25 -100 -273 -305 -200 -472 -300 -400 -500 2007 2008 2009 2010 2011 Cash flow from operations Free cash flow 46
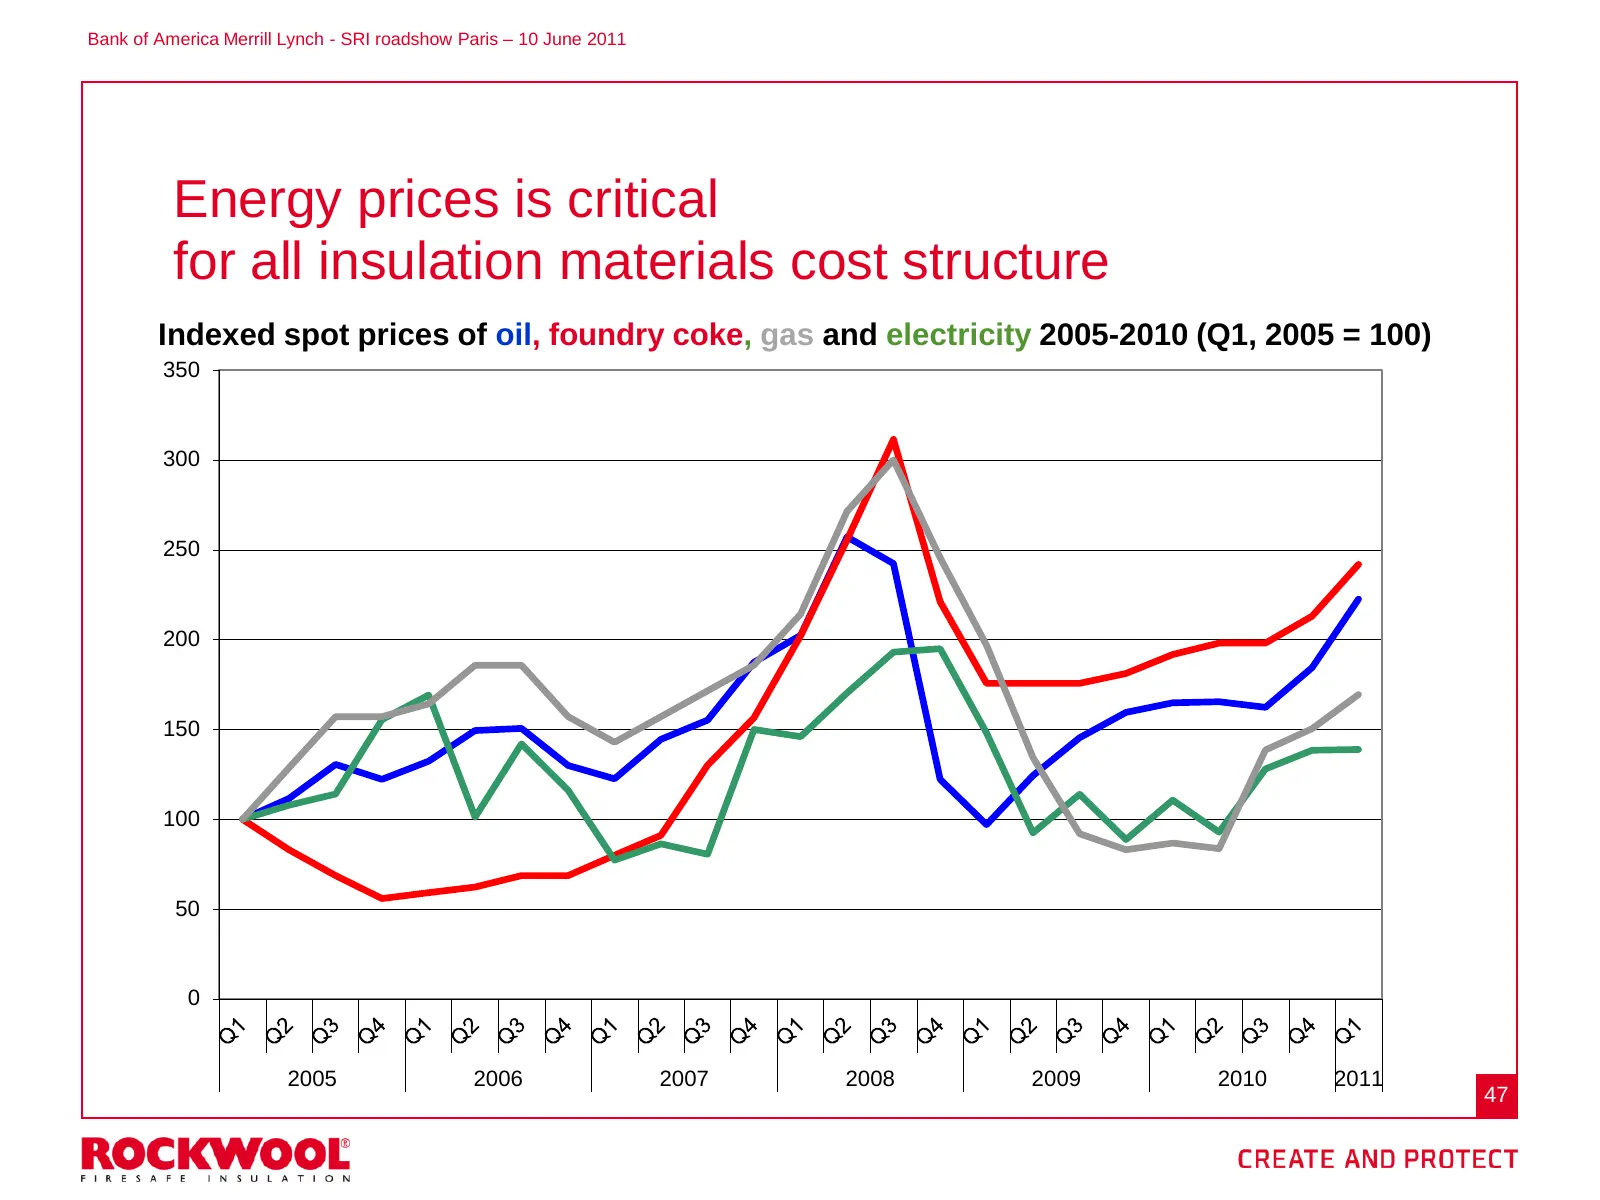
Slide 47: Energy prices is critical for all insulation materials cost structure
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Energy prices is critical for all insulation materials cost structure Indexed spot prices of oil, foundry coke, gas and electricity 2005-2010 (Q1, 2005 = 100) 350 300 250 200 150 100 50 0 2005 2006 2007 2008 2009 2010 2011 47
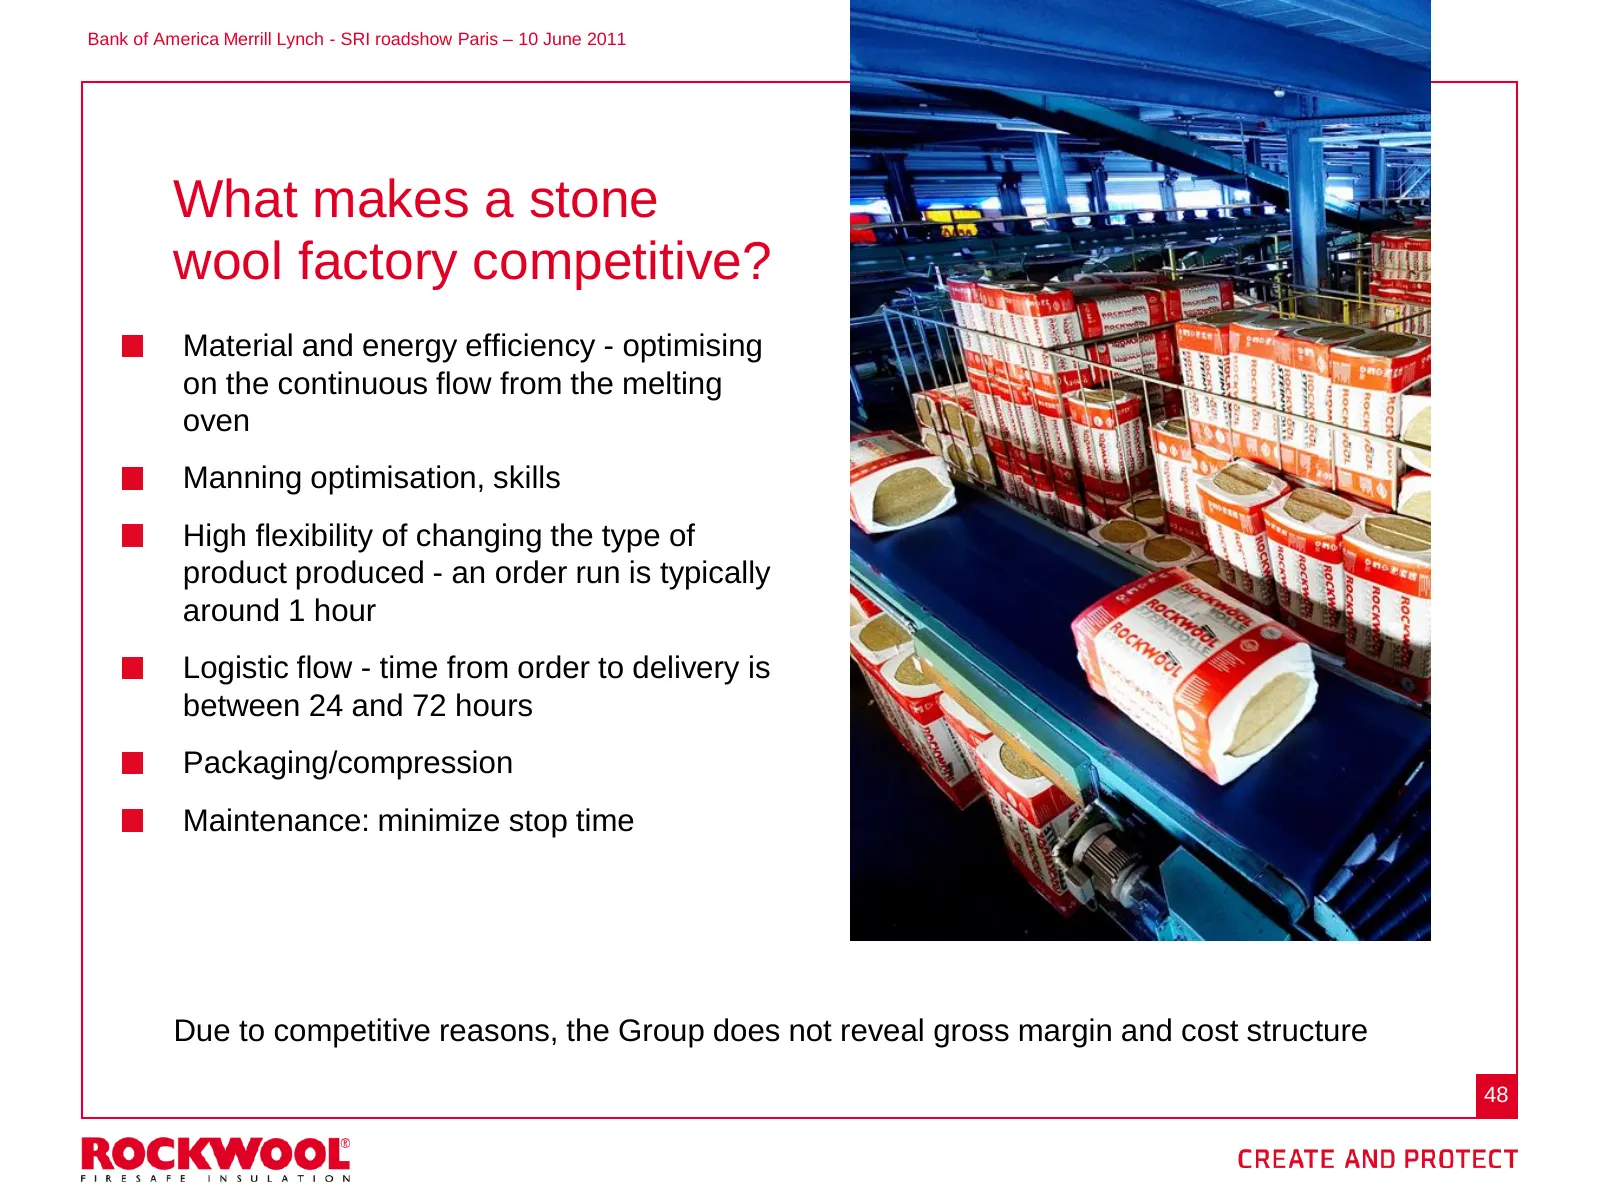
Slide 48: What makes a stone wool factory competitive?
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 What makes a stone wool factory competitive? Material and energy efficiency - optimising on the continuous flow from the melting oven Manning optimisation, skills High flexibility of changing the type of product produced - an order ru
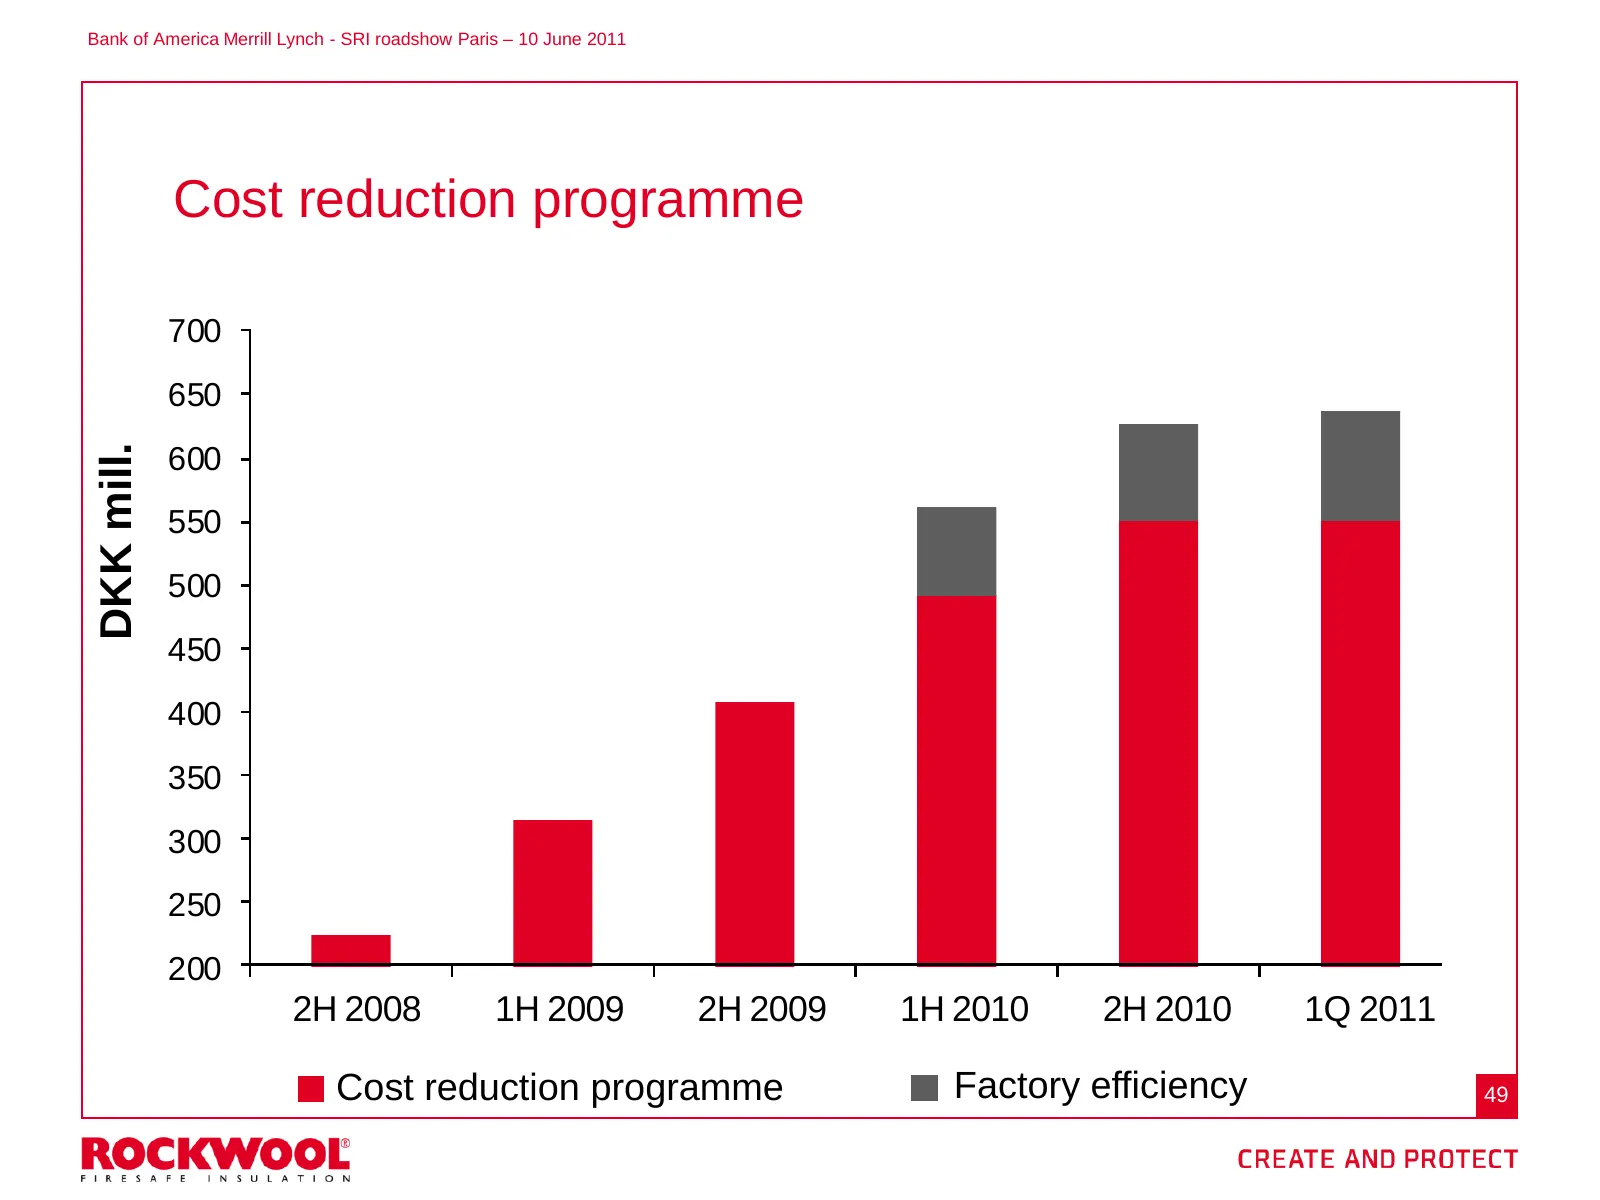
Slide 49: Cost reduction programme
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Cost reduction programme 700 650 DKK mill. 600 550 500 450 400 350 300 250 200 2H 2008 1H 2009 2H 2009 1H 2010 2H 2010 1Q 2011 Cost reduction programme Factory efficiency 49
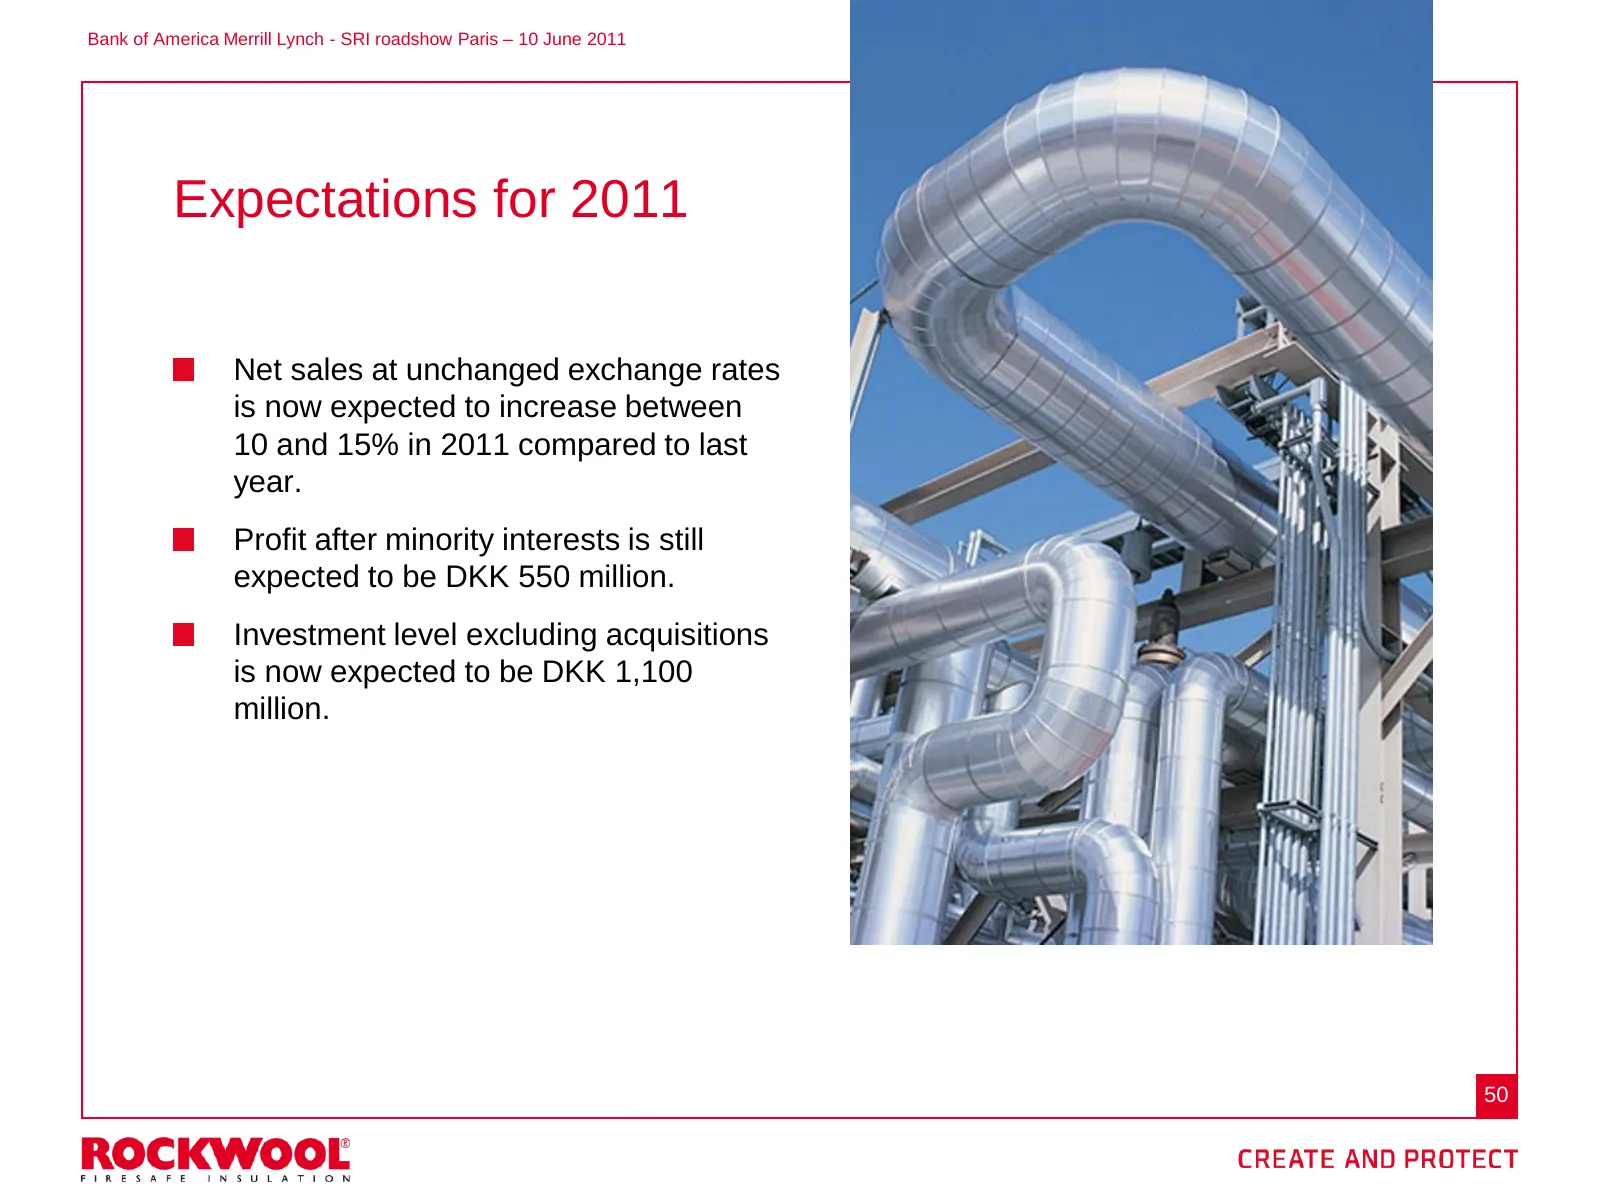
Slide 50: Expectations for 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Expectations for 2011 Net sales at unchanged exchange rates is now expected to increase between 10 and 15% in 2011 compared to last year. Profit after minority interests is still expected to be DKK 550 million. Investment level exclud
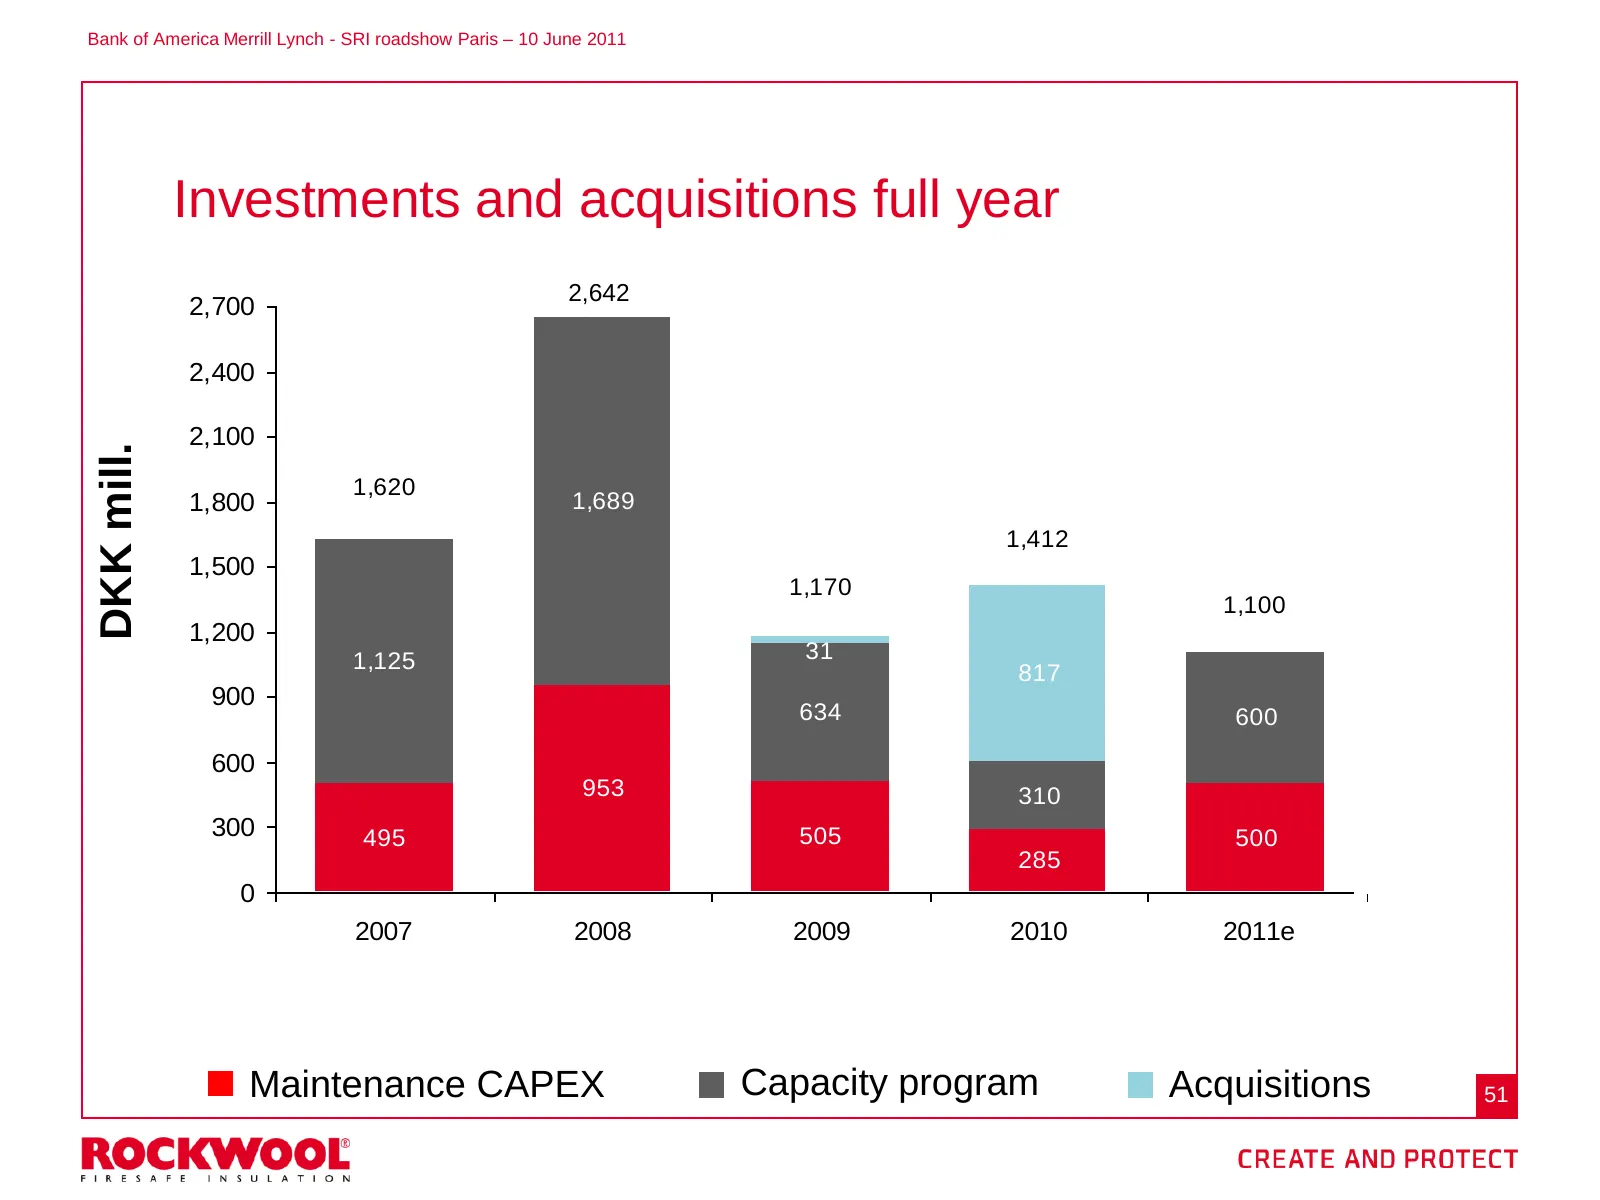
Slide 51: Investments and acquisitions full year
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Investments and acquisitions full year 2,642 2,642 2,700 2,400 2,100 DKK mill. 1,620 1,800 1,689 1,412 1,500 1,170 1,100 1,200 1,125 31 817 900 634 600 600 953 310 300 495 505 500 285 0 2007 2008 2009 2010 2011e Maintenance CAPEX Capa
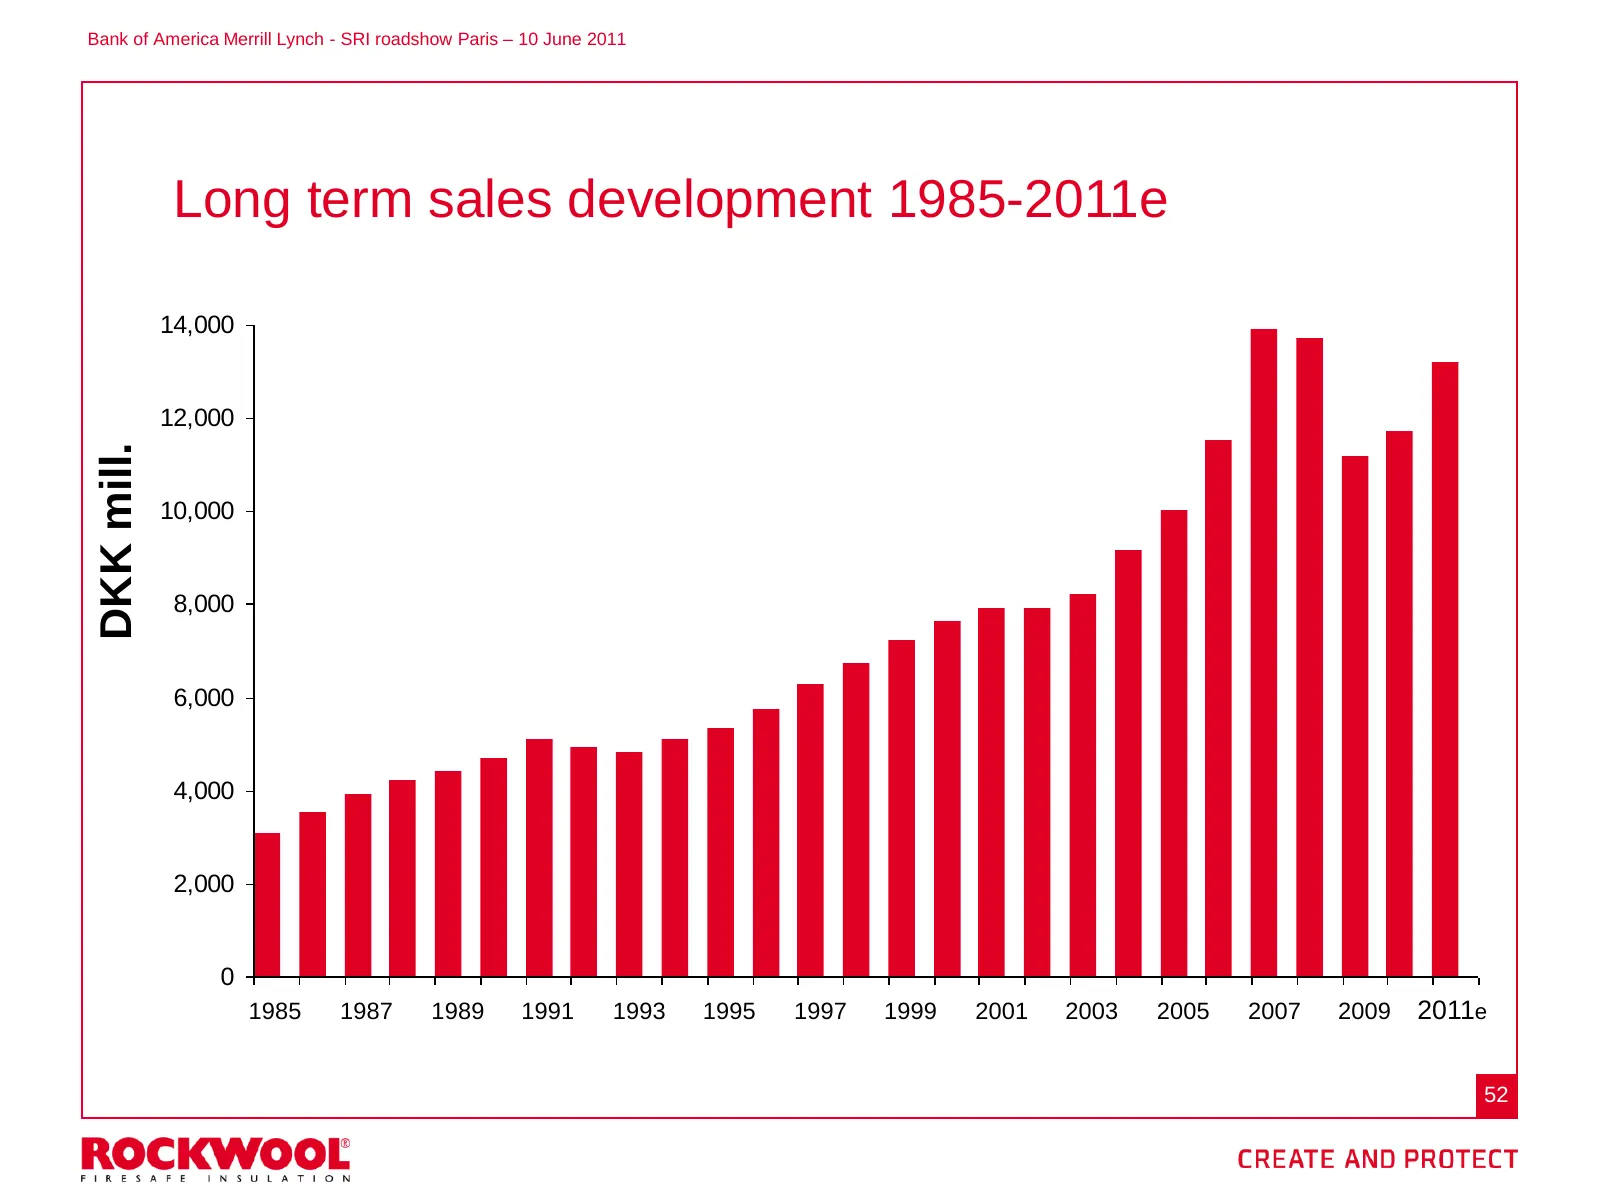
Slide 52: Long term sales development 1985-2011e
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Long term sales development 1985-2011e 14,000 12,000 DKK mill. 10,000 8,000 6,000 4,000 2,000 0 1985 1987 1989 1991 1993 1995 1997 1999 2001 2003 2005 2007 2009 2011 2011e e 52
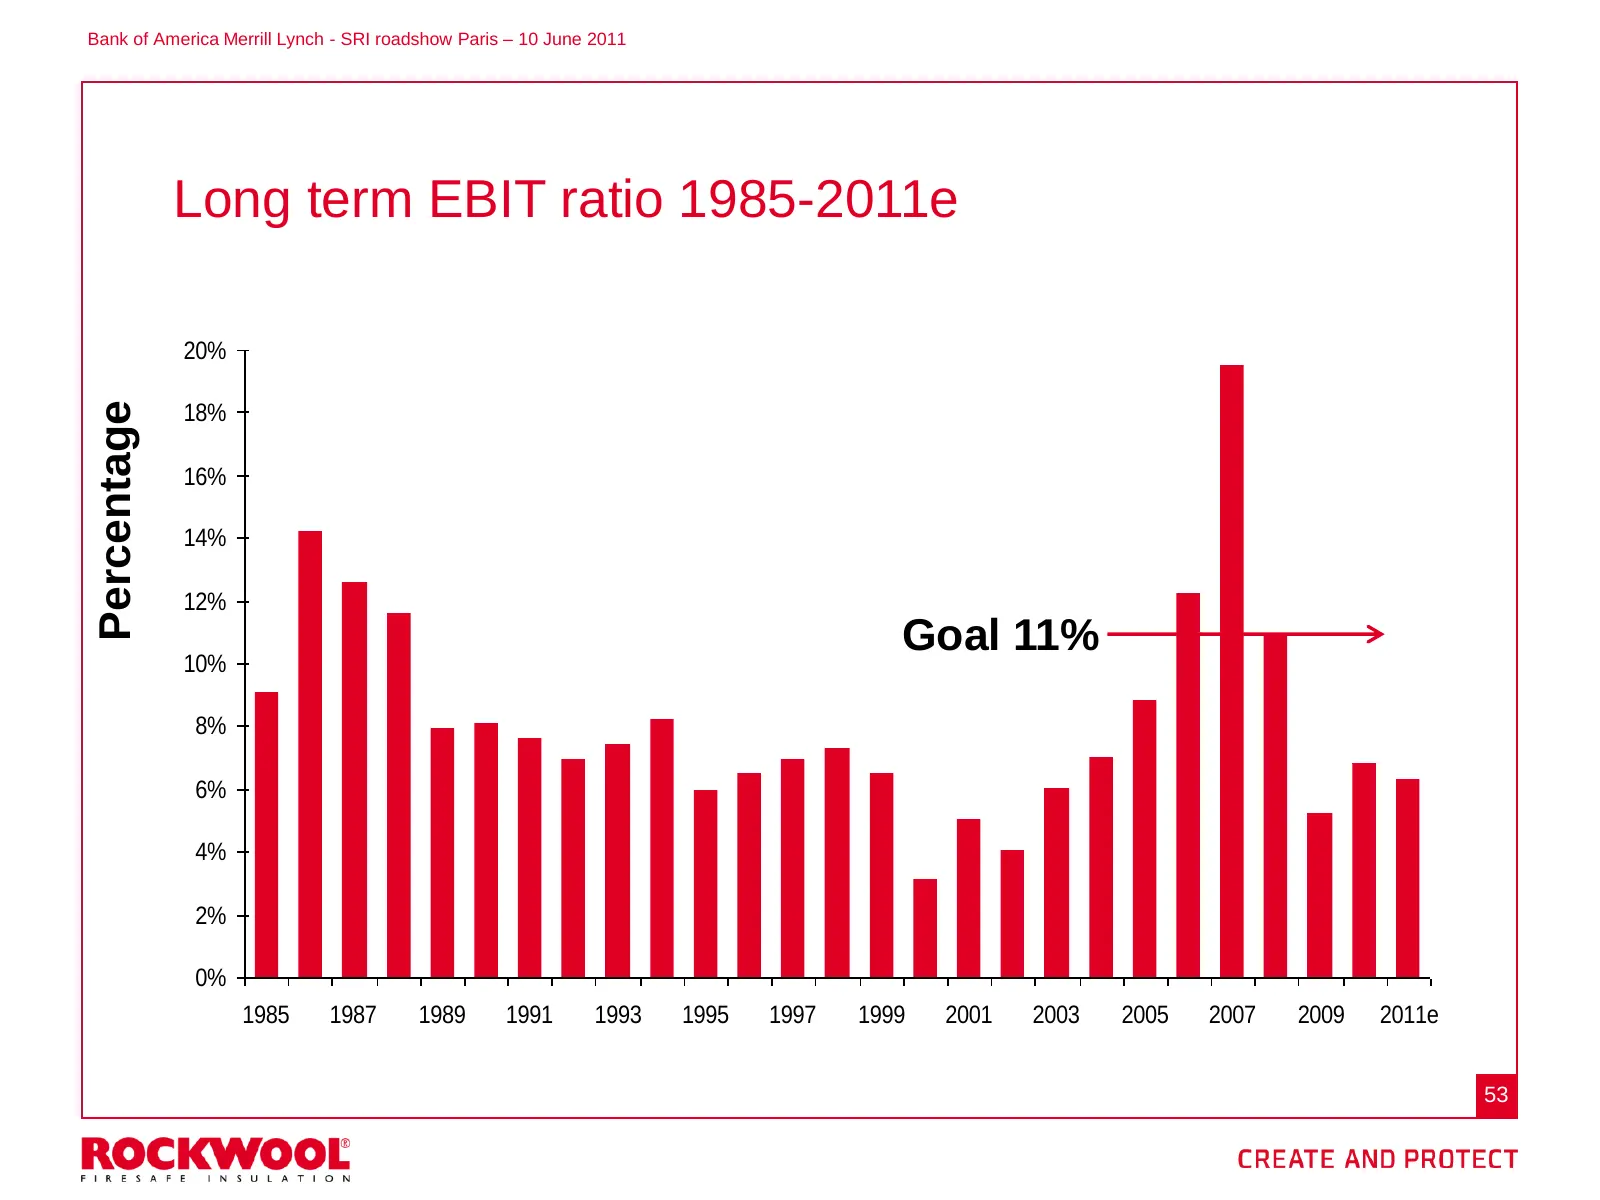
Slide 53: Long term EBIT ratio 1985-2011e
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 Long term EBIT ratio 1985-2011e 20% Percentage 18% 16% 14% 12% Goal 11% 10% 8% 6% 4% 2% 0% 1985 1987 1989 1991 1993 1995 1997 1999 2001 2003 2005 2007 2009 2011e 53
Slide 54: SRI roadshow Paris 10 June 2011
Bank of America Merrill Lynch - SRI roadshow Paris – 10 June 2011 SRI roadshow Paris 10 June 2011 CFO Gilles Maria and VP Thorkild Diness Jensen The Rockwool Group 54
Source: Internet Archive copy of rockwool.com
More decks from Rockwool A/S Class A
 Q2 2026 Earnings Presentation19 slides · Aug 20, 2026
 Q1 2026 Earnings Presentation15 slides · May 20, 2026
 Shareholder Meeting (2026)10 slides · Apr 15, 2026
 Shareholder Meeting (April 2026)46 slides · Apr 15, 2026
 Q4 2025 Earnings Presentation19 slides · Feb 5, 2026
 Q2 2025 Earnings Presentation17 slides · Aug 21, 2025