Southern Community Financial Corp
Southern Community Financial — Merger or Acquisition (July 2003)
20 slides from Southern Community Financial's merger presentation, Jul 30, 2003
Slide 1: An Attractive Franchise Combination
An Attractive Franchise Combination Investor Presentation July 30, 2003
Slide 2: Forward Looking Statement
This presentation contains forward looking statements with respect to the financial condition, results of operations and business of Southern Community Financial Corporation ("SCMF") and The Community Bank ("Community Bank") and assuming the consummation of the transaction, a combined SCMF and Commu
Slide 3: Transaction Summary
Transaction Summary |
Slide 4: Transaction Summary
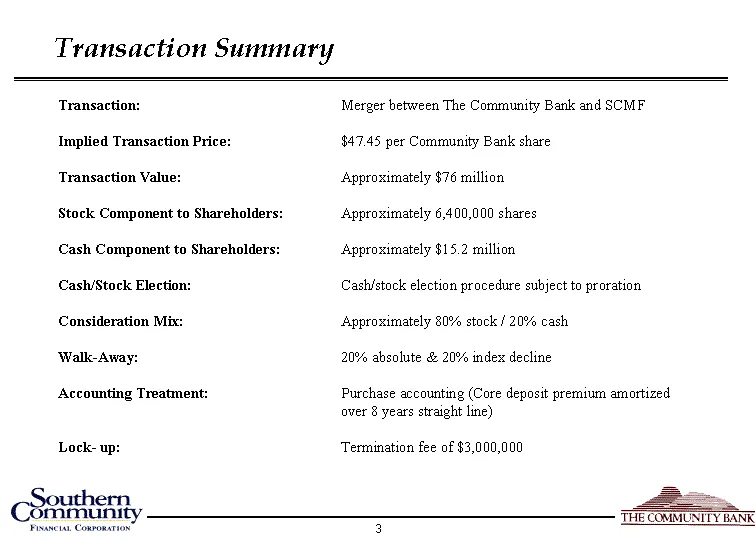
Transaction: Merger between The Community Bank and SCMF Implied Transaction Price: $47.45 per Community Bank share Transaction Value: Approximately $76 million Stock Component to Shareholders: Approximately 6,400,000 shares Cash Component to Shareholders: Approximately $15.2 million Cash/Stock Elect
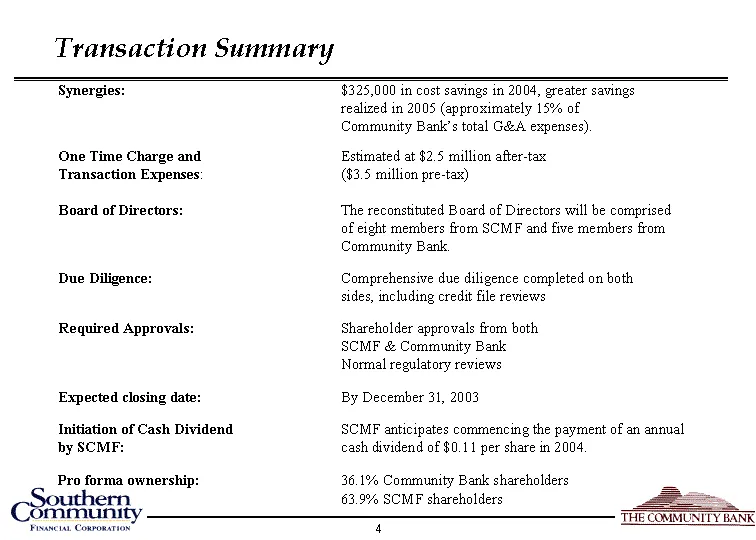
Slide 5: Transaction Summary: Synergies and Pro Forma Ownership
Synergies: $325,000 in cost savings in 2004, greater savings realized in 2005 (approximately 15% of Community Bank's total G&A expenses). One Time Charge and Estimated at $2.5 million after-tax Transaction Expenses: ($3.5 million pre-tax) Board of Directors: The reconstituted Board of Directors will
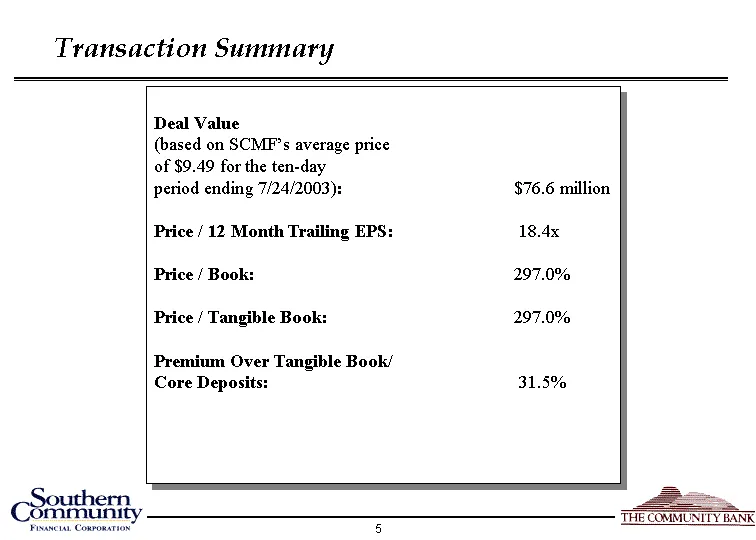
Slide 6: Transaction Summary: Deal Value and Multiples
Deal Value (based on SCMF's average price of $9.49 for the ten-day period ending 7/24/2003): $76.6 million Price / 12 Month Trailing EPS: 18.4x Price / Book: 297.0% Price / Tangible Book: 297.0% Premium Over Tangible Book/ Core Deposits: 31.5% Transaction Summary
Slide 7: Strategic Rationale
Strategic Rationale |
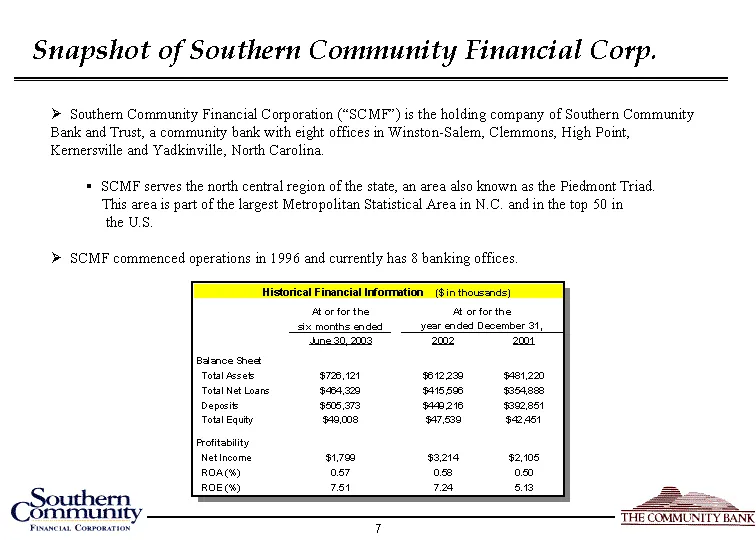
Slide 8: Snapshot of Southern Community Financial Corp.
Snapshot of Southern Community Financial Corp. Southern Community Financial Corporation ("SCMF") is the holding company of Southern Community Bank and Trust, a community bank with eight offices in Winston-Salem, Clemmons, High Point, Kernersville and Yadkinville, North Carolina. SCMF serves the nort
Slide 9: Snapshot of The Community Bank
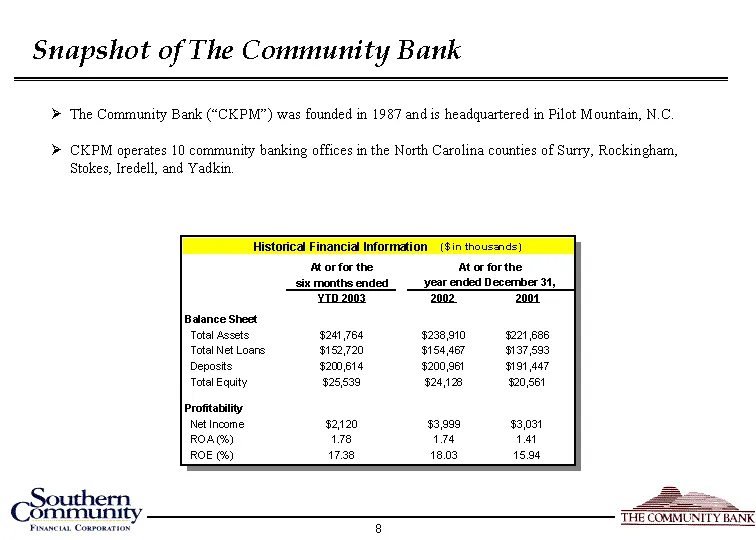
Snapshot of The Community Bank The Community Bank ("CKPM") was founded in 1987 and is headquartered in Pilot Mountain, N.C. CKPM operates 10 community banking offices in the North Carolina counties of Surry, Rockingham, Stokes, Iredell, and Yadkin.
Slide 10: A Compelling Combination
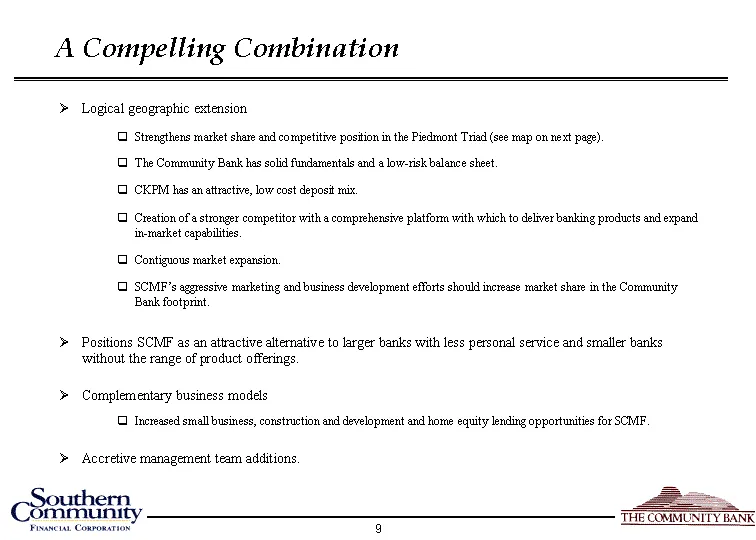
Logical geographic extension Strengthens market share and competitive position in the Piedmont Triad (see map on next page). The Community Bank has solid fundamentals and a low-risk balance sheet. CKPM has an attractive, low cost deposit mix. Creation of a stronger competitor with a comprehensive pl
Slide 11: Building a Strong Commercial Banking Franchise in North Carolina
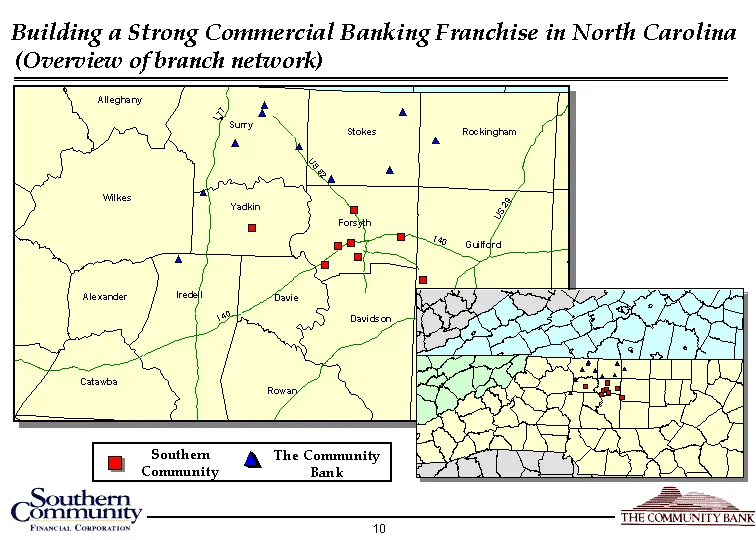
Building a Strong Commercial Banking Franchise in North Carolina Southern Community The Community Bank (Overview of branch network)
Slide 12: Expanding Presence in Desirable Markets
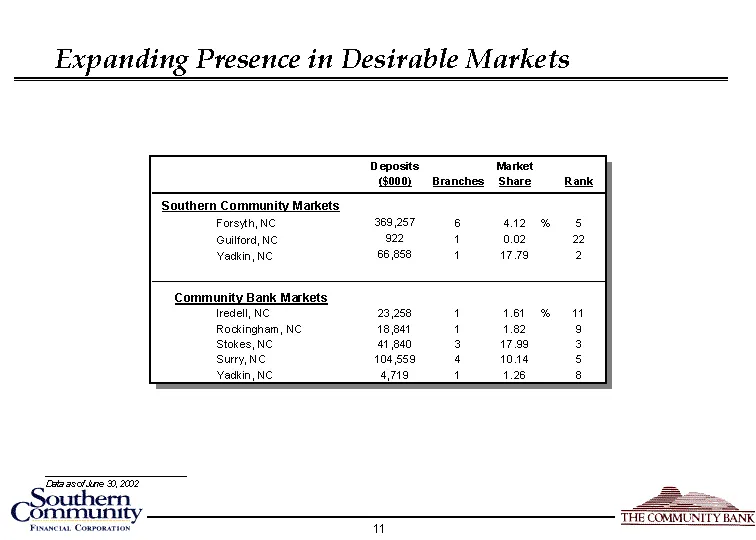
_______________________________________ Data as of June 30, 2002 Expanding Presence in Desirable Markets
Slide 13: Financially Attractive (with Straightforward, Conservative Assumptions)
As structured, the transaction is 3.8% accretive to GAAP EPS in the first full year. Conservative cost savings estimates confirmed through due diligence. Annual cost savings assumed are $325,000 in 2004 with greater savings realized in 2005 (approximately 15% of Community Bank's total G&A expenses).
Slide 14: An Attractive and Complementary Loan Portfolio
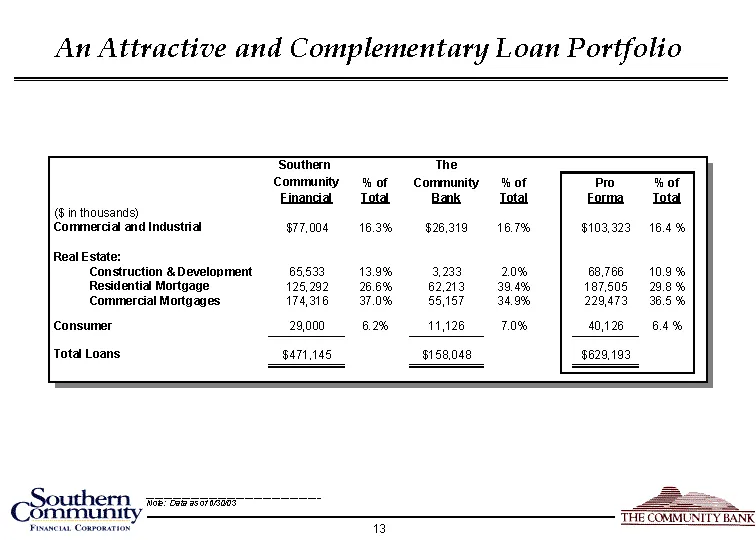
An Attractive and Complementary Loan Portfolio _______________________________________ Note: Data as of 6/30/03
Slide 15: Strong, Low-Cost Deposit Base
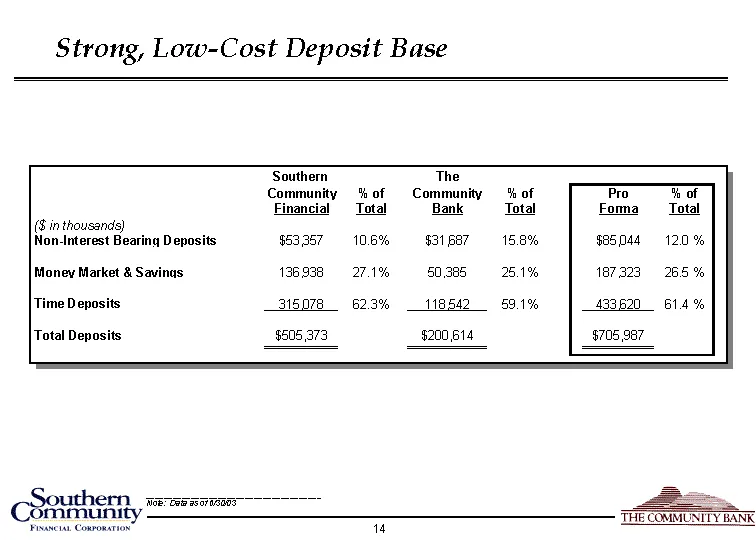
_______________________________________ Note: Data as of 6/30/03 Strong, Low-Cost Deposit Base
Slide 16: Excellent Asset Quality Maintained
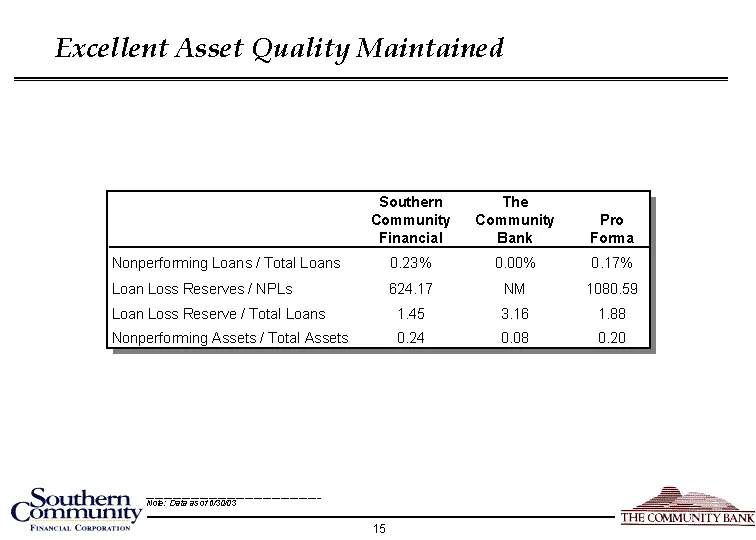
_______________________________________ Note: Data as of 6/30/03 Excellent Asset Quality Maintained
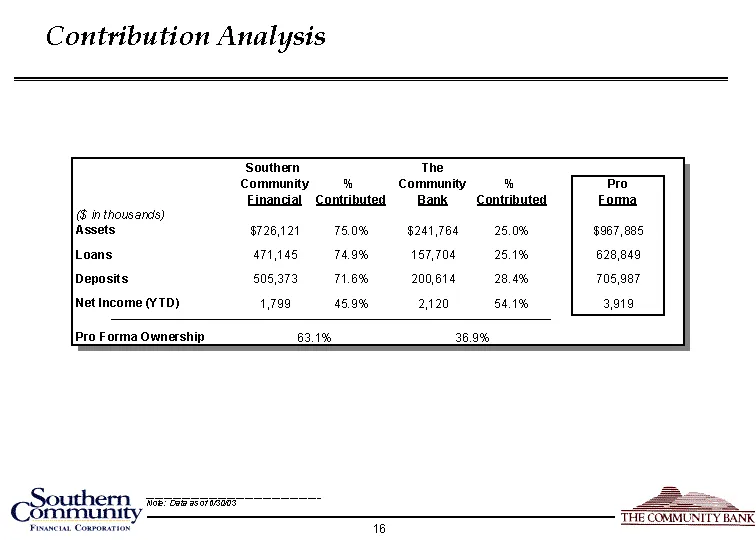
Slide 17: Contribution Analysis
Contribution Analysis _______________________________________ Note: Data as of 6/30/03
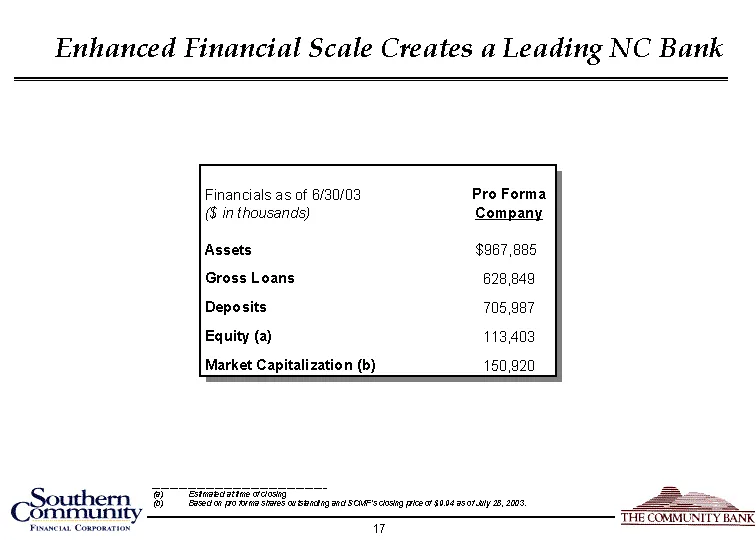
Slide 18: Enhanced Financial Scale Creates a Leading NC Bank
Enhanced Financial Scale Creates a Leading NC Bank _______________________________________ Estimated at time of closing Based on pro forma shares outstanding and SCMF's closing price of $9.94 as of July 28, 2003.
Slide 19: Summary
Summary |
Slide 20: Summary
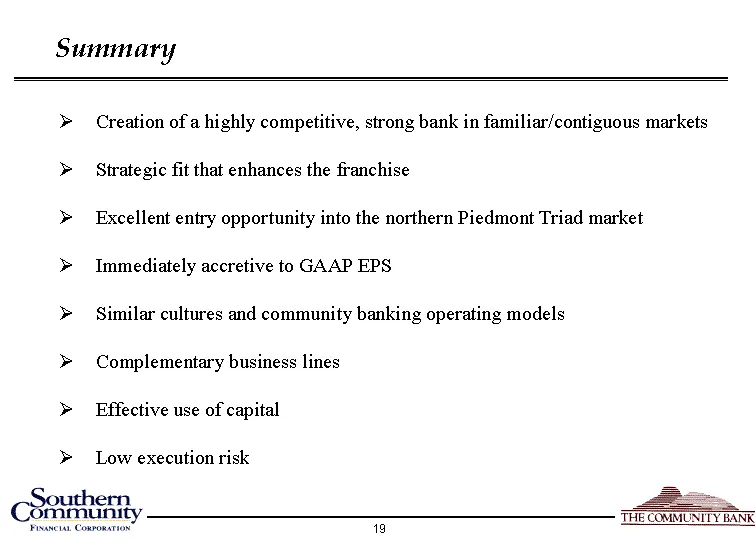
Creation of a highly competitive, strong bank in familiar/contiguous markets Strategic fit that enhances the franchise Excellent entry opportunity into the northern Piedmont Triad market Immediately accretive to GAAP EPS Similar cultures and community banking operating models Complementary business
Source: SEC EDGAR · 8-K filed Jul 30, 2003
More decks from Southern Community Financial Corp
 KBW Investor Conference 201030 slides · Jul 27, 2010
 Investor Presentation (May 2009)26 slides · May 4, 2009
 Conference Presentation (February 2009)26 slides · Feb 6, 2009
 Southeast SuperCommunity Bank Conference (February 2008)28 slides · Feb 11, 2008
 America's Community Bankers Community Bank Investor Conference 200724 slides · Nov 2, 2007
 Emerging Growth Institutional Investor Forum 200727 slides · Mar 26, 2007