Rexel SA · EURONEXT:RXL
Rexel SA — FY2012 Earnings Presentation
63 slides from Rexel SA's earnings presentation, Feb 12, 2013
Slide 1: Q4 & Full-Year 2012 Results
Q4 & Full-Year 2012 RESULTS February 12, 2013 Financial statements at December 31, 2012 were authorized for issue by the Management Board on February 5, 2013 and reviewed by the Supervisory Board held on February 11, 2013. They were audited by statutory auditors.
Slide 2: Results at a Glance
RESULTS AT A GLANCE = ENERGY MOTION
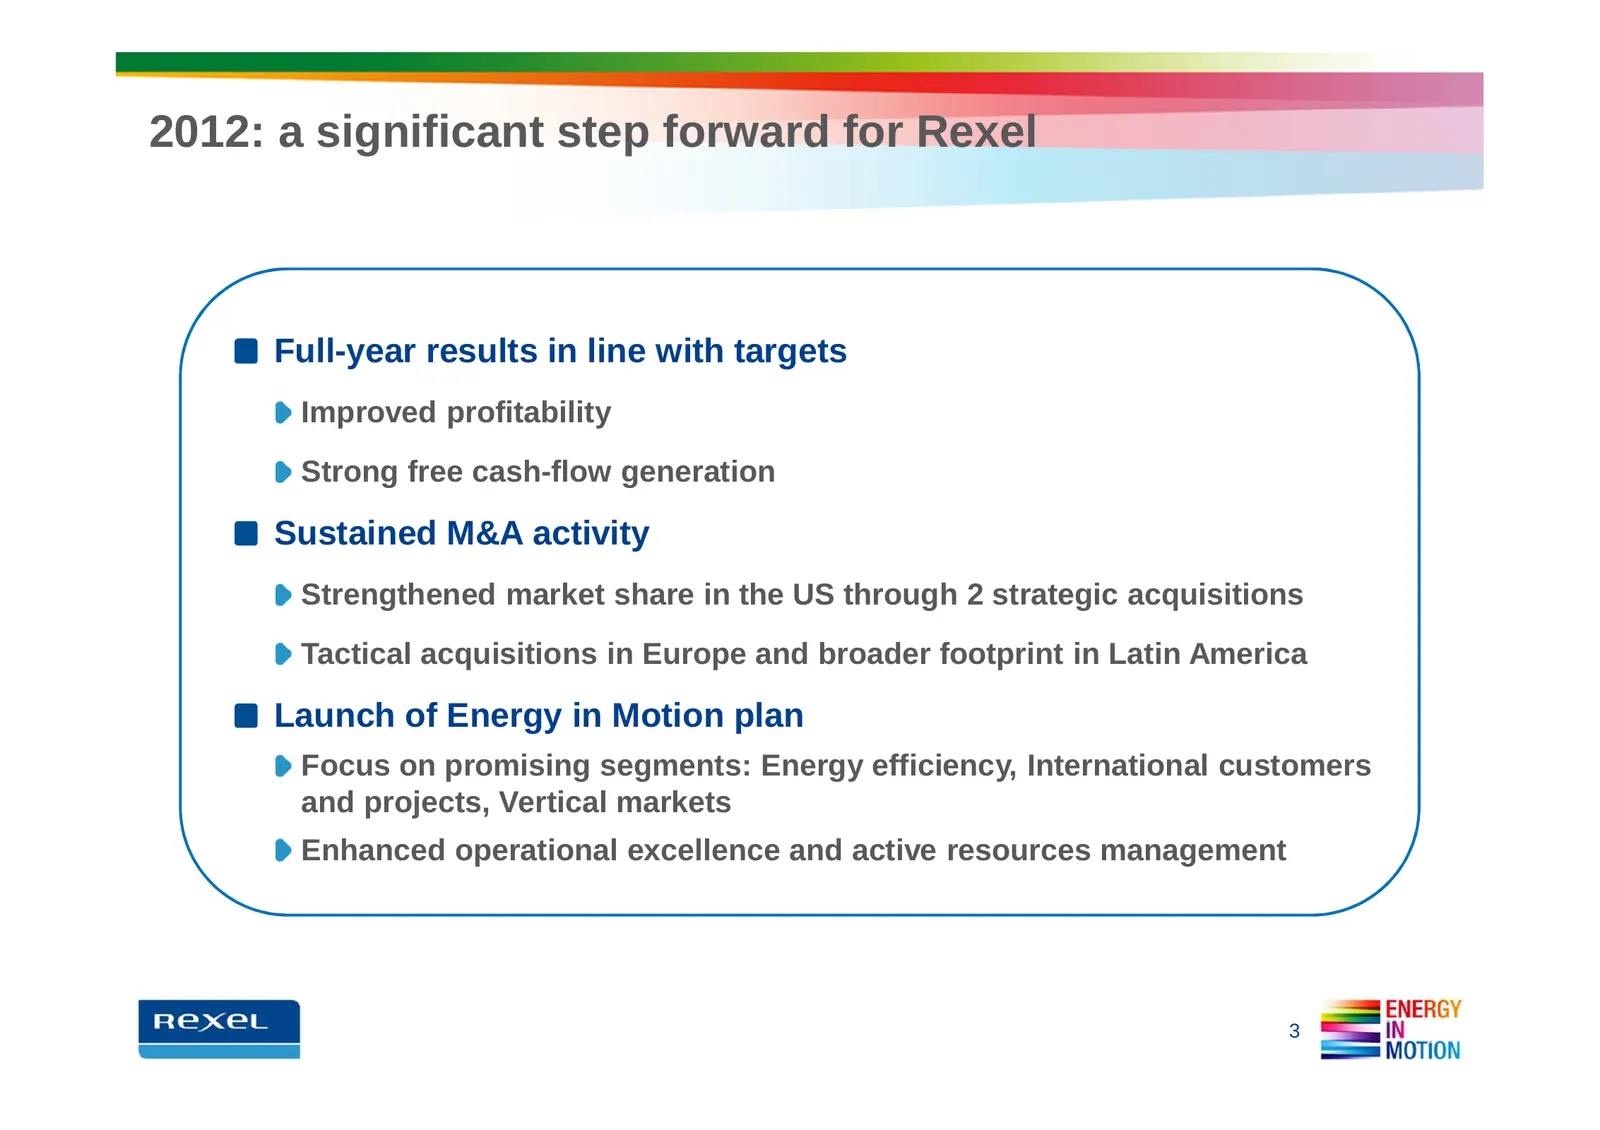
Slide 3: 2012: a significant step forward for Rexel
2012: a significant step forward for Rexel Full-year results in line with targets Improved profitability Strong free cash-flow generation Sustained M&A activity Strengthened market share in the US through 2 strategic acquisitions Tactical acquisitions in Europe and broader footprint in Latin America
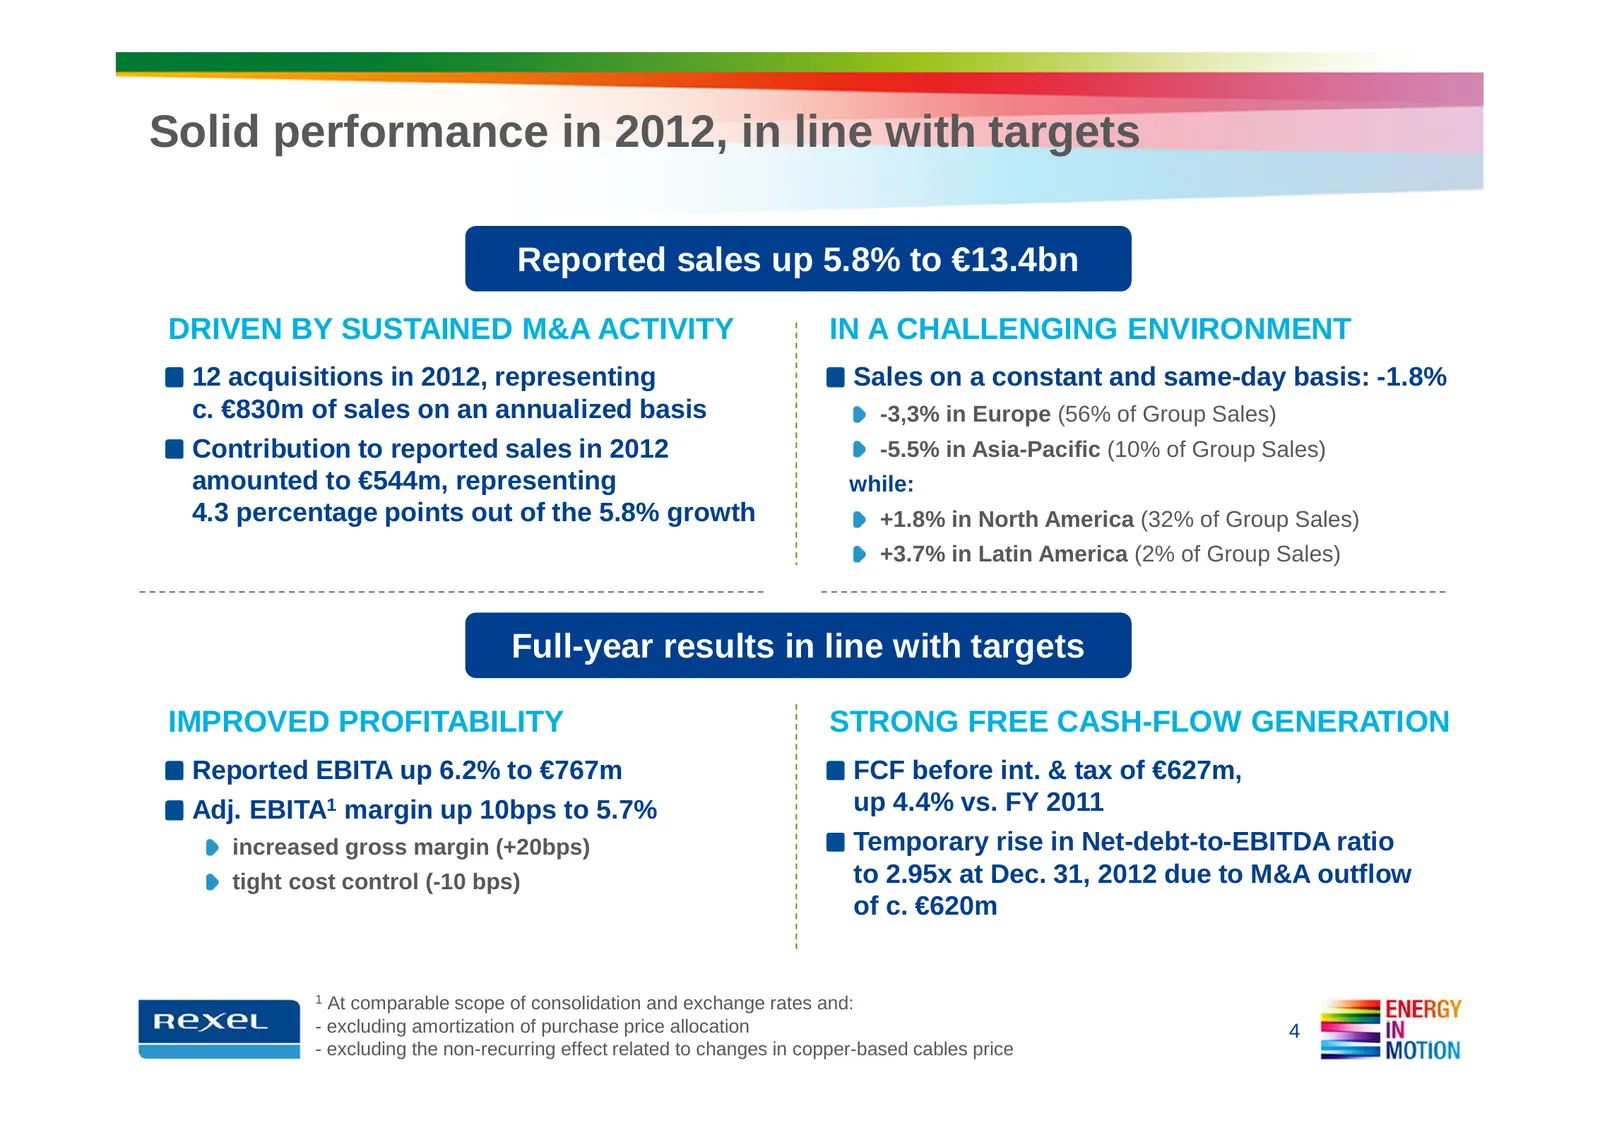
Slide 4: Solid performance in 2012, in line with targets
Solid performance in 2012, in line with targets Reported sales up 5.8% to €13.4bn DRIVEN BY SUSTAINED M&A ACTIVITY IN A CHALLENGING ENVIRONMENT 12 acquisitions in 2012, representing Sales on a constant and same-day basis: -1.8% c. €830m of sales on an annualized basis -3,3% in Europe (56% of Group S
Slide 5: Robust profitability in Q4 despite challenging environment
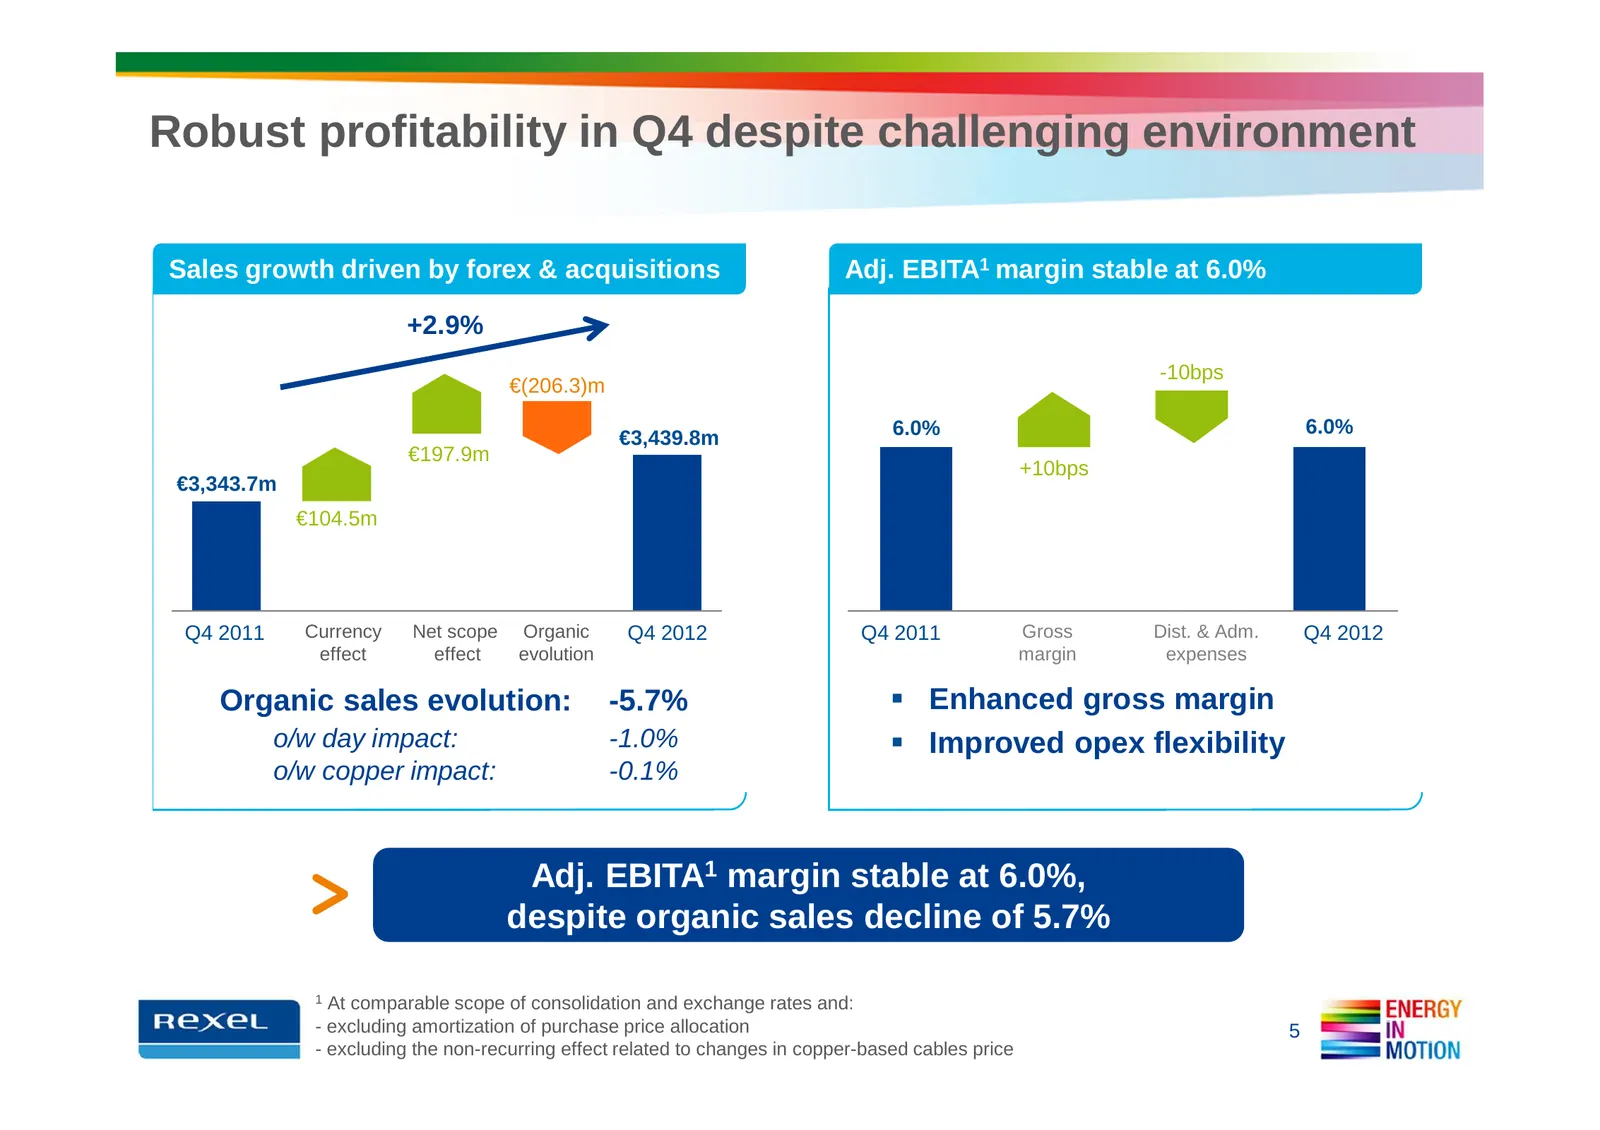
Robust profitability in Q4 despite challenging environment Sales growth driven by forex & acquisitions Adj. EBITA1 margin stable at 6.0% +2.9% -10bps €(206.3)m 6.0% 6.0% €3,439.8m €197.9m +10bps €3,343.7m €104.5m Q4 2011 Currency Net scope Organic Q4 2012 Q4 2011 Gross Dist. & Adm. Q4 2012 effect ef
Slide 6: Improved Adj. EBITA margin in full-year 2012 despite challenging environment
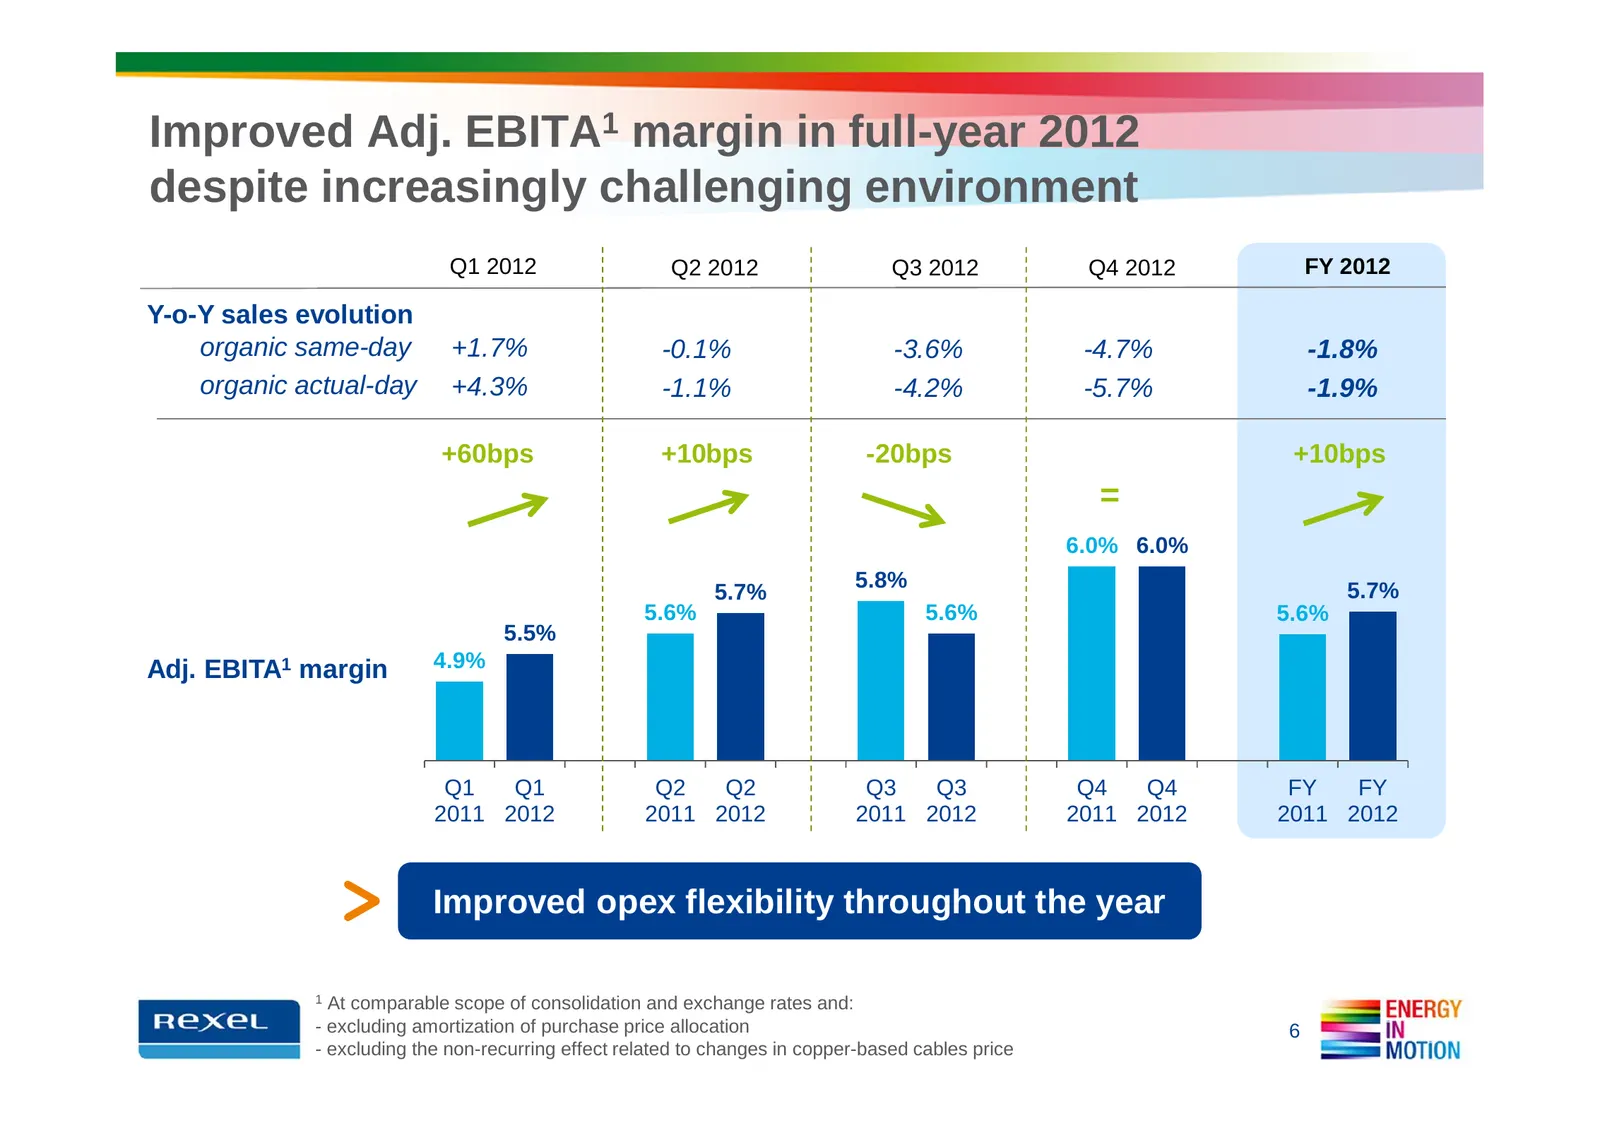
Improved Adj. EBITA1 margin in full-year 2012 despite increasingly challenging environment Q1 2012 Q2 2012 Q3 2012 Q4 2012 FY 2012 Y-o-Y sales evolution organic same-day +1.7% -0.1% -3.6% -4.7% -1.8% organic actual-day +4.3% -1.1% -4.2% -5.7% -1.9% +60bps +10bps -20bps +10bps = 6.0% 6.0% 5.8% 5.7% 5
Slide 7: 88% of Group operations improved their profitability in 2012
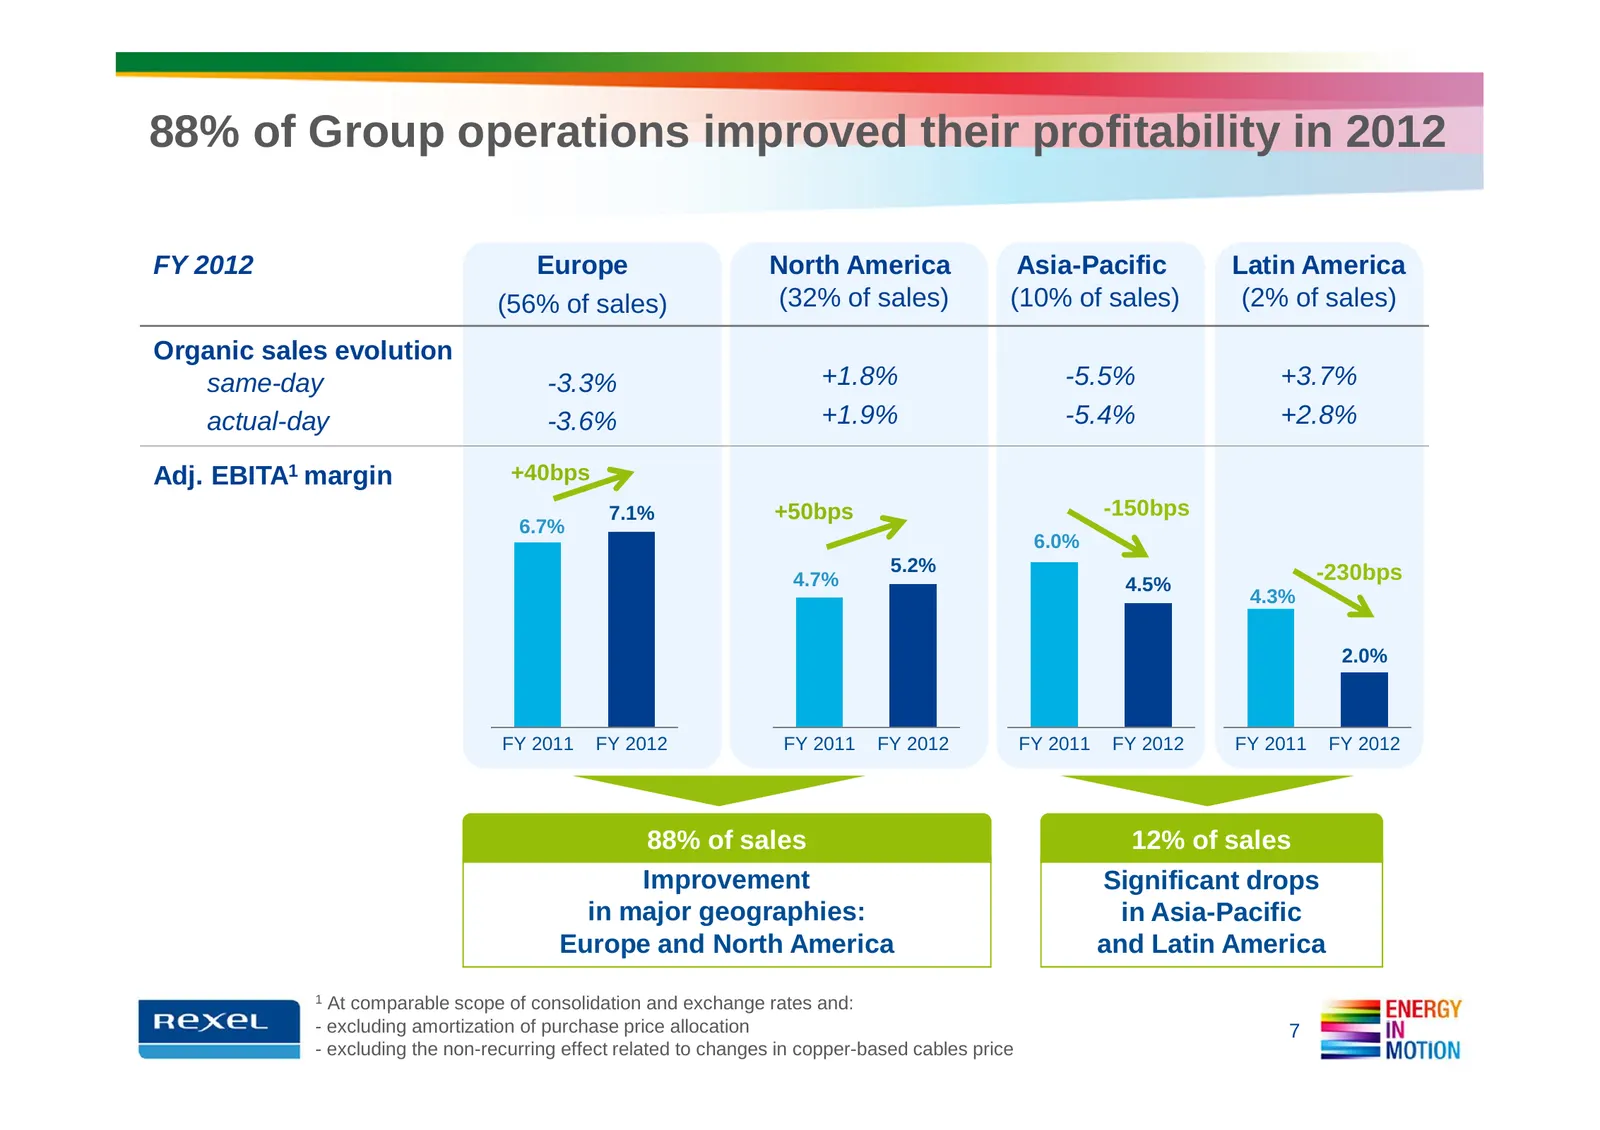
88% of Group operations improved their profitability in 2012 FY 2012 Europe North America Asia-Pacific Latin America (56% of sales) (32% of sales) (10% of sales) (2% of sales) Organic sales evolution same-day -3.3% +1.8% -5.5% +3.7% actual-day -3.6% +1.9% -5.4% +2.8% Adj. EBITA1 margin +40bps 7.1% +
Slide 8: Europe (56% of sales): improved profitability despite slowdown in sales
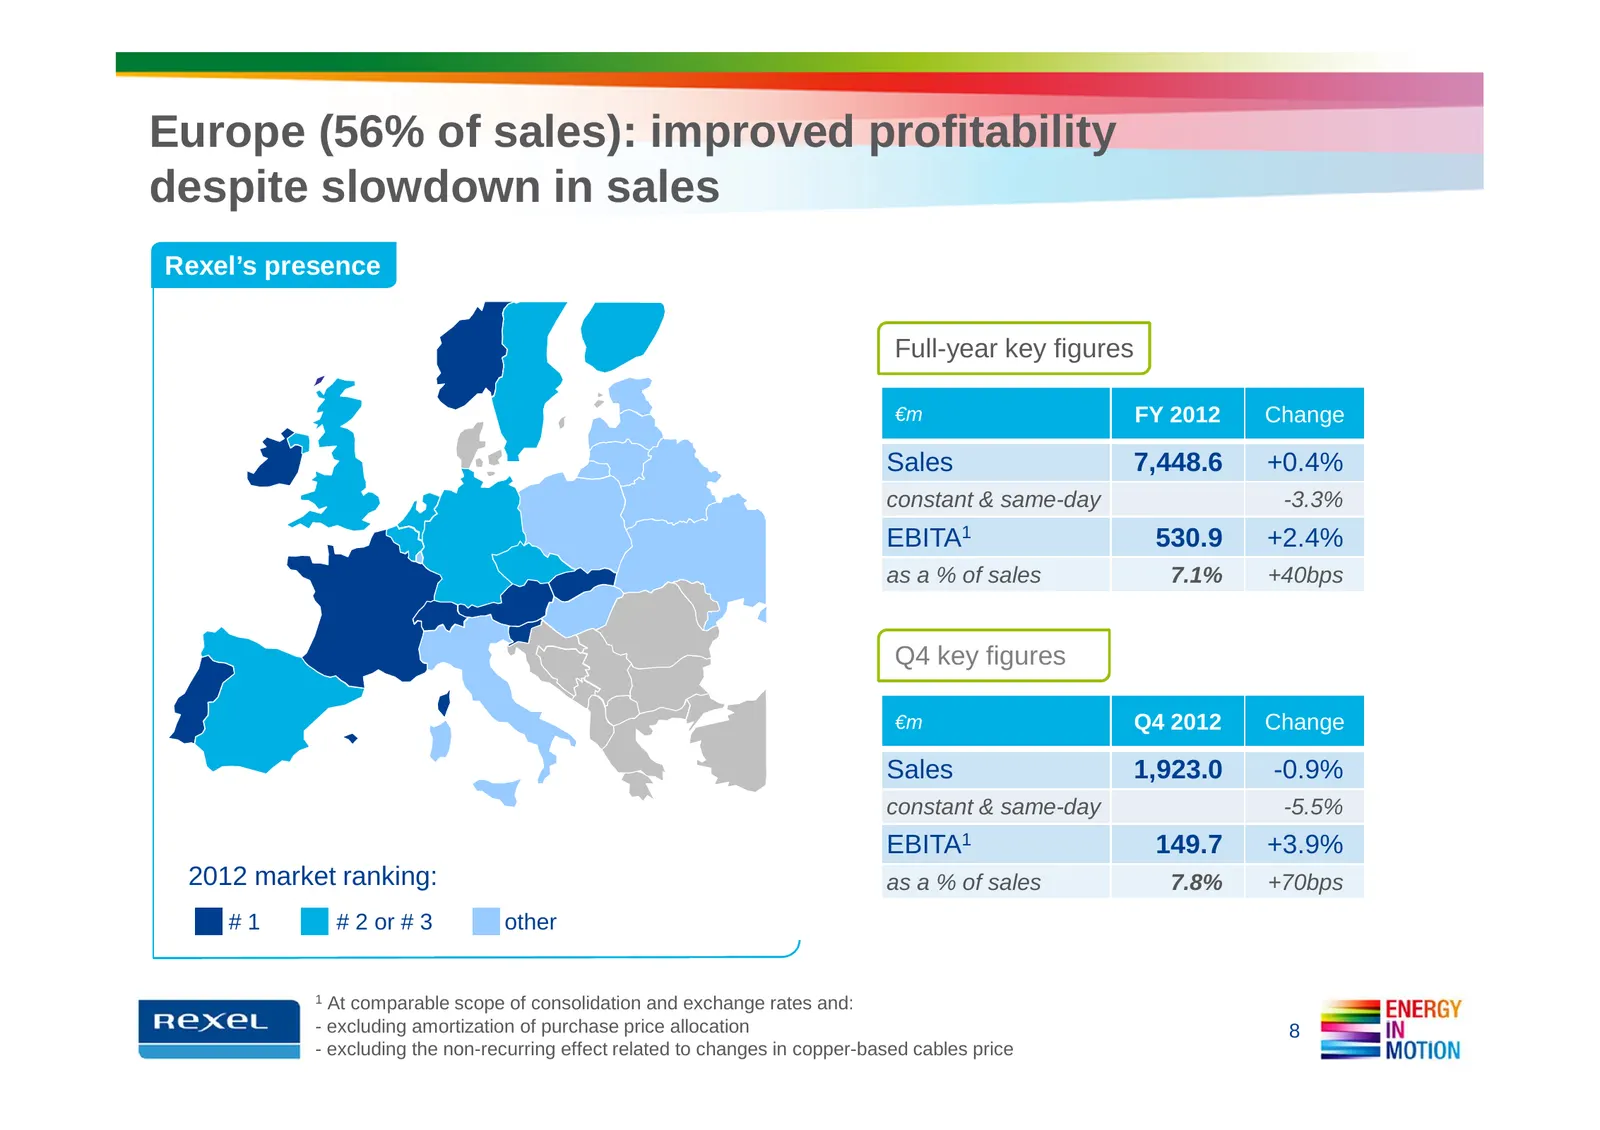
Europe (56% of sales): improved profitability despite slowdown in sales Rexel’s presence Full-year key figures €m FY 2012 Change Sales 7,448.6 +0.4% constant & same-day -3.3% EBITA1 530.9 +2.4% as a % of sales 7.1% +40bps Q4 key figures €m Q4 2012 Change Sales 1,923.0 -0.9% constant & same-day -5.5%
Slide 9: Europe (56% of sales): improved profitability despite slowdown in sales
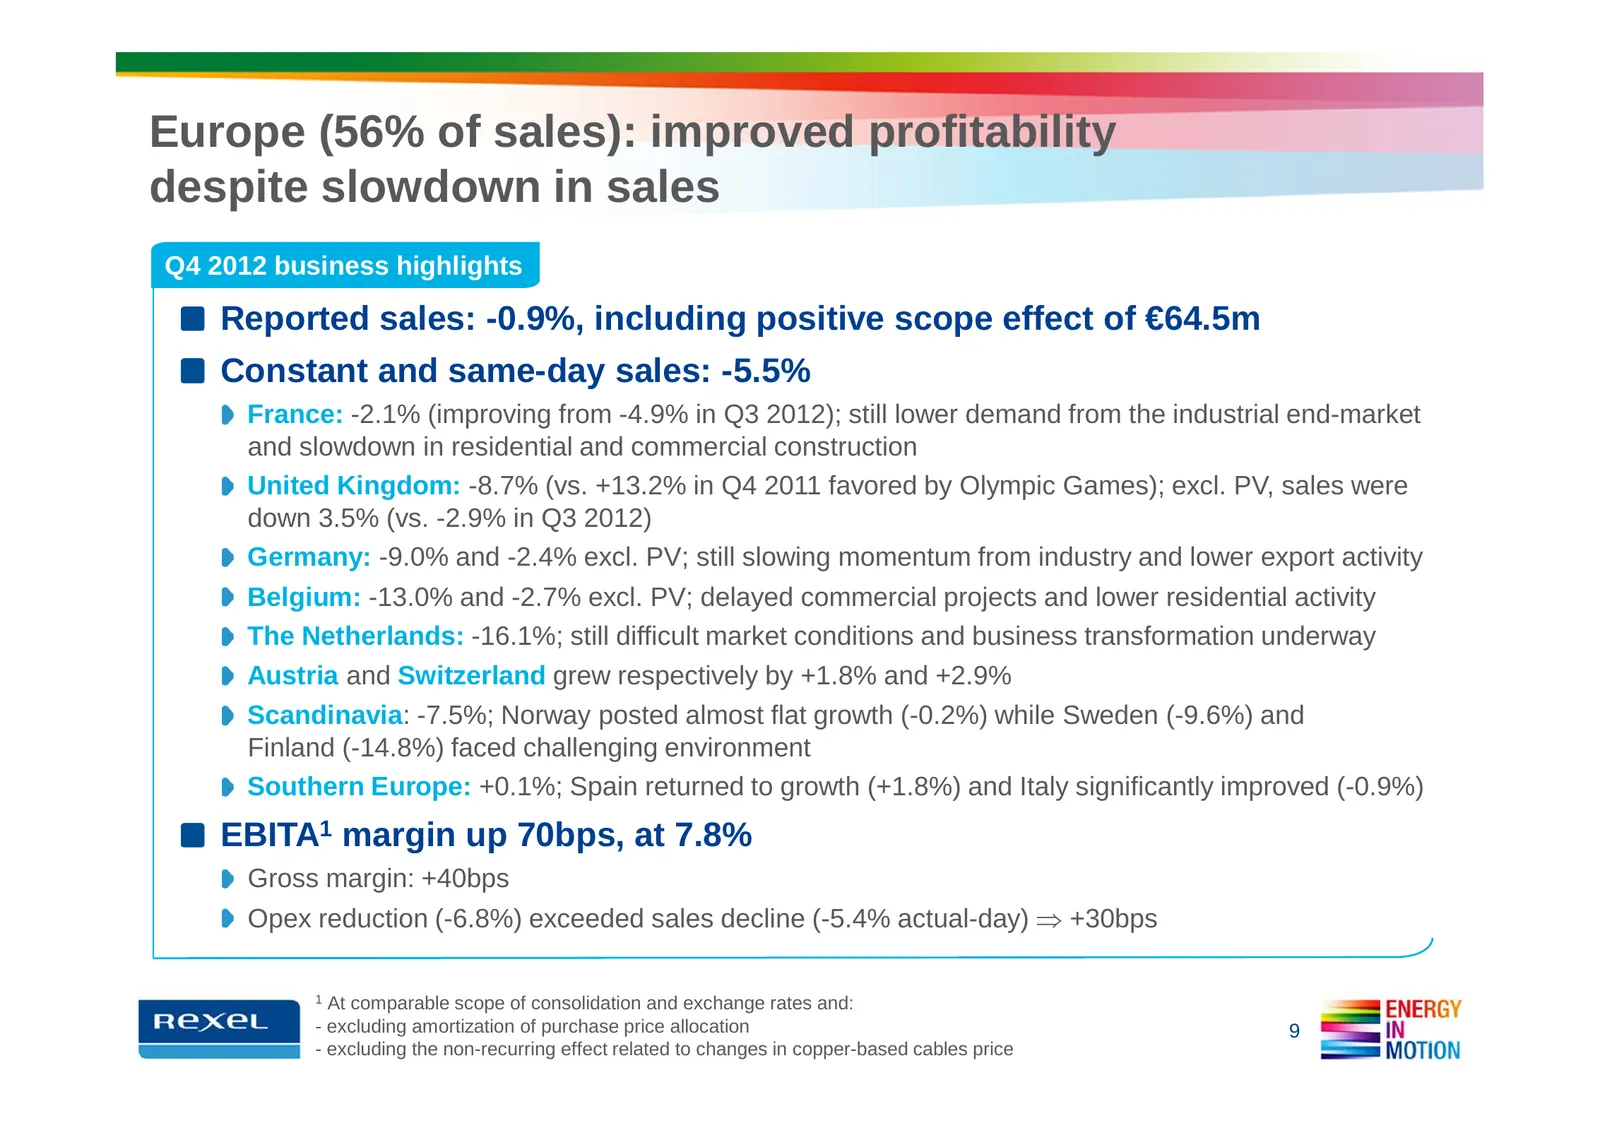
Europe (56% of sales): improved profitability despite slowdown in sales Q4 2012 business highlights Reported sales: -0.9%, including positive scope effect of €64.5m Constant and same-day sales: -5.5% France: -2.1% (improving from -4.9% in Q3 2012); still lower demand from the industrial end-market a
Slide 10: North America (32% of sales): solid full-year performance
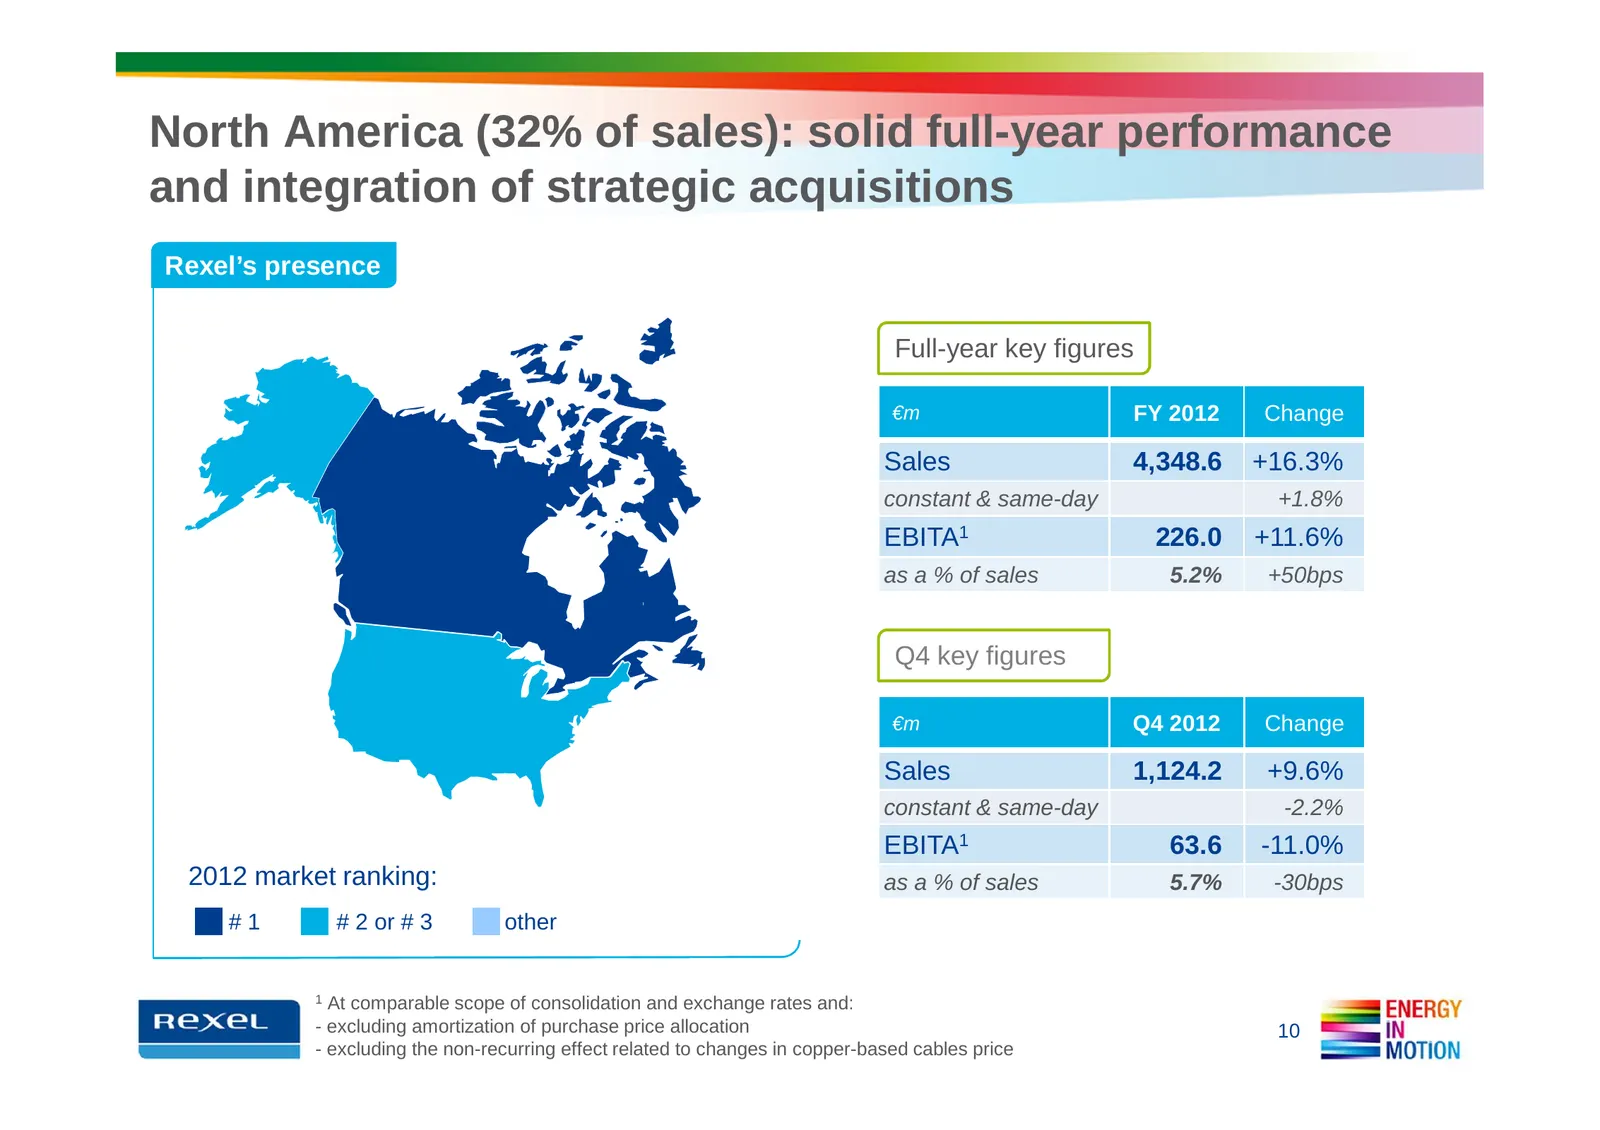
North America (32% of sales): solid full-year performance and integration of strategic acquisitions Rexel’s presence Full-year key figures €m FY 2012 Change Sales 4,348.6 +16.3% constant & same-day +1.8% EBITA1 226.0 +11.6% as a % of sales 5.2% +50bps Q4 key figures €m Q4 2012 Change Sales 1,124.2 +
Slide 11: North America (32% of sales): solid full-year performance
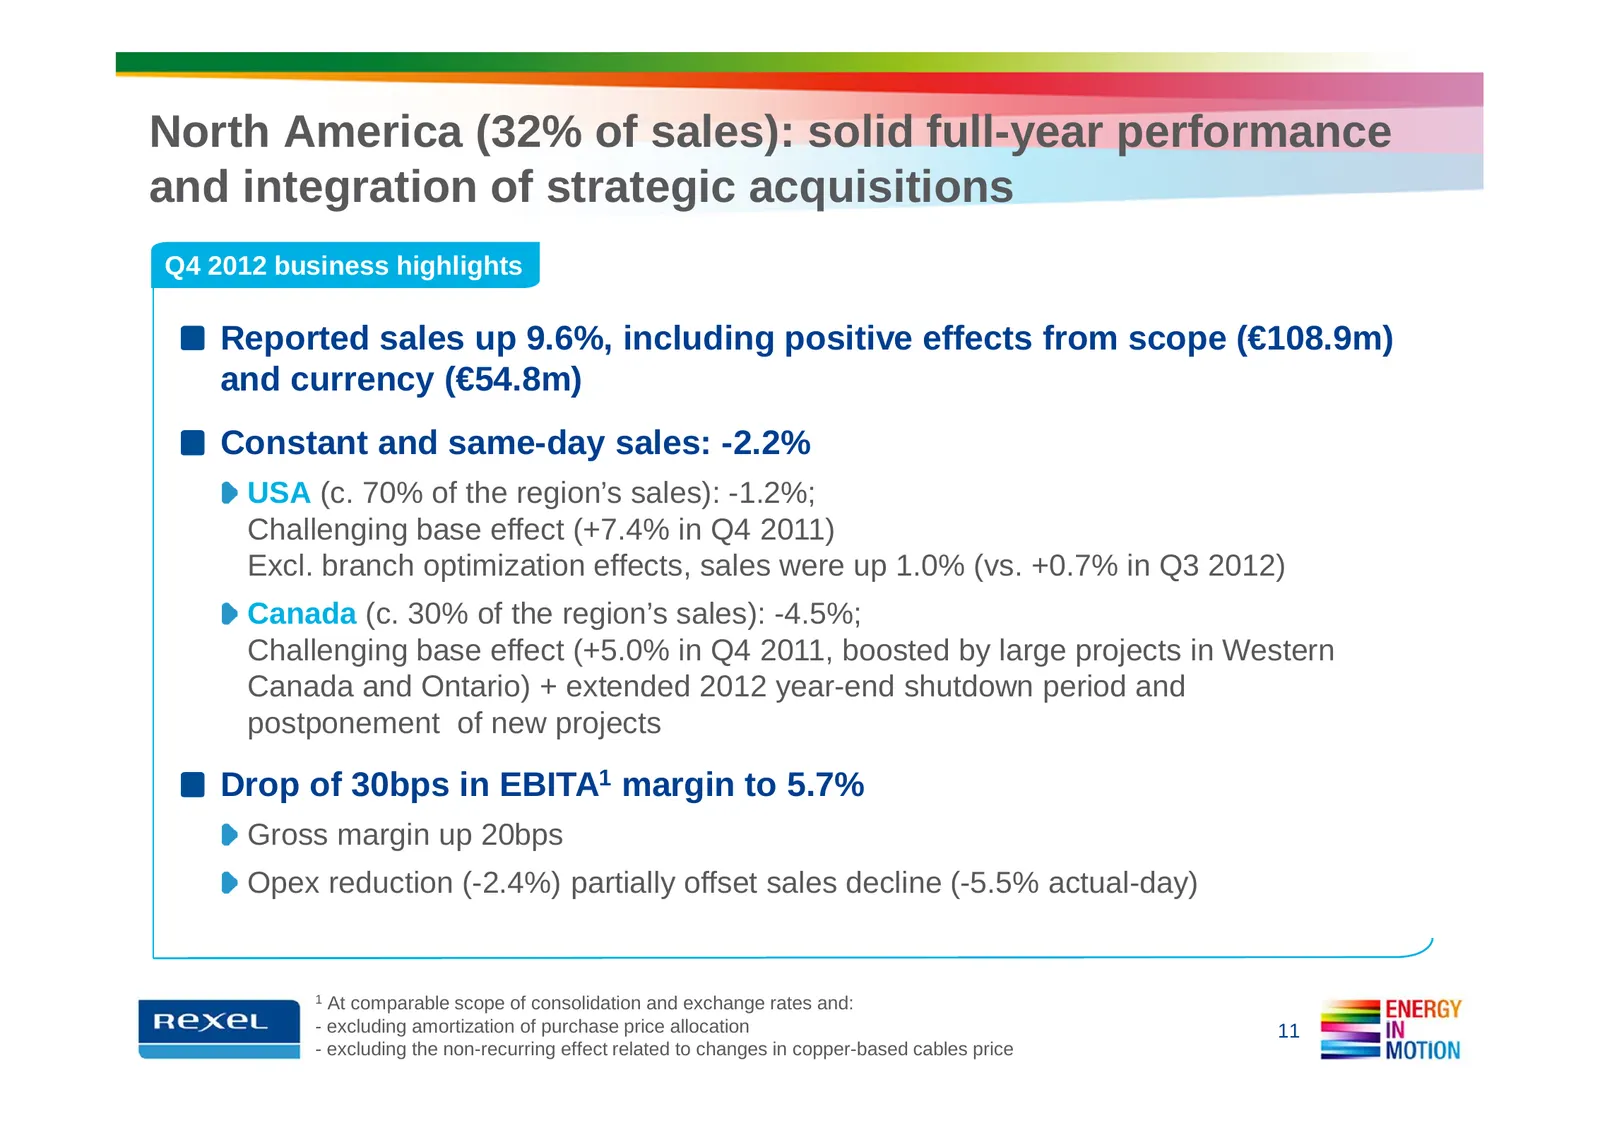
North America (32% of sales): solid full-year performance and integration of strategic acquisitions Q4 2012 business highlights Reported sales up 9.6%, including positive effects from scope (€108.9m) and currency (€54.8m) Constant and same-day sales: -2.2% USA (c. 70% of the region’s sales): -1.2%;
Slide 12: Asia-Pacific (10% of Group sales): growth in China offset by the Pacific region
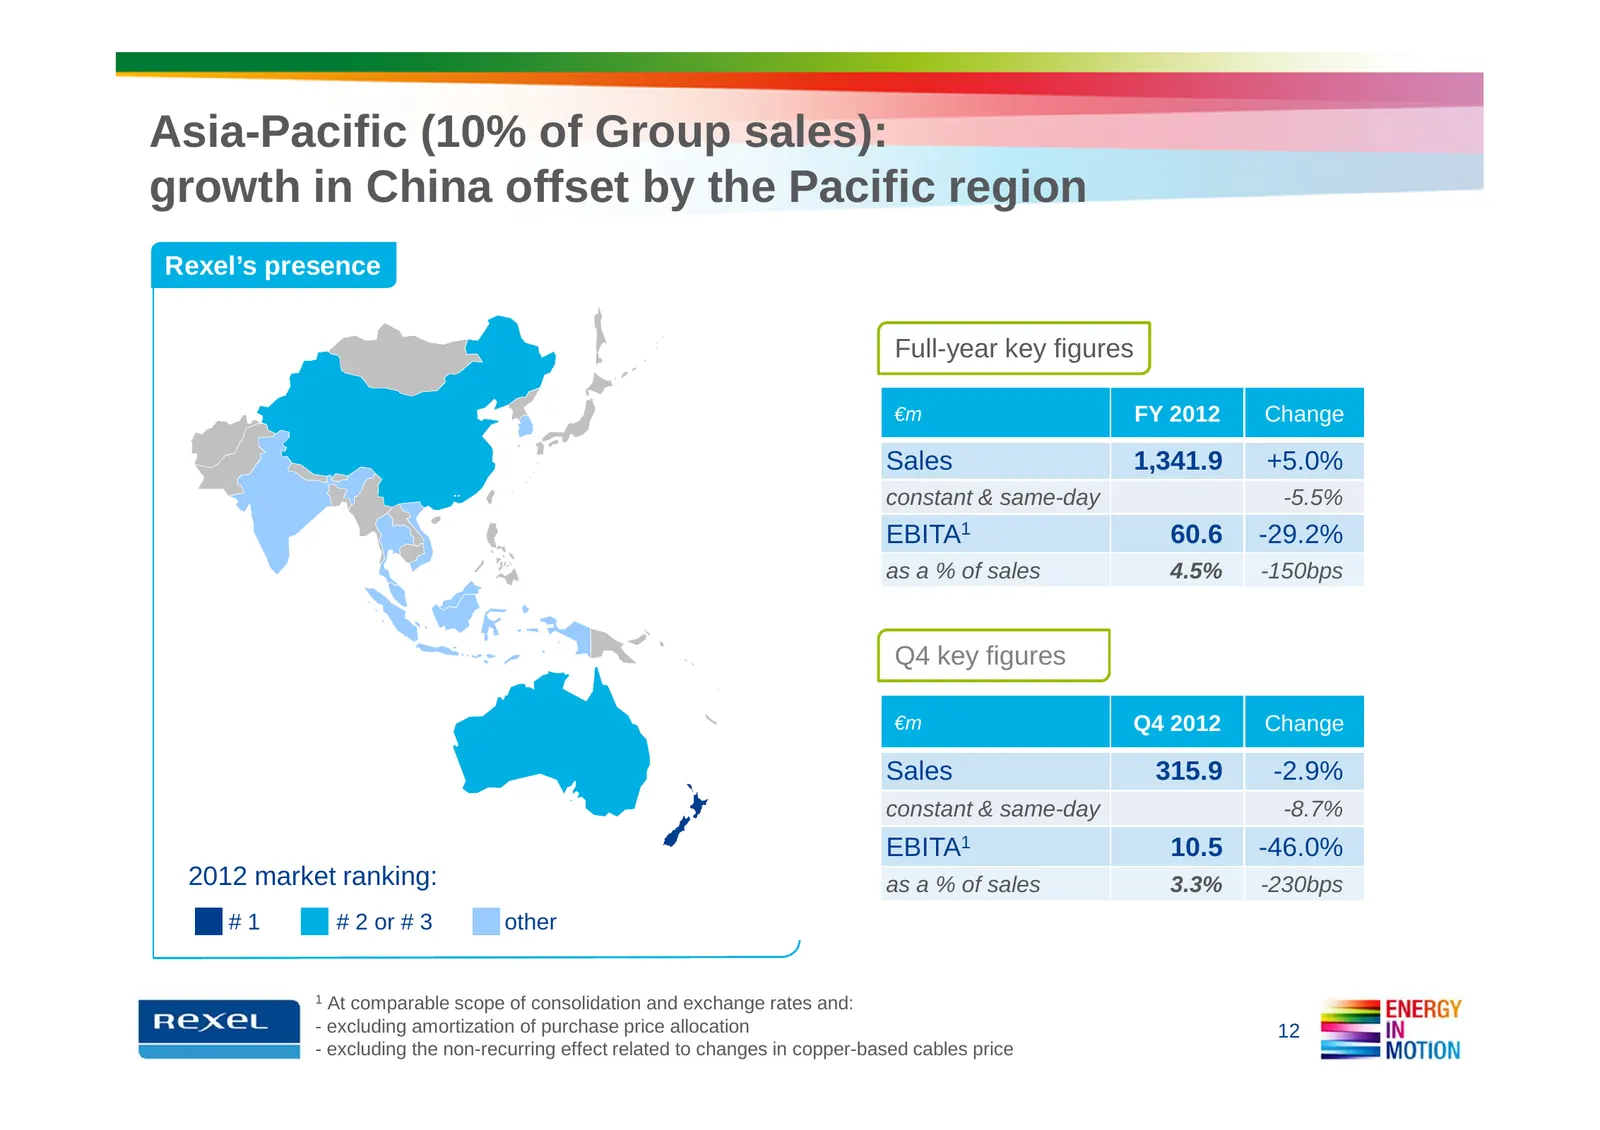
Asia-Pacific (10% of Group sales): growth in China offset by the Pacific region Rexel’s presence Full-year key figures €m FY 2012 Change Sales 1,341.9 +5.0% constant & same-day -5.5% EBITA1 60.6 -29.2% as a % of sales 4.5% -150bps Q4 key figures €m Q4 2012 Change Sales 315.9 -2.9% constant & same-da
Slide 13: Asia-Pacific (10% of Group sales): growth in China offset by the Pacific region
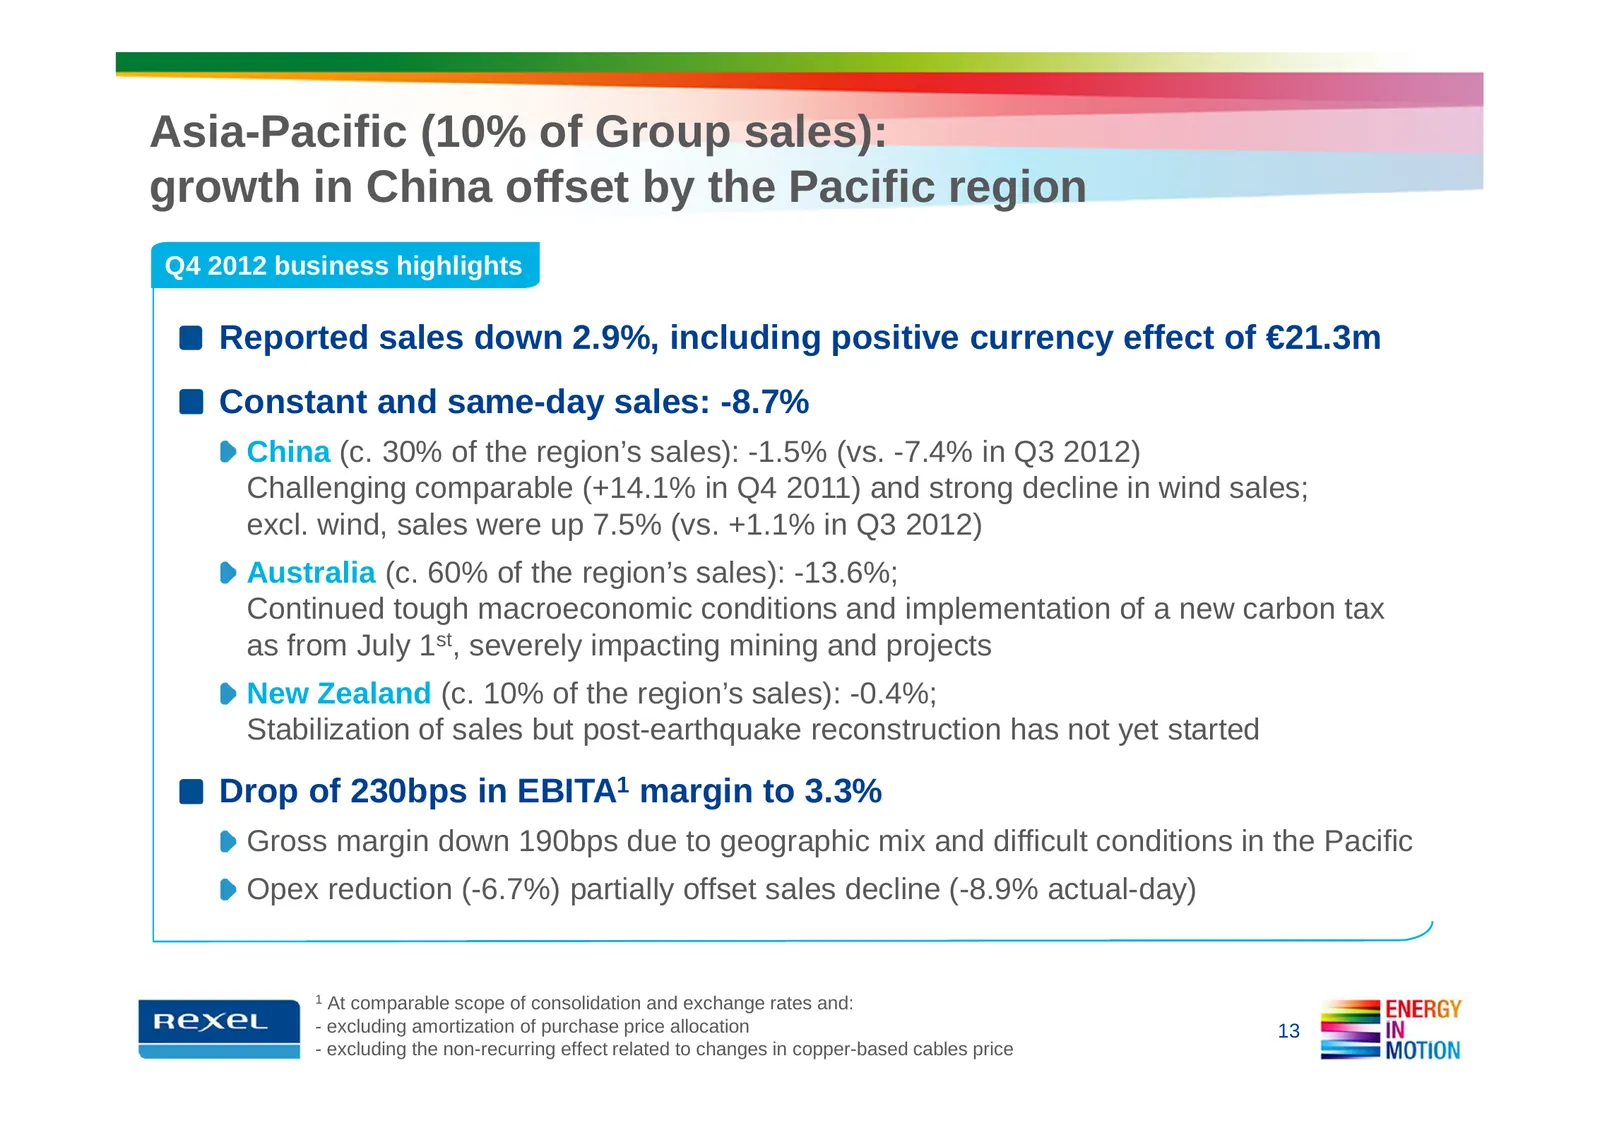
Asia-Pacific (10% of Group sales): growth in China offset by the Pacific region Q4 2012 business highlights Reported sales down 2.9%, including positive currency effect of €21.3m Constant and same-day sales: -8.7% China (c. 30% of the region’s sales): -1.5% (vs. -7.4% in Q3 2012) Challenging compara
Slide 14: Latin America (2% of Group sales): building a solid platform
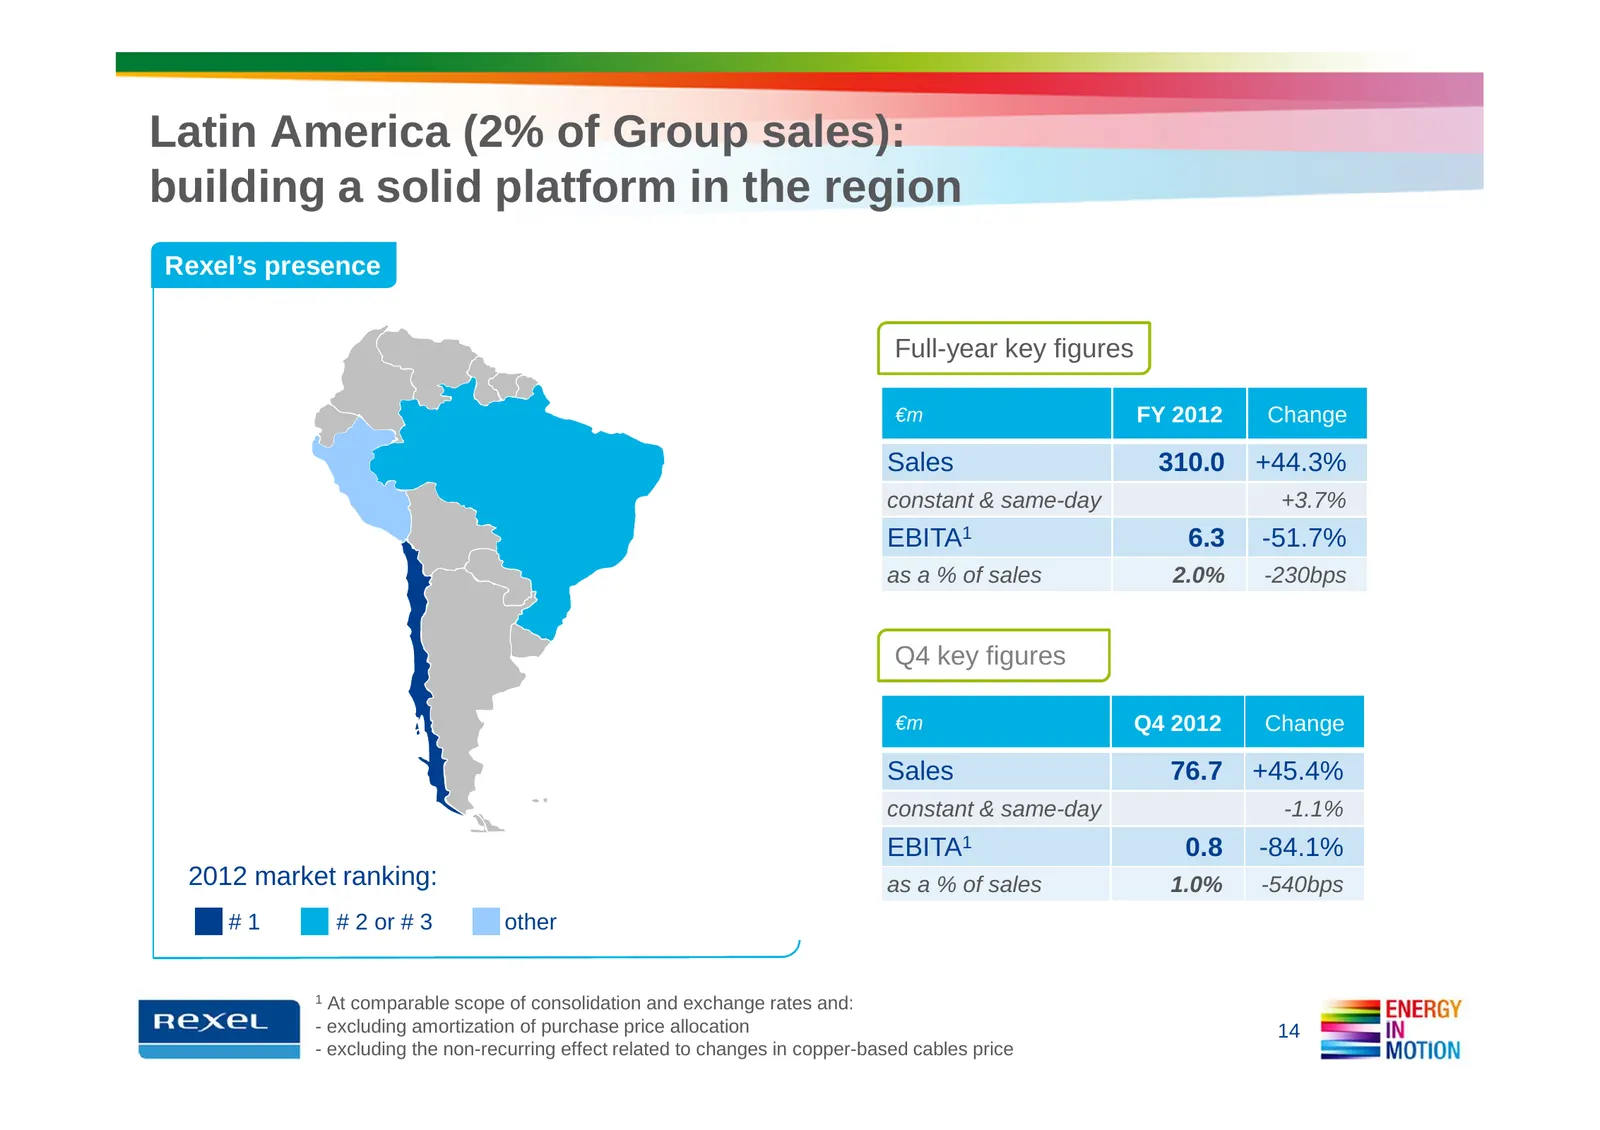
Latin America (2% of Group sales): building a solid platform in the region Rexel’s presence Full-year key figures €m FY 2012 Change Sales 310.0 +44.3% constant & same-day +3.7% EBITA1 6.3 -51.7% as a % of sales 2.0% -230bps Q4 key figures €m Q4 2012 Change Sales 76.7 +45.4% constant & same-day -1.1%
Slide 15: Latin America (2% of Group sales): building a solid platform
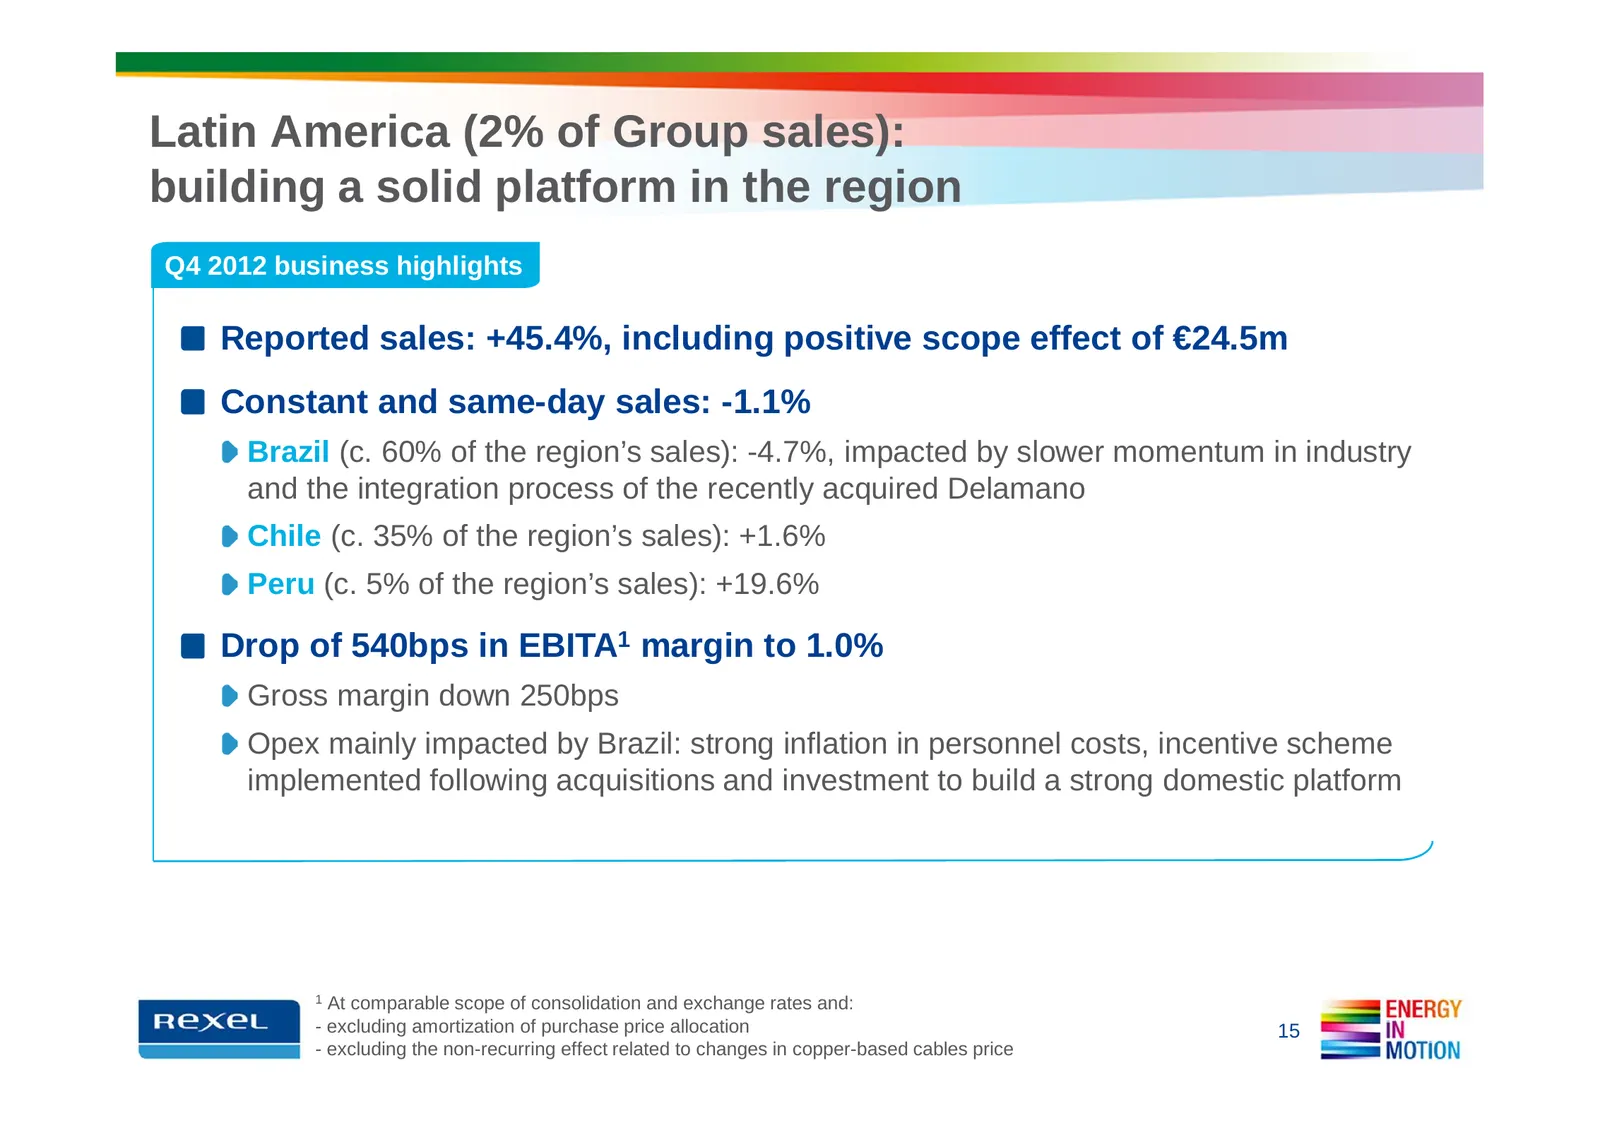
Latin America (2% of Group sales): building a solid platform in the region Q4 2012 business highlights Reported sales: +45.4%, including positive scope effect of €24.5m Constant and same-day sales: -1.1% Brazil (c. 60% of the region’s sales): -4.7%, impacted by slower momentum in industry and the in
Slide 16: Financial Review
FINANCIAL REVIEW = ENERGY MOTION
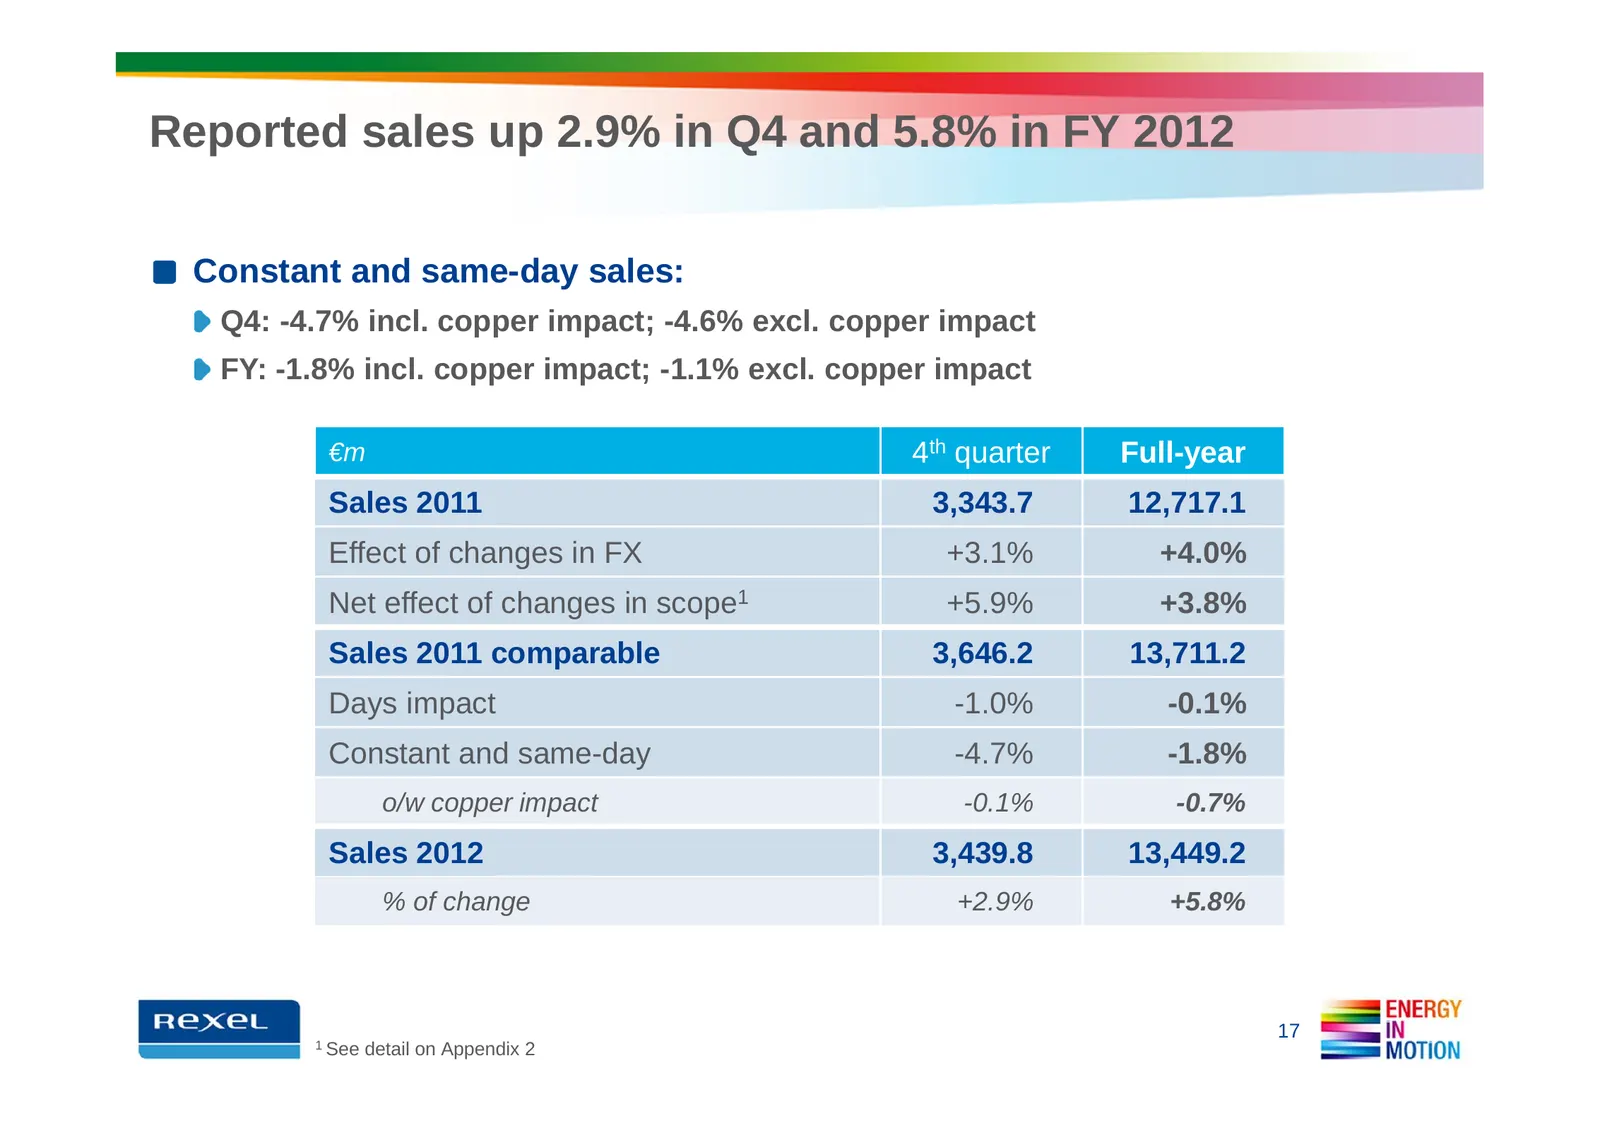
Slide 17: Reported sales up 2.9% in Q4 and 5.8% in FY 2012
Reported sales up 2.9% in Q4 and 5.8% in FY 2012 Constant and same-day sales: Q4: -4.7% incl. copper impact; -4.6% excl. copper impact FY: -1.8% incl. copper impact; -1.1% excl. copper impact €m 4th quarter Full-year Sales 2011 3,343.7 12,717.1 Effect of changes in FX +3.1% +4.0% Net effect of chang
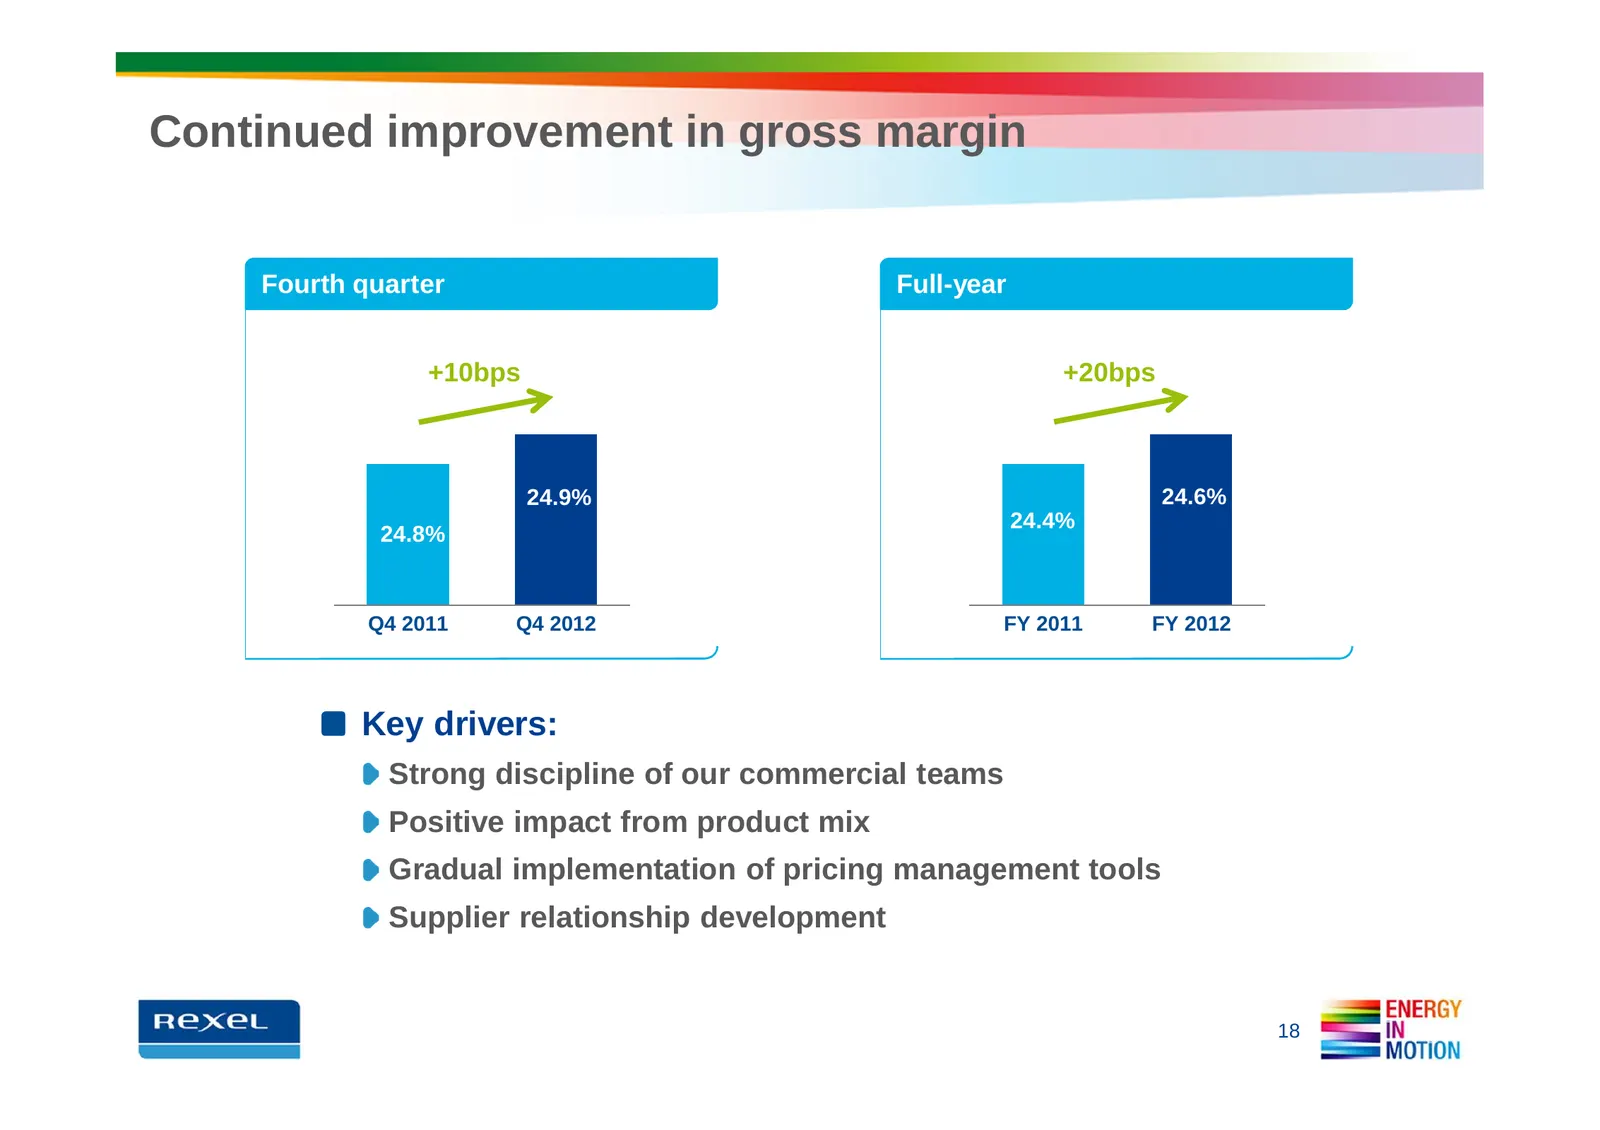
Slide 18: Continued improvement in gross margin
Continued improvement in gross margin Fourth quarter Full-year +10bps +20bps 24.9% 24.6% 24.4% 24.8% Q4 2011 Q4 2012 FY 2011 FY 2012 Key drivers: Strong discipline of our commercial teams Positive impact from product mix Gradual implementation of pricing management tools Supplier relationship develo
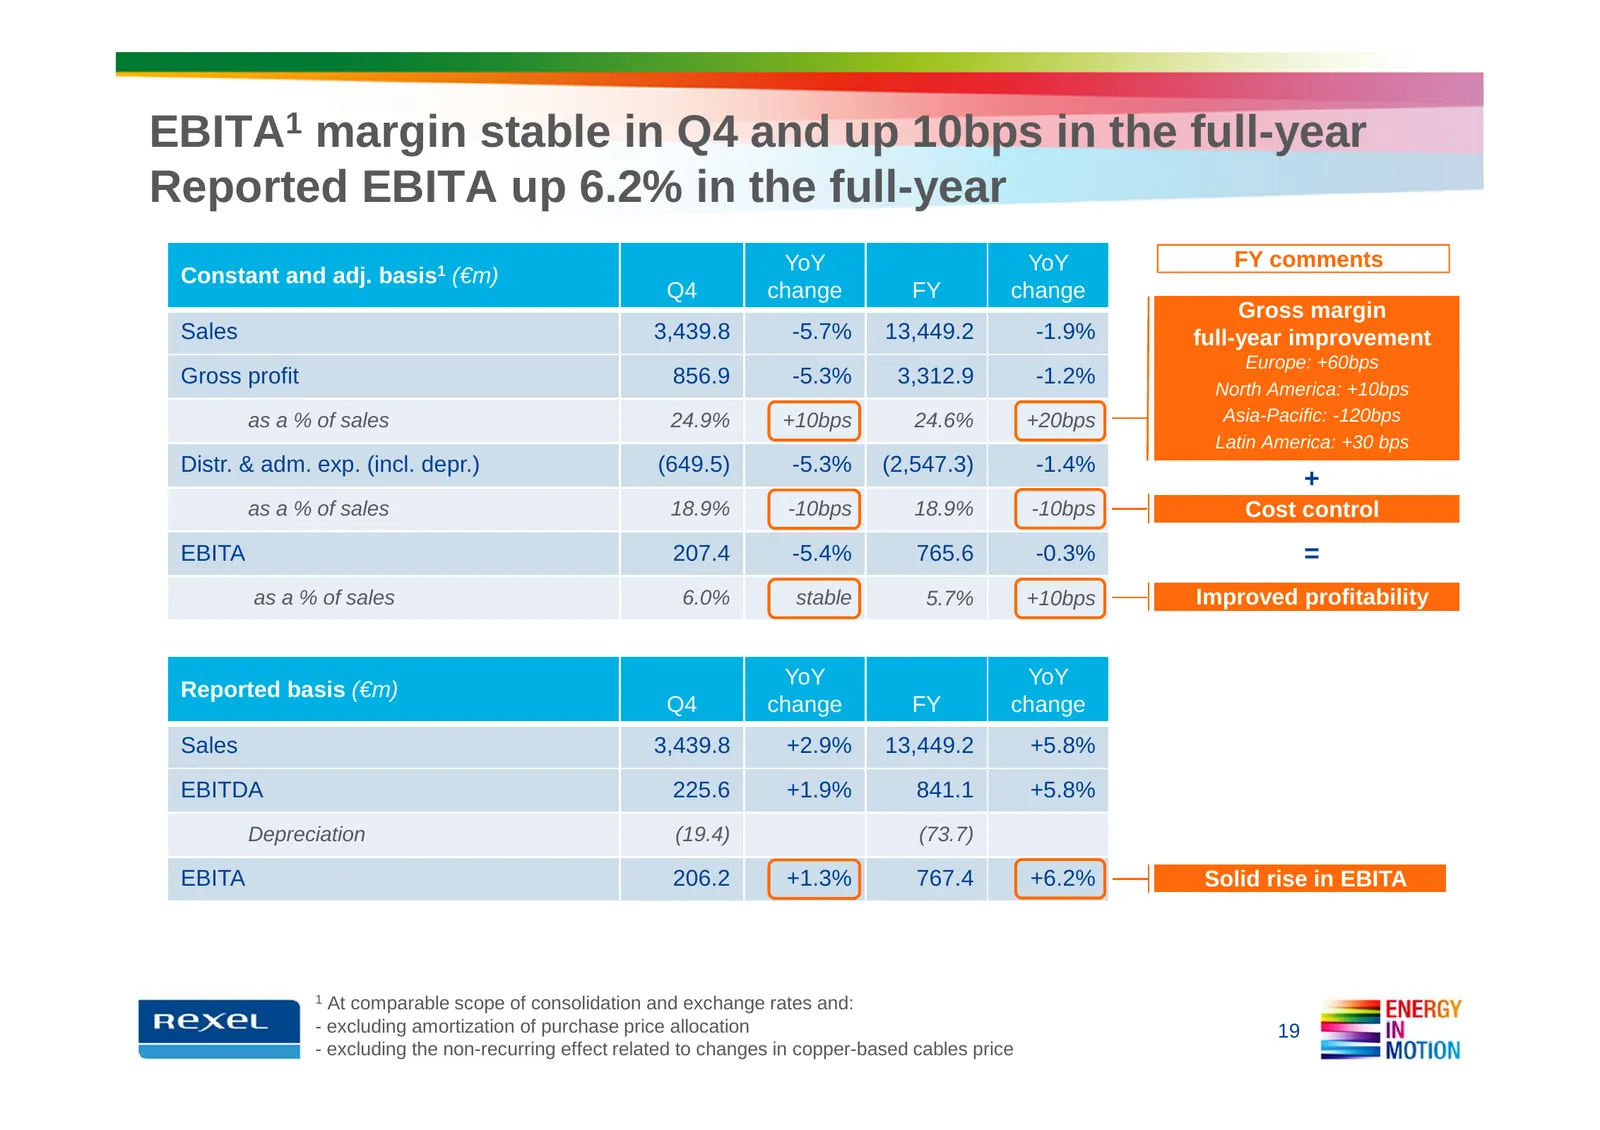
Slide 19: EBITA margin stable in Q4 and up 10bps in the full-year
EBITA1 margin stable in Q4 and up 10bps in the full-year Reported EBITA up 6.2% in the full-year YoY YoY FY comments Constant and adj. basis1 (€m) Q4 change FY change Gross margin Sales 3,439.8 -5.7% 13,449.2 -1.9% full-year improvement Europe: +60bps Gross profit 856.9 -5.3% 3,312.9 -1.2% North Ame
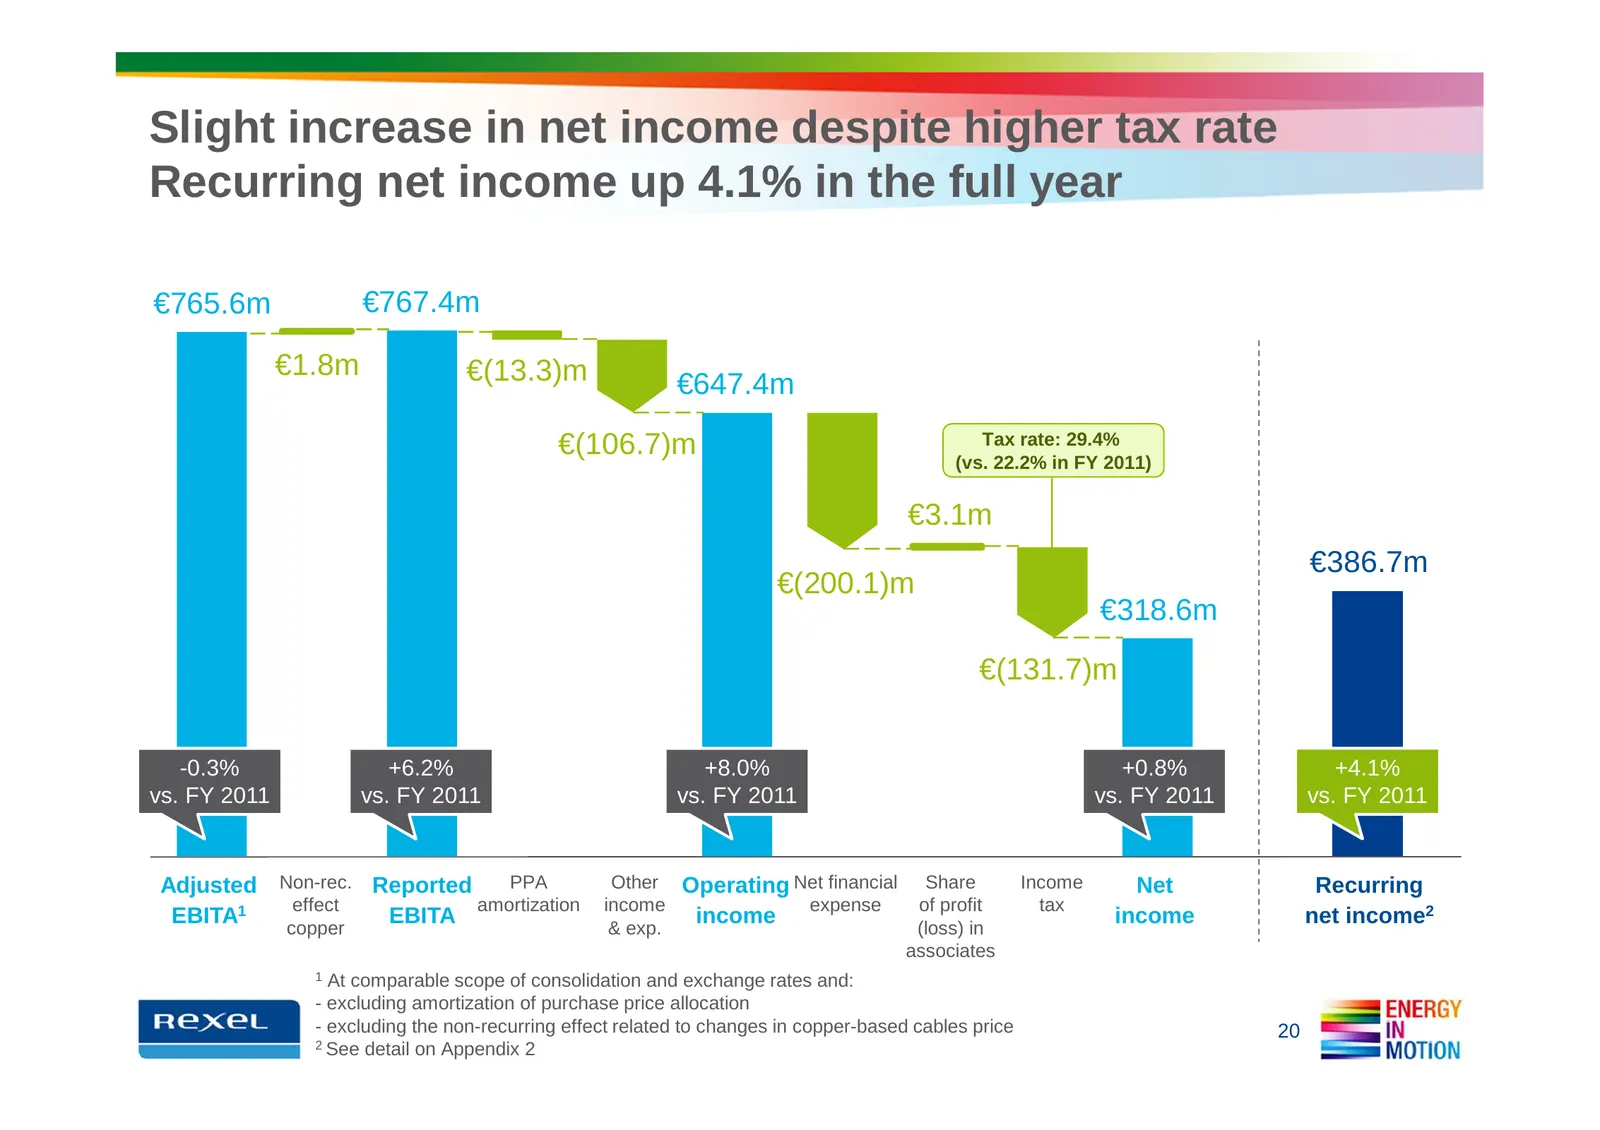
Slide 20: Slight increase in net income despite higher tax rate
Slight increase in net income despite higher tax rate Recurring net income up 4.1% in the full year €765.6m €767.4m €1.8m €(13.3)m €647.4m €(106.7)m Tax rate: 29.4% (vs. 22.2% in FY 2011) €3.1m €386.7m €(200.1)m €318.6m €(131.7)m -0.3% +6.2% +8.0% +0.8% +4.1% vs. FY 2011 vs. FY 2011 vs. FY 2011 vs.
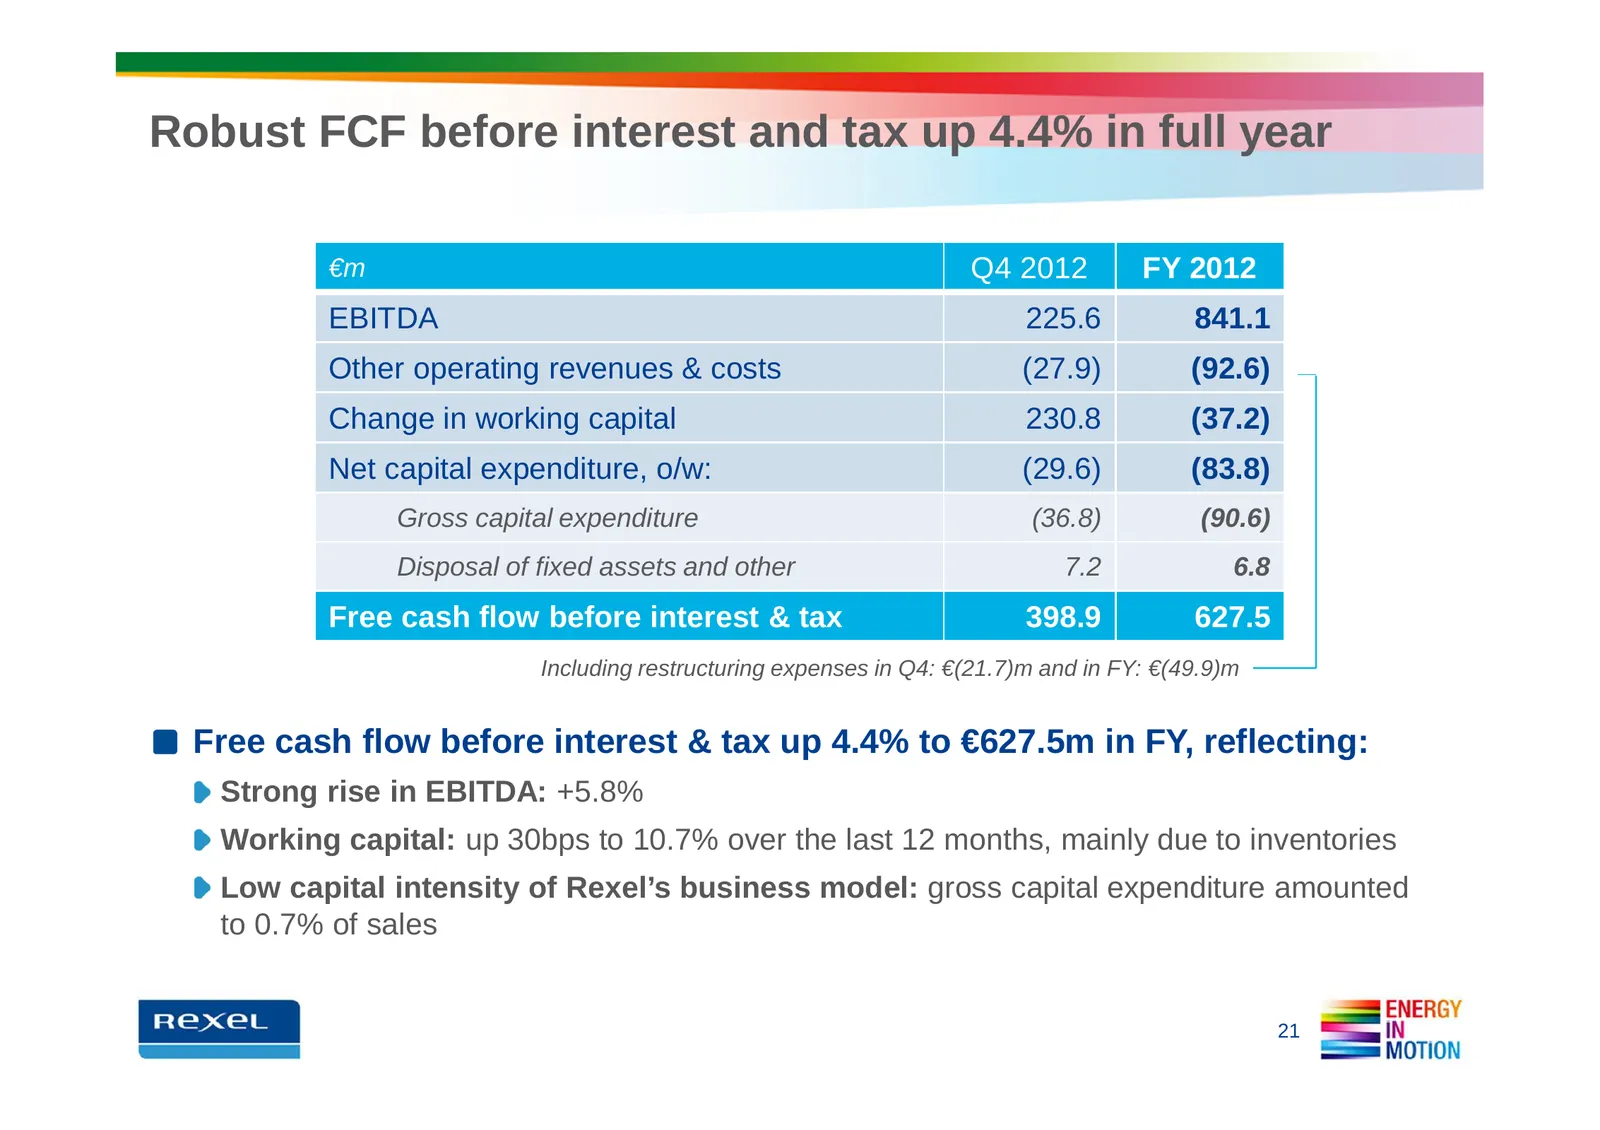
Slide 21: Robust FCF before interest and tax up 4.4% in full year
Robust FCF before interest and tax up 4.4% in full year €m Q4 2012 FY 2012 EBITDA 225.6 841.1 Other operating revenues & costs (27.9) (92.6) Change in working capital 230.8 (37.2) Net capital expenditure, o/w: (29.6) (83.8) Gross capital expenditure (36.8) (90.6) Disposal of fixed assets and other 7
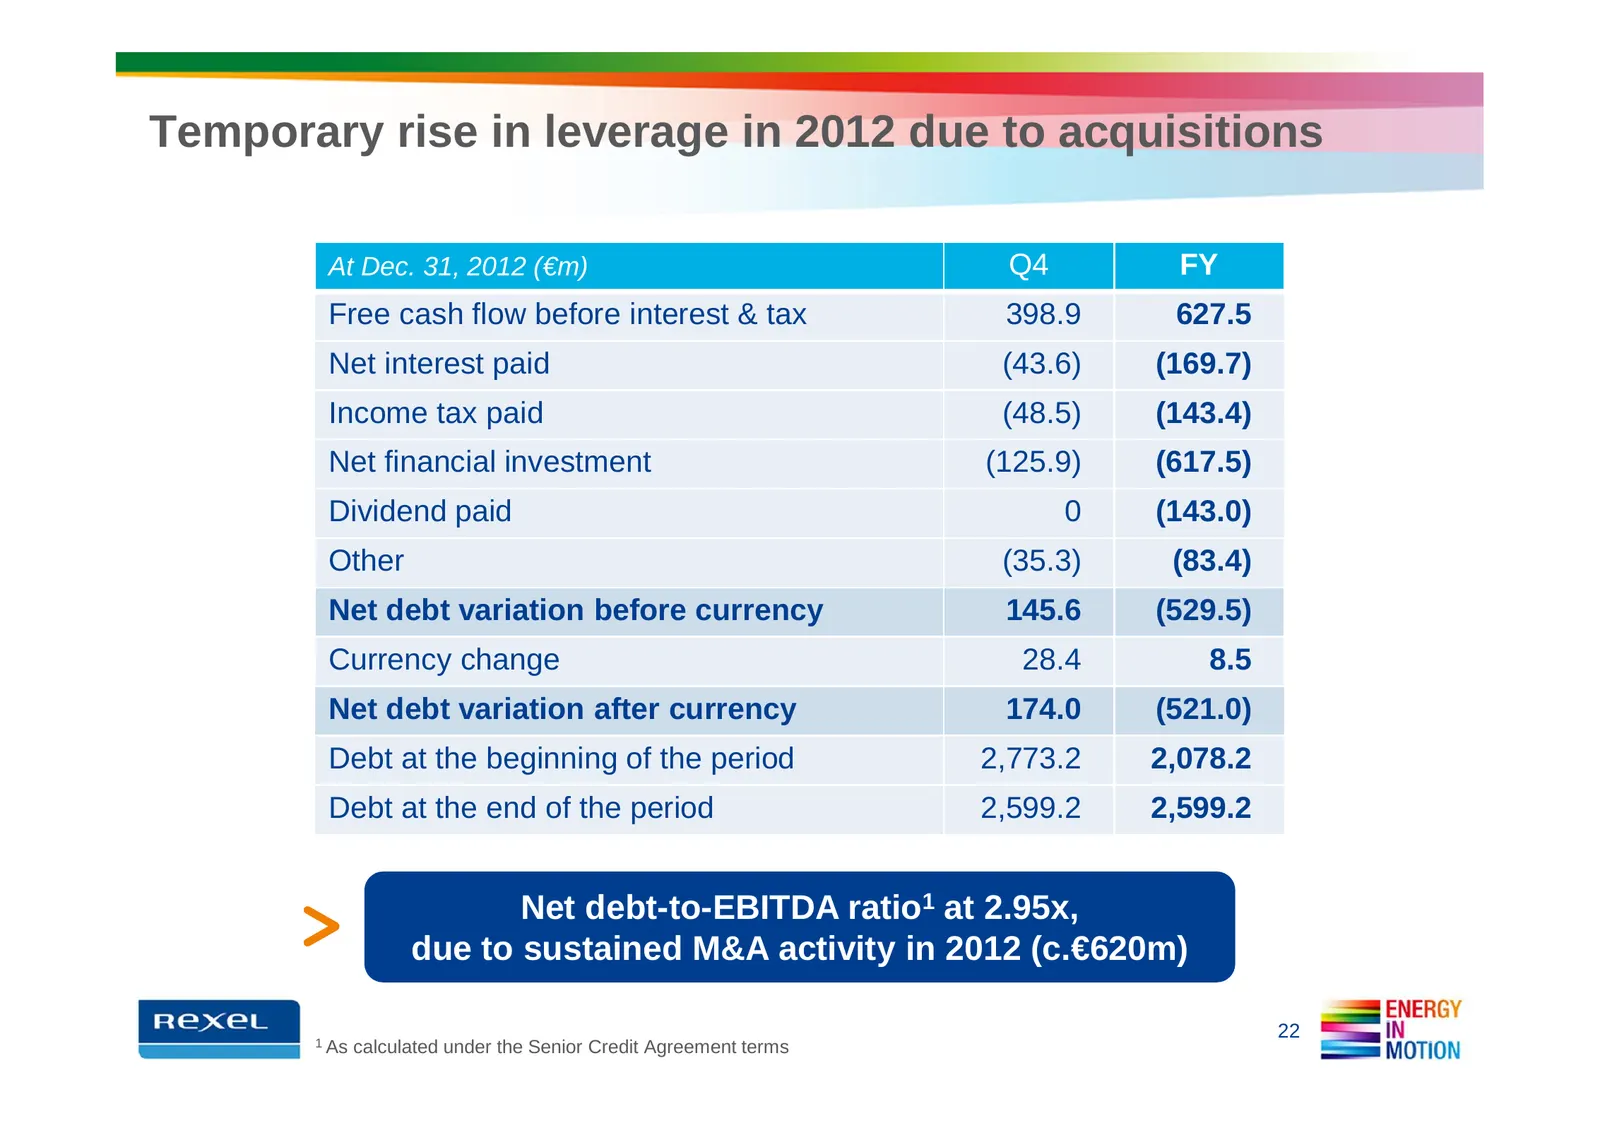
Slide 22: Temporary rise in leverage in 2012 due to acquisitions
Temporary rise in leverage in 2012 due to acquisitions At Dec. 31, 2012 (€m) Q4 FY Free cash flow before interest & tax 398.9 627.5 Net interest paid (43.6) (169.7) Income tax paid (48.5) (143.4) Net financial investment (125.9) (617.5) Dividend paid 0 (143.0) Other (35.3) (83.4) Net debt variation
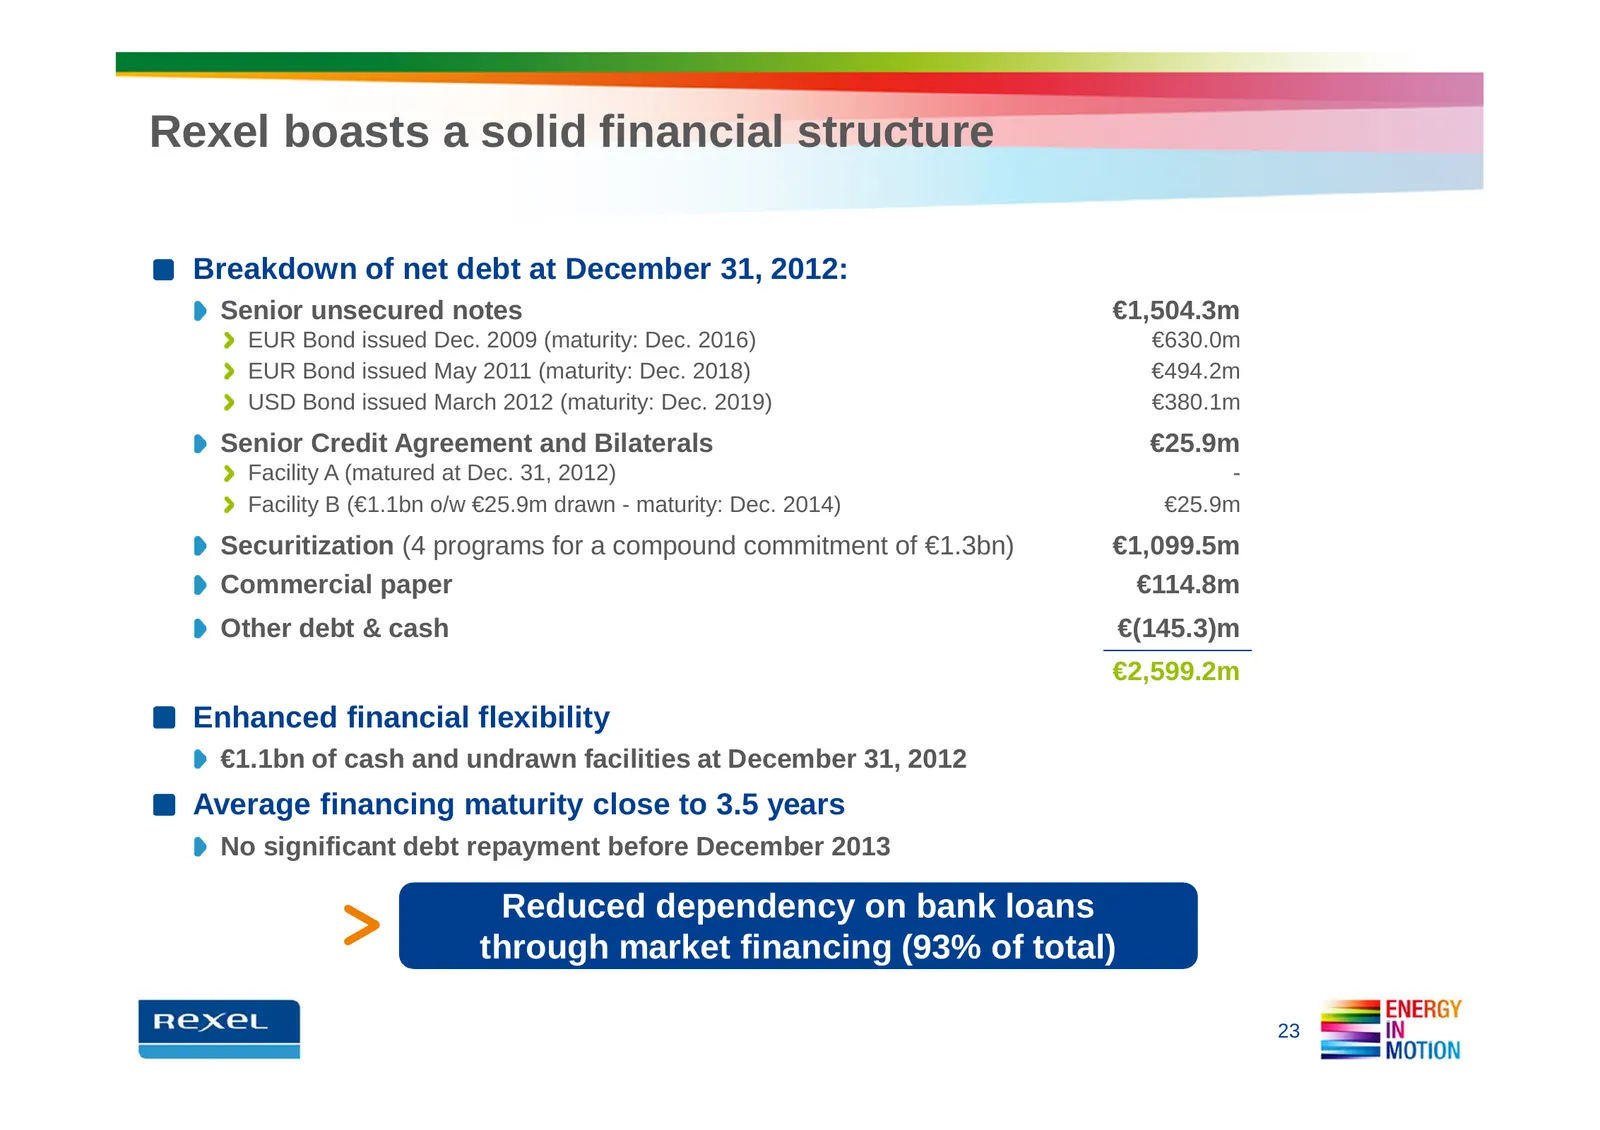
Slide 23: Rexel boasts a solid financial structure
Rexel boasts a solid financial structure Breakdown of net debt at December 31, 2012: Senior unsecured notes €1,504.3m EUR Bond issued Dec. 2009 (maturity: Dec. 2016) €630.0m EUR Bond issued May 2011 (maturity: Dec. 2018) €494.2m USD Bond issued March 2012 (maturity: Dec. 2019) €380.1m Senior Credit
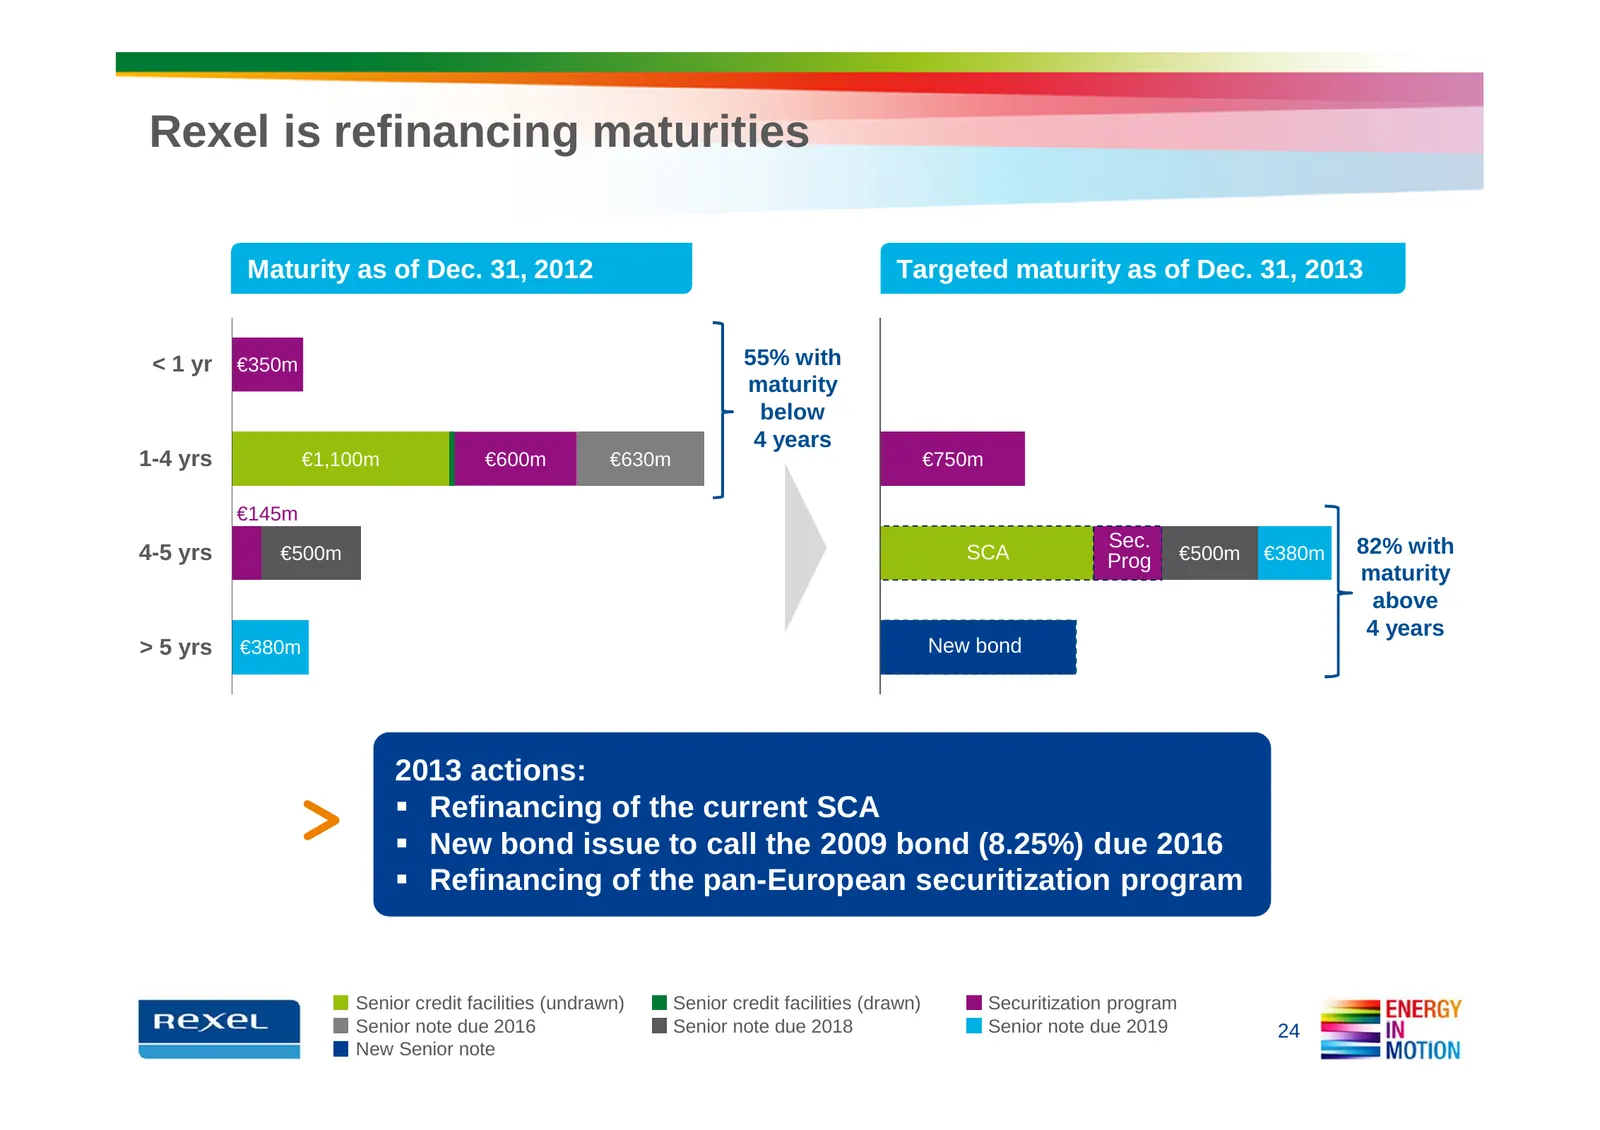
Slide 24: Rexel is refinancing maturities
Rexel is refinancing maturities Maturity as of Dec. 31, 2012 Targeted maturity as of Dec. 31, 2013 < 1 yr €350m 55% with maturity below 4 years 1-4 yrs €1,100m €600m €630m €750m €145m Sec. 82% with 4-5 yrs €500m SCA Prog €500m €380m maturity above 4 years > 5 yrs €380m New bond 2013 actions: Refinan
Slide 25: Rise in proposed dividend to €0.75 per share
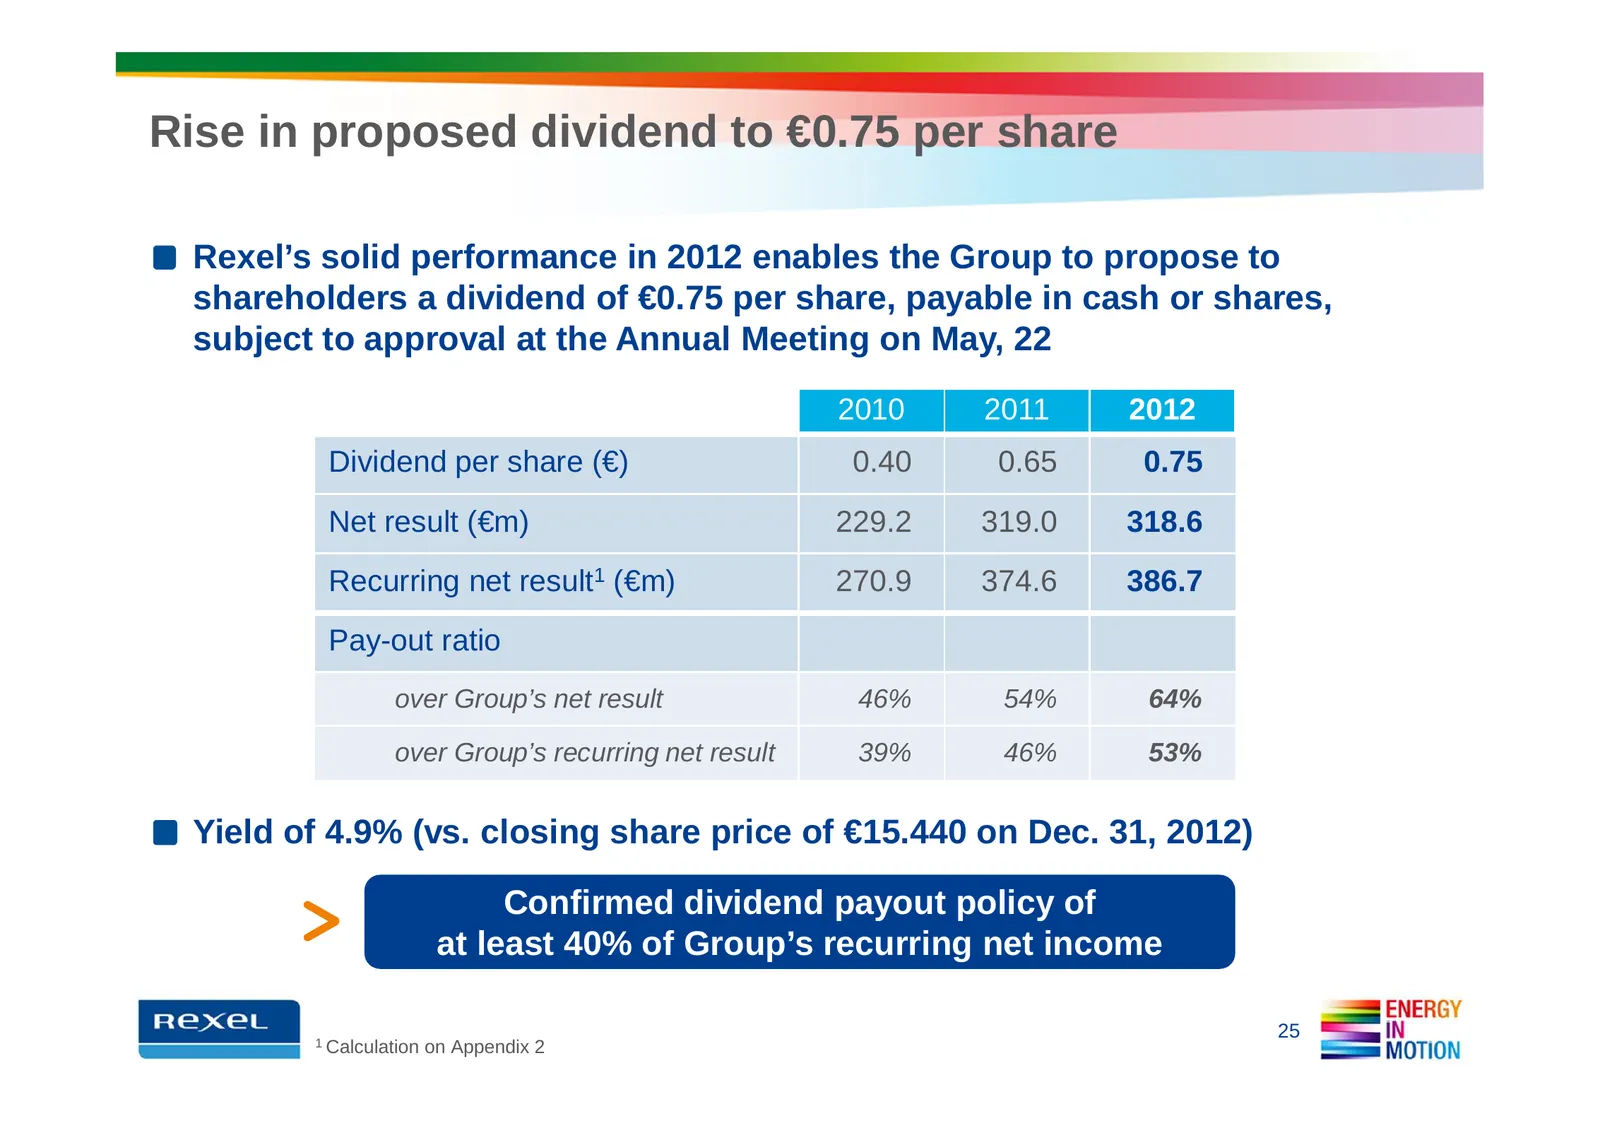
Rise in proposed dividend to €0.75 per share Rexel’s solid performance in 2012 enables the Group to propose to shareholders a dividend of €0.75 per share, payable in cash or shares, subject to approval at the Annual Meeting on May, 22 2010 2011 2012 Dividend per share (€) 0.40 0.65 0.75 Net result (
Slide 26: Strategic Update
STRATEGIC UPDATE = ENERGY MOTION
Slide 27: Energy in Motion: Accelerating in Key Markets
ENERGY IN MOTION: ACCELERATING IN KEY MARKETS
Slide 28: UK: Strong margin improvement despite organic sales drop
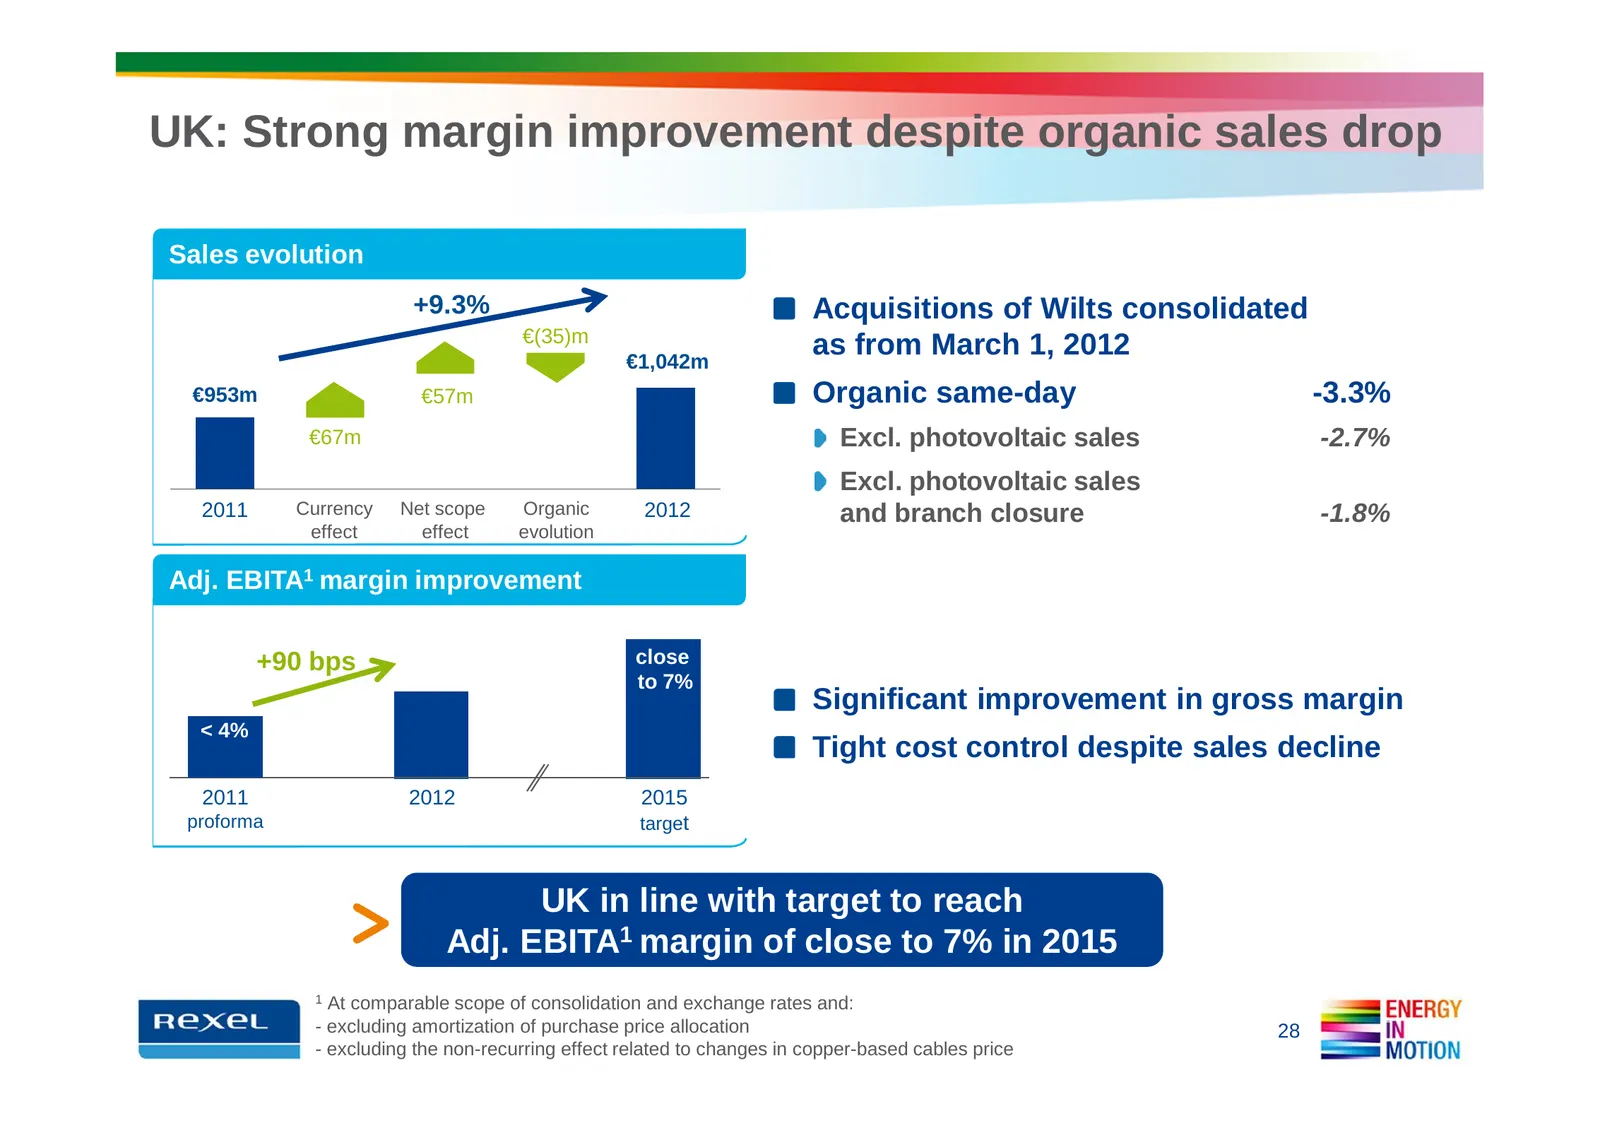
UK: Strong margin improvement despite organic sales drop Sales evolution +9.3% Acquisitions of Wilts consolidated €(35)m €1,042m as from March 1, 2012 €953m €57m Organic same-day -3.3% €67m Excl. photovoltaic sales -2.7% Excl. photovoltaic sales 2011 Currency Net scope Organic 2012 and branch closur
Slide 29: USA: Continued turnaround, further boosted by M&A
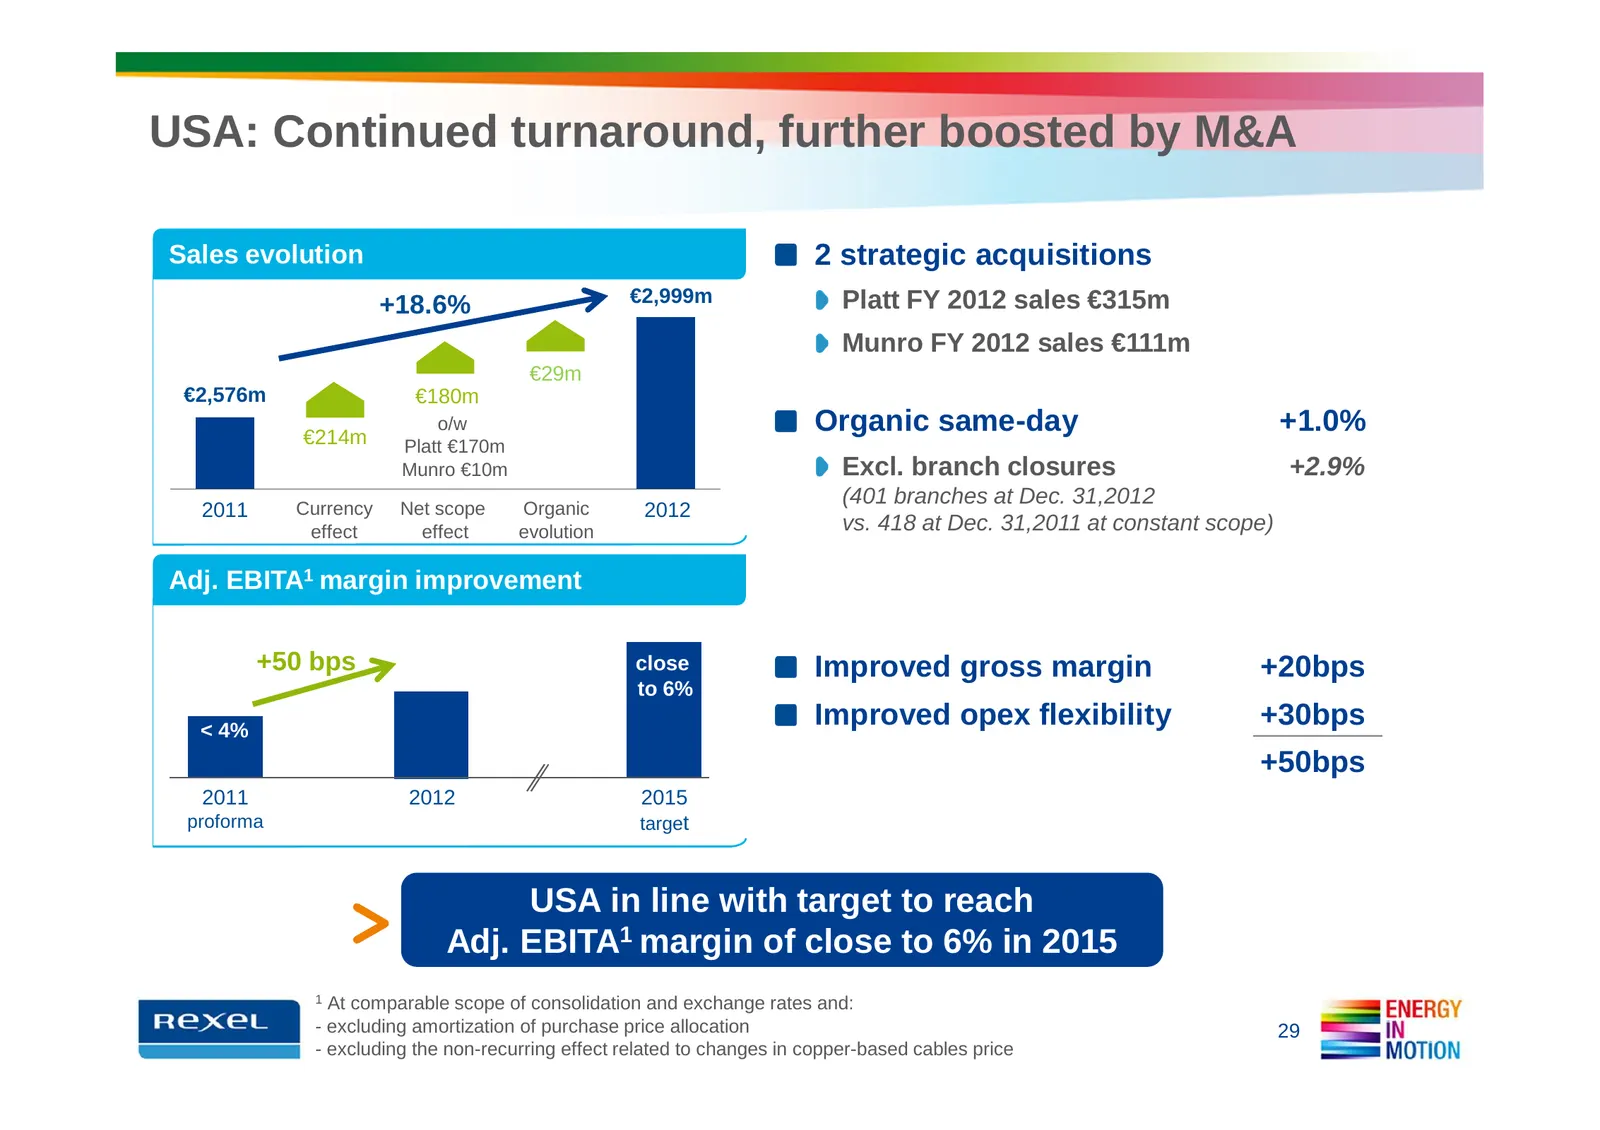
USA: Continued turnaround, further boosted by M&A Sales evolution 2 strategic acquisitions +18.6% €2,999m Platt FY 2012 sales €315m Munro FY 2012 sales €111m €29m €2,576m €180m €214m o/w Organic same-day +1.0% Platt €170m Munro €10m Excl. branch closures +2.9% (401 branches at Dec. 31,2012 2011 Curr
Slide 30: Energy in Motion: Focusing on Growth Priorities
ENERGY IN MOTION: FOCUSING ON GROWTH PRIORITIES
Slide 31: Accelerating organic growth through Energy in Motion drivers
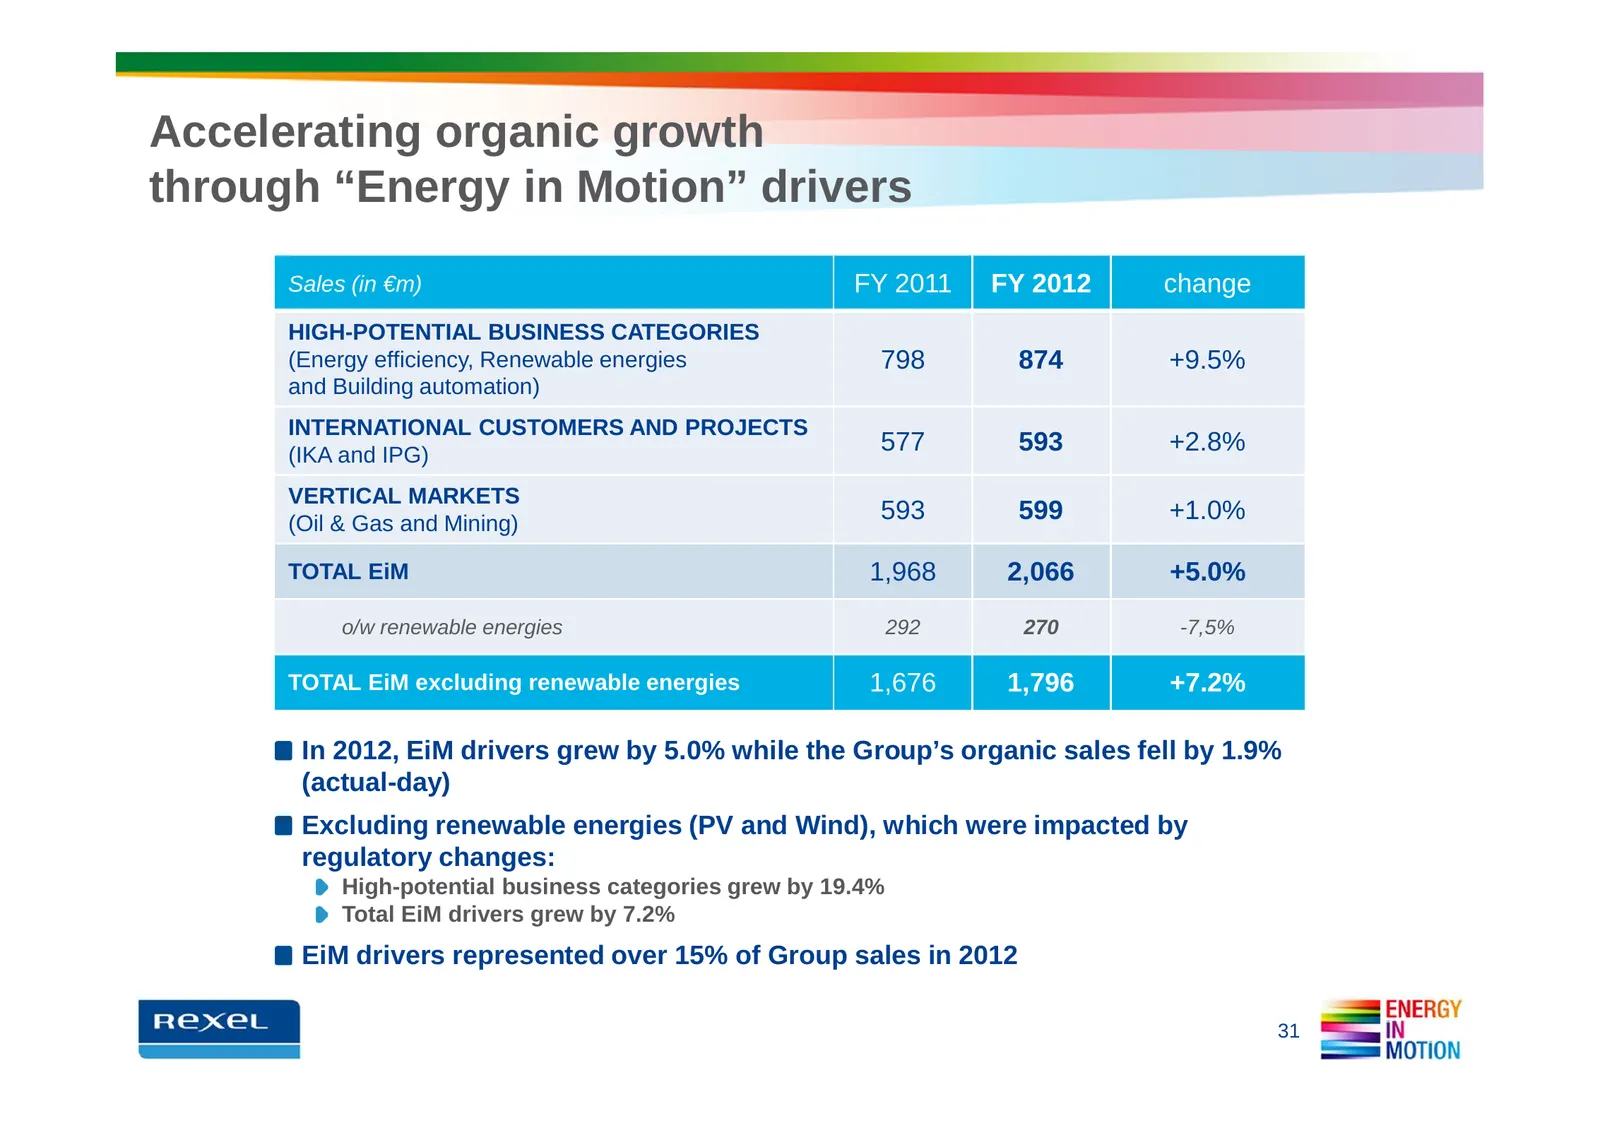
Accelerating organic growth through “Energy in Motion” drivers Sales (in €m) FY 2011 FY 2012 change HIGH-POTENTIAL BUSINESS CATEGORIES (Energy efficiency, Renewable energies 798 874 +9.5% and Building automation) INTERNATIONAL CUSTOMERS AND PROJECTS (IKA and IPG) 577 593 +2.8% VERTICAL MARKETS (Oil
Slide 32: Complementing organic growth with acquisitions
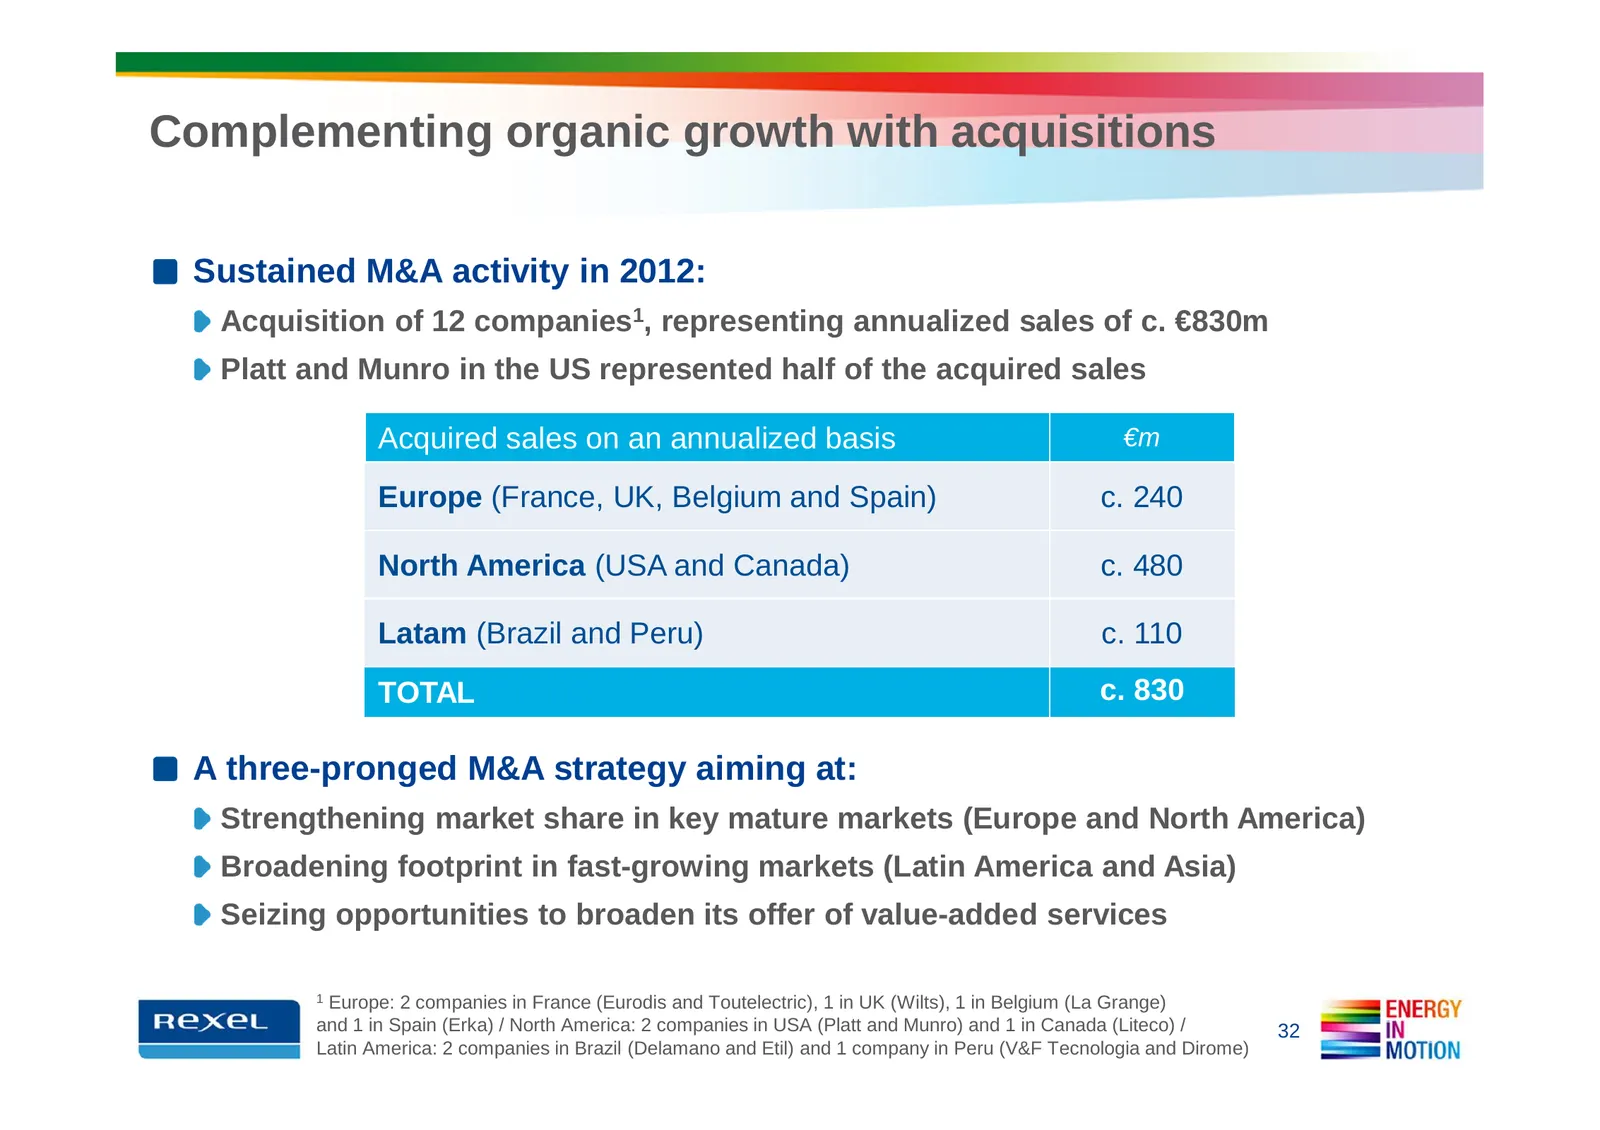
Complementing organic growth with acquisitions Sustained M&A activity in 2012: Acquisition of 12 companies1, representing annualized sales of c. €830m Platt and Munro in the US represented half of the acquired sales Acquired sales on an annualized basis €m Europe (France, UK, Belgium and Spain) c. 2
Slide 33: Growth markets now generate close to €1bn of sales
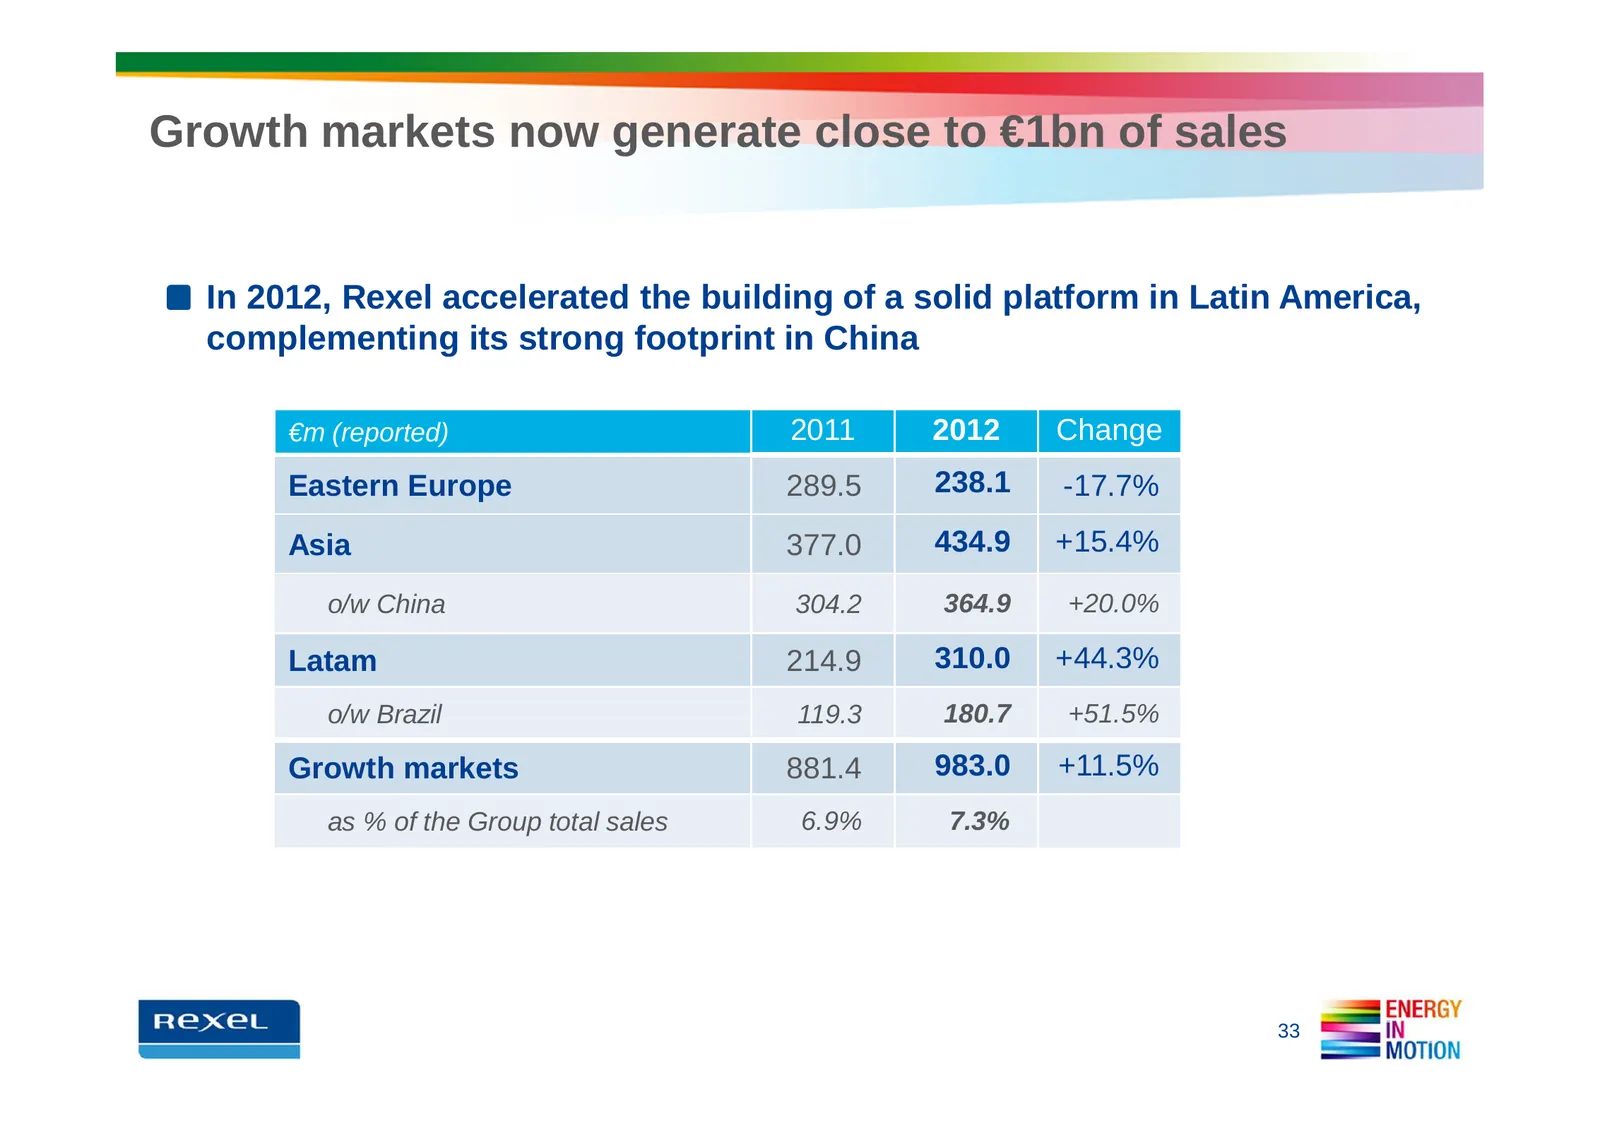
Growth markets now generate close to €1bn of sales In 2012, Rexel accelerated the building of a solid platform in Latin America, complementing its strong footprint in China €m (reported) 2011 2012 Change Eastern Europe 289.5 238.1 -17.7% Asia 377.0 434.9 +15.4% o/w China 304.2 364.9 +20.0% Latam 214
Slide 34: LuxLight acquisition to accelerate energy efficiency offer
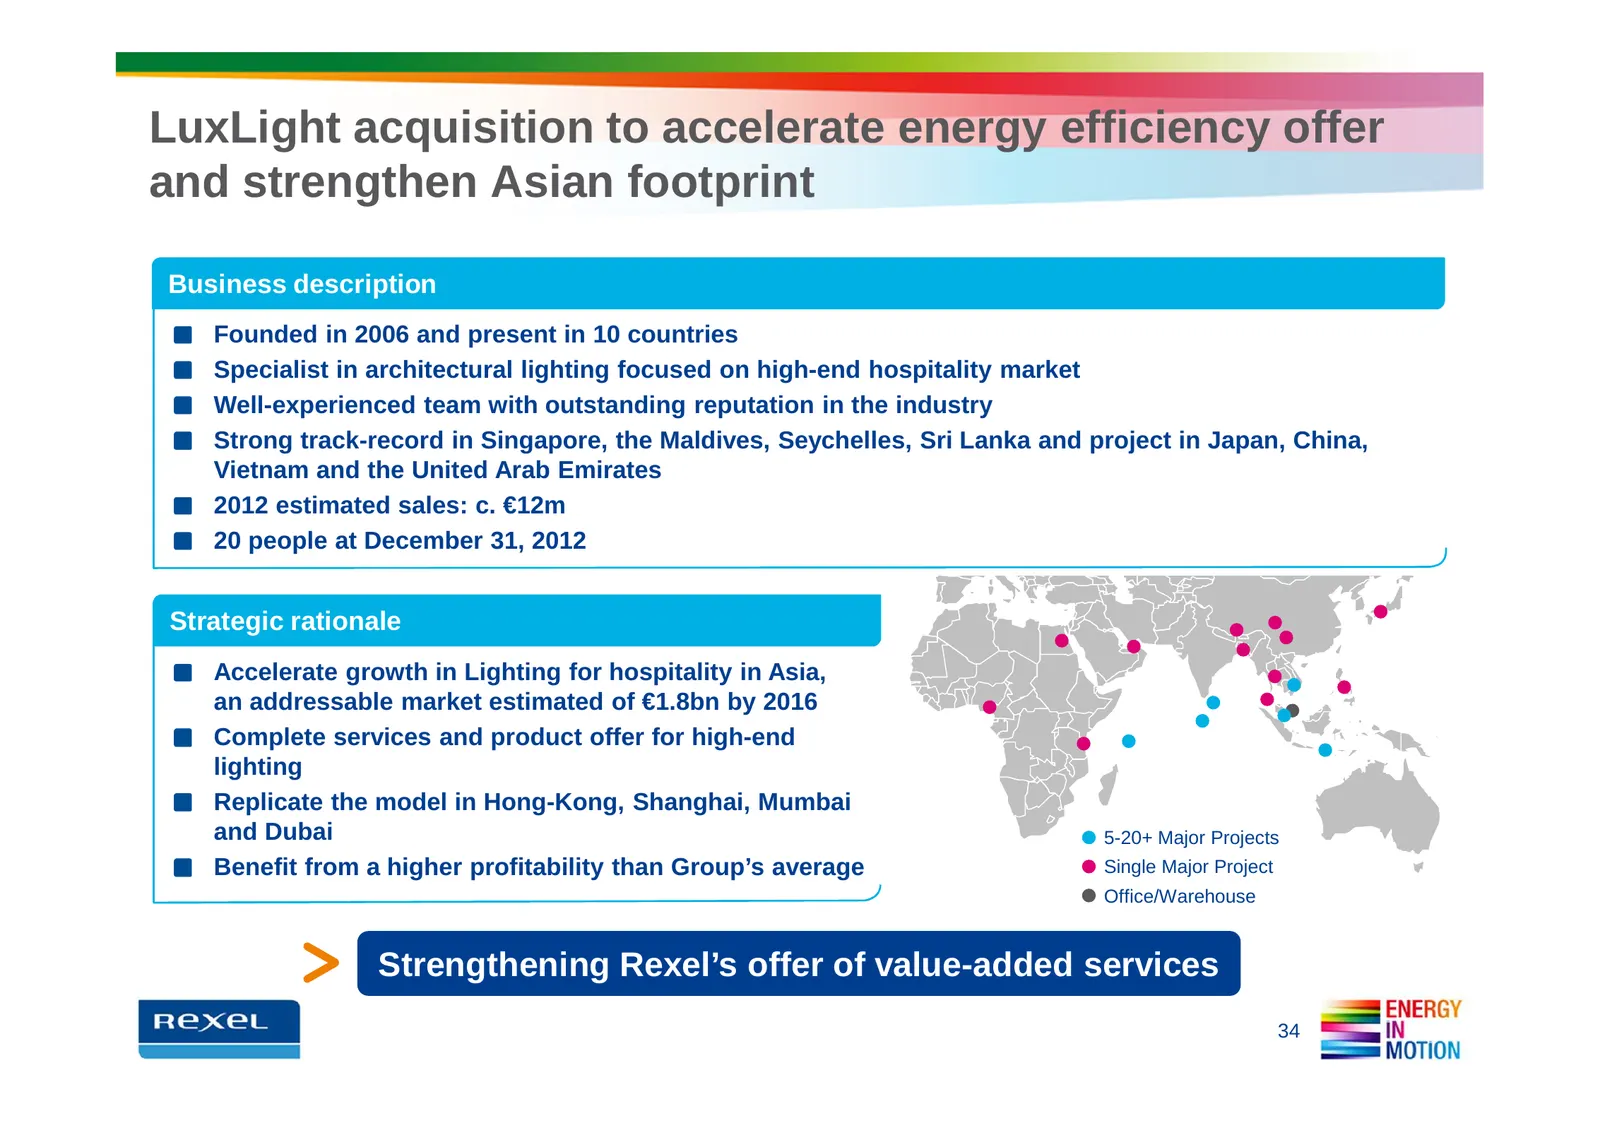
LuxLight acquisition to accelerate energy efficiency offer and strengthen Asian footprint Business description Founded in 2006 and present in 10 countries Specialist in architectural lighting focused on high-end hospitality market Well-experienced team with outstanding reputation in the industry Str
Slide 35: Energy in Motion: Enhancing Organizational Effectiveness
ENERGY IN MOTION: ENHANCING ORGANIZATIONAL EFFECTIVENESS
Slide 36: Leadership accountability to accelerate implementation of Energy in Motion
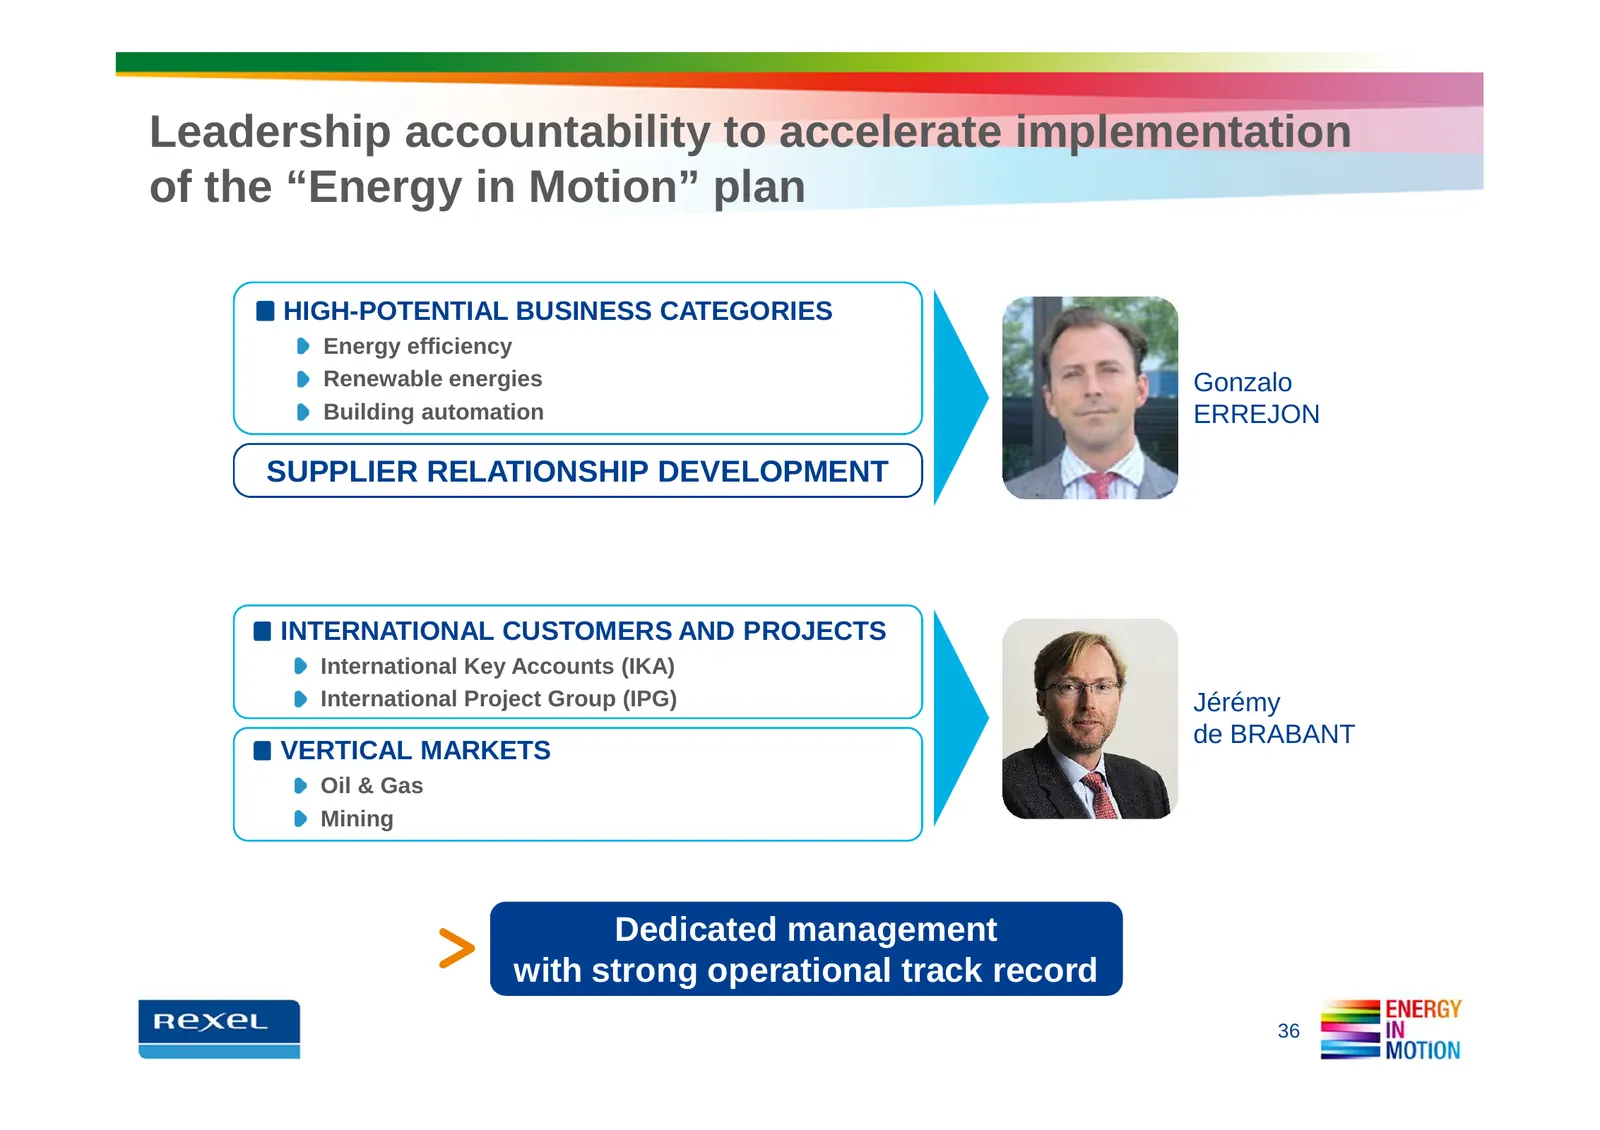
Leadership accountability to accelerate implementation of the “Energy in Motion” plan HIGH-POTENTIAL BUSINESS CATEGORIES Energy efficiency Renewable energies Gonzalo Building automation ERREJON SUPPLIER RELATIONSHIP DEVELOPMENT INTERNATIONAL CUSTOMERS AND PROJECTS International Key Accounts (IKA) In
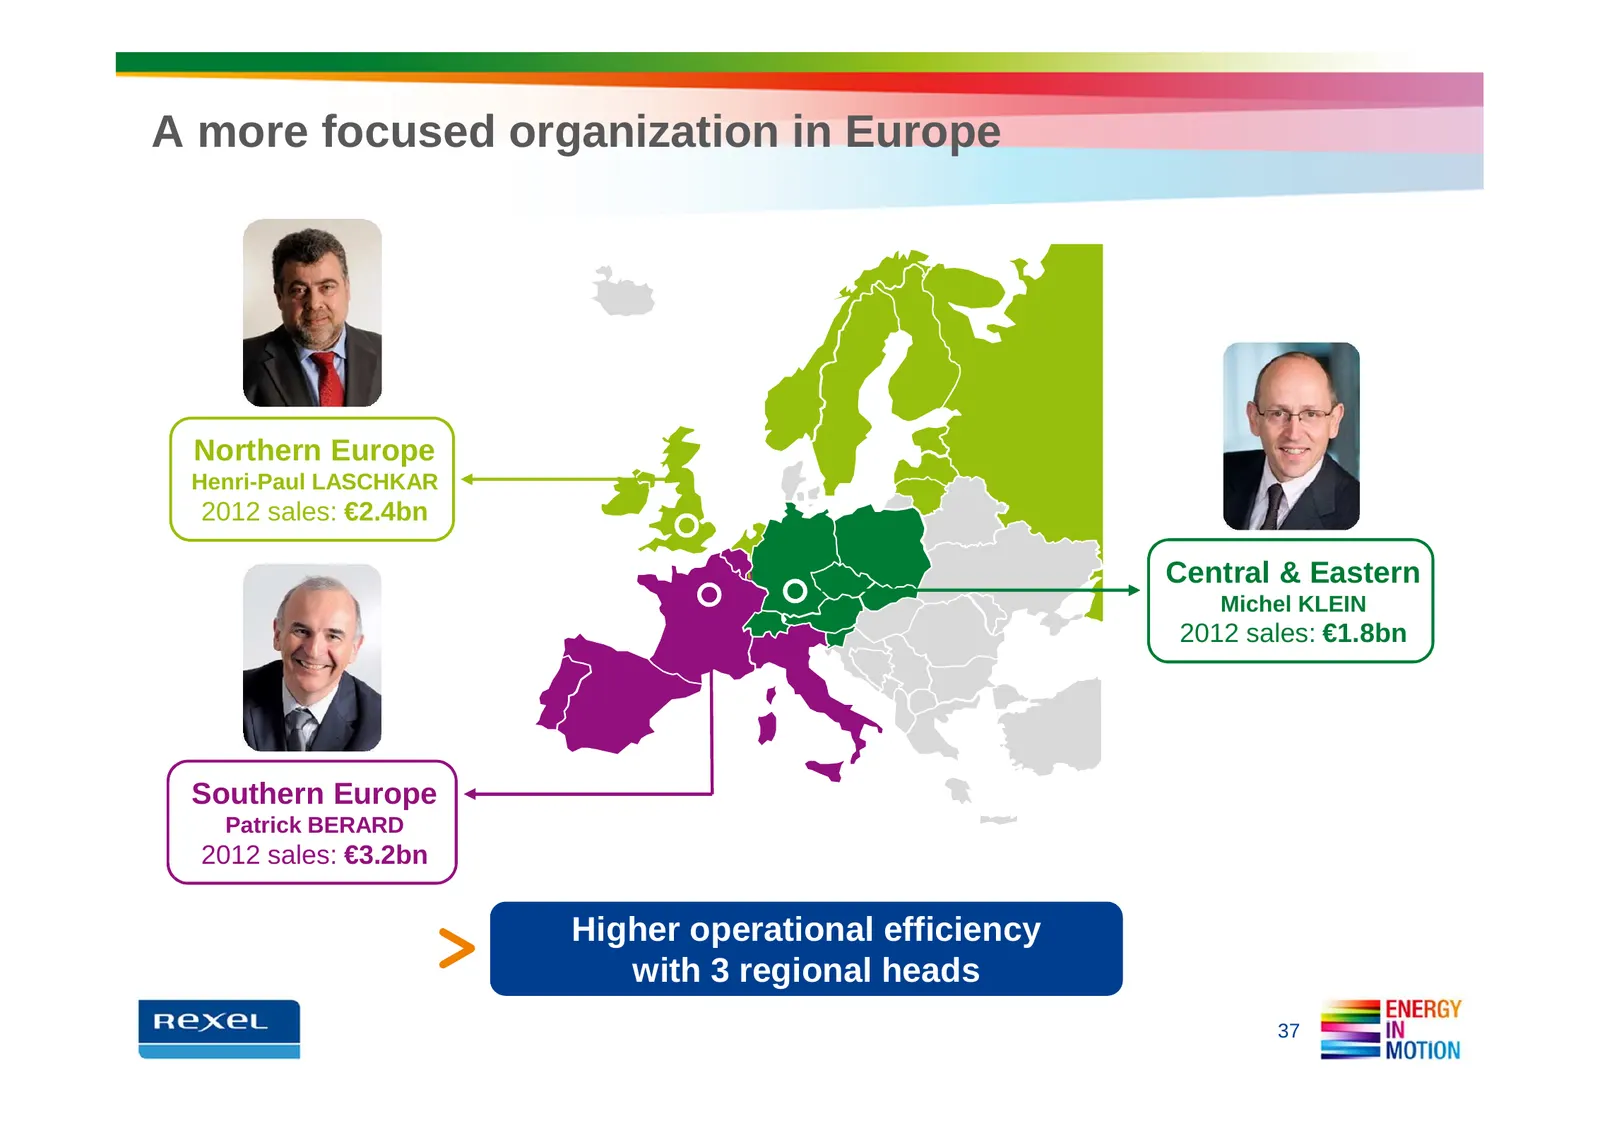
Slide 37: A more focused organization in Europe
A more focused organization in Europe Northern Europe Henri-Paul LASCHKAR 2012 sales: €2.4bn Central & Eastern Michel KLEIN 2012 sales: €1.8bn Southern Europe Patrick BERARD 2012 sales: €3.2bn Higher operational efficiency with 3 regional heads 37
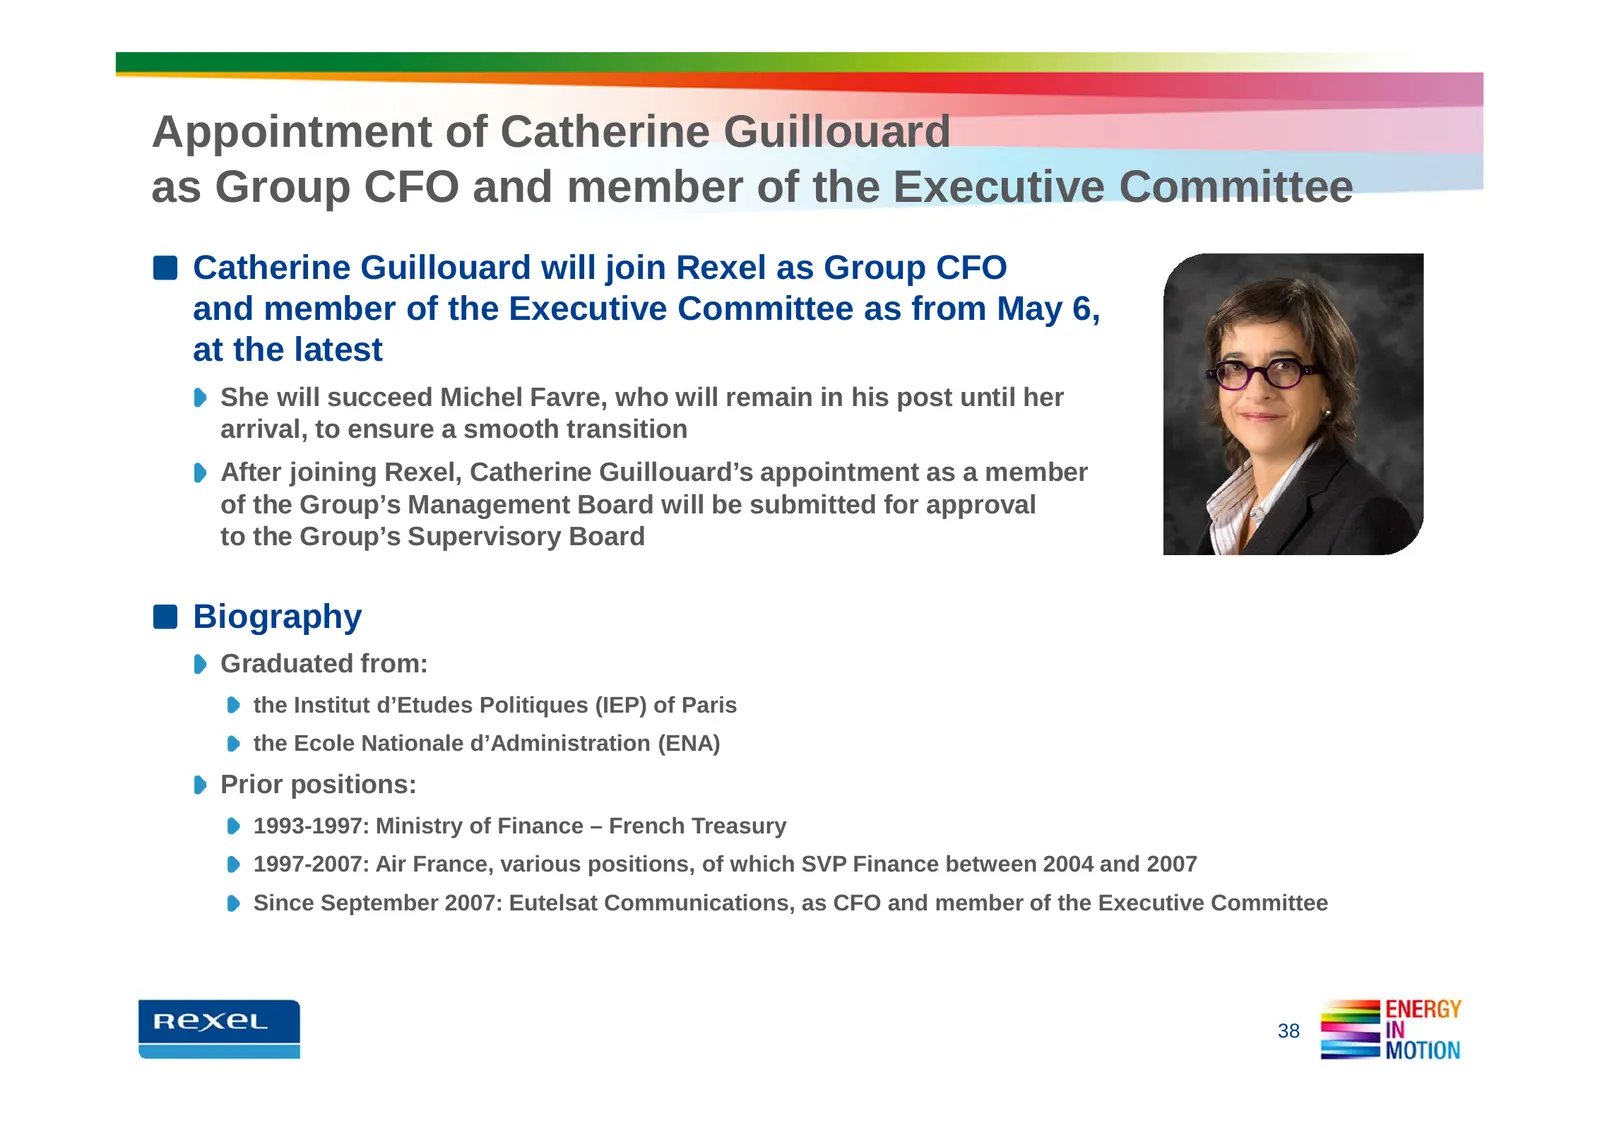
Slide 38: Appointment of Catherine Guillouard as Group CFO
Appointment of Catherine Guillouard as Group CFO and member of the Executive Committee Catherine Guillouard will join Rexel as Group CFO and member of the Executive Committee as from May 6, at the latest She will succeed Michel Favre, who will remain in his post until her arrival, to ensure a smooth
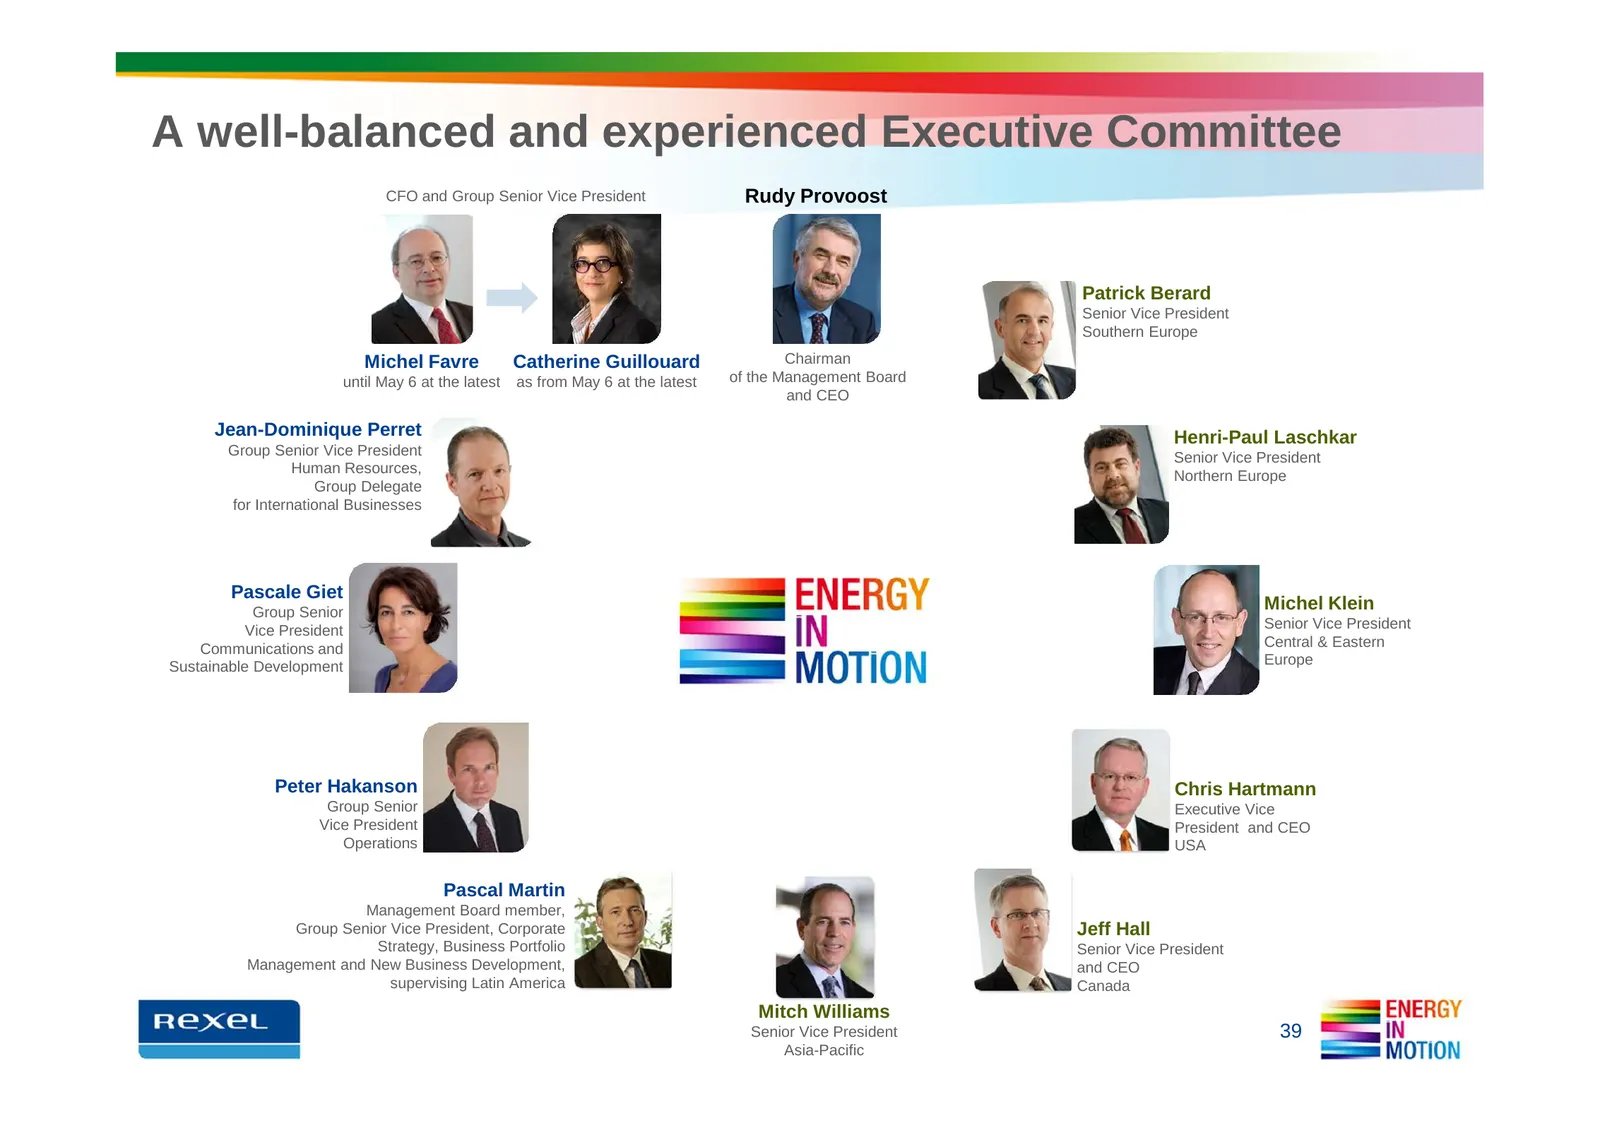
Slide 39: A well-balanced and experienced Executive Committee
A well-balanced and experienced Executive Committee CFO and Group Senior Vice President Rudy Provoost Patrick Berard Senior Vice President Southern Europe Michel Favre Catherine Guillouard Chairman until May 6 at the latest as from May 6 at the latest of the Management Board and CEO Jean-Dominique P
Slide 40: Energy in Motion: Driving Operational Performance
ENERGY IN MOTION: DRIVING OPERATIONAL PERFORMANCE
Slide 41: Continued focus on developing multi-channel sales
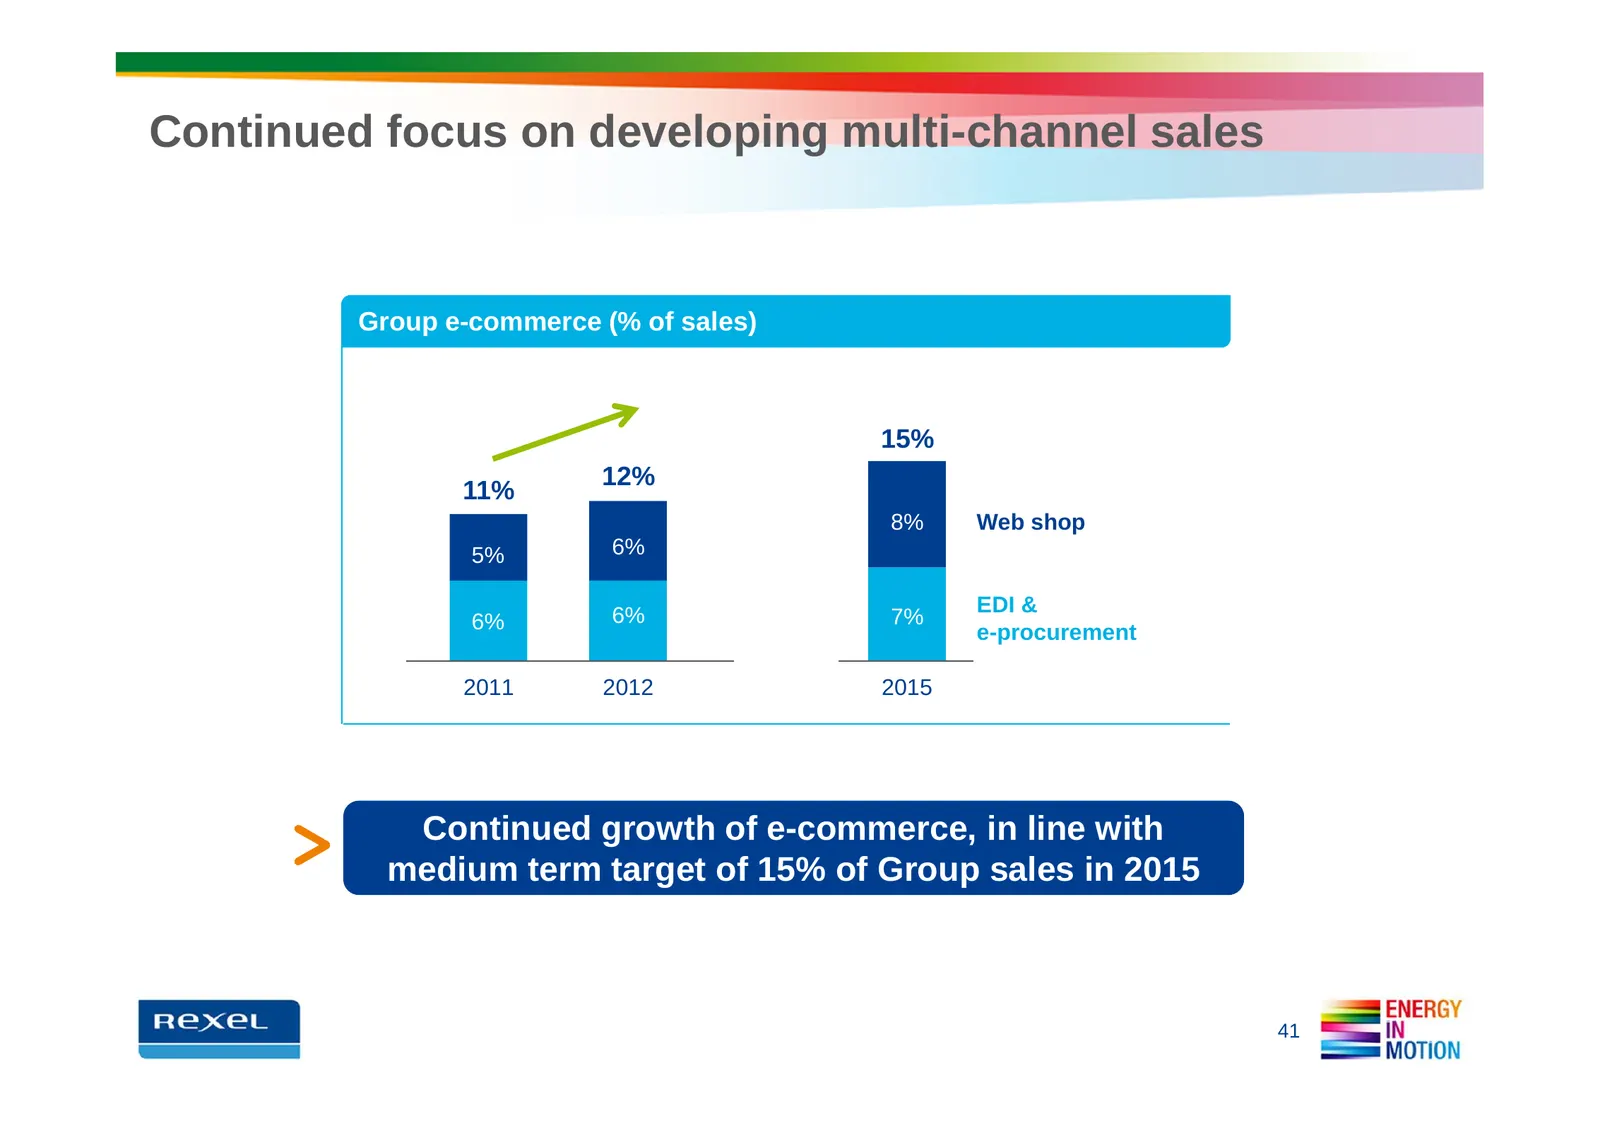
Continued focus on developing multi-channel sales Group e-commerce (% of sales) 15% 12% 11% 8% Web shop 5% 6% 6% EDI & 6% 7% e-procurement 2011 2012 2015 Continued growth of e-commerce, in line with medium term target of 15% of Group sales in 2015 41
Slide 42: Solid pricing management to drive margin
Solid pricing management to drive margin Our pricing actions rely on 3 cornerstones Pricing assessments conducted based on Group methodology (price differentiation, value pricing rather than cost-plus…) Local initiatives supported by the Group (implementation of processes and KPIs, overrides control
Slide 43: Strong financial discipline
Strong financial discipline Tight management of working capital in 2012 WCR represented a limited outflow of €37m, while sales were up 5.8% on a reported basis TWC was flat at constant scope (€1.5bn) but increased as a percentage of sales due to organic sales decline (-1.9%) and temporary impact of
Slide 44: Outlook
OUTLOOK = ENERGY MOTION
Slide 45: Solid targets for 2013, medium-term guidance confirmed
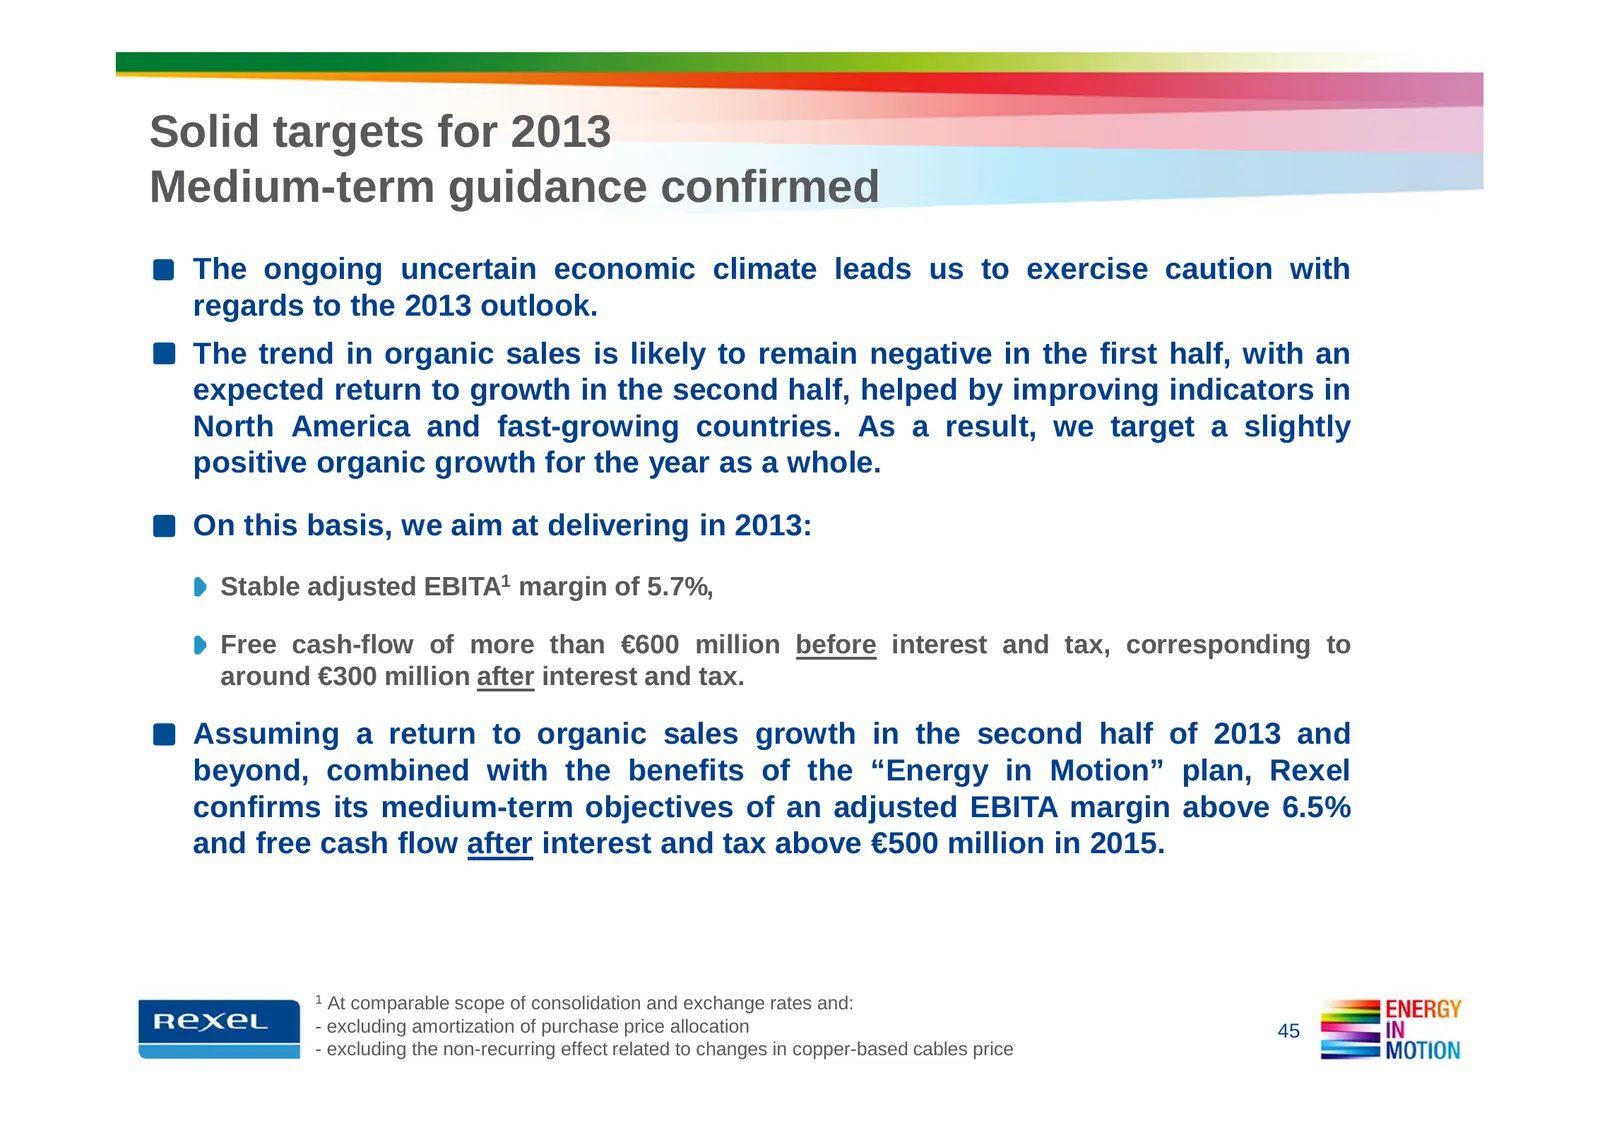
Solid targets for 2013 Medium-term guidance confirmed The ongoing uncertain economic climate leads us to exercise caution with regards to the 2013 outlook. The trend in organic sales is likely to remain negative in the first half, with an expected return to growth in the second half, helped by impro
Slide 46: Appendices
Rexel has elected for early adoption of revised IAS 19 “Employee Benefits” following its endorsement by EU on June 6th, 2012. The early adoption of this amendment improves information of the Group’s financial situation, in APPENDICES particular the presentation in the financial statements of the sur
Slide 47: Appendix 1: Segment reporting – Group
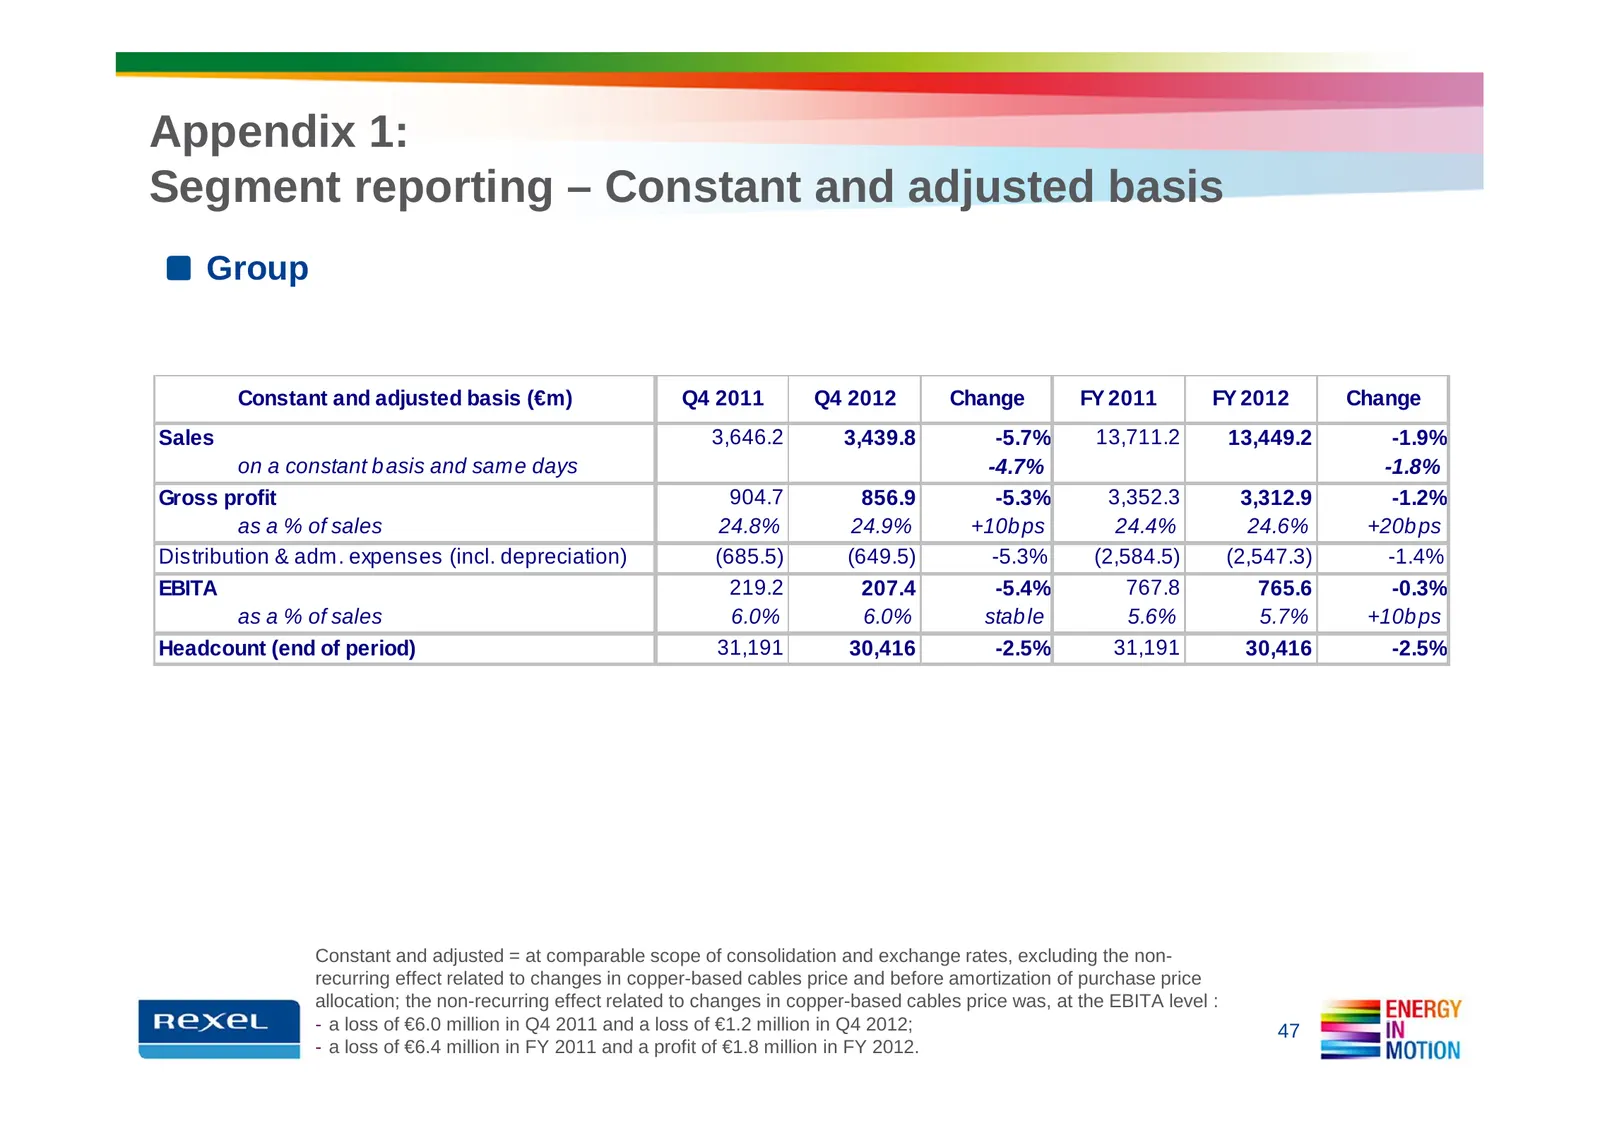
Appendix 1: Segment reporting – Constant and adjusted basis Group Constant and adjusted basis (€m) Q4 2011 Q4 2012 Change FY 2011 FY 2012 Change Sales 3,646.2 3,439.8 -5.7% 13,711.2 13,449.2 -1.9% on a constant b asis and same days -4.7% -1.8% Gross profit 904.7 856.9 -5.3% 3,352.3 3,312.9 -1.2% as
Slide 48: Appendix 1: Segment reporting – Europe
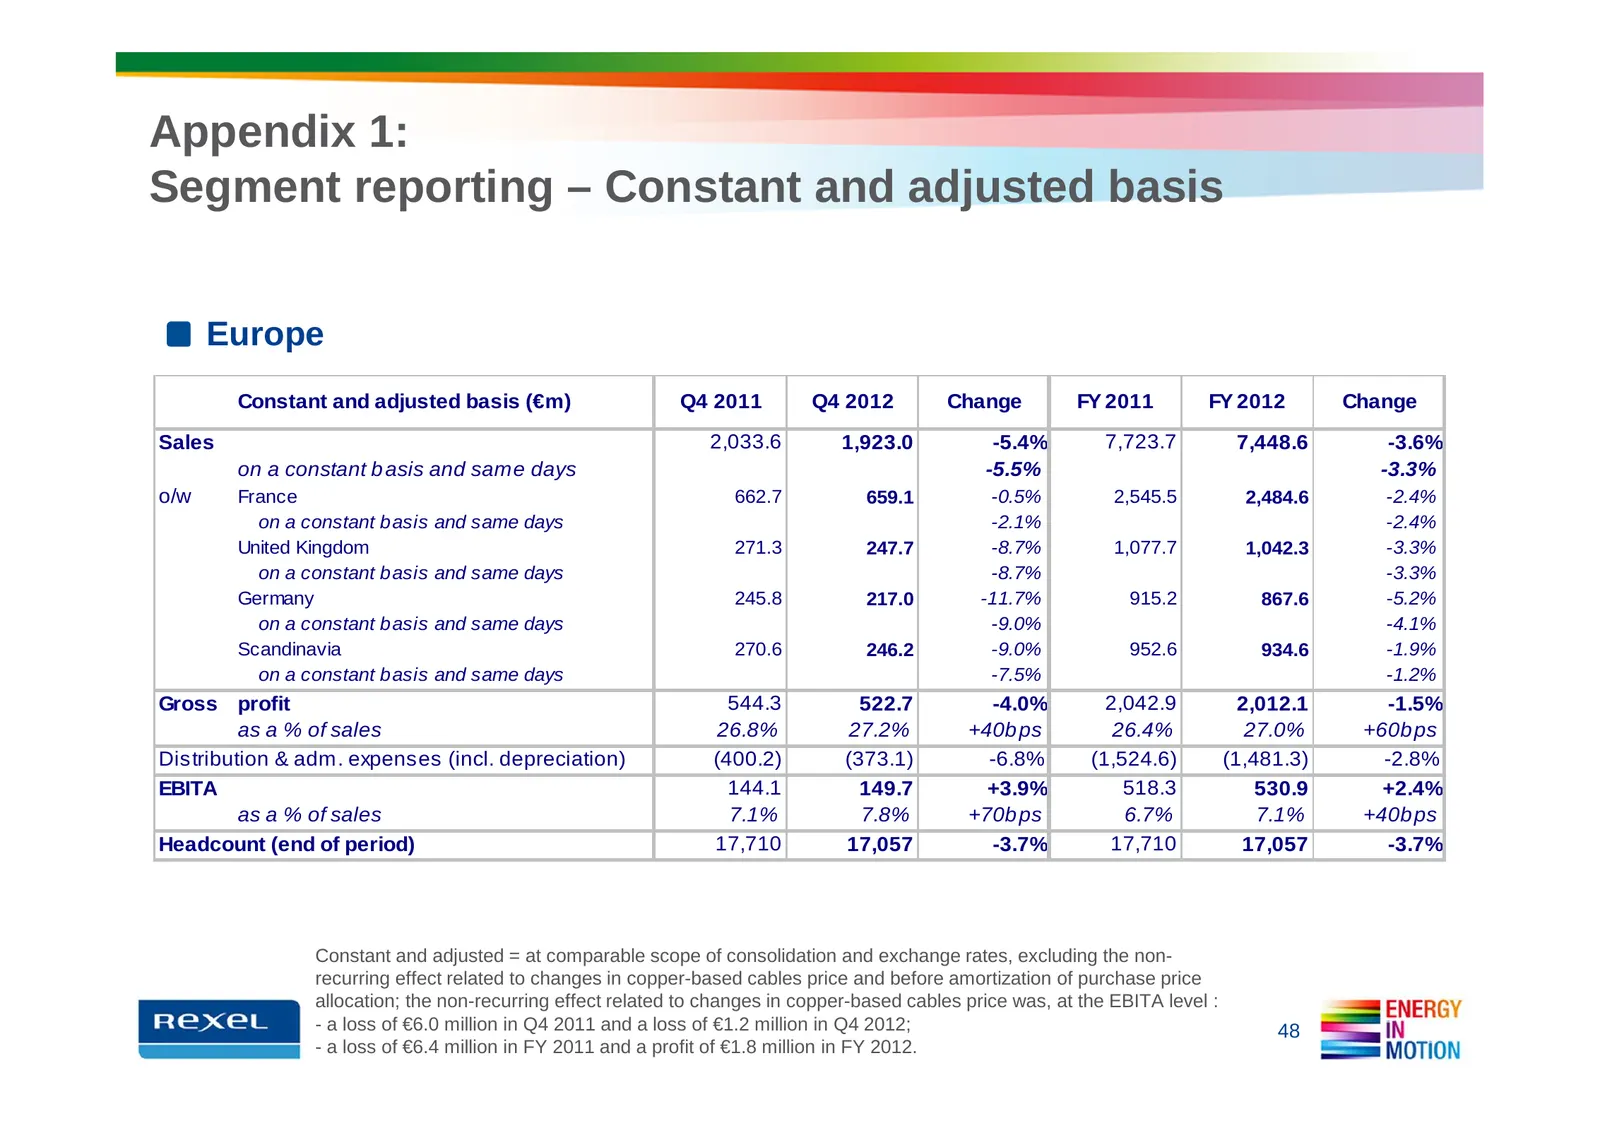
Appendix 1: Segment reporting – Constant and adjusted basis Europe Constant and adjusted basis (€m) Q4 2011 Q4 2012 Change FY 2011 FY 2012 Change Sales 2,033.6 1,923.0 -5.4% 7,723.7 7,448.6 -3.6% on a constant b asis and same days -5.5% -3.3% o/w France 662.7 659.1 -0.5% 2,545.5 2,484.6 -2.4% on a c
Slide 49: Appendix 1: Segment reporting – North America
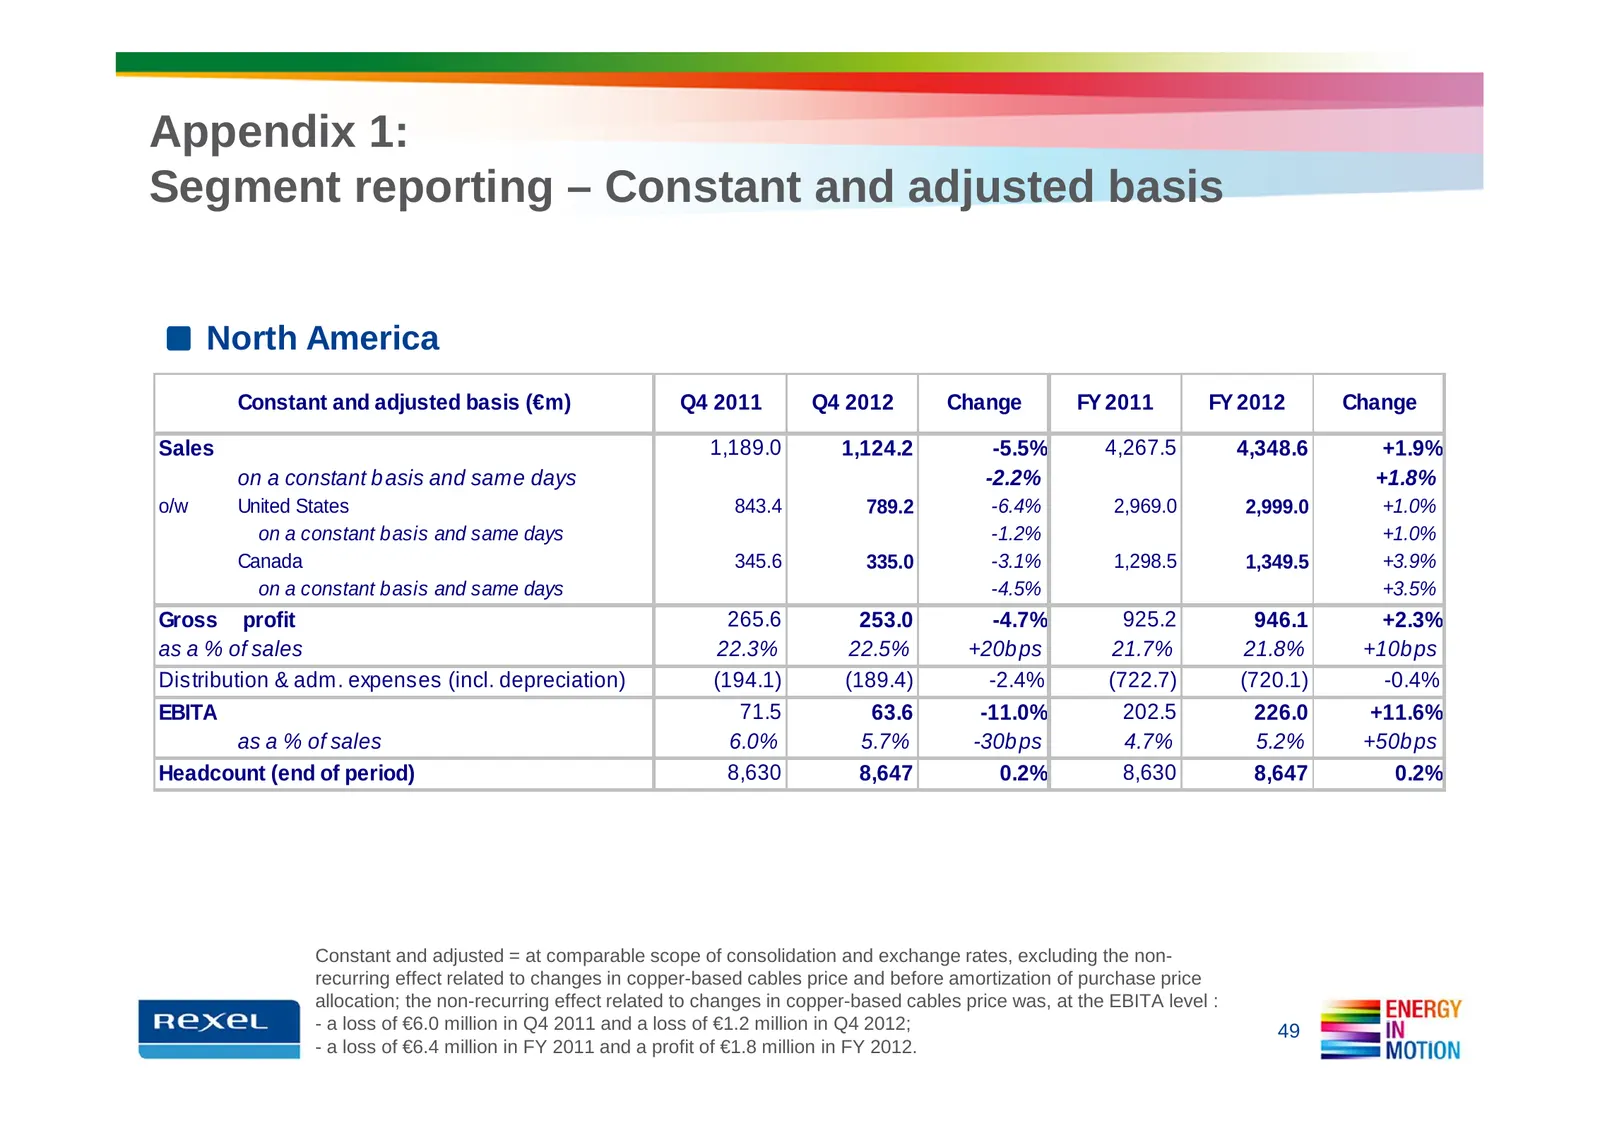
Appendix 1: Segment reporting – Constant and adjusted basis North America Constant and adjusted basis (€m) Q4 2011 Q4 2012 Change FY 2011 FY 2012 Change Sales 1,189.0 1,124.2 -5.5% 4,267.5 4,348.6 +1.9% on a constant b asis and same days -2.2% +1.8% o/w United States 843.4 789.2 -6.4% 2,969.0 2,999.
Slide 50: Appendix 1: Segment reporting – Asia-Pacific
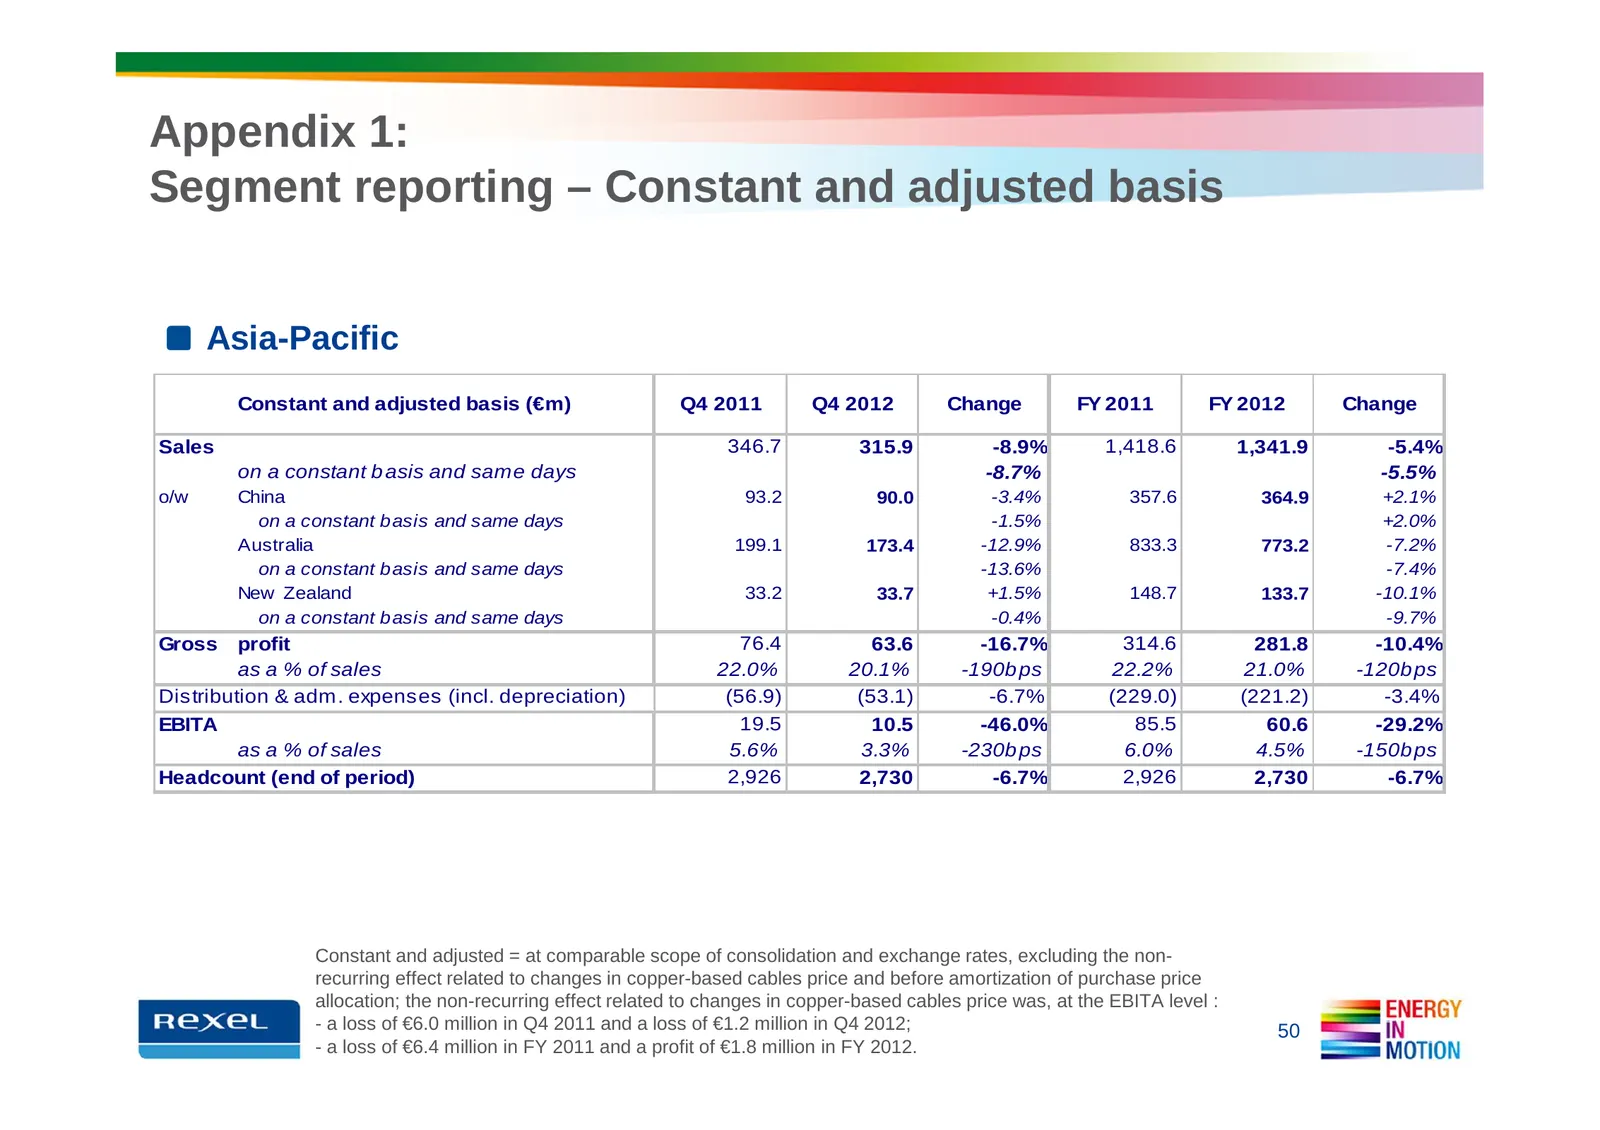
Appendix 1: Segment reporting – Constant and adjusted basis Asia-Pacific Constant and adjusted basis (€m) Q4 2011 Q4 2012 Change FY 2011 FY 2012 Change Sales 346.7 315.9 -8.9% 1,418.6 1,341.9 -5.4% on a constant b asis and same days -8.7% -5.5% o/w China 93.2 90.0 -3.4% 357.6 364.9 +2.1% on a consta
Slide 51: Appendix 1: Segment reporting – Latin America
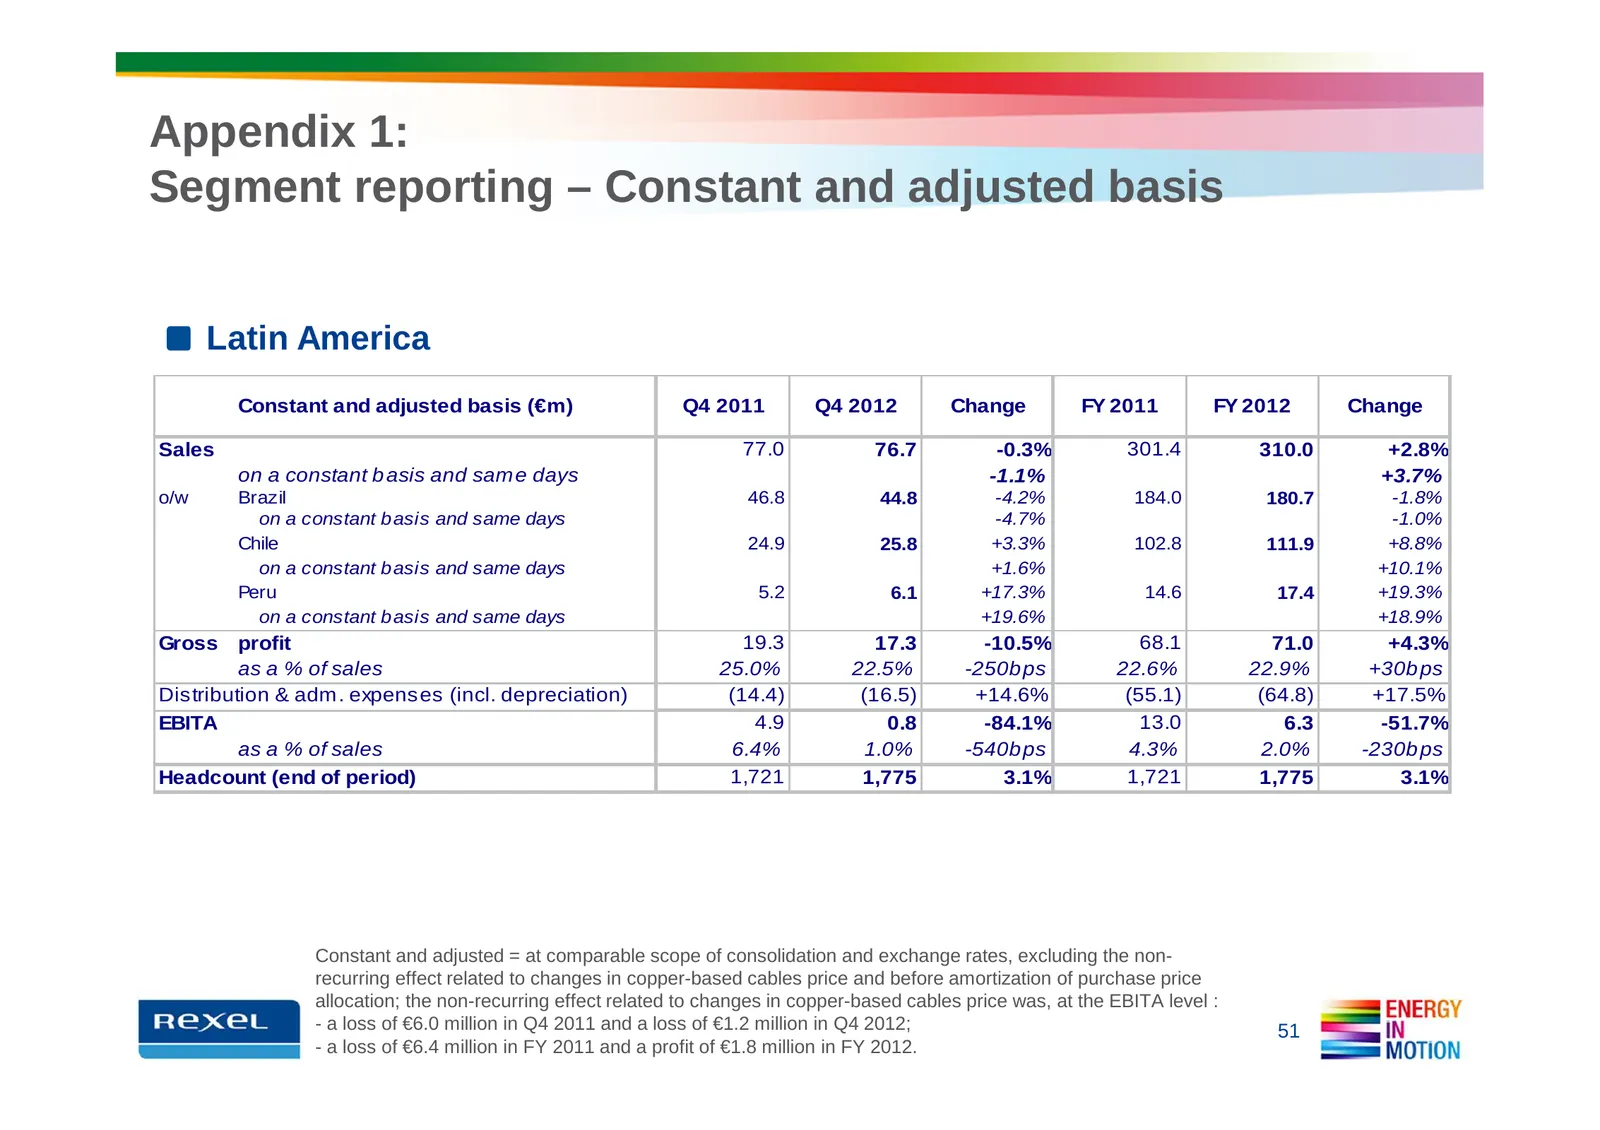
Appendix 1: Segment reporting – Constant and adjusted basis Latin America Constant and adjusted basis (€m) Q4 2011 Q4 2012 Change FY 2011 FY 2012 Change Sales 77.0 76.7 -0.3% 301.4 310.0 +2.8% on a constant b asis and sam e days -1.1% +3.7% o/w Brazil 46.8 44.8 -4.2% 184.0 180.7 -1.8% on a constant
Slide 52: Appendix 2: Consolidated Income Statement
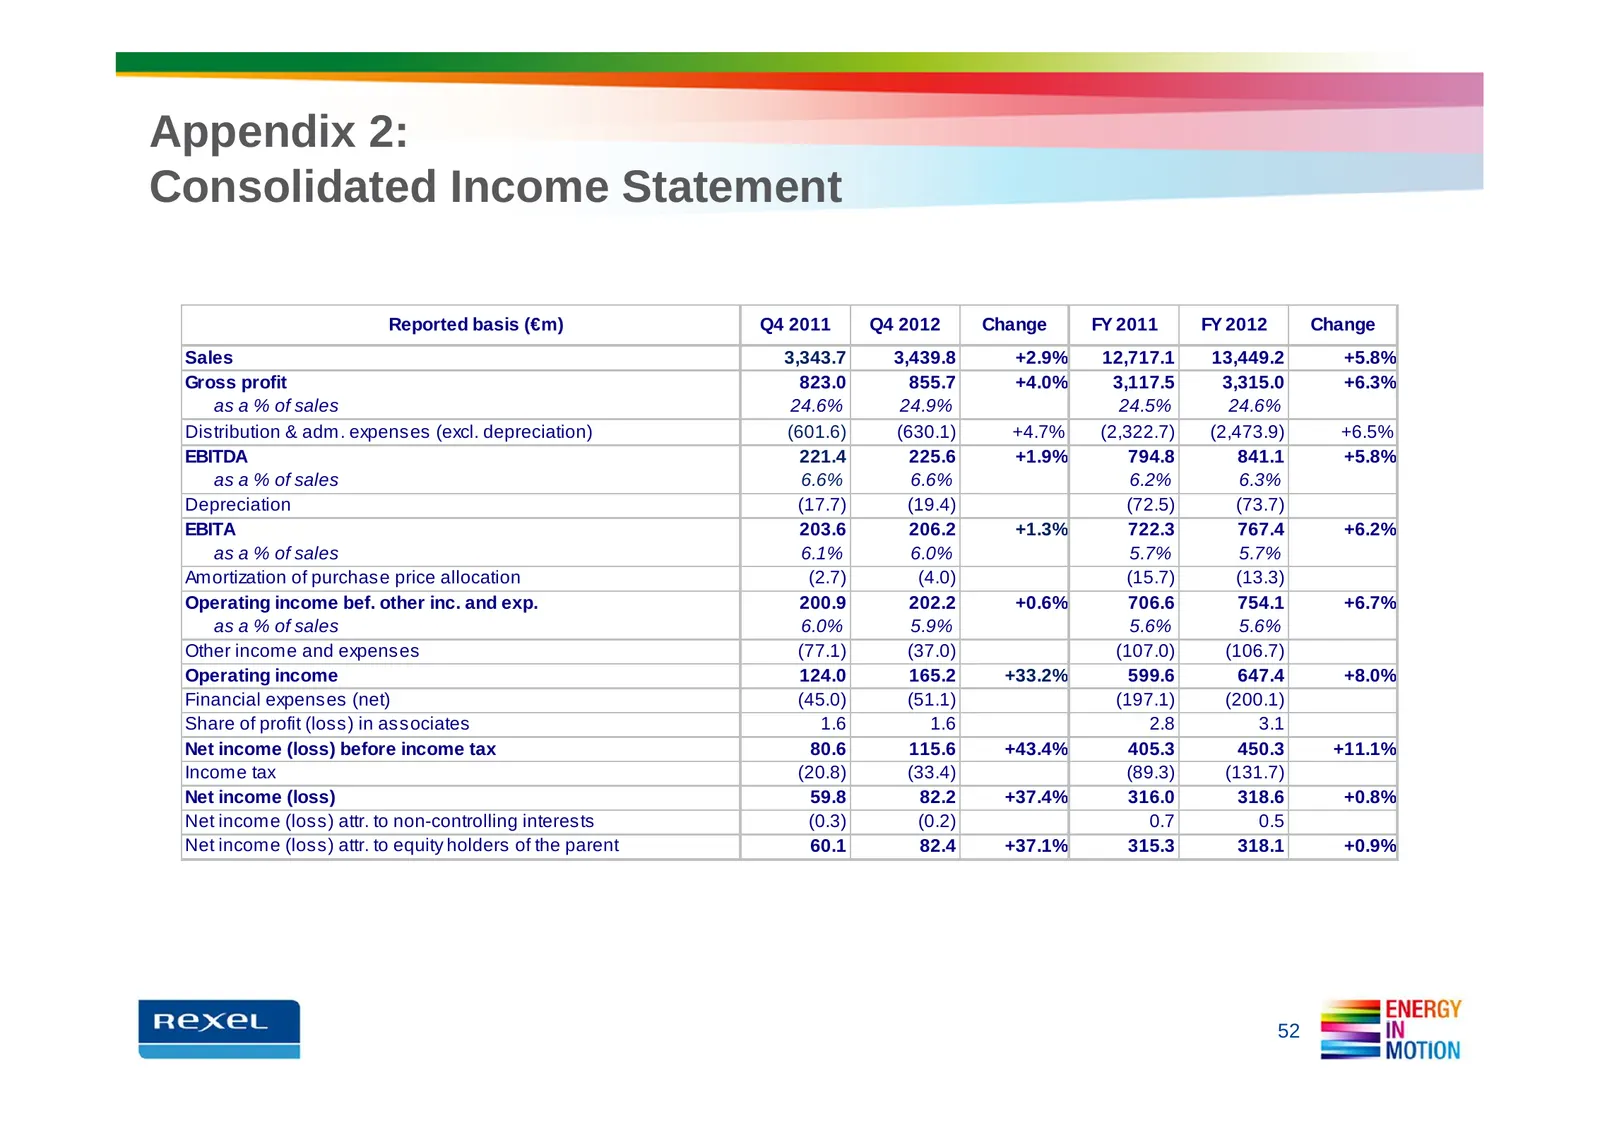
Appendix 2: Consolidated Income Statement Reported basis (€m) Q4 2011 Q4 2012 Change FY 2011 FY 2012 Change Sales 3,343.7 3,439.8 +2.9% 12,717.1 13,449.2 +5.8% Gross profit 823.0 855.7 +4.0% 3,117.5 3,315.0 +6.3% as a % of sales 24.6% 24.9% 24.5% 24.6% Distribution & adm. expenses (excl. depreciatio
Slide 53: Appendix 2: Recurring net income
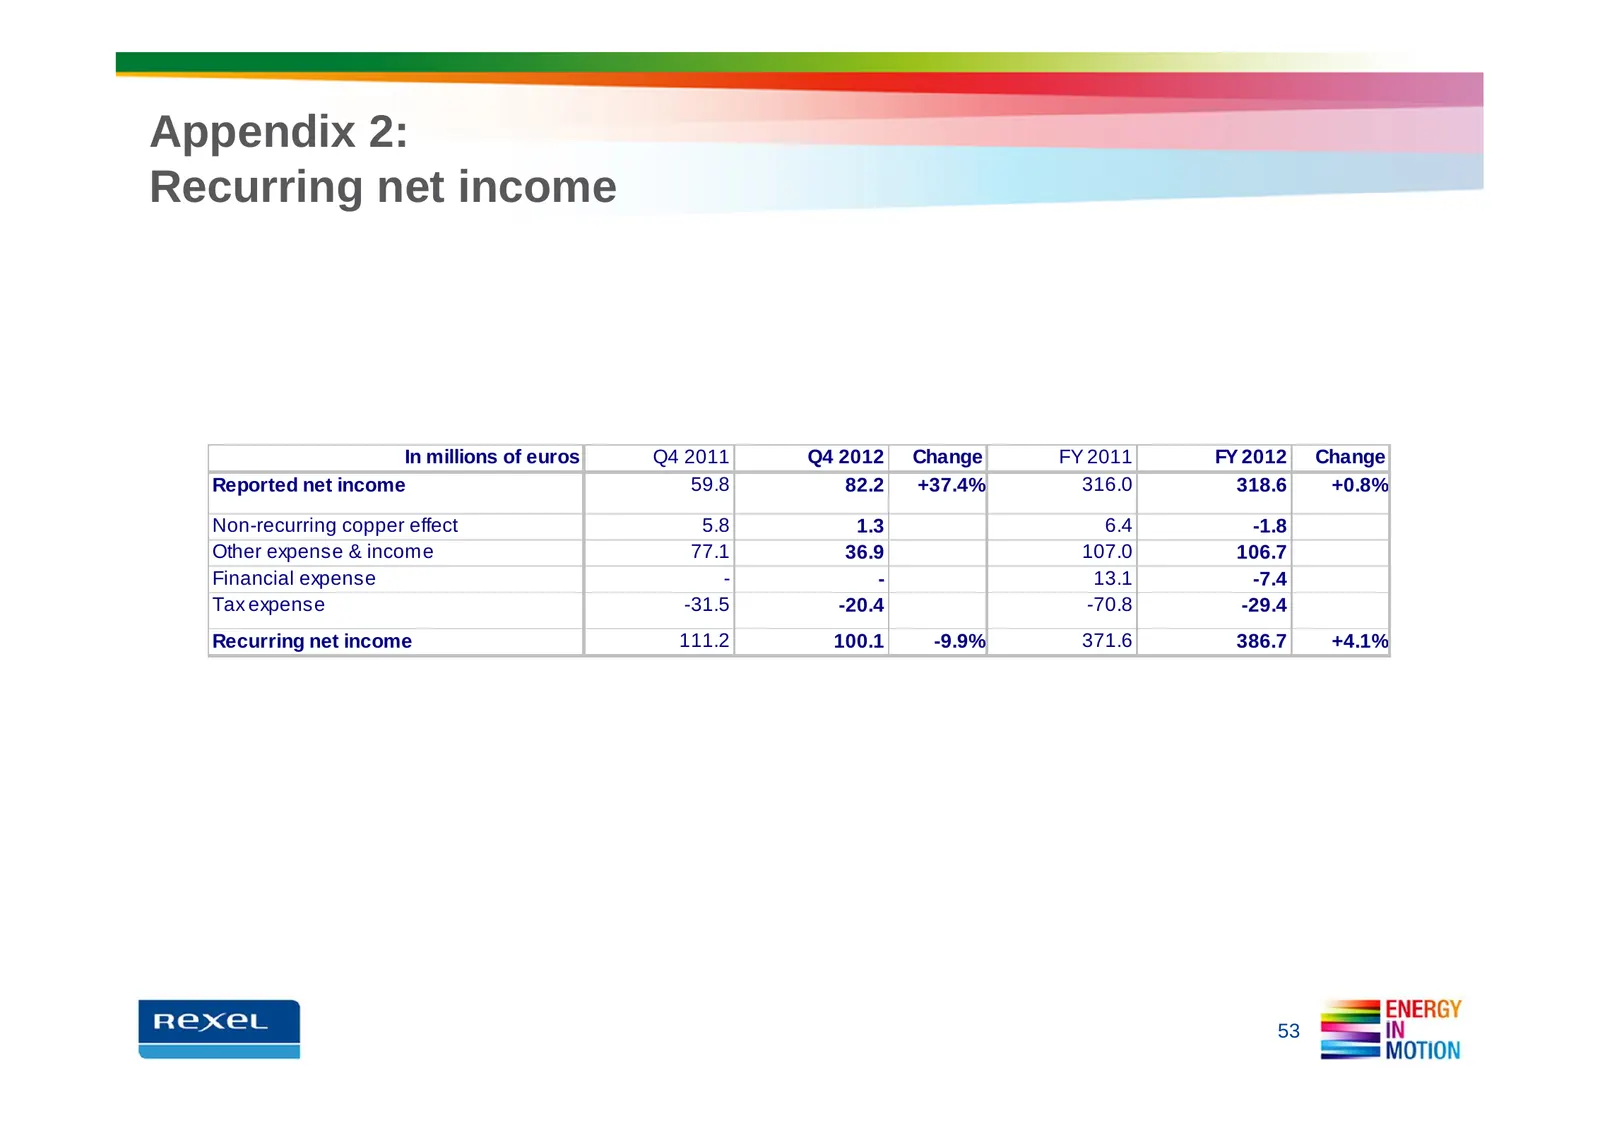
Appendix 2: Recurring net income In millions of euros Q4 2011 Q4 2012 Change FY 2011 FY 2012 Change Reported net income 59.8 82.2 +37.4% 316.0 318.6 +0.8% Non-recurring copper effect 5.8 1.3 6.4 -1.8 Other expense & income 77.1 36.9 107.0 106.7 Financial expense - - 13.1 -7.4 Tax expense -31.5 -20.4
Slide 54: Appendix 2: Sales and profitability by segment – Reported basis
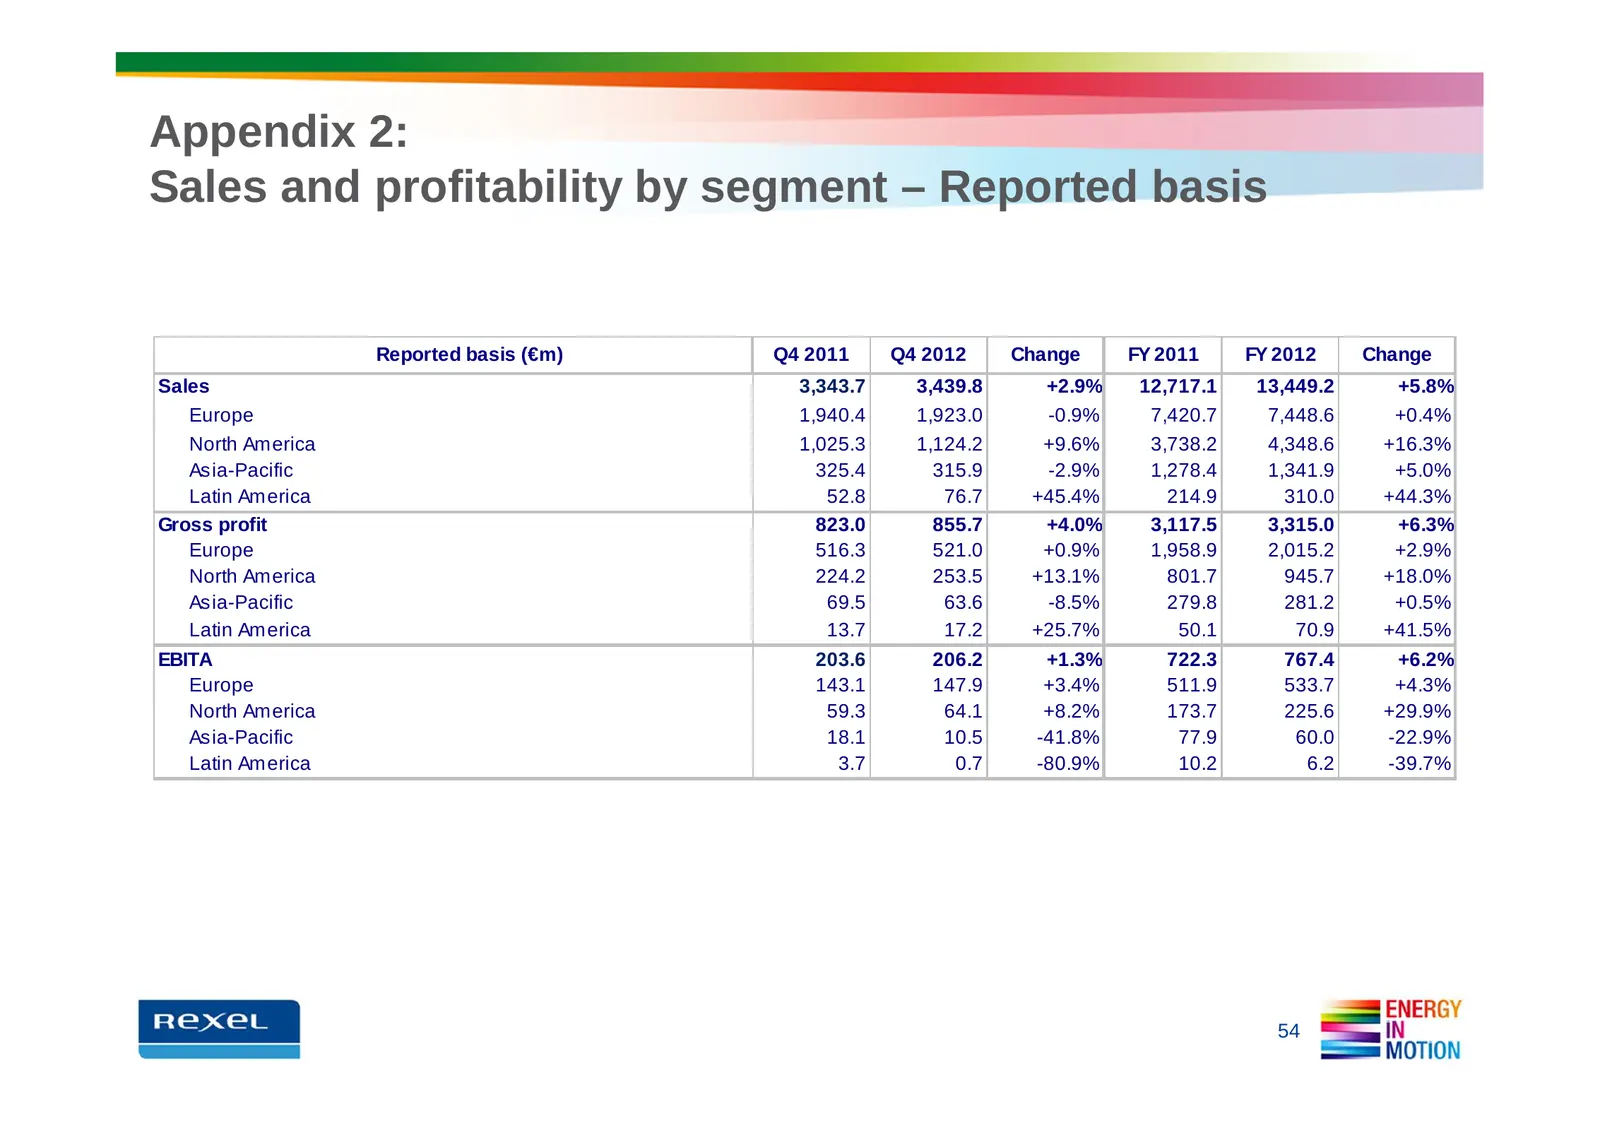
Appendix 2: Sales and profitability by segment – Reported basis Reported basis (€m) Q4 2011 Q4 2012 Change FY 2011 FY 2012 Change Sales 3,343.7 3,439.8 +2.9% 12,717.1 13,449.2 +5.8% Europe 1,940.4 1,923.0 -0.9% 7,420.7 7,448.6 +0.4% North America 1,025.3 1,124.2 +9.6% 3,738.2 4,348.6 +16.3% Asia-Pac
Slide 55: Appendix 2: Impact on sales from changes in scope of consolidation
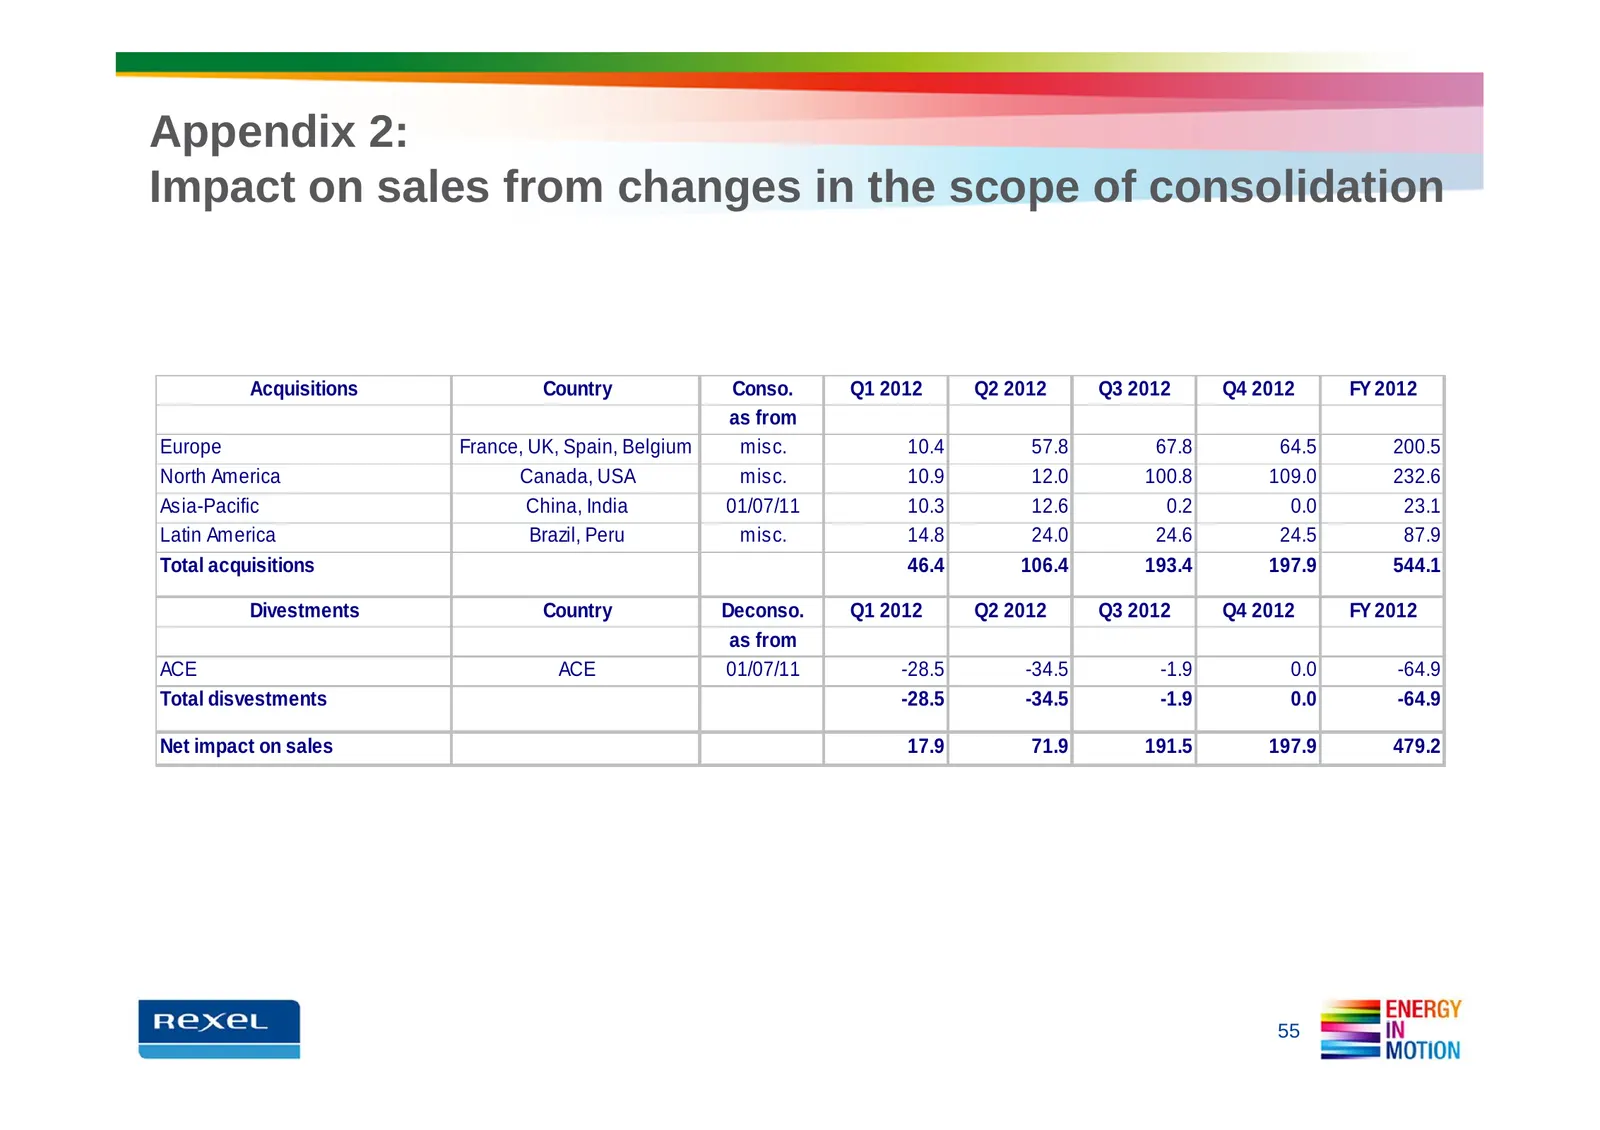
Appendix 2: Impact on sales from changes in the scope of consolidation Acquisitions Country Conso. Q1 2012 Q2 2012 Q3 2012 Q4 2012 FY 2012 as from Europe France, UK, Spain, Belgium misc. 10.4 57.8 67.8 64.5 200.5 North America Canada, USA misc. 10.9 12.0 100.8 109.0 232.6 Asia-Pacific China, India 0
Slide 56: Appendix 2: Consolidated Balance Sheet
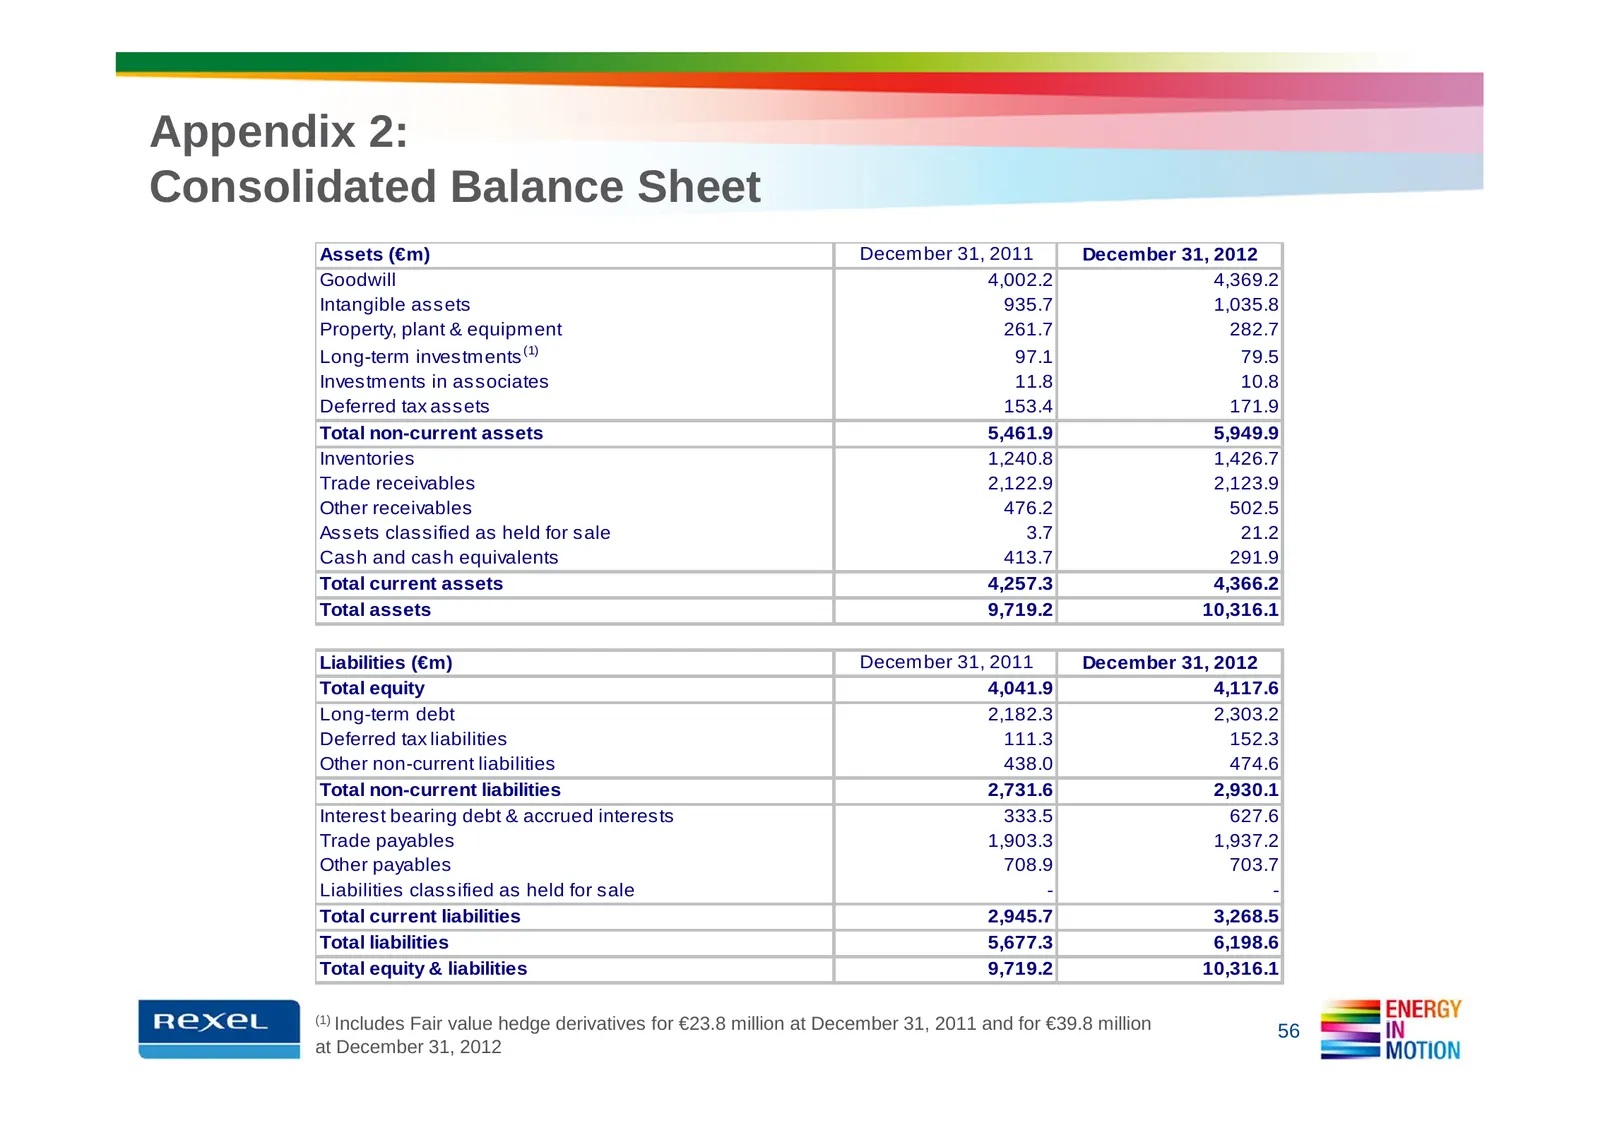
Appendix 2: Consolidated Balance Sheet Assets (€m) December 31, 2011 December 31, 2012 Goodwill 4,002.2 4,369.2 Intangible assets 935.7 1,035.8 Property, plant & equipment 261.7 282.7 Long-term investments (1) 97.1 79.5 Investments in associates 11.8 10.8 Deferred tax assets 153.4 171.9 Total non-cu
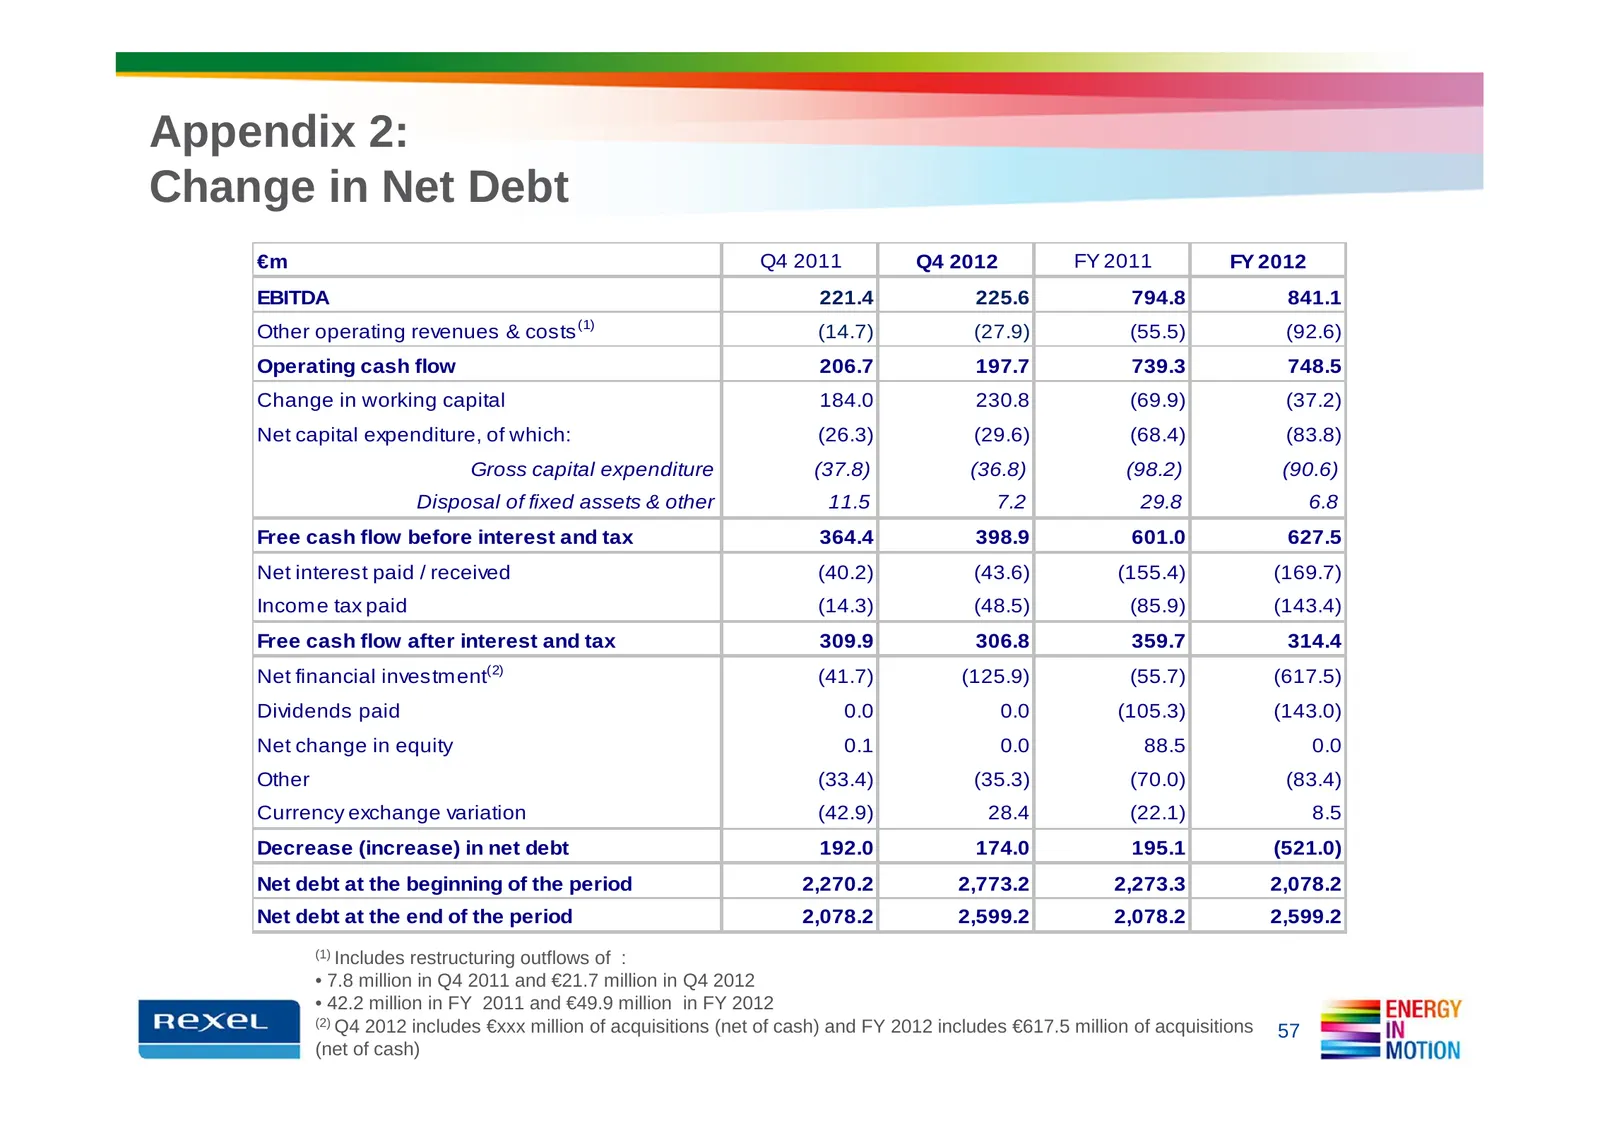
Slide 57: Appendix 2: Change in Net Debt
Appendix 2: Change in Net Debt €m Q4 2011 Q4 2012 FY 2011 FY 2012 EBITDA 221.4 225.6 794.8 841.1 (1) Other operating revenues & costs (14.7) (27.9) (55.5) (92.6) Operating cash flow 206.7 197.7 739.3 748.5 Change in working capital 184.0 230.8 (69.9) (37.2) Net capital expenditure, of which: (26.3)
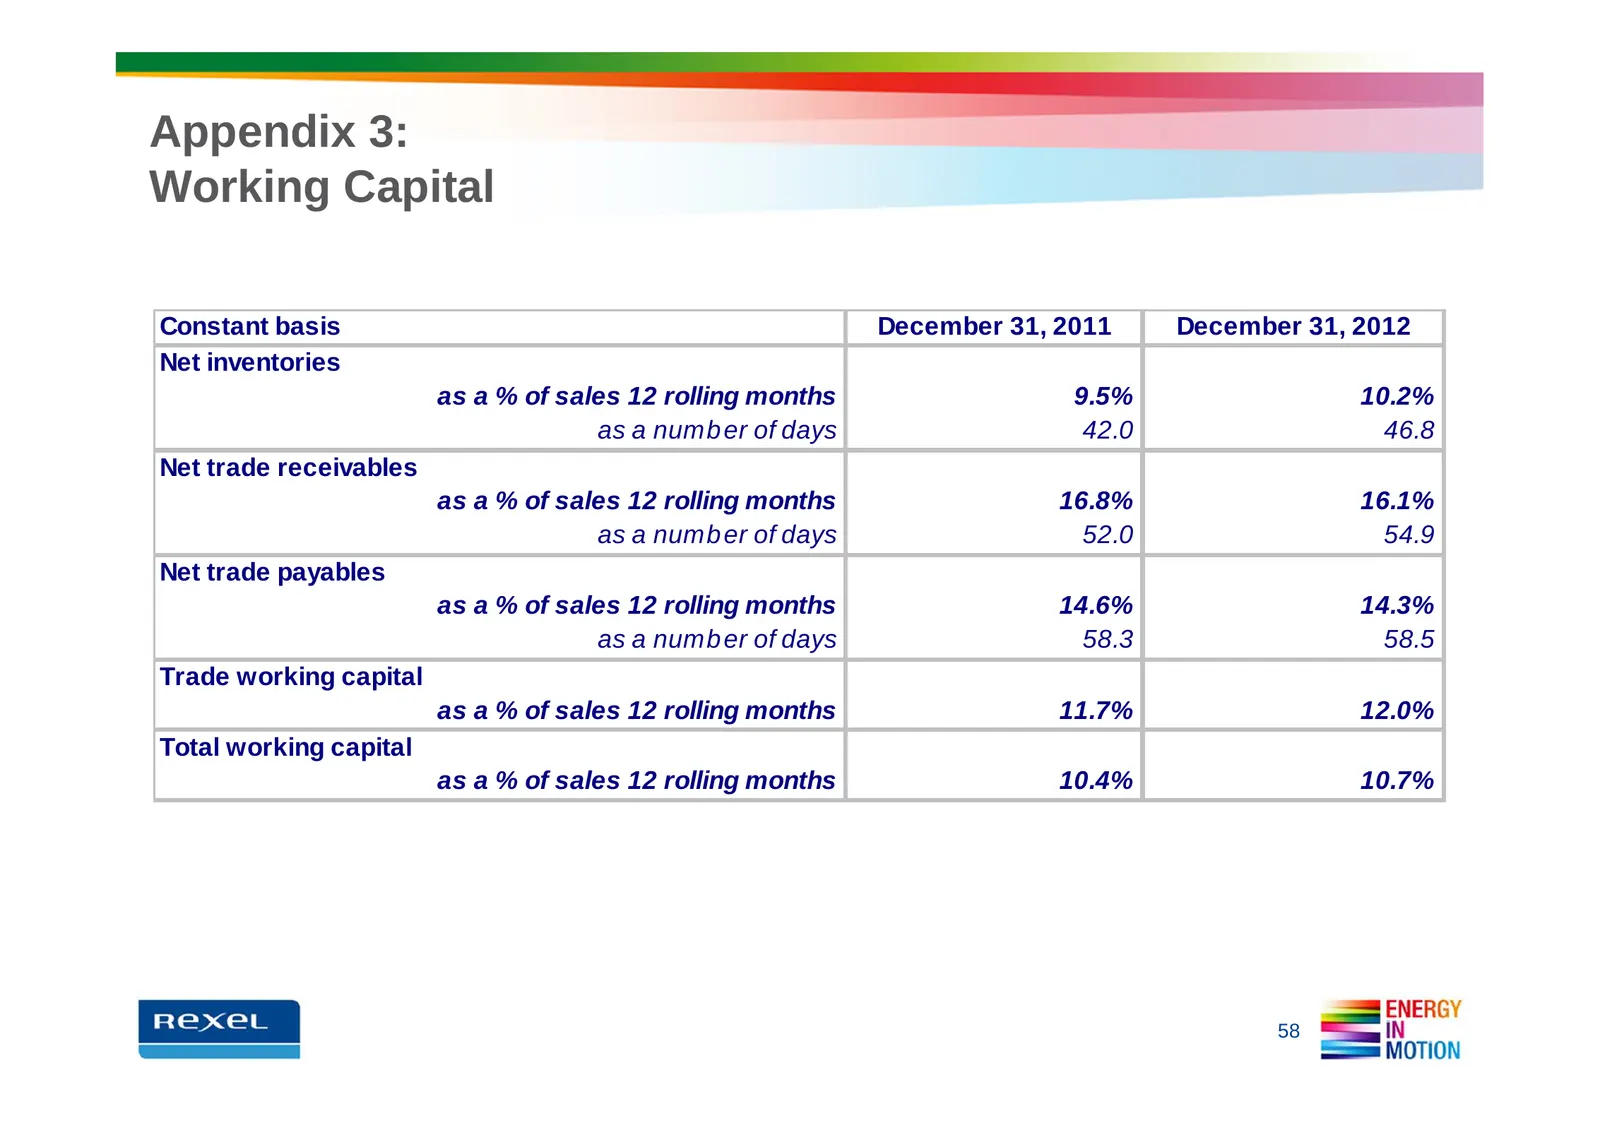
Slide 58: Appendix 3: Working Capital
Appendix 3: Working Capital Constant basis December 31, 2011 December 31, 2012 Net inventories as a % of sales 12 rolling months 9.5% 10.2% as a numb er of days 42.0 46.8 Net trade receivables as a % of sales 12 rolling months 16.8% 16.1% as a numb er of days 52.0 54.9 Net trade payables as a % of s
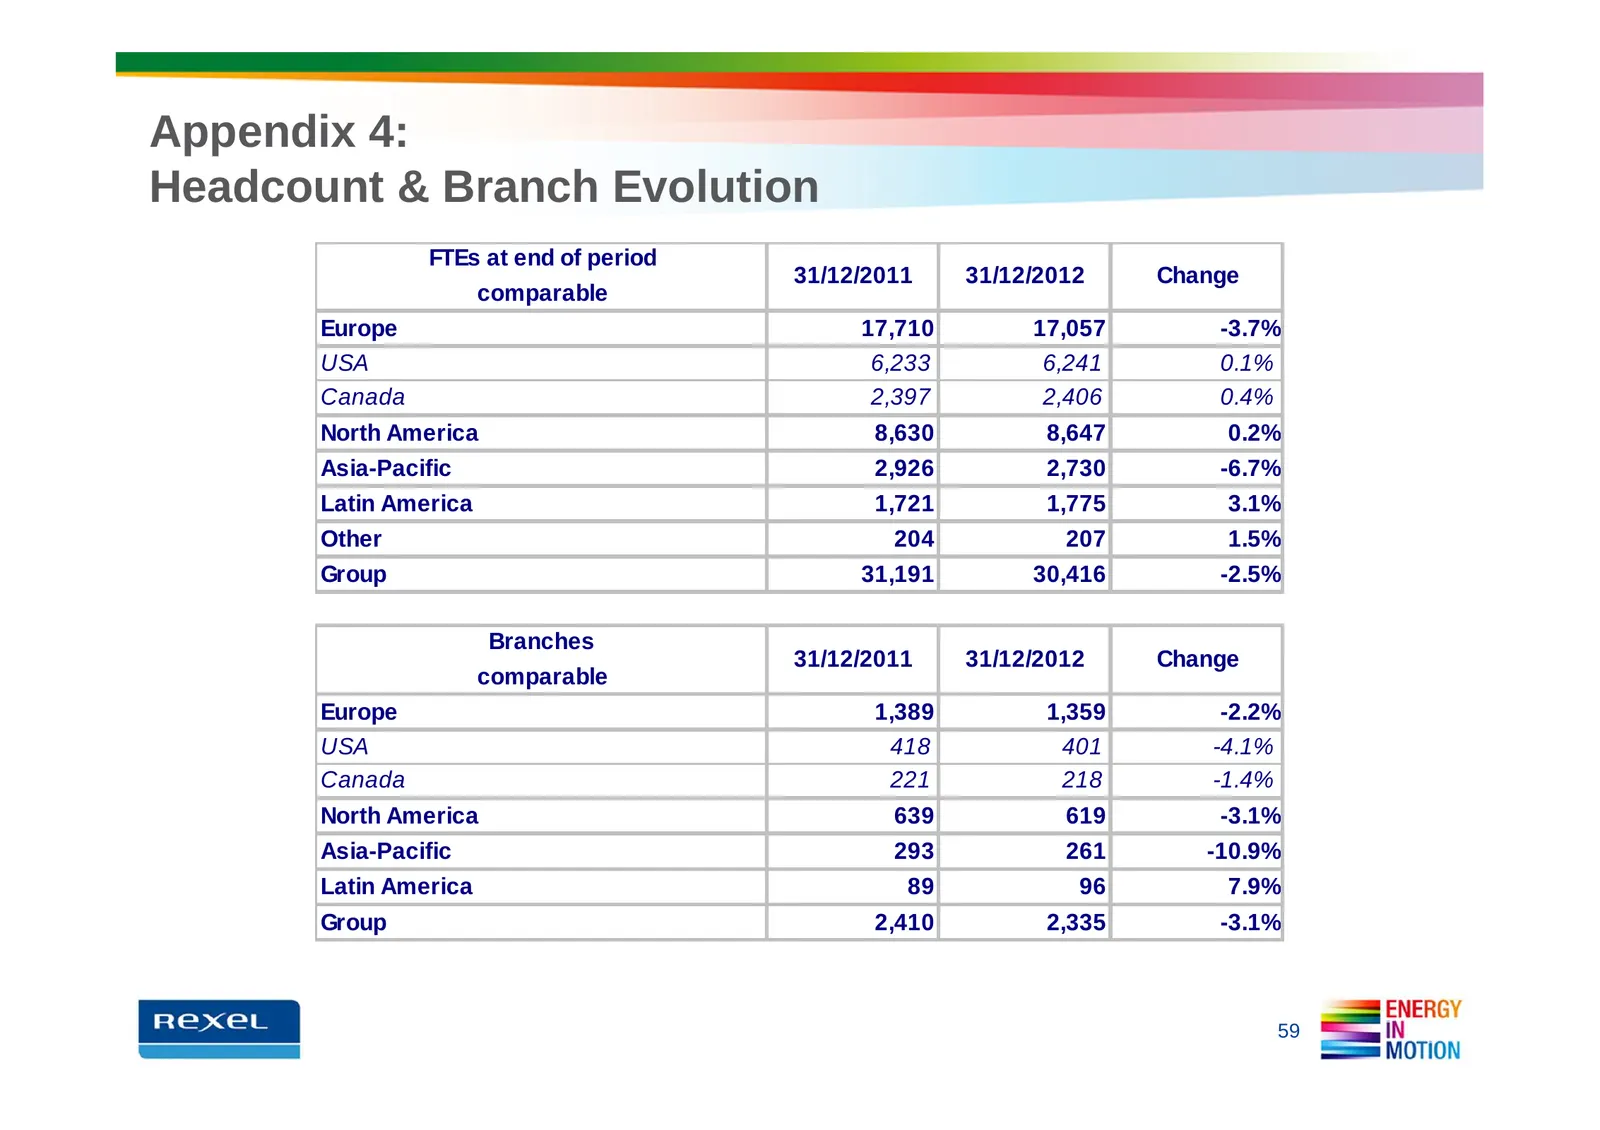
Slide 59: Appendix 4: Headcount & Branch Evolution
Appendix 4: Headcount & Branch Evolution FTEs at end of period 31/12/2011 31/12/2012 Change comparable Europe 17,710 17,057 -3.7% USA 6,233 6,241 0.1% Canada 2,397 2,406 0.4% North America 8,630 8,647 0.2% Asia-Pacific 2,926 2,730 -6.7% Latin America 1,721 1,775 3.1% Other 204 207 1.5% Group 31,191
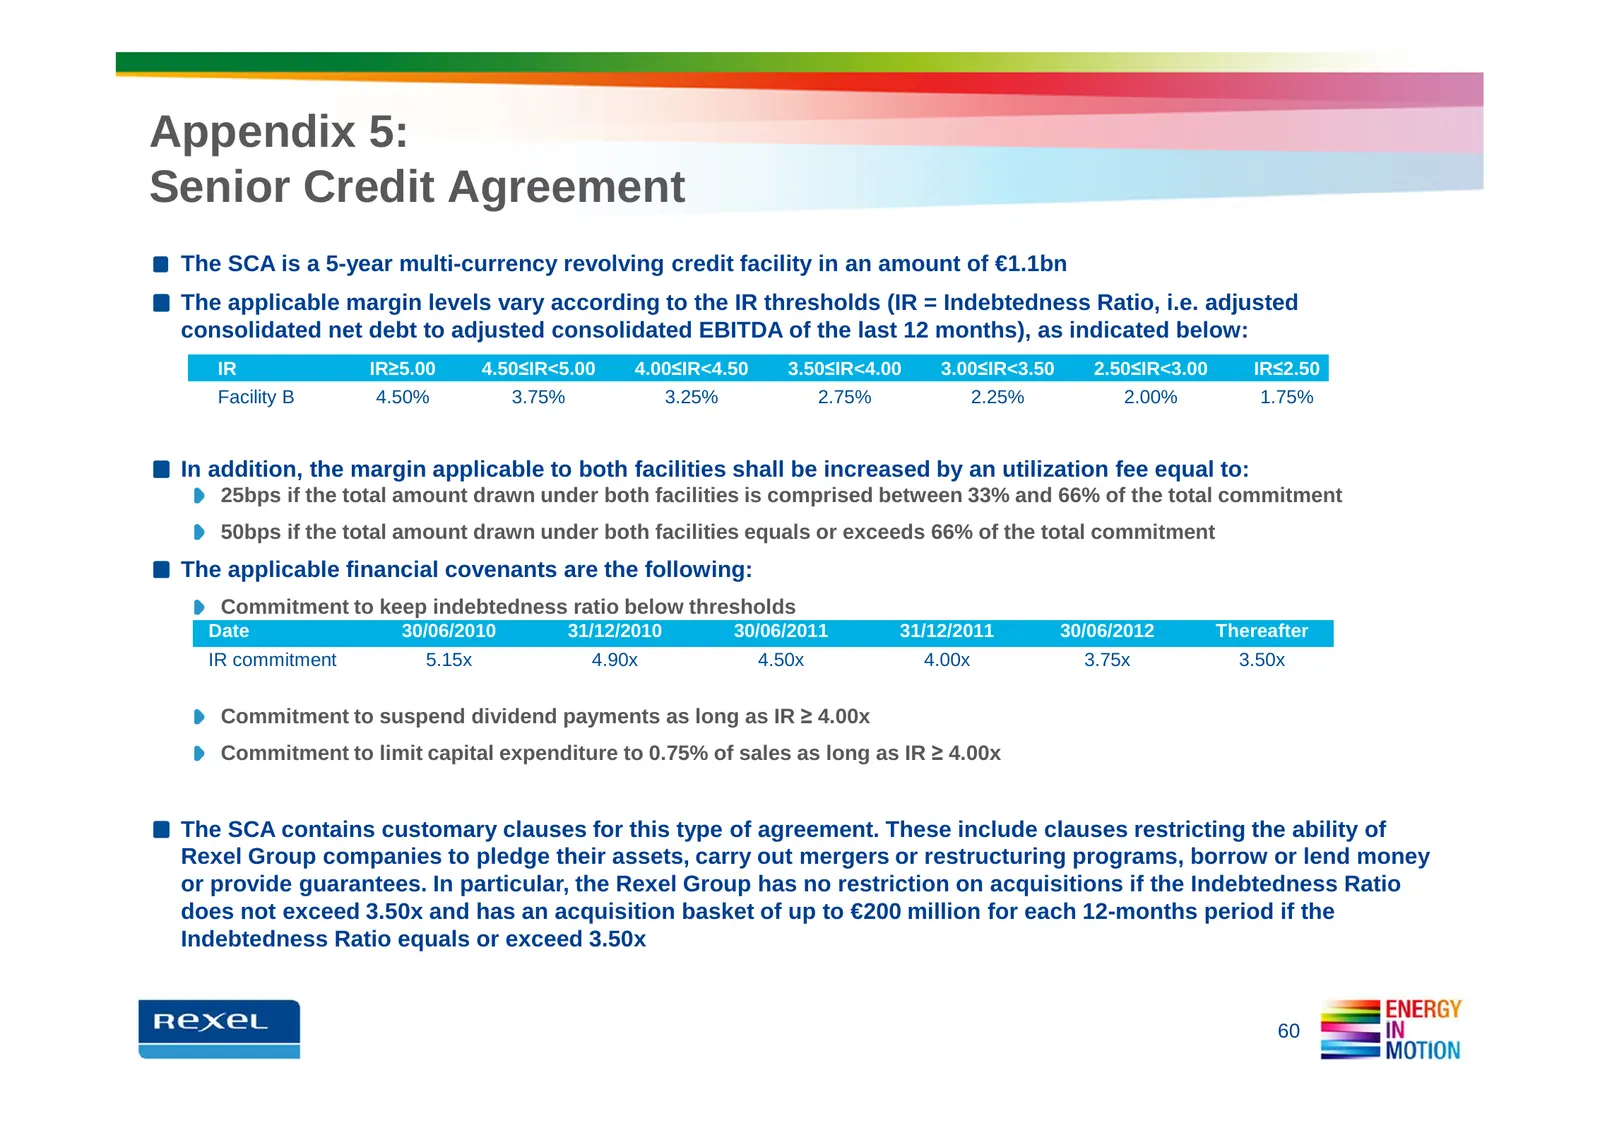
Slide 60: Appendix 5: Senior Credit Agreement
Appendix 5: Senior Credit Agreement The SCA is a 5-year multi-currency revolving credit facility in an amount of €1.1bn The applicable margin levels vary according to the IR thresholds (IR = Indebtedness Ratio, i.e. adjusted consolidated net debt to adjusted consolidated EBITDA of the last 12 months
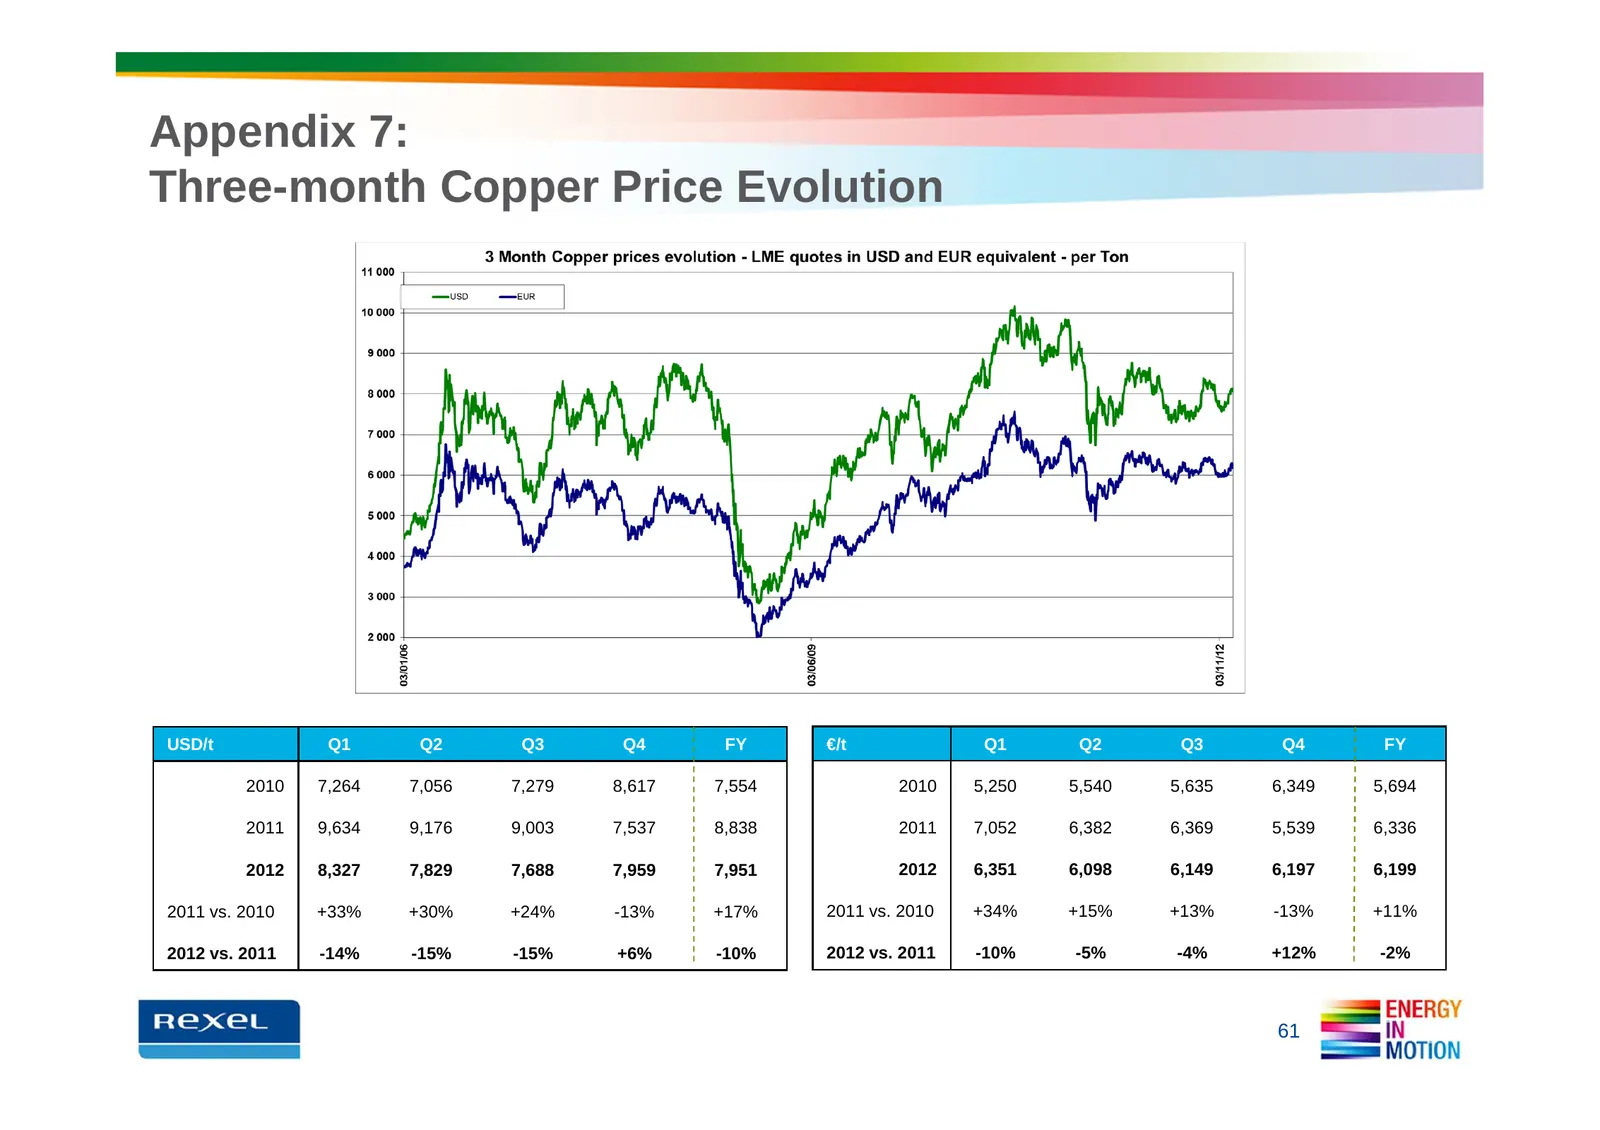
Slide 61: Appendix 7: Three-month Copper Price Evolution
Appendix 7: Three-month Copper Price Evolution USD/t Q1 Q2 Q3 Q4 FY €/t Q1 Q2 Q3 Q4 FY 2010 7,264 7,056 7,279 8,617 7,554 2010 5,250 5,540 5,635 6,349 5,694 2011 9,634 9,176 9,003 7,537 8,838 2011 7,052 6,382 6,369 5,539 6,336 2012 8,327 7,829 7,688 7,959 7,951 2012 6,351 6,098 6,149 6,197 6,199 201
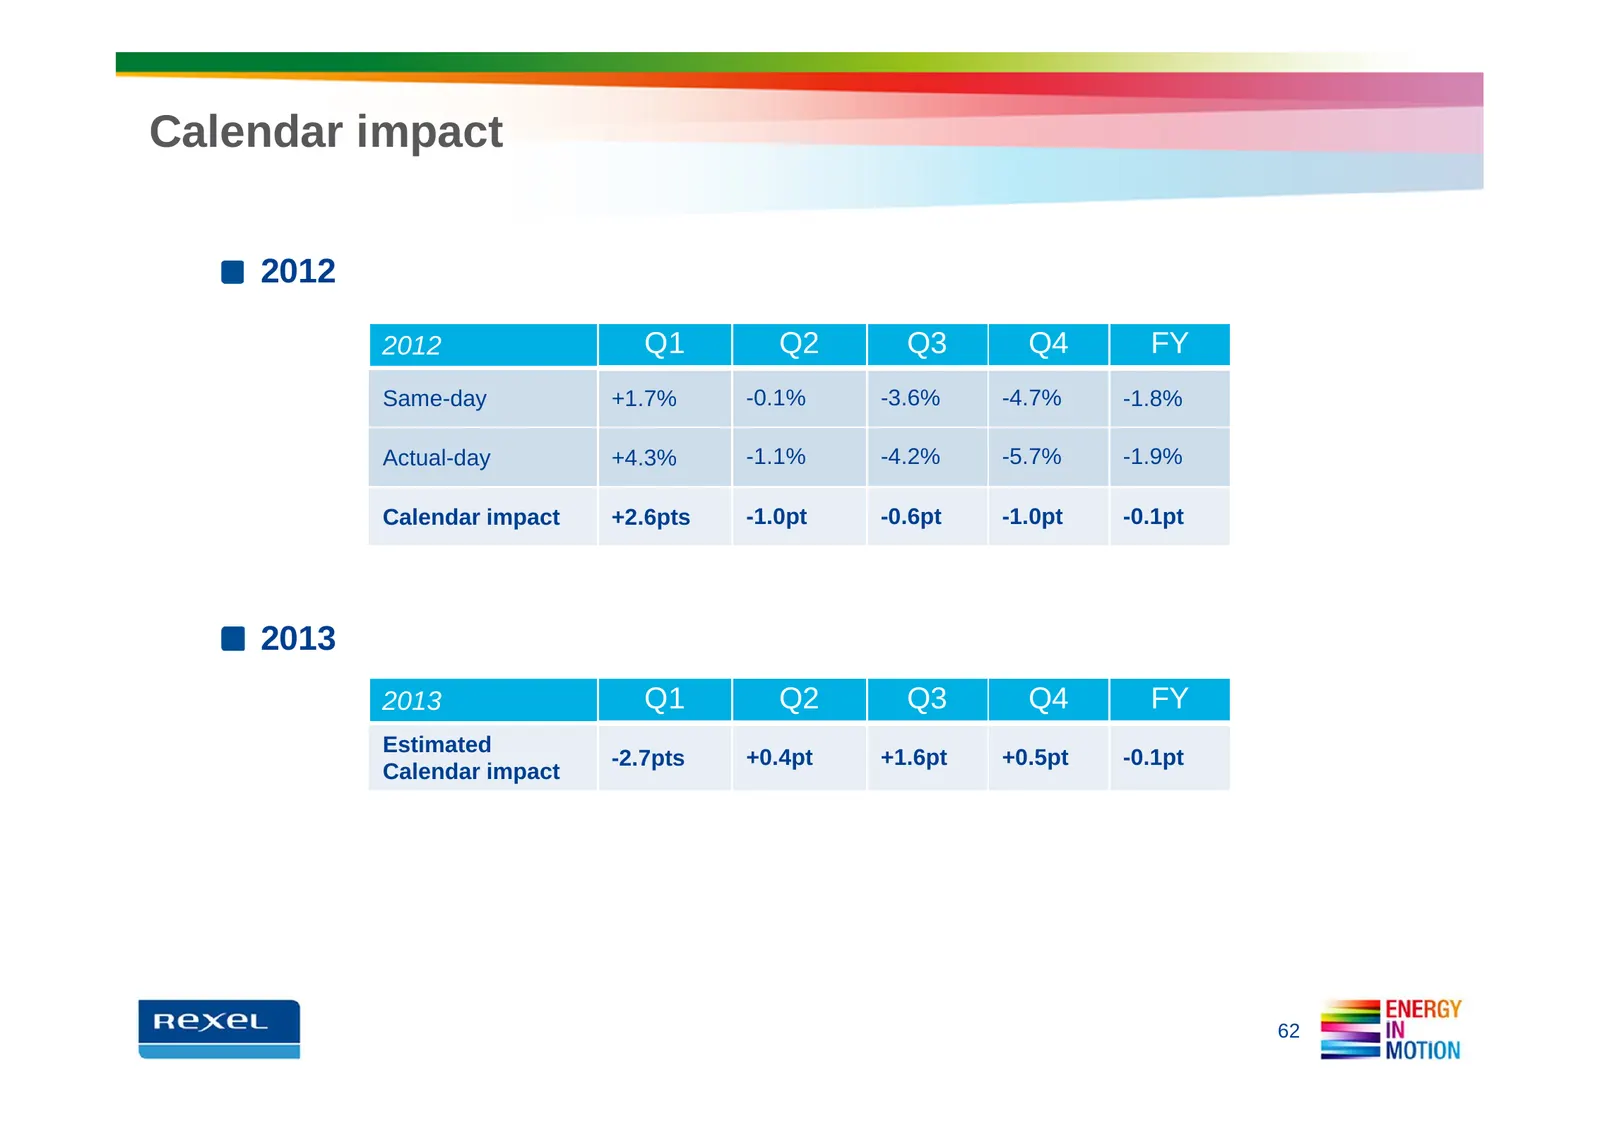
Slide 62: Calendar impact
Calendar impact 2012 2012 Q1 Q2 Q3 Q4 FY Same-day +1.7% -0.1% -3.6% -4.7% -1.8% Actual-day +4.3% -1.1% -4.2% -5.7% -1.9% Calendar impact +2.6pts -1.0pt -0.6pt -1.0pt -0.1pt 2013 2013 Q1 Q2 Q3 Q4 FY Estimated -2.7pts +0.4pt +1.6pt +0.5pt -0.1pt Calendar impact 62
Slide 63: Disclaimer
Disclaimer The Group is exposed to fluctuations in copper prices in connection with its distribution of cable products. Cables accounted for approximately 17% of the Group's sales, and copper accounts for approximately 60% of the composition of cables. This exposure is indirect since cable prices al
Source: Internet Archive copy of rexel.com
More decks from Rexel SA
 Q3 2026 Earnings Presentation13 slides · Oct 22, 2026
 Q2 2026 Earnings Presentation24 slides · Jul 27, 2026
 FY 2025 Earnings Presentation31 slides · Feb 11, 2026
 Q3 2025 Earnings Presentation15 slides · Oct 15, 2025
 Q2 2025 Earnings Presentation20 slides · Jul 28, 2025
 Q1 2025 Earnings Presentation16 slides · Apr 29, 2025