Nick Scali Limited · ASX:NCK
Nick Scali — Investor Presentation (February 2025)
17 slides from Nick Scali's investor presentation, Feb 7, 2025
Slide 1: 1H FY25 Results Presentation
FY23 Summary 1H FY25 Results Presentation 7 February 2025 1
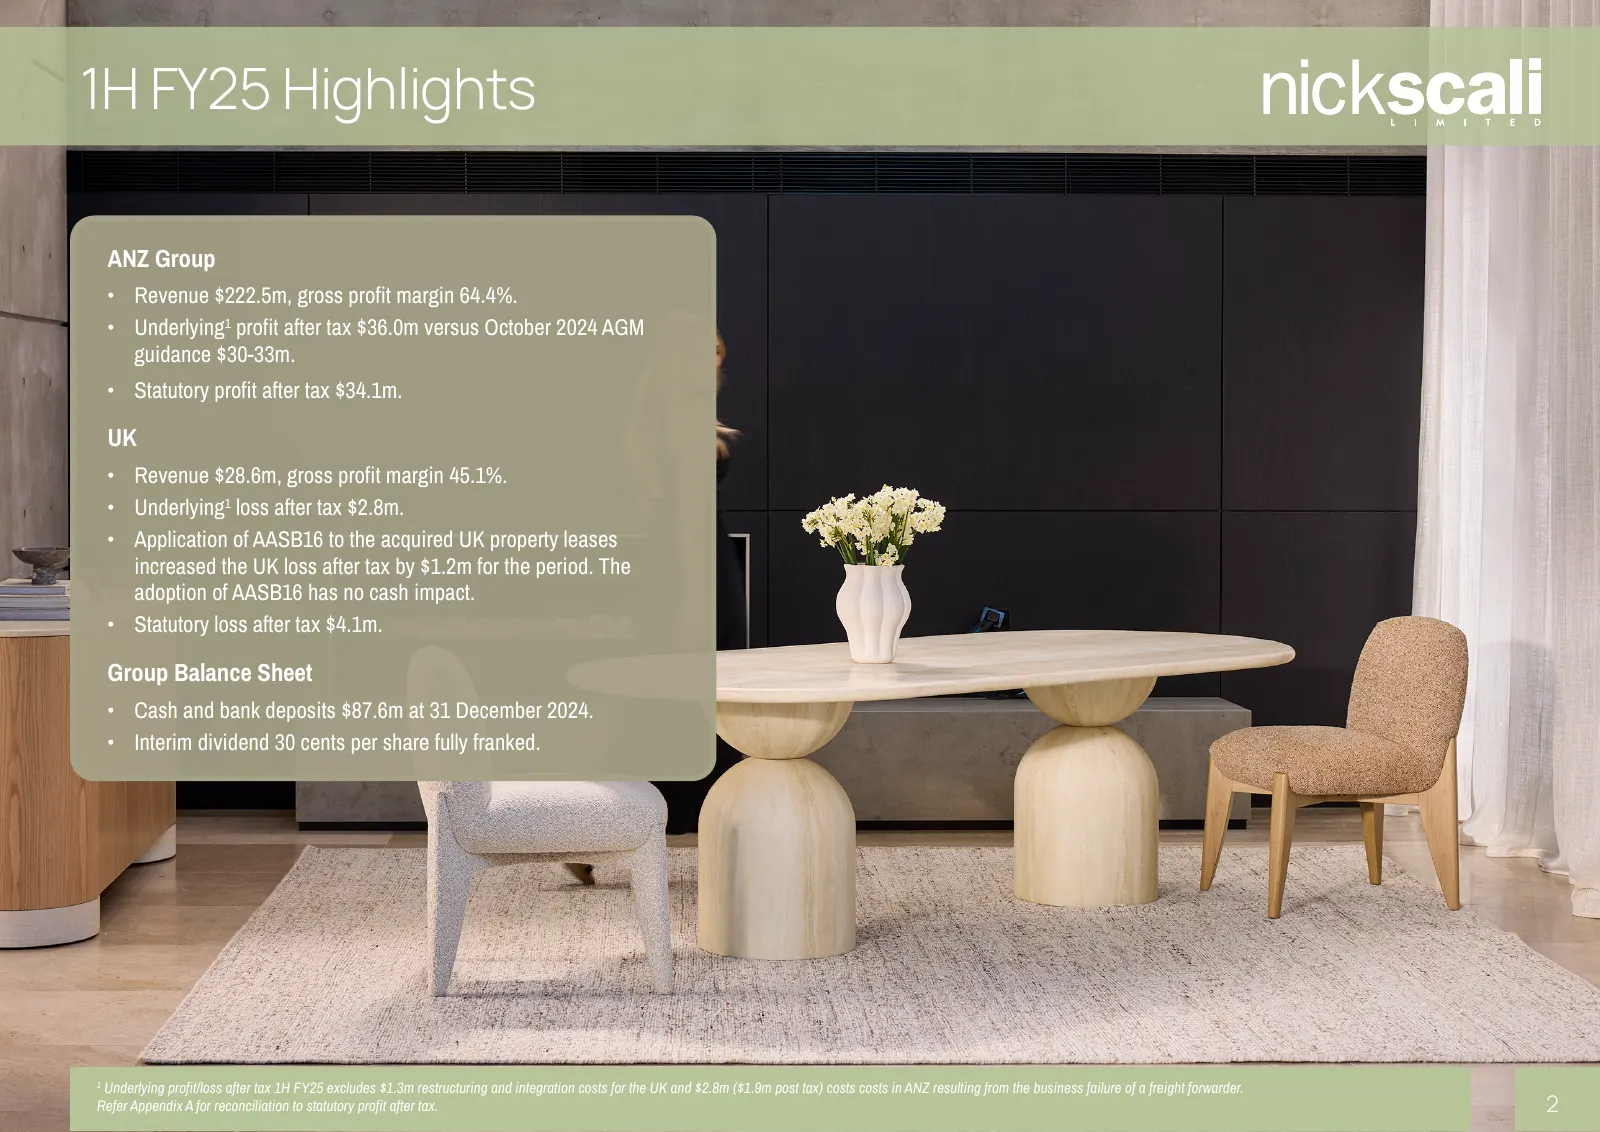
Slide 2: 1H FY25 Highlights
1H FY25 Highlights ANZ Group • Revenue $222.5m, gross profit margin 64.4%. • Underlying1 profit after tax $36.0m versus October 2024 AGM guidance $30-33m. • Statutory profit after tax $34.1m. UK • Revenue $28.6m, gross profit margin 45.1%. • Underlying1 loss after tax $2.8m. • Application of AASB16
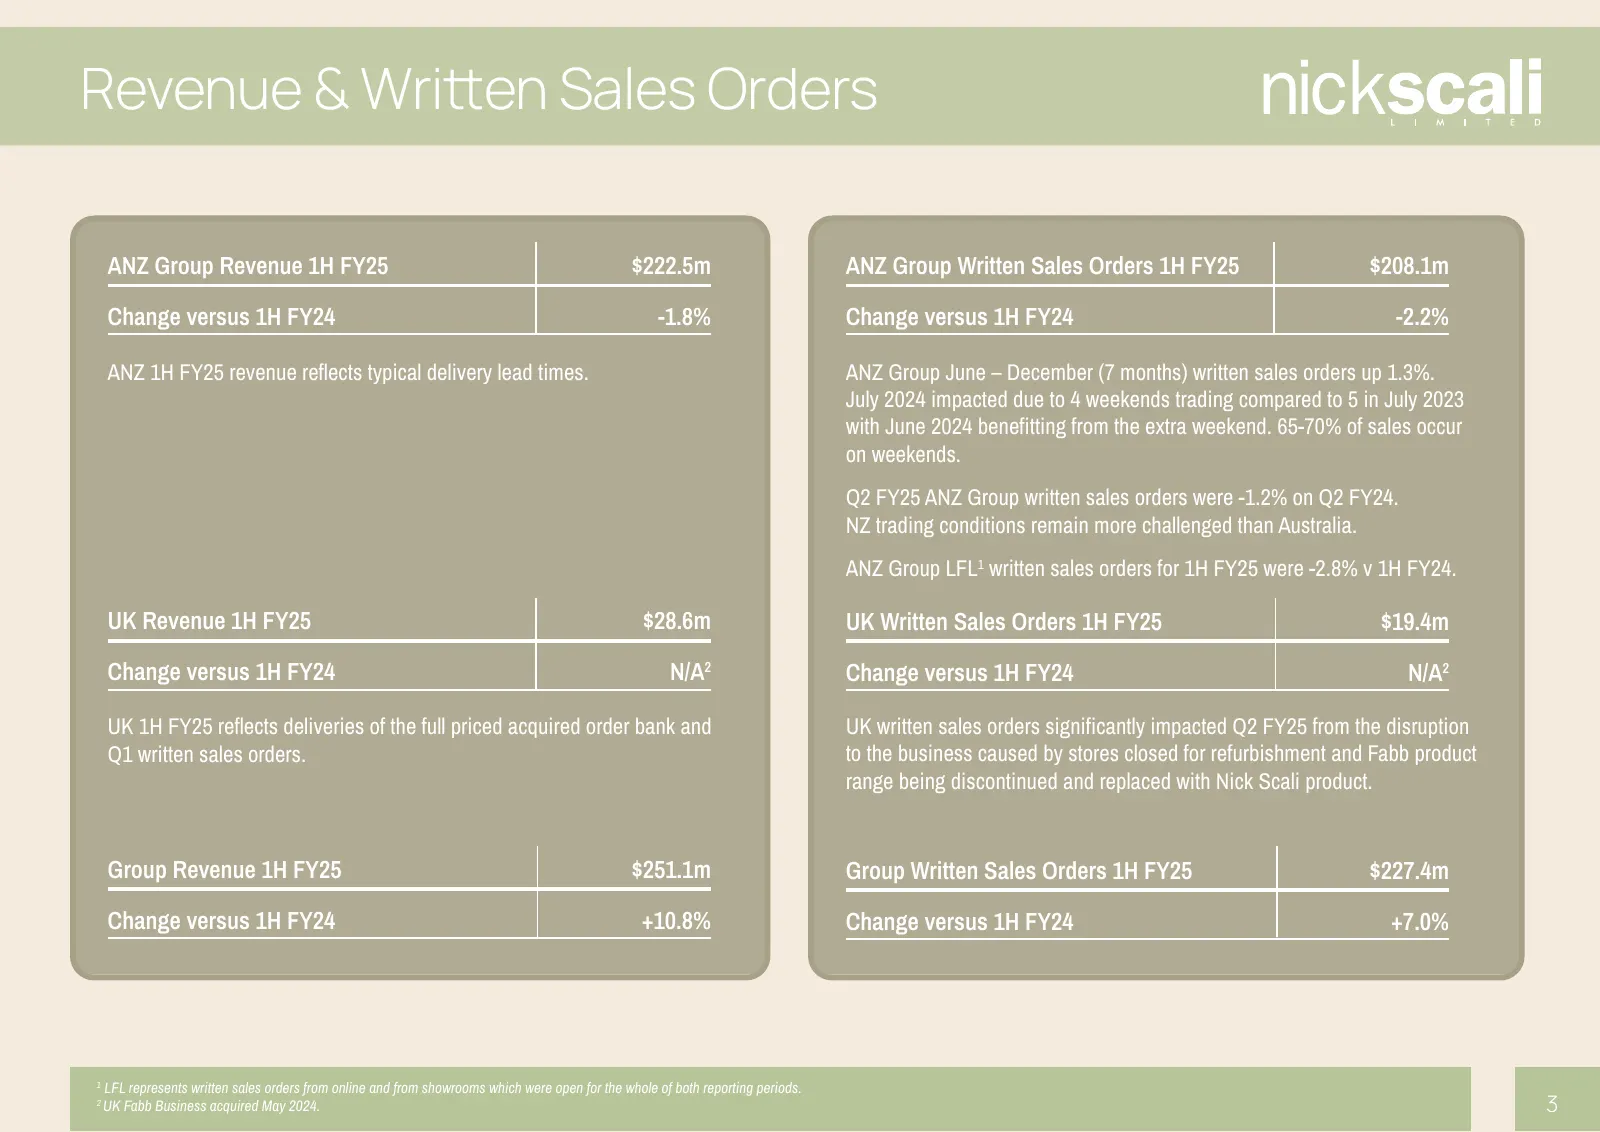
Slide 3: Revenue & Written Sales Orders
Revenue & Written Sales Orders ANZ Group Revenue 1H FY25 $222.5m ANZ Group Written Sales Orders 1H FY25 $208.1m Change versus 1H FY24 -1.8% Change versus 1H FY24 -2.2% ANZ 1H FY25 revenue reflects typical delivery lead times. ANZ Group June – December (7 months) written sales orders up 1.3%. July 20
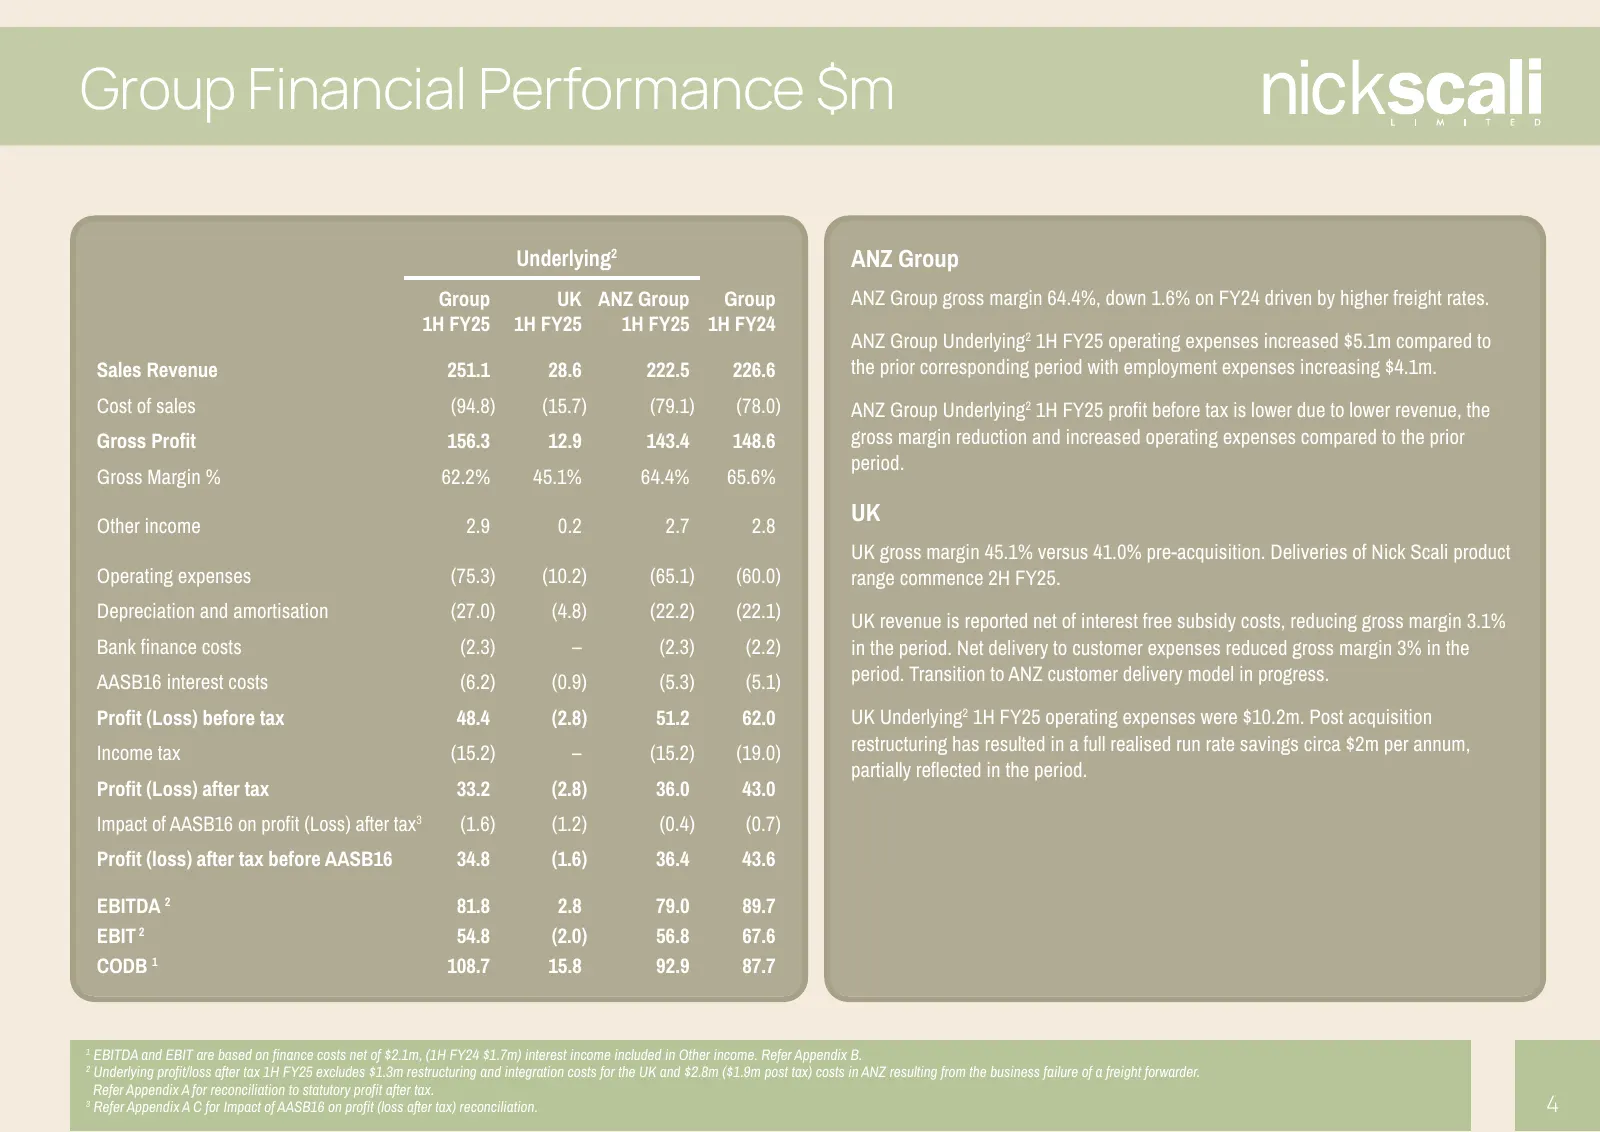
Slide 4: Group Financial Performance $m
Group Financial Performance $m Underlying2 ANZ Group Group UK ANZ Group Group ANZ Group gross margin 64.4%, down 1.6% on FY24 driven by higher freight rates. 1H FY25 1H FY25 1H FY25 1H FY24 ANZ Group Underlying2 1H FY25 operating expenses increased $5.1m compared to Sales Revenue 251.1 28.6 222.5 22
Slide 5: Group Cashflow $m
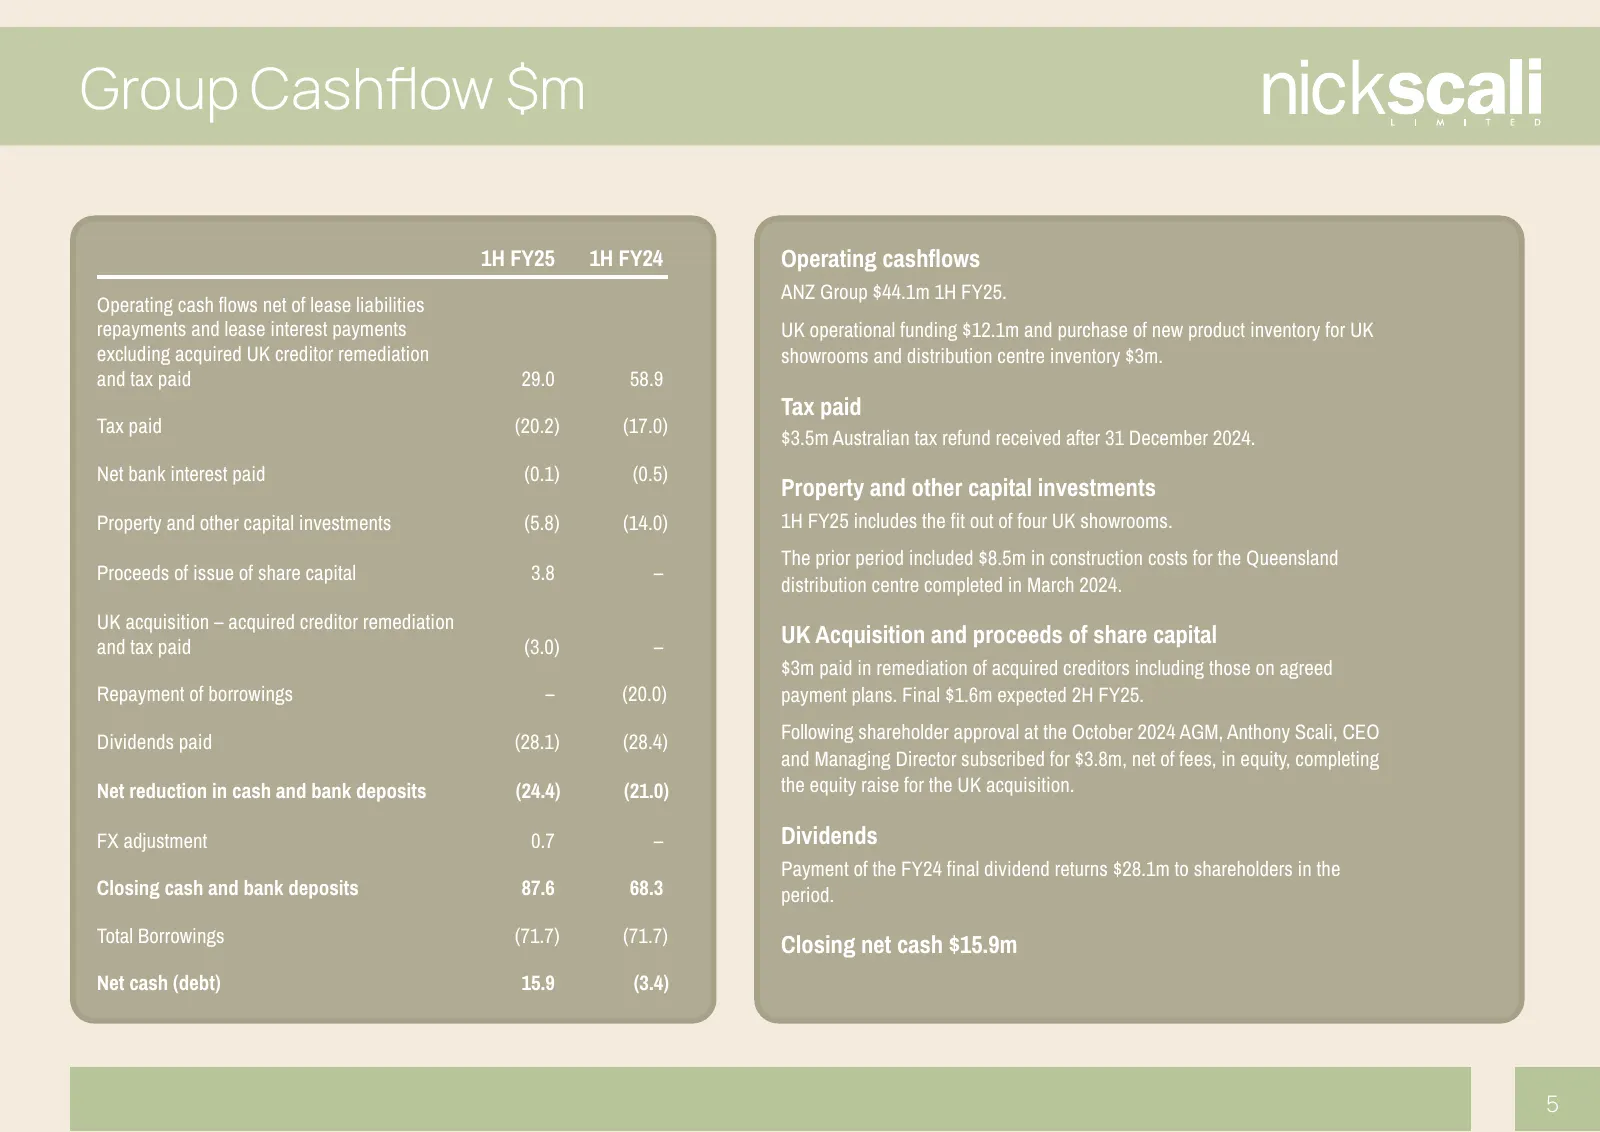
Group Cashflow $m 1H FY25 1H FY24 Operating cashflows ANZ Group $44.1m 1H FY25. Operating cash flows net of lease liabilities repayments and lease interest payments UK operational funding $12.1m and purchase of new product inventory for UK excluding acquired UK creditor remediation showrooms and dis
Slide 6: Group Balance Sheet $m
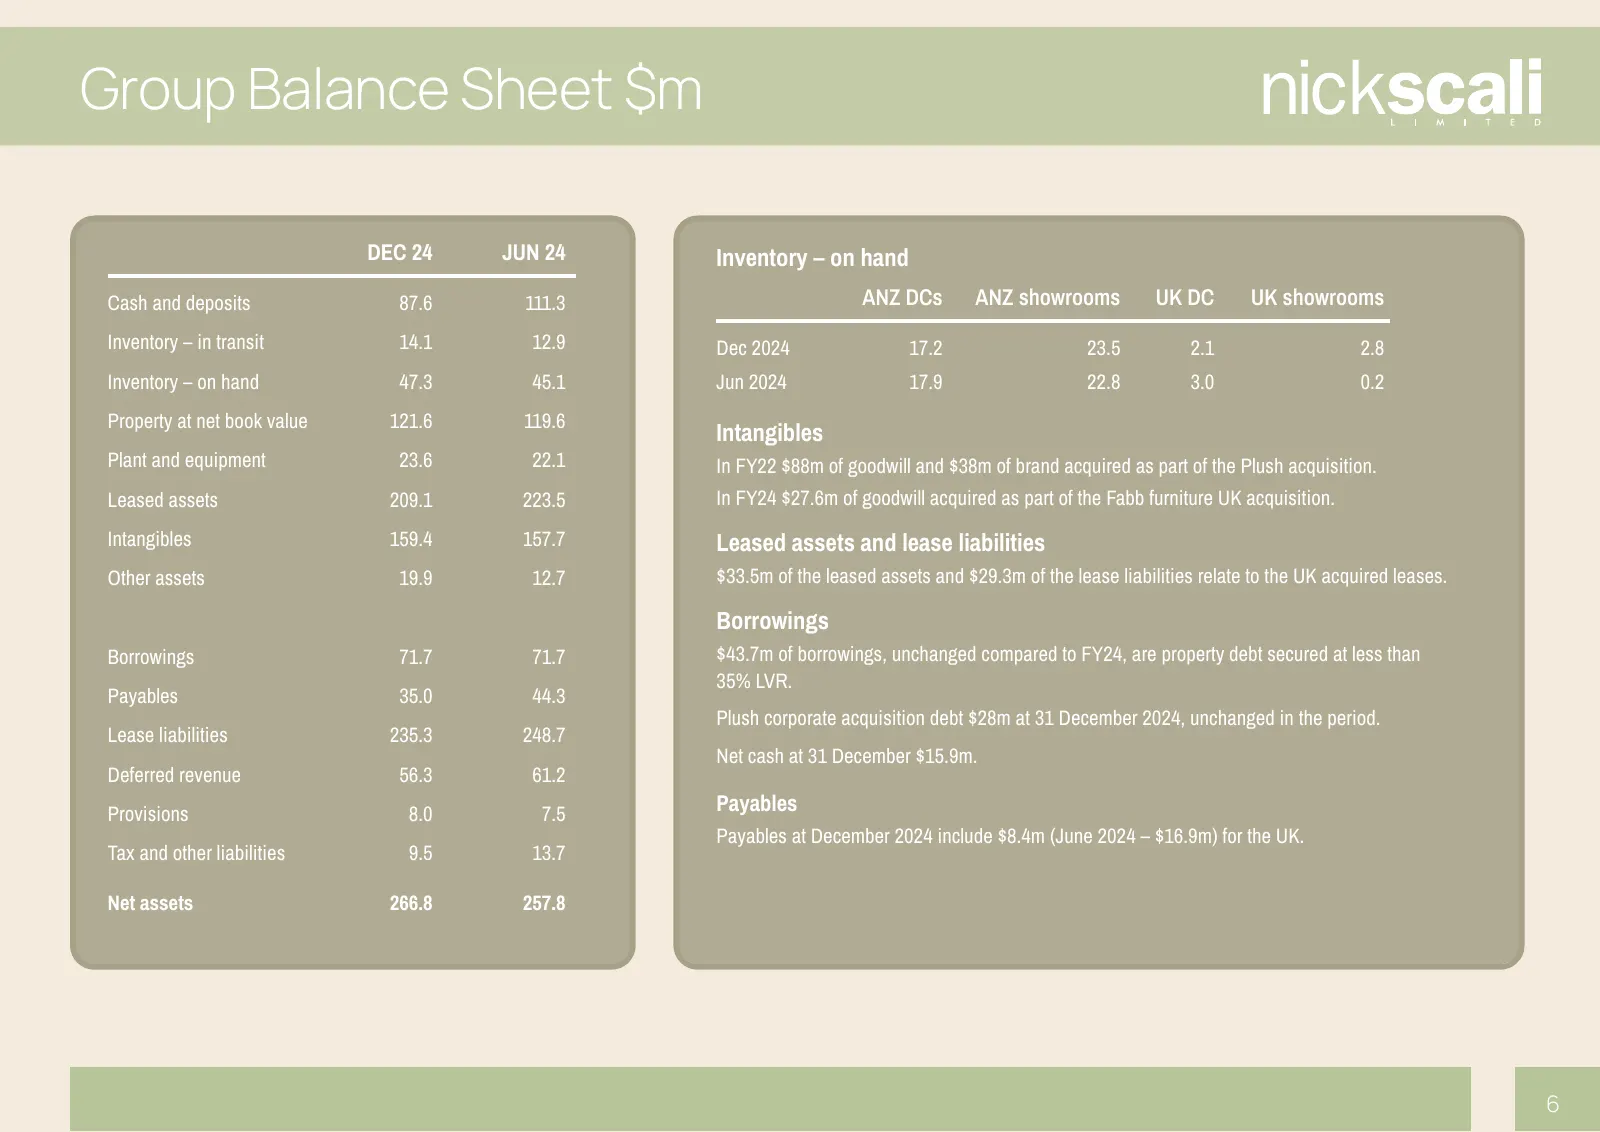
Group Balance Sheet $m DEC 24 JUN 24 Inventory – on hand Cash and deposits 87.6 111.3 ANZ DCs ANZ showrooms UK DC UK showrooms Inventory – in transit 14.1 12.9 Dec 2024 17.2 23.5 2.1 2.8 Inventory – on hand 47.3 45.1 Jun 2024 17.9 22.8 3.0 0.2 Property at net book value 121.6 119.6 Intangibles Plant
Slide 7: ANZ Group Online
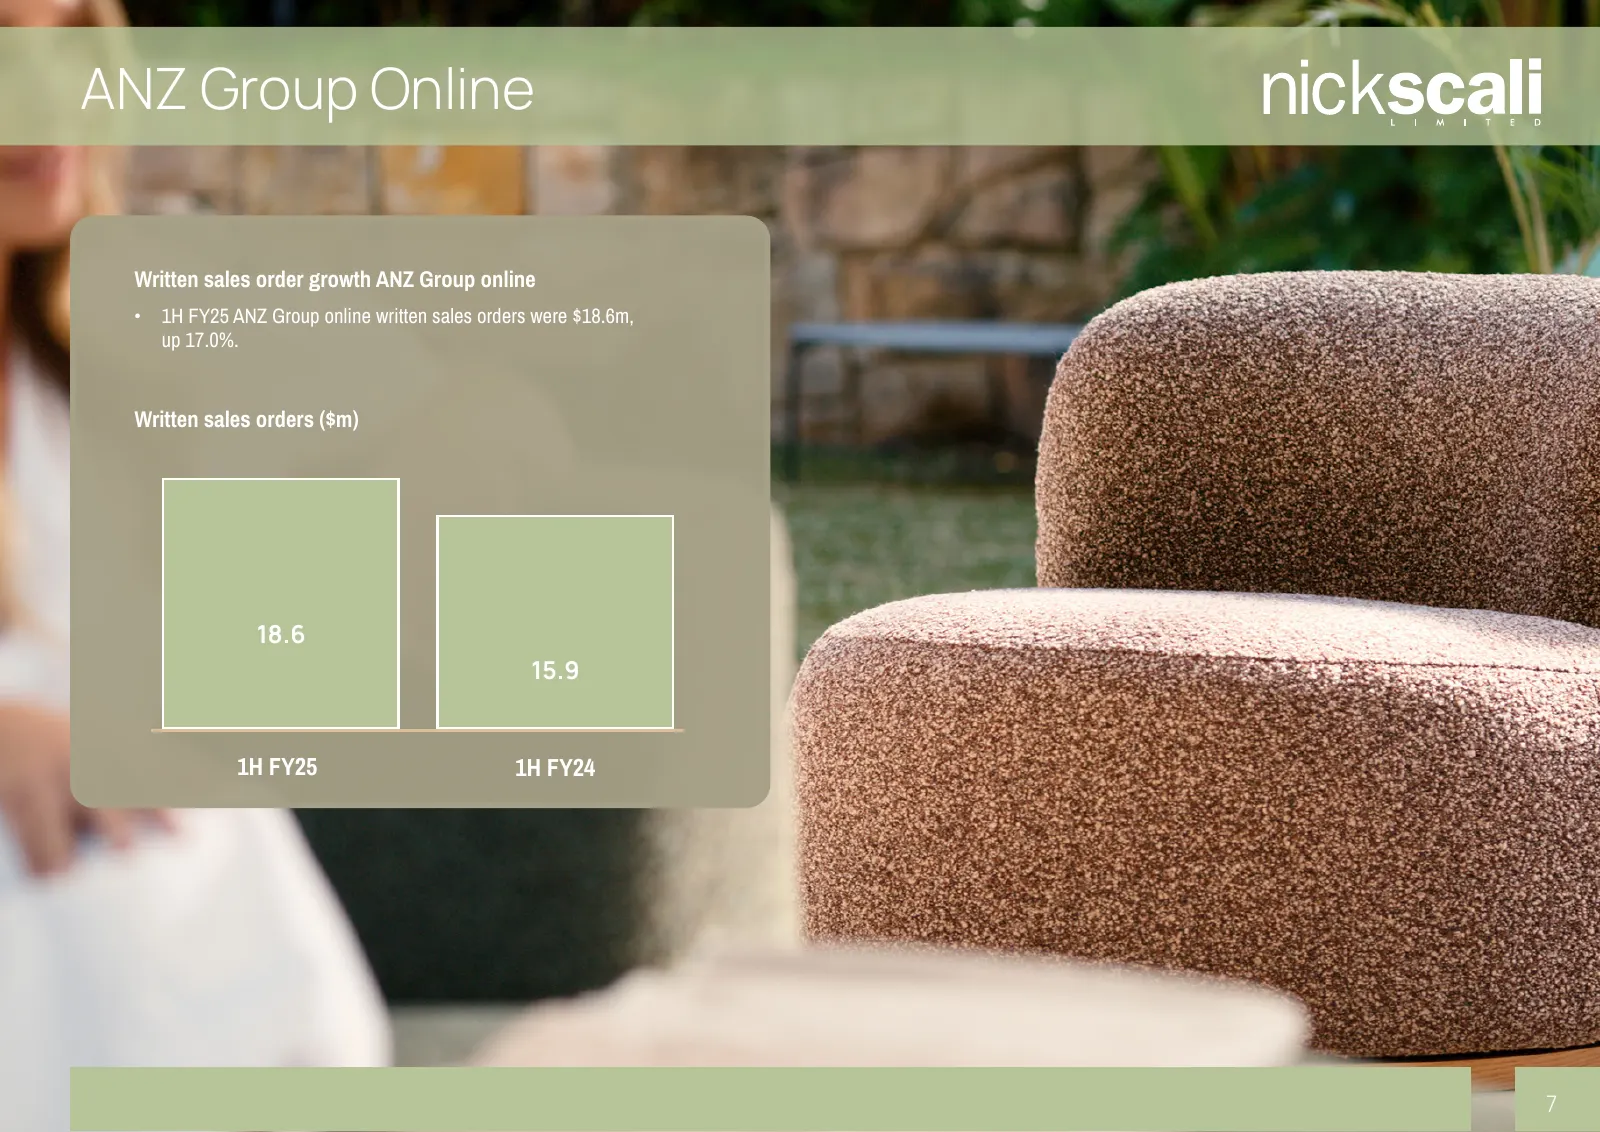
ANZ Group Online Written sales order growth ANZ Group online • 1H FY25 ANZ Group online written sales orders were $18.6m, up 17.0%. Written sales orders ($m) 18.6 15.9 1H FY25 1H FY24 7
Slide 8: 9 month update on implementation of UK acquisition strategy
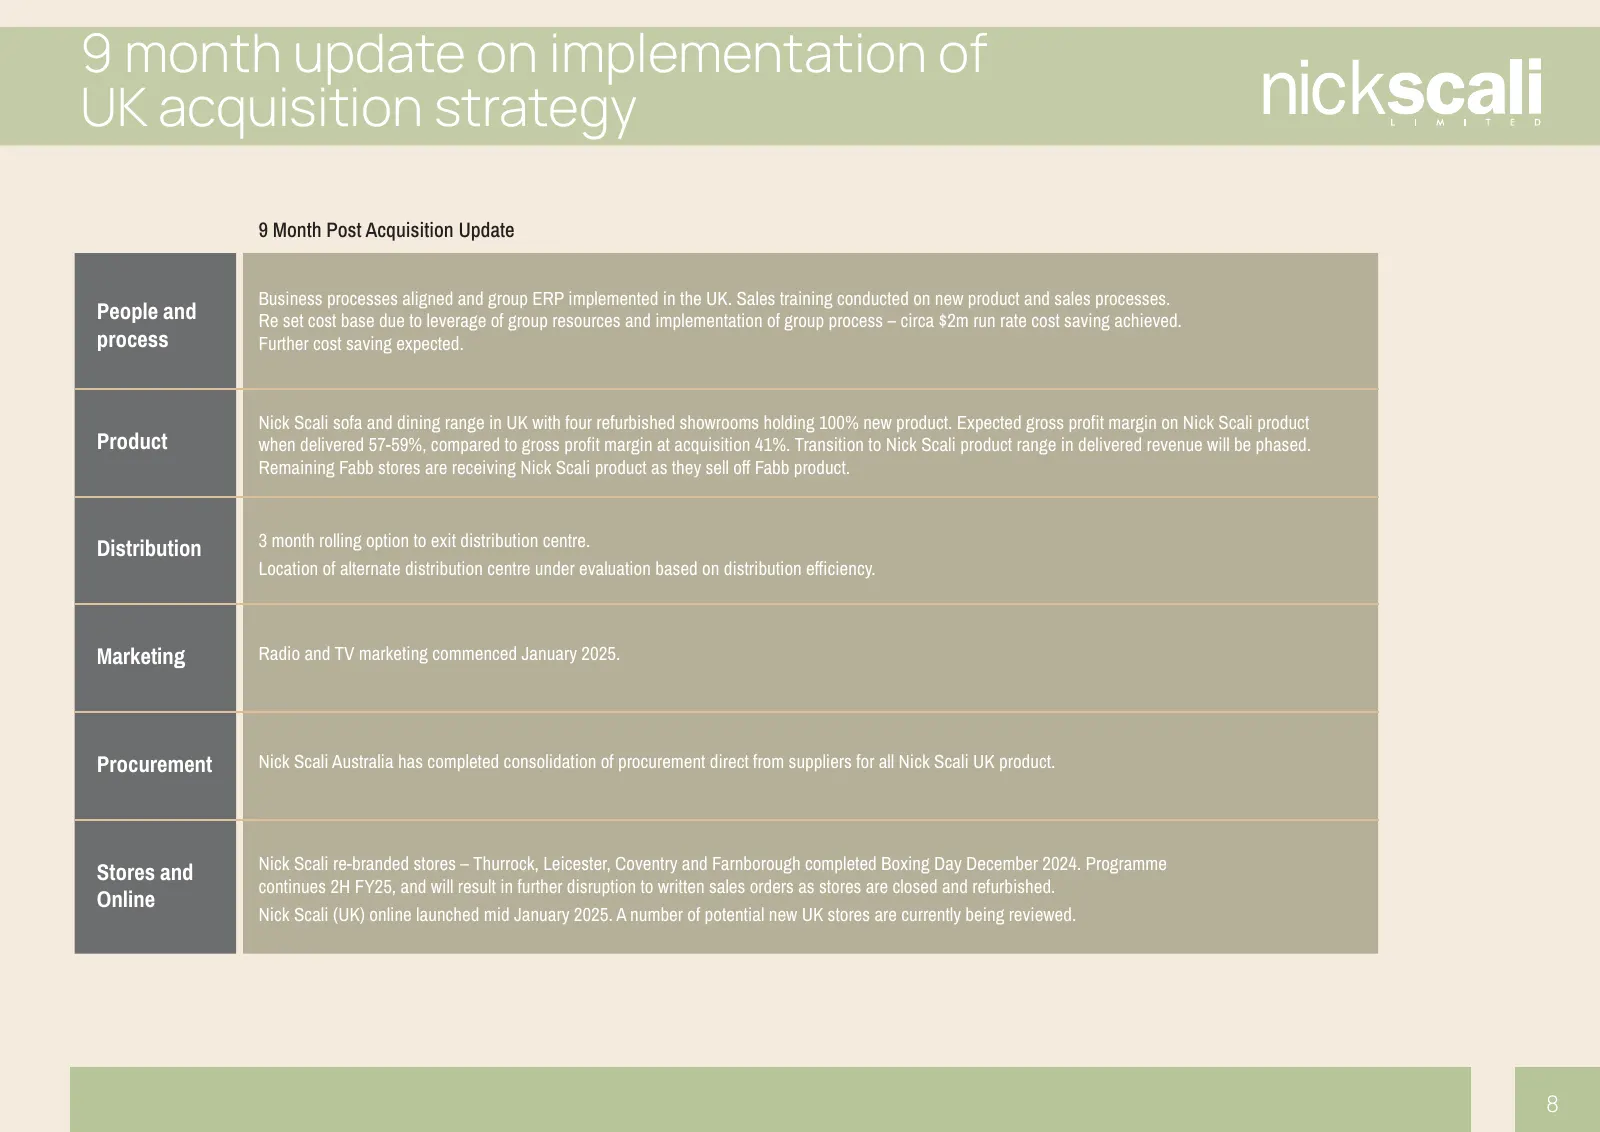
9 month update on implementation of UK acquisition strategy 9 Month Post Acquisition Update Business processes aligned and group ERP implemented in the UK. Sales training conducted on new product and sales processes. People and Re set cost base due to leverage of group resources and implementation o
Slide 9: Nick Scali in the UK
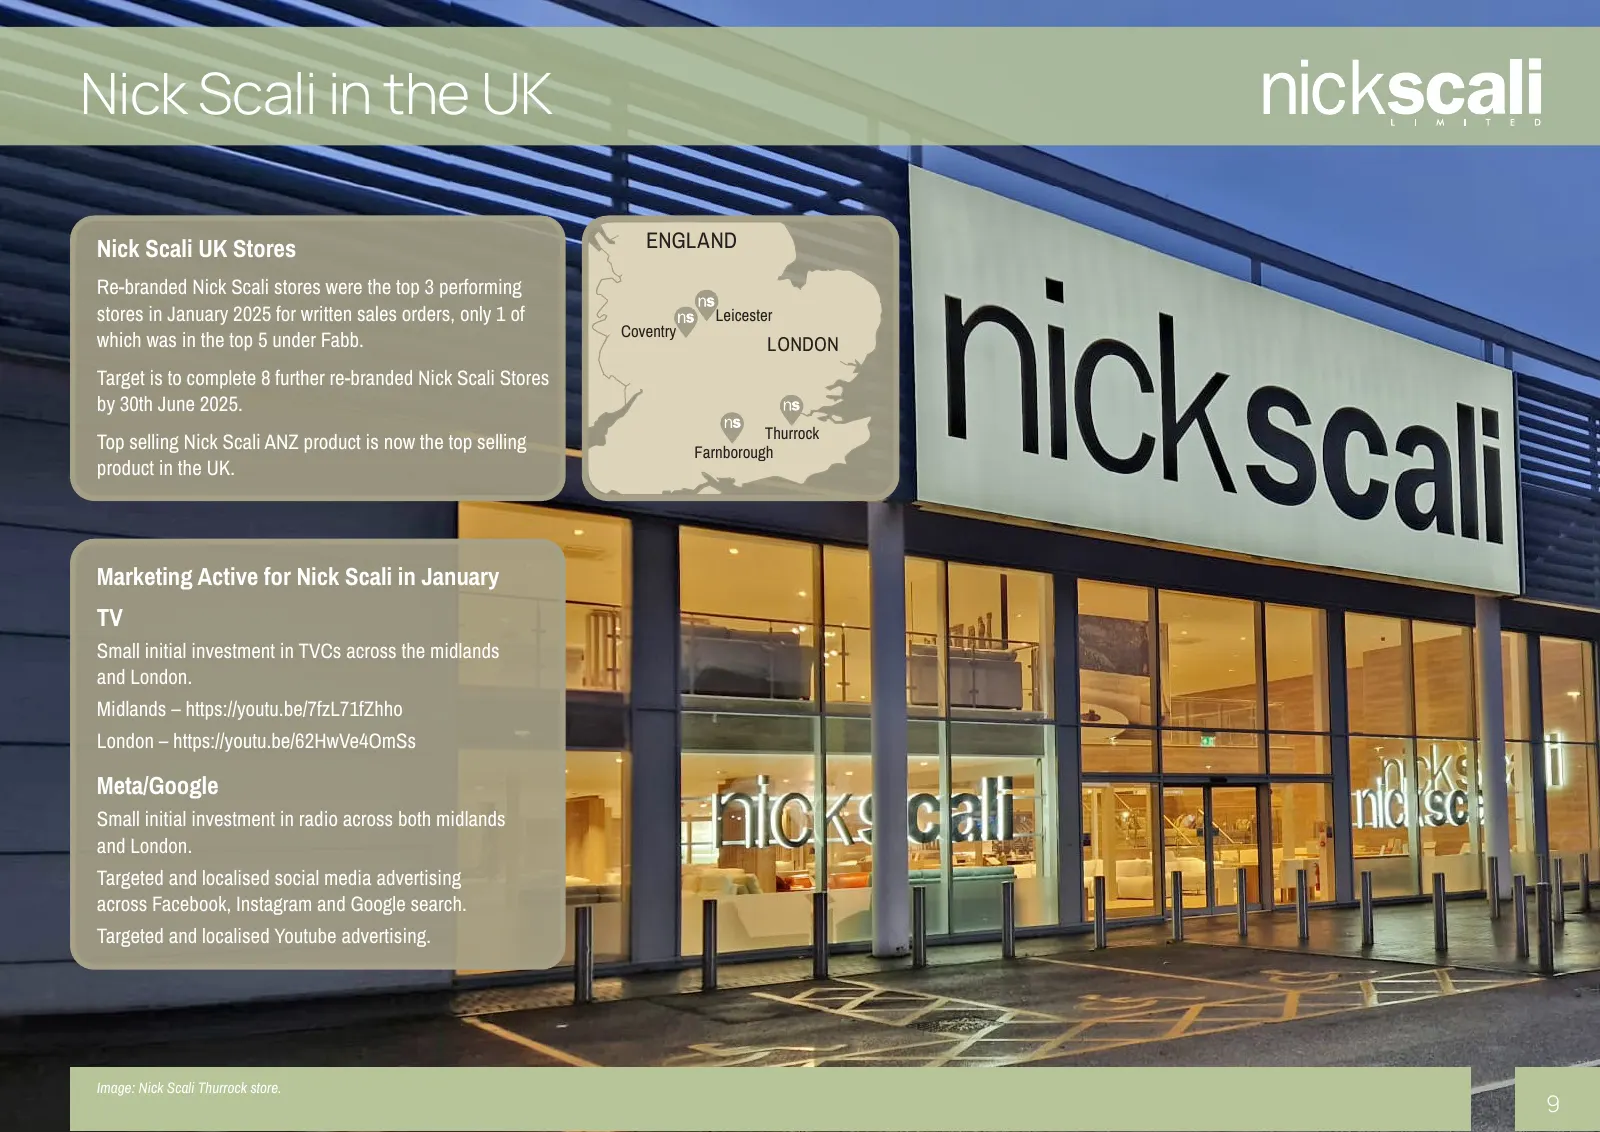
Nick Scali in the UK Nick Scali UK Stores ENGLAND Re-branded Nick Scali stores were the top 3 performing stores in January 2025 for written sales orders, only 1 of Leicester Coventry which was in the top 5 under Fabb. LONDON WALES Target is to complete 8 further re-branded Nick Scali Stores by 30th
Slide 10: Store Network
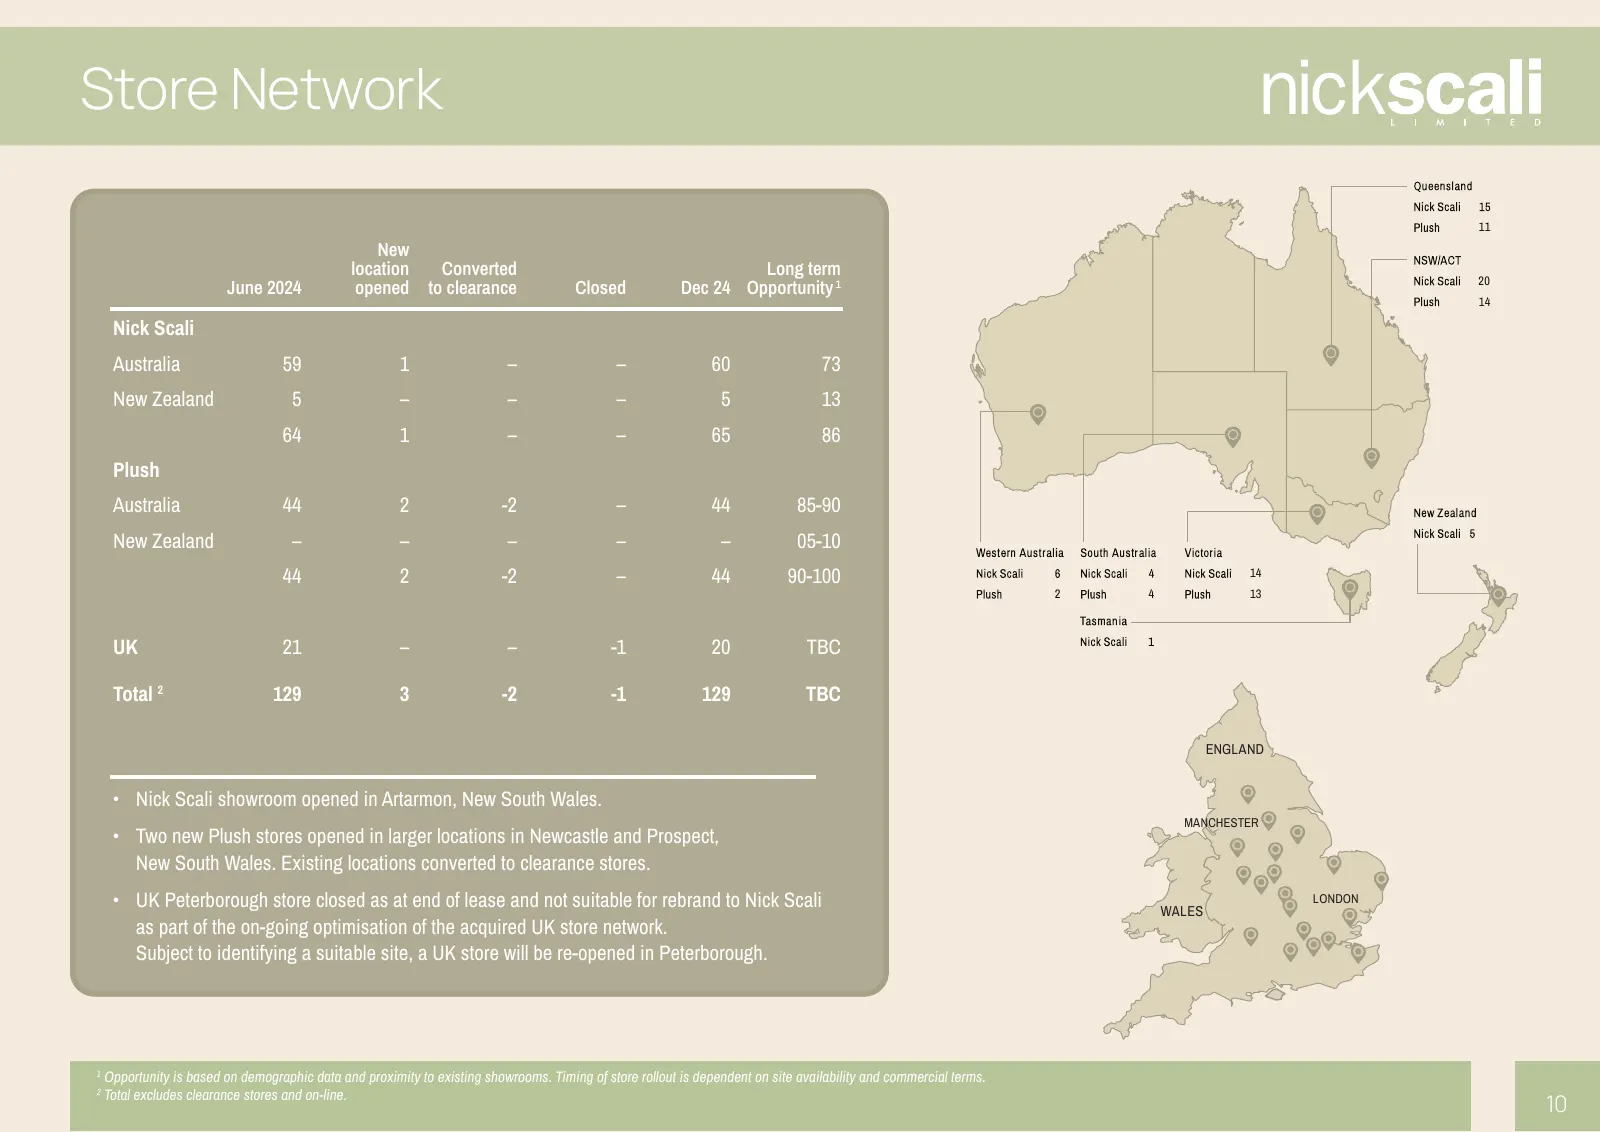
Store Network 11 New location Converted Long term 20 June 2024 opened to clearance Closed Dec 24 Opportunity 1 14 Nick Scali Australia 59 1 – – 60 73 New Zealand 5 – – – 5 13 64 1 – – 65 86 Plush Australia 44 2 -2 – 44 85-90 New Zealand – – – – – 05-10 44 2 -2 – 44 90-100 14 2 4 13 UK 21 – – -1 20 T
Slide 11: Outlook
Outlook Outlook ANZ Trading continues to be volatile with written sales orders down 8.5% in January 2025, whilst the last week of the January Sale in February was positive 5%. This compares to 4.2% positive growth in December 2024. During the second half a further Plush store will open in Melton, Vi
Slide 12: Q&A
Q&A 12
Slide 13: Disclaimer & Important Information
Disclaimer & Important Information Nick Scali Limited (the “Company”) advises that the information in this presentation contains general background information about the Company’s activities as at the date of the presentation. It is information given in summary form and is based on information avail
Slide 14: Supporting Information
Supporting Information 14
Slide 15: Appendix A – Underlying Group Net Profit After Tax Reconciliation $m
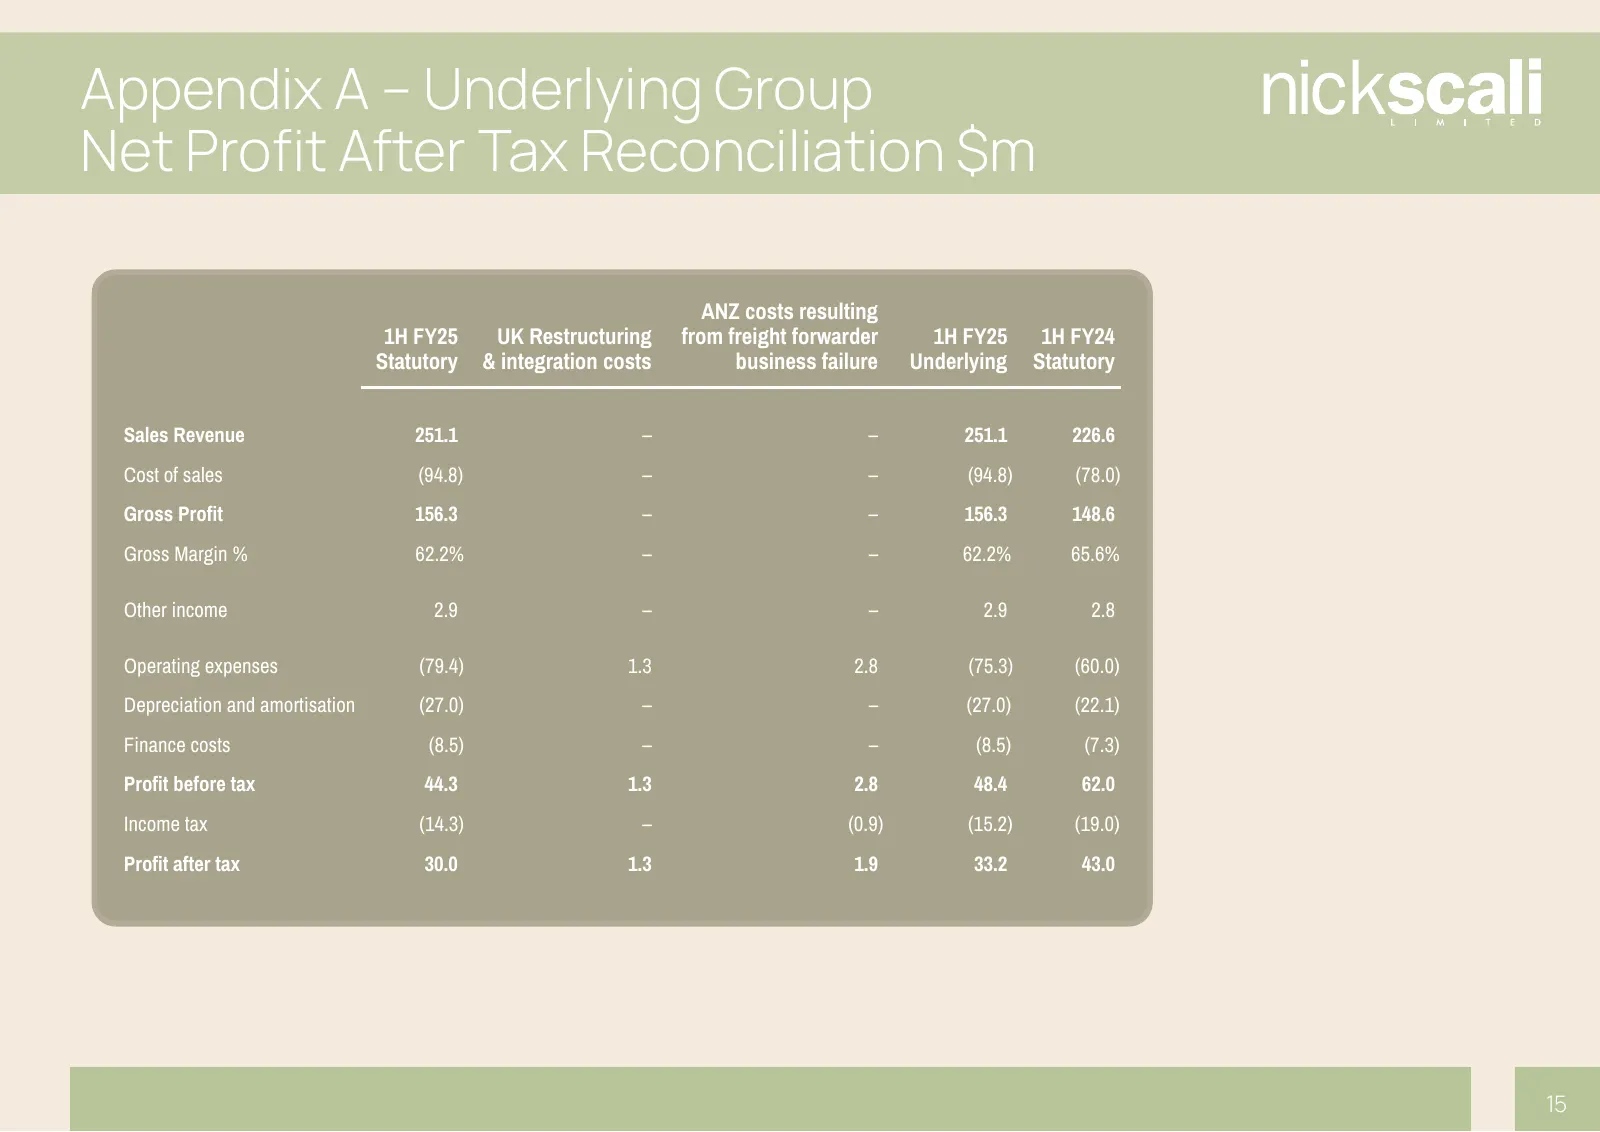
Appendix A – Underlying Group Net Profit After Tax Reconciliation $m ANZ costs resulting 1H FY25 UK Restructuring from freight forwarder 1H FY25 1H FY24 Statutory & integration costs business failure Underlying Statutory Sales Revenue 251.1 – – 251.1 226.6 Cost of sales (94.8) – – (94.8) (78.0) Gros
Slide 16: Appendix B – EBITDA, EBIT and CODB Reconciliations $m
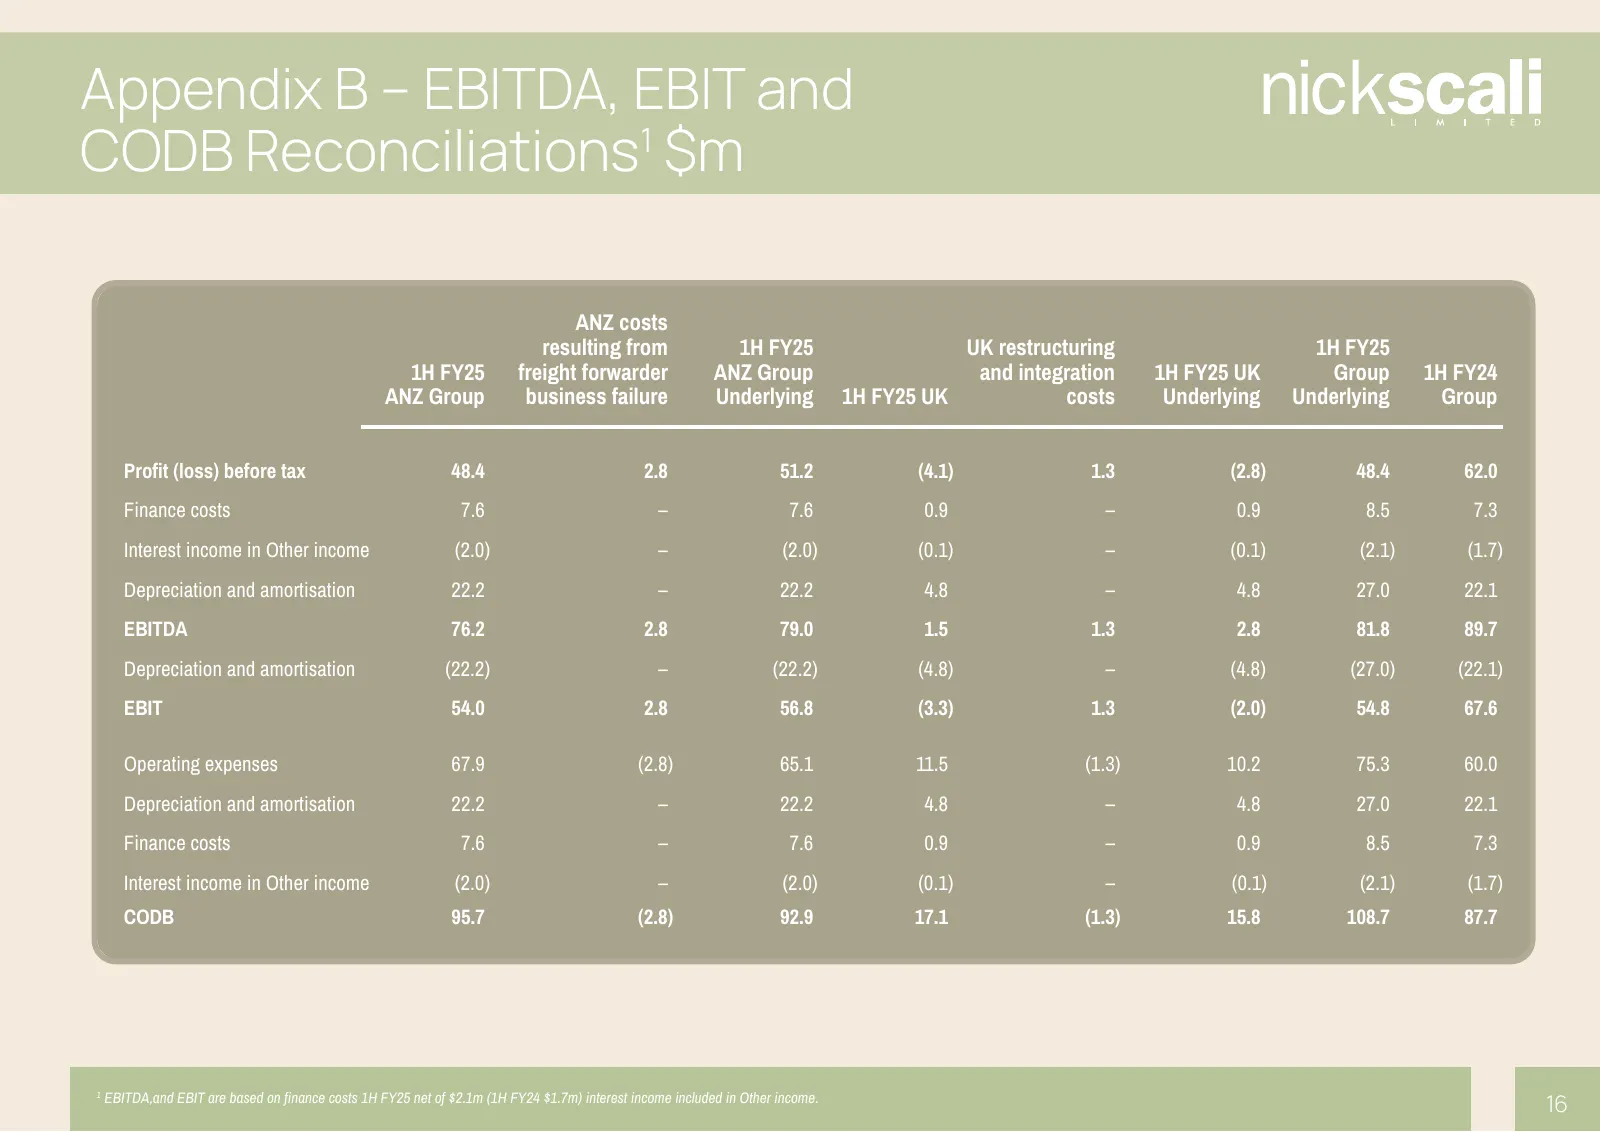
Appendix B – EBITDA, EBIT and CODB Reconciliations1 $m ANZ costs resulting from 1H FY25 UK restructuring 1H FY25 1H FY25 freight forwarder ANZ Group and integration 1H FY25 UK Group 1H FY24 ANZ Group business failure Underlying 1H FY25 UK costs Underlying Underlying Group Profit (loss) before tax 48
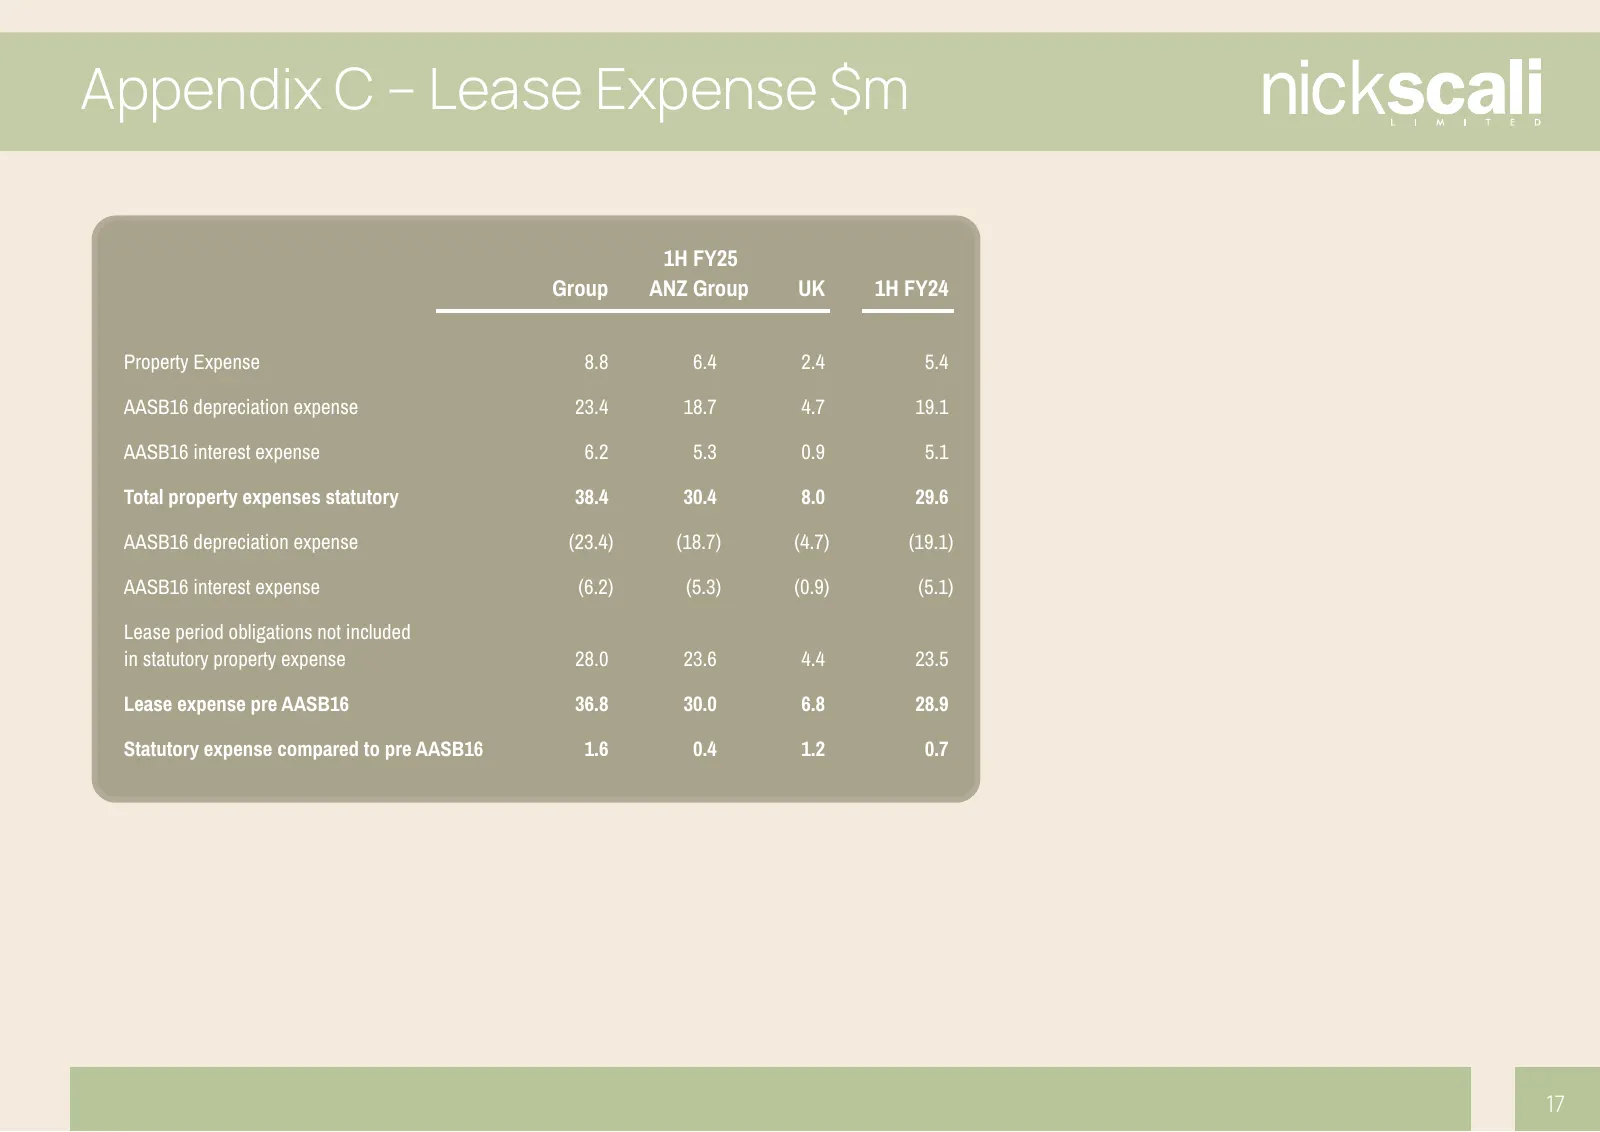
Slide 17: Appendix C – Lease Expense $m
Appendix C – Lease Expense $m 1H FY25 Group ANZ Group UK 1H FY24 Property Expense 8.8 6.4 2.4 5.4 AASB16 depreciation expense 23.4 18.7 4.7 19.1 AASB16 interest expense 6.2 5.3 0.9 5.1 Total property expenses statutory 38.4 30.4 8.0 29.6 AASB16 depreciation expense (23.4) (18.7) (4.7) (19.1) AASB16
Source: ASX announcement via 6ix News
More decks from Nick Scali Limited
 FY2026 Earnings Presentation17 slides · Aug 7, 2026
 Investor Presentation (February 2026)16 slides · Feb 13, 2026
 FY2025 Earnings Presentation18 slides · Aug 8, 2025
 FY2024 Earnings Presentation17 slides · Aug 9, 2024
 Investor Presentation (April 2024)42 slides · Apr 24, 2024
 Investor Presentation (February 2024)13 slides · Feb 6, 2024