Atlantic Coast Financial Corporation
Atlantic Coast Financial — IPO Roadshow (January 2011)
28 slides from Atlantic Coast Financial's IPO roadshow presentation, Jan 11, 2011
Slide 1: Second Step Conversion and Offering
January 2011 Second Step Conversion and Offering 1 Issuer Free Writing Prospectus Dated January 11, 2011 Filed Pursuant to Rule 433 Registration Statement No. 333-167632
Slide 2: Forward-Looking Statements
Forward-Looking Statements 2 This presentation is for informational purposes only and does not constitute an offer to sell nor a solicitation of an offer to buy shares of common stock of Atlantic Coast Financial Corporation. The offer is made only by the prospectus. Please refer to the prospectus da
Slide 3: Forward-Looking Statements
Forward-Looking Statements - -Looking Statements 3 This presentation may contain certain forward-looking statements regarding our prospective performance and strategies within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934
Slide 4: Investment Thesis
Investment Thesis Proven management team $800+ million, well capitalized franchise Business strategy designed for growth and profitability Strategy to maximize return on capital Creates solid value for shareholders Opportunity to participate in recapitalization Opportunity to participate in Florida
Slide 5: Proven Management Team
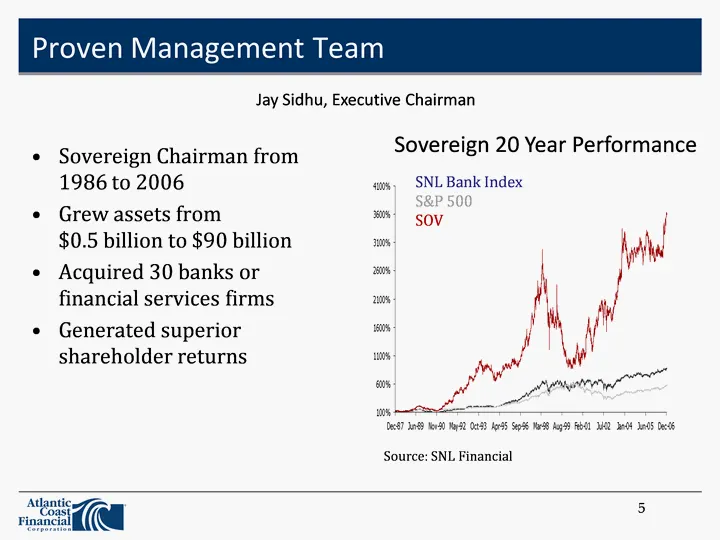
Proven Management Team Sovereign Chairman from 1986 to 2006 Grew assets from $0.5 billion to $90 billion Acquired 30 banks or financial services firms Generated superior shareholder returns Sovereign 20 Year Performance SNL Bank Index S&P 500 SOV 5 Jay Sidhu, Executive Chairman Source: SNL Financial
Slide 6: Proven Management Team
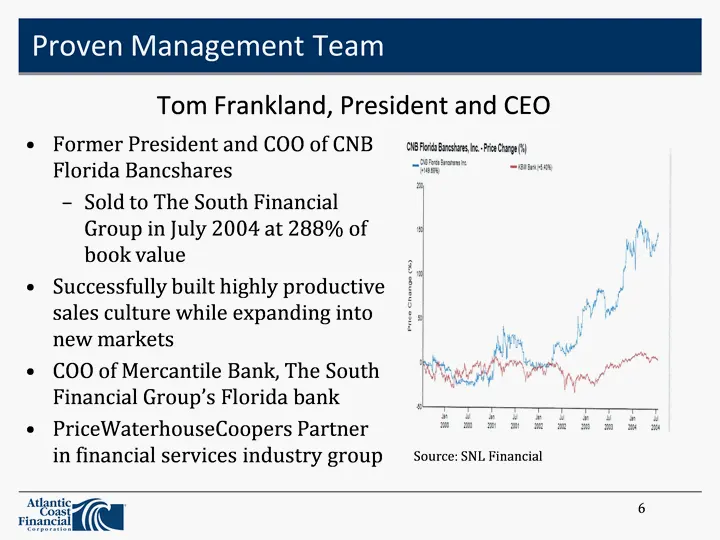
Proven Management Team Tom Frankland, President and CEO Former President and COO of CNB Florida Bancshares Sold to The South Financial Group in July 2004 at 288% of book value Successfully built highly productive sales culture while expanding into new markets COO of Mercantile Bank, The South Financ
Slide 7: Proven Management Team
Proven Management Team Bob Larison, COO Atlantic Coast Bank Tom Wagers, Sr., CFO Barnett Bank Jonathan Lewis Allied Home Mortgage Exec. VP Mortgage Capital Corporation Maureen Britz Home Bank / Banco Senior VP SBA Lending Popular Phillip Buddenbohm SunTrust Chief Risk Officer 7
Slide 8: Scalable Banking Franchise
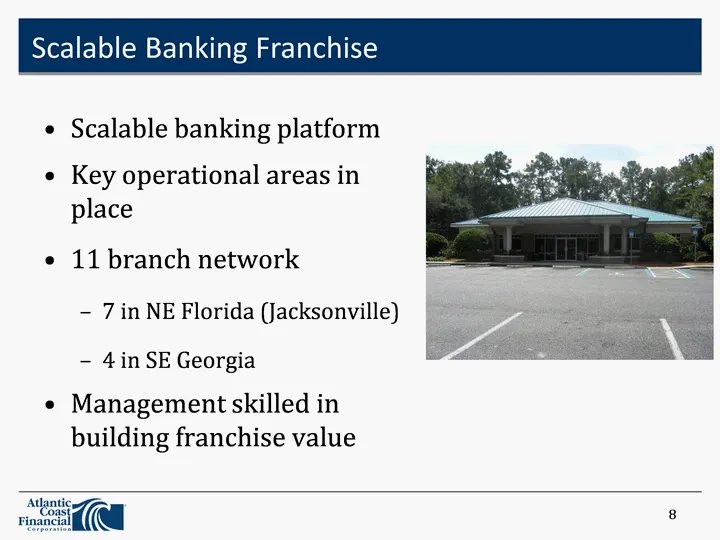
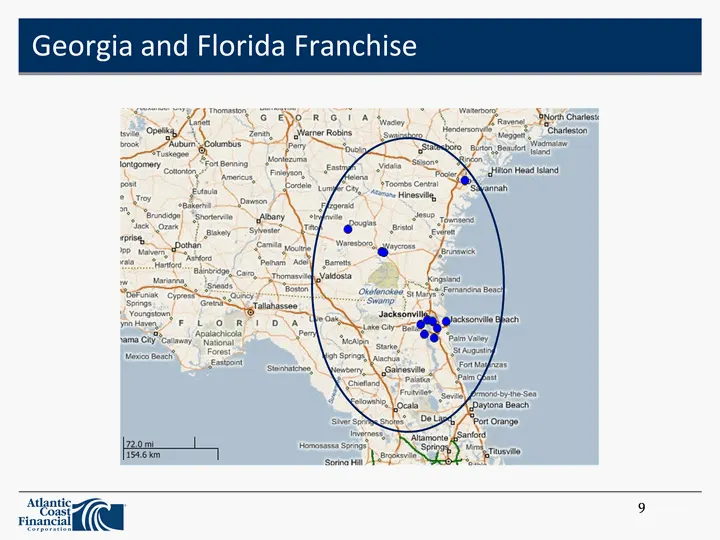
Scalable Banking Franchise 8 Scalable banking platform Key operational areas in place 11 branch network 7 in NE Florida (Jacksonville) 4 in SE Georgia Management skilled in building franchise value building franchise value building franchise value building franchise value building franchise value bu
Slide 9: Georgia and Florida Franchise
Georgia and Florida Franchise 9
Slide 10: Greater Jacksonville Florida Market
Greater Jacksonville Florida Market 14th largest city in US 1.1 million residents Strong demographic trends Grew 10% in past decade Diverse economy Aerospace - Technology Finance - Manufacturing Life Sciences - Supply Logistics Port - US Naval Operations 10
Slide 11: Southeastern Georgia Stable Market
Southeastern Georgia Stable Market Atlantic Coast Bank founded in 1939 Primarily agricultural area Low cost deposits Loyal customers # 1 deposit market share in Ware County with 28% of deposits * * Source: FDIC 11
Slide 12: Loan Portfolio
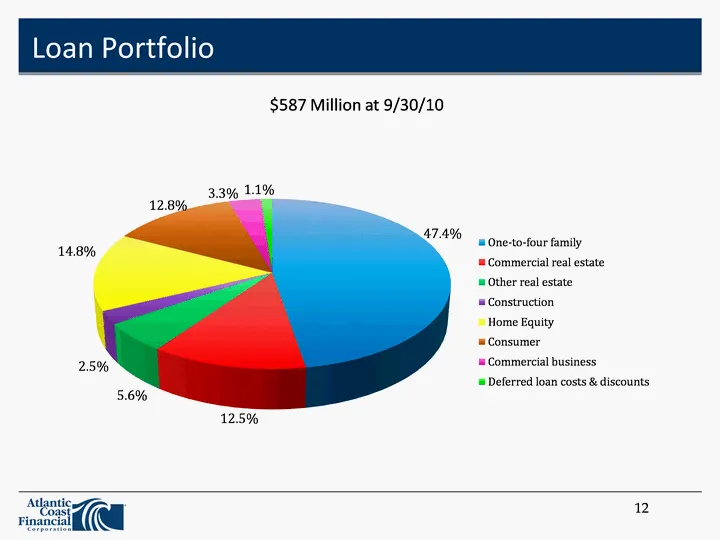
Loan Portfolio 12 $587 Million at 9/30/10 (CHART)
Slide 13: Stabilizing Financial Operation
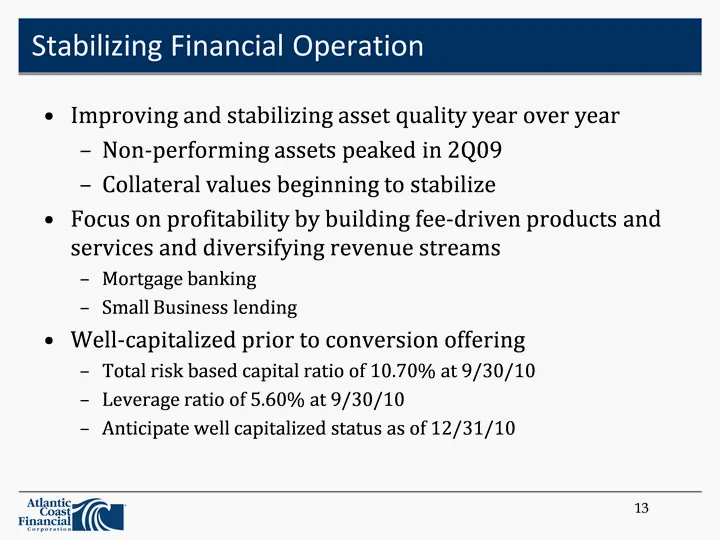
Stabilizing Financial Operation Improving and stabilizing asset quality year over year Non-performing assets peaked in 2Q09 Collateral values beginning to stabilize Focus on profitability by building fee-driven products and services and diversifying revenue streams Mortgage banking Small Business le
Slide 14: Preserving Capital and Improving Asset Quality
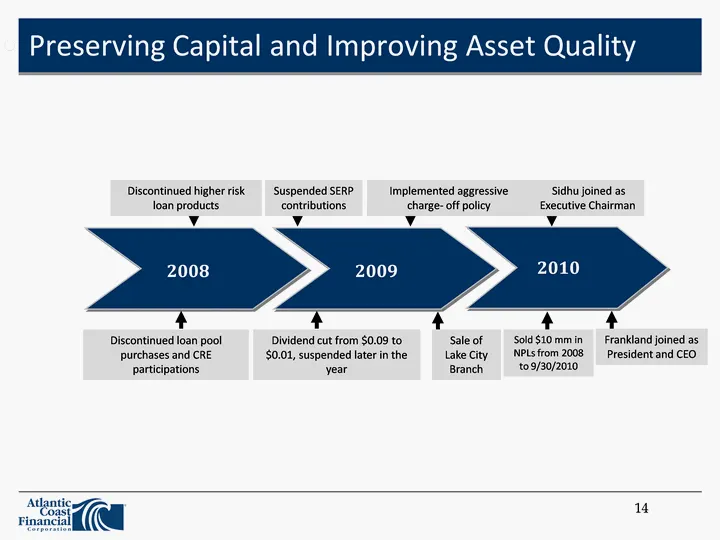
2009 2008 2010 Sale of Lake City Branch Sidhu joined as Executive Chairman Dividend cut from $0.09 to $0.01, suspended later in the year Suspended SERP contributions Implemented aggressive charge- off policy Discontinued higher risk loan products Discontinued loan pool purchases and CRE participatio
Slide 15: Non Performing Asset Composition
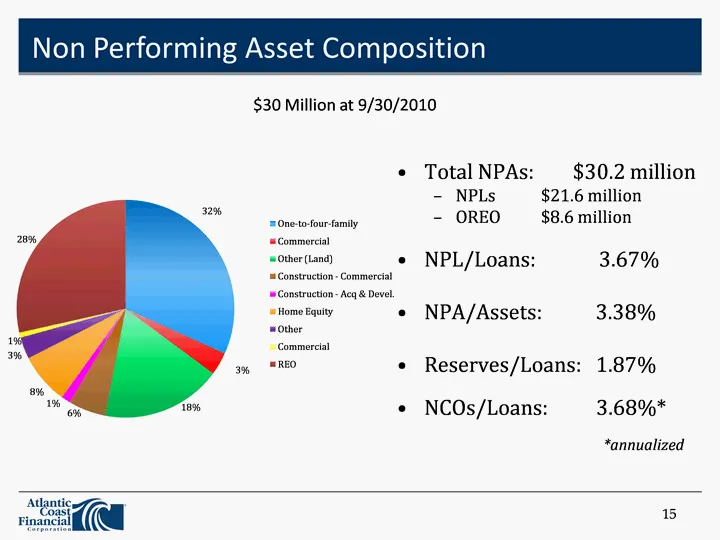
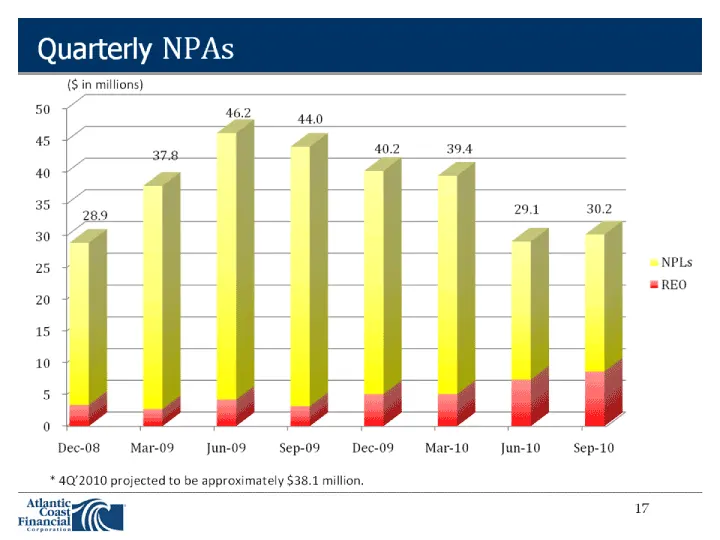
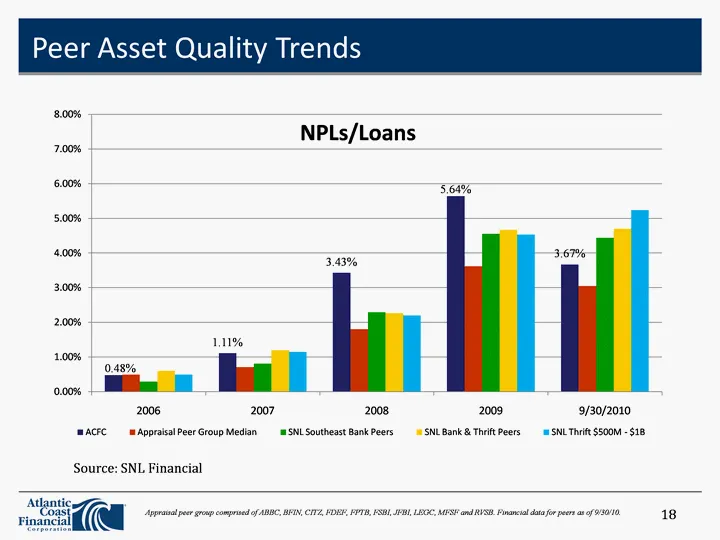
Non Performing Asset Composition 15 Total NPAs: $30.2 million NPLs $21.6 million OREO $8.6 million NPL/Loans: 3.67% NPA/Assets: 3.38% Reserves/Loans: 1.87% NCOs/Loans: 3.68%* *annualized $30 Million at 9/30/2010 (CHART)
Slide 16: Net Charge-Offs
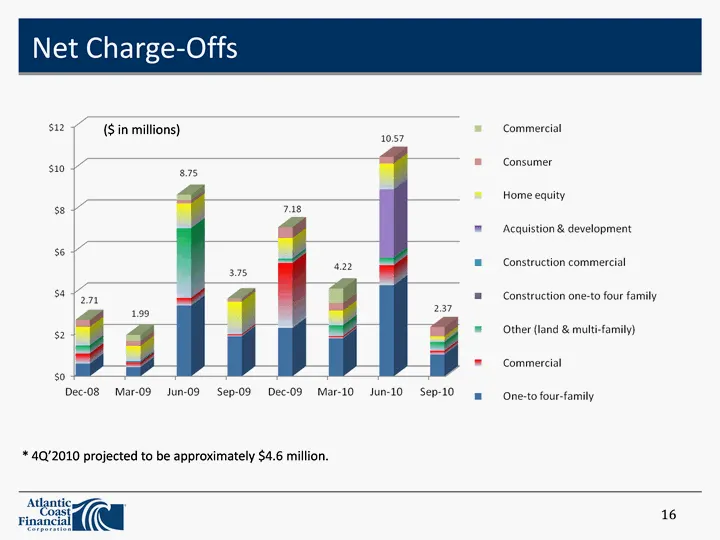
Net Charge-Offs 16 * 4Q'2010 projected to be approximately $4.6 million. ($ in millions)
Slide 17: Quarterly NPAs
17 Quarterly NPAs (CHART) ($ in millions) * 4Q'2010 projected to be approximately $38.1 million.
Slide 18: Peer Asset Quality Trends
Peer Asset Quality Trends 18 Appraisal peer group comprised of ABBC, BFIN, CITZ, FDEF, FPTB, FSBI, JFBI, LEGC, MFSF and RVSB. Financial data for peers as of 9/30/10. (CHART) Source: SNL Financial
Slide 19: Recent Developments
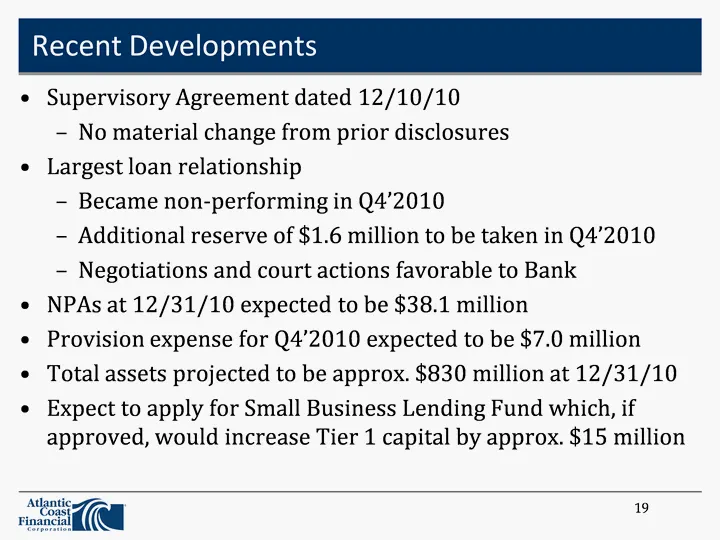
Recent Developments Supervisory Agreement dated 12/10/10 No material change from prior disclosures Largest loan relationship Became non-performing in Q4'2010 Additional reserve of $1.6 million to be taken in Q4'2010 Negotiations and court actions favorable to Bank NPAs at 12/31/10 expected to be $38
Slide 20: Core Profitability Overview
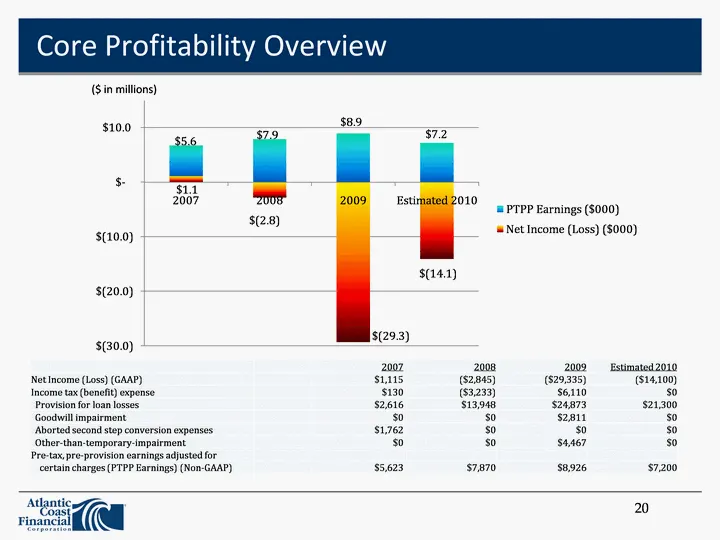
20 Core Profitability Overview ($ in millions) (CHART) 2007 2008 2009 Estimated 2010 Net Income (Loss) (GAAP) $1,115 ($2,845) ($29,335) ($14,100) Income tax (benefit) expense $130 ($3,233) $6,110 $0 Provision for loan losses $2,616 $13,948 $24,873 $21,300 Goodwill impairment $0 $0 $2,811 $0 Aborted
Slide 21: Strategic Growth Plan
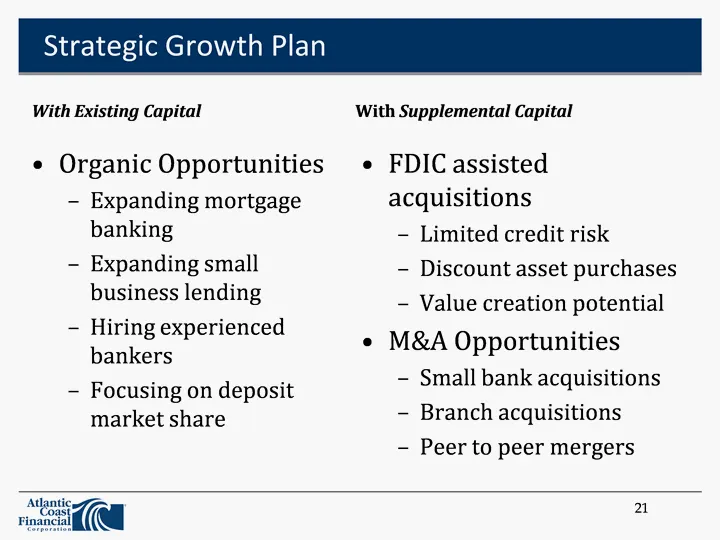
Strategic Growth Plan Organic Opportunities Expanding mortgage banking Expanding small business lending Hiring experienced bankers Focusing on deposit market share FDIC assisted acquisitions Limited credit risk Discount asset purchases Value creation potential M&A Opportunities Small bank acquisitio
Slide 22: Maximize Return on Capital
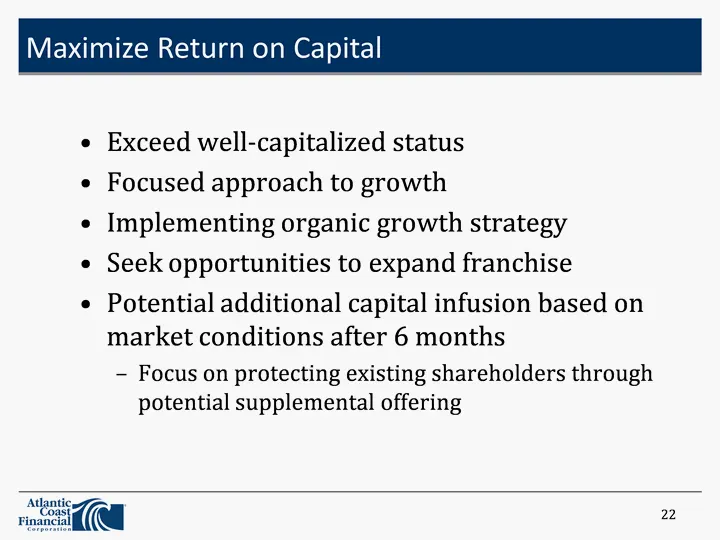
22 Maximize Return on Capital Exceed well-capitalized status Focused approach to growth Implementing organic growth strategy Seek opportunities to expand franchise Potential additional capital infusion based on market conditions after 6 months Focus on protecting existing shareholders through potent
Slide 23: Conversion Rationale
Conversion Rationale Further strengthen capital Flexibility of fully public structure Organic growth and acquisitions Shareholder liquidity Access to capital markets 23
Slide 24: Transaction Structure
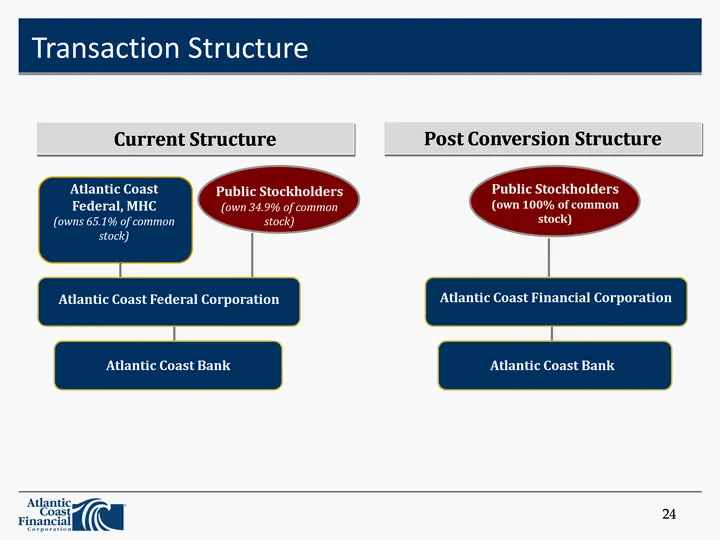
Transaction Structure 24 Atlantic Coast Federal, MHC (owns 65.1% of common stock) Public Stockholders (own 34.9% of common stock) Atlantic Coast Bank Current Structure Atlantic Coast Financial Corporation Atlantic Coast Bank Public Stockholders (own 100% of common stock) Post Conversion Structure At
Slide 25: Management Aligned with Shareholder Interests
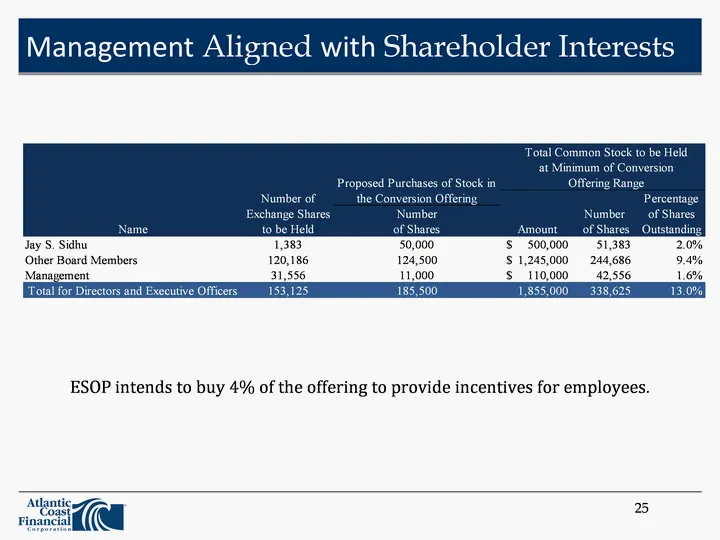
Management Aligned with Shareholder Interests ESOP intends to buy 4% of the offering to provide incentives for employees. 25
Slide 26: Solid Investment Value
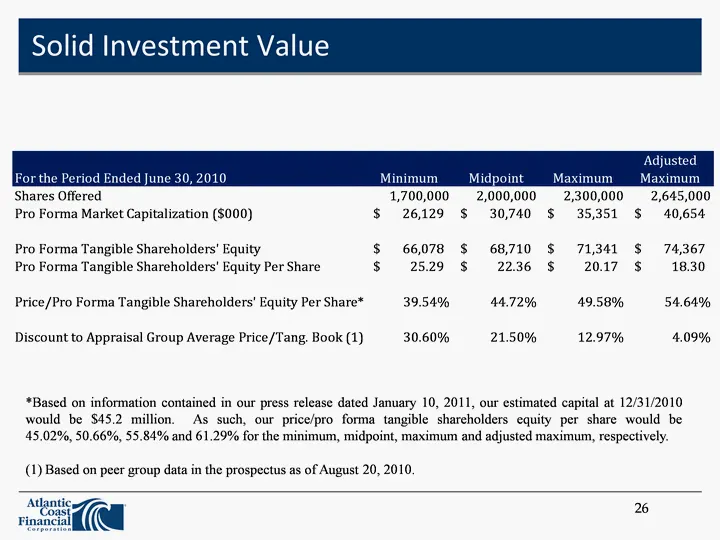
Solid Investment Value 26 *Based on information contained in our press release dated January 10, 2011, our estimated capital at 12/31/2010 would be $45.2 million. As such, our price/pro forma tangible shareholders equity per share would be 45.02%, 50.66%, 55.84% and 61.29% for the minimum, midpoint,
Slide 27: Offering Summary
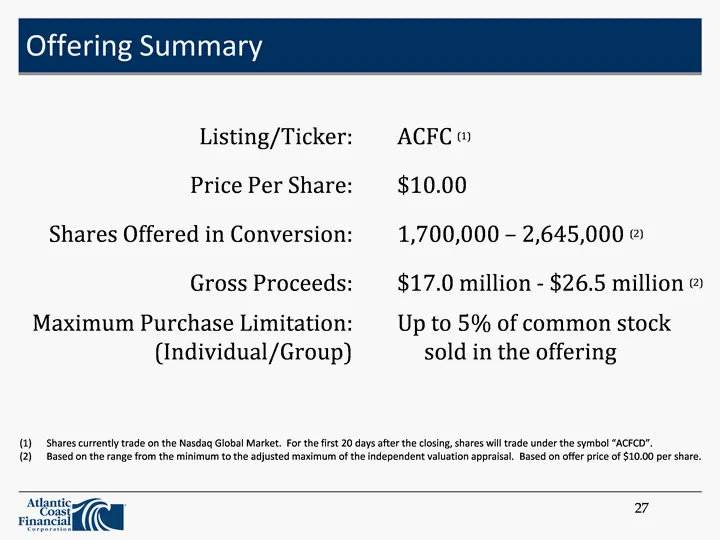
Offering Summary Listing/Ticker: Price Per Share: Shares Offered in Conversion: Gross Proceeds: Maximum Purchase Limitation: (Individual/Group) ACFC (1) $10.00 1,700,000 - 2,645,000 (2) $17.0 million - $26.5 million (2) Up to 5% of common stock sold in the offering Shares currently trade on the Nasd
Slide 28: Questions?
Questions? 28 Stock Information Centers Overnight Delivery: 18 Columbia Turnpike Florham Park NJ, 07932 Hand Delivery: 505 Haines Avenue Waycross, GA 31501 10328 Deerwood Park Boulevard Jacksonville, FL 32256 877-643-8197 10:00 a.m. to 4:00 p.m. (ET) Monday - Friday
Source: SEC EDGAR · FWP filed Jan 11, 2011