Coface SA · EURONEXT:COFA
Coface SA — Global Macro BI Webinar CEER (April 2022)
35 slides from Coface SA's conference presentation, Apr 7, 2022
Slide 1: Global Economic Outlook: Stagflation Ahead
GLOBAL ECONOMIC OUTLOOK S TA G F L AT I O N A H E A D H O W C A N D ATA H E L P Y O U R B U S I N E S S D U R I N G AN ECONOMIC CRISIS? APRIL 7, 2022
Slide 2: Agenda and Your Referents
AGENDA AND YOUR REFERENTS 01 02 GLOBAL ECONOMIC OUTLOOK H O W C A N D ATA H E L P Y O U R STAGFLATION AHEAD BUSINESS DURING AN ECONOMIC CRISIS? JEAN CHRISTOPHE CAFFET D O R O TA A N G O T T I Coface Chief Global Economist Regional Business Information Director Credit Management Services
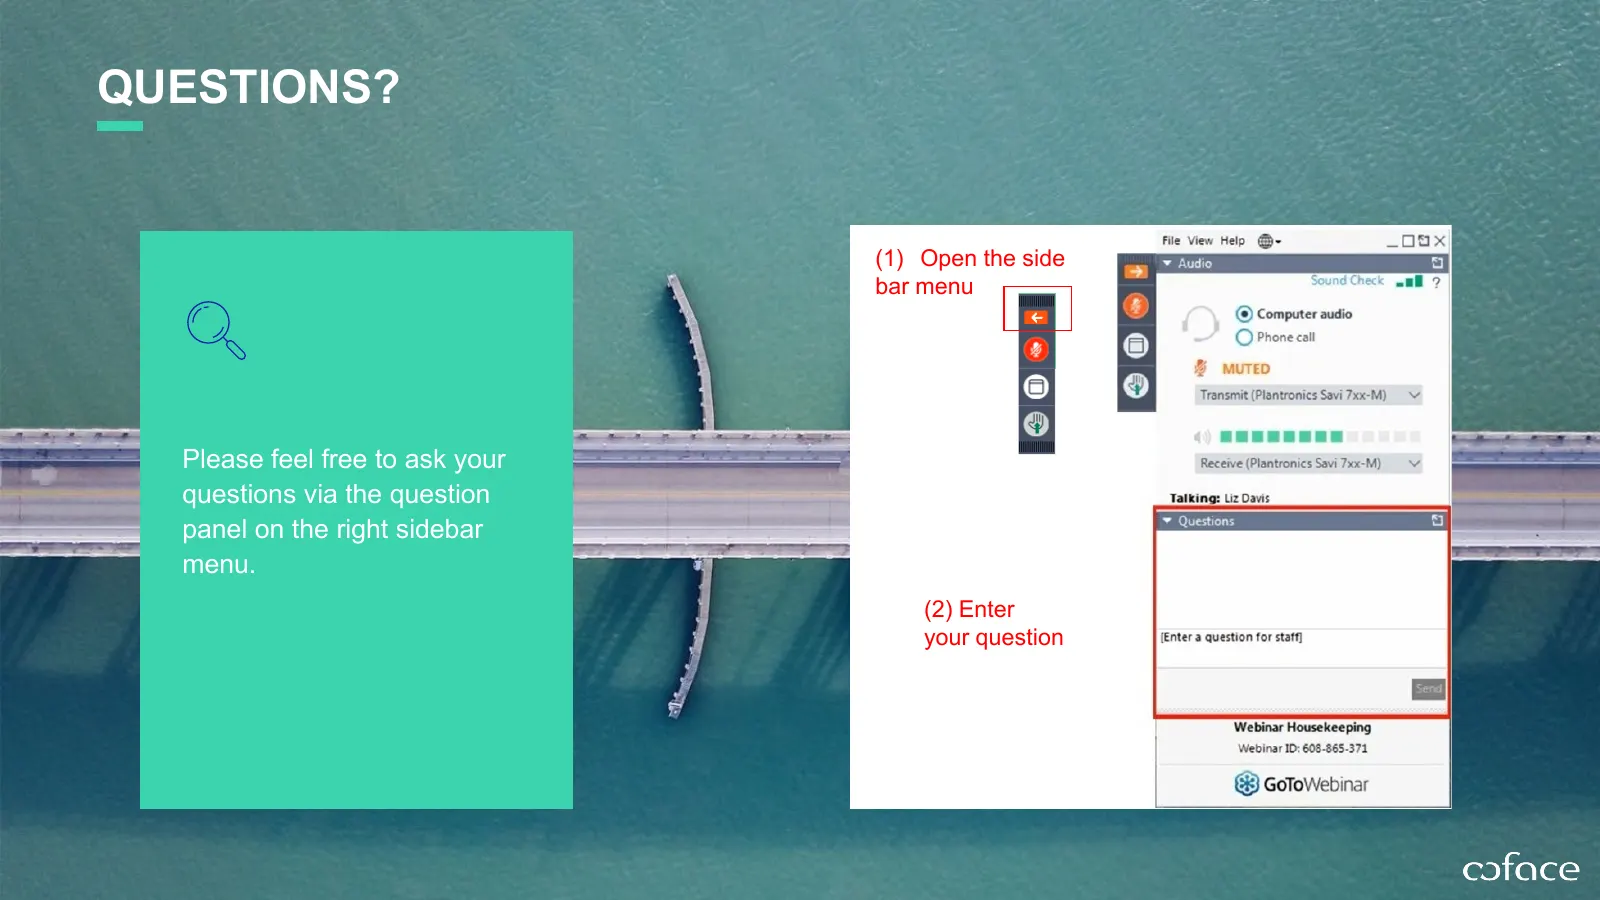
Slide 3: Questions?
QUESTIONS? (1) Open the side bar menu Please feel free to ask your questions via the question panel on the right sidebar menu. (2) Enter your question
Slide 4: Key Takeaways
KEY TAKEAWAYS THE SITUATION HAS STRONGLY AND QUICKLY DETERIORATED › The post-pandemic recovery was on track, albeit losing momentum, with advanced economies leading the way › The Russian # Ukraine conflict reshuffles the deck › Ways to end the crisis still unknown H A R S H S A N C T I O N S L I K E
Slide 5: The Recovery Is (Was?) On Track, Albeit Losing Momentum
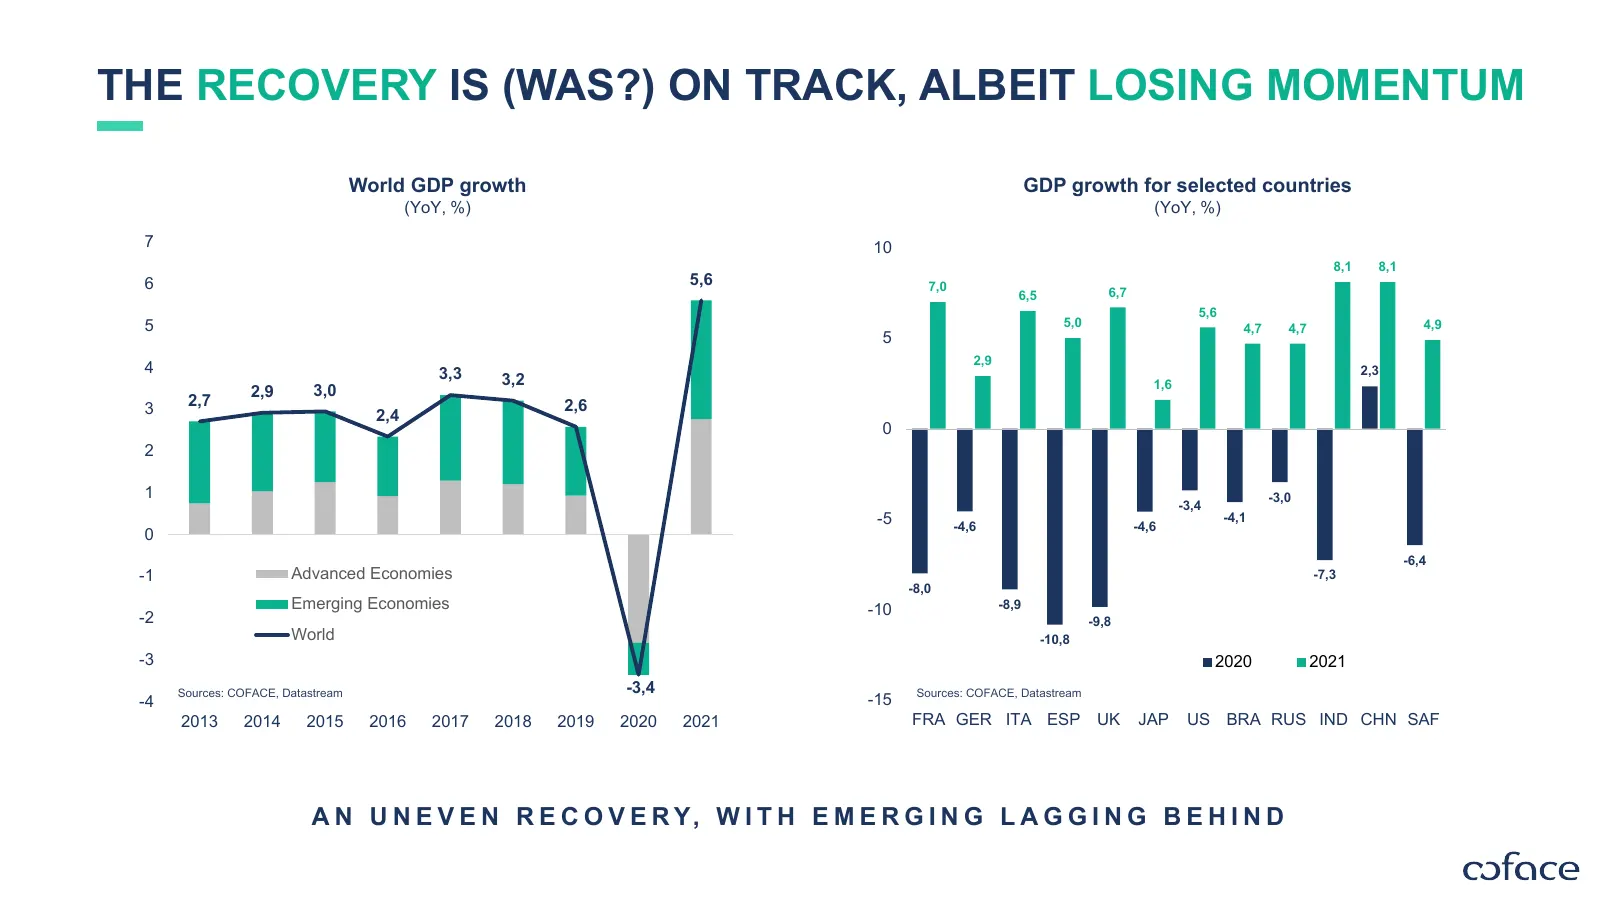
THE RECOVERY IS (WAS?) ON TRACK, ALBEIT LOSING MOMENTUM World GDP growth GDP growth for selected countries (YoY, %) (YoY, %) 7 10 8,1 8,1 6 5,6 7,0 6,5 6,7 5,6 5 5,0 4,7 4,7 4,9 5 2,9 4 3,3 2,3 3,2 1,6 2,9 3,0 2,7 2,6 3 2,4 0 2 1 -3,0 -3,4 -5 -4,6 -4,6 -4,1 0 -6,4 -1 Advanced Economies -7,3 -8,0 Eme
Slide 6: One-Half of World Population Fully Vaccinated
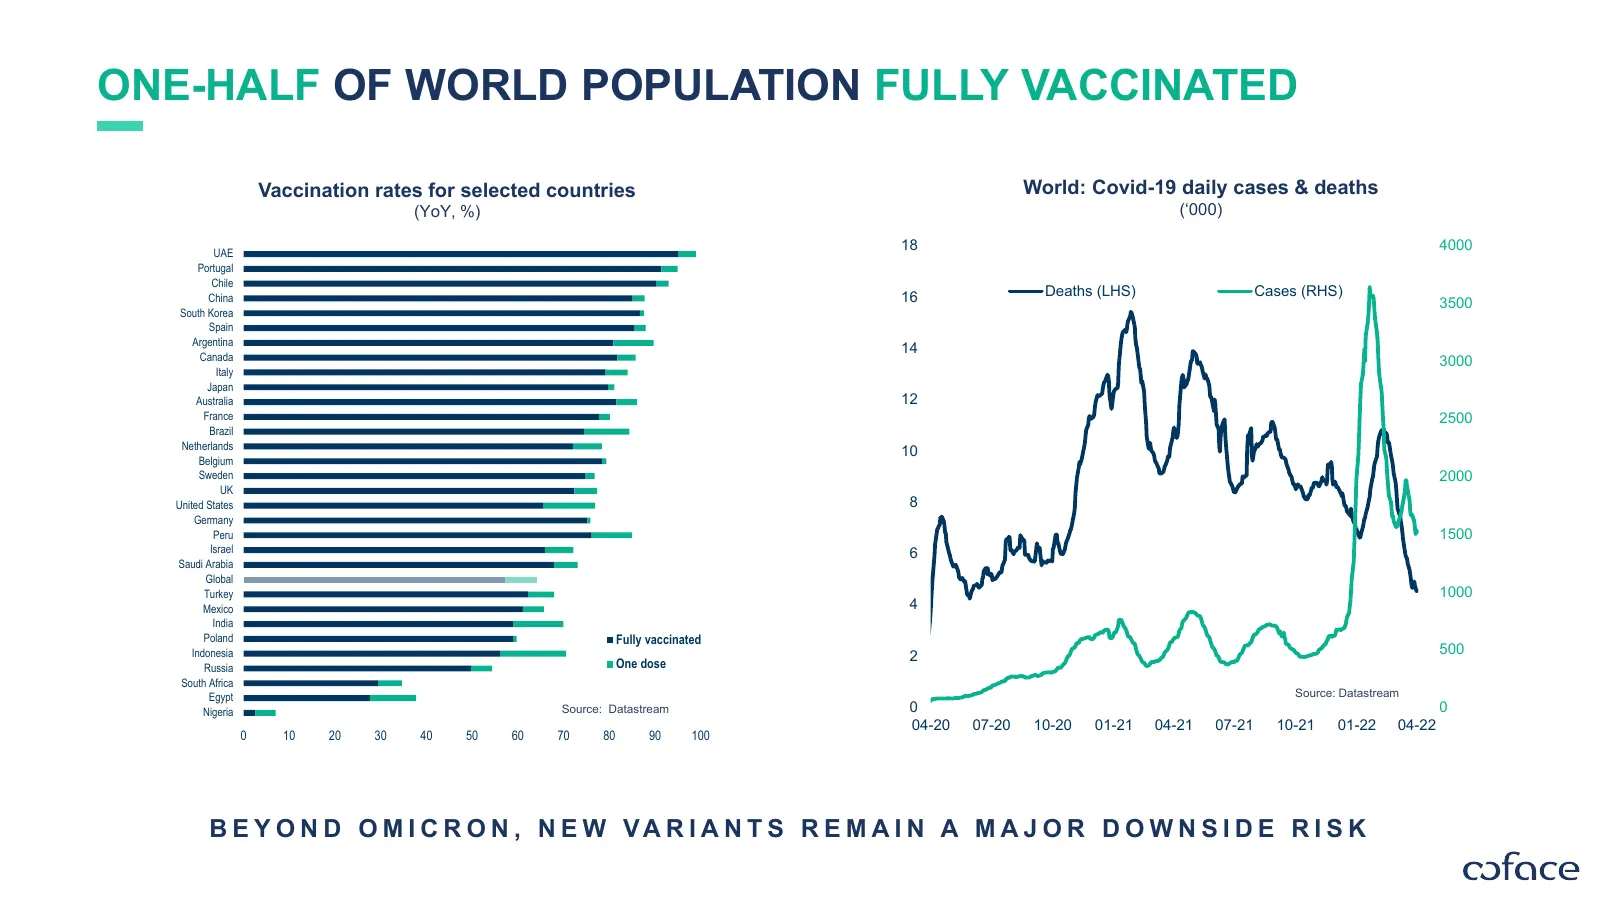
ONE-HALF OF WORLD POPULATION FULLY VACCINATED Vaccination rates for selected countries World: Covid-19 daily cases & deaths (YoY, %) (‘000) UAE 18 4000 Portugal Chile China 16 Deaths (LHS) Cases (RHS) 3500 South Korea Spain Argentina 14 Canada 3000 Italy Japan Australia 12 France 2500 Brazil Netherl
Slide 7: Unprecedented Sanctions Against Russia
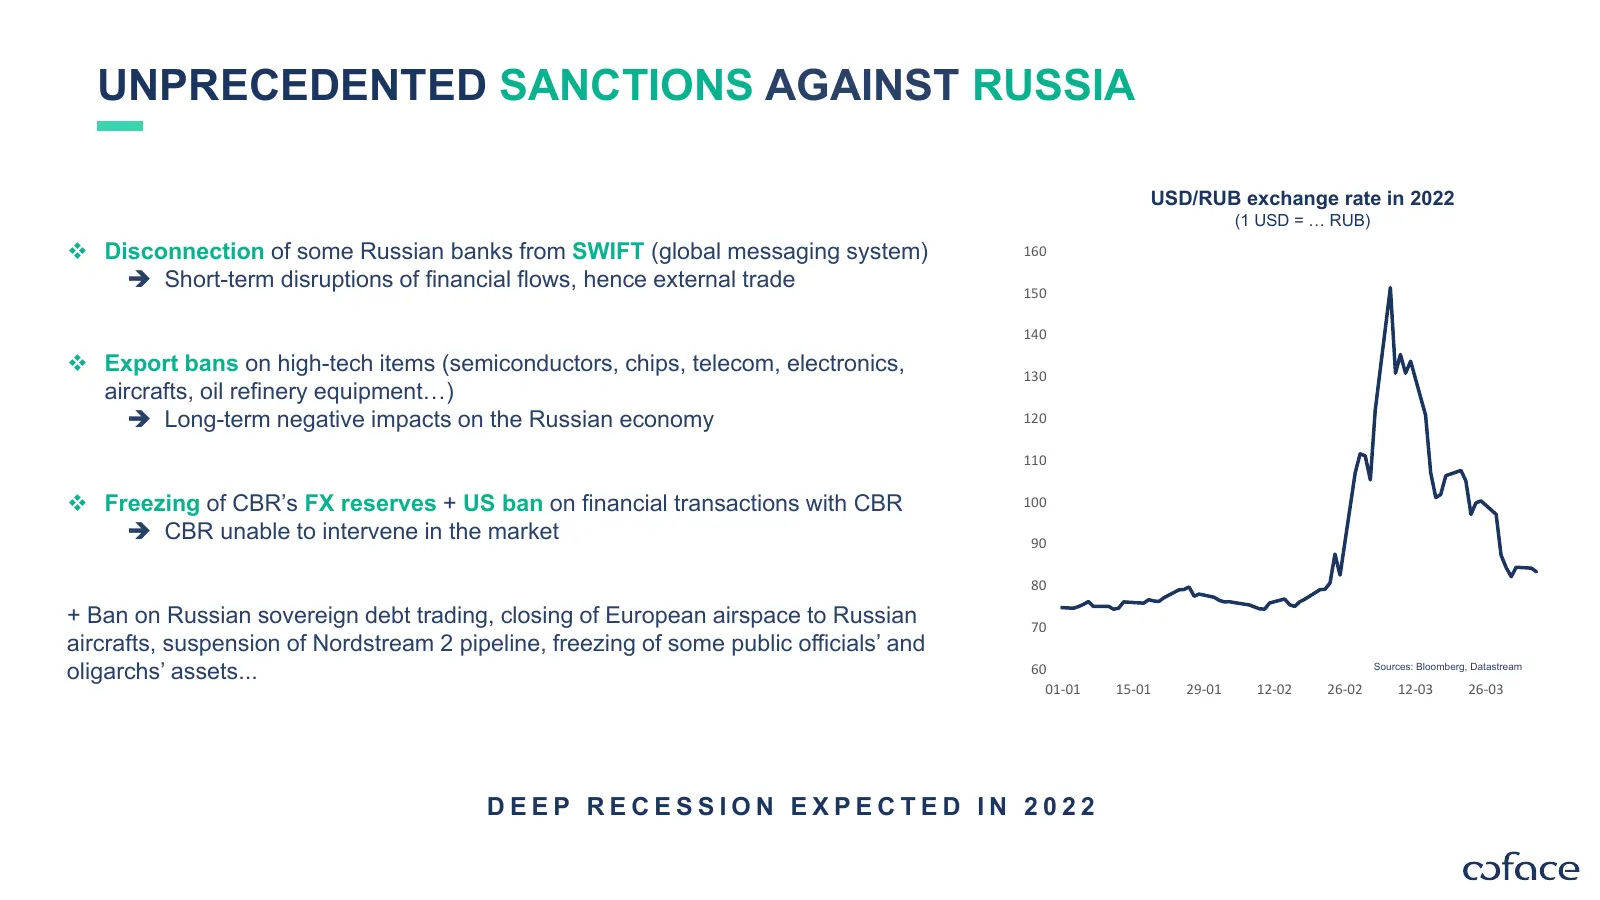
UNPRECEDENTED SANCTIONS AGAINST RUSSIA USD/RUB exchange rate in 2022 (1 USD = … RUB) Disconnection of some Russian banks from SWIFT (global messaging system) 160 Short-term disruptions of financial flows, hence external trade 150 140 Export bans on high-tech items (semiconductors, chips, telec
Slide 8: A Strong Hit to Commodities Flows
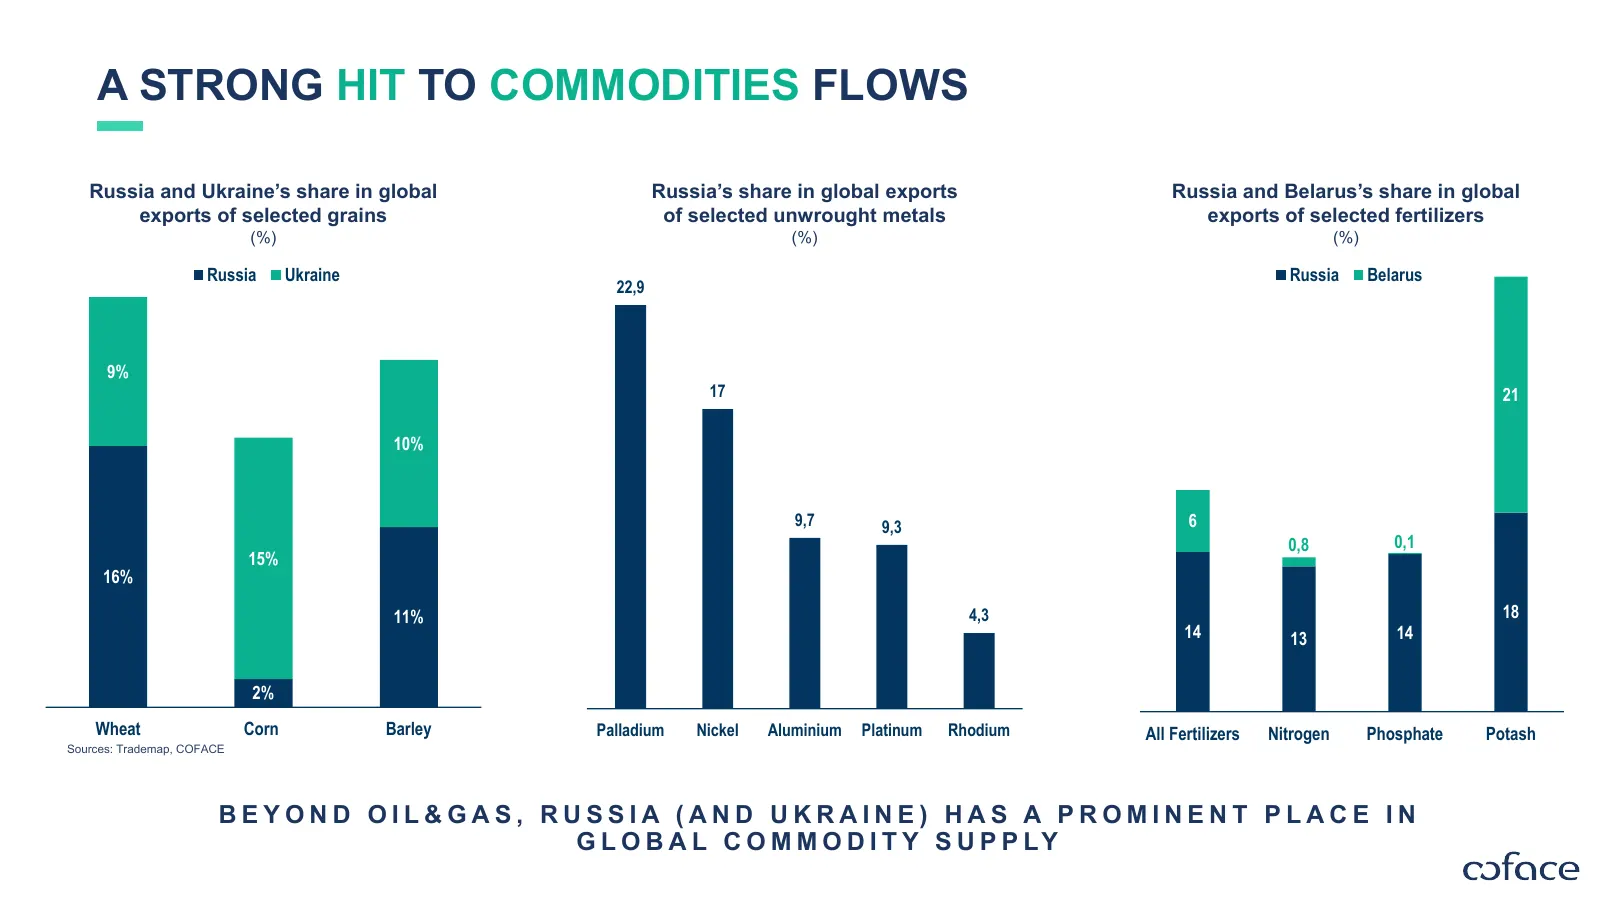
A STRONG HIT TO COMMODITIES FLOWS Russia and Ukraine’s share in global Russia’s share in global exports Russia and Belarus’s share in global exports of selected grains of selected unwrought metals exports of selected fertilizers (%) (%) (%) Russia Ukraine Russia Belarus 22,9 9% 17 21 10% 9,7 9,3 6 0
Slide 9: Inflationary Pressures to Intensify in the Short Term
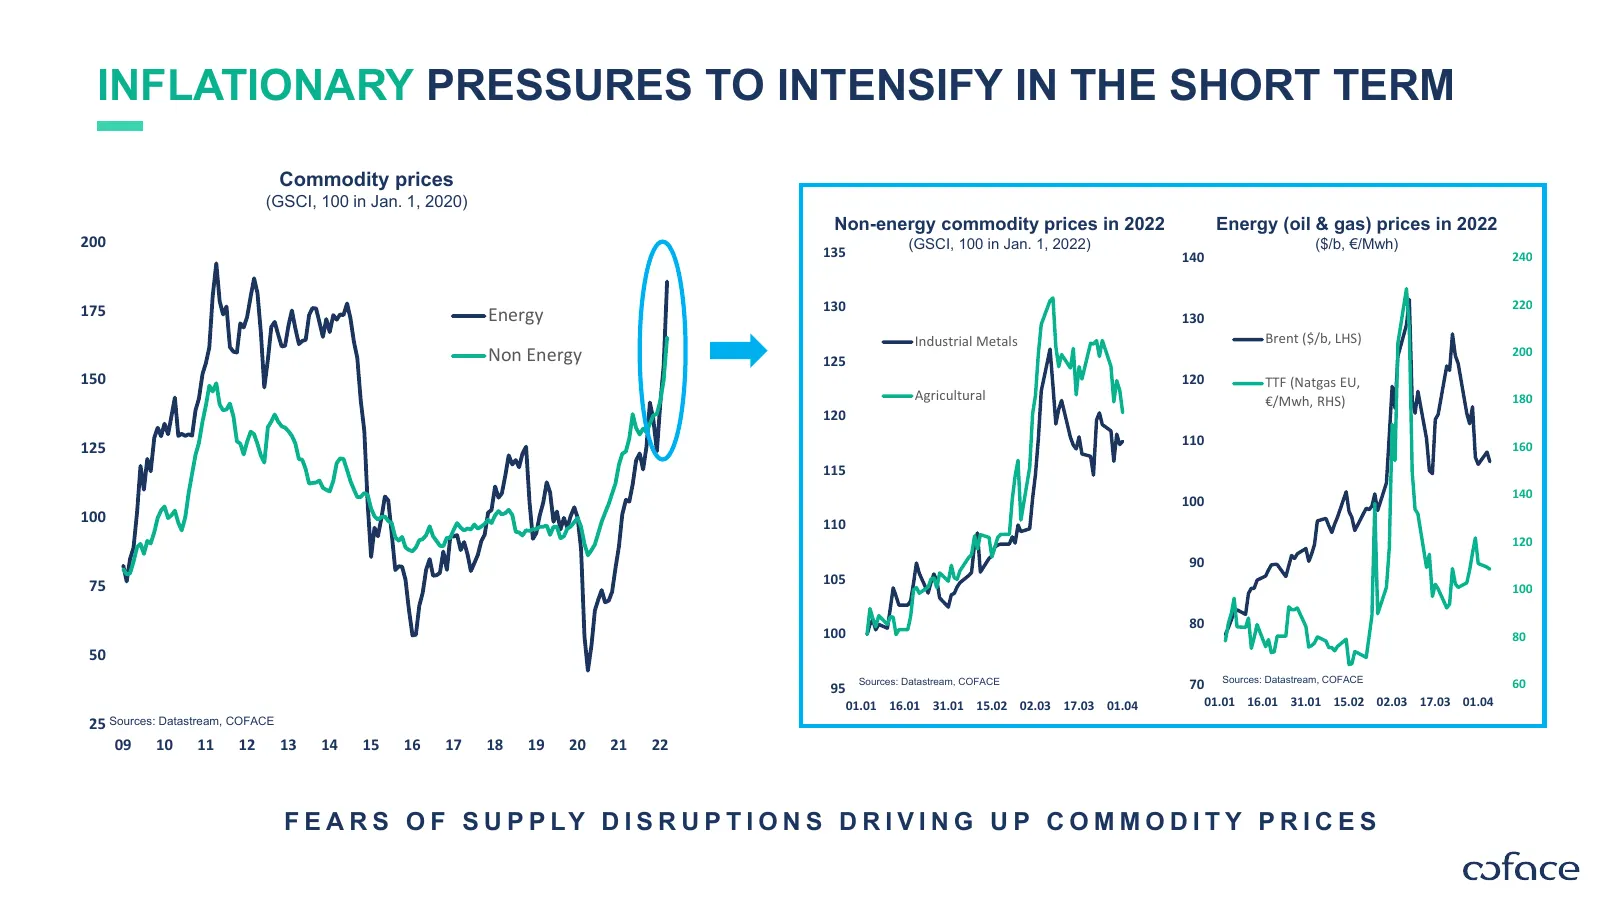
INFLATIONARY PRESSURES TO INTENSIFY IN THE SHORT TERM Commodity prices (GSCI, 100 in Jan. 1, 2020) Non-energy commodity prices in 2022 Energy (oil & gas) prices in 2022 200 (GSCI, 100 in Jan. 1, 2022) ($/b, €/Mwh) 135 140 240 130 220 175 Energy 130 Industrial Metals Brent ($/b, LHS) Non Energy 125 2
Slide 10: Inflation Already at Decades' High in Advanced Economies
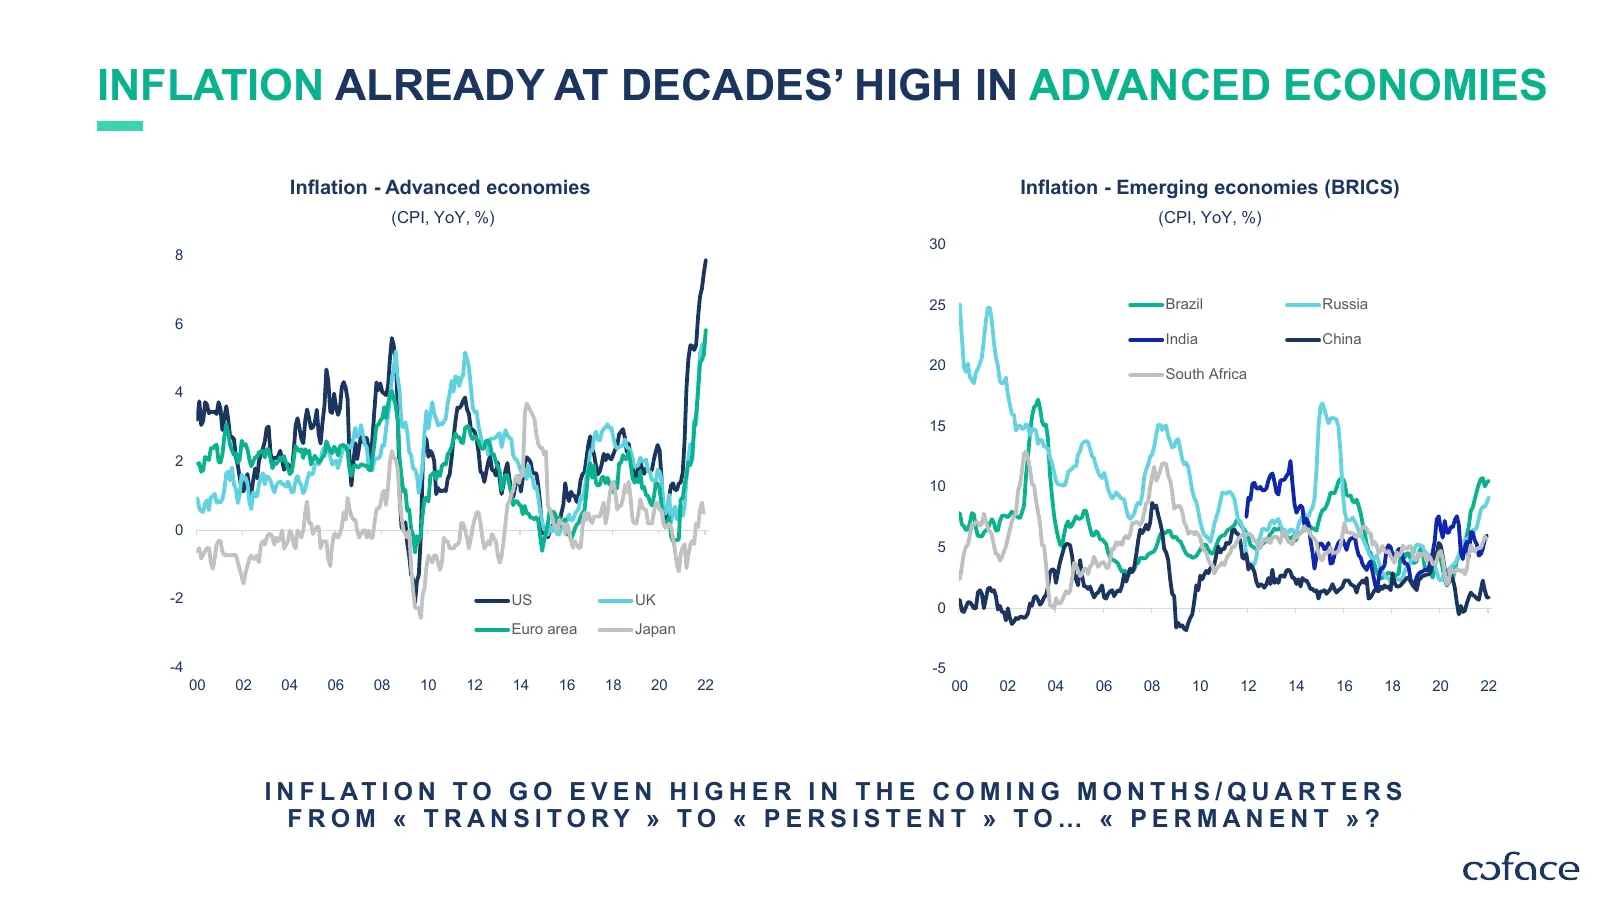
INFLATION ALREADY AT DECADES’ HIGH IN ADVANCED ECONOMIES Inflation - Advanced economies Inflation - Emerging economies (BRICS) (CPI, YoY, %) (CPI, YoY, %) 30 8 25 Brazil Russia 6 India China 20 South Africa 4 15 2 10 0 5 -2 US UK 0 Euro area Japan -4 -5 00 02 04 06 08 10 12 14 16 18 20 22 00 02 04 0
Slide 11: Supply Chains Disruptions: Bis Repetita?
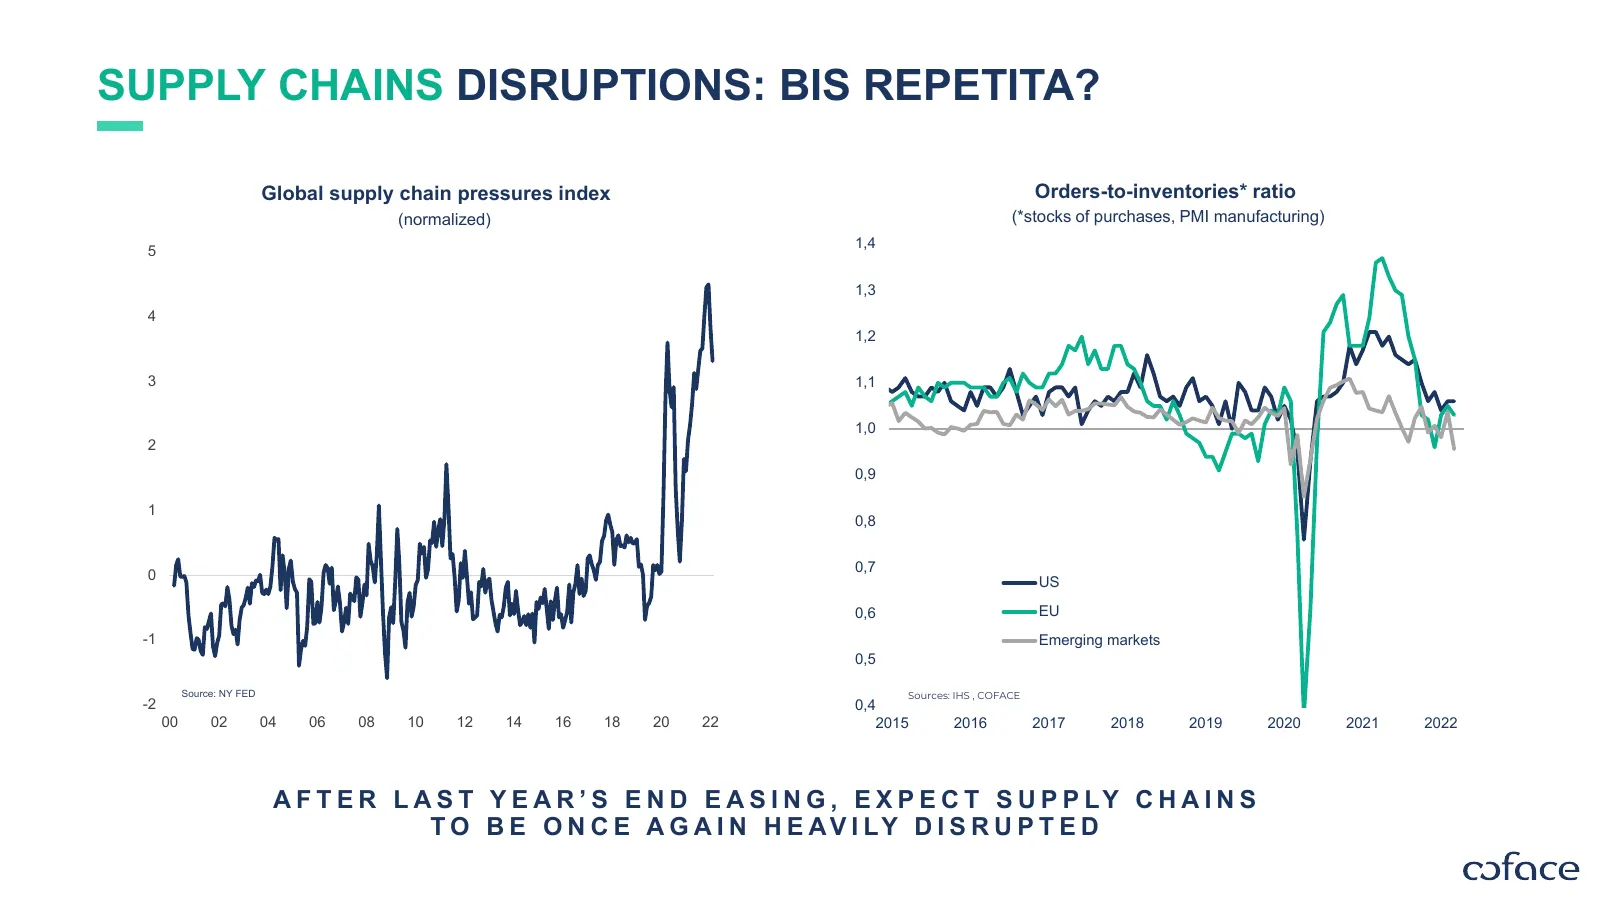
SUPPLY CHAINS DISRUPTIONS: BIS REPETITA? Global supply chain pressures index Orders-to-inventories* ratio (normalized) (*stocks of purchases, PMI manufacturing) 1,4 5 1,3 4 1,2 3 1,1 1,0 2 0,9 1 0,8 0,7 0 US 0,6 EU -1 Emerging markets 0,5 Source: NY FED Sources: IHS , COFACE -2 0,4 00 02 04 06 08 10
Slide 12: Increasing Risks of Stagflation in the Medium Term
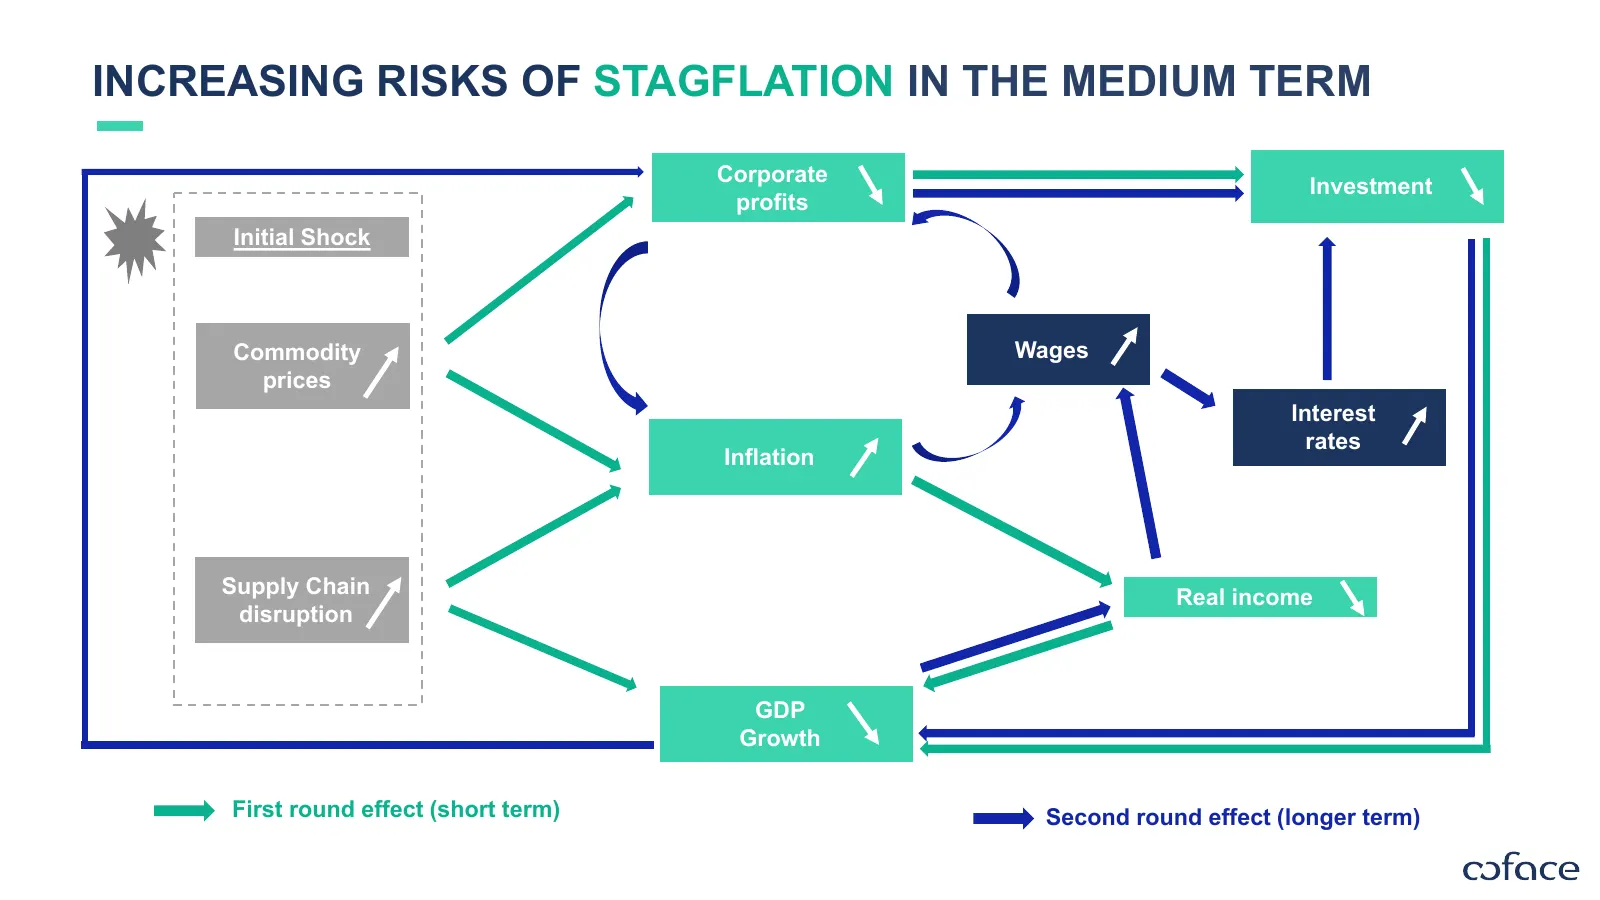
INCREASING RISKS OF STAGFLATION IN THE MEDIUM TERM Corporate Investment profits Initial Shock Commodity Wages prices Interest rates Inflation Supply Chain Real income disruption GDP Growth First round effect (short term) Second round effect (longer term)
Slide 13: Inflation Expectations: First Signs of De-Anchoring
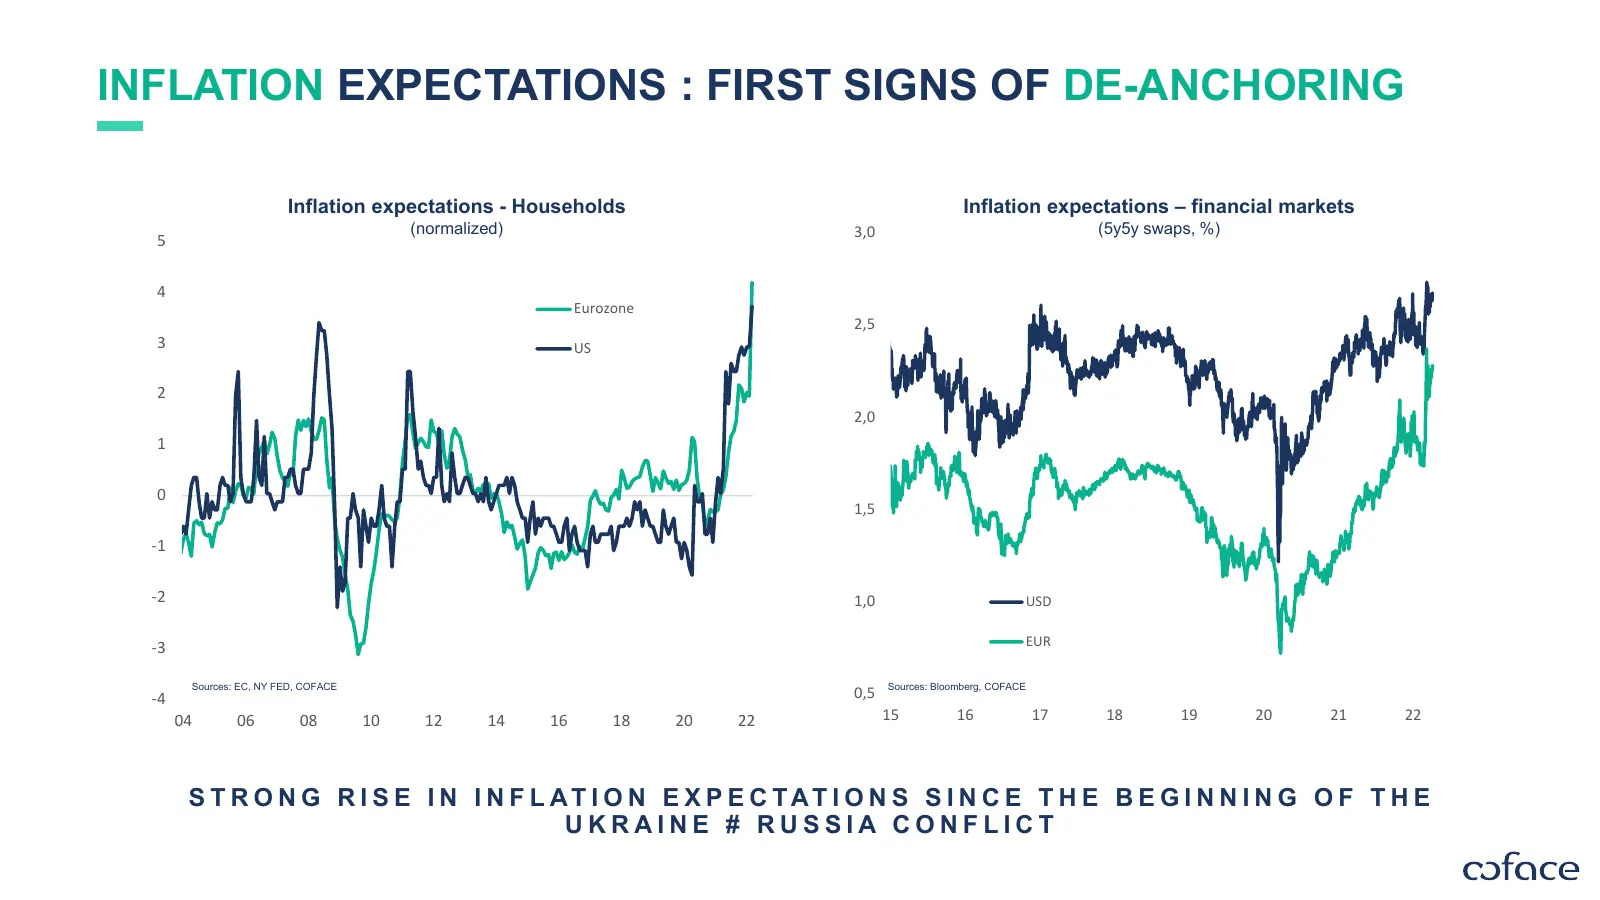
INFLATION EXPECTATIONS : FIRST SIGNS OF DE-ANCHORING Inflation expectations - Households Inflation expectations – financial markets (normalized) 3,0 (5y5y swaps, %) 5 4 Eurozone 2,5 3 US 2 2,0 1 0 1,5 -1 -2 1,0 USD -3 EUR Sources: EC, NY FED, COFACE Sources: Bloomberg, COFACE -4 0,5 04 06 08 10 12 1
Slide 14: Monetary Policies: How Many Rate Hikes in the Pipe?
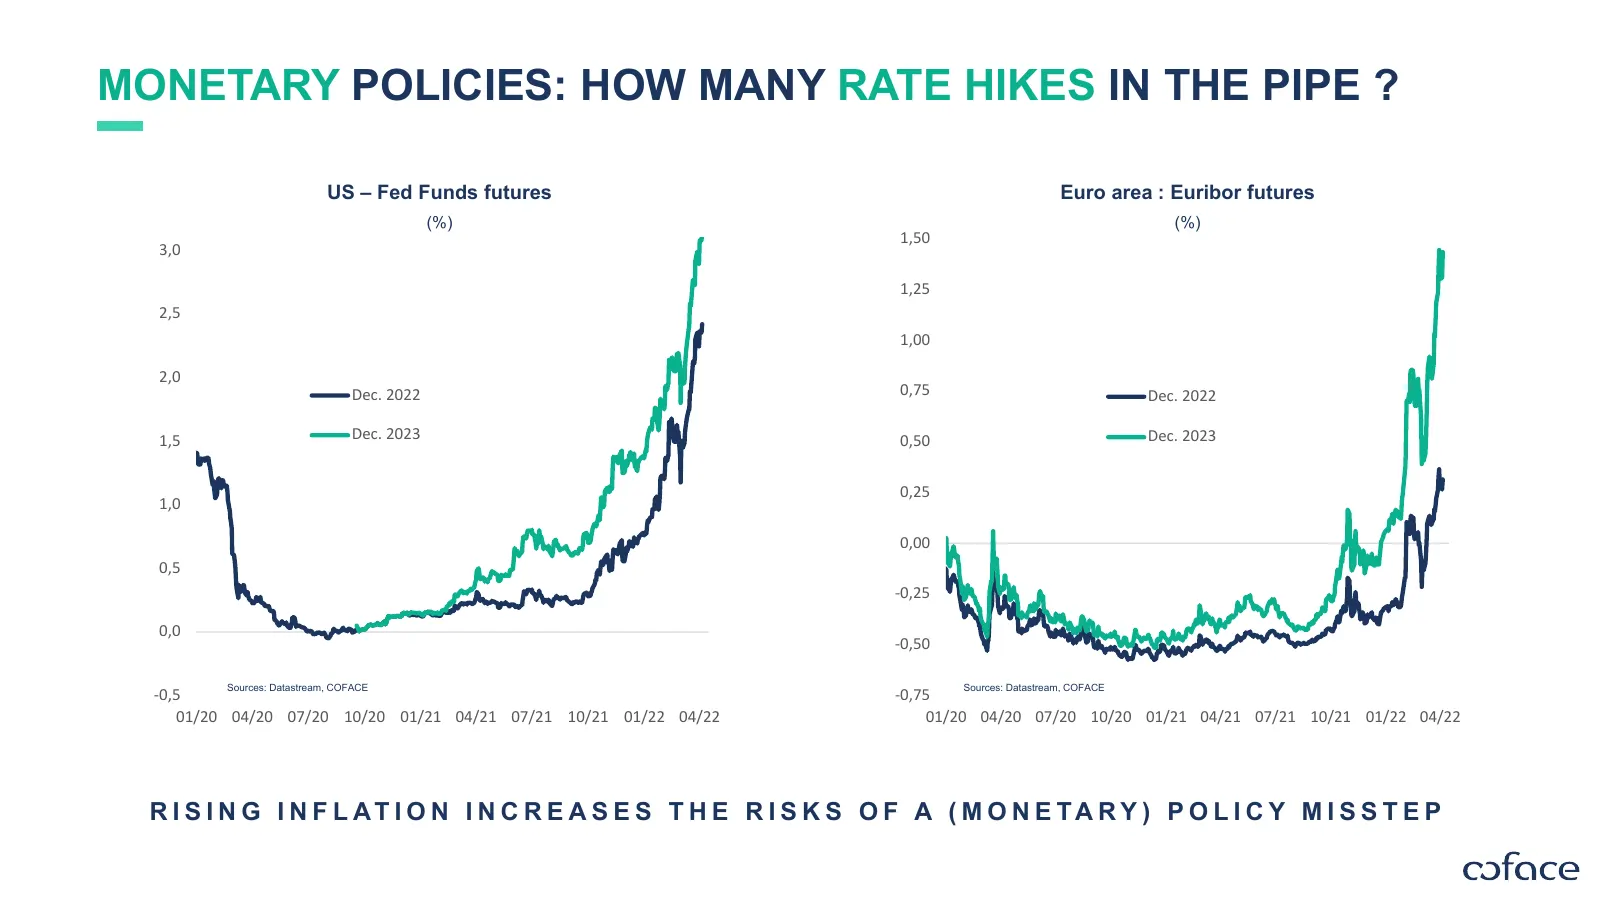
MONETARY POLICIES: HOW MANY RATE HIKES IN THE PIPE ? US – Fed Funds futures Euro area : Euribor futures (%) (%) 1,50 3,0 1,25 2,5 1,00 2,0 Dec. 2022 0,75 Dec. 2022 1,5 Dec. 2023 0,50 Dec. 2023 0,25 1,0 0,00 0,5 -0,25 0,0 -0,50 Sources: Datastream, COFACE Sources: Datastream, COFACE -0,5 -0,75 01/20
Slide 15: Even Stronger Inflationary Pressures in Europe
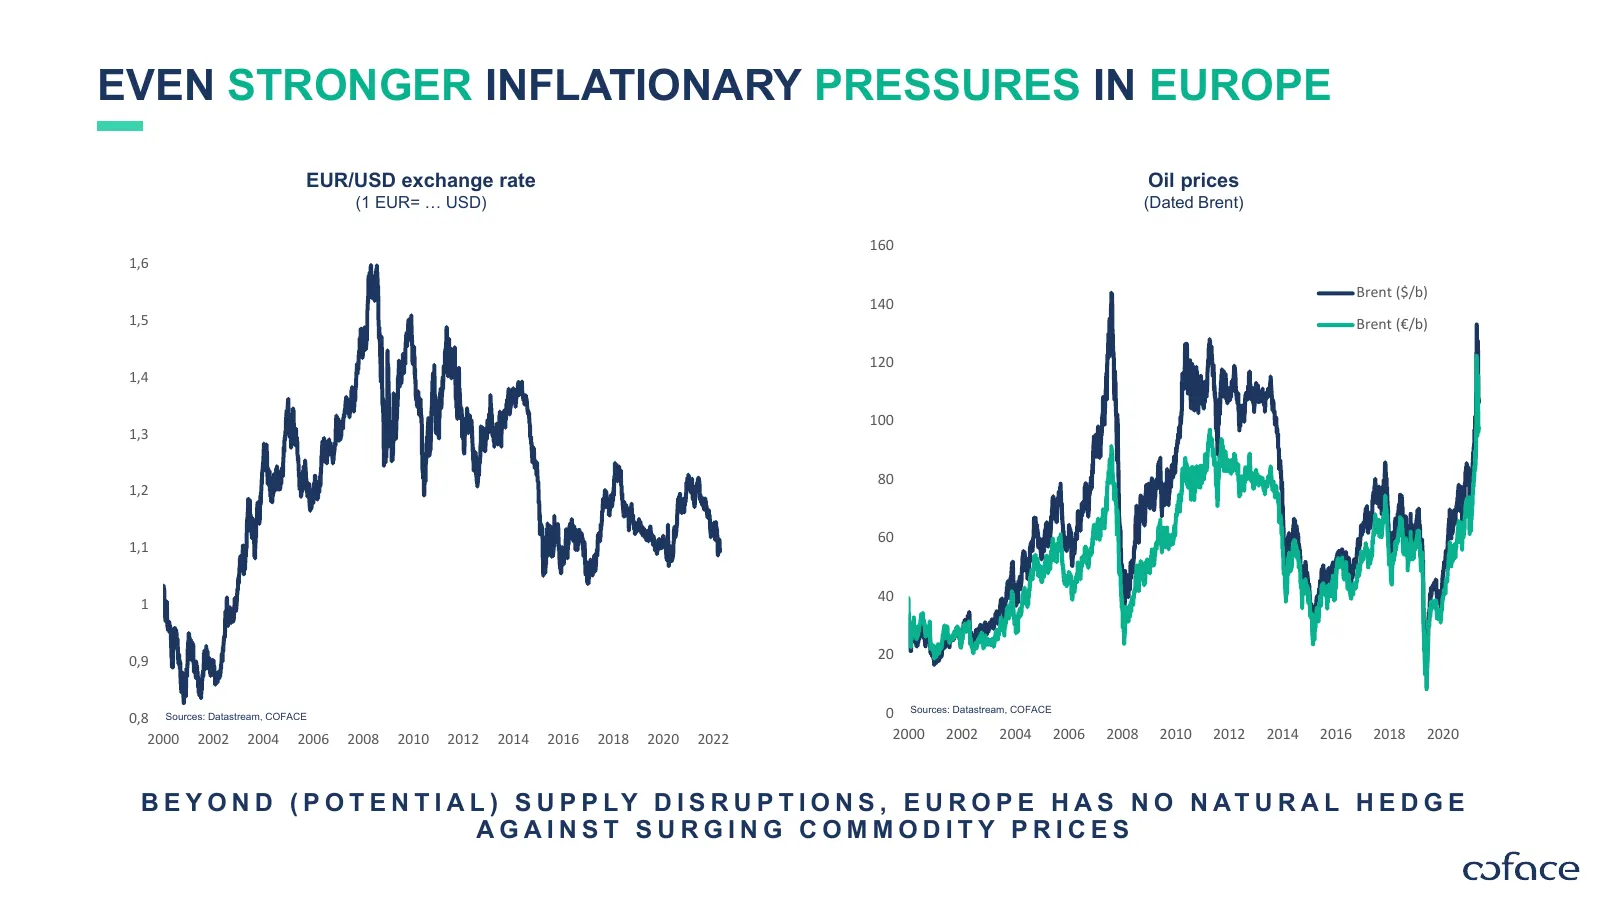
EVEN STRONGER INFLATIONARY PRESSURES IN EUROPE EUR/USD exchange rate Oil prices (1 EUR= … USD) (Dated Brent) 160 1,6 Brent ($/b) 140 1,5 Brent (€/b) 120 1,4 100 1,3 80 1,2 60 1,1 40 1 0,9 20 0,8 Sources: Datastream, COFACE 0 Sources: Datastream, COFACE 2000 2002 2004 2006 2008 2010 2012 2014 2016 20
Slide 16: Europe Economic Growth Will Be Strongly Impacted
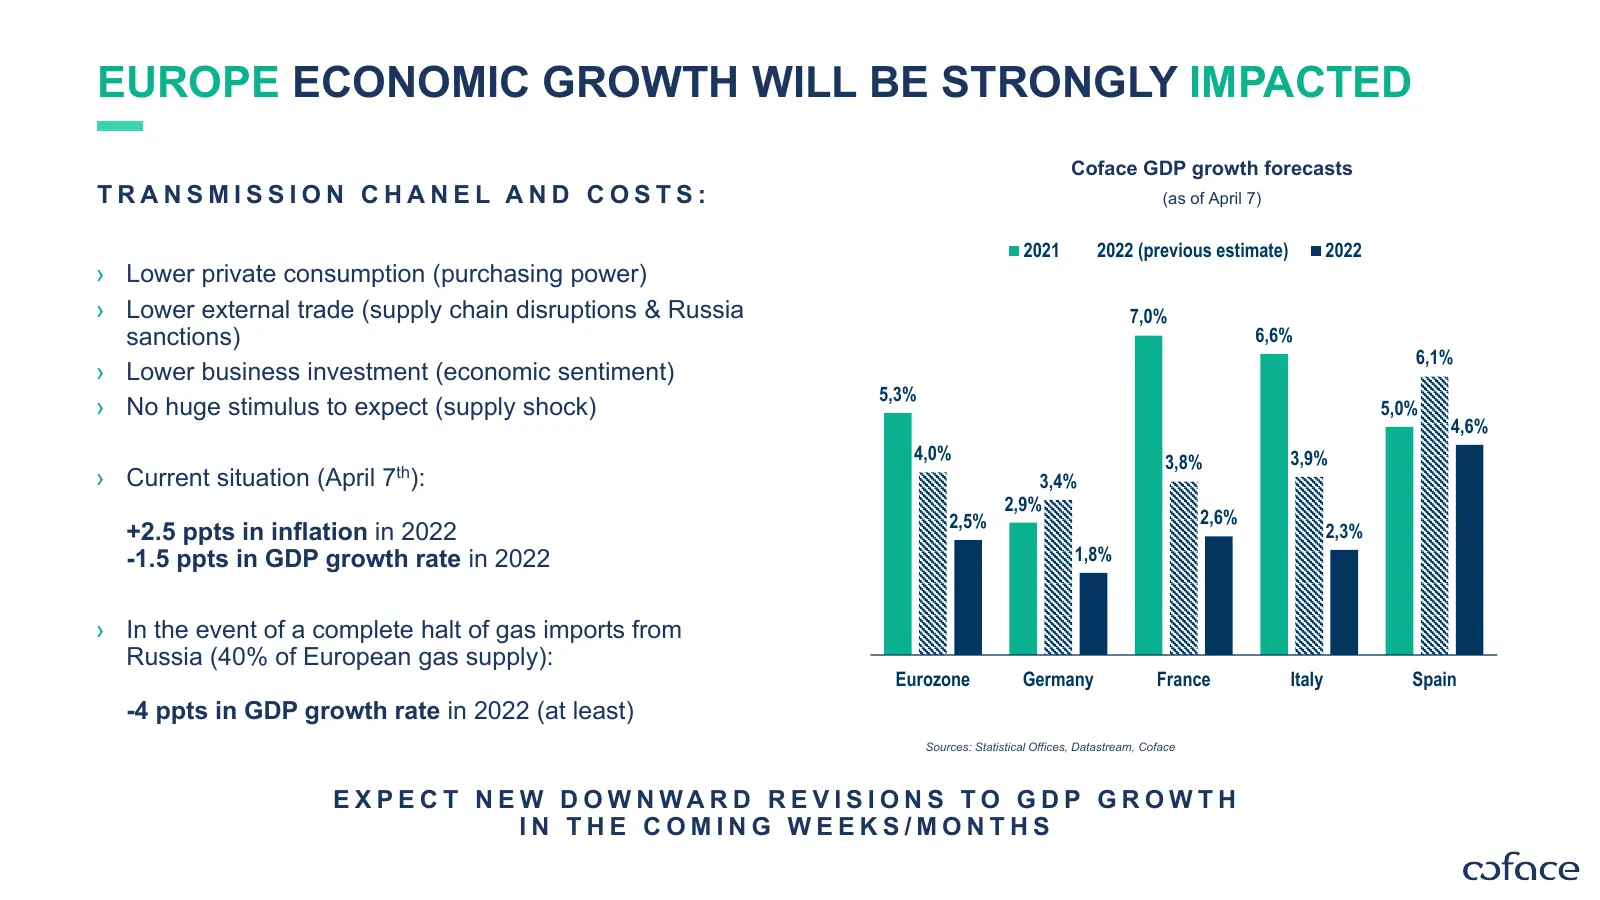
EUROPE ECONOMIC GROWTH WILL BE STRONGLY IMPACTED Coface GDP growth forecasts TRANSMISSION CHANEL AND COSTS: (as of April 7) 2021 2022 (previous estimate) 2022 › Lower private consumption (purchasing power) › Lower external trade (supply chain disruptions & Russia 7,0% sanctions) 6,6% 6,1% › Lower bu
Slide 17: Natgas Supply Disruption Would Be Very Damaging
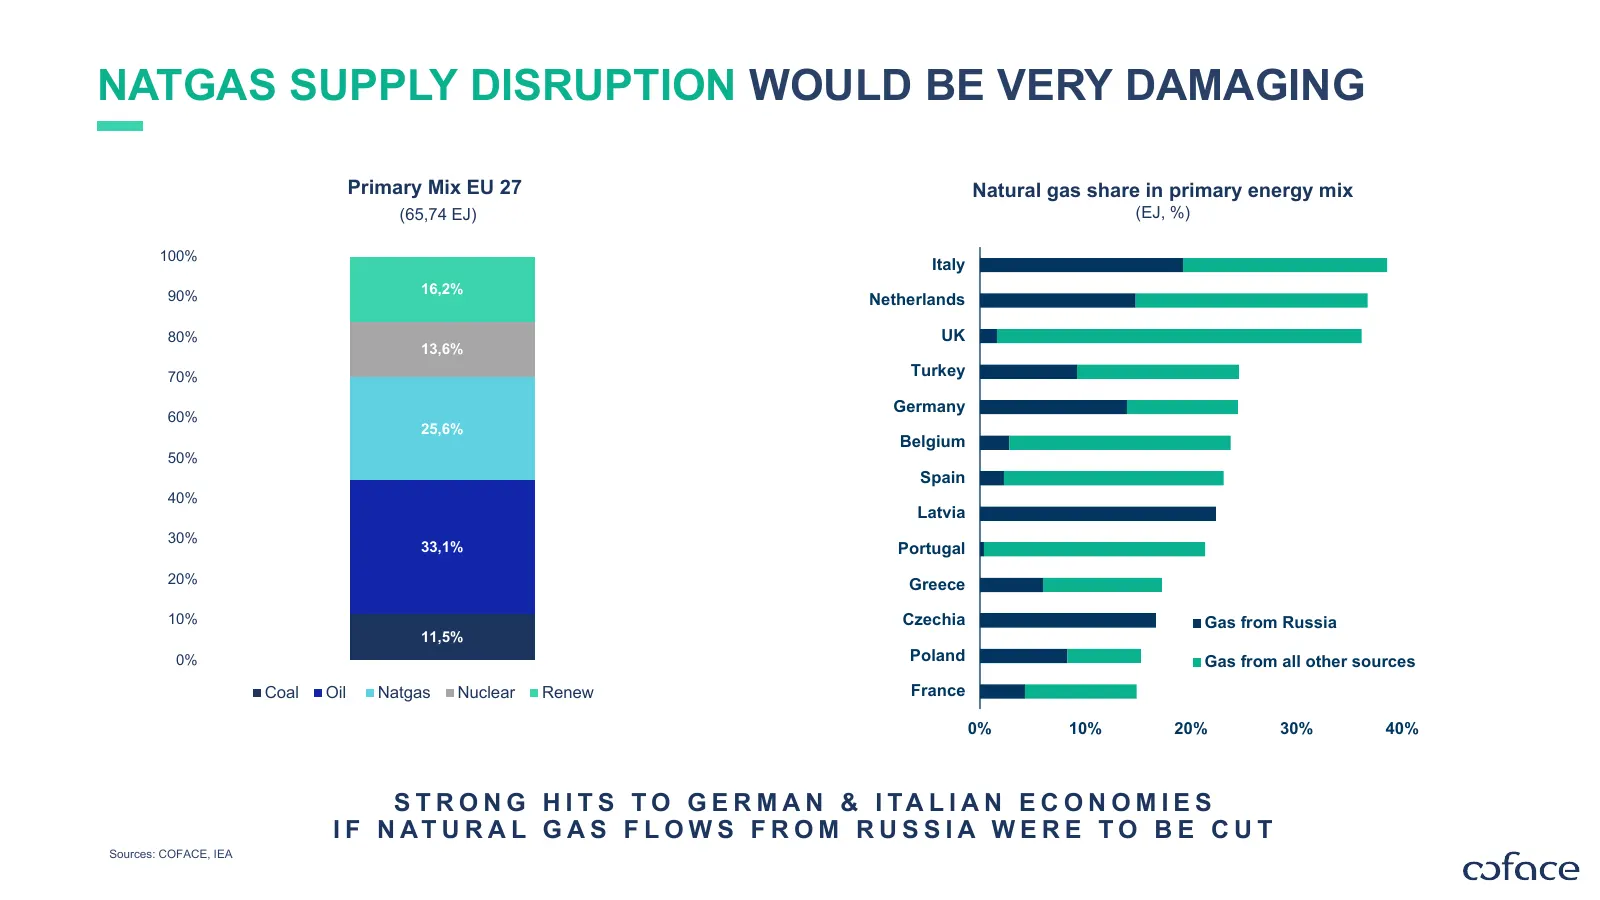
NATGAS SUPPLY DISRUPTION WOULD BE VERY DAMAGING Primary Mix EU 27 Natural gas share in primary energy mix (65,74 EJ) (EJ, %) 100% Italy 90% 16,2% Netherlands 80% UK 13,6% 70% Turkey Germany 60% 25,6% Belgium 50% Spain 40% Latvia 30% 33,1% Portugal 20% Greece 10% Czechia Gas from Russia 11,5% 0% Pola
Slide 18: Revisions to Our GDP Growth Forecasts for 2022
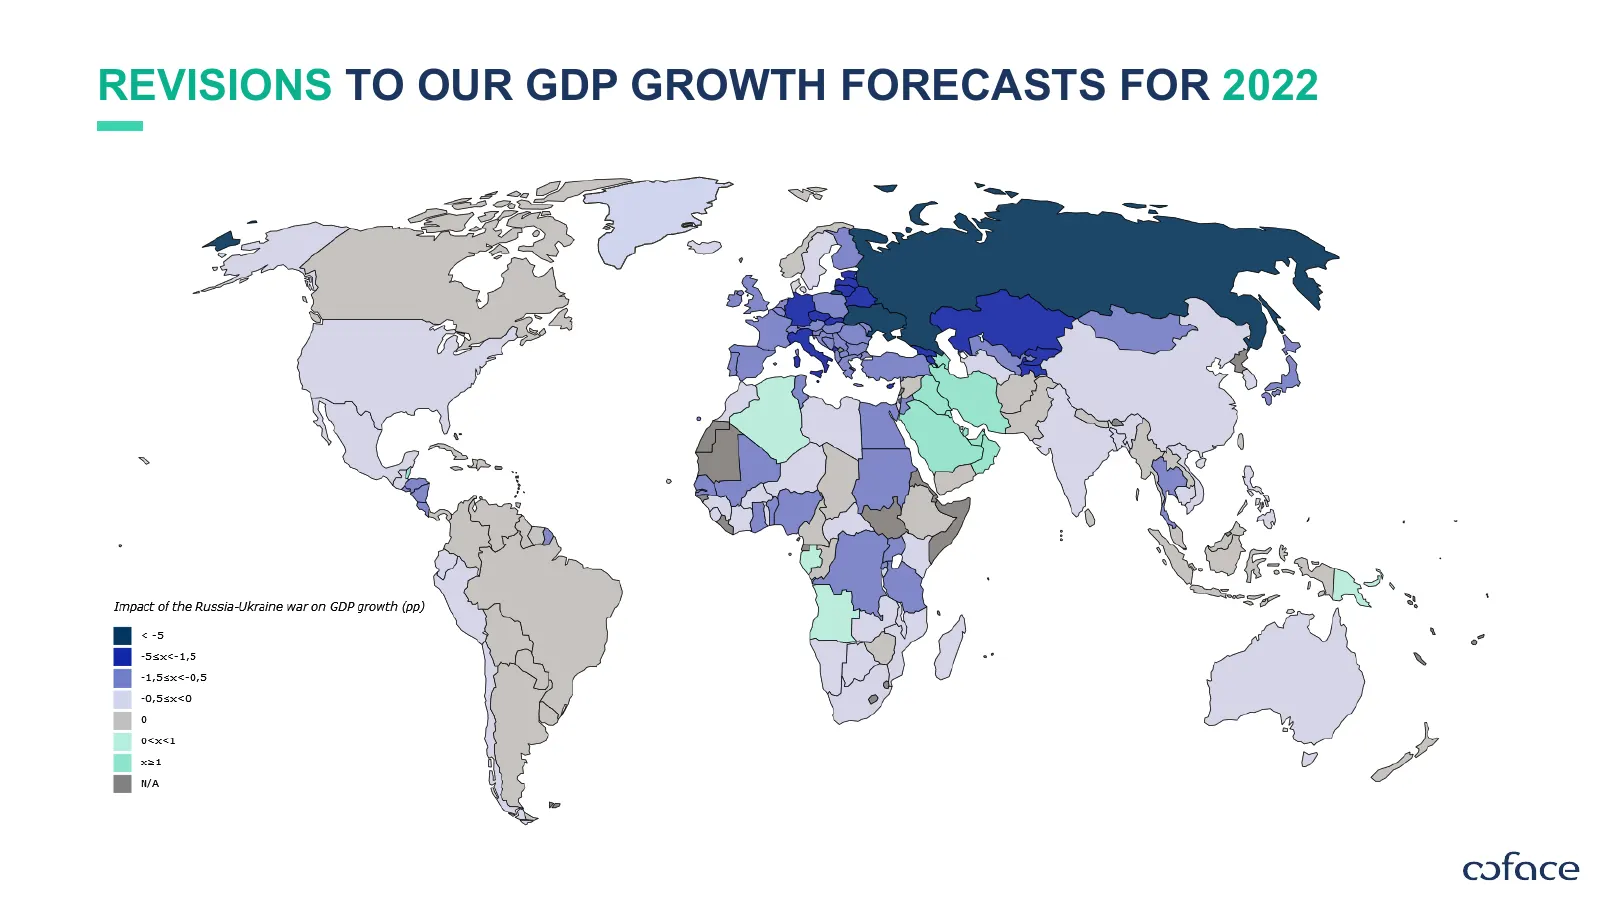
REVISIONS TO OUR GDP GROWTH FORECASTS FOR 2022
Slide 19: A Global Recession Should Not Be Ruled Out
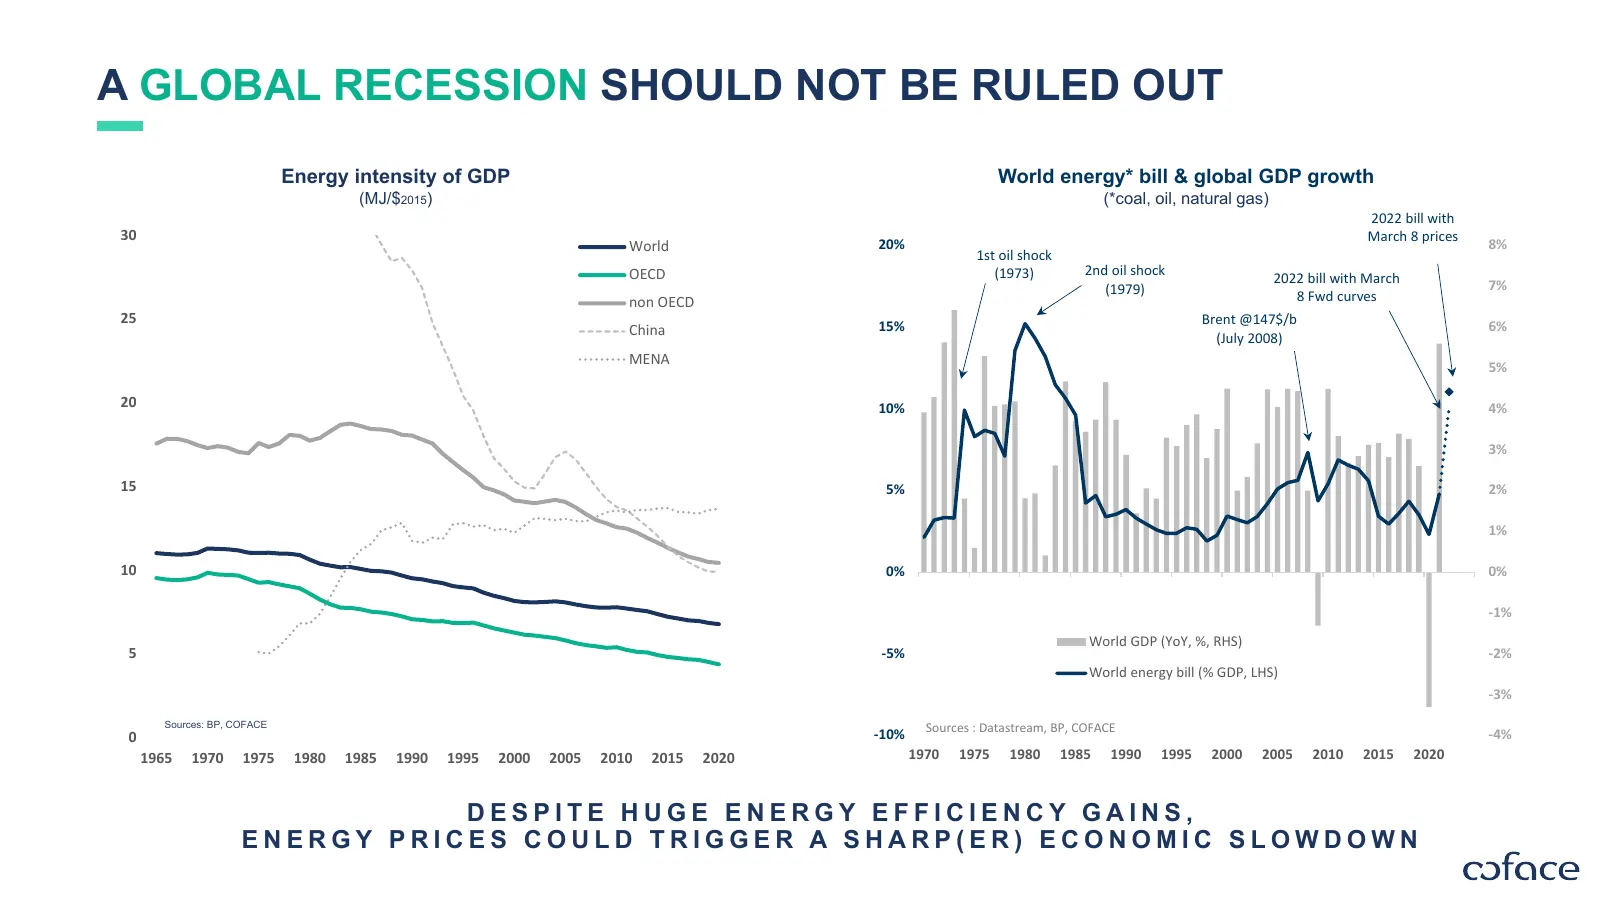
A GLOBAL RECESSION SHOULD NOT BE RULED OUT Energy intensity of GDP World energy* bill & global GDP growth (MJ/$2015) (*coal, oil, natural gas) 2022 bill with 30 March 8 prices World 20% 8% 1st oil shock OECD (1973) 2nd oil shock 2022 bill with March (1979) 7% non OECD 8 Fwd curves 25 15% Brent @147$
Slide 20: Risk of Social Unrest Compounded by Inflation
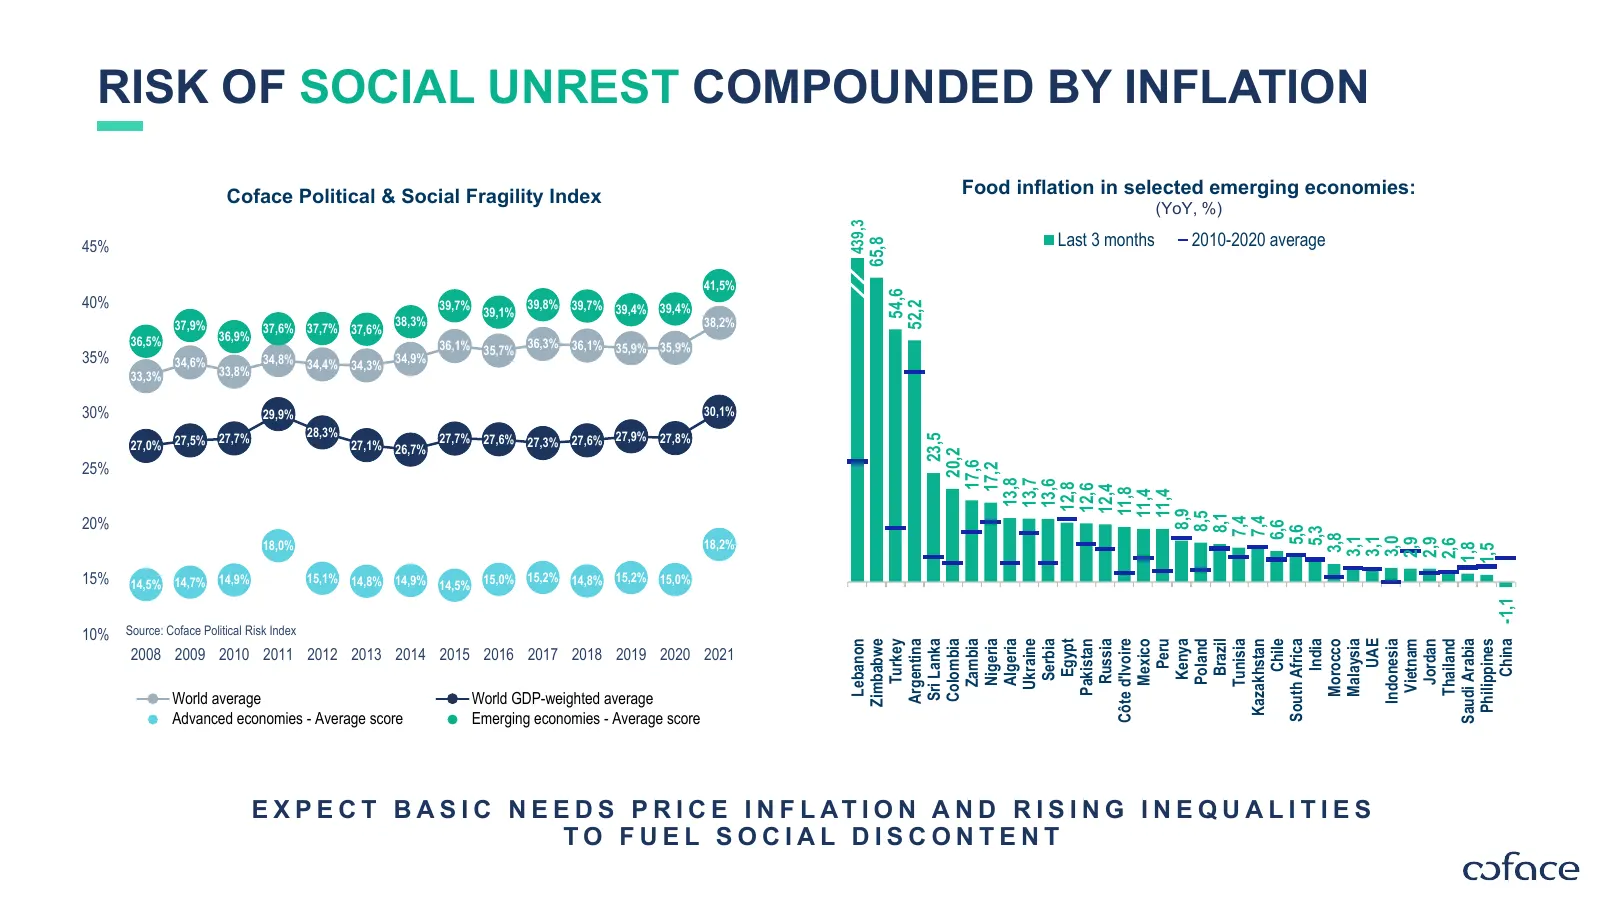
RISK OF SOCIAL UNREST COMPOUNDED BY INFLATION Coface Political & Social Fragility Index Food inflation in selected emerging economies: (YoY, %) 439,3 45% Last 3 months 2010-2020 average 65,8 41,5% 54,6 40% 39,7% 39,1% 39,8% 39,7% 39,4% 39,4% 52,2 37,9% 38,3% 38,2% 37,6% 37,7% 37,6% 36,5% 36,9% 36,1%
Slide 21: All Sectors Will Be Affected
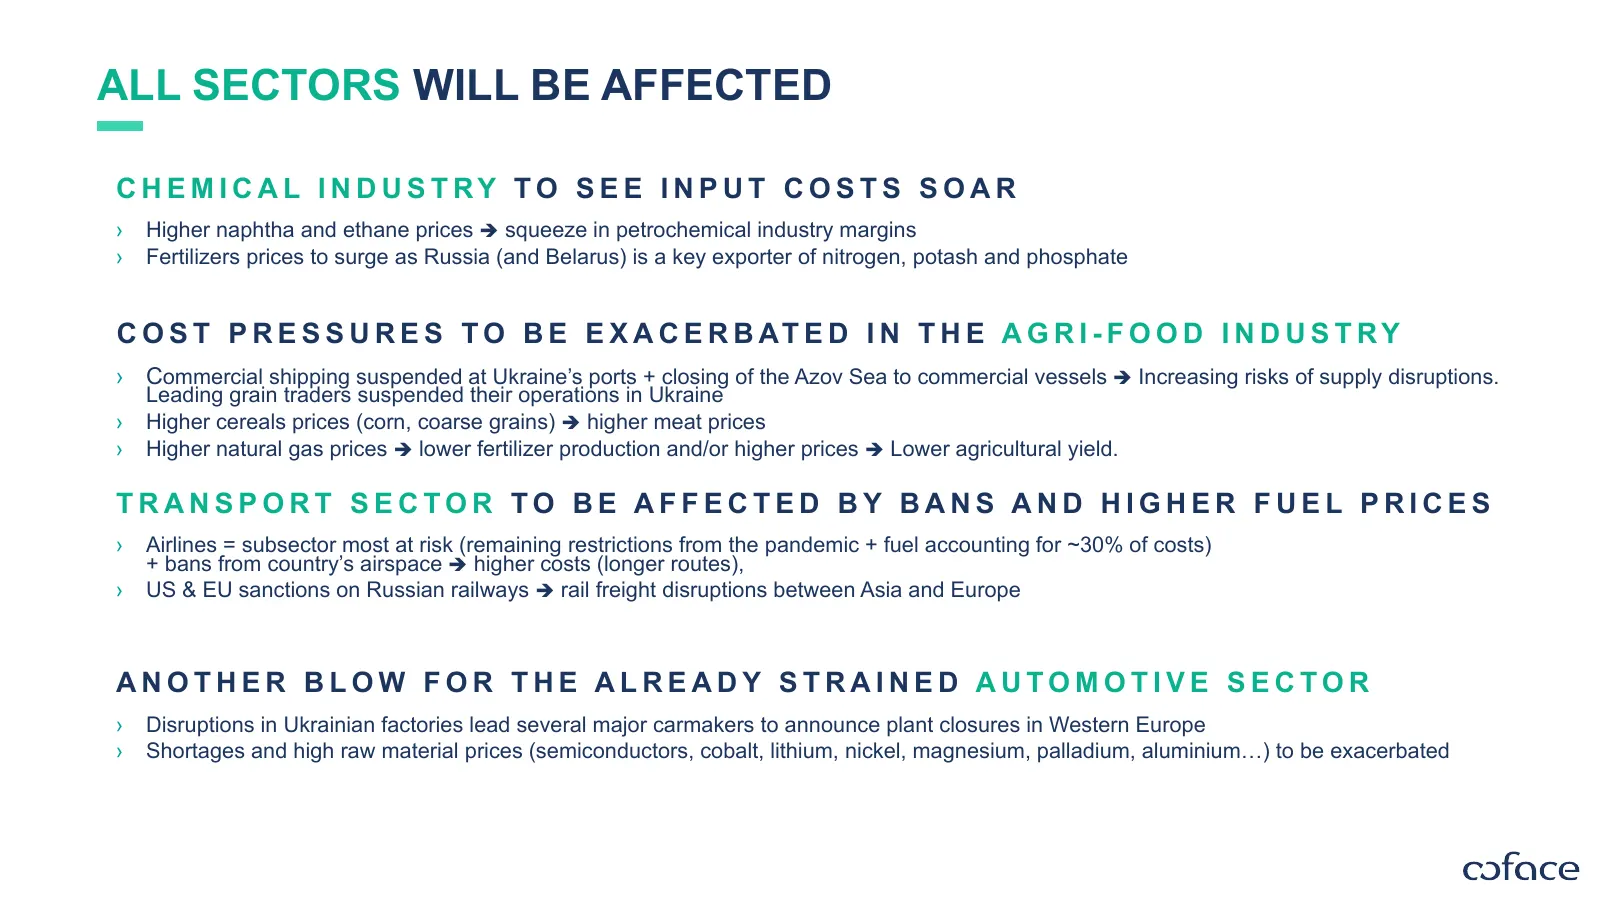
ALL SECTORS WILL BE AFFECTED CHEMI CAL I NDUSTRY TO SEE I NP UT COSTS SOAR › Higher naphtha and ethane prices squeeze in petrochemical industry margins › Fertilizers prices to surge as Russia (and Belarus) is a key exporter of nitrogen, potash and phosphate C O S T P R E S S U R E S T O B E E X A
Slide 22: Information Services: How Can Data Help Your Business
I N F O R M AT I O N S E R V I C E S H O W C A N D ATA H E L P Y O U R B U S I N E S S D U R I N G AN ECONOMIC CRISIS?
Slide 23: Global Solutions, Local Services
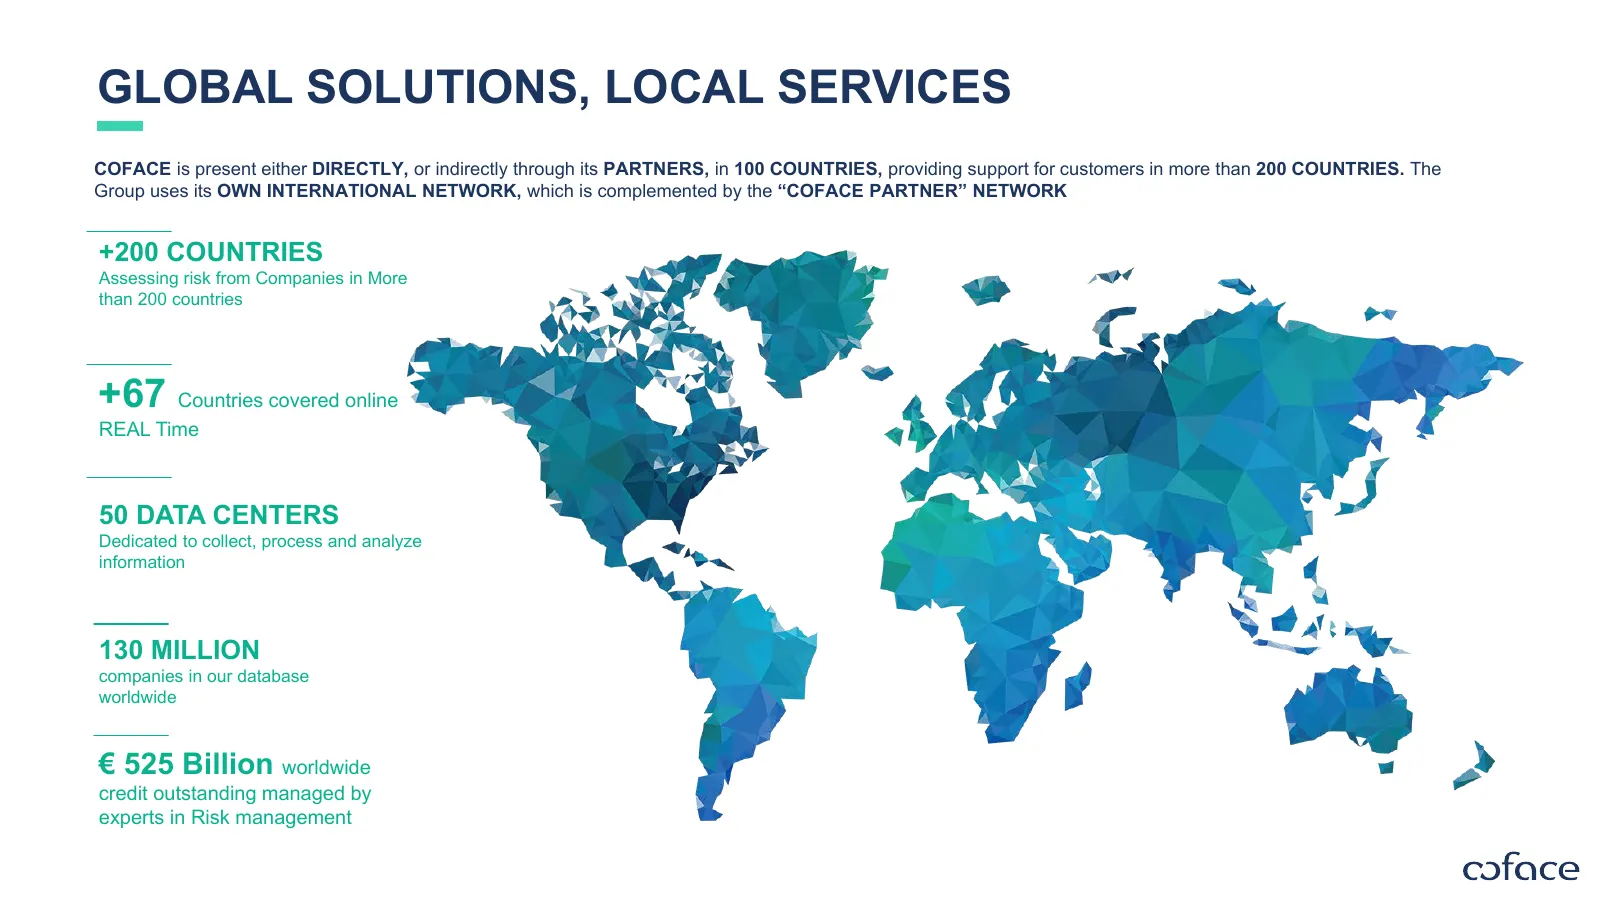
GLOBAL SOLUTIONS, LOCAL SERVICES COFACE is present either DIRECTLY, or indirectly through its PARTNERS, in 100 COUNTRIES, providing support for customers in more than 200 COUNTRIES. The Group uses its OWN INTERNATIONAL NETWORK, which is complemented by the “COFACE PARTNER” NETWORK +200 COUNTRIES Ass
Slide 24: Our Unique Value
OUR UNIQUE VALUE 1 GLOBAL APPROACH 2 PREMIUM DATA 3 EXCLUSIVE ACCESS TO EXPERTISE
Slide 25: Premium Quality Data - Not Just Integrator
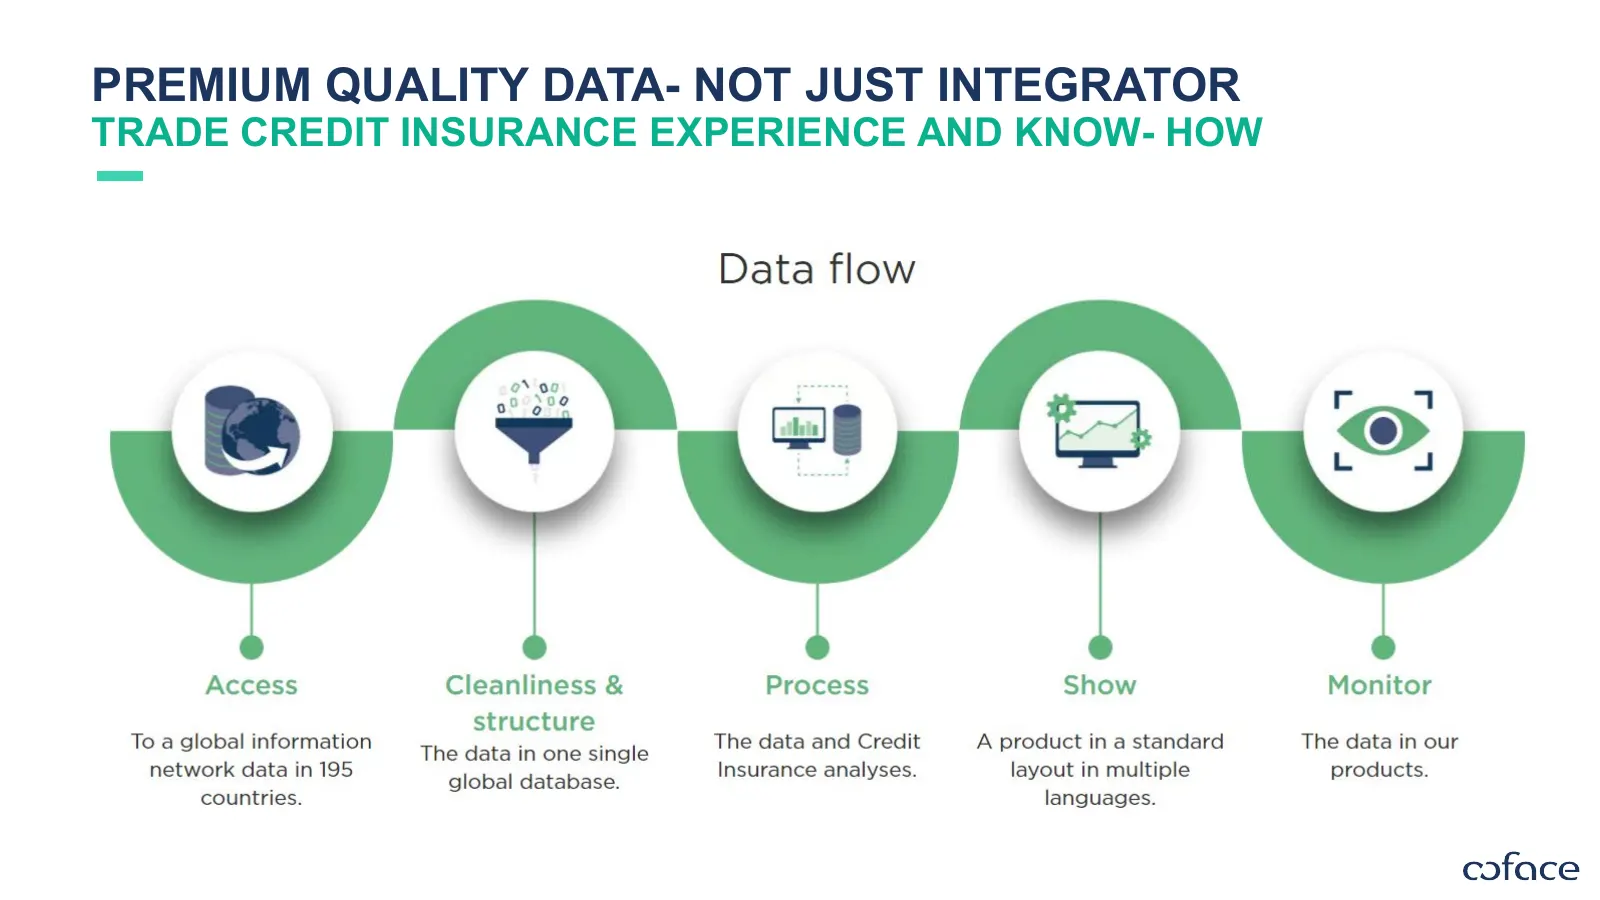
PREMIUM QUALITY DATA- NOT JUST INTEGRATOR TRADE CREDIT INSURANCE EXPERIENCE AND KNOW- HOW
Slide 26: Our Assets
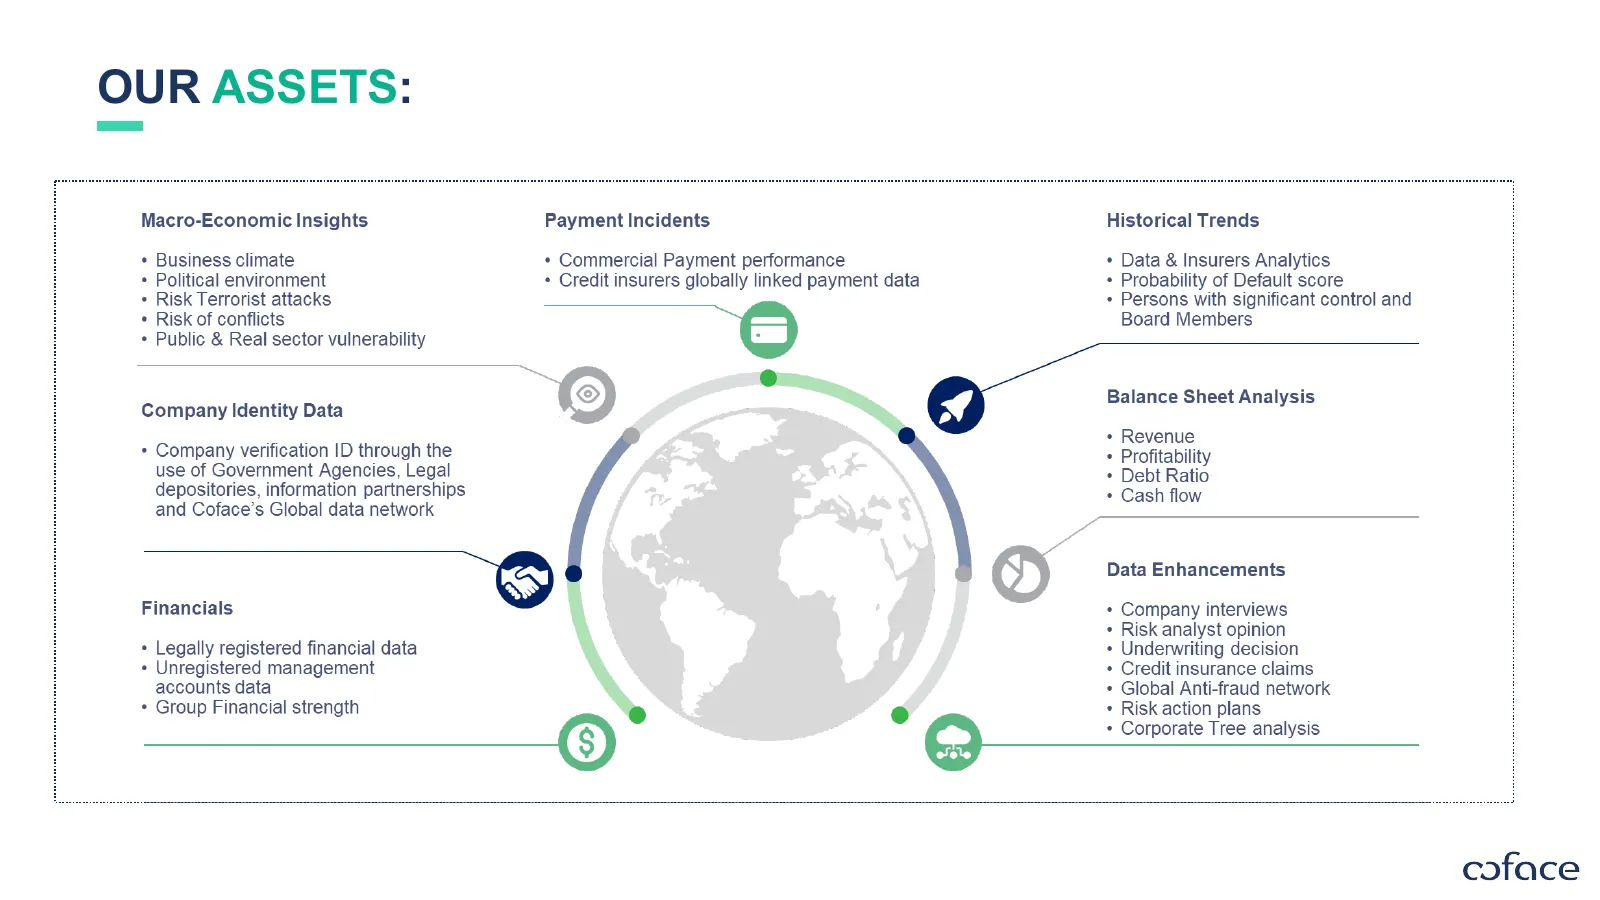
OUR ASSETS: Macro-Economic Insights Payment Incidents Historical Trends * Business climate + Commercial Payment performance + Data & Insurers Analytics * Political environment * Credit insurers globally linked payment data * Probability of Default score + Risk Terrorist attacks + Persons with signif
Slide 27: Business Information Solutions: Strategy & Operational Support
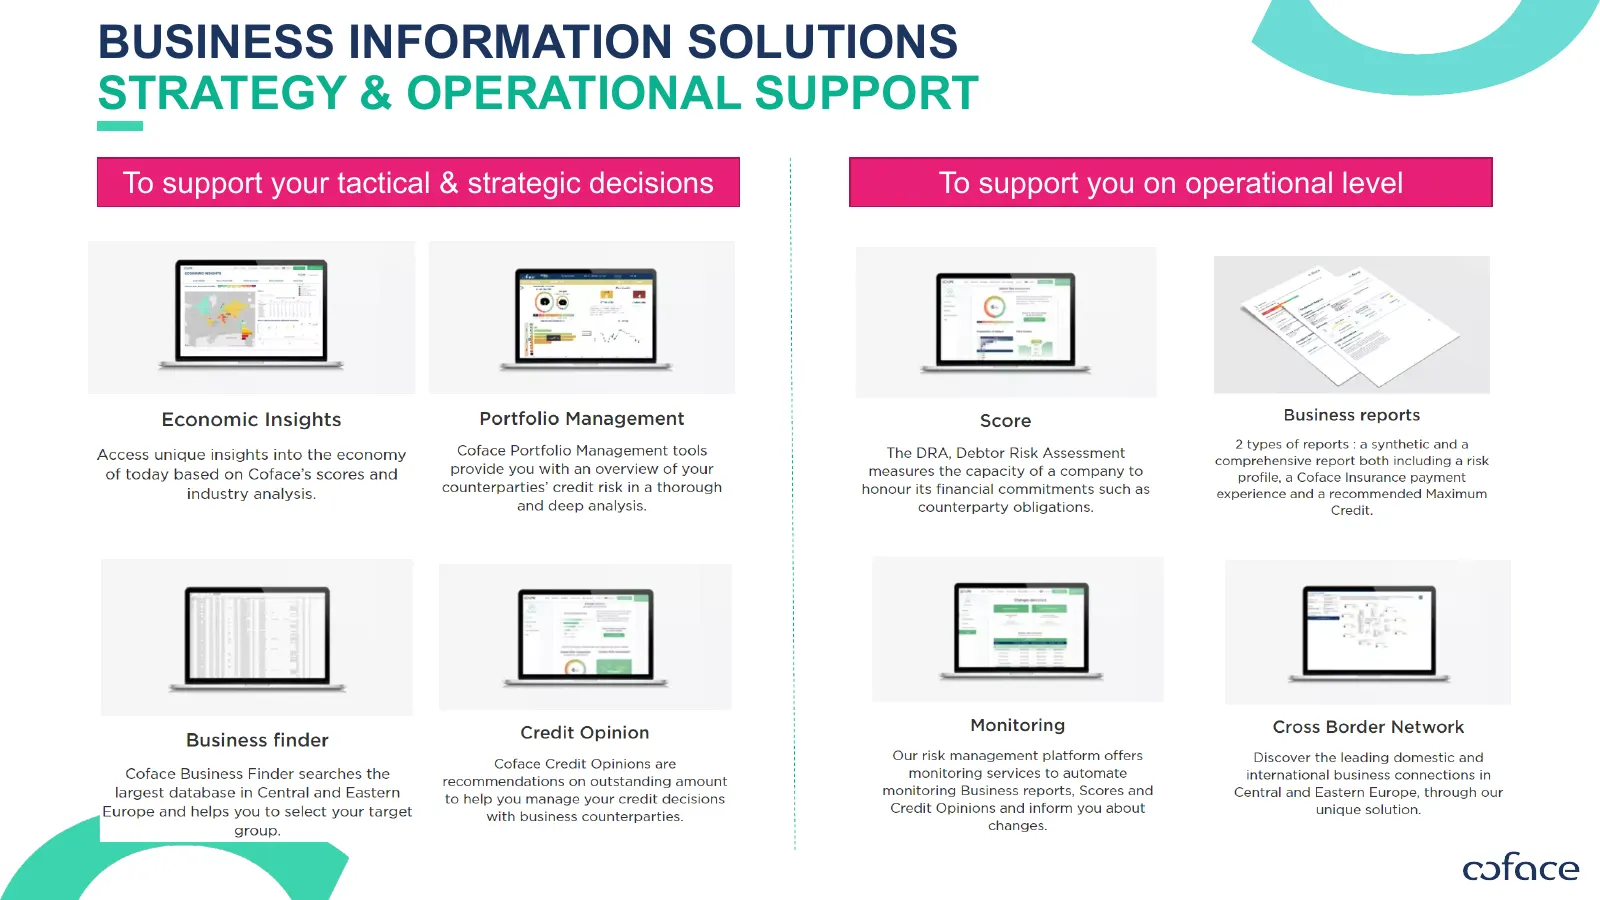
BUSINESS INFORMATION SOLUTIONS STRATEGY & OPERATIONAL SUPPORT To support your tactical & strategic decisions To support you on operational level
Slide 28: Operational Level Support: Business Reports
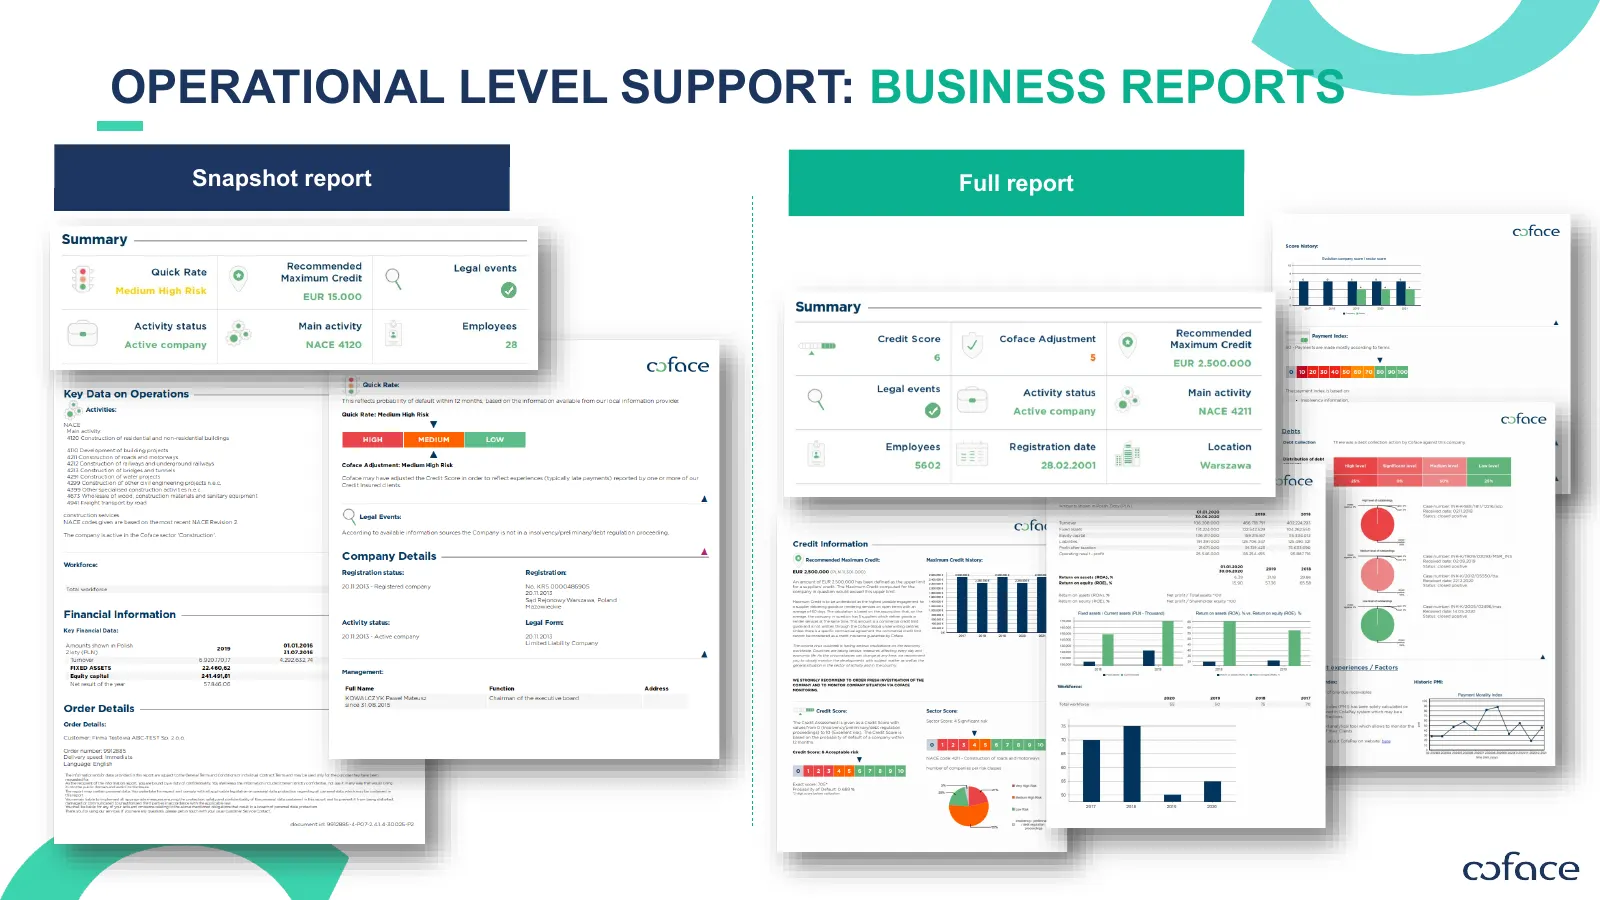
OPERATIONAL LEVEL SUPPORT: BUSINESS REPORTS Snapshot report RAPORT PEŁNY Full report
Slide 29: Credit Opinions
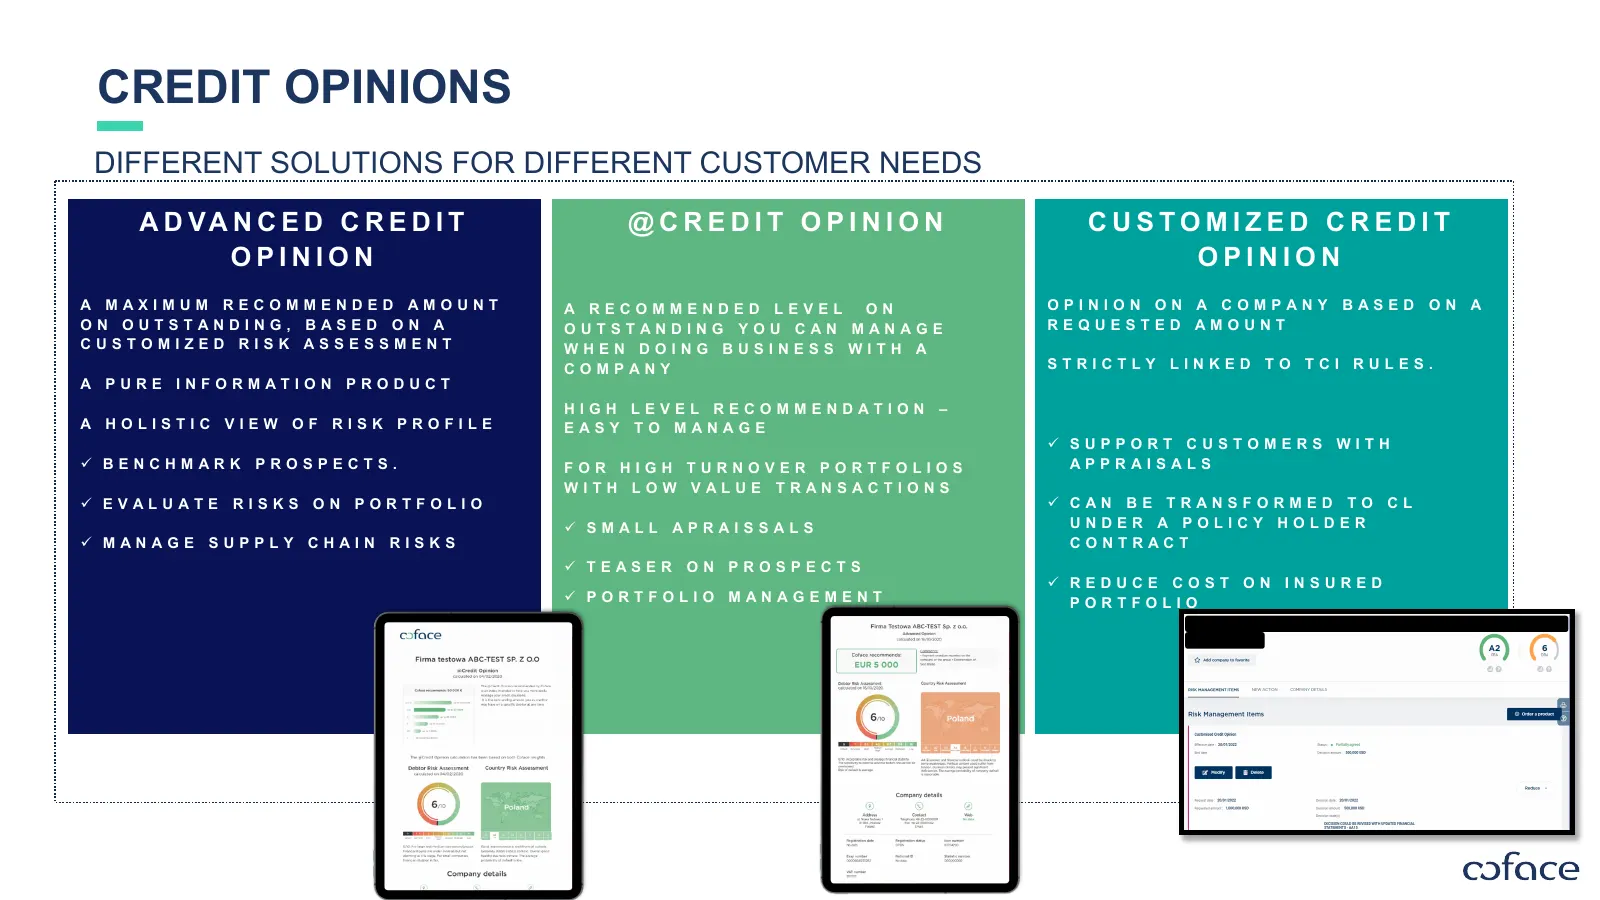
CREDIT OPINIONS DIFFERENT SOLUTIONS FOR DIFFERENT CUSTOMER NEEDS A D VA N C E D C R E D I T @CREDIT OPINION CUSTOMIZED CREDIT OPINION OPINION A MAXIMUM RECOMMENDED AMOUNT A RECOMMENDED LEVEL ON OPINION ON A COMPANY BASED ON A ON OUTSTANDING, BASED ON A OUTSTANDING YOU CAN MANAGE REQUESTED AMOUNT CUS
Slide 30: Economic Insights
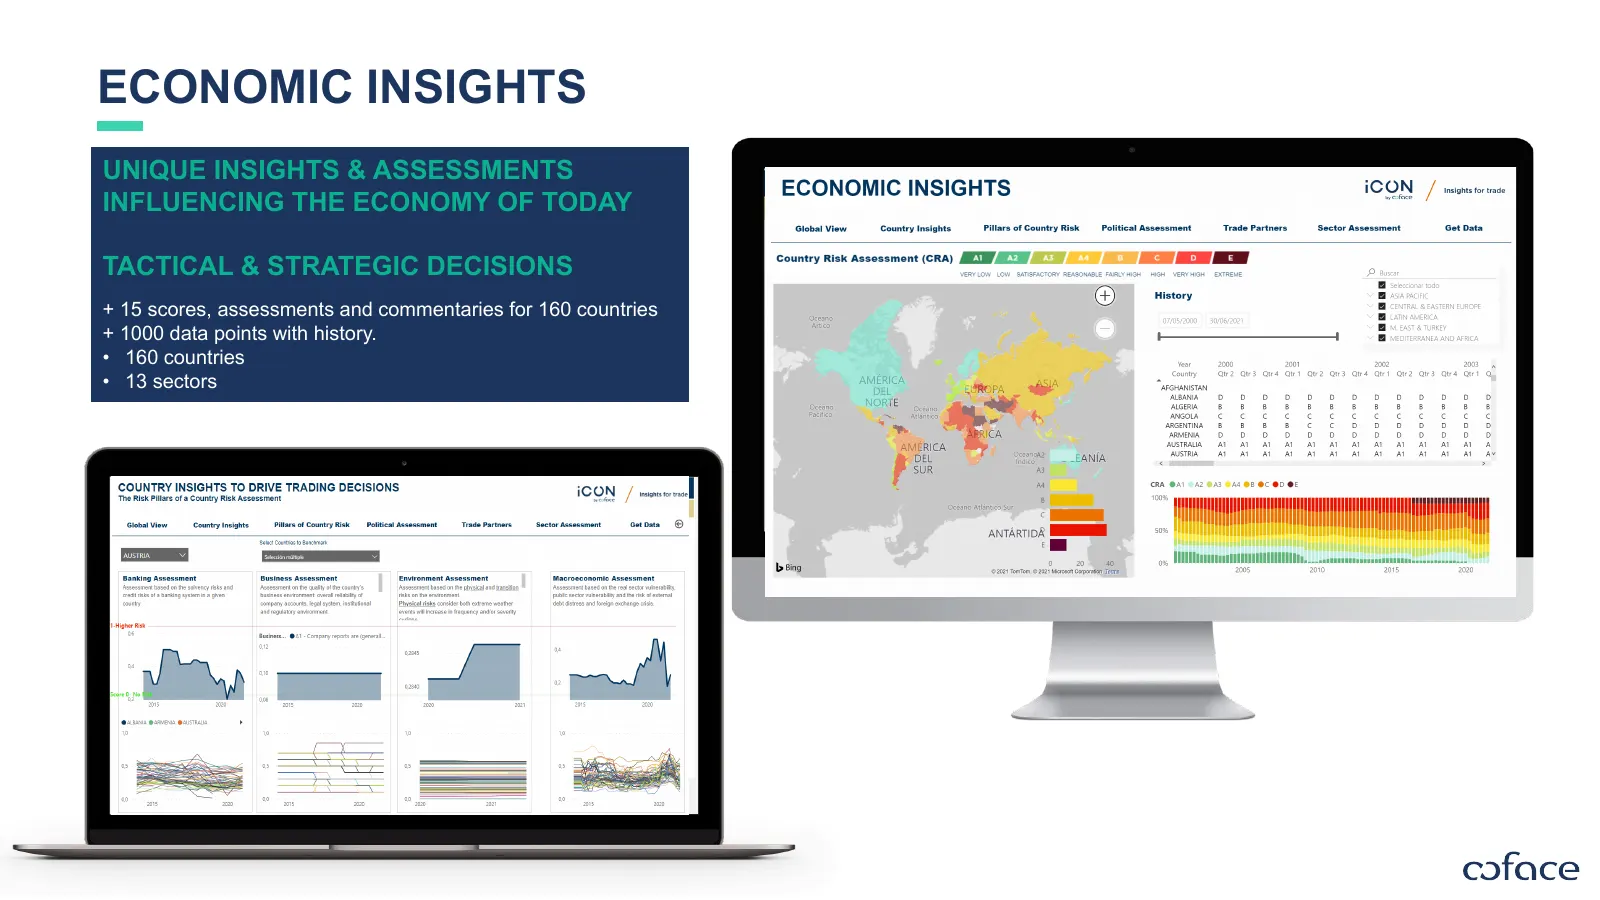
ECONOMIC INSIGHTS UNIQUE INSIGHTS & ASSESSMENTS INFLUENCING THE ECONOMY OF TODAY TACTICAL & STRATEGIC DECISIONS + 15 scores, assessments and commentaries for 160 countries + 1000 data points with history. • 160 countries • 13 sectors
Slide 31: Economic Insights
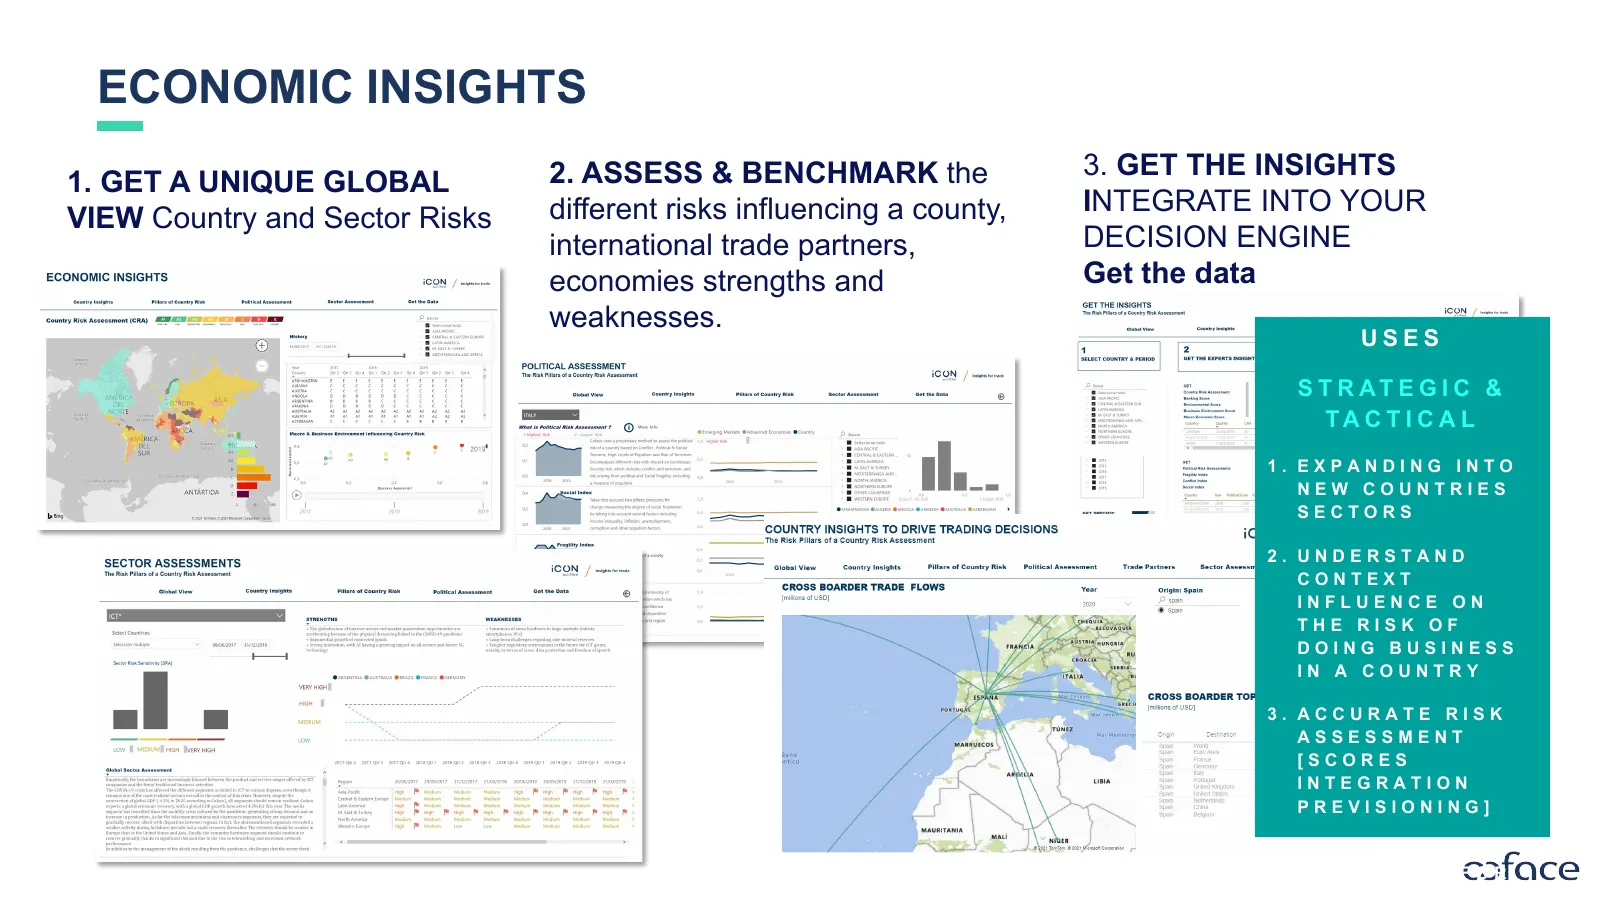
ECONOMIC INSIGHTS 2. ASSESS & BENCHMARK the 3. GET THE INSIGHTS 1. GET A UNIQUE GLOBAL different risks influencing a county, INTEGRATE INTO YOUR VIEW Country and Sector Risks international trade partners, DECISION ENGINE economies strengths and Get the data weaknesses. USES S T R AT E G I C & TA C T
Slide 32: How to Access Our Services
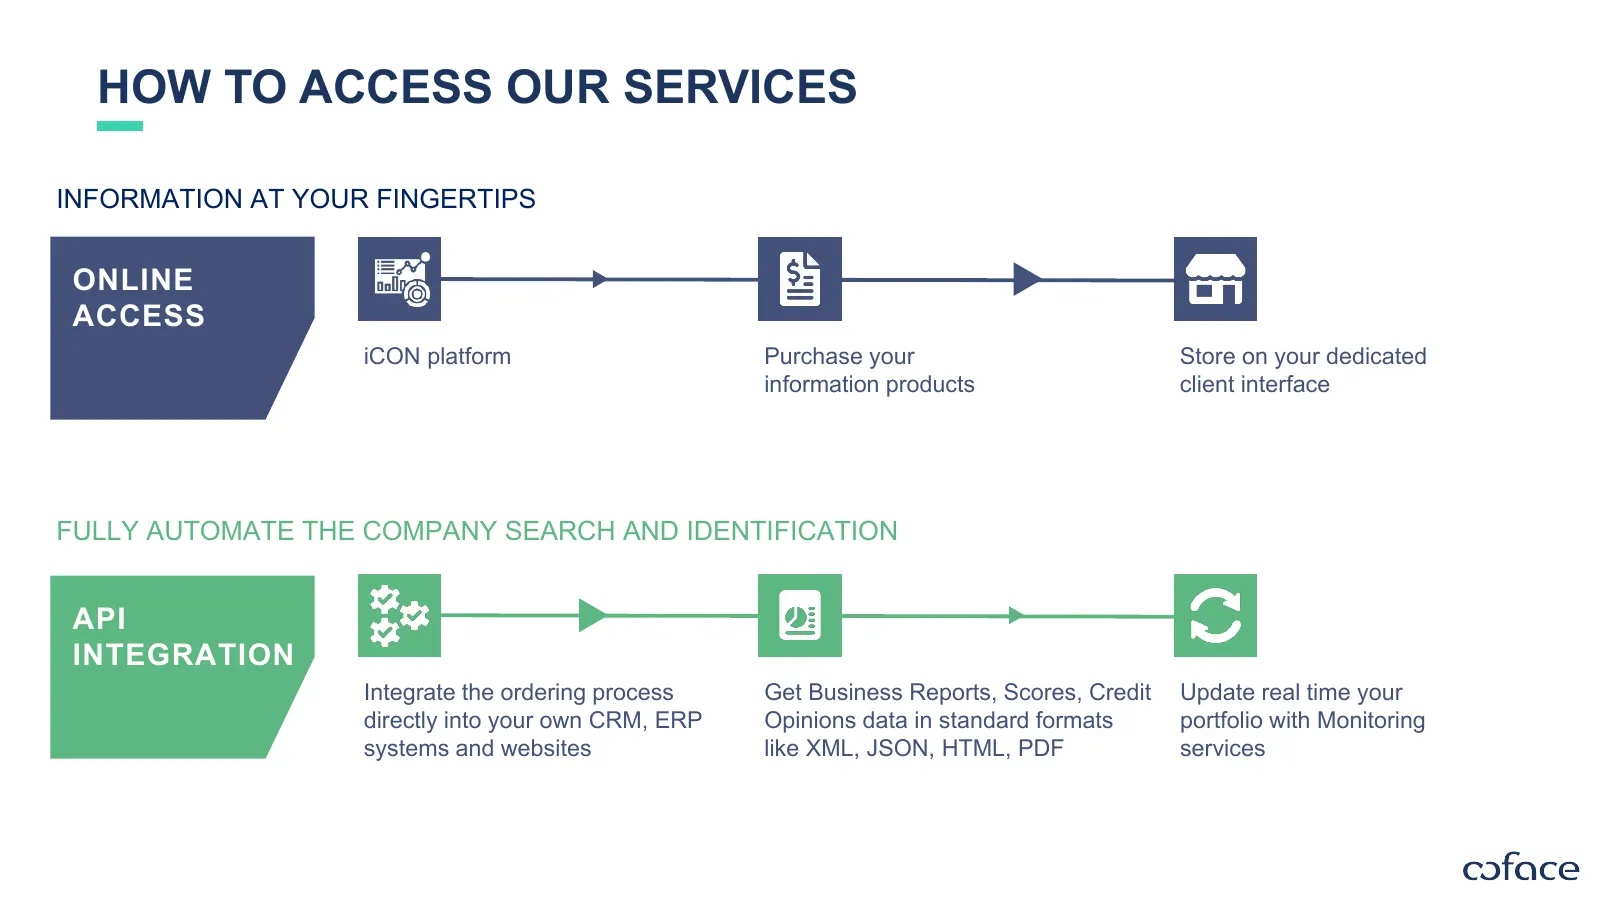
HOW TO ACCESS OUR SERVICES INFORMATION AT YOUR FINGERTIPS ONLINE ACCESS iCON platform Purchase your Store on your dedicated information products client interface FULLY AUTOMATE THE COMPANY SEARCH AND IDENTIFICATION API INTEGRATION Integrate the ordering process Get Business Reports, Scores, Credit U
Slide 33: Thank You for Your Attention Q&A
THANK YOU FOR YOUR ATTENTION Q&A
Slide 34: Thank You for Your Attention
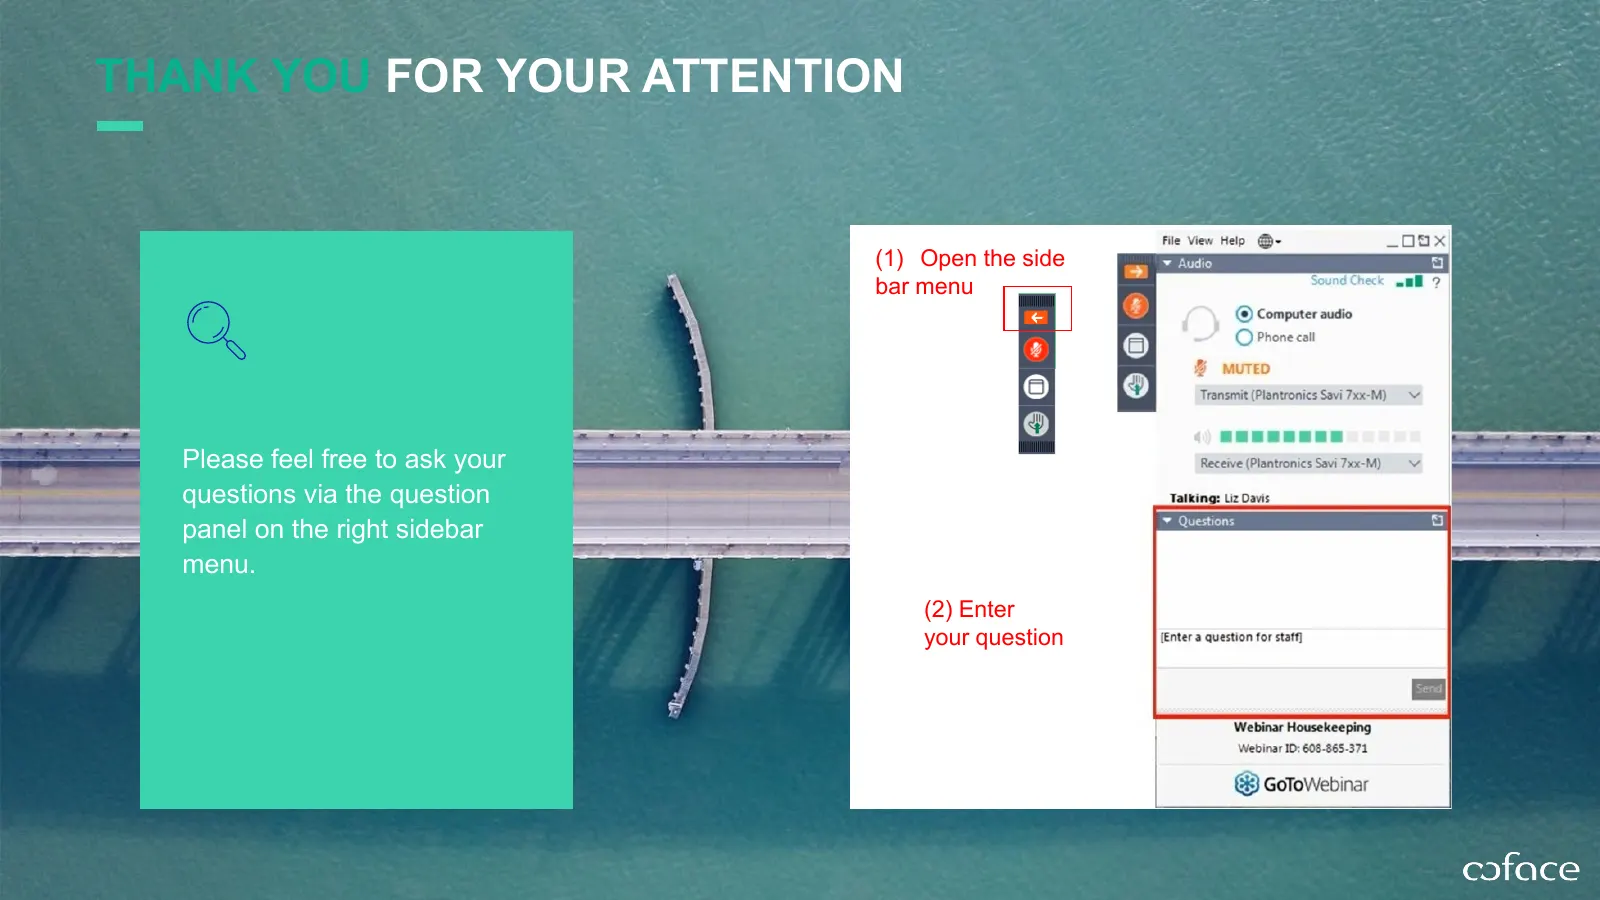
THANK YOU FOR YOUR ATTENTION (1) Open the side bar menu Please feel free to ask your questions via the question panel on the right sidebar menu. (2) Enter your question
Slide 35: Coface on LinkedIn
COFACE ON LINKEDIN W E E N C O U R A G E Y O U TO F O L L O W U S O N C O FA C E LINKEDIN ACCOUNT FOR MORE ECONOMIC RESEARCH, C O M PA N Y U P D AT E S , AND CAREER OPENINGS! H T T P S : / / W W W . L I N K E D I N . C O M / C O M PA N Y / C O F A C E
Source: Internet Archive copy of img.go.coface.com
More decks from Coface SA
 9M-2026 Earnings Presentation28 slides · Nov 2, 2026
 H1 2026 Earnings Presentation37 slides · Jul 30, 2026
 Shareholder Meeting (May 2026)82 slides · May 19, 2026
 Q1 2026 Earnings Presentation28 slides · May 12, 2026
 FY2025 Earnings Presentation37 slides · Feb 19, 2026
 Q3 2025 Earnings Presentation27 slides · Nov 3, 2025