Intercorp Financial Services Inc. · NYSE:IFS
Intercorp Financial Services — 4Q24 Earnings Presentation
53 slides from Intercorp Financial Services's earnings presentation, February 2025
Slide 1: Earnings Presentation 4Q24 & FY24 results
Earnings Presentation 4Q24 & FY24 results
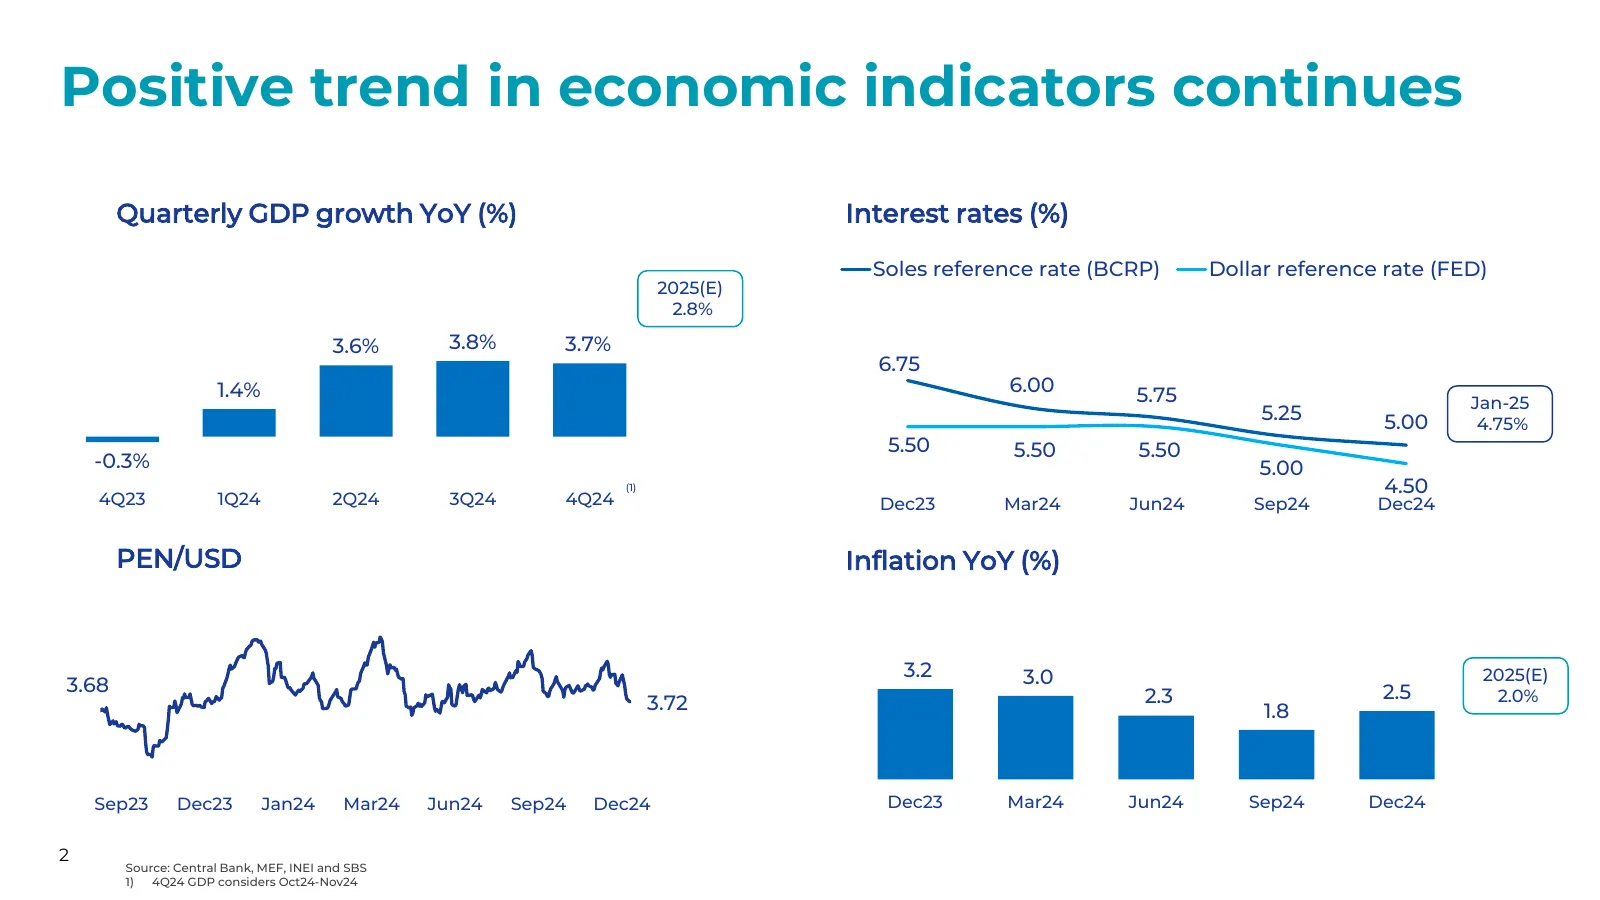
Slide 2: Positive trend in economic indicators continues
Positive trend in economic indicators continues Quarterly GDP growth YoY (%) Interest rates (%) Soles reference rate (BCRP) Dollar reference rate (FED) 2025(E) 2.8% 3.6% 3.8% 3.7% 6.75 1.4% 6.00 5.75 Jan-25 5.25 5.00 4.75% 5.50 5.50 5.50 -0.3% 5.00 (1) 4.50 4Q23 1Q24 2Q24 3Q24 4Q24 Dec23 Mar24 Jun24
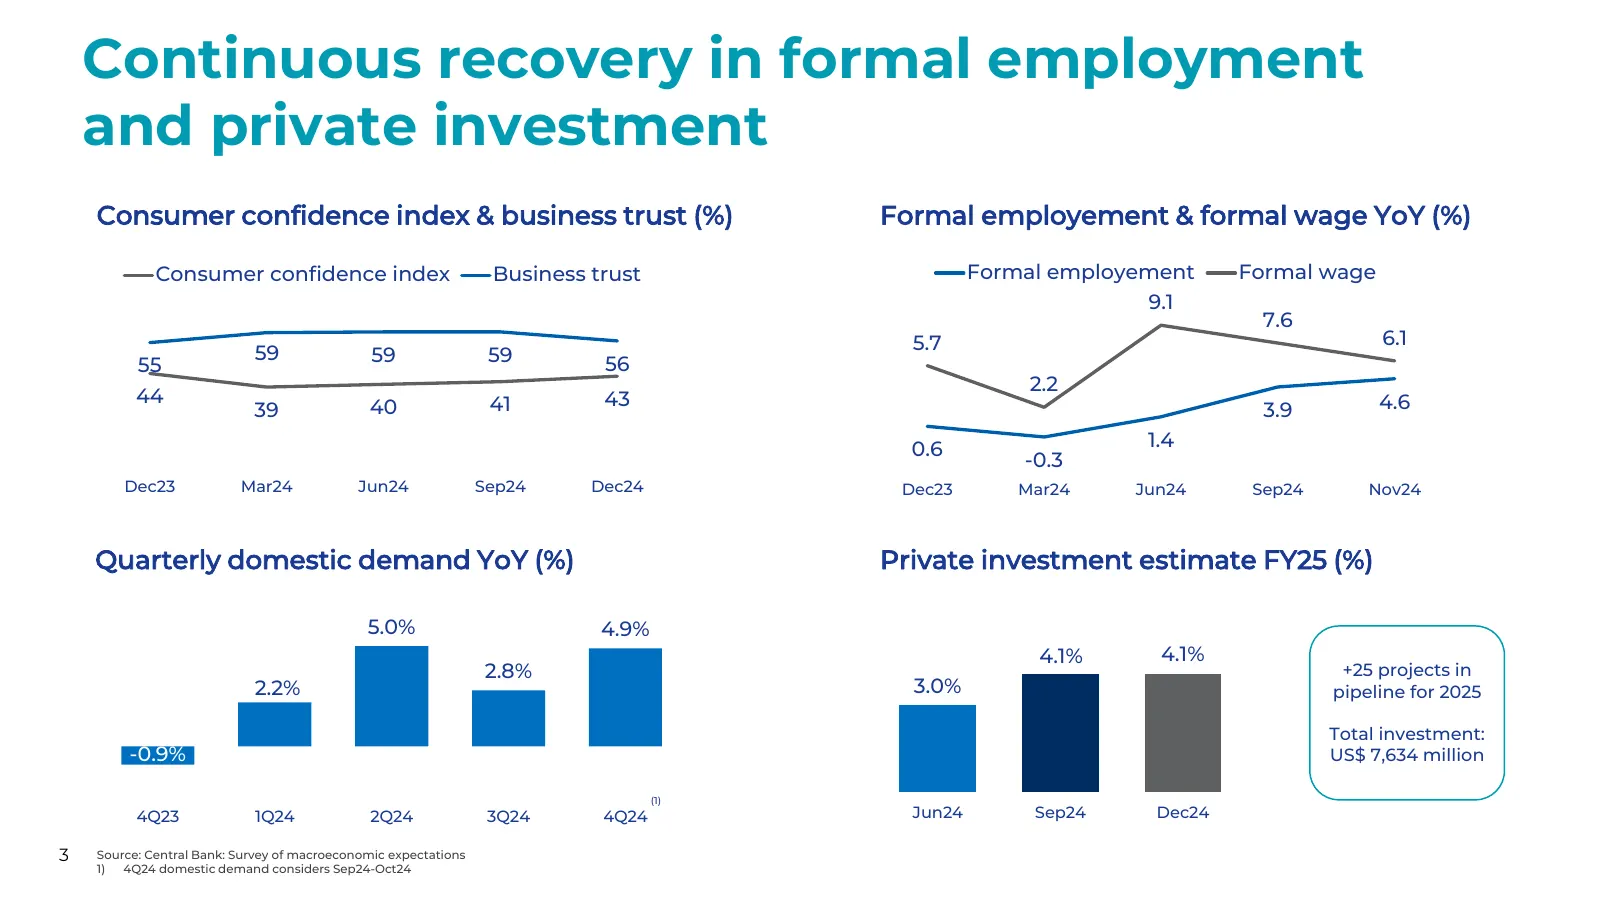
Slide 3: Continuous recovery in formal employment and private investment
Continuous recovery in formal employment and private investment Consumer confidence index & business trust (%) Formal employement & formal wage YoY (%) Consumer confidence index Business trust Formal employement Formal wage 9.1 7.6 5.7 6.1 59 59 59 55 56 2.2 44 41 43 4.6 39 40 3.9 0.6 1.4 -0.3 Dec23
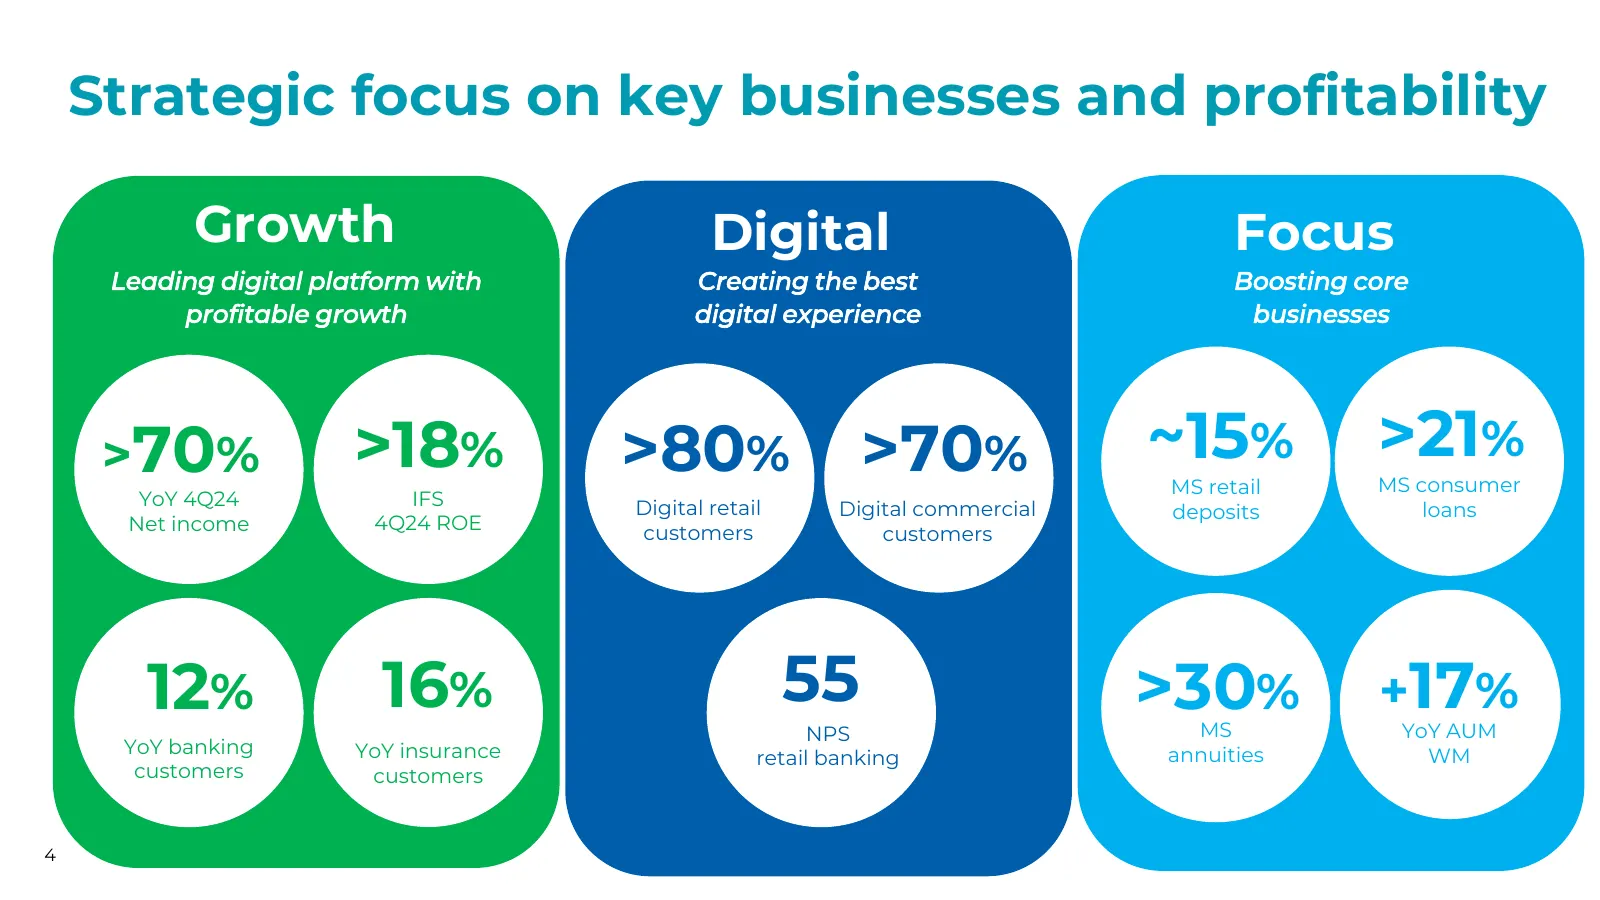
Slide 4: Strategic focus on key businesses and profitability
Strategic focus on key businesses and profitability Growth Digital Focus Leading digital platform with Creating the best Boosting core profitable growth digital experience businesses >70% >18% >80% >70% ~15% >21% MS retail MS consumer YoY 4Q24 IFS Digital retail Digital commercial deposits loans Net
Slide 5: Key messages
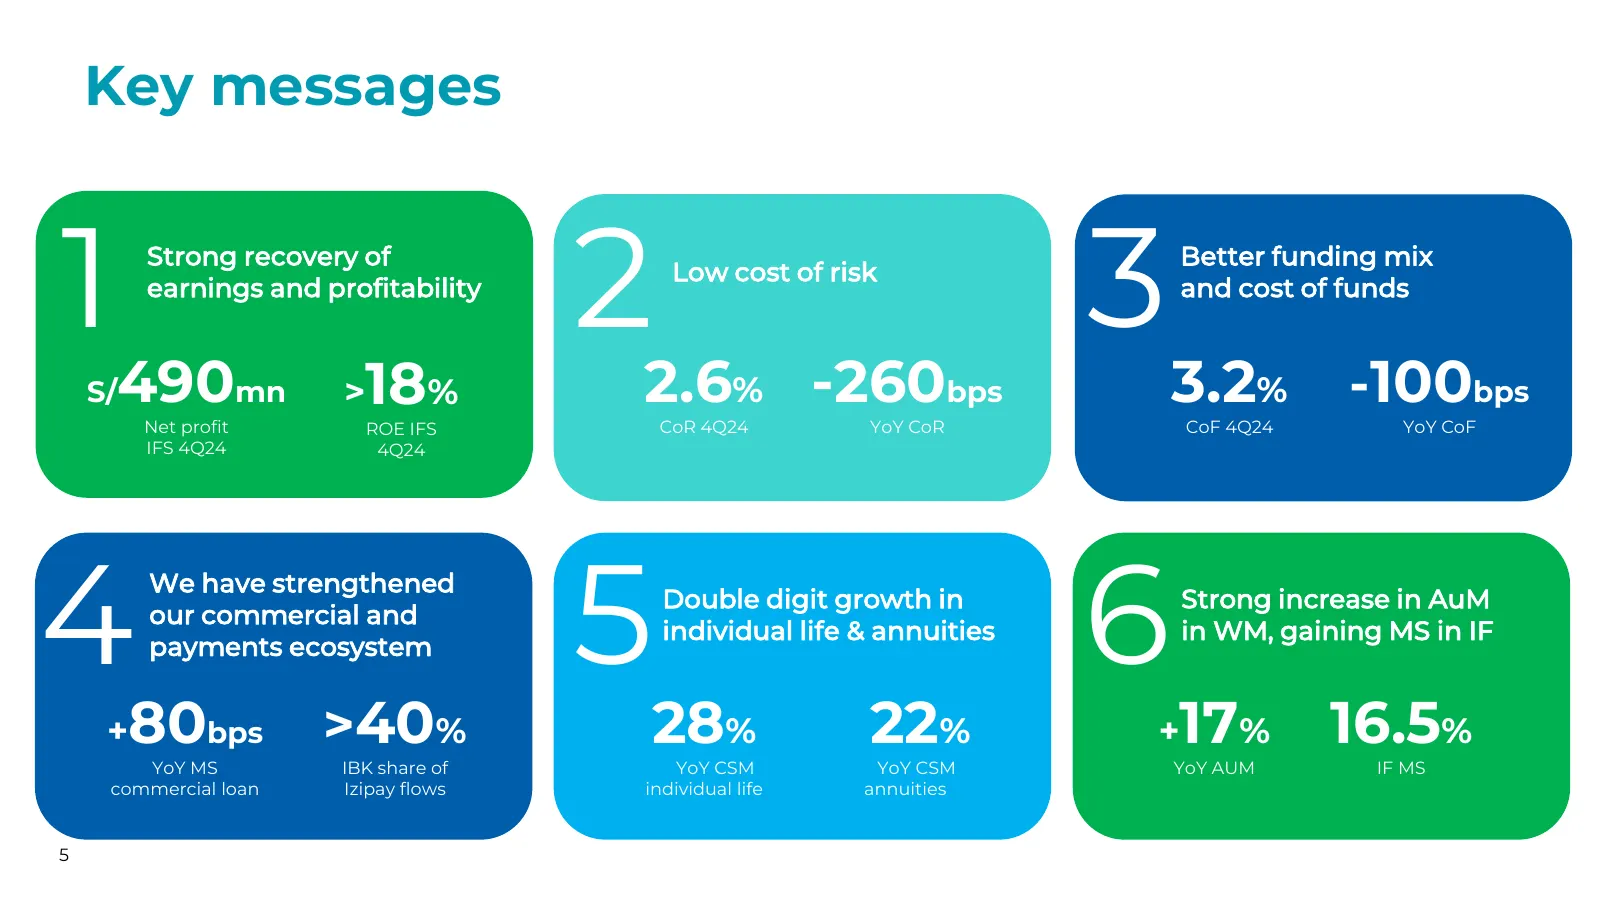
Key messages 1 Strong recovery of earnings and profitability 2 Low cost of risk 3 Better funding mix and cost of funds 490mn S/ > 18% 2.6% -260bps 3.2% -100bps Net profit ROE IFS CoR 4Q24 YoY CoR CoF 4Q24 YoY CoF IFS 4Q24 4Q24 4 5 6 We have strengthened Double digit growth in Strong increase in AuM
Slide 6: Sustainable growth, Digital, Key businesses update, Guidance & takeaways
1 2 Key Sustainable businesses growth 3 Digital update 4 Guidance & takeaways
Slide 7: Sustainable growth, Digital, Key businesses update, Guidance & takeaways
1 2 Key Sustainable businesses growth 3 Digital update 4 Guidance & takeaways
Slide 8: +71% YoY earnings drive quarterly ROE to >18%
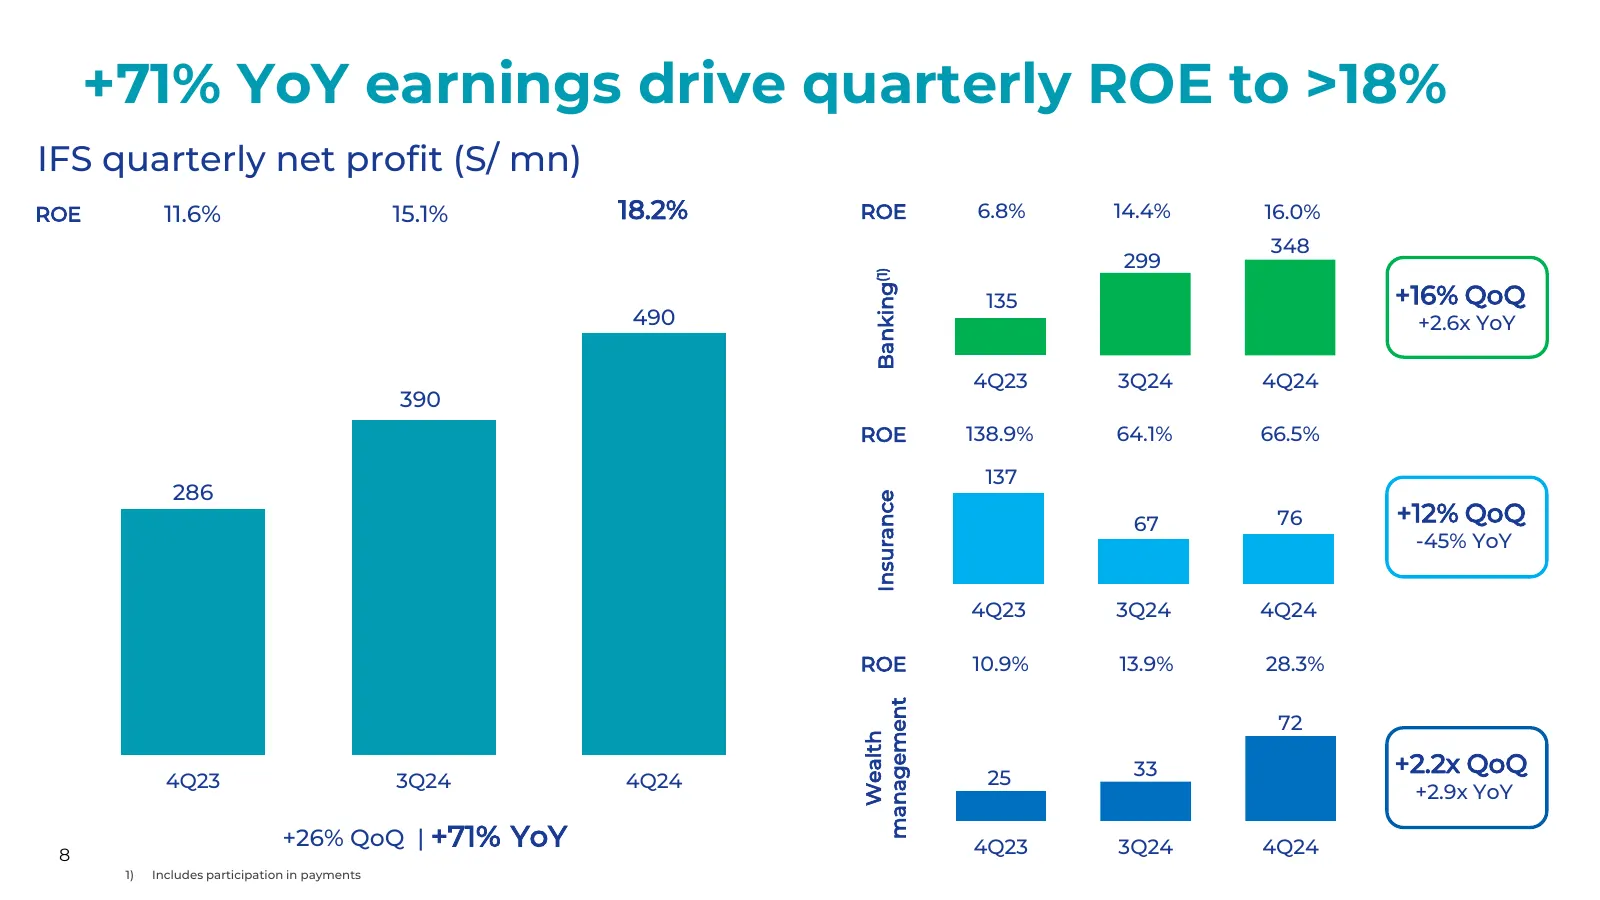
+71% YoY earnings drive quarterly ROE to >18% IFS quarterly net profit (S/ mn) ROE 11.6% 15.1% 18.2% ROE 6.8% 14.4% 16.0% 348 299 Banking(1) 135 +16% QoQ 490 +2.6x YoY 4Q23 3Q24 4Q24 390 ROE 138.9% 64.1% 66.5% 137 286 Insurance 67 76 +12% QoQ -45% YoY 4Q23 3Q24 4Q24 ROE 10.9% 13.9% 28.3% management
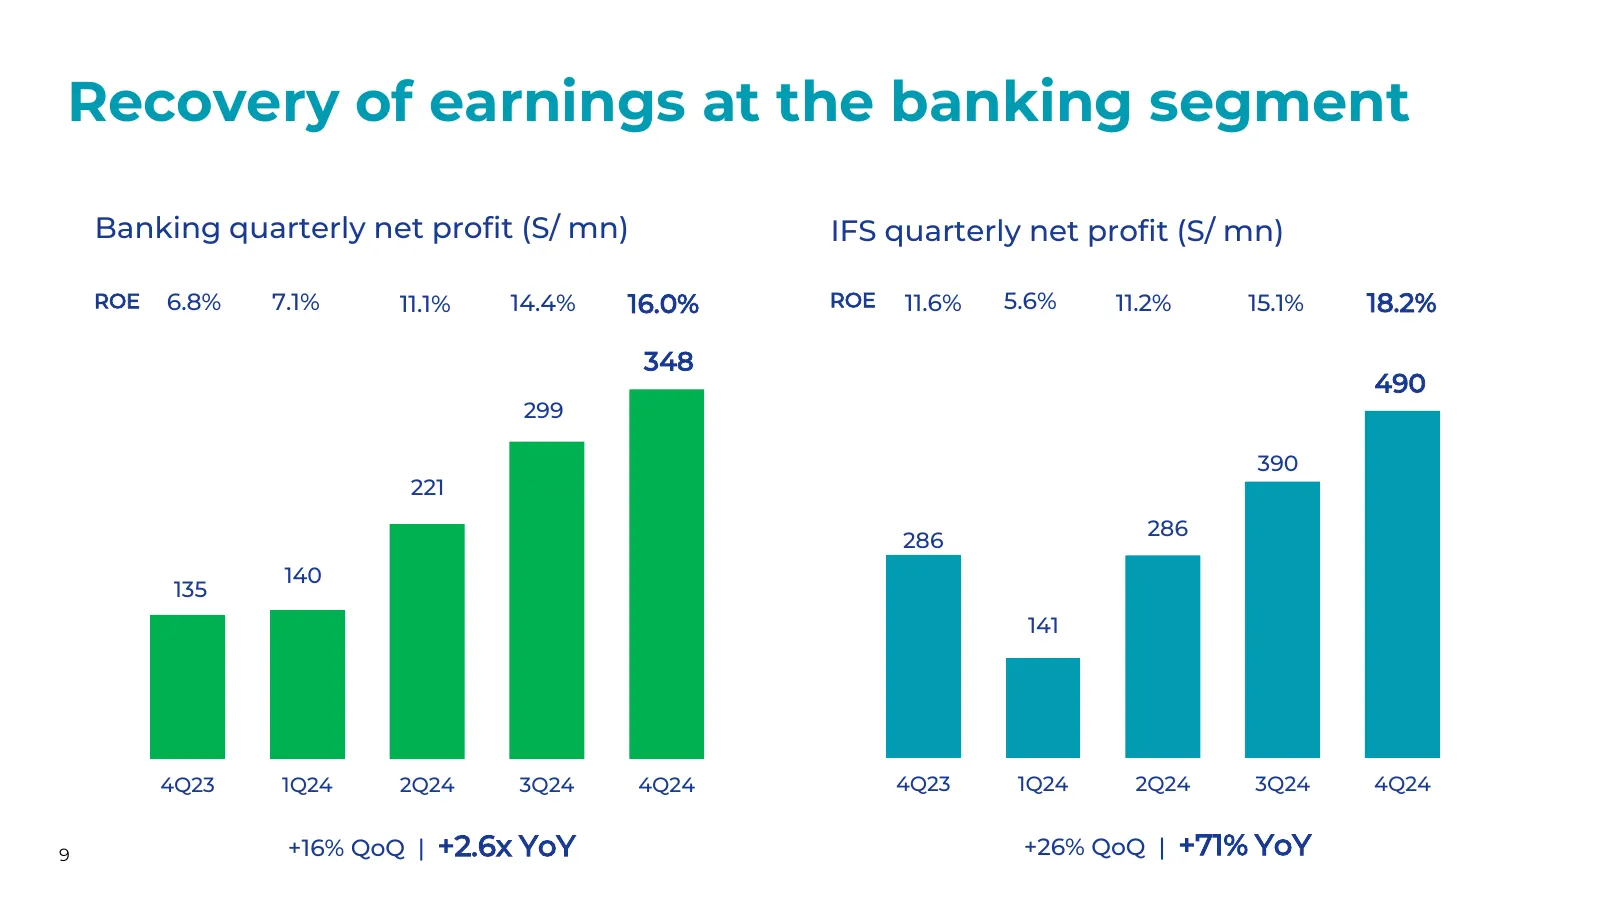
Slide 9: Recovery of earnings at the banking segment
Recovery of earnings at the banking segment Banking quarterly net profit (S/ mn) IFS quarterly net profit (S/ mn) ROE 6.8% 7.1% 11.1% 14.4% 16.0% ROE 11.6% 5.6% 11.2% 15.1% 18.2% 348 490 299 390 221 286 286 140 135 141 4Q23 1Q24 2Q24 3Q24 4Q24 4Q23 1Q24 2Q24 3Q24 4Q24 9 +16% QoQ | +2.6x YoY +26% QoQ
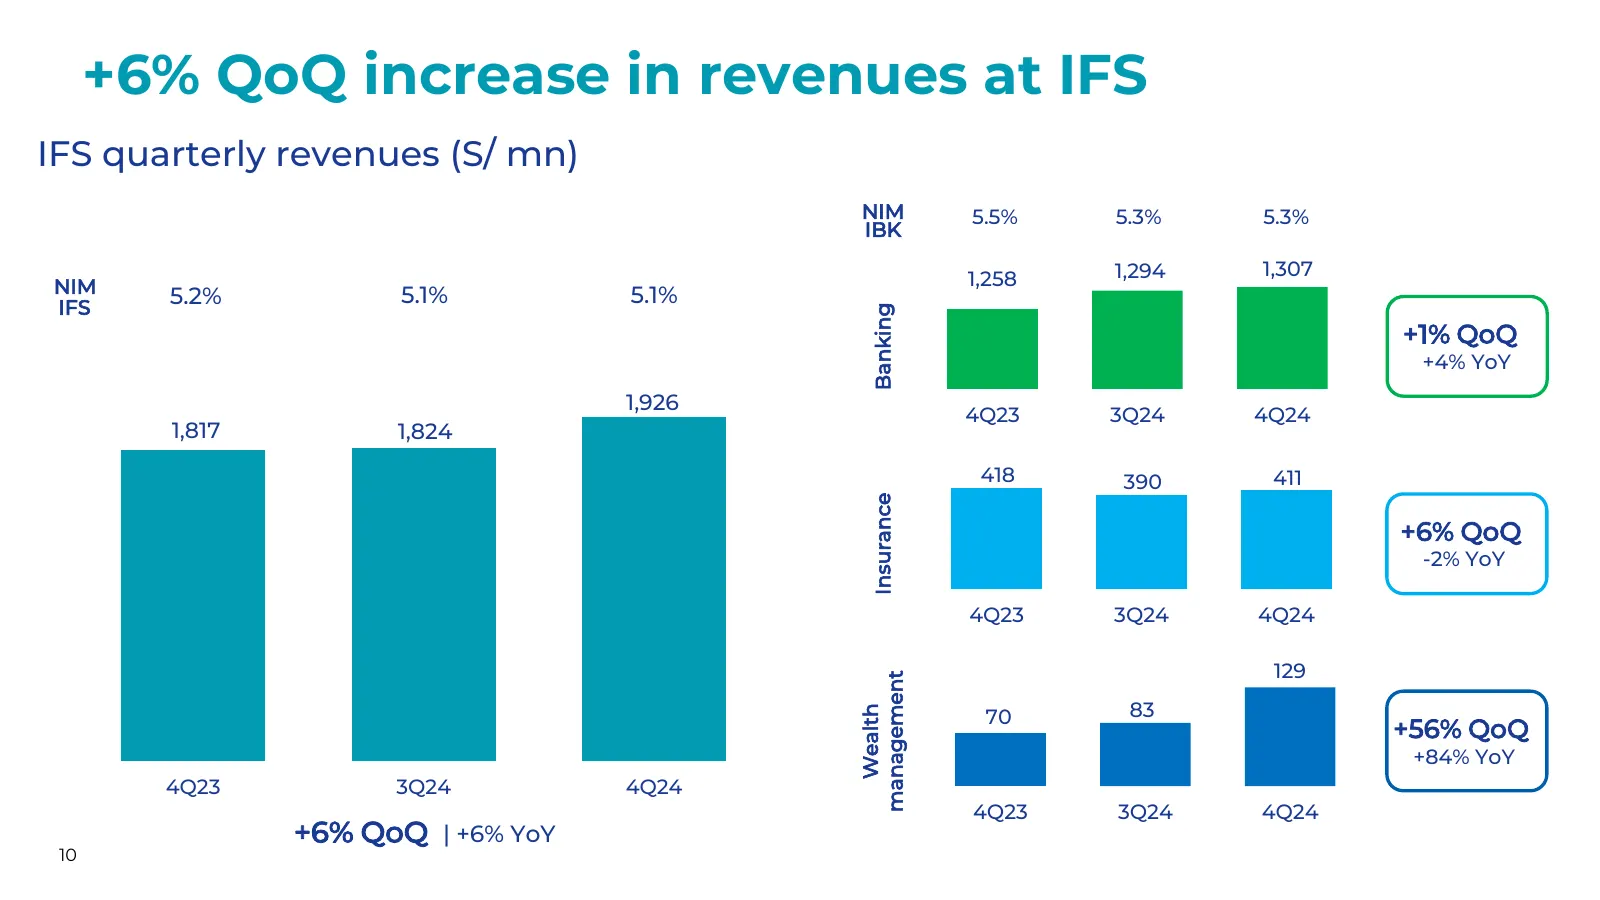
Slide 10: +6% QoQ increase in revenues at IFS
+6% QoQ increase in revenues at IFS IFS quarterly revenues (S/ mn) NIM 5.5% 5.3% 5.3% IBK 1,258 1,294 1,307 NIM 5.1% 5.1% IFS 5.2% Banking +1% QoQ +4% YoY 1,926 4Q23 3Q24 4Q24 1,817 1,824 418 390 411 Insurance +6% QoQ -2% YoY 4Q23 3Q24 4Q24 129 management 83 Wealth 70 +56% QoQ +84% YoY 4Q23 3Q24 4Q2
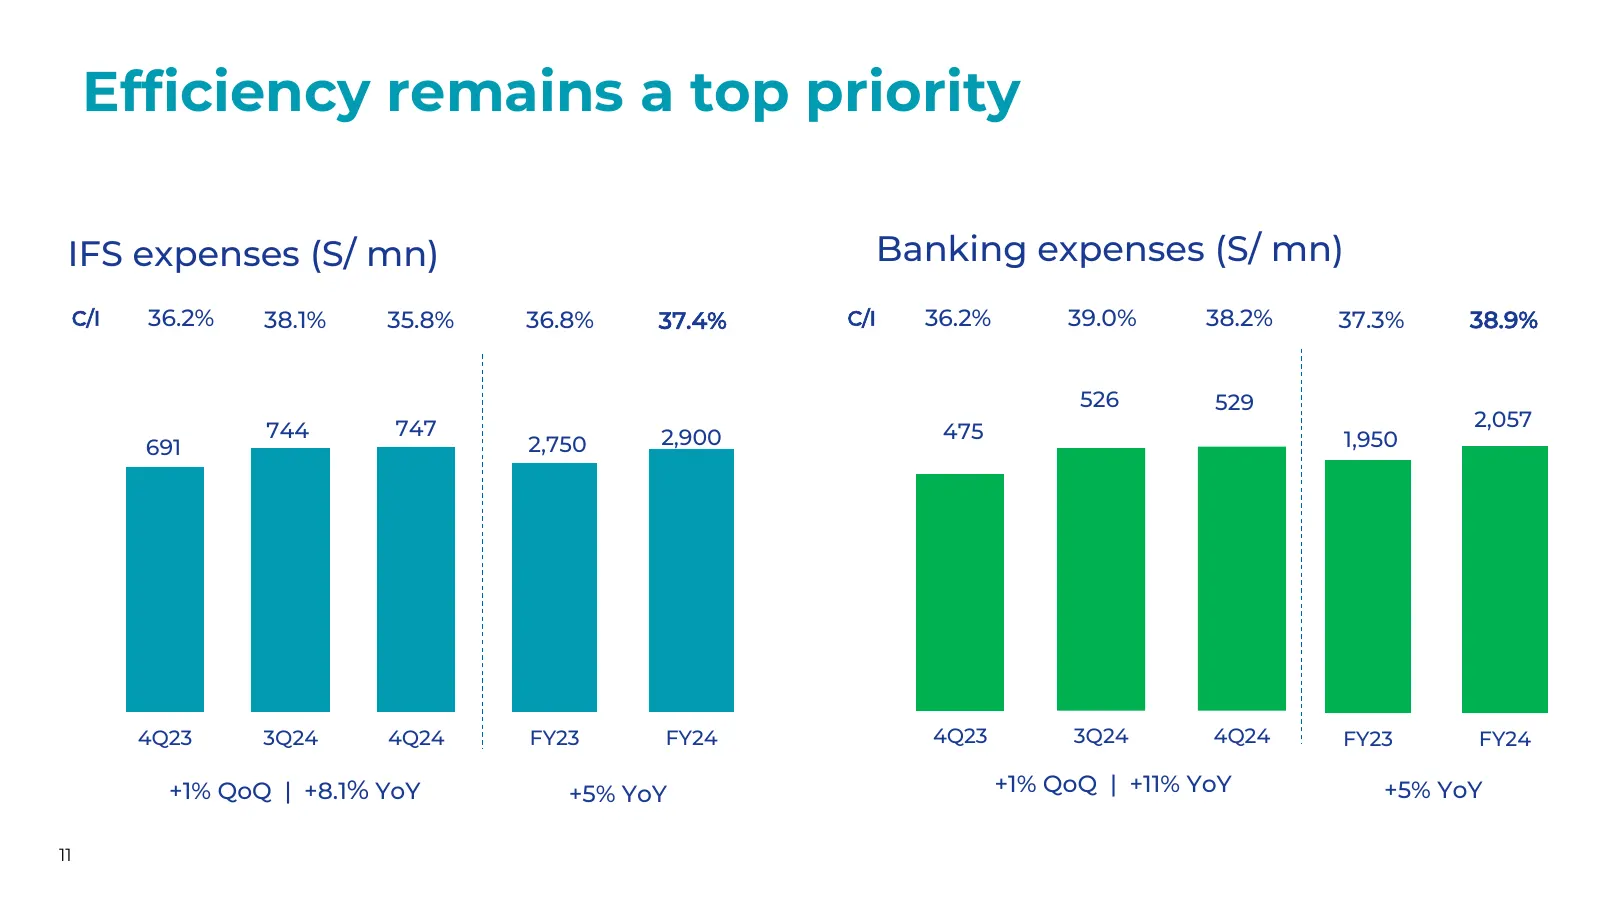
Slide 11: Efficiency remains a top priority
Efficiency remains a top priority IFS expenses (S/ mn) Banking expenses (S/ mn) C/I 36.2% 38.1% 35.8% 36.8% 37.4% C/I 36.2% 39.0% 38.2% 37.3% 38.9% 526 529 744 747 2,057 2,900 475 1,950 691 2,750 4Q23 3Q24 4Q24 FY23 FY24 4Q23 3Q24 4Q24 FY23 FY24 +1% QoQ | +8.1% YoY +5% YoY +1% QoQ | +11% YoY +5% YoY
Slide 12: Sustainable growth, Digital, Key businesses update, Guidance & takeaways
1 2 Key Sustainable businesses growth 3 Digital update 4 Guidance & takeaways
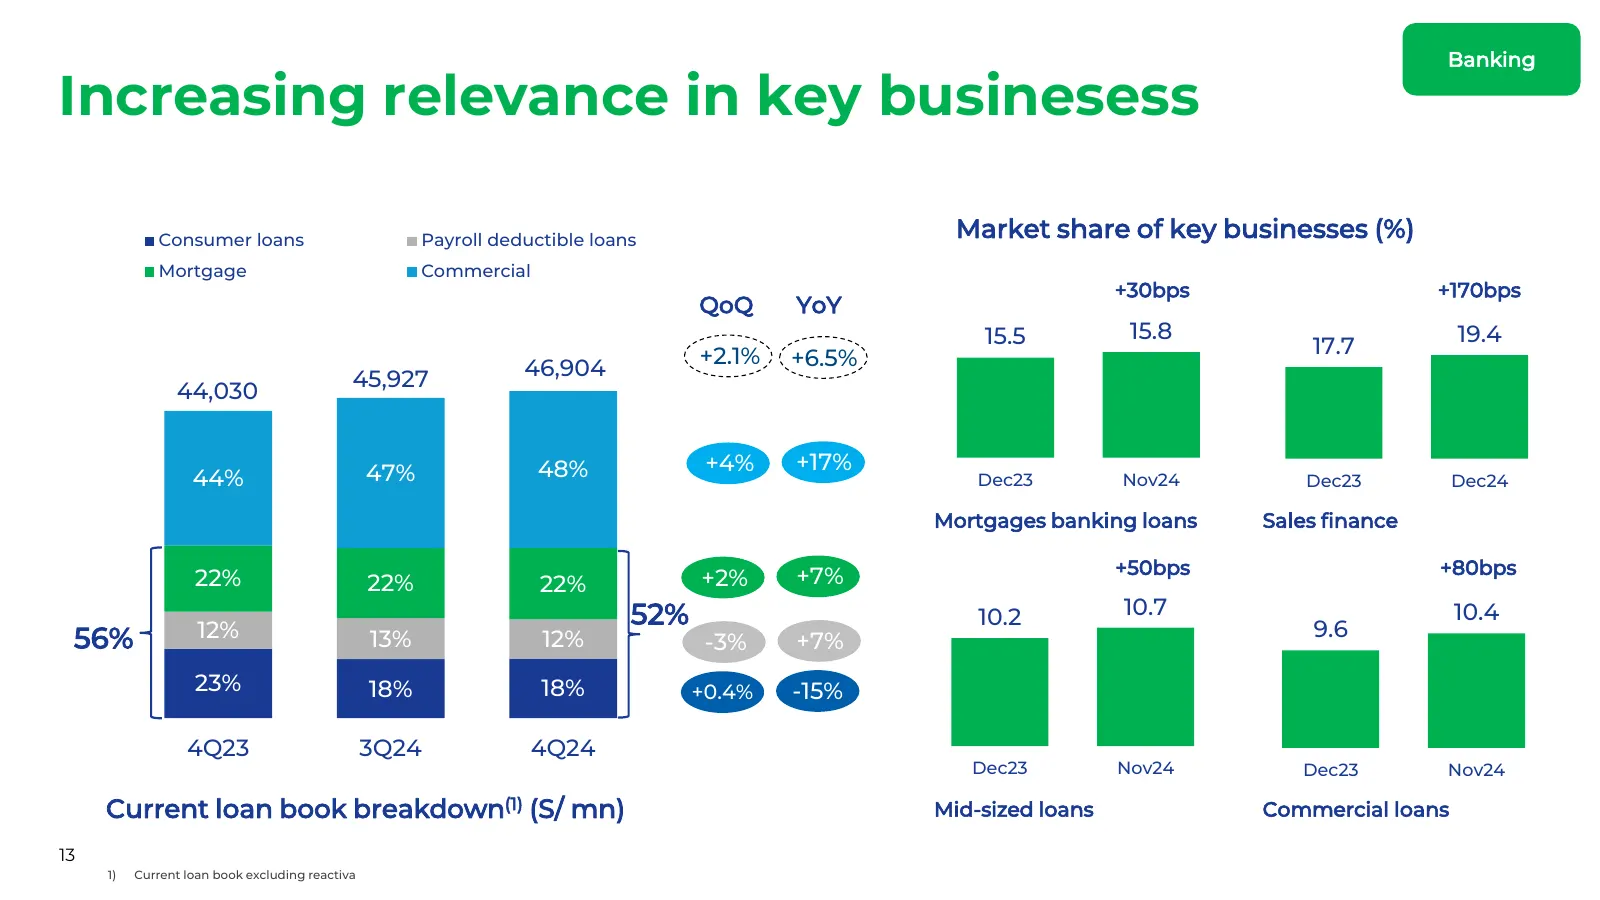
Slide 13: Increasing relevance in key businesses
Banking Increasing relevance in key businesess Consumer loans Payroll deductible loans Market share of key businesses (%) Mortgage Commercial +30bps +170bps QoQ YoY 15.5 15.8 19.4 +2.1% +6.5% 17.7 45,927 46,904 44,030 43% 46% 47% 47% 48% +4% +17% 44% Dec23 Nov24 Dec23 Dec24 Mortgages banking loans S
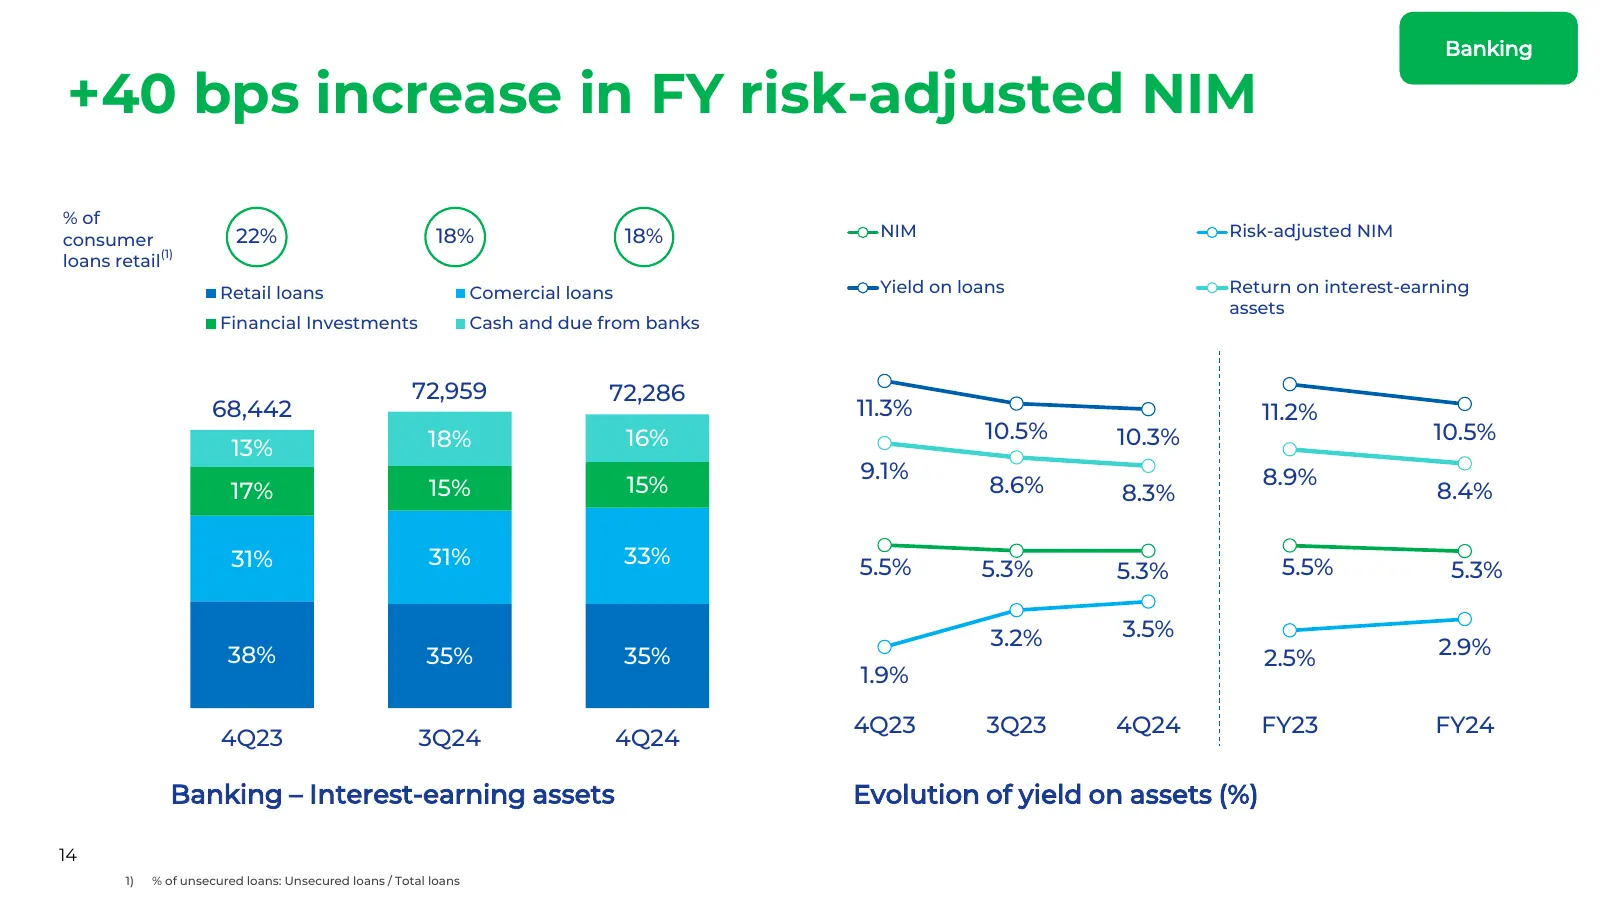
Slide 14: +40 bps increase in FY risk-adjusted NIM
Banking +40 bps increase in FY risk-adjusted NIM % of consumer 22% 18% 18% NIM Risk-adjusted NIM loans retail(1) Retail loans Comercial loans Yield on loans Return on interest-earning assets Financial Investments Cash and due from banks 72,959 72,286 68,442 11.3% 11.2% 18% 16% 10.5% 10.3% 10.5% 13%
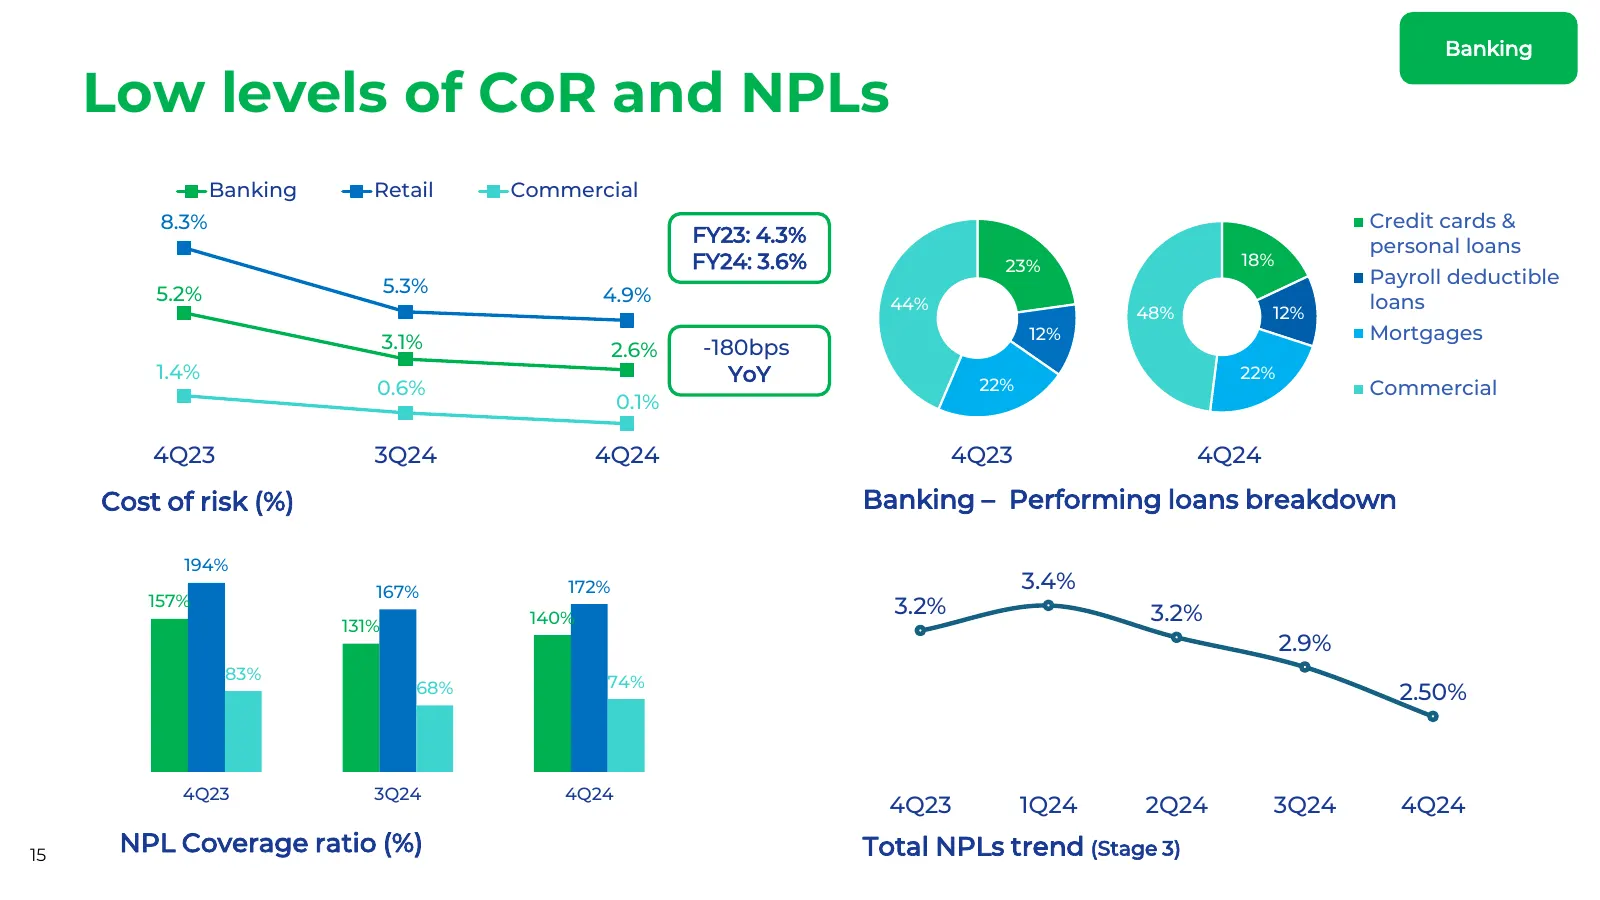
Slide 15: Low levels of CoR and NPLs
Banking Low levels of CoR and NPLs Banking Retail Commercial 8.3% Credit cards & FY23: 4.3% personal loans FY24: 3.6% 23% 18% 5.3% Payroll deductible 5.2% 4.9% 44% loans 48% 12% 3.1% 12% Mortgages 2.6% -180bps 1.4% YoY 22% 0.6% 22% Commercial 0.1% 4Q23 3Q24 4Q24 4Q23 4Q24 Cost of risk (%) Banking –
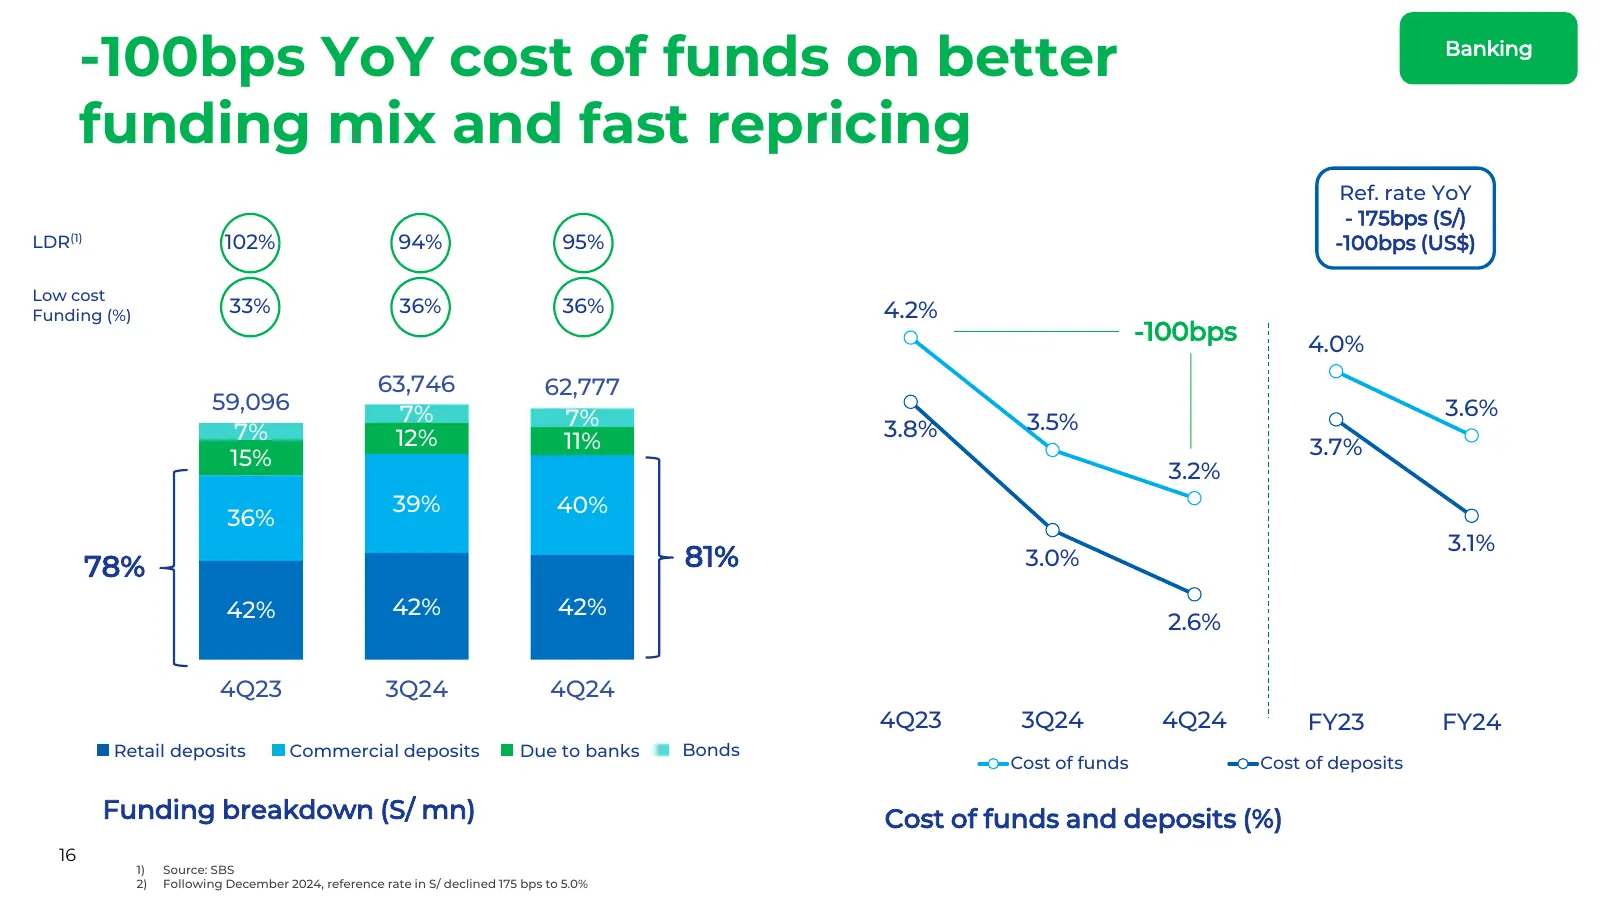
Slide 16: -100bps YoY cost of funds on better funding mix and fast repricing
-100bps YoY cost of funds on better Banking funding mix and fast repricing Ref. rate YoY - 175bps (S/) LDR(1) 102% 94% 95% -100bps (US$) Low cost Funding (%) 33% 36% 36% 4.2% -100bps 4.0% 63,746 62,777 59,096 7% 3.6% 7% 3.8% 3.5% 7% 12% 11% 15% 3.7% 3.2% 39% 40% 36% 3.1% 78% 81% 3.0% 42% 42% 42% 2.6
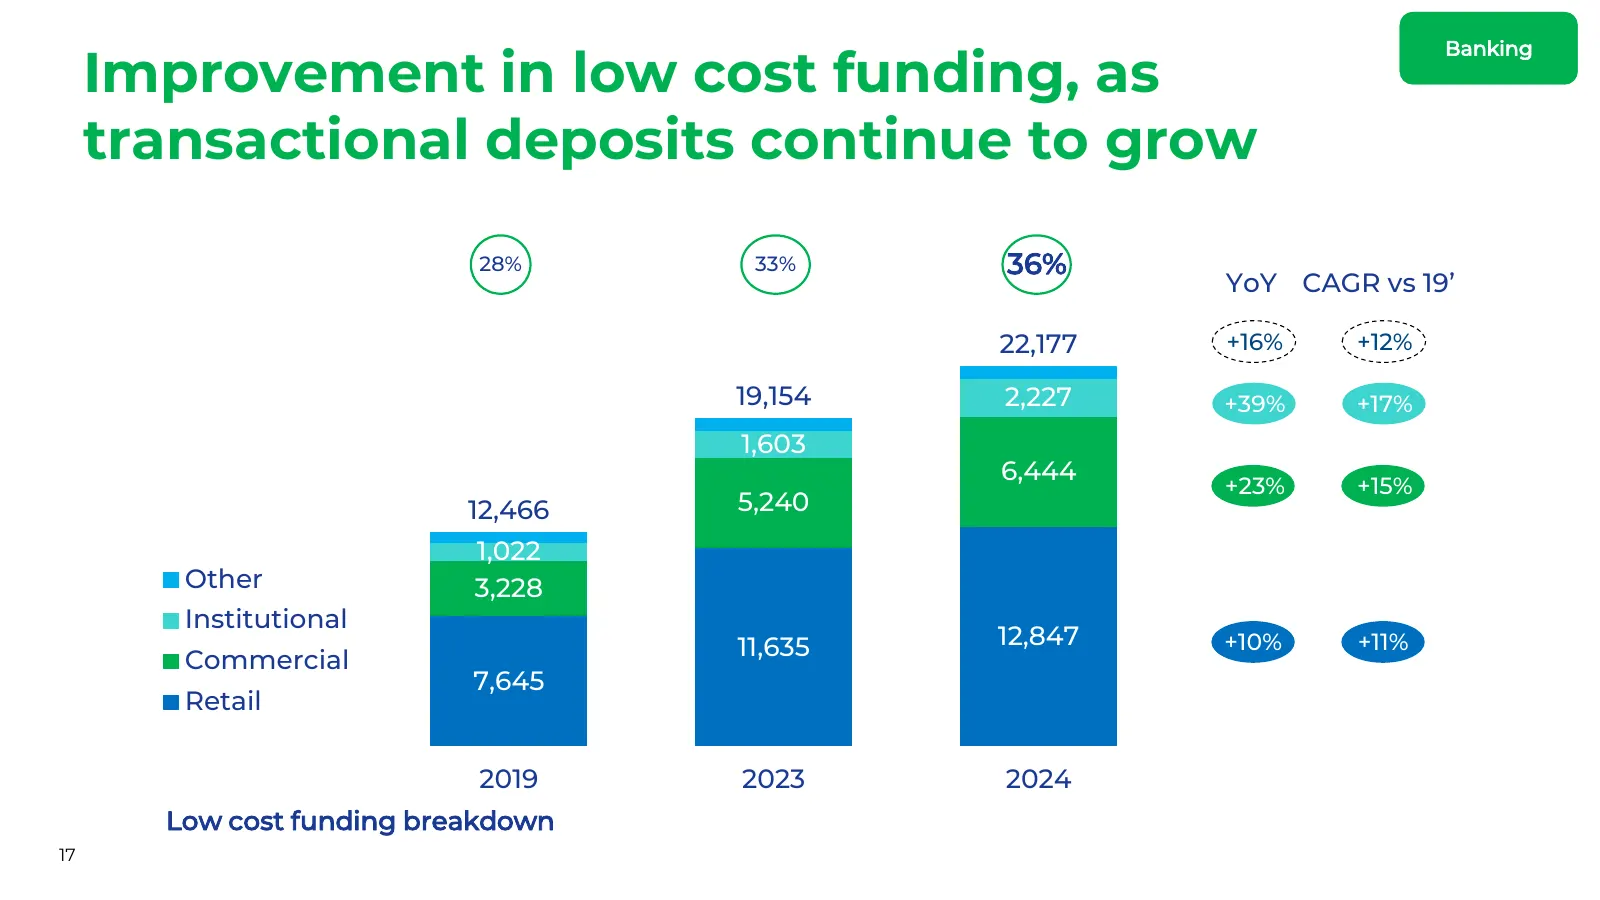
Slide 17: Improvement in low cost funding, as transactional deposits continue to grow
Banking Improvement in low cost funding, as transactional deposits continue to grow 28% 33% 36% YoY CAGR vs 19’ 22,177 +16% +12% 19,154 2,227 +39% +17% 1,603 6,444 +23% +15% 12,466 5,240 1,022 Other 3,228 Institutional 11,635 12,847 +10% +11% Commercial 7,645 Retail 2019 2023 2024 Low cost funding b
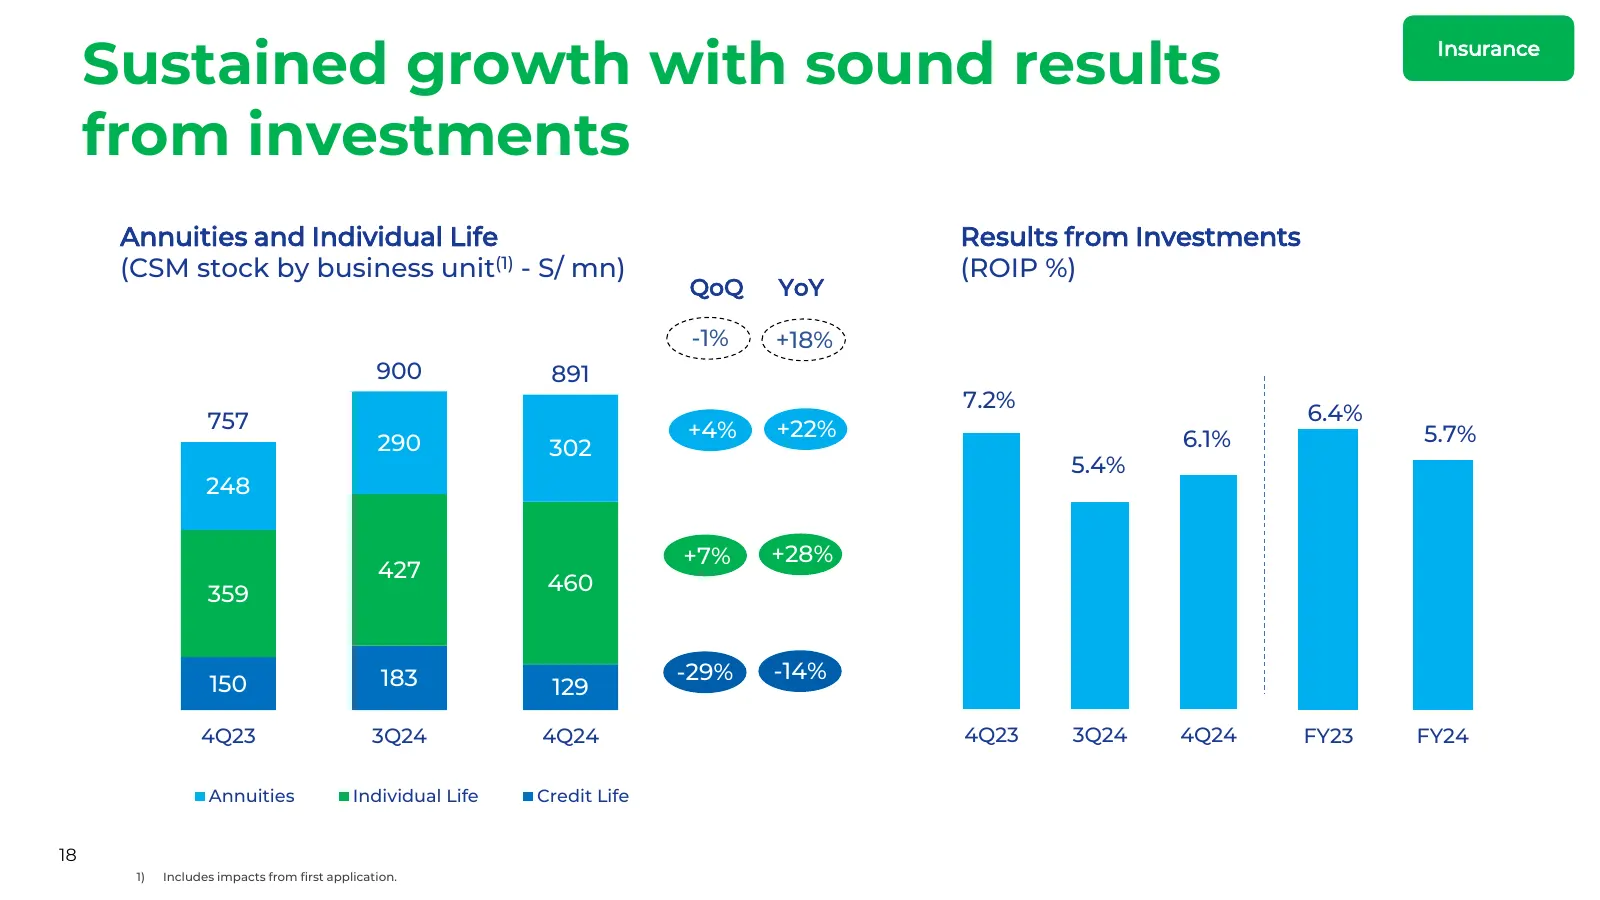
Slide 18: Sustained growth with sound results from investments
Sustained growth with sound results Insurance from investments Annuities and Individual Life Results from Investments (CSM stock by business unit(1) - S/ mn) (ROIP %) QoQ YoY -1% +18% 1,000 900 891 900 7.2% 757 6.4% 800 +4% +22% 6.1% 5.7% 290 302 700 5.4% 600 248 500 +7% +28% 400 427 359 460 300 200
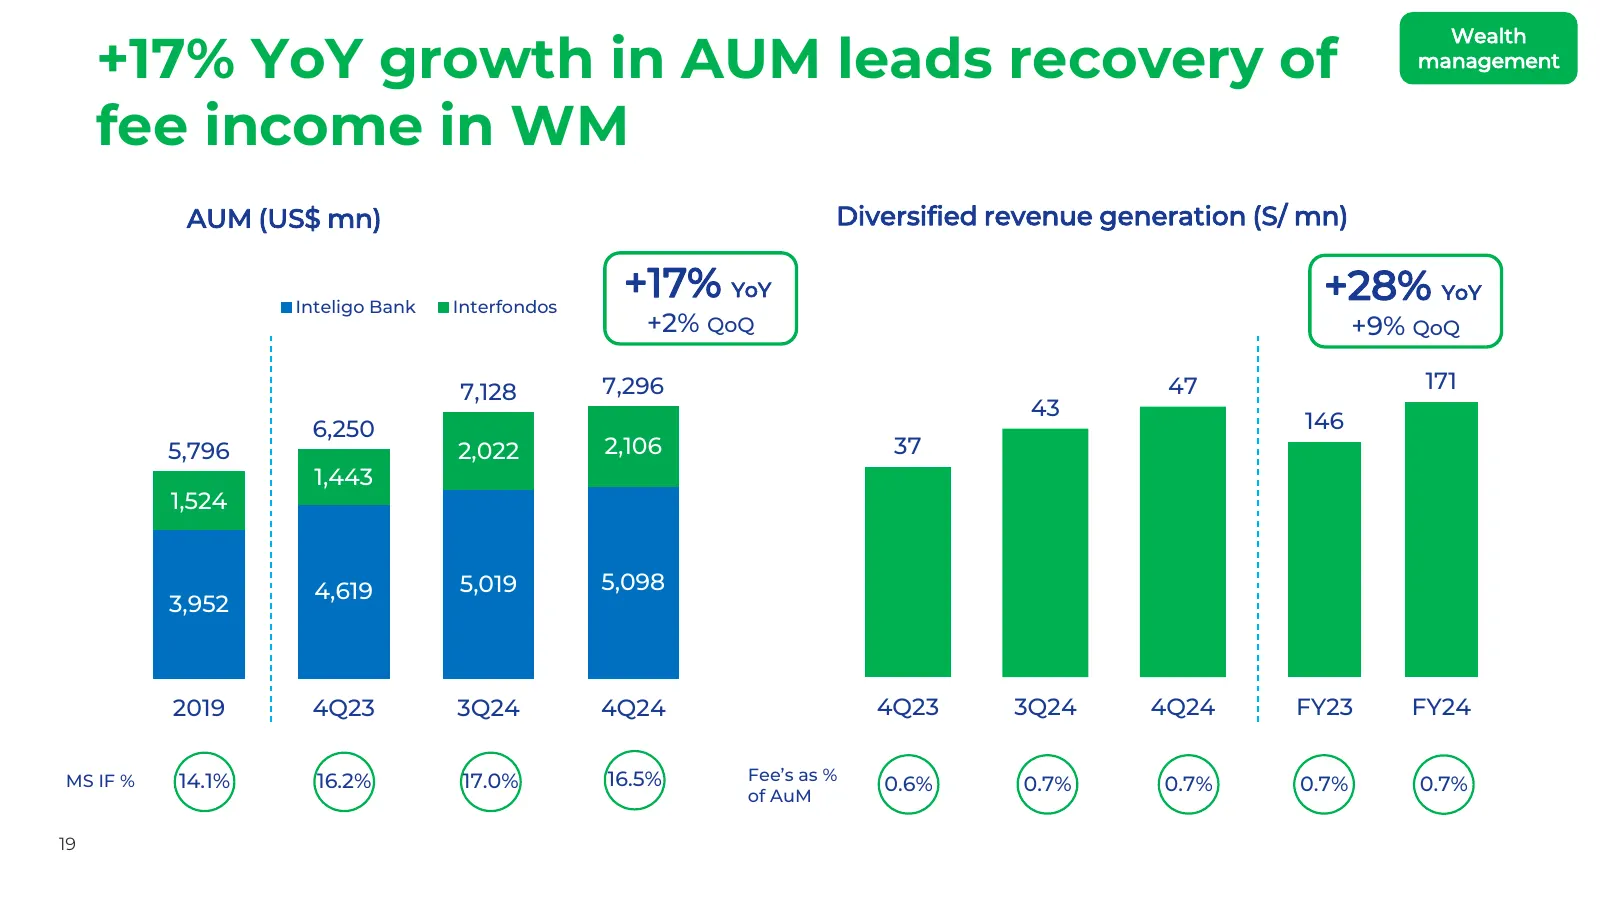
Slide 19: +17% YoY growth in AUM leads recovery of fee income in WM
Wealth +17% YoY growth in AUM leads recovery of management fee income in WM AUM (US$ mn) Diversified revenue generation (S/ mn) Inteligo Bank Interfondos +17% YoY +28% YoY +2% QoQ +9% QoQ 7,128 7,296 47 171 43 6,250 146 5,796 2,022 2,106 37 1,443 1,524 4,619 5,019 5,098 3,952 2019 4Q23 3Q24 4Q24 4Q2
Slide 20: Sustainable growth, Digital, Key businesses update, Guidance & takeaways
1 2 Key Sustainable businesses growth 3 Digital update 4 Guidance & takeaways
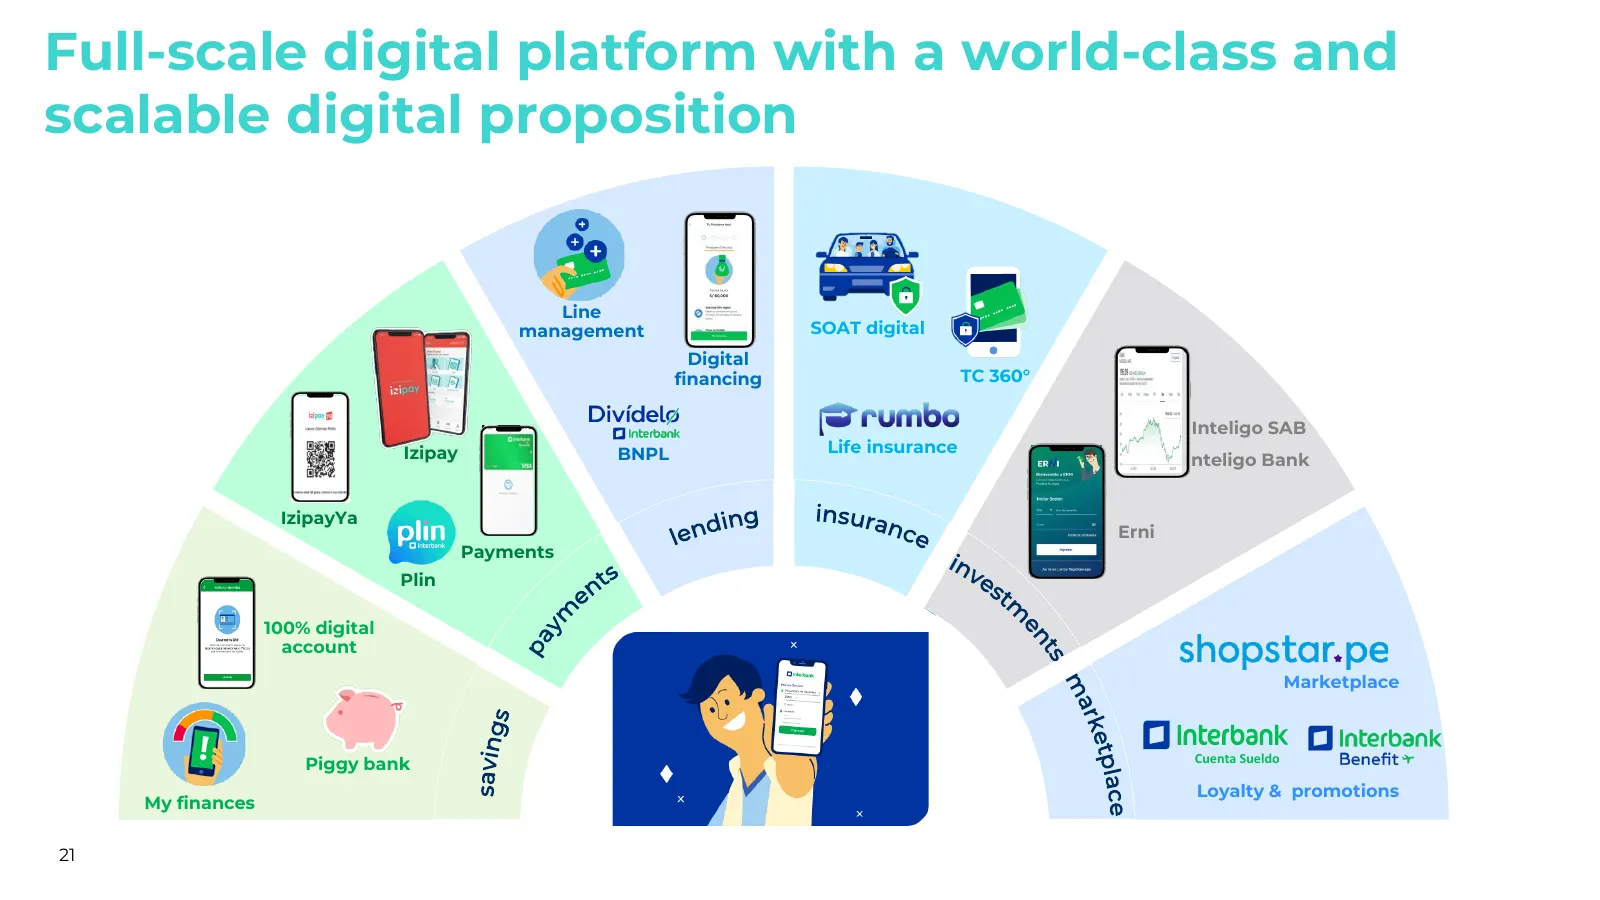
Slide 21: Full-scale digital platform with a world-class and scalable digital proposition
Full-scale digital platform with a world-class and scalable digital proposition Line management SOAT digital Digital financing TC 360° Inteligo SAB Izipay BNPL Life insurance Inteligo Bank insura IzipayYa ding nce len Erni Payments inv Plin nts es e tm ym 100% digital en pa account ts Marketplace m
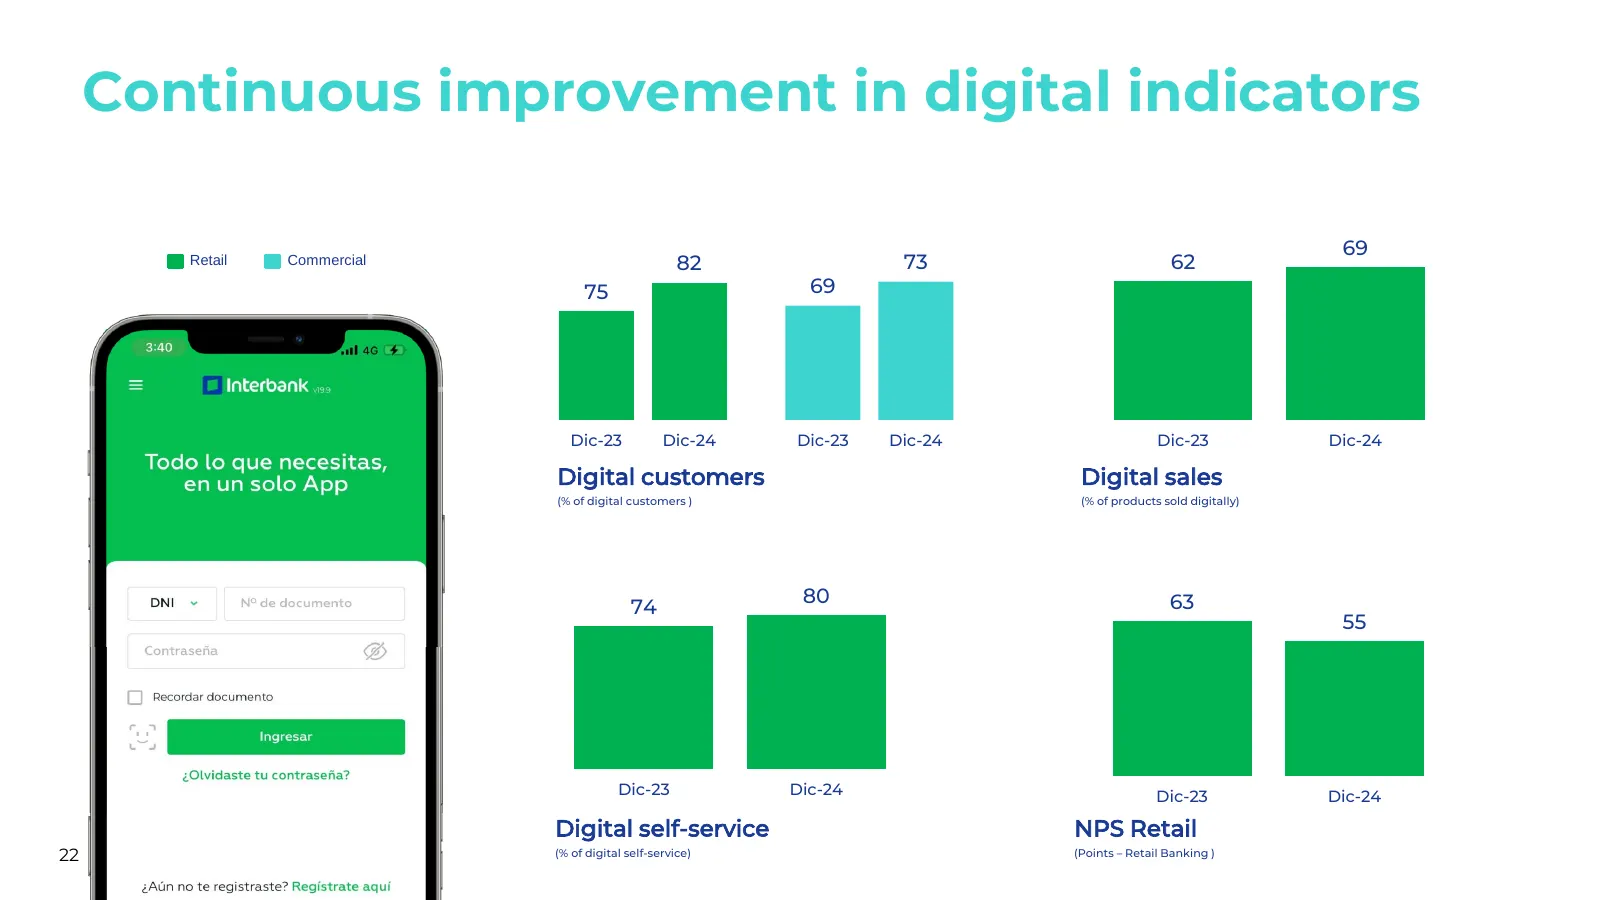
Slide 22: Continuous improvement in digital indicators
Continuous improvement in digital indicators 69 Retail Commercial 82 73 62 75 69 Dic-23 Dic-24 Dic-23 Dic-24 Dic-23 Dic-24 Digital customers Digital sales (% of digital customers ) (% of products sold digitally) 80 63 74 55 Dic-23 Dic-24 Dic-23 Dic-24 Digital self-service NPS Retail 22 (% of digital
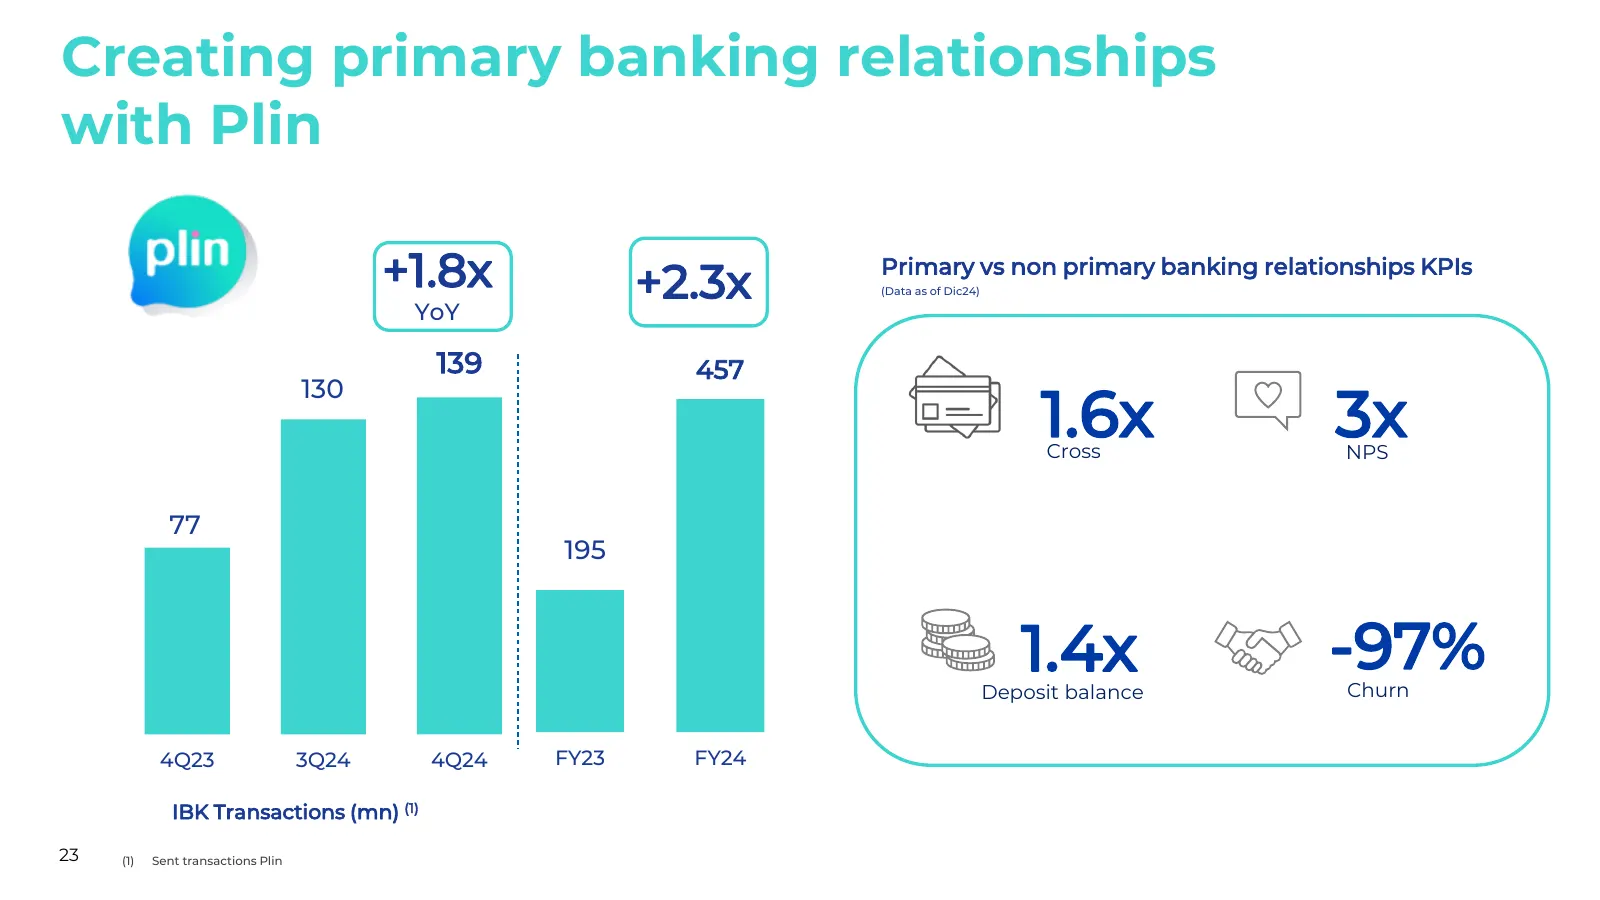
Slide 23: Creating primary banking relationships with Plin
Creating primary banking relationships with Plin +1.8x +2.3x Primary vs non primary banking relationships KPIs (Data as of Dic24) YoY 139 457 130 1.6x Cross 3x NPS 77 195 1.4x Deposit balance -97% Churn 4Q23 3Q24 4Q24 FY23 FY24 IBK Transactions (mn) (1) 23 (1) Sent transactions Plin
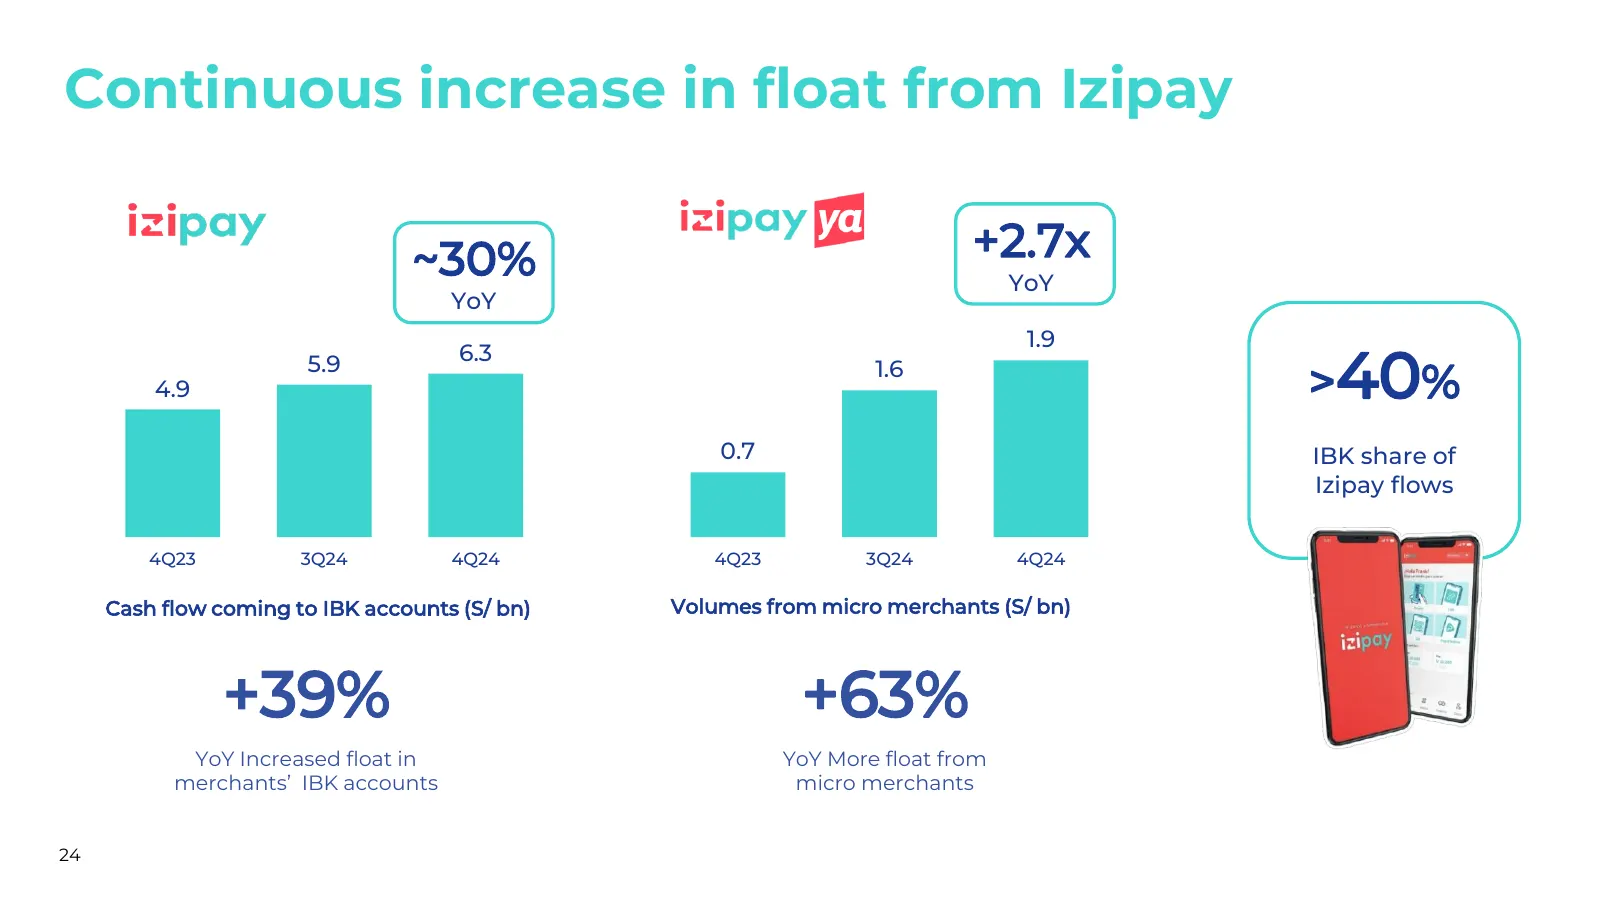
Slide 24: Continuous increase in float from Izipay
Continuous increase in float from Izipay ~30% +2.7x YoY YoY 1.9 >40% 5.9 6.3 1.6 4.9 0.7 IBK share of Izipay flows 4Q23 3Q24 4Q24 4Q23 3Q24 4Q24 Cash flow coming to IBK accounts (S/ bn) Volumes from micro merchants (S/ bn) +39% +63% YoY Increased float in YoY More float from merchants’ IBK accounts
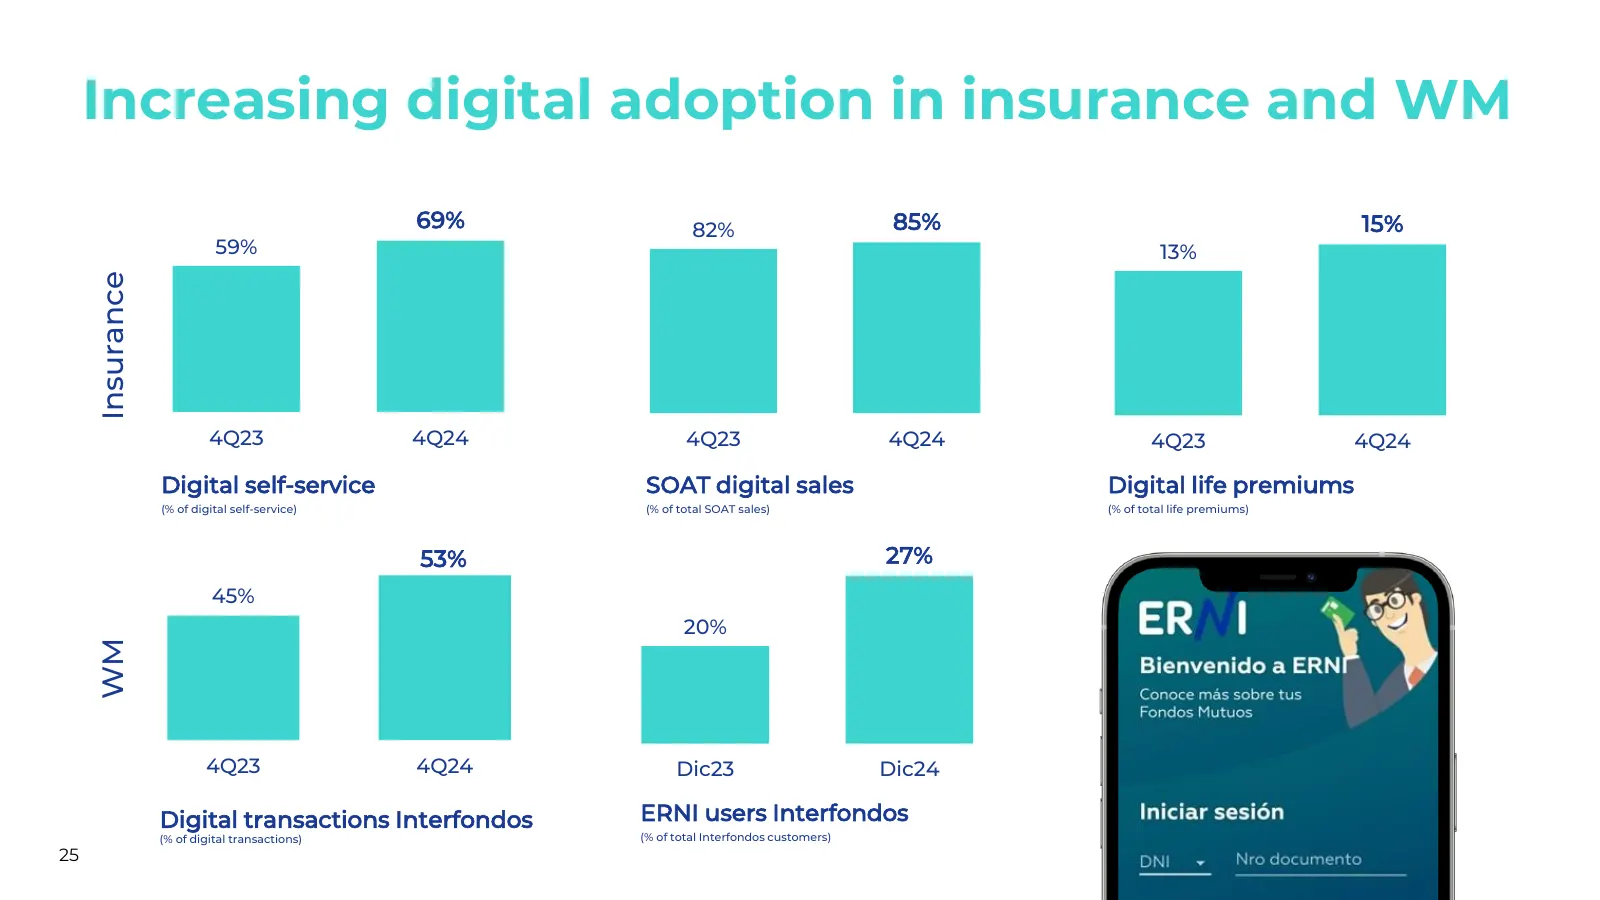
Slide 25: Increasing digital adoption in insurance and WM
Increasing digital adoption in insurance and WM 69% 82% 85% 15% 59% 13% Insurance 4Q23 4Q24 4Q23 4Q24 4Q23 4Q24 Digital self-service SOAT digital sales Digital life premiums (% of digital self-service) (% of total SOAT sales) (% of total life premiums) 53% 27% 45% 20% WM 4Q23 4Q24 Dic23 Dic24 Digita
Slide 26: Sustainable growth, Digital, Key businesses update, Guidance & takeaways
1 2 Key Sustainable businesses growth 3 Digital update 4 Guidance & takeaways
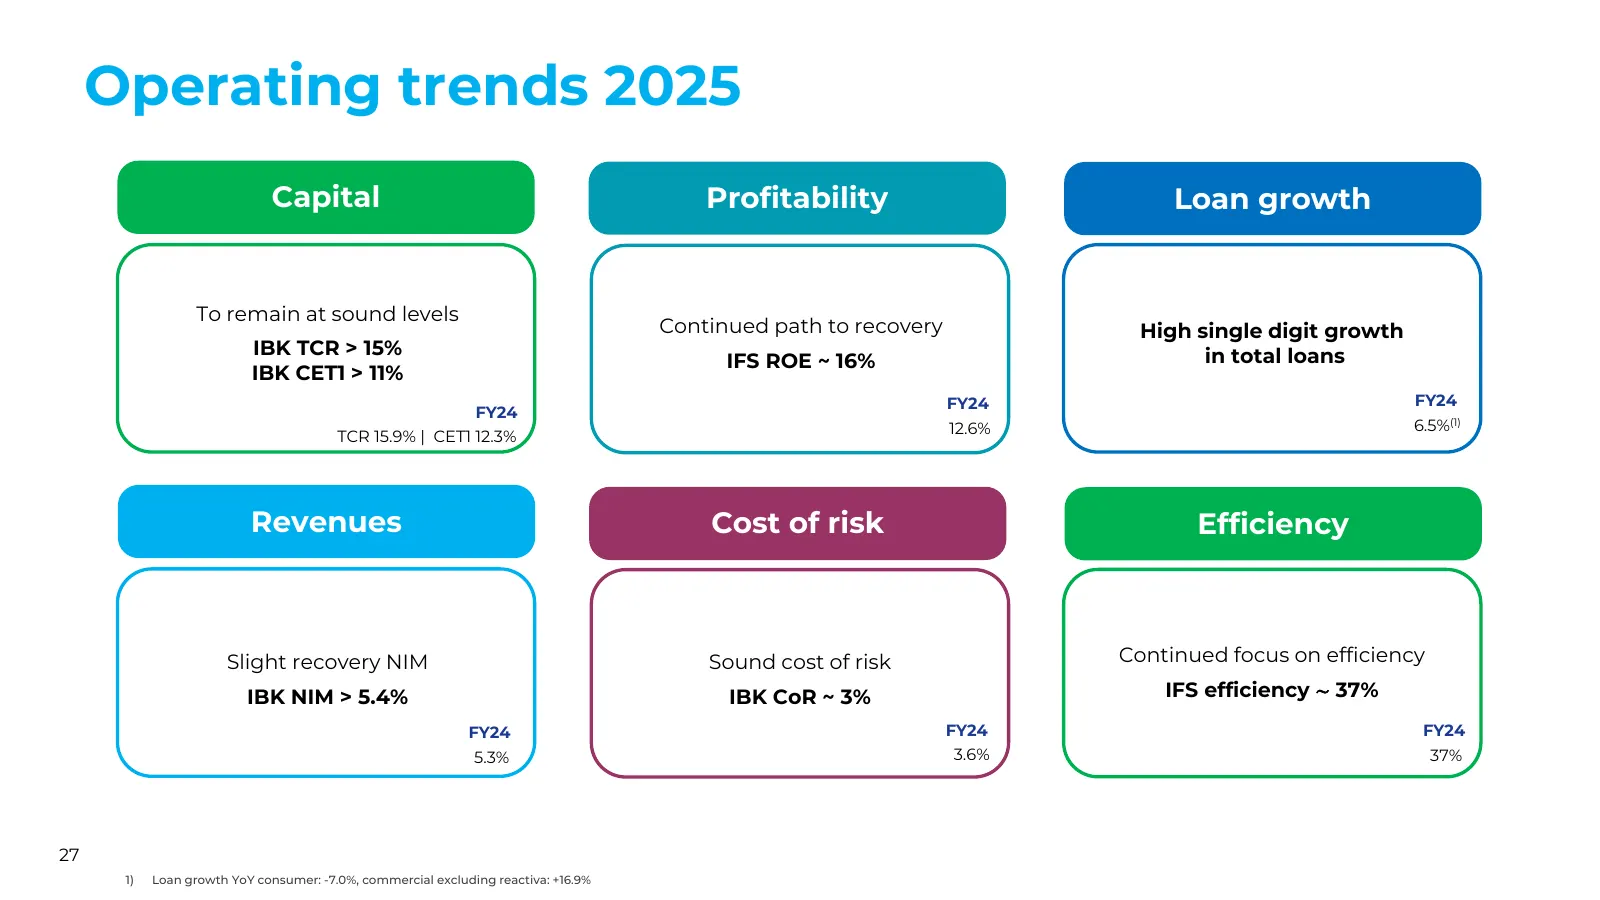
Slide 27: Operating trends 2025
Operating trends 2025 Capital Profitability Loan growth To remain at sound levels Continued path to recovery High single digit growth IBK TCR > 15% in total loans IFS ROE ~ 16% IBK CET1 > 11% FY24 FY24 FY24 12.6% 6.5%(1) TCR 15.9% | CET1 12.3% Revenues Cost of risk Efficiency Slight recovery NIM Sou
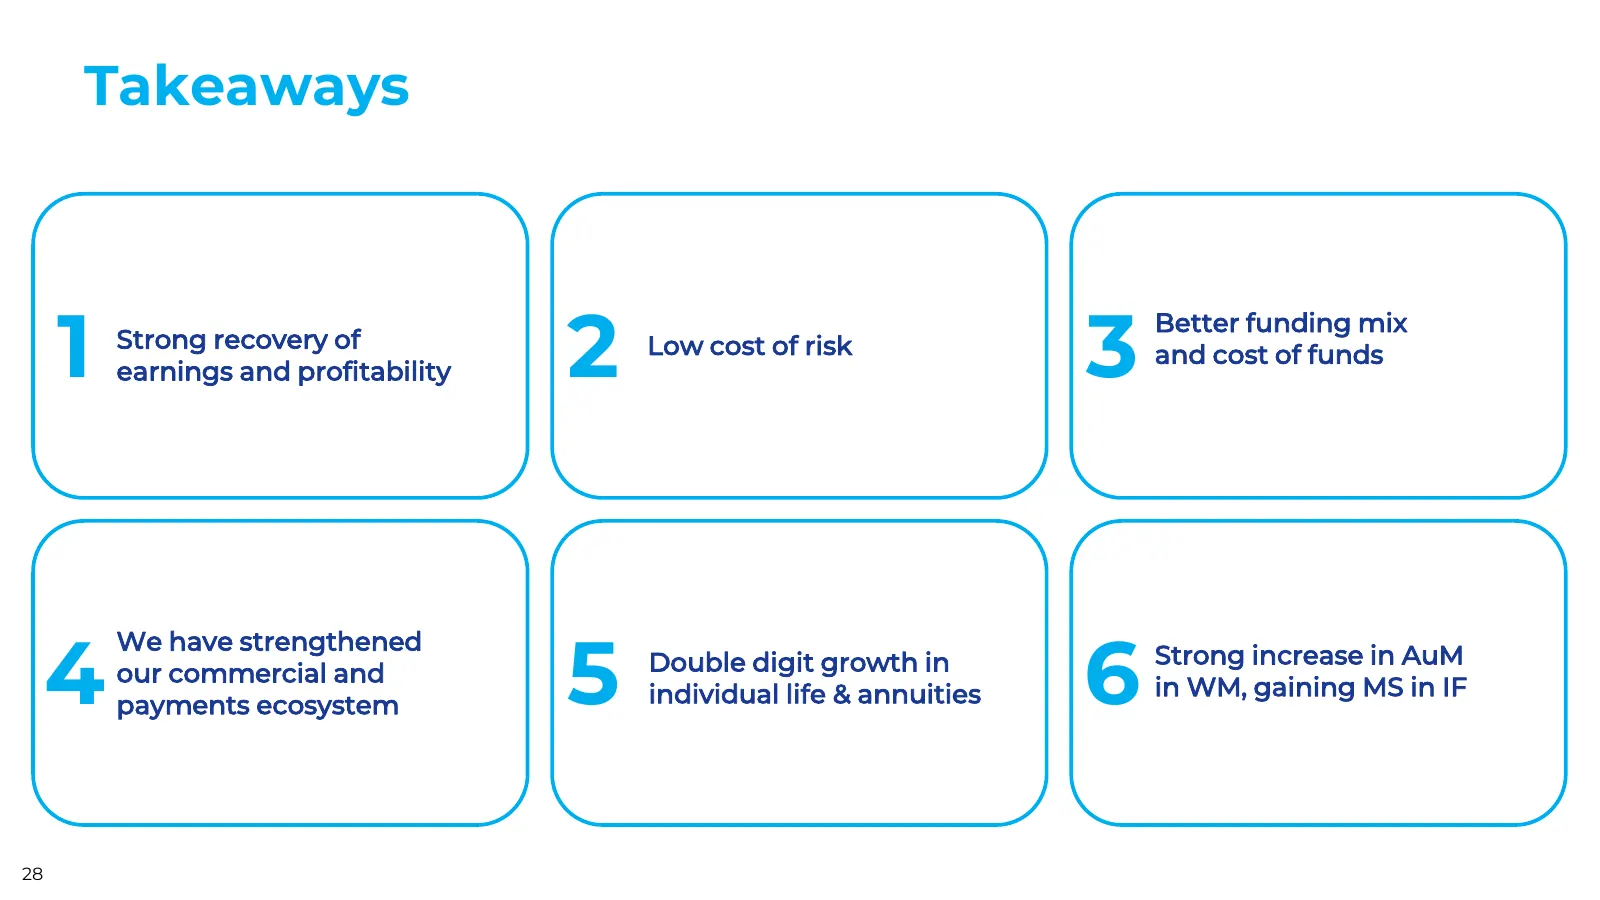
Slide 28: Takeaways
Takeaways 1 2 3 Better funding mix Strong recovery of Low cost of risk and cost of funds earnings and profitability 4 5 6 We have strengthened Double digit growth in Strong increase in AuM our commercial and individual life & annuities in WM, gaining MS in IF payments ecosystem 28
Slide 29: Appendix
Appendix
Slide 30: Operating trends FY24
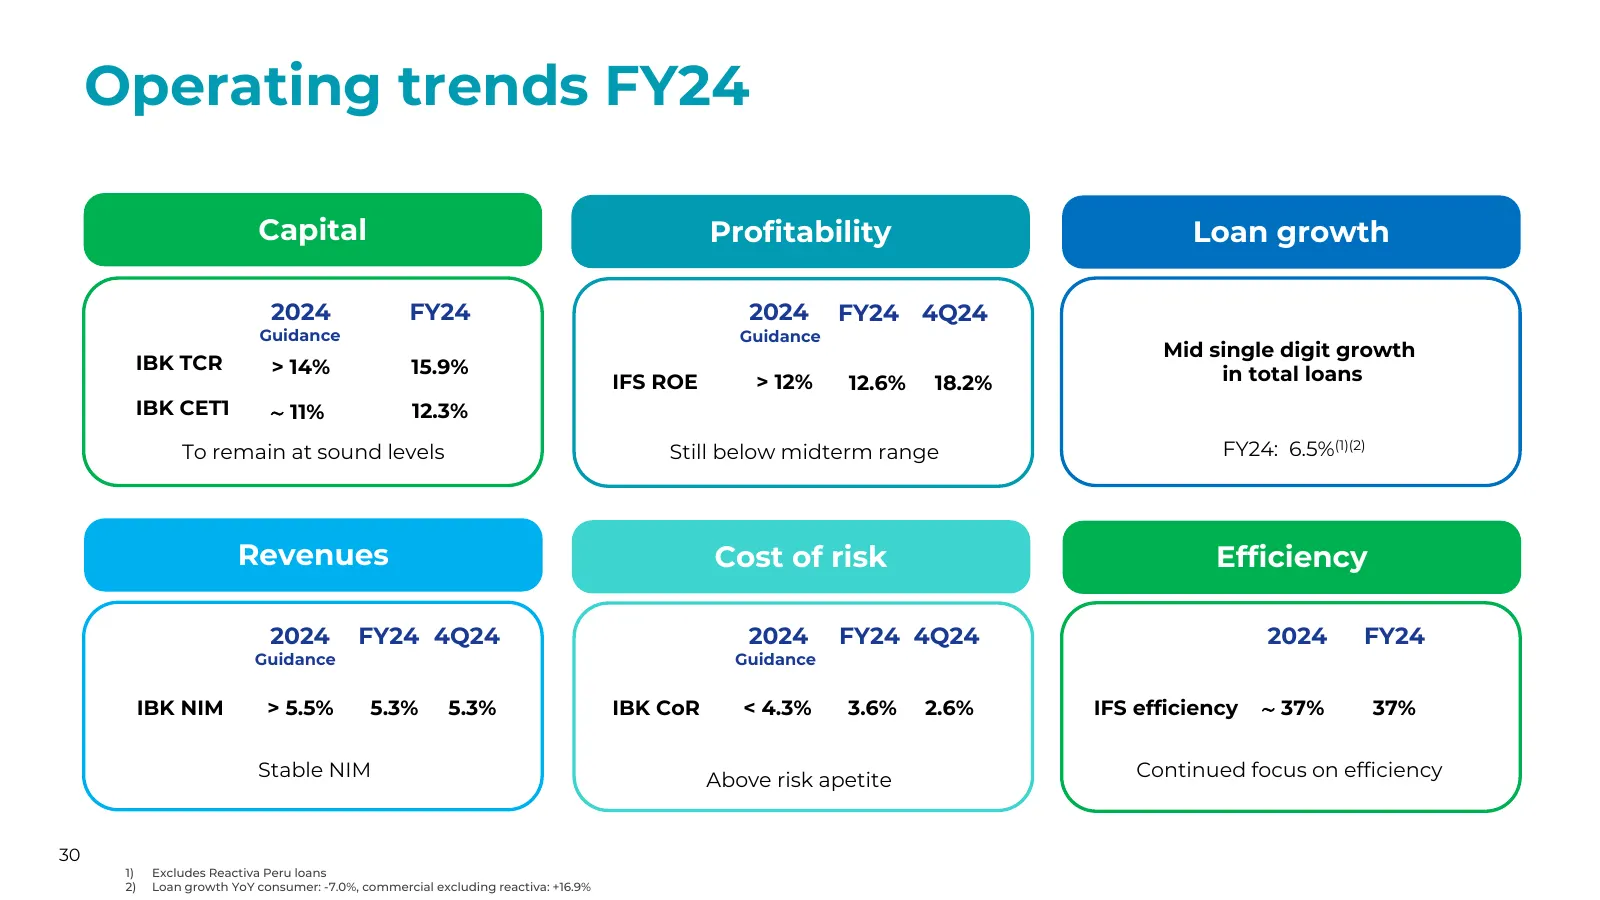
Operating trends FY24 Capital Profitability Loan growth 2024 FY24 2024 FY24 4Q24 Guidance Guidance Mid single digit growth IBK TCR > 14% 15.9% IFS ROE > 12% 12.6% 18.2% in total loans IBK CET1 ∼ 11% 12.3% To remain at sound levels Still below midterm range FY24: 6.5%(1)(2) Revenues Cost of risk Effi
Slide 31: +21% YoY earnings drive annual ROE above 12%
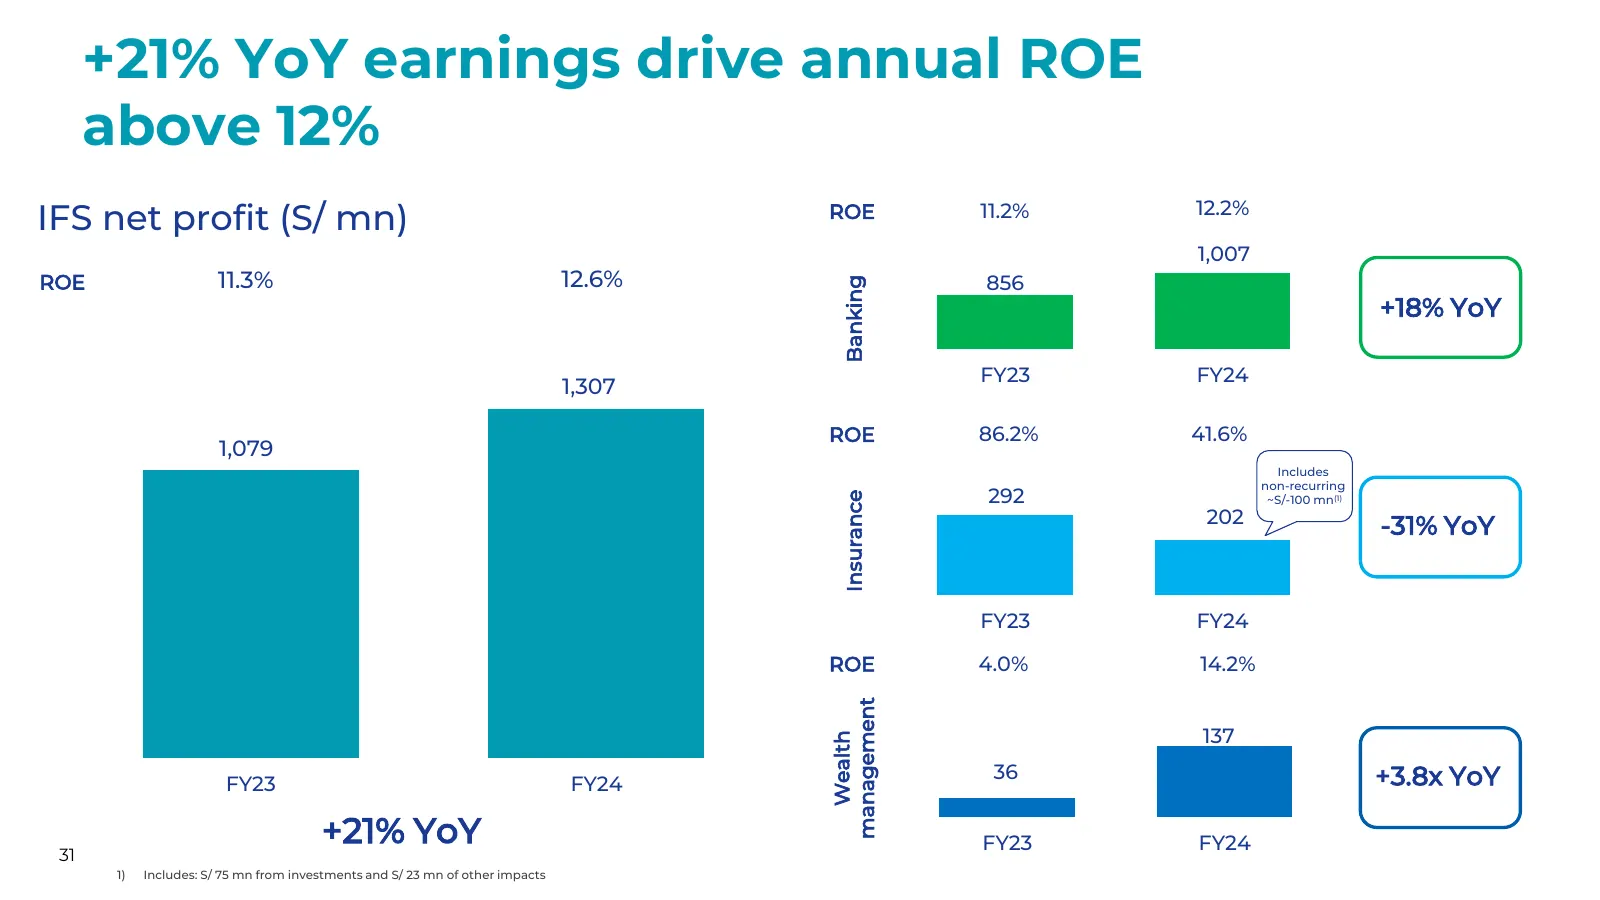
+21% YoY earnings drive annual ROE above 12% 12.2% IFS net profit (S/ mn) ROE 11.2% 1,007 ROE 11.3% 12.6% 856 Banking +18% YoY FY23 FY24 1,307 ROE 86.2% 41.6% 1,079 Includes non-recurring 292 Insurance ~S/-100 mn(1) 202 -31% YoY FY23 FY24 ROE 4.0% 14.2% management 137 Wealth FY23 FY24 36 +3.8x YoY +
Slide 32: +4% YoY increase in revenues at IFS
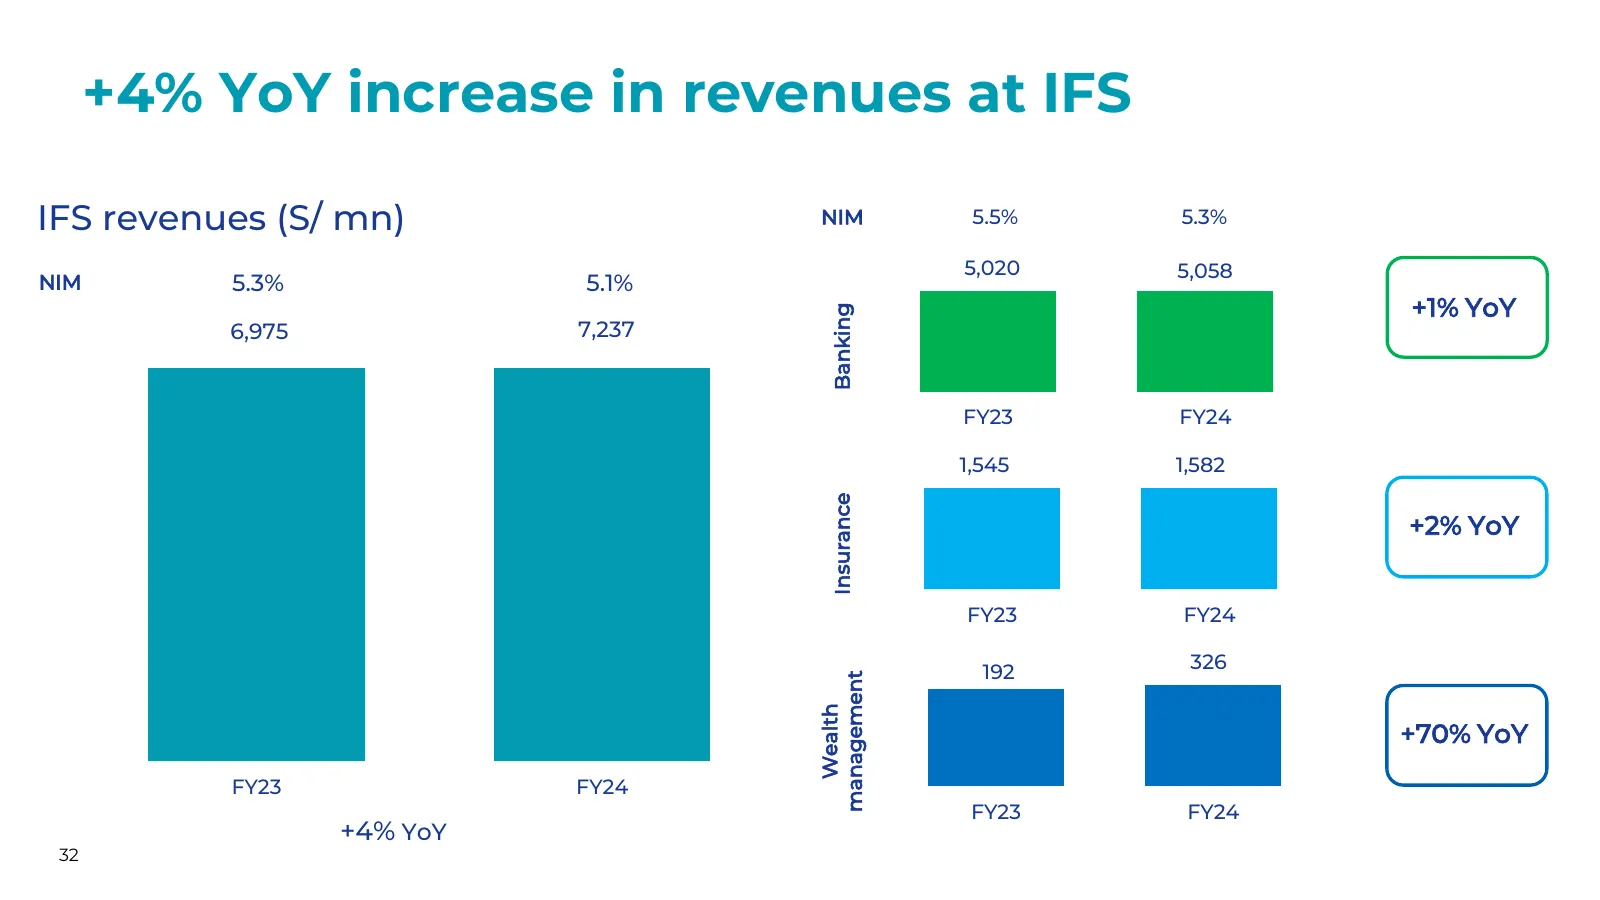
+4% YoY increase in revenues at IFS IFS revenues (S/ mn) NIM 5.5% 5.3% 5,020 5,058 NIM 5.3% 5.1% +1% YoY Banking 6,975 7,237 FY23 FY24 1,545 1,582 Insurance +2% YoY FY23 FY24 192 326 management Wealth +70% YoY FY23 FY24 FY23 FY24 +4% YoY 32
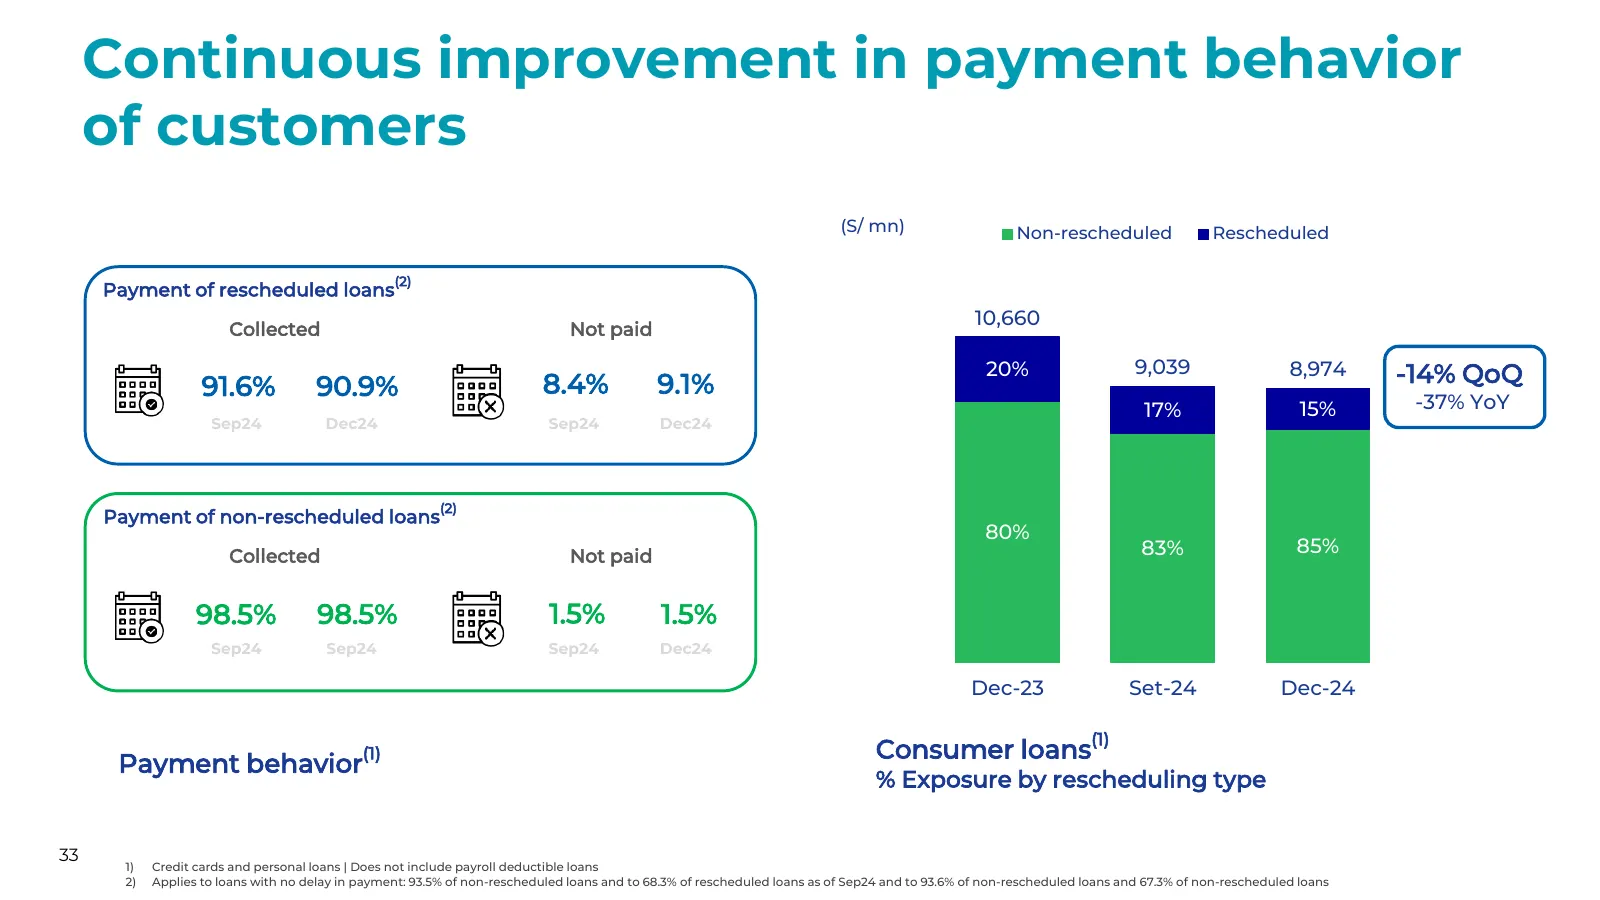
Slide 33: Continuous improvement in payment behavior of customers
Continuous improvement in payment behavior of customers (S/ mn) Non-rescheduled Rescheduled (2) Payment of rescheduled loans 10,660 Collected Not paid 20% 9,039 8,974 -14% QoQ 91.6% 90.9% 8.4% 9.1% 17% 15% -37% YoY Sep24 Dec24 Sep24 Dec24 (2) Payment of non-rescheduled loans 80% Collected Not paid 8
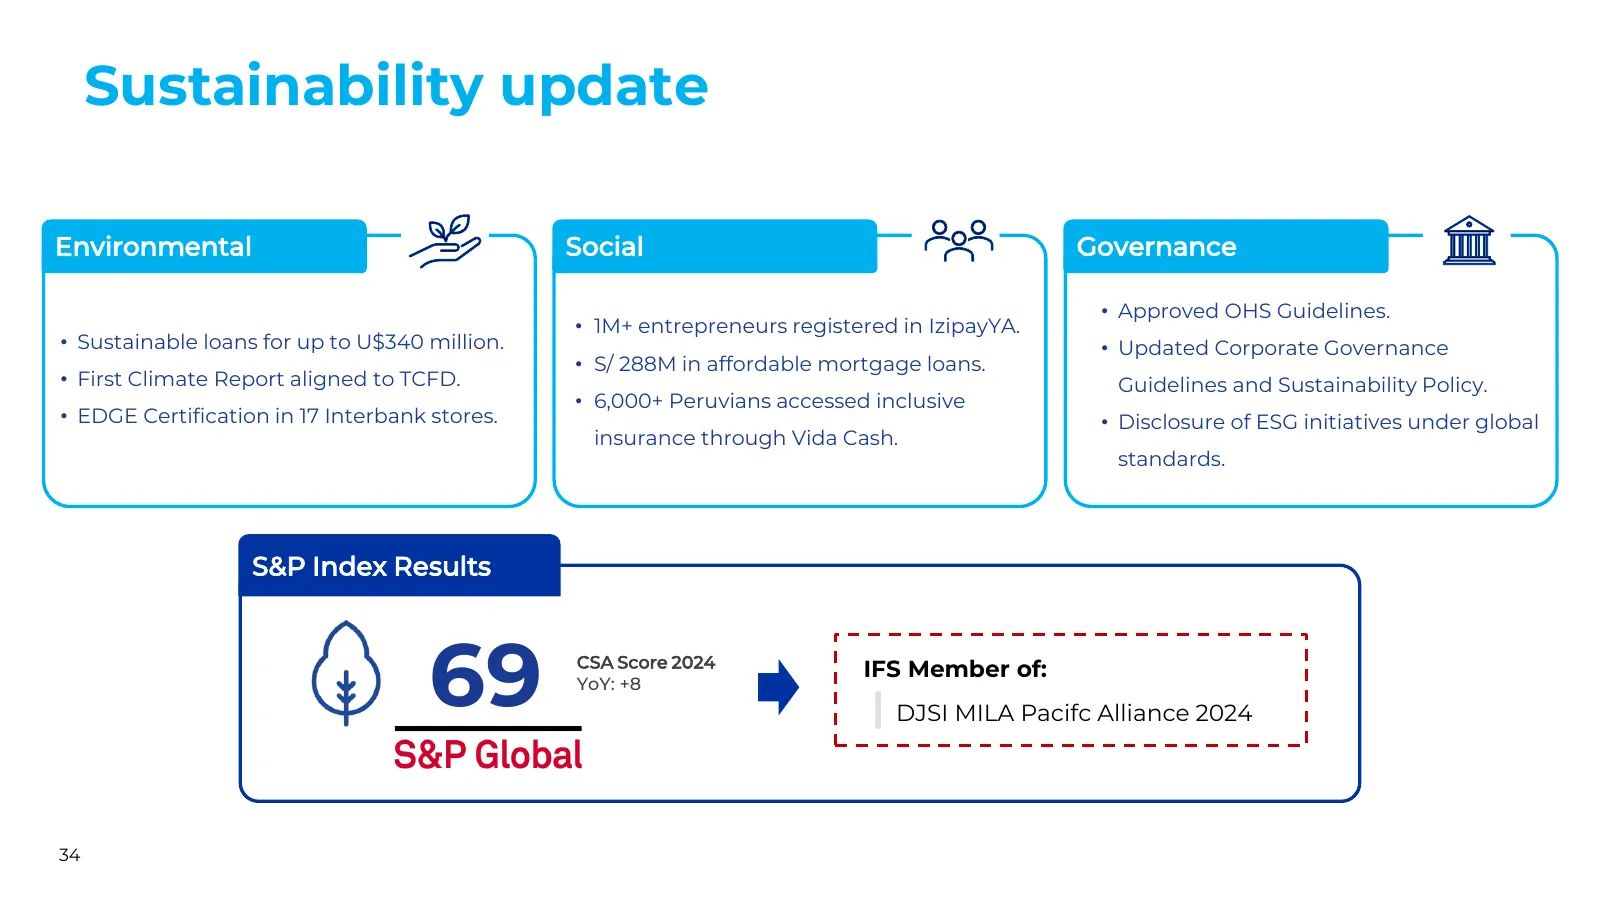
Slide 34: Sustainability update
Sustainability update Environmental Social Governance • Approved OHS Guidelines. • 1M+ entrepreneurs registered in IzipayYA. • Sustainable loans for up to U$340 million. • Updated Corporate Governance • S/ 288M in affordable mortgage loans. • First Climate Report aligned to TCFD. Guidelines and Sust
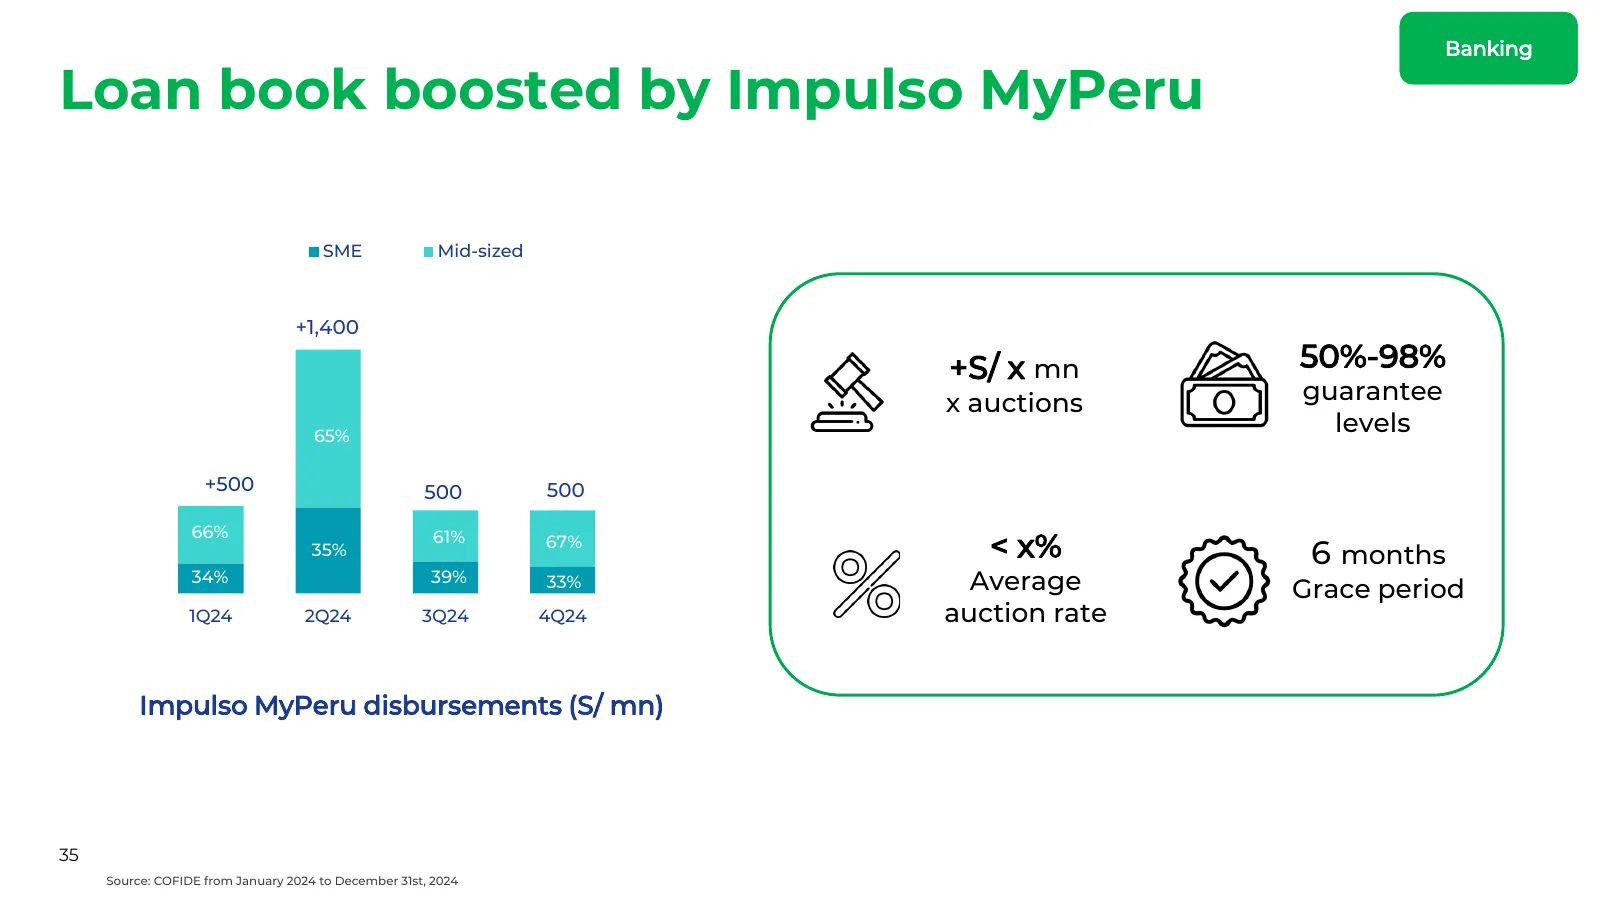
Slide 35: Loan book boosted by Impulso MyPeru
Banking Loan book boosted by Impulso MyPeru SME Mid-sized +1,400 +S/ x mn 50%-98% x auctions guarantee 65% levels +500 500 500 66% 35% 61% 67% < x% 6 months 34% 39% 33% Average Grace period 1Q24 2Q24 3Q24 4Q24 auction rate Impulso MyPeru disbursements (S/ mn) 35 Source: COFIDE from January 2024 to D
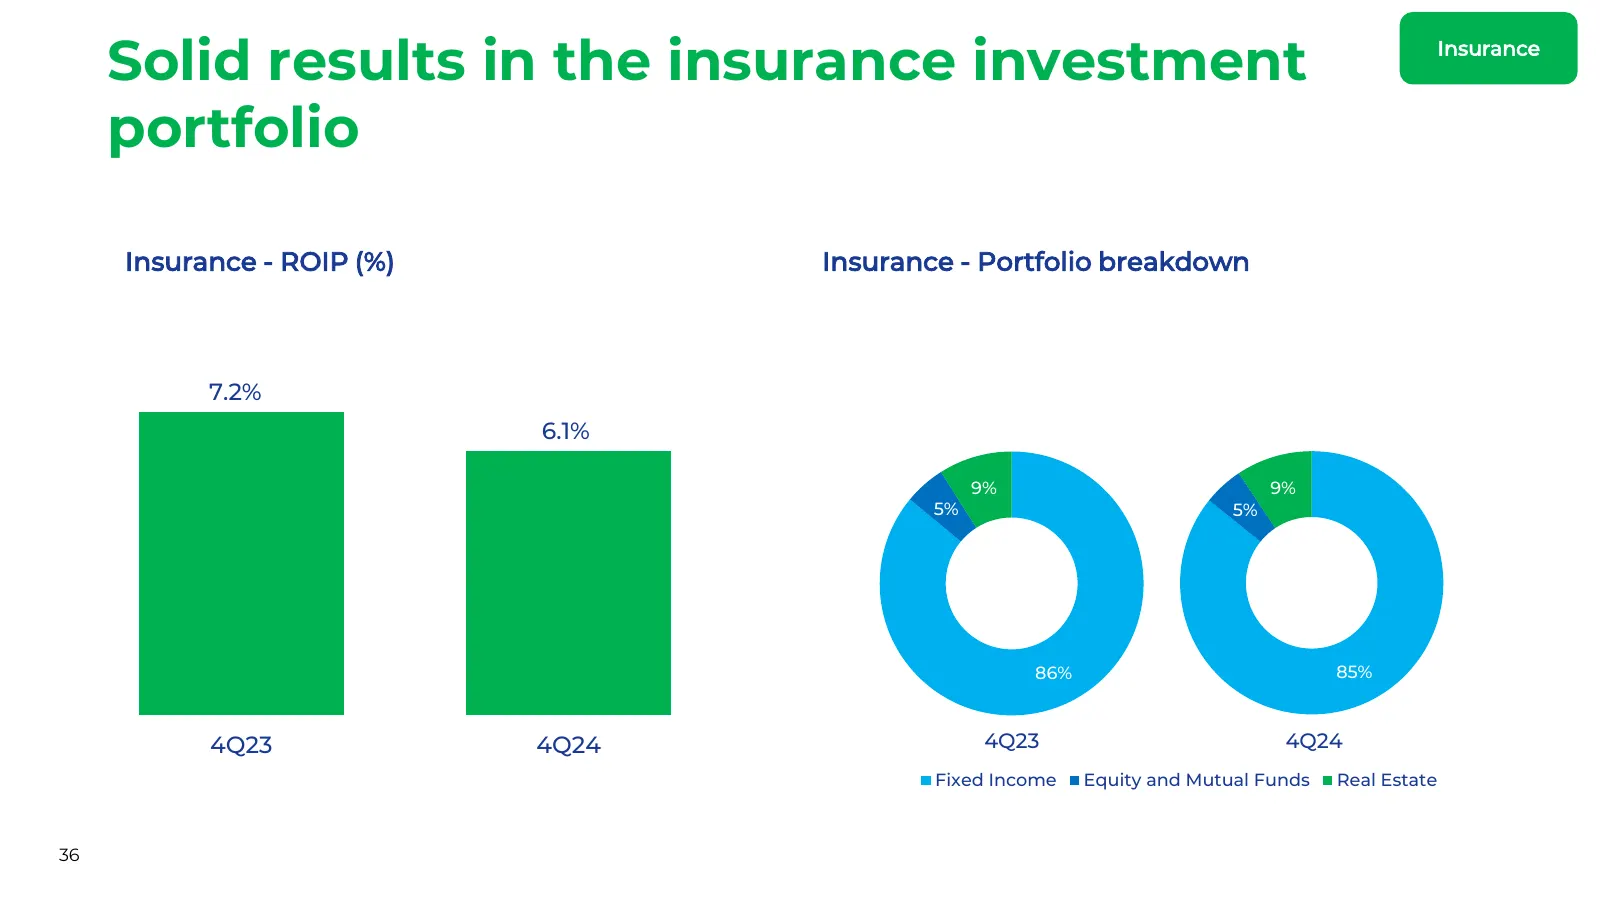
Slide 36: Solid results in the insurance investment portfolio
Solid results in the insurance investment Insurance portfolio Insurance - ROIP (%) Insurance - Portfolio breakdown 7.2% 6.1% 9% 9% 5% 5% 86% 85% 4Q23 4Q24 4Q23 4Q24 Fixed Income Equity and Mutual Funds Real Estate 36
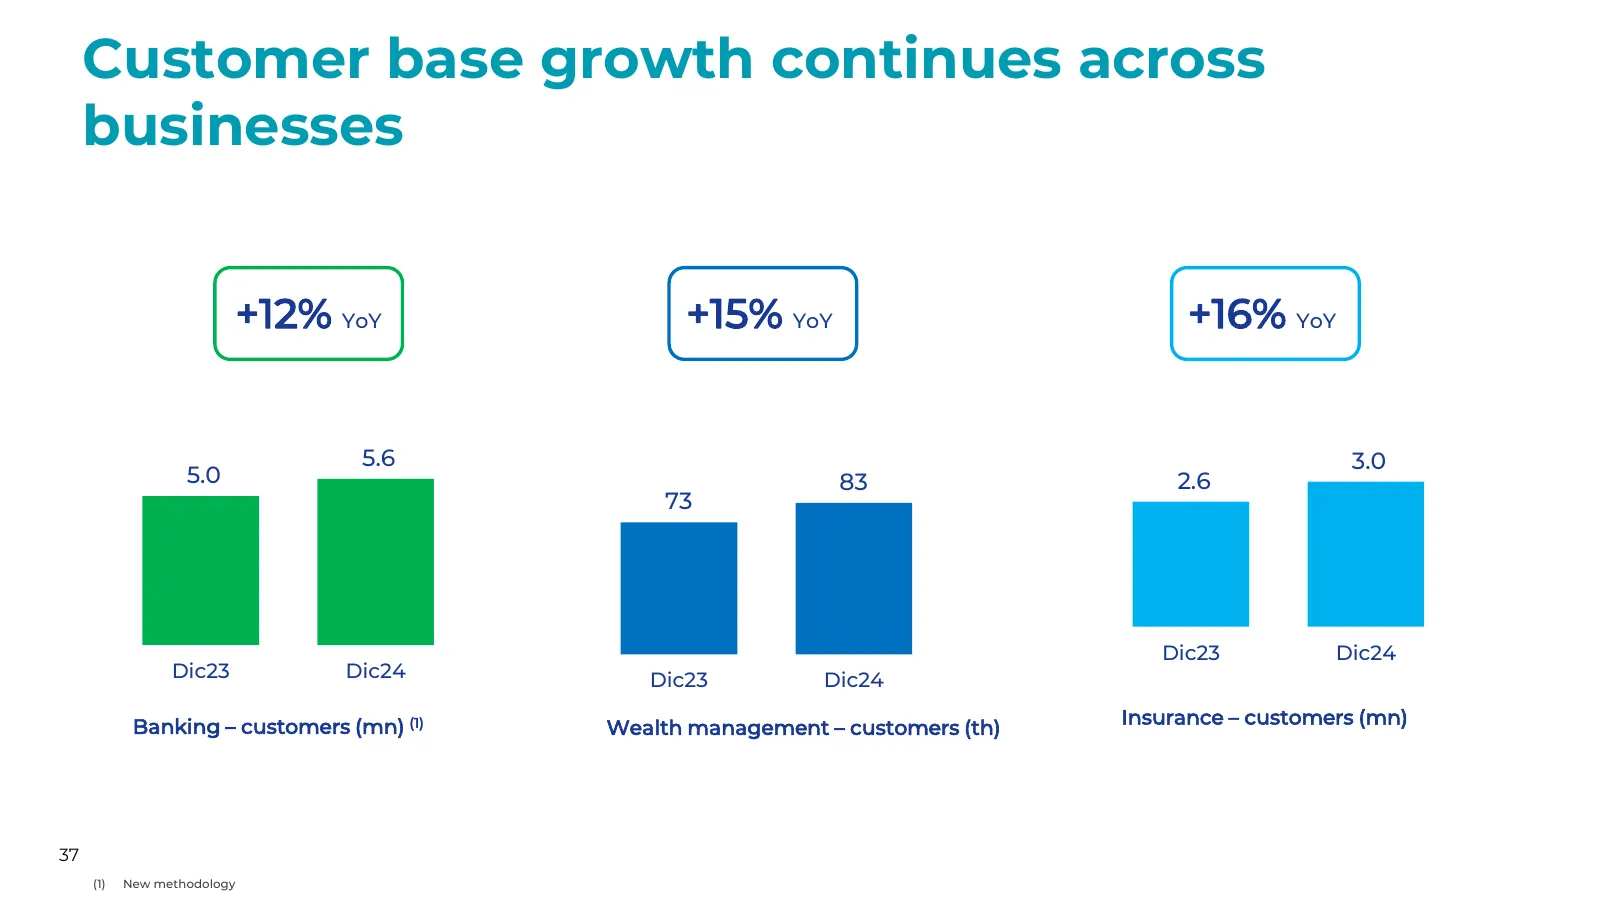
Slide 37: Customer base growth continues across businesses
Customer base growth continues across businesses +12% YoY +15% YoY +16% YoY 5.6 3.0 5.0 83 2.6 73 Dic23 Dic24 Dic23 Dic24 Dic23 Dic24 Banking – customers (mn) (1) Wealth management – customers (th) Insurance – customers (mn) 37 (1) New methodology
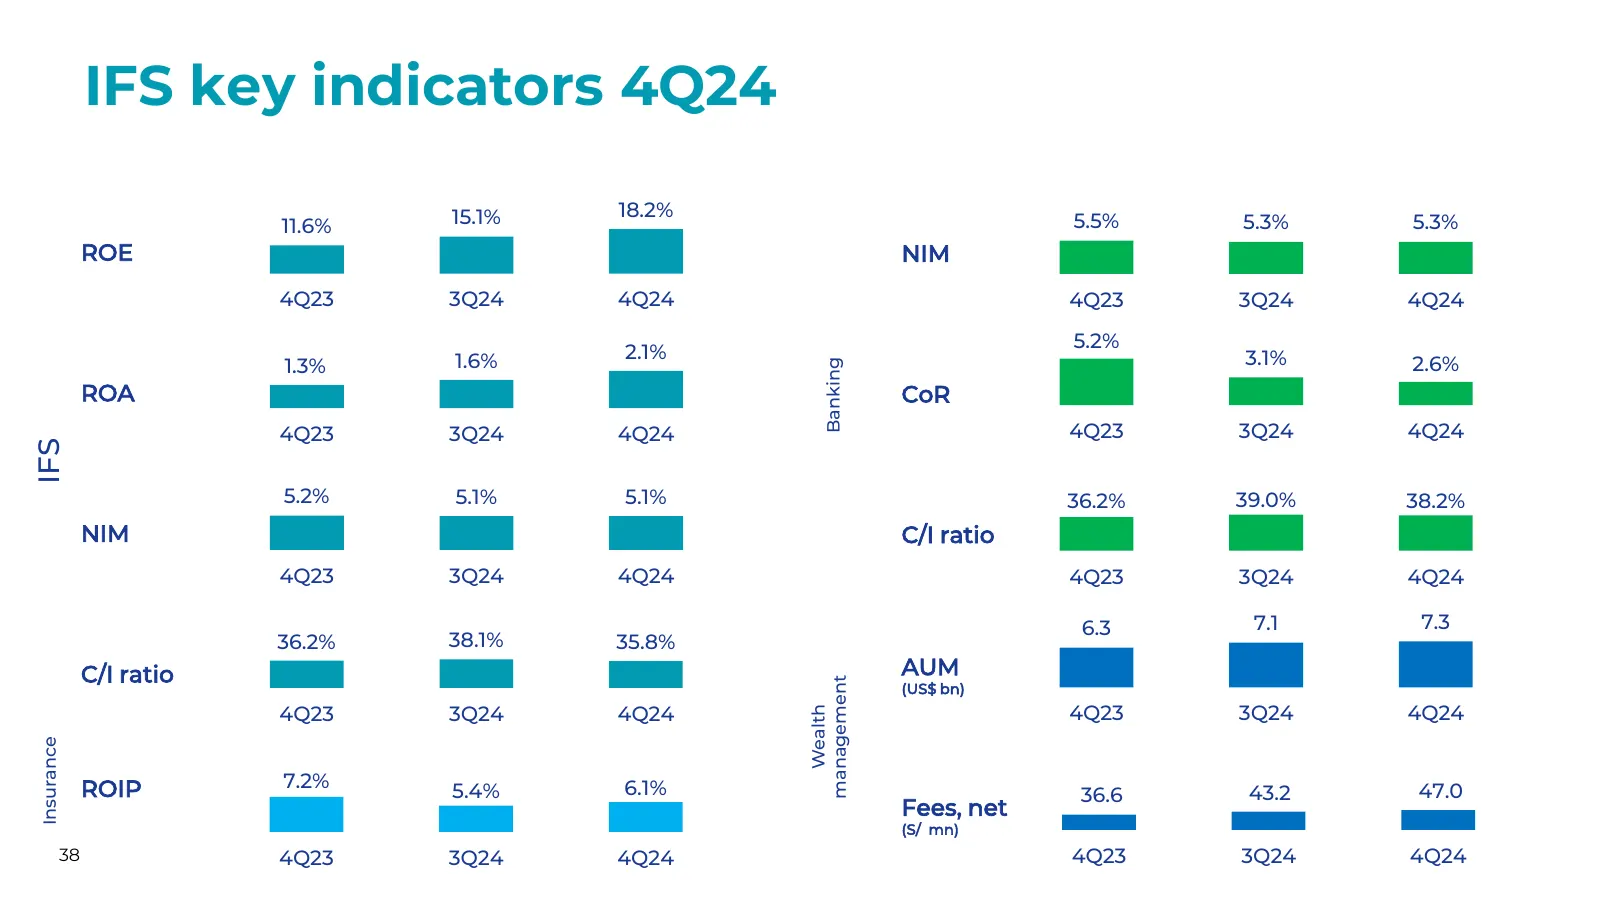
Slide 38: IFS key indicators 4Q24
IFS key indicators 4Q24 15.1% 18.2% 11.6% 5.5% 5.3% 5.3% ROE NIM 4Q23 3Q24 4Q24 4Q23 3Q24 4Q24 5.2% 1.6% 2.1% 3.1% 1.3% 2.6% Banking ROA CoR 4Q23 3Q24 4Q24 4Q23 3Q24 4Q24 IFS 5.2% 5.1% 5.1% 36.2% 39.0% 38.2% NIM C/I ratio 4Q23 3Q24 4Q24 4Q23 3Q24 4Q24 6.3 7.1 7.3 36.2% 38.1% 35.8% C/I ratio AUM mana
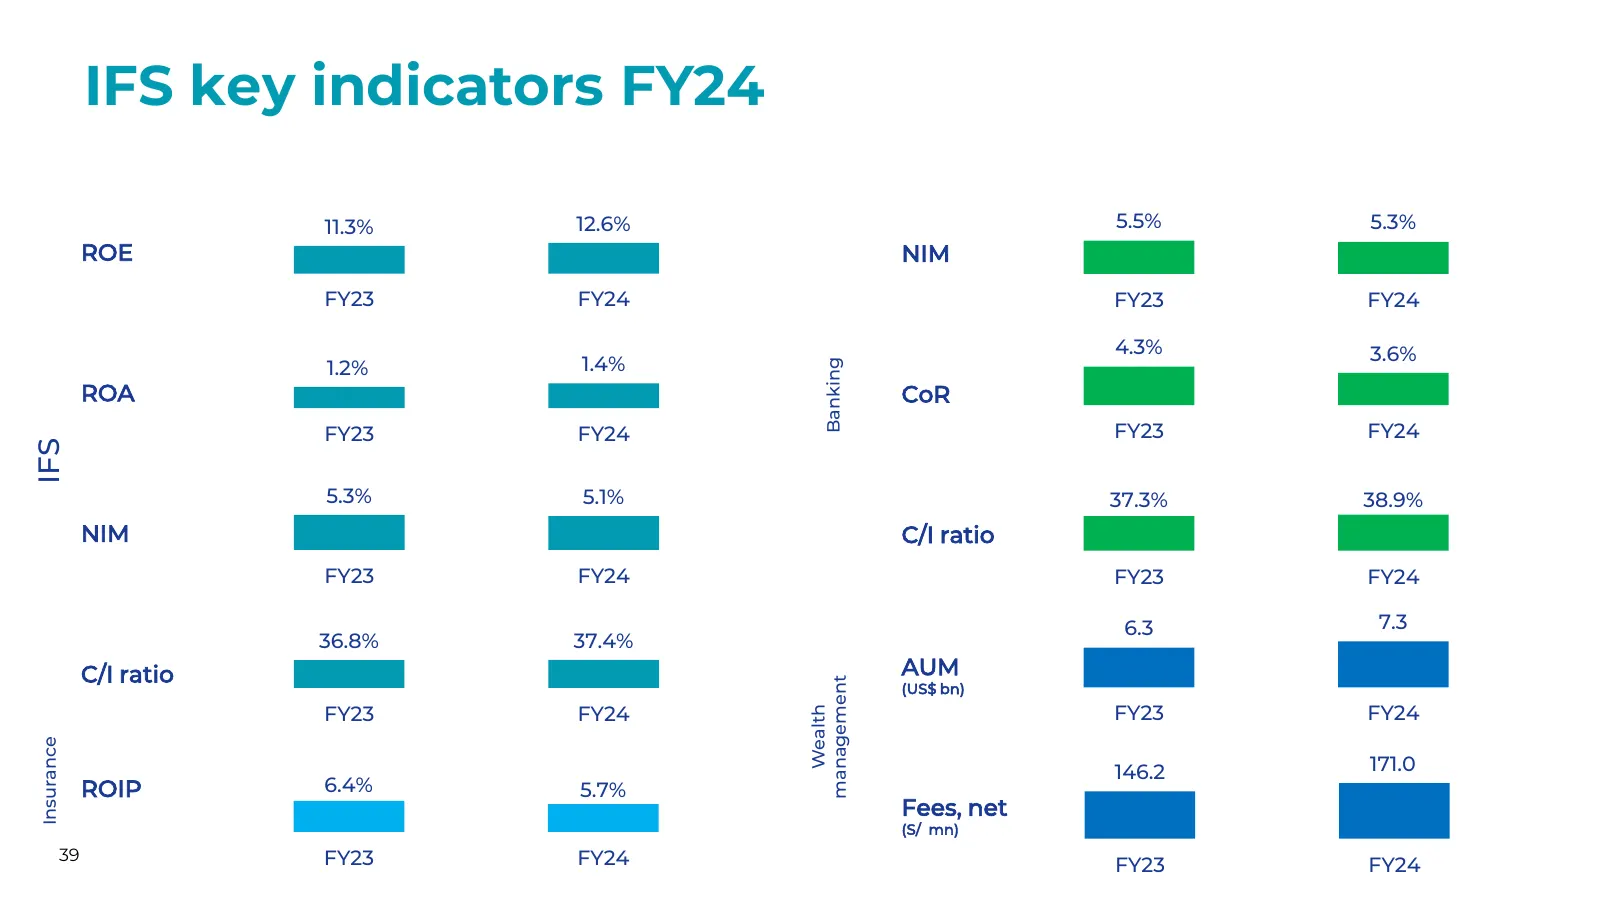
Slide 39: IFS key indicators FY24
IFS key indicators FY24 11.3% 12.6% 5.5% 5.3% ROE NIM FY23 FY24 FY23 FY24 4.3% 3.6% 1.2% 1.4% Banking ROA CoR FY23 FY24 FY23 FY24 IFS 5.3% 5.1% 37.3% 38.9% NIM C/I ratio FY23 FY24 FY23 FY24 6.3 7.3 36.8% 37.4% C/I ratio AUM management (US$ bn) FY23 FY24 FY23 FY24 Wealth Insurance 146.2 171.0 ROIP 6.
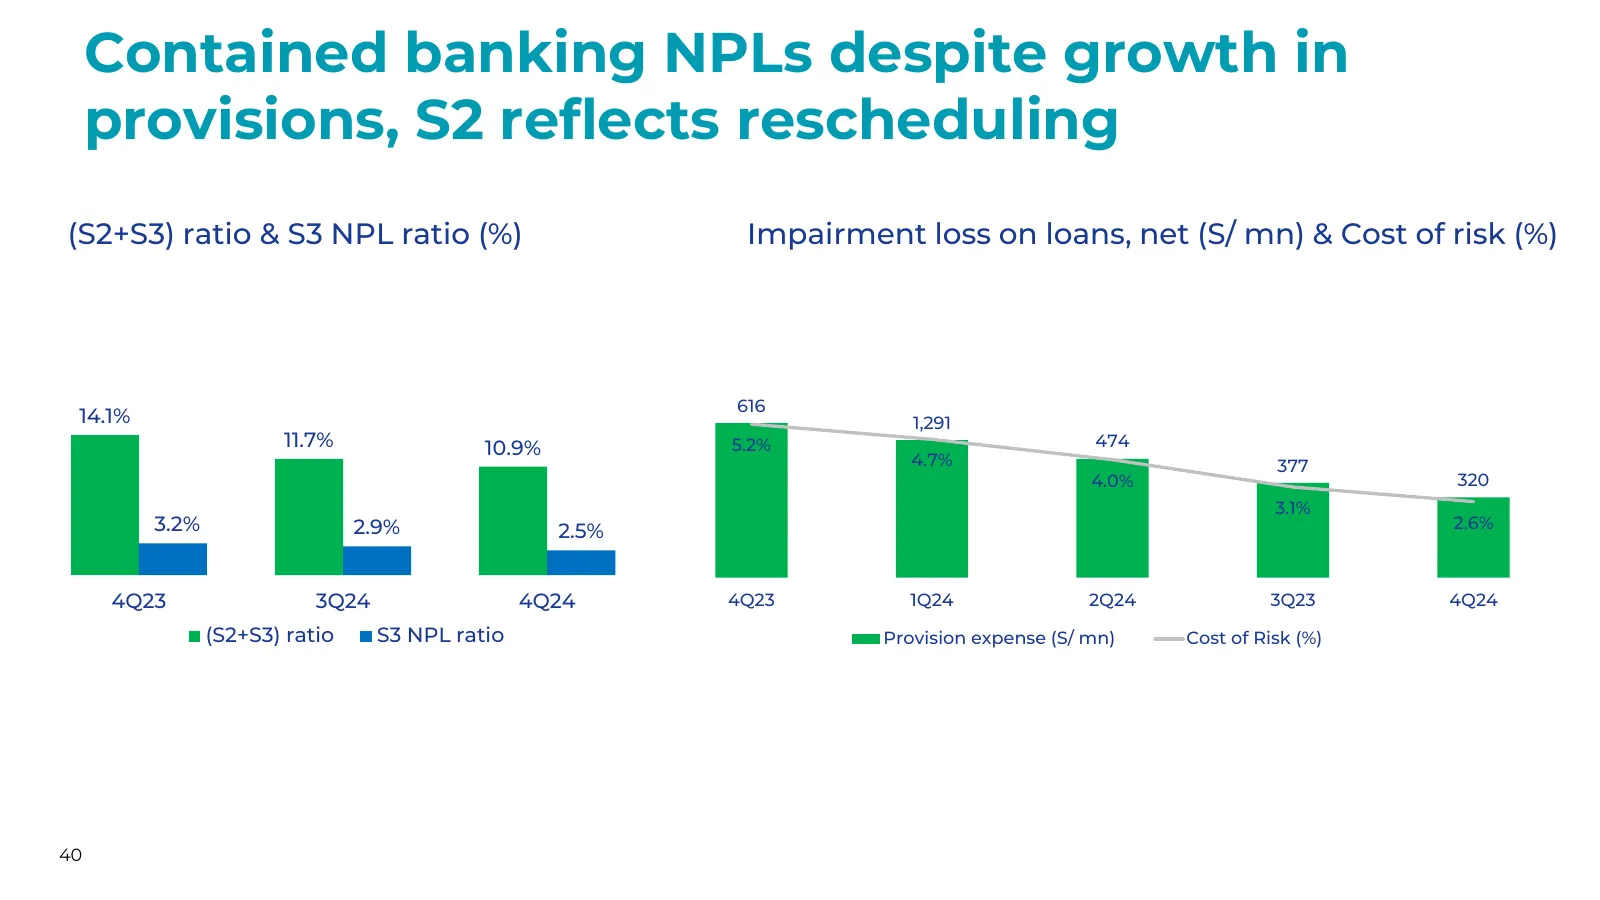
Slide 40: Contained banking NPLs despite growth in provisions, S2 reflects rescheduling
Contained banking NPLs despite growth in provisions, S2 reflects rescheduling (S2+S3) ratio & S3 NPL ratio (%) Impairment loss on loans, net (S/ mn) & Cost of risk (%) 6.0% 616 14.1% 1,291 5.0% 11.7% 10.9% 5.2% 474 4.0% 4.7% 377 4.0% 320 3.0% 3.1% 3.2% 2.0% 2.6% 2.9% 2.5% 1.0% 0.0% 4Q23 3Q24 4Q24 4Q
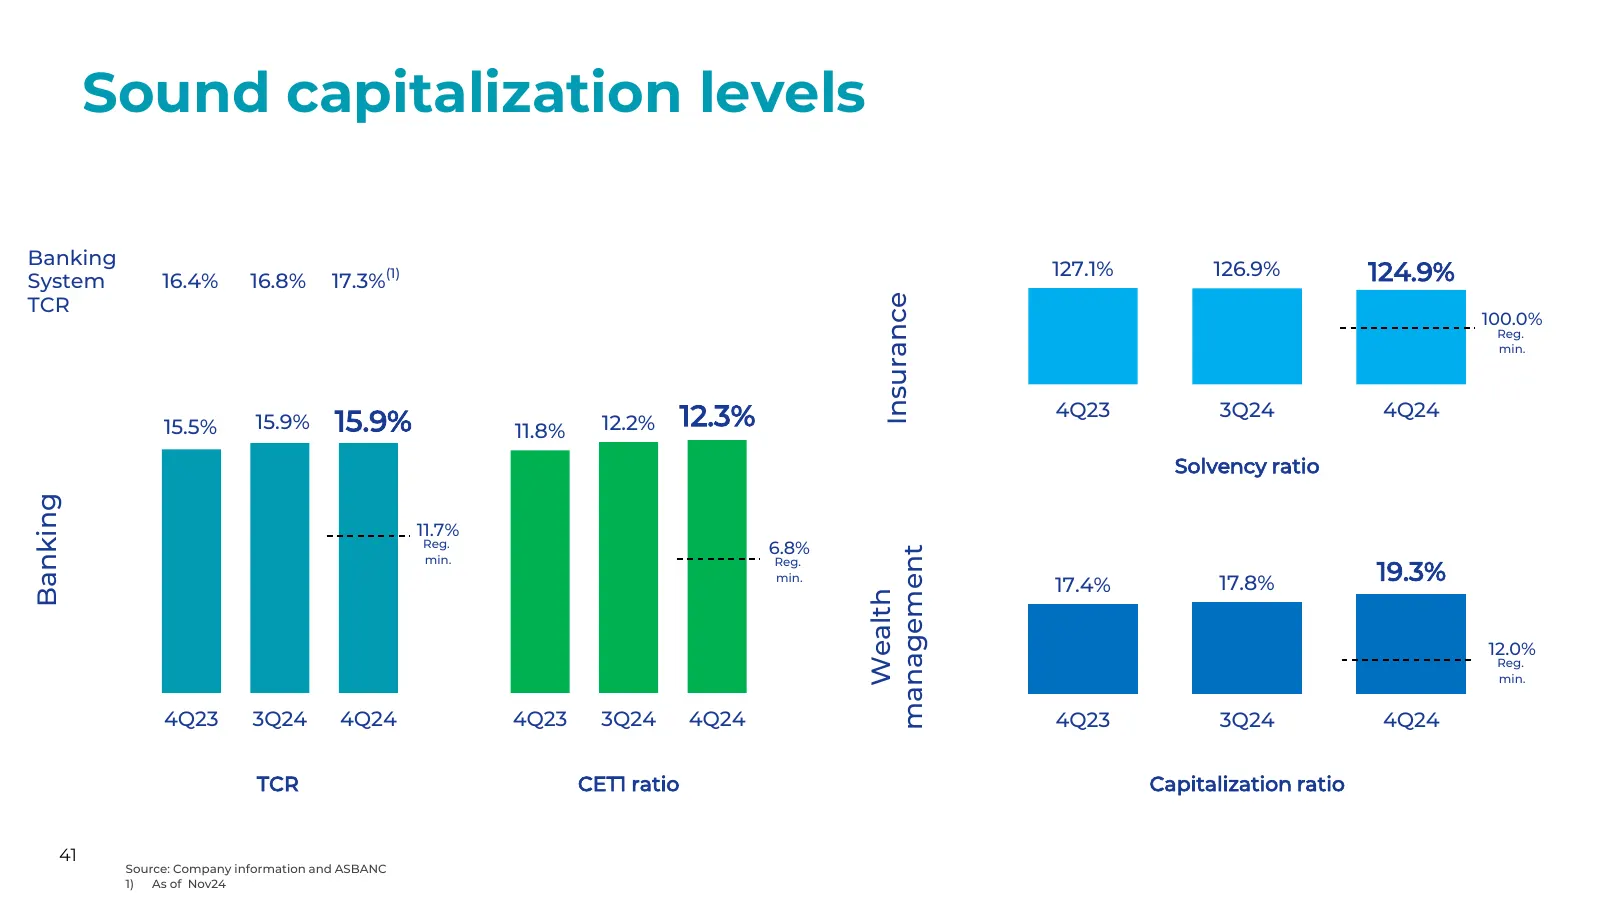
Slide 41: Sound capitalization levels
Sound capitalization levels Banking System 16.4% 16.8% 17.3%(1) 127.1% 126.9% 124.9% TCR Insurance 100.0% Reg. min. 15.5% 15.9% 15.9% 11.8% 12.2% 12.3% 4Q23 3Q24 4Q24 Solvency ratio Banking 11.7% Reg. 6.8% management min. 19.3% Reg. min. 17.4% 17.8% Wealth 12.0% Reg. min. 4Q23 3Q24 4Q24 4Q23 3Q24 4Q
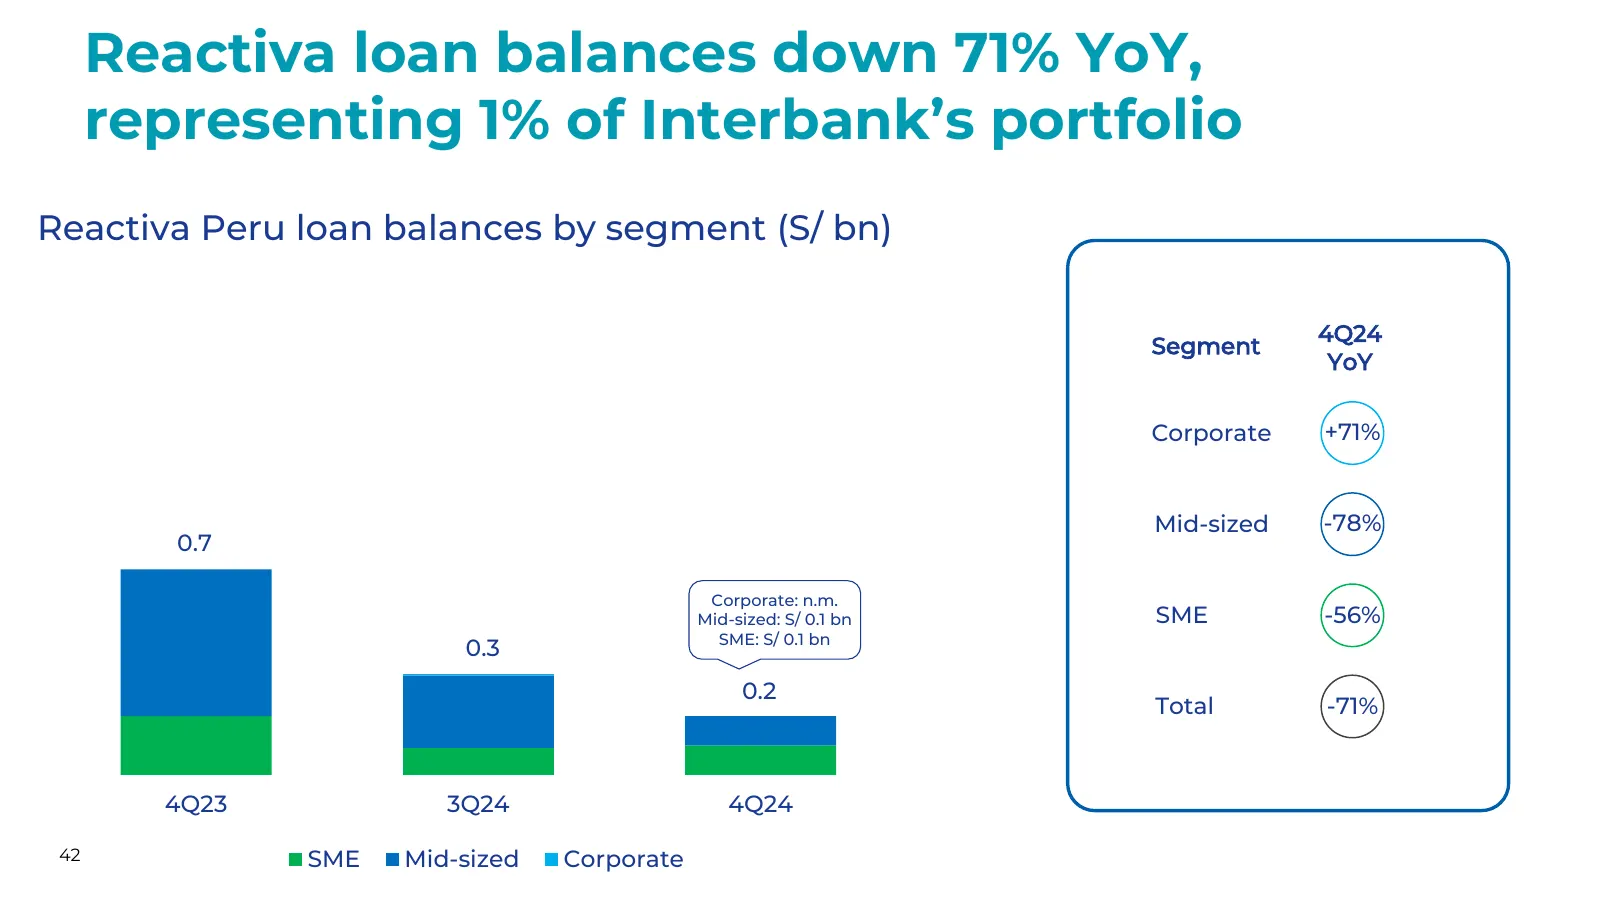
Slide 42: Reactiva loan balances down 71% YoY
Reactiva loan balances down 71% YoY, representing 1% of Interbank’s portfolio Reactiva Peru loan balances by segment (S/ bn) 4Q24 Segment YoY Corporate +71% Mid-sized -78% 0.7 Corporate: n.m. Mid-sized: S/ 0.1 bn SME -56% SME: S/ 0.1 bn 0.3 0.2 Total -71% 4Q23 3Q24 4Q24 42 SME Mid-sized Corporate
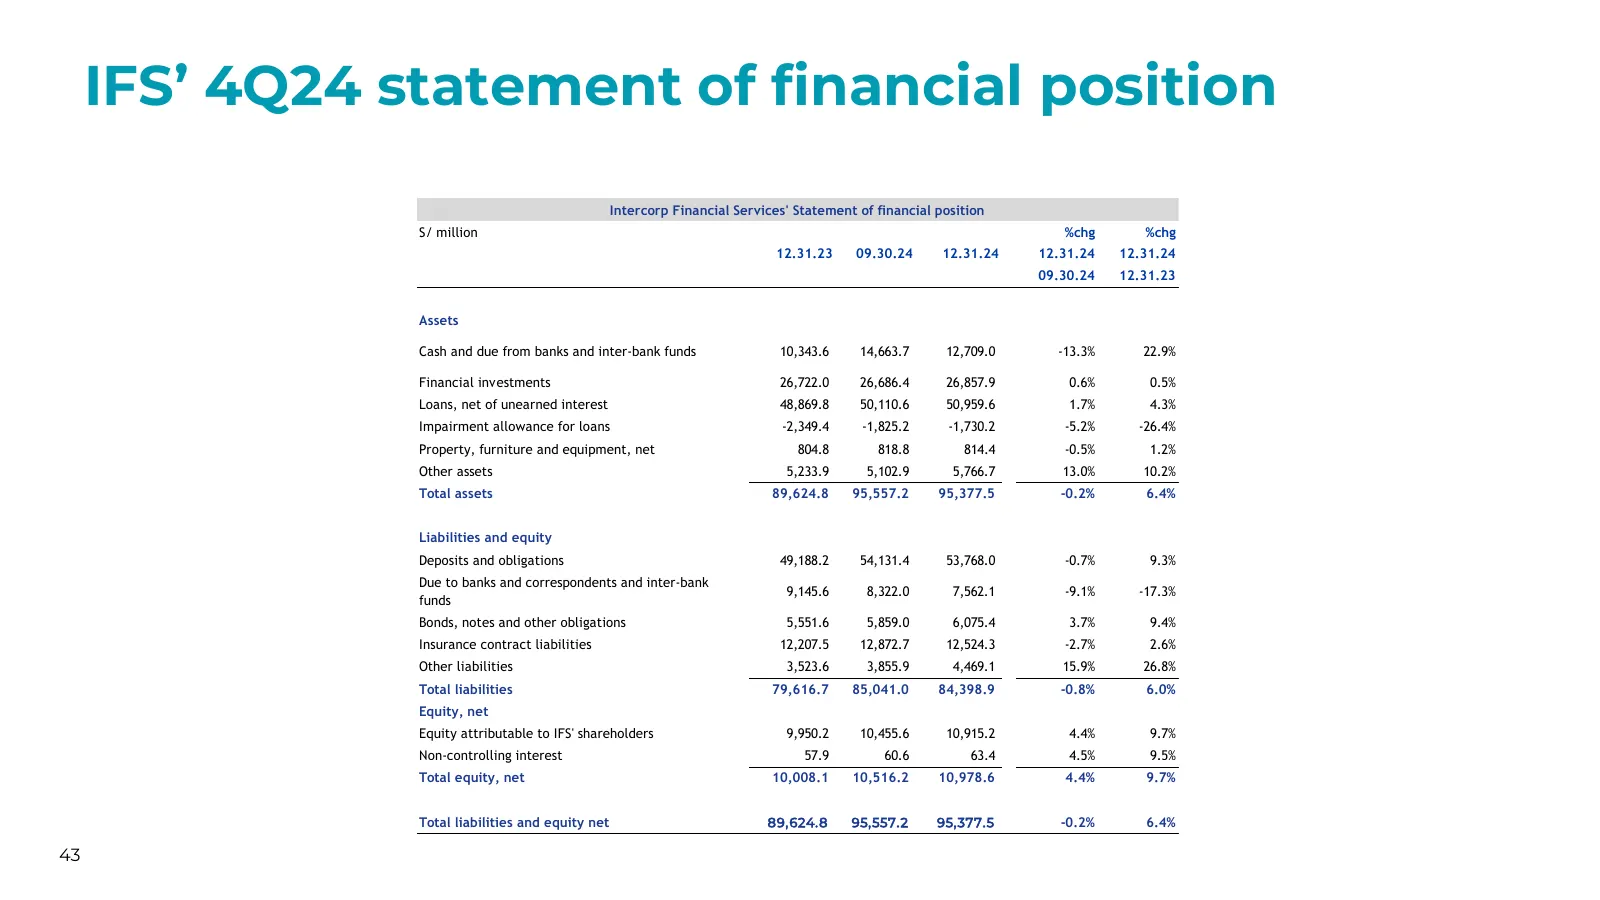
Slide 43: IFS' 4Q24 statement of financial position
IFS’ 4Q24 statement of financial position Intercorp Financial Services' Statement of financial position S/ million %chg %chg 12.31.23 09.30.24 12.31.24 12.31.24 12.31.24 09.30.24 12.31.23 Assets Cash and due from banks and inter-bank funds 10,343.6 14,663.7 12,709.0 -13.3% 22.9% Financial investment
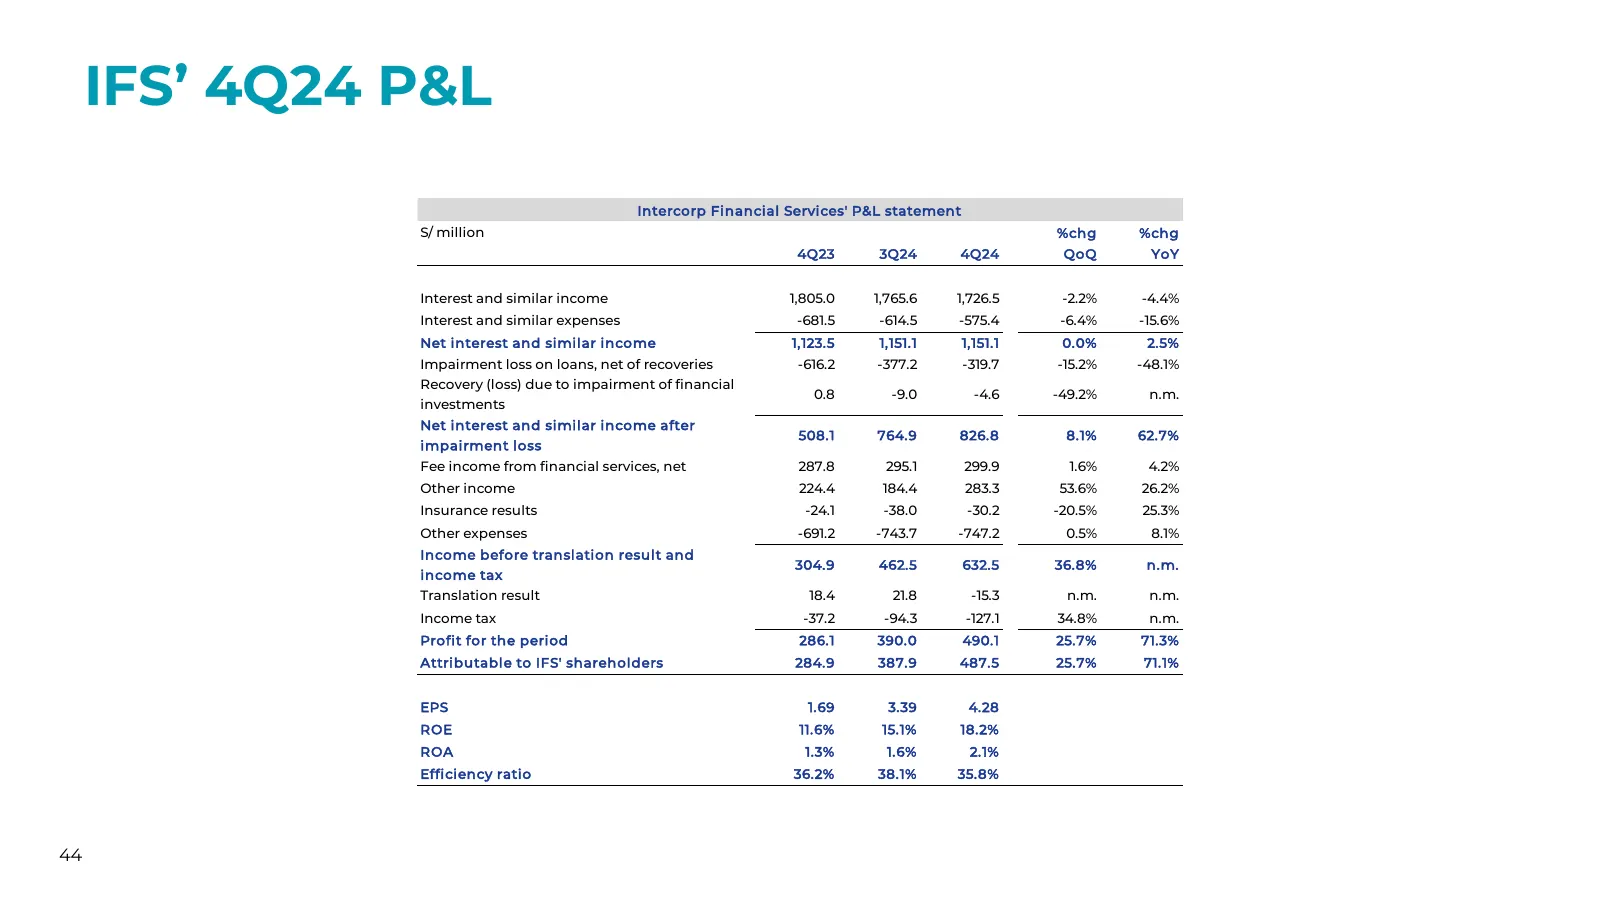
Slide 44: IFS' 4Q24 P&L
IFS’ 4Q24 P&L Intercorp Financial Services' P&L statement S/ million %chg %chg 4Q23 3Q24 4Q24 QoQ YoY Interest and similar income 1,805.0 1,765.6 1,726.5 -2.2% -4.4% Interest and similar expenses -681.5 -614.5 -575.4 -6.4% -15.6% Net interest and similar income 1,123.5 1,151.1 1,151.1 0.0% 2.5% Impa
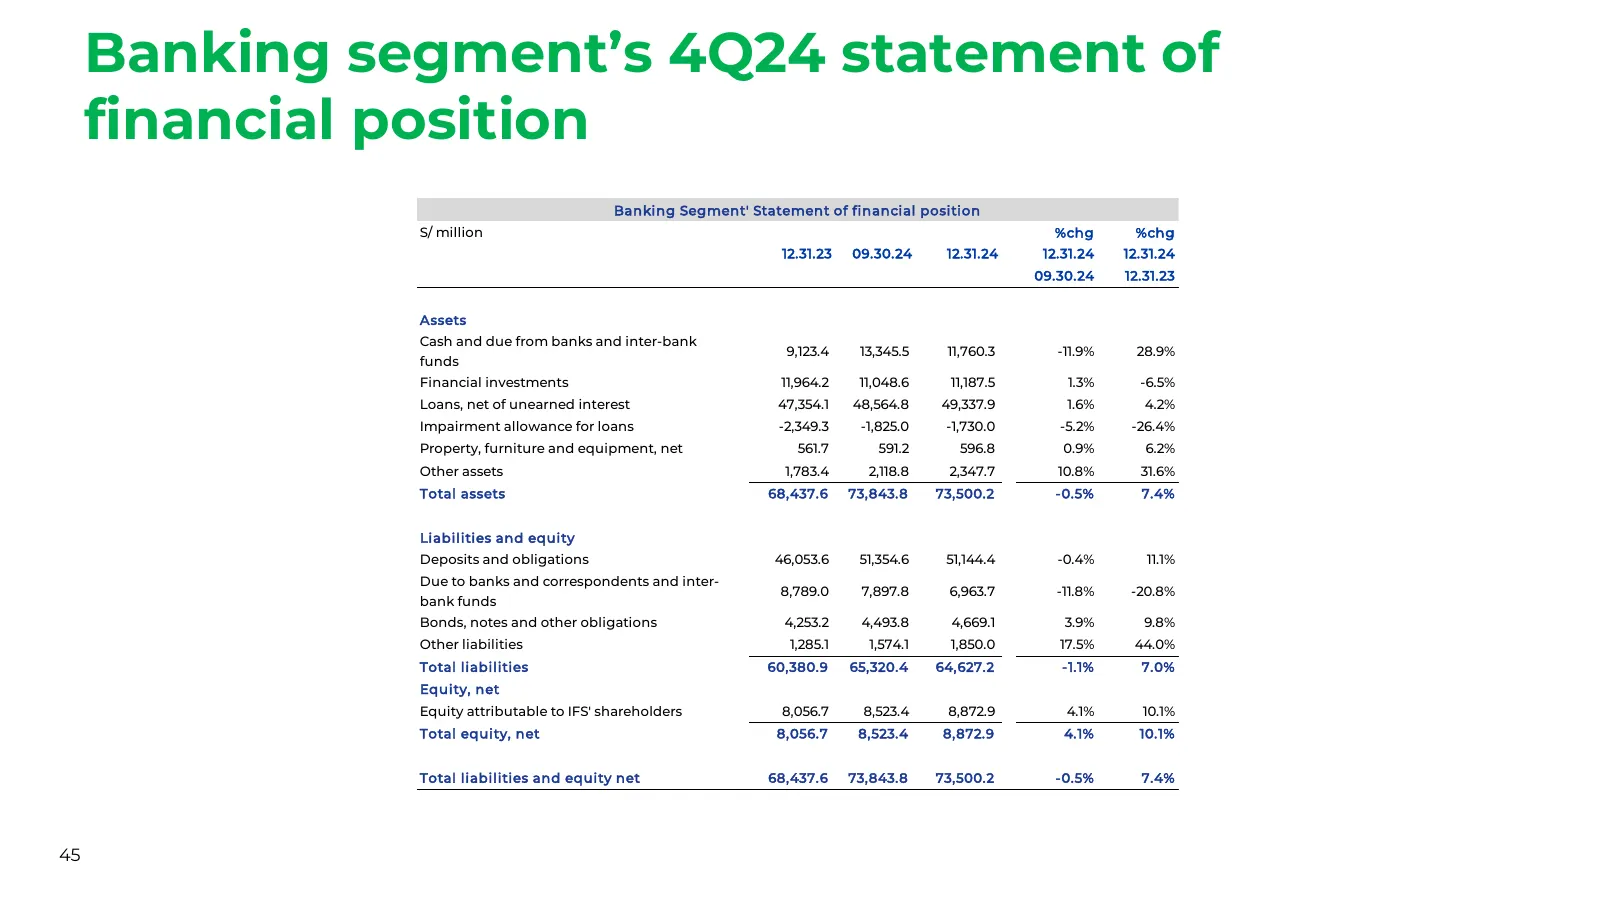
Slide 45: Banking segment's 4Q24 statement of financial position
Banking segment’s 4Q24 statement of financial position Banking Segment' Statement of financial position S/ million %chg %chg 12.31.23 09.30.24 12.31.24 12.31.24 12.31.24 09.30.24 12.31.23 Assets Cash and due from banks and inter-bank 9,123.4 13,345.5 11,760.3 -11.9% 28.9% funds Financial investments
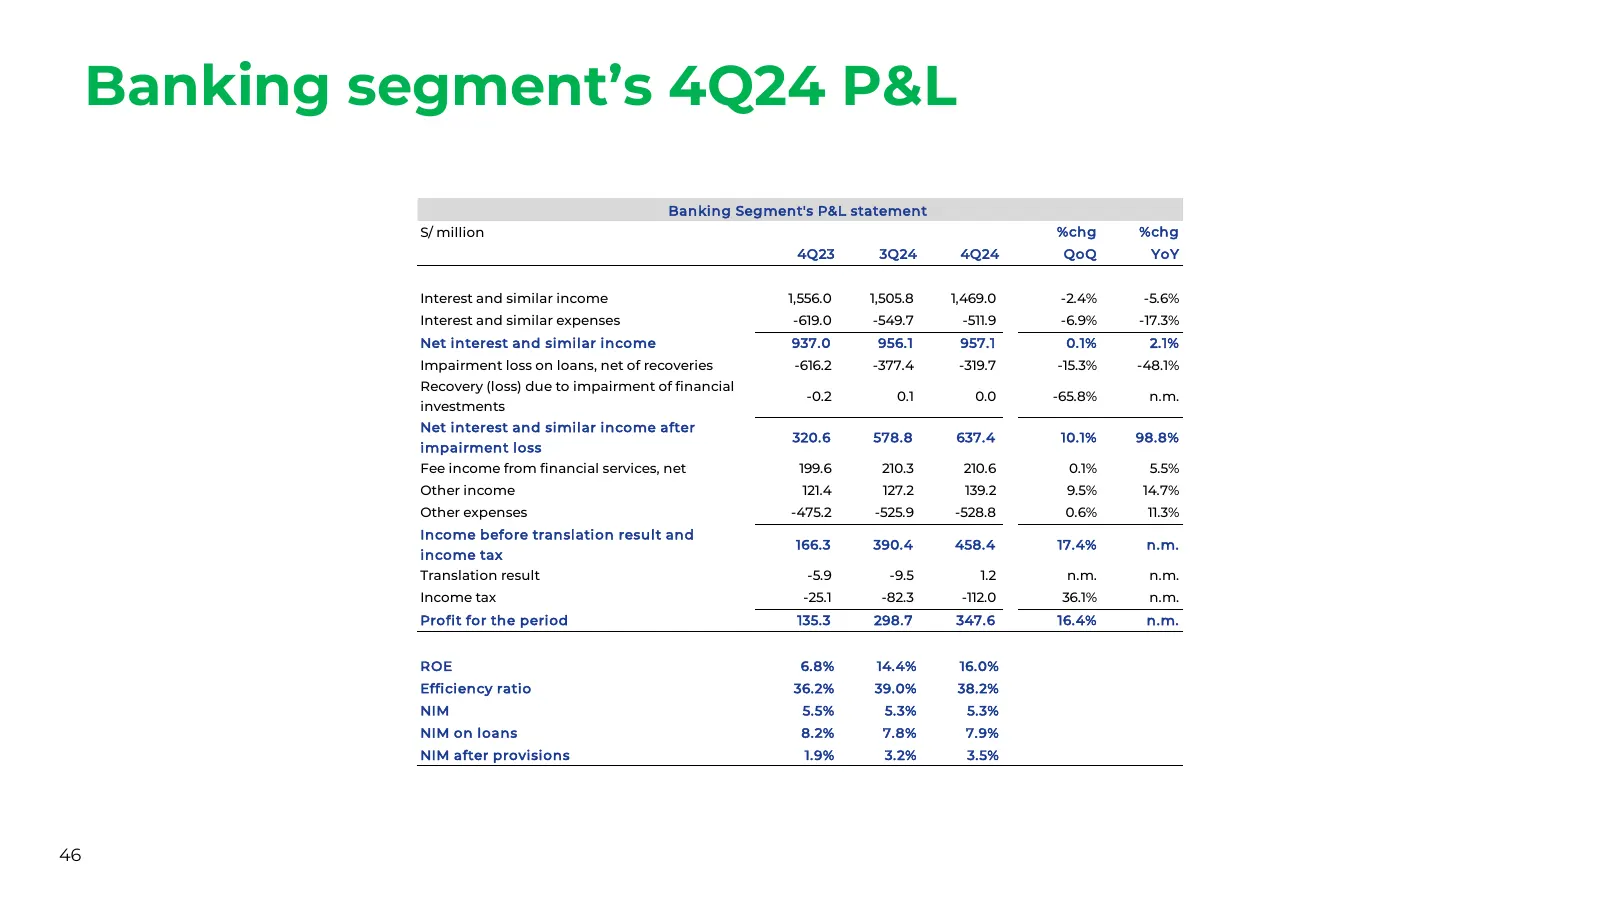
Slide 46: Banking segment's 4Q24 P&L
Banking segment’s 4Q24 P&L Banking Segment's P&L statement S/ million %chg %chg 4Q23 3Q24 4Q24 QoQ YoY Interest and similar income 1,556.0 1,505.8 1,469.0 -2.4% -5.6% Interest and similar expenses -619.0 -549.7 -511.9 -6.9% -17.3% Net interest and similar income 937.0 956.1 957.1 0.1% 2.1% Impairmen
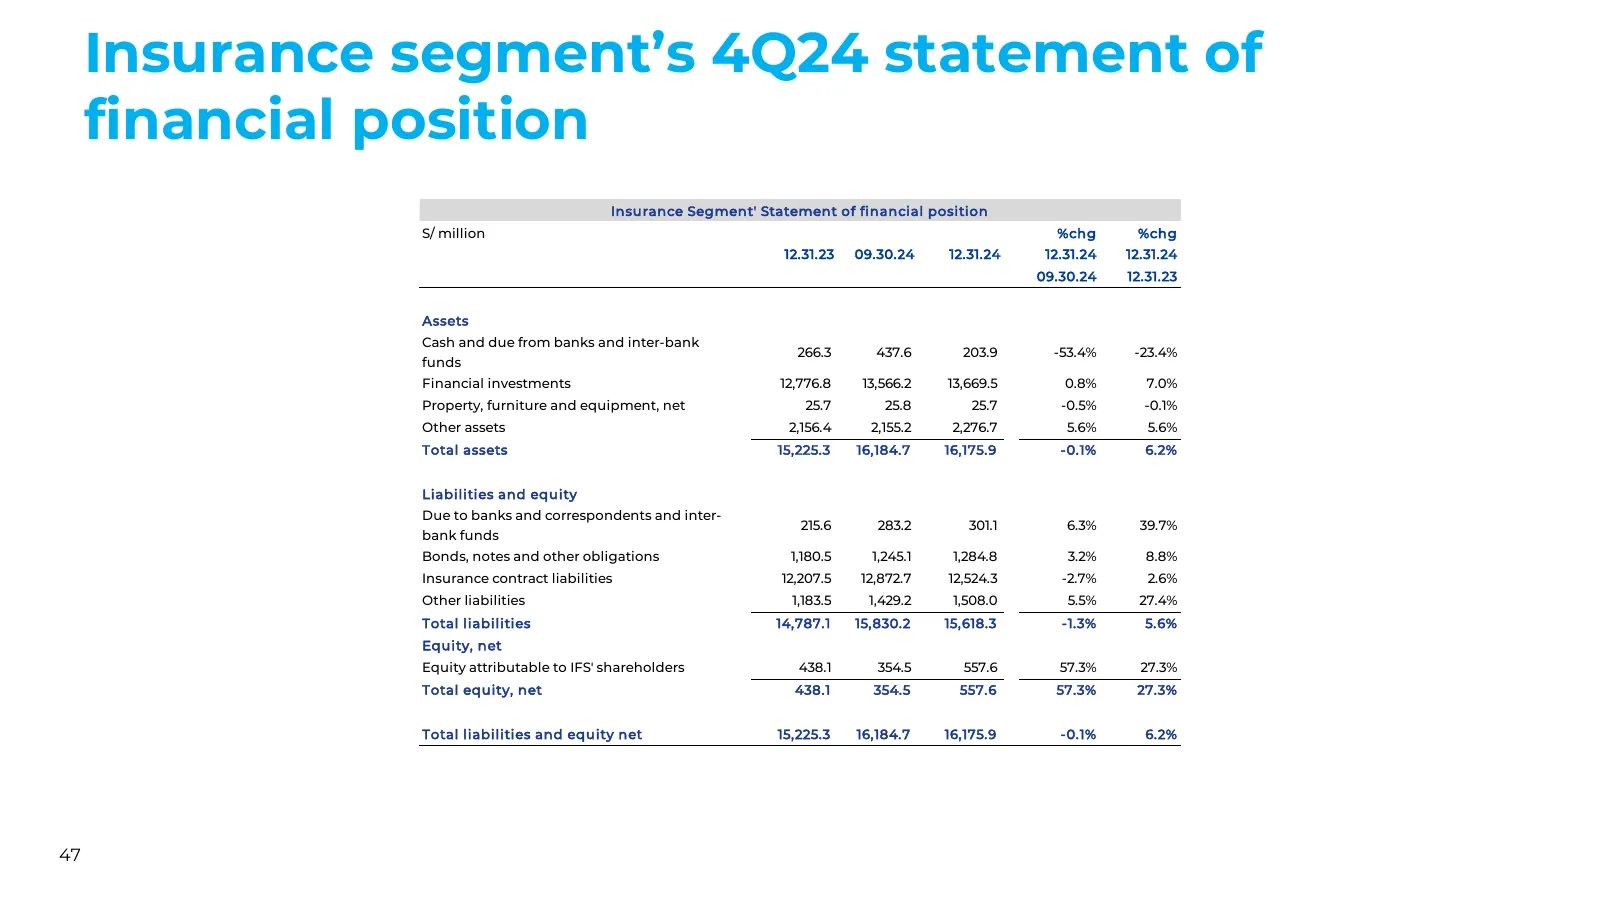
Slide 47: Insurance segment's 4Q24 statement of financial position
Insurance segment’s 4Q24 statement of financial position Insurance Segment' Statement of financial position S/ million %chg %chg 12.31.23 09.30.24 12.31.24 12.31.24 12.31.24 09.30.24 12.31.23 Assets Cash and due from banks and inter-bank 266.3 437.6 203.9 -53.4% -23.4% funds Financial investments 12
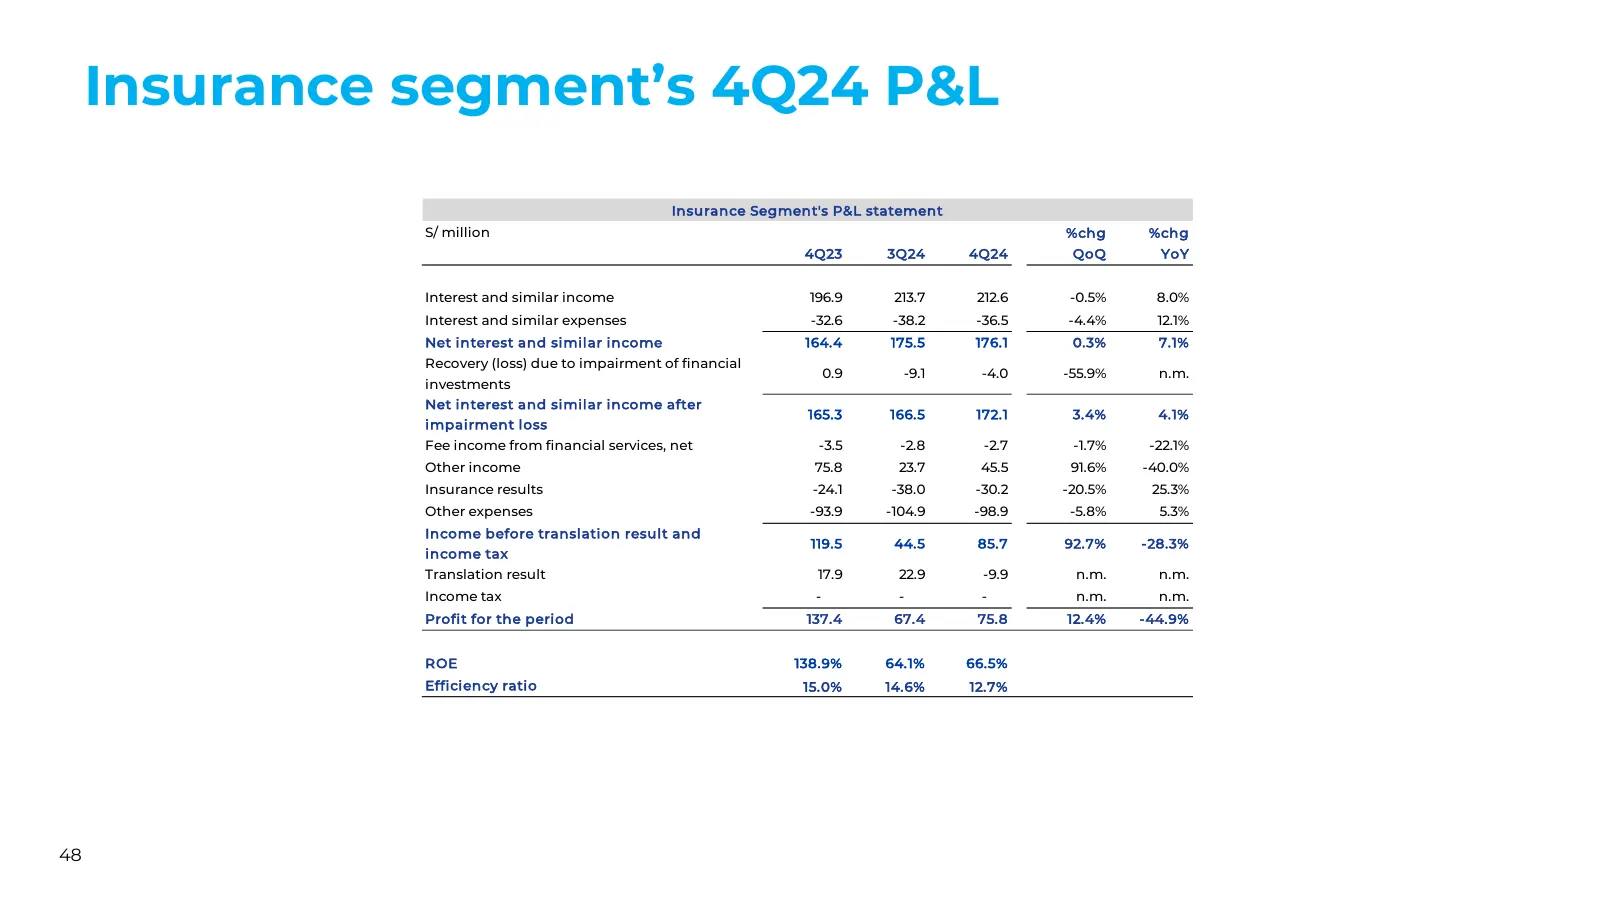
Slide 48: Insurance segment's 4Q24 P&L
Insurance segment’s 4Q24 P&L Insurance Segment's P&L statement S/ million %chg %chg 4Q23 3Q24 4Q24 QoQ YoY Interest and similar income 196.9 213.7 212.6 -0.5% 8.0% Interest and similar expenses -32.6 -38.2 -36.5 -4.4% 12.1% Net interest and similar income 164.4 175.5 176.1 0.3% 7.1% Recovery (loss)
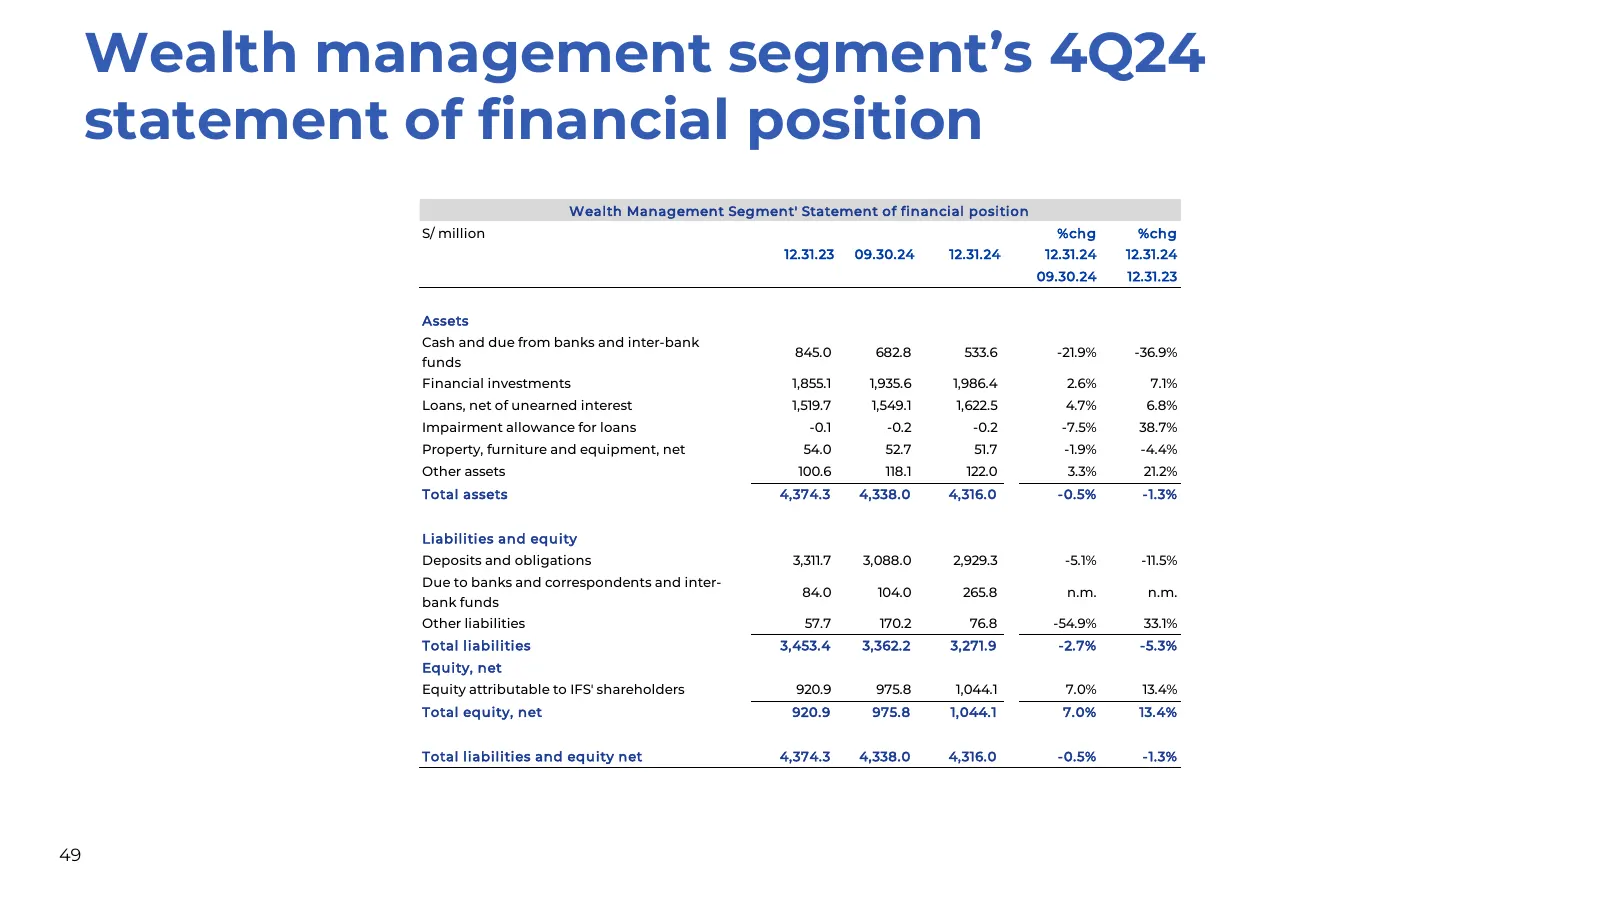
Slide 49: Wealth management segment's 4Q24 statement of financial position
Wealth management segment’s 4Q24 statement of financial position Wealth Management Segment' Statement of financial position S/ million %chg %chg 12.31.23 09.30.24 12.31.24 12.31.24 12.31.24 09.30.24 12.31.23 Assets Cash and due from banks and inter-bank 845.0 682.8 533.6 -21.9% -36.9% funds Financia
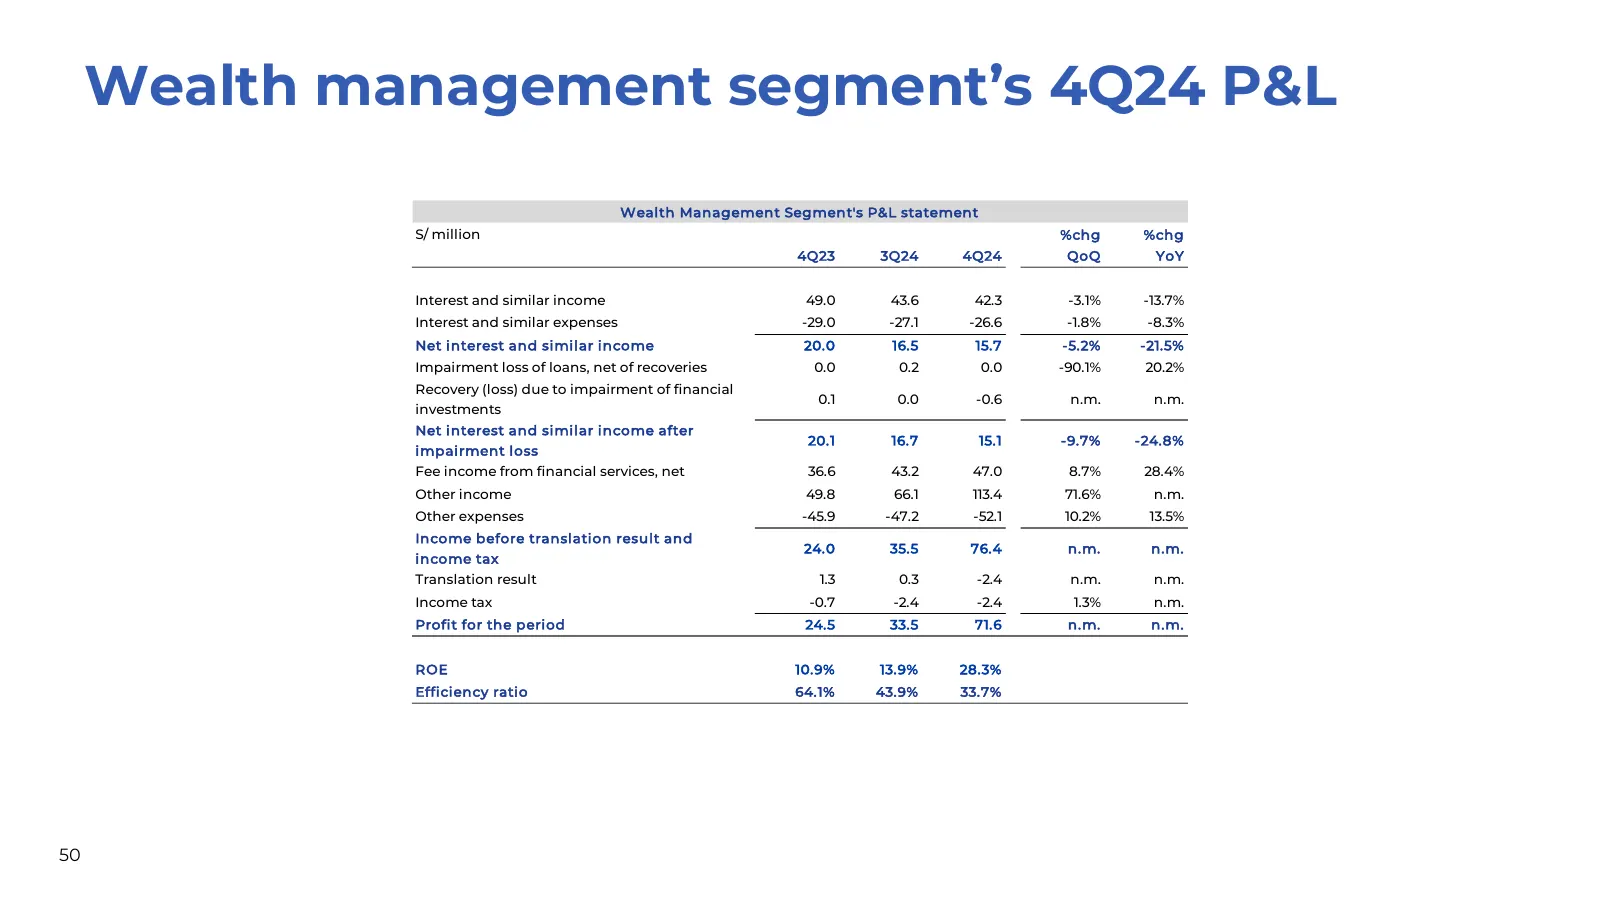
Slide 50: Wealth management segment's 4Q24 P&L
Wealth management segment’s 4Q24 P&L Wealth Management Segment's P&L statement S/ million %chg %chg 4Q23 3Q24 4Q24 QoQ YoY Interest and similar income 49.0 43.6 42.3 -3.1% -13.7% Interest and similar expenses -29.0 -27.1 -26.6 -1.8% -8.3% Net interest and similar income 20.0 16.5 15.7 -5.2% -21.5% I
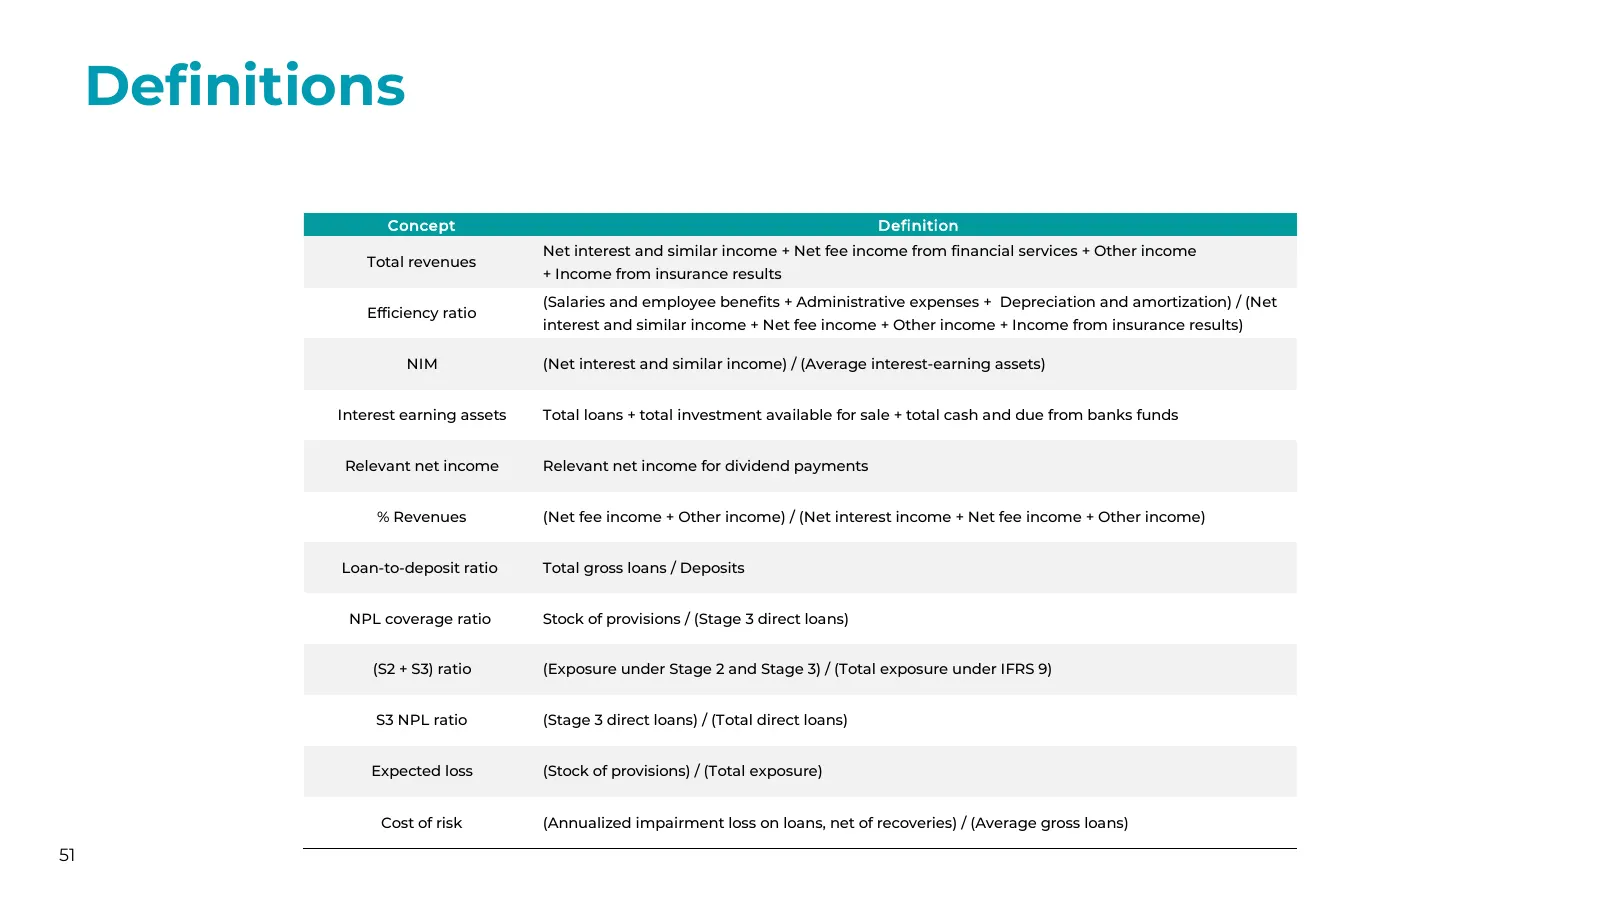
Slide 51: Definitions
Definitions Concept Definition Net interest and similar income + Net fee income from financial services + Other income Total revenues + Income from insurance results (Salaries and employee benefits + Administrative expenses + Depreciation and amortization) / (Net Efficiency ratio interest and simila
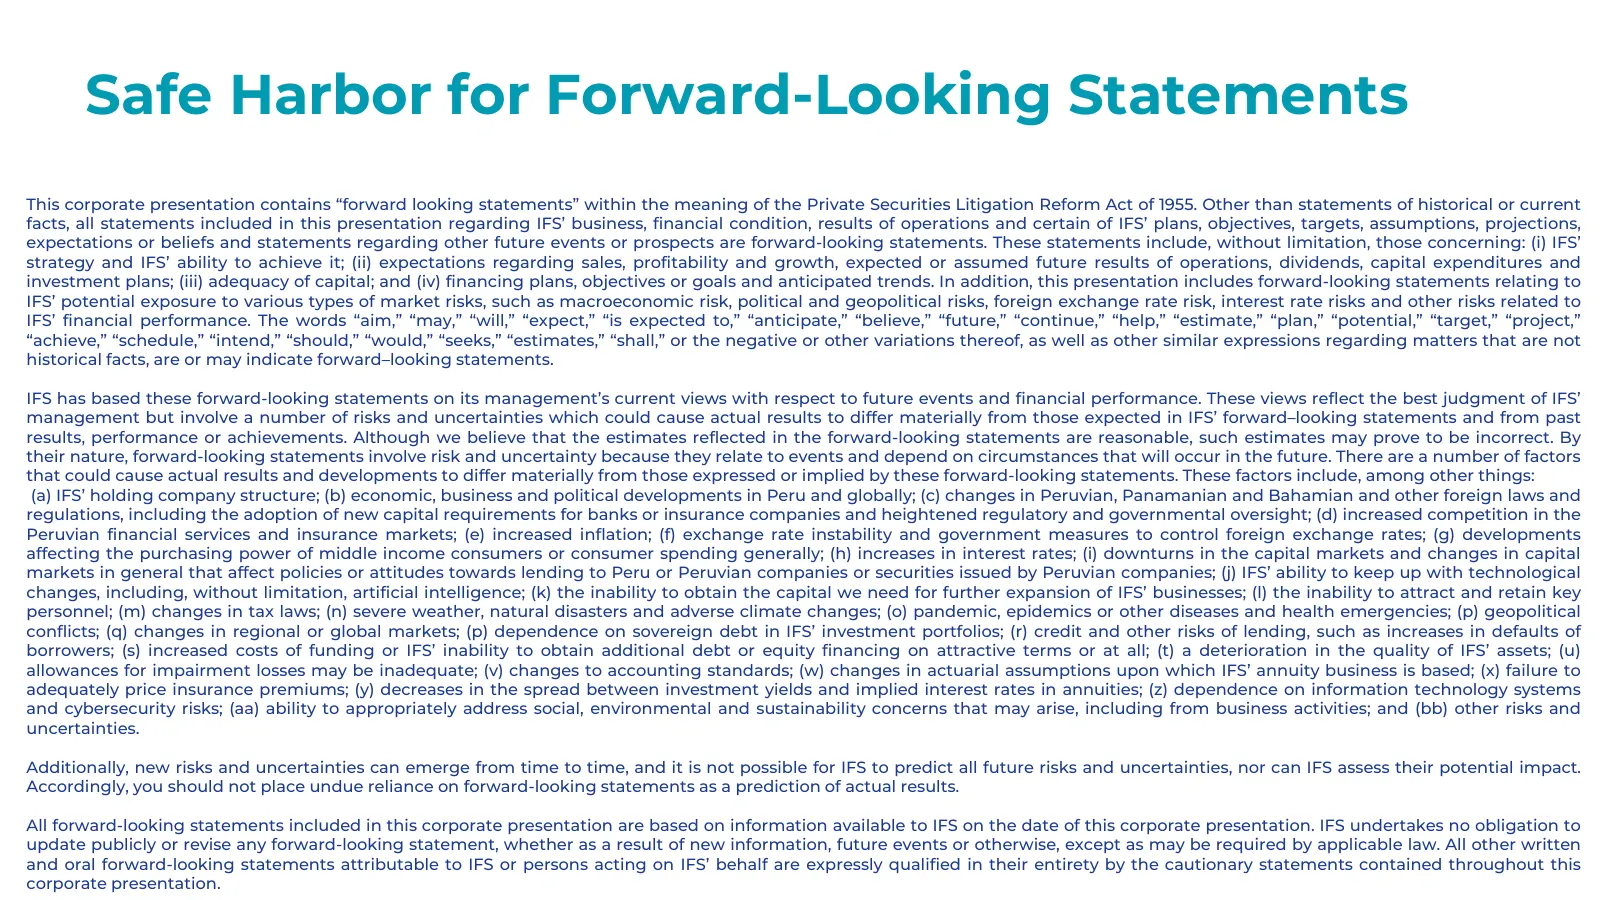
Slide 52: Safe Harbor for Forward-Looking Statements
Safe Harbor for Forward-Looking Statements This corporate presentation contains “forward looking statements” within the meaning of the Private Securities Litigation Reform Act of 1955. Other than statements of historical or current facts, all statements included in this presentation regarding IFS’ b
Slide 53: Intercorp
; EJ Intercorp Fina
Source: company website
More decks from Intercorp Financial Services Inc.
 Q3 2026 Earnings Presentation54 slides · November 2026
 Q2 2026 Earnings Presentation54 slides · Aug 12, 2026
 Q2 2026 Earnings Presentation57 slides · August 2026
 Q2 2026 Earnings Presentation38 slides · August 2026
 Q1 2026 Earnings Presentation54 slides · May 12, 2026
 Q1 2026 Earnings Presentation51 slides · May 2026