Crestwood Midstream Partners LP
Crestwood Midstream Partners LP — NAPTP 2013 MLP Investor Conference
30 slides from Crestwood Midstream Partners LP's conference presentation, May 22, 2013
Slide 1: Crestwood Midstream Partners LP
Filed by Crestwood Midstream Partners LP pursuant to Rule 425 under the Securities Act of 1933 and deemed filed pursuant to Rule 14a-12 under the Securities Exchange Act of 1934 Subject Company: Crestwood Midstream Partners LP Commission File No.: 001-33631 Crestwood Midstream Partners LP National A
Slide 2: Additional Information and Where to Find it
Additional Information and Where to Find it This communication contains information about the proposed merger transaction involving Crestwood Midstream Partners LP (“Crestwood”) and Inergy Midstream, L.P. (“Inergy”). In connection with the proposed merger transaction, Inergy will file with the SEC a
Slide 3: Crestwood Midstream Partners
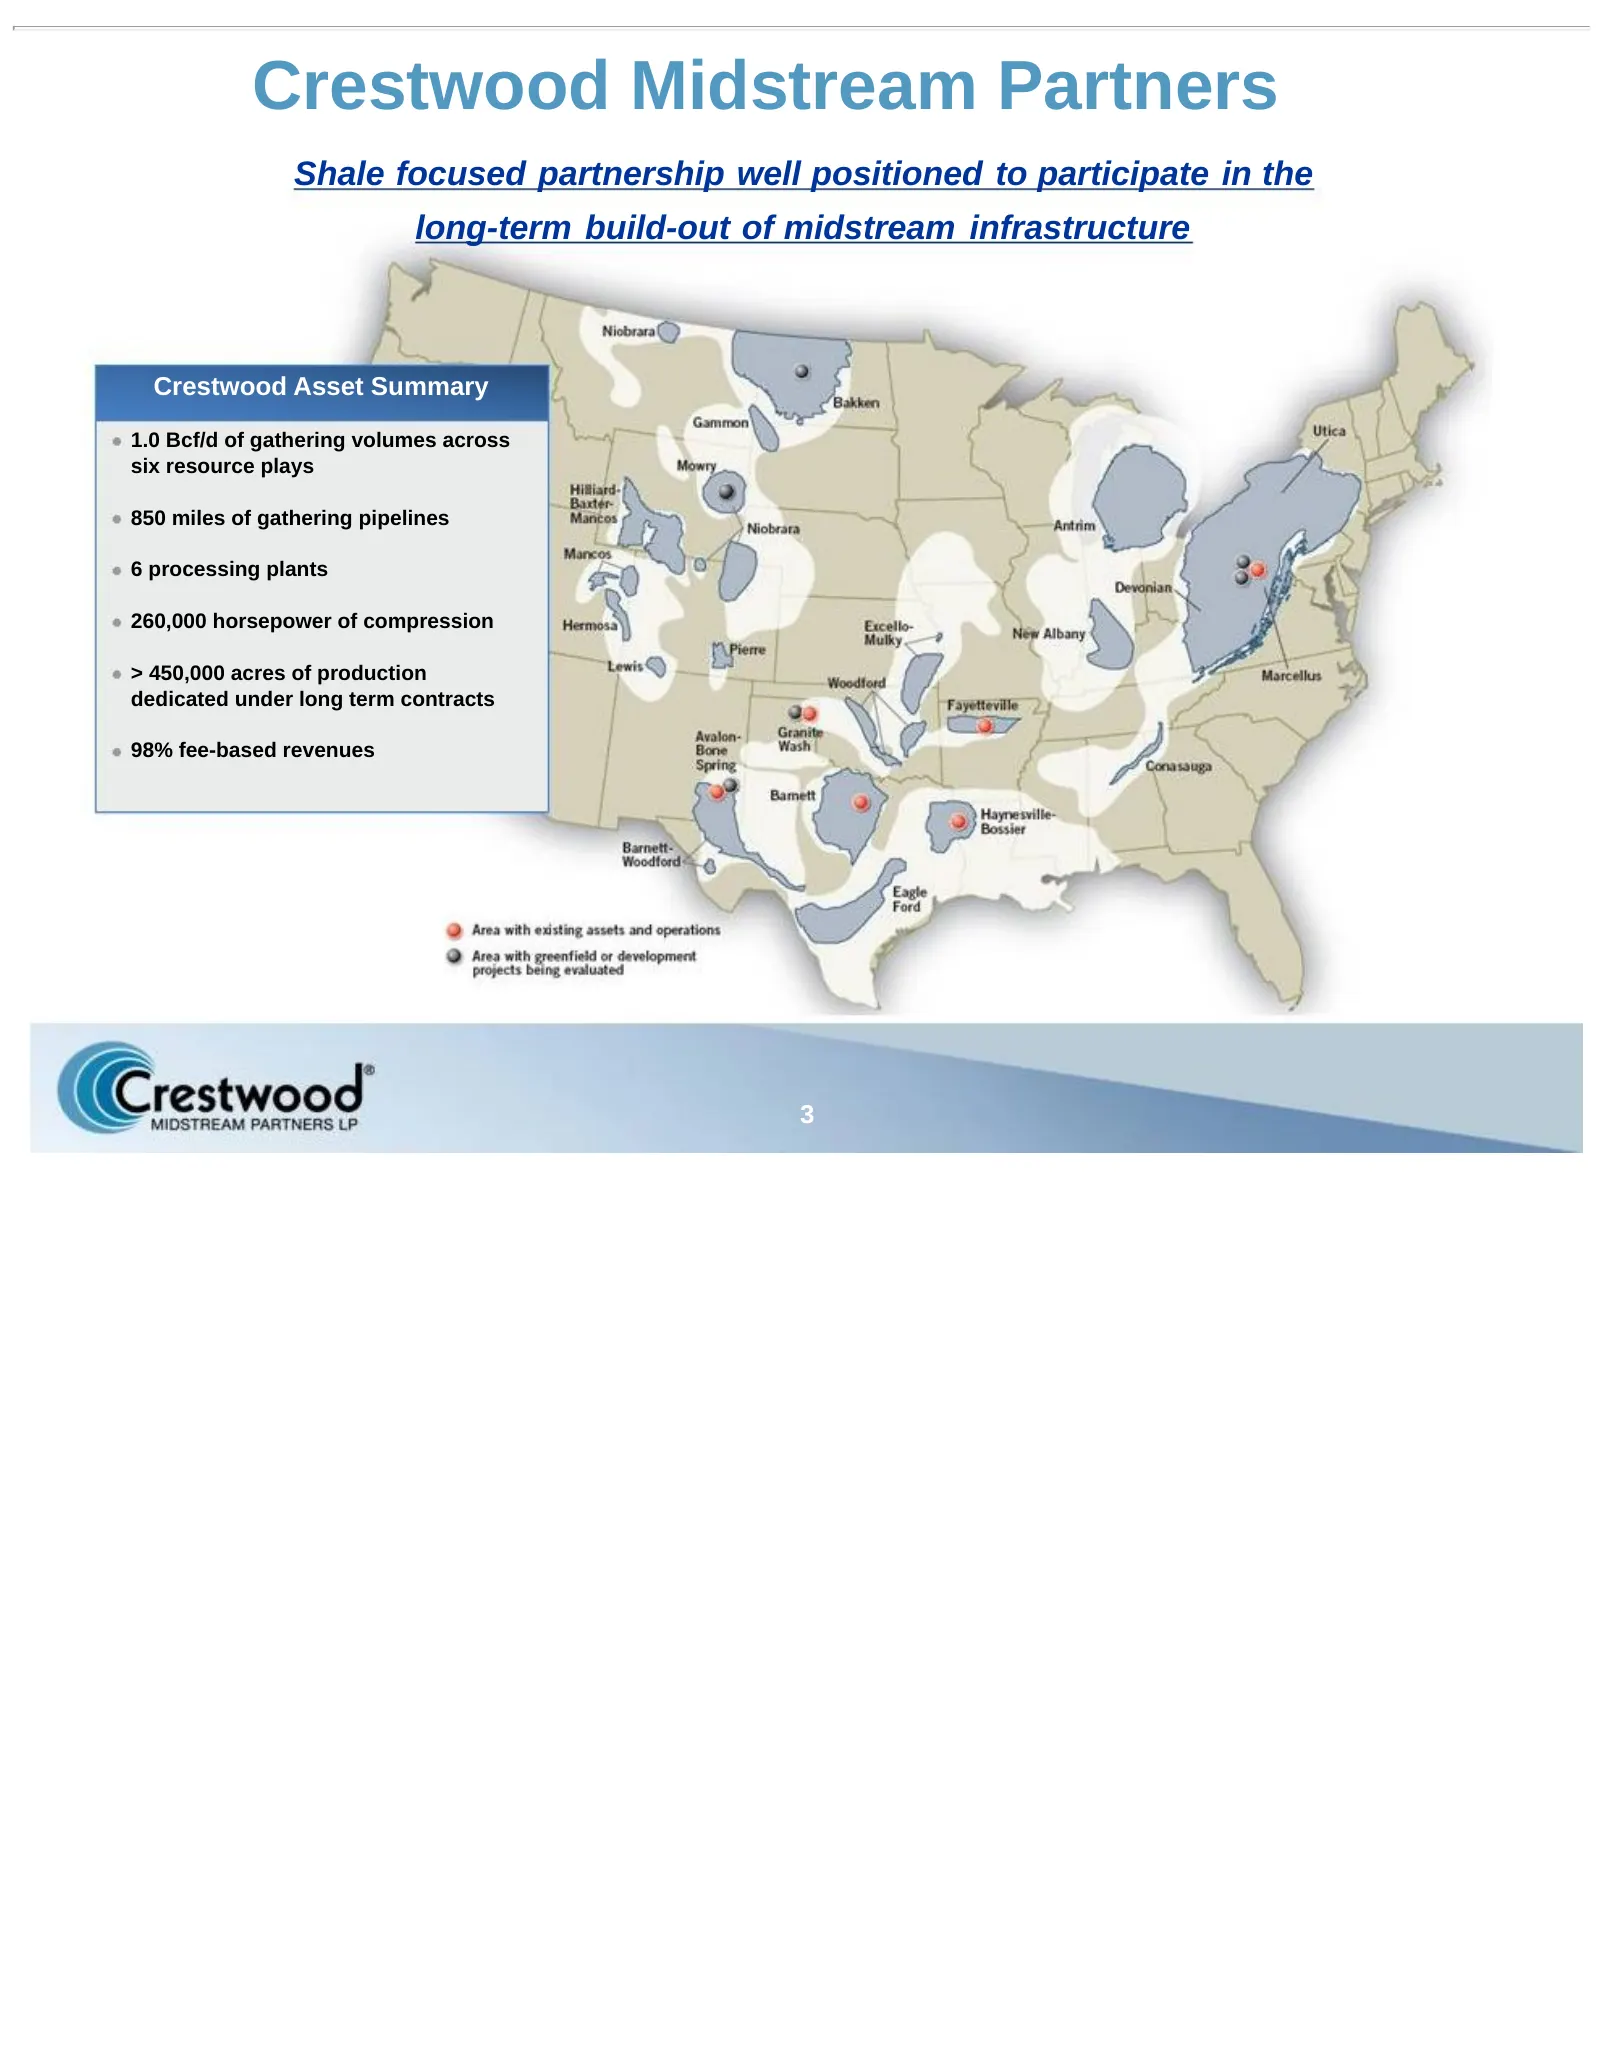
Crestwood Midstream Partners Shale focused partnership well positioned to participate in the long-term build-out of midstream infrastructure Crestwood Asset Summary 1.0 Bcf/d of gathering volumes across six resource plays 850 miles of gathering pipelines 6 processing plants 260,000 horsepower of com
Slide 4: Transformational Combination
Transformational Combination Crestwood and Inergy to merge forming a $7 billion midstream partnership Crestwood Midstream Partners (NYSE: CMLP), Crestwood Holdings LLC, Inergy, L.P. (NYSE:NRGY) and Inergy Midstream, L.P. (NYSE: NRGM) have executed definitive agreements to create a fully integrated m
Slide 5: Crestwood + Inergy = Premier Shale Player
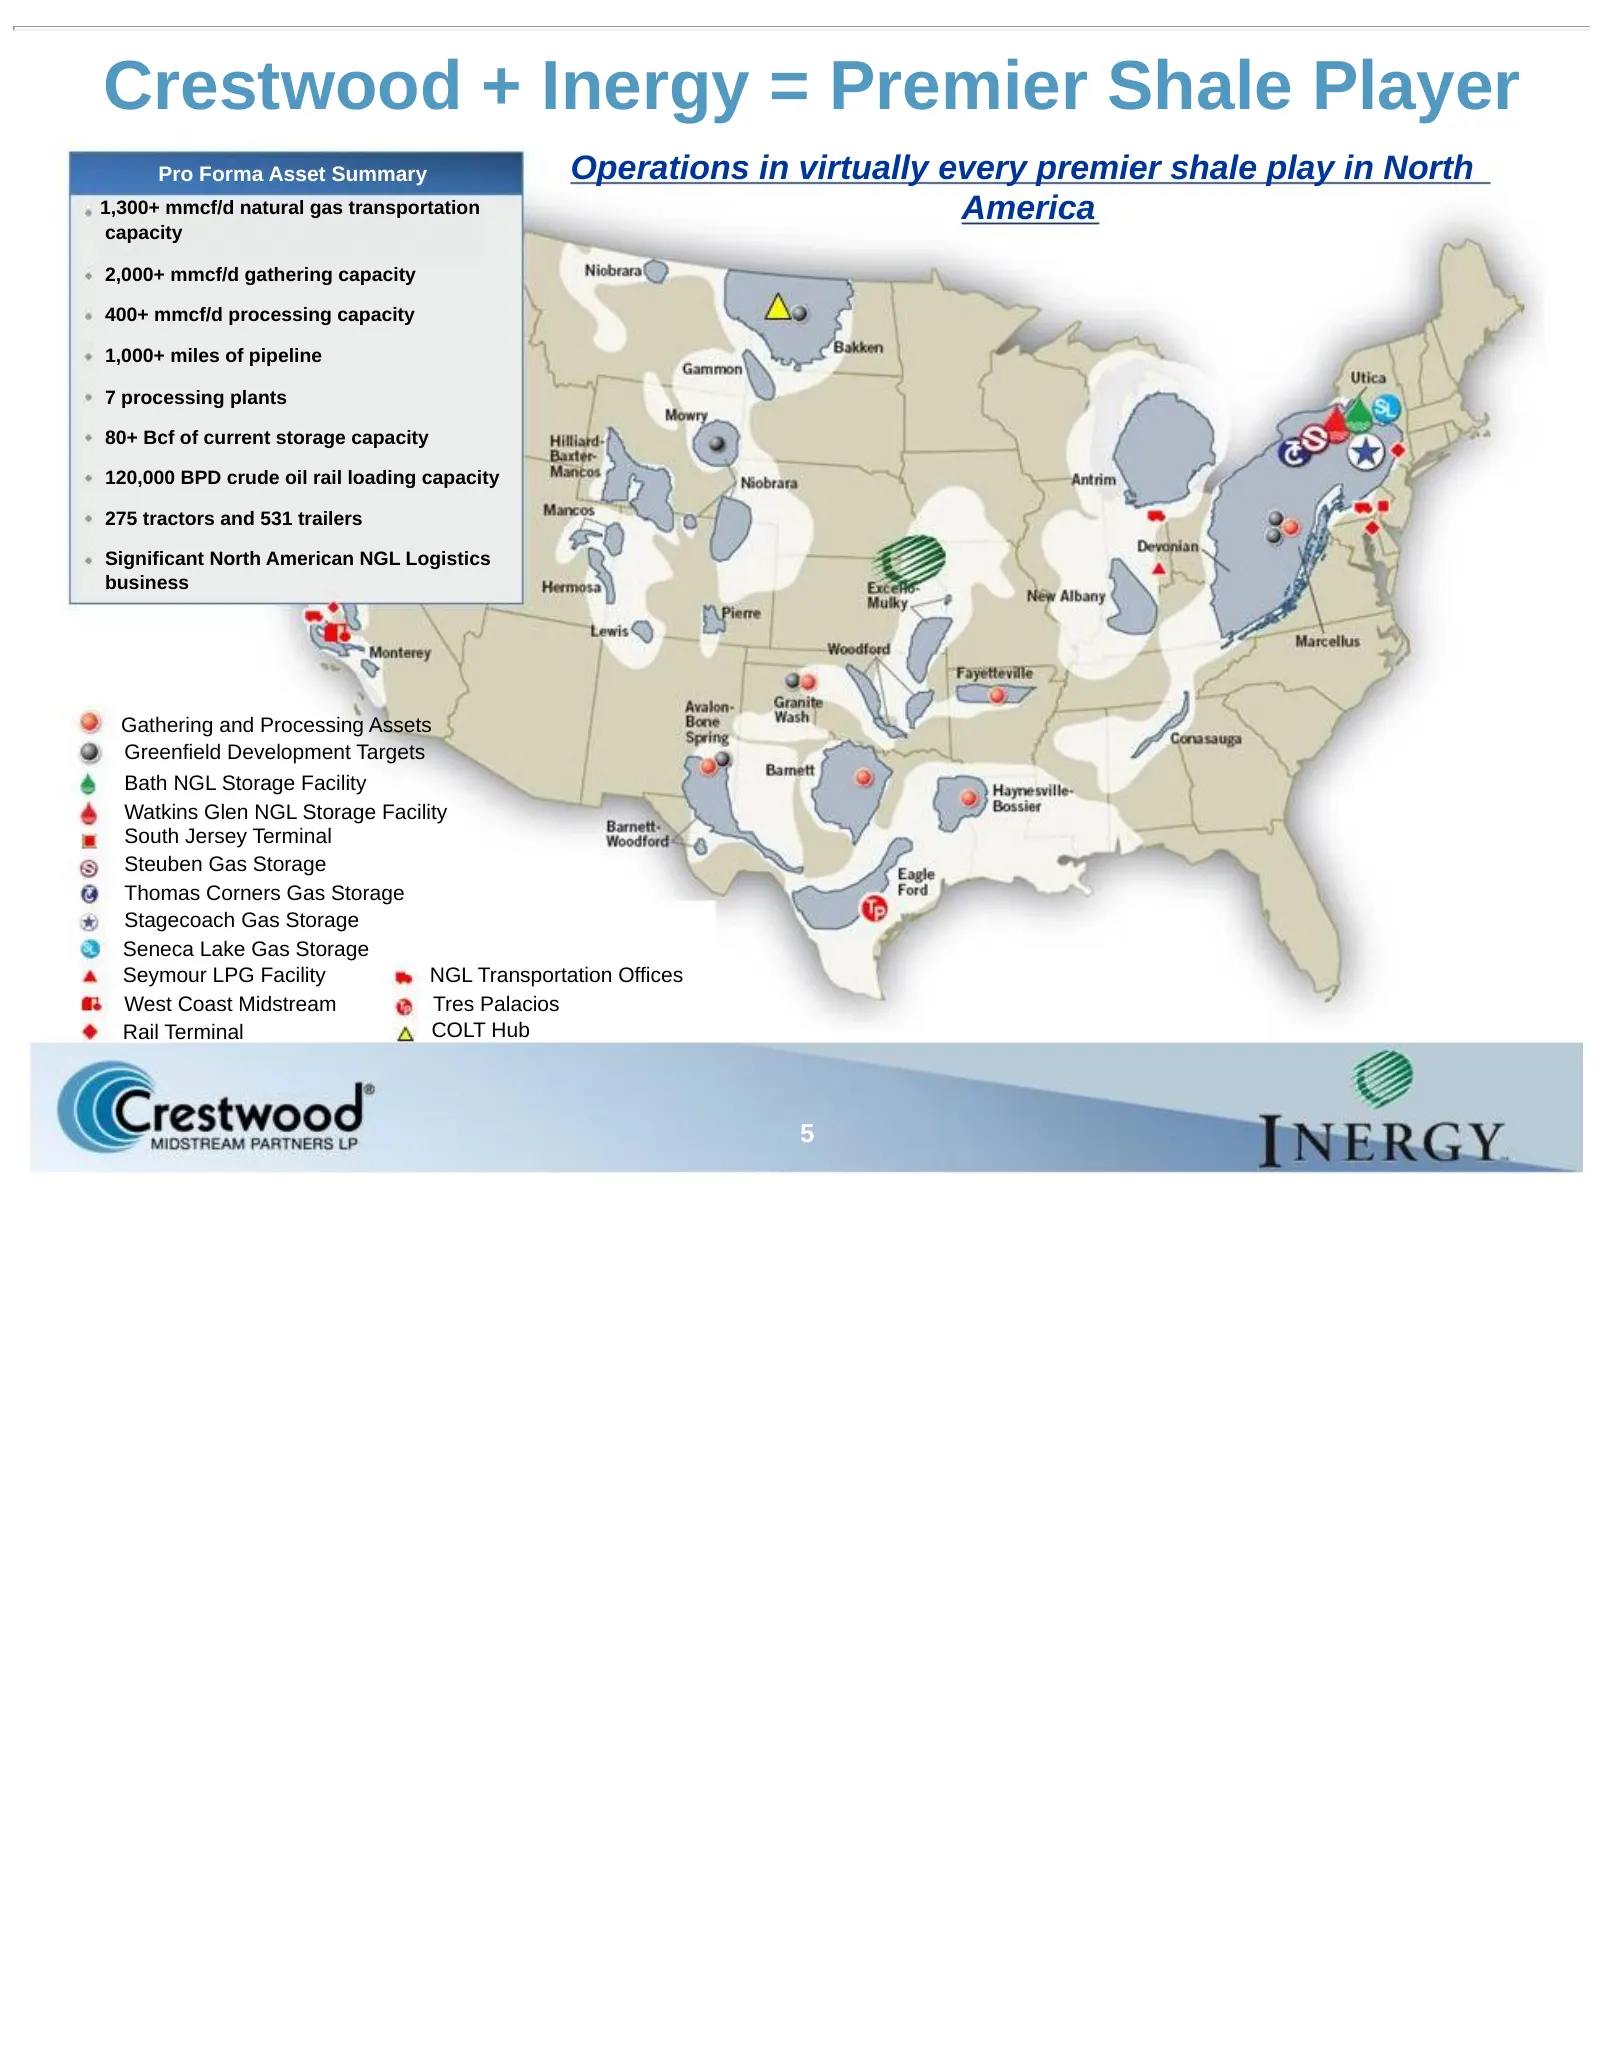
Crestwood + Inergy = Premier Shale Player Pro Forma Asset Summary Operations in virtually every premier shale play in North 1,300+ mmcf/d natural gas transportation America capacity 2,000+ mmcf/d gathering capacity 400+ mmcf/d processing capacity 1,000+ miles of pipeline 7 processing plants 80+ Bcf
Slide 6: Transaction Structure
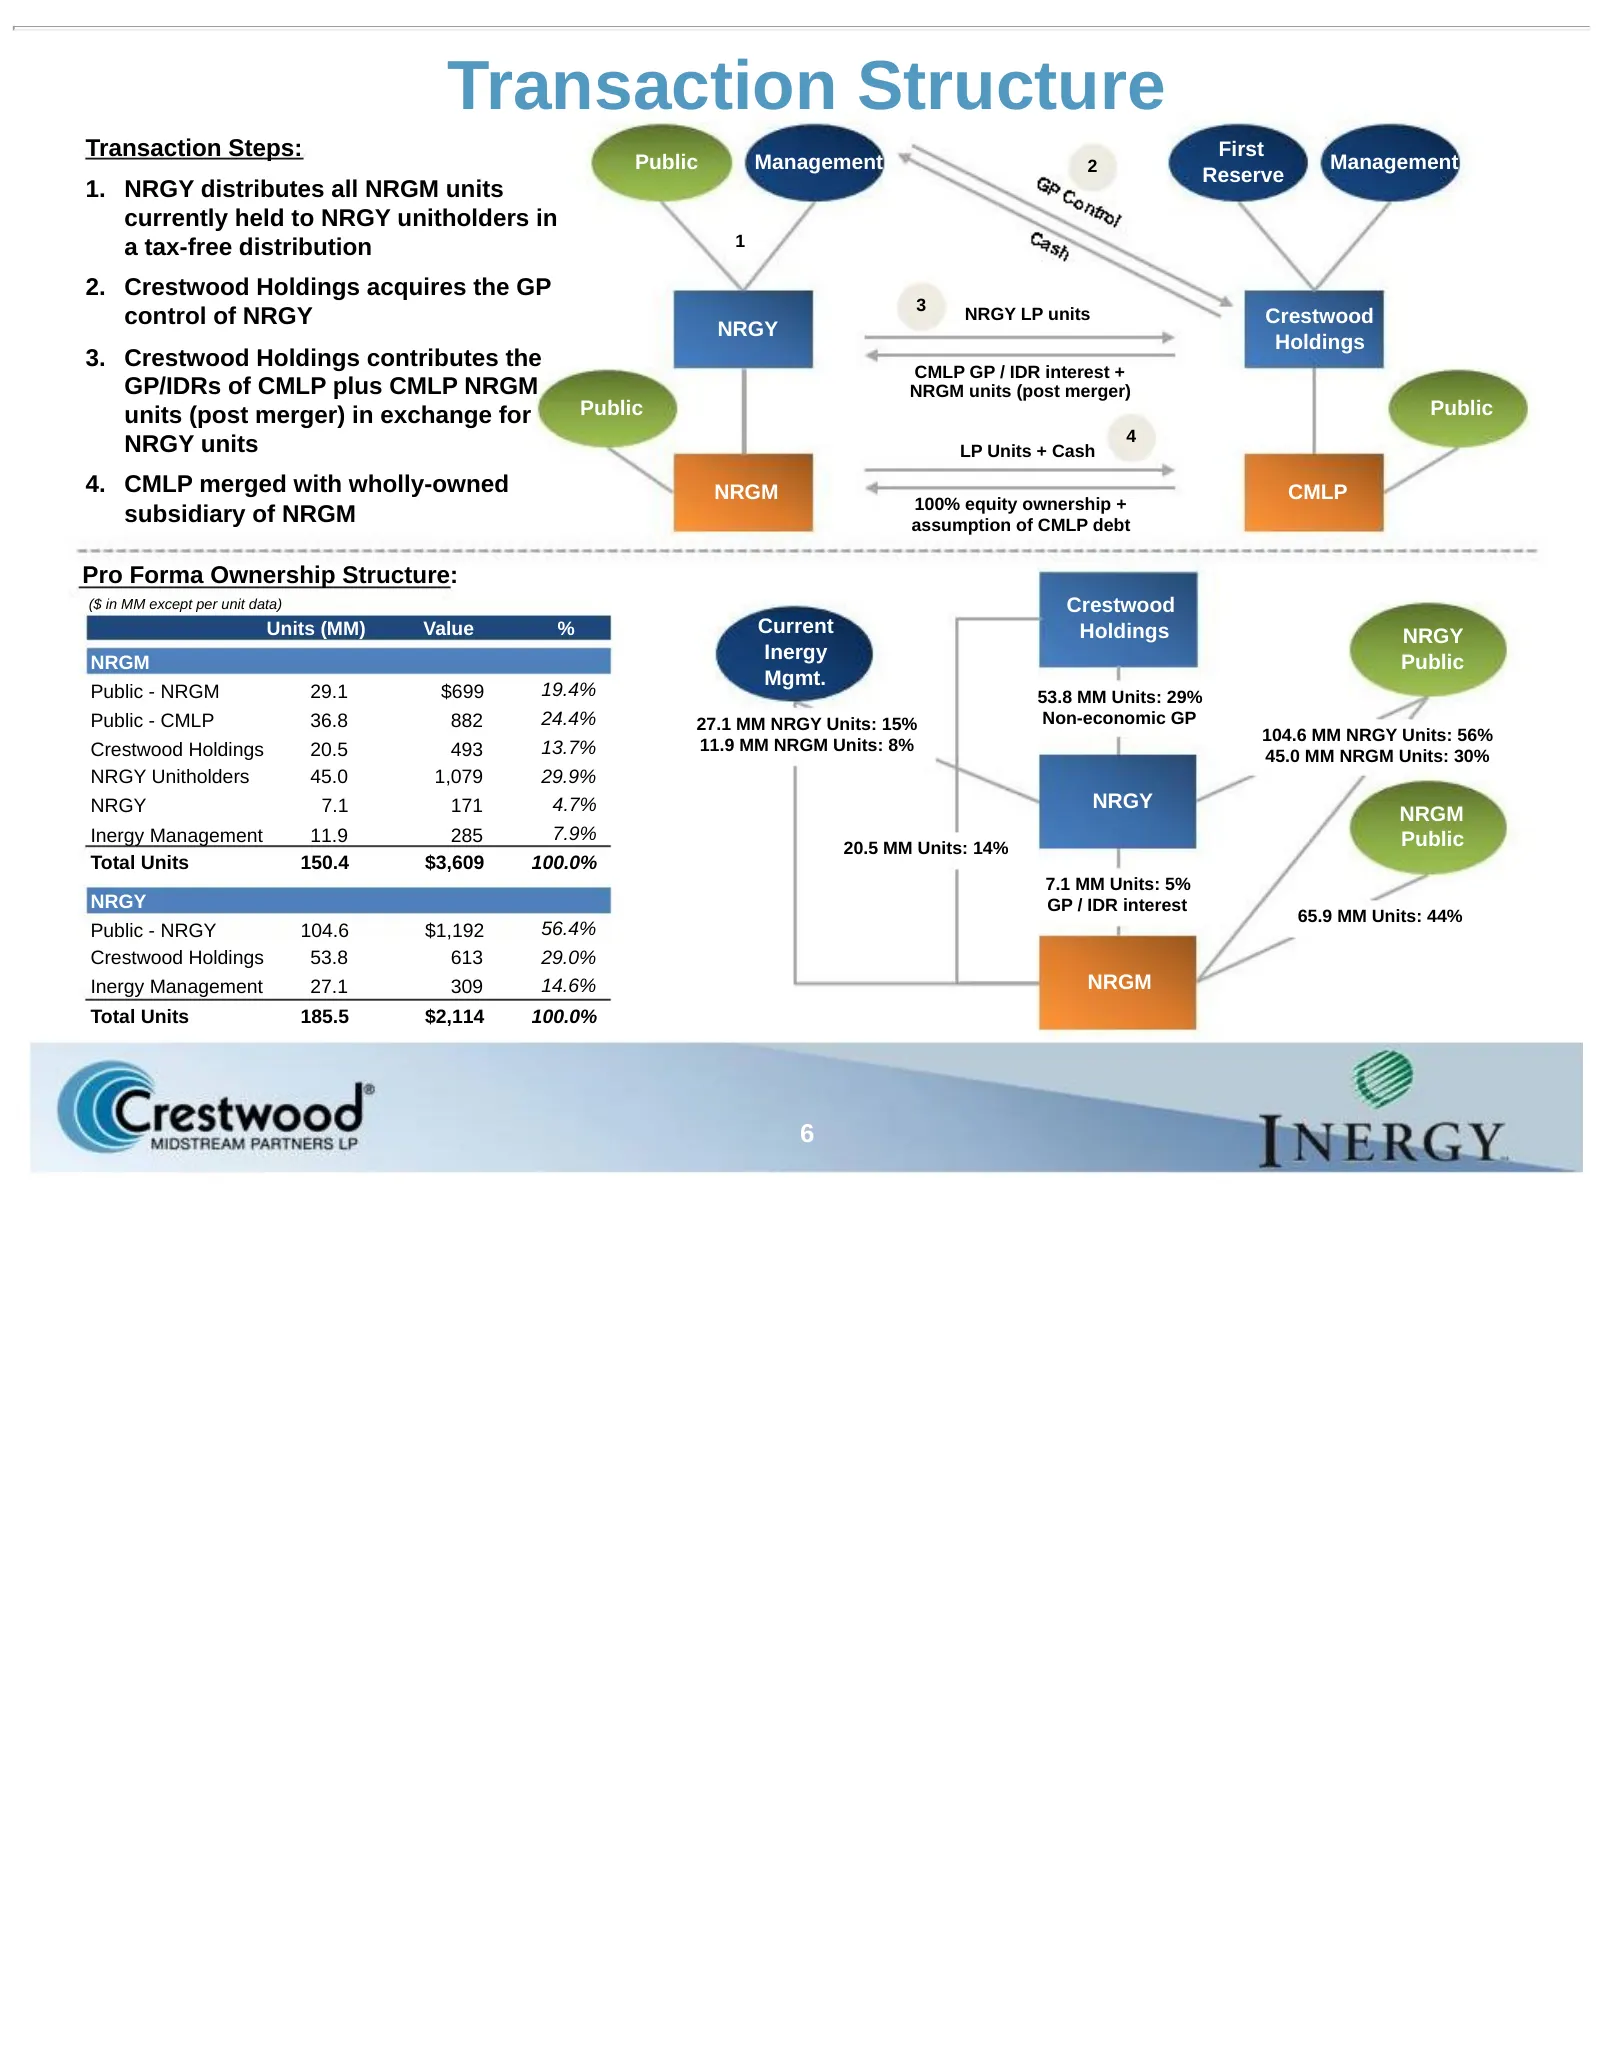
Transaction Structure Transaction Steps: First Public Management 2 Management Reserve 1. NRGY distributes all NRGM units currently held to NRGY unitholders in a tax-free distribution 1 2. Crestwood Holdings acquires the GP 3 control of NRGY NRGY NRGY LP units Crestwood Holdings 3. Crestwood Holdings
Slide 7: Strategic Highlights
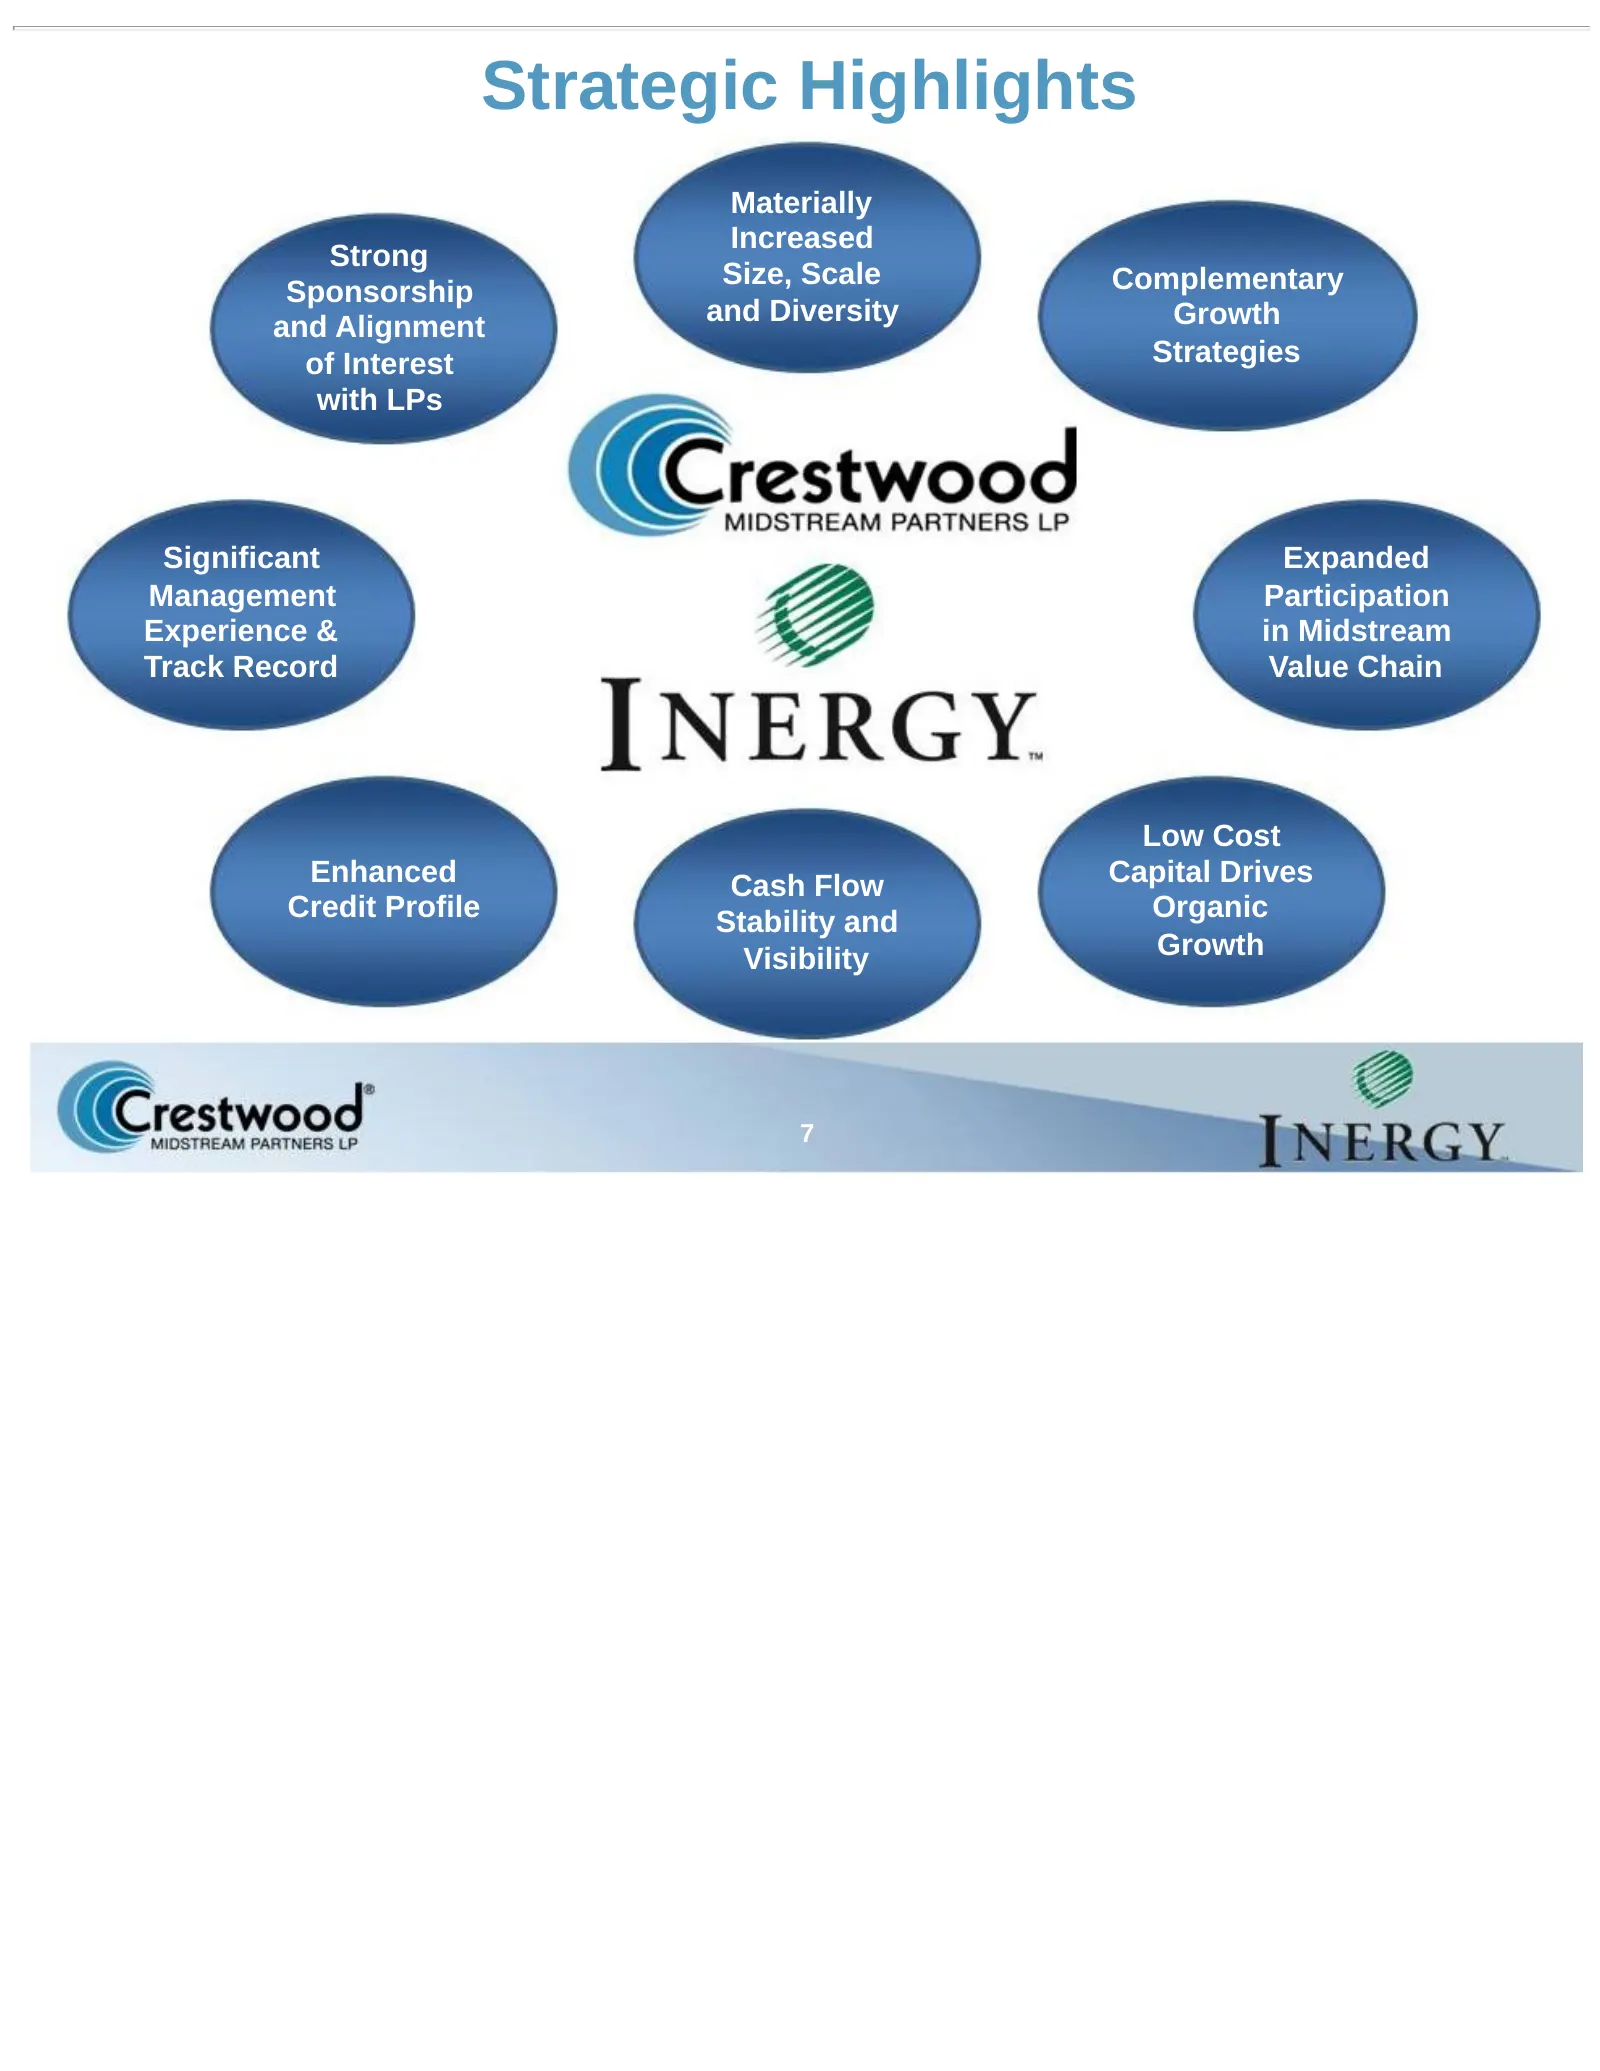
Strategic Highlights Materially Increased Strong Size, Scale Complementary Sponsorship and Diversity Growth and Alignment of Interest Strategies with LPs Significant Expanded Management Participation Experience & in Midstream Track Record Value Chain Low Cost Enhanced Cash Flow Capital Drives Credit
Slide 8: Increasing Scale & Diversification
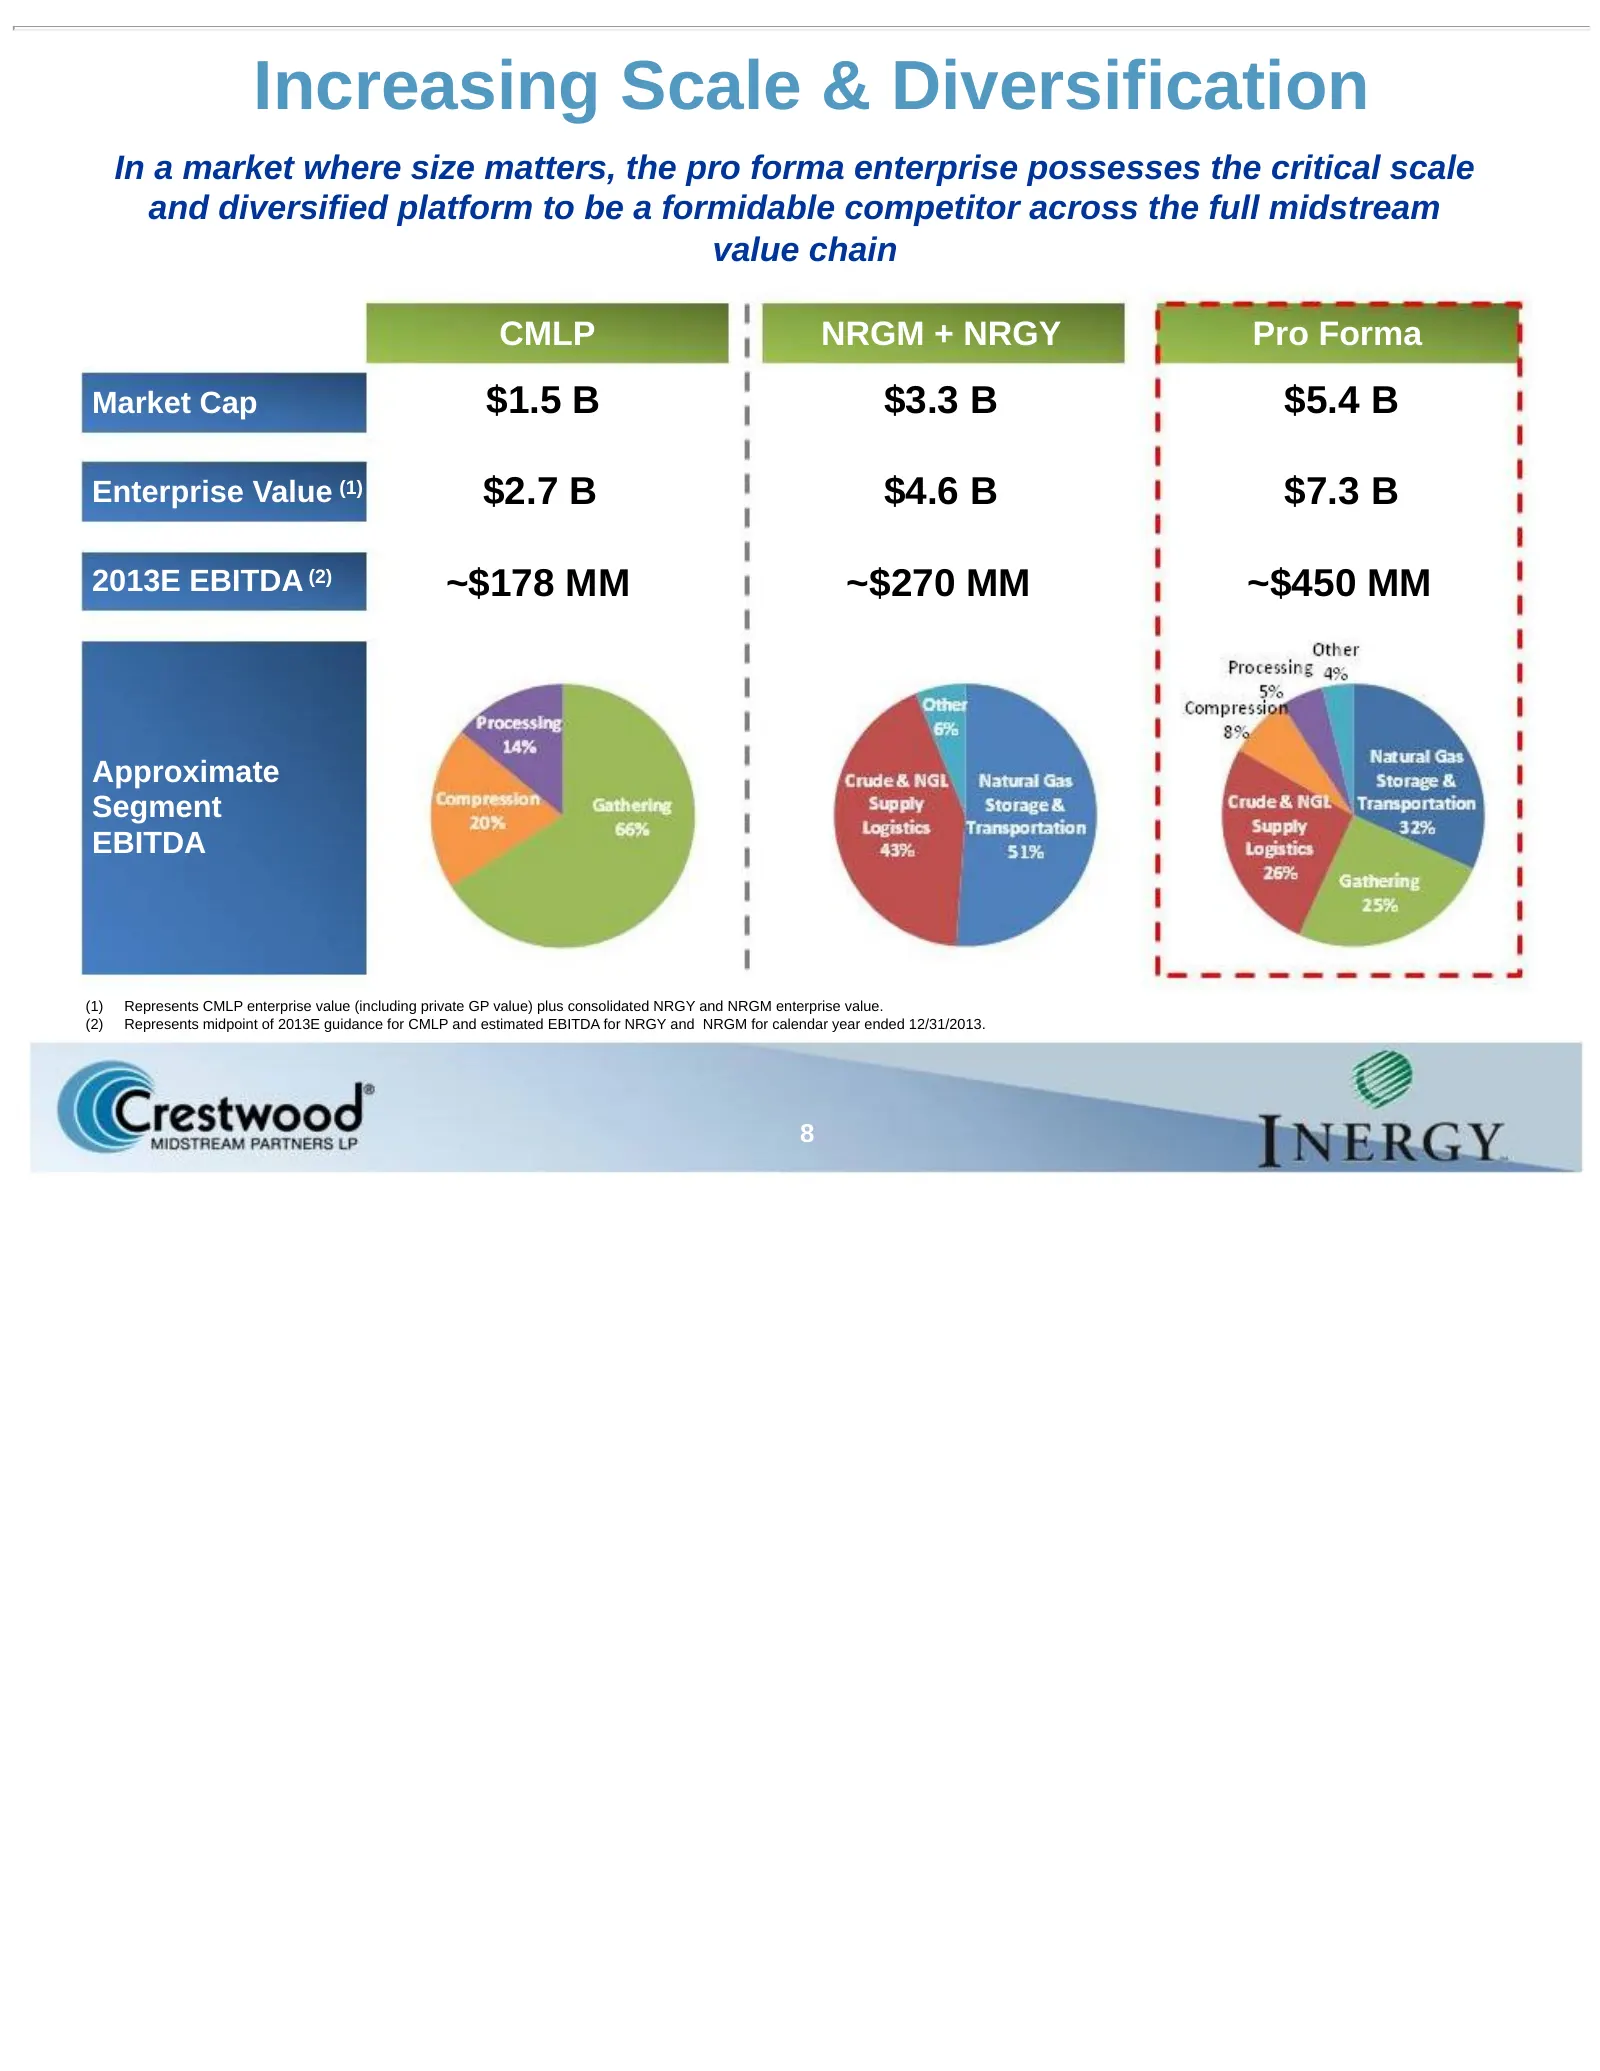
Increasing Scale & Diversification In a market where size matters, the pro forma enterprise possesses the critical scale and diversified platform to be a formidable competitor across the full midstream value chain CMLP NRGM + NRGY Pro Forma Market Cap $1.5 B $3.3 B $5.4 B Enterprise Value (1) $2.7 B
Slide 9: Expanding the Value Chain
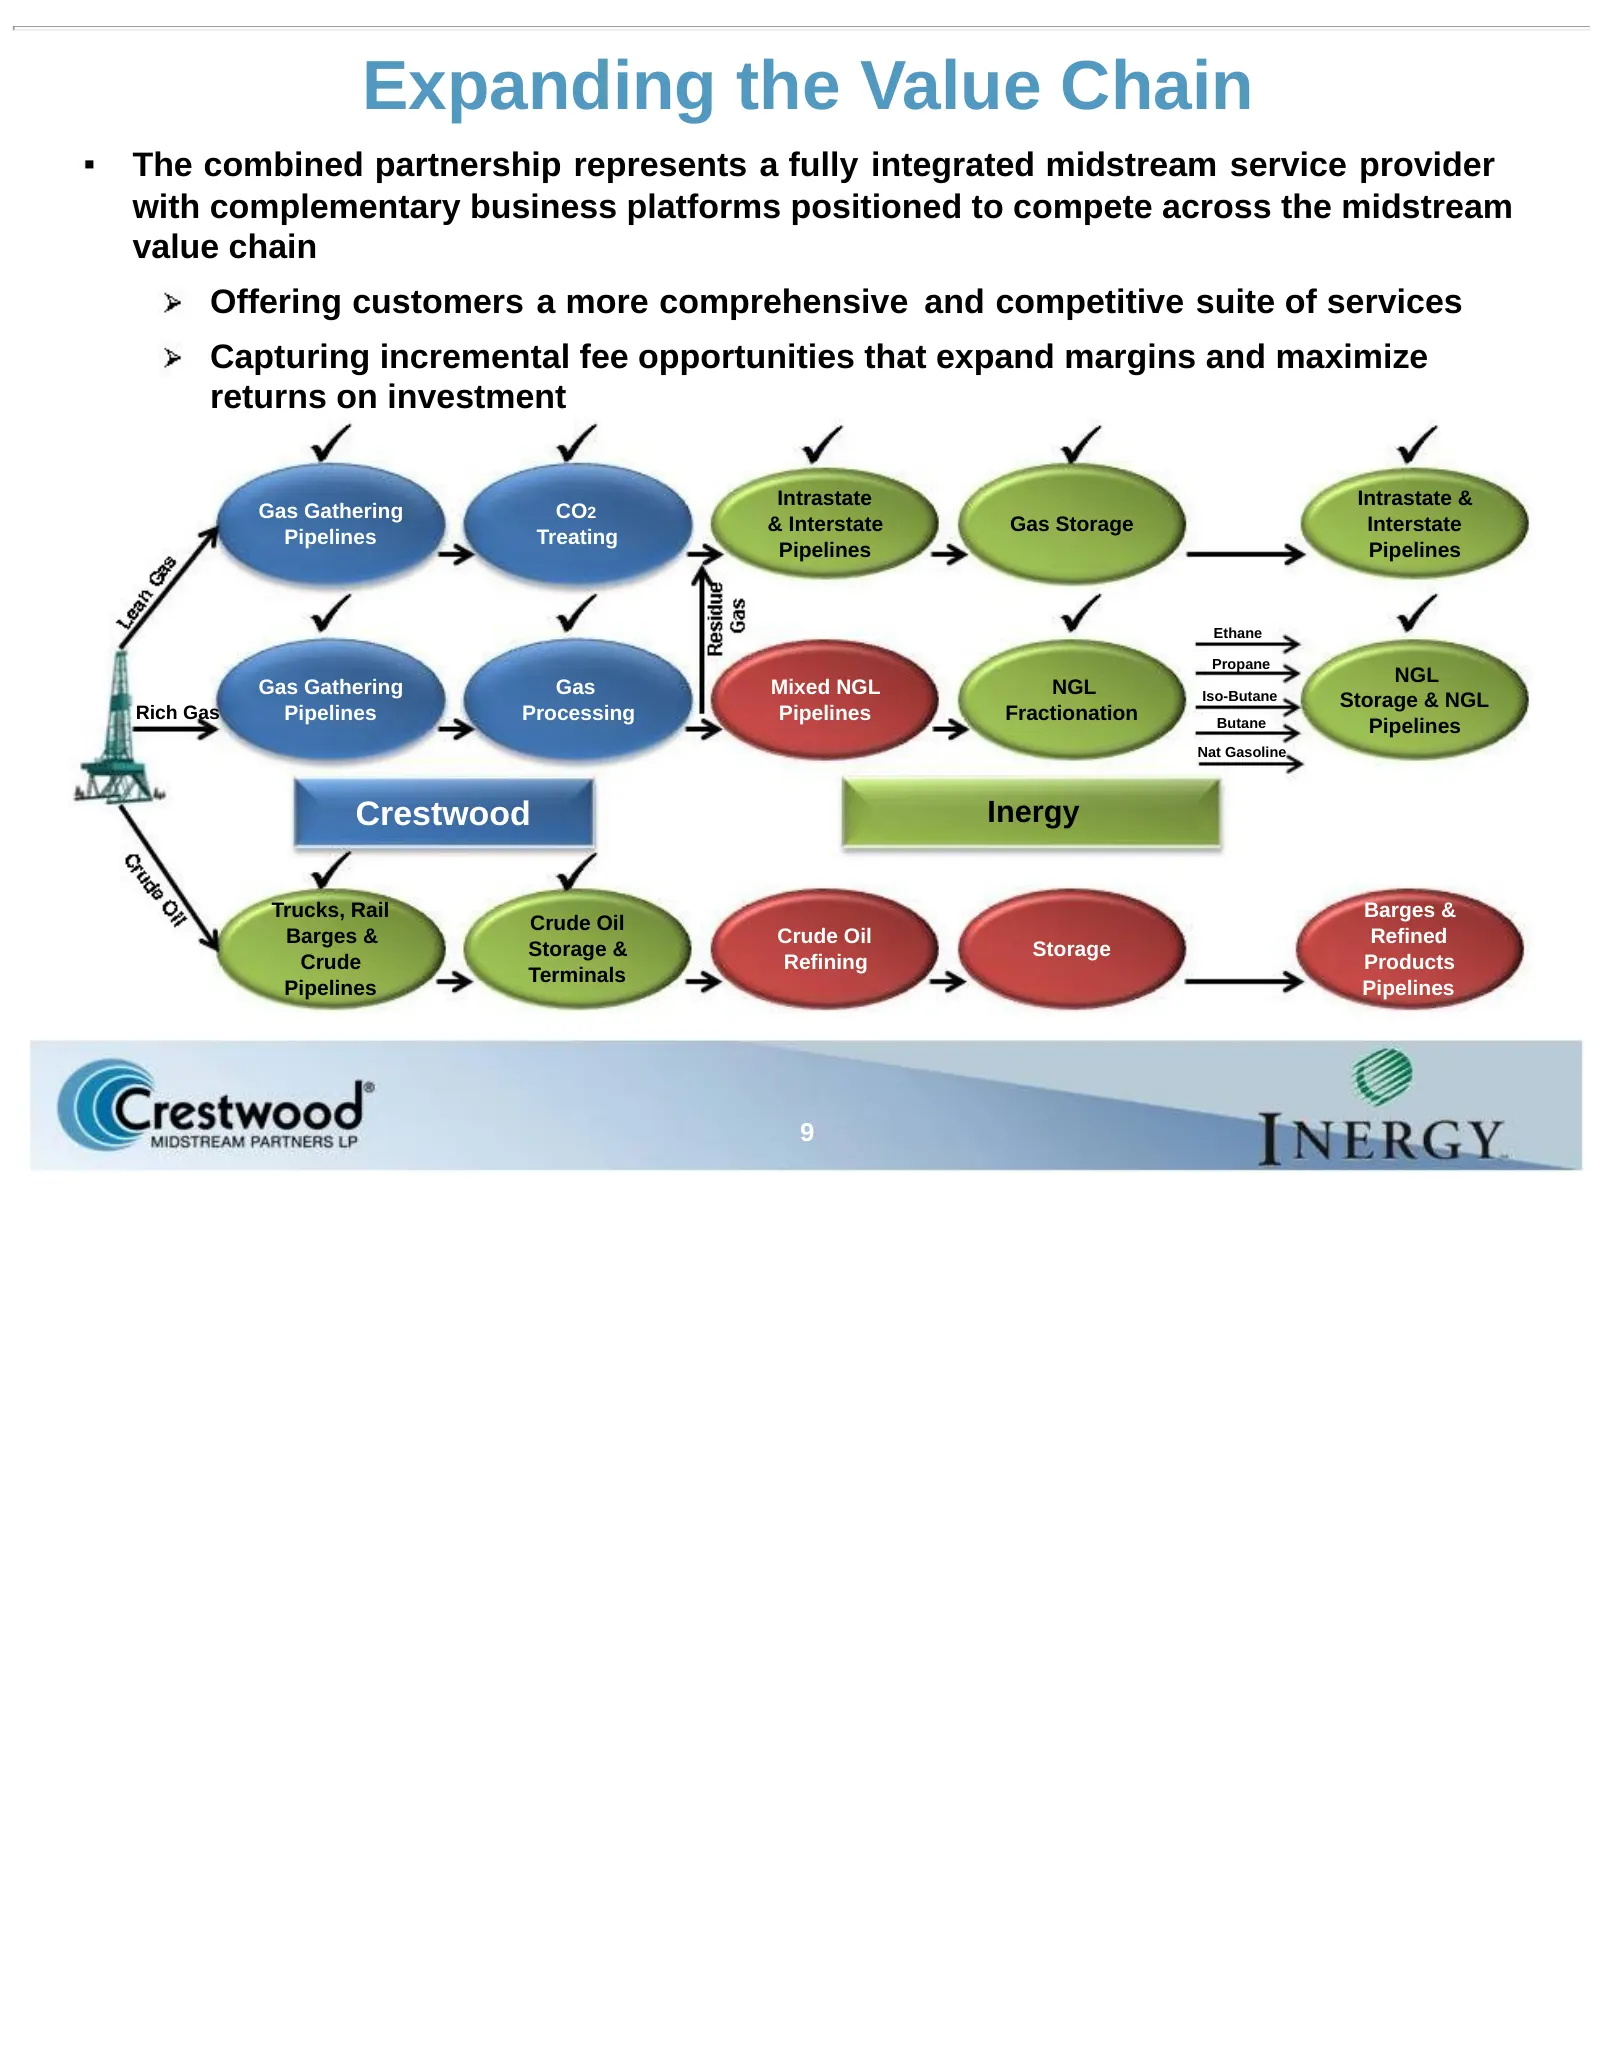
Expanding the Value Chain The combined partnership represents a fully integrated midstream service provider with complementary business platforms positioned to compete across the midstream value chain Offering customers a more comprehensive and competitive suite of services Capturing incremental fee
Slide 10: Linking Supply to Demand
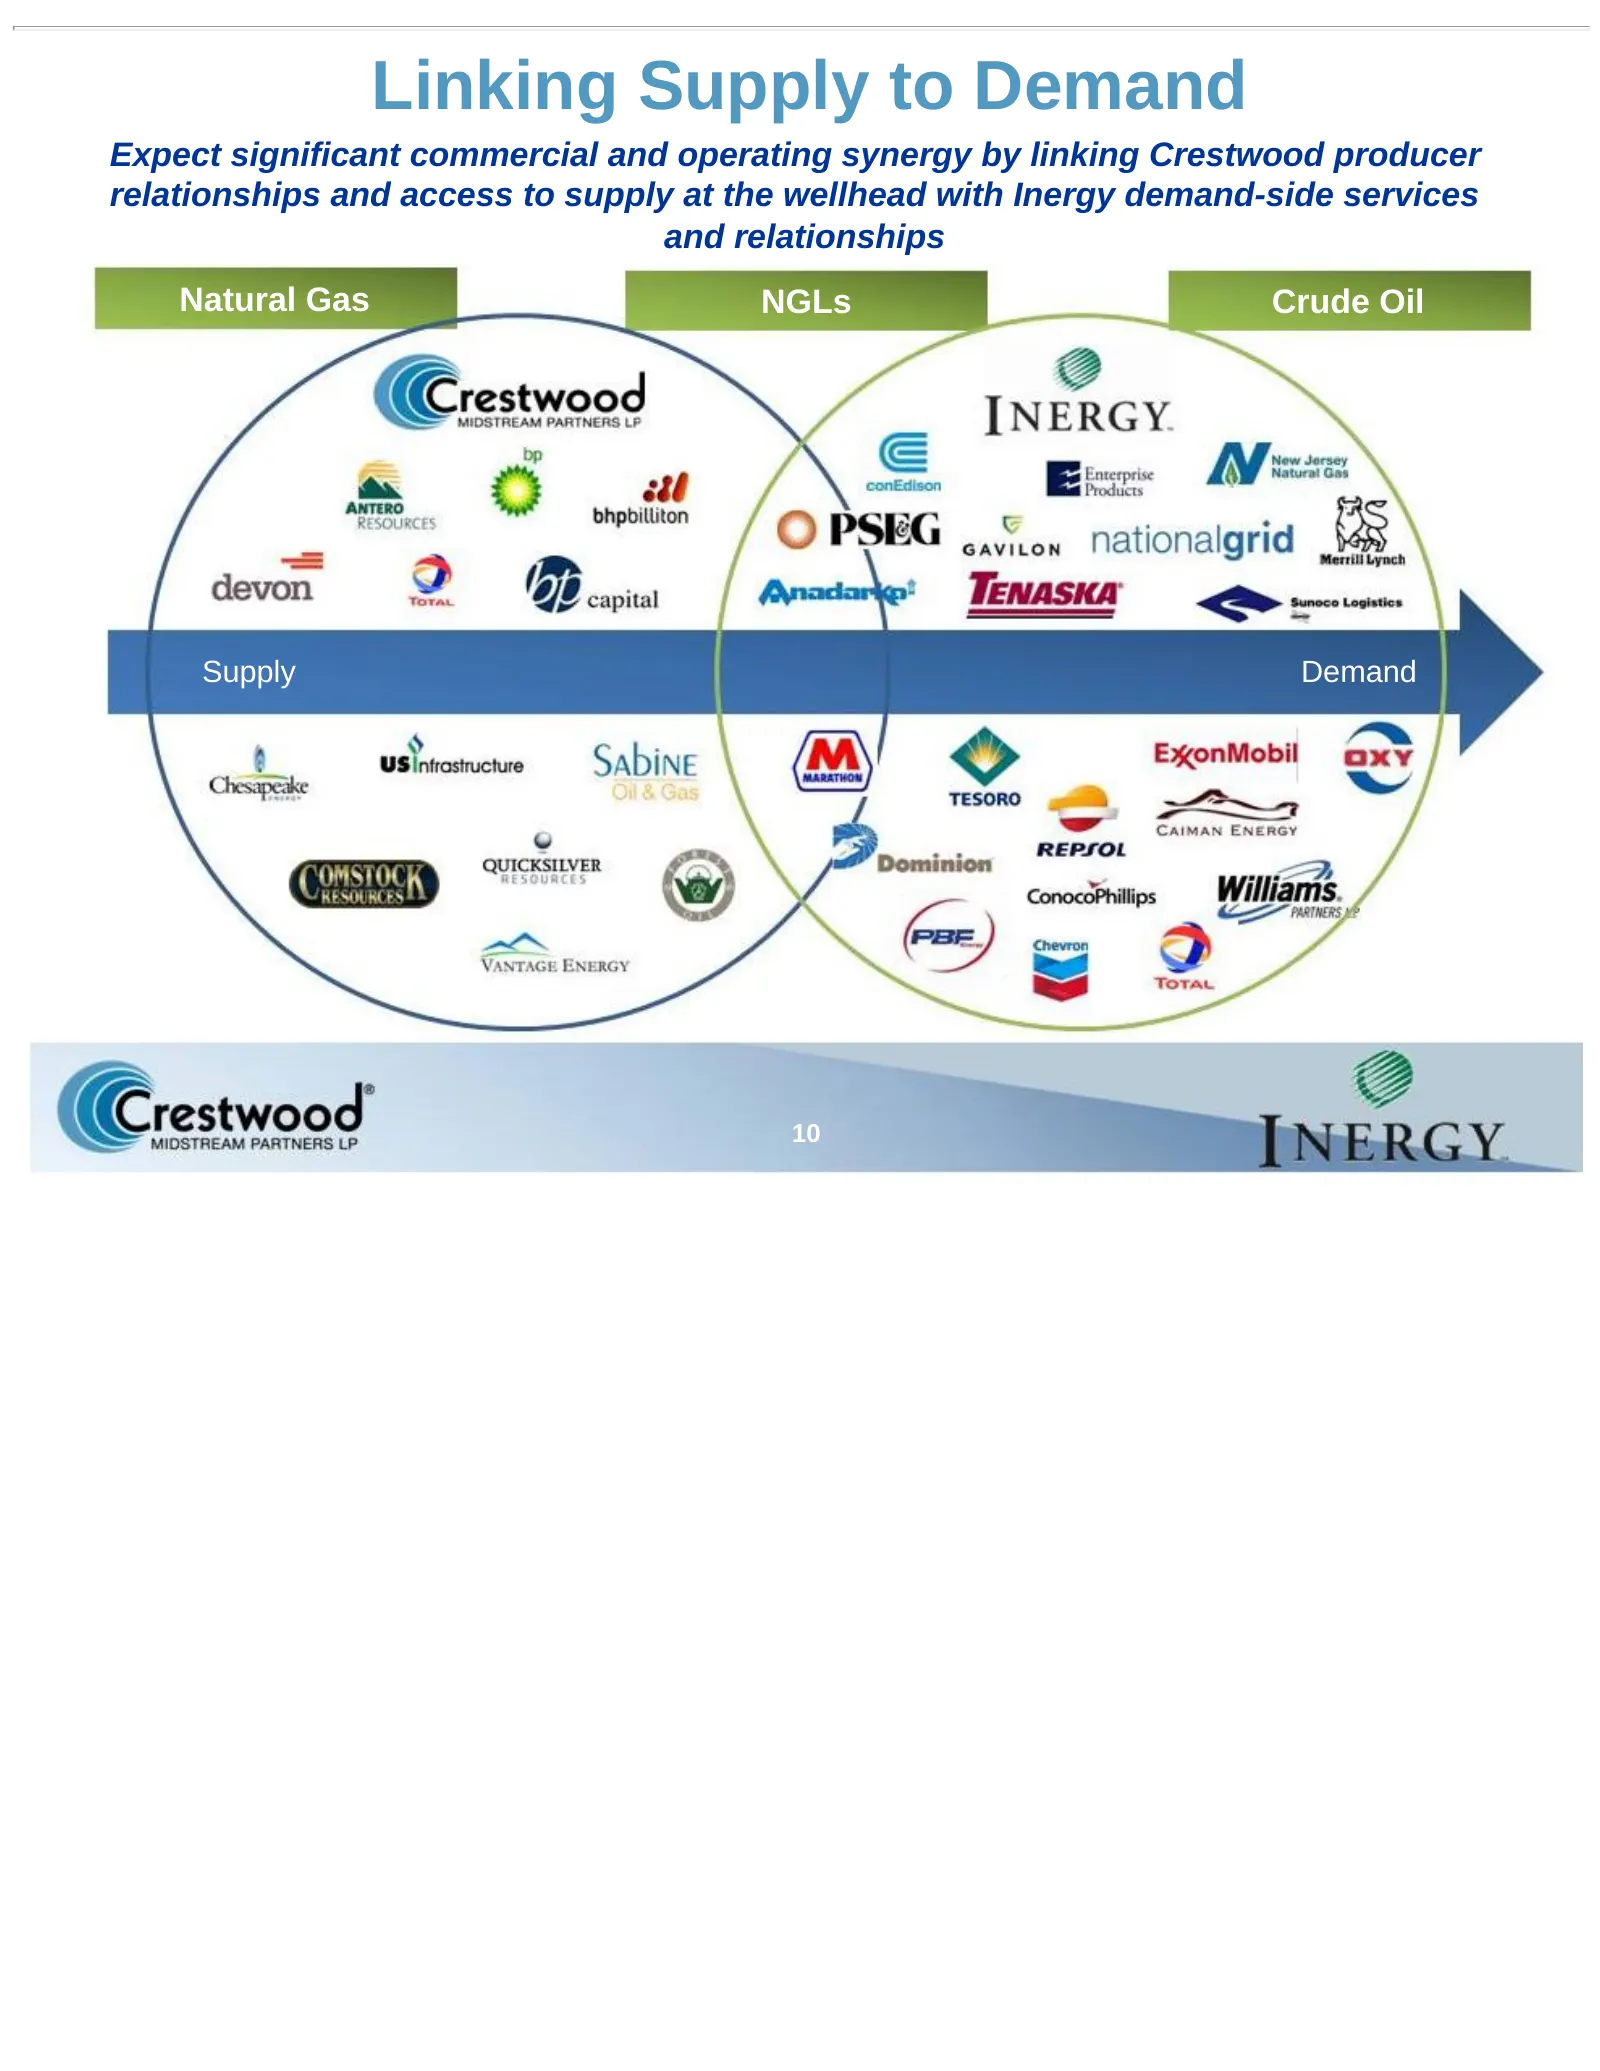
Linking Supply to Demand Expect significant commercial and operating synergy by linking Crestwood producer relationships and access to supply at the wellhead with Inergy demand-side services and relationships Natural Gas NGLs Crude Oil Supply Demand 10
Slide 11: Cash Flow Stability and Visibility
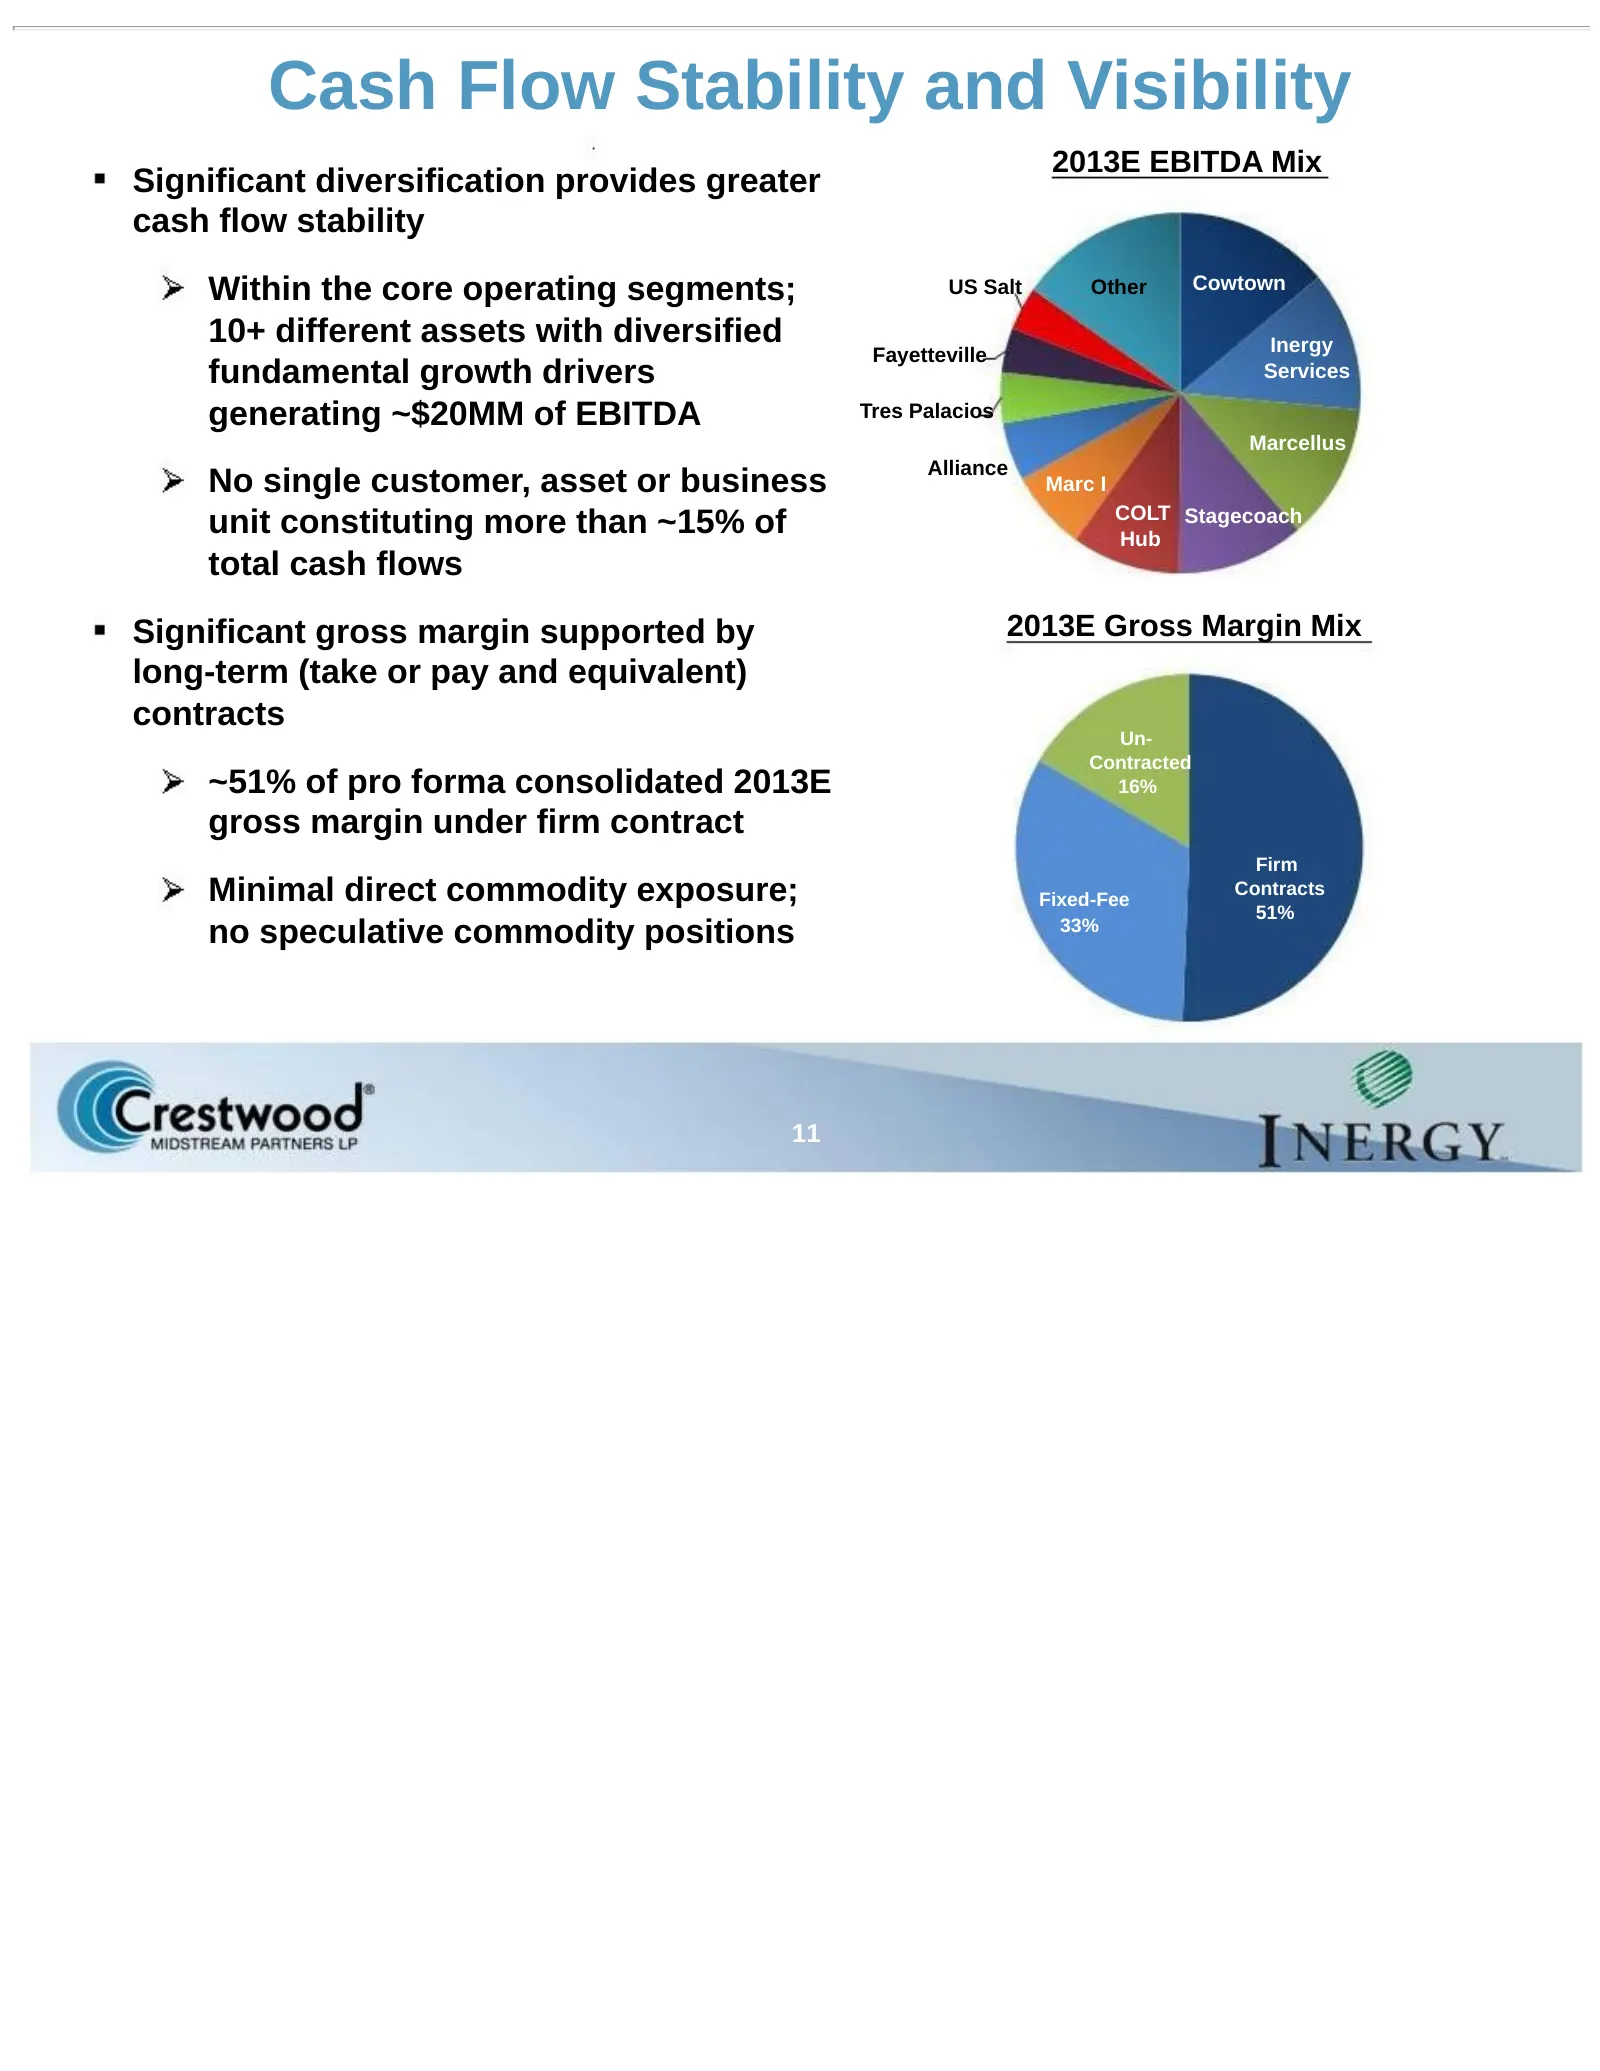
Cash Flow Stability and Visibility 2013E EBITDA Mix Significant diversification provides greater cash flow stability Within the core operating segments; US Salt Other Cowtown 10+ different assets with diversified Inergy Fayetteville fundamental growth drivers Services generating ~$20MM of EBITDA Tre
Slide 12: Enhanced Credit Profile
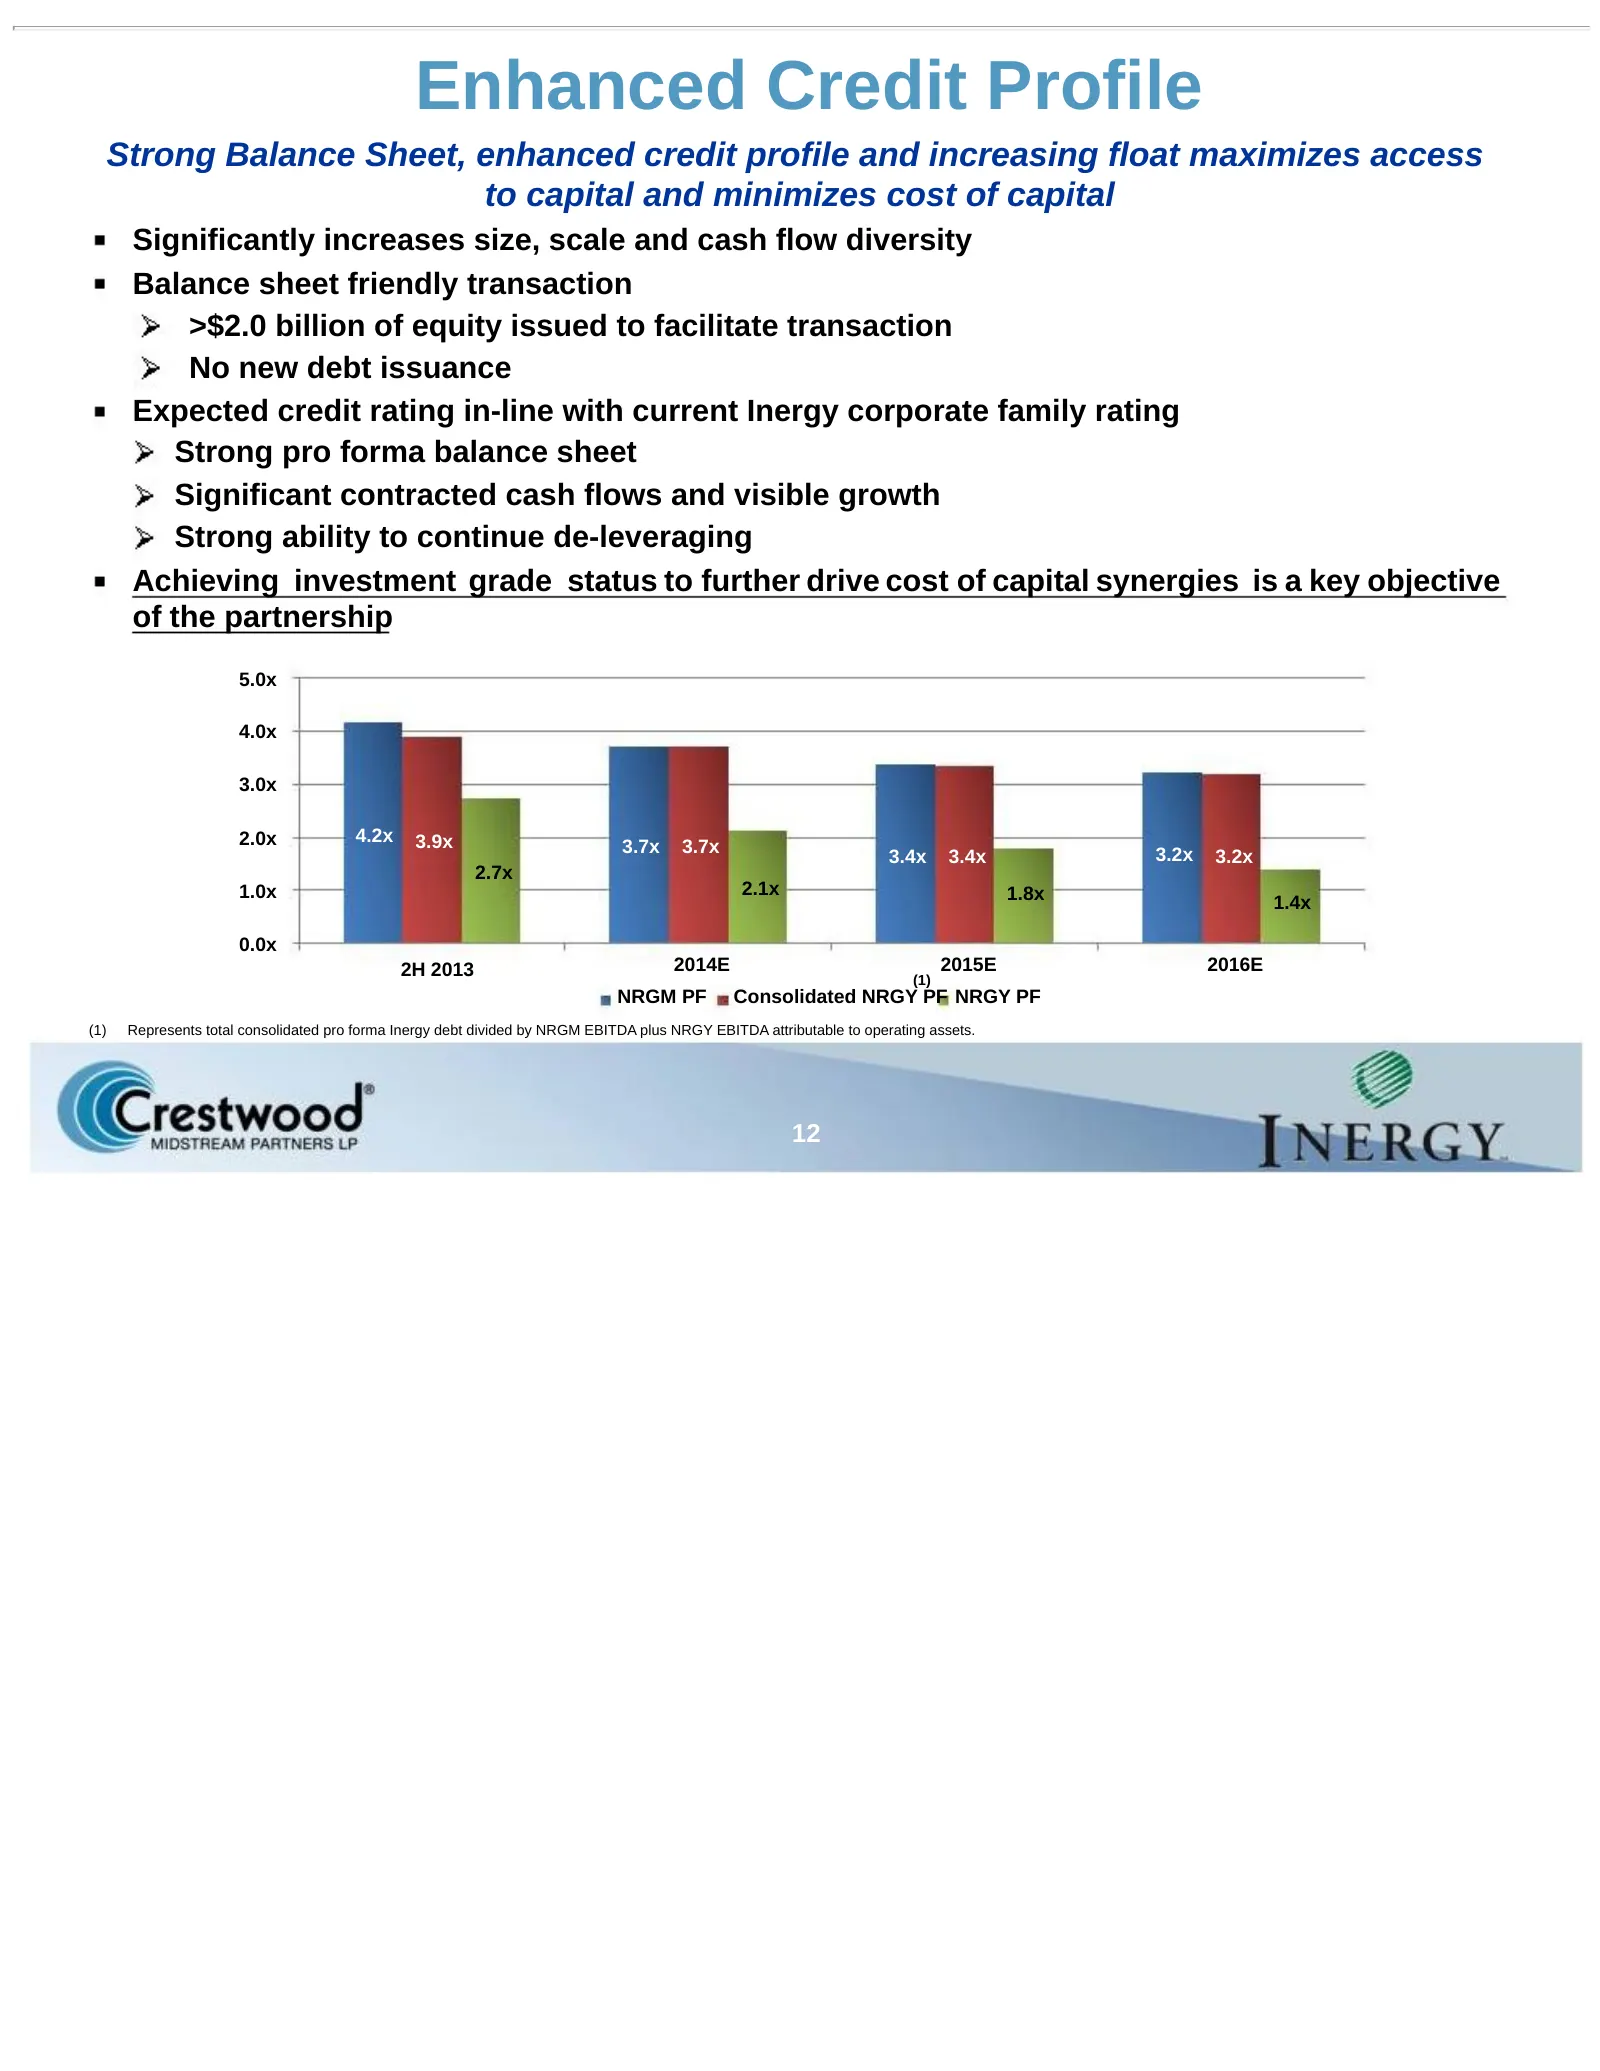
Enhanced Credit Profile Strong Balance Sheet, enhanced credit profile and increasing float maximizes access to capital and minimizes cost of capital Significantly increases size, scale and cash flow diversity Balance sheet friendly transaction >$2.0 billion of equity issued to facilitate transaction
Slide 13: Low Cost Capital Drives Organic Growth
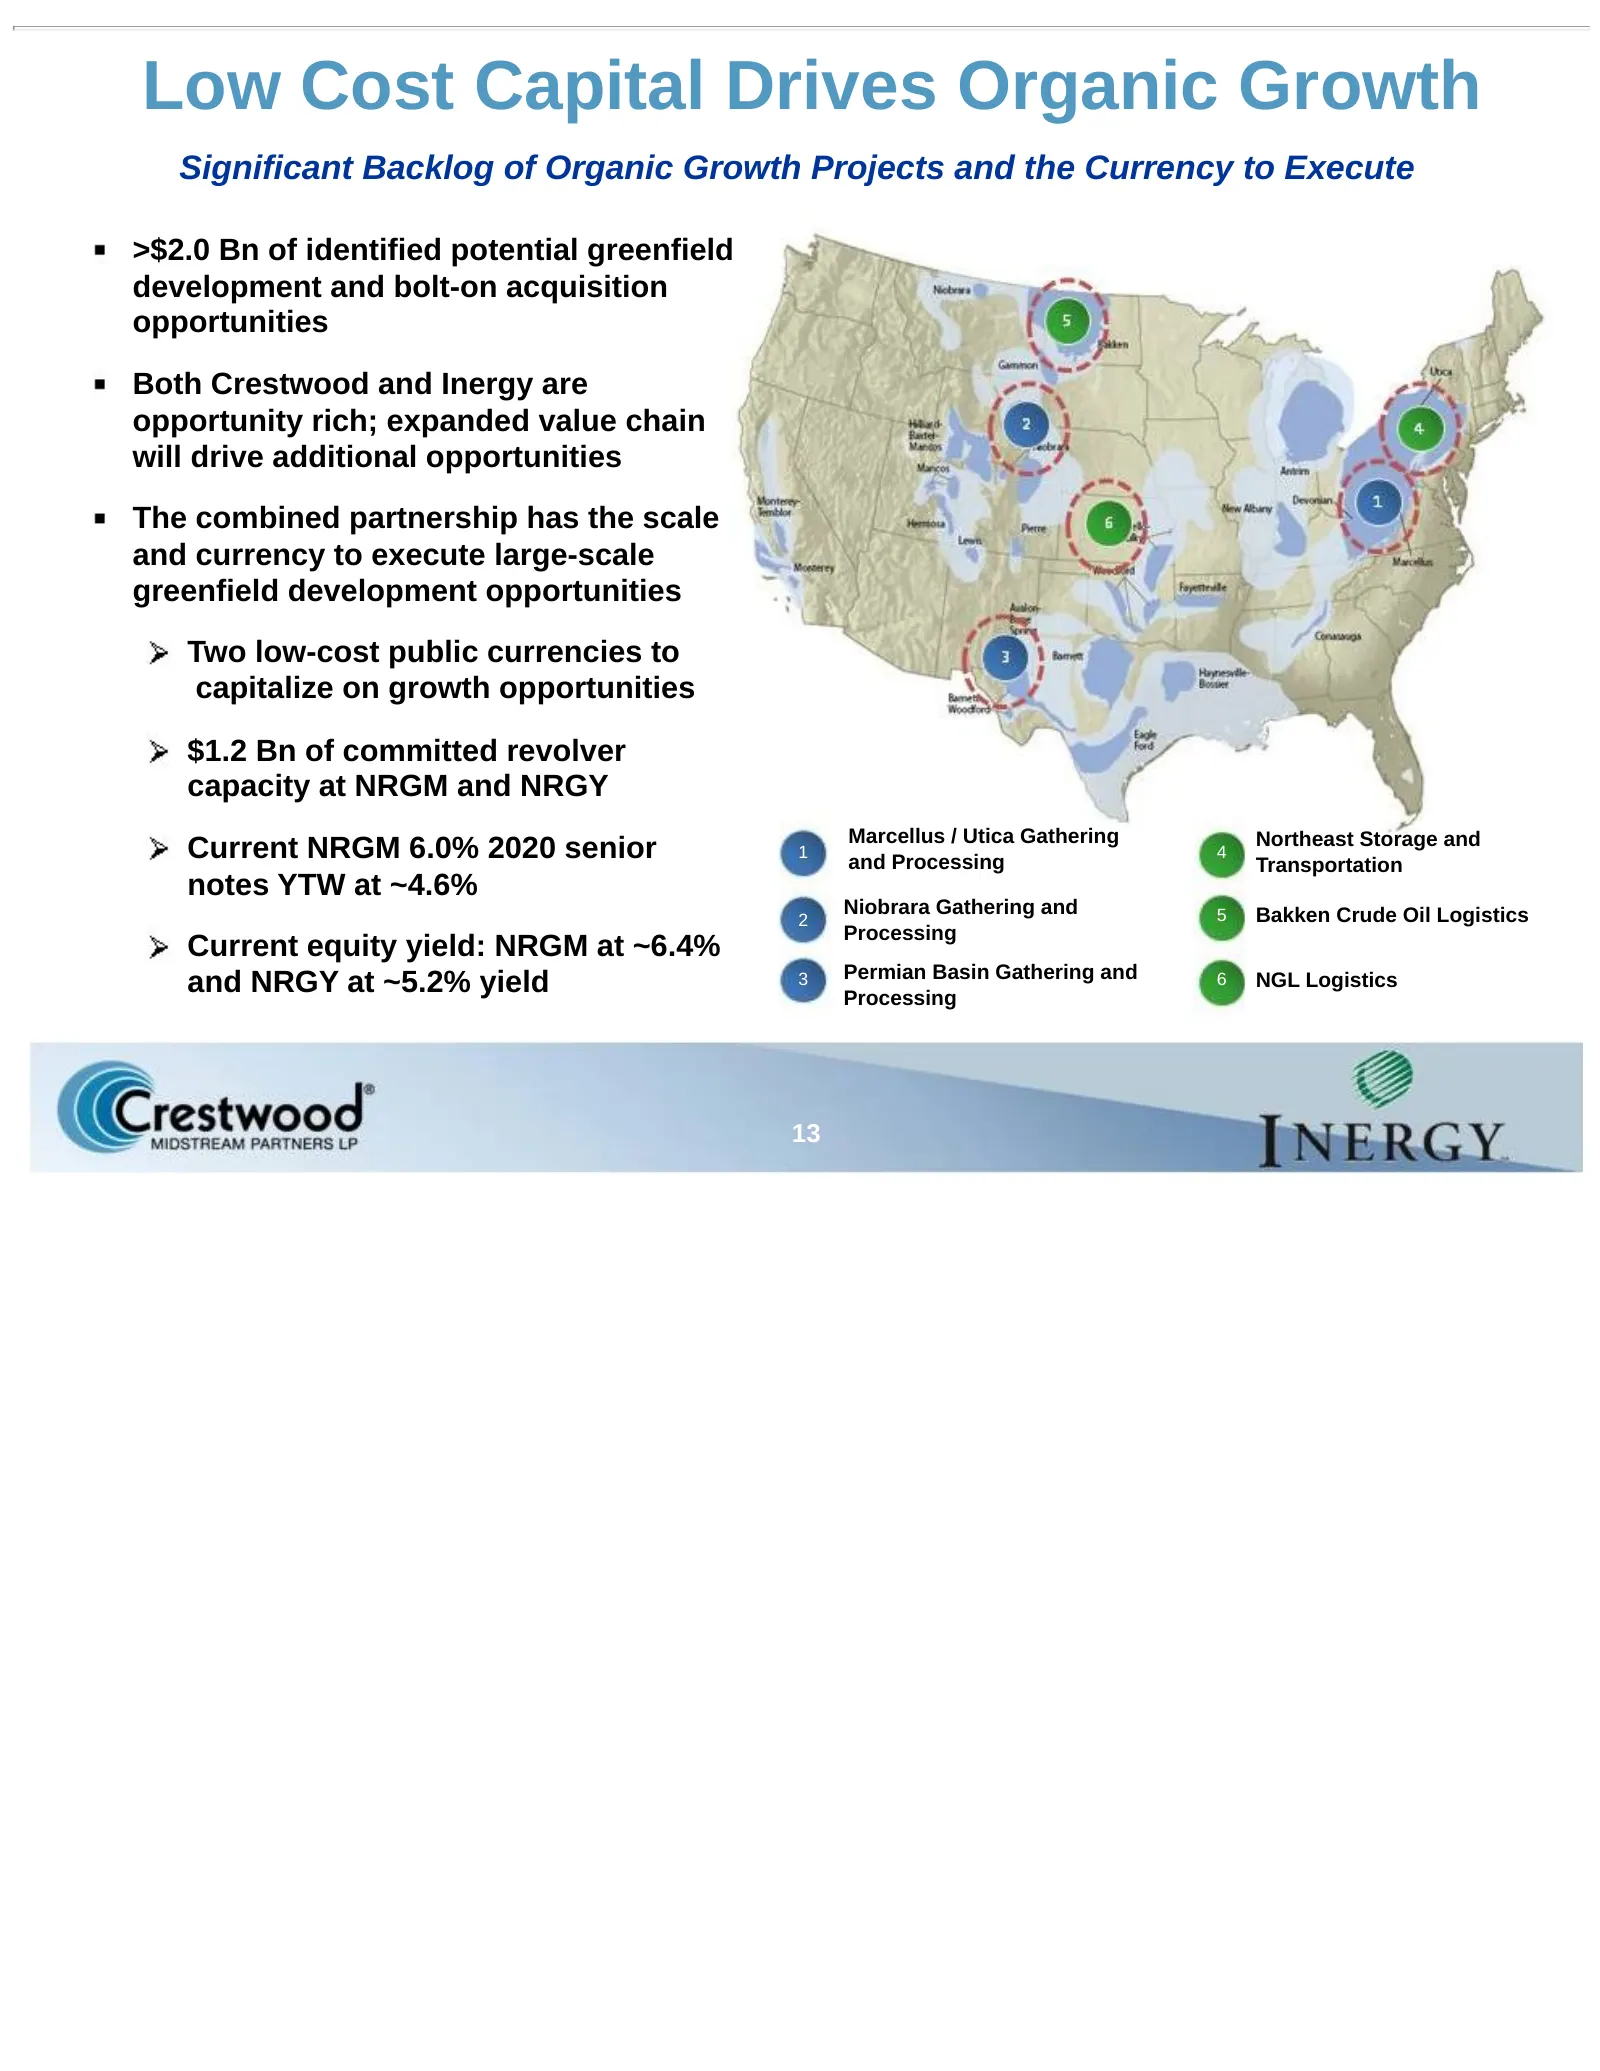
Low Cost Capital Drives Organic Growth Significant Backlog of Organic Growth Projects and the Currency to Execute >$2.0 Bn of identified potential greenfield development and bolt-on acquisition opportunities Both Crestwood and Inergy are opportunity rich; expanded value chain will drive additional o
Slide 14: Strong Sponsorship
Strong Sponsorship After this transaction, First Reserve, Crestwood management and Inergy management will have in excess of $1.5 billion invested in the combined partnership First Reserve, the largest and most experienced private equity firm focused exclusively on energy, continues to demonstrate it
Slide 15: Financial Principles
Financial Principles Continue to grow utilizing a disciplined financial policy Grow pro forma business consistent with stable, fee-based MLP business model Maintain ample liquidity and preserve financial flexibility Fund organic growth and acquisitions with appropriate mix of debt and equity (~50/50
Slide 16: Crestwood is Building a Footprint in High-Growth Shale Plays
Crestwood is Building a Footprint in High-Growth Shale Plays 16
Slide 17: Building a Footprint in High Growth Shale Plays
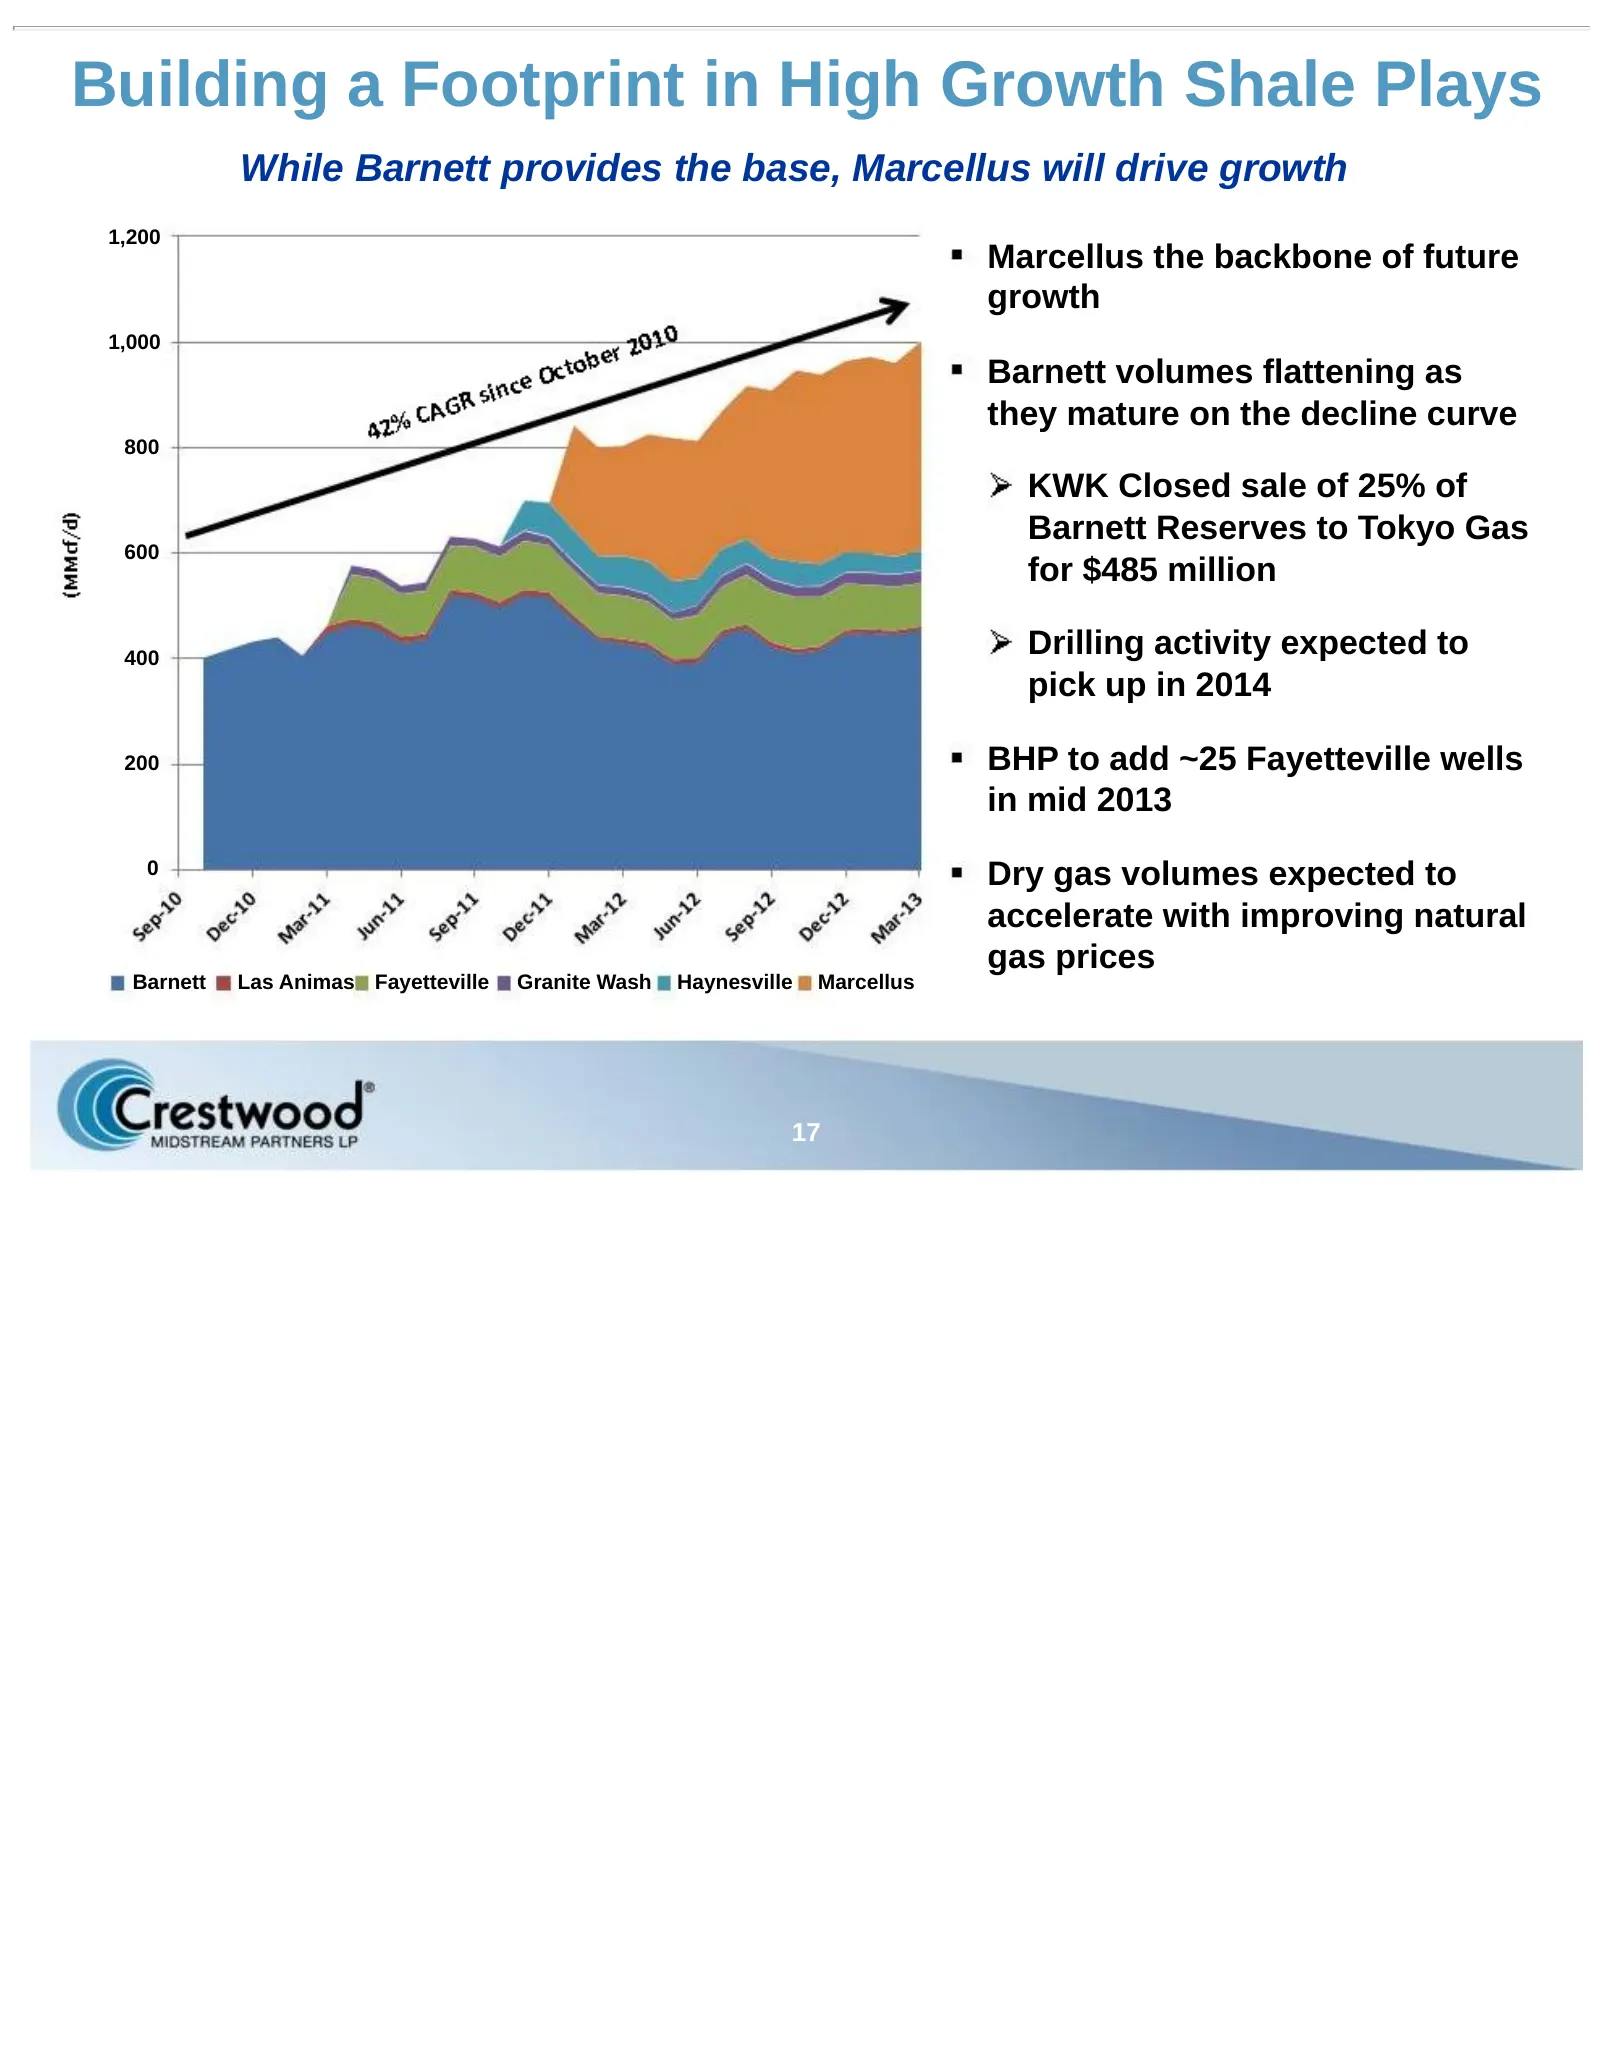
Building a Footprint in High Growth Shale Plays While Barnett provides the base, Marcellus will drive growth 1,200 Marcellus the backbone of future growth 1,000 Barnett volumes flattening as they mature on the decline curve 800 KWK Closed sale of 25% of Barnett Reserves to Tokyo Gas 600 for $485 mil
Slide 18: Building a Footprint in High Growth Shale Plays
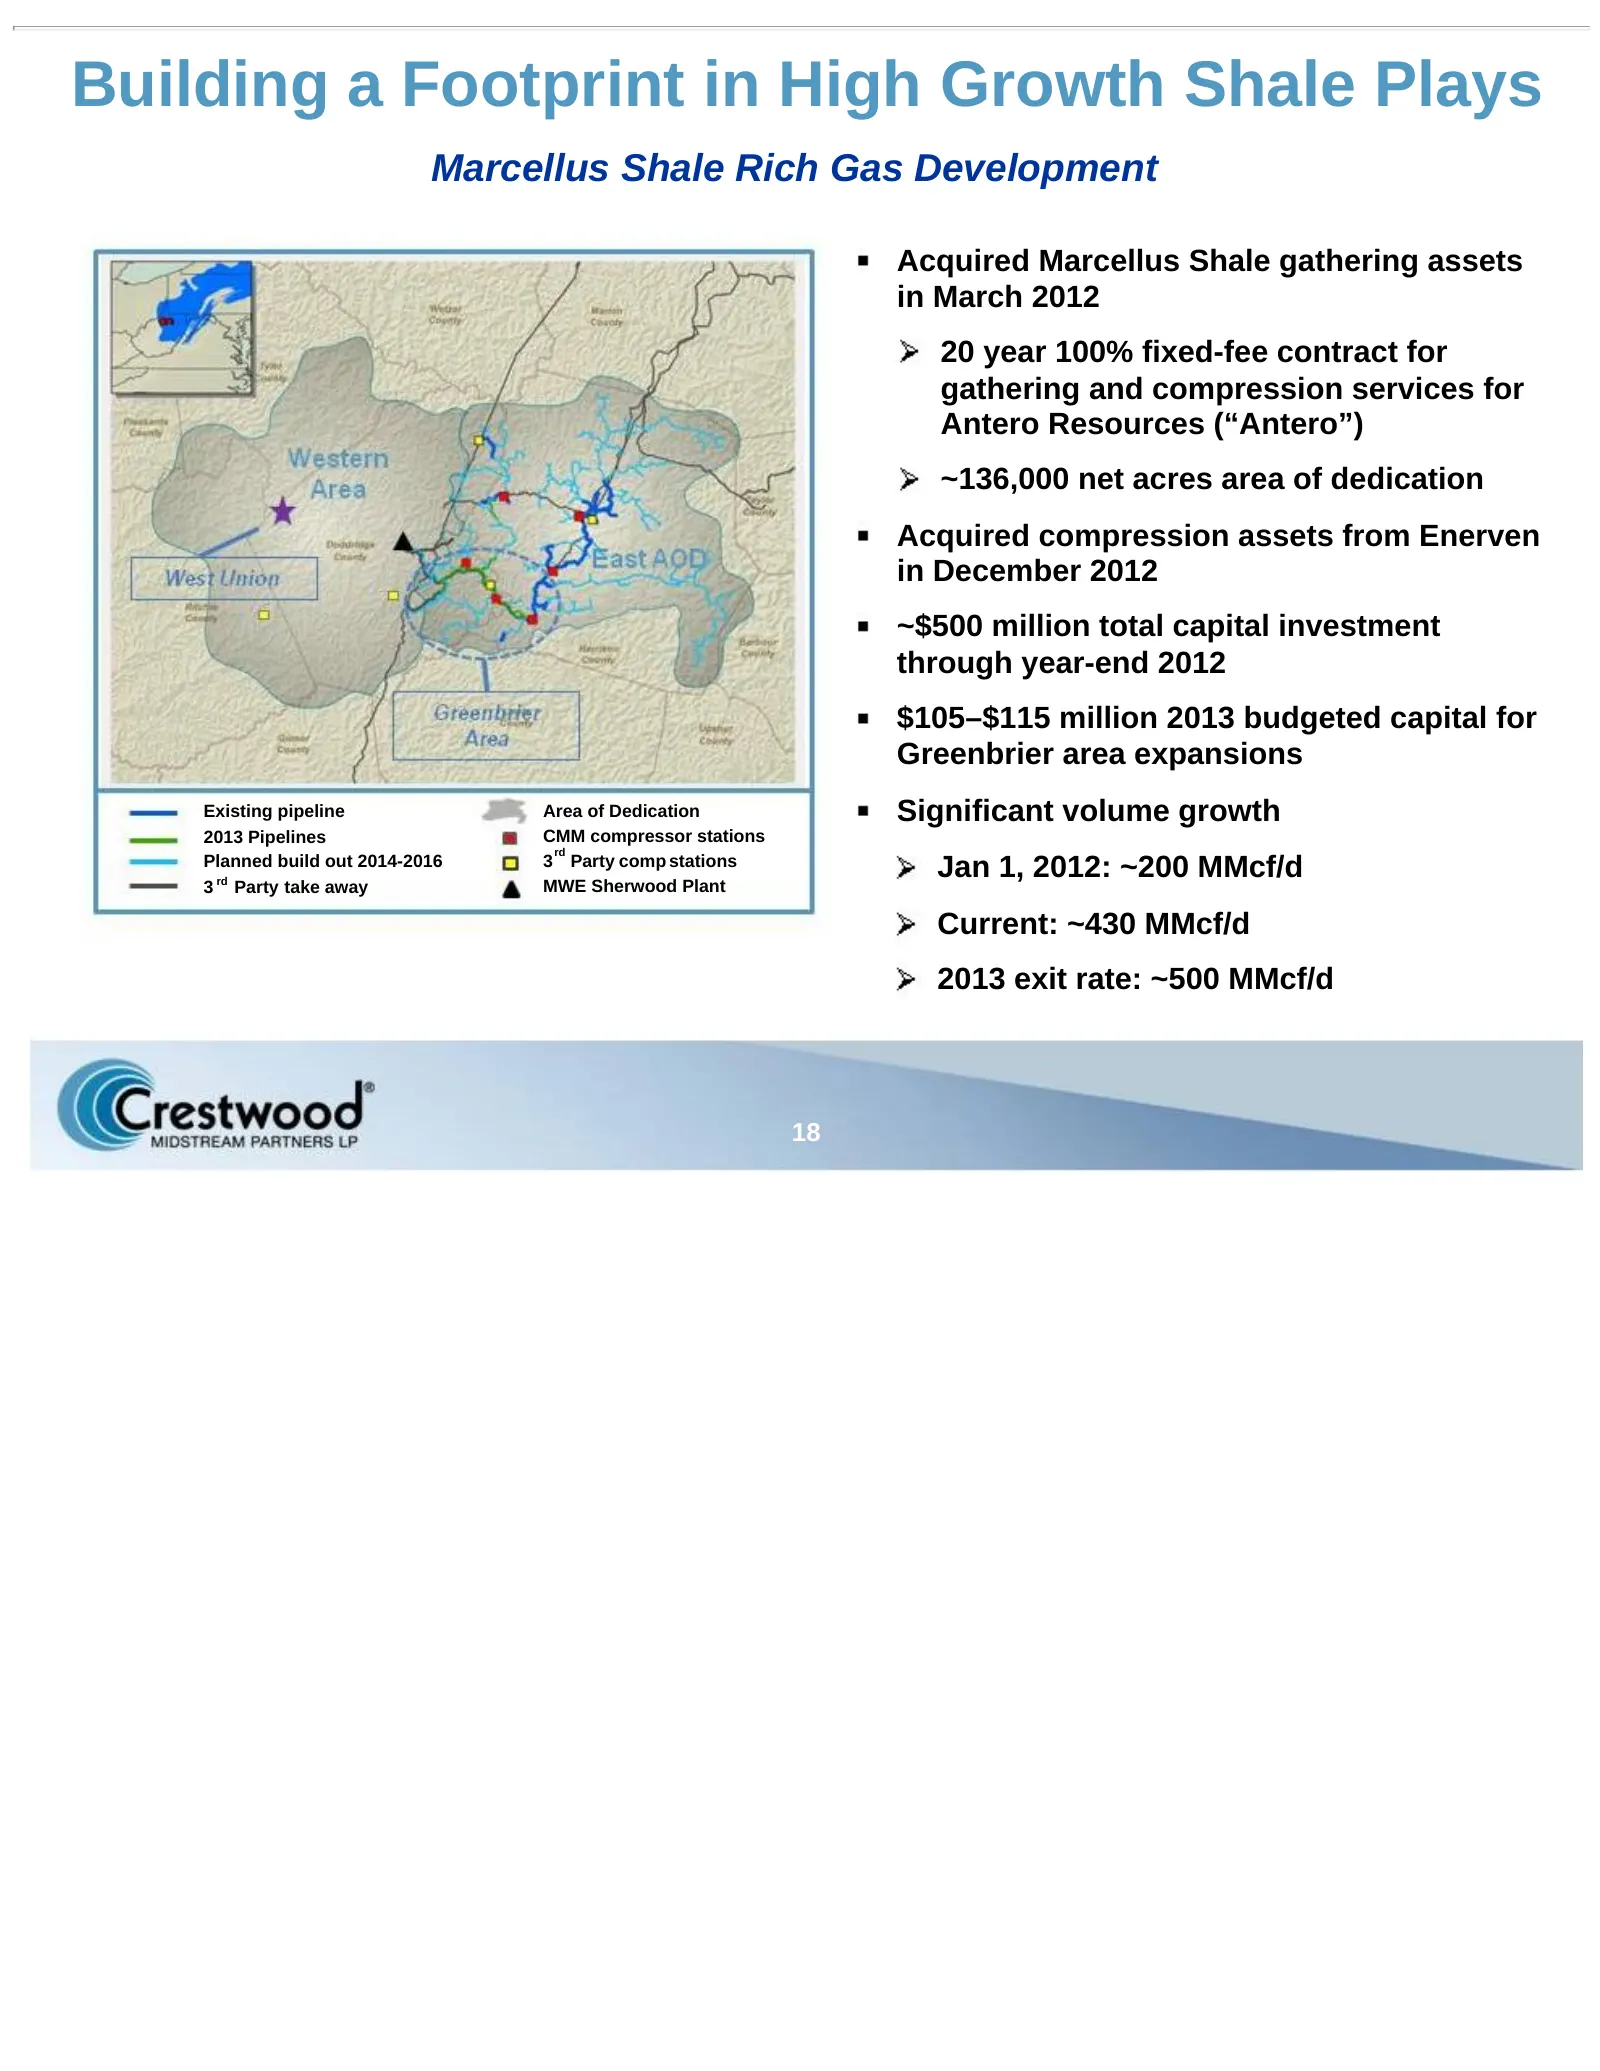
Building a Footprint in High Growth Shale Plays Marcellus Shale Rich Gas Development Acquired Marcellus Shale gathering assets in March 2012 20 year 100% fixed-fee contract for gathering and compression services for Antero Resources (“Antero”) ~136,000 net acres area of dedication Acquired compressi
Slide 19: Building a Footprint in High Growth Shale Plays
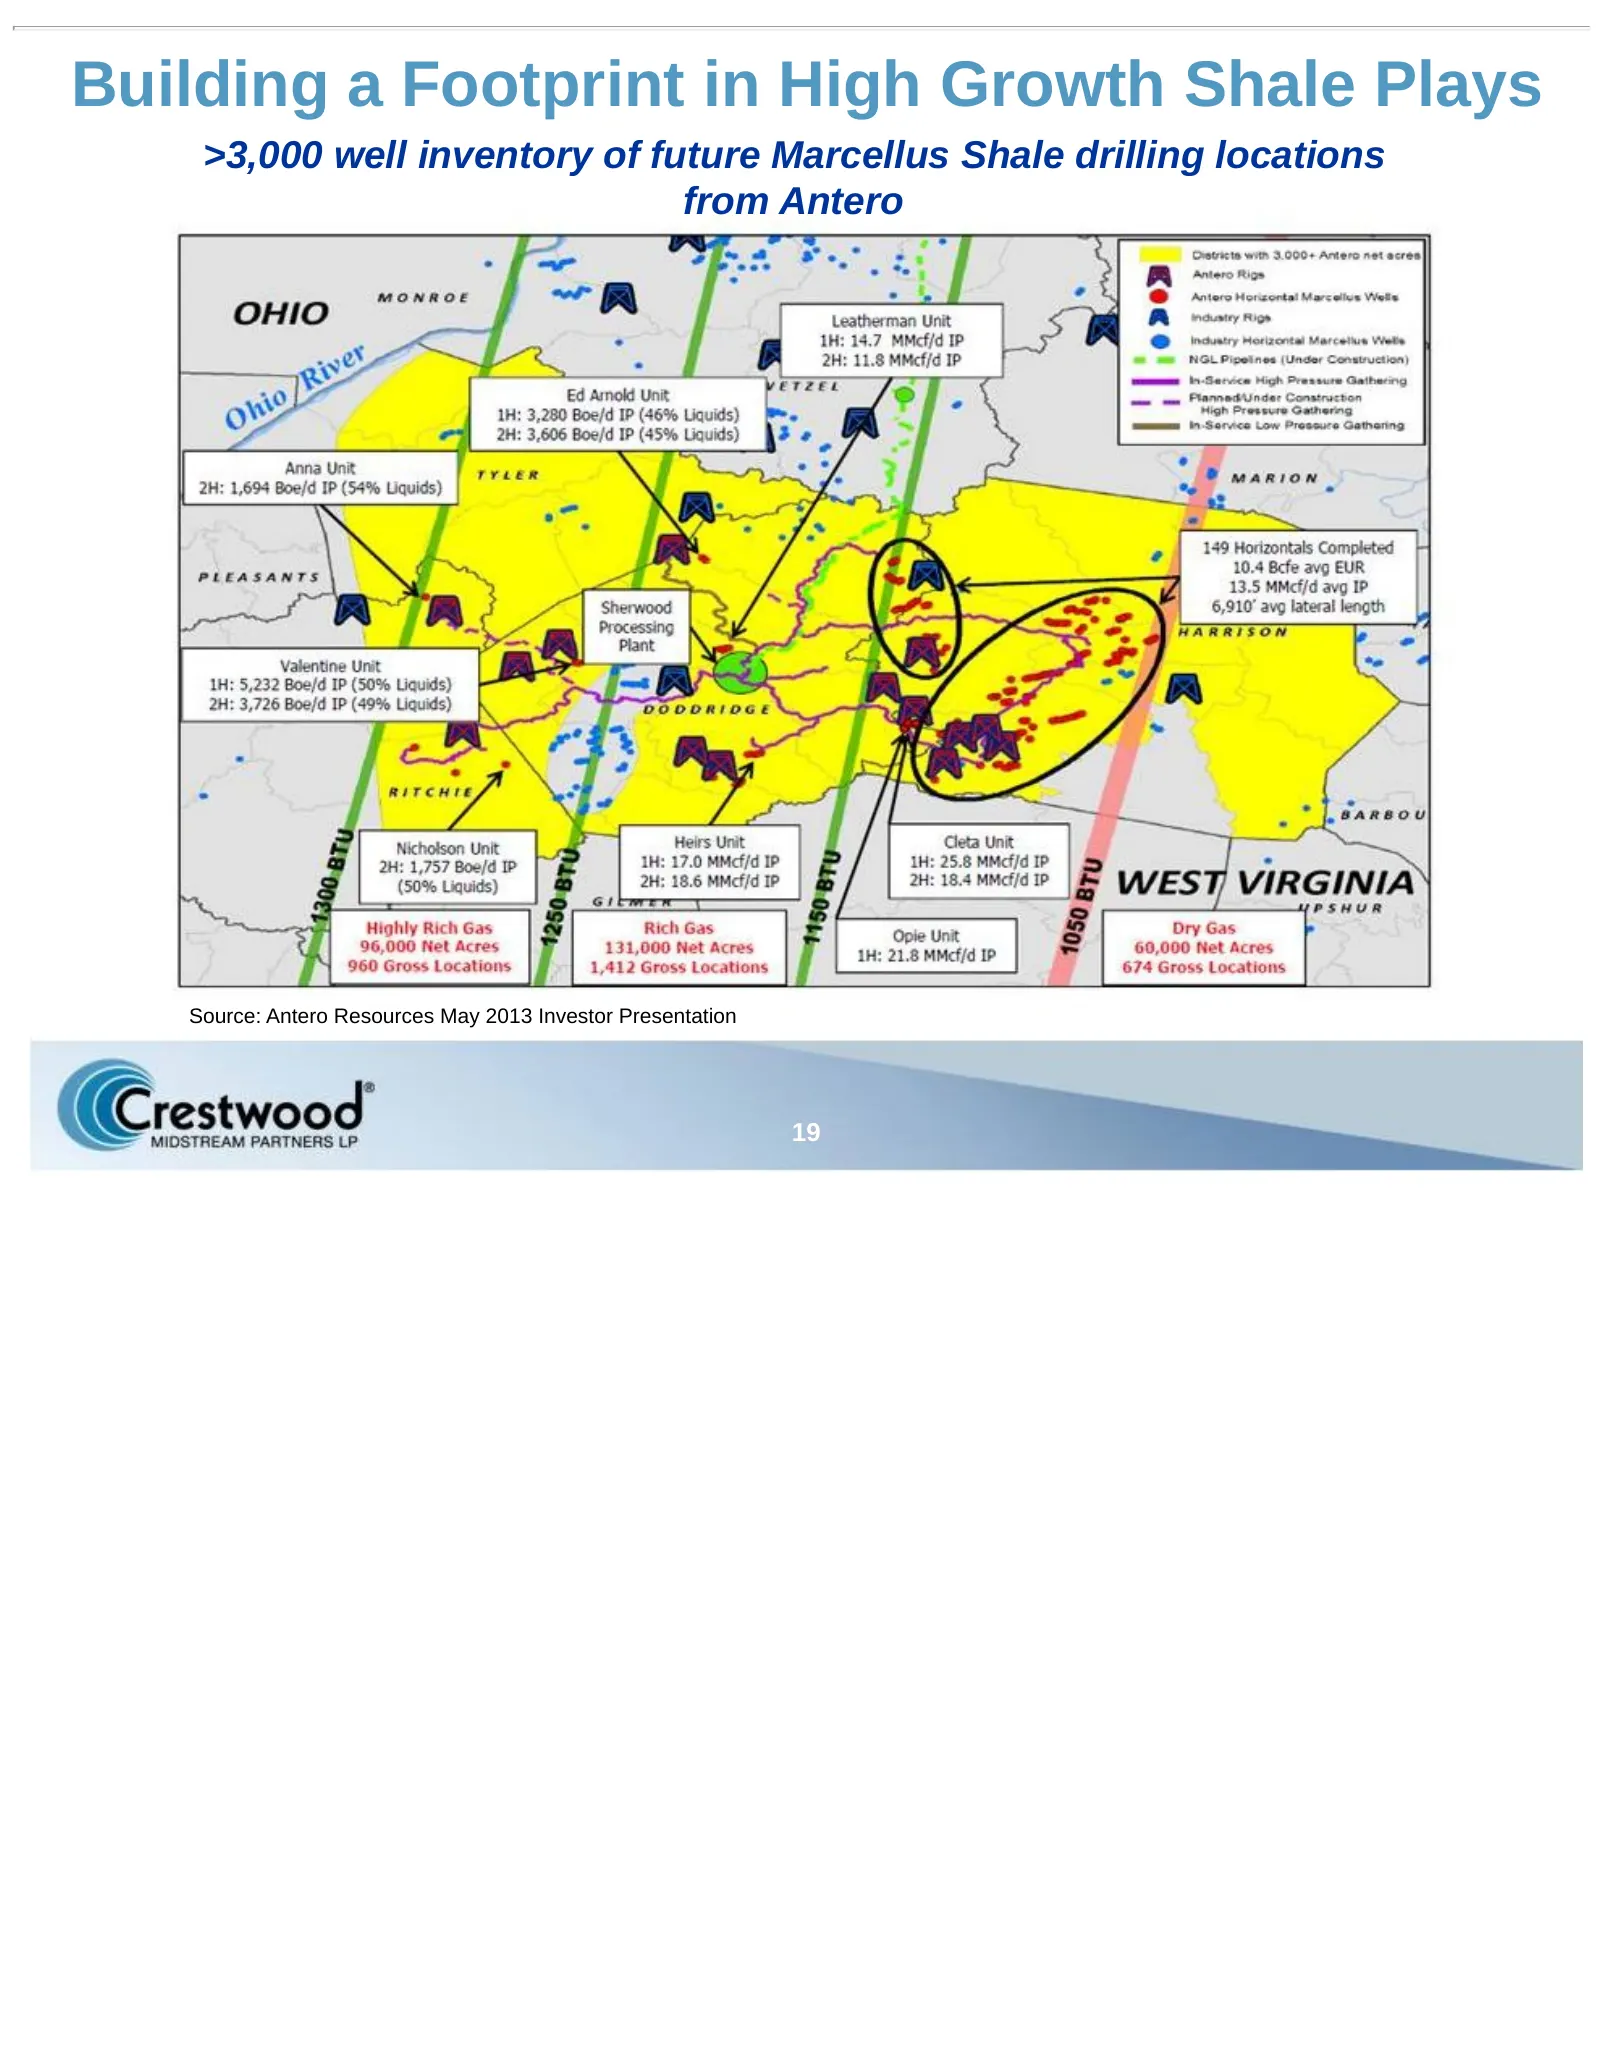
Building a Footprint in High Growth Shale Plays >3,000 well inventory of future Marcellus Shale drilling locations from Antero Source: Antero Resources May 2013 Investor Presentation 19
Slide 20: Building a Footprint in High Growth Shale Plays
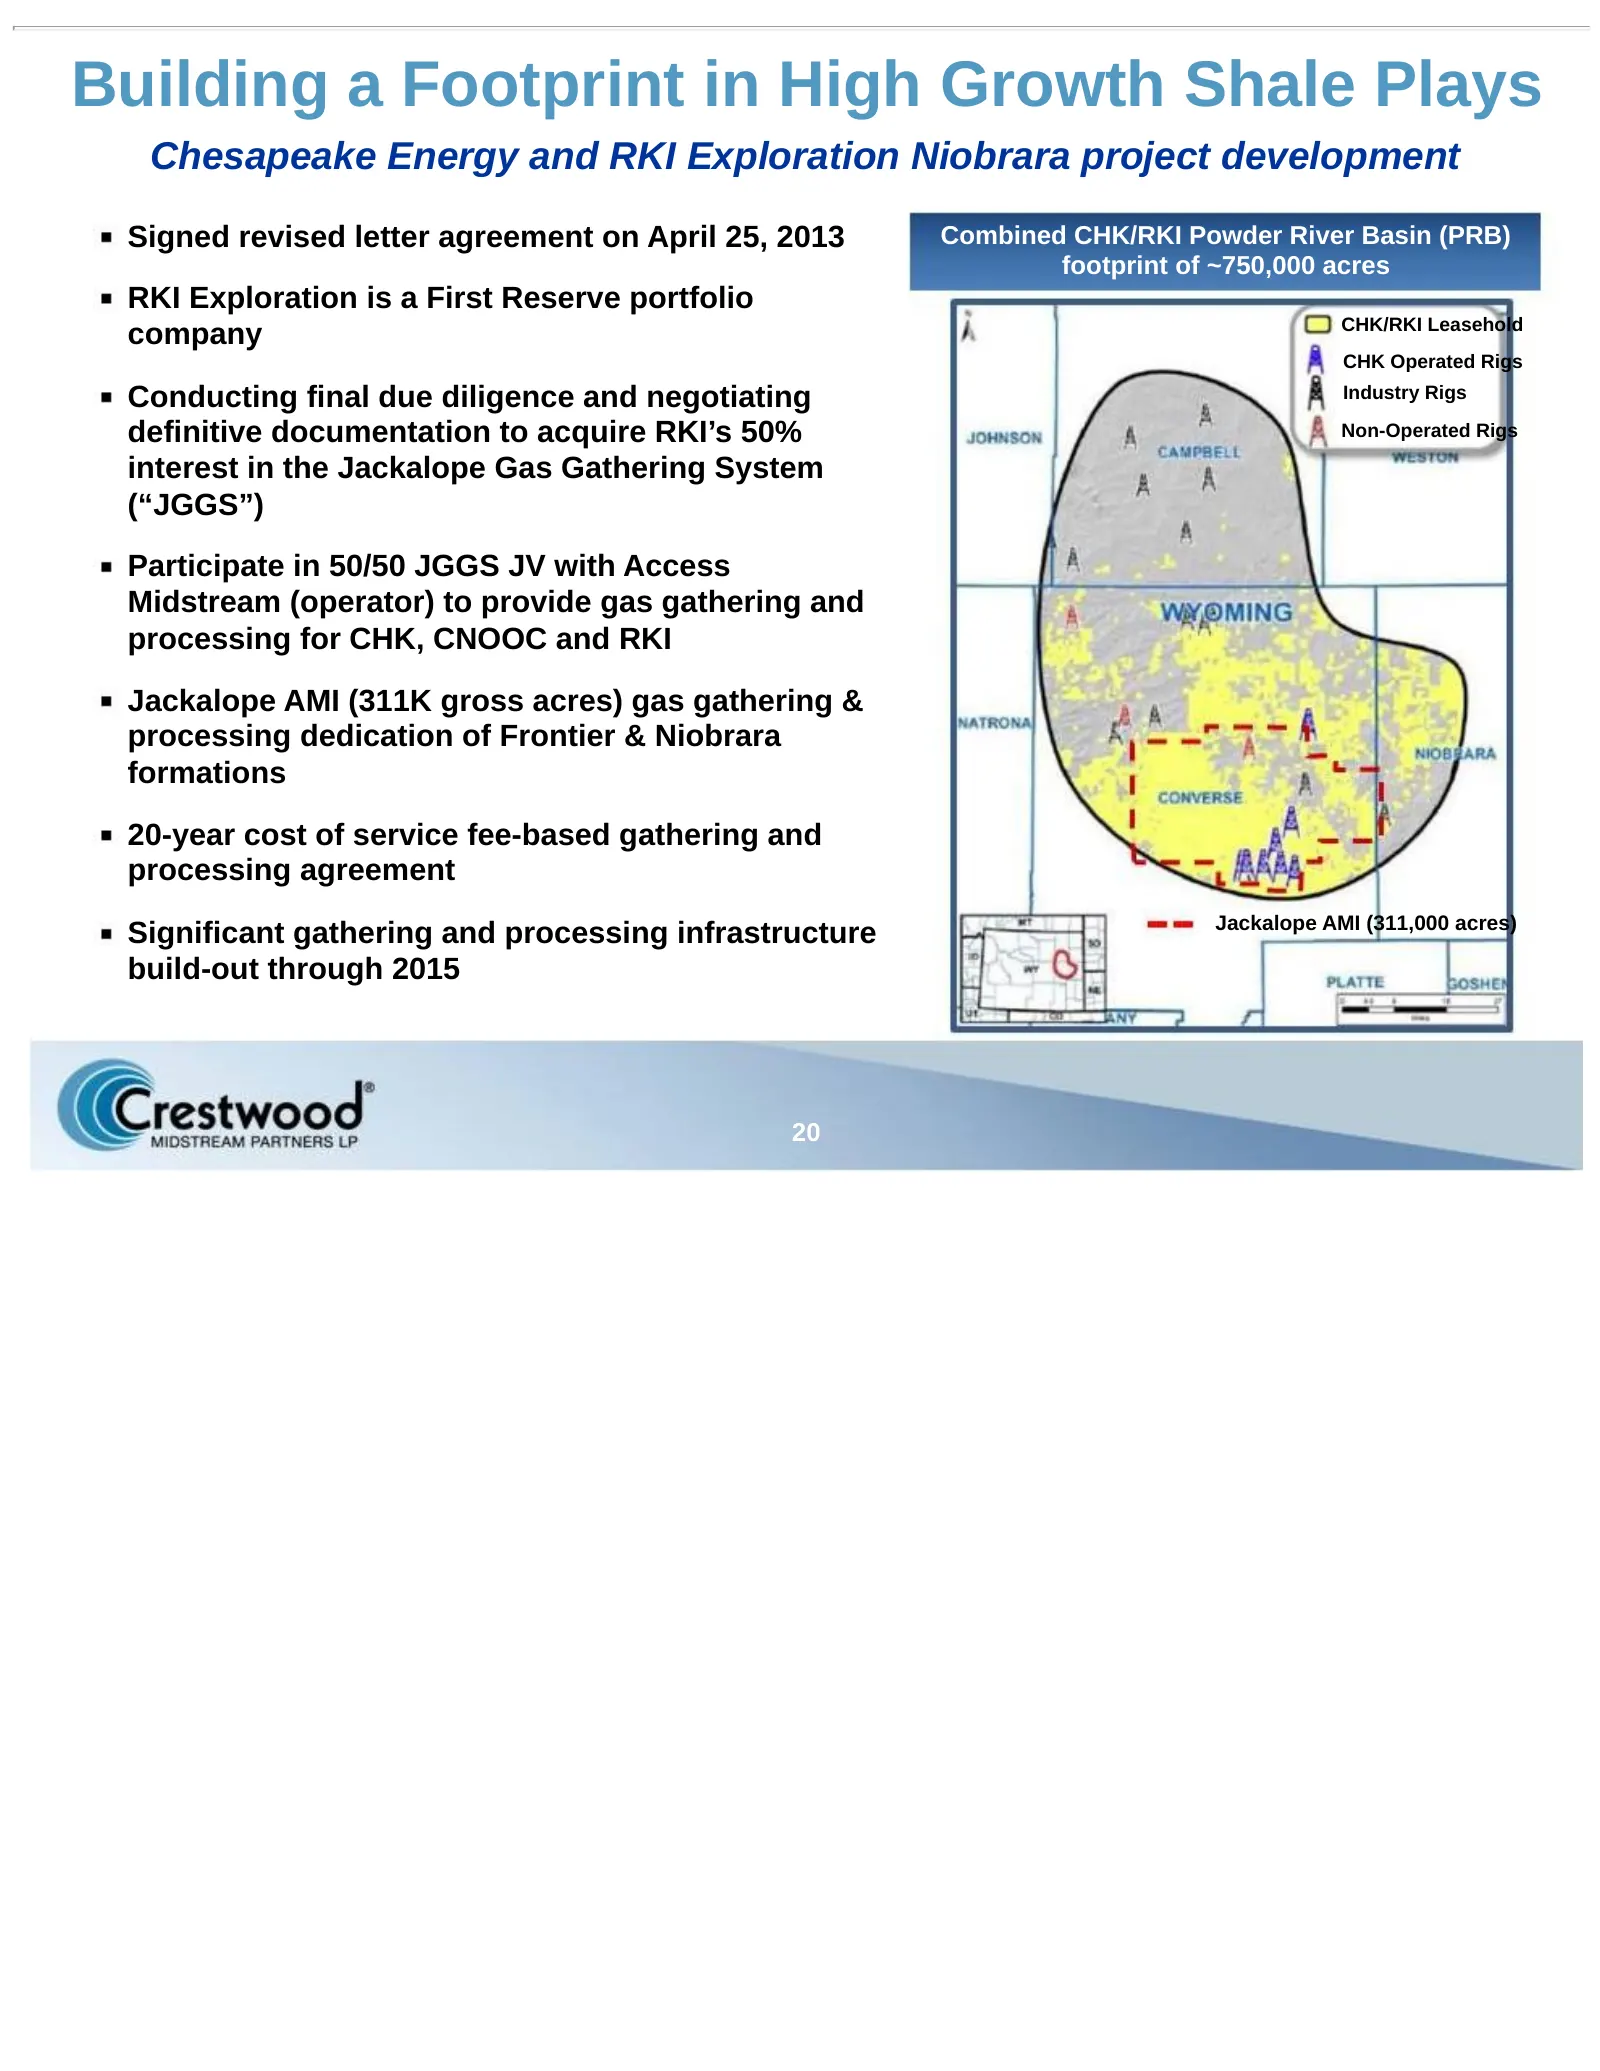
Building a Footprint in High Growth Shale Plays Chesapeake Energy and RKI Exploration Niobrara project development Signed revised letter agreement on April 25, 2013 Combined CHK/RKI Powder River Basin (PRB) footprint of ~750,000 acres RKI Exploration is a First Reserve portfolio CHK/RKI Leasehold co
Slide 21: Building a Footprint in High Growth Shale Plays
Building a Footprint in High Growth Shale Plays CHK / RKI Jackalope drilling activity focused on crude oil and liquids-rich production CHK currently operating 10 rigs within the Jackalope AMI ~$480 million drilling carry from CNOOC drives activity through 2014 Over ~1,000+ drilling locations (>10 yr
Slide 22: Building a Footprint in High Growth Shale Plays
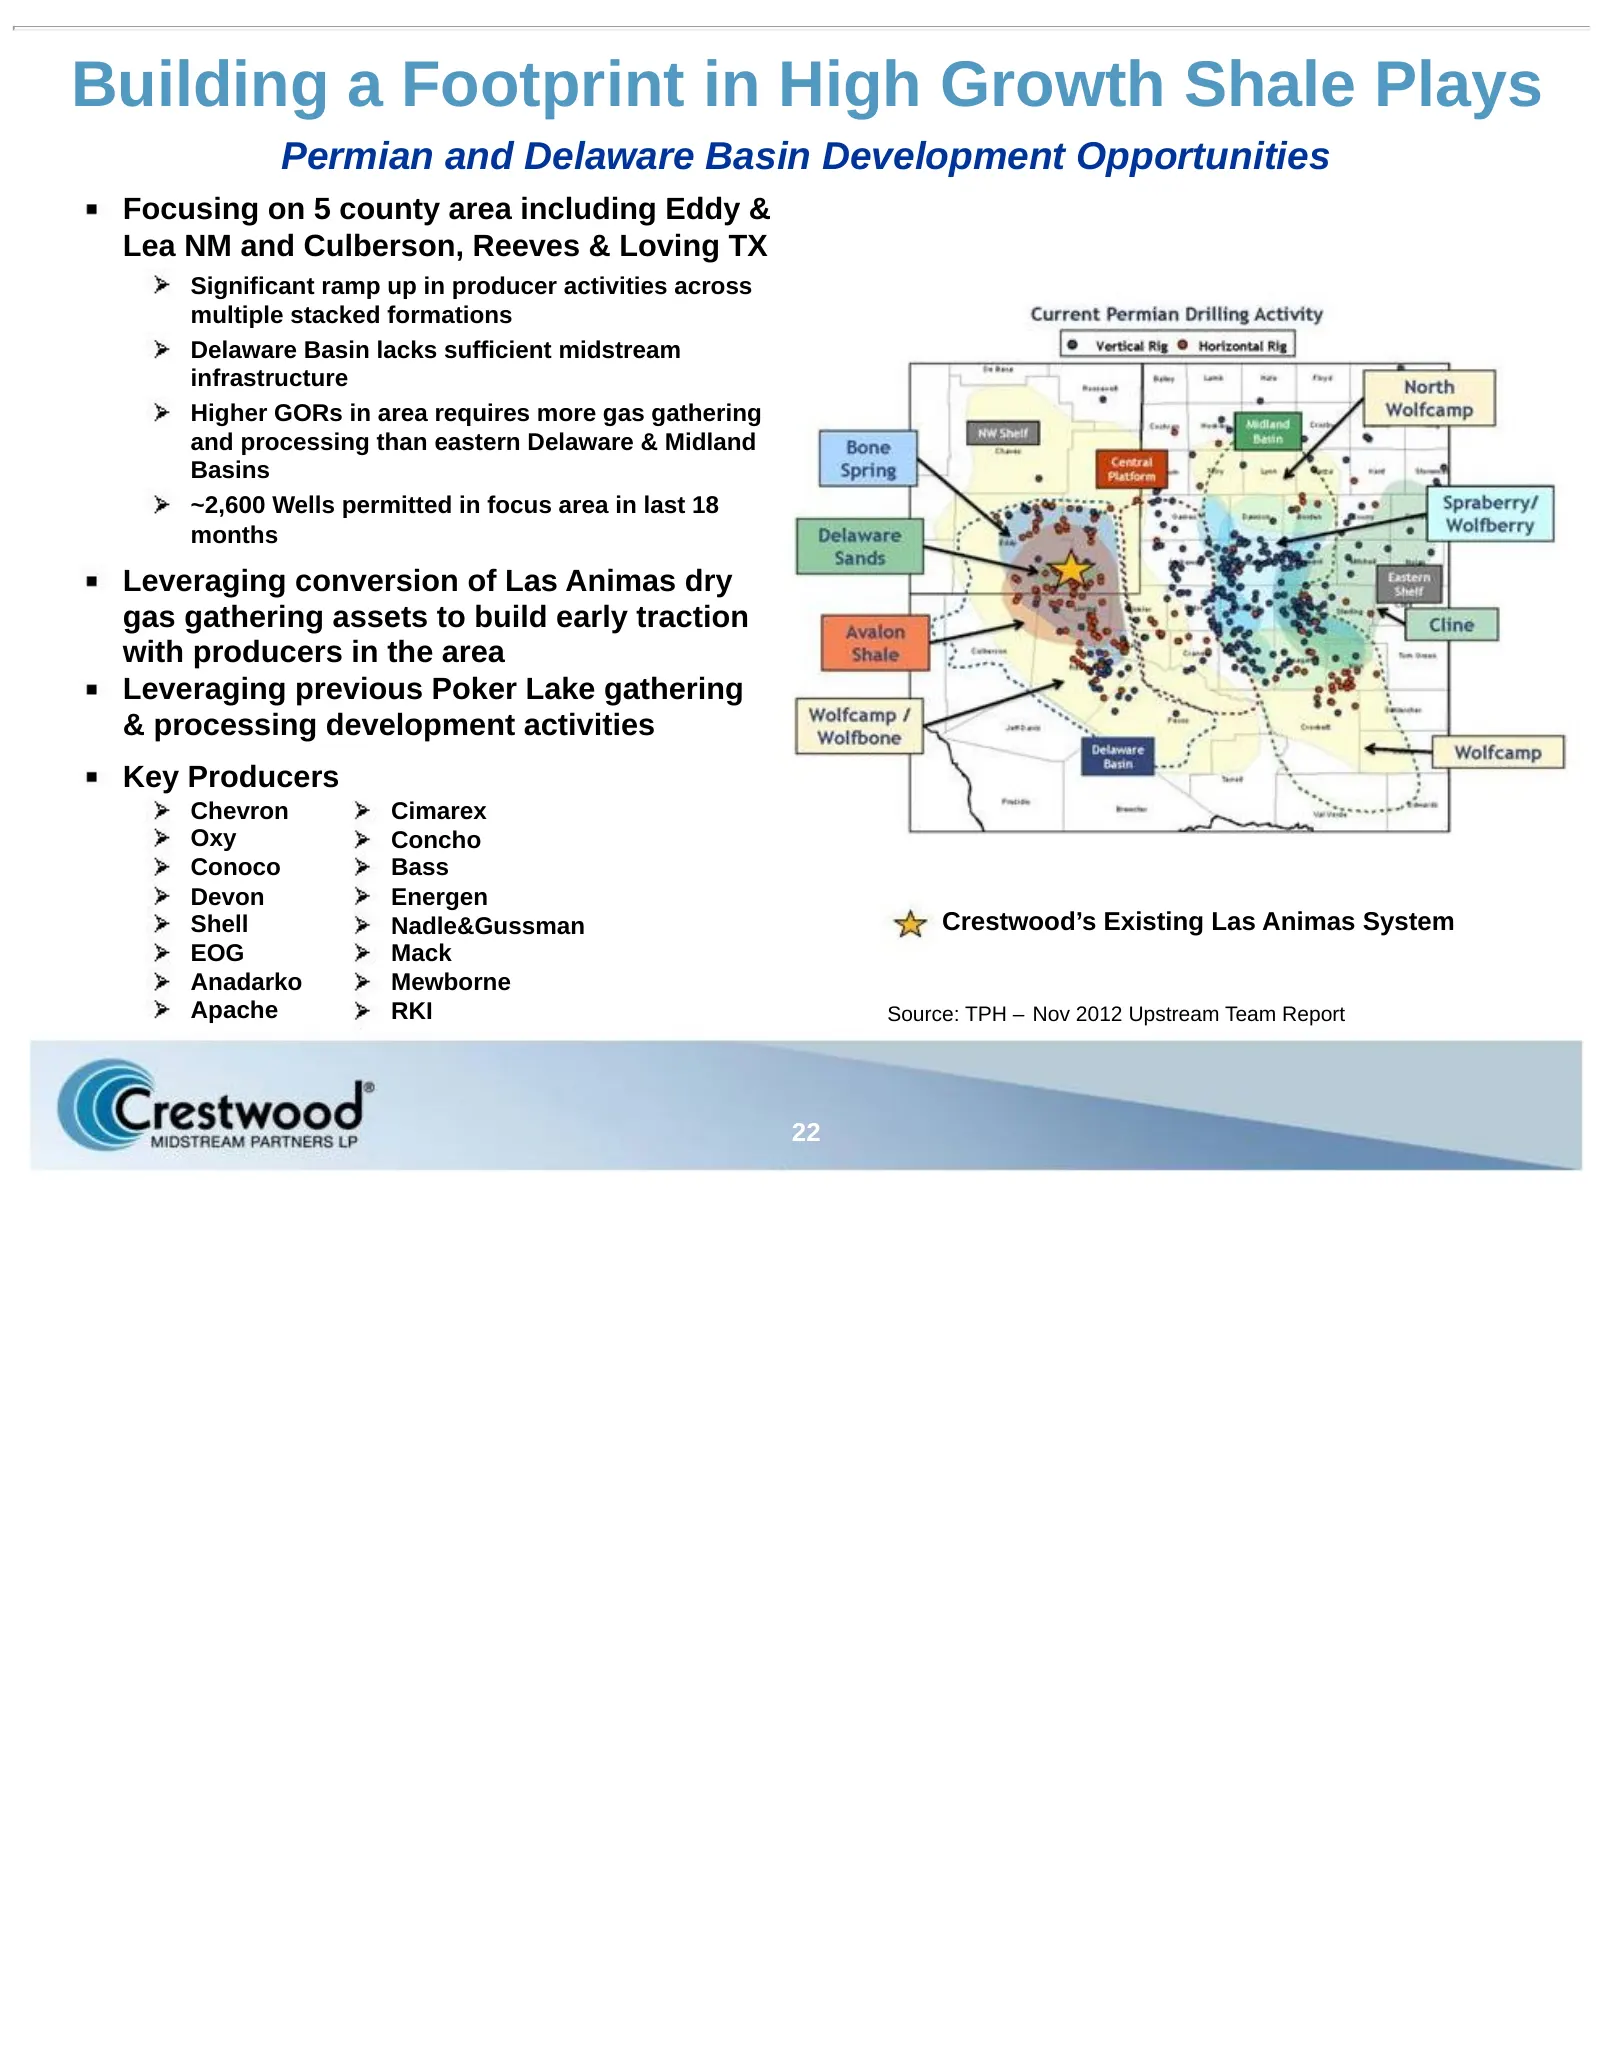
Building a Footprint in High Growth Shale Plays Permian and Delaware Basin Development Opportunities Focusing on 5 county area including Eddy & Lea NM and Culberson, Reeves & Loving TX Significant ramp up in producer activities across multiple stacked formations Delaware Basin lacks sufficient midst
Slide 23: Building a Footprint in High Growth Shale Plays
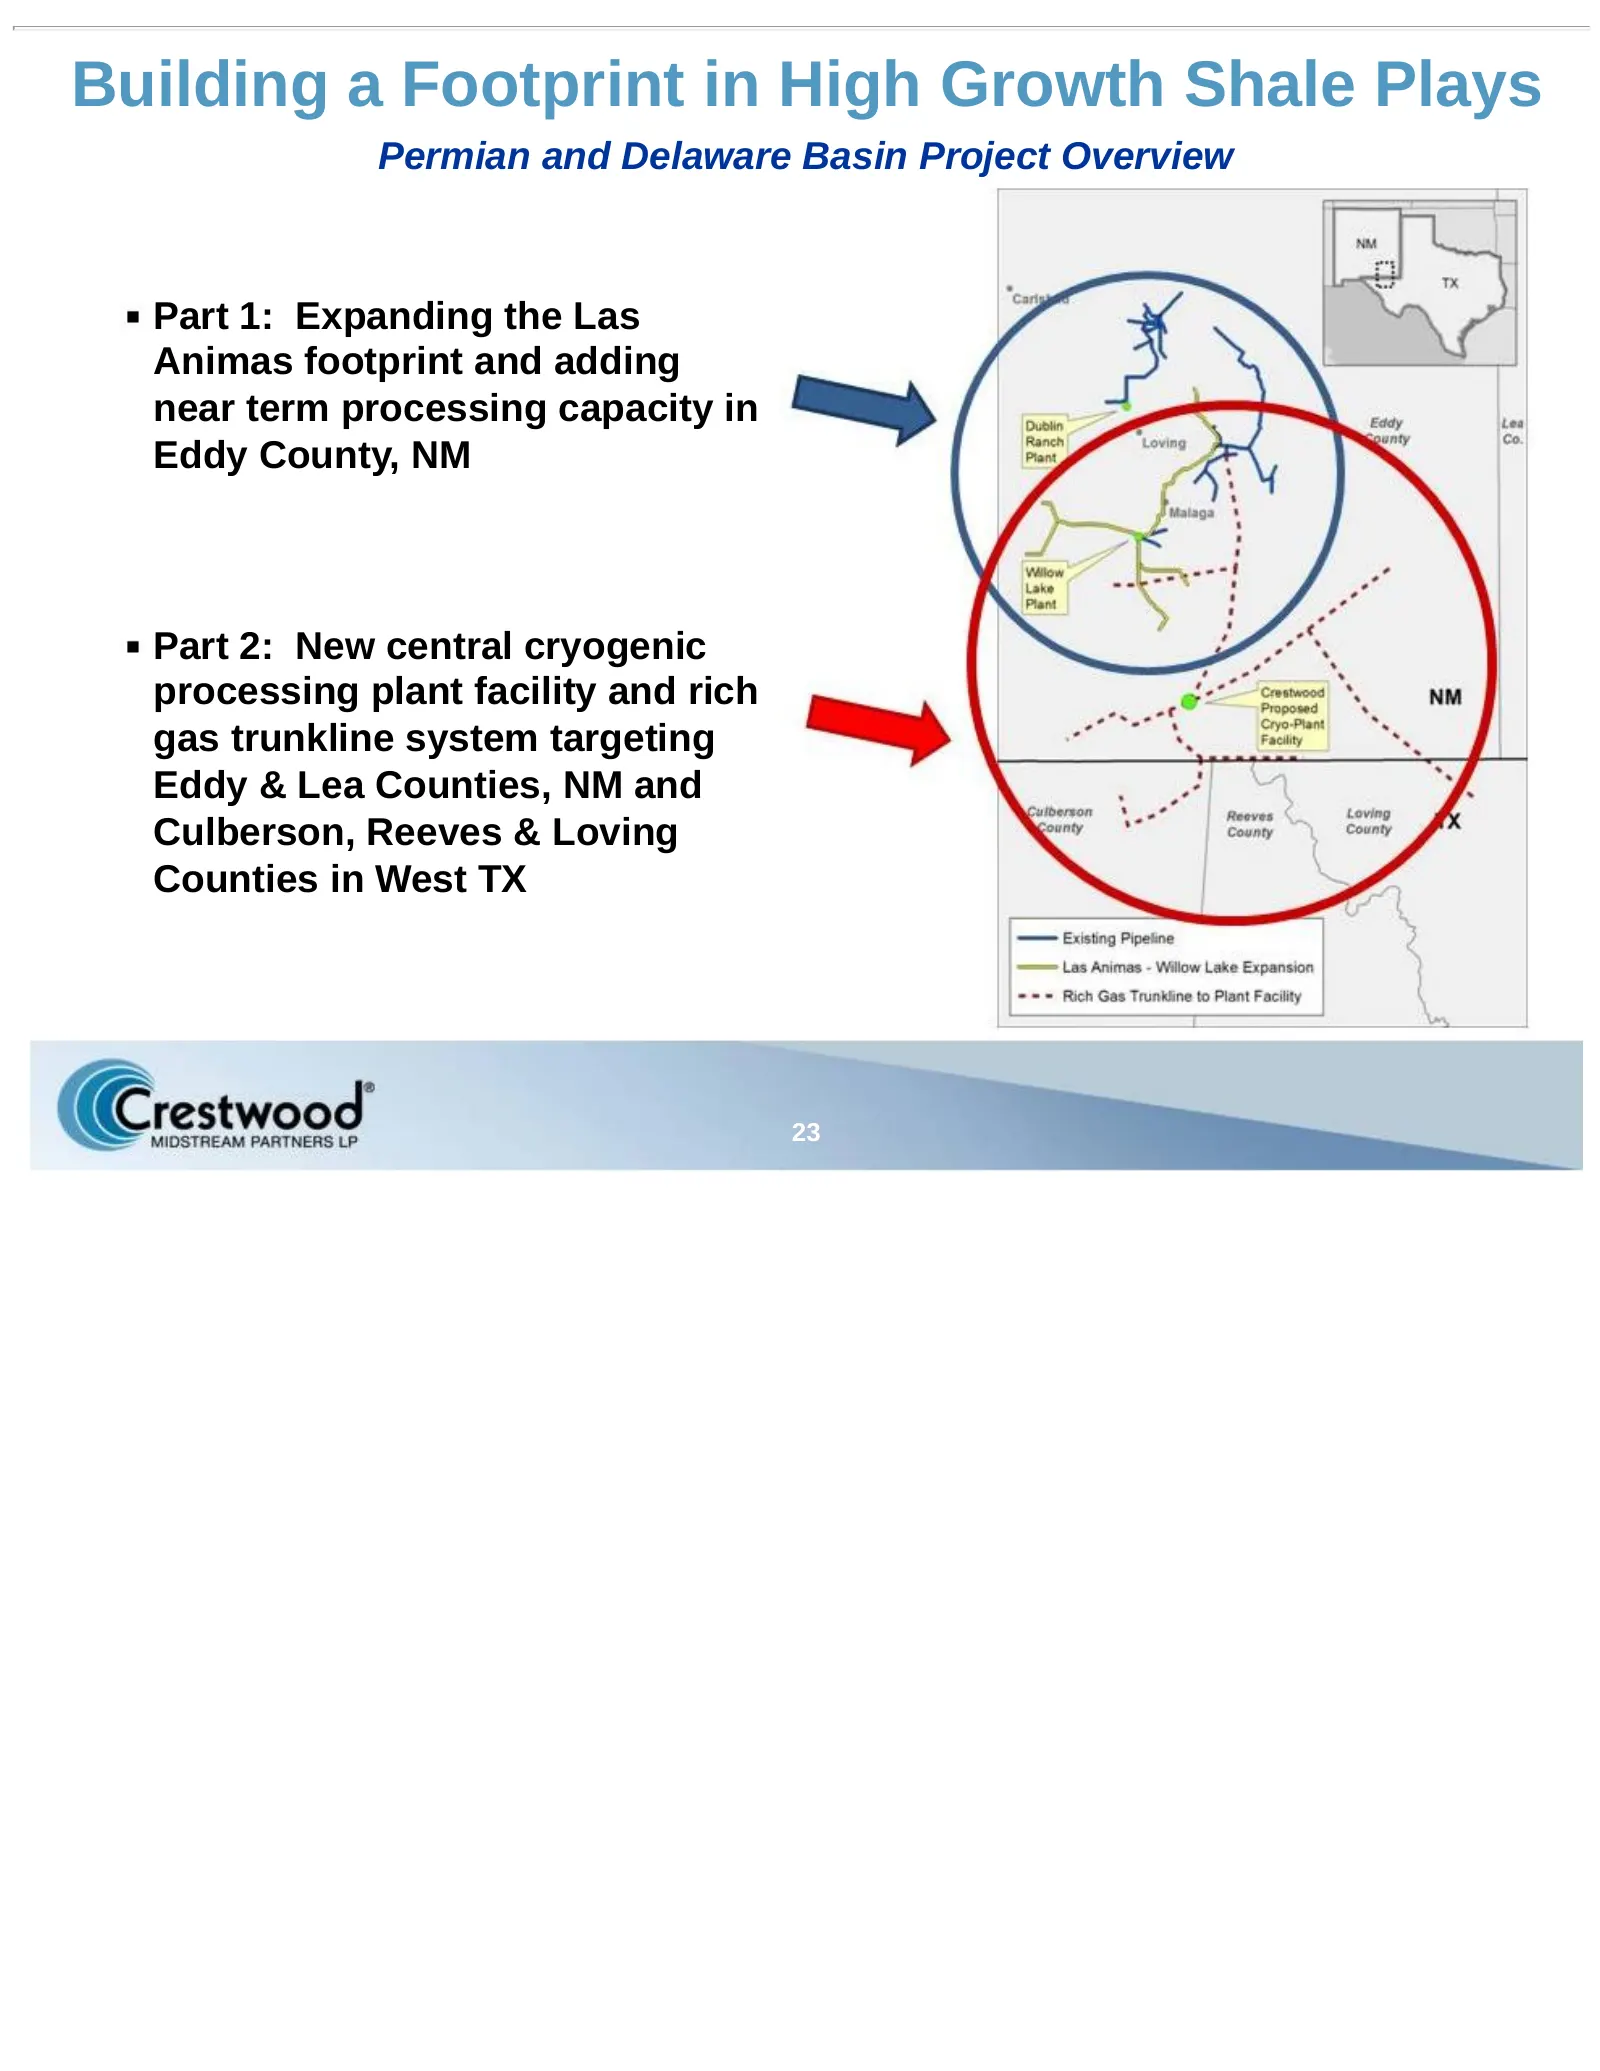
Building a Footprint in High Growth Shale Plays Permian and Delaware Basin Project Overview Part 1: Expanding the Las Animas footprint and adding near term processing capacity in Eddy County, NM Part 2: New central cryogenic processing plant facility and rich gas trunkline system targeting Eddy & Le
Slide 24: Key Investor Highlights
Key Investor Highlights Inergy / Crestwood merger is transformational for future growth objectives Operating and financial platform to compete for large scale infrastructure projects and acquisitions Merger integration to be completed in 4Q 2013 Combined assets and skill sets well-positioned to capt
Slide 25: Appendix
Appendix 25
Slide 26: CMLP Capitalization
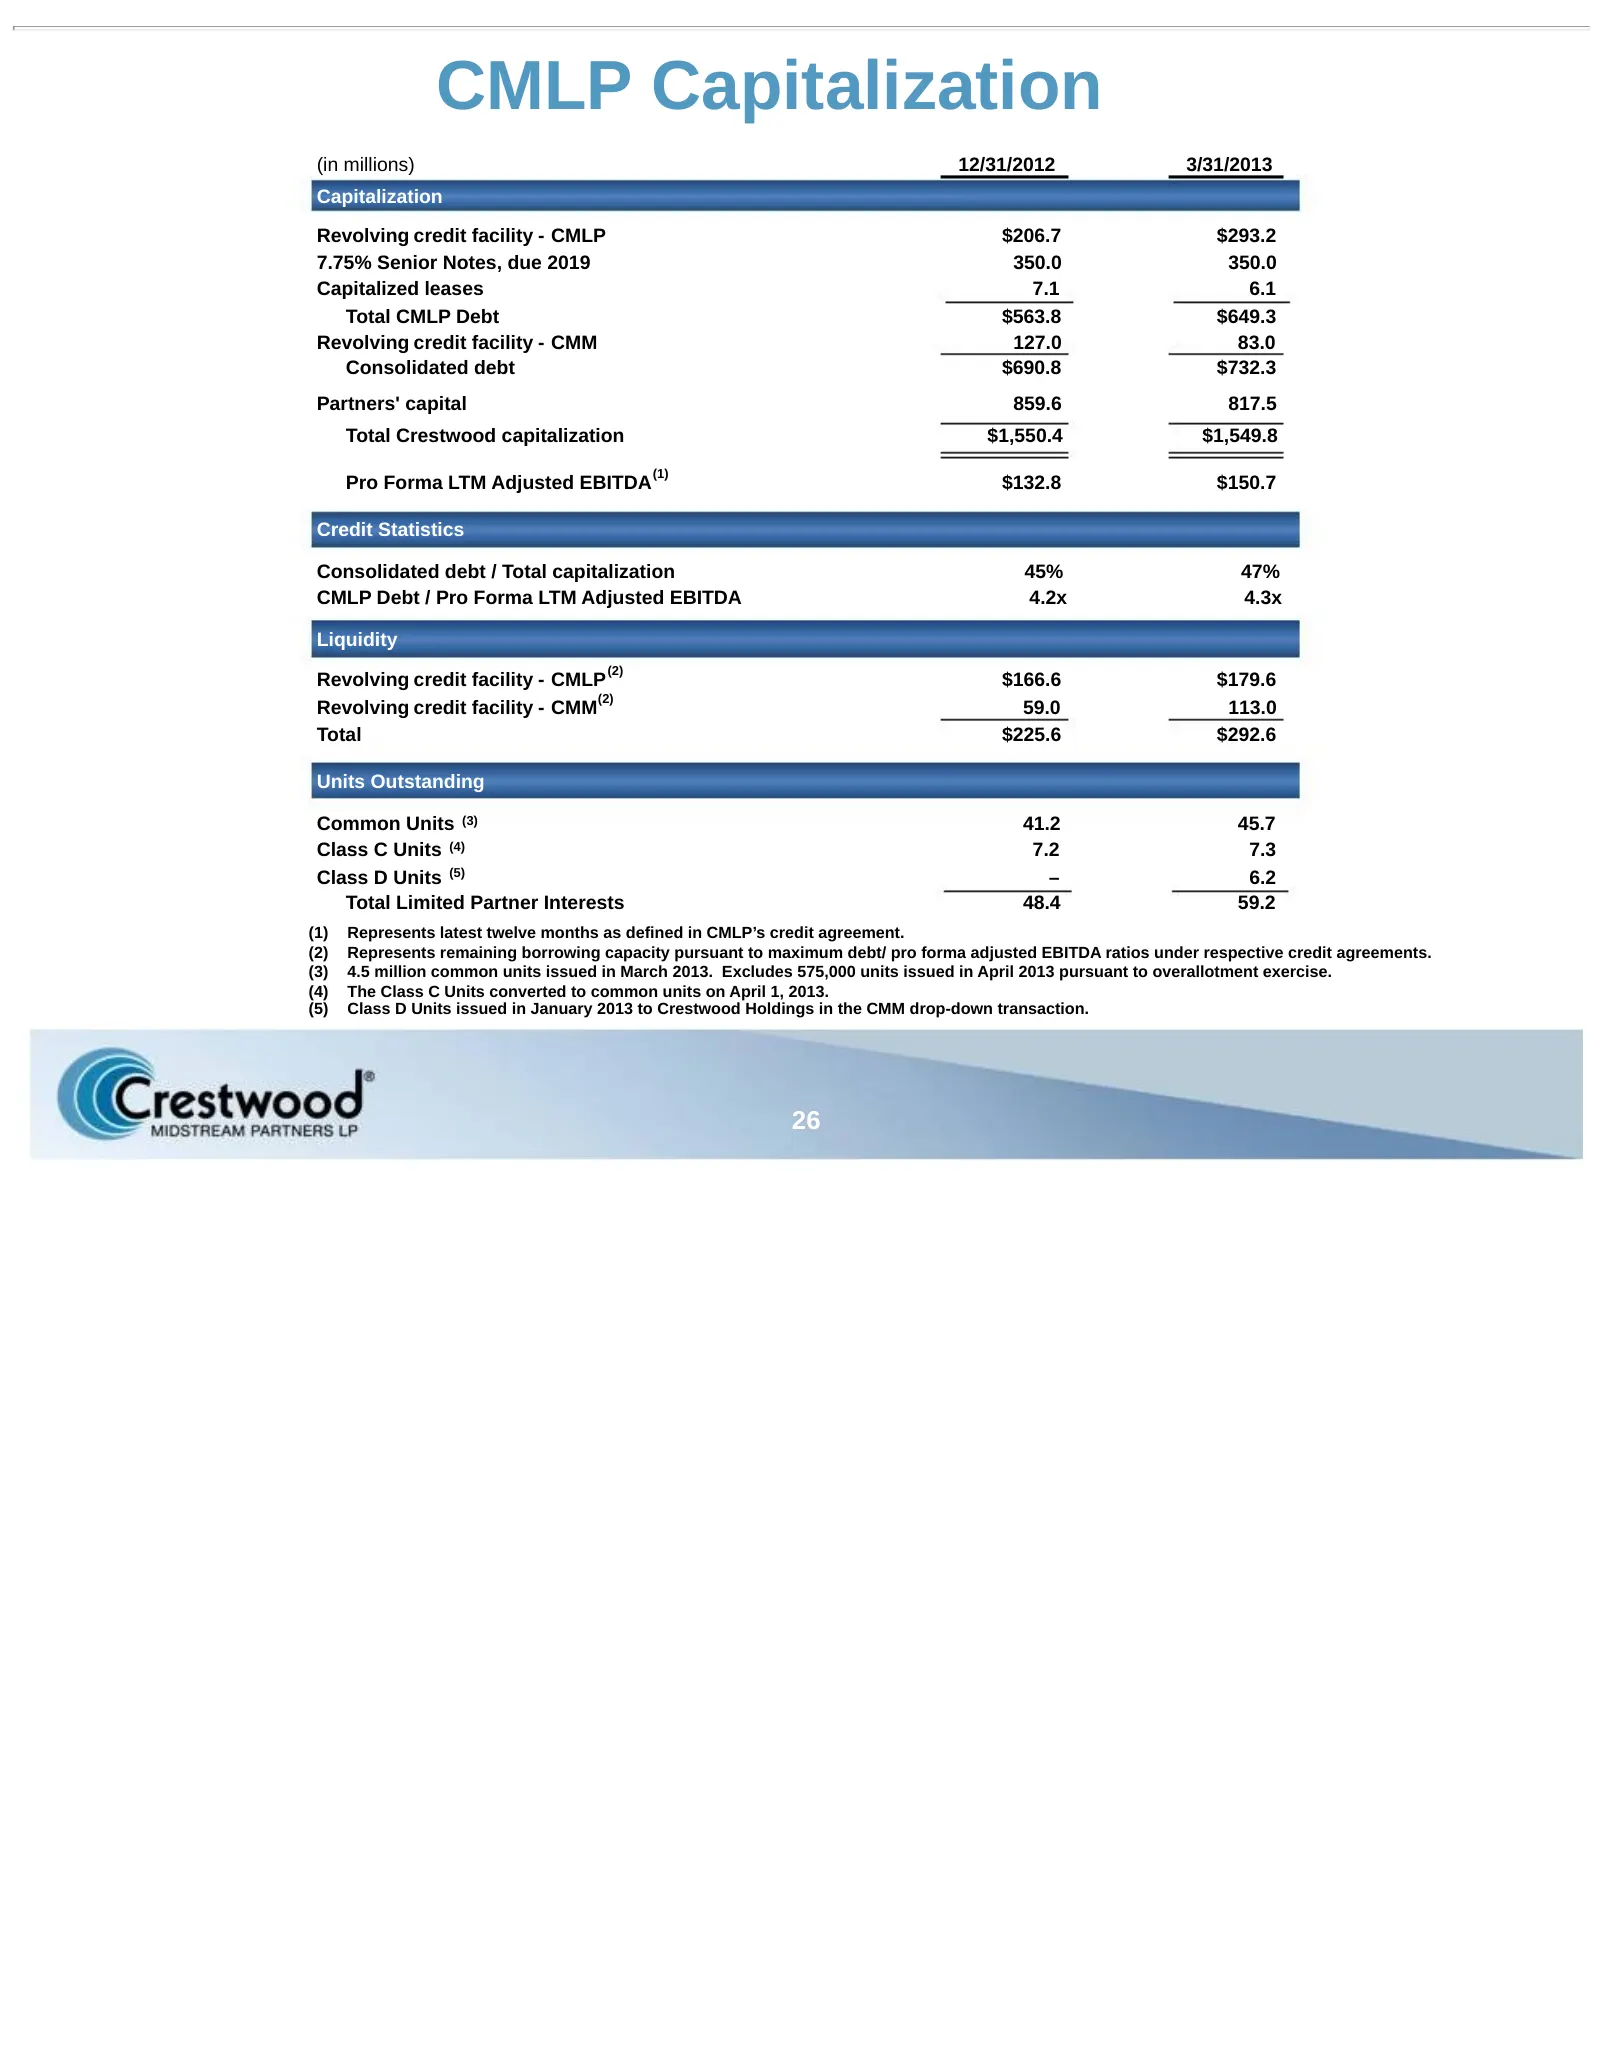
CMLP Capitalization (in millions) 12/31/2012 3/31/2013 Capitalization Revolving credit facility - CMLP $206.7 $293.2 7.75% Senior Notes, due 2019 350.0 350.0 Capitalized leases 7.1 6.1 Total CMLP Debt $563.8 $649.3 Revolving credit facility - CMM 127.0 83.0 Consolidated debt $690.8 $732.3 Partners'
Slide 27: CMLP Financial Forecast
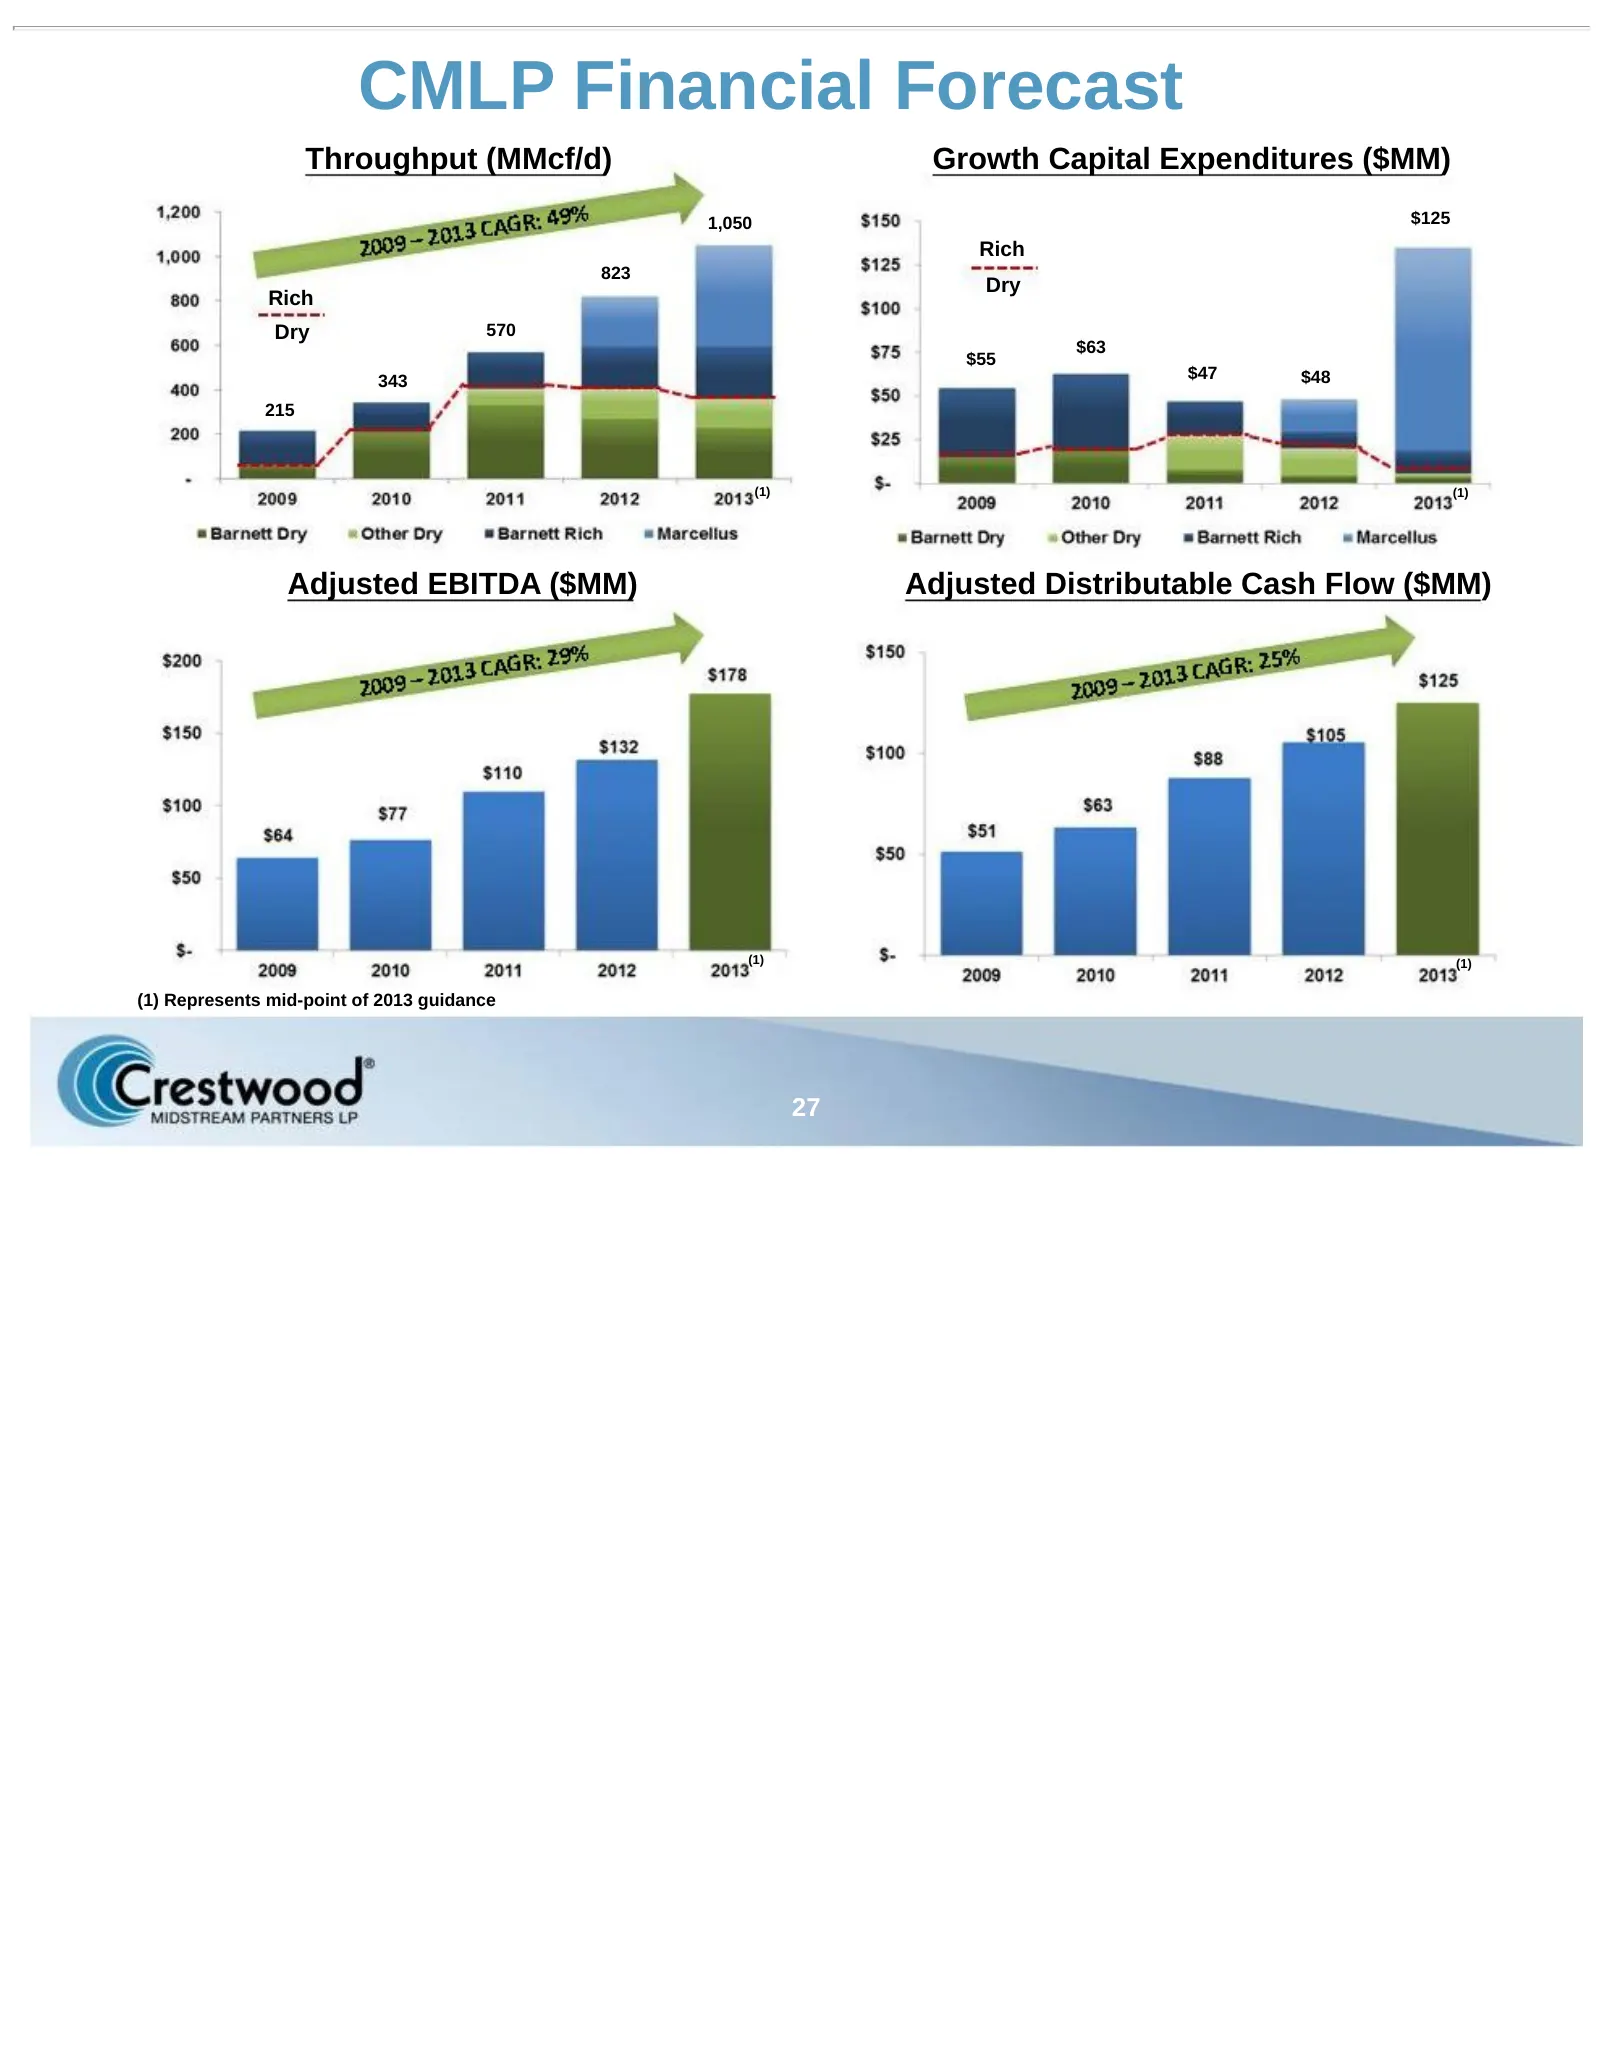
CMLP Financial Forecast Throughput (MMcf/d) Growth Capital Expenditures ($MM) 1,050 $125 Rich 823 Dry Rich Dry 570 $63 $55 343 $47 $48 215 (1) (1) Adjusted EBITDA ($MM) Adjusted Distributable Cash Flow ($MM) (1) (1) (1) Represents mid-point of 2013 guidance 27
Slide 28: Non-GAAP Financial Measures
Non-GAAP Financial Measures The following slides of this presentation provide reconciliations of the non-GAAP financial measures adjusted EBITDA and adjusted distributable cash flow to their most directly comparable financial measures calculated and presented in accordance with generally accepted ac
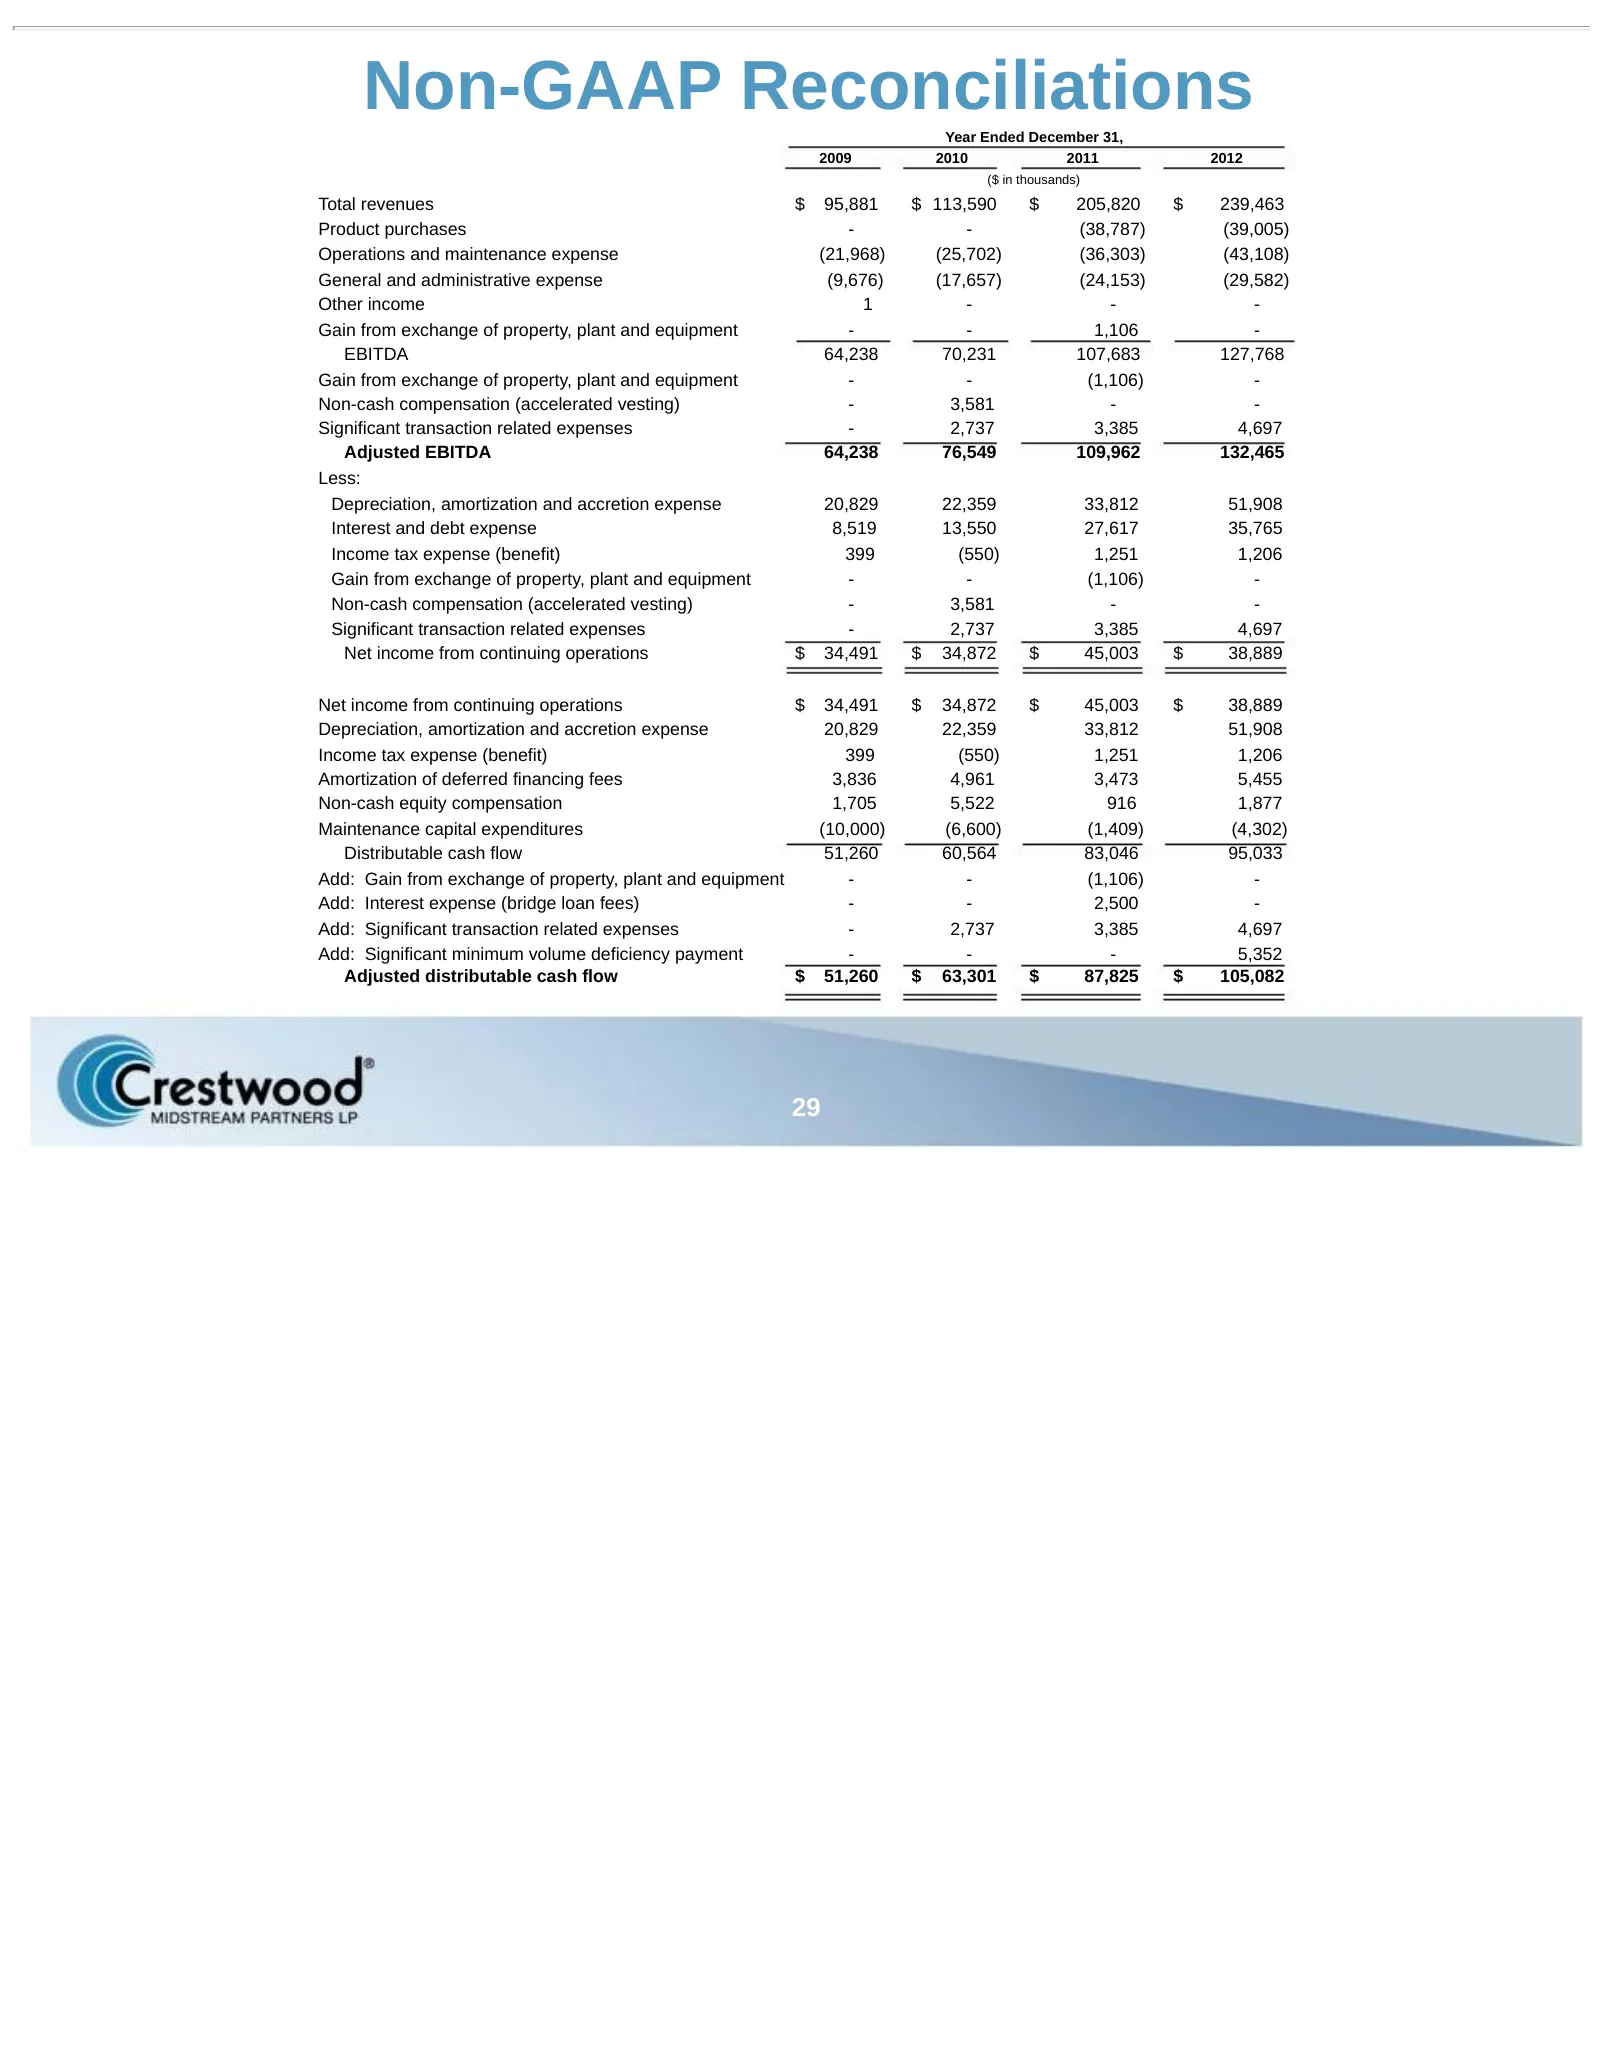
Slide 29: Non-GAAP Reconciliations
Non-GAAP Reconciliations Year Ended December 31, 2009 2010 2011 2012 ($ in thousands) Total revenues $ 95,881 $ 113,590 $ 205,820 $ 239,463 Product purchases - - (38,787) (39,005) Operations and maintenance expense (21,968) (25,702) (36,303) (43,108) General and administrative expense (9,676) (17,65
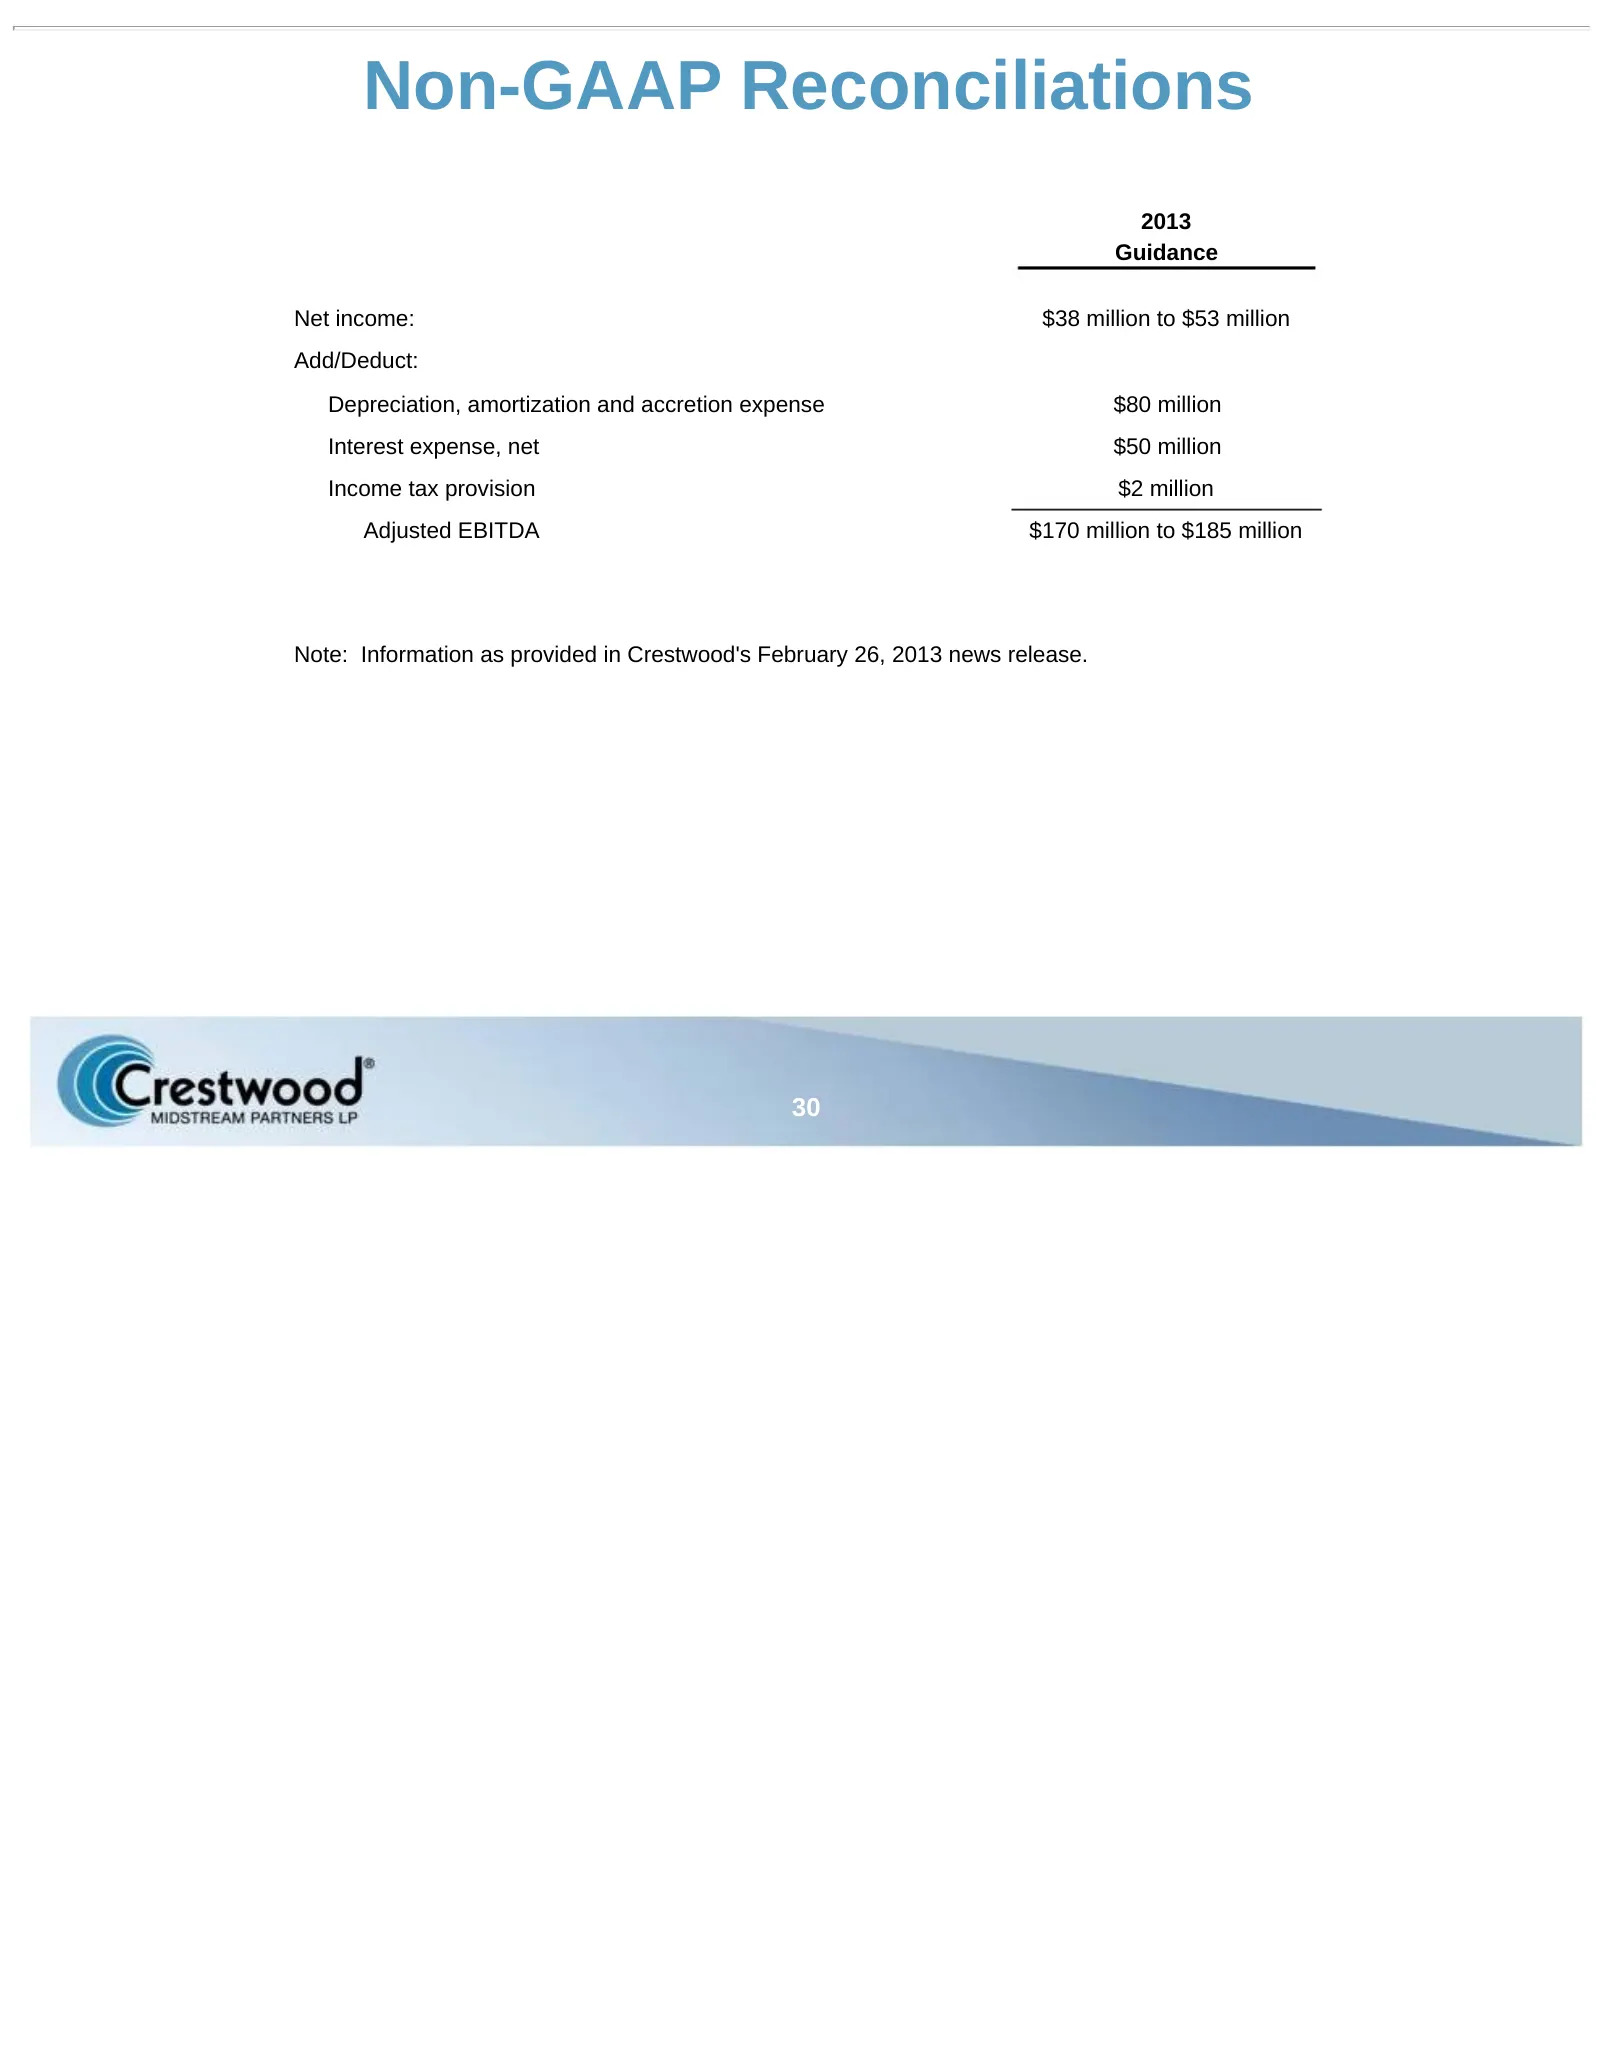
Slide 30: Non-GAAP Reconciliations
Non-GAAP Reconciliations 2013 Guidance Net income: $38 million to $53 million Add/Deduct: Depreciation, amortization and accretion expense $80 million Interest expense, net $50 million Income tax provision $2 million Adjusted EBITDA $170 million to $185 million Note: Information as provided in Crest
Source: SEC EDGAR · 425 filed May 22, 2013
More decks from Crestwood Midstream Partners LP
 Merger or Acquisition (August 2013)28 slides · Aug 21, 2013
 Merger or Acquisition (May 2013)10 slides · May 6, 2013
 Merger or Acquisition (May 2013)21 slides · May 6, 2013
 Morgan Stanley MLP and Diversified Natural Gas Corporate Access Day (March 2012)30 slides · Mar 8, 2012
 Merger or Acquisition (November 2011)9 slides · Nov 1, 2011
 BNP Paribas Loan Syndication Annual Investor Conference (May 2011)21 slides · May 13, 2011