Endeavour International — EnerCom's 2008 Oil & Gas Conference
24 slides from Endeavour International's conference presentation, Aug 14, 2008
Slide 1: EnerCom's 2008 Oil & Gas Conference
EnerCom's 2008 Oil & Gas Conference(r) August 2008
Slide 2: Forward-looking statements and SEC reserves notice
2 This is an oral presentation which is accompanied by slides. Investors are urged to review our SEC filings. This presentation contains certain forward-looking statements regarding various oil and gas discoveries, oil and gas exploration, development and production activities, anticipated and poten
Slide 3: Endeavour at a Glance
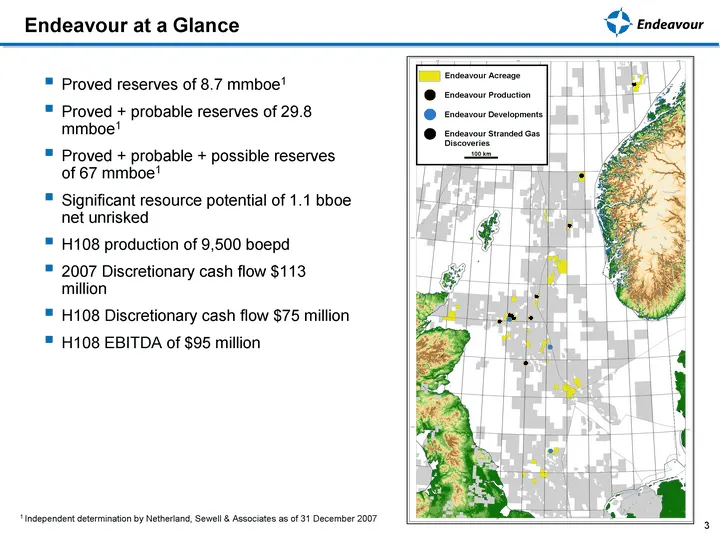
3 Proved reserves of 8.7 mmboe1 Proved + probable reserves of 29.8 mmboe1 Proved + probable + possible reserves of 67 mmboe1 Significant resource potential of 1.1 bboe net unrisked H108 production of 9,500 boepd 2007 Discretionary cash flow $113 million H108 Discretionary cash flow $75 million H108
Slide 4: Balanced Strategy
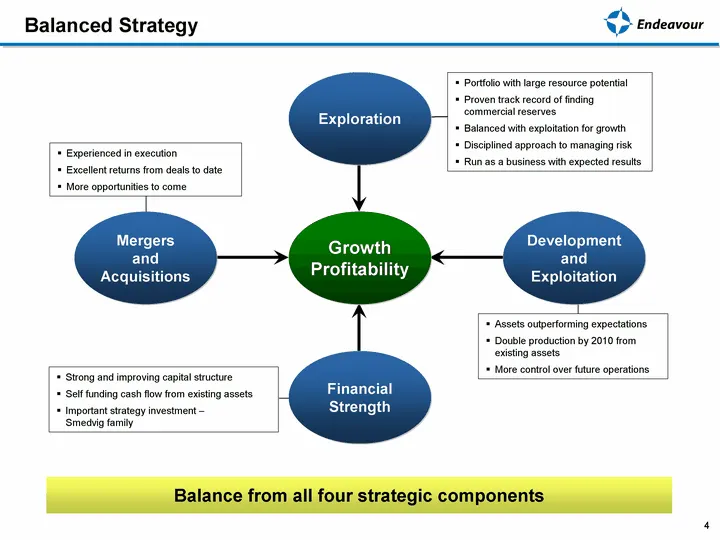
4 Assets outperforming expectations Double production by 2010 from existing assets More control over future operations Balance from all four strategic components Balance from all four strategic components Portfolio with large resource potential Proven track record of finding commercial reserves Bala
Slide 5: Balanced Strategy: Development & Exploitation
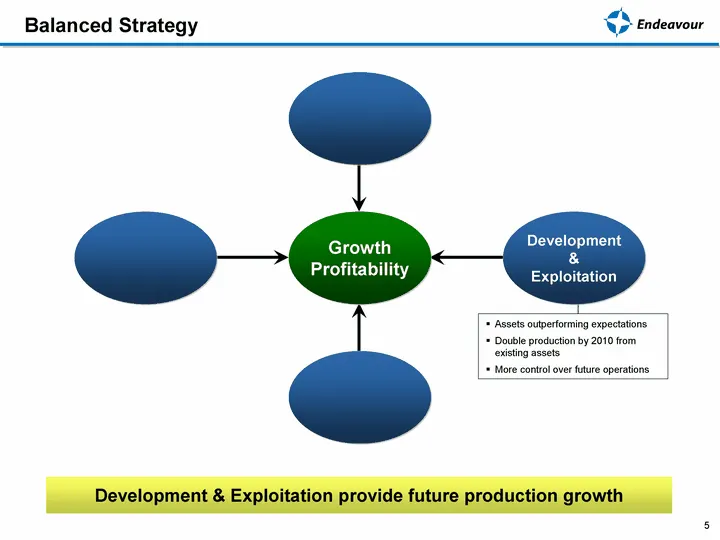
5 Assets outperforming expectations Double production by 2010 from existing assets More control over future operations More control over future operations More control over future operations More control over future operations More control over future operations Development & Exploitation provide fu
Slide 6: Strong reserve base and excellent resource potential
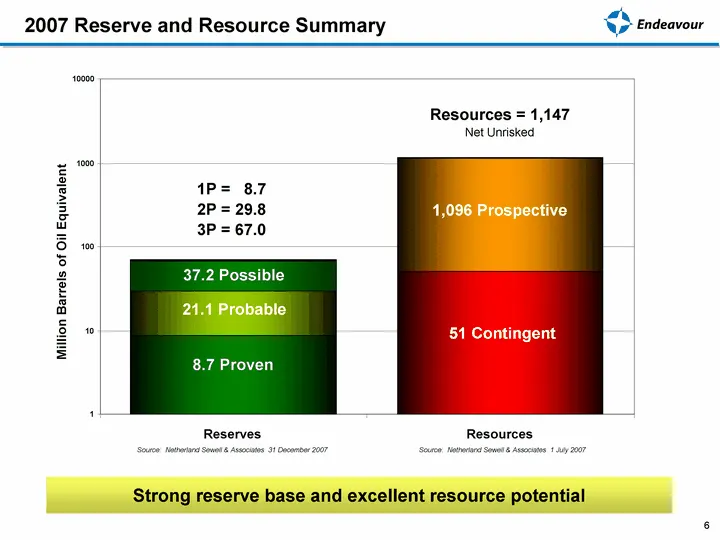
6 Strong reserve base and excellent resource potential 2007 Reserve and Resource Summary 1 10 100 1000 10000 Reserves Resources Million Barrels of Oil Equivalent 8.7 Proven 21.1 Probable 37.2 Possible 51 Contingent 1,096 Prospective 1P = 8.7 2P = 29.8 3P = 67.0 Resources = 1,147 Net Unrisked Source:
Slide 7: Potential Production Growth
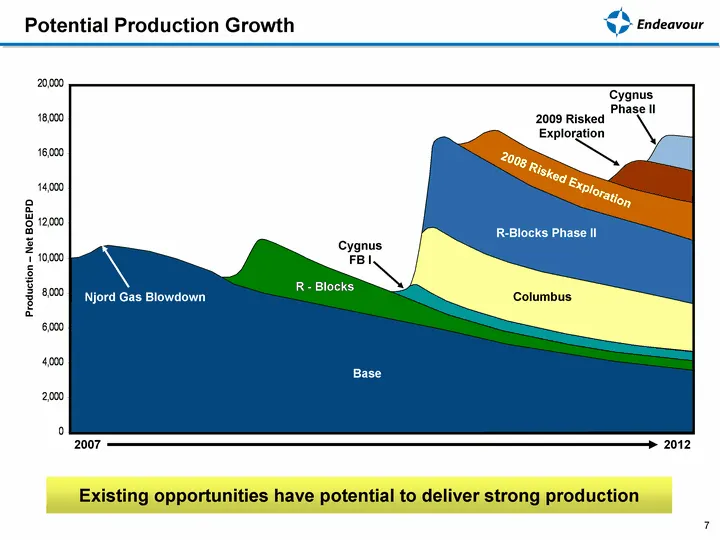
7 Potential Production Growth Production - Net BOEPD 2007 2012 R - Blocks Columbus Njord Gas Blowdown Cygnus FB I R-Blocks Phase II 2008 Risked Exploration 2009 Risked Exploration Cygnus Phase II Base Existing opportunities have potential to deliver strong production
Slide 8: Current Developments
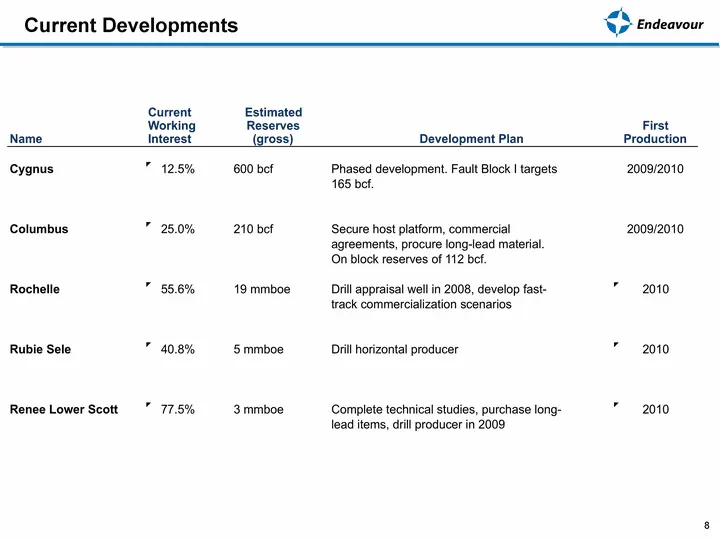
Current Developments raft QD Endeavour Current Estimated Working Reserves First Name Interest (gross) Development Plan Production Cygnus ” 12.5% 600 bef Phased development. Fault Block | targets 2009/2010 165 bef. Columbus "25.0% 210 bef ‘Secure host platform, commercial 2009/2010 agreements, procur
Slide 9: Exploration increases shareholder value
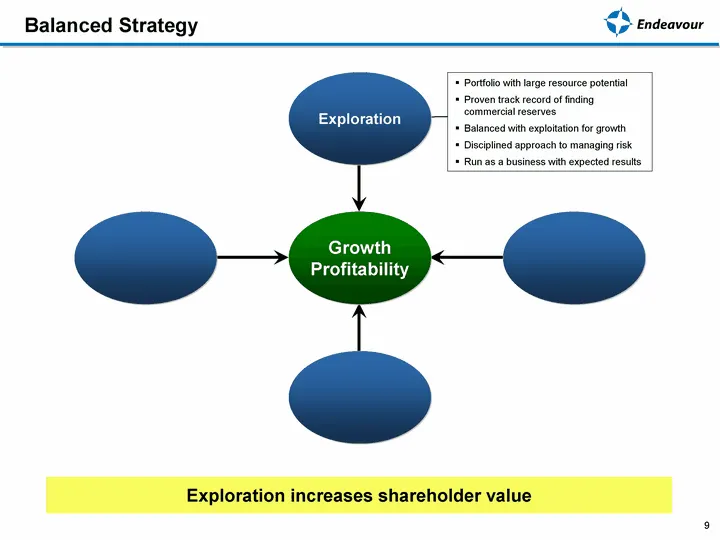
9 Exploration increases shareholder value Portfolio with large resource potential Proven track record of finding commercial reserves Balanced with exploitation for growth Disciplined approach to managing risk Run as a business with expected results Exploration Growth Profitability Balanced Strategy
Slide 10: Planned participation in wells in 2008-2009
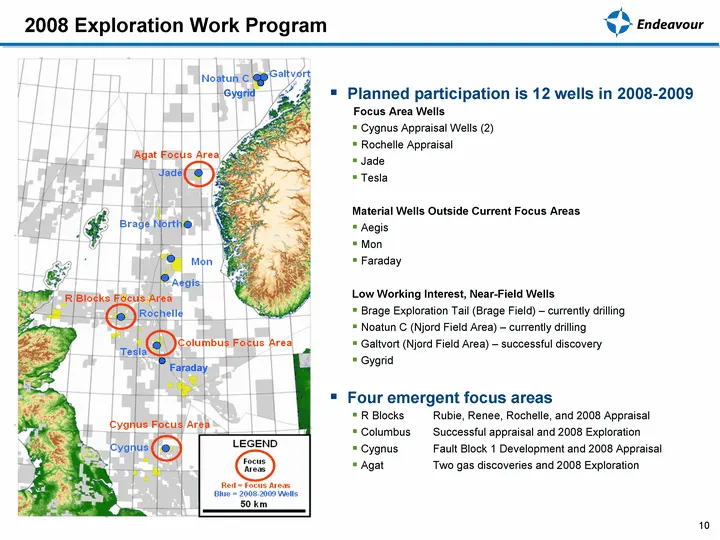
10 Planned participation is 12 wells in 2008-2009 Focus Area Wells Cygnus Appraisal Wells (2) Rochelle Appraisal Jade Tesla Material Wells Outside Current Focus Areas Aegis Mon Faraday Low Working Interest, Near-Field Wells Brage Exploration Tail (Brage Field) - currently drilling Noatun C (Njord Fi
Slide 11: 2008 - 2009 Drilling Schedule
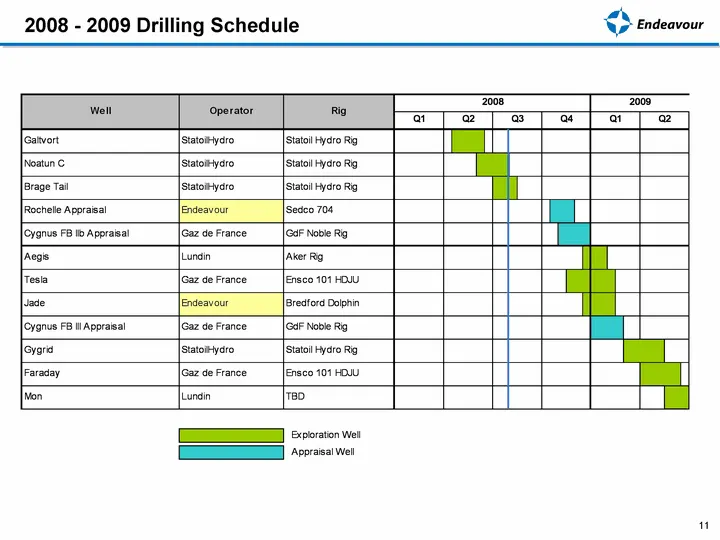
11 2008 - 2009 Drilling Schedule
Slide 12: Cygnus Appraisal - UK
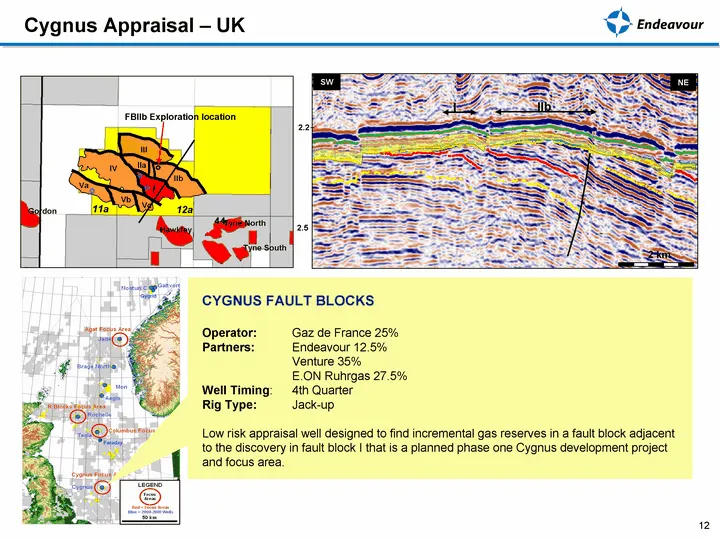
12 Faraday Gygrid 2.2 2.5 SW NE 11a 12a IIb 2 km III IV IIa IIb I Va Vb Vc I I Tyne North Hawkley Tyne South Gordon FBIIb Exploration location Cygnus Appraisal - UK CYGNUS FAULT BLOCKS Operator: Gaz de France 25% Partners: Endeavour 12.5% Venture 35% E.ON Ruhrgas 27.5% Well Timing: 4th Quarter Rig T
Slide 13: Rochelle Appraisal - UK
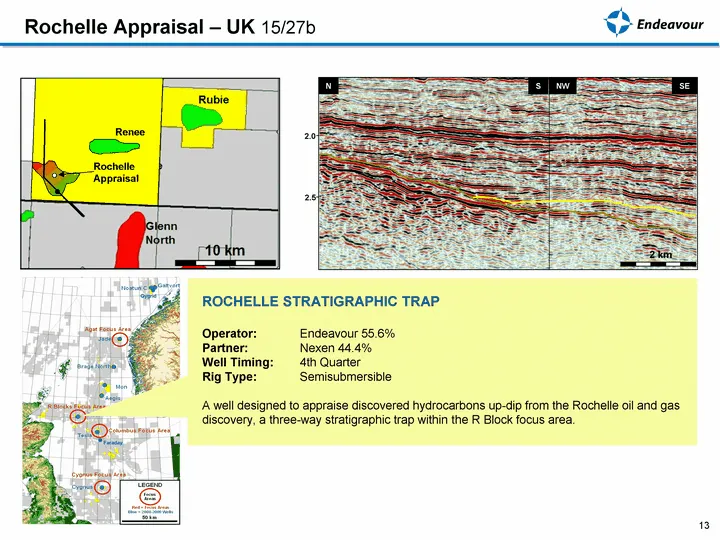
13 Faraday Gygrid Rochelle Appraisal - UK 15/27b SE N 2.0 2.5 2 km S NW Rochelle Appraisal Renee ROCHELLE STRATIGRAPHIC TRAP Operator: Endeavour 55.6% Partner: Nexen 44.4% Well Timing: 4th Quarter Rig Type: Semisubmersible A well designed to appraise discovered hydrocarbons up-dip from the Rochelle
Slide 14: Jade (Agat Area) - Norway
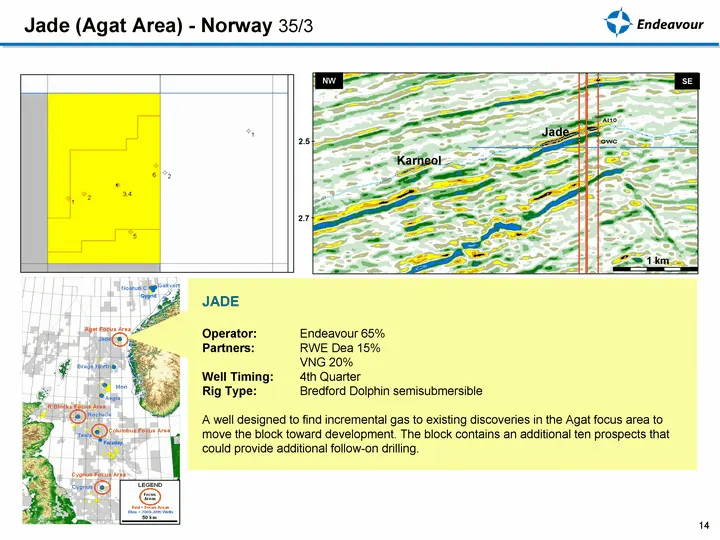
14 Faraday Gygrid SE NW 2.5 2.7 1 km Karneol Jade Jade (Agat Area) - Norway 35/3 JADE Operator: Endeavour 65% Partners: RWE Dea 15% VNG 20% Well Timing: 4th Quarter Rig Type: Bredford Dolphin semisubmersible A well designed to find incremental gas to existing discoveries in the Agat focus area to mo
Slide 15: Tesla - UK
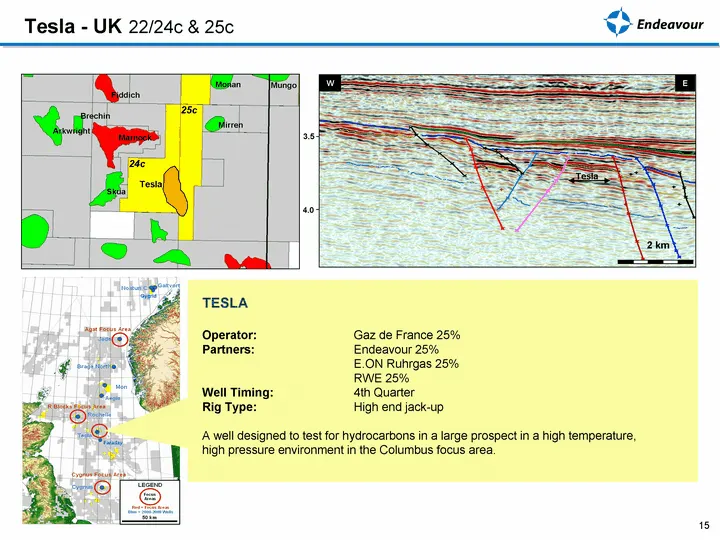
15 Faraday Gygrid 3.5 4.0 E W Tesla 2 km 24c 25c Tesla Skua Fiddich Arkwright Brechin Marnock Mirren Monan Mungo Tesla - UK 22/24c & 25c TESLA Operator: Gaz de France 25% Partners: Endeavour 25% E.ON Ruhrgas 25% RWE 25% Well Timing: 4th Quarter Rig Type: High end jack-up A well designed to test for
Slide 16: Aegis - Norway
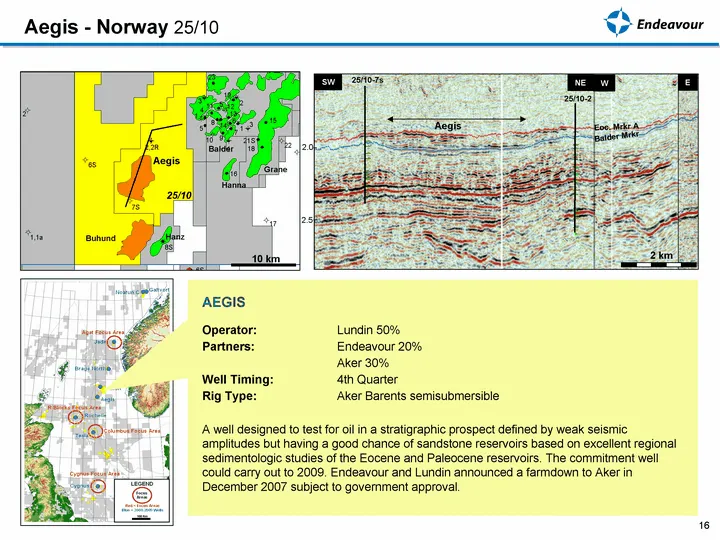
16 Aegis 25/10-7s 25/10-2 Eoc. Mrkr A Balder Mrkr 2 km E SW NE W Aegis Buhund Grane Balder 2.0 2.5 10 km 25/10 Hanz Hanna Aegis - Norway 25/10 AEGIS Operator: Lundin 50% Partners: Endeavour 20% Aker 30% Well Timing: 4th Quarter Rig Type: Aker Barents semisubmersible A well designed to test for oil i
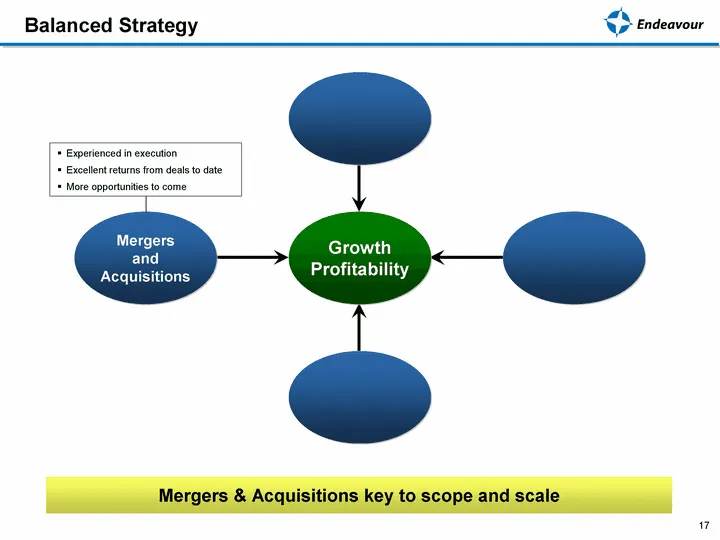
Slide 17: Mergers & Acquisitions key to scope and scale
17 Mergers & Acquisitions key to scope and scale Experienced in execution Excellent returns from deals to date More opportunities to come More opportunities to come More opportunities to come More opportunities to come Balanced Strategy
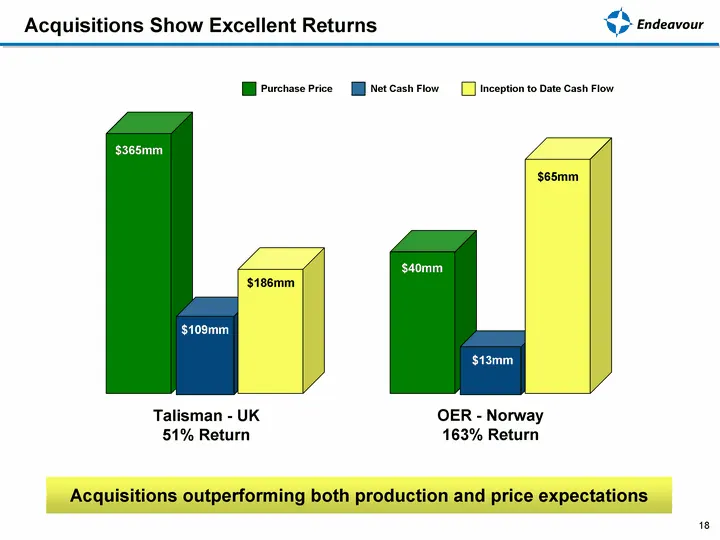
Slide 18: Acquisitions Show Excellent Returns
18 Acquisitions Show Excellent Returns Talisman - UK 51% Return OER - Norway 163% Return Acquisitions outperforming both production and price expectations Purchase Price Net Cash Flow Inception to Date Cash Flow $109mm $365mm $40mm $13mm $186mm $65mm
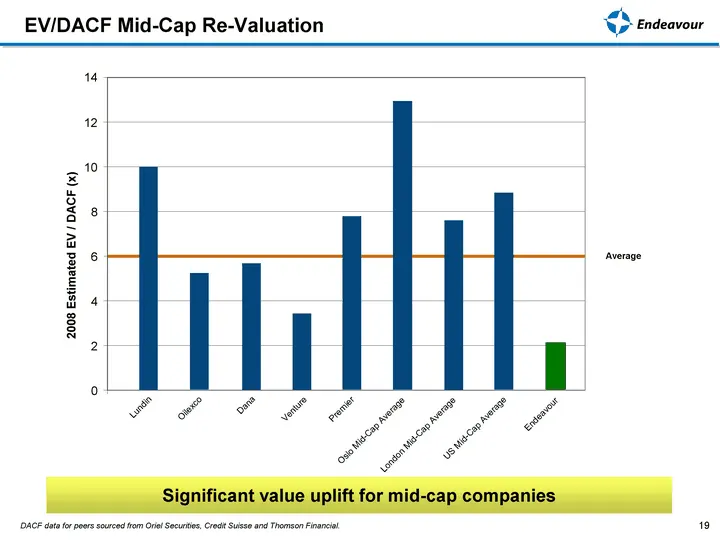
Slide 19: EV/DACF Mid-Cap Re-Valuation
19 EV/DACF Mid-Cap Re-Valuation DACF data for peers sourced from Oriel Securities, Credit Suisse and Thomson Financial. 0 2 4 6 8 10 12 Lundin Oilexco Dana Venture Premier Endeavour 2008 Estimated EV / DACF (x) Oslo Mid-Cap Average London Mid-Cap Average US Mid-Cap Average 14 Significant value uplif
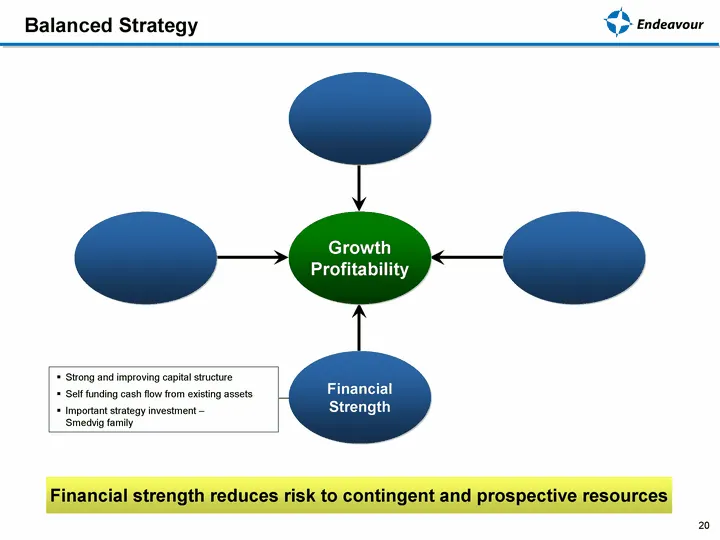
Slide 20: Strong and improving capital structure
20 Strong and improving capital structure Self funding cash flow from existing assets Important strategy investment - Smedvig family Financial strength reduces risk to contingent and prospective resources Financial strength reduces risk to contingent and prospective resources Balanced Strategy
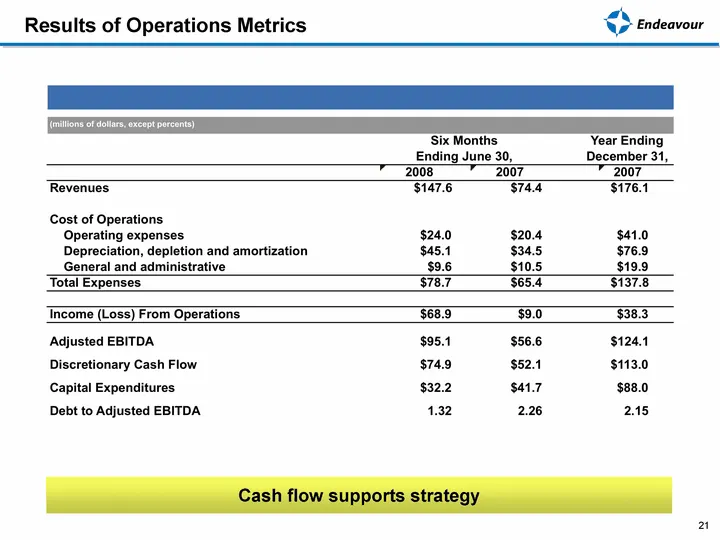
Slide 21: Results of Operations Metrics
21 Results of Operations Metrics Cash flow supports strategy
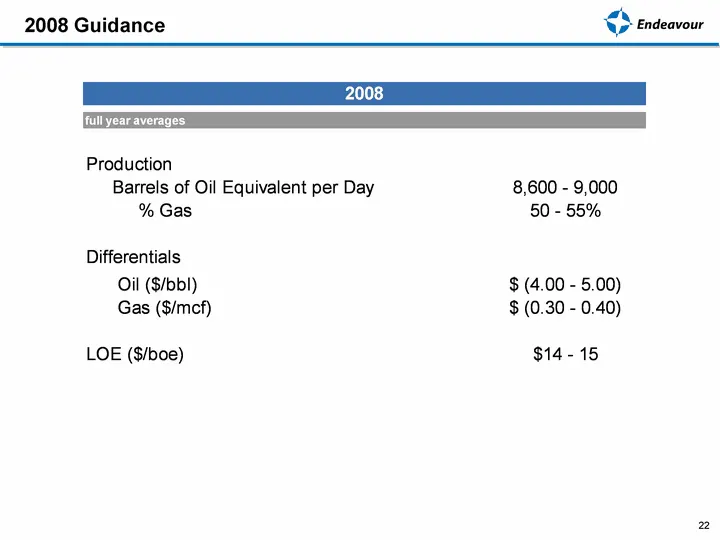
Slide 22: 2008 Guidance
2008 Guidance 3 endeavour full year averages Production Barrels of Oil Equivalent per Day 8,600 - 9,000 % Gas 50 - 55% Differentials Oil ($/bbl) $ (4.00 - 5.00) Gas ($/mef) $ (0.30 - 0.40) LOE ($/boe) $14 - 15
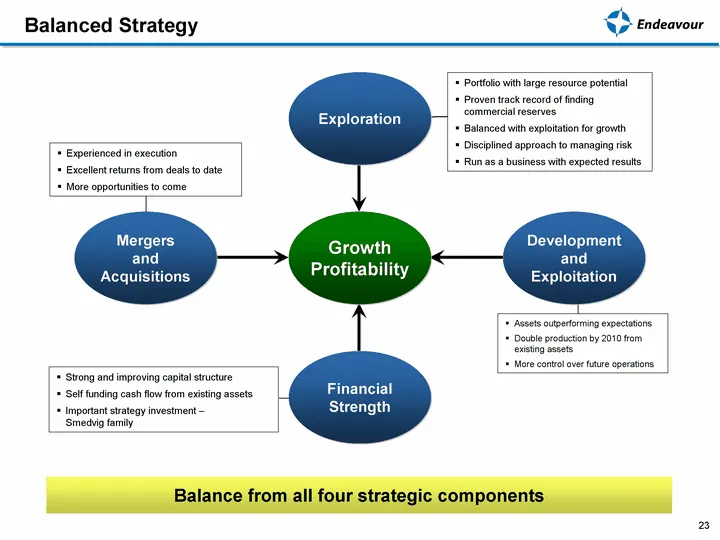
Slide 23: Balance from all four strategic components
23 Balance from all four strategic components Assets outperforming expectations Double production by 2010 from existing assets More control over future operations Balance from all four strategic components Mergers and Acquisitions Financial Strength Development and Exploitation Exploration Growth Pr
Slide 24: Conclusion
24 Balanced strategy with experienced global team in place Strong continuing cash flow from existing assets - self-funding Solid and improving capital structure Multiple growth channels to organically grow company Development and exploitation of existing assets Exploration North Sea consolidation Gl
Source: SEC EDGAR · 8-K filed Aug 14, 2008
More decks from Endeavour International Corp
 Presentation (May 2015)5 slides · May 7, 2015
 Corporate Update (February 2015)23 slides · Feb 27, 2015
 Debt Investor Presentation (October 2014)16 slides · Oct 14, 2014
 Q2 2014 Earnings Presentation12 slides · Aug 5, 2014
 Proxy Contest (May 2014)45 slides · May 8, 2014
 Q1 2014 Earnings Presentation12 slides · May 7, 2014