Galliford Try Holdings PLC · LSE:GFRD
Galliford Try — Investor Day (February 2017)
70 slides from Galliford Try's investor day presentation, February 2017
Slide 1: Strategy to 2021
STRATEGY TO 2021 February 2017 Great Eastern Quays, East London
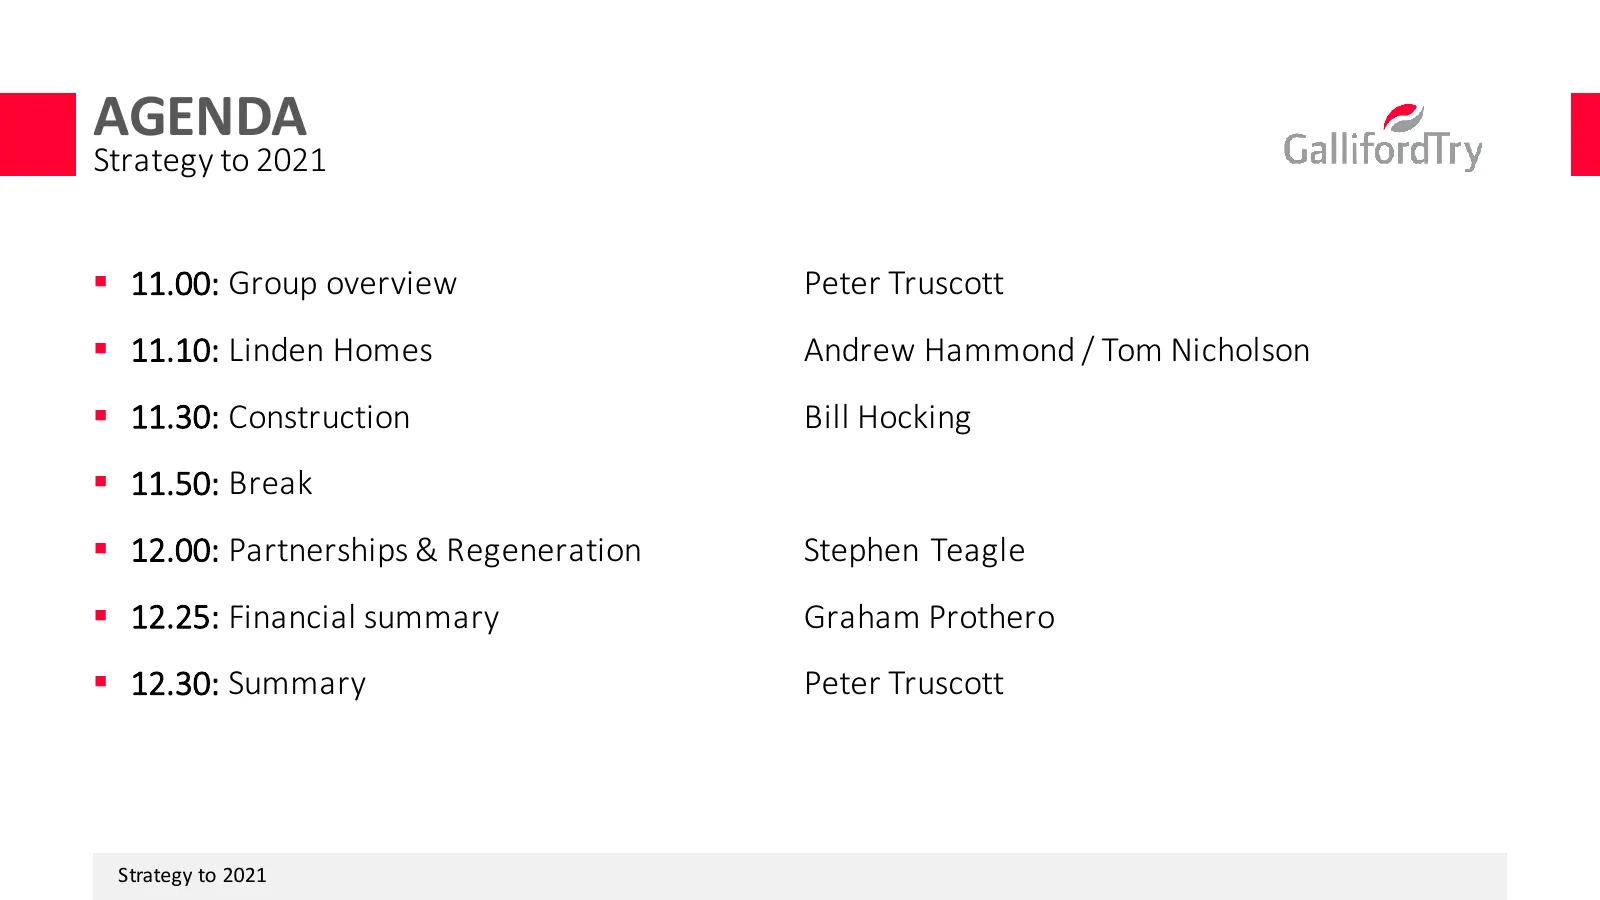
Slide 2: Agenda
AGENDA Strategy to 2021 § 11.00: Group overview Peter Truscott § 11.10: Linden Homes Andrew Hammond / Tom Nicholson § 11.30: Construction Bill Hocking § 11.50: Break § 12.00: Partnerships & R egeneration Stephen Teagle § 12.25: Financial summary Graham Prothero § 12.30: Summary Peter Truscott
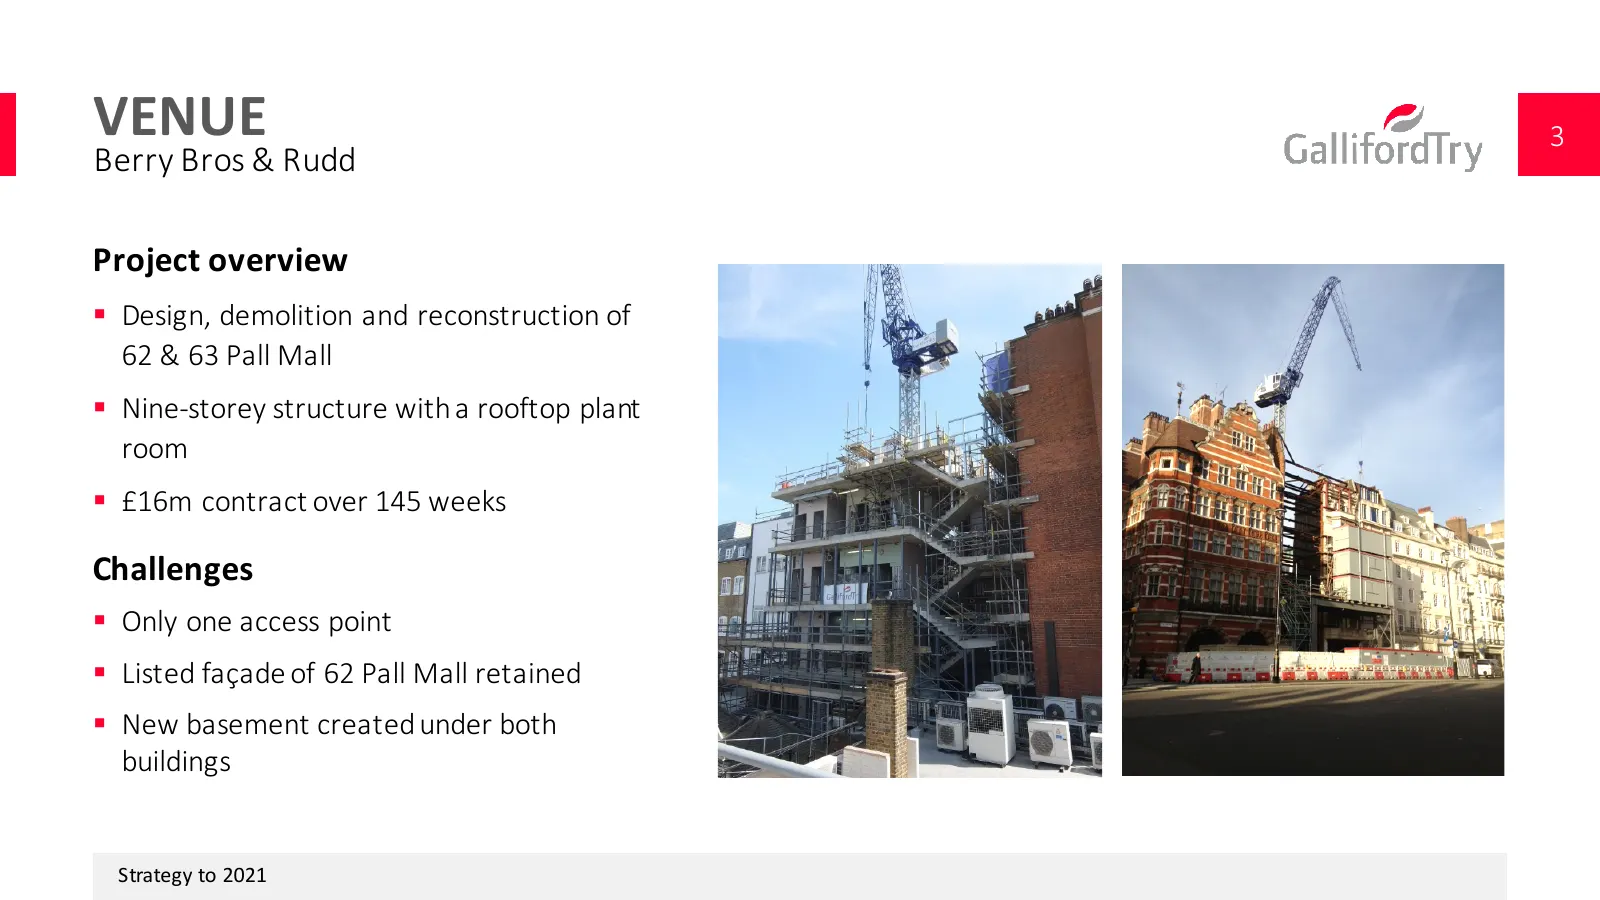
Slide 3: Venue: Berry Bros & Rudd
VENUE 3 Berry Bros & R udd Project overview § Design, demolition and reconstruction of 62 & 63 Pall Mall § Nine-‐storey structure with a rooftop plant room § £16m contract over 145 weeks Challenges § Only one access point § Listed façade of 62 Pall Mall retained § New basement created under b
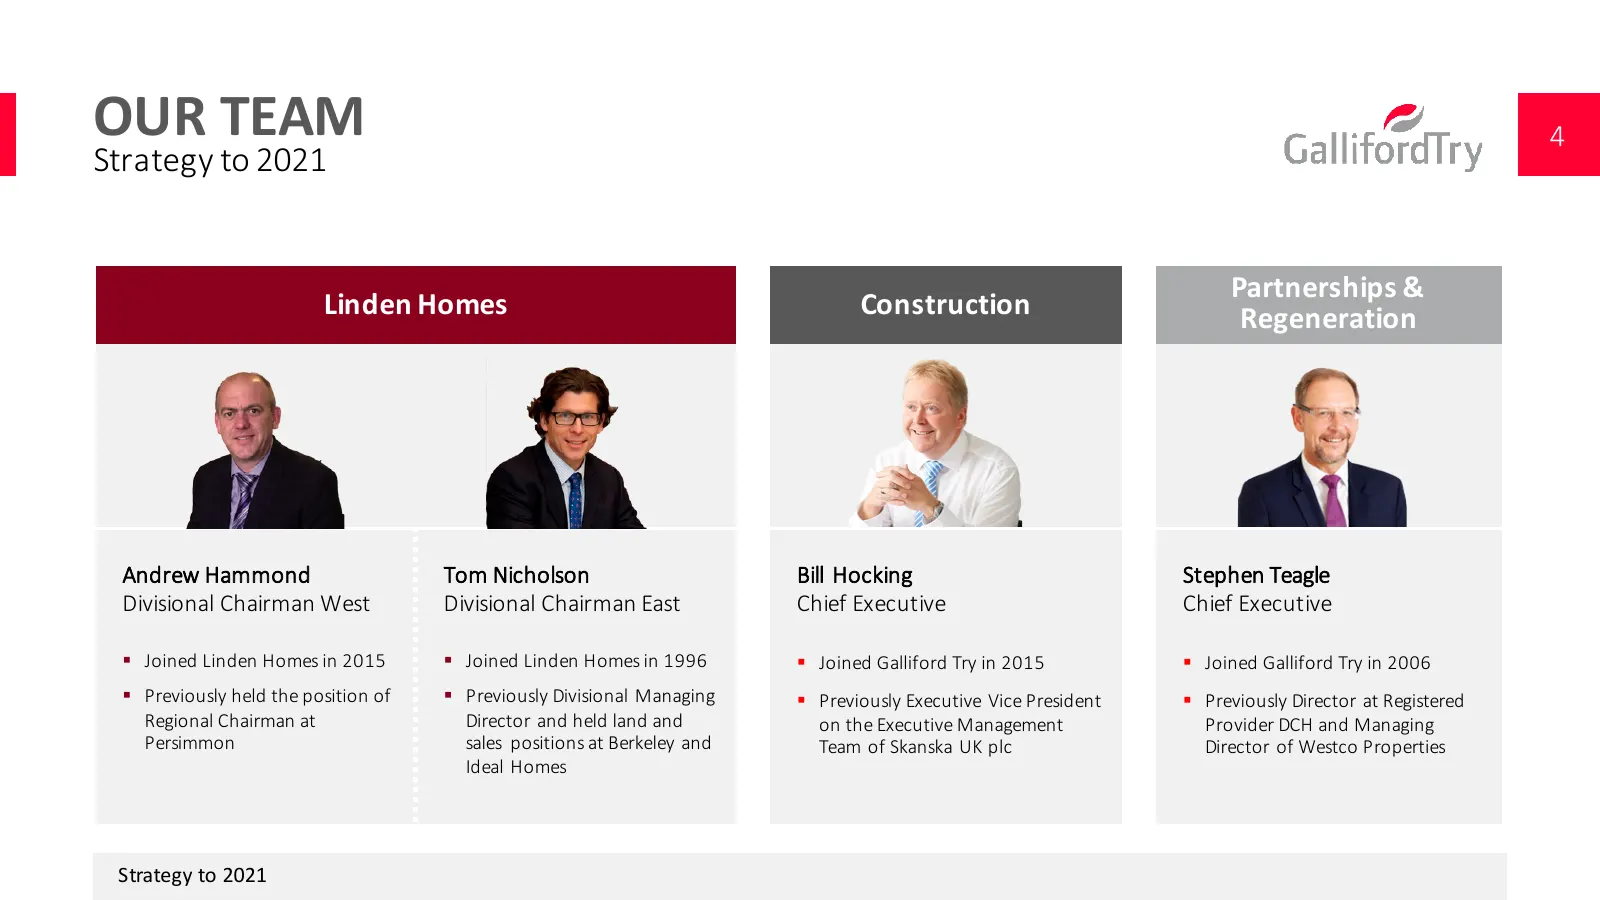
Slide 4: Our Team
OUR TEAM 4 Strategy to 2021 Partnerships & Linden Homes Construction Regeneration Andrew Hammond Tom Nicholson Bill Hocking Stephen Teagle Divisional Chairman West Divisional Chairman East Chief Executive Chief Executive § Joined Linden H omes in 2 015 § Joined Linden H omes in 1 996 § Joined G a
Slide 5: Group Overview
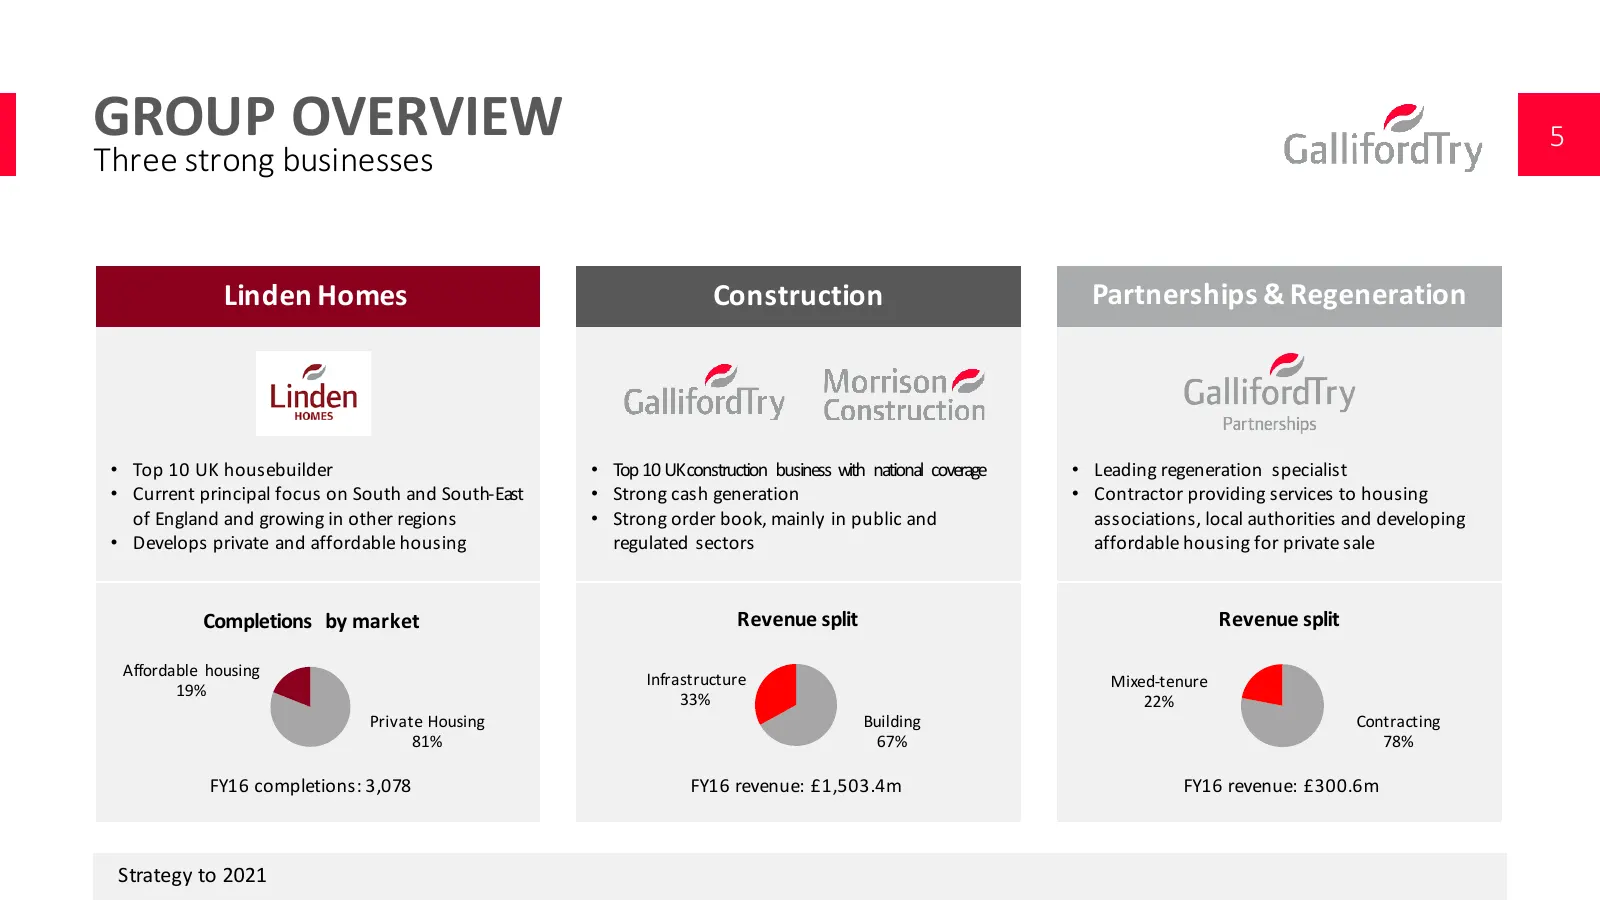
GROUP OVERVIEW 5 Three strong businesses Linden Homes Construction Partnerships & Regeneration • Top 1 0 UK h ousebuilder • Top 10 UK construction business with national coverage • Leading regeneration specialist • Current p rincipal focus on South and South-‐East • Strong cash generation • Contrac
Slide 6: Our Starting Point
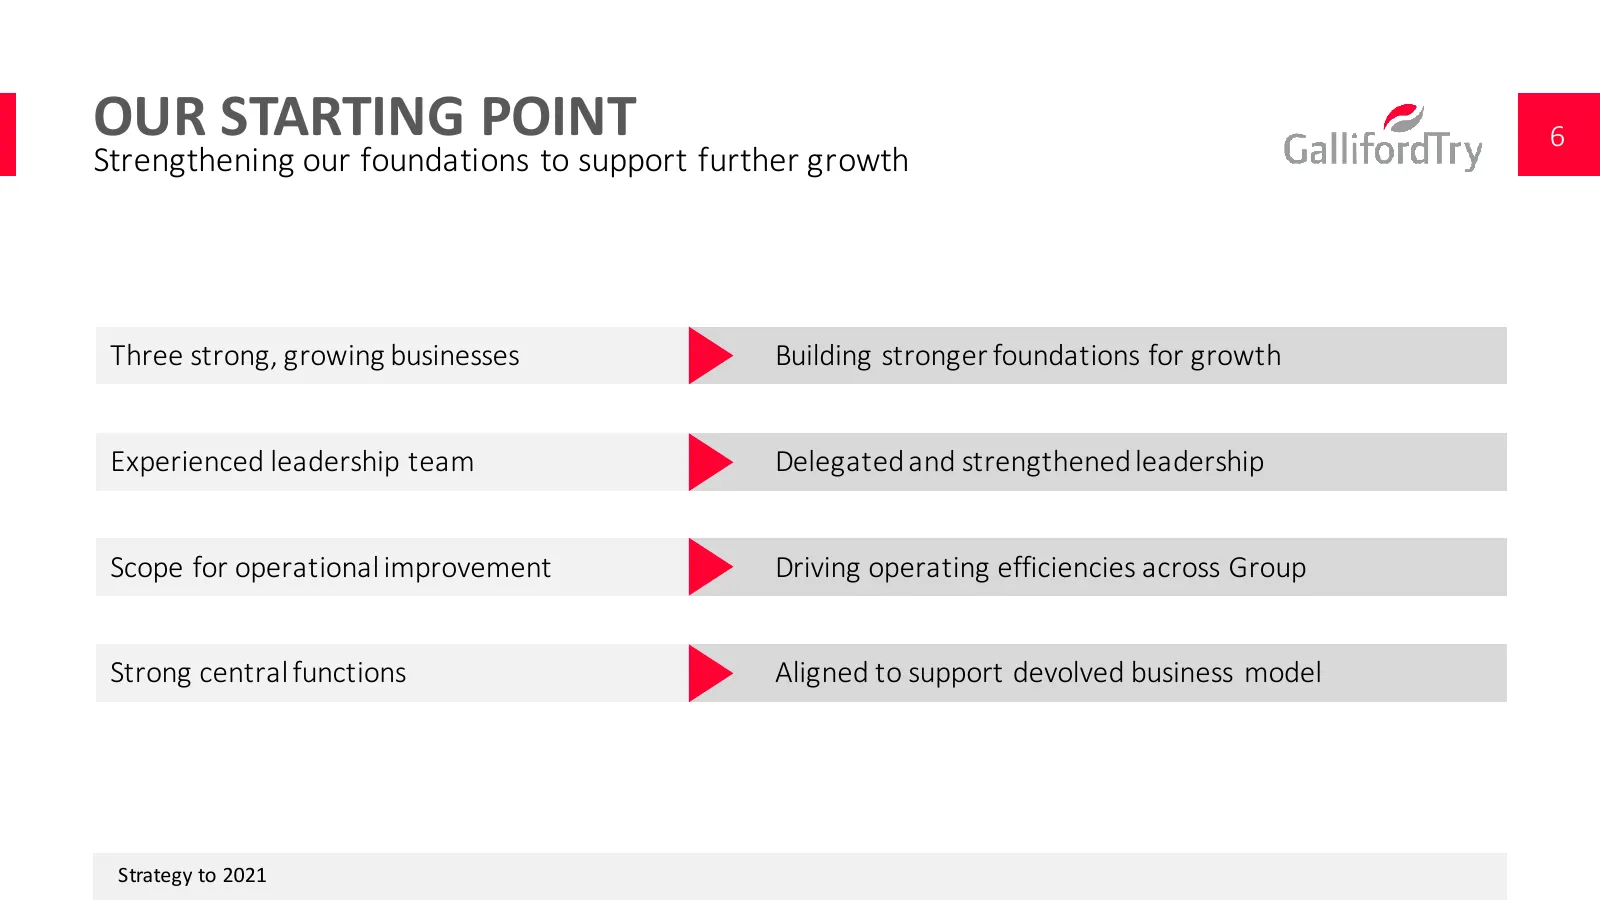
OUR STARTING POINT 6 Strengthening our foundations to support further g rowth Three strong, g rowing businesses Building stronger foundations for g rowth Experienced leadership team Delegated and strengthened leadership Scope for operational improvement Driving operating efficiencies across Group St
Slide 7: Market Drivers
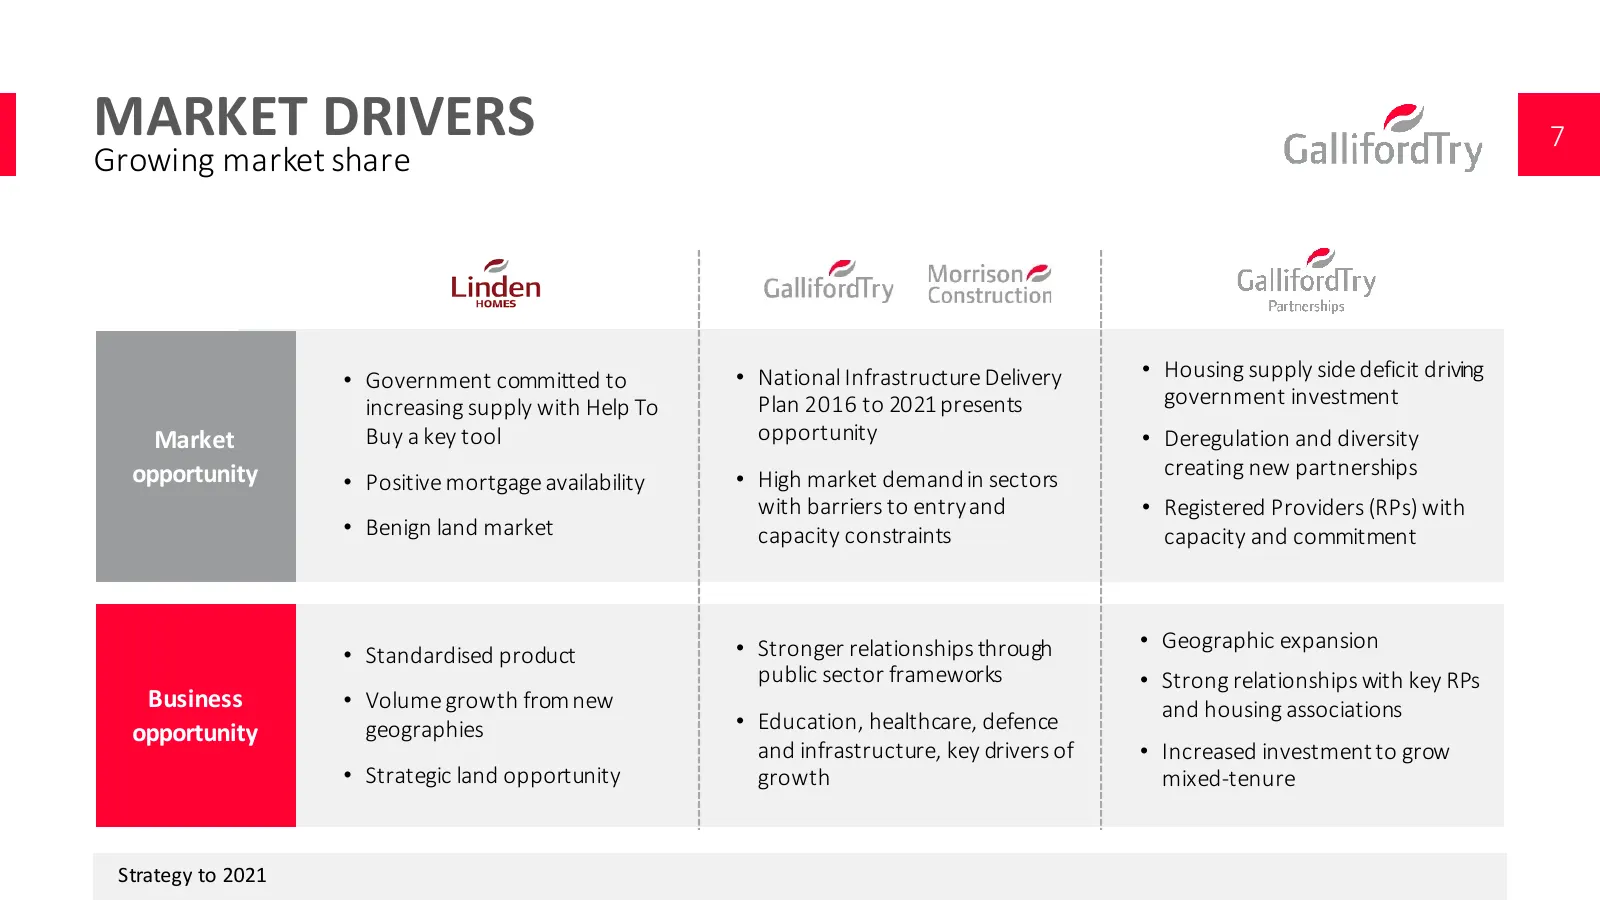
MARKET DRIVERS 7 Growing market share • Government committed t o • National Infrastructure Delivery • Housing supply side deficit driving increasing supply with Help To Plan 2 016 t o 2021 presents government investment Market Buy a key t ool opportunity • Deregulation and diversity opportunity • Hi
Slide 8: Strategy to 2021
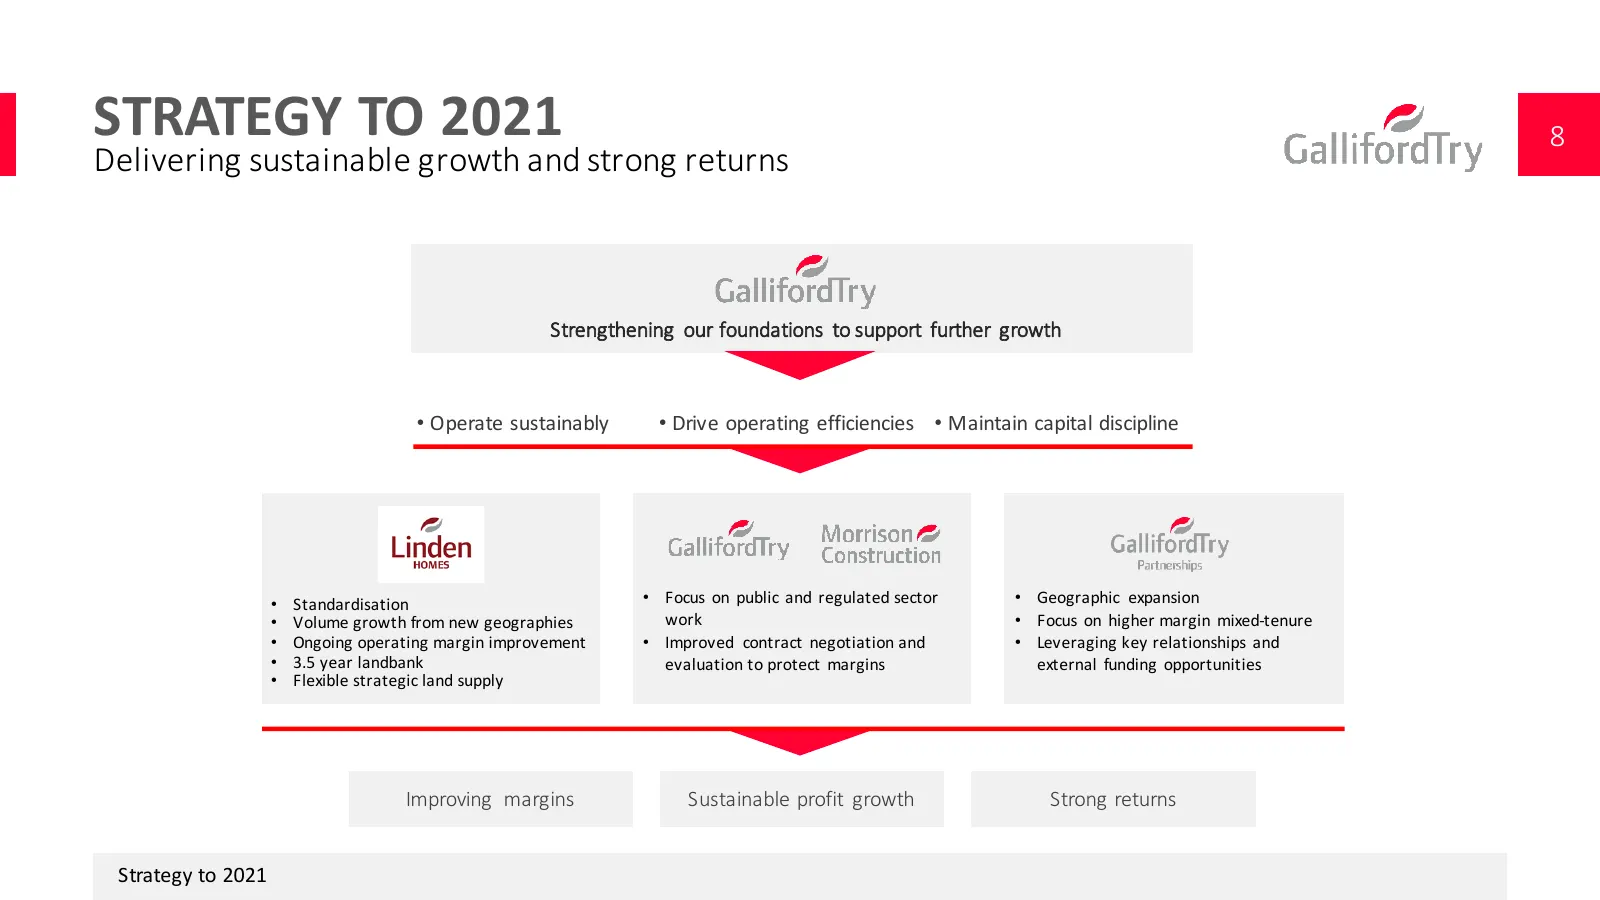
STRATEGY TO 2021 8 Delivering sustainable g rowth and strong r eturns Strengthening our foundations to support further growth • Operate sustainably • Drive operating efficiencies • Maintain capital discipline • Standardisation • Focus on public and regulated sector • Geographic expansion • Volume gr
Slide 9: Linden Homes
LINDEN HOMES Strategy to 2021 Crowdhill Green, H ampshire
Slide 10: Business Overview
BUSINESS OVERVIEW 10 Top 10 housebuilder focused on first-‐time buyer and family homes § Upper quartile Health and Safety performance within housing peer g roup § Committed to high standards of customer service § Proven and experienced senior management § 10 business units with g rowth potentia
Slide 11: Where We Were
WHERE WE WERE 11 Strong business but volume and margin g rowth r estricted by operating structure Multi-‐tiered management structure with slow implementation of change Bespoke design, with complex builds and long lead times Inconsistent branding across the business Inefficient overheads impacting m
Slide 12: Where We Are Now: Product
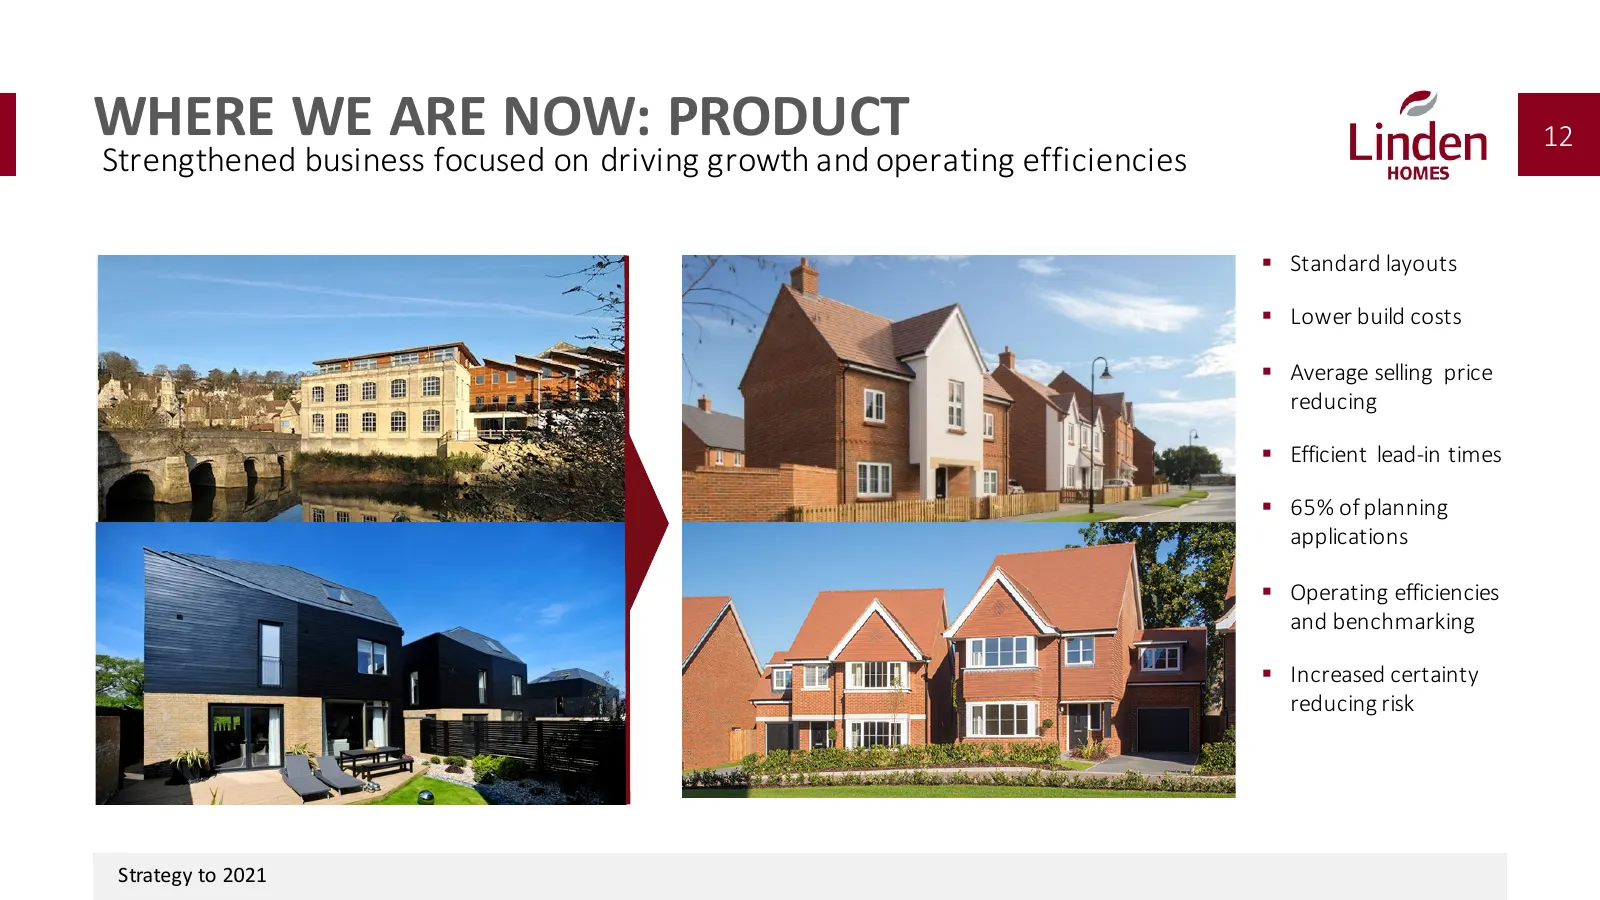
WHERE WE ARE NOW: PRODUCT 12 Strengthened business focused on driving g rowth and operating efficiencies § Standard layouts § Lower build costs § Average selling price reducing § Efficient lead-‐in times Images of LHL product/plotting efficiency § 65% of planning ‘Where we are now – product’ i
Slide 13: Where We Are Now: Structure
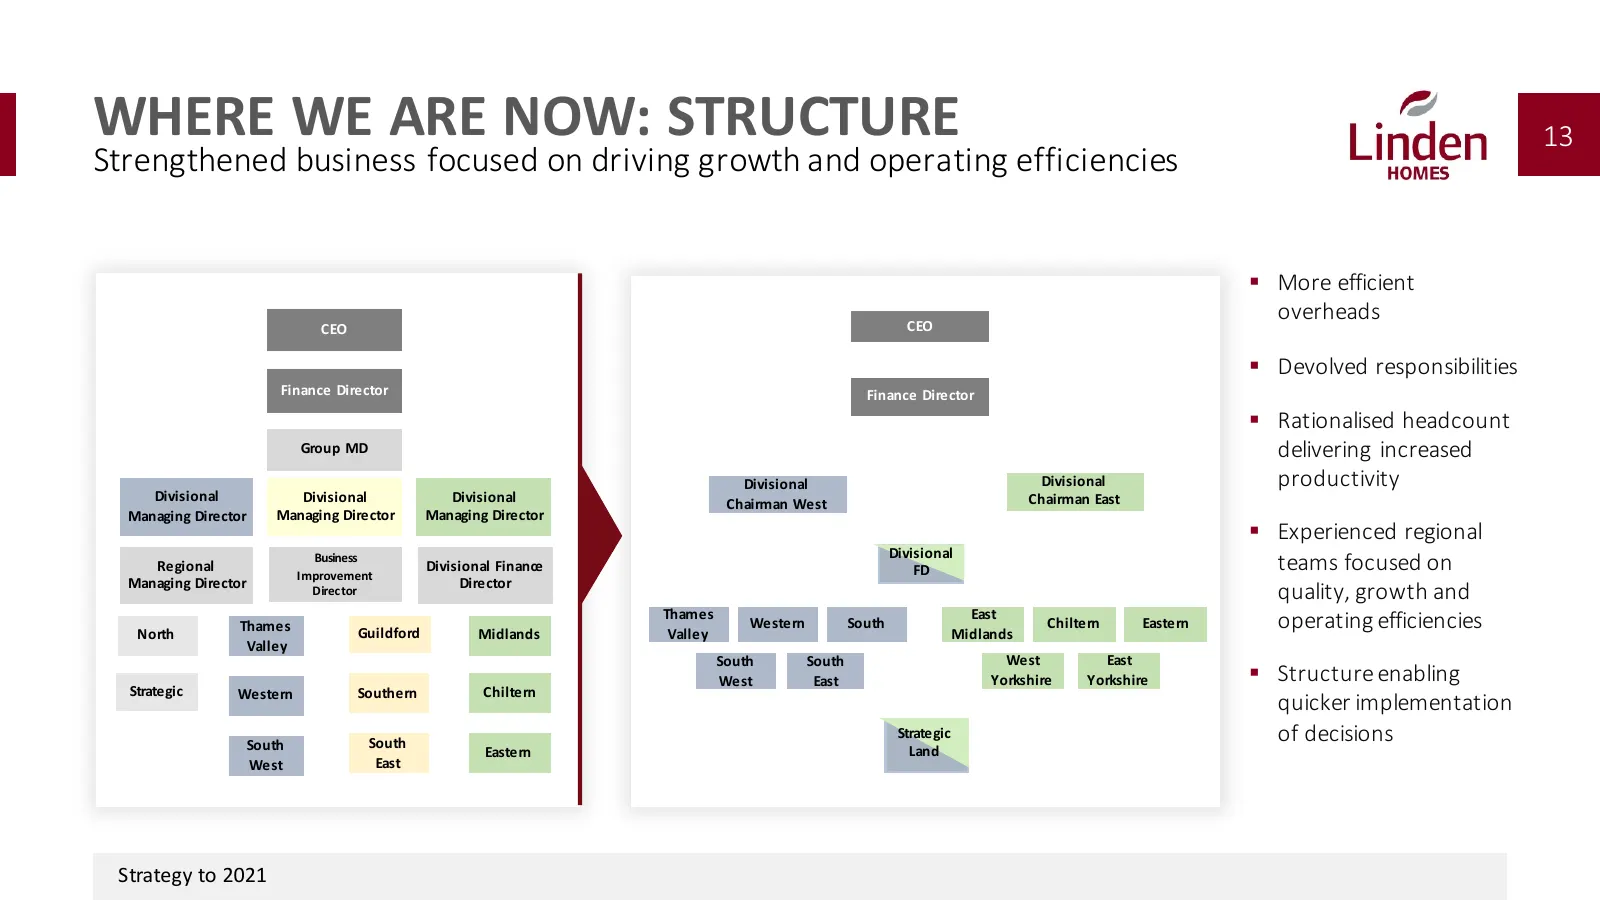
WHERE WE ARE NOW: STRUCTURE 13 Strengthened business focused on driving g rowth and operating efficiencies § More efficient CEO overheads CEO § Devolved responsibilities Finance Director Finance Director § Rationalised headcount Group MD delivering increased Divisional Divisional productivity Div
Slide 14: Where We Are Now: Reach
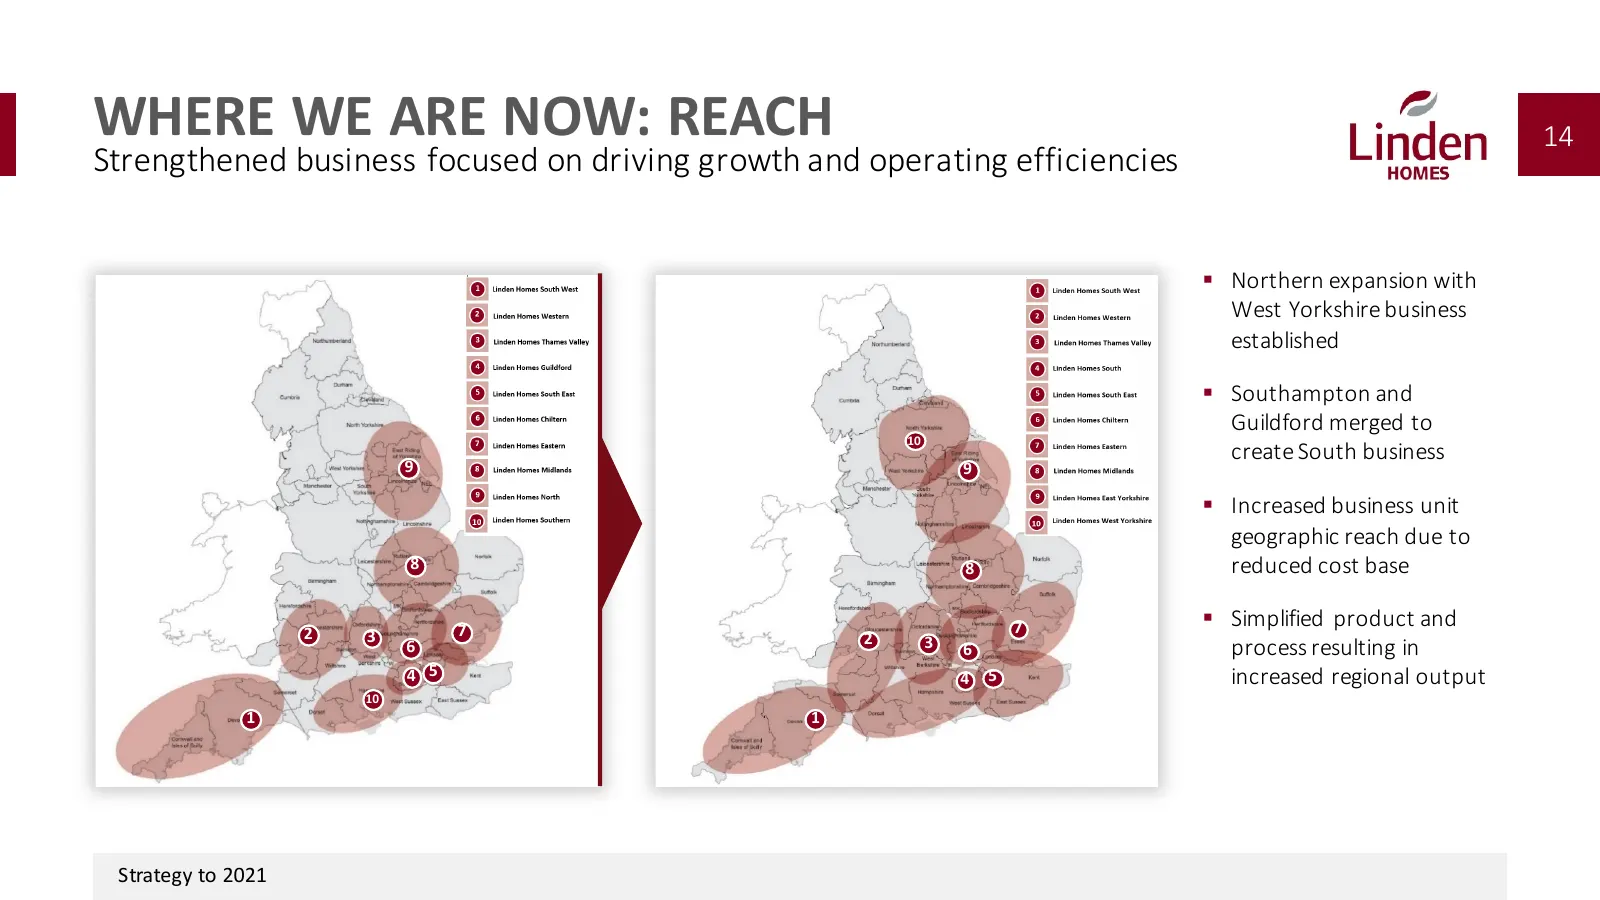
WHERE WE ARE NOW: REACH 14 Strengthened business focused on driving g rowth and operating efficiencies § Northern expansion with West Yorkshire business established § Southampton and Guildford merged to 10 create South business 9 9 § Increased business unit geographic reach due to 8 8 reduced cos
Slide 15: Market Opportunity
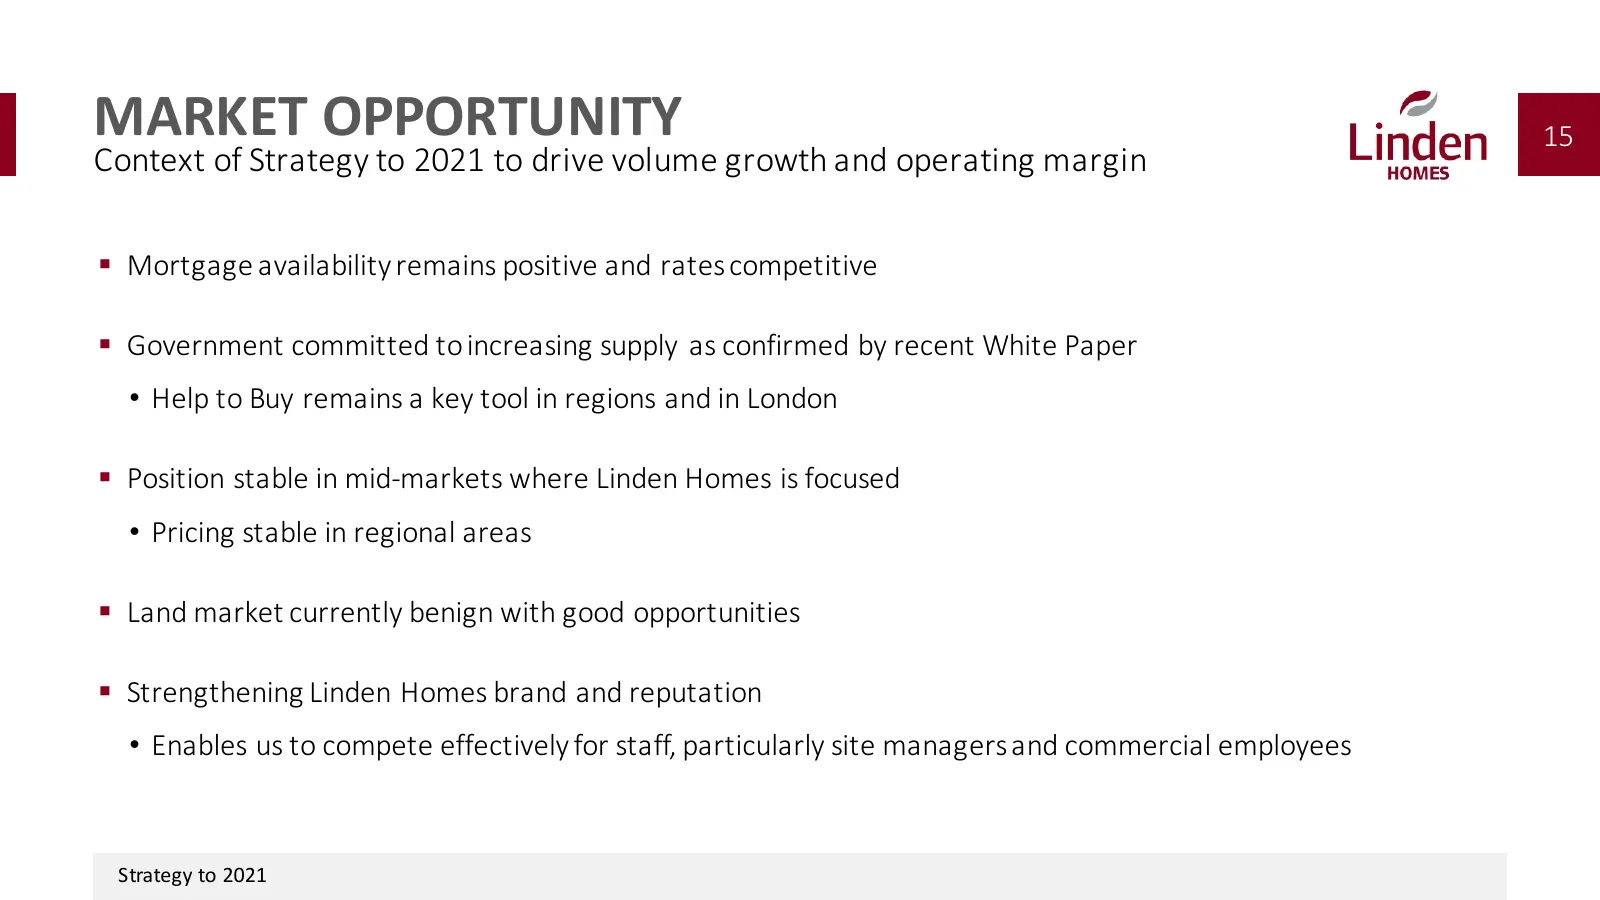
MARKET OPPORTUNITY 15 Context of Strategy to 2021 to drive volume g rowth and operating margin § Mortgage availability remains positive and rates competitive § Government committed to increasing supply as confirmed by recent White Paper • Help to Buy remains a key tool in regions and in London §
Slide 16: Strategy to 2021
STRATEGY TO 2021 16 Three strategic priorities to drive volume g rowth and margin S1 S2 S3 Volume growth Standardisation from existing and Land strategy new geographies Strategy to 2021
Slide 17: S1 Standardisation
S1 STANDARDISATION 17 Strategic priorities to drive volume g rowth and operating margin § Key advantages • Increased build output and quality • Attraction and retention of suppliers, subcontractors and staff • Lower build costs • Shorter lead times and standardisation of build programmes • Improved
Slide 18: S1 Standardisation
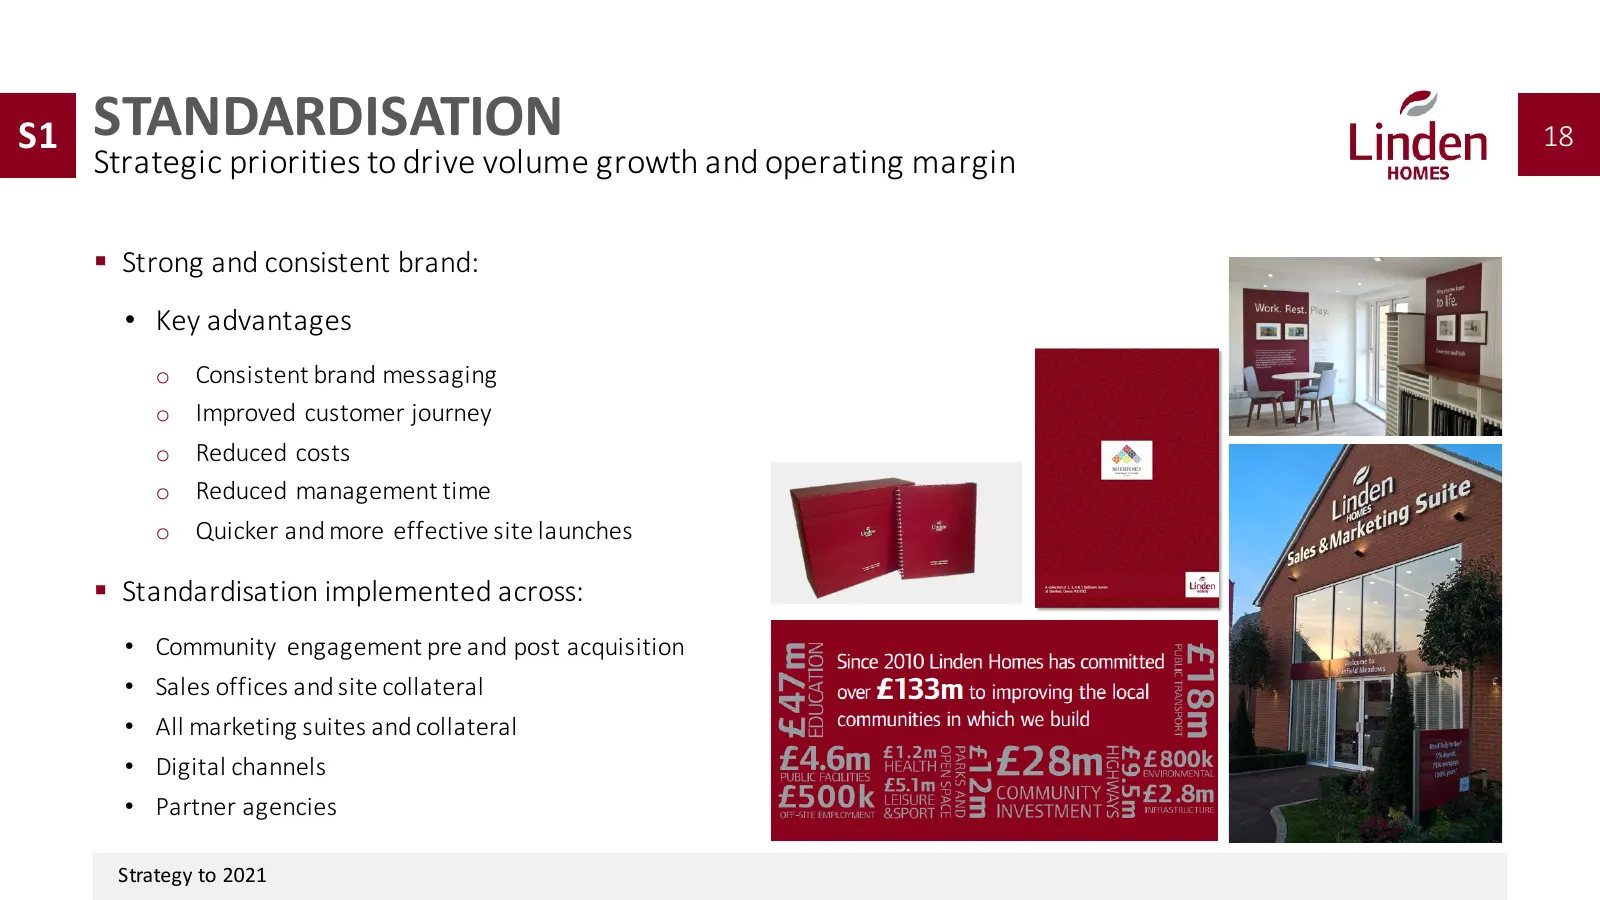
S1 STANDARDISATION 18 Strategic priorities to drive volume g rowth and operating margin § Strong and consistent brand: • Key advantages o Consistent brand messaging o Improved customer journey o Reduced costs o Reduced management time o Quicker and more effective site launches § Standardisation im
Slide 19: Strategy to 2021
STRATEGY TO 2021 19 Three strategic priorities to drive volume g rowth and margins S1 S2 S3 Volume growth Standardisation from existing and Land strategy new geographies Strategy to 2021
Slide 20: S2 Volume Growth
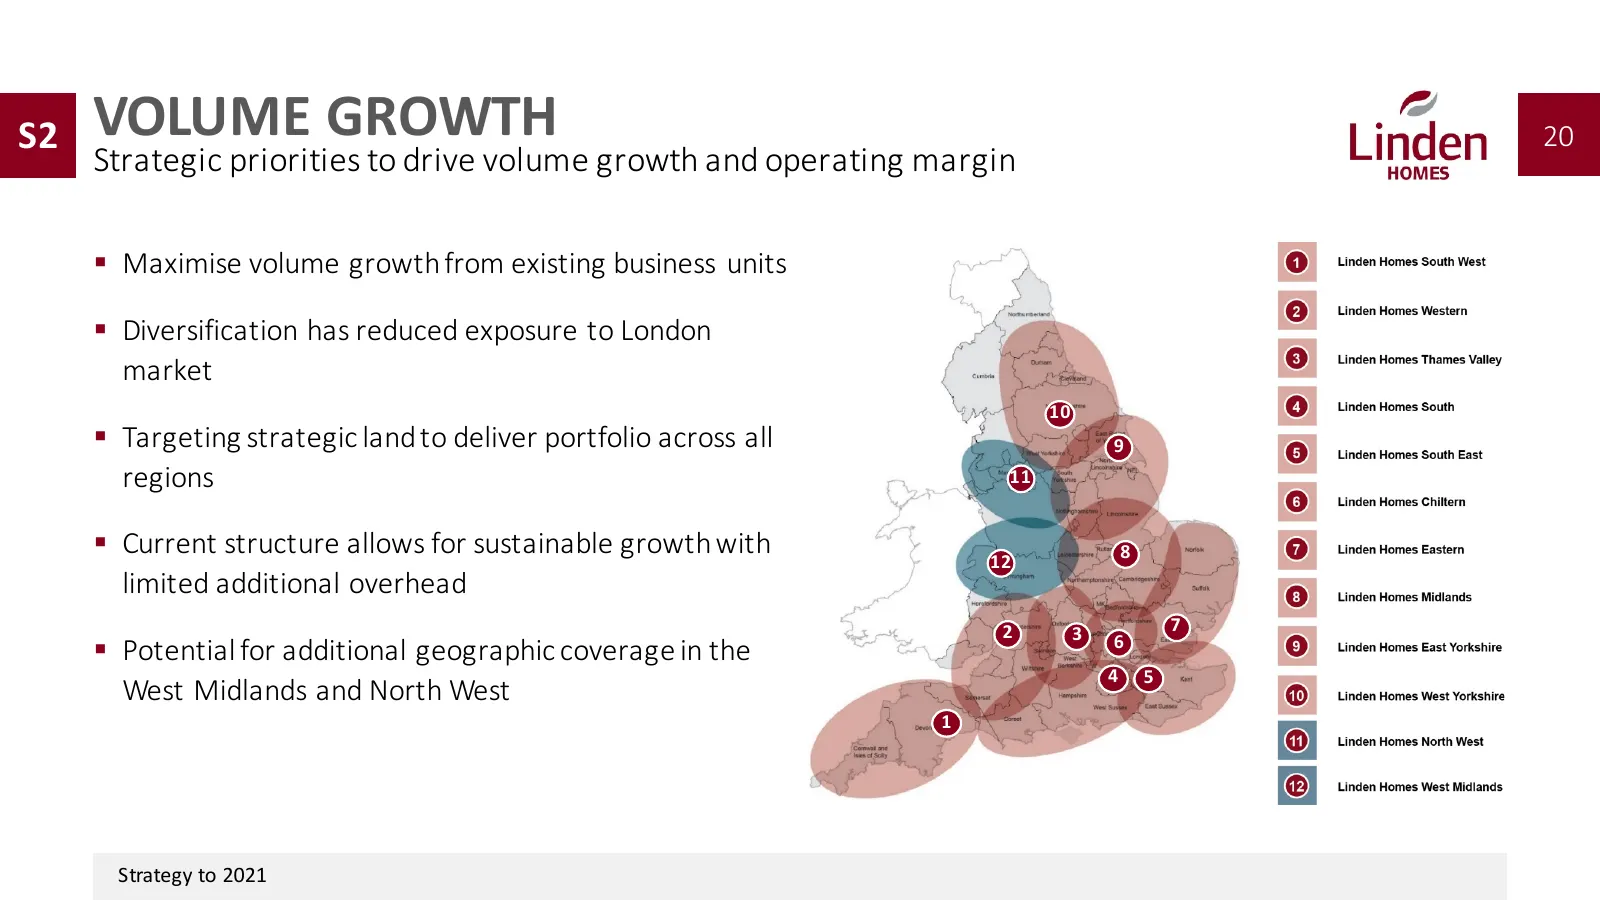
S2 VOLUME GROWTH 20 Strategic priorities to drive volume g rowth and operating margin § Maximise volume growth from existing business units § Diversification has reduced exposure to London market 10 § Targeting strategic land to deliver portfolio across all 9 regions 11 § Current structure allow
Slide 21: Strategy to 2021
STRATEGY TO 2021 21 Three strategic priorities to drive volume g rowth and margin S1 S2 S3 Volume growth Standardisation from existing and Land strategy new geographies Strategy to 2021
Slide 22: S3 Land Strategy
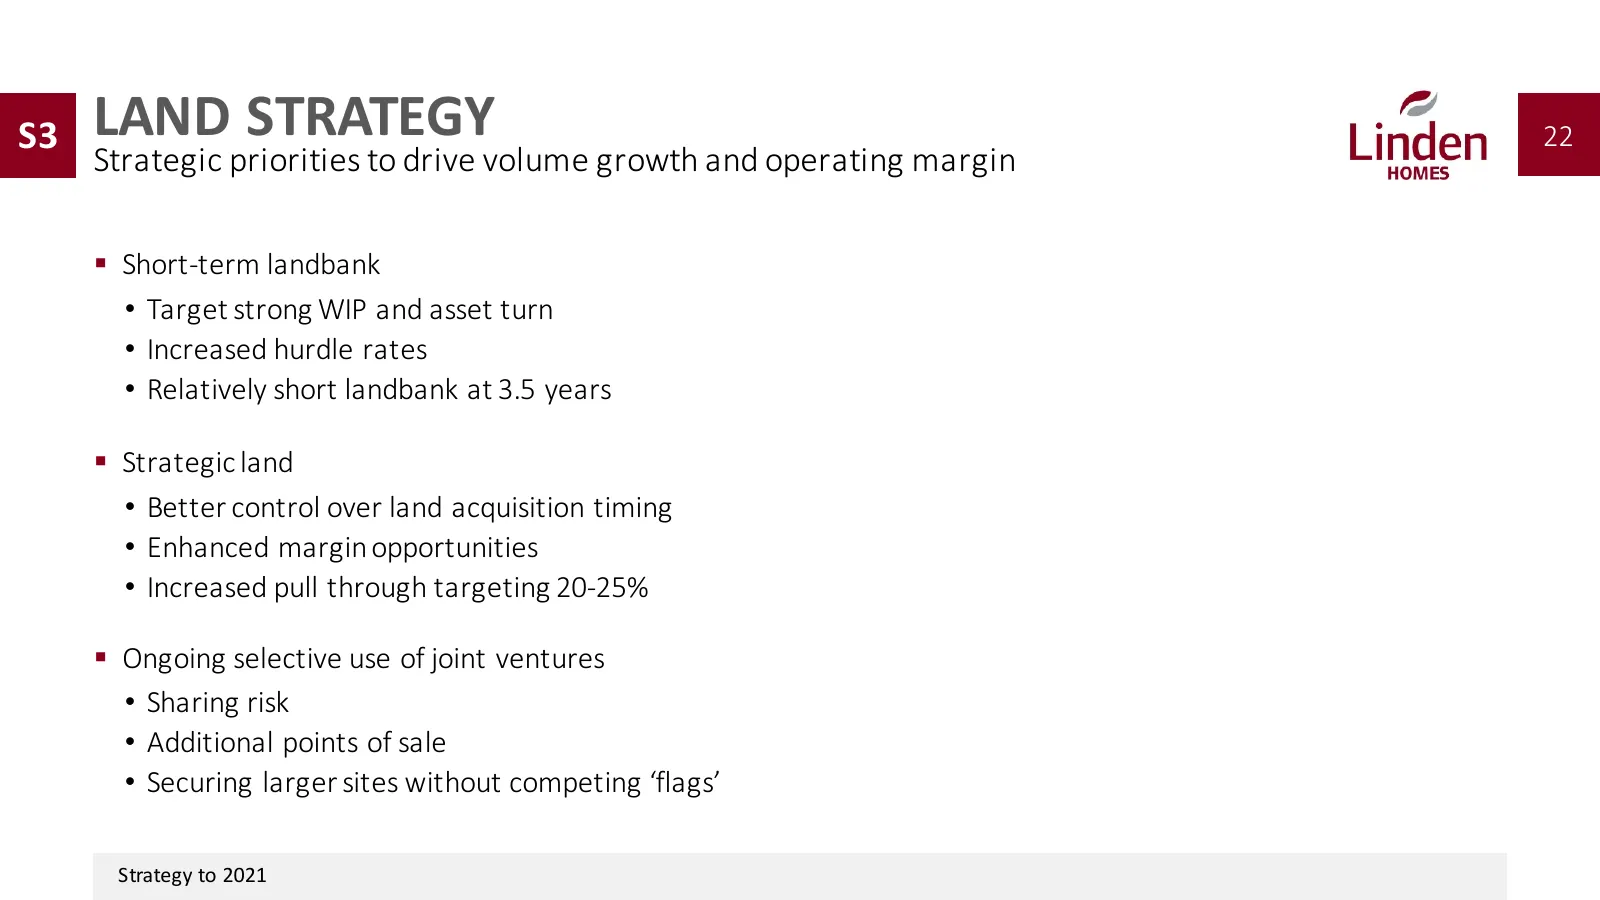
S3 LAND STRATEGY 22 Strategic priorities to drive volume g rowth and operating margin § Short-‐term landbank • Target strong WIP and asset turn • Increased hurdle rates • Relatively short landbank at 3.5 years § Strategic land • Better control over land acquisition timing • Enhanced margin opport
Slide 23: Financial Targets
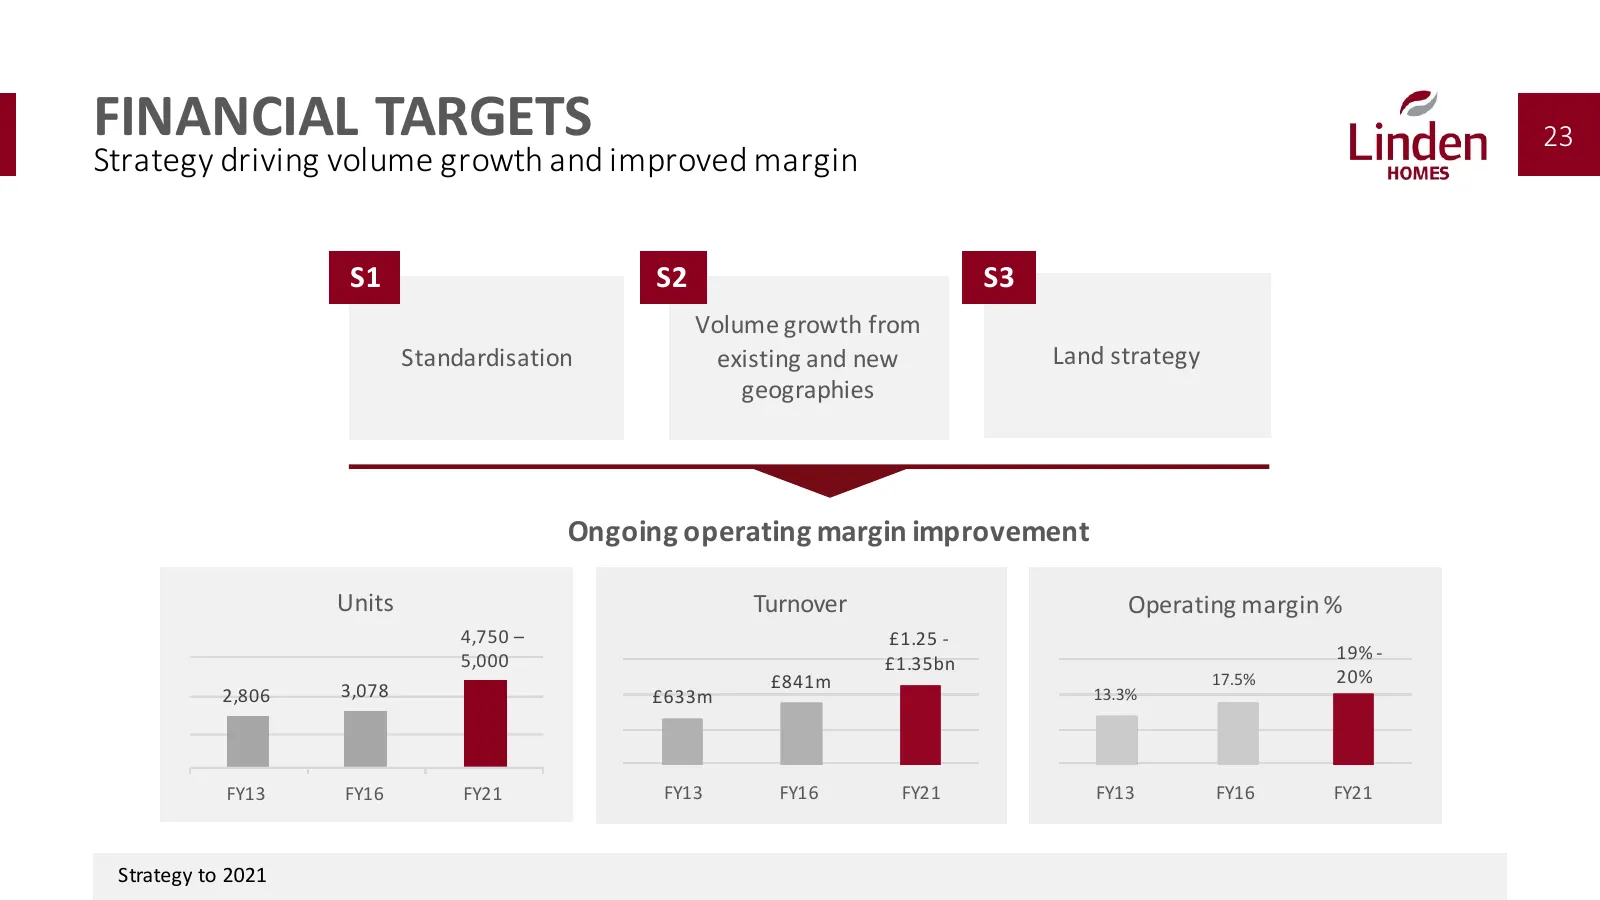
FINANCIAL TARGETS 23 Strategy driving volume g rowth and improved margin S1 S2 S3 Volume growth from Standardisation existing and new Land strategy geographies Ongoing o perating margin improvement Units Turnover Operating m argin % 4,750 – £1.25 -‐ 5,000 19% -‐ £1.35bn £841m 17.5% 20% 2,806 3,078
Slide 24: Summary
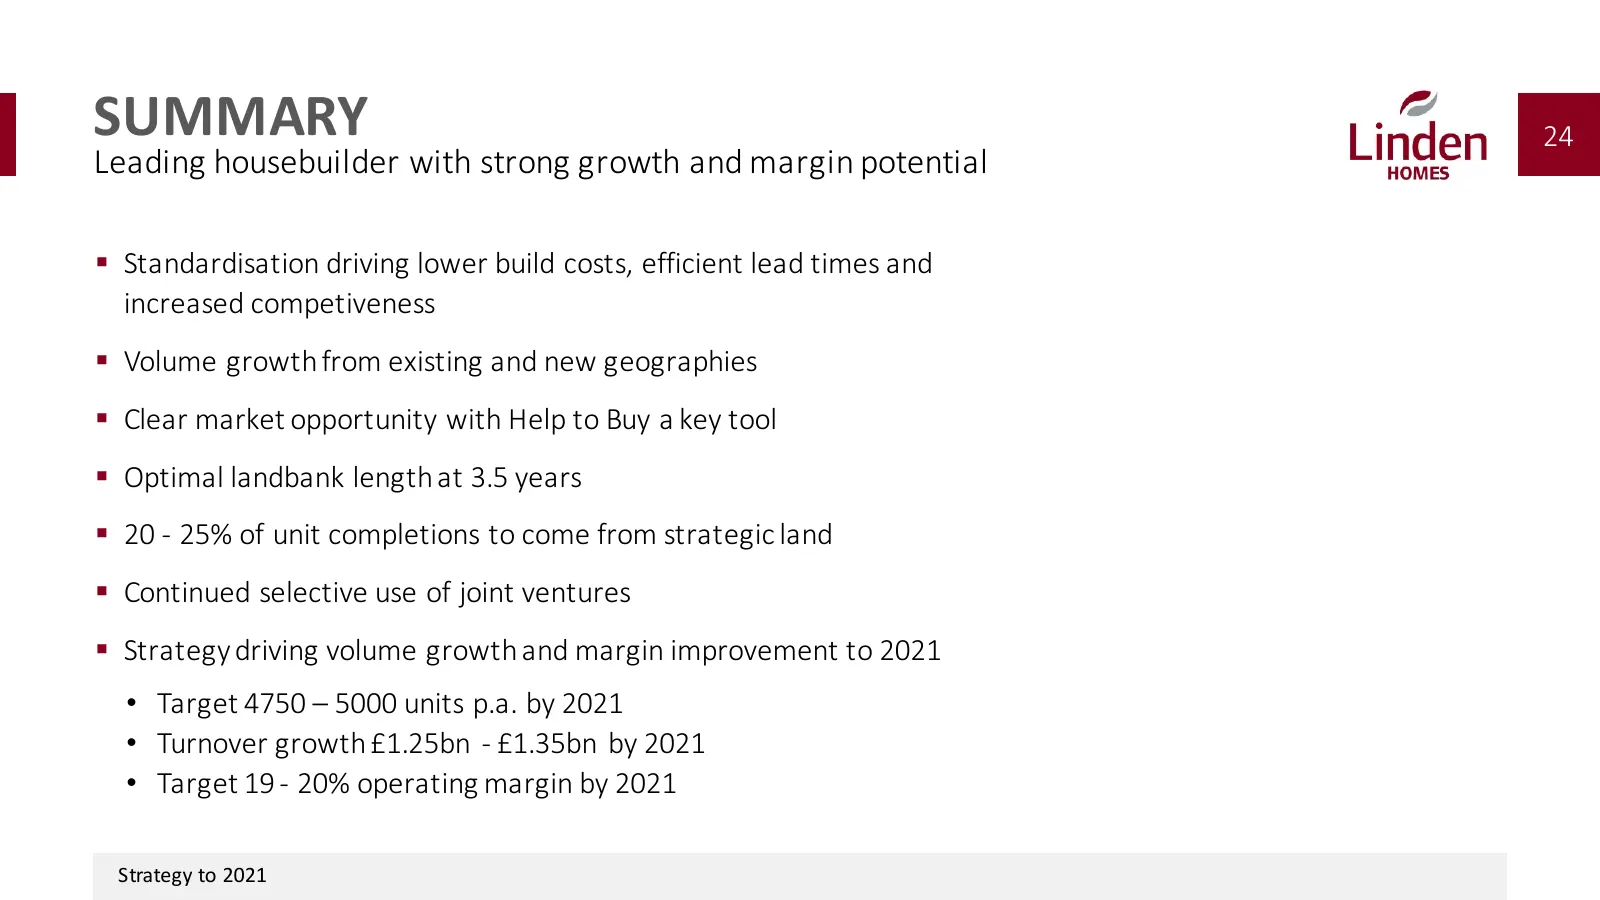
SUMMARY 24 Leading housebuilder with strong g rowth and margin potential § Standardisation driving lower build costs, efficient lead times and increased competiveness § Volume growth from existing and new g eographies § Clear market opportunity with Help to Buy a key tool § Optimal landbank leng
Slide 25: Q&A
Q&A Strategy to 2021 Wilshere Park, H ertfordshire Strategy to 2021
Slide 26: Construction
CONSTRUCTION Strategy to 2021 Queensferry Crossing, Firth o f Forth
Slide 27: Business Overview
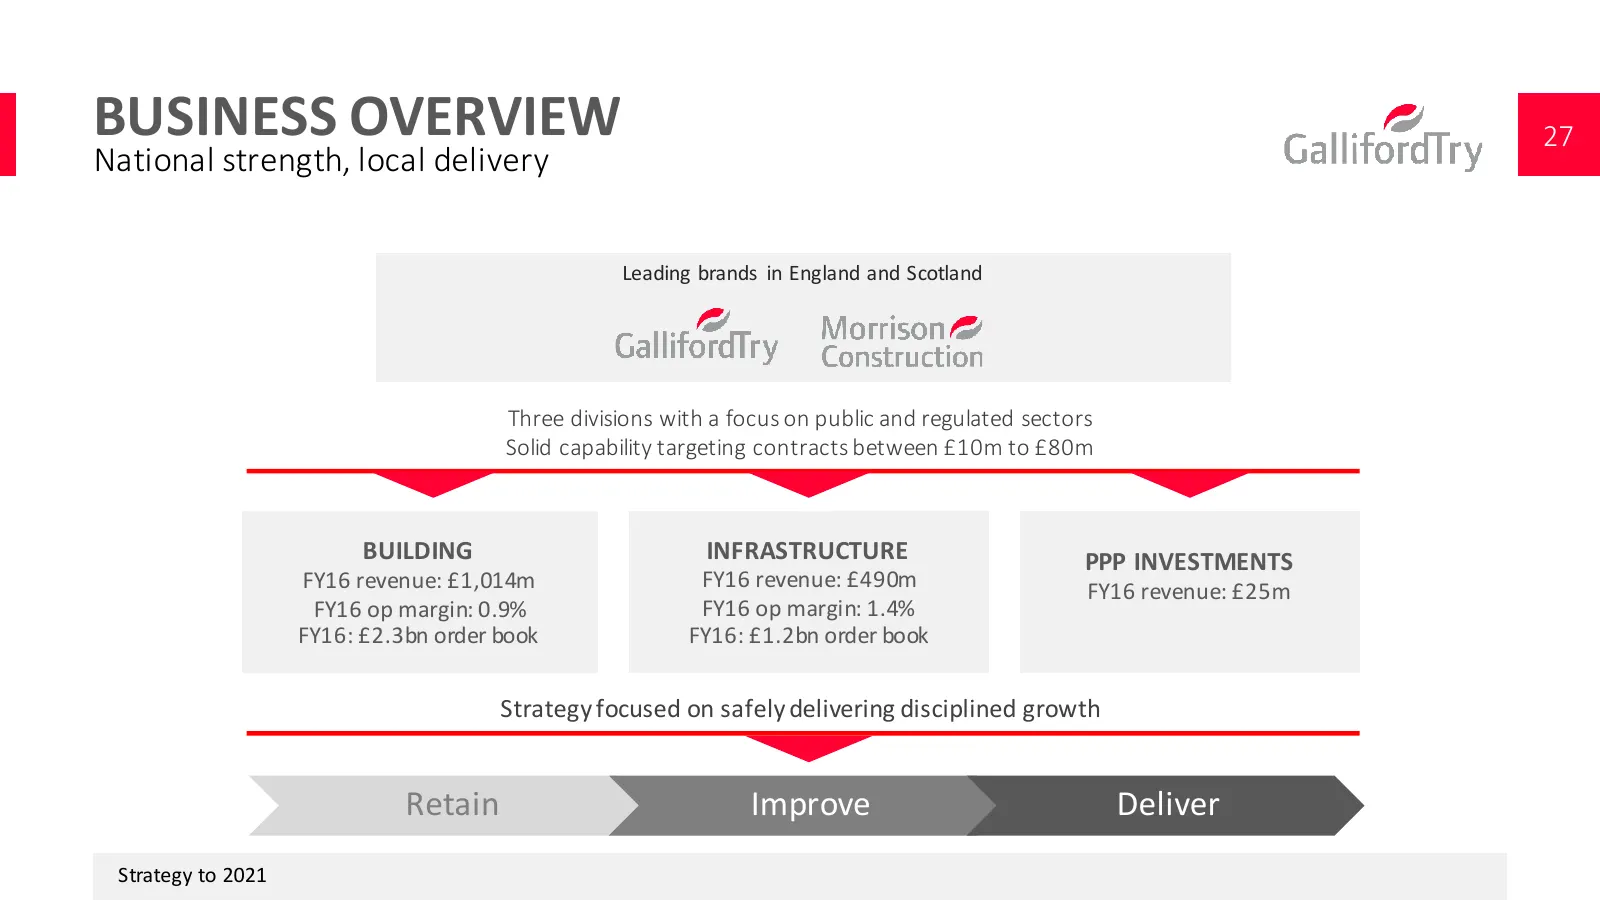
BUSINESS OVERVIEW 27 National strength, local delivery Leading brands in England and Scotland Three divisions with a focus on public and regulated sectors Solid capability t argeting contracts between £ 10m t o £ 80m BUILDING INFRASTRUCTURE PPP INVESTMENTS FY16 revenue: £ 1,014m FY16 revenue: £ 490m
Slide 28: Where We Were
WHERE WE WERE 28 A solid business with scope for operational improvement Skilled employees with a reputation f or quality and performance Legacy contracts impacting margin Business covering multiple sectors and f rameworks Private sector contracts delivering unpredictable and often low returns Syste
Slide 29: Where We Are Now
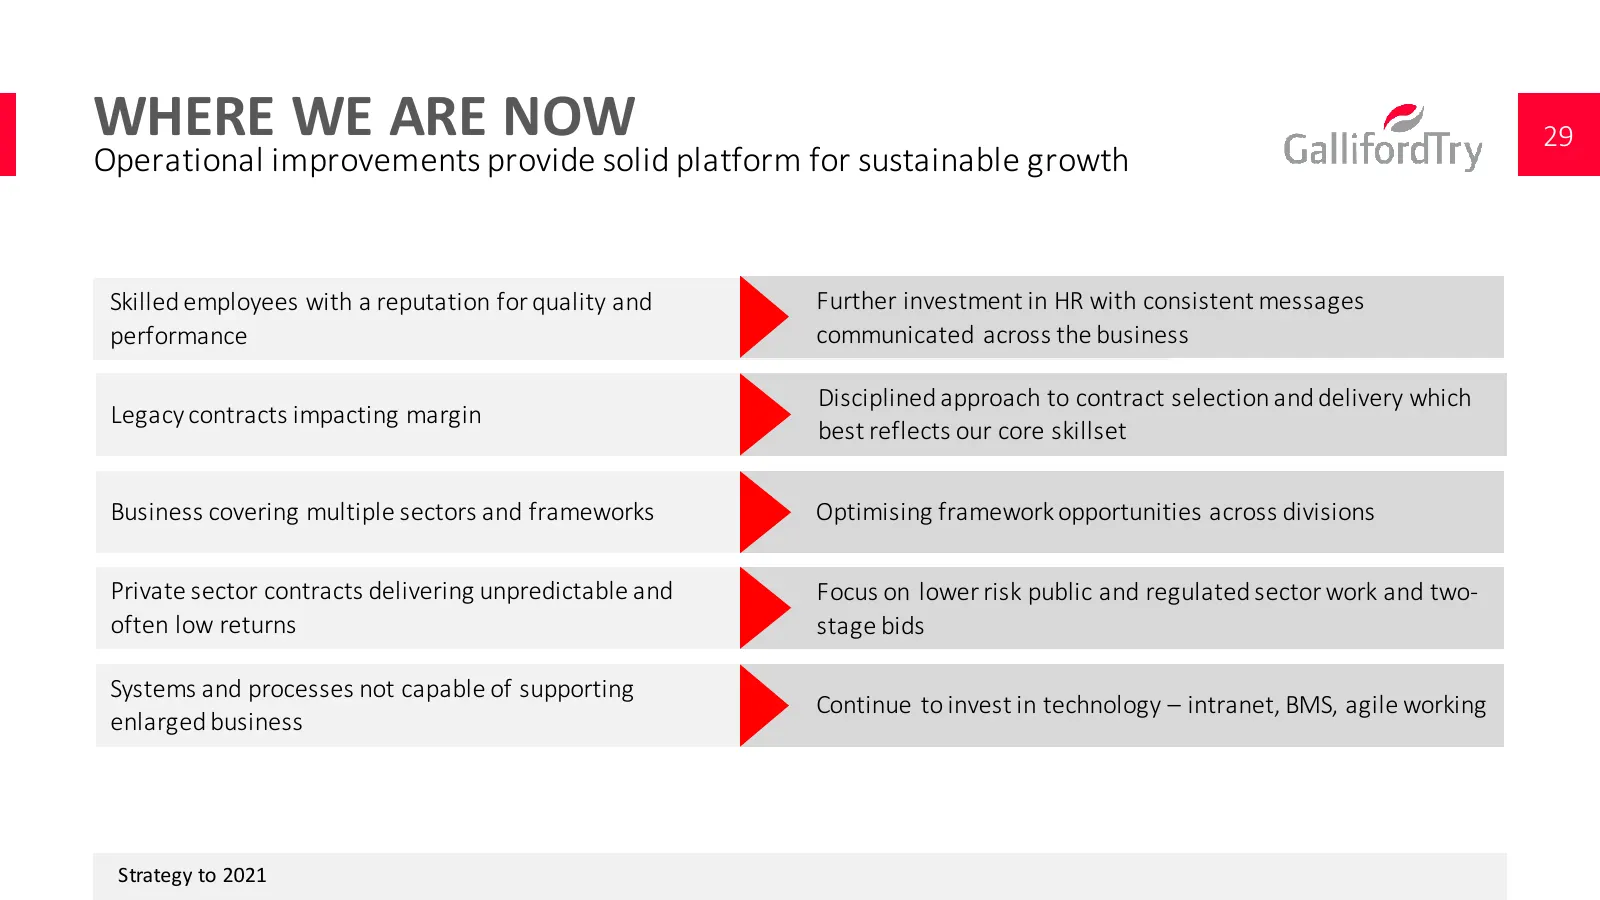
WHERE WE ARE NOW 29 Operational improvements provide solid platform for sustainable g rowth Skilled employees with a reputation f or quality and Further investment in HR with consistent messages performance communicated across the business Disciplined approach to contract selection and delivery whic
Slide 30: Market Opportunity
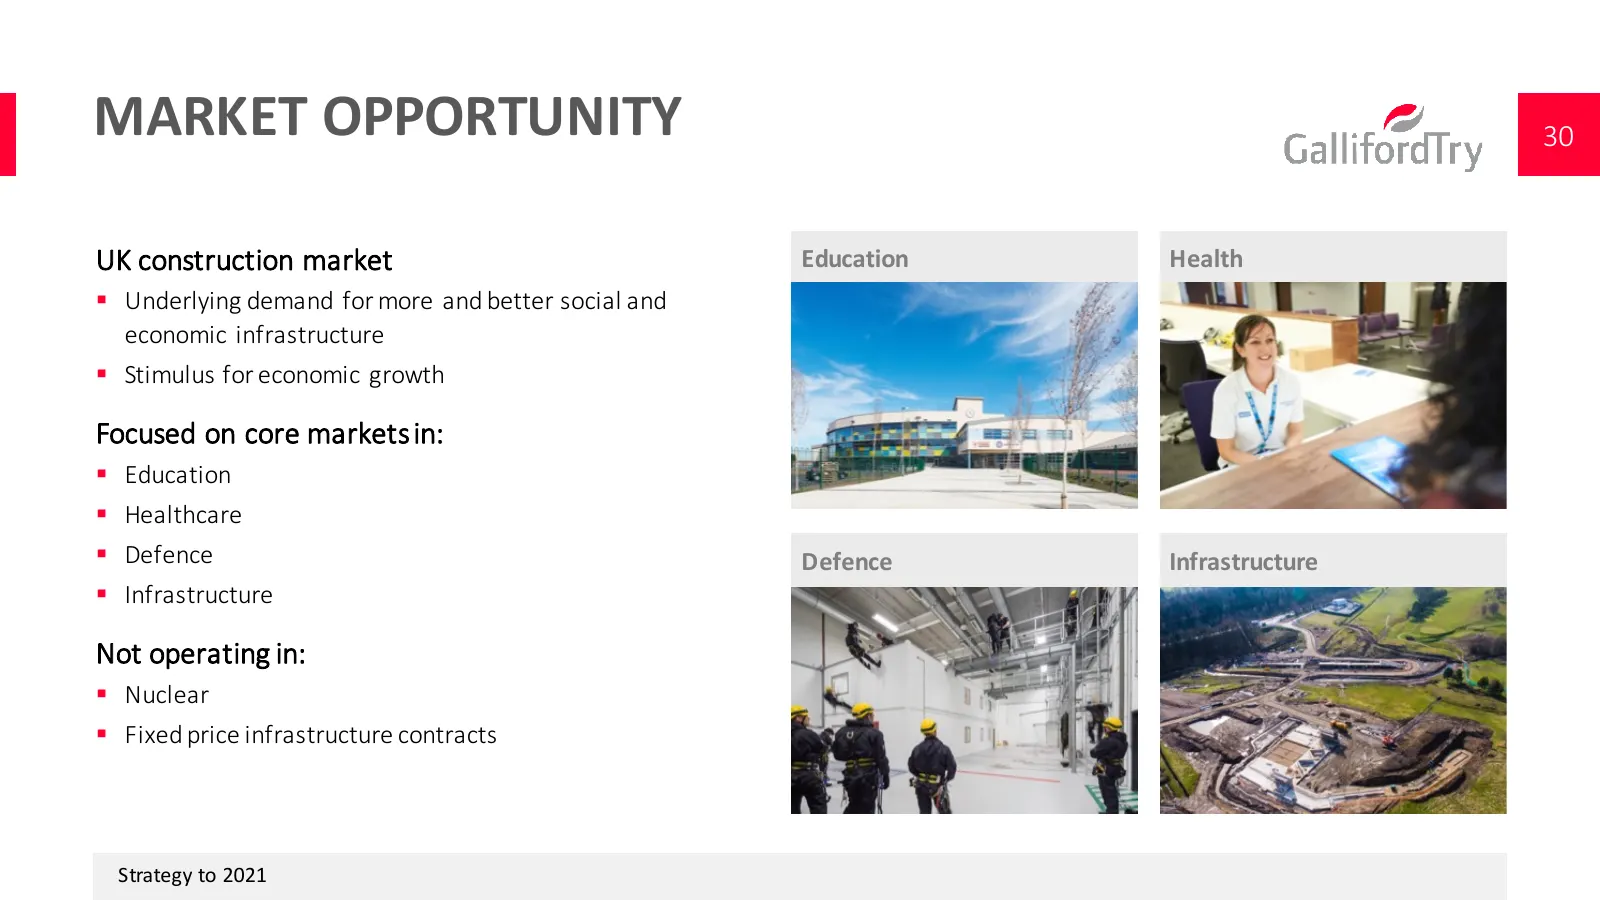
MARKET OPPORTUNITY 30 UK construction market Education Health § Underlying demand for more and better social and economic infrastructure § Stimulus f or economic growth Focused on core markets in: § Education § Healthcare § Defence Defence Infrastructure § Infrastructure Not operating in: § N
Slide 31: Building
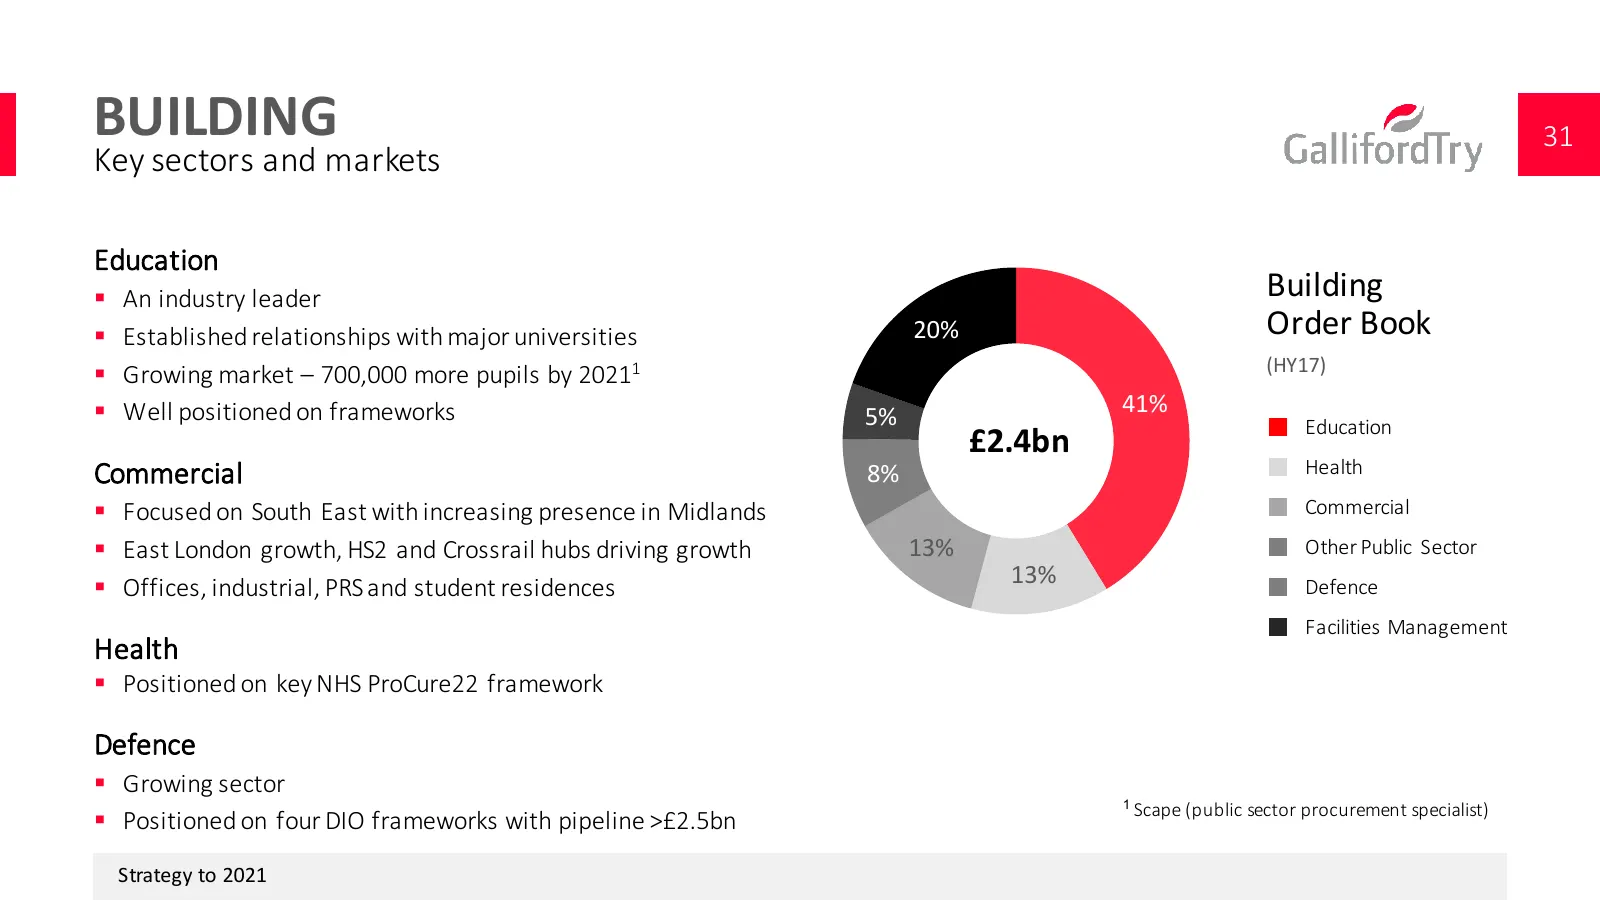
BUILDING 31 Key sectors and markets Education § An industry leader Building § Established relationships with major universities 20% Order Book § Growing market – 700,000 more pupils by 20211 (HY17) § Well positioned on f rameworks 5% 41% Education £2.4bn Commercial 8% Health § Focused on South
Slide 32: Infrastructure
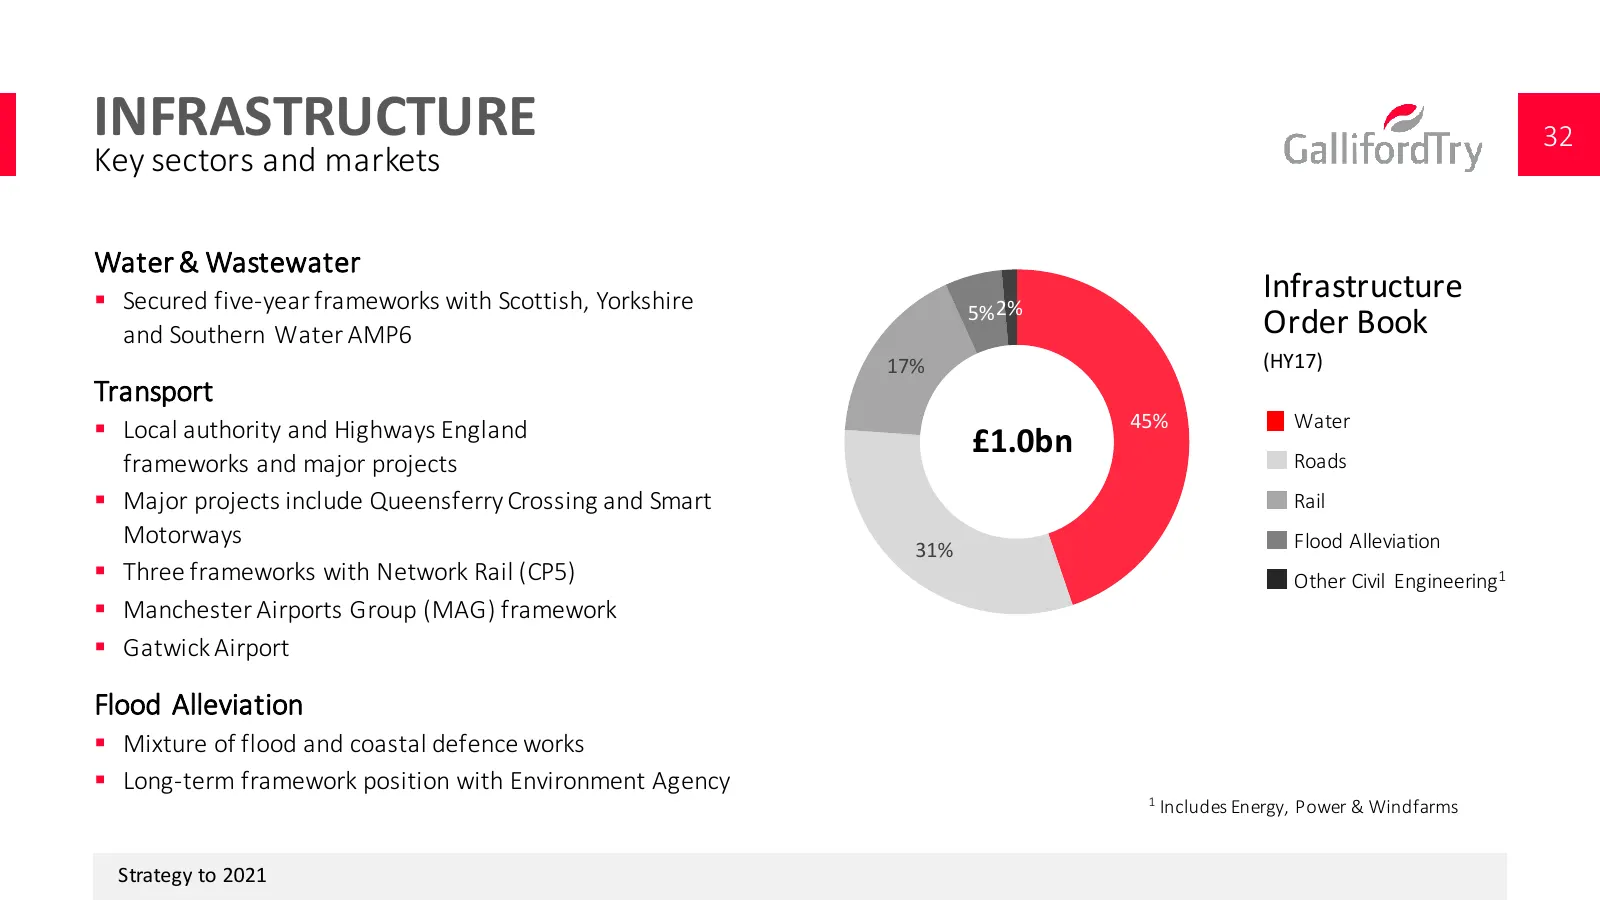
INFRASTRUCTURE 32 Key sectors and markets Water & Wastewater § Secured f ive-‐year f rameworks with Scottish, Yorkshire Infrastructure 5% 2% and Southern Water AMP6 Order Book 17% (HY17) Transport § Local authority and Highways England 45% Water £1.0bn frameworks and major projects Roads § Major
Slide 33: Strategy to 2021
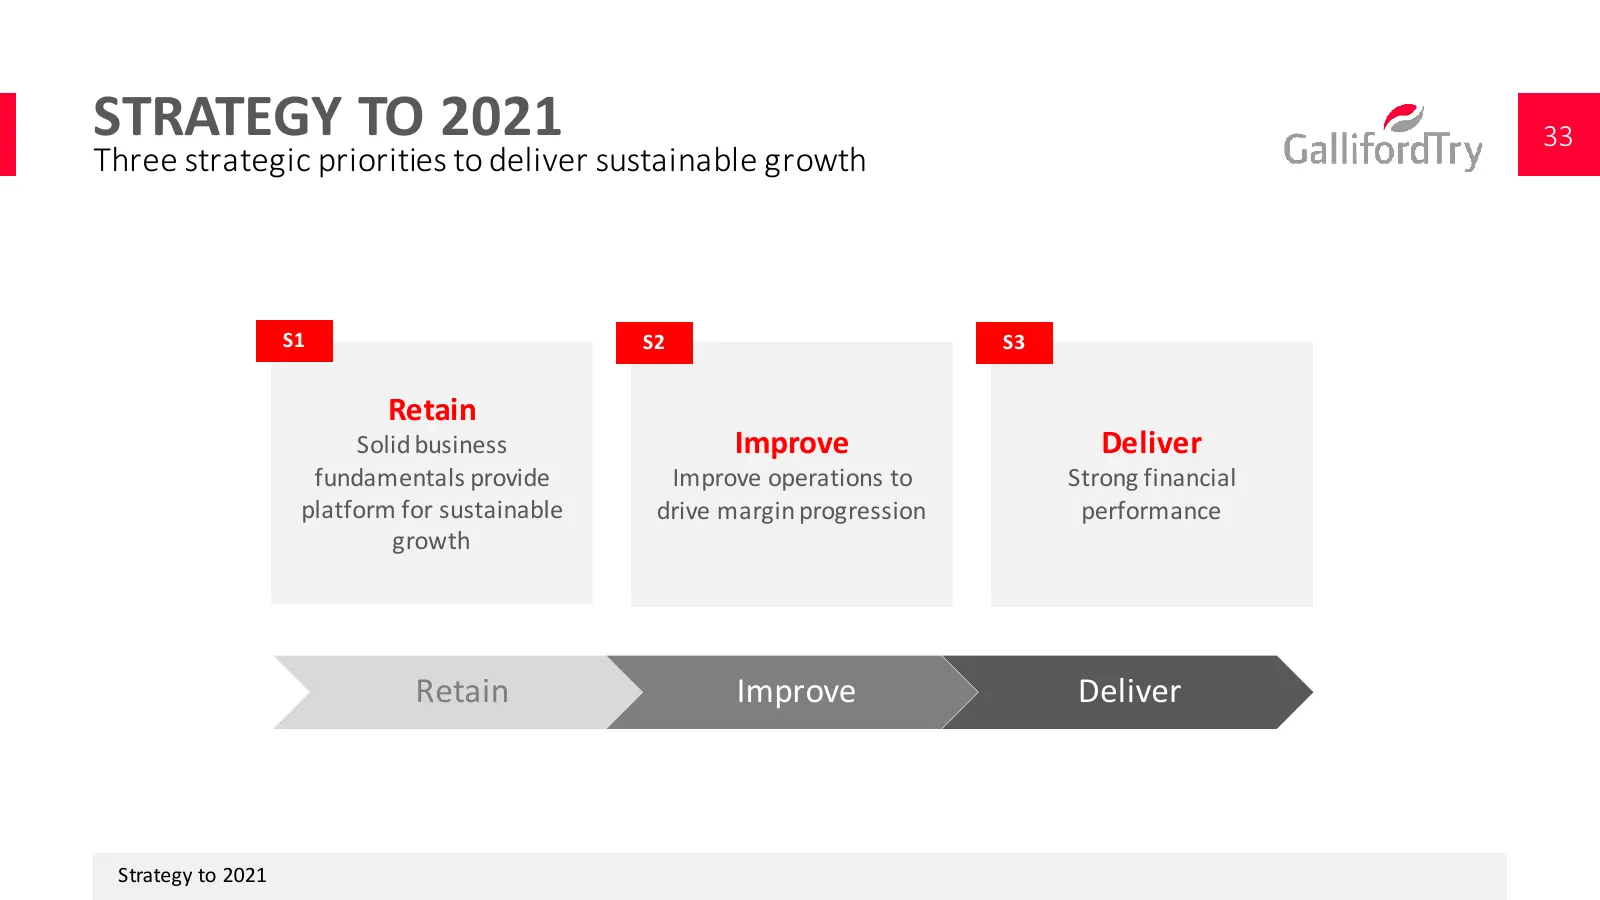
STRATEGY TO 2021 33 Three strategic priorities to deliver sustainable g rowth S1 S2 S3 Retain Solid business Improve Deliver fundamentals provide Improve operations to Strong financial platform for sustainable drive m argin progression performance growth Retain Improve Deliver Strategy to 2021
Slide 34: S1 Retain
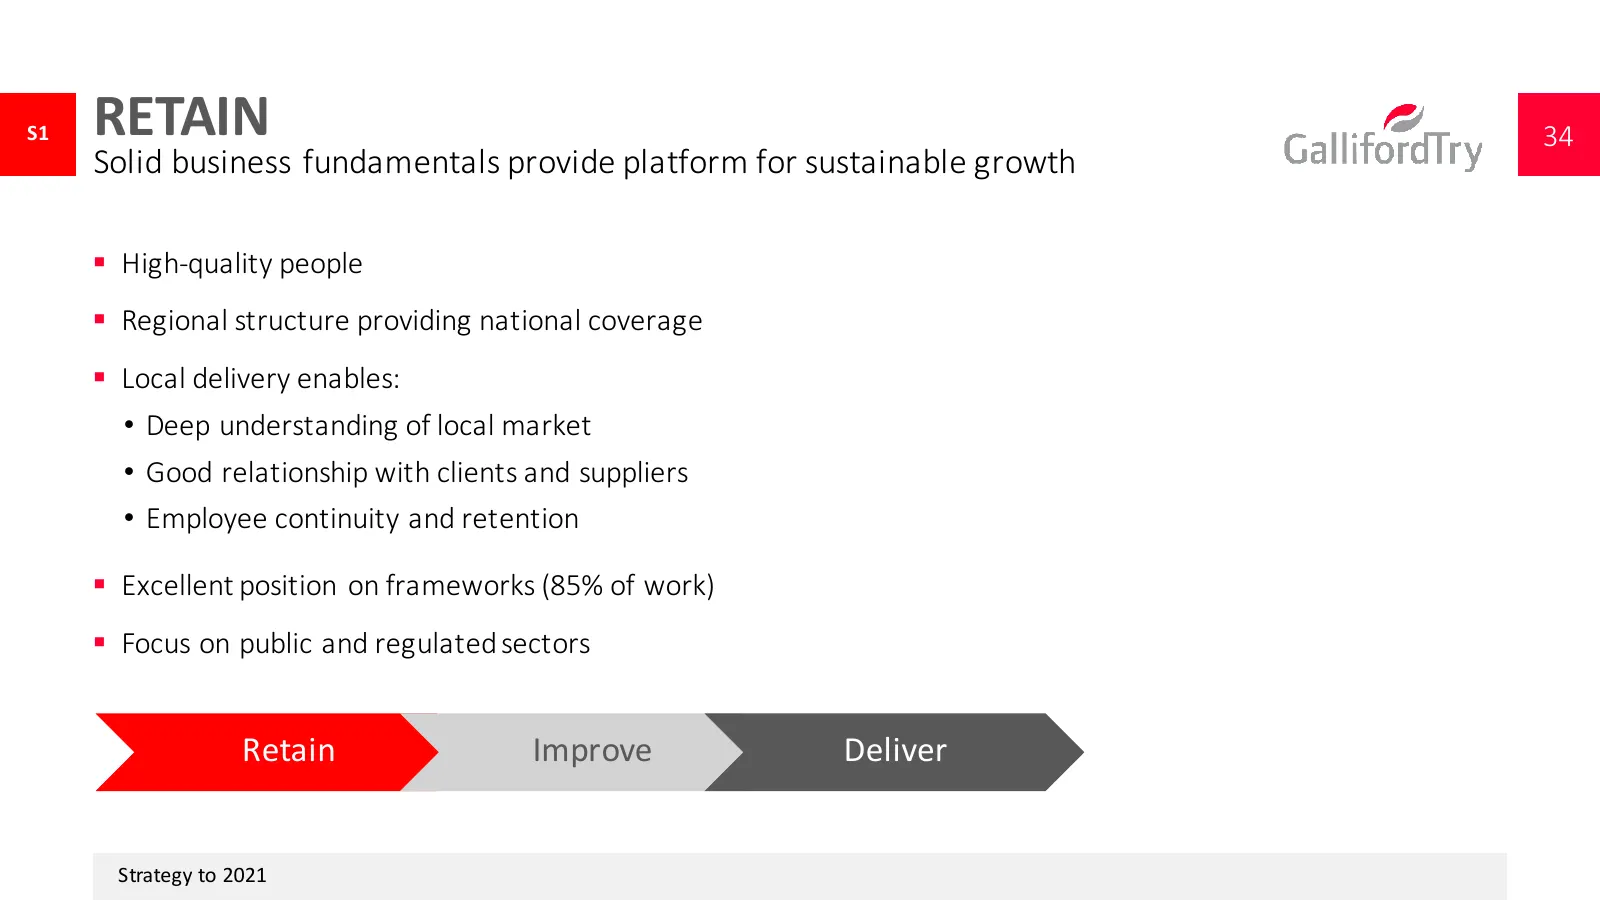
S1 RETAIN 34 Solid business fundamentals provide platform for sustainable g rowth § High-‐quality people § Regional structure providing national coverage § Local delivery enables: • Deep understanding of local market • Good relationship with clients and suppliers • Employee continuity and retent
Slide 35: S2 Improve
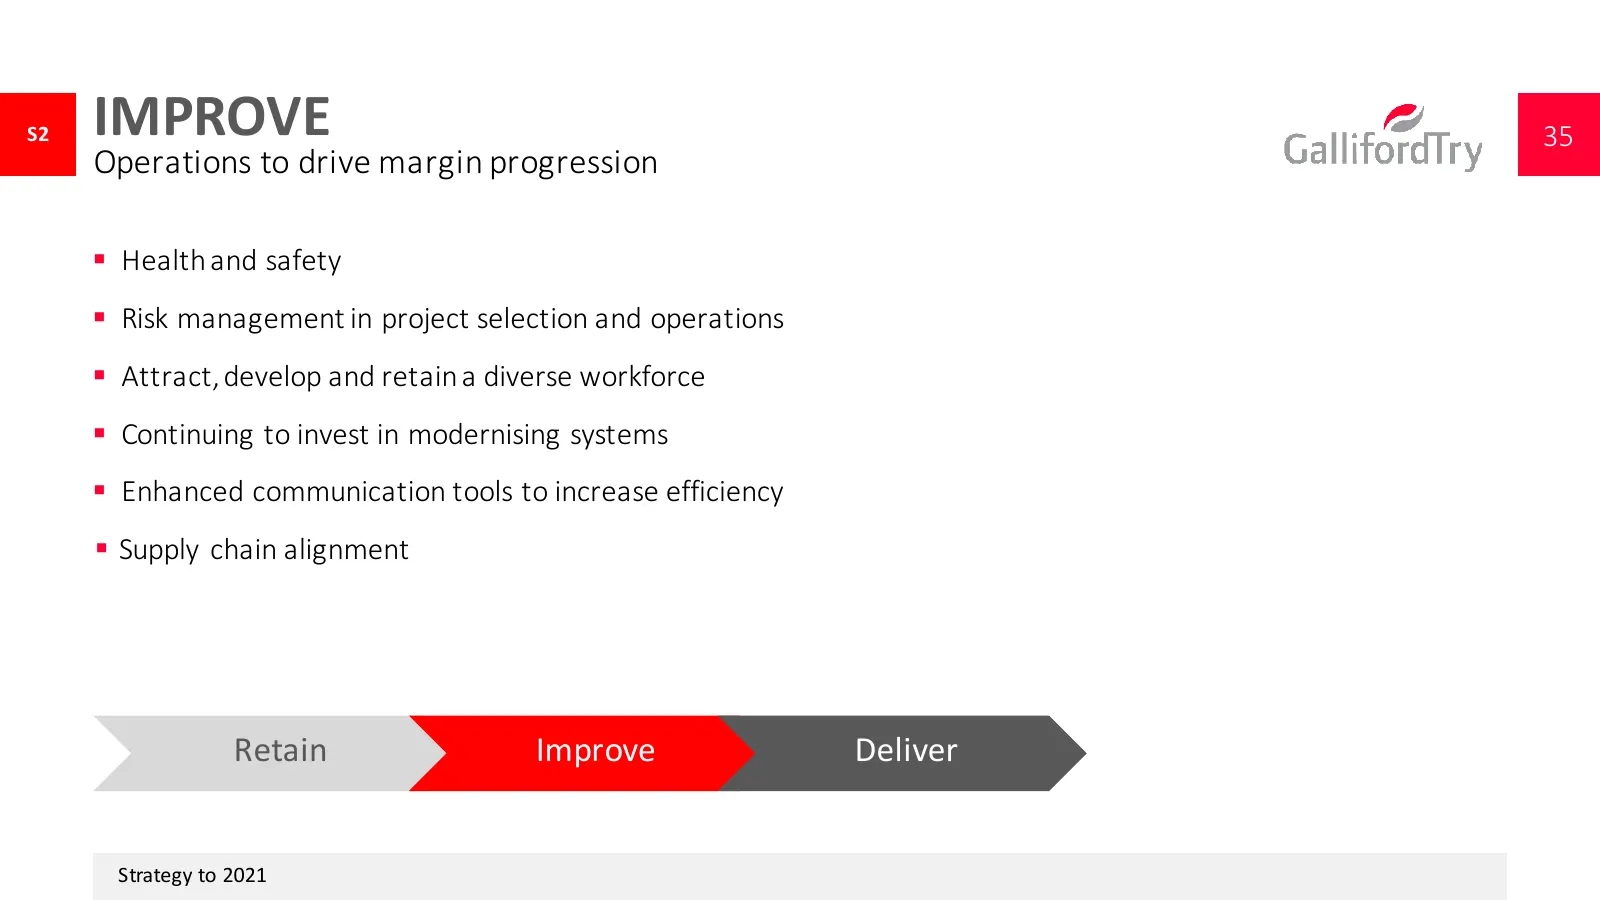
S2 IMPROVE 35 Operations to drive margin progression § Health and safety § Risk management in project selection and operations § Attract, develop and retain a diverse workforce § Continuing to invest in modernising systems § Enhanced communication tools to increase efficiency § Supply chain al
Slide 36: S3 Deliver: Financial Targets
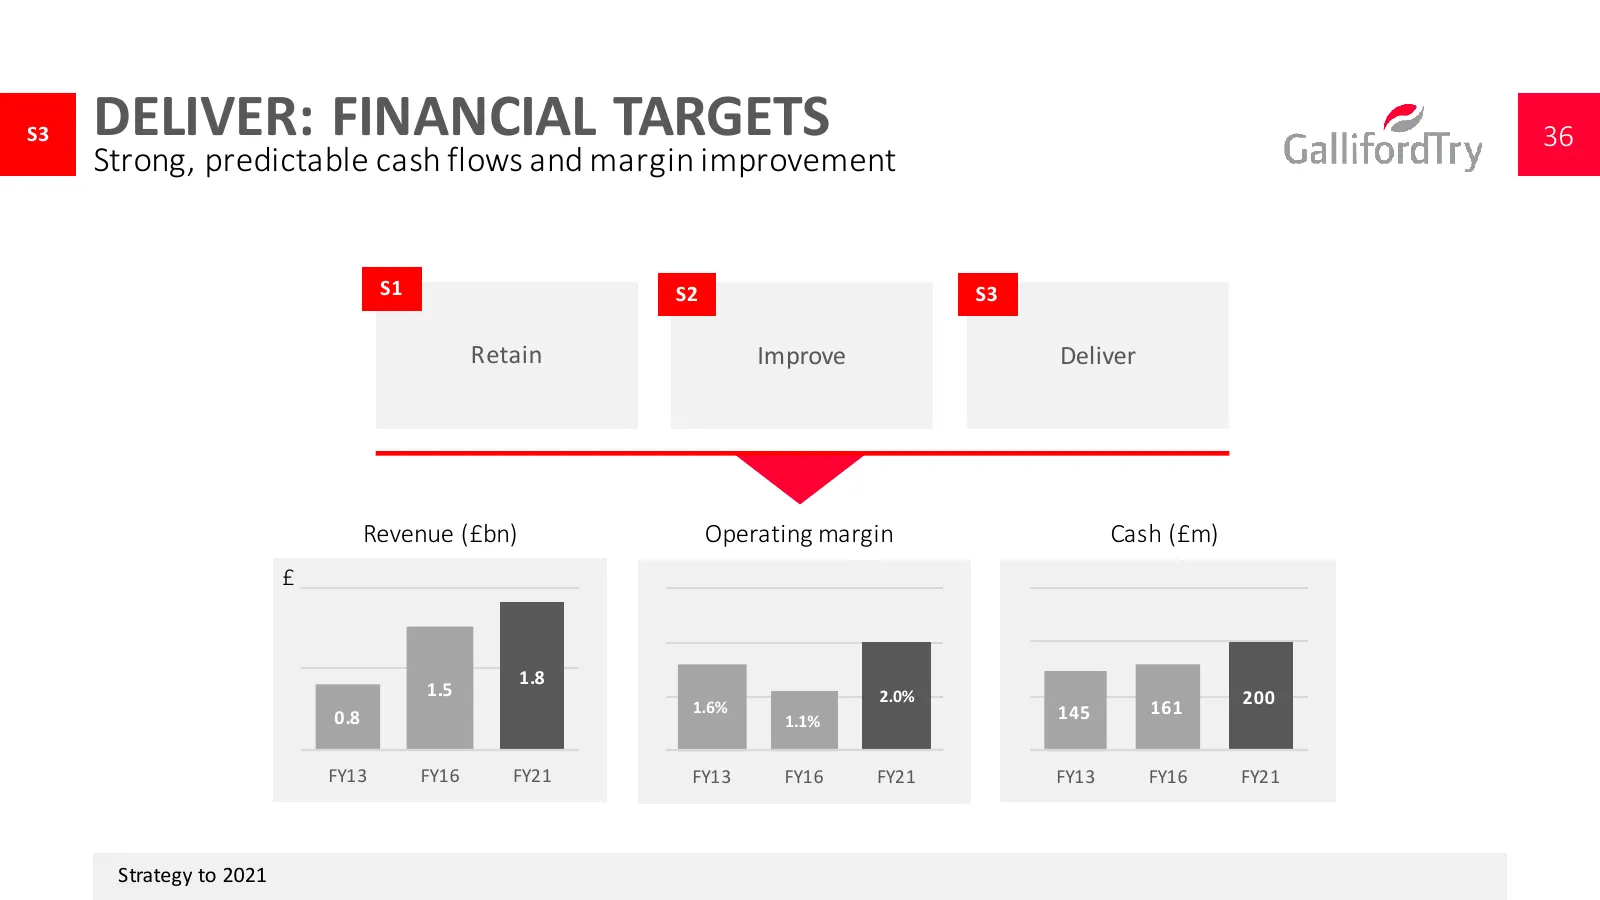
S3 DELIVER: FINANCIAL TARGETS 36 Strong, predictable cash flows and margin improvement S1 S2 S3 Retain Improve Deliver Revenue ( £bn) Operating margin Cash ( £m) £ 1.8 1.5 2.0% 200 1.6% 145 161 0.8 1.1% FY13 FY16 FY21 FY13 FY16 FY21 FY13 FY16 FY21 Strategy to 2021
Slide 37: Summary
SUMMARY 37 A progressive, people-‐orientated business delivering for our clients § Stable markets with education, healthcare, defence and infrastructure key drivers of g rowth § Solid pipeline with excellent access to all significant public sector frameworks § Improved risk management processes
Slide 38: Q&A
Q&A Strategy to 2021 Forbury Place, Reading
Slide 39: Partnerships & Regeneration
PARTNERSHIPS & REGENERATION Strategy to 2021 Tragea Parc, Cornwall
Slide 40: Strategy for Growth
STRATEGY FOR GROWTH 40 Agenda § Business overview § Market opportunity § Market position § Strategy for g rowth § Enablers and financials Cannon’s Road, North London Strategy to 2021
Slide 41: Business Overview
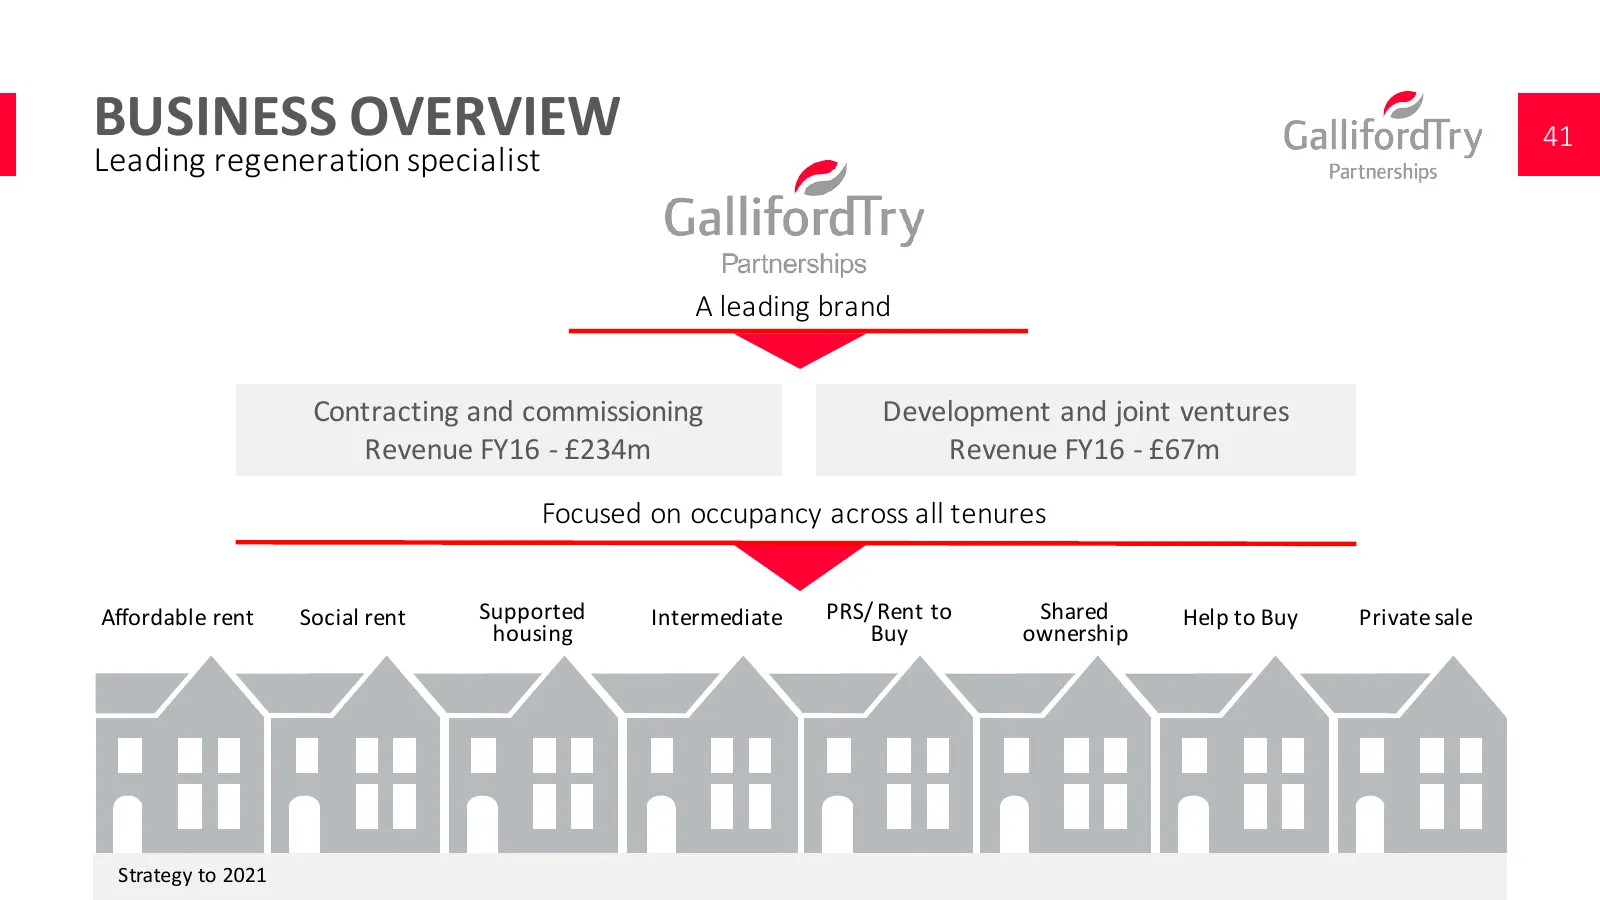
BUSINESS OVERVIEW 41 Leading r egeneration specialist A leading brand Contracting and commissioning Development and joint ventures Revenue FY16 -‐ £234m Revenue FY16 -‐ £67m Focused on occupancy across all tenures Affordable rent Social rent Supported Intermediate PRS/ Rent to Shared Help to Buy P
Slide 42: Where We Were
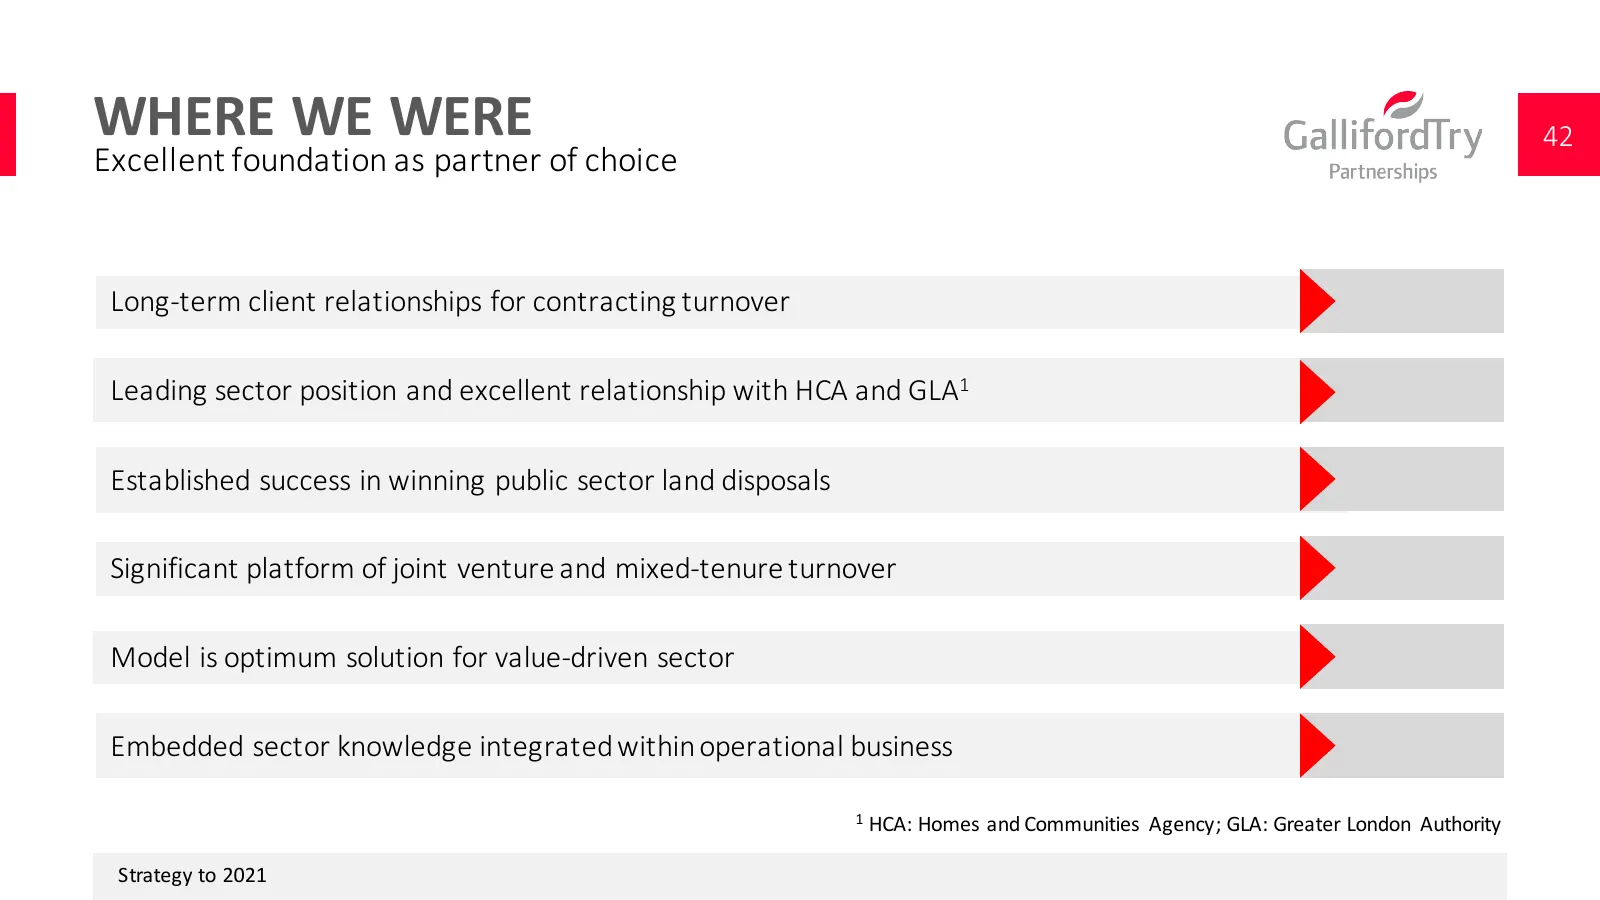
WHERE WE WERE 42 Excellent foundation as partner of choice Long-‐term client relationships for contracting turnover Leading sector position and excellent relationship with HCA and GLA1 Established success in winning public sector land disposals Significant platform of joint venture and mixed-‐tenu
Slide 43: Where We Are Now
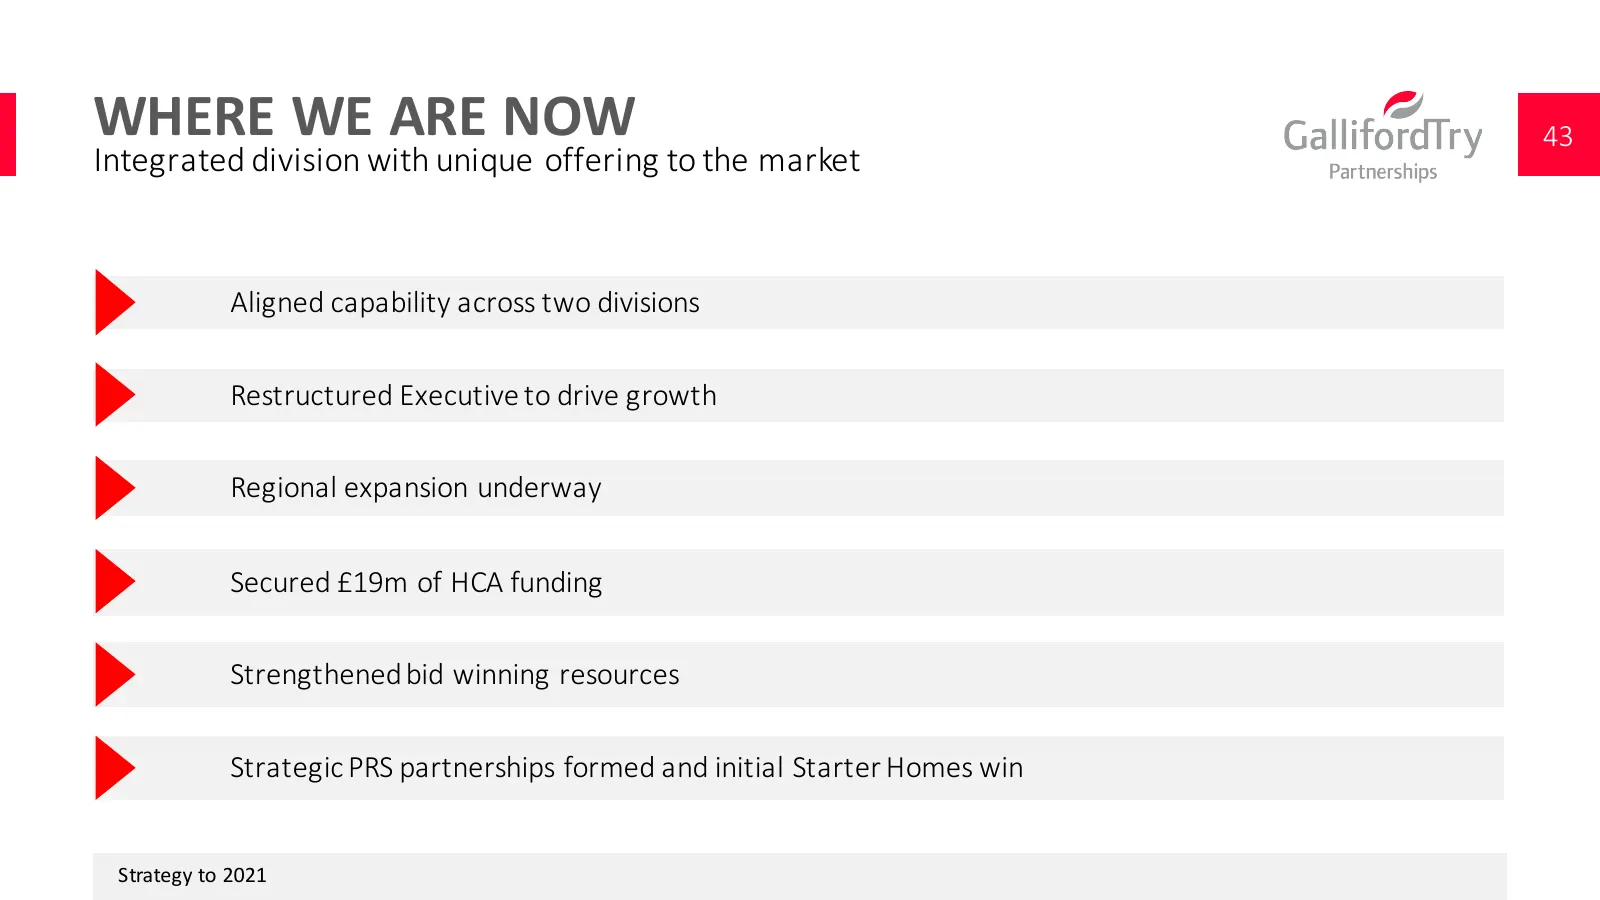
WHERE WE ARE NOW 43 Integrated division with unique offering to the market Aligned capability across two divisions Restructured Executive to drive g rowth Regional expansion underway Secured £19m of HCA funding Strengthened bid winning resources Strategic PRS partnerships formed and initial Starter
Slide 44: Market Opportunity: Supply equation
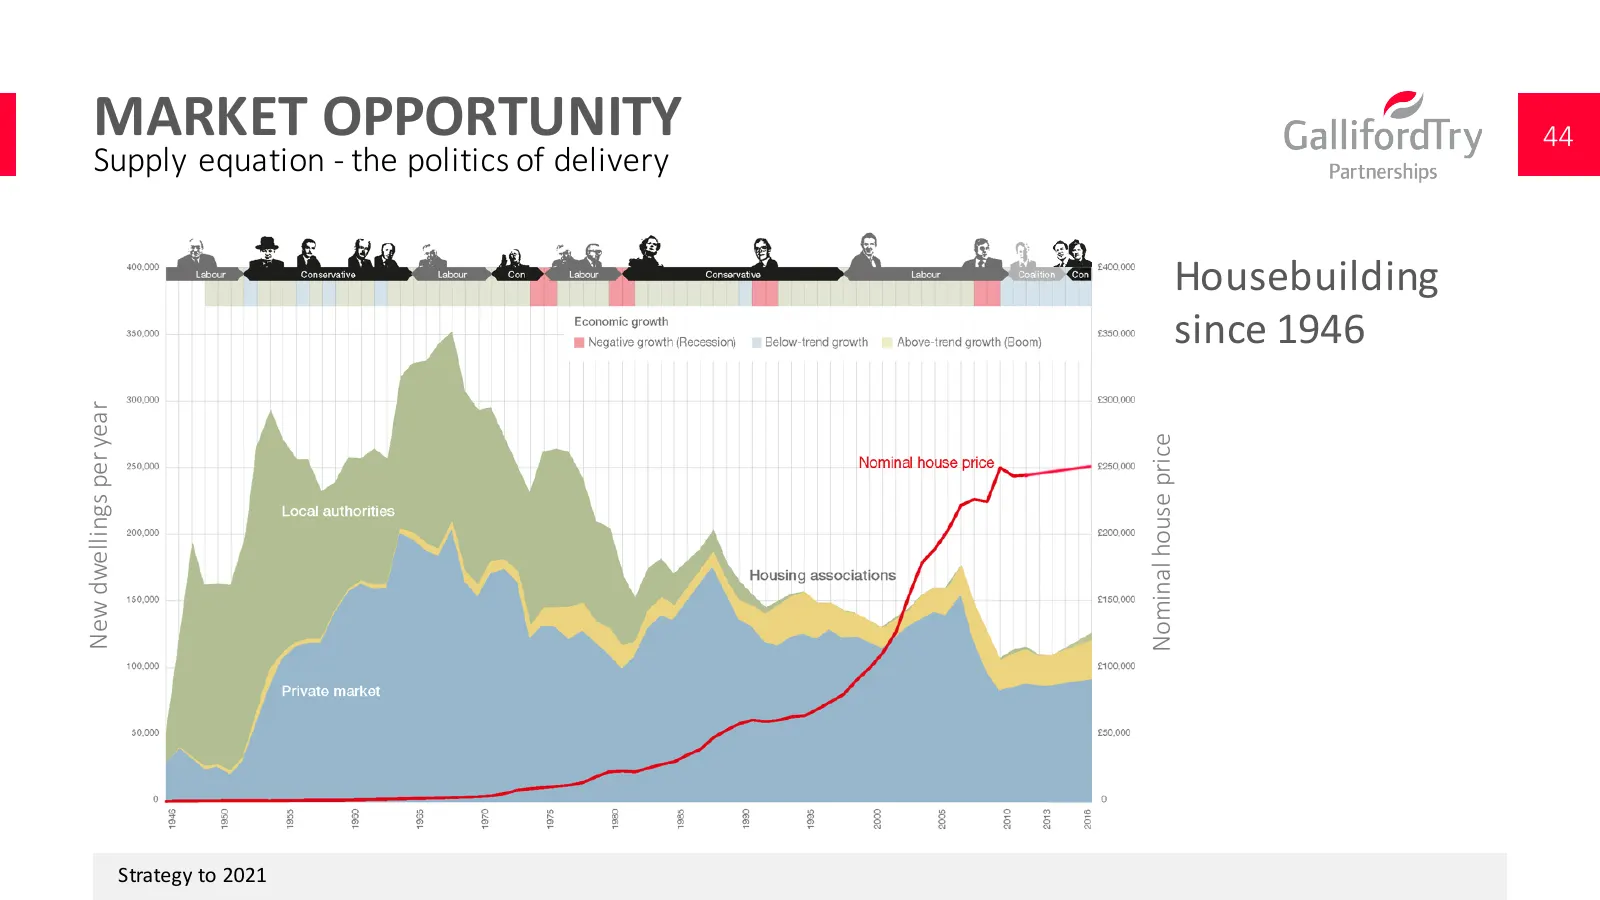
MARKET OPPORTUNITY 44 Supply equation -‐ the politics of delivery Housebuilding since 1946 New dwellings per year Nominal house price Strategy to 2021
Slide 45: Market Opportunity: Key fundamentals
MARKET OPPORTUNITY 45 Key fundamentals § Historic supply side deficit driving demand § Registered Providers and partners with capacity and commitment • Deregulation and diversity creating new partnering opportunities • New entrants in Private Rented and Affordable Housing sectors stimulating deman
Slide 46: Government Response
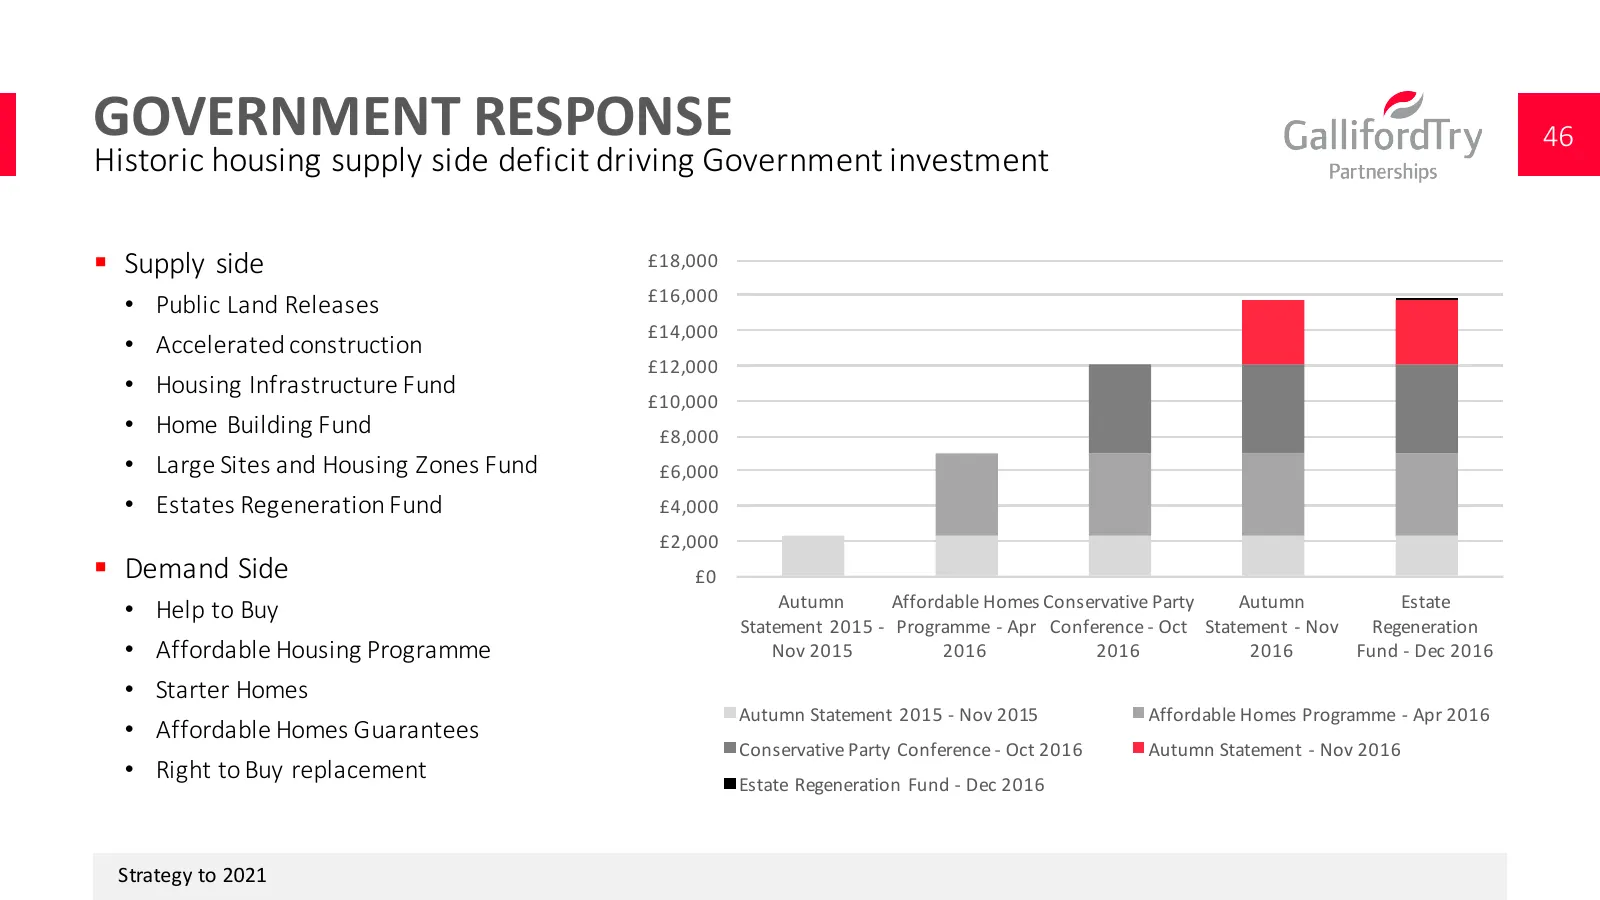
GOVERNMENT RESPONSE 46 Historic housing supply side deficit driving Government investment § Supply side £18,000 £16,000 • Public Land Releases £14,000 • Accelerated construction £12,000 • Housing Infrastructure F und £10,000 • Home Building F und £8,000 • Large Sites and Housing Z ones F und £6,000
Slide 47: Market Position - Business Opportunity
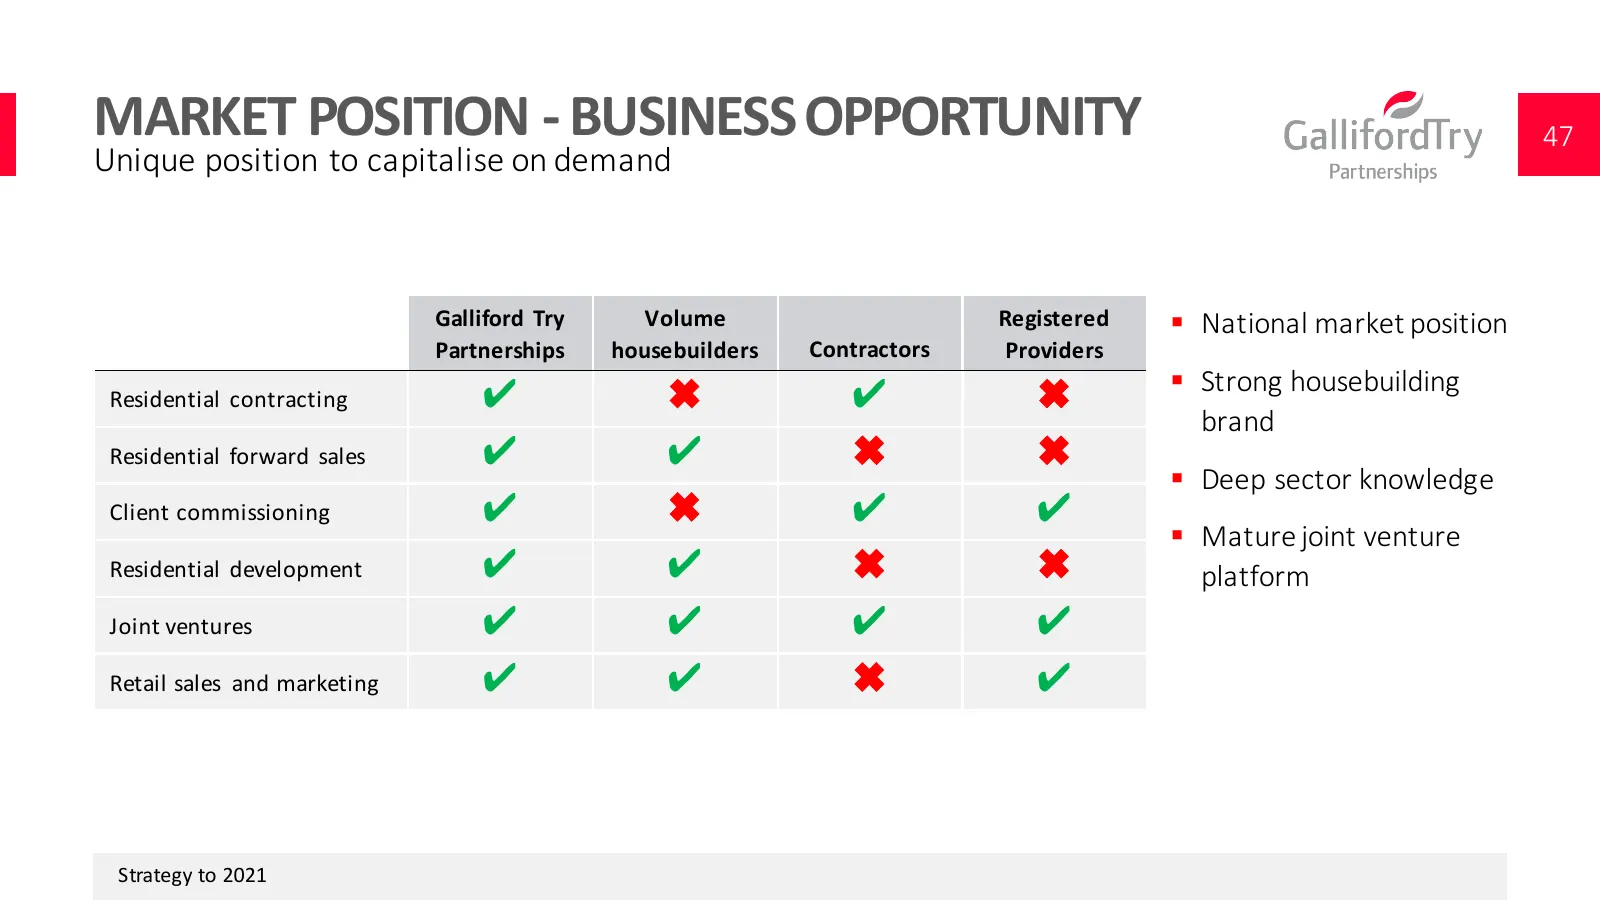
MARKET POSITION -‐ BUSINESS OPPORTUNITY 47 Unique position to capitalise on demand Galliford Try Volume Registered § National market position Partnerships housebuilders Contractors Providers § Strong housebuilding Residential contracting ✔ ✖ ✔ ✖ brand Residential forward sales ✔ ✔ ✖ ✖ § Deep sec
Slide 48: Business Model
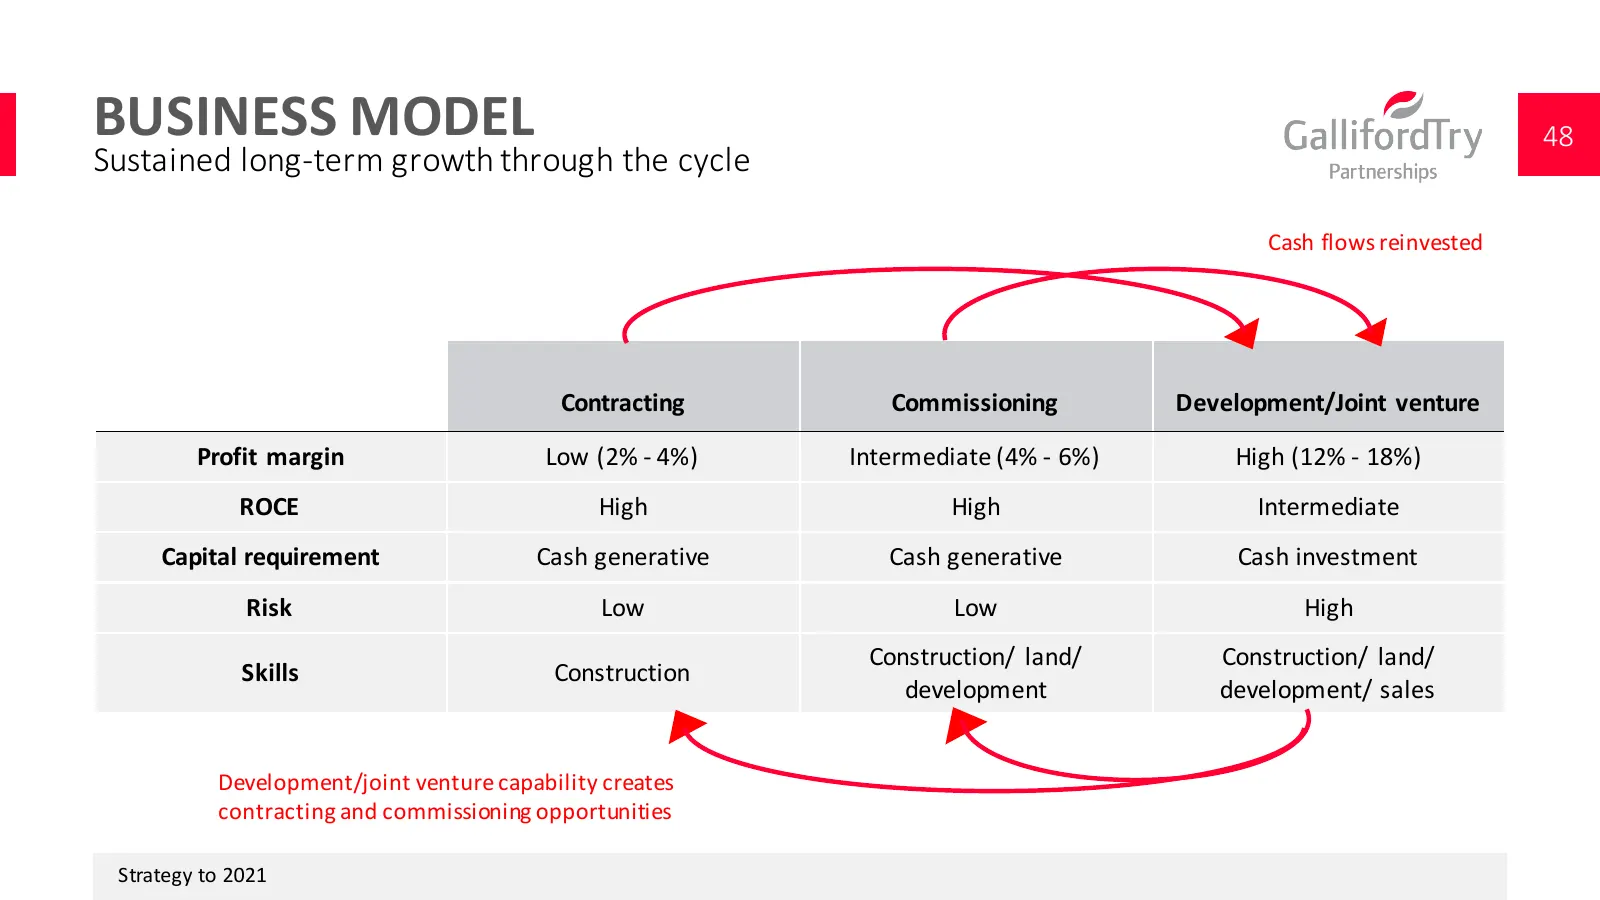
BUSINESS MODEL 48 Sustained long-‐term g rowth through the cycle Cash flows reinvested Contracting Commissioning Development/Joint venture Profit margin Low ( 2% -‐ 4%) Intermediate (4% -‐ 6%) High (12% -‐ 18%) ROCE High High Intermediate Capital requirement Cash generative Cash generative Cash
Slide 49: Strategic Assets
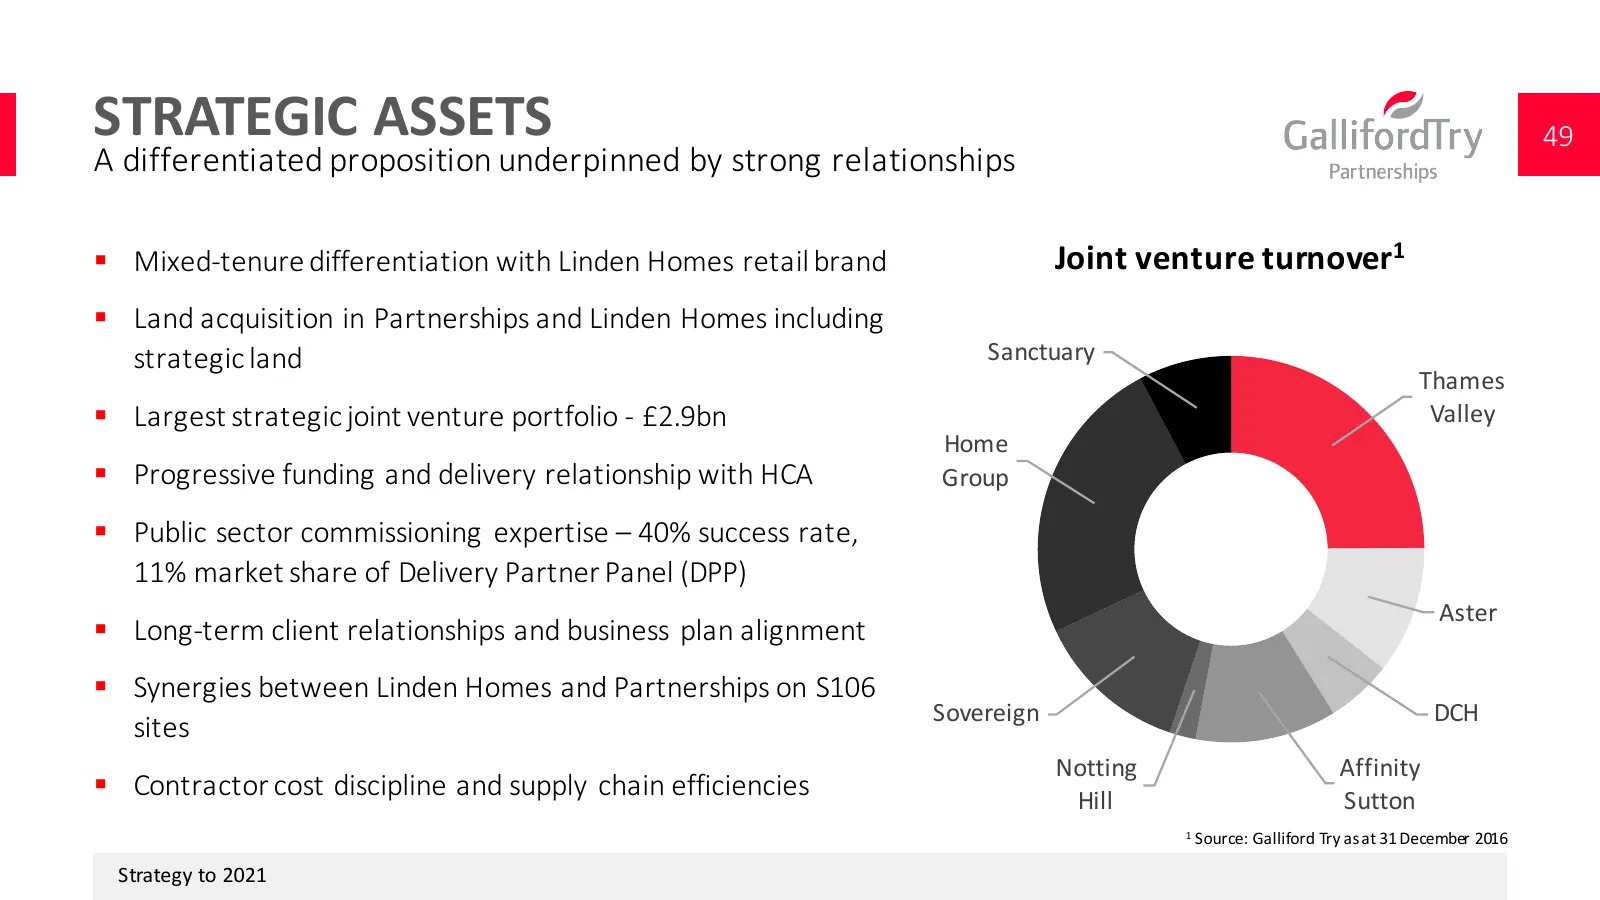
STRATEGIC ASSETS 49 A differentiated proposition underpinned by strong r elationships § Mixed-‐tenure differentiation with Linden Homes retail brand Joint venture turnover1 § Land acquisition in Partnerships and Linden Homes including strategic land Sanctuary Thames § Largest strategic joint ven
Slide 50: Strategy to 2021
STRATEGY TO 2021 50 Aligning g rowth with partner ambitions S1 S2 S3 Grow n ational footprint through continued Drive margin improvement Unlock partners’ capacity in expansion into n ew through leveraging mixed sub-‐markets geographies tenure expertise Strategy to 2021
Slide 51: S1 Grow National Footprint
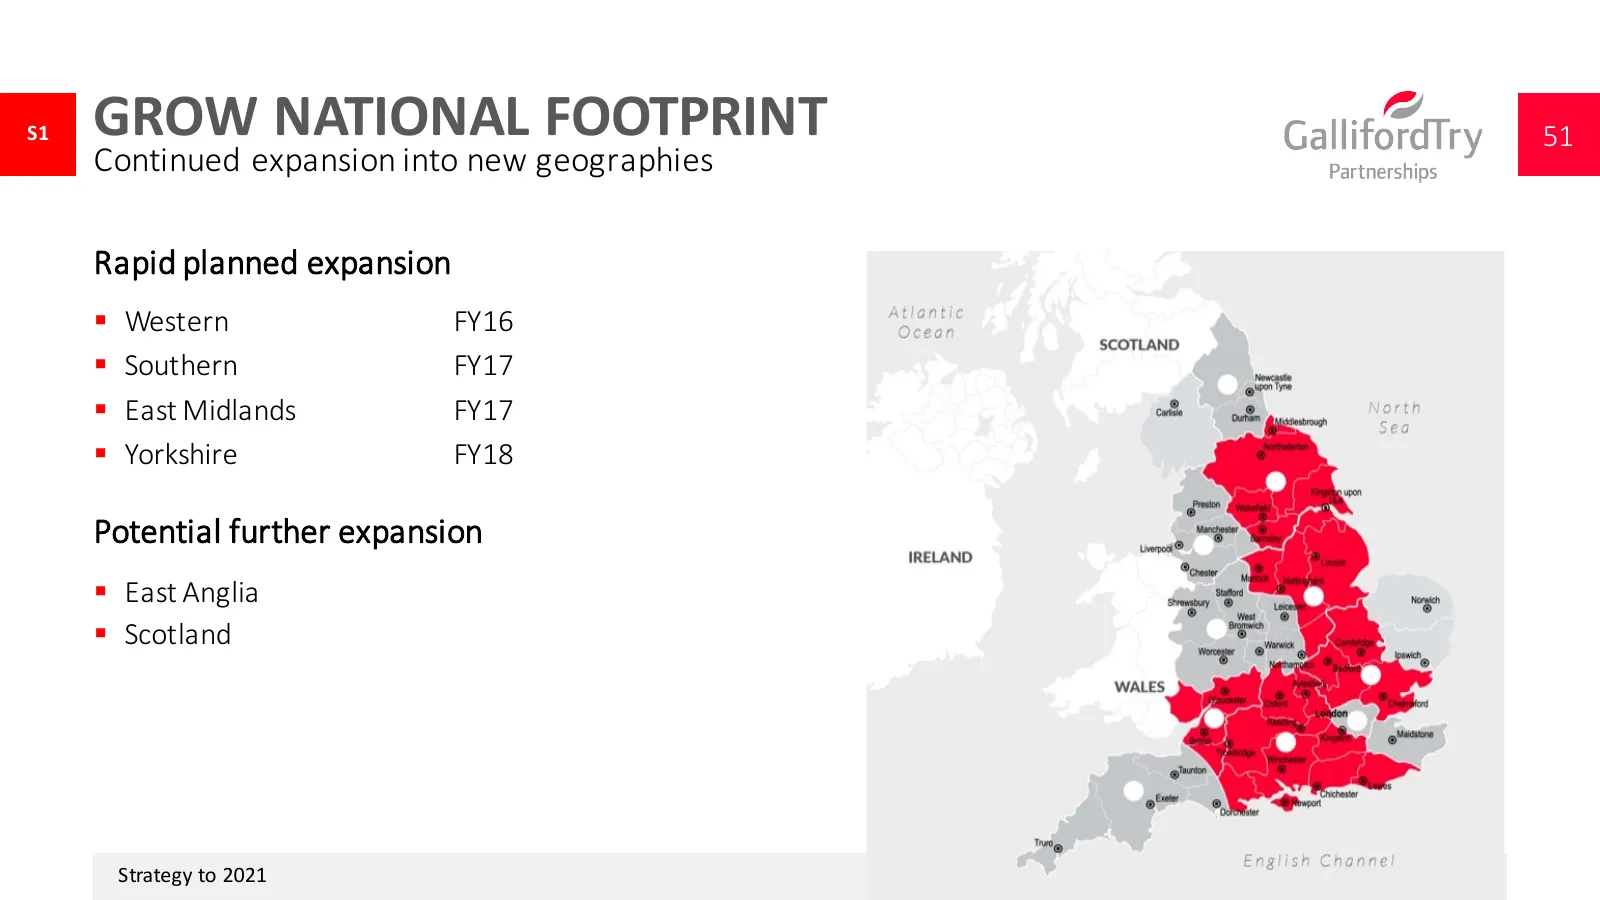
S1 S1 GROW NATIONAL FOOTPRINT 51 Continued expansion into new g eographies Rapid planned expansion § Western FY16 § Southern FY17 § East Midlands FY17 § Yorkshire FY18 Potential further expansion § East Anglia § Scotland Strategy to 2021
Slide 52: Strategy to 2021
STRATEGY TO 2021 52 Aligning g rowth with partner ambitions S1 S2 S3 Grow national footprint through continued Drive margin improvement Unlock partners’ capacity in expansion into new through leveraging mixed sub-‐markets geographies tenure expertise Strategy to 2021
Slide 53: S2 Drive Margin Improvement
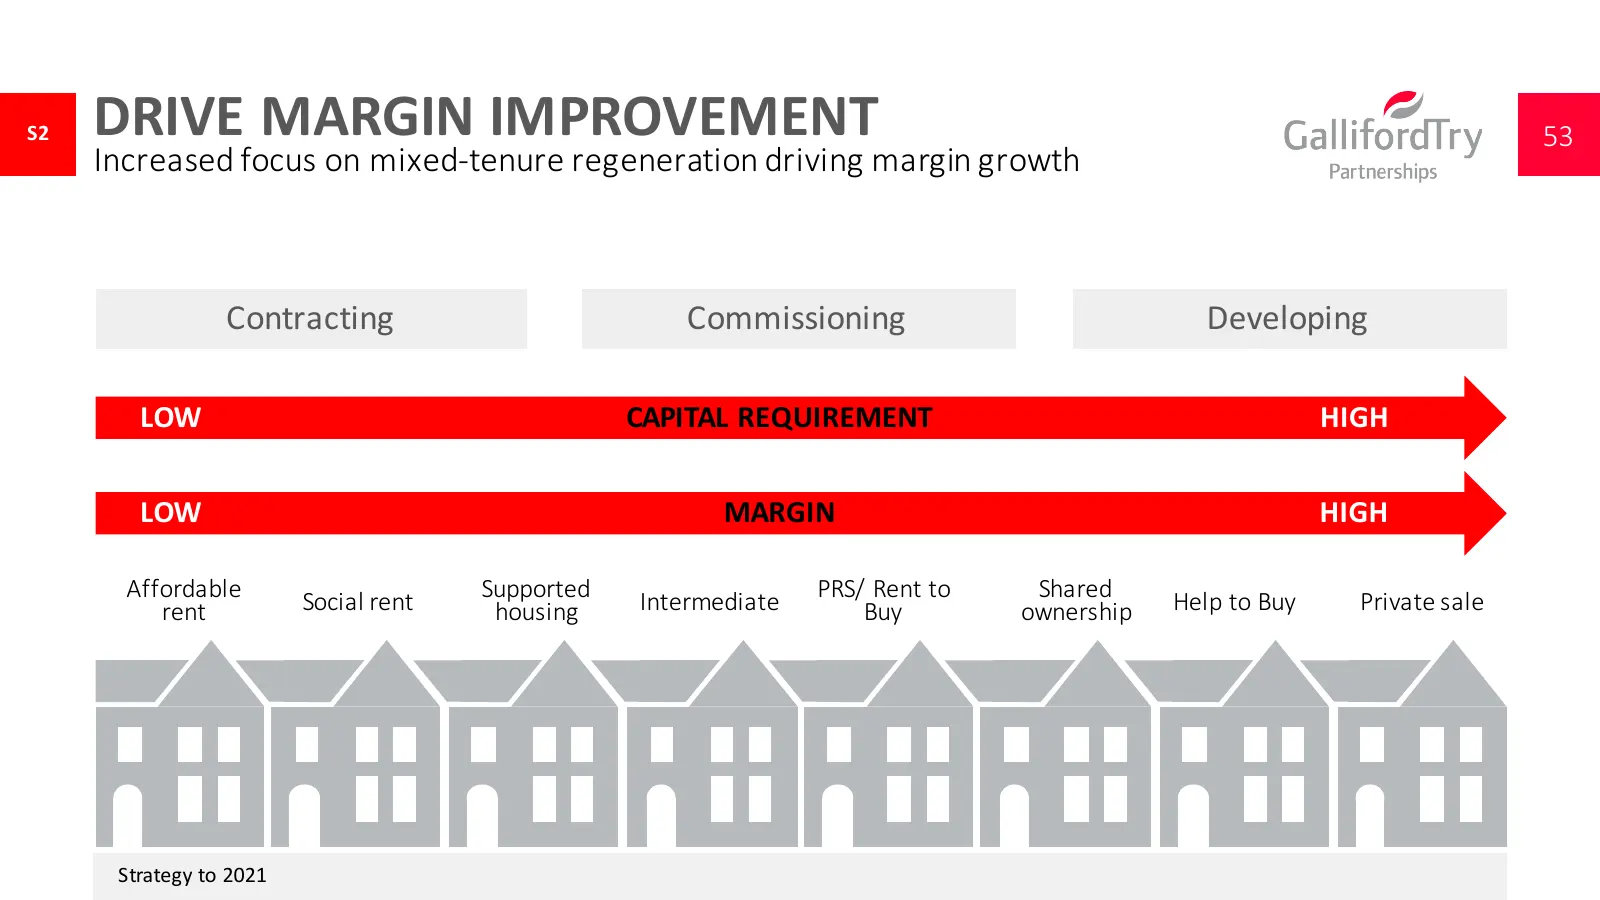
S2 S2 DRIVE MARGIN IMPROVEMENT 53 Increased focus on mixed-‐tenure r egeneration driving margin g rowth Contracting Commissioning Developing LOW CAPITAL REQUIREMENT HIGH LOW MARGIN HIGH Affordable Social rent Supported Intermediate PRS/ Rent to Shared Help to Buy Private s ale rent housing Buy owne
Slide 54: Strategy to 2021
STRATEGY TO 2021 54 Aligning g rowth with partner ambitions S1 S2 S3 Grow national footprint through continued Drive margin improvement Unlock p artners’ capacity expansion into new through leveraging mixed-‐ in sub-‐markets geographies tenure expertise Strategy to 2021
Slide 55: S3 Sub-Markets
S3 S3 SUB-‐MARKETS 55 Unlock client partners’ capacity around tenure products § Leverage sector capacity by placing risk with those best placed to manage it • Joint ventures • Build to Rent and PRS • Private affordable housing providers • Public sector direct commissioning programmes "The sector h
Slide 56: S3 Case Study: Bristol - Open for Business
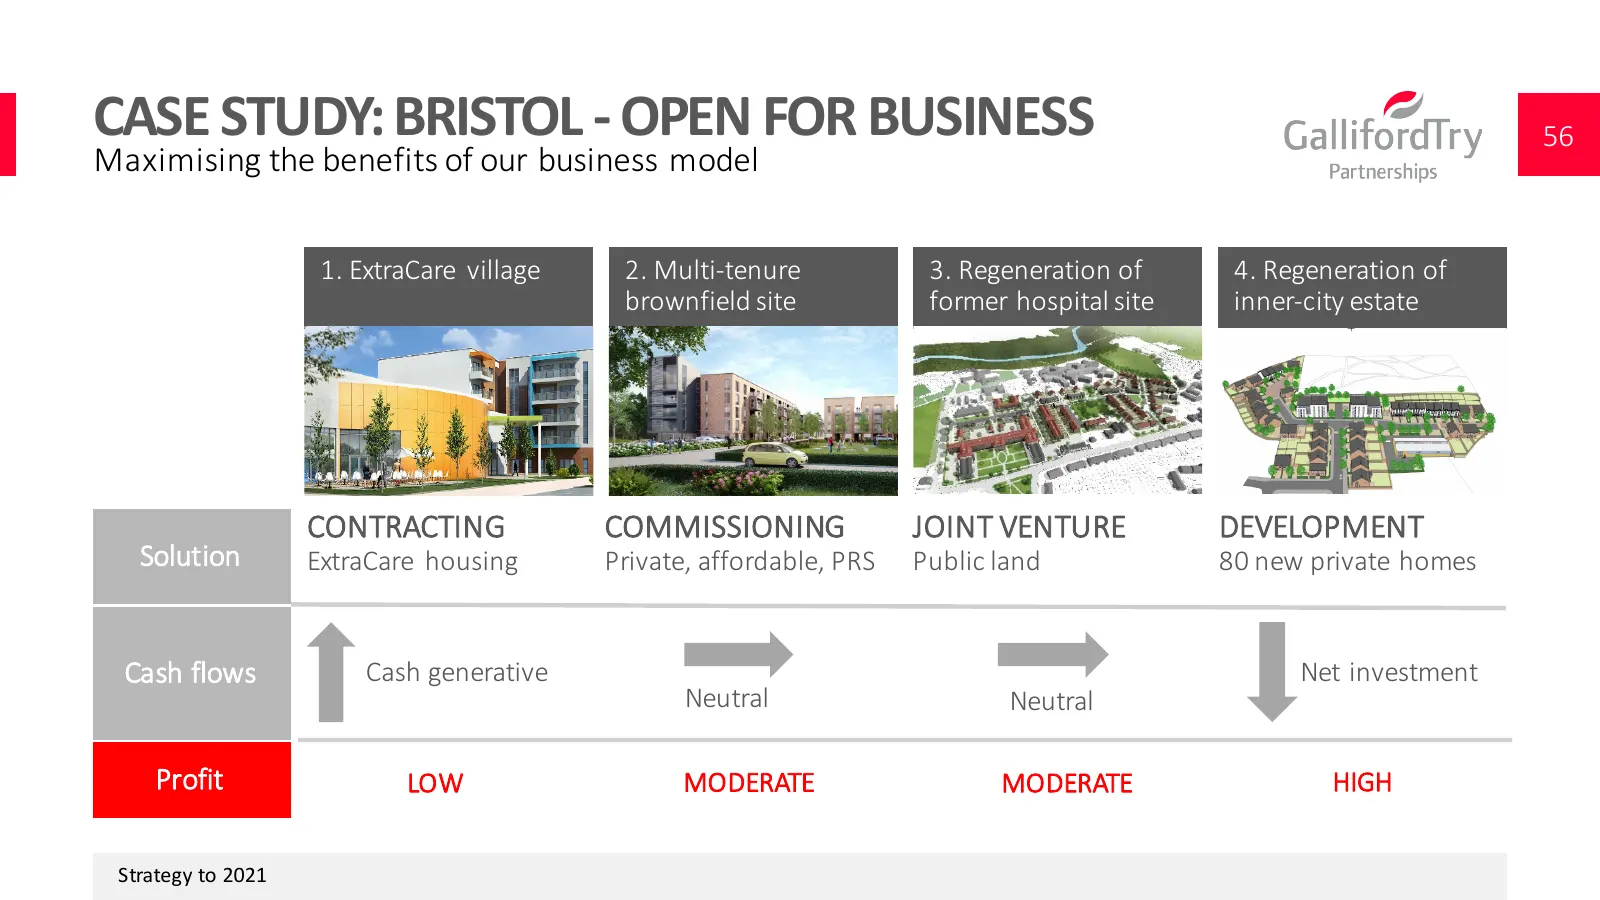
S3 CASE STUDY: BRISTOL -‐ OPEN FOR BUSINESS 56 Maximising the benefits of our business model 1. ExtraCare village 2. Multi-‐tenure 3. Regeneration of 4. Regeneration of brownfield site former hospital site inner-‐city estate CONTRACTING COMMISSIONING JOINT VENTURE DEVELOPMENT Solution ExtraCare h
Slide 57: Enablers and Financials - Financial Targets
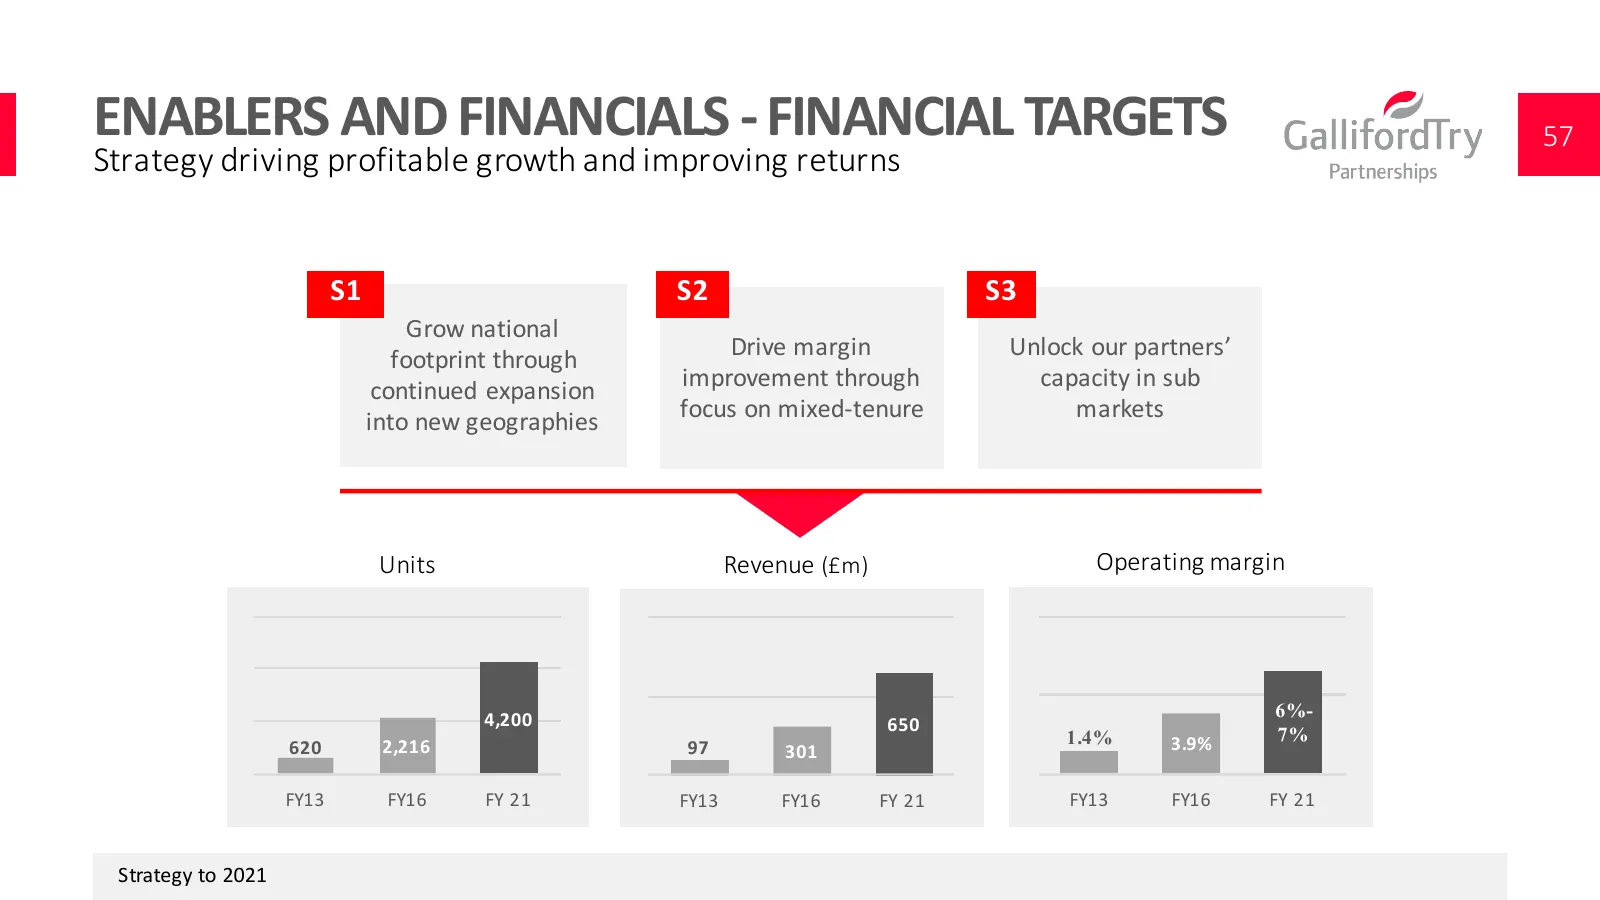
ENABLERS AND FINANCIALS -‐ FINANCIAL TARGETS 57 Strategy driving profitable g rowth and improving r eturns S1 S2 S3 Grow national footprint through Drive m argin Unlock our partners’ continued expansion improvement through capacity in sub into new geographies focus on m ixed-‐tenure markets Units
Slide 58: Forward Order Book & Landbank
FORWARD ORDER BOOK & LANDBANK 58 Visibility of future work § Strong contracting order book of work in all regions -‐ £925m § High percentage of order book is negotiated and repeat work § Valuable landbank of 2,750 plots § Network of LA, RP and PRS clients with pipeline of schemes nationwide §
Slide 59: Summary
SUMMARY 59 Partnerships – Leading r egeneration specialist § Clear strategic vision § Differentiated regeneration business § Strengthened divisional structure to focus on performance delivery § Disciplined approach to margin enhancement and capital management § Strong relationships with partner
Slide 60: Video: Positive client sentiment
VIDEO 60 Positive client sentiment Video Strategy to 2021
Slide 61: Q&A
Q&A Strategy to 2021 King’s H ouse, West London
Slide 62: Financial Summary
FINANCIAL SUMMARY Strategy to 2021 62-‐63 P all M all, London
Slide 63: Balance Sheet
BALANCE SHEET 64 Building strength and r esilience § Extended banking facility to February 2022, with improved covenant profile § Issue of £100m 10-‐year private placement notes provides enhanced funding headroom and liquidity § Period-‐end target maximum g earing remains at 30% § Return on ne
Slide 64: Financial Targets: Assumptions
FINANCIAL TARGETS 65 Assumptions § No significant slowdown in macro environment or consumer confidence § Banking and mortgage markets remain positive § Political context remains supportive Strategy to 2021
Slide 65: Financial Targets: Business targets
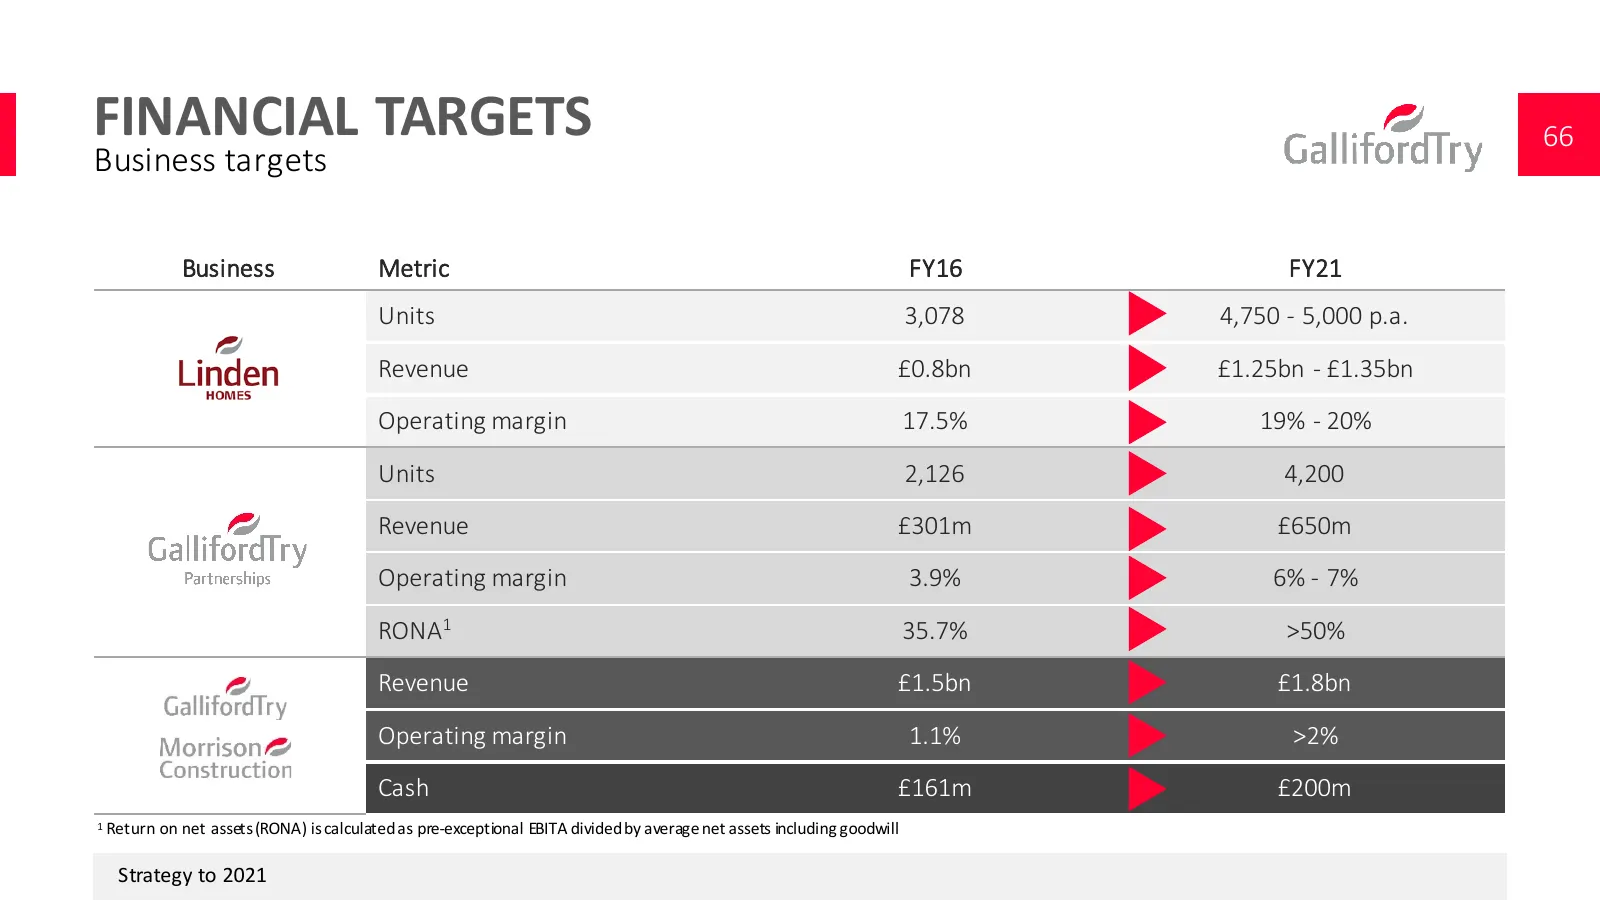
FINANCIAL TARGETS 66 Business targets Business Metric FY16 FY21 Units 3,078 4,750 -‐ 5,000 p.a. Revenue £0.8bn £1.25bn -‐ £1.35bn Operating margin 17.5% 19% -‐ 20% Units 2,126 4,200 Revenue £301m £650m Operating margin 3.9% 6% -‐ 7% RONA1 35.7% >50% Revenue £1.5bn £1.8bn Operating margin 1.1% >2
Slide 66: Financial Targets: Group targets
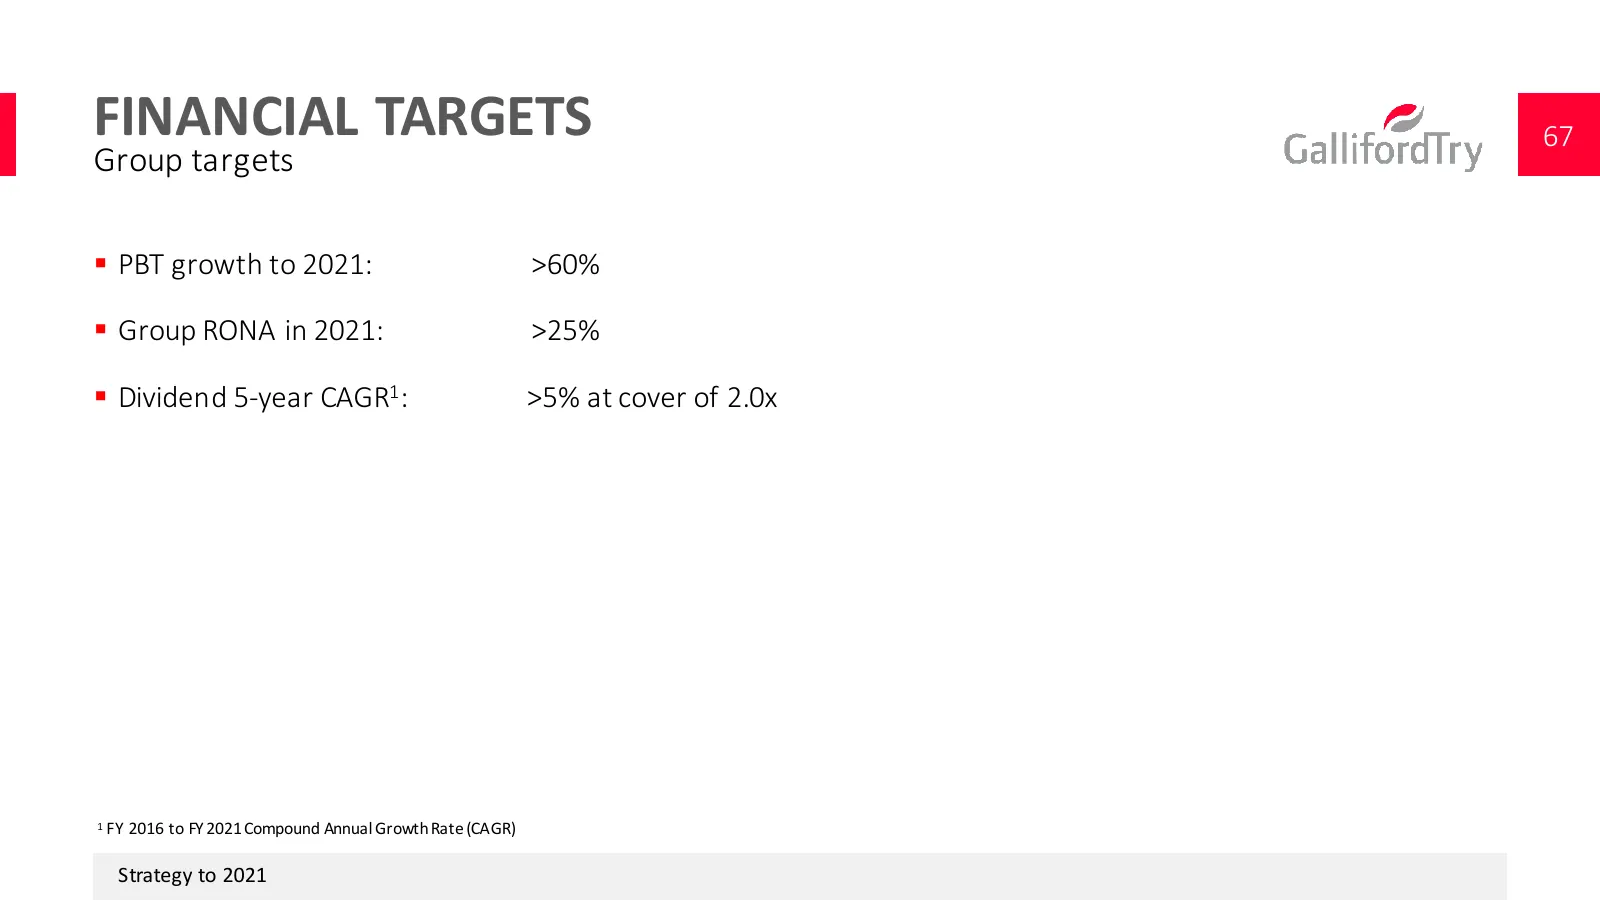
FINANCIAL TARGETS 67 Group targets § PBT g rowth to 2021: >60% § Group RONA in 2021: >25% § Dividend 5-‐year CAGR1 : >5% at cover of 2.0x FY 2016 t o FY 2021 Compound Annual Growth Rate (CAGR) 1 Strategy to 2021
Slide 67: Summary
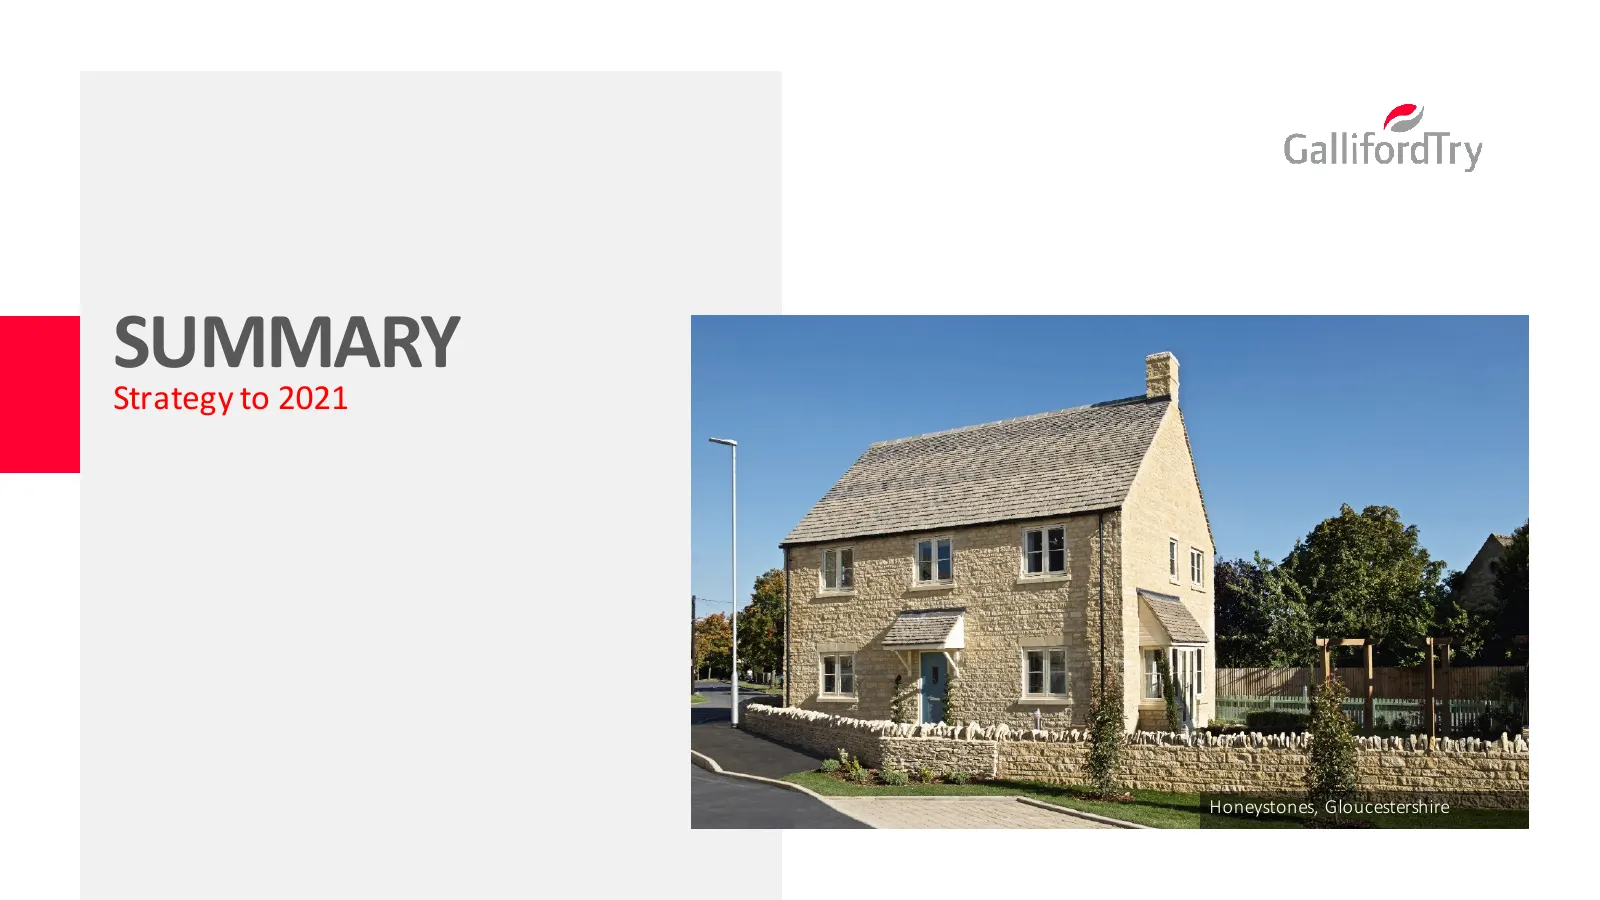
SUMMARY Strategy to 2021 Honeystones, Gloucestershire
Slide 68: Summary
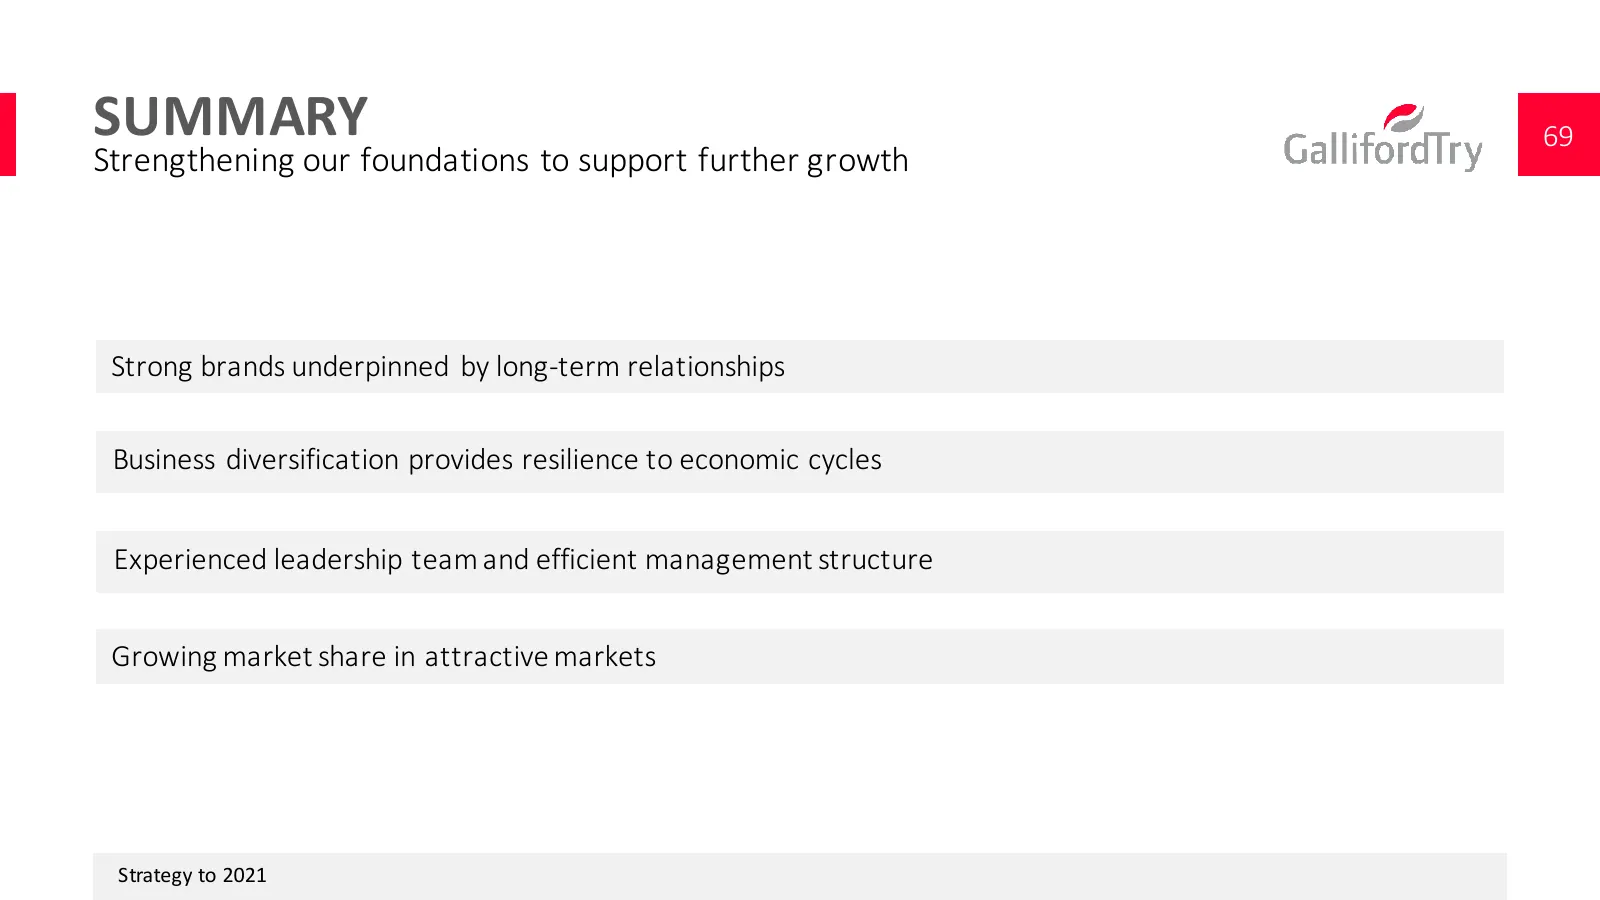
SUMMARY 69 Strengthening our foundations to support further g rowth Strong brands underpinned by long-‐term relationships Business diversification provides resilience to economic cycles Experienced leadership team and efficient management structure Growing market share in attractive markets Strateg
Slide 69: Strategy to 2021
STRATEGY TO 2021 70 Delivering sustainable g rowth and strong r eturns Strengthening our foundations t o support further growth • Operate sustainably • Drive operating efficiencies • Maintain capital discipline Sustainable profit Improving margins Strong returns growth Strategy to 2021
Slide 70: Q&A
Q&A Strategy to 2021 King’s H ouse, West London
Source: company website
More decks from Galliford Try Holdings PLC
 Investor Presentation (September 2026)40 slides · Sep 17, 2026
 FY2026 Earnings Presentation40 slides · Sep 17, 2026
 Investor Presentation (May 2026)24 slides · May 7, 2026
 H1 2026 Earnings Presentation37 slides · Mar 4, 2026
 Investor Presentation (March 2026)42 slides · March 2026
 Investor Presentation (September 2025)39 slides · Sep 17, 2025