Heartland Financial USA — Q3 2021 Earnings Presentation
50 slides from Heartland Financial USA's earnings presentation, Oct 29, 2021
Slide 1: Strength. Insight. Growth. 3Q 2021 Financials
FITLE Strength. Insight. Growth. 34 Quarter 2021 Financials
Slide 2: Safe Harbor
Safe Harbor 2 This release (including any information incorporated herein by reference), and future oral and written statements of the company and its management, may contain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of th
Slide 3: Corporate Profile
3 Corporate Profile
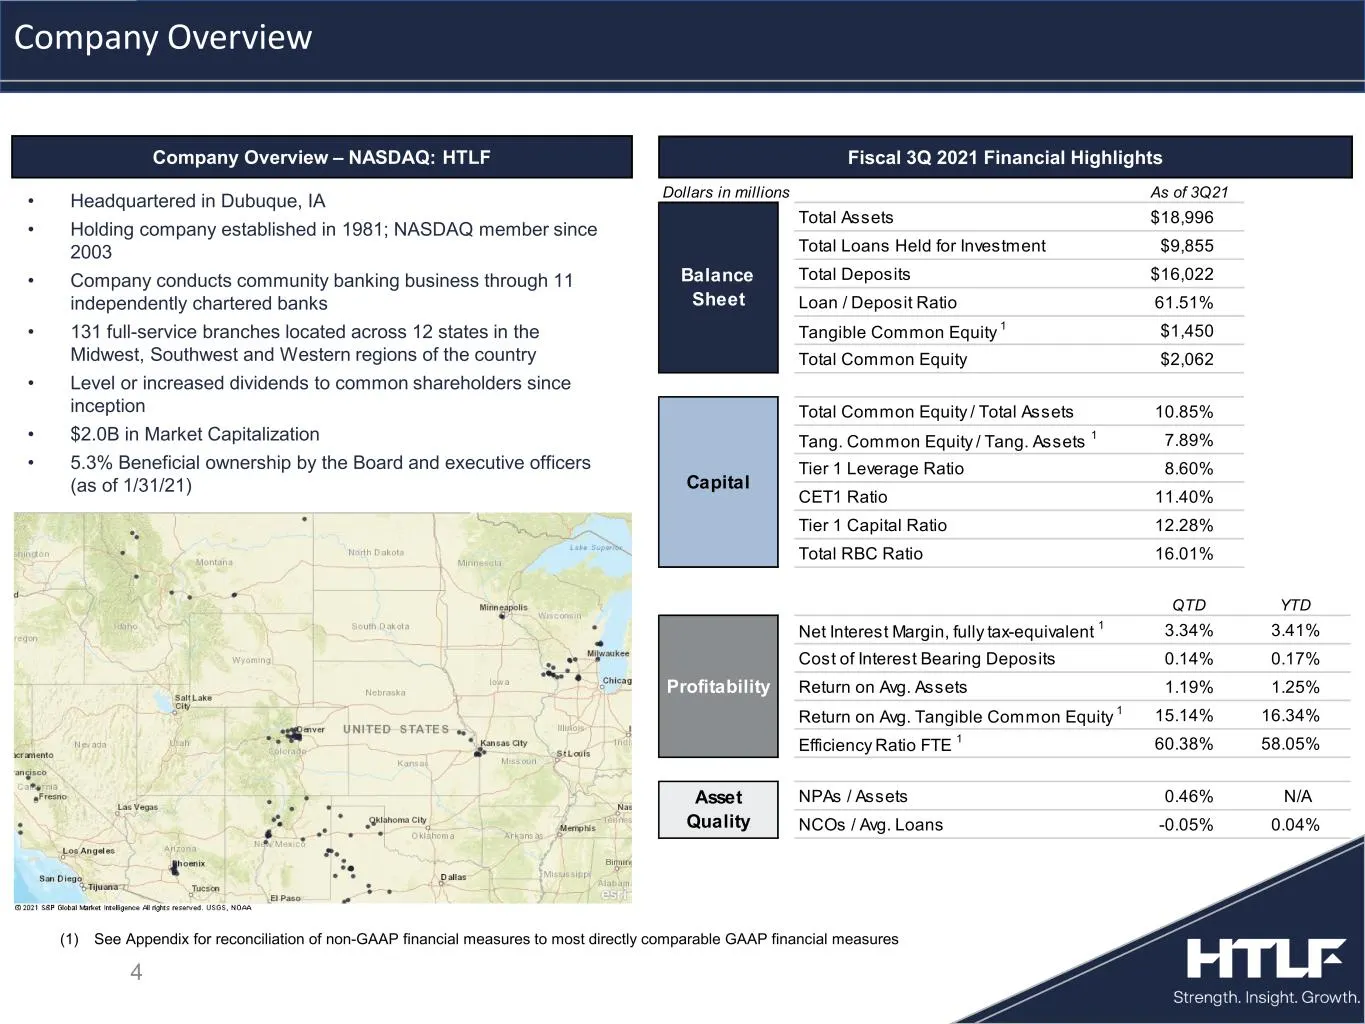
Slide 4: Company Overview – Fiscal 3Q 2021 Financial Highlights
As of 3Q21 Total Assets $18,996 Total Loans Held for Investment $9,855 Total Deposits $16,022 Loan / Deposit Ratio 61.51% Tangible Common Equity 1 $1,450 Total Common Equity $2,062 Total Common Equity / Total Assets 10.85% Tang. Common Equity / Tang. Assets 1 7.89% Tier 1 Leverage Ratio 8.60% CET1 R
Slide 5: Strength. Insight. Growth.
Strength. Insight. Growth. It’s what we bring to our customers, communities, employees and shareholders Strong corporate leadership and innovative thinking have uniquely positioned us Our business model and diverse geographic footprint reduce risk and drive organic growth Complemented by str
Slide 6: Powered by HTLF
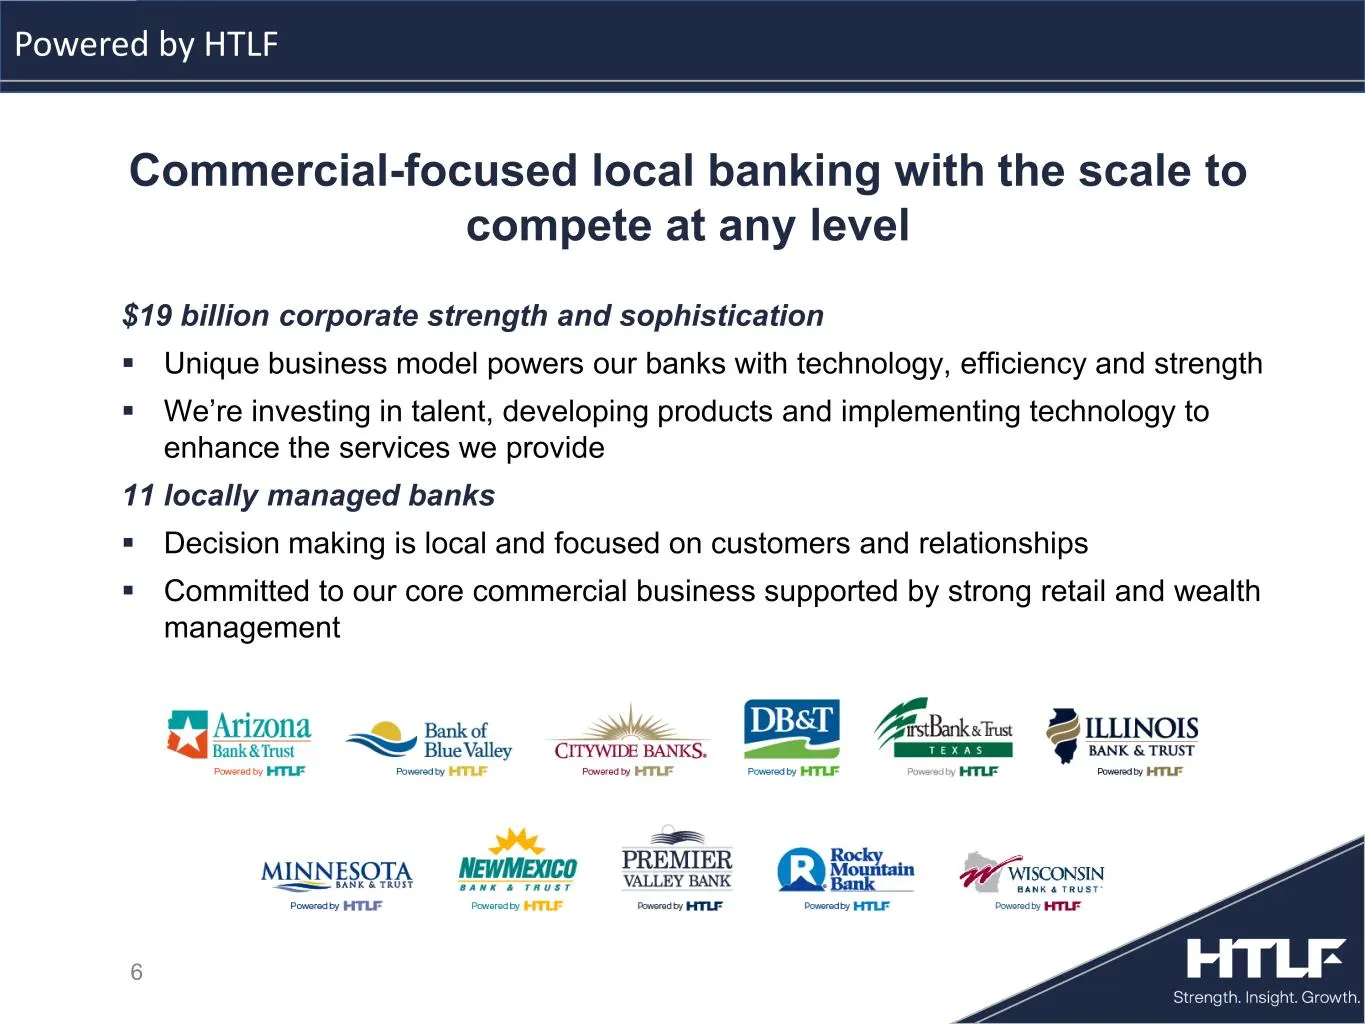
Commercial-focused local banking with the scale to compete at any level $19 billion corporate strength and sophistication Unique business model powers our banks with technology, efficiency and strength We’re investing in talent, developing products and implementing technology to enhance the serv
Slide 7: Corporate Structure Subsidiary Banks by Region
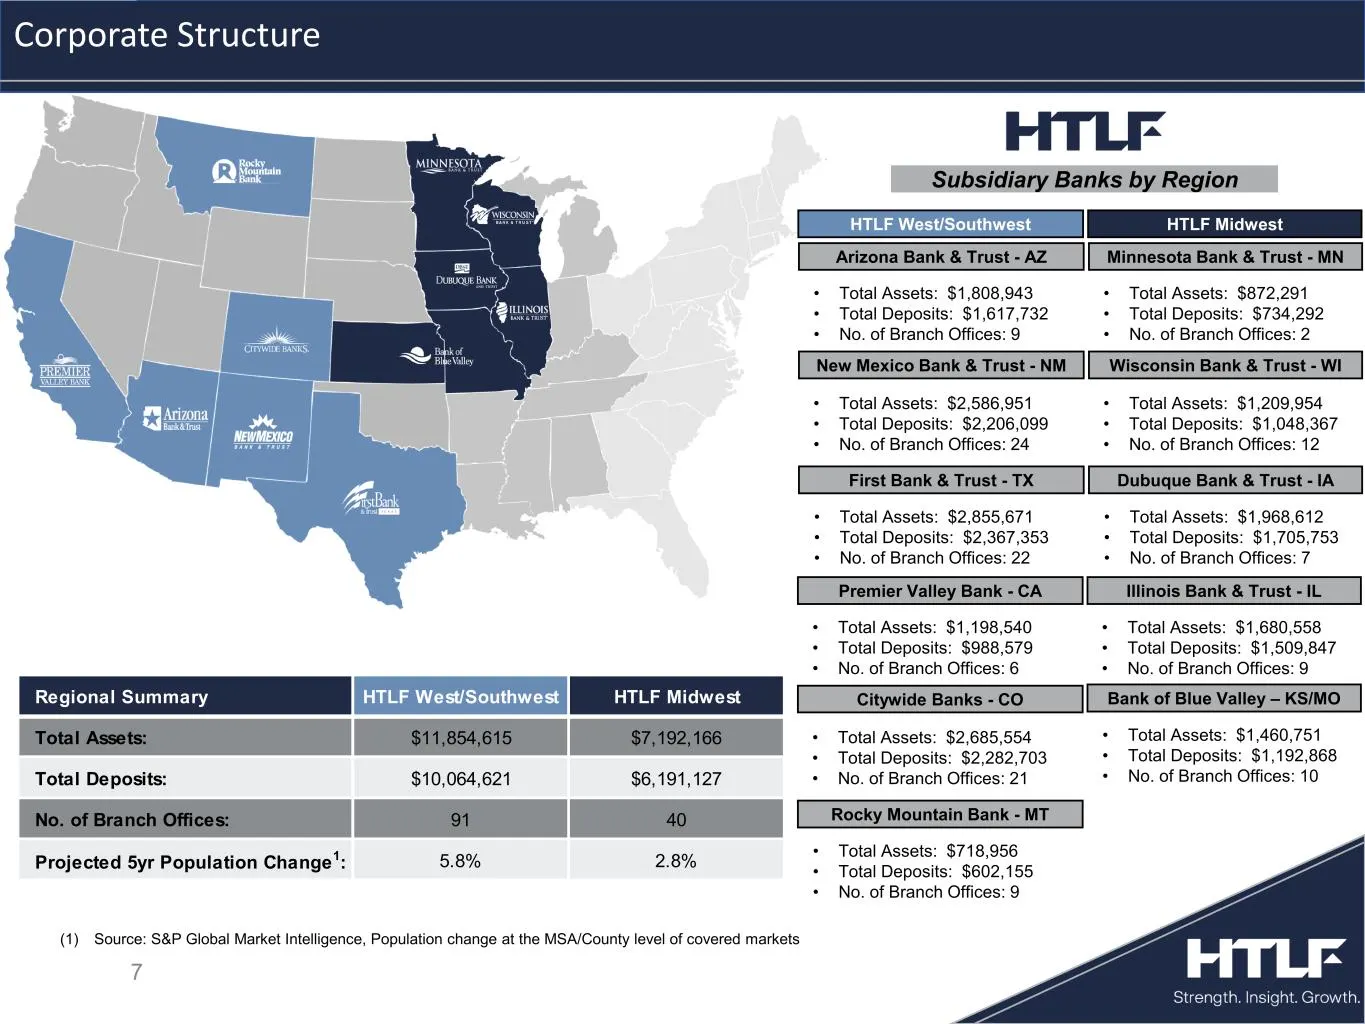
7 Corporate Structure Subsidiary Banks by Region (1) Source: S&P Global Market Intelligence, Population change at the MSA/County level of covered markets Bank of Blue Valley – KS/MO Illinois Bank & Trust - IL Minnesota Bank & Trust - MN HTLF Midwest • Total Assets: $1,680,558 • Total Deposits: $1,50
Slide 8: HTLF West/Southwest Major MSA Coverage
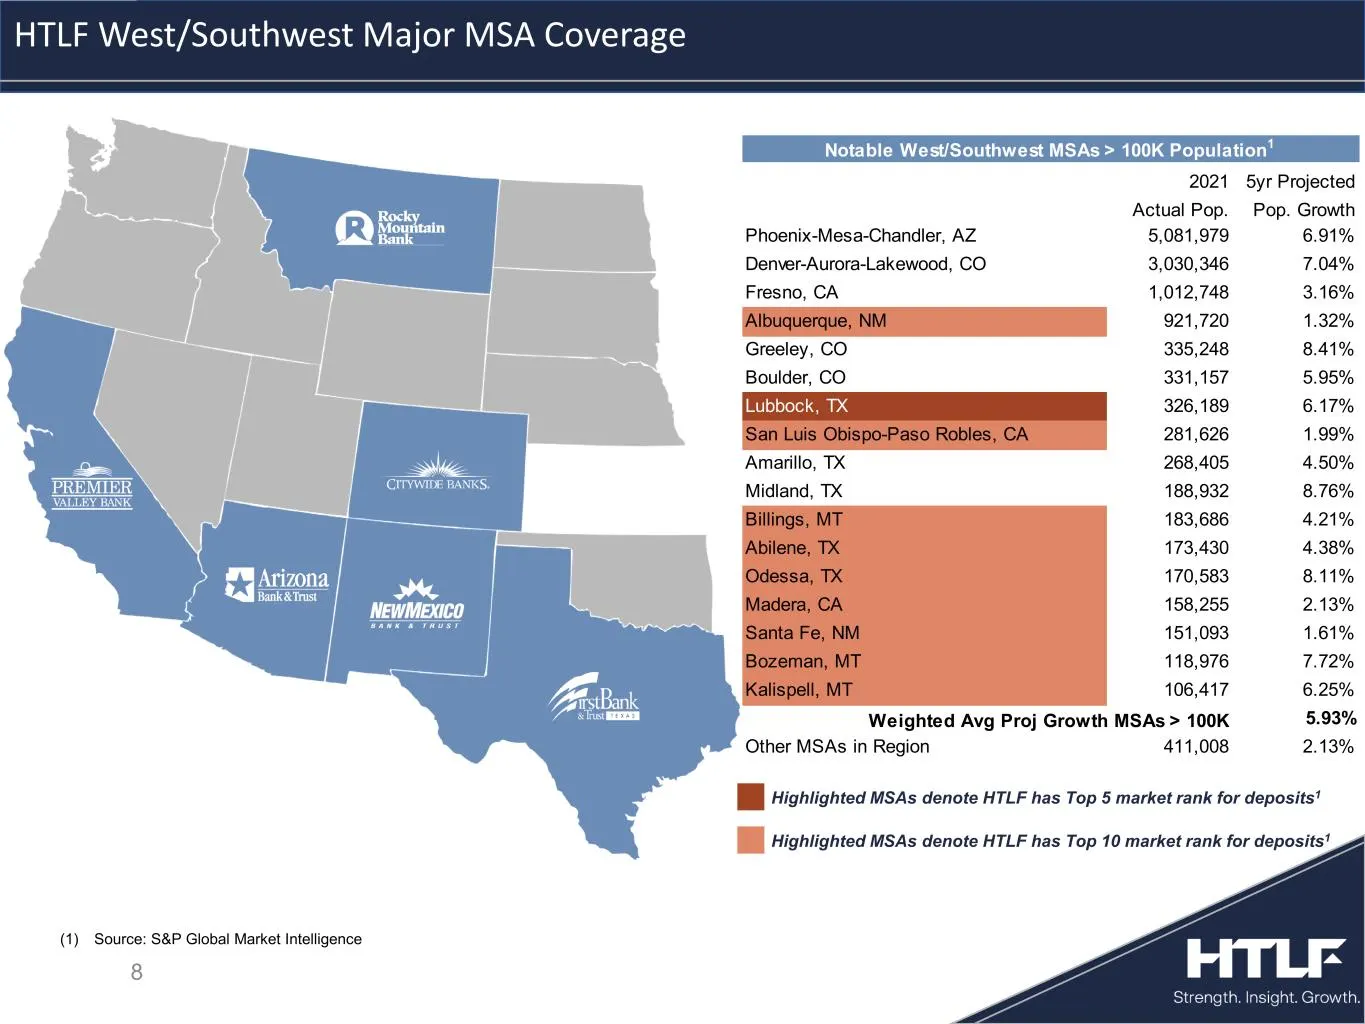
8 HTLF West/Southwest Major MSA Coverage (1) Source: S&P Global Market Intelligence 2021 5yr Projected Actual Pop. Pop. Growth Phoenix-Mesa-Chandler, AZ 5,081,979 6.91% Denver-Aurora-Lakewood, CO 3,030,346 7.04% Fresno, CA 1,012,748 3.16% Albuquerque, NM 921,720 1.32% Greeley, CO 335,248 8.41% Bould
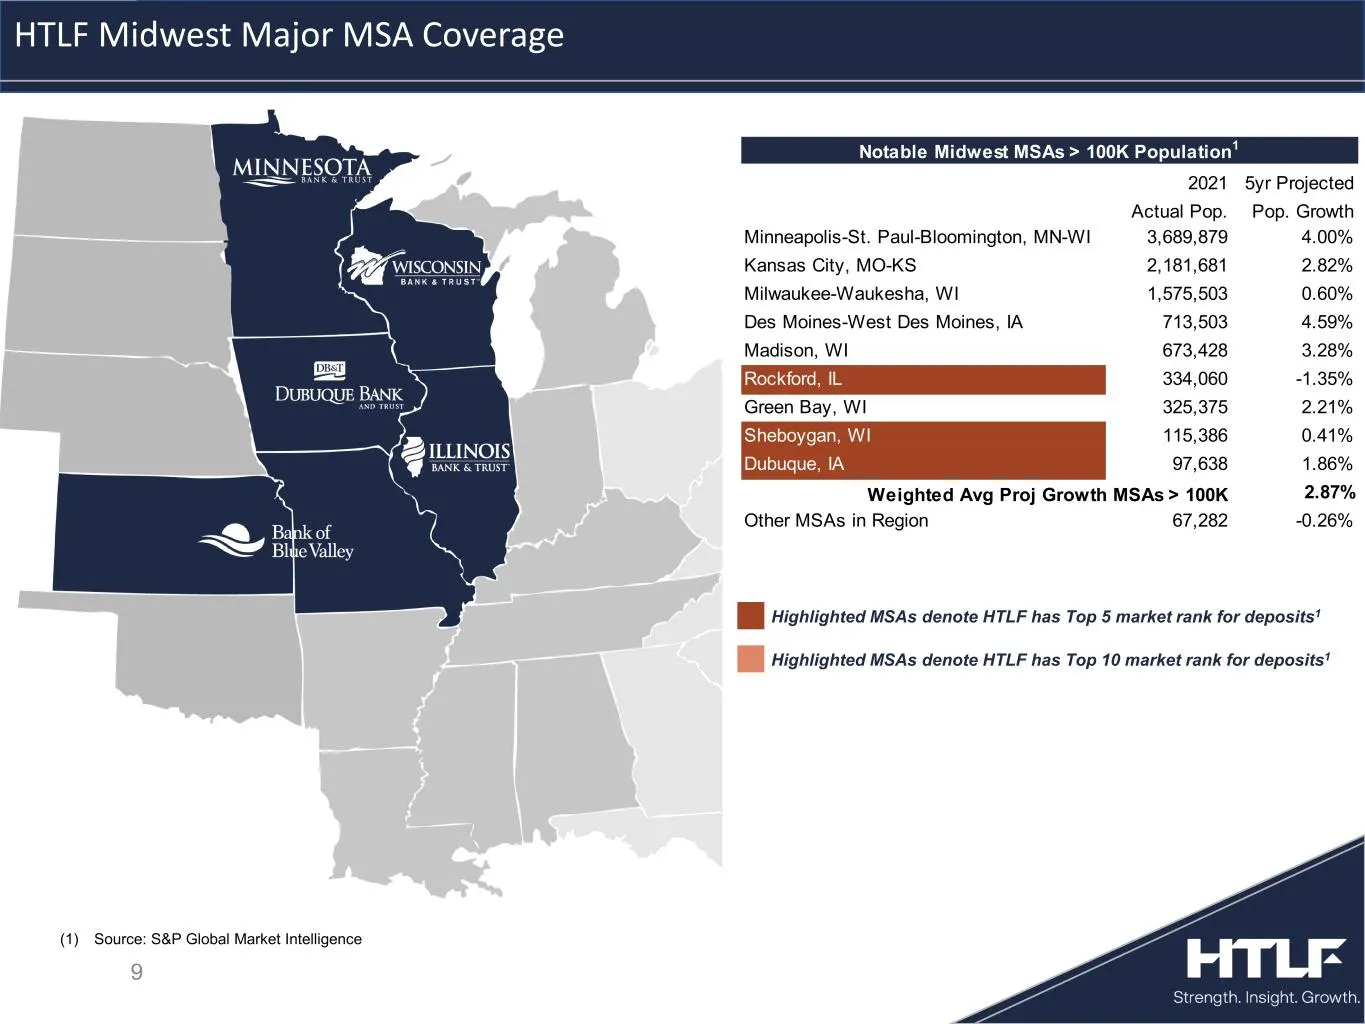
Slide 9: HTLF Midwest Major MSA Coverage
2021 5yr Projected Actual Pop. Pop. Growth Minneapolis-St. Paul-Bloomington, MN-WI 3,689,879 4.00% Kansas City, MO-KS 2,181,681 2.82% Milwaukee-Waukesha, WI 1,575,503 0.60% Des Moines-West Des Moines, IA 713,503 4.59% Madison, WI 673,428 3.28% Rockford, IL 334,060 -1.35% Green Bay, WI 325,375 2.21%
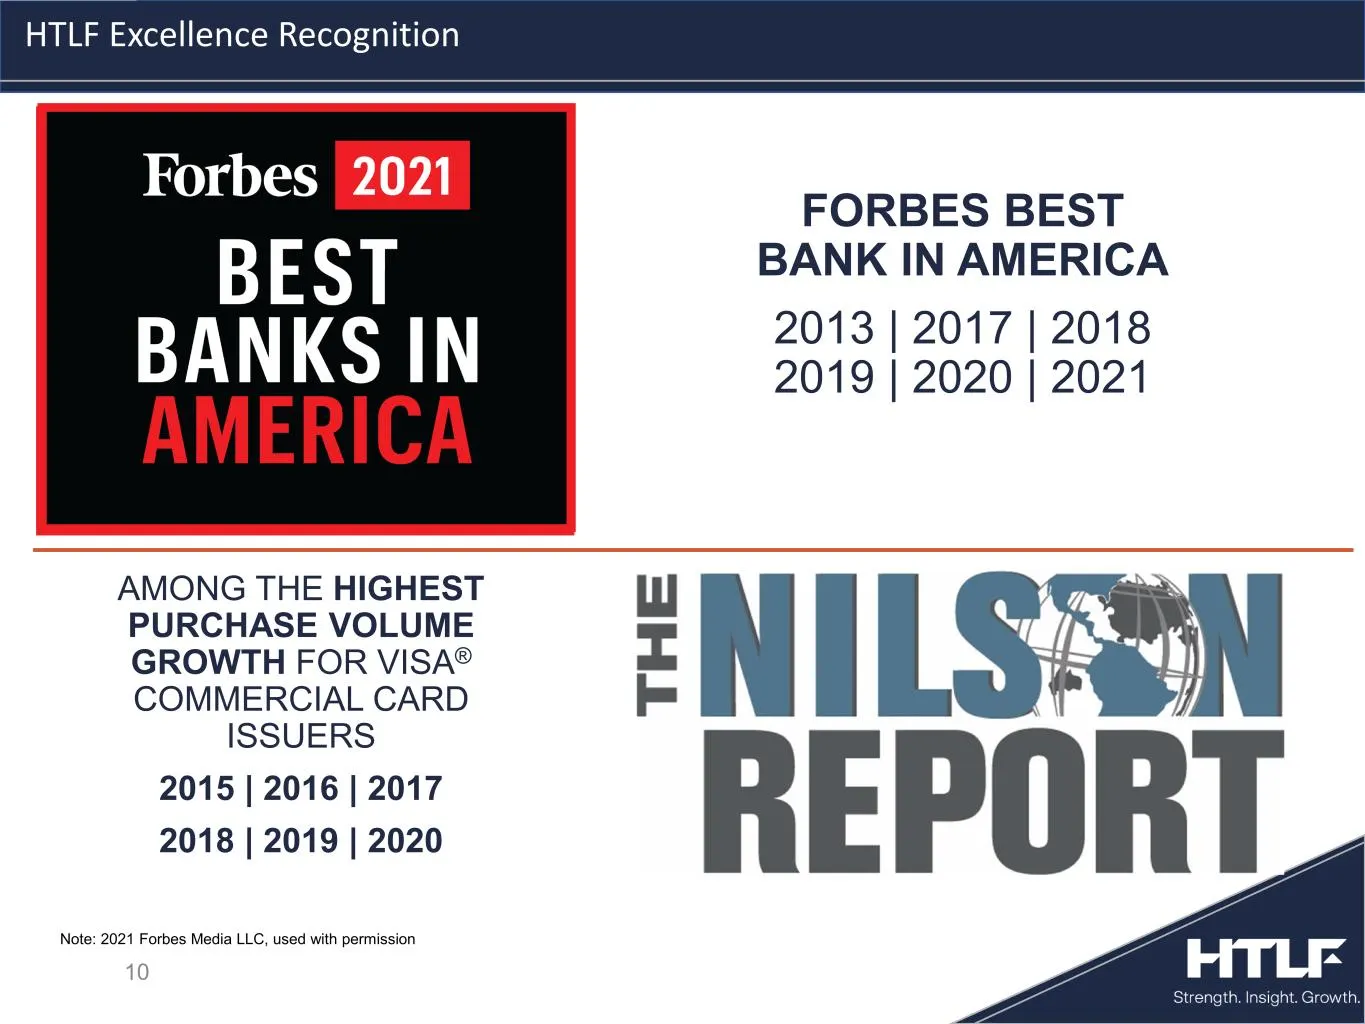
Slide 10: HTLF Excellence Recognition
10 HTLF Excellence Recognition Note: 2021 Forbes Media LLC, used with permission AMONG THE HIGHEST PURCHASE VOLUME GROWTH FOR VISA® COMMERCIAL CARD ISSUERS 2015 | 2016 | 2017 2018 | 2019 | 2020 FORBES BEST BANK IN AMERICA 2013 | 2017 | 2018 2019 | 2020 | 2021
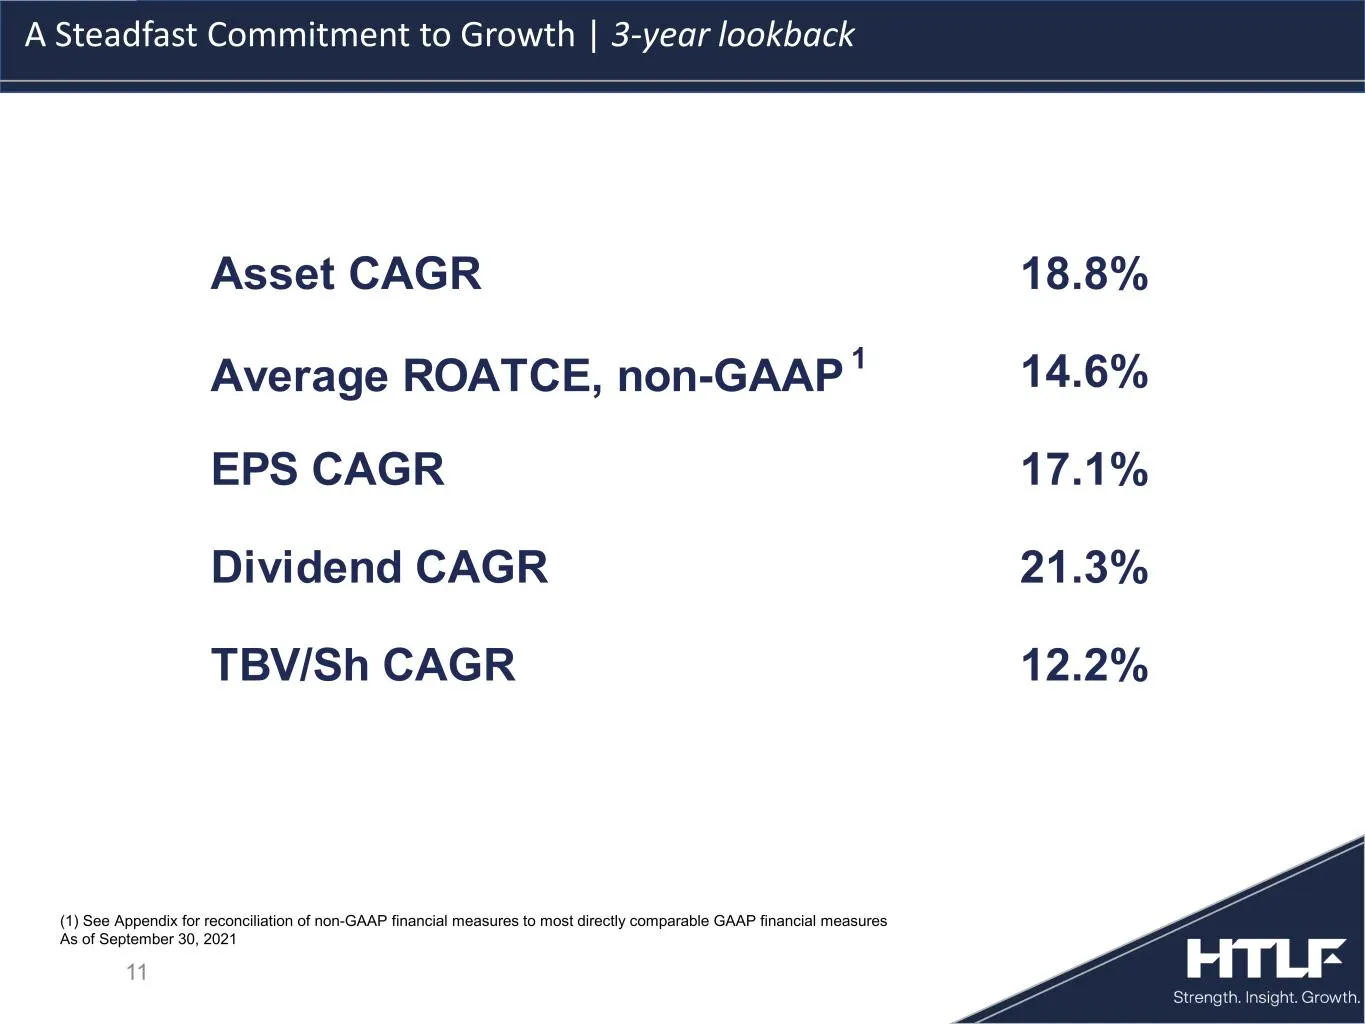
Slide 11: A Steadfast Commitment to Growth
11 A Steadfast Commitment to Growth | 3-year lookback (1) See Appendix for reconciliation of non-GAAP financial measures to most directly comparable GAAP financial measures As of September 30, 2021 Asset CAGR 18.8% Average ROATCE, non-GAAP 1 14.6% EPS CAGR 17.1% Dividend CAGR 21.3% TBV/Sh CAGR 12.2%
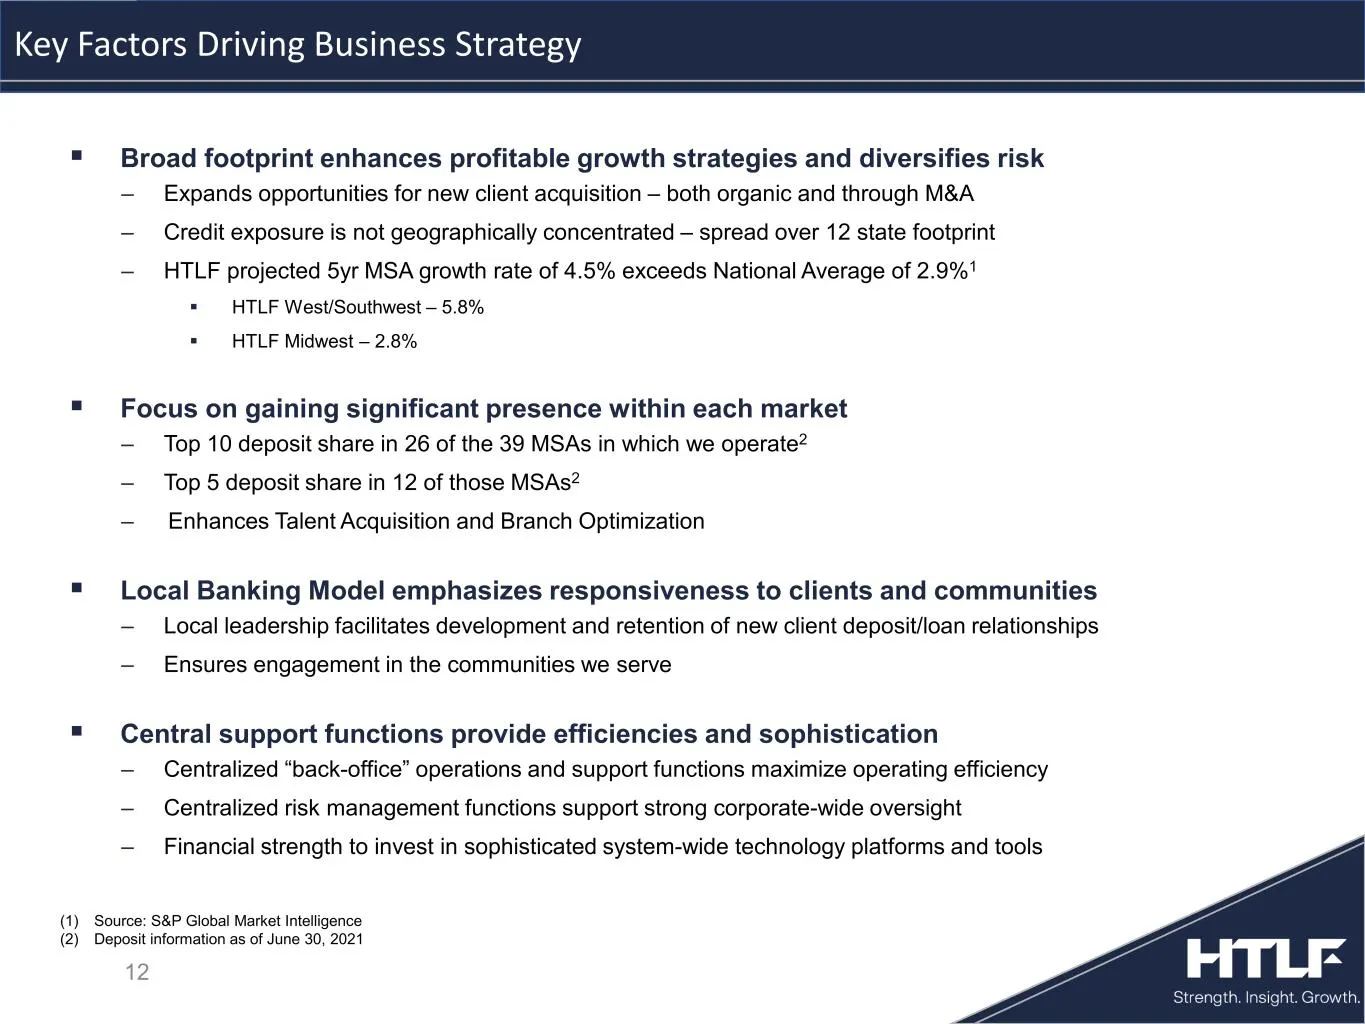
Slide 12: Broad footprint enhances profitable growth strategies
Broad footprint enhances profitable growth strategies and diversifies risk ‒ Expands opportunities for new client acquisition – both organic and through M&A ‒ Credit exposure is not geographically concentrated – spread over 12 state footprint ‒ HTLF projected 5yr MSA growth rate of 4.5% exceeds Na
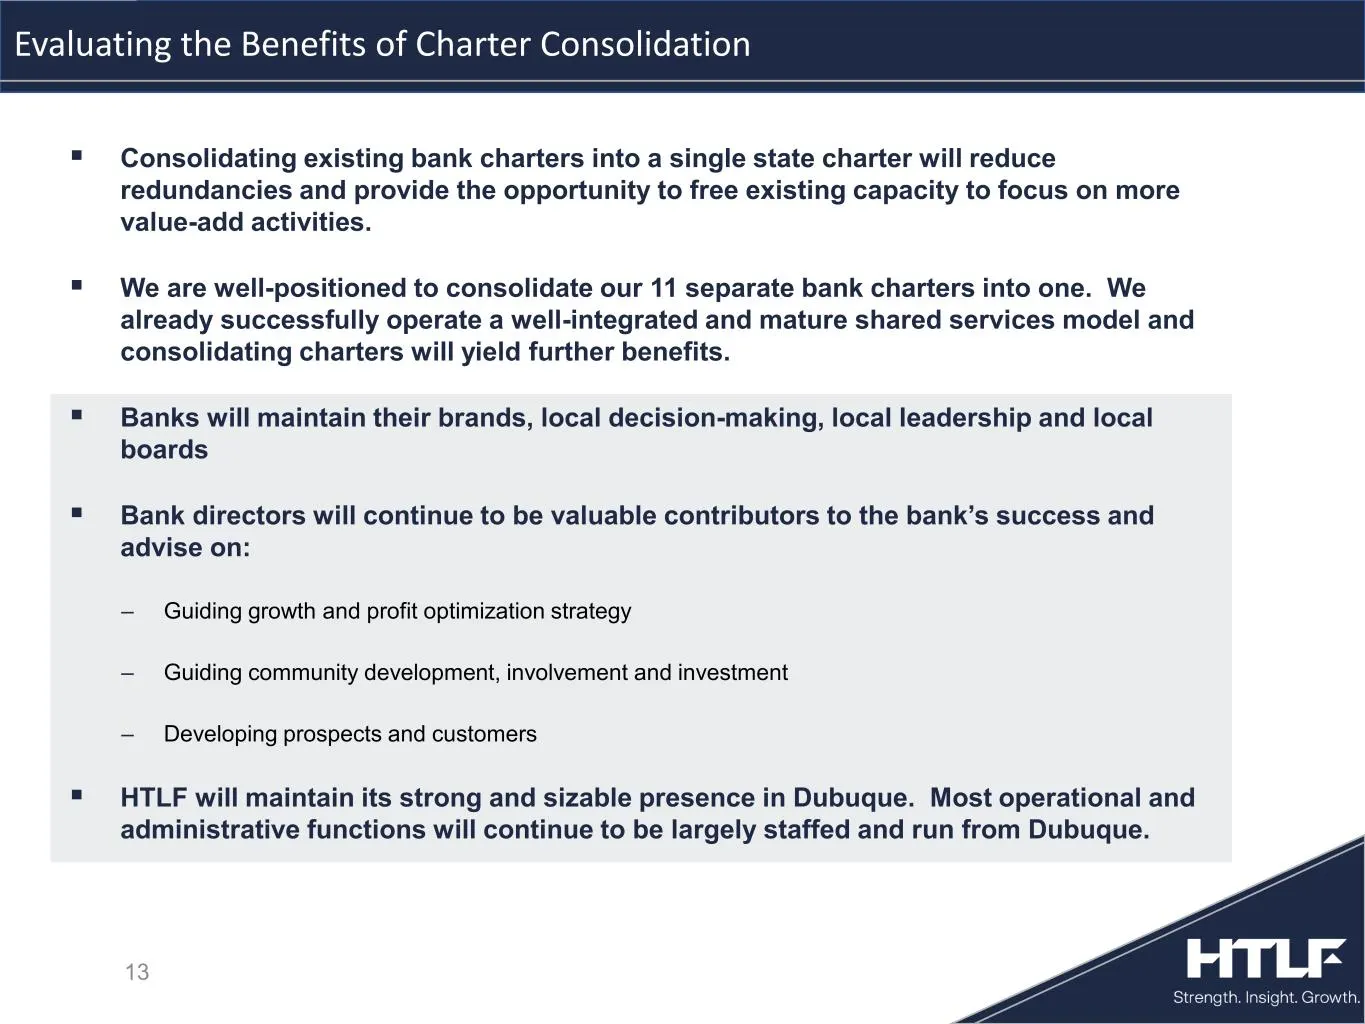
Slide 13: Consolidating bank charters into a single state charter
Consolidating existing bank charters into a single state charter will reduce redundancies and provide the opportunity to free existing capacity to focus on more value-add activities. We are well-positioned to consolidate our 11 separate bank charters into one. We already successfully operate a w
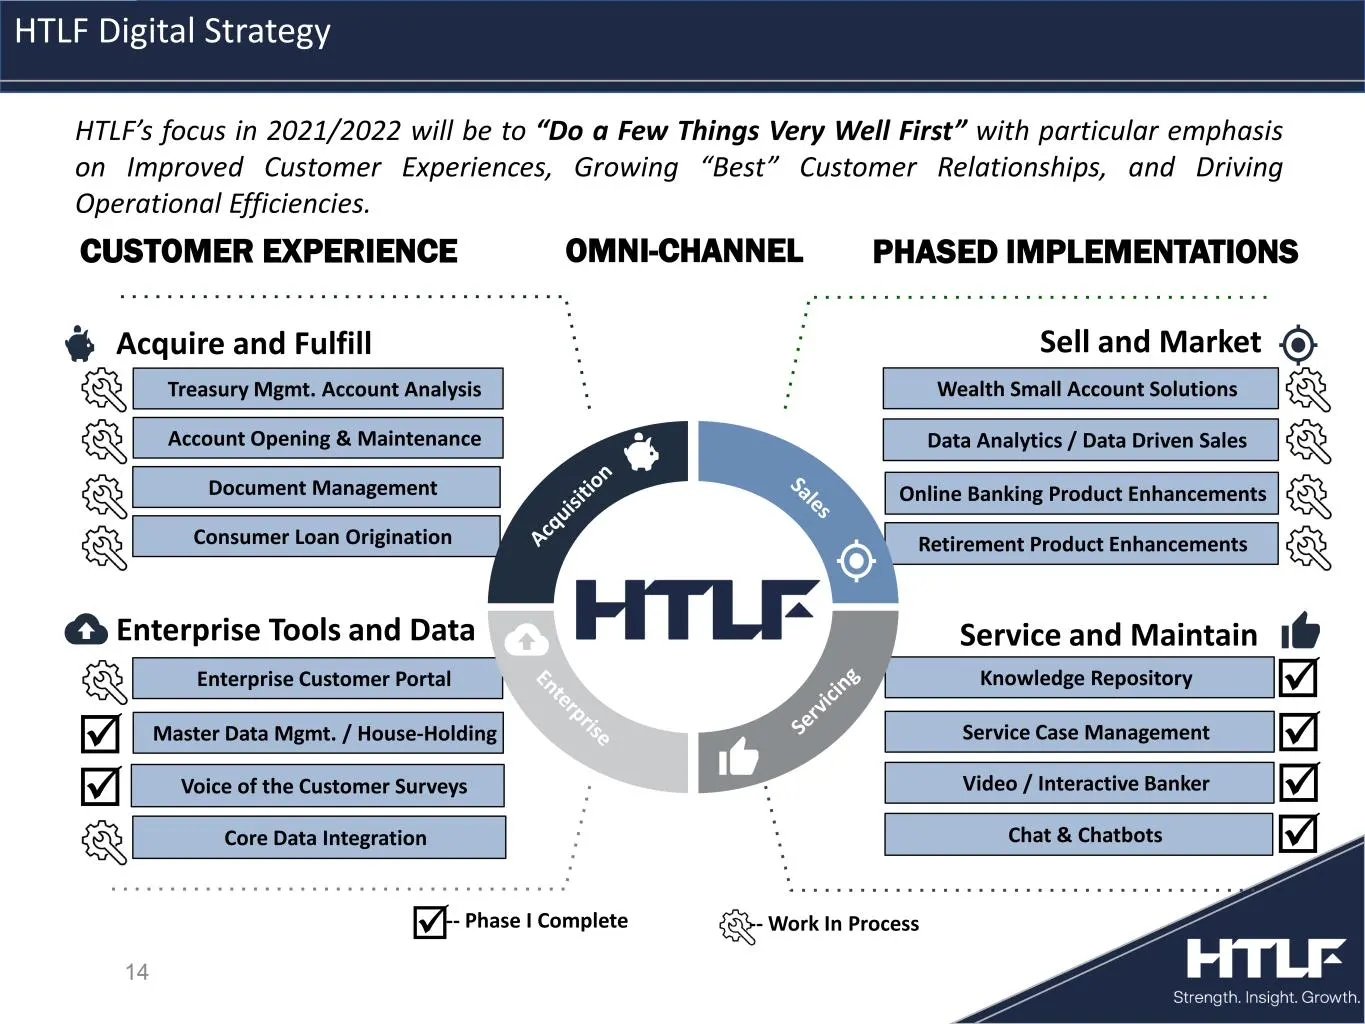
Slide 14: Customer experience and technology phased implementations
14 Retirement Product Enhancements Online Banking Product Enhancements Deposit Account Opening & Consumer LOS Implementation Options Document Management Consumer Loan Origination Account Opening & Maintenance Enterprise Tools and Data Acquire and Fulfill Sell and Market Service and Maintain Enterpri
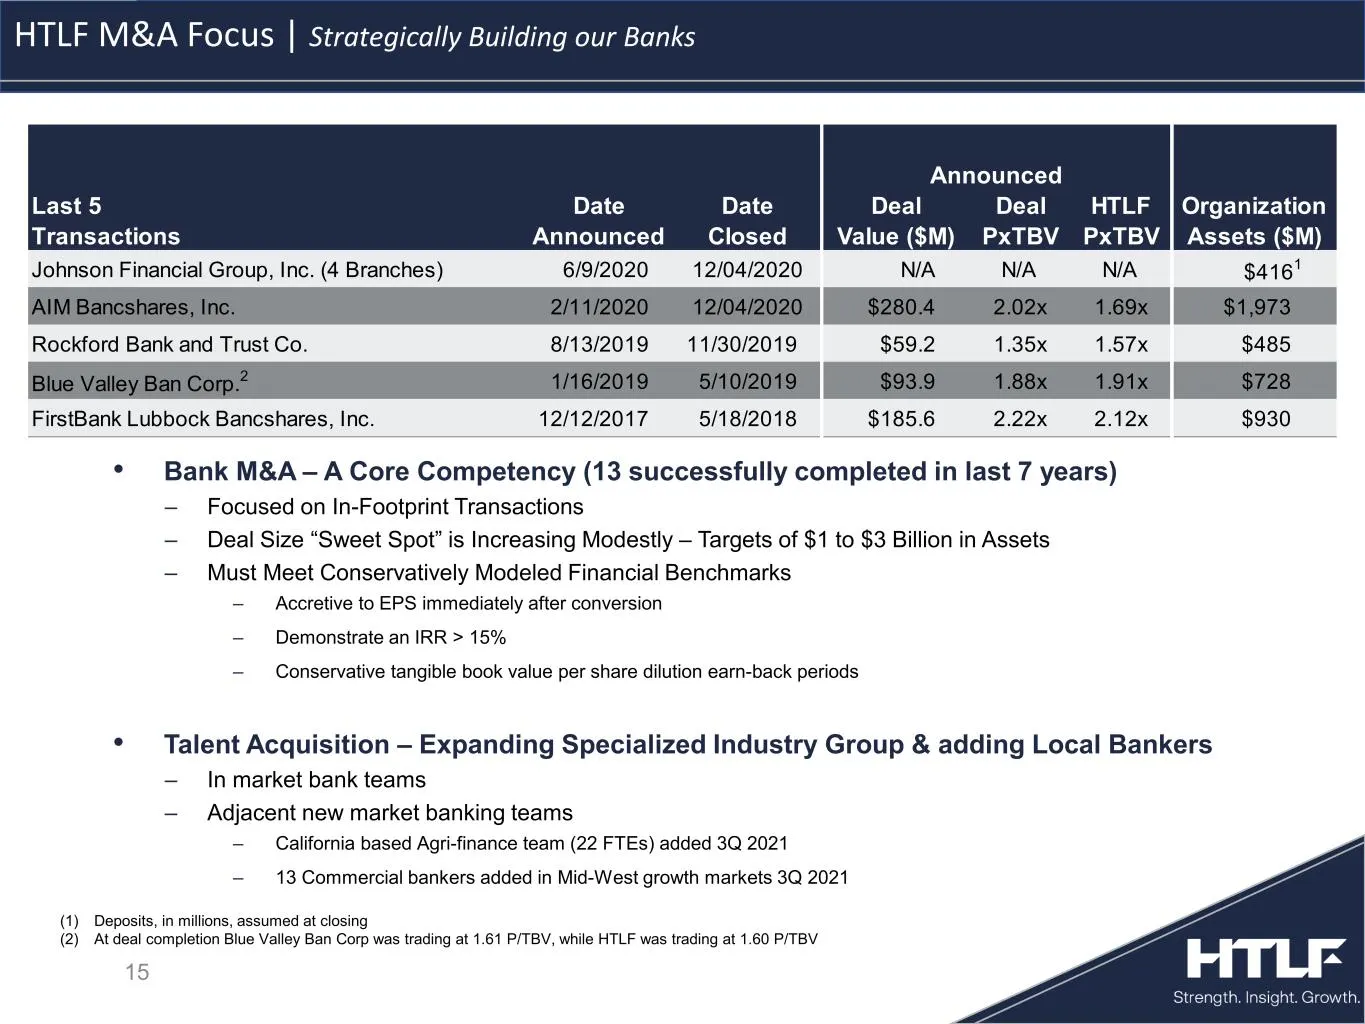
Slide 15: HTLF M&A Focus
15 HTLF M&A Focus | Strategically Building our Banks (1) Deposits, in millions, assumed at closing (2) At deal completion Blue Valley Ban Corp was trading at 1.61 P/TBV, while HTLF was trading at 1.60 P/TBV • Bank M&A – A Core Competency (13 successfully completed in last 7 years) ‒ Focused on In-Fo
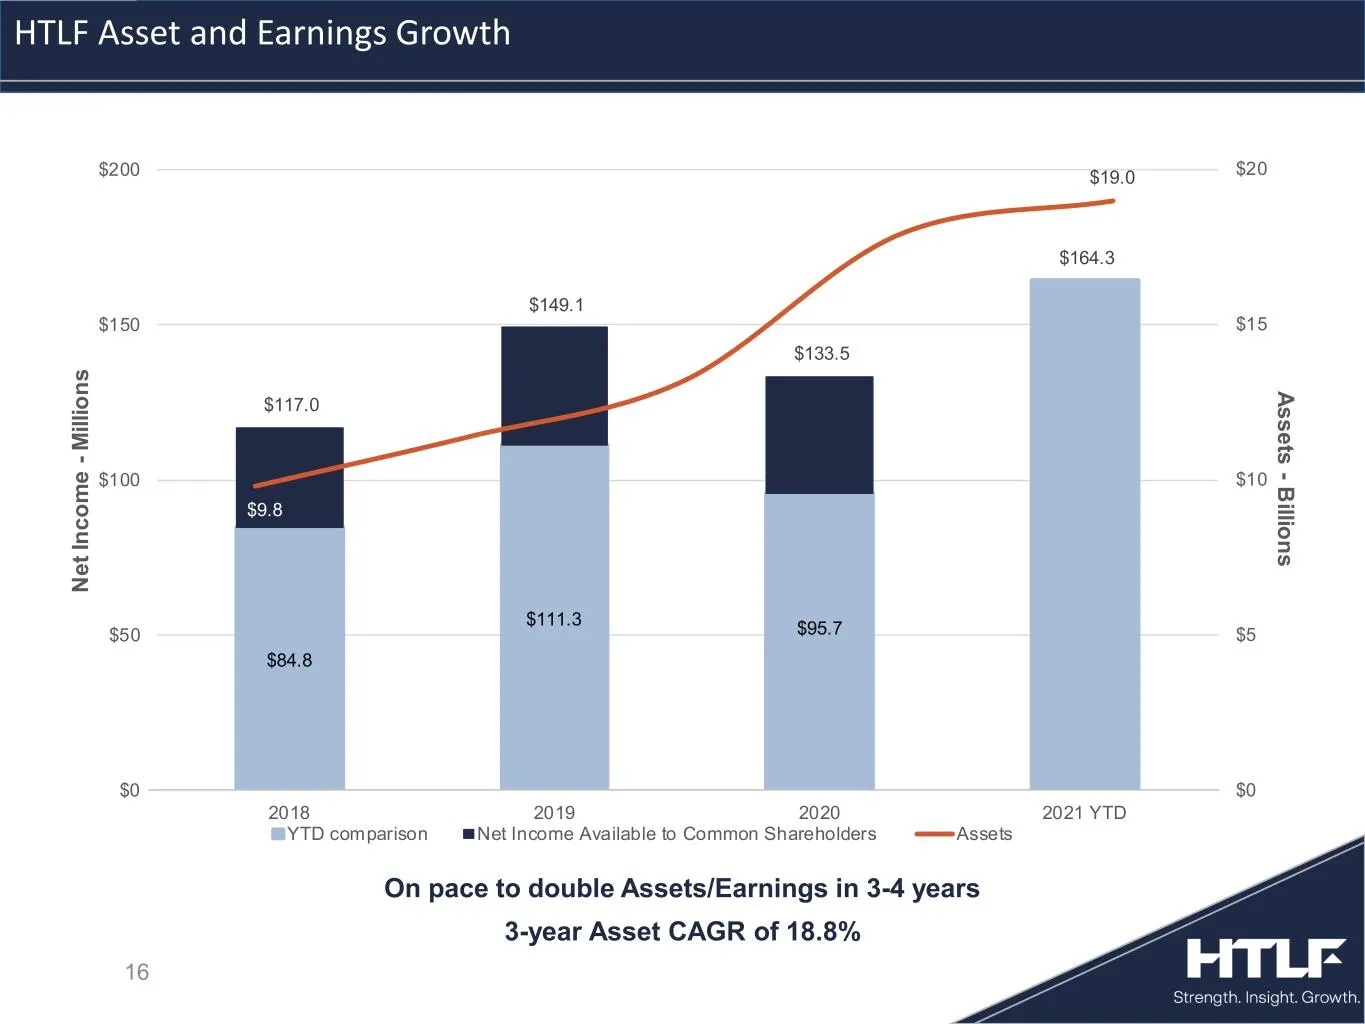
Slide 16: HTLF Asset and Earnings Growth
16 HTLF Asset and Earnings Growth $84.8 $111.3 $95.7 $117.0 $149.1 $133.5 $164.3 $0 $50 $100 $150 $200 2018 2019 2020 2021 YTD N et In co m e -M ill io ns YTD comparison Net Income Available to Common Shareholders $9.8 $19.0 $0 $5 $10 $15 $20 Assets -B illions Assets On pace to double Assets/Earning
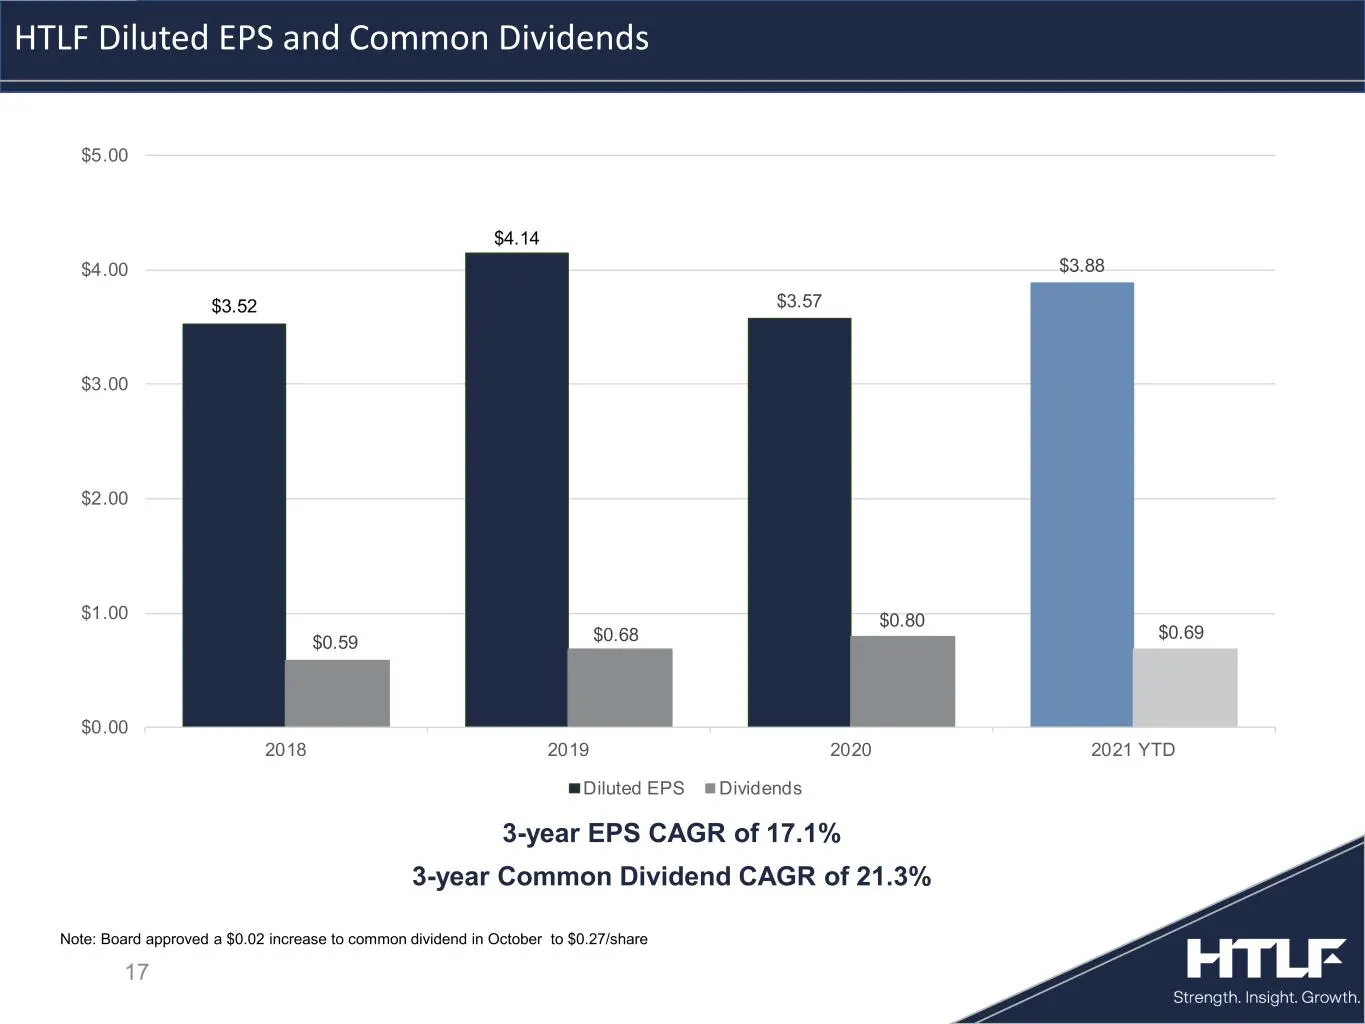
Slide 17: HTLF Diluted EPS and Common Dividends
17 HTLF Diluted EPS and Common Dividends 3-year EPS CAGR of 17.1% 3-year Common Dividend CAGR of 21.3% Note: Board approved a $0.02 increase to common dividend in October to $0.27/share $3.52 $4.14 $3.57 $3.88 $0.59 $0.68 $0.80 $0.69 2018 2019 2020 2021 YTD $0.00 $1.00 $2.00 $3.00 $4.00 $5.00 Dilute
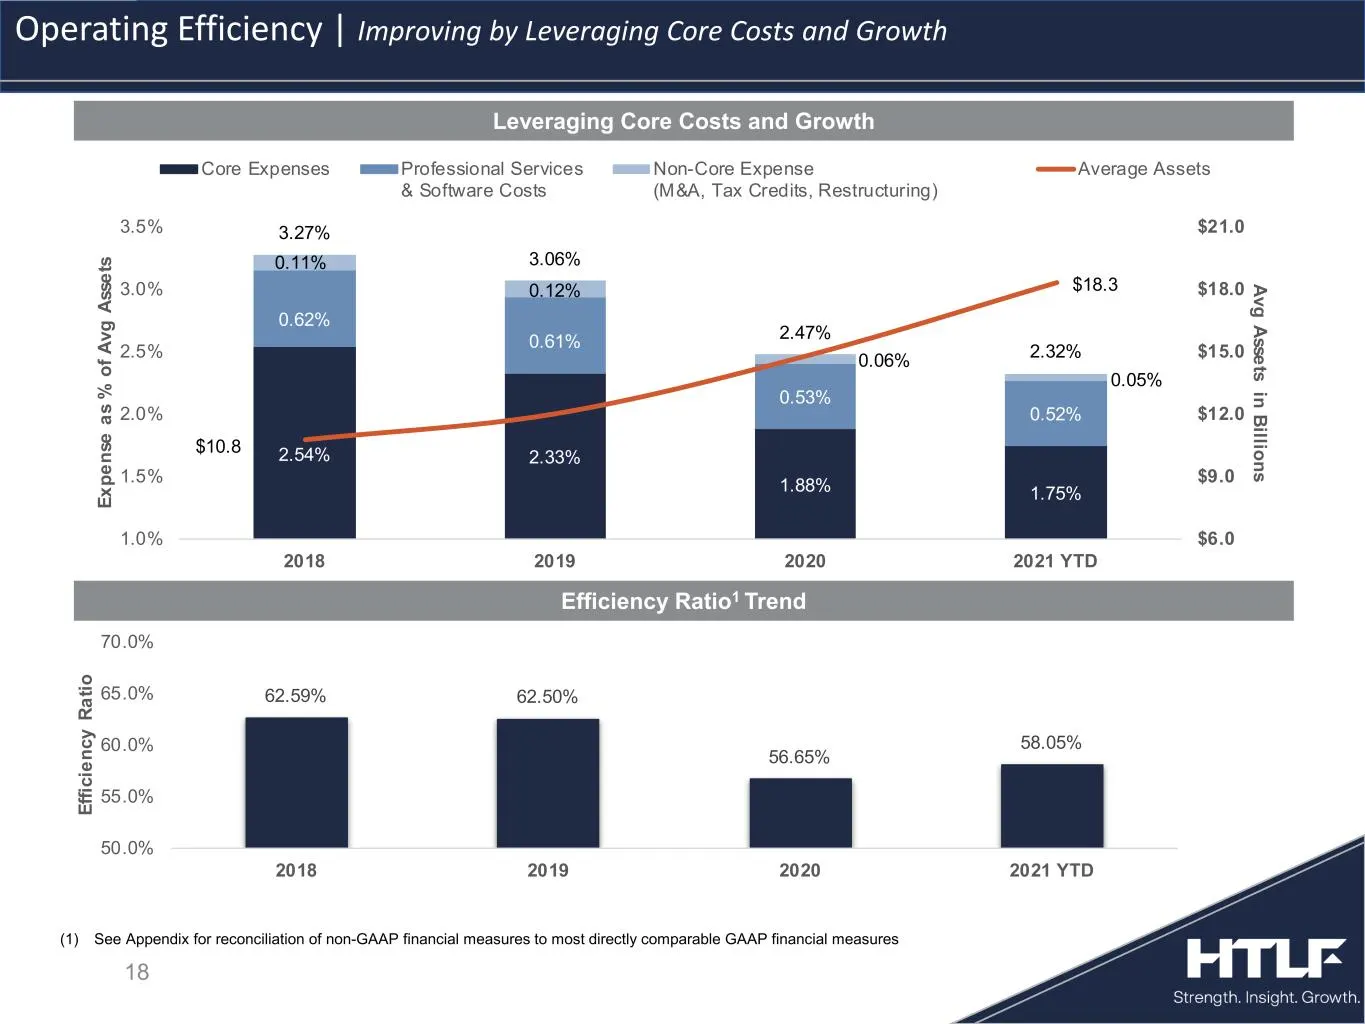
Slide 18: Operating Efficiency
Efficiency Ratio1 Trend 18 Operating Efficiency | Improving by Leveraging Core Costs and Growth 2.54% 2.33% 1.88% 1.75% 0.62% 0.61% 0.53% 0.52% 0.11% 0.12% 0.06% 0.05% 3.27% 3.06% 2.47% 2.32% $10.8 $18.3 $6.0 $9.0 $12.0 $15.0 $18.0 $21.0 1.0% 1.5% 2.0% 2.5% 3.0% 3.5% 2018 2019 2020 2021 YTD Avg Asse
Slide 19: Financial Summary
19 Financial Summary
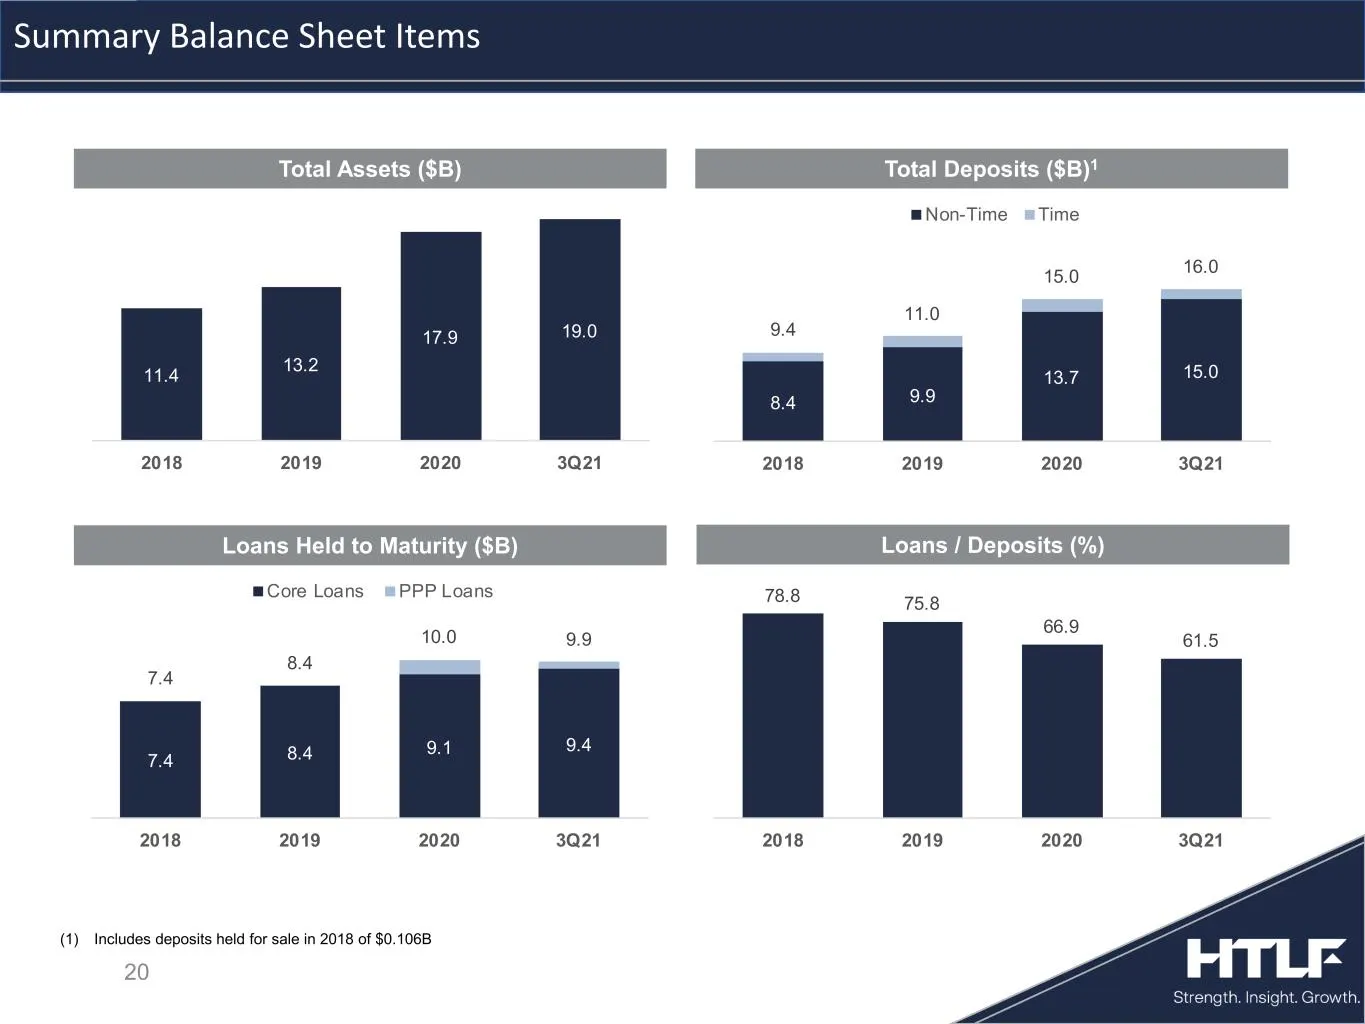
Slide 20: Summary Balance Sheet Items
20 Total Assets ($B) Total Deposits ($B)1 Loans Held to Maturity ($B) Loans / Deposits (%) Summary Balance Sheet Items (1) Includes deposits held for sale in 2018 of $0.106B 11.4 13.2 17.9 19.0 2018 2019 2020 3Q21 8.4 9.9 13.7 15.0 9.4 11.0 15.0 16.0 2018 2019 2020 3Q21 Non-Time Time 78.8 75.8 66.9
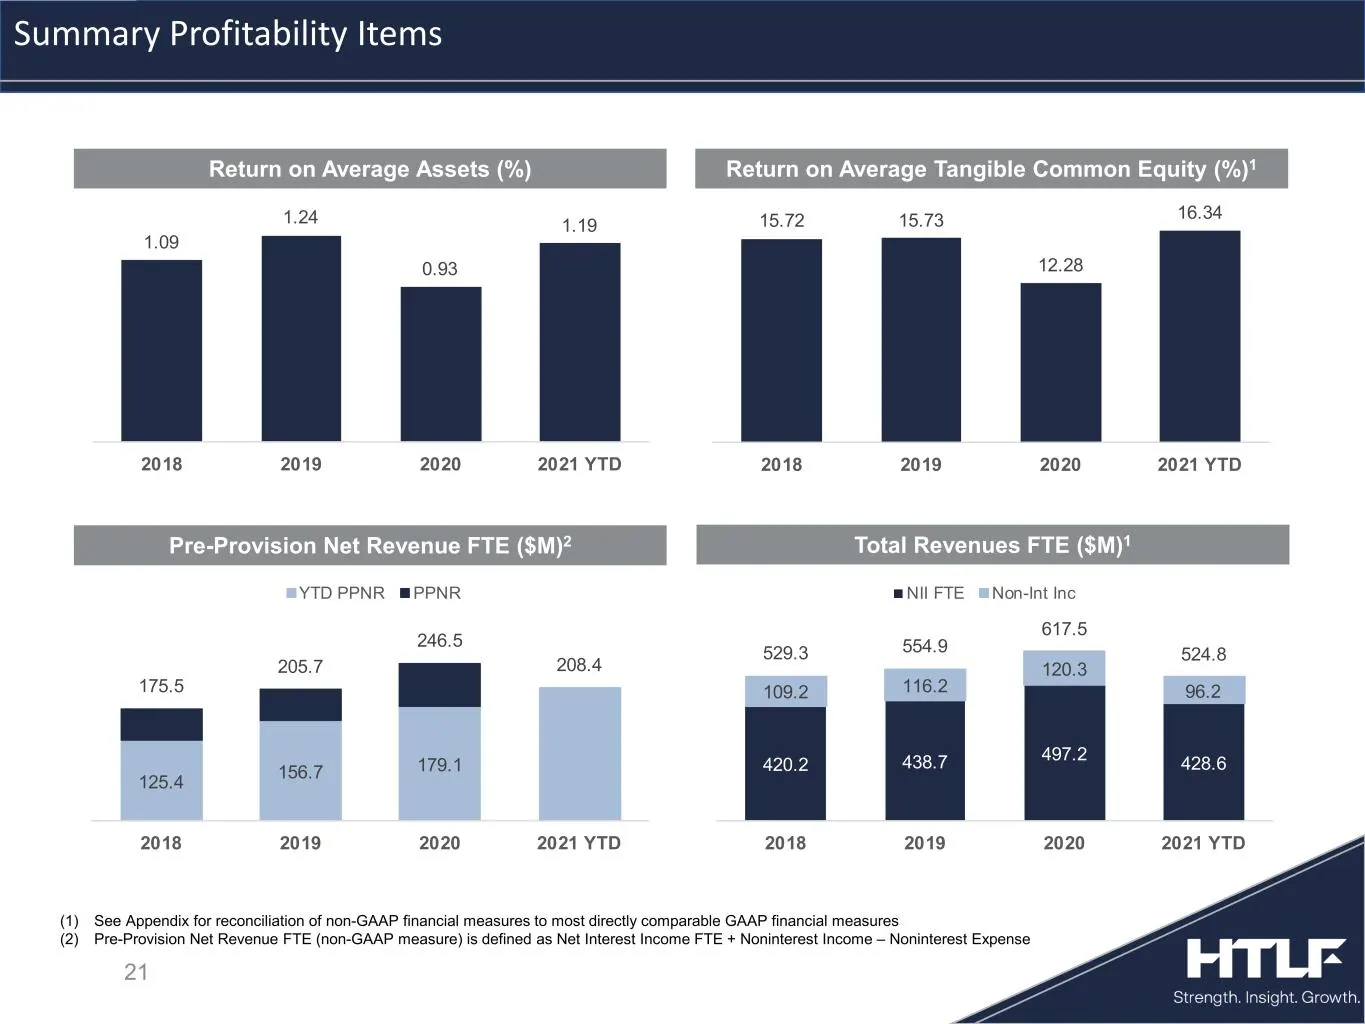
Slide 21: Summary Profitability Items
21 Summary Profitability Items (1) See Appendix for reconciliation of non-GAAP financial measures to most directly comparable GAAP financial measures (2) Pre-Provision Net Revenue FTE (non-GAAP measure) is defined as Net Interest Income FTE + Noninterest Income – Noninterest Expense 1.09 1.24 0.93 1
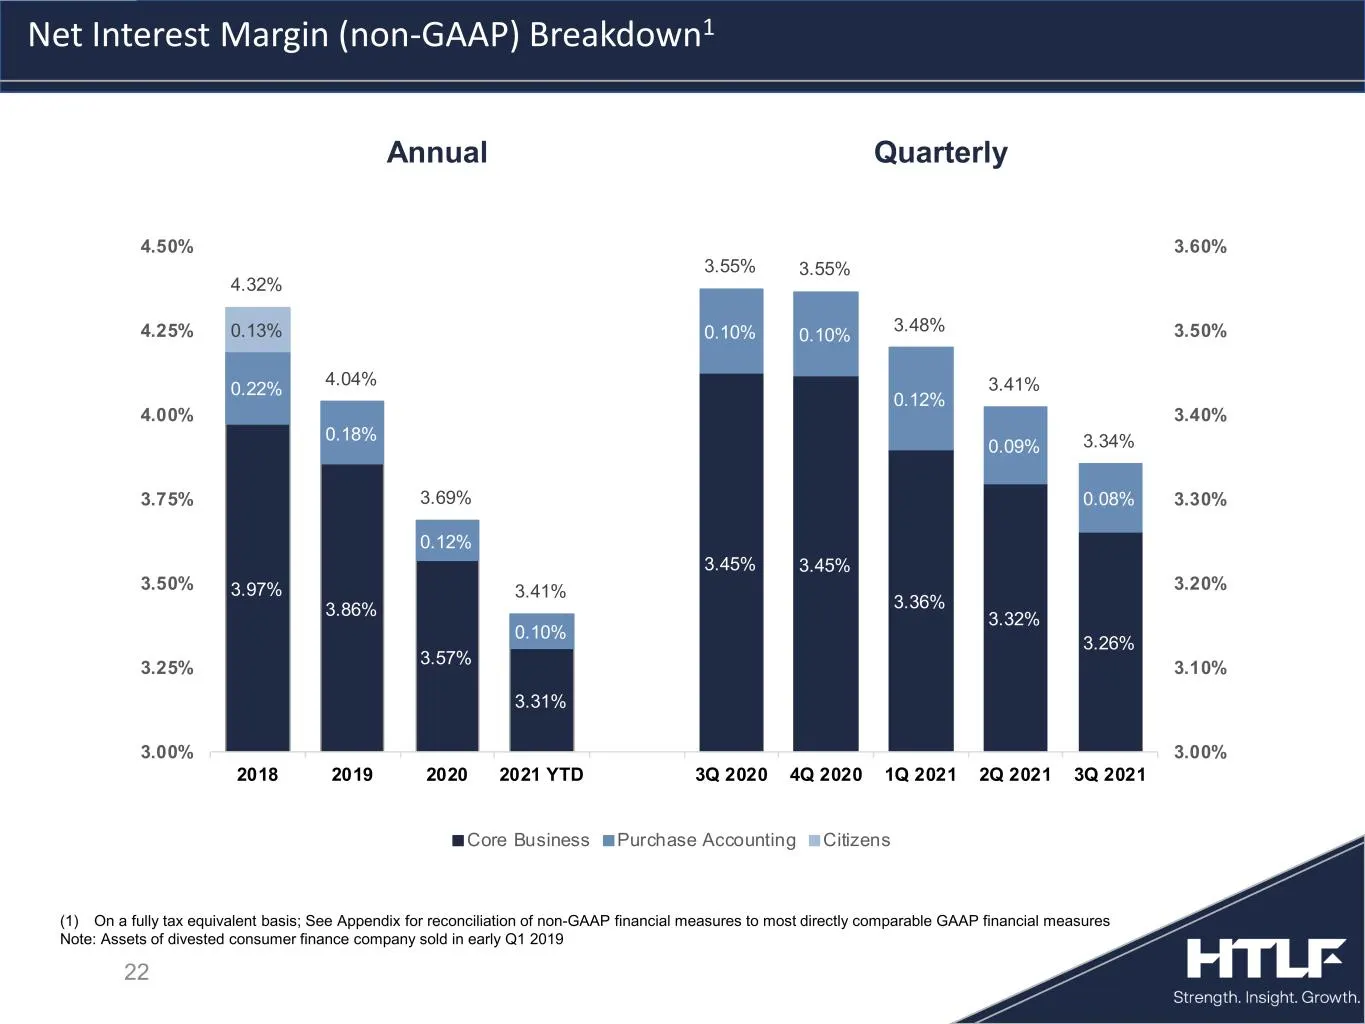
Slide 22: Net Interest Margin Breakdown
22 Net Interest Margin (non-GAAP) Breakdown1 QuarterlyAnnual (1) On a fully tax equivalent basis; See Appendix for reconciliation of non-GAAP financial measures to most directly comparable GAAP financial measures Note: Assets of divested consumer finance company sold in early Q1 2019 3.97% 3.86% 3.5
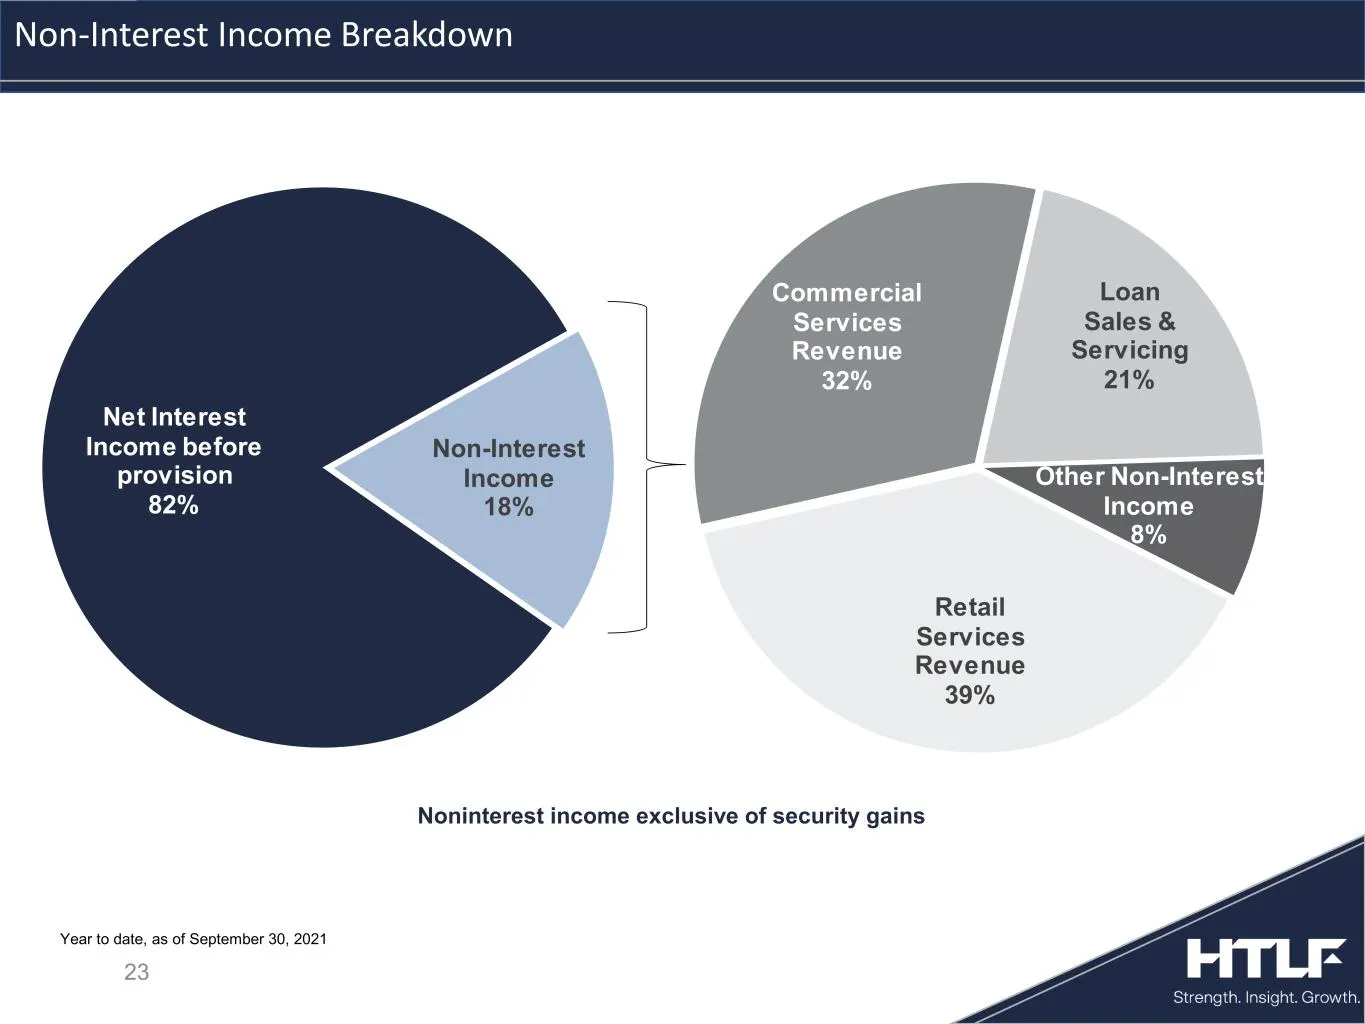
Slide 23: Non-Interest Income Breakdown
23 Noninterest income exclusive of security gains Non-Interest Income Breakdown Year to date, as of September 30, 2021 Net Interest Income before provision 82% Non-Interest Income 18% Retail Services Revenue 39% Commercial Services Revenue 32% Loan Sales & Servicing 21% Other Non-Interest Income 8%
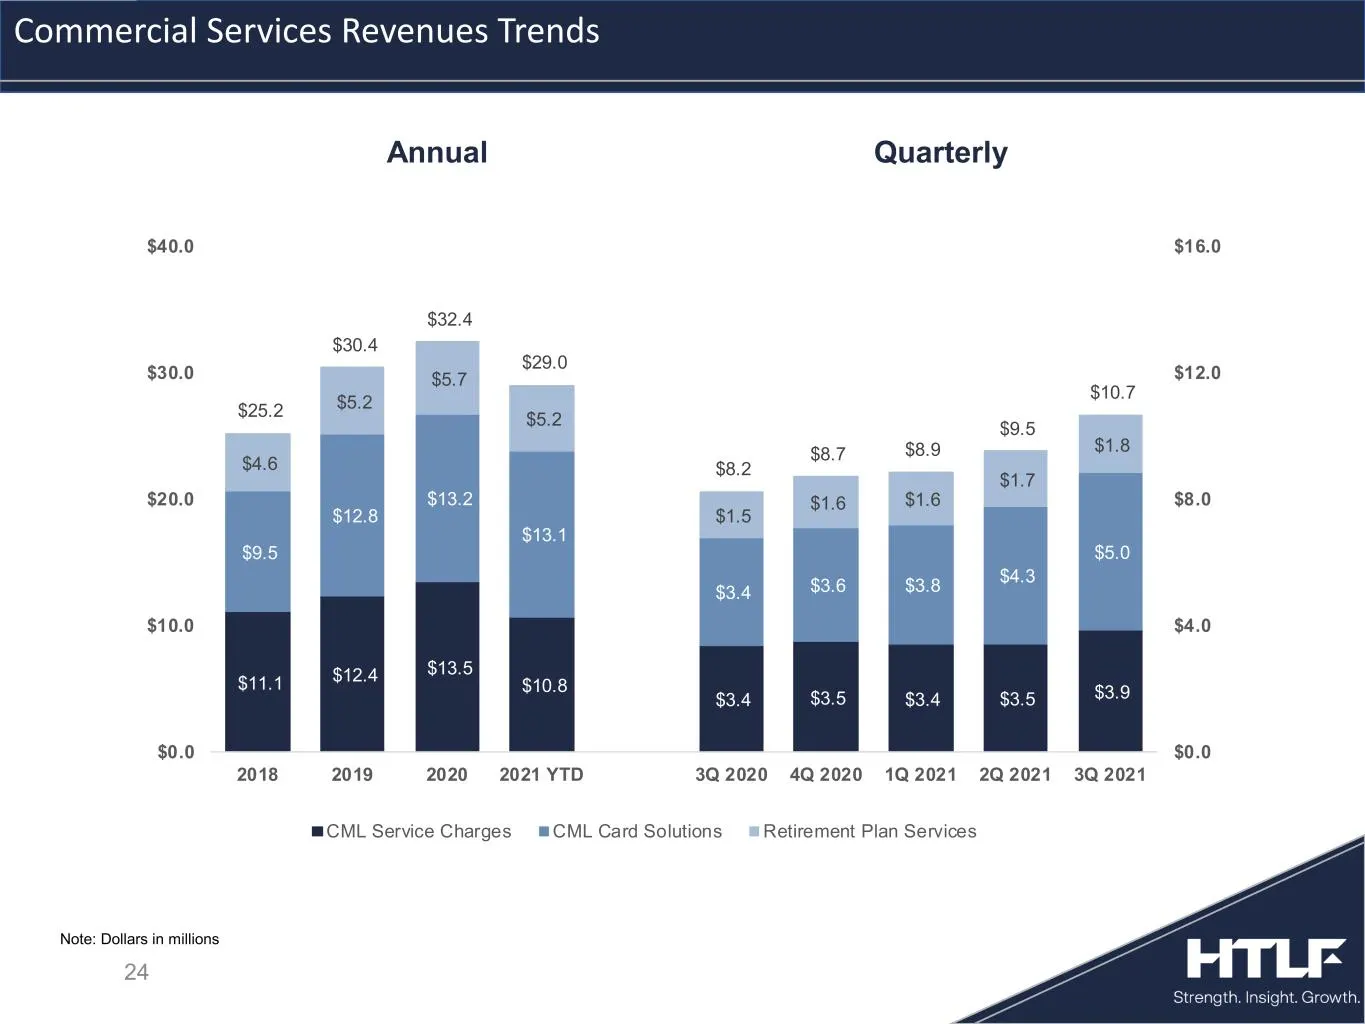
Slide 24: Commercial Services Revenues Trends
24 Commercial Services Revenues Trends Note: Dollars in millions $11.1 $12.4 $13.5 $10.8 $9.5 $12.8 $13.2 $13.1 $4.6 $5.2 $5.7 $5.2 $3.4 $3.5 $3.4 $3.5 $3.9 $3.4 $3.6 $3.8 $4.3 $5.0 $1.5 $1.6 $1.6 $1.7 $1.8 $25.2 $30.4 $32.4 $29.0 $8.2 $8.7 $8.9 $9.5 $10.7 $0.0 $4.0 $8.0 $12.0 $16.0 $0.0 $10.0 $20.0
Slide 25: Consumer Services Revenues Trends
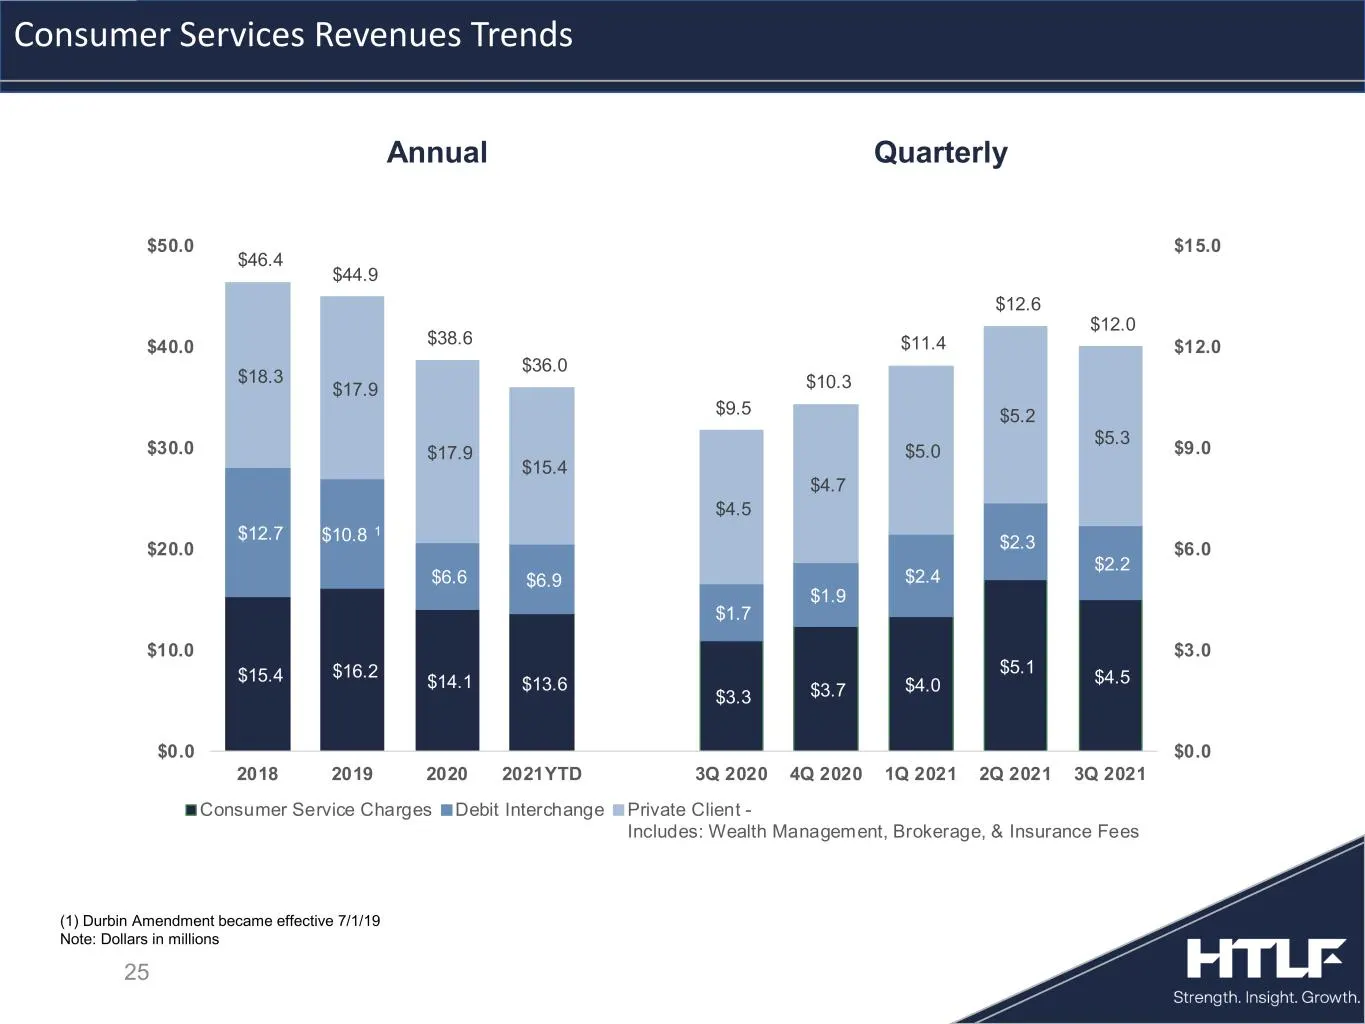
25 Consumer Services Revenues Trends (1) Durbin Amendment became effective 7/1/19 Note: Dollars in millions $15.4 $16.2 $14.1 $13.6 $12.7 $10.8 1 $6.6 $6.9 $18.3 $17.9 $17.9 $15.4 $3.3 $3.7 $4.0 $5.1 $4.5 $1.7 $1.9 $2.4 $2.3 $2.2 $4.5 $4.7 $5.0 $5.2 $5.3 $46.4 $44.9 $38.6 $36.0 $9.5 $10.3 $11.4 $12.
Slide 26: Consolidated Capital Ratios
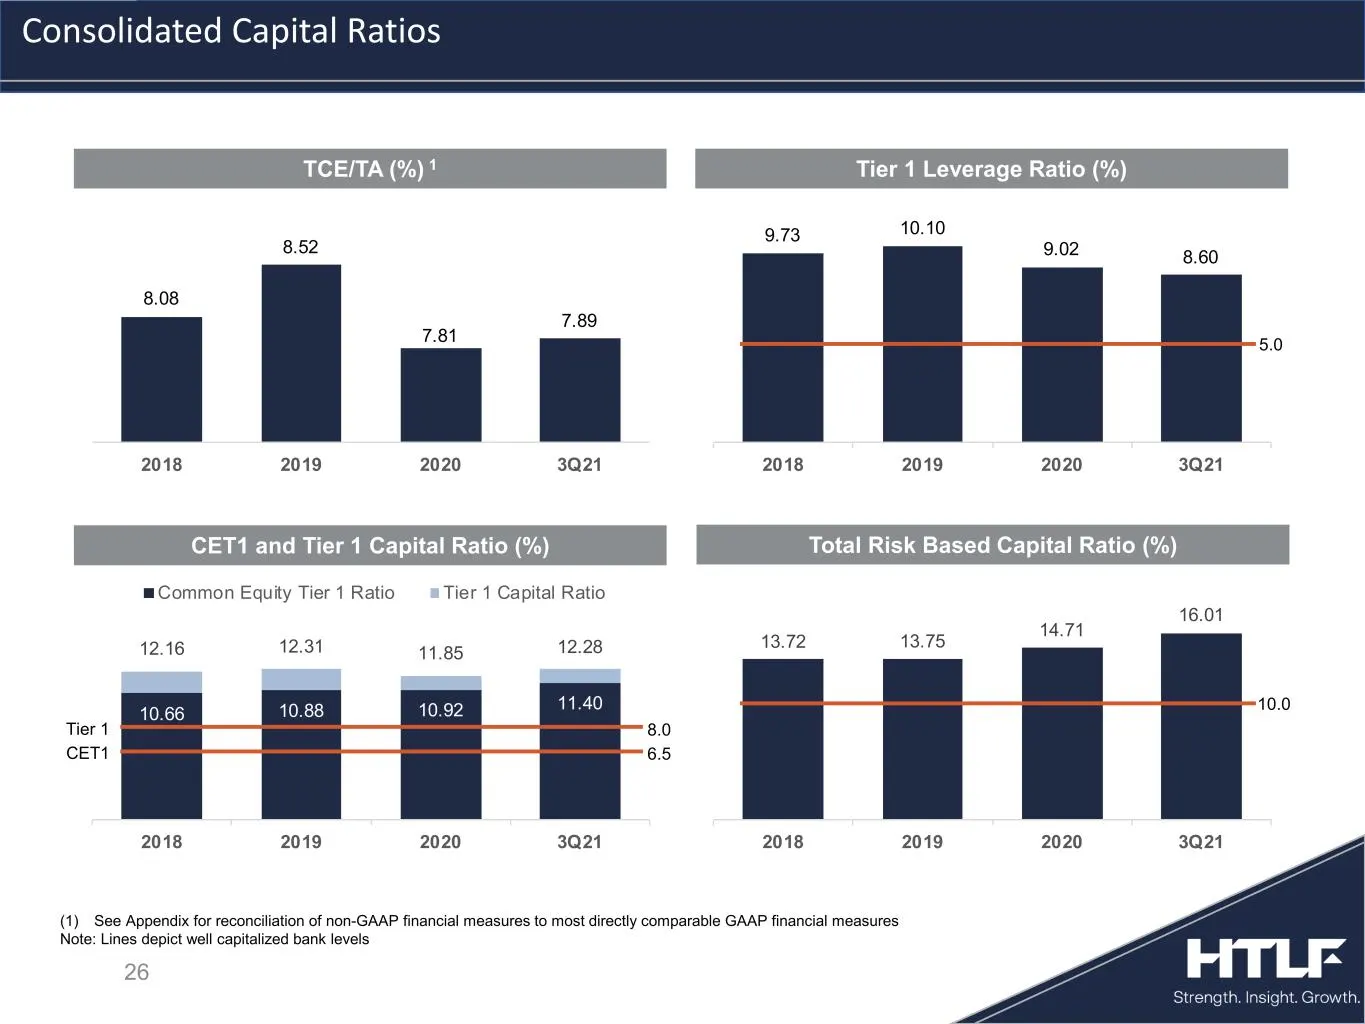
8.08 8.52 7.81 7.89 2018 2019 2020 3Q21 9.73 10.10 9.02 8.60 2018 2019 2020 3Q21 10.66 10.88 10.92 11.40 12.16 12.31 11.85 12.28 2018 2019 2020 3Q21 Common Equity Tier 1 Ratio Tier 1 Capital Ratio 13.72 13.75 14.71 16.01 2018 2019 2020 3Q21 26 Consolidated Capital Ratios Tier 1 CET1 10.0 8.0 6.5 (1)
Slide 27: Loan Portfolio and Asset Quality
27 Loan Portfolio and Asset Quality
Slide 28: Diversified Loan Portfolio
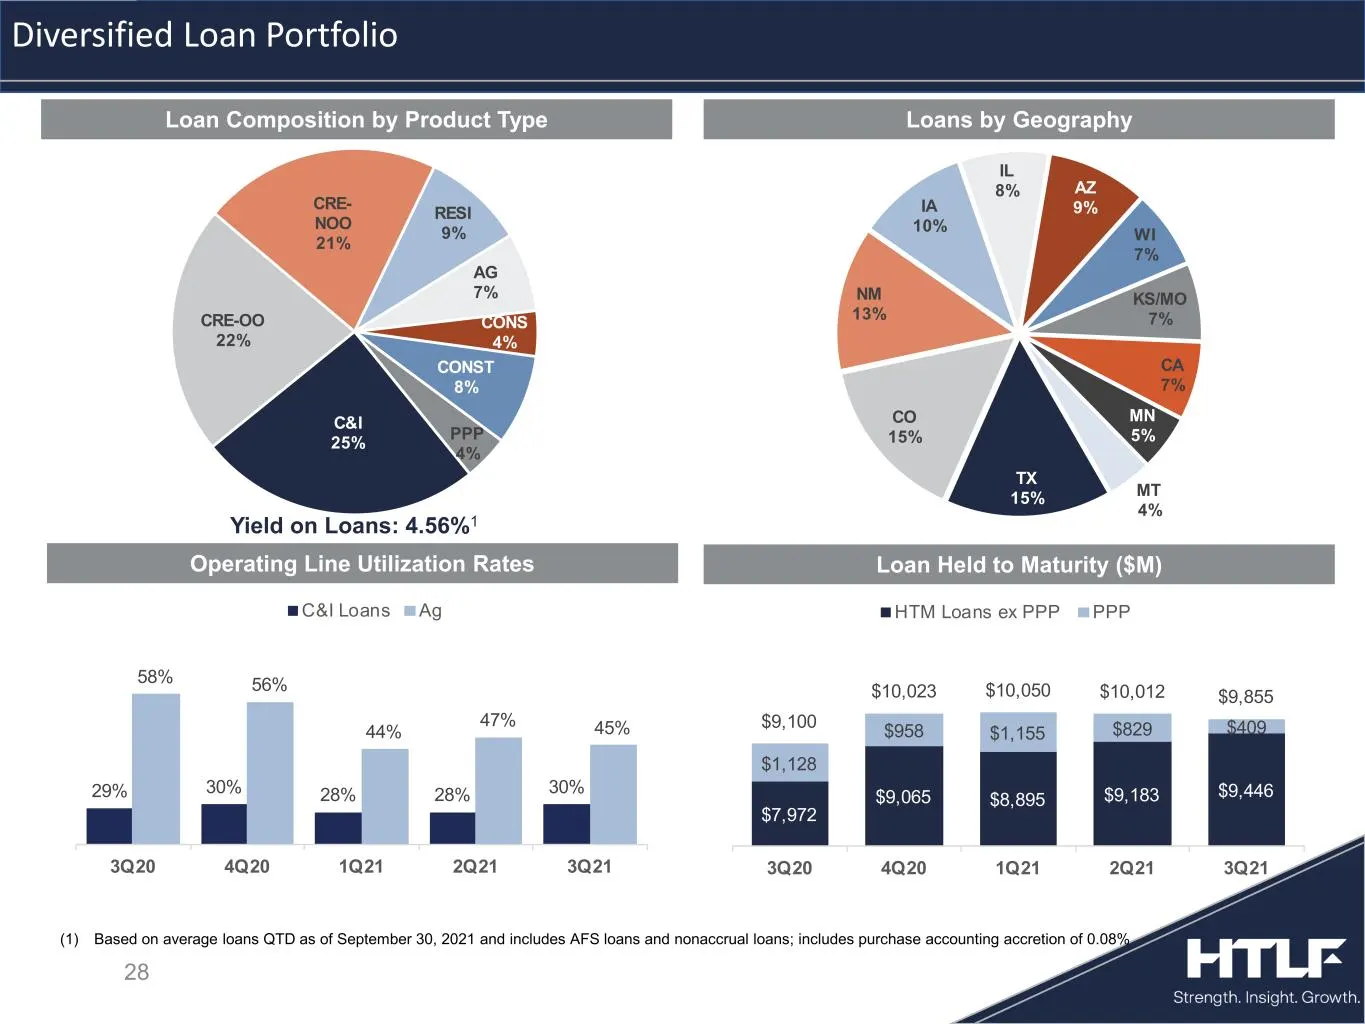
29% 30% 28% 28% 30% 58% 56% 44% 47% 45% 3Q20 4Q20 1Q21 2Q21 3Q21 C&I Loans Ag 28 Loan Composition by Product Type Loans by Geography Loan Held to Maturity ($M) Diversified Loan Portfolio (1) Based on average loans QTD as of September 30, 2021 and includes AFS loans and nonaccrual loans; includes pur
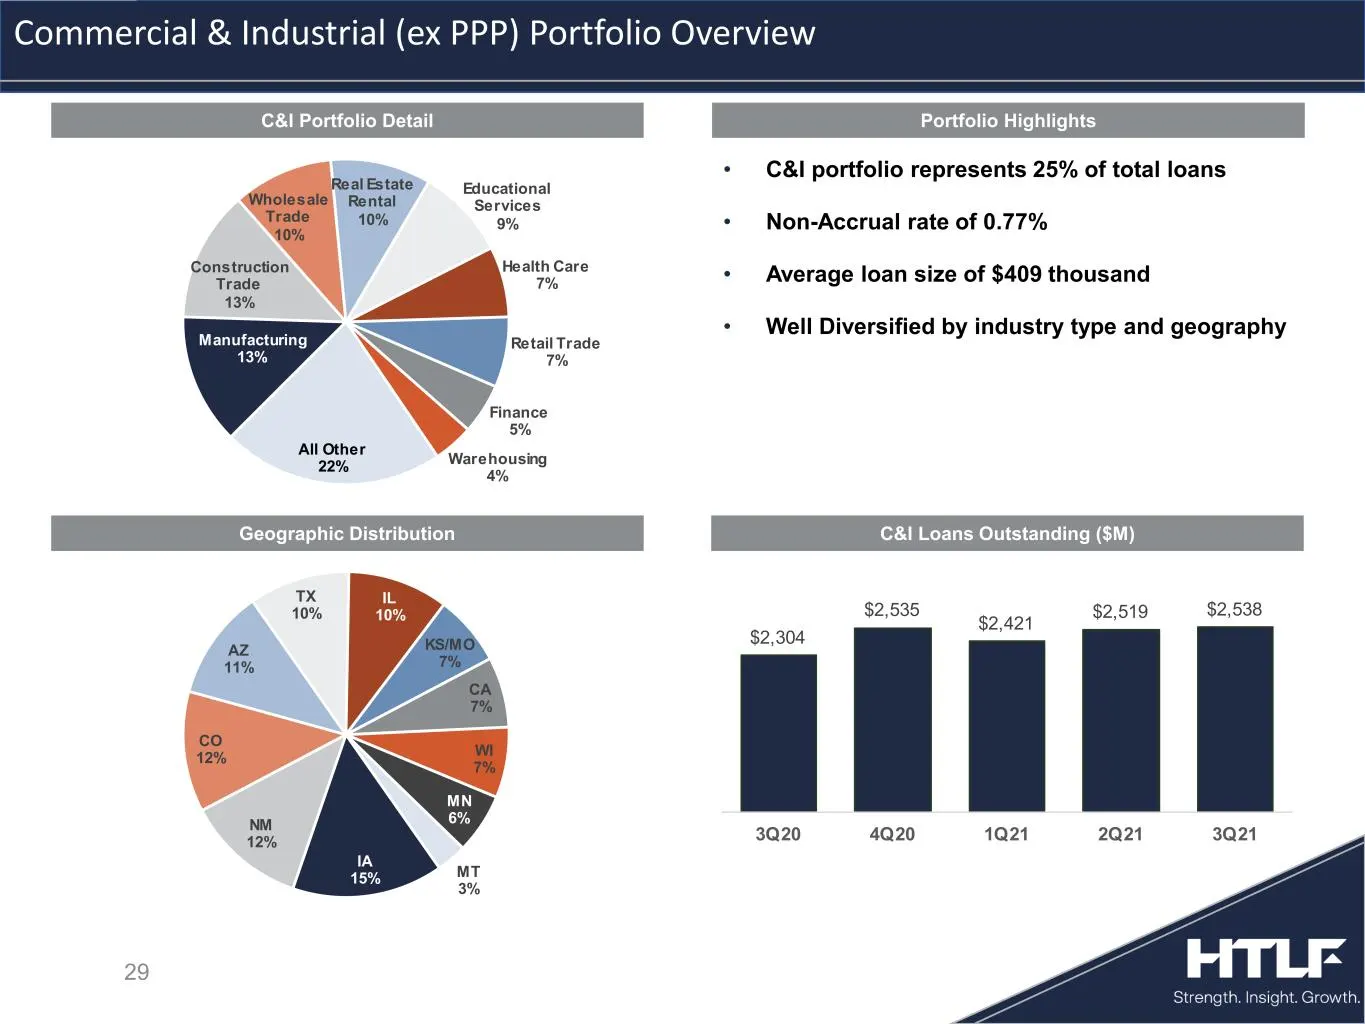
Slide 29: Commercial & Industrial Portfolio Overview
• C&I portfolio represents 25% of total loans • Non-Accrual rate of 0.77% • Average loan size of $409 thousand • Well Diversified by industry type and geography 29 Commercial & Industrial (ex PPP) Portfolio Overview $2,304 $2,535 $2,421 $2,519 $2,538 3Q20 4Q20 1Q21 2Q21 3Q21 IA 15% NM 12% CO 12% AZ
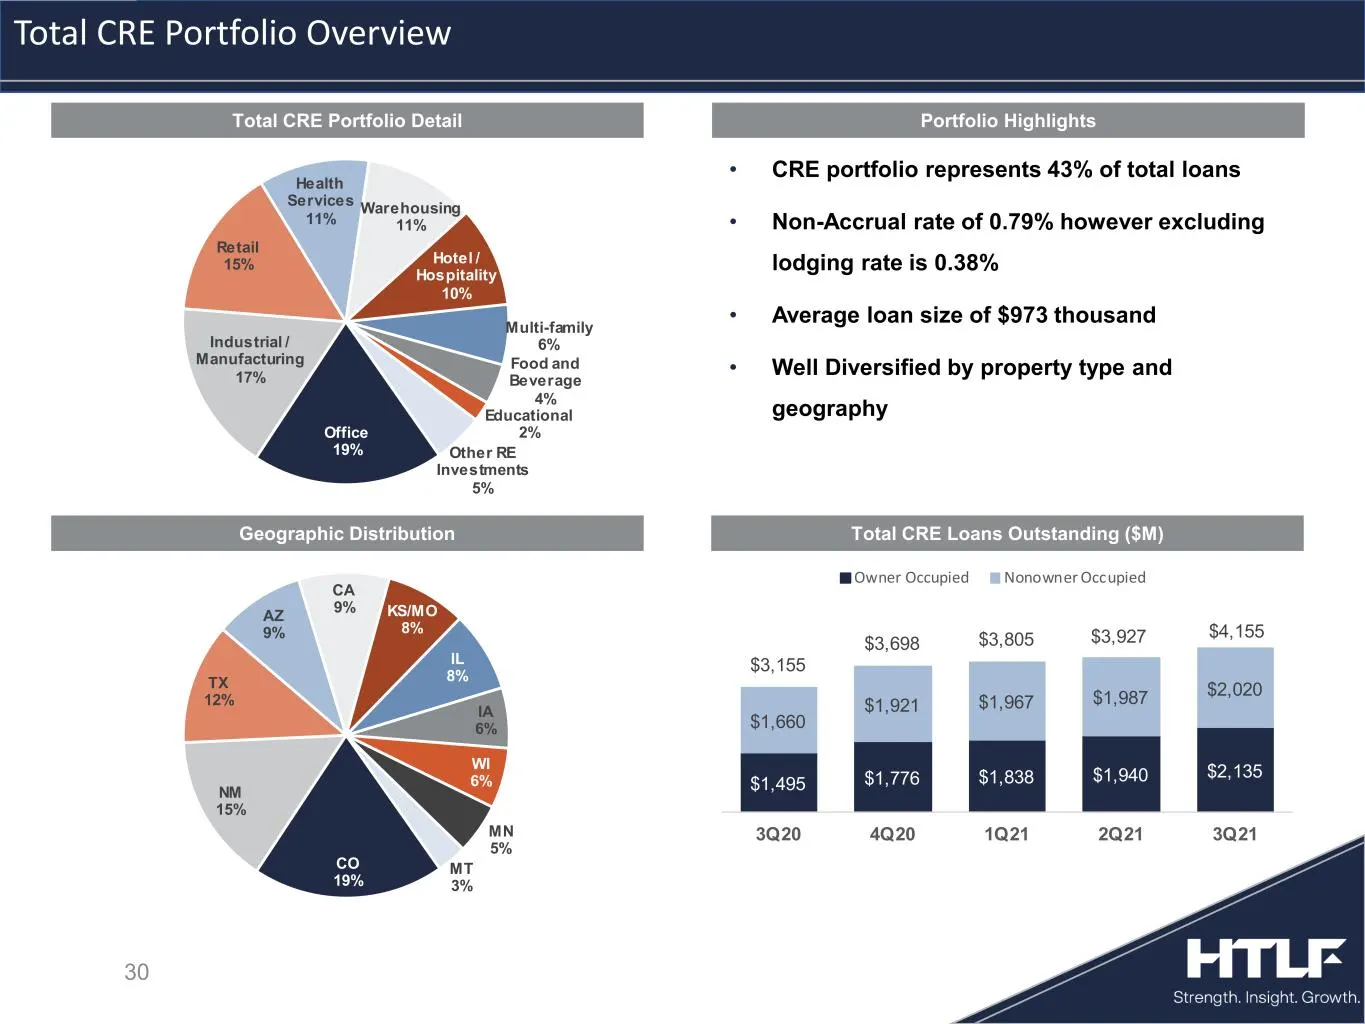
Slide 30: Total CRE Portfolio Overview
• CRE portfolio represents 43% of total loans • Non-Accrual rate of 0.79% however excluding lodging rate is 0.38% • Average loan size of $973 thousand • Well Diversified by property type and geography 30 Total CRE Portfolio Overview $1,495 $1,776 $1,838 $1,940 $2,135 $1,660 $1,921 $1,967 $1,987 $2,0
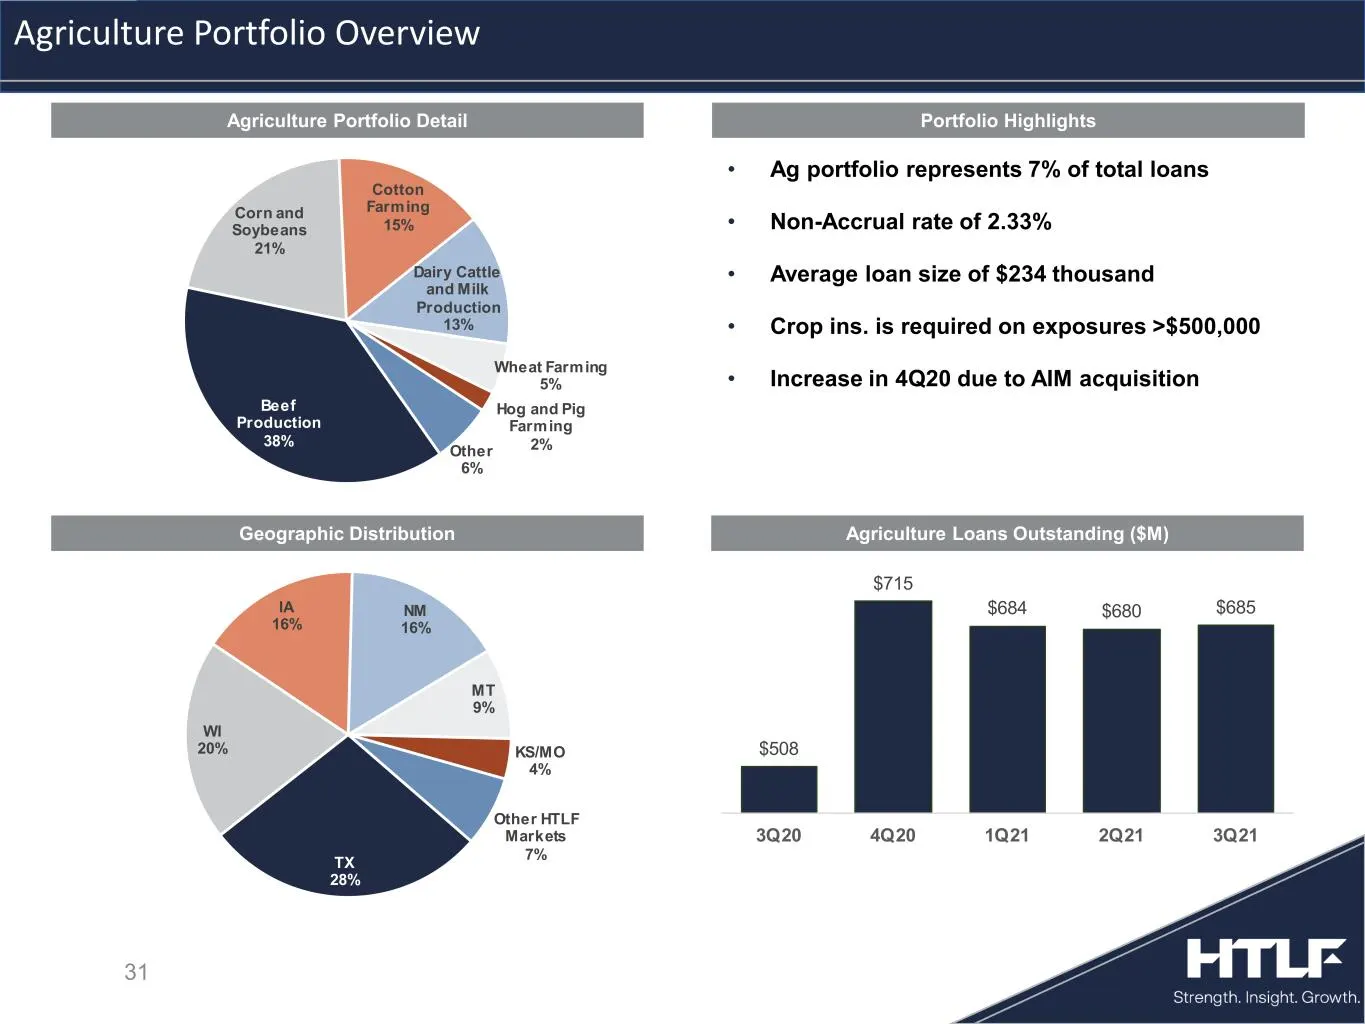
Slide 31: Agriculture Portfolio Overview
• Ag portfolio represents 7% of total loans • Non-Accrual rate of 2.33% • Average loan size of $234 thousand • Crop ins. is required on exposures >$500,000 • Increase in 4Q20 due to AIM acquisition 31 Agriculture Portfolio Overview $508 $715 $684 $680 $685 3Q20 4Q20 1Q21 2Q21 3Q21 Beef Production 38
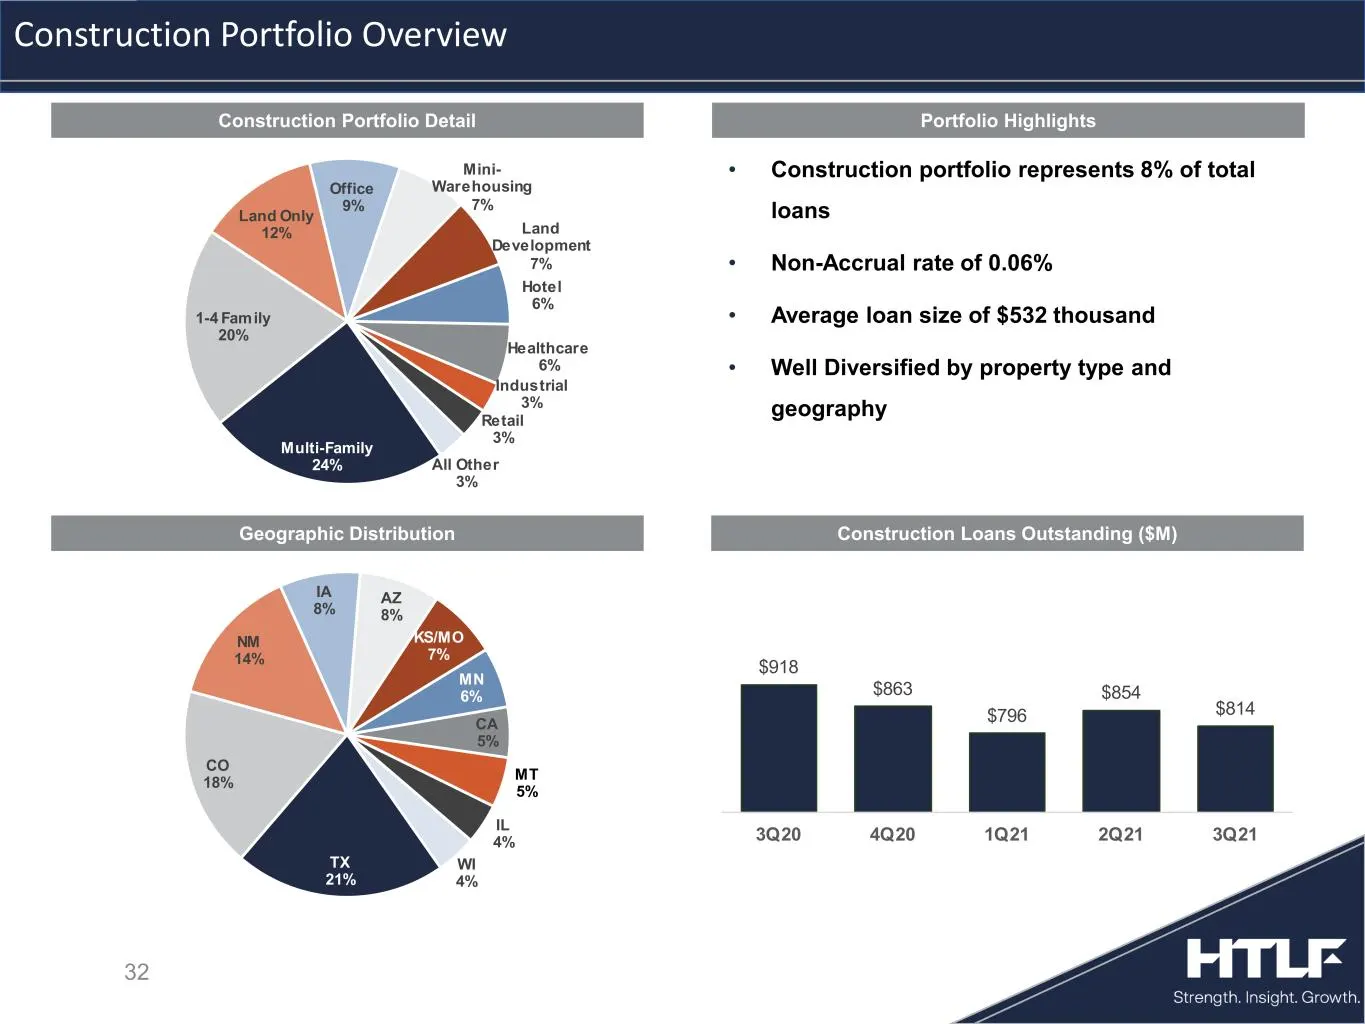
Slide 32: Construction Portfolio Overview
Portfolio HighlightsConstruction Portfolio Detail • Construction portfolio represents 8% of total loans • Non-Accrual rate of 0.06% • Average loan size of $532 thousand • Well Diversified by property type and geography Geographic Distribution Construction Loans Outstanding ($M) 32 Construction Portf
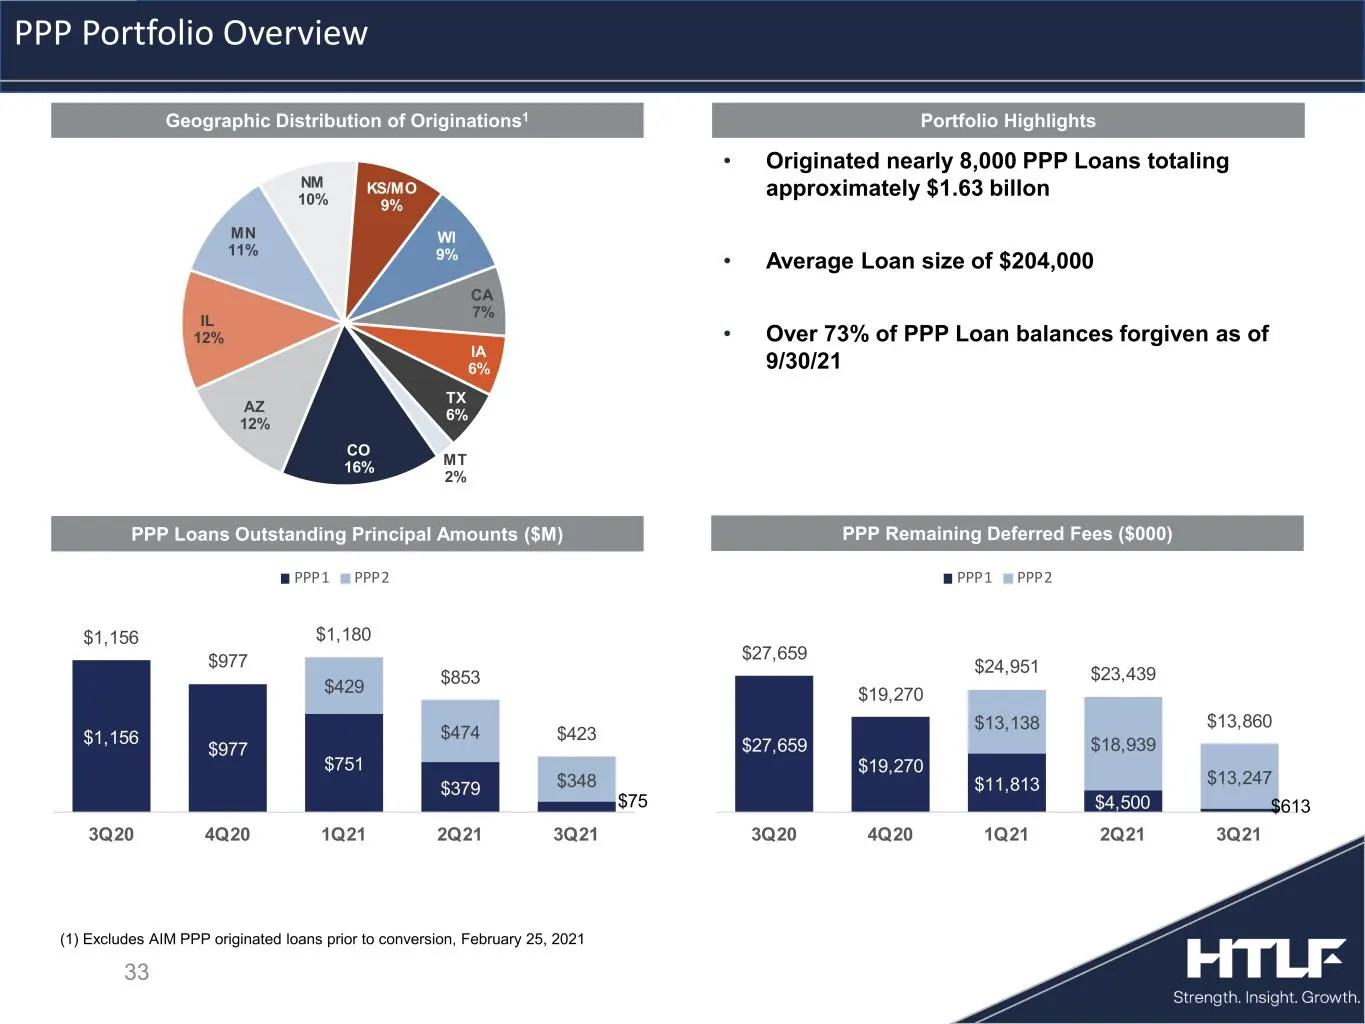
Slide 33: PPP Portfolio Overview
$27,659 $19,270 $11,813 $4,500 $613 $13,138 $18,939 $13,247 $27,659 $19,270 $24,951 $23,439 $13,860 3Q20 4Q20 1Q21 2Q21 3Q21 PPP1 PPP2 CO 16% AZ 12% IL 12% MN 11% NM 10% KS/MO 9% WI 9% CA 7% IA 6% TX 6% MT 2% • Originated nearly 8,000 PPP Loans totaling approximately $1.63 billon • Average Loan size
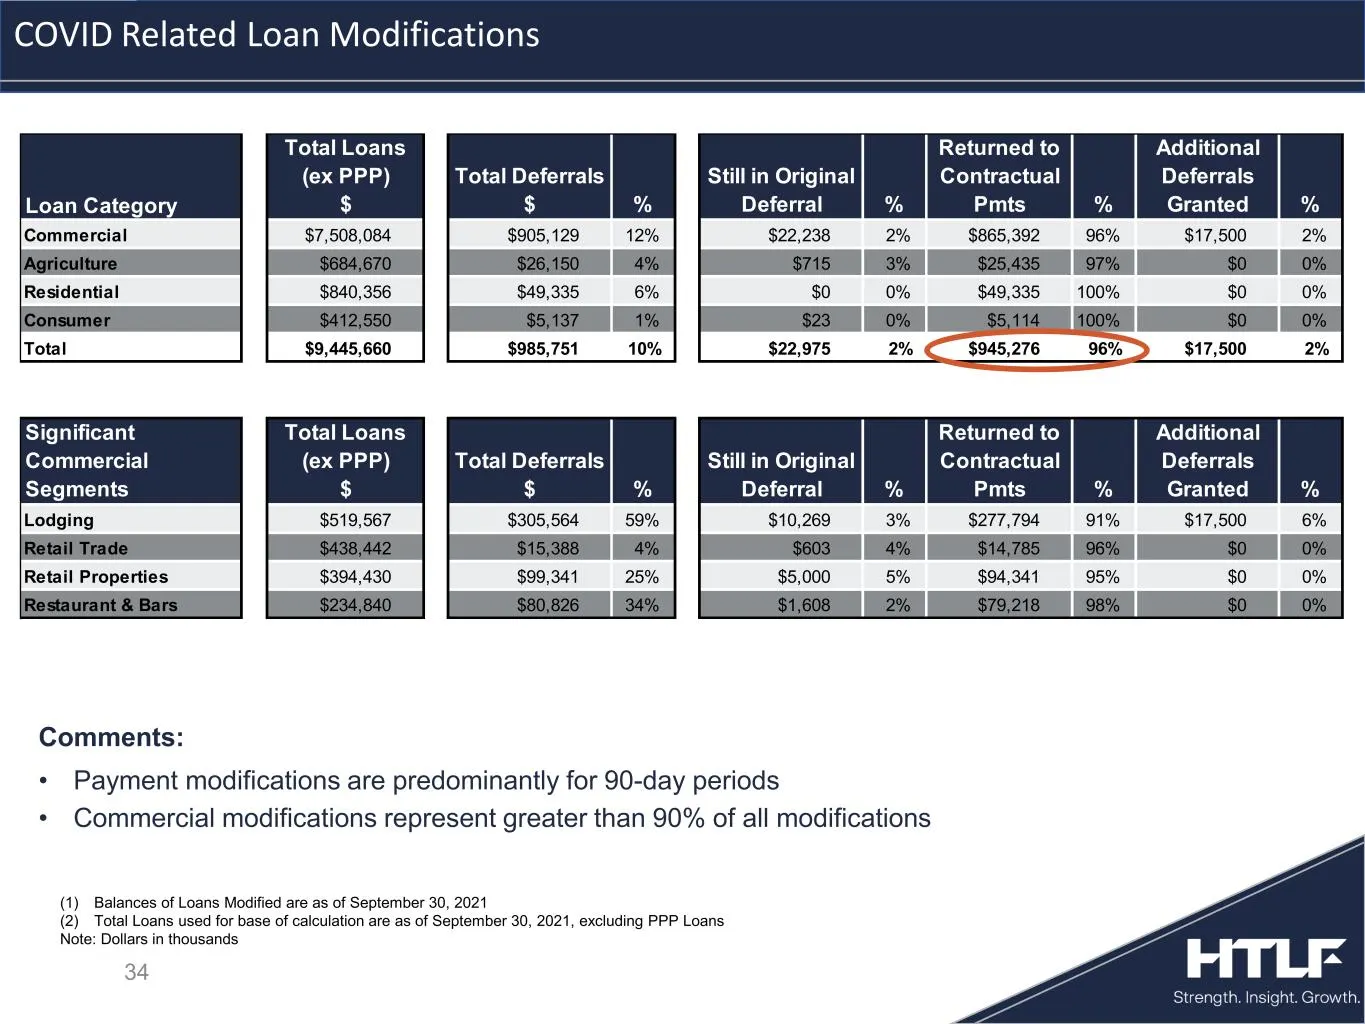
Slide 34: COVID Related Loan Modifications
34 Comments: • Payment modifications are predominantly for 90-day periods • Commercial modifications represent greater than 90% of all modifications COVID Related Loan Modifications (1) Balances of Loans Modified are as of September 30, 2021 (2) Total Loans used for base of calculation are as of Sep
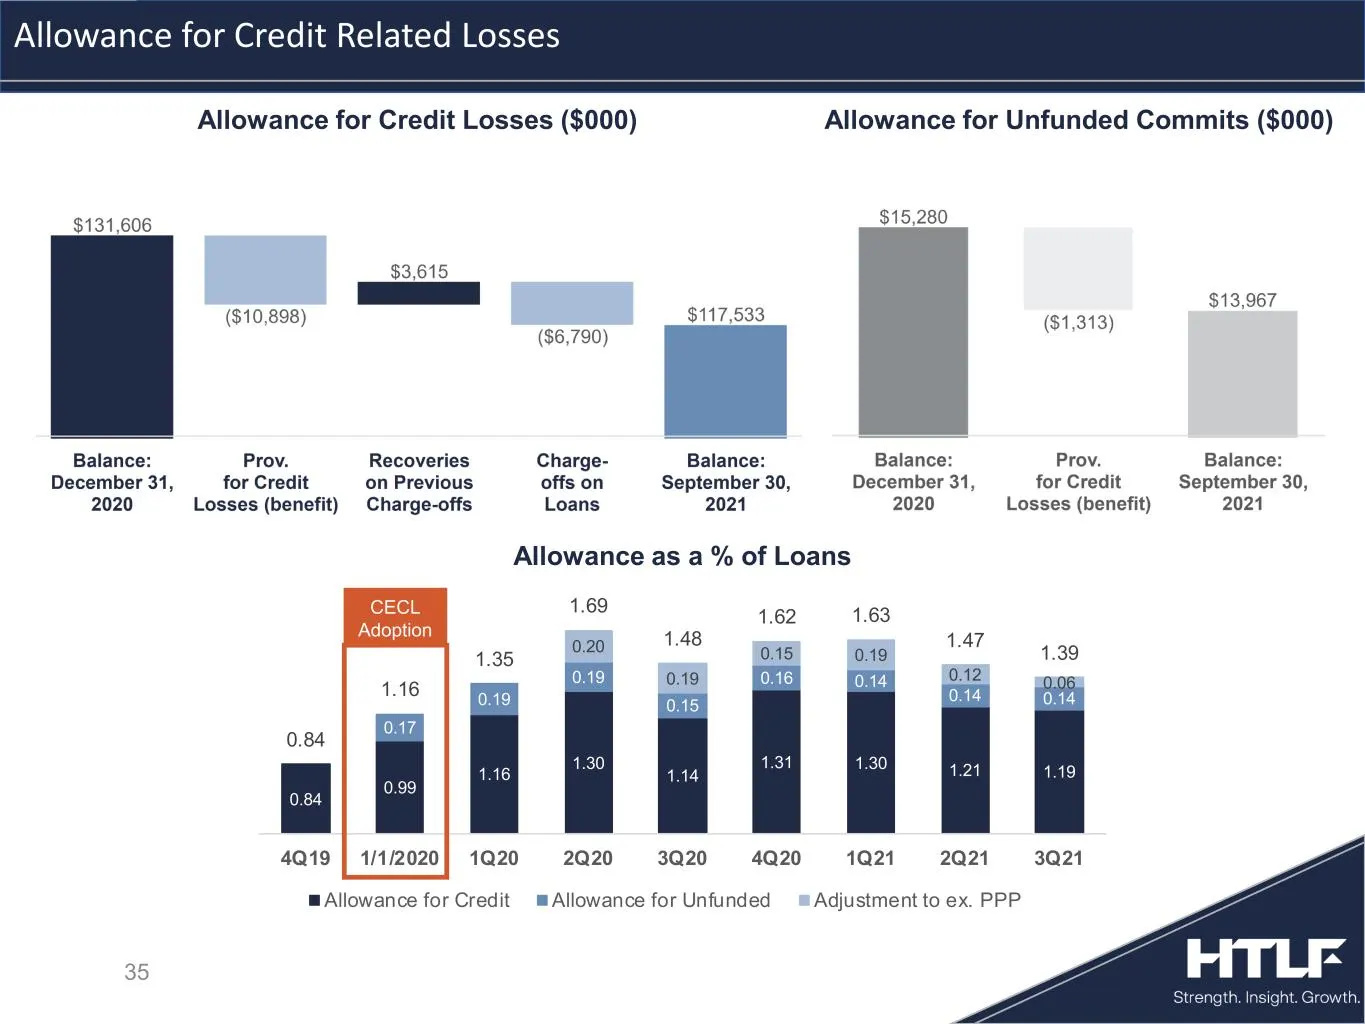
Slide 35: Allowance for Credit Related Losses
35 Allowance for Credit Related Losses Allowance as a % of Loans Allowance for Credit Losses ($000) Allowance for Unfunded Commits ($000) 0.84 0.99 1.16 1.30 1.14 1.31 1.30 1.21 1.19 0.17 0.19 0.19 0.15 0.16 0.14 0.14 0.14 0.20 0.19 0.15 0.19 0.12 0.06 0.84 1.16 1.35 1.69 1.48 1.62 1.63 1.47 1.39 4Q
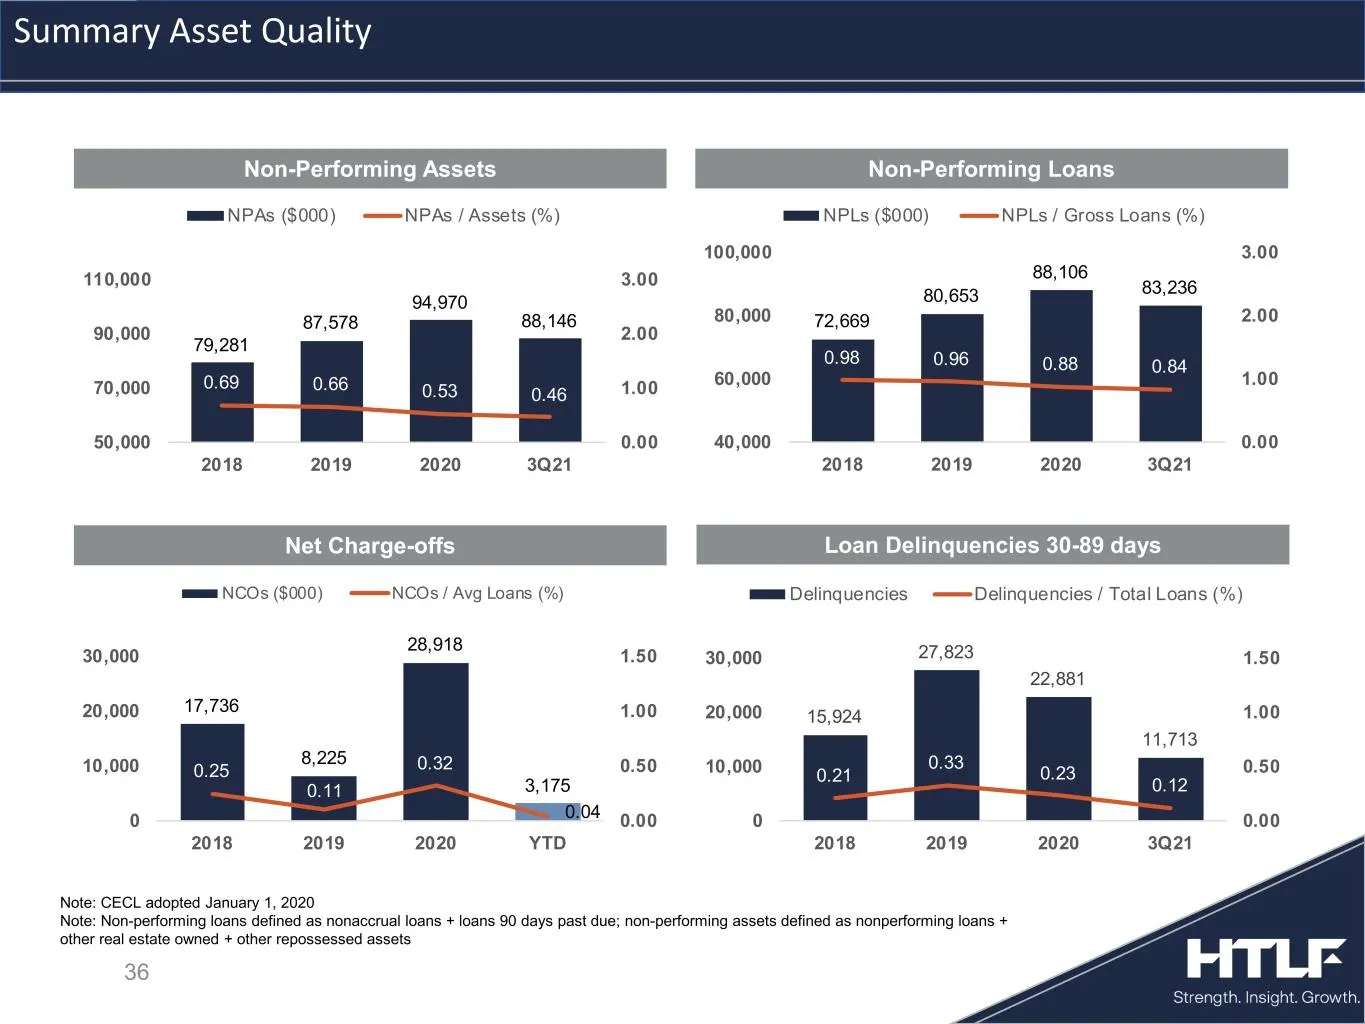
Slide 36: Summary Asset Quality
36 Summary Asset Quality Note: CECL adopted January 1, 2020 Note: Non-performing loans defined as nonaccrual loans + loans 90 days past due; non-performing assets defined as nonperforming loans + other real estate owned + other repossessed assets 72,669 80,653 88,106 83,236 0.98 0.96 0.88 0.84 0.00
Slide 37: Liquidity, Investments, Funding and Capital
37 Liquidity, Investments, Funding and Capital
Slide 38: Deposit Mix
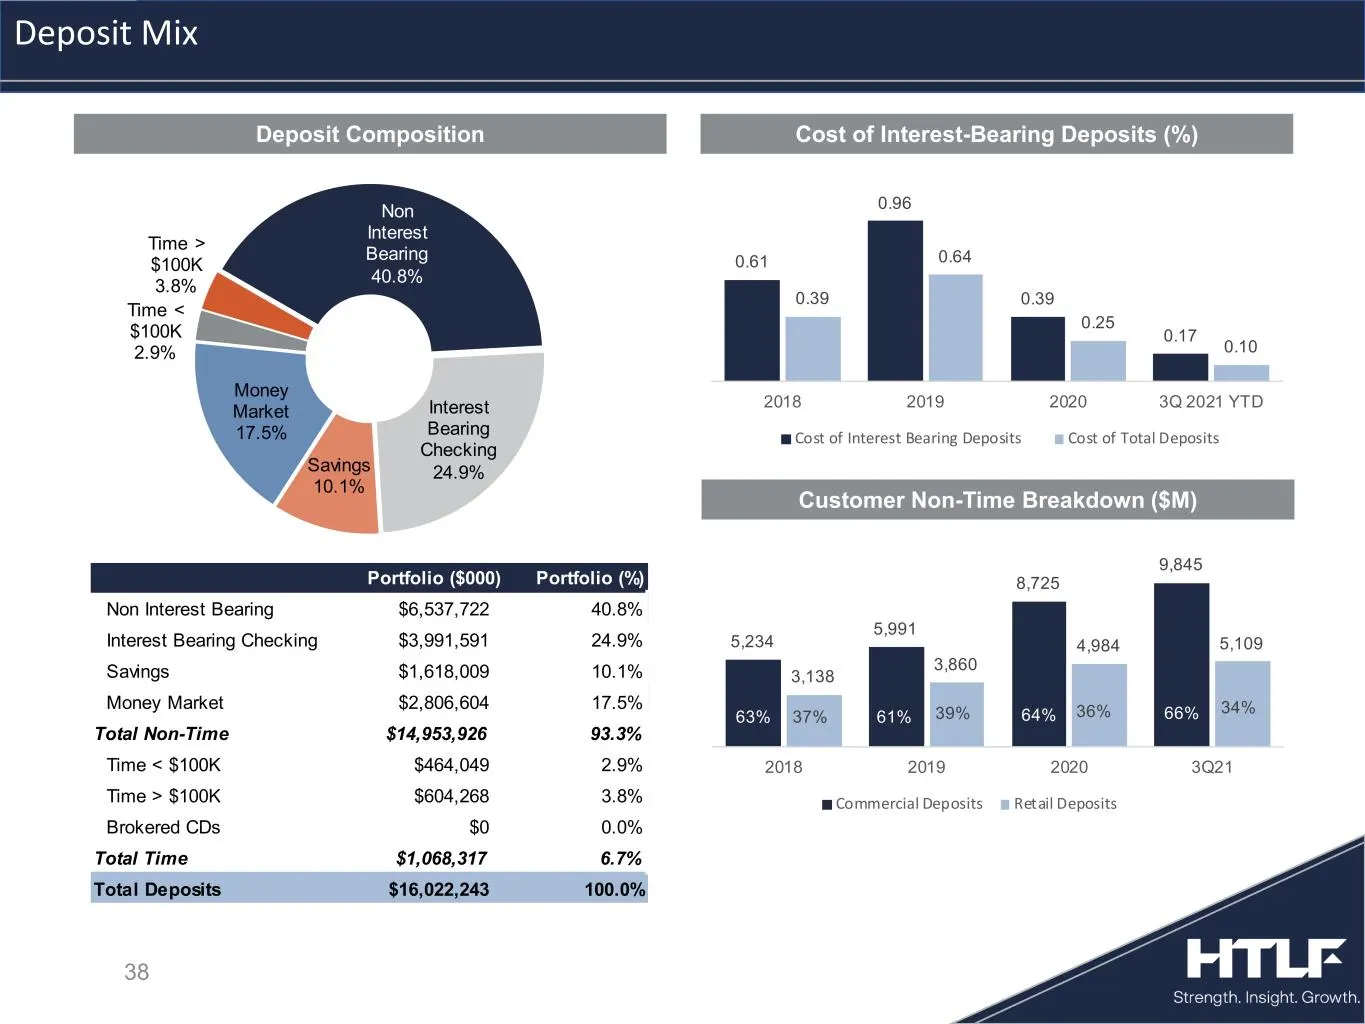
Deposit Composition Cost of Interest-Bearing Deposits (%) Customer Non-Time Breakdown ($M) 38 Deposit Mix Non Interest Bearing 40.8% Interest Bearing Checking 24.9%Savings 10.1% Money Market 17.5% Time < $100K 2.9% Time > $100K 3.8% Portfolio ($000) Portfolio (%) Non Interest Bearing $6,537,722 40.8
Slide 39: Investment Portfolio
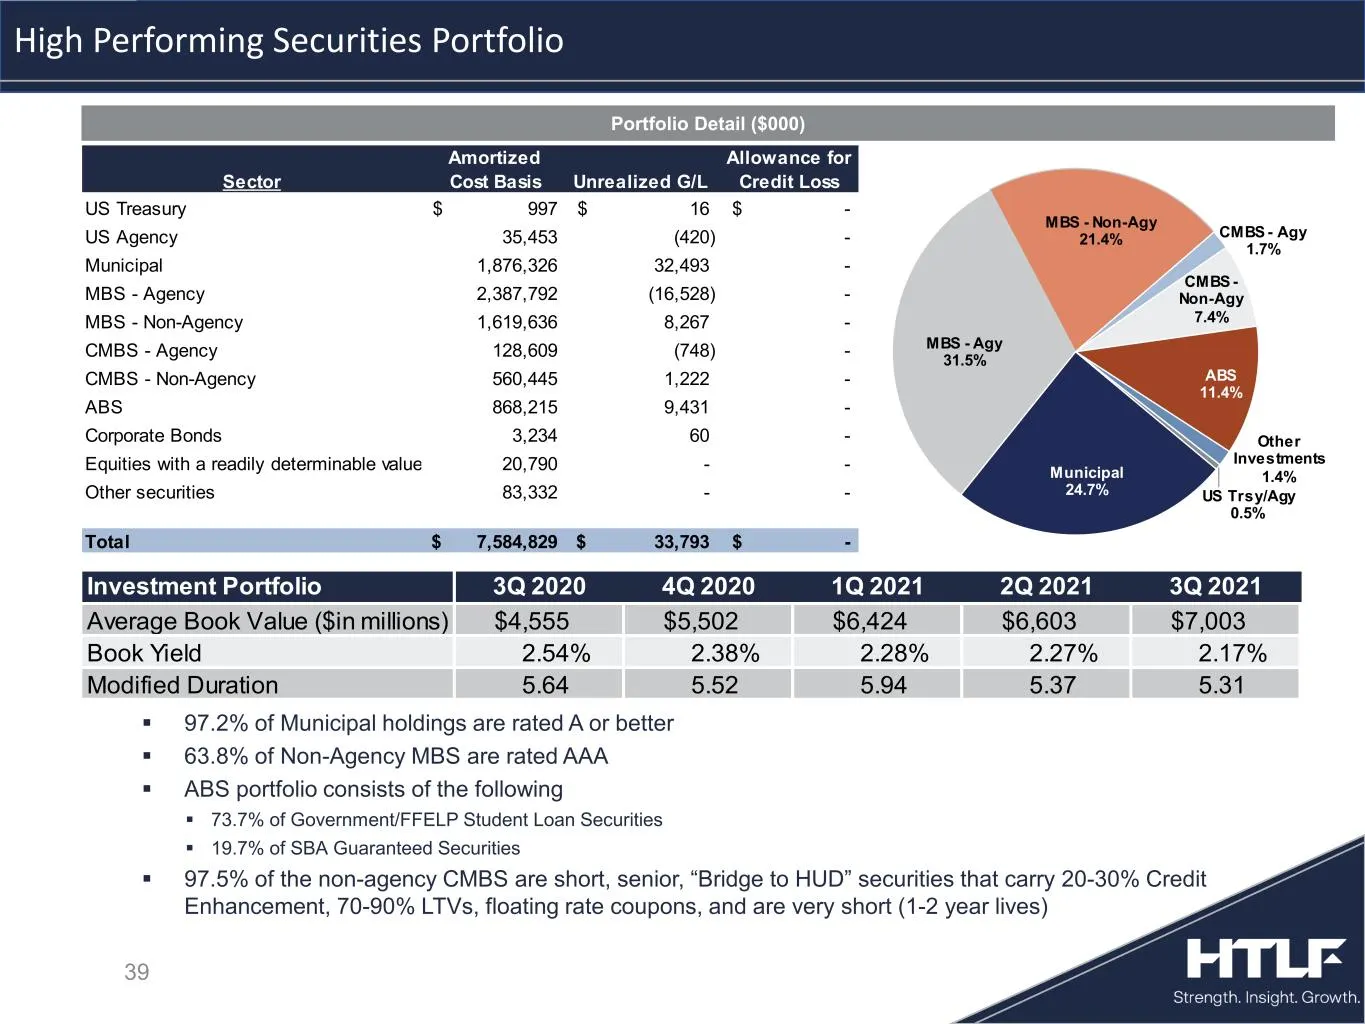
39 97.2% of Municipal holdings are rated A or better 63.8% of Non-Agency MBS are rated AAA ABS portfolio consists of the following 73.7% of Government/FFELP Student Loan Securities 19.7% of SBA Guaranteed Securities 97.5% of the non-agency CMBS are short, senior, “Bridge to HUD” securiti
Slide 40: Capital Instruments and Liquidity Profile
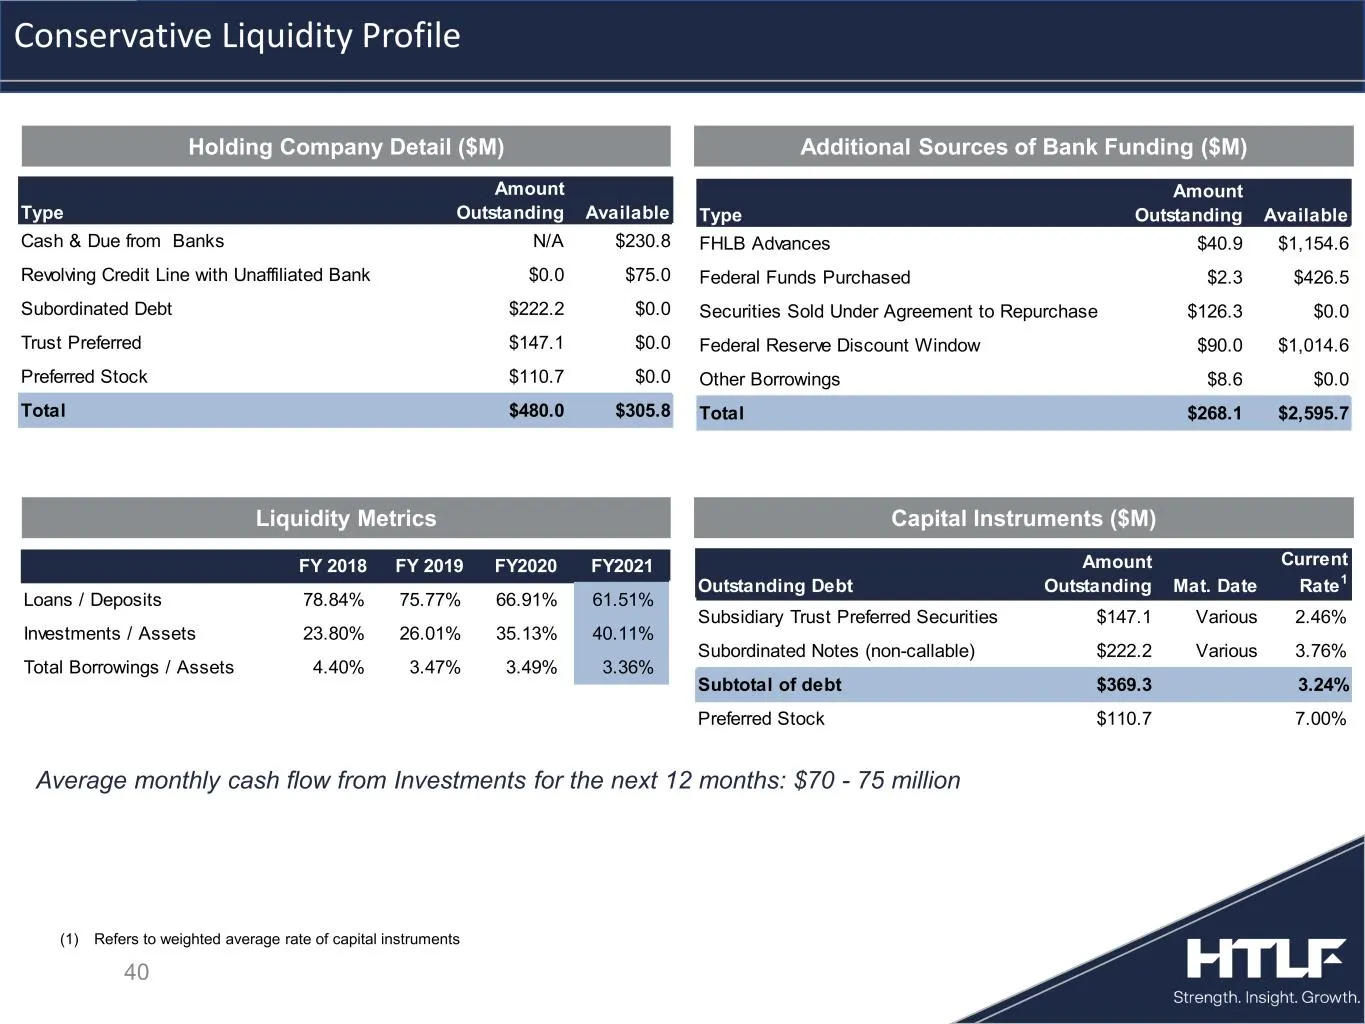
Outstanding Debt Amount Outstanding Mat. Date Current Rate1 Subsidiary Trust Preferred Securities $147.1 Various 2.46% Subordinated Notes (non-callable) $222.2 Various 3.76% Subtotal of debt $369.3 3.24% Preferred Stock $110.7 7.00% 40 Average monthly cash flow from Investments for the next 12 month
Slide 41: HTLF Investor Summary
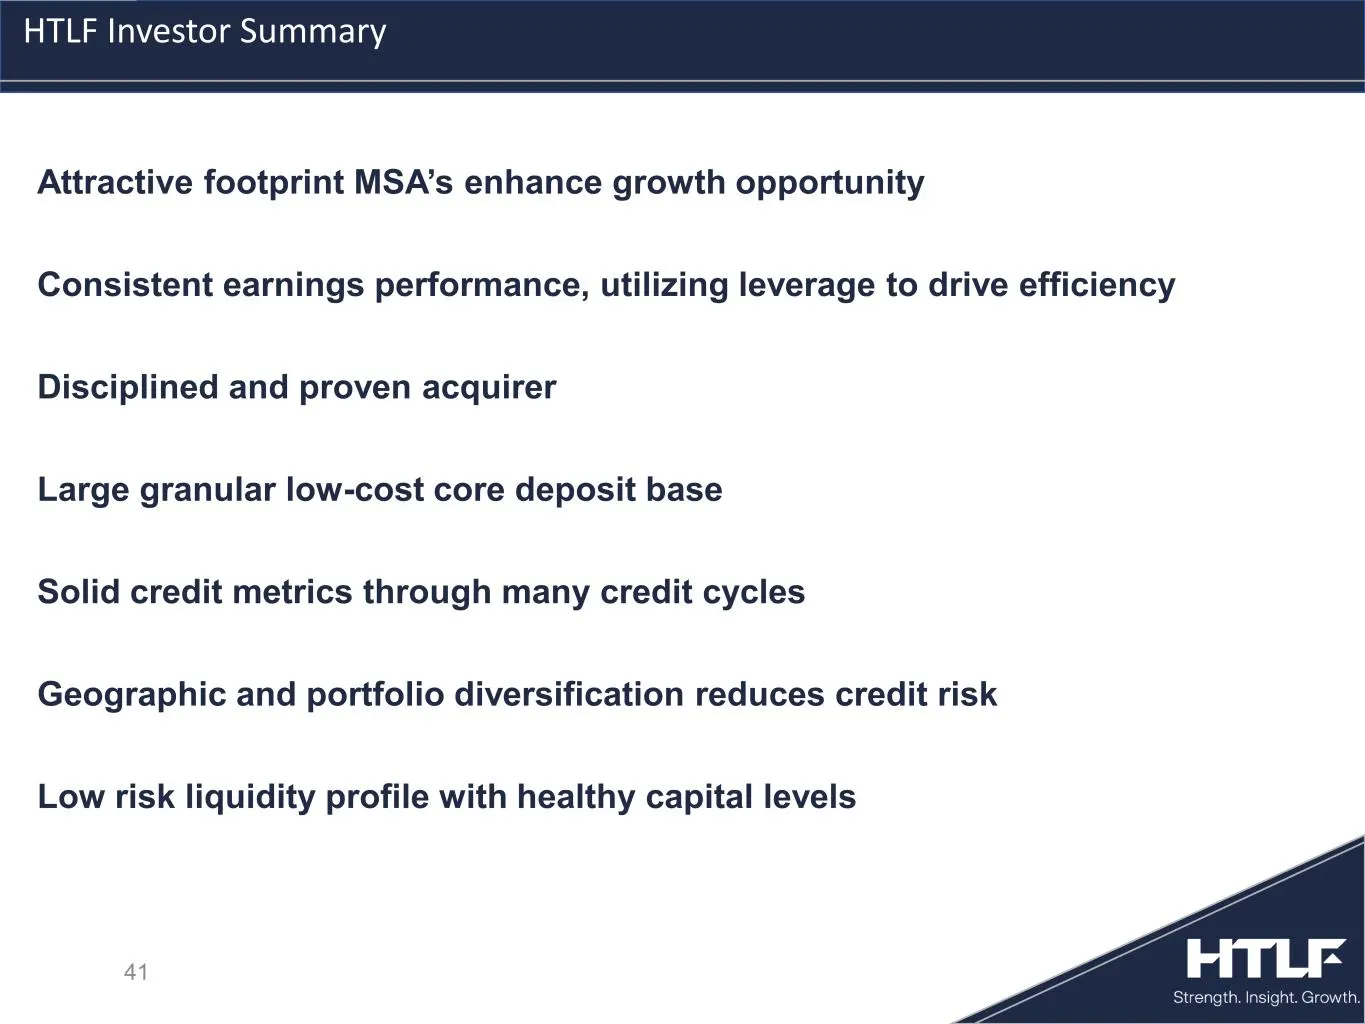
41 HTLF Investor Summary Attractive footprint MSA’s enhance growth opportunity Consistent earnings performance, utilizing leverage to drive efficiency Disciplined and proven acquirer Large granular low-cost core deposit base Solid credit metrics through many credit cycles Geographic and portfolio di
Slide 42: Analyst Ratings | October 2021
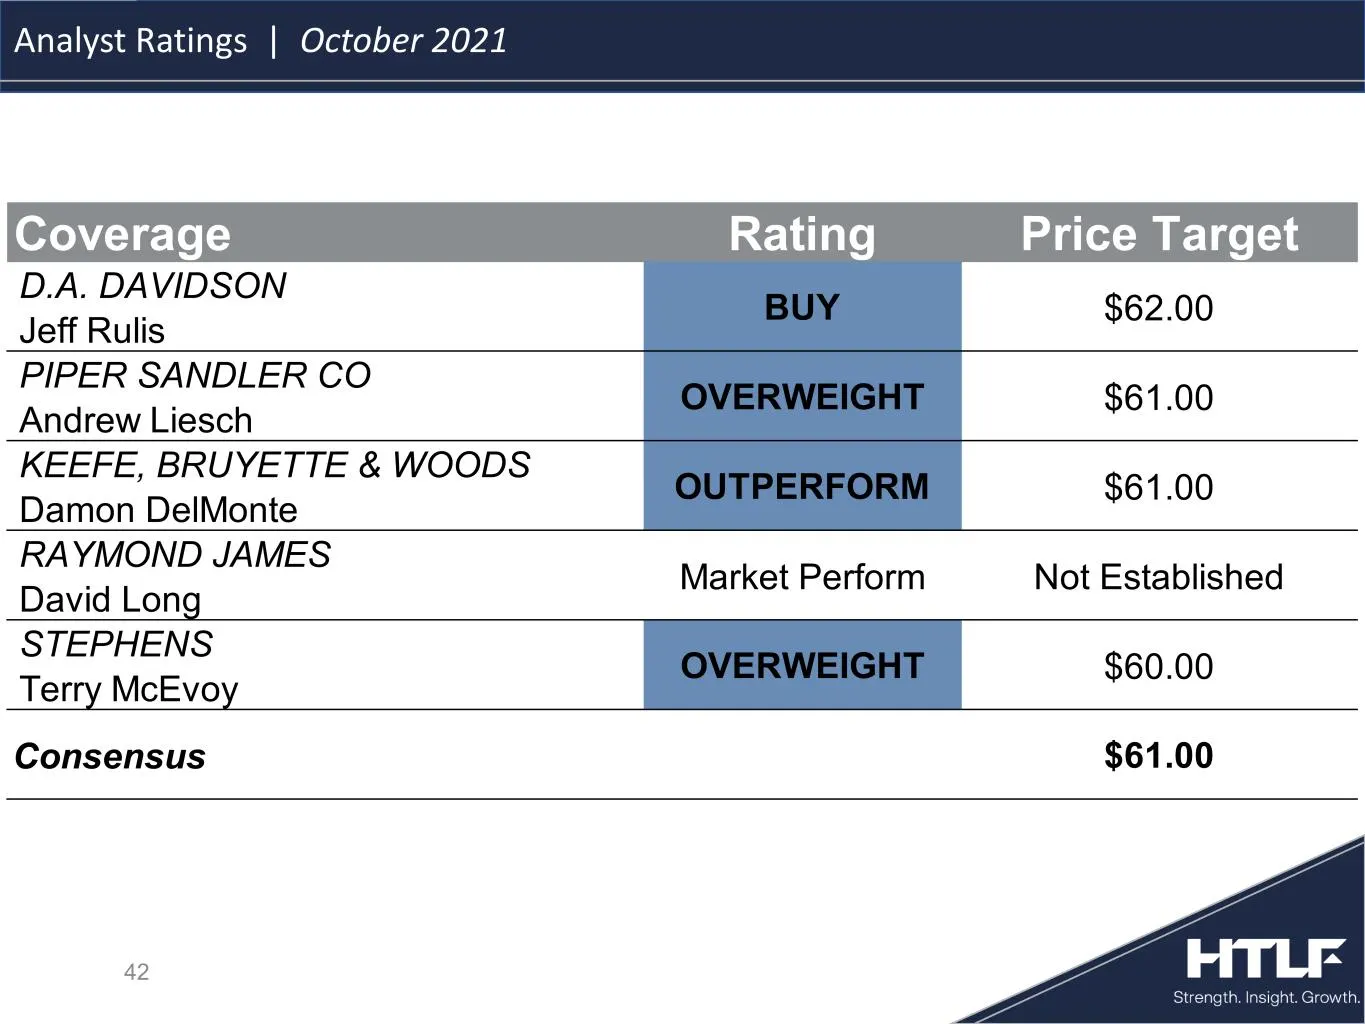
42 Analyst Ratings | October 2021 Coverage Rating Price Target D.A. DAVIDSON Jeff Rulis PIPER SANDLER CO Andrew Liesch KEEFE, BRUYETTE & WOODS Damon DelMonte RAYMOND JAMES David Long STEPHENS Terry McEvoy BUY $62.00 OVERWEIGHT $61.00 OUTPERFORM $61.00 $61.00 Consensus Market Perform Not Established
Slide 43: Contact Information
43 Contact Information
Slide 44: Appendix
44 Appendix
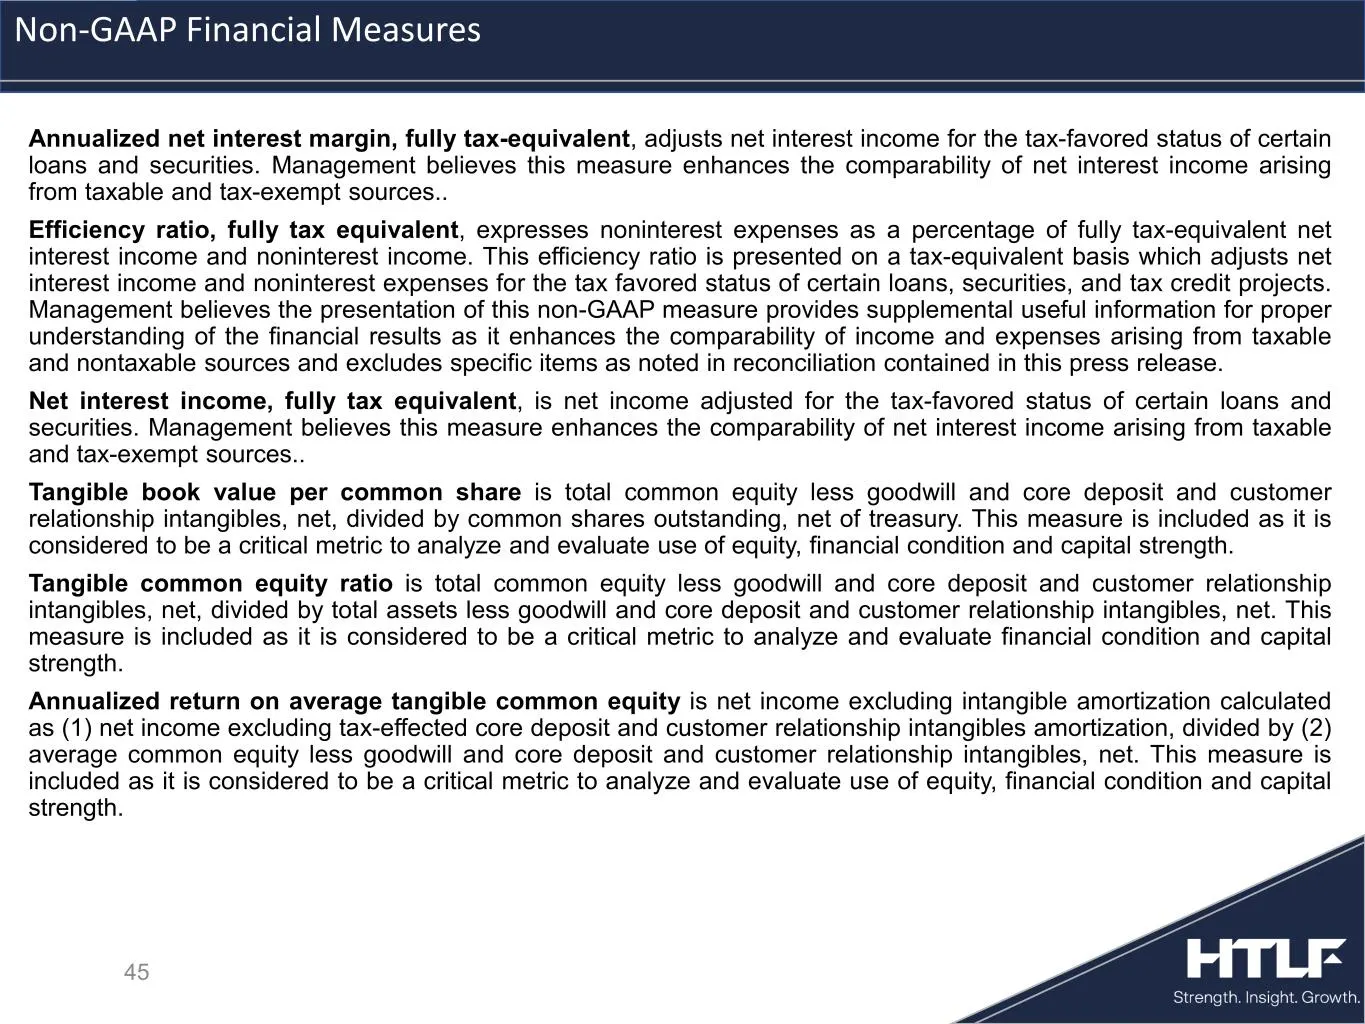
Slide 45: Non-GAAP measure definitions
45 Annualized net interest margin, fully tax-equivalent, adjusts net interest income for the tax-favored status of certain loans and securities. Management believes this measure enhances the comparability of net interest income arising from taxable and tax-exempt sources.. Efficiency ratio, fully ta
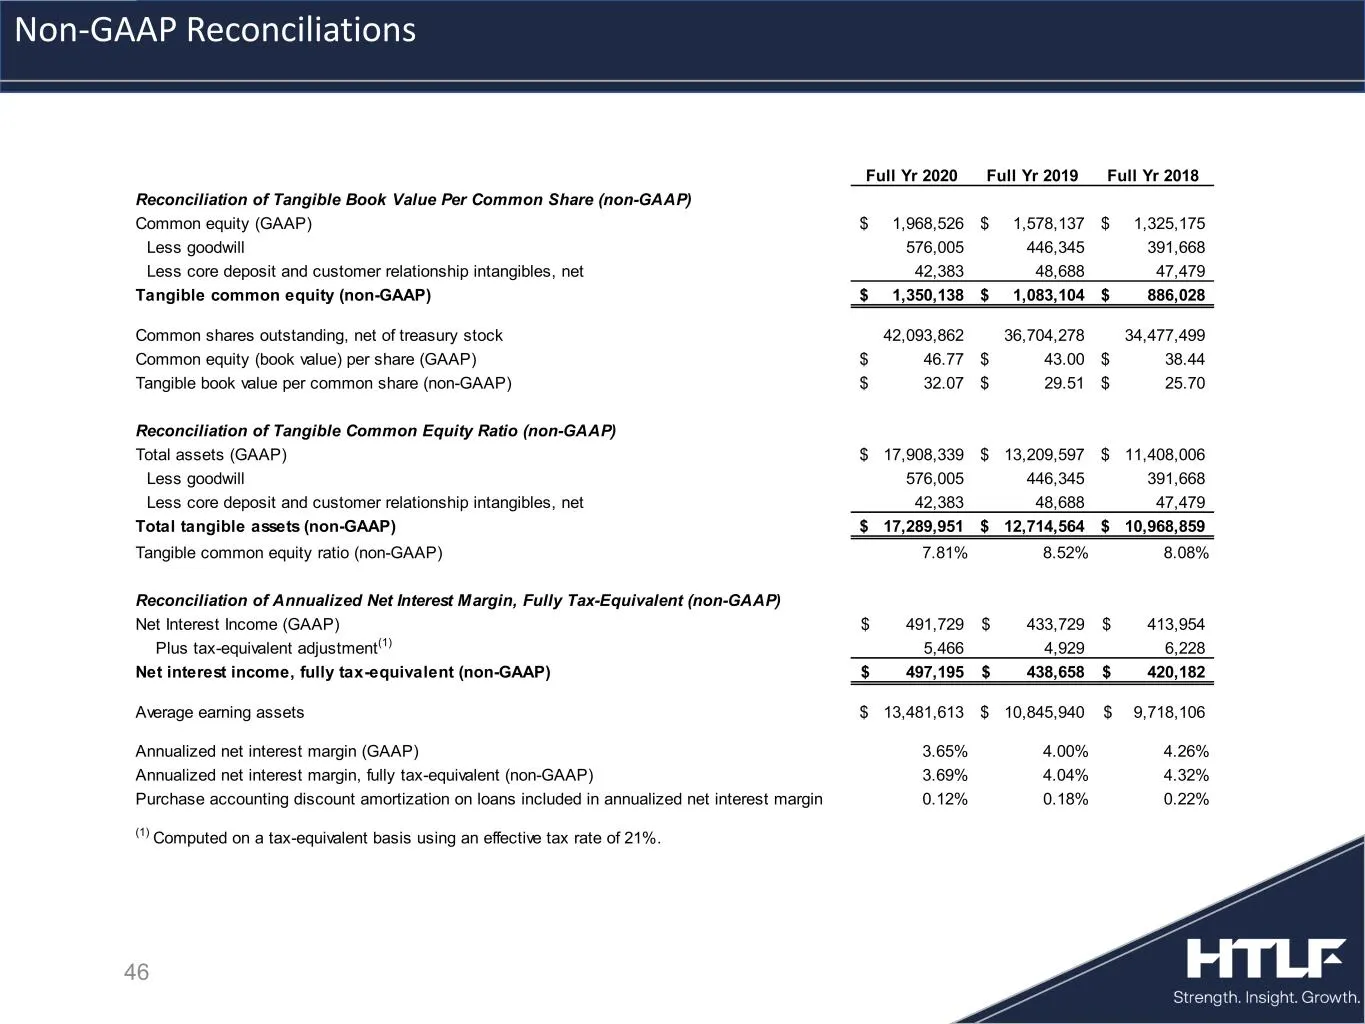
Slide 46: Non-GAAP Reconciliations
46 Non-GAAP Reconciliations Full Yr 2020 Full Yr 2019 Full Yr 2018 Reconciliation of Tangible Book Value Per Common Share (non-GAAP) Common equity (GAAP) 1,968,526$ 1,578,137$ 1,325,175$ Less goodwill 576,005 446,345 391,668 Less core deposit and customer relationship intangibles, net 42,383 48,688
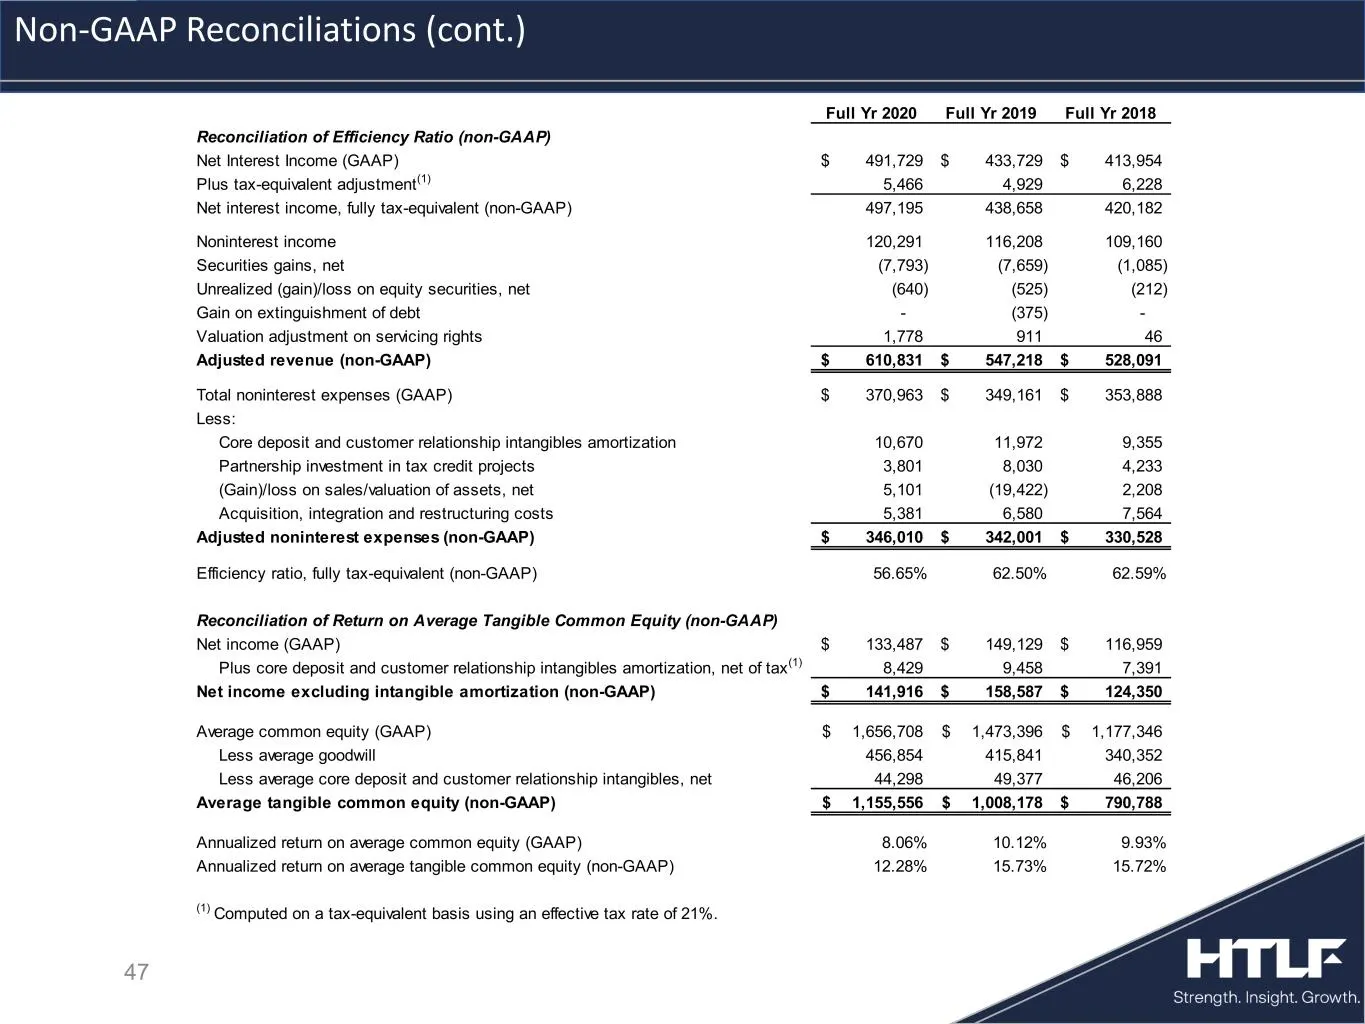
Slide 47: Non-GAAP Reconciliations (cont.)
47 Non-GAAP Reconciliations (cont.) Full Yr 2020 Full Yr 2019 Full Yr 2018 Reconciliation of Efficiency Ratio (non-GAAP) Net Interest Income (GAAP) 491,729$ 433,729$ 413,954$ Plus tax-equivalent adjustment(1) 5,466 4,929 6,228 Net interest income, fully tax-equivalent (non-GAAP) 497,195 438,658 420,
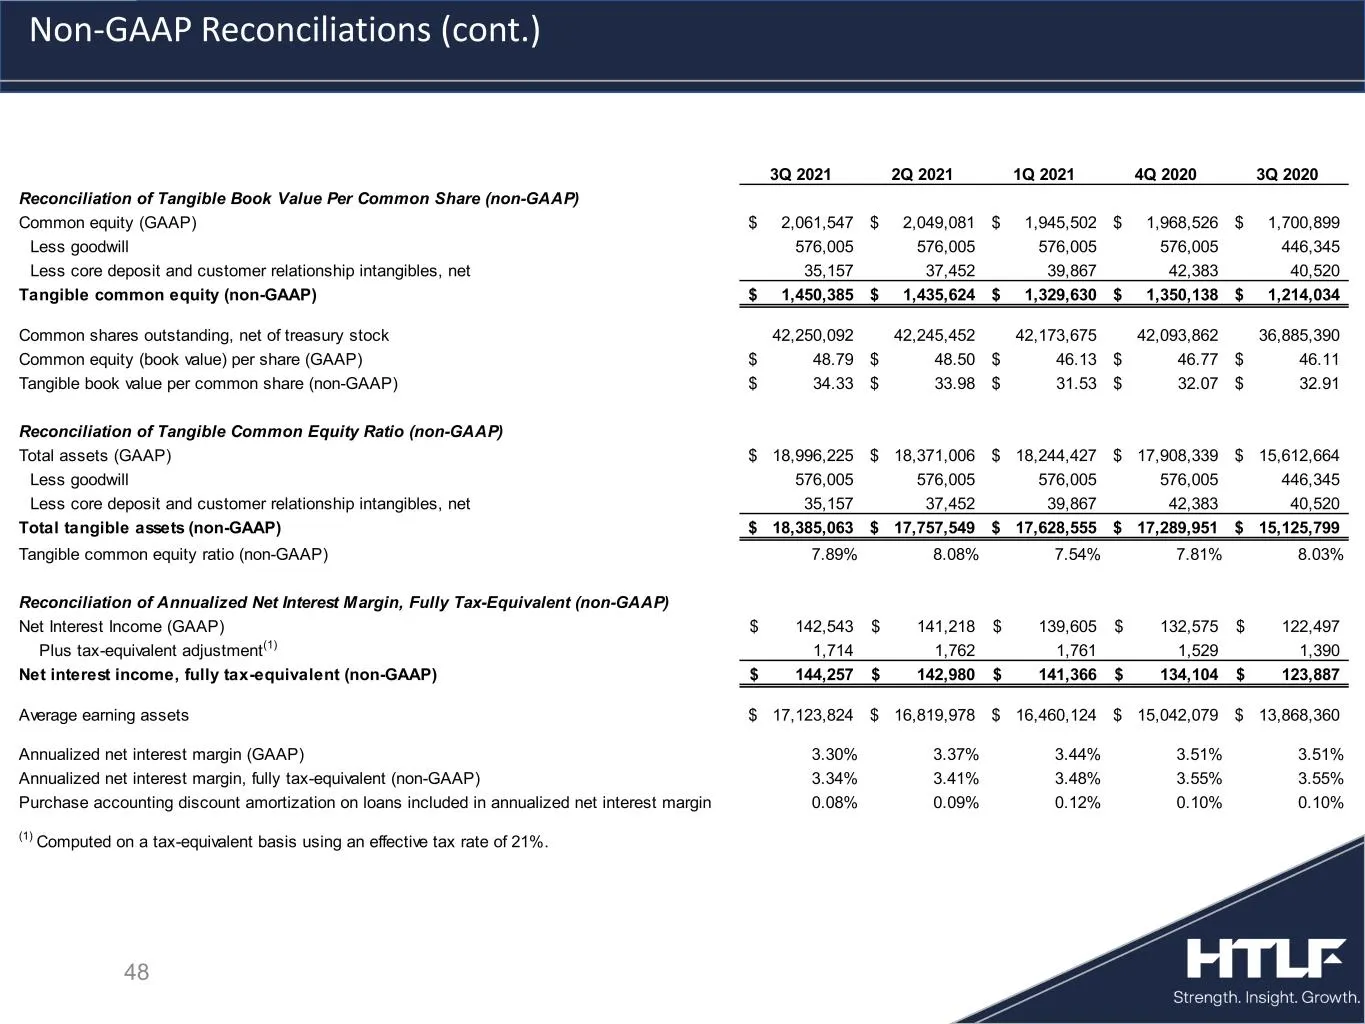
Slide 48: Non-GAAP Reconciliations (cont.)
48 Non-GAAP Reconciliations (cont.) 3Q 2021 2Q 2021 1Q 2021 4Q 2020 3Q 2020 Reconciliation of Tangible Book Value Per Common Share (non-GAAP) Common equity (GAAP) 2,061,547$ 2,049,081$ 1,945,502$ 1,968,526$ 1,700,899$ Less goodwill 576,005 576,005 576,005 576,005 446,345 Less core deposit and custom
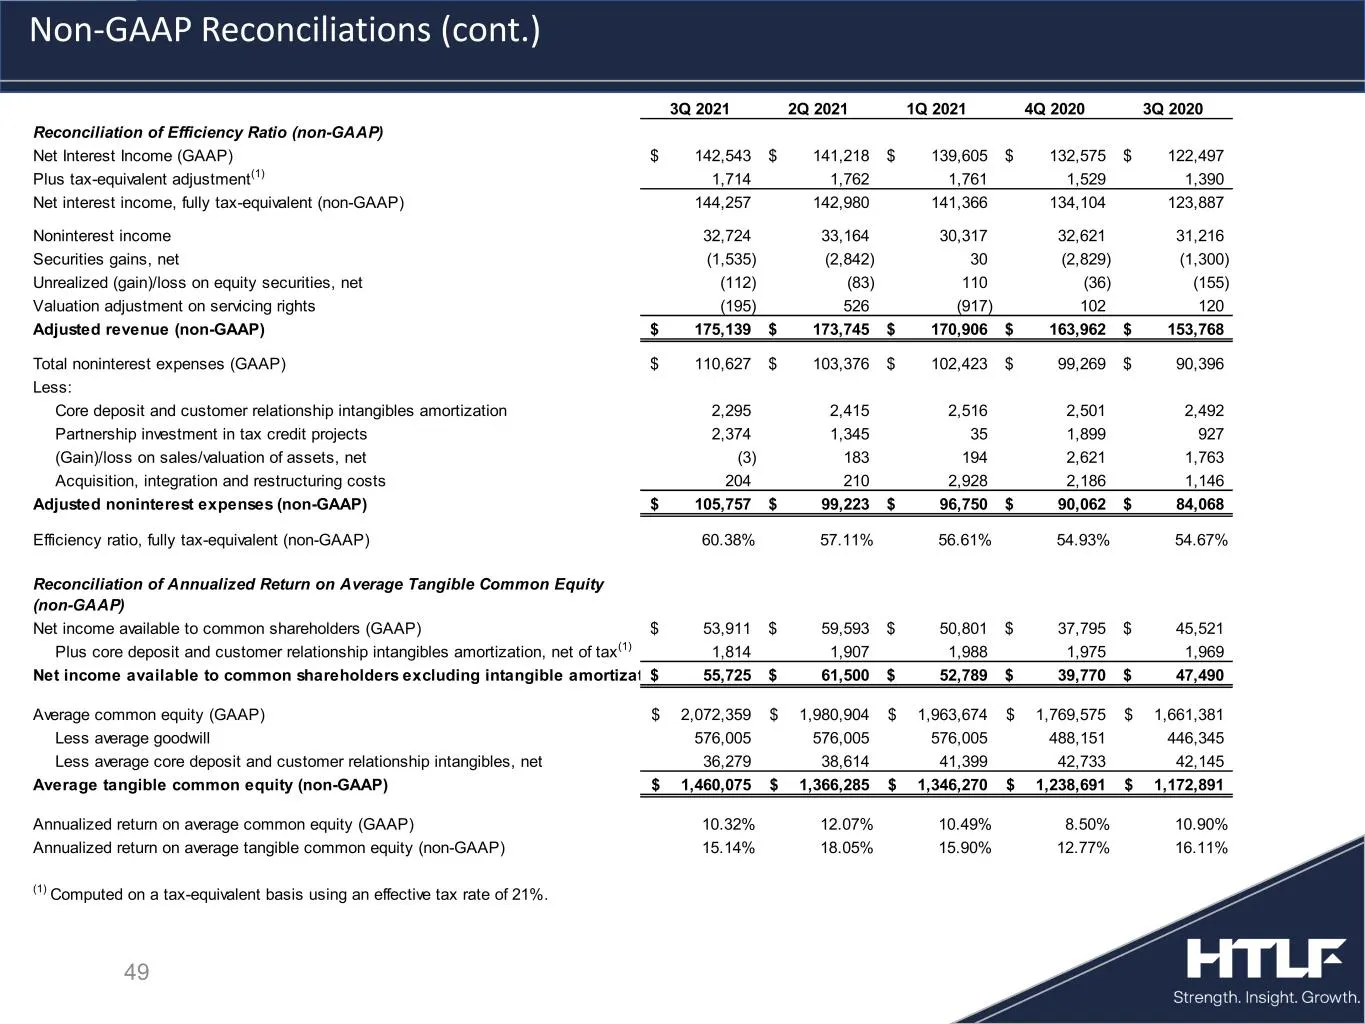
Slide 49: Non-GAAP Reconciliations (cont.)
49 Non-GAAP Reconciliations (cont.) 3Q 2021 2Q 2021 1Q 2021 4Q 2020 3Q 2020 Reconciliation of Efficiency Ratio (non-GAAP) Net Interest Income (GAAP) 142,543$ 141,218$ 139,605$ 132,575$ 122,497$ Plus tax-equivalent adjustment(1) 1,714 1,762 1,761 1,529 1,390 Net interest income, fully tax-equivalent
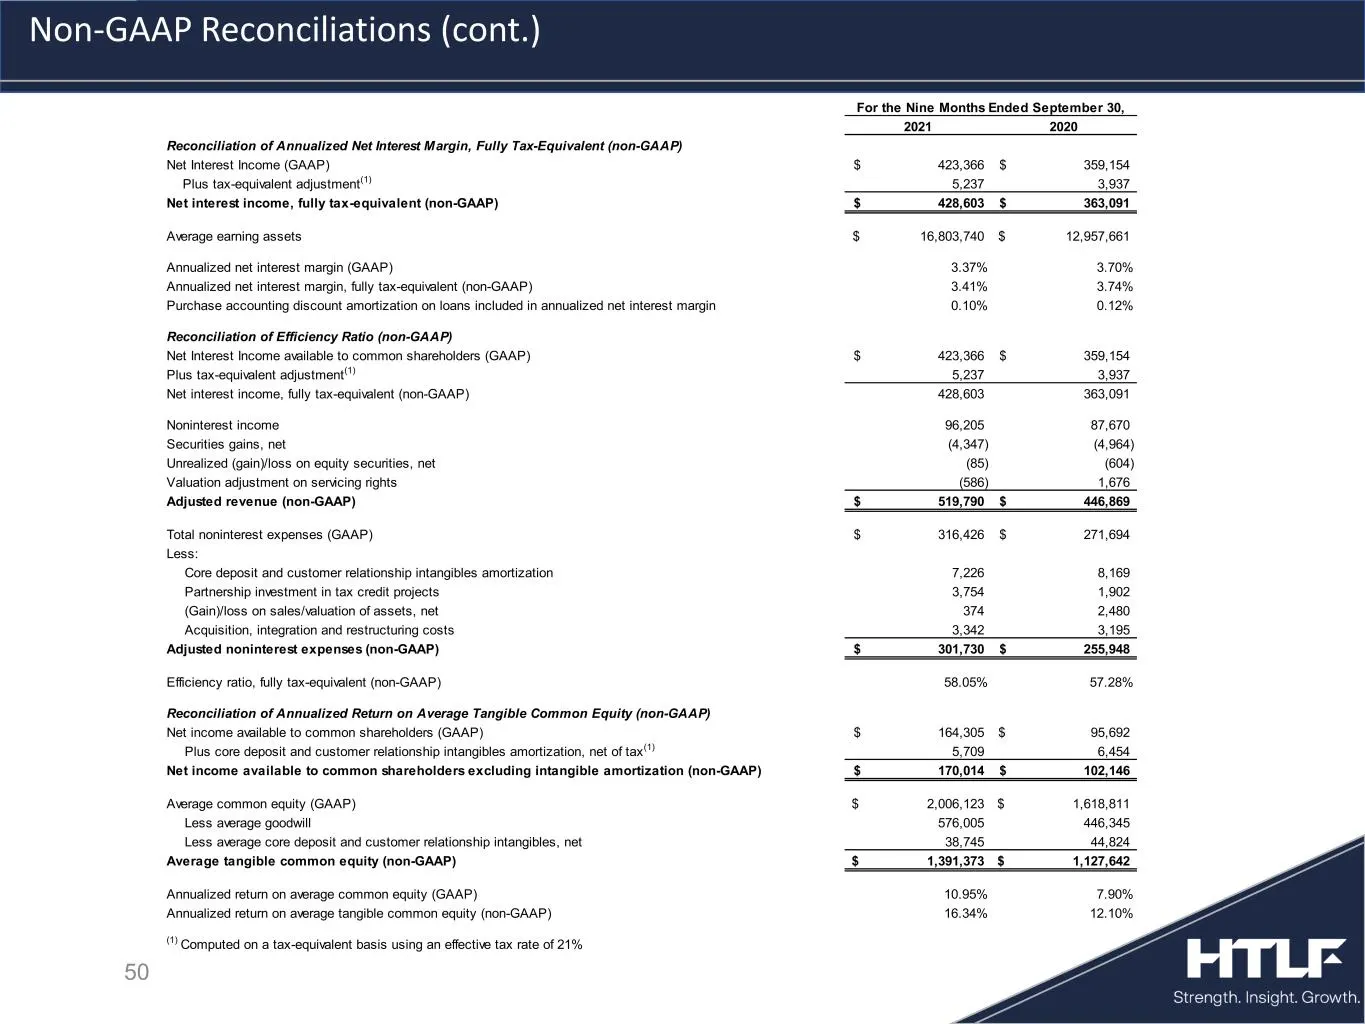
Slide 50: Non-GAAP Reconciliations (cont.)
50 Non-GAAP Reconciliations (cont.) 2021 2020 Reconciliation of Annualized Net Interest Margin, Fully Tax-Equivalent (non-GAAP) Net Interest Income (GAAP) 423,366$ 359,154$ Plus tax-equivalent adjustment(1) 5,237 3,937 Net interest income, fully tax-equivalent (non-GAAP) 428,603$ 363,091$ Average ea
Source: SEC EDGAR · 8-K filed Oct 29, 2021
More decks from Heartland Financial USA Inc
 Merger or Acquisition (July 2024)6 slides · Jul 31, 2024
 Merger or Acquisition (May 2024)6 slides · May 2, 2024
 Merger or Acquisition (May 2024)27 slides · May 2, 2024
 Q4 2023 Earnings Presentation54 slides · Feb 13, 2024
 Q4 2023 Earnings Presentation35 slides · Jan 29, 2024
 Q3 2023 Earnings Presentation55 slides · Nov 15, 2023