BNC Bancorp — Gulf South Bank Conference (May 2010)
28 slides from BNC Bancorp's conference presentation, May 5, 2010
Slide 1: Gulf South Bank Conference
Exhibit 99.1 BNC Bancorp Gulf South Bank Conference May 5, 2010
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains forward-looking statements relating to the financial condition, results of operations and business of BNC Bancorp and its subsidiary Bank of North Carolina. These forward-looking statements involve risks and uncertainties and are based on the bel
Slide 3: Quality
Quality Competence Discipline 3
Slide 4: BNC Bancorp Highlights
BNC Bancorp Highlights • 11 th largest bank headquartered in North Carolina (7 th Pro forma with Beach First) • $1.63 billion in assets as of March 31, 2010 • Annual Regulatory Exam completed in Q1 2010 • 90% of historic growth has been organic • History of strong core earnings and declared dividend
Slide 5: Franchise Overview: Consistent Growth and Profitability
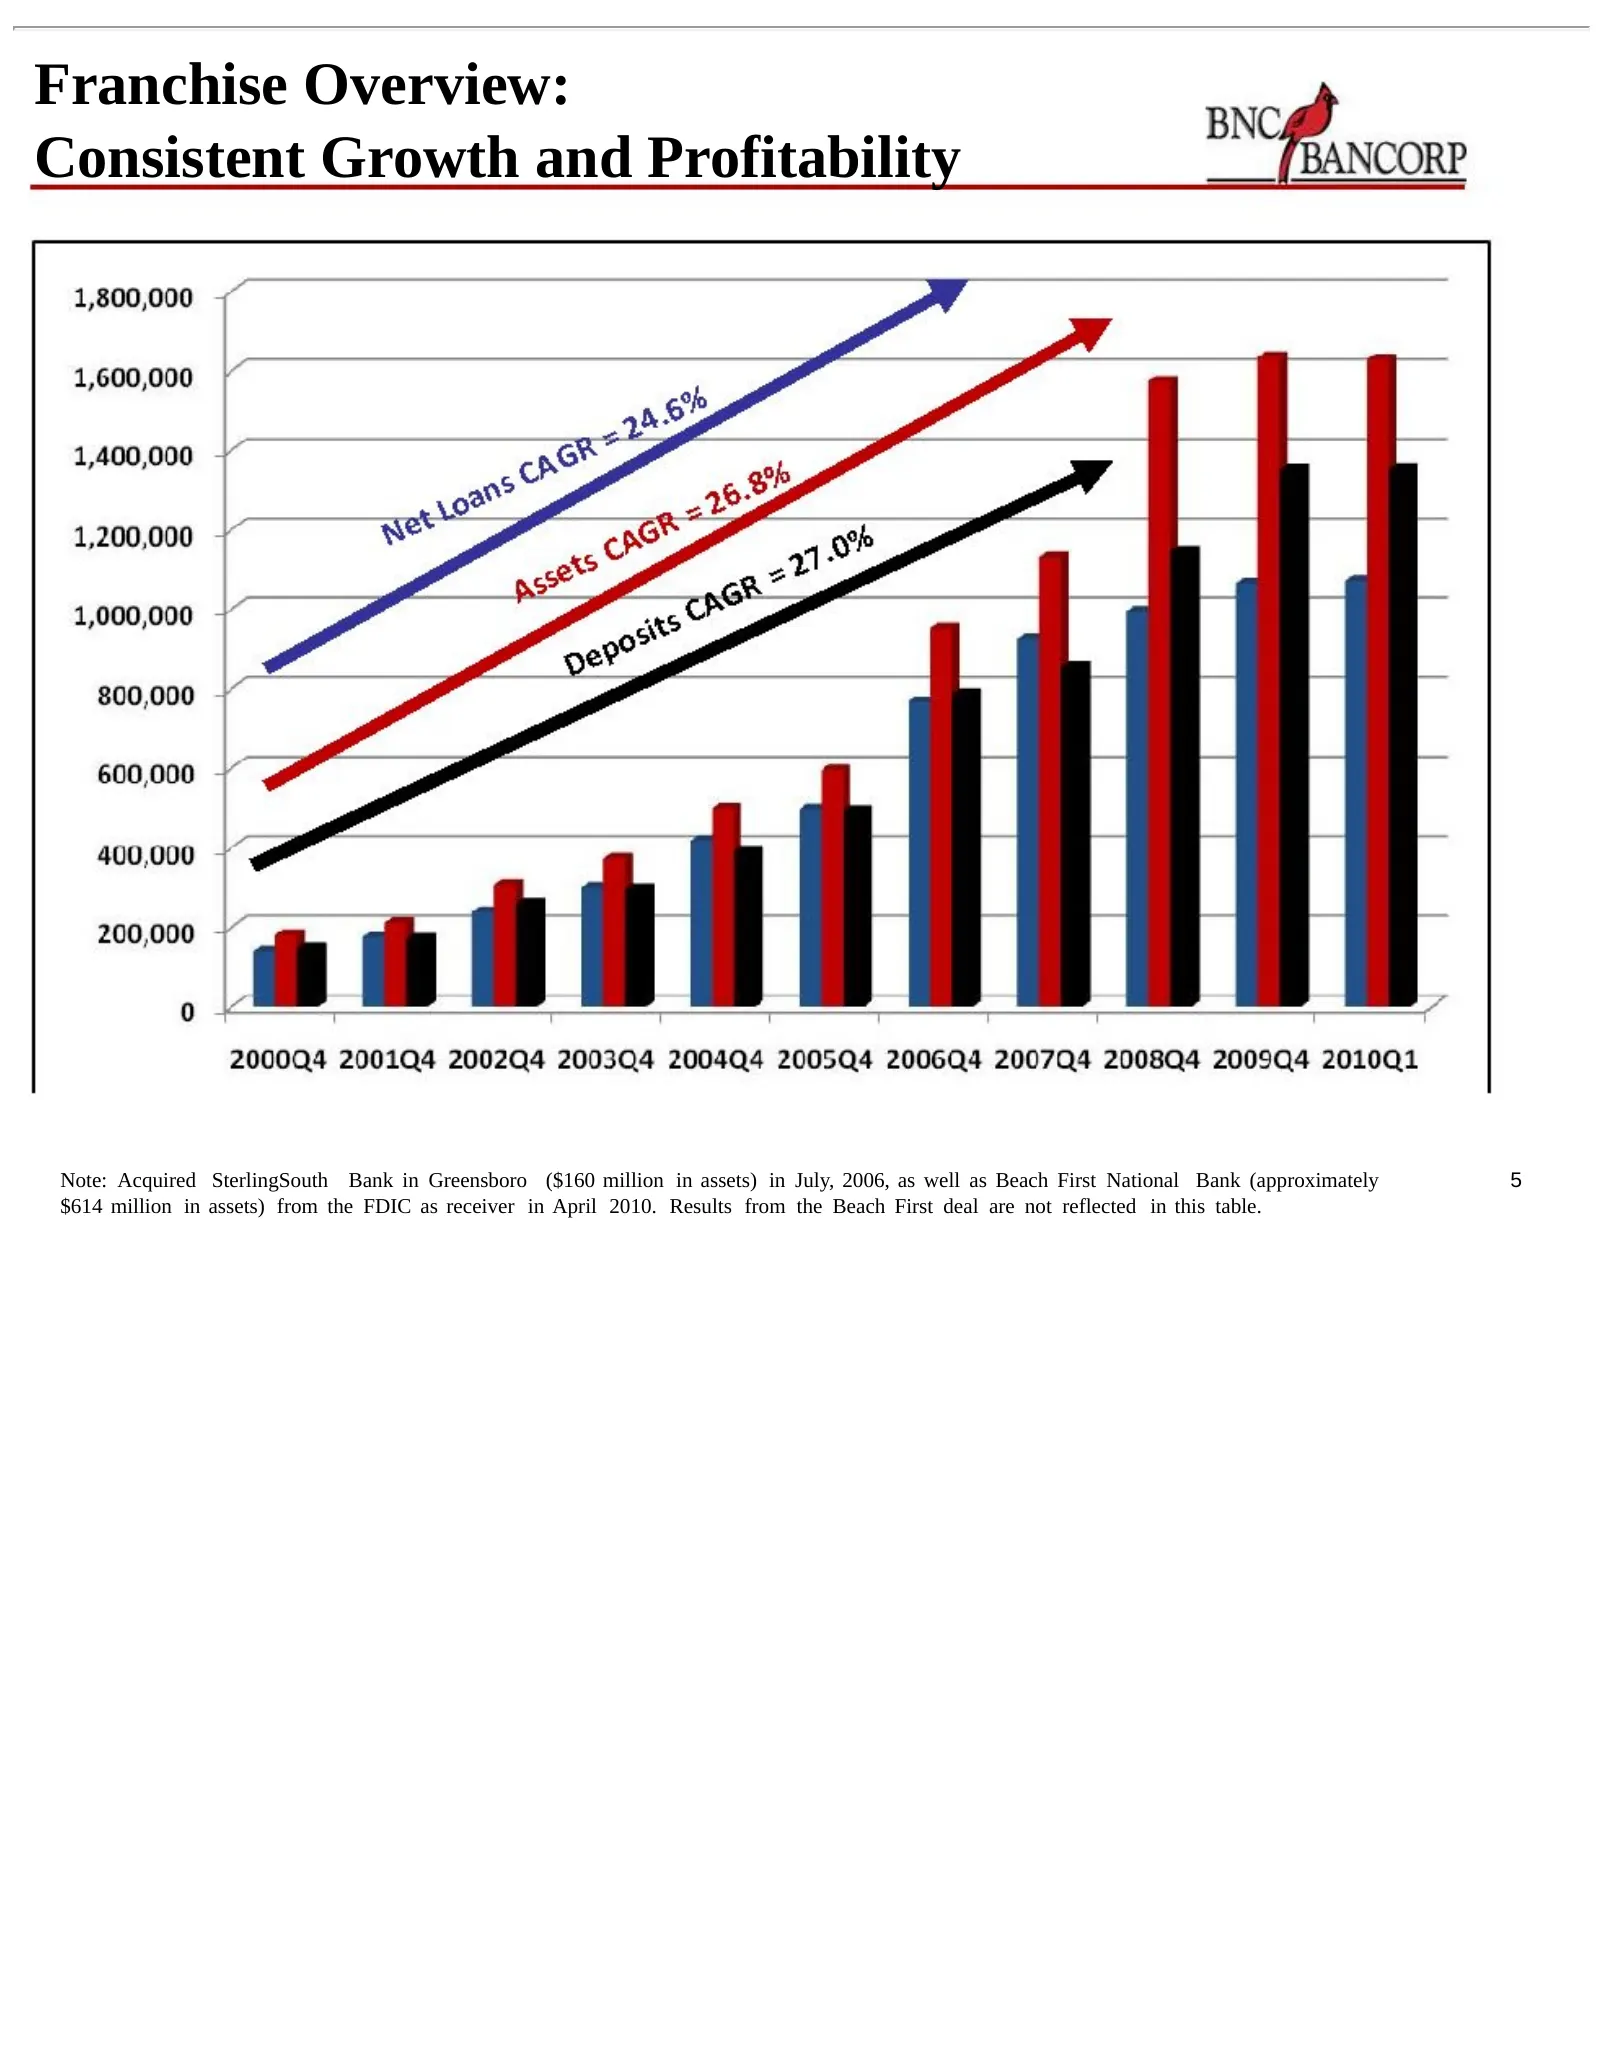
Franchise Overview: Consistent Growth and Profitability Note: Acquired SterlingSouth Bank in Greensboro ($160 million in assets) in July, 2006, as well as Beach First National Bank (approximately 5 $614 million in assets) from the FDIC as receiver in April 2010. Results from the Beach First deal are
Slide 6: Franchise Overview: Consistent Growth and Profitability
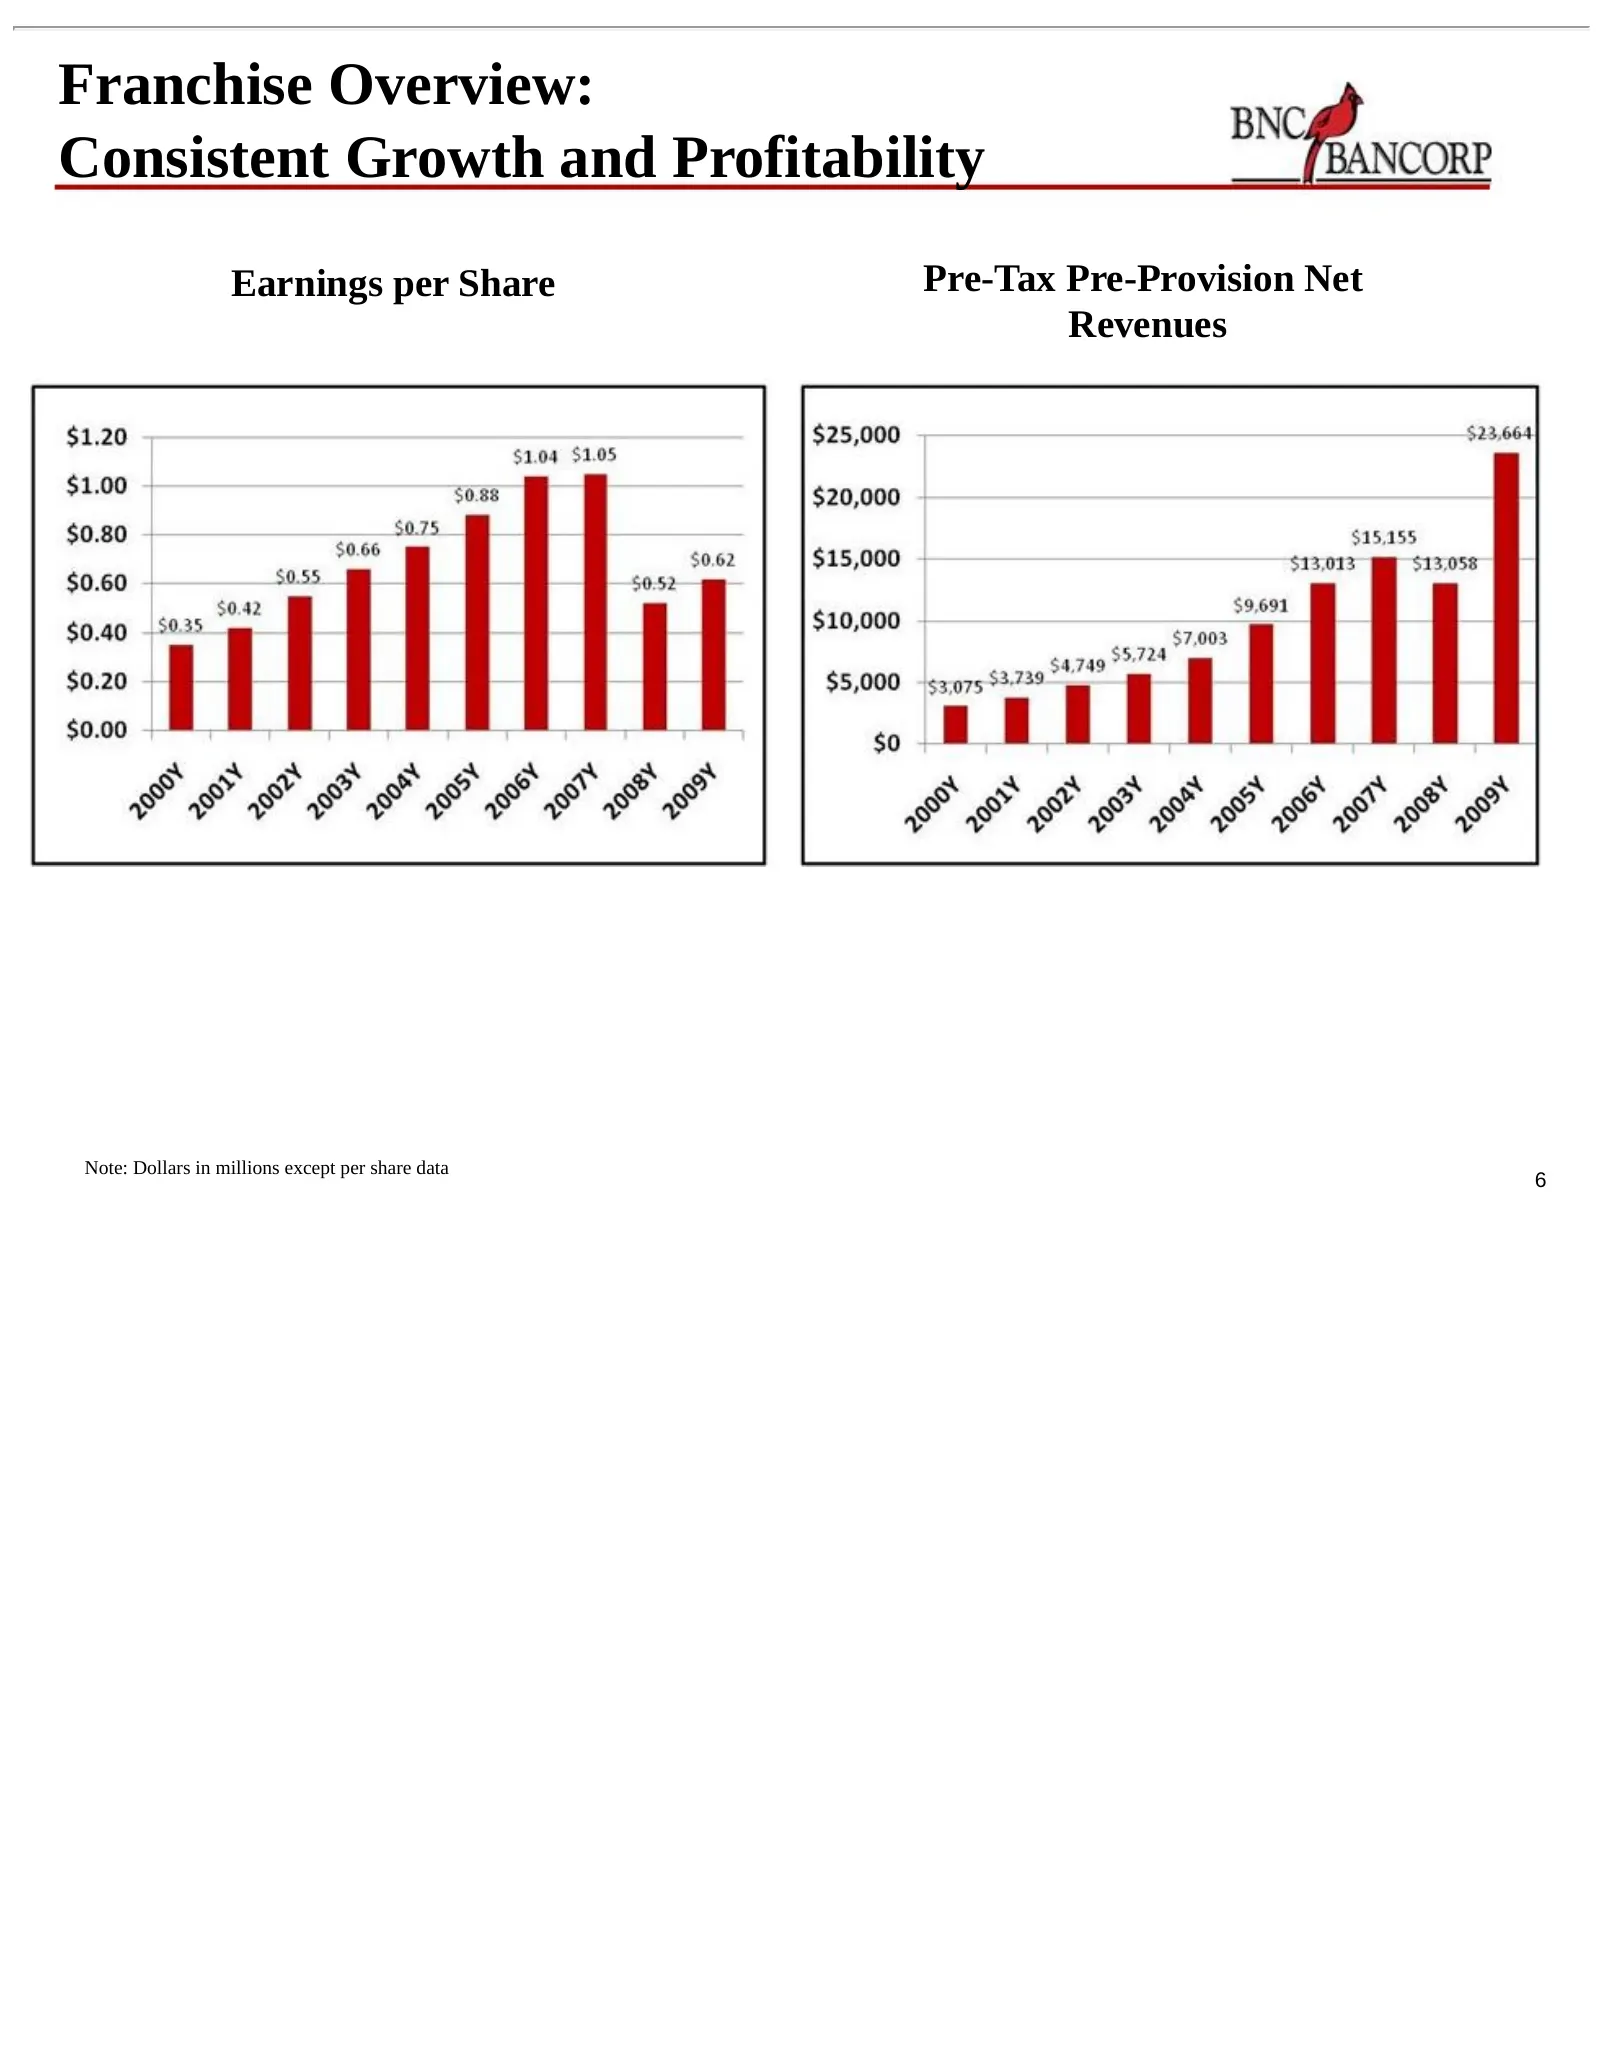
Franchise Overview: Consistent Growth and Profitability Earnings per Share Pre-Tax Pre-Provision Net Revenues Note: Dollars in millions except per share data 6
Slide 7: Franchise Overview: Branch Locations and Market Overview
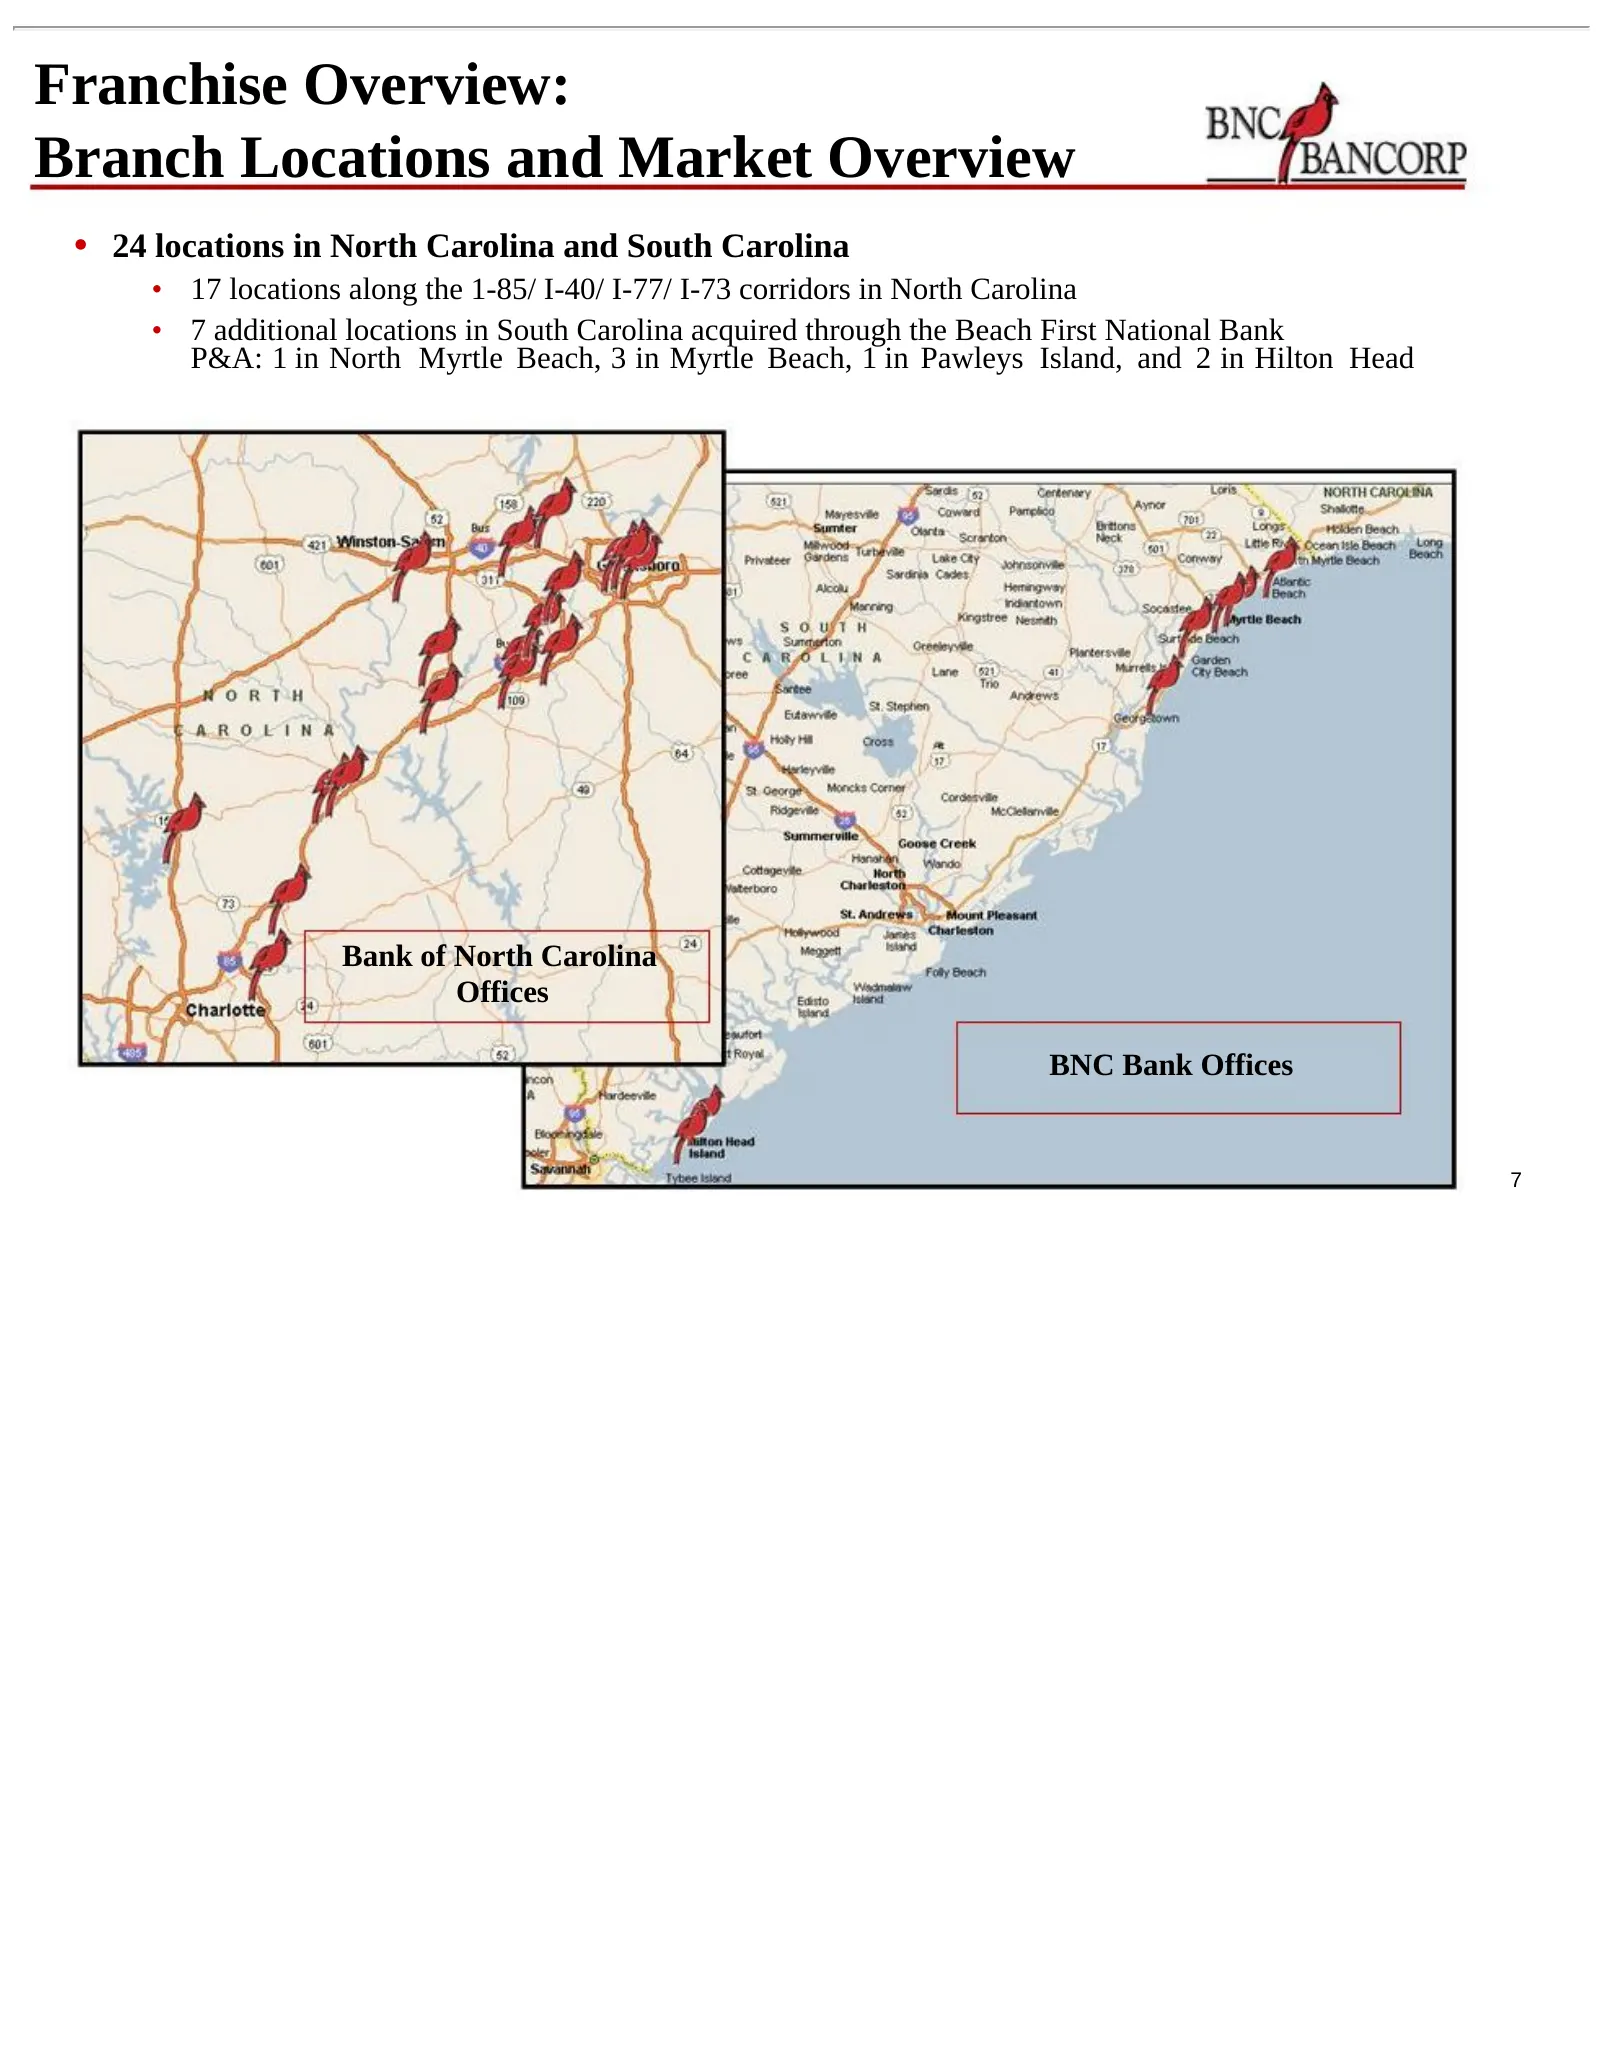
Franchise Overview: Branch Locations and Market Overview • 24 locations in North Carolina and South Carolina • 17 locations along the 1-85/ I-40/ I-77/ I-73 corridors in North Carolina • 7 additional locations in South Carolina acquired through the Beach First National Bank P&A: 1 in North Myrtle Be
Slide 8: North Carolina Franchise Overview: Market Demographics and Position
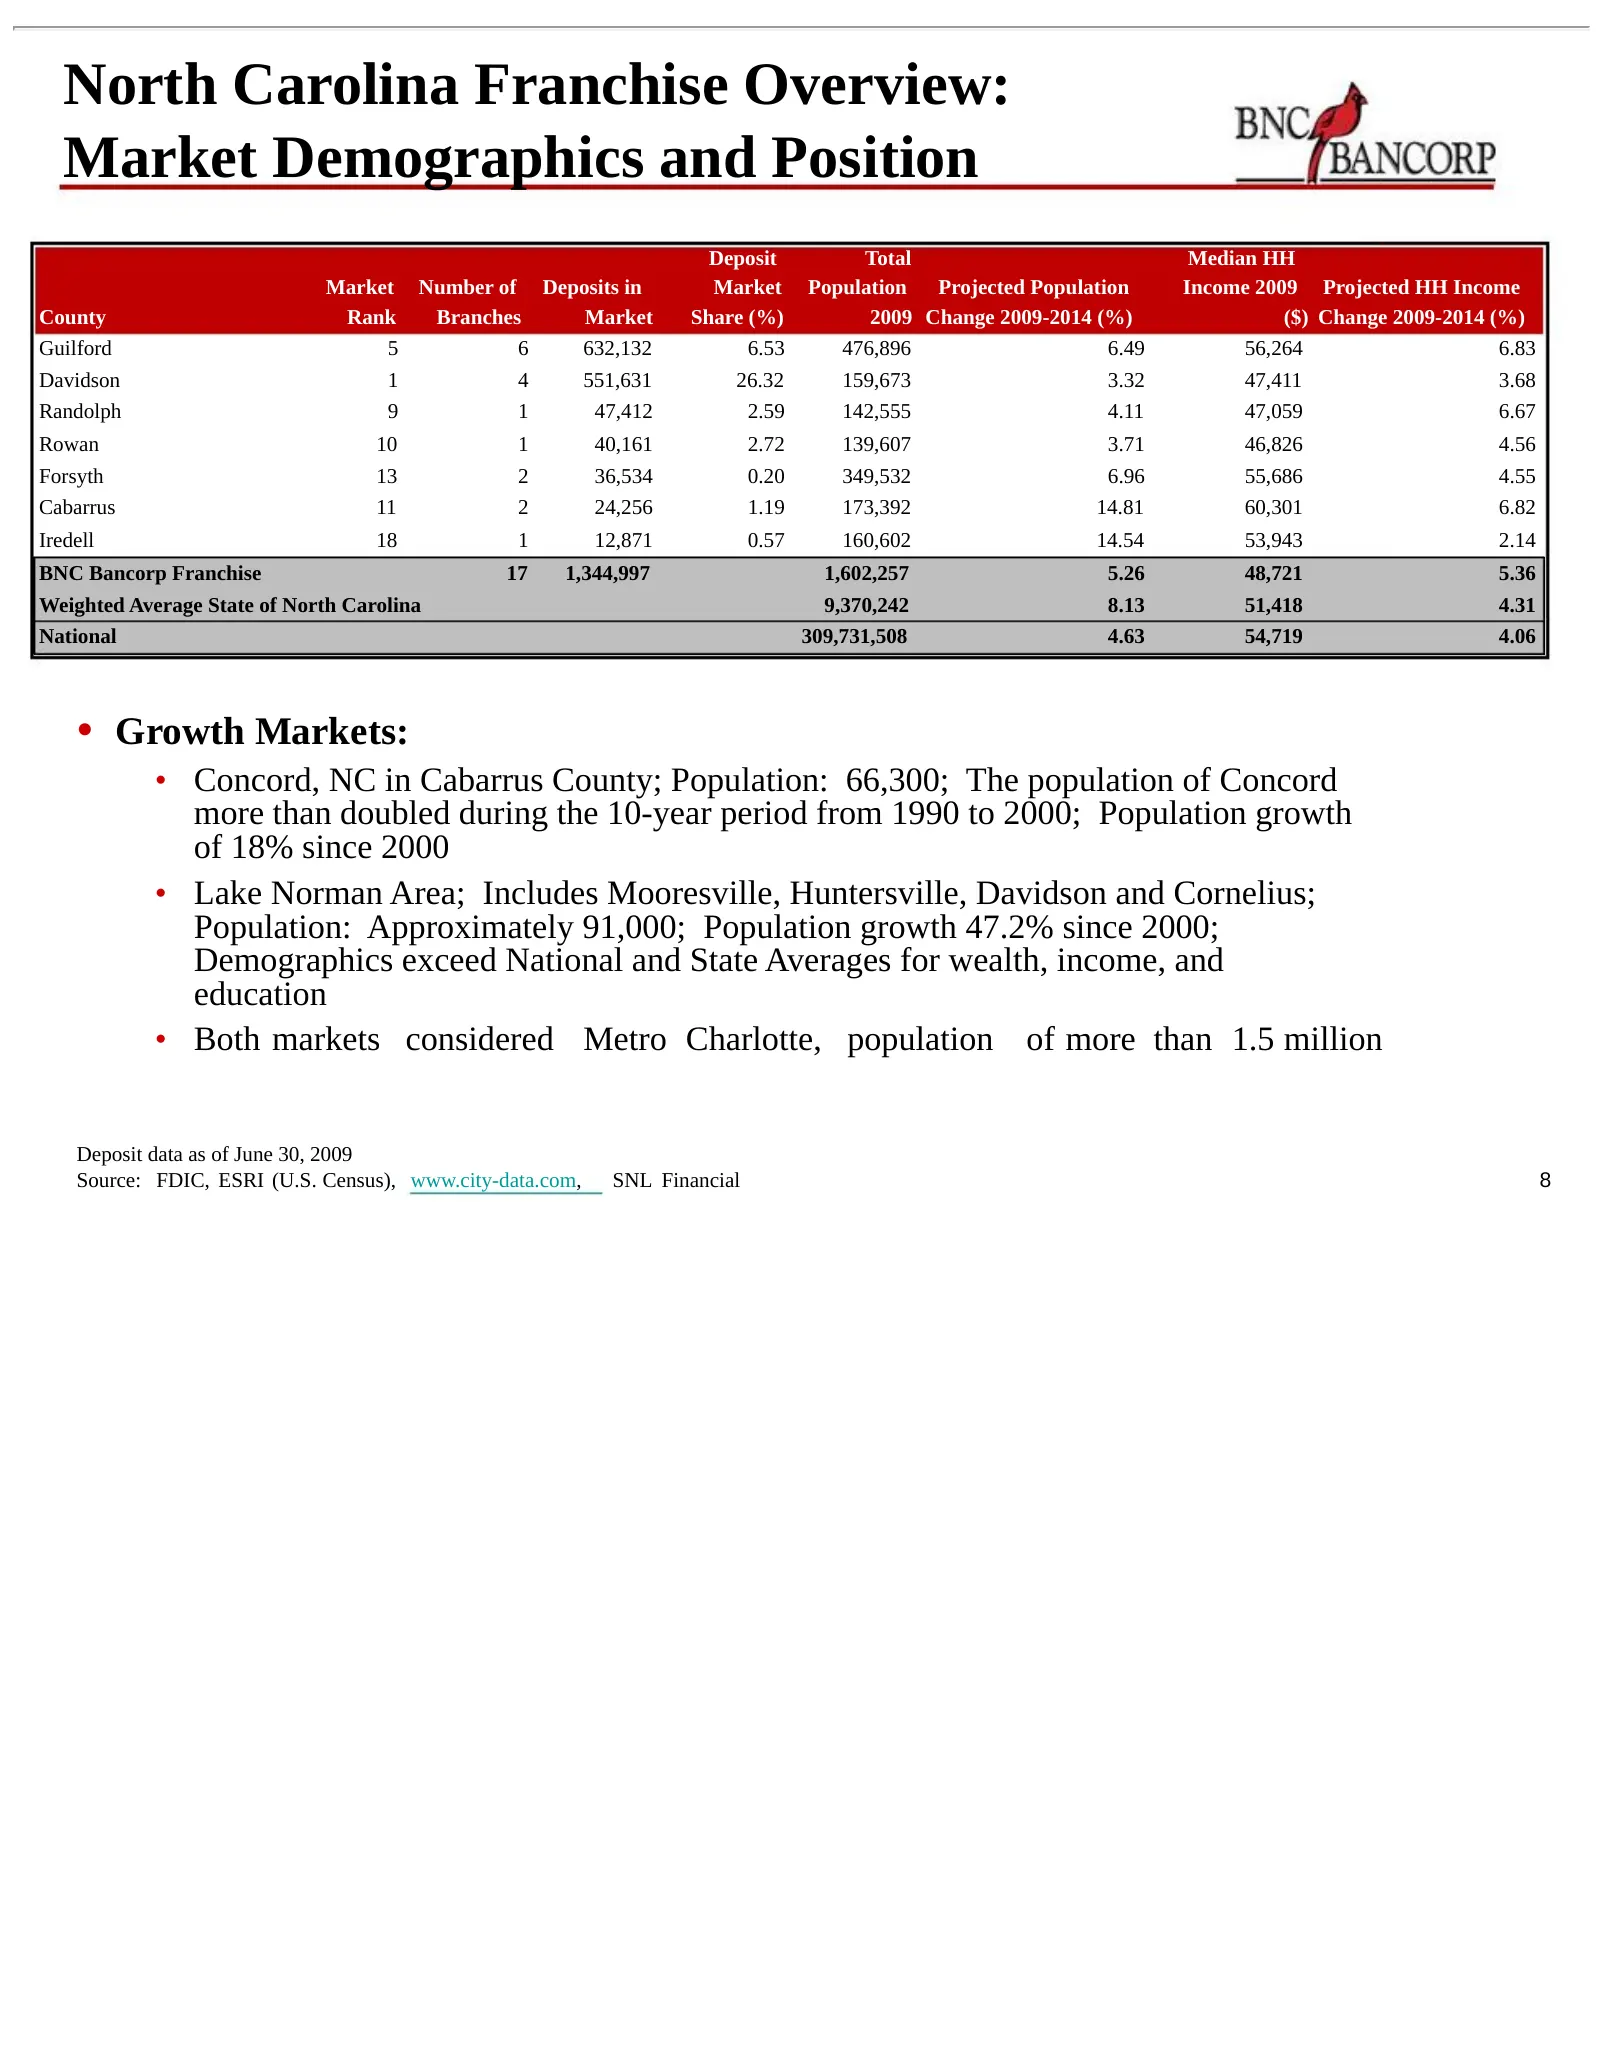
North Carolina Franchise Overview: Market Demographics and Position Deposit Total Median HH Market Number of Deposits in Market Population Projected Population Income 2009 Projected HH Income County Rank Branches Market Share (%) 2009 Change 2009-2014 (%) ($) Change 2009-2014 (%) Guilford 5 6 632,13
Slide 9: Overview of South Carolina Franchise
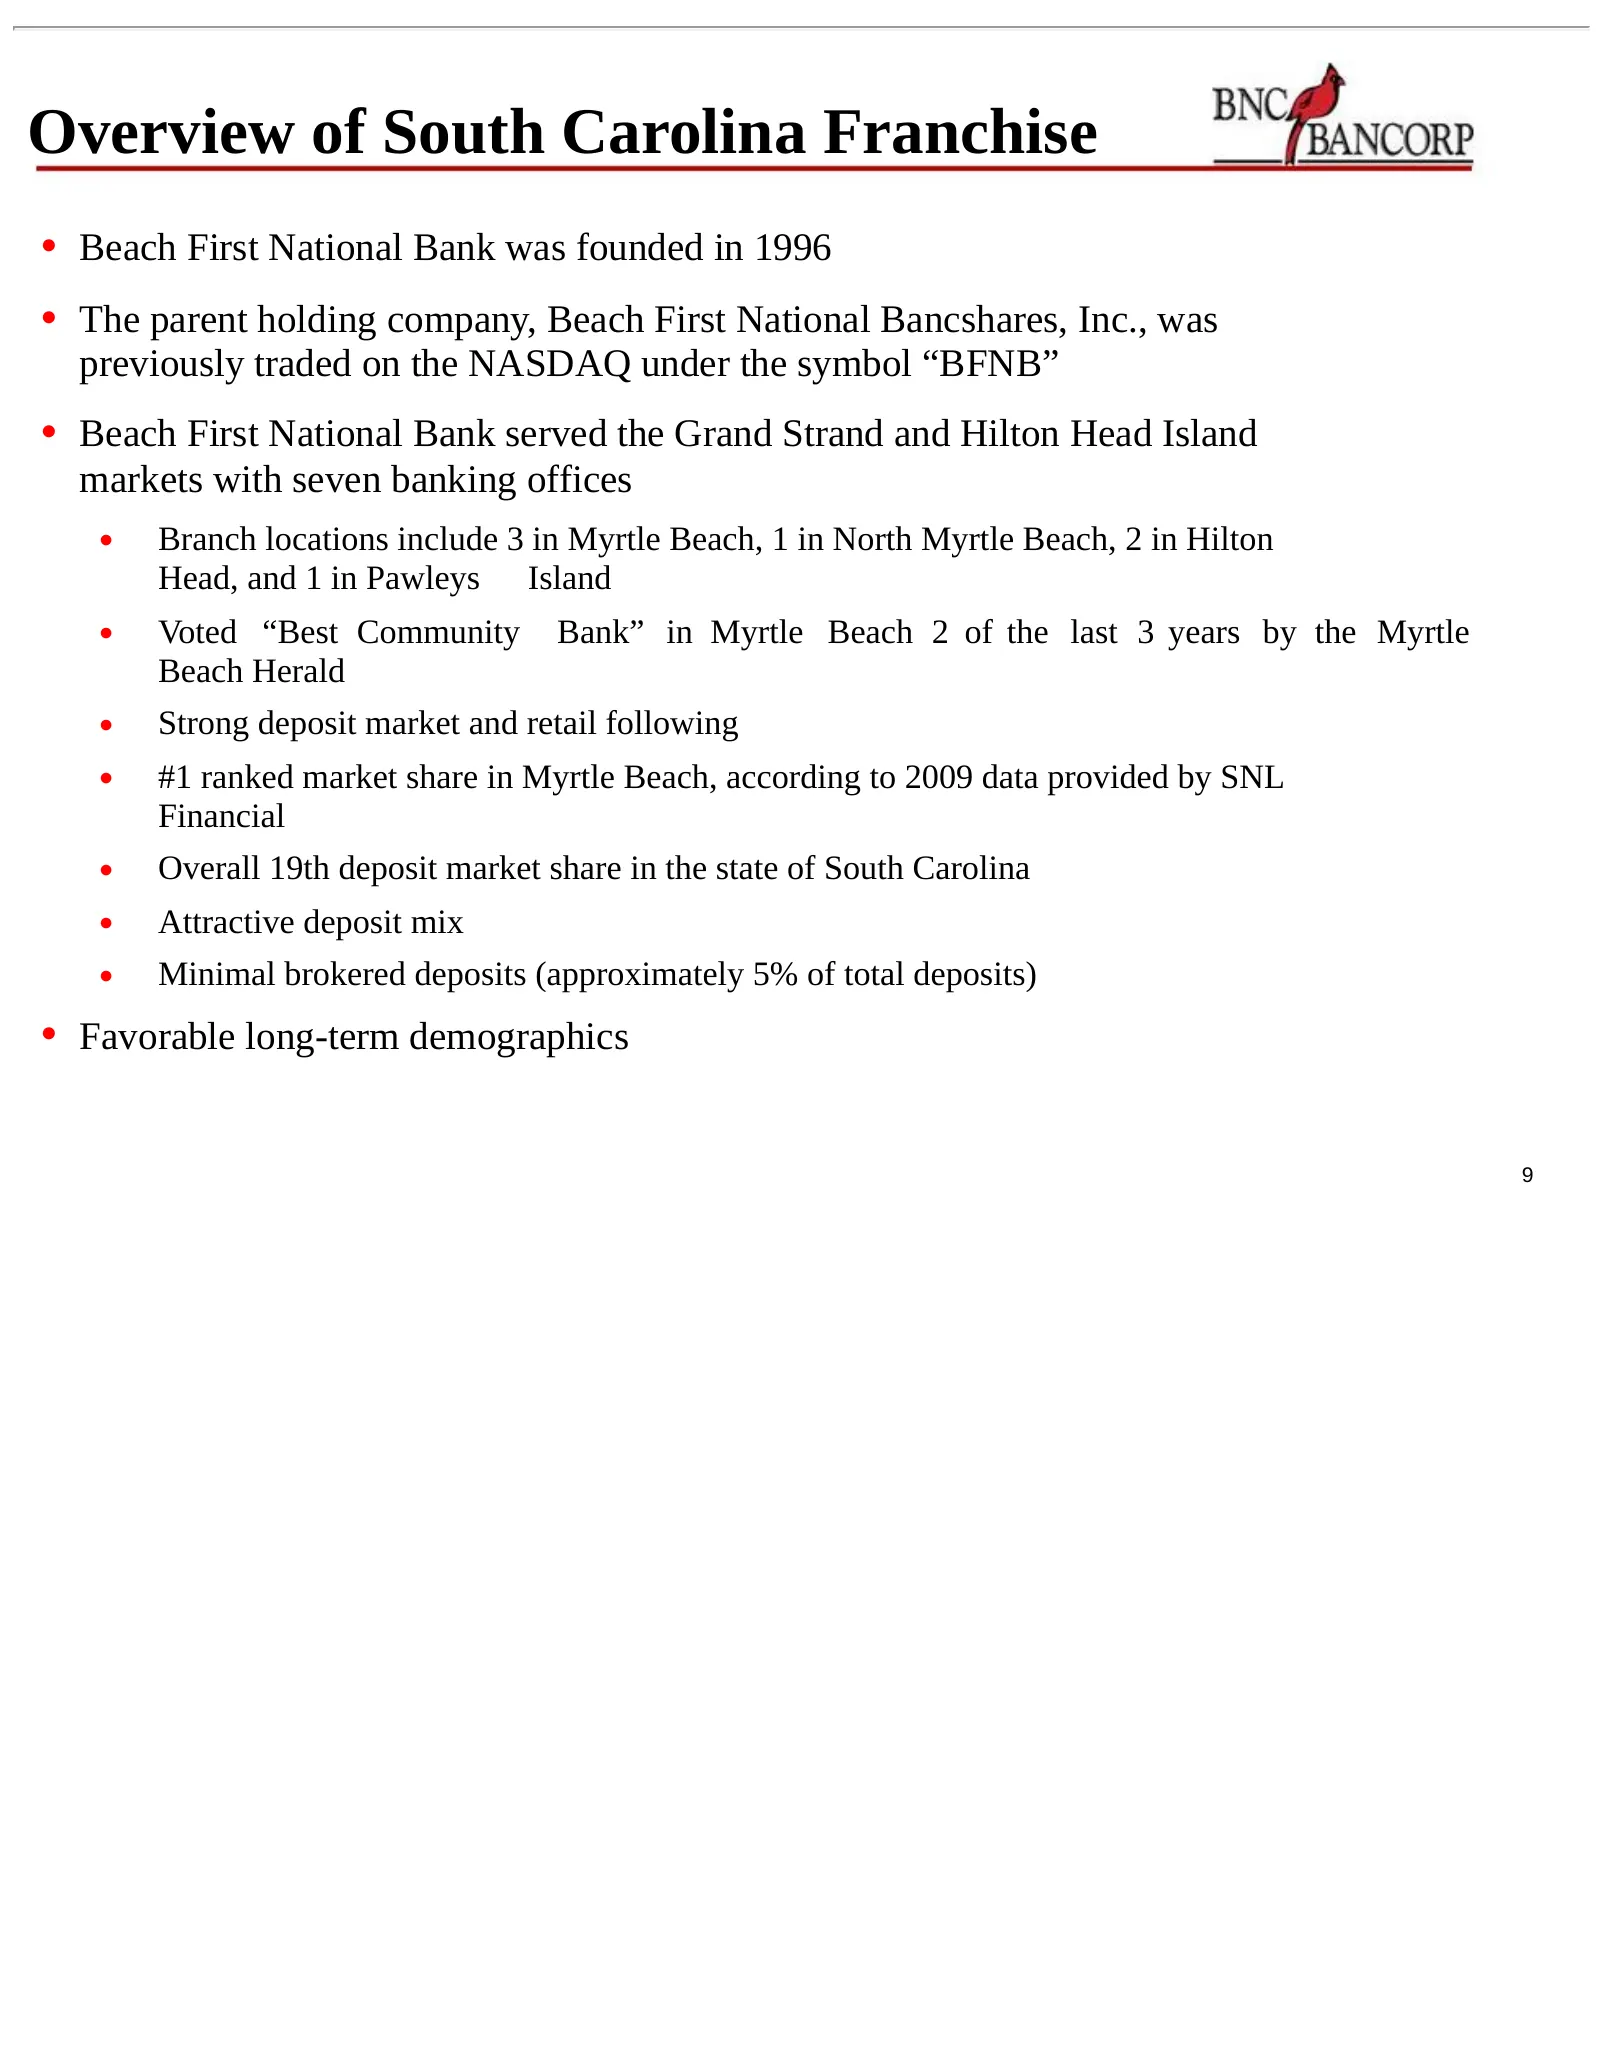
Overview of South Carolina Franchise • Beach First National Bank was founded in 1996 • The parent holding company, Beach First National Bancshares, Inc., was previously traded on the NASDAQ under the symbol “BFNB” • Beach First National Bank served the Grand Strand and Hilton Head Island markets wit
Slide 10: South Carolina Franchise Overview: Market Demographics and Position
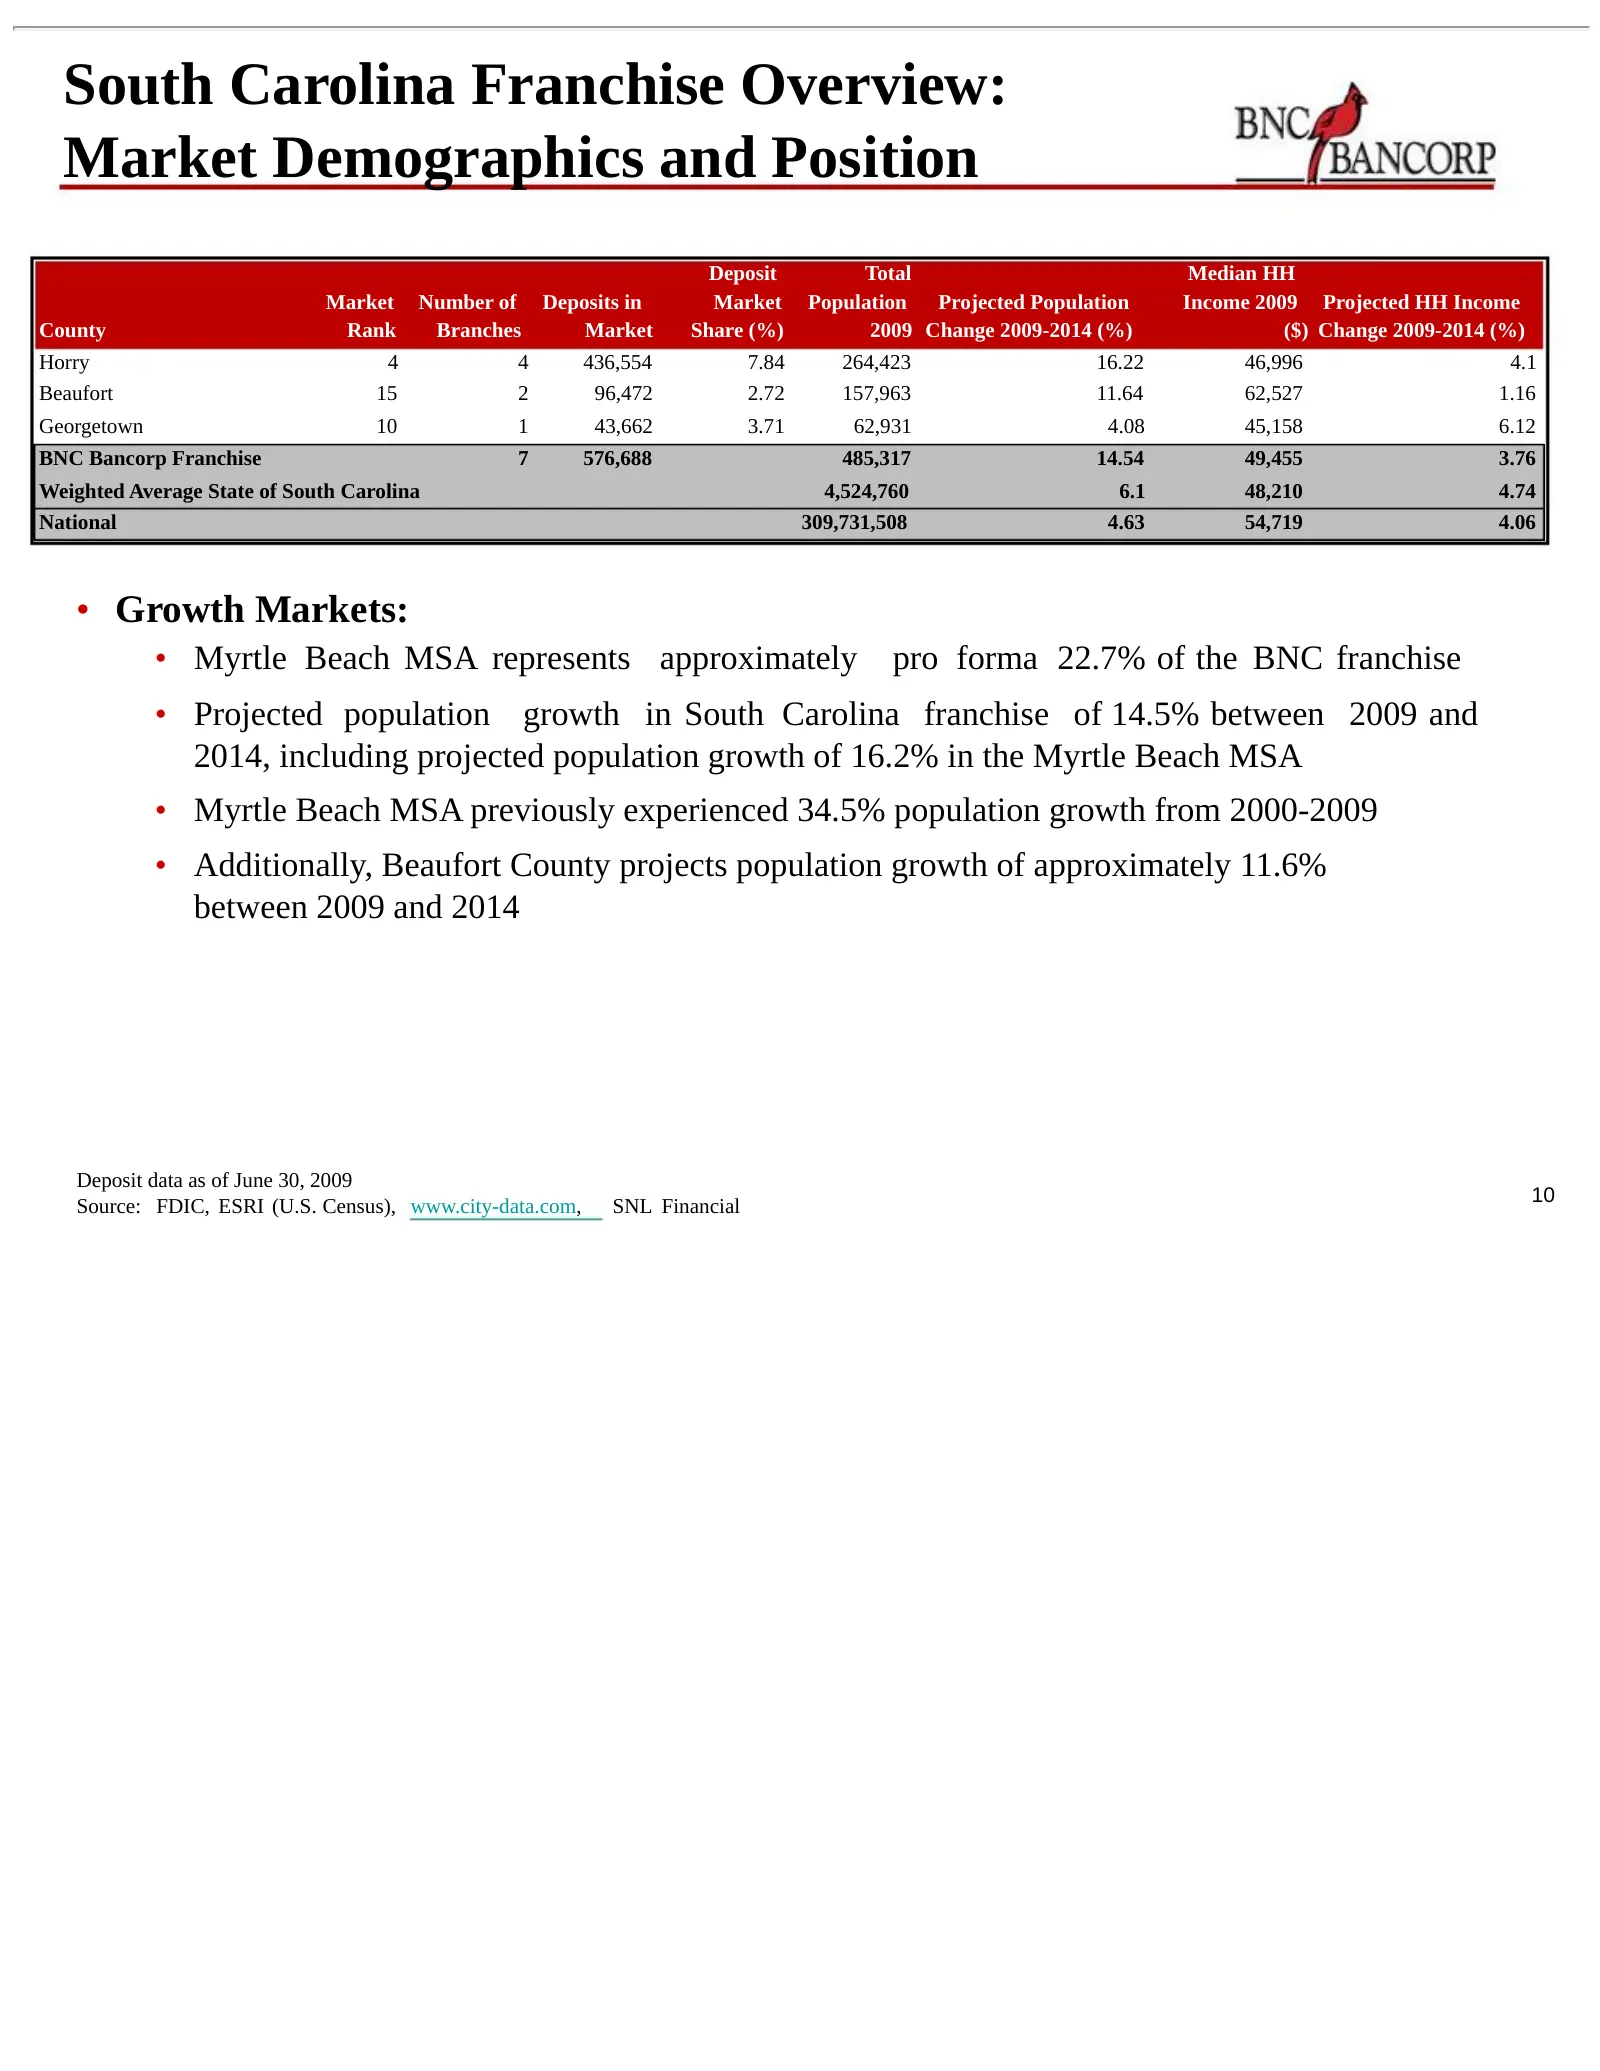
South Carolina Franchise Overview: Market Demographics and Position Deposit Total Median HH Market Number of Deposits in Market Population Projected Population Income 2009 Projected HH Income County Rank Branches Market Share (%) 2009 Change 2009-2014 (%) ($) Change 2009-2014 (%) Horry 4 4 436,554 7
Slide 11: Franchise Overview: Q1 2010 Financial Highlights
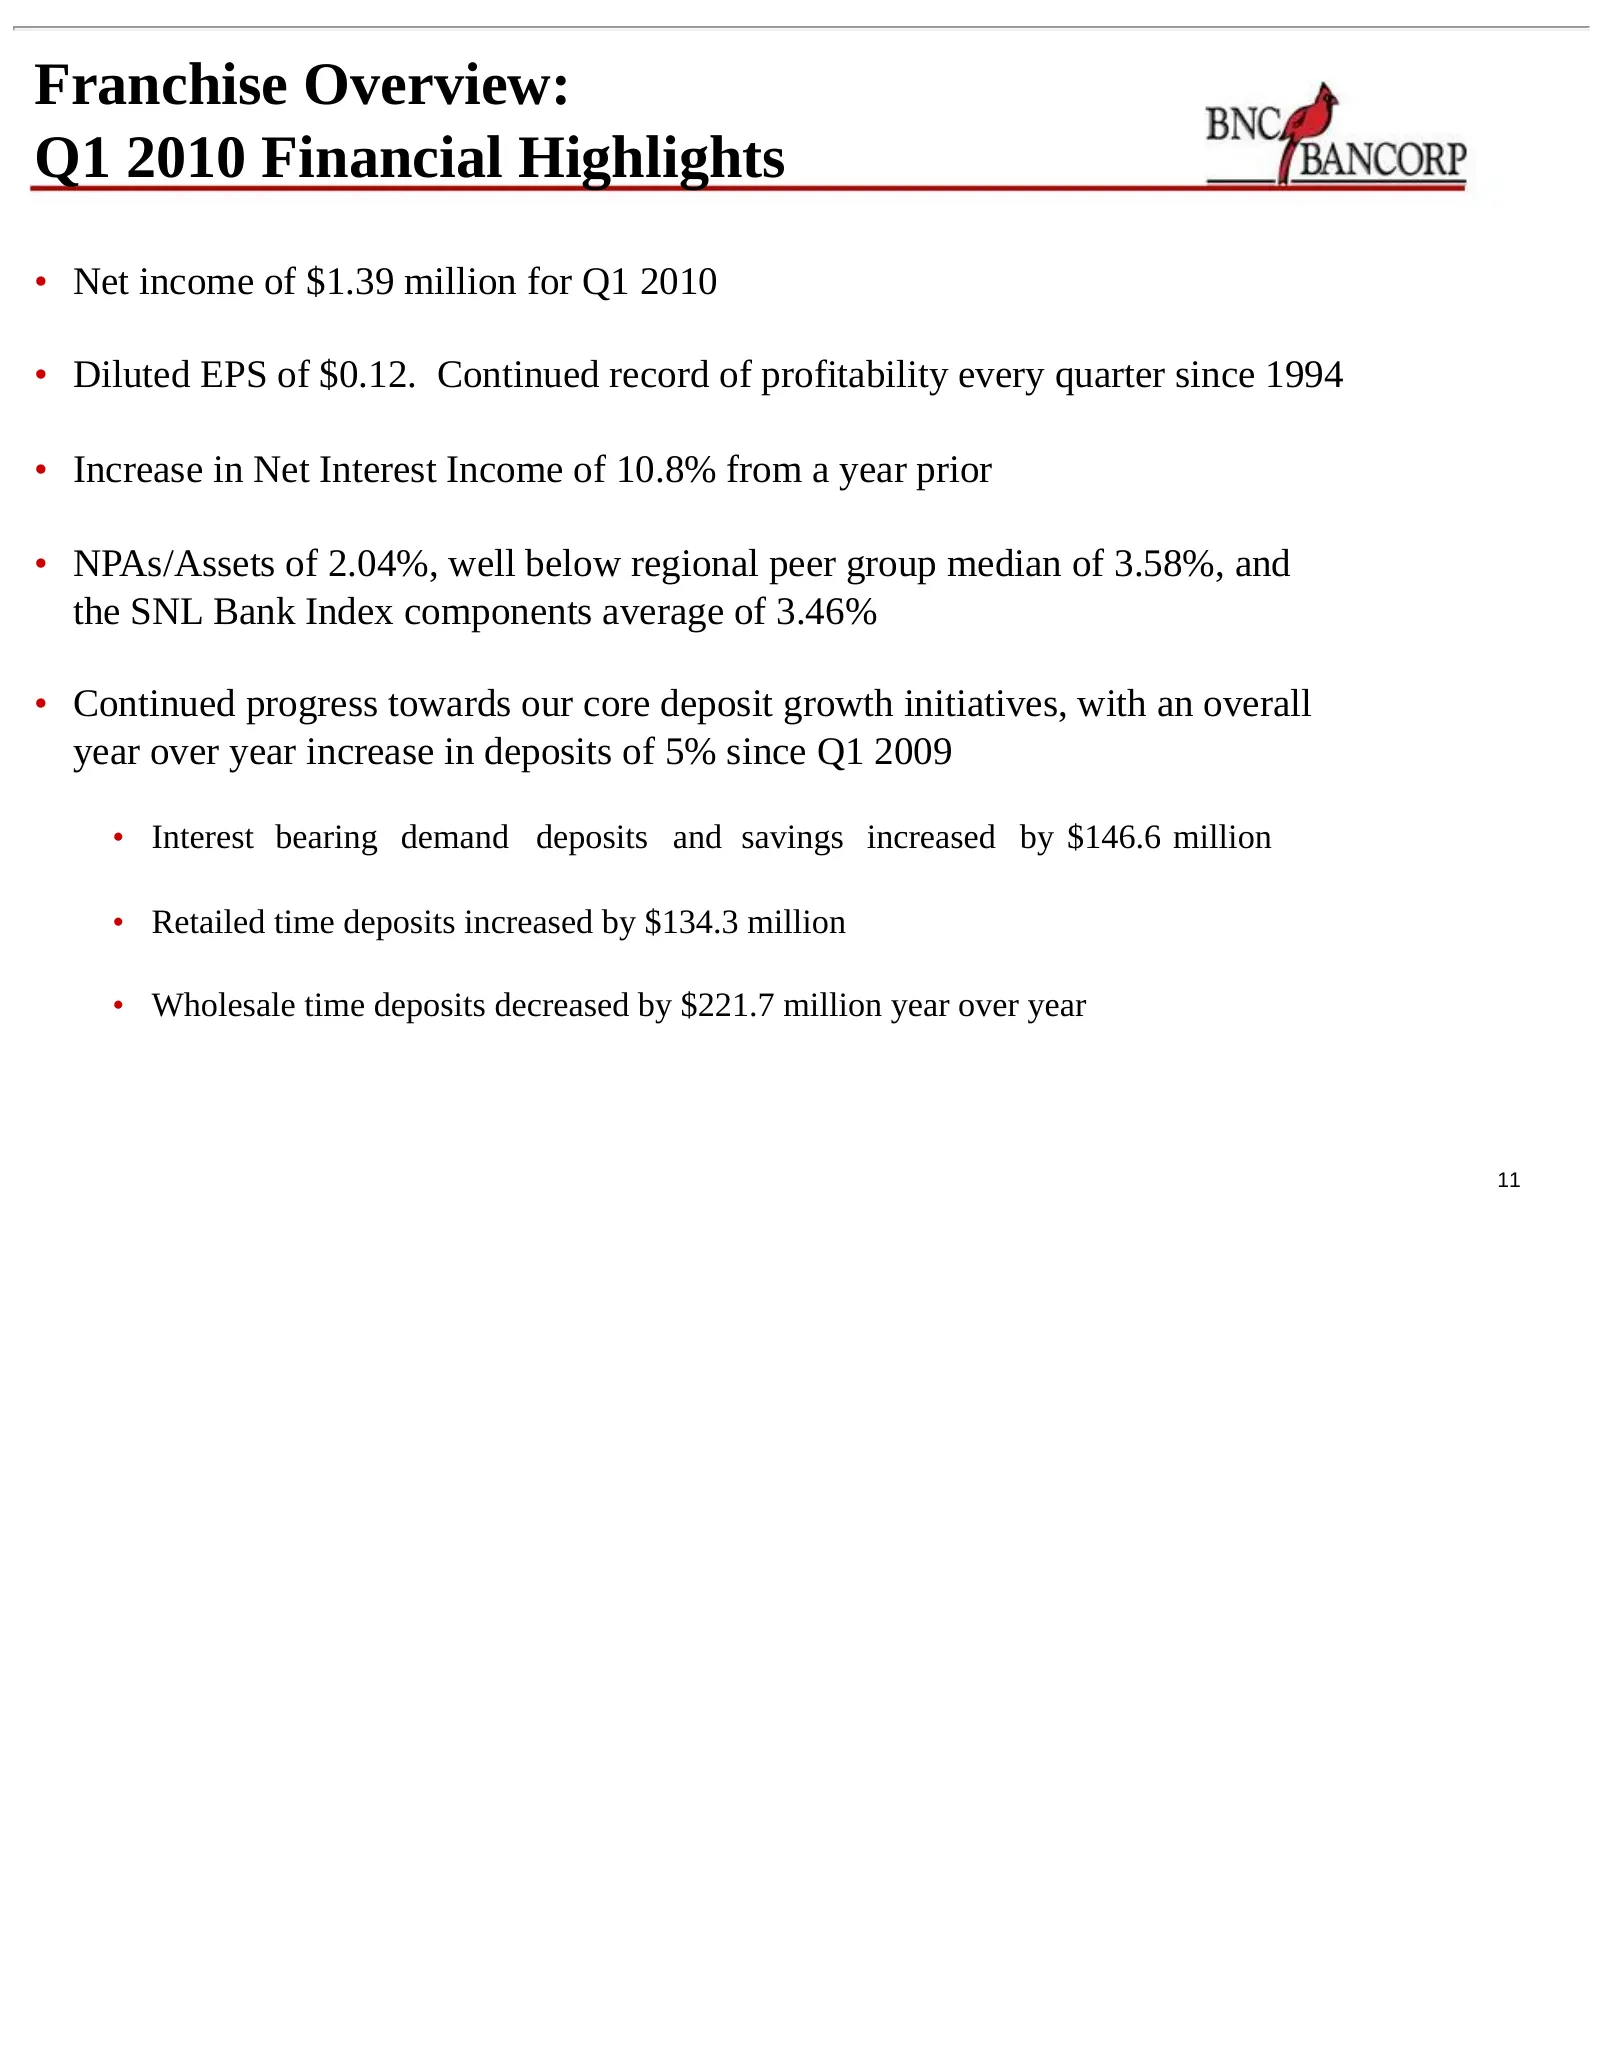
Franchise Overview: Q1 2010 Financial Highlights • Net income of $1.39 million for Q1 2010 • Diluted EPS of $0.12. Continued record of profitability every quarter since 1994 • Increase in Net Interest Income of 10.8% from a year prior • NPAs/Assets of 2.04%, well below regional peer group median of
Slide 12: CD Portfolio: Extending in a Low Rate Environment
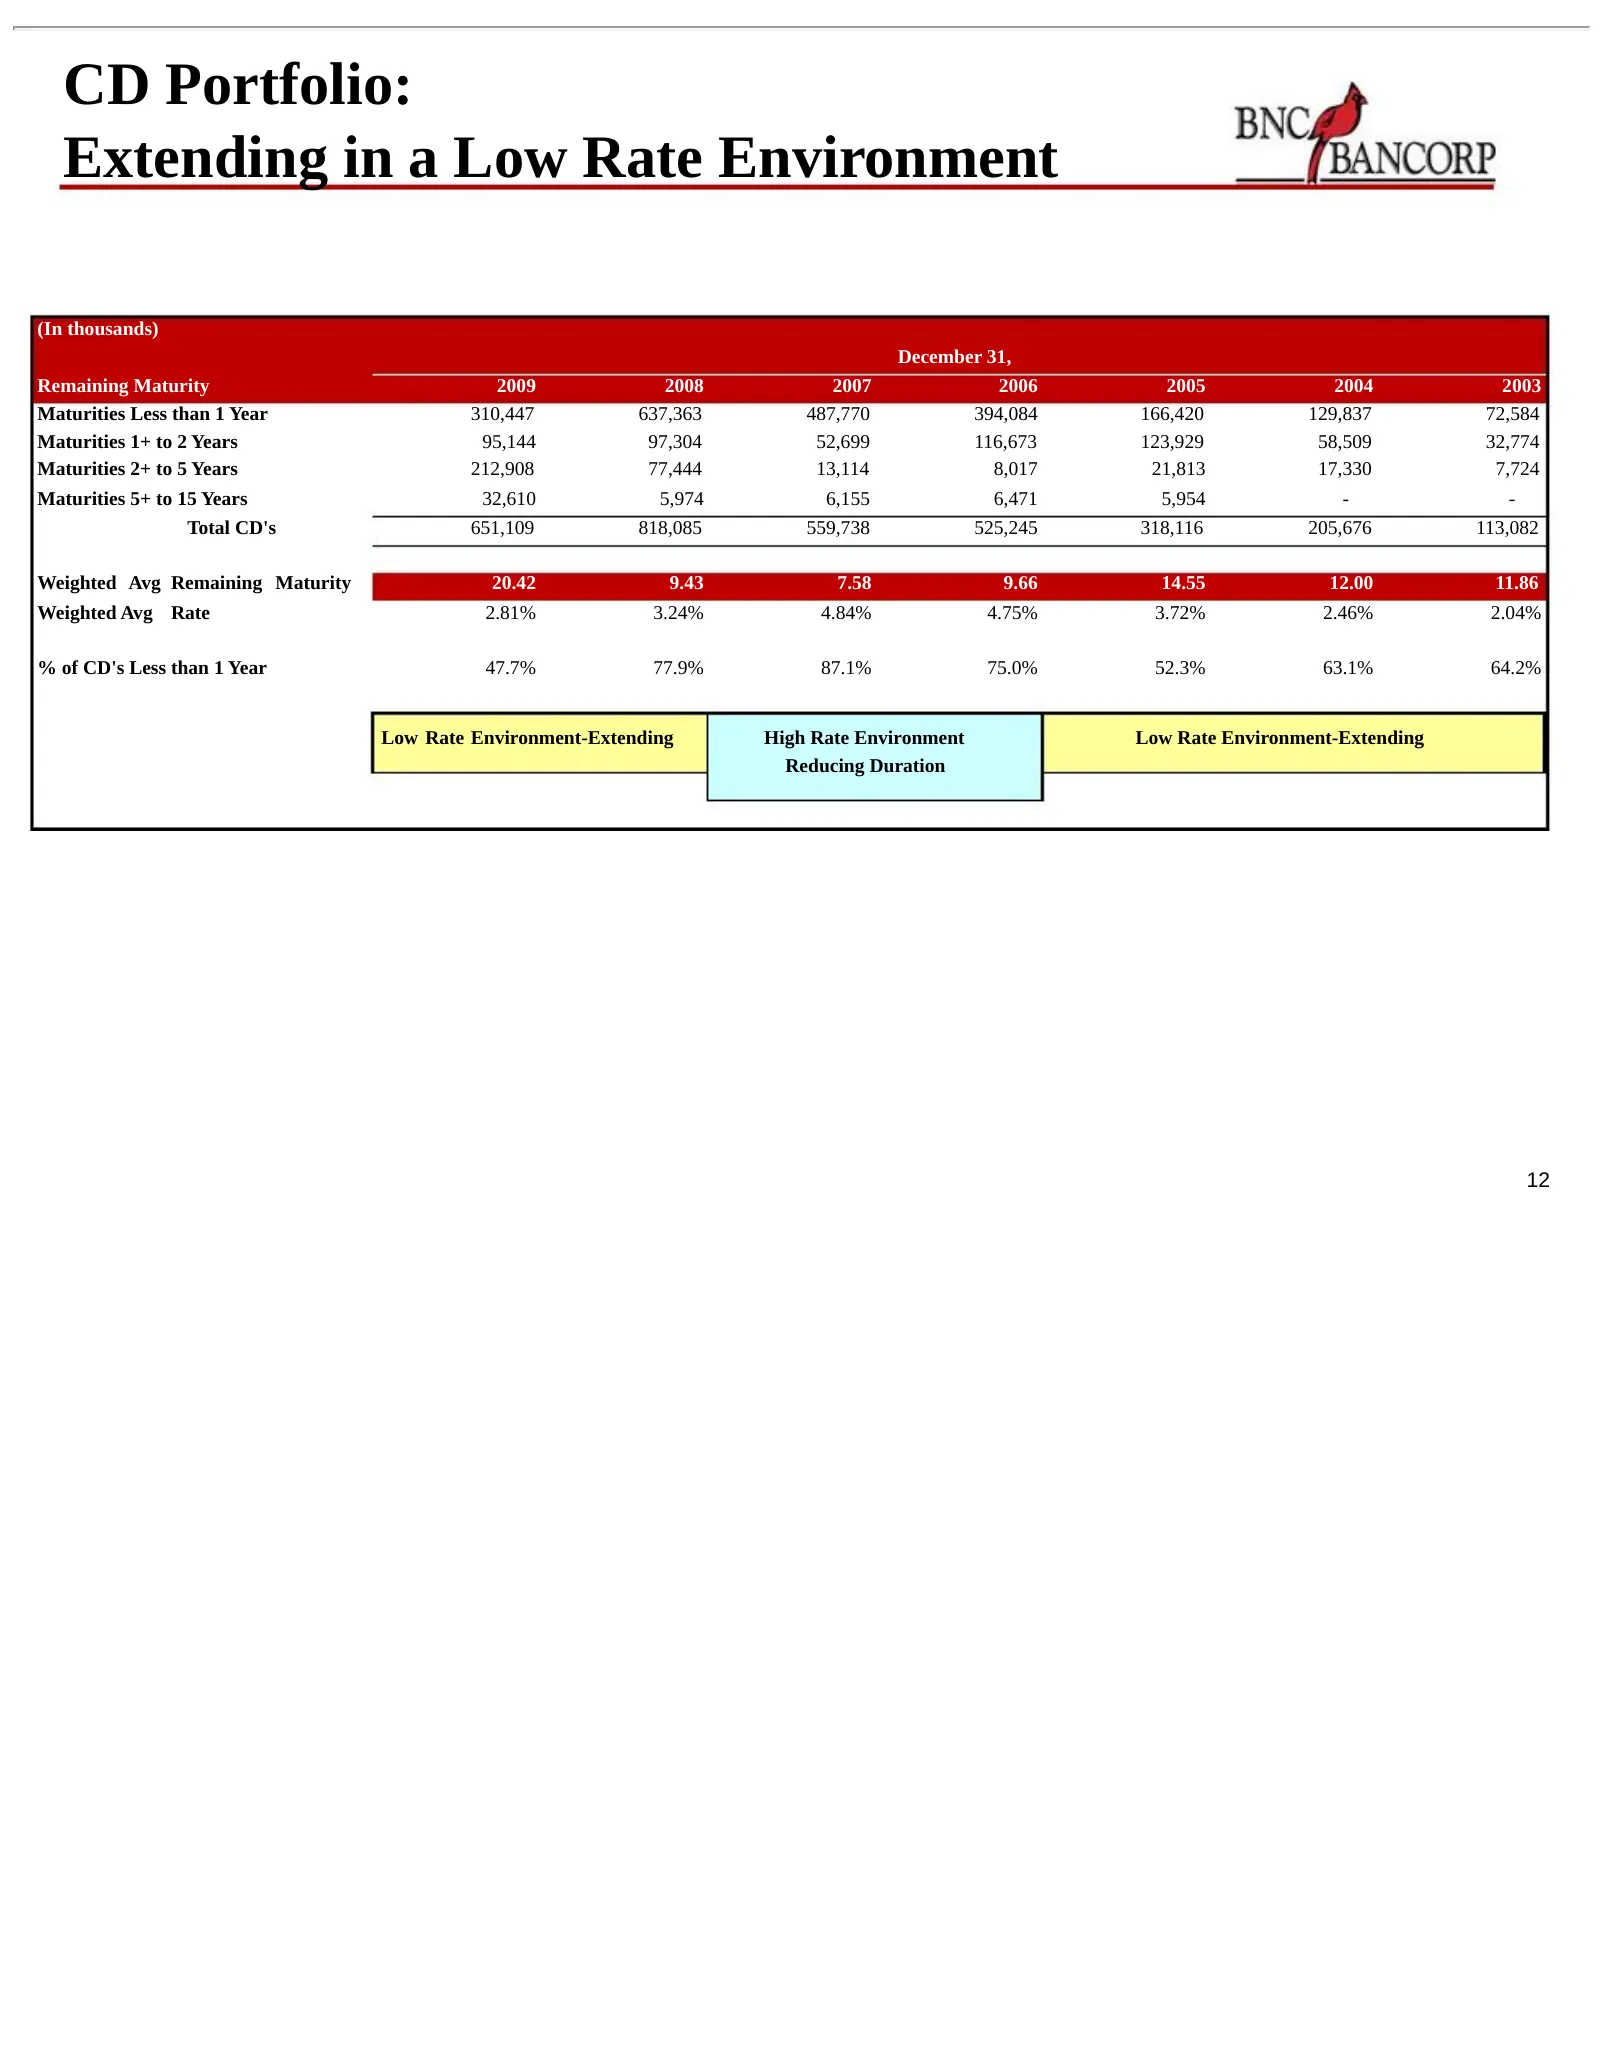
CD Portfolio: Extending in a Low Rate Environment (In thousands) December 31, Remaining Maturity 2009 2008 2007 2006 2005 2004 2003 Maturities Less than 1 Year 310,447 637,363 487,770 394,084 166,420 129,837 72,584 Maturities 1+ to 2 Years 95,144 97,304 52,699 116,673 123,929 58,509 32,774 Maturitie
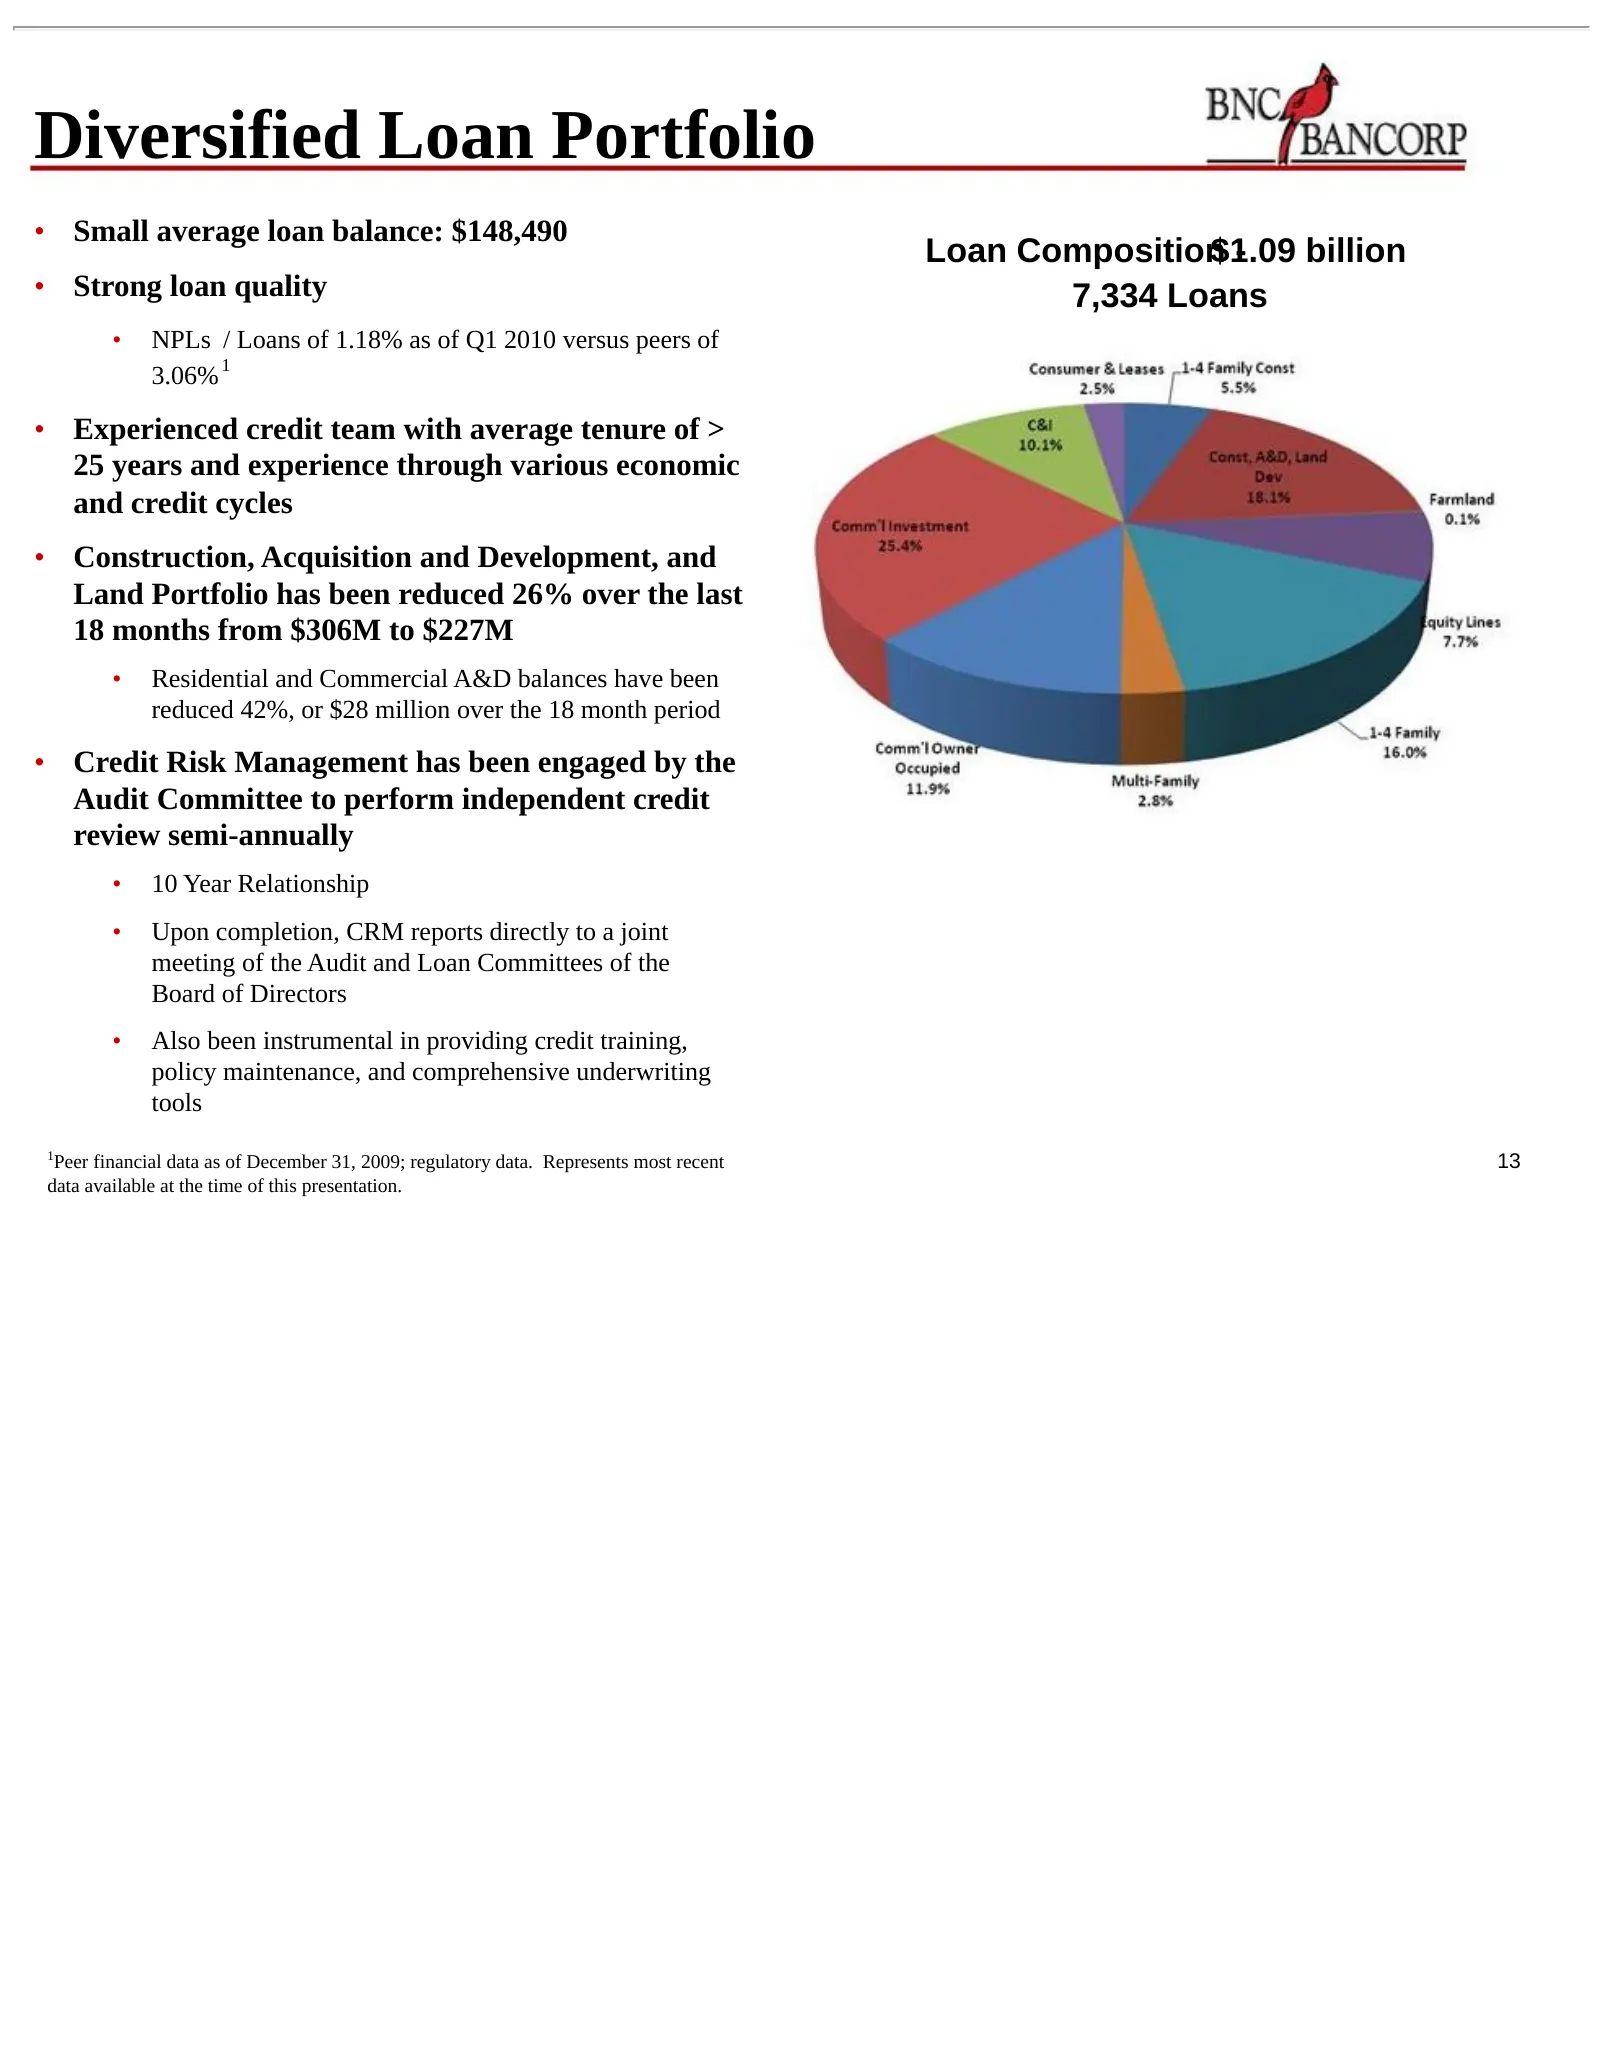
Slide 13: Diversified Loan Portfolio
Diversified Loan Portfolio • Small average loan balance: $148,490 Loan Composition$1.09 - billion • Strong loan quality 7,334 Loans • NPLs / Loans of 1.18% as of Q1 2010 versus peers of 1 3.06% • Experienced credit team with average tenure of > 25 years and experience through various economic and cr
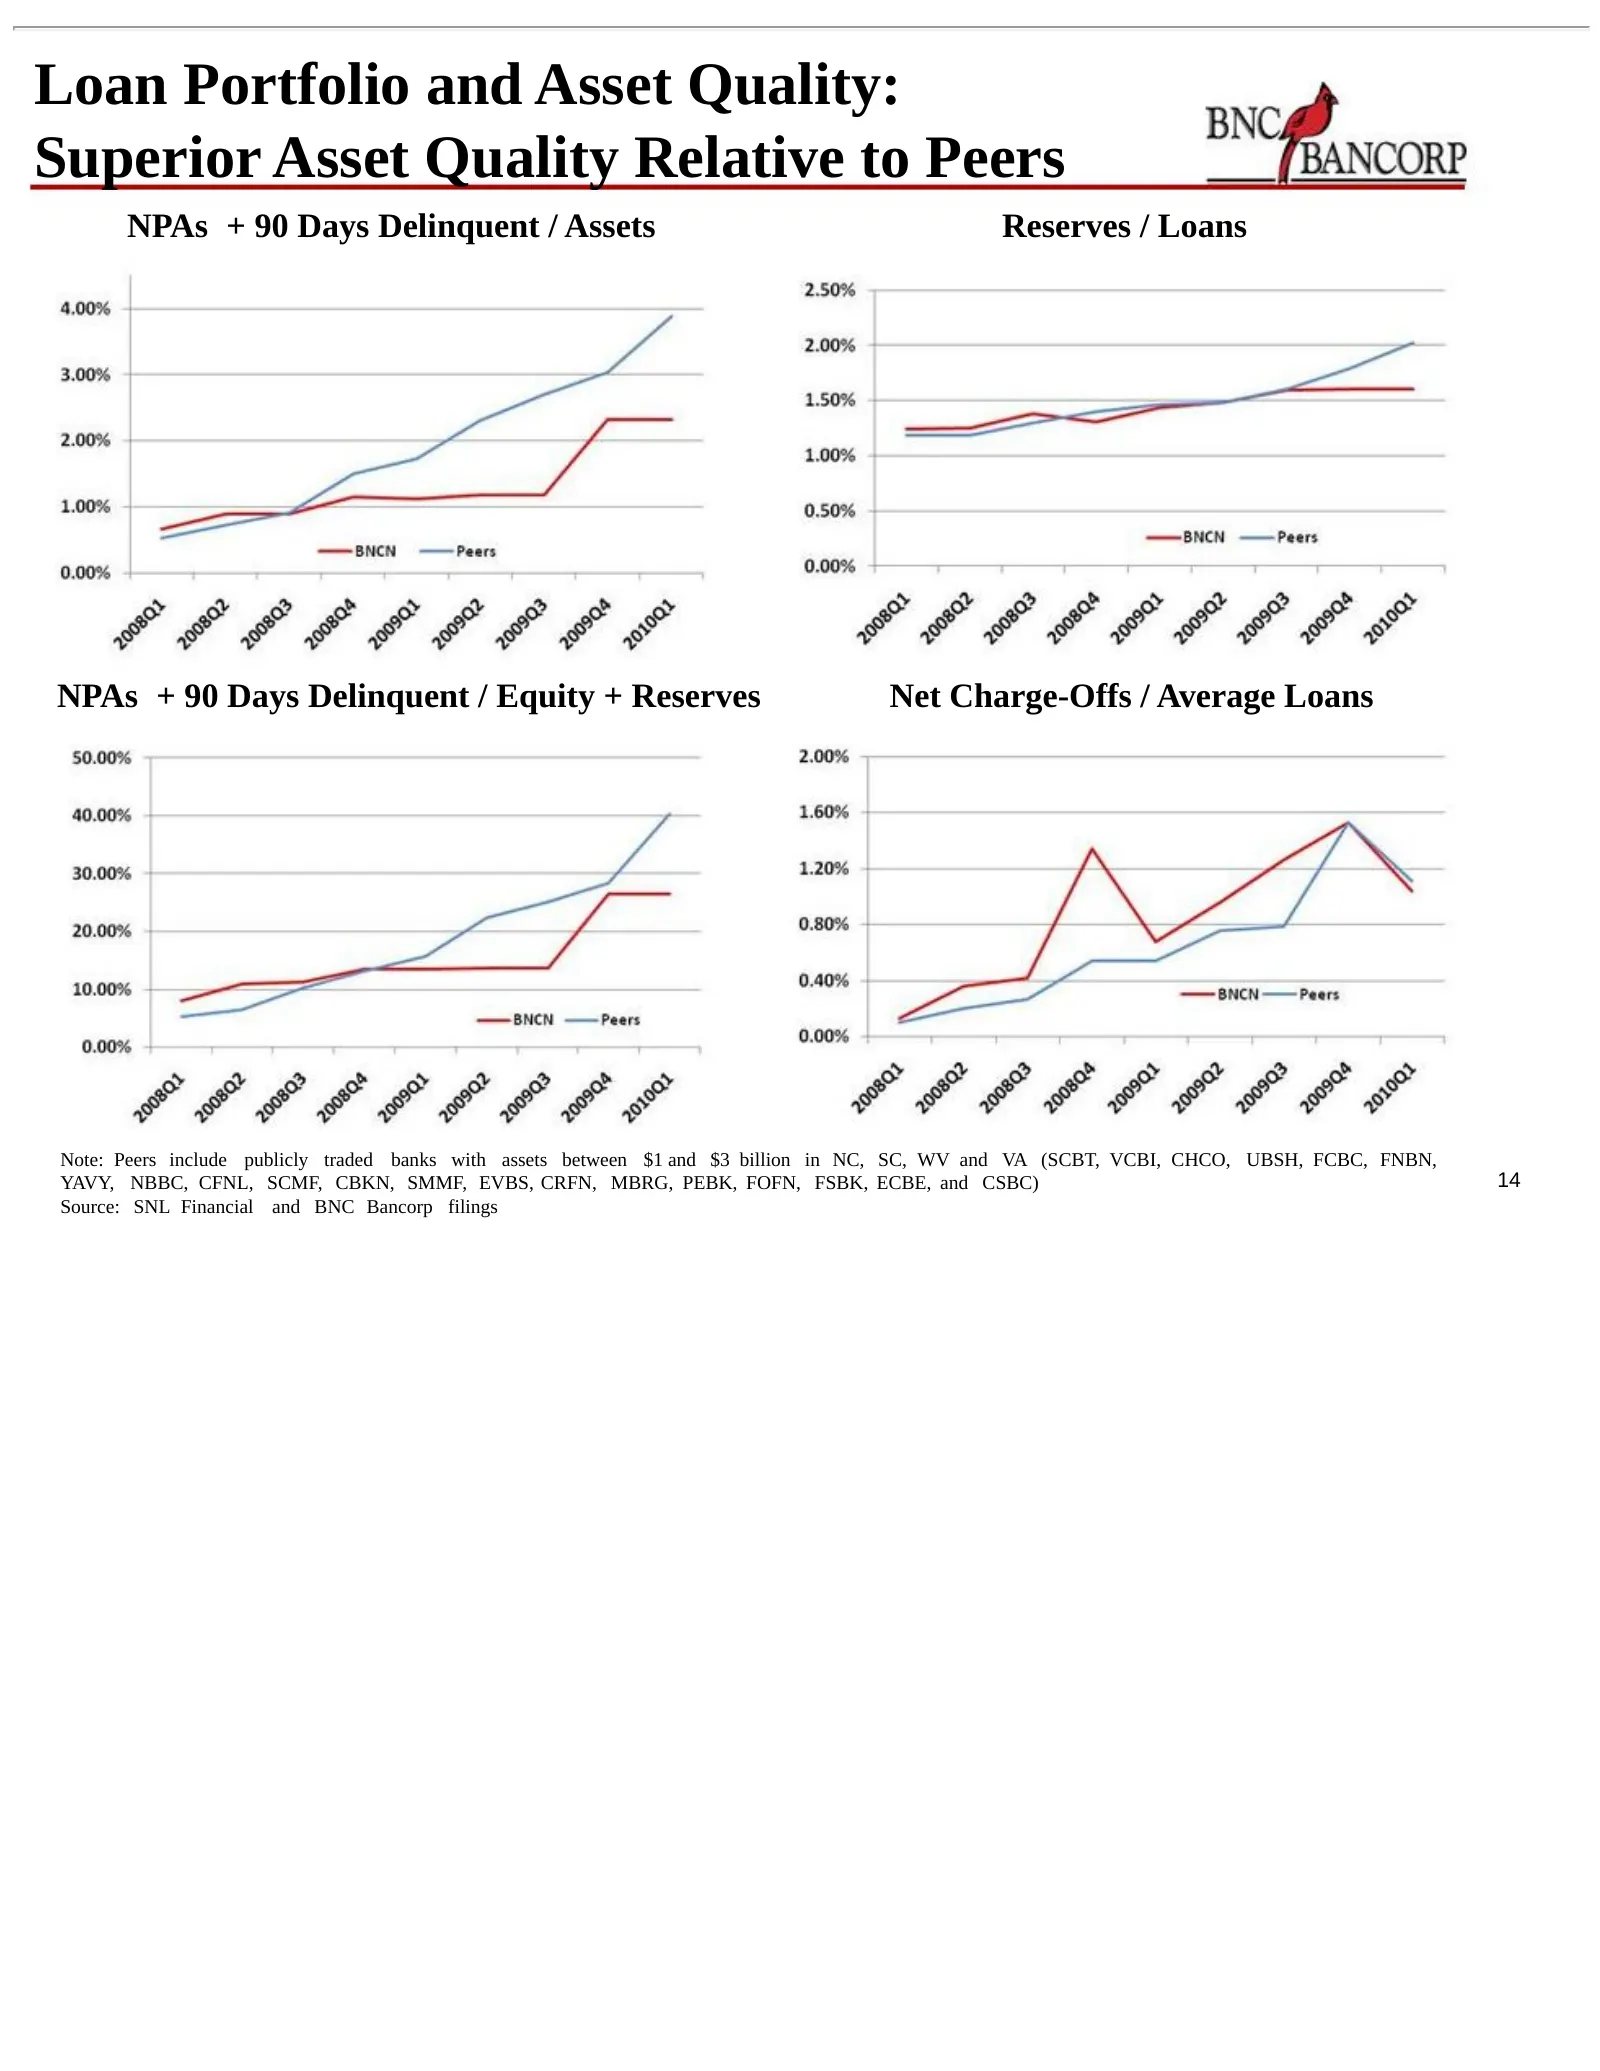
Slide 14: Loan Portfolio and Asset Quality: Superior Asset Quality Relative to Peers
Loan Portfolio and Asset Quality: Superior Asset Quality Relative to Peers NPAs + 90 Days Delinquent / Assets Reserves / Loans NPAs + 90 Days Delinquent / Equity + Reserves Net Charge-Offs / Average Loans Note: Peers include publicly traded banks with assets between $1 and $3 billion in NC, SC, WV a
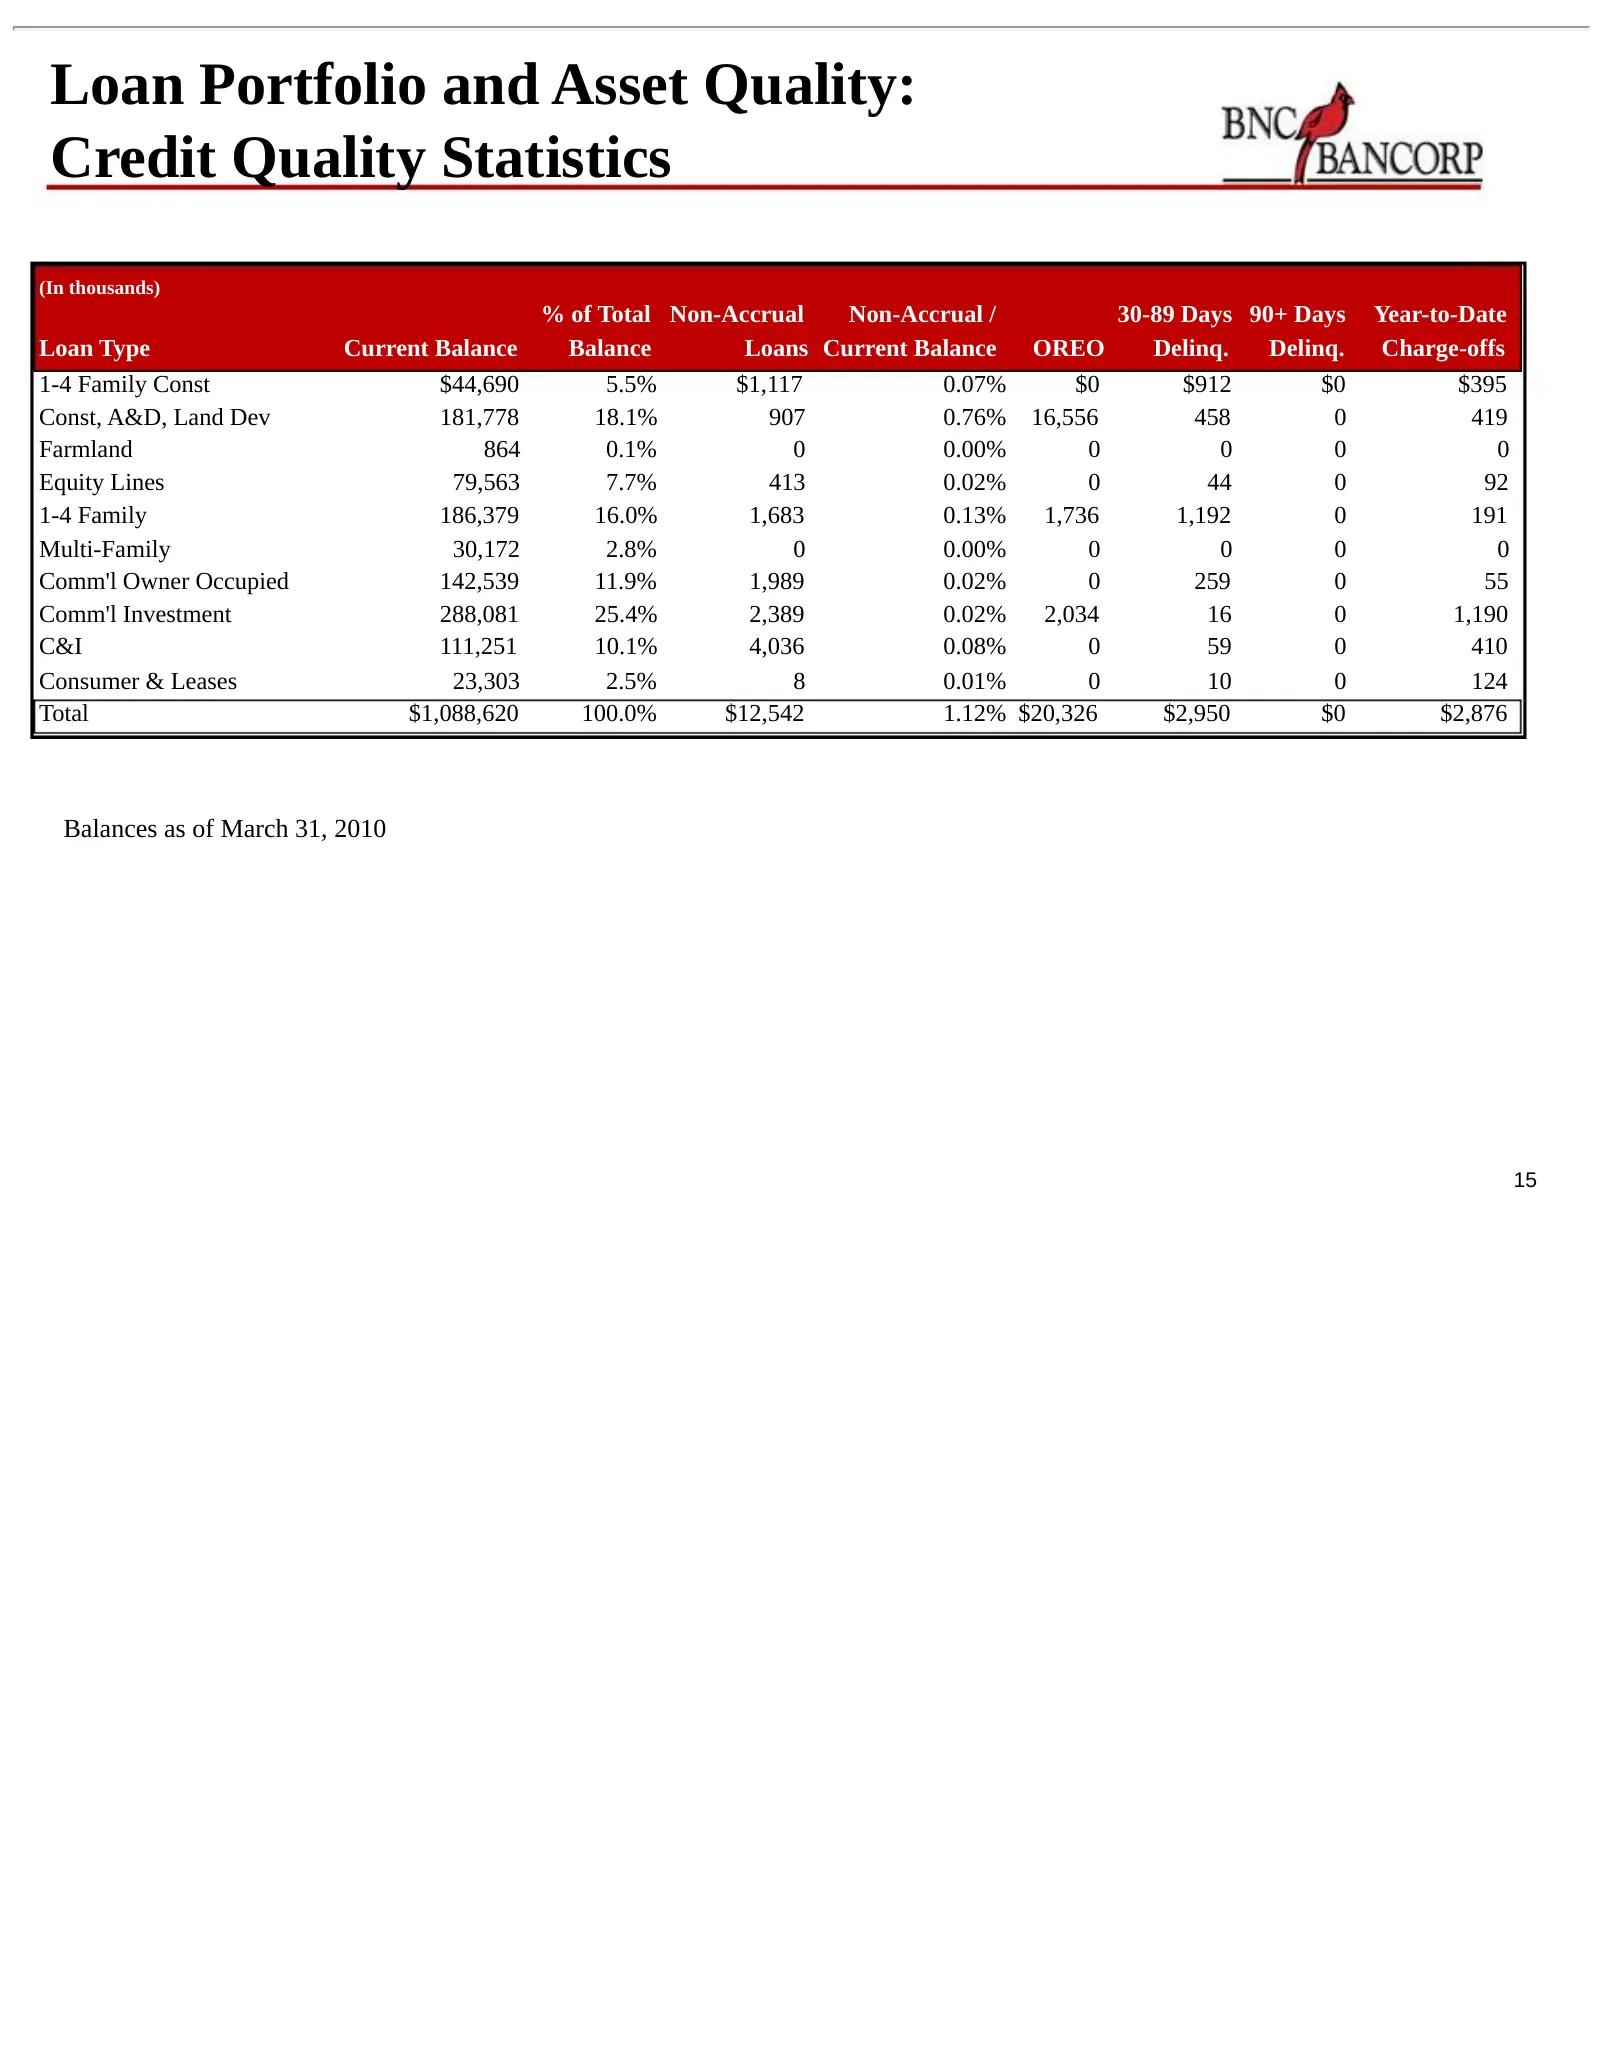
Slide 15: Loan Portfolio and Asset Quality: Credit Quality Statistics
Loan Portfolio and Asset Quality: Credit Quality Statistics (In thousands) % of Total Non-Accrual Non-Accrual / 30-89 Days 90+ Days Year-to-Date Loan Type Current Balance Balance Loans Current Balance OREO Delinq. Delinq. Charge-offs 1-4 Family Const $44,690 5.5% $1,117 0.07% $0 $912 $0 $395 Const,
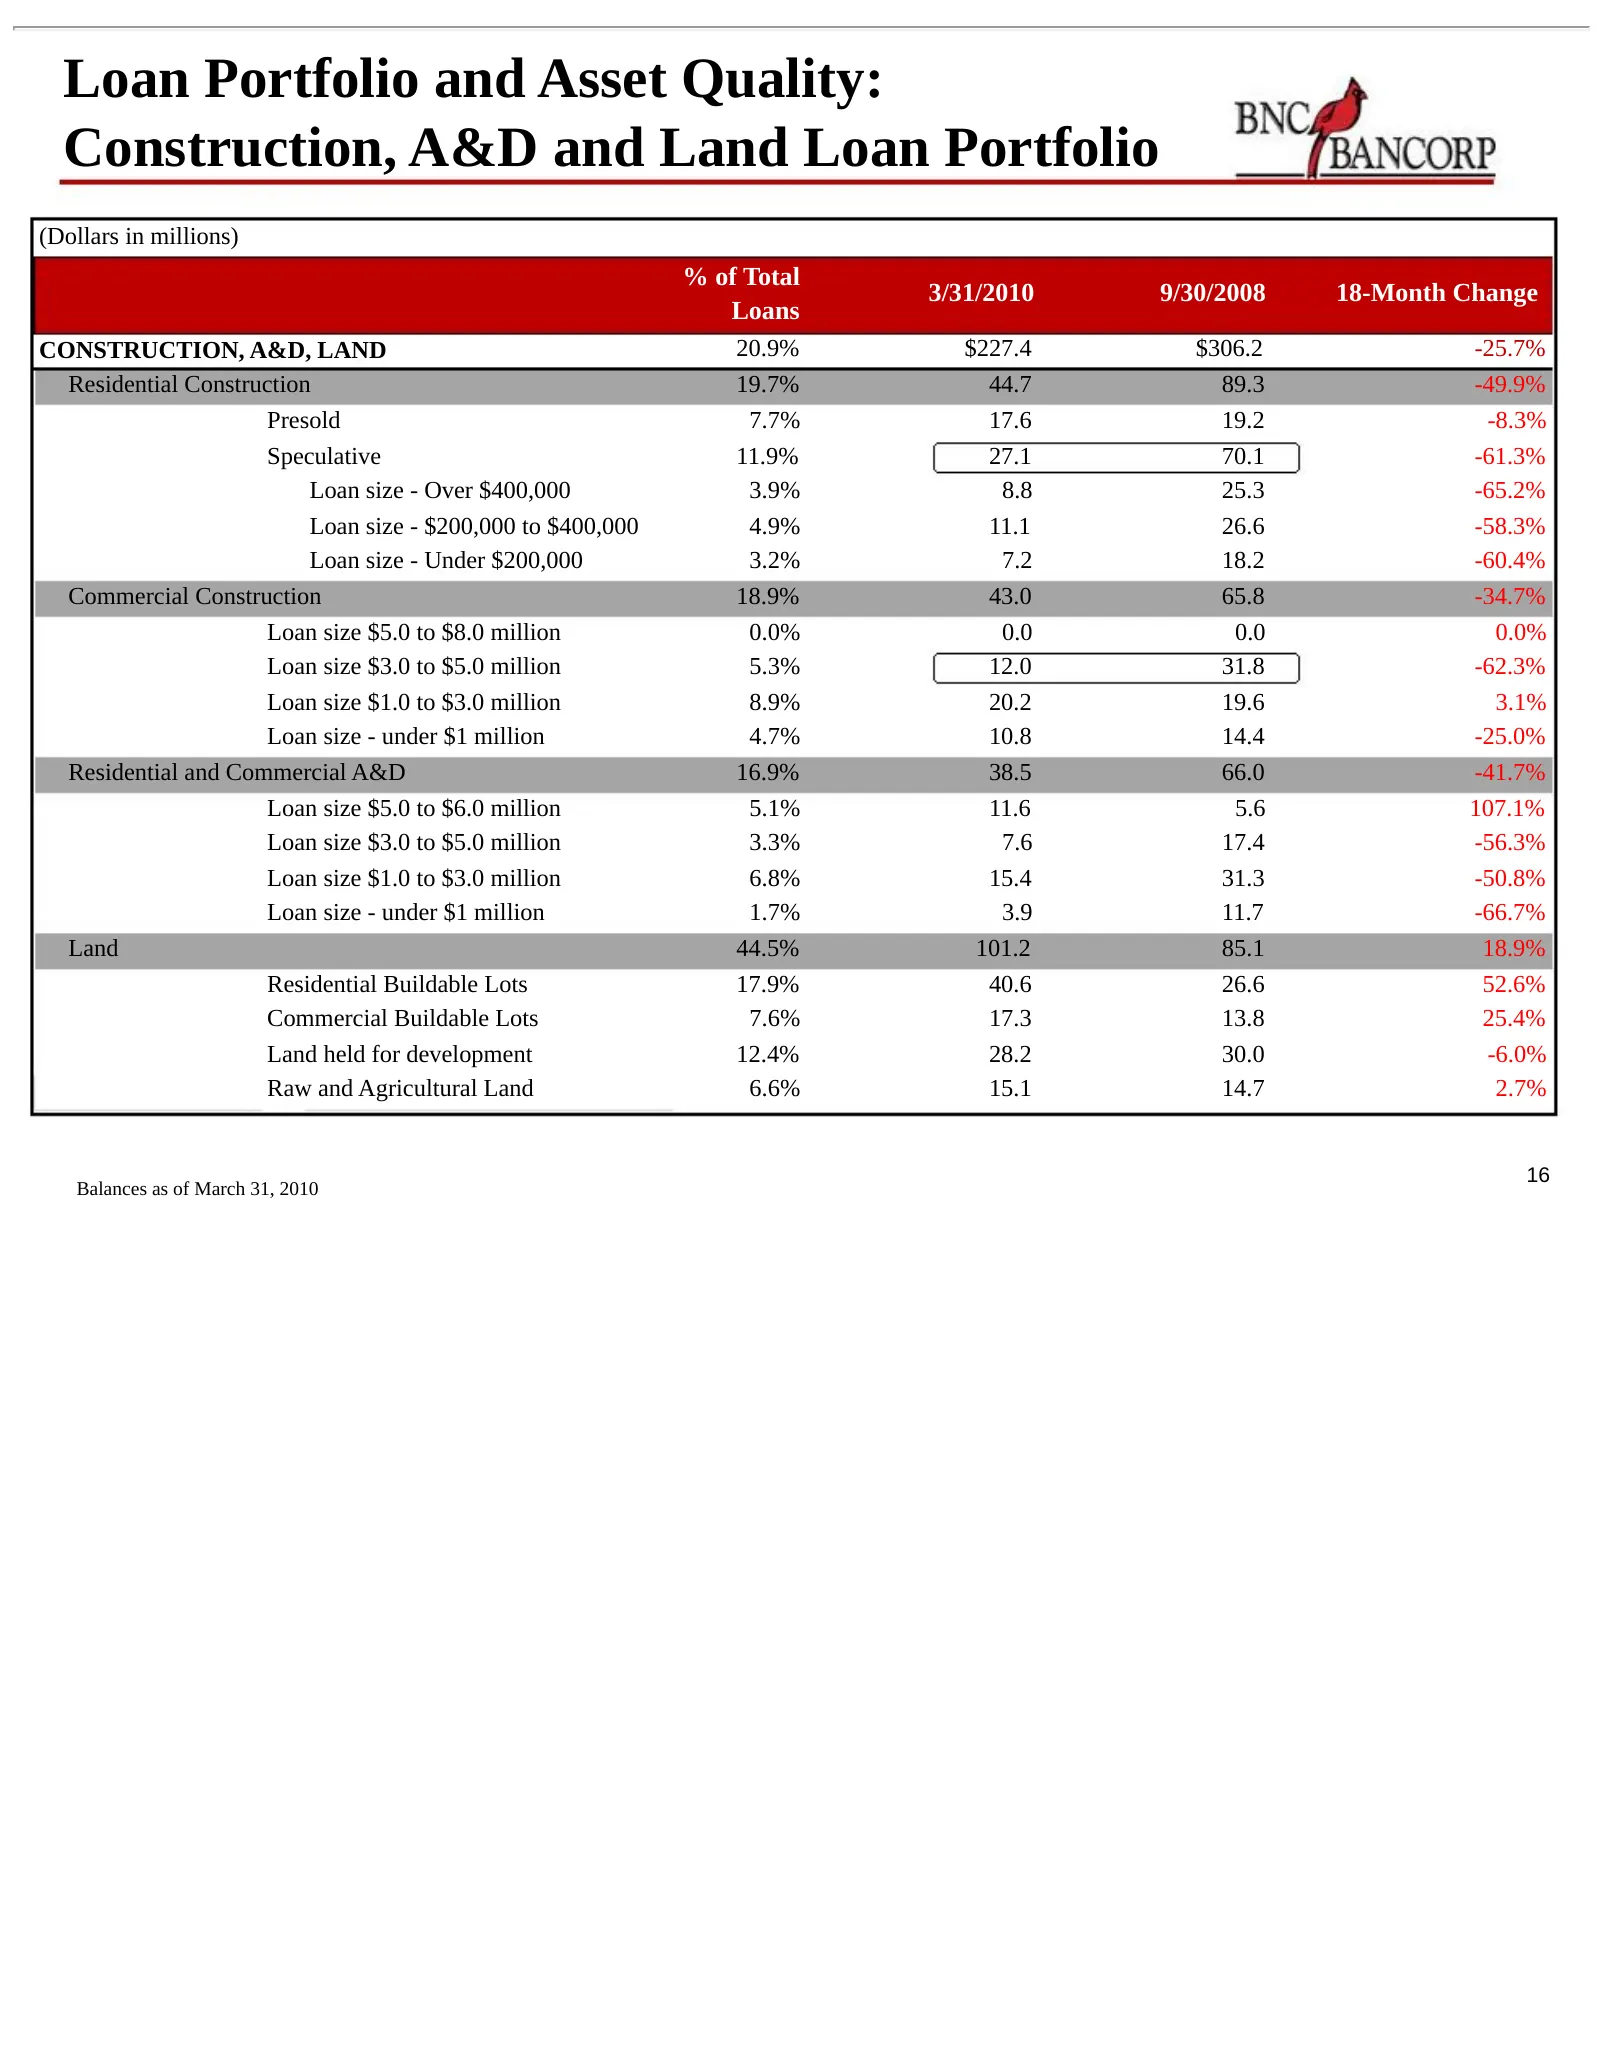
Slide 16: Loan Portfolio and Asset Quality: Construction, A&D and Land Loan Portfolio
Loan Portfolio and Asset Quality: Construction, A&D and Land Loan Portfolio (Dollars in millions) % of Total 3/31/2010 9/30/2008 18-Month Change Loans CONSTRUCTION, A&D, LAND 20.9% $227.4 $306.2 -25.7% Residential Construction 19.7% 44.7 89.3 -49.9% Presold 7.7% 17.6 19.2 -8.3% Speculative 11.9% 27.
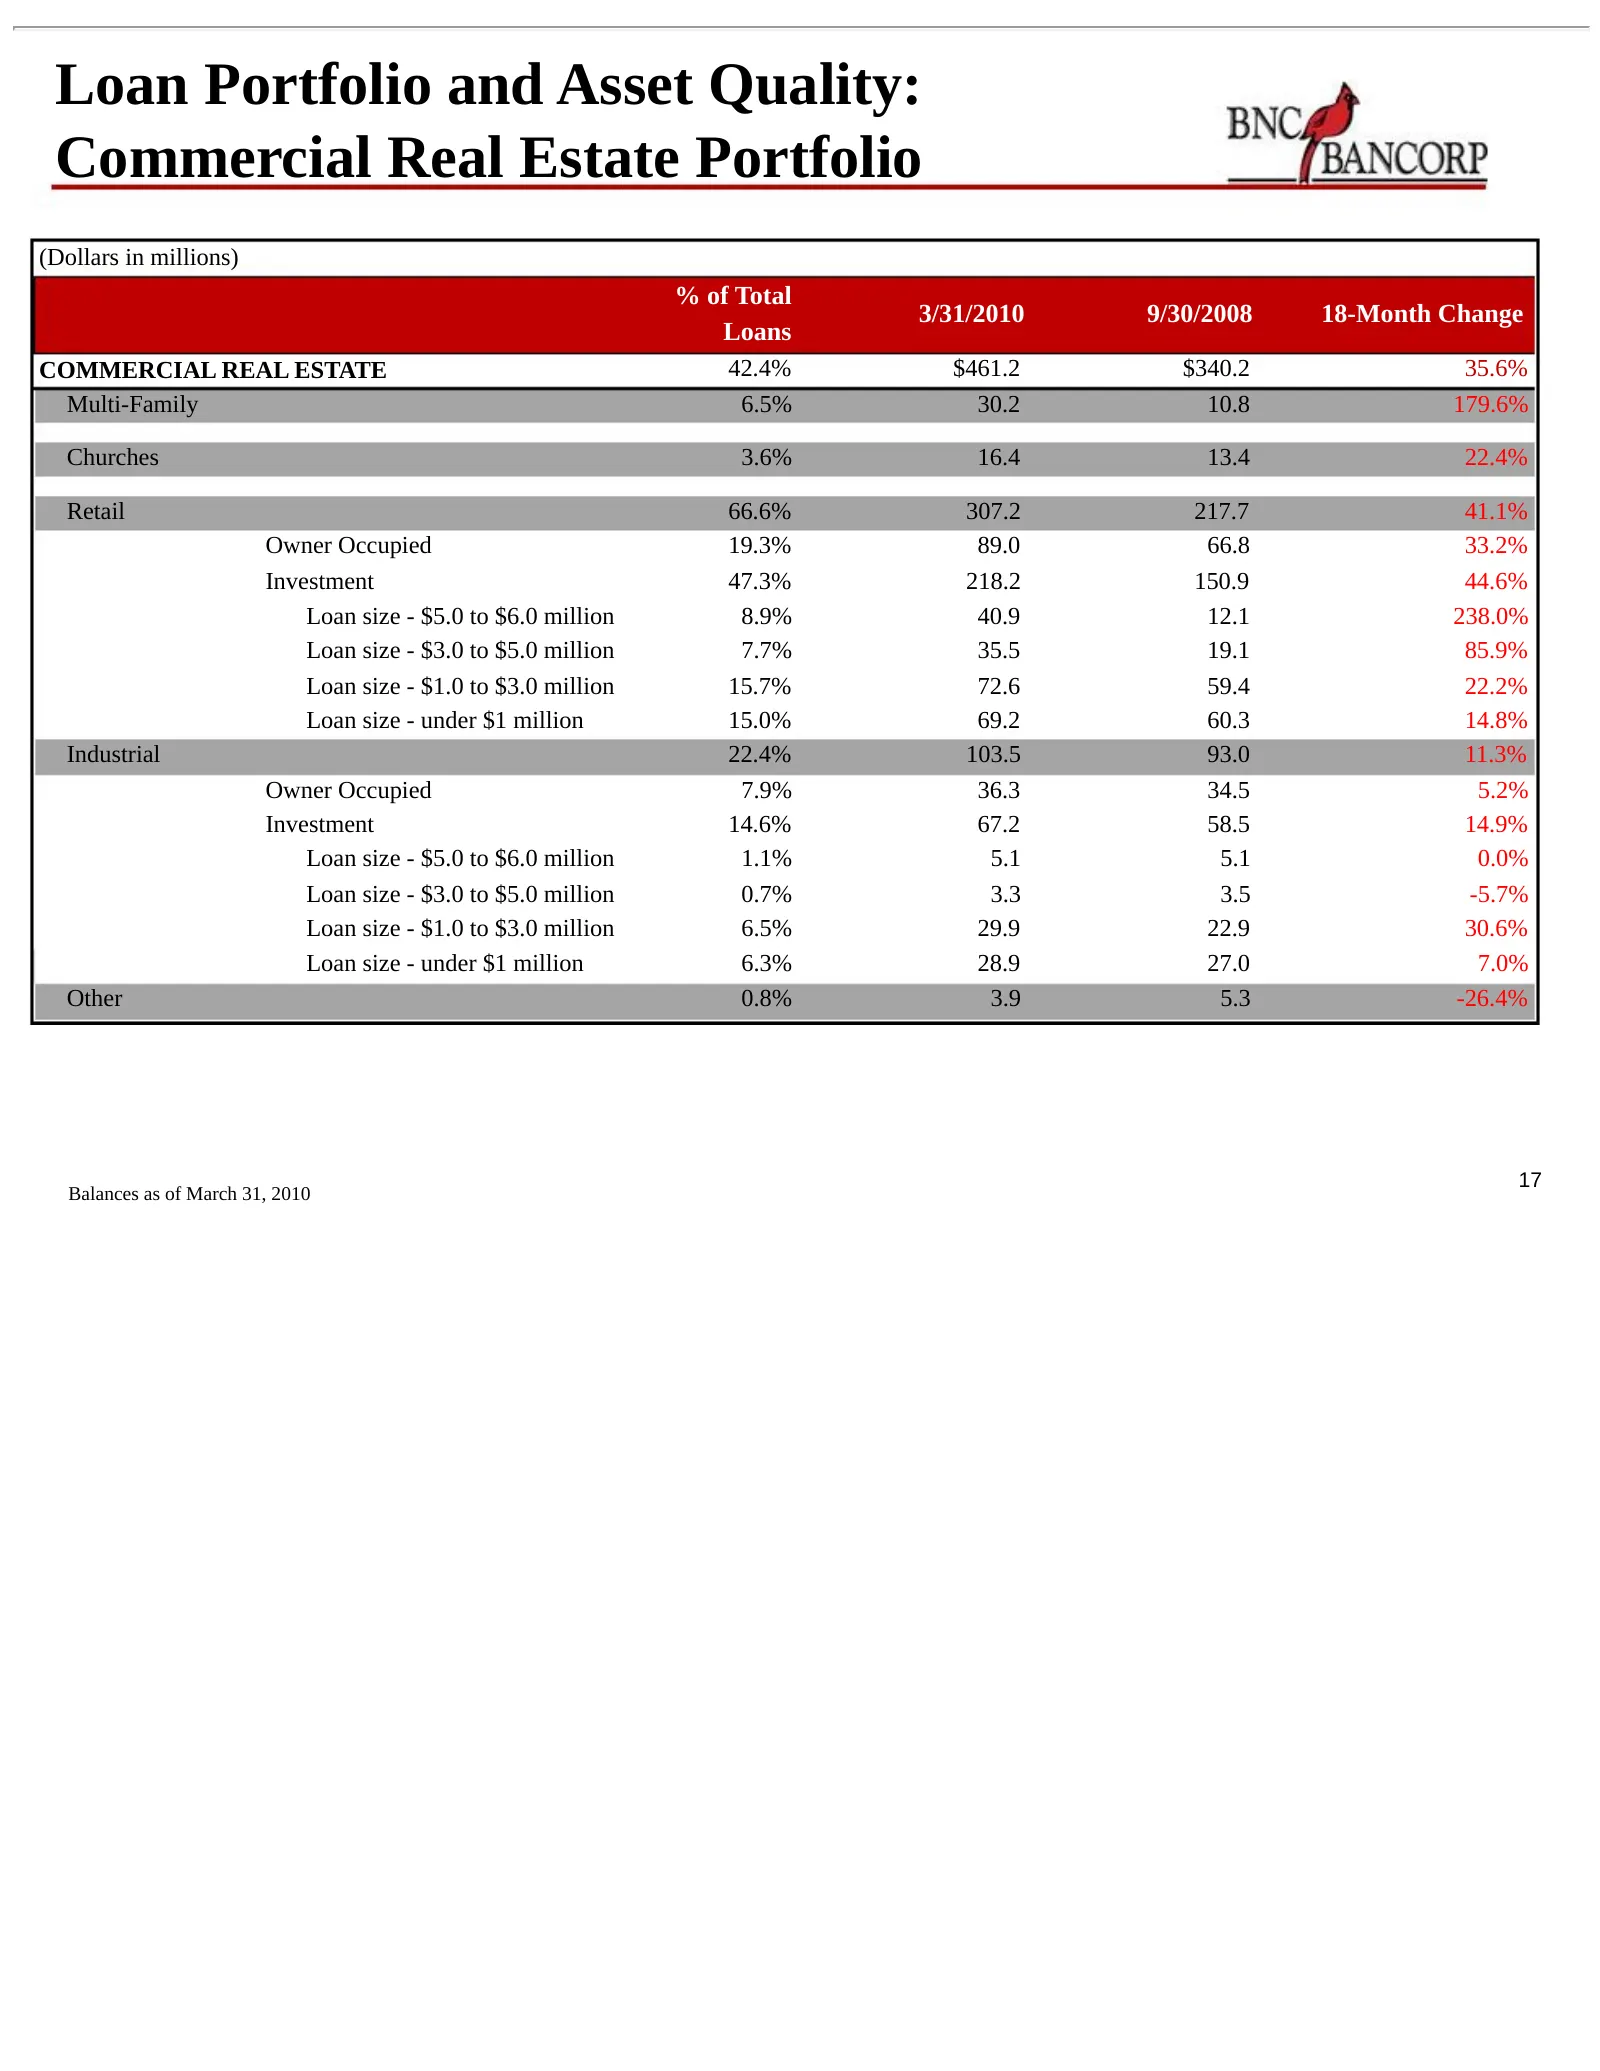
Slide 17: Loan Portfolio and Asset Quality: Commercial Real Estate Portfolio
Loan Portfolio and Asset Quality: Commercial Real Estate Portfolio (Dollars in millions) % of Total 3/31/2010 9/30/2008 18-Month Change Loans COMMERCIAL REAL ESTATE 42.4% $461.2 $340.2 35.6% Multi-Family 6.5% 30.2 10.8 179.6% Churches 3.6% 16.4 13.4 22.4% Retail 66.6% 307.2 217.7 41.1% Owner Occupie
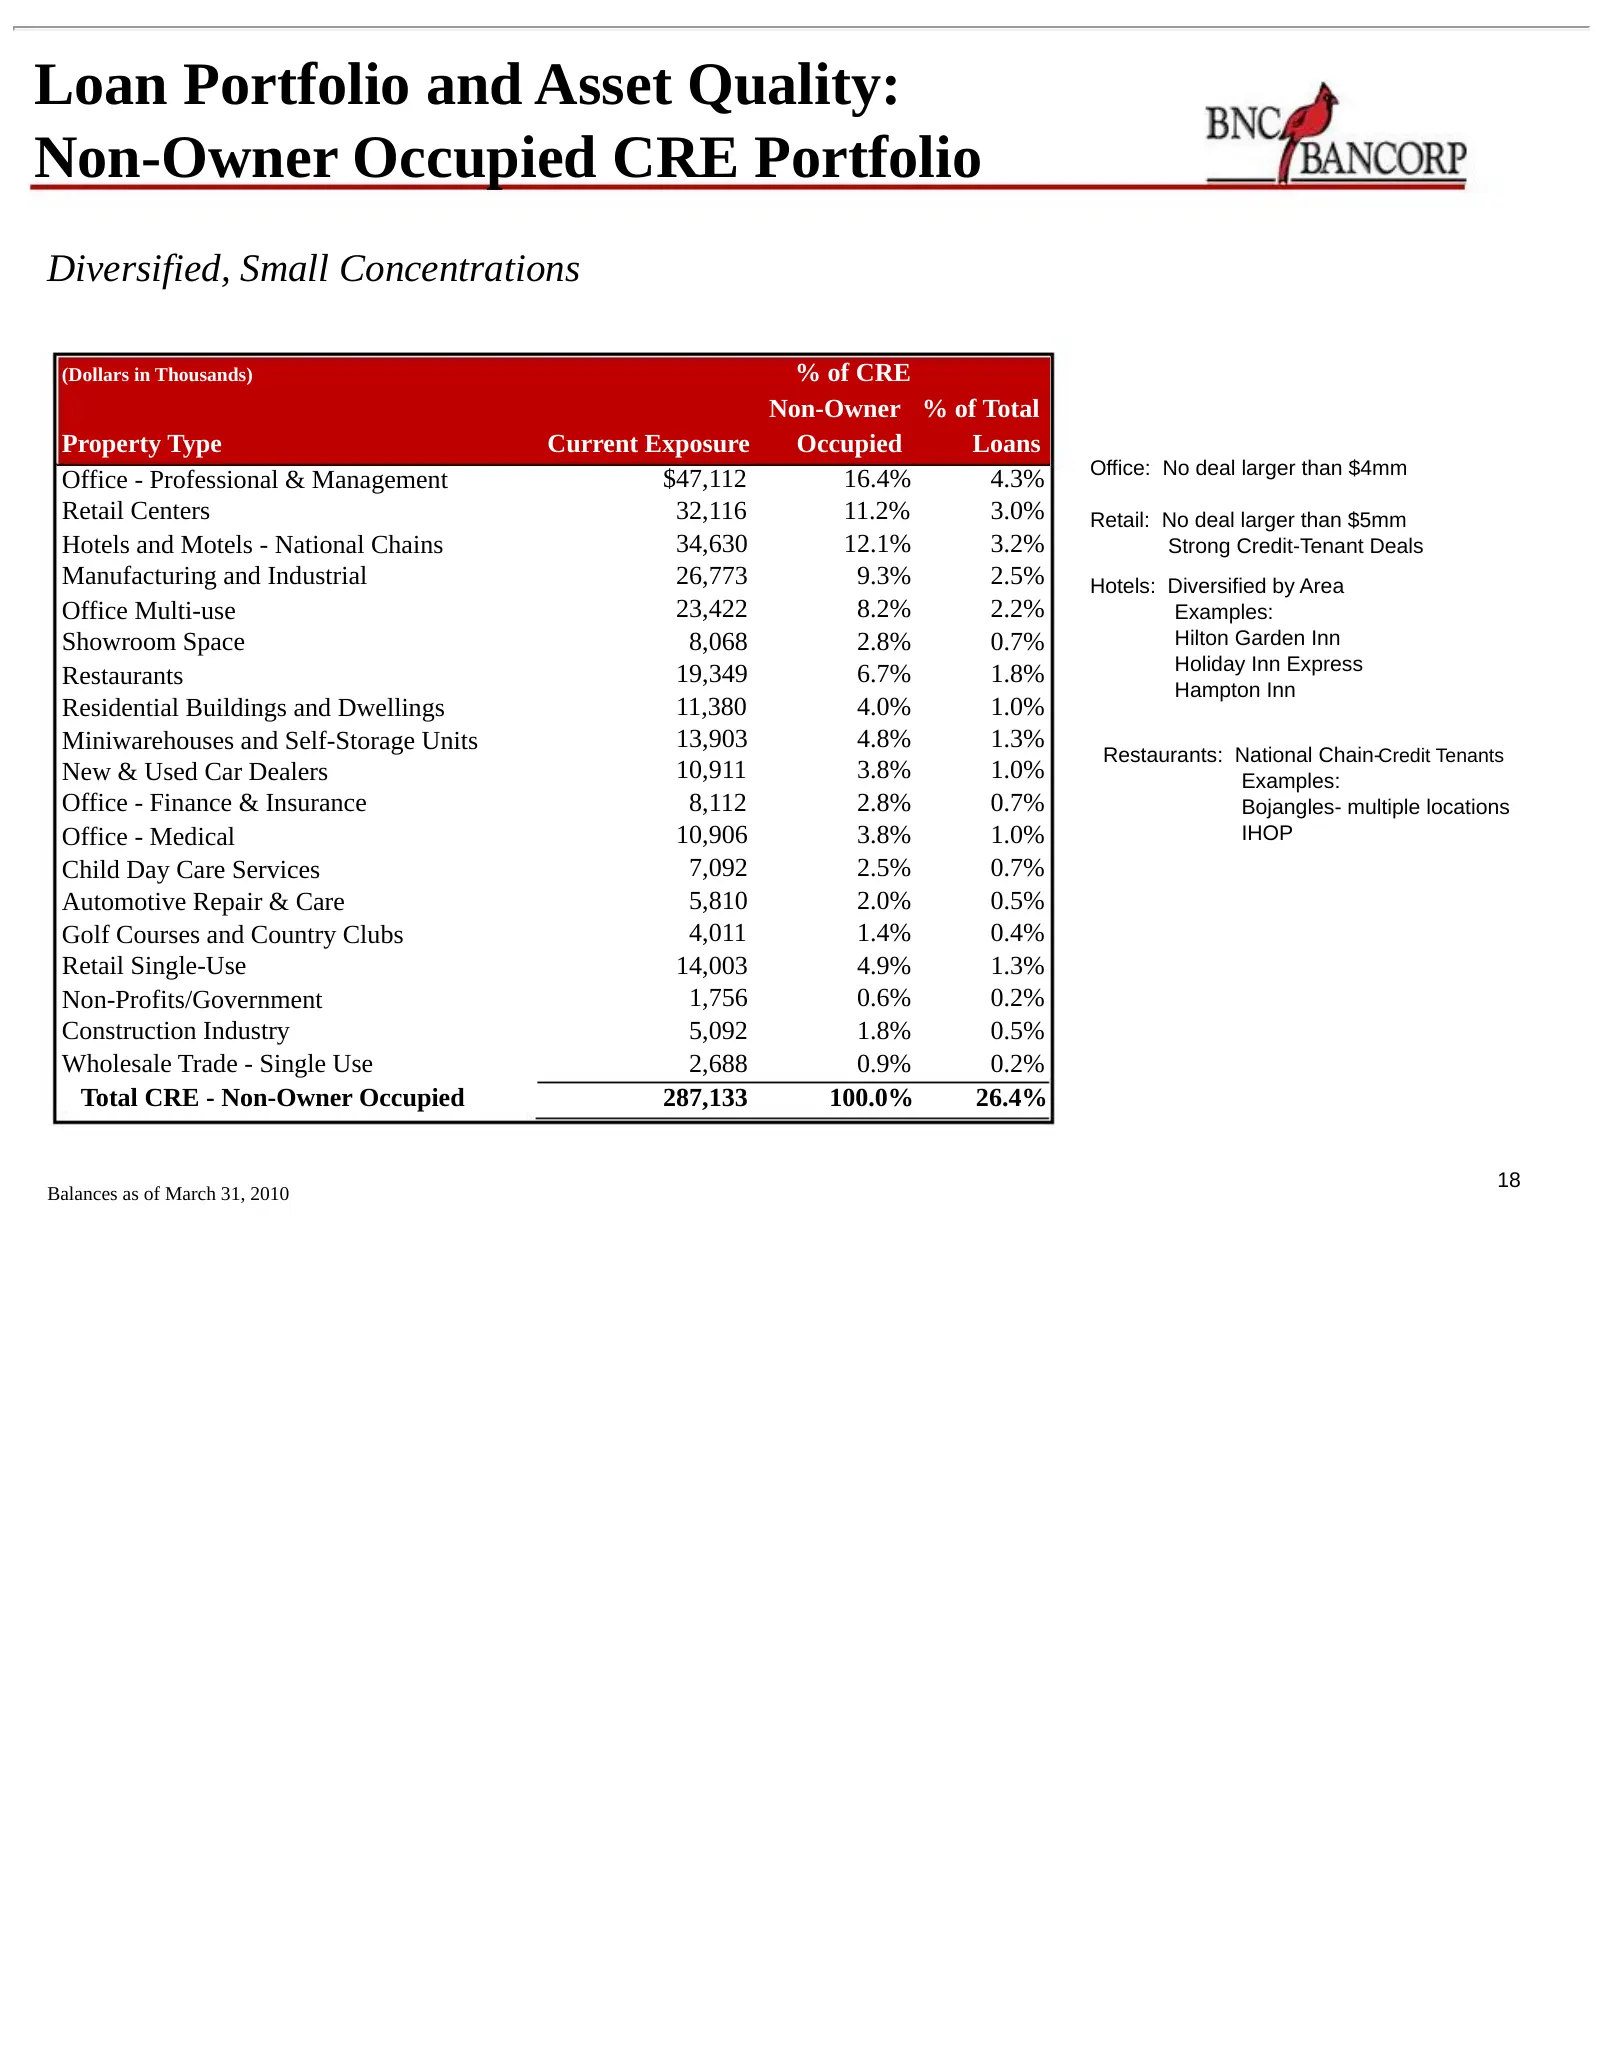
Slide 18: Loan Portfolio and Asset Quality: Non-Owner Occupied CRE Portfolio
Loan Portfolio and Asset Quality: Non-Owner Occupied CRE Portfolio Diversified, Small Concentrations (Dollars in Thousands) % of CRE Non-Owner % of Total Property Type Current Exposure Occupied Loans Office: No deal larger than $4mm Office - Professional & Management $47,112 16.4% 4.3% Retail Center
Slide 19: Competence
Quality Competence Discipline 19
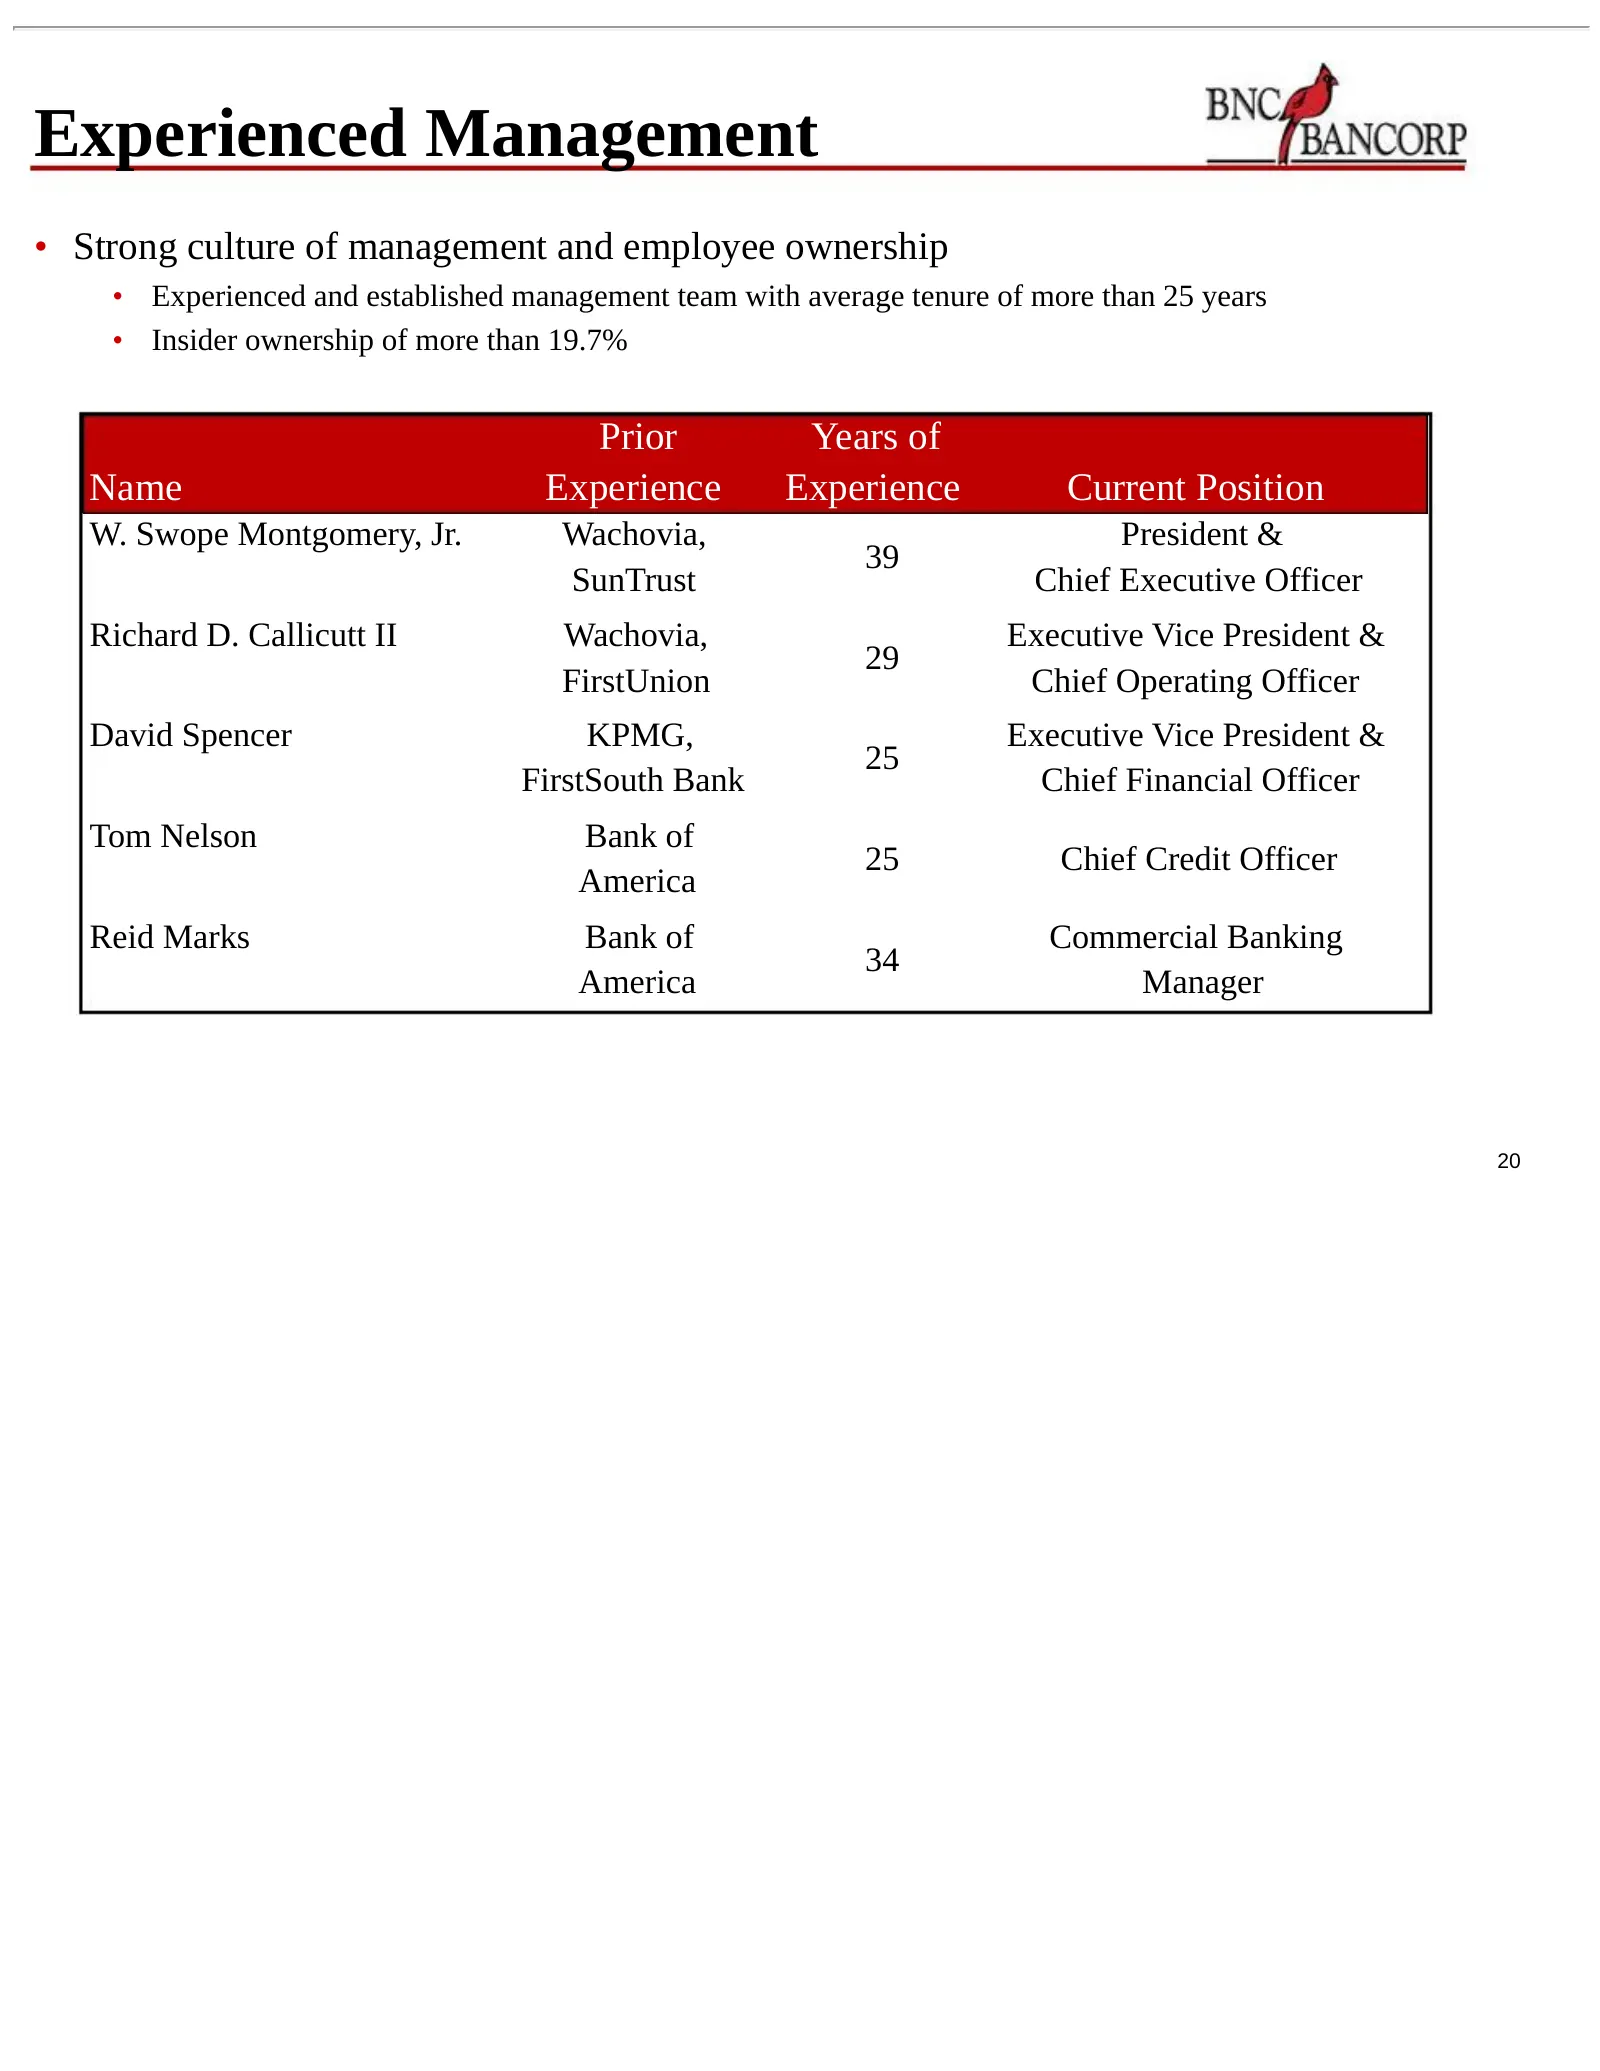
Slide 20: Experienced Management
Experienced Management • Strong culture of management and employee ownership • Experienced and established management team with average tenure of more than 25 years • Insider ownership of more than 19.7% Prior Years of Name Experience Experience Current Position W. Swope Montgomery, Jr. Wachovia, Pr
Slide 21: Veteran Credit Team
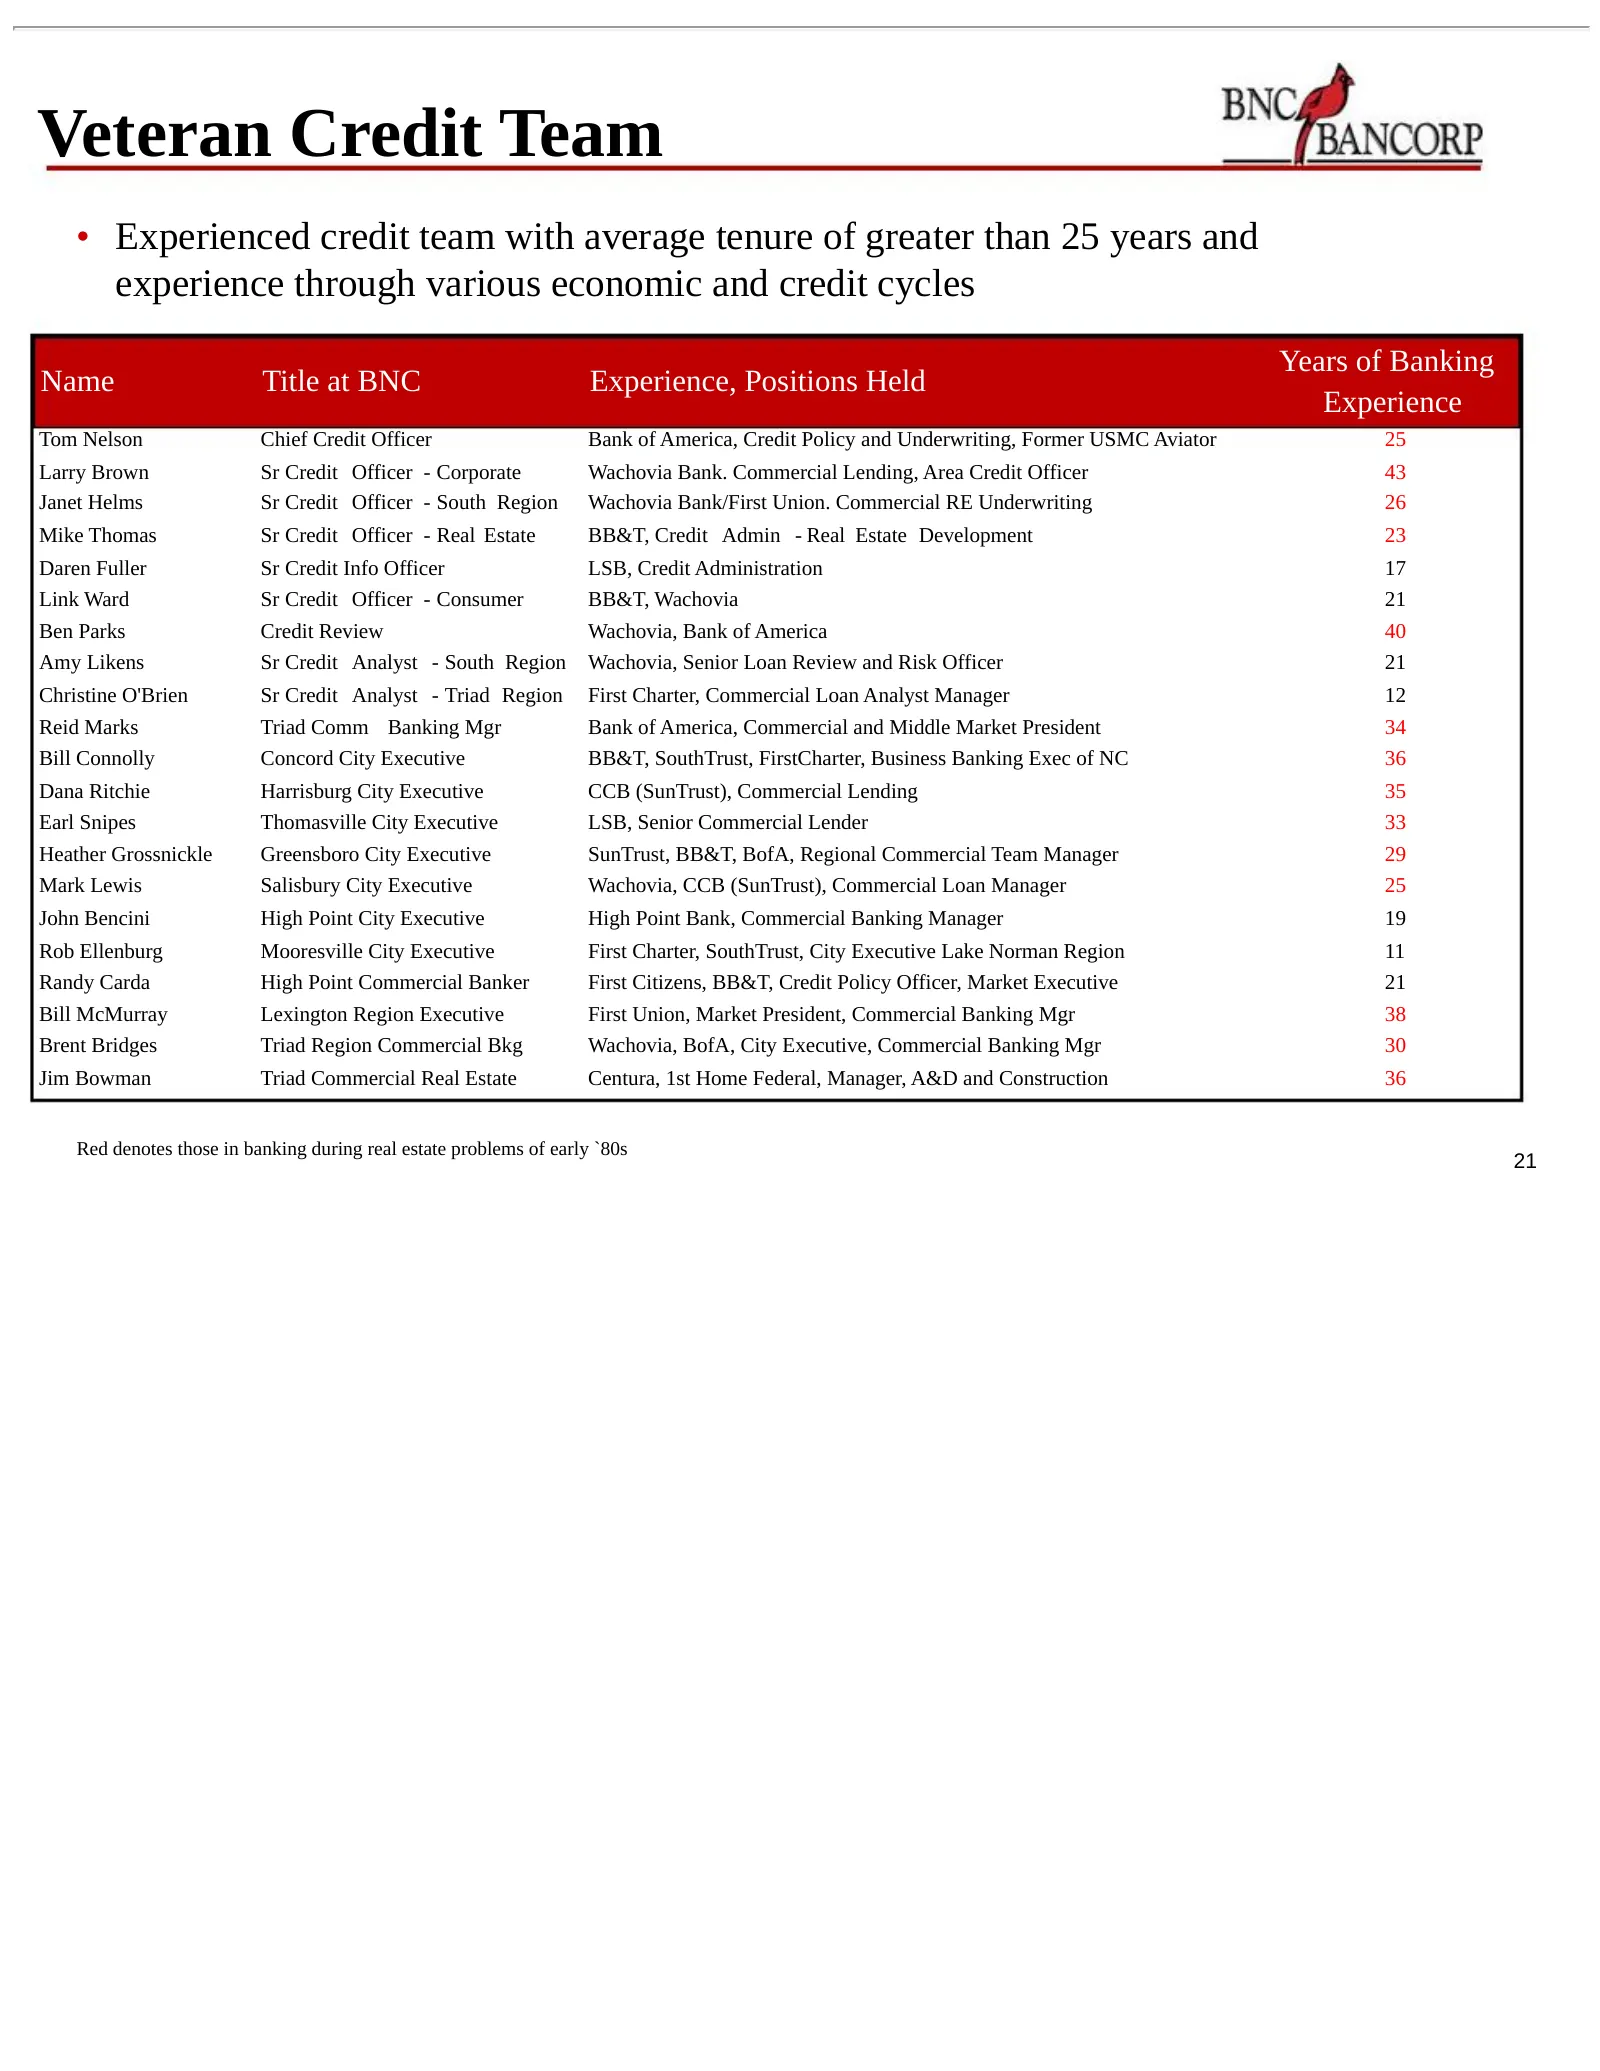
Veteran Credit Team • Experienced credit team with average tenure of greater than 25 years and experience through various economic and credit cycles Years of Banking Name Title at BNC Experience, Positions Held Experience Tom Nelson Chief Credit Officer Bank of America, Credit Policy and Underwritin
Slide 22: Core Deposit Growth Initiatives
Core Deposit Growth Initiatives • Retail Banking • In early 2009, hired seasoned Retail Banking Manager from Wachovia • Creating consistency in delivery, service, products, and sales throughout the retail footprint • Creating greater levels of accountability and rewards for performance • Treasury Se
Slide 23: Leverage Transaction Highlights
Leverage Transaction Highlights • Bought Government Agency MBS at attractive yields and at prices between 98 and 102 • Purchased municipal securities with strong underlying ratings and AAA insurance • Assured Guaranty and Texas School District Fund as primary insurers • Funded overnight initially, w
Slide 24: Discipline
Quality Competence Discipline 24
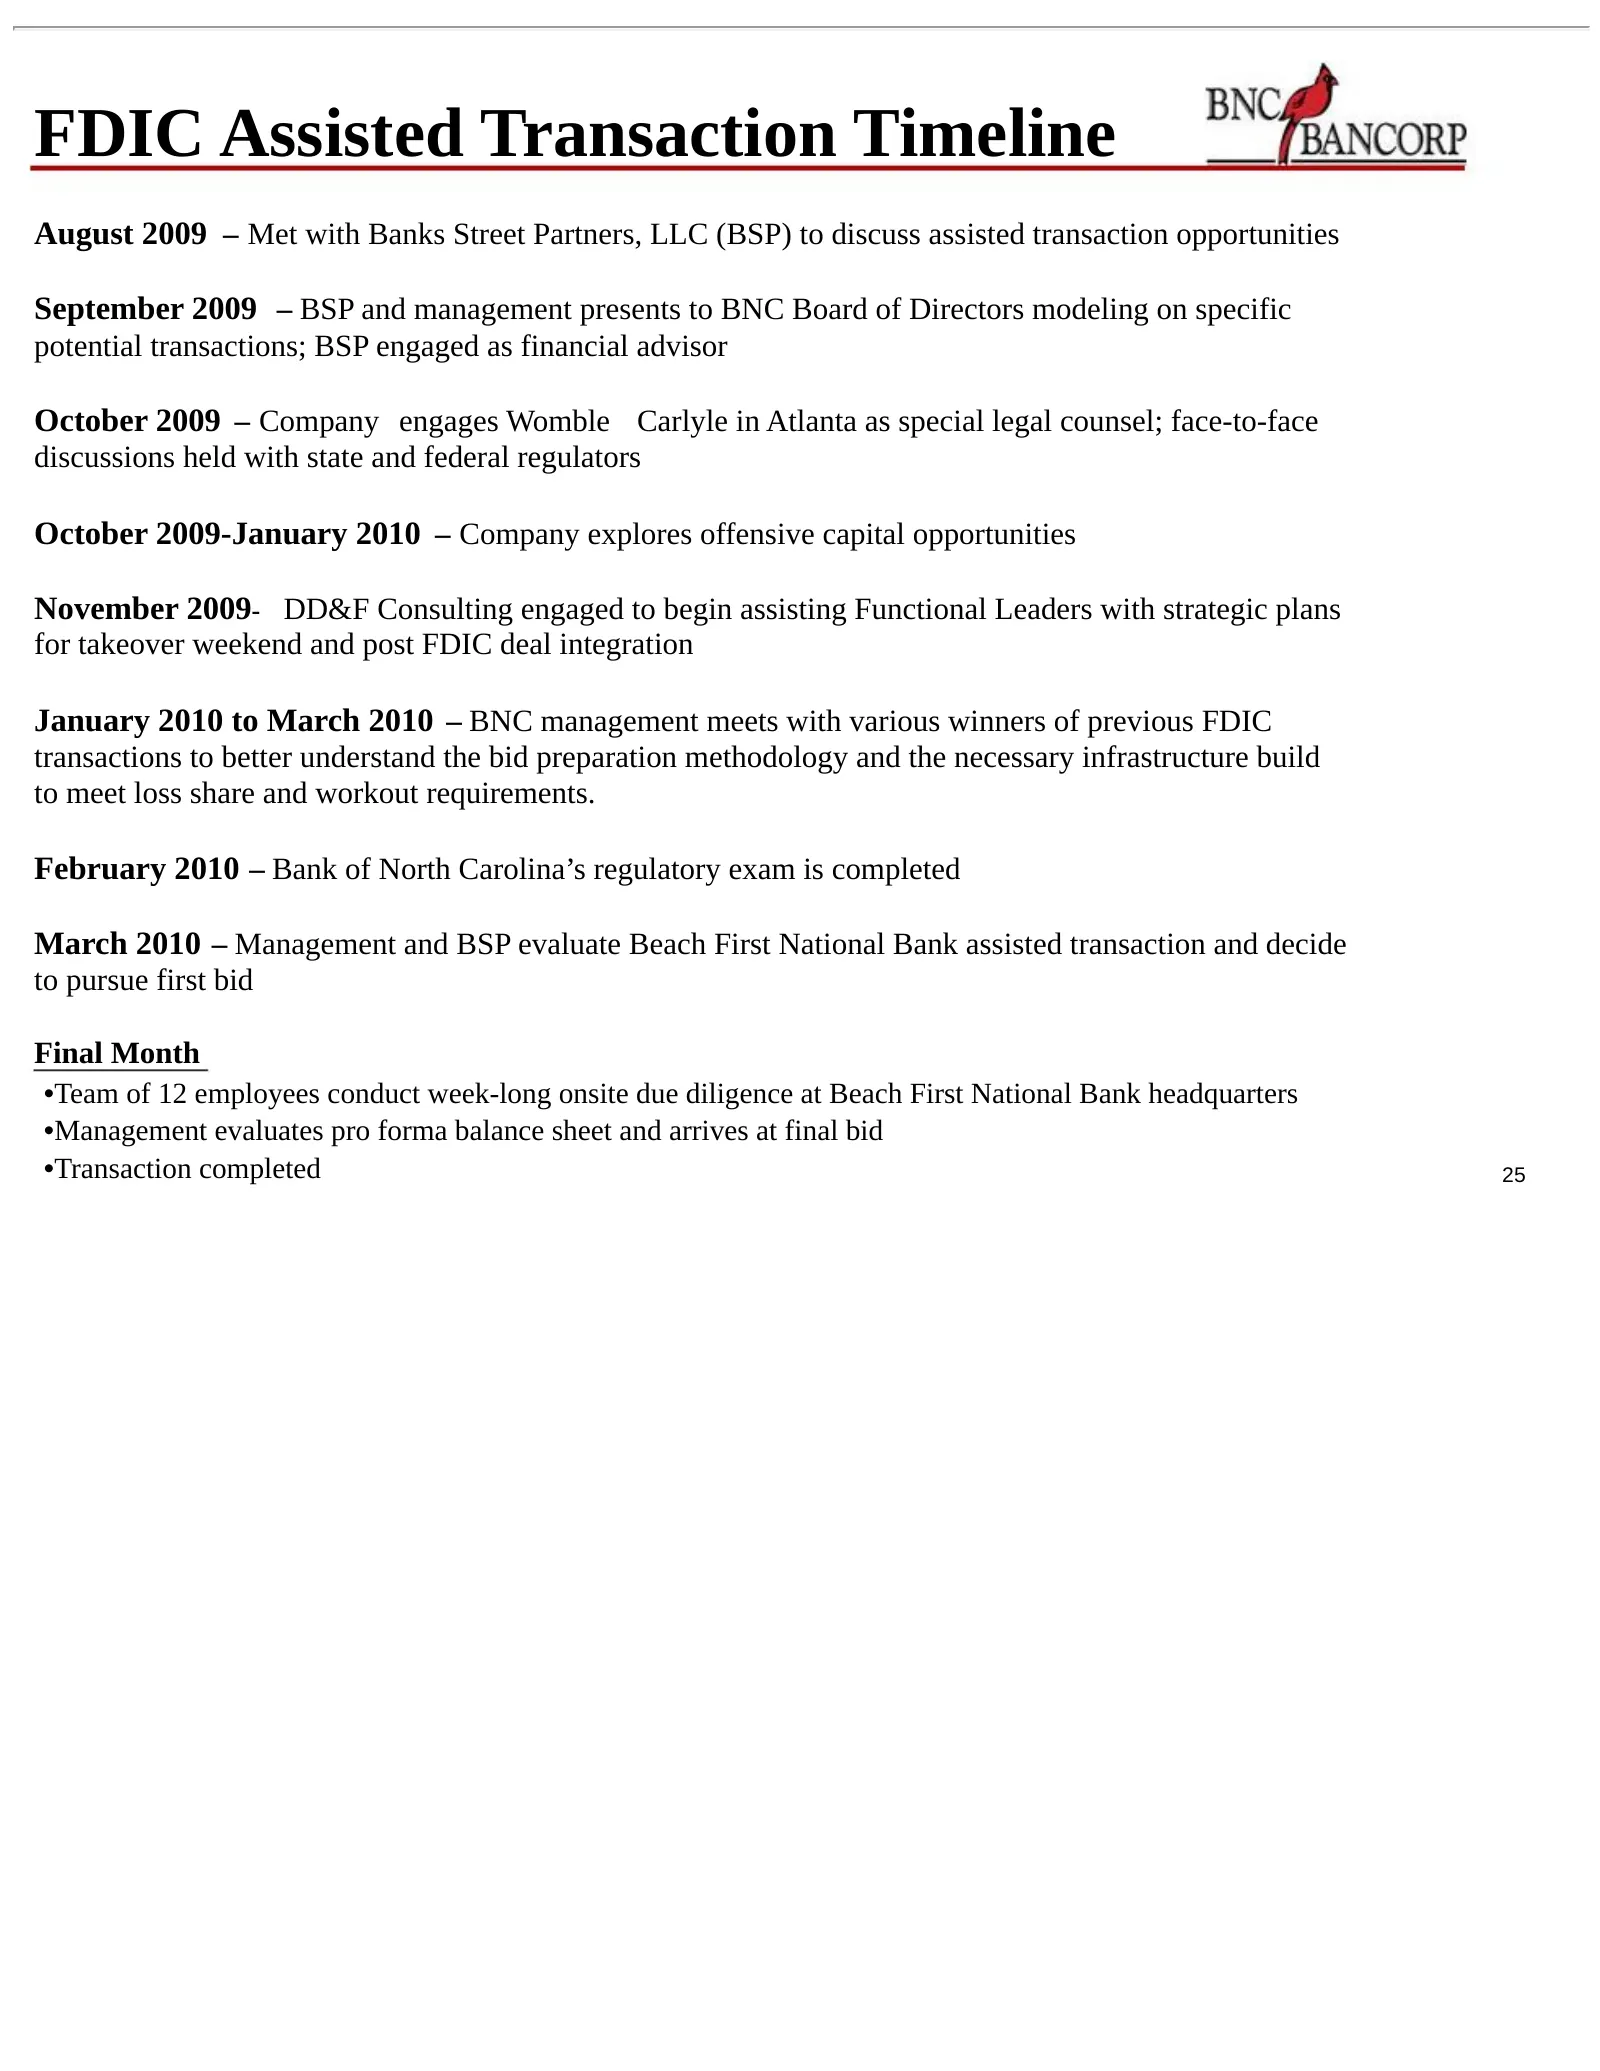
Slide 25: FDIC Assisted Transaction Timeline
FDIC Assisted Transaction Timeline August 2009 – Met with Banks Street Partners, LLC (BSP) to discuss assisted transaction opportunities September 2009 – BSP and management presents to BNC Board of Directors modeling on specific potential transactions; BSP engaged as financial advisor October 2009 –
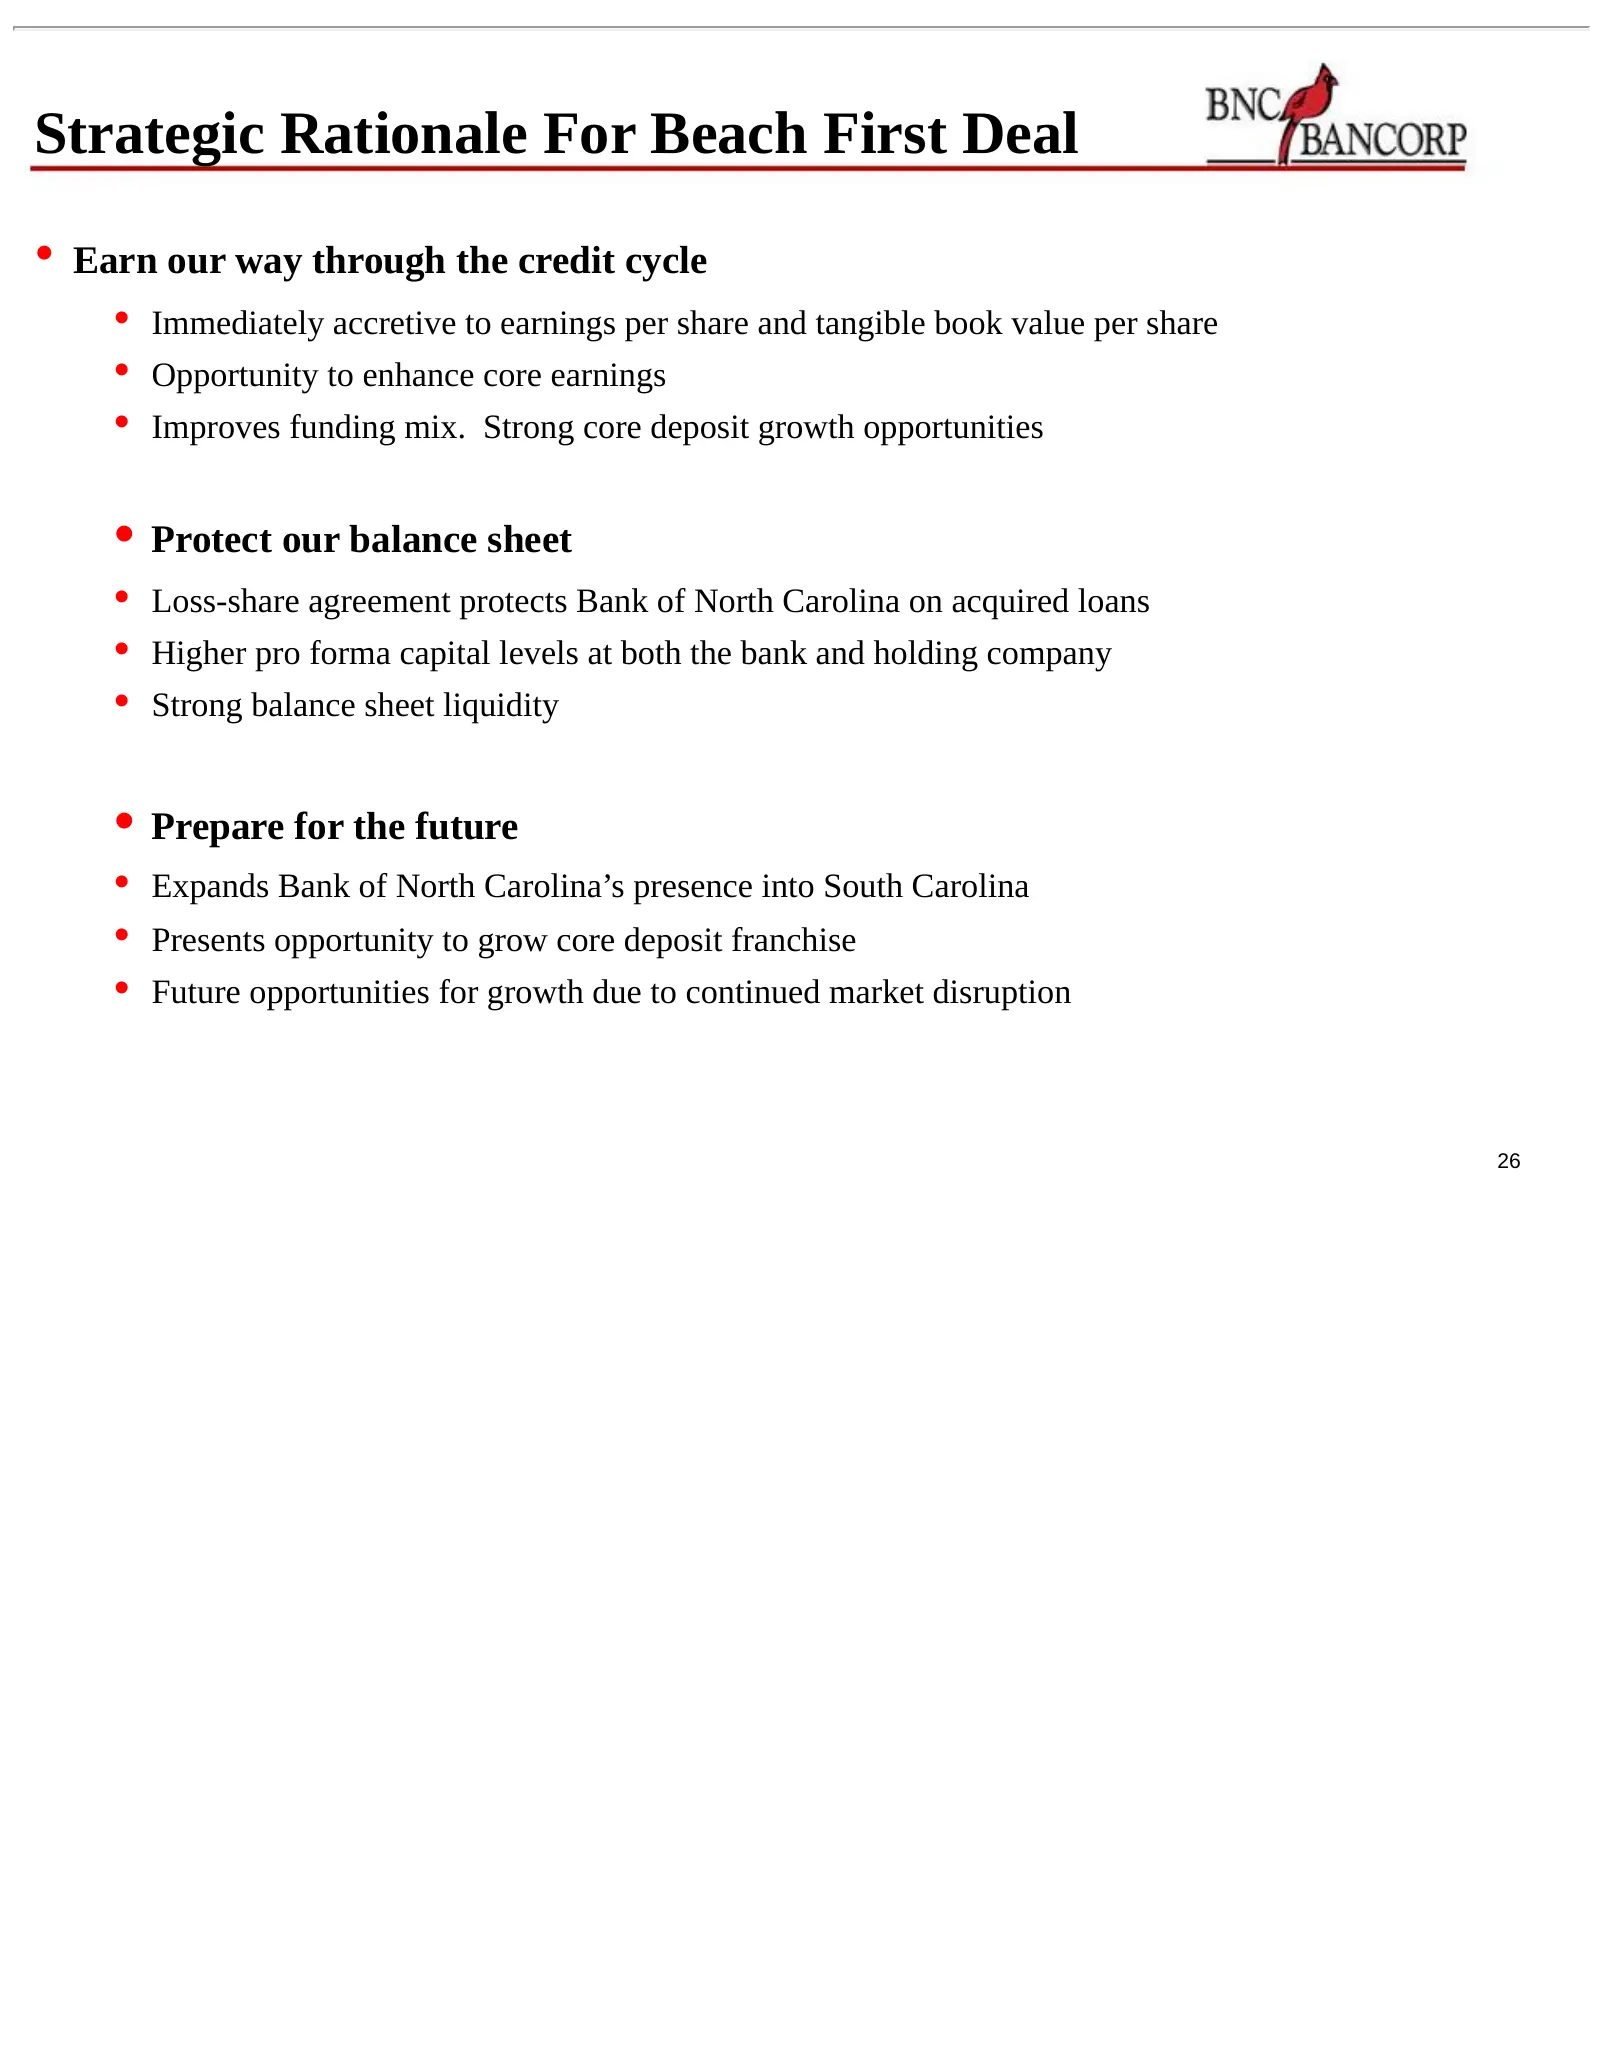
Slide 26: Strategic Rationale For Beach First Deal
Strategic Rationale For Beach First Deal • Earn our way through the credit cycle • Immediately accretive to earnings per share and tangible book value per share • Opportunity to enhance core earnings • Improves funding mix. Strong core deposit growth opportunities • Protect our balance sheet • Loss-
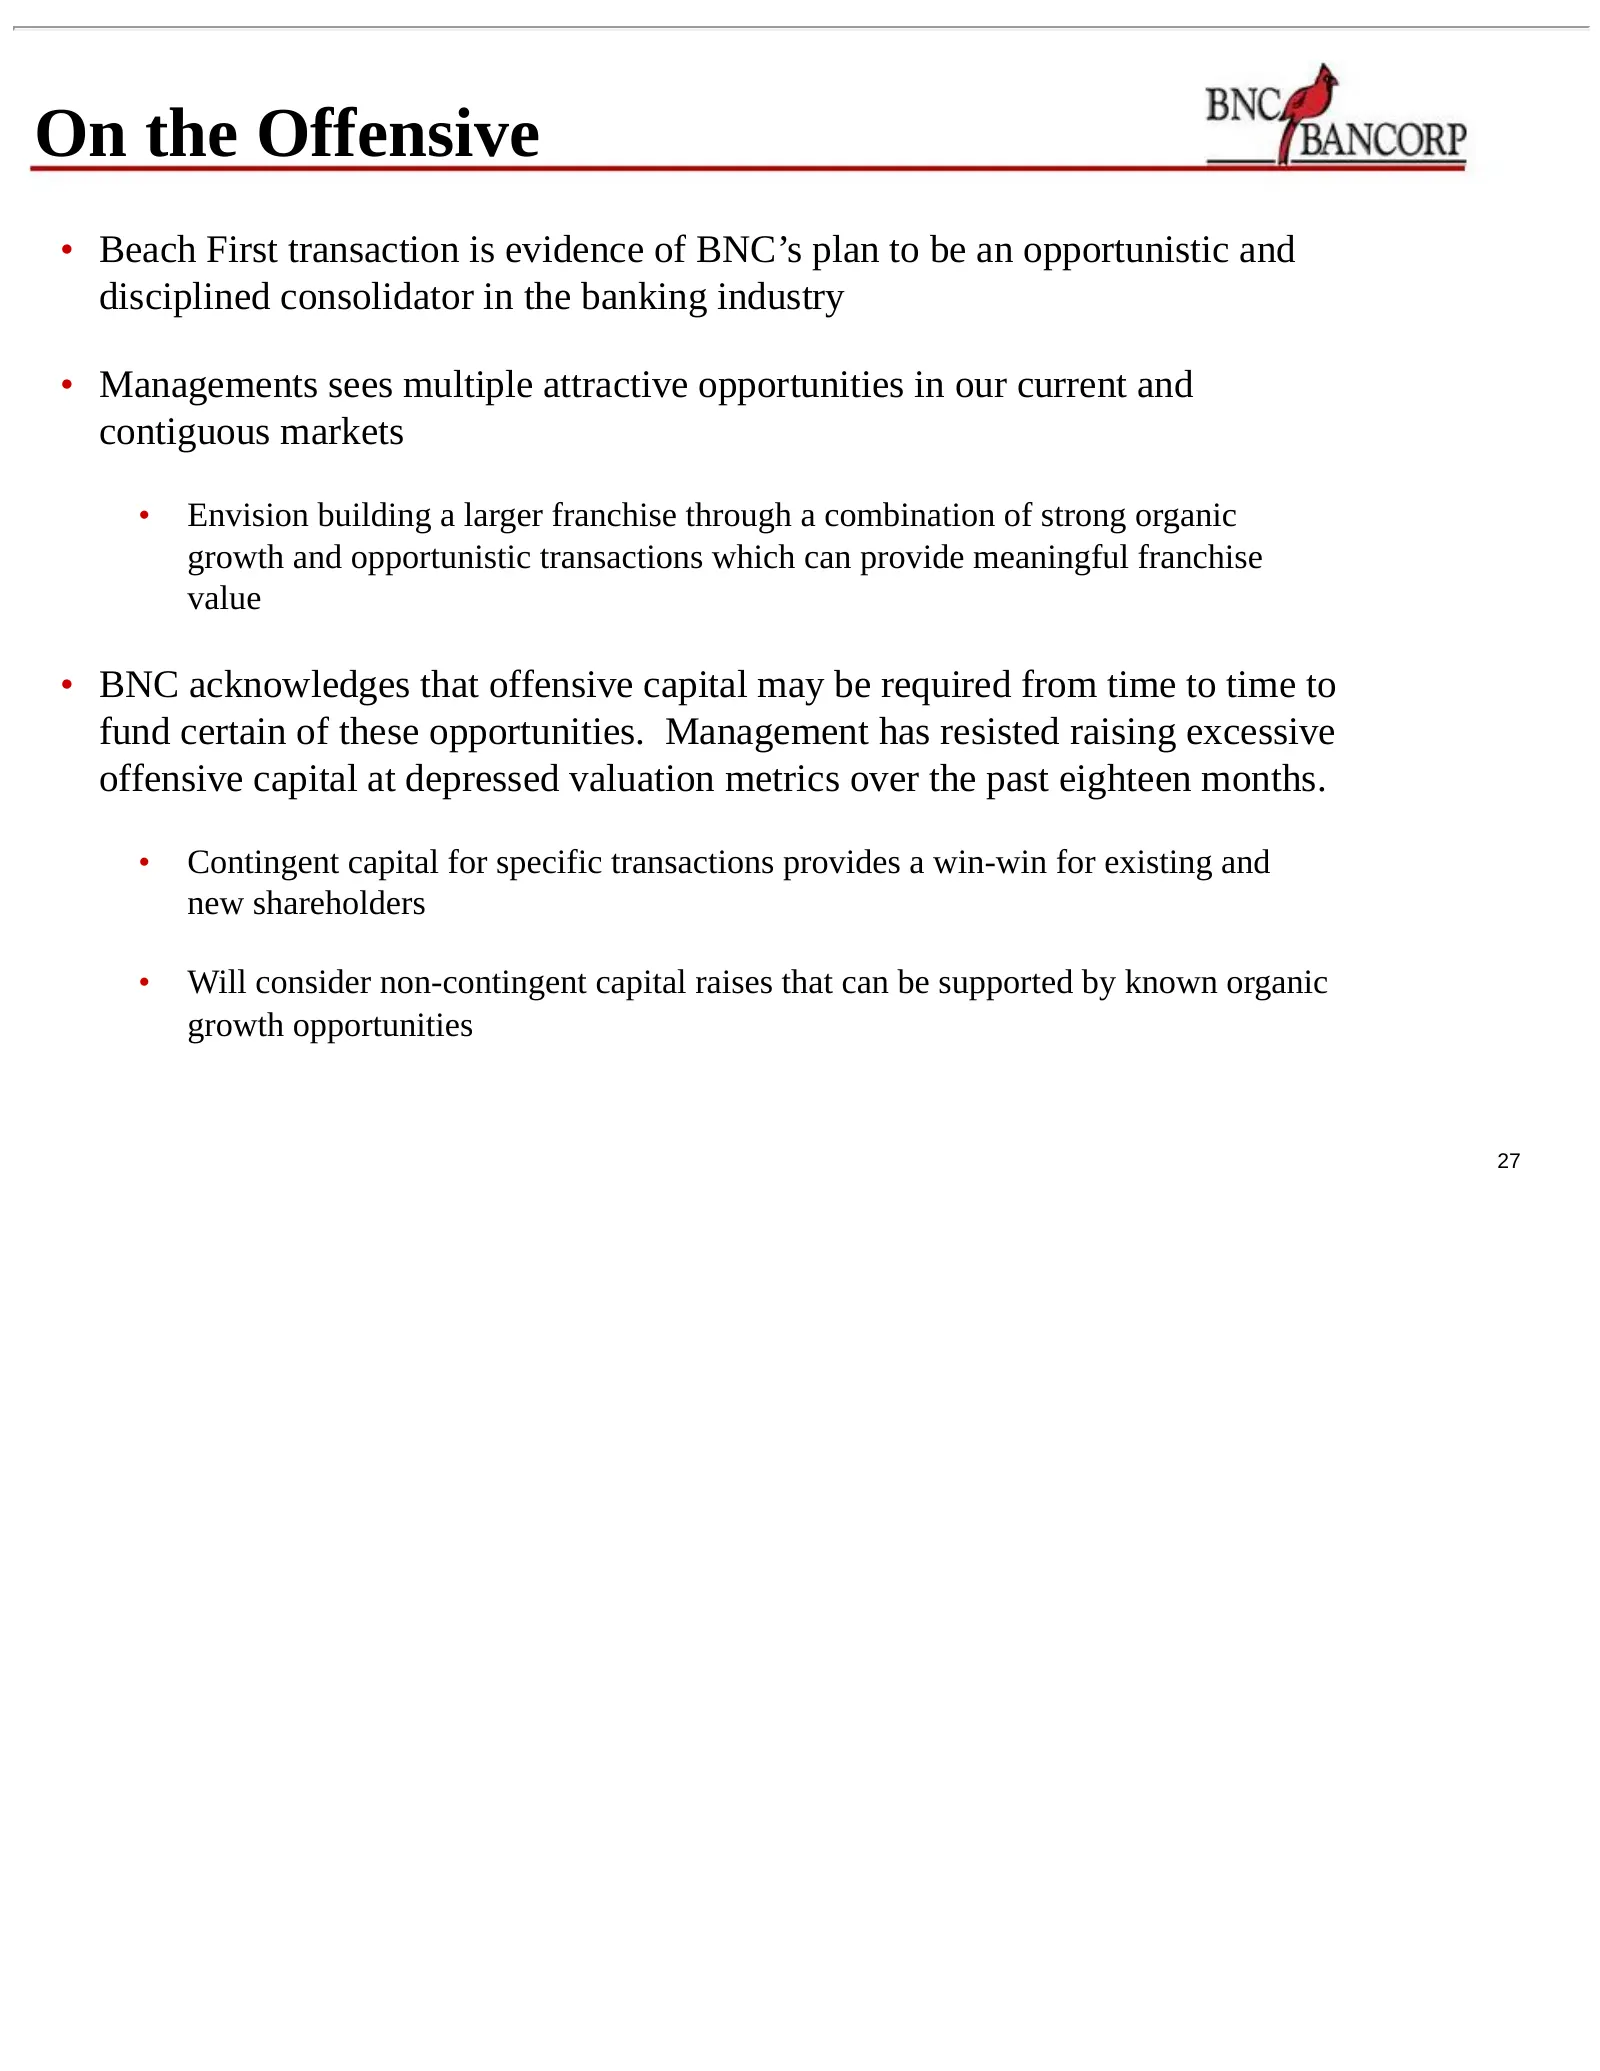
Slide 27: On the Offensive
On the Offensive • Beach First transaction is evidence of BNC’s plan to be an opportunistic and disciplined consolidator in the banking industry • Managements sees multiple attractive opportunities in our current and contiguous markets • Envision building a larger franchise through a combination of
Slide 28: The Place to Be, for All the Right Reasons
The Place to Be, for All the Right Reasons No Customer, Employee, Director, or Financial Representation is worth compromising the Integrity of our Organization. The Integrity of BNC is its most cherished Asset.
Source: SEC EDGAR · 8-K filed May 5, 2010
More decks from BNC Bancorp
 Merger or Acquisition (January 2017)37 slides · Jan 23, 2017
 Stephens Inc. Carolinas Roadshow - Charlotte November 201637 slides · Nov 8, 2016
 IPO Roadshow (July 2016)28 slides · Jul 20, 2016
 2016 Gulf South Bank Conference37 slides · May 2, 2016
 Merger or Acquisition (November 2015)32 slides · Nov 16, 2015
 Merger or Acquisition (August 2015)24 slides · Aug 14, 2015