International Coal — Bear Stearns Commodities and Capital Goods Conference 2006
17 slides from International Coal's conference presentation, Nov 28, 2006
Slide 1: Bear Stearns Commodities and Capital Goods Conference
Exhibit 99.1 Bear Stearns Commodities and Capital Goods Conference November 29, 2006
Slide 2: Forward-Looking Statements
Forward-Looking Statements Statements that are not historical fact are forward-looking statements and may involve a number of risks and uncertainties. We have used the words “believe,” “could,” “estimate,” “expect,” “intend,” “may,” “plan,” “predict,” “project” and similar terms and phrases, includi
Slide 3: Management Presenter
Management Presenter Ben Hatfield President and Chief Executive Officer 2
Slide 4: Key ICG Highlights
Key ICG Highlights Prominent position in 3 of the 4 largest coal producing regions in the U.S. Strong operating assets and large undeveloped reserve base provide attractive internal expansion opportunities Highly productive workforce that is 100% union free Strong balance sheet with minimal long–ter
Slide 5: ICG Overview
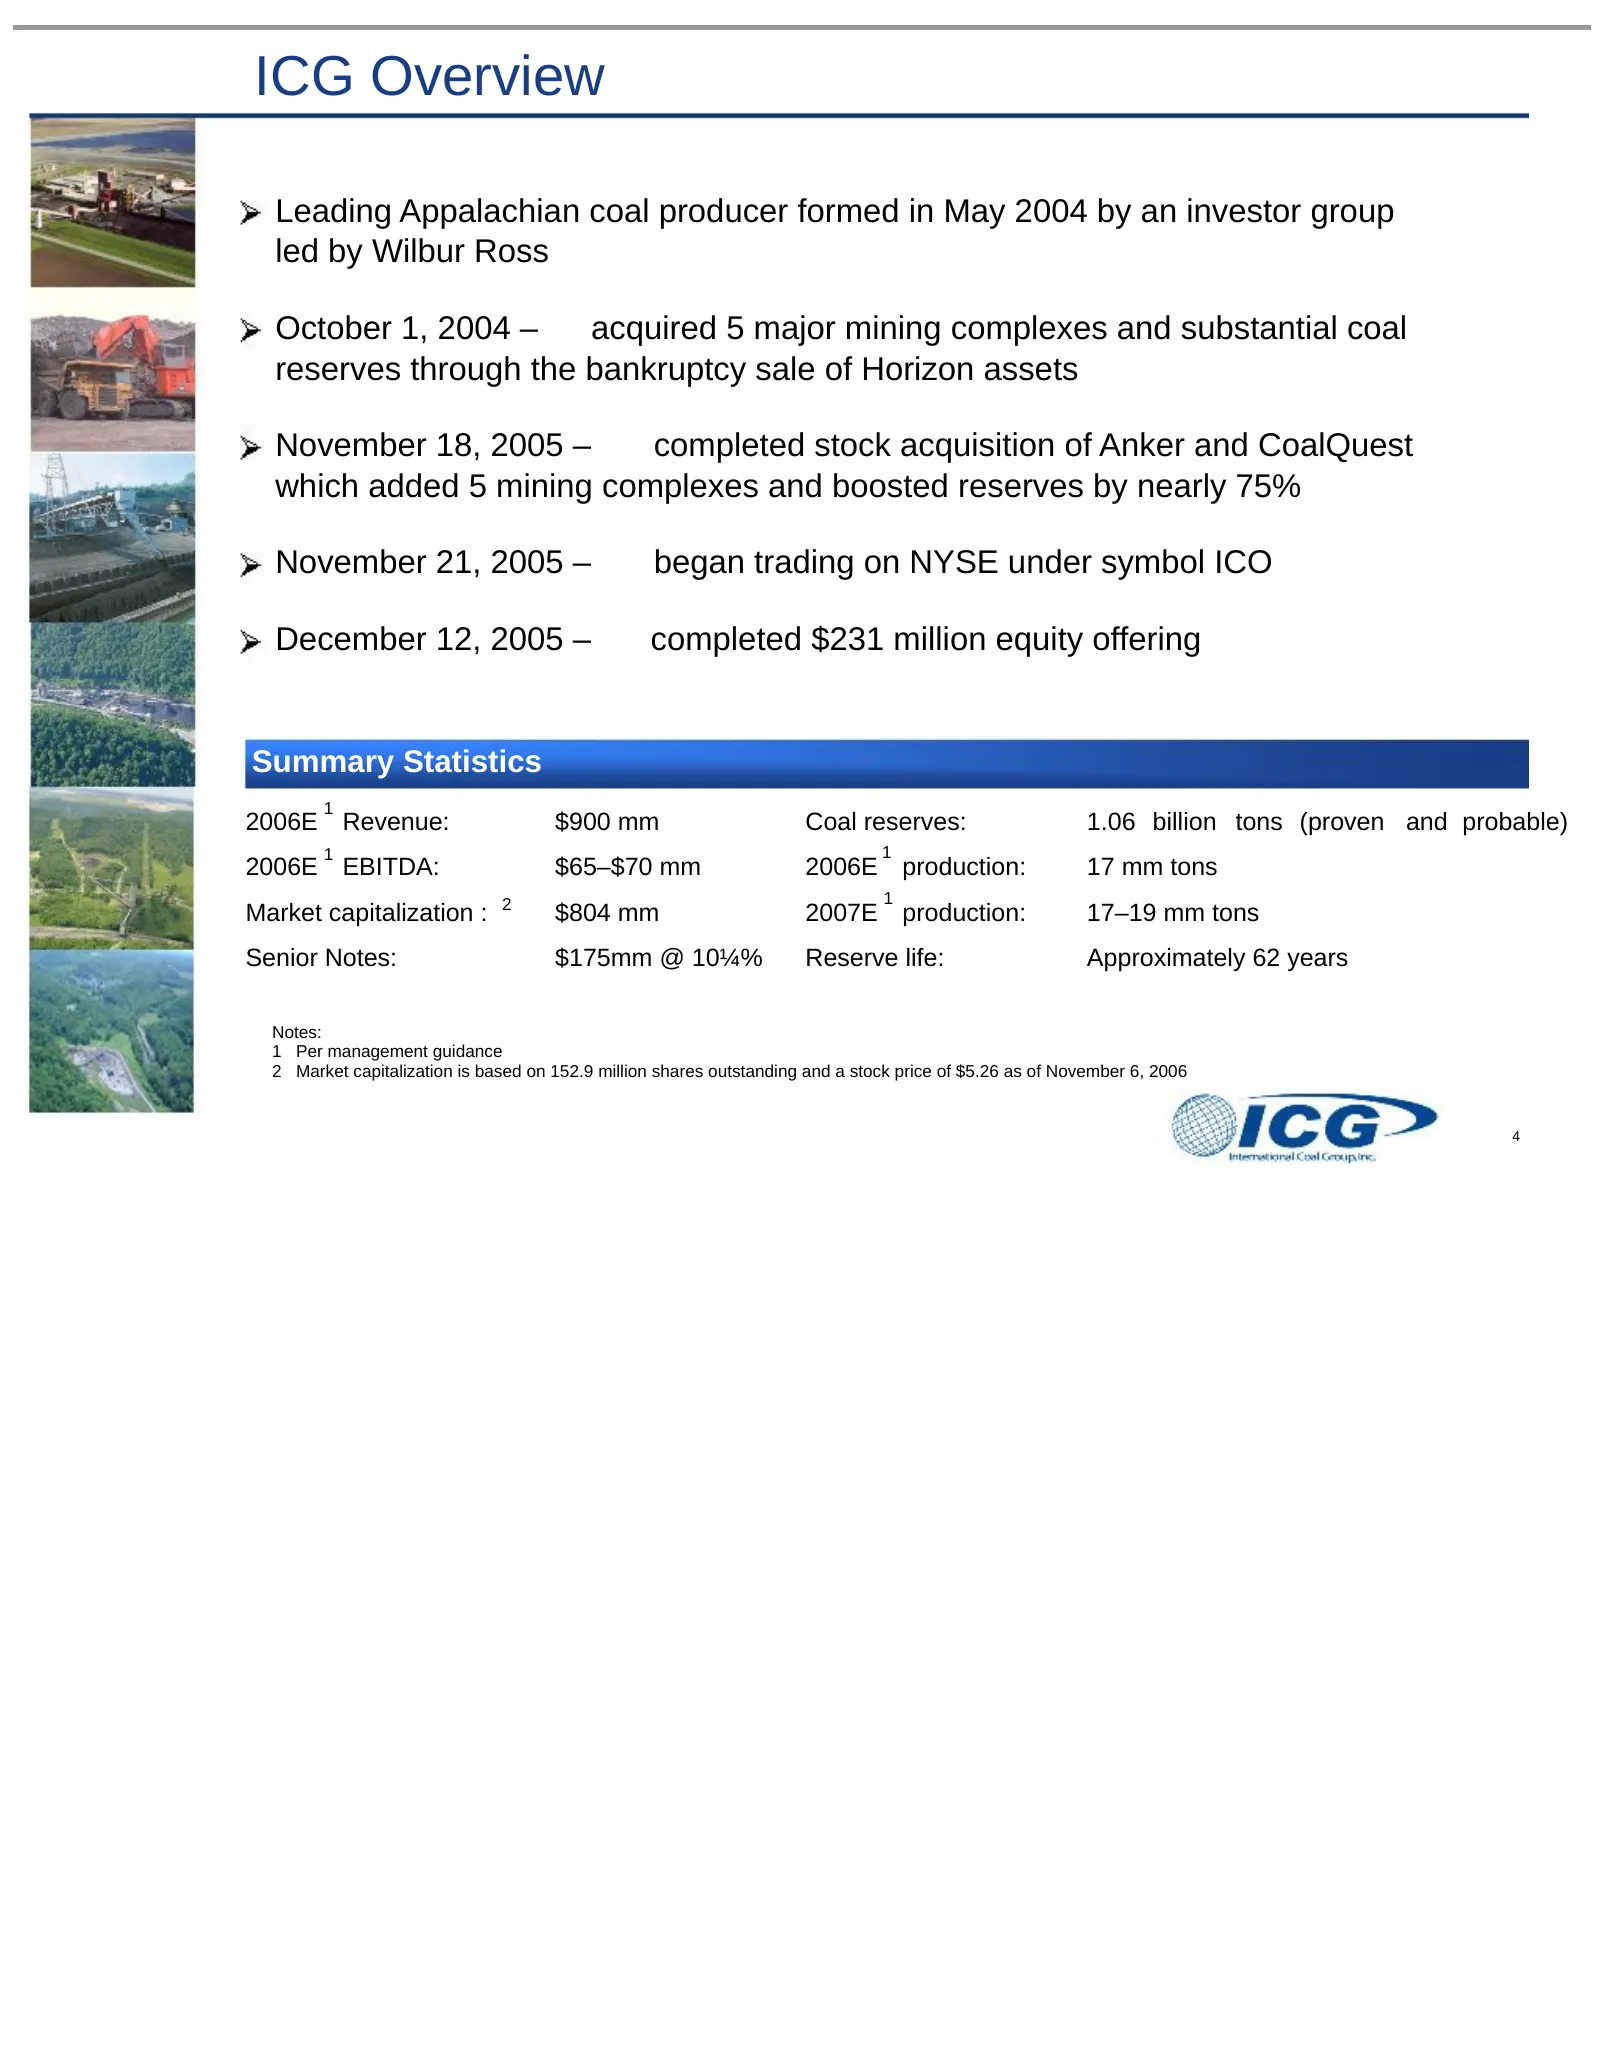
ICG Overview Leading Appalachian coal producer formed in May 2004 by an investor group led by Wilbur Ross October 1, 2004 – acquired 5 major mining complexes and substantial coal reserves through the bankruptcy sale of Horizon assets November 18, 2005 – completed stock acquisition of Anker and CoalQ
Slide 6: Current and Future Operations
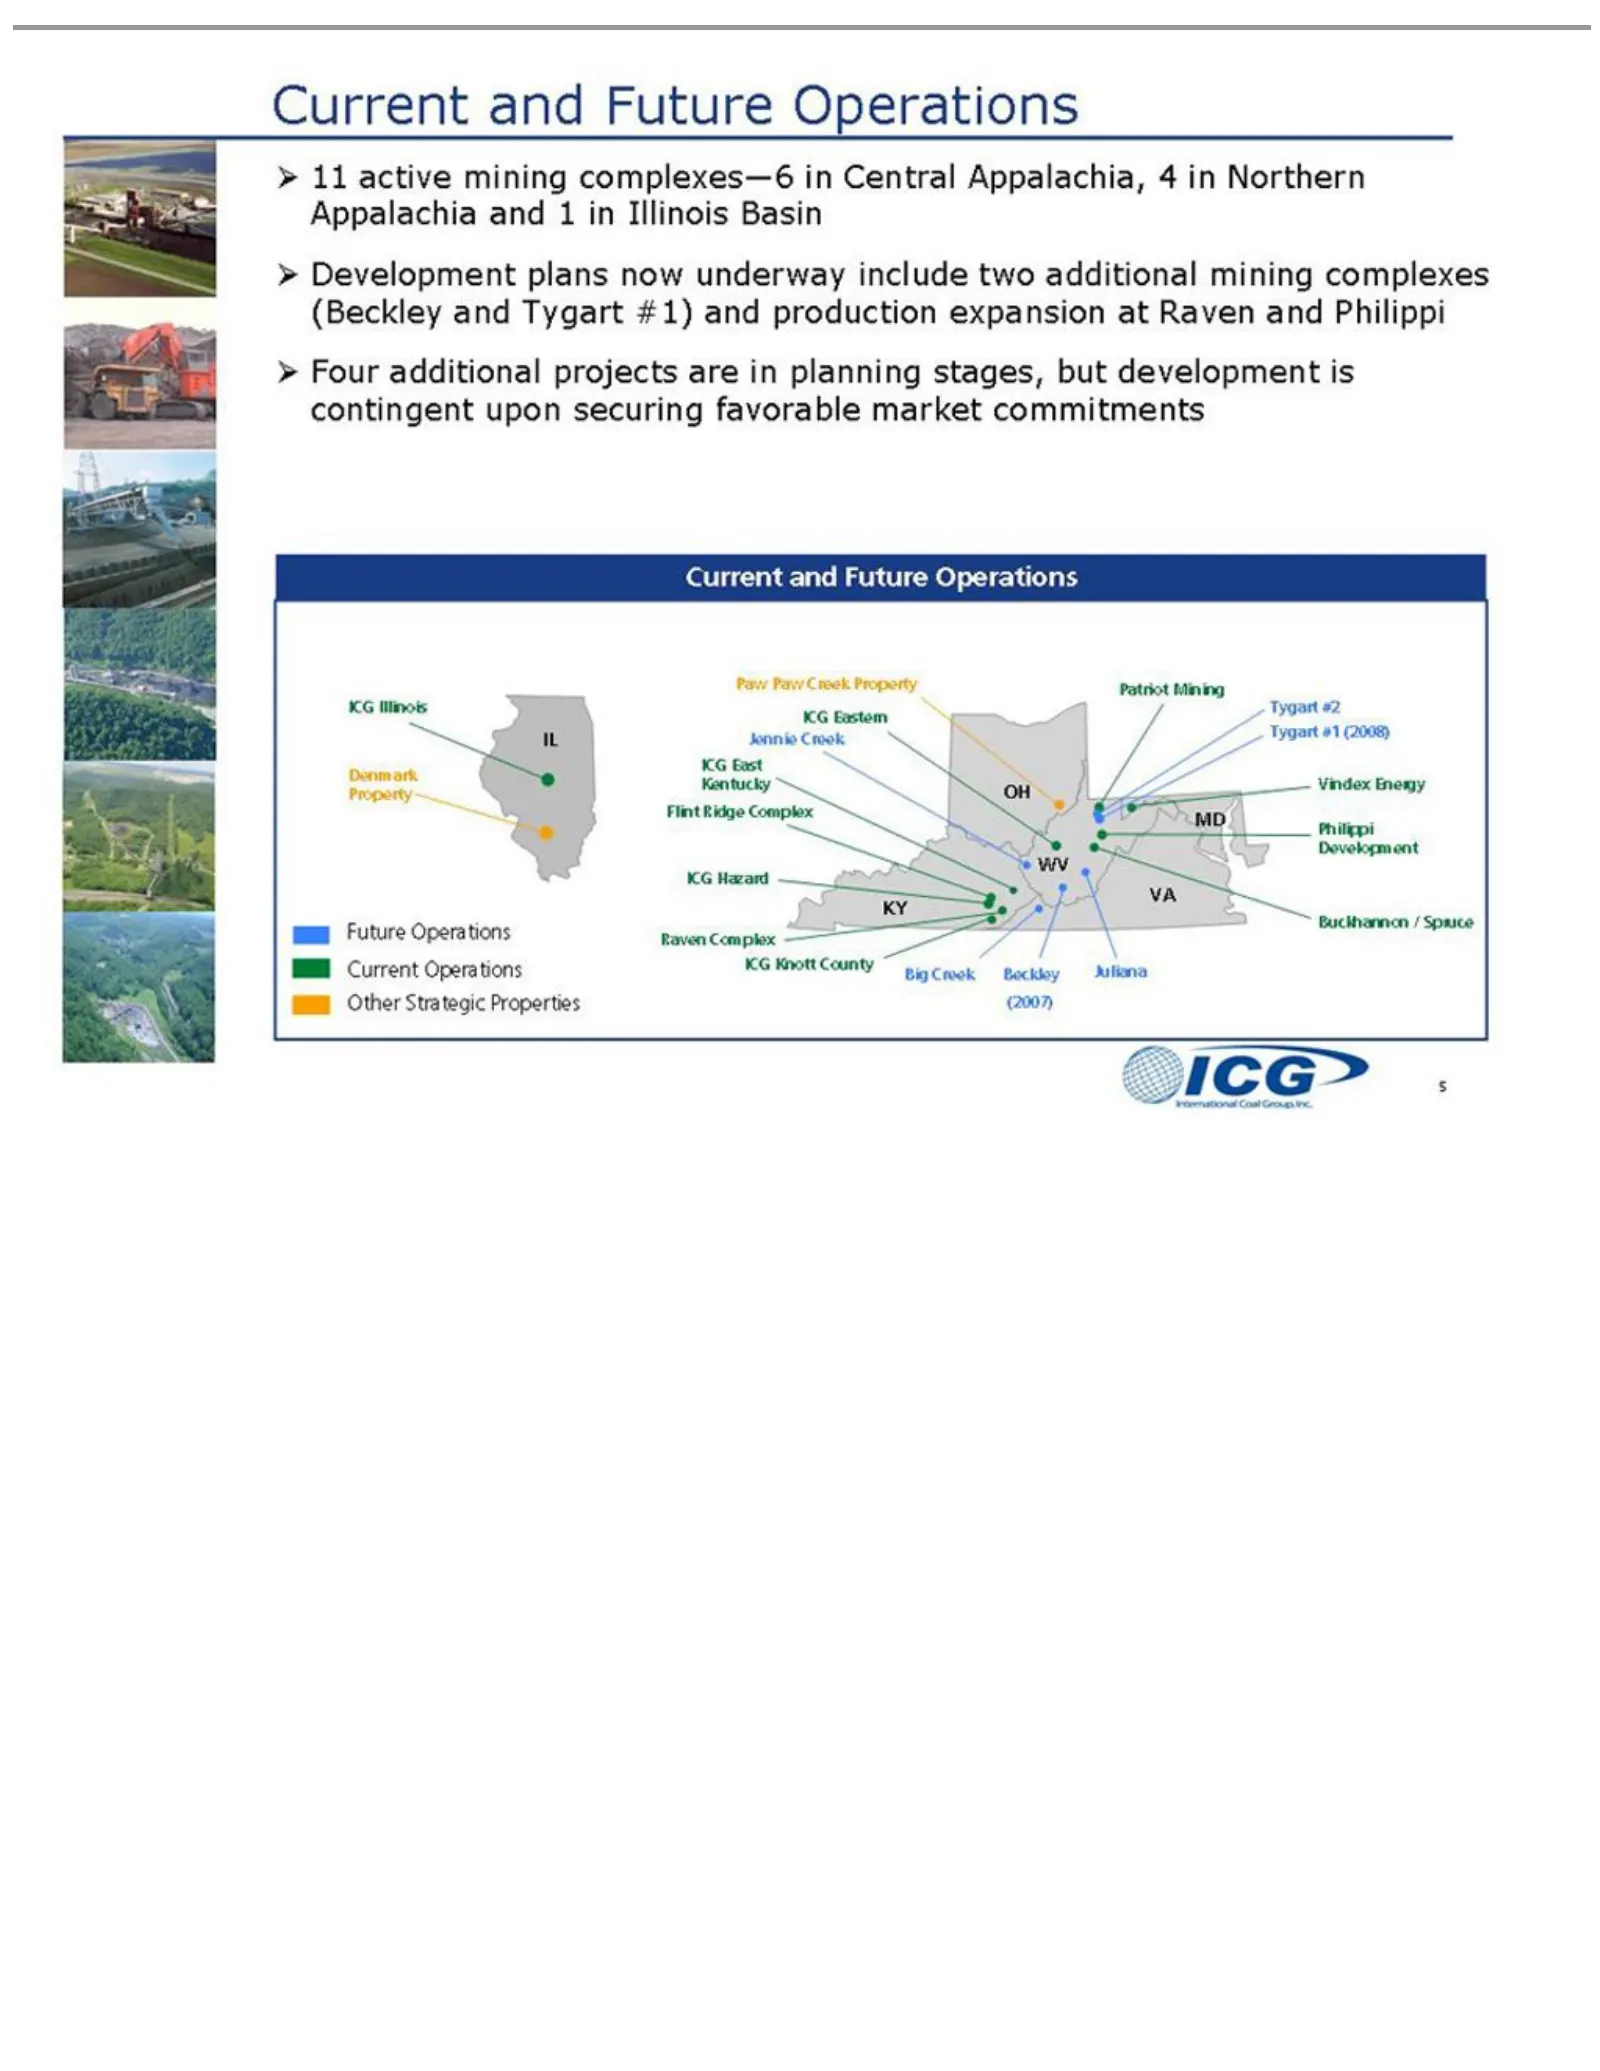
Current and Future Operations >» 11 active mining complexes—6 in Central Appalachia, 4 in Northern Appalachia and 1 in Illinois Basin > Development plans now underway include two additional mining complexes (Beckley and Tygart #1) and production expansion at Raven and Philippi > Four additional proj
Slide 7: New Production Coming On Line 2006-2008
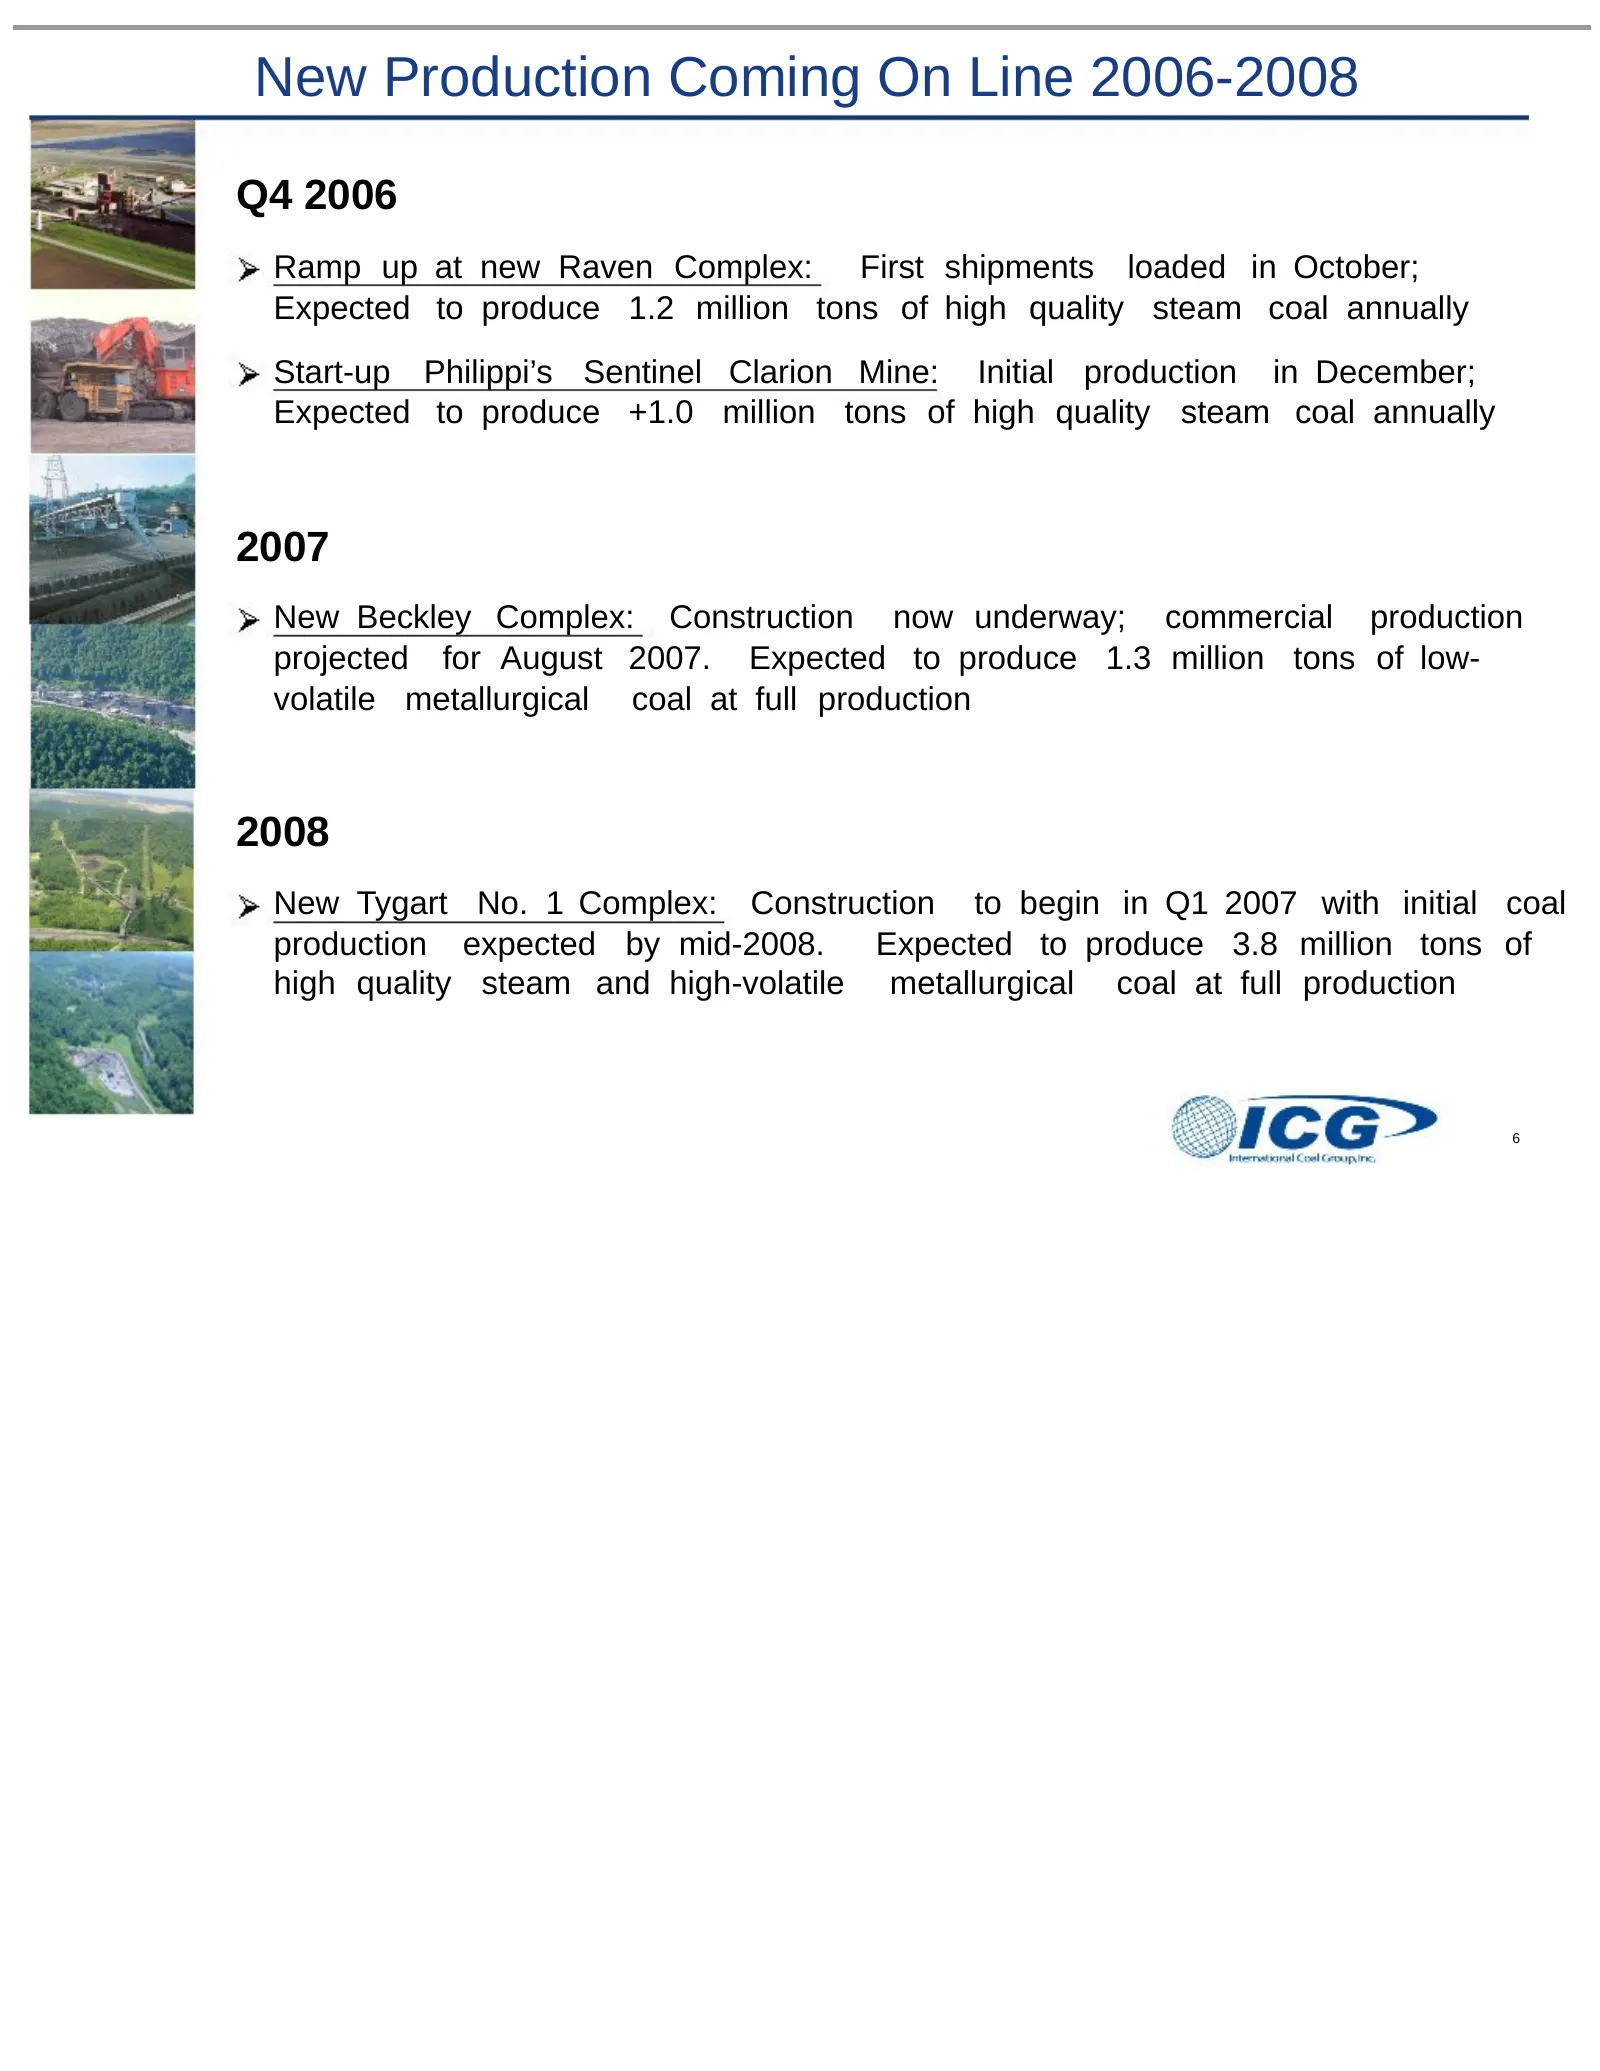
New Production Coming On Line 2006-2008 Q4 2006 Ramp up at new Raven Complex: First shipments loaded in October; Expected to produce 1.2 million tons of high quality steam coal annually Start-up Philippi’s Sentinel Clarion Mine: Initial production in December; Expected to produce +1.0 million tons o
Slide 8: High Caliber Reserve Base
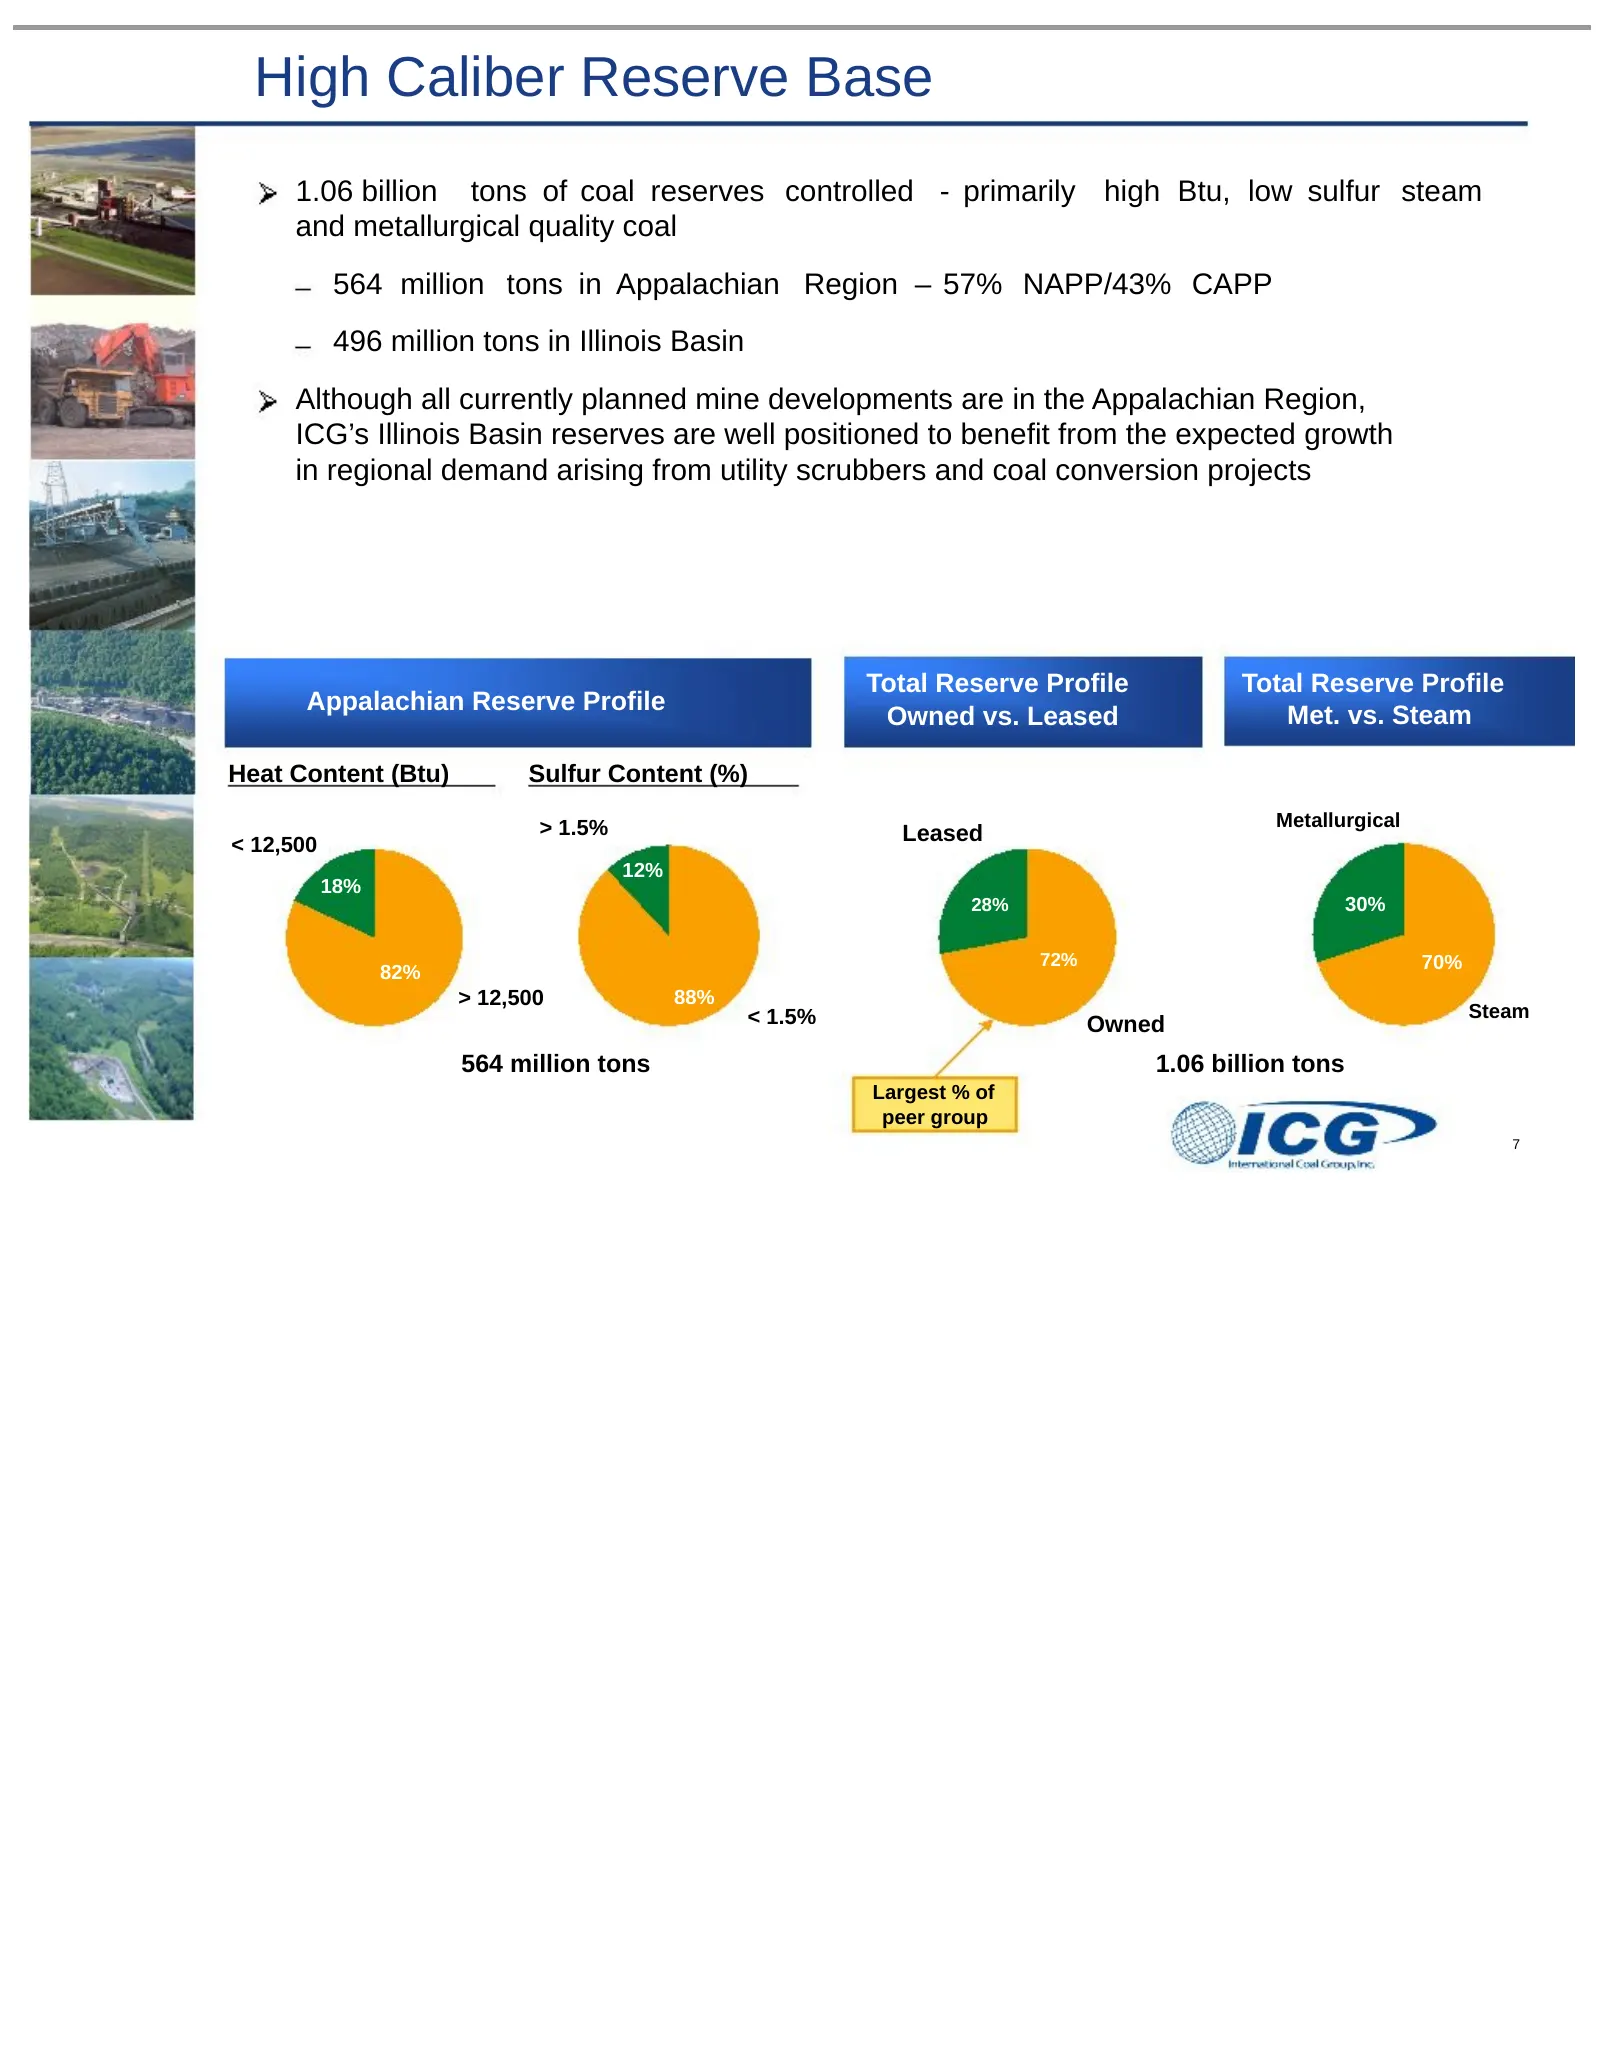
High Caliber Reserve Base 1.06 billion tons of coal reserves controlled - primarily high Btu, low sulfur steam and metallurgical quality coal 564 million tons in Appalachian Region – 57% NAPP/43% CAPP 496 million tons in Illinois Basin Although all currently planned mine developments are in the Appa
Slide 9: Significant Committed Tonnage
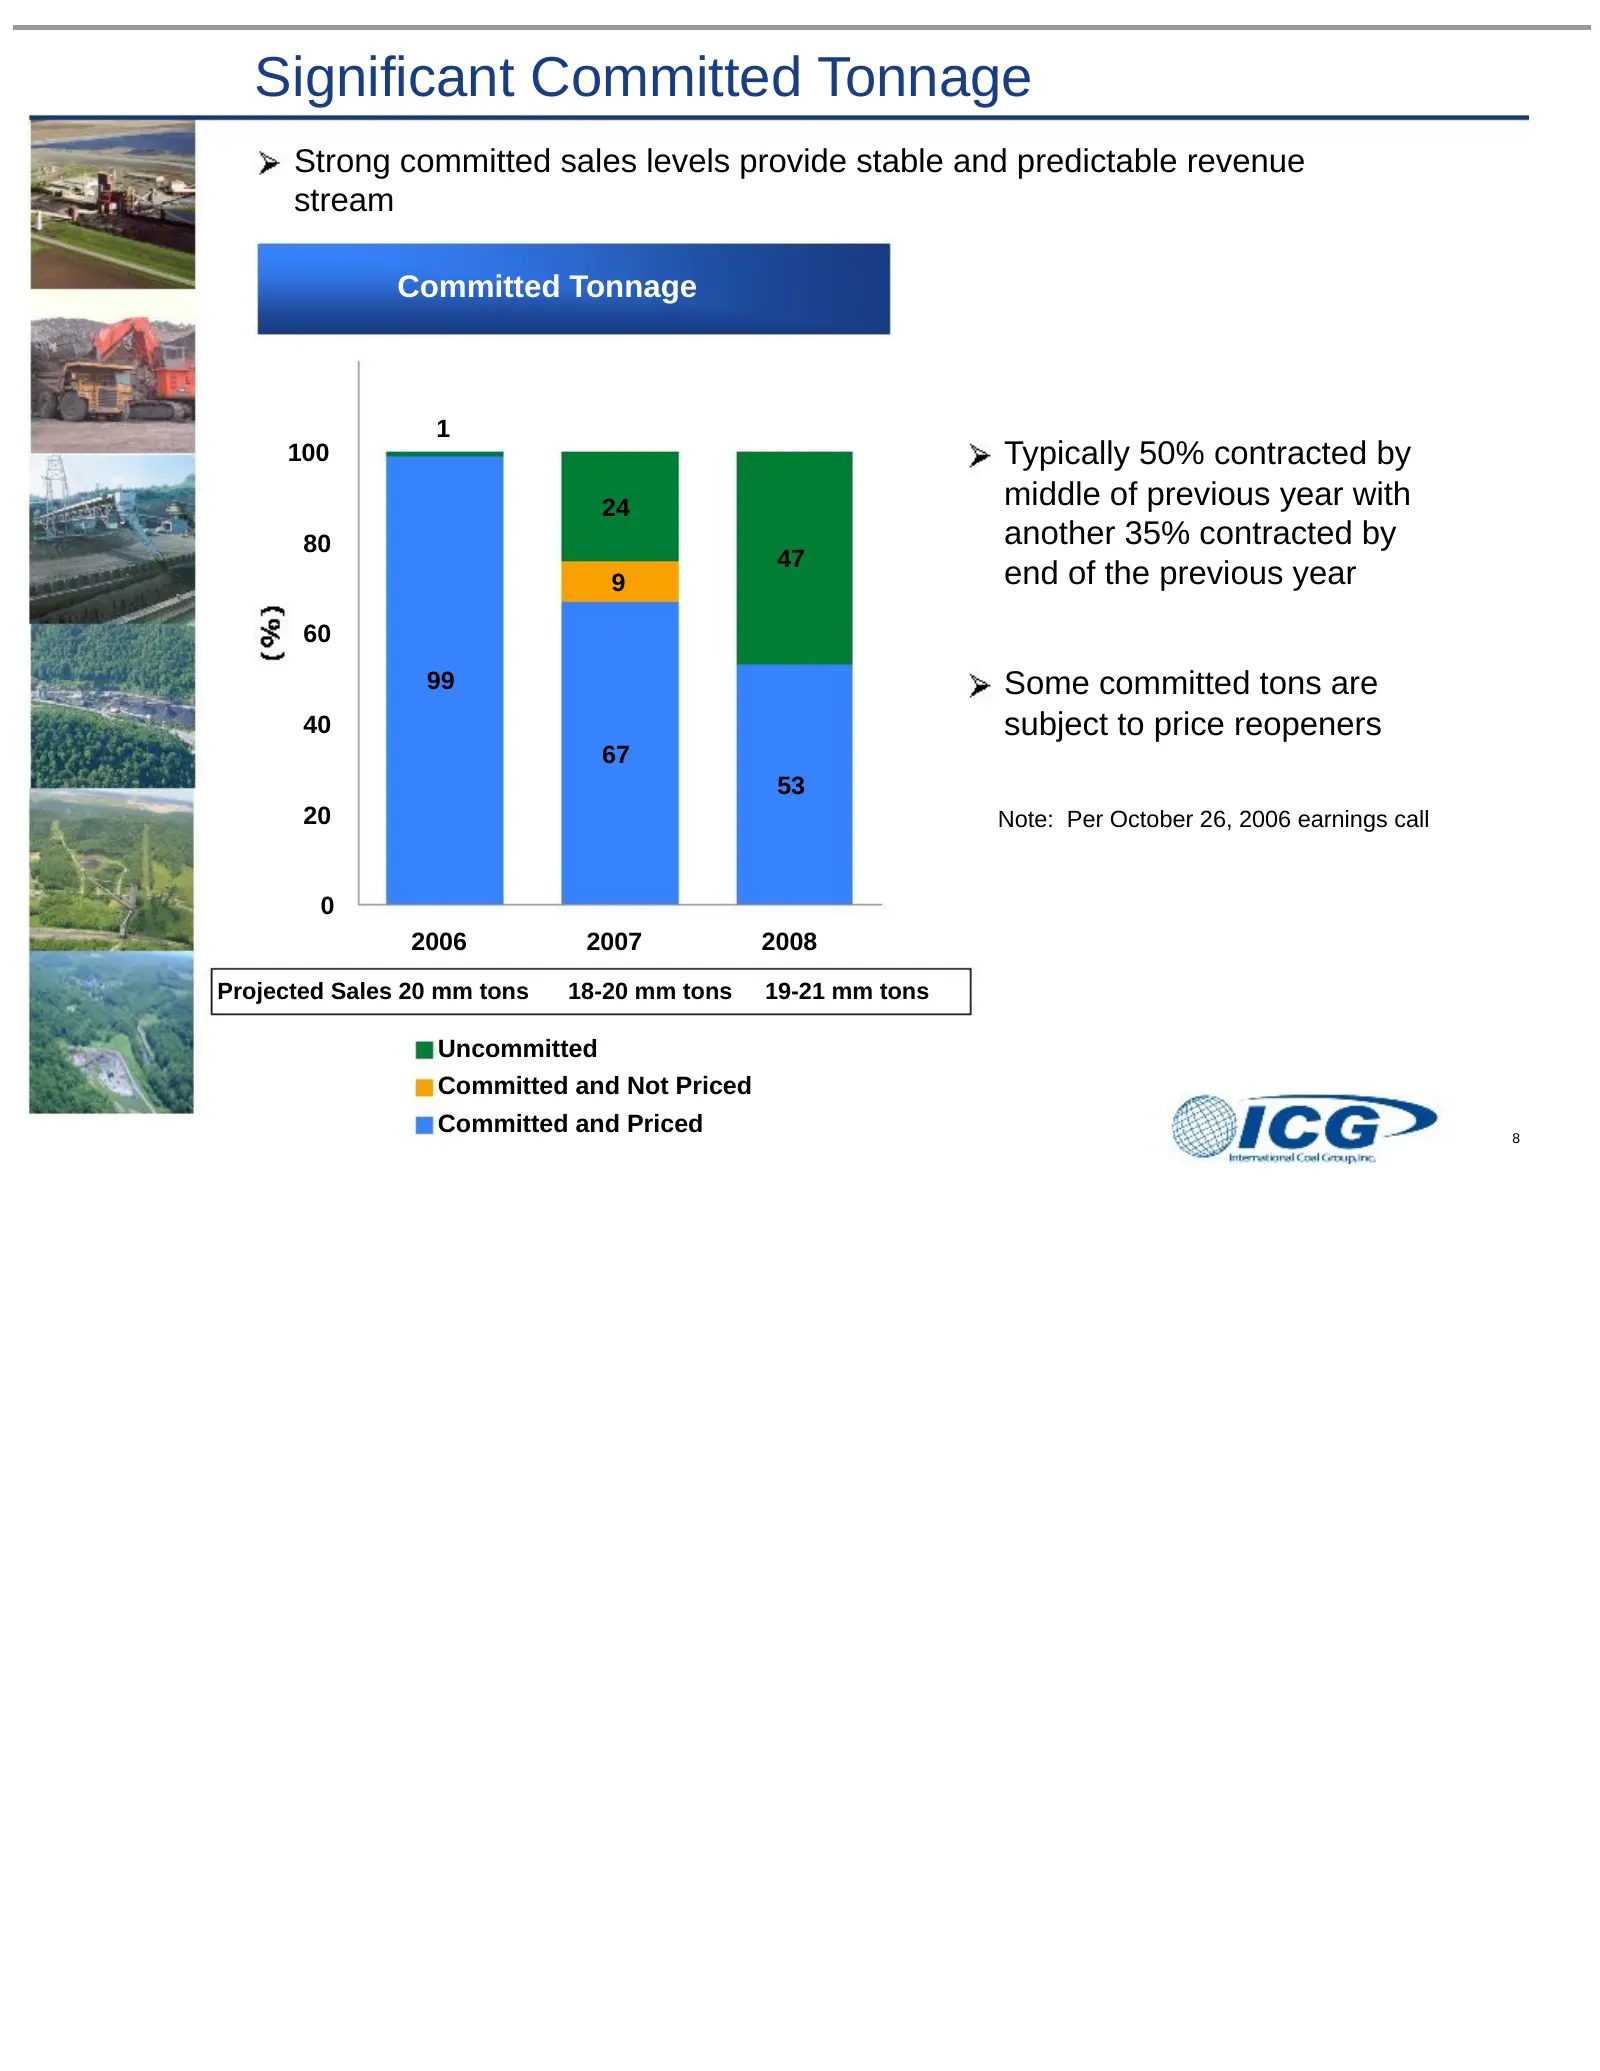
Significant Committed Tonnage Strong committed sales levels provide stable and predictable revenue stream Committed Tonnage 1 100 Typically 50% contracted by 24 middle of previous year with 80 another 35% contracted by 47 9 end of the previous year 60 99 Some committed tons are 40 subject to price r
Slide 10: Highly Productive, Non-Union Workforce
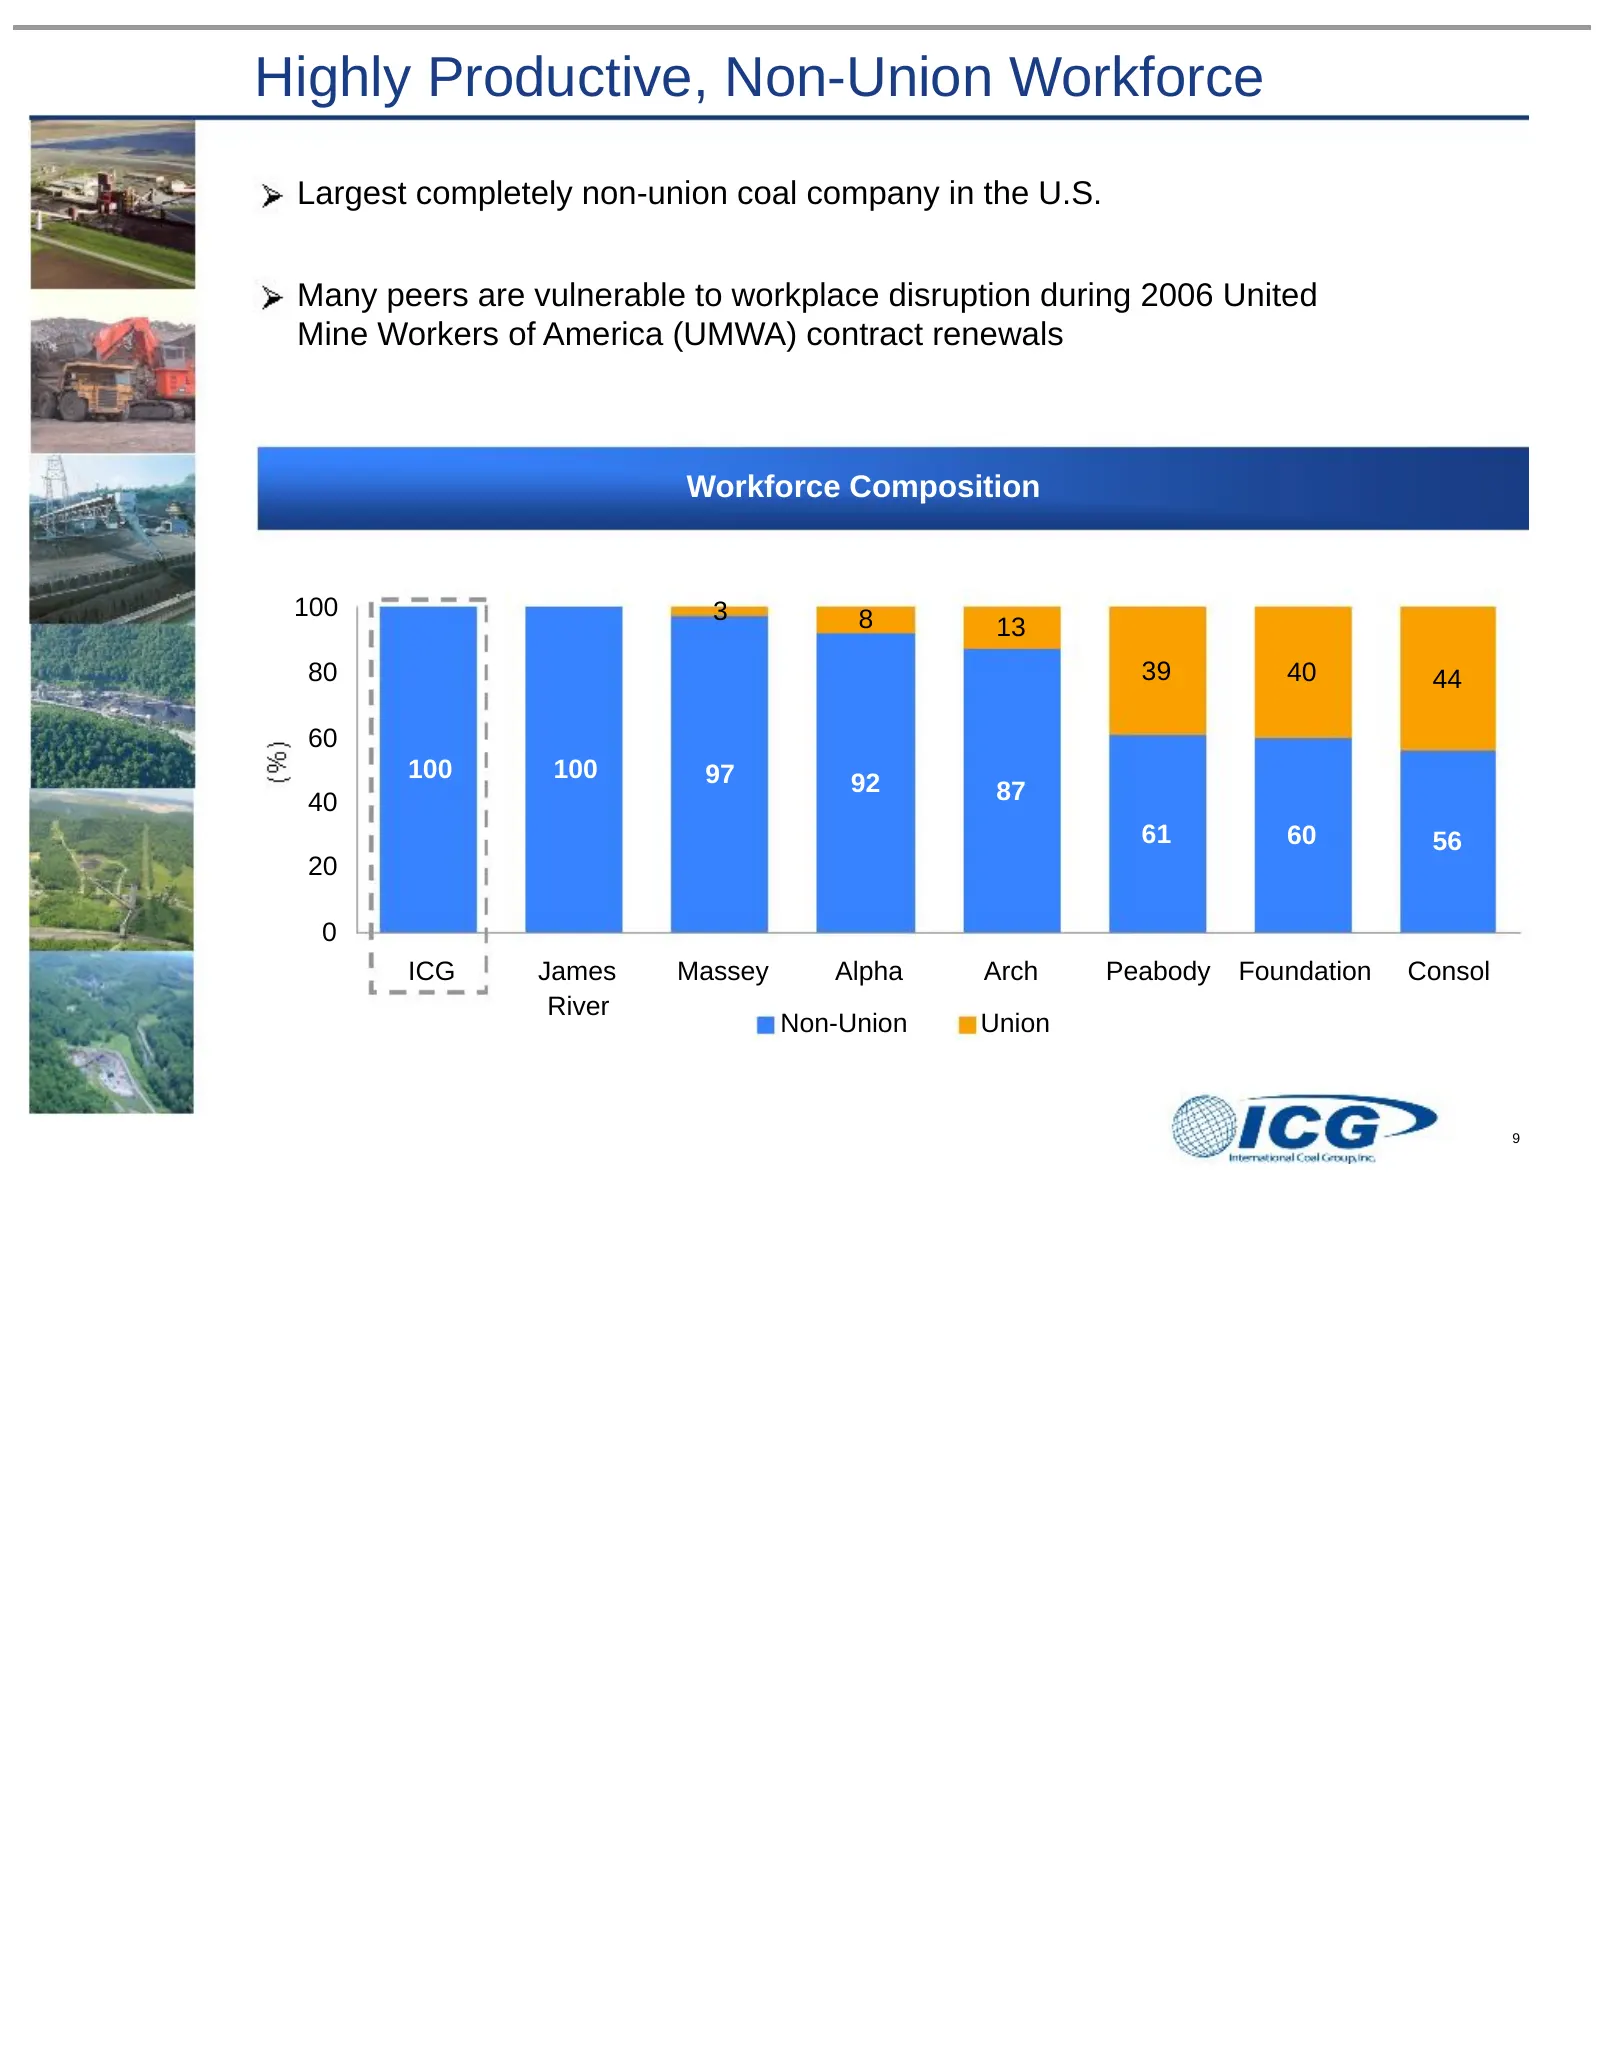
Highly Productive, Non-Union Workforce Largest completely non-union coal company in the U.S. Many peers are vulnerable to workplace disruption during 2006 United Mine Workers of America (UMWA) contract renewals Workforce Composition 100 3 8 13 80 39 40 44 60 100 100 97 92 87 40 61 60 56 20 0 ICG Jam
Slide 11: Low Legacy Liabilities
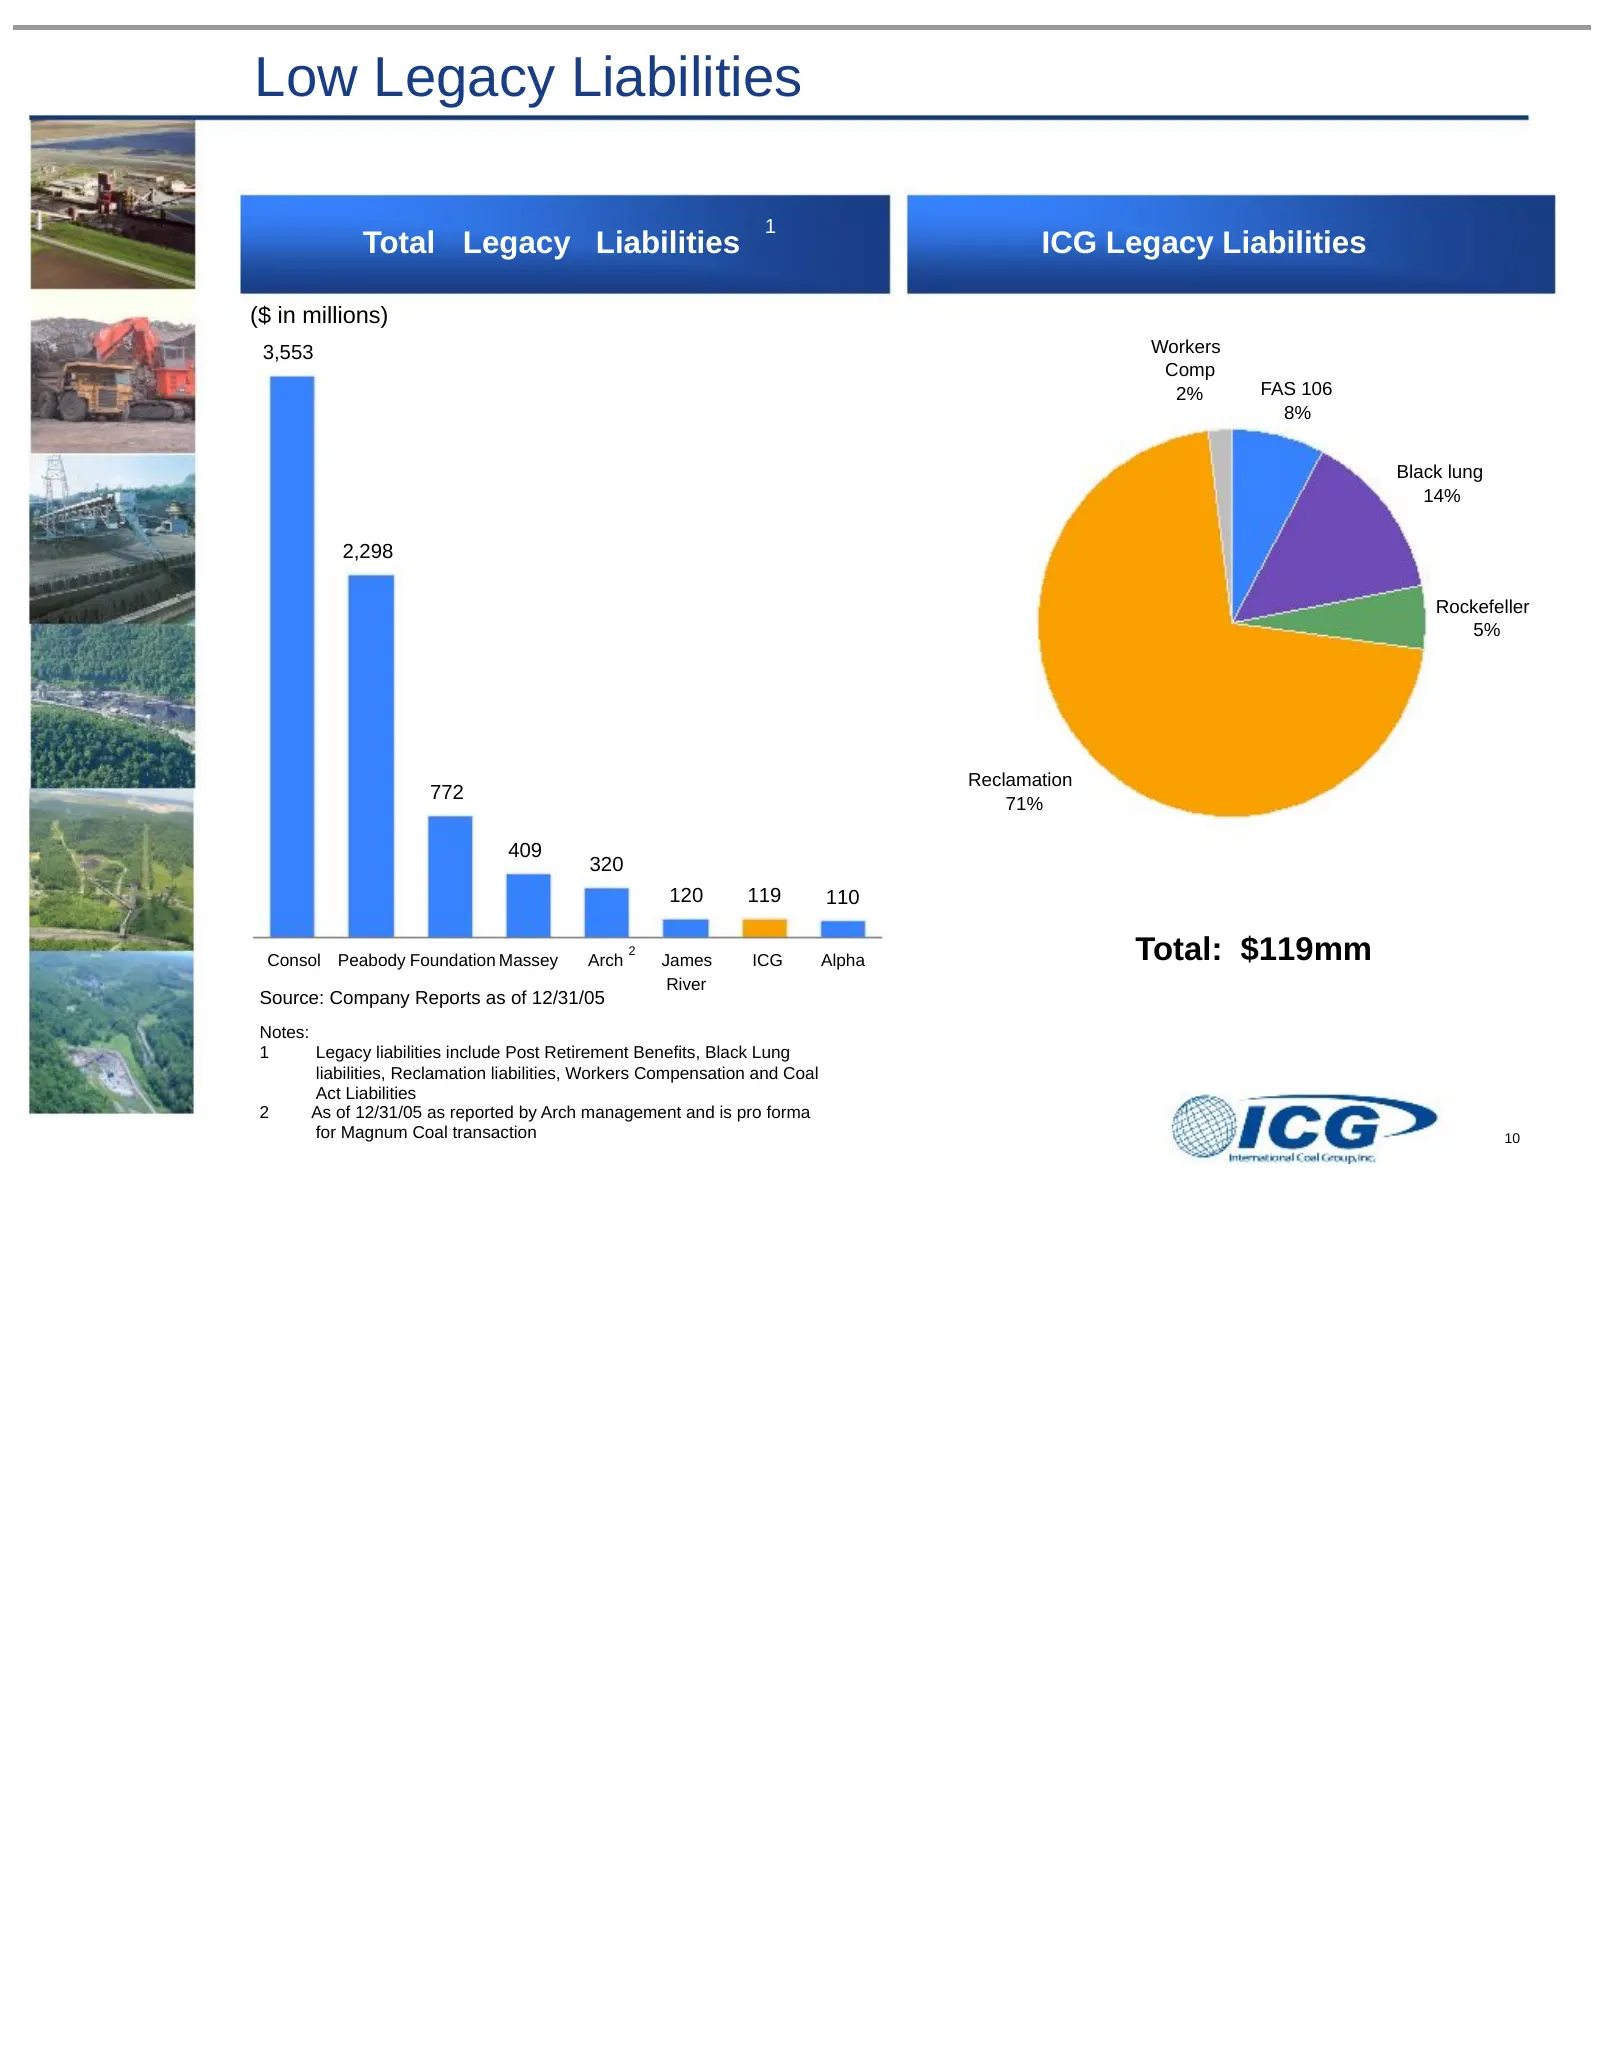
Low Legacy Liabilities 1 Total Legacy Liabilities ICG Legacy Liabilities ($ in millions) 3,553 Workers Comp 2% FAS 106 8% Black lung 14% 2,298 Rockefeller 5% Reclamation 772 71% 409 320 120 119 110 Consol Peabody Foundation Massey Arch 2 James ICG Alpha Total: $119mm River Source: Company Reports as
Slide 12: Total Debt / Capitalization Comparison
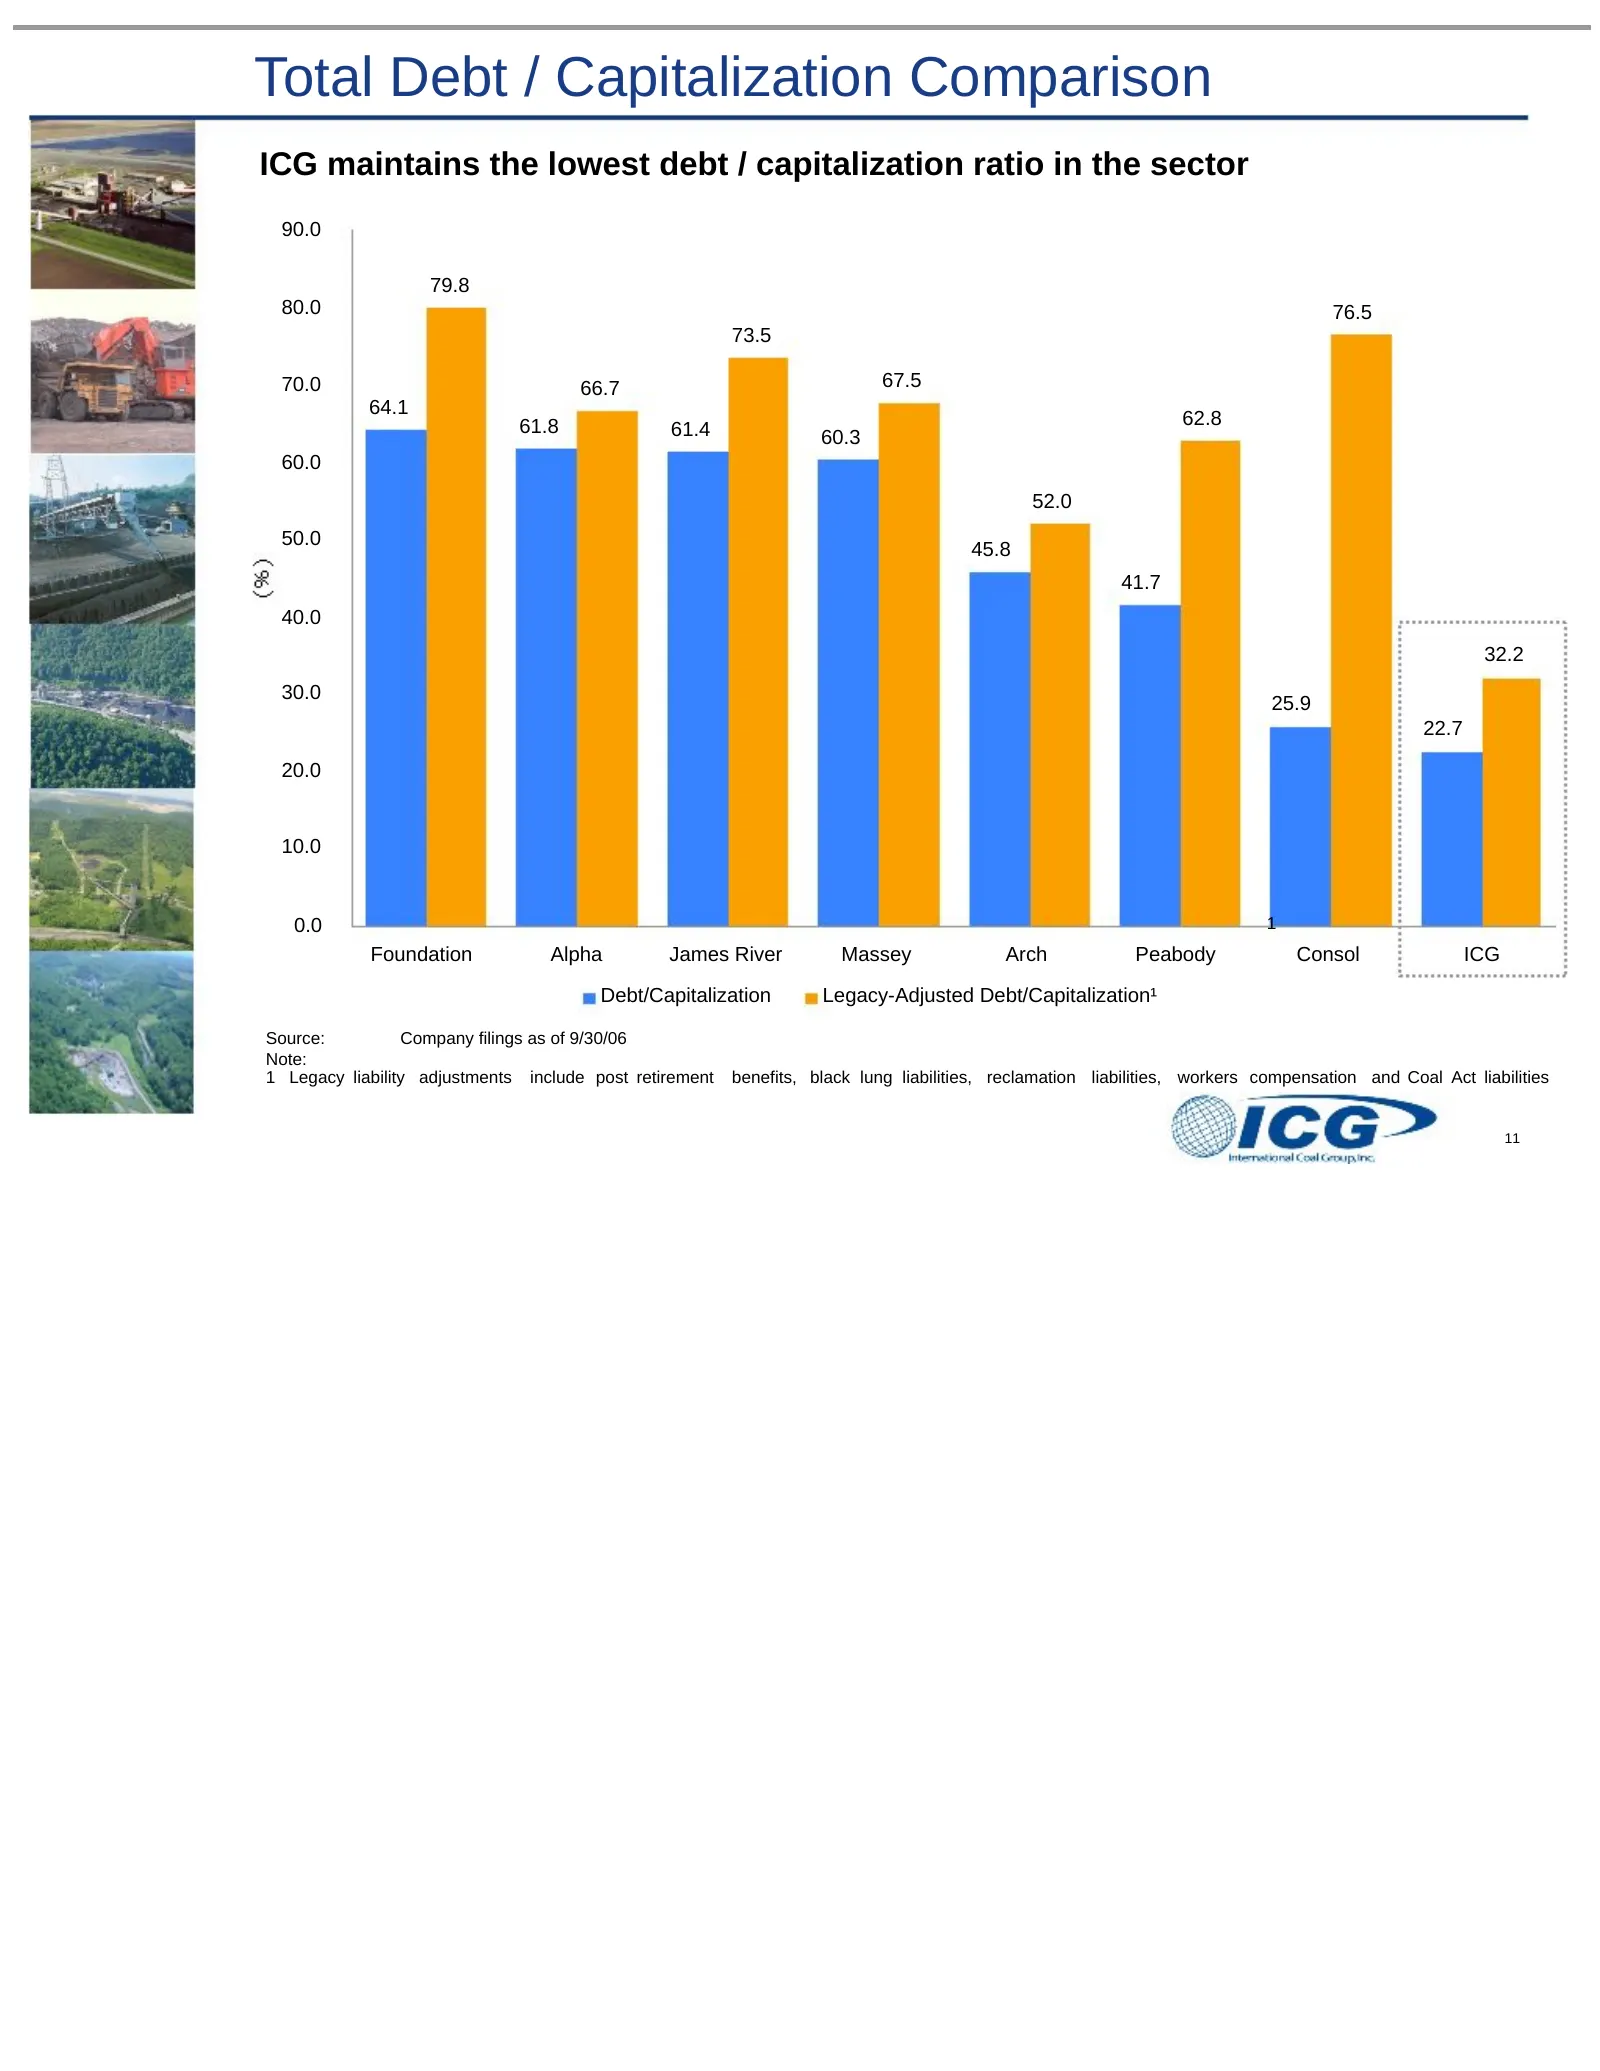
Total Debt / Capitalization Comparison ICG maintains the lowest debt / capitalization ratio in the sector 90.0 79.8 80.0 76.5 73.5 70.0 66.7 67.5 64.1 61.8 62.8 61.4 60.3 60.0 52.0 50.0 45.8 41.7 40.0 32.2 30.0 25.9 22.7 20.0 10.0 0.0 1 Foundation Alpha James River Massey Arch Peabody Consol ICG Deb
Slide 13: Experienced Management Team
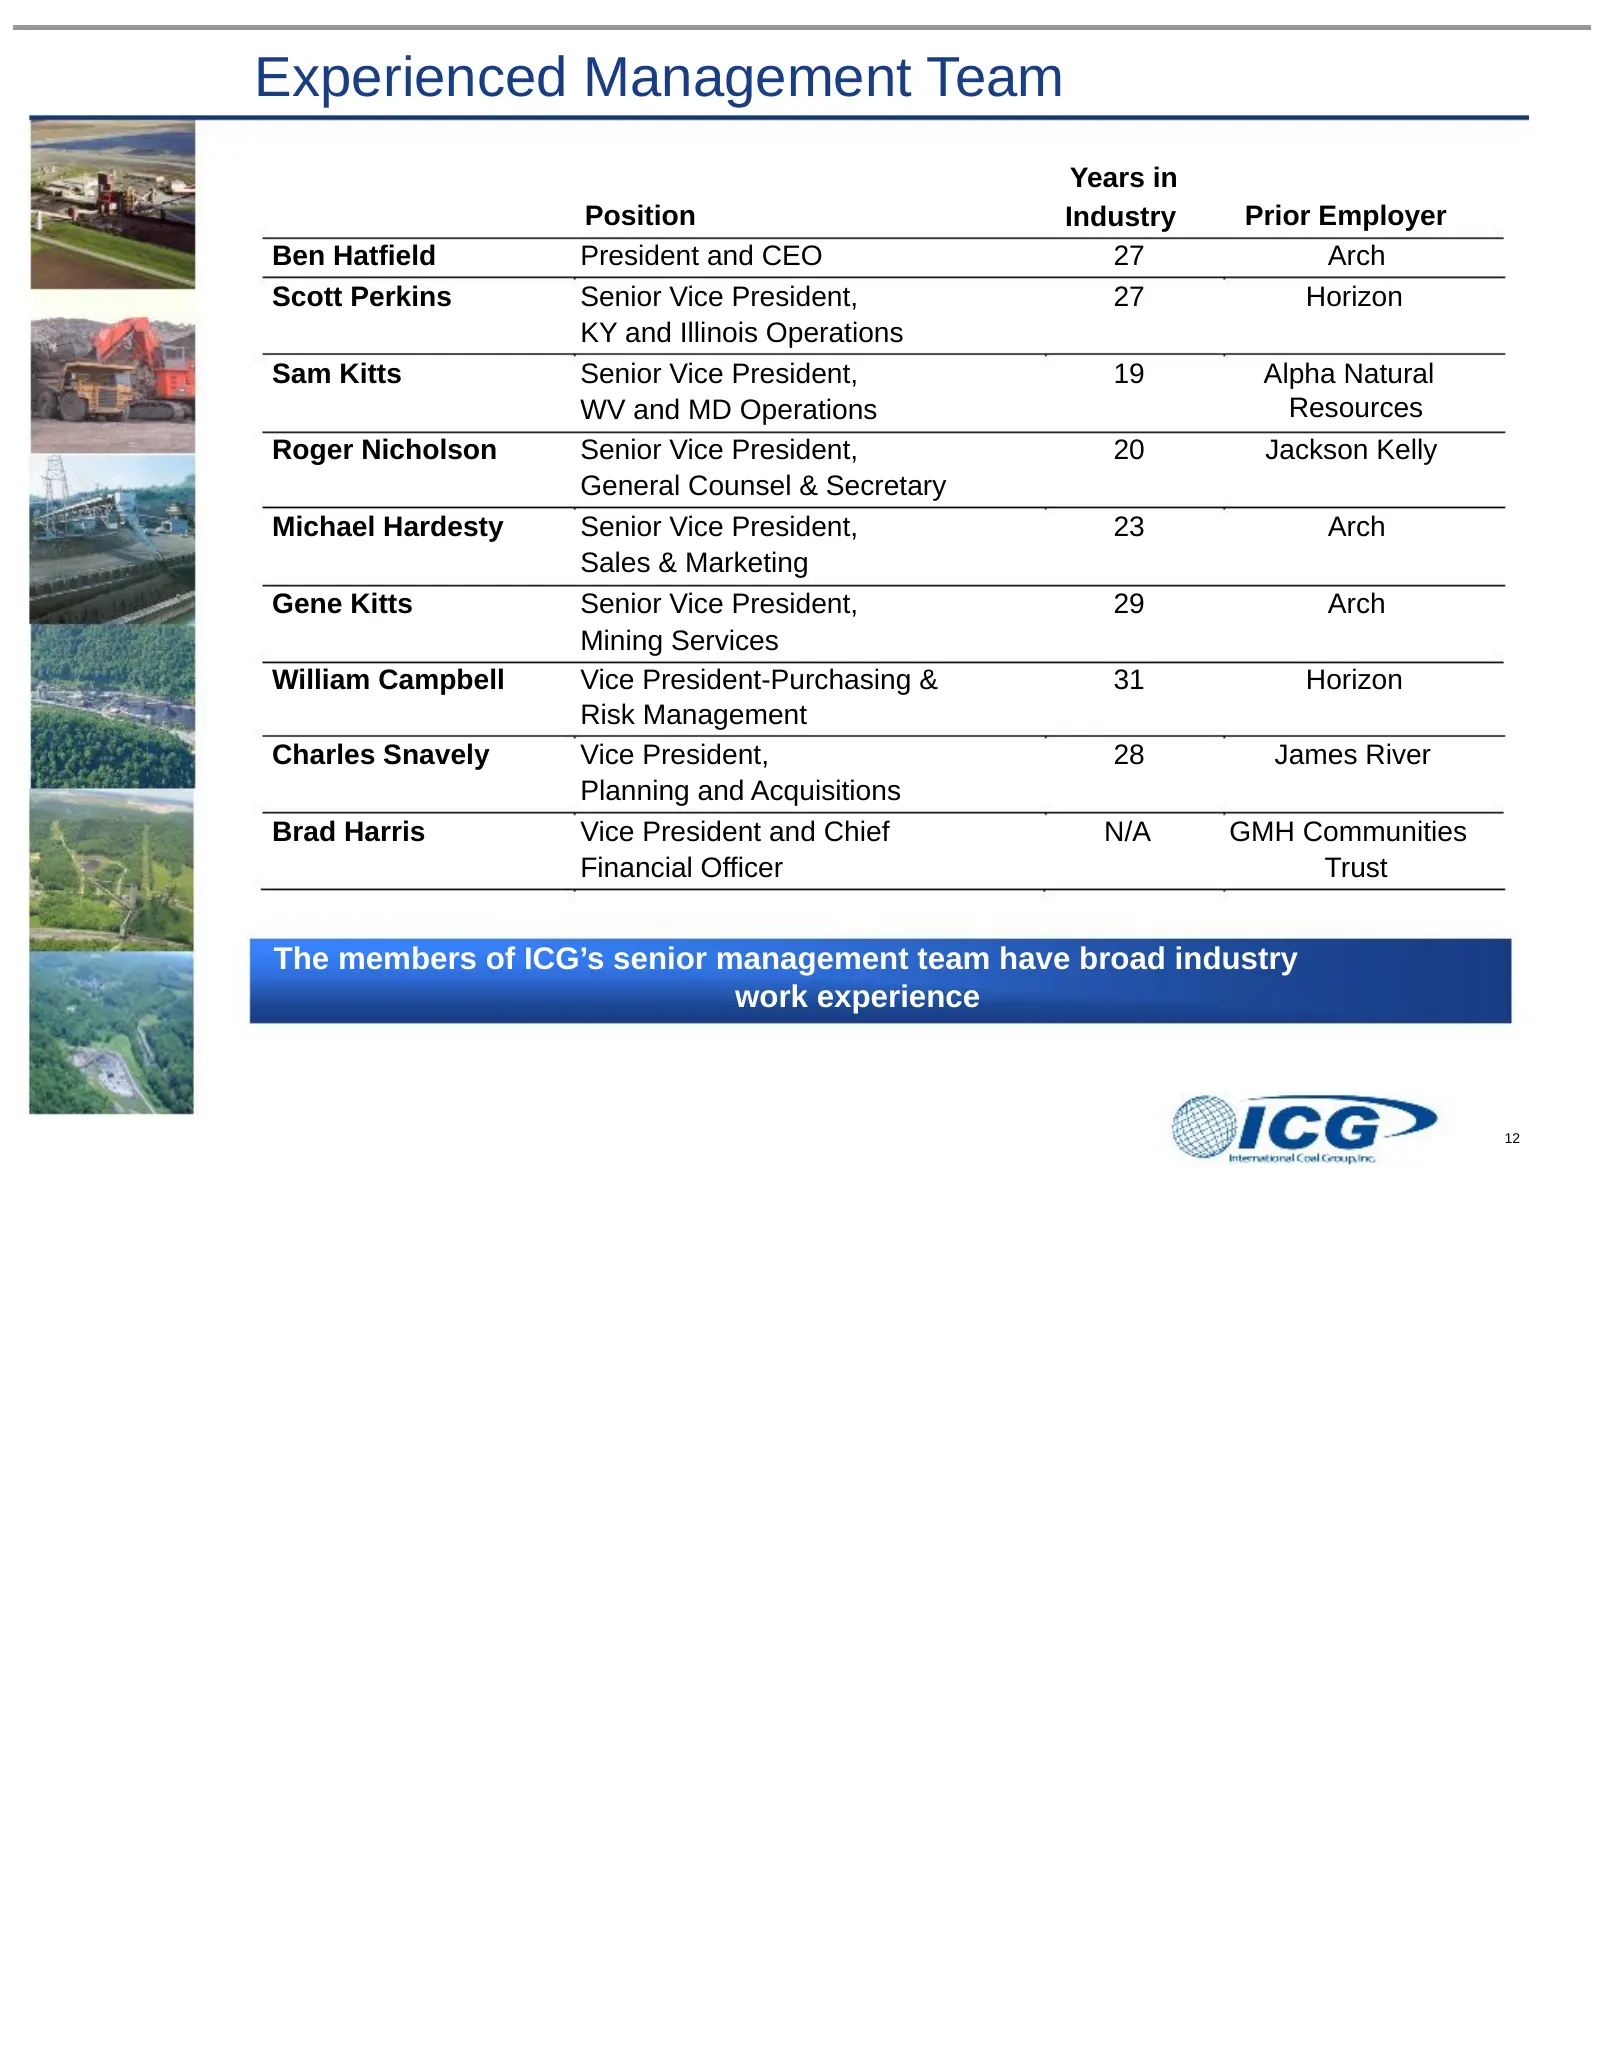
Experienced Management Team Years in Position Industry Prior Employer Ben Hatfield President and CEO 27 Arch Scott Perkins Senior Vice President, 27 Horizon KY and Illinois Operations Sam Kitts Senior Vice President, 19 Alpha Natural WV and MD Operations Resources Roger Nicholson Senior Vice Preside
Slide 14: Long-Term Coal Fundamentals Are Favorable
Long-Term Coal Fundamentals Are Favorable Current market weakness is essentially a short-term correction of the recent supply/demand imbalance - Excess coal supply stems from production growth and mild weather - Broad production cuts now being implemented will take high cost coal off the market - Pr
Slide 15: Outlook For US Coal Industry
Outlook For US Coal Industry Increased consolidation through mergers & acquisitions More disciplined growth pace going forward – Sharp contrast versus the rush to boost output of the past 18-24 months - Increased focus on sales contract commitments pre-investment Appalachian region is expected to ha
Slide 16: Questions & Answers
Questions & Answers 15 _1IcG>
Slide 17: Appendix
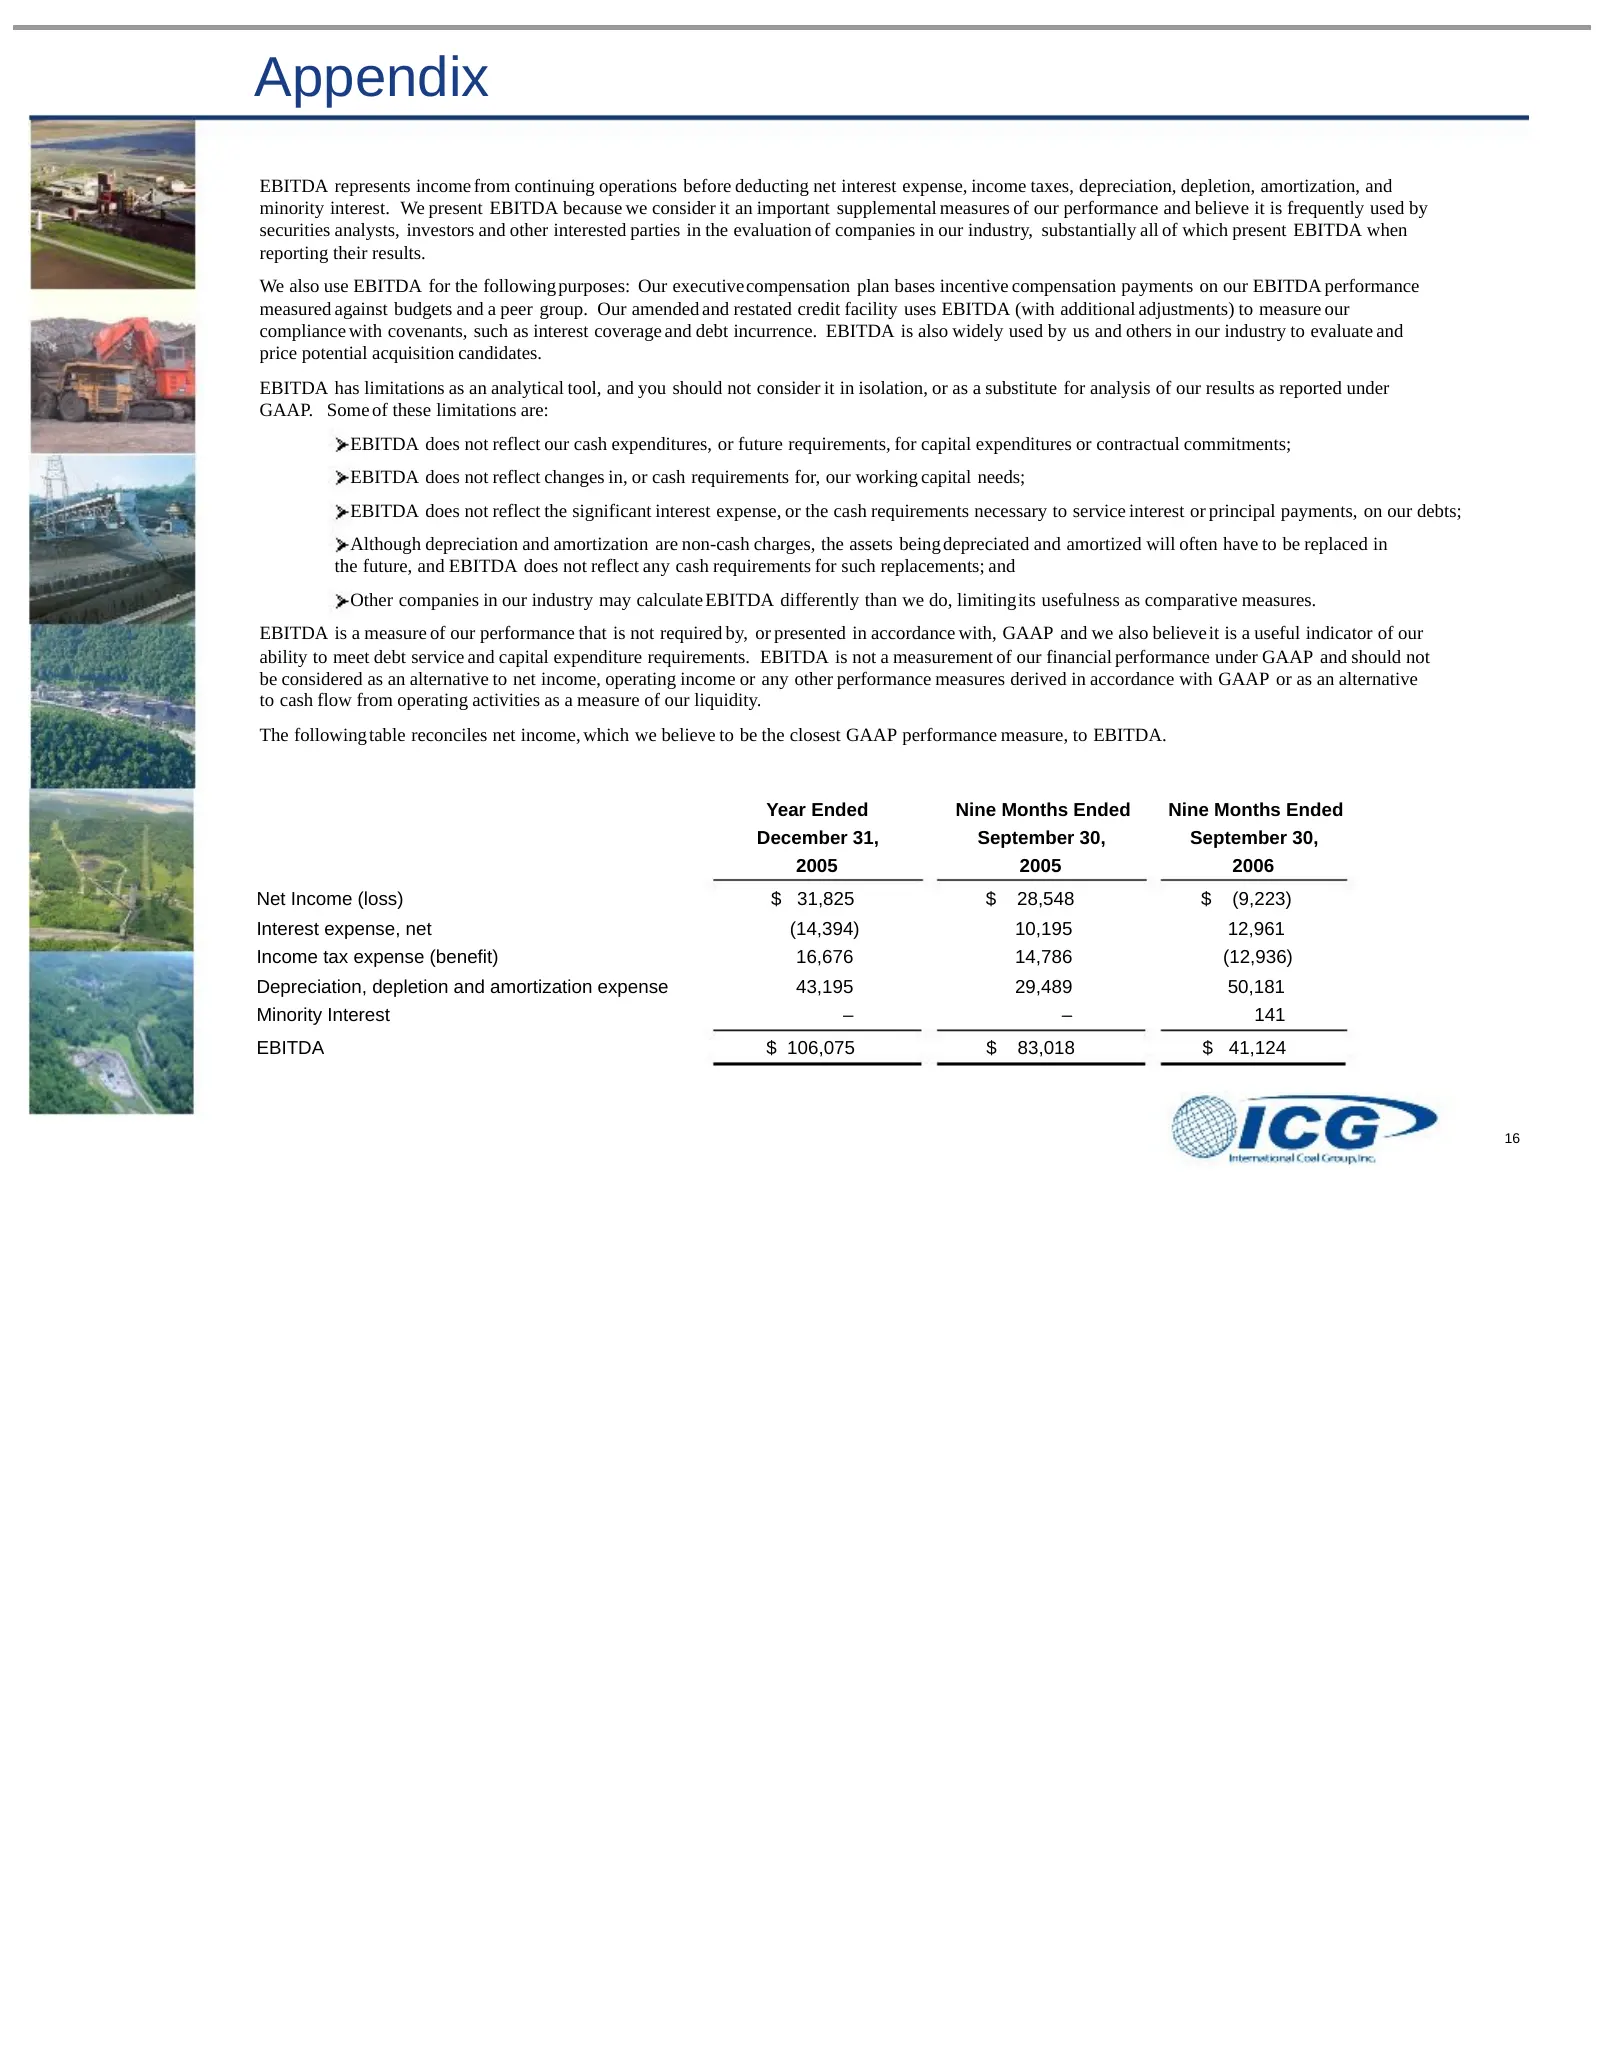
Appendix EBITDA represents income from continuing operations before deducting net interest expense, income taxes, depreciation, depletion, amortization, and minority interest. We present EBITDA because we consider it an important supplemental measures of our performance and believe it is frequently
Source: SEC EDGAR · 8-K filed Nov 28, 2006
More decks from International Coal Group Inc
 Howard Weil Energy Conference 201035 slides · Mar 22, 2010
 Simmons & Company Energy Conference and UBS Energy/Utility Conference 201031 slides · Mar 2, 2010
 UBS Boston Coal Conference 200937 slides · Dec 1, 2009
 Raymond James Coal Investors Conference 200831 slides · Dec 4, 2008
 Davenport Metals & Mining Symposium 200835 slides · Sep 16, 2008
 Howard Weil 36th Annual Energy Conference (April 2008)24 slides · Apr 7, 2008