Massey Energy — Proxy Contest (May 2006)
37 slides from Massey Energy's proxy contest presentation, May 3, 2006
Slide 1: Schedule 14A
UNITED STATES SECURITIES AND EXCHANGE COMMISSION Washington, D.C. 20549 SCHEDULE 14A (Rule 14a-101) INFORMATION REQUIRED IN PROXY STATEMENT SCHEDULE 14A INFORMATION Proxy Statement Pursuant to Section 14(a) of the Securities Exchange Act of 1934 Filed by the Registrant x Filed by a Party other than
Slide 2: Presentation to Institutional Shareholder Services note
The following information was prepared for and presented to Institutional Shareholder Services on May 1, 2006, and may be presented to shareholders, investors and analysts in the future.
Slide 3: Presentation to Institutional Shareholder Services, May 2006
Presentation to Institutional Shareholder Services May 2006 Massey Energy Company
Slide 4: Disclaimer
Disclaimer FORWARD-LOOKING STATEMENTS: Certain statements in this presentation are forward-looking as defined by the Private Securities Litigation Reform Act of 1995. Due to known and unknown risks, the Company’s actualresults may differ materially from its expectations or projections. Factors poten
Slide 5: Table of Contents
Table of Contents SECTION 1 Performance and Business Strategy of the Company 5 SECTION 2 Review of Third Point’s Proposals 19 SECTION 3 Massey’s Director Nominees and Corporate Governance Structure 28 2
Slide 6: Introduction
Introduction William R. Grant Lead Director and Chairman of the Audit Committee Don L. Blankenship Chairman, Chief Executive Officer and President Baxter F. Philips, Jr. Executive Vice President and Chief Administrative Officer 3
Slide 7: Agenda
Agenda Current Business • Strong performance of the Company Strategy is Focused on Building Long-Term • Emphasis on creating long-term, lasting shareholder Value for Shareholders value • Background to the proxy contest Company is • Review of shareholder proposals Responsive to • Action taken Shareho
Slide 8: Performance and Business Strategy of the Company
SECTION 1 Performance and Business Strategy of the Company 5
Slide 9: Massey Snapshot
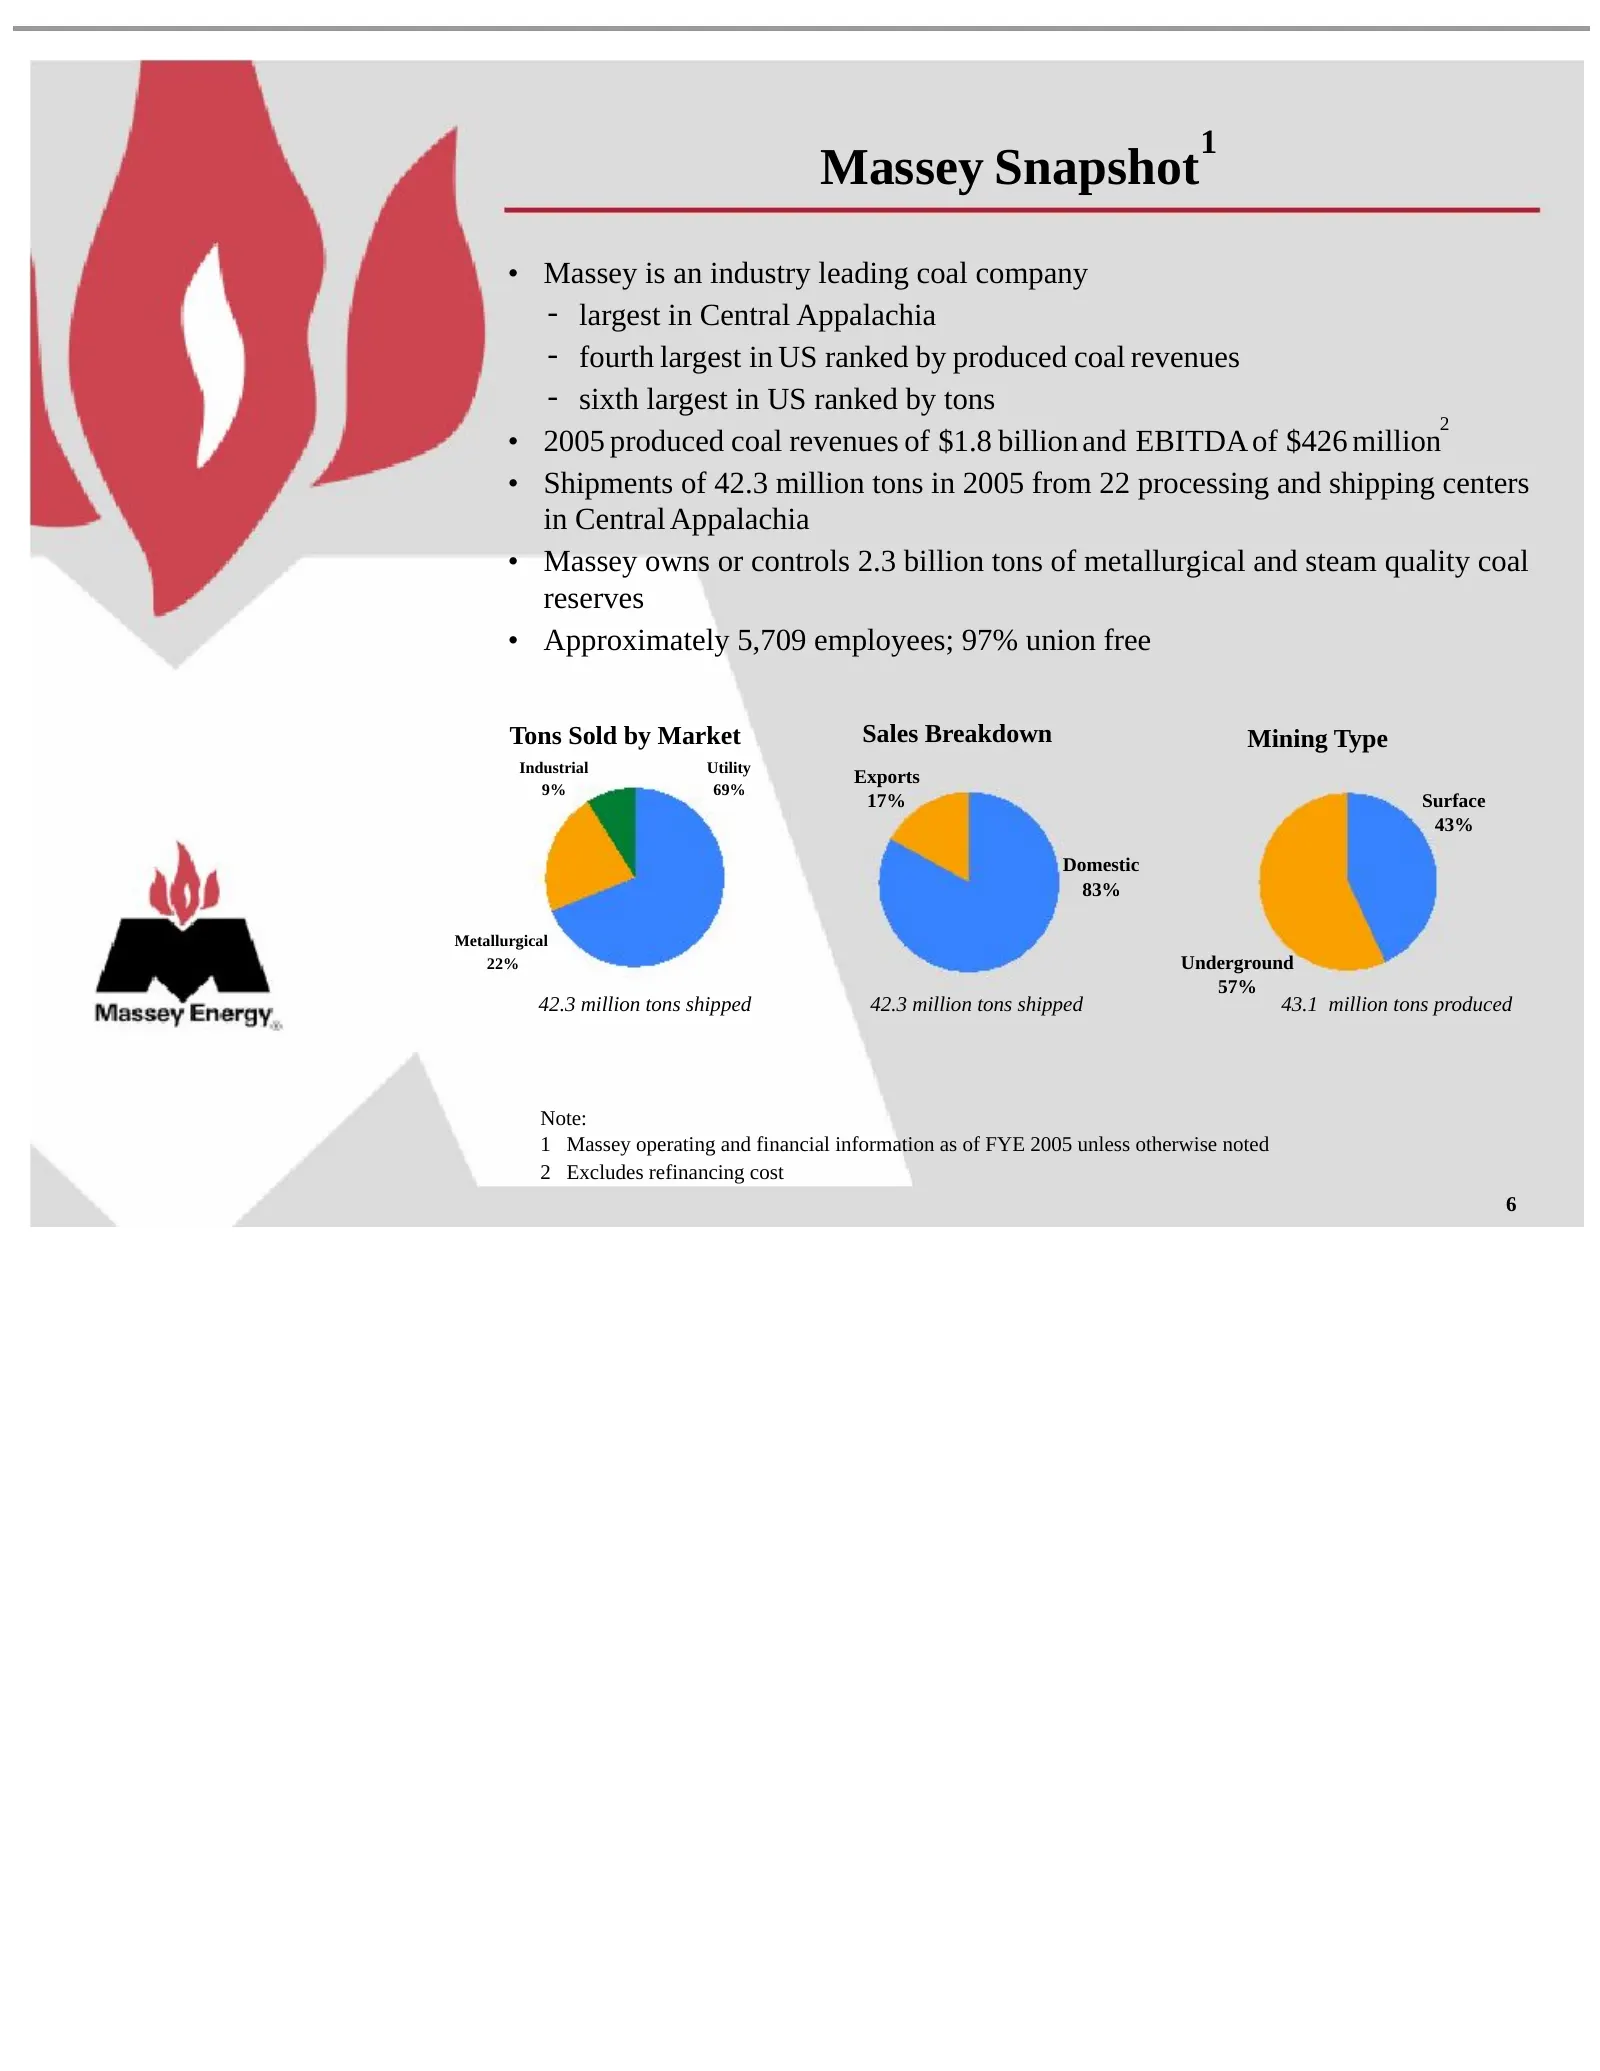
1 Massey Snapshot • Massey is an industry leading coal company - largest in Central Appalachia - fourth largest in US ranked by produced coal revenues - sixth largest in US ranked by tons 2 • 2005 produced coal revenues of $1.8 billion and EBITDA of $426 million • Shipments of 42.3 million tons in 2
Slide 10: Coal Fundamentals and Demand
Coal Fundamentals and Demand • Internationally, coal represents approximately 24.4% of primary energy consumption, according to the World Coal Institute • In the United States in 2005, Platts estimates that coal generated approximately 52% of the electricity produced • Most abundant fossil fuel—coal
Slide 11: Investment Highlights
Investment Highlights • Leading coal producer in Central Appalachia • Poised to benefit from improved industry fundamentals – Large, high quality, diverse reserve base – Modern equipment fleet – Extensive infrastructure and transportation system – Low level of long-term liabilities compared to peers
Slide 12: Demonstrated Ability to Grow Through Strategic Reserve Acquisitions
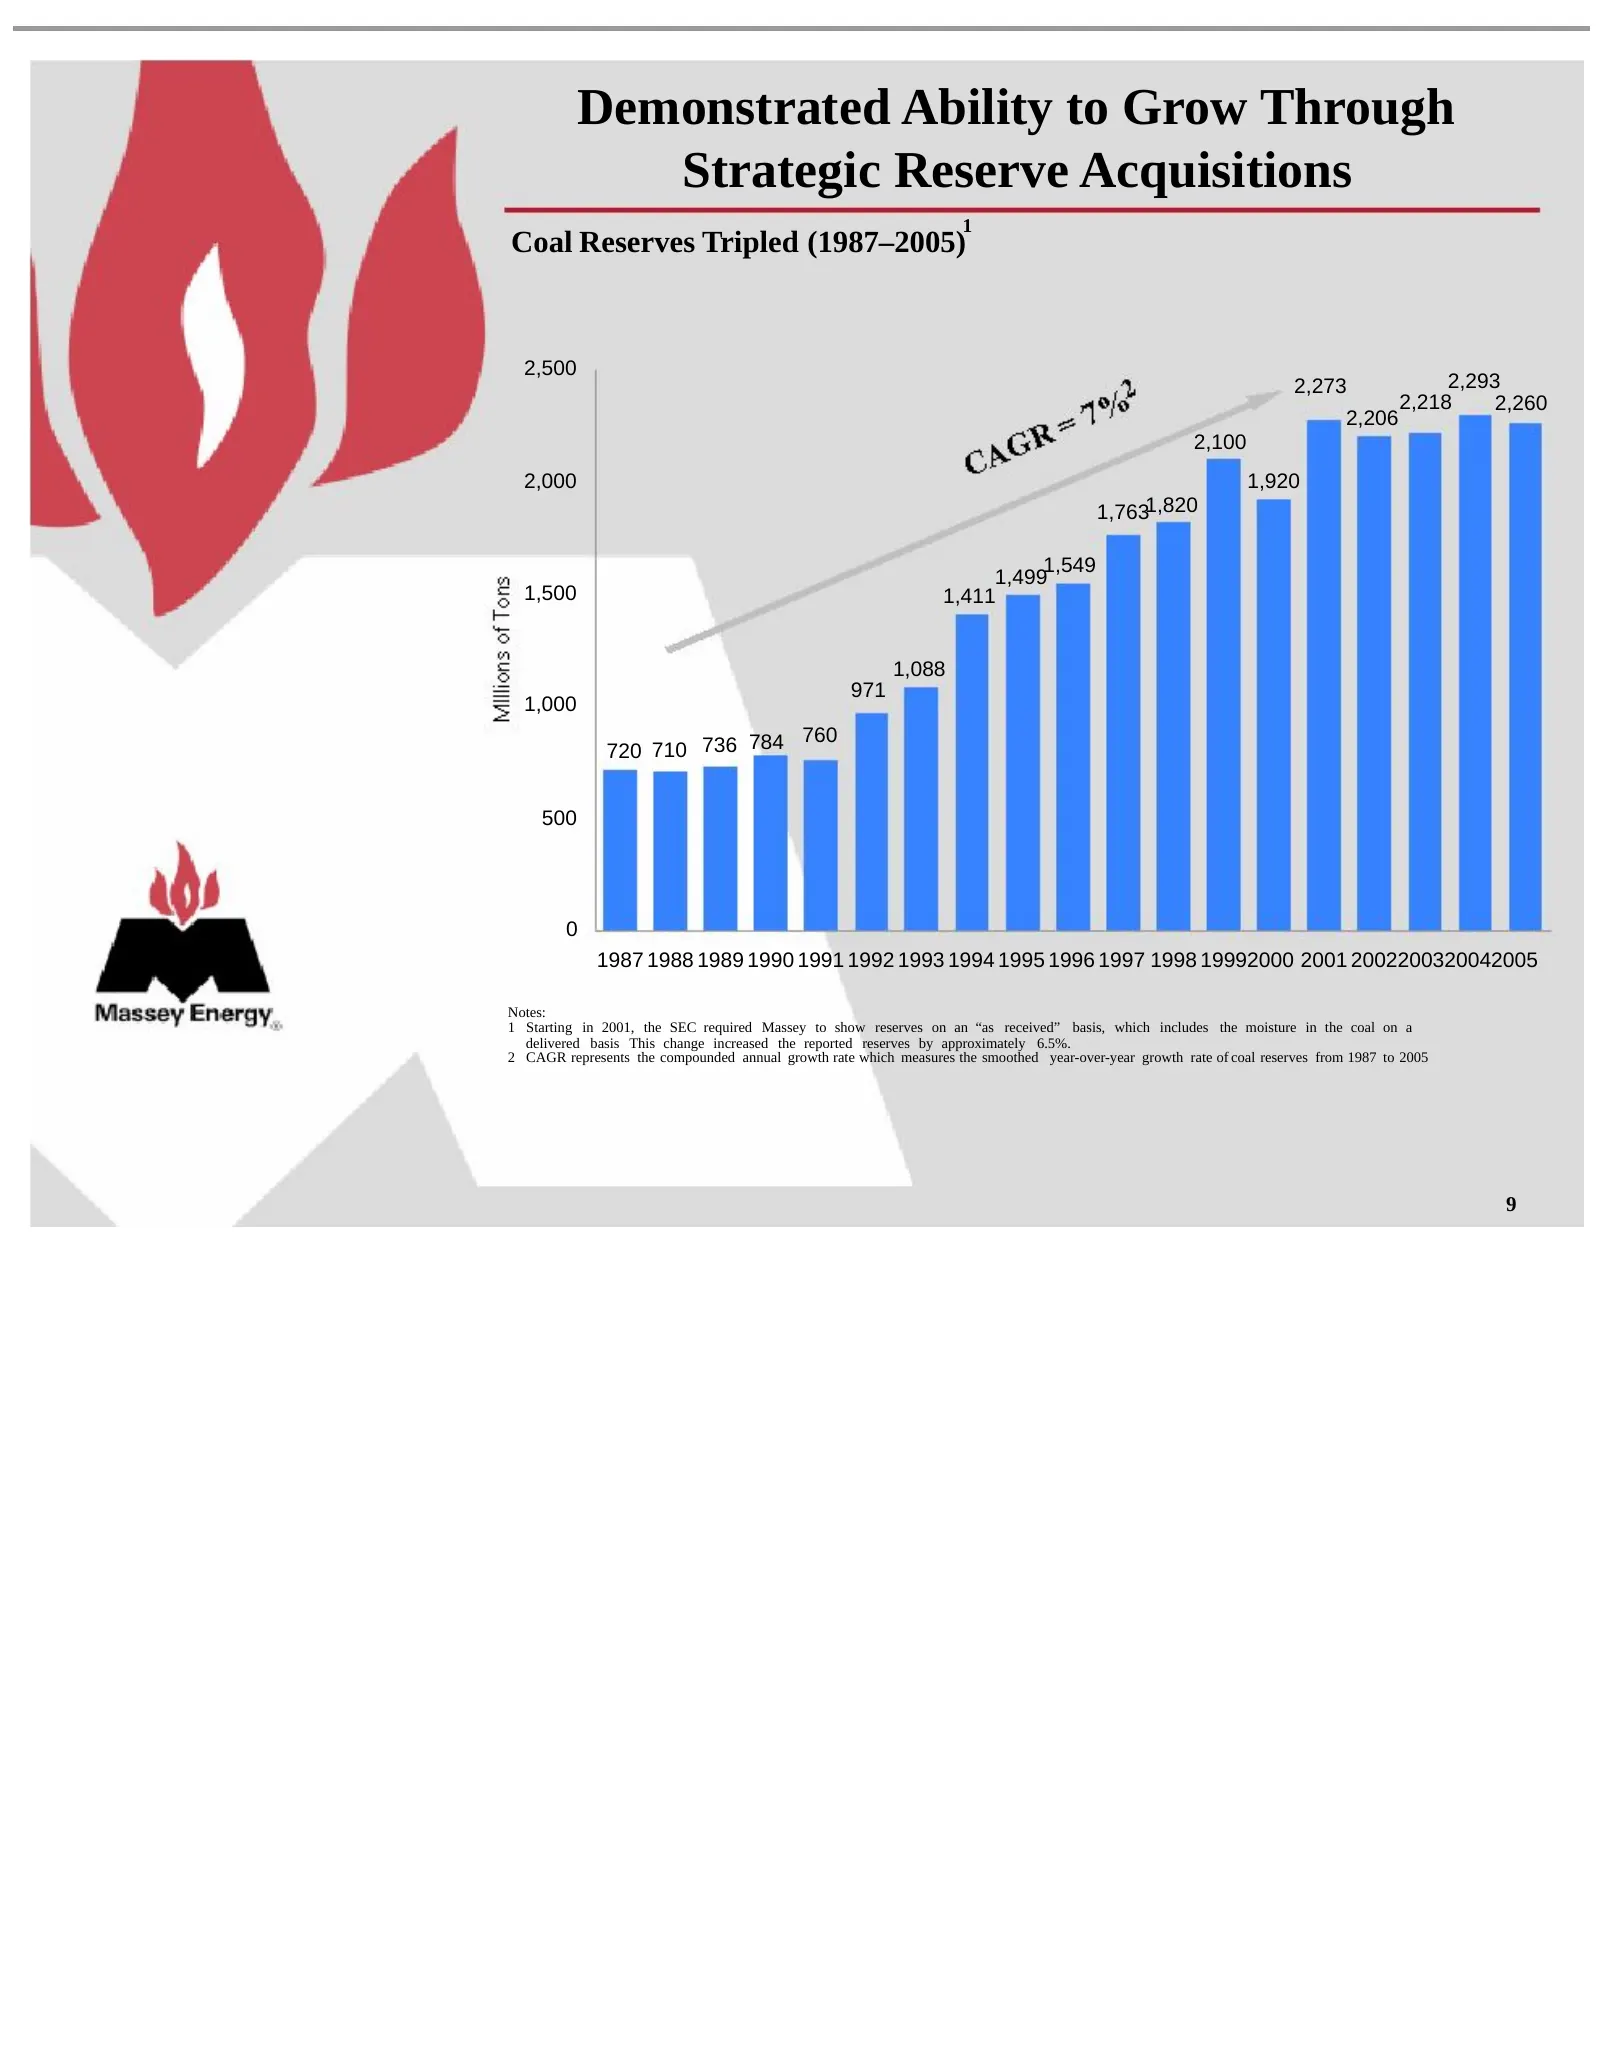
Demonstrated Ability to Grow Through Strategic Reserve Acquisitions 1 Coal Reserves Tripled (1987–2005) 2,500 2,273 2,293 2,218 2,260 2,206 2,100 2,000 1,920 1,7631,820 1,549 1,499 1,500 1,411 1,088 971 1,000 760 720 710 736 784 500 0 1987 1988 1989 1990 1991 1992 1993 1994 1995 1996 1997 1998 19992
Slide 13: Production Has Tracked Reserve Growth
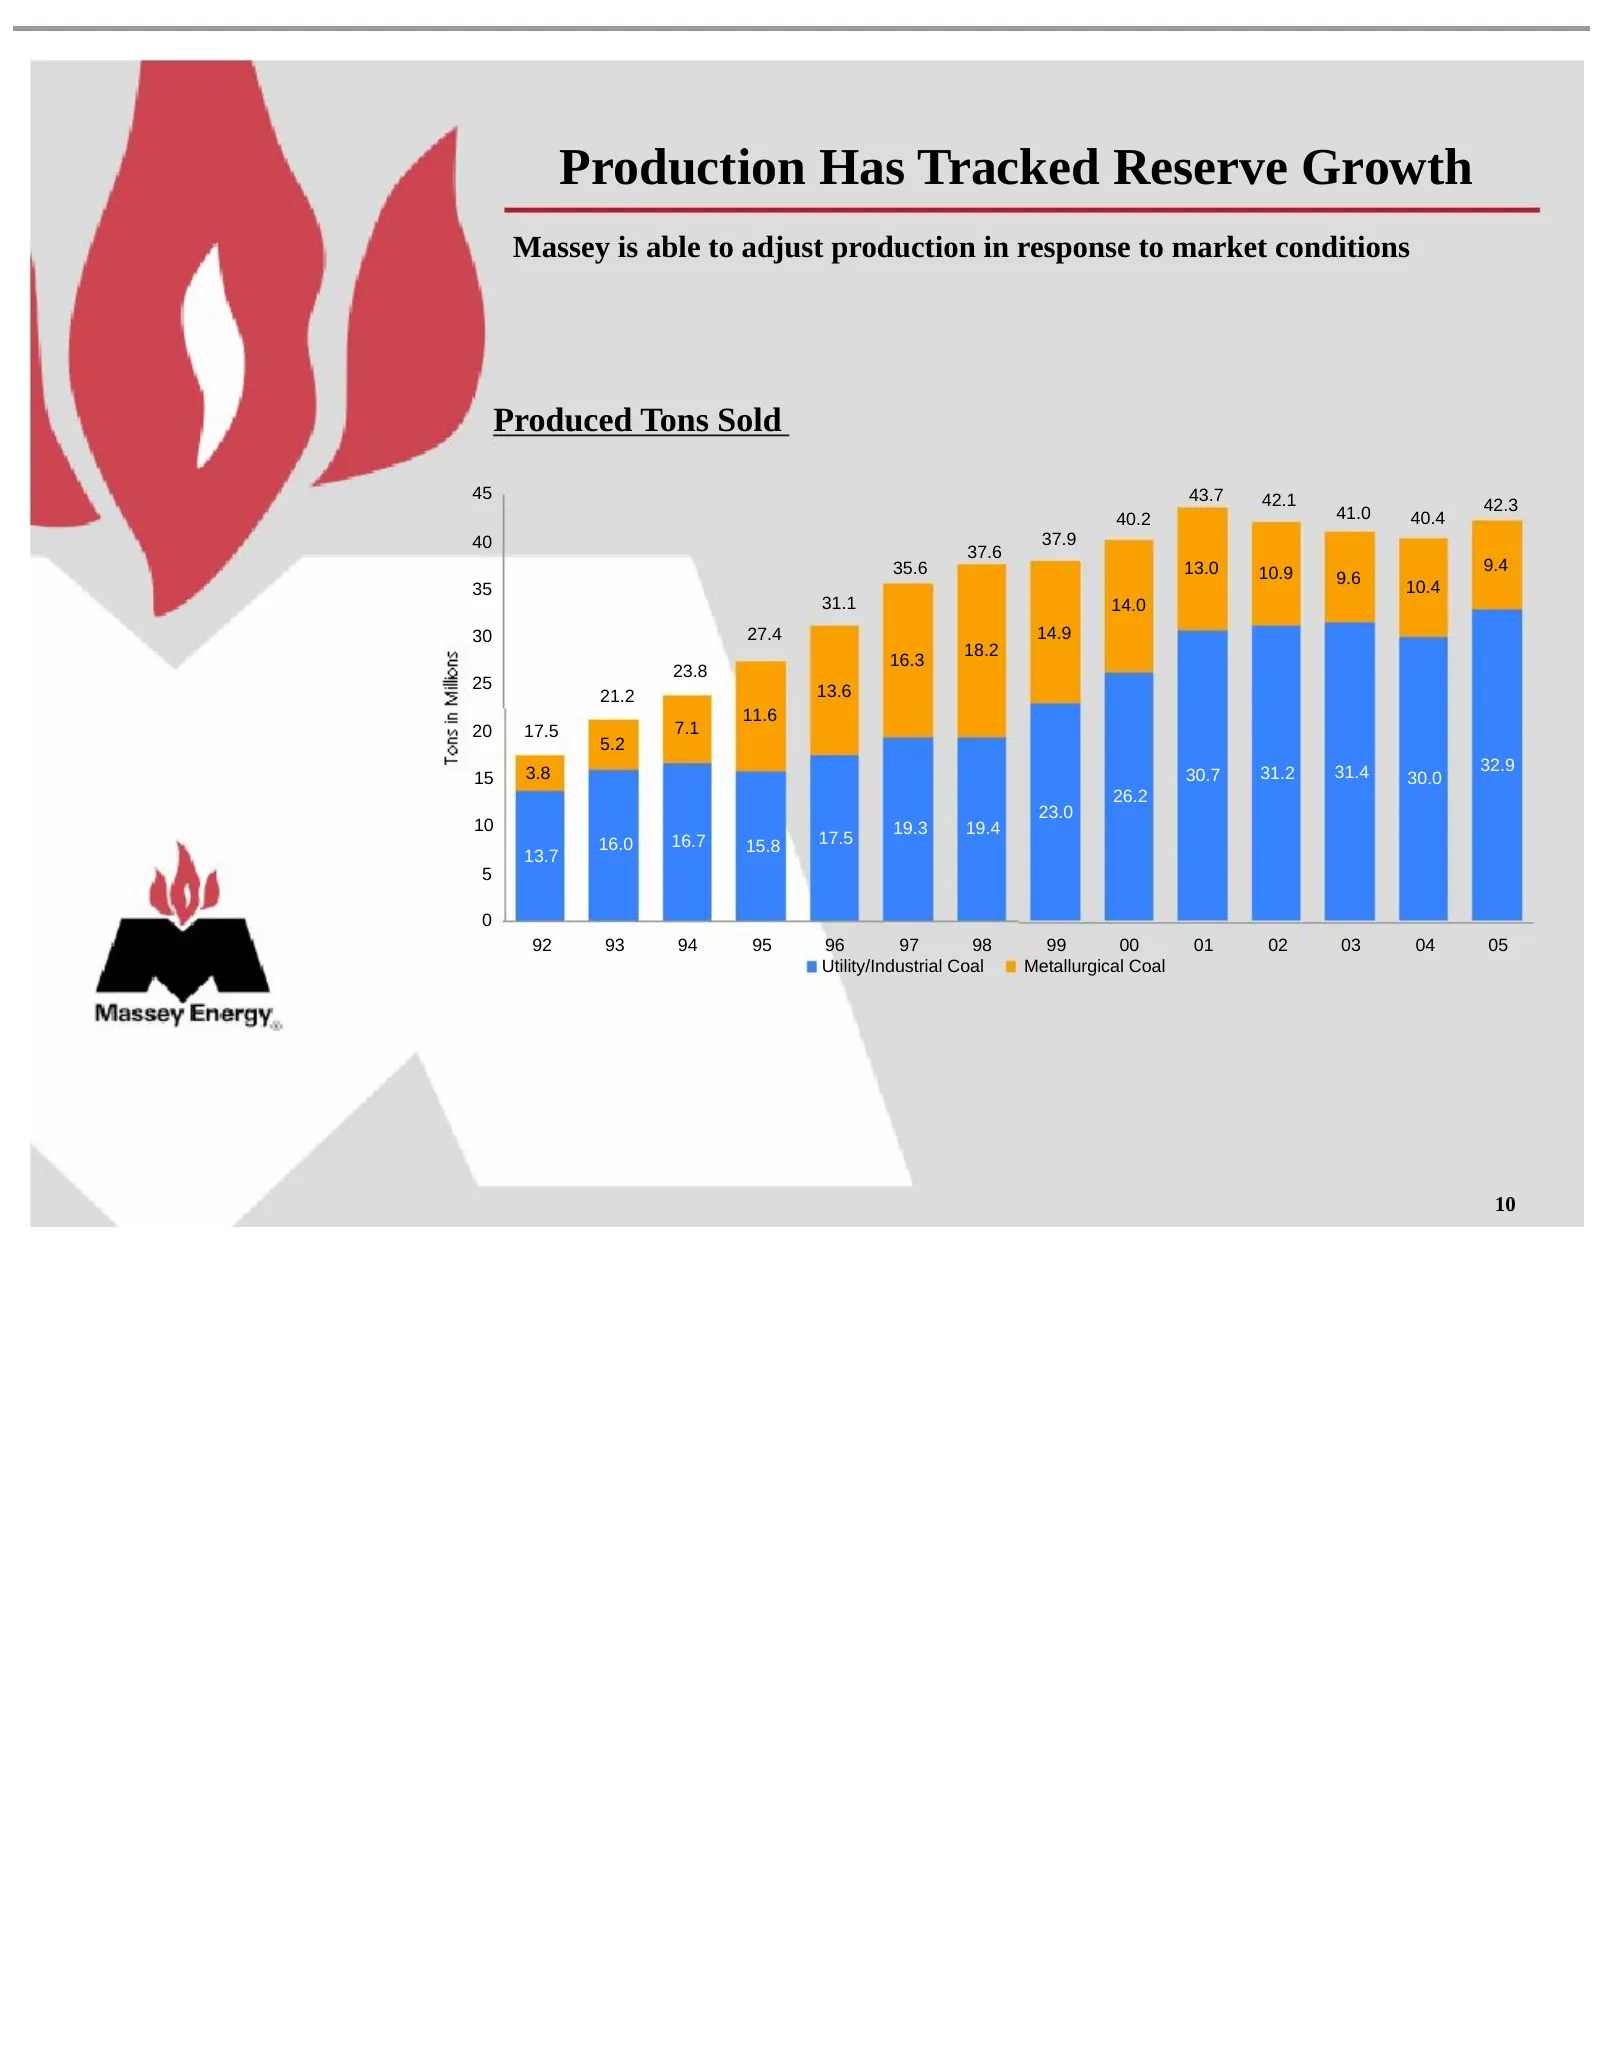
Production Has Tracked Reserve Growth Massey is able to adjust production in response to market conditions Produced Tons Sold 45 43.7 42.1 41.0 42.3 40.2 40.4 40 37.9 37.6 35.6 13.0 10.9 9.4 9.6 35 10.4 31.1 14.0 30 27.4 14.9 18.2 16.3 23.8 25 13.6 21.2 11.6 20 17.5 7.1 5.2 3.8 31.2 31.4 32.9 15 30.
Slide 14: Reserve Life Supporting Future Growth
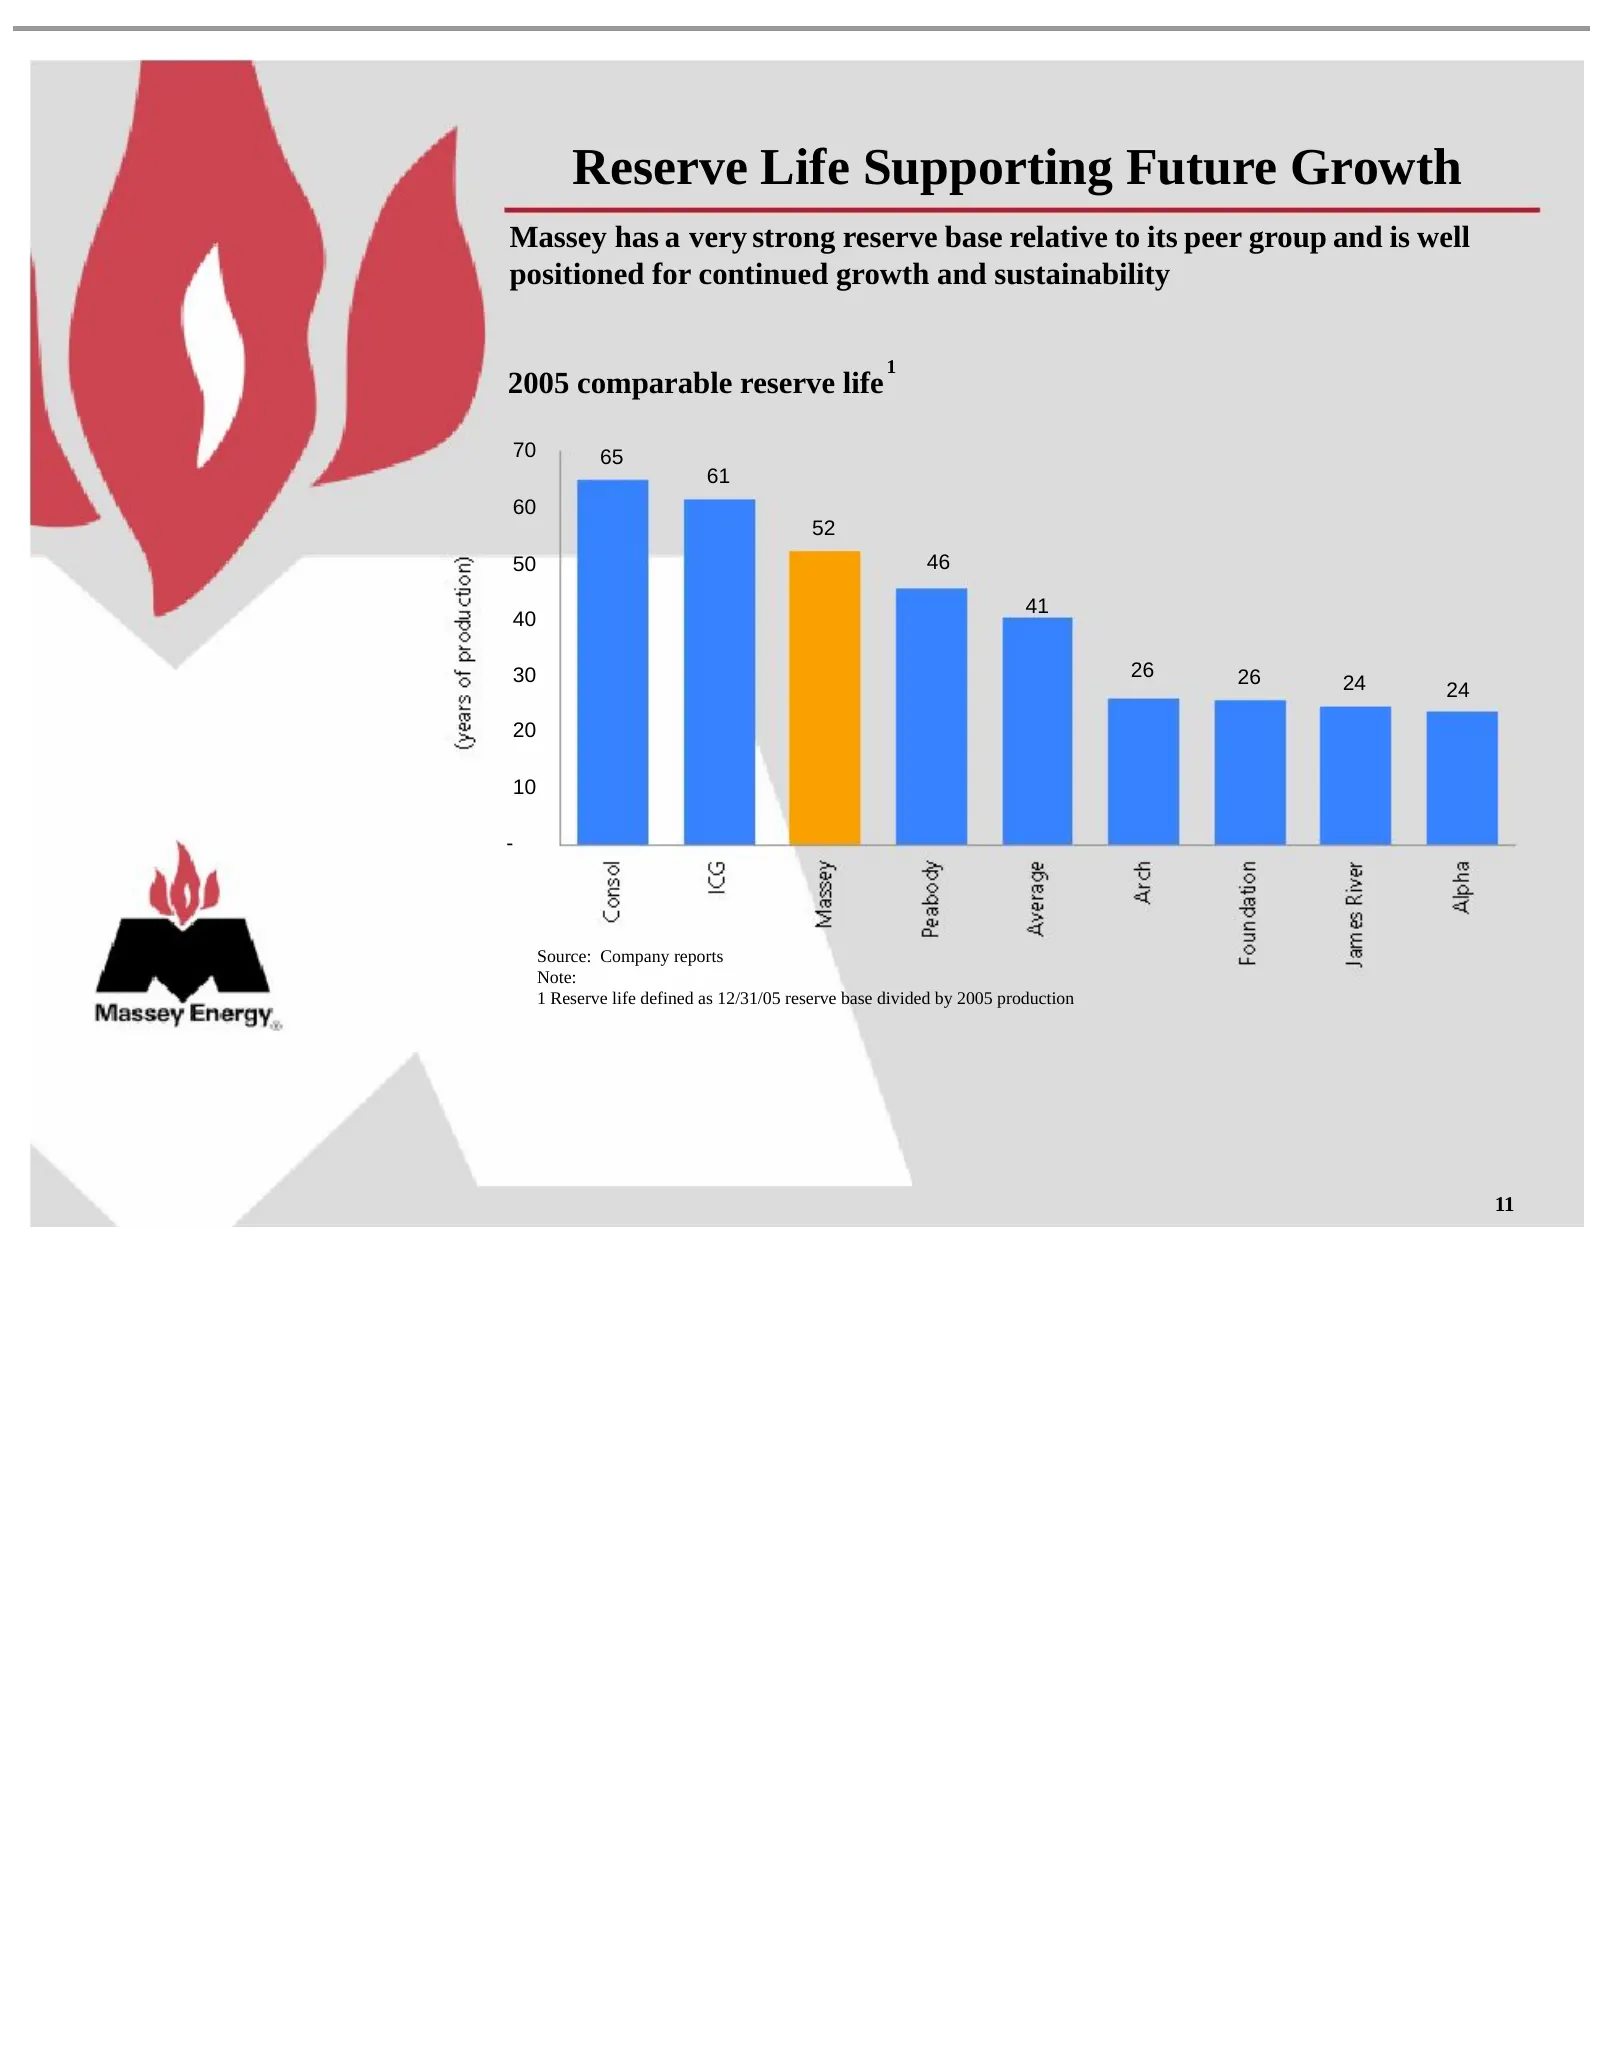
Reserve Life Supporting Future Growth Massey has a very strong reserve base relative to its peer group and is well positioned for continued growth and sustainability 1 2005 comparable reserve life 70 65 61 60 52 50 46 41 40 30 26 26 24 24 20 10 - Source: Company reports Note: 1 Reserve life defined
Slide 15: Coal Sector Challenges
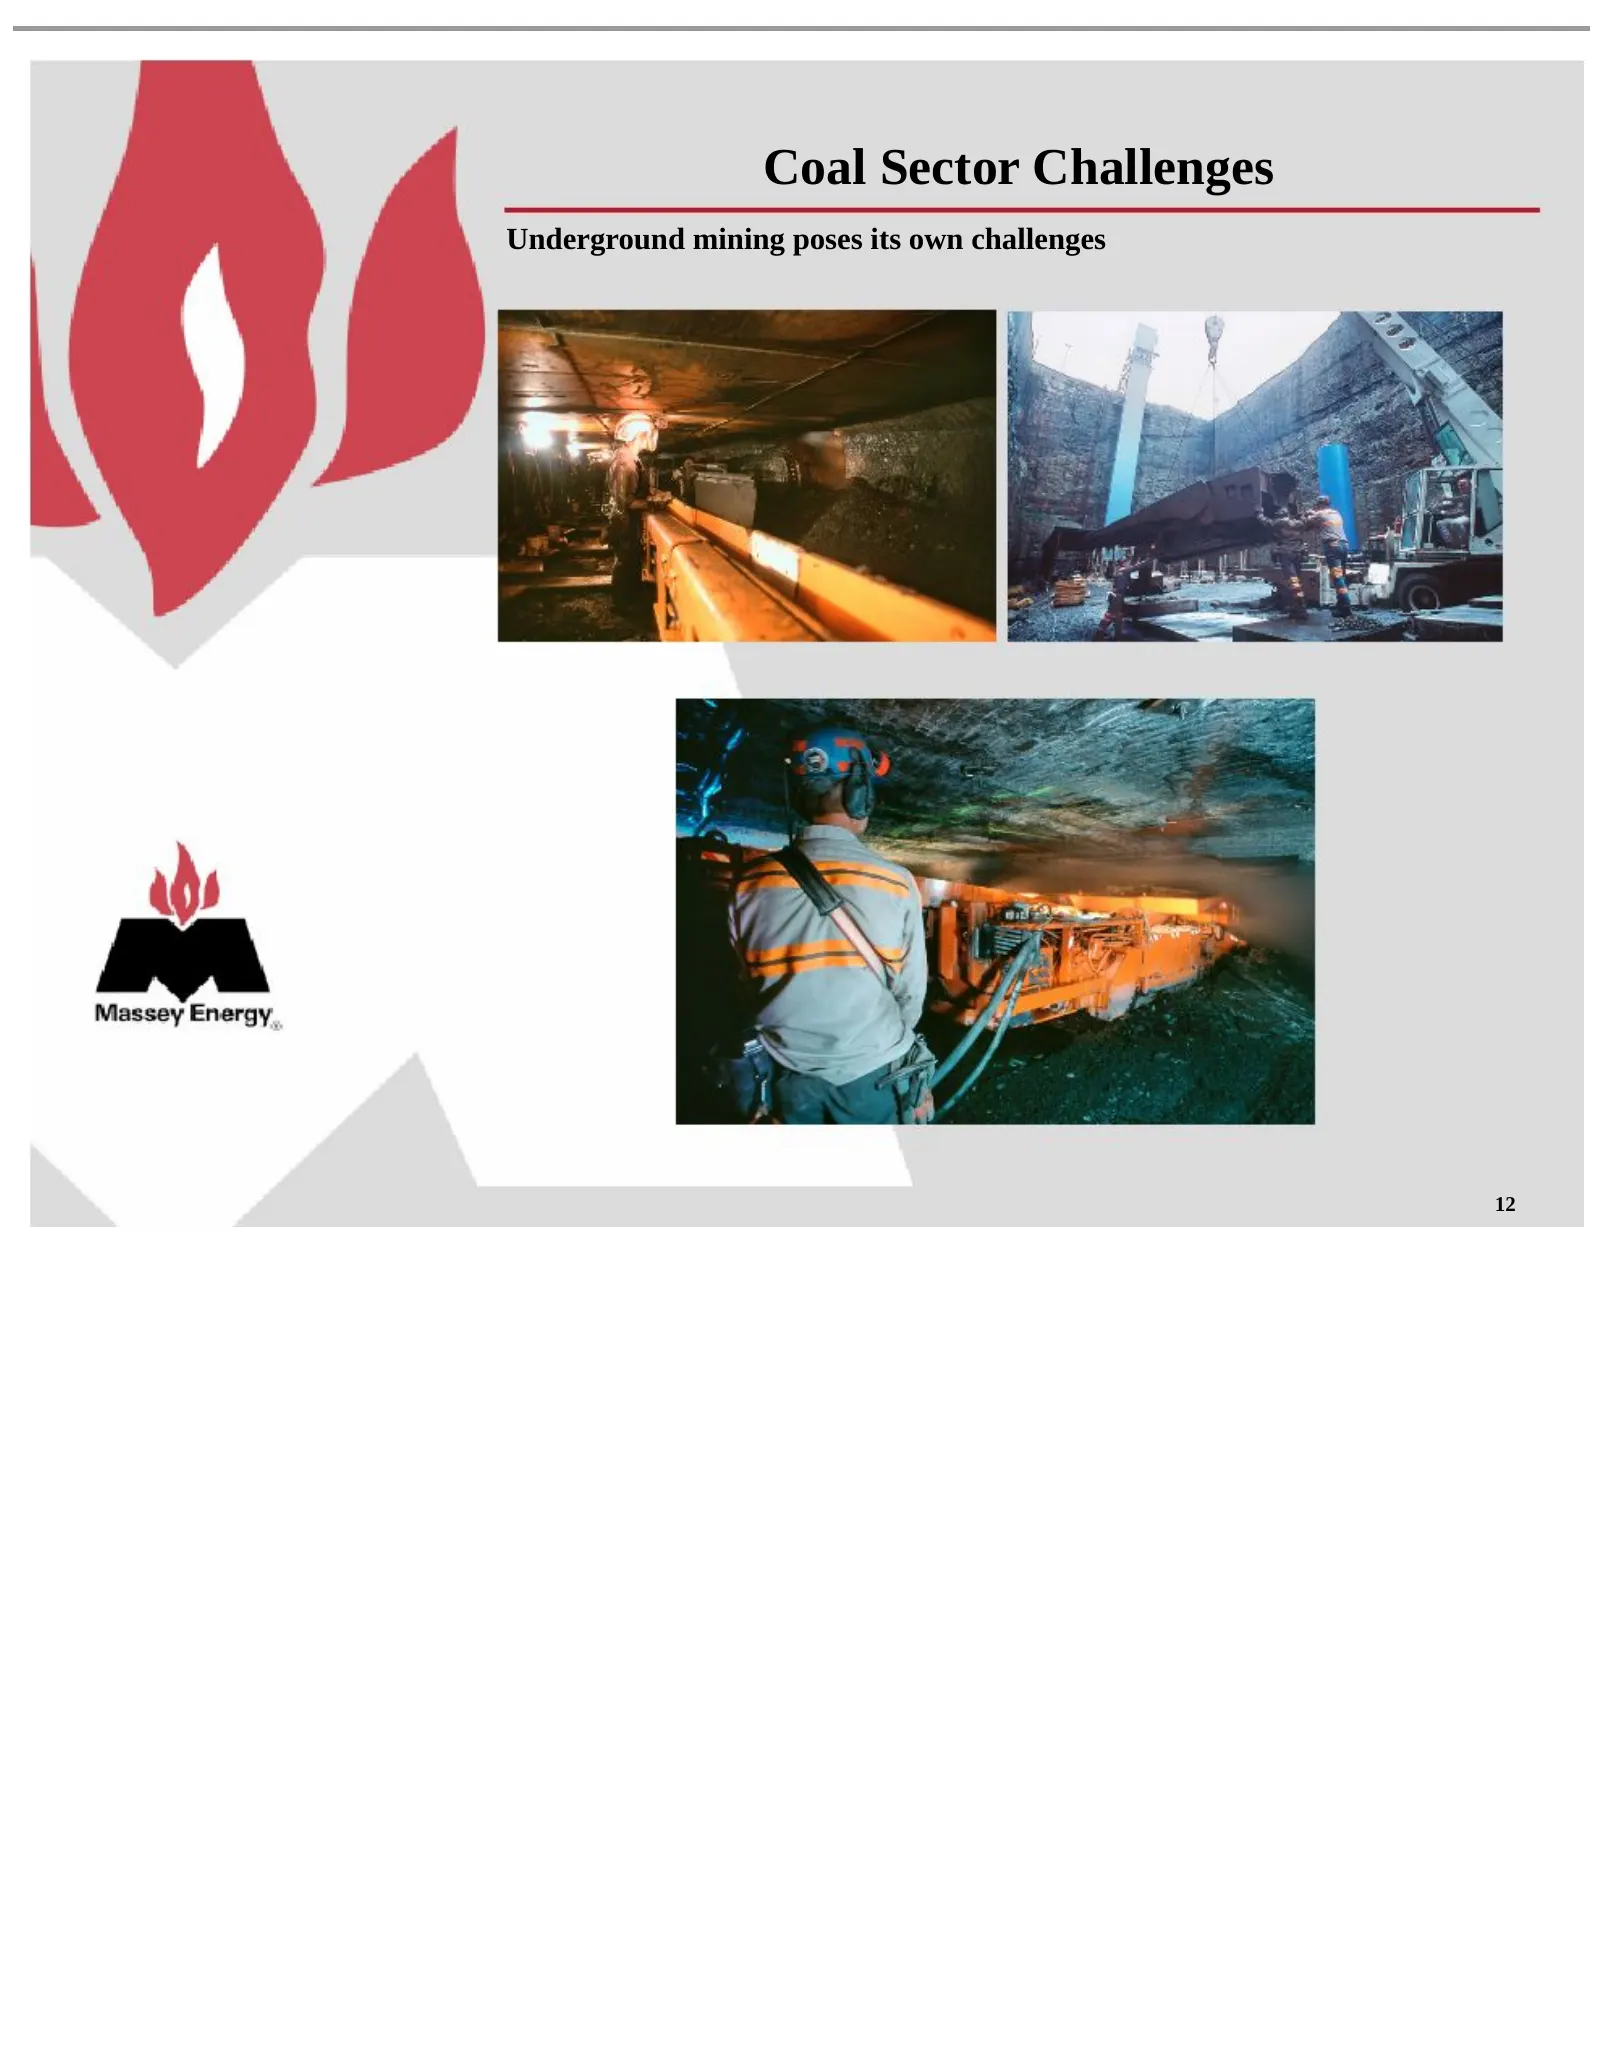
Coal Sector Challenges Underground mining poses its own challenges 12
Slide 16: Proven Ability to Maintain Margin
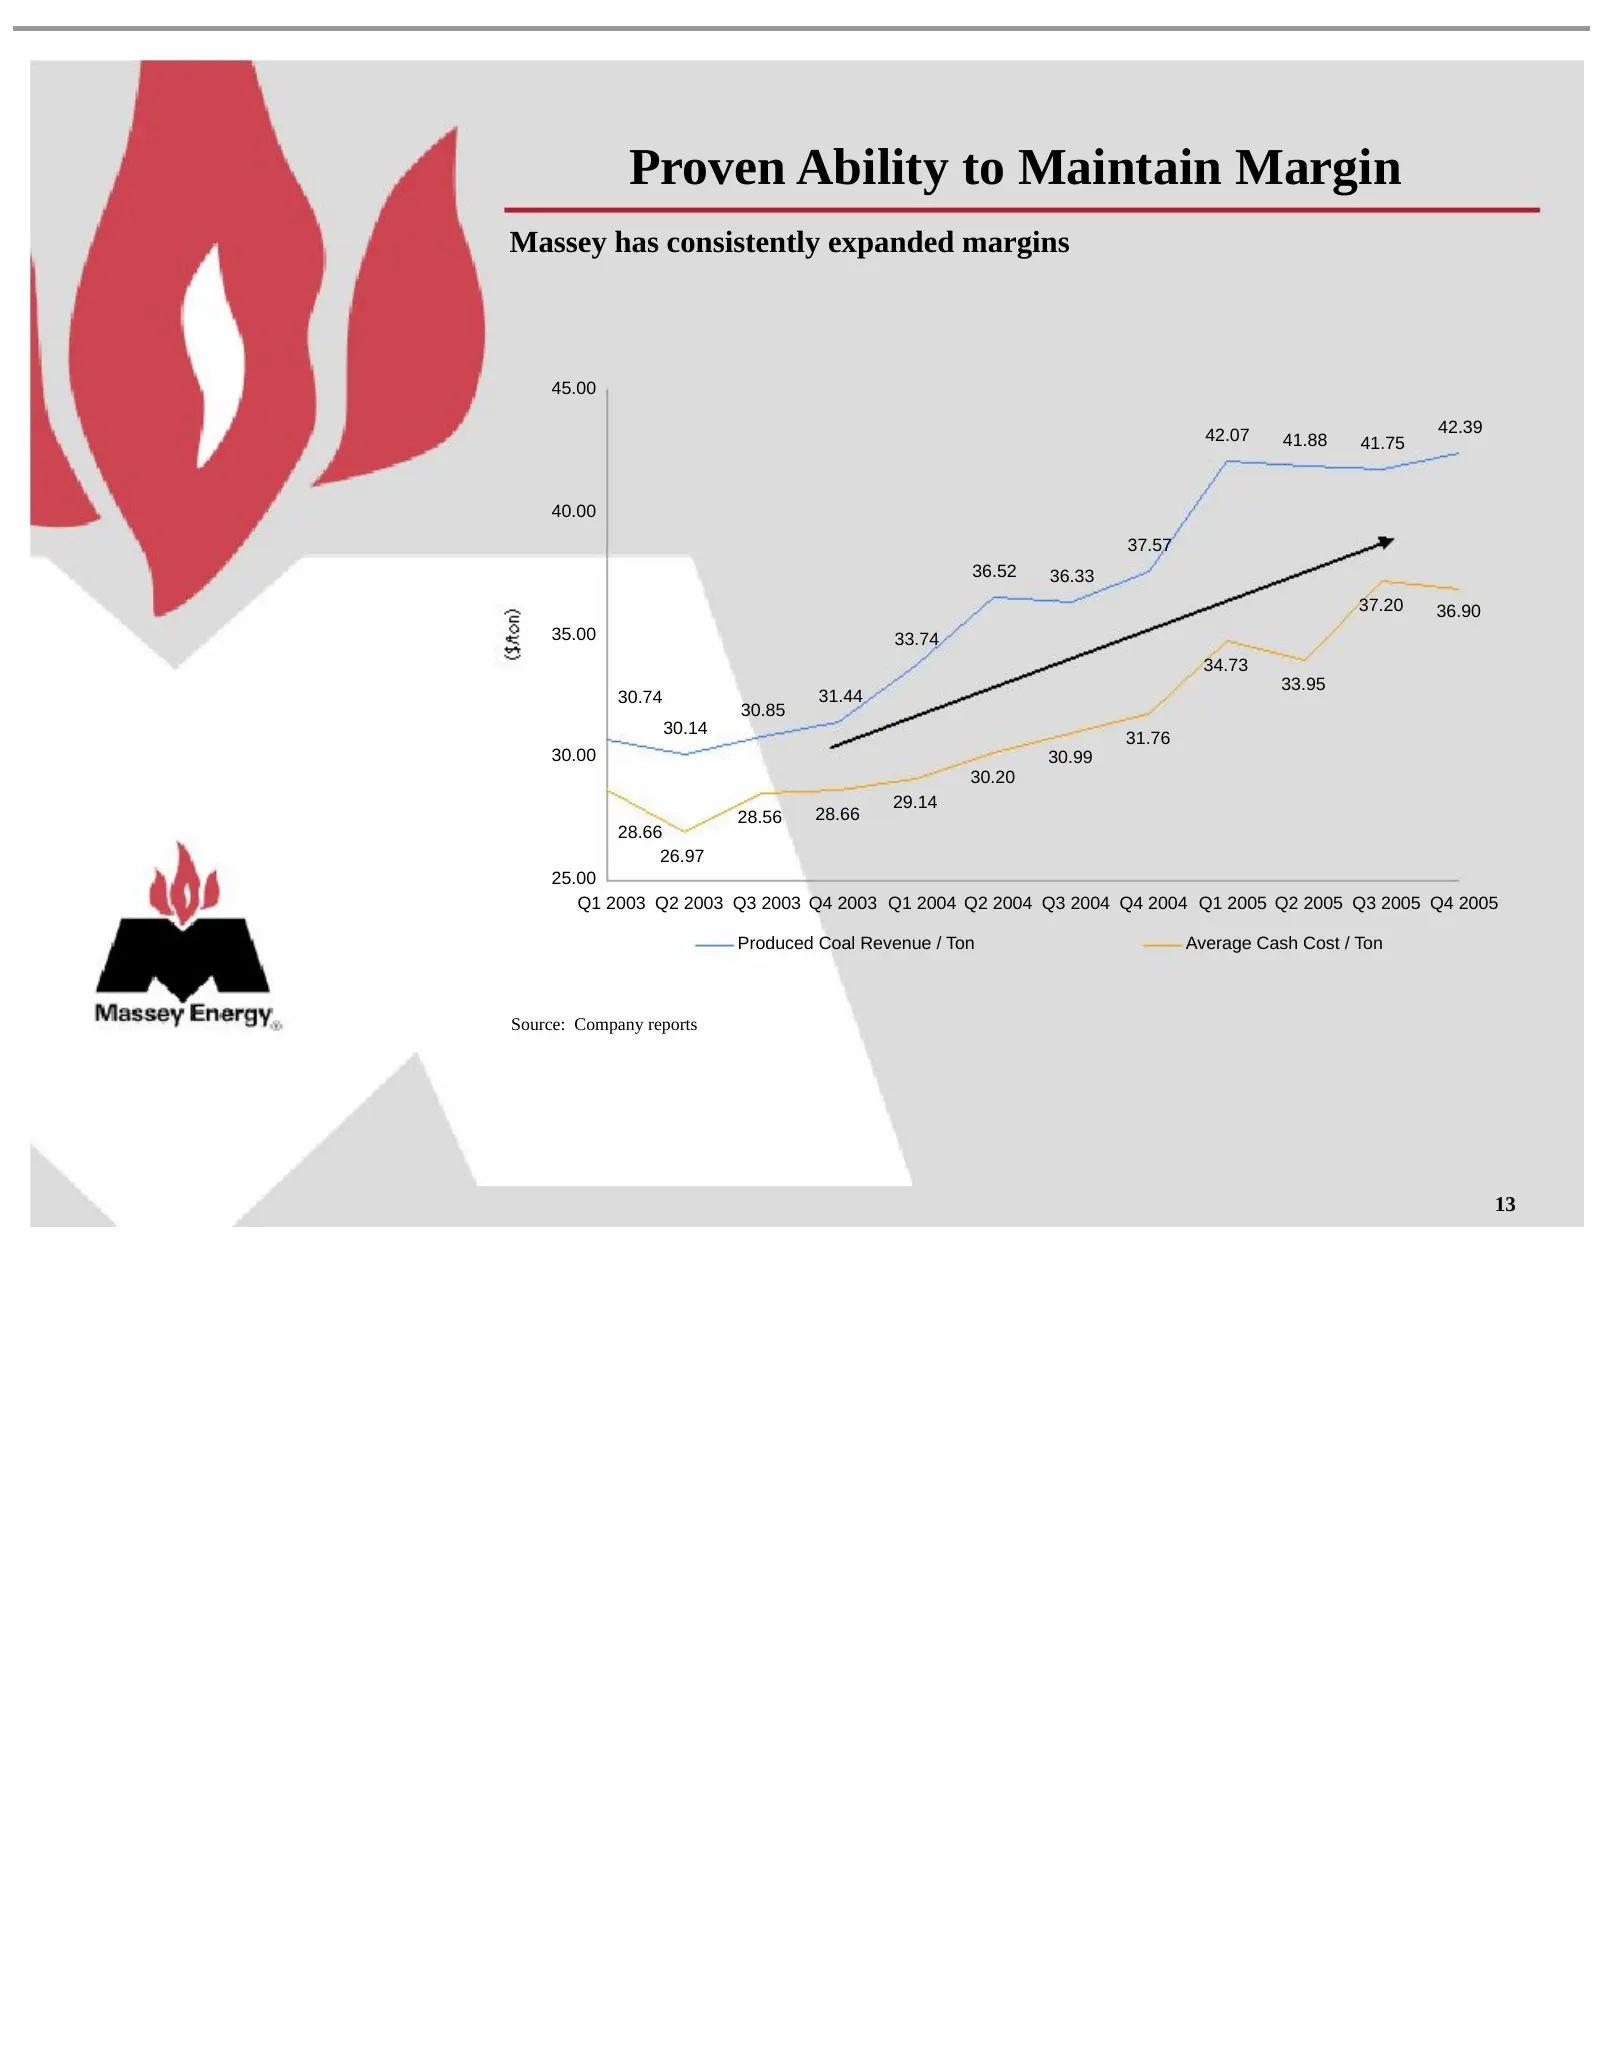
Proven Ability to Maintain Margin Massey has consistently expanded margins 45.00 42.07 42.39 41.88 41.75 40.00 37.57 36.52 36.33 37.20 36.90 35.00 33.74 34.73 33.95 30.74 31.44 30.85 30.14 31.76 30.00 30.99 30.20 29.14 28.56 28.66 28.66 26.97 25.00 Q1 2003 Q2 2003 Q3 2003 Q4 2003 Q1 2004 Q2 2004 Q3
Slide 17: Proven Ability to Grow EBITDA
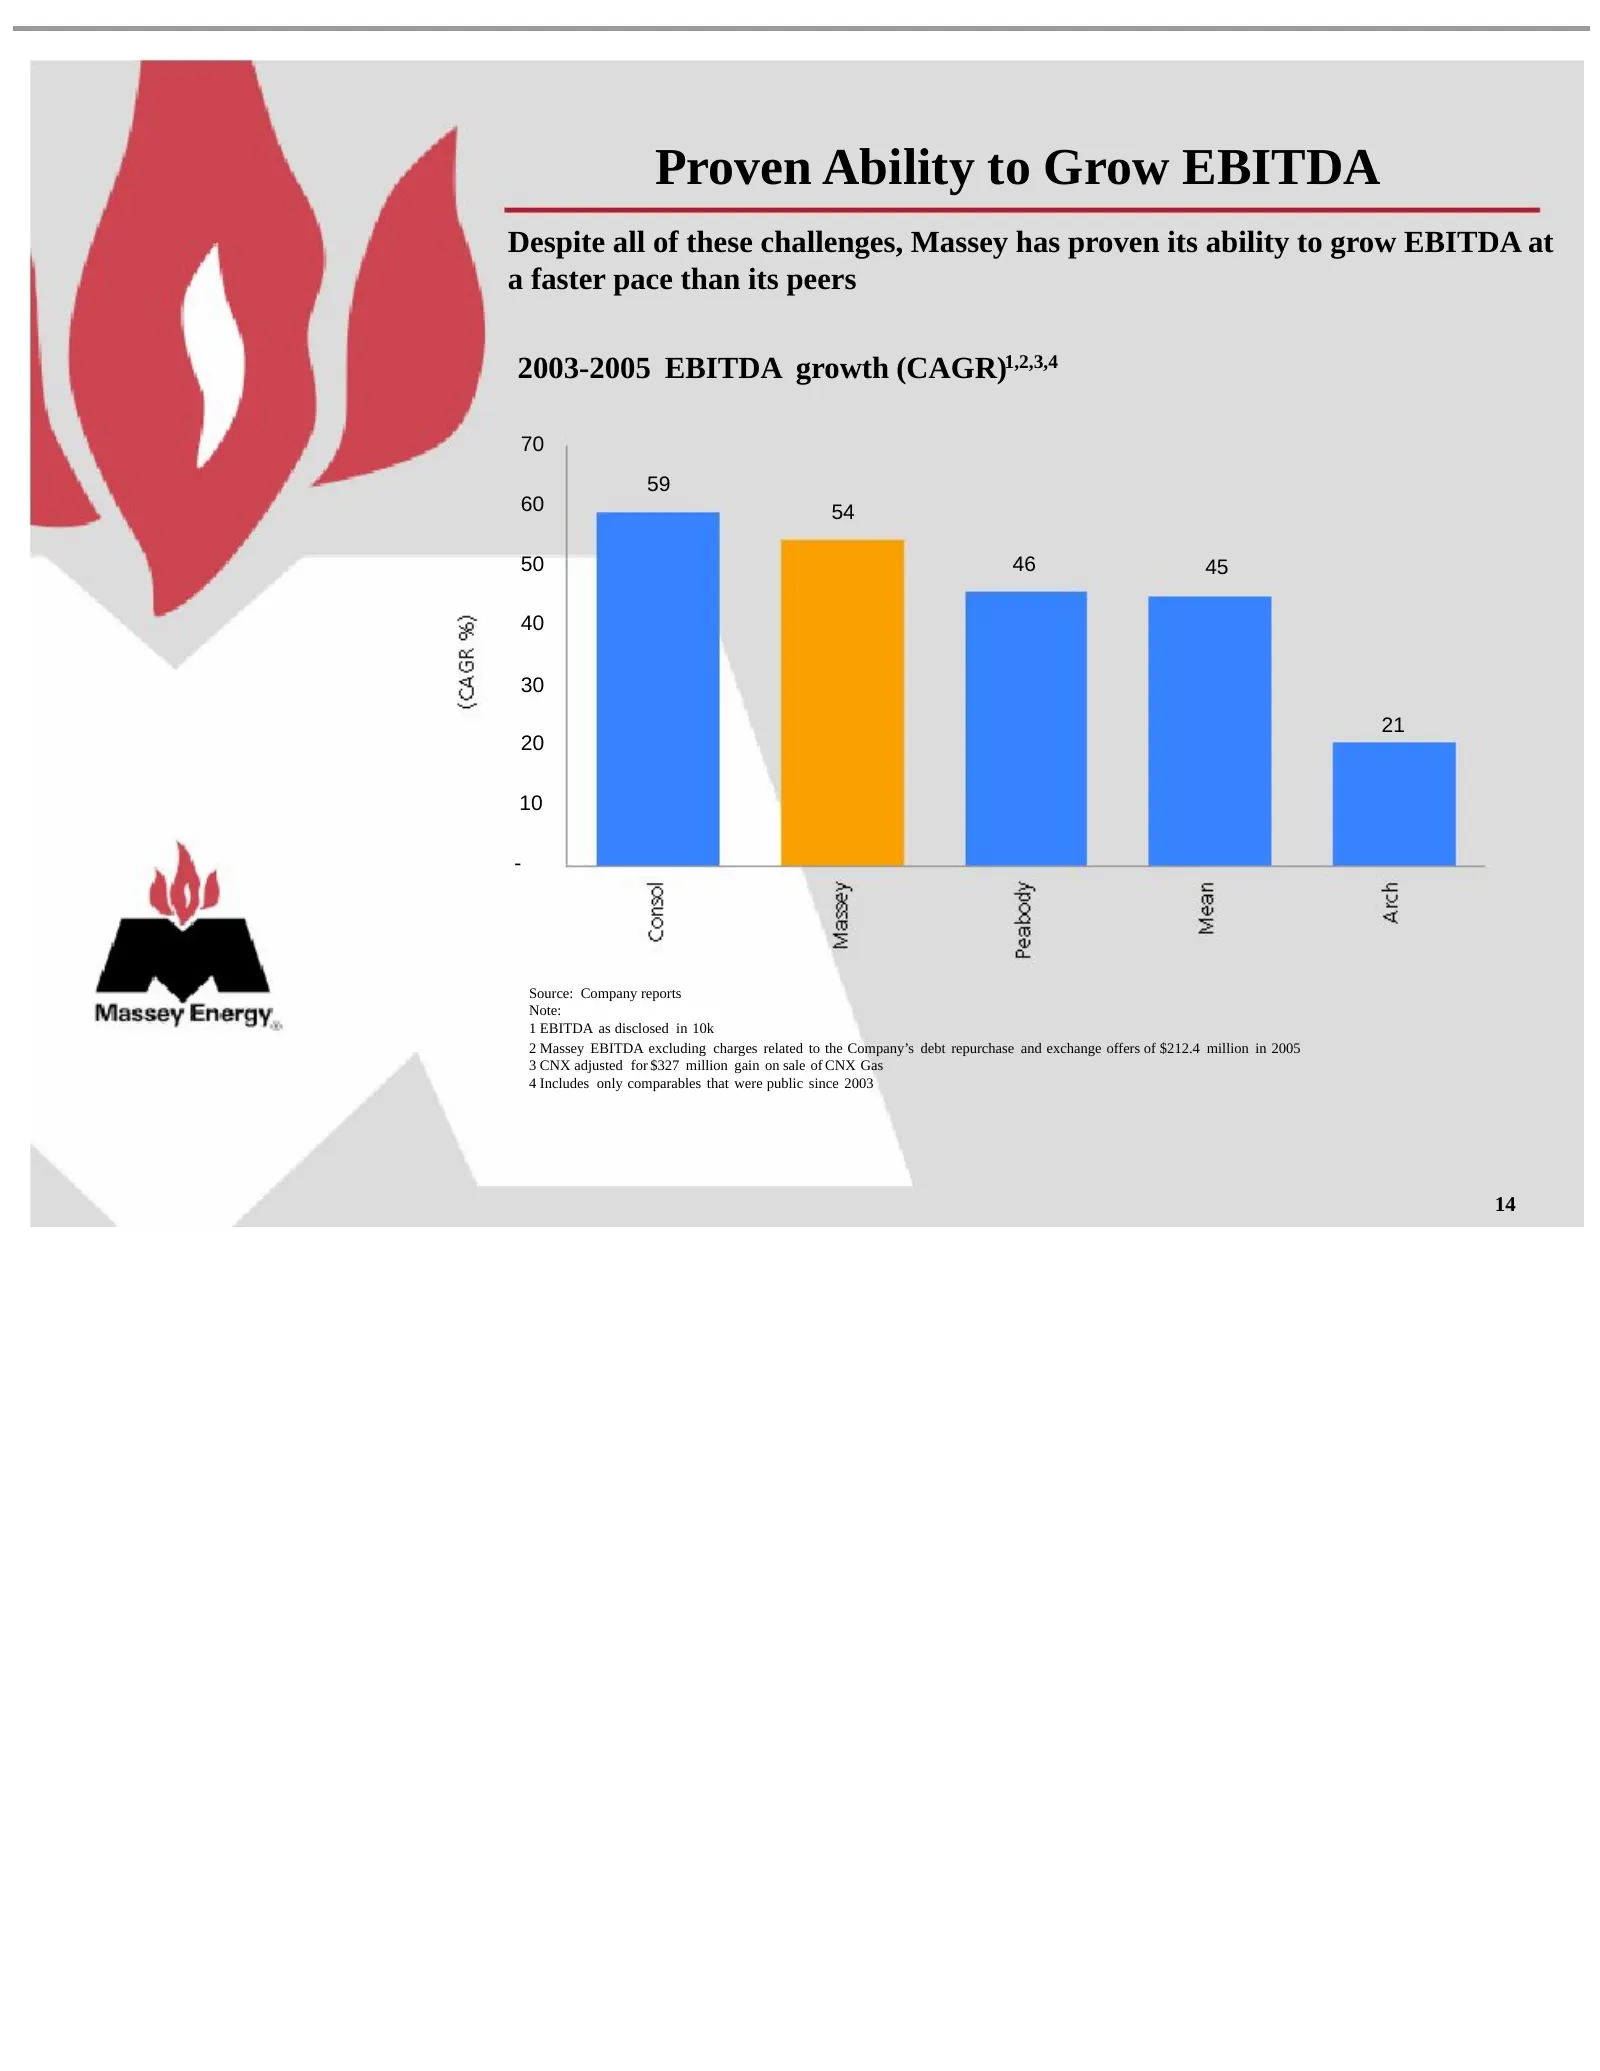
Proven Ability to Grow EBITDA Despite all of these challenges, Massey has proven its ability to grow EBITDA at a faster pace than its peers 2003-2005 EBITDA growth (CAGR)1,2,3,4 70 59 60 54 50 46 45 40 30 21 20 10 - Source: Company reports Note: 1 EBITDA as disclosed in 10k 2 Massey EBITDA excluding
Slide 18: Superior Performance
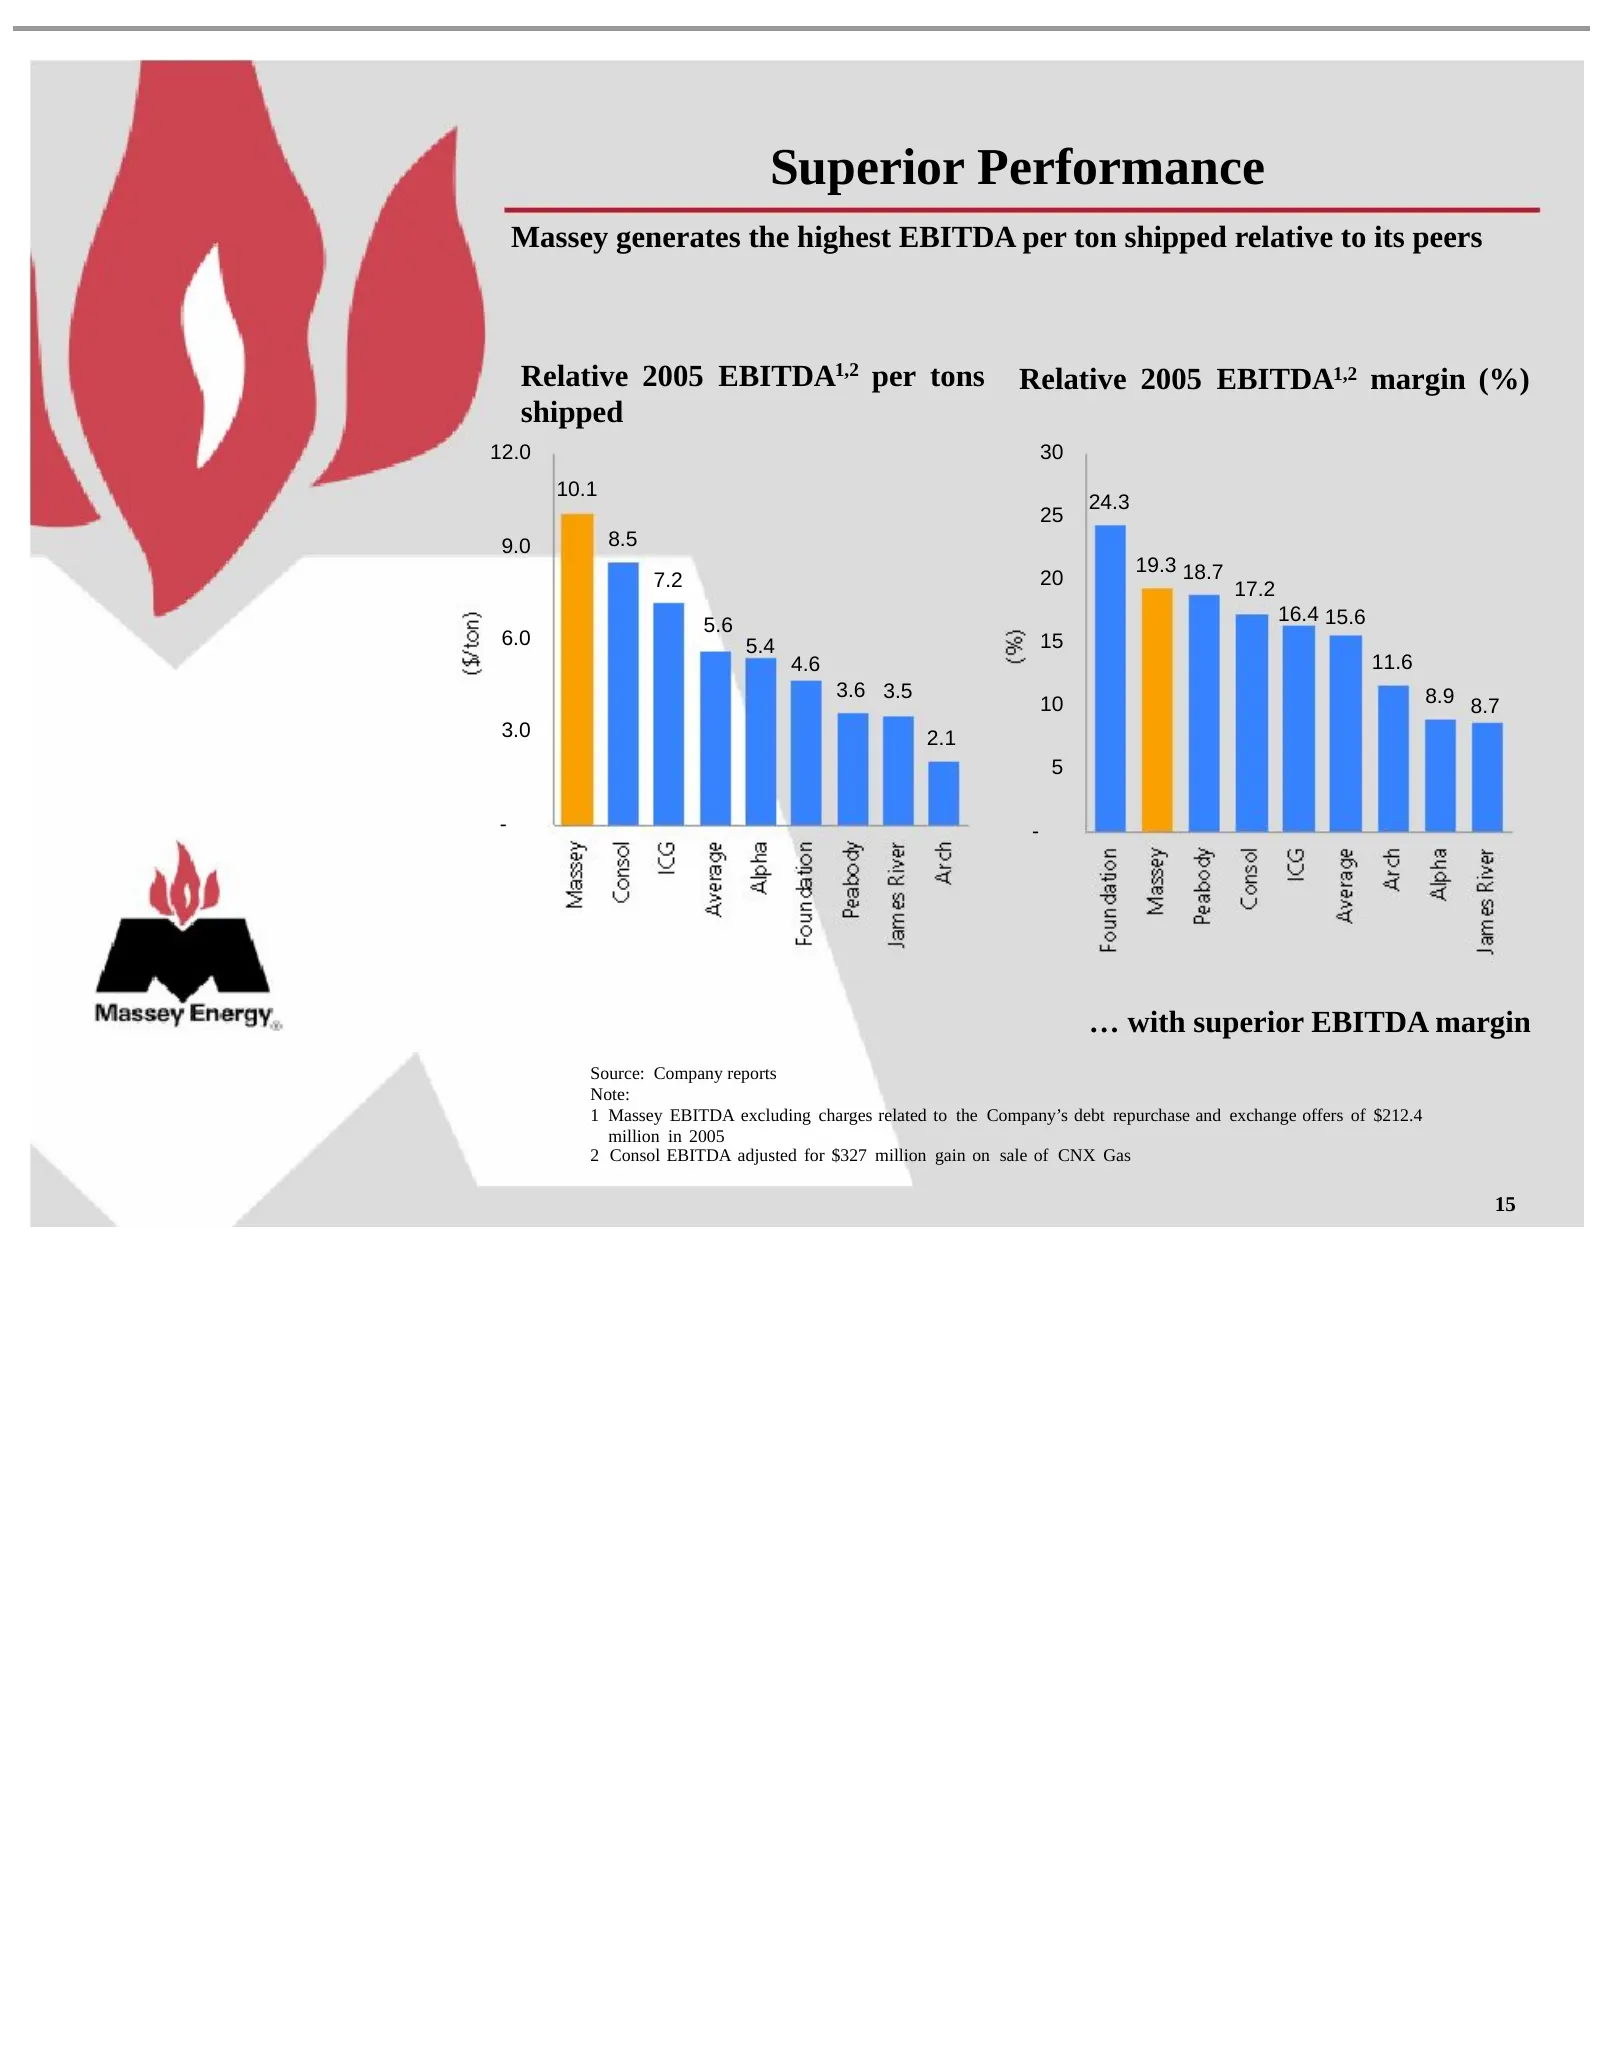
Superior Performance Massey generates the highest EBITDA per ton shipped relative to its peers Relative 2005 EBITDA1,2 per tons Relative 2005 EBITDA1,2 margin (%) shipped 12.0 30 10.1 24.3 25 9.0 8.5 19.3 18.7 7.2 20 17.2 16.4 15.6 5.6 6.0 5.4 15 4.6 11.6 3.6 3.5 8.9 8.7 10 3.0 2.1 5 - - … with supe
Slide 19: Low Legacy Liabilities
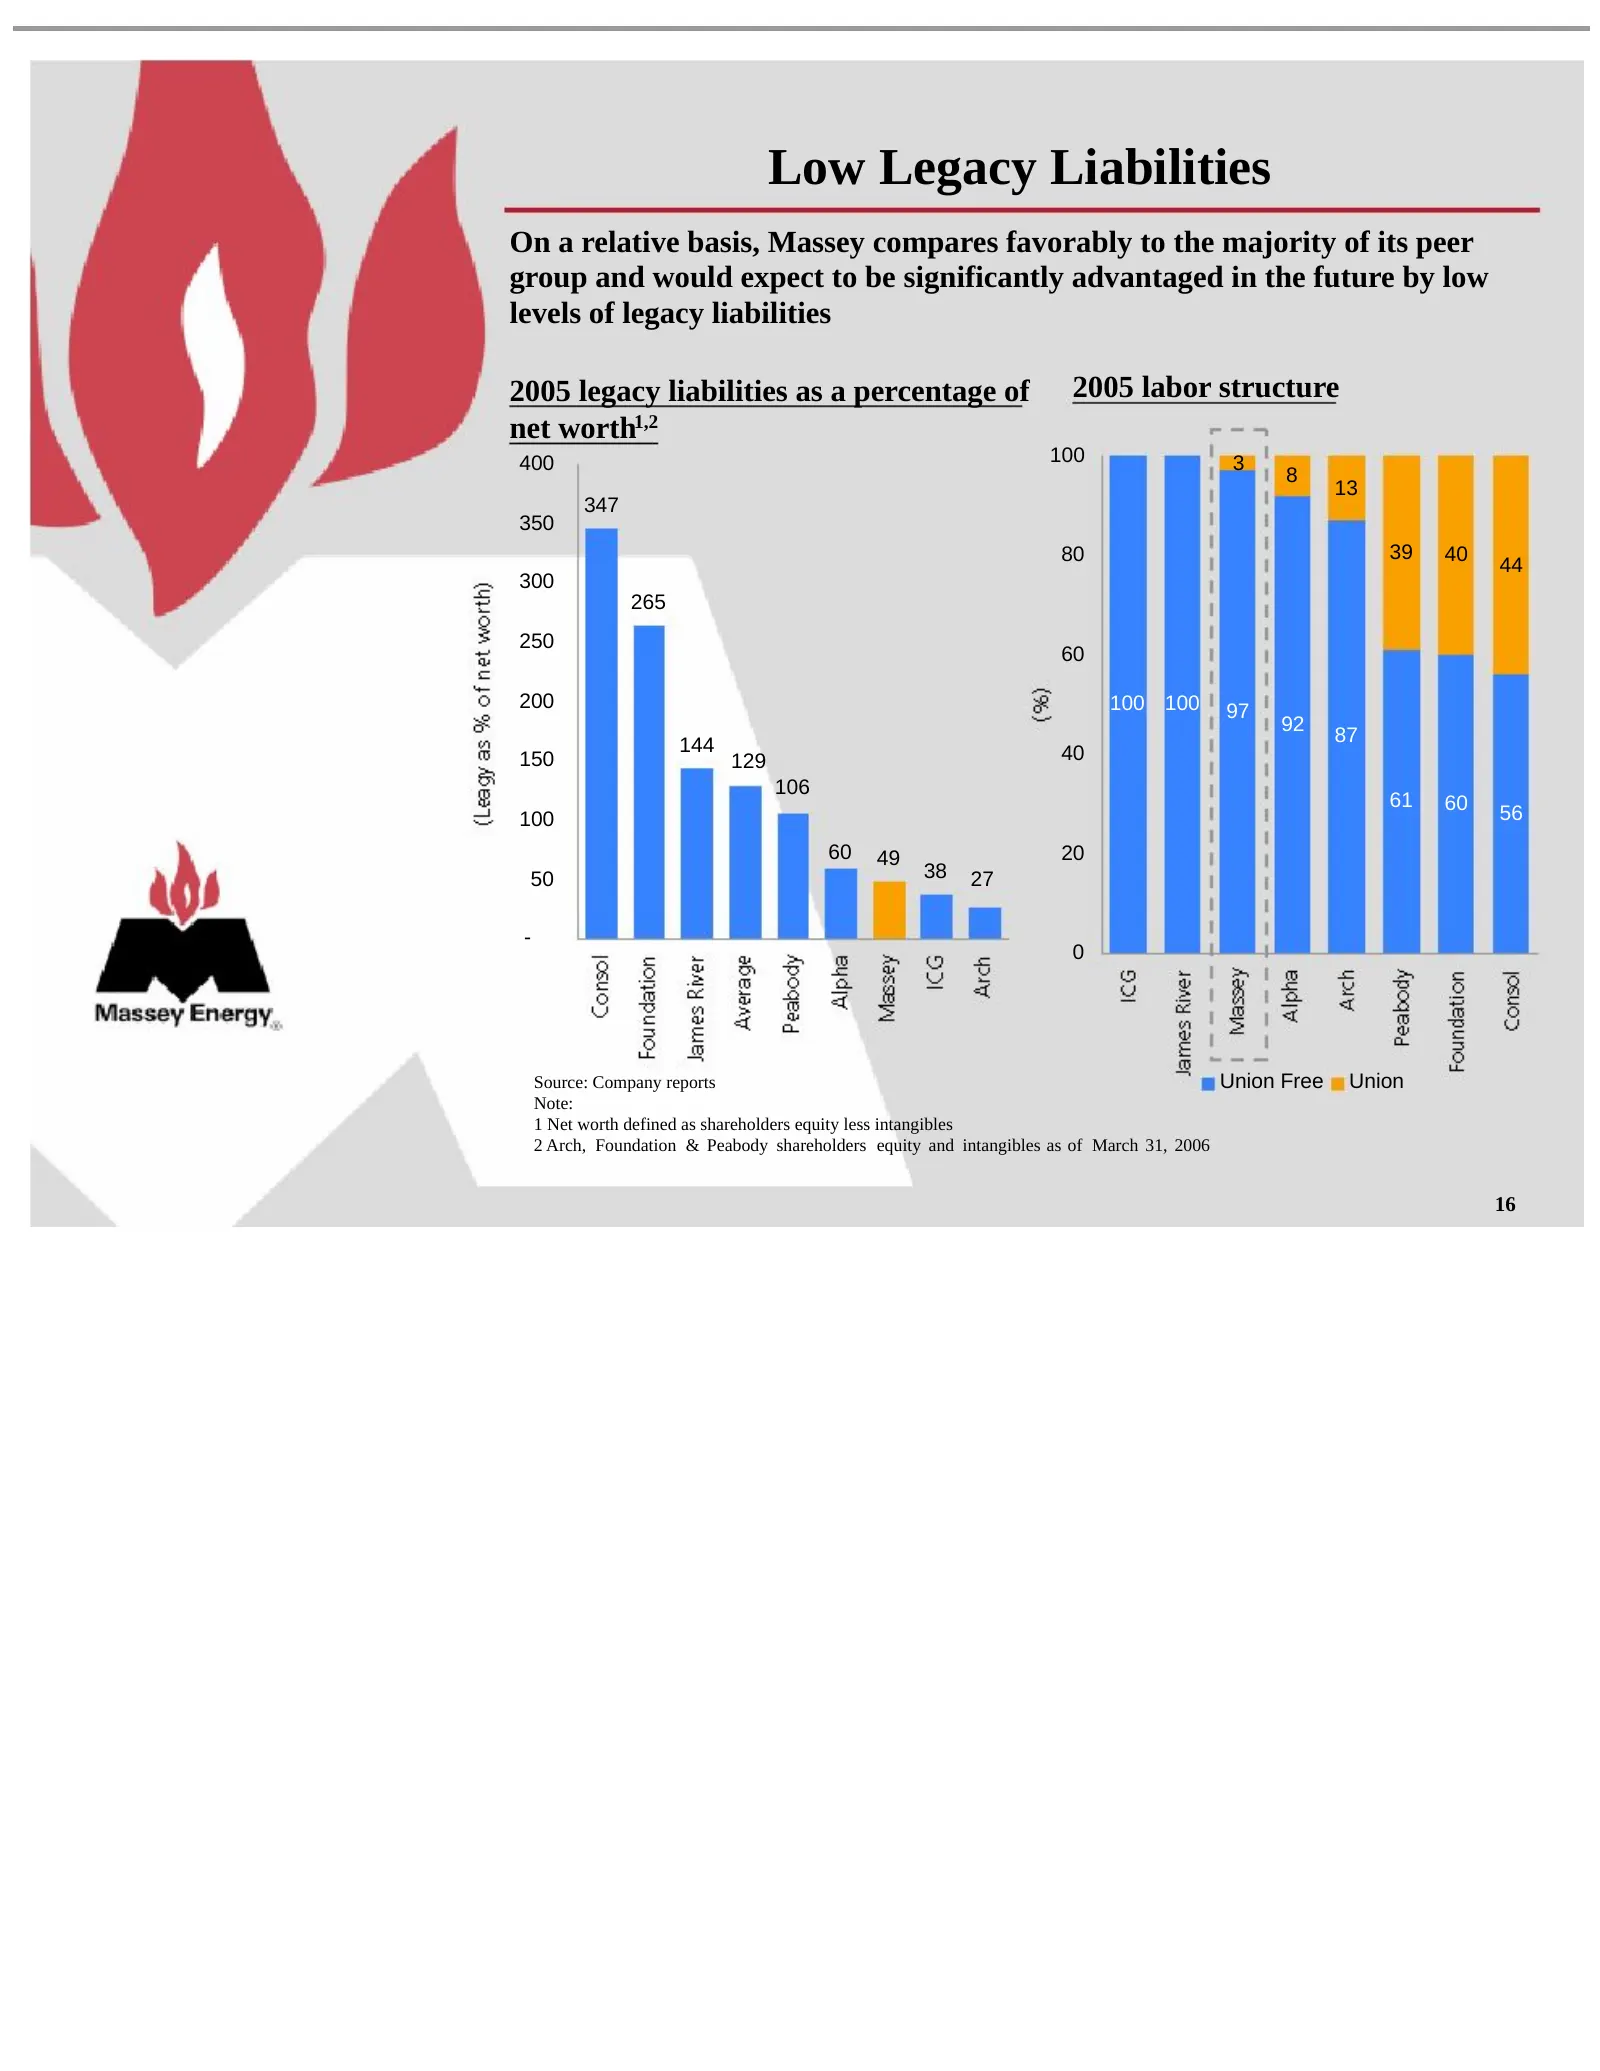
Low Legacy Liabilities On a relative basis, Massey compares favorably to the majority of its peer group and would expect to be significantly advantaged in the future by low levels of legacy liabilities 2005 legacy liabilities as a percentage of 2005 labor structure net worth1,2 400 100 3 8 13 347 35
Slide 20: Total Returns to Shareholders
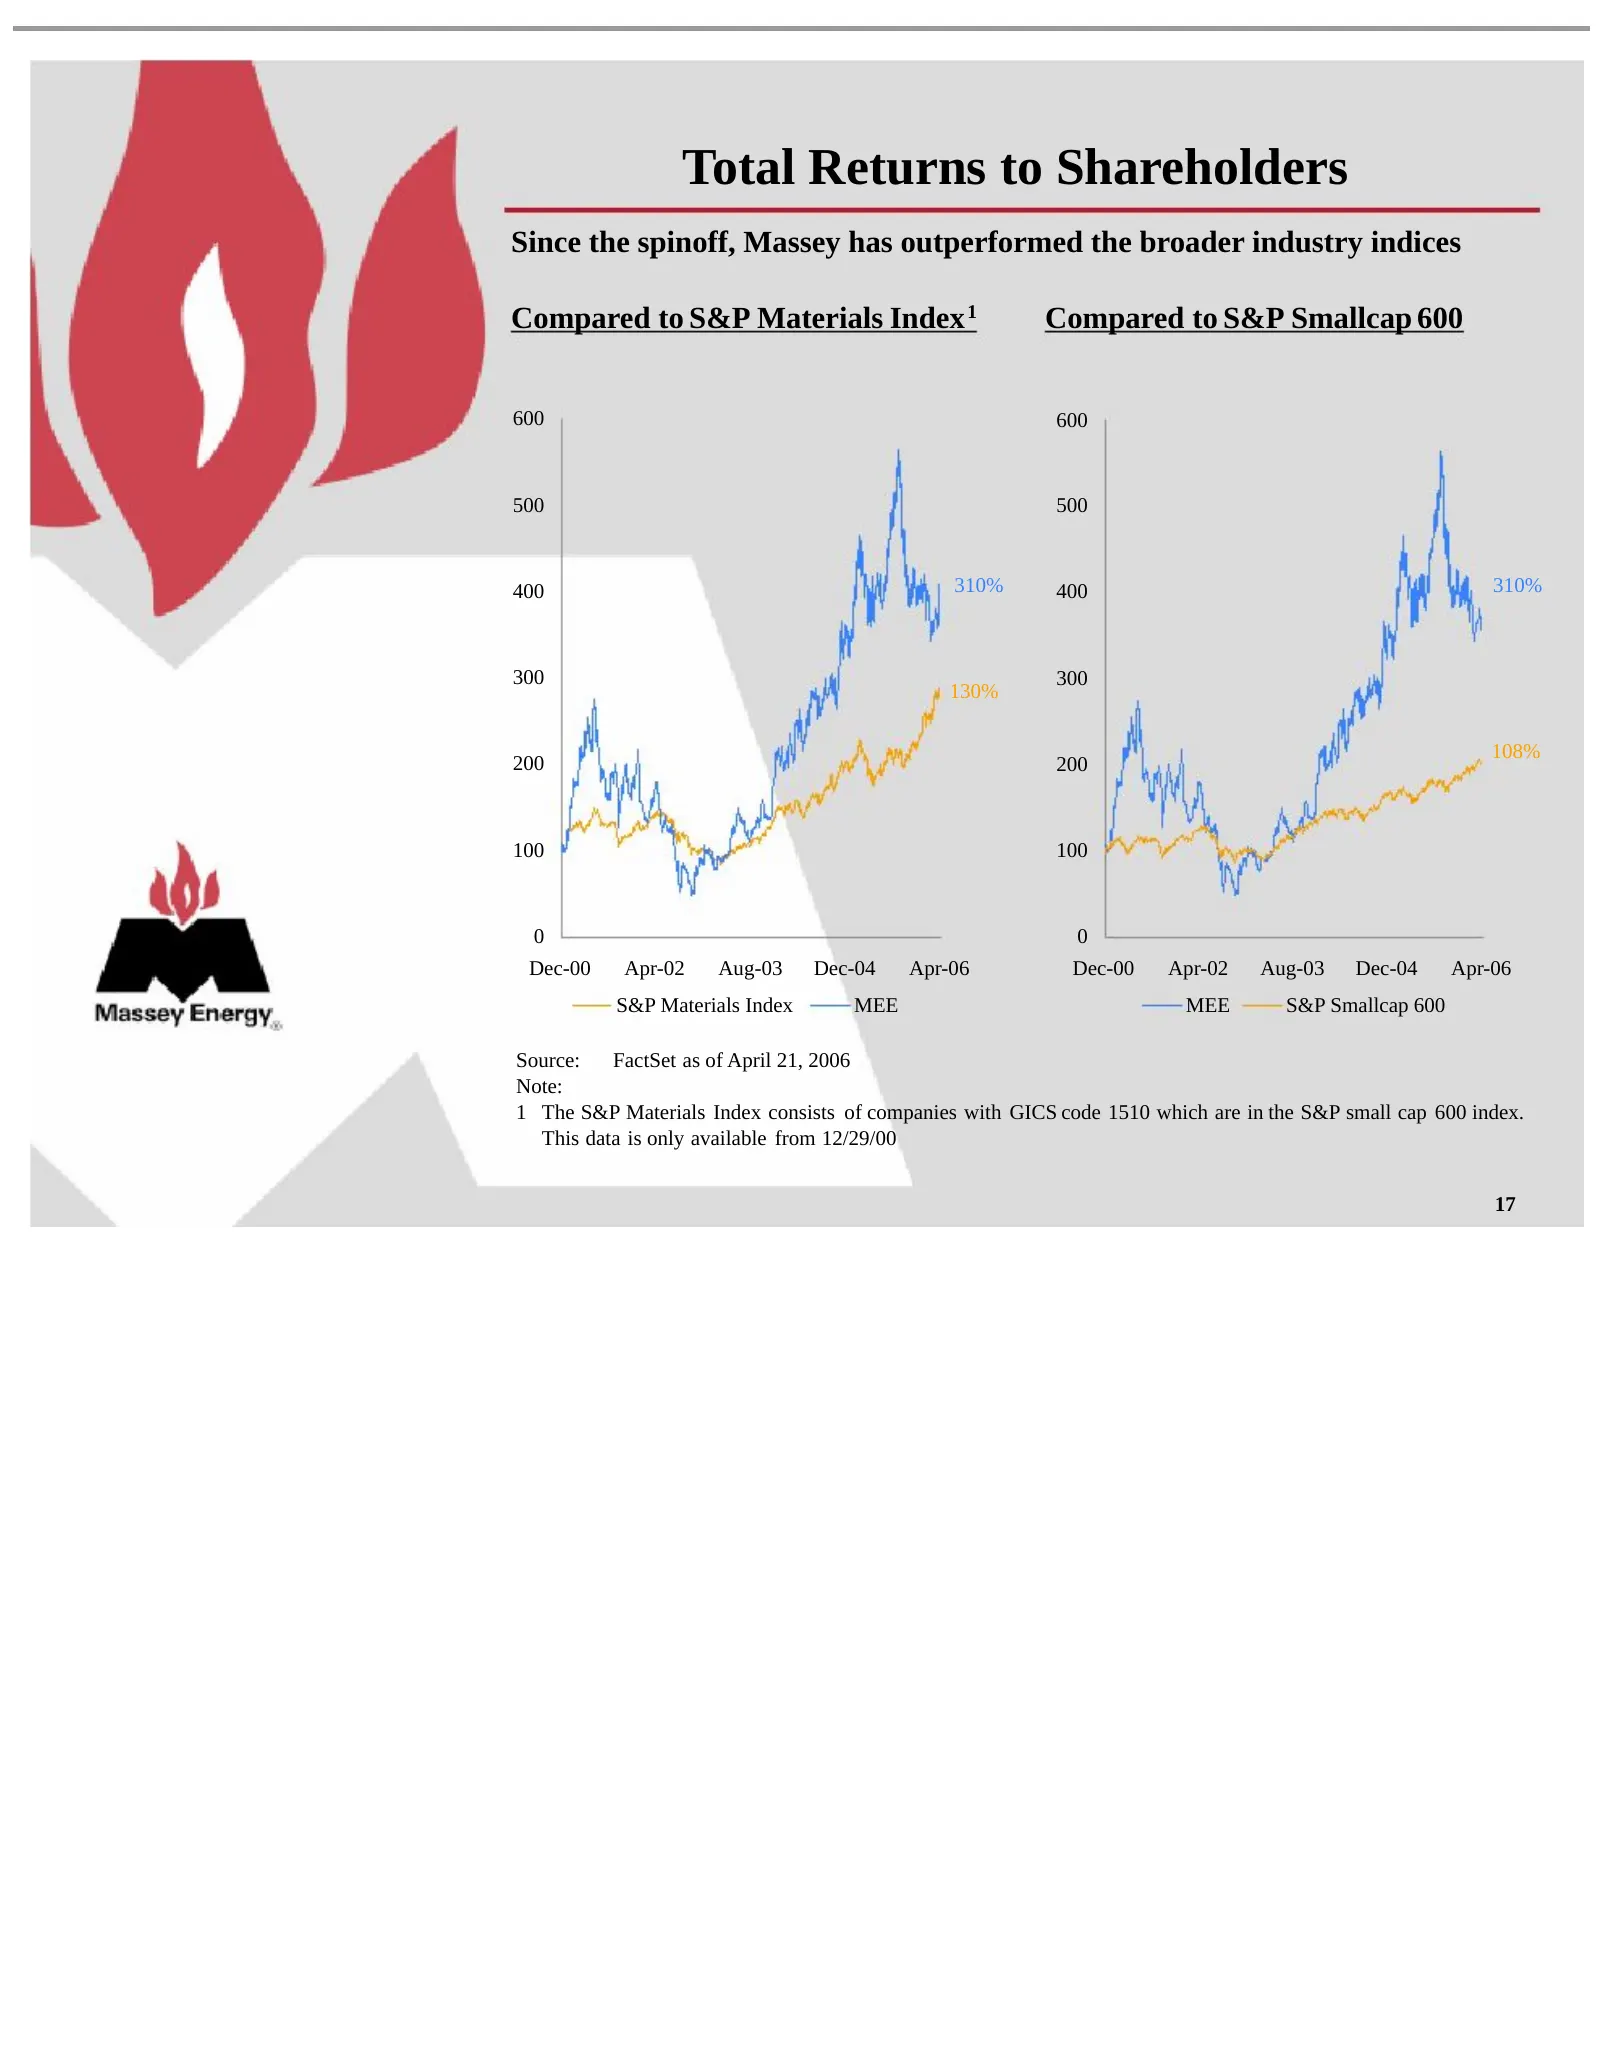
Total Returns to Shareholders Since the spinoff, Massey has outperformed the broader industry indices Compared to S&P Materials Index 1 Compared to S&P Smallcap 600 600 600 500 500 400 310% 400 310% 300 300 130% 108% 200 200 100 100 0 0 Dec-00 Apr-02 Aug-03 Dec-04 Apr-06 Dec-00 Apr-02 Aug-03 Dec-04
Slide 21: Total Returns to Shareholders
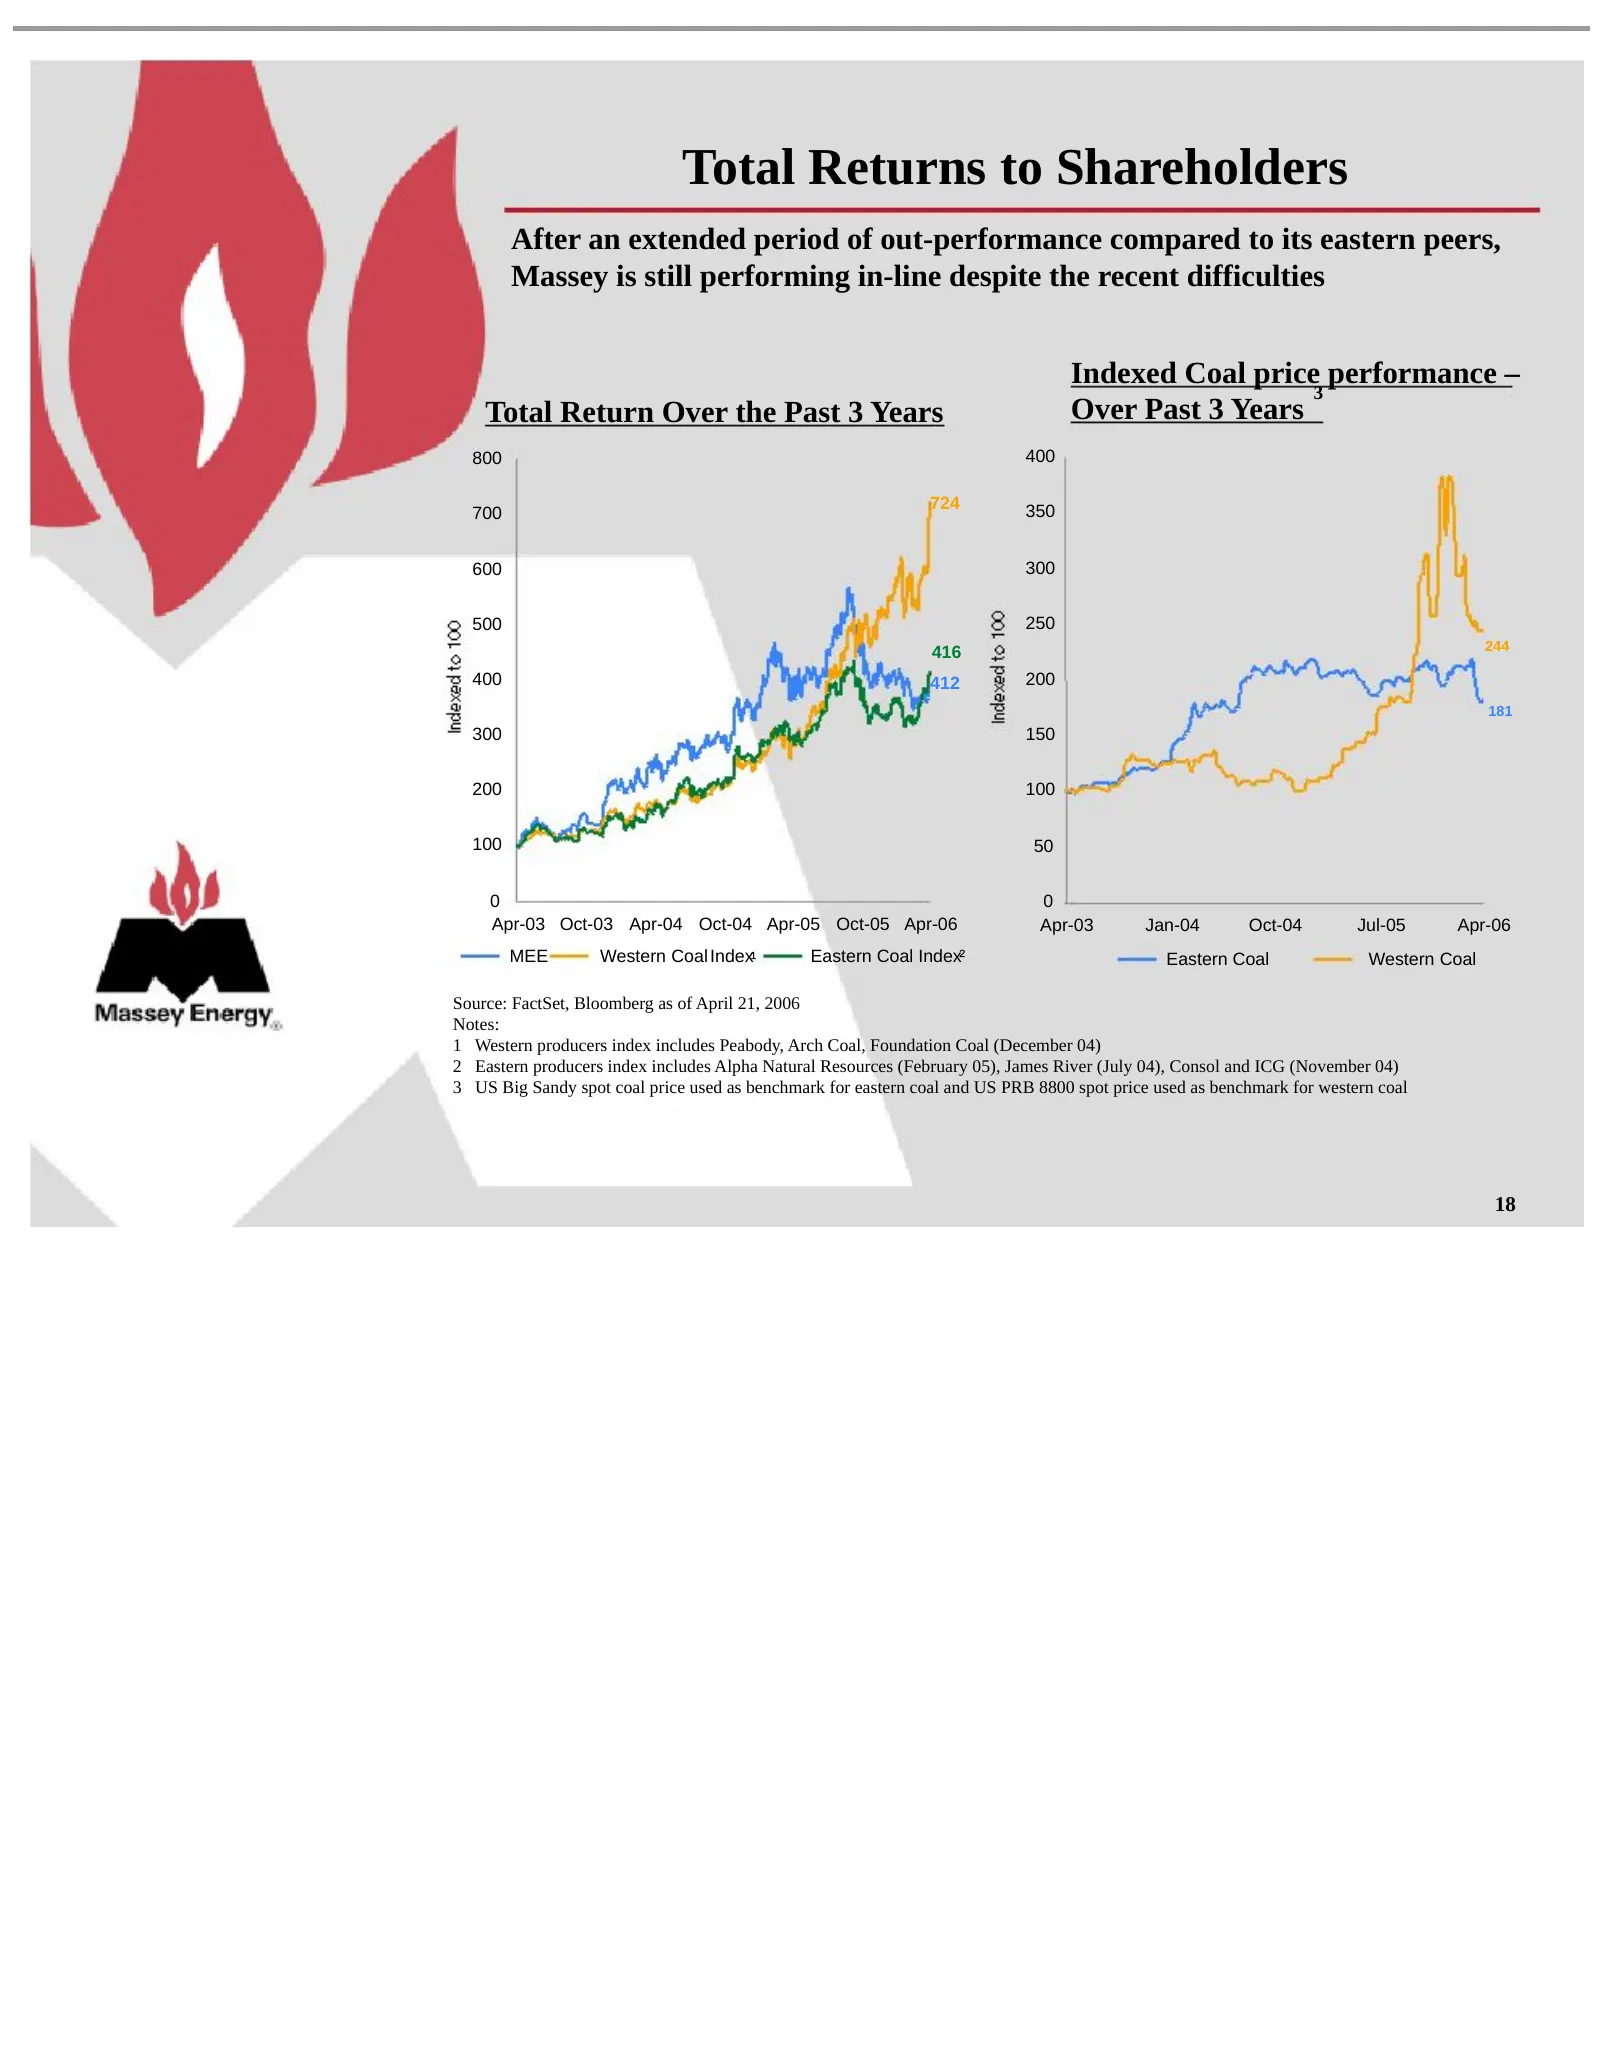
Total Returns to Shareholders After an extended period of out-performance compared to its eastern peers, Massey is still performing in-line despite the recent difficulties Indexed Coal price performance – 3 Total Return Over the Past 3 Years Over Past 3 Years 800 400 724 350 700 600 300 500 250 416
Slide 22: Review of Third Point Proposals
SECTION 2 Review of Third Point Proposals 19
Slide 23: Background to the Proxy Contest
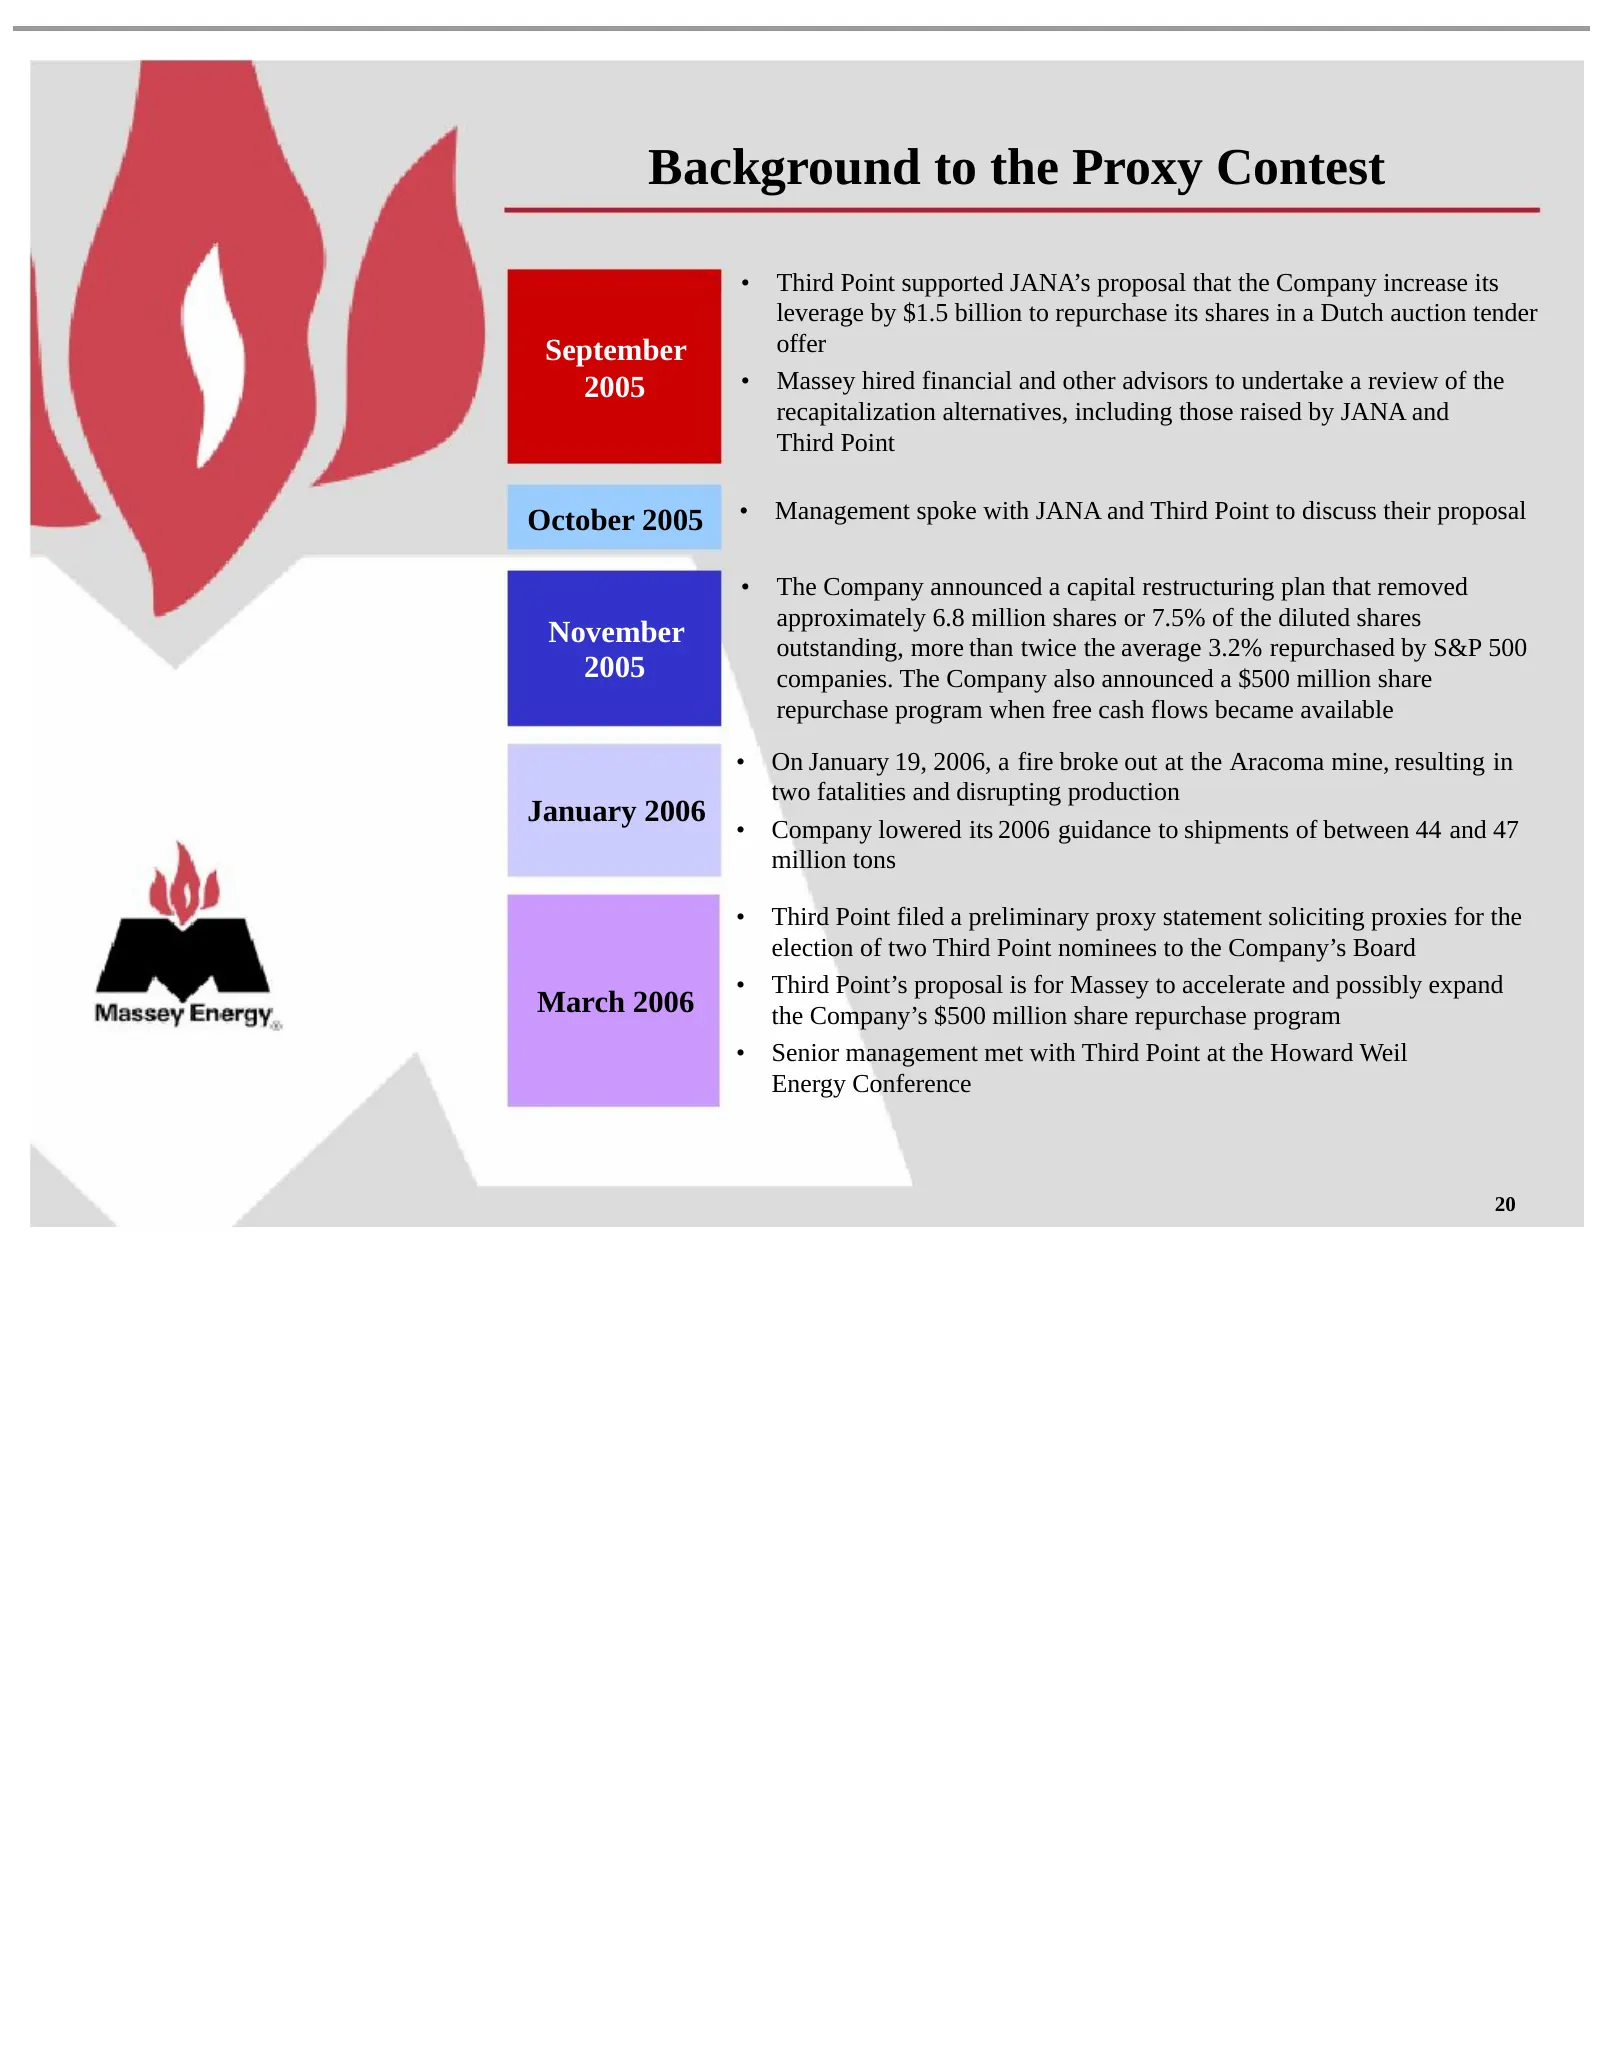
Background to the Proxy Contest • Third Point supported JANA’s proposal that the Company increase its leverage by $1.5 billion to repurchase its shares in a Dutch auction tender September offer 2005 • Massey hired financial and other advisors to undertake a review of the recapitalization alternative
Slide 24: Proposal for $1.5 Billion Accelerated Buyback—Credit Impact
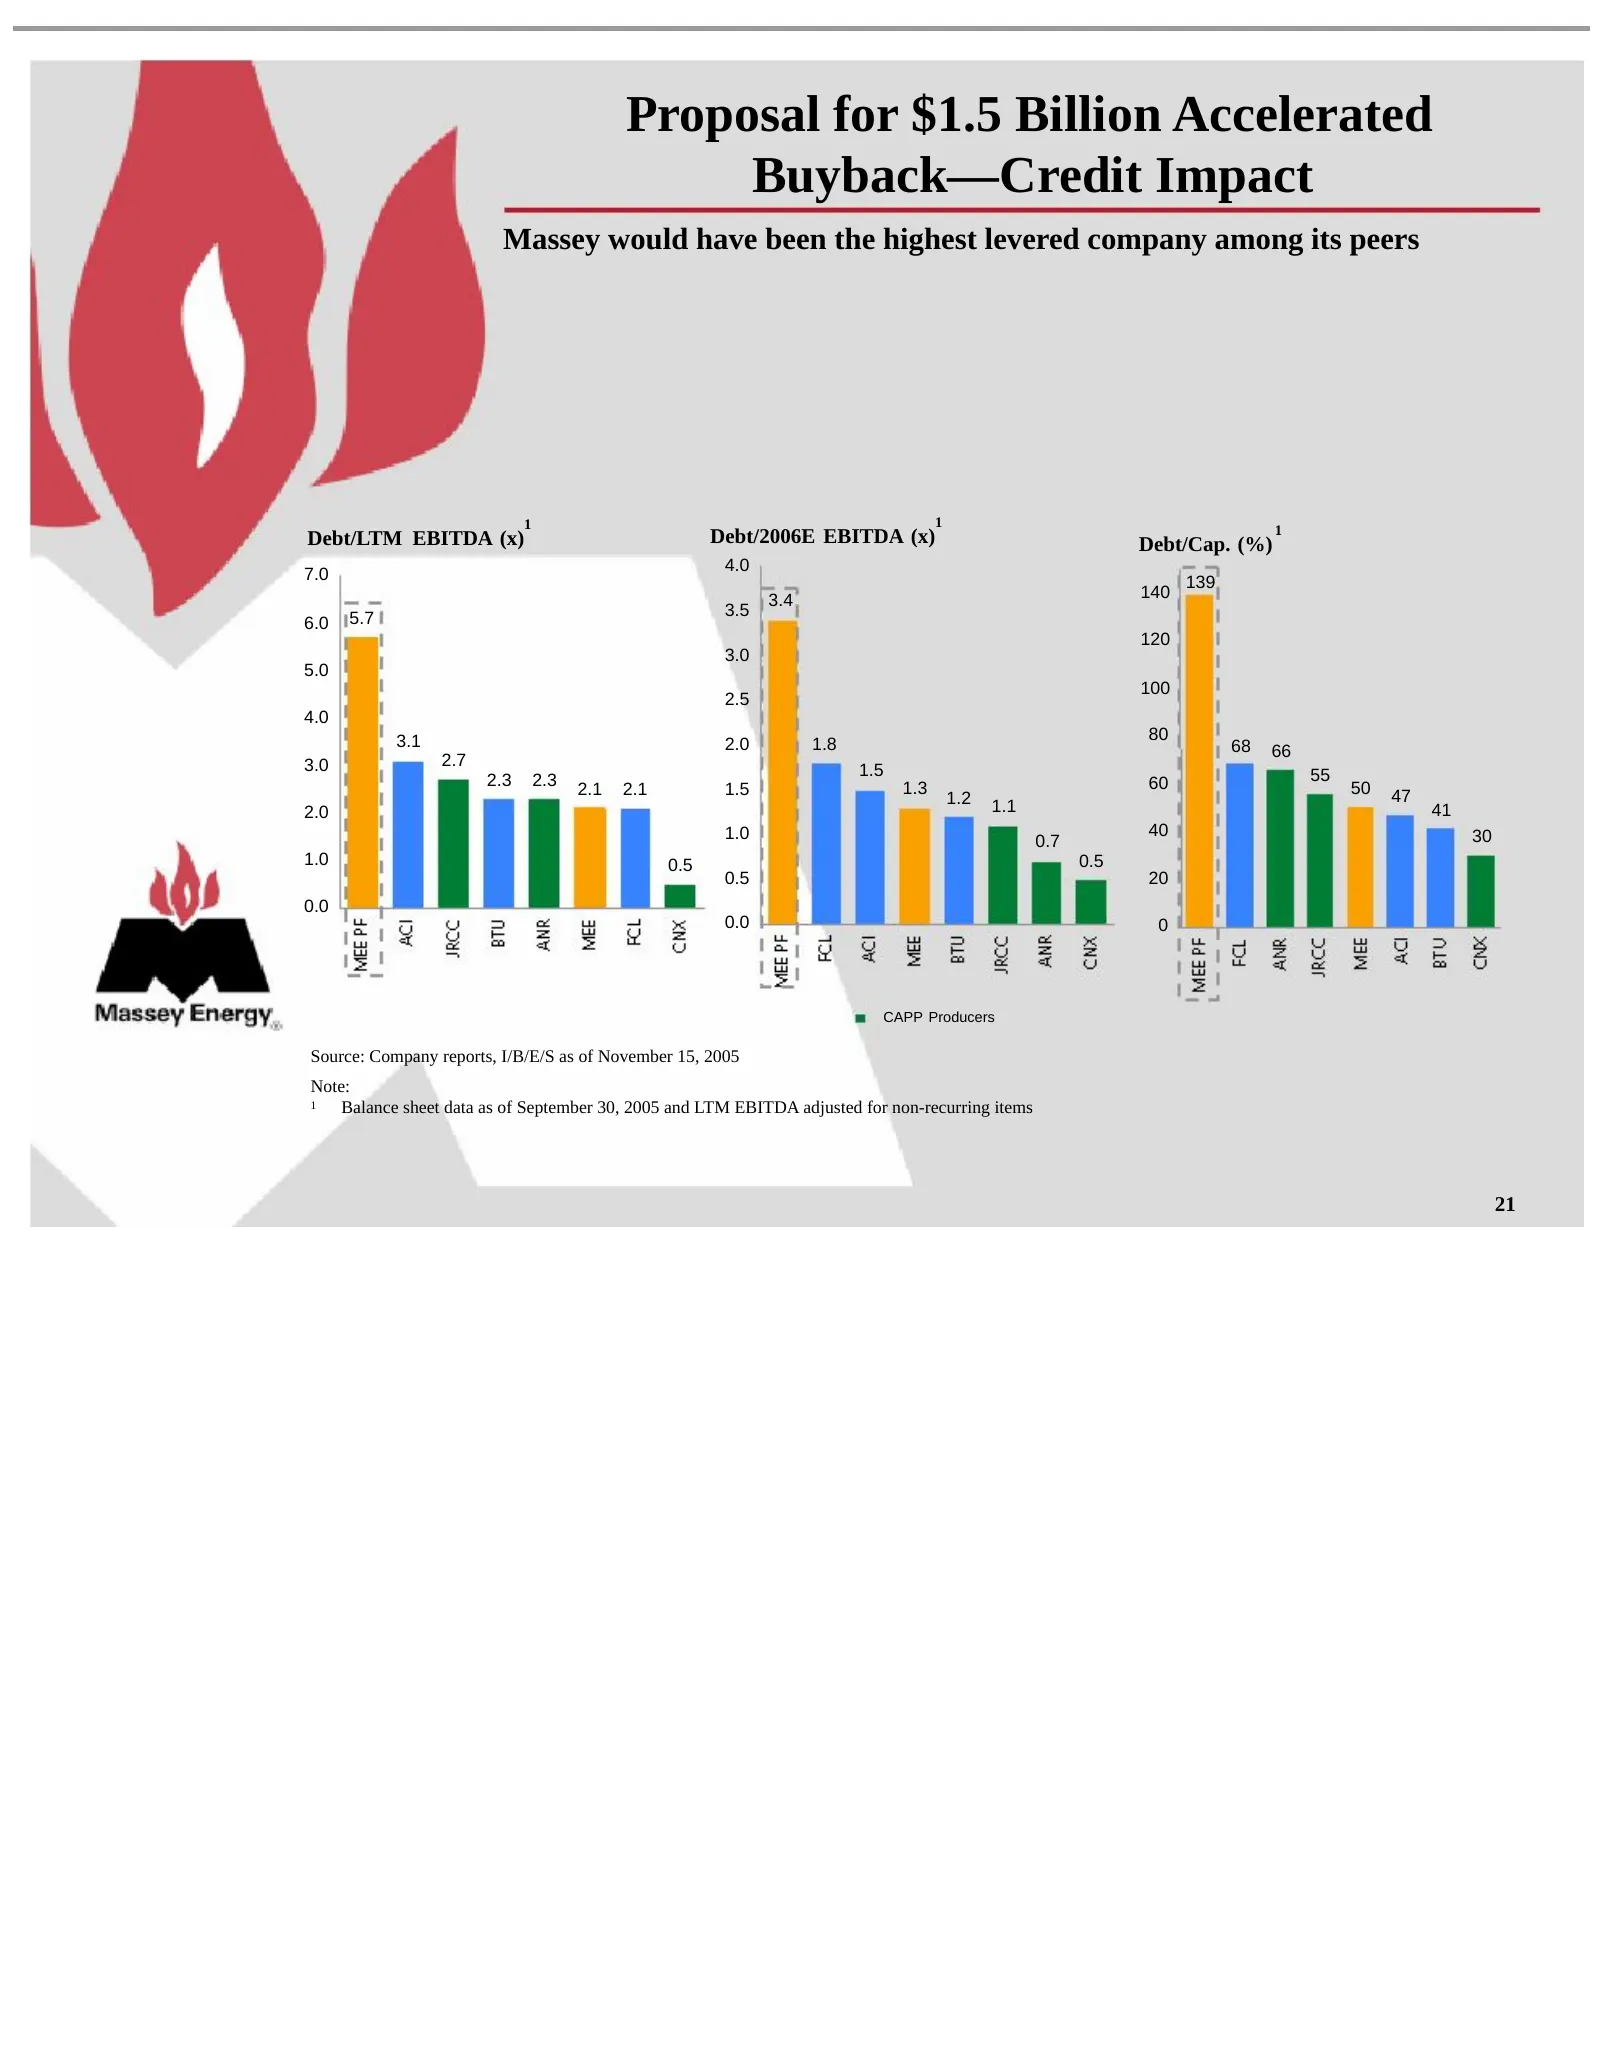
Proposal for $1.5 Billion Accelerated Buyback—Credit Impact Massey would have been the highest levered company among its peers 1 1 1 Debt/LTM EBITDA (x) Debt/2006E EBITDA (x) Debt/Cap. (%) 4.0 7.0 139 3.4 140 5.7 3.5 6.0 120 3.0 5.0 100 2.5 4.0 3.1 80 2.0 1.8 68 66 3.0 2.7 1.5 55 2.3 2.3 1.3 60 50 2
Slide 25: Massey Transaction Summary
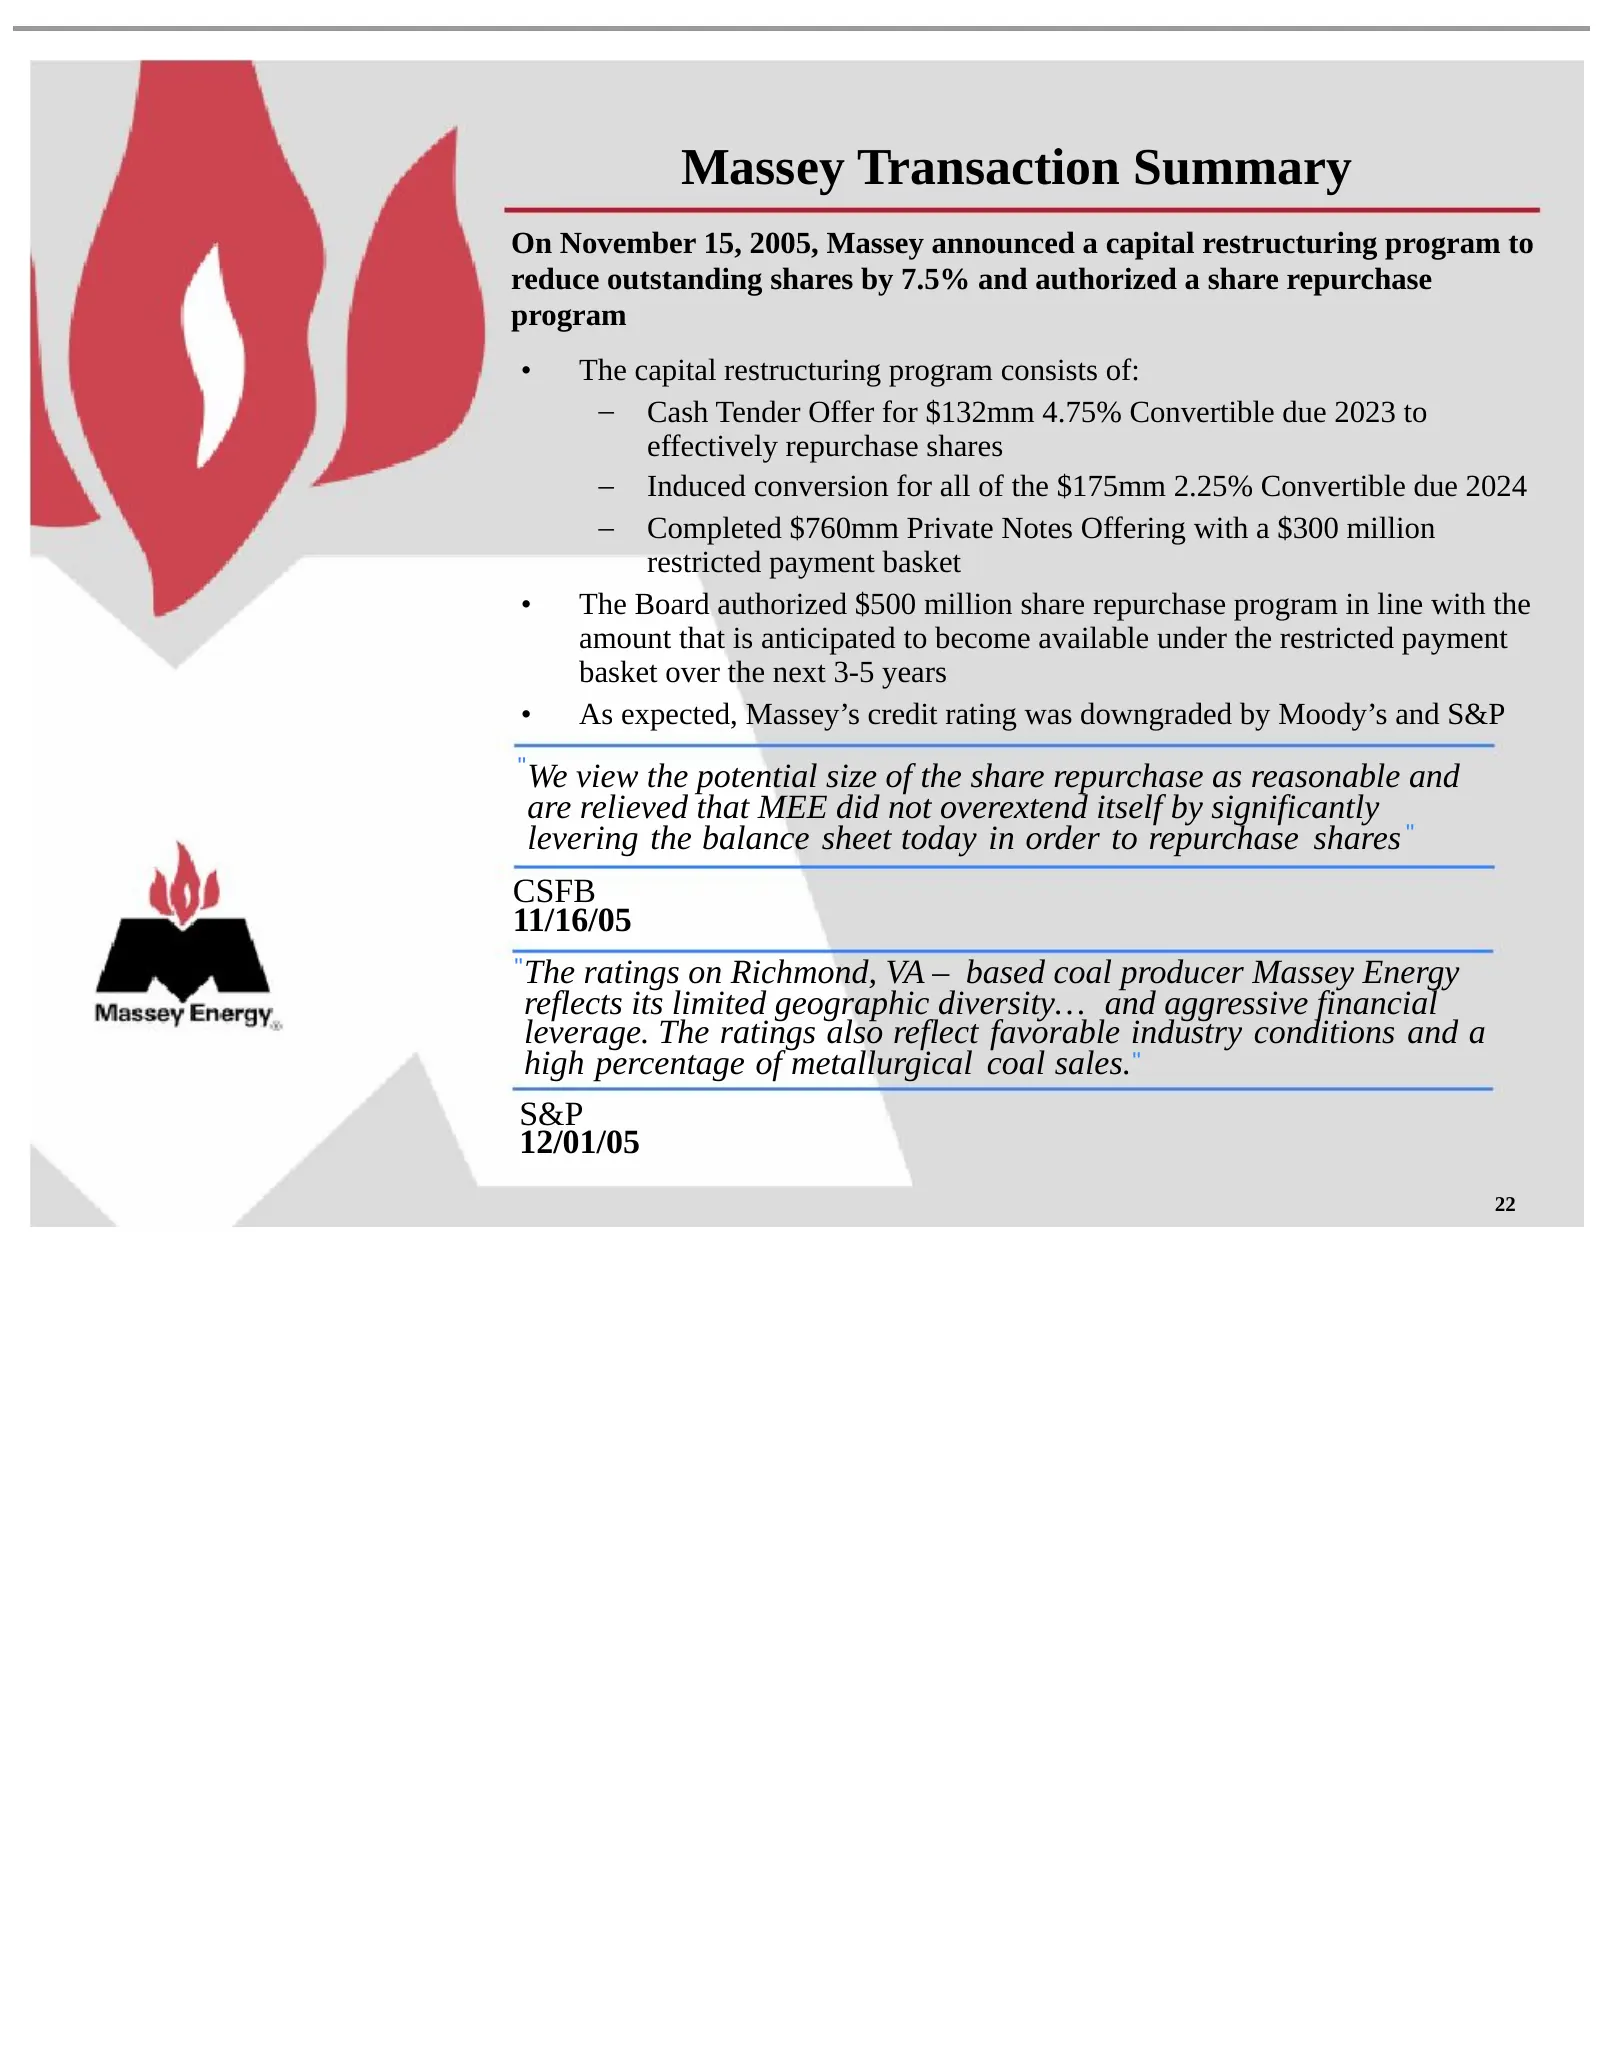
Massey Transaction Summary On November 15, 2005, Massey announced a capital restructuring program to reduce outstanding shares by 7.5% and authorized a share repurchase program • The capital restructuring program consists of: – Cash Tender Offer for $132mm 4.75% Convertible due 2023 to effectively r
Slide 26: Share Repurchase Considerations
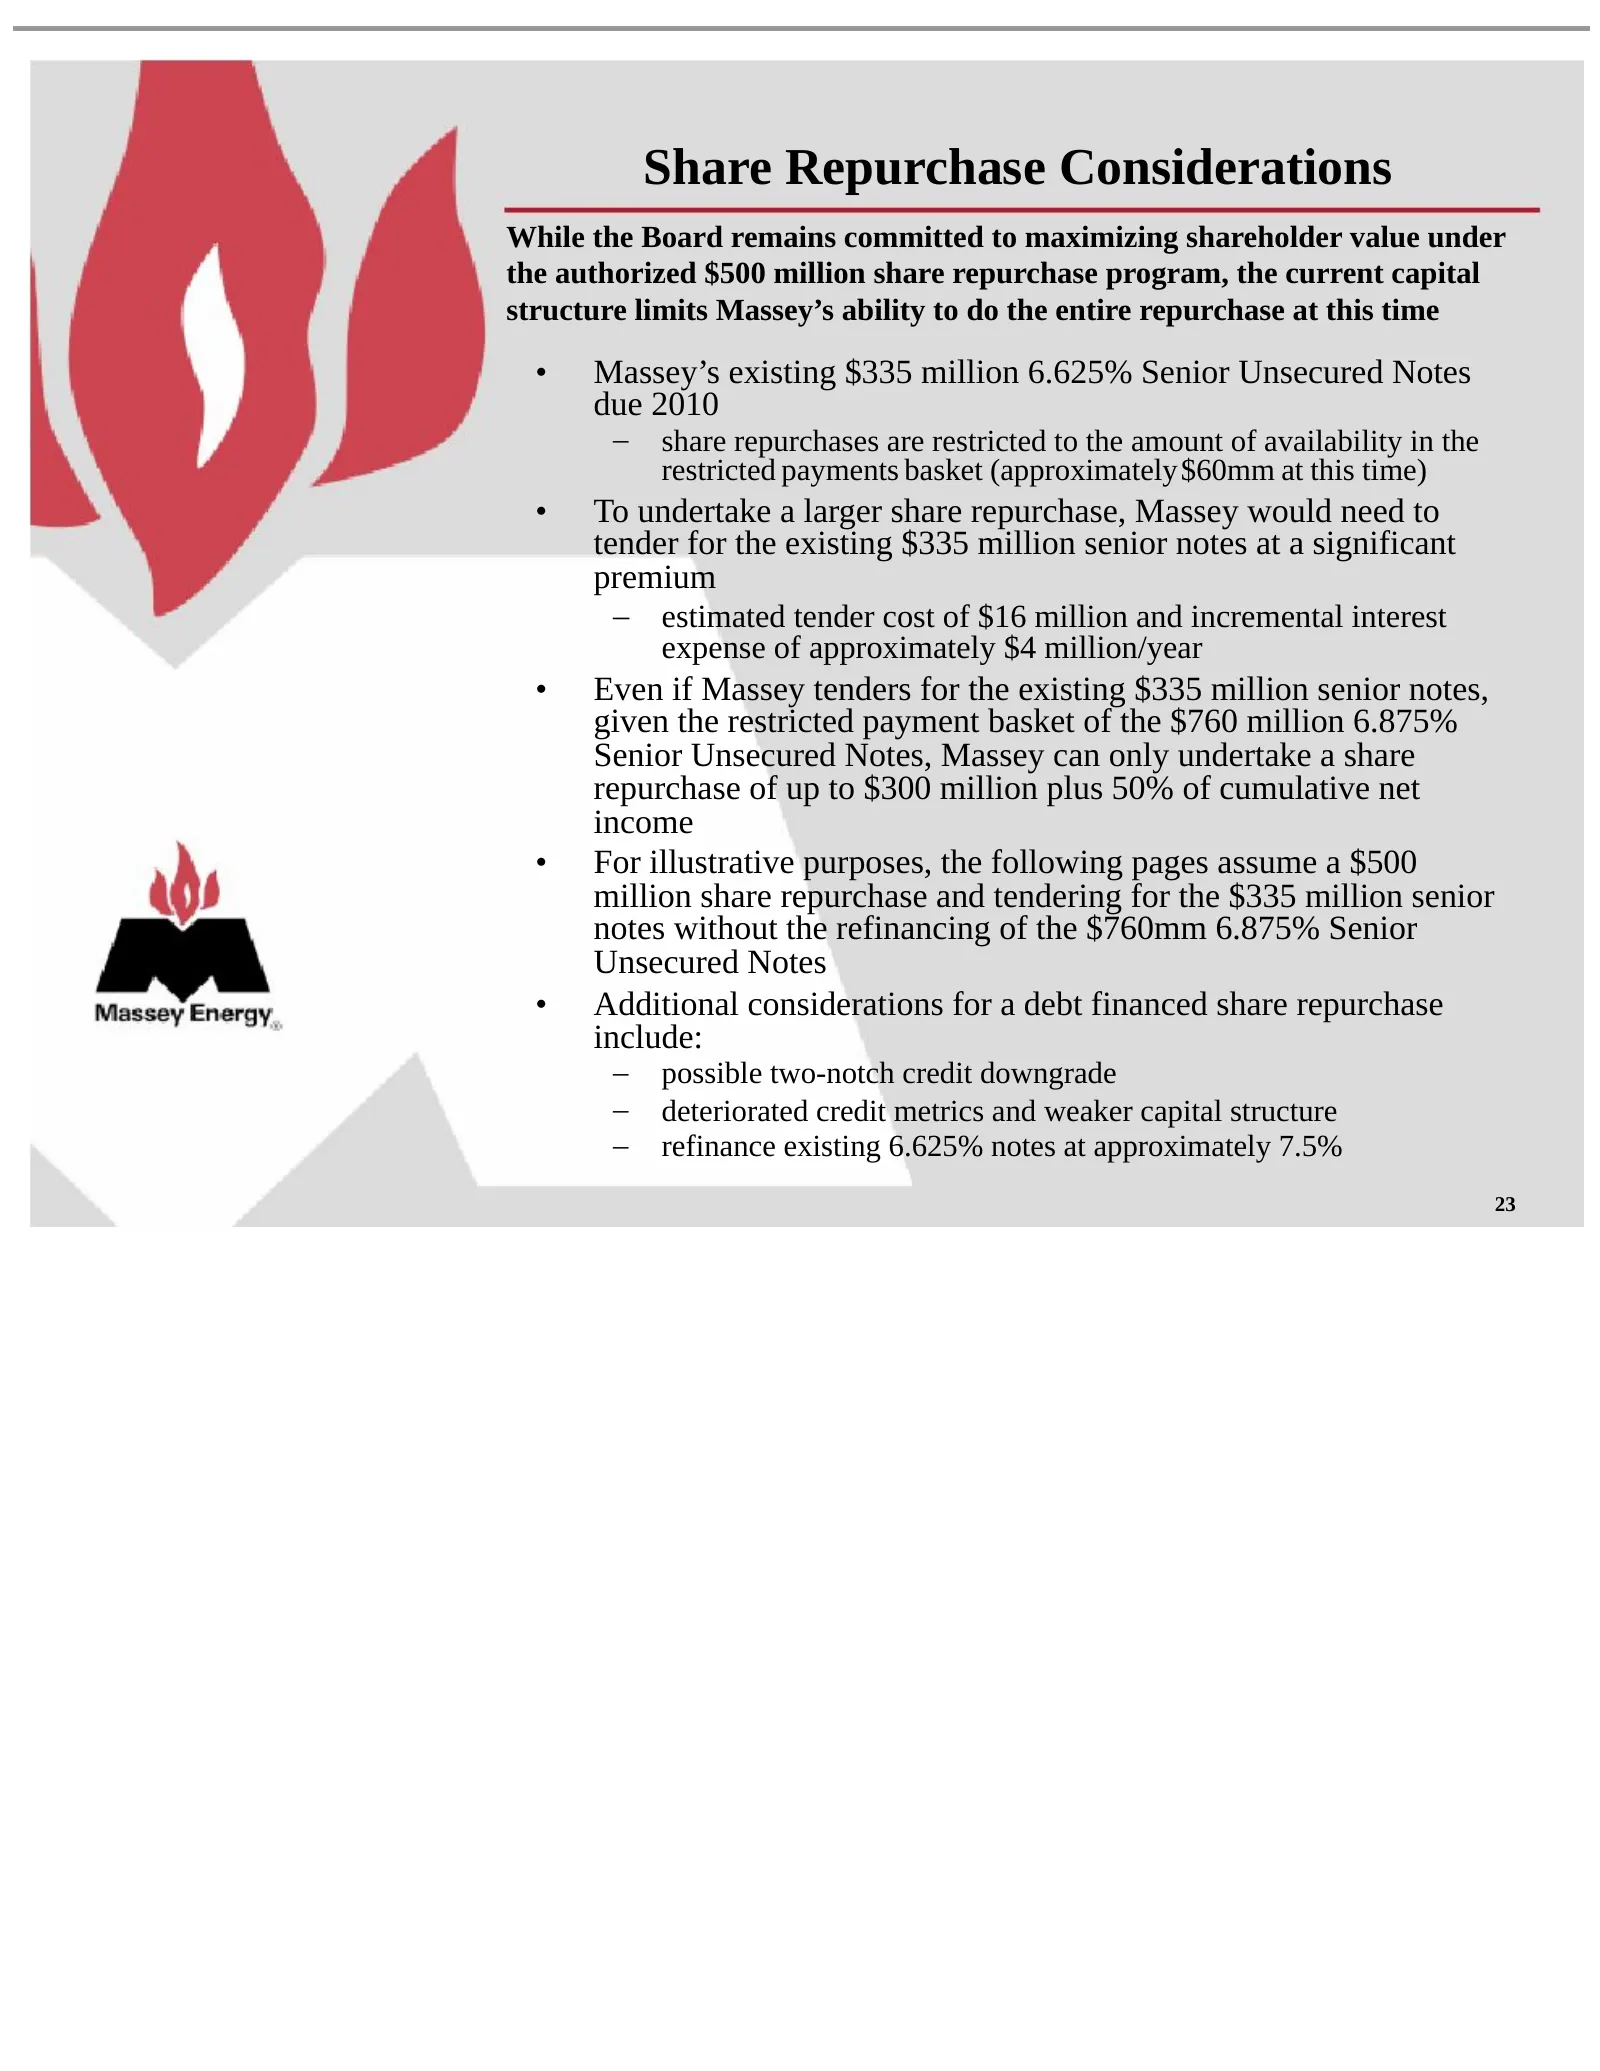
Share Repurchase Considerations While the Board remains committed to maximizing shareholder value under the authorized $500 million share repurchase program, the current capital structure limits Massey’s ability to do the entire repurchase at this time • Massey’s existing $335 million 6.625% Senior
Slide 27: Proposal for $500 million Accelerated Buyback—Credit Impact
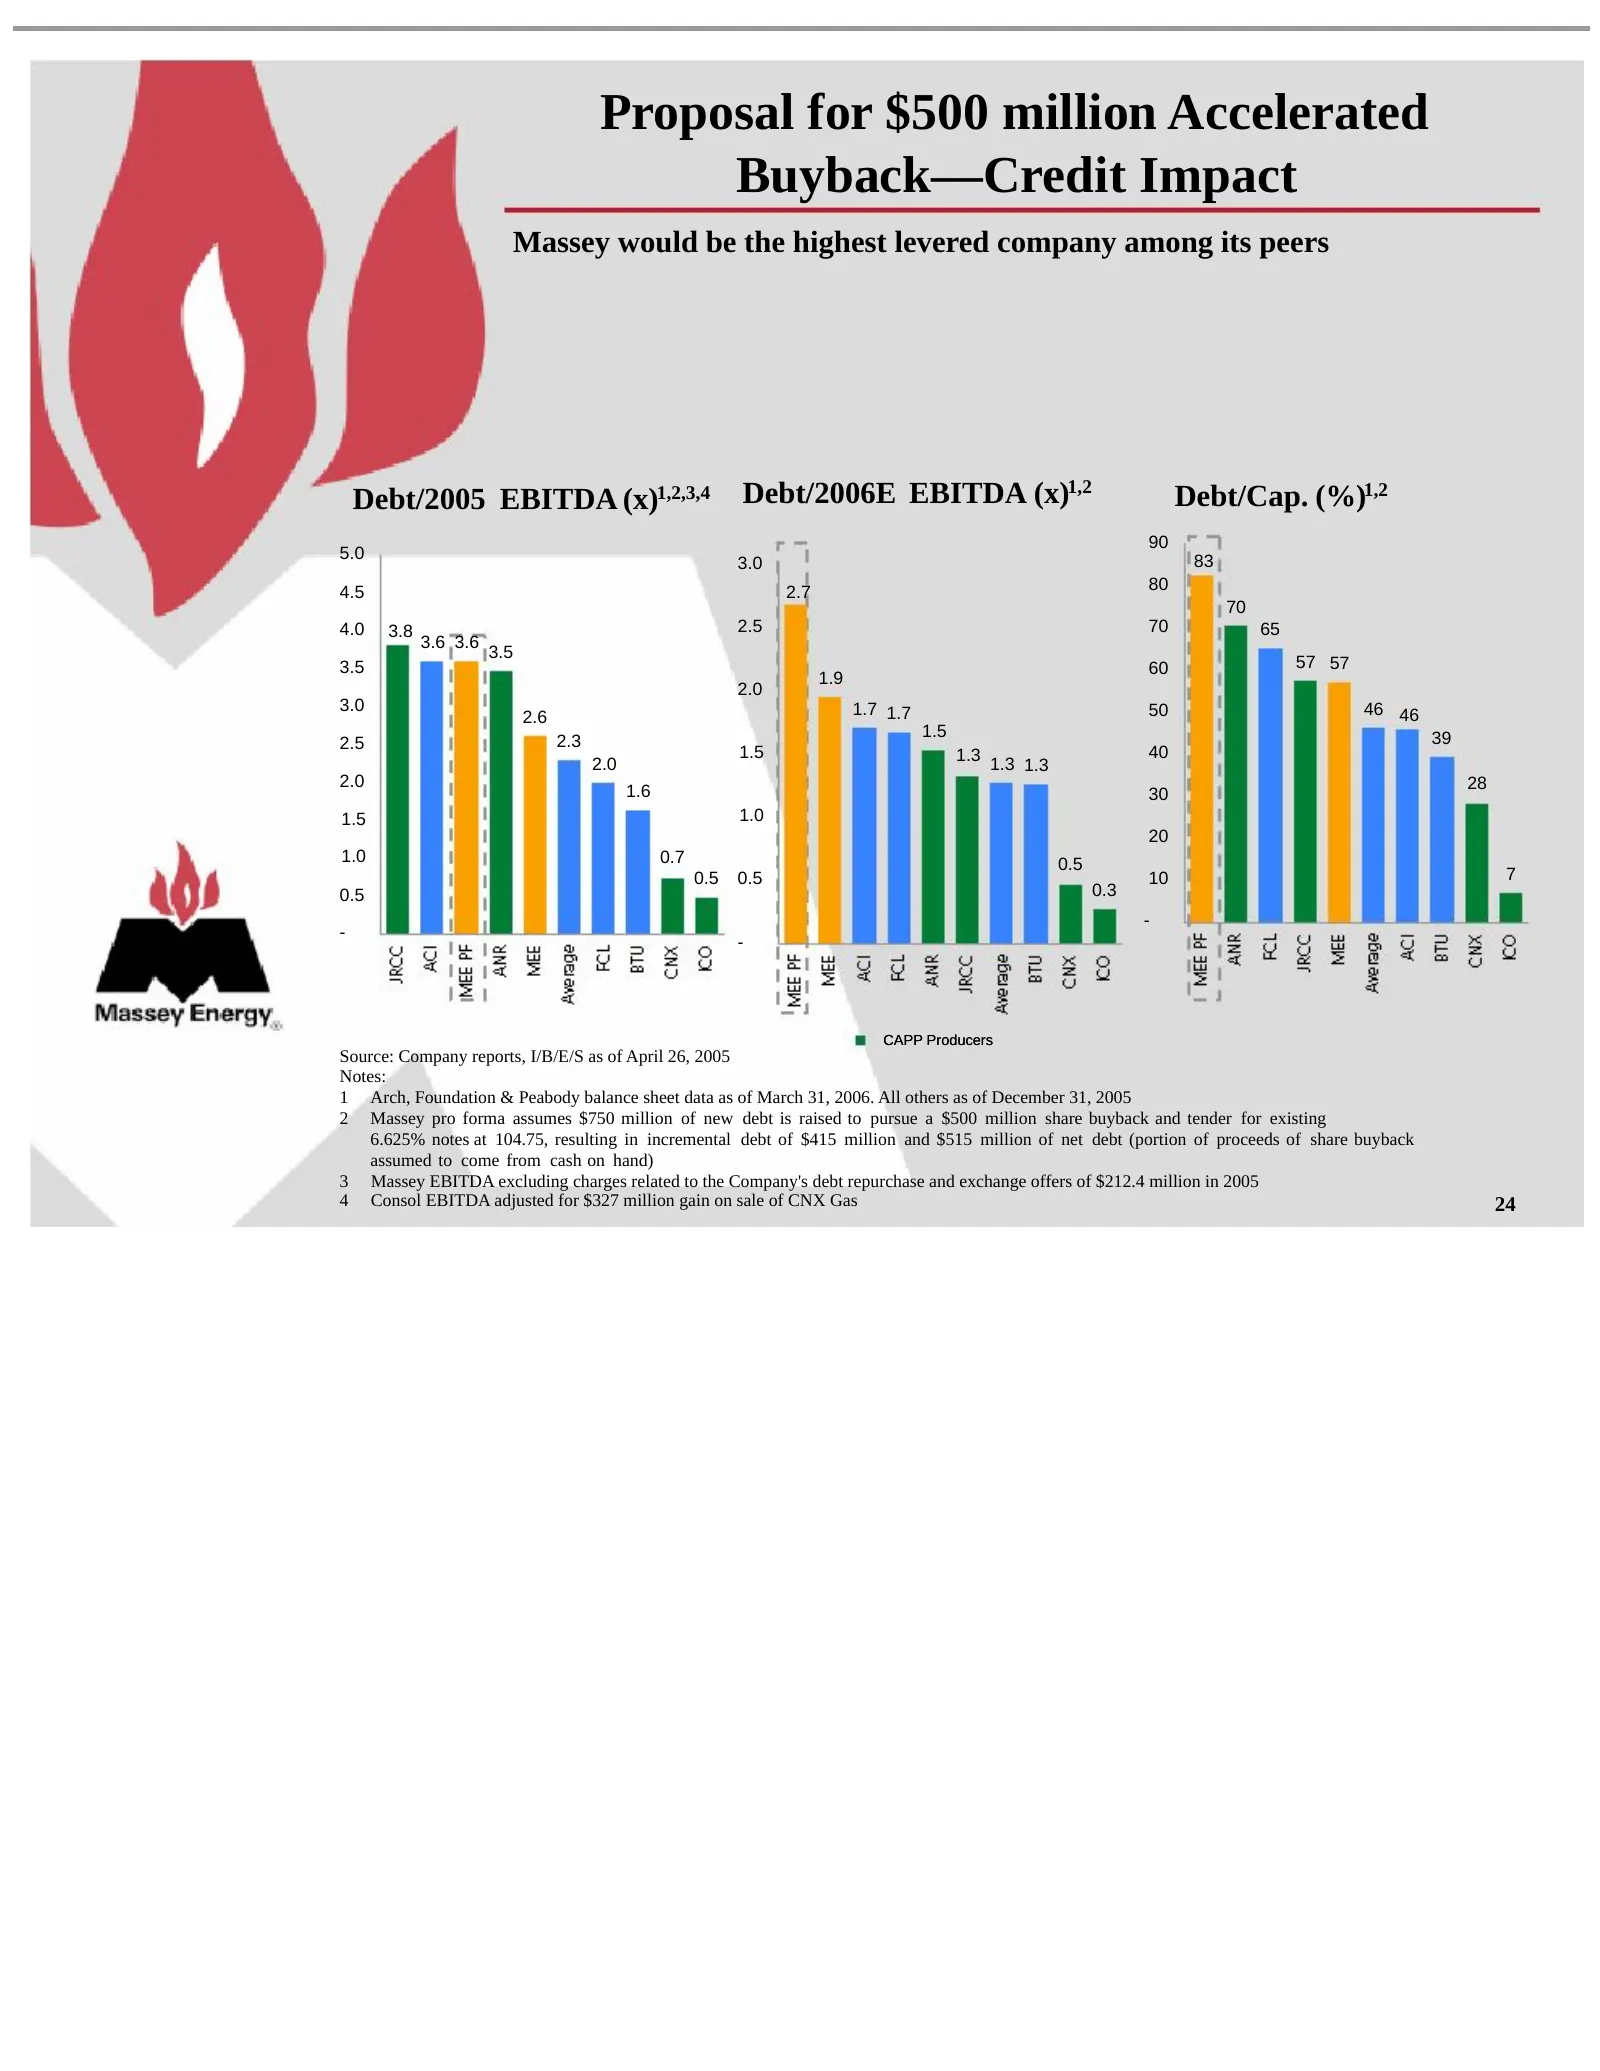
Proposal for $500 million Accelerated Buyback—Credit Impact Massey would be the highest levered company among its peers Debt/2005 EBITDA (x)1,2,3,4 Debt/2006E EBITDA (x)1,2 Debt/Cap. (%)1,2 90 5.0 83 3.0 4.5 2.7 80 70 4.0 3.8 2.5 70 65 3.6 3.6 3.5 3.5 60 57 57 1.9 2.0 3.0 1.7 1.7 50 46 46 2.6 1.5 39
Slide 28: Proposal for $500 million Accelerated Buyback—Credit Impact
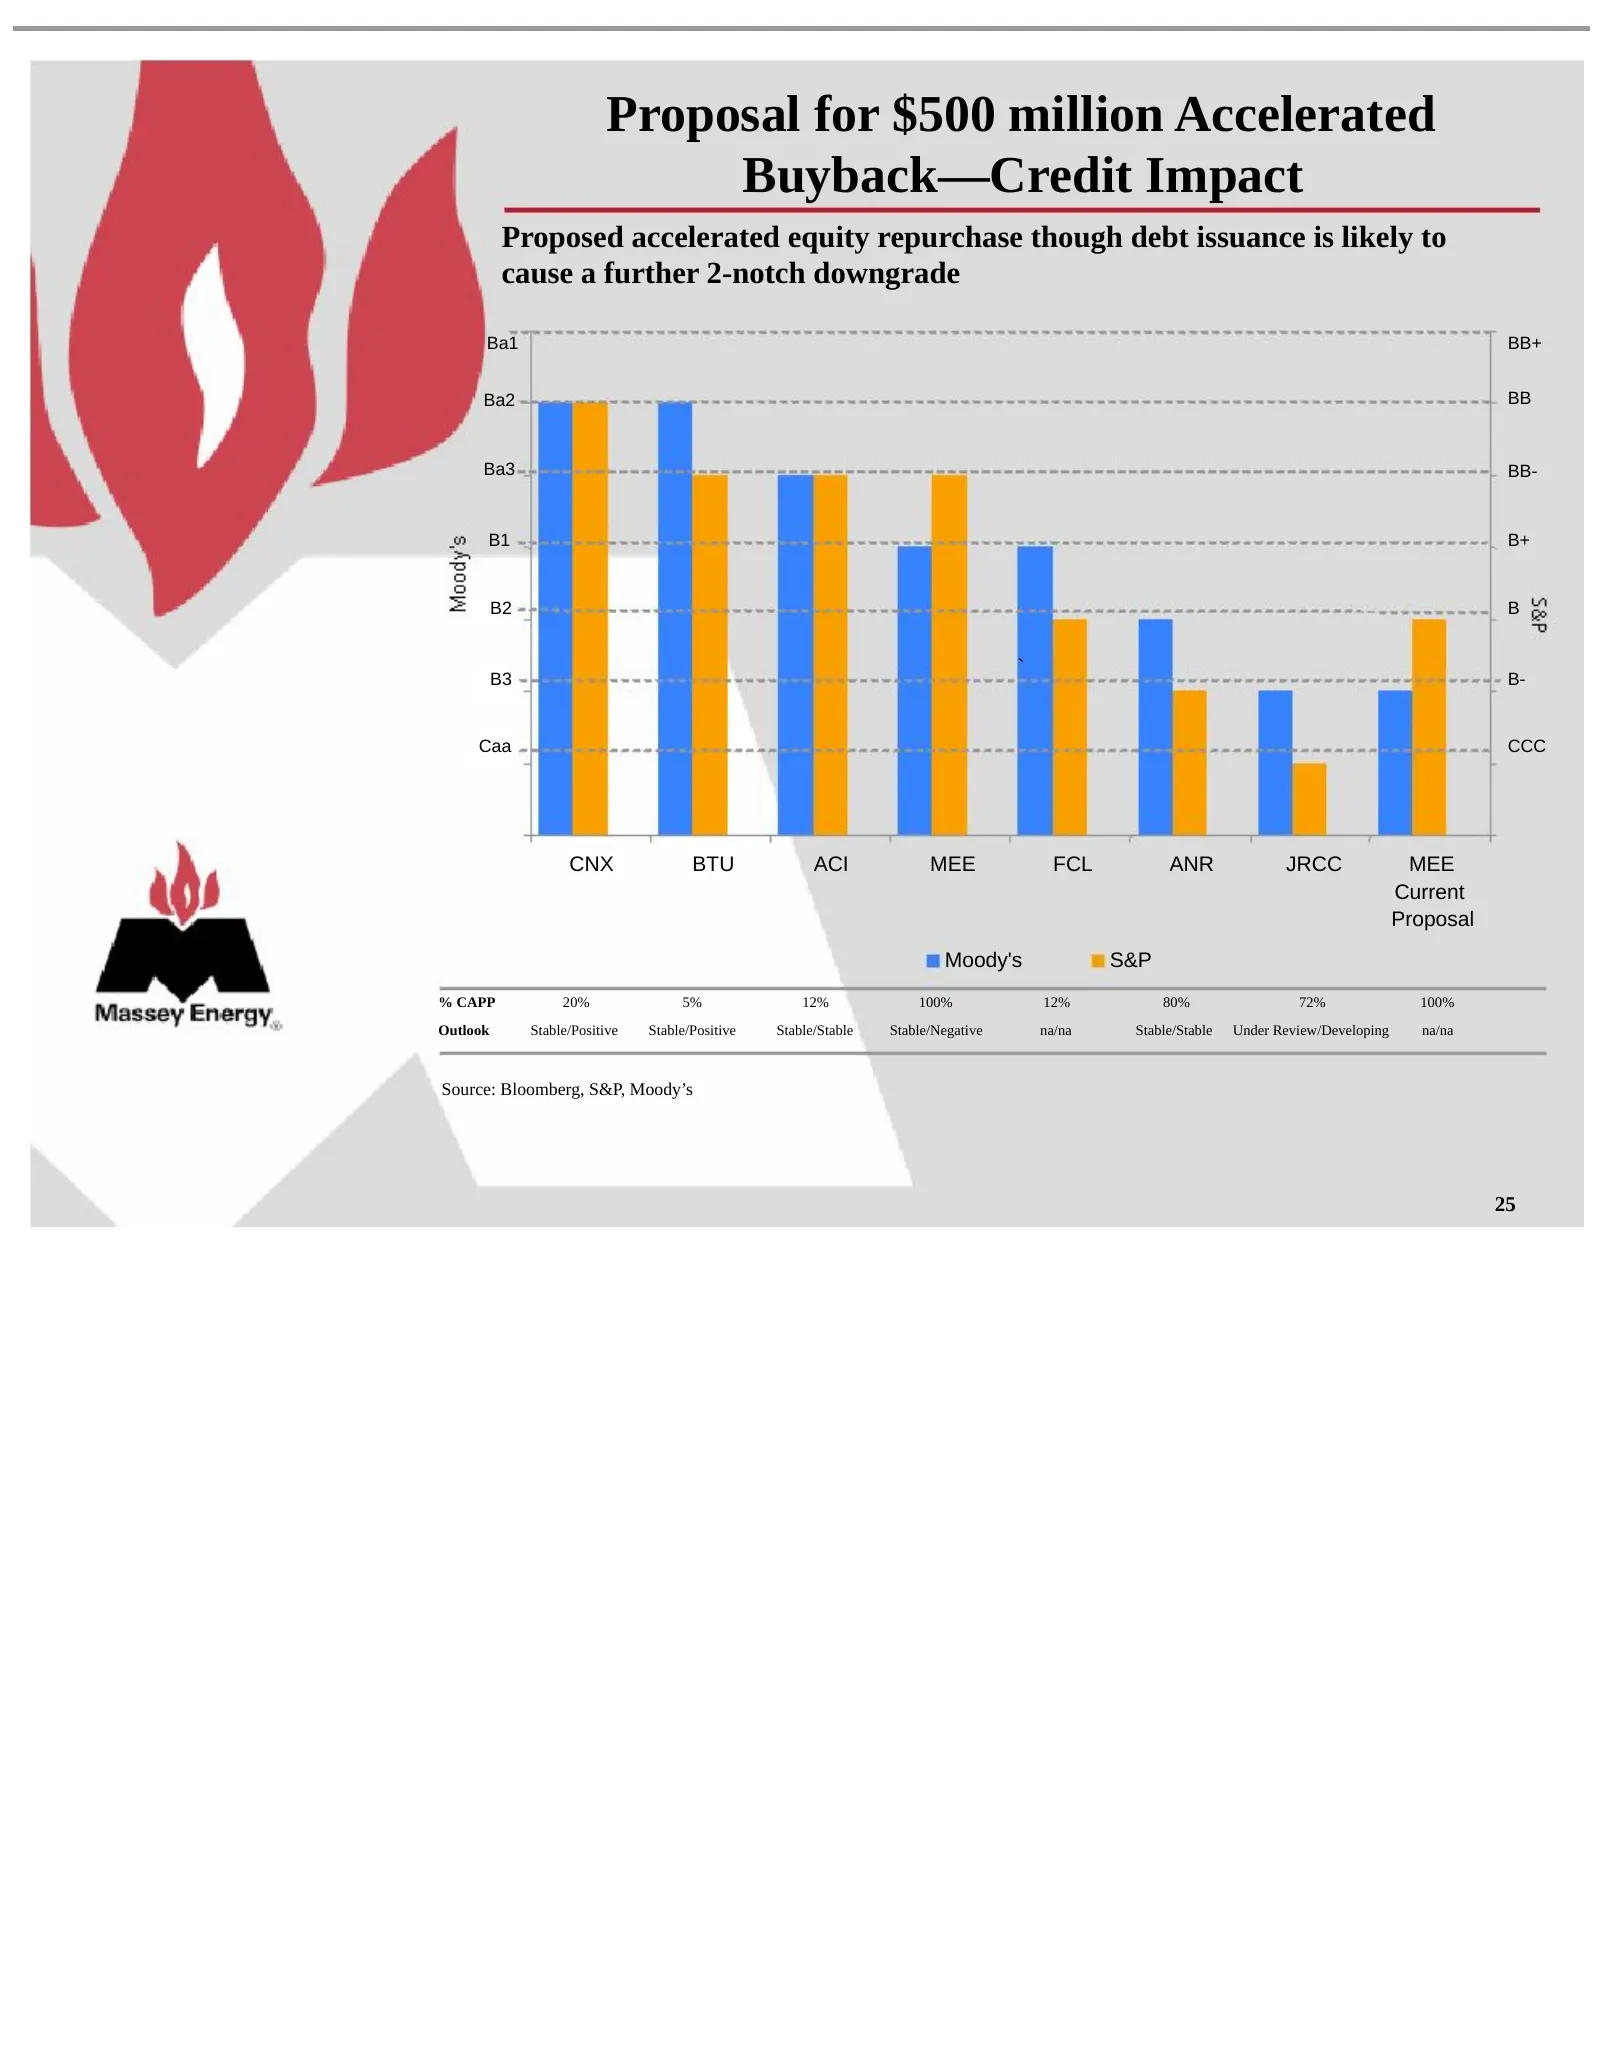
Proposal for $500 million Accelerated Buyback—Credit Impact Proposed accelerated equity repurchase though debt issuance is likely to cause a further 2-notch downgrade Ba1 BB+ Ba2 BB Ba3 BB- B1 B+ B2 B ` B3 B- Caa CCC CNX BTU ACI MEE FCL ANR JRCC MEE Current Proposal Moody's S&P % CAPP 20% 5% 12% 100
Slide 29: Credit Rating Agencies’ Views
Credit Rating Agencies’ Views Operating challenges of Central Appalachia • Permitting for mines in Central Appalachia is a lengthy and time- consuming process, due to regulations, particularly regarding environmental issues • Thinning coal seams, transportation disruptions, and the lack of skilled u
Slide 30: Company’s Proposal
Company’s Proposal • Given Massey’s current share price, the Company has announced the commencement of a share repurchase program – Proposal: undertake up to a $50 million share repurchase in the open market immediately – Monitor opportunities to buy back more shares as operating cash flows improve
Slide 31: Massey’s Director Nominees and Corporate Governance Structure
SECTION 3 Massey’s Director Nominees and Corporate Governance Structure 28
Slide 32: Corporate Governance Structure
Corporate Governance Structure The Company has a strong corporate governance and culture in place that prioritizes shareholder interest The Board has four committees (number of members) to facilitate active oversight on the following areas: – Audit Committee (6) Active Role – Compensation Committee
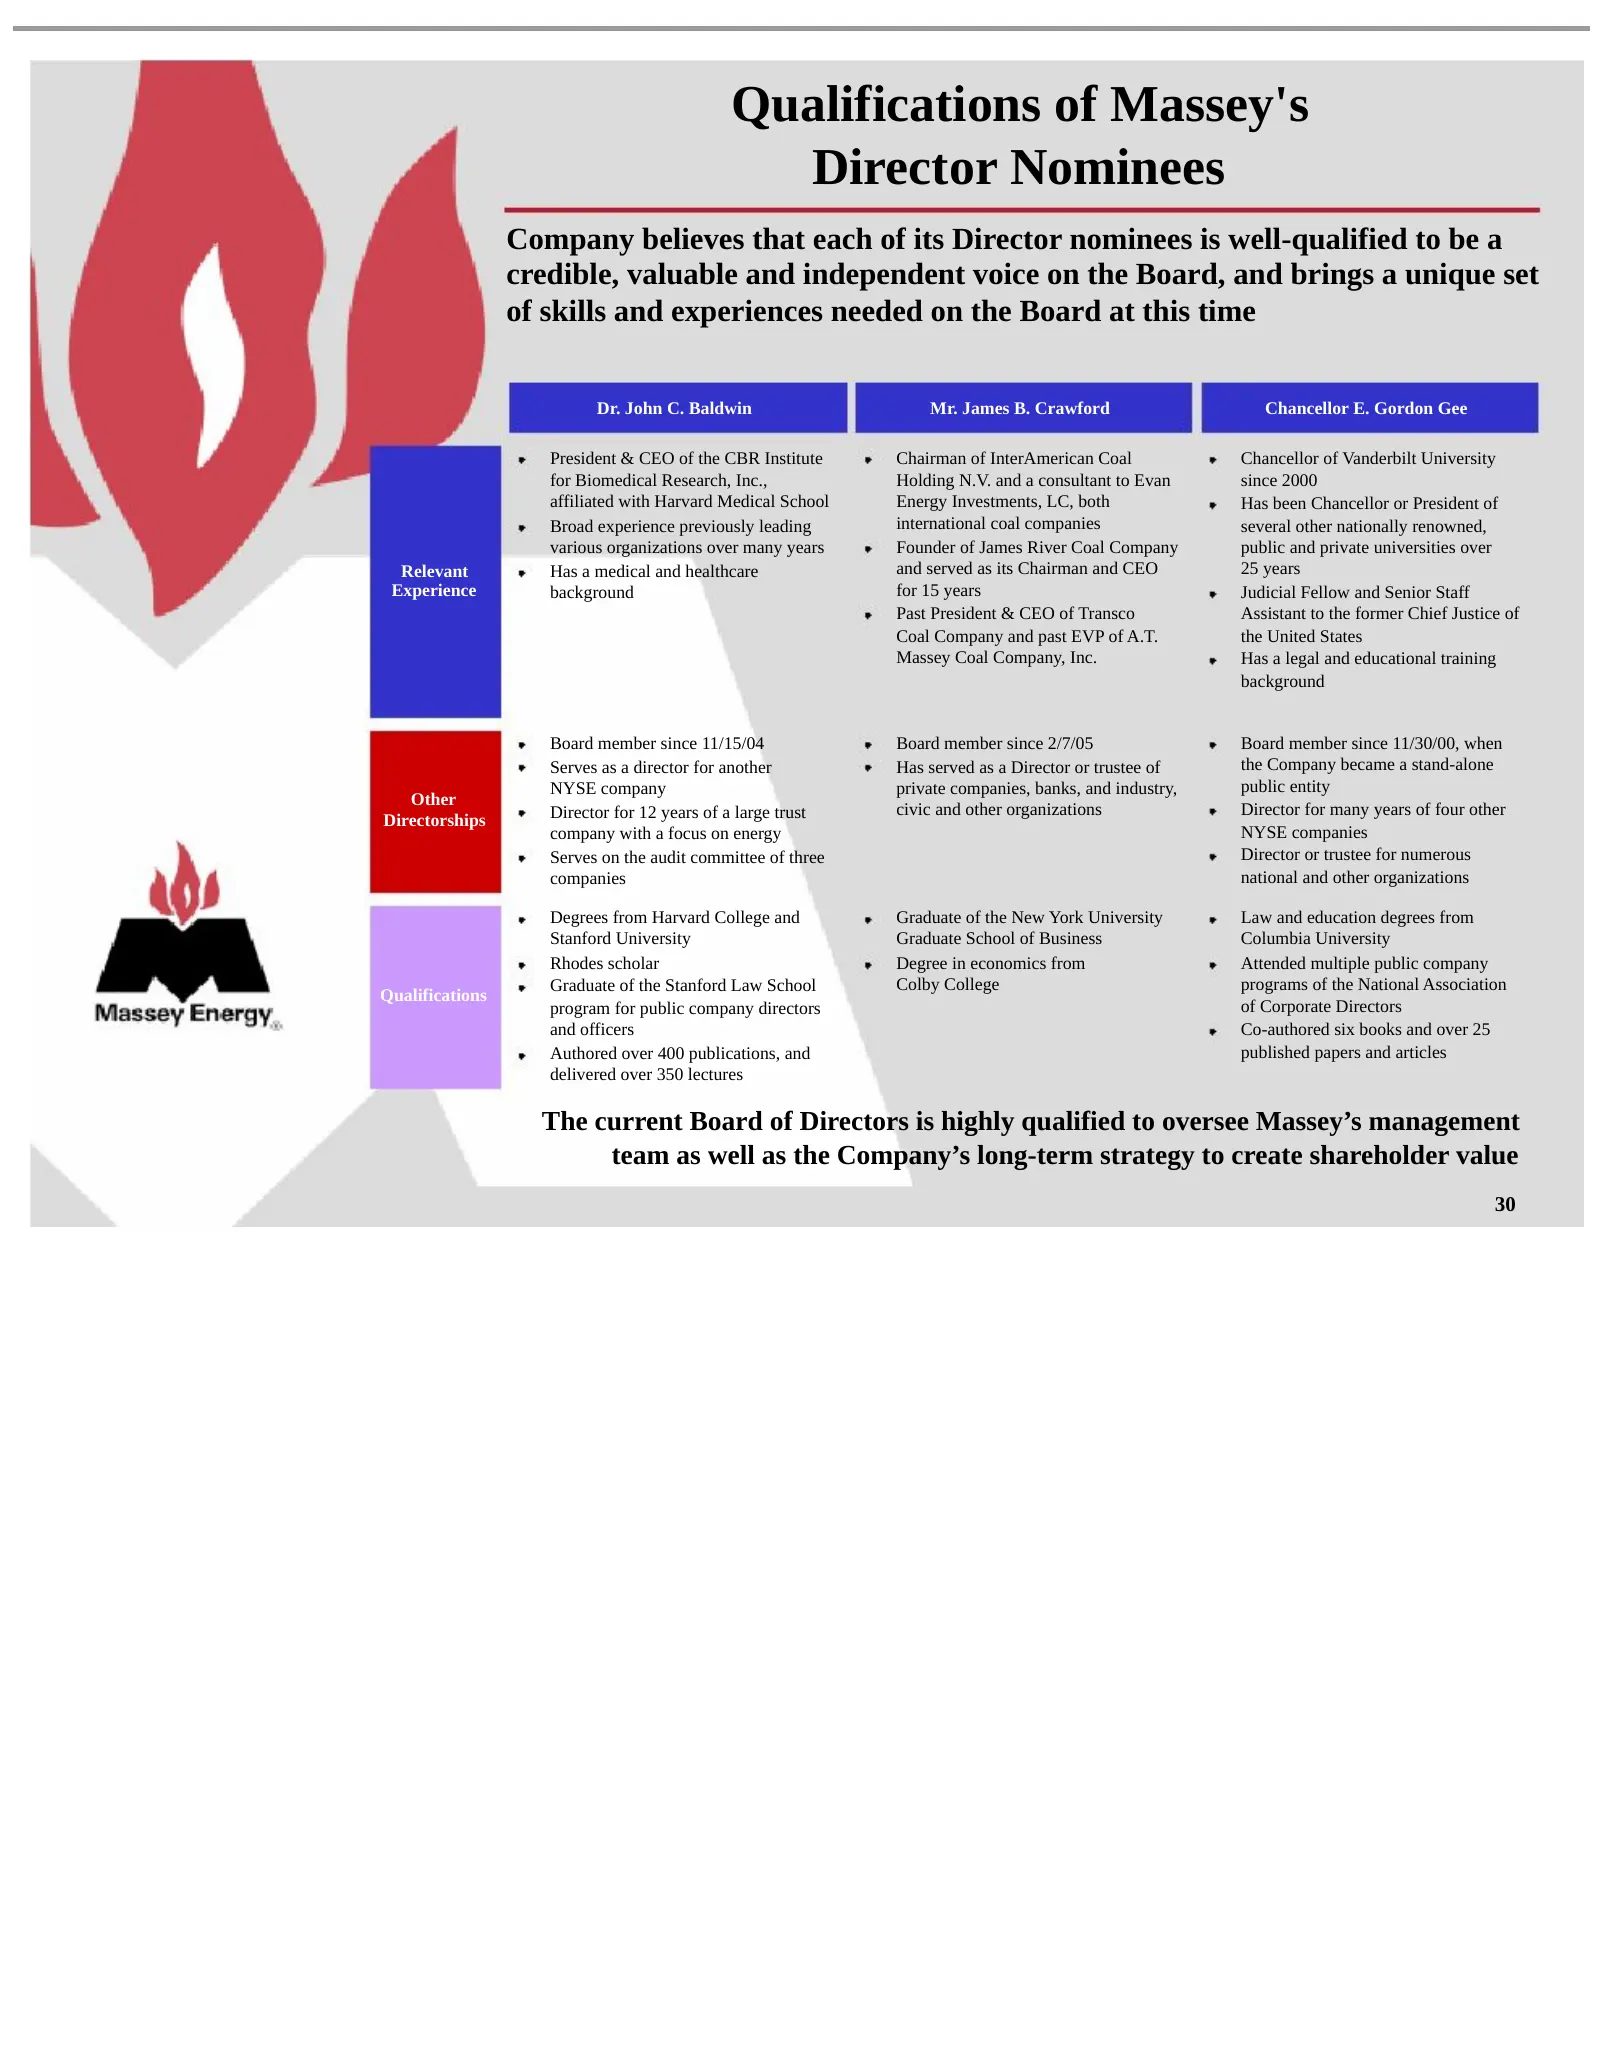
Slide 33: Qualifications of Massey's Director Nominees
Qualifications of Massey's Director Nominees Company believes that each of its Director nominees is well-qualified to be a credible, valuable and independent voice on the Board, and brings a unique set of skills and experiences needed on the Board at this time Dr. John C. Baldwin Mr. James B. Crawfo
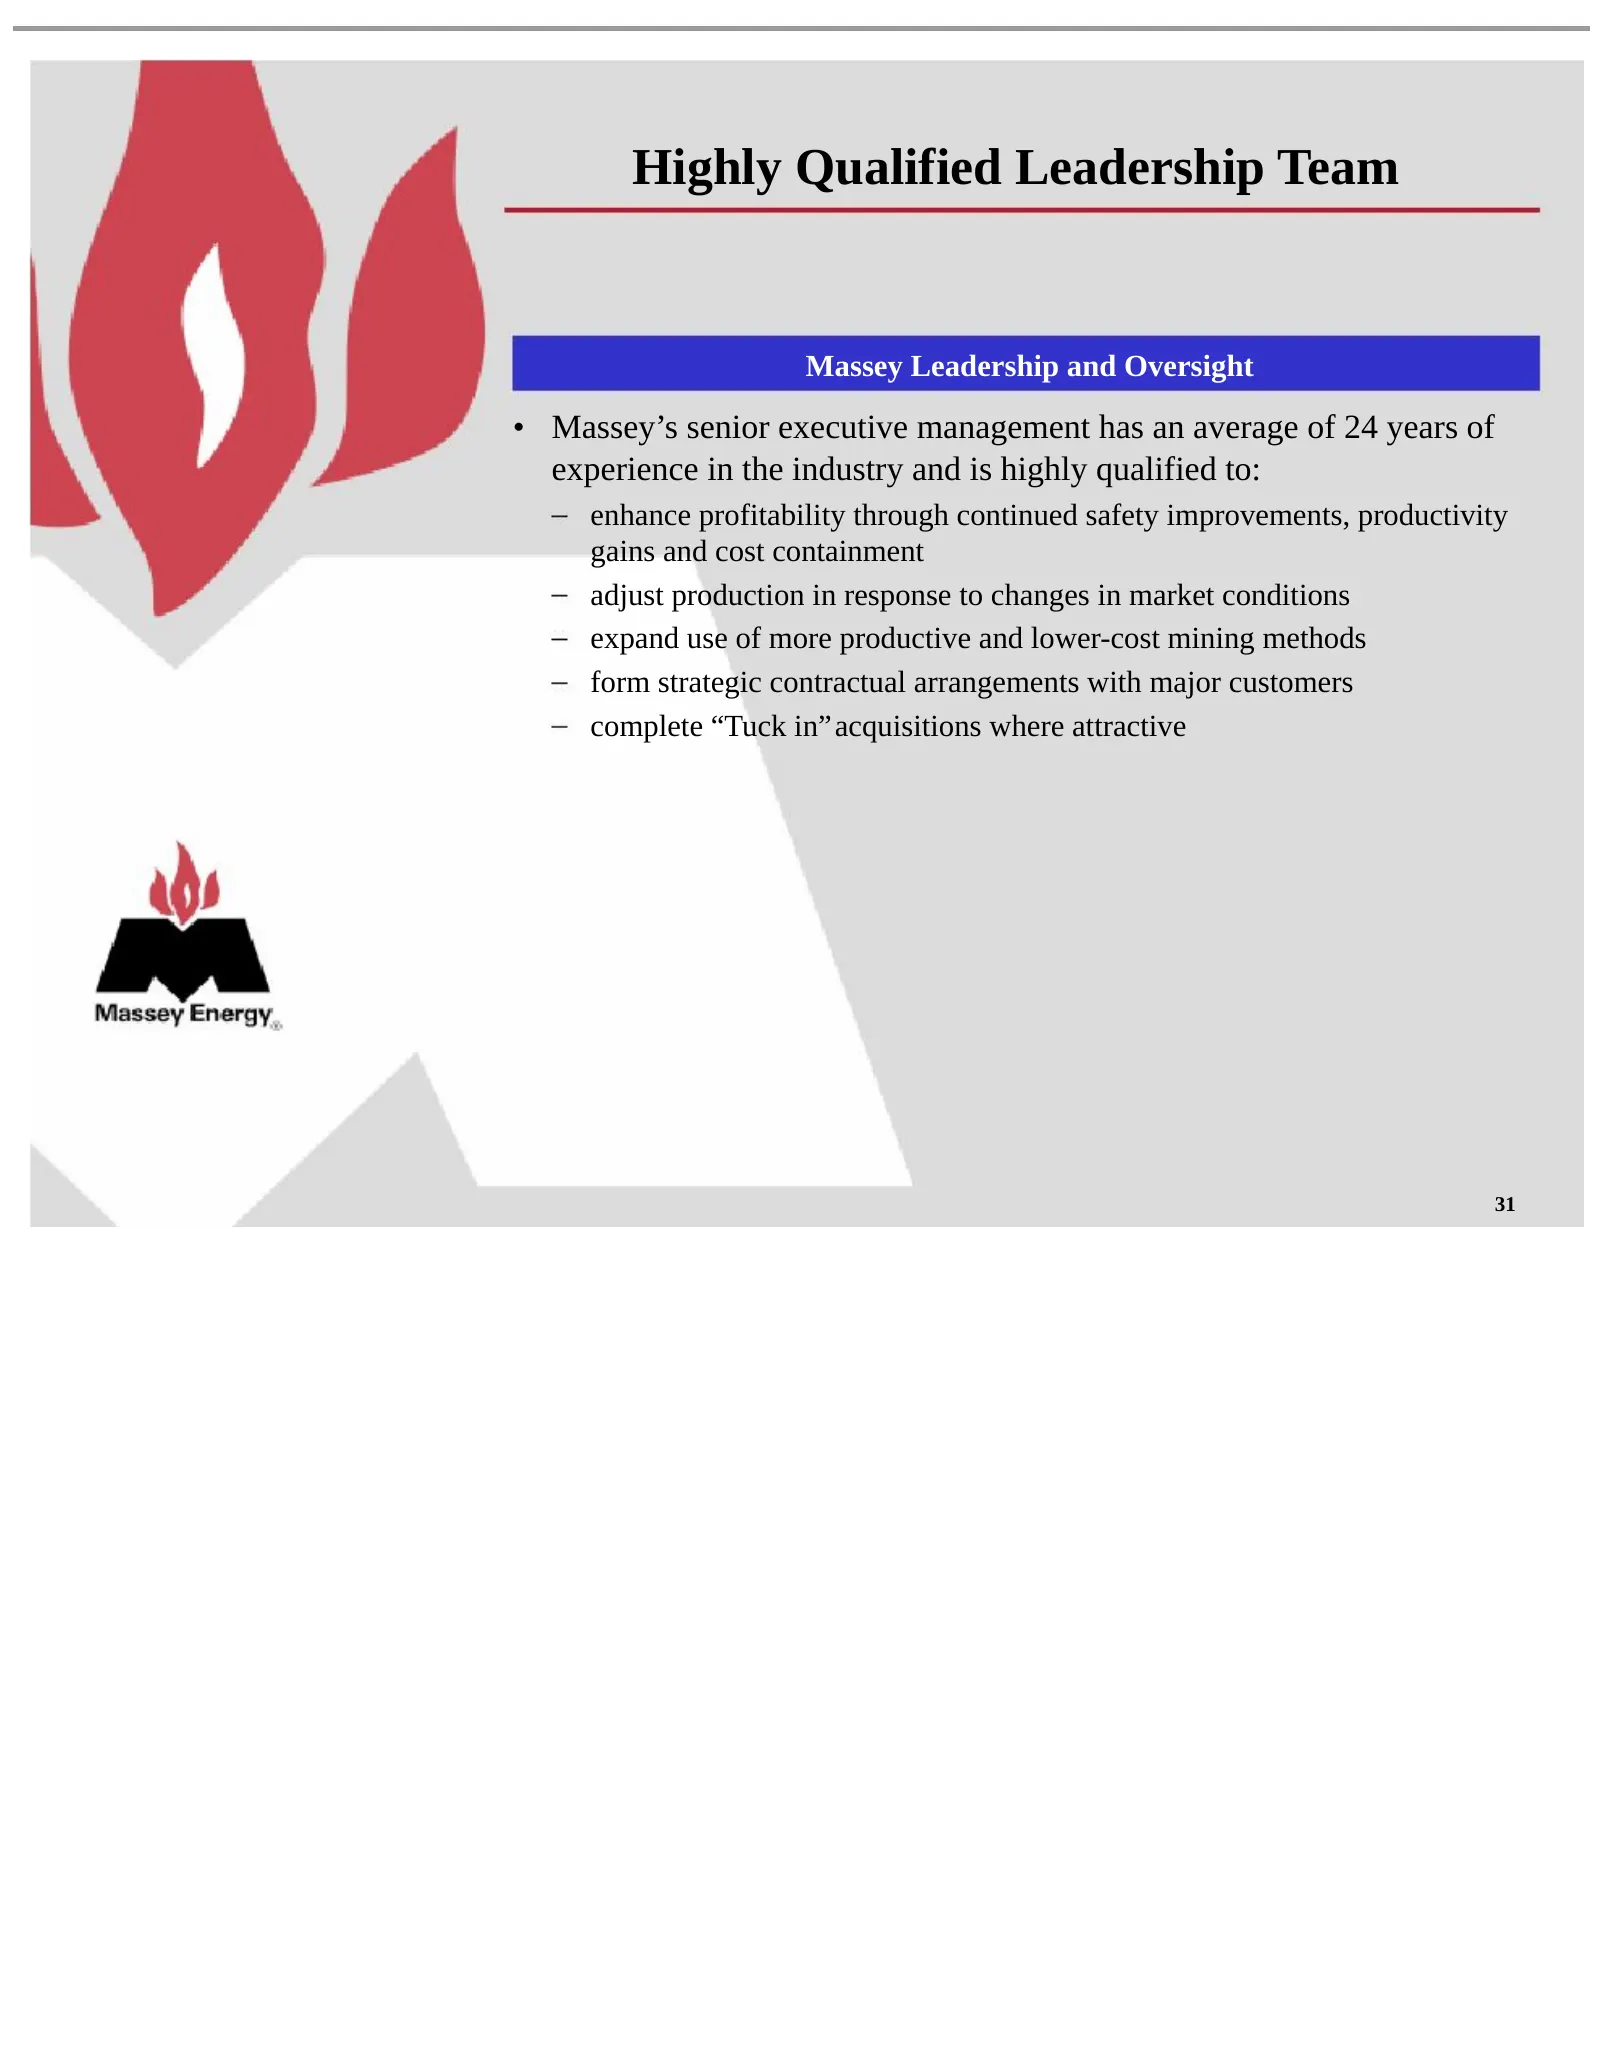
Slide 34: Highly Qualified Leadership Team
Highly Qualified Leadership Team Massey Leadership and Oversight • Massey’s senior executive management has an average of 24 years of experience in the industry and is highly qualified to: enhance profitability through continued safety improvements, productivity gains and cost containment adjust pro
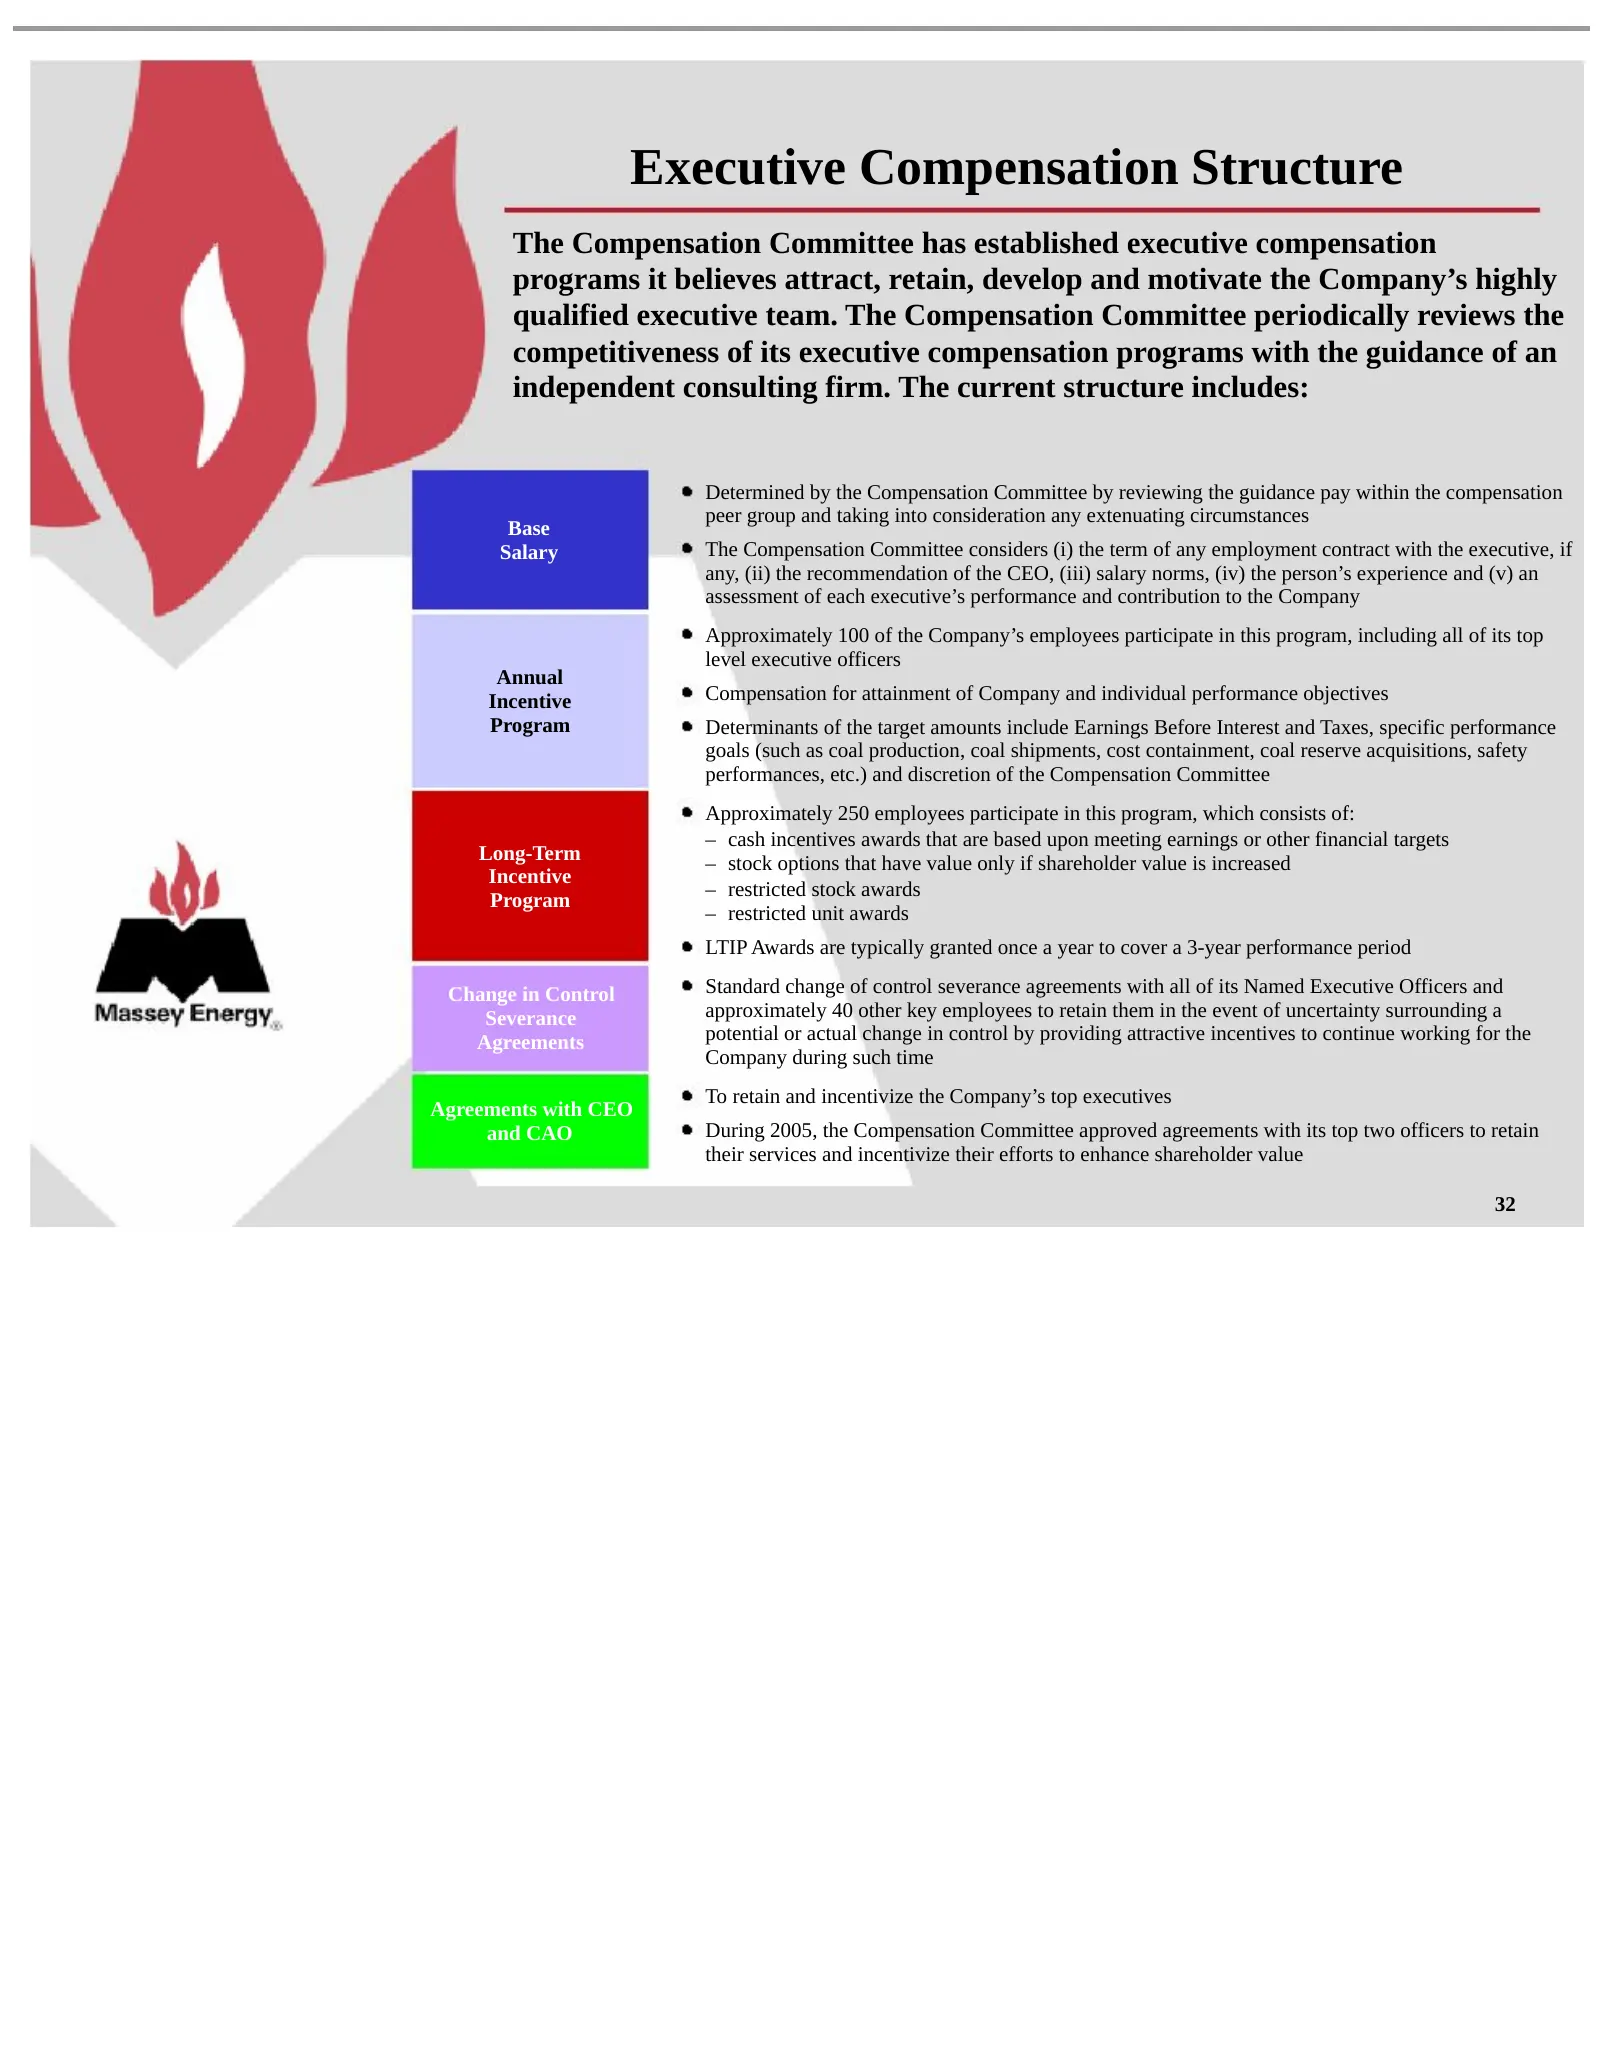
Slide 35: Executive Compensation Structure
Executive Compensation Structure The Compensation Committee has established executive compensation programs it believes attract, retain, develop and motivate the Company’s highly qualified executive team. The Compensation Committee periodically reviews the competitiveness of its executive compensati
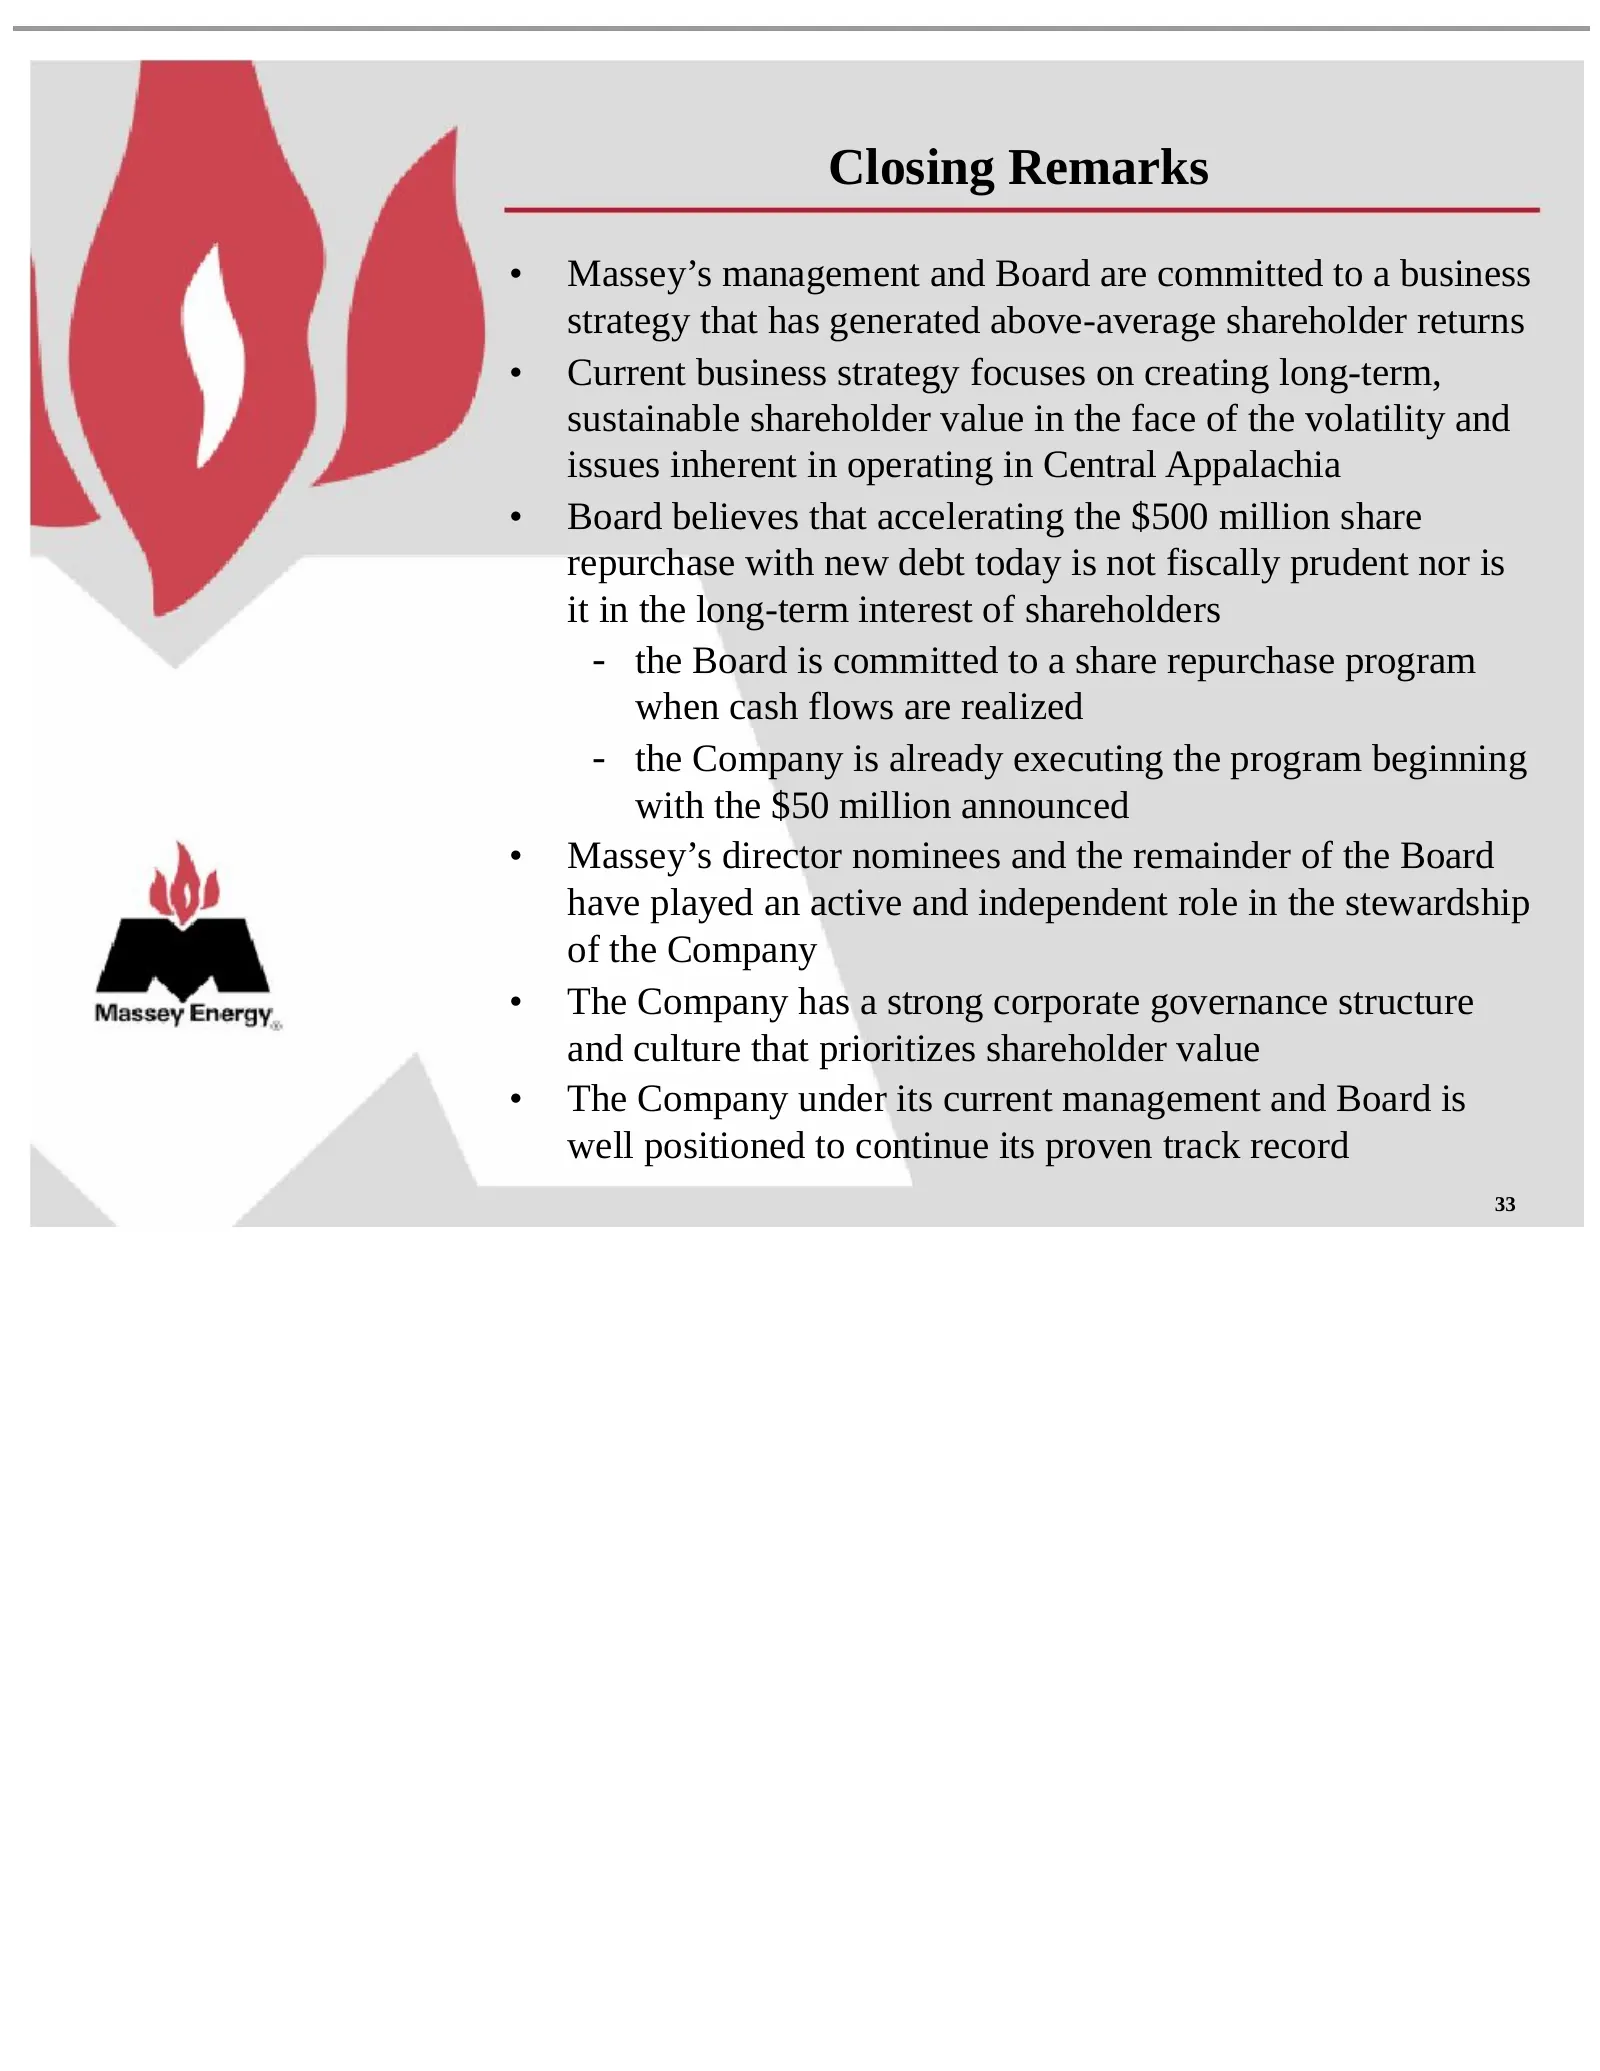
Slide 36: Closing Remarks
Closing Remarks • Massey’s management and Board are committed to a business strategy that has generated above-average shareholder returns • Current business strategy focuses on creating long-term, sustainable shareholder value in the face of the volatility and issues inherent in operating in Central
Slide 37: Disclaimer
Disclaimer FORWARD-LOOKING STATEMENTS: Certain statements in this presentation are forward-looking as defined by the Private Securities Litigation Reform Act of 1995. Such forward-looking statements are based on facts and conditions as they exist at the time such statements are made as well as predi
Source: SEC EDGAR · DEFA14A filed May 3, 2006
More decks from Massey Energy Co
 Merger or Acquisition (March 2011)18 slides · Mar 9, 2011
 BMO Capital Markets 2011 Global Metals & Mining Conference27 slides · Mar 1, 2011
 Credit Suisse Energy Summit 201126 slides · Feb 10, 2011
 Merger or Acquisition (January 2011)19 slides · Jan 31, 2011
 Proxy Contest (May 2010)32 slides · May 5, 2010
 Proxy Contest (April 2010)26 slides · Apr 30, 2010