Tellurian — Investor Presentation (May 2021)
32 slides from Tellurian's investor presentation, May 27, 2021
Slide 1: Tellurian Inc. Corporate presentation May 2021
Tellurian Inc. May 2021 Corporate presentation
Slide 2: Cautionary statements
Cautionary statements The information in this presentation includes “forward - looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. All statements other than statements of historical fact
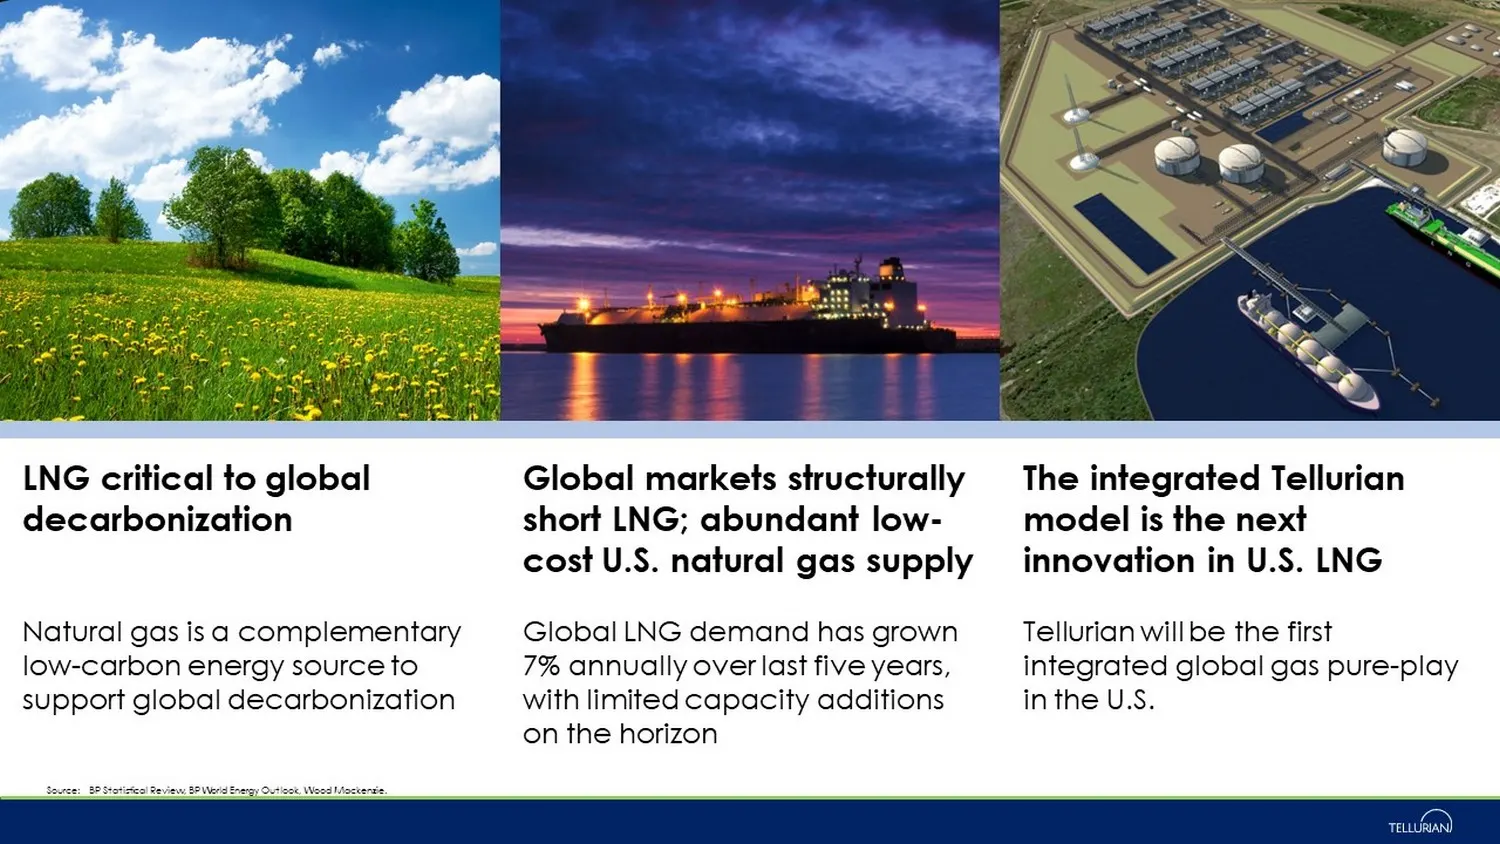
Slide 3: LNG critical to global decarbonization
LNG critical to global decarbonization Source: BP Statistical Review, BP World Energy Outlook, Wood Mackenzie. Global markets structurally short LNG; abundant low - cost U.S. natural gas supply The integrated Tellurian model is the next innovation in U.S. LNG Natural gas is a complementary low - car
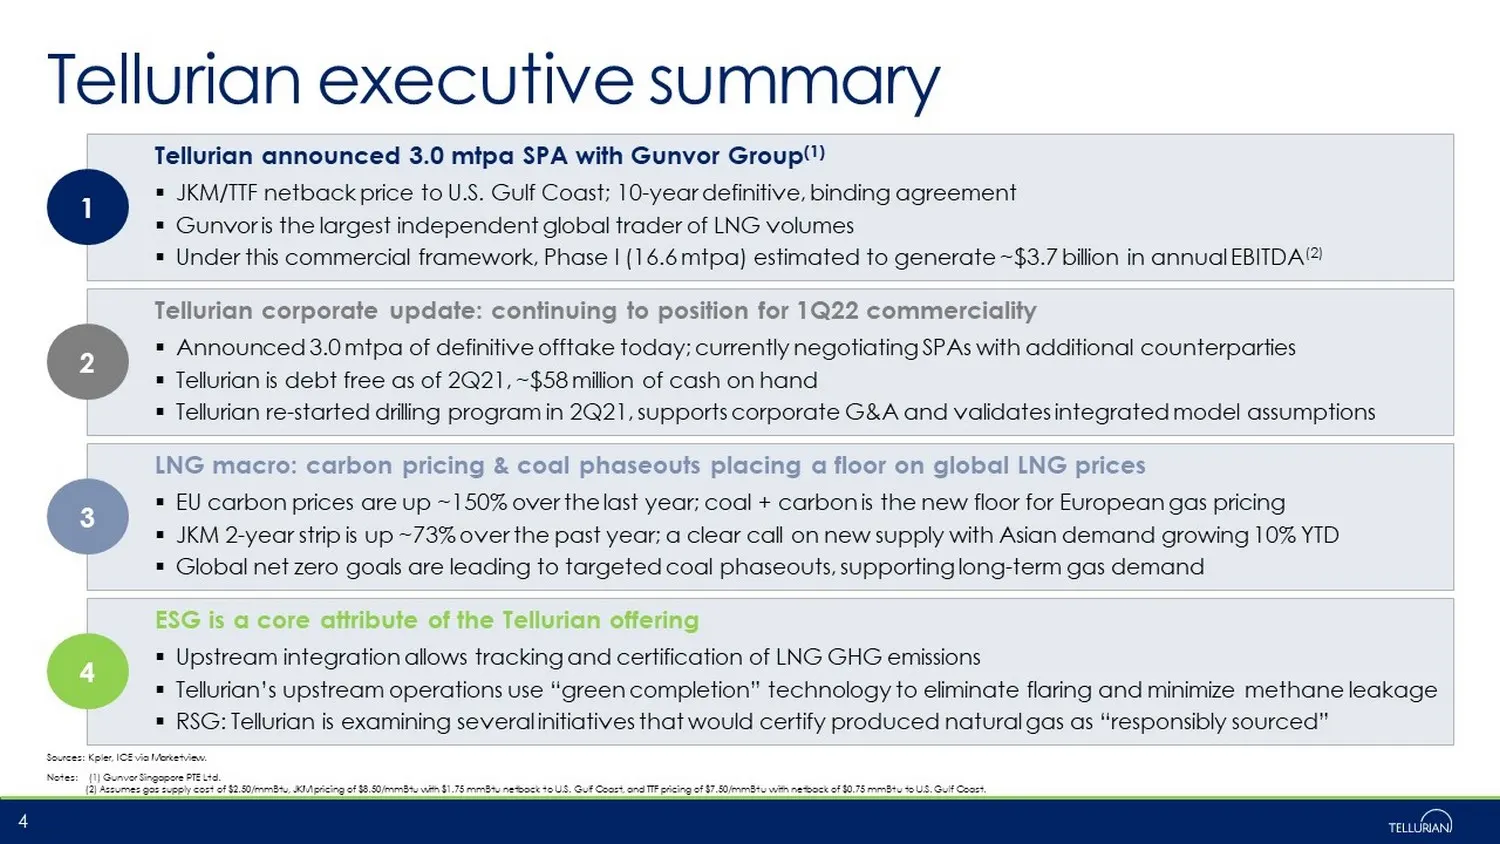
Slide 4: Tellurian executive summary
Tellurian executive summary 4 Tellurian announced 3.0 mtpa SPA with Gunvor Group (1) ▪ JKM/TTF netback price to U.S. Gulf Coast; 10 - year definitive, binding agreement ▪ Gunvor is the largest independent global trader of LNG volumes ▪ Under this commercial framework, Phase I (16.6 mtpa ) estimated
Slide 5: The integrated Tellurian model is the next innovation in U.S. LNG
The integrated Tellurian model is the next innovation in U.S. LNG
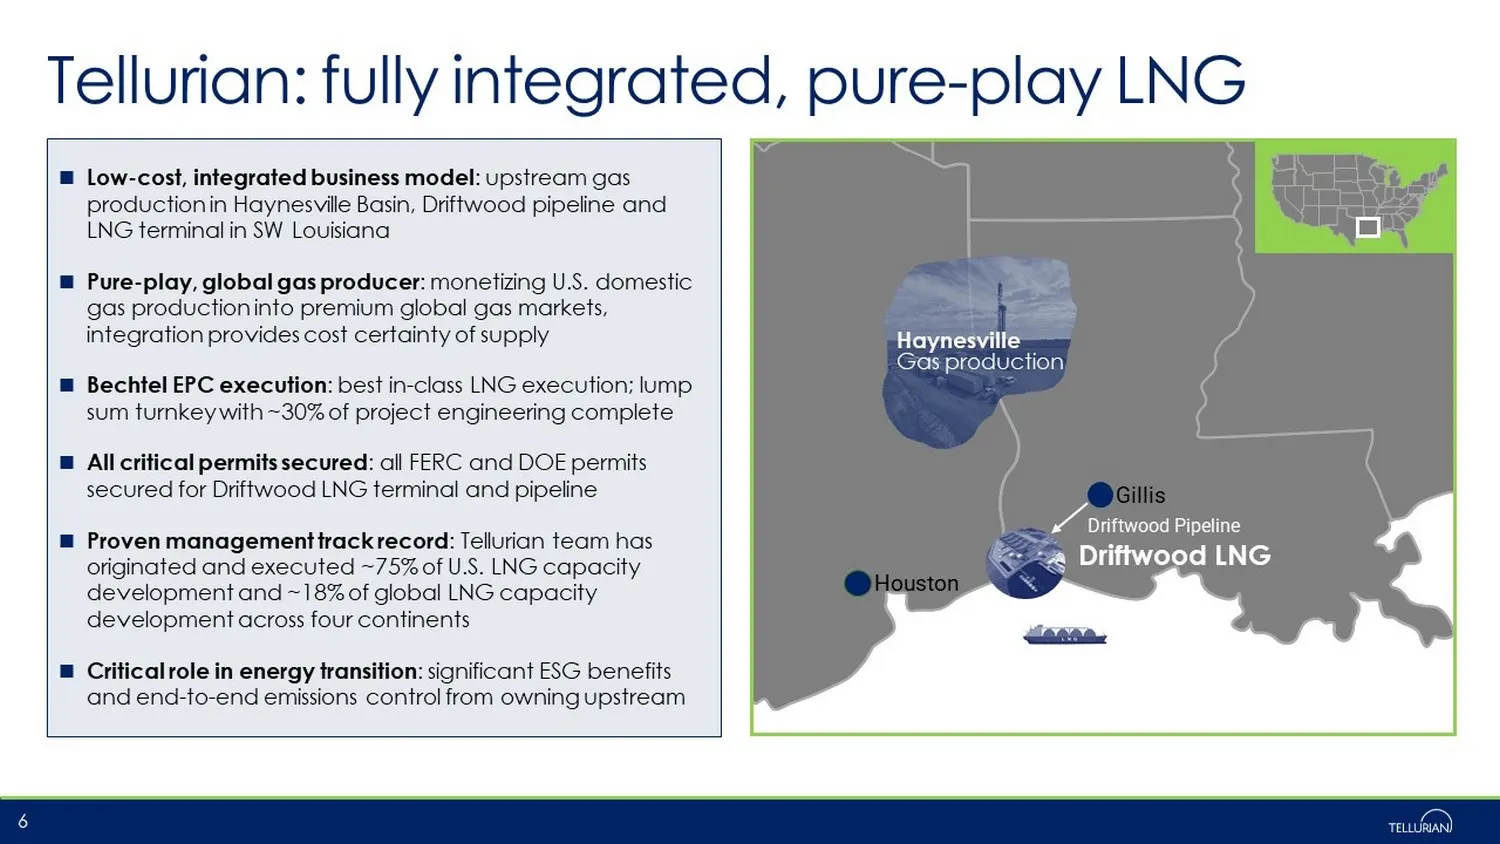
Slide 6: Tellurian: fully integrated, pure-play LNG
Houston Gillis Haynesville Gas production Driftwood LNG Driftwood Pipeline Tellurian: fully integrated, pure - play LNG 6 Low - cost, integrated business model : upstream gas production in Haynesville Basin, Driftwood pipeline and LNG terminal in SW Louisiana Pure - play, global gas producer : monet
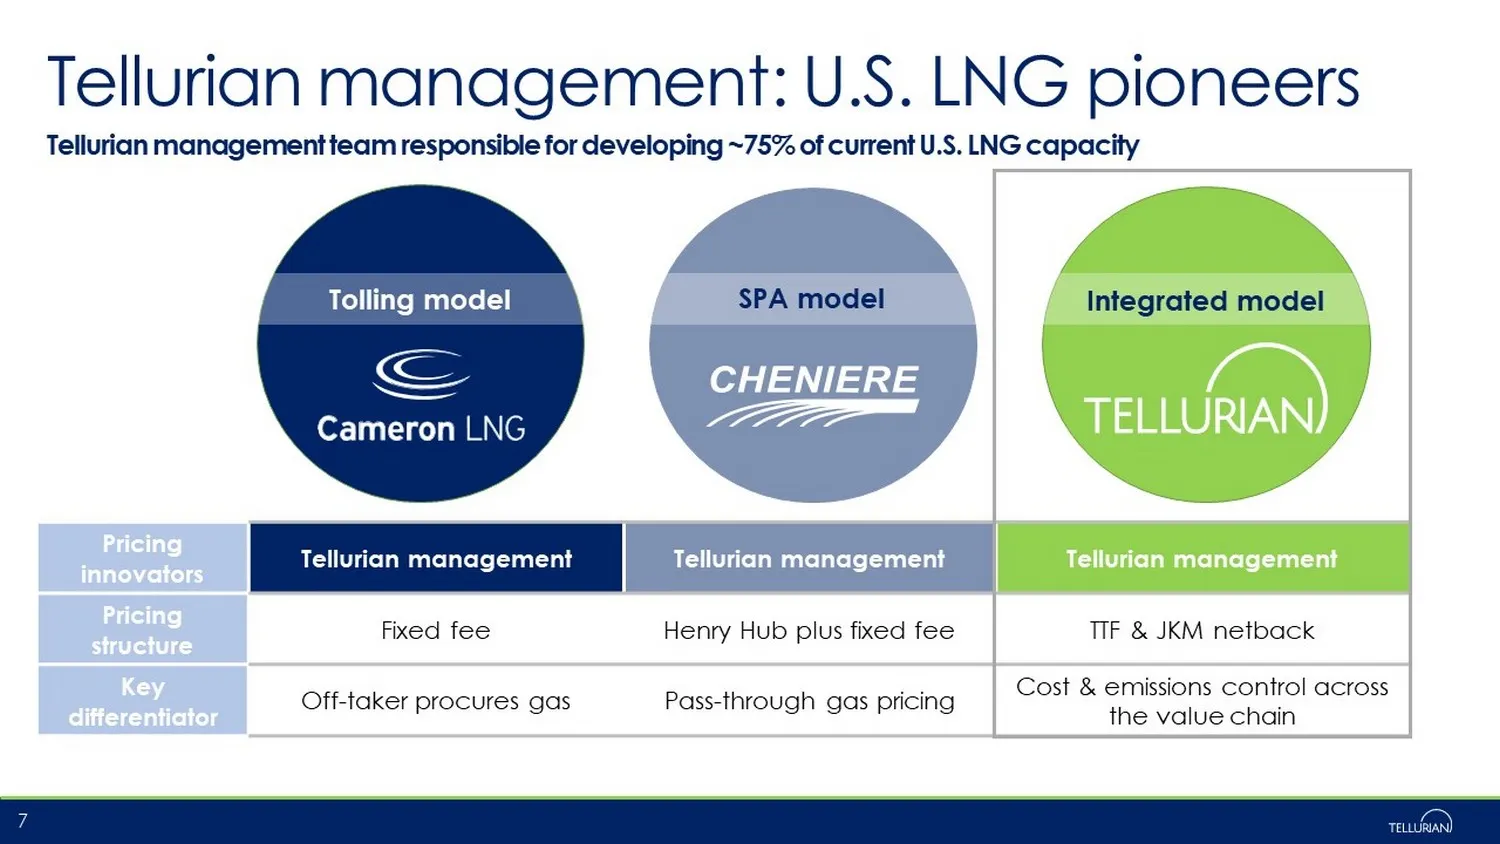
Slide 7: Tellurian management: U.S. LNG pioneers
Tellurian management: U.S. LNG pioneers 7 Tellurian management team responsible for developing ~75% of current U.S. LNG capacity Tolling model SPA model Integrated model Pricing innovators Tellurian management Tellurian management Tellurian management Pricing structure Fixed fee Henry Hub plus fixed
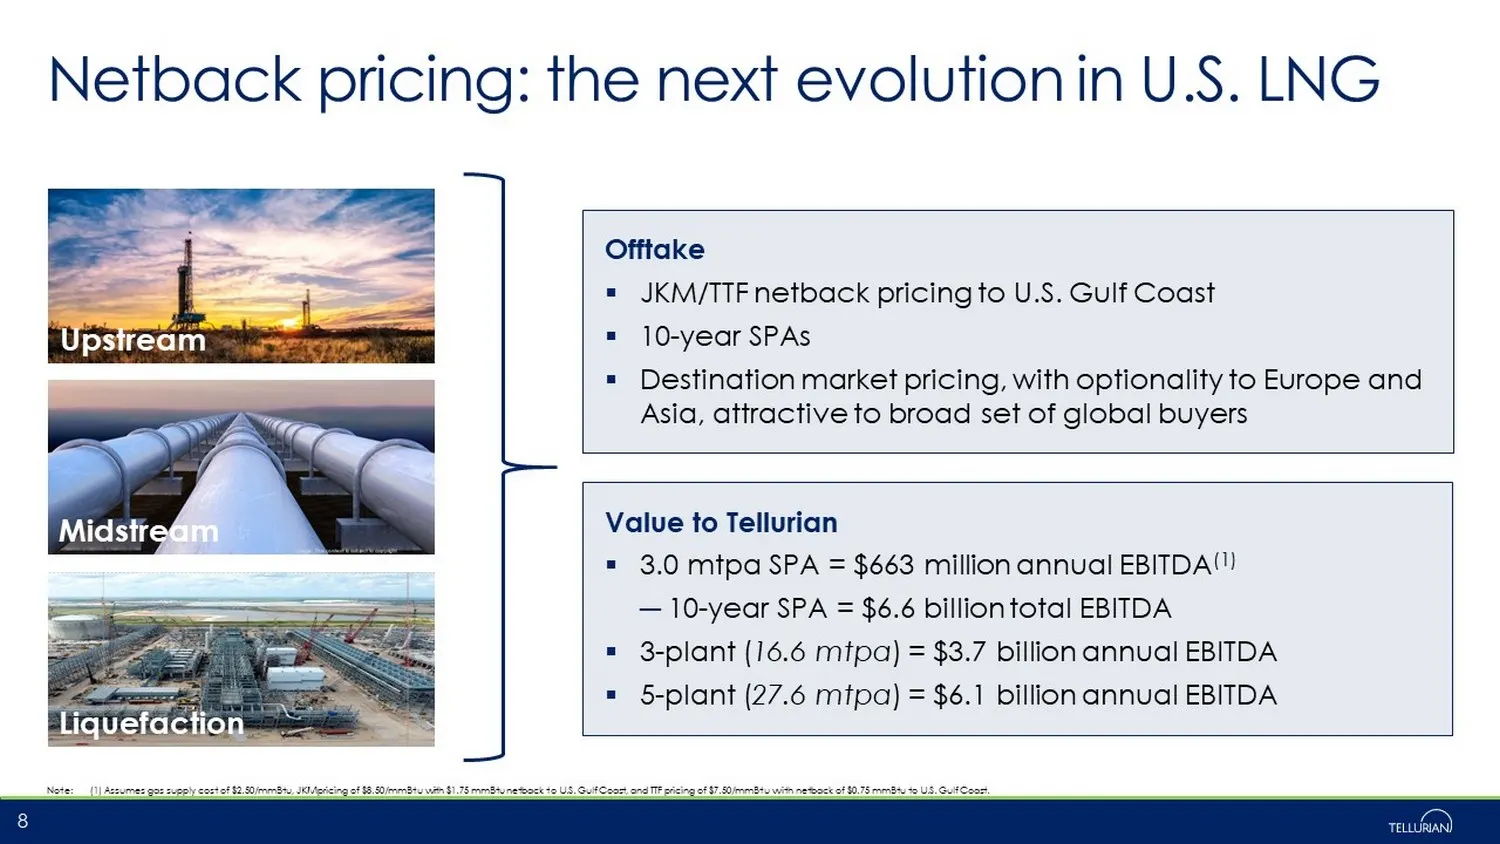
Slide 8: Netback pricing: the next evolution in U.S. LNG
Netback pricing: the next evolution in U.S. LNG Note: (1) Assumes gas supply cost of $2.50/mmBtu, JKM pricing of $8.50/mmBtu with $1.75 mmBtu netback to U.S. Gulf Coast, and TT F pricing of $7.50/mmBtu with netback of $0.75 mmBtu to U.S. Gulf Coast. 8 Value to Tellurian ▪ 3.0 mtpa SPA = $663 million
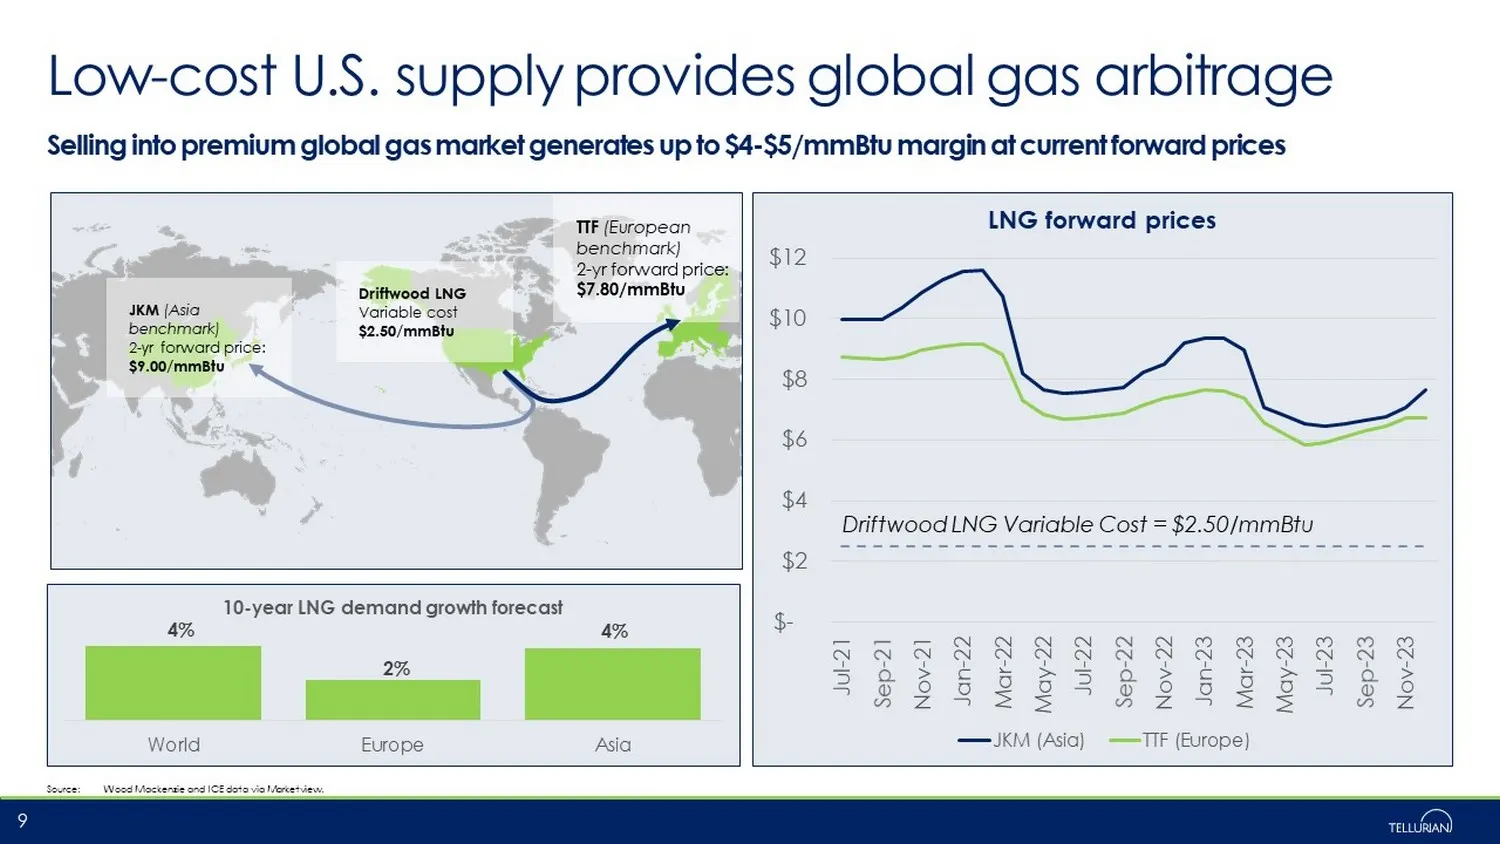
Slide 9: Low-cost U.S. supply provides global gas arbitrage
$- $2 $4 $6 $8 $10 $12 Jul-21 Sep-21 Nov-21 Jan-22 Mar-22 May-22 Jul-22 Sep-22 Nov-22 Jan-23 Mar-23 May-23 Jul-23 Sep-23 Nov-23 LNG forward prices JKM (Asia) TTF (Europe) Low - cost U.S. supply provides global gas arbitrage 9 Selling into premium global gas market generates up to $4 - $5/mmBtu margi
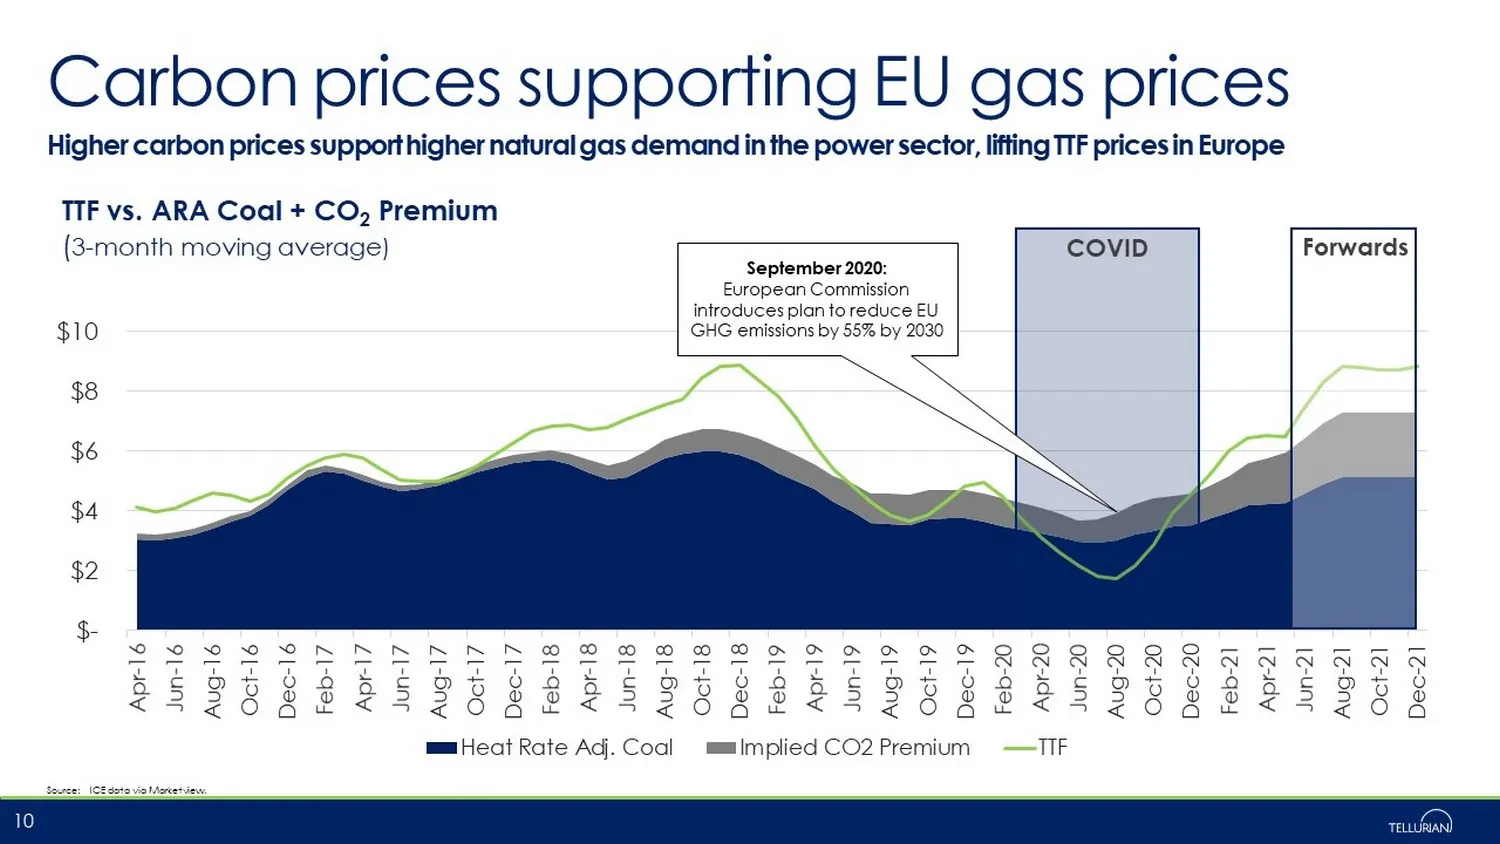
Slide 10: Carbon prices supporting EU gas prices
$- $2 $4 $6 $8 $10 Apr-16 Jun-16 Aug-16 Oct-16 Dec-16 Feb-17 Apr-17 Jun-17 Aug-17 Oct-17 Dec-17 Feb-18 Apr-18 Jun-18 Aug-18 Oct-18 Dec-18 Feb-19 Apr-19 Jun-19 Aug-19 Oct-19 Dec-19 Feb-20 Apr-20 Jun-20 Aug-20 Oct-20 Dec-20 Feb-21 Apr-21 Jun-21 Aug-21 Oct-21 Dec-21 TTF vs. ARA Coal + CO 2 Premium ( 3
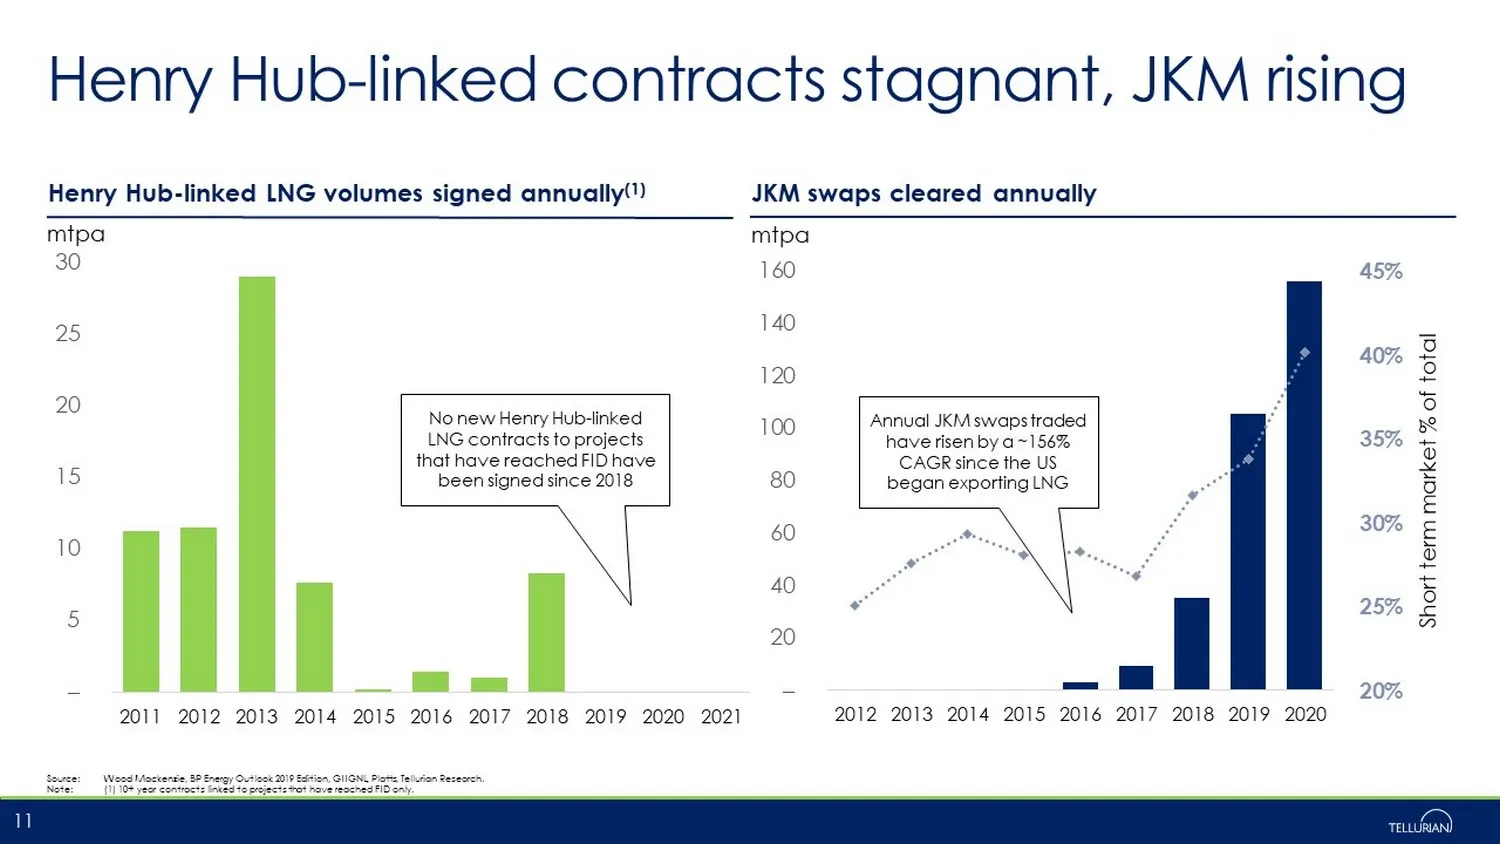
Slide 11: Henry Hub-linked contracts stagnant, JKM rising
– 5 10 15 20 25 30 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 mtpa 20% 25% 30% 35% 40% 45% – 20 40 60 80 100 120 140 160 2012 2013 2014 2015 2016 2017 2018 2019 2020 Short term market % of total Annual JKM swaps traded have risen by a ~156% CAGR since the US began exporting LNG Henry Hub
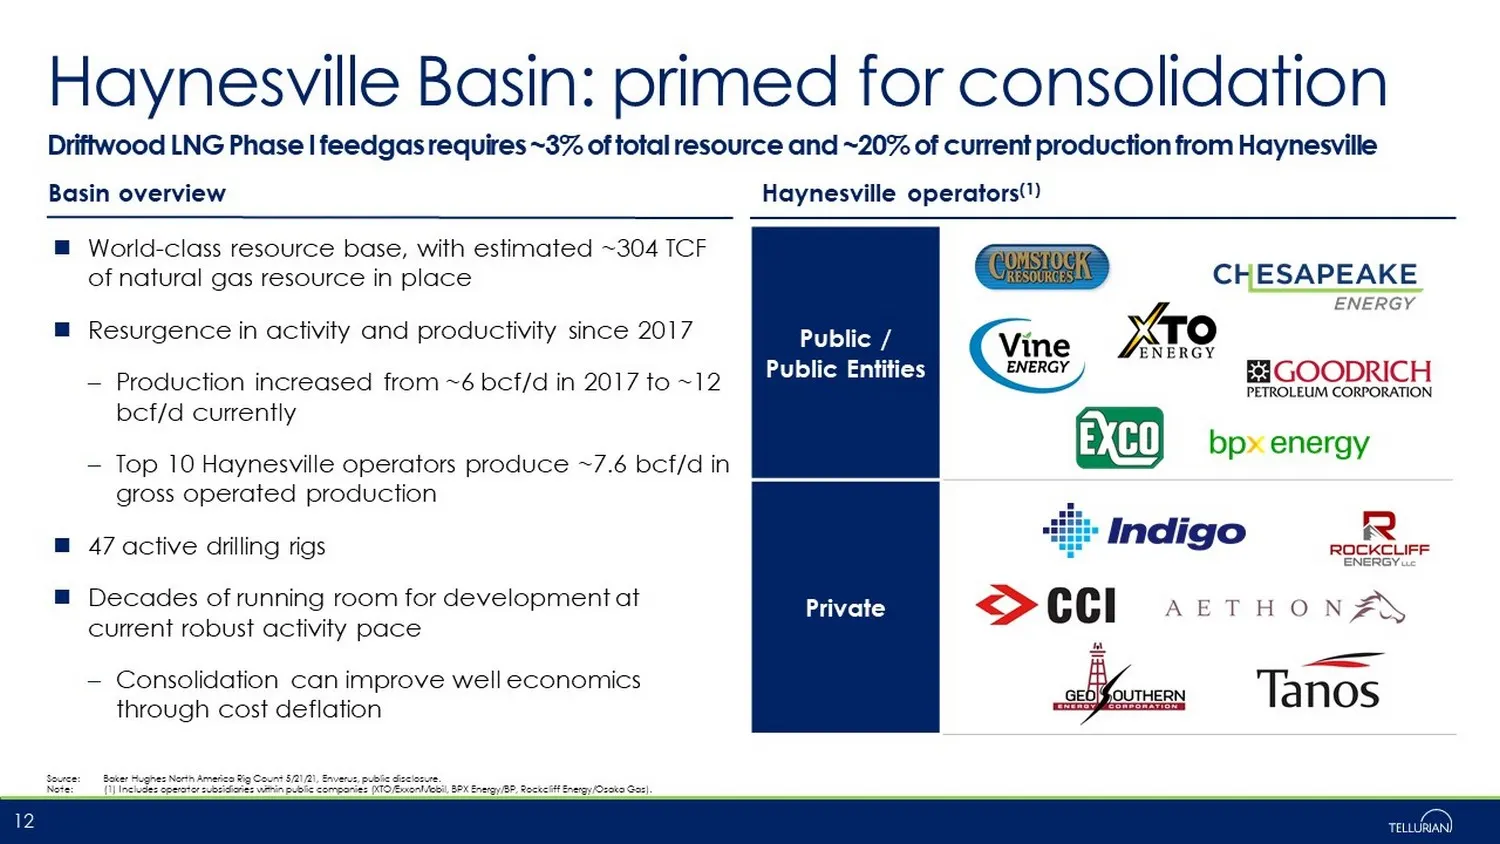
Slide 12: Haynesville Basin: primed for consolidation
Driftwood LNG Phase I feedgas requires ~3% of total resource and ~20% of current production from Haynesville Public / Public Entities Private World - class resource base, with estimated ~304 TCF of natural gas resource in place Resurgence in activity and productivity since 2017 – Production increase
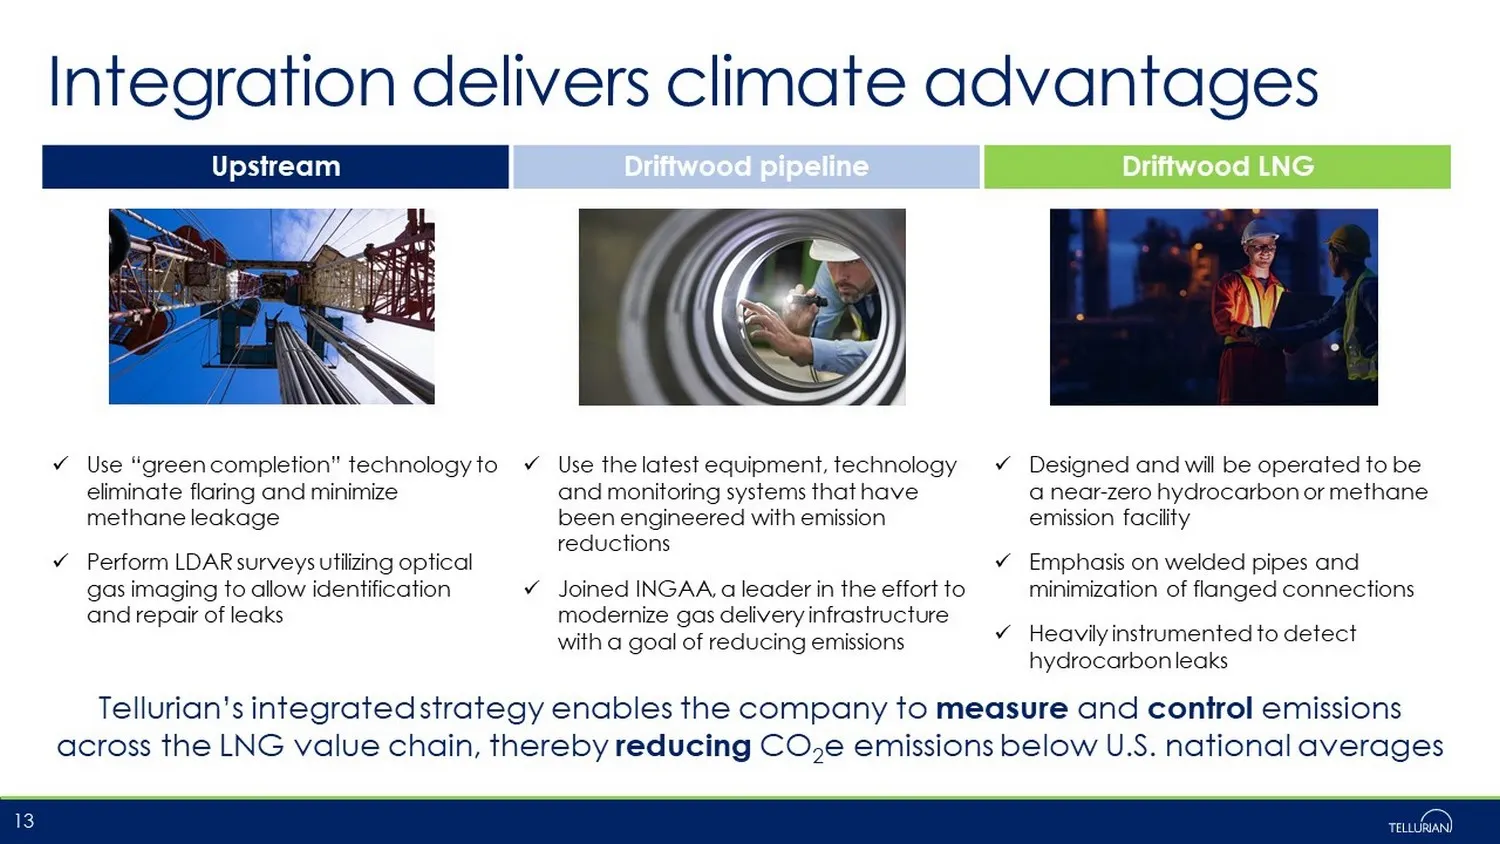
Slide 13: Integration delivers climate advantages
Upstream Driftwood pipeline Driftwood LNG x Use “ green completion” technology to eliminate flaring and minimize methane leakage x Perform LDAR surveys utilizing optical gas imaging to allow identification and repair of leaks x Use the latest equipment, technology and monitoring systems that have be
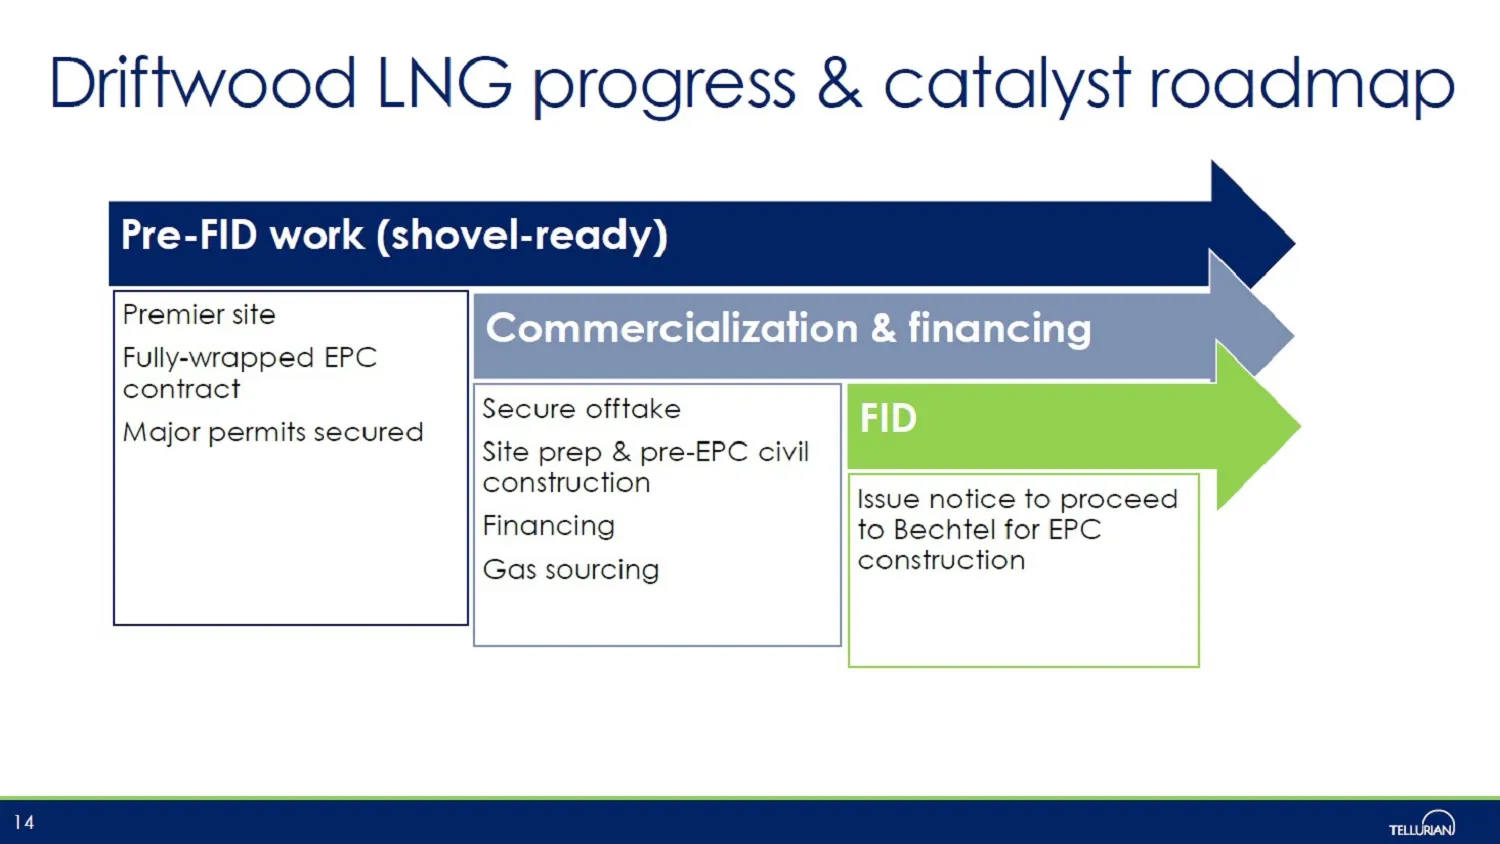
Slide 14: Driftwood LNG progress & catalyst roadmap
Driftwood LNG progress & catalyst roadmap 14 Pre - FID work (shovel - ready) Premier site Fully - wrapped EPC contract Major permits secured Commercialization & financing Secure offtake Site prep & pre - EPC civil construction Financing Gas sourcing FID Issue notice to proceed to Bechtel for EPC con
Slide 15: Contact us
Social media Contact us ▪ Matt Phillips VP, Investor Relations & Finance +1 832 320 9331 matthew.phillips@tellurianinc.com ▪ Joi Lecznar EVP, Public & Government Affairs +1 832 962 4044 joi.lecznar@tellurianinc.com 15 @TellurianLNG ▪ Johan Yokay Director , Investor Relations & Finance +1 832 320 932
Slide 16: Low-cost U.S. natural gas critical in supplying global LNG demand growth
Low - cost U.S. natural gas critical in supplying global LNG demand growth
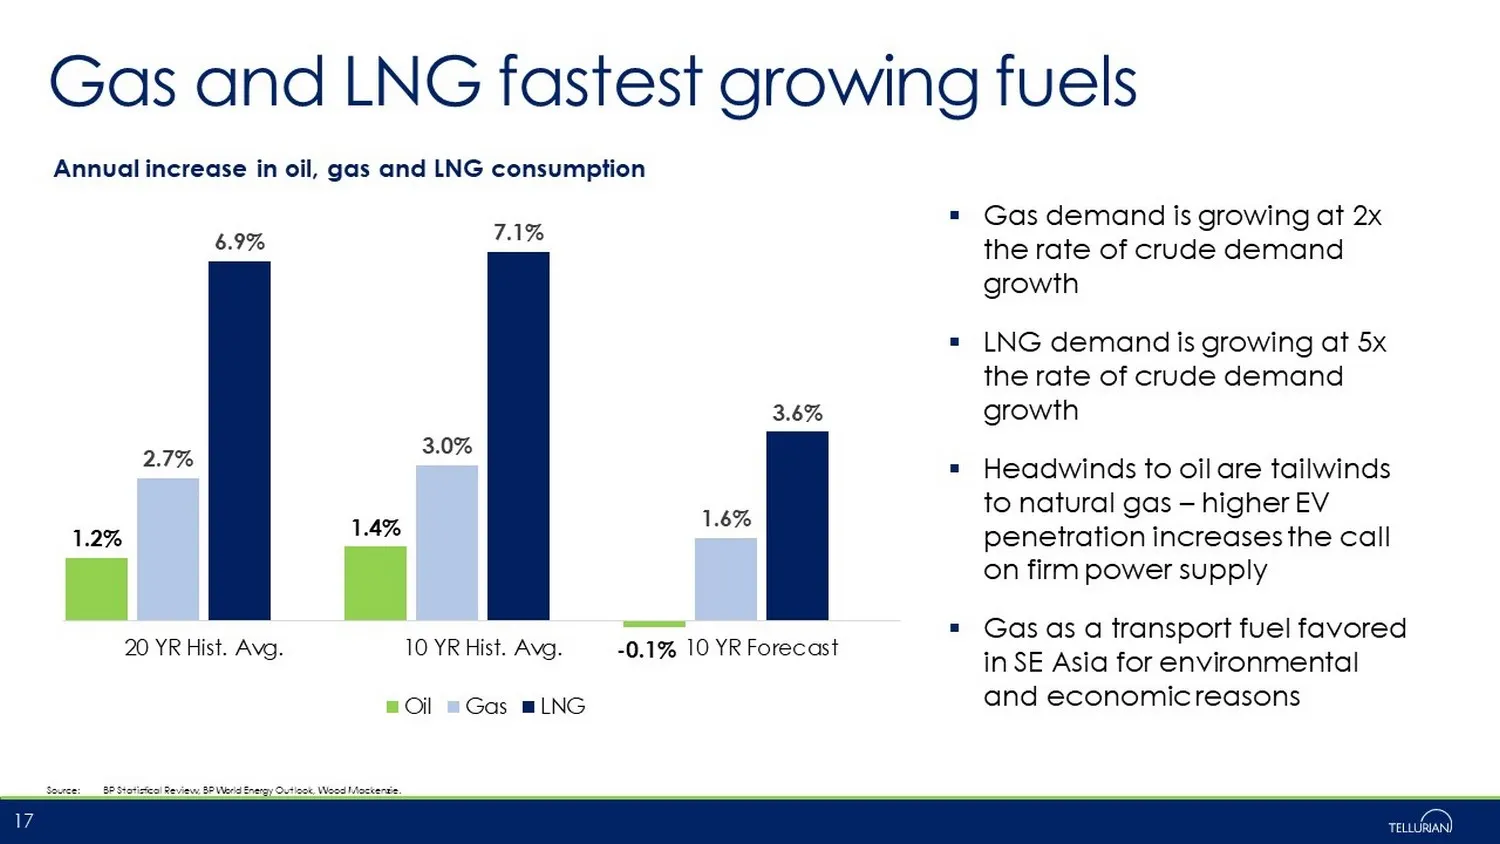
Slide 17: Gas and LNG fastest growing fuels
Gas and LNG fastest growing fuels 1.2% 1.4% - 0.1% 2.7% 3.0% 1.6% 6.9% 7.1% 3.6% 20 YR Hist. Avg. 10 YR Hist. Avg. 10 YR Forecast Annual increase in oil, gas and LNG consumption Oil Gas LNG ▪ Gas demand is growing at 2x the rate of crude demand growth ▪ LNG demand is growing at 5x the rate of crude
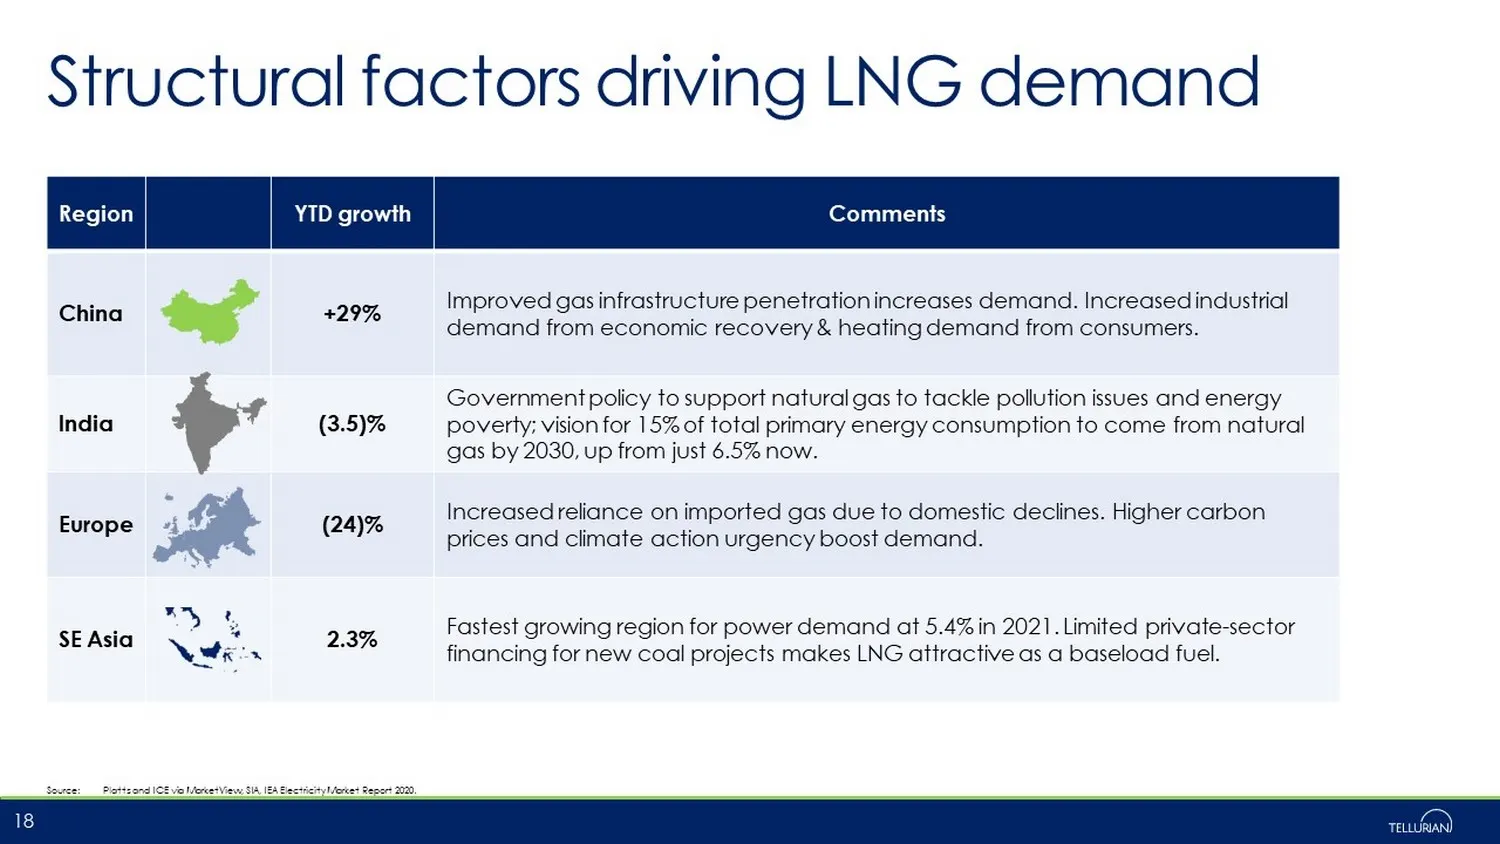
Slide 18: Structural factors driving LNG demand
Structural factors driving LNG demand Source: Platts and ICE via MarketView, SIA, IEA Electricity Market Report 2020. 18 Region YTD growth Comments China +29% Improved gas infrastructure penetration increases demand. Increased industrial demand from economic recovery & heating demand from consumers.
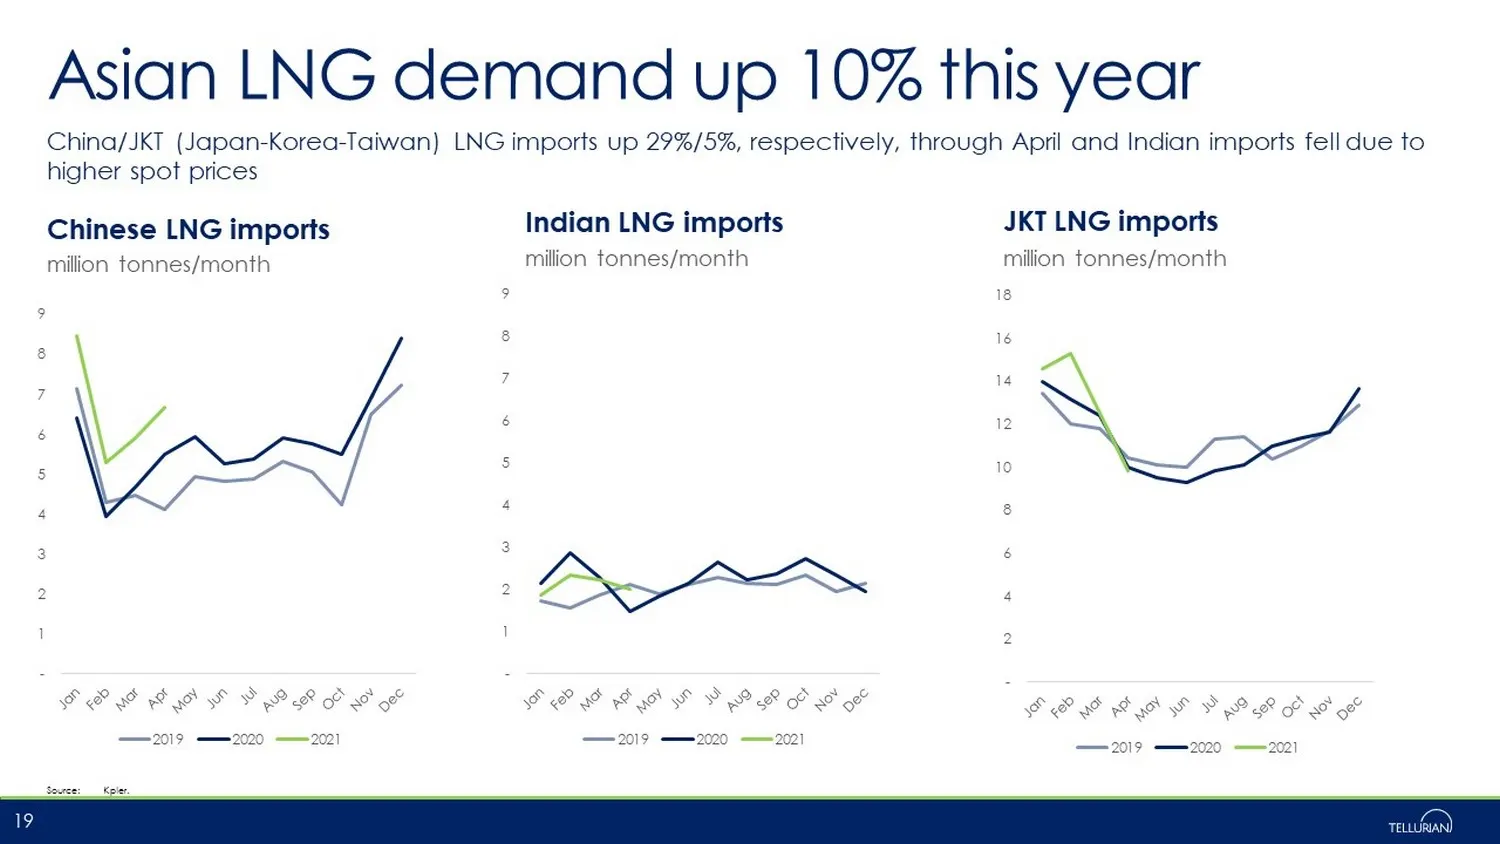
Slide 19: Asian LNG demand up 10% this year
Asian LNG demand up 10% this year China/JKT (Japan - Korea - Taiwan) LNG imports up 29%/5%, respectively, through April and Indian imports fell due to higher spot prices 19 Source: Kpler . Chinese LNG imports Indian LNG imports million tonnes/month million tonnes/month JKT LNG imports million tonnes
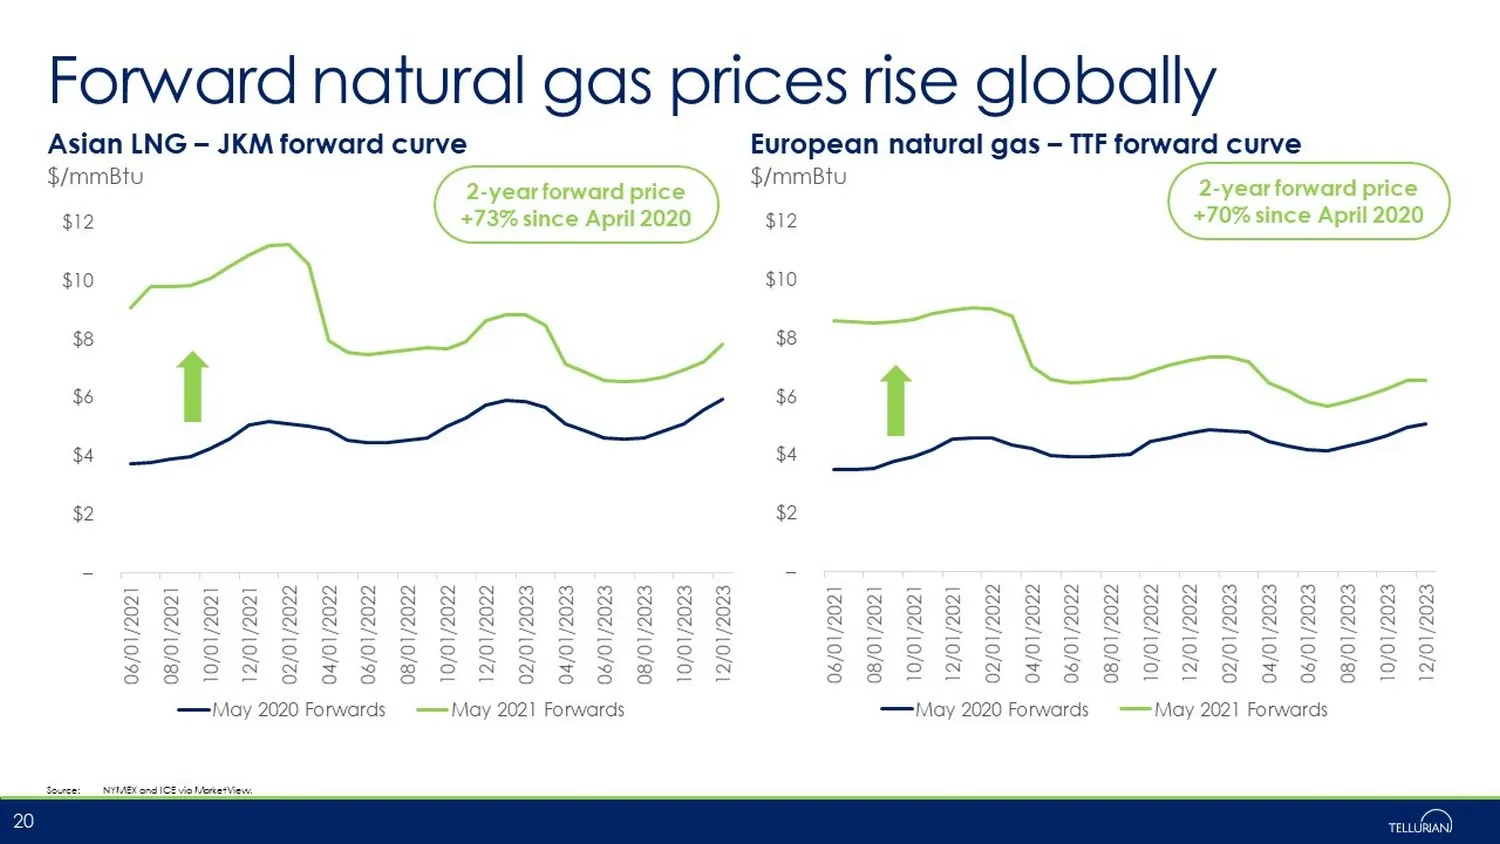
Slide 20: Forward natural gas prices rise globally
– $2 $4 $6 $8 $10 $12 06/01/2021 08/01/2021 10/01/2021 12/01/2021 02/01/2022 04/01/2022 06/01/2022 08/01/2022 10/01/2022 12/01/2022 02/01/2023 04/01/2023 06/01/2023 08/01/2023 10/01/2023 12/01/2023 May 2020 Forwards May 2021 Forwards – $2 $4 $6 $8 $10 $12 06/01/2021 08/01/2021 10/01/2021 12/01/2021
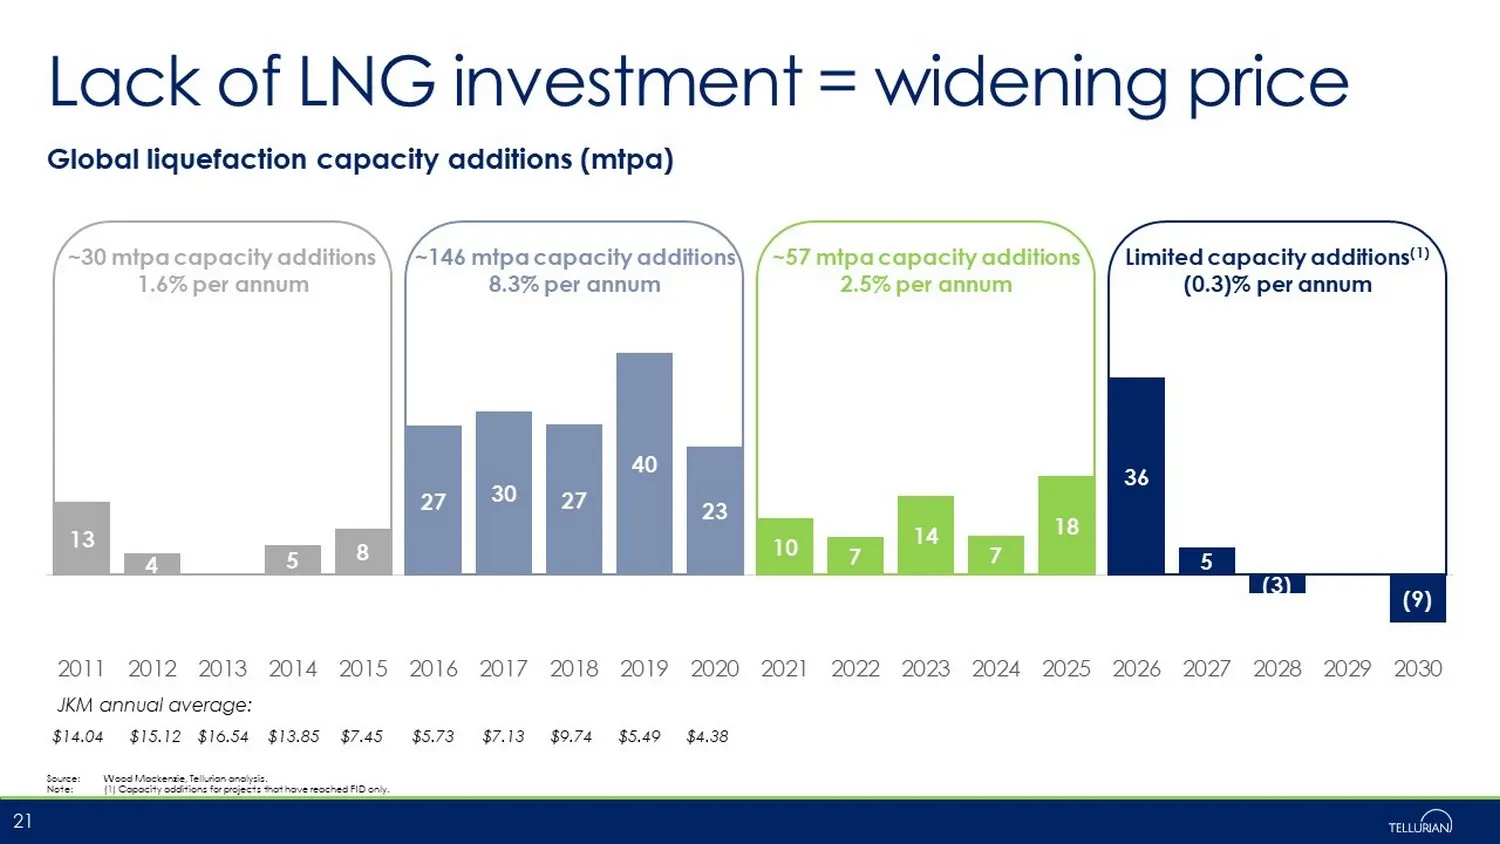
Slide 21: Lack of LNG investment = widening price
Lack of LNG investment = widening price Source: Wood Mackenzie, Tellurian analysis. Note: (1) Capacity additions for projects that have reached FID only. 21 13 4 (0) 5 8 27 30 27 40 23 10 7 14 7 18 36 5 (3) -- (9) 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 2027 2
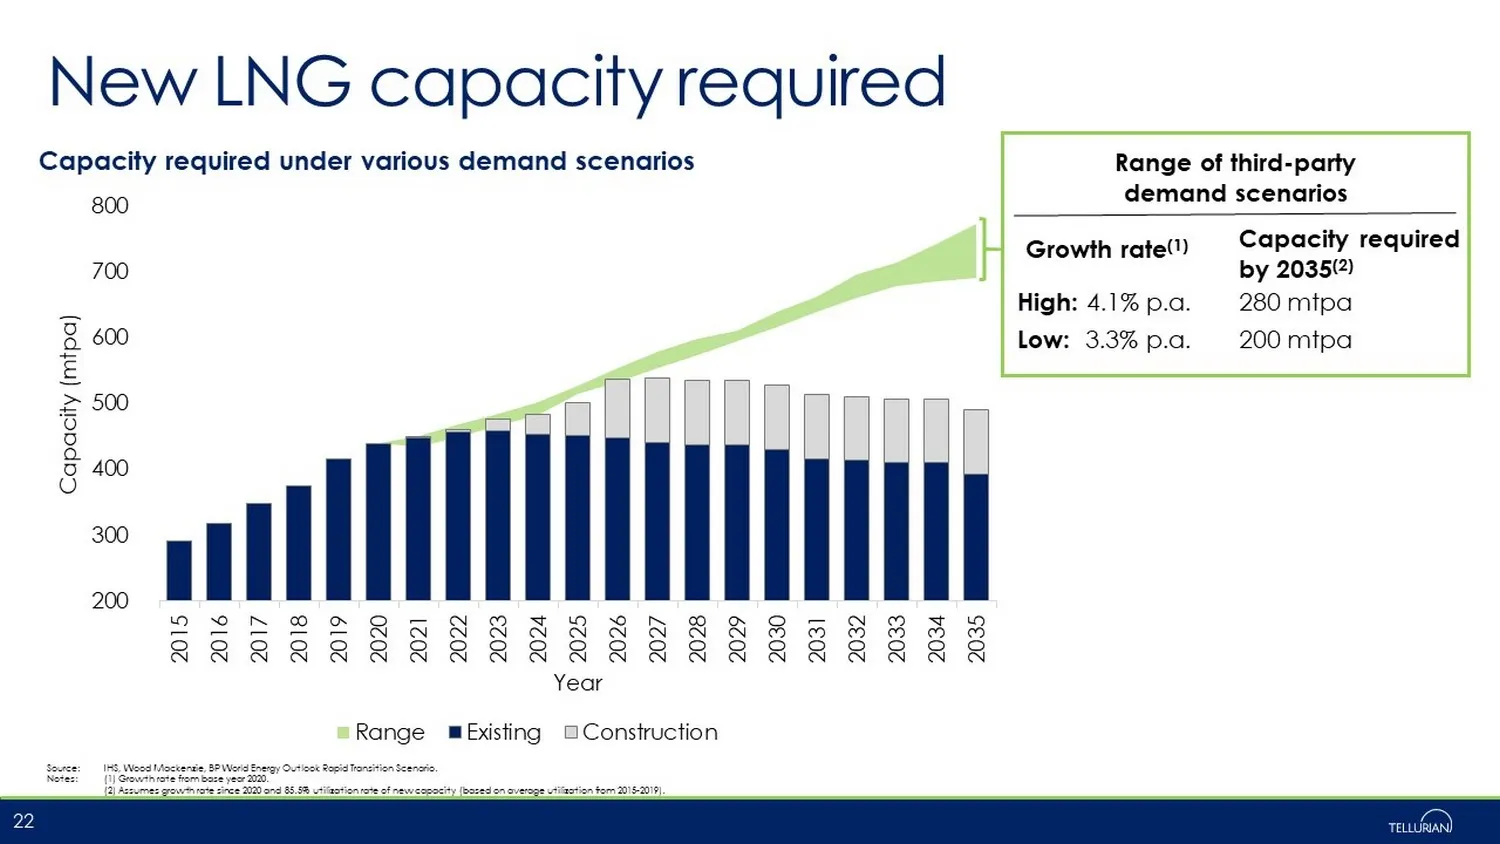
Slide 22: New LNG capacity required
New LNG capacity required Source: IHS, Wood Mackenzie, BP World Energy Outlook Rapid Transition Scenario. Notes: (1) Growth rate from base year 2020. (2) Assumes growth rate since 2020 and 85.5% utilization rate of new capacity (based on average utilization from 2015 - 2019). 22 Range of third - par
Slide 23: LNG critical to global decarbonization
LNG critical to global decarbonization
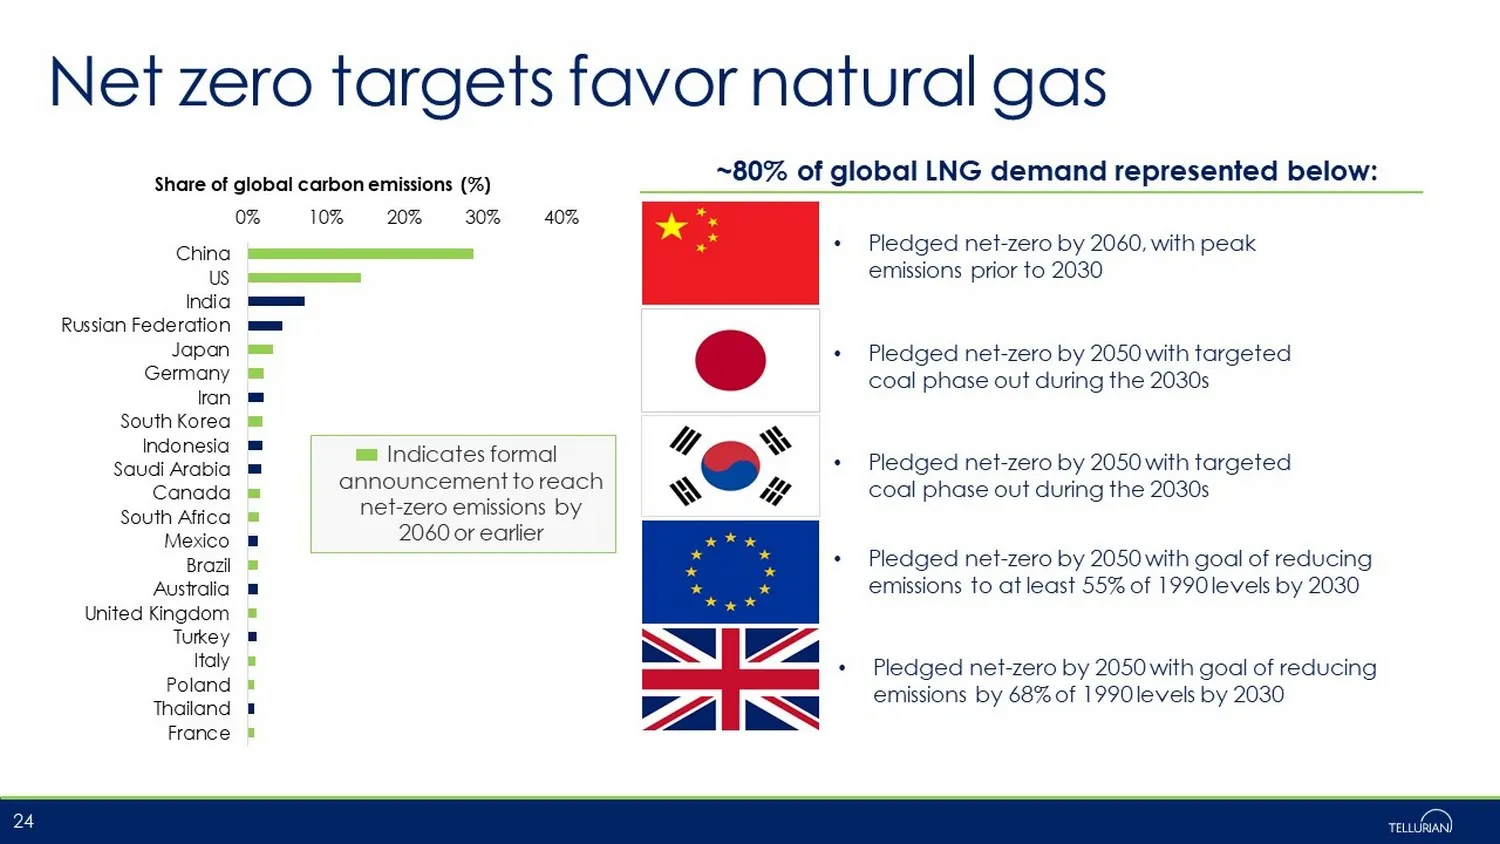
Slide 24: Net zero targets favor natural gas
Indicates formal announcement to reach net - zero emissions by 2060 or earlier 0% 10% 20% 30% 40% China US India Russian Federation Japan Germany Iran South Korea Indonesia Saudi Arabia Canada South Africa Mexico Brazil Australia United Kingdom Turkey Italy Poland Thailand France Share of global car
Slide 25: Carbon reduction: the U.S. template works
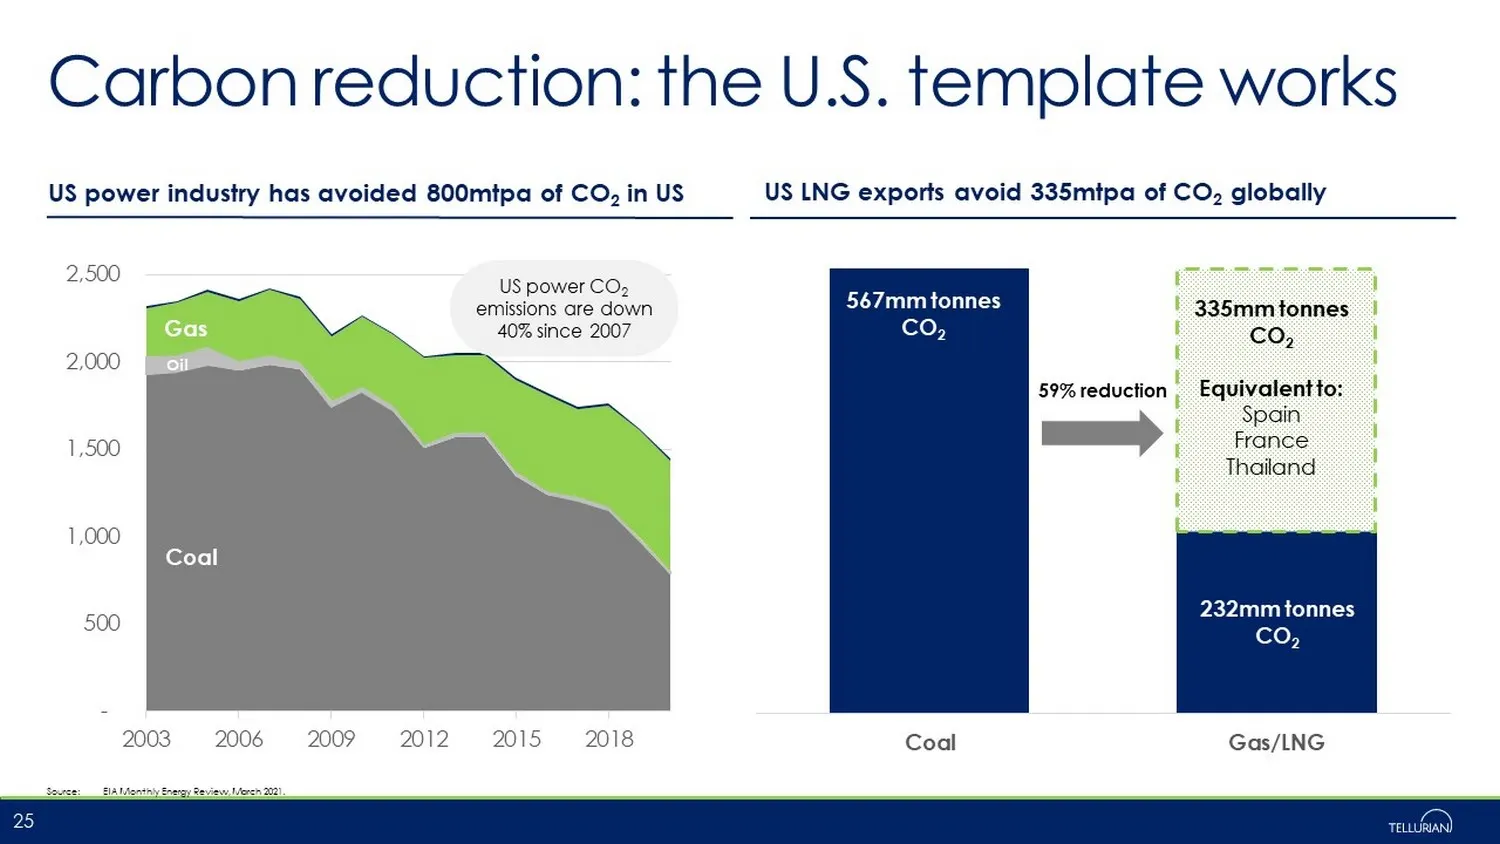
Carbon reduction: the U.S. template works 25 US power industry has avoided 800mtpa of CO 2 in US Source: EIA Monthly Energy Review, March 2021. Coal Gas/LNG 567mm tonnes CO 2 335mm tonnes CO 2 Equivalent to: Spain France Thailand 232mm tonnes CO 2 59% reduction US LNG exports avoid 335mtpa of CO 2 g
Slide 26: Carbon reduction is exportable
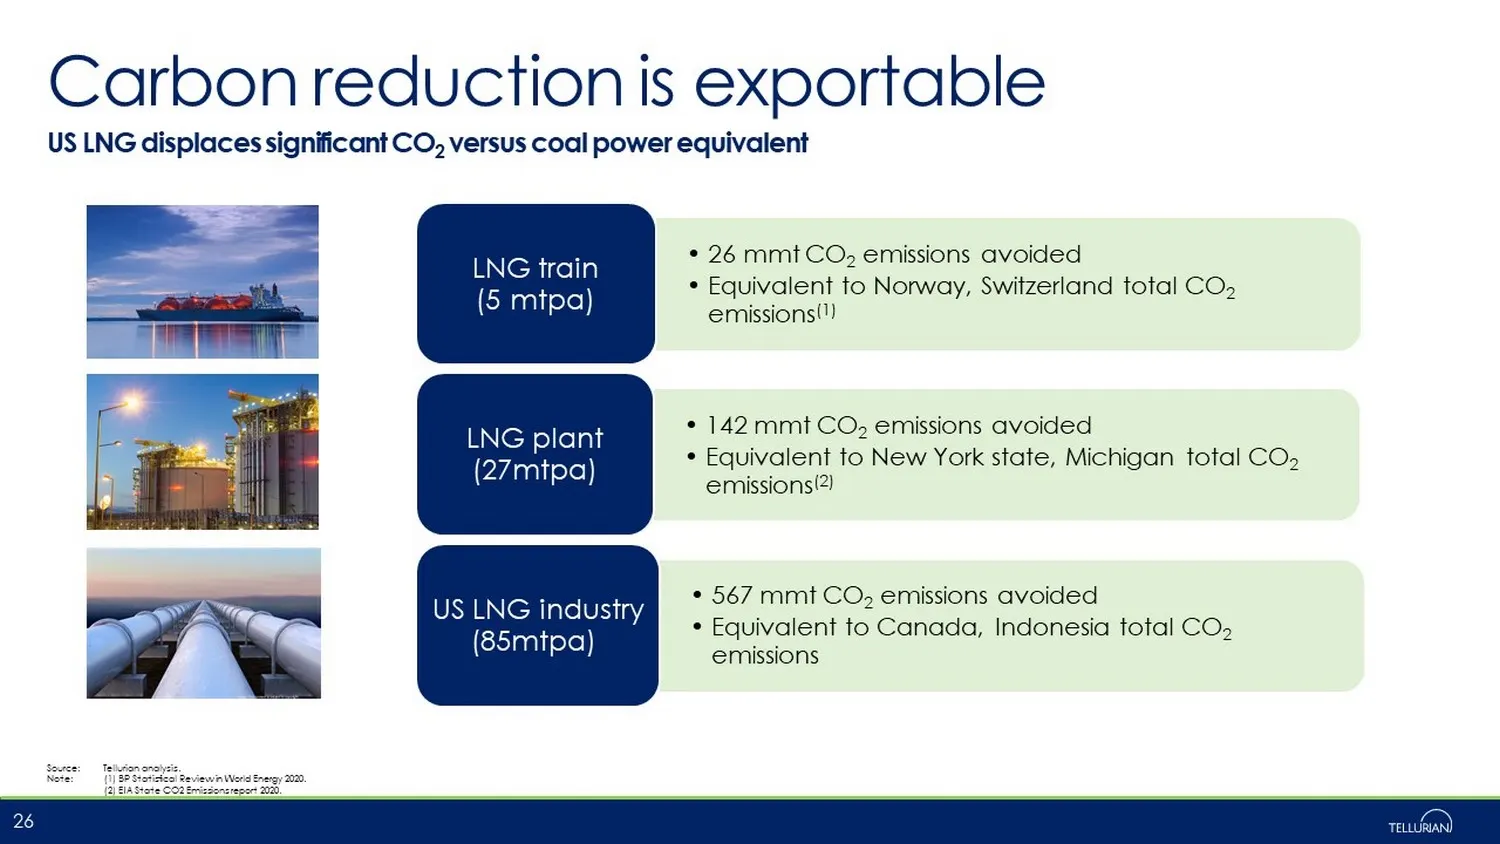
Carbon reduction is exportable Source: Tellurian analysis. Note: (1) BP Statistical Review in World Energy 2020. (2) EIA State CO2 Emissions report 2020. 26 US LNG displaces significant CO 2 versus coal power equivalent • 26 mmt CO 2 emissions avoided • Equivalent to Norway, Switzerland total CO 2 e
Slide 27: Air quality improvements with LNG imports
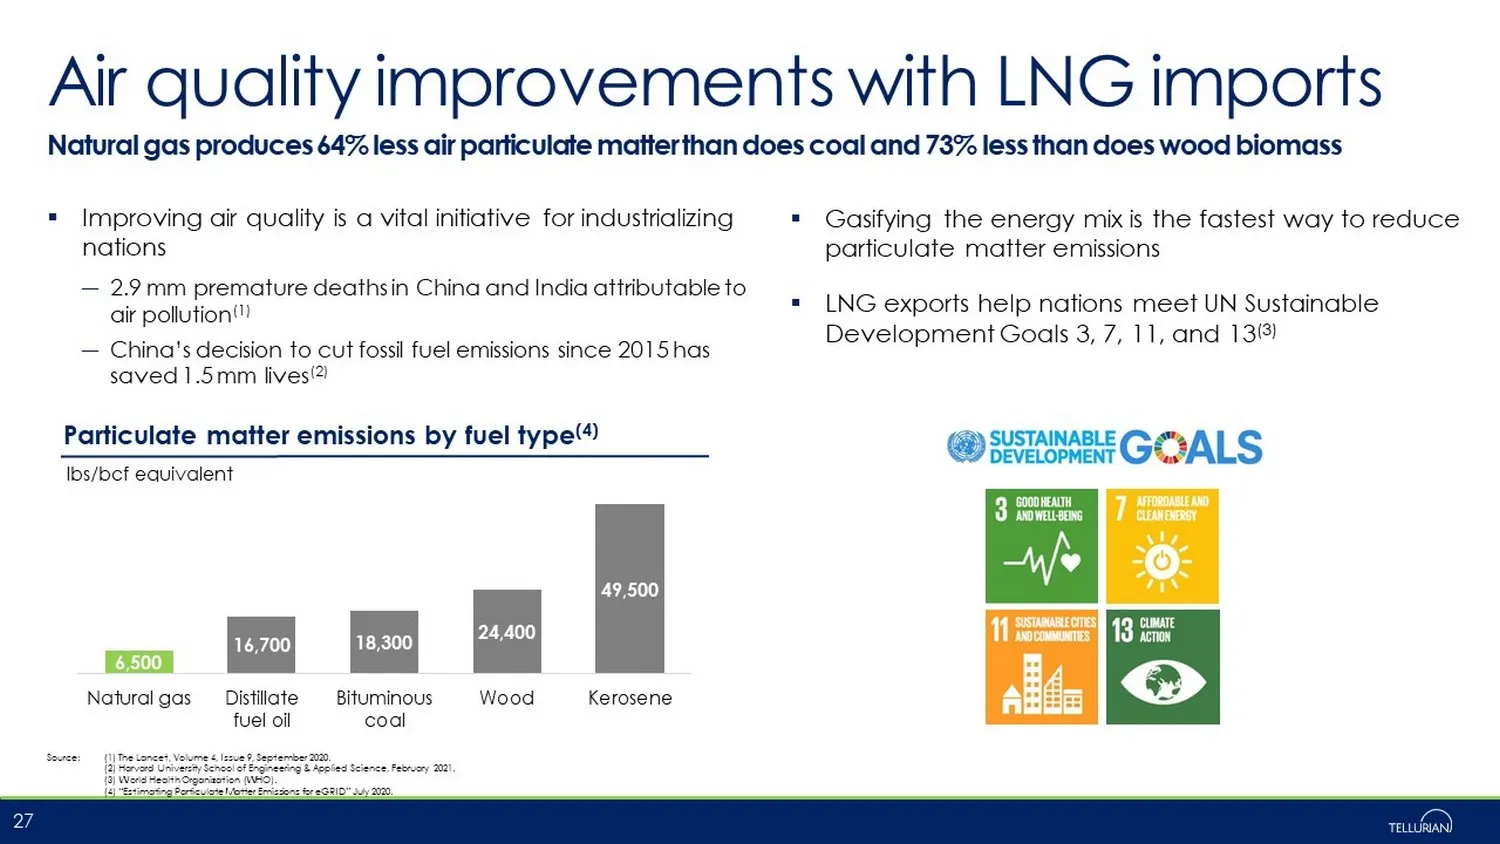
Air quality improvements with LNG imports Natural gas produces 64% less air particulate matter than does coal and 73% less than does wood biomass ▪ Improving air quality is a vital initiative for industrializing nations ― 2.9 mm premature deaths in China and India attributable to air pollution (1) ―
Slide 28: China decarbonization requires natural gas
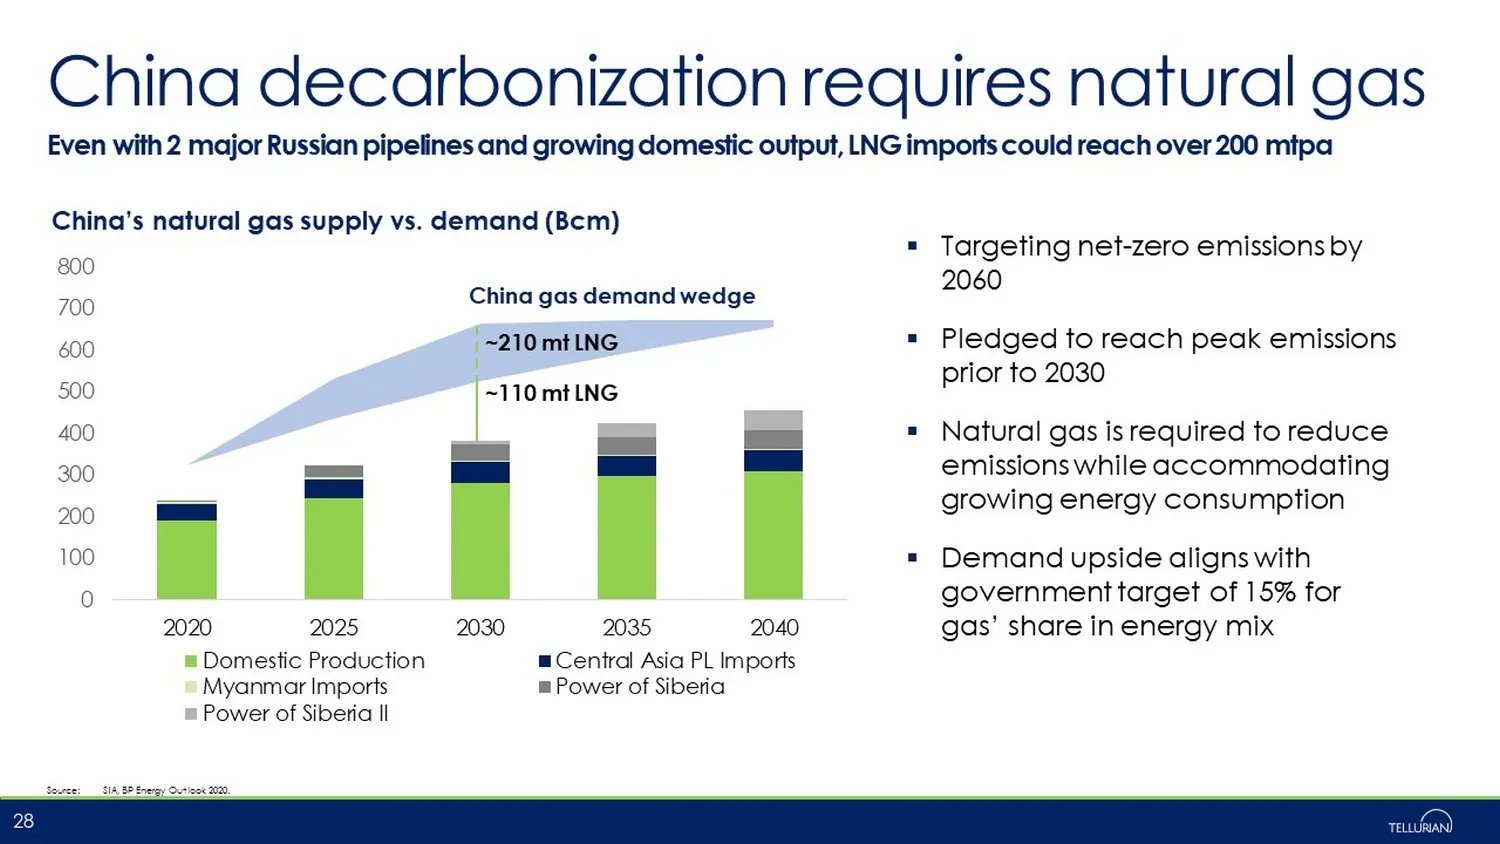
China decarbonization requires natural gas Even with 2 major Russian pipelines and growing domestic output, LNG imports could reach over 200 mtpa ▪ Targeting net - zero emissions by 2060 ▪ Pledged to reach peak emissions prior to 2030 ▪ Natural gas is required to reduce emissions while accommodating
Slide 29: Appendix: Driftwood LNG details
Appendix: Driftwood LNG details
Slide 30: Unmatched LNG development experience
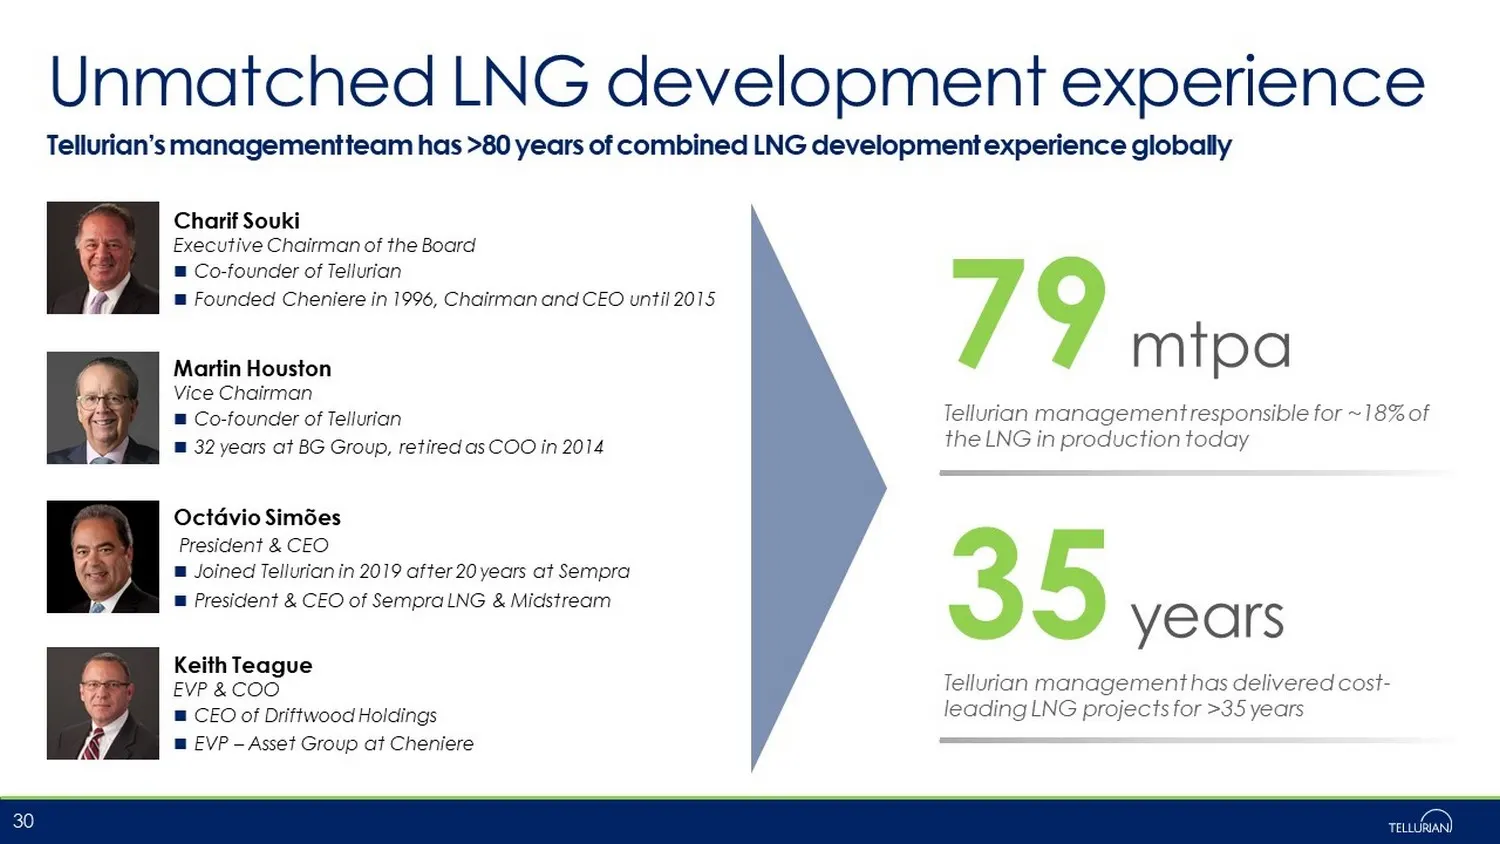
Unmatched LNG development experience Tellurian’s management team has >80 years of combined LNG development experience globally 30 Charif Souki Executive Chairman of the Board Co - founder of Tellurian Founded Cheniere in 1996, Chairman and CEO until 2015 Martin Houston Vice Chairman Co - founder of
Slide 31: Driftwood LNG's ideal site for exports
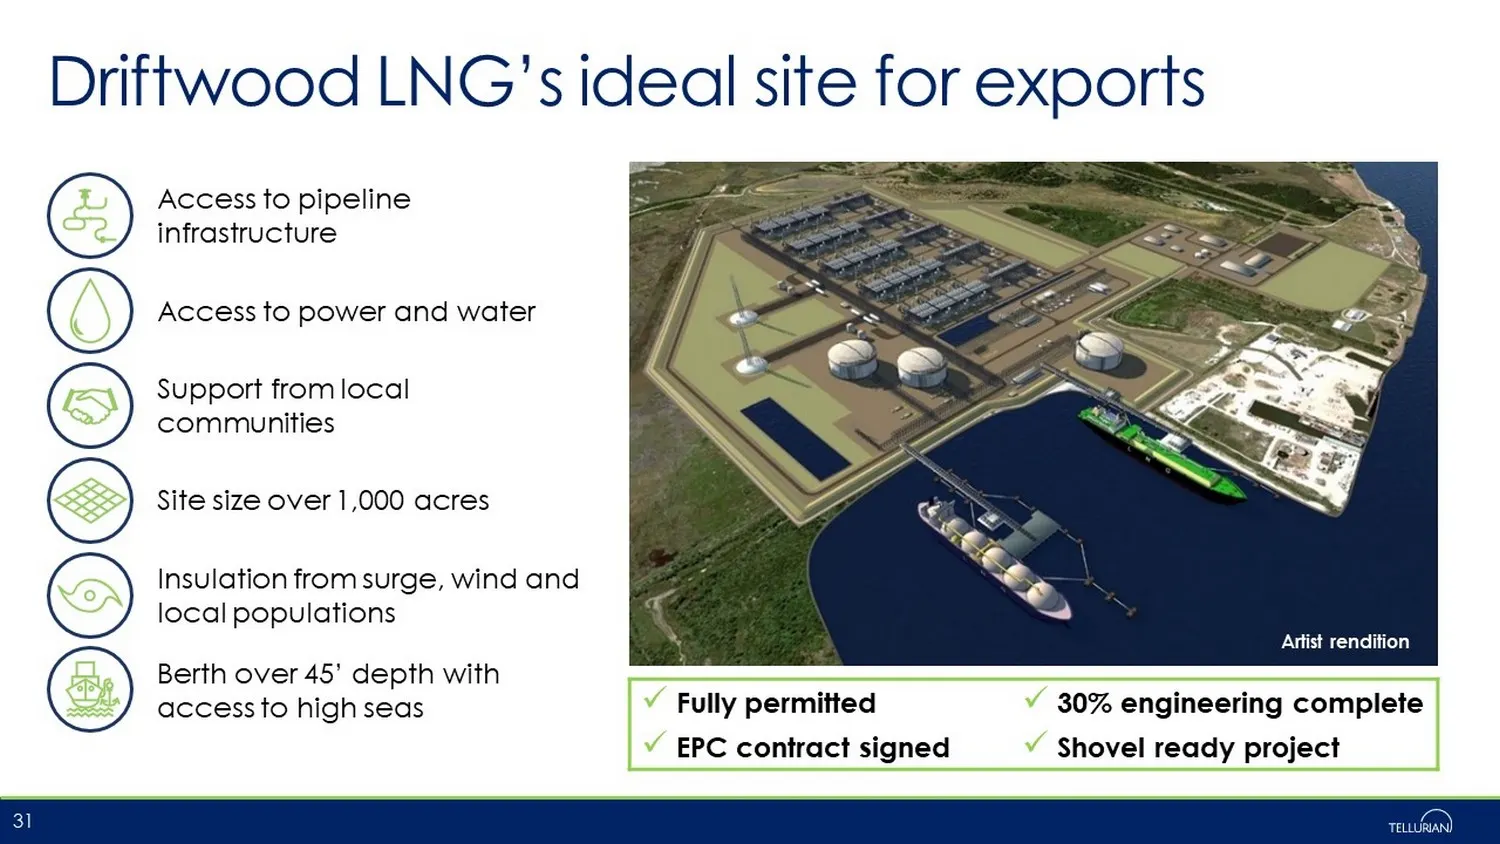
Driftwood LNG’s ideal site for exports 31 Access to power and water Berth over 45’ depth with access to high seas Support from local communities Access to pipeline infrastructure Site size over 1,000 acres Insulation from surge, wind and local populations Artist rendition x Fully permitted x 30% eng
Slide 32: Bechtel LSTK secures project execution
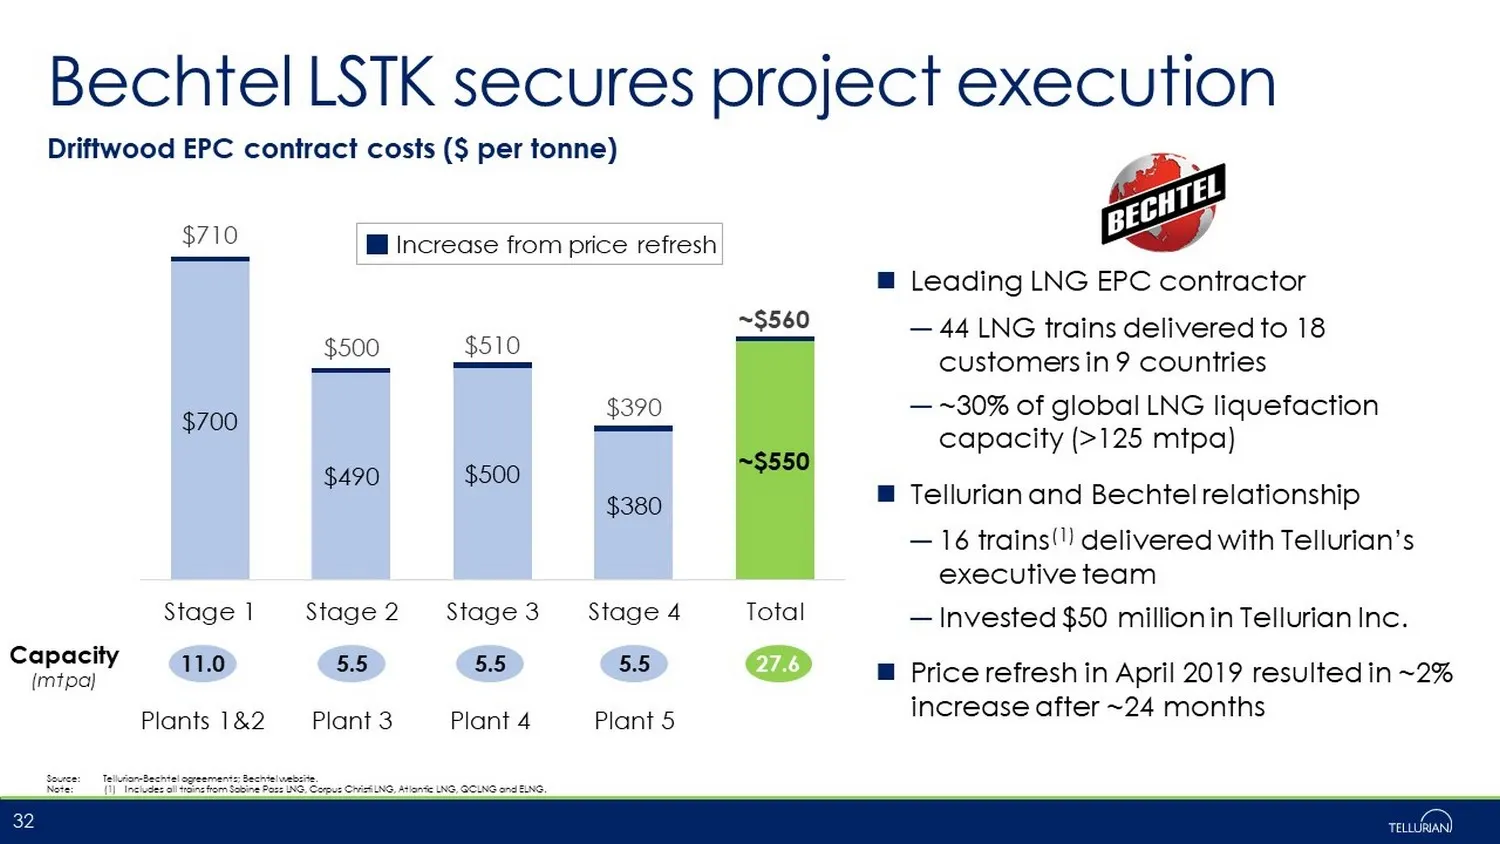
$700 $490 $500 $380 ~$550 $710 $500 $510 $390 ~ $560 Stage 1 Stage 2 Stage 3 Stage 4 Total Bechtel LSTK secures project execution Leading LNG EPC contractor ― 44 LNG trains delivered to 18 customers in 9 countries ― ~30% of global LNG liquefaction capacity (>125 mtpa) Tellurian and Bechtel relations
Source: SEC EDGAR · 8-K filed May 27, 2021
More decks from Tellurian Inc
 Merger or Acquisition (July 2024)27 slides · Jul 22, 2024
 Investor Presentation (March 2024)16 slides · Mar 4, 2024
 Investor Presentation (August 2023)20 slides · Aug 7, 2023
 Investor Presentation (May 2023)20 slides · May 3, 2023
 Investor Presentation (February 2023)21 slides · Feb 22, 2023
 Investor Presentation (November 2022)19 slides · Nov 2, 2022