Aleris International — Shareholder Meeting (May 2006)
31 slides from Aleris International's shareholder meeting presentation, May 18, 2006
Slide 1: Annual Stockholders Meeting
Annual Stockholders Meeting May 18, 2006 Exhibit 99.1
Slide 2: Financial Goals
Aleris Financial Goals Double-digit EBITDA margins ROCE levels in excess of WACC Pursue accretive and strategic acquisitions Generate strong cash flow Deleverage Consistent financial performance with cyclicality muted by ongoing productivity improvements
Slide 3: Step-Change Improvement Continues
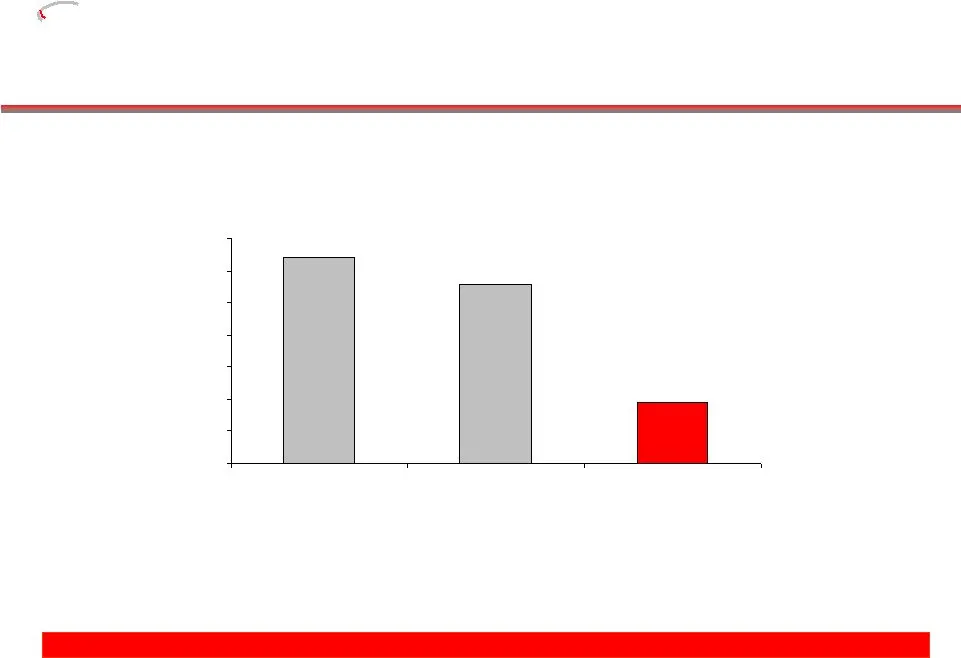
Step-Change Improvement Continues Aleris Safety Performance Step-Change Improvement Continues 6.4 5.6 1.9 0.0 1.0 2.0 3.0 4.0 5.0 6.0 7.0 2004 2005 1Q06
Slide 4: Great Progress; More to Do
Great Progress; More to Do Aleris 2005 Key Accomplishments Achieved record earnings Exceeded merger synergy and productivity expectations Completed four acquisitions at very attractive multiples S&P corporate credit rating upgraded Surpassed $1B in market cap Initiated massive cultural change Great
Slide 5: Outstanding Year!
Outstanding Year! Aleris 2005 Financial Summary (1) (2) ($M – except EPS ) Outstanding Year! Pro Forma 2005 Sales $2,245 $2,429 EBITDA $84.4 $170.4 EBITDA excluding special items $131.2 $230.8 Net Income ($22.7) $74.3 EPS ($0.80) $2.38 Adjusted EPS (3) $0.97 $3.94 2004 (3) 8.75% effective tax rate (
Slide 6: Great Progress; More to Do
Great Progress; More to Do Aleris 2005 Key Accomplishments Achieved record earnings Exceeded merger synergy and productivity expectations Completed four acquisitions at very attractive multiples S&P corporate credit rating upgraded Surpassed $1B in market cap Initiated massive cultural change Great
Slide 7: Exceeding Expectations
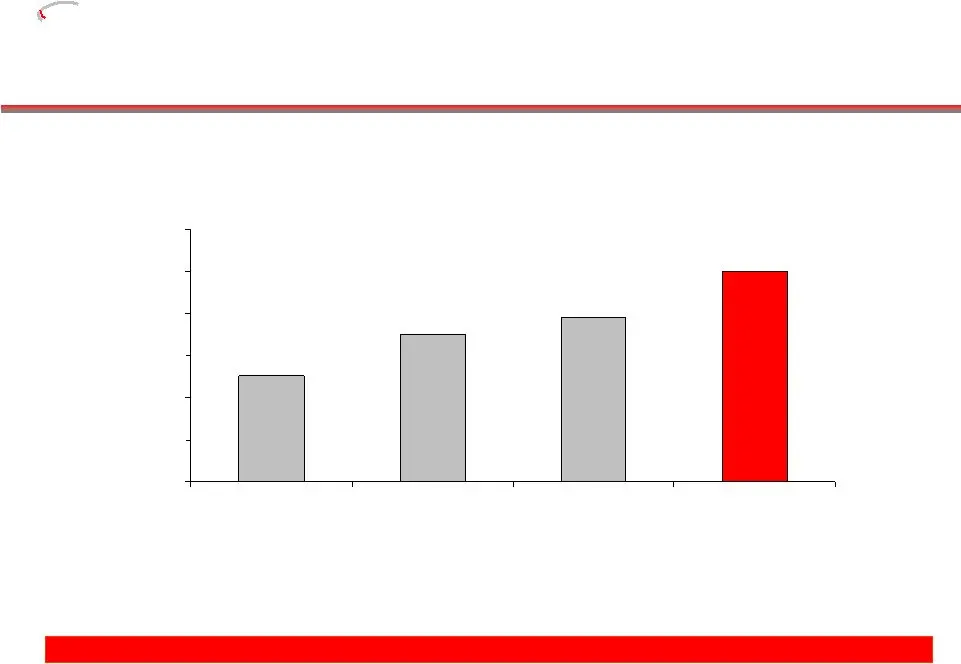
Exceeding Expectations Aleris Merger Synergies/Productivity (1) ($M ) Exceeding Expectations $25 $35 $39 $50 $0 $10 $20 $30 $40 $50 $60 Original Target Revised Target: May '05 4Q05 Current Target (1) Annualized figures.
Slide 8: Great Progress; More to Do
Great Progress; More to Do Aleris 2005 Key Accomplishments Achieved record earnings Exceeded merger synergy and productivity expectations Completed four acquisitions at very attractive multiples S&P corporate credit rating upgraded Surpassed $1B in market cap Initiated massive cultural change Great
Slide 9: Attractive Purchase Multiples
Tomra ALSCO Ormet Alumitech Total Attractive Purchase Multiples Aleris Acquisition Summary ($M ) Base EBITDA (1) $5 $23 $30 $5 $63 Synergy Targets Total $7 $37 $30 $8 $82 Purchase Price $19 $145 $100 (2) $29 $293 Purchase Multiple 2.7X 3.9X 3.3X 3.7X 3.6X Estimated Annual Impact 3.6X Net purchase mu
Slide 10: Great Progress; More to Do
Great Progress; More to Do Aleris 2005 Key Accomplishments Achieved record earnings Exceeded merger synergy and productivity expectations Completed four acquisitions at very attractive multiples S&P corporate credit rating upgraded Surpassed $1B in market cap Initiated massive cultural change Great
Slide 11: Net Debt to EBITDA Summary
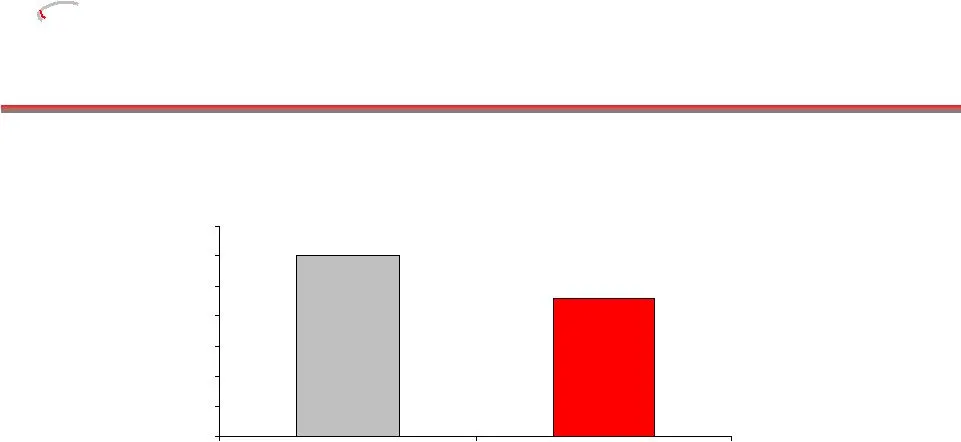
Aleris Net Debt to EBITDA Summary (1) (2) 3.0 2.3 0.0 0.5 1.0 1.5 2.0 2.5 3.0 3.5 2004 2005 (3) (3) Pro-forma for 2005 Acquisitions (Tomra, ALSCO, Ormet and Alumitech) (1) See text on Slide 26 for information regarding our calculations, which are pro forma for the Commonwealth/IMCO merger. (2) See t
Slide 12: Great Progress; More to Do
Great Progress; More to Do Aleris 2005 Key Accomplishments Achieved record earnings Exceeded merger synergy and productivity expectations Completed four acquisitions at very attractive multiples S&P corporate credit rating upgraded Surpassed $1B in market cap Initiated massive cultural change Great
Slide 13: ARS Stock Price
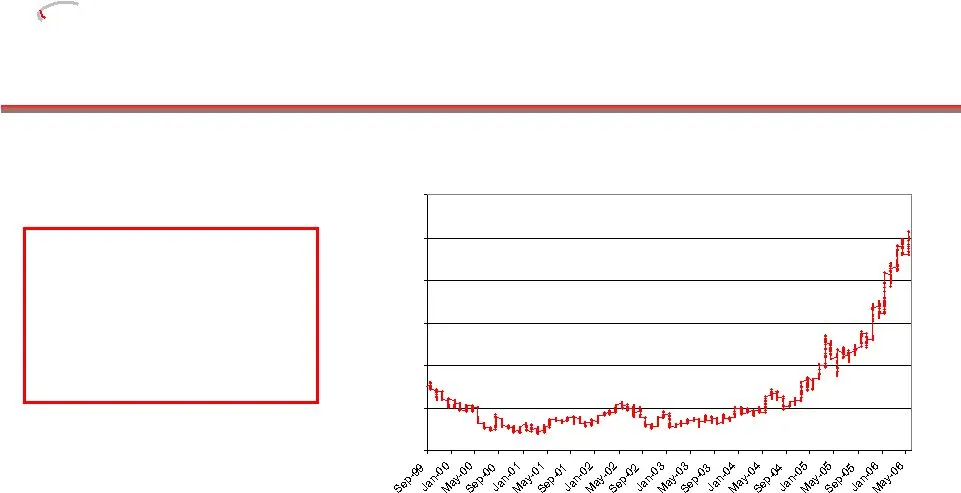
ARS Stock Price Aleris Historical Stock Price (1) Symbol: ARS Exchange: NYSE 52 Wk Range: $17.76 - $52.50 Market Cap: $1.5B (1) As of May 17, 2006 $- $10 $20 $30 $40 $50 $60
Slide 14: Great Progress; More to Do
Great Progress; More to Do Aleris 2005 Key Accomplishments Achieved record earnings Exceeded merger synergy and productivity expectations Completed four acquisitions at very attractive multiples S&P corporate credit rating upgraded Surpassed $1B in market cap Initiated massive cultural change Great
Slide 15: Growth will not Change Aleris's Culture/Values
Growth will not Change Aleris’s Culture/Values Aleris Culture and Key Values Sense of urgency/solve today’s problems today Data driven; clearly defined measures No bureaucracy Relentless drive to be more productive in all we do Unquestionable integrity Global/International Recognize great performanc
Slide 16: Numerous Opportunities to Excel
Numerous Opportunities to Excel Aleris 2006 Key Goals Improve safety performance Improve working capital efficiency Achieve productivity and merger synergy targets Successfully integrate 2005 acquisitions Complete proposed Corus transaction and begin integration Evaluate additional strategic acquisi
Slide 17: Proposed Corus Transaction Summary
Aleris Proposed Corus Transaction Summary Executed non-binding Letter of Intent to acquire Corus’s Aluminum Rolled Products and Extrusions businesses Revenues of approximately US $1.8 billion Net cash purchase price of €700 million, excluding the assumption of debt and certain other liabilities Comm
Slide 18: Corus Strategic Rationale
Aleris Corus Strategic Rationale Expands product breadth into high margin, value-added product lines Significant research and development organization and intellectual property Increases Aleris’s end-use diversity Unique production capabilities Increases scope and scale of Aleris Well regarded manag
Slide 19: Extend Global Reach, Expands Product Breadth
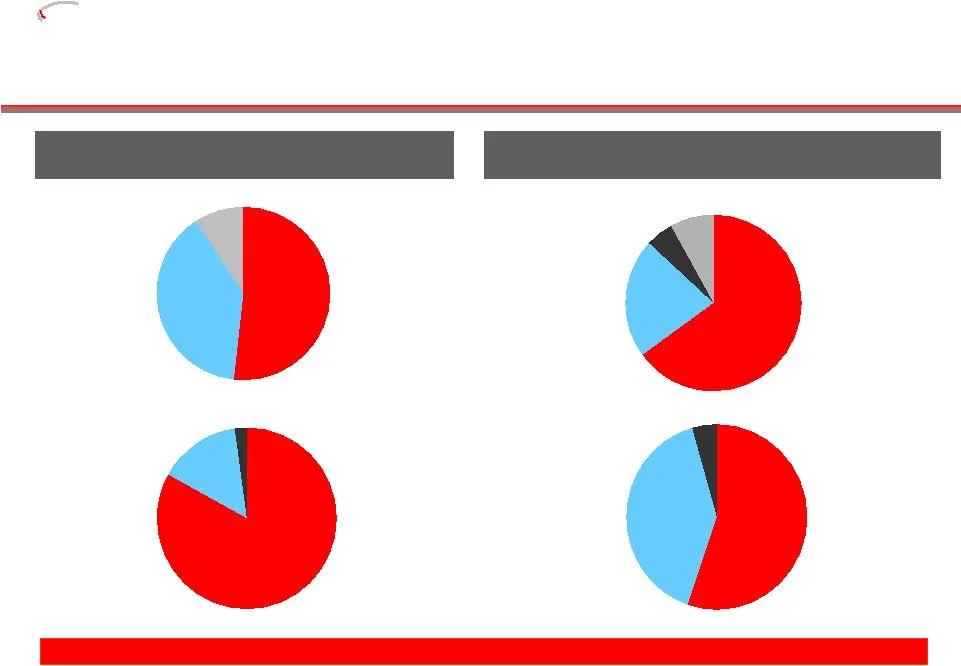
Aleris Aleris With Corus Aluminum and 2005 Acquisitions Extend Global Reach, Expands Product Breadth Aleris Estimated Sales Mix Rolled Products Zinc Aluminum Recycling North America Rest of World Europe Rolled Products Zinc Extrusions Aluminum Recycling North America Rest of World Europe Extend Glob
Slide 20: foto ot og
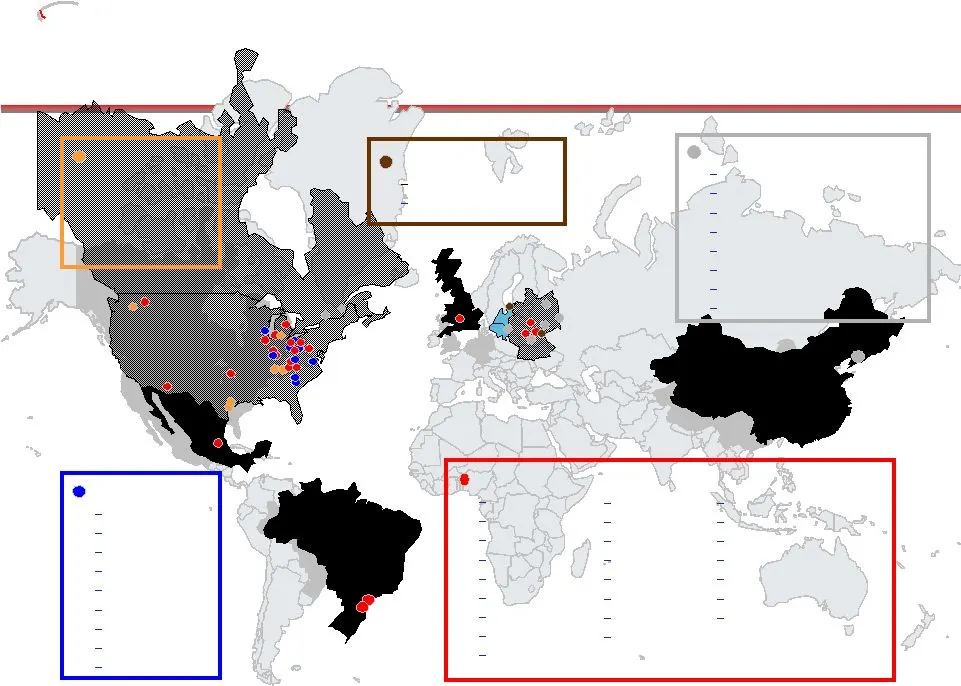
foto ot og
Slide 21
Slide 22
Slide 23
Slide 24
Slide 25
Slide 26: Exceeded Unusually Strong 1Q 2005
Exceeded Unusually Strong 1Q 2005 Aleris 1Q 2006 Financial Summary (1) (2) ($M ) (3) 36.8% effective tax rate Exceeded Unusually Strong 1Q 2005 2005 2006 Sales $645.0 $847.5 EBITDA $56.5 $74.7 EBITDA excluding special items $68.5 $76.7 Net Income $29.1 $28.2 EPS $0.94 $0.89 Adjusted EPS (3) $1.29 $0
Slide 27: Gaining Momentum
Gaining Momentum Aleris Adjusted Quarterly EPS (1) (2) Trend $0.92 $0.65 $0.58 $0.58 $0.93 $0.00 $0.20 $0.40 $0.60 $0.80 $1.00 $1.20 $1.40 1Q05 2Q05 3Q05 4Q05 1Q06 2Q06 Est. Range (2) 36.8% effective tax rate Gaining Momentum (1) See text on Slide 27 for information concerning our calculations exclu
Slide 28: Expect Another Solid Year
Sales EBITDA Expect Another Solid Year Aleris 2006 Outlook Continued favorable scrap spreads in Rolled Products Moderate growth economic environment Continue improvements in recycling operations Initiated Six Sigma effort Acquisitions add to bottom line Complete Corus acquisition Expect Another Soli
Slide 29: Exciting Future
Aleris Exciting Future Strong Board of Directors Acquisitions diversifying product offering/geographic presence Exploring China opportunities Strong cash flow providing new-found financial strength Expanding recycling at several US sites New Stuttgart, Germany recycling startup in 1Q06 Continued to
Slide 30: Aleris
Aleris The “Pro Forma” results combine the operations of IMCO Recycling Inc. and Commonwealth Industries, Inc. as of the beginning of each period presented, adjusted to exclude the results of Commonwealth’s discontinued Alflex division and inter-company sales and to include the change to the average
Slide 31: Aleris
Aleris “EBITDA,” as used in this presentation, and unless otherwise stated, is defined as net income before interest income and expense, taxes, depreciation and amortization and minority interests. “EBITDA excluding special items,” as used in this presentation, is defined as EBITDA excluding restruc
Source: SEC EDGAR · 8-K filed May 18, 2006
More decks from Aleris International Inc
 2008 Bank of America Credit Conference26 slides · Nov 21, 2008
 Deutsche Bank Leverage Finance Conference 200828 slides · Sep 25, 2008
 FY2007 Earnings Presentation33 slides · Mar 31, 2008
 FY2007 Earnings Presentation33 slides · Mar 27, 2008
 Bear Stearns Commodity and Capital Goods Conference November 200723 slides · Nov 28, 2007
 Investor Presentation (October 2007)14 slides · Oct 3, 2007