Intercorp Financial Services Inc. · NYSE:IFS
Intercorp Financial Services — Investor Presentation (December 2025)
36 slides from Intercorp Financial Services's investor presentation, December 2025
Slide 1: Banking Segment
Banking Segment December 2025
Slide 2: Interbank at a glance
Interbank at a glance
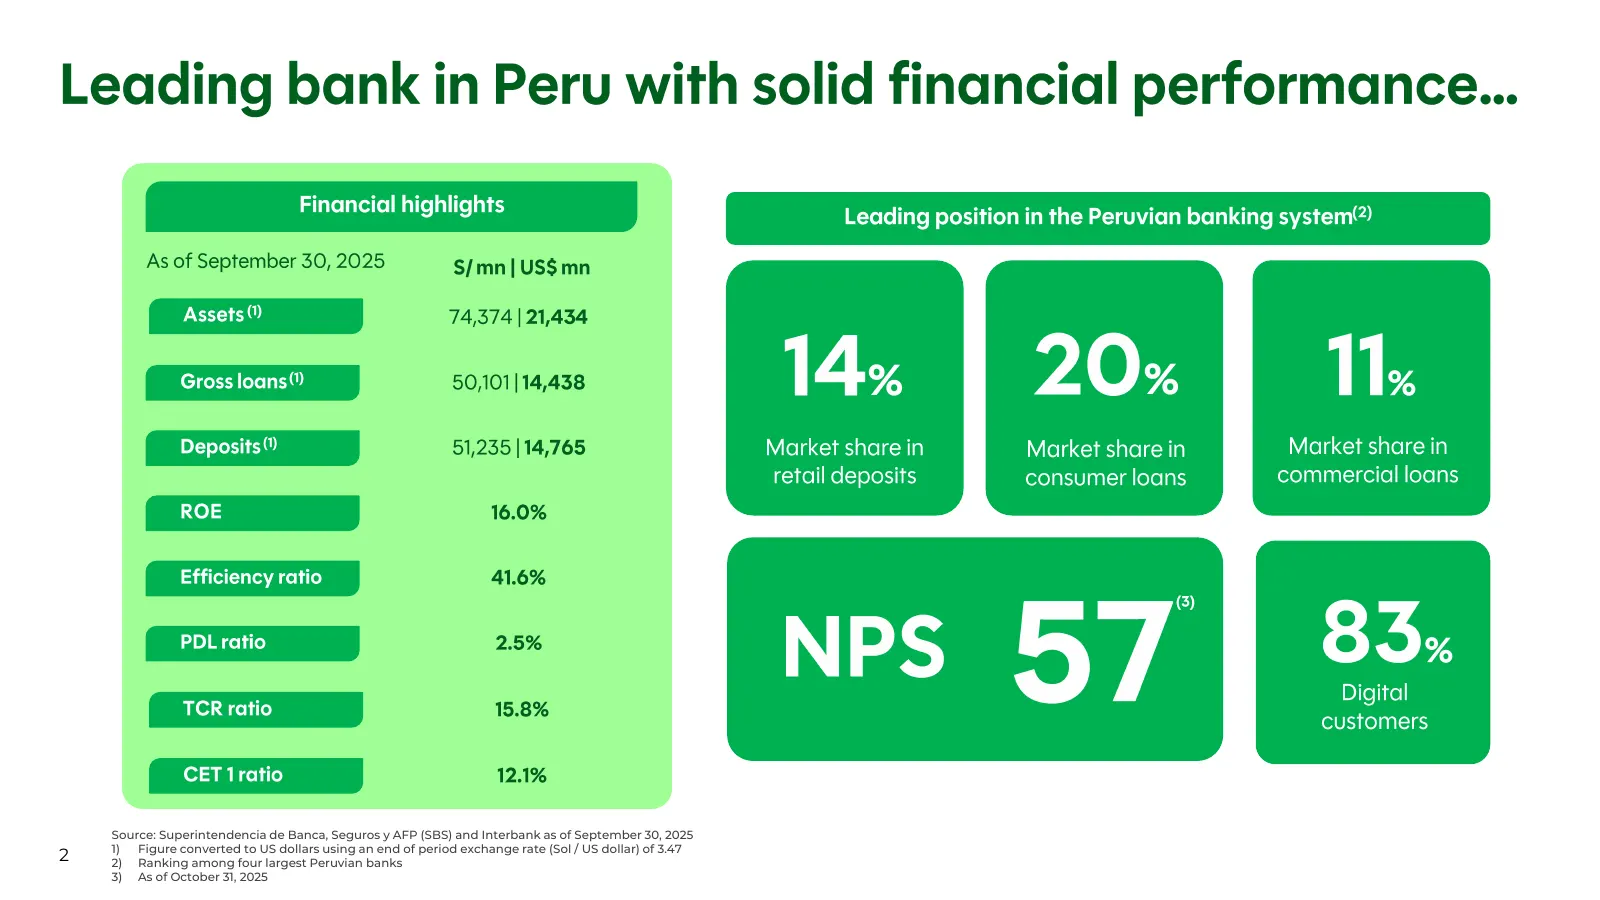
Slide 3: Leading bank in Peru with solid financial performance
Leading bank in Peru with solid financial performance… Financial highlights (2) Leading position in the Peruvian banking system As of September 30, 2025 S/ mn | US$ mn Assets (1) 74,374 | 21,434 Gross loans (1) 50,101 |14,438 14% 20 % 11 % Deposits (1) 51,235 | 14,765 Market share in Market share in
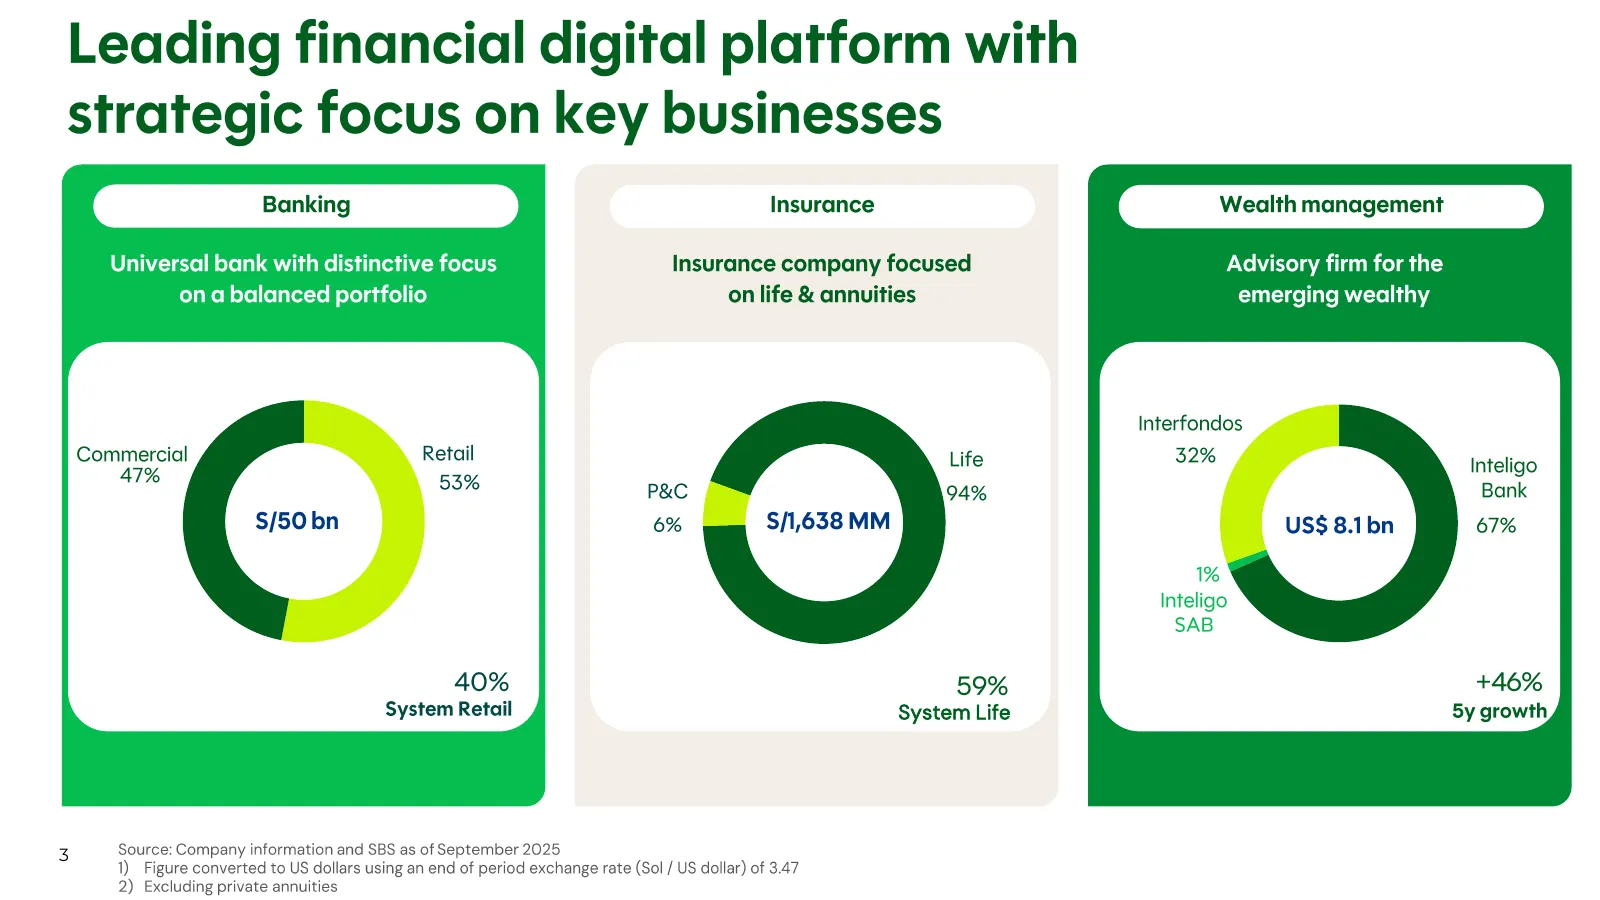
Slide 4: Leading financial digital platform with strategic focus on key businesses
Leading financial digital platform with strategic focus on key businesses Banking Insurance Wealth management Universal bank with distinctive focus Insurance company focused Advisory firm for the on a balanced portfolio on life & annuities emerging wealthy Interfondos Commercial Retail Life 32% 47%
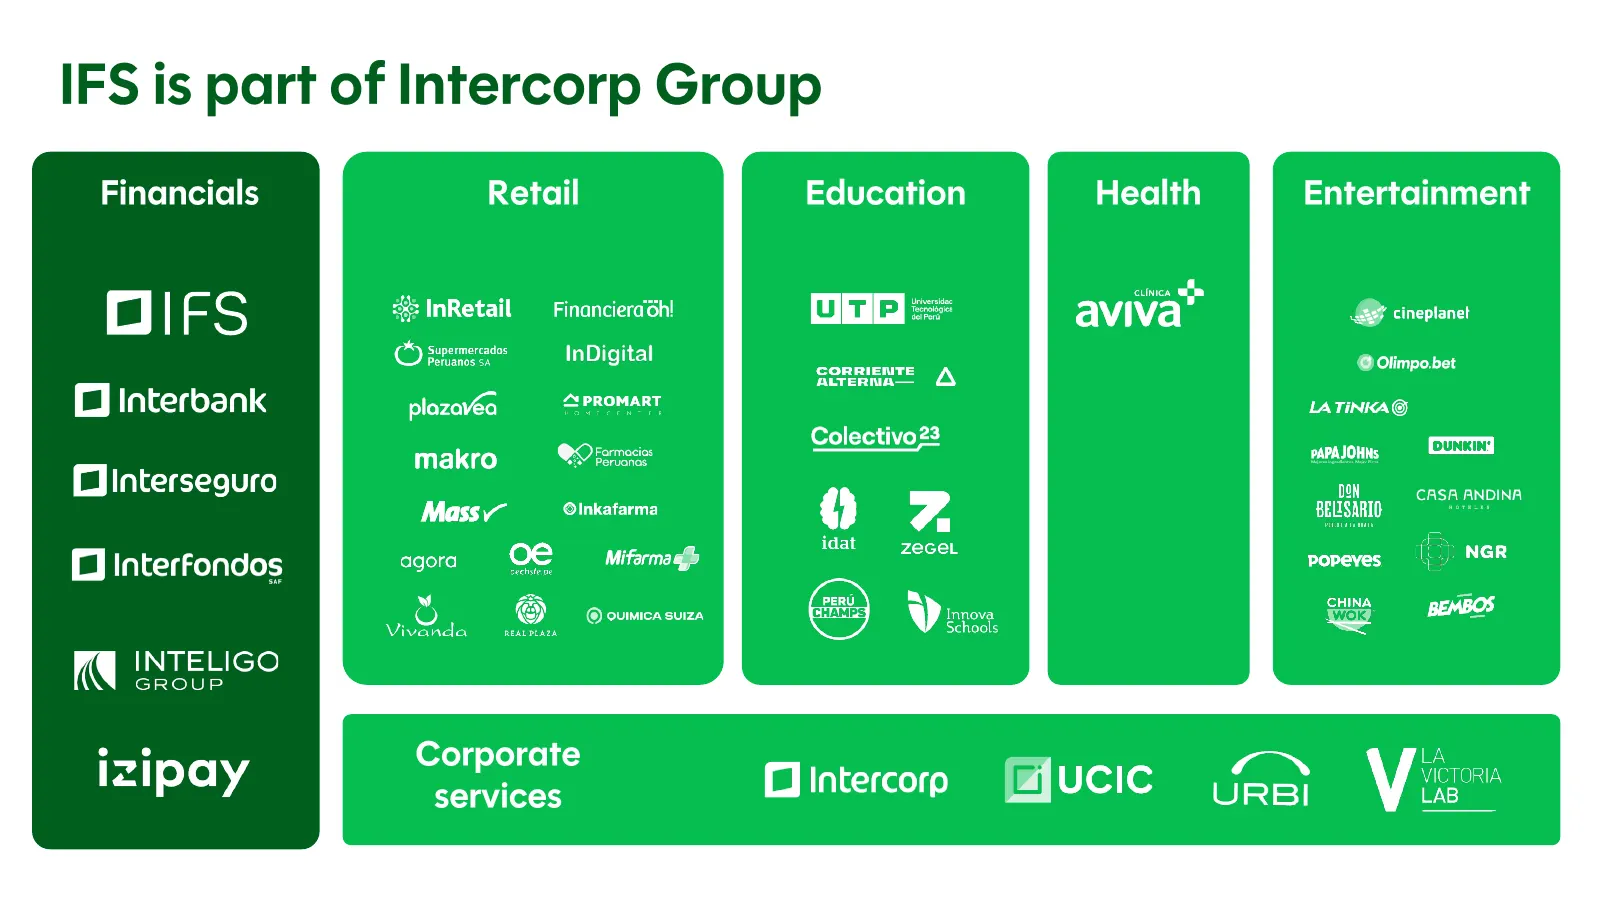
Slide 5: IFS is part of Intercorp Group
IFS is part of Intercorp Group Financials Retail Education Health Entertainment Corporate services
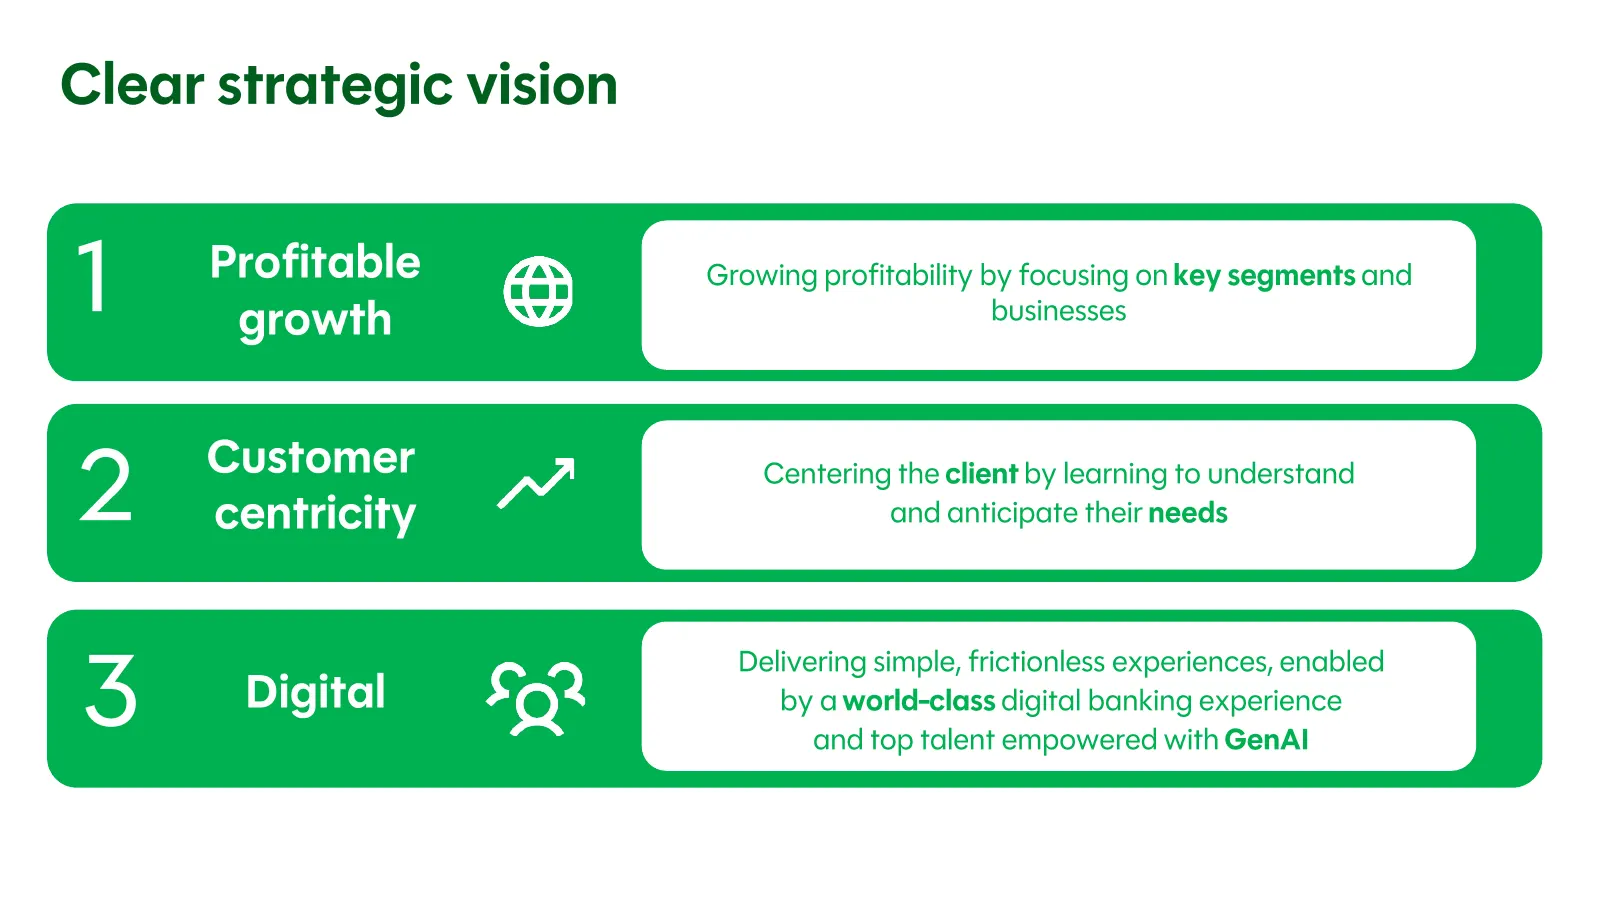
Slide 6: Clear strategic vision
Clear strategic vision 1 Profitable growth Growing profitability by focusing on businesses key segments and Customer 2 centricity Centering the client by learning to understand and anticipate their needs 3 Delivering simple, frictionless experiences, enabled Digital by a world -class digital banking
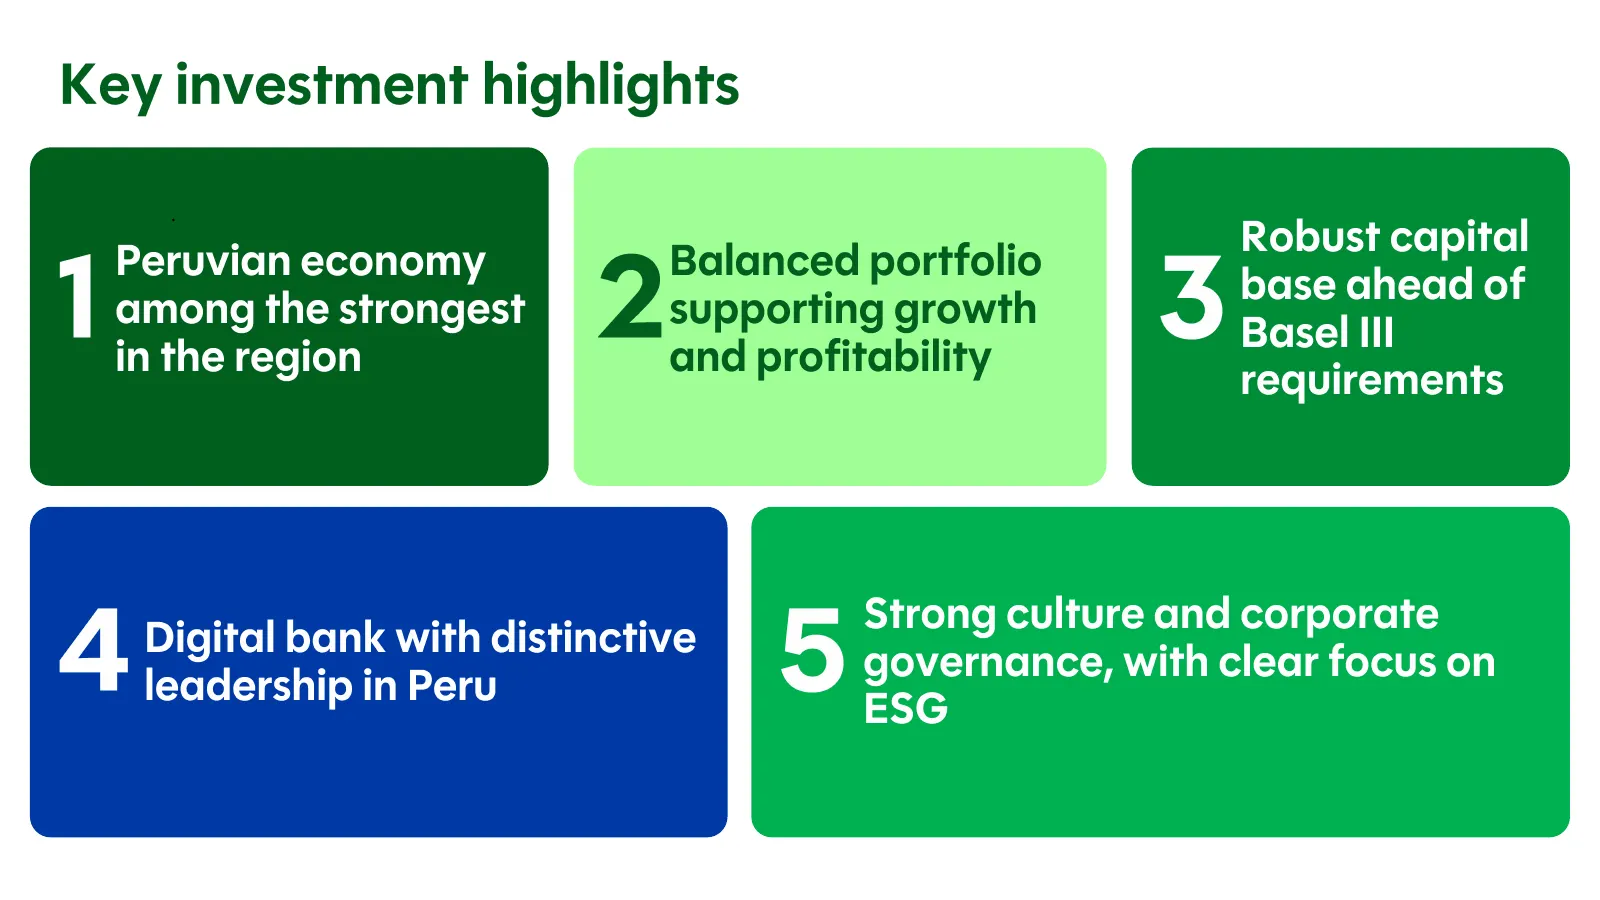
Slide 7: Key investment highlights
Key investment highlights Robust capital Peruvian economy Balanced portfolio 1 among the strongest in the region 2 supporting growth and profitability 3 base ahead of Basel III requirements Strong culture and corporate 4 Digital bank with distinctive leadership in Peru 5 governance, with clear focus
Slide 8: Peruvian economy among the strongest in the region
1 Peruvian economy among the strongest in the region
Slide 9: Peru at a glance
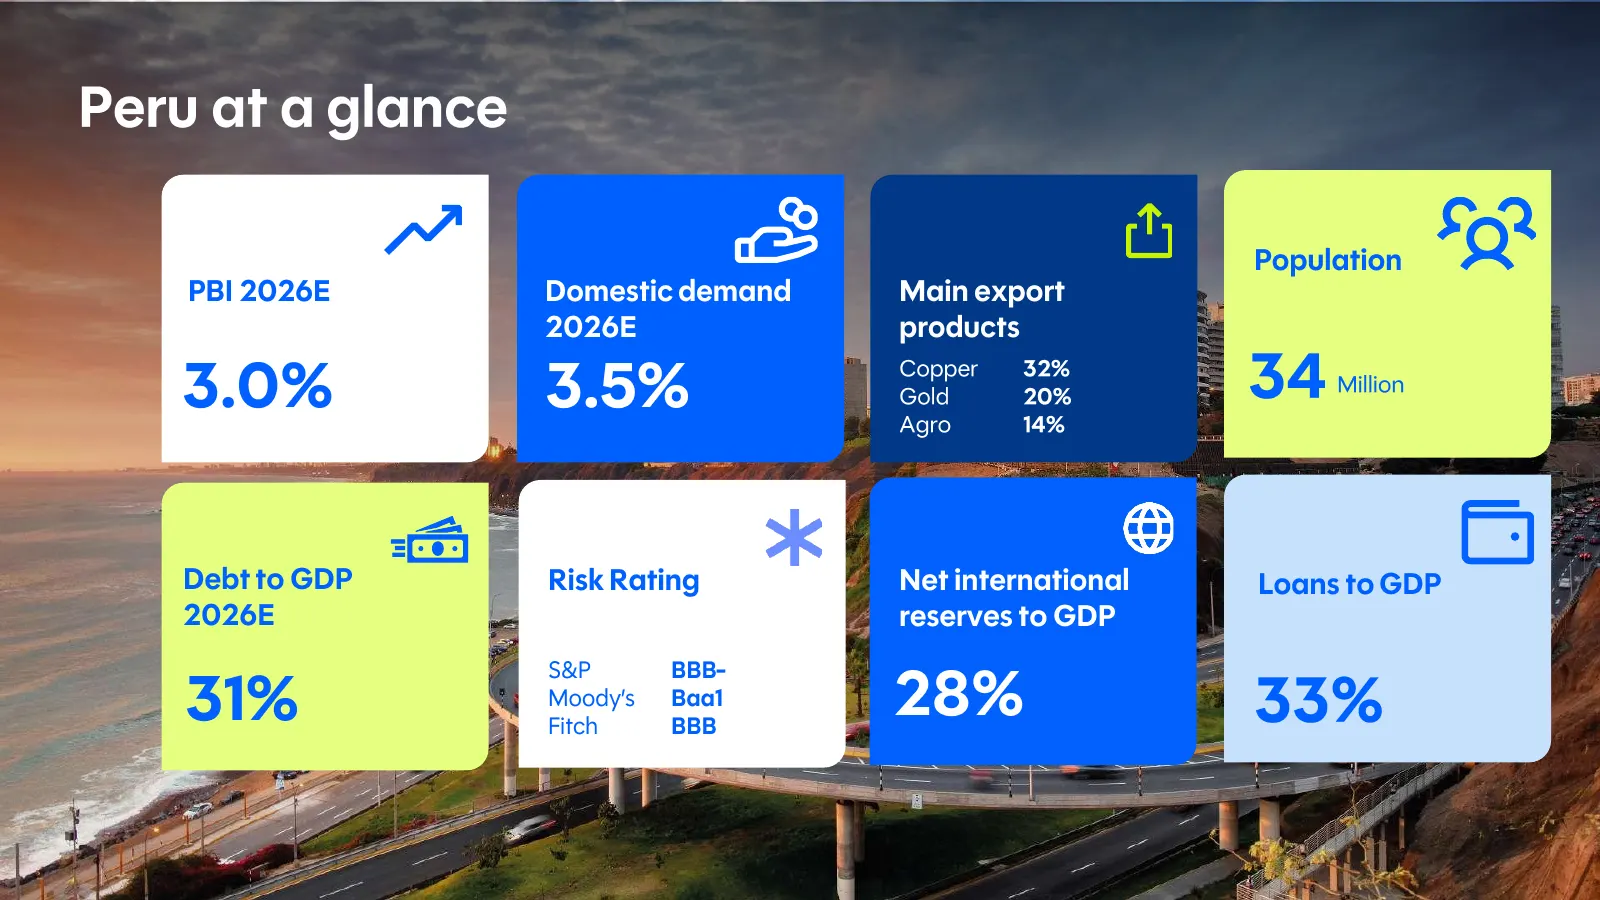
Peru at a glance Population PBI 2026E Domestic demand Main export 2026E products 3.0% 3.5% Copper Gold 32% 20% 34 Million Agro 14% Debt to GDP Risk Rating Net international Loans to GDP 2026E reserves to GDP S&P BBB - 31% Moody’s Fitch Baa1 BBB 28% 33%
Slide 10: Peruvian economy: persistent positive macro indicators
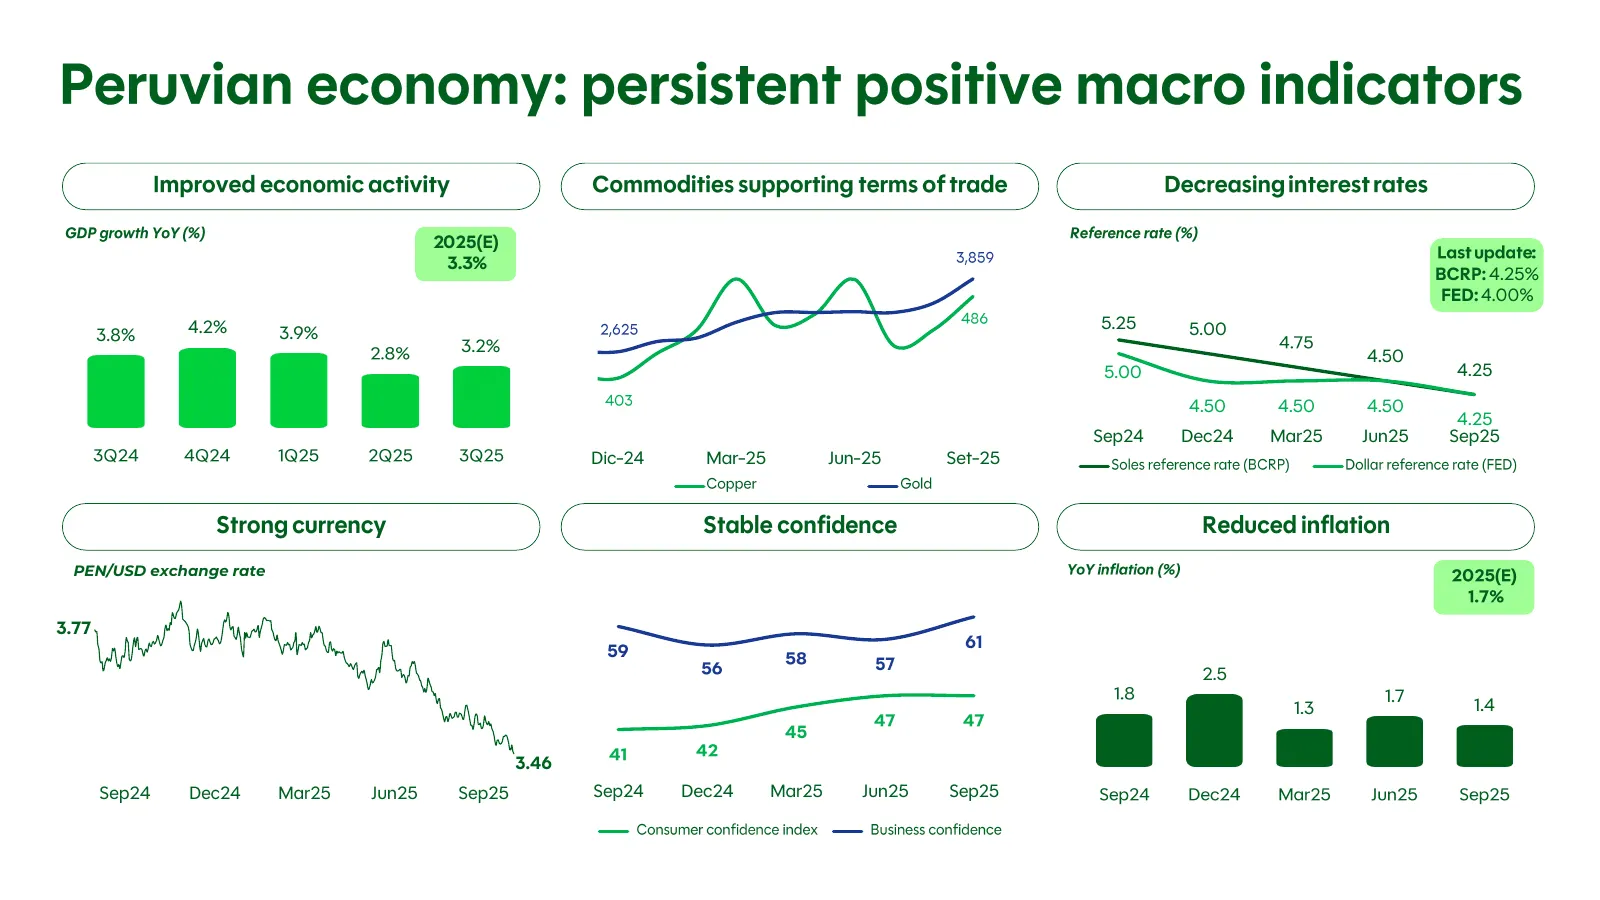
Peruvian economy: persistent positive macro indicators Improved economic activity Commodities supporting terms of trade Decreasing interest rates GDP growth YoY (%) Reference rate (%) 2025(E) 530 3,859 4,300 Last update : 3.3% 510 3,800 BCRP: 4.25% 490 FED: 4.00% 470 3,300 486 5.25 3.8% 4.2% 3.9% 45
Slide 11: Balanced portfolio supporting growth and profitability
2 Balanced portfolio supporting growth and profitability
Slide 12: Balanced portfolio
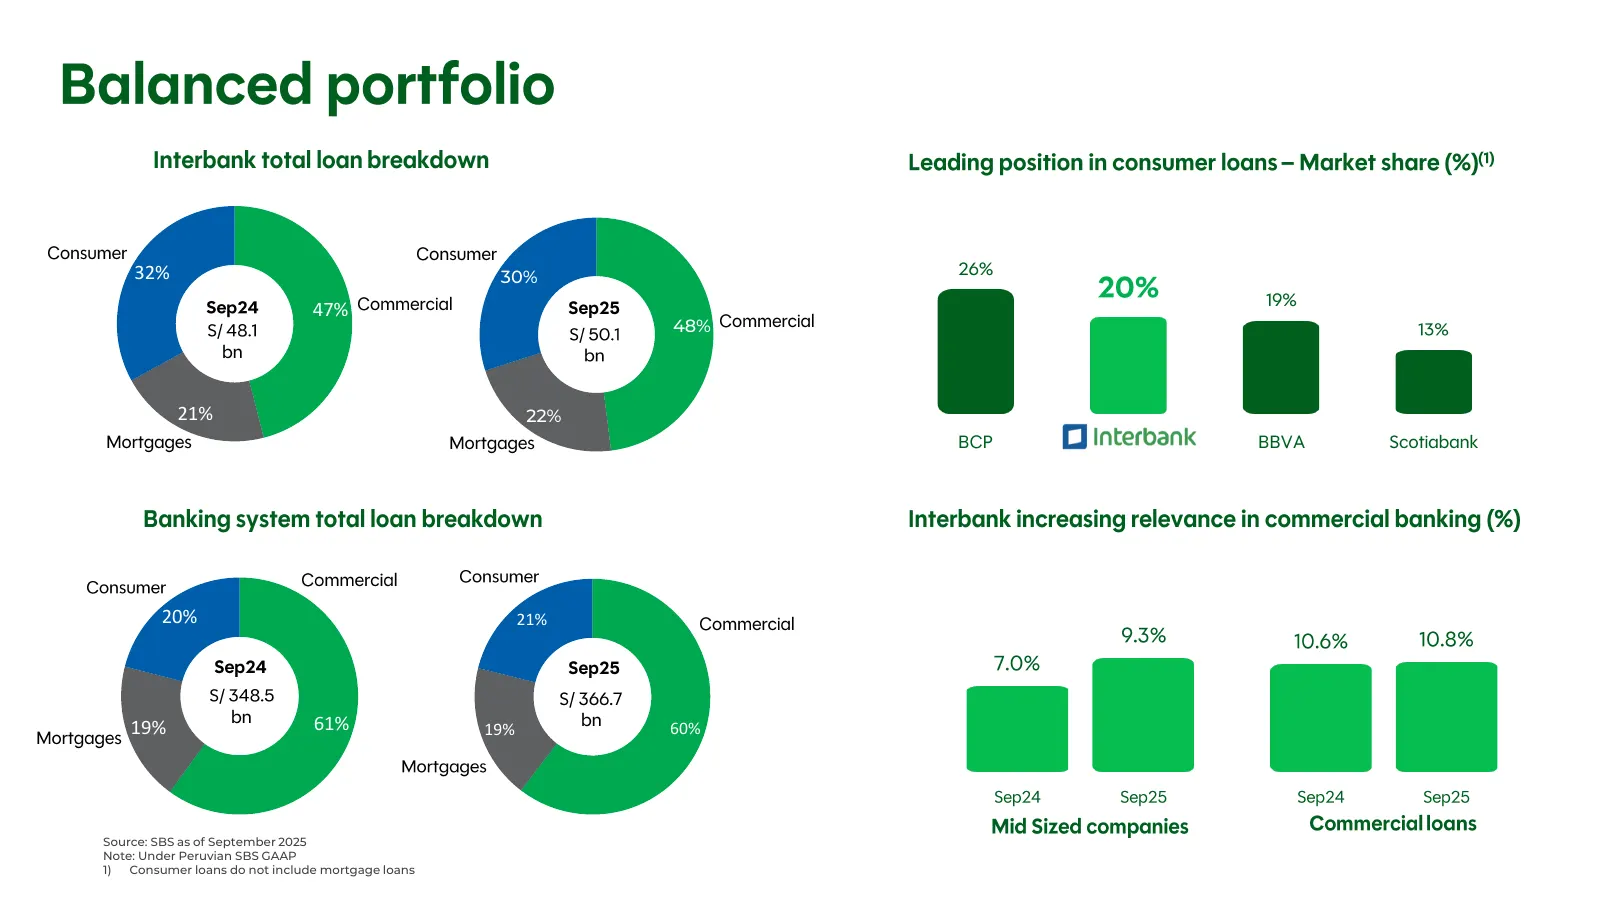
Balanced portfolio Interbank total loan breakdown Leading position in consumer loans – Market share (%) (1) Consumer Consumer 32% 26% 30% 20% 19% Sep24 47% Commercial Sep25 S/ 48.1 S/ 50.1 48% Commercial 13% bn bn 21% 22% Mortgages Mortgages BCP Interbank BBVA Scotiabank Banking system total loan br
Slide 13: Strong PDL ratios
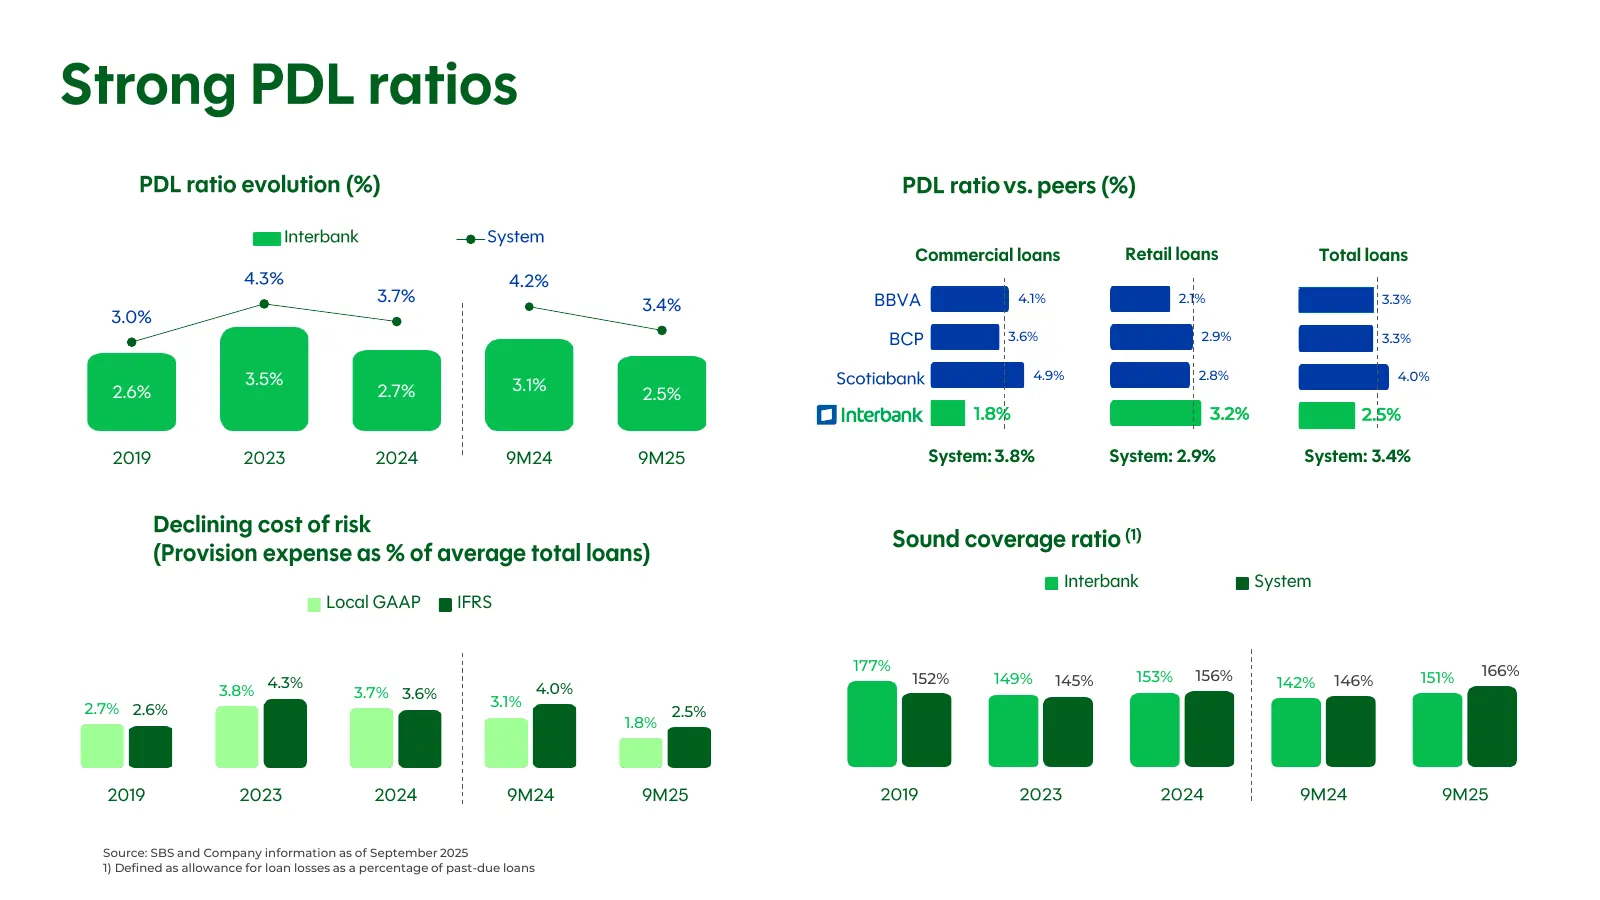
Strong PDL ratios PDL ratio evolution (%) PDL ratio vs. peers (%) Interbank System Commercial loans Retail loans Total loans 4.3% 4.2% 3.7% BBVA BBVA 4.1% 2.1% BBVA 3.3% 3.4% 3.0% BCP BCP 3.6% 2.9% BCP 3.3% 3.5% Scotiabank Scotiabank 4.9% 2.8%Scotiabank 4.0% 2.6% 2.7% 3.1% 2.5% Interbank 1.8% 3.2% I
Slide 14: Diversified funding base
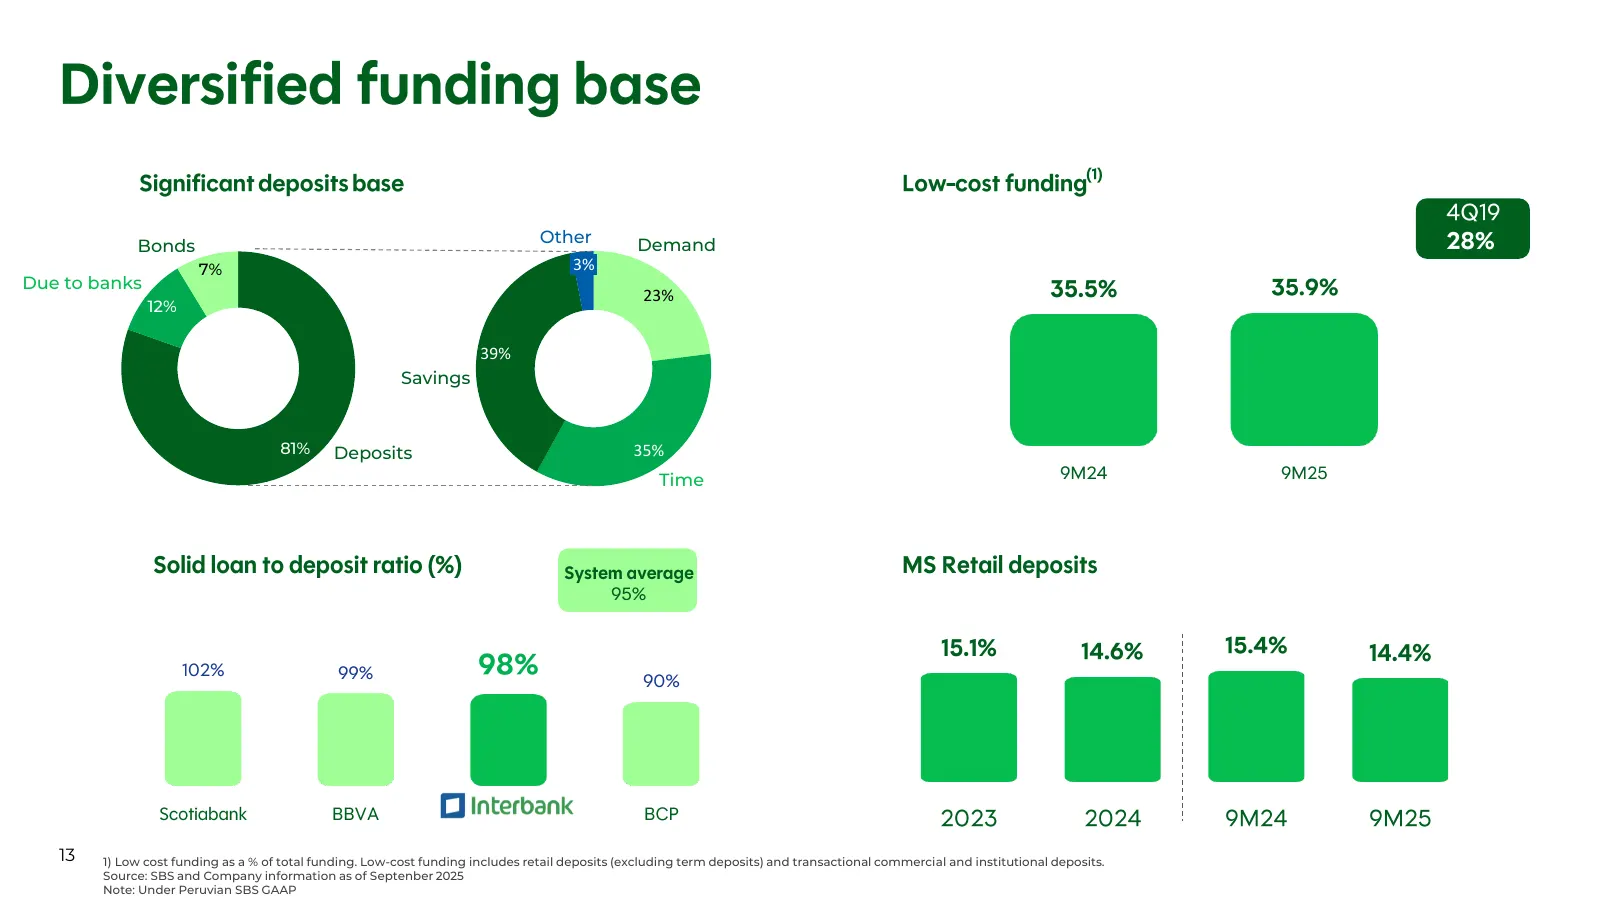
Diversified funding base (1) Significant deposits base Low -cost funding 4Q19 Bonds Other Demand 28% 7% 3% Due to banks 35.5% 35.9% 23% 12% 39% Savings 81% Deposits 35% Time 9M24 9M25 Solid loan to deposit ratio (%) System average MS Retail deposits 95% 15.1% 14.6% 15.4% 14.4% 102% 99% 98% 90% Scoti
Slide 15: Stable NIM
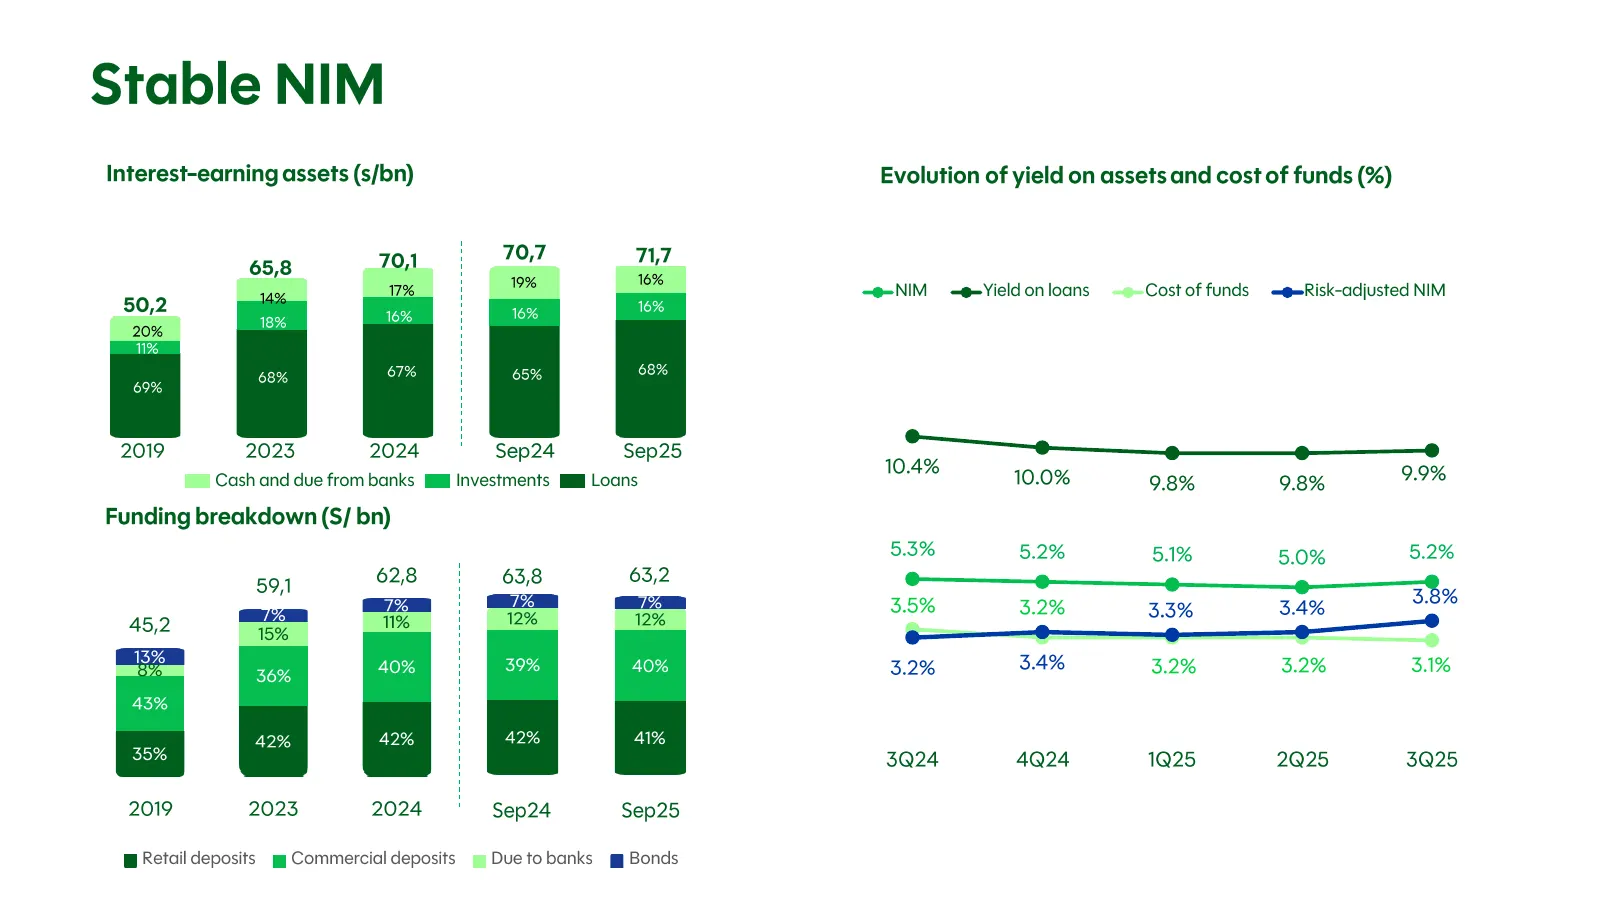
Stable NIM Interest -earning assets (s/bn) Evolution of yield on assets and cost of funds (%) 70,1 70,7 71,7 65,8 16% 19% 14% 17% NIM Yield on loans Cost of funds Risk-adjusted NIM 50,2 16% 16% 16% 18% 20% 11% 67% 65% 68% 68% 69% 2019 2023 2024 Sep24 Sep25 10.4% 9.9% Cash and due from banks Investme
Slide 16: Double digit growth in fee income
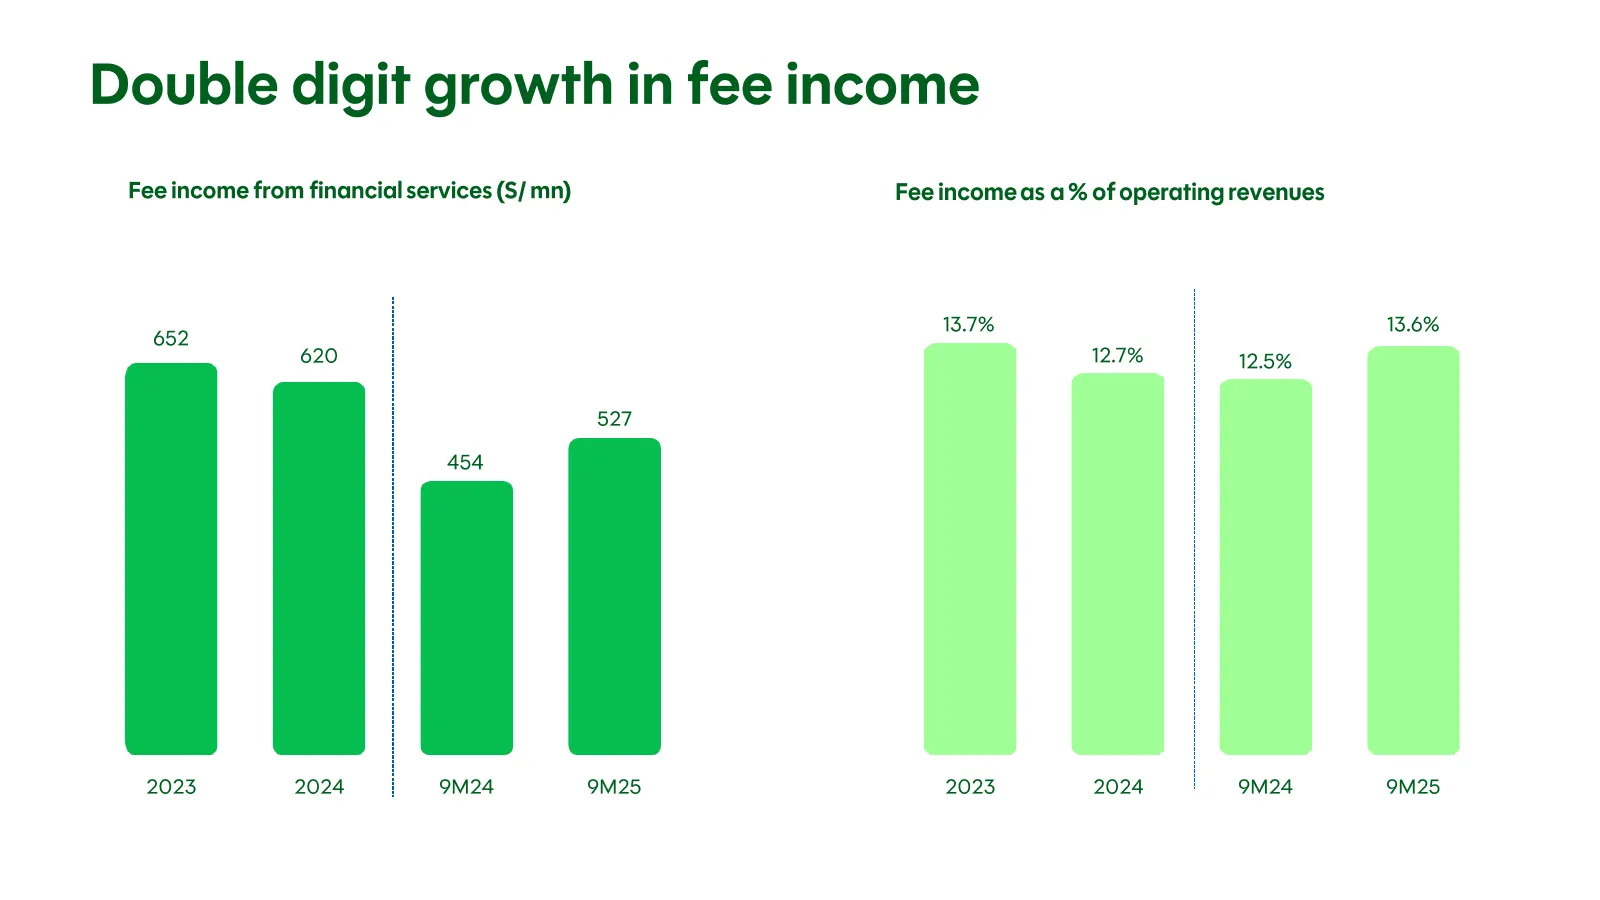
Double digit growth in fee income Fee income from financial services (S/ mn) Fee income as a % of operating revenues 13.7% 13.6% 652 620 12.7% 12.5% 527 454 2023 2024 9M24 9M25 2023 2024 9M24 9M25
Slide 17: Continuous focus on efficiency
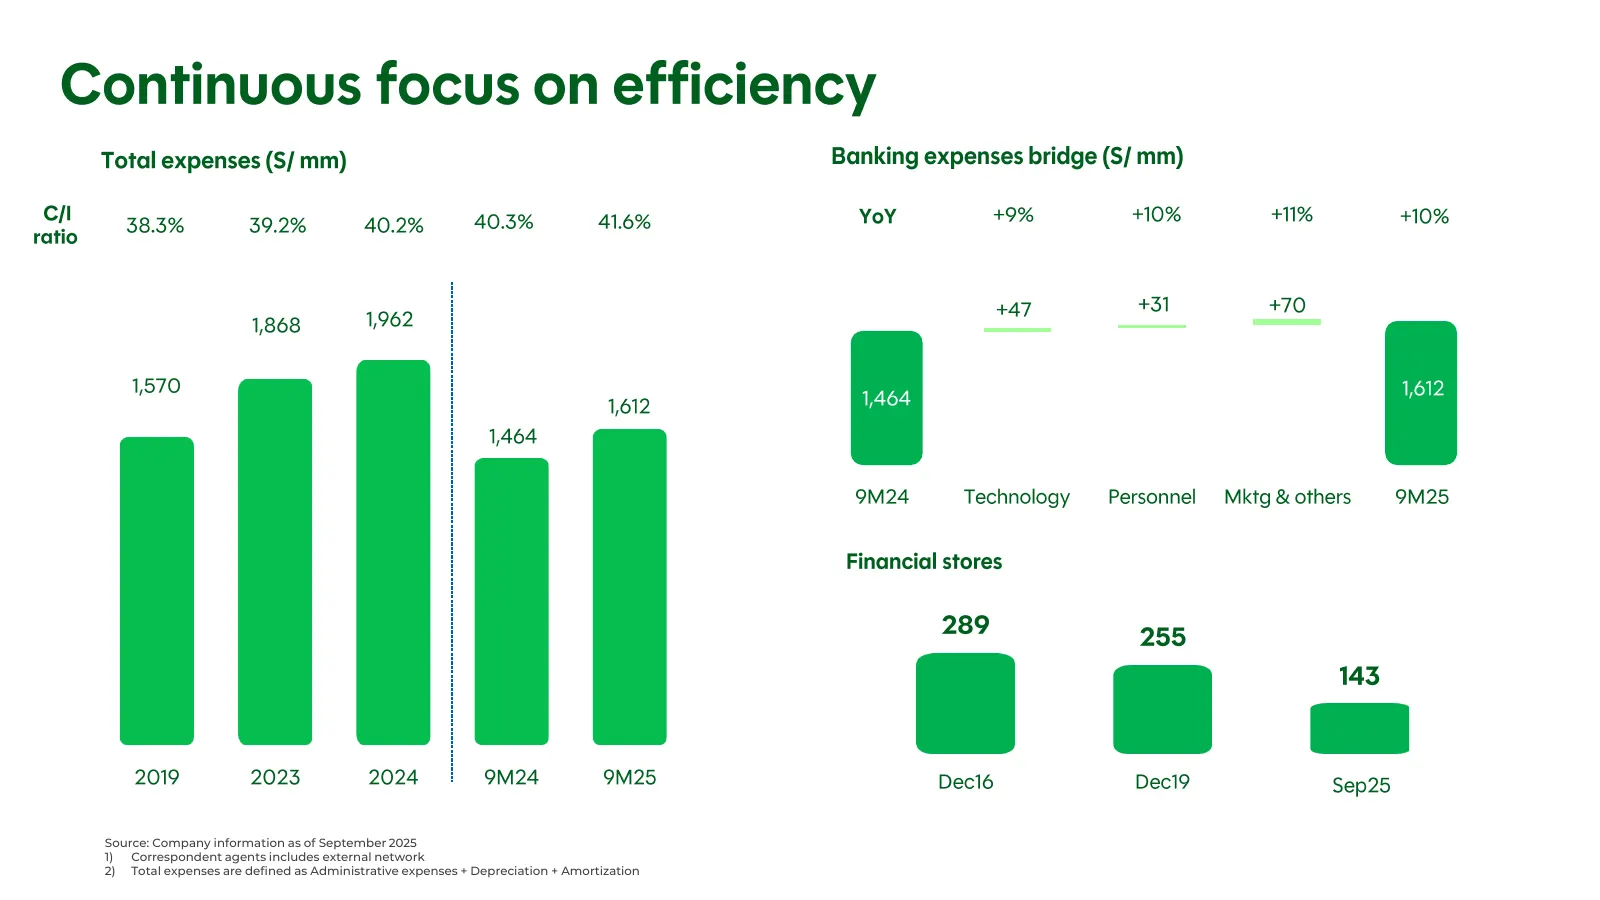
Continuous focus on efficiency Total expenses (S/ mm) Banking expenses bridge (S/ mm) C/I 40.3% 41.6% YoY +9% +10% +11% +10% 38.3% 39.2% 40.2% ratio +47 +31 +70 1,868 1,962 1,570 1,612 1,612 1,464 1,464 9M24 Technology Personnel Mktg & others 9M25 Financial stores 289 255 143 2019 2023 2024 9M24 9M2
Slide 18: Quarterly net profit recovery
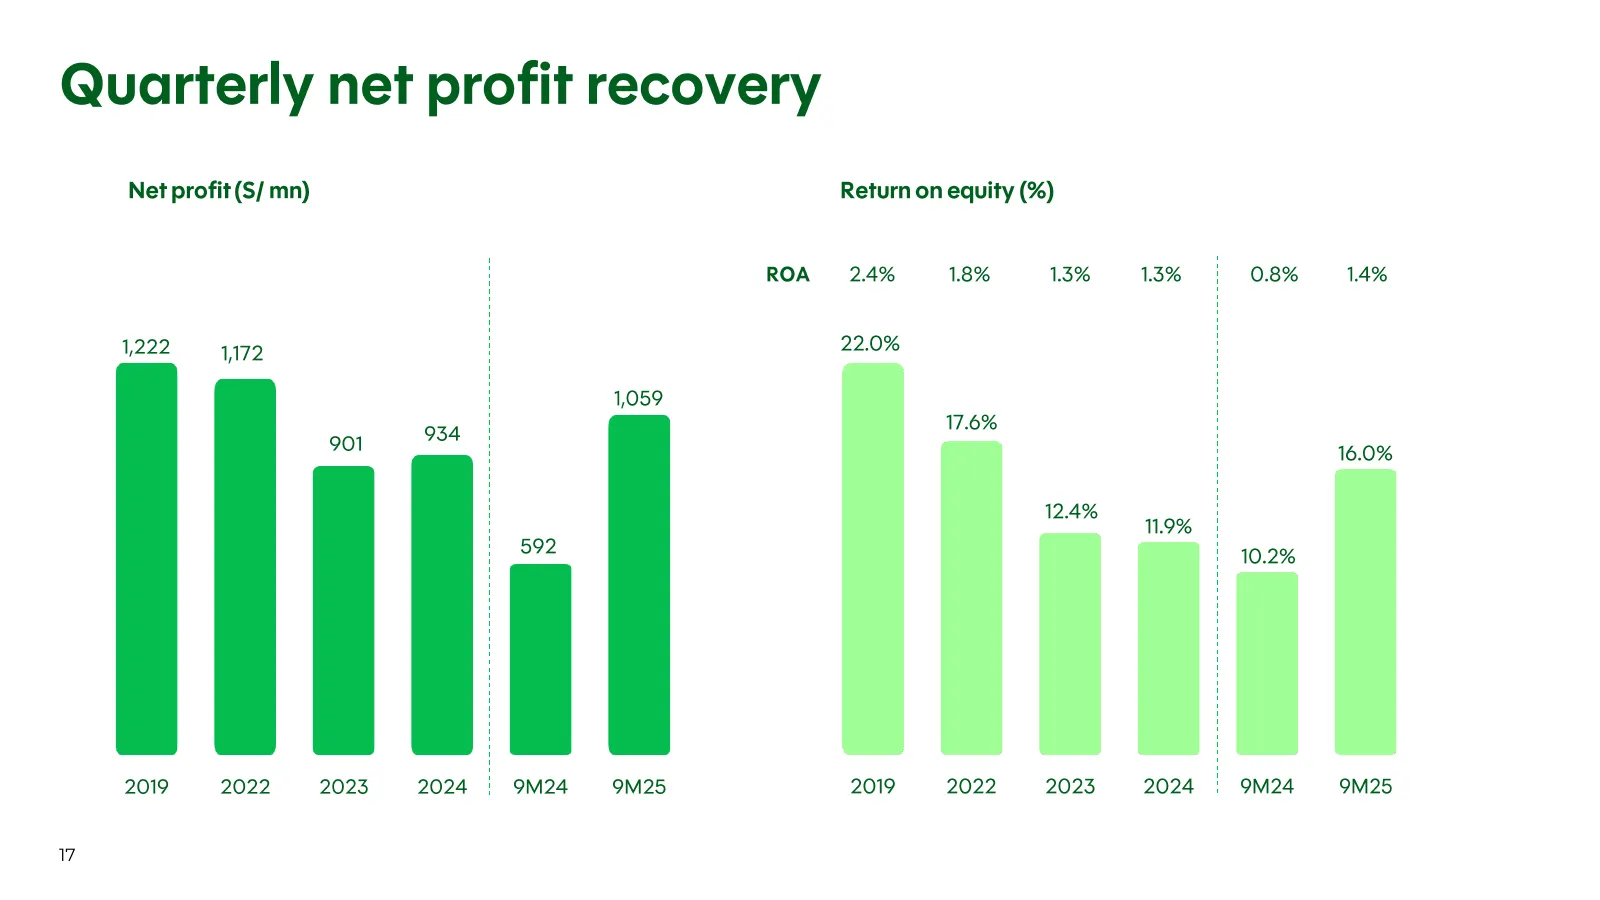
Quarterly net profit recovery Net profit (S/ mn) Return on equity (%) ROA 2.4% 1.8% 1.3% 1.3% 0.8% 1.4% 1,222 1,172 22.0% 1,059 17.6% 901 934 16.0% 12.4% 11.9% 592 10.2% 2019 2022 2023 2024 9M24 9M25 2019 2022 2023 2024 9M24 9M25 17
Slide 19: Robust capital base ahead of Basel III requirements
3 Robust capital base ahead of Basel III requirements
Slide 20: Solid capitalization levels
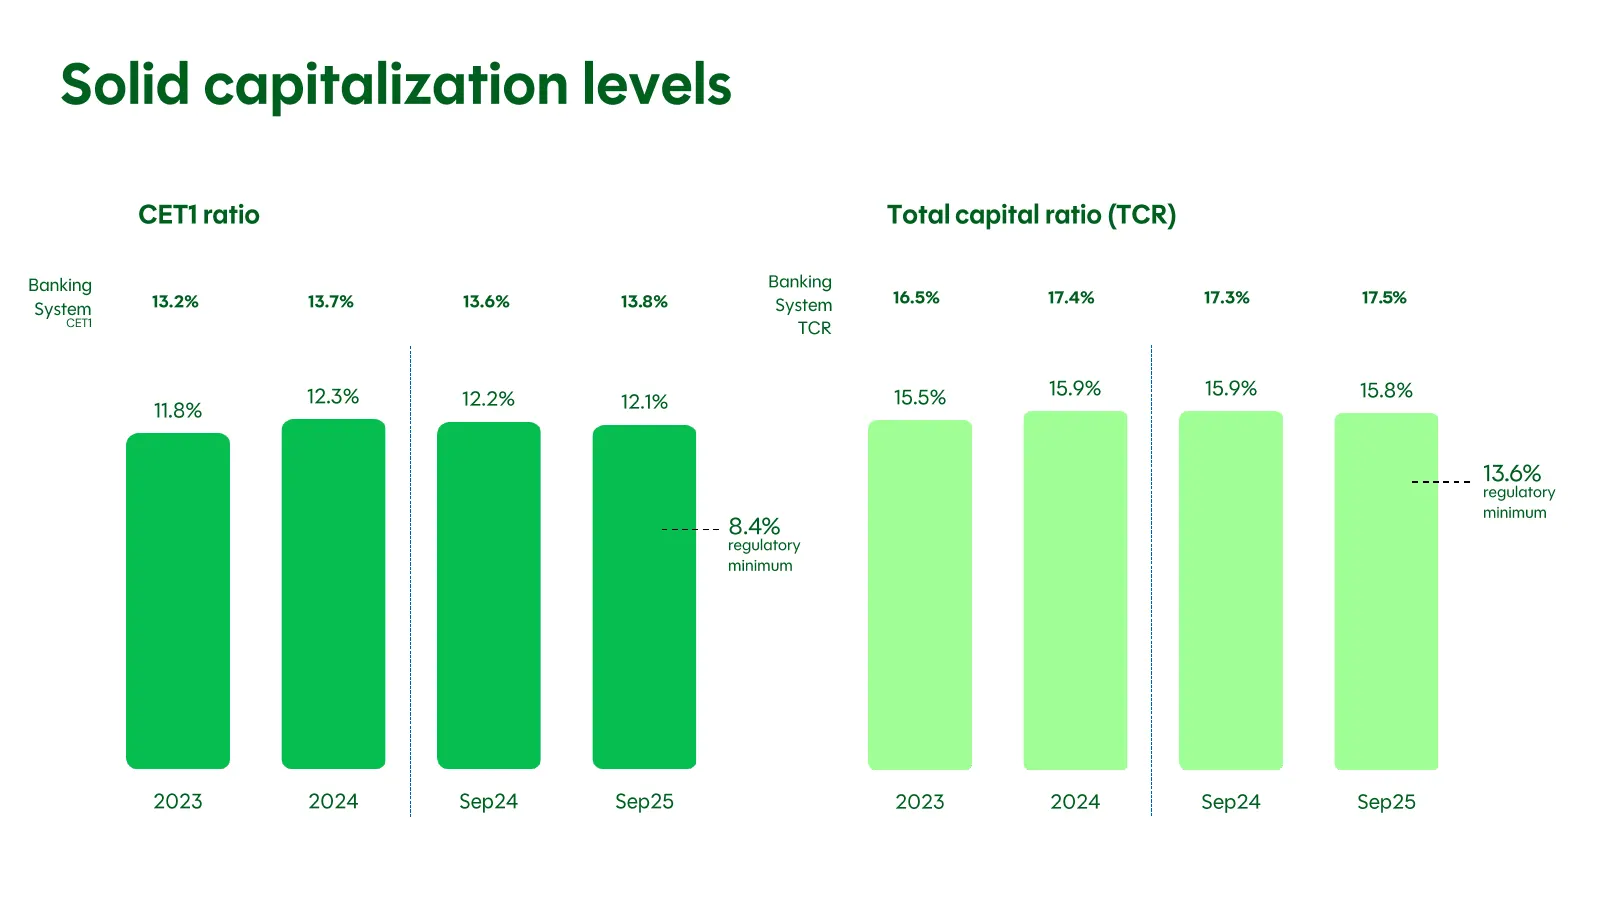
Solid capitalization levels CET1 ratio Total capital ratio (TCR) Banking Banking 13.2% 13.7% 13.6% 13.8 % System 16.5% 17.4% 17.3% 17.5% System CET1 TCR 12.3% 15.5% 15.9% 15.9% 15.8% 12.2% 12.1% 11.8% 13.6% regulatory minimum 8.4% regulatory minimum 2023 2024 Sep24 Sep25 2023 2024 Sep24 Sep25
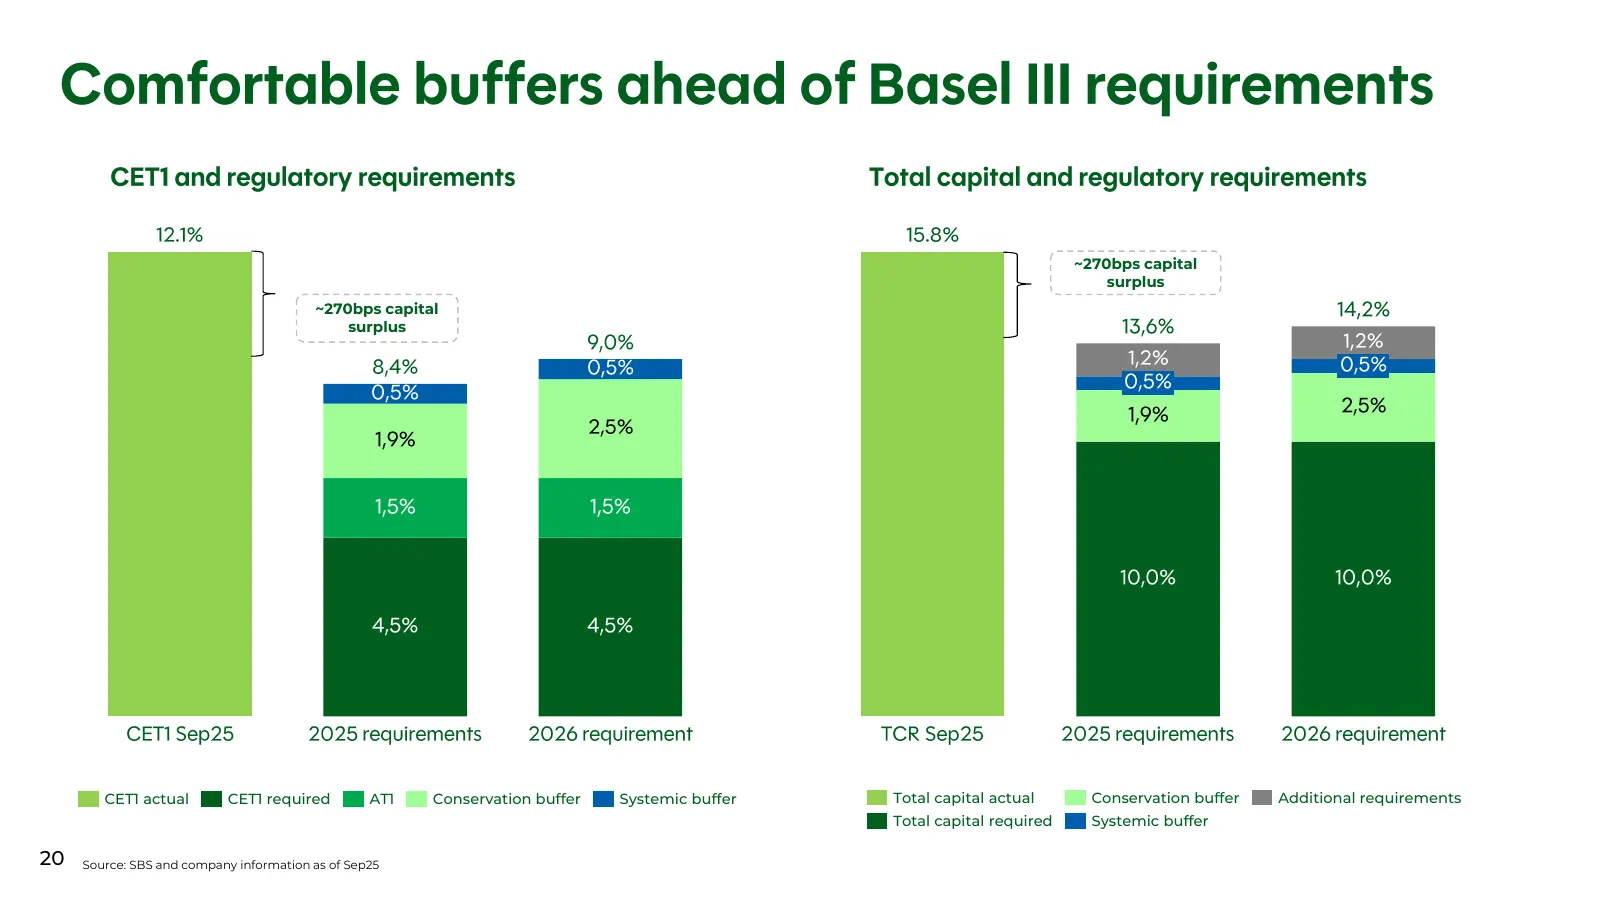
Slide 21: Comfortable buffers ahead of Basel III requirements
Comfortable buffers ahead of Basel III requirements CET1 and regulatory requirements Total capital and regulatory requirements 12.1% 15.8% ~270bps capital surplus ~270bps capital 14,2% surplus 13,6% 9,0% 1,2% 8,4% 0,5% 1,2% 0,5% 0,5% 0,5% 1,9% 2,5% 2,5% 1,9% 1,5% 1,5% 10,0% 10,0% 4,5% 4,5% CET1 Sep2
Slide 22: Digital bank with distinctive leadership in Peru
4 Digital bank with distinctive leadership in Peru
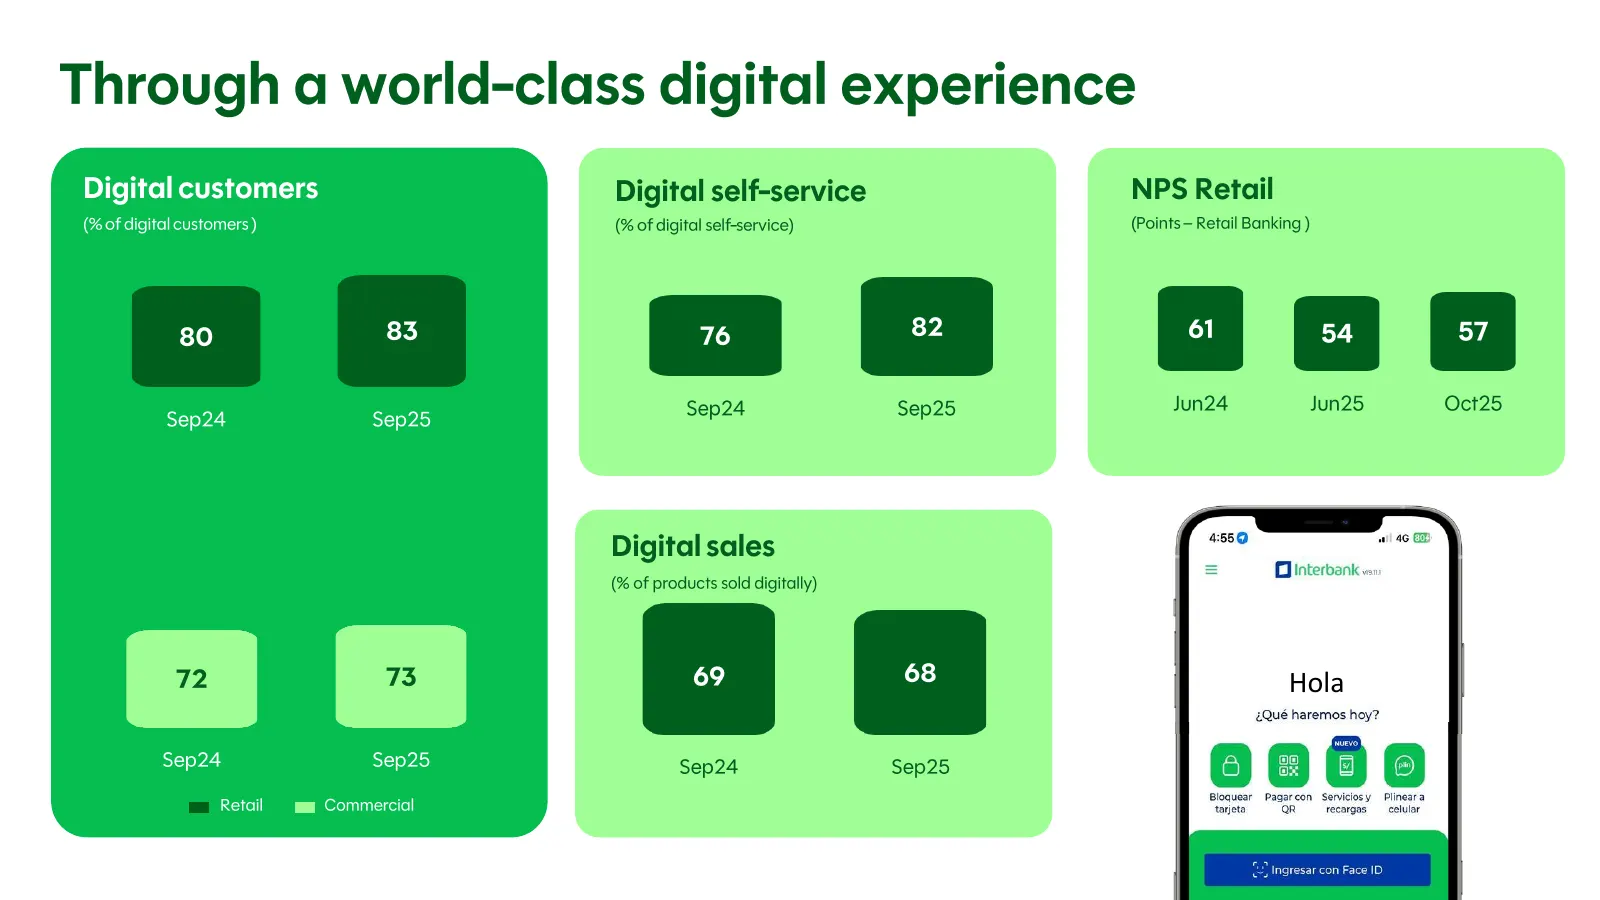
Slide 23: Through a world-class digital experience
Through a world -class digital experience Digital customers Digital self -service NPS Retail (% of digital customers ) (% of digital self -service) (Points – Retail Banking ) 80 83 76 82 61 54 57 Sep24 Sep25 Jun24 Jun25 Oct25 Sep24 Sep25 Digital sales (% of products sold digitally) 72 73 69 68 Hola
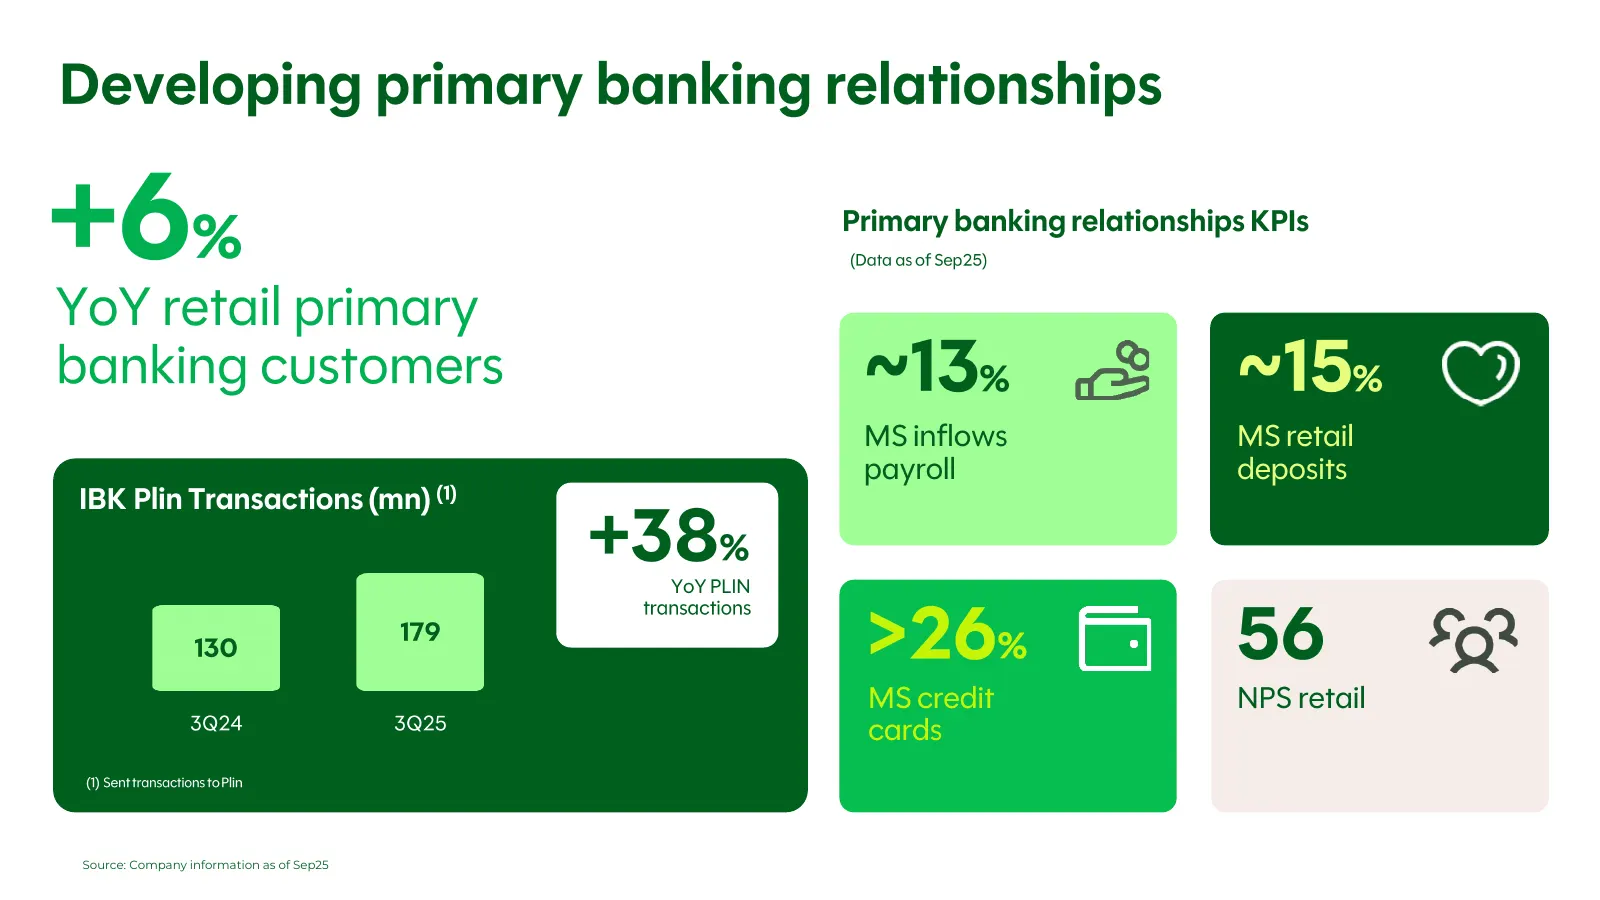
Slide 24: Developing primary banking relationships
Developing primary banking relationships +6 % Primary banking relationships KPIs (Data as of Sep25) YoY retail primary banking customers ~13% ~15% MS inflows MS retail payroll deposits IBK Plin Transactions (mn) (1) +38 % YoY PLIN transactions 130 179 >26 % 56 MS credit NPS retail 3Q24 3Q25 cards (1
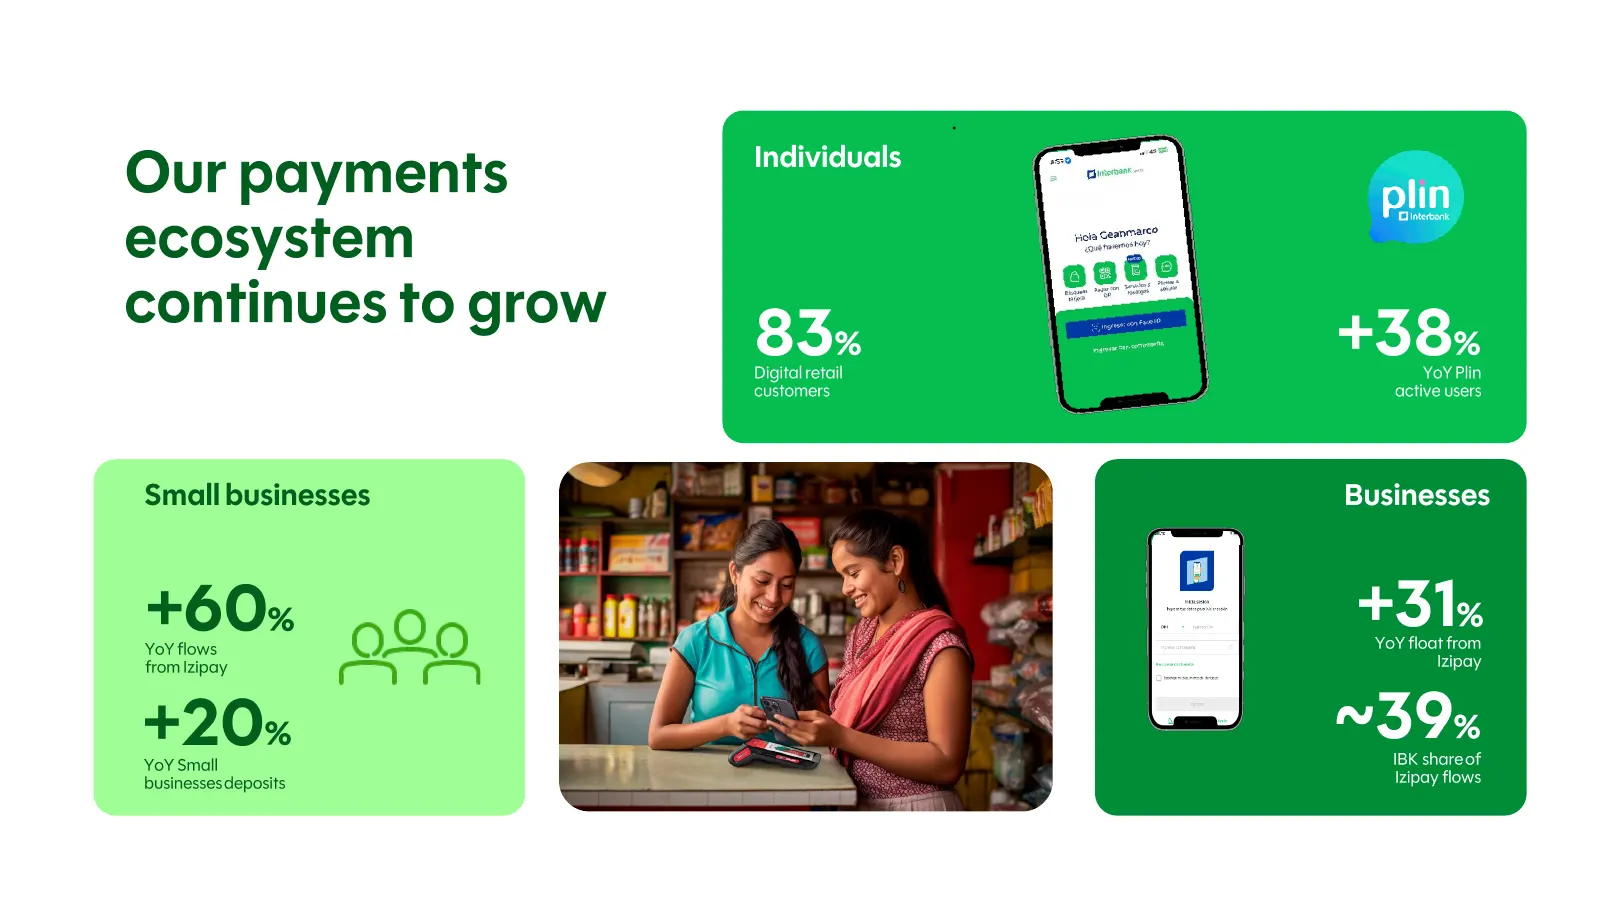
Slide 25: Our payments ecosystem continues to grow
Individuals Our payments ecosystem continues to grow 83 % Digital retail +38 % YoY Plin customers active users Small businesses Businesses +60 % YoY flows +31% YoY float from from Izipay Izipay +20 % YoY Small ~ 39 % IBK share of businesses deposits Izipay flows
Slide 26: Strong culture and corporate governance, with clear focus on ESG
5 Strong culture and corporate governance, with clear focus on ESG
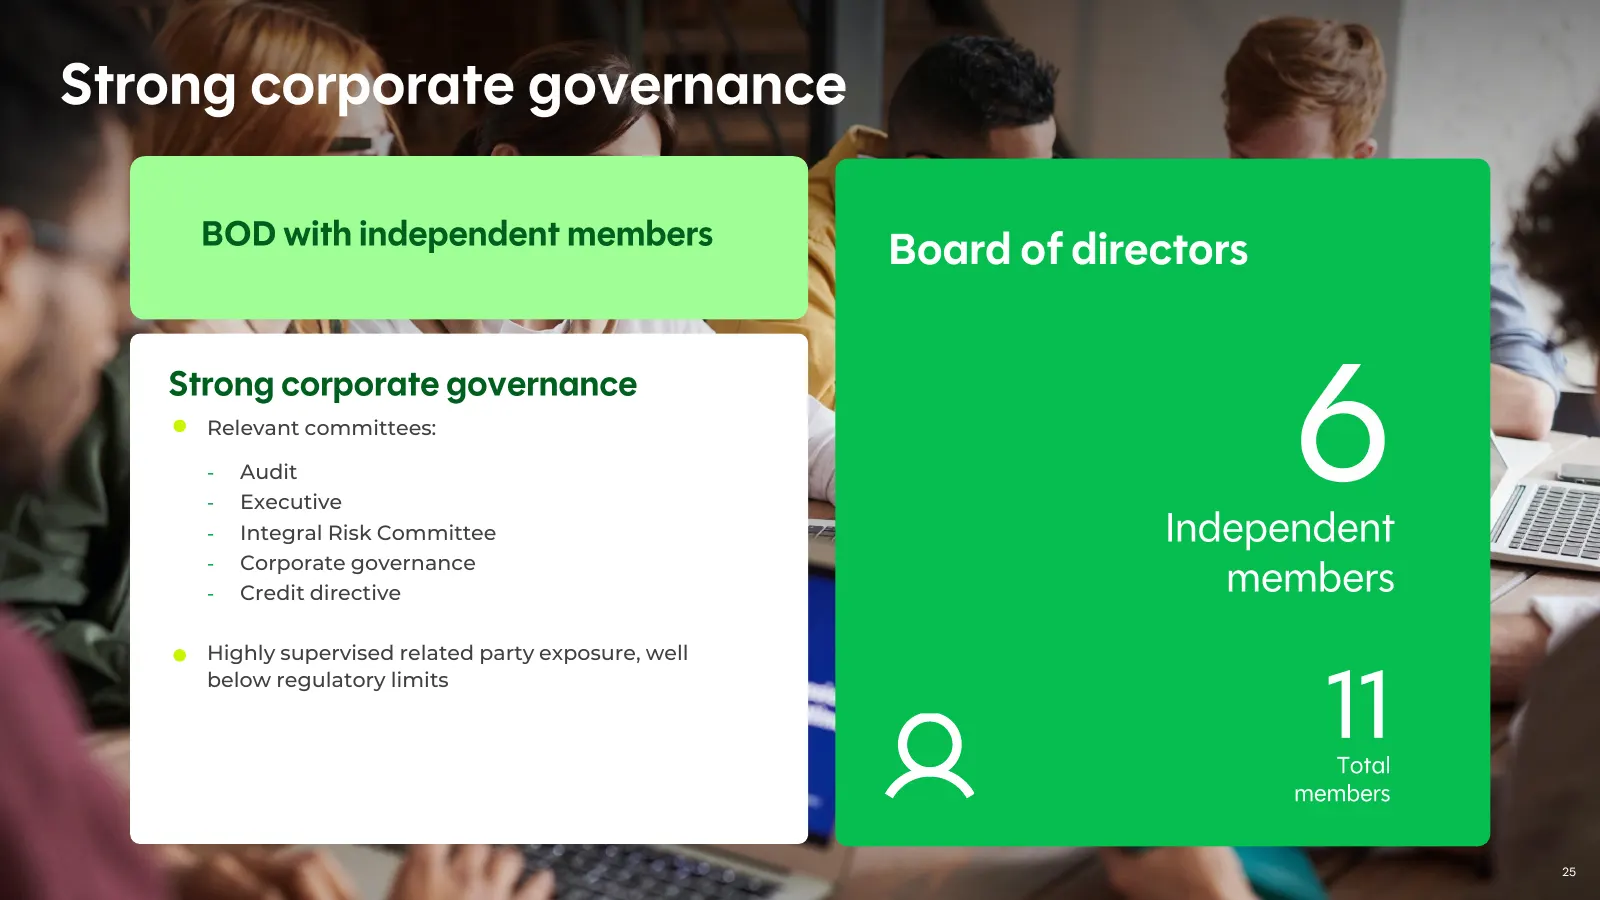
Slide 27: Strong corporate governance
Strong corporate governance BOD with independent members Board of directors 6 Strong corporate governance Relevant committees: - Audit - Executive - Integral Risk Committee Independent - Corporate governance - Credit directive members Highly supervised related party exposure, well 11 below regulator
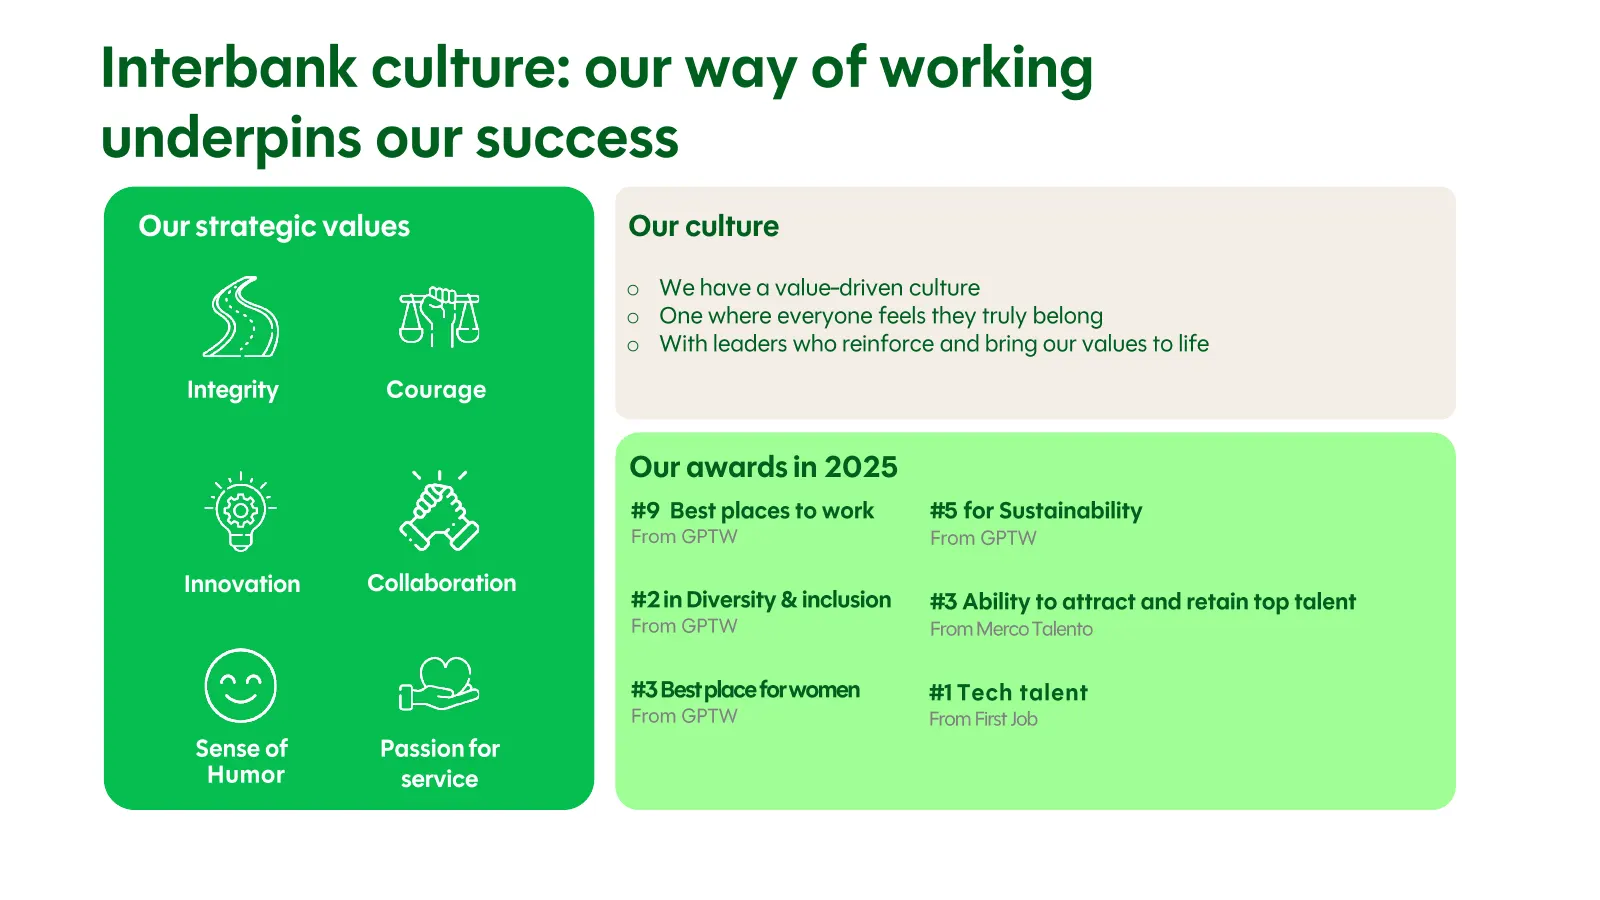
Slide 28: Interbank culture: our way of working underpins our success
Interbank culture: our way of working underpins our success Our strategic values Our culture o We have a value -driven culture o One where everyone feels they truly belong o With leaders who reinforce and bring our values to life Integrity Courage Our awards in 2025 #9 Best places to work #5 for Sus
Slide 29: Sustainability as part of our strategic pillars
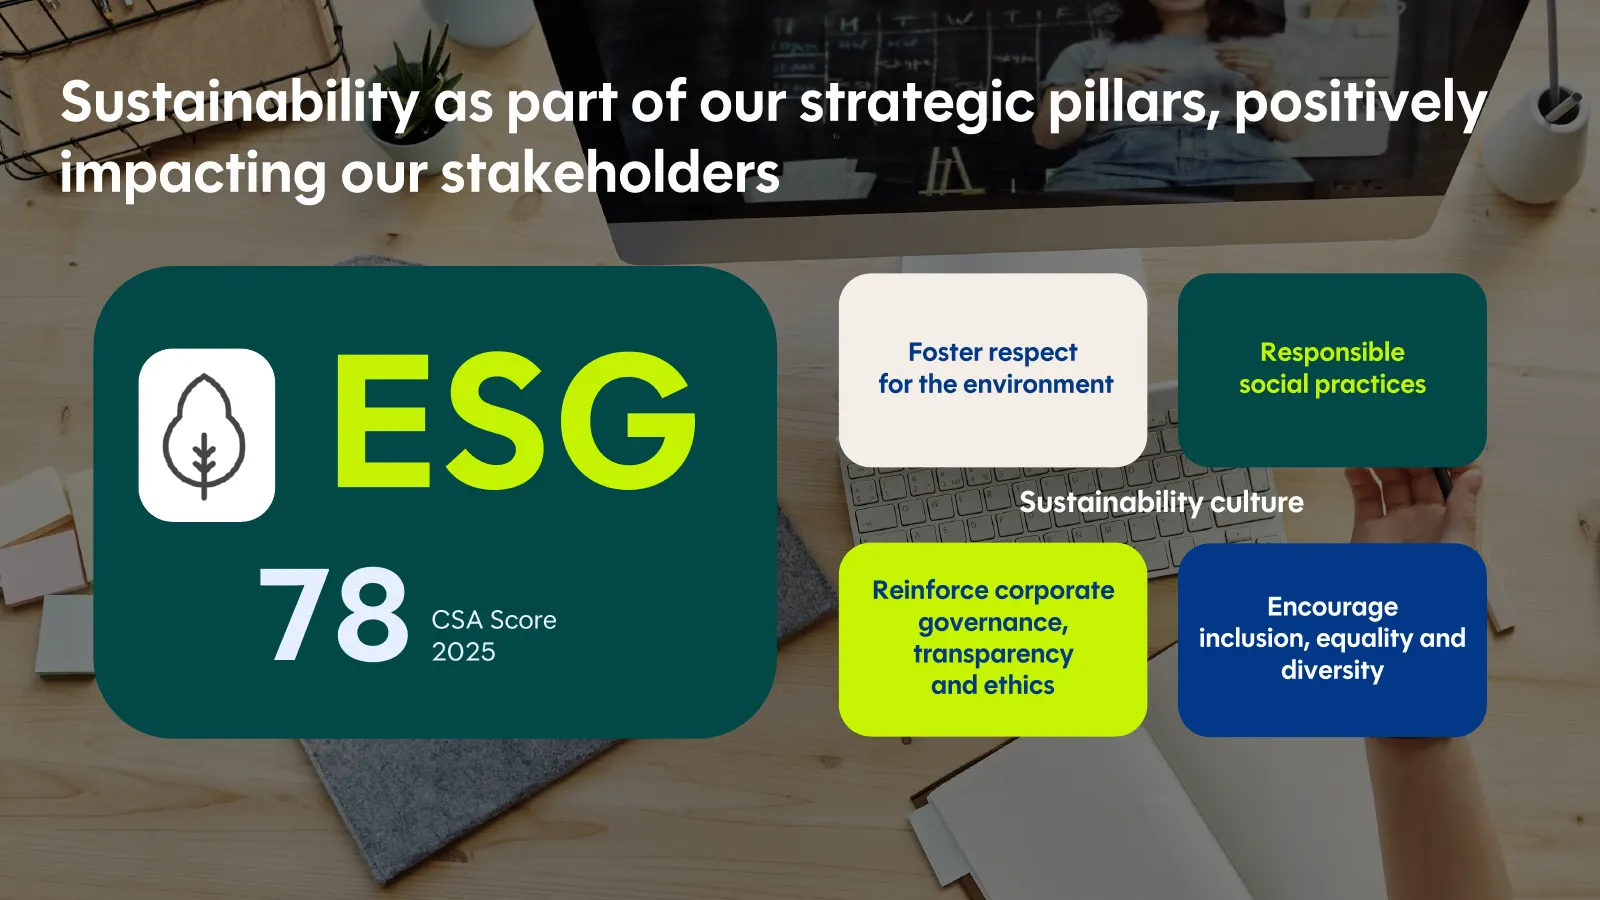
Sustainability as part of our strategic pillars, positively impacting our stakeholders ESG Foster respect Responsible for the environment social practices Sustainability culture 78 CSA Score 2025 Reinforce corporate governance, transparency and ethics Encourage inclusion, equality and diversity
Slide 30: Definitions
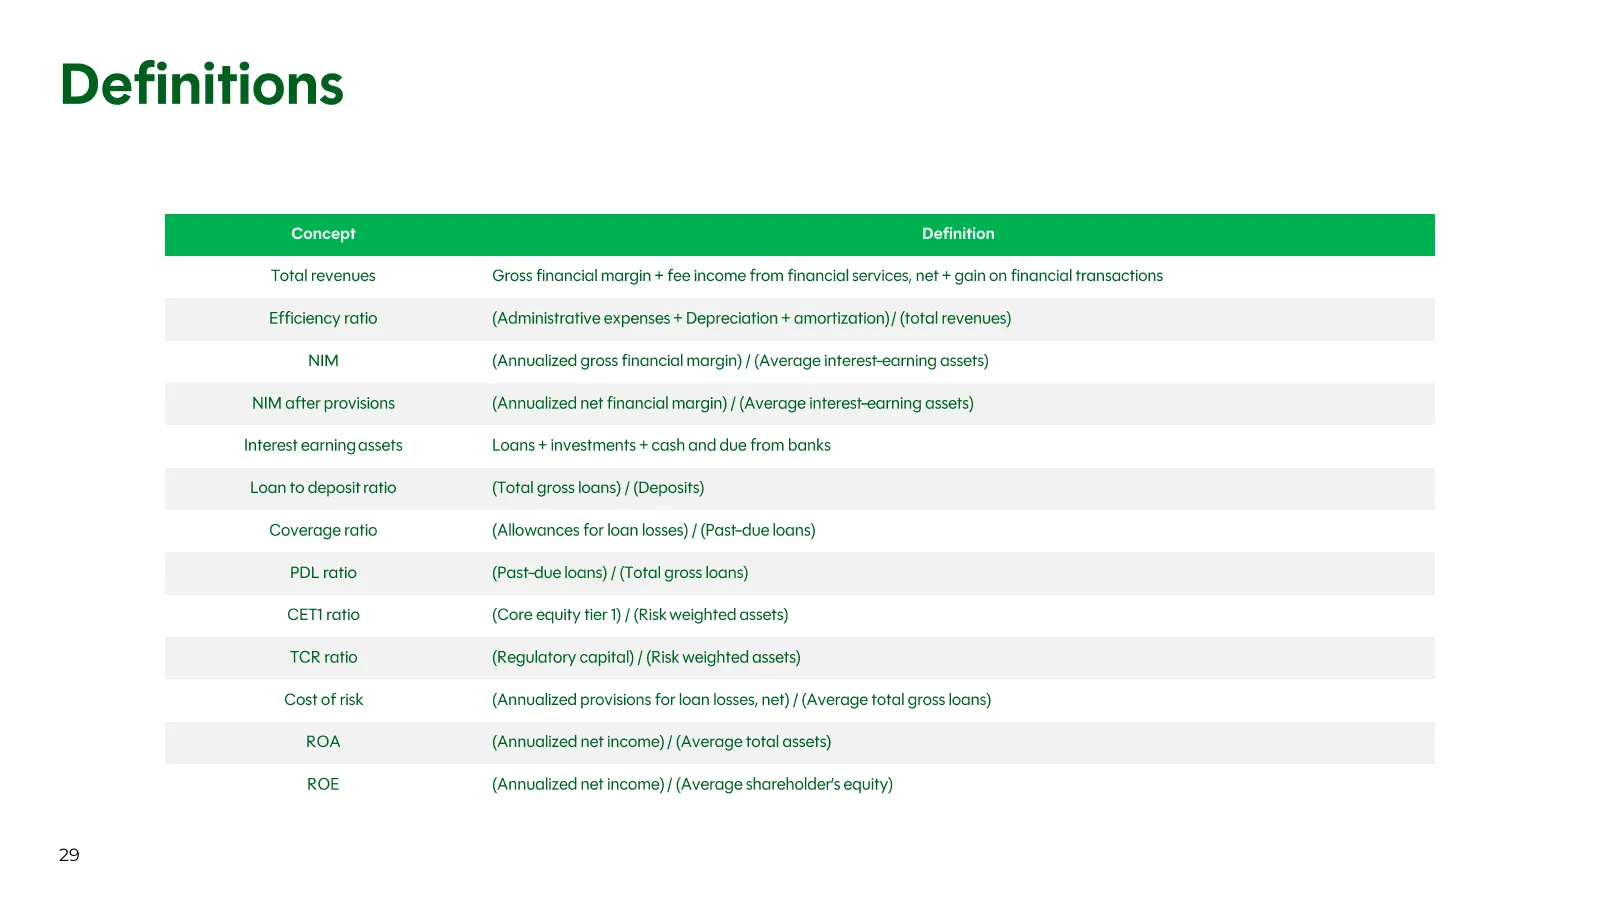
Definitions Concept Definition Total revenues Gross financial margin + fee income from financial services, net + gain on financial transactions Efficiency ratio (Administrative expenses + Depreciation + amortization) / (total revenues) NIM (Annualized gross financial margin) / (Average interest -ear
Slide 31
Slide 32: Appendix
Appendix 31
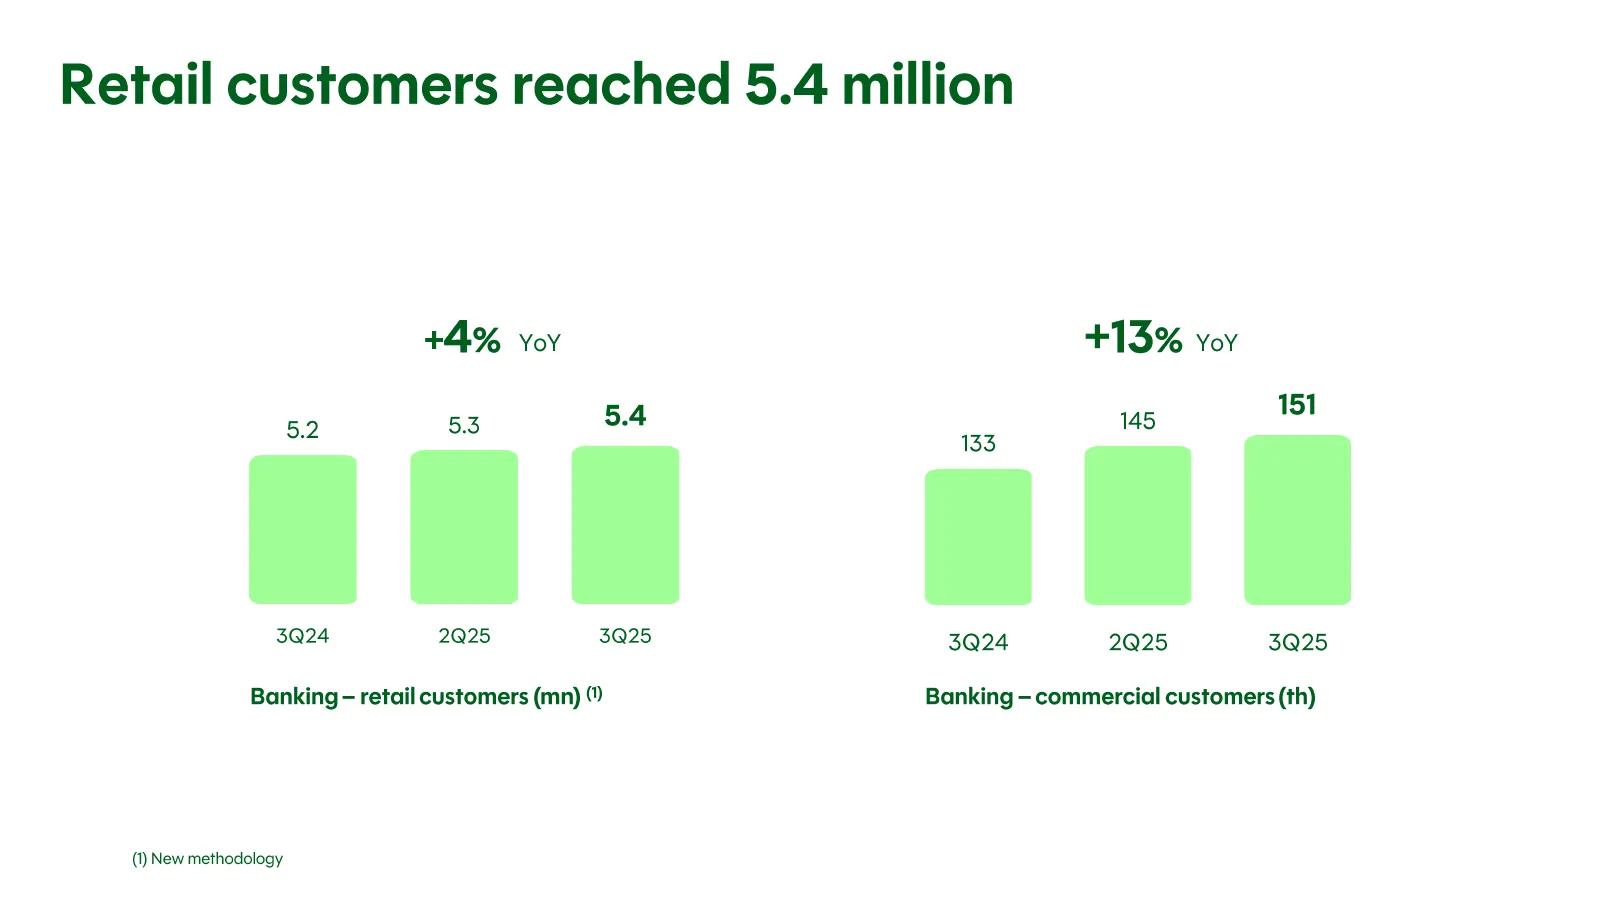
Slide 33: Retail customers reached 5.4 million
Retail customers reached 5.4 million + 4 % YoY +13% YoY 5.4 145 151 5.2 5.3 133 3Q24 2Q25 3Q25 3Q24 2Q25 3Q25 Banking – retail customers (mn) (1) Banking – commercial customers (th) (1) New methodology
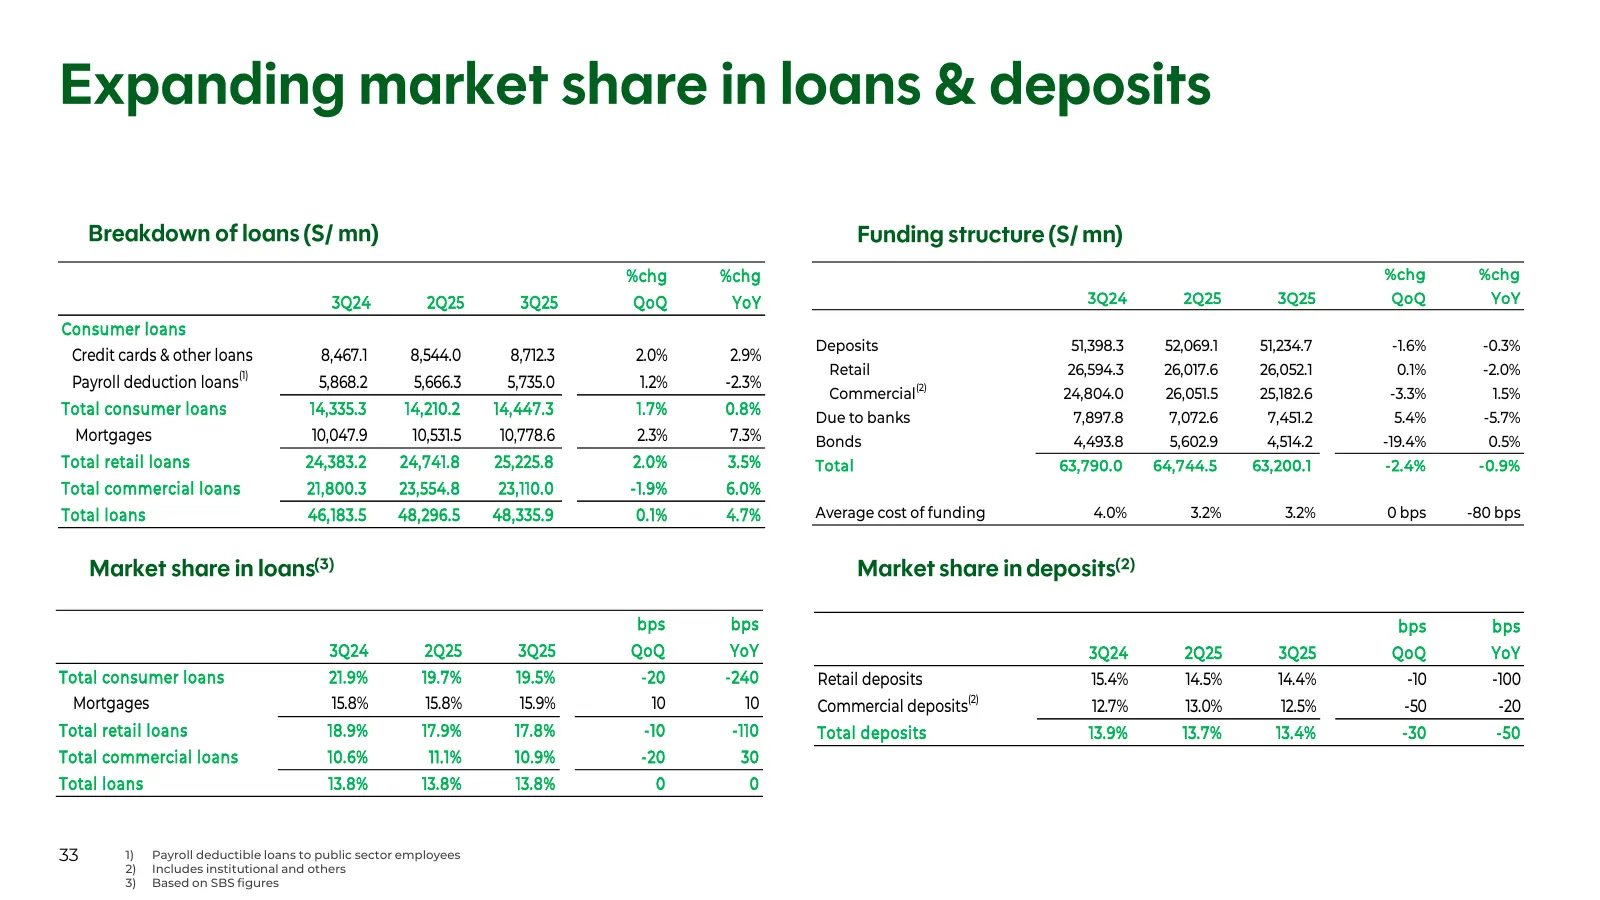
Slide 34: Expanding market share in loans & deposits
Expanding market share in loans & deposits Breakdown of loans (S/ mn) Funding structure (S/ mn) %chg %chg %chg %chg 3Q24 2Q25 3Q25 QoQ YoY 3Q24 2Q25 3Q25 QoQ YoY Consumer loans Deposits 51,398.3 52,069.1 51,234.7 -1.6% -0.3% Credit cards & other loans 8,467.1 8,544.0 8,712.3 2.0% 2.9% (1) Retail 26,
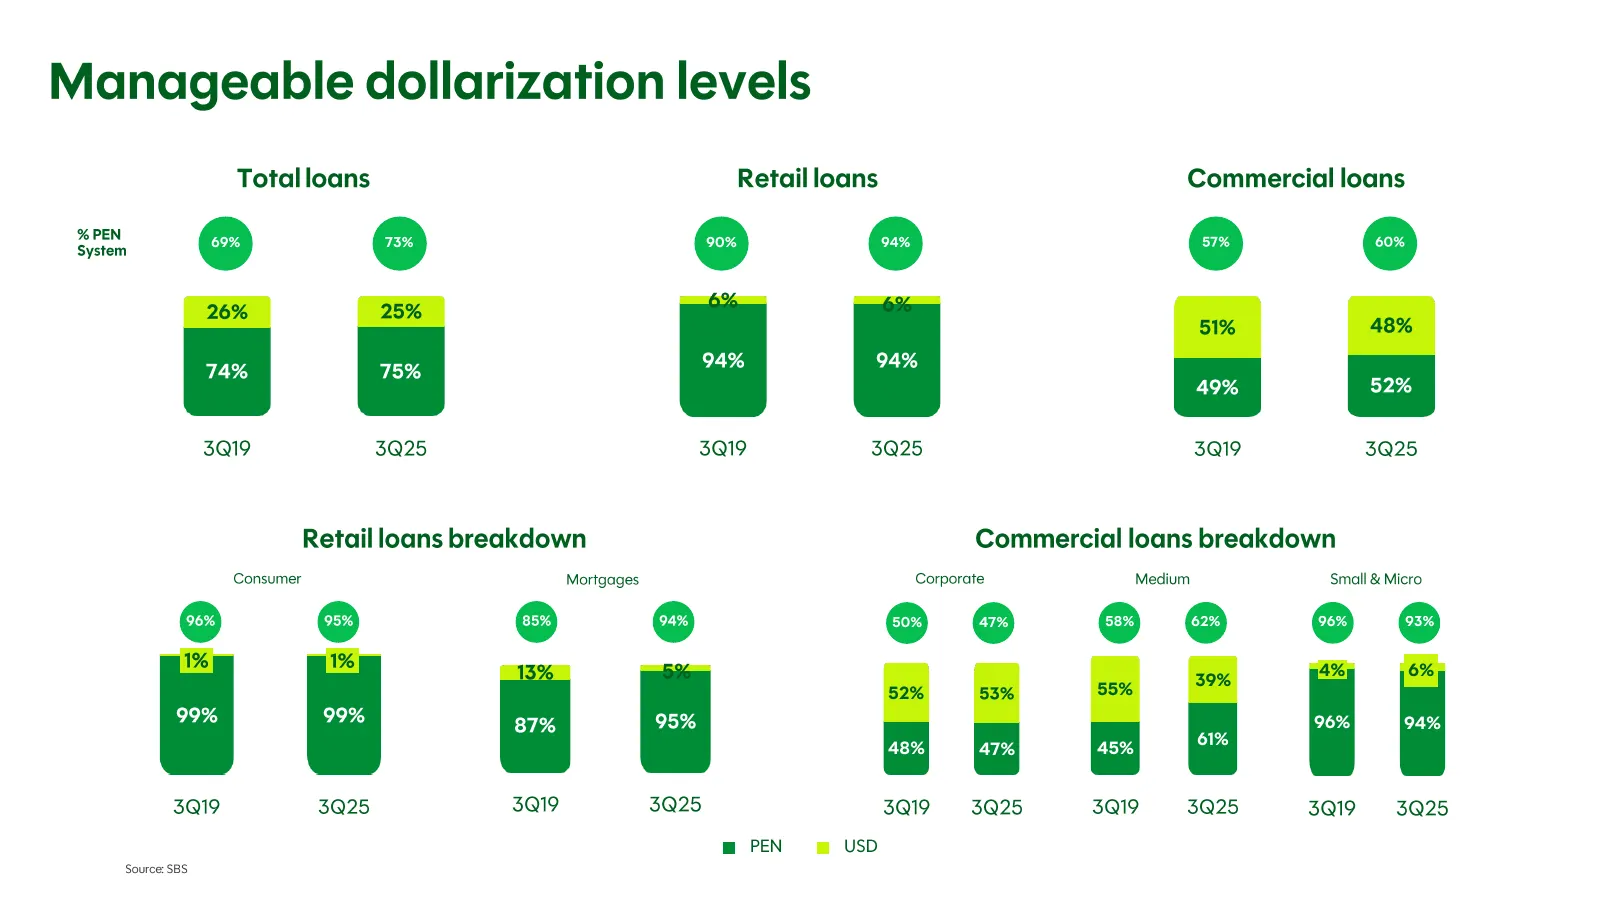
Slide 35: Manageable dollarization levels
Manageable dollarization levels Total loans Retail loans Commercial loans % PEN 69% 73% 90% 94% 57% 60% System 6% 6% 26% 25% 51% 48% 94% 94% 74% 75% 49% 52% 3Q19 3Q25 3Q19 3Q25 3Q19 3Q25 Retail loans breakdown Commercial loans breakdown Consumer Mortgages Corporate Medium Small & Micro 96% 95% 85% 9
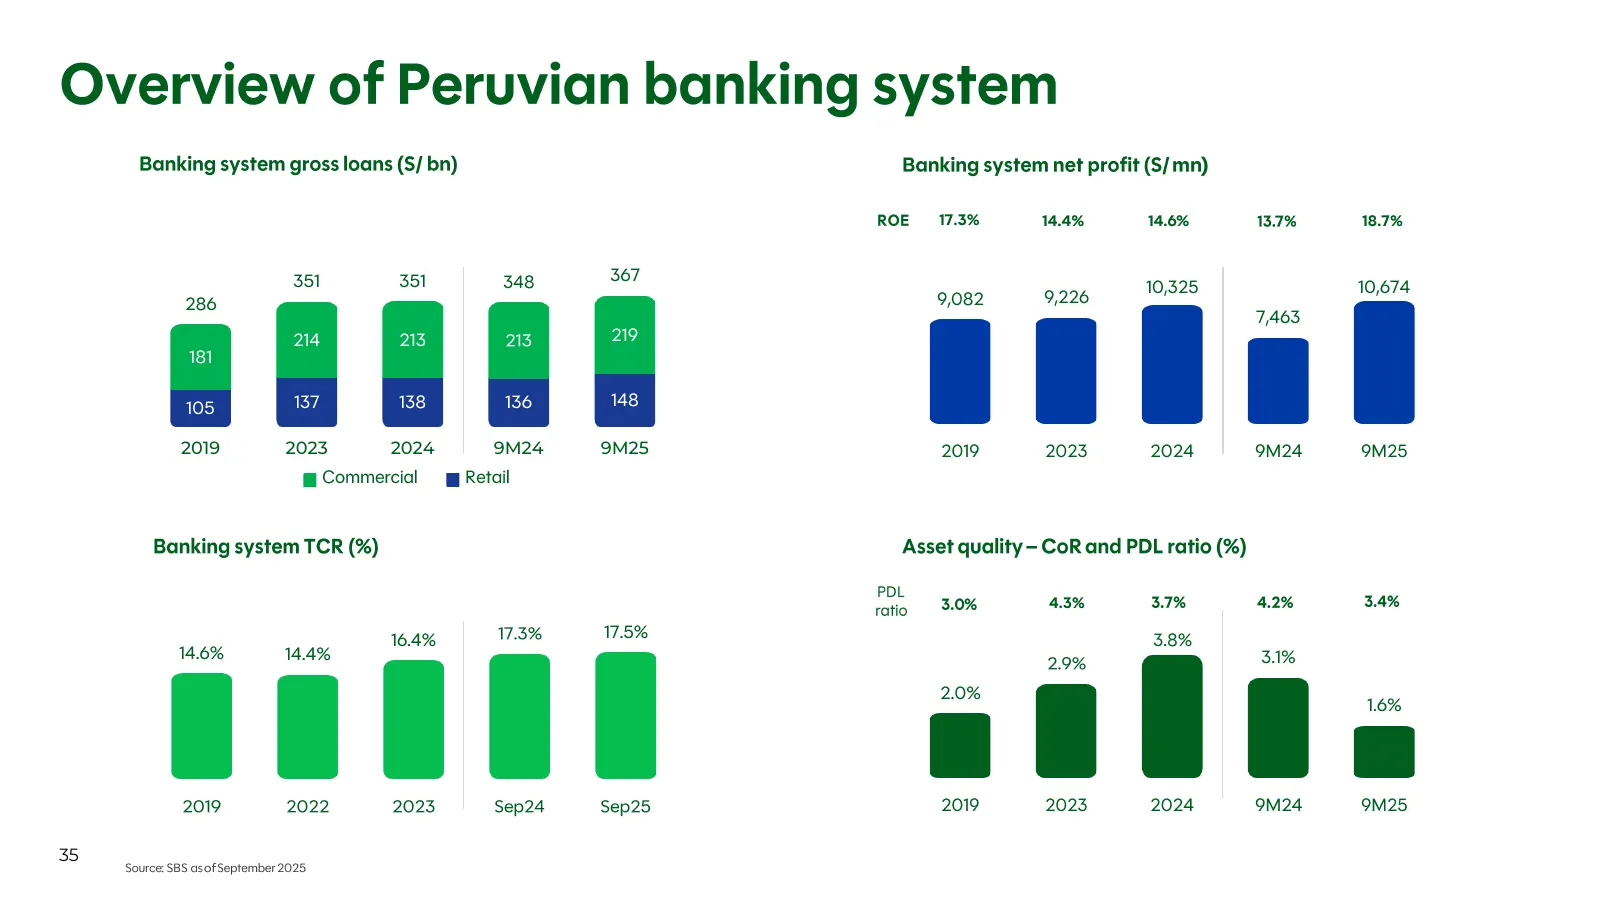
Slide 36: Overview of Peruvian banking system
Overview of Peruvian banking system Banking system gross loans (S/ bn) Banking system net profit (S/ mn) ROE 17.3% 14.4% 14.6% 13.7% 18.7% 351 351 348 367 10,325 10,674 286 9,082 9,226 7,463 214 213 213 219 181 105 137 138 136 148 2019 2023 2024 9M24 9M25 2019 2023 2024 9M24 9M25 Commercial Retail B
Source: company website
More decks from Intercorp Financial Services Inc.
 Q3 2026 Earnings Presentation54 slides · November 2026
 Q2 2026 Earnings Presentation54 slides · Aug 12, 2026
 Q2 2026 Earnings Presentation57 slides · August 2026
 Q2 2026 Earnings Presentation38 slides · August 2026
 Q1 2026 Earnings Presentation54 slides · May 12, 2026
 Q1 2026 Earnings Presentation51 slides · May 2026