Massey Energy — Lehman Brothers 2007 CEO Energy Conference
50 slides from Massey Energy's conference presentation, Sep 5, 2007
Slide 1: Don Blankenship, Chairman and CEO - Lehman Brothers 2007 CEO Energy Conference
Don Blankenship, Chairman and CEO Lehman Brothers 2007 CEO Energy Conference New York September 6, 2007 Exhibit 99.1
Slide 2: Safe Harbor Statement
FORWARD-LOOKING STATEMENTS: certain statements in this presentation are forward-looking as defined by the Private Securities Litigation Reform Act of 1995. Due to known and unknown risks, the company’s actual results may differ materially from its expectations or projections. Factors potentially con
Slide 3: Industry in Transition
Industry in Transition A Time of Opportunity for Massey
Slide 4: Massey Energy Company
Massey Energy Company Massey has an extraordinary strategic opportunity for its shareholders heading into the next three years •Industry in transition and full of opportunities •Proven record of capitalizing on industry cycles •Unprecedented existing competitive advantages •Free cash flow and liquid
Slide 5: Our View of Steam Coal Market
Our View of Steam Coal Market • CAPP utility inventories 24% higher than typical* • 4% CAPP production decline year-to-date 2007 versus 2006 yet utility inventories have continued growing* • Scrubber installations projected to reduce demand for CAPP utility coal up to 33 million tons by 2010 (from 1
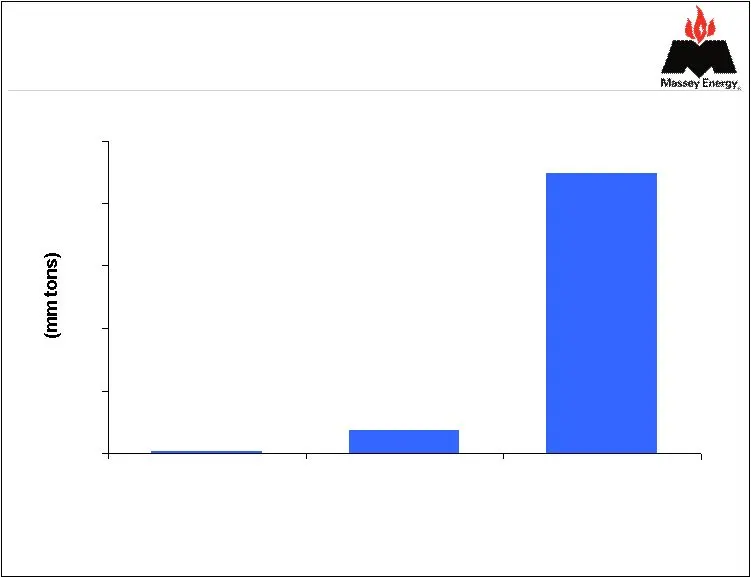
Slide 6: Massey Unpriced Steam Sales
Massey Unpriced Steam Sales* * As of 7/27/07. Total tons sold in 2008 to 2010 based on first half 2007 sales, annualized
Slide 7: Strong Metallurgical Coal Market
Strong Metallurgical Coal Market • Increasing global steel demand • 18.5 mm tons of potential new high vol. metallurgical coal demand planned in Atlantic Basin • Limited Australia coal supply growth • Weak U.S. dollar favors CAPP coal • High ocean freight rates favor all U.S. exports
Slide 8: Strong Metallurgical Coal Market (cont.)
Strong Metallurgical Coal Market (cont.) • 32% of Massey’s revenues from metallurgical coal • Massey represents more than one-quarter of the U.S. high vol. metallurgical coal market • Massey positioned for upside metallurgical coal pricing [about two-thirds of projected 2008 & 2009 metallurgical coa
Slide 9: Meeting Judicial Challenge - Judge Chambers
Meeting Judicial Challenge - Judge Chambers • Environmental litigants are attempting to use stretched interpretations of the Clean Water Act to obstruct surface mining • Massey’s exposure to permitting uncertainty is manageable and less than its Central Appalachian competitors • Vast and diverse res
Slide 10: Meeting Regulatory Challenges - EPA
Meeting Regulatory Challenges - EPA • EPA filed suit over water samples going back over 6 years ago • The samples demonstrate a compliance rate better than comparable peers and better than the 99% rate originally expected by regulators • Discussions to settle the case continue • Third party consulta
Slide 11: Meeting Regulatory Challenges - Safety
Meeting Regulatory Challenges - Safety • Safety regulations are in a continuous state of flux • Underground mining costs are increasing • Utah mining accident will maintain political pressure to ‘do something’ • Regulatory and permitting burdens may lead to fewer small producers in Central Appalachi
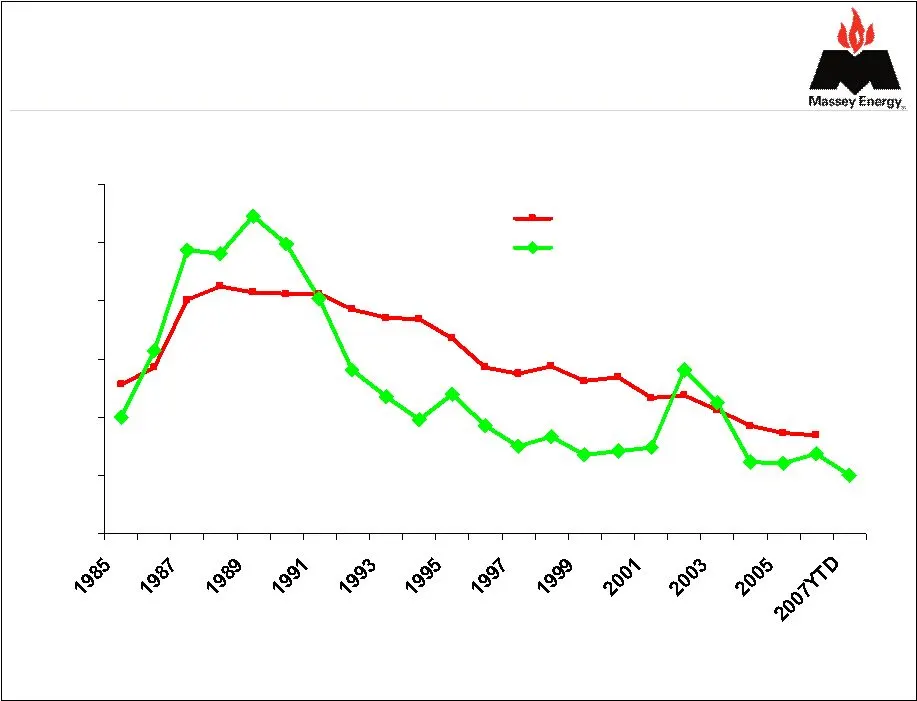
Slide 12: Massey's "Safety First" Program Works
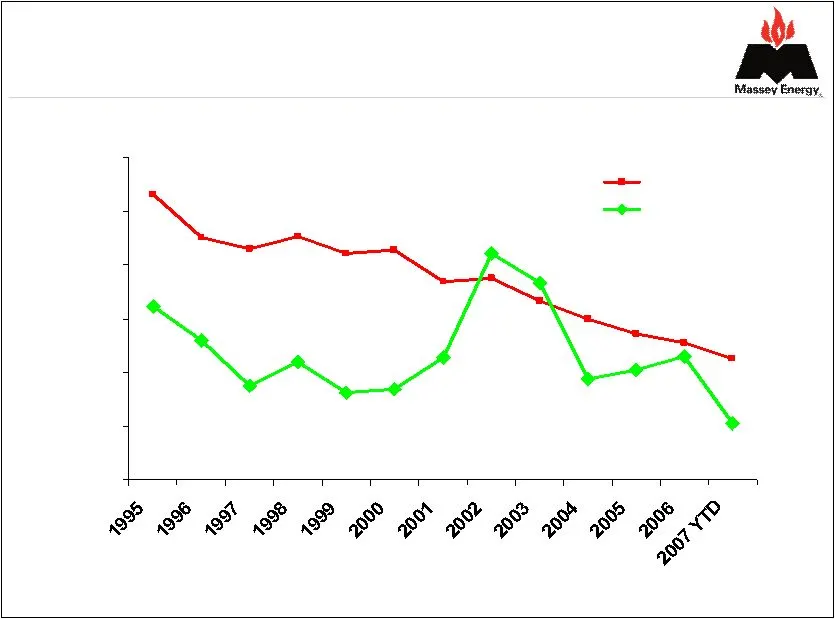
0.00 2.00 4.00 6.00 8.00 10.00 12.00 Industry Massey *Non-Fatal Days Lost per 200,000 hours worked. YTD for first months Massey’s “Safety First” Program Works Massey vs. Industry NFDL* History
Slide 13: Massey Safety Record - Underground
*Non-fatal days lost Massey Safety Record - Underground Massey vs. Industry Underground NFDL* History *Non-Fatal Days Lost per 200,000 hours worked. YTD for first months 0.00 2.00 4.00 6.00 8.00 10.00 12.00 Industry Massey
Slide 14: Massey's "Safety First" Program Works
Massey’s “Safety First” Program Works • Massey operations have recently won safety awards – Elk Run Castle Mine – Elk Run Black Knight 2 – Independence Coal Company Justice 1 – Marfork Prep Plant – Charles Roach – Mine Foreman: Co-Safety Leader of the Year 2006 – Massey West Virginia Mine Rescue Tea
Slide 15: Labor & Productivity Challenges
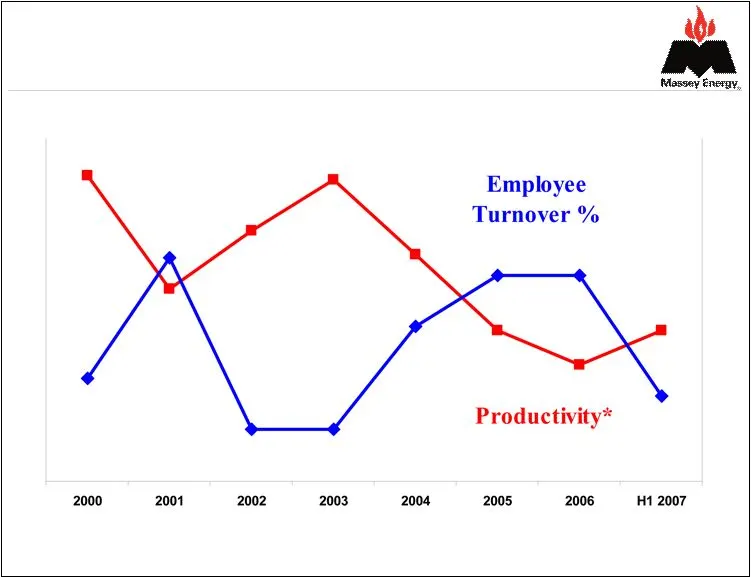
Labor & Productivity Challenges • Coal market correction has reduced overheated competition for experienced labor • Reduced voluntary turnover expected to translate over time to a recovery in productivity • Reduced emphasis on longwall mining • Increased emphasis on metallurgical room and pillar min
Slide 16: Voluntary Turnover vs. Underground Productivity
Voluntary Turnover vs. Underground Productivity* * Productivity measured as feet per shift for Massey underground mines.
Slide 17: Track Record of Growth
Track Record of Growth “Against the Grain”
Slide 18: Key Historical Events - 1980 to 2000
Key Historical Events – 1980 to 2000 • 1978-1980 Developed first large non-union mines in Boone and Mingo Counties, WV • Sued UMWA in the early 1980’s when they responded with violence and property destruction • 1984-1985 Withstood violent UMWA labor strike to obtain a contract which allowed for gro
Slide 19: The Result of "Decisions Against the Grain"
The Result of “Decisions Against the Grain” Massey grew and flourished while competitors who accepted the “status quo” exited Central Appalachia or went into bankruptcy
Slide 20: Growth while Competitors Struggle
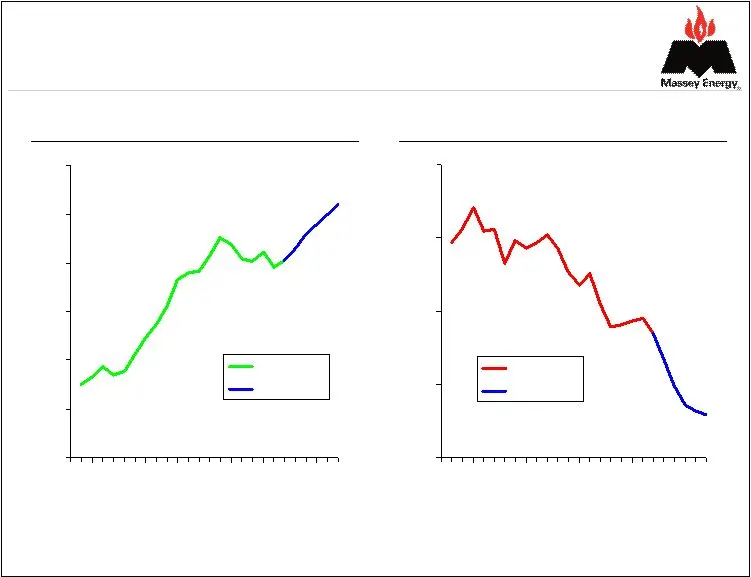
Growth while Competitors Struggle Note: Projection based on Energy Ventures Analysis CAPP forecast and assumed Massey internal growth to 52 million tons by 2012 SOURCE: Energy Ventures Analysis Massey Production (mm tons) CAPP Non-Massey Production (mm tons) 2007E 2012E Historical Projected 2007E 20
Slide 21: Competitor Bankruptcies
Competitor Bankruptcies Cook Brothers James River Coal Pen Coal Pittston * AEI/Horizon Lodestar Quaker Coal Island Creek * Westmoreland 1994 & 1996 * Sold under financial distress
Slide 22: Growth 'Against the Grain'
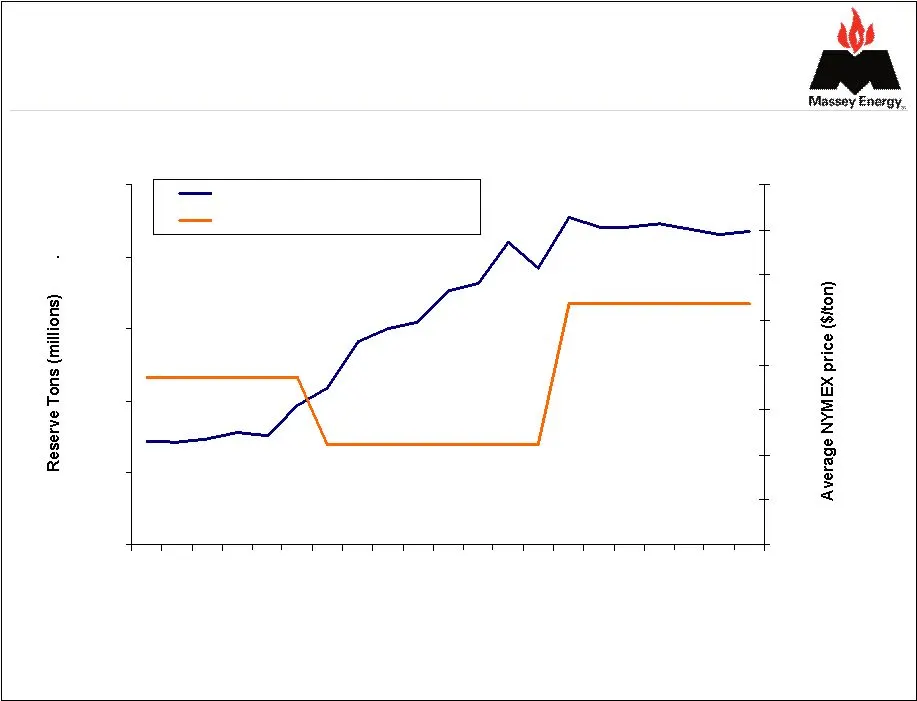
- 1,000 1,500 2,000 2,500 07E $20 $25 $30 $35 $40 $45 $50 $55 $60 Massey Reserves Average Coal Price (real 2006$) Growth ‘Against the Grain’ Note: Average Coal Price for NYMEX quality Central Appalachian coal, 12,500 Btu/ 1% Sulfur SOURCE: Energy Ventures Analysis
Slide 23: Shareholder Value Creation
Shareholder Value Creation Massey has created long-term value for its shareholders by making investments “Against the Grain” • Big Creek • Performance • Bethlehem reserves (Marfork) • Mammoth • Starfire • Delbarton • Nicholas
Slide 24: Massey Approach to External Issues
Massey Approach to External Issues • Advocate ‘real and meaningful’ safety and environmental changes • Work to improve the economic and business climate of Central Appalachia • Educate public on true “cost/benefit” of energy from coal • Invest through the bottom of coal price cycle
Slide 25: Investment Advantages
Investment Advantages
Slide 26: Massey Energy Company
Massey Energy Company • The leading coal producer in Central Appalachia – 92 years of uninterrupted business • 2 billion tons of coal reserves – 3 times that of nearest regional competitor • Strong and growing market share – 2 times that of nearest regional competitor • Abundant growth opportunities
Slide 27: Central Appalachian Advantage
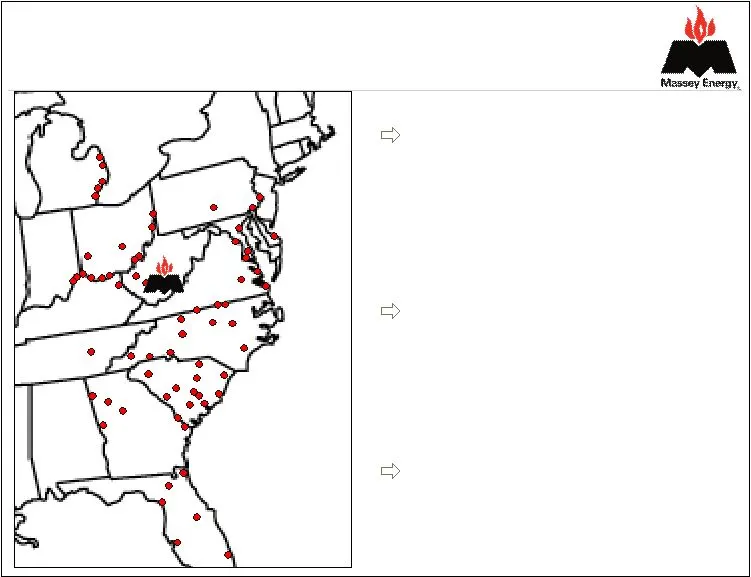
Central Appalachian Advantage $5 per ton or more freight advantaged to Southeastern U.S. markets – with increasing rail rates Transportation advantaged to Atlantic basin export markets Some of the highest quality metallurgical coals in the world • Massey Utility Customers
Slide 28: Product Diversity and Mix
Product Diversity and Mix 100% 43% 62% 38% 2,273 mm 970 mm 1,412 mm 861 mm Total Compliance -1% Sulfur + 1% Sulfur Reserve tons as of 12/31/06 32% Metallurgical 10% Industrial 59% Utility First Half Produced Coal Revenue
Slide 29: Central Appalachian Reserves
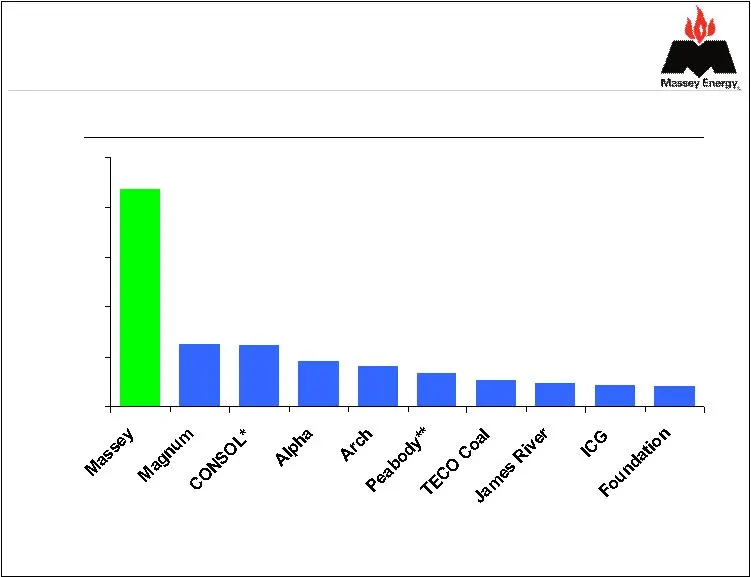
Central Appalachian Reserves * CONSOL pro forma for AMVEST acquisition ** Peabody reserves are as of 12/31/2005 SOURCE: Company Financials and websites 12/31/2006 Central Appalachian Reserves (mm tons) 2,183 - 1,000 1,500 2,000 2,500
Slide 30: Years of Reserves
50 Years of Reserves What does this mean for Massey Energy? • Cost & margin advantage on current production • Organic growth opportunities - 235 mm tons that can easily be put into production with relatively small capital investment • Reserve control is the key to consolidate region and expand marke
Slide 31: Regional Cost & Margin Advantage
Regional Cost & Margin Advantage Over the long-term, Massey expects to record higher per ton margins due to our cost advantage and metallurgical production Higher proportion of metallurgical sales Revenue Advantage: Premium reserves Lower royalties Best practices Equipment/infrastructure/scale Lower
Slide 32: Investment in Process Improvement
Investment in Process Improvement Massey creates value by investing in process and productivity improvements • Slopes for quicker access to mine face • Belting to reduce trucks on the road • Higher capacity preparation facilities • Bigger and better maintained equipment • Extensive best practices do
Slide 33: Operating Cost Advantage
Operating Cost Advantage $0.50 Preparation Plant Scale & Efficiency $1.00 Less Trucking $1.00 Lower Royalty Rates $6.00 Estimated Operating Cost Advantage $3.50 Reserve Mineability Massey Central Appalachian Cost Advantage ($/ton)* * Massey estimates of advantage versus Central Appalachian marginal
Slide 34: Low Legacy Liabilities
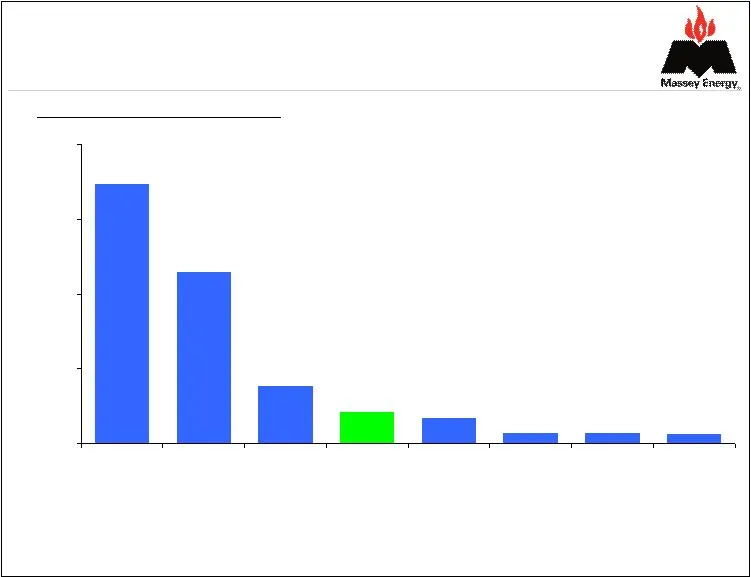
Low Legacy Liabilities Legacy Liabilities* ($ millions) * Legacy Liabilities includes reclamation, black lung, workers compensation, pension, retiree medical and Rockefeller obligations SOURCE: Company financial statements $2,293 $771 $425 $337 $141 $136 $123 $3,476 $0 $1,000 $2,000 $3,000 $4,000 Co
Slide 35: Corporate Responsibility
Corporate Responsibility • Environment • Employee obligations • Governmental regulations • Local community involvement
Slide 36: Strong Liquidity
Strong Liquidity $ In Millions $322 June 30, 2007 Cash $436 $114 Available Liquidity (6/30/07) Credit Facility Availability • Liquidity in a credit nervous market • Financial strength to acquire distressed competitors • Capital to develop reserve base
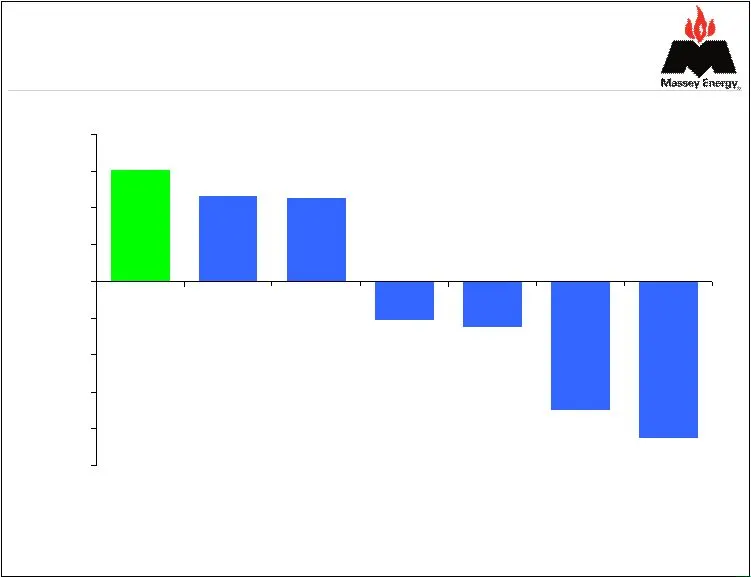
Slide 37: First Six Months 2007 Pre-tax Free Cash Flow
First Six Months 2007 Pre-tax Free Cash Flow* $ in millions * Pre-tax Free Cash Flow excludes changes in working capital. Based on EBT, less gain on swaps, less Capital Expenditures. Capital Expenditures includes ½ of annual Federal Lease Payments and asset acquisitions. SOURCE: Company financial st
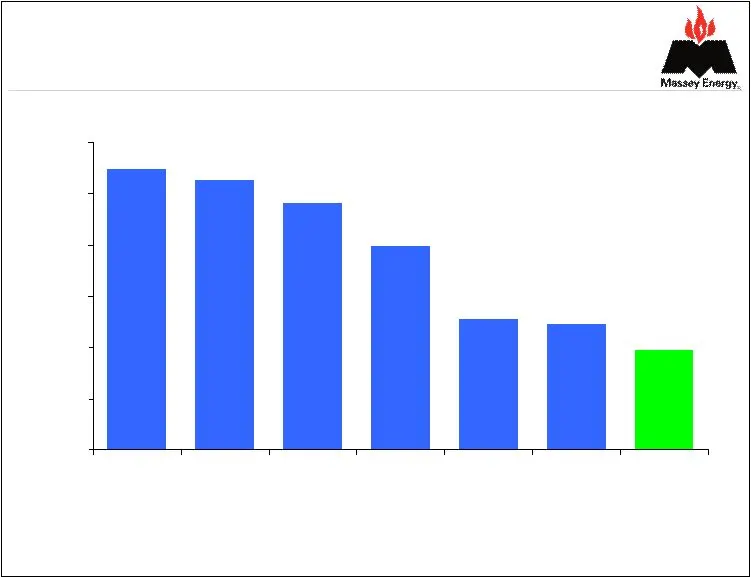
Slide 38: Enterprise Value vs. LTM EBITDA
Enterprise Value vs. LTM EBITDA* * Enterprise Value equals market value of equity as of 8/31/07, plus net debt. Last Twelve Months as of 6/30/07. SOURCE: Bloomberg, Company financial statements 16.5x 15.8x 14.5x 11.9x 7.7x 5.8x 7.4x 0.0x 3.0x 6.0x 9.0x 12.0x 15.0x 18.0x Peer 1 Peer 2 Peer 3 Peer 4 P
Slide 39: Looking Ahead
Looking Ahead
Slide 40: Massey Strategic Vision
Massey 5 Year Strategic Vision • Massey controls 45% of Central Appalachian coal reserves • Massey has 30-40% of Central Appalachian coal production • Massey’s cost advantage in region increases another $2 per ton • Massey’s metallurgical production expanded
Slide 41: Massey Looking Ahead
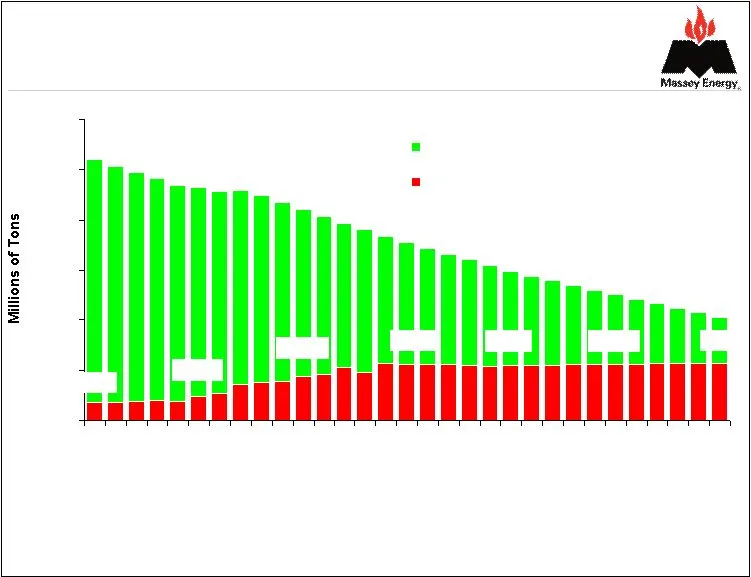
Massey Looking Ahead • Grow while competitors shrink – Acquire reserves and production from distressed competitors – Develop low cost reserves from our portfolio • Expand on our leading margins – Recover our labor productivity – Capture synergies from acquisitions – Minimal reserve degradation while
Slide 42: Massey Looking Ahead
Massey Looking Ahead Note: Projection based on Energy Ventures Analysis Central Appalachian forecast and assumed Massey 60 mm tons of annual reserve acquisitions SOURCE: Energy Ventures Analysis, Company estimates 07E 12E 17E Other CA Coal Reserves Massey Coal Reserves (% of total) Assume Massey acq
Slide 43: Massey Reserve Strength
Massey Reserve Strength 729 mm tons with mineability equal to or better than what we are mining today • mm tons underground with average clean tons/ft 2.62 • mm tons surface with yards/ton ratio 15.10 • 185 mm tons metallurgical & 544 mm tons steam “Our largest competitor’s total reserve base is onl
Slide 44: Growth Potential
Growth Potential All the necessary components are available to be Central Appalachia consolidator: • Capital • Low-cost reserves • Infrastructure • Labor • Acquisition opportunities • 2008 & 2009 sold steam coal position
Slide 45: Acquisition Opportunities
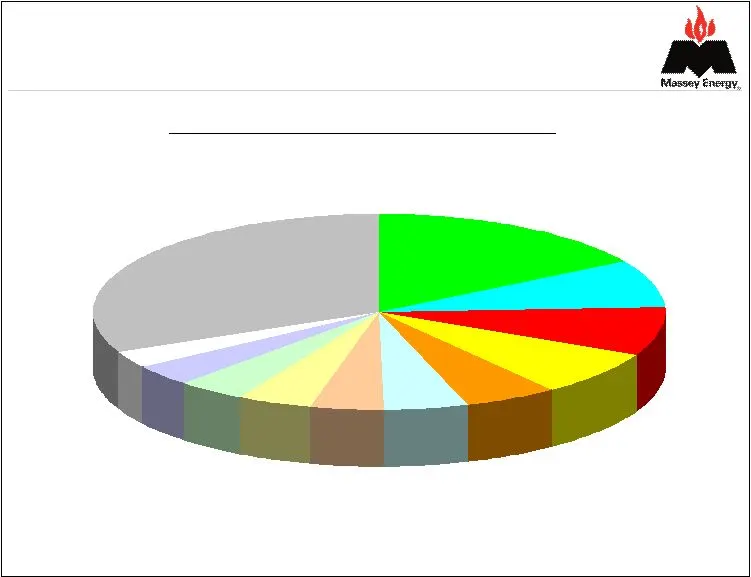
Acquisition Opportunities Central Appalachian Coal Production - SOURCE: Energy Ventures Analysis, Company Financials 8% 8% 8% 5% 5% 4% 4% 4% 3% 16% 32% 4% Massey Misc. small producers
Slide 46: Acquisition Opportunities
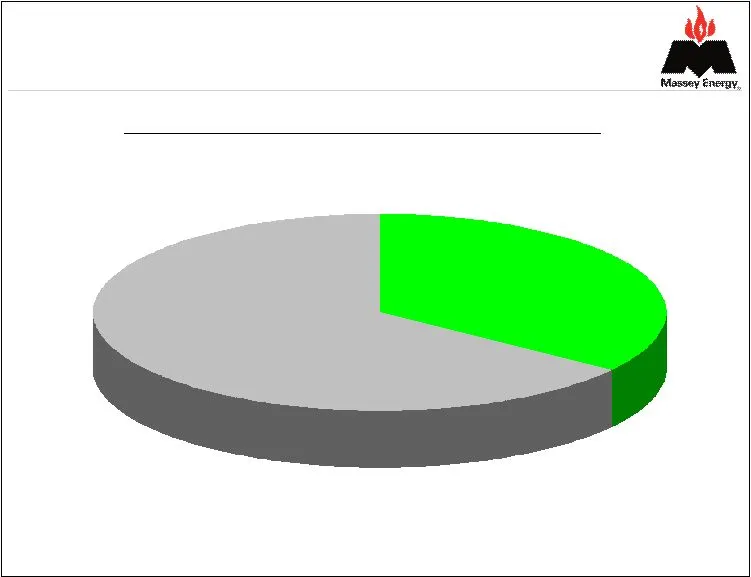
Acquisition Opportunities Projected Central Appalachian Coal Production - SOURCE: Energy Ventures Analysis, Company estimates 35% Massey - Projected Other producers
Slide 47: Massey's Operating Principles
Massey’s Operating Principles • Be the safest coal mining company • Be the most environmentally responsible coal company • Honor our commitments to members • Be forthright and truthful regarding external challenges • Increase market share • Reinvest majority of cash flow in internal growth • Acquire
Slide 48: Disclaimer
Disclaimer FORWARD-LOOKING STATEMENTS: certain statements in this presentation are forward-looking as defined by the private securities litigation reform act of 1995. Such forward-looking statements are based on facts and conditions as they exist at the time such statements are made as well as predi
Slide 49: Disclaimer (continued)
Disclaimer (continued) Included in this presentation is the non-GAAP measure, Pre-tax free cash flow. “Pre-tax free cash flow" is calculated as Income before taxes less the sum of Capital expenditures and Gain on reserve exchange. Although Pre-tax free cash flow is not a measure of performance calcu
Slide 50: Doing the Right Thing...with Energy
Doing the Right Thing…with Energy
Source: SEC EDGAR · 8-K filed Sep 5, 2007
More decks from Massey Energy Co
 Merger or Acquisition (March 2011)18 slides · Mar 9, 2011
 BMO Capital Markets 2011 Global Metals & Mining Conference27 slides · Mar 1, 2011
 Credit Suisse Energy Summit 201126 slides · Feb 10, 2011
 Merger or Acquisition (January 2011)19 slides · Jan 31, 2011
 Proxy Contest (May 2010)32 slides · May 5, 2010
 Proxy Contest (April 2010)26 slides · Apr 30, 2010