Chiquita Brands International Inc
Chiquita Brands International — Merger or Acquisition (August 2014)
48 slides from Chiquita Brands International's merger presentation, Aug 27, 2014
Slide 1: Investor Presentation August 2014
1 1 O Investor Presentation August 2014
Slide 2: Forward-looking statements
2 This presentation contains certain statements that are “forward - looking statements.” These statements are subject to a number of assumptions, risks and uncertainties, many of which are beyond the control of Chiquita and Fyffes plc (“Fyffes”), including: the customary risks experienced by global
Slide 3: Agenda
3 Agenda Introduction Chiquita recent performance Chiquita / Fyffes merger is compelling ChiquitaFyffes is superior to $13.00 conditional offer Conclusion
Slide 4: We Recommend Shareholders Vote in Favor of the ChiquitaFyffes Transaction
4 We Recommend Shareholders Vote in Favor of the ChiquitaFyffes Transaction Benefits of ChiquitaFyffes Why Vote w ith Chiquita Board • Creates a leading global produce company • #1 position in bananas, with a significant presence in packaged salads, melons, and pineapples • Complementary strengths •
Slide 5: Chiquita Recent Performance
5 Chiquita Recent Performance
Slide 6: Overview of Chiquita's Products & Operations
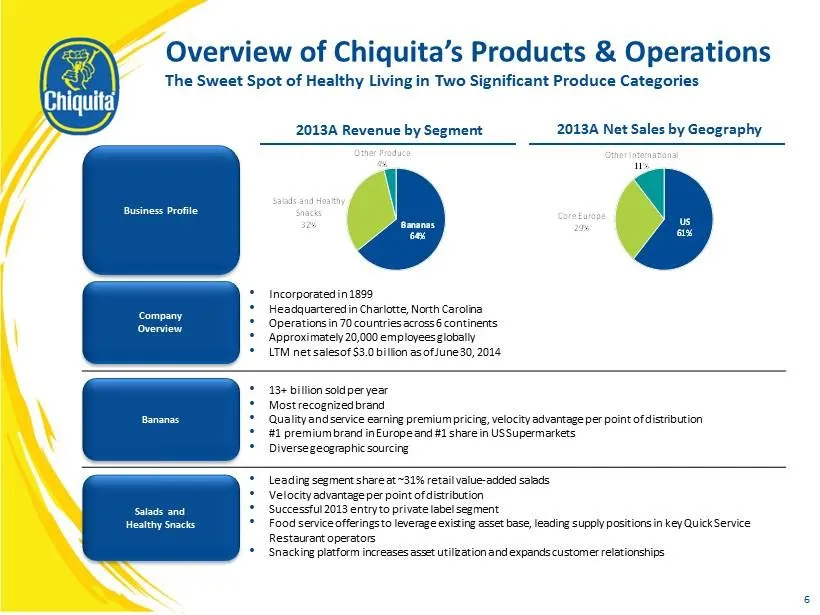
6 Overview of Chiquita’s Products & Operations The Sweet Spot of Healthy Living in Two Significant Produce Categories • Incorporated in 1899 • Headquartered in Charlotte, North Carolina • Operations in 70 countries across 6 continents • Approximately 20,000 employees globally • LTM net sales of $3.0
Slide 7: In 2012 We Changed Strategic Direction
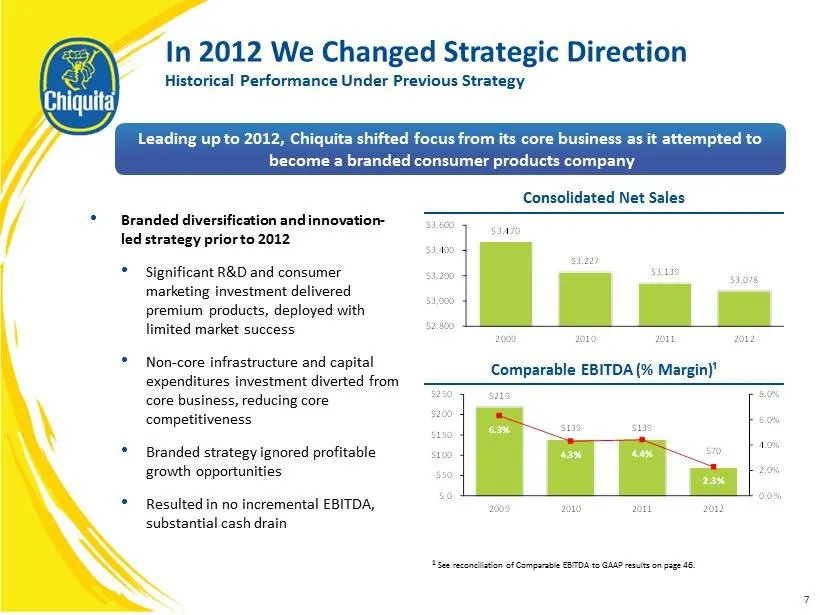
7 In 2012 We Changed Strategic Direction Historical Performance Under Previous Strategy • Branded diversification and innovation - led strategy prior to 2012 • Significant R&D and consumer marketing investment delivered premium products, deployed with limited market success • Non - core infrastructu
Slide 8: Board Oversaw Strategic Change
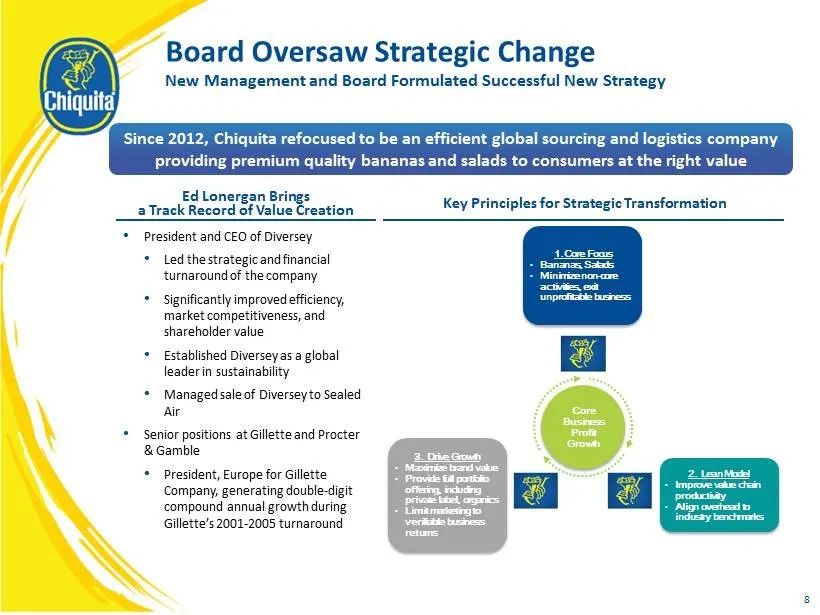
8 Board Oversaw Strategic Change New Management and Board Formulated Successful New Strategy Ed Lonergan Brings a Track Record of Value Creation Key Principles for Strategic Transformation • President and CEO of Diversey • Led the strategic and financial turnaround of the company • Significantly imp
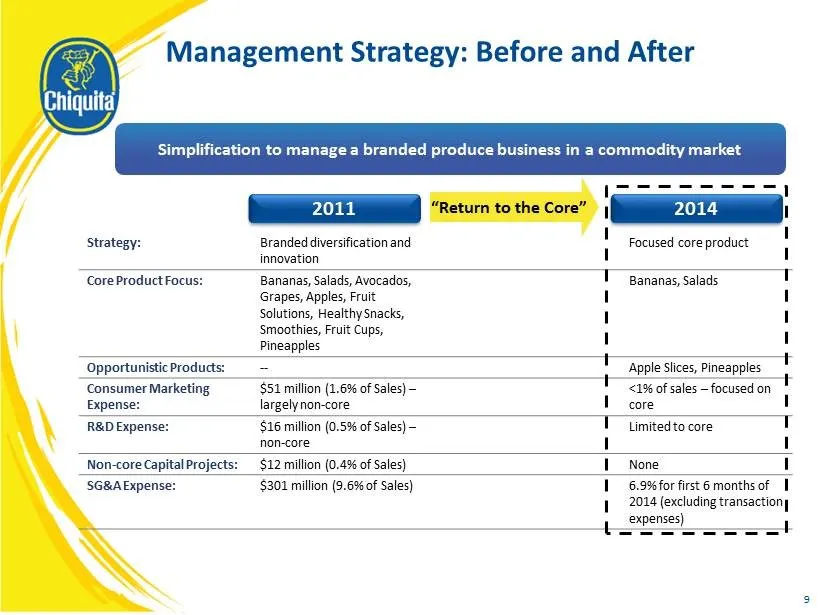
Slide 9: Management Strategy: Before and After Return to the Core
Strategy: Branded diversification and innovation Focused core product Core Product Focus: Bananas, Salads, Avocados, Grapes, Apples, Fruit Solutions, Healthy Snacks, Smoothies, Fruit Cups, Pineapples Bananas, Salads Opportunistic Products: -- Apple Slices, Pineapples Consumer Marketing Expense: $51
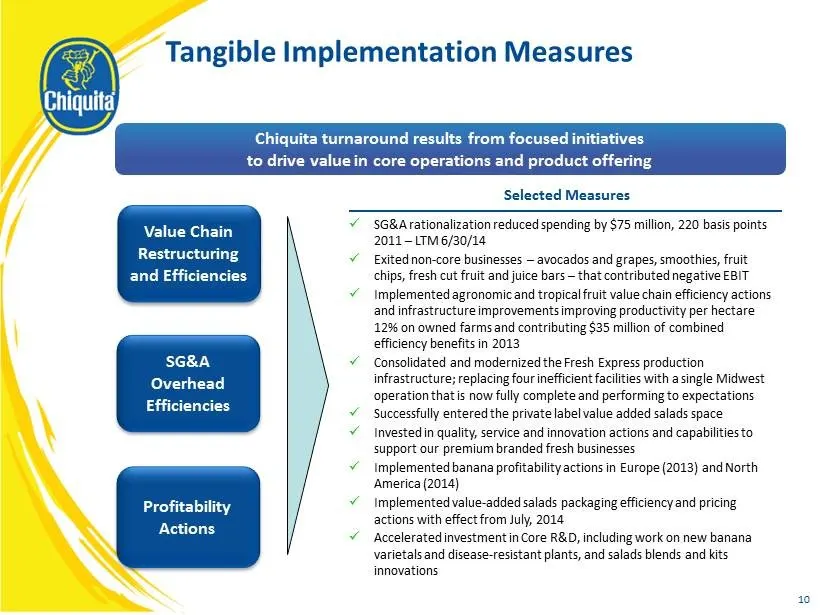
Slide 10: Tangible Implementation Measures
10 Tangible Implementation Measures Value Chain Restructuring and Efficiencies Profitability Actions x SG&A rationalization reduced spending by $75 million, 220 basis points 2011 – LTM 6/30/14 x Exited non - core businesses – avocados and grapes, smoothies, fruit chips, fresh cut fruit and juice bar
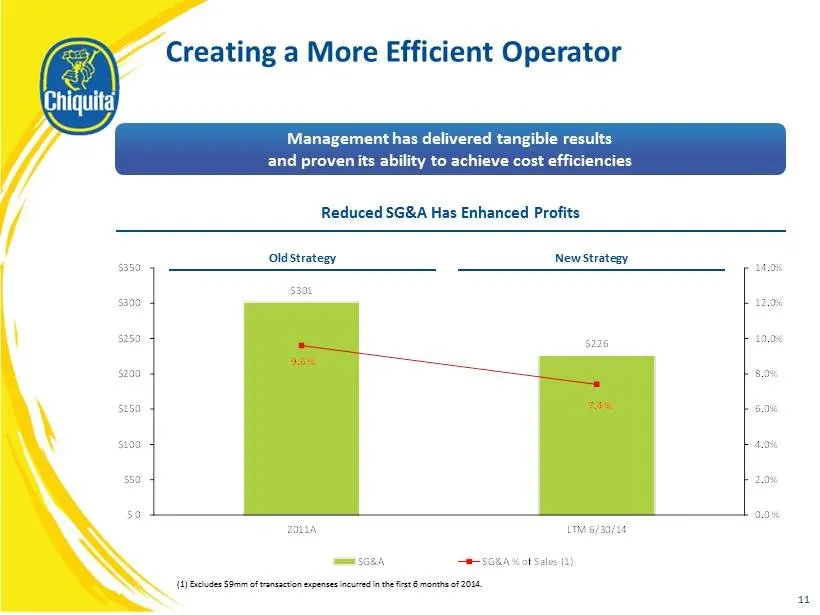
Slide 11: Creating a More Efficient Operator
11 Creating a More Efficient Operator Reduced SG&A Has Enhanced Profits Management has delivered tangible results and proven its ability to achieve cost efficiencies (1) Excludes $9mm of transaction expenses incurred in the first 6 months of 2014. Old Strategy New Strategy $301 $226 9.6 % 7.4 % 0.0
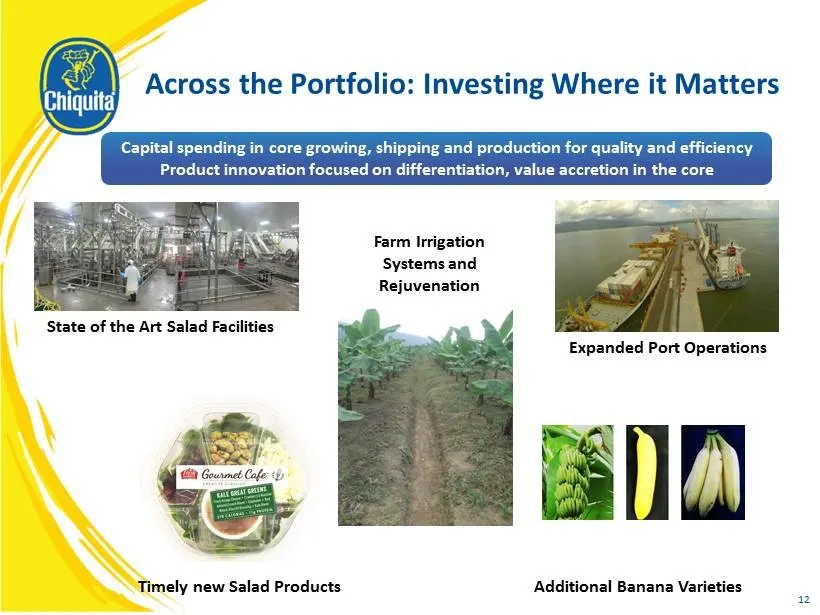
Slide 12: Across the Portfolio: Investing Where it Matters
12 A cross the Portfolio: Investing Where it Matters State of the Art Salad Facilities Timely new Salad Products Farm Irrigation Systems and Rejuvenation Additional Banana Varieties Expanded Port Operations Capital spending in core growing, shipping and production for quality and efficiency Product
Slide 13: Industry-leading Efficiency Actions Continue – US-Gulf Rotation
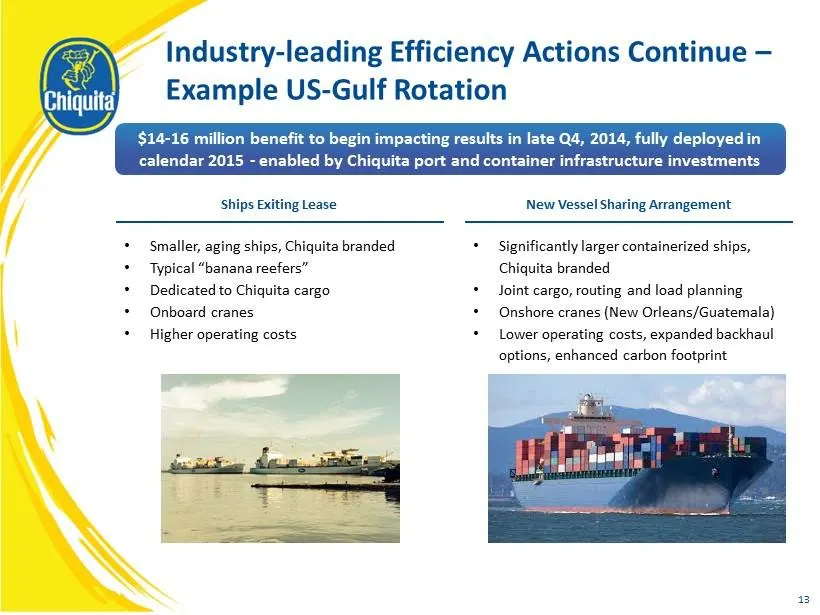
13 Industry - leading Efficiency Actions Continue – Example US - Gulf Rotation • Smaller, aging ships, Chiquita branded • Typical “banana reefers” • Dedicated to Chiquita cargo • Onboard cranes • Higher operating costs • Significantly larger containerized ships, Chiquita branded • Joint cargo, routi
Slide 14: Financial Results Have Dramatically Improved EBITDA Over Time
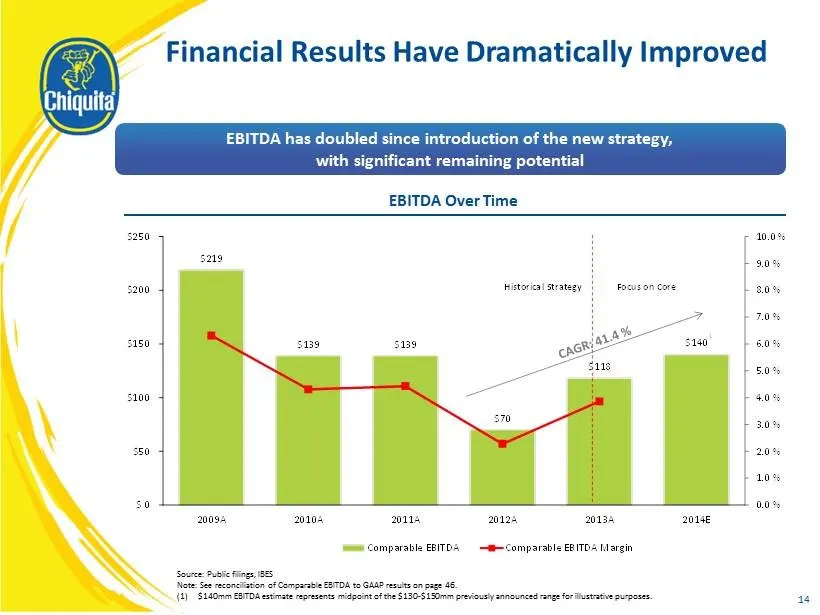
14 Financial Results Have Dramatically Improved EBITDA Over Time EBITDA has doubled since introduction of the new strategy, with significant remaining potential Source: Public filings, IBES Note: See reconciliation of Comparable EBITDA to GAAP results on page 46. (1) $140mm EBITDA estimate represent
Slide 15: Share Price Beginning to Reflect Turnaround
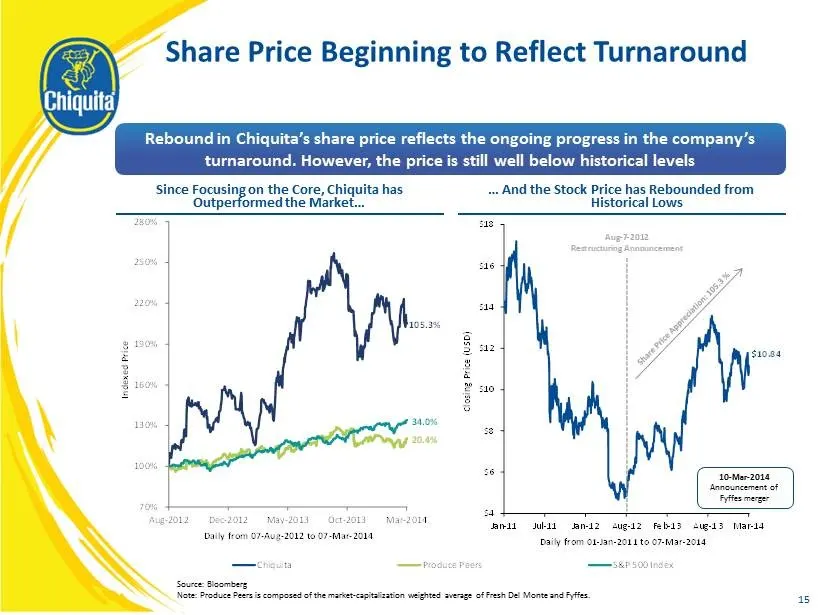
15 Share Price Beginning to Reflect Turnaround Since Focusing on the Core, Chiquita has Outperformed the Market… … And the Stock Price has Rebounded from Historical Lows Source: Bloomberg Note: Produce Peers is composed of the market - capitalization weighted average of Fresh Del Monte and Fyffes. 1
Slide 16: Research Analysts Recognize Our Progress
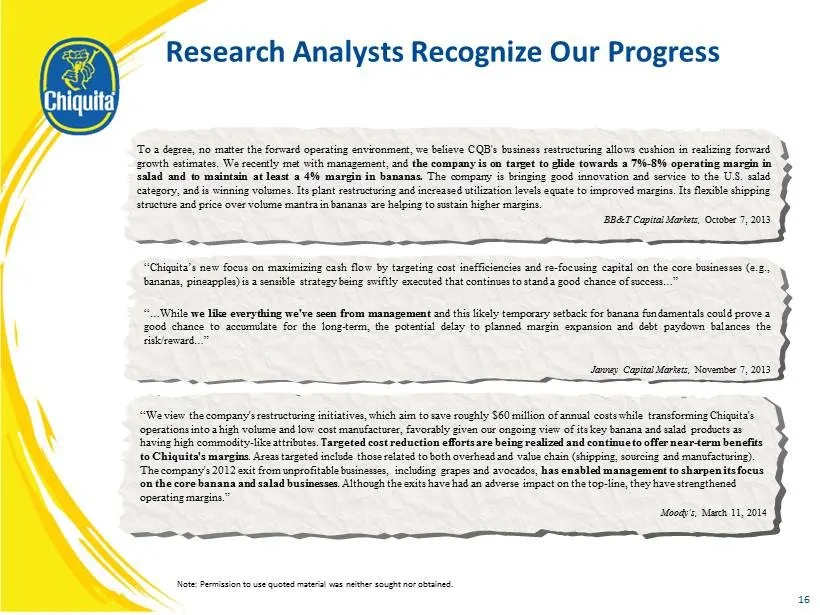
16 Research Analysts Recognize Our Progress “Chiquita’s new focus on maximizing cash flow by targeting cost inefficiencies and re - focusing capital on the core businesses (e . g . , bananas , pineapples) is a sensible strategy being swiftly executed that continues to stand a good chance of success
Slide 17: Chiquita / Fyffes Transaction is Compelling
17 Chiquita / Fyffes Transaction is Compelling
Slide 18: Combination is the Result of a Thorough and Disciplined Process
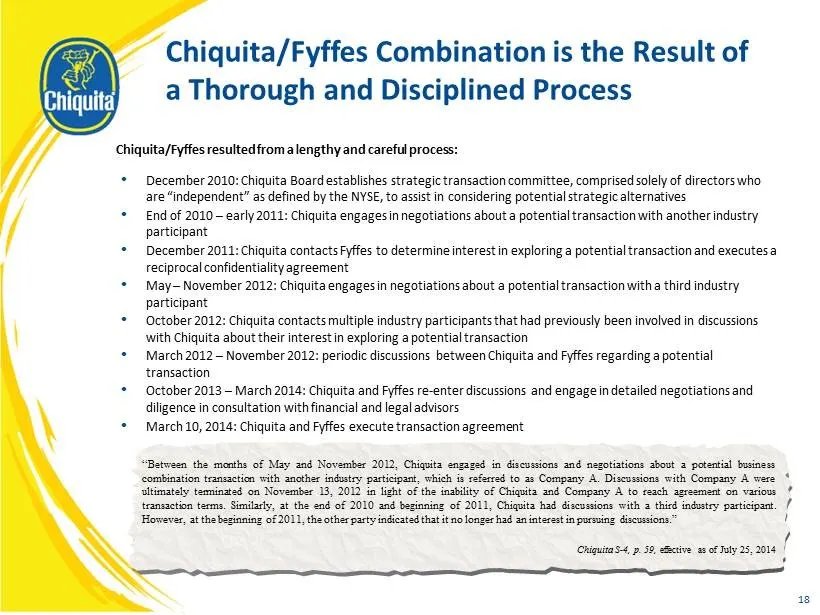
18 Chiquita/Fyffes Combination is the Result of a Thorough and Disciplined Process Chiquita/Fyffes resulted from a lengthy and careful process: • December 2010: Chiquita Board establishes strategic transaction committee, comprised solely of directors who are “independent” as defined by the NYSE, to
Slide 19: Compelling Strategic Rationale
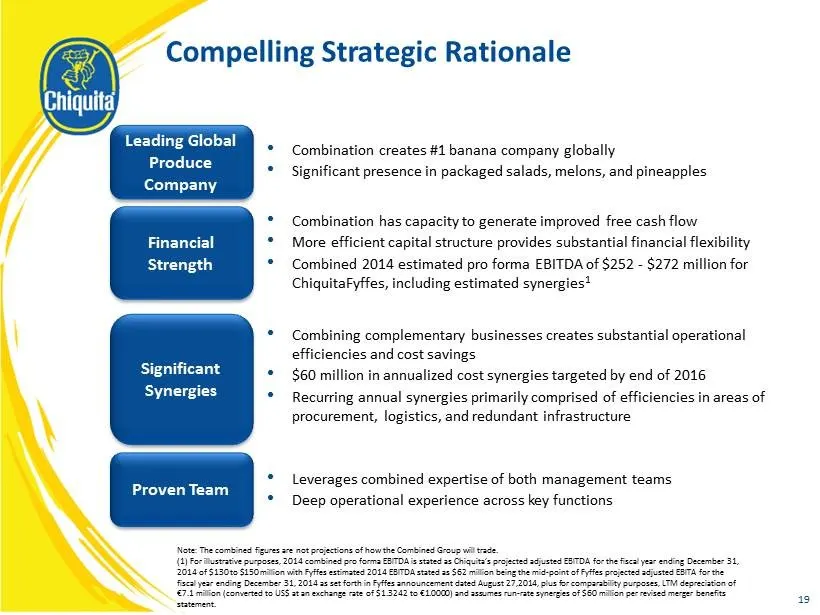
19 Compelling Strategic Rationale Leading Global Produce Company Significant Synergies Financial Strength • Combination creates #1 banana company globally • Significant presence in packaged salads, melons, and pineapples Proven Team • Leverages combined expertise of both management teams • Deep oper
Slide 20: Strategic Rationale Key Takeaways
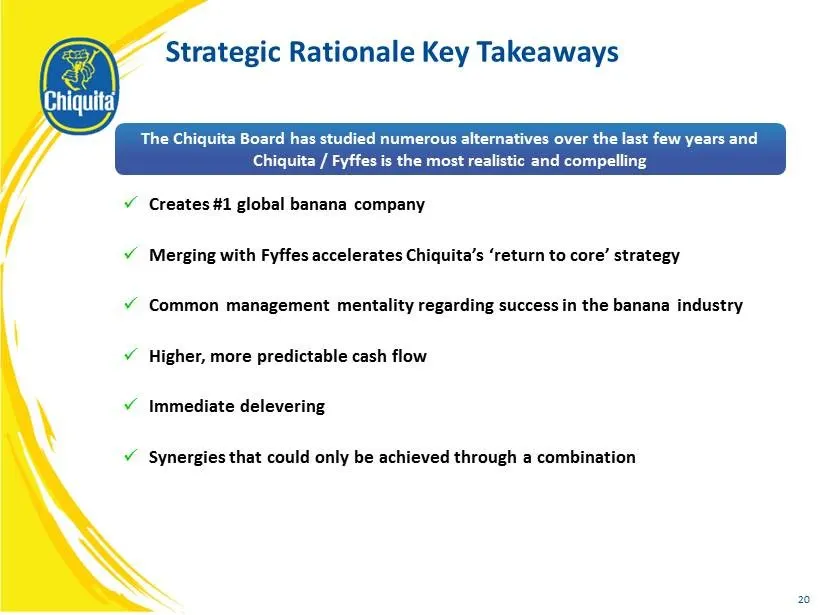
20 Strategic Rationale Key Takeaways x Creates #1 global banana company x Merging with Fyffes accelerates Chiquita’s ‘return to core’ strategy x Common management mentality regarding success in the banana industry x Higher, more predictable cash flow x Immediate delevering x Synergies that could onl
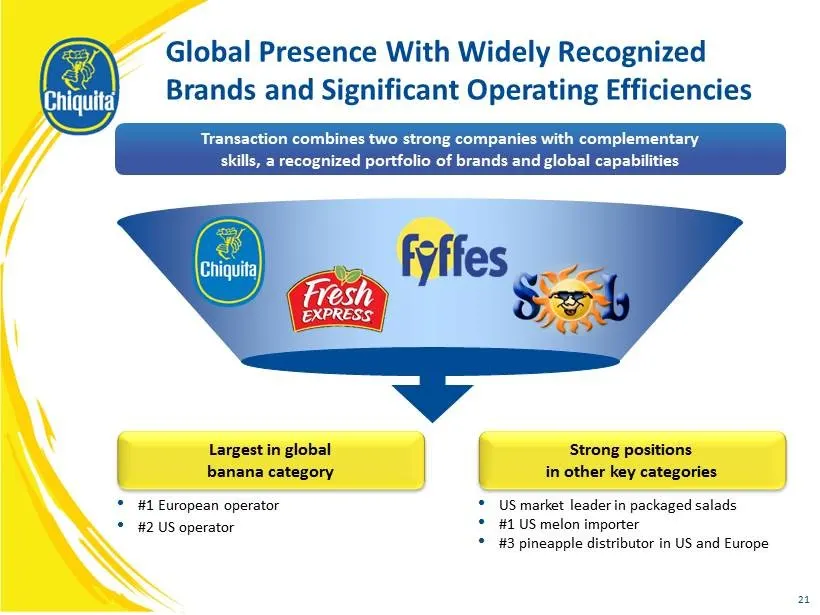
Slide 21: Global Presence With Widely Recognized Brands and Operating Efficiencies
21 Global Presence With Widely Recognized Brands and Significant Operating Efficiencies • #1 European operator • #2 US operator • US market leader in packaged salads • # 1 US melon importer • #3 pineapple distributor in US and Europe Largest in global banana category Strong positions in other key ca
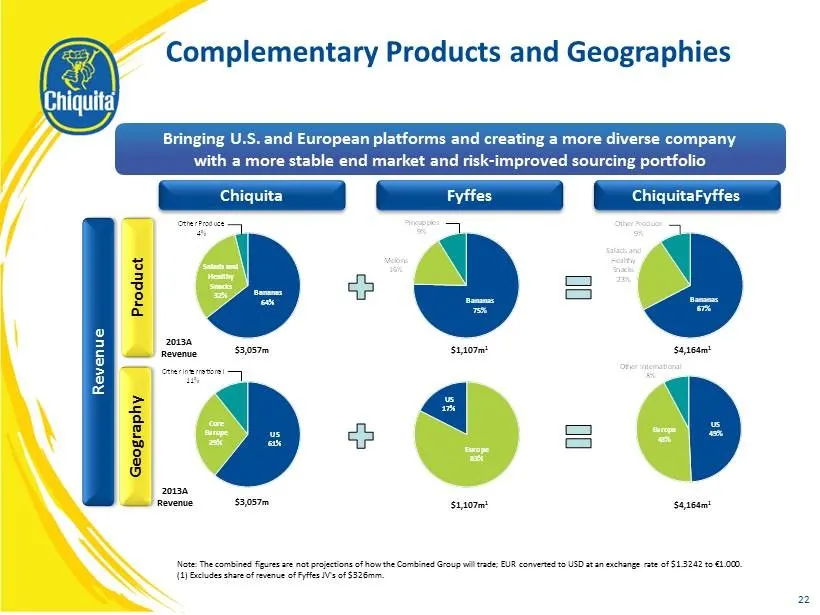
Slide 22: Complementary Products and Geographies
Bananas 75% Melons 16% Pineapples 9% Bananas 64% Salads and Healthy Snacks 32% Other Produce 4% US 61% Core Europe 29% Other International 11% Bananas 67% Salads and Healthy Snacks 23% Other Produce 9% 22 Complementary Products and Geographies Note: The combined figures are not projectio
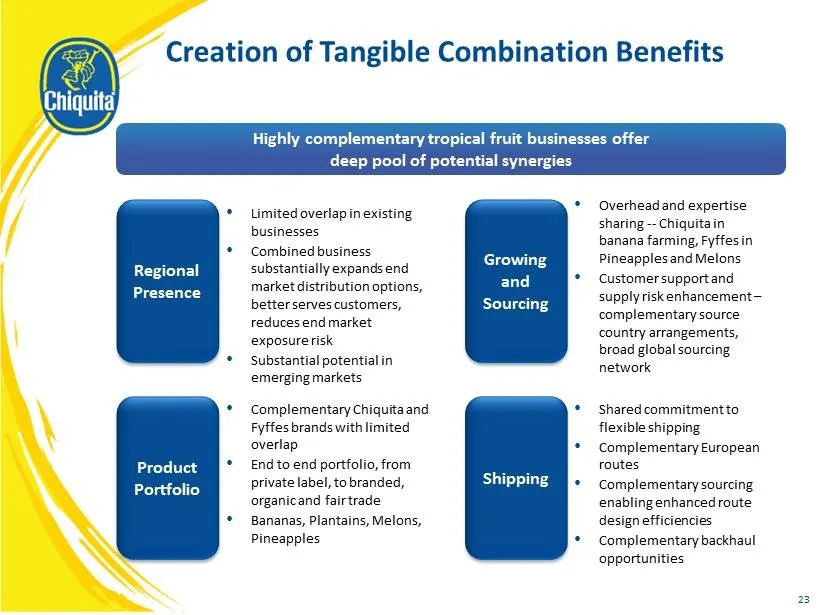
Slide 23: Creation of Tangible Combination Benefits
23 Creation of Tangible Combination Benefits Regional Presence • Limited overlap in existing businesses • Combined business substantially expands end market distribution options, better serves customers, reduces end market exposure risk • Substantial potential in emerging markets Growing and Sourcin
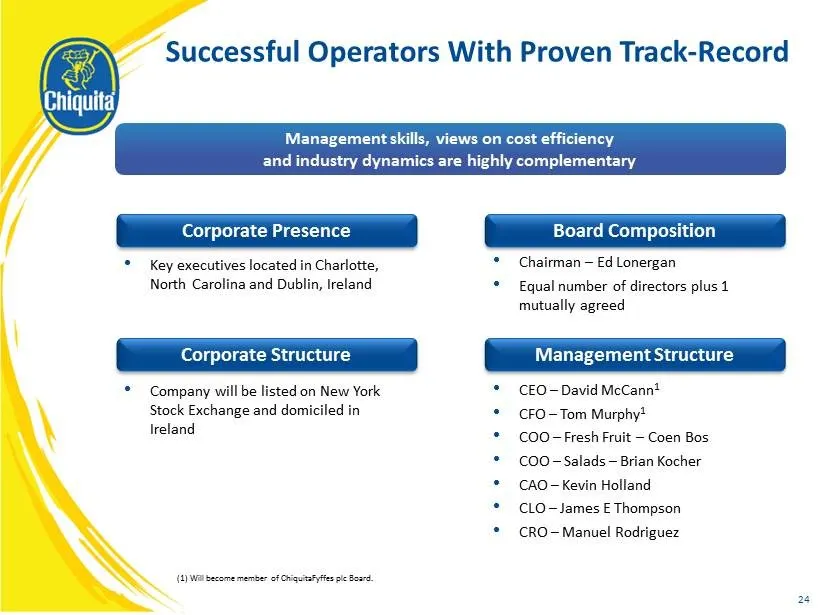
Slide 24: Successful Operators With Proven Track Record
24 Successful Operators With Proven Track - Record Corporate Structure Corporate Presence Management Structure • Key executives located in Charlotte , North Carolina and Dublin, Ireland • Company will be listed on New York Stock Exchange and domiciled in Ireland • CEO – David McCann 1 • CFO – Tom Mu
Slide 25: Chiquita and Fyffes Upsides Since Announcement
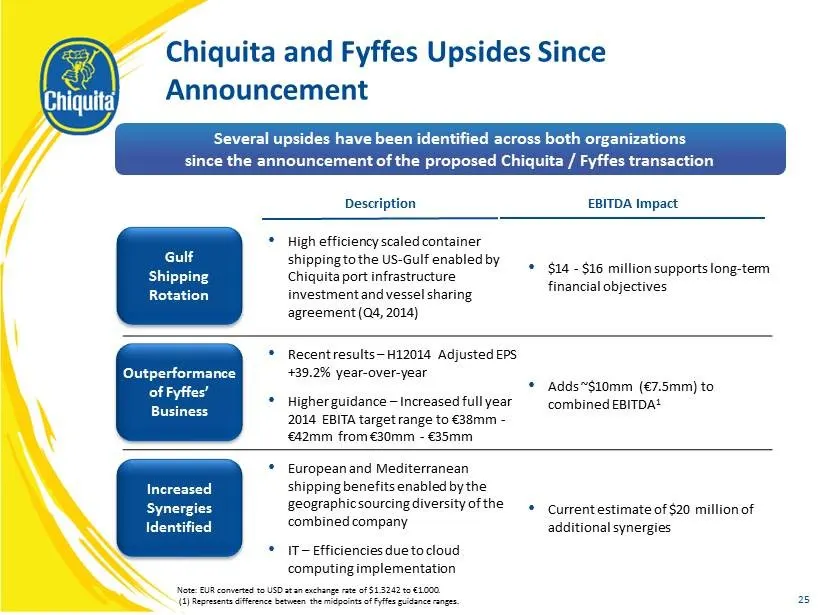
25 Chiquita and Fyffes Upsides Since Announcement • High efficiency scaled container shipping to the US - Gulf enabled by Chiquita port infrastructure investment and vessel sharing agreement (Q4, 2014) • $14 - $16 million supports long - term financial objectives • Recent results – H12014 Adjusted E
Slide 26: Strong Combined Financial Profile
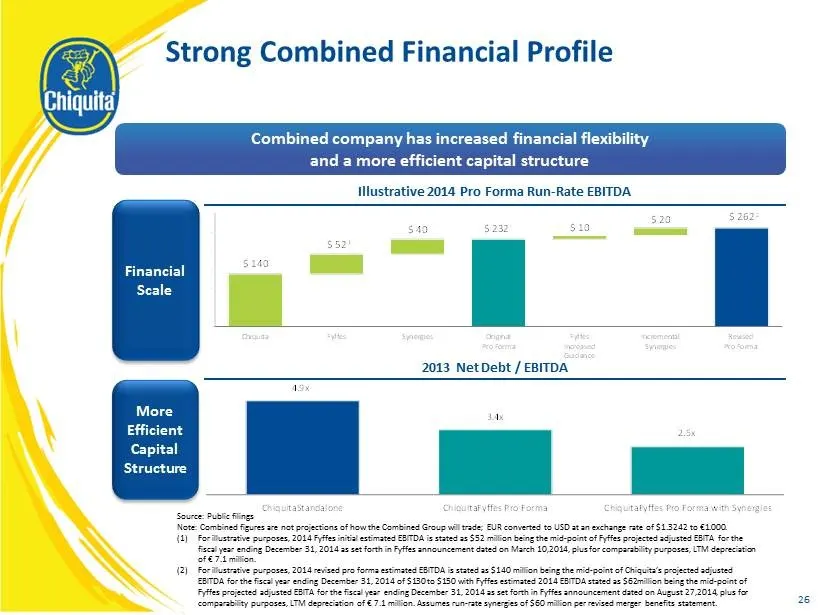
26 Strong Combined Financial Profile Source: Public filings Note : Combined figures are not projections of how the Combined Group will trade ; EUR converted to USD at an exchange rate of $1.3242 to € 1.000. (1) For illustrative purposes, 2014 Fyffes initial estimated EBITDA is stated as $52 million
Slide 27: Salads Stabilized Due to Efficiency and Pricing Actions in 2014
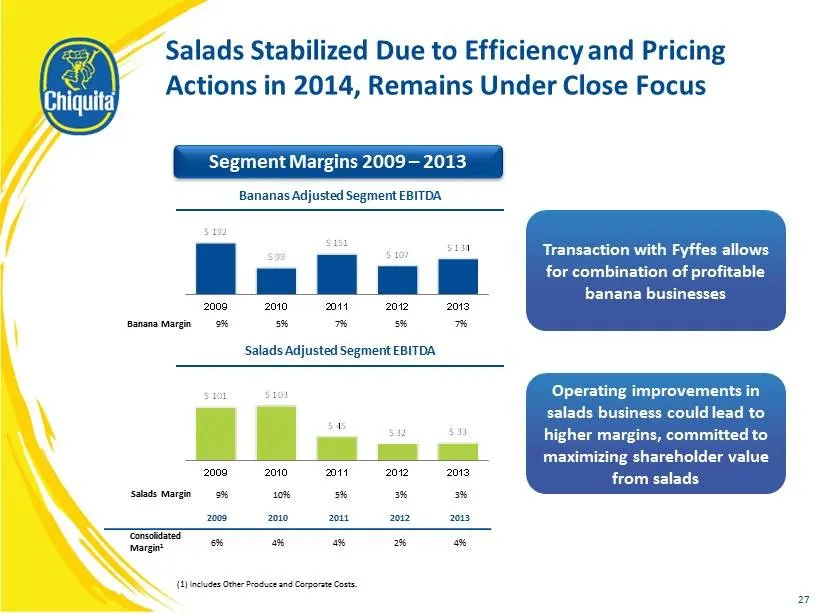
27 Salads Stabilized Due to Efficiency and Pricing Actions in 2014 , Remains Under Close Focus Bananas Adjusted Segment EBITDA Salads Adjusted Segment EBITDA Banana Margin 9% 5% 7% 5% 7% Salads Margin 9% 10% 5% 3% 3% Operating improvements in salads business could lead to higher margins, committed t
Slide 28: ChiquitaFyffes is superior to a $13.00 conditional offer
28 ChiquitaFyffes is superior to a $13.00 conditional offer
Slide 29: ChiquitaFyffes is Superior to $13.00 Conditional Offer
29 ChiquitaFyffes is Superior to $13.00 Conditional Offer 1 Chiquita / Fyffes could trade at prices well in excess of $13 / share post - closing 2 Market and external analysts believe value is greater than $13 / share 3 Cutrale / Safra offer is uncertain and conditional 4 $13 / share is an inadequat
Slide 30: Illustrative ChiquitaFyffes Trading Post Close
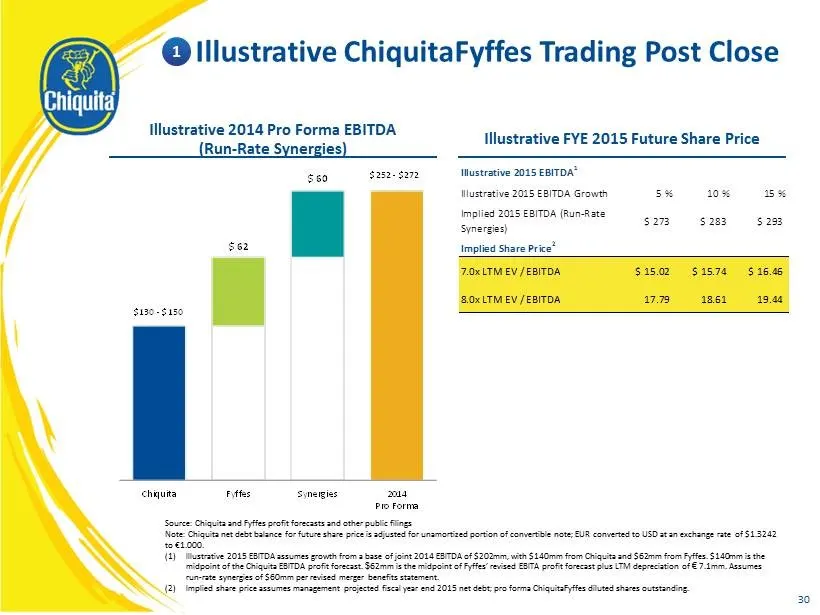
30 Illustrative ChiquitaFyffes Trading Post Close 1 Source : Chiquita and Fyffes profit forecasts and other public filings Note: Chiquita net debt balance for future share price is adjusted for unamortized portion of convertible note; EUR converted to USD at an exchange rate of $1.3242 to € 1.000. (
Slide 31: Valuation Multiples in the U.S. Capital Markets
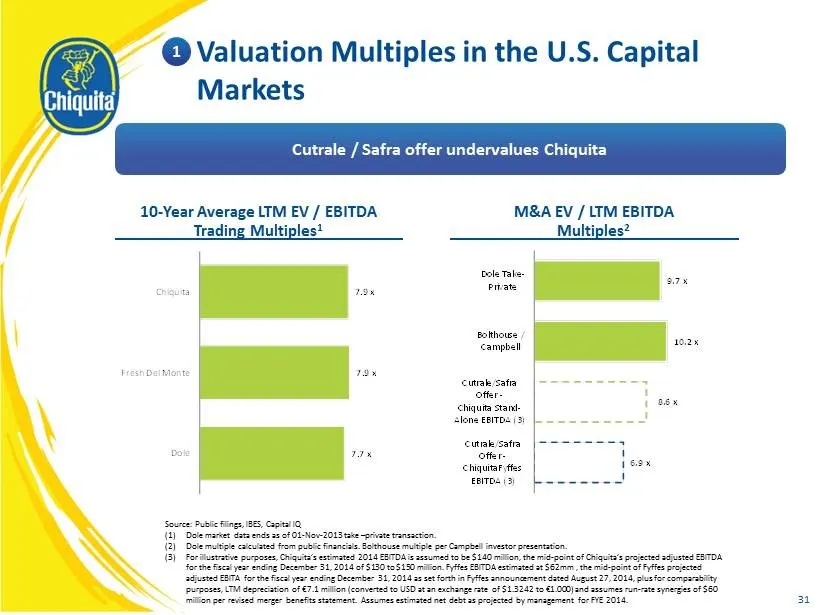
31 Valuation Multiples in the U.S. Capital Markets 10 - Year Average LTM EV / EBITDA Trading Multiples 1 M&A EV / LTM EBITDA Multiples 2 Cutrale / Safra offer undervalues Chiquita Source: Public filings, IBES, Capital IQ (1) Dole market data ends as of 01 - Nov - 2013 take – private transaction . (2
Slide 32: Market and Analysts Believe Value is Greater than $13 / Share
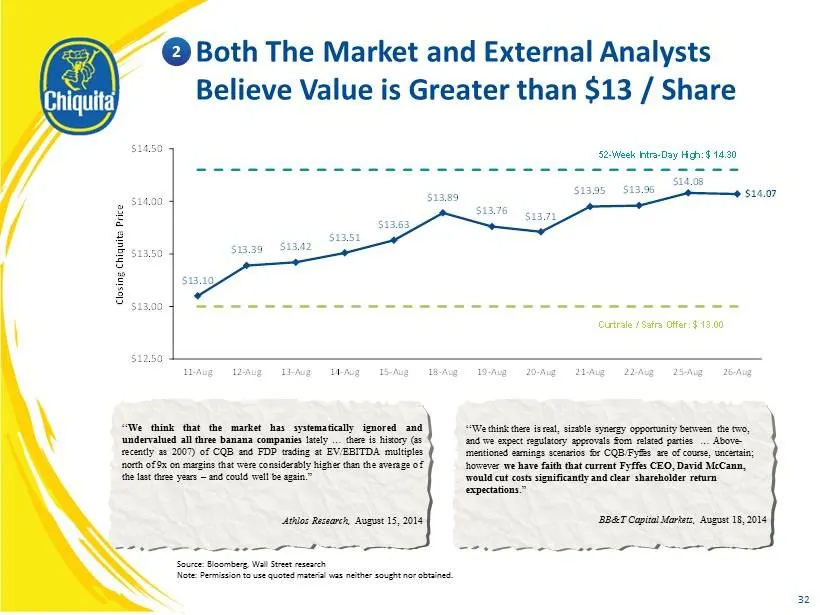
32 Both The Market and External Analysts Believe Value is Greater than $13 / Share Source: Bloomberg, Wall Street research Note : Permission to use quoted material was neither sought nor obtained . 2 “ We think that the market has systematically ignored and undervalued all three banana companies lat
Slide 33: Offer is Uncertain and Conditional
33 Offer is Uncertain and Conditional; Highly conditional, non - binding proposal; No details on financing or commitment; No experience in the banana or salads industries – significant uncertainty about the outcome and length of due diligence; No significant history of successfully completing M&A; D
Slide 34: $13 / Share is an Inadequate Price to Negotiate the Sale
34 $13 / Share is an Inadequate Price to Negotiate the Sale of the Company 4 x Chiquita is at a critical juncture in its turnaround initiated by new management x Multiple and premium on run - rate performance are too low x Chiquita is about to close on a merger with tangible cost synergies that crea
Slide 35: Experienced and Independent Board
35 Experienced and Independent Board 5 x Independent non - executive chairwoman x Seven of eight directors independent x Four of eight directors elected since 2012 x All committees comprised solely of independent directors x Accomplished executives with significant public board, executive management
Slide 36: Effective Corporate Governance
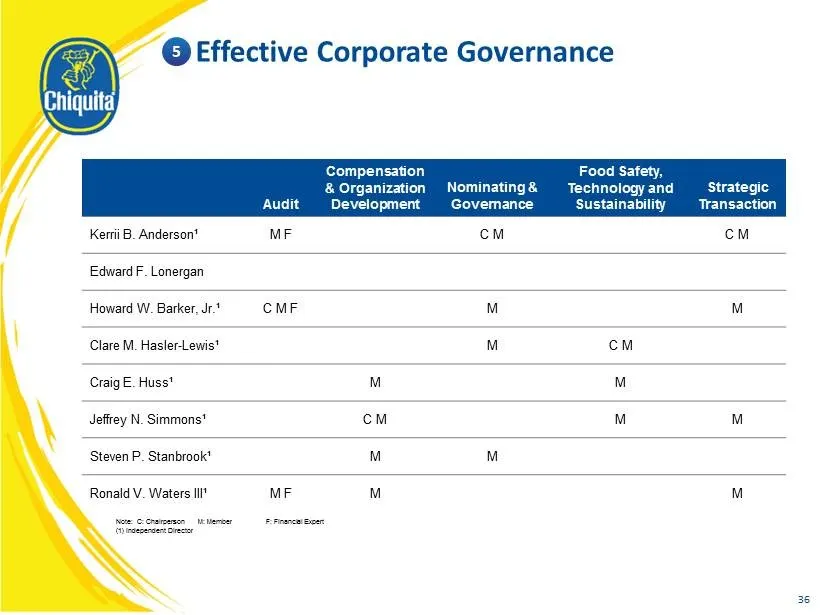
36 Effective Corporate Governance Audit Compensation & Organization Development Nominating & Governance Food Safety, Technology and Sustainability Strategic Transaction Kerrii B. Anderson¹ M F C M C M Edward F. Lonergan Howard W. Barker, Jr.¹ C M F M M Clare M. Hasler - Lewis¹ M C M Craig E. Huss¹ M
Slide 37: Conclusion
Po Conclusion \
Slide 38: Our Board is Squarely Focused on Value Creation
38 Our Board is Squarely Focused on Value Creation Our Track Record: • Strong, capable, and experienced board that understands its fiduciary duties and is committed to enhancing shareholder value • In the past two years the Board has: • Initiated and presided over a significant shift in business str
Slide 39: Inadequate Price to Sell at This Time
39 Inadequate Price to Sell at This Time $13 / Share is an Inadequate Price at which to Sell at this Time • Offer is opportunistic at a low premium and a low multiple off a weak point in the stock price • Proposed Fyffes transaction creates a stronger company that will add value in our stock price •
Slide 40: The Choice for Shareholders
40 The Choice for Shareholders The Choice for Shareholders: 1. A better company, with greater potential to create value for shareholders • ChiquitaFyffes post - merger is a better and a more valuable business than Chiquita stand - alone without the proposed merger 2. No deal with any party • Cutrale
Slide 41: Appendix
Po Appendix \
Slide 42: Chiquita is Well-Governed by its Independent Directors
42 Chiquita is Well - Governed by its Independent Directors • Chairman of the Board is deeply involved in our corporate governance and in the ongoing strategic choices for the company • Chiquita Board has an active role in overseeing the management of Chiquita’s areas of risk, receiving regular repo
Slide 43: A Board of Proven Leaders
43 A Board of Proven Leaders with Executive, Investor, and Financial Backgrounds and Substantial M&A Experience • Kerrii B. Anderson • Chairwoman of the Board of Directors • Former President and CEO of Wendy’s International • Qualifications: Executive Leadership; Finance and Accounting • Edward F. L
Slide 44: Chiquita Board Regularly Evaluates Alternatives to Enhance Shareholder Value
44 Chiquita Board Regularly Evaluates Alternatives to Enhance Shareholder Value • 8 Chiquita Board meetings during fiscal year 2013 and took action by unanimous written consent 3 times • Board regularly review financial alternatives • 4 Chiquita Board meetings and 5 Strategic Transaction Committee m
Slide 45: Overview of Contractual Restrictions
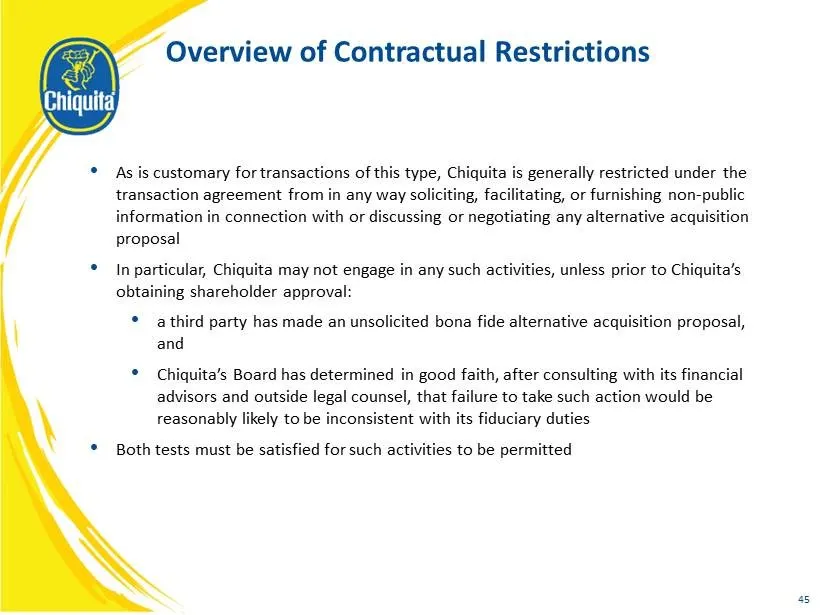
45 Overview of Contractual Restrictions • As is customary for transactions of this type, Chiquita is generally restricted under the transaction agreement from in any way soliciting, facilitating, or furnishing non - public information in connection with or discussing or negotiating any alternative a
Slide 46: Consolidated Reconciliation of Comparable Results to GAAP
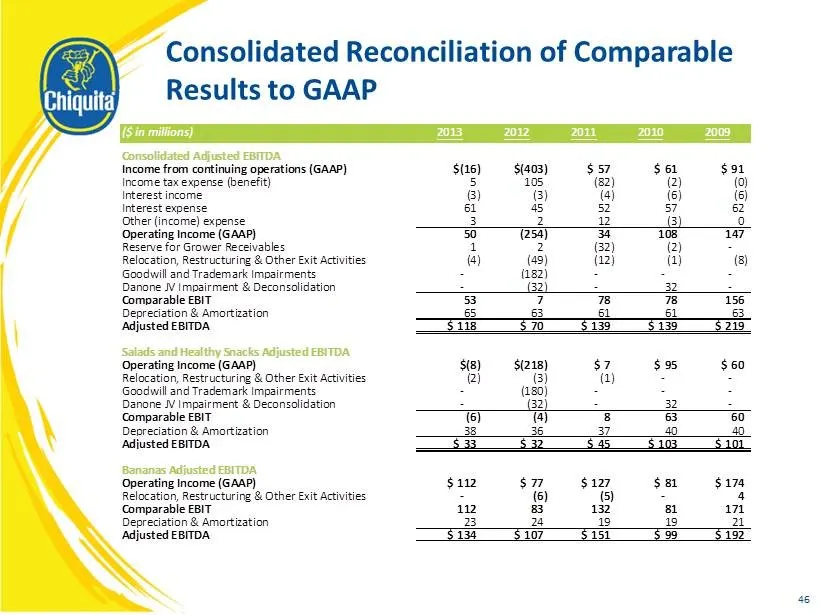
46 Consolidated Reconciliation of Comparable Results to GAAP ($ in millions) 2013 2012 2011 2010 2009 Consolidated Adjusted EBITDA Income from continuing operations (GAAP) $(16) $(403) $57 $61 $91 Income tax expense (benefit) 5 105 (82) (2) (0) Interest income (3) (3) (4) (6) (6) Interest expense 61
Slide 47: Responsibility statement and No Offer and Solicitation
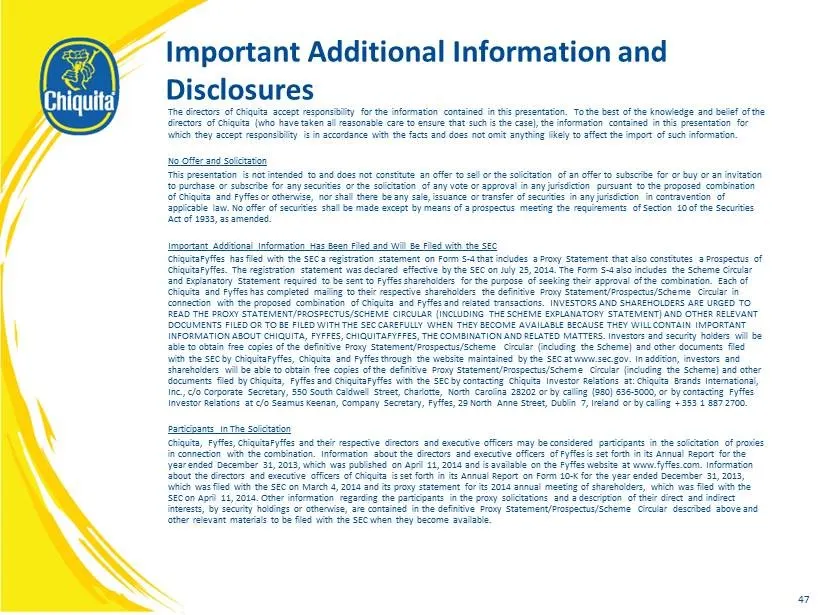
47 The directors of Chiquita accept responsibility for the information contained in this presentation. To the best of the knowle dge and belief of the directors of Chiquita (who have taken all reasonable care to ensure that such is the case), the information contained in this pr esentation for which
Slide 48: No Profit Forecast / Asset Valuations / Basis of Synergies / Non-GAAP Information
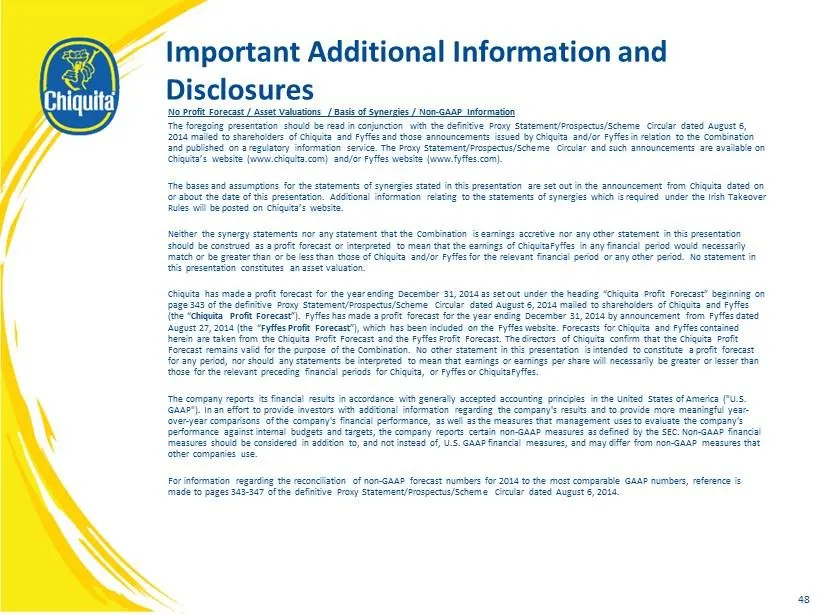
48 No Profit Forecast / Asset Valuations / Basis of Synergies / Non - GAAP Information The foregoing presentation should be read in conjunction with the definitive Proxy Statement/Prospectus/Scheme Circular dated Au gust 6, 2014 mailed to shareholders of Chiquita and Fyffes and those announcements i
Source: SEC EDGAR · 425 filed Aug 27, 2014
More decks from Chiquita Brands International Inc
 Merger or Acquisition (October 2014)24 slides · Oct 20, 2014
 Merger or Acquisition (October 2014)23 slides · Oct 20, 2014
 Proxy Contest (October 2014)15 slides · Oct 16, 2014
 Merger or Acquisition (October 2014)15 slides · Oct 14, 2014
 Proxy Contest (September 2014)28 slides · Sep 23, 2014
 Merger or Acquisition (September 2014)23 slides · Sep 17, 2014