BSP · RUS:BSPB
BSP — Bank Saint Petersburg — Investor Presentation (December 2015)
17 slides from BSP's investor presentation, December 2015
Slide 1: Investor Presentation
@ BANK @ SAINT PETERSBURG Investor Presentation
Slide 2: Disclaimer
Disclaimer • This presentation does not constitute or form part of, and should not be construed as, an offer to sell or issue or the solicitation of an offer to buy or acquire securities of BSPB or any of its subsidiaries in any jurisdiction or an inducement to enter into investment activity in any
Slide 3: Bank Saint Petersburg at a glance
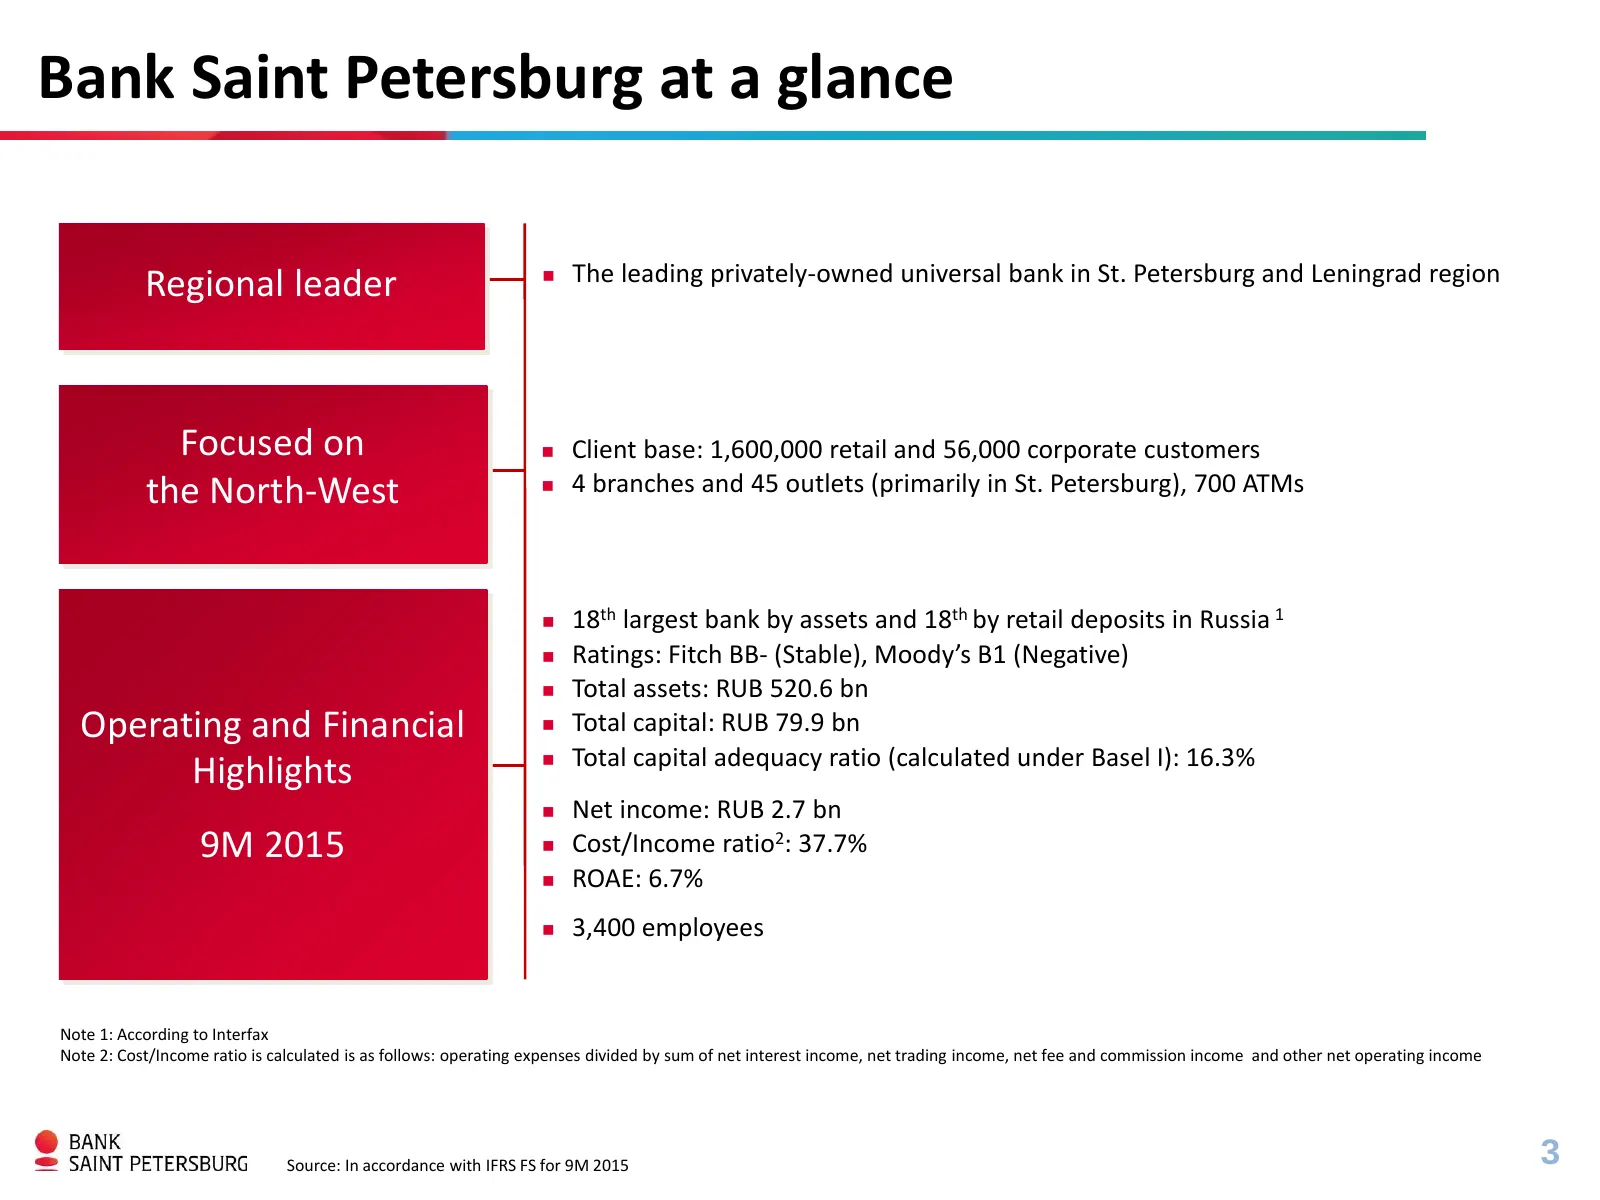
Bank Saint Petersburg at a glance Regional leader The leading privately-owned universal bank in St. Petersburg and Leningrad region Focused on Client base: 1,600,000 retail and 56,000 corporate customers 4 branches and 45 outlets (primarily in St. Petersburg), 700 ATMs the North-West 18th la
Slide 4: Saint Petersburg: the dynamic home market
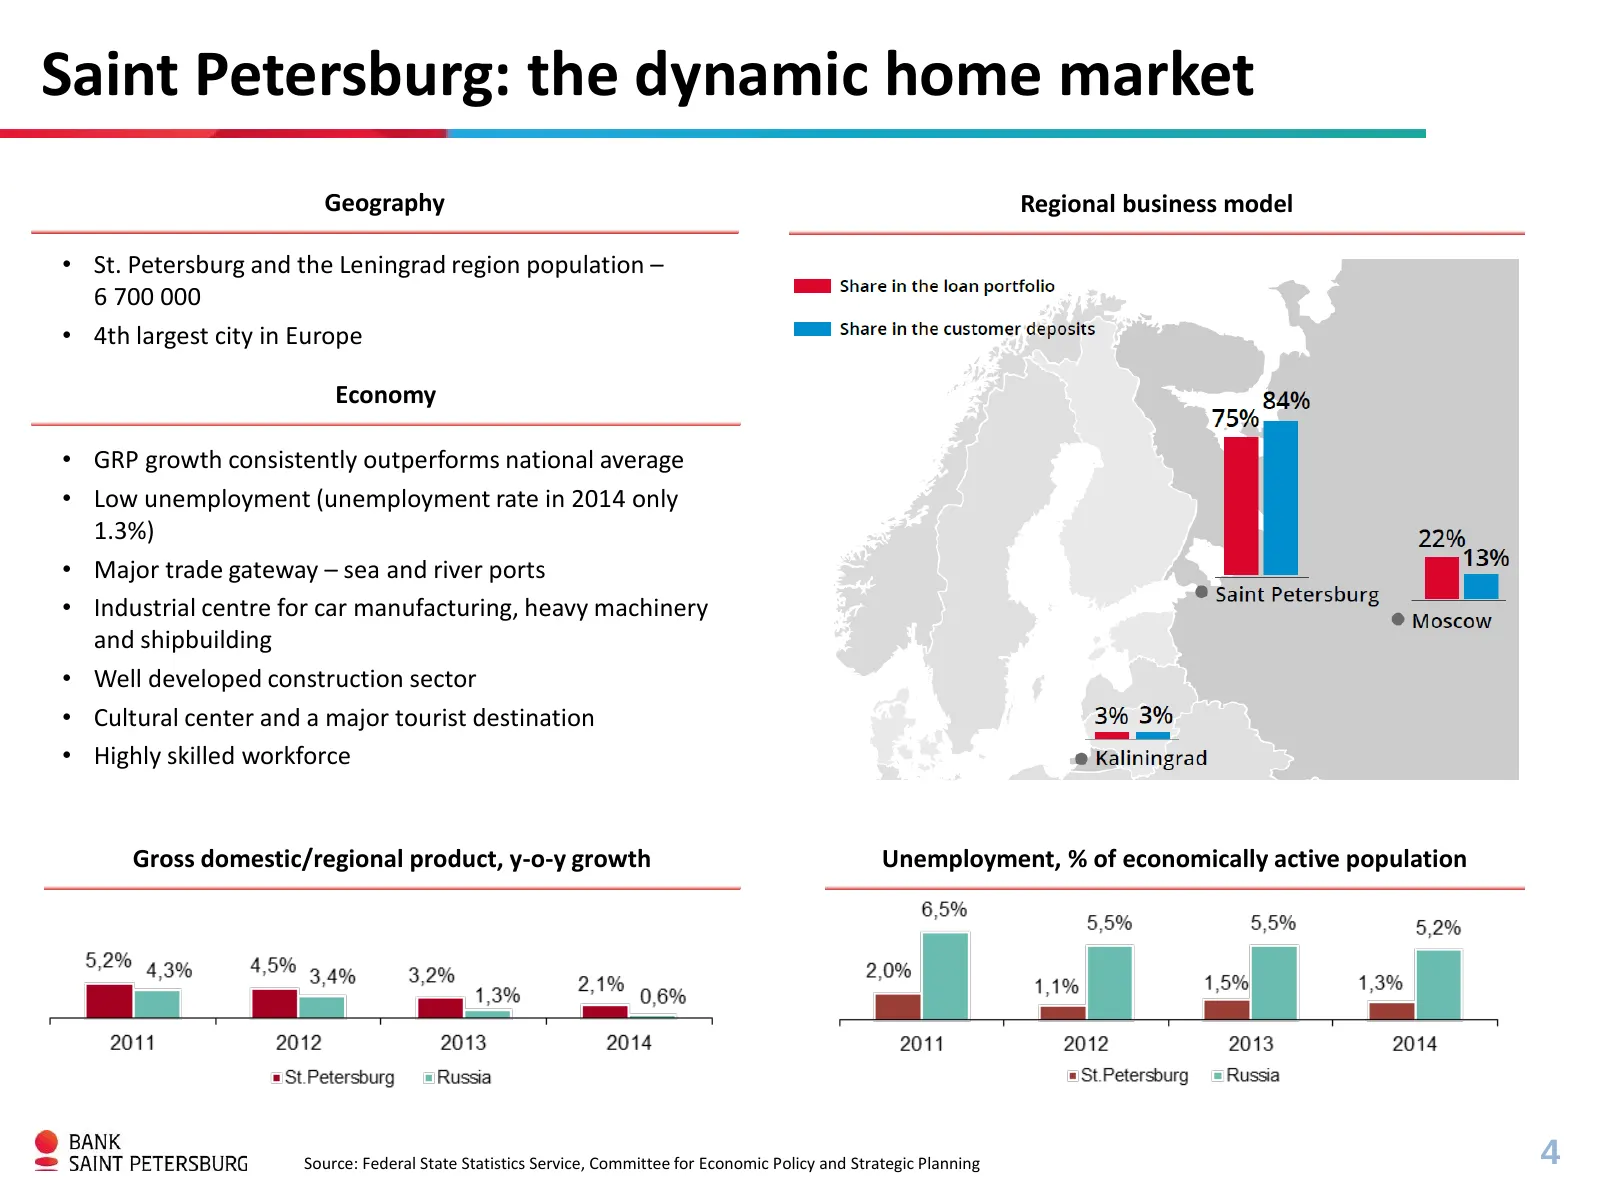
Saint Petersburg: the dynamic home market Geography Regional business model • St. Petersburg and the Leningrad region population – 6 700 000 • 4th largest city in Europe Economy • GRP growth consistently outperforms national average • Low unemployment (unemployment rate in 2014 only 1.3%) • Major tr
Slide 5: The Leading Universal Bank in St Petersburg
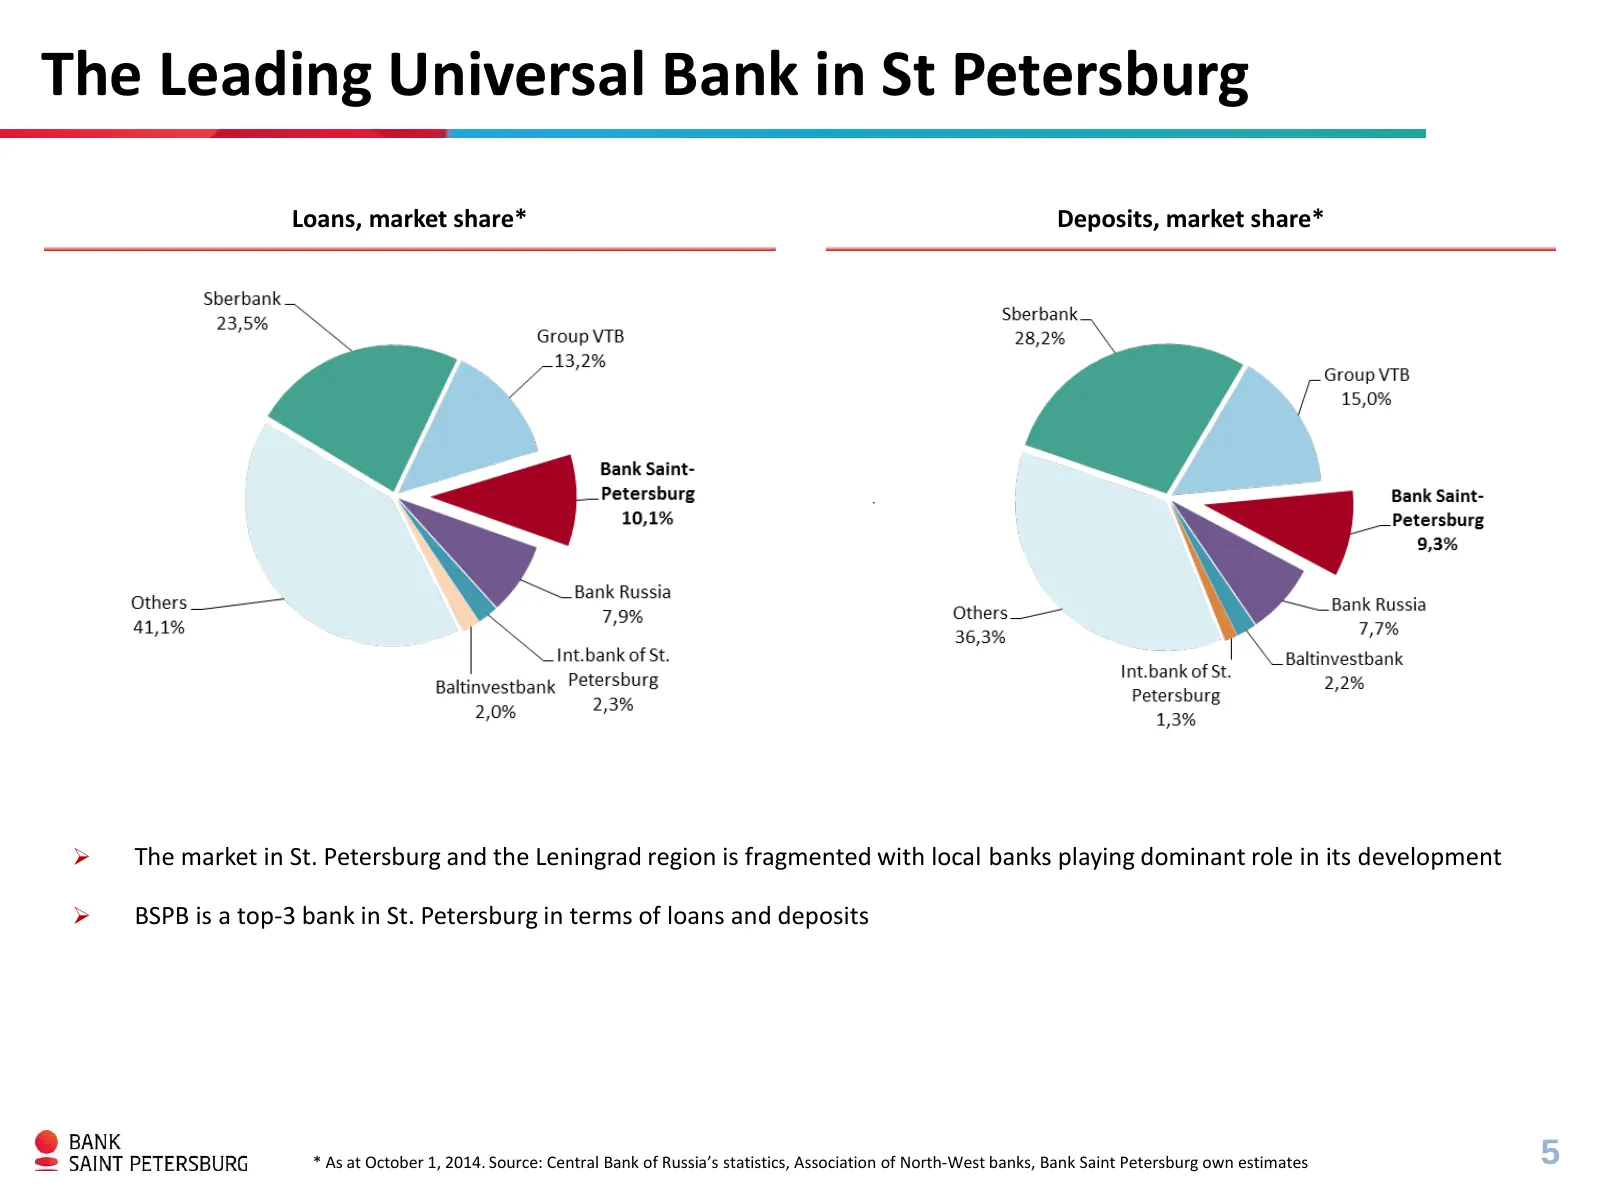
The Leading Universal Bank in St Petersburg Loans, market share* Deposits, market share* . The market in St. Petersburg and the Leningrad region is fragmented with local banks playing dominant role in its development BSPB is a top-3 bank in St. Petersburg in terms of loans and deposits * As at O
Slide 6: Shareholders structure
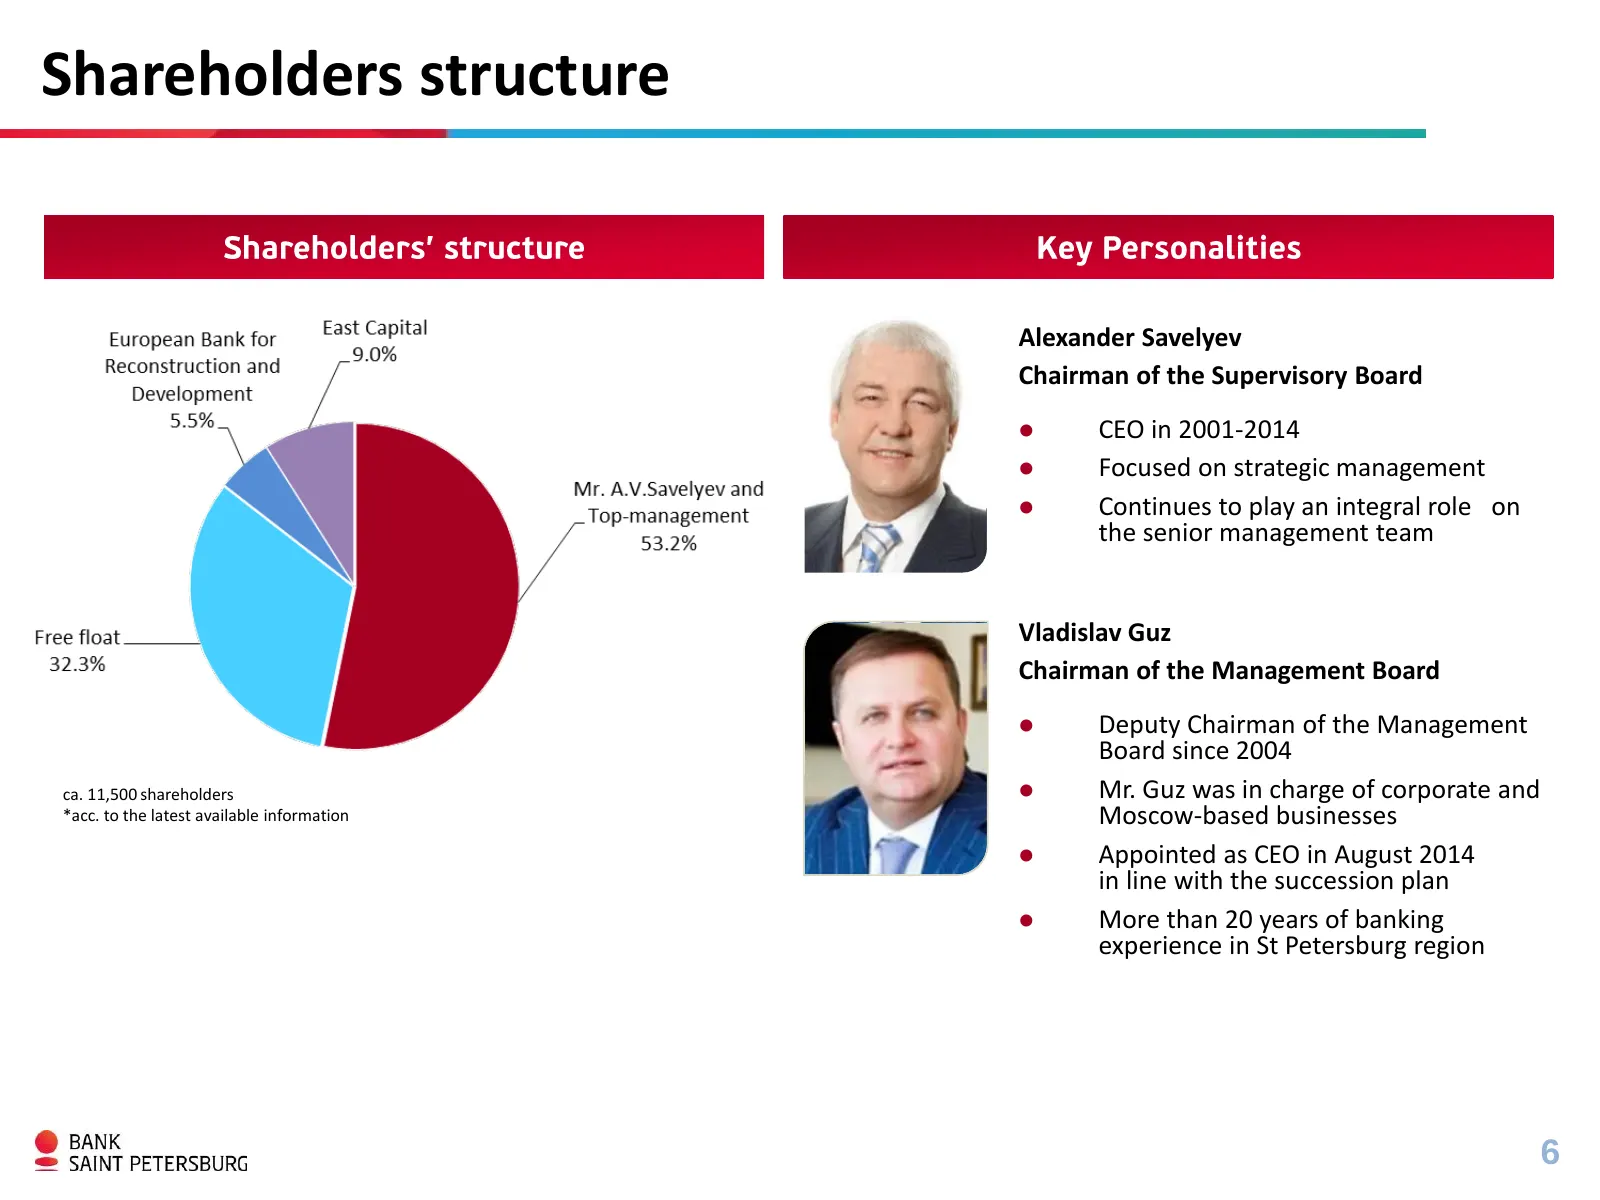
Shareholders structure Alexander Savelyev Chairman of the Supervisory Board CEO in 2001-2014 Focused on strategic management Continues to play an integral role on the senior management team Vladislav Guz Chairman of the Management Board Deputy Chairman of the Management Board since 2004 ca.
Slide 7: Post-IPO financial performance
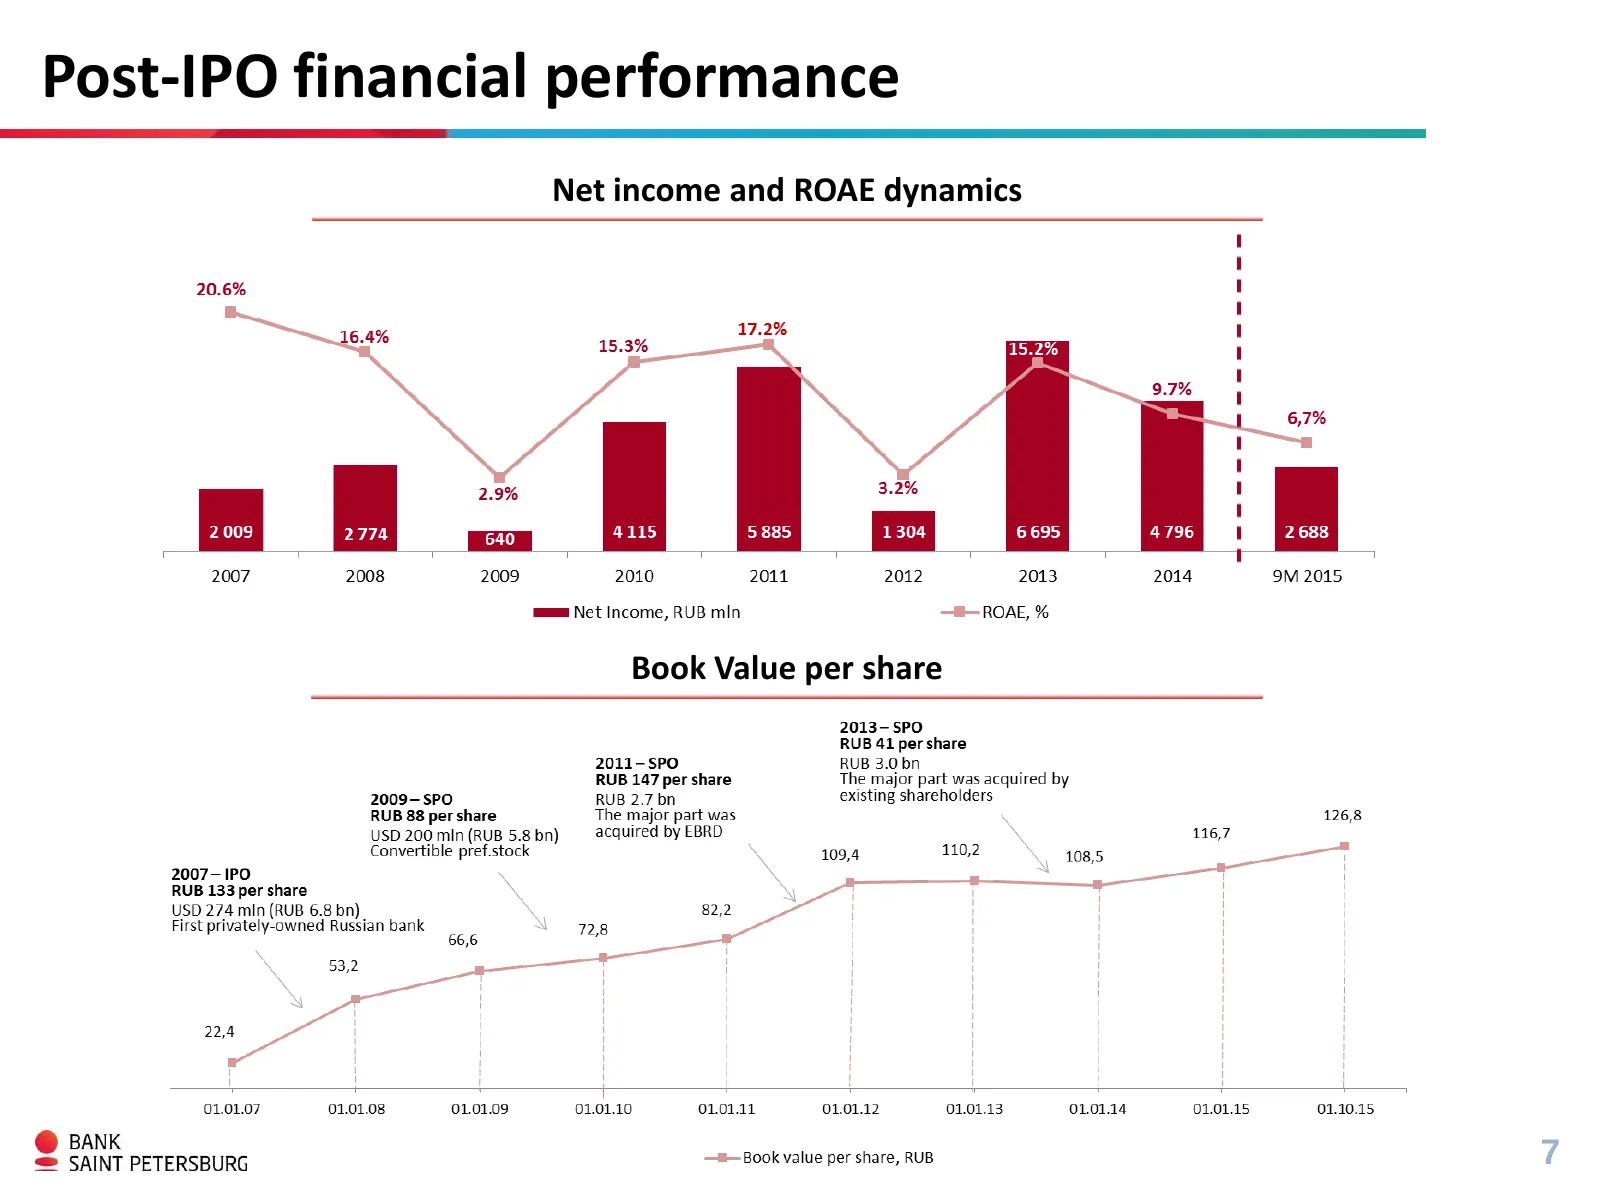
Post-IPO financial performance Net income and ROAE dynamics Book Value per share 7
Slide 8: Corporate vs. Retail banking
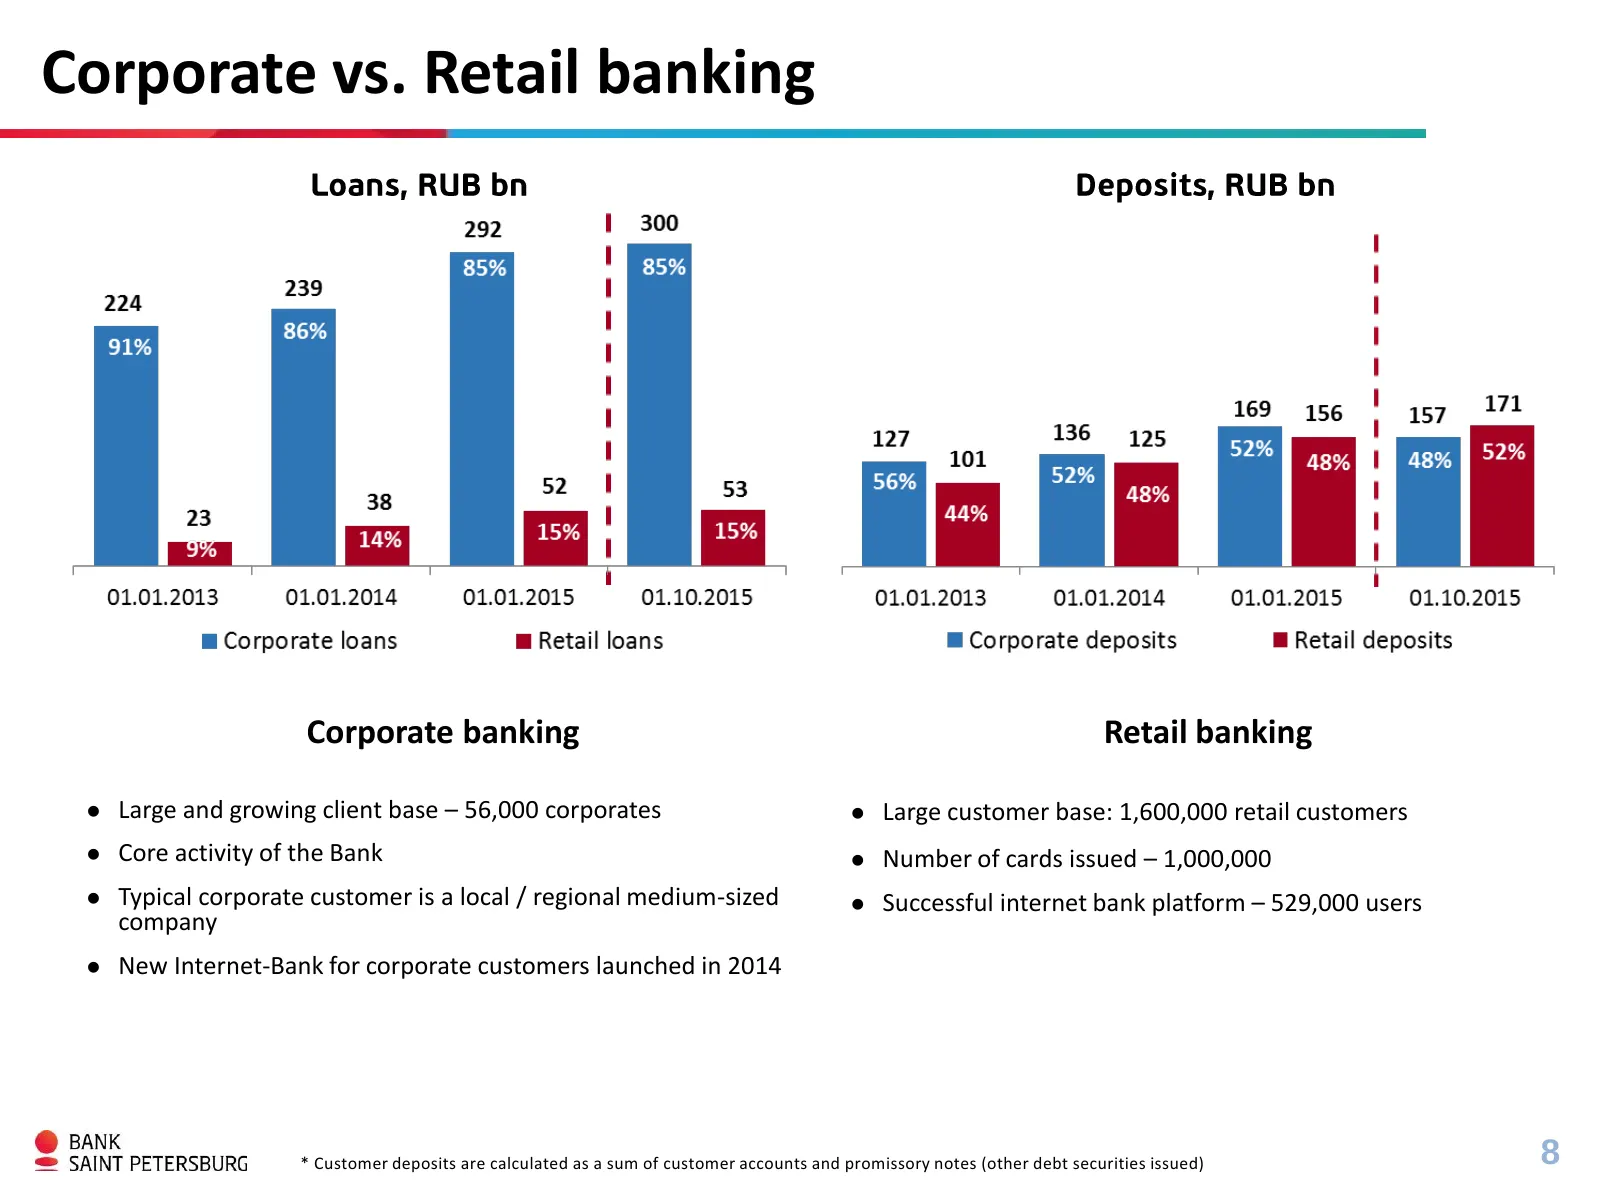
Corporate vs. Retail banking Corporate banking Retail banking Large and growing client base – 56,000 corporates Large customer base: 1,600,000 retail customers Core activity of the Bank Number of cards issued – 1,000,000 Typical corporate customer is a local / regional medium-sized Succe
Slide 9: Business highlights: retail banking
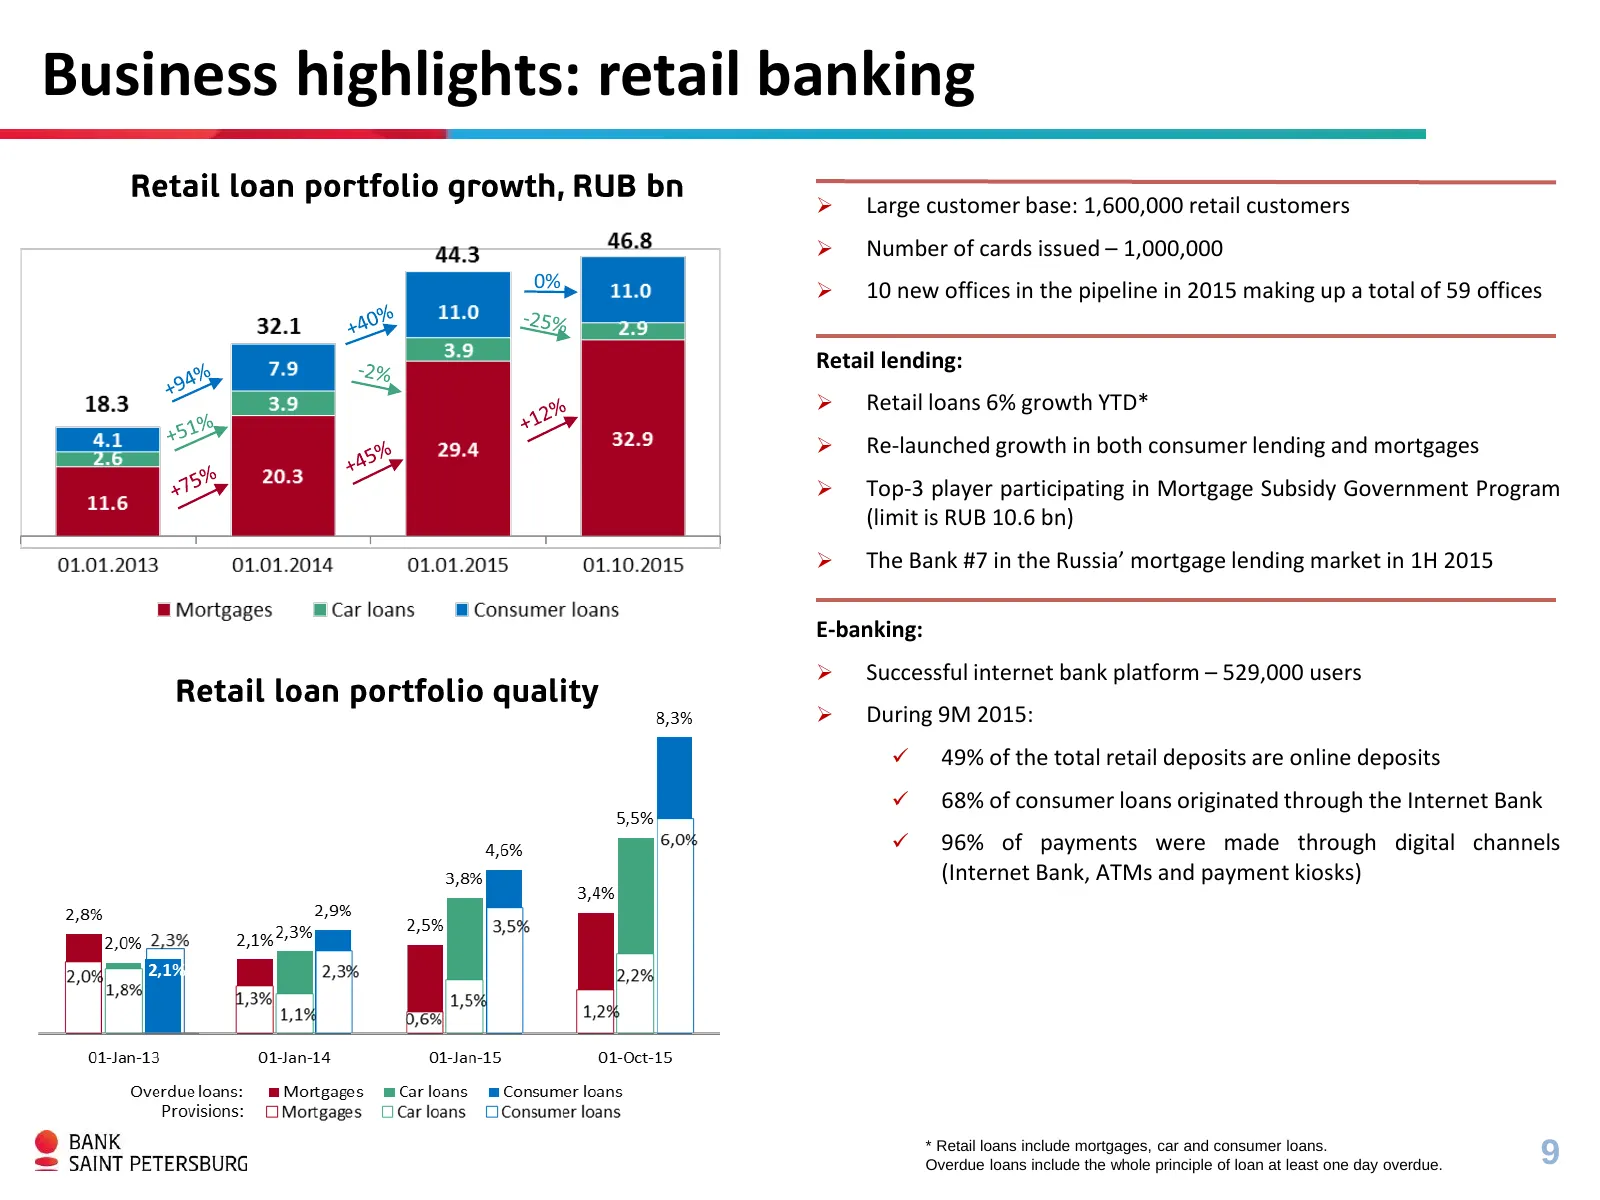
Business highlights: retail banking Large customer base: 1,600,000 retail customers Number of cards issued – 1,000,000 0% 10 new offices in the pipeline in 2015 making up a total of 59 offices Retail lending: Retail loans 6% growth YTD* Re-launched growth in both consumer lending and mortg
Slide 10: Financial Highlights
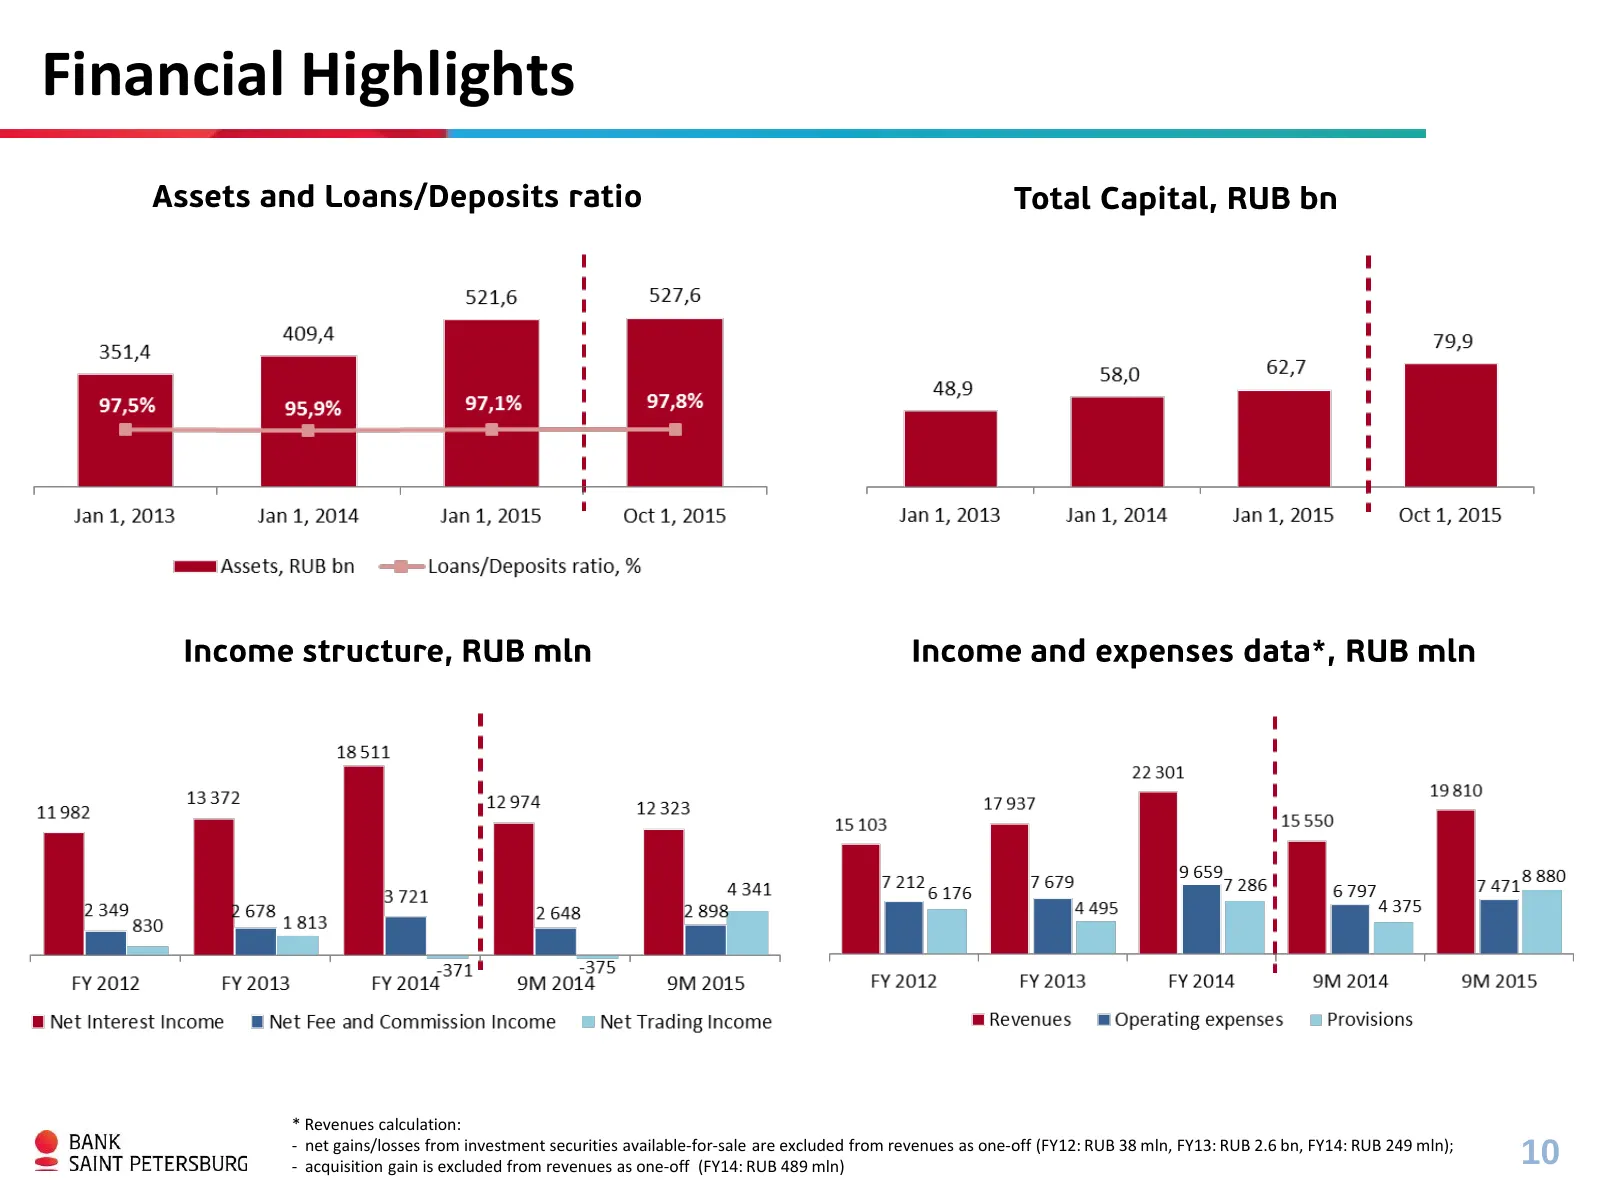
Financial Highlights • * Revenues calculation: • - net gains/losses from investment securities available-for-sale are excluded from revenues as one-off (FY12: RUB 38 mln, FY13: RUB 2.6 bn, FY14: RUB 249 mln); • - acquisition gain is excluded from revenues as one-off (FY14: RUB 489 mln) 10
Slide 11: Financial Highlights
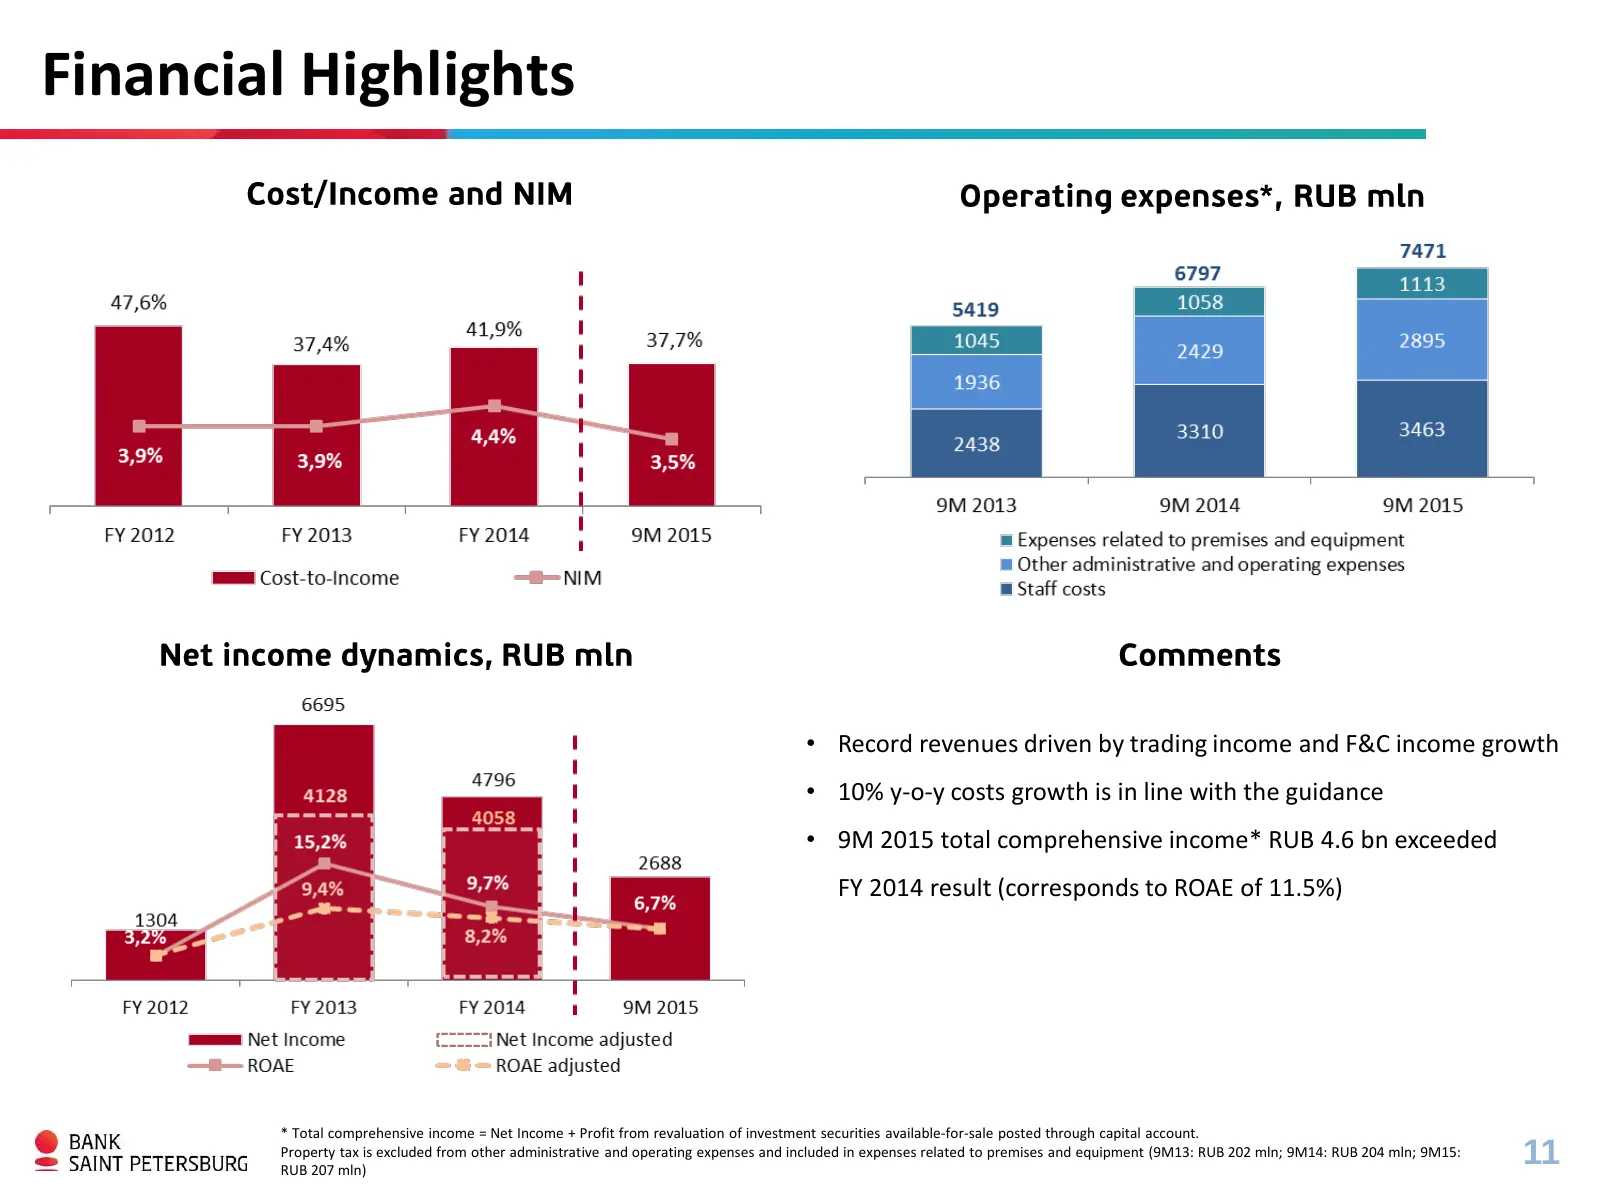
Financial Highlights • Record revenues driven by trading income and F&C income growth • 10% y-o-y costs growth is in line with the guidance • 9M 2015 total comprehensive income* RUB 4.6 bn exceeded FY 2014 result (corresponds to ROAE of 11.5%) * Total comprehensive income = Net Income + Profit from
Slide 12: Loan portfolio and quality
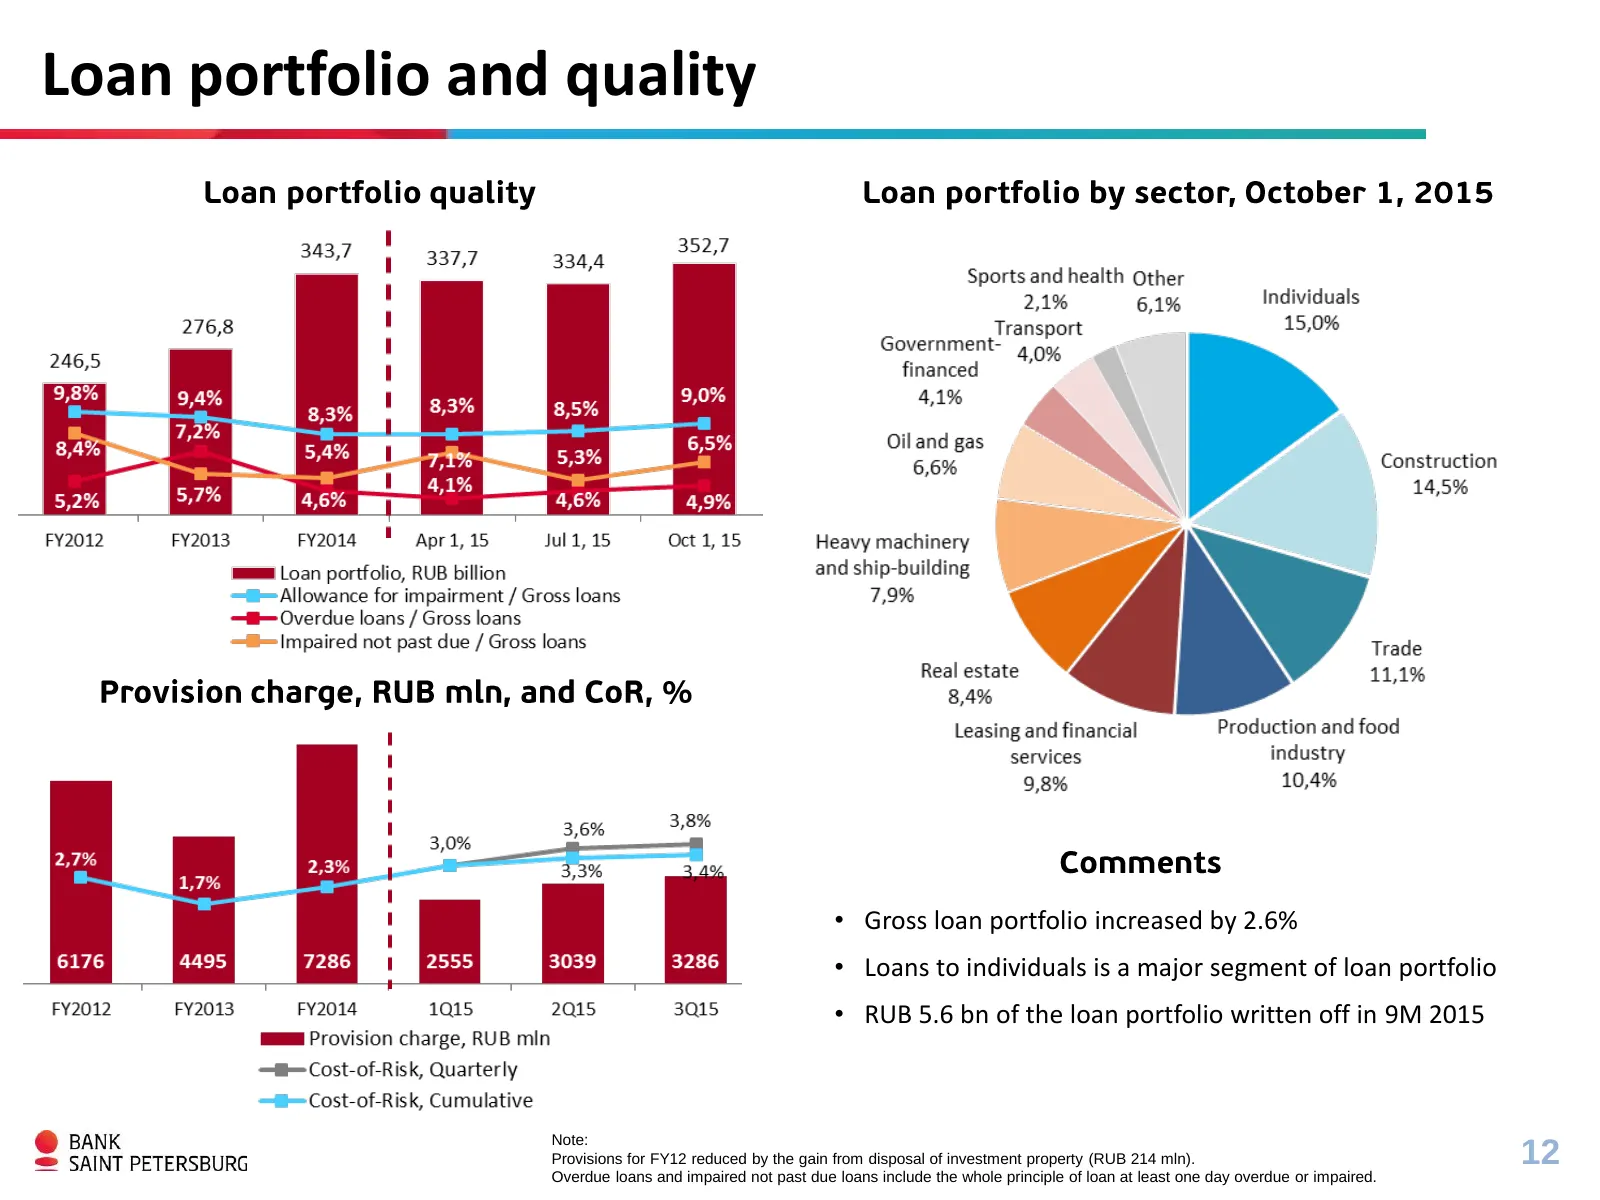
Loan portfolio and quality • Gross loan portfolio increased by 2.6% • Loans to individuals is a major segment of loan portfolio • RUB 5.6 bn of the loan portfolio written off in 9M 2015 Note: Provisions for FY12 reduced by the gain from disposal of investment property (RUB 214 mln). 12 Overdue loans
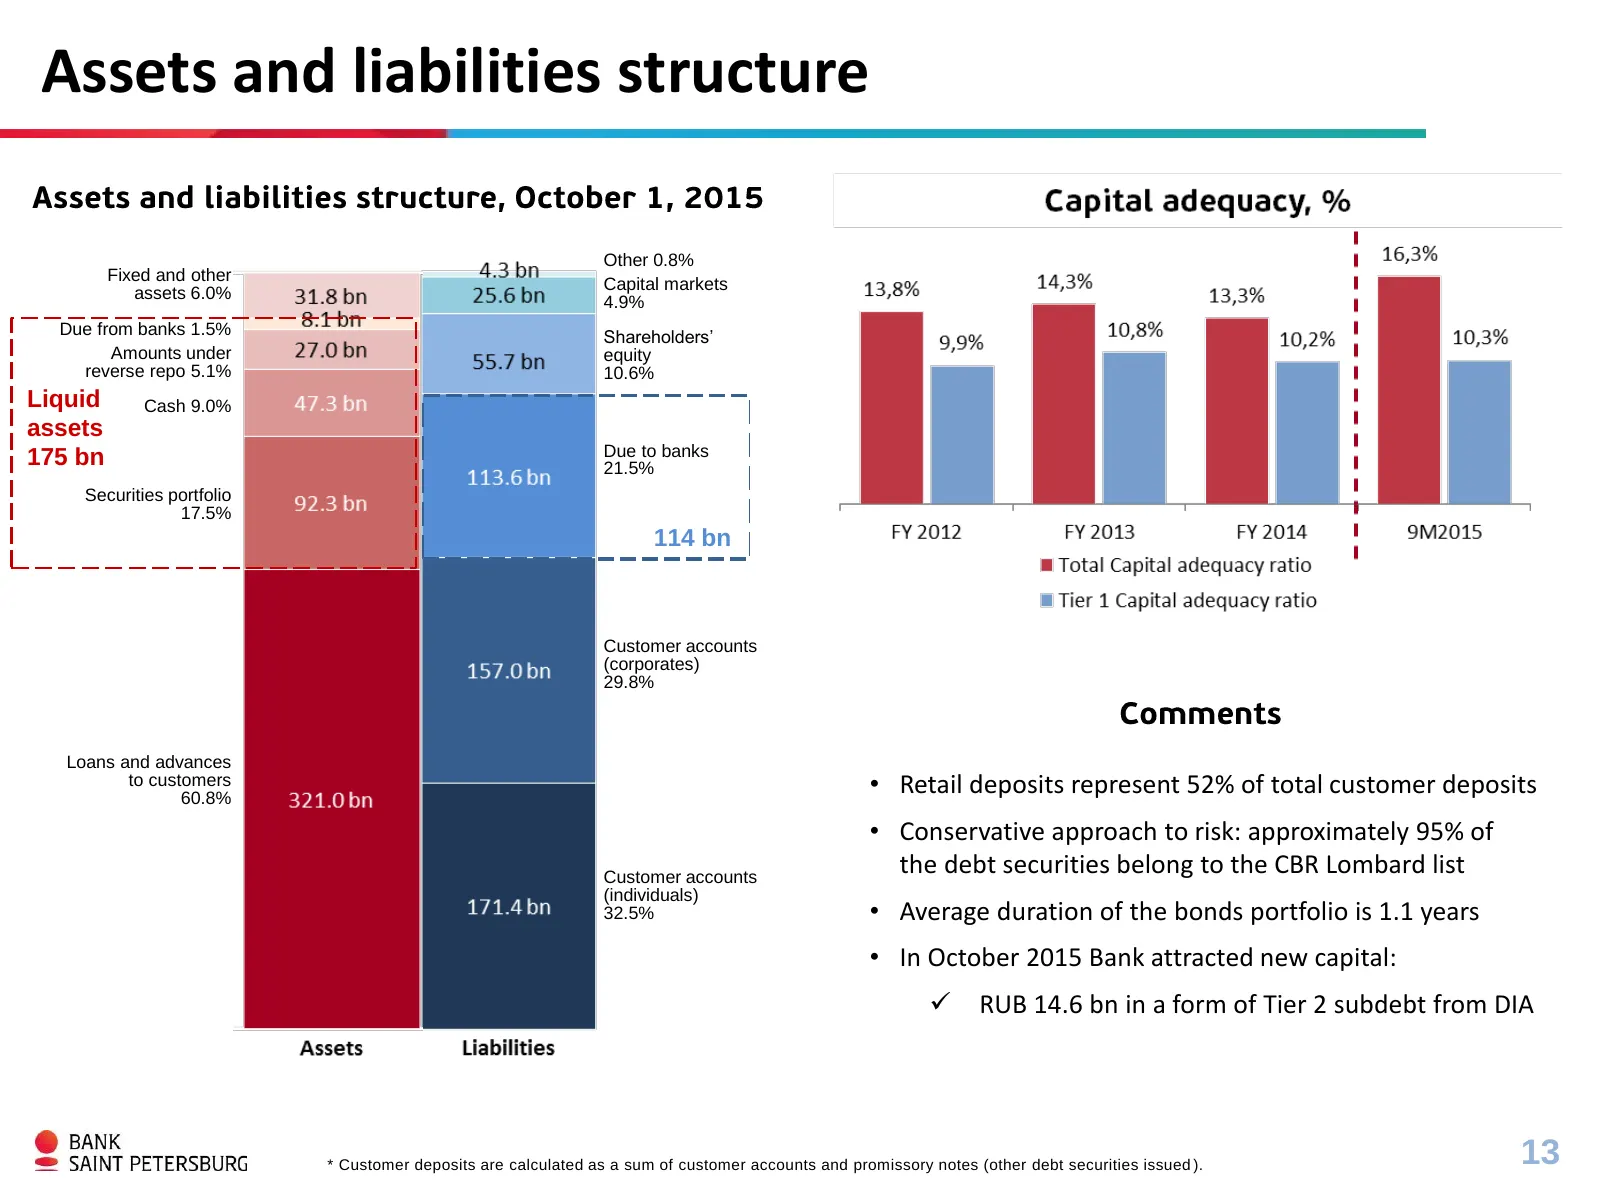
Slide 13: Assets and liabilities structure
Assets and liabilities structure Other 0.8% Fixed and other Capital markets assets 6.0% 4.9% Due from banks 1.5% Shareholders’ Amounts under equity reverse repo 5.1% 10.6% Liquid Cash 9.0% assets Due to banks 175 bn 21.5% Securities portfolio 17.5% 114 bn Customer accounts (corporates) 29.8% Loans a
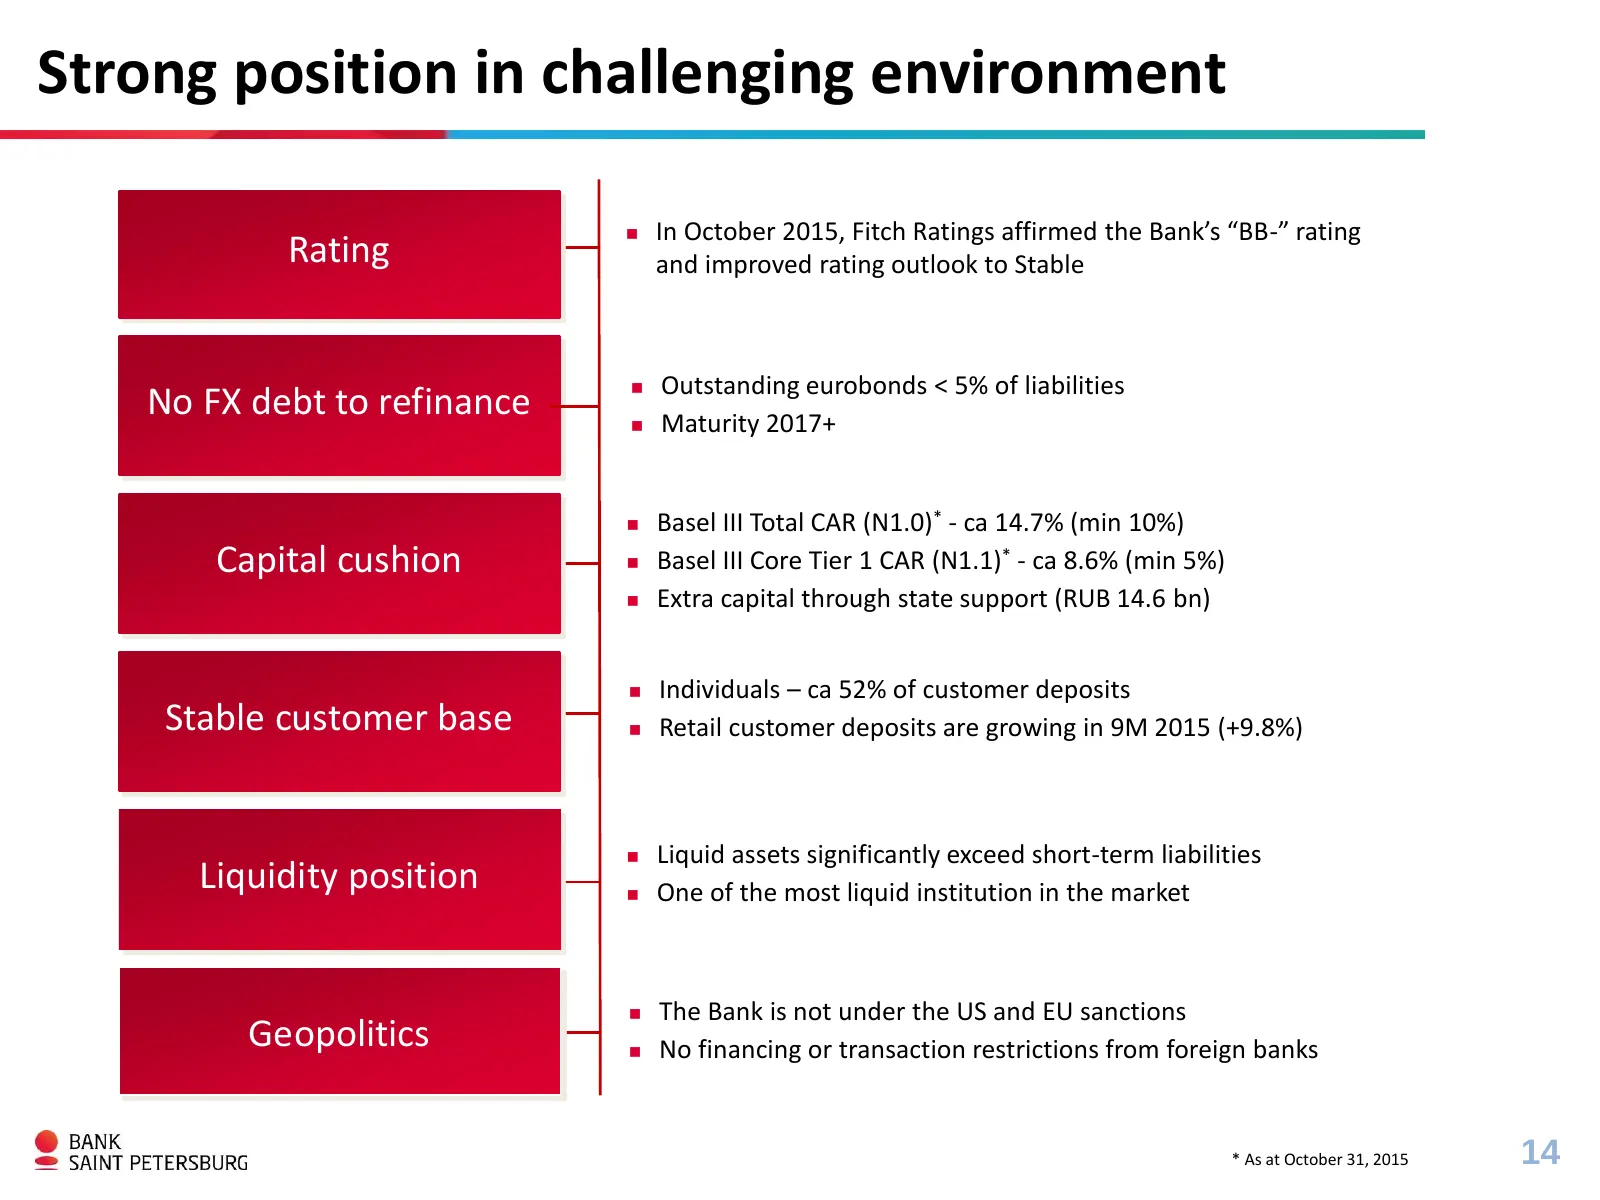
Slide 14: Strong position in challenging environment
Strong position in challenging environment In October 2015, Fitch Ratings affirmed the Bank’s “BB-” rating Rating and improved rating outlook to Stable Outstanding eurobonds < 5% of liabilities No FX debt to refinance Maturity 2017+ Basel III Total CAR (N1.0)* - ca 14.7% (min 10%) Capital cu
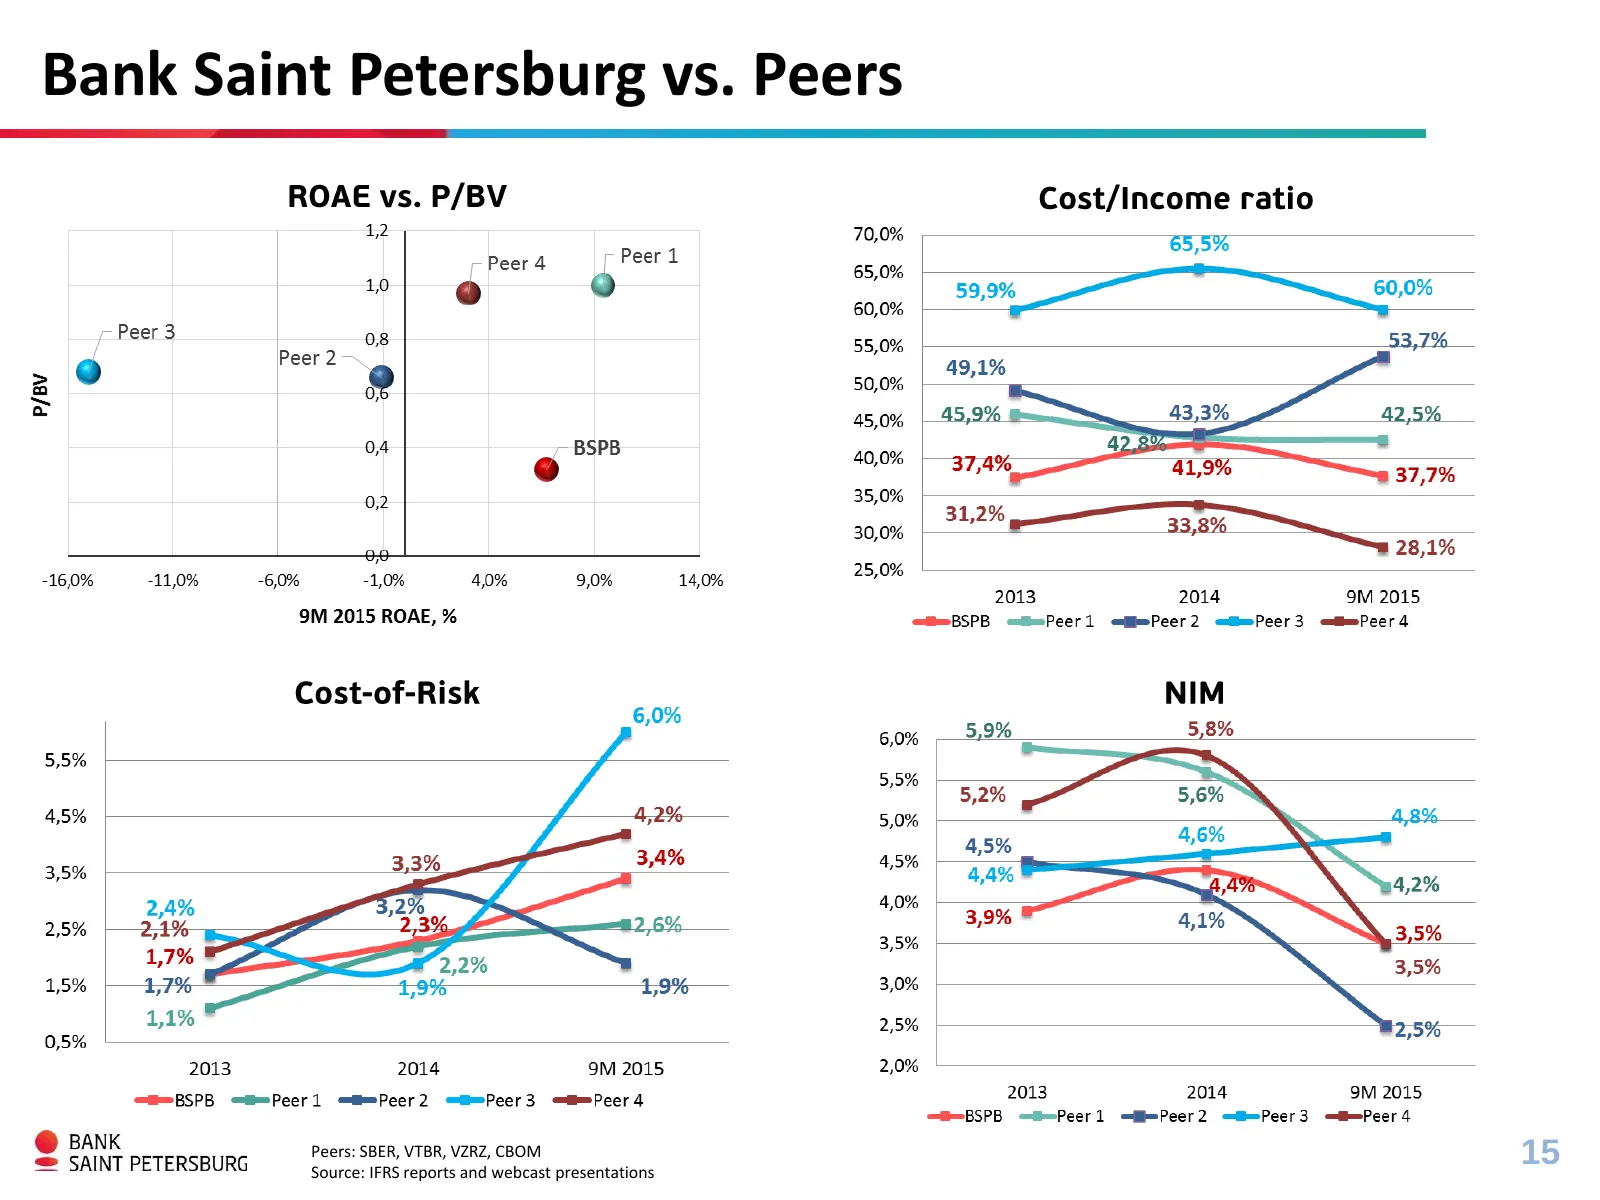
Slide 15: Bank Saint Petersburg vs. Peers
Bank Saint Petersburg vs. Peers Peers: SBER, VTBR, VZRZ, CBOM Source: IFRS reports and webcast presentations 15
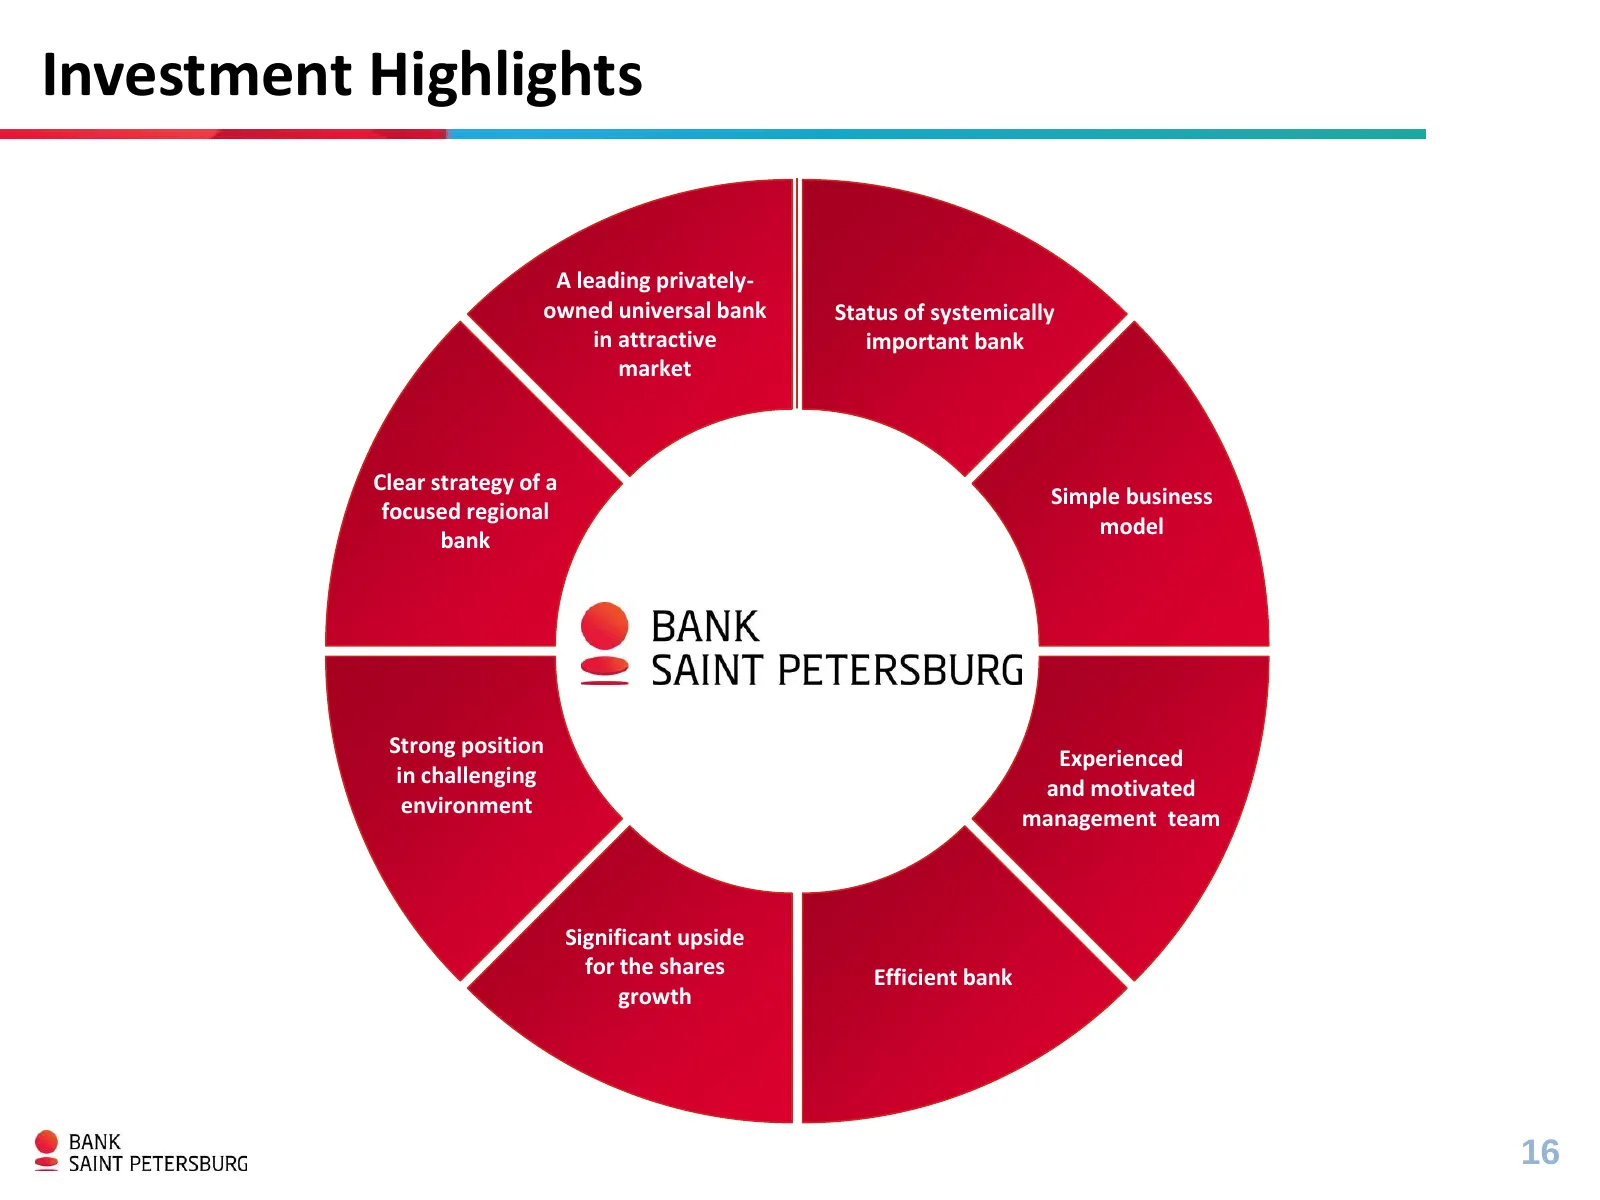
Slide 16: Investment Highlights
Investment Highlights A leading privately- owned universal bank Status of systemically in attractive important bank market Clear strategy of a Simple business focused regional model bank Strong position Experienced in challenging and motivated environment management team Significant upside for the s
Slide 17: Contacts
Contacts All information for the investors is available on the Bank’s website: https://www.bspb.ru/en/investors/ Contact information: E-mail: ir@bspb.ru Phone: +7 /812/ 332 78 36 17
Source: Internet Archive copy of bspb.ru
More decks from BSP
 Investor Presentation (November 2026)30 slides · November 2026
 Bank Saint Petersburg — Q2 2026 Earnings Presentation18 slides · Aug 21, 2026
 Bank Saint Petersburg — Investor Presentation (August 2026)29 slides · August 2026
 Investor Presentation (August 2026)29 slides · August 2026
 Bank Saint Petersburg — Q1 2026 Earnings Presentation17 slides · May 15, 2026
 Bank Saint Petersburg — FY2025 Earnings Presentation19 slides · Mar 6, 2026