Cambridge Capital Acquisition Corp
Cambridge Capital Acquisition — SPAC Merger (November 2015)
31 slides from Cambridge Capital Acquisition's SPAC merger presentation, Nov 16, 2015
Slide 1: A Global Leader in Tactical Communication Interception and Surveillance
1 A Global Leader in Tactical Communication Interception and Surveillance Proposed Merger with Cambridge Capital Acquisition Corporation (NASDAQ: CAMB/CAMBU/CAMBW) November 2015
Slide 2: Safe Harbor
2 Safe Harbor ▪ Neither Cambridge, Ability nor any of their respective affiliates makes any representation or warranty as to the accuracy or completeness of the information contained in this presentation . The sole purpose of the presentation is to assist persons in deciding whether they wish to pro
Slide 3: Agenda
3 Agenda » Presenters » Situation Overview » Investment Highlights » Business Overview » Financial Highlights » Transaction Overview » Comparable Company Analysis » Planned Transaction Timeline » Appendix
Slide 4: Presenters
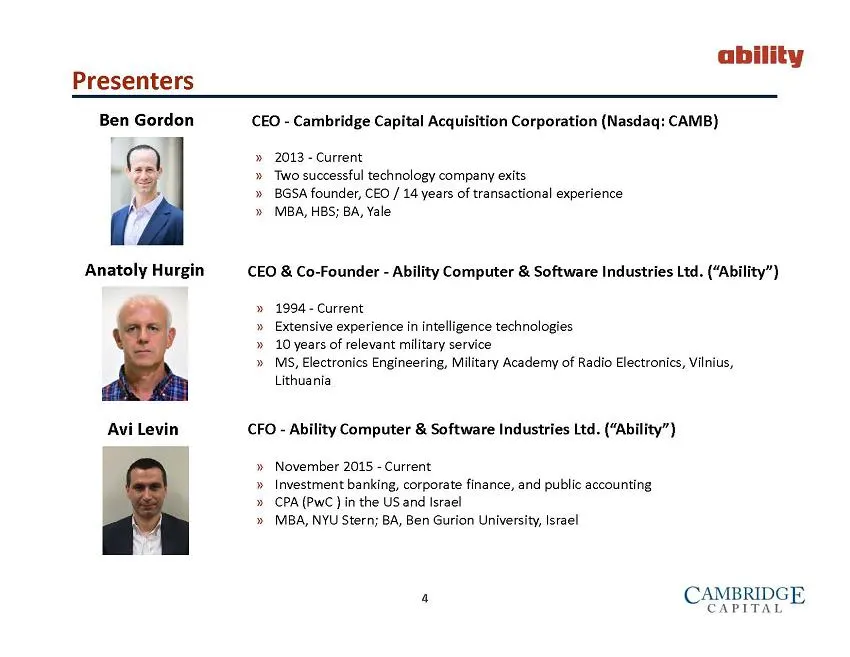
4 Presenters » 1994 - Current » Extensive experience in intelligence technologies » 10 years of relevant military service » MS, Electronics Engineering, Military Academy of Radio Electronics, Vilnius, Lithuania Anatoly Hurgin CEO & Co - Founder - Ability Computer & Software Industries Ltd. (“Ability
Slide 5: Situation Overview
5 Situation Overview » CAMB: special purpose acquisition corporation (SPAC) – December 2013: completed IPO and private placement – Raised $81.3 MM (or approximately $10.10 per share) » Entered merger agreement with Ability on September 8 th , 2015 – $281.7 MM equity valuation; $225.1 MM enterprise v
Slide 6: Investment Highlights
6 Investment Highlights » Pure play in $6B Lawful Interception Market [1] – Upside from entry into U.S. market » Best in class technology / Constant innovation arms race / History of “technology firsts” » Installed base / 50+ countries / High level of repeat clients and upselling » High revenue grow
Slide 7: Ability overview, operating results and global presence
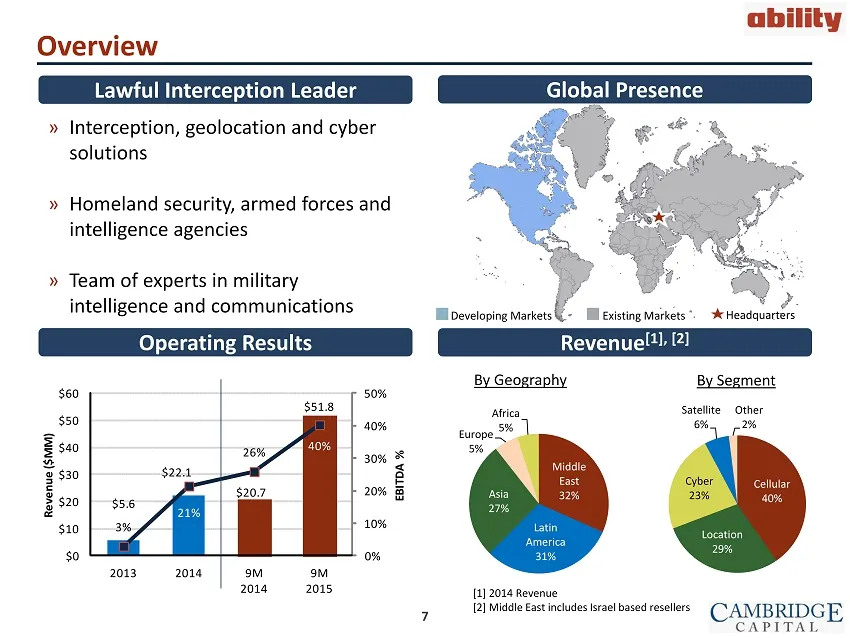
7 $5.6 $22.1 $20.7 $51.8 3% 21% 26% 40% 0% 10% 20% 30% 40% 50% $0 $10 $20 $30 $40 $50 $60 2013 2014 9M 2014 9M 2015 EBITDA % Revenue ($MM) Overview » Interception, geolocation and cyber solutions » Homeland security, armed forces and intelligence agencies » Team of experts in military intelligence a
Slide 8: How Lawful Interception Works
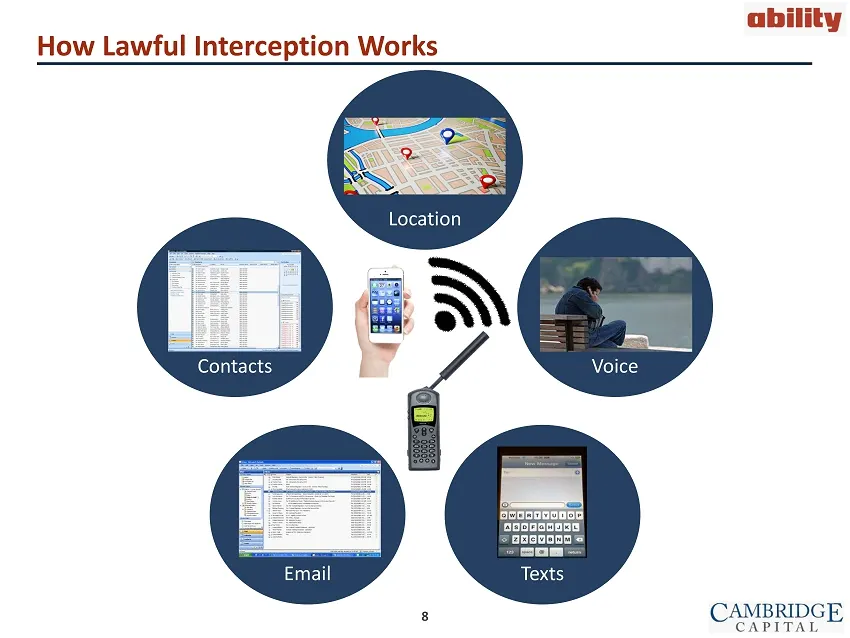
8 Location Voice Texts Email Contacts How Lawful Interception Works
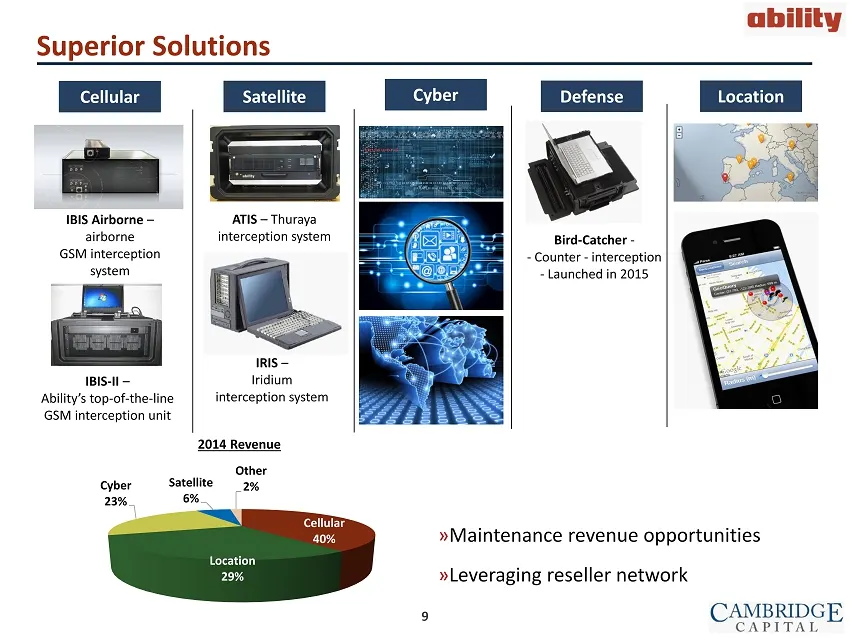
Slide 9: Superior Solutions
9 Superior Solutions Bird - Catcher - - Counter - interception - Launched in 2015 Defense IBIS Airborne – airborne GSM interception system Cellular ATIS – Thuraya interception system Satellite Cyber Location IRIS – Iridium interception system IBIS - II – Ability’s top - of - the - line GSM intercept
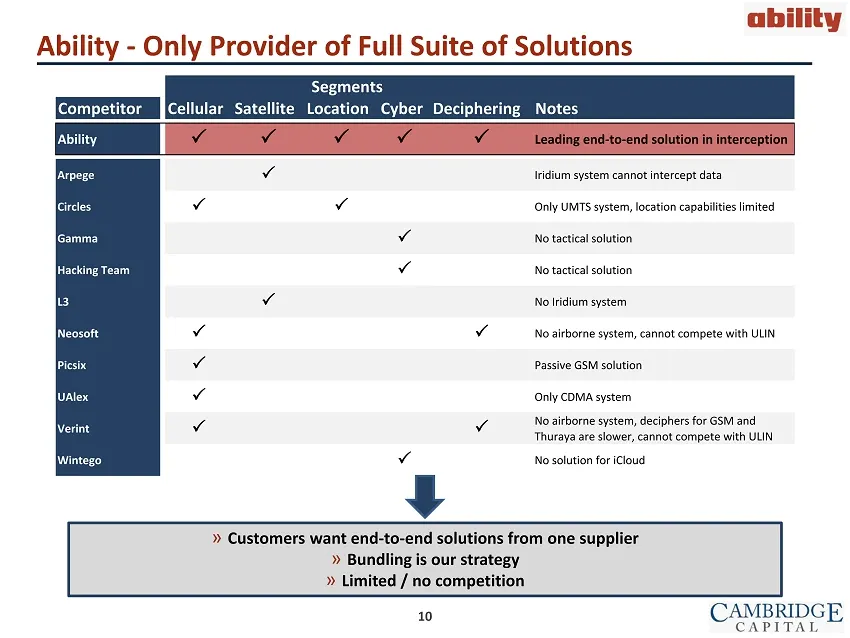
Slide 10: Ability - Only Provider of Full Suite of Solutions
10 Ability - Only Provider of Full Suite of Solutions » Customers want end - to - end solutions from one supplier » Bundling is our strategy » Limited / no competition hoi Segments Competitor Cellular Satellite Location Cyber Deciphering Notes Ability P P P P P Leading end-to-end solution in interce
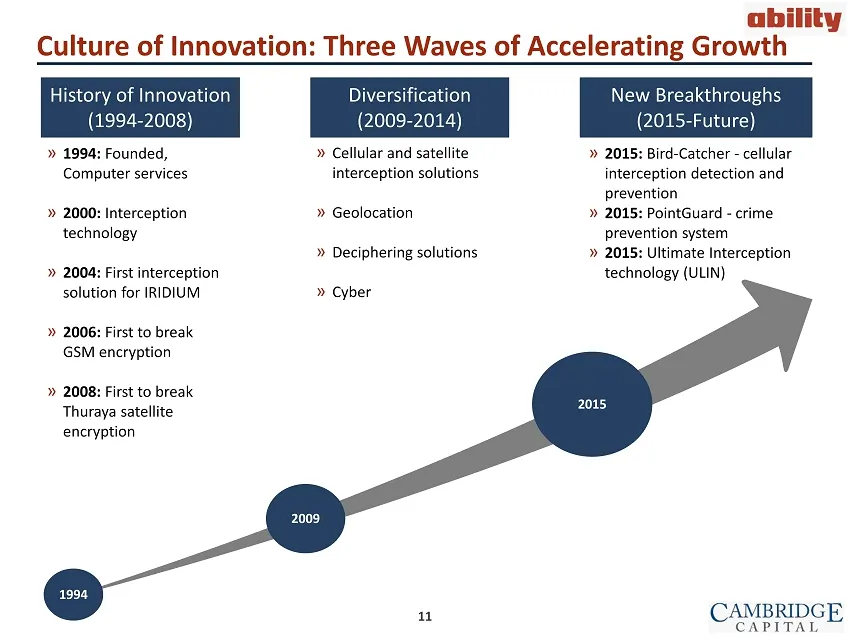
Slide 11: Culture of Innovation: Three Waves of Accelerating Growth
11 Culture of Innovation: Three Waves of Accelerating Growth » 1994: Founded, Computer services » 2000: Interception technology » 2004: First interception solution for IRIDIUM » 2006: First to break GSM encryption » 2008: First to break Thuraya satellite encryption History of Innovation (1994 - 2008
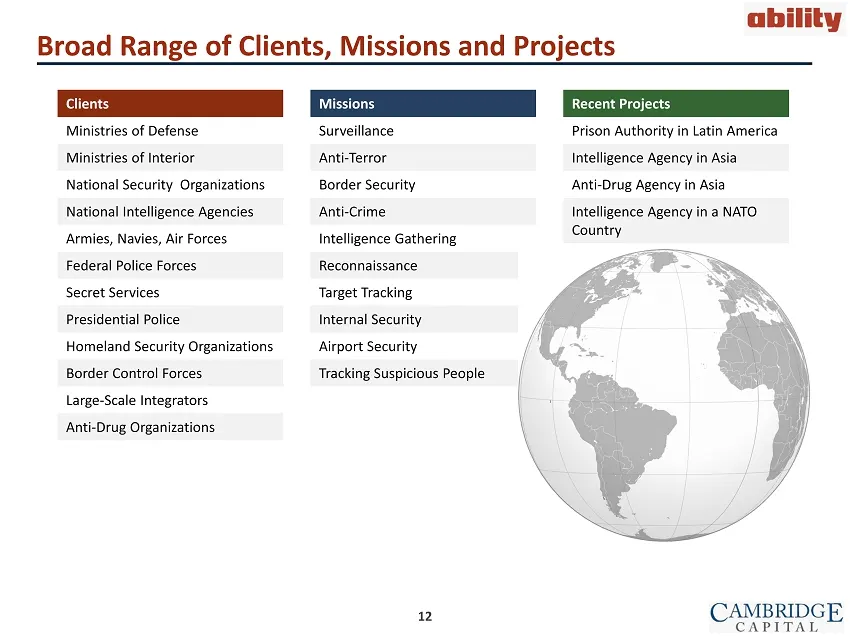
Slide 12: Broad Range of Clients, Missions and Projects
12 Missions Surveillance Anti - Terror Border Security Anti - Crime Intelligence Gathering Reconnaissance Target Tracking Internal Security Airport Security Tracking Suspicious People Clients Ministries of Defense Ministries of Interior National Security Organizations National Intelligence Agencies
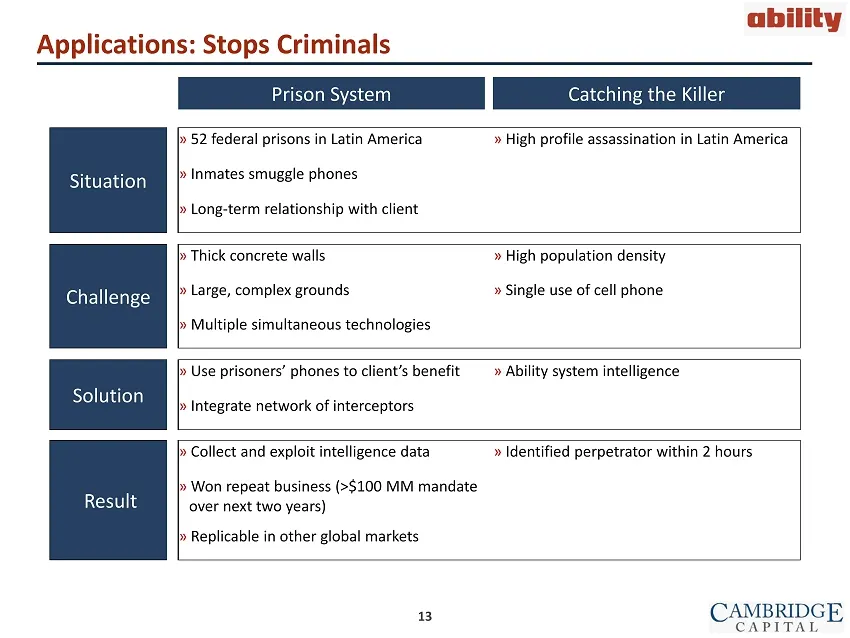
Slide 13: Applications: Stops Criminals
13 Applications: Stops Criminals Prison System Catching the Killer Situation » 52 federal prisons in Latin America » High profile assassination in Latin America » Inmates smuggle phones » Long - term relationship with client Challenge » Thick concrete walls » High population density » Large, complex
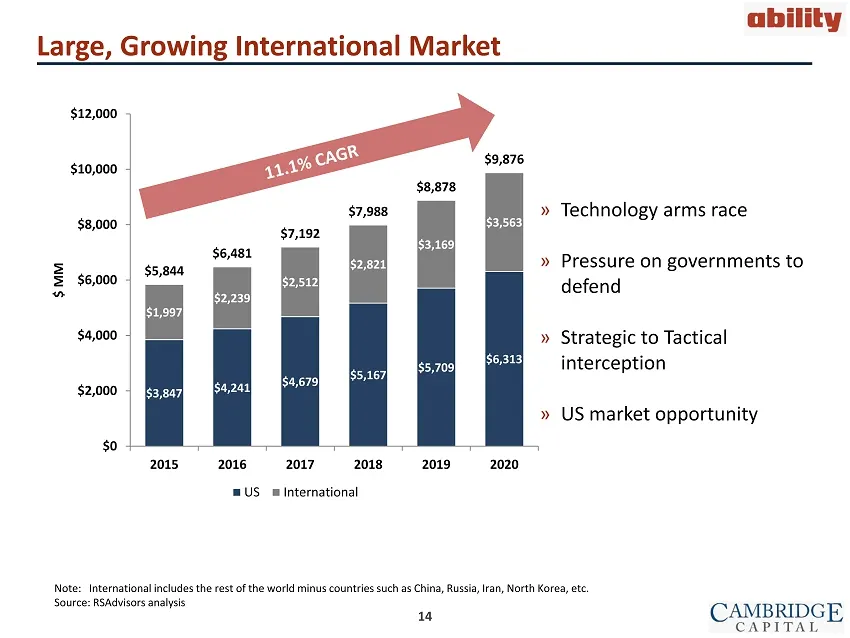
Slide 14: Large, Growing International Market
14 Large, Growing International Market $238 B $106 B $3,847 $4,241 $4,679 $5,167 $5,709 $6,313 $1,997 $2,239 $2,512 $2,821 $3,169 $3,563 $5,844 $6,481 $7,192 $7,988 $8,878 $9,876 $0 $2,000 $4,000 $6,000 $8,000 $10,000 $12,000 2015 2016 2017 2018 2019 2020 $ MM US International » Technology arms race
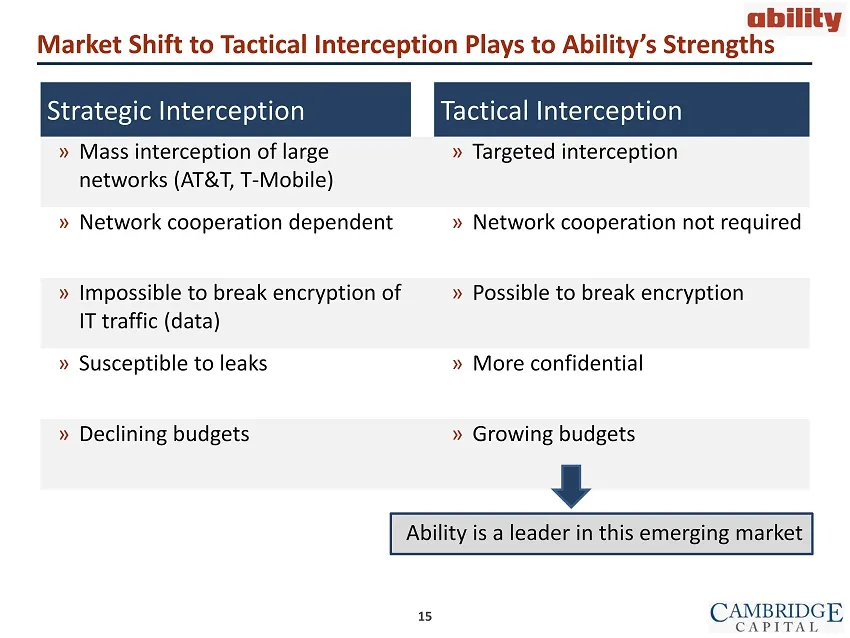
Slide 15: Market Shift to Tactical Interception Plays to Ability's Strengths
15 Strategic Interception Tactical Interception » Mass interception of large networks (AT&T, T - Mobile) » Targeted interception » Network cooperation dependent » Network cooperation not required » Impossible to break encryption of IT traffic (data) » Possible to break encryption » Susceptible to le
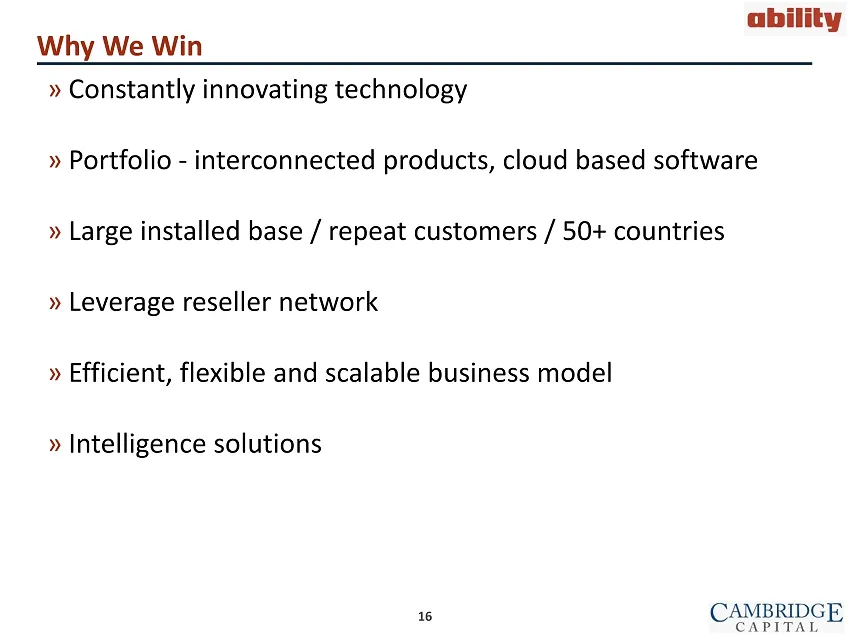
Slide 16: Why We Win
16 Why We Win » Constantly innovating technology » Portfolio - interconnected products, cloud based software » Large installed base / repeat customers / 50+ countries » Leverage reseller network » Efficient, flexible and scalable business model » Intelligence solutions
Slide 17: Strategy Will Continue to Propel Growth
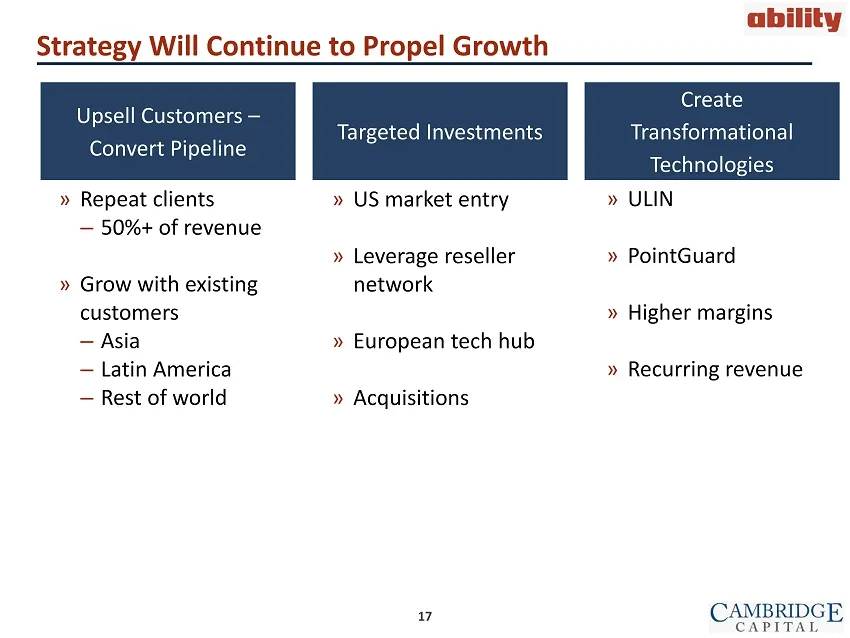
17 Strategy Will Continue to Propel Growth Upsell Customers – Convert Pipeline Targeted Investments Create Transformational Technologies » Repeat clients ‒ 50%+ of revenue » Grow with existing customers ‒ Asia ‒ Latin America ‒ Rest of world » US market entry » Leverage reseller network » European t
Slide 18: Large and Growing Pipeline
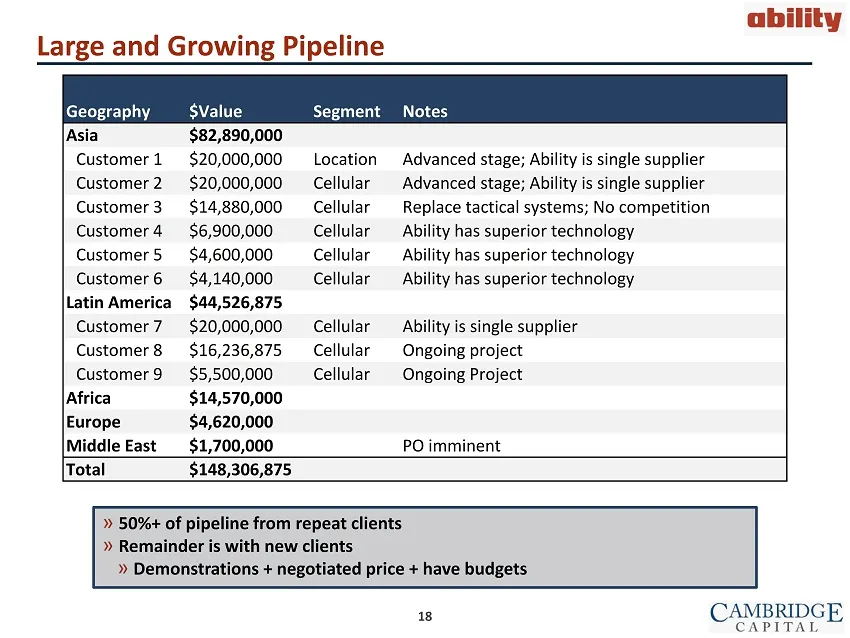
18 Large and Growing Pipeline » 50%+ of pipeline from repeat clients » Remainder is with new clients » Demonstrations + negotiated price + have budgets Geography $Value Segment Notes Asia $82,890,000 Customer 1 $20,000,000 Location Advanced stage; Ability is single supplier Customer 2 $20,000,000 Ce
Slide 19: ULIN (Ultimate Interceptor) - Transformational Technology
19 ULIN (Ultimate Interceptor) - Transformational Technology » New technology for interception of mobile devices » Unique to Ability - No known competitors » Cooperation of Network Operator (AT&T, T - Mobile) not required » Developed in house » Revenue model: – System – Software License – Maintenanc
Slide 20: Upside – Higher Margins and Recurring Revenue
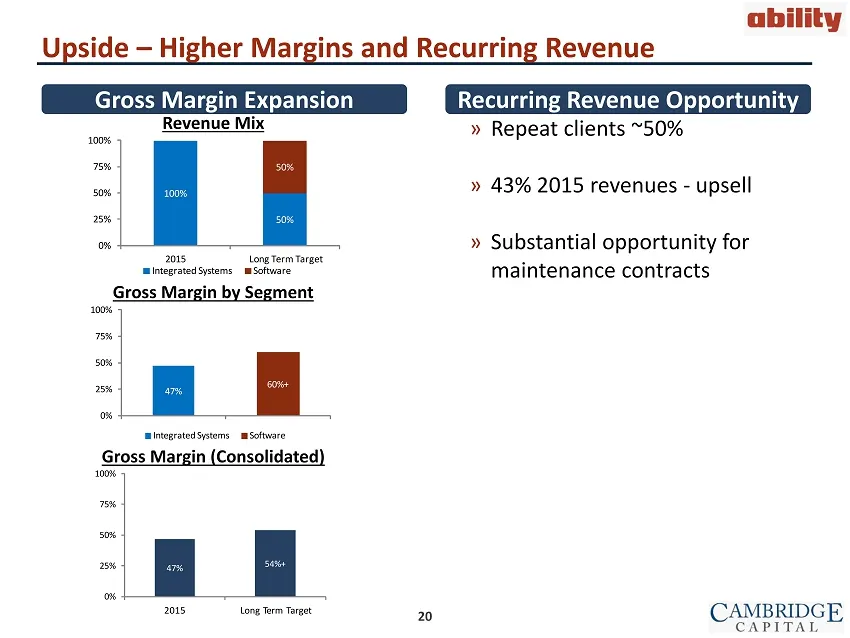
20 47% 54%+ 0% 25% 50% 75% 100% 2015 Long Term Target Blended Gross Margin 47% 60%+ 0% 25% 50% 75% 100% Integrated Systems Software Margin by Segment Integrated Systems Software 100% 50% 50% 0% 25% 50% 75% 100% 2015 Long Term Target Revenue Mix Integrated Systems Software Upside – Higher Margins and
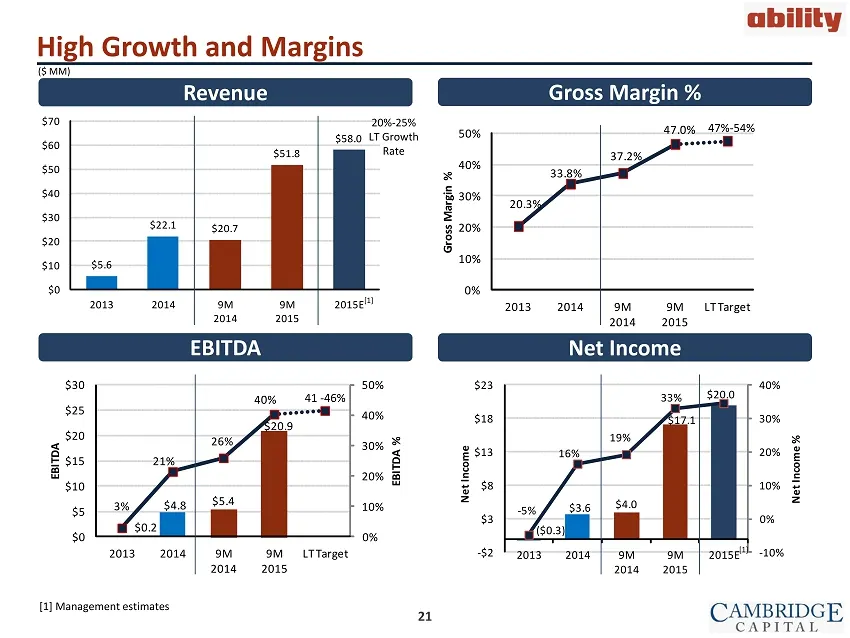
Slide 21: High Growth and Margins
21 ($0.3) $3.6 $4.0 $17.1 $20.0 - 5% 16% 19% 33% - 10% 0% 10% 20% 30% 40% - $2 $3 $8 $13 $18 $23 2013 2014 9M 2014 9M 2015 2015E Net Income % Net Income 20.3% 33.8% 37.2% 47.0% 55% - 60% 0% 10% 20% 30% 40% 50% 2013 2014 9M 2014 9M 2015 LT Target Gross Margin % $0.2 $4.8 $5.4 $20.9 3% 21% 26% 40% 45%
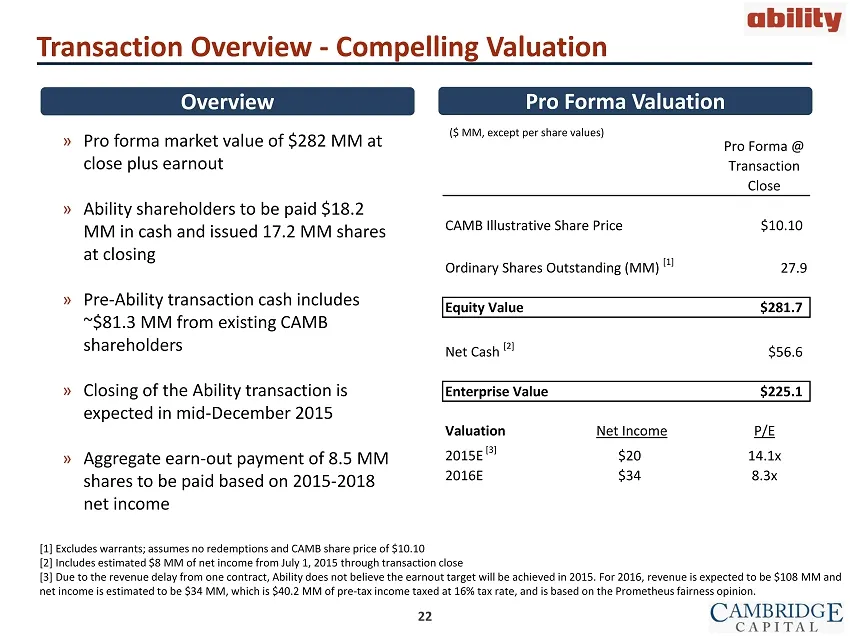
Slide 22: Transaction Overview - Compelling Valuation
22 Transaction Overview - Compelling Valuation » Pro forma market value of $282 MM at close plus earnout » Ability shareholders to be paid $18.2 MM in cash and issued 17.2 MM shares at closing » Pre - Ability transaction cash includes ~$81.3 MM from existing CAMB shareholders » Closing of the Abilit
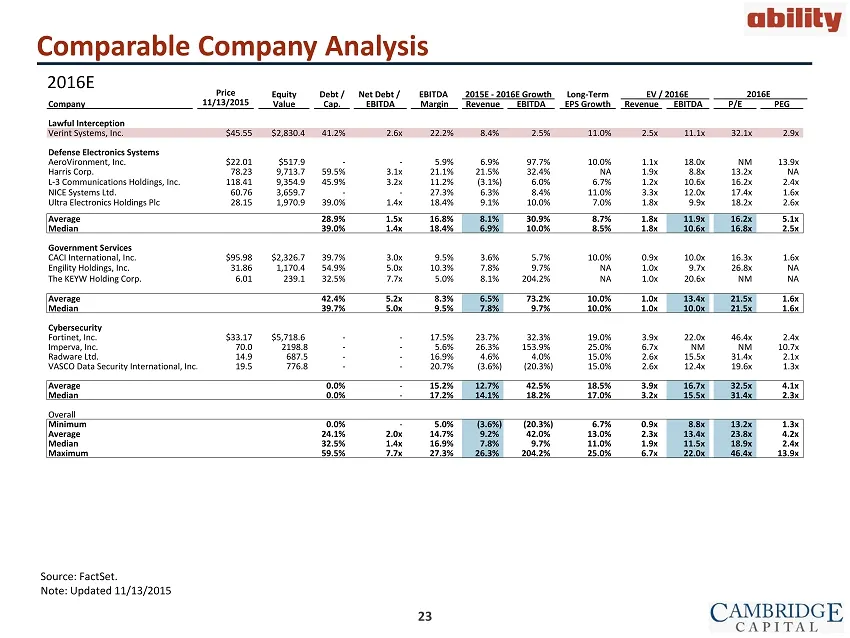
Slide 23: Comparable Company Analysis
23 Comparable Company Analysis 2016E Source: FactSet . Note: Updated 11/13/2015 Price Equity Debt / Net Debt / EBITDA 2015E - 2016E Growth Long-Term EV / 2016E Company 11/13/2015 Value Cap. EBITDA Margin Revenue EBITDA EPS Growth Revenue EBITDA P/E PEG Lawful Interception Verint Systems, Inc. $45.55
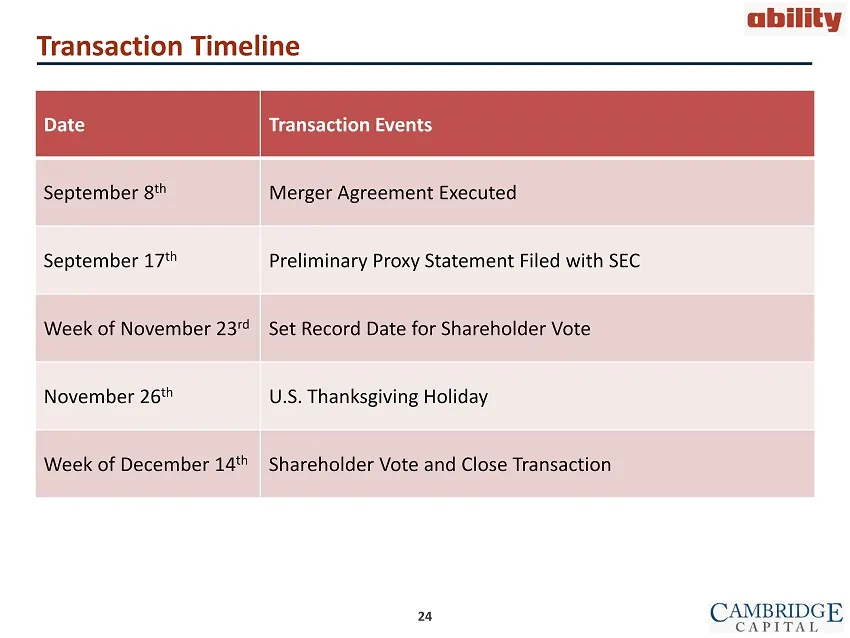
Slide 24: Transaction Timeline
24 Transaction Timeline Date Transaction Events September 8 th Merger Agreement Executed September 17 th Preliminary Proxy Statement Filed with SEC Week of November 23 rd Set Record Date for Shareholder Vote November 26 th U.S. Thanksgiving Holiday Week of December 14 th Shareholder Vote and Close T
Slide 25: Appendix
25 Appendix
Slide 26: Large, Growing Market
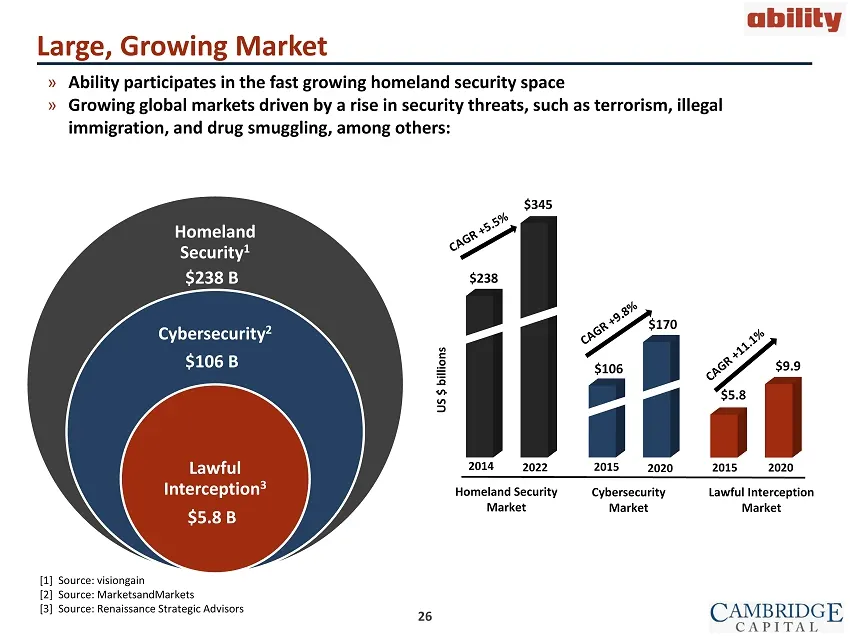
26 Large, Growing Market » Ability participates in the fast growing homeland security space » Growing global markets driven by a rise in security threats, such as terrorism, illegal immigration, and drug smuggling, among others: Homeland Security 1 Cybersecurity 2 Lawful Interception 3 $238 B $106 B
Slide 27: Expanded growth strategy targeting the Commercial Market
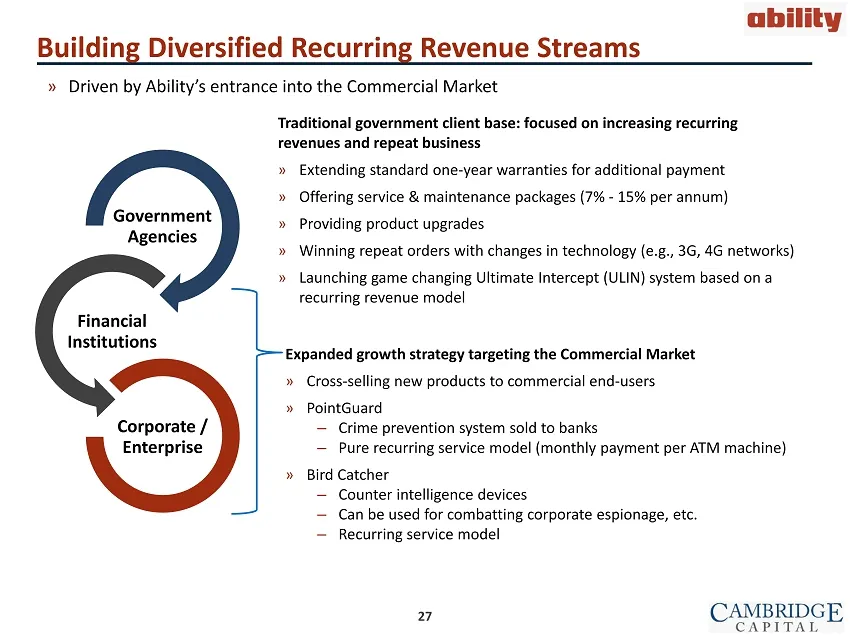
27 Government Agencies Financial Institutions Corporate / Enterprise Expanded growth strategy targeting the Commercial Market » Cross - selling new products to commercial end - users » PointGuard – Crime prevention system sold to banks – Pure recurring service model (monthly payment per ATM machine)
Slide 28: The United States
28 The United States » A huge, untapped market opportunity for Ability » The U.S. lawful interception sector is projected to grow from $3.8 billion in 2015 to $6.3 billion in 2020. » Ability understands the strategic importance of addressing this significant market . » Currently in discussions with
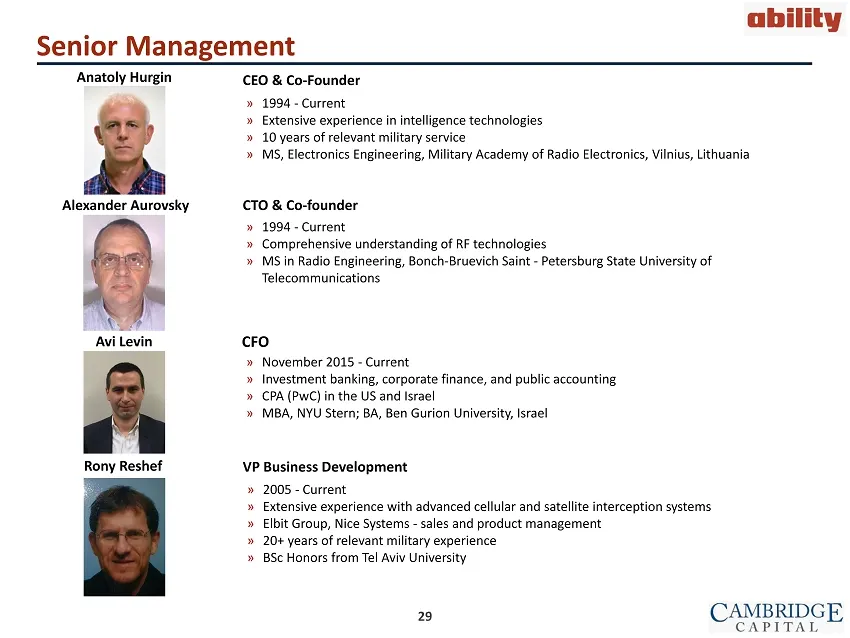
Slide 29: Senior Management
29 Senior Management » 1994 - Current » Comprehensive understanding of RF technologies » MS in Radio Engineering, Bonch - Bruevich Saint - Petersburg State University of Telecommunications Alexander Aurovsky » 2005 - Current » Extensive experience with advanced cellular and satellite interception sy
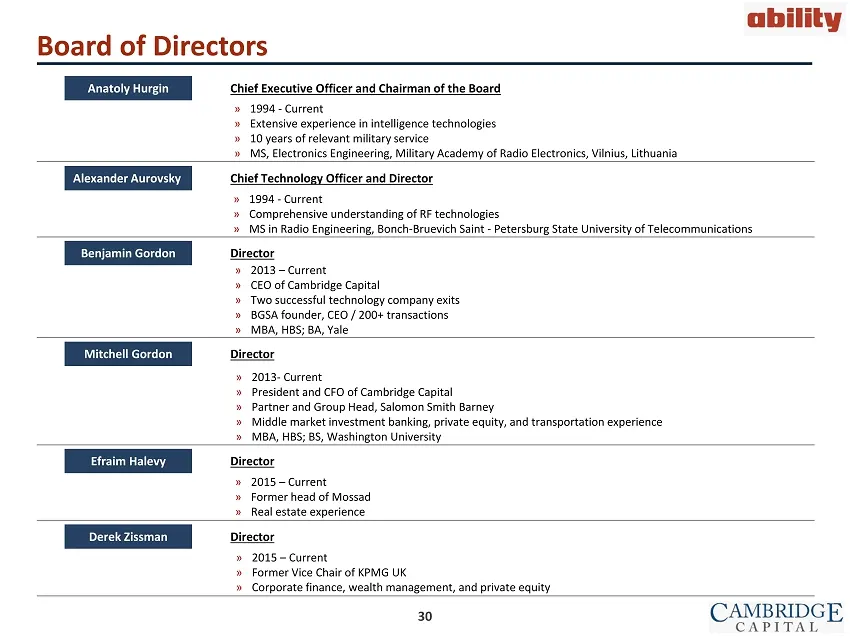
Slide 30: Board of Directors
30 Board of Directors » 1994 - Current » Comprehensive understanding of RF technologies » MS in Radio Engineering, Bonch - Bruevich Saint - Petersburg State University of Telecommunications Alexander Aurovsky » 2013 - Current » President and CFO of Cambridge Capital » Partner and Group Head, Salomon
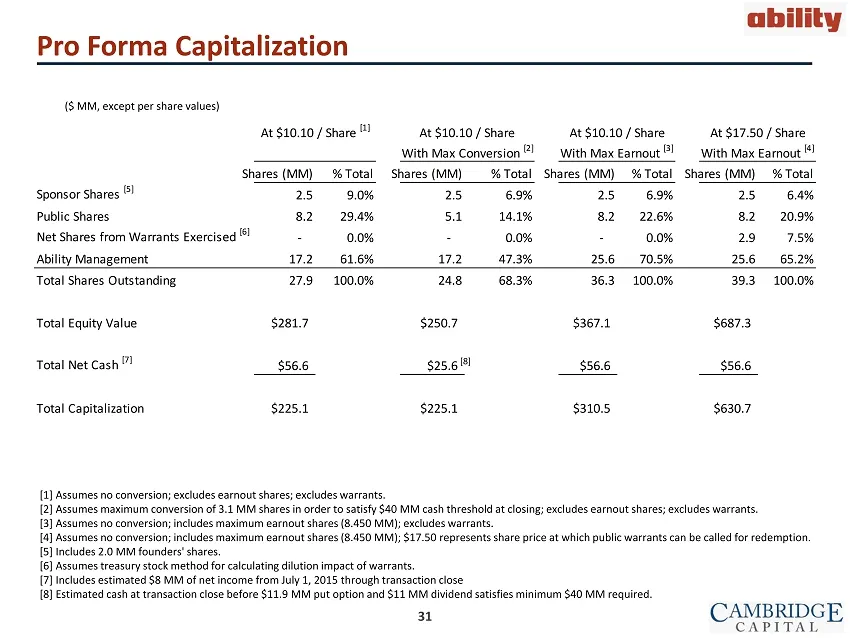
Slide 31: Pro Forma Capitalization
ability Pro Forma Capitalization (S MM, except per share values) ‘At $10.10 / Share ‘At $10.10 / Share ‘At $10.10 / Share ‘At $17.50 / Share With Max Conversion! with Max Eamout ! with Max Earnout Shares (MM) _9%Total Shares (MM) __% Total Shares (MM) _% Total Shares (MM) _% Total Sponsor Shares ‘I
Source: SEC EDGAR · 8-K/A filed Nov 16, 2015
More decks from Cambridge Capital Acquisition Corp
 SPAC Merger (November 2015)32 slides · Nov 30, 2015
 SPAC Merger (September 2015)24 slides · Sep 30, 2015
 SPAC Merger (September 2015)22 slides · Sep 23, 2015
 SPAC Merger (September 2015)31 slides · Sep 23, 2015
 SPAC Merger (March 2015)27 slides · Mar 30, 2015
 SPAC Merger (March 2015)27 slides · Mar 4, 2015