K+s AG · XETR:SDF
K+s — K+S Aktiengesellschaft — Investor Day (November 2015)
18 slides from K+s's investor day presentation, Nov 12, 2015
Slide 1: Tough in Rough Times
K+S Aktiengesellschaft Tough in Rough Times Capital Markets Day Merkers - November 12th, 2015 Dr. Andreas Radmacher, Business Unit Potash and Magnesium Products
Slide 2: The Potash Market: It's complicated... but!
K+S Potash and Magnesium Products The Potash Market It‘s complicated ... ... but! Industry facing supply side driven Long-term dynamics remain positive for challenges fertilizers increasing capacities Continued demand growth makes the fragmentation of the industry potash market still an at
Slide 3: Supplier Structure on the World Potash Market
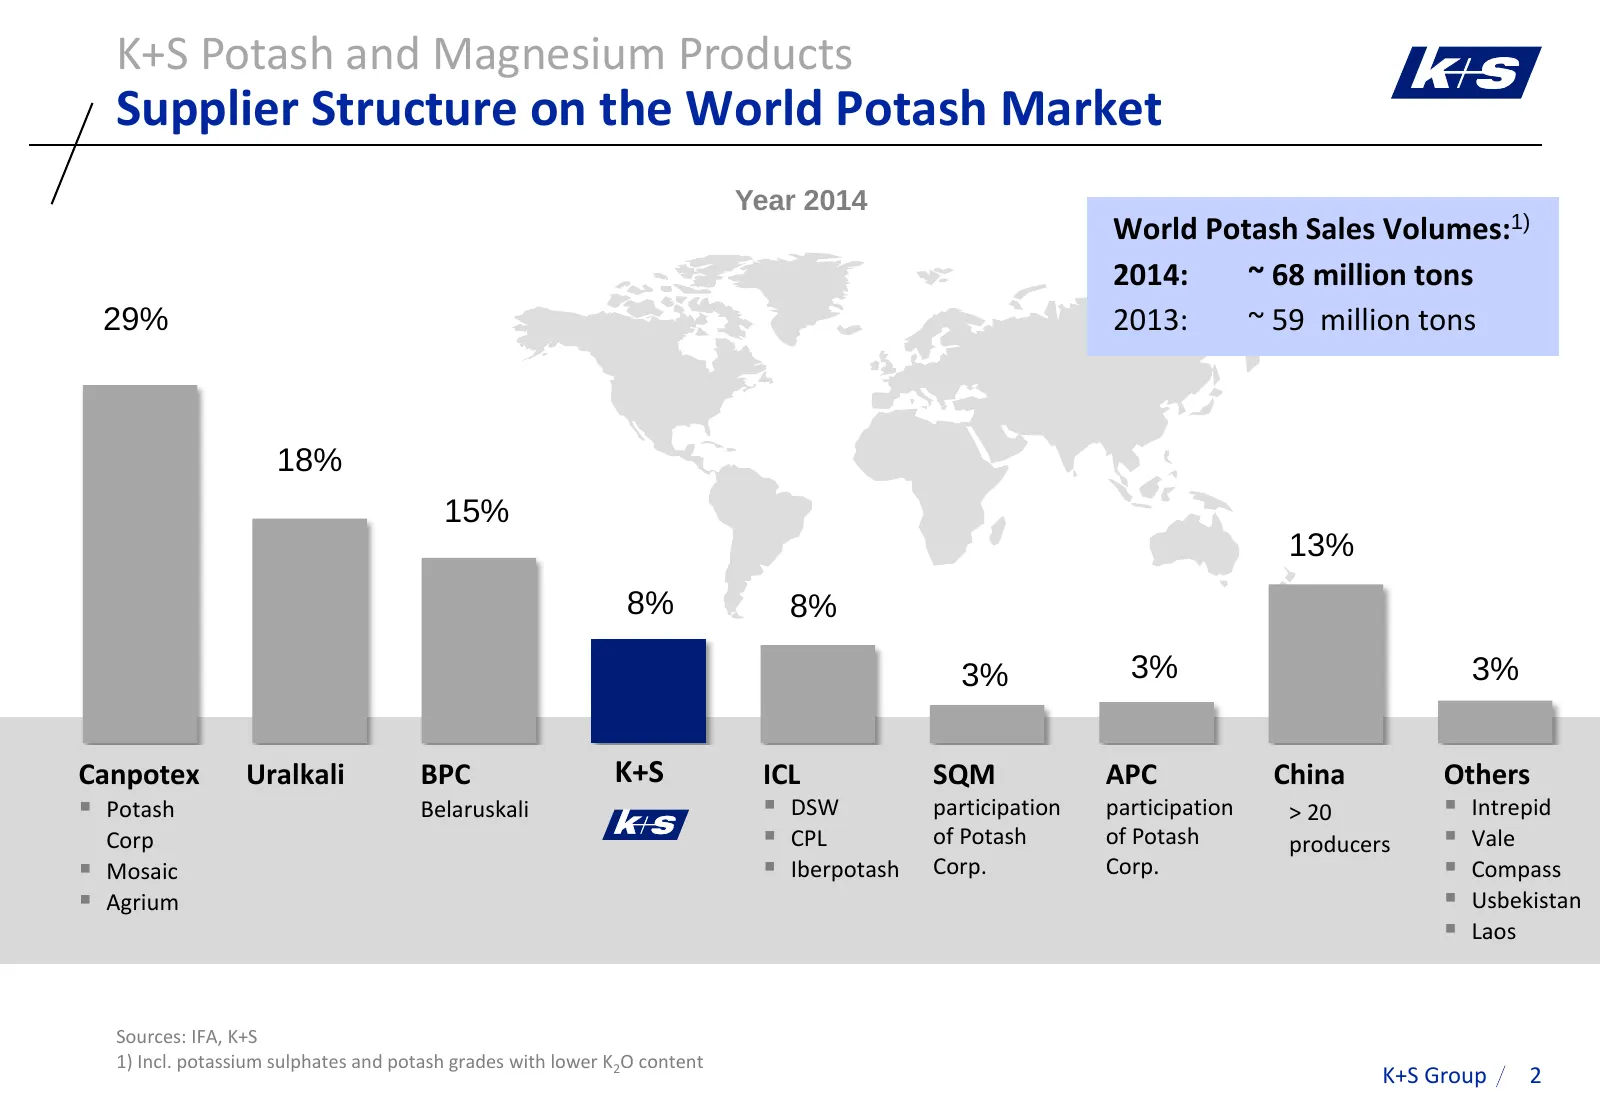
K+S Potash and Magnesium Products Supplier Structure on the World Potash Market Year 2014 World Potash Sales Volumes:1) 2014: ~ 68 million tons 29% 2013: ~ 59 million tons 18% 15% 13% 8% 8% 3% 3% 3% Canpotex Uralkali BPC K+S ICL SQM APC China Others Potash Belaruskali DSW participation participa
Slide 4: Increasing Capacities & Higher Fragmentation
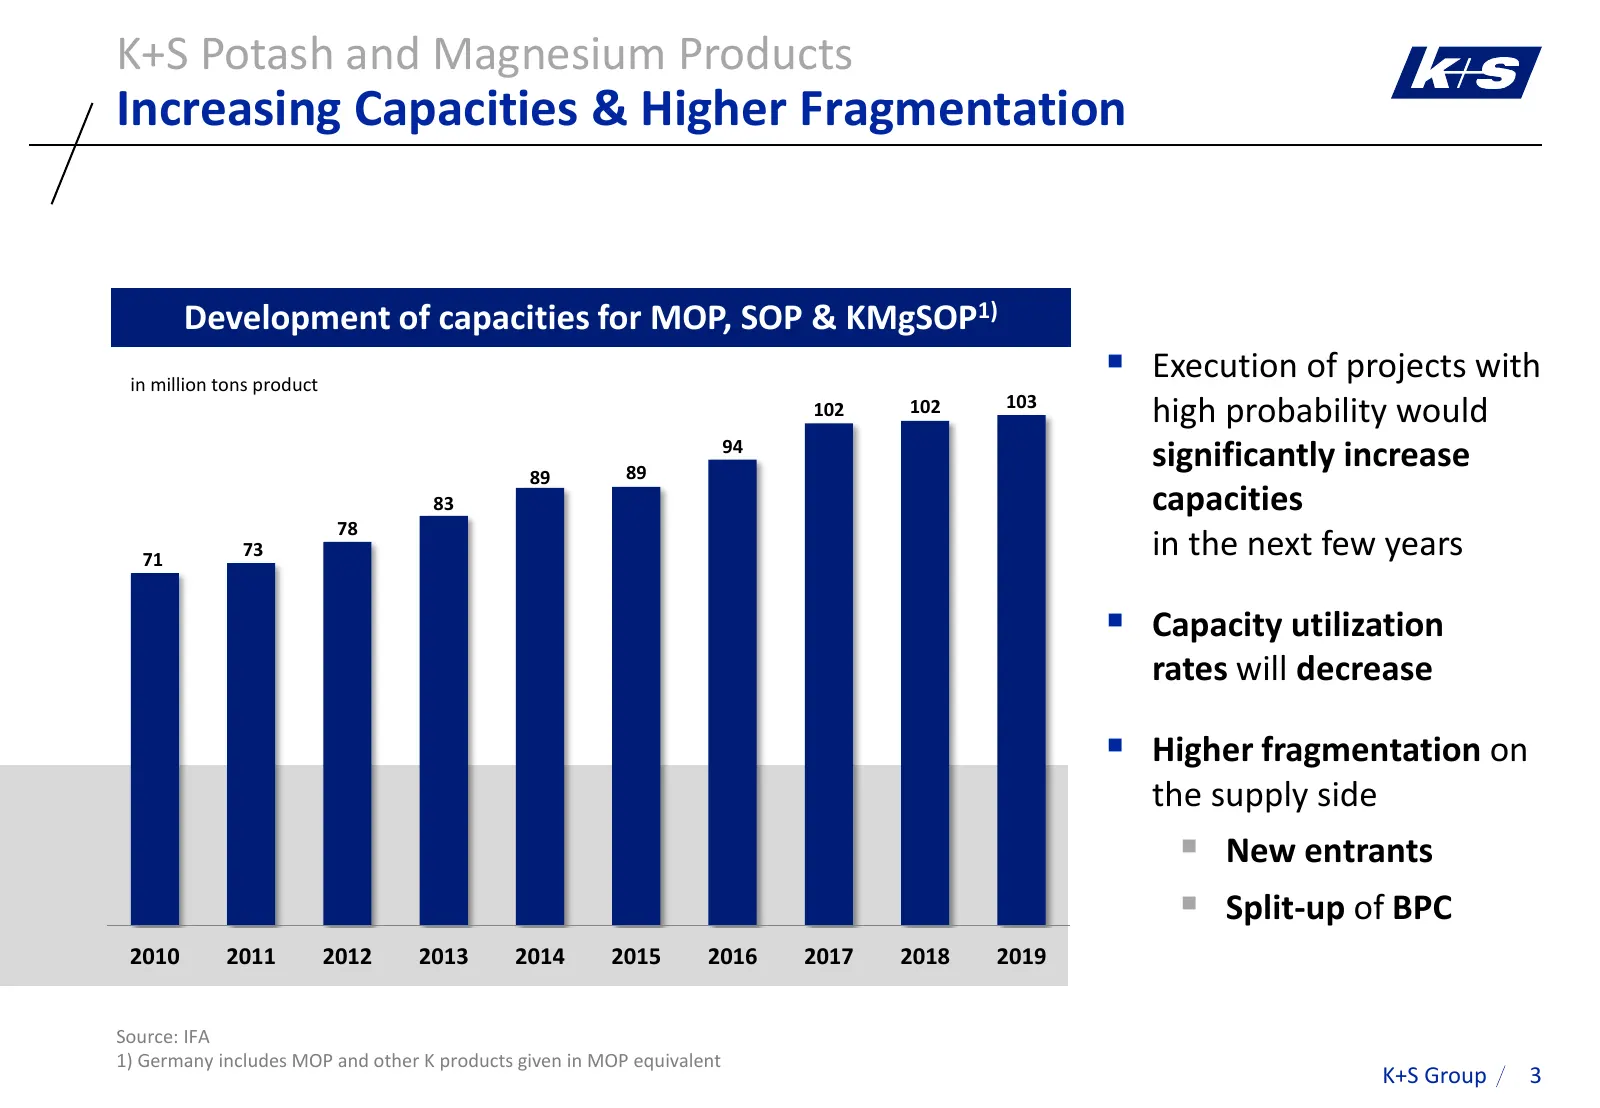
K+S Potash and Magnesium Products Increasing Capacities & Higher Fragmentation Development of capacities for MOP, SOP & KMgSOP1) in million tons product Execution of projects with 103 102 102 high probability would 94 89 89 significantly increase 83 capacities 78 71 73 in the next few years Capa
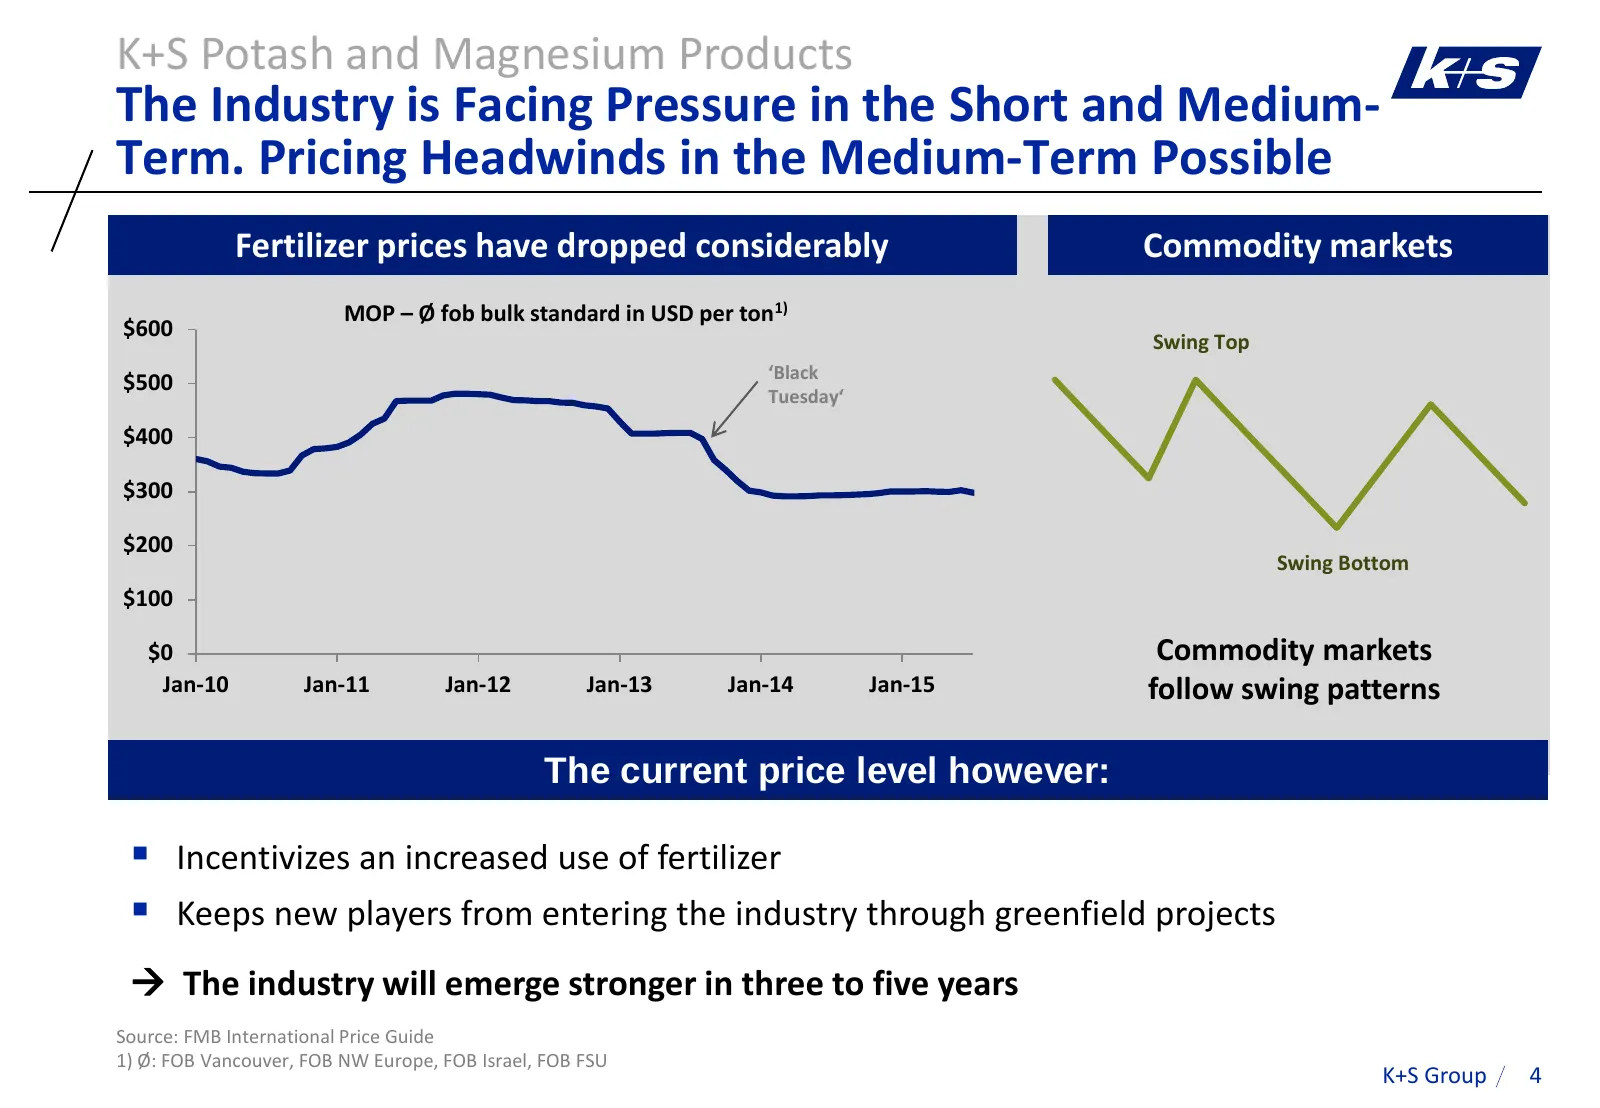
Slide 5: The Industry is Facing Pressure in the Short and Medium-Term
K+S Potash and Magnesium Products The Industry is Facing Pressure in the Short and Medium- Term. Pricing Headwinds in the Medium-Term Possible Fertilizer prices have dropped considerably Commodity markets MOP – Ø fob bulk standard in USD per ton1) $600 Swing Top ‘Black $500 Tuesday‘ $400 $300 $200 S
Slide 6: The Potash Market: It's complicated... but!
K+S Potash and Magnesium Products The Potash Market It‘s complicated ... ... but! Industry facing supply side driven Long-term dynamics remain positive for challenges fertilizers increasing capacities Continued demand growth makes the fragmentation of the industry potash market still an at
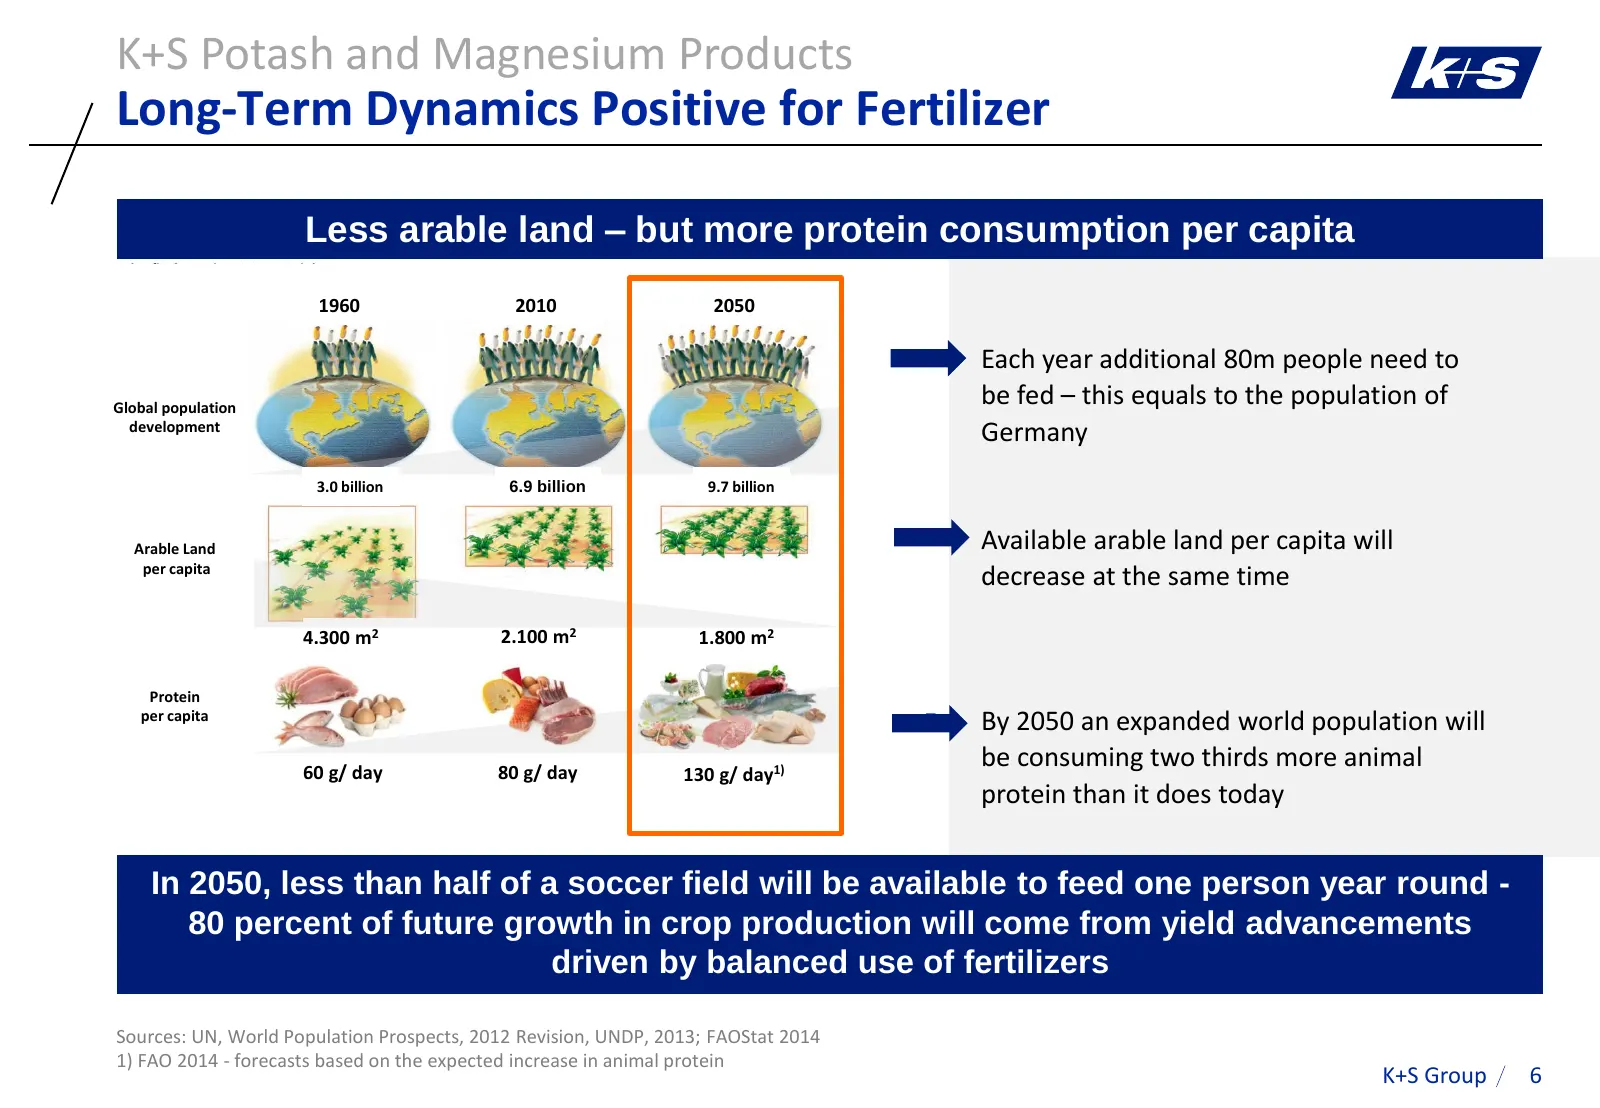
Slide 7: Long-Term Dynamics Positive for Fertilizer
K+S Potash and Magnesium Products Long-Term Dynamics Positive for Fertilizer Less arable land – but more protein consumption per capita Jahr 1960 2010 2050 Each year additional 80m people need to Global population be fed – this equals to the population of development Germany 3.0 billion 6.9 billio
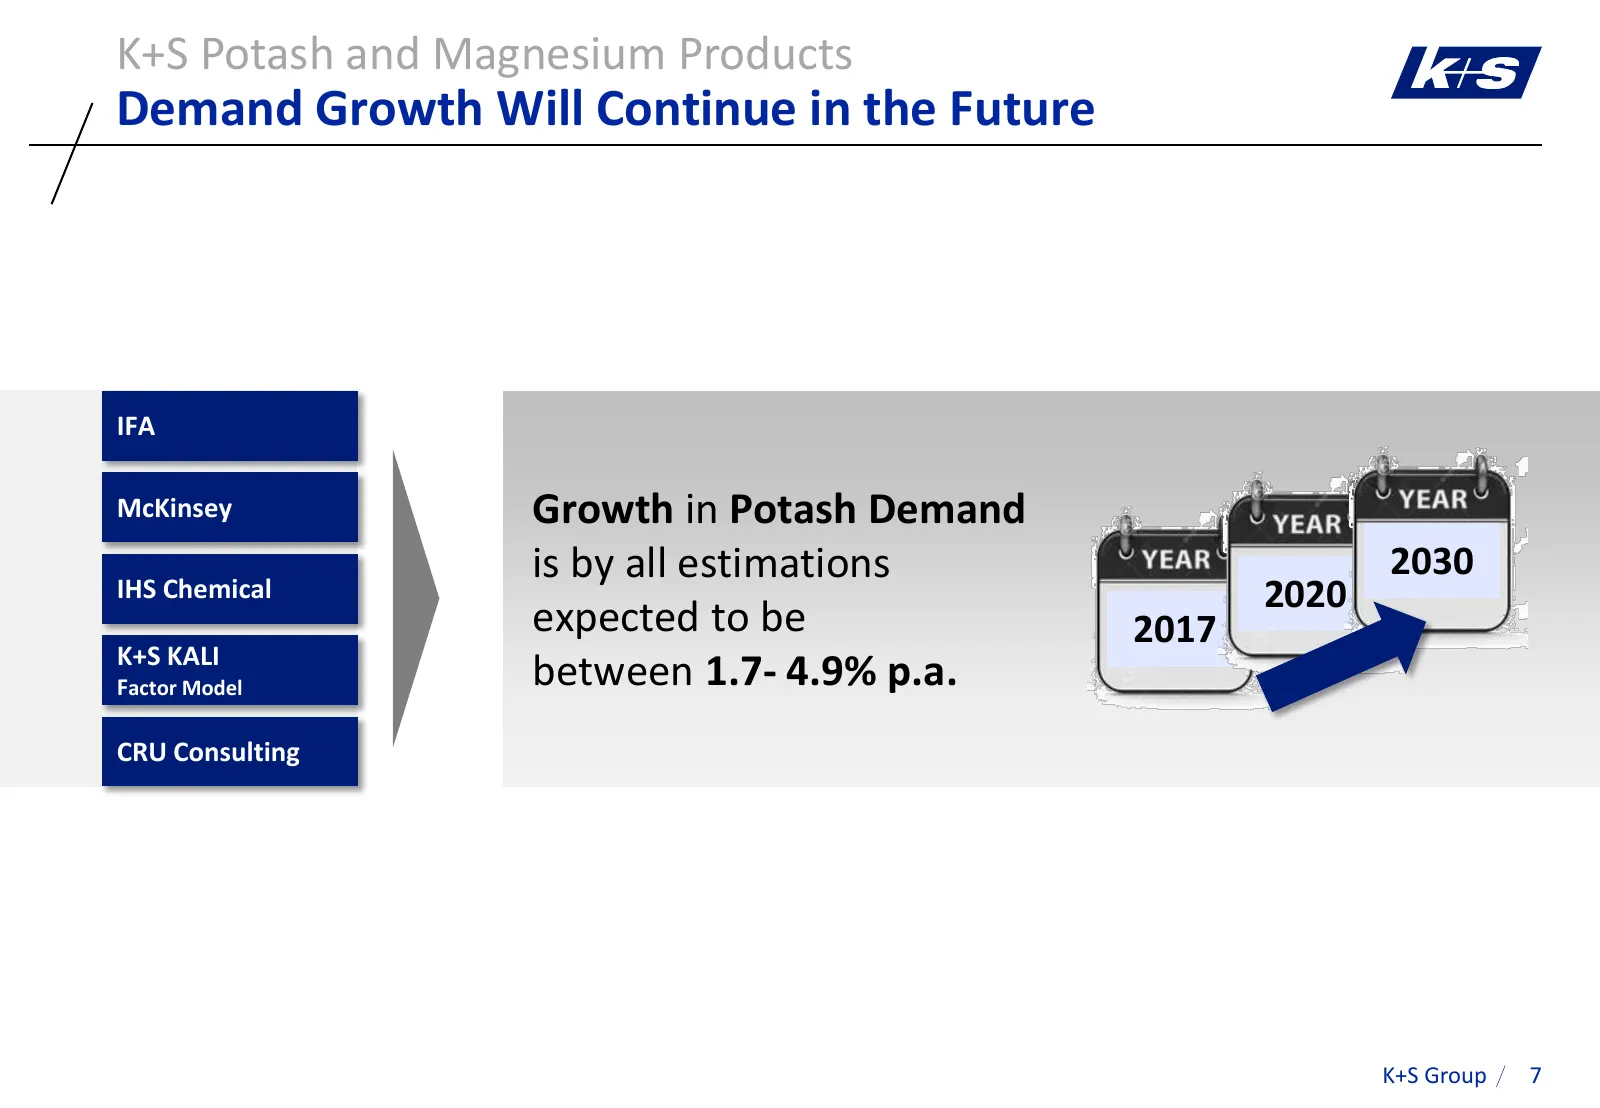
Slide 8: Demand Growth Will Continue in the Future
K+S Potash and Magnesium Products Demand Growth Will Continue in the Future IFA McKinsey Growth in Potash Demand is by all estimations 2030 IHS Chemical 2020 expected to be 2017 K+S KALI Factor Model between 1.7- 4.9% p.a. CRU Consulting K+S Group 7
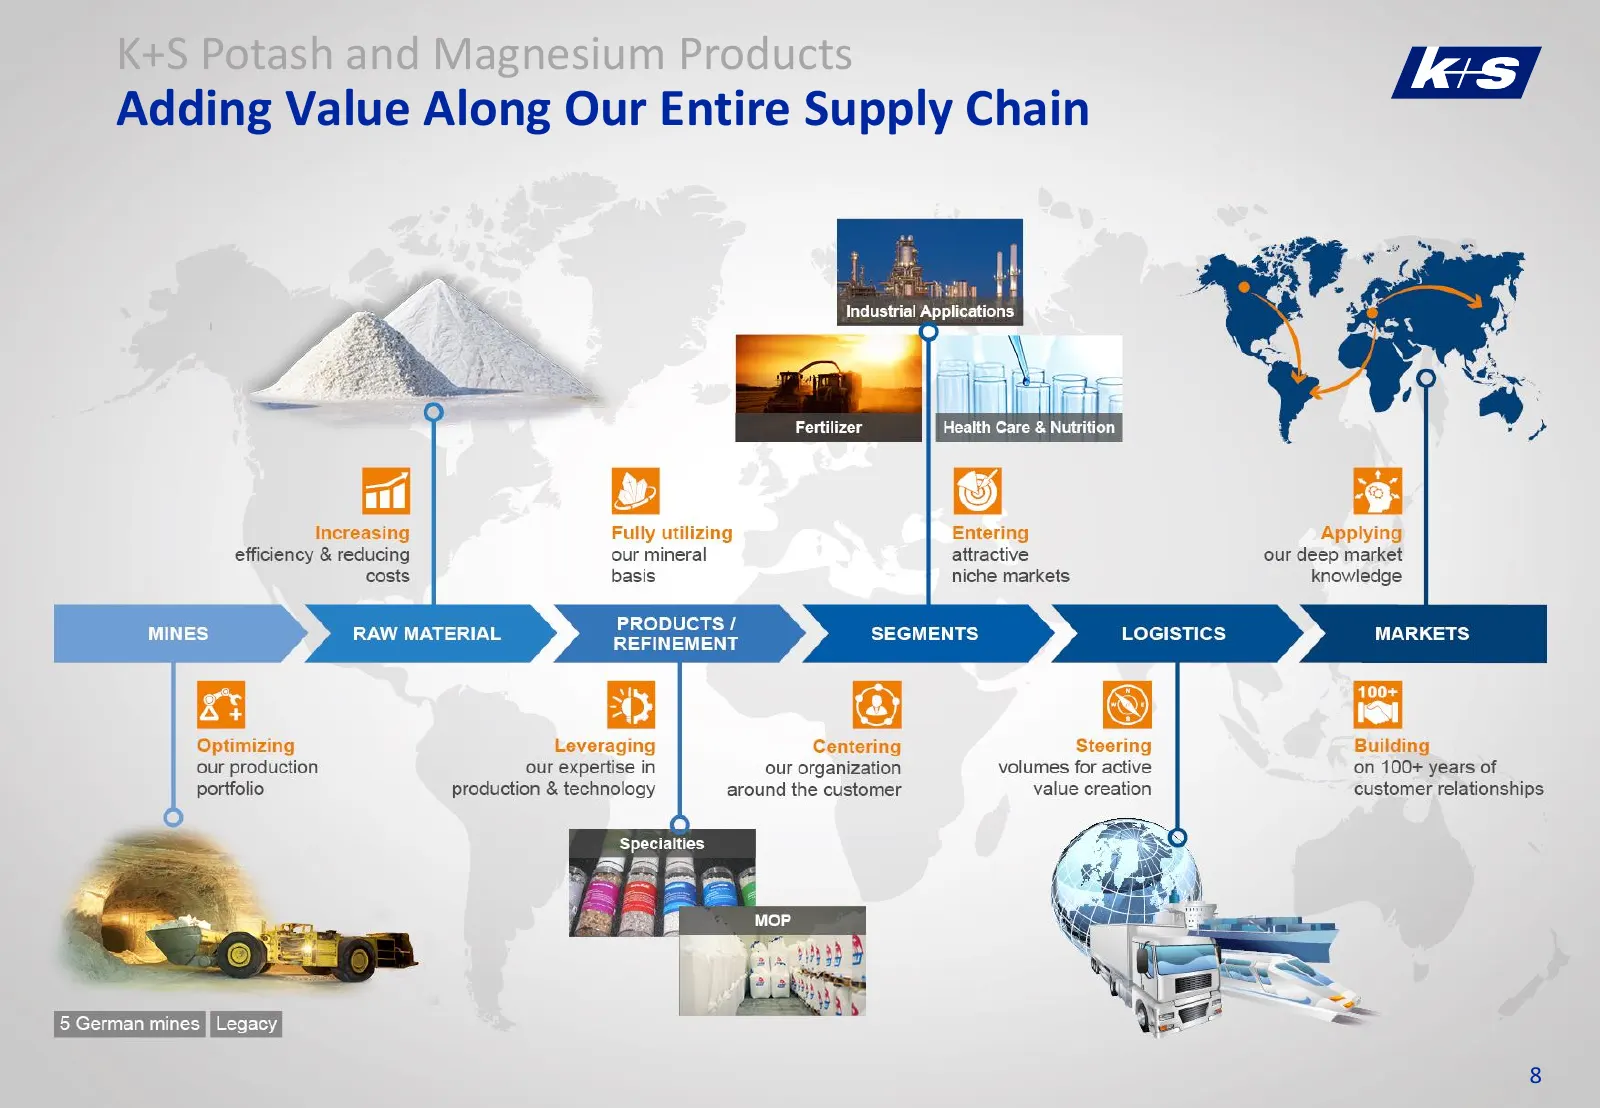
Slide 9: Adding Value Along Our Entire Supply Chain
K+S Potash and Magnesium Products Adding Value Along Our Entire Supply Chain K+S Group 8
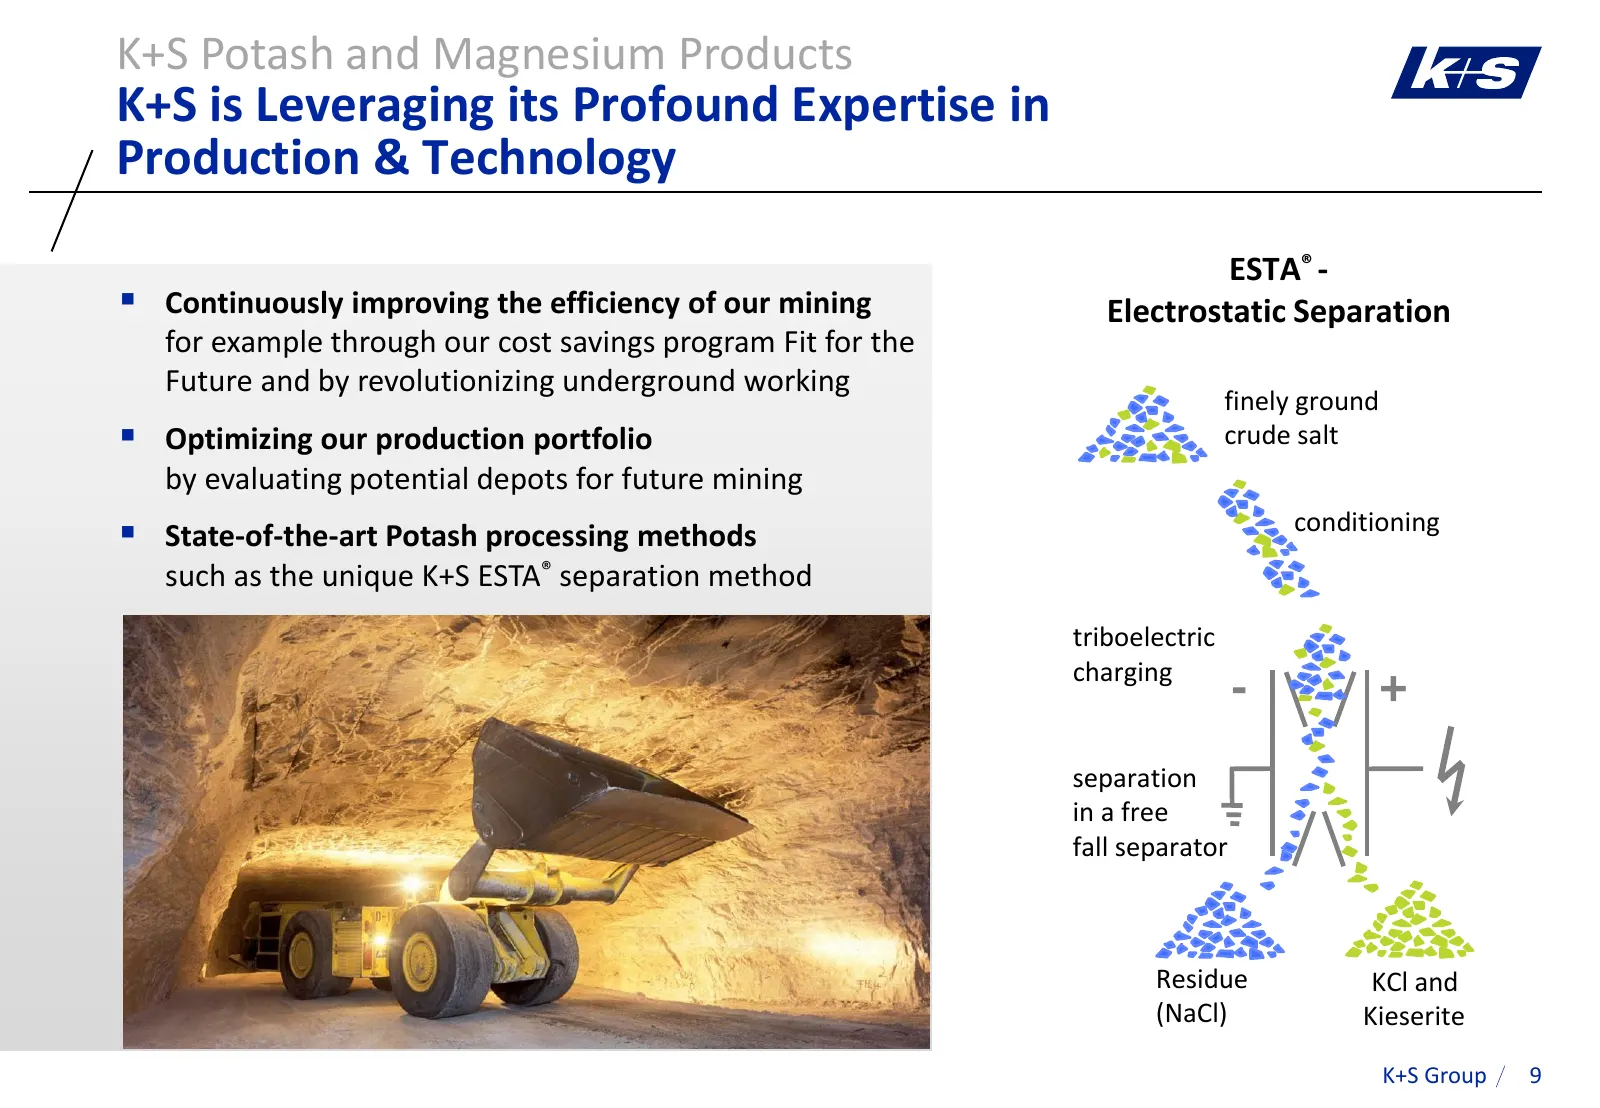
Slide 10: Leveraging Expertise in Production & Technology
K+S Potash and Magnesium Products K+S is Leveraging its Profound Expertise in Production & Technology ESTA® - Continuously improving the efficiency of our mining Electrostatic Separation for example through our cost savings program Fit for the Future and by revolutionizing underground working fine
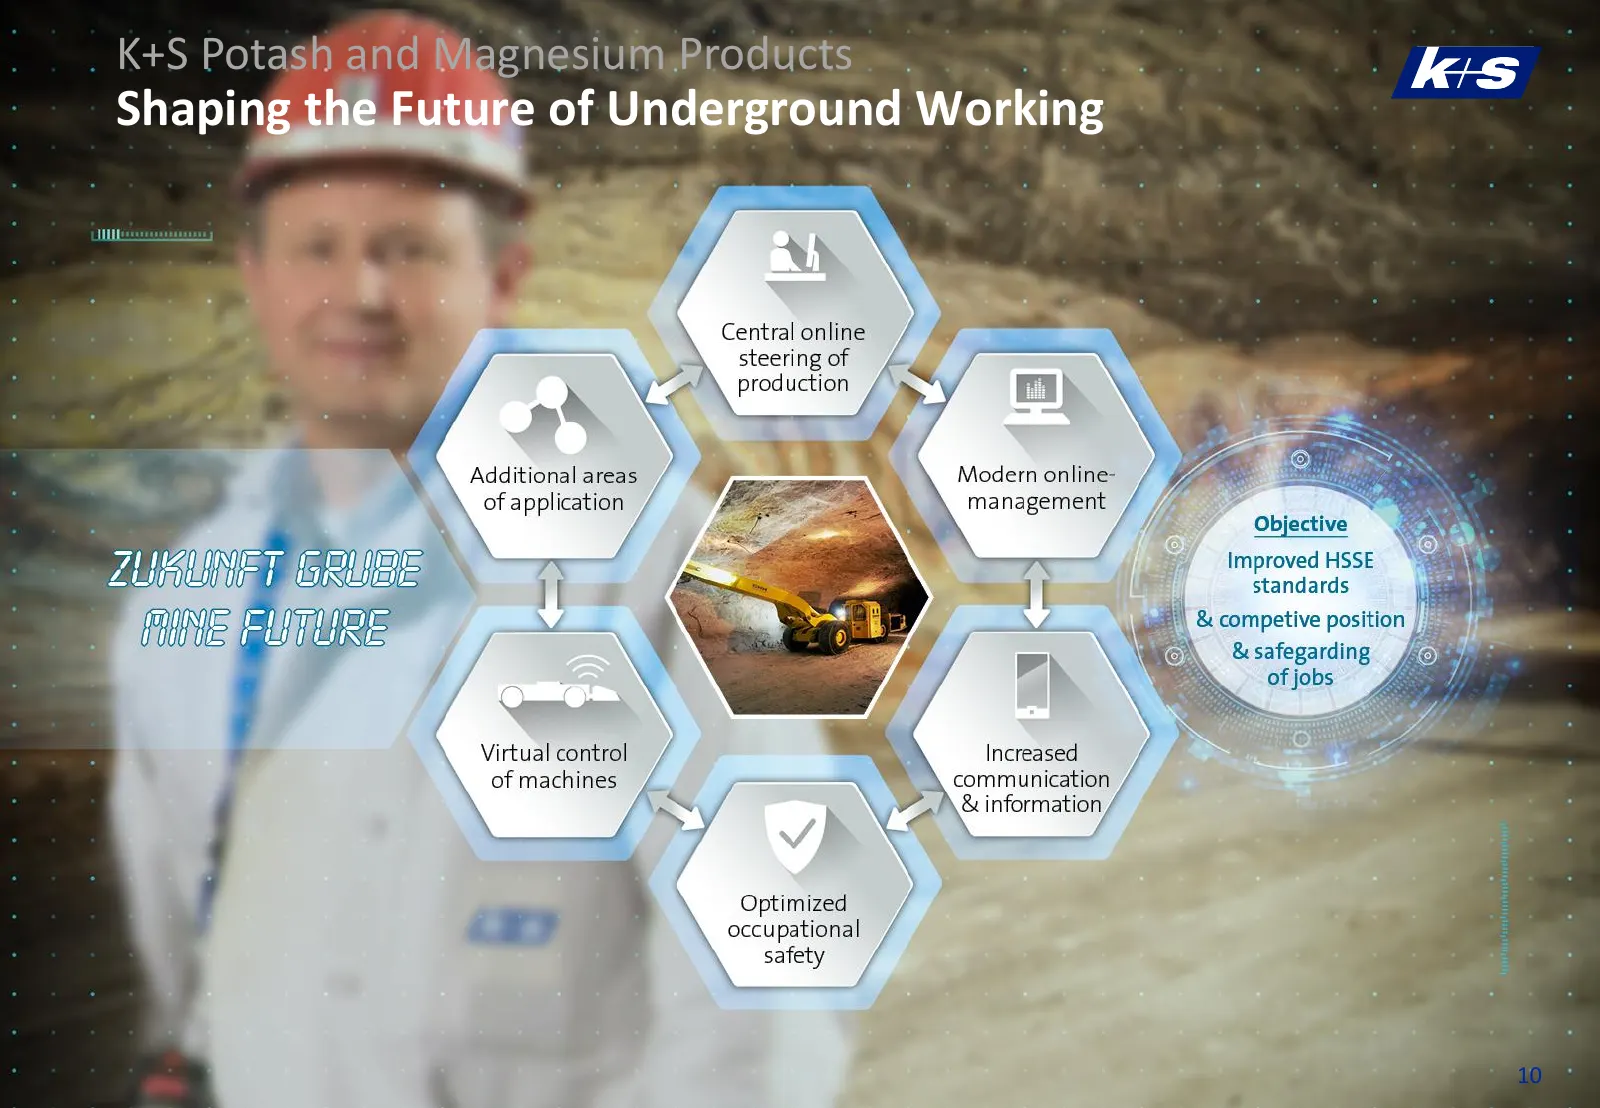
Slide 11: Shaping the Future of Underground Working
K+S Potash and Magnesium Products Shaping the Future of Underground Working K+S Group 10
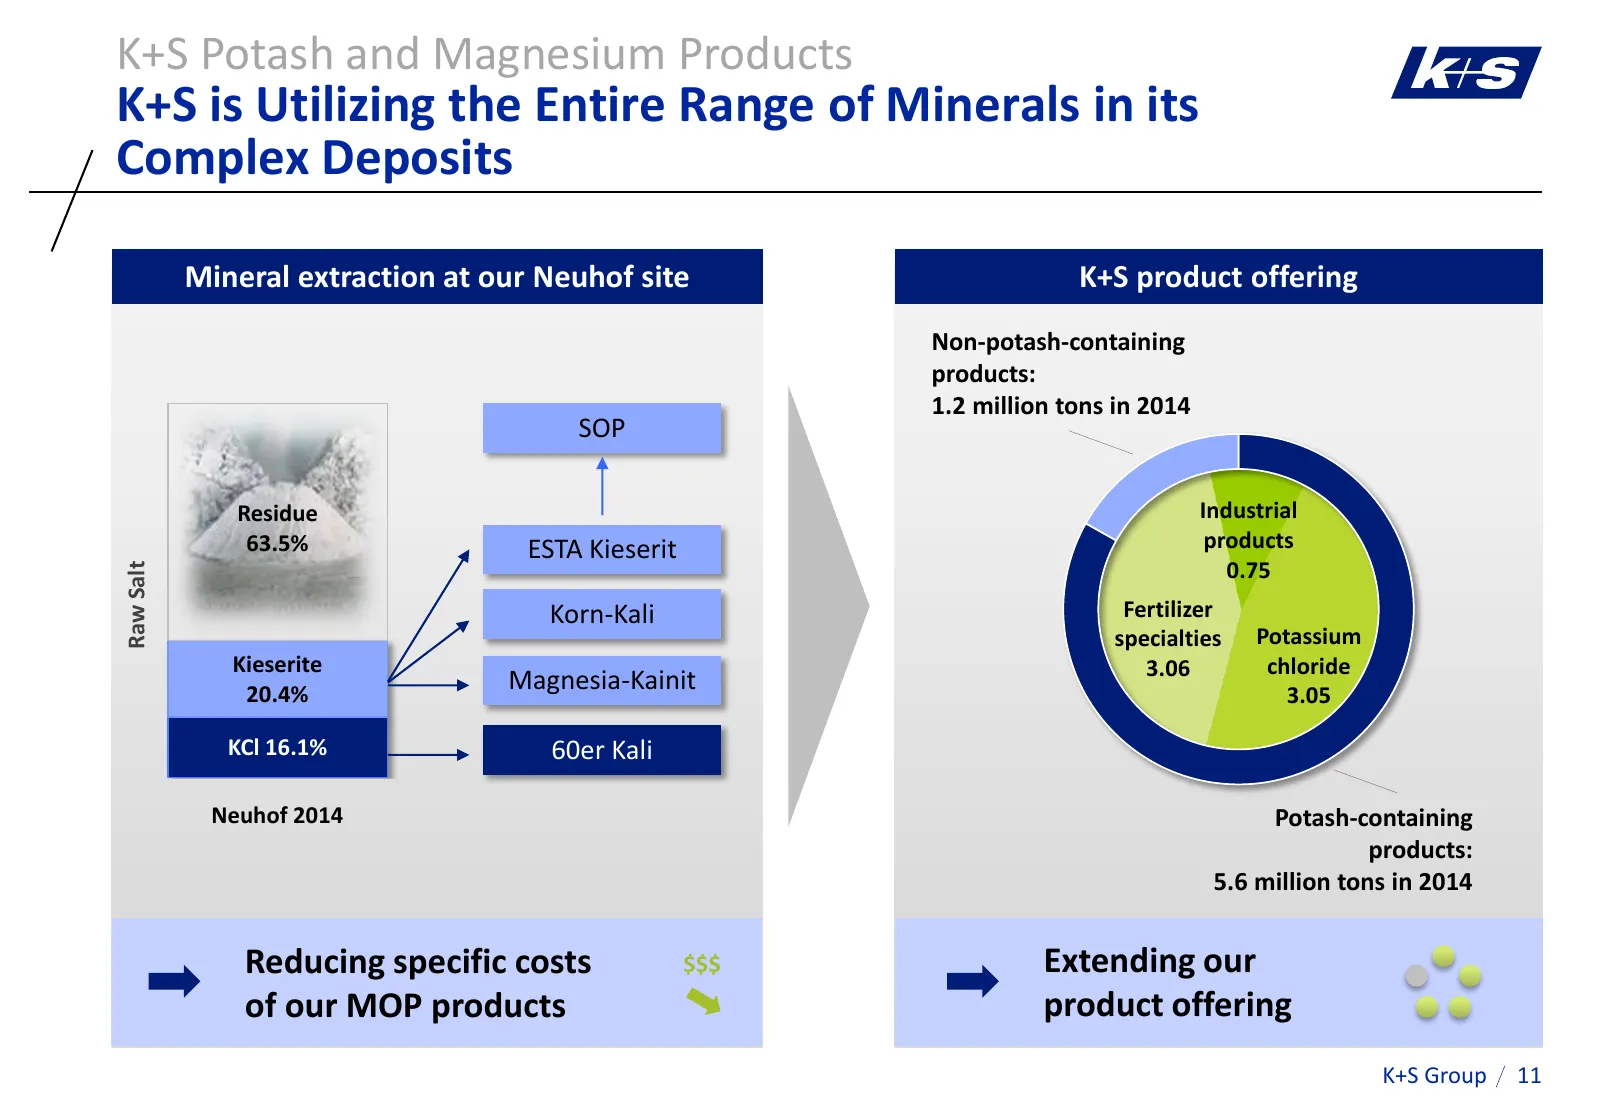
Slide 12: Utilizing the Entire Range of Minerals in Complex Deposits
K+S Potash and Magnesium Products K+S is Utilizing the Entire Range of Minerals in its Complex Deposits Mineral extraction at our Neuhof site K+S product offering Non-potash-containing products: 1.2 million tons in 2014 SOP Residue Industrial 63.5% ESTA Kieserit products 0.75 Raw Salt Korn-Kali Fert
Slide 13: Decoupling from Commodity Volatility with Specialties
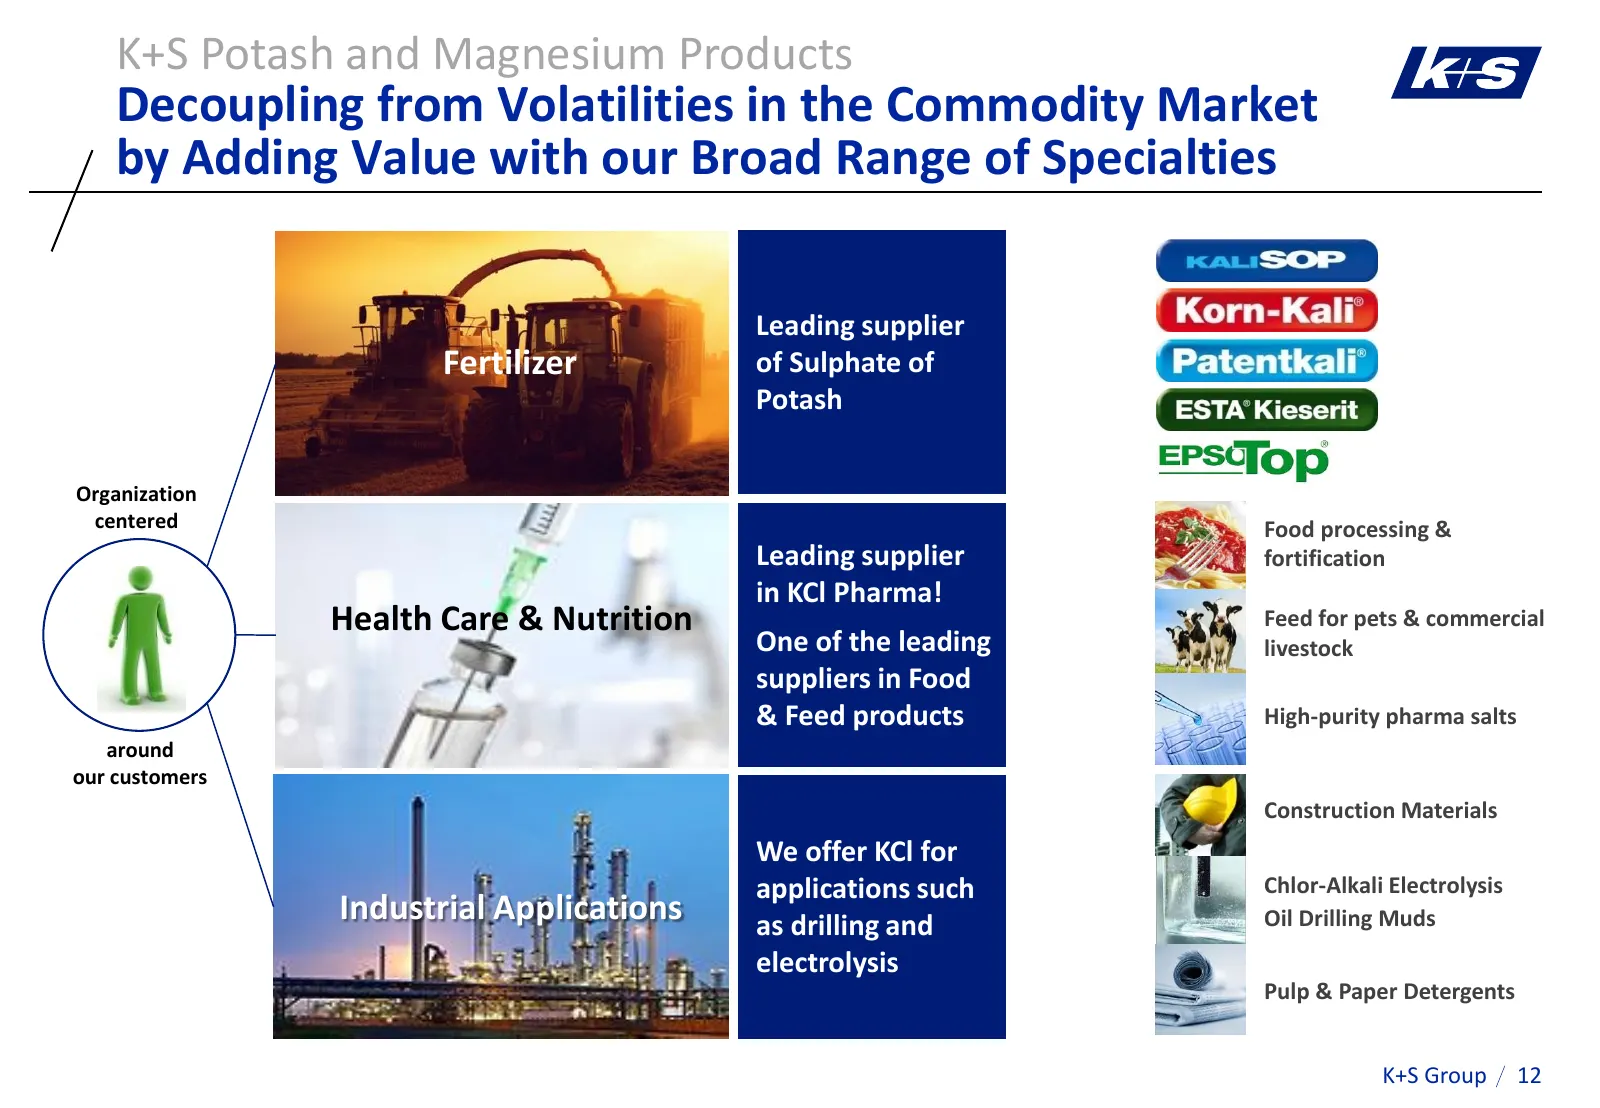
K+S Potash and Magnesium Products Decoupling from Volatilities in the Commodity Market by Adding Value with our Broad Range of Specialties Leading supplier Fertilizer of Sulphate of Potash Organization centered Food processing & Leading supplier fortification in KCl Pharma! Health Care & Nutrition F
Slide 14: Strong Presence in the Drilling Additive Market
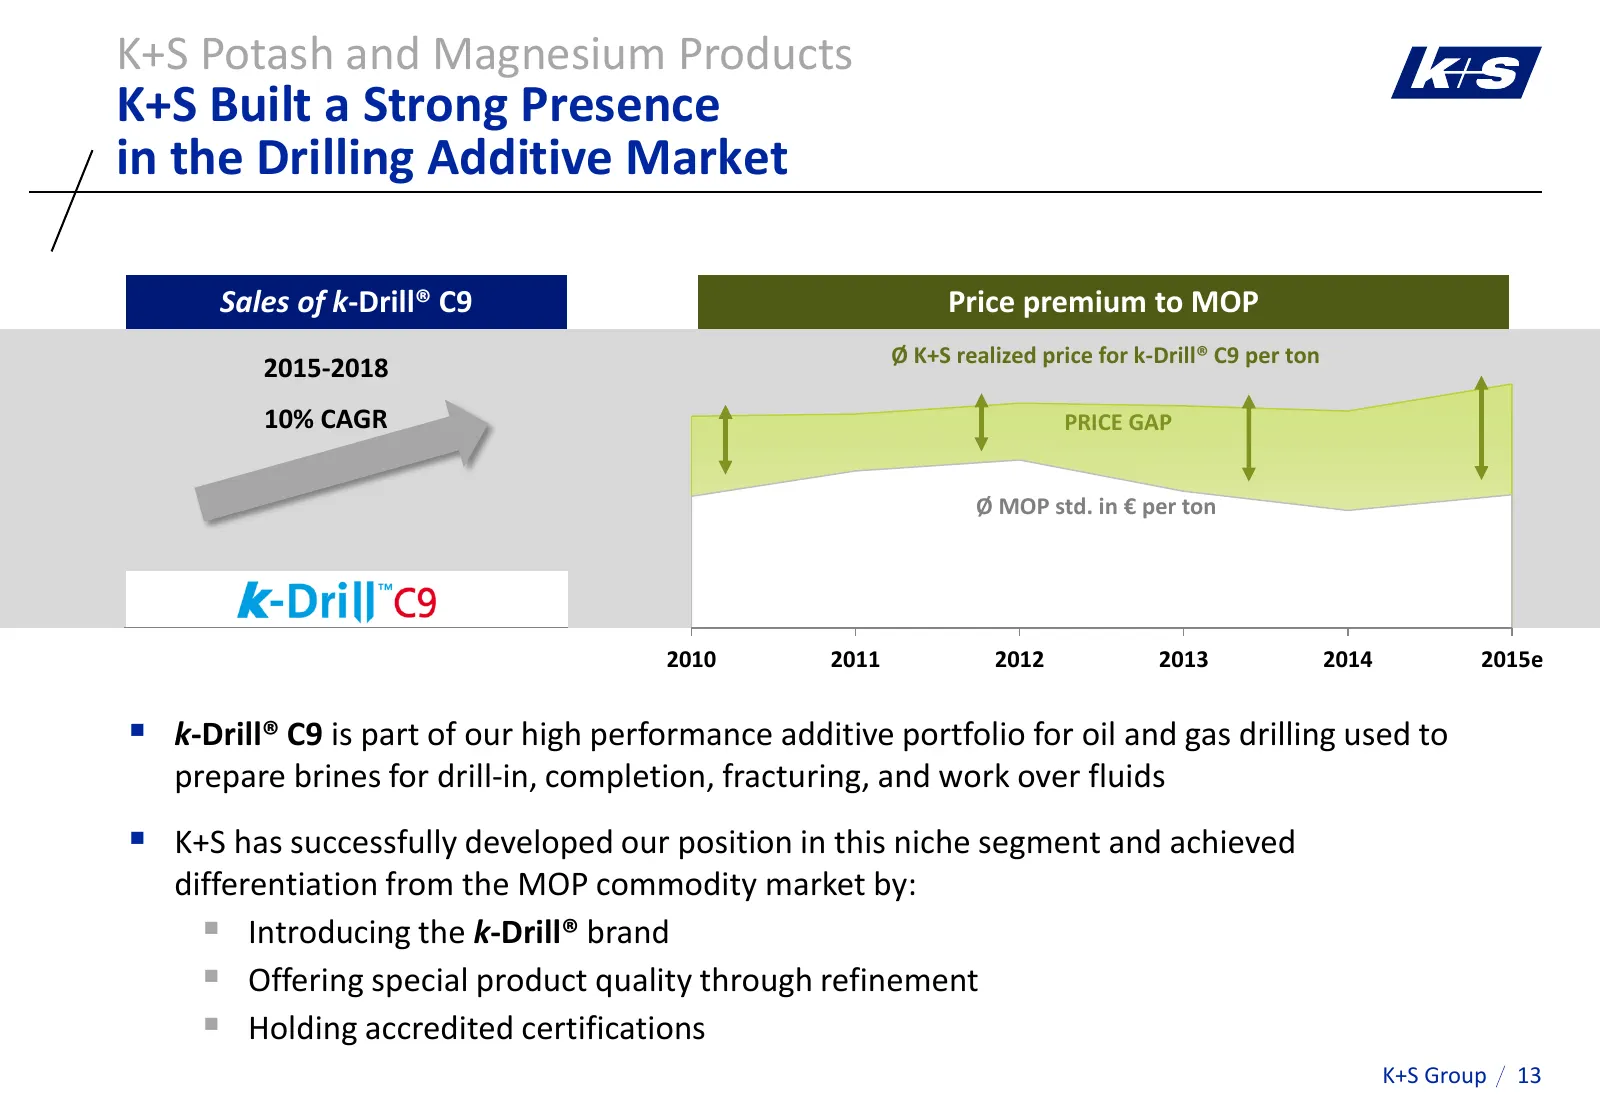
K+S Potash and Magnesium Products K+S Built a Strong Presence in the Drilling Additive Market Sales of k-Drill® C9 Price premium to MOP Ø K+S realized price for k-Drill® C9 per ton 2015-2018 10% CAGR PRICE GAP Ø MOP std. in € per ton 2010 2011 2012 2013 2014 2015e k-Drill® C9 is part of our high p
Slide 15: Leading Position in Europe and Strategic Overseas Presence
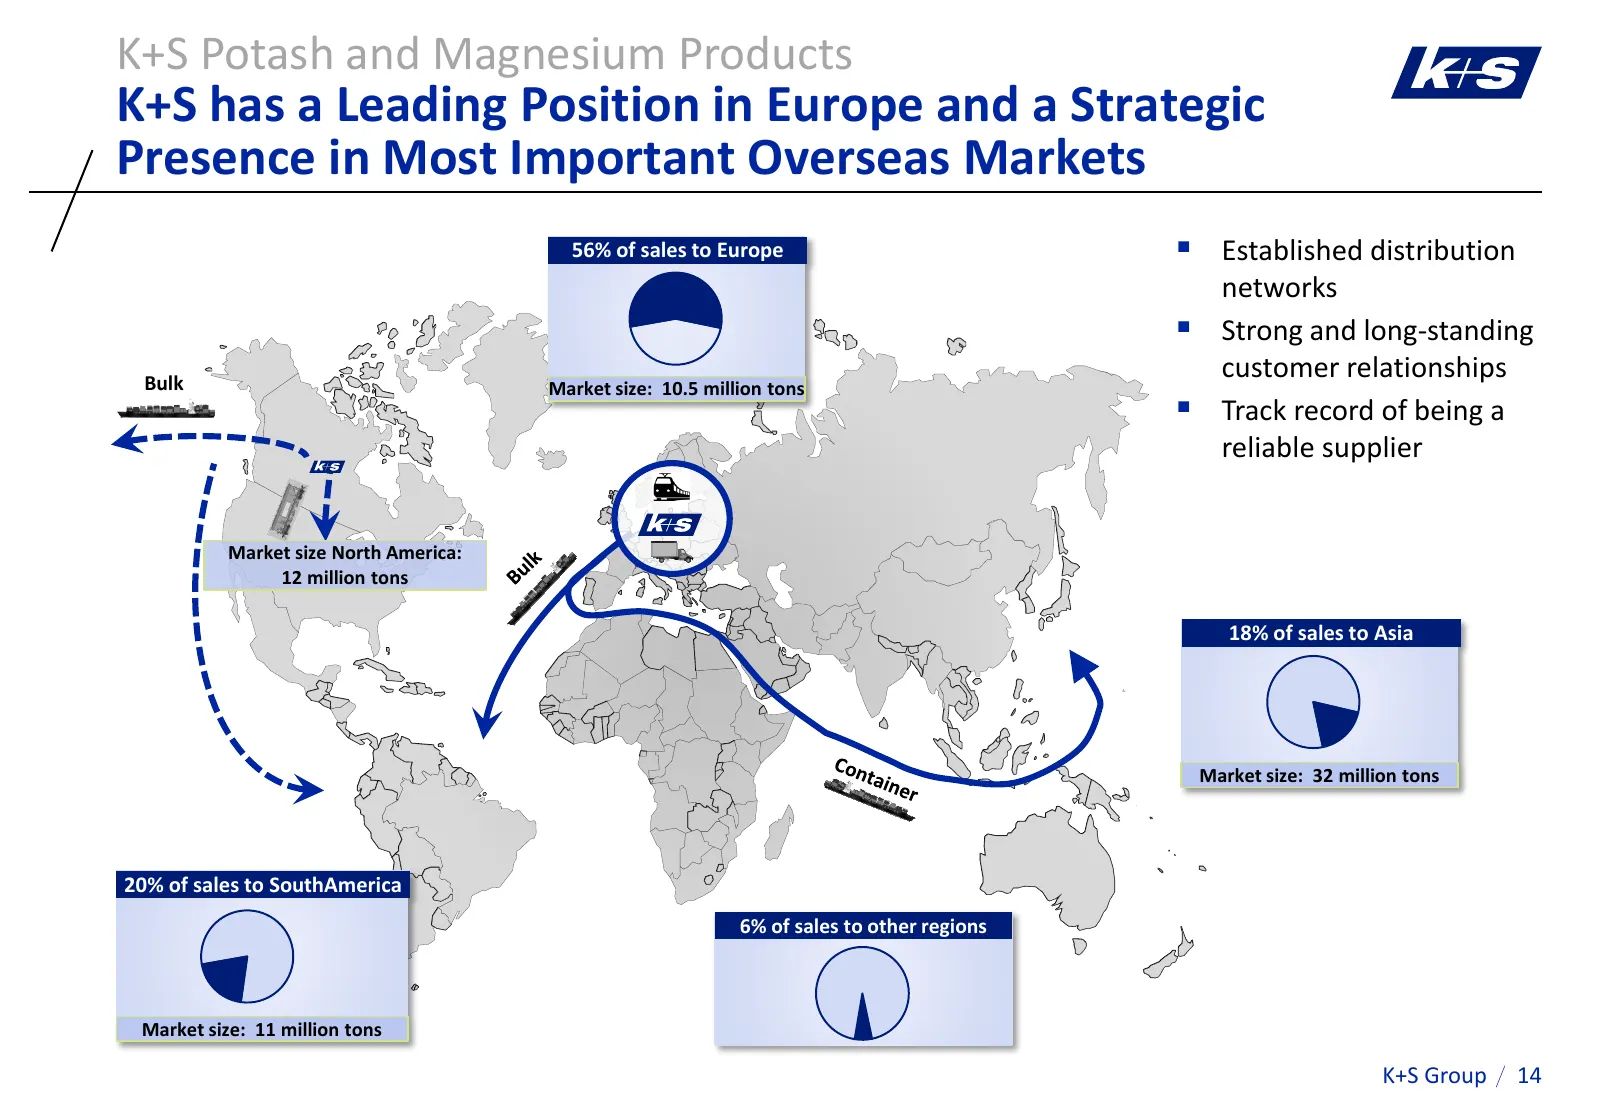
K+S Potash and Magnesium Products K+S has a Leading Position in Europe and a Strategic Presence in Most Important Overseas Markets 56% of sales to Europe Established distribution networks Strong and long-standing Bulk customer relationships Market size: 10.5 million tons Track record of being
Slide 16: Second Source Strategy with the New Legacy Mine
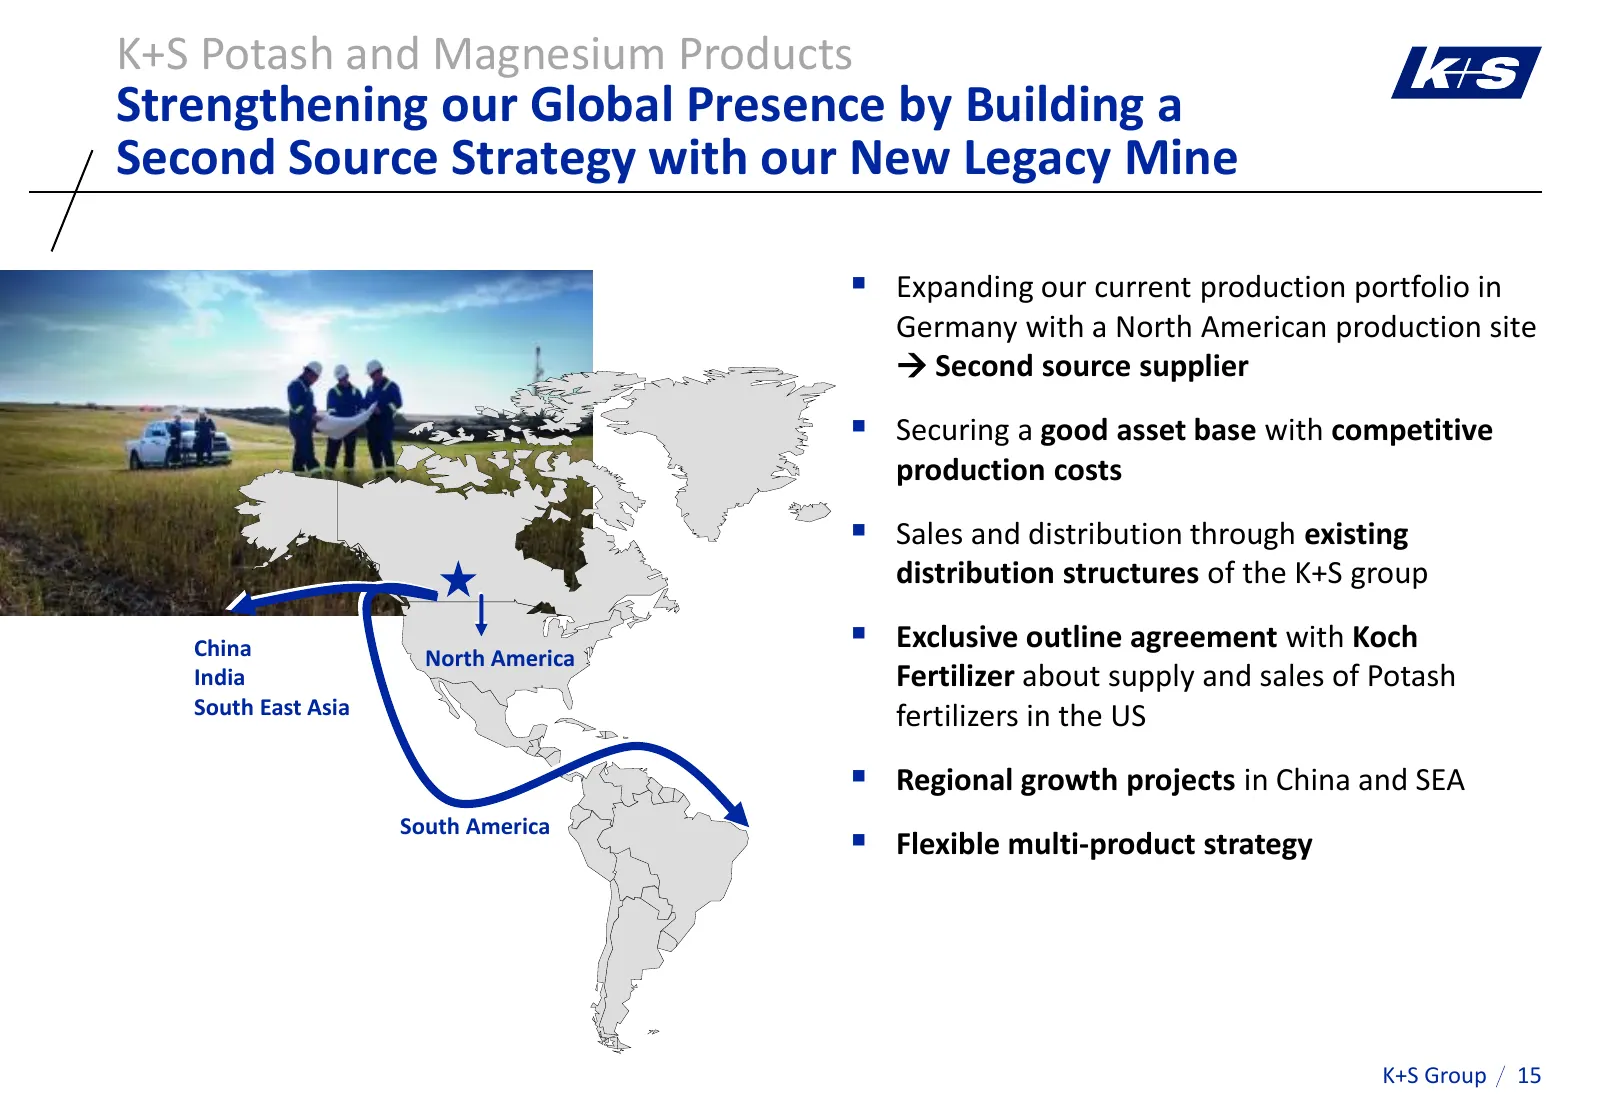
K+S Potash and Magnesium Products Strengthening our Global Presence by Building a Second Source Strategy with our New Legacy Mine Expanding our current production portfolio in Germany with a North American production site Second source supplier Securing a good asset base with competitive produ
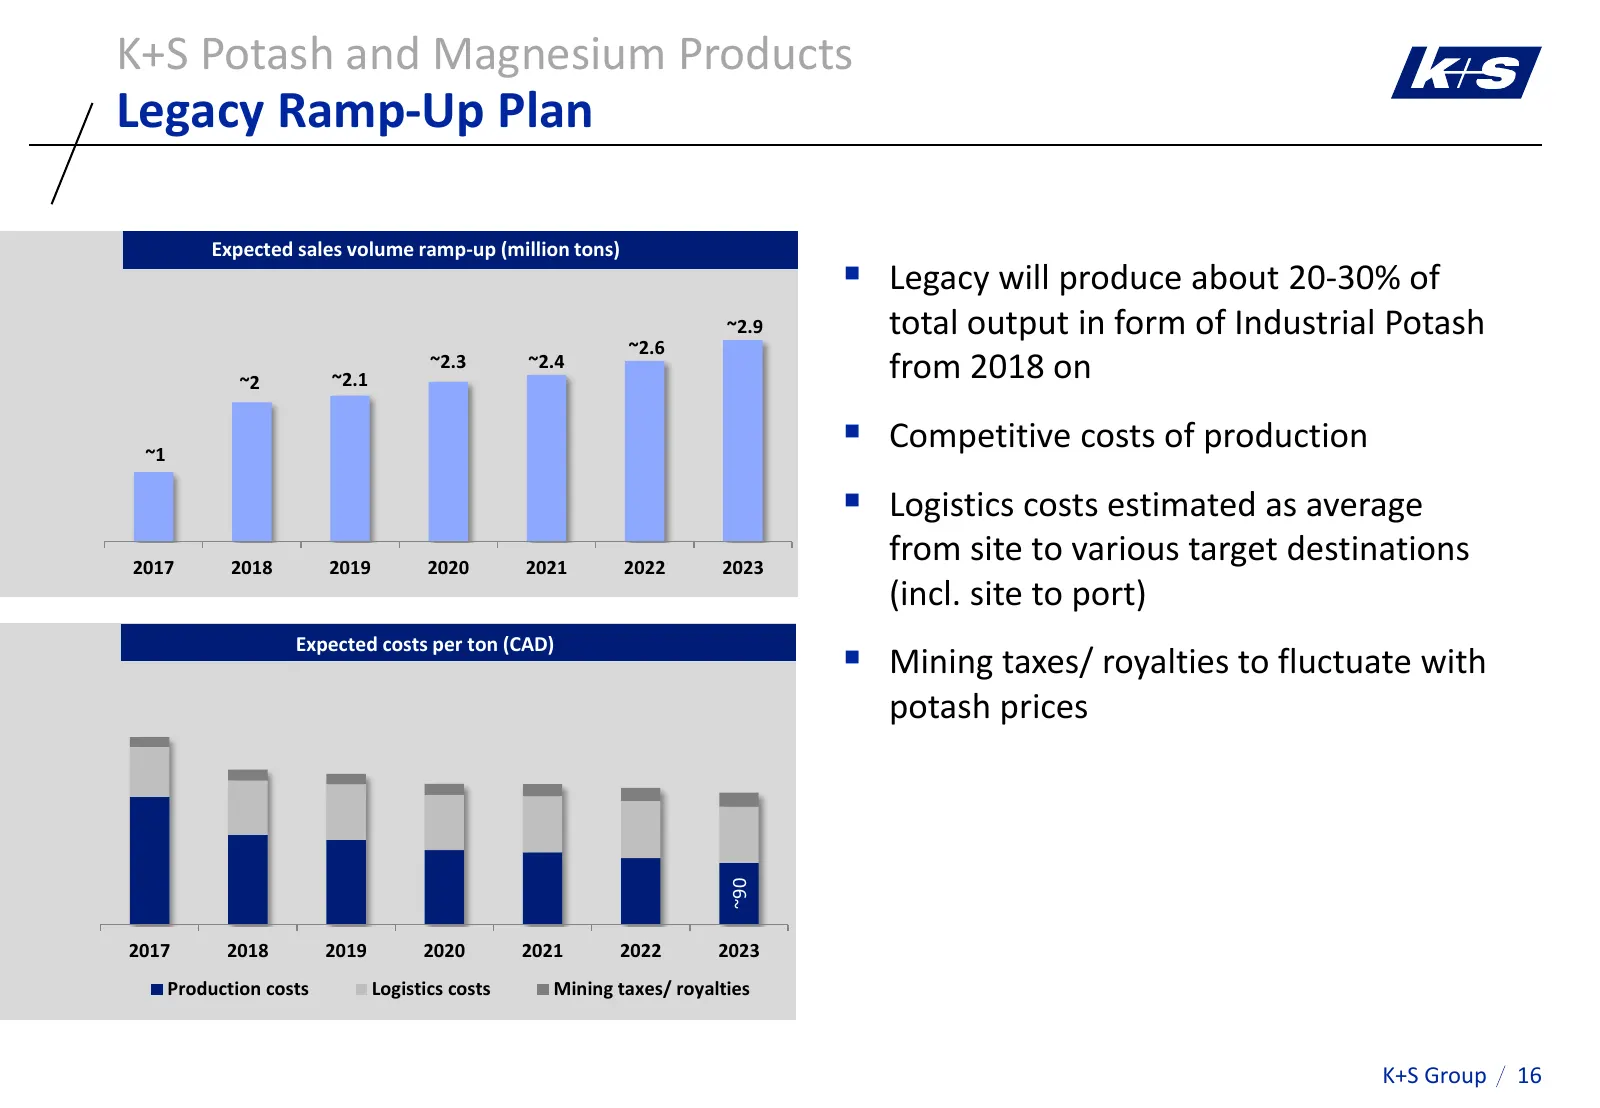
Slide 17: Legacy Ramp-Up Plan
K+S Potash and Magnesium Products Legacy Ramp-Up Plan Expected sales volume ramp-up (million tons) Legacy will produce about 20-30% of ~2.9 total output in form of Industrial Potash ~2.6 ~2 ~2.1 ~2.3 ~2.4 from 2018 on ~1 Competitive costs of production Logistics costs estimated as average 2017
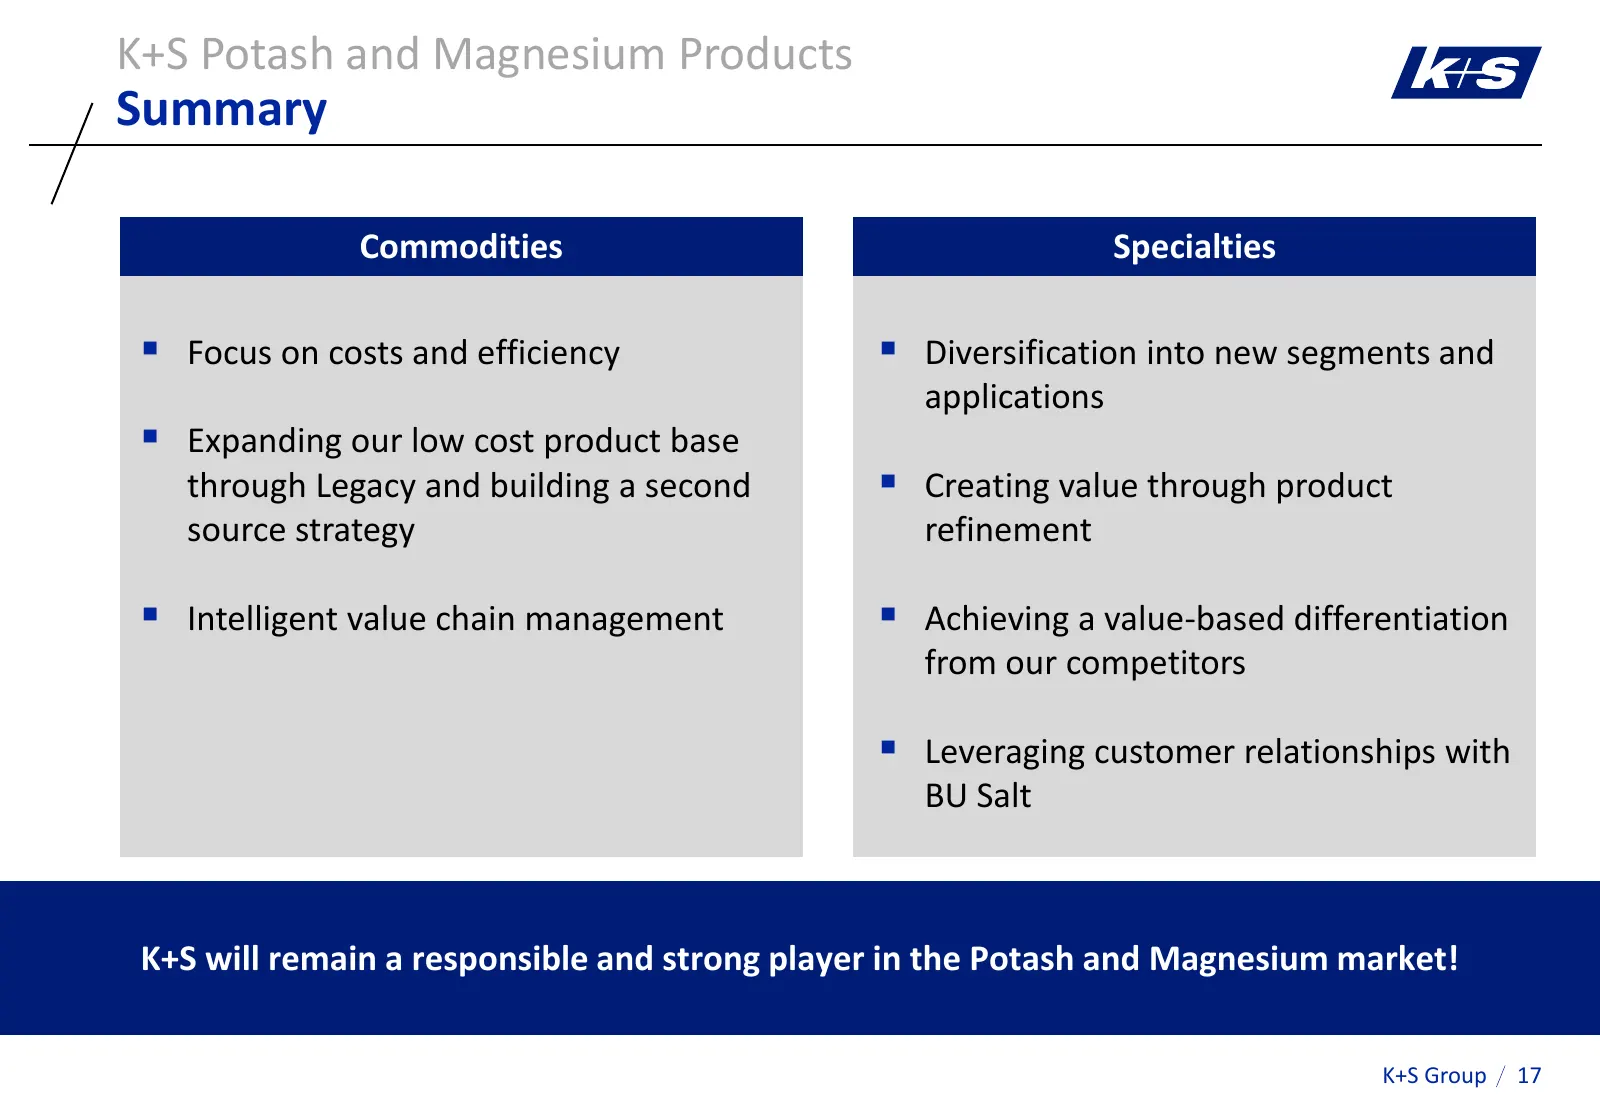
Slide 18: Summary
K+S Potash and Magnesium Products Summary Commodities Specialties Focus on costs and efficiency Diversification into new segments and applications Expanding our low cost product base through Legacy and building a second Creating value through product source strategy refinement Intelligent
Source: Internet Archive copy of k-plus-s.com
More decks from K+s AG
 Investor Presentation (October 2026)100 slides · October 2026
 Q2 2026 Earnings Presentation9 slides · Aug 12, 2026
 Investor Presentation (August 2026)102 slides · August 2026
 Q1 2026 Earnings Presentation11 slides · May 11, 2026
 Investor Presentation (May 2026)89 slides · May 2026
 Q4 2025 Earnings Presentation11 slides · Mar 13, 2026