Billerud AB · OMXSTO:BILL
Billerud AB — BillerudKorsnäs — Investor Day (November 2021)
68 slides from Billerud AB's investor day presentation, Nov 17, 2021
Slide 1: Capital Markets Day 2021
Capital Markets Day 2021 Sustainable profitable growth in packaging materials
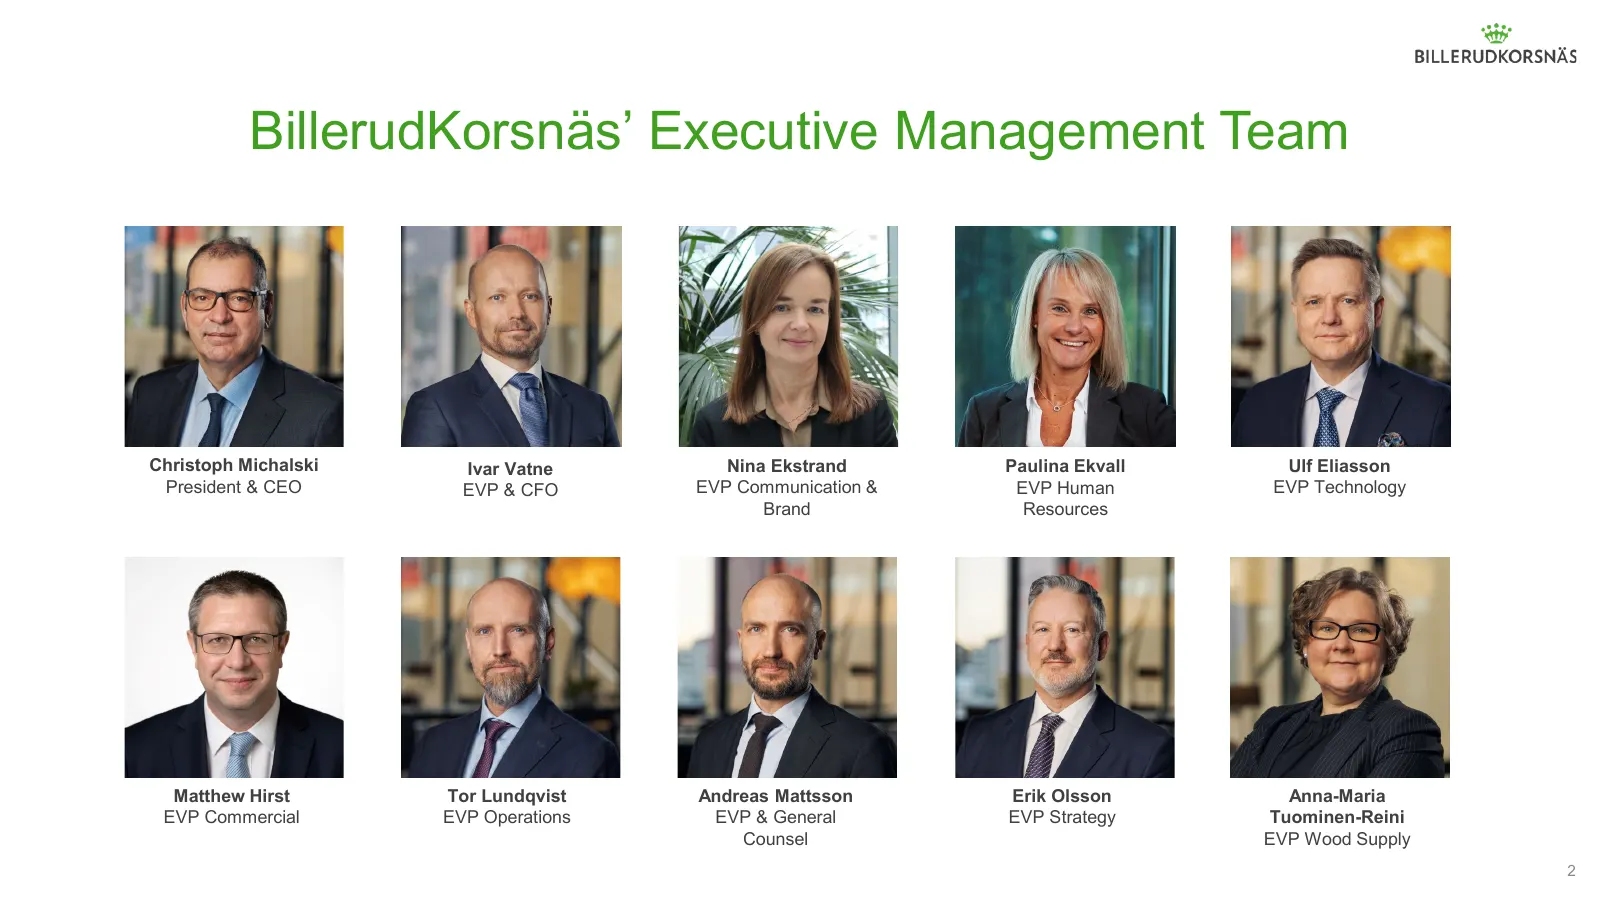
Slide 2: BillerudKorsnäs’ Executive Management Team
BillerudKorsnäs’ Executive Management Team Christoph Michalski Ivar Vatne Nina Ekstrand Paulina Ekvall Ulf Eliasson President & CEO EVP & CFO EVP Communication & EVP Human EVP Technology Brand Resources Matthew Hirst Tor Lundqvist Andreas Mattsson Erik Olsson Anna-Maria EVP Commercial EVP Operations
Slide 3: Agenda
13:00 Journey so far and strategy building blocks Christoph Michalski, CEO and President Market opportunity & commercial strategy Matt Hirst, EVP Commercial Impactful innovation Mikael Nilsson, Director Product Innovation Break Agenda 14:15 Volume growth through operational stability and efficiencie
Slide 4: Journey so far and strategy building blocks
Journey so far and strategy building blocks Christoph Michalski CEO and President
Slide 5: We operate in a very large market with significant growth opportunities
We operate in a very large market with significant growth opportunities underpinned by impactful macro trends Climate crisis and circular economy Demographic shifts and increased demand for packaging material Renewable resources and raw materials Digitalisation as an enabler
Slide 6: First impression as CEO and confirmed since
First impression as CEO and confirmed since What is great? What are the challenges? Sweet spot of trends and Safety record product portfolio Lack of common vision Excellent market positions and focus on the core Highly qualified and Production stability dedicated people Financial performance Innovat
Slide 7: Decent topline performance …
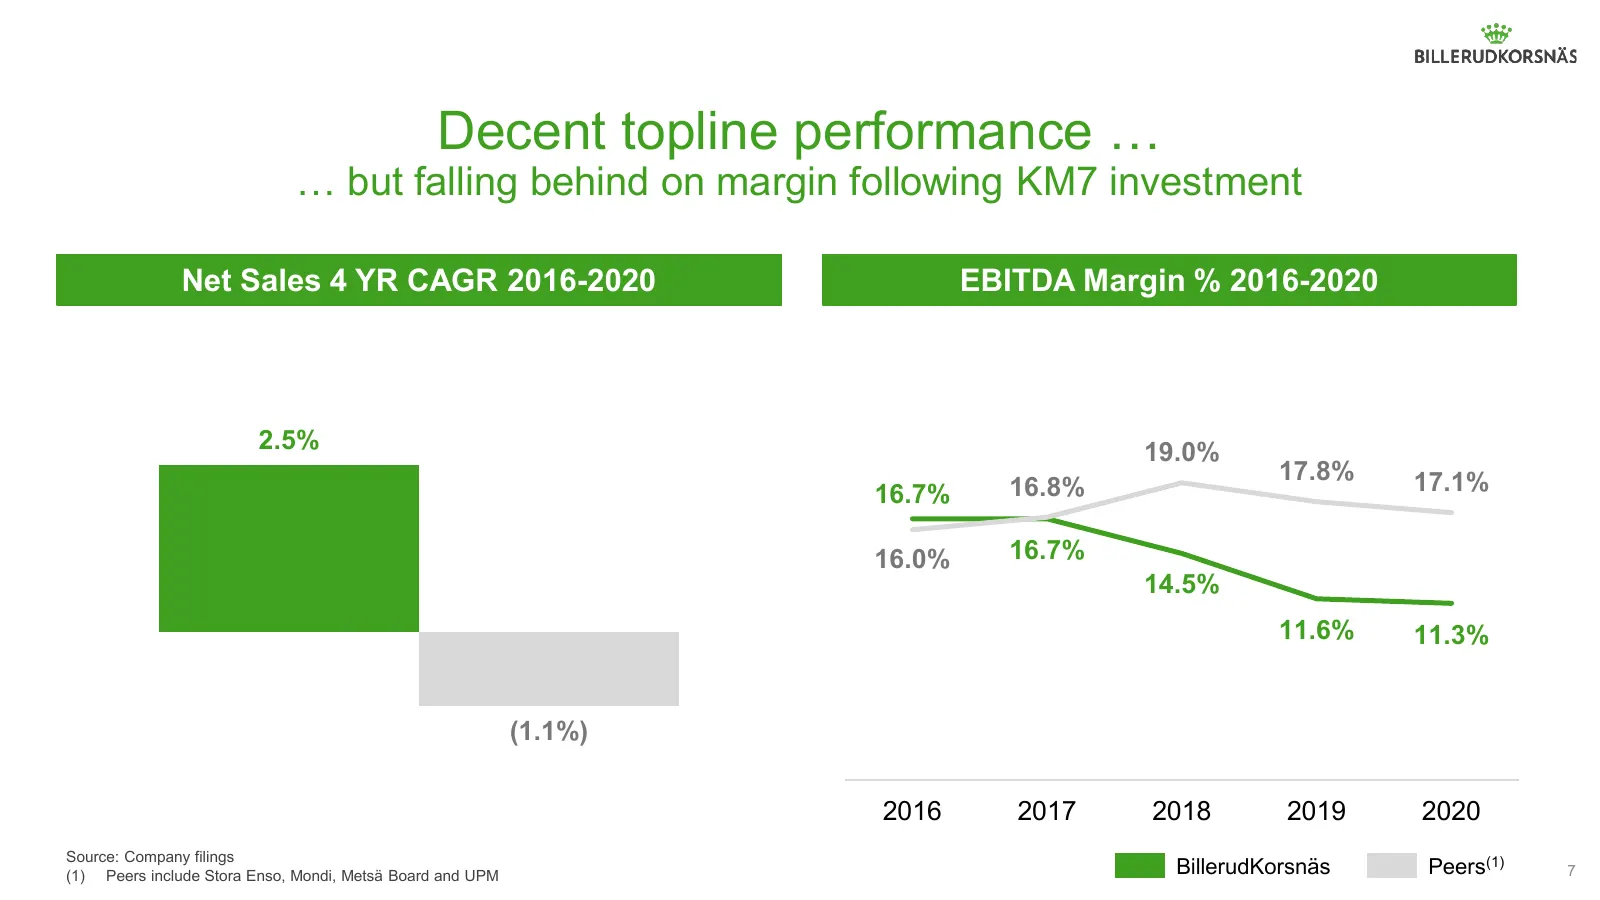
Decent topline performance … … but falling behind on margin following KM7 investment Net Sales 4 YR CAGR 2016-2020 EBITDA Margin % 2016-2020 2.5% 19.0% 17.8% 17.1% 16.7% 16.8% 16.0% 16.7% 14.5% 11.6% 11.3% (1.1%) 2016 2017 2018 2019 2020 Source: Company filings (1) Peers include Stora Enso, Mondi, M
Slide 8: Ongoing priorities 2020-2021 – merged with the new strategy
Ongoing priorities 2020-2021 – merged with the new strategy Ramp-up at Gruvön (KM7) Cost and efficiency programme Safe and stable production Competitive wood supply 8
Slide 9: BillerudKorsnäs’ 2030 strategy
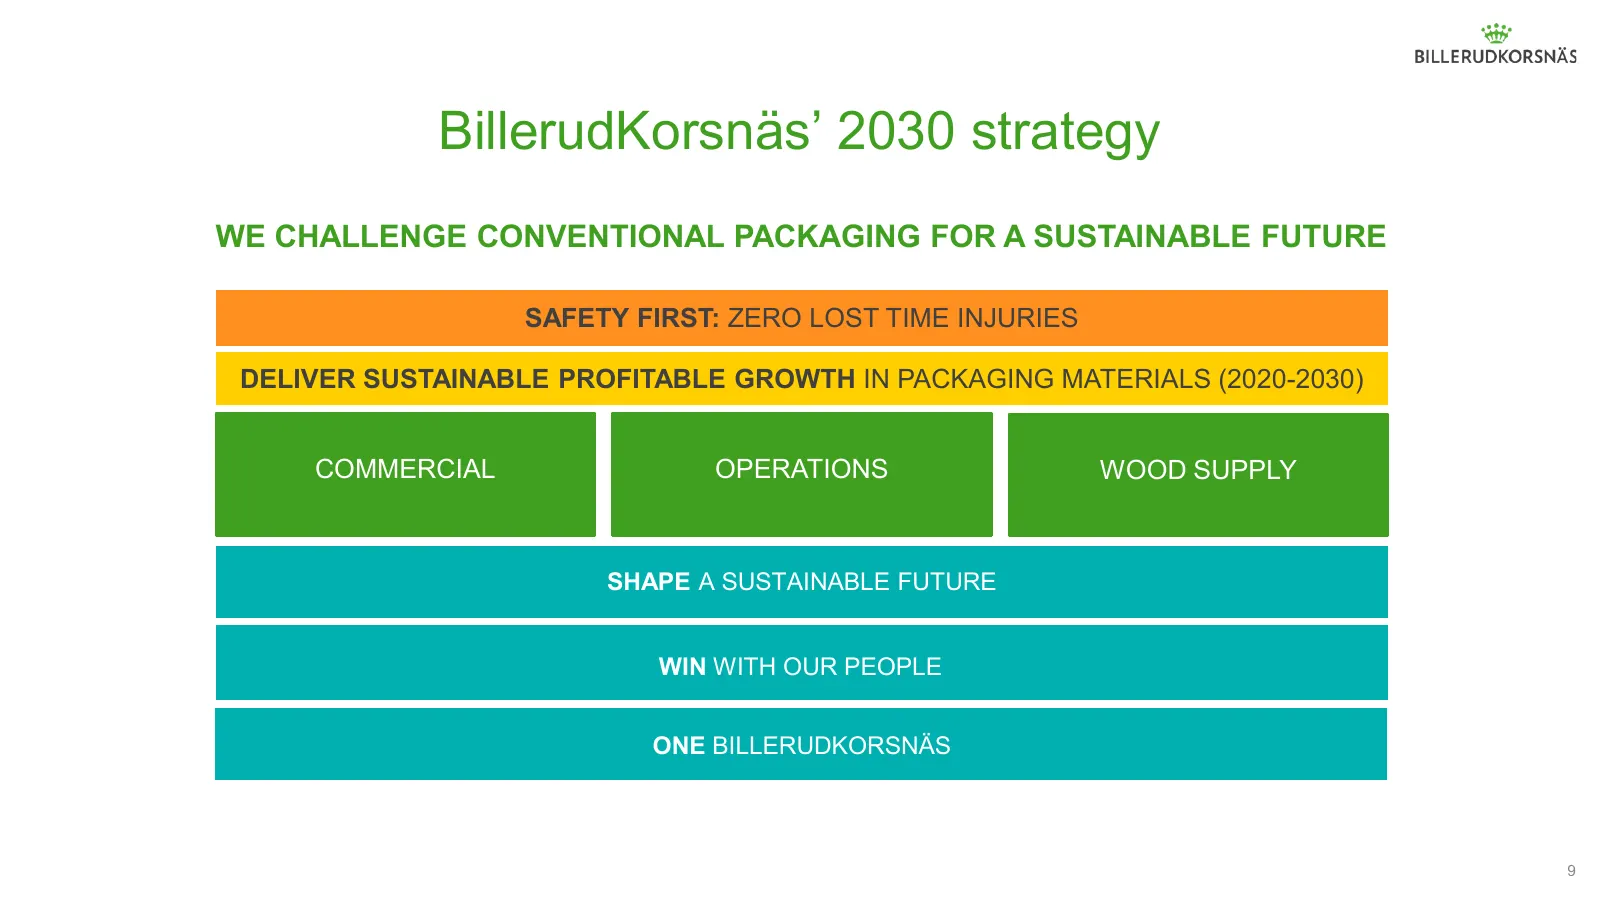
BillerudKorsnäs’ 2030 strategy WE CHALLENGE CONVENTIONAL PACKAGING FOR A SUSTAINABLE FUTURE SAFETY FIRST: ZERO LOST TIME INJURIES DELIVER SUSTAINABLE PROFITABLE GROWTH IN PACKAGING MATERIALS (2020-2030) COMMERCIAL OPERATIONS WOOD SUPPLY SHAPE A SUSTAINABLE FUTURE WIN WITH OUR PEOPLE ONE BILLERUDKORS
Slide 10: Market opportunity & commercial strategy
Market opportunity & commercial strategy Matt Hirst, EVP Commercial
Slide 11: Our strategic choices
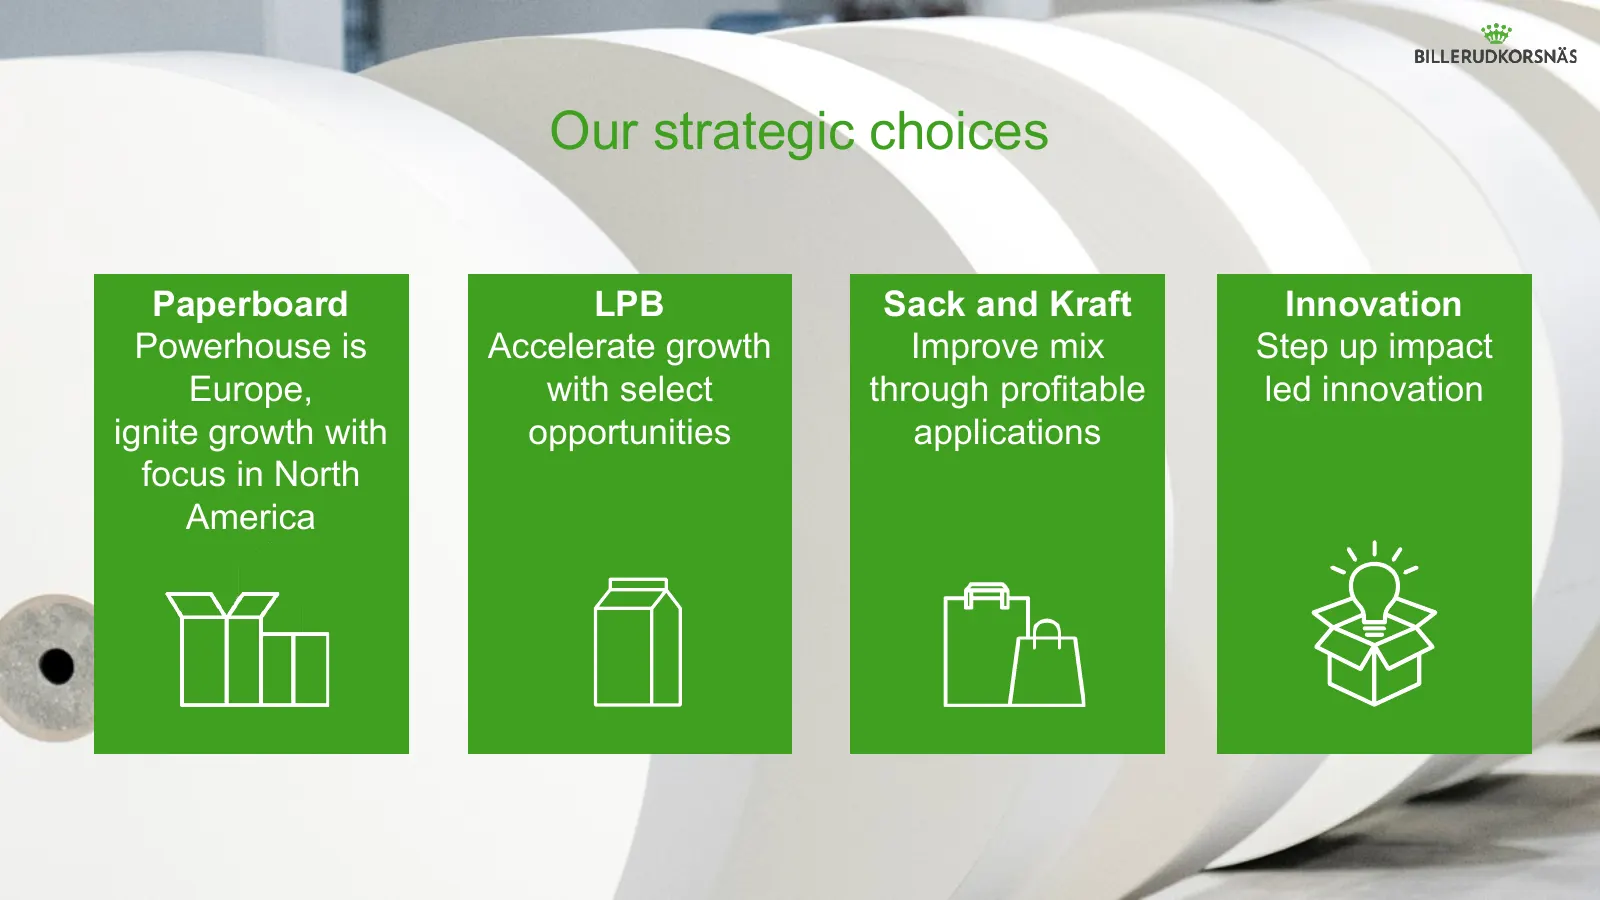
Our strategic choices Paperboard LPB Sack and Kraft Innovation Powerhouse is Accelerate growth Improve mix Step up impact Europe, with select through profitable led innovation ignite growth with opportunities applications focus in North America
Slide 12: We compete in the large niche of primary fibres
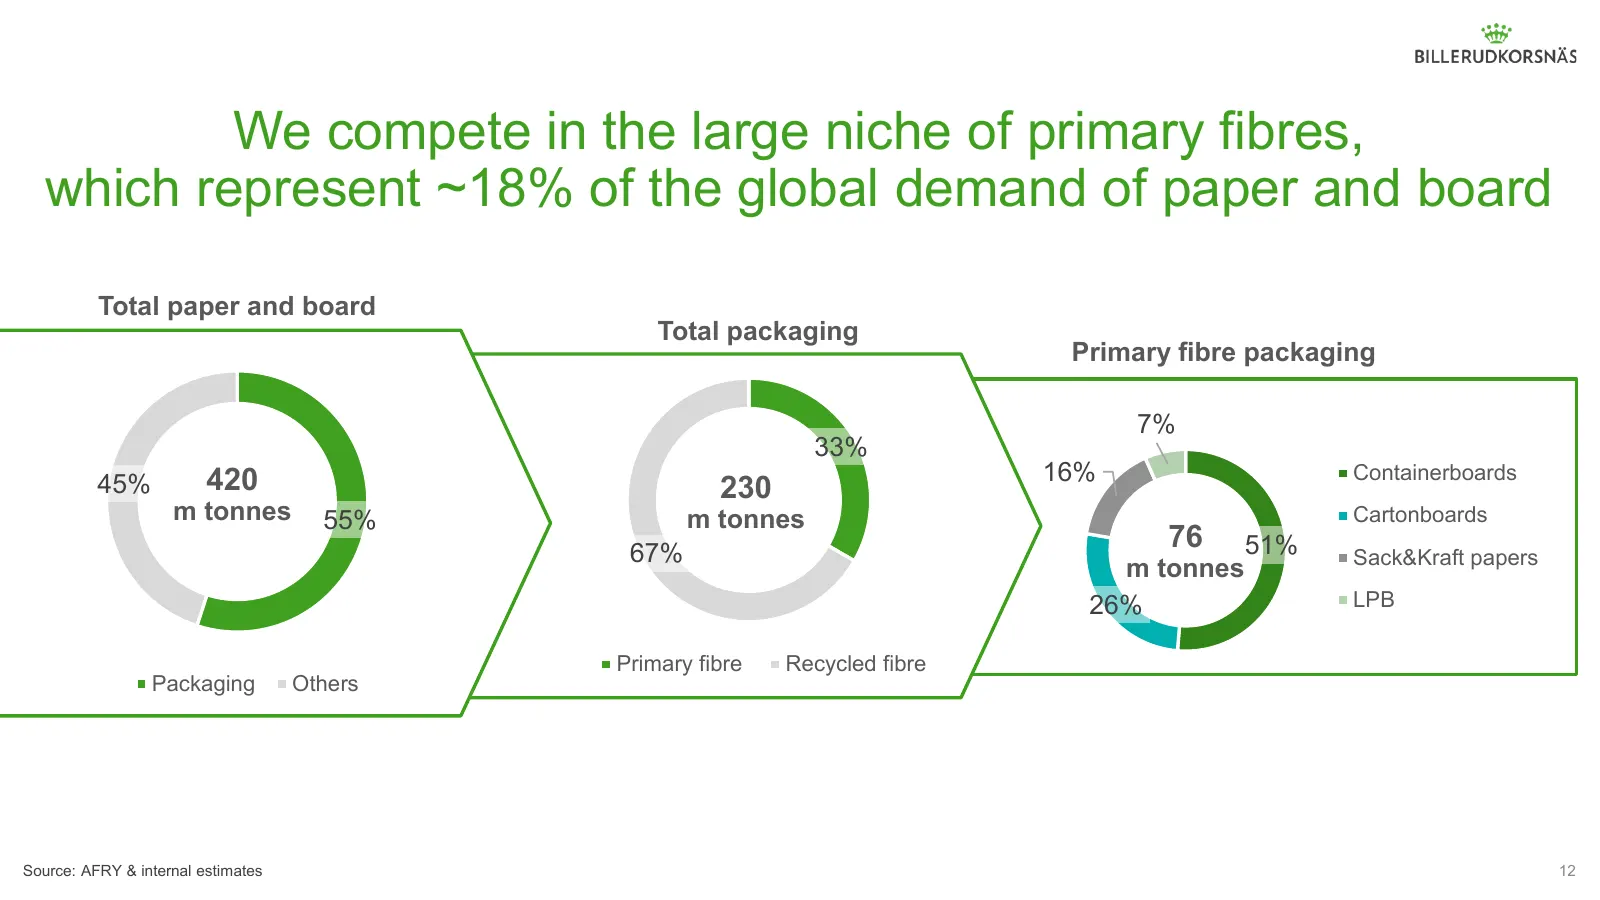
We compete in the large niche of primary fibres, which represent ~18% of the global demand of paper and board Total paper and board Total packaging Primary fibre packaging 7% 33% 45% 420 16% Containerboards 230 m tonnes 55% m tonnes Cartonboards 67% 76 51% Sack&Kraft papers m tonnes 26% LPB Primary
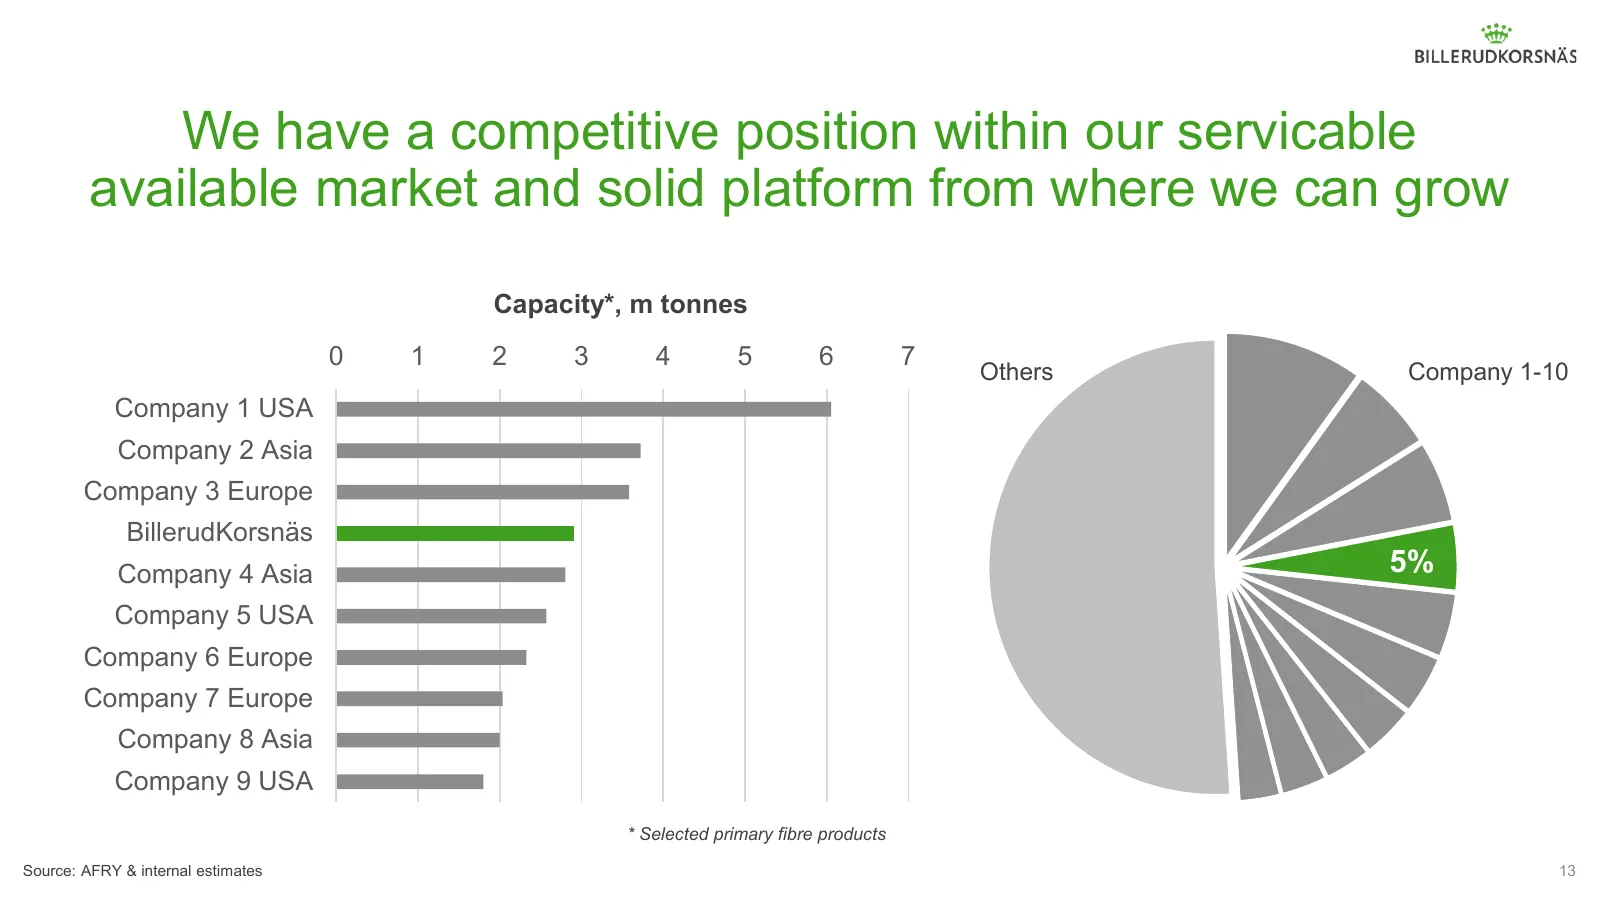
Slide 13: We have a competitive position within our serviceable available market
We have a competitive position within our servicable available market and solid platform from where we can grow Capacity*, m tonnes 0 1 2 3 4 5 6 7 Others Company 1-10 Company 1 USA Company 2 Asia Company 3 Europe BillerudKorsnäs Company 4 Asia 5% Company 5 USA Company 6 Europe Company 7 Europe Comp
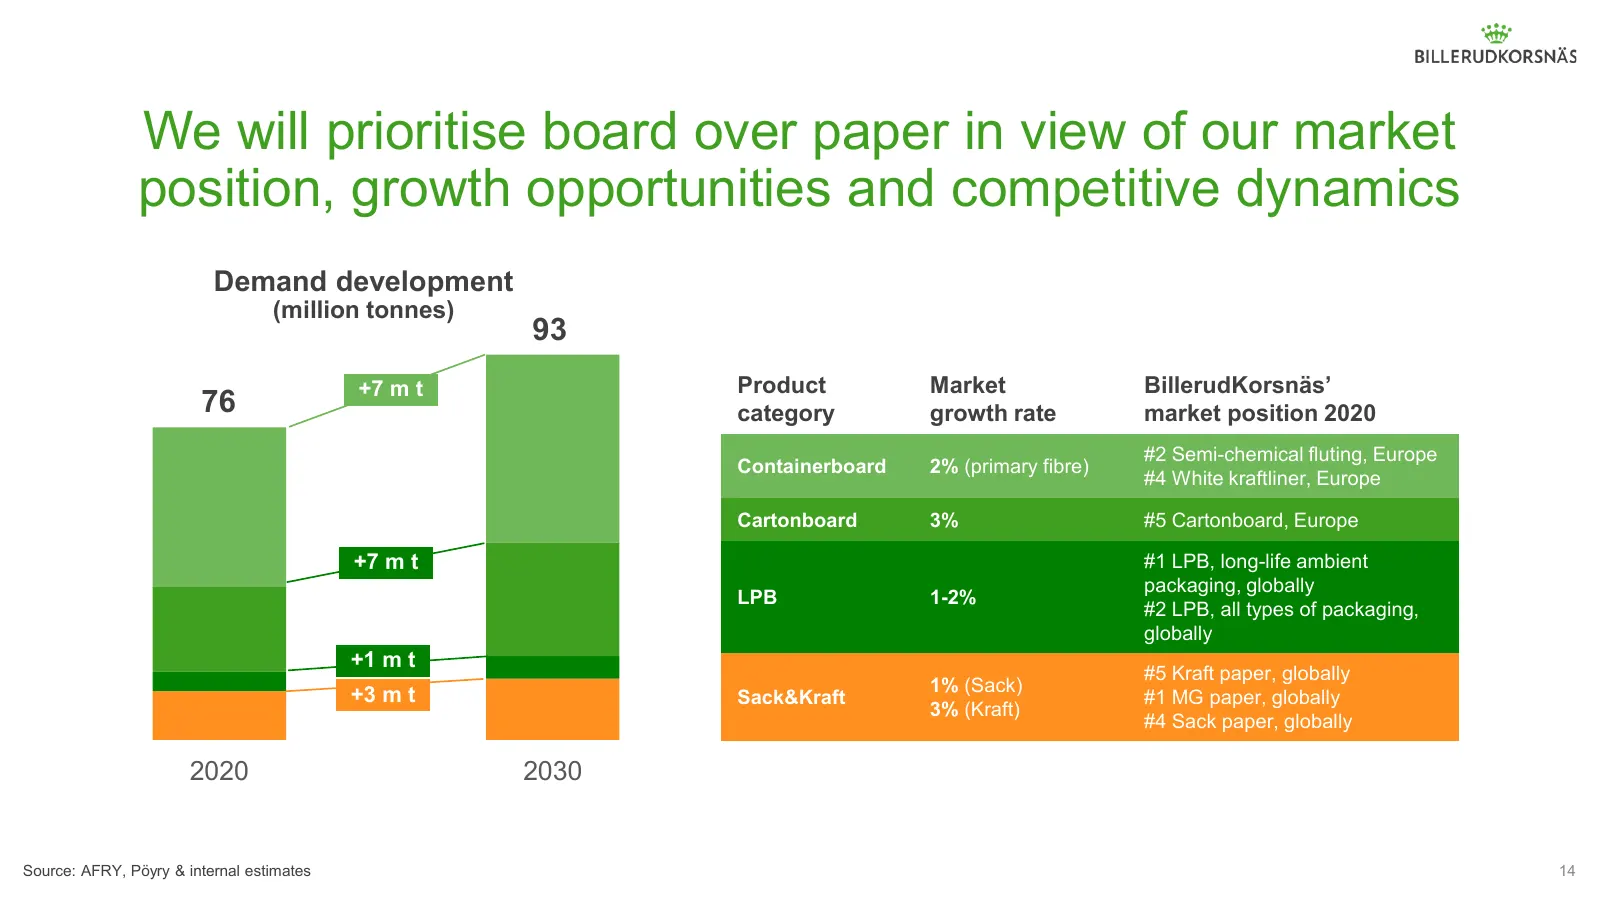
Slide 14: We will prioritise board over paper
We will prioritise board over paper in view of our market position, growth opportunities and competitive dynamics Demand development (million tonnes) 93 +7 m t Product Market BillerudKorsnäs’ 76 category growth rate market position 2020 #2 Semi-chemical fluting, Europe Containerboard 2% (primary fib
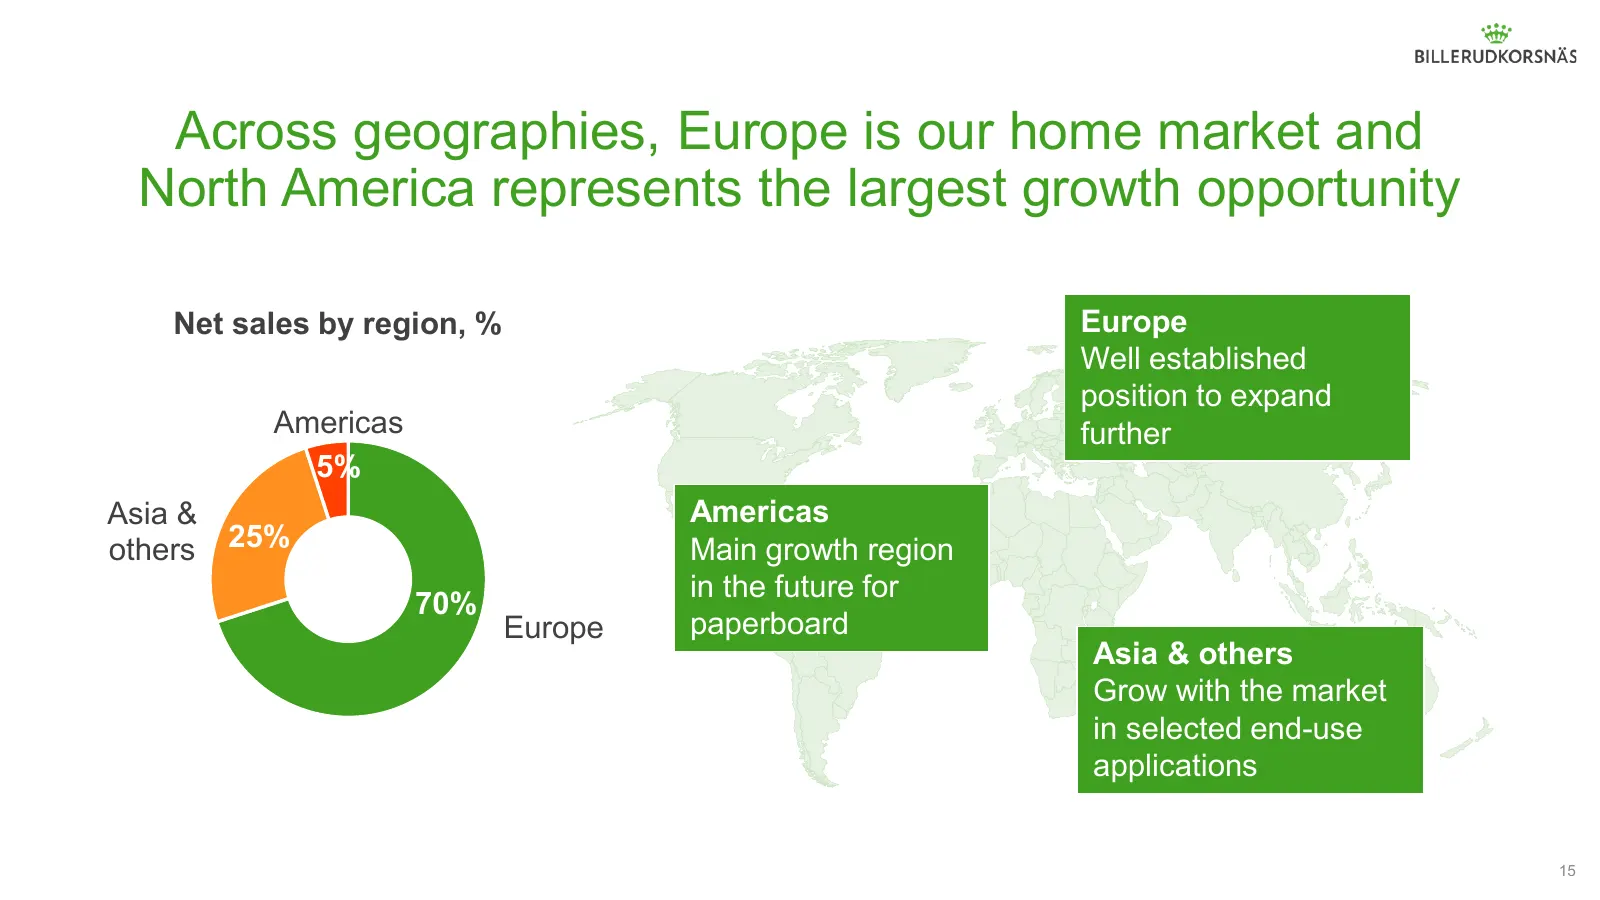
Slide 15: Europe is our home market and North America the largest growth opportunity
Across geographies, Europe is our home market and North America represents the largest growth opportunity Net sales by region, % Europe Well established position to expand Americas further 5% Asia & Americas others 25% Main growth region in the future for 70% Europe paperboard Asia & others Grow wit
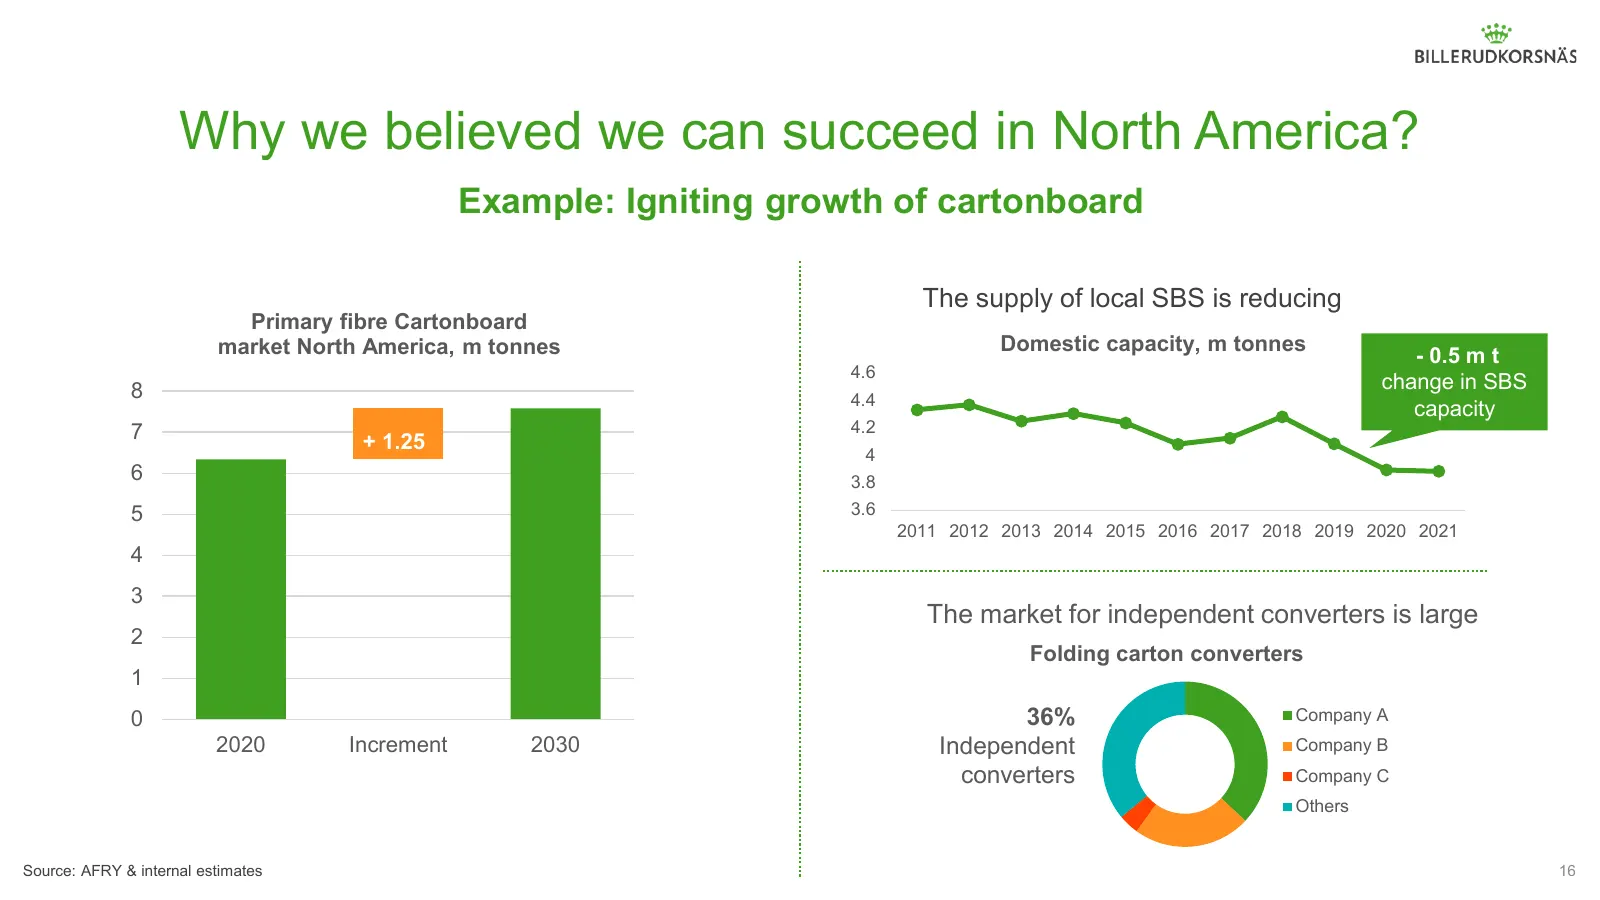
Slide 16: Why we believed we can succeed in North America?
Why we believed we can succeed in North America? Example: Igniting growth of cartonboard The supply of local SBS is reducing Primary fibre Cartonboard market North America, m tonnes Domestic capacity, m tonnes - 0.5 m t 4.6 8 change in SBS 4.4 capacity 7 4.2 + 1.25 4 6 3.8 5 3.6 2011 2012 2013 2014
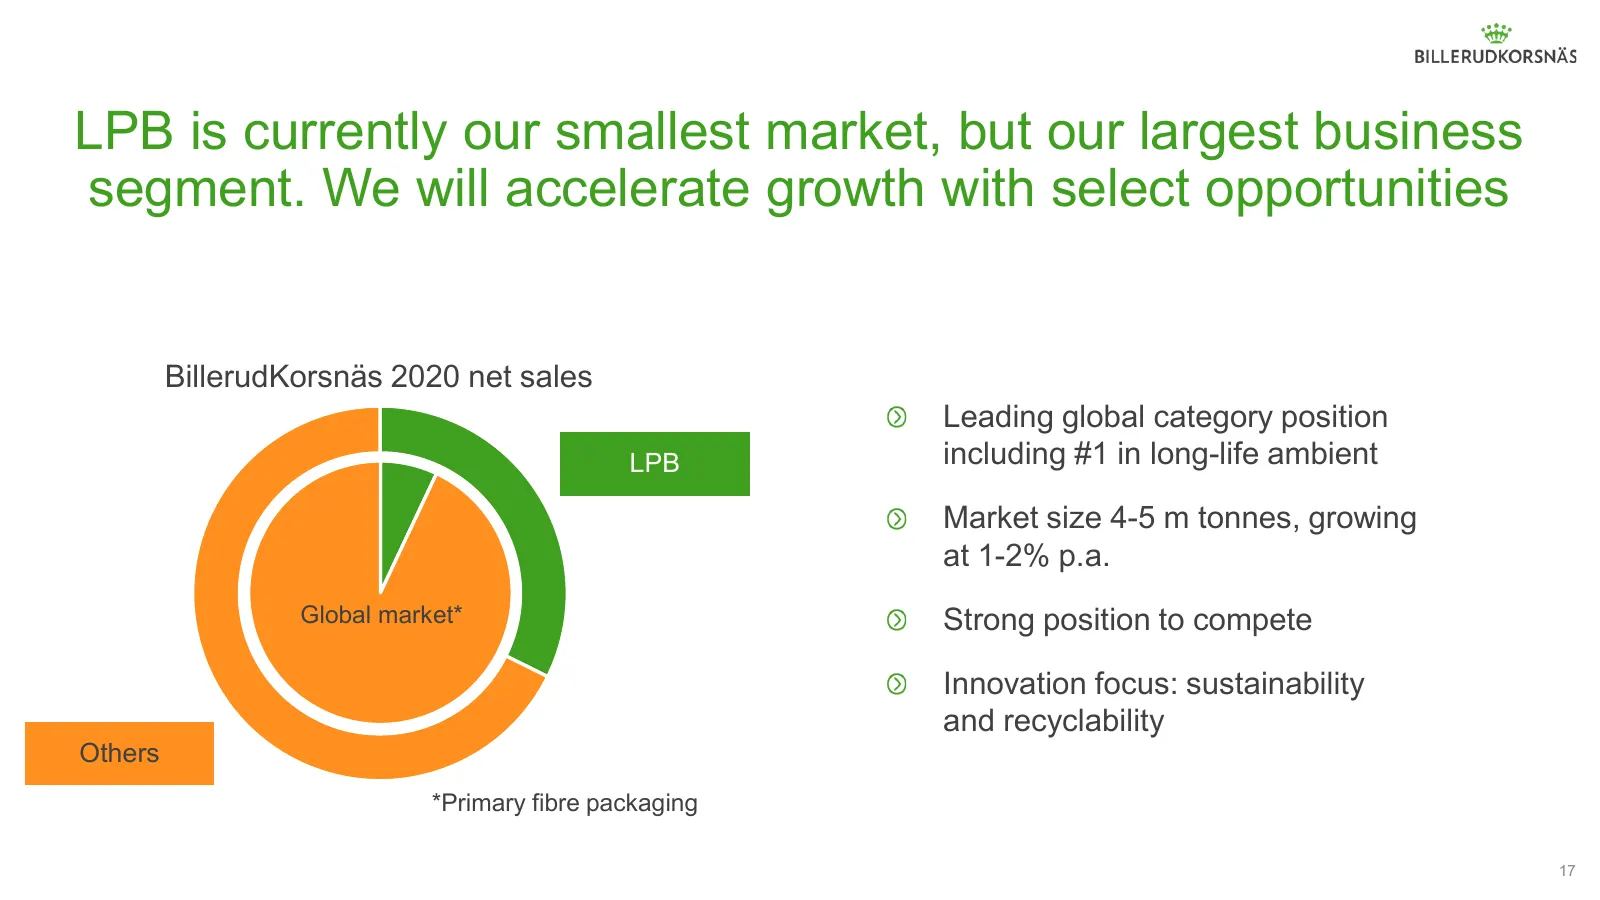
Slide 17: LPB is currently our smallest market, but our largest business segment
LPB is currently our smallest market, but our largest business segment. We will accelerate growth with select opportunities BillerudKorsnäs 2020 net sales Leading global category position LPB including #1 in long-life ambient Market size 4-5 m tonnes, growing at 1-2% p.a. Global market* Strong posit
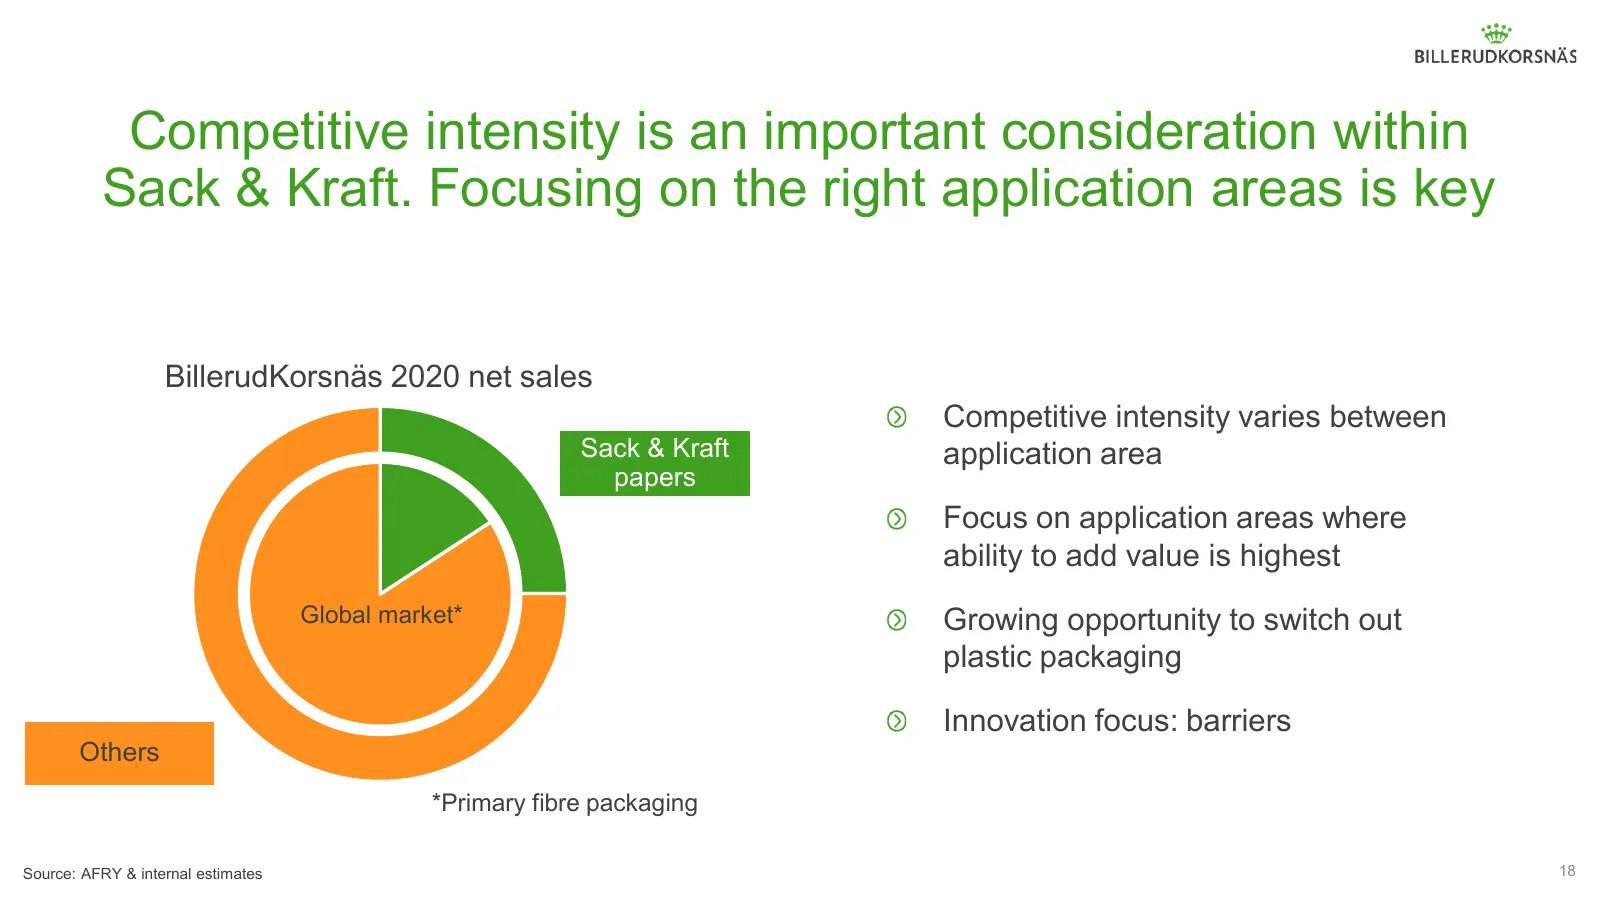
Slide 18: Competitive intensity is an important consideration within Sack & Kraft
Competitive intensity is an important consideration within Sack & Kraft. Focusing on the right application areas is key BillerudKorsnäs 2020 net sales Competitive intensity varies between Sack & Kraft application area papers Focus on application areas where ability to add value is highest Global mar
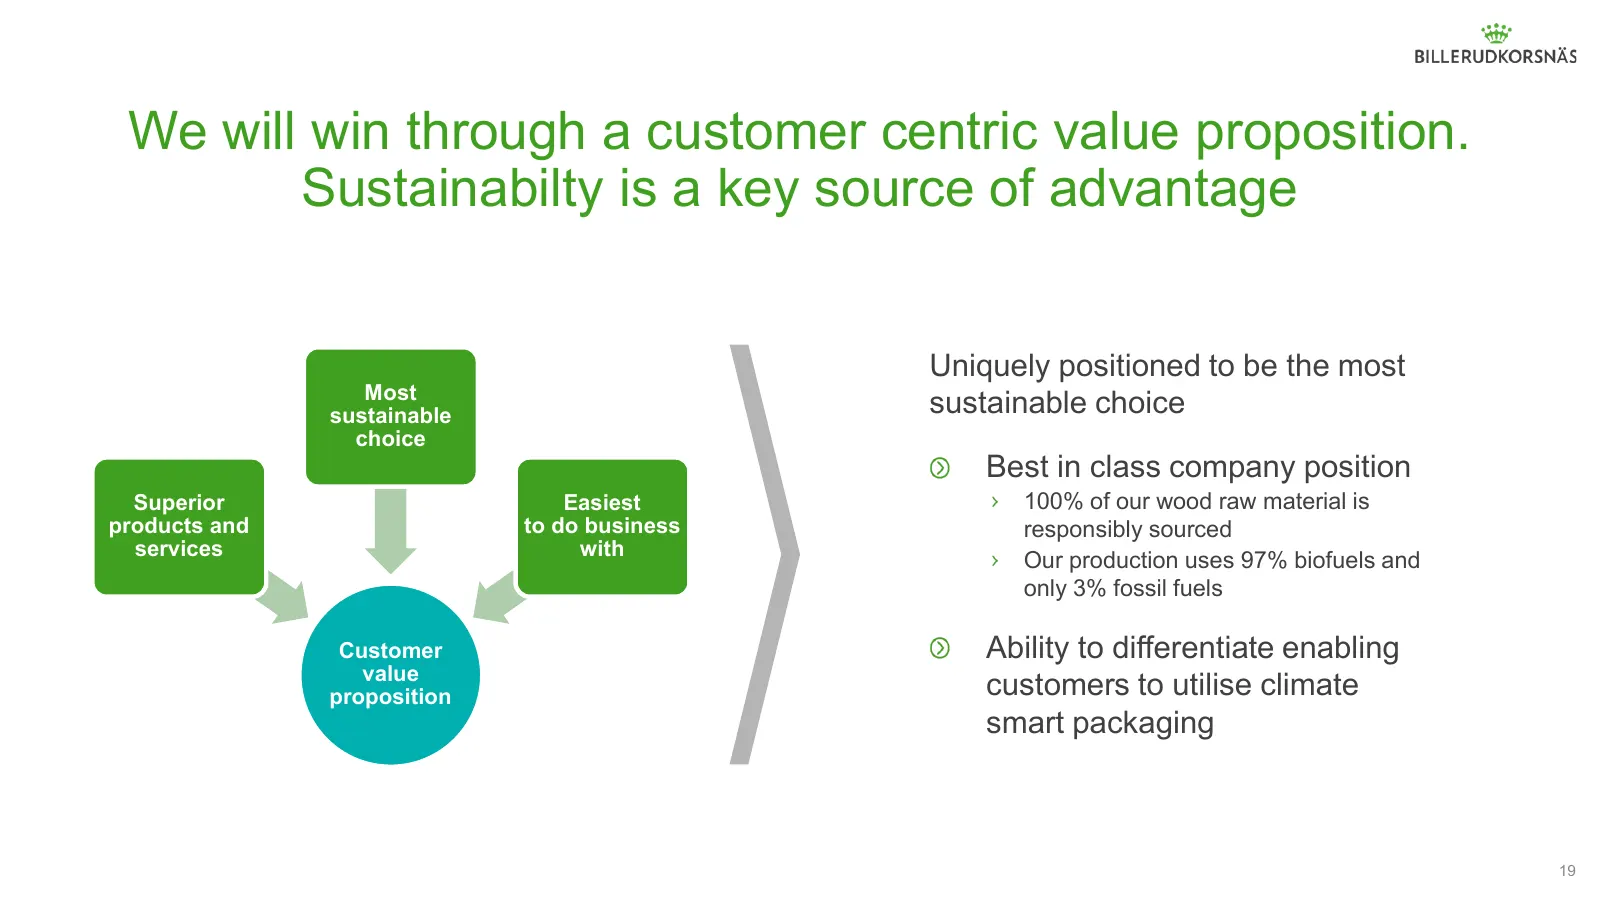
Slide 19: We will win through a customer centric value proposition
We will win through a customer centric value proposition. Sustainabilty is a key source of advantage Uniquely positioned to be the most Most sustainable sustainable choice choice Best in class company position Superior Easiest 100% of our wood raw material is products and to do business responsibly
Slide 20: Impactful innovation
Impactful innovation Mikael Nilsson, Director Product Innovation
Slide 21: We are changing our innovation management methodology
We are changing our innovation management methodology to drive transparency, commercial focus and prioritisation
Slide 22: Aligning our innovation portfolio with our new strategy
Aligning our innovation portfolio with our new strategy In the past… From now on… Parallel processes for short term and One process and governance long term innovation model Gap between long term innovation Commercial focus and clear and business areas accountability Process not allowing prioritisat
Slide 23: Three significant tools to review and manage our innovation portfolio
Three significant tools to review and manage our innovation portfolio Portfolio overview Customer technology Launch plan – Innovation funnel matrix 23
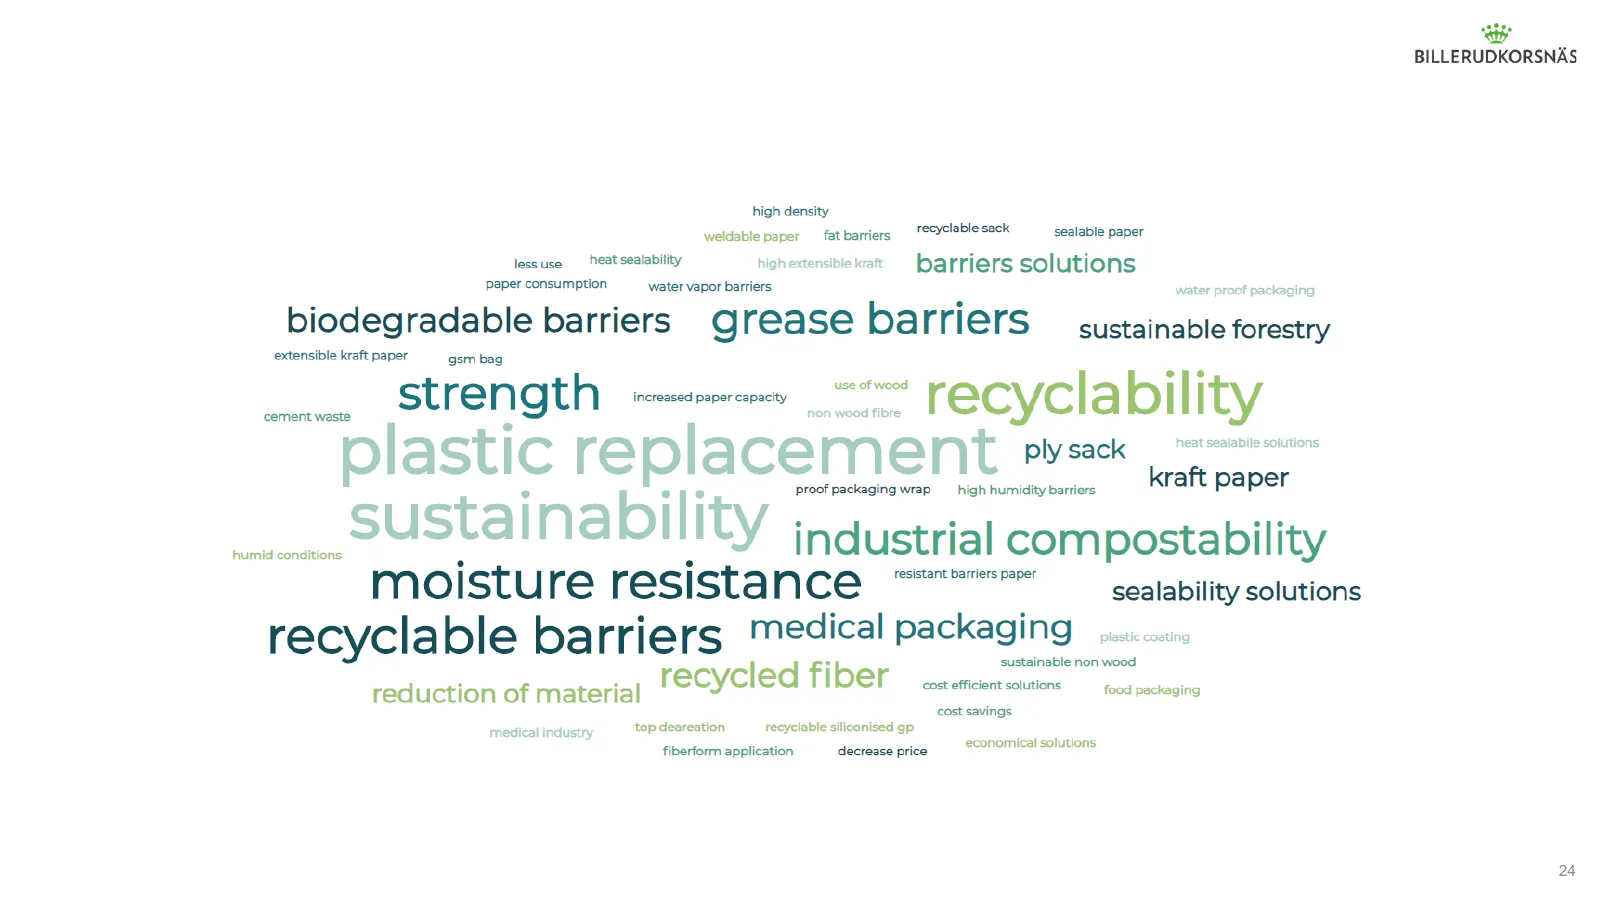
Slide 24: BILLERUDKORSNAS
ie BILLERUDKORSNAS high density weldable paper fat barriers TcyClable sack sealable paper lessuseestseasbity rihexensibieket — barriers solutions Paper consumpsion water vapor barriers water proof packaging biodegradable barriers grease barriers sustainable forestry extensible kraft paper gsm bag ve
Slide 25: We have identified a number of critical priorities
We have identified a number of critical priorities underpinned by ownable technologies Food safety Sustainability Material performance 25
Slide 26: Sustainable barrier development impact new technology requirements
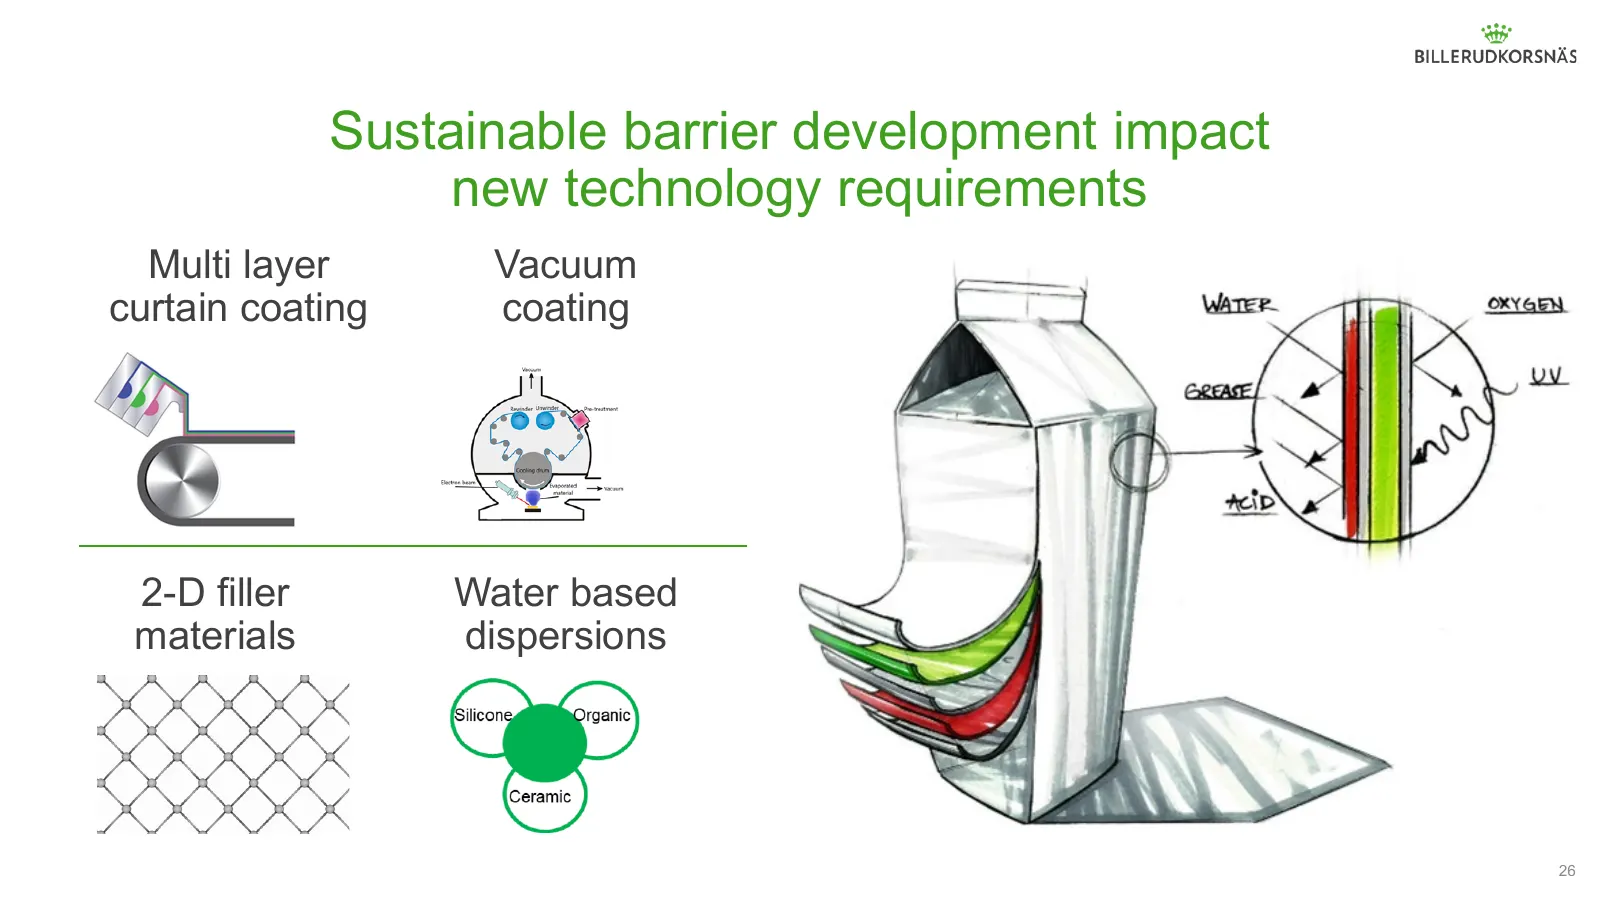
Sustainable barrier development impact new technology requirements Multi layer Vacuum curtain coating coating 2-D filler Water based materials dispersions 26
Slide 27: We continue to invest in PaBoCo
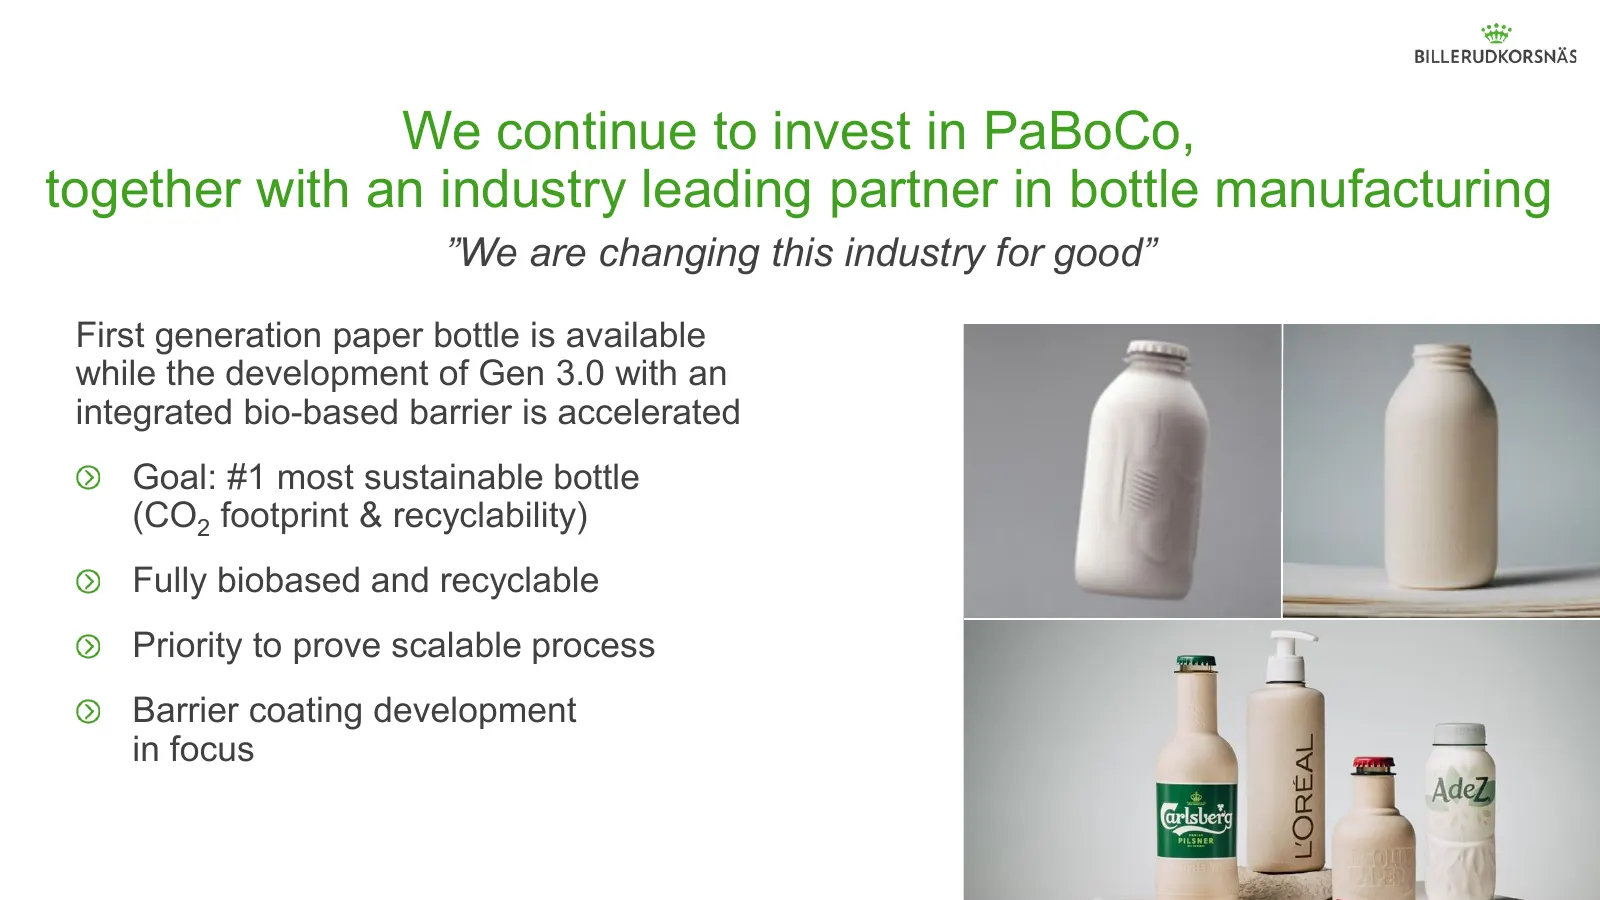
We continue to invest in PaBoCo, together with an industry leading partner in bottle manufacturing ”We are changing this industry for good” First generation paper bottle is available while the development of Gen 3.0 with an integrated bio-based barrier is accelerated Goal: #1 most sustainable bottle
Slide 28: We create customer value by innovating on core products
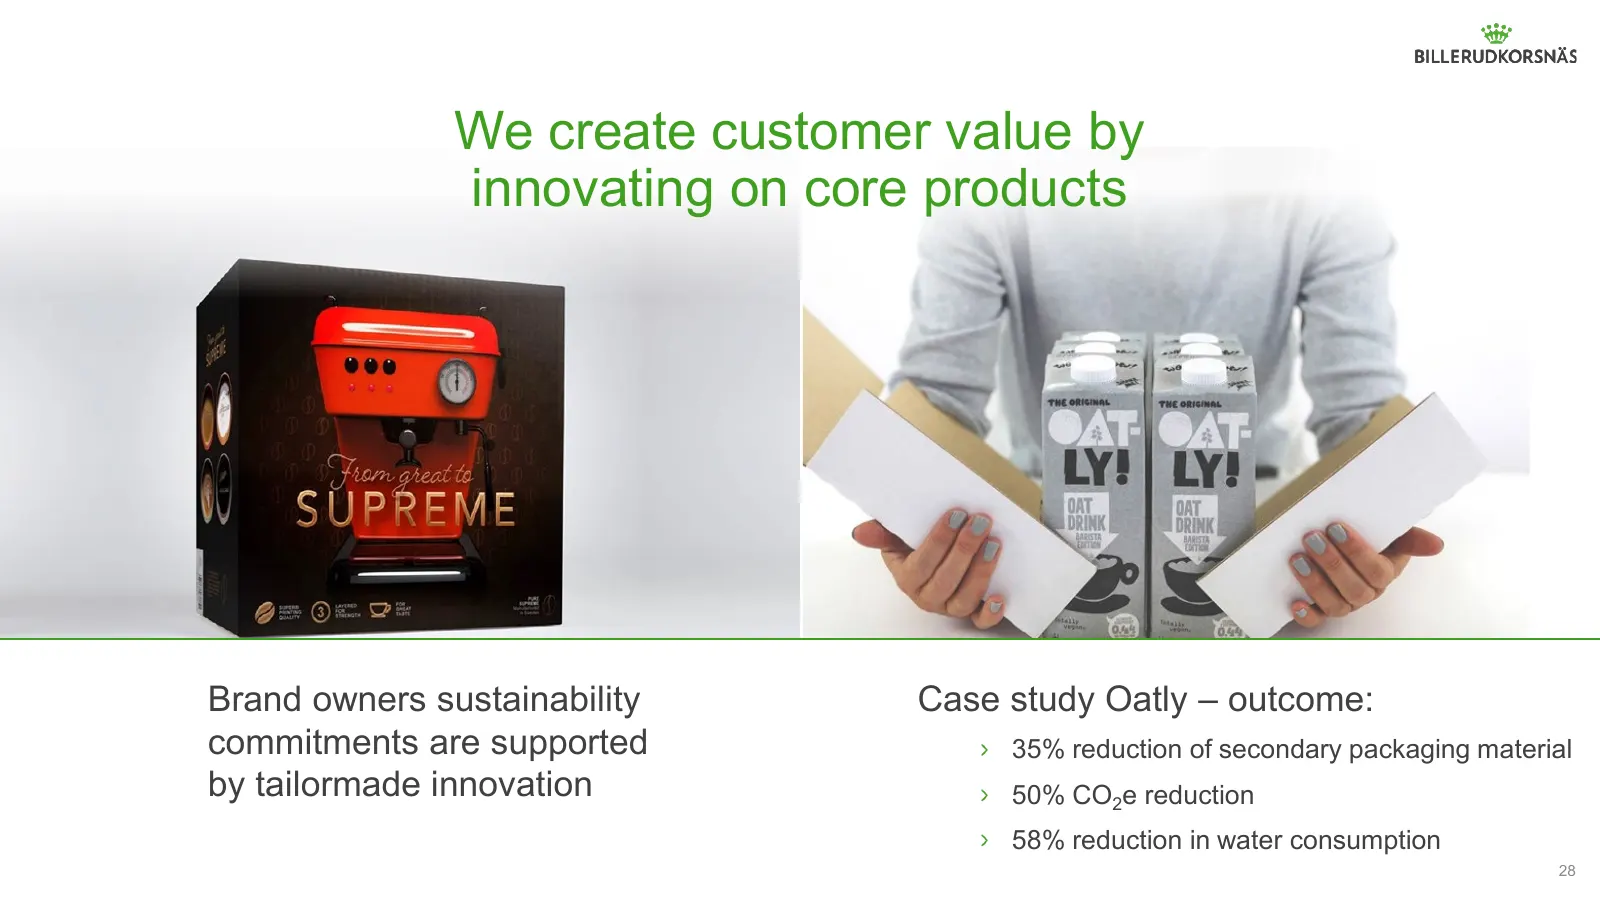
We create customer value by innovating on core products Brand owners sustainability Case study Oatly – outcome: commitments are supported 35% reduction of secondary packaging material by tailormade innovation 50% CO2e reduction 58% reduction in water consumption 28
Slide 29: 29
29
Slide 30: Volume growth through operational stability and efficiencies
Volume growth through operational stability and efficiencies: the journey ahead Tor Lundqvist, EVP Operations
Slide 31: Maximise capacity utilisation at lowest possible unit cost
Maximise capacity utilisation at lowest possible unit cost 31
Slide 32: Our strategic choices
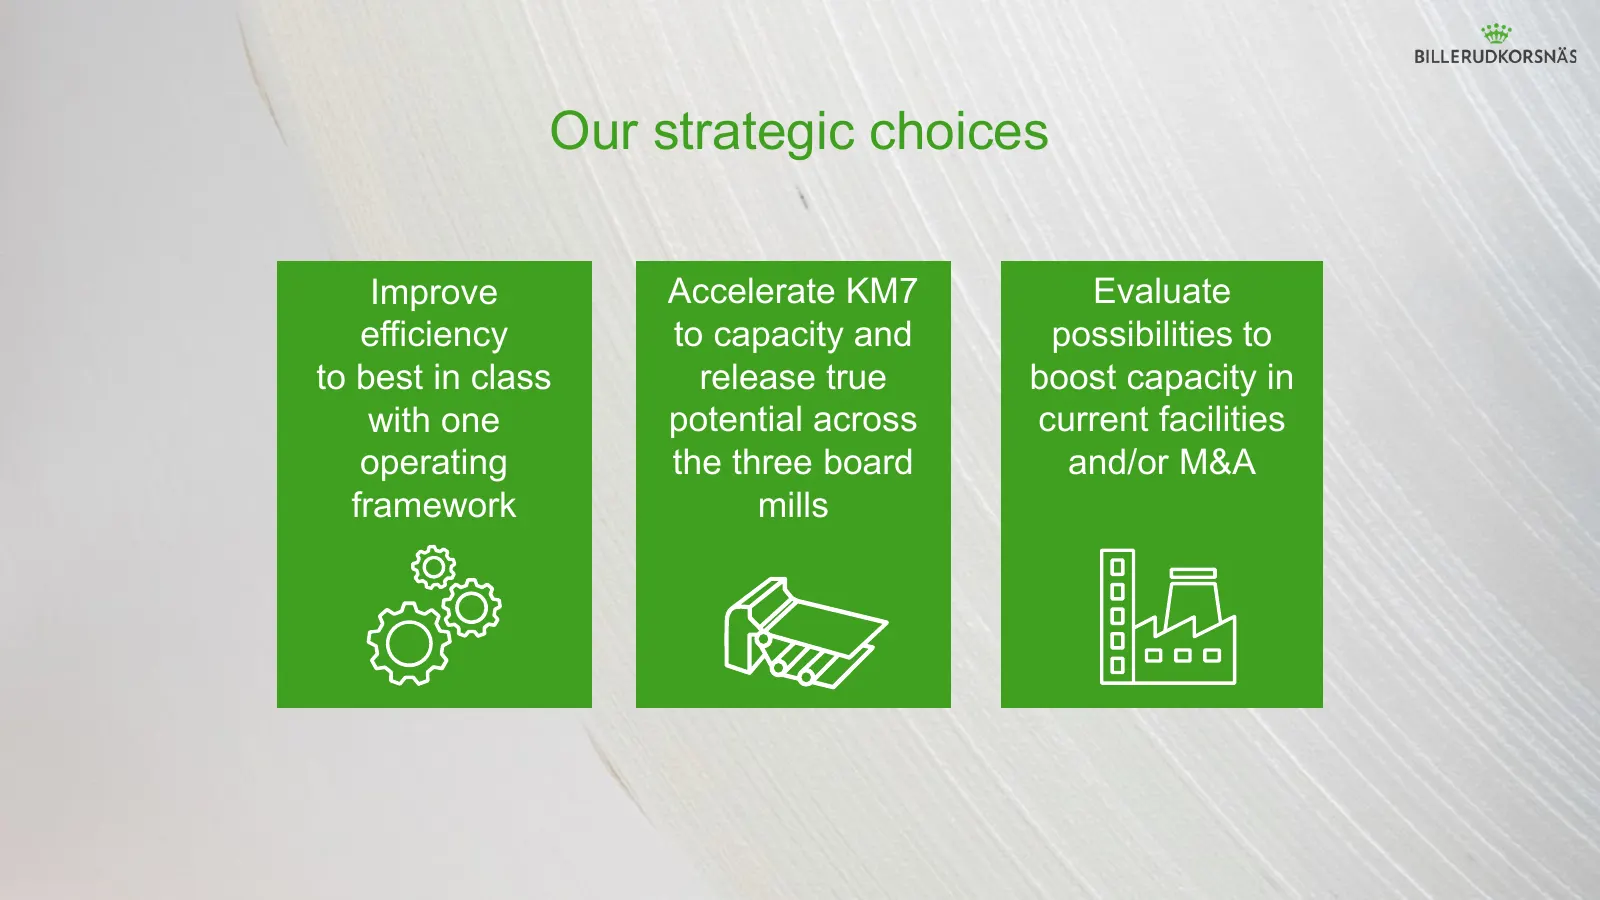
Our strategic choices Improve Accelerate KM7 Evaluate efficiency to capacity and possibilities to to best in class release true boost capacity in with one potential across current facilities operating the three board and/or M&A framework mills
Slide 33: Safety is our first priority
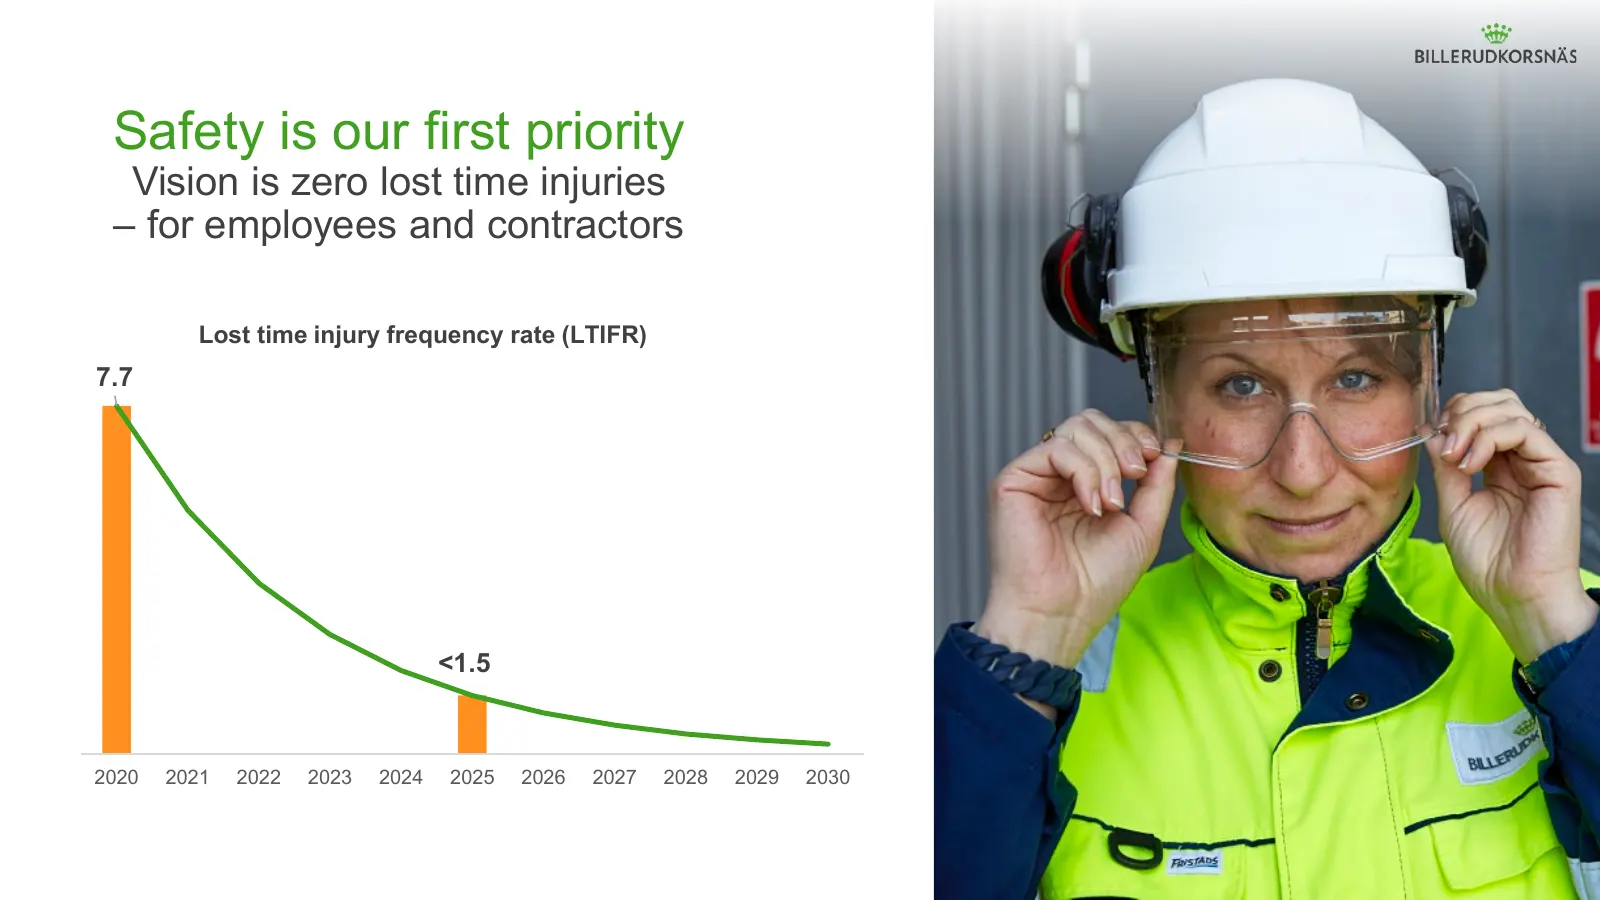
Safety is our first priority Vision is zero lost time injuries – for employees and contractors Lost time injury frequency rate (LTIFR) 7.7 <1.5 2020 2021 2022 2023 2024 2025 2026 2027 2028 2029 2030
Slide 34: On the right path with focused activities
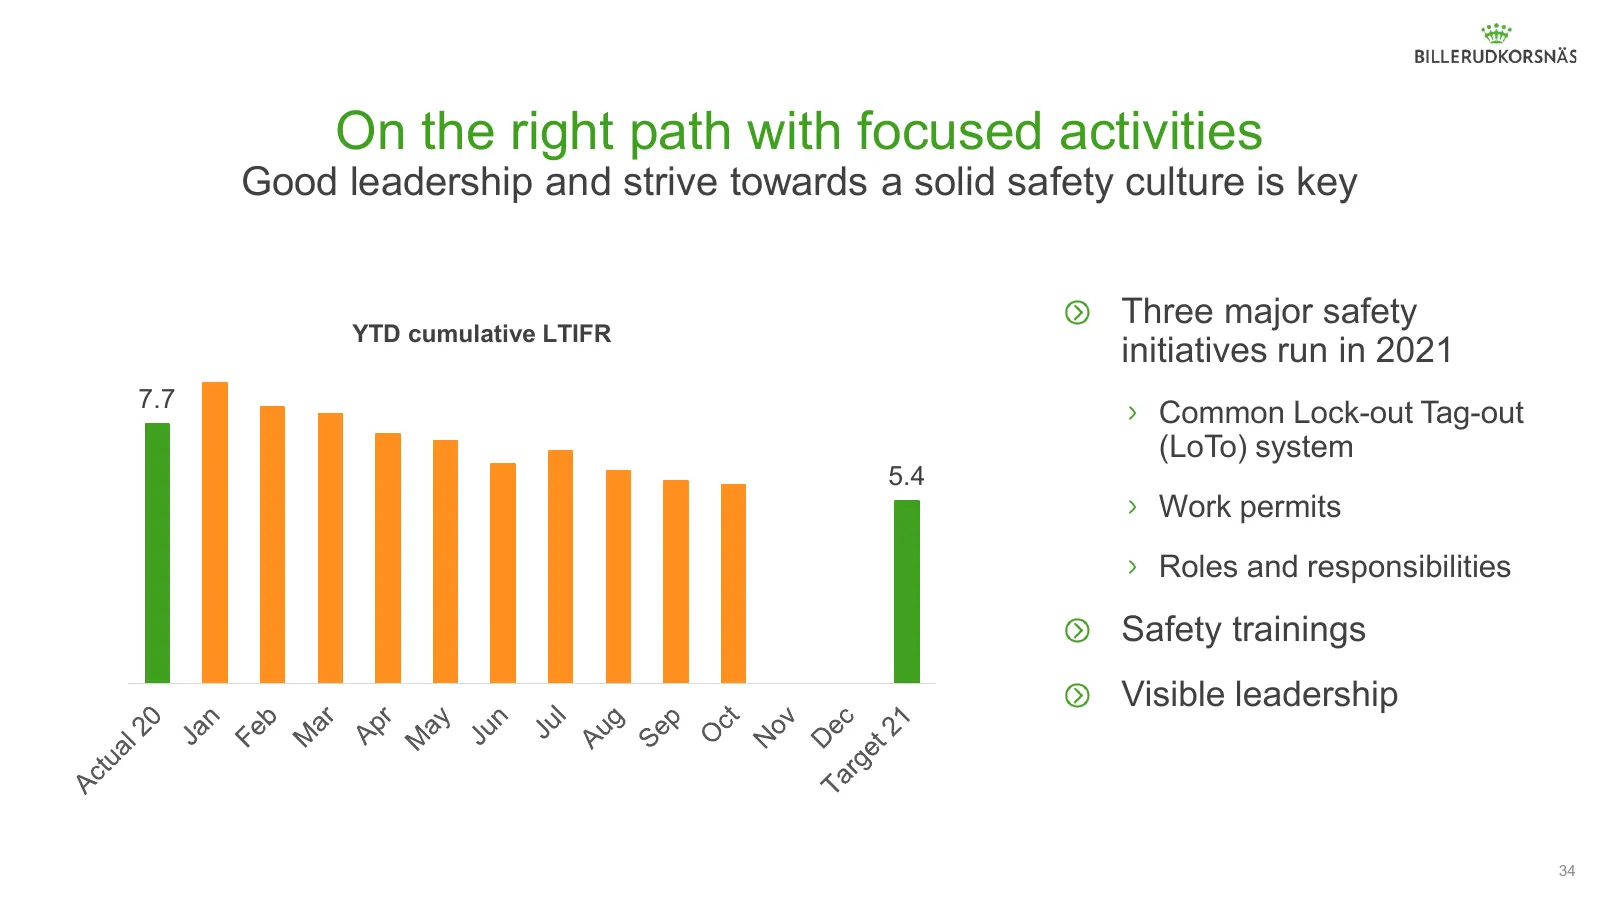
On the right path with focused activities Good leadership and strive towards a solid safety culture is key Three major safety YTD cumulative LTIFR initiatives run in 2021 7.7 Common Lock-out Tag-out (LoTo) system 5.4 Work permits Roles and responsibilities Safety trainings Visible leadership 34
Slide 35: Volume growth is picking up
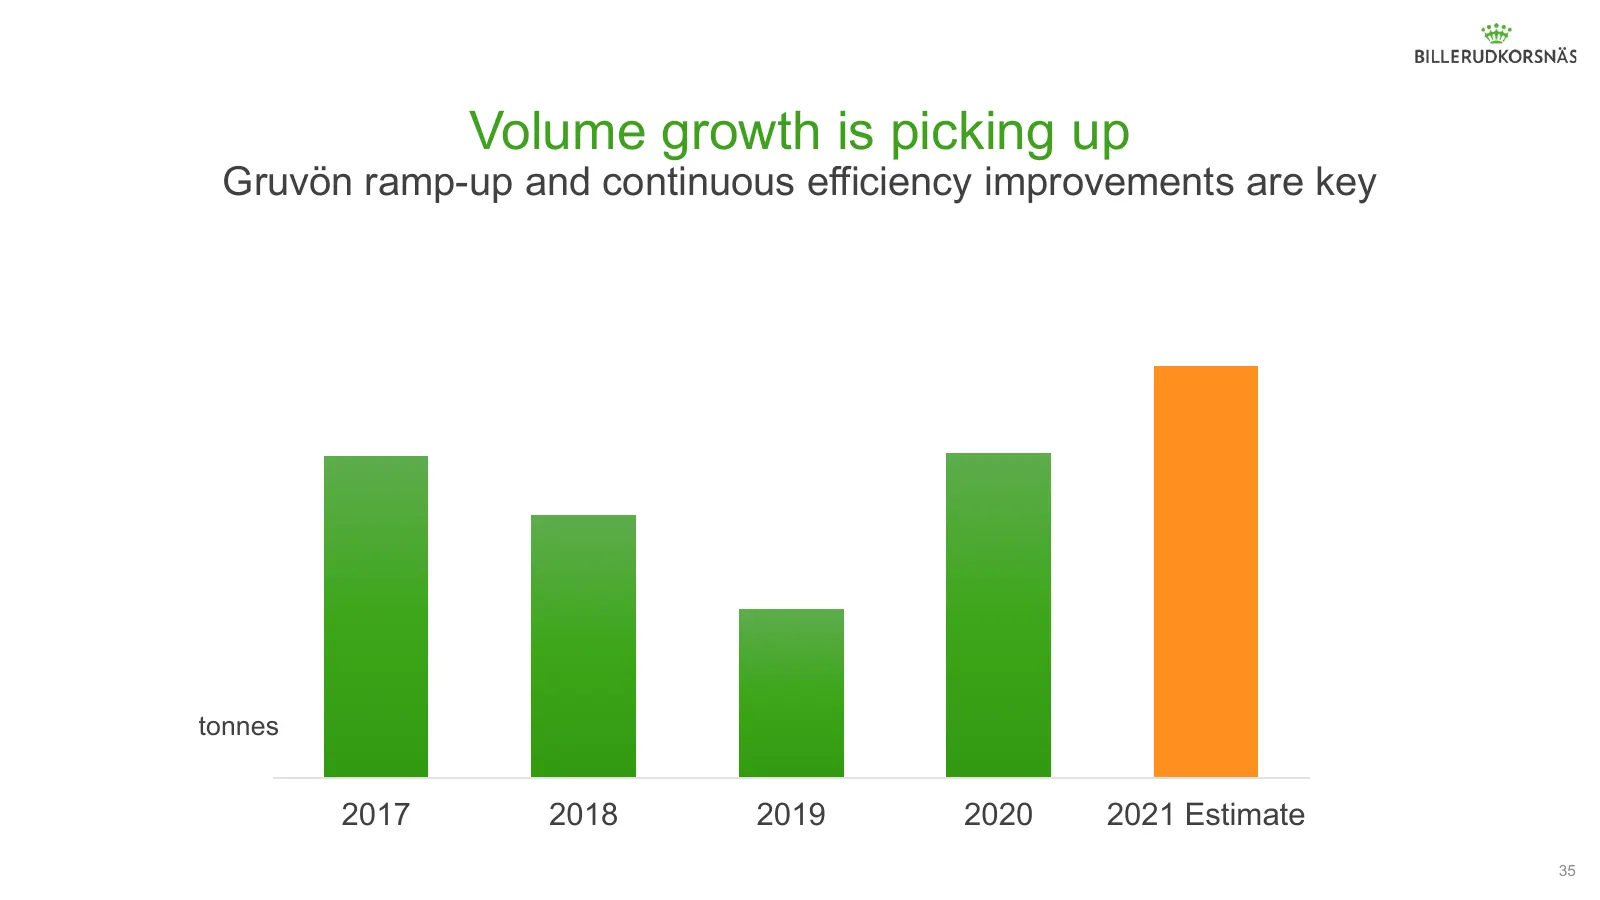
Volume growth is picking up Gruvön ramp-up and continuous efficiency improvements are key tonnes 2017 2018 2019 2020 2021 Estimate 35
Slide 36: Strong volume growth and mix optimisation critical to deliver net sales
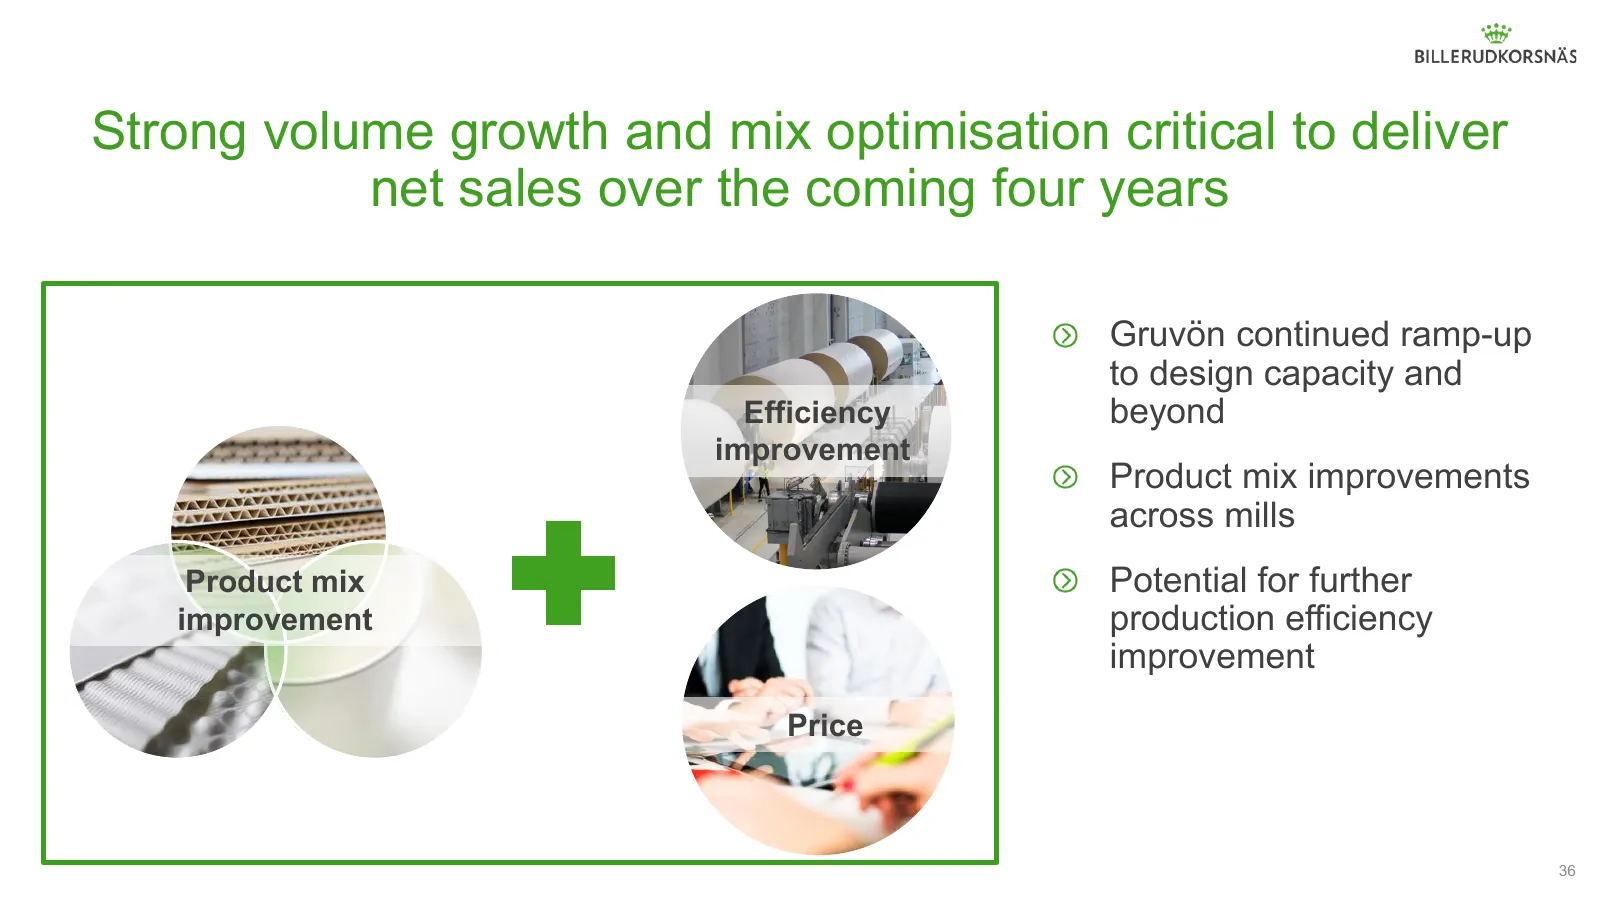
Strong volume growth and mix optimisation critical to deliver net sales over the coming four years Gruvön continued ramp-up to design capacity and Efficiency beyond improvement Product mix improvements across mills Product mix Potential for further improvement production efficiency improvement Price
Slide 37: Production stability will improve with stronger focus on maintenance, CAPEX
Production stability will improve with stronger focus on maintenance, CAPEX and execution Focus on maintenance Focus on CAPEX Programme to lift maintenance to Historic non-strategic base CAPEX common best practice has started has been too low to both maintain and develop the mills External audits of
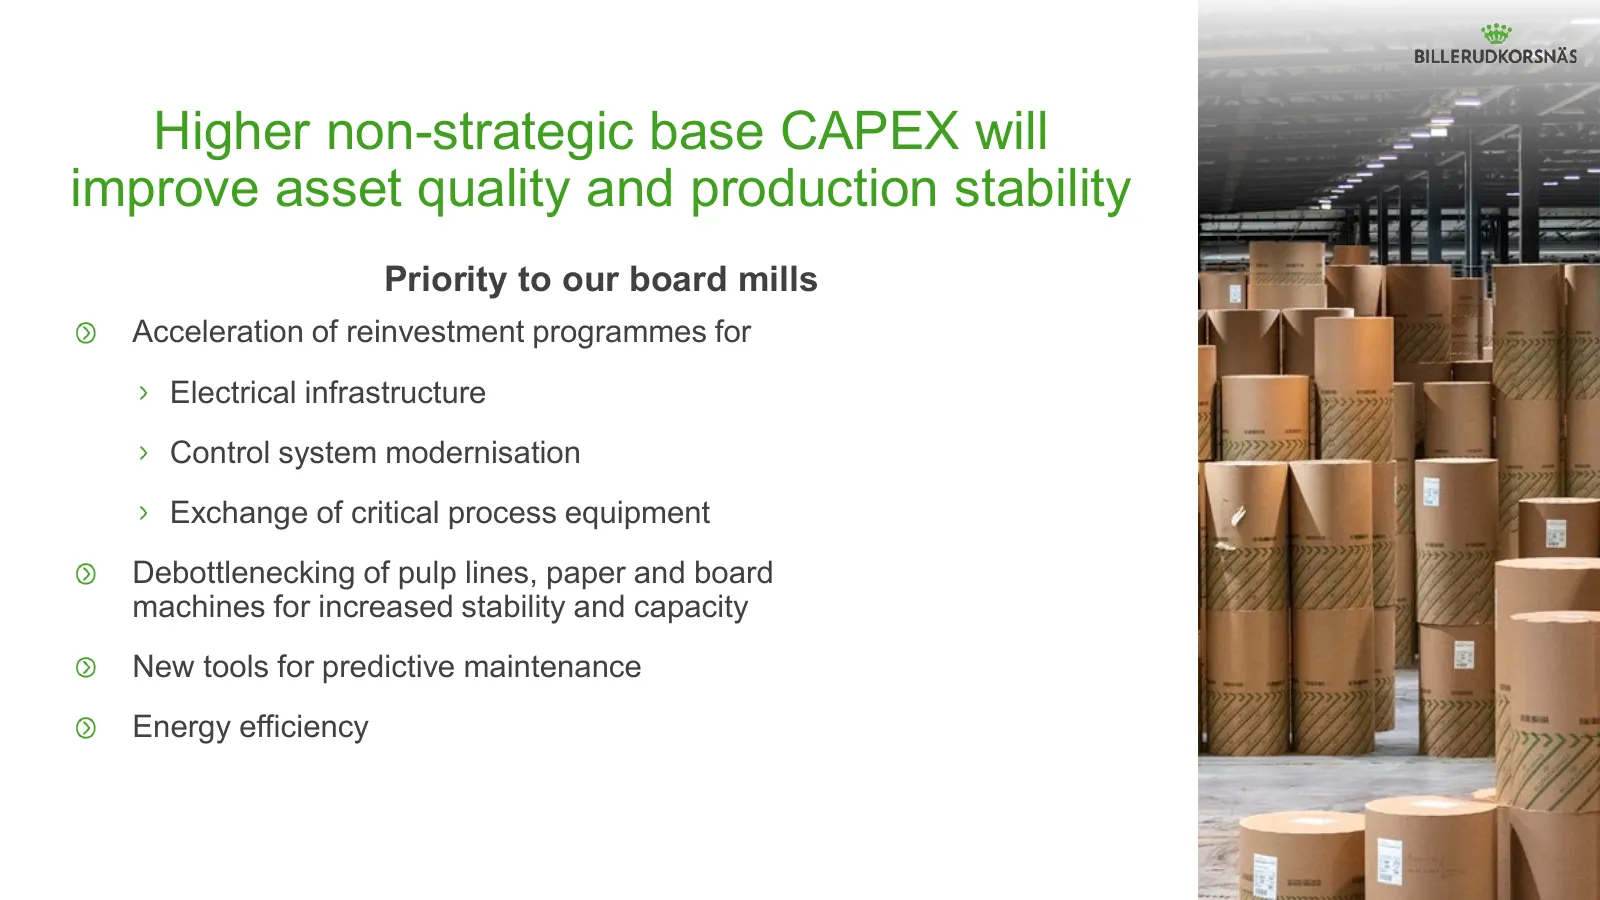
Slide 38: Higher non-strategic base CAPEX will improve asset quality
Higher non-strategic base CAPEX will improve asset quality and production stability Priority to our board mills Acceleration of reinvestment programmes for Electrical infrastructure Control system modernisation Exchange of critical process equipment Debottlenecking of pulp lines, paper and board mac
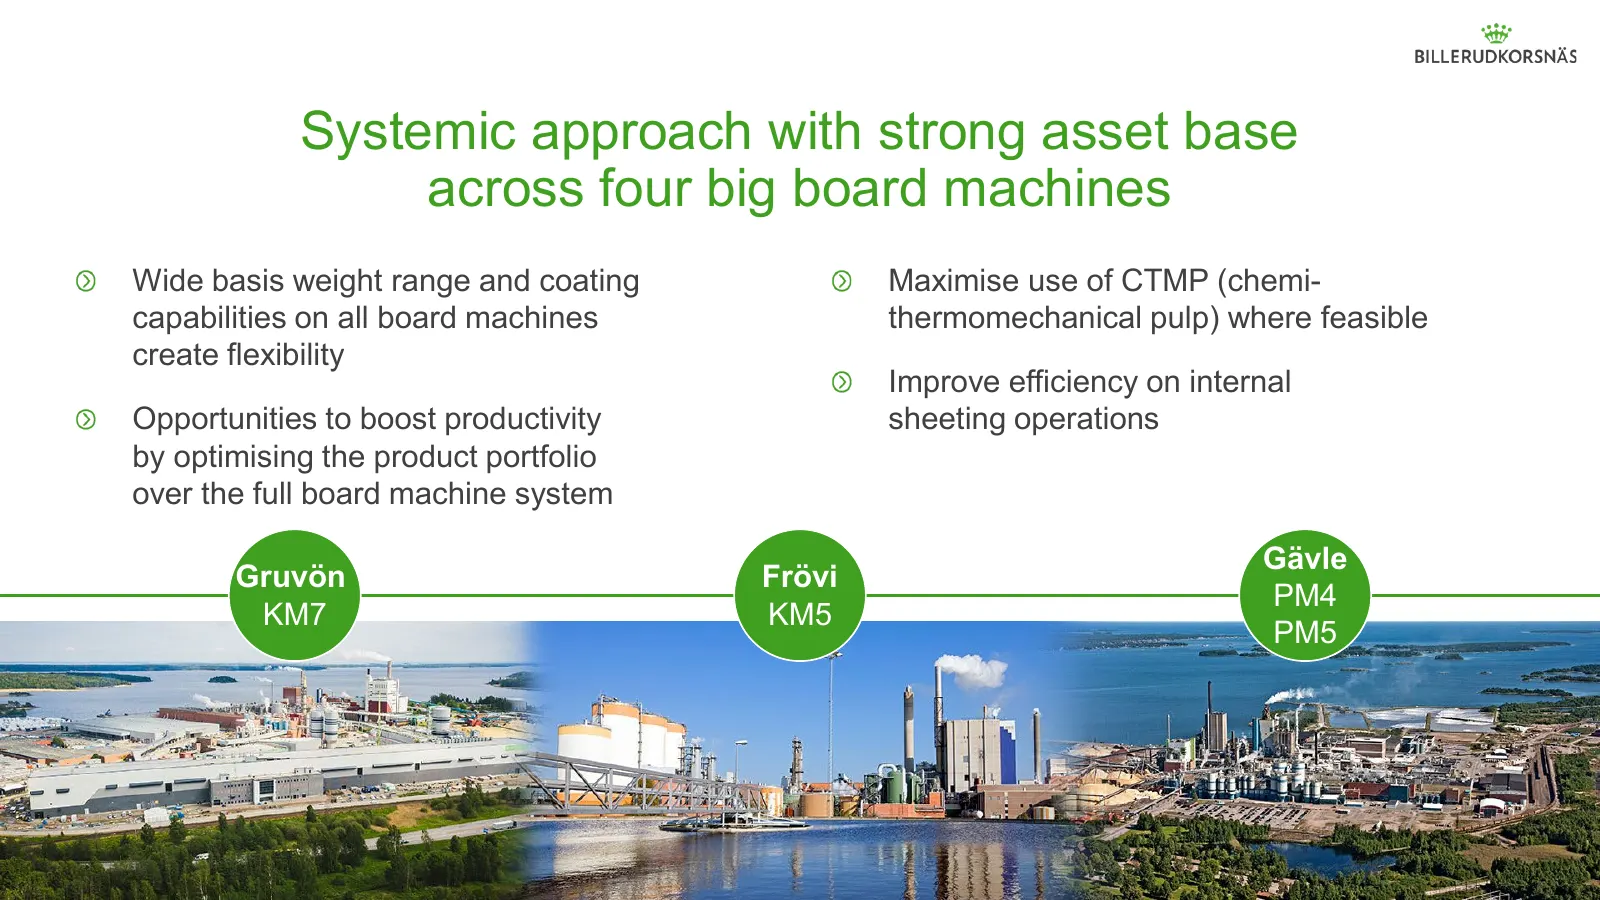
Slide 39: Systemic approach with strong asset base across four big board machines
Systemic approach with strong asset base across four big board machines Wide basis weight range and coating Maximise use of CTMP (chemi- capabilities on all board machines thermomechanical pulp) where feasible create flexibility Improve efficiency on internal Opportunities to boost productivity shee
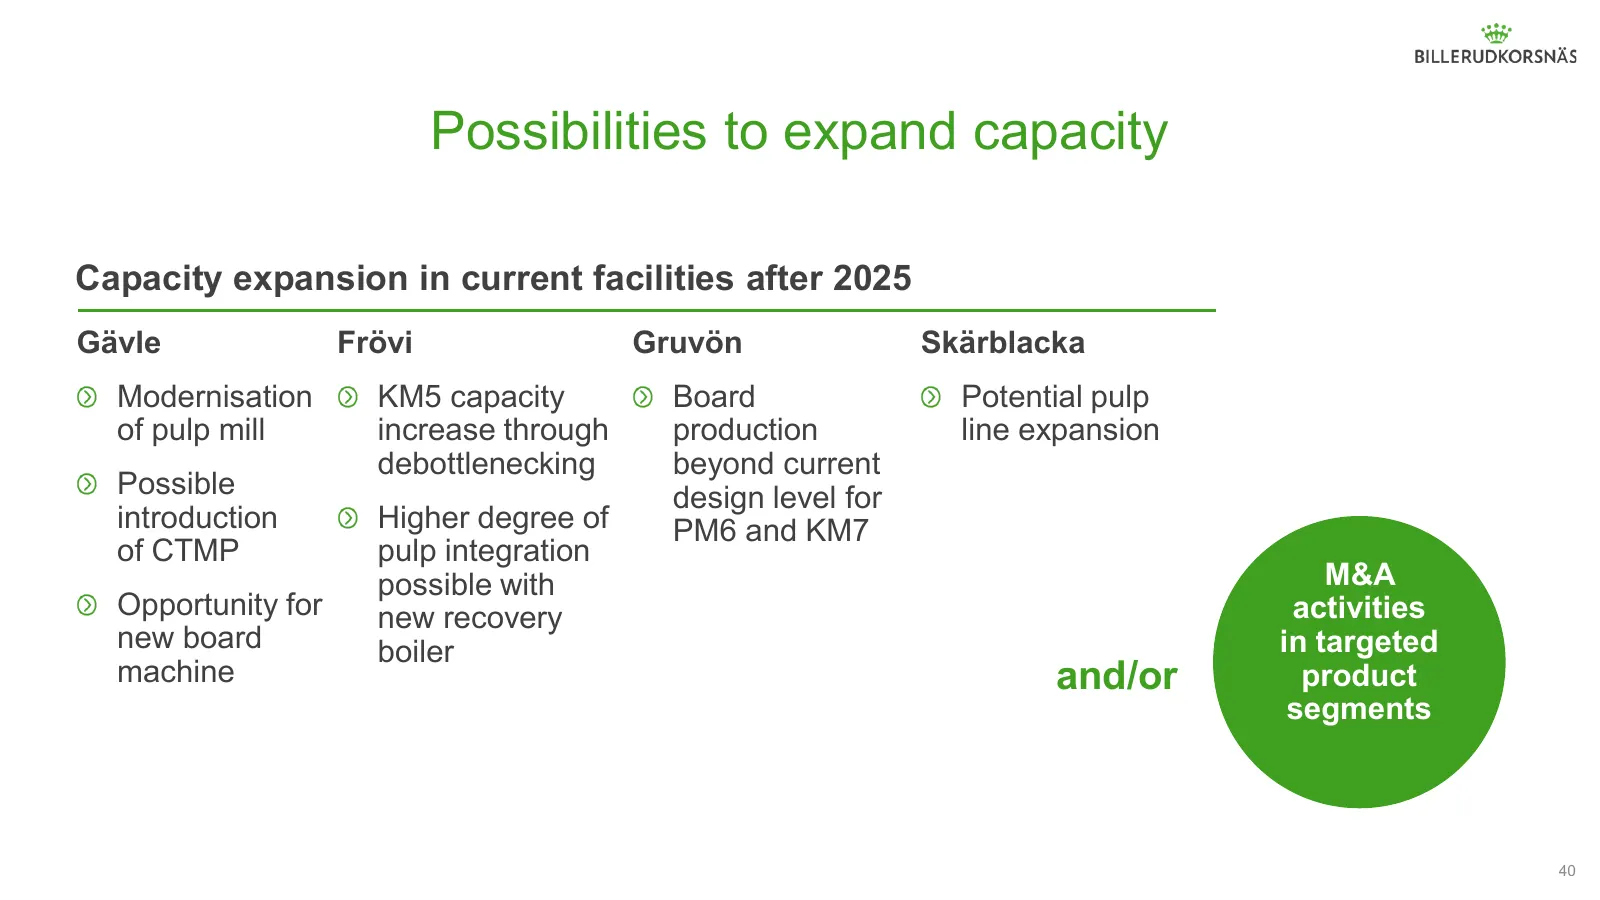
Slide 40: Possibilities to expand capacity
Possibilities to expand capacity Capacity expansion in current facilities after 2025 Gävle Frövi Gruvön Skärblacka Modernisation KM5 capacity Board Potential pulp of pulp mill increase through production line expansion debottlenecking beyond current Possible design level for introduction Higher degr
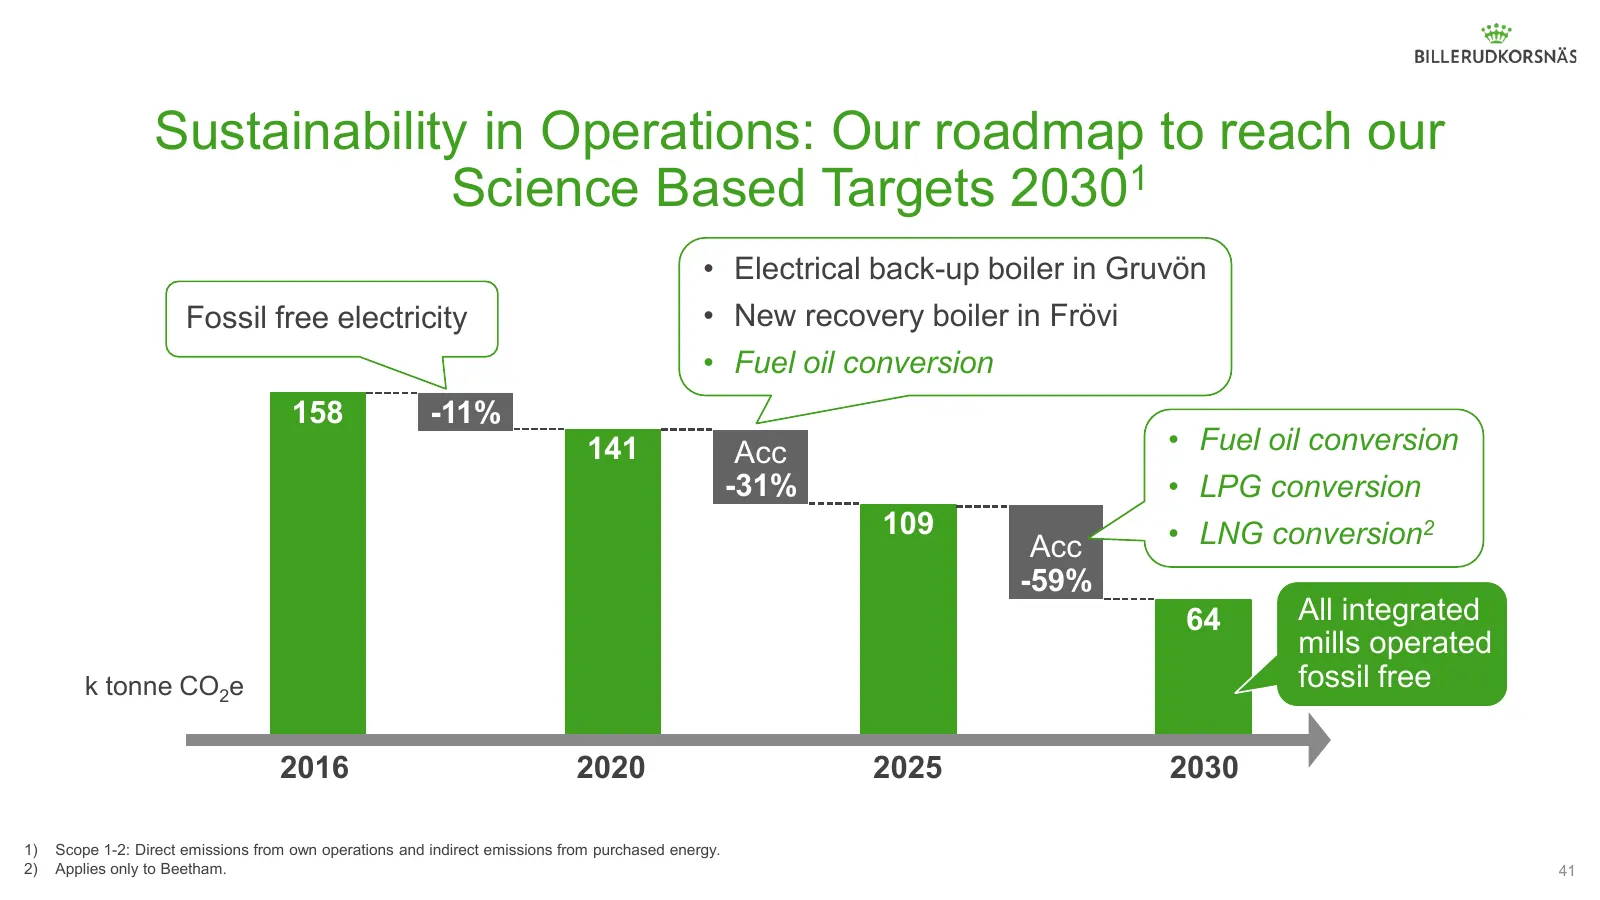
Slide 41: Sustainability in Operations: Our roadmap to reach our Science Based Targets 2030
Sustainability in Operations: Our roadmap to reach our Science Based Targets 20301 • Electrical back-up boiler in Gruvön Fossil free electricity • New recovery boiler in Frövi • Fuel oil conversion 158 -11% 141 Acc • Fuel oil conversion -31% • LPG conversion 109 • LNG conversion2 Acc -59% 64 All int
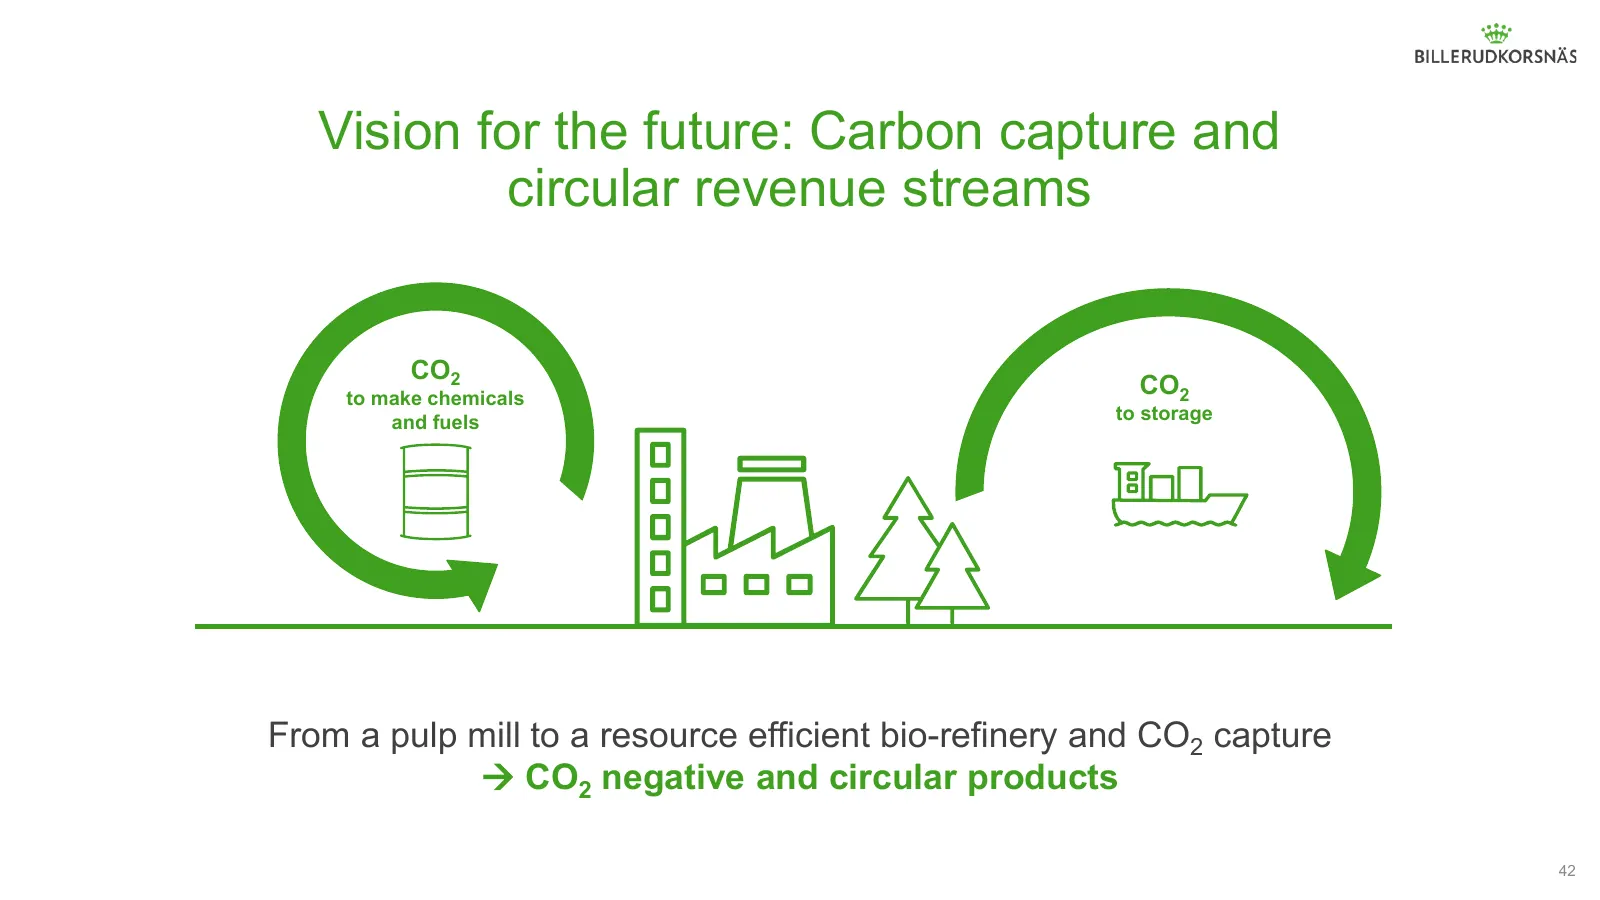
Slide 42: Vision for the future: Carbon capture and circular revenue streams
Vision for the future: Carbon capture and circular revenue streams CO2 to make chemicals CO2 and fuels to storage From a pulp mill to a resource efficient bio-refinery and CO2 capture CO2 negative and circular products 42
Slide 43: Transformation in competitive wood supply
Transformation in competitive wood supply Anna-Maria Tuominen-Reini, EVP Wood Supply
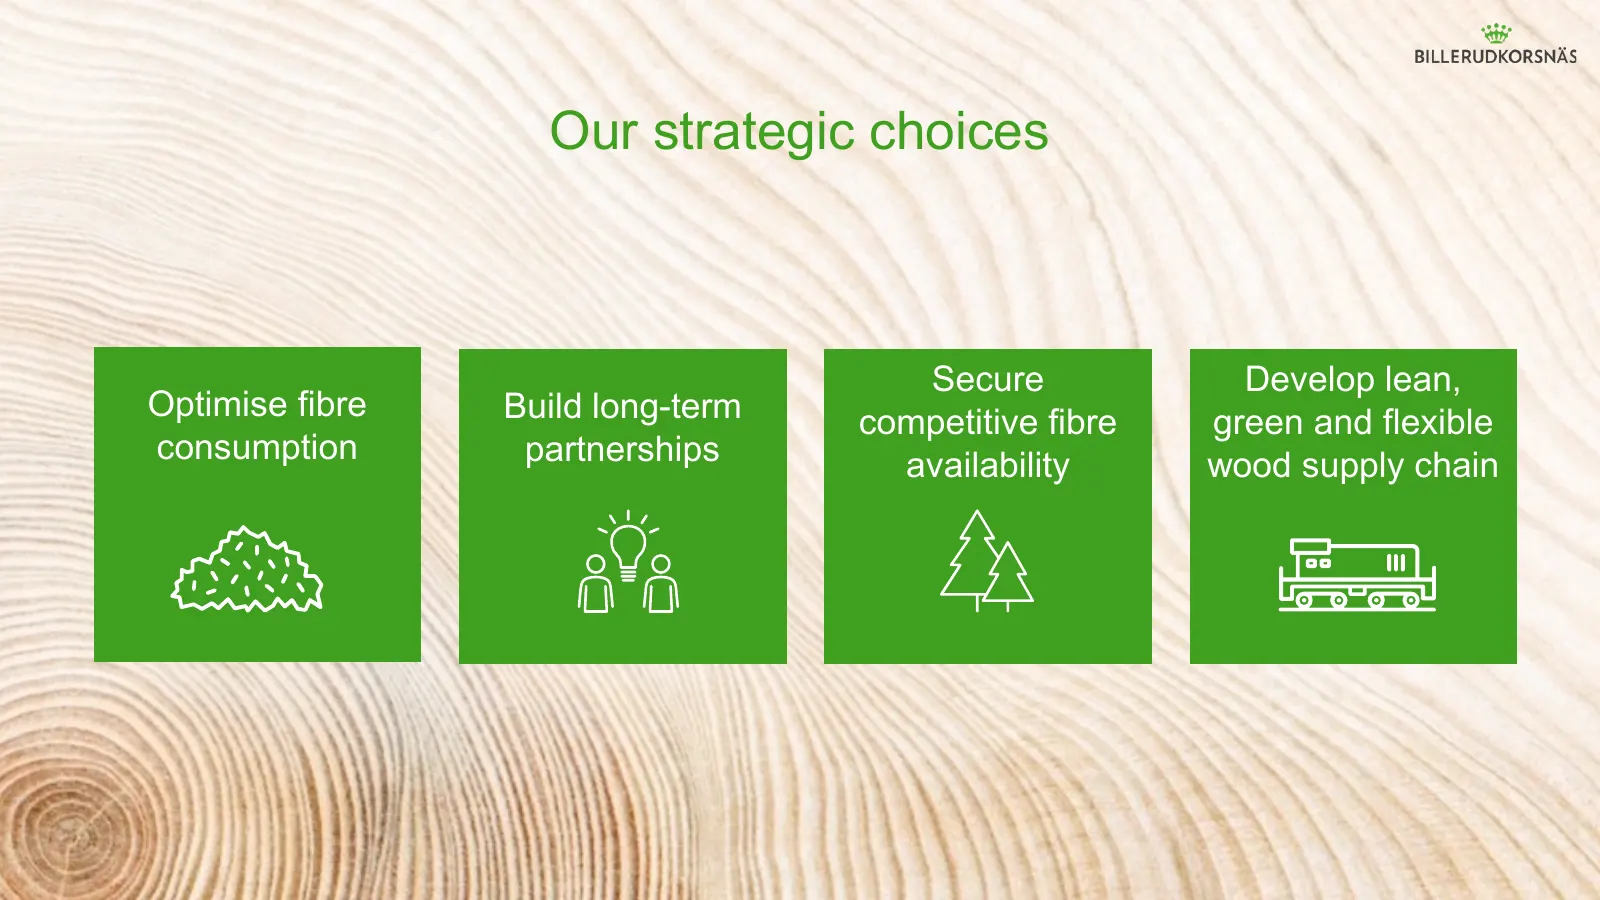
Slide 44: Our strategic choices
Our strategic choices Secure Develop lean, Optimise fibre Build long-term competitive fibre green and flexible consumption partnerships availability wood supply chain
Slide 45: Competitive wood supply
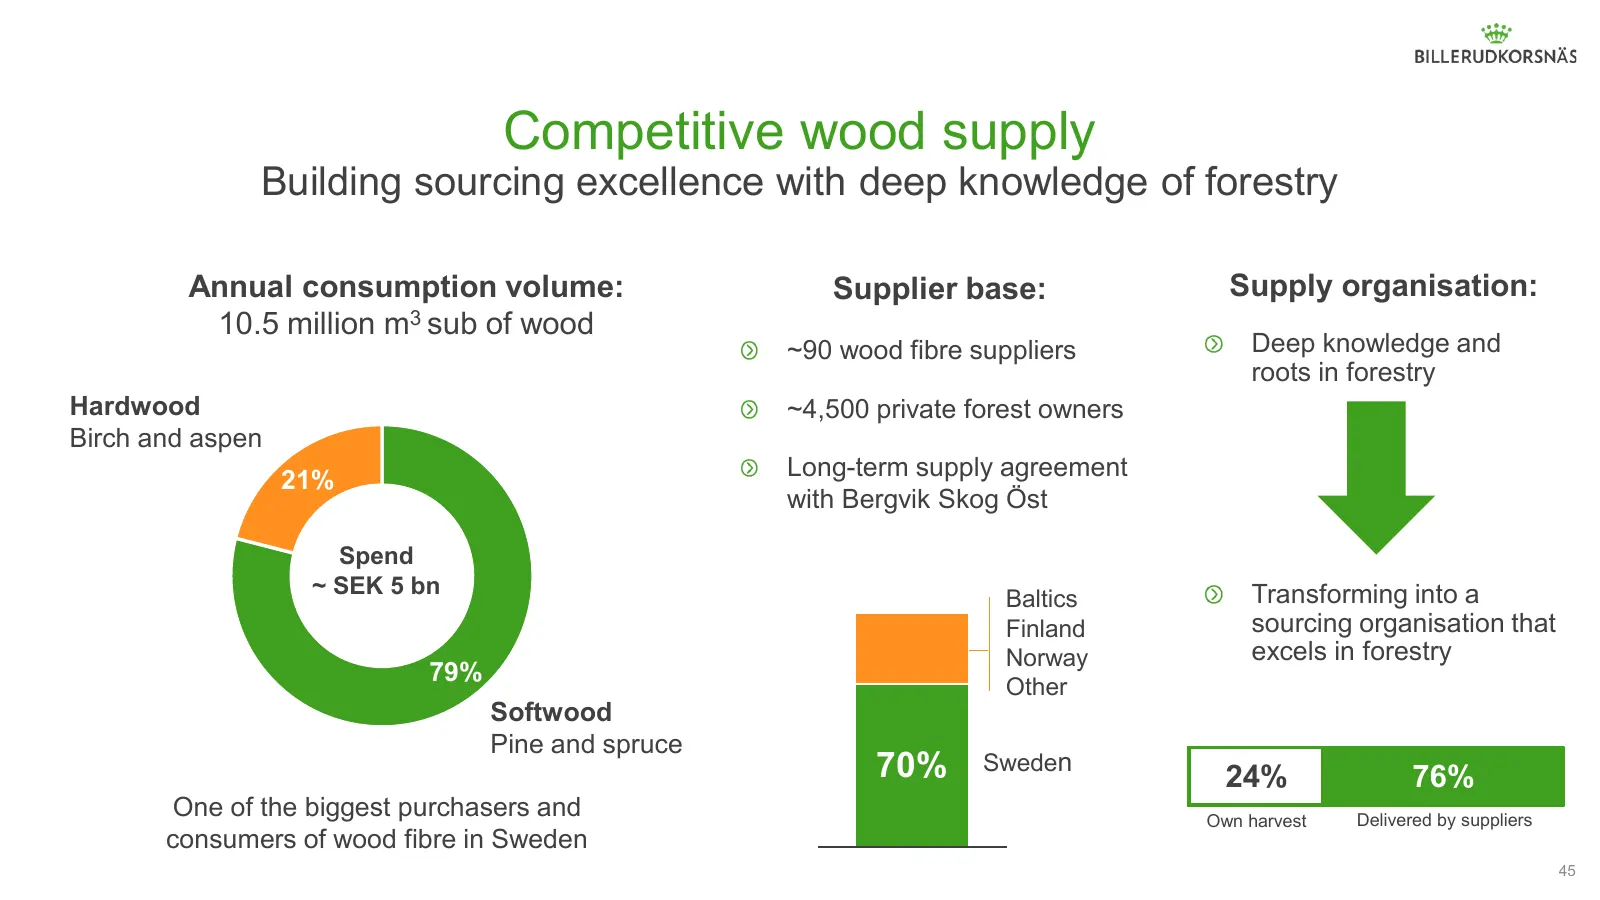
Competitive wood supply Building sourcing excellence with deep knowledge of forestry Annual consumption volume: Supplier base: Supply organisation: 10.5 million m3 sub of wood ~90 wood fibre suppliers Deep knowledge and roots in forestry Hardwood ~4,500 private forest owners Birch and aspen 21% Long
Slide 46: Sustainable wood supply
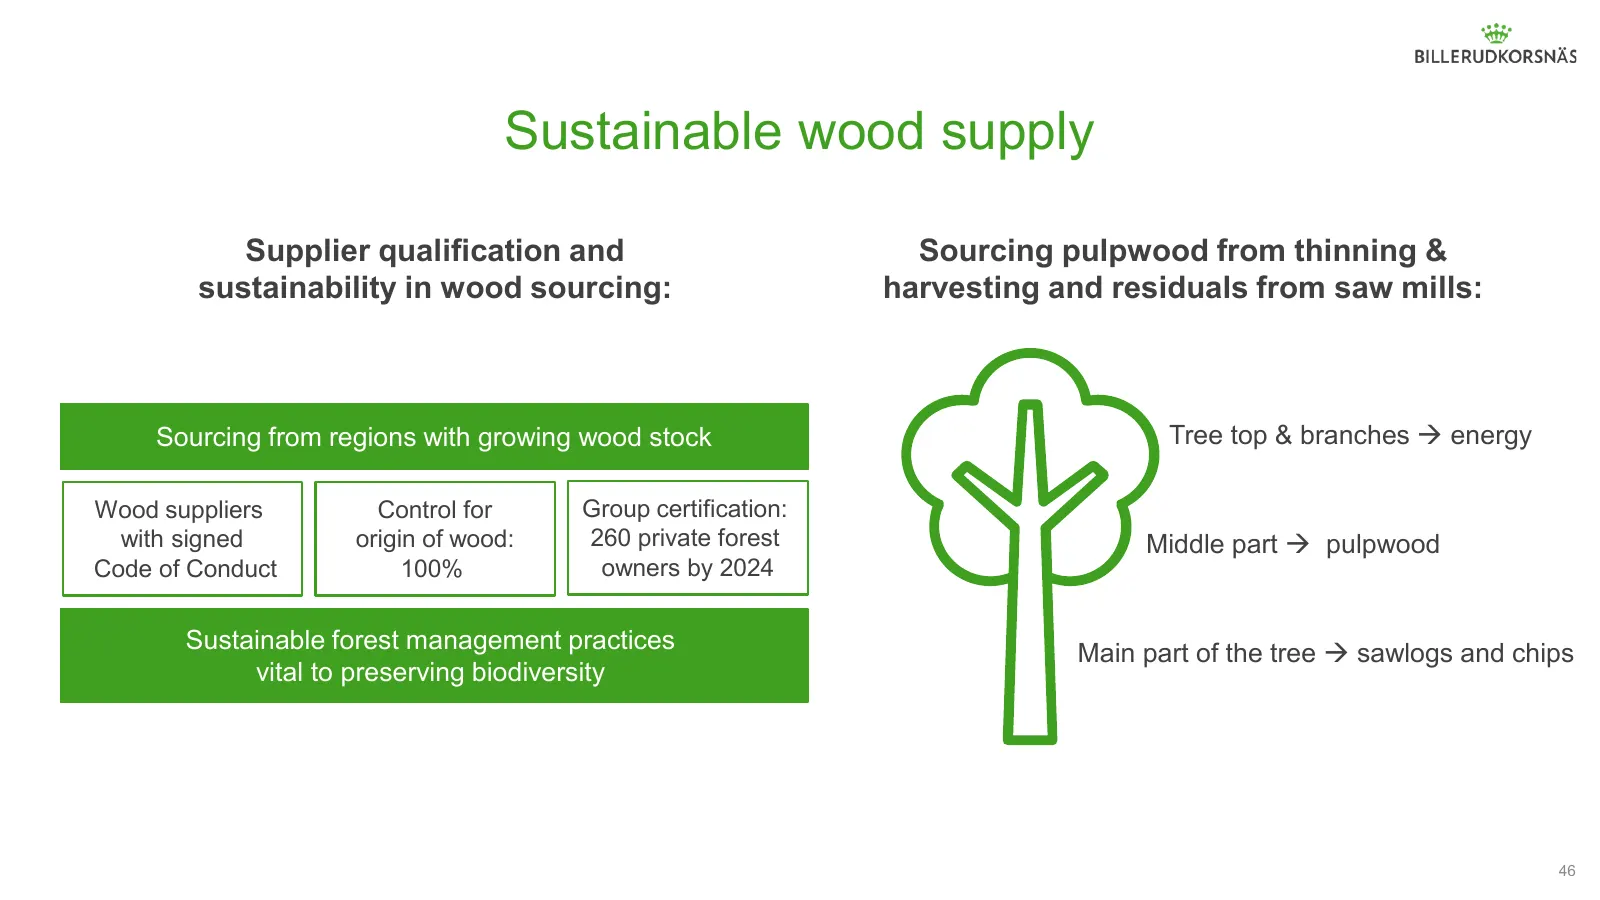
Sustainable wood supply Supplier qualification and Sourcing pulpwood from thinning & sustainability in wood sourcing: harvesting and residuals from saw mills: Sourcing from regions with growing wood stock Tree top & branches energy Wood suppliers Control for Group certification: with signed origin
Slide 47: Good fibre availability in the short term, long-term pressure remains
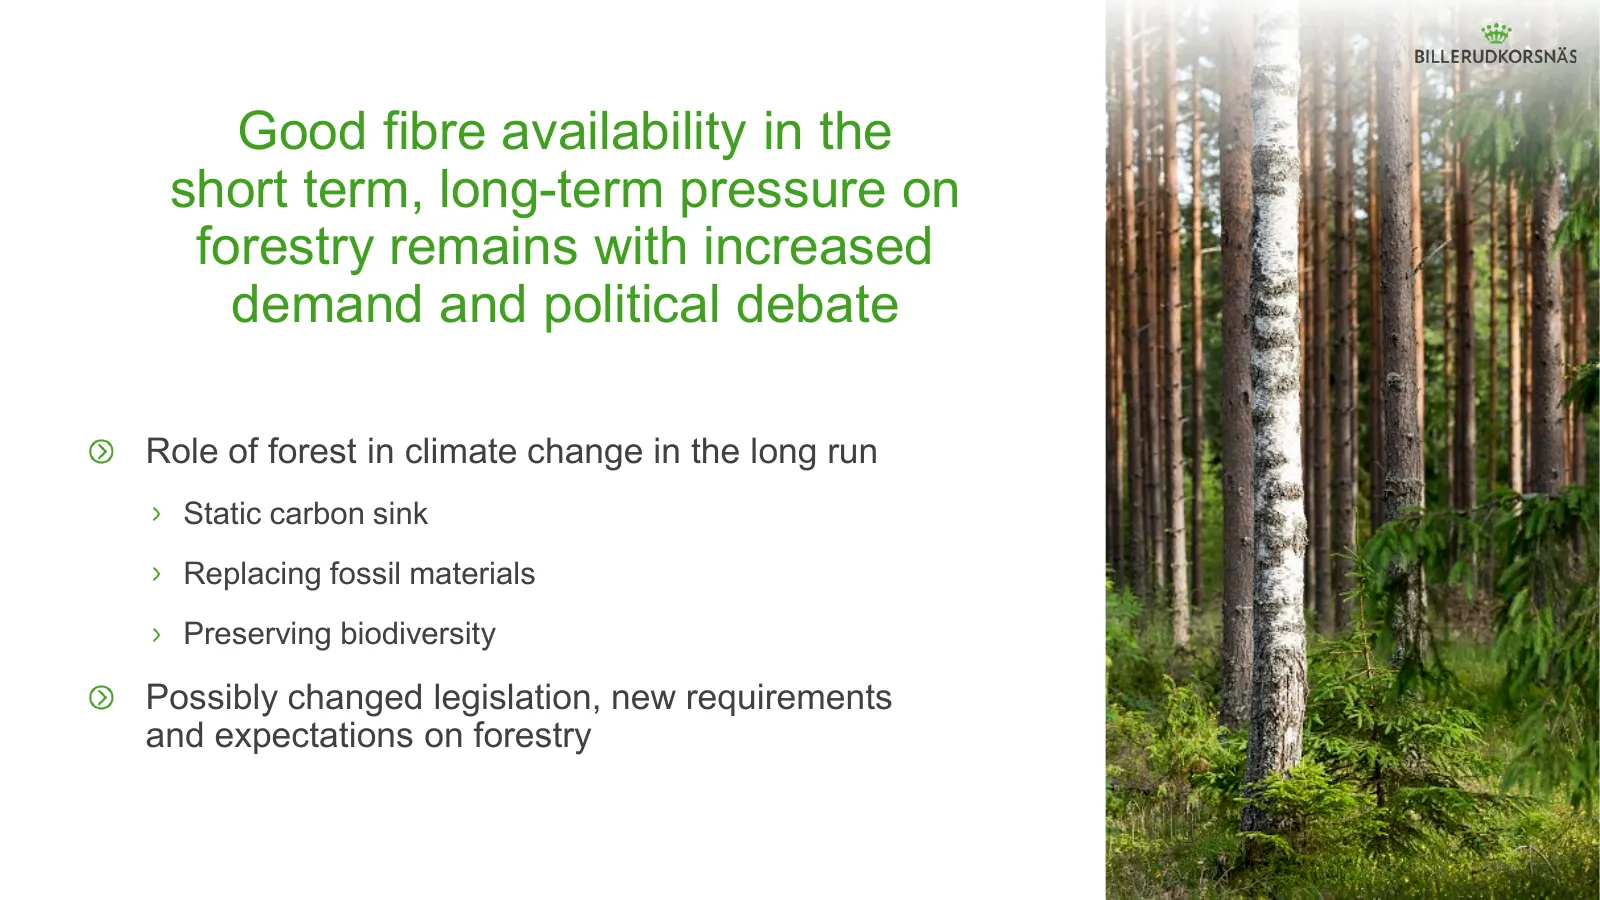
Good fibre availability in the short term, long-term pressure on forestry remains with increased demand and political debate Role of forest in climate change in the long run Static carbon sink Replacing fossil materials Preserving biodiversity Possibly changed legislation, new requirements and expec
Slide 48: Optimise fibre consumption
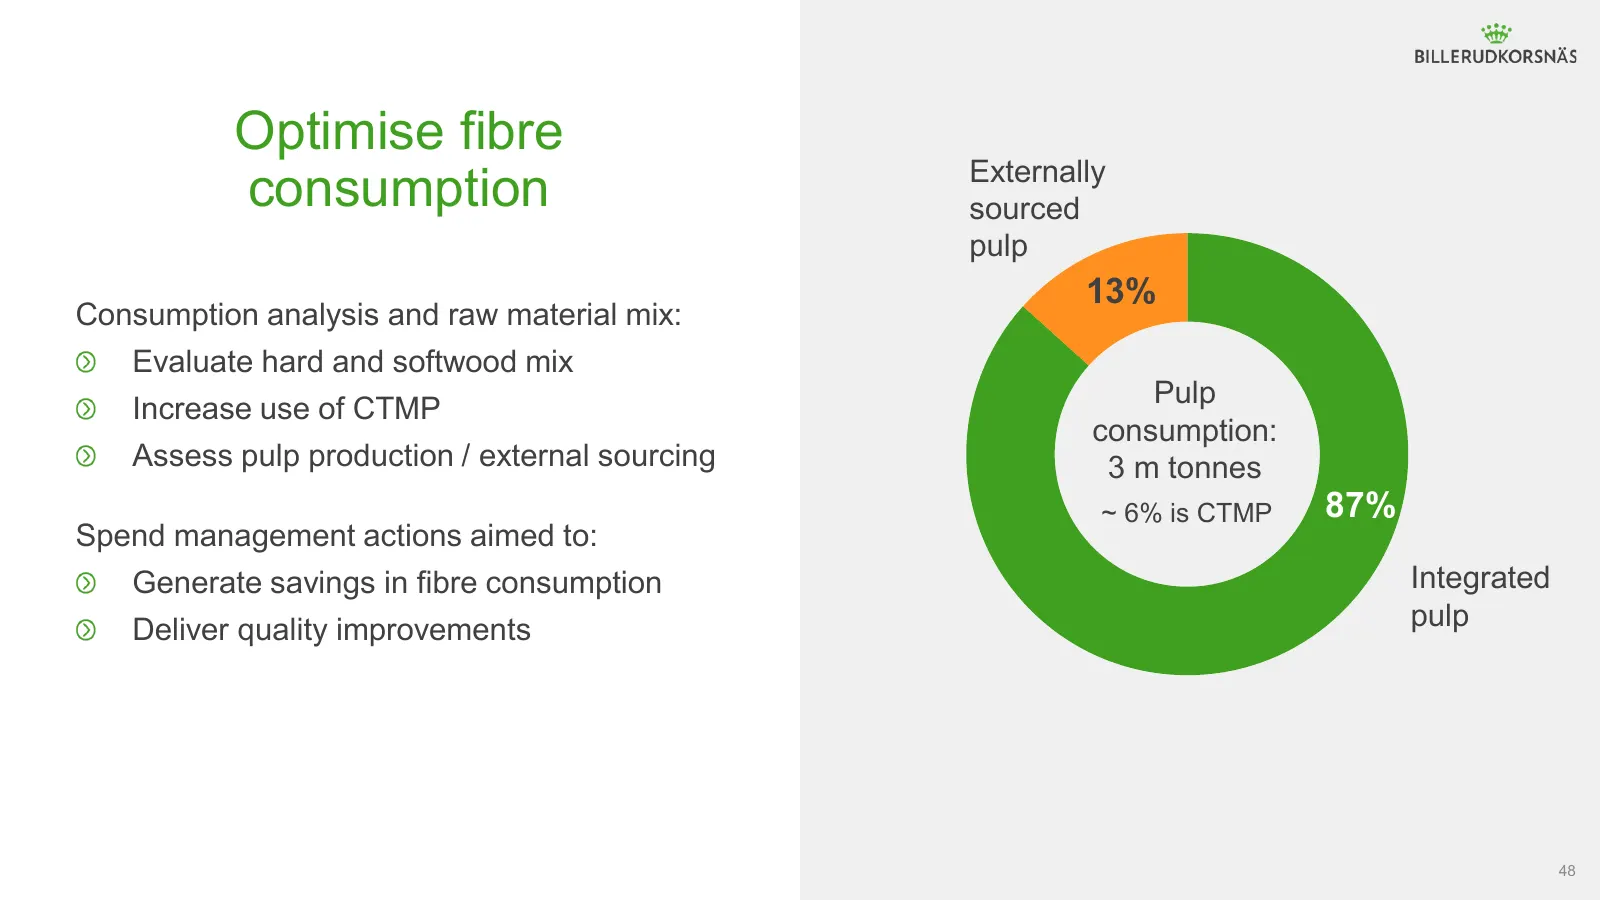
Optimise fibre Externally consumption sourced pulp 13% Consumption analysis and raw material mix: Evaluate hard and softwood mix Increase use of CTMP Pulp consumption: Assess pulp production / external sourcing 3 m tonnes ~ 6% is CTMP 87% Spend management actions aimed to: Generate savings in fibre
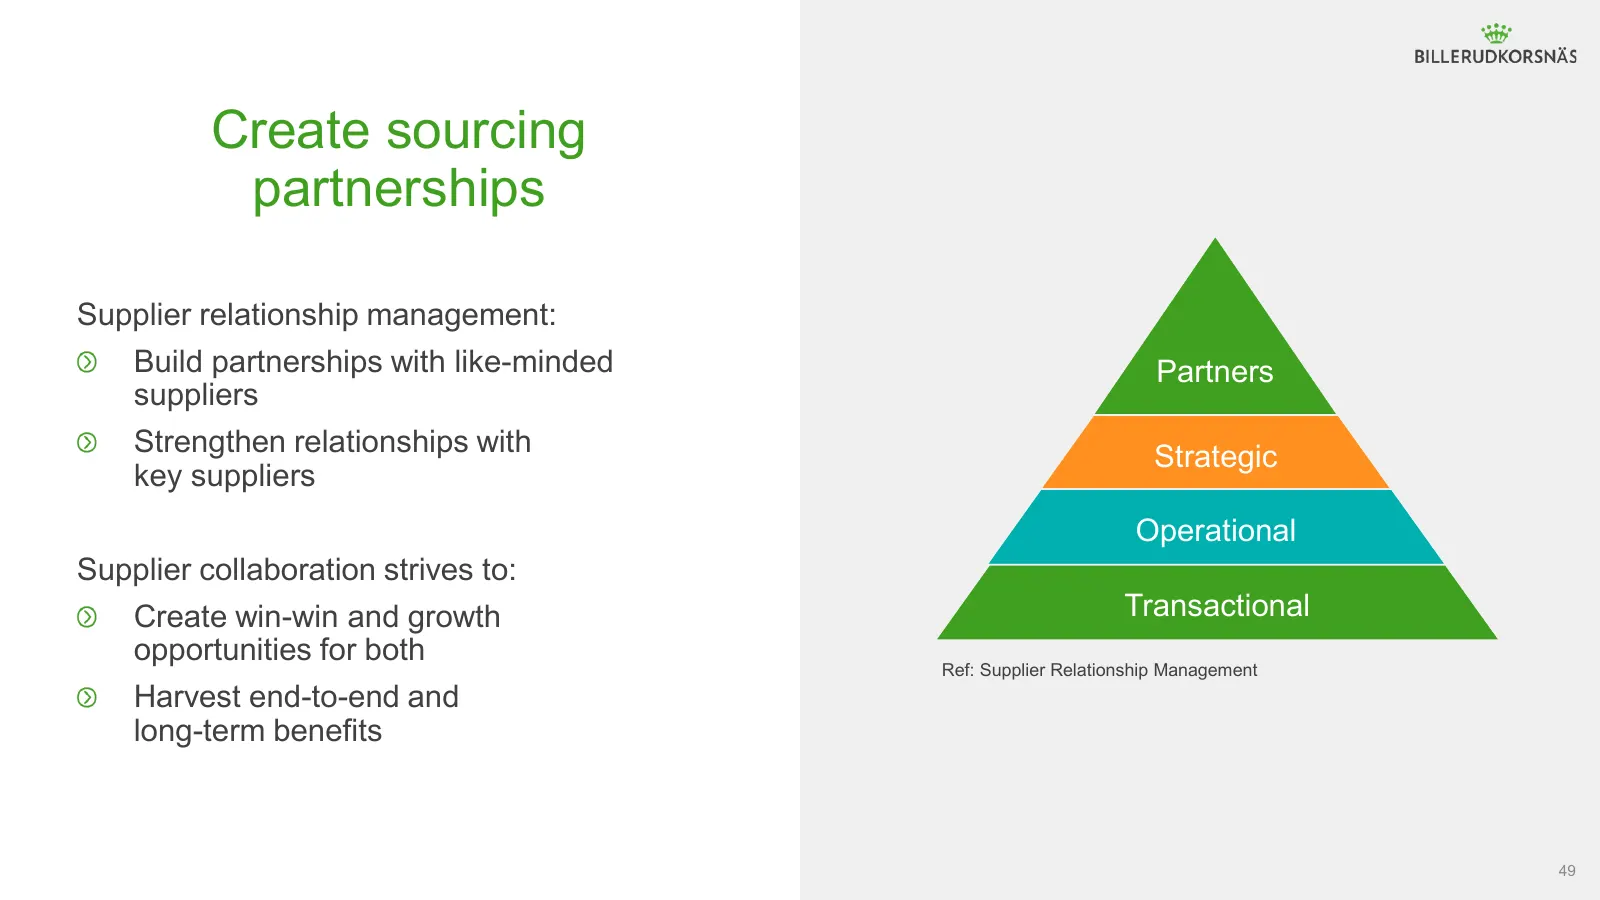
Slide 49: Create sourcing partnerships
Create sourcing partnerships Supplier relationship management: Build partnerships with like-minded Partners suppliers Strengthen relationships with Strategic key suppliers Operational Supplier collaboration strives to: Create win-win and growth Transactional opportunities for both Ref: Supplier Rela
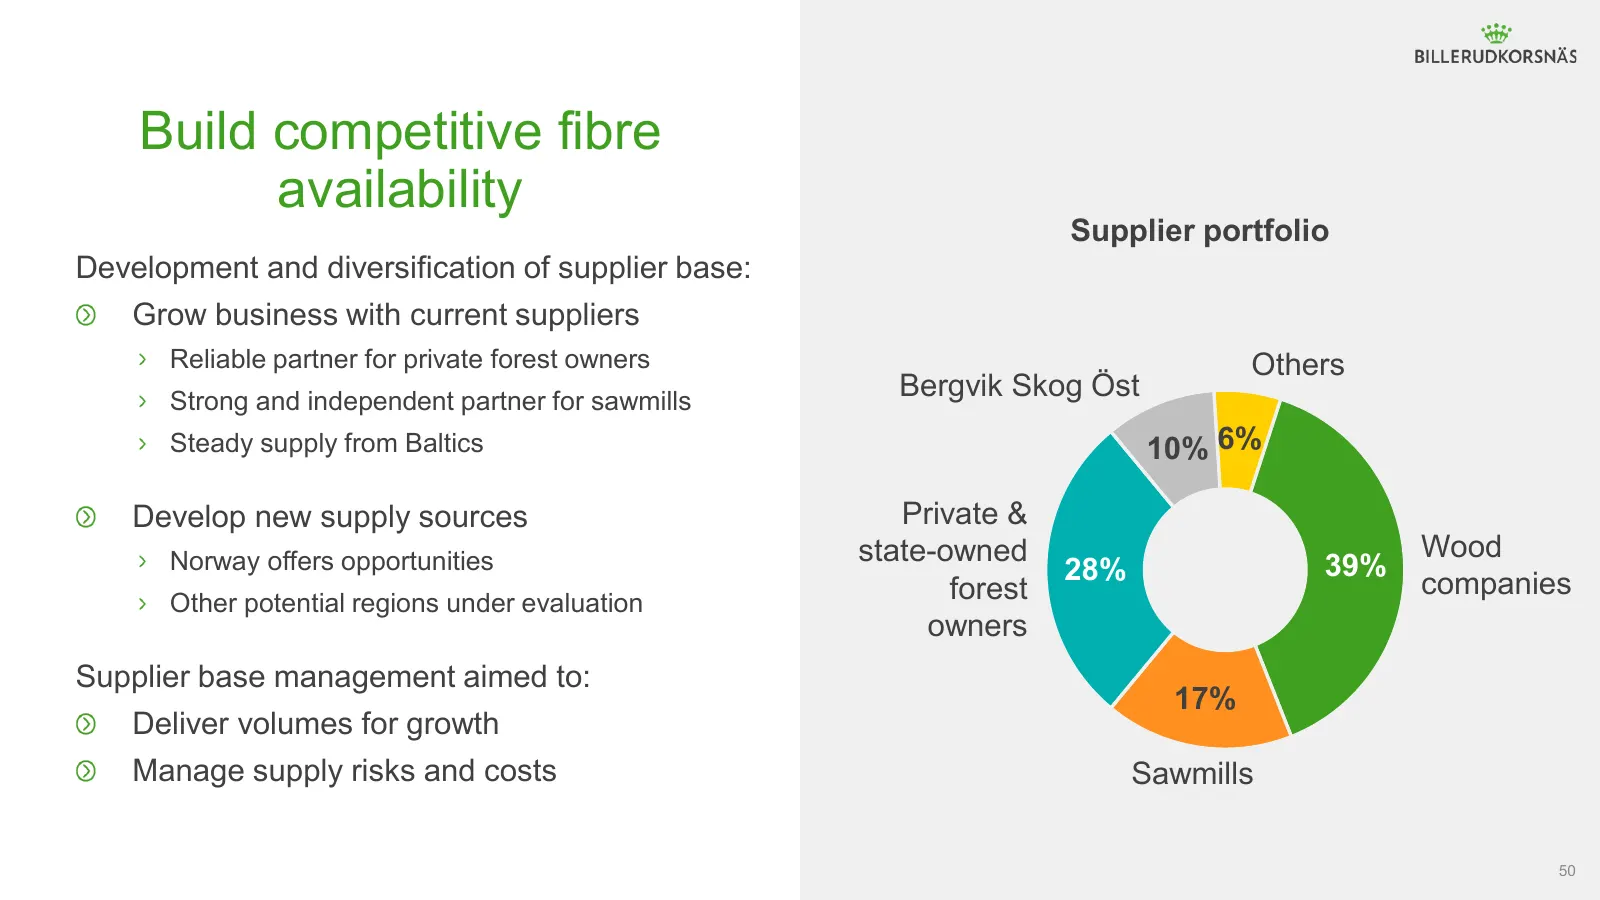
Slide 50: Build competitive fibre availability
Build competitive fibre availability Supplier portfolio Development and diversification of supplier base: Grow business with current suppliers Reliable partner for private forest owners Others Strong and independent partner for sawmills Bergvik Skog Öst Steady supply from Baltics 10% 6% Develop new
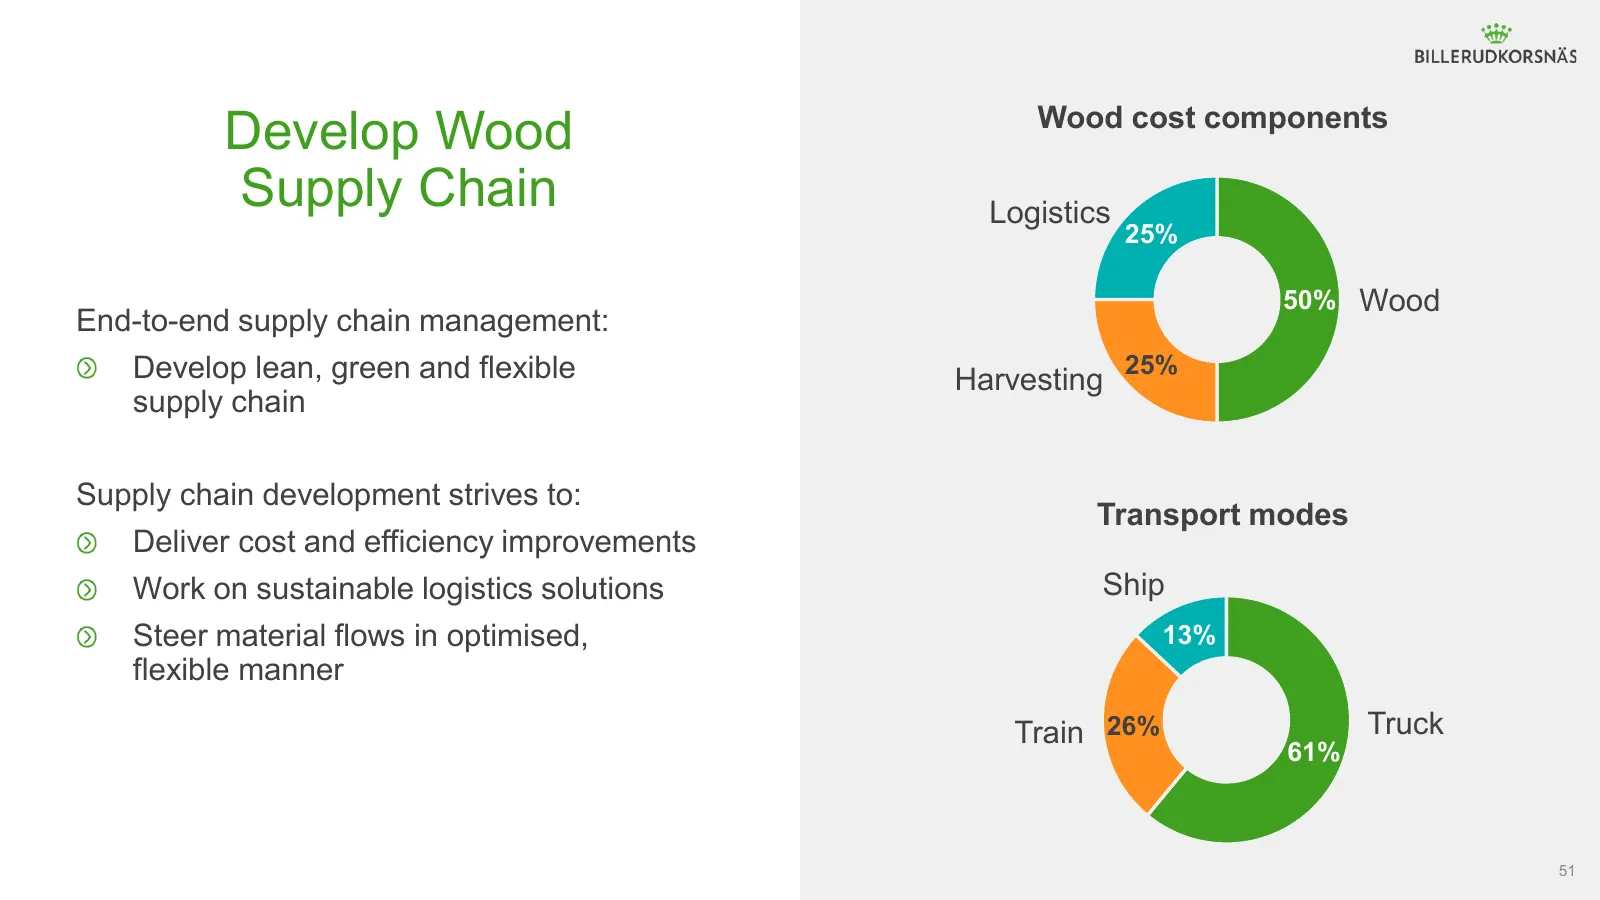
Slide 51: Develop Wood Supply Chain
Develop Wood Wood cost components Supply Chain Logistics 25% 50% Wood End-to-end supply chain management: Develop lean, green and flexible Harvesting 25% supply chain Supply chain development strives to: Transport modes Deliver cost and efficiency improvements Work on sustainable logistics solutions
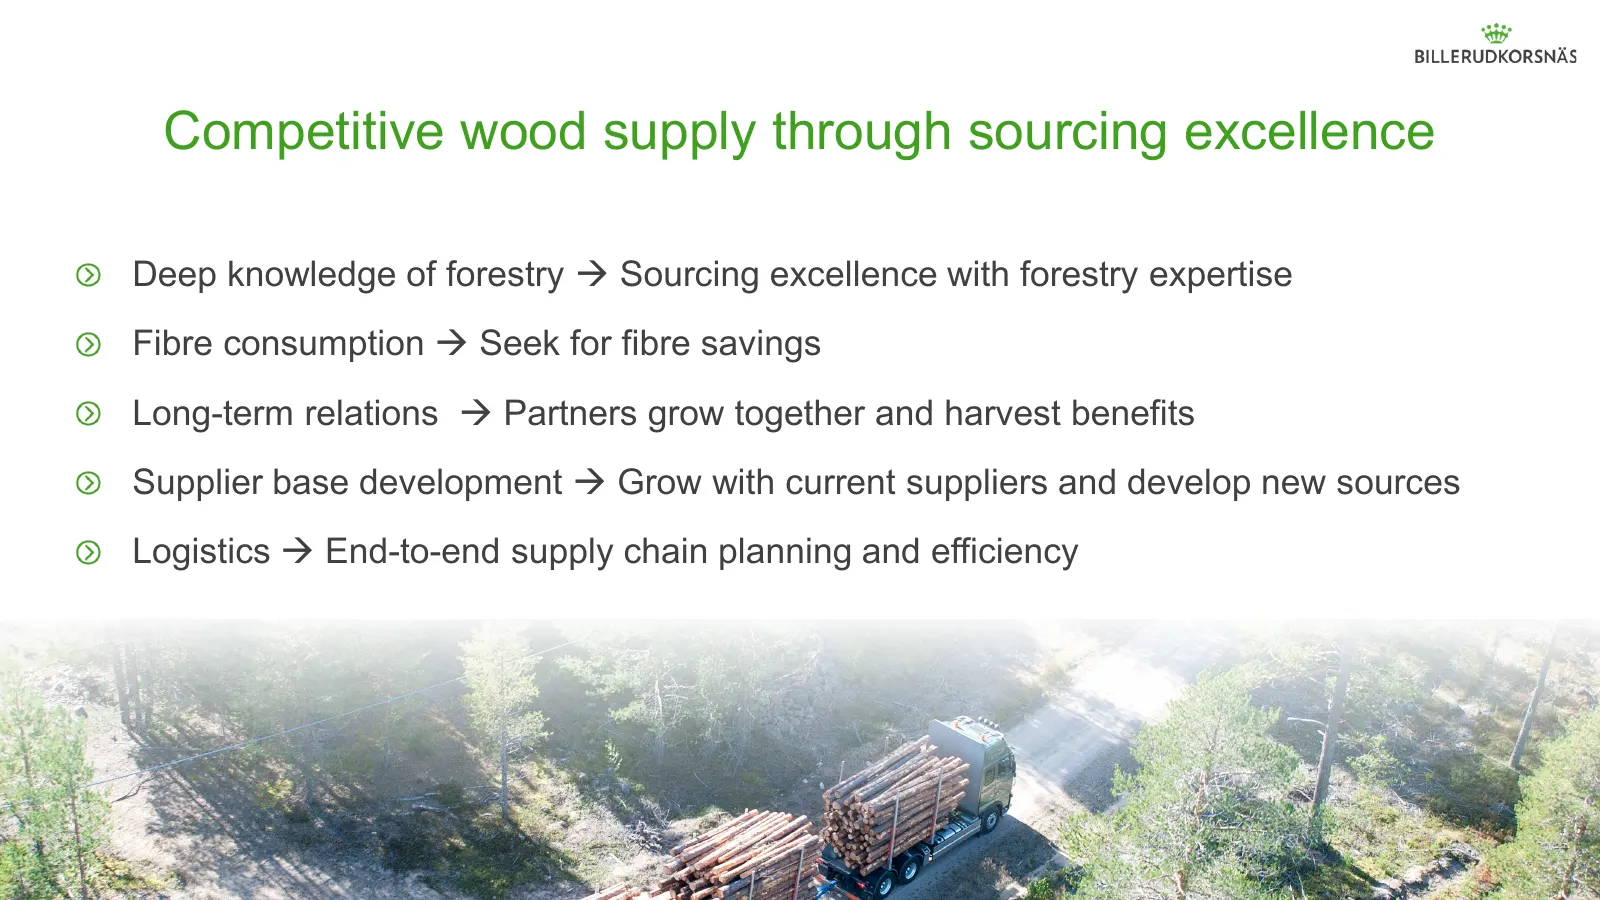
Slide 52: Competitive wood supply through sourcing excellence
Competitive wood supply through sourcing excellence Deep knowledge of forestry Sourcing excellence with forestry expertise Fibre consumption Seek for fibre savings Long-term relations Partners grow together and harvest benefits Supplier base development Grow with current suppliers and develo
Slide 53: Sustainable and balanced financials
Sustainable and balanced financials Ivar Vatne, EVP & CFO
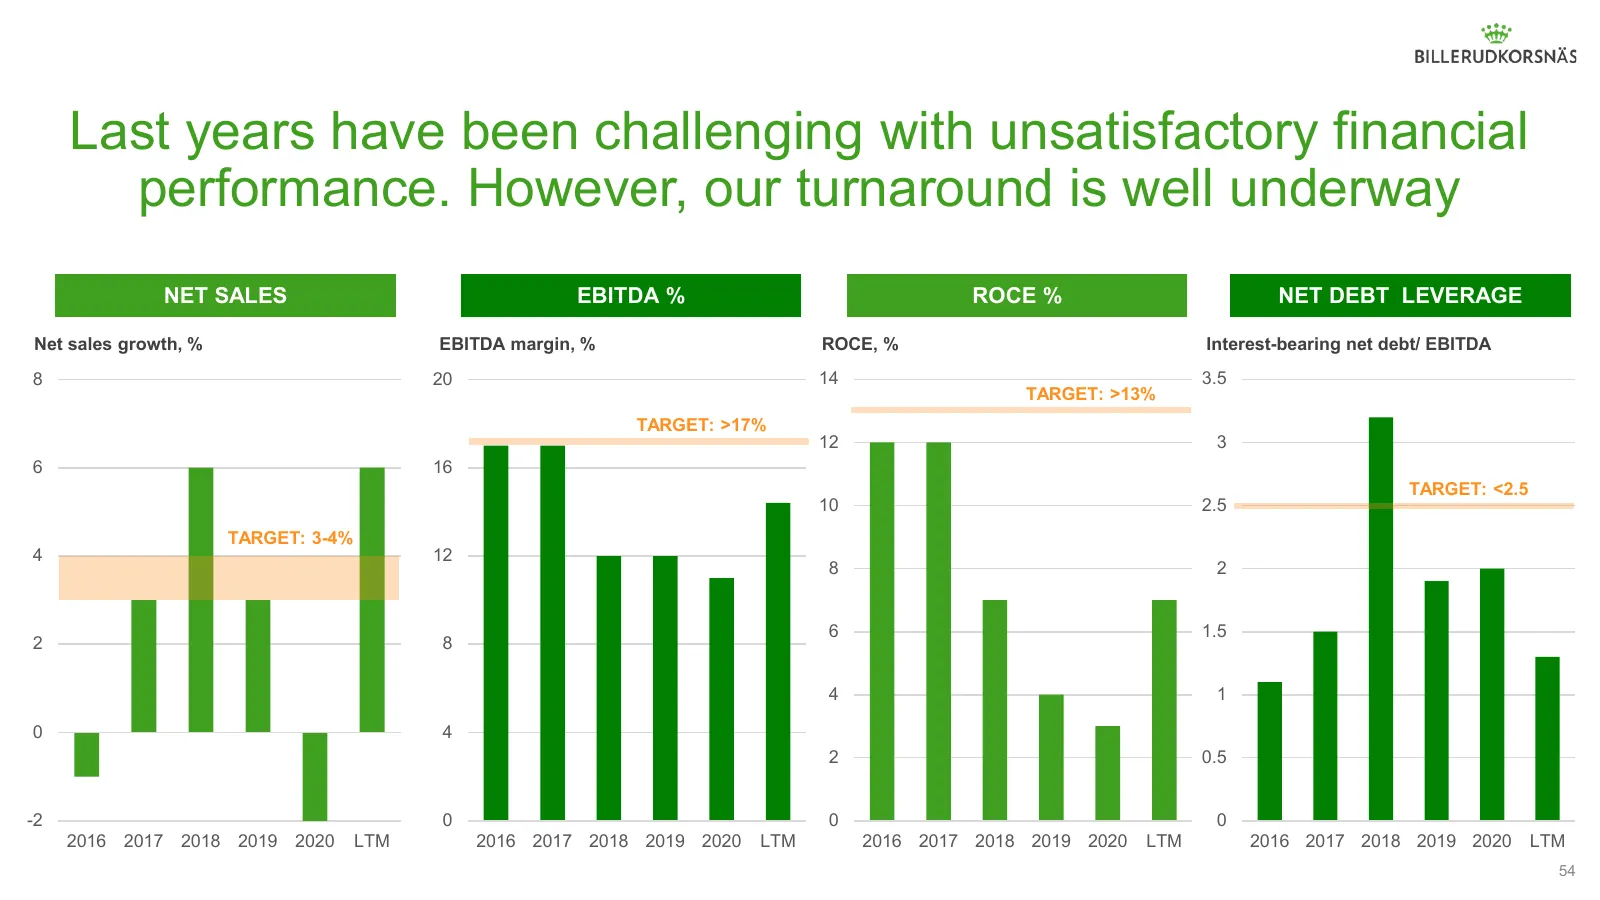
Slide 54: Last years have been challenging, however our turnaround is well underway
Last years have been challenging with unsatisfactory financial performance. However, our turnaround is well underway NET SALES EBITDA % ROCE % NET DEBT LEVERAGE Net sales growth, % EBITDA margin, % ROCE, % Interest-bearing net debt/ EBITDA 8 20 14 3.5 TARGET: >13% TARGET: >17% 12 3 6 16 TARGET: <2.5
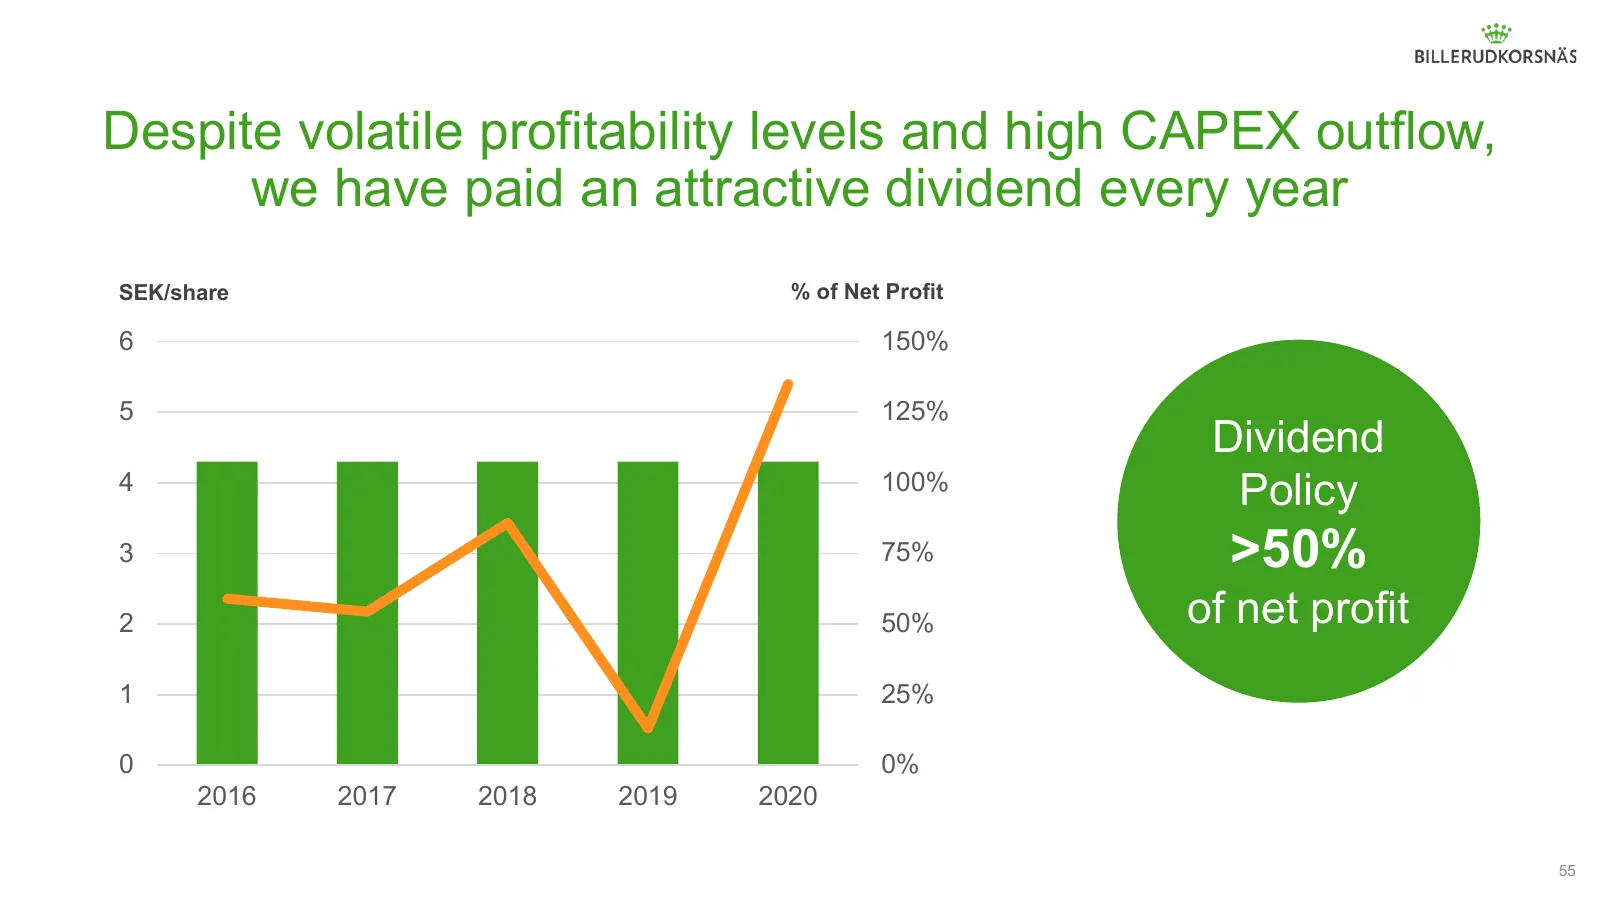
Slide 55: We have paid an attractive dividend every year
Despite volatile profitability levels and high CAPEX outflow, we have paid an attractive dividend every year SEK/share % of Net Profit 6 150% 5 125% Dividend 4 100% Policy 3 75% >50% 2 50% of net profit 1 25% 0 0% 2016 2017 2018 2019 2020 55
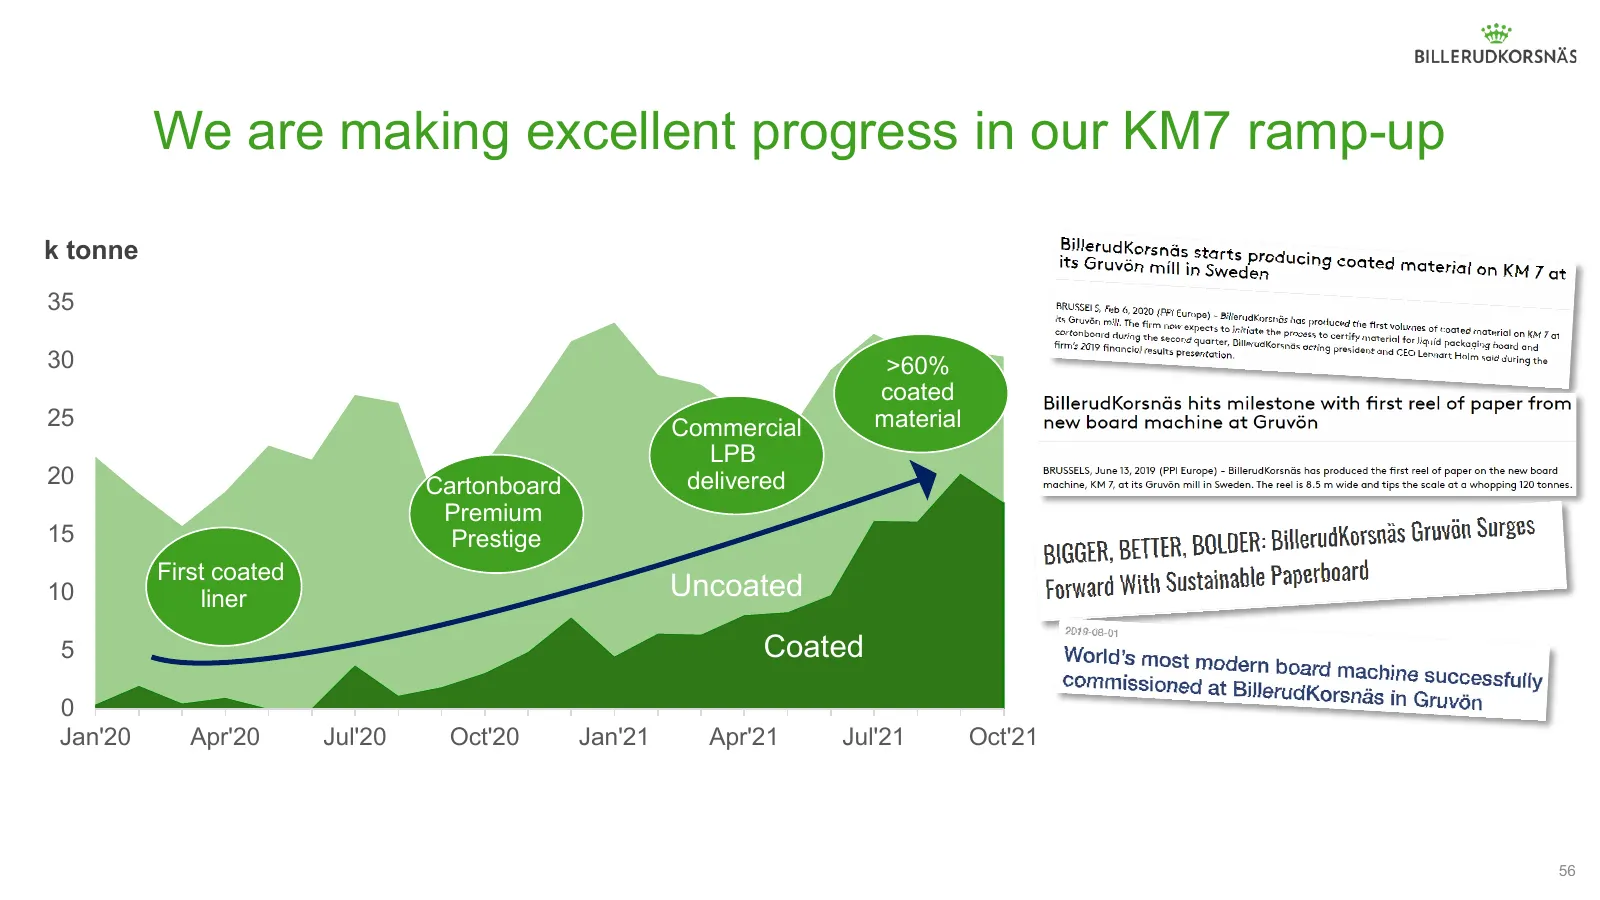
Slide 56: We are making excellent progress in our KM7 ramp-up
We are making excellent progress in our KM7 ramp-up k tonne 35 30 >60% coated 25 Commercial material LPB 20 Cartonboard delivered Premium 15 Prestige First coated 10 liner Uncoated 5 Coated 0 Jan'20 Apr'20 Jul'20 Oct'20 Jan'21 Apr'21 Jul'21 Oct'21 56
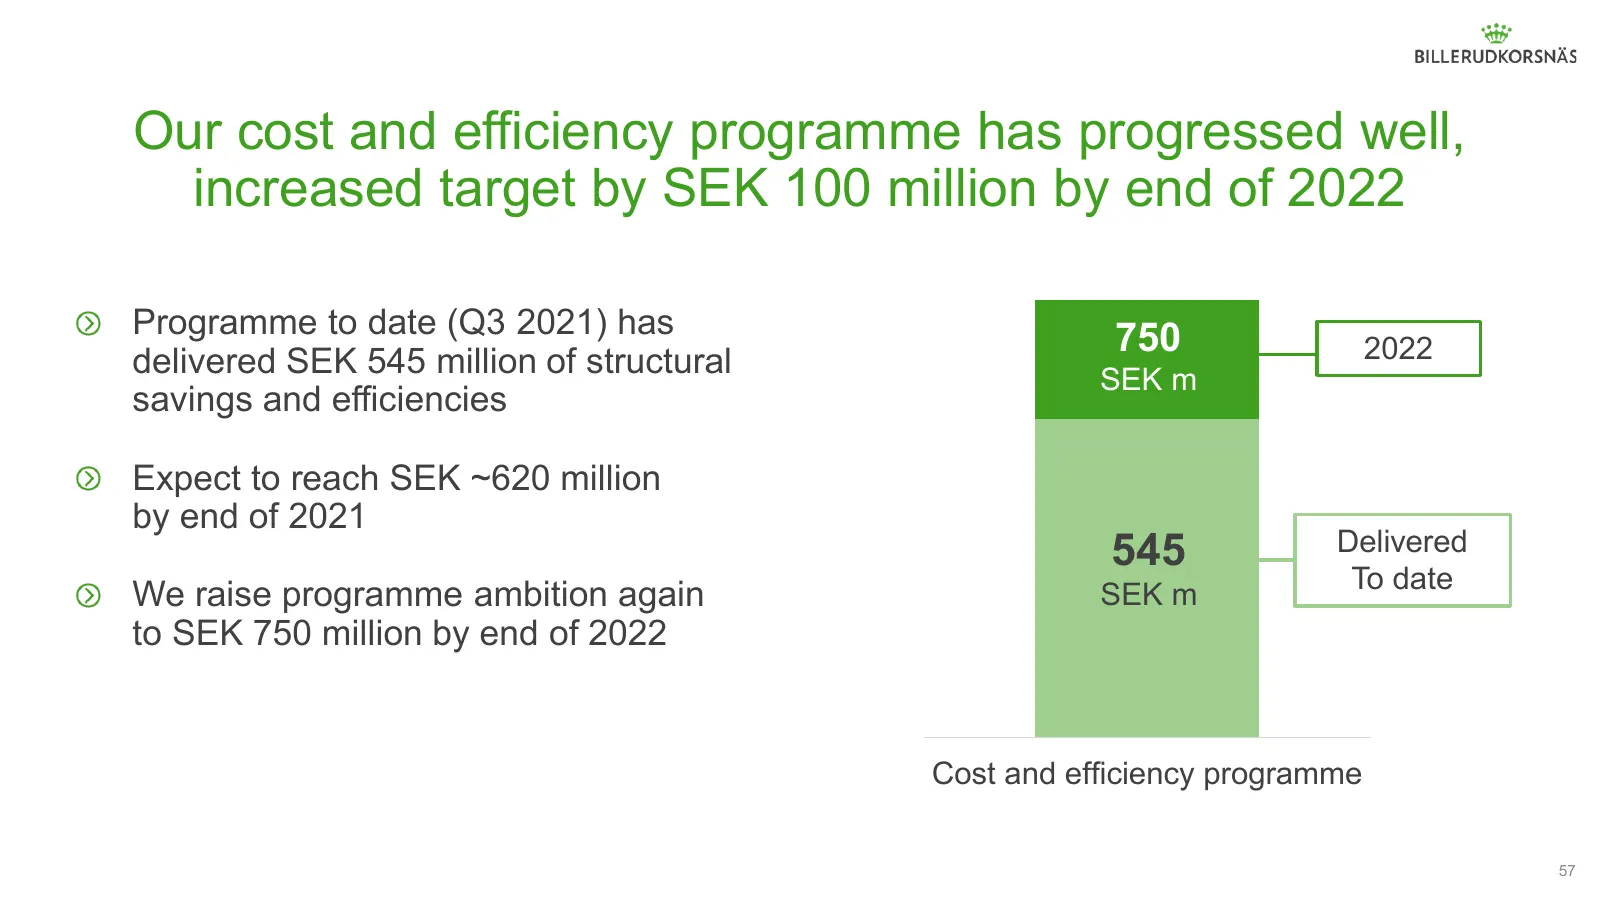
Slide 57: Our cost and efficiency programme has progressed well
Our cost and efficiency programme has progressed well, increased target by SEK 100 million by end of 2022 Programme to date (Q3 2021) has 750 delivered SEK 545 million of structural 2022 SEK m savings and efficiencies Expect to reach SEK ~620 million by end of 2021 545 Delivered To date We raise pro
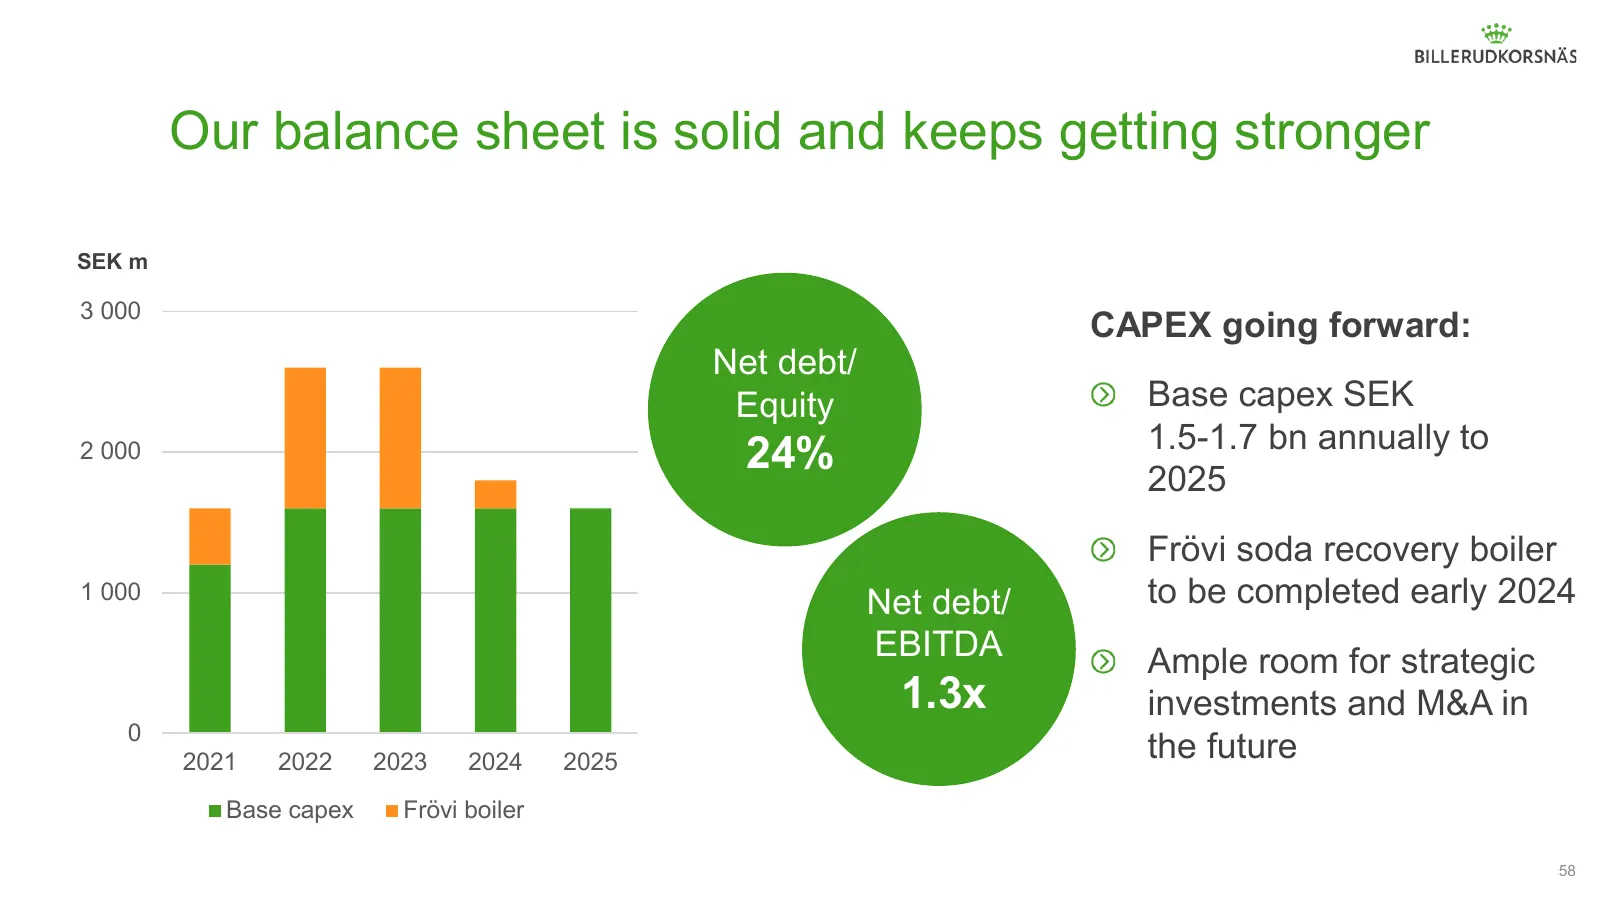
Slide 58: Our balance sheet is solid and keeps getting stronger
Our balance sheet is solid and keeps getting stronger SEK m 3 000 CAPEX going forward: Net debt/ Equity Base capex SEK 1.5-1.7 bn annually to 2 000 24% 2025 Frövi soda recovery boiler 1 000 Net debt/ to be completed early 2024 EBITDA Ample room for strategic 1.3x investments and M&A in 0 2021 2022 2
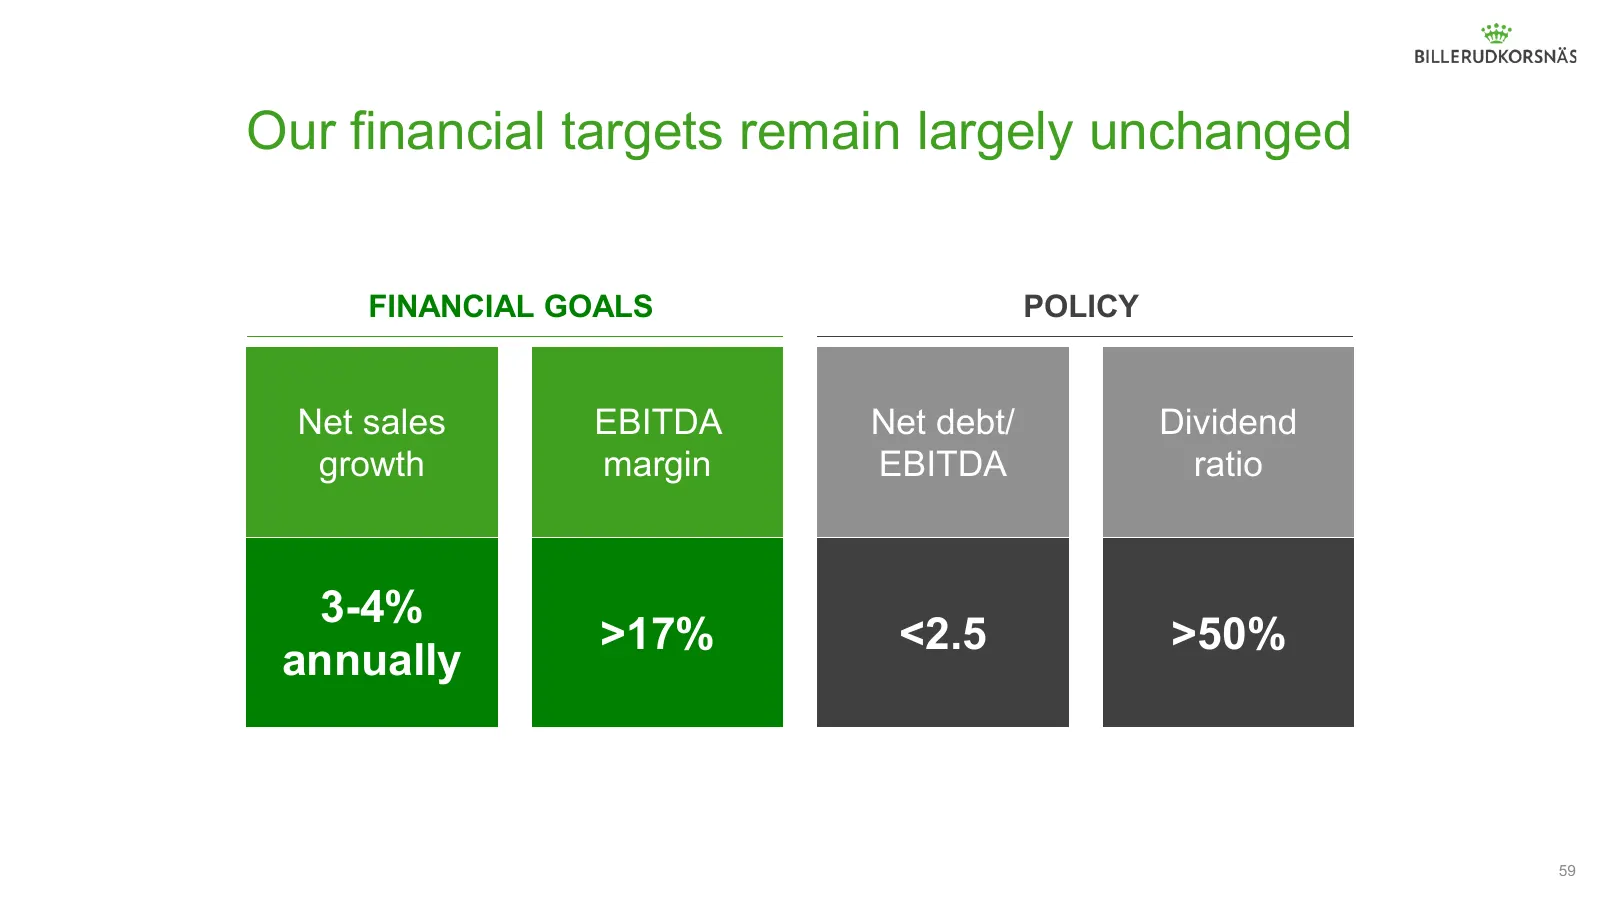
Slide 59: Our financial targets remain largely unchanged
Our financial targets remain largely unchanged FINANCIAL GOALS POLICY Net sales EBITDA Net debt/ Dividend growth margin EBITDA ratio 3-4% >17% <2.5 >50% annually 59
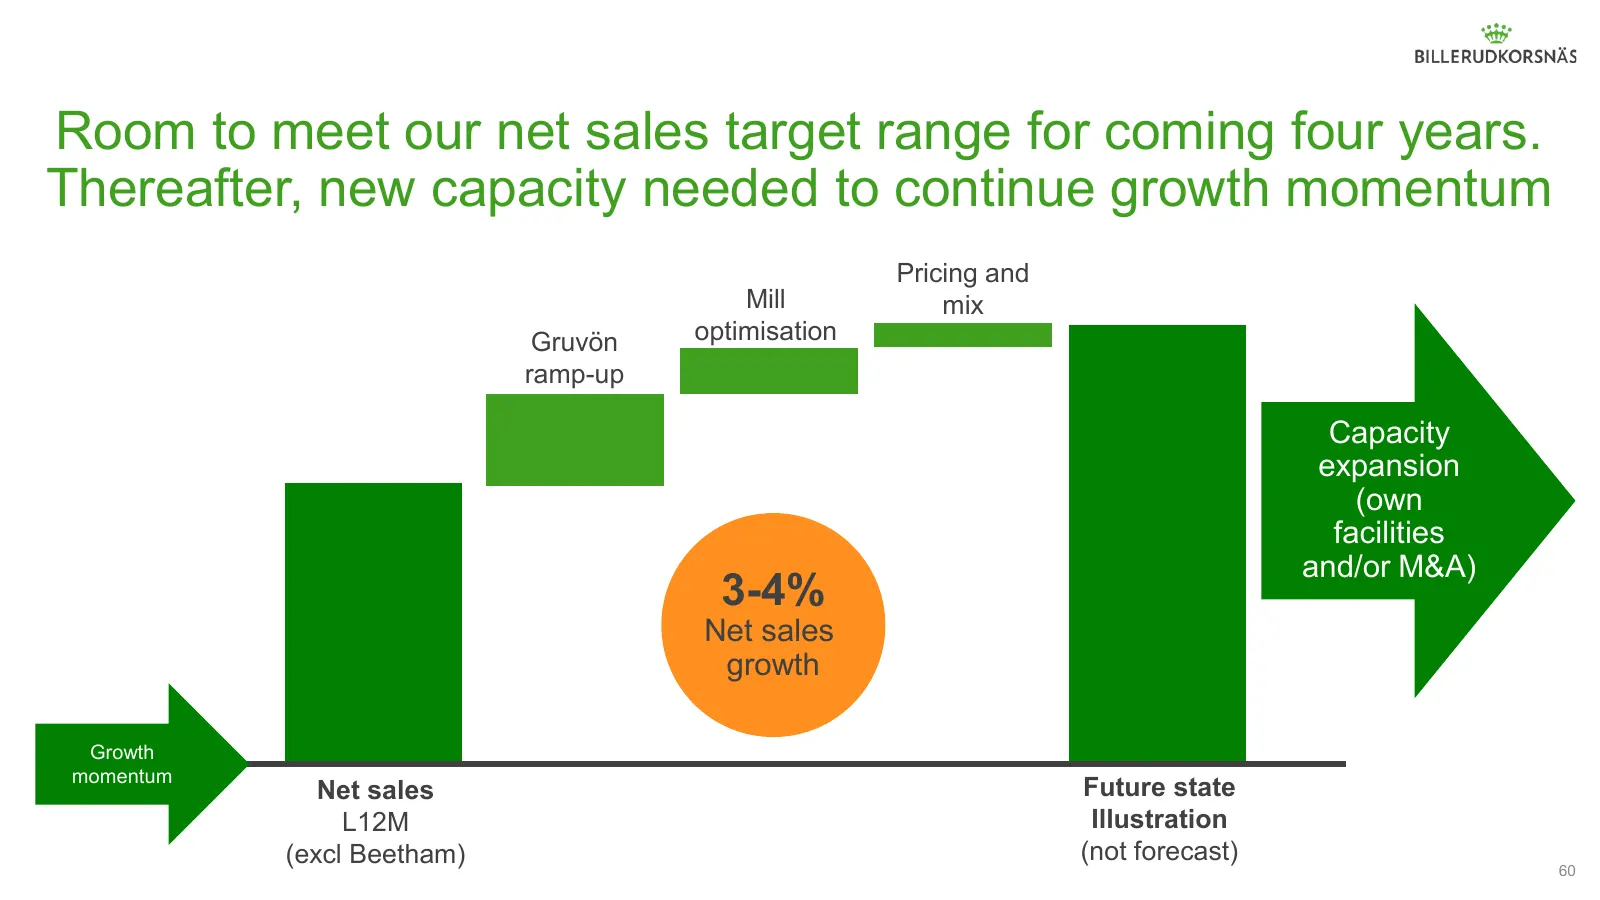
Slide 60: Room to meet our net sales target range for coming four years
Room to meet our net sales target range for coming four years. Thereafter, new capacity needed to continue growth momentum Pricing and Mill mix Gruvön optimisation ramp-up Capacity expansion (own facilities and/or M&A) 3-4% Net sales growth Growth momentum Net sales Future state L12M Illustration (e
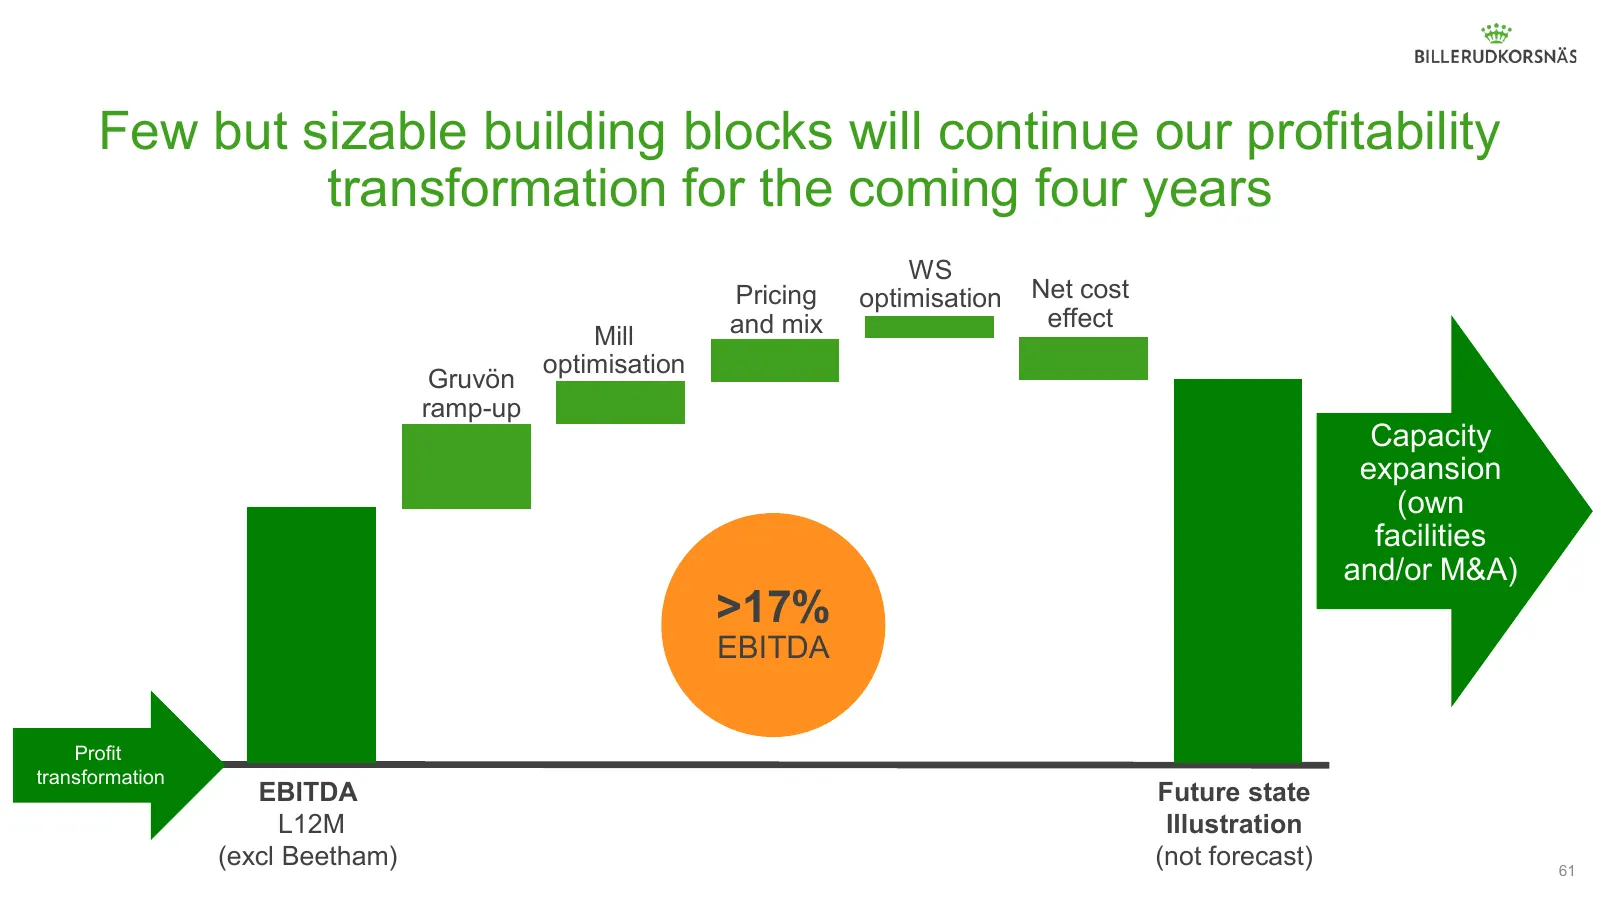
Slide 61: Few but sizable building blocks will continue our profitability transformation
Few but sizable building blocks will continue our profitability transformation for the coming four years WS Pricing optimisation Net cost and mix effect Mill optimisation Gruvön ramp-up Capacity expansion (own facilities and/or M&A) >17% EBITDA Profit transformation EBITDA Future state L12M Illustra
Slide 62: 62
62
Slide 63: Conclusion
Conclusion Christoph Michalski CEO and President
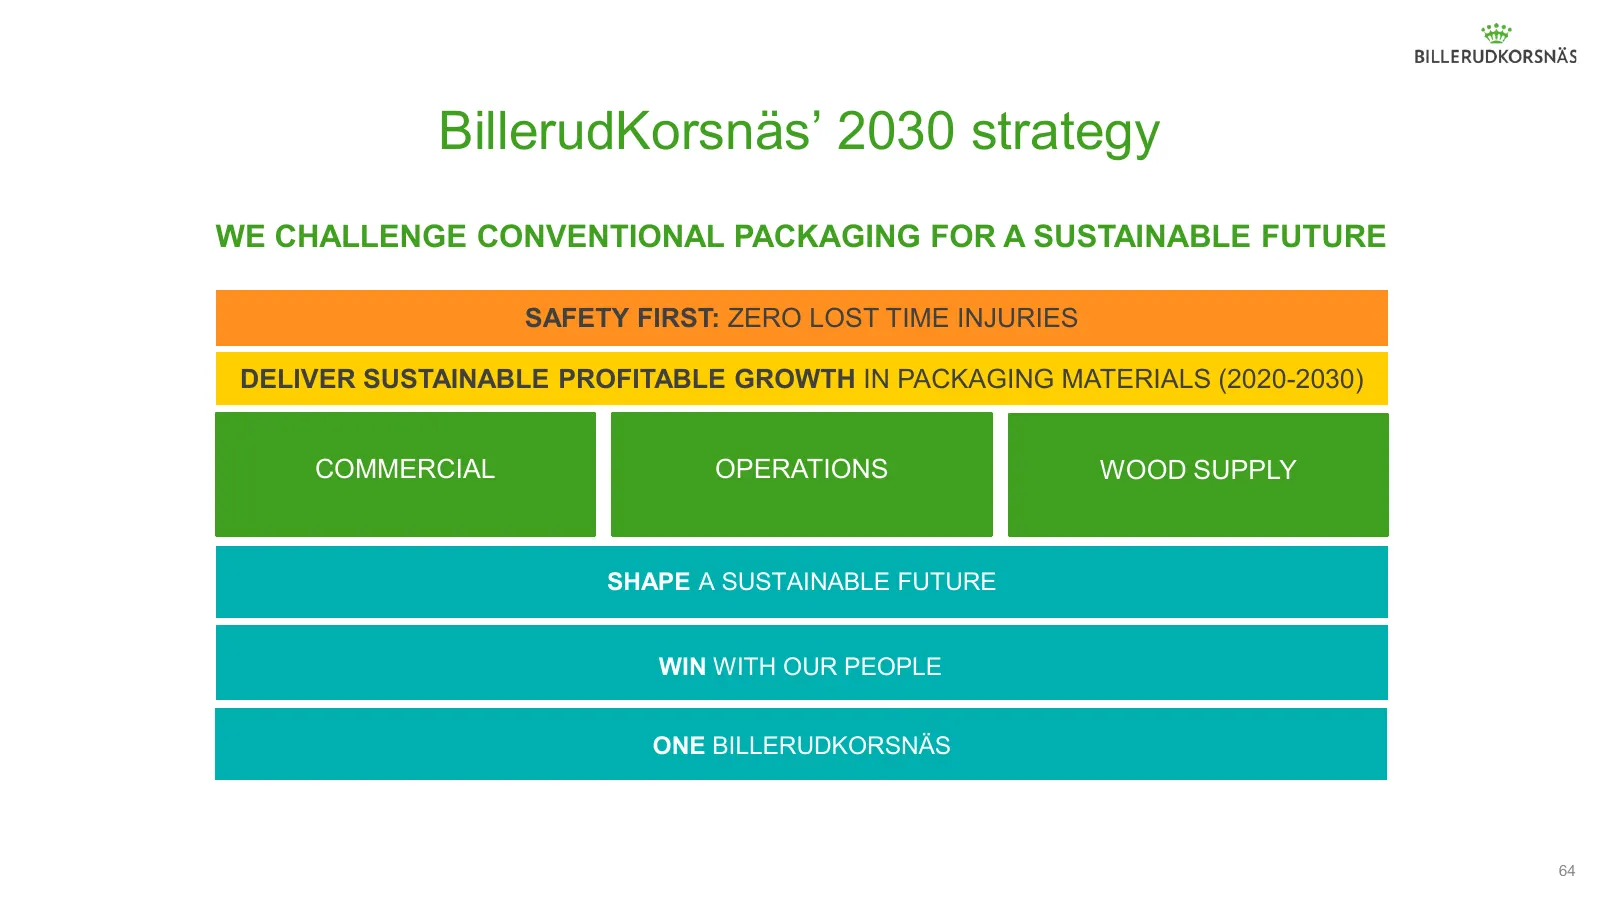
Slide 64: BillerudKorsnäs’ 2030 strategy
BillerudKorsnäs’ 2030 strategy WE CHALLENGE CONVENTIONAL PACKAGING FOR A SUSTAINABLE FUTURE SAFETY FIRST: ZERO LOST TIME INJURIES DELIVER SUSTAINABLE PROFITABLE GROWTH IN PACKAGING MATERIALS (2020-2030) COMMERCIAL OPERATIONS WOOD SUPPLY SHAPE A SUSTAINABLE FUTURE WIN WITH OUR PEOPLE ONE BILLERUDKORS
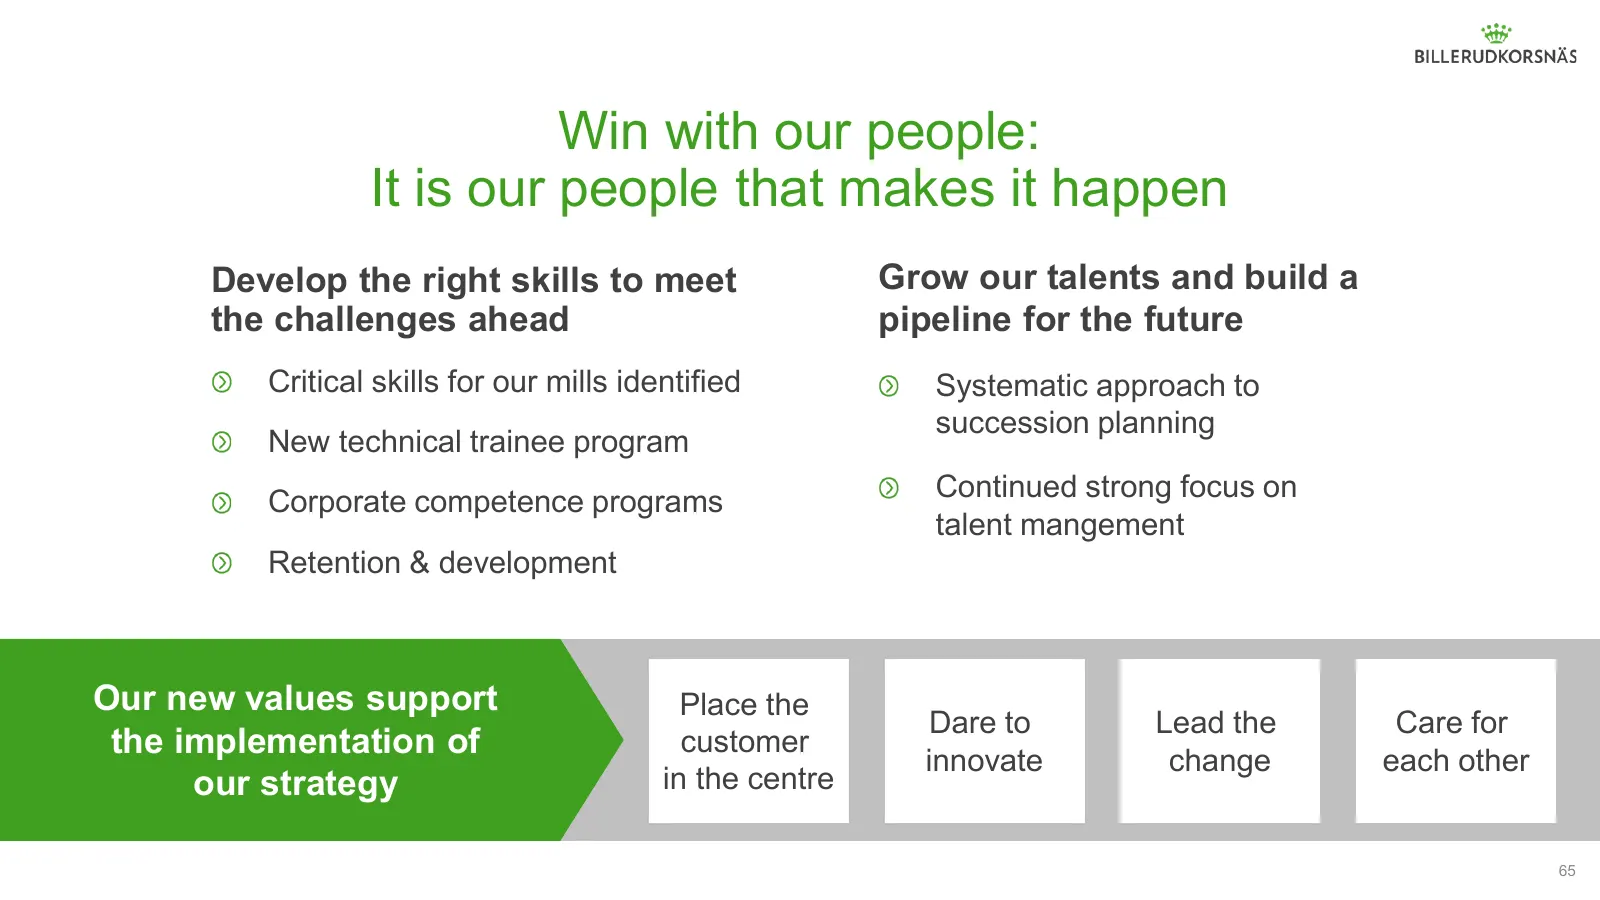
Slide 65: Win with our people: It is our people that makes it happen
Win with our people: It is our people that makes it happen Develop the right skills to meet Grow our talents and build a the challenges ahead pipeline for the future Critical skills for our mills identified Systematic approach to succession planning New technical trainee program Corporate competence
Slide 66: One BillerudKorsnäs – Enabling strategy execution
One BillerudKorsnäs – Enabling strategy execution BillerudKorsnäs today ’One BillerudKorsnäs’- integrating our business Integration debt processes originating from 2012 Several attempts to Core systems to be fix over the years modernised and aligned with business process Struggling to realise transf
Slide 67: Key takeaways
Key takeaways Sweet spot of market trends, product mix and our innovation programme Maximise capacity utilisation at lowest possible unit cost Build fibre sourcing excellence with deep knowledge of forestry Sustainability as an opportunity across the business: customers, operations and wood supply F
Slide 68: BILLERUDKORSNAS
BILLERUDKORSNAS
Source: company website
More decks from Billerud AB
 Q3 2026 Earnings Presentation16 slides · Oct 22, 2026
 Q2 2026 Earnings Presentation17 slides · Jul 17, 2026
 Q1 2026 Earnings Presentation17 slides · Apr 28, 2026
 Q4 2025 Earnings Presentation21 slides · Jan 30, 2026
 DNB Carnegie Nordic Forest Conference 202515 slides · Nov 12, 2025
 Q3 2025 Earnings Presentation18 slides · Oct 23, 2025