Billerud AB · OMXSTO:BILL
Billerud AB — BillerudKorsnäs — Q1 2026 Earnings Presentation
17 slides from Billerud AB's earnings presentation, Apr 28, 2026
Slide 1: Sequential volume uplift with challenged profitability
Sequential volume uplift with challenged profitability Interim report January–March 2026 Ivar Vatne Andrei Krés President & CEO CFO 28 April 2026
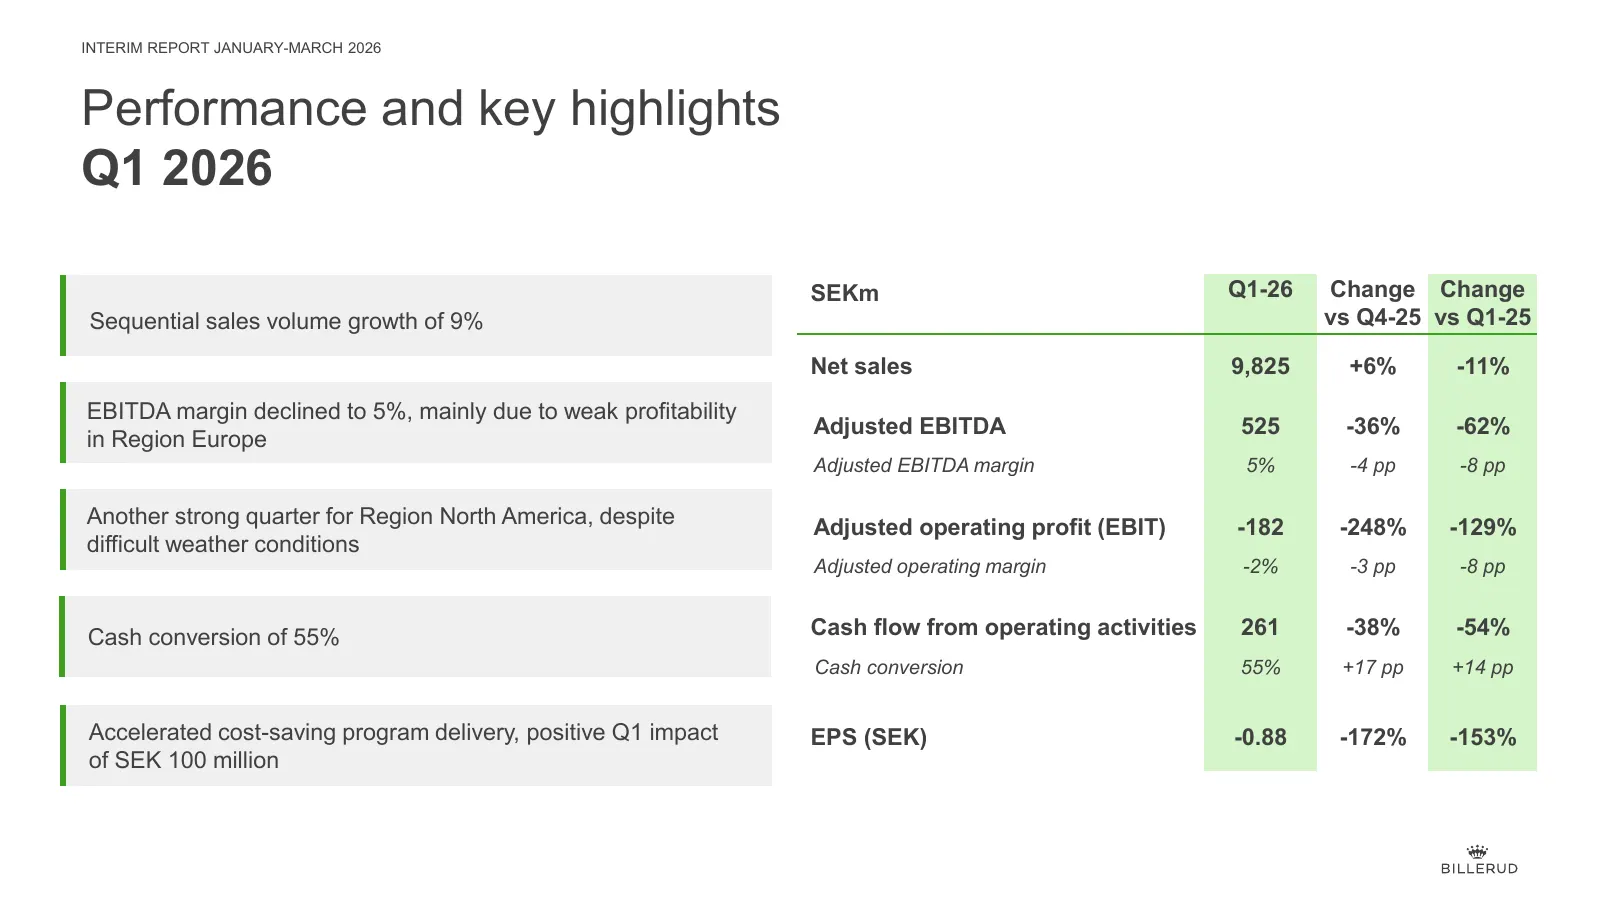
Slide 2: Performance and key highlights
INTERIM REPORT JANUARY-MARCH 2026 Performance and key highlights Q1 2026 SEKm Q1-26 Change Change Sequential sales volume growth of 9% vs Q4-25 vs Q1-25 Net sales 9,825 +6% -11% EBITDA margin declined to 5%, mainly due to weak profitability Adjusted EBITDA 525 -36% -62% in Region Europe Adjusted EBI
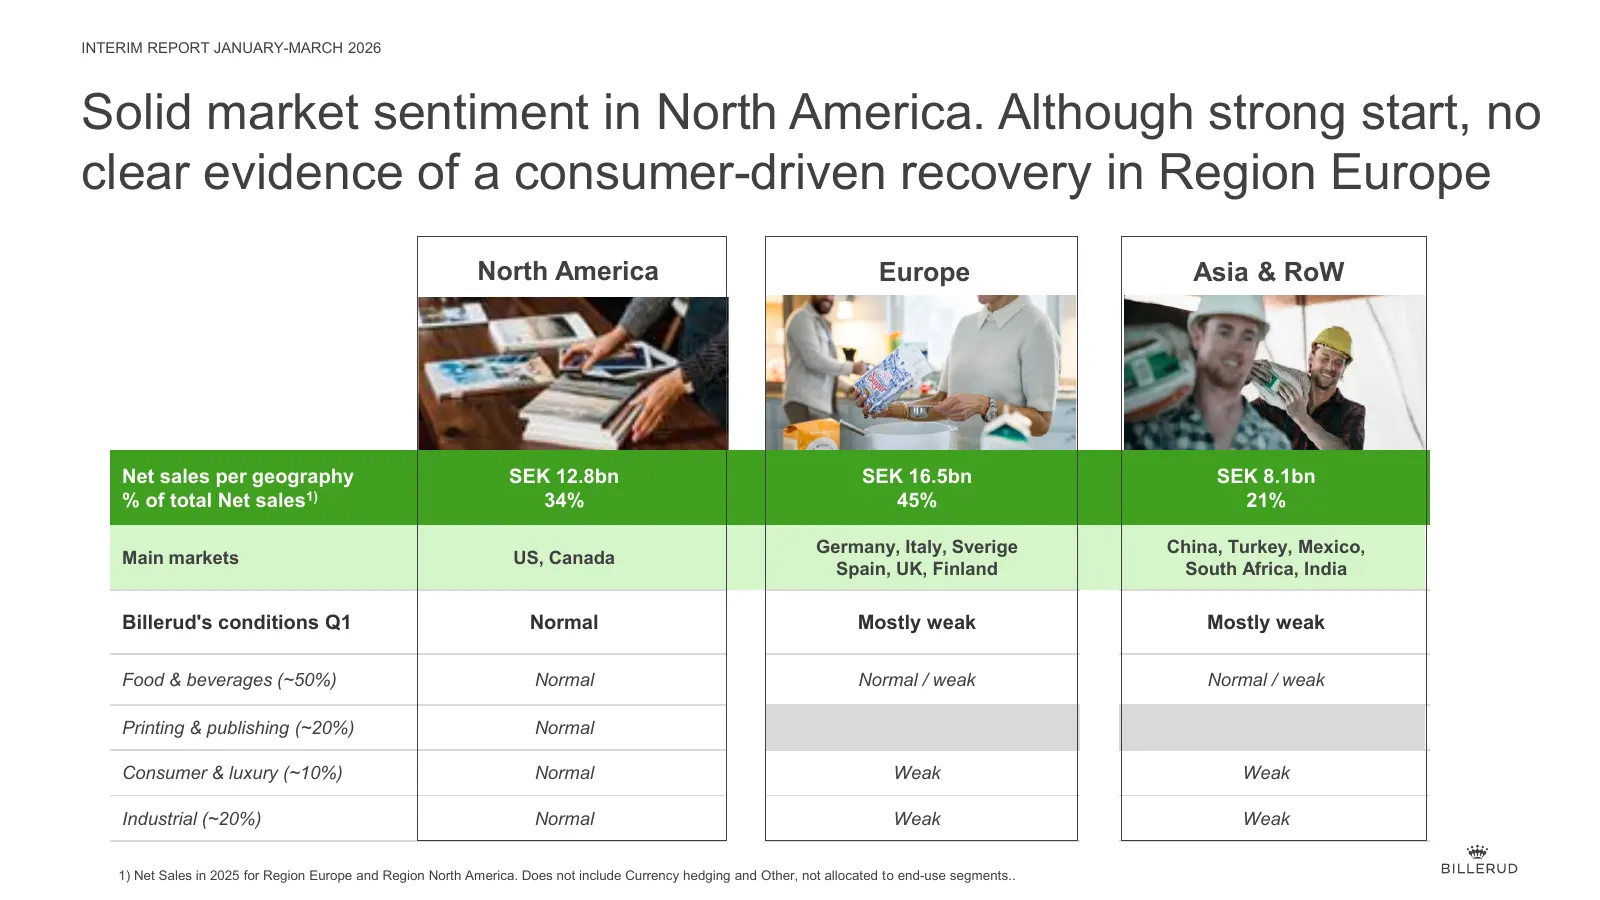
Slide 3: Solid market sentiment in North America; no clear consumer-driven recovery in Europe
INTERIM REPORT JANUARY-MARCH 2026 Solid market sentiment in North America. Although strong start, no clear evidence of a consumer-driven recovery in Region Europe North America Europe Asia & RoW Net sales per geography SEK 12.8bn SEK 16.5bn SEK 8.1bn % of total Net sales1) 34% 45% 21% Germany, Italy
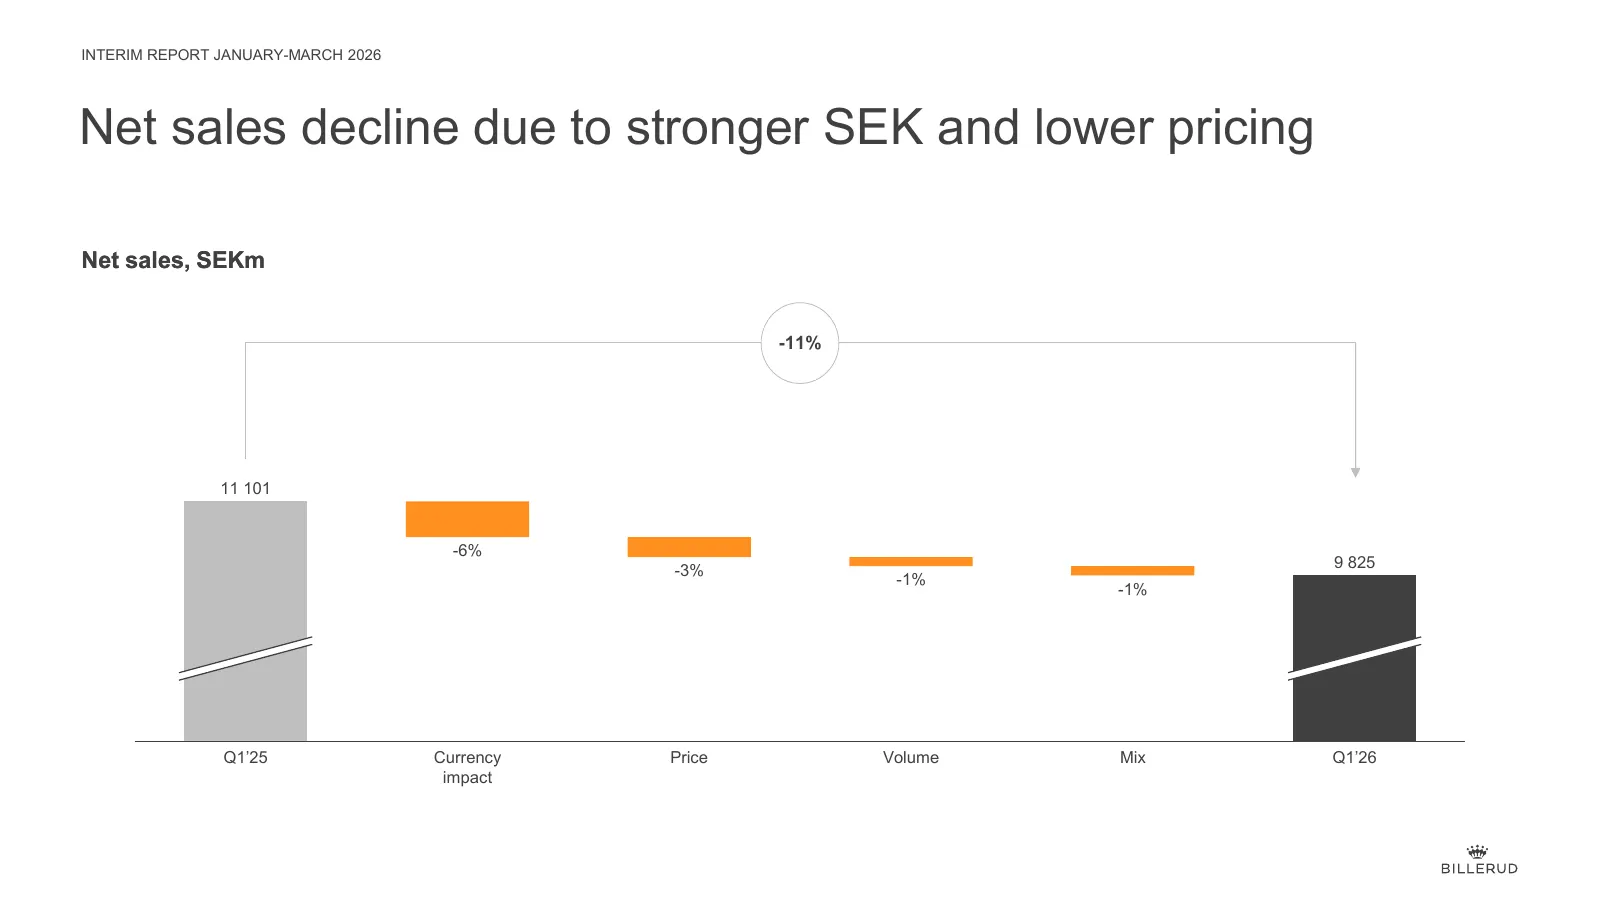
Slide 4: Net sales decline due to stronger SEK and lower pricing
INTERIM REPORT JANUARY-MARCH 2026 Net sales decline due to stronger SEK and lower pricing Net sales, SEKm -11% 11 101 -6% 9 825 -3% -1% -1% Q1’25 Currency Price Volume Mix Q1’26 impact
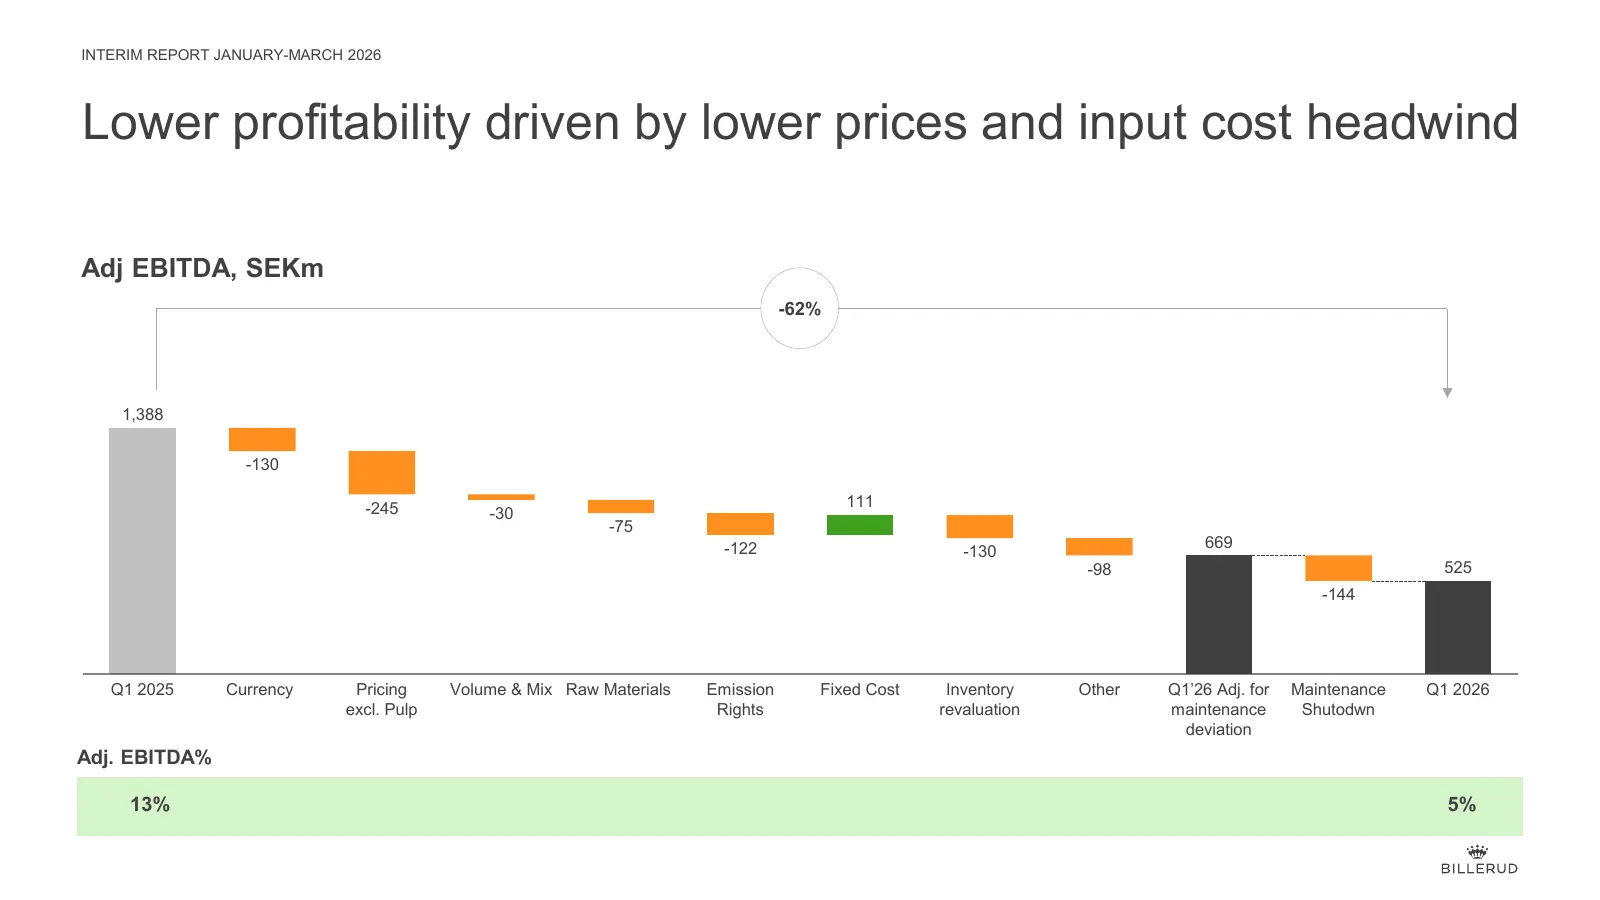
Slide 5: Lower profitability driven by lower prices and input cost headwind
INTERIM REPORT JANUARY-MARCH 2026 Lower profitability driven by lower prices and input cost headwind Adj EBITDA, SEKm -62% 1,388 -130 -245 111 -30 -75 -122 669 -130 -98 525 -144 Q1 2025 Currency Pricing Volume & Mix Raw Materials Emission Fixed Cost Inventory Other Q1’26 Adj. for Maintenance Q1 2026
Slide 6: Region Europe
INTERIM REPORT JANUARY-MARCH 2026 Region Europe
Slide 7: Region Europe
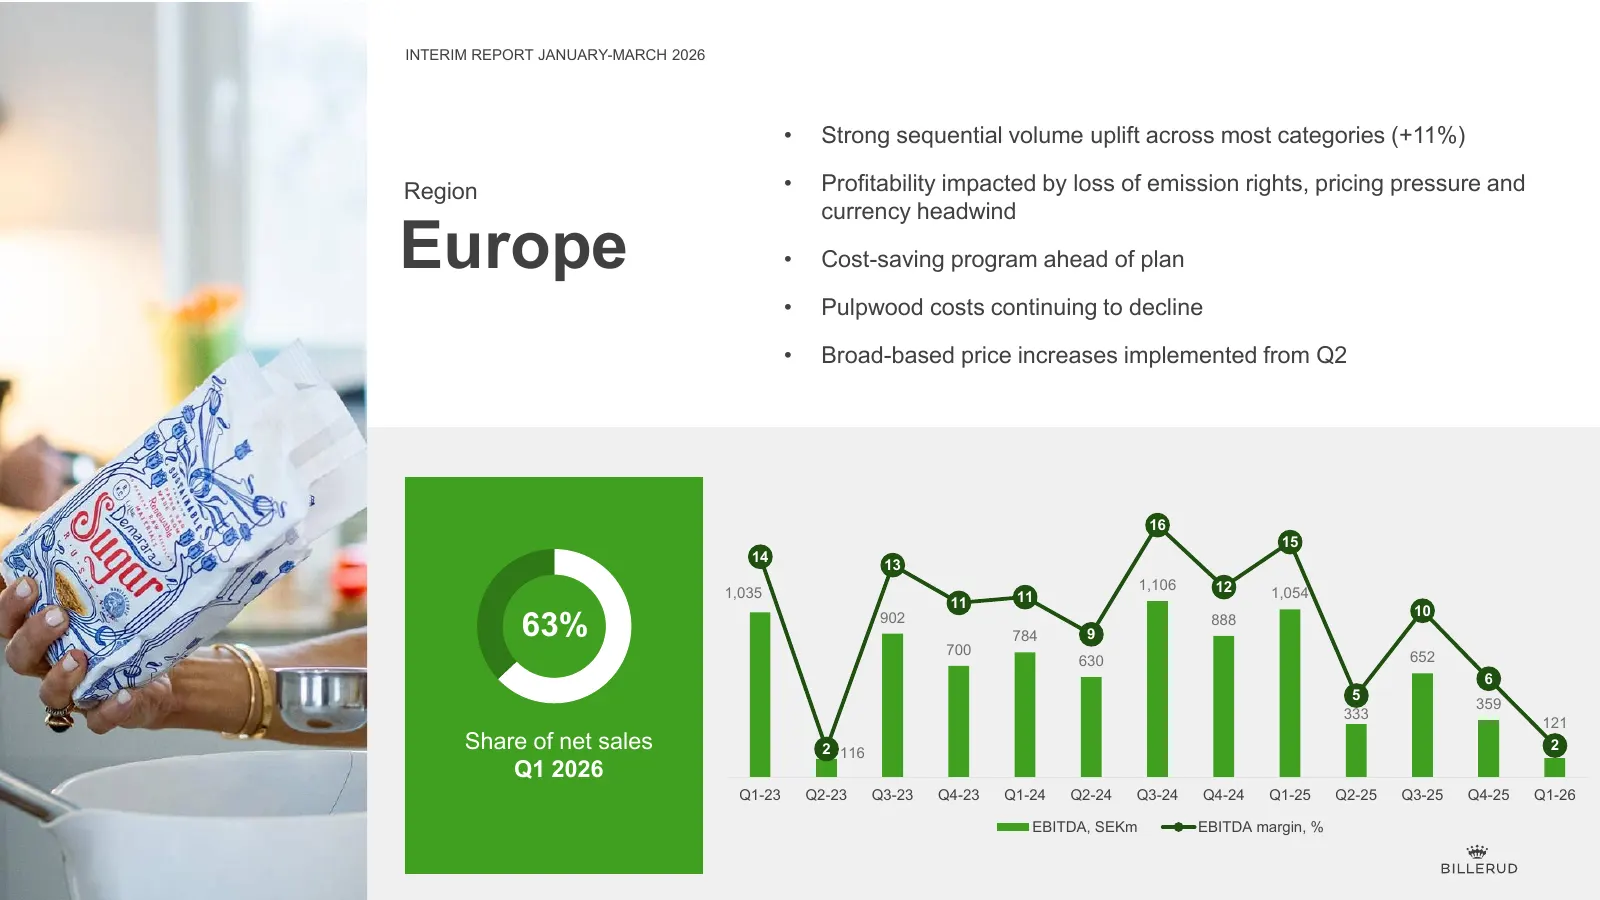
INTERIM REPORT JANUARY-MARCH 2026 • Strong sequential volume uplift across most categories (+11%) Region • Profitability impacted by loss of emission rights, pricing pressure and currency headwind Europe • Cost-saving program ahead of plan • Pulpwood costs continuing to decline • Broad-based price i
Slide 8: Region North America
INTERIM REPORT JANUARY-MARCH 2026 INTERIM REPORT JANUARY-MARCH 2026 Region Region North North America America
Slide 9: Region North America
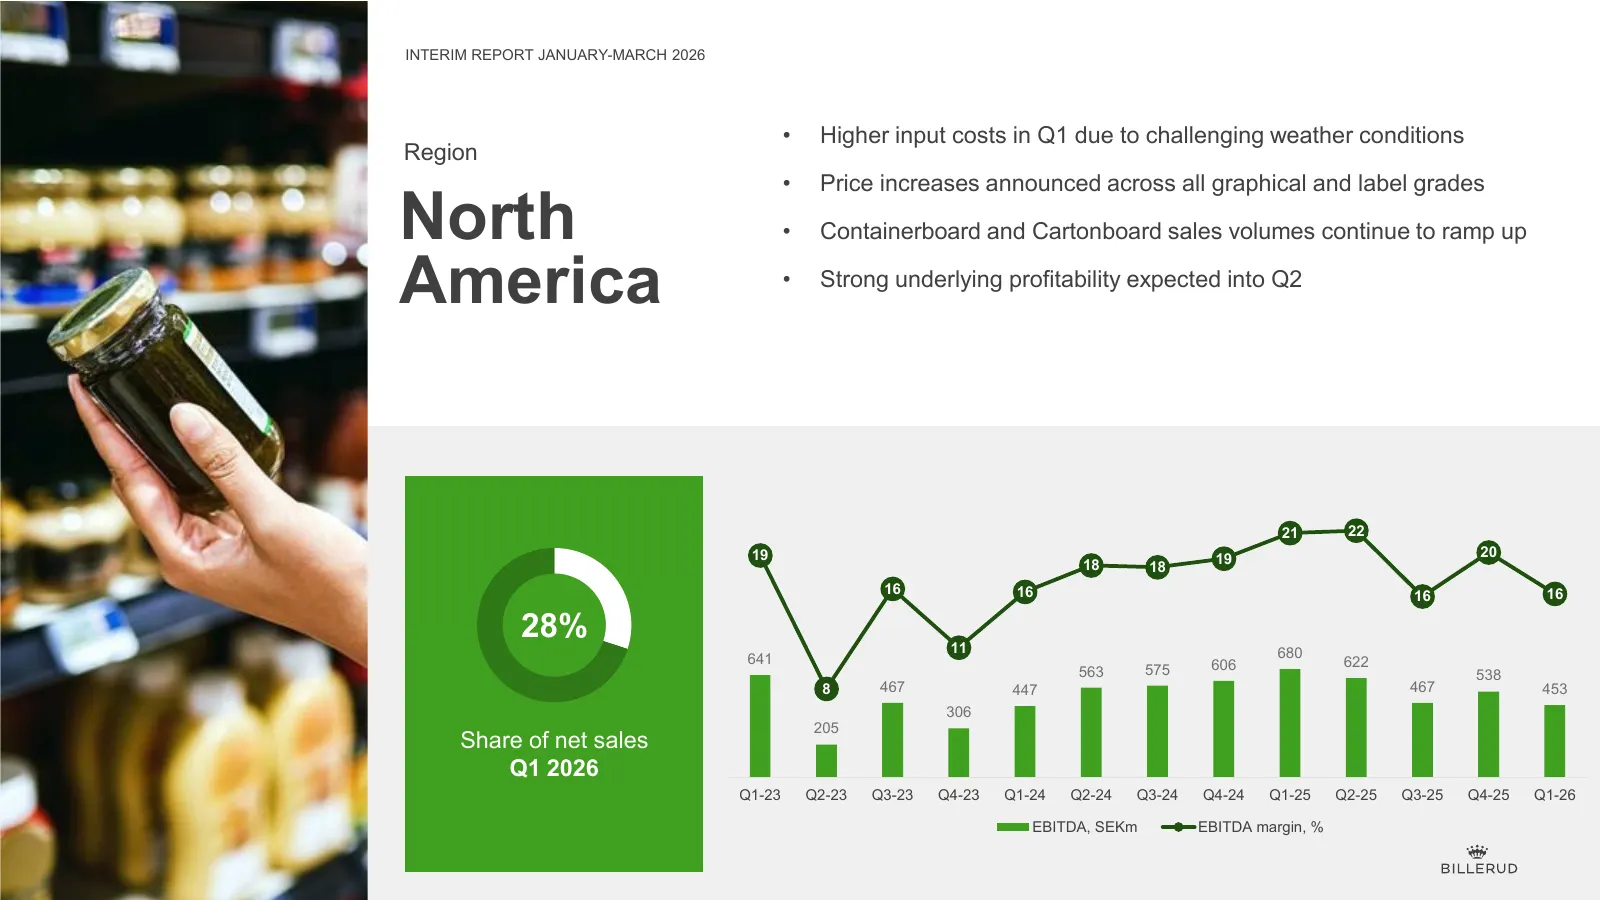
INTERIM REPORT JANUARY-MARCH 2026 • Higher input costs in Q1 due to challenging weather conditions Region • Price increases announced across all graphical and label grades North • Containerboard and Cartonboard sales volumes continue to ramp up America • Strong underlying profitability expected into
Slide 10: Group Input costs
INTERIM REPORT JANUARY-MARCH 2026 GROUP Input costs
Slide 11: Q1: Higher than expected input costs in both regions
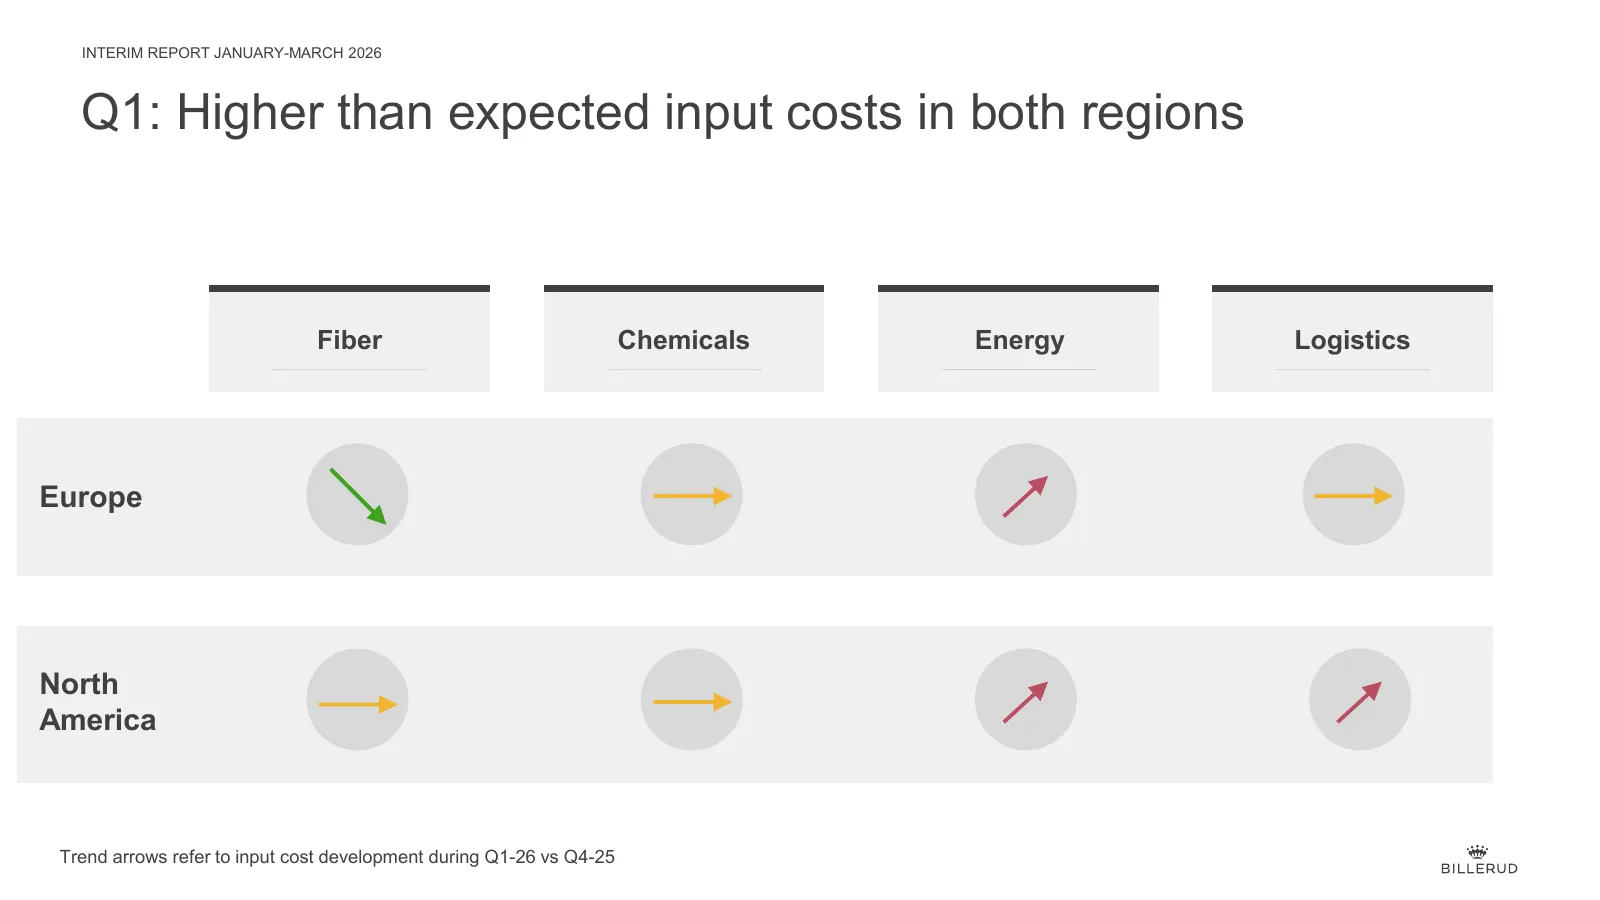
INTERIM REPORT JANUARY-MARCH 2026 Q1: Higher than expected input costs in both regions Fiber Chemicals Energy Logistics Europe North America Trend arrows refer to input cost development during Q1-26 vs Q4-25
Slide 12: Q2: Nordic pulpwood declining, while cost inflation on chemicals and logistics
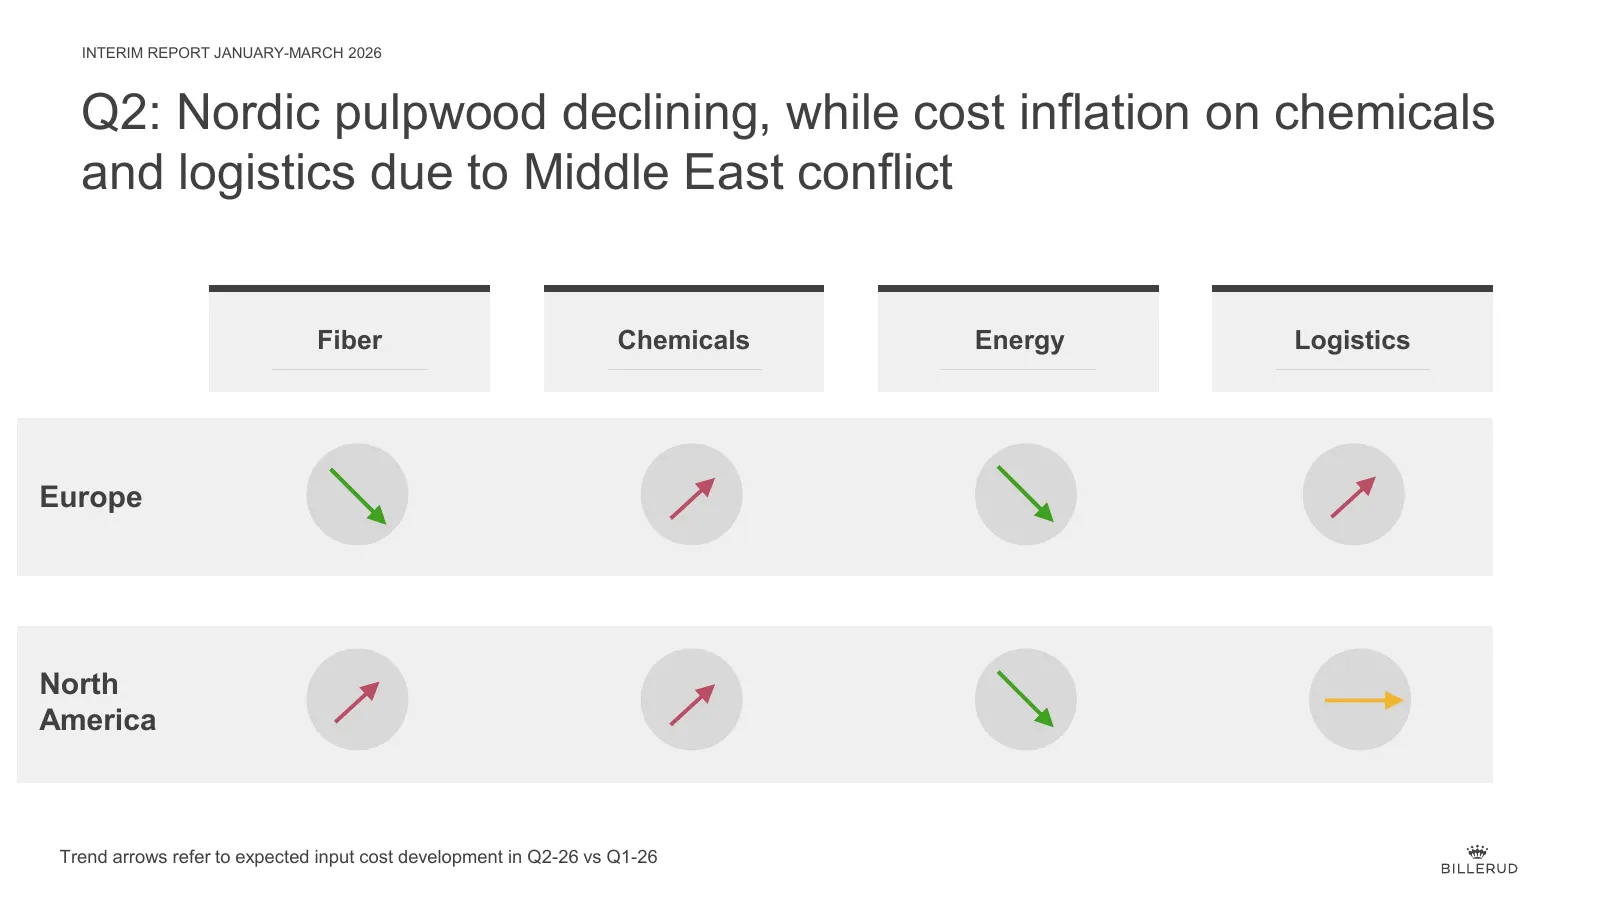
INTERIM REPORT JANUARY-MARCH 2026 Q2: Nordic pulpwood declining, while cost inflation on chemicals and logistics due to Middle East conflict Fiber Chemicals Energy Logistics Europe North America Trend arrows refer to expected input cost development in Q2-26 vs Q1-26
Slide 13: Middle East conflict to have indirect consequences through cost inflation
INTERIM REPORT JANUARY-MARCH 2026 Middle East conflict to have indirect consequences through cost inflation Delivery challenges managed with no impact • No significant exposure through sales to the region • No disturbances to supplies or sales deliveries Expect cost inflation on freight, chemicals a
Slide 14: Cost-saving program ahead of plan
INTERIM REPORT JANUARY-MARCH 2026 Cost-saving program ahead of plan All planned staff reductions completed per end of Q1-’26 Expected 2026 cost savings of SEK 550m (vs 2025) Cost savings vs same period last year, SEKm Q1-26 Q2-26 Q3-26 Q4-26 100 150 150 150 Annualized savings of SEK 800m with full e
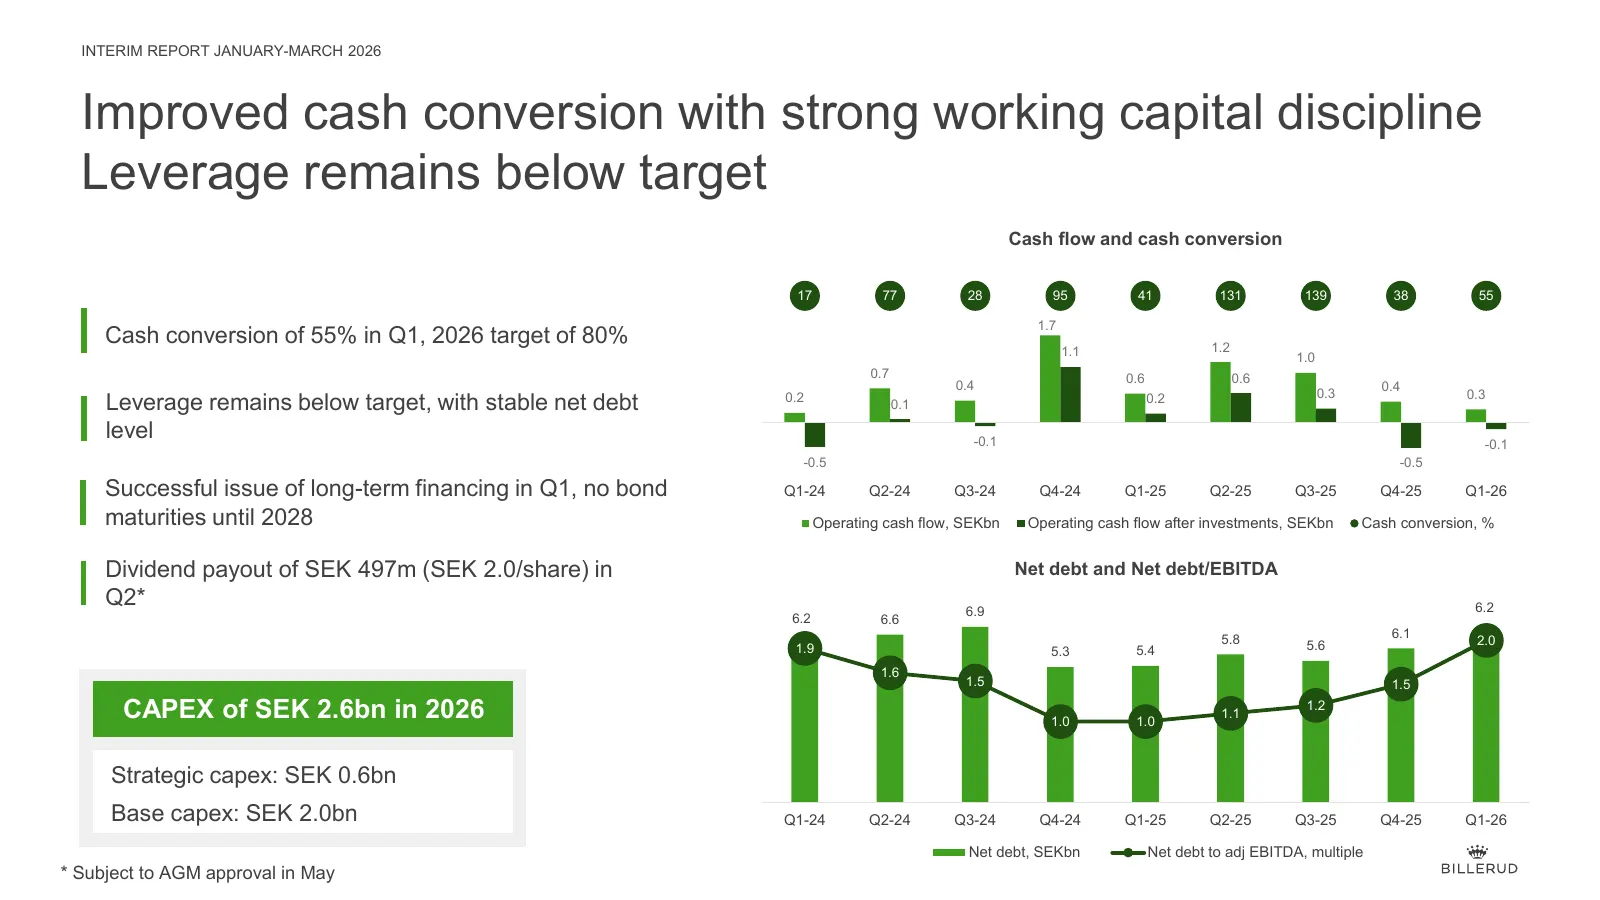
Slide 15: Improved cash conversion with strong working capital discipline; leverage below target
INTERIM REPORT JANUARY-MARCH 2026 Improved cash conversion with strong working capital discipline Leverage remains below target Cash flow and cash conversion 17 77 28 95 41 131 139 38 55 1.7 Cash conversion of 55% in Q1, 2026 target of 80% 1.2 1.1 1.0 0.7 0.6 0.6 0.4 0.4 0.3 0.3 Leverage remains bel
Slide 16: Outlook for Q2 2026
INTERIM REPORT JANUARY-MARCH 2026 Outlook for Q2 2026 Benefits from lower pulpwood prices and cost-saving program but challenging market conditions in Europe Solid market conditions in North America Broad-based price increases in both regions to mitigate cost inflation for chemicals and logistics Se
Slide 17: INTERIM REPORT JANUARY-MARCH 2026
INTERIM REPORT JANUARY-MARCH 2026
Source: 6ix earnings call
More decks from Billerud AB
 Q3 2026 Earnings Presentation16 slides · Oct 22, 2026
 Q2 2026 Earnings Presentation17 slides · Jul 17, 2026
 Q4 2025 Earnings Presentation21 slides · Jan 30, 2026
 DNB Carnegie Nordic Forest Conference 202515 slides · Nov 12, 2025
 Q3 2025 Earnings Presentation18 slides · Oct 23, 2025
 Kepler Cheuvreux Autumn Conference 202516 slides · Sep 10, 2025