Lecroy — Merger or Acquisition (September 2004)
31 slides from Lecroy's merger presentation, Sep 8, 2004
Slide 1: Tom Reslewic, President and CEO; Scott Kantor, VP and CFO
Tom Reslewic President and CEO Scott Kantor Vice President and CFO September 8, 2004
Slide 2: Safe Harbor Statement
Safe Harbor Statement This presentation contains forward-looking statements pertaining to: the Company’s first-quarter fiscal 2005 expectations, LeCroy’s short- and long-term growth, the Company’s intended acquisition of CATC and related expectations, growth expectations in the serial data test mark
Slide 3: LCRY Investment Highlights
LCRY Investment Highlights Successful and Profitable Leading Oscilloscope Provider Proven Management Team with Execution Track Record Positioned to Dominate Emerging Growth Market Leveraged Business Model can reach >15% Op. Margin Sustainable Gross Margins well above 60% Recognized Industry Leading
Slide 4: LeCroy Corporation August 2004
LeCroy Corporation August 2004. Hi-End Digital Oscilloscopes for R&D $140M Annual Run Rate Sales Sales: 1/3 each US, Europe, Asia Global, Technical, Direct Sales Force Major Markets: Computer & Storage 59% Gross Margins 11.5% Operating Margin 382 Employees $366K Revenue per Employee LeCroy Headquart
Slide 5: Sep 2, 2004: LeCroy to Acquire CATC
Sep 2, 2004: LeCroy to Acquire CATC CATC: $20M Run Rate Protocol Analyzers for R&D in Computer and Storage > 80% Gross Margins , just passing 6% Operating Margins Aimed at Emerging Growth Market for Serial Data Test LeCroy will Acquire CATC for $6.00 per share or $118M $81M net cash required Use $31
Slide 6: Transaction Motivation: Challenges in the Digital World
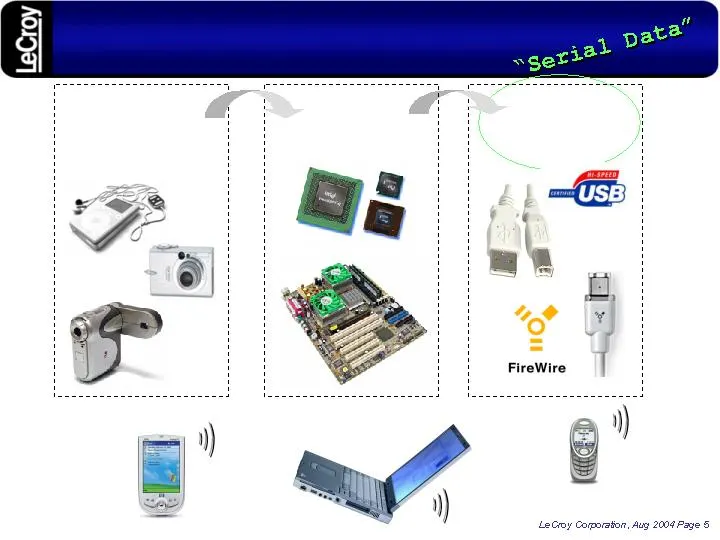
Transaction Motivation: Challenges in the Digital World Digital Media Explosion High-Speed Data Transport Seamless Connectivity High-Speed Processors 10011 1001101001 1001101001
Slide 7: Serial Data Transfer: Faster and Cheaper
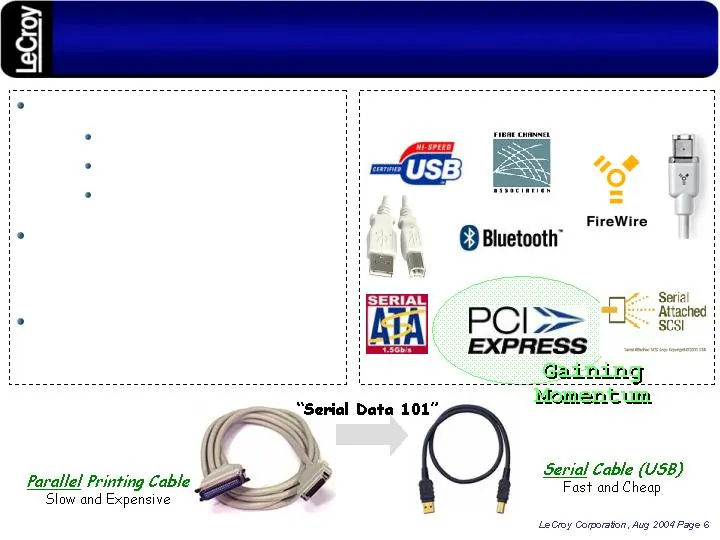
Serial Data Transfer: Faster and Cheaper Serial Data Standards: Enable Consumer Devices Speed Chip-Chip Transfer Origins in Computer & Storage High Speed and Complex Electrical Signals must conform to strict standards: “ Physical Layer ” Complex Protocols : or “connectivity language” must be evaluat
Slide 8: Serial Data Standards Deployment will Accelerate
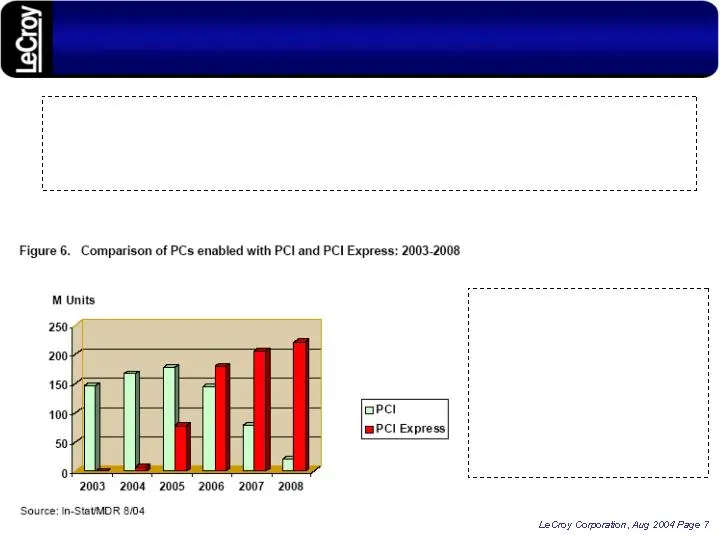
Serial Data Standards Deployment will Accelerate PCI Express will Dominate Computer Bus Architecture “ As chip speeds increase , and as system architectures and associated data streams grow more complex, the PCI bus – which has become far more pervasive than its original framers ever envisioned more
Slide 9: Oscilloscopes: Physical Layer Design Tool
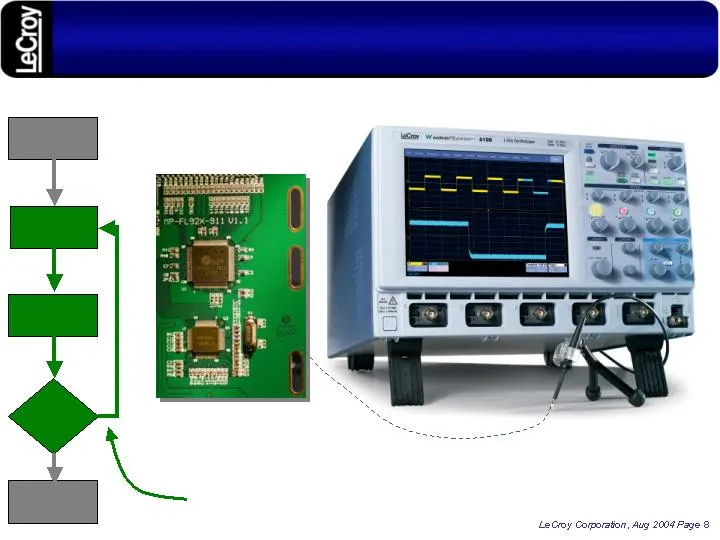
Oscilloscopes: Physical Layer Design Tool Troubleshoots Hardware Problems Design Simulate Prototype Produce Test Productivity in the “Validation Loop” speeds Time-to-Market Oscilloscopes validate electronic designs so they can be produced.
Slide 10: LeCroy Leads in Signal Analysis
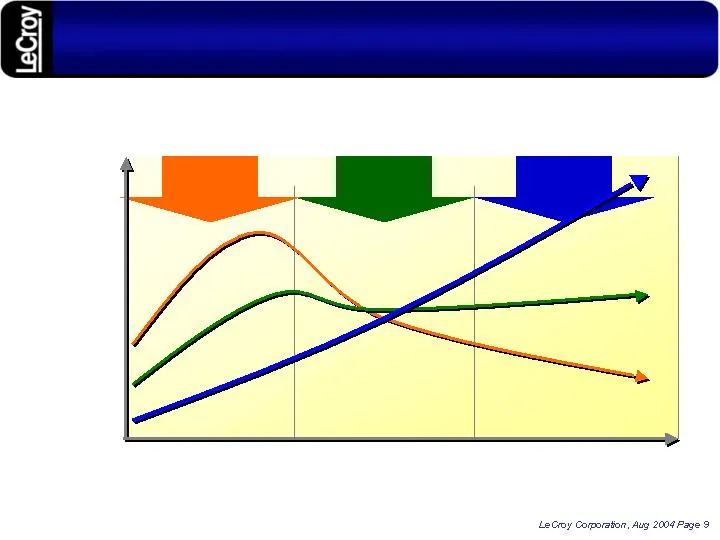
Measure Estimate Analyze LeCroy Leads in Signal Analysis Low Medium High Complexity of Electronic Signals Oscilloscope Utility High Low Value Proposition Agilent Tektronix LeCroy
Slide 11: Serial Data Analyzers
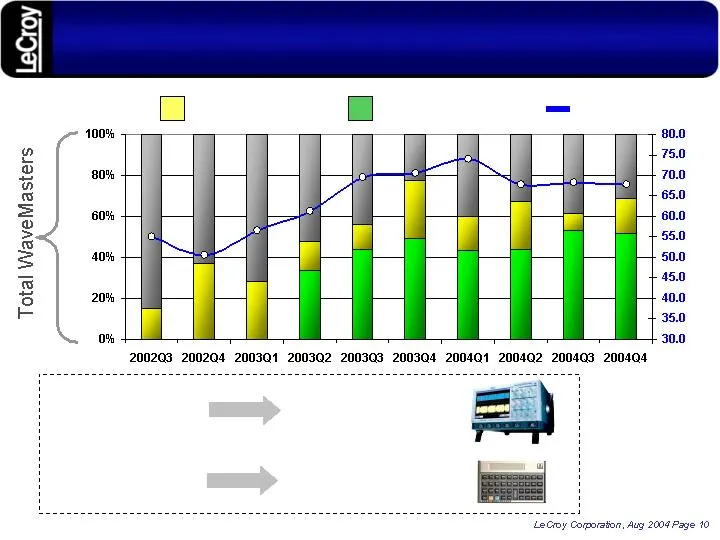
Serial Data Analyzers: 2/3 of LeCroy’s High-End Oscilloscope Business ($45M) $K Disk Drive Analyzer Serial Data Analyzer ASP Serial Data Analyzer General Purpose Calculator Financial Calculator General Purpose Oscilloscope
Slide 12: Protocol Analyzers: Message Layer Design Tool
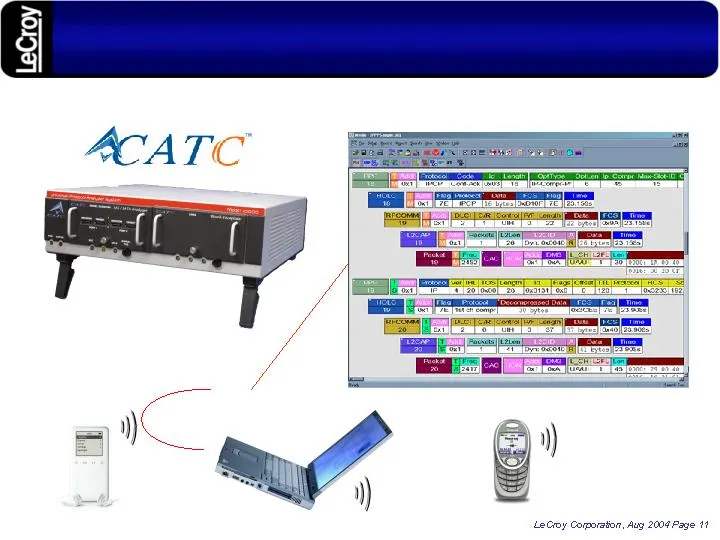
Protocol Analyzers: Message Layer Design Tool Troubleshoots Software Problems “The CATC TRACE” is a patented GUI that maximizes user productivity System Integrators use Protocol Analyzers to find and solve Software Problems 10011010110 1001100011 1001101001
Slide 13: Oscilloscopes and Protocol Analyzers
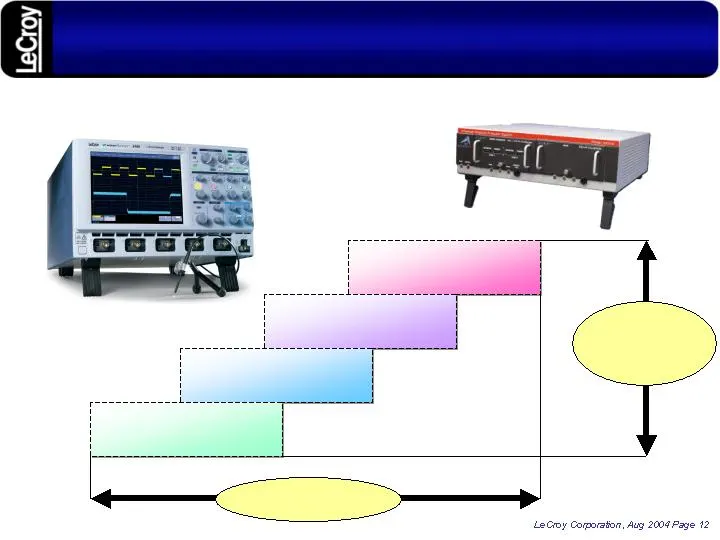
Oscilloscopes and Protocol Analyzers Application Layer Message Layers End-to-End Coverage of the Serial Data Design Cycle Data Layer Protocol Stack WaveShapes Messages Design Cycle Hardware Problems Software Problems Physical Layer
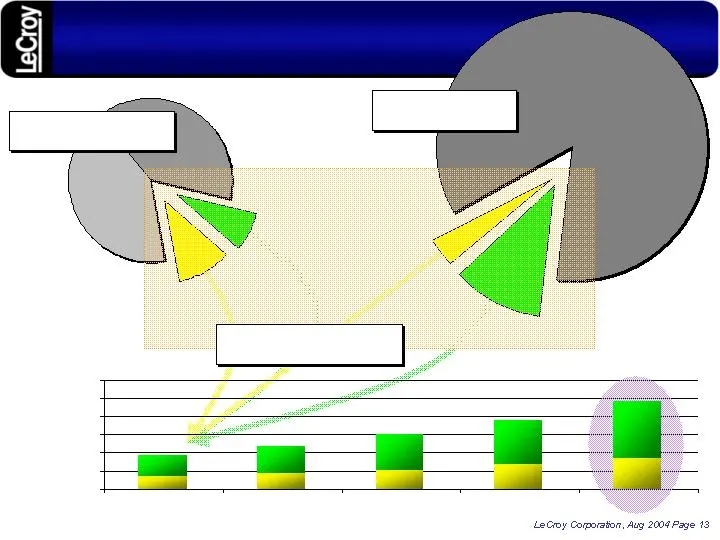
Slide 14: The Market for Serial Data Test Solutions Should Grow Rapidly
The Market for Serial Data Test Solutions Should Grow Rapidly Network I&M Network R&D Data Storage Serial Data Computer Serial Data Protocol Analyzers $350M General Purpose Scopes Oscilloscopes $840M Computer Serial Data Data Storage Serial Data Serial Data Test $190M $0 $100 $200 $300 $400 $500 $60
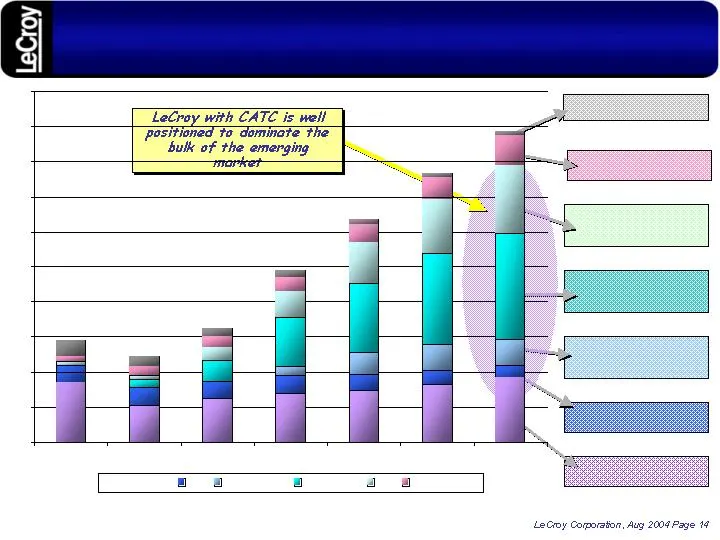
Slide 15: New and Emerging Standards
New and Emerging Standards Dominated by Finisar FiberChannel 80% LeCroy/CATC USB Leverages USB Ownership with Advantage to LeCroy/CATC Wireless USB LeCroy/CATC and Agilent early winners: likely to share PCI Express LeCroy/CATC and Finisar early winners: Likely to share SAS Dominated today by Finisar
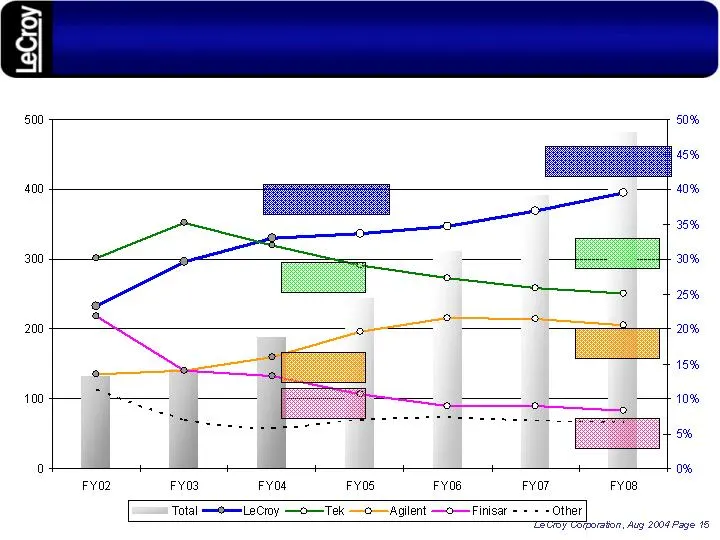
Slide 16: LeCroy with CATC is Well Positioned
LeCroy with CATC is Well Positioned 40% LeCroy/CATC 32% LeCroy/CATC First in Serial Data Test 21% Agilent 25% Tektronix 8% Finisar 16% Agilent 30% Tektronix 13% Finisar Today Projected $Millions
Slide 17: LeCroy and CATC: Perfect Complements
LeCroy and CATC: Perfect Complements No Overlap in Products Cover Design Cycle End-to-End LeCroy Strong in Storage, CATC strong in Computer LeCroy Strong International Sales Force Significant Synergies in G&A, Selling CATC: First Mover Advantage in Standards Adoption LeCroy and CATC: Significant HW
Slide 18: Customers and End Markets
Customers and End Markets El Paso Natural Gas Co. Computer and Semiconductor Data Storage Automotive Electronics ~25% LeCroy Sales ~15% LeCroy Sales ~15% LeCroy Sales
Slide 19: LeCroy can Leverage its Direct Sales Force
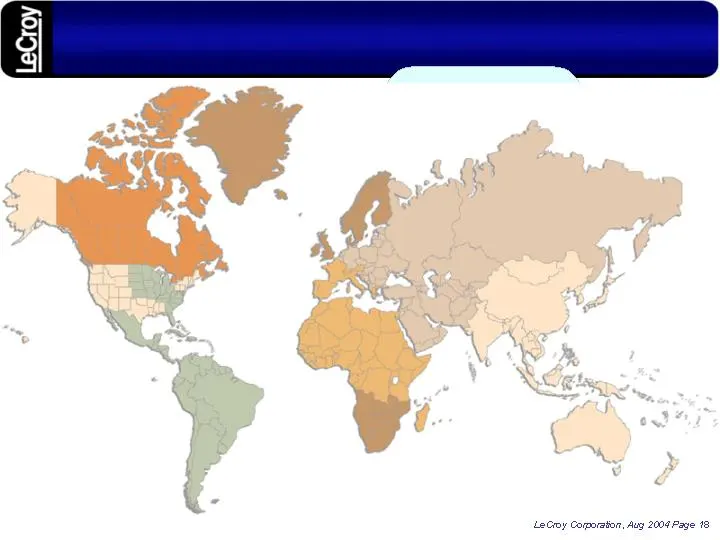
LeCroy can Leverage its Direct Sales Force Japan, Korea, China, Singapore Sales & Service Development Partner (Japan) ASIA-PACIFIC 34 Sales Engineers Switzerland, France, UK, Germany, Italy, Austria, Scandinavia Sales & Service Software Engineering (GVA) Europe HQ (GVA) EMEA 23 Sales Engineers New Y
Slide 20: Financial Overview
Financial Overview Scott Kantor Vice President and CFO
Slide 21: Continued Strong Operating Performance
Continued Strong Operating Performance Total Orders of $34.6M (12 Qtr High) Product Orders Grew 16% to $32.5M (12 Qtr High) 94% product orders from products < 24 mos. old Growth: US=14%, Eur=16%, Asia=11%, Japan=35% Sales grew 18% to $34.9M (12 Qtr High) Record number of scope units ordered (1647) R
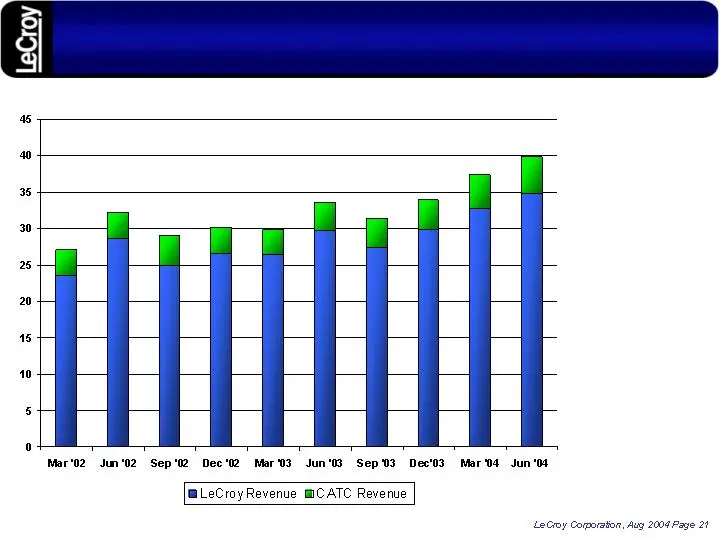
Slide 22: Strong Sales Growth in Recent Quarters
Strong Sales Growth in Recent Quarters Annualized Revenue nears $160M CATC $20M annual Run-rate LCRY $140M annual Run-rate $M
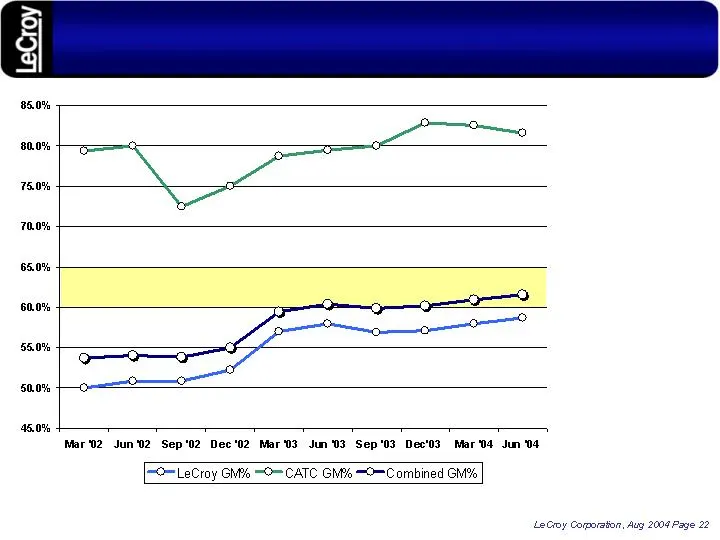
Slide 23: LeCroy and CATC: Strong Margin Trends
LeCroy and CATC: Strong Margin Trends Resultant Gross Margins will reach the mid 60’s
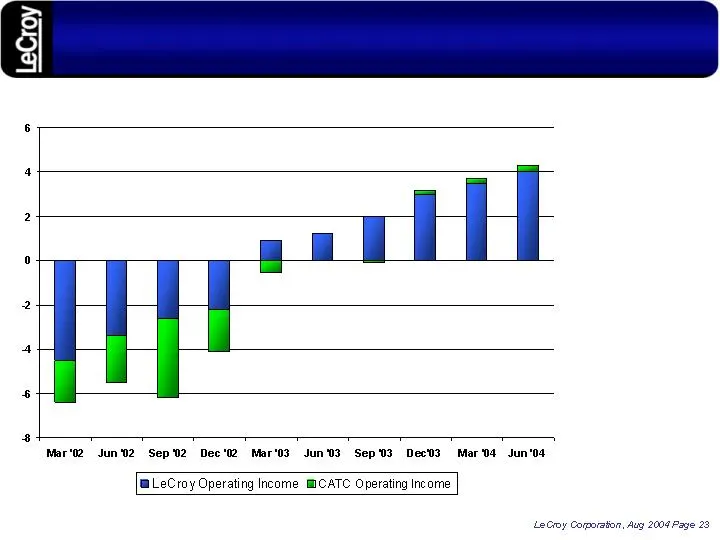
Slide 24: Sustained Up-Trend In Operating Income
Sustained Up-Trend In Operating Income LeCroy can Unlock the Leverage in CATC’s Model LeCroy Continues Strong Operating Profit Momentum CATC begins to capitalize on its leveraged business model $M
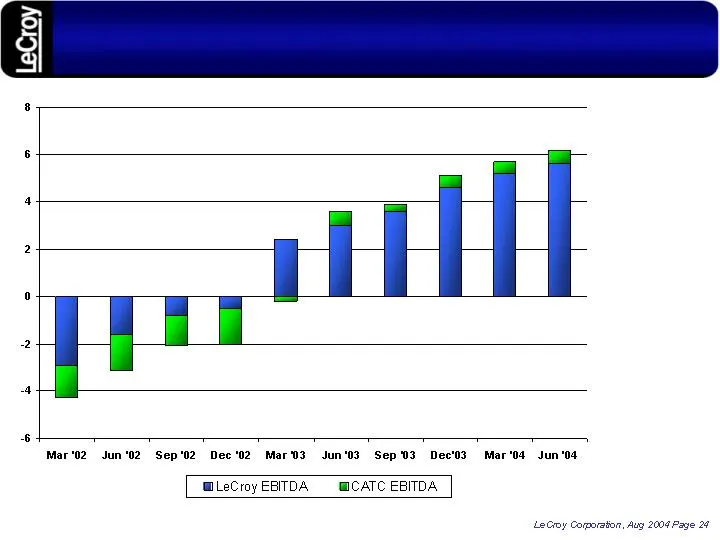
Slide 25: Powerful Cash Generation Capabilities
Powerful Cash Generation Capabilities $M LeCroy’s Combined Annual EBITDA run-rate is about $25M 9th consecutive quarter of improved EBITDA
Slide 26: Post-Transaction Capital Structure
Post-Transaction Capital Structure (a) Post Transaction Capital Structure data reflects the effective combination date of December 1, 2004. (b) Bank debt consists of Term Debt under the $75 million credit facility underwritten by the Bank of New York. Term borrowings will amortize quarterly over 5 y
Slide 27: CATC Provides LeCroy's Growth Engine
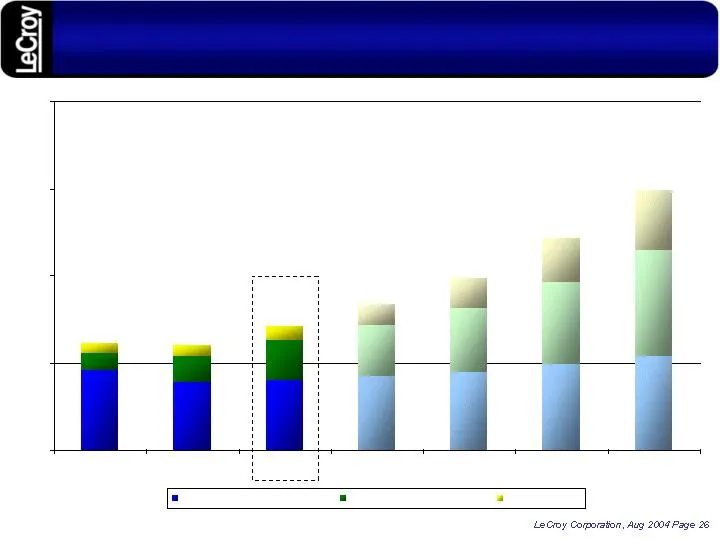
CATC Provides LeCroy’s Growth Engine Opportunity to Dominate Serial Data Test Market FY02 FY03 FY04 FY05 FY06 FY07 FY08 LeCroy Gen Purpose Scopes LeCroy Serial Data Scopes CATC Division $145M
Slide 28: Target Business Model
Target Business Model LeCroy Target Sales Gross Margin % R&D % SG&A % Operating Income % 100 % 56 % 13 % 29 % 14 % LeCroy Jun ’04 $34.9M 58.7 % 12.0 % 35.3 % 11.5 % Combined Target (a) Grow 20 % 62-65 % 15-17 % 28-30 % 15-20 % LeCroy Targets mid 60’s GM% and high-teens OI% (a) Revenues should approa
Slide 29: LeCroy's Mission Sequence from 2002
LeCroy’s Mission Sequence from 2002… CATC Acquisition Meets Strategic Objectives Significantly Improve LeCroy’s Operating Performance Meaningful Profit and Cash Generation Sustainable, Predictable Performance Cleanse and Strengthen LeCroy’s Balance Sheet Eliminated Toxic Financing Improved Managemen
Slide 30: LCRY Investment Highlights
LCRY Investment Highlights Successful and Profitable Leading Oscilloscope Provider Proven Management Team with Execution Track Record Positioned to Dominate Emerging Growth Market Leveraged Business Model can reach >15% Op. Margin Sustainable Gross Margins well above 60% Recognized Industry Leading
Slide 31: Tom Reslewic, President and CEO; Scott Kantor, VP and CFO
Tom Reslewic President and CEO Scott Kantor Vice President and CFO September 8, 2004
Source: SEC EDGAR · 8-K filed Sep 8, 2004