Duke Realty — 2013 NAREIT REITWorld San Francisco
47 slides from Duke Realty's conference presentation, Nov 13, 2013
Slide 1: 2013 NAREIT REITWorld San Francisco
RELIABLE. ANSWERS. 2013 NAREIT REITWorld San Francisco November 13-14 Exhibit 99.1
Slide 2: Why Duke Realty?
RELIABLE. ANSWERS WHY DUKE REALTY? Superior Asset Quality Strategically Located Land Bank and Experienced Development Capabilities Proven Operational Success and Future Growth Opportunities Balance Sheet Strength Relative Value vs. Peers Talent and Leadership Depth to Execute
Slide 3: Three-Pronged Strategy for Success
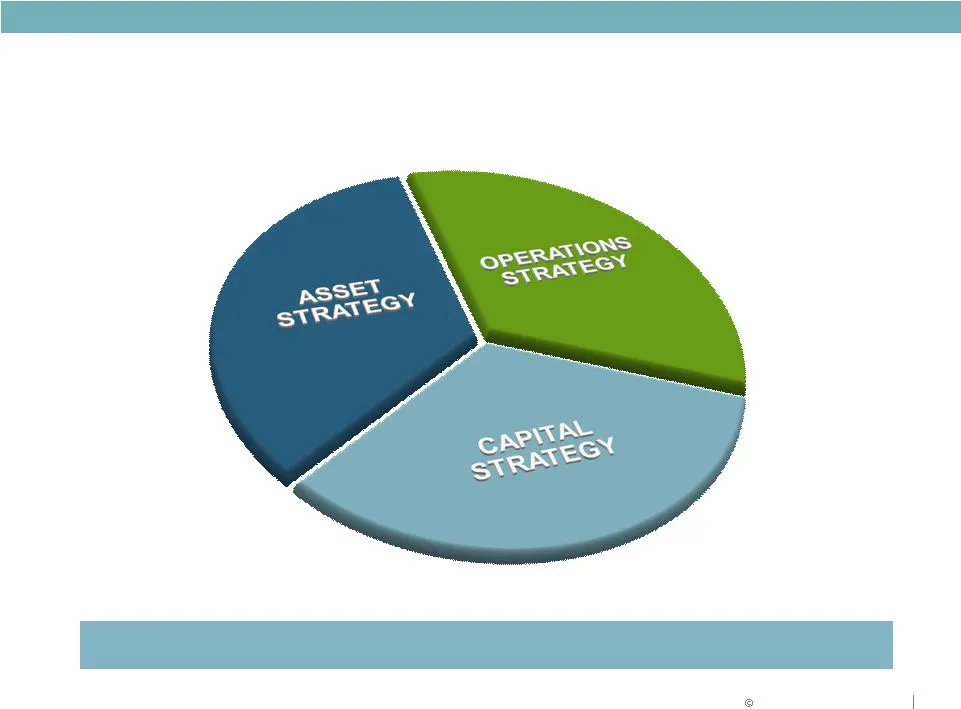
RELIABLE. ANSWERS . Three-Pronged Strategy for Success Strategies for delivering shareholder value
Slide 4: ASSET STRATEGY
ASSET STRATEGY
Slide 5: Asset Strategy Progress
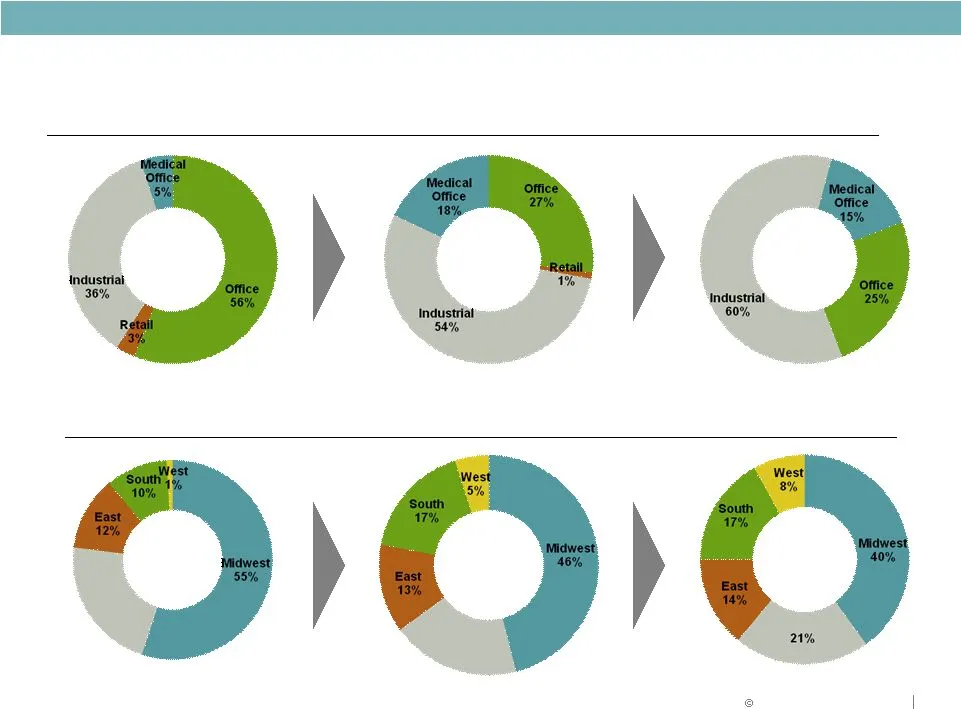
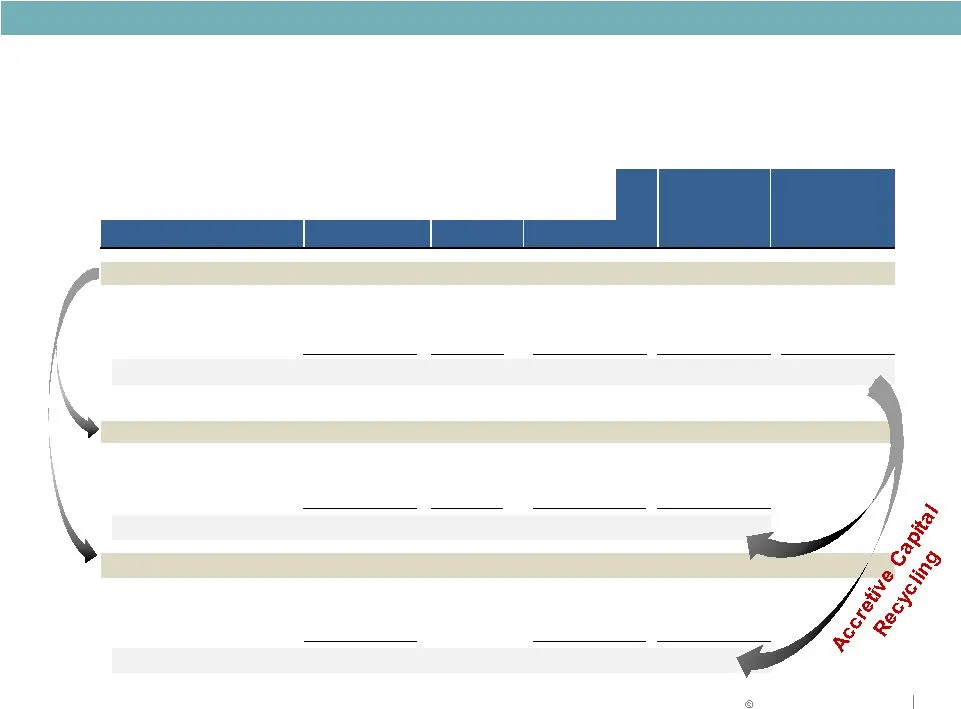
ASSET STRATEGY 3Q 2013 YE Asset Strategy Progress BY PRODUCT BY GEOGRAPHY YE Southeast 22% Southeast 3Q 2013 Southeast 19% Note: Figures represents share of quarterly net operating income
Slide 6
Slide 7: Superior Asset Quality
ASSET STRATEGY Highest quality portfolio of large, modern bulk industrial assets in key distribution markets Best in class MOB development platform and portfolio, with newest properties and highest hospital system credit Built-in annual rent and same property growth Suburban office portfolio now les
Slide 8: Industrial Portfolio
ASSET STRATEGY – INDUSTRIAL PORTFOLIO
Slide 9: Industrial Strategy
ASSET STRATEGY Leverage 40 years of industrial operating and development experience as primary driver of company growth Focus on larger, modern bulk distribution product which results in higher credit quality tenant base with fewer overall tenants to manage Geographic strategy focused on major marke
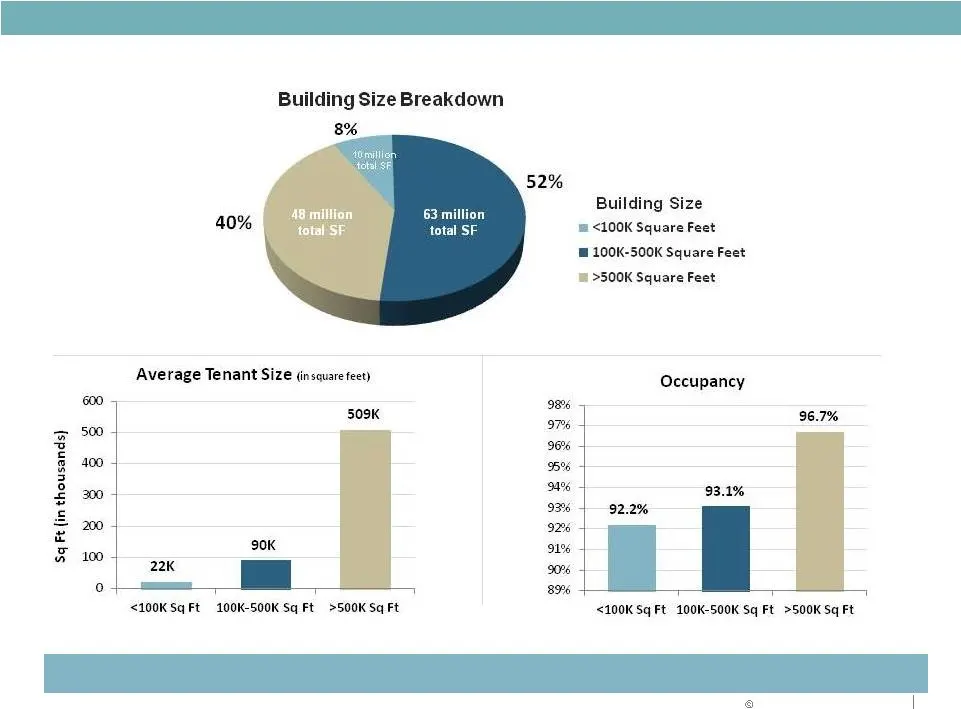
Slide 10: Premier Quality Industrial Portfolio
ASSET STRATEGY Premier Quality Industrial Portfolio Focus on modern bulk warehouse with strong performance characteristics Building Size Building Size
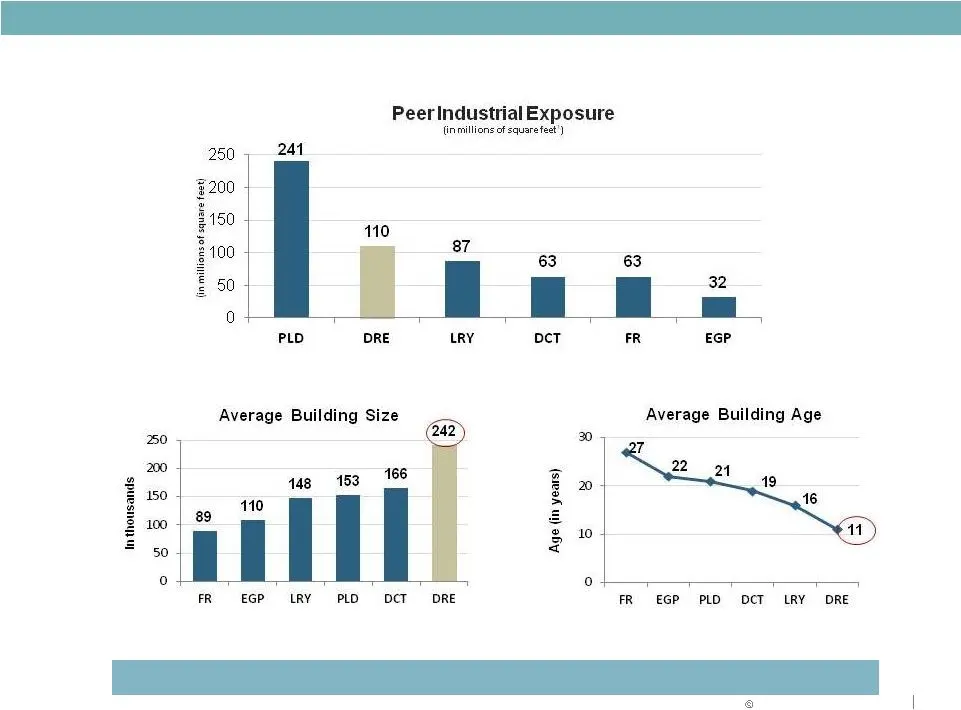
Slide 11: Best in Class Domestic Industrial Portfolio
ASSET STRATEGY Best in Class Domestic Industrial Portfolio Newest and largest facilities to support current supply chain trends (1) Estimates based on pro rata ownership % of domestic, industrial-only facilities. Source: Q3 2013 company supplementals. LRY isan estimate proforma Cabot Source:Per CoSt
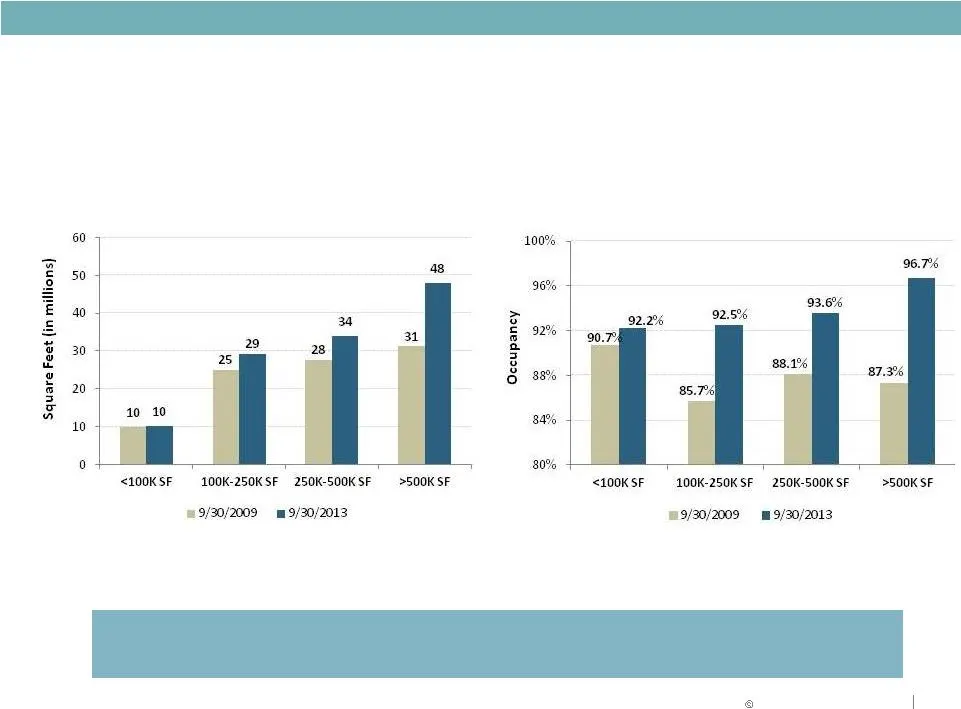
Slide 12: Duke Realty Industrial Portfolio – Then & Now
ASSET STRATEGY Duke Realty Industrial Portfolio – Then & Now Significant occupancy increase and shift to newer, bigger buildings since 2009 Total Square Feet by Building Size Occupancy by Building Size
Slide 13: Big Box vs Small Box
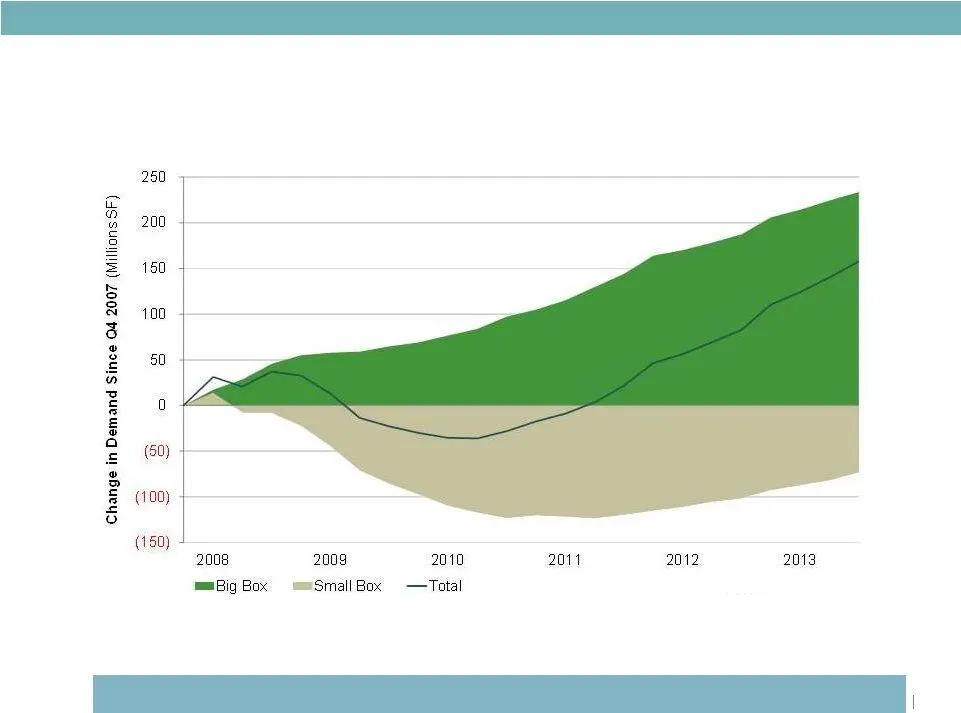
ASSET STRATEGY Big Box vs Small Box Cumulative Net Absorption In Duke Realty Markets Higher demand for modern bulk product As of 13Q3 Sources: CoStar Group, Inc.; PPR. Representative of Duke Realty's 22 markets of the PPR54 *Big Box: 1990 or newer & 100K SF+; Small Box: Older than 1990 or <100K SF
Slide 14: Strong Market Rent Growth Momentum
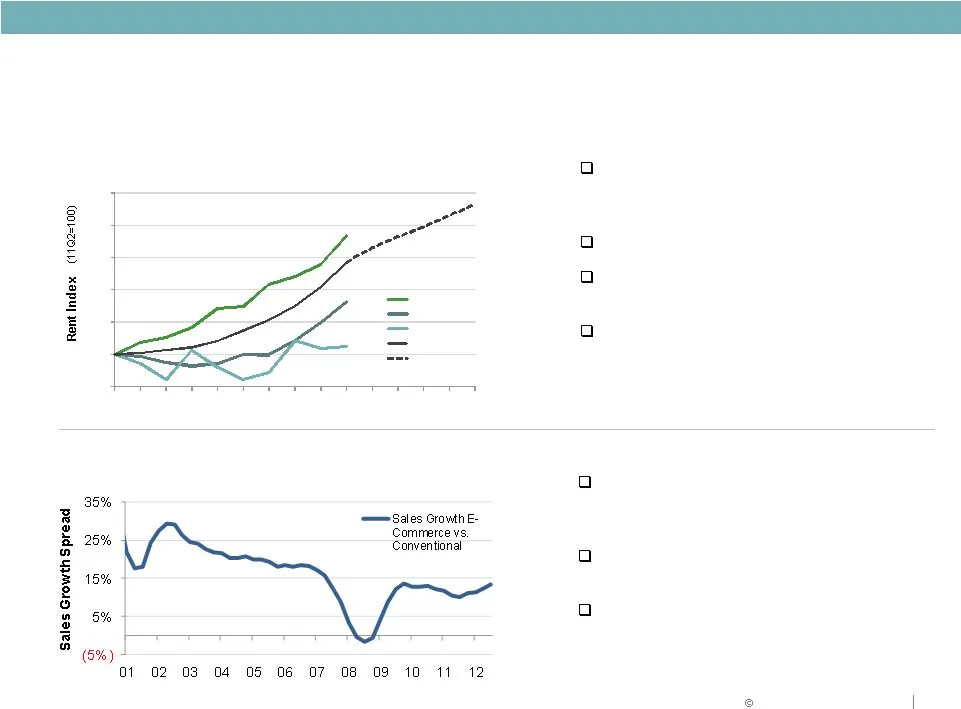
ASSET STRATEGY Strong Market Rent Growth Momentum Big Box : Strong Rent Growth & E-Commerce Trends E-Commerce Sales Growth Very Strong Graph sources: CoStar / PPR; E-commerce & retail sales figures are 4Q rolling avg; *PPR54 minus 22 Duke MSAs; Big Box 1990+ & 100K SF+; Small Box <100K SF Market ren
Slide 15: Office Portfolio
ASSET STRATEGY – OFFICE PORTFOLIO
Slide 16: Office Strategy: Will reach 25% target by year-end 2013
ASSET STRATEGY Will reach 25% target by year-end 2013 Continue to sell older, non-strategic assets Develop remaining office land bank primarily with build to suit projects Own highest quality assets in high growth office markets Office Strategy
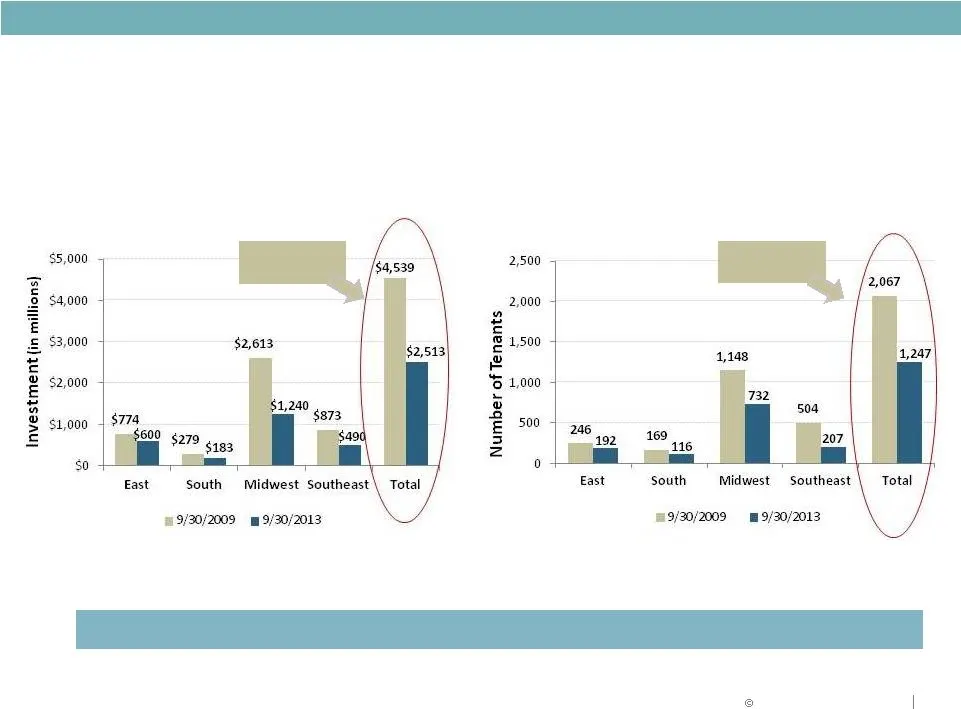
Slide 17: Office Portfolio – Then & Now
ASSET STRATEGY Office Portfolio – Then & Now 45% decrease in investment Significant decrease in investment, less tenants = operating efficiencies Invested $ by Region # of Tenants by Region 40% decrease in tenants
Slide 18: Office Properties Being Marketed
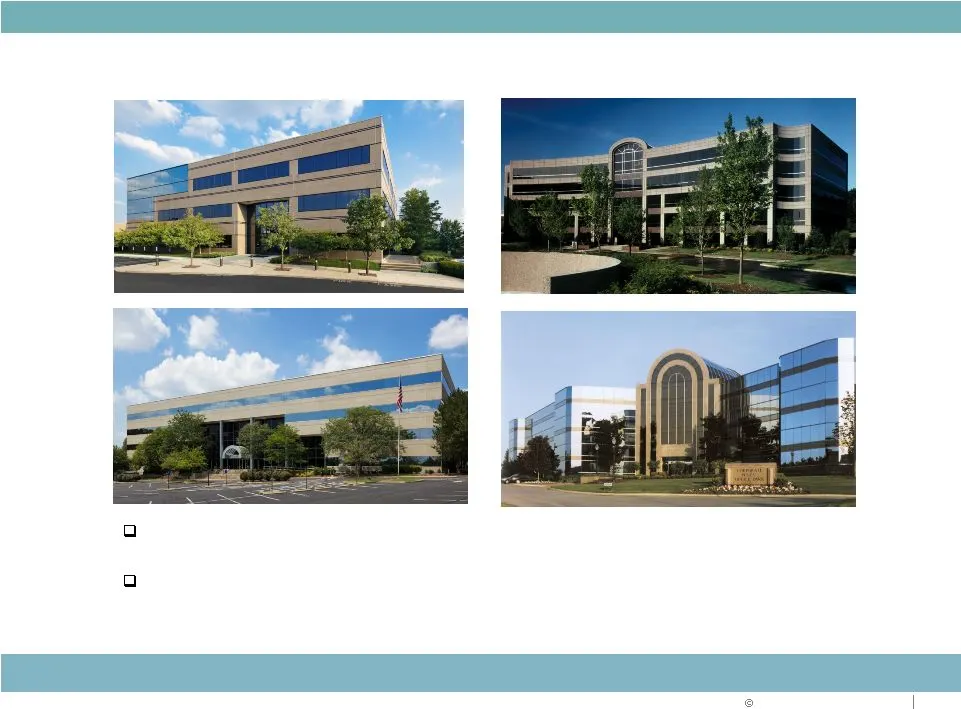
ASSET STRATEGY Office Properties Being Marketed Various properties being marketed in multiple markets, including Cleveland, Cincinnati and St. Louis; Average age of years Approximately $190 million of assets under contract or LOI with expected December closings. In advanced negotiations on another p
Slide 19: Medical Office Portfolio
ASSET STRATEGY – MEDICAL OFFICE PORTFOLIO
Slide 20: MOB Platform Strategy and Benefits to Duke Realty
ASSET STRATEGY MOB Platform Strategy and Benefits to Duke Realty Solid NOI growth and low volatility Growth industry, recession resistant asset class Best in class development team able to produce consistent development opportunities through economic cycles Substantially all on-campus or aligned wit
Slide 21: Healthcare Trends
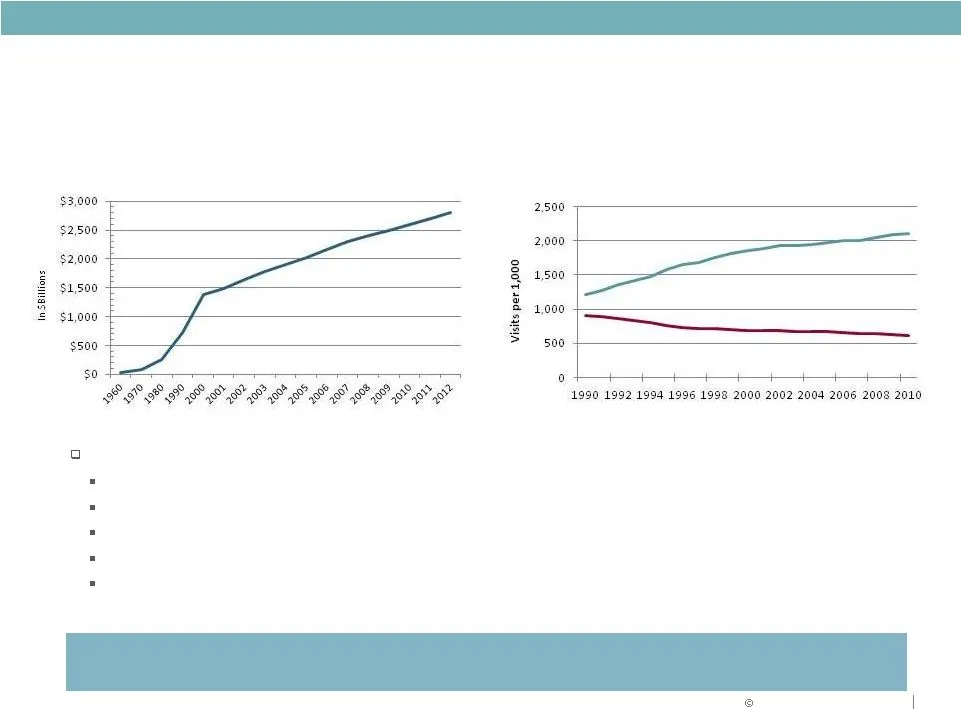
ASSET STRATEGY Healthcare Trends Annual Healthcare Expenditures Source: U.S. Bureau of the Census Growing healthcare expenditures, cost efficiency trends and the Affordable Care Act should further improve demand for lowest-cost setting outpatient (MOB) facilities Affordable Care Act People insured e
Slide 22: Medical Office Portfolio
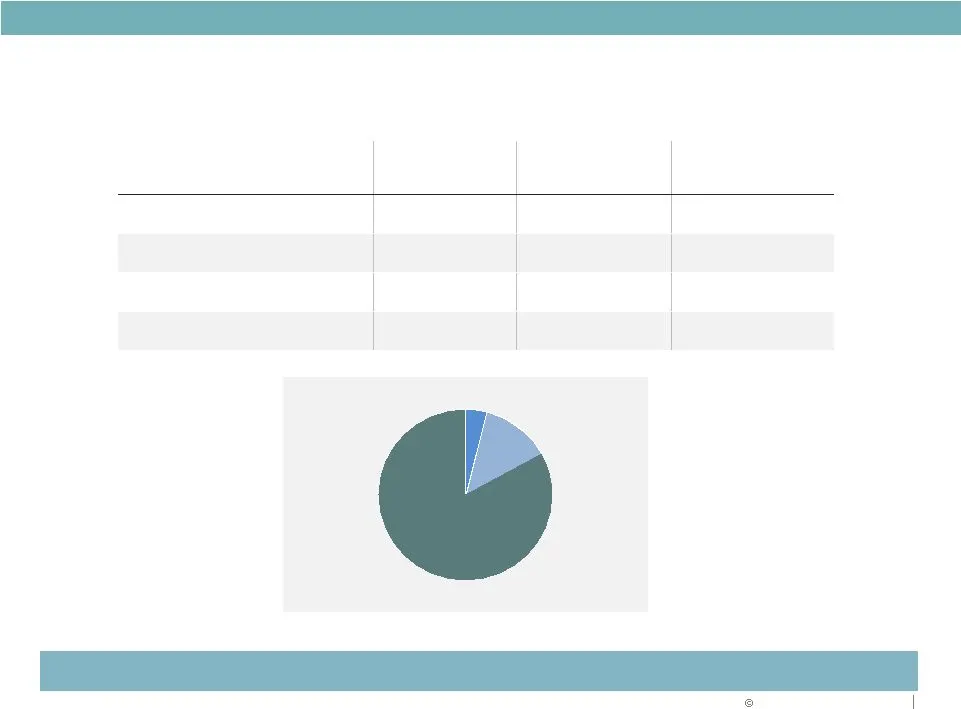
ASSET STRATEGY 4% 13% 83% In-Service Under Development Total Properties Investment $ $1.3 B $240 M $1.5 B Square Feet 5.6 M 817 K 6.4 M Leased Occupancy 94% 100% 94% MOB On-Campus MOB Off-Campus Medical Office Portfolio Highest quality pure MOB portfolio with average age of only 7 years MOB Aligned
Slide 23: Duke Realty Medical Office Portfolio – Then & Now
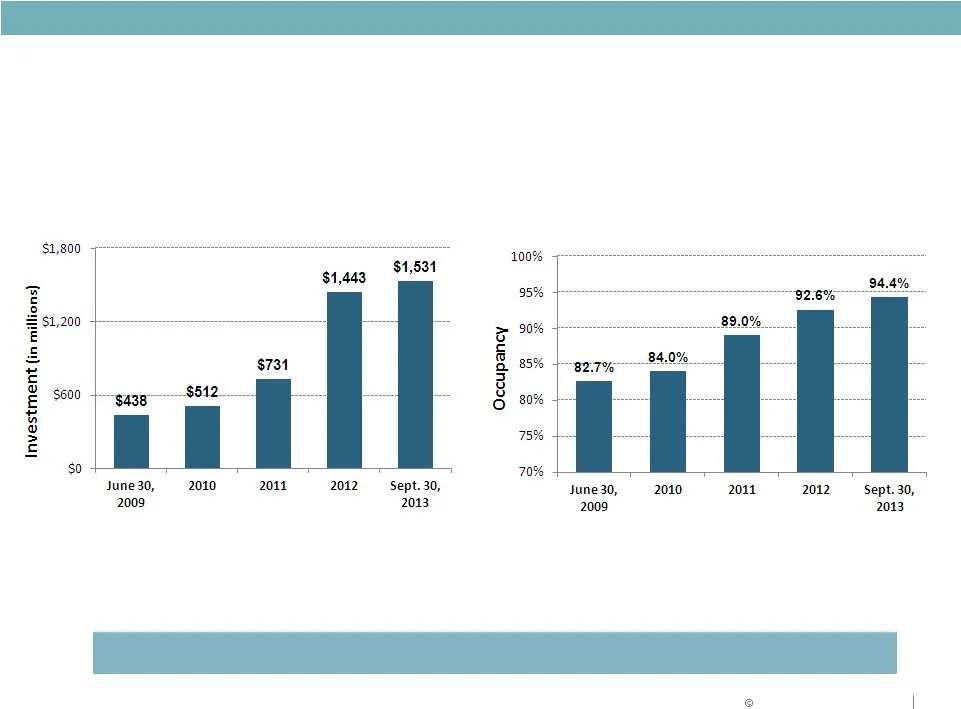
ASSET STRATEGY Duke Realty Medical Office Portfolio – Then & Now Significant increase in investment and occupancy Cumulative Invested $ Occupancy
Slide 24: Top Health System Relationships and Lease Expirations
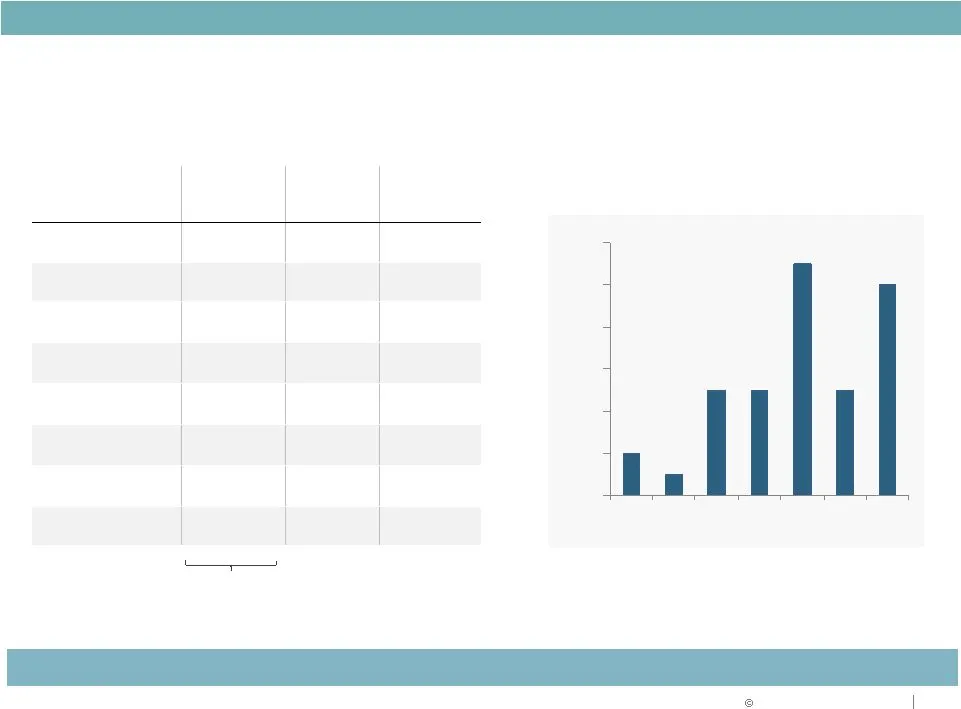
ASSET STRATEGY As of 9/30/13 2% 1% 5% 5% 11% 5% 10% 0% 2% 4% 6% 8% 10% 12% Lease Expirations (% of MOB In-Service Sq. Ft.) High credit tenants and limited lease maturities result in stable and growing cash flow Top Health System Relationships Health System Credit Rating ( Moody's) Rentable SF % of T
Slide 25: Best in Class Medical Office Portfolio – Peer Comparison
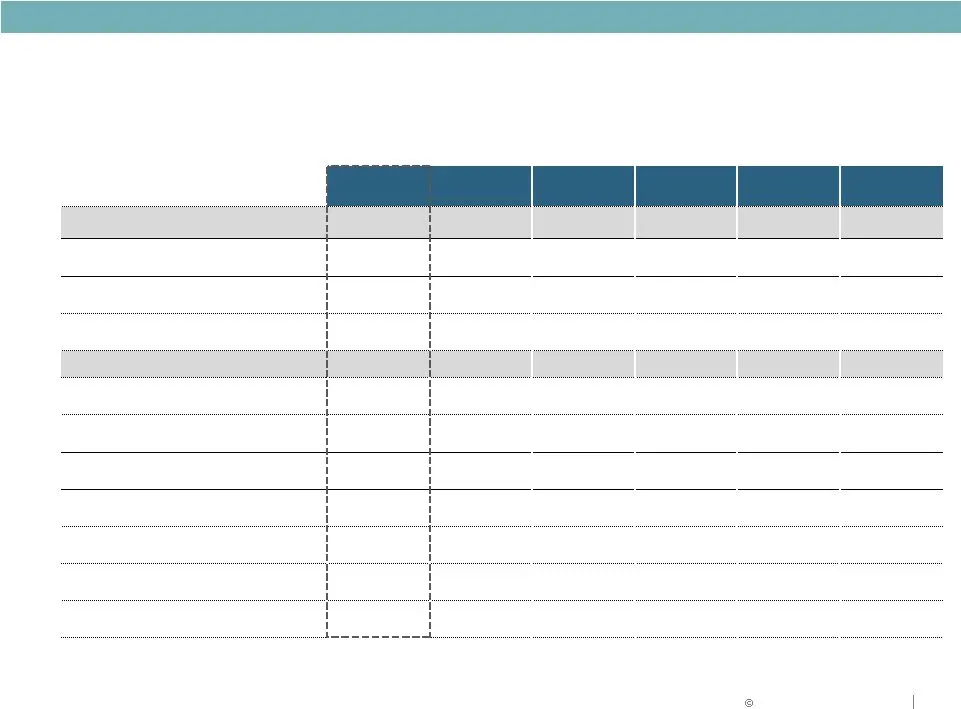
RELIABLE. ANSWERS . DRE HCN HCP HR HTA VTR Portfolio Size Number of Properties Square Feet (in MM's) 6.5 14.1 14.2 13.6 13.6 18.1 Total Investment (in $MM's) $1,531 $3,405 $2,649 $2,934 $2,818 $3,663 Operating Statistics Average Age (1) 7 yrs 12 yrs 20 yrs -- -- -- Square Feet / Property 75k SF 65k
Slide 26: Non-Core Medical Office Portfolio Being Marketed
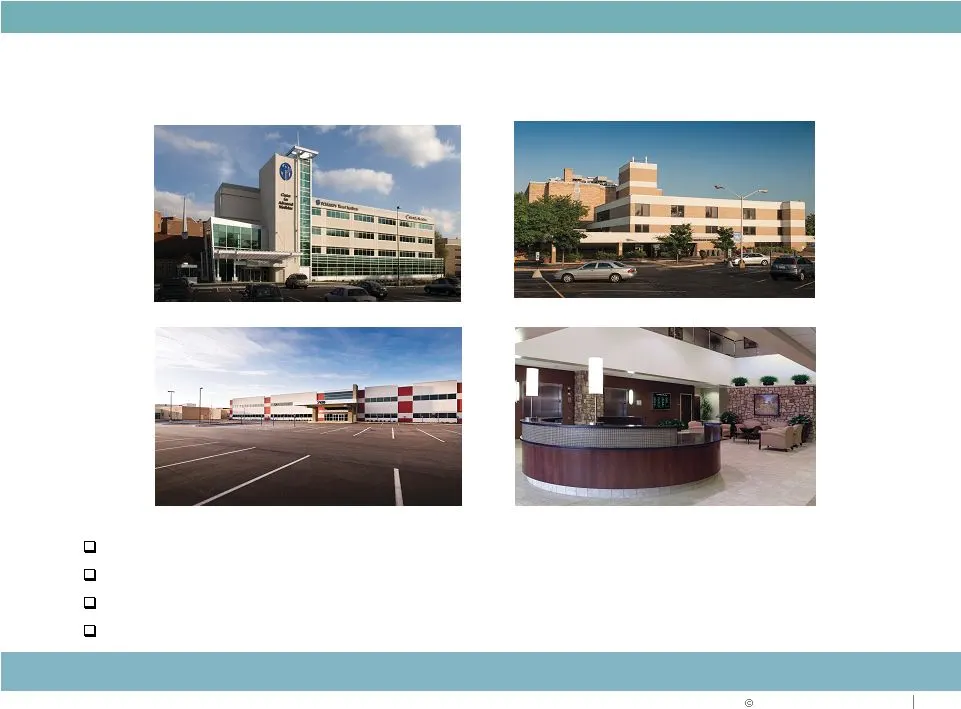
ASSET STRATEGY Non-Core Medical Office Portfolio Being Marketed Seventeen (17) medical office buildings totaling 938,000 square feet, average age of 13 years 97% leased; located primarily in the Midwest Under contract and expect to close in Q4 and early Q1 with proceeds estimated over $250 million A
Slide 27: Healthcare Development Pipeline
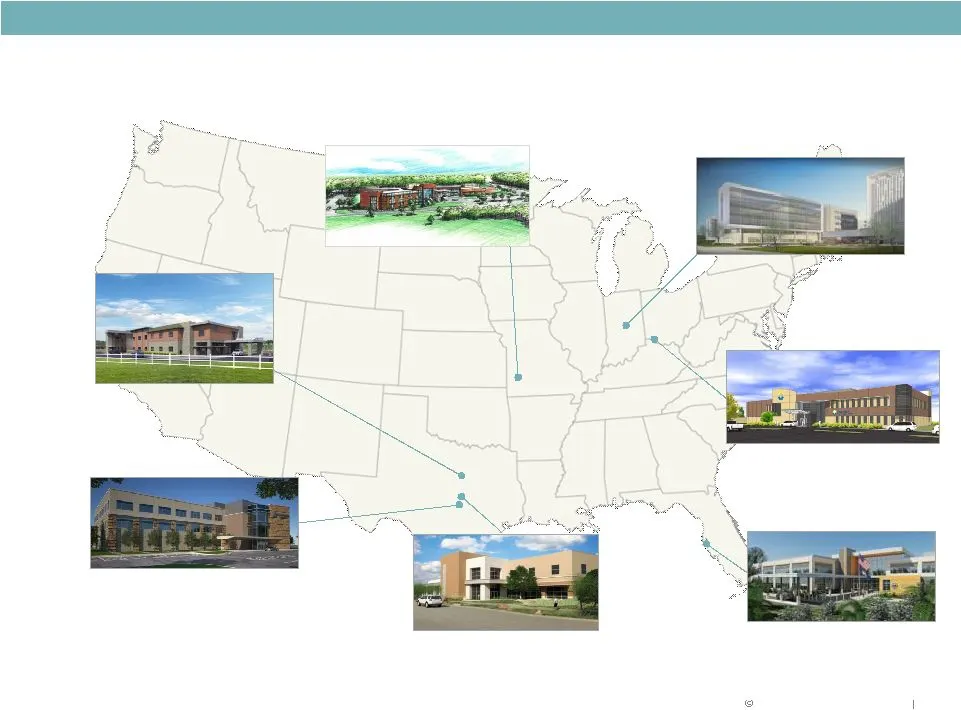
ASSET STRATEGY Healthcare Development Pipeline Department of Veterans Affairs Tampa, FL 117,000 SF, 100% pre-leased Wishard Health Indianapolis, IN 274,000 SF, 100% pre-leased Scott & White Healthcare Temple, TX 78,000 SF, 100% pre-leased Baylor Healthcare (6 Facilities) Dallas, TX 207,000 total SF
Slide 28: Development Capabilities
ASSET STRATEGY – DEVELOPMENT CAPABILITIES
Slide 29: Development Strategic Advantages
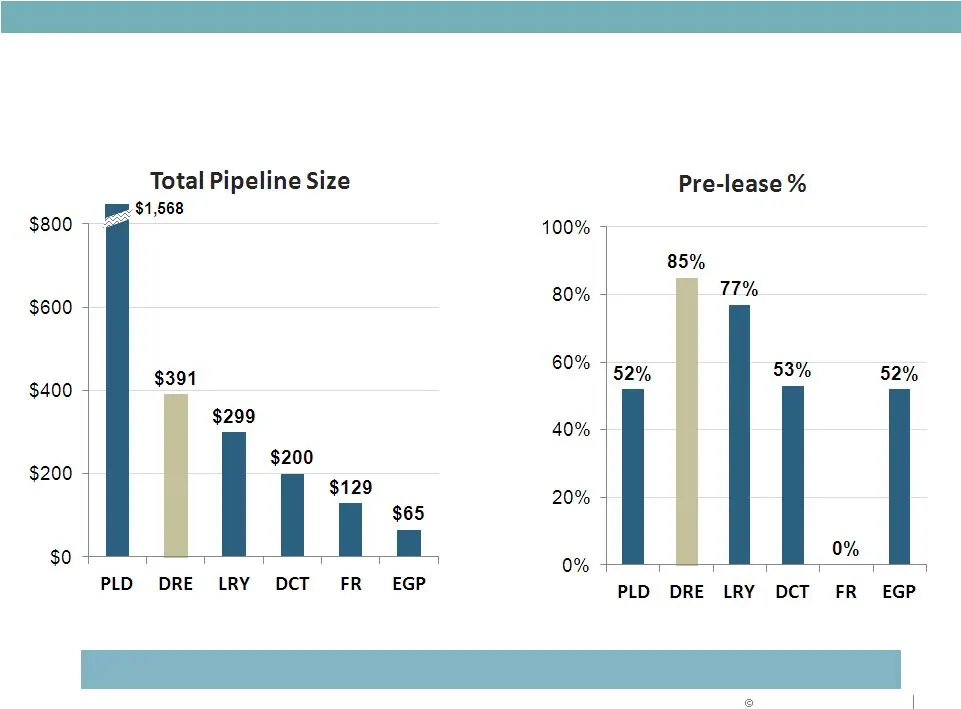
ASSET STRATEGY Development Strategic Advantages Development platform creates significant value 40 years of experience in development Land bank in strategic locations that can support approximately 58 million square feet of development (86% bulk industrial) $391MM pipeline that is 85% leased with 8.9
Slide 30: Development Pipeline Comparison
ASSET STRATEGY Development Pipeline Comparison Duke Realty development pipeline to drive strong external growth (in $millions) Source: Q2 2013 Company Supplementals
Slide 31: Select 2013 YTD Development Starts
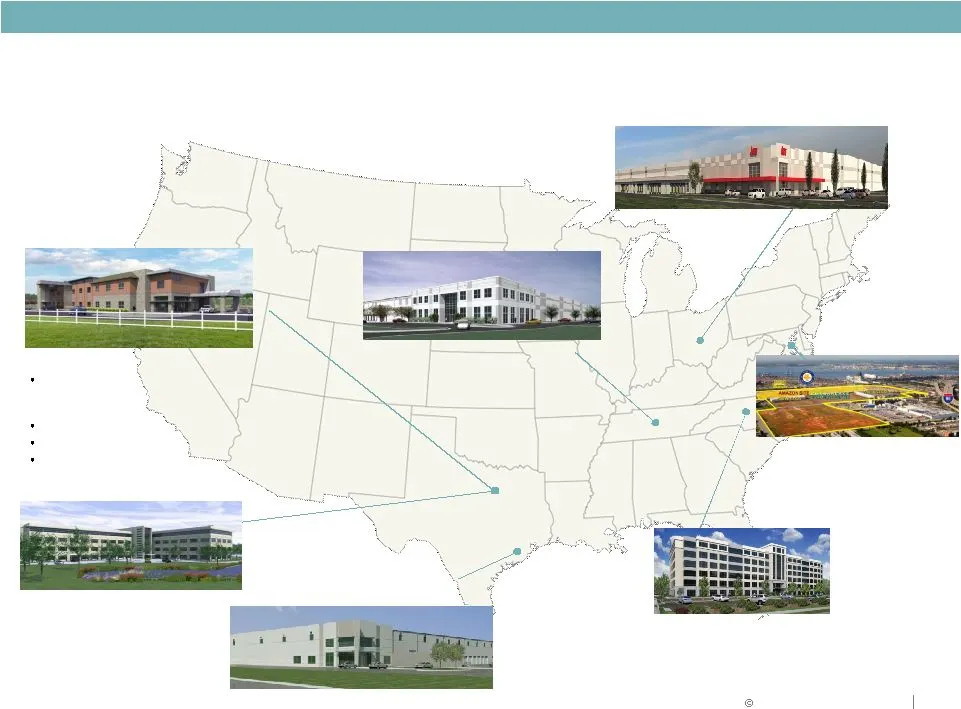
ASSET STRATEGY Select 2013 YTD Development Starts Nashville Industrial • Regional distribution center build-to-suit for Starbucks on Duke Realty land • 680,000 SF; 8 year lease term • 100% pre-leased Dallas Medical Office Five Baylor Emergency (ER) facilities in Metro Dallas (cities of Rockwall, Mur
Slide 32: Strategic Land Bank: Developable Square Feet
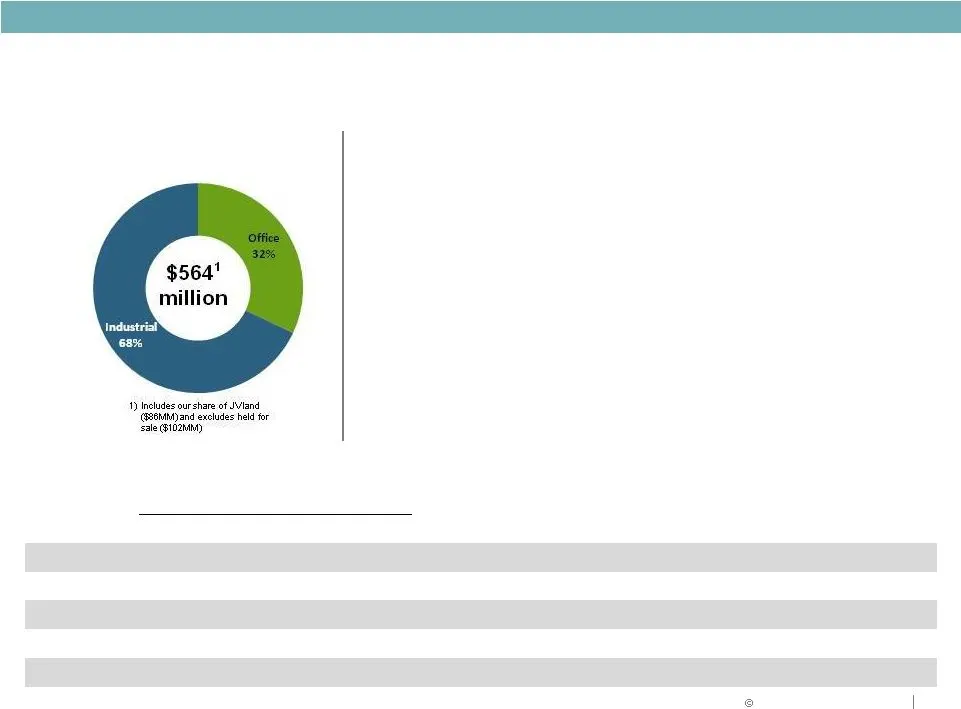
ASSET STRATEGY Developable Square Feet Industrial Office Primary Markets Midwest 26.0 3.1 Indianapolis, Chicago, Cincinnati, Columbus, Minneapolis, & St. Louis East 3.8 1.6 New Jersey, Baltimore, Raleigh and Washington D.C. Southeast 9.4 2.1 Atlanta, Central Florida, and South Florida Southwest 10.8
Slide 33: Operating Strategy
OPERATING STRATEGY
Slide 34: Operational Success and Future Growth Opportunities
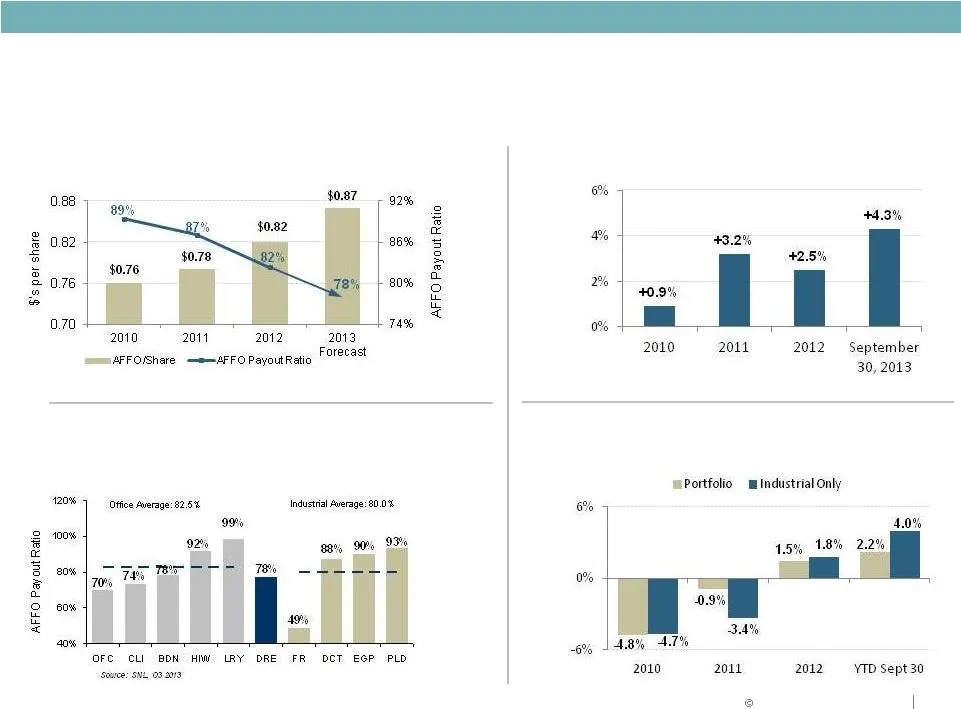
OPERATIONS STRATEGY Completed asset repositioning into higher quality, higher rental rate growth assets with minimal FFO per share dilution and annual growth in AFFO per share AFFO payout ratio of 74% and AFFO multiple of approximately 18x at the low end of the sector and well positioned for continu
Slide 35: Historical Performance Supports Additional Occupancy Upside
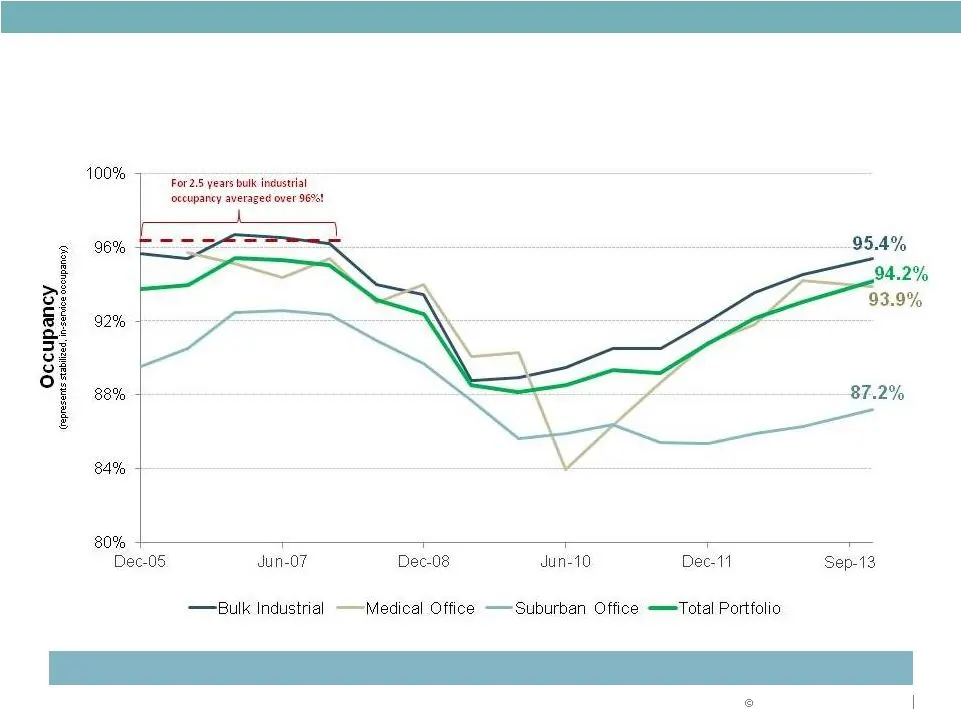
OPERATIONS STRATEGY Historical Performance Supports Additional Occupancy Upside Historical Occupancy Sep-13
Slide 36: Accelerating Rent Growth and Improving Operating Performance
OPERATIONS STRATEGY Accelerating Rent Growth (Represents growth in annual net effective rent on renewal leases) Improving Operating Performance Strong Cash Flow Growth and Payout Ratio Steady Same Property NOI Growth Peer Payout Ratio Analysis
Slide 37: Capital Strategy
CAPITAL STRATEGY
Slide 38: Balance Sheet Quality
CAPITAL STRATEGY Will reach original leverage goals established in 2009 by Q4 Continue to delever through assets sales and funding new development 60/40 equity/debt Well balanced annual debt maturities Significant liquidity with $850 million LOC with little to no borrowings and low near-term maturit
Slide 39: Key Capital Metrics & Goals
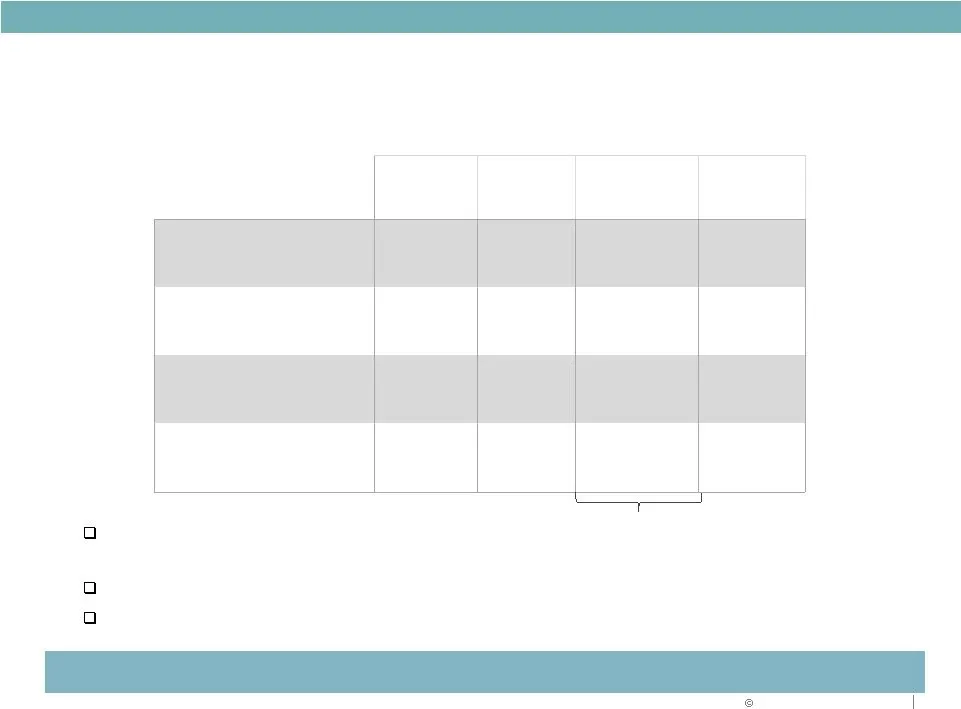
CAPITAL STRATEGY Investment grade rated debt (Baa2/BBB-) for over 16 years with proven access to multiple capital sources Available line of credit - $850 million capacity Conservative AFFO payout ratio for 9 months YTD (74%) Key Capital Metrics & Goals Actual Actual Sept 30, Goal Debt to Gross Asset
Slide 40: Current Liquidity Position
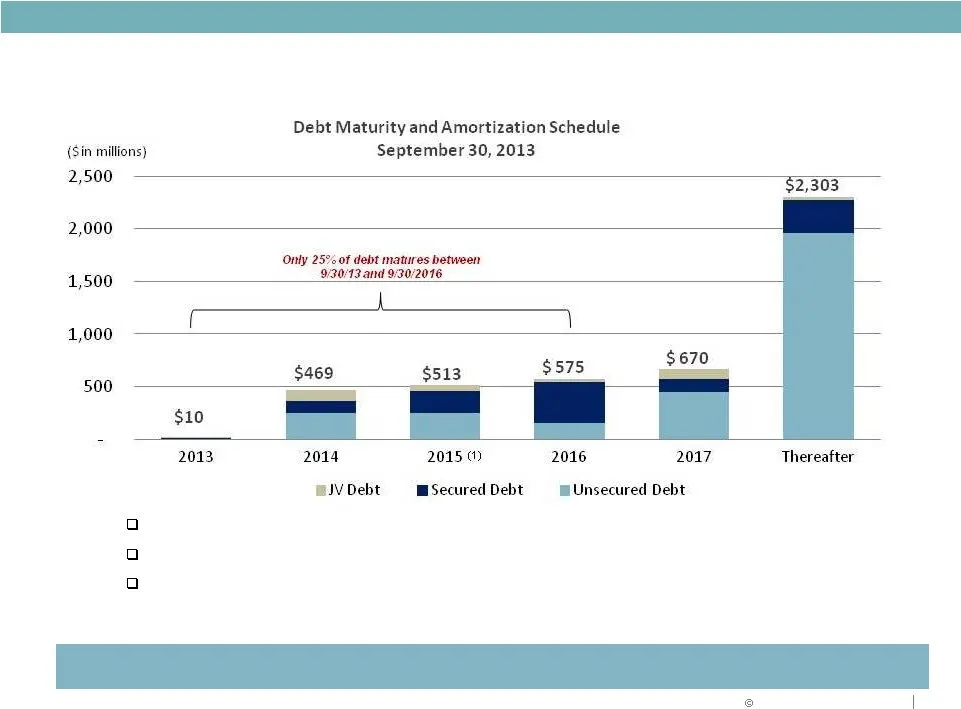
CAPITAL STRATEGY Current Liquidity Position Maturity ladder well balanced and liquidity position significantly enhanced Next unsecured maturity is $250MM in August 2014 No unsecured maturities > $600M in any one year ($600M in 2022) 25% of debt matures over next 3 years ($1.2 billion total), compare
Slide 41: Duke Realty Peer Debt Metrics
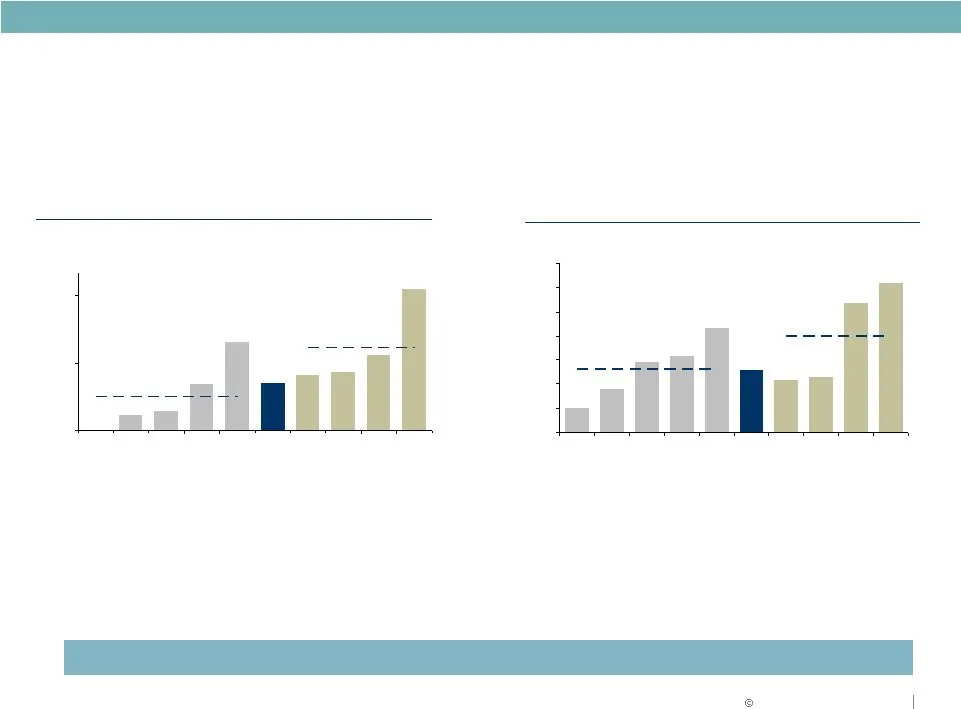
CAPITAL STRATEGY 10% 18% 29% 32% 43% 26% 22% 23% 54% 62% 0.0% 10.0% 20.0% 30.0% 40.0% 50.0% 60.0% 70.0% LRY BDN HIW CLI OFC DRE DCT PLD FR EGP Industrial Average: 40.0% Office Average: 26.5% Secured Debt / Total Debt Peer Set Key: Office - LRY=Liberty; CLI=Mack-Cali; HIW=Highwoods; BDN=Brandywine; O
Slide 42: Why Duke Realty
WHY DUKE REALTY
Slide 43: Duke Realty Scorecard
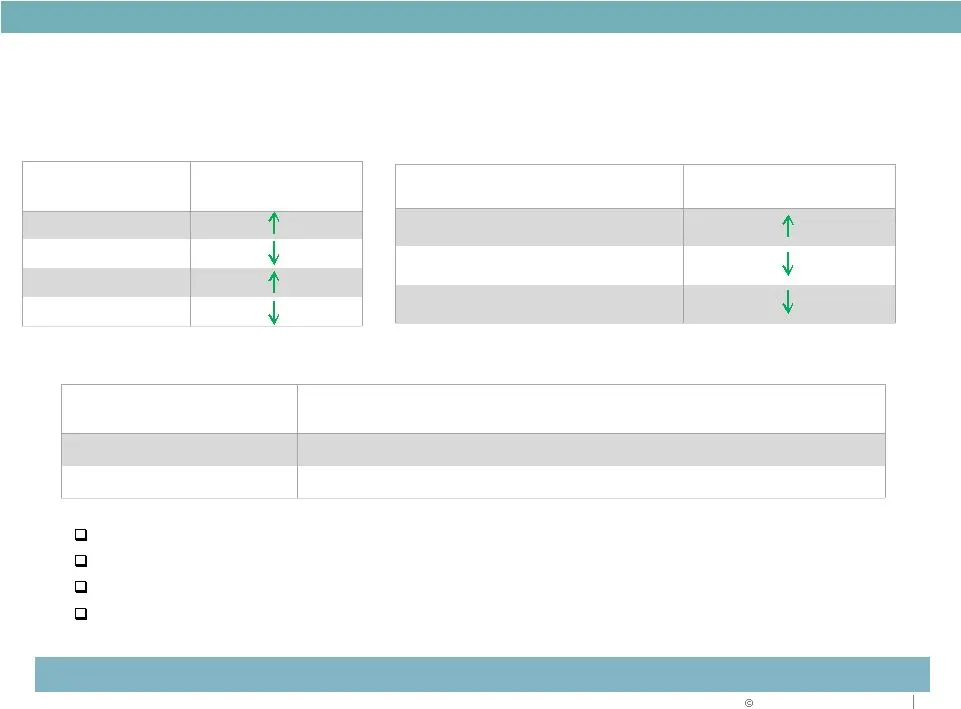
WHY DUKE REALTY Duke Realty Scorecard Asset Strategy Asset Concentration Industrial 42% 60% Office 49% 23% Medical Office 6% 16% Retail 3% 1% Capital Strategy Key Metrics Fixed Charge Coverage 1.79 2.1 Debt Plus Preferred to EBITDA 8.68 < 7.6 Debt Plus Preferred to Gross Assets 55.5% < 50% Operation
Slide 44: Positioned for NAV Growth
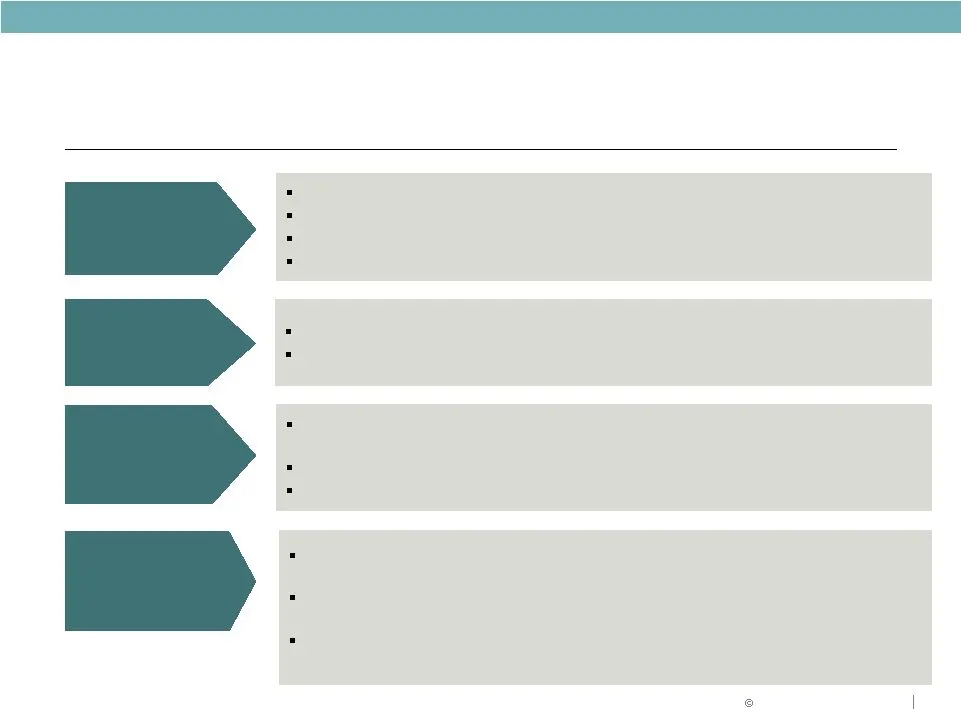
Lease-Up Existing Vacancy Accretive Development Continued Asset Repositioning Increase Rents \ Reduced Capex WHY DUKE REALTY Positioned for NAV Growth KEY NAV GROWTH DRIVERS In-service portfolio occupancy of 93.5% Strong leasing pipeline Demonstrated track record of 65-85% tenant renewal rate Abilit
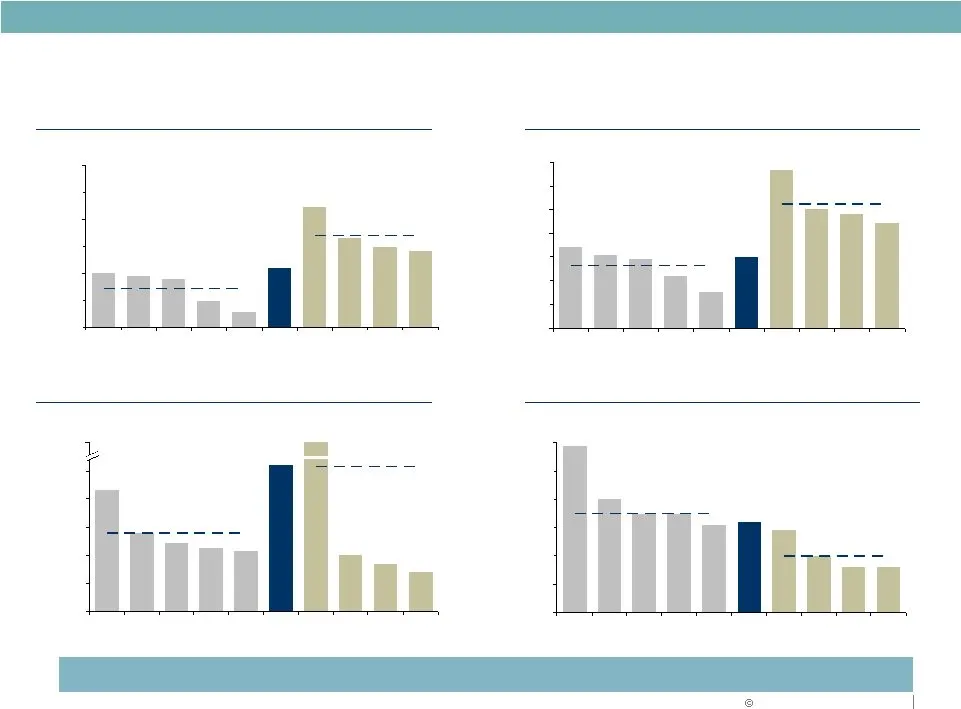
Slide 45: Why Duke Realty: Peer Valuation Multiples
WHY DUKE REALTY 5.6% 5.6% 6.0% 6.9% 7.2% 7.1% 7.5% 7.5% 8.0% 9.9% 4.0% 5.0% 6.0% 7.0% 8.0% 9.0% 10.0% CLI OFC LRY BDN HIW DRE FR DCT PLD EGP 19.8x 18.4x 17.7x 14.9x 12.1x 18.1x 32.7x 26.1x 25.2x 23.7x 6.0x 10.0x 14.0x 18.0x 22.0x 26.0x 30.0x 34.0x HIW LRY BDN OFC CLI DRE PLD EGP FR DCT 17.3x 17.9x 1
Slide 46: Why Duke Realty?
WHY DUKE REALTY WHY DUKE REALTY? Superior Asset Quality Strategically Located Land Bank and Experienced Development Capabilities Proven Operational Success and Future Growth Opportunities Balance Sheet Strength Relative Value vs. Peers Talent and Leadership Depth to Execute
Slide 47: Forward-Looking Statement
RELIABLE. ANSWERS . Forward-Looking Statement This slide presentation contains statements that constitute “forward-looking statements” within the meaning of the Securities Act of 1933 and the Securities Exchange Act of 1934 as amended by the Private Securities Litigation Reform Act of 1995. These fo
Source: SEC EDGAR · 8-K filed Nov 13, 2013
More decks from Duke Realty Corporation
 Merger or Acquisition (June 2022)14 slides · Jun 13, 2022
 Investor Presentation (June 2021)58 slides · Jun 7, 2021
 Investor Presentation (May 2021)44 slides · May 10, 2021
 Investor Presentation (February 2021)58 slides · Feb 22, 2021
 NAREIT REITworld Virtual Investor Conference 202056 slides · Nov 16, 2020
 B of A Securities 2020 Global Real Estate Conference56 slides · Sep 15, 2020