
VANCOUVER, BC, June 29, 2026 /CNW/ - Freeman Gold Corp. (TSXV: FMAN) (OTCQB: FMANF) (FSE: 3WU) ("Freeman" or the "Company") is pleased to announce the results of the Feasibility Study ("FS") for its 100%-owned Lemhi Gold Project ("Lemhi" or the "Project"), located in Lemhi County, Idaho, USA. Prepared by Ausenco Engineering Canada ULC ("Ausenco") in accordance with National Instrument 43-101 Standards of Disclosure for Mineral Projects ("NI 43-101"), the Feasibility Study confirms Lemhi as a technically robust, long-life gold development project supported by a Proven and Probable Mineral Reserve of 1.0 million1 ounces of gold.
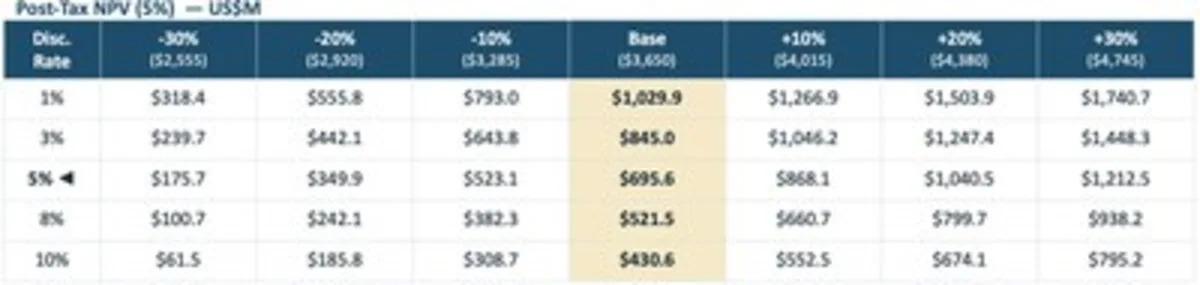
At a base case of US$3,650 per ounce, the study demonstrates strong economics, including a pos-tax Net Present Value ("NPV(5%)") of US$696 million, a post-tax internal Rate of Return ("IRR") of 34.4% and a rapid payback period of 2.5 years. The Project combines scale, simplicity, strong margins and significant exploration upside within one of the most attractive mining jurisdictions in the United States.
Using current spot price of US$4,0902 increases post-tax NPV(5%) to US$904 million, a 29.82% increase from the base case. IRR increases to 41.4% and payback period reduces to 2.1 years, while increasing the NPV-to-initial-capital ratio to 2.74x from 2.11x.
Why Lemhi Stands Out
100%-owned gold development project located in Idaho, USA
Proven and Probable Mineral Reserve of 1.0 million1 ounces of gold
Long-life operation with a 15.2-year mine life
Conventional open-pit mining and carbon-in-leach processing
Average life-of-mine gold recovery of 94.8%
Rapid post-tax payback of 2.5 years
Strong capital efficiency with a 2.11x NPV-to-initial-capital ratio
Significant exploration upside beyond current reserves
Additional 240,000 ounces of Inferred Mineral Resources not included in reserve
___________________________ | |
1 | Based on 43.0 MT at a grade of 0.74g/t. Please see notes for Mineral Reserve Estimate below. |
2 | As at June 26, 2026 |
Feasibility Study Highlights
BASE CASE: US$3,650/oz Gold | 5% Discount Rate
Post-Tax NPV(5%): US$696 Million
Post-Tax IRR: 34.4%
Post-Tax Payback: 2.5 Years
Initial Capital: US$329.7 Million
NPV to Initial Capital Ratio: 2.11x
Proven and Probable Mineral Reserve: 1.0 million3 ounces gold
Mine Life: 15.2 Years
Total Payable Gold: 972,000 ounces
Average Annual Production: 64,141 oz - LOM; 75,100 oz in Years 1 to 10
Average Gold Recovery: 94.8%
C1 Cash Cost: US$1,477/oz;
AISC: US$1,719/oz
AT US$4,090/oz GOLD — UPSIDE SCENARIO
Post-Tax NPV(5%): US$904 Million
Post-Tax IRR: 41.4%
Payback Period: 2.1 Years — capital fully recovered in just two years