
TSXV: ITR; NYSE American: ITRG
www.integraresources.com
VANCOUVER, BC, June 25, 2026 /CNW/ - Integra Resources Corp. ("Integra" or the "Company") (TSXV: ITR) (NYSE American: ITRG) is pleased to announce the results of its updated Technical Report Feasibility Study and Life-of-Mine Plan (the "Technical Report") for the producing Florida Canyon Mine ("Florida Canyon" or the "Project"), located in Nevada. Less than two years after acquiring Florida Canyon for $68 million ("M")1, Integra has transformed the operation into a larger, longer-life asset with a 74% increase in Proven and Probable Mineral Reserves, a 17% increase in annual gold production and active mining extended through 2033. Florida Canyon is now expected to generate over $0.8 billion ("B") from gold production in after-tax free cash flow2 and total payable gold production of 685 thousand ounces ("Koz") over life-of-mine ("LOM"), including 2 years of gold production from residual leaching starting in 2033.
(All amounts in United States ("U.S.") dollars and Metric Units unless otherwise stated)
2026 Florida Canyon Technical Report Highlights:
Robust gold project economics: After-tax net present value 5% ("NPV") of $601 M using base case metal prices3; After-tax NPV of ~$723 M using spot metal prices4.
Significant increase in Proven and Probable Mineral Reserve: Integra replaced gold ("Au") mined at Florida Canyon over the last two years and increased the Proven and Probable Mineral Reserve ("P&P") at Florida Canyon by 74%. The P&P increased from 685 Koz Au in the 2024 Mineral Reserve Statement5 to 1.19 million ounces ("Moz") Au in the 2026 Mineral Reserve Estimate, a 506 Koz Au increase in P&P6.
Substantial increase in oxide Mineral Resources: The Mineral Resource Estimate ("MRE") increased 128% in the oxide Measured and Indicated ("M&I") category and 57% in the oxide Inferred ("Inf.") category, including a MRE on the Standard Mine located south of Florida Canyon.
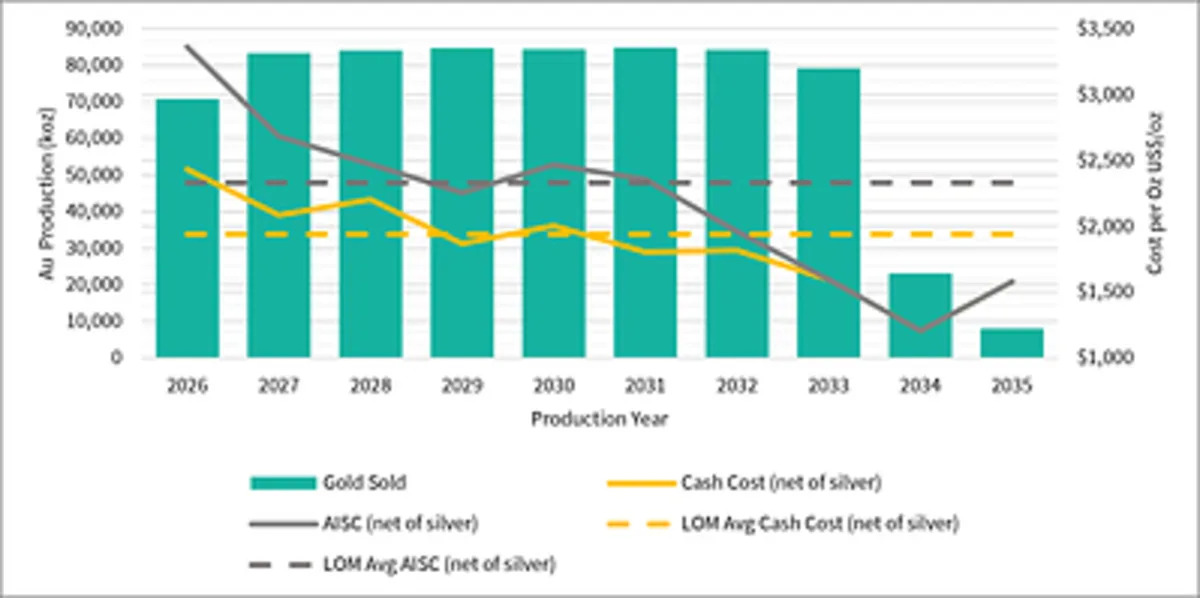
Enhanced gold production profile and extended mine life: The annual production profile in the Technical Report has increased from 70 Koz Au to an average of 82 Koz Au over an 8-year operating mine life (inclusive of 2026), a 12 Koz Au increase in average annual production with operating mine life extending from 2030 to 2033 (not including 2 years of gold production from residual leaching starting in 2033).
Strong free cash flow2 supports growth: Florida Canyon is expected to generate approximately $0.8 B in LOM after-tax free cash flow and average annual after-tax free cash flow of $90 M, supporting growth capital investments at Florida Canyon to increase mine life and annual production profile.
Lower LOM All-in Sustaining Costs2 and Revised 2026 Cost Guidance: Site-level all-in sustaining costs ("AISC") are expected to average approximately $2,331/oz over LOM. Due to the increase in tonnes mined, stacked and processed this year, along with inflationary pressures on diesel fuel and explosives, among others, the Company is revising its 2026 site-level AISC guidance from $2,750 to $2,950 to $3,300 to $3,500 while re-confirming and maintaining production guidance in 2026 of 70 Koz to 75 Koz Au. The updated mine plan in the Technical Report establishes a clear path toward lower long-term costs and higher annual gold production in future years.
Optimized mine plan that unlocks value: Informed by two years of operating experience and a comprehensive review of historical performance and costs, the Technical Report delivers a more stable, predictable and executable mine plan for Florida Canyon. All production growth and planned heap leach pad expansion contemplated in the Technical Report can be supported within the existing Mine Plan of Operations.
Cash flow to support project pipeline: Cash flow from Florida Canyon will support the advancement of the DeLamar Project through permitting, with the Final Environmental Impact Statement and Record of Decision expected in H2 2027, and the Company's Nevada North project. Creating a path for the Company to become a multi-asset, mid-tier precious metals producer in the United States.
Multiple opportunities identified to increase LOM production and gold resource: The Company is evaluating several opportunities to further increase gold recoveries, production and operating efficiency at Florida Canyon, including additional crushing capacity, haul road optimization, and improved truck routing. In addition, a 42,500 m exploration program is underway to identify potential mineral resource growth adjacent to the existing operation and across the Project. These opportunities are conceptual and not included in the current Mineral Reserve Estimate or economic analysis.