
EVERETT, Wash., April 29, 2026 (GLOBE NEWSWIRE) -- Coastal Financial Corporation (Nasdaq: CCB) (the “Company”, "Coastal", "we", "our", or "us"), the holding company for Coastal Community Bank (the “Bank”), through which it operates a community-focused bank segment ("community bank") with an industry leading banking as a service ("BaaS") segment ("CCBX"), today reported unaudited financial results for the quarter ended March 31, 2026, including net income of $12.0 million, or $0.78 per diluted common share, compared to $12.6 million, or $0.82 per diluted common share, for the three months ended December 31, 2025 and $9.7 million, or $0.63 per diluted common share, for the three months ended March 31, 2025.
Management Discussion of the First Quarter Results
"During the first quarter of 2026, total assets increased $922.4 million, or 19.5%, to $5.66 billion at March 31, 2026 compared to $4.74 billion at December 31, 2025, deposits grew by $897.0 million, or 21.6% and loans receivable increased by $109.8 million, representing a 2.9% rise, marking another period of solid growth. Our CCBX segment continued to expand product offerings with existing partners during the quarter, while advancing new partners through onboarding toward launch and active status in alignment with our long-term strategy. We expect growth to continue as current programs scale, new products are introduced, and we leverage our experience in the BaaS space to support disciplined, sustainable expansion,” stated CEO Eric Sprink.
Key Points for First Quarter and Our Go-Forward Strategy
CCBX Partner and Product Expansion. As of March 31, 2026 we had two partners in testing, three in implementation/onboarding, and two signed letters of intent (LOIs). Our active pipeline positions us for continued growth, with new partnership opportunities and product launches expected for 2026. Total BaaS program fee income was $10.9 million for the three months ended March 31, 2026, an increase of $2.0 million, or 22.3%, from the three months ended December 31, 2025. We continue to have contracts with our partners that fully indemnify us against fraud and 98.8% against credit risk on CCBX loan partner balances as of March 31, 2026.
Deepening CCBX Partner Relationships. During the quarter ended March 31, 2026, we advanced multiple partner products through key development and launch stages. We managed progression across key development stages, from internal testing through limited release to full market launch, across credit, deposit and credit card programs, steadily advancing products toward successful launch and deepening strategic partner relationships.
Positive On- and Off-Balance Sheet Trends Continue. Average deposits were $4.38 billion, an increase of $349.9 million, or 8.7%, over the quarter ended December 31, 2025, driven primarily by growth in deposits associated with CCBX partner programs. At March 31, 2026 we swept off $2.81 billion in deposits for FDIC insurance and liquidity purposes, and generated $710,000 in noninterest income during the quarter ended March 31, 2026, an increase of $170,000, or 31.5%, from $540,000 for the quarter ended December 31, 2025.
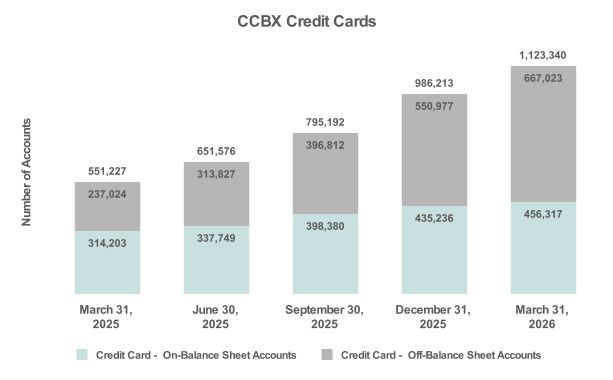
During the first quarter of 2026, we sold $3.28 billion of loans, including $2.63 billion of additional credit card receivables originated through ongoing cardholder spend and revolving activity and sold under existing forward flow arrangements, compared to $2.98 billion of sold loans in the quarter ended December 31, 2025, including $2.26 billion sold under the same forward flow arrangements. We retain a portion of the fee income on sold credit card loans. As of March 31, 2026 there were 667,023 off-balance sheet credit cards with fee earning potential, an increase of 116,046 compared to the quarter ended December 31, 2025 and an increase of 429,999 from March 31, 2025.
First Quarter 2026 Financial Highlights
The tables below outline some of our key operating metrics.
Three Months Ended | |||||||||||||||||||
(Dollars in thousands, except share and per share data; unaudited) | March 31, | December 31, | September 30, | June 30, | March 31, | ||||||||||||||
Income Statement Data: | |||||||||||||||||||
Interest and dividend income | $ | 111,681 | $ | 107,886 | $ | 109,027 | $ | 107,797 | $ | 104,907 | |||||||||
Interest expense | 28,324 | 28,521 | 31,126 | 31,060 | 28,845 | ||||||||||||||
Net interest income | 83,357 | 79,365 | 77,901 | 76,737 | 76,062 | ||||||||||||||
Provision for credit losses | 51,398 | 48,041 | 56,598 | 32,211 | 55,781 | ||||||||||||||
Net interest income after | 31,959 | 31,324 | 21,303 | 44,526 | 20,281 | ||||||||||||||
Noninterest income | 66,077 | 58,661 | 66,777 | 42,693 | 63,477 | ||||||||||||||
Noninterest expense | 83,452 | 72,804 | 70,172 | 72,832 | 71,989 | ||||||||||||||
Provision for income tax | 2,565 | 4,538 | 4,316 | 3,359 | 2,039 | ||||||||||||||
Net income | $ | 12,019 | $ | 12,643 | $ | 13,592 | $ | 11,028 | $ | 9,730 | |||||||||
As of and for the Three Month Period | |||||||||||||||||||
March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||
Balance Sheet Data: | |||||||||||||||||||
Cash and cash equivalents | $ | 1,495,467 | $ | 736,970 | $ | 642,258 | $ | 719,759 | $ | 624,302 | |||||||||
Investment securities | 46,169 | 48,247 | 43,942 | 45,577 | 46,991 | ||||||||||||||
Loans held for sale | 124,039 | 71,216 | 42,894 | 60,474 | 42,132 | ||||||||||||||
Loans receivable | 3,859,379 | 3,749,531 | 3,703,848 | 3,540,330 | 3,517,359 | ||||||||||||||
Allowance for credit losses | (172,427 | ) | (169,530 | ) | (173,813 | ) | (164,794 | ) | (183,178 | ) | |||||||||
Total assets | 5,663,829 | 4,741,437 | 4,553,076 | 4,480,559 | 4,339,282 | ||||||||||||||
Interest bearing deposits | 4,462,003 | 3,564,583 | 3,408,160 | 3,358,216 | 3,251,599 | ||||||||||||||
Noninterest bearing deposits | 579,161 | 579,616 | 564,403 | 555,355 | 539,630 | ||||||||||||||
Core deposits(1) | 5,028,967 | 4,131,911 | 3,959,360 | 3,441,624 | 3,321,772 | ||||||||||||||
Total deposits | 5,041,164 | 4,144,199 | 3,972,563 | 3,913,571 | 3,791,229 | ||||||||||||||
Total borrowings | 48,074 | 48,036 | 47,999 | 47,960 | 47,923 | ||||||||||||||
Total shareholders’ equity | $ | 503,762 | $ | 490,959 | $ | 475,277 | $ | 461,709 | $ | 449,917 | |||||||||
Share and Per Share Data(2): | |||||||||||||||||||
Earnings per share – basic | $ | 0.79 | $ | 0.84 | $ | 0.90 | $ | 0.73 | $ | 0.65 | |||||||||
Earnings per share – diluted | $ | 0.78 | $ | 0.82 | $ | 0.88 | $ | 0.71 | $ | 0.63 | |||||||||
Dividends per share | — | — | — | — | — | ||||||||||||||
Book value per share(3) | $ | 33.05 | $ | 32.43 | $ | 31.45 | $ | 30.59 | $ | 29.98 | |||||||||
Tangible book value per share(4) | $ | 32.76 | $ | 32.13 | $ | 31.45 | $ | 30.59 | $ | 29.98 | |||||||||
Weighted avg outstanding shares – basic | 15,179,447 | 15,116,005 | 15,093,274 | 15,033,296 | 14,962,507 | ||||||||||||||
Weighted avg outstanding shares – diluted | 15,422,822 | 15,455,856 | 15,443,987 | 15,447,923 | 15,462,041 | ||||||||||||||
Shares outstanding at end of period | 15,241,491 | 15,140,192 | 15,112,000 | 15,093,036 | 15,009,225 | ||||||||||||||
Stock options outstanding at end of period | 68,585 | 118,881 | 122,206 | 126,654 | 163,932 | ||||||||||||||
See footnotes that follow the tables below
As of and for the Three Month Period | |||||||||||||||||||
March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||
Credit Quality Data: | |||||||||||||||||||
Nonperforming assets(5)to total assets | 1.19 | % | 1.35 | % | 1.31 | % | 1.36 | % | 1.30 | % | |||||||||
Nonperforming assets(5)to loans receivable and OREO | 1.75 | % | 1.71 | % | 1.61 | % | 1.72 | % | 1.60 | % | |||||||||
Nonperforming loans(5)to total loans receivable | 1.75 | % | 1.71 | % | 1.61 | % | 1.72 | % | 1.60 | % | |||||||||
Allowance for credit losses to nonperforming loans | 253.0 | % | 264.4 | % | 290.8 | % | 270.7 | % | 325.0 | % | |||||||||
Allowance for credit losses to total loans receivable | 4.47 | % | 4.52 | % | 4.69 | % | 4.65 | % | 5.21 | % | |||||||||
Gross charge-offs | $ | 54,523 | $ | 55,189 | $ | 54,534 | $ | 53,780 | $ | 53,686 | |||||||||
Gross recoveries | $ | 4,936 | $ | 5,114 | $ | 5,289 | $ | 4,467 | $ | 5,486 | |||||||||
Net charge-offs to average loans(6) | 5.18 | % | 5.31 | % | 5.37 | % | 5.54 | % | 5.57 | % | |||||||||
Capital Ratios: | |||||||||||||||||||
Company | |||||||||||||||||||
Tier 1 leverage capital | 10.09 | % | 10.62 | % | 10.54 | % | 10.39 | % | 10.67 | % | |||||||||
Common equity Tier 1 risk-based capital | 12.08 | % | 12.43 | % | 12.33 | % | 12.32 | % | 12.13 | % | |||||||||
Tier 1 risk-based capital | 12.17 | % | 12.52 | % | 12.42 | % | 12.41 | % | 12.22 | % | |||||||||
Total risk-based capital | 14.54 | % | 14.95 | % | 14.88 | % | 14.90 | % | 14.73 | % | |||||||||
Bank | |||||||||||||||||||
Tier 1 leverage capital | 10.10 | % | 10.60 | % | 10.49 | % | 10.33 | % | 10.57 | % | |||||||||
Common equity Tier 1 risk-based capital | 12.19 | % | 12.50 | % | 12.37 | % | 12.36 | % | 12.12 | % | |||||||||
Tier 1 risk-based capital | 12.19 | % | 12.50 | % | 12.37 | % | 12.36 | % | 12.12 | % | |||||||||
Total risk-based capital | 13.48 | % | 13.79 | % | 13.66 | % | 13.65 | % | 13.42 | % | |||||||||
(1) Core deposits are defined as all deposits excluding brokered and time deposits.
(2) Share and per share amounts are based on total actual or average common shares outstanding, as applicable.
(3) We calculate book value per share as total shareholders’ equity at the end of the relevant period divided by the outstanding number of our common shares at the end of each period.
(4) Tangible book value per share is a non-GAAP financial measure. We calculate tangible book value per share as total shareholders’ equity at the end of the relevant period, less goodwill and other intangible assets, divided by the outstanding number of our common shares at the end of each period. The most directly comparable GAAP financial measure is book value per share. See reconciliation of the non-GAAP measures at the end of this earnings release for the impact of intangible assets on book value.
(5) Nonperforming assets and nonperforming loans include loans 90+ days past due and accruing interest.
(6) Annualized calculations.
Key Performance Ratios
Return on average assets ("ROA") was 0.98% for the quarter ended March 31, 2026 compared to 1.09% and 0.93% for the quarters ended December 31, 2025 and March 31, 2025, respectively. ROA for the quarter ended March 31, 2026 decreased 0.11%, compared to December 31, 2025 primarily due to an increase in noninterest expense and increased 0.05% compared to March 31, 2025. Noninterest expenses were higher for the quarter ended March 31, 2026 compared to the quarter ended December 31, 2025 driven primarily by a $2.6 million increase in legal and professional expenses and higher BaaS loan expense. The quarter over quarter variance in BaaS loan expense is driven in part by higher yields on certain partner loans, the income of which is passed through to partners, resulting in an increase in loan yield that partially offsets the higher BaaS loan expense, and also by, to a lesser extent, the timing of loan sales. Additionally, recent changes to partner agreements and pricing have contributed to higher BaaS loan expense and a corresponding decrease in loan yield, net of BaaS loan expense, on a quarter-over-quarter basis. Overall, these actions align with a strategic focus on enhanced partner economics and more sustainable, risk-adjusted returns over time. Noninterest expenses were higher than the quarter ended March 31, 2025 due primarily to an increase in data processing and software licenses, salaries and employee benefits, and legal and professional expenses, all of which are related to the growth of the Company and investments in technology and risk management. These increases were partially mitigated by continued discipline in staffing levels over the last year, with full-time equivalent employees decreasing to 496 compared to 517 for the quarter ended March 31, 2025.
Compared to the quarter ended December 31, 2025, yield on earning assets declined 0.17% while yield on loans receivable increased by 0.13%. Average loans receivable as of March 31, 2026 increased $138.6 million compared to December 31, 2025 as net CCBX loans continue to grow, despite selling $3.28 billion in CCBX loans during the quarter ended March 31, 2026. Compared to the quarter ended March 31, 2025, yield on earning assets declined 0.94% and yield on loans receivable declined by 0.57%. Average loans receivable as of March 31, 2026 increased $366.9 million compared to March 31, 2025.
The quarter over quarter volatility in the efficiency ratio and noninterest income to average asset performance metrics were driven by changes in the credit enhancement on CCBX loans, which is included within noninterest income, due to changes in CCBX provision expense. These items have a neutral impact on net income, but they impact the abovementioned metrics quarter over quarter due to changes in reported noninterest income.
The following table shows the Company’s key performance ratios for the periods indicated.
Three Months Ended | |||||||||||||||
(unaudited) | March 31, | December 31, | September 30, | June 30, | March 31, | ||||||||||
Return on average assets(1) | 0.98 | % | 1.09 | % | 1.19 | % | 0.99 | % | 0.93 | % | |||||
Return on average equity(1) | 9.80 | % | 10.41 | % | 11.52 | % | 9.72 | % | 8.91 | % | |||||
Yield on earnings assets(1) | 9.38 | % | 9.55 | % | 9.80 | % | 9.92 | % | 10.32 | % | |||||
Yield on loans receivable(1) | 10.76 | % | 10.63 | % | 10.95 | % | 11.11 | % | 11.33 | % | |||||
Cost of funds(1) | 2.59 | % | 2.77 | % | 3.07 | % | 3.13 | % | 3.11 | % | |||||
Cost of deposits(1) | 2.56 | % | 2.74 | % | 3.04 | % | 3.10 | % | 3.08 | % | |||||
Net interest margin(1) | 7.00 | % | 7.03 | % | 7.00 | % | 7.06 | % | 7.48 | % | |||||
Noninterest expense to average assets(1) | 6.78 | % | 6.25 | % | 6.13 | % | 6.52 | % | 6.87 | % | |||||
Noninterest income to average assets(1) | 5.37 | % | 5.04 | % | 5.83 | % | 3.82 | % | 6.06 | % | |||||
Efficiency ratio | 55.85 | % | 52.75 | % | 48.50 | % | 60.98 | % | 51.59 | % | |||||
Loans receivable to deposits(2) | 79.02 | % | 92.20 | % | 94.32 | % | 92.01 | % | 93.89 | % | |||||
(1) Annualized calculations shown for quarterly periods presented.
(2) Includes loans held for sale.
Management Outlook; CEO Eric Sprink
“We continued to see strength in our CCBX segment in the first quarter, driven by the performance of our existing partners, new products and the addition of new relationships. We’ve been intentional about how we grow, and that includes focusing on credit quality as portfolios mature and ensuring we’re operating in a safe and sound manner as expectations around bank–fintech partnerships continue to evolve. As the rate environment evolves, we expect some pressure on margins, but we believe our diversified business model and funding base continue to position us well. Our focus remains on consistent execution and building long-term value through disciplined growth.” said CEO Eric Sprink.
Coastal Financial Corporation Overview
The Company has one main subsidiary, the Bank, which consists of three segments: CCBX, the community bank and treasury & administration. The CCBX segment includes all of our BaaS activities, the community bank segment includes all community banking activities and the treasury & administration segment includes treasury management, overall administration and all other aspects of the Company.
CCBX Performance Update
Our CCBX segment continues to evolve, and we have 30 relationships, at varying stages, including two partners in testing, three in implementation/onboarding, two signed LOIs and three winding down as of March 31, 2026. This includes a new CCBX correspondent bank partner relationship. We continue to refine our partnership criteria, prioritizing larger, established partners with strong management teams, customer bases, and financial profiles, while selectively pursuing emerging partners aligned with our model, and will proactively manage and exit select relationships in line with our ongoing portfolio optimization efforts, reflecting our focus on enhancing partner quality and long-term value creation.
We are also actively exploring opportunities to expand the CCBX partner base and broaden related product offerings to support continued growth. This dual approach of onboarding new partners while deepening relationships with existing ones supports growth that aligns with our long-term strategic objectives, while leveraging our established relationships to help mitigate incremental risk.
Increased partner activity and transaction volumes are driving growth in noninterest income, a trend we expect to continue as existing products scale and new offerings are introduced. As part of our strategy to manage partner and lending limits, as well as overall portfolio composition and credit quality, we plan to continue selling loans. We also retain a portion of the fee income associated with processing transactions on sold credit card loans. This revenue stream continues to grow and is expected to provide ongoing income without adding balance sheet risk or capital requirements.
As our deposit base grows, we expect to continue moving deposits on and off the balance sheet, subject to applicable agreements, to manage liquidity, FDIC insurance coverage, and deposit program operations. This deposit sweep capability allows us to better manage liquidity and deposit programs. At March 31, 2026 we swept off $2.81 billion in deposits for FDIC insurance and liquidity purposes, and generated $710,000 in noninterest income during the quarter ended March 31, 2026, compared to $540,000 for the quarter ended December 31, 2025. During the quarter ended March 31, 2026, eight partner programs were in various stages of expansion to include additional products, such as lines of credit, deposit programs, credit cards, and other lending products. The expansion of these and other partner initiatives is expected to drive higher partner revenue in upcoming periods.
The following table illustrates the activity and evolution in CCBX relationships for the periods presented.
As of | |||
(unaudited) | March 31, 2026 | December 31, | March 31, 2025 |
Active | 20 | 19 | 19 |
Friends and family / testing | 2 | 2 | 2 |
Implementation / onboarding | 3 | 5 | 3 |
Signed letters of intent | 2 | 1 | 1 |
Wind down - active but preparing to exit relationship | 3 | 1 | 0 |
Total CCBX relationships | 30 | 28 | 25 |
Total exited relationships life to date | 9 | 9 | 8 |
CCBX loans increased $76.6 million, or 4.2%, to $1.88 billion despite selling $3.28 billion in loans during the three months ended March 31, 2026, $2.63 billion of which was new activity on previously sold credit card loans.
The following table details the CCBX loan portfolio:
CCBX | As of | ||||||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||
(dollars in thousands; unaudited) | Balance | % to Total | Balance | % to Total | Balance | % to Total | |||||||||||||||
Commercial and industrial loans: | |||||||||||||||||||||
Capital call lines | $ | 176,384 | 9.4 | % | $ | 210,480 | 11.6 | % | $ | 133,466 | 8.1 | % | |||||||||
All other commercial & industrial loans | 21,792 | 1.2 | 19,166 | 1.1 | 29,702 | 1.8 | |||||||||||||||
Real estate loans: | |||||||||||||||||||||
Residential real estate loans | 266,037 | 14.1 | 264,059 | 14.6 | 285,355 | 17.3 | |||||||||||||||
Consumer and other loans: | |||||||||||||||||||||
Credit cards | 693,485 | 36.8 | 622,681 | 34.4 | 532,775 | 32.2 | |||||||||||||||
Other consumer and other loans | 726,943 | 38.5 | 691,708 | 38.3 | 670,026 | 40.6 | |||||||||||||||
Gross CCBX loans receivable | 1,884,641 | 100.0 | % | 1,808,094 | 100.0 | % | 1,651,324 | 100.0 | % | ||||||||||||
Net deferred origination fees | (517 | ) | (542 | ) | (498 | ) | |||||||||||||||
Loans receivable | $ | 1,884,124 | $ | 1,807,552 | $ | 1,650,826 | |||||||||||||||
Loan Yield - CCBX(1)(2) | 15.01 | % | 14.89 | % | 16.88 | % | |||||||||||||||
(1) CCBX yield does not include the impact of BaaS loan expense. BaaS loan expense represents the amount paid or payable to partners for credit enhancements and originating & servicing CCBX loans. See reconciliation of the non-GAAP measures at the end of this earnings release for the impact of BaaS loan expense on CCBX loan yield.
(2) Loan yield is annualized for the three months ended for each period presented and includes loans held for sale and nonaccrual loans.
The increase in CCBX loans in the quarter ended March 31, 2026, includes an increase of $106.0 million, or 8.1%, in consumer and other loans and an increase of $2.0 million, or 0.7%, in residential real estate loans partially offset by a decrease of $34.1 million, or 16.2%, in capital call lines as a result of normal balance fluctuations and business activities. We sold $3.28 billion in CCBX loans during the quarter ended March 31, 2026 compared to sales of $2.98 billion in the quarter ended December 31, 2025. We continue to manage CCBX credit and concentration levels in an effort to optimize our loan portfolio earnings and generate off-balance sheet fee income. CCBX loan yield increased 0.12% for the quarter ended March 31, 2026 compared to the quarter ended December 31, 2025 due to a change in overall mix of loans compared to the quarter ended December 31, 2025.
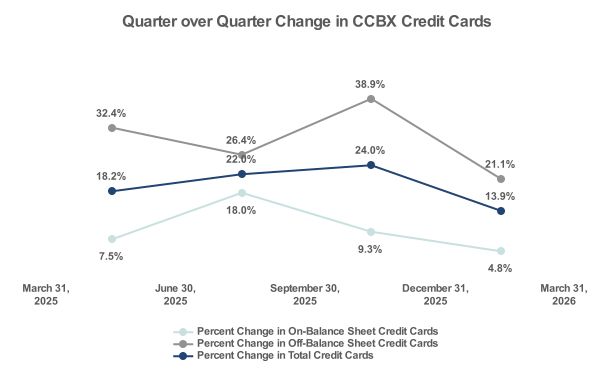
The following charts show the growth and quarter over quarter changes in credit card accounts that generate fee income. This includes accounts with balances, which are included in our loan totals, and accounts that have been sold and have no corresponding balance in our loan totals, both of which generate fee income.
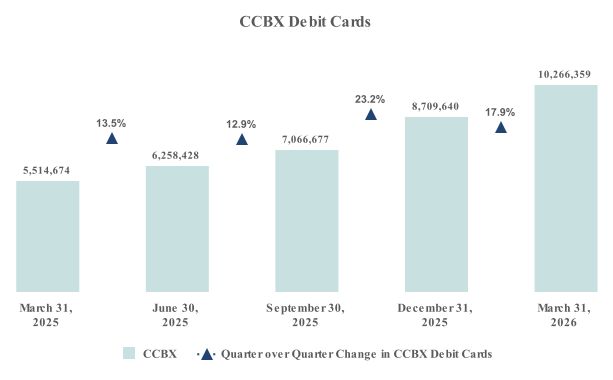
The following chart shows the growth in active CCBX debit cards, which are sources of interchange income.
The following table details the CCBX deposit portfolio:
CCBX | As of | ||||||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||
(dollars in thousands; unaudited) | Balance | % to Total | Balance | % to Total | Balance | % to Total | |||||||||||||||
Demand, noninterest bearing | $ | 77,890 | 2.3 | % | $ | 86,648 | 3.4 | % | $ | 58,416 | 2.6 | % | |||||||||
Interest bearing demand and | 3,121,888 | 90.0 | 2,425,881 | 94.8 | 2,145,608 | 94.6 | |||||||||||||||
Savings | 268,444 | 7.7 | 45,311 | 1.8 | 16,625 | 0.7 | |||||||||||||||
Total core deposits | 3,468,222 | 100.0 | 2,557,840 | 100.0 | 2,220,649 | 97.9 | |||||||||||||||
Other deposits | — | 0.0 | — | 0.0 | 46,359 | 2.1 | |||||||||||||||
Total CCBX deposits | $ | 3,468,222 | 100.0 | % | $ | 2,557,840 | 100.0 | % | $ | 2,267,008 | 100.0 | % | |||||||||
Cost of deposits(1) | 3.17 | % | 3.52 | % | 4.01 | % | |||||||||||||||
(1) Cost of deposits is annualized for the three months ended for each period presented.
CCBX deposits increased $910.4 million, or 35.6%, in the three months ended March 31, 2026 to $3.47 billion, driven largely by new CCBX partner relationships. Management expects the newly added deposits to moderate during the second quarter of 2026 and then normalize. The increase excludes the $2.81 billion in CCBX deposits that were swept off-balance sheet for increased Federal Deposit Insurance Corporation ("FDIC") insurance coverage and liquidity purposes, compared to $843.6 million for the quarter ended December 31, 2025. Using a third-party facilitator/vendor sweep product, amounts in excess of FDIC insurance coverage are swept off-balance sheet to participating financial institutions.
Community Bank Performance Update
In the quarter ended March 31, 2026, the community bank saw net loans increase $33.3 million, or 1.7%, to $1.98 billion, as a result of loan growth and normal balance fluctuations.
The following table details the community bank loan portfolio:
Community Bank | As of | ||||||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||
(dollars in thousands; unaudited) | Balance | % to Total | Balance | % to Total | Balance | % to Total | |||||||||||||||
Commercial and industrial loans | $ | 235,603 | 11.9 | % | $ | 224,439 | 11.5 | % | $ | 149,104 | 8.0 | % | |||||||||
Real estate loans: | |||||||||||||||||||||
Construction, land and land development loans | 234,911 | 11.8 | 222,075 | 11.4 | 166,551 | 8.9 | |||||||||||||||
Residential real estate loans | 199,185 | 10.1 | 202,293 | 10.4 | 202,920 | 10.8 | |||||||||||||||
Commercial real estate loans | 1,300,547 | 65.6 | 1,285,856 | 66.0 | 1,340,647 | 71.6 | |||||||||||||||
Consumer and other loans: | |||||||||||||||||||||
Other consumer and other loans | 11,587 | 0.6 | 14,072 | 0.7 | 13,326 | 0.7 | |||||||||||||||
Gross community bank loans receivable | 1,981,833 | 100.0 | % | 1,948,735 | 100.0 | % | 1,872,548 | 100.0 | % | ||||||||||||
Net deferred origination fees | (6,578 | ) | (6,756 | ) | (6,015 | ) | |||||||||||||||
Loans receivable | $ | 1,975,255 | $ | 1,941,979 | $ | 1,866,533 | |||||||||||||||
Loan Yield(1) | 6.58 | % | 6.52 | % | 6.53 | % | |||||||||||||||
(1) Loan yield is annualized for the three months ended for each period presented and includes loans held for sale and nonaccrual loans.
The increase in community bank loans consisted of an increase of $14.7 million in commercial real estate loans, an increase of $12.8 million in construction, land and land development loans, and an increase of $11.2 million in commercial and industrial loans, partially offset by a decrease of $3.1 million in residential real estate loans and $2.5 million in consumer and other loans during the quarter ended March 31, 2026.
The following table details the community bank deposit portfolio:
Community Bank | As of | ||||||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||
(dollars in thousands; unaudited) | Balance | % to Total | Balance | % to Total | Balance | % to Total | |||||||||||||||
Demand, noninterest bearing | $ | 501,271 | 31.9 | % | $ | 492,968 | 31.1 | % | $ | 481,214 | 31.5 | % | |||||||||
Interest bearing demand and | 1,006,623 | 64.0 | 1,024,798 | 64.6 | 560,416 | 36.8 | |||||||||||||||
Savings | 52,851 | 3.3 | 56,305 | 3.5 | 59,493 | 3.9 | |||||||||||||||
Total core deposits | 1,560,745 | 99.2 | 1,574,071 | 99.2 | 1,101,123 | 72.2 | |||||||||||||||
Other deposits | 1 | 0.0 | 1 | 0.0 | 407,391 | 26.7 | |||||||||||||||
Time deposits less than $100,000 | 4,174 | 0.3 | 4,415 | 0.3 | 5,585 | 0.4 | |||||||||||||||
Time deposits $100,000 and over | 8,022 | 0.5 | 7,872 | 0.5 | 10,122 | 0.7 | |||||||||||||||
Total community bank deposits | $ | 1,572,942 | 100.0 | % | $ | 1,586,359 | 100.0 | % | $ | 1,524,221 | 100.0 | % | |||||||||
Cost of deposits(1) | 1.46 | % | 1.56 | % | 1.76 | % | |||||||||||||||
(1) Cost of deposits is annualized for the three months ended for each period presented.
Community bank deposits decreased $13.4 million, or 0.8%, during the three months ended March 31, 2026 to $1.57 billion as a result of normal balance fluctuations. The community bank segment includes noninterest bearing deposits of $501.3 million, or 31.9%, of total community bank deposits, resulting in a cost of deposits of 1.46%, compared to 1.56% for the quarter ended December 31, 2025 as a result of lower interest rates.
Net Interest Income and Margin Discussion
Net interest income was $83.4 million for the quarter ended March 31, 2026, an increase of $4.0 million, or 5.0%, from $79.4 million for the quarter ended December 31, 2025, and an increase of $7.3 million, or 9.6%, from $76.1 million for the quarter ended March 31, 2025. Net interest income compared to December 31, 2025 and March 31, 2025 was higher due to an increase in interest on loans and interest earning deposits with other banks primarily due to an increase in average loans receivable and average interest earning deposits with other banks as well as a reduced cost of funds due to lower interest rates.
Net interest margin was 7.00% for the three months ended March 31, 2026, compared to 7.03% for the three months ended December 31, 2025. Net interest margin was 7.48% for the three months ended March 31, 2025. The modest decrease in net interest margin for the three months ended March 31, 2026 compared to the three months ended December 31, 2025 was primarily due to lower yields on interest earning deposits with other banks, partially offset by lower cost of funds and higher loan yields. Net interest margin, net of BaaS loan expense, (a reconciliation of the non-GAAP measures are set forth in the Non-GAAP Financial Measures section of this earnings release) was 3.90% for the three months ended March 31, 2026, compared to 4.26% for the three months ended December 31, 2025, and 4.28% for the three months ended March 31, 2025. The quarter-over-quarter decline in net interest margin, net of BaaS loan expense, was primarily driven by an increase in BaaS loan expense. This increase reflects higher yields on certain partner loans, the income of which is passed through to partners, as well as, to a lesser extent, the timing of loan sales. While these higher yields contributed to overall loan yield and partially offset the impact of the higher BaaS loan expense, recent changes to partner agreements and pricing contributed to both higher BaaS loan expense and a corresponding decrease in loan yield, net of BaaS loan expense. These actions align with our strategic focus on enhanced partner economics and more sustainable, risk-adjusted returns over time.
Interest and fees on loans receivable increased $2.7 million, or 2.7%, to $102.9 million for the three months ended March 31, 2026, compared to $100.2 million for the three months ended December 31, 2025, as a result of an increase in loans receivable. Interest and fees on loans receivable increased $4.7 million, or 4.8%, compared to $98.1 million for the three months ended March 31, 2025, due to loan growth.
The following table illustrates how net interest margin and loan yield is affected by BaaS loan expense:
Consolidated | As of and for the Three Months Ended | |||||||||||
(dollars in thousands; unaudited) | March 31 | December 31 | March 31 | |||||||||
Net interest margin, net of BaaS loan expense: | ||||||||||||
Net interest margin(1) | 7.00 | % | 7.03 | % | 7.48 | % | ||||||
Earning assets | 4,830,601 | 4,482,007 | 4,124,065 | |||||||||
Net interest income (GAAP) | 83,357 | 79,365 | 76,062 | |||||||||
Less: BaaS loan expense | (36,940 | ) | (31,256 | ) | (32,507 | ) | ||||||
Net interest income, net of BaaS loan expense(2) | $ | 46,417 | $ | 48,109 | $ | 43,555 | ||||||
Net interest margin, net of BaaS loan expense(1)(2) | 3.90 | % | 4.26 | % | 4.28 | % | ||||||
Loan income net of BaaS loan expense divided by average loans: | ||||||||||||
Loan yield (GAAP)(1) | 10.76 | % | 10.63 | % | 11.33 | % | ||||||
Total average loans receivable | $ | 3,878,626 | $ | 3,740,073 | $ | 3,511,724 | ||||||
Interest and earned fee income on loans (GAAP) | 102,887 | 100,206 | 98,147 | |||||||||
BaaS loan expense | (36,940 | ) | (31,256 | ) | (32,507 | ) | ||||||
Net loan income(2) | $ | 65,947 | $ | 68,950 | $ | 65,640 | ||||||
Loan income, net of BaaS loan expense, divided by average loans(1)(2) | 6.90 | % | 7.31 | % | 7.58 | % | ||||||
(1) Annualized calculations shown for periods presented.
(2) A reconciliation of the non-GAAP measures are set forth at the end of this earnings release.
Average investment securities increased $988,000 to $47.5 million compared to the three months ended December 31, 2025 as a result of held-to-maturity mortgage backed securities purchased for CRA purposes, and increased $259,000 compared to the three months ended March 31, 2025 as a result of securities purchased for CRA purposes, net of principal paydowns.
Cost of funds was 2.59% for the quarter ended March 31, 2026, a decrease of 18 basis points from the quarter ended December 31, 2025 and a decrease of 52 basis points from the quarter ended March 31, 2025. Cost of deposits for the quarter ended March 31, 2026 was 2.56%, compared to 2.74% for the quarter ended December 31, 2025, and 3.08% for the quarter ended March 31, 2025. The decreased cost of funds and deposits compared to December 31, 2025 and March 31, 2025 were largely due to the reductions in the Fed funds rate in 2025.
The following table summarizes the average yield on loans receivable and cost of deposits:
For the Three Months Ended | |||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||
Yield on | Cost of | Yield on | Cost of | Yield on | Cost of | ||||||||||||
Community Bank | 6.58 | % | 1.46 | % | 6.52 | % | 1.56 | % | 6.53 | % | 1.76 | % | |||||
CCBX(1) | 15.01 | % | 3.17 | % | 14.89 | % | 3.52 | % | 16.88 | % | 4.01 | % | |||||
Consolidated | 10.76 | % | 2.56 | % | 10.63 | % | 2.74 | % | 11.33 | % | 3.08 | % | |||||
(1) CCBX yield on loans does not include the impact of BaaS loan expense. BaaS loan expense represents the amount paid or payable to partners for credit and fraud enhancements and originating & servicing CCBX loans. To determine Net BaaS loan income earned from CCBX loan relationships, the Company takes BaaS loan interest income and deducts BaaS loan expense to arrive at Net BaaS loan income, which can be compared to interest income on the Company’s community bank loans. See reconciliation of the non-GAAP measures at the end of this earnings release for the impact of BaaS loan expense on CCBX loan yield.
(2) Annualized calculations for periods presented.
The following table illustrates how BaaS loan interest income is affected by BaaS loan expense resulting in net BaaS loan income and the associated yield:
For the Three Months Ended | ||||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||
(dollars in thousands, unaudited) | Income / Expense | Income / | Income / Expense | Income / | Income / Expense | Income / | ||||||||||||
BaaS loan interest income | $ | 71,153 | 15.01 | % | $ | 68,846 | 14.89 | % | $ | 67,855 | 16.88 | % | ||||||
Less: BaaS loan expense | 36,940 | 7.79 | % | 31,256 | 6.76 | % | 32,507 | 8.09 | % | |||||||||
Net BaaS loan income(1) | $ | 34,213 | 7.22 | % | $ | 37,590 | 8.13 | % | $ | 35,348 | 8.79 | % | ||||||
Average BaaS Loans(3) | $ | 1,922,586 | $ | 1,833,904 | $ | 1,630,088 | ||||||||||||
(1) A reconciliation of the non-GAAP measures are set forth at the end of this earnings release.
(2) Annualized calculations shown for the periods presented.
(3) Includes loans held for sale.
Noninterest Income Discussion
Noninterest income was $66.1 million for the three months ended March 31, 2026, an increase of $7.4 million from $58.7 million for the three months ended December 31, 2025, and an increase of $2.6 million from $63.5 million for the three months ended March 31, 2025. The increase in noninterest income for the quarter ended March 31, 2026 as compared to the quarter ended December 31, 2025 was primarily due to a $3.4 million increase in BaaS credit enhancements related to the increase in provision for credit losses based upon an analysis of the CCBX loan portfolio and a $2.0 million increase in BaaS fraud enhancements, and an increase of $2.0 million in BaaS program income (see “Appendix B” for more information on the accounting for BaaS allowance for credit losses and credit and fraud enhancements).
The $2.6 million increase in noninterest income over the quarter ended March 31, 2025 was primarily due to an increase of $4.6 million in BaaS program income partially offset by a $1.8 million decrease in BaaS credit and fraud enhancements due to mix of loans and improvement in the performance of the CCBX loan portfolio.
Noninterest Expense Discussion
Total noninterest expense increased $10.6 million to $83.5 million for the three months ended March 31, 2026, compared to $72.8 million for the three months ended December 31, 2025, and increased $11.5 million from $72.0 million for the three months ended March 31, 2025. The $10.6 million increase in noninterest expense for the quarter ended March 31, 2026, as compared to the quarter ended December 31, 2025, was primarily due to a $2.6 million increase in legal and professional fees, a $665,000 increase in data processing and software licenses, and a $377,000 increase in salaries and employee benefits, partially offset by a $456,000 decrease in other expenses. Also contributing to the variance is a $5.7 million increase in BaaS loan expense, and a $2.0 million increase in BaaS fraud expense. BaaS loan expense represents the amount paid or payable to partners for credit enhancements and originating & servicing CCBX loans. BaaS fraud expense represents non-credit fraud losses on partner’s customer loan and deposit accounts. A portion of this expense is realized during the quarter in which the loss occurs, and a portion is estimated based on historical or other information from our partners. The $2.6 million increase in legal and professional fees was primarily driven by a CCBX partner's professional fees resulting from our asset acquisition in the prior quarter. Data processing and software license costs increased due to continued investments in growth, technology, and risk management.
The $11.5 million increase in noninterest expenses for the quarter ended March 31, 2026 compared to the quarter ended March 31, 2025 was largely due to a $3.4 million increase in data processing and software licenses due to enhancements and investments in technology and a $1.6 million increase in salary and employee benefits. Also contributing to the variance is a $4.4 million increase in BaaS loan expense, and a $1.1 million increase in BaaS fraud expense.
Certain operating expenses associated with CCBX programs are reimbursed by our CCBX partners. In accordance with GAAP we recognize all expenses in noninterest expense and the reimbursement of expenses from our CCBX partner in noninterest income. The following table reflects the portion of noninterest expenses that are reimbursed by partners to assist in understanding how the increases in noninterest expense are related to expenses incurred and reimbursed by CCBX partners:
Three Months Ended | |||||||||
March 31, | December 31, | March 31, | |||||||
(dollars in thousands; unaudited) | 2026 | 2025 | 2025 | ||||||
Total noninterest expense (GAAP) | $ | 83,452 | $ | 72,804 | $ | 71,989 | |||
Less: BaaS loan expense | 36,940 | 31,256 | 32,507 | ||||||
Less: BaaS fraud expense | 3,059 | 1,090 | 1,993 | ||||||
Less: Reimbursement of expenses (BaaS) | 2,392 | 1,868 | 1,026 | ||||||
Noninterest expense, net of BaaS loan expense, BaaS fraud expense | $ | 41,061 | $ | 38,590 | $ | 36,463 | |||
(1) A reconciliation of the non-GAAP measures are set forth at the end of this earnings release.
Provision for Income Taxes
The provision for income taxes was $2.6 million for the three months ended March 31, 2026, $4.5 million for the three months ended December 31, 2025 and $2.0 million for the first quarter of 2025. The income tax provision was lower for the three months ended March 31, 2026 compared to the quarter ended December 31, 2025 and higher when compared to the quarter ended March 31, 2025 as a result of differences in net income and the taxability of certain equity awards during each period.
As CCBX activities and employee presence expand into additional states, the Company becomes subject to additional state tax jurisdictions, which has increased the overall tax rate used in calculating the provision for income taxes. The Company uses a federal statutory tax rate of 21.0% as a basis for calculating provision for federal income taxes and 5.14% for calculating the provision for state income taxes. The state rate increased in the quarter ended June 30, 2025 primarily as a result of a change in California's tax laws.
Financial Condition Overview
Total assets increased $922.4 million, or 19.5%, to $5.66 billion at March 31, 2026 compared to $4.74 billion at December 31, 2025. The increase is primarily comprised of a $740.0 million increase in interest earning deposits with other banks, a $109.8 million increase in loans receivable, and a $52.8 million increase in loans held for sale.
As of March 31, 2026, in addition to the $1.50 billion in cash on hand, the Company had the capacity to borrow up to a total of $636.6 million from the Federal Reserve Bank discount window and Federal Home Loan Bank, plus an additional $50.0 million from a correspondent bank. There were no borrowings outstanding on these lines as of March 31, 2026.
The Company, on a stand alone basis, had a cash balance of $40.2 million as of March 31, 2026, a portion of which is retained for general operating purposes, including debt repayment, for funding $1.0 million in commitments to bank technology investment funds, with the remaining cash available to be contributed to the Bank as capital.
Uninsured deposits were $1.77 billion as of March 31, 2026, compared to $641.3 million as of December 31, 2025. Uninsured deposits are elevated due to the timing of new partner deposits participating in sweep and reciprocal deposit networks, but are expected to normalize during the second quarter.
Total shareholders’ equity as of March 31, 2026 increased $12.8 million since December 31, 2025. The increase in shareholders’ equity was primarily comprised of $12.0 million in net earnings combined with an increase of $784,000 in common stock outstanding as a result of equity awards vested and exercised during the three months ended March 31, 2026.
The Company and the Bank remained well capitalized at March 31, 2026, as summarized in the following table.
(unaudited) | Coastal | Coastal | Minimum Well | ||||||
Tier 1 Leverage Capital (to average assets) | 10.10 | % | 10.09 | % | 5.00 | % | |||
Common Equity Tier 1 Capital (to risk-weighted assets) | 12.19 | % | 12.08 | % | 6.50 | % | |||
Tier 1 Capital (to risk-weighted assets) | 12.19 | % | 12.17 | % | 8.00 | % | |||
Total Capital (to risk-weighted assets) | 13.48 | % | 14.54 | % | 10.00 | % | |||
(1) Presents the minimum capital ratios for an insured depository institution, such as the Bank, to be considered well capitalized under the Prompt Corrective Action framework. The minimum requirements for the Company to be considered well capitalized under Regulation Y include to maintain, on a consolidated basis, a total risk-based capital ratio of 10.0 percent or greater and a tier 1 risk-based capital ratio of 6.0 percent or greater.
Asset Quality
The allowance for credit losses was $172.4 million and 4.47% of loans receivable at March 31, 2026 compared to $169.5 million and 4.52% at December 31, 2025 and $183.2 million and 5.21% at March 31, 2025. The allowance for credit loss allocated to the CCBX portfolio was $154.3 million and 8.19% of CCBX loans receivable at March 31, 2026, with $18.2 million of allowance for credit loss allocated to the community bank, or 0.92% of total community bank loans receivable.
The following table details the allocation of the allowance for credit loss as of the period indicated:
As of March 31, 2026 | As of December 31, 2025 | As of March 31, 2025 | ||||||||||||||||||||||||||||||||||
(dollars in thousands; unaudited) | Community Bank | CCBX | Total | Community Bank | CCBX | Total | Community Bank | CCBX | Total | |||||||||||||||||||||||||||
Loans receivable | $ | 1,975,255 | $ | 1,884,124 | $ | 3,859,379 | $ | 1,941,979 | $ | 1,807,552 | $ | 3,749,531 | $ | 1,866,533 | $ | 1,650,826 | $ | 3,517,359 | ||||||||||||||||||
Allowance for | (18,153 | ) | (154,274 | ) | (172,427 | ) | (18,231 | ) | (151,299 | ) | (169,530 | ) | (18,992 | ) | (164,186 | ) | (183,178 | ) | ||||||||||||||||||
Allowance for | 0.92 | % | 8.19 | % | 4.47 | % | 0.94 | % | 8.37 | % | 4.52 | % | 1.02 | % | 9.95 | % | 5.21 | % | ||||||||||||||||||
Net charge-offs totaled $49.6 million for the quarter ended March 31, 2026, compared to $50.1 million for the quarter ended December 31, 2025 and $48.2 million for the quarter ended March 31, 2025. Net charge-offs as a percent of average loans decreased to 5.18% for the quarter ended March 31, 2026 compared to 5.31% for the quarter ended December 31, 2025, and 5.57% for the quarter ended March 31, 2025. CCBX partner agreements provide for a credit enhancement that covers the net charge-offs on CCBX loans and negative deposit accounts by indemnifying or reimbursing incurred losses, except in accordance with the program agreement for one partner where the Company was responsible for credit losses on approximately 5% of a $324.0 million loan portfolio. At March 31, 2026, our portion of this portfolio represented $22.0 million in loans. Net charge-offs for this $22.0 million in loans were $1.0 million for the three months ended March 31, 2026, $1.2 million for the three months ended December 31, 2025 and $1.1 million for the three months ended March 31, 2025.
The following table details net charge-offs for the community bank and CCBX for the period indicated:
Three Months Ended | ||||||||||||||||||||||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||||||||||||
(dollars in | Community | CCBX | Total | Community | CCBX | Total | Community | CCBX | Total | |||||||||||||||||||||||||||
Gross charge-offs | $ | 2 | $ | 54,521 | $ | 54,523 | $ | 24 | $ | 55,165 | $ | 55,189 | $ | 4 | $ | 53,682 | $ | 53,686 | ||||||||||||||||||
Gross recoveries | (3 | ) | (4,933 | ) | (4,936 | ) | (2 | ) | (5,112 | ) | (5,114 | ) | (7 | ) | (5,479 | ) | (5,486 | ) | ||||||||||||||||||
Net charge-offs (recoveries) | $ | (1 | ) | $ | 49,588 | $ | 49,587 | $ | 22 | $ | 50,053 | $ | 50,075 | $ | (3 | ) | $ | 48,203 | $ | 48,200 | ||||||||||||||||
Net charge-offs to | 0.00 | % | 10.46 | % | 5.18 | % | 0.00 | % | 10.83 | % | 5.31 | % | 0.00 | % | 11.99 | % | 5.57 | % | ||||||||||||||||||
(1) Annualized calculations shown for periods presented.
During the quarter ended March 31, 2026, a $52.6 million provision for credit losses was recorded for CCBX partner loans, compared to $45.9 million for the quarter ended December 31, 2025. The increase in the provision was largely due to an increase in loans receivable and a change in the mix of loans, bringing the CCBX allowance for credit losses to $154.3 million at March 31, 2026 compared to $151.3 million at December 31, 2025. In general, CCBX loans have a higher level of expected losses than our community bank loans, which is reflected in the factors for the allowance for credit losses. Agreements with our CCBX partners provide for a credit enhancement, which protects the Bank by indemnifying or reimbursing incurred losses.
In accordance with accounting guidance, we estimate and record a provision for expected losses for these CCBX loans and reclassified negative deposit accounts. When the provision for CCBX credit losses and provision for unfunded commitments is recorded, a credit enhancement asset is also recorded on the balance sheet through noninterest income (BaaS credit enhancements). Expected losses are recorded in the allowance for credit losses. The credit enhancement asset is relieved when credit enhancement recoveries are received from the CCBX partner. If our partner is unable to fulfill their contracted obligations then the Bank could be exposed to additional credit losses. Management regularly evaluates and manages this counterparty risk with our CCBX partners.
The factors used in management’s analysis for community bank credit losses indicated that a provision recapture of $1.4 million was needed for the quarter ended March 31, 2026 compared to a provision recapture of $101,000 and a provision of $65,000 for the quarters ended December 31, 2025 and March 31, 2025, respectively. The provision recapture in the current period was due to an improvement in the overall economic outlook, partially offset by a marginal increase in the overall portfolio historical loss rates.
The following table details the provision expense/(recapture) for the community bank and CCBX for the period indicated:
Three Months Ended | |||||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | March 31, | ||||||||
Community bank | $ | (1,428 | ) | $ | (101 | ) | $ | 65 | |||
CCBX | 52,563 | 45,893 | 54,319 | ||||||||
Total provision expense | $ | 51,135 | $ | 45,792 | $ | 54,384 | |||||
Included in provision expense was a $252,000 provision for unfunded commitments, recorded primarily due to an increase in available commitments for CCBX loans, partially offset by a decline in the remaining weighted-average life of the unfunded construction and land portfolio.
At March 31, 2026, our nonperforming assets were $67.6 million, or 1.19%, of total assets, compared to $64.1 million, or 1.35%, of total assets, at December 31, 2025, and $56.4 million, or 1.30%, of total assets, at March 31, 2025. These ratios are impacted by nonperforming CCBX loans that are covered by CCBX partner credit enhancements. As of March 31, 2026, $60.9 million of the $62.8 million in nonperforming CCBX loans were covered by CCBX partner credit enhancements described above. Additionally, certain CCBX partners employ collection practices that place specific loans on nonaccrual status to enhance collectability. As of March 31, 2026, $22.3 million of these loans are less than 90 days past due.
Nonperforming assets increased $3.5 million during the quarter ended March 31, 2026, compared to the quarter ended December 31, 2025. Community bank nonperforming loans decreased $1.7 million from December 31, 2025 to $4.8 million as of March 31, 2026 with the payoff of a nonaccrual loan. CCBX nonperforming loans increased $5.2 million to $62.8 million from December 31, 2025. The increase in CCBX nonperforming loans is due to an increase of $3.2 million in nonaccrual loans from December 31, 2025 to $27.6 million, combined with a $2.1 million increase in CCBX loans that are past due 90 days or more and still accruing interest. As a result of the type of loans (primarily consumer loans) originated through our CCBX partners, we would typically anticipate that balances 90 days past due or more and still accruing will generally increase as those loan portfolios grow. Consumer loans originated through CCBX lending partners may continue to accrue interest beyond 90 days past due. Installment (closed-end) loans generally continue to accrue until 120 past due while revolving (open-end) loans generally continue to accrue until 180 days past due. There were no repossessed assets or other real estate owned at March 31, 2026. Our nonperforming loans to loans receivable ratio was 1.75% at March 31, 2026, compared to 1.71% at December 31, 2025 and 1.60% at March 31, 2025.
For the quarter ended March 31, 2026, there were $1,000 in community bank net charge-offs and $49.6 million in CCBX net charge-offs. These CCBX loans have a higher level of expected losses than our community bank loans, which is reflected in the factors used in the allowance for credit losses.
The following table details the Company’s nonperforming assets for the periods indicated.
Consolidated | As of | ||||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | March 31, | ||||||||
Nonaccrual loans: | |||||||||||
Commercial and industrial loans | $ | 251 | $ | 2,278 | $ | 381 | |||||
Real estate loans: | |||||||||||
Construction, land and land development | — | — | — | ||||||||
Residential real estate | 314 | 38 | — | ||||||||
Commercial real estate | 4,344 | 4,344 | — | ||||||||
Consumer and other loans: | |||||||||||
Credit cards | 24,497 | 21,433 | 13,602 | ||||||||
Other consumer and other loans | 3,015 | 2,875 | 6,376 | ||||||||
Total nonaccrual loans | 32,421 | 30,968 | 20,359 | ||||||||
Accruing loans past due 90 days or more: | |||||||||||
Commercial & industrial loans | 604 | 654 | 782 | ||||||||
Real estate loans: | |||||||||||
Residential real estate loans | 2,241 | 1,961 | 2,407 | ||||||||
Consumer and other loans: | |||||||||||
Credit cards | 24,149 | 22,536 | 27,187 | ||||||||
Other consumer and other loans | 8,205 | 7,993 | 5,632 | ||||||||
Total accruing loans past due 90 days or more | 35,199 | 33,144 | 36,008 | ||||||||
Total nonperforming loans | 67,620 | 64,112 | 56,367 | ||||||||
Real estate owned | — | — | — | ||||||||
Repossessed assets | — | — | — | ||||||||
Total nonperforming assets | $ | 67,620 | $ | 64,112 | $ | 56,367 | |||||
Total nonaccrual loans to loans receivable | 0.84 | % | 0.83 | % | 0.58 | % | |||||
Total nonperforming loans to loans receivable | 1.75 | % | 1.71 | % | 1.60 | % | |||||
Total nonperforming assets to total assets | 1.19 | % | 1.35 | % | 1.30 | % | |||||
The following tables detail the CCBX and community bank nonperforming assets, which are included in the total nonperforming assets table above.
CCBX | As of | ||||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | March 31, | ||||||||
Nonaccrual loans: | |||||||||||
Commercial and industrial loans: | |||||||||||
All other commercial & industrial loans | $ | 81 | $ | 127 | $ | 192 | |||||
Consumer and other loans: | |||||||||||
Credit cards | 24,497 | 21,433 | 13,602 | ||||||||
Other consumer and other loans | 3,015 | 2,875 | 6,376 | ||||||||
Total nonaccrual loans | 27,593 | 24,435 | 20,170 | ||||||||
Accruing loans past due 90 days or more: | |||||||||||
Commercial & industrial loans | 604 | 654 | 782 | ||||||||
Real estate loans: | |||||||||||
Residential real estate loans | 2,241 | 1,961 | 2,407 | ||||||||
Consumer and other loans: | |||||||||||
Credit cards | 24,149 | 22,536 | 27,187 | ||||||||
Other consumer and other loans | 8,205 | 7,993 | 5,632 | ||||||||
Total accruing loans past due 90 days or more | 35,199 | 33,144 | 36,008 | ||||||||
Total nonperforming loans | 62,792 | 57,579 | 56,178 | ||||||||
Other real estate owned | — | — | — | ||||||||
Repossessed assets | — | — | — | ||||||||
Total nonperforming assets | $ | 62,792 | $ | 57,579 | $ | 56,178 | |||||
Total CCBX nonperforming assets to total consolidated assets | 1.11 | % | 1.21 | % | 1.29 | % | |||||
Community Bank | As of | ||||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | March 31, | ||||||||
Nonaccrual loans: | |||||||||||
Commercial and industrial loans | $ | 170 | $ | 2,151 | $ | 189 | |||||
Real estate: | |||||||||||
Residential real estate | 314 | 38 | — | ||||||||
Commercial real estate | 4,344 | 4,344 | — | ||||||||
Total nonaccrual loans | 4,828 | 6,533 | 189 | ||||||||
Accruing loans past due 90 days or more: | |||||||||||
Total accruing loans past due 90 days or more | — | — | — | ||||||||
Total nonperforming loans | 4,828 | 6,533 | 189 | ||||||||
Other real estate owned | — | — | — | ||||||||
Repossessed assets | — | — | — | ||||||||
Total nonperforming assets | $ | 4,828 | $ | 6,533 | $ | 189 | |||||
Total community bank nonperforming assets to total consolidated assets | 0.09 | % | 0.14 | % | — | % | |||||
About Coastal Financial
Coastal Financial Corporation (Nasdaq: CCB) (the “Company”), is an Everett, Washington based bank holding company whose wholly owned subsidiaries are Coastal Community Bank (“Bank”) and Arlington Olympic LLC. The $5.66 billion Bank provides service through 14 full-service branches in Snohomish, Island and King Counties, one loan production office in King County, the Internet and its mobile banking application. The Bank provides banking as a service to digital financial service providers, companies and brands that want to provide financial services to their customers through the Bank's CCBX segment. To learn more about the Company visit www.coastalbank.com.
CCB-ER
Contact
Eric Sprink, Chief Executive Officer, esprink@coastalbank.com
Brandon J. Soto, Executive Vice President & Chief Financial Officer, bsoto@coastalbank.com
Forward-Looking Statements
This earnings release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements reflect our current views with respect to, among other things, future events and our financial performance. Any statements about our management’s expectations, beliefs, plans, predictions, forecasts, objectives, assumptions or future events or performance are not historical facts and may be forward-looking. These statements are often, but not always, made through the use of words or phrases such as “anticipate,” “believes,” “can,” “could,” “may,” “predicts,” “potential,” “should,” “will,” “estimate,” “plans,” “projects,” “continuing,” “ongoing,” “expects,” “intends” and similar words or phrases. Any or all of the forward-looking statements in this earnings release may turn out to be inaccurate. The inclusion of or reference to forward-looking information in this earnings release should not be regarded as a representation by us or any other person that the future plans, estimates or expectations contemplated by us will be achieved. We have based these forward looking statements largely on our current expectations and projections about future events and financial trends that we believe may affect our financial condition, results of operations, business strategy and financial needs. Our actual results could differ materially from those anticipated in such forward-looking statements as a result of risks, uncertainties and assumptions that are difficult to predict. Factors that could cause actual results to differ materially from those in the forward-looking statements include, without limitation, the risk that the conflicts in the Middle East and/or changes in U.S. trade policies, including the imposition of tariffs and retaliatory tariffs, may adversely impact our business, financial condition, and results of operations and those other risks and uncertainties discussed under “Risk Factors” in our Annual Report on Form 10-K for the most recent period filed and in any of our subsequent filings with the Securities and Exchange Commission.
If one or more events related to these or other risks or uncertainties materialize, or if our underlying assumptions prove to be incorrect, actual results may differ materially from what we anticipate. You are cautioned not to place undue reliance on forward-looking statements. Further, any forward-looking statement speaks only as of the date on which it is made, and we undertake no obligation to update or revise any forward-looking statement to reflect events or circumstances after the date on which the statement is made or to reflect the occurrence of unanticipated events, except as required by law.
COASTAL FINANCIAL CORPORATION | |||||||||||||||||||
ASSETS | |||||||||||||||||||
March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||
Cash and due from banks | $ | 52,695 | $ | 34,241 | $ | 34,928 | $ | 29,546 | $ | 43,467 | |||||||||
Interest earning deposits with other banks | 1,442,772 | 702,729 | 607,330 | 690,213 | 580,835 | ||||||||||||||
Investment securities, available-for-sale, at fair value | 28 | 29 | 31 | 33 | 34 | ||||||||||||||
Investment securities, held-to-maturity, at amortized cost | 46,141 | 48,218 | 43,911 | 45,544 | 46,957 | ||||||||||||||
Other investments | 14,023 | 12,837 | 12,778 | 12,521 | 12,589 | ||||||||||||||
Loans held for sale | 124,039 | 71,216 | 42,894 | 60,474 | 42,132 | ||||||||||||||
Loans receivable | 3,859,379 | 3,749,531 | 3,703,848 | 3,540,330 | 3,517,359 | ||||||||||||||
Allowance for credit losses | (172,427 | ) | (169,530 | ) | (173,813 | ) | (164,794 | ) | (183,178 | ) | |||||||||
Total loans receivable, net | 3,686,952 | 3,580,001 | 3,530,035 | 3,375,536 | 3,334,181 | ||||||||||||||
CCBX credit enhancement asset | 180,587 | 177,657 | 177,741 | 167,779 | 183,377 | ||||||||||||||
CCBX receivable | 24,926 | 23,047 | 16,260 | 13,009 | 12,685 | ||||||||||||||
Premises and equipment, net | 29,710 | 29,325 | 29,114 | 29,052 | 28,639 | ||||||||||||||
Lease right-of-use assets | 4,641 | 4,821 | 4,788 | 4,891 | 5,117 | ||||||||||||||
Accrued interest receivable | 20,139 | 18,613 | 20,493 | 20,849 | 21,109 | ||||||||||||||
Bank-owned life insurance, net | 14,044 | 13,910 | 13,777 | 13,648 | 13,501 | ||||||||||||||
Deferred tax asset, net | — | — | — | 3,829 | 3,912 | ||||||||||||||
Intangible assets, net | 4,434 | 4,536 | — | — | — | ||||||||||||||
Other assets | 18,698 | 20,257 | 18,996 | 13,635 | 10,747 | ||||||||||||||
Total assets | $ | 5,663,829 | $ | 4,741,437 | $ | 4,553,076 | $ | 4,480,559 | $ | 4,339,282 | |||||||||
LIABILITIES AND SHAREHOLDERS’ EQUITY | |||||||||||||||||||
LIABILITIES | |||||||||||||||||||
Deposits | $ | 5,041,164 | $ | 4,144,199 | $ | 3,972,563 | $ | 3,913,571 | $ | 3,791,229 | |||||||||
Subordinated debt, net | 44,480 | 44,443 | 44,406 | 44,368 | 44,331 | ||||||||||||||
Junior subordinated debentures, net | 3,594 | 3,593 | 3,593 | 3,592 | 3,592 | ||||||||||||||
Deferred compensation | 251 | 267 | 281 | 295 | 310 | ||||||||||||||
Accrued interest payable | 2,665 | 1,435 | 1,106 | 954 | 1,107 | ||||||||||||||
Lease liabilities | 4,799 | 4,984 | 4,956 | 5,063 | 5,293 | ||||||||||||||
CCBX payable | 28,410 | 27,492 | 31,221 | 32,939 | 29,391 | ||||||||||||||
Deferred tax liability, net | 1,656 | 853 | 799 | — | — | ||||||||||||||
Other liabilities | 33,048 | 23,212 | 18,874 | 18,068 | 14,112 | ||||||||||||||
Total liabilities | 5,160,067 | 4,250,478 | 4,077,799 | 4,018,850 | 3,889,365 | ||||||||||||||
SHAREHOLDERS’ EQUITY | |||||||||||||||||||
Common Stock | 234,222 | 233,438 | 230,399 | 230,423 | 229,659 | ||||||||||||||
Retained earnings | 269,541 | 257,522 | 244,879 | 231,287 | 220,259 | ||||||||||||||
Accumulated other comprehensive | (1 | ) | (1 | ) | (1 | ) | (1 | ) | (1 | ) | |||||||||
Total shareholders’ equity | 503,762 | 490,959 | 475,277 | 461,709 | 449,917 | ||||||||||||||
Total liabilities and shareholders’ equity | $ | 5,663,829 | $ | 4,741,437 | $ | 4,553,076 | $ | 4,480,559 | $ | 4,339,282 | |||||||||
COASTAL FINANCIAL CORPORATION | |||||||||||||||
Three Months Ended | |||||||||||||||
March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||
INTEREST AND DIVIDEND INCOME | |||||||||||||||
Interest and fees on loans | $ | 102,887 | $ | 100,206 | $ | 100,367 | $ | 98,867 | $ | 98,147 | |||||
Interest on interest earning deposits with | 8,128 | 6,810 | 8,007 | 8,085 | 6,070 | ||||||||||
Interest on investment securities | 622 | 635 | 616 | 626 | 650 | ||||||||||
Dividends on other investments | 44 | 235 | 37 | 219 | 40 | ||||||||||
Total interest income | 111,681 | 107,886 | 109,027 | 107,797 | 104,907 | ||||||||||
INTEREST EXPENSE | |||||||||||||||
Interest on deposits | 27,670 | 27,863 | 30,466 | 30,400 | 28,185 | ||||||||||
Interest on borrowed funds | 654 | 658 | 660 | 660 | 660 | ||||||||||
Total interest expense | 28,324 | 28,521 | 31,126 | 31,060 | 28,845 | ||||||||||
Net interest income | 83,357 | 79,365 | 77,901 | 76,737 | 76,062 | ||||||||||
PROVISION FOR CREDIT LOSSES | 51,398 | 48,041 | 56,598 | 32,211 | 55,781 | ||||||||||
Net interest income after | 31,959 | 31,324 | 21,303 | 44,526 | 20,281 | ||||||||||
NONINTEREST INCOME | |||||||||||||||
Service charges and fees | 850 | 882 | 903 | 913 | 860 | ||||||||||
Unrealized gain (loss) on equity securities, | 126 | — | 9 | (439 | ) | 16 | |||||||||
Other income | 410 | 459 | 461 | 496 | 682 | ||||||||||
Noninterest income, excluding BaaS program income and BaaS indemnification income | 1,386 | 1,341 | 1,373 | 970 | 1,558 | ||||||||||
Servicing and other BaaS fees | 2,623 | 2,113 | 1,575 | 1,896 | 1,419 | ||||||||||
Transaction and interchange fees | 5,873 | 4,924 | 4,878 | 5,109 | 3,833 | ||||||||||
Reimbursement of expenses | 2,392 | 1,868 | 1,412 | 646 | 1,026 | ||||||||||
BaaS program income | 10,888 | 8,905 | 7,865 | 7,651 | 6,278 | ||||||||||
BaaS credit enhancements | 50,744 | 47,325 | 55,412 | 31,268 | 53,648 | ||||||||||
BaaS fraud enhancements | 3,059 | 1,090 | 2,127 | 2,804 | 1,993 | ||||||||||
BaaS indemnification income | 53,803 | 48,415 | 57,539 | 34,072 | 55,641 | ||||||||||
Total noninterest income | 66,077 | 58,661 | 66,777 | 42,693 | 63,477 | ||||||||||
NONINTEREST EXPENSE | |||||||||||||||
Salaries and employee benefits | 23,122 | 22,745 | 20,146 | 21,401 | 21,532 | ||||||||||
Occupancy | 859 | 1,091 | 952 | 915 | 1,034 | ||||||||||
Data processing and software licenses | 7,643 | 6,978 | 6,114 | 5,541 | 4,232 | ||||||||||
Legal and professional expenses | 7,002 | 4,447 | 3,957 | 5,962 | 6,488 | ||||||||||
Point of sale expense | 445 | 105 | 69 | 69 | 107 | ||||||||||
Excise taxes | 1,169 | 756 | 696 | 681 | 722 | ||||||||||
Federal Deposit Insurance Corporation | 573 | 817 | 815 | 790 | 755 | ||||||||||
Director and staff expenses | 668 | 870 | 544 | 612 | 631 | ||||||||||
Marketing | 38 | 259 | 272 | 50 | 50 | ||||||||||
Other expense | 1,934 | 2,390 | 1,640 | 1,524 | 1,938 | ||||||||||
Noninterest expense, excluding BaaS loan and BaaS fraud expense | 43,453 | 40,458 | 35,205 | 37,545 | 37,489 | ||||||||||
BaaS loan expense | 36,940 | 31,256 | 32,840 | 32,483 | 32,507 | ||||||||||
BaaS fraud expense | 3,059 | 1,090 | 2,127 | 2,804 | 1,993 | ||||||||||
BaaS loan and fraud expense | 39,999 | 32,346 | 34,967 | 35,287 | 34,500 | ||||||||||
Total noninterest expense | 83,452 | 72,804 | 70,172 | 72,832 | 71,989 | ||||||||||
Income before provision for income | 14,584 | 17,181 | 17,908 | 14,387 | 11,769 | ||||||||||
PROVISION FOR INCOME TAXES | 2,565 | 4,538 | 4,316 | 3,359 | 2,039 | ||||||||||
NET INCOME | $ | 12,019 | $ | 12,643 | $ | 13,592 | $ | 11,028 | $ | 9,730 | |||||
Basic earnings per common share | $ | 0.79 | $ | 0.84 | $ | 0.90 | $ | 0.73 | $ | 0.65 | |||||
Diluted earnings per common share | $ | 0.78 | $ | 0.82 | $ | 0.88 | $ | 0.71 | $ | 0.63 | |||||
Weighted average number of common shares | |||||||||||||||
Basic | 15,179,447 | 15,116,005 | 15,093,274 | 15,033,296 | 14,962,507 | ||||||||||
Diluted | 15,422,822 | 15,455,856 | 15,443,987 | 15,447,923 | 15,462,041 | ||||||||||
COASTAL FINANCIAL CORPORATION | |||||||||||||||||||||||||||||
For the Three Months Ended | |||||||||||||||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||||||||||
Average | Interest & | Yield / | Average | Interest & | Yield / | Average | Interest & | Yield / | |||||||||||||||||||||
Assets | |||||||||||||||||||||||||||||
Interest earning assets: | |||||||||||||||||||||||||||||
Interest earning deposits with | $ | 891,511 | $ | 8,128 | 3.70 | % | $ | 682,663 | $ | 6,810 | 3.96 | % | $ | 553,393 | $ | 6,070 | 4.45 | % | |||||||||||
Investment securities, available-for-sale(2) | 30 | 1 | 13.52 | 31 | — | — | 37 | 1 | 10.96 | ||||||||||||||||||||
Investment securities, held-to-maturity(2) | 47,420 | 621 | 5.31 | 46,431 | 635 | 5.43 | 47,154 | 649 | 5.58 | ||||||||||||||||||||
Other investments | 13,014 | 44 | 1.37 | 12,809 | 235 | 7.28 | 11,757 | 40 | 1.38 | ||||||||||||||||||||
Loans receivable(3) | 3,878,626 | 102,887 | 10.76 | 3,740,073 | 100,206 | 10.63 | 3,511,724 | 98,147 | 11.33 | ||||||||||||||||||||
Total interest earning assets | 4,830,601 | 111,681 | 9.38 | 4,482,007 | 107,886 | 9.55 | 4,124,065 | 104,907 | 10.32 | ||||||||||||||||||||
Noninterest earning assets: | |||||||||||||||||||||||||||||
Allowance for credit losses | (166,987 | ) | (168,725 | ) | (170,542 | ) | |||||||||||||||||||||||
Other noninterest earning assets | 324,660 | 305,068 | 296,993 | ||||||||||||||||||||||||||
Total assets | $ | 4,988,274 | $ | 4,618,350 | $ | 4,250,516 | |||||||||||||||||||||||
Liabilities and Shareholders’ Equity | |||||||||||||||||||||||||||||
Interest bearing liabilities: | |||||||||||||||||||||||||||||
Interest bearing deposits | $ | 3,798,235 | $ | 27,670 | 2.95 | % | $ | 3,443,247 | $ | 27,863 | 3.21 | % | $ | 3,166,384 | $ | 28,185 | 3.61 | % | |||||||||||
FHLB advances and other borrowings | — | — | — | — | — | — | — | 1 | — | ||||||||||||||||||||
Subordinated debt | 44,457 | 599 | 5.46 | 44,420 | 599 | 5.35 | 44,309 | 598 | 5.47 | ||||||||||||||||||||
Junior subordinated debentures | 3,593 | 55 | 6.21 | 3,593 | 59 | 6.51 | 3,592 | 61 | 6.89 | ||||||||||||||||||||
Total interest bearing liabilities | 3,846,285 | 28,324 | 2.99 | 3,491,260 | 28,521 | 3.24 | 3,214,285 | 28,845 | 3.64 | ||||||||||||||||||||
Noninterest bearing deposits | 585,211 | 590,340 | 543,784 | ||||||||||||||||||||||||||
Other liabilities | 59,333 | 55,075 | 49,624 | ||||||||||||||||||||||||||
Total shareholders' equity | 497,445 | 481,675 | 442,823 | ||||||||||||||||||||||||||
Total liabilities and shareholders' equity | $ | 4,988,274 | $ | 4,618,350 | $ | 4,250,516 | |||||||||||||||||||||||
Net interest income | $ | 83,357 | $ | 79,365 | $ | 76,062 | |||||||||||||||||||||||
Interest rate spread | 6.39 | % | 6.31 | % | 6.68 | % | |||||||||||||||||||||||
Net interest margin(4) | 7.00 | % | 7.03 | % | 7.48 | % | |||||||||||||||||||||||
(1) Yields and costs are annualized.
(2) For presentation in this table, average balances and the corresponding average rates for investment securities are based upon historical cost, adjusted for amortization of premiums and accretion of discounts.
(3) Includes loans held for sale and nonaccrual loans.
(4) Net interest margin represents net interest income divided by the average total interest earning assets.
COASTAL FINANCIAL CORPORATION | ||||||||||||||||||||||||||
For the Three Months Ended | ||||||||||||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||
(dollars in thousands, unaudited) | Average | Interest & | Yield / | Average | Interest & | Yield / | Average | Interest & | Yield / | |||||||||||||||||
Community Bank | ||||||||||||||||||||||||||
Assets | ||||||||||||||||||||||||||
Interest earning assets: | ||||||||||||||||||||||||||
Loans receivable(2) | $ | 1,956,040 | $ | 31,734 | 6.58 | % | $ | 1,905,430 | $ | 31,337 | 6.52 | % | $ | 1,881,636 | $ | 30,292 | 6.53 | % | ||||||||
Total interest earning | 1,956,040 | 31,734 | 6.58 | 1,905,430 | 31,337 | 6.52 | 1,881,636 | 30,292 | 6.53 | |||||||||||||||||
Liabilities | ||||||||||||||||||||||||||
Interest bearing liabilities: | ||||||||||||||||||||||||||
Interest bearing | 1,057,293 | 5,571 | 2.14 | % | 1,091,322 | 6,282 | 2.28 | % | 1,045,971 | 6,604 | 2.56 | % | ||||||||||||||
Intrabank liability | 403,880 | 3,625 | 3.64 | 306,684 | 3,059 | 3.96 | 356,337 | 3,909 | 4.45 | |||||||||||||||||
Total interest bearing | 1,461,173 | 9,196 | 2.55 | 1,398,006 | 9,341 | 2.65 | 1,402,308 | 10,513 | 3.04 | |||||||||||||||||
Noninterest bearing | 494,867 | 507,424 | 479,329 | |||||||||||||||||||||||
Net interest income | $ | 22,538 | $ | 21,996 | $ | 19,779 | ||||||||||||||||||||
Net interest margin(3) | 4.67 | % | 4.58 | % | 4.26 | % | ||||||||||||||||||||
CCBX | ||||||||||||||||||||||||||
Assets | ||||||||||||||||||||||||||
Interest earning assets: | ||||||||||||||||||||||||||
Loans receivable(2)(4) | $ | 1,922,586 | $ | 71,153 | 15.01 | % | $ | 1,833,904 | $ | 68,846 | 14.89 | % | $ | 1,630,088 | $ | 67,855 | 16.88 | % | ||||||||
Intrabank asset | 908,700 | 8,156 | 3.64 | 600,937 | 5,995 | 3.96 | 554,781 | 6,085 | 4.45 | |||||||||||||||||
Total interest earning | 2,831,286 | 79,309 | 11.36 | 2,434,841 | 74,841 | 12.19 | 2,184,869 | 73,940 | 13.72 | |||||||||||||||||
Liabilities | ||||||||||||||||||||||||||
Interest bearing liabilities: | ||||||||||||||||||||||||||
Interest bearing | 2,740,942 | 22,099 | 3.27 | % | 2,351,925 | 21,581 | 3.64 | % | 2,120,413 | 21,581 | 4.13 | % | ||||||||||||||
Total interest bearing | 2,740,942 | 22,099 | 3.27 | 2,351,925 | 21,581 | 3.64 | 2,120,413 | 21,581 | 4.13 | |||||||||||||||||
Noninterest bearing | 90,344 | 82,916 | 64,455 | |||||||||||||||||||||||
Net interest income | $ | 57,210 | $ | 53,260 | $ | 52,359 | ||||||||||||||||||||
Net interest margin(3) | 8.19 | % | 8.68 | % | 9.72 | % | ||||||||||||||||||||
Net interest margin, net | 2.90 | % | 3.59 | % | 3.68 | % | ||||||||||||||||||||
For the Three Months Ended | ||||||||||||||||||||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||
(dollars in thousands, unaudited) | Average | Interest & | Yield / | Average | Interest & | Yield / | Average | Interest & | Yield / | |||||||||||||||||
Treasury & Administration | ||||||||||||||||||||||||||
Assets | ||||||||||||||||||||||||||
Interest earning assets: | ||||||||||||||||||||||||||
Loans receivable(2) | $ | — | $ | — | — | % | $ | 739 | $ | 23 | — | % | $ | — | $ | — | — | % | ||||||||
Interest earning | 891,511 | 8,128 | 3.70 | 682,663 | 6,810 | 3.96 | 553,393 | 6,070 | 4.45 | |||||||||||||||||
Investment securities, | 30 | 1 | 3.37 | 31 | — | — | 37 | 1 | 10.96 | |||||||||||||||||
Investment securities, | 47,420 | 621 | 5.31 | 46,431 | 635 | 5.43 | 47,154 | 649 | 5.58 | |||||||||||||||||
Other investments | 13,014 | 44 | 1.37 | 12,809 | 235 | 7.28 | 11,757 | 40 | 1.38 | |||||||||||||||||
Total interest | 951,975 | 8,794 | 3.75 | % | 742,673 | — | 7,703 | 4.11 | % | 612,341 | 6,760 | 4.48 | % | |||||||||||||
Liabilities | ||||||||||||||||||||||||||
Interest bearing | ||||||||||||||||||||||||||
FHLB advances | $ | — | — | — | % | $ | — | — | — | % | $ | — | 1 | — | % | |||||||||||
Subordinated debt | 44,457 | 599 | 5.46 | 44,420 | 599 | 5.35 | 44,309 | 598 | 5.47 | |||||||||||||||||
Junior subordinated | 3,593 | 55 | 6.21 | 3,593 | 59 | 6.51 | 3,592 | 61 | 6.89 | |||||||||||||||||
Intrabank liability, net(7) | 504,820 | 4,531 | 3.64 | 294,253 | 2,936 | 3.96 | 198,444 | 2,176 | 4.45 | |||||||||||||||||
Total interest | 552,870 | 5,185 | 3.80 | 342,266 | 3,594 | 4.17 | 246,345 | 2,836 | 4.67 | |||||||||||||||||
Net interest income | $ | 3,609 | $ | 4,109 | $ | 3,924 | ||||||||||||||||||||
Net interest margin(3) | 1.54 | % | 2.20 | % | 2.60 | % | ||||||||||||||||||||
(1) Yields and costs are annualized.
(2) Includes loans held for sale and nonaccrual loans.
(3) Net interest margin represents net interest income divided by the average total interest earning assets.
(4) CCBX yield does not include the impact of BaaS loan expense. BaaS loan expense represents the amount paid or payable to partners for credit enhancements, fraud enhancements and originating & servicing CCBX loans. See reconciliation of the non-GAAP measures at the end of this earnings release for the impact of BaaS loan expense on CCBX loan yield.
(5) Net interest margin, net of BaaS loan expense, includes the impact of BaaS loan expense. BaaS loan expense represents the amount paid or payable to partners for credit enhancements, fraud enhancements, originating & servicing CCBX loans. See reconciliation of the non-GAAP measures at the end of this earnings release.
(6) For presentation in this table, average balances and the corresponding average rates for investment securities are based upon historical cost, adjusted for amortization of premiums and accretion of discounts.
(7) Intrabank assets and liabilities are consolidated for period calculations and presented as intrabank asset, net or intrabank liability, net in the table above.
Non-GAAP Financial Measures
The Company uses certain non-GAAP financial measures to provide meaningful supplemental information regarding the Company’s operational performance and to enhance investors’ overall understanding of financial performance.
However, these non-GAAP financial measures are supplemental and are not a substitute for an analysis based on GAAP measures. As other companies may use different calculations for these adjusted measures, this presentation may not be comparable to other similarly titled adjusted measures reported by other companies.
The following non-GAAP measures are presented to illustrate the impact of BaaS loan expense on net loan income and yield on loans and CCBX loans and the impact of BaaS loan expense on net interest income and net interest margin.
Loan income, net of BaaS loan expense, divided by average loans, is a non-GAAP measure that includes the impact of BaaS loan expense on loan income and the yield on loans. The most directly comparable GAAP measure is yield on loans.
Net BaaS loan income divided by average CCBX loans is a non-GAAP measure that includes the impact of BaaS loan expense on net BaaS loan income and the yield on CCBX loans. The most directly comparable GAAP measure is yield on CCBX loans.
Net interest income, net of BaaS loan expense, is a non-GAAP measure that includes the impact of BaaS loan expense on net interest income. The most directly comparable GAAP measure is net interest income.
CCBX net interest margin, net of BaaS loan expense, is a non-GAAP measure that includes the impact of BaaS loan expense on net interest rate margin. The most directly comparable GAAP measure is CCBX net interest margin.
Reconciliations of the GAAP and non-GAAP measures are presented below.
CCBX | As of and for the Three Months Ended | |||||||||||
(dollars in thousands; unaudited) | March 31 | December 31 | March 31 | |||||||||
Net BaaS loan income divided by average CCBX loans: | ||||||||||||
CCBX loan yield (GAAP)(1) | 15.01 | % | 14.89 | % | 16.88 | % | ||||||
Total average CCBX loans receivable | $ | 1,922,586 | $ | 1,833,904 | $ | 1,630,088 | ||||||
Interest and earned fee income on CCBX loans (GAAP) | 71,153 | 68,846 | 67,855 | |||||||||
BaaS loan expense | (36,940 | ) | (31,256 | ) | (32,507 | ) | ||||||
Net BaaS loan income | $ | 34,213 | $ | 37,590 | $ | 35,348 | ||||||
Net BaaS loan income divided by average CCBX loans(1) | 7.22 | % | 8.13 | % | 8.79 | % | ||||||
CCBX net interest margin, net of BaaS loan expense: | ||||||||||||
CCBX net interest margin(1) | 8.19 | % | 8.68 | % | 9.72 | % | ||||||
CCBX earning assets | 2,831,286 | 2,434,841 | 2,184,869 | |||||||||
Net interest income (GAAP) | 57,210 | 53,260 | 52,359 | |||||||||
Less: BaaS loan expense | (36,940 | ) | (31,256 | ) | (32,507 | ) | ||||||
Net interest income, net of BaaS | $ | 20,270 | $ | 22,004 | $ | 19,852 | ||||||
CCBX net interest margin, net of BaaS loan expense(1) | 2.90 | % | 3.59 | % | 3.68 | % | ||||||
Consolidated | As of and for the Three Months Ended | |||||||||||
(dollars in thousands; unaudited) | March 31 | December 31 | March 31 | |||||||||
Net interest margin, net of BaaS loan expense: | ||||||||||||
Net interest margin(1) | 7.00 | % | 7.03 | % | 7.48 | % | ||||||
Earning assets | 4,830,601 | 4,482,007 | 4,124,065 | |||||||||
Net interest income (GAAP) | 83,357 | 79,365 | 76,062 | |||||||||
Less: BaaS loan expense | (36,940 | ) | (31,256 | ) | (32,507 | ) | ||||||
Net interest income, net of BaaS loan expense | $ | 46,417 | $ | 48,109 | $ | 43,555 | ||||||
Net interest margin, net of BaaS loan expense(1) | 3.90 | % | 4.26 | % | 4.28 | % | ||||||
Loan income net of BaaS loan expense divided by average loans: | ||||||||||||
Loan yield (GAAP)(1) | 10.76 | % | 10.63 | % | 11.33 | % | ||||||
Total average loans receivable | $ | 3,878,626 | $ | 3,740,073 | $ | 3,511,724 | ||||||
Interest and earned fee income on loans (GAAP) | 102,887 | 100,206 | 98,147 | |||||||||
BaaS loan expense | (36,940 | ) | (31,256 | ) | (32,507 | ) | ||||||
Net loan income | $ | 65,947 | $ | 68,950 | $ | 65,640 | ||||||
Loan income, net of BaaS loan expense, divided by average loans(1) | 6.90 | % | 7.31 | % | 7.58 | % | ||||||
(1) Annualized calculations for periods presented.
The following non-GAAP measure is presented to illustrate the impact of BaaS loan expense, BaaS fraud expense and reimbursement of expenses (BaaS) on noninterest expense. Certain noninterest expenses are reimbursed by our CCBX partners. In accordance with GAAP we recognize all expenses in noninterest expense and the reimbursement of expenses from our CCBX partners in noninterest income. This non-GAAP measure is intended to help investors distinguish between noninterest expenses borne by the Company and those incurred for, and reimbursed by, CCBX partners.The most comparable GAAP measure is noninterest expense.
As of and for the Three Months Ended | |||||||||
(dollars in thousands, unaudited) | March 31, | December 31, | March 31, | ||||||
Noninterest expense, net of BaaS loan expense, BaaS fraud expense and reimbursement of expenses (BaaS) | |||||||||
Noninterest expense (GAAP) | $ | 83,452 | $ | 72,804 | $ | 71,989 | |||
Less: BaaS loan expense | 36,940 | 31,256 | 32,507 | ||||||
Less: BaaS fraud expense | 3,059 | 1,090 | 1,993 | ||||||
Less: Reimbursement of expenses | 2,392 | 1,868 | 1,026 | ||||||
Noninterest expense, net of BaaS loan expense, BaaS fraud expense | $ | 41,061 | $ | 38,590 | $ | 36,463 | |||
The following non-GAAP measure is presented to illustrate the impact of intangible assets on book value per share. We calculate tangible book value per share as total shareholders’ equity at the end of the relevant period, less goodwill and other intangible assets, divided by the outstanding number of our common shares at the end of each period. The most directly comparable GAAP financial measure is book value per share.
As of | |||||||||||||||
(dollars in thousands, except per share information, unaudited) | March 31, | December 31, | September 30, | June 30, | March 31, | ||||||||||
Tangible book value per share | |||||||||||||||
Book value (GAAP) | $ | 33.05 | $ | 32.43 | $ | 31.45 | $ | 30.59 | $ | 29.98 | |||||
Total shareholders' equity | 503,762 | 490,959 | 475,277 | 461,709 | 449,917 | ||||||||||
Less: Intangible assets | 4,434 | 4,536 | — | — | — | ||||||||||
Tangible book value | $ | 499,328 | $ | 486,423 | $ | 475,277 | $ | 461,709 | $ | 449,917 | |||||
Common shares outstanding | 15,241,491 | 15,140,192 | 15,112,000 | 15,093,036 | 15,009,225 | ||||||||||
Tangible book value per share | $ | 32.76 | $ | 32.13 | $ | 31.45 | $ | 30.59 | $ | 29.98 | |||||
APPENDIX A
As of March 31, 2026
Industry Concentration
We have a diversified loan portfolio, representing a wide variety of industries. Our major categories of loans are commercial real estate, consumer and other loans, residential real estate, commercial and industrial, and construction, land and land development loans. Together they represent $3.87 billion in outstanding loan balances. When combined with $2.59 billion in unused commitments the total of these categories is $6.45 billion.
Commercial real estate loans represent the largest segment of our loans, comprising 33.6% of our total balance of outstanding loans as of March 31, 2026. Unused commitments to extend credit represents an additional $35.4 million, and the combined total in commercial real estate loans represents $1.34 billion, or 20.7% of our total outstanding loans and loan commitments.
The following table summarizes our loan commitments by industry for our commercial real estate portfolio as of March 31, 2026:
(dollars in thousands; unaudited) | Outstanding Balance | Available | Total | % of Total | Average Loan Balance | Number of Loans | |||||||||||
Apartments | $ | 357,711 | $ | 13,442 | $ | 371,153 | 5.7 | % | $ | 3,726 | 96 | ||||||
Hotel/Motel | 178,339 | 862 | 179,201 | 2.8 | 7,134 | 25 | |||||||||||
Convenience Store | 143,092 | 3,345 | 146,437 | 2.3 | 2,236 | 64 | |||||||||||
Warehouse | 100,075 | 250 | 100,325 | 1.5 | 1,853 | 54 | |||||||||||
Retail | 97,447 | 427 | 97,874 | 1.5 | 1,071 | 91 | |||||||||||
Mixed use | 95,791 | 6,498 | 102,289 | 1.6 | 1,076 | 89 | |||||||||||
Office | 84,678 | 4,216 | 88,894 | 1.4 | 1,045 | 81 | |||||||||||
Mini Storage | 79,326 | 303 | 79,629 | 1.2 | 4,407 | 18 | |||||||||||
Strip Mall | 42,779 | — | 42,779 | 0.7 | 6,111 | 7 | |||||||||||
Manufacturing | 32,139 | 1,195 | 33,334 | 0.5 | 1,286 | 25 | |||||||||||
Groups < 0.50% of total | 89,170 | 4,880 | 94,050 | 1.5 | 1,173 | 76 | |||||||||||
Total | $ | 1,300,547 | $ | 35,418 | $ | 1,335,965 | 20.7 | % | $ | 2,078 | 626 | ||||||
Consumer loans comprise 37.0% of our total balance of outstanding loans as of March 31, 2026. Unused commitments to extend credit represents an additional $1.07 billion, and the combined total in consumer and other loans represents $2.51 billion, or 38.8% of our total outstanding loans and loan commitments. The $1.07 billion in commitments is subject to CCBX partner/portfolio maximum limits. As illustrated in the table below, our CCBX partners bring in a large number of mostly smaller dollar loans, resulting in an average consumer loan balance of just $700. CCBX consumer loans are underwritten to CCBX credit standards, and underwriting of these loans is regularly tested, including quarterly testing for partners with the largest exposures.
The following table summarizes our loan commitments by industry for our consumer and other loan portfolio as of March 31, 2026:
(dollars in thousands; unaudited) | Outstanding Balance | Available Loan Commitments(1) | Total | % of Total Loans | Average Loan Balance | Number of Loans | |||||||||||
CCBX consumer loans | |||||||||||||||||
Credit cards | $ | 693,485 | $ | 1,008,183 | $ | 1,701,668 | 26.4 | % | $ | 1.5 | 456,317 | ||||||
Installment loans | 669,544 | 35,963 | 705,507 | 10.9 | 0.7 | 1,026,896 | |||||||||||
Lines of credit | 29,956 | 26,968 | 56,924 | 0.9 | 0.1 | 303,549 | |||||||||||
Other loans | 27,443 | — | 27,443 | 0.4 | 0.1 | 297,989 | |||||||||||
Community bank consumer loans | |||||||||||||||||
Installment loans | 1,088 | 5 | 1,093 | 0.0 | 43.5 | 25 | |||||||||||
Lines of credit | 163 | 387 | 550 | 0.0 | 5.3 | 31 | |||||||||||
Other loans | 10,336 | 3,000 | 13,336 | 0.2 | 28.2 | 366 | |||||||||||
Total | $ | 1,432,015 | $ | 1,074,506 | $ | 2,506,521 | 38.8 | % | $ | 0.7 | 2,085,173 | ||||||
(1) Total exposure on CCBX loans is subject to CCBX partner/portfolio maximum limits.
Residential real estate loans comprise 12.0% of our total balance of outstanding loans as of March 31, 2026. Unused commitments to extend credit represents an additional $713.7 million, which is subject to partner/portfolio maximum limits, and the combined total in residential real estate loans represents $1.18 billion, or 18.3% of our total outstanding loans and loan commitments.
The following table summarizes our loan commitments by industry for our residential real estate loan portfolio as of March 31, 2026:
(dollars in thousands; unaudited) | Outstanding Balance | Available Loan Commitments(1) | Total | % of Total Loans | Average Loan Balance | Number of Loans | |||||||||||
CCBX residential real estate loans | |||||||||||||||||
Home equity lines of credit | $ | 266,037 | $ | 661,716 | $ | 927,753 | 14.4 | % | $ | 23 | 11,336 | ||||||
Community bank residential real estate loans | |||||||||||||||||
Closed end, secured by first liens | 156,550 | 546 | 157,096 | 2.4 | 293 | 293 | |||||||||||
Home equity lines of credit | 32,962 | 49,812 | 82,774 | 1.3 | 257 | 257 | |||||||||||
Closed end, second liens | 9,673 | 1,605 | 11,278 | 0.2 | 28 | 28 | |||||||||||
Total | $ | 465,222 | $ | 713,679 | $ | 1,178,901 | 18.3 | % | $ | 39 | 11,914 | ||||||
(1) Total exposure on CCBX loans is subject to CCBX partner/portfolio maximum limits.
Commercial and industrial loans comprise 11.3% of our total balance of outstanding loans as of March 31, 2026. Unused commitments to extend credit represents an additional $673.3 million, and the combined total in commercial and industrial loans represents $1.11 billion, or 17.2% of our total outstanding loans and loan commitments. Included in commercial and industrial loans is $176.4 million in outstanding capital call lines, with an additional $573.8 million in available loan commitments which is limited to a $350.0 million portfolio maximum. Capital call lines are provided to venture capital firms through one of our CCBX BaaS clients. These loans are secured by the capital call rights and are individually underwritten to the Bank’s credit standards, and the underwriting is reviewed by the Bank on every capital call line.
The following table summarizes our loan commitment by industry for our commercial and industrial loan portfolio as of March 31, 2026:
(dollars in thousands; unaudited) | Outstanding Balance | Available Loan Commitments(1) | Total | % of Total Loans | Average Loan Balance | Number of Loans | |||||||||||
CCBX C&I loans | |||||||||||||||||
Capital call lines | $ | 176,384 | $ | 573,832 | $ | 750,216 | 11.6 | % | $ | 1,446 | 122 | ||||||
Retail and other | 21,792 | 34,620 | 56,412 | 0.9 | 9 | 2,332 | |||||||||||
Community bank C&I loans | |||||||||||||||||
Financial institutions | 102,025 | — | 102,025 | 1.6 | 4,251 | 24 | |||||||||||
Construction/Contractor services | 32,716 | 30,889 | 63,605 | 1.0 | 186 | 176 | |||||||||||
Medical / Dental / Other care | 5,387 | 282 | 5,669 | 0.1 | 449 | 12 | |||||||||||
Transportation | 4,302 | 31 | 4,333 | 0.1 | 615 | 7 | |||||||||||
Manufacturing | 4,144 | 4,007 | 8,151 | 0.1 | 115 | 36 | |||||||||||
Groups < 0.10% of total | 87,029 | 29,605 | 116,634 | 1.8 | 418 | 208 | |||||||||||
Total | $ | 433,779 | $ | 673,266 | $ | 1,107,045 | 17.2 | % | $ | 149 | 2,917 | ||||||
(1) Total exposure on CCBX loans is subject to CCBX partner/portfolio maximum limits.
Construction, land and land development loans comprise 6.1% of our total balance of outstanding loans as of March 31, 2026. Unused commitments to extend credit represent an additional $90.0 million, and the combined total in construction, land and land development loans represents $324.9 million, or 5.0% of our total outstanding loans and loan commitments.
The following table details our loan commitment for our construction, land and land development portfolio as of March 31, 2026:
(dollars in thousands; unaudited) | Outstanding Balance | Available Loan Commitments | Total | % of Total Loans | Average Loan Balance | Number of Loans | |||||||||||
Commercial construction | $ | 138,232 | $ | 35,954 | $ | 174,186 | 2.7 | % | $ | 9,215 | 15 | ||||||
Residential construction | 34,241 | 42,322 | 76,563 | 1.2 | 1,105 | 31 | |||||||||||
Land development | 22,950 | 11,316 | 34,266 | 0.5 | 2,295 | 10 | |||||||||||
Undeveloped land loans | 20,633 | — | 20,633 | 0.3 | 1,376 | 15 | |||||||||||
Developed land loans | 18,855 | 420 | 19,275 | 0.3 | 1,178 | 16 | |||||||||||
Total | $ | 234,911 | $ | 90,012 | $ | 324,923 | 5.0 | % | $ | 2,700 | 87 | ||||||
Exposure and risk in our construction, land and land development portfolio increased compared to recent periods as indicated in the following table:
Outstanding Balance as of | |||||||||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | September 30, | June 30, | March 31, | ||||||||||
Commercial construction | $ | 138,232 | $ | 124,894 | $ | 124,240 | $ | 104,078 | $ | 96,716 | |||||
Residential construction | 34,241 | 37,395 | 35,929 | 39,831 | 39,375 | ||||||||||
Undeveloped land loans | 20,633 | 20,704 | 20,584 | 20,067 | 16,684 | ||||||||||
Developed land loans | 18,855 | 20,559 | 22,756 | 22,875 | 7,788 | ||||||||||
Land development | 22,950 | 18,523 | 14,552 | 7,299 | 5,988 | ||||||||||
Total | $ | 234,911 | $ | 222,075 | $ | 218,061 | $ | 194,150 | $ | 166,551 | |||||
Commitments to extend credit total $2.59 billion at March 31, 2026, however we do not anticipate our customers using the $2.59 billion that is showing as available due to CCBX partner and portfolio limits.
The following table presents outstanding commitments to extend credit as of March 31, 2026:
Consolidated | |||
(dollars in thousands; unaudited) | As of March 31, | ||
Commitments to extend credit: | |||
Credit cards | $ | 1,008,183 | |
Residential real estate loans | 713,679 | ||
Commercial and industrial loans – capital call lines | 573,832 | ||
Commercial and industrial loans | 99,434 | ||
Consumer and other loans | 66,323 | ||
Construction – commercial real estate loans | 47,691 | ||
Construction – residential real estate loans | 42,321 | ||
Commercial real estate loans | 35,418 | ||
Total commitments to extend credit | $ | 2,586,881 | |
(1) Total exposure on CCBX loans is subject to CCBX partner/portfolio maximum limits.
We have individual CCBX partner portfolio limits with each of our partners to manage loan concentration risk, liquidity risk and counterparty partner risk. For example, as of March 31, 2026, capital call lines outstanding balance totaled $176.4 million and, while commitments to underlying customers totaled $573.8 million, the commitments are limited to a maximum of $350.0 million by agreement with the partner. If a CCBX partner goes over their individual limit, it would be a breach of their contract and the Bank may impose penalties and would have the choice to fund or not fund the loan.
See the table below for CCBX portfolio maximums and related available commitments:
CCBX | |||||||||||||||
(dollars in thousands; unaudited) | Balance | Percent of CCBX | Available | Maximum Portfolio | Cash | ||||||||||
Commercial and industrial loans: | |||||||||||||||
Capital call lines | $ | 176,384 | 9.4 | % | $ | 573,832 | $ | 350,000 | $ | — | |||||
All other commercial & industrial loans | 21,792 | 1.2 | 34,620 | 512,975 | 1,066 | ||||||||||
Real estate loans: | |||||||||||||||
Home equity lines of credit(2) | 266,037 | 14.1 | 661,716 | 450,000 | 32,108 | ||||||||||
Consumer and other loans: | |||||||||||||||
Credit cards - cash secured | 398 | 16 | — | ||||||||||||
Credit cards - unsecured | 693,087 | 1,008,167 | 49,605 | ||||||||||||
Credit cards - total | 693,485 | 36.8 | 1,008,183 | 1,125,000 | 49,605 | ||||||||||
Installment loans - cash secured | 174,036 | 35,963 | — | ||||||||||||
Installment loans - unsecured | 495,508 | — | (11,175 | ) | |||||||||||
Installment loans - total | 669,544 | 35.5 | 35,963 | 1,962,891 | (11,175 | ) | |||||||||
Other consumer and other loans | 57,399 | 3.0 | 26,968 | 459,134 | 835 | ||||||||||
Gross CCBX loans receivable | 1,884,641 | 100.0 | % | $ | 2,341,282 | $ | 4,860,000 | $ | 72,439 | ||||||
Net deferred origination fees | (517 | ) | |||||||||||||
Loans receivable | $ | 1,884,124 | |||||||||||||
(1) Remaining commitment available, net of outstanding balance.
(2) These home equity lines of credit are secured by residential real estate and are accessed by using a credit card, but are classified as 1-4 family residential properties per regulatory guidelines.
APPENDIX B
As of March 31, 2026
CCBX – BaaS Reporting Information
During the quarter ended March 31, 2026, $50.7 million was recorded in BaaS credit enhancements related to the provision for credit losses - loans and reserve for unfunded commitments for CCBX partner loans and negative deposit accounts. Agreements with our CCBX partners provide for a credit enhancement provided by the partner which protects the Bank by indemnifying or reimbursing incurred losses. In accordance with accounting guidance, we estimate and record a provision for expected losses for these CCBX loans, unfunded commitments, negative deposit accounts and accrued interest receivable on CCBX partner loans. When the provision for credit losses - loans and provision for unfunded commitments is recorded, a credit enhancement asset is also recorded on the balance sheet through noninterest income (BaaS credit enhancements) in recognition of the CCBX partner legal commitment to indemnify or reimburse losses. The credit enhancement asset is relieved as credit enhancement payments and recoveries are received from the CCBX partner or taken from the partner's cash reserve account. Agreements with our CCBX partners also provide protection to the Bank from fraud by indemnifying or reimbursing incurred fraud losses. BaaS fraud includes non-credit fraud losses on loans and deposits originated through partners. Generally fraud losses related to loans are comprised primarily of first payment defaults. Fraud losses are recorded when incurred as losses in noninterest expense, and the enhancement received from the CCBX partner is recorded in noninterest income, resulting in a net impact of zero to the income statement.
Many CCBX partners also pledge a cash reserve account at the Bank, which the Bank can collect from when losses occur that is then replenished by the partner on a regular interval. Although agreements with our CCBX partners provide for credit enhancements that provide protection to the Bank from credit and fraud losses if our partner is unable to fulfill their contractual obligation and if the cash flows on the loans were not sufficient to fund the reimbursement of loan losses, then the Bank would be exposed to additional loan and deposit losses as a result of this counterparty risk. If a CCBX partner does not replenish their cash reserve account, the Bank may consider an alternative plan for funding the cash reserve. This may involve the possibility of adjusting the funding amounts or timelines to better align with the partner's specific situation. If a mutually agreeable funding plan is not agreed to, the Bank could declare the agreement in default, take over servicing and cease paying the partner for servicing the loan and providing credit enhancements. In the event of a partner default, the Bank would evaluate any remaining credit enhancement asset associated with that partner to determine whether a write-off is appropriate. If a write-off occurs, the Bank would stop payments to the CCBX partner and retain the full yield and any fee income on the loan portfolio going forward, decreasing our BaaS loan expense.
The Bank records contractual interest earned from the borrowers on CCBX partner loans in interest income, adjusted for origination costs, which are paid or payable to the CCBX partners. BaaS loan expense represents the amount paid or payable to partners for credit and fraud enhancements and originating & servicing CCBX loans. To determine net revenue (Net BaaS loan income) earned from CCBX loan relationships, the Bank takes BaaS loan interest income and deducts BaaS loan expense to arrive at Net BaaS loan income (a reconciliation of the non-GAAP measures are set forth in the preceding section of this earnings release) which can be compared to interest income on the Company’s community bank loans.
The following table illustrates how CCBX partner loan income and expenses are recorded in the financial statements:
Loan income and related loan expense | Three Months Ended | |||||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | March 31, | |||||||||
Yield on loans(1) | 15.01 | % | 14.89 | % | 16.88 | % | ||||||
BaaS loan interest income | $ | 71,153 | $ | 68,846 | $ | 67,855 | ||||||
Less: BaaS loan expense | 36,940 | 31,256 | 32,507 | |||||||||
Net BaaS loan income(2) | $ | 34,213 | $ | 37,590 | $ | 35,348 | ||||||
Net BaaS loan income divided by average BaaS loans(1)(2) | 7.22 | % | 8.13 | % | 8.79 | % | ||||||
(1) Annualized calculation for quarterly periods shown.
(2) A reconciliation of the non-GAAP measures are set forth in the preceding section of this earnings release.
An increase in average loans receivable resulted in increased interest income on CCBX loans during the quarter ended March 31, 2026 compared to the quarter ended December 31, 2025, however net BaaS loan income decreased as a result of higher BaaS loan expense, compared to the previous quarter. This is a result of recent changes to partner agreements and pricing changes that resulted in lower loan yields, net of BaaS loan expense. These actions reflect a strategic shift toward enhanced partner economics and more sustainable, risk-adjusted returns over time. Our strategy is to optimize the CCBX loan portfolio and strengthen our balance sheet through originating higher quality new loans with enhanced credit standards. These higher quality loans tend to have lower stated rates and expected losses than some of our CCBX loans historically. We continue to manage CCBX credit and concentration levels in an effort to optimize our loan portfolio and also generate off-balance sheet fee income. Growth in CCBX loans has resulted in an increase in interest income for the quarter ended March 31, 2026 compared to the quarter ended March 31, 2025, and a slight increase in net BaaS loan income.
The following tables are a summary of the interest components, direct fees and expenses of BaaS for the periods indicated and are not inclusive of all income and expense related to BaaS.
Interest income | Three Months Ended | ||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | March 31, | ||||||
BaaS loan interest income | $ | 71,153 | $ | 68,846 | $ | 67,855 | |||
Total BaaS loan interest income | $ | 71,153 | $ | 68,846 | $ | 67,855 | |||
Interest expense | Three Months Ended | ||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | March 31, | ||||||
BaaS interest expense | $ | 22,099 | $ | 21,581 | $ | 21,581 | |||
Total BaaS interest expense | $ | 22,099 | $ | 21,581 | $ | 21,581 | |||
BaaS income | Three Months Ended | ||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | March 31, | ||||||
BaaS program income: | |||||||||
Servicing and other BaaS fees | $ | 2,623 | $ | 2,113 | $ | 1,419 | |||
Transaction and interchange fees | 5,873 | 4,924 | 3,833 | ||||||
Reimbursement of expenses | 2,392 | 1,868 | 1,026 | ||||||
Total BaaS program income | 10,888 | 8,905 | 6,278 | ||||||
BaaS indemnification income: | |||||||||
BaaS credit enhancements | 50,744 | 47,325 | 53,648 | ||||||
BaaS fraud enhancements | 3,059 | 1,090 | 1,993 | ||||||
BaaS indemnification income | 53,803 | 48,415 | 55,641 | ||||||
Total noninterest BaaS income | $ | 64,691 | $ | 57,320 | $ | 61,919 | |||
Servicing and other BaaS fees increased $510,000, and transaction and interchange fees increased $949,000 in the quarter ended March 31, 2026 compared to the quarter ended December 31, 2025. We expect servicing and other BaaS fees to be higher when bringing on new partners and then to decrease when transaction and interchange fees increase as partner activity grows and these recurring fees exceed contracted minimum fees. Increases in BaaS reimbursement of fees offset increases in noninterest expense from BaaS expenses covered by CCBX partners.
BaaS loan and fraud expense: | Three Months Ended | ||||||||
(dollars in thousands; unaudited) | March 31, | December 31, | March 31, | ||||||
BaaS loan expense | $ | 36,940 | $ | 31,256 | $ | 32,507 | |||
BaaS fraud expense | 3,059 | 1,090 | 1,993 | ||||||
Total BaaS loan and fraud expense | $ | 39,999 | $ | 32,346 | $ | 34,500 | |||
Photos accompanying this announcement are available at https://www.globenewswire.com/NewsRoom/AttachmentNg/7ec8185f-b892-430b-91b3-ebc8fefd208c
https://www.globenewswire.com/NewsRoom/AttachmentNg/d33a96dd-d34e-47a5-8f96-57b6b00480c6
https://www.globenewswire.com/NewsRoom/AttachmentNg/cdf3699e-6064-4d8e-b9e9-01b5984203da