Blue Hills Bancorp — Piper Jaffray New England Bank Symposium 2017
24 slides from Blue Hills Bancorp's conference presentation, Sep 28, 2017
Slide 1: Transformation. Diversification. Growth.
Title 1 Footnote. Piper Jaffray New England Bank Symposium September 27-28, 2017 Transformation. Diversification. Growth.
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation, as well as other written communications made from time to time by the Company and its subsidiaries and oral communications made from time to time by authorized officers of the Company, may contain statements relating to the future results of the Company
Slide 3: Asset Size: Transformation. Diversification. Growth.
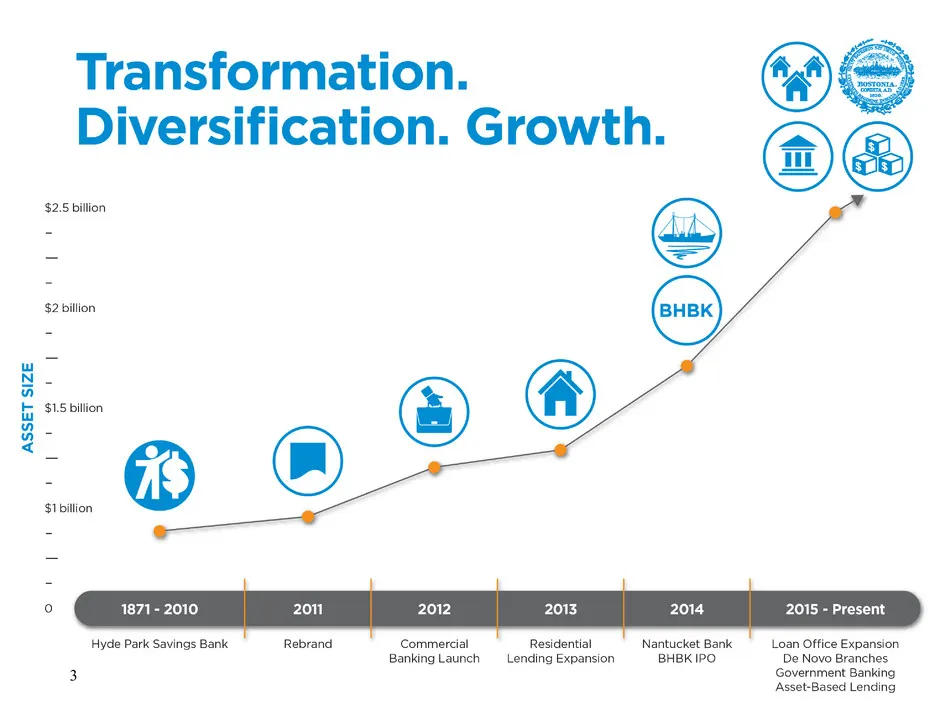
ASSET SIZE Transformation. Diversification. Growth. $25 billion $2 billion $15 billion $1billion ° 1871-2010 Hyde Park Savings Bank Rebrand ce Bani mmercial ‘1 ial king Launch Residenti Lending Expat insion BHBK Nantucket Bank BHBK IPO. 2015 - Present Loan Office Expansion De Novo Branches Governmen
Slide 4: Building Franchise Value
Building Franchise Value Experienced leadership team Upgraded leverageable infrastructure Diversified business model Strong direct lending capabilities Strong asset quality Attractive deposit mix with ongoing growth Improving spread / fee revenue diversity 4
Slide 5: Attractive Footprint
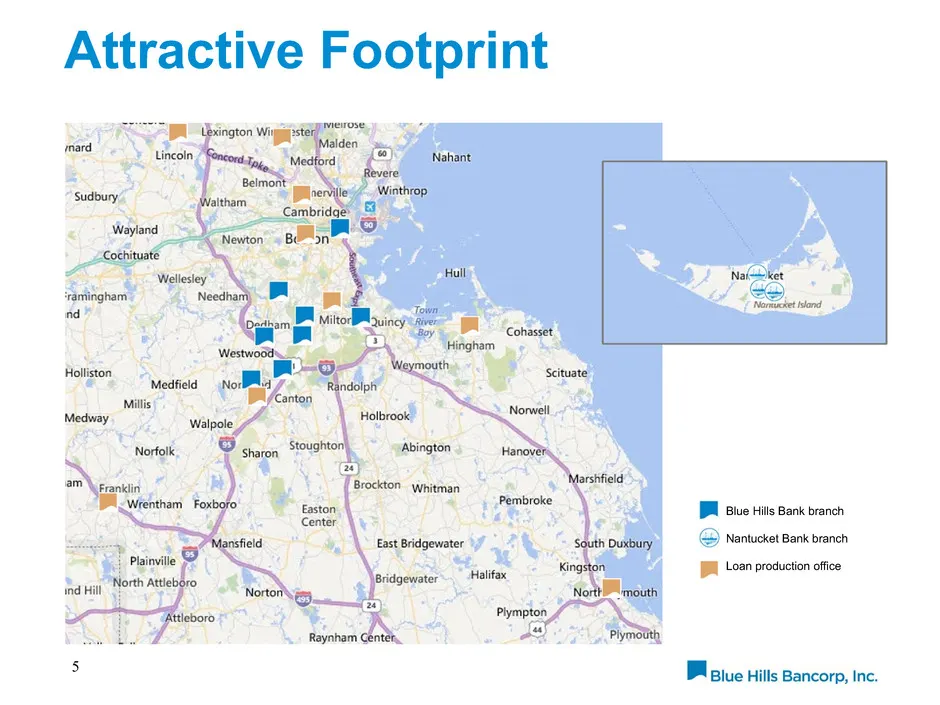
Attractive Footprint 5 Blue Hills Bank branch Loan production office Nantucket Bank branch
Slide 6: Loan Driven Growth
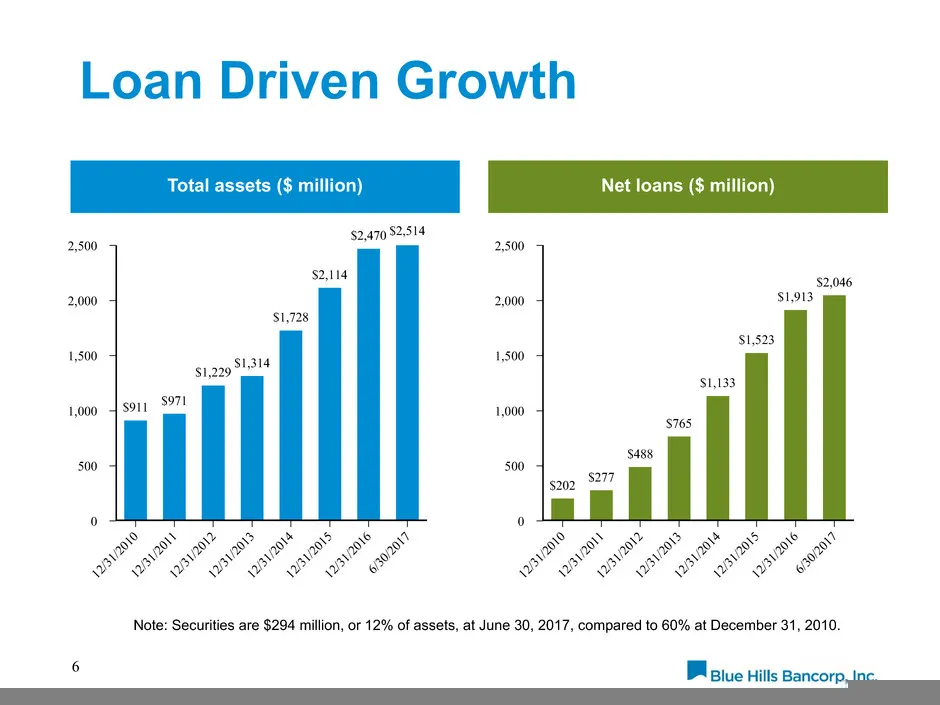
Loan Driven Growth 6 Total assets ($ million) Net loans ($ million) 2,500 2,000 1,500 1,000 500 0 12 /31 /20 10 12 /31 /20 11 12 /31 /20 12 12 /31 /20 13 12 /31 /20 14 12 /31 /20 15 12 /31 /20 16 6/3 0/2 01 7 $911 $971 $1,229 $1,314 $1,728 $2,114 $2,470 $2,514 2,500 2,000 1,500 1,000 500 0 12 /31 /2
Slide 7: Well Diversified Portfolio
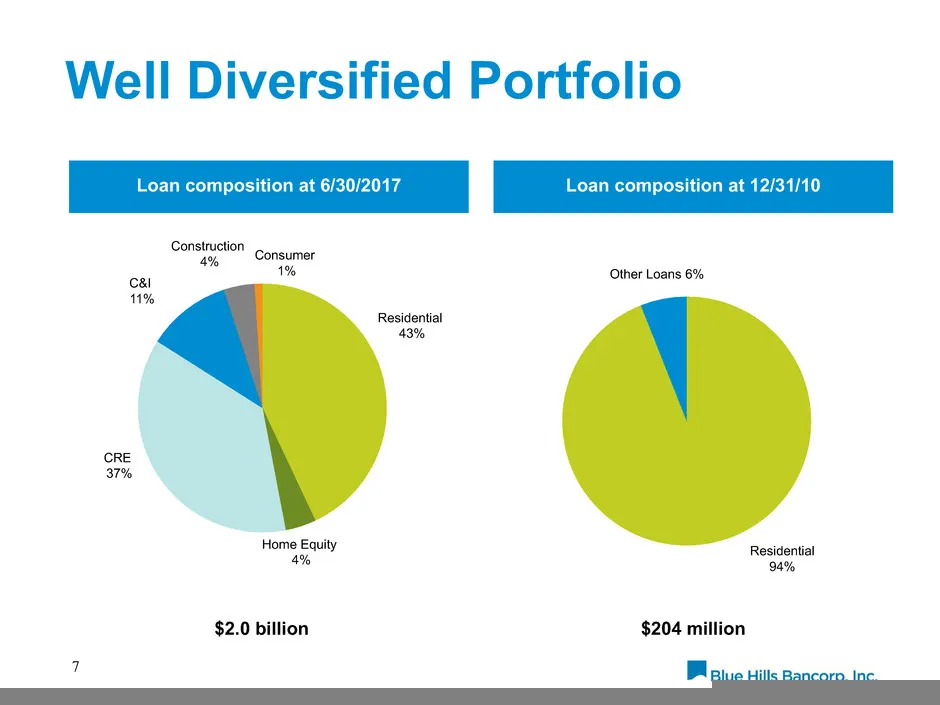
Well Diversified Portfolio 7 Loan composition at 6/30/2017 Loan composition at 12/31/10 $2.0 billion $204 million Other Loans 6% Residential 94% Consumer 1% Construction 4% C&I 11% CRE 37% Home Equity 4% Residential 43%
Slide 8: Valuable Origination Platform
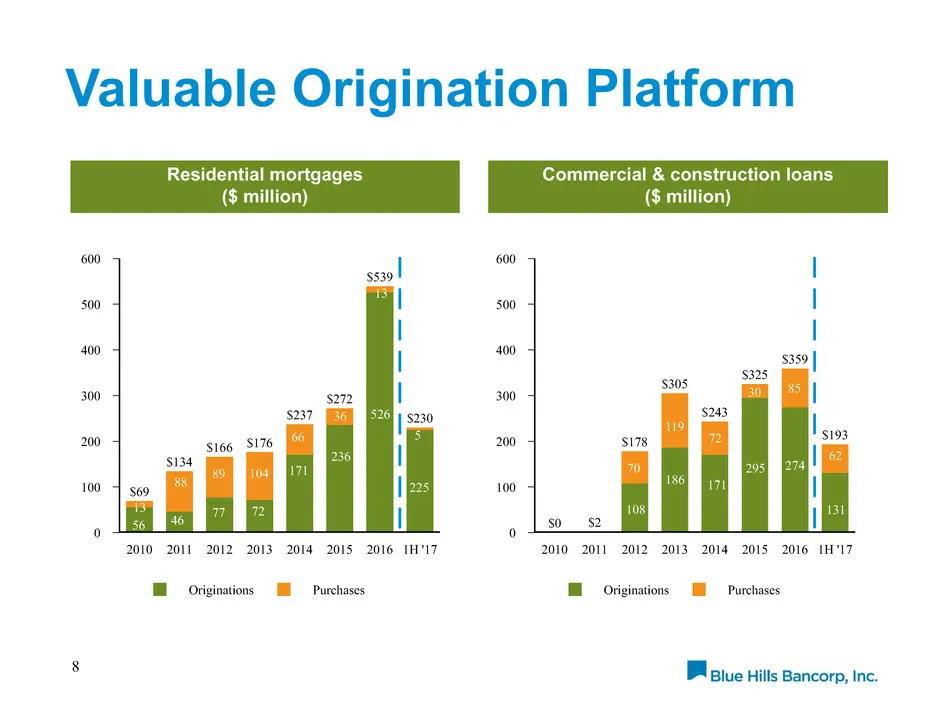
Valuable Origination Platform 8 Residential mortgages ($ million) Commercial & construction loans ($ million) Originations Purchases 600 500 400 300 200 100 0 2010 2011 2012 2013 2014 2015 2016 1H '17 $69 $134 $166 $176 $237 $272 $539 $230 Originations Purchases 600 500 400 300 200 100 0 2010 2011 2
Slide 9: Securities Restructuring
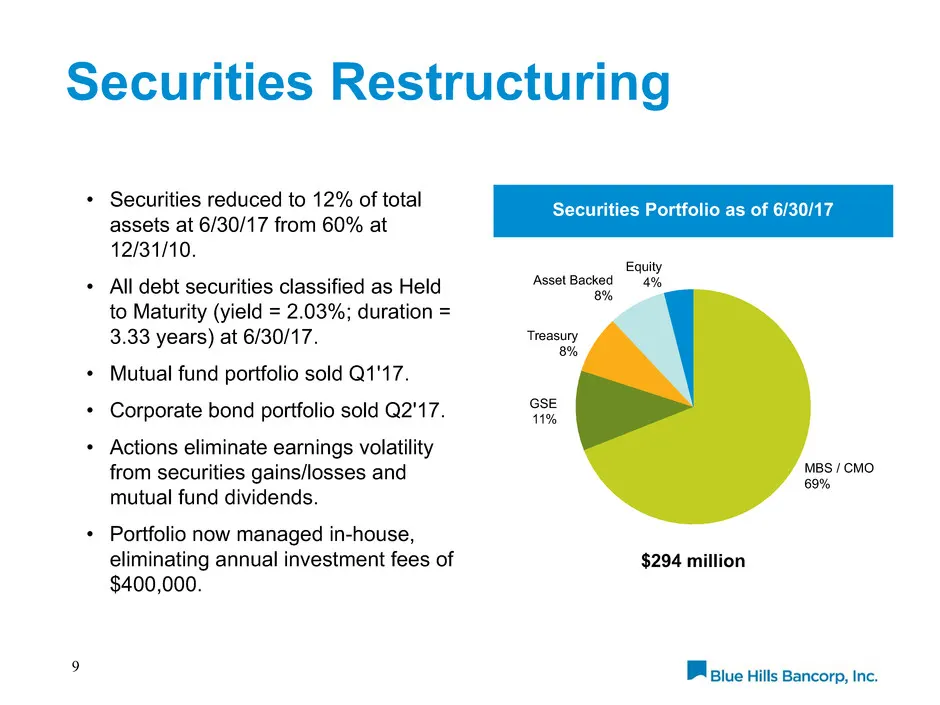
Securities Restructuring MBS / CMO 69% GSE 11% Treasury 8% Asset Backed 8% Equity 4% • Securities reduced to 12% of total assets at 6/30/17 from 60% at 12/31/10. • All debt securities classified as Held to Maturity (yield = 2.03%; duration = 3.33 years) at 6/30/17. • Mutual fund portfolio sold Q1'17
Slide 10: Improved Deposit Mix
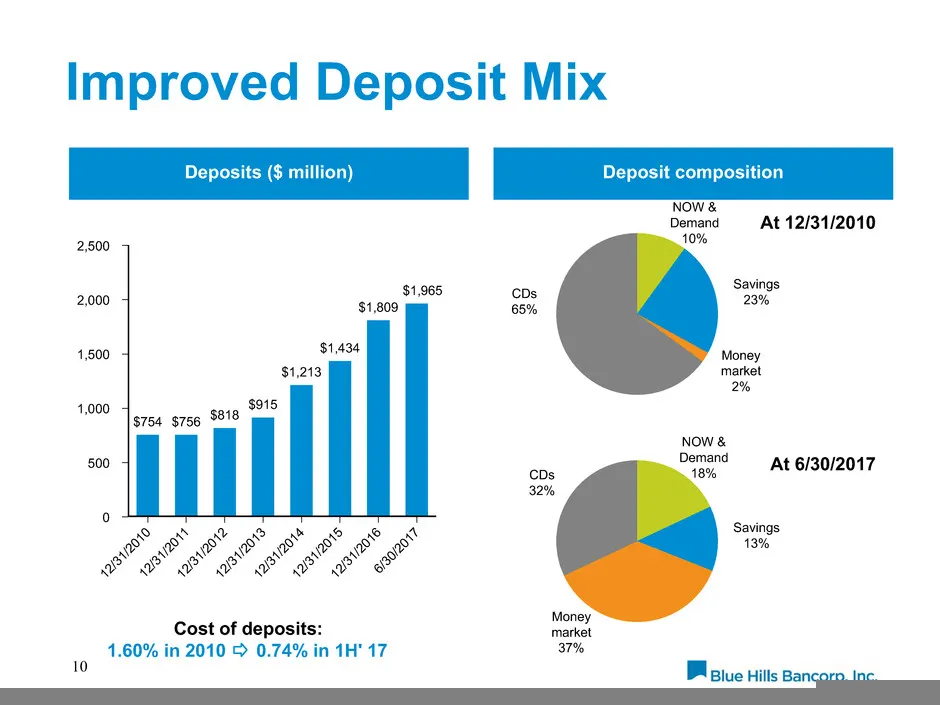
Improved Deposit Mix 10 Deposits ($ million) Deposit composition At 12/31/2010 At 6/30/2017 Cost of deposits: 1.60% in 2010 0.74% in 1H' 17 2,500 2,000 1,500 1,000 500 0 12 /31 /20 10 12 /31 /20 11 12 /31 /20 12 12 /31 /20 13 12 /31 /20 14 12 /31 /20 15 12 /31 /20 16 6/3 0/2 01 7 $754 $756 $818 $915
Slide 11: Net Interest Income Growth
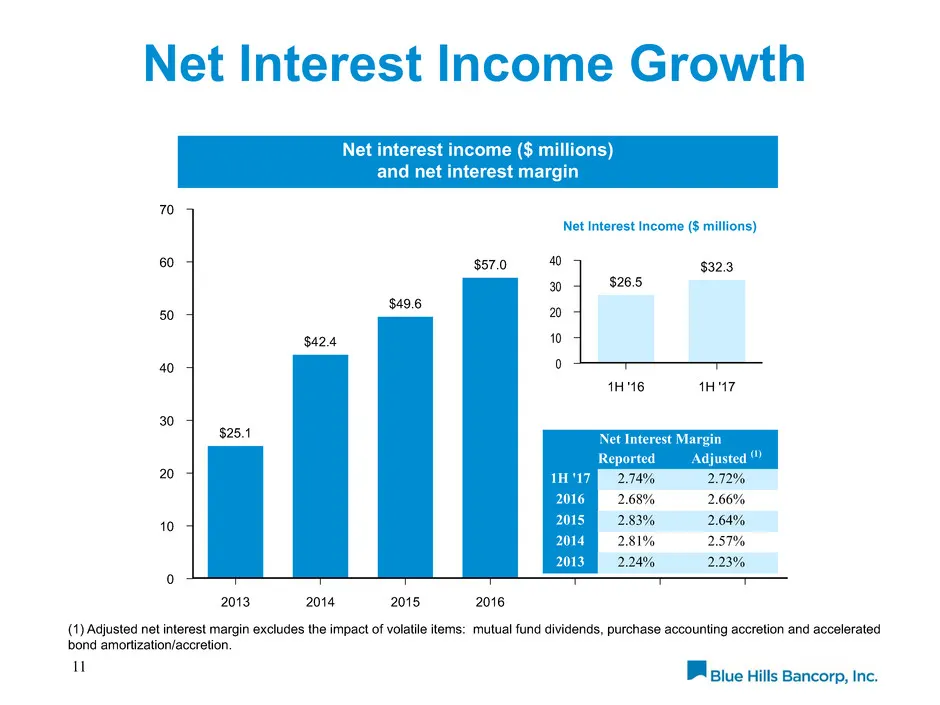
Net Interest Income Growth 11 Net interest income ($ millions) and net interest margin (1) Adjusted net interest margin excludes the impact of volatile items: mutual fund dividends, purchase accounting accretion and accelerated bond amortization/accretion. 70 60 50 40 30 20 10 0 2013 2014 2015 2016
Slide 12: Improving Core Fee Income
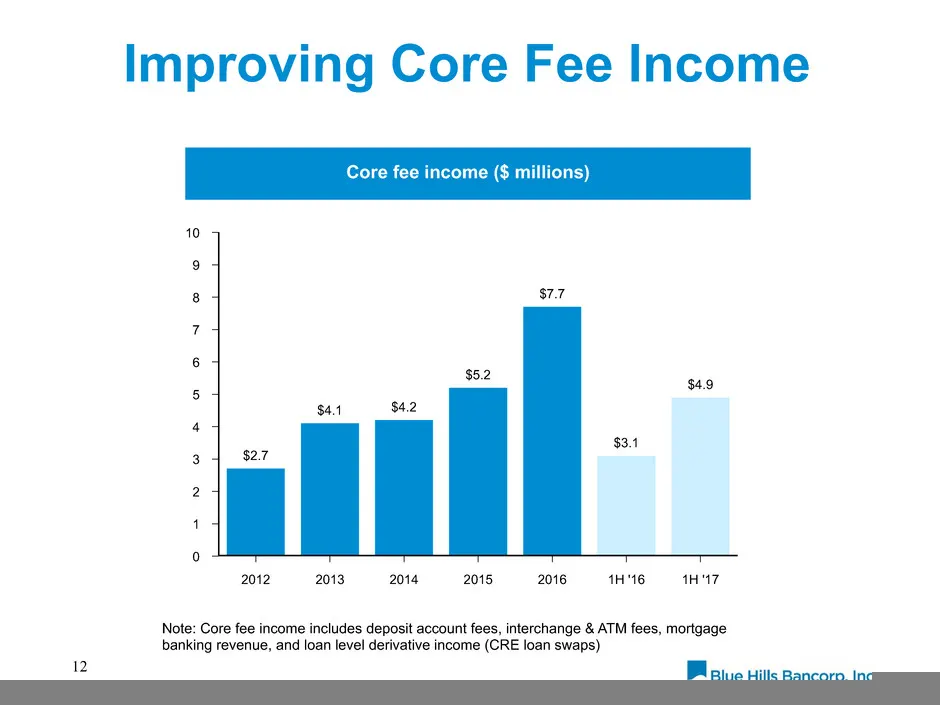
Improving Core Fee Income Note: Core fee income includes deposit account fees, interchange & ATM fees, mortgage banking revenue, and loan level derivative income (CRE loan swaps) 12 Core fee income ($ millions) 10 9 8 7 6 5 4 3 2 1 0 2012 2013 2014 2015 2016 1H '16 1H '17 $2.7 $4.1 $4.2 $5.2 $7.7 $3
Slide 13: Leverageable Infrastructure
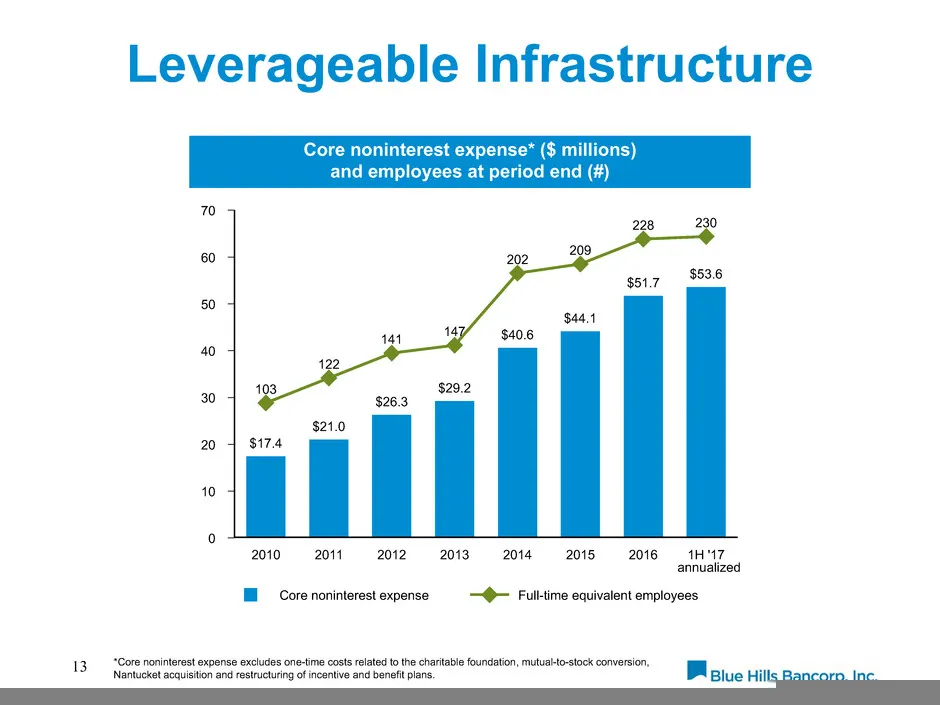
Leverageable Infrastructure 13 Core noninterest expense* ($ millions) and employees at period end (#) *Core noninterest expense excludes one-time costs related to the charitable foundation, mutual-to-stock conversion, Nantucket acquisition and restructuring of incentive and benefit plans. Core nonin
Slide 14: Noninterest Expense Growth
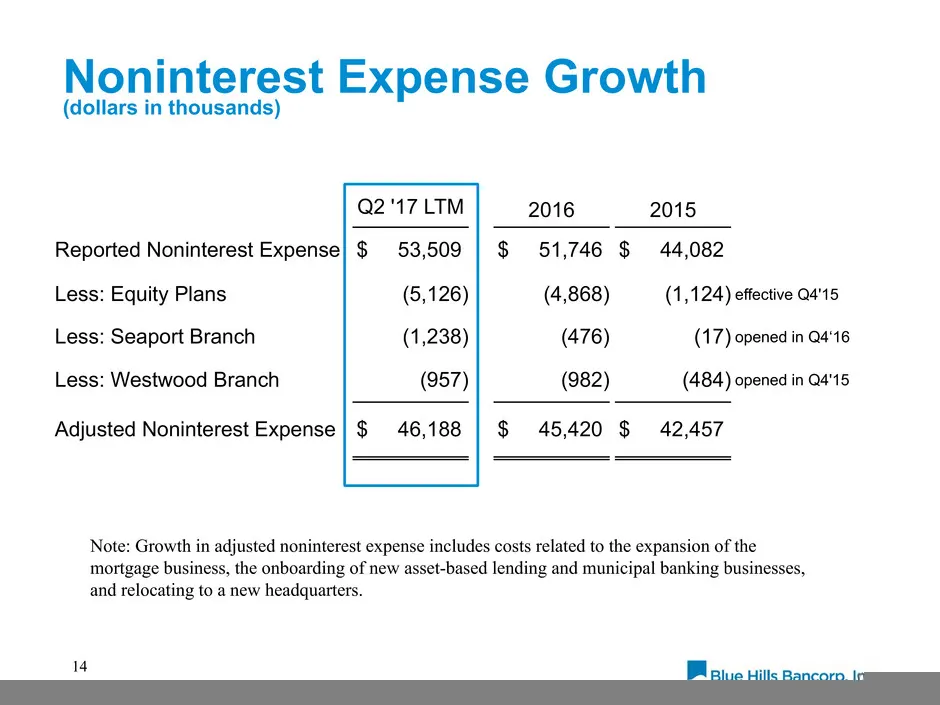
Noninterest Expense Growth (dollars in thousands) 14 Q2 '17 LTM 2016 2015 Reported Noninterest Expense $ 53,509 $ 51,746 $ 44,082 Less: Equity Plans (5,126) (4,868) (1,124) effective Q4'15 Less: Seaport Branch (1,238) (476) (17) opened in Q4‘16 Less: Westwood Branch (957) (982) (484) opened in Q4'15
Slide 15: Improvement in Earnings
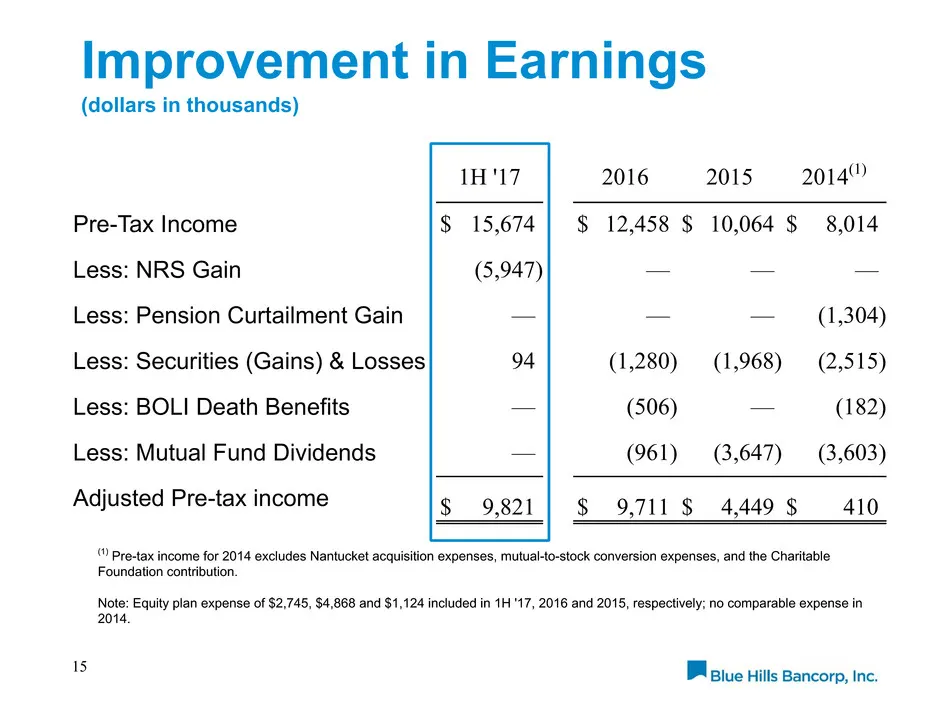
Improvement in Earnings (dollars in thousands) 15 1H '17 2016 2015 2014(1) Pre-Tax Income $ 15,674 $ 12,458 $ 10,064 $ 8,014 Less: NRS Gain (5,947) — — — Less: Pension Curtailment Gain — — — (1,304) Less: Securities (Gains) & Losses 94 (1,280) (1,968) (2,515) Less: BOLI Death Benefits — (506) — (182
Slide 16: Positive Operating Leverage
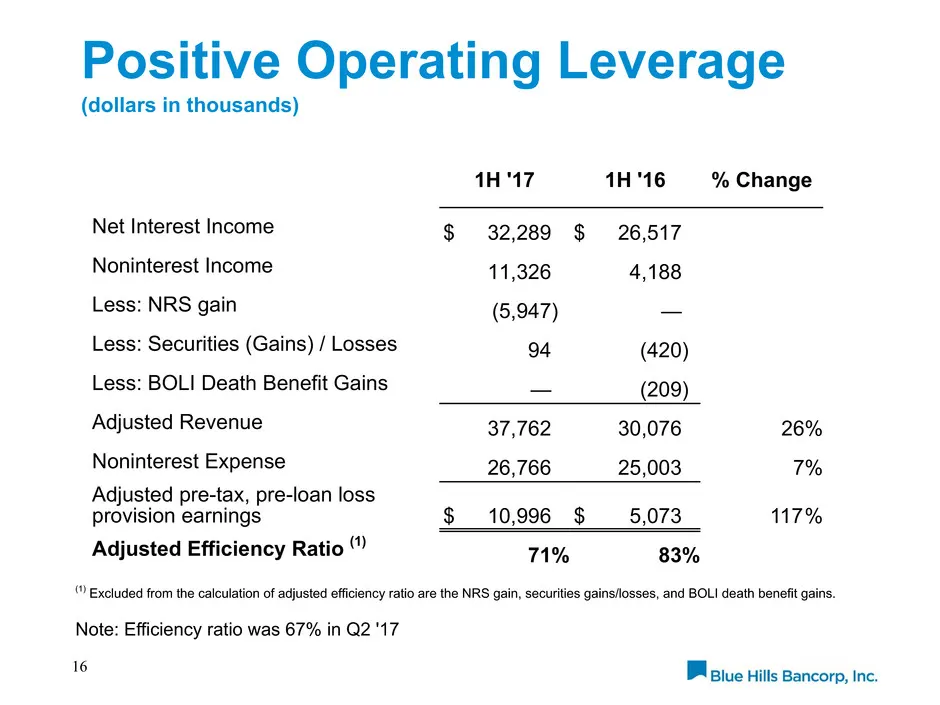
Positive Operating Leverage (dollars in thousands) 16 1H '17 1H '16 % Change Net Interest Income $ 32,289 $ 26,517 Noninterest Income 11,326 4,188 Less: NRS gain (5,947) — Less: Securities (Gains) / Losses 94 (420) Less: BOLI Death Benefit Gains — (209) Adjusted Revenue 37,762 30,076 26% Noninterest
Slide 17: Reserve Coverage
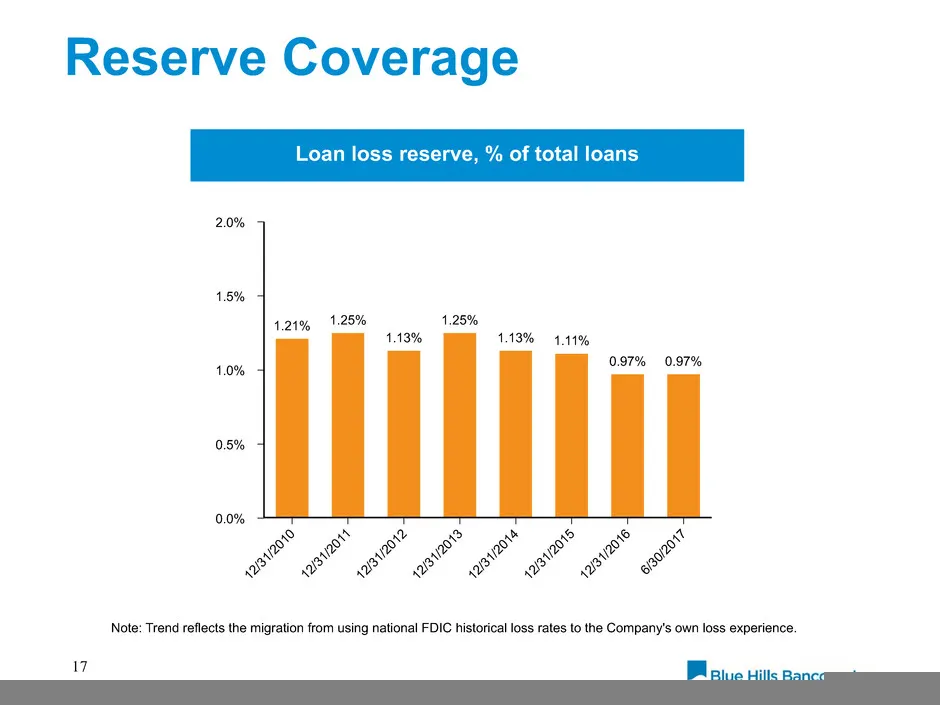
Reserve Coverage 17 Loan loss reserve, % of total loans Note: Trend reflects the migration from using national FDIC historical loss rates to the Company's own loss experience. 2.0% 1.5% 1.0% 0.5% 0.0% 12 /31 /20 10 12 /31 /20 11 12 /31 /20 12 12 /31 /20 13 12 /31 /20 14 12 /31 /20 15 12 /31 /20 16 6
Slide 18: Nonperforming Assets
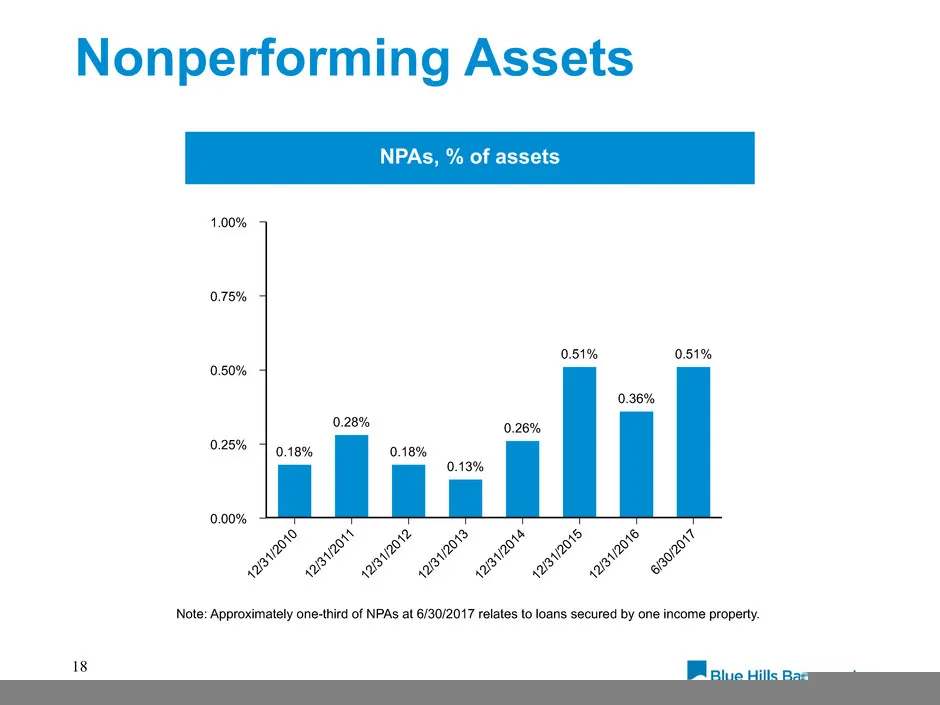
Nonperforming Assets 18 NPAs, % of assets 1.00% 0.75% 0.50% 0.25% 0.00% 12 /31 /20 10 12 /31 /20 11 12 /31 /20 12 12 /31 /20 13 12 /31 /20 14 12 /31 /20 15 12 /31 /20 16 6/3 0/2 01 7 0.18% 0.28% 0.18% 0.13% 0.26% 0.51% 0.36% 0.51% Note: Approximately one-third of NPAs at 6/30/2017 relates to loans s
Slide 19: Challenges and Opportunities Ahead
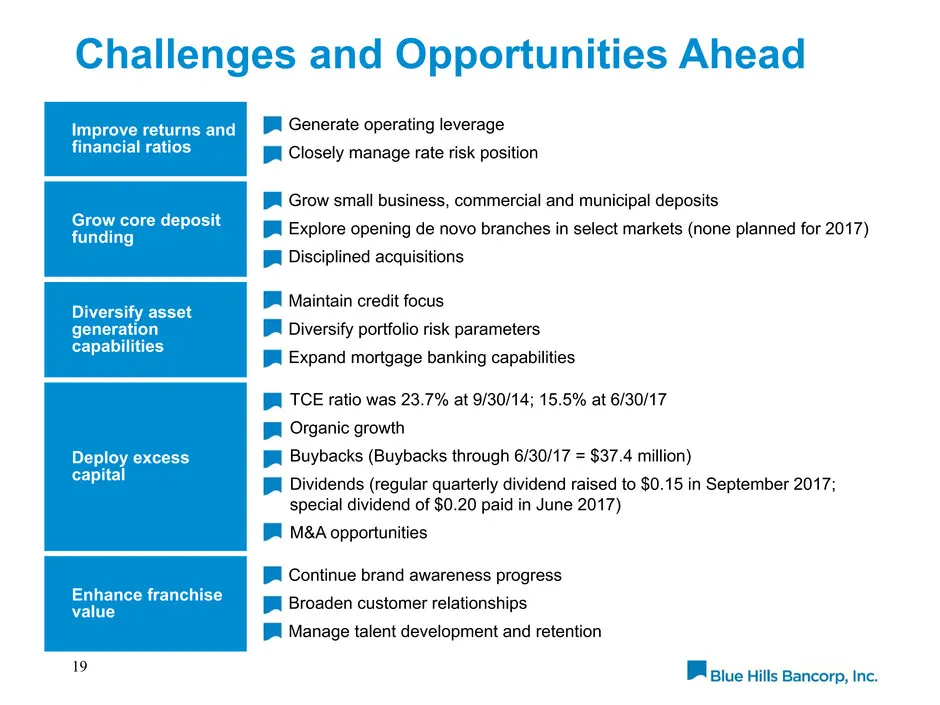
Challenges and Opportunities Ahead 19 Improve returns and financial ratios Generate operating leverage Closely manage rate risk position Grow core deposit funding Grow small business, commercial and municipal deposits Explore opening de novo branches in select markets (none planned for 2017) Discipl
Slide 20: Appendix
Appendix 20
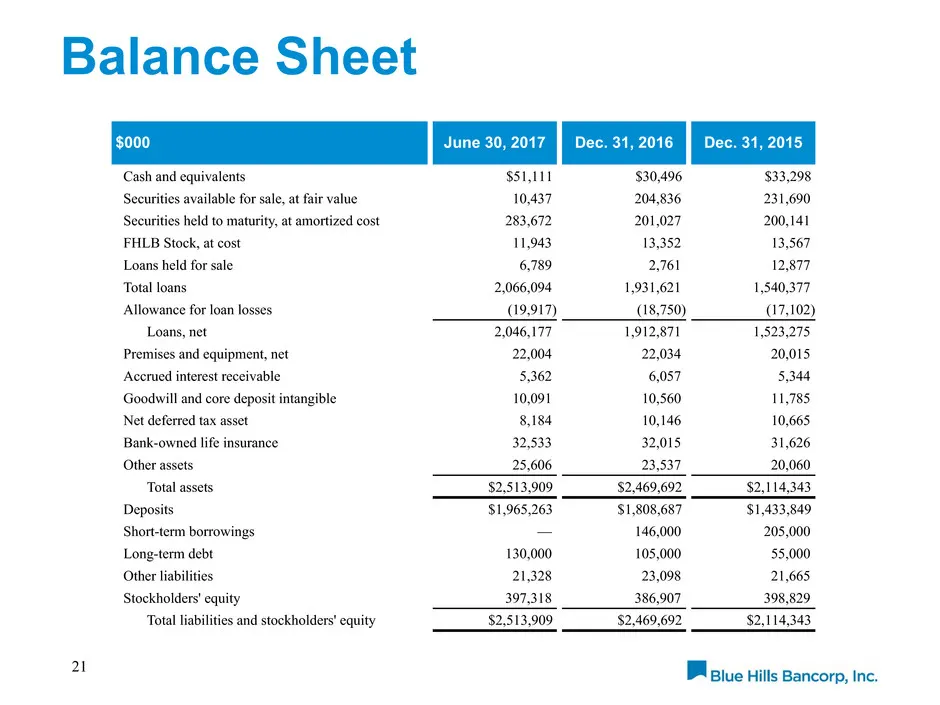
Slide 21: Balance Sheet
21 $000 June 30, 2017 Dec. 31, 2016 Dec. 31, 2015 Cash and equivalents $51,111 $30,496 $33,298 Securities available for sale, at fair value 10,437 204,836 231,690 Securities held to maturity, at amortized cost 283,672 201,027 200,141 FHLB Stock, at cost 11,943 13,352 13,567 Loans held for sale 6,789
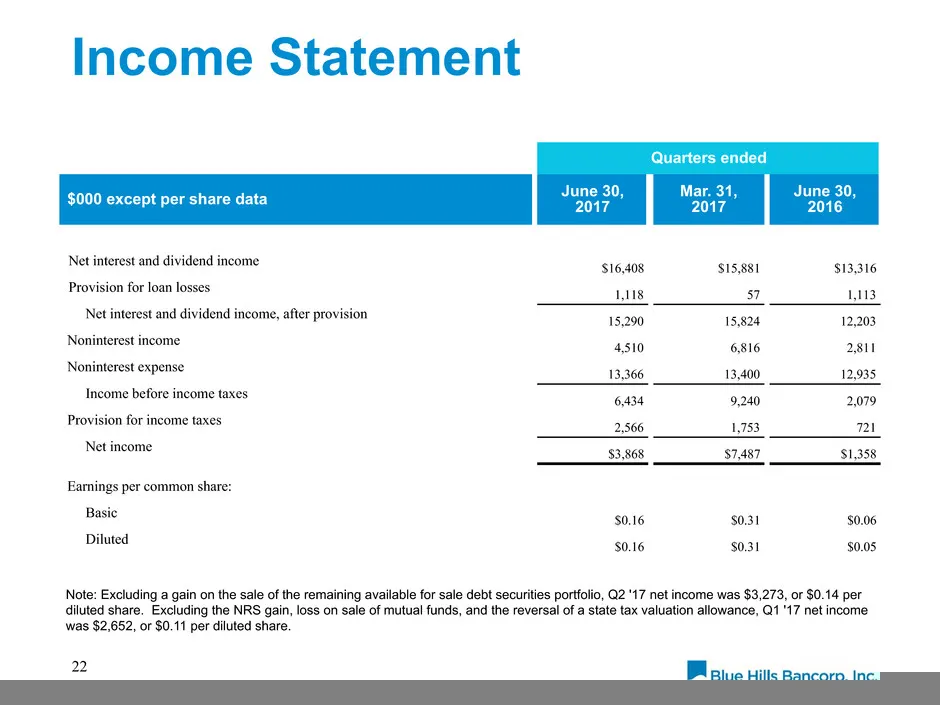
Slide 22: Income Statement
22 Quarters ended $000 except per share data June 30,2017 Mar. 31, 2017 June 30, 2016 Net interest and dividend income $16,408 $15,881 $13,316 Provision for loan losses 1,118 57 1,113 Net interest and dividend income, after provision 15,290 15,824 12,203 Noninterest income 4,510 6,816 2,811 Noninter
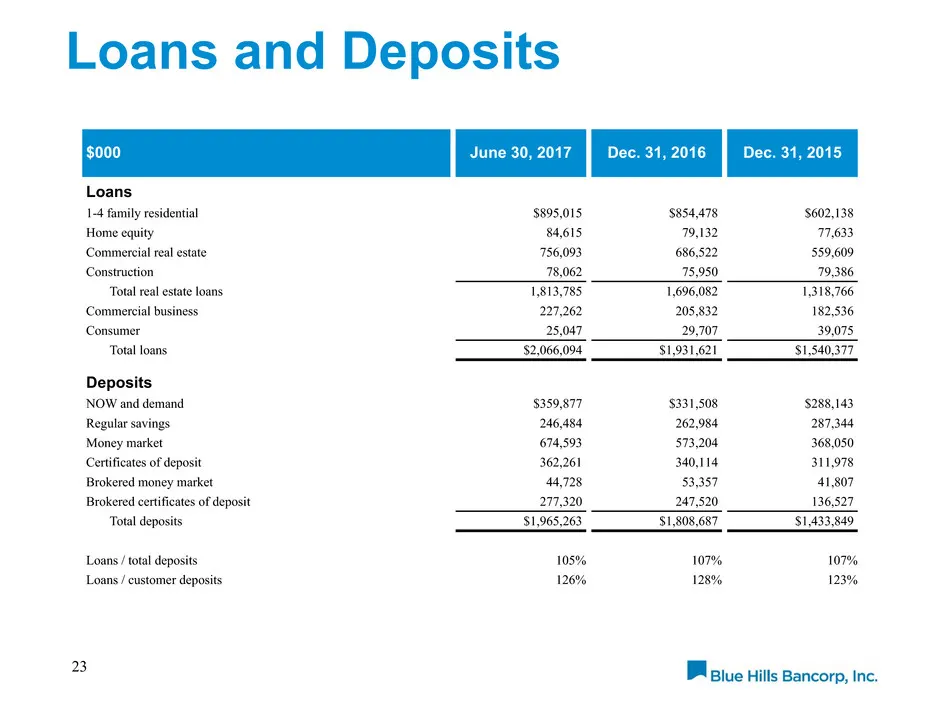
Slide 23: Loans and Deposits
23 Loans and Deposits $000 June 30, 2017 Dec. 31, 2016 Dec. 31, 2015 Loans 1-4 family residential $895,015 $854,478 $602,138 Home equity 84,615 79,132 77,633 Commercial real estate 756,093 686,522 559,609 Construction 78,062 75,950 79,386 Total real estate loans 1,813,785 1,696,082 1,318,766 Commerc
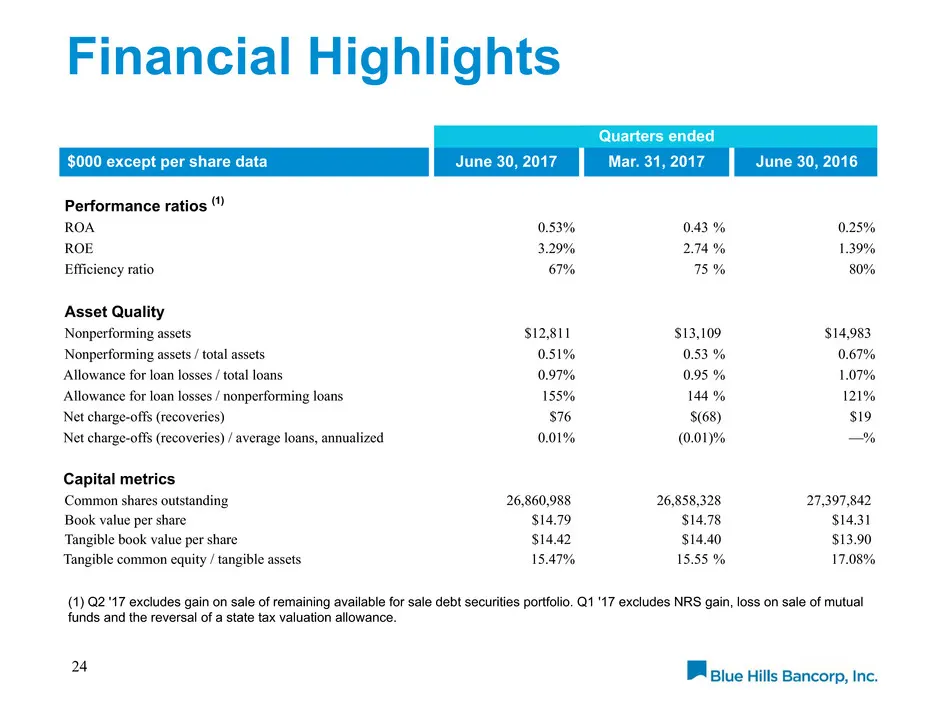
Slide 24: Financial Highlights
24 Financial Highlights Quarters ended $000 except per share data June 30, 2017 Mar. 31, 2017 June 30, 2016 Performance ratios (1) ROA 0.53% 0.43 % 0.25% ROE 3.29% 2.74 % 1.39% Efficiency ratio 67% 75 % 80% Asset Quality Nonperforming assets $12,811 $13,109 $14,983 Nonperforming assets / total asset
Source: SEC EDGAR · 8-K filed Sep 28, 2017
More decks from Blue Hills Bancorp Inc
 Merger or Acquisition (September 2018)16 slides · Sep 20, 2018
 Keefe Bruyette & Woods 2018 Community Bank Investor Conference28 slides · Jul 31, 2018
 Shareholder Meeting (May 2018)24 slides · May 16, 2018
 Piper Jaffray Financial Institutions Conference 201823 slides · May 11, 2018
 Compass Point Investor Meetings (December 2017)24 slides · Dec 6, 2017
 Keefe, Bruyette & Woods 2017 Community Bank Investor Conference24 slides · Aug 1, 2017